 filings.tools
Arch Capital Group 10-K 2015-12-31
Filed 2016-02-26. 21 sections, 1053K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 a201510-k.htm 10-K
| UNITED STATES | ||
| SECURITIES AND EXCHANGE COMMISSION | ||
| Washington, D.C. 20549 | ||
| FORM 10-K | ||
| þ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 | |
| OR | ||
| o | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 | |
| For the Fiscal Year Ended December 31, 2015 | Commission File No. 0-26456 |
ARCH CAPITAL GROUP LTD.
(Exact name of registrant as specified in its charter)
| Bermuda | Not applicable |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
| Waterloo House, Ground Floor | |
| 100 Pitts Bay Road, Pembroke HM 08, Bermuda | (441) 278-9250 |
| (Address of principal executive offices) | (Registrant’s telephone number, including area code) |
Securities registered pursuant to Section 12(b) of the Exchange Act:
| Title of each class | Name of each exchange on which registered |
| Common Shares, $0.0033 par value per share | NASDAQ Stock Market (Common Shares) |
| 6.75% Non-Cumulative Preferred Shares, Series C, $0.01 par value per share | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Exchange Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes þ No o
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Exchange Act.
Yes o No þ
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Exchange Act during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes þ No o
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes þ No o
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. o
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act. Large accelerated Filer þ Accelerated Filer o Non-accelerated Filer o Smaller reporting company o
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes o No þ
The aggregate market value of the voting and non-voting common equity held by non-affiliates, computed by reference to the closing price as reported by the NASDAQ Stock Market as of the last business day of the Registrant’s most recently completed second fiscal quarter, was approximately $7.89 billion.
As of February 23, 2016, there were 122,078,177 of the registrant’s common shares outstanding.
| DOCUMENTS INCORPORATED BY REFERENCE | |
| Portions of Part III and Part IV incorporate by reference our definitive proxy statement for the 2016 annual meeting of shareholders to be filed with the Securities and Exchange Commission pursuant to Regulation 14A before April 30, 2016. | |
CAUTIONARY NOTE REGARDING FORWARD‑LOOKING STATEMENTS
The Private Securities Litigation Reform Act of 1995 (“PSLRA”) provides a “safe harbor” for forward-looking statements. This report or any other written or oral statements made by or on behalf of us may include forward-looking statements, which reflect our current views with respect to future events and financial performance. All statements other than statements of historical fact included in or incorporated by reference in this report are forward-looking statements. Forward-looking statements, for purposes of the PSLRA or otherwise, can generally be identified by the use of forward-looking terminology such as “may,” “will,” “expect,” “intend,” “estimate,” “anticipate,” “believe” or “continue” and similar statements of a future or forward-looking nature or their negative or variations or similar terminology.
Forward-looking statements involve our current assessment of risks and uncertainties. Actual events and results may differ materially from those expressed or implied in these statements. Important factors that could cause actual events or results to differ materially from those indicated in such statements are discussed below, elsewhere in this report and in our periodic reports filed with the Securities and Exchange Commission (“SEC”), and include:
| • | our ability to successfully implement our business strategy during “soft” as well as “hard” markets; |
| • | acceptance of our business strategy, security and financial condition by rating agencies and regulators, as well as by brokers and our insureds and reinsureds; |
| • | our ability to maintain or improve our ratings, which may be affected by our ability to raise additional equity or debt financings, by ratings agencies’ existing or new policies and practices, as well as other factors described herein; |
| • | general economic and market conditions (including inflation, interest rates, foreign currency exchange rates, prevailing credit terms and the depth and duration of a recession) and conditions specific to the reinsurance and insurance markets (including the length and magnitude of the current “soft” market) in which we operate; |
| • | competition, including increased competition, on the basis of pricing, capacity (including alternative sources of capital), coverage terms, or other factors; |
| • | developments in the world’s financial and capital markets and our access to such markets; |
| • | our ability to successfully enhance, integrate and maintain operating procedures (including information technology) to effectively support our current and new business; |
| • | the loss of key personnel; |
| • | the integration of businesses we have acquired or may acquire into our existing operations; |
| • | accuracy of those estimates and judgments utilized in the preparation of our financial statements, including those related to revenue recognition, insurance and other reserves, reinsurance recoverables, investment valuations, intangible assets, bad debts, income taxes, contingencies and litigation, and any determination to use the deposit method of accounting, which for a relatively new insurance and reinsurance company, like our company, are even more difficult to make than those made in a mature company since relatively limited historical information has been reported to us through December 31, 2015; |
| • | greater than expected loss ratios on business written by us and adverse development on claim and/or claim expense liabilities related to business written by our insurance and reinsurance subsidiaries; |
| • | severity and/or frequency of losses; |
| • | claims for natural or man-made catastrophic events in our insurance or reinsurance business could cause large losses and substantial volatility in our results of operations; |
| • | acts of terrorism, political unrest and other hostilities or other unforecasted and unpredictable events; |
| • | availability to us of reinsurance to manage our gross and net exposures and the cost of such reinsurance; |
| • | the failure of reinsurers, managing general agents, third party administrators or others to meet their obligations to us; |
| • | the timing of loss payments being faster or the receipt of reinsurance recoverables being slower than anticipated by us; |
| • | our investment performance, including legislative or regulatory developments that may adversely affect the fair value of our investments; |
| • | changes in general economic conditions, including new or continued sovereign debt concerns in Eurozone countries or downgrades of U.S. securities by credit rating agencies, which could affect our business, financial condition and results of operations; |
| • | the volatility of our shareholders’ equity from foreign currency fluctuations, which could increase due to us not matching portions of our projected liabilities in foreign currencies with investments in the same currencies; |
| • | losses relating to aviation business and business produced by a certain managing underwriting agency for which we may be liable to the purchaser of our prior reinsurance business or to others in connection with the May 5, 2000 asset sale described in our periodic reports filed with the SEC; |
| • | changes in accounting principles or policies or in our application of such accounting principles or policies; |
| • | changes in the political environment of certain countries in which we operate or underwrite business; |
| • | statutory or regulatory developments, including as to tax policy and matters and insurance and other regulatory matters such as the adoption of proposed legislation that would affect Bermuda-headquartered companies and/or Bermuda-based insurers or reinsurers and/or changes in regulations or tax laws applicable to us, our subsidiaries, brokers or customers; and |
| • | the other matters set forth under Item 1A “Risk Factors,” Item 7 “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and other sections of this Annual Report on Form 10-K, as well as the other factors set forth in Arch Capital Group Ltd.’s other documents on file with the SEC, and management’s response to any of the aforementioned factors. |
All subsequent written and oral forward-looking statements attributable to us or persons acting on our behalf are expressly qualified in their entirety by these cautionary statements. The foregoing review of important factors should not be construed as exhaustive and should be read in conjunction with other cautionary statements that are included herein or elsewhere. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events or otherwise.
PART I
Item 1. BUSINESS
As used in this report, references to “we,” “us,” “our” or the “Company” refer to the consolidated operations of Arch Capital Group Ltd. (“ACGL”) and its subsidiaries. Tabular amounts are in U.S. Dollars in thousands, except share amounts, unless otherwise noted. We refer you to Item 1A “Risk Factors” for a discussion of risk factors relating to our business.
OUR COMPANY
General
Arch Capital Group Ltd. is a Bermuda public limited liability company with $7.10 billion in capital at December 31, 2015 and, through operations in Bermuda, the United States, Europe, Canada, Australia and Dubai, writes insurance and reinsurance on a worldwide basis. While we are positioned to provide a full range of property, casualty and mortgage insurance and reinsurance lines, we focus on writing specialty lines of insurance and reinsurance. For 2015, we wrote $3.35 billion of net premiums and reported net income available to Arch common shareholders of $515.8 million. Book value per common share was $47.95 at December 31, 2015, compared to $45.58 per share at December 31, 2014.
ACGL’s registered office is located at Clarendon House, 2 Church Street, Hamilton HM 11, Bermuda (telephone number: (441) 295-1422), and its principal executive offices are located at Waterloo House, Ground Floor, 100 Pitts Bay Road, Pembroke HM 08, Bermuda (telephone number: (441) 278-9250). ACGL makes available free of charge through its website, located at www.archcapgroup.com, its annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and all amendments to those reports as soon as reasonably practicable after such material is electronically filed with, or furnished to, the SEC. The public may read and copy any materials ACGL files with the SEC at the SEC’s Public Reference Room at 100 F Street, NE, Washington, D.C. 20549. The public may obtain information on the operation of the Public Reference Room by calling 1-800-SEC-0330. The SEC also maintains an Internet site that contains reports, proxy and information statements, and other information regarding issuers that file electronically with the SEC (such as ACGL) and the address of that site is www.sec.gov.
Our History
Our current operations were built on an existing underwriting platform through an underwriting initiative in October 2001 to meet current and future demand in the global insurance and reinsurance markets. Since that time, we have attracted a proven management team with extensive industry experience and enhanced our existing global underwriting platform for our insurance and reinsurance businesses. It is our belief that our underwriting platform, our experienced management team and our strong capital base that is unencumbered by significant pre-2002 risks have enabled us to establish a strong presence in the global insurance and reinsurance markets.
Prior to the 2001 underwriting initiative, our insurance underwriting platform consisted of Arch Insurance (Bermuda), a division of Arch Reinsurance Ltd. (“Arch Re Bermuda”), our Bermuda-based reinsurer and insurer, and our U.S.-licensed insurers, Arch Insurance Company (“Arch Insurance”), Arch Excess & Surplus Insurance Company (“Arch E&S”), Arch Specialty Insurance Company (“Arch Specialty”) and Arch Indemnity Insurance Company (“Arch Indemnity”). We established Arch Insurance Company (Europe) Limited (“Arch Insurance Company Europe”), our United Kingdom-based subsidiary, in 2004, and we expanded our North American presence when Arch Insurance opened a branch office in Canada in 2005. In January 2013, Arch Insurance Canada Ltd. (“Arch Insurance Canada”), a Canada domestic company, commenced operations and replaced the branch office. In 2009, we established a managing agent and syndicate 2012 (“Arch Syndicate 2012”) at Lloyd’s of London (“Lloyd’s”). See “Operations—Insurance Operations” for further details on our insurance operations.
Prior to the 2001 underwriting initiative, our reinsurance underwriting platform consisted of Arch Re Bermuda and Arch Reinsurance Company (“Arch Re U.S.”), our U.S.-licensed reinsurer. Our reinsurance operations in Europe began in November 2006 with the formation of a Swiss branch of Arch Re Bermuda, and the formation of a Danish underwriting agency in 2007. In addition to the U.S. reinsurance activities of Arch Re U.S., we launched our property facultative reinsurance underwriting operations in 2007, which underwrite in the U.S., Canada and Europe. We formed Arch Reinsurance Europe Designated Activity Company (formerly Arch Reinsurance Underwriting Europe Limited and referred to as “Arch Re Europe”), our Ireland-based reinsurance company, in 2008. In 2011, we launched treaty operations in
Canada and in April 2012 we acquired the credit and surety reinsurance operations of Ariel Reinsurance Company Ltd. (“Ariel Re”). In May 2015, we obtained complete ownership and effective control of Gulf Reinsurance Limited, previously a joint venture. See “Operations—Reinsurance Operations” for further details on our reinsurance operations.
Our mortgage group includes the results of Arch Mortgage Insurance Company (“Arch MI U.S.”) and Arch Mortgage Insurance Designated Activity Company (formerly Arch Mortgage Insurance Limited and referred to as “Arch MI Europe”), leading providers of mortgage insurance products and services to the U.S. and European markets, respectively. Arch MI U.S. is approved as an eligible mortgage insurer by Federal National Mortgage Association (“Fannie Mae”) and Federal Home Loan Mortgage Corporation (“Freddie Mac”), each a government sponsored enterprise, or “GSE.” The mortgage segment also includes GSE credit risk-sharing transactions and mortgage reinsurance for the U.S. and Australian markets. See “Operations—Mortgage Operations” for further details on our mortgage operations.
On March 20, 2014, we acquired approximately 11% of Watford Holdings Ltd.’s common equity and a warrant to purchase additional common equity for $100 million. Watford Holdings Ltd. is the parent of Watford Re Ltd., a then newly-formed multi-line Bermuda reinsurance company (together with Watford Holdings Ltd., “Watford Re”). Watford Re raised approximately $1.1 billion of capital. We serve as Watford Re’s reinsurance underwriting manager and Highbridge Principal Strategies, LLC (“Highbridge”), a subsidiary of JPMorgan Chase & Co., manages Watford Re’s investment assets, each under separate long term services agreements. The results of Watford Re are included in our consolidated financial statements. See “Operations—Other Operations” for further details on Watford Re.
The growth of our underwriting platforms was supported through the net proceeds of: (1) an equity capital infusion of $763 million led by funds affiliated with Warburg Pincus LLC and Hellman & Friedman LLC in late 2001; (2) a public offering of 7.5 million of our common shares with net proceeds of $179 million in April 2002; (3) the exercise of class A warrants by our principal shareholders and other investors in September 2002, which provided net proceeds of $74 million; (4) a March 2004 public offering of 4.7 million of our common shares with net proceeds of $179 million; (5) a May 2004 public offering of $300 million principal amount of our 7.35% senior notes due May 2034; (6) a February 2006 public offering of $200 million of our 8.00% series A non-cumulative preferred shares; (7) a May 2006 public offering of $125 million of our 7.875% series B non-cumulative preferred shares; (8) an April 2012 public offering of $325 million of our 6.75% series C non-cumulative preferred shares which was used to redeem all series A and series B preferred shares; and (9) a December 2013 public offering of $500 million principal amount of 5.144% senior notes due November 1, 2043 by Arch Capital Group (U.S.) Inc. (“Arch-U.S.”), a wholly owned subsidiary of ACGL, and fully and unconditionally guaranteed by ACGL.
The board of directors of ACGL has authorized the invest
Showing the first 8K of 236K characters. Open the full section
Item 1A. RISK FACTORS
Set forth below are risk factors relating to our business. You should also refer to the other information provided in this report, including our “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and our accompanying consolidated financial statements, as well as the information under the heading “Cautionary Note Regarding Forward-Looking Statements.”
Risks Relating to Our Industry
We operate in a highly competitive environment, and we may not be able to compete successfully in our industry.
The insurance and reinsurance industry is highly competitive. We compete with major U.S. and non-U.S. insurers and reinsurers, many of which have greater financial, marketing and management resources than we do, as well as other potential providers of capital willing to assume insurance and/or reinsurance risk. We also compete with new companies that continue to be formed to enter the insurance and reinsurance markets. In addition, continued consolidation within the insurance and reinsurance industry will further enhance the already competitive underwriting environment. These consolidated entities may use their enhanced market power and broader capital base to negotiate price reductions for products and services that compete with ours, and we may experience rate declines and possibly write less business. In our insurance business, we compete with insurers that provide specialty property and casualty lines of insurance, including Alleghany Corporation, Allied World Assurance Company, Ltd., American International Group, Inc., AXIS Capital Holdings Limited, Berkshire Hathaway, Inc., Chubb Limited, CNA, Endurance Specialty Holdings Ltd., The Hartford Financial Services Group, Inc., HCC Insurance Holdings, Inc., Ironshore Inc., Liberty Mutual Insurance, Lloyd’s, Markel Insurance Company, RLI Corp., The Travelers Companies, W.R. Berkley Corp., XL Group plc and Zurich Insurance Group. In our reinsurance business, we compete with reinsurers that provide property and casualty lines of reinsurance, including Alleghany Corporation, Argo International Holdings, Ltd., AXIS Capital Holdings Limited, Berkshire Hathaway, Inc., Chubb Limited, Endurance Specialty Holdings Ltd., Everest Re Group Ltd., Hannover Rückversicherung AG, Lloyd’s, Markel Global Reinsurance, Munich Re Group, PartnerRe Ltd., RenaissanceRe Holdings Ltd., SCOR Global P&C, SCOR Global Life, Swiss Reinsurance Company, Third Point Reinsurance Ltd., Validus Holdings Ltd. and XL Group plc. We do not believe that we have a significant market share in any of our markets.
Financial institutions and other capital markets participants also offer alternative products and services similar to our own or alternative products that compete with insurance and reinsurance products, such as insurance/risk-linked securities, catastrophe bonds and derivatives. In recent years, capital market participants have been increasingly active in the reinsurance market and markets for related risks. Certain of the new companies entering the insurance and reinsurance markets are pursuing more aggressive investment strategies than do we and other traditional reinsurers, which may result in further downward pressure on premium rates. In this regard, we co-sponsored Watford Re, a newly formed property and casualty reinsurer, in 2014. We perform underwriting services and Highbridge manages the investments, seeking higher yields and potentially assuming more risk than in our investment portfolio. If the investment and/or insurance underwriting strategies are not successful, we may be exposed to a risk of loss on our investment and in respect of the reinsurance cessions. In addition, we may not be aware of other companies that may be planning to enter the segments of the insurance and reinsurance market in which we operate.
Our competitive position is based on many factors, including our perceived overall financial strength, ratings assigned by independent rating agencies, geographic scope of business, client and broker relationships, premiums charged, contract terms and conditions, products and services offered (including the ability to design customized programs), appropriate and timely claim payments, reputation, experience and qualifications of employees and local presence. We may not be successful in competing with others on any of these bases, and the intensity of competition in our industry may erode profitability and result in less favorable policy terms and conditions for insurance and reinsurance companies generally, including us.
In our U.S. mortgage business, we compete with six active U.S. mortgage insurers, which include the mortgage insurance subsidiaries of Essent Group Ltd., Genworth Financial Inc., MGIC Investment Corporation, NMI Holdings Inc., Radian Group Inc. and United Guaranty Corporation. The level of competition within the private mortgage insurance industry has been intense and is not expected to diminish. In response to competitive pressures, among other factors, we reduced certain premium rates in 2015. In addition to pricing, we compete with other private mortgage insurers on the basis of underwriting guidelines, loss mitigation practices, financial strength, reputation, customer relationships, technology, service and other factors. One or more private mortgage insurers may seek increased market share by reducing pricing, or loosening their underwriting guidelines or practices, which could adversely affect our mortgage insurance operations. Competition within the private mortgage insurance industry could result in the loss of customers, lower premiums, riskier credit guidelines and other changes that could lower our revenues or increase our expenses.
The mortgage insurance industry’s business has been limited as a result of competition with the FHA, which substantially increased its market share beginning in 2008. In January 2015, FHA reduced the annual mortgage insurance premium it charges from 1.35% of the loan amount to 0.85%. This premium reduction made private mortgage insurance
less competitive with the FHA for borrowers with certain credit characteristics. Other factors that could cause FHA to maintain or increase its share of the mortgage insurance market include: a further reduction in the premiums charged, or a shortening of the duration for which premiums are charged, for government mortgage insurance or a loosening of underwriting guidelines; imposition of additional loan level fees by the government sponsored entities (“GSEs”), Fannie Mae and Freddie Mac, on loans that require mortgage insurance; increases in GSE guaranty fees and the difference in the spread between Fannie Mae mortgage-backed securities (“MBS”) and Ginnie Mae MBS; and the implementation of new regulations under the Dodd-Frank Act and the Basel III Rules.
If the FHA or other government-sponsored mortgage insurance programs maintain or increase their share of the mortgage insurance market, our mortgage insurance business could be adversely affected. In addition to FHA and other federal mortgage insurance programs, lenders and investors may select other alternatives to private mortgage insurance, including: state-supported mortgage insurance funds in several states; lenders and other investors holding mortgages in portfolio and self-insuring; investors using credit enhancements other than mortgage insurance, using other credit enhancements in conjunction with reduced levels of mortgage insurance coverage, or accepting credit risk without credit enhancement; and lenders originating mortgages using “piggy-back” structures to avoid mortgage insurance, such as a first mortgage with an 80% loan-to-value and a second mortgage with a 10%, 15% or 20% loan-to-value (referred to as 80-10-10, 80-15-5 or 80-20 loans, respectively) rather than a first mortgage with a 90%, 95% or 100% loan-to-value that has mortgage insurance.
Arch MI U.S. and other private mortgage insurers increasingly compete with well c
Showing the first 8K of 145K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
We lease office space in Bermuda where our principal offices are located. Our reinsurance group leases space for offices in the U.S., Bermuda, Europe, Canada and Dubai. Our insurance group leases space for offices in the U.S., Canada, Bermuda, Europe, South Africa and Australia. Our mortgage group leases space for offices in the U.S. and Australia. We believe that the above described office space is adequate for our needs. However, as we continue to develop our business, we may open additional office locations in 2016.
Item 3. LEGAL PROCEEDINGS
We, in common with the insurance industry in general, are subject to litigation and arbitration in the normal course of our business. As of December 31, 2015, we were not a party to any litigation or arbitration which is expected by management to have a material adverse effect on our results of operations and financial condition and liquidity.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
MARKET INFORMATION
Our common shares are traded on the NASDAQ Stock Market under the symbol “ACGL.” The following table sets forth the high and low sales prices for our common shares for the two most recent fiscal years by quarter:
| 2015 | 2014 | ||||||||||||||
| High | Low | High | Low | ||||||||||||
| 1st Quarter | $63.01 | $57.67 | $59.55 | $52.23 | |||||||||||
| 2nd Quarter | $68.01 | $59.78 | $58.52 | $55.61 | |||||||||||
| 3rd Quarter | $74.98 | $64.28 | $58.24 | $52.98 | |||||||||||
| 4th Quarter | $78.81 | $67.98 | $60.10 | $52.51 |
On February 23, 2016, the high and low sales prices and the closing price for our common shares as reported on the NASDAQ Stock Market were $68.59, $66.39 and $68.16, respectively.
HOLDERS
As of February 23, 2016, and based on information provided to us by our transfer agent and proxy solicitor, there were 1,053 holders of record of our common shares and approximately 23,000 beneficial holders of our common shares.
ISSUER PURCHASES OF EQUITY SECURITIES
The following table summarizes our purchases of our common shares for the 2015 fourth quarter:
| Issuer Purchases of Equity Securities | |||||||||||||
| Period | Total Number of Shares Purchased (1) | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Approximate Dollar Value of Shares that May Yet be Purchased Under the Plan or Programs (2) | |||||||||
| 10/1/2015-10/31/2015 | 1,948 | $ | 75.89 | — | $ | 521,757 | |||||||
| 11/1/2015-11/30/2015 | 10,198 | $ | 73.95 | — | $ | 521,757 | |||||||
| 12/1/2015-12/31/2015 | 2,956 | $ | 70.10 | — | $ | 521,757 | |||||||
| Total | 15,102 | $ | 73.45 | — | $ | 521,757 |
| (1) | Includes repurchases by ACGL of shares, from time to time, from employees in order to facilitate the payment of withholding taxes on restricted shares granted and the exercise of stock appreciation rights. We purchased these shares at their fair market value, as determined by reference to the closing price of our common shares on the day the restricted shares vested or the stock appreciation rights were exercised. |
| (2) | Remaining amount available at December 31, 2015 under ACGL’s share repurchase authorization, under which repurchases may be effected from time to time in open market or privately negotiated transactions through December 31, 2016. |
DIVIDENDS
Any determination to pay dividends on ACGL’s Series C non-cumulative preferred shares (“Series C preferred shares”) or common shares will be at the discretion of ACGL’s board of directors (or a duly authorized committee of the board of directors) and will be dependent upon its results of operations, financial condition and other factors deemed relevant by ACGL’s board of directors. As a holding company, ACGL will depend on future dividends and other permitted payments from its subsidiaries to pay dividends to its shareholders. ACGL’s subsidiaries’ ability to pay dividends, as well as its ability to pay dividends, is subject to regulatory, contractual, rating agency and other constraints. So long as any Series C preferred shares remain outstanding for any dividend period, unless the full dividends for the latest completed dividend period on all outstanding Series C preferred shares and parity shares have been declared and paid (or declared and a sum sufficient for the payment thereof has been set aside), (a) no dividend may be paid or declared on ACGL’s common shares or any of its other securities ranking junior to the Series C preferred shares (other than a dividend payable solely in common shares or in such other junior securities) and (b) no common shares or other junior shares may be purchased, redeemed or otherwise acquired for consideration by ACGL, directly or indirectly (other than (i) as a result of a reclassification of junior shares for or into other junior shares, or the exchange or conversion of one junior share for or into another junior share, (ii) through the use of the proceeds of a substantially contemporaneous sale of junior shares and (iii) as permitted by the bye-laws of ACGL in effect on the date of issuance of the Series C preferred shares).
PERFORMANCE GRAPH
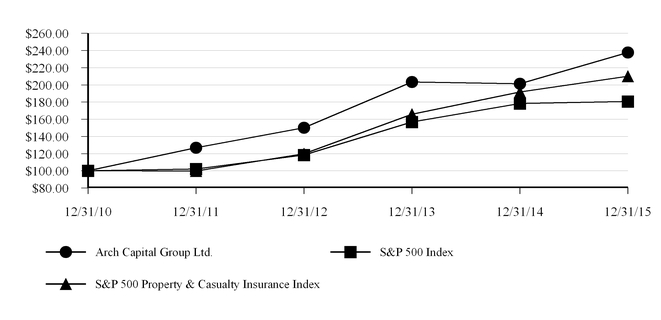
The following graph compares the cumulative total shareholder return on our common shares for each of the last five years through December 31, 2015 to the cumulative total return, assuming reinvestment of dividends, of (1) S&P 500 Composite Stock Index (“S&P 500 Index”) and (2) the S&P 500 Property & Casualty Insurance Index. The share price performance presented below is not necessarily indicative of future results.
CUMULATIVE TOTAL SHAREHOLDER RETURN (1)(2)(3)
| Base Period | |||||||||||||||||||
| Company Name/Index | 12/31/10 | 12/31/11 | 12/31/12 | 12/31/13 | 12/31/14 | 12/31/15 | |||||||||||||
| l | Arch Capital Group Ltd. | $100.00 | $126.85 | $149.98 | $203.37 | $201.36 | $237.65 | ||||||||||||
| n | S&P 500 Index | $100.00 | $102.11 | $118.45 | $156.82 | $178.28 | $180.75 | ||||||||||||
| p | S&P 500 Property & Casualty Insurance Index | $100.00 | $99.75 | $119.81 | $165.69 | $191.78 | $210.05 |
| (1) | Stock price appreciation plus dividends. |
| (2) | The above graph assumes that the value of the investment was $100 on December 31, 2010. |
| (3) | This graph is not “soliciting material,” is not deemed filed with the SEC and is not to be incorporated by reference in any filing by us under the Securities Act of 1933 or the Securities and Exchange Act of 1934, whether made before or after the date hereof and irrespective of any general incorporation language in any such filing. |
Item 6. SELECTED FINANCIAL DATA
The following tables set forth summary historical consolidated financial and operating data (including the results of the ‘other’ segment) and should be read in conjunction with “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and our financial statements and the related notes.
| (U.S. dollars in thousands except share data) | Year Ended December 31, | ||||||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||||||||||
| Statement of Income Data: | |||||||||||||||||||
| Net premiums written | $ | 3,817,531 | $ | 3,891,938 | $ | 3,351,367 | $ | 3,052,235 | $ | 2,673,326 | |||||||||
| Net premiums earned | 3,733,905 | 3,593,748 | 3,145,952 | 2,935,140 | 2,631,815 | ||||||||||||||
| Net investment income | 348,090 | 302,585 | 267,219 | 294,895 | 338,198 | ||||||||||||||
| Equity in net income (loss) of investment funds accounted for using the equity method | 25,455 | 19,883 | 35,701 | 73,510 | (9,605 | ) | |||||||||||||
| Net realized gains | (185,842 | ) | 102,917 | 74,018 | 194,228 | 110,646 | |||||||||||||
| Total revenues | 3,936,590 | 3,988,873 | 3,526,157 | 3,482,381 | 3,063,307 | ||||||||||||||
| Income before income taxes | 567,194 | 844,247 | 742,505 | 589,387 | 426,370 | ||||||||||||||
| Net income | $ | 526,582 | $ | 821,260 | $ | 709,731 | $ | 593,397 | $ | 436,163 | |||||||||
| Net (income) loss attributable to noncontrolling interests | 11,156 | 13,095 | — | — | — | ||||||||||||||
| Net income available to Arch | 537,738 | 834,355 | 709,731 | 593,397 | 436,163 | ||||||||||||||
| Preferred dividends | (21,938 | ) | (21,938 | ) | (21,938 | ) | (25,079 | ) | (25,844 | ) | |||||||||
| Loss on repurchase of preferred shares | — | — | — | (10,612 | ) | — | |||||||||||||
| Net income available to Arch common shareholders | $ | 515,800 | $ | 812,417 | $ | 687,793 | $ | 557,706 | $ | 410,319 | |||||||||
| Diluted net income per share | $ | 4.09 | $ | 6.02 | $ | 5.07 | $ | 4.03 | $ | 2.97 | |||||||||
| Cash dividends per share | — | — | — | — | — | ||||||||||||||
| After-tax operating income available to Arch common shareholders (1) | $ | 565,199 | $ | 617,312 | $ | 595,715 | $ | 350,640 | $ | 303,382 | |||||||||
| After-tax operating income available to Arch common shareholders per share — diluted (1) | $ | 4.48 | $ | 4.58 | $ | 4.39 | $ | 2.54 | $ | 2.19 | |||||||||
| After-tax operating return on average common equity (2) | 9.7 | % | 11.1 | % | 11.7 | % | 7.7 | % | 7.2 | % | |||||||||
| Weighted average common shares and common share equivalents outstanding — diluted | 126,038,743 | 134,922,322 | 135,777,183 | 138,258,847 | 138,289,702 |
| (1) | After-tax operating income available to Arch common shareholders is defined as net income available to Arch common shareholders, excluding net realized gains or losses, net impairment losses included in earnings, equity in net income or loss of investment funds accounted for using the equity method, net foreign exchange gains or losses and loss on repurchase of preferred shares, net of income taxes. The presentation of after-tax operating income available to Arch common shareholders is a “non-GAAP financial measure” as defined in Regulation G. See “Management’s Discussion and Analysis—General—Comment on Non-GAAP Financial Measures” for further details. |
| (2) | Equals after-tax operating income available to Arch common shareholders divided by the average of beginning and ending common shareholders’ equity for each period presented. |
| (U.S. dollars in thousands except share data) | December 31, | ||||||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||||||||||
| Balance Sheet Data: | |||||||||||||||||||
| Total investable assets (1) | $ | 16,340,938 | $ | 15,762,730 | $ | 14,049,525 | $ | 13,045,134 | $ | 12,316,205 | |||||||||
| Premiums receivable | 983,443 | 948,695 | 753,924 | 688,873 | 501,563 | ||||||||||||||
| Reinsurance recoverables on unpaid and paid losses and loss adjustment expenses | 1,867,373 | 1,812,845 | 1,804,330 | 1,870,037 | 1,851,584 | ||||||||||||||
| Total assets | 23,177,270 | 22,006,081 | 19,557,054 | 17,813,419 | 17,101,951 | ||||||||||||||
| Reserves for losses and loss adjustment expenses: | |||||||||||||||||||
| Before unpaid losses and loss adjustment expenses recoverable | 9,125,250 | 9,036,448 | 8,824,696 | 8,933,292 | 8,456,210 | ||||||||||||||
| Net of unpaid losses and loss adjustment expenses recoverable | 7,296,413 | 7,258,145 | 7,076,446 | 7,104,222 | 6,638,163 | ||||||||||||||
| Unearned premiums: | |||||||||||||||||||
| Before prepaid reinsurance premiums | 2,333,932 | 2,231,578 | 1,896,365 | 1,647,978 | 1,411,872 | ||||||||||||||
| Net of prepaid reinsurance premiums | 1,906,323 | 1,854,500 | 1,568,022 | 1,349,494 | 1,146,176 | ||||||||||||||
| Senior notes | 791,306 | 791,141 | 790,960 | 296,657 | 296,594 | ||||||||||||||
| Revolving credit agreement borrowings | 530,434 | 100,000 | 100,000 | 100,000 | 100,000 | ||||||||||||||
| Total liabilities | 16,028,376 | 14,887,435 | 13,909,558 | 12,644,541 | 12,509,877 | ||||||||||||||
| Total shareholders’ equity | 6,943,712 | 6,899,134 | 5,647,496 | 5,168,878 | 4,592,074 | ||||||||||||||
| Total shareholders' equity available to Arch | 6,204,881 | 6,130,053 | 5,647,496 | 5,168,878 | 4,592,074 | ||||||||||||||
| Preferred shareholders' equity | 325,000 | 325,000 | 325,000 | 325,000 | 325,000 | ||||||||||||||
| Common shareholders' equity available to Arch | $ | 5,879,881 | $ | 5,805,053 | $ | 5,322,496 | $ | 4,843,878 | $ | 4,267,074 | |||||||||
| Common shares outstanding, net of treasury shares (2) | 122,627,783 | 127,367,934 | 133,674,884 | 133,842,613 | 134,358,345 | ||||||||||||||
| Book value per common share (3) | $ | 47.95 | $ | 45.58 | $ | 39.82 | $ | 36.19 | $ | 31.76 |
| (1) | This table excludes the collateral received and reinvested and includes the securities pledged under securities lending agreements, at fair value. |
| (2) | Reflects the impact of our share repurchase program. |
| (3) | Excludes the effects of stock options and restricted stock units. |
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion and analysis contains forward-looking statements which involve inherent risks and uncertainties. All statements other than statements of historical fact are forward-looking statements. These statements are based on our current assessment of risks and uncertainties. Actual results may differ materially from those expressed or implied in these statements and, therefore, undue reliance should not be placed on them. Important factors that could cause actual events or results to differ materially from those indicated in such statements are discussed in this report, including the sections entitled “Cautionary Note Regarding Forward-Looking Statements,” and “Risk Factors.”
This discussion and analysis should be read in conjunction with our audited consolidated financial statements and notes thereto presented under Item 8. Tabular amounts are in U.S. Dollars in thousands, except share amounts, unless otherwise noted.
GENERAL
Overview
Arch Capital Group Ltd. (“ACGL” and, together with its subsidiaries, “we” or “us”) is a Bermuda public limited liability company with approximately $7.10 billion in capital at December 31, 2015 and, through operations in Bermuda, the United States, Europe and Canada, writes insurance and reinsurance on a worldwide basis. While we are positioned to provide a full range of property and casualty insurance and reinsurance lines, we focus on writing specialty lines of insurance and reinsurance. It is our belief that our underwriting platform, our experienced management team and our strong capital base that is unencumbered by significant pre-2002 risks have enabled us to establish a strong presence in the insurance and reinsurance markets.
The worldwide insurance and reinsurance industry is highly competitive and has traditionally been subject to an underwriting cycle in which a hard market (high premium rates, restrictive underwriting standards, as well as terms and conditions, and underwriting gains) is eventually followed by a soft market (low premium rates, relaxed underwriting standards, as well as broader terms and conditions, and underwriting losses). Insurance market conditions may affect, among other things, the demand for our products, our ability to increase premium rates, the terms and conditions of the insurance policies we write, changes in the products offered by us or changes in our business strategy.
The financial results of the insurance and reinsurance industry are influenced by factors such as the frequency and/or severity of claims and losses, including natural disasters or other catastrophic events, variations in interest rates and financial markets, changes in the legal, regulatory and judicial environments, inflationary pressures and general economic conditions. These factors influence, among other things, the demand for insurance or reinsurance, the supply of which is generally related to the total capital of competitors in the market.
Current Outlook
The broad market environment continues to be competitive in our business reflecting a continuation of softening in pricing and broadening pressures on terms and conditions. This has been true in both our insurance and reinsurance property casualty segments and has led us to continue to reduce writings in certain lines in 2015. With the continued low interest rate environment, additional increases are needed in many lines in order for us to achieve our return requirements. Our underwriting teams continue to execute a disciplined strategy by emphasizing small and medium-sized accounts over large accounts.
Arch Mortgage Insurance Company (“Arch MI U.S.”) continues to expand into the U.S. mortgage insurance marketplace. As of December 31, 2015, Arch MI U.S. reviewed and approved 904 master policy applications from banks, and 460 of these clients have submitted loans to Arch MI U.S. In addition, Arch MI U.S. launched RateStar, a new risk-based pricing program, in the 2015 fourth quarter. RateStar uses a combination of loan characteristics and other risk factors to determine premium rates for each loan.
Our objective is to achieve an average operating return on average equity of 15% or greater over the insurance cycle, as opposed to any one calendar year, which we believe to be an attractive return to our common shareholders given the risks we assume. We continue to look for opportunities to find acceptable books of business to underwrite without
sacrificing underwriting discipline and continue to write a portion of our overall book in catastrophe-exposed business which has the potential to increase the volatility of our operating results.
Changing economic conditions could have a material impact on the frequency and severity of claims and, therefore, could negatively impact our underwriting returns. In addition, volatility in the financial markets could continue to significantly affect our investment returns, reported results and shareholders’ equity. We consider the potential impact of economic trends in the estimation process for establishing unpaid losses and loss adjustment expenses and in determining our investment strategies. In addition, weakness of the U.S., European countries and other key economies, projected budget deficits for the U.S., European countries and other governments and the consequences associated with potential downgrades of securities of the U.S., European countries and other governments by credit rating agencies is inherently unpredictable and could have a material adverse effect on financial markets and economic conditions in the U.S. and throughout the world. In turn, this could have a material adverse effect on our business, financial condition and results of operations and, in particular, this could have a material adverse effect on the value and liquidity of securities in our investment portfolio.
Natural Catastrophe Risk
We monitor our natural catastrophe risk globally for all perils and regions, in each case, where we believe there is significant exposure. Our models employ both proprietary and vendor-based systems and include cross-line correlations for property, marine, offshore energy, aviation, workers compensation and personal accident. Currently, we seek to limit our 1-in-250 year return period net probable maximum pre-tax loss from a severe catastrophic event in any geographic zone to approximately 25% of total shareholders’ equity available to Arch. We reserve the right to change this threshold at any time. Based on in-force exposure estimated as of January 1, 2016, our modeled peak zone catastrophe exposure is a windstorm affecting the Northeastern U.S., with a net probable maximum pre-tax loss of $489 million, followed by windstorms affecting the Gulf of Mexico and Florida Tri-County with net probable maximum pre-tax losses of $444 million and $362 million, respectively. Our exposures to other perils, such as U.S. earthquake and international events, were less than the exposures arising from U.S. windstorms and hurricanes in both periods. As of January 1, 2016, our modeled peak zone earthquake exposure (Los Angeles area earthquake) represented approximately 58% of our peak zone catastrophe exposure, and our modeled peak zone international exposure (Japan earthquake) was substantially less than both our peak zone windstorm and earthquake exposures.
Net probable maximum pre-tax loss estimates are net of expected reinsurance recoveries, before income tax and before excess reinsurance reinstatement premiums. Loss estimates are reflective of the zone indicated and not the entire portfolio. Since hurricanes and windstorms can affect more than one zone and make multiple landfalls, our loss estimates include clash estimates from other zones. The loss estimates shown above do not represent our maximum exposures and it is highly likely that our actual incurred losses would vary materially from the modeled estimates. There can be no assurances that we will not suffer a net loss greater than 25%
Showing the first 8K of 275K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
Reference is made to the information appearing above under the subheading “Market Sensitive Instruments and Risk Management” under the caption “Management’s Discussion and Analysis of Financial Condition and Results of Operation,” which information is hereby incorporated by reference.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
| Index to Financial Statements | Page No. | |
| Report of Independent Registered Public Accounting Firm | 137 | |
| Consolidated Balance Sheets | ||
| At December 31, 2015 and December 31, 2014 | 138 | |
| Consolidated Statements of Income | ||
| For the years ended December 31, 2015, 2014 and 2013 | 139 | |
| Consolidated Statements of Comprehensive Income | ||
| For the years ended December 31, 2015, 2014 and 2013 | 140 | |
| Consolidated Statements of Changes in Shareholders’ Equity | ||
| For the years ended December 31, 2015, 2014 and 2013 | 141 | |
| Consolidated Statements of Cash Flows | ||
| For the years ended December 31, 2015, 2014 and 2013 | 141 | |
| Notes to Consolidated Financial Statements | 143 |
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Shareholders of
Arch Capital Group Ltd.:
In our opinion, the consolidated financial statements listed in the accompanying index, present fairly, in all material respects, the financial position of Arch Capital Group Ltd. and its subsidiaries (the “Company”) at December 31, 2015 and December 31, 2014, and the results of their operations and their cash flows for each of the three years in the period ended December 31, 2015 in conformity with accounting principles generally accepted in the United States of America. In addition, in our opinion, the financial statement schedules listed in the index appearing under Item 15(a)(2) present fairly, in all material respects, the information set forth therein when read in conjunction with the related consolidated financial statements. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). The Company's management is responsible for these financial statements and financial statement schedules, for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in Management's Annual Report on Internal Control Over Financial Reporting appearing under Item 9A. Our responsibility is to express opinions on these financial statements, on the financial statement schedules, and on the Company's internal control over financial reporting based on our integrated audits. We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the financial statements are free of material misstatement and whether effective internal control over financial reporting was maintained in all material respects. Our audits of the financial statements included examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements, assessing the accounting principles used and significant estimates made by management, and evaluating the overall financial statement presentation. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ PricewaterhouseCoopers LLP
New York, New York
February 26, 2016
| ARCH CAPITAL GROUP LTD. AND SUBSIDIARIES CONSOLIDATED BALANCE SHEETS (U.S. dollars in thousands, except share data) | |||||||
| December 31, | |||||||
| 2015 | 2014 | ||||||
| Assets | |||||||
| Investments: | |||||||
| Fixed maturities available for sale, at fair value (amortized cost: $10,515,440 and $10,701,557) | $ | 10,459,353 | $ | 10,750,770 | |||
| Short-term investments available for sale, at fair value (amortized cost: $591,141 and $801,758) | 587,904 | 797,226 | |||||
| Collateral received under securities lending, at fair value (amortized cost: $385,984 and $40,473) | 389,336 | 44,301 | |||||
| Equity securities available for sale, at fair value (cost: $543,767 and $562,534) | 618,405 | 658,182 | |||||
| Other investments available for sale, at fair value (cost: $261,343 and $264,747) | 300,476 | 296,224 | |||||
| Investments accounted for using the fair value option | 2,894,494 | 2,425,053 | |||||
| Investments accounted for using the equity method | 592,973 | 349,014 | |||||
| Total investments | 15,842,941 | 15,320,770 | |||||
| Cash | 553,326 | 485,702 | |||||
| Accrued investment income | 87,206 | 74,316 | |||||
| Securities pledged under securities lending, at fair value (amortized cost: $386,411 and $52,076) | 384,081 | 50,802 | |||||
| Premiums receivable | 983,443 | 948,695 | |||||
| Reinsurance recoverable on unpaid and paid losses and loss adjustment expenses | 1,867,373 | 1,812,845 | |||||
| Contractholder receivables | 1,486,296 | 1,309,192 | |||||
| Prepaid reinsurance premiums | 427,609 | 377,078 | |||||
| Deferred acquisition costs, net | 433,477 | 414,525 | |||||
| Receivable for securities sold | 45,505 | 78,170 | |||||
| Goodwill and intangible assets | 97,531 | 109,539 | |||||
| Other assets | 968,482 | 1,024,447 | |||||
| Total assets | $ | 23,177,270 | $ | 22,006,081 | |||
| Liabilities | |||||||
| Reserve for losses and loss adjustment expenses | $ | 9,125,250 | $ | 9,036,448 | |||
| Unearned premi |
Showing the first 8K of 326K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Evaluation of Disclosure Controls and Procedures
In connection with the filing of this Form 10-K, our management, including the Chief Executive Officer and Chief Financial Officer, conducted an evaluation, as of December 31, 2015, for the purposes set forth in the applicable rules under the Securities and Exchange Act of 1934, as amended (the “Exchange Act”). Based on that evaluation, the Chief Executive Officer and Chief Financial Officer concluded that the disclosure controls and procedures are effective.
We continue to enhance our operating procedures and internal controls (including information technology initiatives and controls over financial reporting) to effectively support our business and our regulatory and reporting requirements. Our management does not expect that our disclosure controls or our internal controls will prevent all errors and all fraud. A control system, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. Further, the design of a control system must reflect the fact that there are resource constraints, and the benefits of controls must be considered relative to their costs. As a result of the inherent limitations in all control systems, no evaluation of controls can provide absolute assurance that all control issues and instances of fraud, if any, within the company have been detected. These inherent limitations include the realities that judgments in decision making can be faulty, and that breakdowns can occur because of simple error or mistake. Additionally, controls can be circumvented by the individual acts of some persons or by collusion of two or more people. The design of any system of controls also is based in part upon certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions; over time, controls may become inadequate because of changes in conditions, or the degree of compliance with the policies or procedures may deteriorate. As a result of the inherent limitations in a cost-effective control system, misstatement due to error or fraud may occur and not be detected. Accordingly, our disclosure controls and procedures are designed to provide reasonable, not absolute, assurance that the disclosure controls and procedures are met.
Management’s Annual Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting, as defined in Rules 13a-15(f) and 15d-15(f) under the Exchange Act. Our management assessed the effectiveness of our internal control over financial reporting as of December 31, 2015. In making this assessment, management used the criteria set forth by the Committee of Sponsoring Organizations (COSO) of the Treadway Commission in Internal Control-Integrated Framework (2013).
Based on our assessment, management determined that, as of December 31, 2015, our internal control over financial reporting was effective. The effectiveness of our internal control over financial reporting as of December 31, 2015 has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report included in Item 8.
Changes in Internal Control Over Financial Reporting
There have been no changes in internal control over financial reporting that occurred in connection with our evaluation required pursuant to Rules 13a-15 and 15d-15 under the Exchange Act during the fiscal quarter ended December 31, 2015 that have materially affected, or are reasonably likely to materially affect, internal control over financial reporting.
Item 9B. OTHER INFORMATION
None.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
The information required by this item is incorporated by reference from the information to be included in our definitive proxy statement (“Proxy Statement”) for our annual meeting of shareholders to be held in 2016, which we intend to file with the SEC pursuant to Regulation 14A before April 30, 2016. Copies of our code of ethics applicable to our chief executive officer, chief financial officer and principal accounting officer or controller are available free of charge to investors upon written request addressed to the attention of ACGL’s corporate secretary, Waterloo House, 100 Pitts Bay Road, Pembroke HM 08, Bermuda. In addition, our code of ethics and certain other basic corporate documents, including the charters of our audit committee, compensation committee and nominating committee are posted on our website. If any substantive amendments are made to the code of ethics or if there is a grant of a waiver, including any implicit waiver, we will disclose the nature of such amendment or waiver on our website or in a report on Form 8-K, to the extent required by applicable law or the rules and regulations of any exchange applicable to us. Our website address is intended to be an inactive, textual reference only and none of the material on our website is incorporated by reference into this report.
Item 11. EXECUTIVE COMPENSATION
The information required by this item is incorporated by reference from the information to be included in the Proxy Statement which we intend to file pursuant to Regulation 14A with the SEC before April 30, 2016, which Proxy Statement is incorporated by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
Other than the information set forth below, the information required by this item is incorporated by reference from the information to be included in the Proxy Statement which we intend to file pursuant to Regulation 14A with the SEC before April 30, 2016, which Proxy Statement is incorporated by reference.
The following information is as of December 31, 2015:
| Column A | Column B | Column C | |||||||||
| Plan Category | Number of Securities to be Issued Upon Exercise of Outstanding Stock Options(1), Warrants and Rights | Weighted-Average Exercise Price of Outstanding Stock Options(1), Warrants and Rights ($) | Number of Securities Remaining Available for Future Issuance Under Equity Compensation Plans (Excluding Securities Reflected in Column A | ||||||||
| Equity compensation plans approved by security holders | 7,895,826 | $ | 38.07 | 4,756,257 | |||||||
| Equity compensation plans not approved by security holders | — | — | — | ||||||||
| Total | 7,895,826 | $ | 38.07 | 4,756,257 | (2) |
| (1) | Includes all vested and unvested stock options outstanding of 7,482,462 and restricted stock units outstanding of 413,364. The weighted average exercise price does not take into account restricted stock units. In addition, the weighted average remaining contractual life of the Company's outstanding exercisable stock options and SARs at December 31, 2015 was 5.38 years. |
| (2) | Includes 563,259 common shares remaining available for future issuance under our Employee Share Purchase Plan and 4,192,998 common shares remaining available for future issuance under our equity compensation plans. Shares available for future issuance under our equity compensation plans may be issued in the form of stock options, SARs, restricted shares, restricted share units payable in common shares or cash, share awards in lieu of cash awards, dividend equivalents, performance shares and performance units and other share-based awards. In addition, 2,415,308 common shares, or 57.6% of the 4,192,998 common shares remaining available for future issuance may be issued in connection with full value awards (i.e., awards other than stock options or SARs). |
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
The information required by this item is incorporated by reference from the information to be included in the Proxy Statement which we intend to file pursuant to Regulation 14A with the SEC before April 30, 2016, which Proxy Statement is incorporated by reference.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
The information required by this item is incorporated by reference from the information to be included in our Proxy Statement which we intend to file pursuant to Regulation 14A with the SEC before April 30, 2016, which Proxy Statement is incorporated by reference.
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
(a) Financial Statements, Financial Statement Schedules and Exhibits.
| 1. | Financial Statements |
Included in Part II – see Item 8 of this report.
2.Financial Statement Schedules
| Page No. | |
| III. Supplementary Insurance Information | |
| For the years ended December 31, 2015, 2014 and 2013 | 216 |
| IV. Reinsurance | |
| For the years ended December 31, 2015, 2014 and 2013 | 217 |
| VI. Supplementary Information for Property and Casualty Insurance Underwriters | |
| For the years ended December 31, 2015, 2014 and 2013 | 218 |
Schedules other than those listed above are omitted for the reason that they are not applicable or the information is provided in Item 8 of this report.
- Exhibits
| Exhibit Number | Description | |
| 3.1 | Memorandum of Association of ACGL(b) | |
| 3.2 | Bye-Laws of ACGL(u) | |
| 3.3 | ACGL Certificate of Deposit of Memorandum of Increase of Share Capital(u) | |
| 4.1 | Certificate of Designations of Series C Non-Cumulative Preferred Shares(x) | |
| 4.2.1 | Specimen Common Share Certificate(c) | |
| 4.2.2 | Specimen Series C Non-Cumulative Preferred Share Certificate(x) | |
| 4.3 | Indenture and First Supplemental Indenture, dated as of May 4, 2004, between ACGL and JPMorgan Chase Bank, N.A. (formerly JPMorgan Chase Bank) (“JPMCB”)(h) | |
| 4.3 | Indenture and First Supplemental Indenture, dated as of December 13, 2013, between Arch Capital Group (U.S.) Inc. (“Arch U.S.”), ACGL and The Bank of New York Mellon, as trustee(gg) | |
| 10.1.1 | ACGL 2002 Long Term Incentive and Share Award Plan (“2002 Plan”)(e)† | |
| 10.1.2 | First Amendment to the 2002 Plan(f)† | |
| 10.1.3 | Second Amendment to the 2002 Plan(q)† | |
| 10.2 | Second Amended and Restated ACGL Incentive Compensation Plan (q)† | |
| 10.3.1 | ACGL 2007 Long Term Incentive and Share Award Plan(m)† | |
| 10.3.2 | ACGL 2012 Long Term Incentive and Share Award Plan(w)† | |
| 10.3.3 | ACGL 2007 Employee Share Purchase Plan (“2007 ESPP”)(m)† | |
| 10.3.4 | Amendment to ACGL 2007 ESPP, dated as of November 7, 2007(n)† | |
| 10.3.5 | ACGL 2015 Long Term Incentive and Share Award Plan(ll)† | |
| 10.4.1 | Restricted Share Unit Agreement with ACGL-Constantine Iordanou-February 20, 2003 grant (“February RSU Agreement”)(g), First Amendment to February RSU Agreement-December 9, 2008 grant(q) and Second Amendment to February RSU Agreement-July 9, 2009 grant(r)† | |
| 10.4.2 | Restricted Share Unit Agreement with ACGL-Mark D. Lyons-May 9, 2008 grant(p), May 6, 2009 grant(s), May 5, 2010 grant(t), May 6, 2011 grant(v) and May 9, 2012 grant(aa)† | |
| 10.4.3 | Restricted Share Unit Agreement with ACGL-David McElroy-September 6, 2012 grant(ee) and May 9, 2013 grant(ff)† | |
| 10.4.4 | Restricted Share Agreement with ACGL-Mark D. Lyons-September 6, 2012 grant(ee)† | |
| 10.4.5 | Restricted Share Agreements with ACGL substantially in the form signed by each of Constantine Iordanou, Louis T. Petrillo, W. Preston Hutchings and Marc Grandisson-November 12, 2012 grants(ee)† | |
| 10.4.6 | Restricted Share Agreements with ACGL substantially in the form signed by each of Constantine Iordanou, Louis T. Petrillo, W. Preston Hutchings, David H. McElroy and Marc Grandisson-May 9, 2012 grant(aa)† | |
| 10.4.7 | Restricted Share Agreements with ACGL substantially in the form signed by each of Constantine Iordanou, Louis T. Petrillo, W. Preston Hutchings, Mark D. Lyons and Marc Grandisson-May 9, 2013 grants(ff)† | |
| 10.4.8 | Restricted Share Agreement with ACGL. substantially in the form signed by the Non-Employee Directors of ACGL-May 9, 2014 grants(ii)† | |
| 10.4.9 | Restricted Share Agreement with ACGL substantially in the form signed by each of Constantine Iordanou, Mark D. Lyons, Marc Grandisson, W. Preston Hutchings and Louis T. Petrillo-May 13, 2014 grants(ii)† | |
| 10.4.10 | Restricted Share Unit Agreement with ACGL-David McElroy-May 13, 2014 grant(ii)† | |
| 10.4.11 | Restricted Share Agreement with ACGL substantially in the form signed by each of Louis J. Paglia and Eugene S. Sunshine-July 14, 2014 grants(kk)† | |
| 10.4.12 | Restricted Share Agreement with ACGL-Marc Grandisson-November 6, 2014 grant(mm)† | |
| 10.4.13 | Restricted Share Agreement with ACGL substantially in the form signed by the Non-Employee Directors of ACGL-May 7, 2015 grants(nn)† | |
| 10.4.14 | Restricted Share Agreement with ACGL substantially in the form signed by each of Constantine Iordanou, Mark D. Lyons, Marc Grandisson, W. Preston Hutchings, David McElroy and Louis T. Petrillo-May 13, 2015 grants(nn)† | |
| 10.4.15 | Restricted Share Unit Agreement with ACGL-David McElroy-May 13, 2015 grant(nn)† | |
| 10.5.1 | Stock Option Agreement with ACGL-Marc Grandisson-November 15, 2005 grant(k)† | |
| 10.5.2 | Stock Option Agreements with ACGL and Constantine Iordanou, John D. Vollaro and Marc Grandisson-February 23, 2006 grants(l)† | |
| 10.5.3 | Stock Option Agreement with ACGL-W. Preston Hutchings-February 23, 2006 grant(l)† |
| 10.5.4 | Non-Qualified Stock Option Agreement with Constantine Iordanou, Mark D. Lyons, Marc Grandisson, W. Preston Hutchings, David McElroy and Louis T. Petrillo-May 13, 2015 grants(nn)† | |
| 10.6.1 | Share Appreciation Right Agreement with ACGL substantially in the form signed by Louis T. Petrillo and W. Preston Hutchings-May 11, 2007 grants(n)† | |
| 10.6.2 | Share Appreciation Right Agreement with ACGL substantially in the form signed by Constantine Iordanou, John D. Vollaro and Marc Grandisson-May 11, 2007 grants(n)† | |
| 10.6.3 | Share Appreciation Right Agreement with ACGL substantially in the form signed by each of Constantine Iordanou, John D. Vollaro, Marc Grandisson, W. Preston Hutchings, Mark D. Lyons and Louis T. Petrillo-May 9, 2008 grants(p)† | |
| 10.6.4 | Share Appreciation Right Agreement with ACGL substantially in the form signed by each of Constantine Iordanou, Marc Grandisson, W. Preston Hutchings, Mark D. Lyons, John D. Vollaro and Louis T. Petrillo-May 6, 2009 grants(s)† | |
| 10.6.5 | Share Appreciation Right Agreement with ACGL substantially in the form signed by each of Constantine Iordanou, Marc Grandisson, W. Preston Hutchings, Mark D. Lyons and Louis T. Petrillo-May 5, 2010 grants(t) May 6, 2011 grants(v), May 9, 2012 grants(aa) and May 9, 2013 grants (includes David H. McElroy)(ff)† | |
| 10.6.6 | Share Appreciation Right Agreement with ACGL-Constantine Iordanou-February 25, 2010 grant(aa),February 29, 2012 grant(aa) and September 6, 2012 grants(ee)† | |
| 10.6.7 | Share Appreciation Right Agreement with ACGL-David H. McElroy-June 8, 2009 grant(cc) and September 6, 2012 grants(ee)† | |
| 10.6.8 | Share Appreciation Right Agreement with ACGL-Mark D. Lyons-September 6, 2012 grant(ee)† | |
| 10.6.9 | Share Appreciation Right Agreement with ACGL substantially in the form signed by each of Constantine Iordanou, Marc Grandisson, W. Preston Hutchings and Louis T. Petrillo-November 12, 2012 grants(ee)† | |
| 10.6.10 | Share Appreciation Right Agreement with ACGL substantially in the form signed by each of Constantine Iordanou, Mark D. Lyons, Marc Grandisson, W. Preston Hutchings, David McElroy and Louis T. Petrillo for May 13, 2014 grants(ii)† | |
| 10.6.11 | Share Appreciation Right Agreement with ACGL-Mark D. Lyons-February 28, 2014 grant(ii)† | |
| 10.6.12 | Share Appreciation Right Agreement with ACGL-Constantine Iordanou-February 28, 2014 grant(ii)† | |
| 10.6.13 | Share Appreciation Right Agreement with ACGL-Marc Grandisson-November 6, 2014 grant(mm)† | |
| 10.7 | Employment and Change in Control Agreement, dated as of May 5, 2000, between ACGL and Louis T. Petrillo(a) and Amendment to Change in Control Agreement, dated as of December 31, 2008(q)† | |
| 10.8 | Employment Agreement, dated as of October 23, 2001, among ACGL, Arch Re Bermuda and Marc Grandisson(d), First Amendment to same, dated as of November 16, 2005(k) and Second Amendment to same, dated as of November 24, 2008(q)† | |
| 10.9 | Employment Letter Agreement, dated as of May 29, 2005, between ACGL and W. Preston Hutchings(j) and Amendment to same, dated as of May 21, 2008(o)† | |
| 10.10 | Employment Agreement, dated as of July 25, 2012, between ACGL and Mark D. Lyons(y)† | |
| 10.11 | Employment Agreement, dated as of June 5, 2009, between Arch Insurance Group Inc. and David McElroy(z) and Amendment to same, dated as of July 25, 2012(z)† | |
| 10.12.1 | Amended and Restated Employment Agreement, dated October 1, 2014, between ACGL and Constantine Iordanou(jj)† | |
| 10.12.2 | Amended and Restated Employment Agreement, dated February 27, 2015, between ACGL and John D. Vollaro(mm)† | |
| 10.13 | Assumption of Change in Control Agreements(c)† | |
| 10.14 | Arch U.S. Executive Supplemental Non-Qualified Savings and Retirement Plan(q)† | |
| 10.15 | Asset Purchase Agreement, dated as of February 7, 2013 (“PMI Asset Purchase Agreement”), by and among the Receiver of PMI Mortgage Insurance Co. in Rehabilitation on behalf of PMI Mortgage Insurance Co. (the “Receiver”), Arch U.S. MI Services Inc. and Arch U.S.(bb) and the Amendment No.1, dated as of May 31, 2013, to the PMI Asset Purchase Agreement (dd) | |
| 10.16 | Stock Purchase Agreement, dated as of February 7, 2013 (“CMG Stock Purchase Agreement”), by and among the Receiver, CMFG Life Insurance Company, CMG Mortgage Insurance Company, Arch U.S. MI Holdings Inc. and Arch U.S.(bb) and Amendment No. 1, dated as of May 31, 2013, to the CMG Stock Purchase Agreement(dd) | |
| 10.17 | Amended and Restated Credit Agreement, dated as of June 30, 2014, by and among ACGL and its subsidiaries, Arch Capital Group (U.S.) Inc., Arch Reinsurance Ltd., Arch Reinsurance Company, Arch Reinsurance Europe Underwriting Designated Activity Company, Arch Insurance Company, Arch Specialty Insurance Company and Arch Insurance Company (Europe) Limited, and Bank of America, N.A., as Administrative Agent, Fronting Bank and L/C Administrator, JPMorgan Chase Bank, N.A. and Wells Fargo Bank, National Association, as Co-Syndication Agents, U.S. Bank National Association and Lloyds Bank plc, as Co-Documentation Agents, Merrill Lynch, Pierce, Fenner & Smith Incorporated, J.P. Morgan Securities LLC and Wells Fargo Securities, LLC, as Joint Lead Arrangers and Joint Book Managers and the other lenders party thereto(hh) | |
| 12 | Statement regarding computation of ratios (filed herewith) | |
| 21 | Subsidiaries of Registrant (filed herewith) | |
| 23 | Consent of PricewaterhouseCoopers LLP (filed herewith) |
| 24 | Power of Attorney (filed herewith) | |
| 25 | Form T-1 Statement of Eligibility of Trustee(i)(gg) | |
| 31.1 | Certification of Chief Executive Officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002 (filed herewith) | |
| 31.2 | Certification of Chief Financial Officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002 (filed herewith) | |
| 32.1 | Certification of Chief Executive Officer pursuant to Section 906 of the Sarbanes-Oxley Act of 2002 (filed herewith) | |
| 32.2 | Certification of Chief Financial Officer pursuant to Section 906 of the Sarbanes-Oxley Act of 2002 (filed herewith) | |
| 101 | The following financial information from ACGL’s Annual Report on Form 10-K for the year ended December 31, 2015 formatted in XBRL: (i) Consolidated Balance Sheets at December 31, 2015 and 2014; (ii) Consolidated Statements of Income for the years ended December 31, 2015, 2014 and 2013; (iii) Consolidated Statements of Comprehensive Income for the years ended December 31, 2015, 2014 and 2013; (iv) Consolidated Statements of Changes in Shareholders’ Equity for the years ended December 31, 2015, 2014 and 2013; (v) Consolidated Statements of Cash Flows for the years ended December 31, 2015, 2014 and 2013; and (vi) Notes to Consolidated Financial Statements (filed herewith) |
| (a) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on September 8, 2000, and incorporated by reference. |
| (b) | Filed as an annex to our Definitive Proxy Statement/Prospectus included in our Registration Statement on Form S-4 (No. 333-45418), as filed with the SEC on September 26, 2000, and incorporated by reference. |
| (c) | Filed as an exhibit to our Annual Report on Form 10-K for the year ended December 31, 2000, as filed with the SEC on April 2, 2001, and incorporated by reference. |
| (d) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on January 4, 2002, and incorporated by reference. |
| (e) | Filed as an exhibit to our Report on Form 10-Q for the period ended June 30, 2002, as filed with the SEC on August 14, 2002, and incorporated by reference. |
| (f) | Filed as an exhibit to our Report on Form 10-Q for the period ended September 30, 2003, as filed with the SEC on November 12, 2003, and incorporated by reference. |
| (g) | Filed as an exhibit to our Annual Report on Form 10-K for the year ended December 31, 2003, as filed with the SEC on March 10, 2004, and incorporated by reference. |
| (h) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on May 7, 2004, and incorporated by reference. |
| (i) | Revised form of agreement originally filed as an exhibit to our Report on Form 8-K, as filed with the SEC on September 28, 2004, and incorporated by reference. |
| (j) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on June 9, 2005, and incorporated by reference. |
| (k) | Filed as an exhibit to our Annual Report on Form 10-K for the year ended December 31, 2005, as filed with the SEC on March 13, 2006, and incorporated by reference. |
| (l) | Filed as an exhibit to our Report on Form 10-Q for the period ending September 30, 2006, as filed with the SEC on November 9, 2006, and incorporated by reference. |
| (m) | Filed as an appendix to our Definitive Proxy Statement, as filed with the SEC on April 3, 2007, and incorporated by reference. |
| (n) | Filed as an exhibit to our Annual Report on Form 10-K for the year ended December 31, 2007, as filed with the SEC on February 29, 2008, and incorporated by reference. |
| (o) | Filed as an exhibit to our Report on Form 10-Q for the period ending June 30, 2008, as filed with the SEC on August 8, 2008, and incorporated by reference. |
| (p) | Filed as an exhibit to our Report on Form 10-Q for the period ending September 30, 2008, as filed with the SEC on November 10, 2008, and incorporated by reference. |
| (q) | Filed as an exhibit to our Annual Report on Form 10-K for the year ended December 31, 2008, as filed with the SEC on March 2, 2009, and incorporated by reference. |
| (r) | Filed as an exhibit to our Report on Form 10-Q for the period ending September 30, 2009, as filed with the SEC on November 9, 2009, and incorporated by reference. |
| (s) | Filed as an exhibit to our Annual Report on Form 10-K for the year ended December 31, 2009, as filed with the SEC on February 26, 2010, and incorporated by reference. |
| (t) | Filed as an exhibit to our Report on Form 10-Q for the period ending September 30, 2010, as filed with the SEC on November 8, 2010, and incorporated by reference. |
| (u) | Filed as an exhibit to our Annual Report on Form 10-K for the period ending December 31, 2010, as filed with the SEC on February 28, 2011, and incorporated by reference. |
| (v) | Filed as an exhibit to our Report on Form 10-Q for the period ending September 30, 2011, as filed with the SEC on November 8, 2011, and incorporated by reference. |
| (w) | Filed as an appendix to our Definitive Proxy Statement, as filed with the SEC on March 27, 2012, and incorporated by reference. |
| (x) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on April 2, 2012, and incorporated by reference. |
| (y) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on July 30, 2012, and incorporated by reference. |
| (z) | Filed as an exhibit to our Report on Form 10-Q for the period ending June 30, 2012, as filed with the SEC on August 8, 2012, and incorporated by reference. |
| (aa) | Filed as an exhibit to our Report on Form 10-Q for the period ending September 30, 2012, as filed with the SEC on November 9, 2012, and incorporated by reference. |
| (bb) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on February 8, 2013, and incorporated by reference. |
| (cc) | Filed as an exhibit to our Annual Report on Form 10-K for the year ended December 31, 2012, as filed with the SEC on March 1, 2013, and incorporated by reference. |
| (dd) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on June 5, 2013, and incorporated by reference. |
| (ee) | Filed as an exhibit to our Report on Form 10-Q for the period ending June 30, 2013, as filed with the SEC on August 9, 2013, and incorporated by reference. |
| (ff) | Filed as an exhibit to our Report on Form 10-Q for the period ending September 30, 2013, as filed with the SEC on November 8, 2013, and incorporated by reference. |
| (gg) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on December 13, 2013, and incorporated by reference. |
| (hh) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on July 1, 2014, and incorporated by reference. |
| (ii) | Filed as an exhibit to our Report on Form 10-Q for the period ending June 30, 2014, as filed with the SEC on August 8, 2014, and incorporated by reference. |
| (jj) | Filed as an exhibit to our Report on Form 8-K, as filed with the SEC on October 6, 2014, and incorporated by reference. |
| (kk) | Filed as an exhibit to our Report on Form 10-Q for the period ending September 30, 2014, as filed with the SEC on November 7, 2014, and incorporated by reference. |
| (ll) | Filed as an appendix to our Definitive Proxy Statement, as filed with the SEC on March 26, 2015, and incorporated by reference. |
| (mm) | Filed as an exhibit to our Report on Form 10-Q for the period ending March 31, 2015, as filed with the SEC on May 8, 2015, and incorporated by reference. |
| (nn) | Filed as an exhibit to our Report on Form 10-Q for the period ending June 30, 2015, as filed with the SEC on August 7, 2015, and incorporated by reference. |
† Management contract or compensatory plan or arrangement.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| ARCH CAPITAL GROUP LTD. (Registrant) | |||
| By: | /s/ Constantine Iordanou | ||
| Name: | Constantine Iordanou | ||
| Title: | Chairman of the Board of Directors and Chief Executive Officer |
February 26, 2016
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the dates indicated.
| Name | Title | Date |
| /s/ Constantine Iordanou | ||
| Constantine Iordanou | Chairman of the Board of Directors and Chief Executive Officer (Principal Executive Officer) | February 26, 2016 |
| /s/ Mark D. Lyons | ||
| Mark D. Lyons | Executive Vice President, Chief Financial Officer and Treasurer (Principal Financial and Principal Accounting Officer) | February 26, 2016 |
| * | ||
| John L. Bunce. Jr. | Director | February 26, 2016 |
| * | ||
| Eric W. Doppstadt | Director | February 26, 2016 |
| * | ||
| Kewsong Lee | Director | February 26, 2016 |
| * | ||
| Yiorgos Lillikas | Director | February 26, 2016 |
| Name | Title | Date |
| * | ||
| Deanna M. Mulligan | Director | February 26, 2016 |
| * | ||
| Louis J. Paglia | Director | February 26, 2016 |
| * | ||
| John M. Pasquesi | Director | February 26, 2016 |
| * | ||
| Brian S. Posner | Director | February 26, 2016 |
| * | ||
| Eugene S. Sunshine | Director | February 26, 2016 |
| * | ||
| John D. Vollaro | Director | February 26, 2016 |
| * | By Mark D. Lyons, as attorney-in-fact and agent, pursuant to a power of attorney, a copy of which has been filed with the Securities and Exchange Commission as Exhibit 24 to this report. |
| /s/ Mark D. Lyons | |
| Name: | Mark D. Lyons Attorney-in-Fact |
SCHEDULE III
ARCH CAPITAL GROUP LTD. AND SUBSIDIARIES
SUPPLEMENTARY INSURANCE INFORMATION
(U.S. dollars in thousands)
| Deferred Acquisition Costs, Net | Reserves for Losses and Loss Adjustment Expenses | Unearned Premiums | Net Premiums Earned | Net Investment Income (1) | Net Losses and Loss Adjustment Expenses Incurred | Amortization of Deferred Acquisition Costs | Other Operating Expenses (2) | Net Premiums Written | |||||||||||||||||
| December 31, 2015 | |||||||||||||||||||||||||
| Insurance | $166,771 | $6,050,922 | $1,217,490 | $2,044,808 | NM | $1,292,647 | $299,317 | $354,416 | $2,045,671 | ||||||||||||||||
| Reinsurance | 138,184 | 2,672,044 | 650,138 | 1,077,135 | NM | 440,350 | 223,632 | 155,811 | 1,038,408 | ||||||||||||||||
| Mortgage | 53,079 | 111,287 | 216,324 | 214,110 | NM | 40,247 | 45,076 | 82,370 | 267,493 | ||||||||||||||||
| Other | 75,443 | 290,997 | 249,980 | 397,852 | NM | 277,659 | 113,451 | 14,919 | 465,959 | ||||||||||||||||
| Total | $433,477 | $9,125,250 | $2,333,932 | $3,733,905 | NM | $2,050,903 | $681,476 | $607,516 | $3,817,531 | ||||||||||||||||
| December 31, 2014 | |||||||||||||||||||||||||
| Insurance | $178,545 | $6,161,500 | $1,237,099 | $2,017,370 | NM | $1,260,953 | $316,308 | $335,157 | $2,146,654 | ||||||||||||||||
| Reinsurance | 148,130 | 2,690,070 | 666,233 | 1,279,328 | NM | 532,450 | 261,438 | 147,964 | 1,265,991 | ||||||||||||||||
| Mortgage | 38,321 | 118,550 | 148,232 | 193,573 | NM | 55,674 | 49,400 | 66,891 | 204,837 | ||||||||||||||||
| Other | 49,529 | 66,328 | 180,014 | 103,477 | NM | 70,173 | 30,116 | 6,268 | 274,456 | ||||||||||||||||
| Total | $414,525 | $9,036,448 | $2,231,578 | $3,593,748 | NM | $1,919,250 | $657,262 | $556,280 | $3,891,938 | ||||||||||||||||
| December 31, 2013 | |||||||||||||||||||||||||
| Insurance | $158,121 | $6,137,121 | $1,192,188 | $1,876,014 | NM | $1,188,445 | $311,904 | $315,387 | $1,948,796 | ||||||||||||||||
| Reinsurance | 167,642 | 2,680,288 | 612,725 | 1,218,672 | NM | 486,236 | 234,373 | 134,563 | 1,313,001 | ||||||||||||||||
| Mortgage | 16,551 | 7,287 | 91,452 | 51,266 | NM | 4,743 | 17,826 | 8,377 | 89,570 | ||||||||||||||||
| Total | $342,314 | $8,824,696 | $1,896,365 | $3,145,952 | NM | $1,679,424 | $564,103 | $458,327 | $3,351,367 |
| (1) | The Company does not manage its assets by segment and, accordingly, net investment income is not allocated to each underwriting segment. See Note 5 for information related to the ‘other’ segment. |
| (2) | Certain other operating expenses relate to the Company’s corporate segment (non-underwriting). Such amounts are not reflected in the table above. See Note 5. |
SCHEDULE IV
ARCH CAPITAL GROUP LTD. AND SUBSIDIARIES
REINSURANCE
(U.S. dollars in thousands)
| Gross Amount | Ceded to Other Companies (1) | Assumed From Other Companies (1) | Net Amount | Percentage of Amount Assumed to Net | ||||||||||||||
| Year Ended December 31, 2015 | ||||||||||||||||||
| Premiums Written: | ||||||||||||||||||
| Insurance | $ | 2,908,906 | $ | (898,347 | ) | $ | 35,112 | $ | 2,045,671 | 1.7 | % | |||||||
| Reinsurance | 28,510 | (380,614 | ) | 1,390,512 | 1,038,408 | 133.9 | % | |||||||||||
| Mortgage | 137,338 | (28,064 | ) | 158,219 | 267,493 | 59.1 | % | |||||||||||
| Other | 12,165 | (22,940 | ) | 476,734 | 465,959 | 102.3 | % | |||||||||||
| Total | $ | 3,086,919 | $ | (979,632 | ) | $ | 1,710,244 | $ | 3,817,531 | 44.8 | % | |||||||
| Year Ended December 31, 2014 | ||||||||||||||||||
| Premiums Written: | ||||||||||||||||||
| Insurance | $ | 2,974,996 | $ | (862,015 | ) | $ | 33,673 | $ | 2,146,654 | 1.6 | % | |||||||
| Reinsurance | 22,405 | (261,255 | ) | 1,504,841 | 1,265,991 | 118.9 | % | |||||||||||
| Mortgage | 103,545 | (22,519 | ) | 123,811 | 204,837 | 60.4 | % | |||||||||||
| Other | — | (14,171 | ) | 288,627 | 274,456 | 105.2 | % | |||||||||||
| Total | $ | 3,100,946 | $ | (948,678 | ) | $ | 1,739,670 | $ | 3,891,938 | 44.7 | % | |||||||
| Year Ended December 31, 2013 | ||||||||||||||||||
| Premiums Written: | ||||||||||||||||||
| Insurance | $ | 2,682,446 | $ | (763,713 | ) | $ | 30,063 | $ | 1,948,796 | 1.5 | % | |||||||
| Reinsurance | 72,136 | (86,620 | ) | 1,327,485 | 1,313,001 | 101.1 | % | |||||||||||
| Mortgage | — | — | 89,570 | 89,570 | 100.0 | % | ||||||||||||
| Total | $ | 2,754,582 | $ | (845,256 | ) | $ | 1,442,041 | $ | 3,351,367 | 43.0 | % |
| (1) | Certain amounts included in the gross premiums written of each segment are related to intersegment transactions and are included in the gross premiums written of each segment. Accordingly, the sum of gross premiums written for each segment does not agree to the total gross premiums written as shown in the table above due to the elimination of intersegment transactions in the total. |
SCHEDULE VI
ARCH CAPITAL GROUP LTD. AND SUBSIDIARIES
SUPPLEMENTARY INFORMATION FOR PROPERTY AND CASUALTY INSURANCE UNDERWRITERS
(U.S. dollars in thousands)
| Column A | Column B | Column C | Column D | Column E | Column F | Column G | Column H | Column I | Column J | Column K | |||||||||||||||||||||||
| Affiliation with Registrant | Deferred Acquisition Costs, Net | Reserves for Losses and Loss Adjustment Expenses | Discount, if any, deducted in Column C | Unearned Premiums | Net Premiums Earned | Net Investment Income | Net Losses and Loss Adjustment Expenses Incurred Related to | Amortization of Deferred Acquisition Costs | Net Paid Losses and Loss Adjustment Expenses | Net Premiums Written | |||||||||||||||||||||||
| (a) Current Year | (b) Prior Years | ||||||||||||||||||||||||||||||||
| Consolidated Subsidiaries | |||||||||||||||||||||||||||||||||
| 2015 | $ | 433,477 | $ | 9,125,250 | $ | 16,789 | $ | 2,333,932 | $ | 3,733,905 | $ | 348,090 | $ | 2,336,026 | $ | (285,123 | ) | $ | 681,476 | $ | 1,869,244 | $ | 3,817,531 | ||||||||||
| 2014 | 414,525 | 9,036,448 | 14,732 | 2,231,578 | 3,593,748 | 302,585 | 2,246,152 | (326,902 | ) | 657,262 | 1,697,736 | 3,891,938 | |||||||||||||||||||||
| 2013 | 342,314 | 8,824,696 | 12,539 | 1,896,365 | 3,145,952 | 267,219 | 1,943,466 | (264,042 | ) | 564,103 | 1,708,817 | 3,351,367 |