 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
154K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Ameren, headquartered in St. Louis, Missouri, is a public utility holding company whose primary assets are its equity interests in its subsidiaries. Ameren’s subsidiaries are separate, independent legal entities with separate businesses, assets, and liabilities. Dividends on Ameren’s common stock and the payment of expenses by Ameren depend on distributions made to it by its subsidiaries.
Below is a summary description of Ameren’s principal subsidiaries – Ameren Missouri, Ameren Illinois, and ATXI. Ameren also has other subsidiaries that conduct other activities, such as providing shared services. A more detailed description can be found in Note 1 – Summary of Significant Accounting Policies under Part II, Item 8, of this report.
| • | Ameren Missouri operates a rate-regulated electric generation, transmission, and distribution business and a rate-regulated natural gas distribution business in Missouri. |
| • | Ameren Illinois operates rate-regulated electric transmission, electric distribution, and natural gas distribution businesses in Illinois. |
| • | ATXI operates a FERC rate-regulated electric transmission business in the MISO. |
Ameren has four segments: Ameren Missouri, Ameren Illinois Electric Distribution, Ameren Illinois Natural Gas, and Ameren Transmission. The Ameren Missouri segment includes all of the operations of Ameren Missouri. Ameren Illinois Electric Distribution consists of the electric distribution business of Ameren Illinois. Ameren Illinois Natural Gas consists of the natural gas business of Ameren Illinois. Ameren Transmission primarily consists of the aggregated electric transmission businesses of Ameren Illinois and ATXI. See Note 16 – Segment Information under Part II, Item 8, of this report for further discussion of Ameren’s, Ameren Missouri’s, and Ameren Illinois’ Segments.
Ameren’s financial statements are prepared on a consolidated basis and therefore include the accounts of its majority-owned subsidiaries. All intercompany transactions have been eliminated, except as disclosed in Note 13 – Related-party Transactions under Part II, Item 8, of this report. Ameren Missouri and Ameren Illinois have no subsidiaries. All tabular and graphical dollar amounts are in millions, unless otherwise indicated.
The following discussion should be read in conjunction with the financial statements contained in this Form 10-K. We intend for this discussion to provide the reader with information that will assist in understanding our financial statements, the changes in certain key items in those financial statements, and the primary factors that accounted for those changes, as well as how certain accounting principles affect our financial statements. The discussion also provides information about the financial results of our business segments to provide a better understanding of how those segments and their results affect the financial condition and results of operations of Ameren as a whole. Discussion regarding our financial condition and results of operations for the year ended December 31, 2017, including comparisons with the year ended December 31, 2018, is included in Item 7 of our Form 10-K for the year ended December 31, 2018, filed with the SEC on February 26, 2019.
In addition to presenting results of operations and earnings amounts in total, we present certain information in cents per share. These amounts reflect factors that directly affect Ameren’s earnings. We believe this per share information helps readers to understand the impact of these factors on Ameren’s earnings per share.
OVERVIEW
Our core strategy to invest in regulated infrastructure, continuously improve performance, and advocate for responsible policies to deliver superior customer and shareholder value is driven by three pillars.
| Investing in and operating our utilities in a manner consistent with existing regulatory frameworks | Enhancing regulatory frameworks and advocating for responsible energy and economic policies | Creating and capitalizing on opportunities for investment for the benefit of our customers and shareholders | |||
| We seek to earn competitive returns on investments in our businesses. Accordingly, we remain focused on disciplined cost management and strategic capital allocation. We align our overall spending, both operating and capital, with economic conditions and with the frameworks established by our regulators, to create and capitalize on investment opportunities for the benefit of our customers and shareholders. We focus on minimizing the gap between allowed and earned ROEs and allocating capital resources to business opportunities that we expect will provide the most benefit to our customers and offer the most attractive risk-adjusted return potential. | We seek to partner with our stakeholders, including our customers, regulators, federal and state legislators, and RTOs, to enhance our regulatory frameworks and advocate for responsible energy and economic policies for the benefit of our customers and shareholders. We believe constructive regulatory frameworks for investment exist at all of Ameren's business segments. Accordingly, we expect to earn competitive returns on investments in our businesses and realize timely recovery of our costs in the coming years with the benefits accruing to both customers and shareholders. | We seek to make prudent investments that benefit our customers. The goal of these investments is to maintain and enhance the reliability of our services, develop cleaner sources of energy, create economic development opportunities in our region, and provide customers with more options and greater control over their energy usage, among other things. By prudently investing in our businesses, we believe that we deliver superior value to both customers and shareholders. | |||
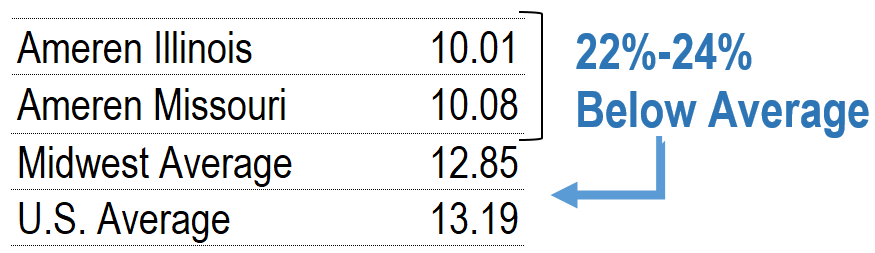
| Customer Rates, (¢/KWH)****(d) | |||||
 | |||||
| Rate Base ($ in billions)****(a) | Constructive Regulatory Frameworks | TSR 2014-2019**(e)** | |||
 | Segment | Regulatory Framework | 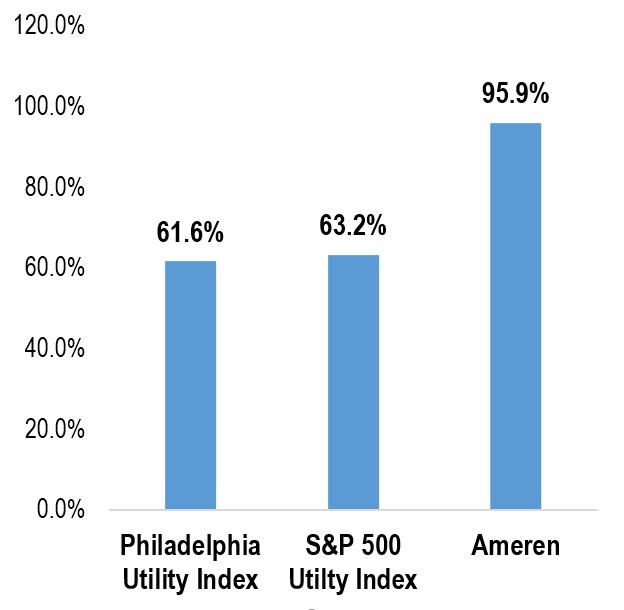 | ||
| Ameren Transmission | Formula ratemaking Allowed ROE is 10.38% | ||||
| Ameren Illinois Natural Gas | Future test year ratemaking and QIP, PGA, VBA Allowed ROE is 9.87% | ||||
| Ameren Illinois Electric Distribution | Formula ratemaking Allowed ROE is 30-year U.S. Treasury + 5.8% | ||||
| Ameren Missouri | Historical test year ratemaking and PISA, RESRAM, FAC, MEEIA Allowed ROE is 9.2% - 9.7%(c) | ||||
(a) Reflects year-end rate base except for Ameren Transmission, which is average rate base.
(b) Compound annual growth rate.
(c) Allowed ROE applicable to electric service.
(d) Average residential electric prices. Source: Edison Electric Institute, “Typical Bills and Average Rates Report” for the 12 months ended June 30, 2019.
(e) Ameren management cautions that the stock price performance shown above should not be considered indicative of future stock price performance.
Below are some key announcements, updates, legislative actions, and regulatory outcomes that occurred in 2019 and early 2020.
In March 2019, Ameren issued its Building a Cleaner Energy Future report, which sets forth Ameren’s plan for reducing carbon emissions and addressing climate risk. The plan is largely reflected in the Ameren Missouri 2017 IRP, which includes expanding renewable sources by adding 700 megawatts of wind generation by the end of 2020 and adding 100 megawatts of solar generation by 2027. Ameren Missouri expects to file its next integrated resource plan in September 2020.
In August 2019, Ameren entered into a forward sale agreement with a counterparty relating to 7.5 million shares of common stock. The forward sale agreement can be settled at Ameren’s discretion on or prior to March 31, 2021. On a settlement date or dates, if Ameren elects to physically settle the forward sale agreement, Ameren will issue shares of common stock to the counterparty at the then-applicable forward sale price. The forward sale agreement will be physically settled unless Ameren elects to settle in cash or to net share settle. If physically settled, Ameren expects to receive between $540 million and $550 million upon settlement, which is expected to be used to fund a portion of Ameren Missouri’s wind generation investments. See Note 5 – Long-term Debt and Equity Financings under Part II, Item 8, of this report for additional information.
Consistent with its 2017 IRP filing, in May 2019, Ameren Missouri entered into a build-transfer agreement to acquire, after construction, an up-to 300-megawatt wind generation facility. In 2018, Ameren Missouri entered into a build-transfer agreement to acquire, after construction, an up-to 400-megawatt wind generation facility. These two agreements are subject to customary contract terms and conditions. The two build-transfer acquisitions collectively represent $1.2 billion of capital expenditures, are expected to be completed by the end of 2020, and would support Ameren Missouri’s compliance with the Missouri renewable energy standard. Both acquisitions have received all regulatory approvals, and both projects have received all applicable zoning approvals, have entered into RTO interconnection agreements, and have begun construction activities. The MoPSC has approved a RESRAM, which is designed to mitigate the impacts of regulatory lag for the cost of compliance with Missouri’s renewable energy standard, including recovery of investments in wind and other renewable energy generation, by providing more timely recovery of costs and a return on investments not already provided for in customer rates or recovered under the PISA. See Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report for more information regarding Ameren Missouri wind generation facilities.
In July 2019, Ameren Missouri filed a request with the MoPSC seeking approval to decrease its annual revenues for electric service by $1 million. In February 2020, Ameren Missouri, the MoPSC staff, the MoOPC, and certain intervenors filed a nonunanimous stipulation and agreement with the MoPSC to decrease Ameren Missouri’s annual revenues for electric service by $32 million. The remaining intervenor did not object to the agreement. The stipulation and agreement, which is subject to MoPSC approval, specified an allowed ROE range of 9.4% to 9.8%, but did not specify the common equity percentage or rate base. The stipulation and agreement includes the continued use of the FAC and trackers that the MoPSC previously authorized in earlier electric rate orders. Ameren Missouri cannot predict whether the MoPSC will approve the stipulation and agreement or, if approved, whether any application for rehearing or appeal will be filed, or the outcome if so filed. A decision by the MoPSC is expected by March 2020, with new rates effective as early as April 1, 2020. The percentage of net energy cost variances from the amount set in base rates allowed to be recovered or refunded under the FAC and costs from services provided by affiliates are still being challenged by the MoOPC, and are expected to be addressed in a proceeding that would begin in March 2020. A MoPSC decision would be expected in the proceeding by the end of May 2020. If a change to the percentage of net energy cost variances from the amount set in base rates allowed to be recovered or refunded under the FAC is ordered by the MoPSC, the ordered percentage will be reflected in the FAC. If any investments or expenses are disallowed by the MoPSC, the effect on customer rates of such disallowances will be deferred as a regulatory liability and refunded to customers over a period of time determined in the next regulatory rate review. See Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report for more information regarding the Ameren Missouri 2019 electric service regulatory rate review.
In September 2019, the United States District Court for the Eastern District of Missouri issued an order in a case brought by the Department of Justice, on behalf of the EPA, alleging that in performing projects at its coal-fired Rush Island Energy Center in 2007 and 2010, Ameren Missouri violated provisions of the Clean Air Act and Missouri law. The order requires Ameren Missouri to install a flue gas desulfurization system at the Rush Island Energy Center and a dry sorbent injection system at the Labadie Energy Center. In October 2019, Ameren Missouri appealed the district court’s ruling to the United States Court of Appeals for the Eighth Circuit. Additionally, in October 2019, following a request by Ameren Missouri, the district court stayed implementation of the majority of its order requirements while the case is appealed. As a result of the district court’s stay, Ameren Missouri does not expect to make significant capital expenditures or incur operations and maintenance expenses related to the district court’s order while the case is under appeal. The ultimate resolution of this matter could have a material adverse effect on the results of operations, financial position, and liquidity of Ameren and Ameren Missouri. See Note 14 – Commitments and Contingencies under Part II, Item 8, of this report for more information regarding NSR and clean air litigation.
In February 2020, Ameren Missouri filed an update to its Smart Energy Plan with the MoPSC, which includes a five-year capital investment overview with a detailed one-year plan for 2020. The plan is designed to upgrade Ameren Missouri’s electric infrastructure and includes investments that will upgrade the grid and accommodate more renewable energy. Investments under the plan are expected to total approximately $7.6 billion over the five-year period from 2020 through 2024, with expenditures largely recoverable under the PISA and the RESRAM. As a part of its Smart Energy Plan, Ameren Missouri expects to build solar generation facilities, including utility scale facilities and nonresidential customer site facilities. In September 2019, Ameren Missouri filed for certificates of convenience and necessity with the MoPSC to build three solar facilities in its service territory. Each 10-megawatt solar energy generation facility will connect to battery storage in order to improve system reliability. All three facilities are expected to be completed by 2022. Also in 2019, the MoPSC approved Ameren Missouri’s Charge Ahead program, which provides incentives for the development of over 1,000 electric vehicle charging stations along highways and at various locations in communities throughout Ameren Missouri’s service territory. The purpose of the program is to promote the development of electric vehicle charging infrastructure that will enable long-distance electric vehicle travel and encourage electrification of the transportation sector.
In February 2020, the MoPSC issued an order approving a stipulation and agreement allowing Ameren Missouri to defer and amortize maintenance expenses related to scheduled refueling and maintenance outages at its Callaway Energy Center. Beginning with the fall 2020 refueling and maintenance outage, Ameren Missouri will defer the maintenance expenses incurred related to a refueling and maintenance outage as a regulatory asset and amortize those expenses after completion of the outage. Maintenance expenses will be amortized over the period between refueling and maintenance outages, which is approximately 18 months. Deferring and amortizing refueling maintenance
expenses allows the timing of expense recognition to more closely align with revenues and mitigates future earnings volatility between outage and non-outage years.
In December 2019, the ICC issued an order that approved a $7 million decrease in Ameren Illinois’ electric distribution service rates beginning in January 2020. In November 2019, the ICC issued an order that approved Ameren Illinois’ 2020 electric customer energy-efficiency rates of $44 million, which represents an increase of $10 million from 2019 rates.
In February 2020, Ameren Illinois filed a request with the ICC seeking approval to increase its annual revenues for natural gas delivery service by $102 million, which included an estimated $46 million of annual revenues that would otherwise be recovered under the QIP and other riders. The request is based on a 10.5% allowed ROE, a capital structure composed of 54.1% common equity, and a rate base of $2.1 billion. See Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report for more information regarding Ameren Illinois’ natural gas delivery service regulatory rate review.
In November 2019, the FERC issued an order addressing two customer complaint cases filed in November 2013 and February 2015, respectively. The complaint cases were seeking a reduction in the allowed base ROE for FERC-regulated transmission rate base under the MISO tariff of 12.38%. The order set the allowed base ROE at 9.88% and required refunds, with interest, for the periods November 2013 to February 2015 and from late September 2016 forward. In December 2019, Ameren and the MISO transmission owners, including Ameren Missouri, Ameren Illinois, and ATXI, as well as numerous other parties, filed requests for rehearing with the FERC. The FERC has not ruled on the merits of the rehearing requests and is under no deadline to do so. As of December 31, 2019, Ameren and Ameren Illinois had recorded current liabilities of $40 million and $23 million, respectively, to reflect the expected refunds, including interest. See Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report for more information regarding the FERC complaint cases.
ATXI continues to make progress with construction activities for its MISO-approved multi-value projects. The Mark Twain project, located in northern Missouri, was completed and placed in service in December 2019. Construction of the Illinois Rivers project is substantially complete and eight of its nine line segments have been completed and placed in service, with the last section expected to be completed in 2020.
In October 2019, Ameren’s board of directors increased the quarterly common stock dividend to 49.5 cents per share, resulting in an annualized equivalent dividend rate of $1.98 per share.
Earnings
Net income attributable to Ameren common shareholders was $828 million, or $3.35 per diluted share, for 2019, and $815 million, or $3.32 per diluted share, for 2018. Net income was favorably affected in 2019, compared with 2018, by increased investments in infrastructure at the Ameren Transmission and Ameren Illinois Electric Distribution segments, each of which benefits from formulaic ratemaking, and by the recognition of MEEIA performance incentives. Earnings were also favorably affected in 2019, compared with 2018, by charitable donations returning to more normal levels and lower income tax expense, primarily because of the absence of a noncash charge to earnings for the revaluation of deferred taxes recorded in 2018 related to the TCJA and increased tax benefits related to stock-based compensation. Net income was unfavorably affected in 2019, compared with 2018, by milder summer temperatures and higher property taxes, both at Ameren Missouri, and by higher depreciation and amortization expenses at Ameren Illinois Natural Gas and Ameren Missouri. Earnings were also unfavorably affected in 2019, compared with 2018, by a lower recognized ROE at Ameren Illinois Electric Distribution.
Liquidity
At December 31, 2019, Ameren, on a consolidated basis, had available liquidity in the form of cash on hand and amounts available under the Credit Agreements of $1.9 billion. In December 2019, the Credit Agreements were extended and now mature in December 2024.
Capital Expenditures
Ameren remains focused on strategic capital allocation. We believe we have constructive regulatory frameworks for investment at all of our utility businesses and invested $2.4 billion in those businesses in 2019. The following chart presents 2019 capital expenditures by segment and the midpoint of projected cumulative capital expenditures for 2020 through 2024 by segment:
| 2019 Capital Expenditures by Segment (in billions) | 2020 – 2024 Projected Capital Expenditures by Segment (in billions) | |||||
 |  | |||||
| Ameren Missouri | Ameren Illinois Natural Gas | |||||
| Ameren Illinois Electric Distribution | Ameren Transmission |
For 2020 through 2024, Ameren’s cumulative capital expenditures are projected to range from $15.4 billion to $16.6 billion. The following table presents the range of projected spending by segment:
| Range (in billions) | ||||||||
| Ameren Missouri | $ | 7.8 | – | $ | 8.4 | |||
| Ameren Illinois Electric Distribution | 2.8 | – | 3.0 | |||||
| Ameren Illinois Natural Gas | 1.7 | – | 1.8 | |||||
| Ameren Transmission | 3.1 | – | 3.4 | |||||
| Ameren | $ | 15.4 | – | $ | 16.6 |
RESULTS OF OPERATIONS
Our results of operations and financial position are affected by many factors. Economic conditions, energy-efficiency investments by our customers and by us, technological advances, distributed generation, and the actions of key customers can significantly affect the demand for our services. Ameren and Ameren Missouri results are also affected by seasonal fluctuations in winter heating and summer cooling demands, as well as by nuclear refueling and other energy center maintenance outages. Additionally, fluctuations in interest rates and conditions in the capital and credit markets affect our cost of borrowing, and our pension and postretirement benefits costs. Almost all of Ameren’s revenues are subject to state or federal regulation. This regulation has a material impact on the rates we charge customers for our services. Customer rates are determined under various regulatory mechanisms. See Note 2 – Rate and Regulatory Matters for additional information regarding Ameren Missouri’s, Ameren Illinois’, and ATXI’s regulatory mechanisms. Our results of operations, financial position, and liquidity are affected by our ability to align our overall spending, both operating and capital, within the frameworks established by our regulators.
Ameren Missouri principally uses coal and enriched uranium for fuel in its electric operations and purchases natural gas for its customers. Ameren Illinois purchases power and natural gas for its customers. The prices for these commodities can fluctuate significantly because of the global economic and political environment, weather, supply, demand, and many other factors. We have natural gas cost
recovery mechanisms for our Illinois and Missouri natural gas distribution businesses, a purchased power cost recovery mechanism for Ameren Illinois’ electric distribution business, and a FAC for Ameren Missouri’s electric business.
We employ various risk management strategies to reduce our exposure to commodity risk and other risks inherent in our business. The reliability of Ameren Missouri’s energy centers and our transmission and distribution systems and the level and timing of operations and maintenance costs and capital investment are key factors that we seek to manage in order to optimize our results of operations, financial position, and liquidity.
Earnings Summary
The following table presents a summary of Ameren’s earnings for the years ended December 31, 2019 and 2018:
| 2019 | 2018 | ||||||
| Net income attributable to Ameren common shareholders | $ | 828 | $ | 815 | |||
| Earnings per common share – diluted | 3.35 | 3.32 |
Net income attributable to Ameren common shareholders in 2019 increased $13 million, or $0.03 per diluted share, from 2018. The increase was due to net income increases of $21 million, $14 million, and $10 million, at Ameren Transmission, Ameren Illinois Natural Gas, and Ameren Illinois Electric Distribution, respectively. Additionally, the net loss for activity not reported as part of a segment, primarily at Ameren (parent), decreased $20 million. The increases in net income were largely offset by a decrease in net income of $52 million at Ameren Missouri.
Earnings per share in 2019, compared with 2018, were favorably affected by:
| • | increased Ameren Transmission and Ameren Illinois Electric Distribution earnings under formula ratemaking, primarily as a result of additional rate base investment and Ameren Illinois Electric Distribution energy-efficiency investments (14 cents per share); |
| • | decreased other operation and maintenance expenses not subject to riders or regulatory tracking mechanisms, excluding the Callaway Energy Center’s scheduled refueling and maintenance outage costs, primarily because of changes in the cash surrender value of company-owned life insurance (10 cents per share); |
| • | increased other income, net, primarily because charitable donations returned to more normal levels at Ameren Missouri and Ameren (parent), and increased non-service cost components of net periodic benefit income (9 cents per share); |
| • | the recognition of MEEIA 2013 and MEEIA 2016 performance incentives (8 cents per share); |
| • | the absence of a noncash charge to earnings for the revaluation of deferred taxes recorded in 2018 related to the TCJA (5 cents per share); |
| • | a decrease in the effective income tax rate at Ameren (parent), primarily because of an increase in the income tax benefit related to stock-based compensation (5 cents per share); |
| • | an increase in base rates at Ameren Illinois Natural Gas pursuant to the ICC’s November 2018 natural gas rate order (2 cents per share); |
| • | decreased net financing costs at Ameren Missouri, primarily as a result of the regulatory deferral of interest expense pursuant to the PISA and lower interest rates, partially offset by lower levels of the allowance for funds used during construction (2 cents per share); |
| • | increased Ameren Transmission earnings resulting from the net impact of the November 2019 FERC order addressing the allowed base ROE for FERC-regulated transmission rate base under the MISO tariff (2 cents per share); and |
| • | increased Ameren Illinois Natural Gas earnings under the QIP rider resulting from investments in qualifying infrastructure (1 cent per share). |
Earnings per share in 2019, compared with 2018, were unfavorably affected by:
| • | decreased electric retail sales at Ameren Missouri, primarily because of milder summer temperatures experienced in 2019 (estimated at 26 cents per share); |
| • | increased other operation and maintenance expenses related to the Callaway Energy Center’s scheduled refueling and maintenance outage that was completed in May 2019, as compared with no refueling and maintenance outage in 2018 (9 cents per share); |
| • | increased taxes other than income taxes at Ameren Missouri due to higher property taxes (5 cents per share); |
| • | increased depreciation and amortization expenses not subject to riders or regulatory tracking mechanisms at Ameren Illinois Natural Gas and Ameren Missouri, primarily because of additional property, plant, and equipment (5 cents per share); |
| • | decreased Ameren Illinois Electric Distribution earnings under formula ratemaking because of a lower recognized ROE (4 cents per share); |
| • | increased transmission services charges at Ameren Missouri (3 cents per share); and |
| • | increased weighted-average basic common shares outstanding (3 cents per share). |
The cents per share information presented is based on the weighted-average basic shares outstanding in 2018 and does not reflect any change in earnings per share resulting from dilution, unless otherwise noted. Amounts other than variances related to income taxes have been presented net of income taxes using Ameren’s 2018 statutory tax rate of 27%. For additional details regarding the Ameren Companies’ results of operations, including explanations of Electric and Natural Gas Margins, Other Operations and Maintenance Expenses, Depreciation and Amortization, Taxes Other Than Income Taxes, Other Income, Net, Interest Charges, and Income Taxes, see the major headings below.
Below is Ameren’s table of income statement components by segment for the years ended December 31, 2019 and 2018:
| 2019 | Ameren Missouri | Ameren Illinois Electric Distribution | Ameren Illinois Natural Gas | Ameren Transmission | Other / Intersegment Eliminations | Ameren | |||||||||||||||||
| Electric margins | $ | 2,381 | $ | 1,074 | $ | — | $ | 464 | $ | (29 | ) | $ | 3,890 | ||||||||||
| Natural gas margins | 81 | — | 519 | — | (2 | ) | 598 | ||||||||||||||||
| Other operations and maintenance expenses | (960 | ) | (498 | ) | (233 | ) | (60 | ) | 6 | (1,745 | ) | ||||||||||||
| Depreciation and amortization | (556 | ) | (273 | ) | (78 | ) | (84 | ) | (4 | ) | (995 | ) | |||||||||||
| Taxes other than income taxes | (329 | ) | (73 | ) | (67 | ) | (4 | ) | (8 | ) | (481 | ) | |||||||||||
| Other income, net | 58 | 33 | 12 | 8 | 19 | 130 | |||||||||||||||||
| Interest charges | (178 | ) | (71 | ) | (38 | ) | (74 | ) | (20 | ) | (381 | ) | |||||||||||
| Income (taxes) benefit | (68 | ) | (45 | ) | (30 | ) | (64 | ) | 25 | (182 | ) | ||||||||||||
| Net income (loss) | 429 | 147 | 85 | 186 | (13 | ) | 834 | ||||||||||||||||
| Noncontrolling interests – preferred stock dividends | (3 | ) | (1 | ) | (1 | ) | (1 | ) | — | (6 | ) | ||||||||||||
| Net income (loss) attributable to Ameren common shareholders | $ | 426 | $ | 146 | $ | 84 | $ | 185 | $ | (13 | ) | $ | 828 | ||||||||||
| 2018 | |||||||||||||||||||||||
| Electric margins | $ | 2,518 | $ | 1,065 | $ | — | $ | 433 | $ | (27 | ) | $ | 3,989 | ||||||||||
| Natural gas margins | 82 | — | 497 | — | (1 | ) | 578 | ||||||||||||||||
| Other operations and maintenance expenses | (972 | ) | (506 | ) | (241 | ) | (63 | ) | 10 | (1,772 | ) | ||||||||||||
| Depreciation and amortization | (550 | ) | (259 | ) | (65 | ) | (77 | ) | (4 | ) | (955 | ) | |||||||||||
| Taxes other than income taxes | (329 | ) | (75 | ) | (66 | ) | (4 | ) | (9 | ) | (483 | ) | |||||||||||
| Other income, net | 56 | 26 | 9 | 7 | 4 | 102 | |||||||||||||||||
| Interest charges | (200 | ) | (73 | ) | (38 | ) | (75 | ) | (15 | ) | (401 | ) | |||||||||||
| Income (taxes) benefit | (124 | ) | (41 | ) | (25 | ) | (56 | ) | 9 | (237 | ) | ||||||||||||
| Net income (loss) | 481 | 137 | 71 | 165 | (33 | ) | 821 | ||||||||||||||||
| Noncontrolling interests – preferred stock dividends | (3 | ) | (1 | ) | (1 | ) | (1 | ) | — | (6 | ) | ||||||||||||
| Net income (loss) attributable to Ameren common shareholders | $ | 478 | $ | 136 | $ | 70 | $ | 164 | $ | (33 | ) | $ | 815 |
Below is Ameren Illinois’ table of income statement components by segment for the years ended December 31, 2019 and 2018:
| 2019 | Ameren Illinois Electric Distribution | Ameren Illinois Natural Gas | Ameren Illinois Transmission | Ameren Illinois | |||||||||||
| Electric margins | $ | 1,074 | $ | — | $ | 288 | $ | 1,362 | |||||||
| Natural gas margins | — | 519 | — | 519 | |||||||||||
| Other operations and maintenance expenses | (498 | ) | (233 | ) | (51 | ) | (782 | ) | |||||||
| Depreciation and amortization | (273 | ) | (78 | ) | (55 | ) | (406 | ) | |||||||
| Taxes other than income taxes | (73 | ) | (67 | ) | (3 | ) | (143 | ) | |||||||
| Other income, net | 33 | 12 | 8 | 53 | |||||||||||
| Interest charges | (71 | ) | (38 | ) | (38 | ) | (147 | ) | |||||||
| Income taxes | (45 | ) | (30 | ) | (35 | ) | (110 | ) | |||||||
| Net income | 147 | 85 | 114 | 346 | |||||||||||
| Preferred stock dividends | (1 | ) | (1 | ) | (1 | ) | (3 | ) | |||||||
| Net income attributable to common shareholder | $ | 146 | $ | 84 | $ | 113 | $ | 343 | |||||||
| 2018 | |||||||||||||||
| Electric margins | $ | 1,065 | $ | — | $ | 267 | $ | 1,332 | |||||||
| Natural gas margins | — | 497 | — | 497 | |||||||||||
| Other operations and maintenance expenses | (506 | ) | (241 | ) | (52 | ) | (799 | ) | |||||||
| Depreciation and amortization | (259 | ) | (65 | ) | (50 | ) | (374 | ) | |||||||
| Taxes other than income taxes | (75 | ) | (66 | ) | (3 | ) | (144 | ) | |||||||
| Other income, net | 26 | 9 | 7 | 42 | |||||||||||
| Interest charges | (73 | ) | (38 | ) | (38 | ) | (149 | ) | |||||||
| Income taxes | (41 | ) | (25 | ) | (32 | ) | (98 | ) | |||||||
| Net income | 137 | 71 | 99 | 307 | |||||||||||
| Preferred stock dividends | (1 | ) | (1 | ) | (1 | ) | (3 | ) | |||||||
| Net income attributable to common shareholder | $ | 136 | $ | 70 | $ | 98 | $ | 304 |
Margins
We consider electric and natural gas margins useful measures to analyze the change in profitability of our electric and natural gas operations between periods. We have included the analysis below as a complement to the financial information we provide in accordance with GAAP. However, these margins may not be a presentation defined under GAAP, and they may not be comparable to other companies’ presentations or more useful than the GAAP information we provide elsewhere in this report.
Electric Margins
| Total by Segment**(a)** | Increase (Decrease) by Segment | |||
| (Overall Ameren Decrease of $99 Million) |


| (a) | Includes other/intersegment eliminations of $(29) million and $(27) million in 2019 and 2018, respectively. |
Natural Gas Margins
| Total by Segment**(a)** | Increase (Decrease) by Segment | |||
| (Overall Ameren Increase of $20 Million) |

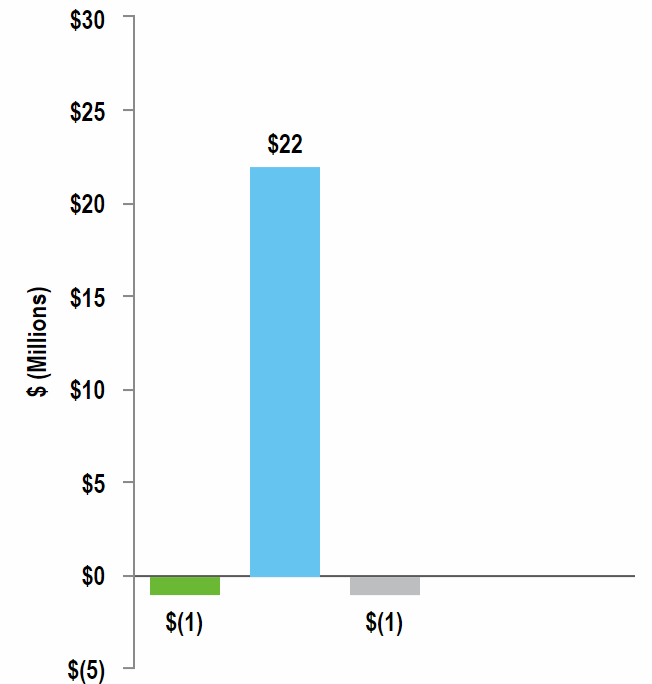
| (a) | Includes other/intersegment eliminations of $(2) million and $(1) million in 2019 and 2018, respectively. |
The following table presents the favorable (unfavorable) variations by segment for electric and natural gas margins in 2019, compared with 2018:
| Electric and Natural Gas Margins | |||||||||||||||||||||||
| 2019 versus 2018 | Ameren Missouri | Ameren Illinois Electric Distribution | Ameren Illinois Natural Gas | Ameren Transmission**(a)** | Other / Intersegment Eliminations | Ameren | |||||||||||||||||
| Electric revenue change: | |||||||||||||||||||||||
| Effect of weather (estimate)(b) | $ | (118 | ) | $ | — | $ | — | $ | — | — | $ | (118 | ) | ||||||||||
| Base rates, including the effects of TCJA (estimate)(c) | (39 | ) | 5 | — | 31 | — | (3 | ) | |||||||||||||||
| Power restoration efforts provided to other utilities | (11 | ) | (9 | ) | — | — | — | (20 | ) | ||||||||||||||
| Changes in customer usage patterns and sales volumes (excluding the estimated effects of weather and MEEIA) | 5 | — | — | — | — | 5 | |||||||||||||||||
| Off-system sales and capacity revenues | (140 | ) | — | — | — | — | (140 | ) | |||||||||||||||
| MEEIA 2013 and MEEIA 2016 performance incentives | 26 | — | — | — | — | 26 | |||||||||||||||||
| Energy-efficiency program investments | — | 12 | — | — | — | 12 | |||||||||||||||||
| Other | — | — | — | — | (4 | ) | (4 | ) | |||||||||||||||
| Cost recovery mechanisms – offset in fuel and purchased power(d) | (49 | ) | (53 | ) | — | — | — | (102 | ) | ||||||||||||||
| Other cost recovery mechanisms(e) | (16 | ) | 2 | — | — | — | (14 | ) | |||||||||||||||
| Total electric revenue change | $ | (342 | ) | $ | (43 | ) | $ | — | $ | 31 | $ | (4 | ) | $ | (358 | ) | |||||||
| Fuel and purchased power change: | |||||||||||||||||||||||
| Energy costs (excluding the estimated effect of weather) | $ | 146 | $ | — | $ | — | $ | — | $ | — | $ | 146 | |||||||||||
| Effect of weather (estimate)(b) | 21 | — | — | — | — | 21 | |||||||||||||||||
| Transmission services charges | (9 | ) | — | — | — | — | (9 | ) | |||||||||||||||
| Other | (2 | ) | (1 | ) | — | — | 2 | (1 | ) | ||||||||||||||
| Cost recovery mechanisms – offset in electric revenue(d) | 49 | 53 | — | — | — | 102 | |||||||||||||||||
| Total fuel and purchased power change | $ | 205 | $ | 52 | $ | — | $ | — | $ | 2 | $ | 259 | |||||||||||
| Net change in electric margins | $ | (137 | ) | $ | 9 | $ | — | $ | 31 | $ | (2 | ) | $ | (99 | ) | ||||||||
| Natural gas revenue change: | |||||||||||||||||||||||
| Effect of weather (estimate)(b) | $ | (4 | ) | $ | — | $ | — | $ | — | $ | — | $ | (4 | ) | |||||||||
| Base rates (estimate) | (1 | ) | — | 8 | — | — | 7 | ||||||||||||||||
| QIP rider | — | — | 7 | — | — | 7 | |||||||||||||||||
| Software licensing agreement | — | — | 5 | — | — | 5 | |||||||||||||||||
| Other | 1 | — | 2 | — | (1 | ) | 2 | ||||||||||||||||
| Cost recovery mechanisms – offset in natural gas purchased for resale(d) | 1 | — | (40 | ) | — | — | (39 | ) | |||||||||||||||
| Other cost recovery mechanisms(e) | (1 | ) | — | — | — | — | (1 | ) | |||||||||||||||
| Total natural gas revenue change | $ | (4 | ) | $ | — | $ | (18 | ) | $ | — | $ | (1 | ) | $ | (23 | ) | |||||||
| Natural gas purchased for resale change: | |||||||||||||||||||||||
| Effect of weather (estimate)(b) | $ | 4 | $ | — | $ | — | $ | — | $ | — | $ | 4 | |||||||||||
| Cost recovery mechanisms – offset in natural gas revenue(d) | (1 | ) | — | 40 | — | — | 39 | ||||||||||||||||
| Total natural gas purchased for resale change | $ | 3 | $ | — | $ | 40 | $ | — | $ | — | $ | 43 | |||||||||||
| Net change in natural gas margins | $ | (1 | ) | $ | — | $ | 22 | $ | — | $ | (1 | ) | $ | 20 |
| (a) | Includes an increase in transmission margins of $21 million in 2019, compared with 2018, at Ameren Illinois. |
| (b) | Represents the estimated variation resulting primarily from changes in cooling and heating degree days on electric and natural gas demand compared with the prior year; this variation is based on temperature readings from the National Oceanic and Atmospheric Administration weather stations at local airports in our service territories. |
| (c) | For Ameren Illinois Electric Distribution and Ameren Transmission, base rates include increases or decreases to operating revenues related to the revenue requirement reconciliation adjustment under formula rates. |
| (d) | Electric and natural gas revenue changes are offset by corresponding changes in “Fuel,” “Purchased power,” and “Natural gas purchased for resale” on the statement of income, resulting in no change to electric and natural gas margins. |
| (e) | Offsetting expense increases or decreases are reflected in “Other operations and maintenance,” “Depreciation and amortization,” or in “Taxes other than income taxes,” within the “Operating Expenses” section of the statement of income. These items have no overall impact on earnings. |
Ameren
Ameren’s electric margins decreased $99 million, or 2%, in 2019, compared with 2018, primarily because of decreased margins at Ameren Missouri, partially offset by increased margins at Ameren Transmission and Ameren Illinois Electric Distribution, as discussed below. Ameren’s natural gas margins increased $20 million, or 3%, between years primarily because of increased margins at Ameren Illinois Natural Gas, as discussed below.
Ameren Transmission
Ameren Transmission’s margins increased $31 million, or 7%, in 2019, compared with 2018. Margins were favorably affected by increased capital investment, as evidenced by a 12% increase in rate base used to calculate the revenue requirement between years.
Ameren Missouri
Ameren Missouri’s electric margins decreased $137 million, or 5%, in 2019, compared with 2018. Ameren Missouri’s natural gas margins were comparable between years.
The following items had an unfavorable effect on Ameren Missouri’s electric margins in 2019, compared with 2018:
| • | Summer temperatures were milder as cooling degree days decreased 13%, and winter temperatures were warmer as heating degree days decreased 4%. The aggregate effect of weather decreased margins by an estimated $97 million. The change in margins due to weather is the sum of the effect of weather (estimate) on electric revenues (-$118 million) and the effect of weather (estimate) on fuel and purchased power (+$21 million) in the table above. |
| • | The reduction of customer rates in accordance with the TCJA provisions in Missouri law, which decreased revenues an estimated $39 million. |
| • | Revenues from other cost recovery mechanisms due primarily to gross receipts taxes, which decreased margins $16 million. See Taxes Other Than Income Taxes in this section for the related offsetting decrease in gross receipts tax. |
| • | A reduction in power restoration assistance provided to other utilities and the associated recovery of labor and benefit costs for crews supporting those efforts, which decreased revenues $11 million. |
| • | Increased transmission services charges resulting from cost-sharing by all MISO participants of additional MISO-approved electric transmission investments made by other entities, which decreased margins $9 million. |
The following items had a favorable effect on Ameren Missouri’s electric margins in 2019, compared with 2018:
| • | The MEEIA 2013 and 2016 performance incentives, which increased revenues $26 million. See Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report for information regarding the MEEIA 2013 and MEEIA 2016 performance incentives. |
| • | Net energy costs increased margins $6 million as a result of lower energy costs (+$146 million), largely offset by a reduction in off-system sales revenue (-$140 million). The decrease in energy costs is the result of lower fuel costs and decreased generation volumes, while the reduction in off-system sales revenue is primarily due to generation facility outages. |
| • | Excluding the estimated effects of weather and MEEIA customer energy-efficiency programs, electric revenues increased an estimated $5 million, primarily due to an increase in the average retail price per kilowatthour due to changes in customer usage patterns. While the MEEIA customer energy-efficiency programs reduced retail sales volumes, the recovery of lost electric margins ensured that electric margins were not affected. |
Ameren Illinois
Ameren Illinois’ electric margins increased $30 million, or 2%, in 2019, compared with 2018, driven by increased margins at Ameren Illinois Transmission (+$21 million) and Ameren Illinois Electric Distribution (+$9 million). Ameren Illinois Natural Gas’ margins increased $22 million, or 4%, between years.
Ameren Illinois Electric Distribution
Ameren Illinois Electric Distribution’s margins increased $9 million, or 1%, in 2019, compared with 2018. The following items had a favorable effect on Ameren Illinois Electric Distribution’s margins between years:
| • | Revenues increased $12 million due to return on increased energy-efficiency program investments (+$2 million) and recovery of associated expenses (+$10 million) under formula ratemaking. |
| • | Increased margins due to higher rate base (+$10 million) and higher recoverable expenses (+$5 million), partially offset by lower recognized ROE (-$10 million) due to a 53 basis point decrease in the annual average of the monthly 30-year United States Treasury bond yields under formula ratemaking. The sum of these changes collectively increased margins $5 million. |
Ameren Illinois Electric Distribution’s margins were unfavorably affected by a reduction in power restoration assistance provided to other utilities and the associated recovery of labor and benefit costs for crews supporting those efforts, which decreased revenues $9 million in 2019, compared with 2018.
Ameren Illinois Natural Gas
Ameren Illinois Natural Gas’ margins increased $22 million, or 4%, in 2019, compared with 2018. The following items had a favorable effect on Ameren Illinois Natural Gas’ margins:
| • | Higher natural gas base rates as a result of the November 2018 natural gas rate order, which increased revenues $8 million. |
| • | Revenues from QIP recoveries due to additional investment in qualified natural gas infrastructure, which increased margins $7 million. |
| • | A software licensing agreement with Ameren Missouri, which increased revenues $5 million. See Note 13 – Related-party Transactions under Software Licensing Agreement for information regarding this transaction. |
Ameren Illinois Transmission
Ameren Illinois Transmission’s margins increased $21 million, or 8%, in 2019, compared with 2018. Margins were favorably affected by increased capital investment, as evidenced by a 17% increase in rate base used to calculate the revenue requirement between years.
Other Operations and Maintenance Expenses
| Total by Segment**(a)** | Increase (Decrease) by Segment | |||
| (Overall Ameren Decrease of $27 Million) |
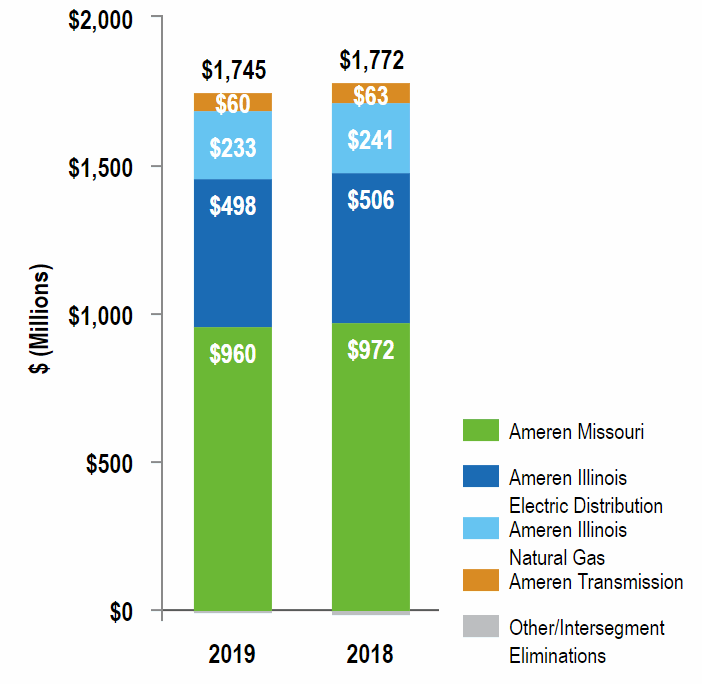
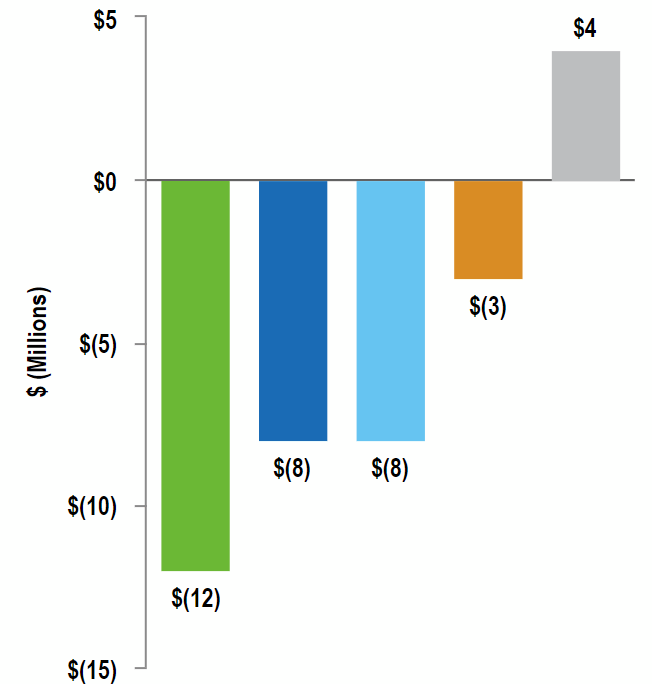
| (a) | Includes other/intersegment eliminations of $(6) million and $(10) million in 2019 and 2018, respectively. |
Ameren
Other operations and maintenance expenses were $27 million lower in 2019, compared with 2018. In addition to changes by segment discussed below, other operations and maintenance expenses increased $4 million in 2019 for activity not reported as part of a segment, as reflected in “Other/Intersegment Eliminations” above, primarily because of increased costs for support services.
Ameren Transmission
The $3 million decrease in other operations and maintenance expenses in 2019, compared with 2018, was primarily due to an increase in the cash surrender value of company-owned life insurance due to favorable market conditions.
Ameren Missouri
The $12 million decrease in other operations and maintenance expenses in 2019, compared with 2018, was primarily due to the following items:
| • | The cash surrender value of company-owned life insurance increased $19 million, primarily because of favorable market conditions. |
| • | Nonnuclear energy center operations and maintenance costs decreased $15 million, primarily because of higher-than-normal scheduled outages and increased routine maintenance work in 2018. |
| • | Power restoration assistance provided to other utilities decreased $11 million. |
The following items partially offset the decrease in other operations and maintenance expenses between years:
| • | Callaway Energy Center operations and maintenance costs increased $28 million, primarily because of the refueling and maintenance outage that was completed in May 2019. The previous Callaway Energy Center refueling and maintenance outage took place in the fourth quarter of 2017. |
| • | Employee benefit costs increased $3 million because of higher medical costs. |
Ameren Illinois
Other operations and maintenance expenses were $17 million lower at Ameren Illinois in 2019 compared with 2018, as discussed below. Other operations and maintenance expenses were comparable at Ameren Illinois Transmission between 2019 and 2018.
Ameren Illinois Electric Distribution
The $8 million decrease in other operations and maintenance expenses in 2019, compared with 2018, was primarily due to the following items:
| • | Power restoration assistance provided to other utilities decreased $9 million. |
| • | The cash surrender value of company-owned life insurance increased $8 million, primarily because of favorable market conditions. |
| • | Bad debt costs, which are recoverable through a rider, decreased $6 million, primarily because of improved collections experience. |
| • | Meter reading costs decreased $4 million, primarily because of increased automated meter deployment. |
The following items partially offset the decrease in other operations and maintenance expense between years:
| • | Amortization of regulatory assets associated with energy-efficiency program investments increased $8 million. |
| • | Environmental remediation costs, which are recoverable through a rider, increased $6 million, primarily because of increased remediation efforts. |
Ameren Illinois Natural Gas
The $8 million decrease in other operations and maintenance expenses in 2019, compared with 2018, was primarily due to an increase in the cash surrender value of company-owned life insurance, primarily due to favorable market conditions, and decreased meter reading costs, primarily due to increased automated meter deployment.
Depreciation and Amortization
| Total by Segment**(a)** | Increase (Decrease) by Segment | |||
| (Overall Ameren Increase of $40 Million) |
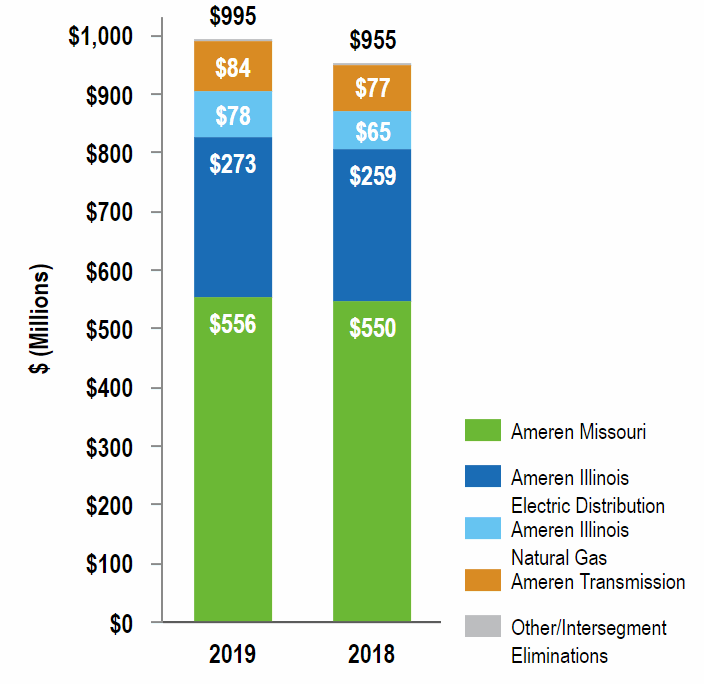
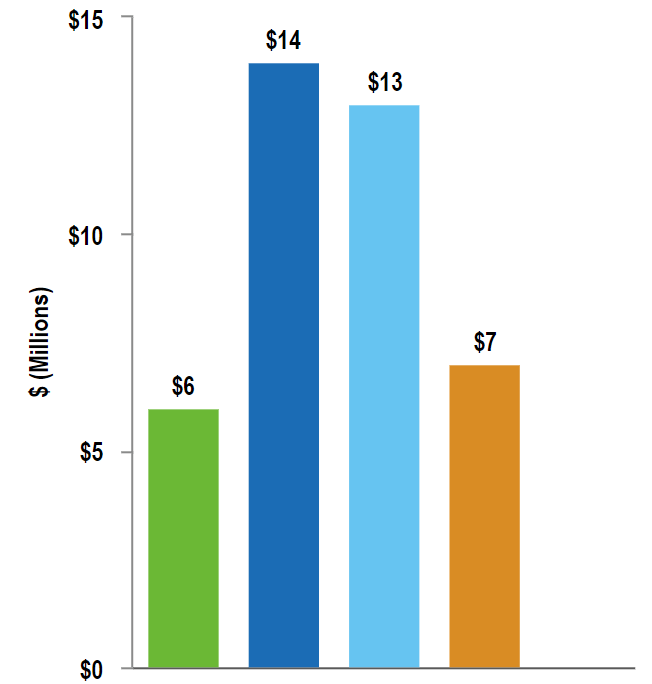
| (a) | Includes other/intersegment eliminations of $4 million and $4 million in 2019 and 2018, respectively. |
The $40 million, $6 million, and $32 million increase in depreciation and amortization expenses in 2019, compared with 2018, at Ameren, Ameren Missouri, and Ameren Illinois, respectively, was primarily due to additional property, plant, and equipment across their respective segments. Ameren Missouri’s depreciation and amortization expenses include a reduction for the regulatory deferral of depreciation and amortization expenses pursuant to the PISA of $22 million between years.
Taxes Other Than Income Taxes
| Total by Segment**(a)** | Increase (Decrease) by Segment | |||
| (Overall Ameren Decrease of $2 Million) |


| (a) | Includes $4 million and $4 million at Ameren Transmission in 2019 and 2018, respectively, and other/intersegment eliminations of $8 million and $9 million in 2019 and 2018, respectively. |
Taxes other than income taxes were comparable between 2019 and 2018. Ameren Missouri’s property taxes increased $17 million, primarily because of higher assessed values, which was offset by a $17 million decrease in excise taxes as a result of reduced sales, primarily driven by mild summer temperatures. See Excise Taxes in Note 15 – Supplemental Information under Part II, Item 8, of this report for additional information.
Other Income, Net
| Total by Segment | Increase (Decrease) by Segment | |||
| (Overall Ameren Increase of $28 Million) |
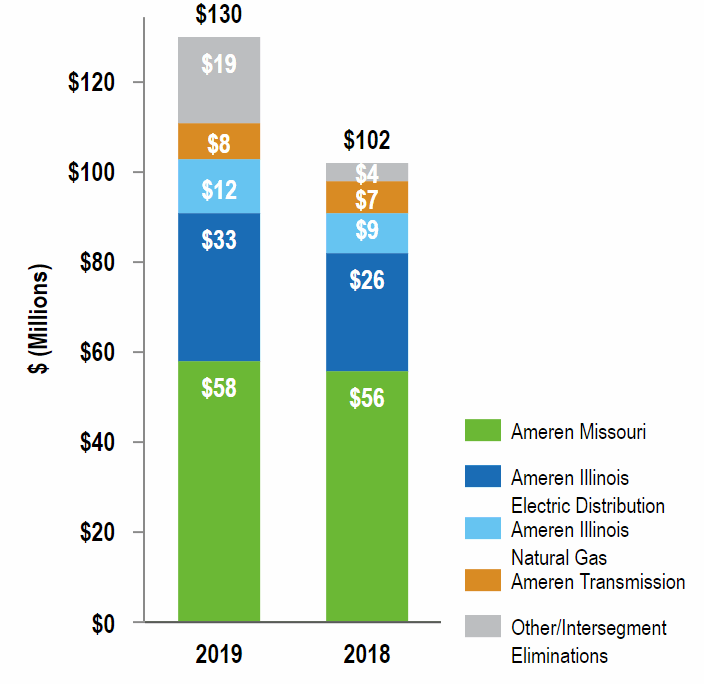
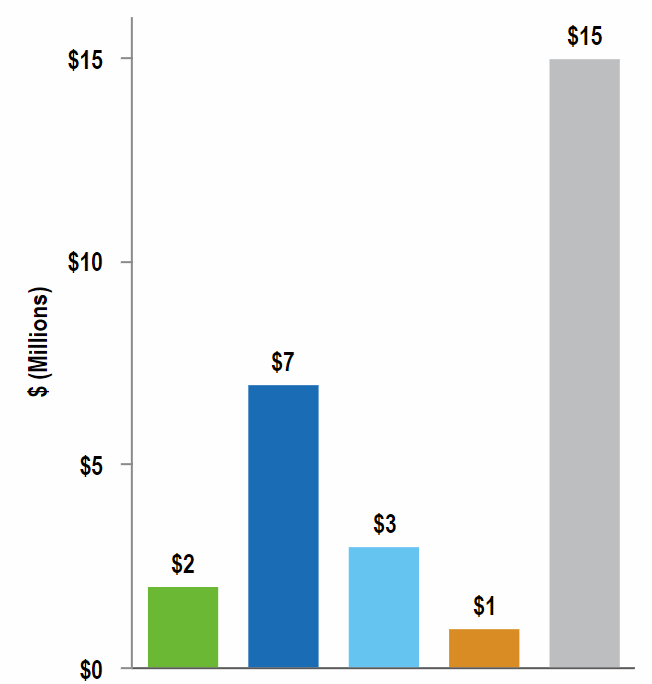
The $28 million increase in Other Income, net in 2019, compared with 2018, was primarily due to an $11 million decrease in charitable donations at Ameren Missouri and a $10 million decrease in charitable donations at Ameren (parent), which is reflected in “Other/Intersegment Eliminations” above. Charitable donations returned to more normal levels in 2019. Additionally, the non-service cost components of net periodic benefit income increased $9 million, $5 million, and $4 million at Ameren Illinois Electric Distribution, for activity not reported as part of a segment (as reflected in “Other/Intersegment Eliminations” above), and at Ameren Illinois Natural Gas, respectively. These increases were partially offset by an $8 million reduction in allowance for equity funds used during construction at Ameren Missouri, resulting from a lower average equity-to-debt ratio and a lower average balance of construction work in progress. See Note 6 – Other Income, Net under Part II, Item 8, of this report for additional information. See Note 10 – Retirement Benefits under Part II, Item 8, of this report for more information on the non-service cost components of net periodic benefit income.
Interest Charges
| Total by Segment | Increase (Decrease) by Segment | |||
| (Overall Ameren Decrease of $20 Million) |


The $20 million decrease in interest charges in 2019, compared with 2018, was primarily due to a $22 million reduction in interest charges at Ameren Missouri, which resulted from increased regulatory deferrals of interest expense pursuant to the PISA of $16 million between years and lower average interest rates on long-term debt. The decrease at Ameren Missouri was partially offset by a $5 million increase for activity not reported as part of a segment, as reflected in “Other/Intersegment Eliminations” above, primarily due to a higher average interest rate on an increased level of short-term borrowings and an increased level of long-term debt at Ameren (parent).
Income Taxes
The following table presents effective income tax rates for the years ended December 31, 2019 and 2018:
| 2019 | 2018 | |||
| Ameren | 18% | 22% | ||
| Ameren Missouri | 14% | 20% | ||
| Ameren Illinois | 24% | 24% | ||
| Ameren Illinois Electric Distribution | 23% | 23% | ||
| Ameren Illinois Natural Gas | 26% | 26% | ||
| Ameren Illinois Transmission | 24% | 24% | ||
| Ameren Transmission | 25% | 25% |
See Note 12 – Income Taxes under Part II, Item 8, of this report for information regarding reconciliations of effective income tax rates for Ameren, Ameren Missouri, and Ameren Illinois. See Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report for information regarding reductions in revenues related to the lower federal statutory corporate income tax rate enacted under the TCJA and the return of excess deferred income taxes to customers.
Ameren
The effective income tax rate was lower in 2019 compared with 2018, primarily because of higher amortization of excess deferred income taxes in 2019 as discussed below, along with revaluation of certain deferred taxes in 2018. Additionally, the effective tax rate was lower because of lower tax benefits related to company-owned life insurance in 2018.
Ameren Transmission
The effective tax rate was comparable between years.
Ameren Missouri
The effective income tax rate was lower in 2019 compared with 2018, primarily because of a full year of amortization of excess deferred income taxes in 2019 compared with a partial year in 2018.
Ameren Illinois
The effective tax rate was comparable between years at Ameren Illinois and its respective segments.
LIQUIDITY AND CAPITAL RESOURCES
Collections from our tariff-based revenues are our principal source of cash provided by operating activities. A diversified retail customer mix, primarily consisting of rate-regulated residential, commercial, and industrial customers, provides us with a reasonably predictable source of cash. In addition to using cash provided by operating activities, we use available cash, drawings under committed credit agreements, commercial paper issuances, and/or, in the case of Ameren Missouri and Ameren Illinois, short-term affiliate borrowings to support normal operations and temporary capital requirements. We may reduce our short-term borrowings with cash provided by operations or, at our discretion, with long-term borrowings, or, in the case of Ameren Missouri and Ameren Illinois, with capital contributions from Ameren (parent). In the near term, our operating cash flows will decrease due to the reduction in the federal statutory income tax rate enacted under the TCJA. The decrease in operating cash flows results from reduced customer rates, reflecting the tax rate decrease, without a corresponding reduction in income tax payments until about 2020 because of our use of net operating losses and tax credit carryforwards, which we expect to be fully utilized in 2020. Additionally, operating cash flows will be further reduced by lower customer rates, resulting from the return of excess deferred income taxes. Over time, the decrease in operating cash flows will be offset as temporary differences between book and taxable income reverse, and by increased customer rates due to higher rate base amounts resulting from lower accumulated deferred income tax liabilities. We expect to make significant capital expenditures over the next five years as we invest in our electric and natural gas utility infrastructure to support overall system reliability, grid modernization, renewable energy requirements, environmental compliance, and other improvements. As part of its plan to fund these cash flow requirements, Ameren is using newly issued shares of common stock, rather than market-purchased shares, to satisfy requirements under the DRPlus and employee benefit plans and expects to continue to do so through at least 2024. Ameren expects these issuances to provide equity funding of about $100 million annually. Ameren also plans to issue incremental common equity to fund a portion of Ameren Missouri’s wind generation investments through the physical settlement of the forward sale agreement entered into in August 2019 relating to 7.5 million shares of common stock. Additionally, Ameren plans to issue incremental equity of about $150 million annually from 2021 to 2024. For additional information about the forward sale agreement, see Note 5 – Long-term Debt and Equity Financings under Part II, Item 8, of this report. Ameren expects its equity to total capitalization to be about 45% through the period ending December 2024, with the long-term intent to support solid investment-grade credit ratings.
The use of cash provided by operating activities and short-term borrowings to fund capital expenditures and other long-term investments at the Ameren Companies frequently results in a working capital deficit, defined as current liabilities exceeding current assets, as was the case at December 31, 2019. The working capital deficit as of December 31, 2019, was primarily the result of current maturities of long-term debt and our decision to finance our businesses with lower-cost commercial paper issuances. With the credit capacity available under the Credit Agreements, along with cash and cash equivalents, the Ameren Companies had net available liquidity of $1.9 billion at December 31, 2019. See Credit Facility Borrowings and Liquidity below for additional information.
The following table presents net cash provided by (used in) operating, investing and financing activities for the years ended December 31, 2019 and 2018:
| Net Cash Provided by Operating Activities | Net Cash Used in Investing Activities | Net Cash Provided by (Used in) Financing Activities | |||||||||||||||||||||||||||||||||
| 2019 | 2018 | Variance | 2019 | 2018 | Variance | 2019 | 2018 | Variance | |||||||||||||||||||||||||||
| Ameren | $ | 2,170 | $ | 2,170 | $ | — | $ | (2,435 | ) | $ | (2,336 | ) | $ | (99 | ) | $ | 334 | $ | 205 | $ | 129 | ||||||||||||||
| Ameren Missouri | 1,067 | 1,260 | (193 | ) | (1,095 | ) | (976 | ) | (119 | ) | 59 | (283 | ) | 342 | |||||||||||||||||||||
| Ameren Illinois | 962 | 659 | 303 | (1,205 | ) | (1,248 | ) | 43 | 288 | 628 | (340 | ) |
Cash Flows from Operating Activities
Our cash provided by operating activities is affected by fluctuations of trade accounts receivable, inventories, and accounts and wages payable, among other things, as well as the unique regulatory environment for each of our businesses. Substantially all expenditures related to fuel, purchased power, and natural gas purchased for resale are recovered from customers through rate-adjustment mechanisms, which may be adjusted without a traditional regulatory rate review, subject to prudence reviews. Similar regulatory mechanisms exist for certain operating expenses that can also affect the timing of cash provided by operating activities. The timing of cash payments for costs recoverable under our regulatory mechanisms differs from the recovery period of those costs. Additionally, the seasonality of our electric and natural gas businesses, primarily caused by changes in customer demand due to weather, significantly affect the amount and timing of our cash provided
by operating activities. See Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report for more information about our regulatory mechanisms.
Ameren
Ameren’s cash from operating activities was flat in 2019, compared with 2018. The following items increased cash from operating activities between periods:
| • | A $36 million decrease in pension and postretirement benefit plan contributions. |
| • | A net $15 million increase in collateral received from counterparties, primarily resulting from changes in the market prices of power and natural gas, changes in contracted commodity volumes, and increases resulting from Ameren Illinois’ renewable energy contracts entered into pursuant to the FEJA. |
| • | A $14 million decrease in payments to contractors for electric distribution maintenance costs, primarily due to decreased vegetation management costs at Ameren Illinois. |
| • | A $13 million decrease in payments related to charitable donations. |
| • | An $11 million decrease in property tax payments at Ameren Missouri due to lower property tax values. |
The following items decreased Ameren’s cash from operating activities between periods:
| • | A $33 million decrease resulting from decreased customer collections, primarily due to a decrease in weather-related sales volumes at Ameren Missouri, and a net decrease attributable to regulatory recovery mechanisms, partially offset by decreased fuel costs and generation volumes at Ameren Missouri and decreased purchase power costs and volumes and natural gas costs at Ameren Illinois. |
| • | A $28 million increase in payments for nuclear refueling and maintenance outages at Ameren Missouri’s Callaway Energy Center. There was no refueling and maintenance outage in 2018. |
| • | A $14 million decrease resulting from increased Ameren Missouri purchases to maintain coal inventory at near targeted levels. |
Ameren Missouri
Ameren Missouri’s cash from operating activities decreased $193 million in 2019, compared with 2018. The following items contributed to the decrease:
| • | A $236 million decrease resulting from decreased customer collections, primarily due to a decrease in weather-related sales volumes, and a net decrease attributable to regulatory recovery mechanisms, partially offset by decreased fuel costs and generation volumes. |
| • | A $28 million increase in payments for nuclear refueling and maintenance outages at the Callaway Energy Center. There was no refueling and maintenance outage in 2018. |
| • | A $14 million decrease resulting from increased purchases to maintain coal inventory at near targeted levels. |
The following items partially offset the decrease in Ameren Missouri’s cash from operating activities between periods:
| • | A $27 million decrease in income tax payments to Ameren (parent) pursuant to the tax allocation agreement, primarily due to lower taxable income in 2019. |
| • | A $15 million decrease in pension and postretirement benefit plan contributions. |
| • | A net $11 million increase in collateral received from counterparties, primarily resulting from changes in the market prices of power and natural gas and in contracted commodity volumes. |
| • | An $11 million decrease in property tax payments due to lower property tax values. |
Ameren Illinois
Ameren Illinois’ cash from operating activities increased $303 million in 2019, compared with 2018. The following items contributed to the increase:
| • | A $200 million increase primarily resulting from decreased purchased power costs and volumes, decreased natural gas costs, and a net increase attributable to regulatory recovery mechanisms. |
| • | A $24 million decrease in income tax payments to Ameren (parent) pursuant to the tax allocation agreement, primarily due to the timing of payments. |
| • | A $16 million decrease in pension and postretirement benefit plan contributions. |
| • | A $14 million decrease in payments to contractors for electric distribution maintenance costs, primarily due to decreased vegetation management costs. |
| • | A net $4 million increase in collateral received from counterparties, primarily resulting from changes in the market prices of power and natural gas, changes in contracted commodity volumes, and increases resulting from renewable energy contracts entered into pursuant to the FEJA. |
Pension Plans
Ameren’s pension plans are funded in compliance with income tax regulations, federal funding requirements, and other regulatory requirements. As a result, Ameren expects to fund its pension plans at a level equal to the greater of the pension cost or the legally required minimum contribution. Based on Ameren’s assumptions at December 31, 2019, its investment performance in 2019, and its pension funding policy, Ameren expects to make annual contributions of up to $45 million in each of the next five years, with aggregate estimated contributions of $70 million. We estimate that Ameren Missouri’s and Ameren Illinois’ portions of the future funding requirements will be approximately 30% and 60%, respectively. These estimates may change based on actual investment performance, changes in interest rates, changes in our assumptions, changes in government regulations, and any voluntary contributions. In 2019, Ameren contributed $23 million to its pension plans. See Note 10 – Retirement Benefits under Part II, Item 8, of this report for additional information.
Cash Flows from Investing Activities
Ameren’s cash used in investing activities increased $99 million during 2019, compared with 2018, primarily as a result of increased capital expenditures of $125 million, partially offset by a $21 million decrease due to the timing of nuclear fuel expenditures. In addition to the capital expenditure changes at Ameren Missouri and Ameren Illinois discussed below, ATXI’s capital expenditures increased $38 million. ATXI’s capital expenditures increased as a result of increased expenditures on the Mark Twain project offset by decreased capital expenditures on the Spoon River project. The Mark Twain project was placed in service in December 2019, while the Spoon River project was placed in service in February 2018.
Ameren Missouri’s cash used in investing activities increased $119 million during 2019, compared with 2018, primarily as a result of increased capital expenditures of $162 million, partially offset by a $21 million decrease due to the timing of nuclear fuel expenditures. Ameren Missouri’s $162 million increase in capital expenditures between periods was primarily related to energy delivery infrastructure upgrades and substation upgrades.
Ameren Illinois’ cash used in investing activities decreased $43 million during 2019, compared with 2018, due to decreased capital expenditures of $50 million, primarily related to electric transmission system reliability projects.
Capital Expenditures
The following charts present our capital expenditures for the years ended December 31, 2019, and 2018:
| 2019 - Total Ameren $2,411**(a)** | 2018 - Total Ameren $2,286**(a)** | |||||
 |  | |||||
| Ameren Missouri | Ameren Illinois Transmission | |||||
| Ameren Illinois Electric Distribution | Ameren Transmission Company of Illinois | |||||
| Ameren Illinois Natural Gas |
| (a) | Includes Other capital expenditures of $(29) million and $(4) million for the years ended December 31, 2019 and 2018, respectively, which includes amounts for the elimination of intercompany transfers. |
Ameren’s 2019 capital expenditures consisted of expenditures made by its subsidiaries, including ATXI, which spent $156 million primarily on the Mark Twain and Illinois Rivers projects. In 2019, Ameren Illinois spent $372 million on transmission projects, $203 million on natural gas projects eligible for QIP recovery, and $67 million on IEIMA projects. In both years, other capital expenditures were made principally to maintain, upgrade, and improve the reliability of the transmission and distribution systems of Ameren Missouri and Ameren Illinois by investing in substation upgrades, energy center projects, and smart-grid technology. Additionally, the Ameren Companies invested in various software projects. As of December 31, 2019, Ameren Illinois exceeded the minimum capital spending levels required pursuant to IEIMA.
Ameren’s 2018 capital expenditures consisted of expenditures made by its subsidiaries, including ATXI, which spent $118 million primarily on the Illinois Rivers and Mark Twain projects. In 2018, Ameren Illinois spent $444 million on transmission projects, $188 million on natural gas projects eligible for QIP recovery, and $89 million on IEIMA projects.
The following table presents Ameren’s estimate of capital expenditures that will be incurred from 2020 through 2024, including construction expenditures, allowance for funds used during construction, and expenditures for compliance with existing environmental regulations:
| 2020 | 2021-2024 | Total | |||||||||||||||||
| Ameren Missouri | $ | 2,440 | $ | 5,380 | – | $ | 5,945 | $ | 7,820 | – | $ | 8,385 | |||||||
| Ameren Illinois Electric Distribution | 550 | 2,245 | – | 2,480 | 2,795 | – | 3,030 | ||||||||||||
| Ameren Illinois Natural Gas | 345 | 1,310 | – | 1,450 | 1,655 | – | 1,795 | ||||||||||||
| Ameren Illinois Transmission | 605 | 2,310 | – | 2,555 | 2,915 | – | 3,160 | ||||||||||||
| ATXI | 85 | 110 | – | 120 | 195 | – | 205 | ||||||||||||
| Other | 5 | 10 | – | 10 | 15 | – | 15 | ||||||||||||
| Ameren | $ | 4,030 | $ | 11,365 | – | $ | 12,560 | $ | 15,395 | – | $ | 16,590 |
Ameren Missouri’s estimated capital expenditures include transmission, distribution, grid modernization, and generation-related investments, as well as expenditures for compliance with environmental regulations. In addition, Ameren Missouri’s estimated capital
expenditures include approximately $1.2 billion in wind generation investments expected to be acquired by the end of 2020. Ameren Illinois’ estimated capital expenditures are primarily for electric and natural gas transmission and distribution-related investments, capital expenditures to modernize its distribution system pursuant to the IEIMA, and capital expenditures for qualified investments in natural gas infrastructure under the QIP rider. ATXI’s estimated capital expenditures include expenditures for the Illinois Rivers MISO-approved multi-value transmission project, and construction of a transmission operating center.
Ameren Missouri continually reviews its generation portfolio and expected power needs. As a result, Ameren Missouri could modify its plan for generation capacity, the type of generation asset technology that will be employed, and whether capacity or power may be purchased, among other changes. Additionally, we continually review the reliability of our transmission and distribution systems, expected capacity needs, and opportunities for transmission investments within and outside our service territories. The timing and amount of investments could vary because of changes in expected capacity, the condition of transmission and distribution systems, and our ability and willingness to pursue transmission investments, among other factors. Any changes in future generation, transmission, or distribution needs could result in significant changes in capital expenditures or losses, which could be material. Compliance with environmental regulations could also have significant impacts on the level of capital expenditures.
Environmental Capital Expenditures
Ameren Missouri will continue to incur costs to comply with federal and state regulations, including those requiring the reduction of SO2, NOx, and mercury emissions from its coal-fired energy centers. See Note 14 – Commitments and Contingencies under Part II, Item 8, of this report for a discussion of existing and proposed environmental laws that affect, or may affect, our facilities and capital expenditures to comply with such laws.
Cash Flows from Financing Activities
Cash provided by, or used in, financing activities is a result of our financing needs, which depend on the level of cash provided by operating activities, the level of cash used in investing activities, the level of dividends, and our long-term debt maturities, among other things.
In 2019, Ameren issued $1,527 million of long-term debt to repay then-outstanding commercial paper borrowings, including short-term debt incurred in connection with the repayment at maturity of long-term debt, and to repay at maturity other long-term debt. Collectively, in 2019, Ameren repaid long-term debt of $580 million and net commercial paper borrowings totaling $157 million. In comparison, in 2018, Ameren utilized net proceeds from the issuance of $1,352 million of long-term debt, along with cash on-hand, to repay then-outstanding commercial paper borrowings, including short-term debt incurred in connection with the repayment at maturity of long-term debt, and to repay at maturity other long-term debt. Collectively, in 2018, Ameren repaid $841 million of long-term debt and received $112 million from net commercial paper issuances. In 2019 and 2018, Ameren used cash provided by financing activities to fund, in part, investing activities.
In 2019, Ameren Missouri issued $778 million of long-term debt to repay then-outstanding commercial paper borrowings, including short-term debt incurred in connection with the repayment at maturity of long-term debt, and to repay at maturity other long-term debt. Collectively, in 2019, Ameren Missouri repaid long-term debt of $580 million and received $179 million from net commercial paper issuances. In comparison, in 2018, Ameren Missouri utilized net proceeds of $423 million from the issuance in long-term debt, along with cash on hand, to repay then-outstanding commercial paper borrowings, including short-term debt incurred in connection with the repayment at maturity of long-term debt, and to repay at maturity other long-term debt. Collectively, in 2018, Ameren Missouri received $16 million from net commercial paper issuances. Collectively, in 2018, Ameren Missouri repaid $384 million of long-term debt. During 2019, Ameren Missouri paid common stock dividends of $430 million, compared with $375 million in dividend payments in the year-ago period. In addition, during 2019, Ameren Missouri received $124 million in capital contributions from Ameren (parent) associated with the tax allocation agreement, compared with $45 million received in 2018. In 2019, Ameren Missouri used cash provided by financing activities to fund, in part, investing activities.
In 2019, Ameren Illinois issued $299 million of long-term debt to repay then outstanding commercial paper borrowings. Ameren Illinois repaid outstanding net commercial paper borrowings totaling $19 million. In comparison, in 2018, Ameren Illinois utilized net proceeds of $929 million from the issuance of long-term debt to repay then-outstanding commercial paper borrowings, including short-term debt incurred in connection with the repayment at maturity of long-term debt, and to repay at maturity other long-term debt. Collectively, in 2018, Ameren Illinois repaid $457 million of long-term debt and received $10 million from net commercial paper issuances. In addition, during 2019, Ameren Illinois received $15 million in capital contributions from Ameren (parent) associated with the tax allocation agreement, compared with $160 million received in 2018. In 2019 and 2018, Ameren Illinois used cash provided by financing activities to fund, in part, investing activities.
Credit Facility Borrowings and Liquidity
The liquidity needs of the Ameren Companies are typically supported through the use of available cash, drawings under committed credit agreements, commercial paper issuances, or, in the case of Ameren Missouri and Ameren Illinois, short-term affiliate borrowings. See Note 4 – Short-term Debt and Liquidity under Part II, Item 8, of this report for additional information on credit agreements, commercial paper issuances, Ameren’s money pool arrangements and related borrowings, and relevant interest rates.
The following table presents Ameren’s consolidated net available liquidity as of December 31, 2019:
| Available at December 31, 2019 | ||||
| Ameren (parent) and Ameren Missouri**(a)****:** | ||||
| Missouri Credit Agreement – borrowing capacity | $ | 1,200 | ||
| Less: Ameren (parent) commercial paper outstanding | 98 | |||
| Less: Ameren Missouri commercial paper outstanding | 234 | |||
| Less: Letters of credit | 2 | |||
| Missouri Credit Agreement – subtotal | 866 | |||
| Ameren (parent) and Ameren Illinois**(b)****:** | ||||
| Illinois Credit Agreement – borrowing capacity | 1,100 | |||
| Less: Ameren (parent) commercial paper outstanding | 55 | |||
| Less: Ameren Illinois commercial paper outstanding | 53 | |||
| Less: Letters of credit | 1 | |||
| Illinois Credit Agreement – subtotal | 991 | |||
| Subtotal | $ | 1,857 | ||
| Cash and cash equivalents | 16 | |||
| Net Available Liquidity | $ | 1,873 |
| (a) | The maximum aggregate amount available to Ameren (parent) and Ameren Missouri under the Missouri Credit Agreement is $900 million and $850 million, respectively. See Note 4 – Short-term Debt and Liquidity under Part II, Item 8, of this report for further discussion of the Credit Agreements. |
| (b) | The maximum aggregate amount available to Ameren (parent) and Ameren Illinois under the Illinois Credit Agreement is $500 million and $800 million, respectively. See Note 4 – Short-term Debt and Liquidity under Part II, Item 8, of this report for further discussion of the Credit Agreements. |
In December 2019, the Credit Agreements were amended and restated. The amended and restated agreements, among other things, provide $2.3 billion of credit until maturity in December 2024. See Note 4 – Short-term Debt and Liquidity under Part II, Item 8, of this report for additional information on the amended and restated agreements. Issuances under the Ameren (parent), Ameren Missouri, and Ameren Illinois commercial paper programs were available at lower interest rates than the interest rates of borrowings under the Credit Agreements. Commercial paper issuances were thus preferred to credit facility borrowings as a source of third-party short-term debt.
Ameren has a money pool agreement with and among its utility subsidiaries to coordinate and to provide for certain short-term cash and working capital requirements. As short-term capital needs arise, and based on availability of funding sources, Ameren Missouri and Ameren Illinois will access funds from the utility money pool, the Credit Agreements, or the commercial paper programs depending on which option has the lowest interest rates.
The issuance of short-term debt securities by Ameren’s utility subsidiaries is subject to FERC approval under the Federal Power Act. In 2018, the FERC issued orders authorizing Ameren Missouri and Ameren Illinois to each issue up to $1 billion of short-term debt securities through March 2020 and September 2020, respectively. In July 2019, the FERC issued an order authorizing ATXI to issue up to $300 million of short-term debt securities through July 2021.
The Ameren Companies continually evaluate the adequacy and appropriateness of their liquidity arrangements for changing business conditions. When business conditions warrant, changes may be made to existing credit agreements or to other short-term borrowing arrangements.
Long-term Debt and Equity
The following table presents Ameren’s equity issuances, as well as issuances (net of issuance premiums or discounts), redemptions, repurchases, and maturities of long-term debt for the years ended December 31, 2019 and 2018. For additional information related to the terms and uses of these issuances and effective registration statements, and Ameren’s forward sale agreement relating to common stock, see Note 5 – Long-term Debt and Equity Financings under Part II, Item 8, of this report. For information on capital contributions received by Ameren Missouri and Ameren Illinois from Ameren (parent), see Note 13 – Related-party Transactions under Part II, Item 8 of this report.
| Month Issued, Redeemed, Repurchased, or Matured | 2019 | 2018 | |||||||
| Issuances of Long-term Debt | |||||||||
| Ameren: | |||||||||
| 2.50% Senior unsecured notes due 2024 | September | $ | 450 | $ | — | ||||
| Ameren Missouri: | |||||||||
| 3.50% First mortgage bonds due 2029 | March | 450 | — | ||||||
| 3.25% First mortgage bonds due 2049 | October | 328 | — | ||||||
| 4.00% First mortgage bonds due 2048 | April | — | 423 | ||||||
| Ameren Illinois: | |||||||||
| 3.25% First mortgage bonds due 2050 | November | 299 | — | ||||||
| 3.80% First mortgage bonds due 2028 | May | — | 430 | ||||||
| 4.50% First mortgage bonds due 2049 | November | — | 499 | ||||||
| Total long-term debt issuances | $ | 1,527 | $ | 1,352 | |||||
| Issuances of Common Stock | |||||||||
| Ameren: | |||||||||
| DRPlus and 401(k)(a)(b) | Various | $ | 68 | $ | 74 | ||||
| Total common stock issuances | $ | 68 | $ | 74 | |||||
| Total Ameren long-term debt and common stock issuances | $ | 1,595 | $ | 1,426 | |||||
| Redemptions, Repurchases, and Maturities of Long-term Debt | |||||||||
| Ameren Missouri: | |||||||||
| 6.70% Senior secured notes due 2019 | February | $ | 329 | $ | — | ||||
| 5.10% Senior unsecured notes due 2019 | October | 244 | — | ||||||
| 5.45% First mortgage bonds due 2028 | October | (c) | |||||||
| 6.00% Senior secured notes due 2018 | April | — | 179 | ||||||
| 5.10% Senior secured notes due 2018 | August | — | 199 | ||||||
| City of Bowling Green financing obligation (Peno Creek CT) | December | 7 | 6 | ||||||
| Ameren Illinois: | |||||||||
| 5.70% First mortgage bonds due 2024 | September | (c) | — | ||||||
| 5.90% First mortgage bonds due 2023 | October | (c) | — | ||||||
| 6.25% Senior secured notes due 2018 | April | — | 144 | ||||||
| 9.75% Senior secured notes due 2018 | November | — | 313 | ||||||
| Total long-term debt redemptions, repurchases, and maturities | $ | 580 | $ | 841 |
| (a) | Ameren issued a total of 0.9 million and 1.2 million shares of common stock under its DRPlus and 401(k) plan in 2019 and 2018, respectively. |
| (b) | Excludes 0.8 million and 0.7 million shares of common stock valued at $54 million and $35 million issued for no cash consideration in connection with stock-based compensation in 2019 and 2018, respectively. |
| (c) | Amount less than $1 million. |
The Ameren Companies may sell securities registered under their effective registration statements if market conditions and capital requirements warrant such sales. Any offer and sale will be made only by means of a prospectus that meets the requirements of the Securities Act of 1933 and the rules and regulations thereunder.
Indebtedness Provisions and Other Covenants
At December 31, 2019, the Ameren Companies were in compliance with the provisions and covenants contained within their credit agreements, indentures, and articles of incorporation, as applicable, and ATXI was in compliance with the provisions and covenants contained in its note purchase agreement. See Note 4 – Short-term Debt and Liquidity and Note 5 – Long-term Debt and Equity Financings under Part II, Item 8, of this report for a discussion of covenants and provisions (and applicable cross-default provisions) contained in our credit agreements, certain of the Ameren Companies’ indentures and articles of incorporation, and ATXI’s note purchase agreement.
We consider access to short-term and long-term capital markets to be a significant source of funding for capital requirements not satisfied by cash provided by our operating activities. Inability to raise capital on reasonable terms, particularly during times of uncertainty in the capital markets, could negatively affect our ability to maintain and expand our businesses. After assessing its current operating performance, liquidity, and credit ratings (see Credit Ratings below), Ameren, Ameren Missouri, and Ameren Illinois each believes that it will continue to have access to the capital markets. However, events beyond Ameren’s, Ameren Missouri’s, and Ameren Illinois’ control may create uncertainty in the capital markets or make access to the capital markets uncertain or limited. Such events could increase our cost of capital and adversely affect our ability to access the capital markets.
Dividends
Ameren paid to its shareholders common stock dividends totaling $472 million, or $1.9200 per share, in 2019 and $451 million, or $1.8475 per share, in 2018. The amount and timing of dividends payable on Ameren’s common stock are within the sole discretion of Ameren’s board of directors. Ameren’s board of directors has not set specific targets or payout parameters when declaring common stock dividends, but it considers various factors, including Ameren’s overall payout ratio, payout ratios of our peers, projected cash flow and potential future cash flow requirements, historical earnings and cash flow, projected earnings, impacts of regulatory orders or legislation, and other key business considerations. Ameren expects its dividend payout ratio to be between 55% and 70% of earnings over the next few years. On February 14, 2020, the board of directors of Ameren declared a quarterly dividend on Ameren’s common stock of 49.5 cents per share, payable on March 31, 2020, to shareholders of record on March 11, 2020.
Certain of our financial agreements and corporate organizational documents contain covenants and conditions that, among other things, restrict the Ameren Companies’ payment of dividends in certain circumstances.
Ameren Illinois’ articles of incorporation require its dividend payments on common stock to be based on ratios of common stock to total capitalization and other provisions with respect to certain operating expenses and accumulations of earned surplus. Additionally, Ameren has committed to the FERC to maintain a minimum of 30% equity in the capital structure at Ameren Illinois.
Ameren Missouri and Ameren Illinois, as well as certain other nonregistrant Ameren subsidiaries, are subject to Section 305(a) of the Federal Power Act, which makes it unlawful for any officer or director of a public utility, as defined in the Federal Power Act, to participate in the making or paying of any dividend from any funds “properly included in capital account.” The FERC has consistently interpreted the provision to allow dividends to be paid as long as (1) the source of the dividends is clearly disclosed, (2) the dividends are not excessive, and (3) there is no self-dealing on the part of corporate officials. At a minimum, Ameren believes that dividends can be paid by its subsidiaries that are public utilities from net income and from retained earnings. In addition, under Illinois law, Ameren Illinois and ATXI may not pay any dividend on their respective stock unless, among other things, their respective earnings and earned surplus are sufficient to declare and pay a dividend after provisions are made for reasonable and proper reserves, or unless Ameren Illinois or ATXI has specific authorization from the ICC.
At December 31, 2019, the amount of restricted net assets of Ameren’s subsidiaries that may not be distributed to Ameren in the form of a loan or dividend was $3.1 billion.
The following table presents common stock dividends declared and paid by Ameren Corporation to its common shareholders and by Ameren subsidiaries to their parent, Ameren:
| 2019 | 2018 | ||||||
| Ameren | $ | 472 | $ | 451 | |||
| Ameren Missouri | 430 | 375 | |||||
| Ameren Illinois | — | — | |||||
| ATXI | 15 | 75 |
Ameren Missouri and Ameren Illinois each have issued preferred stock, which provides for cumulative preferred stock dividends. Each company’s board of directors considers the declaration of preferred stock dividends to shareholders of record on a certain date, stating the date on which the dividend is payable and the amount to be paid. See Note 5 – Long-term Debt and Equity Financings under Part II, Item 8, of this report for further detail concerning the preferred stock issuances.
Contractual Obligations
The following table presents our contractual obligations as of December 31, 2019. See Note 10 – Retirement Benefits under Part II, Item 8, of this report for information regarding expected minimum funding levels for our pension plans, which are not included in the table below. In addition, routine short-term purchase order commitments are not included.
| 2020 | 2021 – 2022 | 2023 – 2024 | 2025 and Thereafter | Total | |||||||||||||||
| Ameren: | |||||||||||||||||||
| Long-term debt and financing obligations(a) | $ | 442 | $ | 513 | $ | 1,090 | $ | 7,397 | $ | 9,442 | |||||||||
| Interest payments | 378 | 733 | 674 | 4,582 | 6,367 | ||||||||||||||
| Operating leases | 8 | 15 | 11 | 5 | 39 | ||||||||||||||
| Other obligations(b) | 763 | 696 | 260 | 167 | 1,886 | ||||||||||||||
| Total cash contractual obligations | $ | 1,591 | $ | 1,957 | $ | 2,035 | $ | 12,151 | $ | 17,734 | |||||||||
| Ameren Missouri: | |||||||||||||||||||
| Long-term debt and financing obligations(a) | $ | 92 | $ | 63 | $ | 590 | $ | 3,484 | $ | 4,229 | |||||||||
| Interest payments | 188 | 373 | 338 | 2,140 | 3,039 | ||||||||||||||
| Operating leases | 8 | 13 | 11 | 5 | 37 | ||||||||||||||
| Other obligations(b) | 471 | 501 | 229 | 109 | 1,310 | ||||||||||||||
| Total cash contractual obligations | $ | 759 | $ | 950 | $ | 1,168 | $ | 5,738 | $ | 8,615 | |||||||||
| Ameren Illinois: | |||||||||||||||||||
| Long-term debt(a) | $ | — | $ | 400 | $ | — | $ | 3,213 | $ | 3,613 | |||||||||
| Interest payments | 143 | 282 | 264 | 2,261 | 2,950 | ||||||||||||||
| Operating leases | — | 2 | — | — | 2 | ||||||||||||||
| Other obligations(b) | 281 | 190 | 31 | 24 | 526 | ||||||||||||||
| Total cash contractual obligations | $ | 424 | $ | 874 | $ | 295 | $ | 5,498 | $ | 7,091 |
| (a) | Excludes unamortized discount and premium and debt issuance costs of $85 million, $39 million, and $38 million at Ameren, Ameren Missouri, and Ameren Illinois, respectively. See Note 5 – Long-term Debt and Equity Financings under Part II, Item 8 of this report, for discussion of items included herein. |
| (b) | See Other Obligations in Note 14 – Commitments and Contingencies under Part II, Item 8 of this report, for discussion of items included herein. |
Off-balance-sheet Arrangements
At December 31, 2019, none of the Ameren Companies had any significant off-balance-sheet financing arrangements, other than a forward sale agreement relating to common stock, variable interest entities, letters of credit, and Ameren (parent) guarantee arrangements on behalf of its subsidiaries. See Note 1 – Summary of Significant Accounting Policies under Part II, Item 8, of this report for further detail concerning variable interest entities. See Note 5 – Long-term Debt and Equity Financings under Part II, Item 8, of this report for further detail concerning the forward sale agreement relating to common stock.
Credit Ratings
Our credit ratings affect our liquidity, our access to the capital markets and credit markets, our cost of borrowing under our credit facilities and our commercial paper programs, and our collateral posting requirements under commodity contracts.
The following table presents the principal credit ratings of the Ameren Companies by Moody’s and S&P effective on the date of this report:
| Moody’s | S&P | |
| Ameren: | ||
| Issuer/corporate credit rating | Baa1 | BBB+ |
| Senior unsecured debt | Baa1 | BBB |
| Commercial paper | P-2 | A-2 |
| Ameren Missouri: | ||
| Issuer/corporate credit rating | Baa1 | BBB+ |
| Secured debt | A2 | A |
| Senior unsecured debt | Baa1 | Not Rated |
| Commercial paper | P-2 | A-2 |
| Ameren Illinois: | ||
| Issuer/corporate credit rating | A3 | BBB+ |
| Secured debt | A1 | A |
| Senior unsecured debt | A3 | BBB+ |
| Commercial paper | P-2 | A-2 |
| ATXI: | ||
| Issuer credit rating | A2 | Not Rated |
| Senior unsecured debt | A2 | Not Rated |
A credit rating is not a recommendation to buy, sell, or hold securities. It should be evaluated independently of any other rating. Ratings are subject to revision or withdrawal at any time by the rating organization.
Collateral Postings
Any weakening of our credit ratings may reduce access to capital and trigger additional collateral postings and prepayments. Such changes may also increase the cost of borrowing, resulting in an adverse effect on earnings. Cash collateral postings and prepayments made with external parties, including postings related to exchange-traded contracts, and cash collateral posted by external parties were immaterial at December 31, 2019. A sub-investment-grade issuer or senior unsecured debt rating (below “Baa3” from Moody’s or below “BBB-” from S&P) at December 31, 2019, could have resulted in Ameren, Ameren Missouri, or Ameren Illinois being required to post additional collateral or other assurances for certain trade obligations amounting to $143 million, $111 million, and $32 million, respectively.
Changes in commodity prices could trigger additional collateral postings and prepayments. Based on credit ratings at December 31, 2019, if market prices were 15% higher or lower than December 31, 2019 levels in the next 12 months and 20% higher or lower thereafter through the end of the term of the commodity contracts, then Ameren, Ameren Missouri, or Ameren Illinois could be required to post an immaterial amount, compared to each company’s liquidity, of collateral or provide other assurances for certain trade obligations.
OUTLOOK
Below are some key trends, events, and uncertainties that may reasonably affect our results of operations, financial condition, or liquidity, as well as our ability to achieve strategic and financial objectives, for 2020 and beyond.
Operations
| • | In 2018, Missouri Senate Bill 564 was enacted and Ameren Missouri elected the PISA in accordance with the provisions of the law. Pursuant to its PISA election, Ameren Missouri is permitted to defer and recover 85% of the depreciation expense and a return at the applicable WACC on investments in certain property, plant, and equipment placed in service after September 1, 2018, and not included in base rates. The regulatory asset for accumulated PISA deferrals also earns a return at the applicable WACC, with all approved PISA deferrals added to rate base prospectively and recovered over a period of 20 years following a regulatory rate review. Additionally, under the RESRAM, Ameren Missouri is permitted to recover the 15% of depreciation expense and a return at the applicable WACC for investments in renewable generation plant placed in service and not recovered under the PISA. Accumulated RESRAM deferrals earn carrying costs at short-term interest rates. The PISA and the RESRAM mitigate the effects of regulatory lag between regulatory rate reviews. Those investments not eligible for recovery under the PISA and the remaining 15% of certain property, plant, and equipment placed in service, unless eligible for recovery under the RESRAM, remain subject to regulatory lag. Ameren Missouri recognizes the cost of debt on PISA deferrals in revenue, instead of using the applicable WACC, with the difference recognized in revenues when recovery of such deferrals is reflected in customer rates. As a result of the PISA election, additional provisions of the law apply to Ameren Missouri, including limitations on electric customer rate increases. Both the rate increase limitation and PISA are effective through December 2023, unless Ameren Missouri requests and receives MoPSC approval of an extension through December 2028. |
| • | In February 2020, Ameren Missouri filed an update to its Smart Energy Plan with the MoPSC, which includes a five-year capital investment overview with a detailed one-year plan for 2020. The plan is designed to upgrade Ameren Missouri’s electric infrastructure and includes investments that will upgrade the grid and accommodate more renewable energy. Investments under the plan are expected to total approximately $7.6 billion over the five-year period from 2020 through 2024, with expenditures largely recoverable under the PISA and the RESRAM. The planned investments in 2024 are based on the assumption that Ameren Missouri requests and receives MoPSC approval of an extension of the PISA through December 2028. As a part of its Smart Energy Plan, Ameren Missouri expects to build solar generation facilities, including utility scale facilities and nonresidential customer site facilities. In September 2019, Ameren Missouri filed for certificates of convenience and necessity with the MoPSC to build three solar facilities in its service territory. Each 10-megawatt solar energy generation facility will connect to battery storage in order to improve system reliability. All three facilities are expected to be completed by 2022. Also in 2019, the MoPSC approved Ameren Missouri’s Charge Ahead program, which provides incentives for the development of over 1,000 electric vehicle charging stations along highways and at various locations in communities throughout Ameren Missouri’s service territory. The purpose of the program is to promote the development of electric vehicle charging infrastructure that will enable long-distance electric vehicle travel and encourage electrification of the transportation sector. |
| • | In 2018, the MoPSC issued an order approving Ameren Missouri’s MEEIA 2019 plan. The plan includes a portfolio of customer energy-efficiency programs through December 2021 and low-income customer energy-efficiency programs through December 2024, along with a rate-adjustment mechanism. Ameren Missouri intends to invest $226 million over the life of the plan, including $65 million per year through 2021. The plan includes the continued use of the MEEIA rider, which allows Ameren Missouri to collect from, or refund to, customers any difference in actual MEEIA program costs and related lost electric margins and the amounts collected from customers. In addition, the plan includes a performance incentive that provides Ameren Missouri an opportunity to earn additional revenues by achieving certain customer energy-efficiency goals. If the target goals are achieved for 2019, 2020, and 2021, additional revenues of $7 million, $10 million, and $13 million would be recognized in late 2020, 2021, and 2022, respectively. Incremental additional revenues of $1 million, $3 million, and $3 million may be earned for 2019, 2020, and 2021, respectively, and would be recognized in the respective following year, if Ameren Missouri exceeds its targeted energy savings goals. Ameren Missouri recognized $28 million, $11 million, and $37 million in revenues related to MEEIA performance incentives in 2016, 2018, and 2019, respectively. |
| • | In June 2018, the MoPSC approved Ameren Missouri’s Renewable Choice Program, which allows large commercial and industrial customers and municipalities to elect to receive up to 100% of their energy from renewable resources. The tariff-based program is designed to recover the costs of the election. Ameren Missouri is working to meet its customers’ top priorities for this program, including prices competitive with existing rates, long-term price predictability, and the preference for renewable power generated in Missouri. Ameren Missouri has not yet developed a project that effectively meets the needs of those customers who have expressed an interest in the program. Ameren Missouri will remain focused on finding solutions to best meet customer needs and expectations. |
| • | In July 2019, Ameren Missouri filed a request with the MoPSC seeking approval to decrease its annual revenues for electric service by $1 million. In February 2020, Ameren Missouri, the MoPSC staff, the MoOPC, and certain intervenors filed a nonunanimous stipulation and agreement with the MoPSC to decrease Ameren Missouri’s annual revenues for electric service by $32 million. The remaining intervenor did not object to the agreement. The stipulation and agreement, which is subject to MoPSC approval, specified an allowed ROE range of 9.4% to 9.8%, but did not specify the common equity percentage or rate base. The stipulation and agreement includes the continued use of the FAC and trackers for pension and postretirement benefits, uncertain income tax positions, certain excess deferred income taxes, and renewable energy standard compliance costs that the MoPSC previously authorized in earlier electric rate orders. Ameren Missouri cannot predict whether the MoPSC will approve the stipulation and agreement or, if approved, whether any application for rehearing or appeal will be filed, or the outcome if so filed. A decision by the MoPSC is expected by March 2020, with new rates effective as early as April 1, 2020.The percentage of net energy cost variances from the amount set in base rates allowed to be recovered or refunded under the FAC and costs from services provided by affiliates are still being challenged by the MoOPC, and are expected to be addressed in a proceeding that would begin in March 2020. A MoPSC decision would be expected in the proceeding by the end of May 2020. |
| • | Ameren Illinois and ATXI use a forward-looking rate calculation with an annual revenue requirement reconciliation for each company’s electric transmission business. Based on expected rate base growth and the currently allowed 10.38% ROE, the revenue requirements that will be included in 2020 rates for Ameren Illinois’ and ATXI’s electric transmission businesses are $311 million and $190 million, respectively. These revenue requirements represent an increase in Ameren Illinois’ and ATXI’s revenue requirements of $14 million and $13 million, respectively, from the revenue requirements reflected in 2019 rates, primarily due to the expected rate base growth. These rates will affect Ameren Illinois’ and ATXI’s cash receipts during 2020, but will not determine their respective electric transmission service operating revenues, which will instead be based on 2020 actual recoverable costs, rate base, and a return on rate base at the applicable WACC as calculated under the FERC formula ratemaking framework. |
| • | The ROE for MISO transmission owners, including Ameren Illinois and ATXI, is the subject of FERC complaint cases filed in November 2013 and February 2015 challenging the allowed base ROE. In November 2019, the FERC issued an order addressing the November 2013 complaint case, which set the allowed base ROE at 9.88% and required refunds, with interest, for the periods November 2013 to February 2015 and from late September 2016 forward. The order also dismissed the February 2015 complaint case. As a result of this |
order, Ameren and Ameren Illinois expect to pay refunds of approximately $40 million and $23 million, respectively, in 2020. In December 2019, Ameren and the MISO transmission owners, including Ameren Missouri, Ameren Illinois, and ATXI, filed requests for rehearing with the FERC. Additionally, in December 2019, various parties filed requests for rehearing with the FERC, challenging the dismissal of the February 2015 complaint case. The FERC has not ruled on the merits of the rehearing requests and is under no deadline to do so. In March 2019, the FERC issued separate Notices of Inquiry regarding its allowed base ROE policy and its transmission incentives policy. Initial comments were due by June 2019, and reply comments were due by late August 2019. The Notice of Inquiry addressing the FERC’s base ROE policy, among other things, broadened the ability to comment on the new methodology beyond electric utilities that are participants in the complaint cases. The transmission incentives Notice of Inquiry was open for comment on the FERC’s transmission incentive policy, including incentive adders to the base ROE. Ameren is unable to predict the ultimate impact of the Notices of Inquiry or the requests for rehearing at this time. A 50 basis point reduction in the FERC-allowed base ROE would reduce Ameren’s and Ameren Illinois’ annual net income by an estimated $10 million and $6 million, respectively, based on each company’s 2020 projected rate base.
| • | Ameren Illinois’ electric distribution service performance-based formula ratemaking framework allows Ameren Illinois to reconcile electric distribution service rates to its actual revenue requirement on an annual basis. If a given year’s revenue requirement varies from the amount collected from customers, an adjustment is made to electric operating revenues with an offset to a regulatory asset or liability to reflect that year’s actual revenue requirement, independent of actual sales volumes. The regulatory balance is then collected from, or refunded to, customers within two years from the end of the year. Unless extended, the formula ratemaking framework expires at the end of 2022. If not extended, Ameren Illinois would then be required to establish future rates through a traditional regulatory rate review with the ICC. The decoupling provisions extend beyond the end of the formula ratemaking by law, which ensures that Ameren Illinois’ electric distribution revenues authorized in a regulatory rate review are not affected by changes in sales volumes. |
| • | In December 2019, the ICC issued an order in Ameren Illinois’ annual update filing that approved a $7 million decrease in Ameren Illinois’ electric distribution service rates beginning in January 2020. Illinois law provides for an annual reconciliation of the electric distribution revenue requirement as is necessary to reflect the actual costs incurred and a return at the applicable WACC on year-end rate base in a given year with the revenue requirement that was reflected in customer rates for that year. Consequently, Ameren Illinois’ 2020 electric distribution service revenues will be based on its 2020 actual recoverable costs, 2020 year-end rate base, and return at the applicable WACC as calculated under the Illinois performance-based formula ratemaking framework. The 2020 revenue requirement is expected to be higher than the 2019 revenue requirement because of an expected increase in recoverable costs and expected rate base growth of approximately 7%, partially offset by the impact of an expected decrease in the annual average of the monthly yields of the 30-year United States Treasury bonds. The 2020 revenue requirement reconciliation is expected to result in a regulatory asset that will be collected from customers in 2022. A 50 basis point change in the annual average of the monthly yields of the 30-year United States Treasury bonds would result in an estimated $9 million change in Ameren’s and Ameren Illinois’ annual net income, based on Ameren Illinois’ 2020 projected year-end rate base. |
| • | In February 2020, Ameren Illinois filed a request with the ICC seeking approval to increase its annual revenues for natural gas delivery service by $102 million, which included an estimated $46 million of annual revenues that would otherwise be recovered under the QIP and other riders. The request is based on a 10.5% allowed ROE, a capital structure composed of 54.1% common equity, and a rate base of $2.1 billion. |
| • | Ameren Illinois earns a return at the applicable WACC on its electric energy-efficiency program investments. Ameren Illinois’ electric energy-efficiency investments are deferred as a regulatory asset and earn a return at the applicable WACC, with the ROE based on the annual average of the monthly yields of the 30-year United States Treasury bonds plus 580 basis points. The allowed ROE on electric energy-efficiency investments can be increased or decreased by up to 200 basis points, depending on the achievement of annual energy savings goals. Pursuant to the FEJA, Ameren Illinois plans to invest up to approximately $100 million per year in electric energy-efficiency programs through 2024, and will earn a return on those investments. While the ICC has approved a plan consistent with this spending level through 2021, the ICC has the ability to reduce the amount of electric energy-efficiency savings goals in future plan program years if there are insufficient cost-effective programs available, which could reduce the investments in electric energy-efficiency programs. The electric energy-efficiency program investments and the return on those investments are collected from customers through a rider and are not included in the electric distribution formula ratemaking framework. |
| • | In February 2020, the MoPSC issued an order approving a stipulation and agreement allowing Ameren Missouri to defer and amortize maintenance expenses related to scheduled refueling and maintenance outages at its Callaway Energy Center. Beginning with the fall 2020 refueling and maintenance outage, Ameren Missouri will defer the maintenance expenses incurred related to a refueling and maintenance outage as a regulatory asset and amortize those expenses after completion of the outage. Maintenance expenses will be amortized over the period between refueling and maintenance outages, which is approximately 18 months. Ameren Missouri expects to incur approximately $40 million in maintenance expenses related to the fall 2020 outage. During a scheduled outage, depending on the availability of its other generation sources and the market prices for power, Ameren Missouri’s purchased power costs may increase and the amount of excess power available for sale may decrease versus non-outage years. Changes in purchased power costs and excess |
power available for sale are included in the FAC, which results in limited impacts to earnings. Prior to 2020, maintenance expenses for refueling and maintenance outages were expensed as incurred.
| • | Ameren Missouri and Ameren Illinois continue to make infrastructure investments and expect to seek increases to electric and natural gas rates to recover the cost of investments and earn an adequate return. Ameren Missouri and Ameren Illinois will also seek new, or to maintain existing, legislative solutions to address regulatory lag and to support investment in their utility infrastructure for the benefit of their customers. Ameren Missouri and Ameren Illinois continue to face cost recovery pressures, including limited economic growth in their service territories, customer conservation efforts, the impacts of additional customer energy-efficiency programs, and increased customer use of increasingly cost-effective technological advances, including private generation and energy storage. However, over the long-term, we expect the decreased demand to be partially offset by increased demand resulting from increased electrification of the economy for efficiencies and as a means to address economywide CO2 emission concerns. Increased investments, including expected future investments for environmental compliance, system reliability improvements, and potential new generation sources, result in rate base and revenue growth but also higher depreciation and financing costs. |
For additional information regarding recent rate orders, lawsuits, and pending requests filed with state and federal regulatory commissions, see Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report.
Liquidity and Capital Resources
| • | Ameren Missouri’s 2017 IRP targets cleaner and more diverse sources of energy generation, including solar, wind, natural gas, hydro, and nuclear power. It also includes expanding renewable sources by adding 700 megawatts of wind generation by the end of 2020 in Missouri and adding 100 megawatts of solar generation by 2027. These new renewable energy sources would support Ameren Missouri’s compliance with the state of Missouri’s requirement of achieving 15% of native load sales from renewable energy sources by 2021, subject to customer rate increase limitations. Based on current and projected market prices for energy and for wind and solar generation technologies, among other factors, Ameren Missouri expects its ownership of these renewable resources would represent the lowest-cost option for customers. The plan also provides for the expected implementation of continued customer energy-efficiency programs. Ameren Missouri’s plan for the addition of renewable resources could be affected by, among other factors: the availability of federal production and investment tax credits related to renewable energy and Ameren Missouri’s ability to use such credits; the cost of wind and solar generation technologies; energy prices; Ameren Missouri’s ability to obtain timely interconnection agreements with the MISO or other RTOs at an acceptable cost; and Ameren Missouri’s ability to obtain a certificate of convenience and necessity from the MoPSC, and any other required project approvals. Ameren Missouri expects to file its next integrated resource plan in September 2020. Ameren Missouri will seek stakeholder feedback and assess different scenarios to meet future energy needs, which will be used to create an updated plan for its current generation portfolio and ongoing transition to cleaner sources of energy. |
| • | In connection with the 2017 IRP filing, Ameren Missouri established a goal of reducing CO2 emissions 80% by 2050 from a 2005 base level. Ameren Missouri is also targeting a 35% CO2 emission reduction by 2030 and a 50% reduction by 2040 from the 2005 level. In order to meet these goals, among other things, Ameren Missouri expects to retire its coal-fired generation at the end of each energy center’s useful life. The Meramec, Sioux, Labadie, and Rush Island energy centers are expected to be retired in 2022, 2033, 2042, and 2045, respectively. |
| • | Consistent with its 2017 IRP filing, in May 2019, Ameren Missouri entered into a build-transfer agreement to acquire, after construction, an up-to 300-megawatt wind generation facility. In 2018, Ameren Missouri entered into a build-transfer agreement to acquire, after construction, an up-to 400-megawatt wind generation facility. These two agreements are subject to customary contract terms and conditions. The two build-transfer acquisitions collectively represent $1.2 billion of capital expenditures, are expected to be completed by the end of 2020, and would support Ameren Missouri’s compliance with the Missouri renewable energy standard. Both acquisitions have received all regulatory approvals, and both projects have received all applicable zoning approvals, have entered into RTO interconnection agreements, and have begun construction activities. |
| • | Through 2024, we expect to make significant capital expenditures to improve our electric and natural gas utility infrastructure, with a major portion directed to our transmission and distribution systems. We estimate that we will invest up to $16.6 billion (Ameren Missouri – up to $8.4 billion; Ameren Illinois – up to $8.0 billion; ATXI – up to $0.2 billion) of capital expenditures during the period from 2020 through 2024. Ameren’s and Ameren Missouri’s estimates exclude any capital expenditures related to pollution control equipment that may be required as a result of the NSR and Clean Air Act litigation discussed in Note 14 – Commitments and Contingencies under Part II, Item 8, of this report. |
| • | Environmental regulations, including those related to CO2 emissions, or other actions taken by the EPA, could result in significant increases in capital expenditures and operating costs. Certain of these regulations are being challenged through litigation, or reviewed or recommended for repeal by the EPA, or new replacement or alternative regulations are being contemplated, proposed, or adopted by the EPA and state regulators. The ultimate implementation of any of these regulations, as well as the timing of any such implementation, is uncertain. However, the individual or combined effects of existing and new environmental regulations could result in significant capital |
expenditures, increased operating costs, or the closure or alteration of some of Ameren Missouri’s coal-fired energy centers. Ameren Missouri’s capital expenditures are subject to MoPSC prudence reviews, which could result in cost disallowances as well as regulatory lag. The cost of Ameren Illinois’ purchased power and natural gas purchased for resale could increase. However, Ameren Illinois expects that these costs would be recovered from customers with no material adverse effect on its results of operations, financial position, or liquidity. Ameren’s and Ameren Missouri’s earnings could benefit from increased investment to comply with environmental regulations if those investments are reflected and recovered on a timely basis in customer rates.
| • | The Ameren Companies have multiyear credit agreements that cumulatively provide $2.3 billion of credit through December 2024, subject to a 364-day repayment term for Ameren Missouri and Ameren Illinois, with the option to seek incremental commitments to increase the cumulative credit provided to $2.7 billion. See Note 4 – Short-term Debt and Liquidity under Part II, Item 8, of this report for additional information regarding the Credit Agreements. Ameren, Ameren Missouri, and Ameren Illinois believe that their liquidity is adequate given their expected operating cash flows, capital expenditures, and related financing plans. However, there can be no assurance that significant changes in economic conditions, disruptions in the capital and credit markets, or other unforeseen events will not materially affect their ability to execute their expected operating, capital, or financing plans. |
| • | Ameren expects its cash used for currently planned capital expenditures and dividends to exceed cash provided by operating activities over the next several years. As part of its plan to fund these cash flow requirements, Ameren is using newly issued shares of common stock, rather than market-purchased shares, to satisfy requirements under the DRPlus and employee benefit plans and expects to continue to do so through at least 2024. Ameren expects these issuances to provide equity funding of about $100 million annually. Ameren also plans to issue incremental common equity to fund a portion of Ameren Missouri’s wind generation investments through the settlement of the forward sale agreement discussed below. Additionally, Ameren plans to issue incremental equity of about $150 million annually from 2021 to 2024. Ameren expects its equity to total capitalization to be about 45% through the period ending December 2024, with the long-term intent to support solid investment-grade credit ratings. Ameren Missouri and Ameren Illinois expect to fund cash flow needs through debt issuances, adjustments of dividends to Ameren (parent), and/or capital contributions from Ameren (parent). |
| • | In August 2019, Ameren entered into a forward sale agreement with a counterparty relating to 7.5 million shares of common stock. The forward sale agreement can be settled at Ameren’s discretion on or prior to March 31, 2021. On a settlement date or dates, if Ameren elects to physically settle the forward sale agreement, Ameren will issue shares of common stock to the counterparty at the then-applicable forward sale price. The forward sale agreement will be physically settled unless Ameren elects to settle in cash or to net share settle. If physically settled, Ameren expects to receive between $540 million and $550 million upon settlement. See Note 5 – Long-term Debt and Equity Financings under Part II, Item 8, of this report for additional information. |
| • | Federal income tax legislation enacted under the TCJA will continue to have significant impacts on our results of operations, financial position, liquidity, and financial metrics. The TCJA, among other things, reduced the federal statutory corporate income tax rate from 35% to 21%, effective January 1, 2018. Customer rates were reduced to reflect the lower income tax rate, without a corresponding reduction in income tax payments because of our use of net operating losses and tax credit carryforwards until about 2020. Customer rates were also reduced to reflect the return of excess deferred income taxes. The result of these customer rate reductions is a decrease in operating cash flows in the near term. Over time, the decrease in operating cash flows will be offset as temporary differences between book and taxable income reverse, and by increased customer rates due to higher rate base amounts resulting from lower accumulated deferred income tax liabilities. |
| • | The following table presents the net regulatory liabilities/(assets) associated with excess deferred income taxes as of December 31, 2019, and the related amortization periods: |
| Amortization Period | Ameren Missouri | Ameren Illinois | ATXI | Total | |||||||||||
| 25 – 65 years | $ | 913 | $ | 774 | $ | 84 | $ | 1,771 | |||||||
| 6 – 10 years | 502 | (3 | ) | 1 | 500 | ||||||||||
| Total | $ | 1,415 | $ | 771 | $ | 85 | $ | 2,271 |
| • | As of December 31, 2019, Ameren had $98 million in tax benefits related to federal and state income tax credit carryforwards. Ameren has utilized all tax benefits from net operating loss carryforwards. Future expected income tax payments and refunds are based on planned capital expenditures and any related income tax credits and, in the case of Ameren Missouri and Ameren Illinois, are consistent with the tax allocation agreement between Ameren (parent) and its subsidiaries. Ameren expects to make income tax payments between $5 million and $75 million in each year from 2020 to 2024, totaling $150 million to $200 million for the five-year period. Ameren Missouri expects to make income tax payments to Ameren (parent) between $35 million and $45 million in 2020. Additionally, Ameren Missouri expects to receive refunds from Ameren (parent) in each year from 2021 to 2024, totaling $60 million to $100 million for the four-year period. Ameren Illinois expects to make income tax payments to Ameren (parent) between $20 million and $30 million in 2020 and between $50 million and $90 million in each year from 2021 to 2024, totaling $260 million to $310 million for the five-year period. |
| • | Ameren Missouri expects its 2020 wind generation acquisitions to generate federal production tax credits between $65 million and $70 million in each year from 2021 to 2030. Ameren expects to utilize approximately $140 million of these federal production tax credits from 2021 to 2024. Delays in the timely completion of the wind generation facilities may affect the ability to realize some or all of the anticipated federal production tax credits. If these facilities are not completed in 2020, Ameren Missouri will need to satisfy additional IRS requirements in order to qualify for some or all of the anticipated federal production tax credits. |
| • | In 2018, legislation modifying Missouri tax law was enacted to decrease the state’s corporate income tax rate from 6.25% to 4%, effective January 1, 2020. Ameren Missouri anticipates that the effect of this tax decrease will be reflected in customer rates upon completion of its current electric service regulatory rate review. Ameren (parent) and nonregistrant subsidiaries do not expect this income tax decrease to have a material impact on net income. |
The above items could have a material impact on our results of operations, financial position, and liquidity. Additionally, in the ordinary course of business, we evaluate strategies to enhance our results of operations, financial position, and liquidity. These strategies may include acquisitions, divestitures, opportunities to reduce costs or increase revenues, and other strategic initiatives to increase Ameren’s shareholder value. We are unable to predict which, if any, of these initiatives will be executed. The execution of these initiatives may have a material impact on our future results of operations, financial position, or liquidity.
REGULATORY MATTERS
See Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report.
ACCOUNTING MATTERS
Critical Accounting Estimates
Preparation of the financial statements and related disclosures in compliance with GAAP requires the application of appropriate technical accounting rules and guidance, as well as the use of estimates. These estimates involve judgments regarding many factors that in and of themselves could materially affect the financial statements and disclosures. We have outlined below the critical accounting estimates that we believe are the most difficult, subjective, or complex. Any change in the assumptions or judgments applied in determining the following matters, among others, could have a material impact on future financial results.
| Accounting Estimate | Uncertainties Affecting Application |
Regulatory Mechanisms and Cost Recovery
We defer costs and recognize revenues that we intend to collect in future rates.
| • | Regulatory environment and external regulatory decisions and requirements |
| • | Anticipated future regulatory decisions and our assessment of their impact |
| • | The impact of prudence reviews, complaint cases, limitations on electric rate increases in Missouri, and opposition during the ratemaking process that may limit our ability to timely recover costs and earn a fair return on our investments |
| • | Ameren Illinois’ assessment of and ability to estimate the current year’s electric distribution service costs to be reflected in revenues and recovered from customers in a subsequent year under performance-based formula ratemaking framework |
| • | Ameren Illinois’ and ATXI’s assessment of and ability to estimate the current year’s electric transmission service costs to be reflected in revenues and recovered from customers in a subsequent year under the FERC ratemaking frameworks |
| • | Ameren Missouri’s estimate of revenue recovery under the MEEIA plans |
Basis for Judgment
The application of accounting guidance for rate-regulated businesses results in recording regulatory assets and liabilities. Regulatory assets represent the deferral of incurred costs that are probable of future recovery in customer rates. Regulatory assets are amortized as the incurred costs are recovered through customer rates. In some cases, we record regulatory assets before approval for recovery has been received from the applicable regulatory commission. We must use judgment to conclude that costs deferred as regulatory assets are probable of future recovery. We base our conclusion on certain factors including, but not limited to, orders issued by our regulatory commissions, legislation, or historical experience, as well as discussions with legal counsel. If facts and circumstances lead us to conclude that a recorded regulatory asset is no longer probable of recovery or that plant assets are probable of disallowance, we record a charge to earnings, which could be material. Regulatory liabilities represent revenues received from customers to fund expected costs that have not yet been incurred or that are probable of future refunds to customers. We also recognize revenues for alternative revenue programs authorized by our regulators that allow for an automatic rate adjustment, are probable of recovery, and are collected within 24 months following the end of the annual period in which they are recognized. Under performance-based formula ratemaking, which expires at the end of 2022 unless extended, Ameren Illinois estimates its annual electric distribution revenue requirement for interim periods by using internal forecasted rate base and published forecasted data regarding the annual average of the monthly yields of the 30-year United States Treasury bonds. Ameren Illinois estimates its annual revenue requirement as of December 31 of each year using that year’s actual operating results and assesses the probability of recovery from or refund to customers that the ICC will order at the end of the following year. Variations in investments made or orders by the ICC or courts can result in a subsequent change in Ameren Illinois’ estimate. Ameren Illinois and ATXI follow a similar process for their FERC rate-regulated electric transmission businesses. Ameren Missouri estimates lost electric margins resulting from its MEEIA customer energy-efficiency programs, which are subsequently recovered through the MEEIA rider. See Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report for a description of our regulatory mechanisms and quantification of these assets or liabilities for each of the Ameren Companies.
Benefit Plan Accounting
Based on actuarial calculations, we accrue costs of providing future employee benefits for the benefit plans we offer our employees. See Note 10 – Retirement Benefits under Part II, Item 8, of this report.
| • | Future rate of return on pension and other plan assets |
| • | Valuation inputs and assumptions used in the fair value measurements of plan assets, excluding those inputs that are readily observable |
| • | Discount rate |
| • | Future compensation increase assumption |
| • | Health care cost trend rates |
| • | Timing of employee retirements and mortality assumptions |
| • | Ability to recover certain benefit plan costs from our customers |
| • | Changing market conditions that may affect investment and interest rate environments |
Basis for Judgment
Ameren has defined benefit pension and postretirement benefit plans covering substantially all of its union employees. Ameren has defined benefit pension plans covering substantially all of its non-union employees and postretirement benefit plans covering non-union employees hired before October 2015. Our ultimate selection of the discount rate, health care trend rate, and expected rate of return on pension and other postretirement benefit plan assets is based on our consistent application of assumption-setting methodologies and our review of available historical, current, and projected rates, as applicable. We also make mortality assumptions to estimate our pension and other postretirement benefit obligations. See Note 10 – Retirement Benefits under Part II, Item 8, of this report for these assumptions and the sensitivity of Ameren’s benefit plans to potential changes in these assumptions.
Accounting for Contingencies
We make judgments and estimates in the recording and the disclosing of liabilities for claims, litigation, environmental remediation, the actions of various regulatory agencies, or other matters that occur in the normal course of business. We record a loss contingency when it is probable that a liability has been incurred and that the amount of the loss can be reasonably estimated.
| • | Estimating financial impact of events |
| • | Estimating likelihood of various potential outcomes |
| • | Regulatory and political environments and requirements |
| • | Outcome of legal proceedings, settlements, or other factors |
| • | Changes in regulation, expected scope of work, technology, or timing of environmental remediation |
Basis for Judgment
The determination of a loss contingency requires significant judgment as to the expected outcome of the contingency in future periods. In making the determination as to the amount of potential loss and the probability of loss, we consider the nature of the litigation, the claim or assessment, opinions or views of legal counsel, and the expected outcome of potential litigation, among other things. If no estimate is better than another within our range of estimates, we record as our best estimate of a loss the minimum value of our estimated range of outcomes. As additional information becomes available, we reassess the potential liability related to the contingency and revise our estimates. The amount recorded for any contingency may differ from actual costs incurred when the contingency is resolved. Contingencies are normally resolved over long periods of time. In our evaluation of legal matters, management consults with legal counsel and relies on analysis of relevant case law and legal precedents. See Note 2 – Rate and Regulatory Matters, Note 9 – Callaway Energy Center, and Note 14 – Commitments and Contingencies under Part II, Item 8, of this report for information on the Ameren Companies’ contingencies.
Accounting for Income Taxes
We record a provision for income taxes, deferred tax assets and liabilities, and a valuation allowance against net deferred tax assets, if any. See Note 12 – Income Taxes under Part II, Item 8, of this report.
| • | Changes in business, industry, laws, technology, or economic and market conditions affecting forecasted financial condition and/or results of operations |
| • | Estimates of the amount and character of future taxable income and forecasted use of our tax credit carryforwards |
| • | Enacted tax rates applicable to taxable income in years in which temporary differences are recovered or settled |
| • | Effectiveness of implementing tax planning strategies |
| • | Changes in income tax laws, including amounts subject to income tax, and the regulatory treatment of any tax reform changes |
| • | Results of audits and examinations by taxing authorities |
Basis for Judgment
The reporting of tax-related assets and liabilities requires the use of estimates and significant management judgment. Deferred tax assets and liabilities are recorded to represent future effects on income taxes for temporary differences between the basis of assets for financial reporting and tax purposes. Although management believes that current estimates for deferred tax assets and liabilities are reasonable, actual results could differ from these estimates for a variety of reasons, including: a change in forecasted financial condition and/or results of operations; changes in income tax laws, enacted tax rates or amounts subject to income tax; the form, structure, and timing of asset or stock sales or dispositions; changes in the regulatory treatment of any tax reform benefits; and changes resulting from audits and examinations by taxing authorities. Valuation allowances against deferred tax assets are recorded when management concludes it is more likely than not such asset will not be realized in future periods. Accounting for income taxes also requires that only tax benefits for positions taken or expected to be taken on tax returns that meet the more-likely-than-not recognition threshold can be recognized or continue to be recognized. Management evaluates each position solely on the technical merits and facts and circumstances of the position, assuming that the position will be examined by a taxing authority that has full knowledge of all relevant information. Significant judgment is required to determine recognition thresholds and the related amount of tax benefits to be recognized. At each period end, and as new developments occur, management reevaluates its tax positions. See Note 12 – Income Taxes under Part II, Item 8, of this report for the amount of deferred income taxes recorded at December 31, 2019.
Accounting for Asset Retirement Obligations
We record the estimated fair value of legal obligations associated with the retirement of tangible long-lived assets. See Note 1 – Summary of Significant Accounting Policies under Part II, Item 8, of this report.
| • | Discount rates |
| • | Cost escalation rates |
| • | Changes in regulation, expected scope of work, technology, or timing of environmental remediation |
| • | Estimates as to the probability, timing, or amount of cash expenditures associated with AROs |
Basis for Judgment
We record the estimated fair value of legal obligations associated with the retirement of tangible long-lived assets in the period in which the liabilities are incurred or when sufficient information becomes available to determine fair value and capitalize a corresponding amount as part of the book value of the related long-lived asset. In subsequent periods, we adjust AROs based on changes in the estimated fair values of the obligations with a corresponding increase or decrease in the asset book value. We estimate the fair value of our AROs using present value techniques, in which we make various assumptions about discount rates and cost escalation rates. In addition, these estimates include assumptions of the probability, timing, and amount of cash expenditures to settle the ARO, and are based on currently available technology. Ameren and Ameren Missouri have recorded AROs for retirement costs associated with Ameren Missouri’s Callaway Energy Center decommissioning, CCR facilities, and river structures. Also, Ameren, Ameren Missouri, and Ameren Illinois have recorded AROs for retirement costs associated with asbestos removal and the disposal of certain transformers. An increase of 0.25% in the assumed escalation rates would increase Ameren’s AROs at December 31, 2019 by $35 million. See Note 15 – Supplemental Information under Part II, Item 8, of this report for the amount of AROs recorded at December 31, 2019.
Impact of New Accounting Pronouncements
See Note 1 – Summary of Significant Accounting Policies under Part II, Item 8, of this report.
EFFECTS OF INFLATION AND CHANGING PRICES
Ameren’s rates for retail electric and natural gas utility service are regulated by the MoPSC and the ICC. Nonretail electric rates are regulated by the FERC. Rate regulation is generally based on the recovery of historical or projected costs. As a result, revenue increases could lag behind changing prices. The current replacement cost of our utility plant substantially exceeds our recorded historical cost. Under existing regulatory practice, only the historical cost of plant is recoverable from customers. As a result, customer rates designed to provide recovery of historical costs through depreciation might not be adequate to replace plant in future years.
Ameren Illinois participates in performance-based formula ratemaking for its electric distribution business and its electric energy-efficiency investments. Within Ameren Illinois’ formula ratemaking frameworks, the annual average of the monthly yields of the 30-year United States Treasury bonds are the basis for Ameren Illinois’ allowed ROE. Therefore, there is a direct correlation between the yield of United States Treasury bonds, which are affected by inflation, and the allowed ROE applicable to Ameren Illinois’ electric distribution business and electric energy-efficiency investments. Ameren Illinois’ and ATXI’s electric transmission rates are determined pursuant to formula ratemaking. Additionally, Ameren Illinois and ATXI use a company-specific, forward-looking formula ratemaking framework in setting their transmission rates. These forward-looking rates are updated each January with forecasted information. A reconciliation during the year, which adjusts for the actual revenue requirement and for actual sales volumes, is used to adjust billing rates in a subsequent year.
Ameren Missouri recovers the cost of fuel for electric generation and the cost of purchased power by adjusting rates as allowed through the FAC. However, the FAC excludes substantially all transmission revenues and charges. Ameren Missouri is therefore exposed to transmission charges to the extent that they exceed transmission revenues. Ameren Illinois is required to purchase all of its expected power supply through procurement processes administered by the IPA. The cost of procured power can be affected by inflation. Ameren Illinois recovers power supply costs from electric customers by adjusting rates through a rider mechanism to accommodate changes in power prices.
In our Missouri and Illinois retail natural gas utility jurisdictions, changes in natural gas costs are generally reflected in billings to natural gas customers through PGA clauses.
See Part I, Item 1, and Note 2 – Rate and Regulatory Matters under Part II, Item 8, of this report for additional information on our recovery mechanisms.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK