 filings.tools
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
157K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Executive Summary
In 2018, AES delivered strong financial results and achieved significant milestones on its strategic goals, including continuing to enhance the resilience of the portfolio and growing the backlog of renewable projects. The Company achieved a key investment grade metric, completed construction of 1.3 GW of new projects and signed long-term PPAs for 2 GW of renewable capacity. See Overview of our Strategy included in Item 1.—Business of this Form 10-K for further information.
During 2018, the Company saw increased margins at its South America, MCAC and US and Utilities SBUs. These increases were primarily due to higher tariffs and rates in Argentina and the U.S., higher contract prices in Colombia, new PPAs in Chile, and increased sales due to the commencement of operations at the Colon combined cycle facility in Panama and Eagle Valley CCGT in the U.S. The Company also experienced decreased margins in the Eurasia SBU due to completed sales of Masinloc in 2018 and the Kazakhstan facilities in 2017. In addition, the Company reduced its recourse debt by approximately $1 billion in 2018, resulting in a decrease in Parent Company interest.
Overview of 2018 Results
Earnings Per Share Results in 2018 (in millions, except per share amounts)
| Years Ended December 31, | 2018 | 2017 | 2016 | ||||||||
| Diluted earnings (loss) per share from continuing operations | $ | 1.48 | $ | (0.77 | ) | $ | (0.04 | ) | |||
| Adjusted EPS (a non-GAAP measure) (1) | 1.24 | 1.08 | 0.94 |
| (1) | See reconciliation and definition under SBU Performance Analysis—Non-GAAP Measures. |
Diluted earnings per share from continuing operations increased $2.25 to $1.48 for the year ended December 31, 2018, as compared to a loss of $0.77 for the year ended December 31, 2017. This increase was primarily due to the current year gains on sales of Masinloc, CTNG and Electrica Santiago, prior year loss on sale of the Kazakhstan CHPs and HPPs, prior year impairments at DPL, Laurel Mountain and in Kazakhstan, lower interest expense at the Parent Company and Gener, a one-time transition tax on foreign earnings following the enactment of the TCJA in the prior year, and higher margins. These increases were partially offset by higher current year tax expense due to the new GILTI rules in the U.S. in large part due to the sale of our interest in Masinloc, the current year impairment at Shady Point, other-than-temporary impairment of the Guacolda equity method investment in Chile, foreign exchange losses mainly due to the devaluation of the Argentine peso and foreign currency gains in the prior year, higher current year losses on extinguishment of debt, and a favorable legal settlement at Uruguaiana in the prior year.
Adjusted EPS, a non-GAAP measure, increased $0.16, or 15%, to $1.24, reflecting higher margins at the South America, US and Utilities and MCAC SBUs and lower interest on Parent Company debt. These increases were partially offset by lower margin at the Eurasia SBU mainly driven by the sales of Masinloc and Kazakhstan.
Review of Consolidated Results of Operations
| Years Ended December 31, | 2018 | 2017 | 2016 | % Change 2018 vs. 2017 | % Change 2017 vs. 2016 | ||||||||||||
| (in millions, except per share amounts) | |||||||||||||||||
| Revenue: | |||||||||||||||||
| US and Utilities SBU | $ | 4,230 | $ | 4,162 | $ | 4,330 | 2 | % | -4 | % | |||||||
| South America SBU | 3,533 | 3,252 | 2,956 | 9 | % | 10 | % | ||||||||||
| MCAC SBU | 1,728 | 1,519 | 1,274 | 14 | % | 19 | % | ||||||||||
| Eurasia SBU | 1,255 | 1,590 | 1,670 | -21 | % | -5 | % | ||||||||||
| Corporate and Other | 41 | 35 | 77 | 17 | % | -55 | % | ||||||||||
| Eliminations | (51 | ) | (28 | ) | (26 | ) | -82 | % | -8 | % | |||||||
| Total Revenue | 10,736 | 10,530 | 10,281 | 2 | % | 2 | % | ||||||||||
| Operating Margin: | |||||||||||||||||
| US and Utilities SBU | 733 | 693 | 719 | 6 | % | -4 | % | ||||||||||
| South America SBU | 1,017 | 862 | 823 | 18 | % | 5 | % | ||||||||||
| MCAC SBU | 534 | 465 | 390 | 15 | % | 19 | % | ||||||||||
| Eurasia SBU | 227 | 422 | 427 | -46 | % | -1 | % | ||||||||||
| Corporate and Other | 58 | 23 | 14 | NM | 64 | % | |||||||||||
| Eliminations | 4 | — | 10 | NM | -100 | % | |||||||||||
| Total Operating Margin | 2,573 | 2,465 | 2,383 | 4 | % | 3 | % | ||||||||||
| General and administrative expenses | (192 | ) | (215 | ) | (194 | ) | -11 | % | 11 | % | |||||||
| Interest expense | (1,056 | ) | (1,170 | ) | (1,134 | ) | -10 | % | 3 | % | |||||||
| Interest income | 310 | 244 | 245 | 27 | % | — | % | ||||||||||
| Loss on extinguishment of debt | (188 | ) | (68 | ) | (13 | ) | NM | NM | |||||||||
| Other expense | (58 | ) | (58 | ) | (80 | ) | — | % | -28 | % | |||||||
| Other income | 72 | 120 | 64 | -40 | % | 88 | % | ||||||||||
| Gain (loss) on disposal and sale of business interests | 984 | (52 | ) | 29 | NM | NM | |||||||||||
| Asset impairment expense | (208 | ) | (537 | ) | (1,096 | ) | -61 | % | -51 | % | |||||||
| Foreign currency transaction gains (losses) | (72 | ) | 42 | (15 | ) | NM | NM | ||||||||||
| Other non-operating expense | (147 | ) | — | (2 | ) | NM | -100 | % | |||||||||
| Income tax expense | (708 | ) | (990 | ) | (32 | ) | -28 | % | NM | ||||||||
| Net equity in earnings of affiliates | 39 | 71 | 36 | -45 | % | 97 | % | ||||||||||
| INCOME (LOSS) FROM CONTINUING OPERATIONS | 1,349 | (148 | ) | 191 | NM | NM | |||||||||||
| Income (loss) from operations of discontinued businesses, net of income tax benefit (expense) of $(2), $(21), and $229, respectively | (9 | ) | (18 | ) | 151 | -50 | % | NM | |||||||||
| Gain (loss) from disposal and impairments of discontinued businesses, net of income tax benefit (expense) of $(44), $0, and $266, respectively | 225 | (611 | ) | (1,119 | ) | NM | -45 | % | |||||||||
| NET INCOME (LOSS) | 1,565 | (777 | ) | (777 | ) | NM | — | % | |||||||||
| Noncontrolling interests: | |||||||||||||||||
| Less: Income from continuing operations attributable to noncontrolling interests and redeemable stock of subsidiaries | (364 | ) | (359 | ) | (211 | ) | 1 | % | 70 | % | |||||||
| Less: Loss (income) from discontinued operations attributable to noncontrolling interests | 2 | (25 | ) | (142 | ) | NM | -82 | % | |||||||||
| NET INCOME (LOSS) ATTRIBUTABLE TO THE AES CORPORATION | $ | 1,203 | $ | (1,161 | ) | $ | (1,130 | ) | NM | 3 | % | ||||||
| AMOUNTS ATTRIBUTABLE TO THE AES CORPORATION COMMON STOCKHOLDERS: | |||||||||||||||||
| Income (loss) from continuing operations, net of tax | $ | 985 | $ | (507 | ) | $ | (20 | ) | NM | NM | |||||||
| Income (loss) from discontinued operations, net of tax | 218 | (654 | ) | (1,110 | ) | NM | -41 | % | |||||||||
| NET INCOME (LOSS) ATTRIBUTABLE TO THE AES CORPORATION | $ | 1,203 | $ | (1,161 | ) | $ | (1,130 | ) | NM | 3 | % | ||||||
| Net cash provided by operating activities | $ | 2,343 | $ | 2,504 | $ | 2,897 | -6 | % | -14 | % | |||||||
| DIVIDENDS DECLARED PER COMMON SHARE | $ | 0.53 | $ | 0.49 | $ | 0.45 | 8 | % | 9 | % |
Components of Revenue, Cost of Sales and Operating Margin — Revenue includes revenue earned from the sale of energy from our utilities and the capacity and production of energy from our generation plants, which are classified as regulated and non-regulated, respectively, on the Consolidated Statements of Operations. Revenue also includes the gains or losses on derivatives associated with the sale of electricity.
Cost of sales includes costs incurred directly by the businesses in the ordinary course of business. Examples include electricity and fuel purchases, operations and maintenance costs, depreciation and amortization expense, bad debt expense and recoveries, and general administrative and support costs (including employee-related costs directly associated with the operations of the business). Cost of sales also includes the gains or losses on derivatives (including embedded derivatives other than foreign currency embedded derivatives) associated with the purchase of electricity or fuel.
Operating margin is defined as revenue less cost of sales.
Consolidated Revenue and Operating Margin
Year Ended December 31, 2018
Revenue
(in millions)
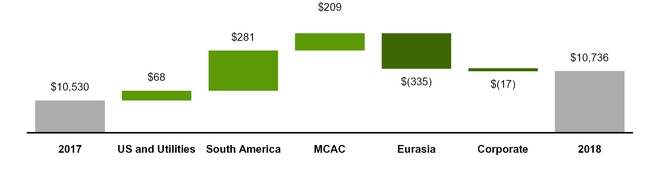
Consolidated Revenue — Revenue increased $206 million, or 2%, in 2018 compared to 2017. Excluding the unfavorable FX impact of $52 million, primarily in South America partially offset by Eurasia, this increase was driven by:
| • | $357 million in South America primarily due to higher contract sales and prices in Colombia and the commencement of new PPAs at Angamos and Cochrane in Chile, as well as higher capacity prices in Argentina resulting from market reforms enacted in 2017; |
| • | $215 million in MCAC primarily due to to the commencement of operations at the Colon combined cycle facility as well as improved hydrology at Panama, higher pass-through fuel prices in Mexico, higher contracted energy sales due to commencement of operations at the Los Mina combined cycle facility in June 2017, and higher spot prices in the Dominican Republic; and |
| • | $68 million in US and Utilities driven primarily by higher market energy sales at Southland, higher regulated rates commencing in November 2017 at DPL, higher wholesale volume due to the new CCGT coming online as well as higher retail demand at IPL, and higher prices due to tariff reset and higher energy prices in El Salvador, partially offset by the sale and closure of several generation facilities at DPL. |
These favorable impacts were partially offset by decreases of $366 million in Eurasia due to the sale of the Masinloc power plant in March 2018, as well as the sale of the Kazakhstan CHPs and expiration of the Kazakhstan HPP concession agreement in 2017.
Operating Margin
(in millions)
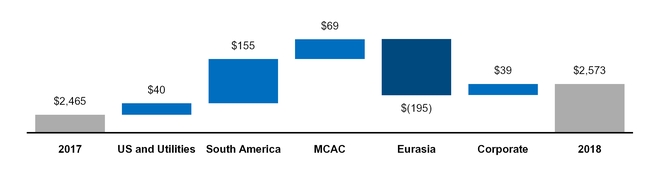
Consolidated Operating Margin — Operating margin increased $108 million, or 4%, in 2018 compared to 2017. Excluding the favorable impact of FX of $8 million, primarily driven by Eurasia, this increase was driven by:
| • | $154 million in South America primarily due to the drivers discussed above and the absence of maintenance costs for planned outages in 2018 versus maintenance performed in Q3 2017 at Gener Chile; |
| • | $70 million in MCAC primarily due to drivers discussed above; and |
| • | $40 million in US and Utilities mostly due to the drivers discussed above and the favorable impact of a one time reduction in the ARO liability at DPL's closed plants, Stuart and KIllen. |
These favorable impacts were partially offset by a decrease of $204 million in Eurasia due to the drivers discussed above.
Year Ended December 31, 2017
Revenue
(in millions)
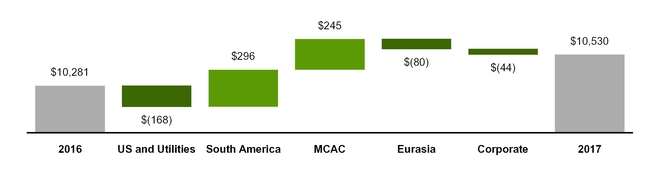
Consolidated Revenue — Revenue increased $249 million, or 2%, in 2017 compared to 2016. Excluding the net favorable FX impact of $38 million, primarily in South America, the increase was driven by:
| • | $249 million in South America primarily due to the start of commercial operations at Cochrane as well as higher availability at Argentina, partially offset by lower spot sales at Chivor; and |
| • | $248 million in MCAC primarily due to the commencement of the combined cycle operations at Los Mina in June 2017 as well as higher rates in the Dominican Republic. |
These favorable impacts were partially offset by decreases of $168 million in US & Utilities mainly due to lower retail tariffs, lower wholesale volume and price at DPL as well as hurricane impacts at Puerto Rico, partially offset by higher pass through costs in El Salvador.
Operating Margin
(in millions)

Consolidated Operating Margin — Operating margin increased $82 million, or 3%, in 2017 compared to 2016. Excluding the favorable impact of FX of $39 million, primarily in Brazil, Argentina, and Colombia, the increase was primarily driven by:
| • | $73 million in MCAC due to the commencement of the Los Mina combined cycle operations in June 2017 in the Dominican Republic as well as higher availability due to forced outages in 2016 at Mexico. |
These positive impacts were partially offset by a decreases of $26 million in US and Utilities driven by lower retain margin, lower volumes, and lower commercial availability at DPL as well as a negative impact at IPL mainly due to one-off accruals due to the implementation of new base rates in Q2 2016.
See Item 7.—Management's Discussion and Analysis of Financial Condition and Results of Operations—SBU Performance Analysis of this Form 10-K for additional discussion and analysis of operating results for each SBU.
Consolidated Results of Operations — Other
General and administrative expenses
General and administrative expenses include expenses related to corporate staff functions and initiatives, executive management, finance, legal, human resources and information systems, as well as global development costs.
General and administrative expenses decreased $23 million, or 11%, to $192 million for 2018, compared to $215 million for 2017 primarily due to reduced people costs, professional fees and business development activity.
General and administrative expenses increased $21 million, or 11%, to $215 million for 2017, compared to $194 million for 2016 primarily due to severance costs related to workforce reductions associated with a major restructuring program, increased professional fees and increased business development activity.
Interest expense
Interest expense decreased $114 million, or 10%, to $1,056 million for 2018, compared to $1,170 million for 2017 primarily due to the reduction of debt at the Parent Company, favorable impacts from interest rate swaps in Chile and increased capitalized interest at Alto Maipo.
Interest expense increased $36 million, or 3%, to $1,170 million for 2017, compared to $1,134 million for 2016 primarily due to an increase at the South America SBU, driven by lower capitalized interest in 2017 due to the Cochrane plant starting commercial operations in the second half of 2016.
Interest income
Interest income increased $66 million, or 27%, to $310 million for 2018, compared to $244 million for 2017 primarily due to higher interest rates and increased long term receivables as a result of the adoption of the new revenue recognition standard. See Note 1—General and Summary of Significant Accounting Policies included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Interest income decreased $1 million in 2017 from 2016 with no material drivers.
Loss on extinguishment of debt
Loss on extinguishment of debt increased $120 million to $188 million for 2018, compared to $68 million for 2017. This increase was primarily due to higher losses at the Parent Company of $79 million from the redemption of senior notes and a prior year gain on early retirement of debt at AES Argentina of $65 million; partially offset by lower losses at other subsidiaries of $24 million in 2018.
Loss on extinguishment of debt increased $55 million to $68 million for 2017, compared to $13 million for 2016 primarily related to losses of $92 million, $20 million, and $9 million on debt extinguishments at the Parent Company, AES Gener, and IPALCO, respectively. The loss was partially offset by a gain on early retirement of debt at AES Argentina of $65 million.
Other income
Other income decreased $48 million, or 40%, to $72 million for 2018, compared to $120 million for 2017 primarily due to the 2017 favorable settlement of legal proceedings at Uruguaiana related to YPF's breach of the parties’ gas supply agreement and a decrease in allowance for funds used during construction in the US and Utilities SBU. These decreases were partially offset by a gain on remeasurement of contingent liabilities for projects in Hawaii in 2018.
Other income increased $56 million, or 88%, to $120 million for 2017, compared to $64 million for 2016 primarily due to the 2017 favorable legal settlement mentioned above.
Other expense
Other expense remained flat at $58 million for 2018, compared to 2017 primarily due to a loss resulting from damage associated with a lightning incident at the Andres facility in the Dominican Republic in 2018 and higher non-service pension and other postretirement costs in 2018. This was offset by the 2017 write-off of water rights for projects that were no longer being pursued in the South America SBU and a loss on disposal of assets at DPL as a result of the decision to close the coal-fired and diesel-fired generating units at Stuart and Killen.
Other expense decreased $22 million, or 28%, to $58 million for 2017, compared to $80 million for 2016 primarily due to the 2016 recognition of a full allowance on a non-trade receivable in the MCAC SBU as a result of payment delays. This decrease was partially offset by the 2017 loss on disposal of assets at DPL as a result of the decision to close the coal-fired and diesel-fired generating units at Stuart and Killen and the write-off of water rights in the South America SBU for projects that are no longer being pursued.
See Note 19—Other Income and Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Gain (loss) on disposal and sale of business interests
Gain on disposal and sale of business interests was $984 million for 2018 primarily due to the $772 million gain on sale of Masinloc and the $129 million and $69 million gains on sales of CTNG and Electrica Santiago, respectively, in Chile.
Loss on disposal and sale of business interests was $52 million for 2017 primarily due to the $49 million and $33 million losses on sale of Kazakhstan CHPs and HPPs, respectively, partially offset by the recognition of a $23 million gain related to the expiration of a contingency at Masinloc.
Gain on disposal and sale of business interests was $29 million for 2016 primarily due to the $49 million gain on sale of DPLER, partially offset by the $20 million loss on the deconsolidation of U.K. Wind.
See Note 23—Held-For-Sale and Dispositions included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Goodwill impairment expense
There were no goodwill impairments for the years ended December 31, 2018, 2017, or 2016.
See Note 8—Goodwill and Other Intangible Assets included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Asset impairment expense
Asset impairment expense decreased $329 million, or 61%, to $208 million for 2018, compared to $537 million for 2017 mainly driven by prior year impairments of $186 million recognized in Kazakhstan due to the classification of the CHPs and HPPs as held-for-sale and $296 million in the U.S. as a result of the decision to sell the DPL peaker assets and a decline in forward pricing at Laurel Mountain, partially offset by a current year impairment of $157 million due to decreased future cash flows and the decision to sell Shady Point.
Asset impairment expense decreased $559 million, or 51%, to $537 million for 2017, compared to $1,096 million for 2016 mainly driven by the impairment of $859 million at DPL in 2016, partially offset by a $121 million impairment at Laurel Mountain in 2017 as a result of a decline in forward pricing.
See Note 20—Asset Impairment Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Foreign currency transaction gains (losses)
Foreign currency transaction gains (losses) in millions were as follows:
| Years Ended December 31, | 2018 | 2017 | 2016 | ||||||||
| Argentina (1) | $ | (71 | ) | $ | 1 | $ | 37 | ||||
| Chile | (13 | ) | 8 | (9 | ) | ||||||
| Bulgaria | (6 | ) | 14 | (8 | ) | ||||||
| United Kingdom | (2 | ) | (3 | ) | 13 | ||||||
| Philippines | (1 | ) | 15 | 12 | |||||||
| Mexico | — | 17 | (8 | ) | |||||||
| Colombia | 6 | (23 | ) | (8 | ) | ||||||
| Corporate | 11 | 3 | (50 | ) | |||||||
| Other | 4 | 10 | 6 | ||||||||
| Total (2) | $ | (72 | ) | $ | 42 | $ | (15 | ) |
| (1) | Primarily associated with the peso-denominated energy receivable indexed to the USD through the FONINVEMEM agreement which is considered a foreign currency derivative. See Note 6—Financing Receivables included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information. |
| (2) | Includes gains of $23 million, losses of $21 million, and gains of $17 million on foreign currency derivative contracts for the years ended December 31, 2018, 2017 and 2016, respectively. |
The Company recognized net foreign currency transaction losses of $72 million for the year ended December 31, 2018 primarily due to the unrealized losses from the devaluation of receivables denominated in Argentine pesos and realized losses from Chilean pesos. These losses were partially offset by foreign currency derivative gains at the Parent Company.
The Company recognized net foreign currency transaction gains of $42 million for the year ended December 31, 2017 primarily driven by transactions associated with VAT activity in Mexico, the amortization of frozen embedded derivatives in the Philippines, and appreciation of the Euro in Bulgaria. These gains were partially offset by foreign currency derivative losses in Colombia due to a change in functional currency.
The Company recognized net foreign currency transaction losses of $15 million for the year ended December 31, 2016 primarily due to remeasurement losses on intercompany notes, and losses on swaps and options at the Parent Company. These losses were partially offset by foreign currency derivative gains related to government receivables in Argentina.
Other non-operating expense
Other non-operating expense was $147 million in 2018 primarily due to the $144 million other-than-temporary impairment of the Guacolda equity method investment as a result of increased renewable generation in Chile lowering energy prices and impacting the ability of Guacolda to re-contract its existing PPAs after they expire.
There were no significant other non-operating expenses in 2017 and 2016.
See Note 7—Investments in and Advances to Affiliates included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Income tax expense
Income tax expense decreased $282 million to $708 million in 2018 as compared to $990 million for 2017. The Company's effective tax rates were 35% and 128% for the years ended December 31, 2018 and 2017, respectively.
The net decrease in the 2018 effective tax rate was primarily due to greater 2017 impacts related to U.S. tax reform one-time transition tax and remeasurement of deferred tax assets, relative to the 2018 U.S. tax reform impact to adjust the provisional estimate recorded under SAB 118, which provides SEC guidance on the application of the accounting standards for the initial enactment impacts of the TCJA. This net decrease was also attributable to the impact of the sale of the Company's entire 51% equity interest in Masinloc, offset by taxation of our foreign subsidiaries under U.S. GILTI rules.
Income tax expense increased $958 million to $990 million in 2017 as compared to $32 million for 2016. The Company's effective tax rates were 128% and 17% for the years ended December 31, 2017 and 2016, respectively.
The net increase in the 2017 effective tax rate was due primarily to the enactment of the TCJA in the U.S., partially offset by the impacts of the 2016 Chilean tax law reform and the 2016 devaluation of the Mexican peso. See Note 21—Income Taxes included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional information regarding the 2016 Chilean income tax law reform.
Our effective tax rate reflects the tax effect of significant operations outside the U.S., which are generally taxed at rates different than the U.S. statutory rate. Foreign earnings may be taxed at rates higher than the U.S. corporate rate of 21% and are also subject to current U.S. taxation under the GILTI rules introduced by the TCJA. A future proportionate change in the composition of income before income taxes from foreign and domestic tax jurisdictions could impact our periodic effective tax rate. The Company also benefits from reduced tax rates in certain countries as a result of satisfying specific commitments regarding employment and capital investment. See Note 21—Income Taxes included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional information regarding these reduced rates.
Net equity in earnings of affiliates
Net equity in earnings of affiliates decreased $32 million, or 45%, to $39 million for 2018, compared to $71 million for 2017 primarily due to losses at Fluence, which was formed in the first quarter of 2018, decreased income at Guacolda, and larger gains on projects that achieved commercial operations in 2017 than in 2018 at sPower, which was purchased in the third quarter of 2017.
Net equity in earnings of affiliates increased $35 million, or 97%, to $71 million in 2017, compared to $36 million for 2016 primarily due to earnings at the sPower equity method investment purchased in 2017, partially offset by fixed asset impairments in 2017 at the Distributed Energy entities, accounted for as equity affiliates.
See Note 7—Investments In and Advances to Affiliates included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Net income (loss) from discontinued operations
Net income from discontinued operations was $216 million for the year ended December 31, 2018 primarily due to the after-tax gain on sale of Eletropaulo of $199 million recognized in the second quarter of 2018 and the recognition of a $26 million deferred gain upon liquidation of Borsod in October 2018.
Net loss from discontinued operations was $629 million for the year ended December 31, 2017 primarily due to the after-tax loss on deconsolidation of Eletropaulo of $611 million recognized in the fourth quarter of 2017. The remaining loss was due to a loss contingency recognized by our equity affiliate, partially offset by the income from operations of Eletropaulo prior to the date of deconsolidation.
Net loss from discontinued operations was $968 million for the year ended December 31, 2016 due to the sale of Sul, partially offset by the income from operations of Eletropaulo. The loss includes an after-tax loss on the impairment of Sul of $382 million recognized in the second quarter of 2016 and an additional after-tax loss on the sale of Sul of $737 million recognized upon disposal in October 2016. There was no significant loss from operations related to the Sul discontinued business.
See Note 22—Discontinued Operations included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Net income attributable to noncontrolling interests and redeemable stock of subsidiaries
Net income attributable to noncontrolling interests and redeemable stock of subsidiaries decreased $22 million, or 6%, to $362 million in 2018, compared to $384 million in 2017. This decrease was primarily due to:
-
Current year other-than-temporary impairment of Guacolda;
-
Prior year favorable impact of a legal settlement at Uruguaiana; and
-
Lower earnings due to deconsolidation of Eletropaulo in November 2017 and the sale of Masinloc in March 2018.
These decreases were partially offset by:
-
Current year gains on sales of Electrica Santiago and CTNG in Chile;
-
Higher earnings in Colombia primarily due to higher contract sales and prices; and
-
Higher earnings in Vietnam due to the adoption of the new revenue recognition standard (See Note 1—General and Summary of Significant Accounting Policies included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information).
Net income attributable to noncontrolling interests and redeemable stock of subsidiaries increased $31 million, or 9%, to $384 million in 2017, compared to $353 million in 2016. This increase was primarily due to:
- Asset impairments at Buffalo Gap I and II in 2016.
These increases were partially offset by:
- Income tax benefits at Eletropaulo in 2016 (reflected within discontinued operations).
Net income (loss) attributable to The AES Corporation
Net income attributable to The AES Corporation increased $2,364 million to $1,203 million in 2018, compared to a loss of $1,161 million in 2017. This increase was primarily due to:
| • | Gains on the sales of Masinloc, Eletropaulo (reflected within discontinued operations), CTNG, and Electrica Santiago, and prior year losses on the sales of Kazakhstan CHPs and HPPs; |
| • | Prior year loss on deconsolidation of Eletropaulo (reflected within discontinued operations); |
| • | Prior year impact of U.S. tax reform enacted in December 2017; |
| • | Prior year asset impairments at DPL, Laurel Mountain and in Kazakhstan; |
| • | Lower interest expense at the Parent Company and Gener; and |
| • | Higher margins at our South America, MCAC and US and Utilities SBUs. |
These increases were partially offset by:
| • | Higher current year tax expense due to the new GILTI rules in the U.S.; |
| • | Current year impairment at Shady Point; |
| • | Current year other-than-temporary impairment of Guacolda; |
| • | Higher losses on extinguishment of debt in the current year; |
| • | Current year foreign exchange losses primarily due to the devaluation of the Argentine peso and foreign currency gains in the prior year; |
| • | Prior year favorable impact of a legal settlement at Uruguaiana; and |
| • | Lower margins in the current year at our Eurasia SBU as a result of the sales of Masinloc and Kazakhstan. |
Net loss attributable to The AES Corporation increased $31 million, or 3%, to $1,161 million in 2017, compared to $1,130 million in 2016. This increase was primarily due to:
| • | Impact of U.S. tax reform enacted in December 2017; |
| • | Losses on the sales of Kazakhstan CHPs and HPPs; |
| • | Loss on deconsolidation of Eletropaulo (reflected within discontinued operations); |
| • | Impairments at Laurel Mountain, Kilroot and in Kazakhstan; and |
| • | Higher loss on extinguishment of debt. |
These increases were partially offset by:
| • | Impairments at DPL in 2016; |
| • | Loss on sale of Sul in 2016 (reflected within discontinued operations); |
| • | Favorable impact of a legal settlement at Uruguaiana; |
| • | Higher gains on foreign currency transactions; and |
| • | Higher margins at our MCAC SBU. |
SBU Performance Analysis
Segments
We are organized into four market-oriented SBUs: US and Utilities (United States, Puerto Rico and El Salvador); South America (Chile, Colombia, Argentina and Brazil); MCAC (Mexico, Central America and the Caribbean); and Eurasia (Europe and Asia). During the first quarter of 2018, the Andes and Brazil SBUs were merged in order to leverage scale and are now reported together as part of the South America SBU. Further, the Puerto Rico and El Salvador businesses, formerly part of the MCAC SBU, were combined with the US SBU, which is now reported as the US and Utilities SBU.
Non-GAAP Measures
Adjusted Operating Margin, Adjusted PTC and Adjusted EPS are non-GAAP supplemental measures that are used by management and external users of our Consolidated Financial Statements such as investors, industry analysts and lenders.
Effective January 1, 2018, the Company changed the definitions of Adjusted PTC and Adjusted EPS to exclude unrealized gains or losses from equity securities resulting from a newly effective accounting standard. We believe excluding these gains or losses provides a more accurate picture of continuing operations. Factors in this determination include the variability due to unrealized gains or losses related to equity securities remeasurement.
Adjusted Operating Margin
We define Adjusted Operating Margin as Operating Margin, adjusted for the impact of NCI, excluding (a) unrealized gains or losses related to derivative transactions; (b) benefits and costs associated with dispositions and acquisitions of business interests, including early plant closures; and (c) costs directly associated with a major restructuring program, including, but not limited to, workforce reduction efforts, relocations and office consolidation. The allocation of HLBV earnings to noncontrolling interests is not adjusted out of Adjusted Operating Margin. See Review of Consolidated Results of Operations for definitions of Operating Margin and cost of sales.
The GAAP measure most comparable to Adjusted Operating Margin is Operating Margin. We believe that Adjusted Operating Margin better reflects the underlying business performance of the Company. Factors in this determination include the impact of NCI, where AES consolidates the results of a subsidiary that is not wholly owned by the Company, as well as the variability due to unrealized gains or losses related to derivative transactions and strategic decisions to dispose of or acquire business interests. Adjusted Operating Margin should not be construed as an alternative to Operating Margin, which is determined in accordance with GAAP.
| Reconciliation of Adjusted Operating Margin (in millions) | Years Ended December 31, | ||||||||||
| 2018 | 2017 | 2016 | |||||||||
| Operating Margin | $ | 2,573 | $ | 2,465 | $ | 2,383 | |||||
| Noncontrolling interests adjustment (1) | (686 | ) | (689 | ) | (645 | ) | |||||
| Unrealized derivative losses (gains) | 19 | (5 | ) | 9 | |||||||
| Disposition/acquisition losses | 21 | 22 | — | ||||||||
| Restructuring costs (2) | 1 | 22 | — | ||||||||
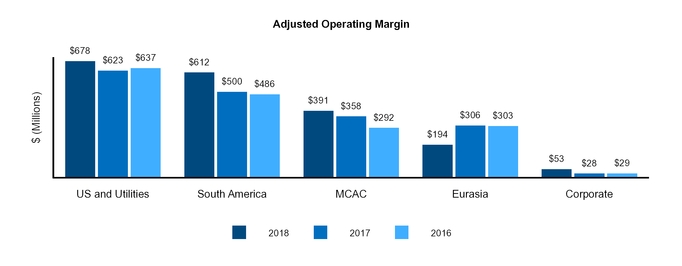
| Total Adjusted Operating Margin | $ | 1,928 | $ | 1,815 | $ | 1,747 |
| (1) | The allocation of HLBV earnings to noncontrolling interests is not adjusted out of Adjusted Operating Margin. |
| (2) | In February 2018, the Company announced a reorganization as a part of its ongoing strategy to simplify its portfolio, optimize its cost structure and reduce its carbon intensity. |
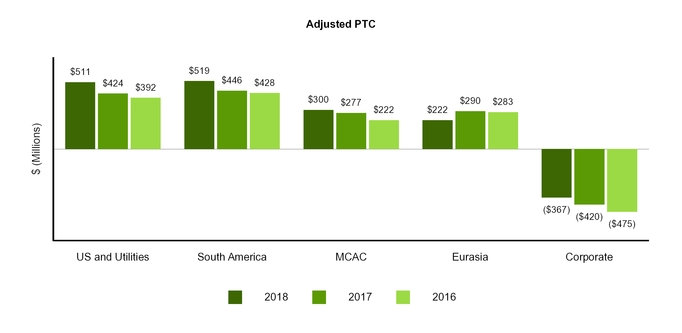
Adjusted PTC
We define Adjusted PTC as pre-tax income from continuing operations attributable to The AES Corporation excluding gains or losses of the consolidated entity due to (a) unrealized gains or losses related to derivative transactions and equity securities; (b) unrealized foreign currency gains or losses; (c) gains, losses, benefits and costs associated with dispositions and acquisitions of business interests, including early plant closures; (d) losses due to impairments; (e) gains, losses and costs due to the early retirement of debt; and (f) costs directly associated with a major restructuring program, including, but not limited to, workforce reduction efforts, relocations and office consolidation. Adjusted PTC also includes net equity in earnings of affiliates on an after-tax basis adjusted for the same gains or losses excluded from consolidated entities.
Adjusted PTC reflects the impact of NCI and excludes the items specified in the definition above. In addition to the revenue and cost of sales reflected in Operating Margin, Adjusted PTC includes the other components of our Consolidated Statement of Operations, such as general and administrative expenses in the Corporate segment, as well as business development costs, interest expense and interest income, other expense and other income, realized foreign currency transaction gains and losses, and net equity in earnings of affiliates.
The GAAP measure most comparable to Adjusted PTC is income from continuing operations attributable to The AES Corporation. We believe that Adjusted PTC better reflects the underlying business performance of the Company and is the most relevant measure considered in the Company's internal evaluation of the financial performance of its segments. Factors in this determination include the variability due to unrealized gains or losses related to derivative transactions or equity securities remeasurement, unrealized foreign currency gains or losses, losses due to impairments and strategic decisions to dispose of or acquire business interests, retire debt or implement restructuring initiatives, which affect results in a given period or periods. In addition, earnings before tax represents the business performance of the Company before the application of statutory income tax rates and tax adjustments, including the effects of tax planning, corresponding to the various jurisdictions in which the Company operates. Given its large number of businesses and complexity, the Company concluded that Adjusted PTC is a more transparent measure that better assists investors in determining which businesses have the greatest impact on the Company's results.
Adjusted PTC should not be construed as an alternative to income from continuing operations attributable to The AES Corporation, which is determined in accordance with GAAP.
| Reconciliation of Adjusted PTC (in millions) | Years Ended December 31, | ||||||||||
| 2018 | 2017 | 2016 | |||||||||
| Income (loss) from continuing operations, net of tax, attributable to The AES Corporation | $ | 985 | $ | (507 | ) | $ | (20 | ) | |||
| Income tax expense (benefit) attributable to The AES Corporation | 563 | 828 | (111 | ) | |||||||
| Pre-tax contribution | 1,548 | 321 | (131 | ) | |||||||
| Unrealized derivative and equity securities losses (gains) | 33 | (3 | ) | (9 | ) | ||||||
| Unrealized foreign currency losses (gains) | 51 | (59 | ) | 22 | |||||||
| Disposition/acquisition losses (gains) | (934 | ) | 123 | 6 | |||||||
| Impairment expense | 307 | 542 | 933 | ||||||||
| Loss on extinguishment of debt | 180 | 62 | 29 | ||||||||
| Restructuring costs (1) | — | 31 | — | ||||||||
| Total Adjusted PTC | $ | 1,185 | $ | 1,017 | $ | 850 |
| (1) | In February 2018, the Company announced a reorganization as a part of its ongoing strategy to simplify its portfolio, optimize its cost structure and reduce its carbon intensity. |
Adjusted EPS
We define Adjusted EPS as diluted earnings per share from continuing operations excluding gains or losses of both consolidated entities and entities accounted for under the equity method due to (a) unrealized gains or losses related to derivative transactions and equity securities; (b) unrealized foreign currency gains or losses; (c) gains, losses, benefits and costs associated with dispositions and acquisitions of business interests, including early plant closures, and the tax impact from the repatriation of sales proceeds; (d) losses due to impairments; (e) gains, losses and costs due to the early retirement of debt; (f) costs directly associated with a major restructuring program, including, but not limited to, workforce reduction efforts, relocations and office consolidation; and (g) tax benefit or expense related to the enactment effects of 2017 U.S. tax law reform and related regulations and any subsequent period adjustments related to enactment effects.
The GAAP measure most comparable to Adjusted EPS is diluted earnings per share from continuing operations. We believe that Adjusted EPS better reflects the underlying business performance of the Company and is considered in the Company's internal evaluation of financial performance. Factors in this determination include the variability due to unrealized gains or losses related to derivative transactions or equity securities remeasurement, unrealized foreign currency gains or losses, losses due to impairments and strategic decisions to dispose of or acquire business interests, retire debt or implement restructuring initiatives, which affect results in a given period or periods. Adjusted EPS should not be construed as an alternative to diluted earnings per share from continuing operations, which is determined in accordance with GAAP.
The Company reported a loss from continuing operations of $0.77 and $0.04 per share for the years ended December 31, 2017 and 2016, respectively. For purposes of measuring diluted loss per share under GAAP, common stock equivalents were excluded from weighted average shares as their inclusion would be anti-dilutive. However, for purposes of computing Adjusted EPS, the Company has included the impact of anti-dilutive common stock equivalents. The table below reconciles the weighted average shares used in GAAP diluted loss per share to
the weighted average shares used in calculating the non-GAAP measure of Adjusted EPS. No reconciliation is necessary for the year ended December 31, 2018 as the Company reported income from continuing operations.
| Reconciliation of Denominator Used For Adjusted Earnings Per Share | Year Ended December 31, 2017 | Year Ended December 31, 2016 | ||||||||||||||||||||
| (in millions, except per share data) | Loss | Shares | $ per share | Loss | Shares | $ per share | ||||||||||||||||
| GAAP DILUTED LOSS PER SHARE | ||||||||||||||||||||||
| Loss from continuing operations attributable to The AES Corporation common stockholders | $ | (507 | ) | 660 | $ | (0.77 | ) | $ | (25 | ) | 660 | $ | (0.04 | ) | ||||||||
| EFFECT OF ANTI-DILUTIVE SECURITIES | ||||||||||||||||||||||
| Restricted stock units | — | 2 | 0.01 | — | 2 | — | ||||||||||||||||
| NON-GAAP DILUTED LOSS PER SHARE | $ | (507 | ) | 662 | $ | (0.76 | ) | $ | (25 | ) | 662 | $ | (0.04 | ) |
| Reconciliation of Adjusted EPS | Years Ended December 31, | |||||||||||
| 2018 | 2017 | 2016 | ||||||||||
| Diluted earnings (loss) per share from continuing operations | $ | 1.48 | $ | (0.76 | ) | $ | (0.04 | ) | ||||
| Unrealized derivative and equity securities losses (gains) | 0.05 | — | (0.01 | ) | ||||||||
| Unrealized foreign currency losses (gains) | 0.09 | (1) | (0.10 | ) | 0.03 | |||||||
| Disposition/acquisition losses (gains) | (1.41 | ) | (2) | 0.19 | (3) | 0.01 | ||||||
| Impairment expense | 0.46 | (4) | 0.82 | (5) | 1.41 | (6) | ||||||
| Loss on extinguishment of debt | 0.27 | (7) | 0.09 | (8) | 0.05 | (9) | ||||||
| Restructuring costs | — | 0.05 | — | |||||||||
| U.S. Tax Law Reform Impact | 0.18 | (10) | 1.08 | (11) | — | |||||||
| Less: Net income tax expense (benefit) | 0.12 | (12) | (0.29 | ) | (13) | (0.51 | ) | (14) | ||||
| Adjusted EPS | $ | 1.24 | $ | 1.08 | $ | 0.94 |
| (1) | Amount primarily relates to unrealized FX losses of $22 million, or $0.03 per share, associated with the devaluation of long-term receivables denominated in Argentine pesos, and unrealized FX losses of $14 million, or $0.02 per share, on intercompany receivables denominated in Euros and British pounds at the Parent Company. |
| (2) | Amount primarily relates to gain on sale of Masinloc of $772 million, or $1.16 per share, gain on sale of CTNG of $86 million, or $0.13 per share, gain on sale of Electrica Santiago of $36 million, or $0.05 per share, gain on remeasurement of contingent consideration at AES Oahu of $32 million, or $0.05 per share, gain on sale related to the Company's contribution of AES Advancion energy storage to the Fluence joint venture of $23 million, or $0.03 per share and realized derivative gains associated with the sale of Eletropaulo of $21 million, or $0.03 per share; partially offset by loss on disposal of the Beckjord facility and additional shutdown costs related to Stuart and Killen at DPL of $21 million, or $0.03 per share. |
| (3) | Amount primarily relates to loss on sale of Kazakhstan CHPs of $49 million, or $0.07 per share, realized derivative losses associated with the sale of Sul of $38 million, or $0.06 per share, loss on sale of Kazakhstan HPPs of $33 million, or $0.05 per share, and costs associated with early plant closures at DPL of $24 million, or $0.04 per share; partially offset by gain on Masinloc contingent consideration of $23 million, or $0.03 per share and gain on sale of Miami Fort and Zimmer of $13 million, or $0.02 per share. |
| (4) | Amount primarily relates to asset impairments at Shady Point of $157 million, or $0.24 per share, and Nejapa of $37 million, or $0.06 per share, and other-than-temporary impairment of Guacolda of $96 million, or $0.14 per share. |
| (5) | Amount primarily relates to asset impairments at Kazakhstan CHPs of $94 million, or $0.14 per share, at Kazakhstan HPPs of $92 million, or $0.14 per share, at Laurel Mountain of $121 million, or $0.18 per share, at DPL of $175 million, or $0.27 per share and at Kilroot of $37 million, or $0.05 per share. |
| (6) | Amount primarily relates to asset impairments at DPL of $859 million, or $1.30 per share, at Buffalo Gap II of $159 million ($49 million, or $0.07 per share, net of NCI) and at Buffalo Gap I of $77 million ($23 million, or $0.03 per share, net of NCI). |
| (7) | Amount primarily relates to loss on early retirement of debt at the Parent Company of $171 million, or $0.26 per share. |
| (8) | Amount primarily relates to losses on early retirement of debt at the Parent Company of $92 million, or $0.14 per share, at AES Gener of $20 million, or $0.02 per share, and at IPALCO of $9 million or $0.01 per share; partially offset by a gain on early retirement of debt at AES Argentina of $65 million, or $0.10 per share. |
| (9) | Amount primarily relates to the loss on early retirement of debt at the Parent Company of $19 million, or $0.03 per share. |
| (10) | Amount relates to a SAB 118 charge to finalize the provisional estimate of one-time transition tax on foreign earnings of $194 million, or $0.29 per share, partially offset by a SAB 118 income tax benefit to finalize the provisional estimate of remeasurement of deferred tax assets and liabilities to the lower corporate tax rate of $77 million, or $0.11 per share. |
| (11) | Amount relates to a one-time transition tax on foreign earnings of $675 million, or $1.02 per share and the remeasurement of deferred tax assets and liabilities to the lower corporate tax rate of $39 million, or $0.06 per share. |
| (12) | Amount primarily relates to the income tax expense under the GILTI provision associated with the gains on sales of business interests, primarily Masinloc, of $97 million, or $0.15 per share, and income tax expense associated with gains on sale of CTNG of $36 million, or $0.05 per share and Electrica Santiago of $13 million, or $0.02 per share; partially offset by income tax benefits associated with the loss on early retirement of debt at the Parent Company of $36 million, or $0.05 per share, and income tax benefits associated with the impairment at Shady Point of $33 million, or $0.05 per share. |
| (13) | Amount primarily relates to the income tax benefit associated with asset impairments of $148 million, or $0.22 per share. |
| (14) | Amount primarily relates to the income tax benefit associated with asset impairments of $332 million, or $0.50 per share. |
US AND UTILITIES SBU
The following table summarizes Operating Margin, Adjusted Operating Margin and Adjusted PTC (in millions) for the periods indicated:
| For the Years Ended December 31, | 2018 | 2017 | 2016 | $ Change 2018 vs. 2017 | % Change 2018 vs. 2017 | $ Change 2017 vs. 2016 | % Change 2017 vs. 2016 | |||||||||||||||||||
| Operating Margin | $ | 733 | $ | 693 | $ | 719 | $ | 40 | 6 | % | $ | (26 | ) | -4 | % | |||||||||||
| Adjusted Operating Margin (1) | 678 | 623 | 637 | 55 | 9 | % | (14 | ) | -2 | % | ||||||||||||||||
| Adjusted PTC (1) | 511 | 424 | 392 | 87 | 21 | % | 32 | 8 | % |
| (1) | A non-GAAP financial measure, adjusted for the impact of NCI. See SBU Performance Analysis—Non-GAAP Measures for definition and Item 1.—Business for the respective ownership interest for key businesses. |
Fiscal year 2018 versus 2017
Operating Margin increased $40 million, or 6%, which was driven primarily by the following (in millions):
| Increase at DPL primarily due to higher regulated rates following the approval of the 2017 ESP and the 2018 distribution rate order and favorable weather | $ | 35 | |
| Increase at DPL driven by a one-time credit to depreciation expense, primarily as a result of a reduction in the ARO liability at DPL's closed plants, Stuart and Killen | 32 | ||
| Increase at IPL due to higher wholesale margins driven by Eagle Valley coming online and higher retail margins due to favorable weather | 23 | ||
| Increase at Southland driven by higher market energy sales, partially offset by a decrease in capacity sales and lower ancillary services due to the expiration of long-term agreements | 12 | ||
| Decrease at Hawaii primarily due to higher coal prices and lower gain on valuation of MTM commodity swaps | (24 | ) | |
| Impact of the sale and closure of generation plants at DPL | (12 | ) | |
| Decrease at IPL due to higher maintenance expense due to increased current year outages | (21 | ) | |
| Other | (5 | ) | |
| Total US and Utilities SBU Operating Margin Increase | $ | 40 |
Adjusted Operating Margin increased $55 million primarily due to the drivers above, adjusted for a $24 million unrealized loss on coal derivatives in Hawaii partially offset by restructuring charges in the prior year.
Adjusted PTC increased $87 million, primarily driven by the increase in Adjusted Operating Margin described above, as well as an increase in the Company's share of earnings at Distributed Energy due to new solar project growth, lower interest expense and the HLBV allocation of noncontrolling interest earnings at Buffalo Gap, partially offset by lower allowance for equity funds used during construction at IPALCO.
Fiscal year 2017 versus 2016
Operating Margin decreased $26 million, or 4%, which was driven primarily by the following (in millions):
| Decrease at DPL driven by lower retail margins due to lower regulated rates | $ | (22 | ) |
| Decrease at DPL primarily due to lower volumes due to the shutdown of Stuart Unit 1 and lower commercial availability | (21 | ) | |
| Decrease at IPL due to implementation of new base rates in Q2 2016 which resulted in a favorable change in accrual | (18 | ) | |
| Increase at DPL as a result of lower depreciation expense due to lower PP&E carrying values from impairments in 2016 and 2017 | 26 | ||
| Other | 9 | ||
| Total US and Utilities SBU Operating Margin Decrease | $ | (26 | ) |
Adjusted Operating Margin decreased $14 million primarily due to the drivers above, excluding unrealized gains and losses on derivatives, restructuring charges and costs associated with early plant closures.
Adjusted PTC increased $32 million, driven by earnings from equity affiliates due to the 2017 acquisition of sPower, the Company's share of earnings at Distributed Energy due to new solar project growth and an increase in insurance recoveries at DPL. The increase in Adjusted PTC was partially offset by the decrease of $14 million in Adjusted Operating Margin described above and a 2016 gain on contract termination at DP&L.
SOUTH AMERICA SBU
The following table summarizes Operating Margin, Adjusted Operating Margin and Adjusted PTC (in millions) for the periods indicated:
| For the Years Ended December 31, | 2018 | 2017 | 2016 | $ Change 2018 vs. 2017 | % Change 2018 vs. 2017 | $ Change 2017 vs. 2016 | % Change 2017 vs. 2016 | |||||||||||||||||||
| Operating Margin | $ | 1,017 | $ | 862 | $ | 823 | $ | 155 | 18 | % | $ | 39 | 5 | % | ||||||||||||
| Adjusted Operating Margin (1) | 612 | 500 | 486 | 112 | 22 | % | 14 | 3 | % | |||||||||||||||||
| Adjusted PTC (1) | 519 | 446 | 428 | 73 | 16 | % | 18 | 4 | % |
| (1) | A non-GAAP financial measure, adjusted for the impact of NCI. See SBU Performance Analysis—Non-GAAP Measures for definition and Item 1.—Business for the respective ownership interest for key businesses. |
Fiscal year 2018 versus 2017
Operating Margin increased $155 million, or 18%, which was driven primarily by the following (in millions):
| Increase in Argentina mainly related to higher capacity prices resulting from market reforms enacted in 2017 and lower fixed costs primarily due to the devaluation of the Argentine peso | $ | 71 | |
| Increase in Colombia mainly related to higher contract pricing in 2018 and higher generation | 64 | ||
| Margin on new PPAs in Chile at Gener, Angamos and Cochrane | 50 | ||
| Impact of the sale of Electrica Santiago | (38 | ) | |
| Lower fixed costs at Gener associated with planned maintenance performed in Q3 2017 | 21 | ||
| Lower contract sales to distribution companies in Chile net of higher revenue associated with a contract termination | (24 | ) | |
| Other | 11 | ||
| Total South America SBU Operating Margin Increase | $ | 155 |
Adjusted Operating Margin increased $112 million primarily due to the drivers above, adjusted for NCI.
Adjusted PTC increased $73 million, mainly due to the increase in Adjusted Operating Margin described above and lower interest in Chile, partially offset by a $28 million decrease associated with a gain recognized in the prior year from the settlement of a legal dispute with YPF at Uruguaiana, higher interest expense in Brazil, lower equity earnings in Chile and higher realized foreign currency losses in Argentina.
Fiscal year 2017 versus 2016
Including the favorable impact of foreign currency translation and remeasurement of $38 million, Operating Margin increased $39 million, or 5%, which was driven primarily by the following (in millions):
| Start of operations at Cochrane Units I and II in July and October 2016, respectively | $ | 72 | |
| Higher capacity payments in Argentina primarily due to changes in regulation in 2017 | 64 | ||
| Net impact of volume and prices of lower energy purchased in spot market at Tietê | 71 | ||
| Higher contract sales at Chivor primarily due to an increase in contracted capacity at higher prices | 35 | ||
| Higher volume due to acquisition of new wind entities - Alto Sertão II | 23 | ||
| Favorable FX impacts at Tietê | 21 | ||
| Net impact of volume and prices of bilateral contracts due to higher energy purchased at Tietê | (100 | ) | |
| Negative impact in Gener due to new regulation on emissions (Green Taxes) | (41 | ) | |
| Lower spot sales at Chivor mainly due to lower generation and lower spot prices | (37 | ) | |
| Lower availability of efficient generation resulting in higher replacement energy and fixed costs, mainly associated with major maintenance at Ventanas Complex in Chile | (29 | ) | |
| Lower margin at the SING market primarily due to lower contract sales and increase in coal prices at Norgener partially offset by higher spot sales | (21 | ) | |
| Lower generation at CTSN mainly due to lower demand | (26 | ) | |
| Other | 7 | ||
| Total South America SBU Operating Margin Increase | $ | 39 |
Adjusted Operating Margin increased $14 million primarily due to the drivers above, adjusted for NCI.
Adjusted PTC increased $18 million, driven by a $28 million increase from the settlement of a legal dispute with YPF at Uruguaiana in 2017 and the $14 million increase in Adjusted Operating Margin described above, as well as foreign currency gains in Argentina associated with the collection of financing receivables, prepayment of financial debt denominated in U.S. dollars in 2017 and lower foreign currency losses associated with the sale of Argentina’s sovereign bonds at Termoandes. These positive impacts were partially offset by higher interest expense, mainly due to the acquisition of Alto Sertão II debt, issuance of debt at Argentina and lower interest capitalization in Cochrane and Chivor, and the write-off of water rights at Gener resulting from a business development project that is no longer pursued.
MCAC SBU
The following table summarizes Operating Margin, Adjusted Operating Margin and Adjusted PTC (in millions) for the periods indicated:
| For the Years Ended December 31, | 2018 | 2017 | 2016 | $ Change 2018 vs. 2017 | % Change 2018 vs. 2017 | $ Change 2017 vs. 2016 | % Change 2017 vs. 2016 | |||||||||||||||||||
| Operating Margin | $ | 534 | $ | 465 | $ | 390 | $ | 69 | 15 | % | $ | 75 | 19 | % | ||||||||||||
| Adjusted Operating Margin (1) | 391 | 358 | 292 | 33 | 9 | % | 66 | 23 | % | |||||||||||||||||
| Adjusted PTC (1) | 300 | 277 | 222 | 23 | 8 | % | 55 | 25 | % |
| (1) | A non-GAAP financial measure, adjusted for the impact of NCI. See SBU Performance Analysis—Non-GAAP Measures for definition and Item 1.—Business for the respective ownership interest for key businesses. |
Fiscal year 2018 versus 2017
Operating Margin increased $69 million, or 15%, which was driven primarily by the following (in millions):
| Increase in Dominican Republic due to higher spot prices | $ | 32 | |
| Higher contracted energy sales in Panama mainly driven by the commencement of operations at the Colon combined cycle facility in September 2018 | 21 | ||
| Higher availability driven by improved hydrology in Panama | 17 | ||
| Higher contracted energy sales in Dominican Republic mainly driven by the commencement of operations at the Los Mina combined cycle facility in June 2017 and lower forced maintenance outages | 12 | ||
| Decrease in Mexico due to pension plan pass-through adjustments and higher fuel costs | (8 | ) | |
| Other | (5 | ) | |
| Total MCAC SBU Operating Margin Increase | $ | 69 |
Adjusted Operating Margin increased $33 million primarily due to the drivers above, adjusted for NCI.
Adjusted PTC increased $23 million, mainly driven by the increase in Adjusted Operating Margin as described above, partially offset by lower capitalized interest due to project completions in Panama and Dominican Republic and lower foreign currency gains in Mexico.
Fiscal year 2017 versus 2016
Operating Margin increased $75 million, or 19%, which was driven primarily by the following (in millions):
| Higher contracted energy sales in Dominican Republic net of LNG fuel consumption, mainly driven by Los Mina combined cycle commencement of operations in June 2017 | $ | 34 | |
| Higher availability driven by improved hydrology in Panama | 26 | ||
| Higher availability in Mexico mainly driven by unplanned maintenance in 2016 | 13 | ||
| Other | 2 | ||
| Total MCAC SBU Operating Margin Increase | $ | 75 |
Adjusted Operating Margin increased $66 million primarily due to the drivers above, adjusted for NCI.
Adjusted PTC increased $55 million, driven by the increase in Adjusted Operating Margin of $66 million as described above.
EURASIA SBU
The following table summarizes Operating Margin, Adjusted Operating Margin and Adjusted PTC (in millions) for the periods indicated:
| For the Years Ended December 31, | 2018 | 2017 | 2016 | $ Change 2018 vs. 2017 | % Change 2018 vs. 2017 | $ Change 2017 vs. 2016 | % Change 2017 vs. 2016 | |||||||||||||||||||
| Operating Margin | $ | 227 | $ | 422 | $ | 427 | $ | (195 | ) | -46 | % | $ | (5 | ) | -1 | % | ||||||||||
| Adjusted Operating Margin (1) | 194 | 306 | 303 | (112 | ) | -37 | % | 3 | 1 | % | ||||||||||||||||
| Adjusted PTC (1) | 222 | 290 | 283 | (68 | ) | -23 | % | 7 | 2 | % |
| (1) | A non-GAAP financial measure, adjusted for the impact of NCI. See SBU Performance Analysis—Non-GAAP Measures for definition and Item 1.—Business for the respective ownership interest for key businesses. |
Fiscal year 2018 versus 2017
Including favorable FX impacts of $8 million, Operating Margin decreased $195 million, or 46%, which was driven primarily by the following (in millions):
| Impact of the sale of Masinloc power plant in March 2018 | $ | (122 | ) |
| Impact of the sale of the Kazakhstan CHPs and the expiration of HPP concession in 2017 | (36 | ) | |
| Decrease in Vietnam due to adoption of the new revenue recognition standard in 2018 and higher maintenance costs | (33 | ) | |
| Other | (4 | ) | |
| Total Eurasia SBU Operating Margin Decrease | $ | (195 | ) |
Adjusted Operating Margin decreased $112 million, or 37%, primarily due to the drivers above, adjusted for NCI.
Adjusted PTC decreased $68 million, primarily driven by the decrease in Adjusted Operating Margin discussed above, partially offset by the positive impact in Vietnam due to increased interest income from the higher financing component of contract consideration as a result of adoption of the new revenue recognition standard in 2018. See Note 1—General and Summary of Significant Accounting Policies—New Accounting Standards Adopted included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Fiscal year 2017 versus 2016
Operating Margin decreased $5 million, or 1%, and Adjusted Operating Margin increased $3 million, or 1%, with no material drivers.
Adjusted PTC increased $7 million, primarily driven by the increase in Adjusted Operating Margin, adjusted for NCI and excluding unrealized gains and losses on derivatives.
Key Trends and Uncertainties
During 2019 and beyond, we expect to face the following challenges at certain of our businesses. Management expects that improved operating performance at certain businesses, growth from new businesses, and global cost reduction initiatives may lessen or offset their impact. If these favorable effects do not occur, or if the challenges described below and elsewhere in this section impact us more significantly than we currently anticipate, or if volatile foreign currencies and commodities move more unfavorably, then these adverse factors (or other adverse factors unknown to us) may impact our operating margin, net income attributable to The AES Corporation and cash flows. We continue to monitor our operations and address challenges as they arise. For the risk factors related to our business, see Item 1.—Business and Item 1A.—Risk Factors of this Form 10-K.
Macroeconomic and Political
The macroeconomic and political environments in some countries where our subsidiaries conduct business have changed during 2018. This could result in significant impacts to tax laws and environmental and energy policies. Additionally, we operate in multiple countries and as such are subject to volatility in exchange rates at the subsidiary level. See Item 7A.—Quantitative and Qualitative Disclosures About Market Risk for further information.
United States Tax Law Reform
In December 2017, the United States enacted the TCJA. The legislation significantly revised the U.S. corporate income tax system by, among other things, lowering the corporate income tax rate, introducing new limitations on interest expense deductions, subjecting foreign earnings in excess of an allowable return to current U.S. taxation, and adopting a semi-territorial corporate tax system. These changes impacted our 2018 effective tax rate and will materially impact our effective tax rate in future periods. Furthermore, we anticipate that higher U.S. tax expense may fully utilize our remaining net operating loss carryforwards in the near term, which could lead to material cash tax payments in the United States. Specific provisions of the TCJA and their potential impacts on the Company are noted below. Our interpretation of the TCJA may change as the U.S. Treasury and the Internal Revenue Service issue additional guidance. Such changes may be material.
Transition Tax — As further explained in Note 21—Income Taxes included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K we have concluded our analysis of the implementation impacts of the TCJA and included adjustments to our previous estimates in accordance with the guidance of SAB 118. Our revised estimates took into account interpretative guidance issued in 2018 by the U.S. Treasury in proposed regulations. In the first quarter of 2019, the U.S. Treasury issued final regulations related to the one-time transition tax which further amended the guidance of the proposed regulations. We are still evaluating the final regulations which may have a material impact on our financial statements. The impacts of the final regulations will be reflected in our financial statements during the quarter ended March 31, 2019.
Limitation on Interest Expense Deductions — The TCJA introduced a new limitation on the deductibility of net interest expense beginning January 1, 2018. The deduction will be limited to interest income, plus 30 percent of tax basis EBITDA through 2021 (30 percent of EBIT beginning January 1, 2022). This determination is made at the consolidated group level, although it applies separately to partnerships. While interest expense of regulated utilities may be exempt from the limitation, the proposed regulations issued by the U.S. Treasury in 2018 would effectively limit interest expense of our U.S. utilities. The proposed regulations may change before they are fully enacted in final form and are not retroactive; we have not early adopted the proposed regulations. Given typical project financing and current U.S. holding company debt levels, we anticipate that this limitation will materially, negatively impact our effective tax rate.
Global Intangible Low Taxed Income (“GILTI”) — The TCJA subjects the earnings of foreign subsidiaries to current U.S. taxation to the extent that those earnings exceed an allowable economic return on investment. The foreign earnings subject to current taxation under the GILTI provision are not limited to those derived from intangible property and may include gains derived from some future asset sales. The GILTI provision will subject a significant portion of our foreign earnings to current U.S. taxation. In 2018, the GILTI provision materially, negatively impacted our effective tax rate and we expect this to continue in future years. Prospectively, the consequences of the new GILTI provision may be partially mitigated by foreign tax credits. Proposed regulations
were issued in 2018 by the U.S. Treasury which provided further guidance on GILTI and the related foreign tax credit, however there are further regulations expected and they may change before enacted in final form.
State Taxes — The reactions of the individual states to federal tax reform are still evolving. Most states will assess whether and how the federal changes will be incorporated into their state tax legislation. Some states have already decided whether to conform to new provisions of the federal tax law, such as the one-time transition tax and GILTI, while many other states have not yet enacted final legislation. As we expect higher taxable income in the future due to the federal changes, this may also lead to higher state taxable income. Our current state tax provisions predominantly have full valuation allowances against state net operating losses. These positions will be re-assessed in the future as state tax law evolves and may result in material changes in position.
Tax Equity Structures — Our U.S. renewable energy portfolio operates primarily through tax equity partnerships. We cannot be certain of the impacts U.S. tax reform may have on availability or pricing of tax equity for future growth opportunities. Impacts of provisions such as the lower tax rate and immediate expensing may impact the amount and timing of returns allocable to our partners in our existing tax equity structures.
Puerto Rico — Our subsidiaries in Puerto Rico have a long-term PPA with state-owned PREPA, which has been facing economic challenges that could result in a material adverse effect on our business in Puerto Rico.
The Puerto Rico Oversight, Management, and Economic Stability Act (“PROMESA”) was enacted to create a structure for exercising federal oversight over the fiscal affairs of U.S. territories and created procedures for adjusting debt accumulated by the Puerto Rico government and, potentially, other territories (“Title III”). Finally, PROMESA expedites the approval of key energy projects and other critical projects in Puerto Rico.
PROMESA allowed for the establishment of an Oversight Board with broad powers of budgetary and financial control over Puerto Rico. The Oversight Board filed for bankruptcy on behalf of PREPA under Title III in July 2017. As a result of the bankruptcy filing, AES Puerto Rico and AES Ilumina’s non-recourse debt of $317 million and $34 million, respectively, continue to be in default and are classified as current as of December 31, 2018. The Company is in compliance with its debt payment obligations as of December 31, 2018.
After the events of Hurricanes Irma and Maria in September 2017, Puerto Rico’s infrastructure was severely damaged, including electric infrastructure and transmission lines. AES Puerto Rico resumed generation during the first quarter of 2018 and continues to be the lowest cost and EPA compliant energy provider in Puerto Rico and a critical supplier to PREPA. According to the US Federal Emergency Management Agency, as of January 2019 PREPA's recovery status is at 99%.
The Company's receivable balances in Puerto Rico as of December 31, 2018 totaled $68 million, of which $18 million was overdue. Despite the disruption caused by the hurricanes and the Title III protection, PREPA has been making substantially all of its payments to the generators in line with historical payment patterns.
A proposed Energy Public Policy law was introduced in October 2018 which includes the elimination of coal as a source for electricity generation by January 1, 2028 and the accelerated deployment of renewables (20% by 2025; 50% by 2040 and 100% by 2050). AES Puerto Rico's long-term PPA with PREPA expires December 31, 2027. Puerto Rico's Senate and House of Representatives are still debating certain amendments.
Considering the information available as of the filing date, Management believes the carrying amount of our assets in Puerto Rico of $598 million is recoverable as of December 31, 2018.
Argentina — During the second quarter of 2018, all of the three-year cumulative inflation rates commonly used to evaluate Argentina’s inflation exceeded 100%. Therefore, Argentina’s economy was determined to be highly inflationary. Since the tariffs and debt at our primary businesses in Argentina are denominated in USD, the functional currency of those businesses is USD. As such, the determination that the Argentina economy is highly inflationary is not expected to have a material impact on the Company’s financial statements.
United Kingdom — In June 2016, the UK held a referendum in which voters approved an exit from the EU, commonly referred to as “Brexit.” In January 2019, the UK parliament rejected a proposed withdrawal agreement that the EU had supported. The UK is expected to exit the EU on March 29, 2019. While the full impact of the Brexit remains uncertain, these changes are not expected to have a material adverse effect on our operations and consolidated financial results.
LIBOR Phase Out — In July 2017, the UK Financial Conduct Authority announced the phase out of LIBOR by the end of 2021. The Alternative Reference Rate Committee at the Federal Reserve is working to establish a new benchmark replacement rate. While AES maintains financial instruments that use LIBOR as an interest rate
benchmark, the full impact of the phase out is uncertain until a new replacement benchmark is determined and implementation plans are more fully developed.
Regulatory
Maritza PPA Review — The DG Comp continues to review whether Maritza’s PPA with NEK is compliant with the European Commission’s state aid rules. Although no formal investigation has been launched by DG Comp to date, Maritza has engaged in discussions with the DG Comp case team and representatives of Bulgaria to discuss the agency’s review. In the near term, Maritza expects that it will engage in discussions with Bulgaria to attempt to reach a negotiated resolution concerning DG Comp’s review. The anticipated discussions could involve a range of potential outcomes, including but not limited to termination of the PPA and payment of some level of compensation to Maritza. Any negotiated resolution would be subject to mutually acceptable terms, lender consent, and DG Comp approval. At this time, we cannot predict the outcome of the anticipated discussions between Maritza and Bulgaria, nor can we predict how DG Comp might resolve its review if the discussions fail to result in an agreement concerning the review. Maritza believes that its PPA is legal and in compliance with all applicable laws, and it will take all actions necessary to protect its interests, whether through negotiated agreement or otherwise. However, there can be no assurances that this matter will be resolved favorably; if it is not, there could be a material adverse impact on Maritza’s and the Company’s respective financial statements.
Considering the information available as of the filing date, Management believes the carrying value of our long-lived assets at Maritza of approximately $1.1 billion is recoverable as of December 31, 2018.
Foreign Exchange
We operate in multiple countries and as such are subject to volatility in exchange rates at varying degrees at the subsidiary level and between our functional currency, the USD, and currencies of the countries in which we operate. In 2018, there was a significant devaluation in the Argentine peso against the USD, which had an impact on our 2018 results. Continued material devaluation of the Argentine peso against the USD could have an impact on our future results. For additional information, refer to Item 7A.—Quantitative and Qualitative Disclosures About Market Risk.
Alto Maipo
Alto Maipo has experienced cost overruns which have resulted in increased projected costs over the original $2 billion budget. Construction at the project is continuing, and the project is 75% complete.
In February 2018, Alto Maipo entered into a new construction contract with Strabag. The new contract is fixed-price and lump sum, transfers geological and construction risk to Strabag and provides a date certain for completion with strong performance and completion guarantees.
In May 2018, Alto Maipo and the project's senior lenders executed the financial restructuring of the project. The restructuring, among other things, includes additional funding commitments of up to $400 million of which $200 million was already contributed by AES Gener. Any unused portion of AES Gener's commitment will be used to prepay project debt.
If Alto Maipo is unable to meet certain construction milestones, there could be a material impact to the financing and value of the project which could have a material impact on the Company. The carrying value of long-lived assets and deferred tax assets of Alto Maipo as of December 31, 2018 was approximately $2 billion and $60 million, respectively. Management believes the carrying value of the long-lived asset group is recoverable as of December 31, 2018. In addition, Management believes it is more likely than not the deferred tax assets will be realized; however, the deferred tax assets could be reduced if estimates of future taxable income are decreased.
Andres
On September 3, 2018, lightning affected the Andres 319 MW combined cycle natural gas facility in the Dominican Republic (“the Plant”) resulting in significant damage to its steam turbine and generator. The Company has business interruption and property damage insurance coverage, subject to pre-defined deductibles, under its existing programs.
On September 25, 2018, the Plant restarted operations running the gas turbine in simple cycle at partial load of approximately 120 MW. Management estimates that the Plant will operate the gas turbine in simple cycle at full load of approximately 185 MW starting in the second quarter of 2019, and in combined cycle at full capacity by the fourth quarter of 2019.
To mitigate the impact of the reduced capacity in the local energy market, the Company installed 120 MW of rental power (gas turbines) until the combined cycle facility is at full load. The rental units were fully operational beginning in December 2018.
Considering the information available as of the filing date, Management believes the carrying amount of our long-lived assets in Andres of $395 million is recoverable as of December 31, 2018.
Changuinola Tunnel Leak
Increased water levels were noted in a creek near the Changuinola power plant, a 223 MW hydroelectric power facility in Panama. After the completion of an assessment, the Company has confirmed loss of water in specific sections of the tunnel. The plant is in operation and can generate up to its maximum capacity. Repairs will be needed to ensure the long term performance of the facility, during which time the affected units of the plant will be out of service. Subject to final inspection, the repairs may take up to 10 months to complete and are expected to commence during the first quarter of 2019. The Company has notified its insurers of a potential claim and has asserted claims against its construction contractor. However, there can be no assurance of collection. The Company continues to monitor the situation to identify any potential changes to the tunnel. The Company has not identified any indicators of impairment and believes the carrying value of the long-lived asset group of $931 million is recoverable as of December 31, 2018.
Impairments
Long-lived Assets and Equity Affiliates — During the year ended December 31, 2018, the Company recognized asset and other-than-temporary impairment expense of $355 million. See Note 7—Investments In and Advances To Affiliates and Note 20—Asset Impairment Expense included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information. After recognizing this impairment expense, the carrying value of the equity affiliates and the asset groups, including long-lived assets, and those asset groups that were assessed and not impaired, totaled $661 million at December 31, 2018.
Events or changes in circumstances that may necessitate recoverability tests and potential impairments of long-lived assets may include, but are not limited to, adverse changes in the regulatory environment, unfavorable changes in power prices or fuel costs, increased competition due to additional capacity in the grid, technological advancements, declining trends in demand, or an expectation it is more likely than not the asset will be disposed of before the end of its estimated useful life.
Goodwill — The Company considers a reporting unit at risk of impairment when its fair value does not exceed its carrying amount by more than 10%. During the annual goodwill impairment test performed as of October 1, 2018, the Company determined that the fair value of its Gener reporting unit exceeded its carrying value by 7%. Therefore, Gener's $868 million goodwill balance was considered to be "at risk" as of December 31, 2018, largely due to the fact that a market participant would no longer assume perpetual cash flows from coal-fired power plants due to the increased penetration of renewable energy in Chile.
Through 2028, Gener’s plants remain largely contracted, with most of its PPAs expiring between 2029 and 2037. The Company utilized the income approach in deriving the fair value of the Gener reporting unit, which included estimated cash flows assuming a 20-year annuity for thermal generation and longer term cash flows for hydro generation. These cash flows were discounted using a weighted average cost of capital of 7%, which was determined based on the Capital Asset Pricing Model. See Item 7.—Critical Accounting Policies and Estimates—Fair Value of Nonfinancial Assets and Liabilities and Note 8—Goodwill and Other Intangible Assets included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
The Company monitors its reporting units at risk of Step 1 failure on an ongoing basis, and believes that the estimates and assumptions used in the calculations are reasonable. Should the fair value of any of the Company’s reporting units fall below its carrying amount because of reduced operating performance, market declines, changes in the discount rate, regulatory changes, or other adverse conditions, goodwill impairment charges may be necessary in future periods.
Capital Resources and Liquidity
Overview — As of December 31, 2018, the Company had unrestricted cash and cash equivalents of $1.2 billion, of which $24 million was held at the Parent Company and qualified holding companies. The Company also had $313 million in short term investments, held primarily at subsidiaries. In addition, we had restricted cash and debt service reserves of $837 million. The Company also had non-recourse and recourse aggregate principal amounts of debt outstanding of $15.6 billion and $3.7 billion, respectively. Of the approximately $1.7 billion of our current non-recourse debt, $825 million was presented as such because it is due in the next twelve months, $351
million relates to debt considered in default due to covenant violations, and $483 million relates to debt at Colon which is in compliance with its covenants, but is presented as current since it is probable that the Company cannot meet a technical covenant requirement by its deadline. None of the defaults are payment defaults, but are instead technical defaults triggered by failure to comply with other covenants and/or other conditions such as (but not limited to) failure to meet information covenants, complete construction or other milestones in an allocated time, meet certain minimum or maximum financial ratios, or other requirements contained in the non-recourse debt documents of the Company. The Company expects to modify the Colon loan agreement in 2019 to amend the requirements of this technical covenant, after which the debt will be re-classified as noncurrent.
We expect such current maturities will be repaid from net cash provided by operating activities of the subsidiary to which the debt relates, through opportunistic refinancing activity or some combination thereof. We have $5 million of recourse debt which matures within the next twelve months. From time to time, we may elect to repurchase our outstanding debt through cash purchases, privately negotiated transactions or otherwise when management believes that such securities are attractively priced. Such repurchases, if any, will depend on prevailing market conditions, our liquidity requirements and other factors. The amounts involved in any such repurchases may be material.
We rely mainly on long-term debt obligations to fund our construction activities. We have, to the extent available at acceptable terms, utilized non-recourse debt to fund a significant portion of the capital expenditures and investments required to construct and acquire our electric power plants, distribution companies and related assets. Our non-recourse financing is designed to limit cross default risk to the Parent Company or other subsidiaries and affiliates. Our non-recourse long-term debt is a combination of fixed and variable interest rate instruments. Generally, a portion or all of the variable rate debt is fixed through the use of interest rate swaps. In addition, the debt is typically denominated in the currency that matches the currency of the revenue expected to be generated from the benefiting project, thereby reducing currency risk. In certain cases, the currency is matched through the use of derivative instruments. The majority of our non-recourse debt is funded by international commercial banks, with debt capacity supplemented by multilaterals, export credit agencies and local regional banks.
Given our long-term debt obligations, the Company is subject to interest rate risk on debt balances that accrue interest at variable rates. When possible, the Company will borrow funds at fixed interest rates or hedge its variable rate debt to fix its interest costs on such obligations. In addition, the Company has historically tried to maintain at least 70% of its consolidated long-term obligations at fixed interest rates, including fixing the interest rate through the use of interest rate swaps. These efforts apply to the notional amount of the swaps compared to the amount of related underlying debt. Presently, the Parent Company's only material unhedged exposure to variable interest rate debt relates to indebtedness under its $366 million outstanding secured term loan due 2022. On a consolidated basis, of the Company's $19.7 billion of total gross debt outstanding as of December 31, 2018, approximately $3.2 billion bore interest at variable rates that were not subject to a derivative instrument which fixed the interest rate. Brazil holds $1.1 billion of our floating rate non-recourse exposure as we have no ability to fix local debt interest rates efficiently.
In addition to utilizing non-recourse debt at a subsidiary level when available, the Parent Company provides a portion, or in certain instances all, of the remaining long-term financing or credit required to fund development, construction or acquisition of a particular project. These investments have generally taken the form of equity investments or intercompany loans, which are subordinated to the project's non-recourse loans. We generally obtain the funds for these investments from our cash flows from operations, proceeds from the sales of assets and/or the proceeds from our issuances of debt, common stock and other securities. Similarly, in certain of our businesses, the Parent Company may provide financial guarantees or other credit support for the benefit of counterparties who have entered into contracts for the purchase or sale of electricity, equipment or other services with our subsidiaries or lenders. In such circumstances, if a business defaults on its payment or supply obligation, the Parent Company will be responsible for the business' obligations up to the amount provided for in the relevant guarantee or other credit support. At December 31, 2018, the Parent Company had provided outstanding financial and performance-related guarantees or other credit support commitments to or for the benefit of our businesses, which were limited by the terms of the agreements, of approximately $712 million in aggregate (excluding those collateralized by letters of credit and other obligations discussed below).
As a result of the Parent Company's below investment grade rating, counterparties may be unwilling to accept our general unsecured commitments to provide credit support. Accordingly, with respect to both new and existing commitments, the Parent Company may be required to provide some other form of assurance, such as a letter of credit, to backstop or replace our credit support. The Parent Company may not be able to provide adequate assurances to such counterparties. To the extent we are required and able to provide letters of credit or other collateral to such counterparties, this will reduce the amount of credit available to us to meet our other liquidity
needs. At December 31, 2018, we had $78 million in letters of credit outstanding, provided under our senior secured credit facility, $368 million in letters of credit outstanding, provided under our unsecured senior credit facility. These letters of credit operate to guarantee performance relating to certain project development and construction activities and business operations. During the year ended December 31, 2018, the Company paid letter of credit fees ranging from 1% to 3% per annum on the outstanding amounts.
We expect to continue to seek, where possible, non-recourse debt financing in connection with the assets or businesses that we or our affiliates may develop, construct or acquire. However, depending on local and global market conditions and the unique characteristics of individual businesses, non-recourse debt may not be available on economically attractive terms or at all. If we decide not to provide any additional funding or credit support to a subsidiary project that is under construction or has near-term debt payment obligations and that subsidiary is unable to obtain additional non-recourse debt, such subsidiary may become insolvent, and we may lose our investment in that subsidiary. Additionally, if any of our subsidiaries lose a significant customer, the subsidiary may need to withdraw from a project or restructure the non-recourse debt financing. If we or the subsidiary choose not to proceed with a project or are unable to successfully complete a restructuring of the non-recourse debt, we may lose our investment in that subsidiary.
Many of our subsidiaries depend on timely and continued access to capital markets to manage their liquidity needs. The inability to raise capital on favorable terms, to refinance existing indebtedness or to fund operations and other commitments during times of political or economic uncertainty may have material adverse effects on the financial condition and results of operations of those subsidiaries. In addition, changes in the timing of tariff increases or delays in the regulatory determinations under the relevant concessions could affect the cash flows and results of operations of our businesses.
Long-Term Receivables — As of December 31, 2018, the Company had approximately $116 million of accounts receivable classified as Other noncurrent assets primarily related to certain of its generation businesses in Argentina. These noncurrent receivables mostly consist of accounts receivable in Argentina that, pursuant to amended agreements or government resolutions, have collection periods that extend beyond December 31, 2019, or one year from the latest balance sheet date. The majority of Argentinian receivables have been converted into long-term financing for the construction of power plants. See Note 6—Financing Receivables included in Item 8.—Financial Statements and Supplementary Data and Item 1.—Business—Regulatory Matters—Argentina of this Form 10-K for further information.
As of December 31, 2018, the Company had approximately $1.4 billion of loans receivable primarily related to the Mong Duong II facility constructed under a build, operate, and transfer contract in Vietnam. This loan receivable represents contract consideration related to the construction of the facility, which was substantially completed in 2015, and will be collected over the 25 year term of the plant's PPA. See Note 18—Revenue included in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for further information.
Cash Sources and Uses
The primary sources of cash for the Company in the year ended December 31, 2018 were cash flows from operating activities, proceeds from the sales of business interests, and debt financings. The primary uses of cash in the year ended December 31, 2018 were repayments of debt, capital expenditures, and purchases of short-term investments.
The primary sources of cash for the Company in the year ended December 31, 2017 were cash flows from operating activities, debt financings, and sales of short-term investments. The primary uses of cash in the year ended December 31, 2017 were repayments of debt, purchases of short-term investments, and capital expenditures.
The primary sources of cash for the Company in the year ended December 31, 2016 were cash flows from operating activities, debt financings, and sales of short-term investments. The primary uses of cash in the year ended December 31, 2016 were repayments of debt, purchases of short-term investments, and capital expenditures.
A summary of cash-based activities are as follows (in millions):
| Year Ended December 31, | |||||||||||
| Cash Sources: | 2018 | 2017 | 2016 | ||||||||
| Net income, adjusted for non-cash items (1) | $ | 2,529 | $ | 2,569 | $ | 2,344 | |||||
| Proceeds from the sale of business interests, net of cash and restricted cash sold | 2,020 | 108 | 538 | ||||||||
| Issuance of non-recourse debt | 1,928 | 3,222 | 2,978 | ||||||||
| Borrowings under revolving credit facilities | 1,865 | 2,156 | 1,465 | ||||||||
| Sale of short-term investments | 1,302 | 3,540 | 4,904 | ||||||||
| Issuance of recourse debt | 1,000 | 1,025 | 500 | ||||||||
| Contributions from noncontrolling interests and redeemable security holders | 43 | 73 | 190 | ||||||||
| Release of working capital(2) | — | — | 553 | ||||||||
| Other | 175 | 102 | 171 | ||||||||
| Total Cash Sources | $ | 10,862 | $ | 12,795 | $ | 13,643 | |||||
| Cash Uses: | |||||||||||
| Repayments under revolving credit facilities | $ | (2,238 | ) | $ | (1,742 | ) | $ | (1,433 | ) | ||
| Capital expenditures | (2,121 | ) | (2,177 | ) | (2,345 | ) | |||||
| Repayments of recourse debt | (1,933 | ) | (1,353 | ) | (808 | ) | |||||
| Purchase of short-term investments | (1,411 | ) | (3,310 | ) | (5,151 | ) | |||||
| Repayments of non-recourse debt | (1,411 | ) | (2,360 | ) | (2,666 | ) | |||||
| Dividends paid on AES common stock | (344 | ) | (317 | ) | (290 | ) | |||||
| Distributions to noncontrolling interests | (340 | ) | (424 | ) | (476 | ) | |||||
| Payments for financed capital expenditures | (275 | ) | (179 | ) | (113 | ) | |||||
| Increase in working capital(2) | (186 | ) | (65 | ) | — | ||||||
| Contributions to equity affiliates | (145 | ) | (89 | ) | (6 | ) | |||||
| Acquisitions of businesses, net of cash acquired, and equity method investments | (66 | ) | (609 | ) | (52 | ) | |||||
| Payments for financing fees | (39 | ) | (100 | ) | (105 | ) | |||||
| Other | (138 | ) | (242 | ) | (189 | ) | |||||
| Total Cash Uses | $ | (10,647 | ) | $ | (12,967 | ) | $ | (13,634 | ) | ||
| Net increase (decrease) in Cash, Cash Equivalents, and Restricted Cash | $ | 215 | $ | (172 | ) | $ | 9 |
| (1) | Refer to the table within the Operating Activities section below for a reconciliation of non-cash items affecting net income during the applicable period. |
| (2) | Refer to the table within the Operating Activities section below for explanations of the variance in working capital requirements. |
Consolidated Cash Flows
The following table reflects the changes in operating, investing, and financing cash flows for the comparative twelve month periods (in millions):
| December 31, | $ Change | |||||||||||||||||||
| Cash flows provided by (used in): | 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | |||||||||||||||
| Operating activities | $ | 2,343 | $ | 2,504 | $ | 2,897 | $ | (161 | ) | $ | (393 | ) | ||||||||
| Investing activities | (505 | ) | (2,599 | ) | (2,136 | ) | 2,094 | (463 | ) | |||||||||||
| Financing activities | (1,643 | ) | 43 | (747 | ) | (1,686 | ) | 790 |
Operating Activities
The following table summarizes the key components of our consolidated operating cash flows (in millions):
| December 31, | $ Change | |||||||||||||||||||
| 2018 | 2017 | 2016 | 2018 vs. 2017 | 2017 vs. 2016 | ||||||||||||||||
| Net income (loss) | $ | 1,565 | $ | (777 | ) | $ | (777 | ) | $ | 2,342 | $ | — | ||||||||
| Depreciation and amortization | 1,003 | 1,169 | 1,176 | (166 | ) | (7 | ) | |||||||||||||
| Loss (gain) on disposal and sale of business interests | (984 | ) | 52 | (29 | ) | (1,036 | ) | 81 | ||||||||||||
| Impairment expenses | 355 | 537 | 1,098 | (182 | ) | (561 | ) | |||||||||||||
| Loss on extinguishment of debt | 188 | 68 | 20 | 120 | 48 | |||||||||||||||
| Deferred income taxes | 313 | 672 | (793 | ) | (359 | ) | 1,465 | |||||||||||||
| Net loss (gain) from disposal and impairments of discontinued businesses | (269 | ) | 611 | 1,383 | (880 | ) | (772 | ) | ||||||||||||
| Other adjustments to net income | 358 | 237 | 266 | 121 | (29 | ) | ||||||||||||||
| Non-cash adjustments to net income (loss) | 964 | 3,346 | 3,121 | (2,382 | ) | 225 | ||||||||||||||
| Net income, adjusted for non-cash items | $ | 2,529 | $ | 2,569 | $ | 2,344 | $ | (40 | ) | $ | 225 | |||||||||
| Changes in working capital (1) | (186 | ) | (65 | ) | 553 | (121 | ) | (618 | ) | |||||||||||
| Net cash provided by operating activities (2) | $ | 2,343 | $ | 2,504 | $ | 2,897 | $ | (161 | ) | $ | (393 | ) |
| (1) | Refer to the table below for explanations of the variance in operating assets and liabilities. |
| (2) | Amounts included in the table above include the results of discontinued operations, where applicable. |
Fiscal Year 2018 versus 2017
Cash provided by operating activities decreased $161 million for the year ended December 31, 2018, compared to December 31, 2017, primarily driven by a decrease in net income, adjusted for non-cash items of $40 million, and a $121 million increase in working capital requirements.
The increase in working capital requirements of $121 million for the year ended December 31, 2018, compared to December 31, 2017, was primarily driven by (in millions):
| Decreases in operating cash flow resulting from changes in: | |||
| Prepaid expenses and other current assets, primarily due to an insurance recovery receivable at Andres, advance payments to gas suppliers at Colon, and prior year collections of net regulatory assets at Eletropaulo, which was deconsolidated in Q4 2017; partially offset by the impact of the sales of Miami Fort and Zimmer and the retirement of the Stuart facility at DPL | $ | (129 | ) |
| Accounts payable and other current liabilities, primarily due to the deconsolidation of Eletropaulo in Q4 2017 and the timing of payments on coal purchases at Gener; partially offset by the timing of payments on coal purchases at Puerto Rico | (101 | ) | |
| Other liabilities, primarily due to the deconsolidation of Eletropaulo in Q4 2017; partially offset by a prior year decrease in deferred tax and derivative liabilities at the Parent Company | (57 | ) | |
| Accounts receivable, primarily due to lower collections at Los Mina and Itabo, and higher sales at Colon and Chivor; partially offset by the deconsolidation of Eletropaulo in Q4 2017 and higher CAMMESA collections at Alicura | (29 | ) | |
| Increases in operating cash flow resulting from changes in: | |||
| Other assets, primarily related to the deconsolidation of Eletropaulo in Q4 2017 and collections on the construction performance obligation from the offtaker at Vietnam | 263 | ||
| Other | (68 | ) | |
| Total decrease in operating cash flow from higher working capital requirements | $ | (121 | ) |
Fiscal Year 2017 versus 2016
Cash provided by operating activities decreased $393 million for the year ended December 31, 2017, compared to December 31, 2016, primarily driven by an increase in net income, adjusted for non-cash items of $225 million and a $618 million increase in working capital requirements.
The increase in working capital requirements of $618 million for the year ended December 31, 2017, compared to December 31, 2016, was primarily driven by (in millions):
| Decreases in operating cash flow resulting from changes in: | |||
| Prepaid expenses and other current assets, primarily short-term regulatory assets at Eletropaulo and Sul | $ | (763 | ) |
| Accounts receivable, primarily at Maritza and Eletropaulo | (414 | ) | |
| Other liabilities, primarily due to higher deferrals into regulatory liabilities related to energy costs in 2016 compared to 2017 at Eletropaulo | (361 | ) | |
| Increases in operating cash flow resulting from changes in: | |||
| Accounts payable and other current liabilities, primarily at Eletropaulo, Tietê, Gener and Maritza; partially offset at the Parent Company | 782 | ||
| Income taxes payable, net, and other taxes payable, primarily at Gener, Tietê and Eletropaulo | 252 | ||
| Other | (114 | ) | |
| Total decrease in operating cash flow from higher working capital requirements | $ | (618 | ) |
Investing Activities
Fiscal Year 2018 versus 2017
Net cash used in investing activities decreased $2,094 million for the year ended December 31, 2018 compared to December 31, 2017, which was primarily driven by (in millions):
| Increases in: | |||
| Proceeds from the sales of business interests, net of cash and restricted cash sold, primarily due to the current year sales of Masinloc, Electrica Santiago, Eletropaulo, CTNG and the DPL Peaker assets, partially offset by the sale of the Kazakhstan CHPs in 2017 and transaction costs incurred for the Beckjord sale | $ | 1,912 | |
| Decreases in: | |||
| Payments for the acquisitions of business interests, net of cash and restricted cash acquired, primarily due to the acquisitions of sPower and Alto Sertão II in 2017 | 543 | ||
| Capital expenditures (1) | 56 | ||
| Cash resulting from net purchases of short-term investments | (339 | ) | |
| Other investing activities | (78 | ) | |
| Total decrease in net cash used in investing activities | $ | 2,094 |
| (1) | Refer to the tables below for a breakout of capital expenditure by type and by primary business driver. |
The following table summarizes the Company's capital expenditures for growth investments, maintenance, and environmental reported in investing cash activities for the periods indicated (in millions):
| December 31, | ||||||||||||
| 2018 | 2017 | $ Change | ||||||||||
| Growth Investments | $ | 1,663 | $ | 1,549 | $ | 114 | ||||||
| Maintenance | 423 | 552 | (129 | ) | ||||||||
| Environmental | 35 | 76 | (41 | ) | ||||||||
| Total capital expenditures | $ | 2,121 | $ | 2,177 | $ | (56 | ) |
Cash used for capital expenditures decreased $56 million for the year ended December 31, 2018 compared to December 31, 2017, which was primarily driven by (in millions):
| Decreases in: | |||
| Growth expenditures at the MCAC SBU, primarily related to the completion of the Colon project, and lower spending at Los Mina due to the completion of the Combined Cycle project | $ | (242 | ) |
| Maintenance and environmental expenditures at the South America SBU, primarily due to the deconsolidation of Eletropaulo in Q4 2017 | (183 | ) | |
| Increases in: | |||
| Growth expenditures at the US and Utilities SBU, primarily due to increased spending for the Southland re-powering project | 373 | ||
| Other capital expenditures | (4 | ) | |
| Total decrease in capital expenditures | $ | (56 | ) |
Fiscal Year 2017 versus 2016
Net cash used in investing activities increased $463 million for the year ended December 31, 2017 compared to December 31, 2016, which was primarily driven by (in millions):
| Increases in: | |||
| Payments for the acquisitions of businesses, net of cash and restricted cash acquired, and equity method investees (related to the acquisitions of sPower and Alto Sertão II in 2017, partially offset by reduced acquisitions of Distributed Energy projects in 2016) | $ | (557 | ) |
| Contributions to equity investments at OPGC and sPower | (83 | ) | |
| Cash resulting from net sales of short-term investments | 477 | ||
| Decreases in: | |||
| Proceeds from the sale of business, net of cash and restricted cash sold, related to the sale of Sul in 2016, partially offset by the sale of Zimmer and Miami Fort | (430 | ) | |
| Capital expenditures (1) | 168 | ||
| Other investing activities | (38 | ) | |
| Total increase in net cash used in investing activities | $ | (463 | ) |
| (1) | Refer to the tables below for a breakout of capital expenditures by type and by primary business driver. |
The following table summarizes the Company's capital expenditures for growth investments, maintenance and environmental for the periods indicated (in millions):
| December 31, | ||||||||||||
| 2017 | 2016 | $ Change | ||||||||||
| Growth Investments | $ | 1,549 | $ | 1,510 | $ | 39 | ||||||
| Maintenance | 552 | 617 | (65 | ) | ||||||||
| Environmental (1) | 76 | 218 | (142 | ) | ||||||||
| Total capital expenditures | $ | 2,177 | $ | 2,345 | $ | (168 | ) |
| (1) | Includes both recoverable and non-recoverable environmental capital expenditures. |
Cash used for capital expenditures decreased by $168 million for the year ended December 31, 2017 compared to December 31, 2016, which was primarily driven by (in millions):
| Decreases in: | |||
| Growth expenditures at the South America SBU, primarily due to the completion of the Cochrane project and slower than anticipated productivity by construction contractors at Alto Maipo | $ | (114 | ) |
| Growth expenditures at the Eurasia SBU, primarily due to timing of payments resulting in more financed capex | (73 | ) | |
| Maintenance and environmental expenditures at the US and Utilities SBU, primarily due to lower spending at IPALCO on the NPDES and MATS compliance and Harding Street refueling projects, decreased spending on CCR compliance, and decreased spending at DPL on Stuart and Killen facilities due to planned plant closures | (180 | ) | |
| Increases in: | |||
| Growth expenditures at the US and Utilities SBU, primarily due to increased spending for the Southland re-powering project and various Distributed Energy projects; partially offset by lower spending related to Eagle Valley at IPALCO | 233 | ||
| Other capital expenditures | (34 | ) | |
| Total decrease in capital expenditures | $ | (168 | ) |
Financing Activities
Net cash used in financing activities increased $1,686 million for the year ended December 31, 2018 compared to December 31, 2017, which was primarily driven by (in millions):
| Increases in: | |||
| Net repayments of recourse debt at the Parent Company (1) | $ | (605 | ) |
| Net repayments of non-recourse debt at Angamos, DPL, Chivor, and Maritza | (372 | ) | |
| Net repayments on revolving credit facilities at IPALCO and Gener | (370 | ) | |
| Net issuance of non-recourse debt at Southland | 199 | ||
| Decreases in: | |||
| Net issuance of non-recourse debt at AES Argentina, Tietê, Colon, Alto Maipo, US Generation, and Los Mina | (614 | ) | |
| Net borrowing on revolving credit facilities at the Parent Company | (413 | ) | |
| Net repayments of non-recourse debt at IPALCO and Gener | 518 | ||
| Other financing activities | (29 | ) | |
| Total increase in net cash used in financing activities | $ | (1,686 | ) |
| (1) | See Note 10—Debt in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for more information regarding significant recourse debt transactions. |
Net cash provided by financing activities increased $790 million for the year ended December 31, 2017 compared to December 31, 2016, which was primarily driven by (in millions):
| Increases in: | |||
| Net issuance of non-recourse debt at Southland, Tiete, Eletropaulo, AES Argentina, and Colon | $ | 1,396 | |
| Net repayments of non-recourse debt at Gener and IPALCO | (628 | ) | |
| Net borrowing on revolving credit facilities at the Parent Company and Gener | 297 | ||
| Decreases in: | |||
| Net repayments on revolving credit facilities at IPALCO | 123 | ||
| Net issuance of non-recourse debt at Cochrane | (170 | ) | |
| Proceeds from the sale of redeemable stock of subsidiaries at IPALCO | (134 | ) | |
| Contributions from noncontrolling interests and redeemable security holders at Colon, IPALCO, and Distributed Energy | (117 | ) | |
| Other financing activities | 23 | ||
| Total Increase in net cash provided by financing activities | $ | 790 |
Parent Company Liquidity
The following discussion of Parent Company Liquidity is included as a useful measure of the liquidity available to The AES Corporation, or the Parent Company, given the non-recourse nature of most of our indebtedness. Parent Company Liquidity as outlined below is a non-GAAP measure and should not be construed as an alternative to cash and cash equivalents which is determined in accordance with GAAP. Parent Company Liquidity may differ from similarly titled measures used by other companies. The principal sources of liquidity at the Parent Company level are dividends and other distributions from our subsidiaries, including refinancing proceeds, proceeds from debt and equity financings at the Parent Company level, including availability under our credit facilities, and proceeds from asset sales. Cash requirements at the Parent Company level are primarily to fund interest; principal repayments of debt; construction commitments; other equity commitments; common stock repurchases; acquisitions; taxes; Parent Company overhead and development costs; and dividends on common stock.
The Company defines Parent Company Liquidity as cash available to the Parent Company plus available borrowings under existing credit facilities plus cash at qualified holding companies. The cash held at qualified holding companies represents cash sent to subsidiaries of the Company domiciled outside of the U.S. Such subsidiaries have no contractual restrictions on their ability to send cash to the Parent Company. Parent Company
Liquidity is reconciled to its most directly comparable U.S. GAAP financial measure, Cash and cash equivalents, at December 31, 2018 and 2017 as follows:
| Parent Company Liquidity (in millions) | 2018 | 2017 | ||||||
| Consolidated cash and cash equivalents | $ | 1,166 | $ | 949 | ||||
| Less: Cash and cash equivalents at subsidiaries | (1,142 | ) | (938 | ) | ||||
| Parent and qualified holding companies' cash and cash equivalents | 24 | 11 | ||||||
| Commitments under Parent Company credit facilities | 1,100 | 1,100 | ||||||
| Less: Letters of credit under the credit facilities | (78 | ) | (35 | ) | ||||
| Less: Borrowings under the credit facilities | — | (207 | ) | |||||
| Borrowings available under Parent Company credit facilities | 1,022 | 858 | ||||||
| Total Parent Company Liquidity | $ | 1,046 | $ | 869 |
The Parent Company paid dividends of $0.52 per share to its common stockholders during the year ended December 31, 2018. While we intend to continue payment of dividends and believe we will have sufficient liquidity to do so, we can provide no assurance that we will continue to pay dividends, or if continued, the amount of such dividends.
Recourse Debt
Our total recourse debt was $3.7 billion and $4.6 billion at December 31, 2018 and 2017, respectively. See Note 10—Debt in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional detail.
While we believe that our sources of liquidity will be adequate to meet our needs for the foreseeable future, this belief is based on a number of material assumptions, including, without limitation, assumptions about our ability to access the capital markets, the operating and financial performance of our subsidiaries, currency exchange rates, power market pool prices, and the ability of our subsidiaries to pay dividends. In addition, our subsidiaries' ability to declare and pay cash dividends to us (at the Parent Company level) is subject to certain limitations contained in loans, governmental provisions and other agreements. We can provide no assurance that these sources will be available when needed or that the actual cash requirements will not be greater than anticipated. See Item 1A.—Risk Factors—The AES Corporation is a holding company and its ability to make payments on its outstanding indebtedness, including its public debt securities, is dependent upon the receipt of funds from its subsidiaries by way of dividends, fees, interest, loans or otherwise, of this Form 10-K.
Various debt instruments at the Parent Company level, including our senior secured credit facilities, contain certain restrictive covenants. The covenants provide for, among other items, limitations on other indebtedness; liens, investments and guarantees; limitations on dividends, stock repurchases and other equity transactions; restrictions and limitations on mergers and acquisitions, sales of assets, leases, transactions with affiliates and off-balance sheet and derivative arrangements; maintenance of certain financial ratios; and financial and other reporting requirements. As of December 31, 2018, we were in compliance with these covenants at the Parent Company level.
Non-Recourse Debt
While the lenders under our non-recourse debt financings generally do not have direct recourse to the Parent Company, defaults thereunder can still have important consequences for our results of operations and liquidity, including, without limitation:
| • | reducing our cash flows as the subsidiary will typically be prohibited from distributing cash to the Parent Company during the time period of any default; |
| • | triggering our obligation to make payments under any financial guarantee, letter of credit or other credit support we have provided to or on behalf of such subsidiary; |
| • | causing us to record a loss in the event the lender forecloses on the assets; and |
| • | triggering defaults in our outstanding debt at the Parent Company. |
For example, our senior secured credit facilities and outstanding debt securities at the Parent Company include events of default for certain bankruptcy related events involving material subsidiaries. In addition, our revolving credit agreement at the Parent Company includes events of default related to payment defaults and accelerations of outstanding debt of material subsidiaries.
Some of our subsidiaries are currently in default with respect to all or a portion of their outstanding indebtedness. The total non-recourse debt classified as current in the accompanying Consolidated Balance Sheets amounts to $1.7 billion. As of December 31, 2018, $351 million of non-recourse debt was current related to such defaults at two subsidiaries, AES Puerto Rico and AES Ilumina, and $483 million relates to debt at Colon which is in
compliance with its covenants, but is presented as current since it is probable that the Company cannot meet a technical covenant requirement by its deadline. The Company expects to modify the Colon loan agreement in 2019 to amend the requirements of this technical covenant, after which the debt will be re-classified as noncurrent. See Note 10—Debt in Item 8.—Financial Statements and Supplementary Data of this Form 10-K for additional detail.
None of the subsidiaries that are currently in default are subsidiaries that met the applicable definition of materiality under AES' corporate debt agreements as of December 31, 2018 in order for such defaults to trigger an event of default or permit acceleration under AES' indebtedness. However, as a result of additional dispositions of assets, other significant reductions in asset carrying values or other matters in the future that may impact our financial position and results of operations or the financial position of the individual subsidiary, it is possible that one or more of these subsidiaries could fall within the definition of a "material subsidiary" and thereby upon an acceleration, trigger an event of default and possible acceleration of the indebtedness under the Parent Company's outstanding debt securities. A material subsidiary is defined in the Company's senior secured revolving credit facilities as any business that contributed 20% or more of the Parent Company's total cash distributions from businesses for the four most recently completed fiscal quarters. As of December 31, 2018, none of the defaults listed above individually or in the aggregate results in or is at risk of triggering a cross-default under the recourse debt of the Company.
Contractual Obligations and Parent Company Contingent Contractual Obligations
A summary of our contractual obligations, commitments and other liabilities as of December 31, 2018 is presented below and excludes any businesses classified as discontinued operations or held-for-sale (in millions):
| Contractual Obligations | Total | Less than 1 year | 1-3 years | 3-5 years | More than 5 years | Other | Footnote Reference**(4)** | |||||||||||||||||||||||
| Debt obligations (1) | $ | 19,687 | — | $ | 1,701 | — | $ | 3,567 | — | $ | 4,407 | — | $ | 10,012 | $ | — | 10 | |||||||||||||
| Interest payments on long-term debt (2) | 6,967 | 846 | 1,625 | 1,194 | 3,302 | — | n/a | |||||||||||||||||||||||
| Capital lease obligations | 12 | 1 | 2 | 2 | 7 | — | 11 | |||||||||||||||||||||||
| Operating lease obligations | 643 | 74 | 63 | 51 | 455 | — | 11 | |||||||||||||||||||||||
| Electricity obligations | 7,573 | 786 | 973 | 627 | 5,187 | — | 11 | |||||||||||||||||||||||
| Fuel obligations | 6,175 | 1,494 | 1,909 | 1,038 | 1,734 | — | 11 | |||||||||||||||||||||||
| Other purchase obligations | 3,944 | 1,375 | 1,017 | 774 | 778 | — | 11 | |||||||||||||||||||||||
| Other long-term liabilities reflected on AES' consolidated balance sheet under GAAP (3) | 809 | — | 263 | 207 | 326 | 13 | n/a | |||||||||||||||||||||||
| Total | $ | 45,810 | $ | 6,277 | $ | 9,419 | $ | 8,300 | $ | 21,801 | $ | 13 |
| (1) | Includes recourse and non-recourse debt presented on the Consolidated Balance Sheet. These amounts exclude capital lease obligations which are included in the capital lease category. |
| (2) | Interest payments are estimated based on final maturity dates of debt securities outstanding at December 31, 2018 and do not reflect anticipated future refinancing, early redemptions or new debt issuances. Variable rate interest obligations are estimated based on rates as of December 31, 2018. |
| (3) | These amounts do not include current liabilities on the Consolidated Balance Sheet except for the current portion of uncertain tax obligations. Noncurrent uncertain tax obligations are reflected in the "Other" column of the table above as the Company is not able to reasonably estimate the timing of the future payments. In addition, these amounts do not include: (1) regulatory liabilities (See Note 9—Regulatory Assets and Liabilities), (2) contingencies (See Note 12—Contingencies), (3) pension and other postretirement employee benefit liabilities (see Note 13—Benefit Plans), (4) derivatives and incentive compensation (See Note 5—Derivative Instruments and Hedging Activities) or (5) any taxes (See Note 21—Income Taxes) except for uncertain tax obligations, as the Company is not able to reasonably estimate the timing of future payments. See the indicated notes to the Consolidated Financial Statements included in Item 8 of this Form 10-K for additional information on the items excluded. |
| (4) | For further information see the note referenced below in Item 8.—Financial Statements and Supplementary Data of this Form 10-K. |
The following table presents our Parent Company's contingent contractual obligations as of December 31, 2018:
| Contingent contractual obligations | Amount (in millions) | Number of Agreements | Maximum Exposure Range for Each Agreement (in millions) | |||||
| Guarantees and commitments | $ | 685 | 33 | $0 — 157 | ||||
| Letters of credit under the unsecured credit facility | 368 | 10 | $1 — 247 | |||||
| Letters of credit under the senior secured credit facility | 78 | 23 | $0 — 49 | |||||
| Asset sale related indemnities (1) | 27 | 1 | $27 | |||||
| Total | $ | 1,158 | 67 |
| (1) | Excludes normal and customary representations and warranties in agreements for the sale of assets (including ownership in associated legal entities) where the associated risk is considered to be nominal. |
We have a diverse portfolio of performance-related contingent contractual obligations. These obligations are designed to cover potential risks and only require payment if certain targets are not met or certain contingencies occur. The risks associated with these obligations include change of control, construction cost overruns, subsidiary default, political risk, tax indemnities, spot market power prices, sponsor support and liquidated damages under power sales agreements for projects in development, in operation and under construction. In addition, we have an
asset sale program through which we may have customary indemnity obligations under certain assets sale agreements. While we do not expect that we will be required to fund any material amounts under these contingent contractual obligations beyond 2018, many of the events which would give rise to such obligations are beyond our control. We can provide no assurance that we will be able to fund our obligations under these contingent contractual obligations if we are required to make substantial payments thereunder.
Critical Accounting Policies and Estimates
The Consolidated Financial Statements of AES are prepared in conformity with U.S. GAAP, which requires the use of estimates, judgments and assumptions that affect the reported amounts of assets and liabilities at the date of the financial statements and the reported amounts of revenue and expenses during the periods presented. AES' significant accounting policies are described in Note 1—General and Summary of Significant Accounting Policies to the Consolidated Financial Statements included in Item 8 of this Form 10-K.
An accounting estimate is considered critical if the estimate requires management to make assumptions about matters that were highly uncertain at the time the estimate was made, different estimates reasonably could have been used, or the impact of the estimates and assumptions on financial condition or operating performance is material.
Management believes that the accounting estimates employed are appropriate and the resulting balances are reasonable; however, actual results could materially differ from the original estimates, requiring adjustments to these balances in future periods. Management has discussed these critical accounting policies with the Audit Committee, as appropriate. Listed below are the Company's most significant critical accounting estimates and assumptions used in the preparation of the Consolidated Financial Statements.
Income Taxes — We are subject to income taxes in both the U.S. and numerous foreign jurisdictions. Our worldwide income tax provision requires significant judgment and is based on calculations and assumptions that are subject to examination by the Internal Revenue Service and other taxing authorities. Certain of the Company's subsidiaries are under examination by relevant taxing authorities for various tax years. The Company regularly assesses the potential outcome of these examinations in each tax jurisdiction when determining the adequacy of the provision for income taxes. Accounting guidance for uncertainty in income taxes prescribes a more likely than not recognition threshold. Tax reserves have been established, which the Company believes to be adequate in relation to the potential for additional assessments. Once established, reserves are adjusted only when there is more information available or when an event occurs necessitating a change to the reserves. While the Company believes that the amounts of the tax estimates are reasonable, it is possible that the ultimate outcome of current or future examinations may be materially different than the reserve amounts.
Because we have a wide range of statutory tax rates in the multiple jurisdictions in which we operate, any changes in our geographical earnings mix could materially impact our effective tax rate. Furthermore, our tax position could be adversely impacted by changes in tax laws, tax treaties or tax regulations or the interpretation or enforcement thereof and such changes may be more likely or become more likely in view of recent economic trends in certain of the jurisdictions in which we operate. As an example, new tax laws were enacted in December 2017 in the U.S. which decreased the statutory income tax rate from 35% to 21%, required a one-time transition tax, and introduced numerous other changes. As further outlined in Key Trends and Uncertainties, the Company anticipates that the GILTI provisions of U.S. tax reform could materially impact the effective tax rate in future periods. See Note 21—Income Taxes to the Consolidated Financial Statements included in Item 8 of this Form 10-K for additional information.
In accordance with SAB 118, the Company made reasonable estimates of the impacts of U.S. tax reform on its 2017 financial results, and recorded adjustments to those estimates in 2018 as analysis was completed. As of December 31, 2018, our analysis of the one-time impacts of the TCJA is complete under SAB 118. However, in the first quarter of 2019, the U.S. Treasury Department issued final regulations on the one-time transition tax. The final regulations include changes from the proposed regulations issued in 2018 and we expect to record the impacts of the final regulations in the first quarter of 2019. We are still evaluating the final regulations which may have a material impact on our financial statements.
In addition, no taxes have been recorded on undistributed earnings for certain of our non-U.S. subsidiaries to the extent such earnings are considered to be indefinitely reinvested in the operations of those subsidiaries. Should the earnings be remitted as dividends, the Company may be subject to additional foreign withholding and state income taxes.
Deferred tax assets and liabilities are recognized for the future tax consequences attributable to differences between the financial statement carrying amounts of the existing assets and liabilities, and their respective income
tax bases. The Company establishes a valuation allowance when it is more likely than not that all or a portion of a deferred tax asset will not be realized. The Company has elected to treat GILTI as an expense in the period in which the tax is accrued. Accordingly, no deferred tax assets or liabilities are recorded related to GILTI.
Sales of Noncontrolling Interests — Sales of noncontrolling interests are recognized within stockholders' equity. Effective January 1, 2018, the Company adopted ASU No. 2017-05, Other Income—Gains and Losses from the Derecognition of Nonfinancial Assets, which clarified the accounting for the sale of business interests as either the sale of nonfinancial assets or the sale of businesses. Among other things, under the newly adopted guidance fewer transactions are expected to meet the definition of a business under the scope of ASC 810 and will fall under the scope of the sale of nonfinancial assets.
Prior to January 1, 2018, the accounting for a sale of noncontrolling interests was dependent on whether the sale was considered a sale of in-substance real estate, where the gain (loss) on sale would be recognized in earnings rather than within stockholders' equity. In-substance real estate is composed of land plus improvements and integral equipment. The determination of whether property, plant and equipment is integral equipment is based on the significance of the costs to remove the equipment from its existing location (including the cost of repairing damage resulting from the removal), combined with the decrease in the fair value of the equipment as a result of those removal activities. When the combined total of removal costs and the decrease in fair value of the equipment exceeds 10% of the fair value of the equipment, the equipment is considered integral equipment. The accounting standards specifically identify power plants as an example of in-substance real estate. Where the consolidated entity in which noncontrolling interests have been sold contains in-substance real estate, management estimates the extent to which the total fair value of the assets of the entity is represented by the in-substance real estate and whether significant value exists beyond the in-substance real estate. This estimation considers all qualitative and quantitative factors relevant for each sale and, where appropriate, includes making quantitative estimates about the fair value of the entity and its identifiable assets and liabilities (including any favorable or unfavorable contracts) by analogy to the accounting standards on business combinations. As such, these estimates may require significant judgment and assumptions, similar to the critical accounting estimates discussed below for impairments and fair value.
Impairments — Our accounting policies on goodwill and long-lived assets are described in detail in Note 1—General and Summary of Significant Accounting Policies, included in Item 8 of this Form 10-K. The Company makes considerable judgments in its impairment evaluations of goodwill and long-lived assets, starting with determining if an impairment indicator exists. Events that may result in an impairment analysis being performed include, but are not limited to: adverse changes in the regulatory environment, unfavorable changes in power prices or fuel costs, increased competition due to additional capacity in the grid, technological advancements, declining trends in demand, or an expectation it is more likely than not that the asset will be disposed of before the end of its previously estimated useful life. The Company exercises judgment in determining if these events represent an impairment indicator requiring the computation of the fair value of goodwill and/or the recoverability of long-lived assets. The fair value determination is typically the most judgmental part in an impairment evaluation. Please see Fair Value below for further detail.
As part of the impairment evaluation process, management analyzes the sensitivity of fair value to various underlying assumptions. The level of scrutiny increases as the gap between fair value and carrying amount decreases. Changes in any of these assumptions could result in management reaching a different conclusion regarding the potential impairment, which could be material. Our impairment evaluations inherently involve uncertainties from uncontrollable events that could positively or negatively impact the anticipated future economic and operating conditions.
Further discussion of the impairment charges recognized by the Company can be found within Note 8—Goodwill and Other Intangible Assets and Note 20—Asset Impairment Expense to the Consolidated Financial Statements included in Item 8 of this Form 10-K.
Fair Value
Fair Value — For information regarding the fair value hierarchy, see Note 1—General and Summary of Significant Accounting Policies included in Item 8 of this Form 10-K.
Fair Value of Financial Instruments — A significant number of the Company's financial instruments are carried at fair value with changes in fair value recognized in earnings or other comprehensive income each period. Investments are generally fair valued based on quoted market prices or other observable market data such as interest rate indices. The Company's investments are primarily certificates of deposit and mutual funds. Derivatives are valued using observable data as inputs into internal valuation models. The Company's derivatives primarily consist of interest rate swaps, foreign currency instruments, and commodity and embedded derivatives. Additional
discussion regarding the nature of these financial instruments and valuation techniques can be found in Note 4—Fair Value included in Item 8 of this Form 10-K.
Fair Value of Nonfinancial Assets and Liabilities — Significant estimates are made in determining the fair value of long-lived tangible and intangible assets (i.e., property, plant and equipment, intangible assets and goodwill) during the impairment evaluation process. In addition, the majority of assets acquired and liabilities assumed in a business combination and asset acquisitions by VIEs are required to be recognized at fair value under the relevant accounting guidance.
The Company may engage an independent valuation firm to assist management with the valuation. The Company generally utilizes the income approach to value nonfinancial assets and liabilities, specifically a Discounted Cash Flow ("DCF") model to estimate fair value by discounting cash flow forecasts, adjusted to reflect market participant assumptions, to the extent necessary, at an appropriate discount rate.
Management applies considerable judgment in selecting several input assumptions during the development of our cash flow forecasts. Examples of the input assumptions that our forecasts are sensitive to include macroeconomic factors such as growth rates, industry demand, inflation, exchange rates, power prices and commodity prices. Whenever appropriate, management obtains these input assumptions from observable market data sources (e.g., Economic Intelligence Unit) and extrapolates the market information if an input assumption is not observable for the entire forecast period. Many of these input assumptions are dependent on other economic assumptions, which are often derived from statistical economic models with inherent limitations such as estimation differences. Further, several input assumptions are based on historical trends which often do not recur. It is not uncommon that different market data sources have different views of the macroeconomic factor expectations and related assumptions. As a result, macroeconomic factors and related assumptions are often available in a narrow range; however, in some situations these ranges become wide and the use of a different set of input assumptions could produce significantly different budgets and cash flow forecasts.
A considerable amount of judgment is also applied in the estimation of the discount rate used in the DCF model. To the extent practical, inputs to the discount rate are obtained from market data sources (e.g., Bloomberg). The Company selects and uses a set of publicly traded companies from the relevant industry to estimate the discount rate inputs. Management applies judgment in the selection of such companies based on its view of the most likely market participants. It is reasonably possible that the selection of a different set of likely market participants could produce different input assumptions and result in the use of a different discount rate.
Accounting for Derivative Instruments and Hedging Activities — We enter into various derivative transactions in order to hedge our exposure to certain market risks. We primarily use derivative instruments to manage our interest rate, commodity and foreign currency exposures. We do not enter into derivative transactions for trading purposes. See Note 5—Derivative Instruments and Hedging Activities included in Item 8 of this Form 10-K for further information on the classification.
The fair value measurement standard requires the Company to consider and reflect the assumptions of market participants in the fair value calculation. These factors include nonperformance risk (the risk that the obligation will not be fulfilled) and credit risk, both of the reporting entity (for liabilities) and of the counterparty (for assets). Due to the nature of the Company's interest rate swaps, which are typically associated with non-recourse debt, credit risk for AES is evaluated at the subsidiary level rather than at the Parent Company level. Nonperformance risk on the Company's derivative instruments is an adjustment to the initial asset/liability fair value position that is derived from internally developed valuation models that utilize observable market inputs.
As a result of uncertainty, complexity and judgment, accounting estimates related to derivative accounting could result in material changes to our financial statements under different conditions or utilizing different assumptions. As a part of accounting for these derivatives, we make estimates concerning nonperformance, volatilities, market liquidity, future commodity prices, interest rates, credit ratings (both ours and our counterparty's), and future exchange rates. Refer to Note 4—Fair Value included in Item 8 of this Form 10-K for additional details.
The fair value of our derivative portfolio is generally determined using internal and third party valuation models, most of which are based on observable market inputs, including interest rate curves and forward and spot prices for currencies and commodities. The Company derives most of its financial instrument market assumptions from market efficient data sources (e.g., Bloomberg, Reuters and Platt's). In some cases, where market data is not readily available, management uses comparable market sources and empirical evidence to derive market assumptions to determine a financial instrument's fair value. In certain instances, the published curve may not extend through the remaining term of the contract and management must make assumptions to extrapolate the curve. Specifically, where there is limited forward curve data with respect to foreign exchange contracts, beyond the traded points the Company utilizes the interest rate differential approach to construct the remaining portion of the
forward curve. Additionally, in the absence of quoted prices, we may rely on "indicative pricing" quotes from financial institutions to input into our valuation model for certain of our foreign currency swaps. These indicative pricing quotes do not constitute either a bid or ask price and therefore are not considered observable market data. For individual contracts, the use of different valuation models or assumptions could have a material effect on the calculated fair value.
Regulatory Assets — Management continually assesses whether the regulatory assets are probable of future recovery by considering factors such as applicable regulatory changes, recent rate orders applicable to other regulated entities and the status of any pending or potential deregulation legislation. If future recovery of costs ceases to be probable, any asset write-offs would be required to be recognized in operating income.
Consolidation — The Company enters into transactions impacting the Company's equity interests in its affiliates. In connection with each transaction, the Company must determine whether the transaction impacts the Company's consolidation conclusion by first determining whether the transaction should be evaluated under the variable interest model or the voting model. In determining which consolidation model applies to the transaction, the Company is required to make judgments about how the entity operates, the most significant of which are whether (i) the entity has sufficient equity to finance its activities, (ii) the equity holders, as a group, have the characteristics of a controlling financial interest, and (iii) whether the entity has non-substantive voting rights.
If the entity is determined to be a variable interest entity, the most significant judgment in determining whether the Company must consolidate the entity is whether the Company, including its related parties and de facto agents, collectively have power and benefits. If AES is determined to have power and benefits, the entity will be consolidated by AES.
Alternatively, if the entity is determined to be a voting model entity, the most significant judgments involve determining whether the non-AES shareholders have substantive participating rights. The assessment of shareholder rights and whether they are substantive participating rights requires significant judgment since the rights provided under shareholders' agreements may include selecting, terminating, and setting the compensation of management responsible for implementing the subsidiary's policies and procedures, and establishing operating and capital decisions of the entity, including budgets, in the ordinary course of business. On the other hand, if shareholder rights are only protective in nature (referred to as protective rights) then such rights would not overcome the presumption that the owner of a majority voting interest shall consolidate its investee. Significant judgment is required to determine whether minority rights represent substantive participating rights or protective rights that do not affect the evaluation of control. While both represent an approval or veto right, a distinguishing factor is the underlying activity or action to which the right relates.
Pension and Other Postretirement Plans — The Company recognizes a net asset or liability reflecting the funded status of pension and other postretirement plans with current-year changes in actuarial gains or losses recognized in AOCL, except for those plans at certain of the Company's regulated utilities that can recover portions of their pension and postretirement obligations through future rates. The valuation of the Company's benefit obligation, fair value of plan assets, and net periodic benefit costs requires various estimates and assumptions, the most significant of which include the discount rate and expected return on plan assets. These assumptions are reviewed by the Company on an annual basis. Refer to Note 1—General and Summary of Significant Accounting Policies included in Item 8 of this Form 10-K for further information.
Revenue Recognition — The Company recognizes revenue to depict the transfer of energy, capacity and other services to customers in an amount that reflects the consideration to which we expect to be entitled. In applying the revenue model, we determine whether the sale of energy, capacity and other services represent a single performance obligation based on the individual market and terms of the contract. Generally, the promise to transfer energy and capacity represent a performance obligation that is satisfied over time and meets the criteria to be accounted for as a series of distinct goods or services. Progress toward satisfaction of a performance obligation is measured using output methods, such as MWhs delivered or MWs made available, and when we are entitled to consideration in an amount that corresponds directly to the value of our performance completed to date, we recognize revenue in the amount to which we have the right to invoice. For further information regarding the nature of our revenue streams and our critical accounting policies affecting revenue recognition, see Note 1—General and Summary of Significant Accounting Policies included in Item 8 of this Form 10-K.
New Accounting Pronouncements — See Note 1—General and Summary of Significant Accounting Policies included in Item 8 of this Form 10-K for further information about new accounting pronouncements adopted during 2018 and accounting pronouncements issued, but not yet effective.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK