 filings.tools
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
138K characters. Original on sec.gov · Markdown
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The condensed consolidated financial statements included in Item 1.—Financial Statements of this Form 10-Q and the discussions contained herein should be read in conjunction with our 2023 Form 10-K.
Forward-Looking Information
The following discussion may contain forward-looking statements regarding us, our business, prospects and our results of operations, that are subject to certain risks and uncertainties posed by many factors and events that could cause our actual business, prospects and results of operations to differ materially from those that may be anticipated by such forward-looking statements. These statements include, but are not limited to, statements regarding management’s intents, beliefs, and current expectations and typically contain, but are not limited to, the terms “anticipate,” “potential,” “expect,” “forecast,” “target,” “will,” “would,” “intend,” “believe,” “project,” “estimate,” “plan,” and similar words. Forward-looking statements are not intended to be a guarantee of future results, but instead constitute current expectations based on reasonable assumptions. Factors that could cause or contribute to such differences include, but are not limited to, those described in Item 1A.—Risk Factors of this Form 10-Q, Item 1A.—Risk Factors and Item 7.—Management’s Discussion and Analysis of Financial Condition and Results of Operations of our 2023 Form 10-K and subsequent filings with the SEC.
Readers are cautioned not to place undue reliance on these forward-looking statements which speak only as of the date of this report. We undertake no obligation to revise any forward-looking statements in order to reflect events or circumstances that may subsequently arise. If we do update one or more forward-looking statements, no inference should be drawn that we will make additional updates with respect to those or other forward-looking statements. Readers are urged to carefully review and consider the various disclosures made by us in this report and in our other reports filed with the SEC that advise of the risks and factors that may affect our business.
Overview of Our Business
We are a diversified power generation and utility company organized into the following four SBUs, mainly organized by technology: Renewables (solar, wind, energy storage, and hydro), Utilities (AES Indiana, AES Ohio, and AES El Salvador), Energy Infrastructure (natural gas, LNG, coal, pet coke, diesel, and oil), and New Energy Technologies (green hydrogen, Fluence, Uplight, and 5B). Our businesses in Chile, which have a mix of generation sources, including renewables, are also included within the Energy Infrastructure SBU, as the generation from all sources is pooled to service our existing PPAs. For additional information regarding our business, see Item 1.—Business of our 2023 Form 10-K.
We have two lines of business: generation and utilities. Our Renewables, Utilities and Energy Infrastructure SBUs participate in our first business line, generation, in which we own and/or operate power plants to generate and sell power to customers, such as utilities, industrial users, and other intermediaries. Our Utilities SBU participates in our second business line, utilities, in which we own and/or operate utilities to generate or purchase, distribute, transmit, and sell electricity to end-user customers in the residential, commercial, industrial, and governmental sectors within a defined service area. In certain circumstances, our utilities also generate and sell electricity on the wholesale market. Our New Energy Technologies SBU includes investments in new and innovative technologies to support leading-edge greener energy solutions.
Executive Summary
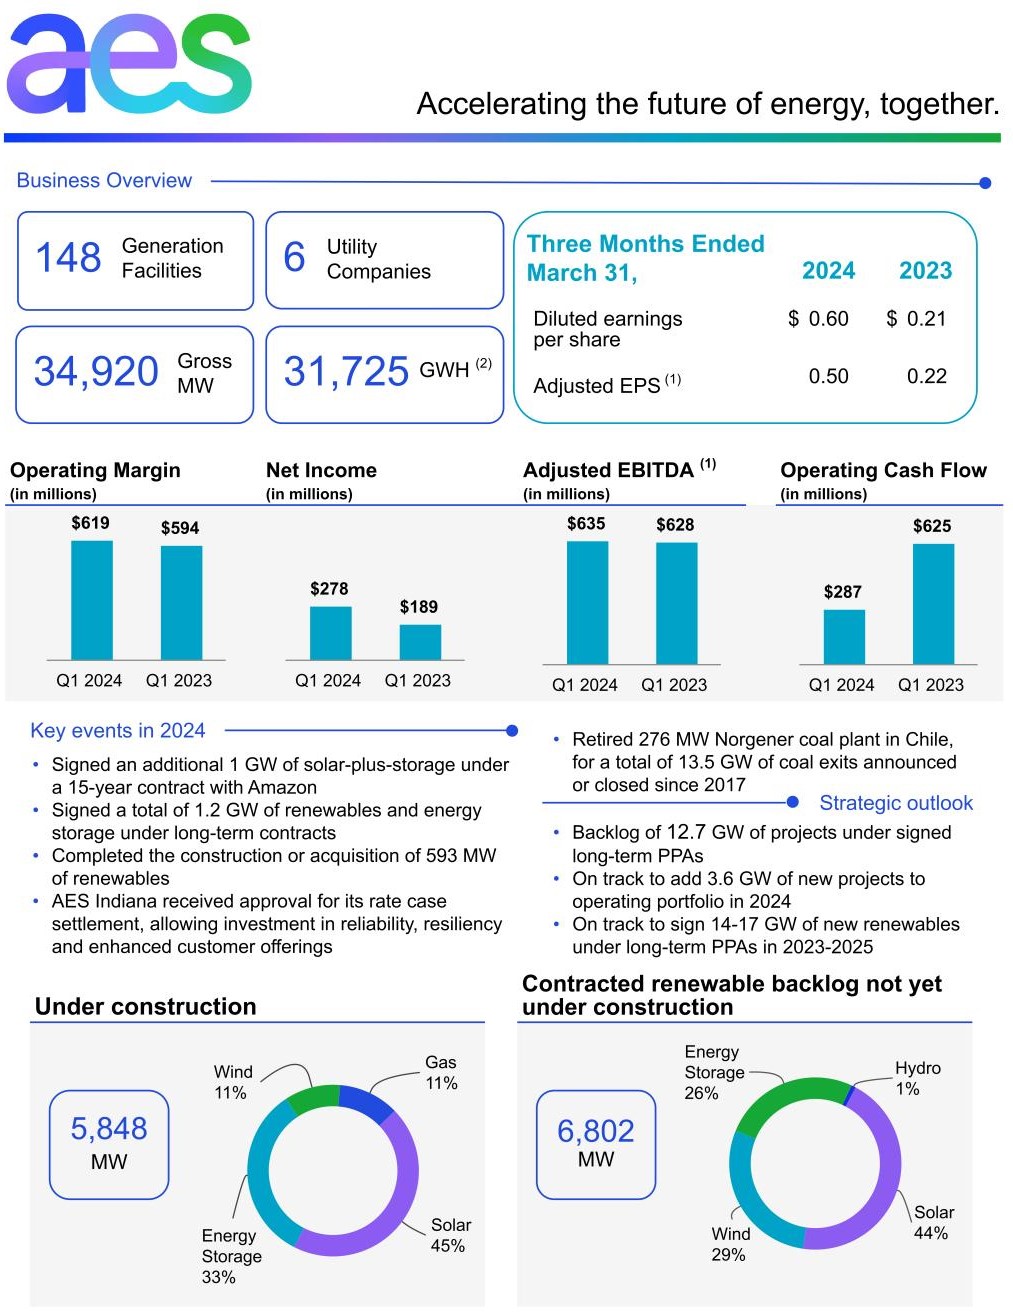
Compared with last year, first quarter net income increased $89 million, from $189 million to $278 million. This increase is the result of favorable contributions at the Utilities and New Energy Technologies SBUs, partially offset by lower contributions from the Renewables and Energy Infrastructure SBUs.
Adjusted EBITDA, a non-GAAP measure, increased $7 million, from $628 million to $635 million, mainly driven by higher revenues under a PPA termination agreement at the Energy Infrastructure SBU, higher contributions at the Utilities SBU, and lower losses from affiliates at the New Energy Technologies SBU; partially offset by lower LNG transactions, higher contract generation cost, and outages at the Energy Infrastructure SBU, and worse hydrology and lower wind generation at the Renewables SBU.
Adjusted EBITDA with Tax Attributes, a non-GAAP measure, increased $222 million, from $641 million to $863 million primarily due to higher realized tax attributes driven by more renewables projects placed in service, and the drivers above.
Compared with last year, first quarter diluted earnings per share from continuing operations increased $0.39,
31 | The AES Corporation | March 31, 2024 Form 10-Q
from $0.21 to $0.60. This increase is mainly driven by lower income tax expense, higher contributions from renewables projects placed in service in the current year, and a gain on dilution of our interest in Uplight; partially offset by higher asset impairments in the current year.
Adjusted EPS, a non-GAAP measure, increased $0.28 from $0.22 to $0.50, mainly driven by a lower adjusted tax rate and higher contributions from renewables projects placed in service in the current year.
32 | The AES Corporation | March 31, 2024 Form 10-Q
| (1) Non-GAAP measure. See Item 2.—Management’s Discussion and Analysis of Financial Condition and Results of Operations—SBU Performance Analysis—Non-GAAP Measures for reconciliation and definition. | |||||
| (2) GWh sold in 2023. |
33 | The AES Corporation | March 31, 2024 Form 10-Q
Overview of Strategic Performance
AES is leading the industry's transition to clean energy by investing in renewables, utilities, and technology businesses.
-
As of the end of the first quarter of 2024, the Company’s backlog, which consists of projects with signed contracts, but which are not yet operational, is 12.7 GW, including 5.8 GW under construction.
-
Since the Company's fourth quarter 2023 earnings call in February 2024, the Company completed the construction or acquisition of 593 MW of wind, solar and energy storage and expects to add a total of 3.6 GW to its operating portfolio by year-end 2024.
-
Since the Company's fourth quarter 2023 earnings call in February 2024, the Company signed 1.2 GW of long-term contracts for new renewables.
-
Including the 1 GW of Bellefield 2 signed in the first quarter of 2024, the Company has signed long-term PPAs for 5.9 GW of renewables to serve data center and technology customers in the U.S. and South America since 2018.
-
AES Indiana received approval from the IURC to implement new customer rates beginning in mid-May 2024. AES Indiana will continue to be among the lowest residential rates of any investor-owned utility in Indiana.
Review of Consolidated Results of Operations (Unaudited)
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| (in millions, except per share amounts) | 2024 | 2023 | $ change | % change | |||||||||||||||||||||||||||||||||||||||||||
| Revenue: | |||||||||||||||||||||||||||||||||||||||||||||||
| Renewables SBU | $ | 619 | $ | 495 | $ | 124 | 25 | % | |||||||||||||||||||||||||||||||||||||||
| Utilities SBU | 873 | 971 | (98) | -10 | % | ||||||||||||||||||||||||||||||||||||||||||
| Energy Infrastructure SBU | 1,614 | 1,724 | (110) | -6 | % | ||||||||||||||||||||||||||||||||||||||||||
| New Energy Technologies SBU | — | 74 | (74) | -100 | % | ||||||||||||||||||||||||||||||||||||||||||
| Corporate and Other | 33 | 27 | 6 | 22 | % | ||||||||||||||||||||||||||||||||||||||||||
| Eliminations | (54) | (52) | (2) | -4 | % | ||||||||||||||||||||||||||||||||||||||||||
| Total Revenue | 3,085 | 3,239 | (154) | -5 | % | ||||||||||||||||||||||||||||||||||||||||||
| Operating Margin: | |||||||||||||||||||||||||||||||||||||||||||||||
| Renewables SBU | 53 | 88 | (35) | -40 | % | ||||||||||||||||||||||||||||||||||||||||||
| Utilities SBU | 120 | 105 | 15 | 14 | % | ||||||||||||||||||||||||||||||||||||||||||
| Energy Infrastructure SBU | 404 | 375 | 29 | 8 | % | ||||||||||||||||||||||||||||||||||||||||||
| New Energy Technologies SBU | (2) | (4) | 2 | -50 | % | ||||||||||||||||||||||||||||||||||||||||||
| Corporate and Other | 65 | 57 | 8 | 14 | % | ||||||||||||||||||||||||||||||||||||||||||
| Eliminations | (21) | (27) | 6 | 22 | % | ||||||||||||||||||||||||||||||||||||||||||
| Total Operating Margin | 619 | 594 | 25 | 4 | % | ||||||||||||||||||||||||||||||||||||||||||
| General and administrative expenses | (75) | (55) | (20) | 36 | % | ||||||||||||||||||||||||||||||||||||||||||
| Interest expense | (357) | (330) | (27) | 8 | % | ||||||||||||||||||||||||||||||||||||||||||
| Interest income | 105 | 123 | (18) | -15 | % | ||||||||||||||||||||||||||||||||||||||||||
| Loss on extinguishment of debt | (1) | (1) | — | — | % | ||||||||||||||||||||||||||||||||||||||||||
| Other expense | (38) | (14) | (24) | NM | |||||||||||||||||||||||||||||||||||||||||||
| Other income | 35 | 10 | 25 | NM | |||||||||||||||||||||||||||||||||||||||||||
| Gain on disposal and sale of business interests | 43 | — | 43 | NM | |||||||||||||||||||||||||||||||||||||||||||
| Asset impairment expense | (46) | (20) | (26) | NM | |||||||||||||||||||||||||||||||||||||||||||
| Foreign currency transaction losses | (8) | (42) | 34 | -81 | % | ||||||||||||||||||||||||||||||||||||||||||
| Income tax benefit (expense) | 16 | (72) | 88 | NM | |||||||||||||||||||||||||||||||||||||||||||
| Net equity in losses of affiliates | (15) | (4) | (11) | NM | |||||||||||||||||||||||||||||||||||||||||||
| NET INCOME | 278 | 189 | 89 | 47 | % | ||||||||||||||||||||||||||||||||||||||||||
| Less: Net loss (income) attributable to noncontrolling interests and redeemable stock of subsidiaries | 154 | (38) | 192 | NM | |||||||||||||||||||||||||||||||||||||||||||
| NET INCOME ATTRIBUTABLE TO THE AES CORPORATION | $ | 432 | $ | 151 | $ | 281 | NM | ||||||||||||||||||||||||||||||||||||||||
| Net cash provided by operating activities | $ | 287 | $ | 625 | $ | (338) | -54 | % |
Components of Revenue, Cost of Sales, and Operating Margin — Revenue includes revenue earned from the sale of energy from our utilities and the production and sale of energy from our generation plants, which are classified as regulated and non-regulated*,* respectively, on the Condensed Consolidated Statements of Operations. Revenue also includes the gains or losses on derivatives associated with the sale of electricity.
34 | The AES Corporation | March 31, 2024 Form 10-Q
Cost of sales includes costs incurred directly by the businesses in the ordinary course of business. Examples include electricity and fuel purchases, operations and maintenance costs, depreciation and amortization expenses, bad debt expense and recoveries, and general administrative and support costs (including employee-related costs directly associated with the operations of the business). Cost of sales also includes the gains or losses on derivatives associated with the purchase of electricity or fuel.
Operating margin is defined as revenue less cost of sales.
Consolidated Revenue and Operating Margin
Three Months Ended March 31, 2024
Revenue
(in millions)
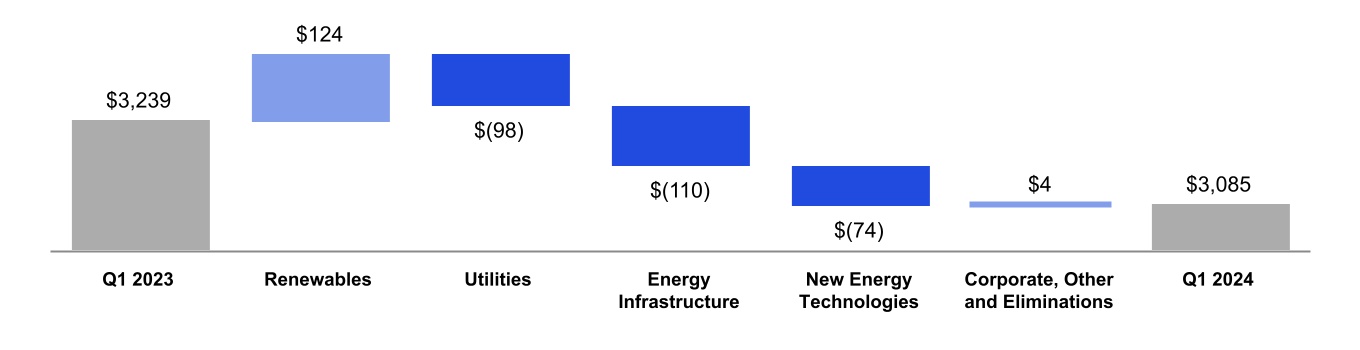
Consolidated Revenue — Revenue decreased $154 million, or 5%, for the three months ended March 31, 2024, compared to the three months ended March 31, 2023, driven by:
-
$110 million at Energy Infrastructure driven by lower regulated contract sales and prices, lower CO2 purchases passed through due to lower production, the impact of the depreciation of the Argentine peso, and lower generation due to higher outages; partially offset by higher revenues due to a PPA termination agreement and realized and unrealized derivative gains;
-
$98 million at Utilities mainly driven by lower Fuel Adjustment Charge rider revenue and lower wholesale revenue due to lower rates; partially offset by higher TDSIC rider and transmission revenues, and higher demand due to favorable weather; and
-
$74 million at New Energy Technologies mainly driven by the sale of the Fallbrook project in the prior year.
These unfavorable impacts were partially offset by an increase of $124 million at Renewables mainly driven by higher spot sales prices, new projects placed in service, unrealized commodity derivative gains, and the impact of the appreciation of the Colombian peso; partially offset by the impact of the depreciation of the Argentine peso.
Operating Margin
(in millions)
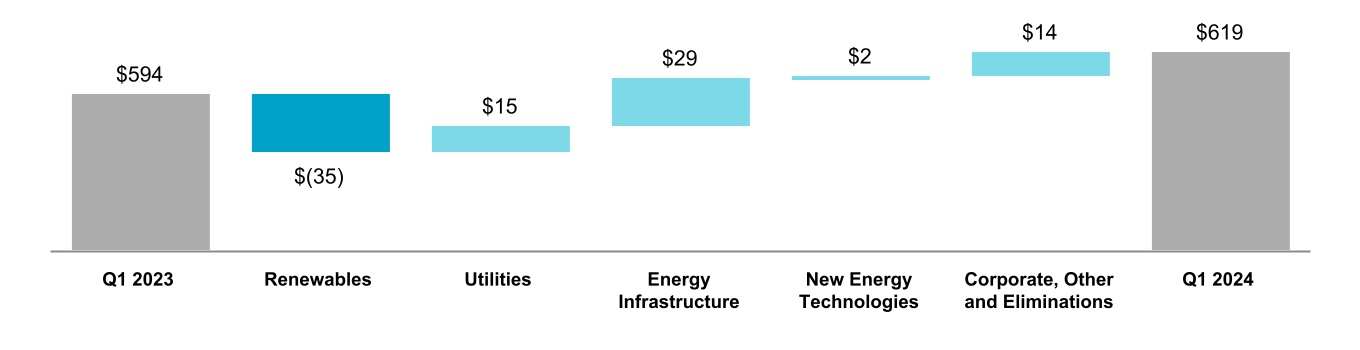
Consolidated Operating Margin — Operating margin increased $25 million, or 4%, for the three months ended March 31, 2024, compared to the three months ended March 31, 2023, driven by:
- $29 million at Energy Infrastructure mainly driven by higher revenues due to a PPA termination agreement
35 | The AES Corporation | March 31, 2024 Form 10-Q
and derivative gains as part of our commercial hedging strategy; partially offset by lower LNG transactions, higher contract generation costs, and higher outages;
-
$15 million at Utilities mainly driven by higher demand due to favorable weather, and an increase in transmission and distribution revenues; partially offset by higher fixed costs and depreciation; and
-
$14 million at Corporate and Other primarily driven by higher charge-outs of IT and other costs to the businesses and higher premiums earned by the AES self-insurance company.
These favorable impacts were partially offset by a decrease of $35 million at Renewables mainly driven by worse hydrology, lower wind generation, higher energy purchase prices, and higher fixed costs and depreciation related to new projects; partially offset by unrealized derivative gains.
See Item 2.—Management’s Discussion and Analysis of Financial Condition and Results of Operations—SBU Performance Analysis of this Form 10-Q for additional discussion and analysis of operating results for each SBU.
Consolidated Results of Operations — Other
General and administrative expenses
General and administrative expenses increased $20 million, or 36%, to $75 million for the three months ended March 31, 2024, compared to $55 million for the three months ended March 31, 2023, primarily due to increased business development activity and higher people costs and professional fees.
Interest expense
Interest expense increased $27 million, or 8%, to $357 million for the three months ended March 31, 2024, compared to $330 million for the three months ended March 31, 2023. This increase is primarily due to a higher weighted average interest rate and debt balance at the Parent Company as well as new debt issued at the Utilities and Renewables SBUs; partially offset by an increase in capitalized interest.
Interest capitalized during development and construction increased $46 million to $157 million for the three months ended March 31, 2024, compared to $111 million for the three months ended March 31, 2023, primarily due to more projects in development at the Renewables SBU and higher interest rates.
Interest income
Interest income decreased $18 million, or 15%, to $105 million for the three months ended March 31, 2024, compared to $123 million for the three months ended March 31, 2023, primarily due to lower short-term investments at the Renewables and Energy Infrastructure SBUs.
Other income and expense
Other income increased $25 million to $35 million for the three months ended March 31, 2024, compared to $10 million for the three months ended March 31, 2023, mainly due to gains on remeasurement of contingent consideration at AES Clean Energy, a gain on commencement of a sales-type lease on land, and insurance proceeds primarily associated with property damage at AES Andes.
Other expense increased $24 million to $38 million for the three months ended March 31, 2024, compared to $14 million for the three months ended March 31, 2023, primarily driven by legal expenses and other direct costs related to the troubled debt restructuring at Puerto Rico, and a valuation allowance on receivables classified as held-for-sale at Warrior Run.
See Note 15—Other Income and Expense included in Item 1.—Financial Statements of this Form 10-Q for further information.
Gain on disposal and sale of business interests
Gain on disposal and sale of business interests was $43 million for the three months ended March 31, 2024, driven by the gain on dilution of AES’ ownership interest in Uplight as a result of the AutoGrid acquisition, partially offset by the loss on the selldown of Amman East and IPP4 in Jordan, which is now accounted for as an equity method investment. See Note 7—Investments in and Advances to Affiliates and Note 18—Held-for-Sale and Dispositions for further information.
36 | The AES Corporation | March 31, 2024 Form 10-Q
Asset impairment expense
Asset impairment expense increased $26 million to $46 million for the three months ended March 31, 2024, compared to $20 million for the three months ended March 31, 2023. This increase was the result of a $37 million impairment at Mong Duong, due to the carrying value exceeding the expected sales proceeds, partially offset by impairments in the prior year of Amman East and IPP4 in Jordan due to the delay in closing the sale transaction.
See Note 16—Asset Impairment Expense included in Item 1.—Financial Statements of this Form 10-Q for further information.
Foreign currency transaction losses
| Three Months Ended March 31, | |||||||||||||||||||||||
| (in millions) | 2024 | 2023 | |||||||||||||||||||||
| Chile | $ | (6) | $ | (16) | |||||||||||||||||||
| Brazil | (6) | 12 | |||||||||||||||||||||
| Argentina | (1) | (33) | |||||||||||||||||||||
| Other | 5 | (5) | |||||||||||||||||||||
| Total (1) | $ | (8) | $ | (42) |
(1)Includes gains of $18 million and losses of $8 million on foreign currency derivative contracts for the three months ended March 31, 2024 and 2023, respectively.
The Company recognized net foreign currency transaction losses of $8 million for the three months ended March 31, 2024, primarily driven by realized losses on receivables denominated in the Chilean peso as well as unrealized losses on debt denominated in the Brazilian real.
The Company recognized net foreign currency transaction losses of $42 million for the three months ended March 31, 2023, primarily due to unrealized losses due to depreciating receivables denominated in the Argentine peso and unrealized losses related to an intercompany loan denominated in the Colombian peso.
Income tax benefit (expense)
Income tax benefit was $16 million for the three months ended March 31, 2024, compared to $72 million of income tax expense for the three months ended March 31, 2023. The Company’s effective tax rates were (6)% and 27% for the three months ended March 31, 2024 and 2023, respectively. This net decrease in the effective tax rate was largely due to the current year benefits associated with a restructuring of a foreign holding company, as well as U.S. investment tax credits (“ITCs”).
Our effective tax rate reflects the tax effect of significant operations outside the U.S., which are generally taxed at rates different than the U.S. statutory rate of 21%. Furthermore, our foreign earnings may be subjected to incremental U.S. taxation under the GILTI rules. A future proportionate change in the composition of income before income taxes from foreign and domestic tax jurisdictions could impact our periodic effective tax rate.
Net equity in losses of affiliates
Net equity in losses of affiliates increased $11 million to $15 million for the three months ended March 31, 2024, compared to $4 million for the three months ended March 31, 2023. This increase was primarily driven by a decrease in earnings from Mesa La Paz, primarily due to the prior year termination of derivative positions due to a contract amendment.
See Note 7—Investments in and Advances to Affiliates included in Item 1.—Financial Statements of this Form 10-Q for further information.
Net income (loss) attributable to noncontrolling interests and redeemable stock of subsidiaries
Net income attributable to noncontrolling interests and redeemable stock of subsidiaries decreased $192 million to a $154 million loss for the three months ended March 31, 2024, compared to income of $38 million for the three months ended March 31, 2023. This decrease was primarily due to:
-
Higher allocation of losses to tax equity investors on renewables projects placed in service;
-
Lower earnings due to worse hydrology, lower wind generation and increased costs associated with the growth of our business at the Renewables SBU; and
-
Held-for-sale impairment at Mong Duong.
37 | The AES Corporation | March 31, 2024 Form 10-Q
These decreases were partially offset by:
- Prior year impairment at Jordan at the Energy Infrastructure SBU.
Net income attributable to The AES Corporation
Net income attributable to The AES Corporation increased $281 million to $432 million for the three months ended March 31, 2024, compared to $151 million for the three months ended March 31, 2023. This increase was primarily due to:
-
Higher contributions from renewables projects placed in service in the current year;
-
Higher earnings from the Energy Infrastructure SBU due to the PPA termination agreement at Warrior Run;
-
Lower income tax expense;
-
Gain on dilution of our interest in Uplight; and
-
Lower unrealized foreign currency losses at the Energy Infrastructure SBU.
These increases were partially offset by:
-
Higher long-lived asset impairments in the current year; and
-
Lower LNG transactions, higher contract generation cost, and outages at the Energy Infrastructure SBU.
SBU Performance Analysis
Non-GAAP Measures
EBITDA, Adjusted EBITDA, Adjusted EBITDA with Tax Attributes, Adjusted PTC, and Adjusted EPS are non-GAAP supplemental measures that are used by management and external users of our condensed consolidated financial statements such as investors, industry analysts, and lenders.
During the first quarter of 2024, the Company updated the definitions of Adjusted EBITDA, Adjusted PTC, and Adjusted EPS add-back (a) unrealized gains or losses related to derivative transactions and equity securities to include financial assets and liabilities measured using the fair value option, and updated add-back (e) gains, losses, and costs due to the early retirement of debt to include troubled debt restructuring. We believe excluding these gains or losses better reflects the underlying business performance of the Company. The Company also removed the adjustment for net gains at Angamos, one of our businesses in the Energy Infrastructure SBU, associated with the early contract terminations with Minera Escondida and Minera Spence. As this adjustment was specific to certain contract terminations that occurred in 2020, we believe removing this adjustment from our non-GAAP definitions provides simplification and clarity for our investors. There were no such impacts in 2023 or 2024 to date.
EBITDA, Adjusted EBITDA and Adjusted EBITDA with Tax Attributes
We define EBITDA as earnings before interest income and expense, taxes, depreciation, and amortization. We define Adjusted EBITDA as EBITDA adjusted for the impact of NCI and interest, taxes, depreciation, and amortization of our equity affiliates, adding back interest income recognized under service concession arrangements, and excluding gains or losses of both consolidated entities and entities accounted for under the equity method due to (a) unrealized gains or losses pertaining to derivative transactions, equity securities, and financial assets and liabilities measured using the fair value option; (b) unrealized foreign currency gains or losses; (c) gains, losses, benefits and costs associated with dispositions and acquisitions of business interests, including early plant closures, and gains and losses recognized at commencement of sales-type leases; (d) losses due to impairments; and (e) gains, losses, and costs due to the early retirement of debt or troubled debt restructuring.
In addition to the revenue and cost of sales reflected in Operating Margin, Adjusted EBITDA includes the other components of our Consolidated Statement of Operations, such as general and administrative expenses in Corporate and Other as well as business development costs, other expense and other income, realized foreign currency transaction gains and losses, and net equity in earnings of affiliates.
We further define Adjusted EBITDA with Tax Attributes as Adjusted EBITDA, adding back the pre-tax effect of Production Tax Credits (“PTCs”), Investment Tax Credits (“ITCs”), and depreciation tax deductions allocated to tax equity investors, as well as the tax benefit recorded from tax credits retained or transferred to third parties.
The GAAP measure most comparable to EBITDA, Adjusted EBITDA, and Adjusted EBITDA with Tax Attributes is Net income. We believe that EBITDA, Adjusted EBITDA, and Adjusted EBITDA with Tax Attributes better reflect
38 | The AES Corporation | March 31, 2024 Form 10-Q
the underlying business performance of the Company. Adjusted EBITDA is the most relevant measure considered in the Company’s internal evaluation of the financial performance of its segments. Factors in this determination include the variability due to unrealized gains or losses pertaining to derivative transactions, equity securities, or financial assets and liabilities remeasurement, unrealized foreign currency gains or losses, losses due to impairments, strategic decisions to dispose of or acquire business interests or retire debt, and the variability of allocations of earnings to tax equity investors, which affect results in a given period or periods. In addition, each of these metrics represents the business performance of the Company before the application of statutory income tax rates and tax adjustments, including the effects of tax planning, corresponding to the various jurisdictions in which the Company operates. Given its large number of businesses and overall complexity, the Company concluded that Adjusted EBITDA is a more transparent measure than Net income that better assists investors in determining which businesses have the greatest impact on the Company’s results.
EBITDA, Adjusted EBITDA, and Adjusted EBITDA with Tax Attributes should not be construed as alternatives to Net income, which is determined in accordance with GAAP.
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||
| Reconciliation of Adjusted EBITDA and Adjusted EBITDA with Tax Attributes (in millions) | 2024 | 2023 | |||||||||||||||||||||||||||||||||
| Net income | $ | 278 | $ | 189 | |||||||||||||||||||||||||||||||
| Income tax expense (benefit) | (16) | 72 | |||||||||||||||||||||||||||||||||
| Interest expense | 357 | 330 | |||||||||||||||||||||||||||||||||
| Interest income | (105) | (123) | |||||||||||||||||||||||||||||||||
| Depreciation and amortization | 312 | 273 | |||||||||||||||||||||||||||||||||
| EBITDA | $ | 826 | $ | 741 | |||||||||||||||||||||||||||||||
| Less: Adjustment for noncontrolling interests and redeemable stock of subsidiaries (1) | (162) | (170) | |||||||||||||||||||||||||||||||||
| Less: Income tax expense (benefit), interest expense (income) and depreciation and amortization from equity affiliates | 33 | 39 | |||||||||||||||||||||||||||||||||
| Interest income recognized under service concession arrangements | 17 | 18 | |||||||||||||||||||||||||||||||||
| Unrealized derivatives, equity securities, and financial assets and liabilities gains | (85) | (39) | |||||||||||||||||||||||||||||||||
| Unrealized foreign currency losses (gains) | (9) | 32 | |||||||||||||||||||||||||||||||||
| Disposition/acquisition gains | (43) | (3) | |||||||||||||||||||||||||||||||||
| Impairment losses | 26 | 9 | |||||||||||||||||||||||||||||||||
| Loss on extinguishment of debt and troubled debt restructuring | 32 | 1 | |||||||||||||||||||||||||||||||||
| Adjusted EBITDA (1) | $ | 635 | $ | 628 | |||||||||||||||||||||||||||||||
| Tax attributes | 228 | 13 | |||||||||||||||||||||||||||||||||
| Adjusted EBITDA with Tax Attributes (2) | $ | 863 | $ | 641 |
(1) The allocation of earnings and losses to tax equity investors from both consolidated entities and equity affiliates is removed from Adjusted EBITDA.
(2) Adjusted EBITDA with Tax Attributes includes the impact of the share of the ITCs, PTCs, and depreciation deductions allocated to tax equity investors under the HLBV accounting method and recognized as Net loss (income) attributable to noncontrolling interests and redeemable stock of subsidiaries on the Condensed Consolidated Statements of Operations. It also includes the tax benefit recorded from tax credits retained or transferred to third parties. The tax attributes are related to the Renewables and Utilities SBUs.
39 | The AES Corporation | March 31, 2024 Form 10-Q
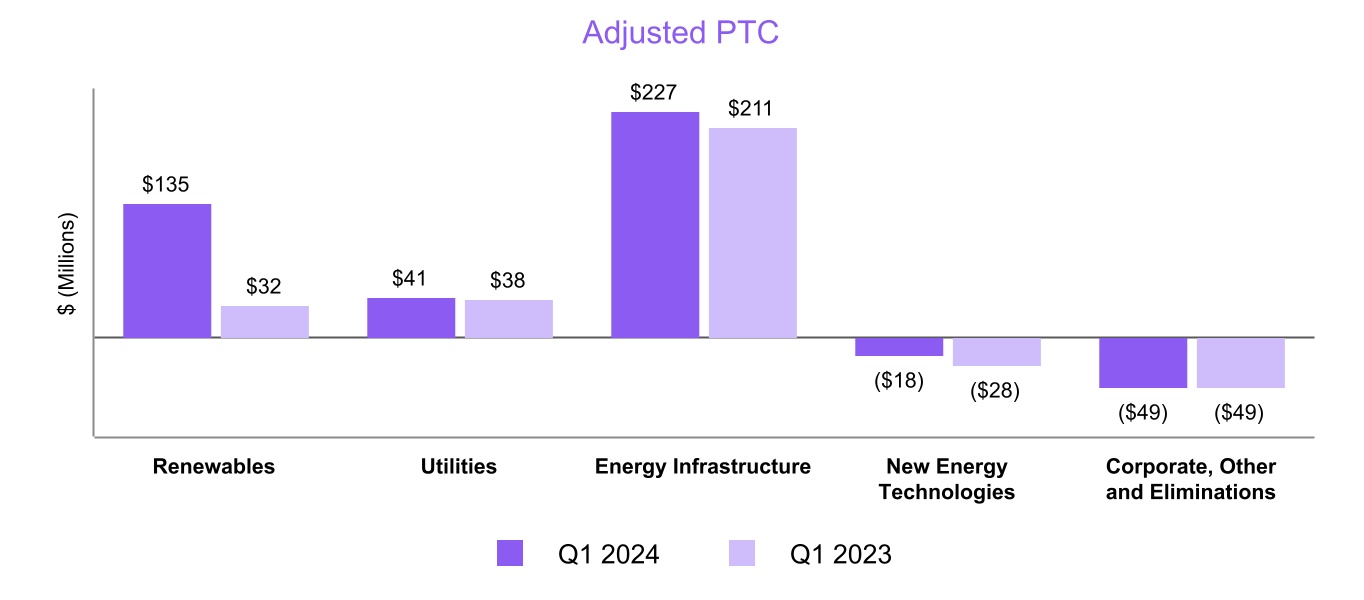
Adjusted PTC
We define Adjusted PTC as pre-tax income from continuing operations attributable to The AES Corporation excluding gains or losses of the consolidated entity due to (a) unrealized gains or losses pertaining to derivative transactions, equity securities, and financial assets and liabilities measured using the fair value option; (b) unrealized foreign currency gains or losses; (c) gains, losses, benefits, and costs associated with dispositions and acquisitions of business interests, including early plant closures, and gains and losses recognized at commencement of sales-type leases; (d) losses due to impairments; and (e) gains, losses, and costs due to the early retirement of debt or troubled debt restructuring. Adjusted PTC also includes net equity in earnings of affiliates on an after-tax basis adjusted for the same gains or losses excluded from consolidated entities.
Adjusted PTC reflects the impact of NCI and excludes the items specified in the definition above. In addition to the revenue and cost of sales reflected in Operating Margin, Adjusted PTC includes the other components of our Consolidated Statement of Operations, such as general and administrative expenses in Corporate and Other as well as business development costs, interest expense and interest income, other expense and other income, realized foreign currency transaction gains and losses, and net equity in earnings of affiliates.
The GAAP measure most comparable to Adjusted PTC is Income from continuing operations attributable to The AES Corporation. We believe that Adjusted PTC better reflects the underlying business performance of the Company and is a relevant measure considered in the Company’s internal evaluation of the financial performance of its segments. Factors in this determination include the variability due to unrealized gains or losses pertaining to derivative transactions, equity securities, or financial assets and liabilities remeasurement, unrealized foreign currency gains or losses, losses due to impairments, and strategic decisions to dispose of or acquire business interests or retire debt, which affect results in a given period or periods. In addition, Adjusted PTC represents the business performance of the Company before the application of statutory income tax rates and tax adjustments, including the effects of tax planning, corresponding to the various jurisdictions in which the Company operates. Given its large number of businesses and complexity, the Company concluded that Adjusted PTC is a more transparent measure than Income from continuing operations attributable to The AES Corporation that better assists investors in determining which businesses have the greatest impact on the Company’s results.
Adjusted PTC should not be construed as an alternative to Income from continuing operations attributable to The AES Corporation, which is determined in accordance with GAAP.
40 | The AES Corporation | March 31, 2024 Form 10-Q
| Three Months Ended March 31, | |||||||||||||||||||||||
| Reconciliation of Adjusted PTC (in millions) | 2024 | 2023 | |||||||||||||||||||||
| Income from continuing operations, net of tax, attributable to The AES Corporation | $ | 432 | $ | 151 | |||||||||||||||||||
| Income tax expense (benefit) from continuing operations attributable to The AES Corporation | (19) | 51 | |||||||||||||||||||||
| Pre-tax contribution | 413 | 202 | |||||||||||||||||||||
| Unrealized derivatives, equity securities, and financial assets and liabilities gains | (85) | (39) | |||||||||||||||||||||
| Unrealized foreign currency losses (gains) | (9) | 31 | |||||||||||||||||||||
| Disposition/acquisition gains | (43) | (3) | |||||||||||||||||||||
| Impairment losses | 26 | 9 | |||||||||||||||||||||
| Loss on extinguishment of debt and troubled debt restructuring | 34 | 4 | |||||||||||||||||||||
| Adjusted PTC | $ | 336 | $ | 204 |
Adjusted EPS
We define Adjusted EPS as diluted earnings per share from continuing operations excluding gains or losses of both consolidated entities and entities accounted for under the equity method due to (a) unrealized gains or losses pertaining to derivative transactions, equity securities, and financial assets and liabilities measured using the fair value option; (b) unrealized foreign currency gains or losses; (c) gains, losses, benefits and costs associated with dispositions and acquisitions of business interests, including early plant closures, and the tax impact from the repatriation of sales proceeds, and gains and losses recognized at commencement of sales-type leases; (d) losses due to impairments; and (e) gains, losses, and costs due to the early retirement of debt or troubled debt restructuring.
The GAAP measure most comparable to Adjusted EPS is Diluted earnings per share from continuing operations. We believe that Adjusted EPS better reflects the underlying business performance of the Company and is considered in the Company’s internal evaluation of financial performance. Factors in this determination include the variability due to unrealized gains or losses pertaining to derivative transactions, equity securities, or financial assets and liabilities remeasurement, unrealized foreign currency gains or losses, losses due to impairments, and strategic decisions to dispose of or acquire business interests or retire debt, which affect results in a given period or periods.
Adjusted EPS should not be construed as an alternative to Diluted earnings per share from continuing operations, which is determined in accordance with GAAP.
The Company reported diluted earnings per share of $0.60 for the three months ended March 31, 2024. For purposes of measuring earnings per share under U.S. GAAP, income available to AES common stockholders is reduced by increases in the carrying amount of redeemable stock of subsidiaries to redemption value. While the adjustment reduced earnings per share, it did not impact Net income on the Condensed Consolidated Statement of Operations. For purposes of computing Adjusted EPS, the Company excluded the adjustment to redemption value from the numerator. The table below reconciles the income available to AES common stockholders used in GAAP diluted earnings per share to the income from continuing operations used in calculating the non-GAAP measure of
41 | The AES Corporation | March 31, 2024 Form 10-Q
Adjusted EPS.
| Reconciliation of Numerator Used for Adjusted EPS | Three Months Ended March 31, 2024 | ||||||||||||||||
| (in millions, except per share data) | Income | Shares | $ per Share | ||||||||||||||
| GAAP DILUTED EARNINGS PER SHARE | |||||||||||||||||
| Income available to The AES Corporation common stockholders | $ | 426 | 712 | $ | 0.60 | ||||||||||||
| Add back: Adjustment to redemption value of redeemable stock of subsidiaries | 6 | — | 0.01 | ||||||||||||||
| NON-GAAP DILUTED EARNINGS PER SHARE | $ | 432 | 712 | $ | 0.61 |
| Three Months Ended March 31, | ||||||||||||||||||||||||||
| Reconciliation of Adjusted EPS | 2024 | 2023 | ||||||||||||||||||||||||
| Diluted earnings per share from continuing operations | $ | 0.61 | $ | 0.21 | ||||||||||||||||||||||
| Unrealized derivatives, equity securities, and financial assets and liabilities gains | (0.12) | (1) | (0.06) | (2) | ||||||||||||||||||||||
| Unrealized foreign currency losses (gains) | (0.01) | 0.04 | (3) | |||||||||||||||||||||||
| Disposition/acquisition gains | (0.06) | (4) | — | |||||||||||||||||||||||
| Impairment losses | 0.04 | (5) | 0.01 | |||||||||||||||||||||||
| Loss on extinguishment of debt and troubled debt restructuring | 0.04 | (6) | 0.01 | |||||||||||||||||||||||
| Less: Net income tax expense | — | 0.01 | ||||||||||||||||||||||||
| Adjusted EPS | $ | 0.50 | $ | 0.22 |
(1)Amount primarily relates to net unrealized derivative gains at the Energy Infrastructure SBU of $68 million, or $0.10 per share.
(2)Amount primarily relates to unrealized derivative gains at the Energy Infrastructure SBU of $48 million, or $0.07 per share.
(3)Amount primarily relates to unrealized foreign currency losses mainly associated with the devaluation of long-term receivables denominated in Argentine pesos of $25 million, or $0.03 per share.
(4)Amount primarily relates to gain on dilution of ownership in Uplight due to its acquisition of AutoGrid of $52 million, or $0.07 per share, partially offset by the loss on partial sale of our ownership interest in Amman East and IPP4 in Jordan of $10 million, or $0.01 per share.
(5)Amount primarily relates to impairment at Mong Duong of $19 million, or $0.03 per share.
(6)Amount primarily relates to costs incurred due to troubled debt restructuring at Puerto Rico of $19 million, or $0.03 per share.
Renewables SBU
The following table summarizes Operating Margin, Adjusted EBITDA, and Adjusted EBITDA with Tax Attributes (in millions) for the periods indicated:
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2023 | $ Change | % Change | ||||||||||||||||||||||||||||||||||||||||||||
| Operating Margin | $ | 53 | $ | 88 | $ | (35) | -40 | % | |||||||||||||||||||||||||||||||||||||||
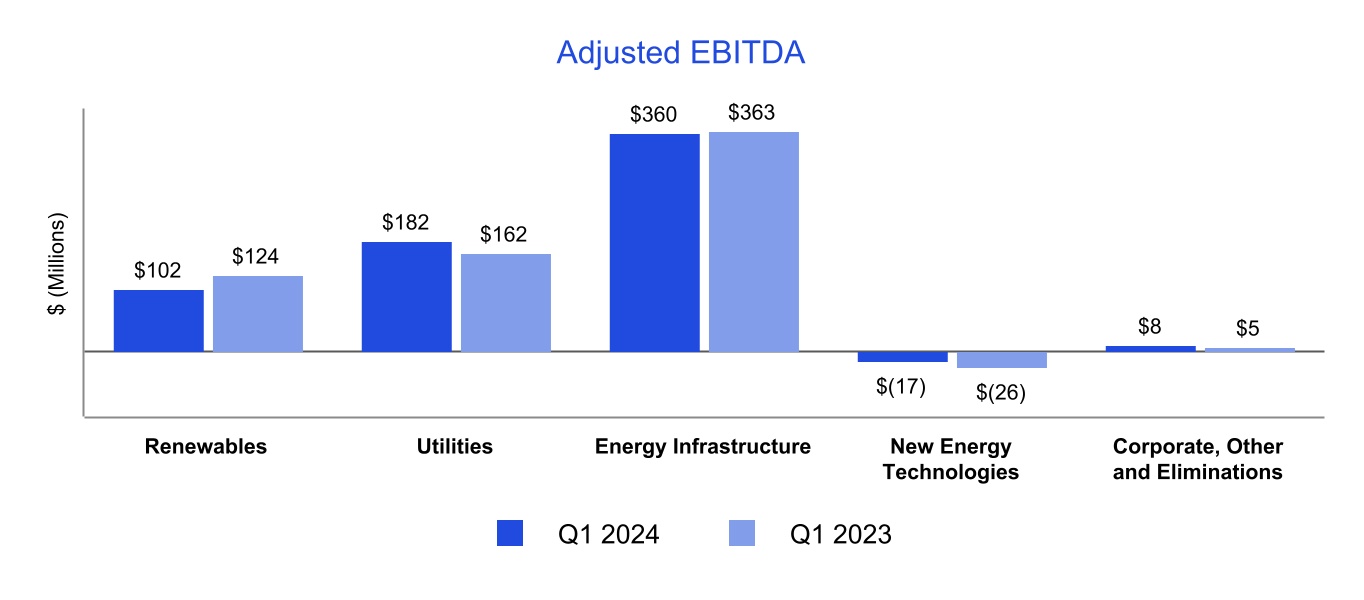
| Adjusted EBITDA (1) | 102 | 124 | (22) | -18 | % | ||||||||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA with Tax Attributes (1) | 328 | 137 | 191 | NM | |||||||||||||||||||||||||||||||||||||||||||
(1) A non-GAAP financial measure. See SBU Performance Analysis—Non-GAAP Measures for definition.
Operating Margin for the three months ended March 31, 2024 decreased $35 million, driven primarily by worse hydrology, lower wind generation, higher energy purchase prices, and higher fixed costs and depreciation related to new projects. This decrease was partially offset by unrealized derivative gains.
Adjusted EBITDA for the three months ended March 31, 2024 decreased $22 million, primarily due to the drivers mentioned above, adjusted for NCI, unrealized derivatives, and depreciation.
Adjusted EBITDA with Tax Attributes for the three months ended March 31, 2024 increased $191 million, primarily due to higher realized tax attributes driven by more renewables projects placed in service, partially offset by the decrease in Adjusted EBITDA. During the three months ended March 31, 2024 and 2023, we realized $226 million and $13 million, respectively, from tax attributes earned by our U.S. renewables business.
Utilities SBU
The following table summarizes Operating Margin, Adjusted EBITDA, Adjusted EBITDA with Tax Attributes, and Adjusted PTC (in millions) for the periods indicated:
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2023 | $ Change | % Change | ||||||||||||||||||||||||||||||||||||||||||||
| Operating Margin | $ | 120 | $ | 105 | $ | 15 | 14 | % | |||||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA (1) | 182 | 162 | 20 | 12 | % | ||||||||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA with Tax Attributes (1) | 184 | 162 | 22 | 14 | % | ||||||||||||||||||||||||||||||||||||||||||
| Adjusted PTC (1) (2) | 41 | 38 | 3 | 8 | % |
(1) A non-GAAP financial measure. See SBU Performance Analysis—Non-GAAP Measures for definition.
42 | The AES Corporation | March 31, 2024 Form 10-Q
(2) Adjusted PTC remains a key metric used by management for analyzing our businesses in the utilities industry.
Operating Margin for the three months ended March 31, 2024 increased $15 million, mainly driven by higher demand due to the impact of weather, higher distribution investment rider revenues as a result of the ESP 4 approved in the fourth quarter of 2023, and an increase in transmission and TDSIC rider revenues, partially offset by higher fixed costs.
Adjusted EBITDA for the three months ended March 31, 2024 increased $20 million, primarily due to the drivers above, adjusted for NCI and depreciation expense.
Adjusted EBITDA with Tax Attributes increased $22 million due to the drivers above, as well as $2 million of realized tax attributes related to the Hardy Hills solar project in the current year.
Adjusted PTC for the three months ended March 31, 2024 increased $3 million due to the drivers above, partially offset by higher depreciation expense and higher interest expense, primarily due to increased borrowings at IPALCO.
Energy Infrastructure SBU
The following table summarizes Operating Margin and Adjusted EBITDA (in millions) for the periods indicated:
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2023 | $ Change | % Change | ||||||||||||||||||||||||||||||||||||||||||||
| Operating Margin | $ | 404 | $ | 375 | $ | 29 | 8 | % | |||||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA (1) | 360 | 363 | (3) | -1 | % | ||||||||||||||||||||||||||||||||||||||||||
(1) A non-GAAP financial measure. See SBU Performance Analysis—Non-GAAP Measures for definition.
Operating Margin for the three months ended March 31, 2024 increased $29 million, driven primarily by higher revenues due to a PPA termination agreement and gains resulting mainly from derivatives as part of our commercial hedging strategy. These increases were partially offset by lower LNG transactions, higher contract generation cost, and higher outages.
Adjusted EBITDA for the three months ended March 31, 2024 decreased $3 million, primarily due to the drivers above, adjusted for NCI, depreciation, and unrealized derivative gains, as well as higher realized foreign currency losses.
New Energy Technologies SBU
The following table summarizes Operating Margin and Adjusted EBITDA (in millions) for the periods indicated:
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 2023 | $ Change | % Change | ||||||||||||||||||||||||||||||||||||||||||||
| Operating Margin | $ | (2) | $ | (4) | $ | 2 | -50 | % | |||||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA (1) | (17) | (26) | 9 | -35 | % | ||||||||||||||||||||||||||||||||||||||||||
(1) A non-GAAP financial measure. See SBU Performance Analysis—Non-GAAP Measures for definition.
Operating Margin for the three months ended March 31, 2024 increased $2 million, with no material drivers.
Adjusted EBITDA for the three months ended March 31, 2024 increased $9 million, primarily due to a reduction in losses at Fluence, driven by increases in margin on the newer Gen 6 solutions projects.
Key Trends and Uncertainties
During 2024 and beyond, we expect to face the following challenges at certain of our businesses. Management expects that improved operating performance at certain businesses, growth from new businesses, and global cost reduction initiatives may lessen or offset their impact. If these favorable effects do not occur, or if the challenges described below and elsewhere in this section impact us more significantly than we currently anticipate, or if volatile foreign currencies and commodities move more unfavorably, then these adverse factors (or other adverse factors unknown to us) may have a material impact on our operating margin, net income attributable to The AES Corporation, and cash flows. We continue to monitor our operations and address challenges as they arise. For the risk factors related to our business, see Item 1.—Business and Item 1A.—Risk Factors of our 2023 Form 10-K.
Operational
43 | The AES Corporation | March 31, 2024 Form 10-Q
Trade Restrictions and Supply Chain — On March 29, 2022, the U.S. Department of Commerce (“Commerce”) announced the initiation of an investigation into whether imports into the U.S. of solar cells and panels imported from Cambodia, Malaysia, Thailand, and Vietnam (“Southeast Asia”) are circumventing antidumping and countervailing duty (“AD/CVD”) orders on solar cells and panels from China. This investigation resulted in significant systemic disruptions to the import of solar cells and panels from Southeast Asia. On June 6, 2022, President Biden issued a Proclamation waiving any circumvention duties on imported solar cells and panels from Southeast Asia that result from this investigation for a 24-month period ending June 6, 2024. Suppliers resumed importing cells and panels from Southeast Asia into the U.S. pursuant to a Commerce certification regime implementing the Proclamation.
On December 2, 2022, Commerce issued country-wide affirmative preliminary determinations that circumvention had occurred in each of the four Southeast Asian countries. Commerce also evaluated numerous individual companies and issued preliminary determinations that circumvention had occurred with respect to many but not all of these companies. Additionally, Commerce issued a preliminary determination that circumvention would not be deemed to occur for any solar cells and panels imported from the four countries if the wafers were manufactured outside of China or if no more than two out of six specifically identified components were produced in China. On August 18, 2023, Commerce issued its final determinations on the matter and affirmed its preliminary findings in most respects. Additionally, Commerce found that three of the specific companies it investigated were not circumventing.
On December 29, 2023, Auxin Solar and Concept Clean Energy filed a lawsuit with the U.S. Court of International Trade, challenging certain aspects of the final rule promulgated by Commerce to implement the Proclamation. The lawsuit specifically challenges Commerce’s decisions not to suspend the final disposition of certain entries of imported solar cells and panels from Southeast Asia made prior to June 6, 2024, and not to collect AD/CVD deposits with respect to those entries. The Department of Justice has responded by filing a motion to dismiss the lawsuit.
On April 24, 2024, new Commerce regulations with respect to the administration of AD/CVD cases went into effect, including regulations pertaining to transnational subsidization and particular market situations. On the same day, several companies filed a petition requesting that Commerce initiate an investigation into whether new AD/CVD duties should be imposed on cells and modules imported from Thailand, Cambodia, Malaysia, and Vietnam. If Commerce initiates such an investigation, it could cause disruptions to the import of solar cells and panels from such countries.
Additionally, the Uyghur Forced Labor Prevention Act (“UFLPA”) seeks to block the import of products made with forced labor in certain areas of China and may lead to certain suppliers being blocked from importing solar cells and panels to the U.S. While this has impacted the U.S. market, AES has managed this issue without significant impact to our projects. Further disruptions may impact our suppliers’ ability or willingness to meet their contractual agreements or to continue to supply cells or panels into the U.S. market on terms that we deem satisfactory.
The impact of new Commerce investigations or any additional adverse Commerce determinations or other tariff disputes or litigation, the impact of the UFLPA, potential future disruptions to the solar panel supply chain and their effect on AES’ U.S. solar project development and construction activities remain uncertain. AES will continue to monitor developments and take prudent steps towards maintaining a robust supply chain for our renewables projects.
We have contracted and secured our expected requirements for solar panels for U.S. projects targeted to achieve commercial operations in 2024.
Operational Sensitivity to Dry Hydrological Conditions — Our hydroelectric generation facilities are sensitive to changes in the weather, particularly the level of water inflows into generation facilities. Dry hydrological conditions in Panama, Brazil, Colombia and Chile can present challenges for our businesses in these markets. Low inflows can result in low reservoir levels, reduced generation output, and subsequently possible increased prices for electricity. If our hydroelectric generation facilities cannot generate sufficient energy to meet contractual arrangements, we may need to purchase energy to fulfill our obligations, which could have an adverse impact on AES. As mitigation, AES has invested in thermal, wind, and solar generation assets, which have a complementary profile to hydroelectric plants. These plants are expected to have increased generation in low hydrology scenarios, offsetting possible impacts described from hydro assets.
According to the National Oceanic and Atmospheric Administration ("NOAA"), El Niño conditions are observed and forecasted through the beginning of Q3 of 2024. A transition from El Niño to ENSO-neutral is likely by mid-2024, with the indications of La Niña developing by late Q3 of 2024.
44 | The AES Corporation | March 31, 2024 Form 10-Q
In Panama, consistent with expected El Niño impacts, local hydrological forecasts indicate below historical average inflows persisting into Q2 of 2024, which could impact our results of operations. AES reduced its total generation exposure in Panama to dry hydrological conditions through investments in such complementary assets as the Colon LNG power facility, which commenced operations in 2018, the Penonome Wind Farm, and solar projects, providing a stable and independent diversified energy supply during periods of drought or when hydroelectric generation is limited. In Panama, the La Niña phenomenon in contrast to El Niño typically means wetter conditions than average, although local system impacts may vary due to other factors. Higher hydrology may result in energy surpluses after covering the contracted hydro positions, available to be sold in the spot market after fulfilling contract obligations.
In Colombia, El Niño is characterized by drought and may result in higher spot prices as observed in Q1 of 2024 and early Q2 2024. Lower overall AES Chivor hydrology may result in increased spot price energy exposure to cover contracted positions. The basin where AES Chivor is located typically experiences wet conditions from June through September in contrast with the broader system, which can result in additional energy available to sell in the spot market after fulfilling contract obligations. La Niña in Colombia is typically characterized by more rainfall possibly leading to a decrease in spot prices. However, during La Niña impacts vary and the basin where Chivor is located may experience drier conditions than the system.
In Brazil, El Niño generally means more rainfall in the South and higher temperatures in the central region of the country, as seen in the last quarter of 2023, while La Niña results in more rainfall in the North, drier conditions in the South and milder temperatures in the central region, which could result in lower demand. Current system reservoir levels remain high, which supports lower spot prices through the remainder of 2024 mitigating hydrological risk following a dry Q1, which led to higher power prices. Lower prices limit external thermal generation which, if dispatched, could impact demand for the AES hydro generation.
In Chile, the primary driver for AES’ hydro assets is snowpack volumes. Lower snowpack, together with reduced rainfall in the system, could increase both spot prices and energy purchase volumes required to meet contracted positions.
The exact behavior pattern and strength of El Niño and the potential evolution towards La Niña is unknown and therefore the impacts could vary from those described above, and may include impacts to our businesses beyond hydrology, including with respect to power generation from other renewable sources of energy and demand. Even if rainfall and water inflows return to or exceed historical averages, in some cases high market prices and low generation could persist until reservoir levels are fully recovered. Further, investments made in thermal, wind, and solar power generation may benefit from uncontracted spot sales at higher market prices. Impacts may be material to our results of operations.
Macroeconomic and Political
During the past few years, some countries where our subsidiaries conduct business have experienced macroeconomic and political changes. In the event these trends continue, there could be an adverse impact on our businesses.
Inflation Reduction Act and U.S. Renewable Energy Tax Credits — The Inflation Reduction Act (the “IRA”) was signed into law in the United States. The IRA includes provisions that are expected to benefit the U.S. clean energy industry, including increases, extensions, direct transfers and/or new tax credits for onshore and offshore wind, solar, storage and hydrogen projects. We expect that the extension of the current solar investment tax credits ("ITCs"), as well as higher credits available for projects that satisfy wage and apprenticeship requirements, will increase demand for our renewables products.
Our U.S. renewables business has a 51 GW pipeline that we intend to utilize to continue to grow our business, and these changes in tax policy are supportive of this strategy. We account for U.S. renewables projects according to U.S. GAAP, which, when partnering with tax-equity investors to monetize tax benefits, utilizes the HLBV method. This method recognizes the tax-credit value that is transferred to tax equity investors at the time of its creation, which for projects utilizing the investment tax credit begins in the quarter the project is placed in service. For projects utilizing the production tax credit, this value is recognized over 10 years as the facility produces energy.
The IRA also allows us to directly transfer investment tax credits to unrelated tax credit buyers. We account for the transfer proceeds as tax benefit throughout the year the renewables project is placed in service.
In 2023, we realized $611 million of earnings from Tax Attributes, comprised of $593 million from the Renewables SBU and $18 million from the Utilities SBU. In 2024, we expect an increase in Tax Attributes earned by
45 | The AES Corporation | March 31, 2024 Form 10-Q
our U.S. renewables business in line with the growth in that business. Based on construction schedules, a significant portion of these earnings will be realized in the fourth quarter.
The implementation of the IRA requires substantial guidance from the U.S. Department of Treasury and other government agencies. While some of that guidance remains pending, there will be uncertainty with respect to the implementation of certain provisions of the IRA.
Argentina — The recent election of President Javier Milei on December 10, 2023, marks a pivotal moment in Argentina's economic landscape. The entering administration issued Decree No. 55/23, signaling a commitment to total economic deregulation. This decree declares a state of emergency in the power sector, tariff revisions for electric power and natural gas transport and distribution, and a broader proposal for sector-wide reform.
President Milei also proposed a new bill, currently under review by Congress, that seeks to overhaul the energy regulatory framework. Emphasizing deregulation, the bill opens avenues for privatization of state-owned energy companies. These proposed changes may have a profound impact on the sector, influencing our operations and financial results. It is not yet possible to predict the impact of these regulations in our consolidated results of operations, cash flows, and financial condition.
Global Tax — The macroeconomic and political environments in the U.S. and in some countries where our subsidiaries conduct business have changed in recent years. This could result in significant impacts to future tax law. In the U.S., the IRA includes a 15% corporate alternative minimum tax based on adjusted financial statement income. Additional guidance is expected to be issued in 2024.
During 2023, the Netherlands, Bulgaria and Vietnam adopted legislation to implement Pillar 2 effective as of January 1, 2024. We will continue to monitor the issuance of draft legislation in other non-EU countries where the Company operates that are considering Pillar 2 amendments and new interpretive guidance. The impact to the Company during 2024 is not expected to be material.
Inflation — In the markets in which we operate, there have been higher rates of inflation recently. While most of our contracts in our international businesses are indexed to inflation, in general, our U.S.-based generation contracts are not indexed to inflation. If inflation continues to increase in our markets, it may increase our expenses that we may not be able to pass through to customers. It may also increase the costs of some of our development projects that could negatively impact their competitiveness. Our utility businesses do allow for recovering of operations and maintenance costs through the regulatory process, which may have timing impacts on recovery.
Interest Rates — In the U.S. and other markets in which we operate, there has been a rise in interest rates since 2021, and interest rates are expected to remain volatile in the near term.
As discussed in Item 3—Quantitative and Qualitative Disclosures about Market Risk, although most of our existing corporate and subsidiary debt is at fixed rates, an increase in interest rates can have several impacts on our business. For any existing debt under floating rate structures and any future debt refinancings, rising interest rates will increase future financing costs. In most cases in which we have floating rate debt, our revenues serving this debt are indexed to inflation, which helps mitigate the impact of rising rates. For future debt refinancings, AES actively manages a hedging program to reduce uncertainty and exposure to future interest rates. For new business, higher interest rates increase the financing costs for new projects under development and which have not yet secured financing.
AES typically seeks to incorporate expected financing costs into our new PPA pricing such that we maintain our target investment returns, but higher financing costs may negatively impact our returns or the competitiveness of some of our development projects. Additionally, we typically seek to enter into interest rate hedges shortly after signing PPAs to mitigate the risk of rising interest rates prior to securing long-term financing.
Puerto Rico — As discussed in Item 7—Management’s Discussion and Analysis of Financial Condition and Results of Operations—Key Trends and Uncertainties of the 2023 Form 10-K, our subsidiaries in Puerto Rico have long-term PPAs with state-owned PREPA, which has been facing economic challenges that could result in a material adverse effect on our business in Puerto Rico. Despite the Title III protection, PREPA has been making substantially all of its payments to the generators in line with historical payment patterns.
The Puerto Rico Oversight, Management, and Economic Stability Act (“PROMESA”) was enacted to create a structure for exercising federal oversight over the fiscal affairs of U.S. territories and created procedures for adjusting debt accumulated by the Puerto Rico government and, potentially, other territories (“Title III”). PROMESA also expedites the approval of key energy projects and other critical projects in Puerto Rico.
46 | The AES Corporation | March 31, 2024 Form 10-Q
PROMESA allowed for the establishment of an Oversight Board with broad powers of budgetary and financial control over Puerto Rico. The Oversight Board filed for bankruptcy on behalf of PREPA under Title III in July 2017. As a result of the bankruptcy filing, AES Ilumina’s non-recourse debt of $24 million continues to be in technical default and is classified as current as of March 31, 2024.
On April 12, 2022, a mediation team was appointed to prepare the plan to resolve the PREPA Title III case and related proceedings. A disclosure statement hearing was held on April 28, 2023. The mediation was extended through August 4, 2023. On November 14, 2023, the Judge presiding over the case approved the supplemental disclosure statement for PREPA’s Fourth Modified Third Amended Title III Plan of Adjustment. The
confirmation trial ended on March 18, 2024, with the Judge’s decision pending.
In 2023, AES Puerto Rico took certain measures to address identified liquidity challenges. On July 6, 2023, PREPA agreed to the release of funds in the escrow account guaranteeing AES Puerto Rico’s obligations under the Power Purchase and Operating Agreement (“PPOA”) in order to provide additional liquidity for the business. During the fourth quarter of 2023, a restructuring support agreement was executed by AES Puerto Rico and its noteholders and a PPOA amendment was approved by PREPA. Under this new agreement, PREPA’s bankruptcy under Title III does not result in a technical default for AES Puerto Rico, and therefore its non-recourse debt of $161 million is classified as long-term. The restructuring closed on March 5, 2024. See Note 8—Debt included in Item 1.—Financial Statements of this Form 10-Q for further information.
Despite these challenges and considering the information available as of the filing date, management believes the carrying amount of our long-lived assets at AES Puerto Rico of $78 million is recoverable as of March 31, 2024.
Mexico Migration — The interconnection agreements for TEG and TEP under the self-supply energy regime in Mexico were due to expire in April 2024. Consequently, TEG and TEP are required to migrate into the new energy regime established by the Electricity Industry Law of 2021 (“LIE”) and to execute new interconnection agreements prior to the expiration of the current interconnection agreements. In February and September 2022, respectively, TEG and TEP made formal requests to the Mexican Comision Reguladora de Energia (“CRE”) to update the projects’ permits and allow them to migrate into the LIE (“Migration Requests”). On March 26, 2024, CRE granted the migration permits for TEG and TEP. On March 27, 2024, TEG and TEP filed their request with El Centro Nacional de Control de Energía (CENACE) for the execution of the new interconnection agreements, and on April 18, 2024, the agreements were executed.
Decarbonization Initiatives
Our strategy involves shifting towards clean energy platforms, including renewable energy, energy storage, LNG, and modernized grids. It is designed to position us for continued growth while reducing our carbon intensity and to be in support of our mission of accelerating the future of energy, together. We have made significant progress on our exit of coal generation, and we intend to exit the substantial majority of our remaining coal facilities by year-end 2025 and intend to exit all of the coal facilities by year-end 2027, subject to necessary approvals.
In addition, initiatives have been announced by regulators, including in Chile, Puerto Rico, and Bulgaria, and offtakers in recent years, with the intention of reducing GHG emissions generated by the energy industry. In parallel, the shift towards renewables has caused certain customers to migrate to other low-carbon energy solutions and this trend may continue.
Although we cannot currently estimate the financial impact of these decarbonization initiatives, new legislative or regulatory programs further restricting carbon emissions or other initiatives to voluntarily exit coal generation could require material capital expenditures, resulting in a reduction of the estimated useful life of certain coal facilities, or have other material adverse effects on our financial results.
For further information about the risks associated with decarbonization initiatives, see Item 1A.—Risk Factors—Concerns about GHG emissions and the potential risks associated with climate change have led to increased regulation and other actions that could impact our businesses included in the 2023 Form 10-K.
Regulatory
AES Maritza PPA Review — DG Comp is conducting a preliminary review of whether AES Maritza’s PPA with NEK is compliant with the European Union's State Aid rules. No formal investigation has been launched by DG Comp to date. AES Maritza has previously engaged in discussions with the DG Comp case team and the Government of Bulgaria (“GoB”) to attempt to reach a negotiated resolution of the DG Comp’s review (“PPA Discussions”). There are no active PPA Discussions at present but those discussions could resume at any time. The
47 | The AES Corporation | March 31, 2024 Form 10-Q
PPA continues to remain in place. However, there can be no assurance that, in the context of DG Comp’s preliminary review or any future PPA Discussions, the other parties will not seek a prompt termination of the PPA.
We do not believe termination of the PPA is justified. Nevertheless, the PPA Discussions involved a range of potential outcomes, including but not limited to the termination of the PPA and payment of some level of compensation to AES Maritza. Any negotiated resolution would be subject to mutually acceptable terms, lender consent, and DG Comp approval. At this time, we cannot predict whether and when the PPA Discussions might resume or the outcome of any such discussions. Nor can we predict how DG Comp might resolve its review if the PPA Discussions do not resume or if any such discussions fail to result in an agreement concerning the agency's review. AES Maritza believes that its PPA is legal and in compliance with all applicable laws, and it will take all actions necessary to protect its interests, whether through negotiated agreement or otherwise. However, there can be no assurance that this matter will be resolved favorably; if it is not, there could be a material adverse effect on the Company’s financial condition, results of operations, and cash flows. As of March 31, 2024, the carrying value of our long-lived assets at Maritza is $332 million.
AES Indiana Regulatory Rate Review — On April 17, 2024, the IURC issued an order (the “2024 Rate Order”) approving the Stipulation and Settlement Agreement that AES Indiana entered into on November 22, 2023, with the Office of Utility Consumer Counselor (“OUCC”) and the other intervening parties in AES Indiana’s base rate case filing. Among other matters and consistent with the Stipulation and Settlement Agreement, the 2024 Rate Order approves an increase in AES Indiana's total annual operating revenue of $71 million for AES Indiana’s electric service and provides a return on common equity of 9.9% and cost of long-term debt of 4.90% on a rate base of approximately $3.5 billion. Updated customer rates and charges are expected to be effective in May 2024.
AES Indiana Petersburg Repowering — On March 11, 2024, AES Indiana filed for approval of a CPCN seeking for IURC approval to repower Petersburg Generation Units 3 & 4 from coal to natural gas and to recover costs through future rates. The conversion of Unit 3 is expected to begin in February 2026 and be completed by June 2026 and the conversion of Unit 4 is expected to begin in June 2026 and be completed by December 2026. A hearing for this case is expected to be held in August 2024, and we expect the IURC to issue an order on this proceeding during the fourth quarter of 2024.
AES Ohio Smart Grid Phase 2 Filing — In February 2024, AES Ohio filed a Smart Grid Phase 2 with the PUCO proposing to invest approximately $683 million in capital projects over a 10-year period following the Smart Grid Phase 1, which ends June 2025.
Foreign Exchange Rates
We operate in multiple countries and as such are subject to volatility in exchange rates at varying degrees at the subsidiary level and between our functional currency, the USD, and currencies of the countries in which we operate.
The overall economic climate in Argentina has deteriorated, resulting in volatility and increased the risk that a further significant devaluation of the Argentine peso against the USD, similar to the devaluations experienced by the country in 2018, 2019, and 2023, may occur. A continued trend of peso devaluation could result in increased inflation, a deterioration of the country’s risk profile, and other adverse macroeconomic effects that could significantly impact our results of operations. For additional information, refer to Item 3.—Quantitative and Qualitative Disclosures About Market Risk.
Impairments
Long-lived Assets and Current Assets Held-for-Sale — During the three months ended March 31, 2024, the Company recognized asset impairment expense of $46 million. See Note 16*—Asset Impairment Expense* included in Item 1.—Financial Statements of this Form 10-Q for further information. After recognizing this impairment expense, the carrying value of long-lived assets and current assets held-for-sale that were assessed for impairment totaled $78 million at March 31, 2024.
Events or changes in circumstances that may necessitate recoverability tests and potential impairments of long-lived assets may include, but are not limited to, adverse changes in the regulatory environment, unfavorable changes in power prices or fuel costs, increased competition due to additional capacity in the grid, technological advancements, declining trends in demand, evolving industry expectations to transition away from fossil fuel sources for generation, or an expectation it is more likely than not the asset will be disposed of before the end of its estimated useful life.
48 | The AES Corporation | March 31, 2024 Form 10-Q
Environmental
The Company is subject to numerous environmental laws and regulations in the jurisdictions in which it operates. The Company faces certain risks and uncertainties related to these environmental laws and regulations, including existing and potential GHG legislation or regulations, and actual or potential laws and regulations pertaining to water discharges, waste management (including disposal of coal combustion residuals) and certain air emissions, such as SO2, NOx, particulate matter, mercury, and other hazardous air pollutants, and species and habitat protections. Such risks and uncertainties could result in increased capital expenditures or other compliance costs which could have a material adverse effect on certain of our U.S. or international subsidiaries and our consolidated results of operations. For further information about these risks, see Item 1A.—Risk Factors—Our operations are subject to significant government regulation and could be adversely affected by changes in the law or regulatory schemes; Several of our businesses are subject to potentially significant remediation expenses, enforcement initiatives, private party lawsuits and reputational risk associated with CCR; Our businesses are subject to stringent environmental laws, rules and regulations; and Concerns about GHG emissions and the potential risks associated with climate change have led to increased regulation and other actions that could impact our businesses included in the 2023 Form 10-K.
CSAPR — CSAPR addresses the “good neighbor” provision of the CAA, which prohibits sources within each state from emitting any air pollutant in an amount which will contribute significantly to any other state’s nonattainment, or interference with maintenance of, any NAAQS. The CSAPR required significant reductions in SO2 and NOx emissions from power plants in many states in which subsidiaries of the Company operate. The Company is required to comply with the CSAPR in certain states, including Indiana and Maryland. The CSAPR is implemented, in part, through a market-based program under which compliance may be achievable through the acquisition and use of emissions allowances created by the EPA. The Company complies with CSAPR through operation of existing controls and purchases of allowances on the open market, as needed.
In October 2016, the EPA published a final rule to update the CSAPR to address the 2008 ozone NAAQS (“CSAPR Update Rule”). The CSAPR Update Rule found that NOx ozone season emissions in 22 states (including Indiana and Maryland) affected the ability of downwind states to attain and maintain the 2008 ozone NAAQS, and, accordingly, the EPA issued federal implementation plans that both updated existing CSAPR NOx ozone season emission budgets for electric generating units within these states and implemented these budgets through modifications to the CSAPR NOx ozone season allowance trading program. Implementation started in the 2017 ozone season (May-September 2017). Affected facilities receive fewer ozone season NOx allowances in 2017 and later, possibly resulting in the need to purchase additional allowances. Following legal challenges to the CSAPR Update Rule, on April 30, 2021, the EPA issued the Revised CSAPR Update Rule. The Revised CSAPR Update Rule required affected EGUs within certain states (including Indiana and Maryland) to participate in a new trading program, the CSAPR NOx Ozone Season Group 3 trading program. These affected EGUs received fewer NOx Ozone Season allowances beginning in 2021.
On June 5, 2023, the EPA published a final Federal Implementation Plan to address air quality impacts with respect to the 2015 Ozone NAAQS. The rule establishes a revised CSAPR NOx Ozone Season Group 3 trading program for 22 states, including Indiana and Maryland, and became effective during 2023. The FIP also includes enhancements to the revised Group 3 trading program, which include a dynamic budget setting process beginning in 2026, annual recalibration of the allowance bank to reflect changes to affected sources, a daily backstop emissions rate limit for certain coal-fired electric generating units beginning in 2024, and a secondary emissions limit prohibiting certain emissions associated with state assurance levels. It is too early to determine the impact of this final rule, but it may result in the need to purchase additional allowances or make operational adjustments.
While the Company's additional CSAPR compliance costs to date have been immaterial, the future availability of and cost to purchase allowances to meet the emission reduction requirements is uncertain at this time, but it could be material.
Mercury and Air Toxics Standard — In April 2012, the EPA’s rule to establish maximum achievable control technology standards for hazardous air pollutants regulated under the CAA emitted from coal and oil-fired electric utilities, known as “MATS”, became effective and AES facilities implemented measures to comply, as applicable. In June 2015, the U.S. Supreme Court remanded MATS to the D.C. Circuit due to the EPA’s failure to consider costs before deciding to regulate power plants under Section 112 of the CAA and subsequently remanded MATS to the EPA without vacatur. On May 22, 2020, the EPA published a final finding that it is not “appropriate and necessary” to regulate hazardous air pollutant emissions from coal- and oil-fired electric generating units (EGUs) (reversing its prior 2016 finding), but that the EPA would not remove the source category from the CAA Section 112(c) list of source categories and would not change the MATS requirements. On March 6, 2023, the EPA
49 | The AES Corporation | March 31, 2024 Form 10-Q
published a final rule to revoke its May 2020 finding and reaffirm its 2016 finding that it is appropriate and necessary to regulate these emissions. On April 24, 2023, the EPA published a proposed rule, the MATS Risk and Technology Review (RTR) Rule to lower certain emissions limits and revise certain other aspects of MATS. On April 25, 2024, the EPA released a pre-publication version of the final MATS RTR Rule. We are currently reviewing the final rule and it is too early to determine the potential impacts.
Further rulemakings and/or proceedings are possible; however, in the meantime, MATS remains in effect. We currently cannot predict the outcome of the regulatory or judicial process, or its impact, if any, on our MATS compliance planning or ultimate costs.
Climate Change Regulation — On July 8, 2019, the EPA published the final Affordable Clean Energy (“ACE”) Rule which would have established CO2 emission rules for existing power plants under CAA Section 111(d) and would have replaced the EPA's 2015 Clean Power Plan Rule (“CPP”). However, on January 19, 2021, the D.C. Circuit vacated and remanded the ACE Rule. Subsequently, on June 30, 2022, the Supreme Court reversed the judgment of the D.C. Circuit Court and remanded for further proceedings consistent with its opinion holding that the “generation shifting” approach in the CPP exceeded the authority granted to the EPA by Congress under Section 111(d) of the CAA. As a result of the June 30, 2022 Supreme Court decision, on October 27, 2022, the D.C. Circuit issued a partial mandate, holding pending challenges to the ACE Rule in abeyance while the EPA developed a replacement rule. On May 23, 2023, the EPA published a proposed rule that would vacate the ACE Rule, and proposed New Source Performance Standards (“NSPSs”) that would establish emissions guidelines in the form of CO2 emissions limitations for certain existing electric generating units (“EGUs”) and would require states to develop State Plans that establish standards of performance for such EGUs that are at least as stringent as EPA’s emissions guidelines. Depending on various EGU-specific factors, the bases of proposed emissions guidelines range from routine methods of operation to carbon capture and sequestration or co-firing low-GHG hydrogen starting in the 2030s. On April 25, 2024, the EPA released a prepublication version of the final NSPSs for GHGs for new, modified, and reconstructed fossil-fuel fired EGUs, Emissions Guidelines for existing fossil fuel-fired EGUs, and the Repeal of the ACE Rule. We are currently reviewing these rules. The impact of the rules, the results of further proceedings, and potential future greenhouse gas emissions regulations remain uncertain but could be material.
Waste Management — On October 19, 2015, an EPA rule regulating CCR under the Resource Conservation and Recovery Act as nonhazardous solid waste became effective. The rule established nationally applicable minimum criteria for the disposal of CCR in new and currently operating landfills and surface impoundments, including location restrictions, design and operating criteria, groundwater monitoring, corrective action and closure requirements, and post-closure care. The primary enforcement mechanisms under this regulation would be actions commenced by the states and private lawsuits. On December 16, 2016, the Water Infrastructure Improvements for the Nation Act ("WIN Act") was signed into law. This includes provisions to implement the CCR rule through a state permitting program, or if the state chooses not to participate, a possible federal permit program. If this rule is finalized before Indiana or Puerto Rico establishes a state-level CCR permit program, AES CCR units in those locations could eventually be required to apply for a federal CCR permit from the EPA. The EPA has indicated that it will implement a phased approach to amending the CCR Rule, which is ongoing. On August 28, 2020, the EPA published final amendments to the CCR Rule titled "A Holistic Approach to Closure Part A: Deadline to Initiate Closure," that, among other amendments, required certain CCR units to cease waste receipt and initiate closure by April 11, 2021. The CCR Part A Rule also allowed for extensions of the April 11, 2021 deadline if the EPA determines certain criteria are met. Facilities seeking such an extension were required to submit a demonstration to the EPA by November 30, 2020. On January 11, 2022, the EPA released the first in a series of proposed determinations regarding CCR Part A Rule demonstrations and compliance-related letters notifying certain other facilities of their compliance obligations under the federal CCR regulations. The determinations and letters include interpretations regarding implementation of the CCR Rule. On April 8, 2022, petitions for review were filed challenging these EPA actions. The petitions are consolidated in Electric Energy, Inc. v. EPA. It is too early to determine the direct or indirect impact of these letters or any determinations that may be made.
On May 18, 2023, the EPA published a proposed rule that would expand the scope of CCR units regulated by the CCR Rule to include inactive surface impoundments at inactive generating facilities as well as additional inactive and closed landfills and certain other accumulations of CCR. On April 25, 2024, the EPA released the pre-publication version of the final rule, which we are currently reviewing. It is too early to determine the potential impact.
The CCR rule, current or proposed amendments to or interpretations of the CCR rule, the results of groundwater monitoring data, or the outcome of CCR-related litigation could have a material impact on our business, financial condition, and results of operations. AES Indiana would seek recovery of any resulting expenditures; however, there is no guarantee we would be successful in this regard.
50 | The AES Corporation | March 31, 2024 Form 10-Q
Cooling Water Intake — The Company's facilities are subject to a variety of rules governing water use and discharge. In particular, the Company's U.S. facilities are subject to the CWA Section 316(b) rule issued by the EPA effective in 2014 that seeks to protect fish and other aquatic organisms drawn into cooling water systems at power plants and other facilities. These standards require affected facilities to choose among seven BTA options to reduce fish impingement. In addition, certain facilities must conduct studies to assist permitting authorities to determine whether and what site-specific controls, if any, would be required to reduce entrainment of aquatic organisms. It is possible that this process, which includes permitting and public input, could result in the need to install closed-cycle cooling systems (closed-cycle cooling towers) or other technology. Finally, the standards require that new units added to an existing facility to increase generation capacity are required to reduce both impingement and entrainment. It is not yet possible to predict the total impacts of this final rule at this time, including any challenges to such final rule and the outcome of any such challenges. However, if additional capital expenditures are necessary, they could be material.
AES Southland's current plan is to comply with the SWRCB OTC Policy by shutting down and permanently retiring all existing generating units at AES Alamitos, AES Huntington Beach, and AES Redondo Beach that utilize OTC by the compliance dates included in the OTC Policy.
The Company’s California subsidiaries have signed 20-year term PPAs with Southern California Edison for new generating capacity, which have been approved by the California Public Utilities Commission. Construction of new generating capacity began in June 2017 at AES Huntington Beach and July 2017 at AES Alamitos. The new air-cooled combined cycle gas turbine generators and battery energy storage systems were constructed at the AES Alamitos and AES Huntington Beach generating stations. The new air-cooled combined cycle gas turbine generators at the AES Alamitos and AES Huntington Beach generating stations began commercial operation in early 2020 and there is currently no plan to replace the OTC generating units at the AES Redondo Beach generating station following the retirement. Certain OTC units were required to be retired in 2019 to provide interconnection capacity and/or emissions credits prior to startup of the new generating units, and the remaining AES OTC generating units in California will be shut down and permanently retired by the OTC Policy compliance dates for these units. The SWRCB OTC Policy required the shutdown and permanent retirement of all remaining OTC generating units at AES Alamitos, AES Huntington Beach, and AES Redondo Beach by December 31, 2020. The initial amendment extended the deadline for shutdown and retirement of AES Alamitos and AES Huntington Beach’s remaining OTC generating units to December 31, 2023 and extended the deadline for shutdown and retirement of AES Redondo Beach’s remaining OTC generating units to December 31, 2021 (the “AES Redondo Beach Extension”). In October 2020, the cities of Redondo Beach and Hermosa Beach filed a state court lawsuit challenging the AES Redondo Beach Extension. AES opposed the action and the court granted an order dismissing the matter. The case remains open subject to the resolution of counter claims between parties other than AES. Plaintiffs have initiated an additional challenge to the permit, and the outcome of that lawsuit is unclear. On March 16, 2021, the SACCWIS released their draft 2021 report to SWRCB. The report summarizes the State of California’s current electrical grid reliability needs and recommended a two-year extension to the compliance schedule for AES Redondo Beach to address system-wide grid reliability needs. The SWRCB public hearing regarding the final decision on the amendment of the OTC policy was held on October 19, 2021 and the Board voted in favor of extending the compliance date for AES Redondo Beach to December 31, 2023. The AES Redondo Beach NPDES permit has been administratively extended. On September 30, 2022, the Statewide Advisory Committee on Cooling Water Intake Structures approved a recommendation to the SWRCB to consider an extension of the OTC compliance dates for AES Huntington Beach, LLC and AES Alamitos, LLC to December 31, 2026, in support of grid reliability. On August 15, 2023, the State Water Board considered the SACCWIS recommendation and adopted an amendment to the OTC Policy that established a final compliance date of December 31, 2026 for the Alamitos and Huntington Beach facilities. This extension is contingent upon the facilities participating in the Strategic Reserve established by AB 205.
Power plants are required to comply with the more stringent of state or federal requirements. At present, the California state requirements are more stringent and have earlier compliance dates than the federal EPA requirements, and are therefore applicable to the Company's California assets. The Company anticipates that compliance with CWA Section 316(b) regulations and associated costs could have a material impact on our consolidated financial condition or results of operations.
Water Discharges — In June 2015, the EPA and the U.S. Army Corps of Engineers ("the Agencies") published a rule defining federal jurisdiction over waters of the U.S., known as the "Waters of the U.S." (“WOTUS”) rule. WOTUS defines the geographic reach and authority of the Agencies to regulate streams, wetlands, and other water bodies under the CWA. There have been multiple Supreme Court decisions and dueling regulatory definitions over the past several years concerning the proper standard for how to properly determine whether a wetland or
51 | The AES Corporation | March 31, 2024 Form 10-Q
stream that is not navigable is considered a WOTUS. On May 25, 2023, the U.S. Supreme Court rendered a decision (“Decision”) in the case of Sackett v. Environmental Protection Agency, addressing the definition of WOTUS with regards to the CWA. This decision provides a clear standard that substantially restricts the Agencies' ability to regulate certain types of wetlands and streams. Specifically, under this decision, wetlands that do not have a continuous surface connection with traditional interstate navigable water are not federally jurisdictional.
On September 8, 2023, the Agencies published final rule amendments in the Federal Register to amend the final “Revised Definition of ‘Waters of the United States’” rule. This final rule conforms the definition to the definition adopted in the Decision. The Agencies have amended key aspects of the regulatory text to conform the rule to the Decision. It is too early to determine whether the outcome of litigation or current or future revisions to rules interpreting federal jurisdiction over WOTUS may have a material impact on our business, financial condition, or results of operations.
In November 2015, the EPA published its final ELG rule to reduce toxic pollutants discharged into waters of the U.S. by steam-electric power plants through technology applications. These effluent limitations for existing and new sources include dry handling of fly ash, closed-loop or dry handling of bottom ash, and more stringent effluent limitations for flue gas desulfurization wastewater. AES Indiana Petersburg has installed a dry bottom ash handling system in response to the CCR rule and wastewater treatment systems in response to the NPDES permits in advance of the ELG compliance date. Other U.S. businesses already include dry handling of fly ash and bottom ash and do not generate flue gas desulfurization wastewater. Following the 2019 U.S. Court of Appeals vacatur and remand of portions of the 2015 ELG rule related to leachate and legacy water, on March 29, 2023, the EPA published a proposed rule revising the 2020 Reconsideration Rule. The proposed rule would establish new best available technology economically achievable effluent limits for flue gas desulfurization wastewater, bottom ash treatment water, and combustion residual leachate. On April 25, 2024, the EPA released a pre-publication version of the final rule. We are currently reviewing this rule. It is too early to determine whether any outcome of litigation or current or future revisions to the ELG rule might have a material impact on our business, financial condition, and results of operations.
Capital Resources and Liquidity
Overview
As of March 31, 2024, the Company had unrestricted cash and cash equivalents of $2 billion, of which $90 million was held at the Parent Company and qualified holding companies. The Company had $394 million in short-term investments, held primarily at subsidiaries, and restricted cash and debt service reserves of $561 million. The Company also had non-recourse and recourse aggregate principal amounts of debt outstanding of $23.9 billion and $5.3 billion, respectively. Of the $4 billion of our current non-recourse debt, $3.9 billion was presented as such because it is due in the next twelve months and $174 million relates to debt considered in default. None of the defaults are payment defaults but are instead technical defaults triggered by failure to comply with covenants or other requirements contained in the non-recourse debt documents. As of March 31, 2024, the Company also had $875 million outstanding related to supplier financing arrangements, which are classified as Supplier financing arrangements.
We expect current maturities of non-recourse debt, recourse debt, and amounts due under supplier financing arrangements to be repaid from net cash provided by operating activities of the subsidiary to which the liability relates, through opportunistic refinancing activity, or some combination thereof. We have $200 million in recourse debt which matures within the next twelve months, as well as amounts due under supplier financing arrangements, of which $725 million has a Parent Company guarantee. From time to time, we may elect to repurchase our outstanding debt through cash purchases, privately negotiated transactions, or otherwise when management believes that such securities are attractively priced. Such repurchases, if any, will depend on prevailing market conditions, our liquidity requirements, and other factors. The amounts involved in any such repurchases may be material.
We rely mainly on long-term debt obligations to fund our construction activities. We have, to the extent available at acceptable terms, utilized non-recourse debt to fund a significant portion of the capital expenditures and investments required to construct and acquire our electric power plants, distribution companies, and related assets. Our non-recourse financing is designed to limit cross-default risk to the Parent Company or other subsidiaries and affiliates. Our non-recourse long-term debt is a combination of fixed and variable interest rate instruments. Debt is typically denominated in the currency that matches the currency of the revenue expected to be generated from the benefiting project, thereby reducing currency risk. In certain cases, the currency is matched through the use of derivative instruments. The majority of our non-recourse debt is funded by international commercial banks, with debt
52 | The AES Corporation | March 31, 2024 Form 10-Q
capacity supplemented by multilaterals and local regional banks.
Given our long-term debt obligations, the Company is subject to interest rate risk on debt balances that accrue interest at variable rates. When possible, the Company will borrow funds at fixed interest rates or hedge its variable rate debt to fix its interest costs on such obligations. In addition, the Company has historically tried to maintain at least 70% of its consolidated long-term obligations at fixed interest rates, including fixing the interest rate through the use of interest rate swaps. These efforts apply to the notional amount of the swaps compared to the amount of related underlying debt. Presently, the Parent Company’s only material unhedged exposure to variable interest rate debt relates to $200 million in senior unsecured term loans. Additionally, commercial paper issuances are short term in nature and subject the Parent Company to interest rate risk at the time of refinancing the paper. On a consolidated basis, of the Company’s $29.6 billion of total gross debt outstanding as of March 31, 2024, approximately $10.2 billion accrues interest at variable rates. Brazil holds $2.3 billion of our floating rate non-recourse exposure as variable rate instruments act as a natural hedge against inflation in Brazil. The Company actively hedges its current and expected variable rate exposure through a combination of currently effective and forward starting interest rate swaps. As of March 31, 2024, the total maximum outstanding amount of hedges protecting the company against variable rate exposure was $7.7 billion. These hedges generally provide economic protection through the entire expected life of the projects, regardless of the type of debt issued to finance construction or refinance the projects in the future.
In addition to utilizing non-recourse debt at a subsidiary level when available, the Parent Company provides a portion, or in certain instances all, of the remaining long-term financing or credit required to fund development, construction, or acquisition of a particular project. These investments have generally taken the form of equity investments or intercompany loans, which are subordinated to the project’s non-recourse loans. We generally obtain the funds for these investments from our cash flows from operations, proceeds from the sales of assets and/or the proceeds from our issuances of debt, common stock and other securities. Similarly, in certain of our businesses, the Parent Company may provide financial guarantees or other credit support for the benefit of counterparties who have entered into contracts for the purchase or sale of electricity, equipment, or other services with our subsidiaries or lenders. In such circumstances, if a business defaults on its payment or supply obligation, the Parent Company will be responsible for the business’ obligations up to the amount provided for in the relevant guarantee or other credit support. As of March 31, 2024, the Parent Company had provided outstanding financial and performance-related guarantees or other credit support commitments to or for the benefit of our businesses, which were limited by the terms of the agreements, of approximately $3.6 billion in aggregate (excluding those collateralized by letters of credit and other obligations discussed below).
Some counterparties may be unwilling to accept our general unsecured commitments to provide credit support. Accordingly, with respect to both new and existing commitments, the Parent Company may be required to provide some other form of assurance, such as a letter of credit, to backstop or replace our credit support. The Parent Company may not be able to provide adequate assurances to such counterparties. To the extent we are required and able to provide letters of credit or other collateral to such counterparties, this will reduce the amount of credit available to us to meet our other liquidity needs. As of March 31, 2024, we had $234 million in letters of credit under bilateral agreements, $210 million in letters of credit outstanding provided under our unsecured credit facilities, and $29 million in letters of credit outstanding provided under our revolving credit facility. These letters of credit operate to guarantee performance relating to certain project development and construction activities and business operations. During the quarter ended March 31, 2024, the Company paid letter of credit fees ranging from 1% to 3% per annum on the outstanding amounts.
Additionally, in connection with certain project financings, some of the Company's subsidiaries have expressly undertaken limited obligations and commitments. These contingent contractual obligations are issued at the subsidiary level and are non-recourse to the Parent Company. As of March 31, 2024, the maximum undiscounted potential exposure to guarantees issued by our subsidiaries was $2.6 billion, including $1.6 billion of customary payment guarantees under EPC contracts and other agreements, and $995 million of tax equity financing related guarantees. In addition, as of March 31, 2024, our subsidiaries had $643 million of letters of credit outstanding.
We expect to continue to seek, where possible, non-recourse debt financing in connection with the assets or businesses that we or our affiliates may develop, construct, or acquire. However, depending on local and global market conditions and the unique characteristics of individual businesses, non-recourse debt may not be available on economically attractive terms or at all. If we decide not to provide any additional funding or credit support to a subsidiary project that is under construction or has near-term debt payment obligations and that subsidiary is unable to obtain additional non-recourse debt, such subsidiary may become insolvent, and we may lose our investment in that subsidiary. Additionally, if any of our subsidiaries lose a significant customer, the subsidiary may need to withdraw from a project or restructure the non-recourse debt financing. If we or the subsidiary choose not to
53 | The AES Corporation | March 31, 2024 Form 10-Q
proceed with a project or are unable to successfully complete a restructuring of the non-recourse debt, we may lose our investment in that subsidiary.
Many of our subsidiaries depend on timely and continued access to capital markets to manage their liquidity needs. The inability to raise capital on favorable terms, to refinance existing indebtedness, or to fund operations and other commitments during times of political or economic uncertainty may have material adverse effects on the financial condition and results of operations of those subsidiaries. In addition, changes in the timing of tariff increases or delays in the regulatory determinations under the relevant concessions could affect the cash flows and results of operations of our businesses.
Long-Term Receivables
As of March 31, 2024, the Company had approximately $92 million of gross accounts receivable classified as Other noncurrent assets. These noncurrent receivables mostly consist of accounts receivable in the U.S. and Chile that, pursuant to amended agreements or government resolutions, have collection periods that extend beyond March 31, 2025, or one year from the latest balance sheet date. Noncurrent receivables in the U.S. pertain to the sale of the Redondo Beach land. Noncurrent receivables in Chile pertain primarily to revenues recognized on regulated energy contracts that were impacted by the Stabilization Funds created by the Chilean government. See Note 5*—Financing Receivables* in Item 1.—Financial Statements of this Form 10-Q for further information.
As of March 31, 2024, the Company had approximately $1 billion of loans receivable primarily related to the Mong Duong facility in Vietnam, which was constructed under a build, operate, and transfer contract. This loan receivable represents contract consideration related to the construction of the facility, which was substantially completed in 2015, and will be collected over the 25-year term of the plant’s PPA. As of March 31, 2024, Mong Duong met the held-for-sale criteria and the loan receivable balance of $1 billion, net of CECL reserves of $25 million, was classified in held-for-sale assets. Of the loan receivable balance, $111 million was classified as Current held-for-sale assets, and $934 million was classified as Noncurrent held-for-sale assets on the Condensed Consolidated Balance Sheets. See Note 14*—Revenue* in Item 1.—Financial Statements of this Form 10-Q for further information.
Cash Sources and Uses
The primary sources of cash for the Company in the three months ended March 31, 2024 were debt financings, cash flows from operating activities, and purchases under supplier financing arrangements. The primary uses of cash in the three months ended March 31, 2024 were capital expenditures, repayments of debt, and repayments of obligations under supplier financing arrangements.
The primary sources of cash for the Company in the three months ended March 31, 2023 were debt financings, cash flows from operating activities, purchases under supplier financing arrangements, and sales of short-term investments. The primary uses of cash in the three months ended March 31, 2023 were repayments of debt, capital expenditures, repayments of obligations under supplier financing arrangements, and purchases of short-term investments.
54 | The AES Corporation | March 31, 2024 Form 10-Q
A summary of cash-based activities is as follows (in millions):
| Three Months Ended March 31, | ||||||||||||||
| Cash Sources: | 2024 | 2023 | ||||||||||||
| Issuance of non-recourse debt | $ | 2,131 | $ | 690 | ||||||||||
| Borrowings under the revolving credit facilities | 1,741 | 1,415 | ||||||||||||
| Commercial paper borrowings (repayments), net | 719 | 350 | ||||||||||||
| Purchases under supplier financing arrangements | 486 | 529 | ||||||||||||
| Net cash provided by operating activities | 287 | 625 | ||||||||||||
| Sale of short-term investments | 141 | 356 | ||||||||||||
| Sales to noncontrolling interests | 125 | — | ||||||||||||
| Proceeds from the sale of business interests, net of cash and restricted cash sold | 11 | 98 | ||||||||||||
| Issuance of recourse debt | — | 500 | ||||||||||||
| Other | 122 | 18 | ||||||||||||
| Total Cash Sources | $ | 5,763 | $ | 4,581 | ||||||||||
| Cash Uses: | ||||||||||||||
| Capital expenditures | $ | (2,148) | $ | (1,551) | ||||||||||
| Repayments under the revolving credit facilities | (1,037) | (1,055) | ||||||||||||
| Repayments of non-recourse debt | (915) | (660) | ||||||||||||
| Repayments of obligations under supplier financing arrangements | (516) | (587) | ||||||||||||
| Purchase of short-term investments | (144) | (418) | ||||||||||||
| Dividends paid on AES common stock | (116) | (111) | ||||||||||||
| Purchase of emissions allowances | (56) | (78) | ||||||||||||
| Other | (266) | (131) | ||||||||||||
| Total Cash Uses | $ | (5,198) | $ | (4,591) | ||||||||||
| Net increase (decrease) in Cash, Cash Equivalents, and Restricted Cash | $ | 565 | $ | (10) |
Consolidated Cash Flows
The following table reflects the changes in operating, investing, and financing cash flows for the comparative three-month period (in millions):
| Three Months Ended March 31, | |||||||||||||||||||||||
| Cash flows provided by (used in): | 2024 | 2023 | $ Change | ||||||||||||||||||||
| Operating activities | $ | 287 | $ | 625 | $ | (338) | |||||||||||||||||
| Investing activities | (2,386) | (1,624) | (762) | ||||||||||||||||||||
| Financing activities | 2,606 | 1,016 | 1,590 |
Operating Activities
Net cash provided by operating activities decreased $338 million for the three months ended March 31, 2024, compared to the three months ended March 31, 2023.
Operating Cash Flows
(in millions)
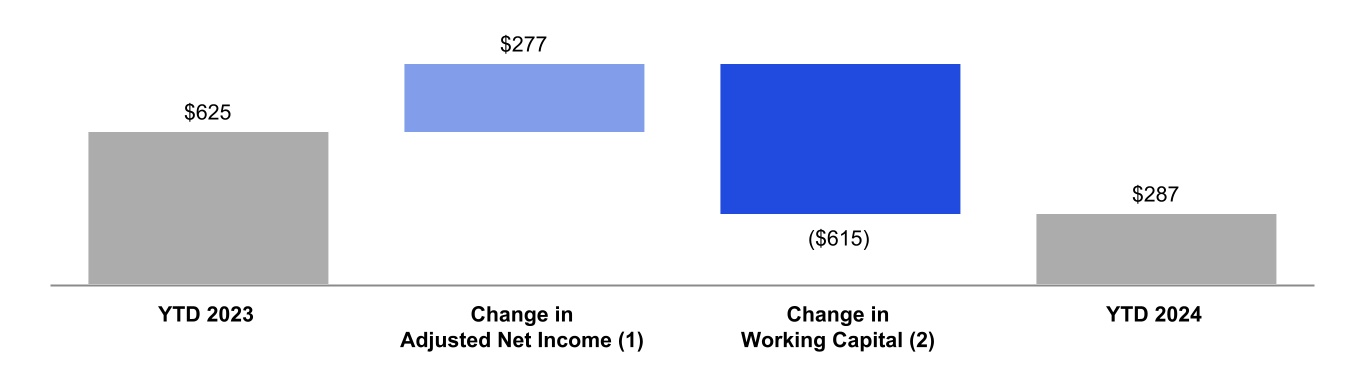
(1)The change in adjusted net income is defined as the variance in net income, net of the total adjustments to net income as shown on the Condensed Consolidated Statements of Cash Flows in Item 1—Financial Statements of this Form 10-Q.
(2)The change in working capital is defined as the variance in total changes in operating assets and liabilities as shown on the Condensed Consolidated Statements of Cash Flows in Item 1—Financial Statements of this Form 10-Q.
55 | The AES Corporation | March 31, 2024 Form 10-Q
-
Adjusted net income increased $277 million, primarily due to higher margins at our Energy Infrastructure and Utilities SBUs; partially offset by lower margins at our Renewables SBU, an increase in interest expense, and a decrease in interest income.
-
Working capital requirements increased $615 million, primarily due to an increase in accounts receivable resulting from lower collections and an increase in receivables under the Warrior Run PPA termination agreement; partially offset by a decrease in accounts payable due to lower inventory purchases at lower prices.
Investing Activities
Net cash used in investing activities increased $762 million for the three months ended March 31, 2024, compared to the three months ended March 31, 2023.
Investing Cash Flows
(in millions)
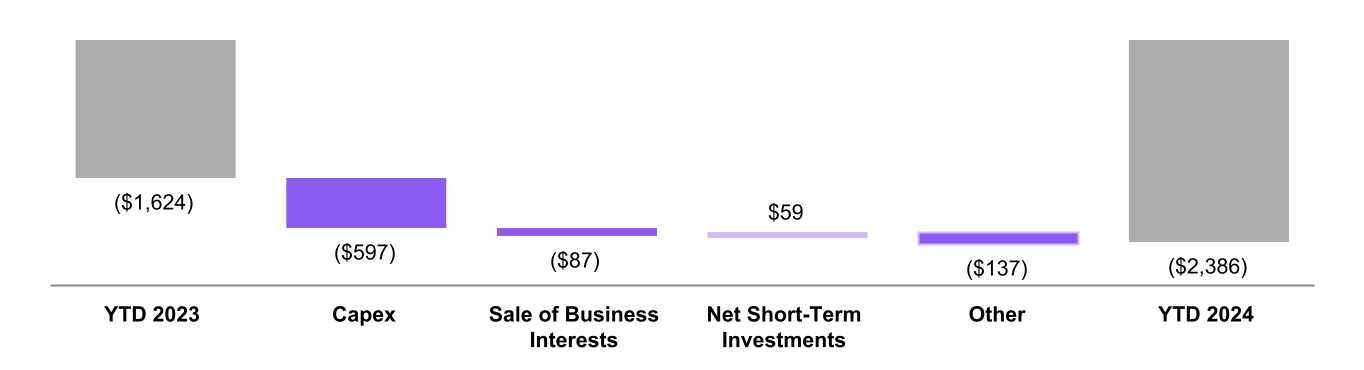
-
Proceeds from sales of business interests decreased $87 million, primarily due to the selldown of sPower OpCo B in 2023.
-
Cash used for short-term investing activities decreased $59 million, primarily as a result of lower net short-term investment purchases at our Renewables SBU.
-
Capital expenditures increased $597 million, discussed further below.
Capital Expenditures
(in millions)

(1)Growth expenditures generally include expenditures related to development projects in construction, expenditures that increase capacity of a facility beyond the original design, and investments in general load growth or system modernization.
(2)Maintenance expenditures generally include expenditures that are necessary to maintain regular operations or net maximum capacity of a facility.
(3)Environmental expenditures generally include expenditures to comply with environmental laws and regulations, expenditures for safety programs and other expenditures to ensure a facility continues to operate in an environmentally responsible manner.
-
Growth expenditures increased $585 million, primarily driven by an increase in U.S. renewables projects.
-
Maintenance expenditures increased $13 million, primarily due to higher transmission and distribution project investments at our Utilities SBU.
-
Environmental expenditures decreased $1 million, with no material drivers.
56 | The AES Corporation | March 31, 2024 Form 10-Q
Financing Activities
Net cash provided by financing activities increased $1.6 billion for the three months ended March 31, 2024, compared to the three months ended March 31, 2023.
Financing Cash Flows
(in millions)
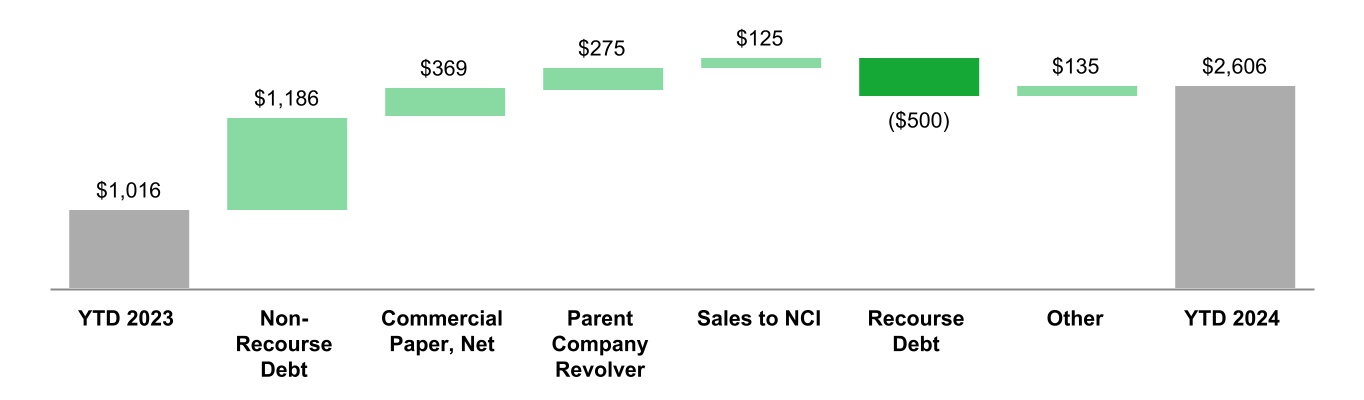
See Notes 8—Debt and 12—Equity in Item 1—Financial Statements of this Form 10-Q for more information regarding significant debt and equity transactions.
*•*The $1.2 billion impact from non-recourse debt transactions is mainly due to the issuances of the 5.70% First Mortgage Bonds due April 2054 and the 5.75% senior secured notes due April 2034 at AES Indiana, and the issuance of the 6.30% senior unsecured notes due April 2029 at AES Andes.
-
The $369 million impact from commercial paper is due to higher net borrowings in the current period.
-
The $275 million impact from the Parent Company revolver is primarily due to higher net repayments in the prior period.
*•*The $125 million impact from sales to noncontrolling interests is primarily due to proceeds received at AES Clean Energy from the sales of ownership in project companies to tax equity investors, and the sale of Mesamávida under the Chile Renovables renewables partnership with GIP.
- The $500 million impact from recourse debt is primarily due to the issuance of a bridge loan, fully guaranteed by the Parent Company, at AES Clean Energy in March 2023.
Parent Company Liquidity
The following discussion is included as a useful measure of the liquidity available to The AES Corporation, or the Parent Company, given the non-recourse nature of most of our indebtedness. Parent Company Liquidity, as outlined below, is a non-GAAP measure and should not be construed as an alternative to Cash and cash equivalents, which is determined in accordance with GAAP. Parent Company Liquidity may differ from similarly titled measures used by other companies. The principal sources of liquidity at the Parent Company level are dividends and other distributions from our subsidiaries, including refinancing proceeds; proceeds from debt and equity financings at the Parent Company level, including availability under our revolving credit facility and commercial paper program; and proceeds from asset sales. The Parent Company credit facility and commercial paper program are generally used for short-term cash needs to bridge the timing of distributions from subsidiaries. Cash requirements at the Parent Company level are primarily to fund interest and principal repayments of debt, construction commitments, other equity commitments, acquisitions, taxes, Parent Company overhead and development costs, and dividends on common stock.
The Company defines Parent Company Liquidity as cash available to the Parent Company, including cash at qualified holding companies, plus available borrowings under our existing credit facility and commercial paper program. The cash held at qualified holding companies represents cash sent to subsidiaries of the Company domiciled outside of the U.S. Such subsidiaries have no contractual restrictions on their ability to send cash to the Parent Company. Parent Company Liquidity is reconciled to its most directly comparable GAAP financial measure, Cash and cash equivalents, at the periods indicated as follows (in millions):
57 | The AES Corporation | March 31, 2024 Form 10-Q
| March 31, 2024 | December 31, 2023 | ||||||||||
| Consolidated cash and cash equivalents | $ | 1,994 | $ | 1,426 | |||||||
| Less: Cash and cash equivalents at subsidiaries | (1,904) | (1,393) | |||||||||
| Parent Company and qualified holding companies’ cash and cash equivalents | 90 | 33 | |||||||||
| Commitments under the Parent Company credit facility | 1,500 | 1,500 | |||||||||
| Less: Letters of credit under the credit facility | (29) | (124) | |||||||||
| Less: Borrowings under the credit facility | (110) | — | |||||||||
| Less: Borrowings under the commercial paper program | (719) | — | |||||||||
| Borrowings available under the Parent Company credit facility | 642 | 1,376 | |||||||||
| Total Parent Company Liquidity | $ | 732 | $ | 1,409 |
The Parent Company paid dividends of $0.1725 per outstanding share to its common stockholders during the first quarter of 2024 for dividends declared in December 2023. While we intend to continue payment of dividends and believe we will have sufficient liquidity to do so, we can provide no assurance that we will continue to pay dividends, or if continued, the amount of such dividends.
Recourse Debt
Our total recourse debt was $5.3 billion and $4.5 billion as of March 31, 2024 and December 31, 2023, respectively. See Note 8—Debt in Item 1.—Financial Statements of this Form 10-Q and Note 11—Debt in Item 8.—Financial Statements and Supplementary Data of our 2023 Form 10-K for additional detail.
We believe that our sources of liquidity will be adequate to meet our needs for the foreseeable future. This belief is based on a number of material assumptions, including, without limitation, assumptions about our ability to access the capital markets, the operating and financial performance of our subsidiaries, currency exchange rates, power market pool prices, and the ability of our subsidiaries to pay dividends. In addition, our subsidiaries’ ability to declare and pay cash dividends to us (at the Parent Company level) is subject to certain limitations contained in loans, governmental provisions and other agreements. We can provide no assurance that these sources will be available when needed or that the actual cash requirements will not be greater than anticipated. We have met our interim needs for shorter-term and working capital financing at the Parent Company level with our revolving credit facility and commercial paper program. See Item 1A.—Risk Factors—The AES Corporation’s ability to make payments on its outstanding indebtedness is dependent upon the receipt of funds from our subsidiaries of the Company’s 2023 Form 10-K for additional information.
Various debt instruments at the Parent Company level, including our revolving credit facility and commercial paper program, contain certain restrictive covenants. The covenants provide for, among other items, limitations on other indebtedness, liens, investments and guarantees; limitations on dividends, stock repurchases and other equity transactions; restrictions and limitations on mergers and acquisitions, sales of assets, leases, transactions with affiliates and off-balance sheet and derivative arrangements; maintenance of certain financial ratios; and financial and other reporting requirements. As of March 31, 2024, we were in compliance with these covenants at the Parent Company level.
Non-Recourse Debt
While the lenders under our non-recourse debt financings generally do not have direct recourse to the Parent Company, defaults thereunder can still have important consequences for our results of operations and liquidity, including, without limitation:
-
reducing our cash flows as the subsidiary will typically be prohibited from distributing cash to the Parent Company during the time period of any default;
-
triggering our obligation to make payments under any financial guarantee, letter of credit, or other credit support we have provided to or on behalf of such subsidiary;
-
causing us to record a loss in the event the lender forecloses on the assets; and
-
triggering defaults in our outstanding debt at the Parent Company.
For example, our revolving credit facility and outstanding debt securities at the Parent Company include events of default for certain bankruptcy-related events involving material subsidiaries. In addition, our revolving credit agreement at the Parent Company includes events of default related to payment defaults and accelerations of outstanding debt of material subsidiaries.
Some of our subsidiaries are currently in default with respect to all or a portion of their outstanding indebtedness. The total non-recourse debt classified as current in the accompanying Condensed Consolidated Balance Sheets amounts to $4 billion. The portion of current debt related to such defaults was $174 million at March
58 | The AES Corporation | March 31, 2024 Form 10-Q
31, 2024, all of which was non-recourse debt related to three subsidiaries: AES Mexico Generation Holdings, AES Ilumina, and AES Jordan Solar. None of the defaults are payment defaults, but are instead technical defaults triggered by failure to comply with other covenants or other conditions contained in the non-recourse debt documents. See Note 8—Debt in Item 1.—Financial Statements of this Form 10-Q for additional detail.
None of the subsidiaries that are currently in default are subsidiaries that met the applicable definition of materiality under the Parent Company’s debt agreements as of March 31, 2024, in order for such defaults to trigger an event of default or permit acceleration under the Parent Company’s indebtedness. However, as a result of additional dispositions of assets, other significant reductions in asset carrying values or other matters in the future that may impact our financial position and results of operations or the financial position of the individual subsidiary, it is possible that one or more of these subsidiaries could fall within the definition of a “material subsidiary” and thereby trigger an event of default and possible acceleration of the indebtedness under the Parent Company’s outstanding debt securities. A material subsidiary is defined in the Parent Company’s revolving credit agreement as any business that contributed 20% or more of the Parent Company’s total cash distributions from businesses for the four most recently ended fiscal quarters. As of March 31, 2024, none of the defaults listed above resulted in a cross-default under the recourse debt of the Parent Company. Furthermore, none of the non-recourse debt in default listed above is guaranteed by the Parent Company.
Critical Accounting Policies and Estimates
The condensed consolidated financial statements of AES are prepared in conformity with U.S. GAAP, which requires the use of estimates, judgments, and assumptions that affect the reported amounts of assets and liabilities at the date of the financial statements and the reported amounts of revenue and expenses during the periods presented.
The Company’s significant accounting policies are described in Note 1 — General and Summary of Significant Accounting Policies of our 2023 Form 10-K. The Company’s critical accounting estimates are described in Item 7.—Management’s Discussion and Analysis of Financial Condition and Results of Operations in the 2023 Form 10-K. An accounting estimate is considered critical if the estimate requires management to make an assumption about matters that were highly uncertain at the time the estimate was made, if different estimates reasonably could have been used, or if changes in the estimate that would have a material impact on the Company’s financial condition or results of operations are reasonably likely to occur from period to period. Management believes that the accounting estimates employed are appropriate and resulting balances are reasonable; however, actual results could differ from the original estimates, requiring adjustments to these balances in future periods. The Company has reviewed and determined that these remain as critical accounting policies as of and for the three months ended March 31, 2024.
Previous: Item 1. FINANCIAL STATEMENTS · Next: Item 3. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK