 filings.tools
Item 1. BUSINESS
39K characters. Original on sec.gov · Markdown
Item 1. BUSINESS
OVERVIEW
Aflac Incorporated (the Parent Company) was incorporated in 1973 under the laws of the state of Georgia. The Parent Company and its subsidiaries (collectively, the Company) provide financial protection to more than 50 million people worldwide. The Company’s principal business is supplemental health and life insurance products with the goal to provide customers the best value in supplemental insurance products in the United States (U.S.) and Japan. When a policyholder or insured gets sick or hurt, the Company pays cash benefits fairly and promptly for eligible claims, directly to the insured (unless assigned otherwise). For more than sixty years, the Company’s supplemental insurance policies have given policyholders the opportunity to focus on recovery, not financial stress.
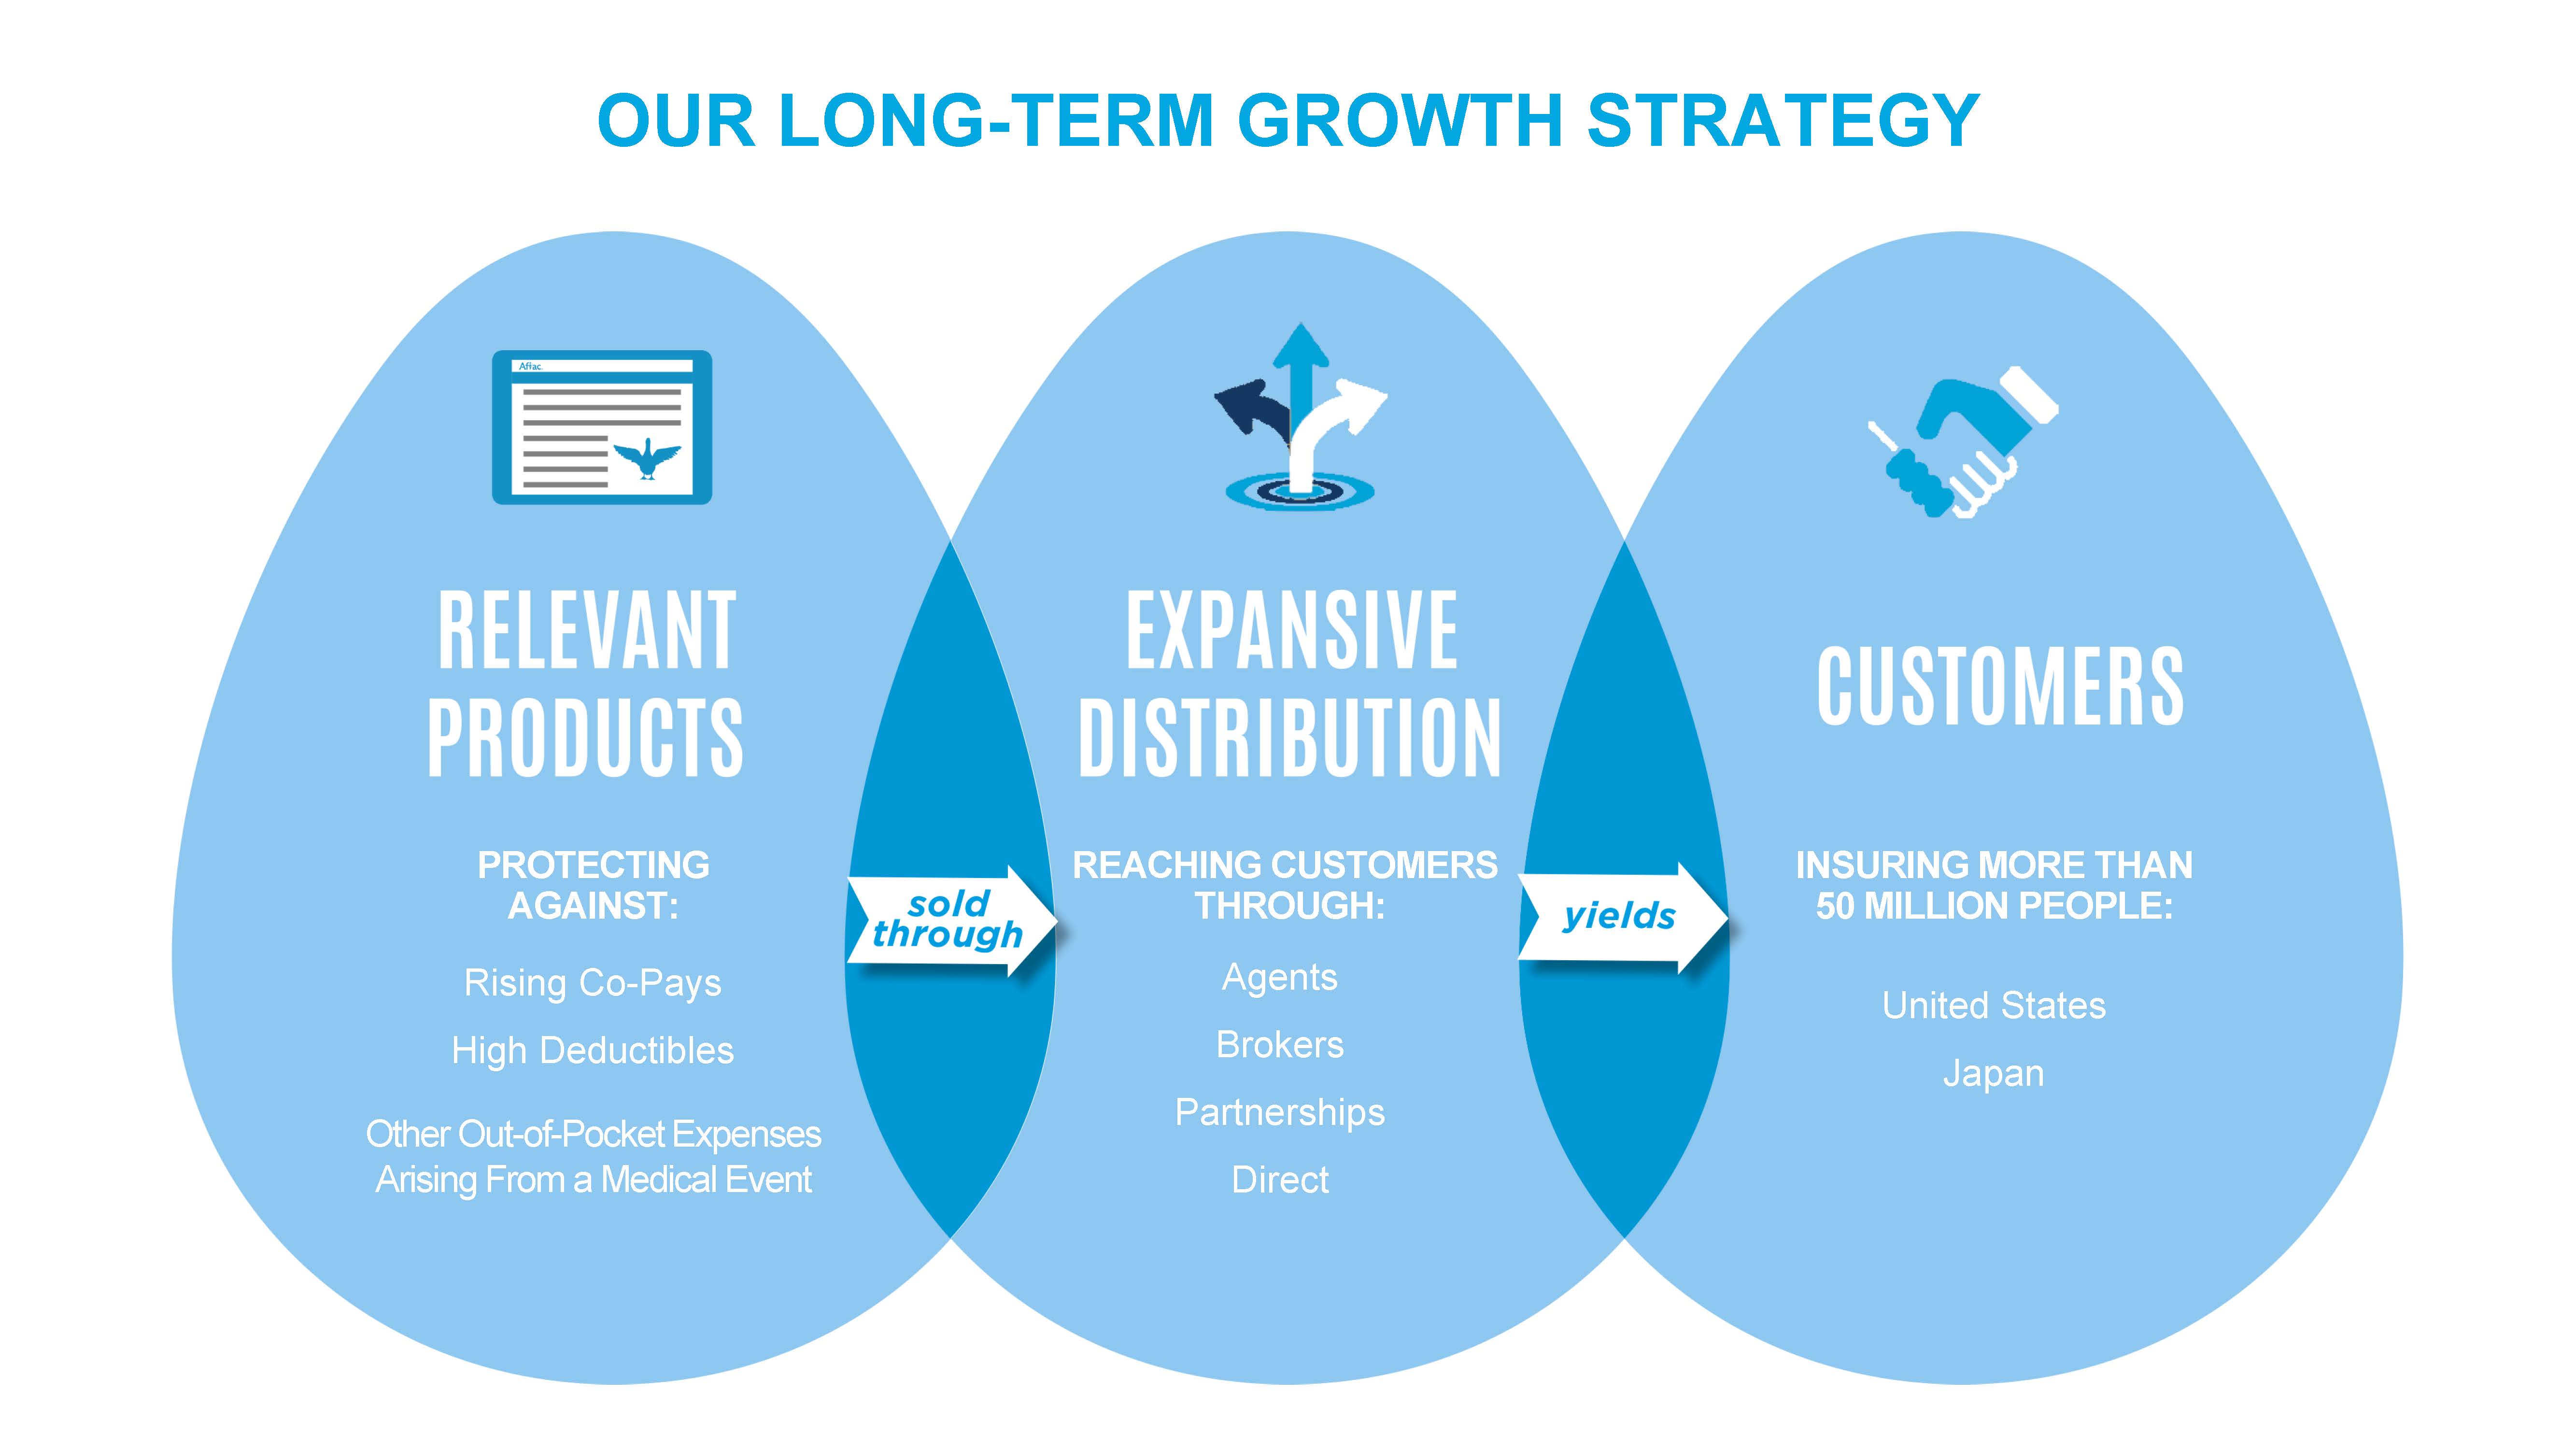
The Company's strategy for growth in the U.S. and Japan has remained straightforward and consistent for many years. The Company develops relevant supplemental insurance products and sells them through expanded distribution channels. To help promote its insurance products, the Company’s marketing campaigns feature the Aflac Duck.
In 1999, the Company had been running commercials for nearly a decade, but its brand awareness was hovering at about 10%. An innovative marketing campaign with something unique and memorable that would build brand awareness was needed. The Aflac Duck’s first commercial in the U.S., “Park Bench,” aired on January 1, 2000 and taught consumers how to pronounce “Aflac.” The Aflac Duck made his international debut in Japan in 2003. In the two decades since his U.S. debut, the Aflac Duck has become one of the most familiar advertising icons in the world, appearing in several commercials and countless print ads in both the U.S. and Japan. Today, the Aflac Duck is a helpmate who increases brand knowledge and connection.
The Company is authorized to conduct insurance business in all 50 states, the District of Columbia, several U.S. territories and Japan. The Company’s website is: www.aflac.com. Information included on the Company’s website is not incorporated by reference into this filing. The Company makes available free of charge through its website, its annual report on Form 10-K, its quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports as soon as reasonably practicable after they have been electronically filed with or furnished to the Securities and Exchange Commission (SEC).
REPORTING SEGMENTS
The Company's insurance business consists of two reporting segments: Aflac Japan and Aflac U.S. The Parent Company’s primary insurance subsidiaries are Aflac Life Insurance Japan Ltd. in Japan (Aflac Japan) and American Family Life Assurance Company of Columbus (Aflac); Continental American Insurance Company (CAIC), branded as Aflac Group Insurance (AGI); American Family Life Assurance Company of New York (Aflac New York) and Tier One Insurance Company (TOIC) in the U.S. (collectively, Aflac U.S.).
Aflac Japan is the principal contributor to the Parent Company’s consolidated earnings. Aflac Japan's revenues, including realized gains and losses on its investment portfolio, accounted for 69% of the Company's total revenues in 2019, compared with 70% in both 2018 and 2017. The percentage of the Company's total assets attributable to Aflac Japan was 83% and 84% at December 31, 2019 and 2018, respectively. The conversion of Aflac Japan to a subsidiary structure in April 2018 did not affect the Company's segment reporting structure.
Effective January 1, 2018, investments of Aflac U.S. as well as certain sub-advised assets of Aflac Japan, are managed by the Company’s U.S. asset management subsidiary, Aflac Asset Management LLC (AAM), and investments of Aflac Japan are managed pursuant to an investment advisory agreement between Aflac Japan and the Company's asset management subsidiary in Japan, Aflac Asset Management Japan Ltd. (AAMJ). AAMJ is licensed as a discretionary asset manager under the Japan Financial Instruments and Exchange Act and is subject to rules of the Japan Investment Advisors Association, a self-regulatory organization with mandatory membership for Japan investment managers. AAM and AAMJ are reported in the "Corporate and other segment" category; however, the assets that they manage are reported in the respective Aflac Japan and Aflac U.S. business segments.
In November 2019, the Company acquired Argus Holdings, LLC and its subsidiary Argus Dental & Vision, Inc. (Argus), a benefits management organization and national network dental and vision company, which provides a platform for Aflac Dental and Vision. The Company paid $75 million at closing and made an additional commitment of up to $21 million in contingent consideration payable over three years based on the achievement by Argus of certain performance targets. Argus is an addition to the Aflac U.S. segment.
Revenues derived from any customer did not exceed 10% of consolidated premiums and other revenues for the years ended December 31, 2019 and 2018. For information on the Company's results of operations and financial information by segment, see Item 7. Management Discussion and Analysis (MD&A) and Note 2 of the Notes to the Consolidated Financial Statements in this report.
AFLAC JAPAN
Aflac Japan is the largest insurer in Japan in terms of cancer and medical (third sector insurance products) policies in force. As of December 31, 2019, Aflac Japan exceeded 24 million individual policies in force in Japan. Aflac Japan continued to be the number one seller of cancer insurance policies in Japan throughout 2019, with more than 15 million cancer policies in force as of December 31, 2019.
Insurance Products
Aflac Japan's third sector insurance products are designed to help consumers pay for medical and nonmedical costs that are not reimbursed under Japan's national health insurance system. Changes in Japan's economy and an aging population have put increasing pressure on Japan's national health care system. As a result, more costs have been shifted to Japanese consumers, who in turn have become increasingly interested in insurance products that help them manage those costs. Aflac Japan has responded to this consumer need by enhancing existing products and developing new products. The focus at Aflac Japan remains on maintaining leadership in third sector insurance products that are less interest rate sensitive and have strong and stable margins. At the same time, Aflac Japan complements this core business with similarly profitable first sector protection products as outlined below.
| THIRD SECTOR INSURANCE | FIRST SECTOR INSURANCE | |||||
| Life insurance products include: | ||||||
| ▪ Cancer | Protection type: | Savings type: | ||||
| ▪ Medical | ▪ Term Life | ▪ WAYS | ||||
| ▪ Income Support | ▪ Whole Life | ▪ Child Endowment | ||||
| ▪ GIFT |
Cancer Insurance Aflac Japan pioneered the cancer insurance market in Japan in 1974, and remains the number one provider of cancer insurance in Japan today. Aflac Japan's cancer insurance products provide a lump-sum benefit upon initial diagnosis of cancer and fixed daily benefits for subsequent hospitalization and outpatient treatments due to cancer, as well as cancer-related surgical and convalescent care benefits.
Medical Insurance Aflac Japan's medical insurance products provide benefits for hospitalization, surgeries and outpatient treatment of various illnesses, as well as lump sum benefits related to three critical illnesses: cancer, heart attack, and stroke.
Income Support Insurance Aflac Japan's Income Support Insurance provides fixed-benefit amounts in the event that a policyholder is unable to work due to significant illness or injury and was developed to supplement the disability coverage within Japan’s social security system.
Whole Life Aflac Japan launched Prepare Smart Whole-Life Insurance in 2018, a whole life insurance product with low cash surrender value, which offers non-smoking policyholders further discounted premiums, and it provides beneficiaries, typically a designated family member, with a pre-determined benefit payment upon the death of the insured.
GIFT GIFT is a term life insurance product that provides a designated family member with a fixed amount of money every month upon a breadwinner’s death or serious disability as family support.
WAYS and Child Endowment Beginning in 2013, Aflac Japan began to curtail sales of WAYS and Child Endowment, first sector savings-type products, due to persistent low interest rates in Japan and, in particular, the relatively large capital commitment required by such products and their lower profitability, in such an environment.
Distribution Channels
Traditional Sales Channel This distribution channel includes individual agencies, independent corporate agencies and affiliated corporate agencies. Aflac Japan was represented by more than 9,000 sales agencies at the end of 2019, with more than 109,000 licensed sales associates employed by those agencies, including individual agencies.
Banks Consumers in Japan rely on banks to provide not only traditional bank services, but also as one key source to provide insurance solutions and other services. By the end of 2019, Aflac Japan had agreements with approximately 90% of the total number of banks in Japan to sell its products.
Dai-ichi Life Aflac Japan's alliance with Dai-ichi Life was launched in 2001, and approximately 40,000 Dai-ichi Life representatives offer Aflac's cancer products.
Japan Post Group Aflac Japan's alliance with Japan Post Group was launched in 2008. After the alliance strengthened in 2013, the number of postal outlets of Japan Post Co. Ltd. (JPC) selling Aflac Japan's cancer product increased to more than 20,000 since 2015. Japan Post Insurance Co., Ltd. (JPI) offers Aflac Japan cancer products through its 76 directly managed sales offices. In 2018, the Company’ entered a strategic alliance with Japan Post Holdings Co., Ltd. (Japan Post Holdings), the parent company of Japan Post Co. Ltd (JPC) and Japan Post Insurance Co., Ltd. (JPI). See the "Aflac Japan Segment" subsection of MD&A for more about this alliance.
Daido Life In 2013, Aflac Japan and Daido Life Insurance entered into an agreement for Daido to sell Aflac Japan's cancer insurance products specifically to the Hojinkai market, which is an association of small businesses. Currently, Daido also sells Aflac Japan's cancer insurance products to the market in the tax payment association, which is a not-for-profit association for small businesses to support tax related matters.
Competition
The Company competes with other insurance carriers through policyholder service, price, product design and sales efforts, as the number of insurance companies offering stand-alone cancer and medical insurance has more than doubled since the deregulation of the Japan market in 2001. However, based on Aflac Japan's growth of annualized premiums in force and diversified distribution network, the Company does not believe that Aflac Japan's market-leading position has been significantly impacted by increased competition. Furthermore, the Company believes the continued development and maintenance of operating efficiencies will allow Aflac Japan to offer affordable products that appeal to consumers. The Company believes Aflac Japan will remain a leading provider of cancer and medical insurance coverage in Japan, principally due to its experience in the market, well-known brand, low-cost operations, expansive marketing system and product expertise.
Regulation
Financial Services Agency (FSA) The financial and business affairs of Aflac Japan are subject to examination by Japan's FSA. Aflac Japan files annual reports and financial statements for the Japanese insurance operations based on a March 31 fiscal year end, prepared in accordance with Japanese regulatory accounting practices prescribed or permitted by the FSA. Japanese regulatory basis earnings are determined using accounting principles that differ materially from U.S. generally
accepted accounting principles (U.S. GAAP). Capital and surplus of Aflac Japan, based on Japanese regulatory accounting practices, was $7.8 billion at December 31, 2019, compared with $6.4 billion at December 31, 2018. Two FSA regulations applicable to Aflac Japan are outlined below.
| • | Privacy and Cybersecurity |
With regard to personal information obtained from policyholders, the insured, or others, Aflac Japan is regulated in Japan by the Act on the Protection of Personal Information (APPI) and guidelines issued by FSA and other governmental authorities. The FSA updated its guidelines regarding cybersecurity in October 2018.
| • | FSA Solvency Standard |
The FSA maintains a solvency standard, the solvency margin ratio (SMR), which is used by Japanese regulators to monitor the financial strength of insurance companies. As of December 31, 2019, Aflac Japan's SMR was 1,043%, compared with 965% at December 31, 2018. Aflac Japan's SMR is sensitive to interest rate, credit spread and foreign exchange rate changes. See the Liquidity and Capital Resources section of the MD&A for a discussion of measures the Company has taken to mitigate the sensitivity of Aflac Japan's SMR.
Japan Company Law As a branch of Aflac prior to April 1, 2018, Aflac Japan repatriated a portion of its accumulated earnings, as determined on a Japanese regulatory accounting basis, to Aflac U.S. provided that Aflac Japan had determined that it adequately protected policyholders' interests as measured by its SMR. After the conversion of Aflac Japan to a subsidiary structure on April 1, 2018 and starting in the fourth quarter of 2018, Aflac Japan distributes dividends to the Parent Company. Such dividends are subject to permitted dividend capacity under the Japan Company Law.
Policyholder Protection The Japanese insurance industry has a policyholder protection corporation that provides funds for the policyholders of insolvent insurers. For additional information, see the policyholder protection section of the MD&A.
For additional information regarding Aflac Japan's operations and regulations, see the "Aflac Japan Segment" subsection of MD&A and Notes 2 and 13 of the Notes to the Consolidated Financial Statements in this report.
AFLAC U.S.
The Company designs its U.S. insurance products to provide supplemental coverage for people who already have major medical or primary insurance coverage, as Aflac U.S. insurance policies pay benefits regardless of other insurance. Aflac U.S. products are distributed in the individual and group supplemental insurance markets. Aflac's individual policies are portable, meaning that individuals may retain their full insurance coverage upon separation from employment or affiliation with a group, generally at the same premium. Individual policies are typically guaranteed-renewable for the lifetime of the policyholder (to age 75 for short-term disability policies).
Insurance Products
| ▪ Cancer | ▪ Critical Illness | ▪ Vision |
| ▪ Accident | ▪ Hospital Indemnity | ▪ Life (Term and Whole) |
| ▪ Short-Term Disability | ▪ Dental |
Cancer Insurance Aflac U.S.'s cancer insurance products provide a lump-sum benefit upon initial diagnosis of cancer and subsequent benefits for treatment received due to cancer. Aflac U.S. offers cancer insurance on an individual basis.
Accident Insurance Aflac U.S. offers accident coverage on both an individual and group basis. These policies pay cash benefits in the event of a covered injury. The accident portion of the policy includes lump-sum benefits for accidental death, dismemberment and specific injuries as well as fixed benefits for hospital confinement. Additional benefits are also available for home modifications, wellness and increased benefits for injuries related to participations in an organized sporting activity.
Short-Term Disability Insurance Aflac U.S. offers short-term disability benefits on both an individual and group basis. The individual short-term disability product offers an Aflac Value Rider that pays a benefit, less claims, for every consecutive five-year term that the policy is in force.
Critical Illness Insurance Aflac U.S. offers coverage for critical illness plans on both an individual and group basis. These policies are designed to pay cash benefits in the event of critical illnesses such as heart attack, stroke or cancer.
Hospital Indemnity Insurance Aflac U.S. offers hospital indemnity coverage on both an individual and group basis. Hospital indemnity products provide policyholders fixed dollar benefits triggered by hospitalization due to accident or sickness. Indemnity benefits for inpatient and outpatient surgeries, as well as various other diagnostic events, are also available. Aflac U.S. also offers a lump sum rider for a range of critical illness events that can be added to its individual accident, short-term disability and hospital indemnity products.
Dental and Vision Insurance Aflac U.S. now offers network dental and vision products on a group basis. Aflac U.S. offers fixed-benefit dental coverage on both an individual and group basis. Aflac U.S. offers Vision NowSM, an individually issued policy which provides benefits for serious eye health conditions and loss of sight as well as coverage for corrective eye materials and exam benefits.
Life (Term and Whole) Aflac U.S. offers term- and whole-life policies on both an individual and group basis.
Distribution Channels
Independent Associates/Career Agents The career agent channel in Aflac U.S. focuses on marketing Aflac to the small business market, defined as employers of between three and 99 employees. Sales associates in the U.S. are independent contractors and are paid commissions and other variable compensation based on first-year and renewal premiums from their sales of insurance products.
Brokers The broker channel of Aflac U.S. focuses on selling to the mid- and large-case market, which is comprised of employers with 100 or more employees and typically an average size of 1,000 employees or more. Brokers in the U.S. are independent contractors and are paid commissions based on first-year and renewal premiums from their sales of insurance products.
Aflac U.S. concentrates on marketing its insurance products at the worksite. This method offers policies to individuals through employment, trade and other associations. Aflac U.S. believes that worksite marketing enables sales associates and brokers to reach a greater number of prospective policyholders and lowers distribution costs, compared with individually marketed business. Aflac U.S. is also expanding its distribution strategy to reach consumers outside of the traditional worksite through digital lead generation.
Competition
Aflac U.S. competes against several supplemental insurance carriers on a national and regional basis. Aflac U.S. believes its policies, premium rates, platforms, value-added services and sales commissions are competitive by product type. Moreover, Aflac U.S. believes that its products are distinct from competitive offerings given its product focus (including features, benefits and claims service model), distribution capabilities and brand awareness.
Since Aflac products provide an additional level of financial protection for policyholders, the Company believes the increased financial exposure some employees may face creates a favorable opportunity for Aflac U.S. products. However, given the profitability erosion some major medical carriers are facing in their core lines of business, the Company has seen a more competitive landscape as these carriers seek entry into Aflac's supplemental product segments and leverage their core benefit offerings by bundling and discounting products in order to gain market share.
One Day PaySM is a claims initiative that Aflac U.S. has focused on to process, approve and pay eligible claims in just one day. The Company believes that this claims practice enhances the Aflac U.S. brand reputation and the trust policyholders have in Aflac, and it helps Aflac stand out from competitors.
Regulation
Insurance Regulation The Parent Company and its U.S. insurance subsidiaries, Aflac, CAIC, TOIC (Nebraska-domiciled insurance companies) and Aflac New York (a New York-domiciled insurance company) are subject to state regulations in the U.S. as an insurance holding company system. Such regulations generally provide that transactions between companies within the holding company system must be fair and equitable. In addition, transfers of assets among such affiliated companies, certain dividend payments from insurance subsidiaries and certain transactions between companies within the system, including management fees, loans and advances are subject to prior notice to, or approval by, state regulatory authorities. These laws generally require, among other things, the insurance holding company and each insurance company directly owned by the holding company to register with the insurance departments of their respective domiciliary states and to furnish annually financial and other information about the operations of companies within the holding company system.
Like all U.S. insurance companies, Aflac, Aflac New York, CAIC and TOIC are subject to regulation and supervision in the jurisdictions in which they do business. In general, the insurance laws of the various jurisdictions establish supervisory agencies with broad administrative powers relating to, among other things:
| • | granting and revoking licenses to transact business |
| • | regulating trade and claims practices |
| • | licensing of insurance agents and brokers |
| • | approval of policy forms and premium rates |
| • | standards of solvency and maintenance of specified policy benefit reserves and minimum loss ratio requirements |
| • | capital requirements |
| • | limitations on dividends to shareholders |
| • | the nature of and limitations on investments |
| • | deposits of securities for the benefit of policyholders |
| • | filing of financial statements prepared in accordance with statutory insurance accounting practices prescribed or permitted by regulatory authorities |
| • | periodic examinations of the market conduct, financial, and other affairs of insurance companies |
The insurance laws of Nebraska that govern Aflac's activities provide that the acquisition or change of “control” of a domestic insurer or of any person that controls a domestic insurer cannot be consummated without the prior approval of the Nebraska Department of Insurance (NDOI). A person seeking to acquire control, directly or indirectly, of a domestic insurance company or of any person controlling a domestic insurance company (in the case of Aflac, CAIC and TOIC, the Parent Company) must generally file with the NDOI an application for change of control containing certain information required by statute and published regulations and provide a copy to Aflac. In Nebraska, control is generally presumed to exist if any person, directly or indirectly, acquires 10% or more of an insurance company or of any other person or entity controlling the insurance company. The 10% presumption is not conclusive and control may be found to exist at less than 10%. Similar laws apply in New York, the domiciliary jurisdiction of Aflac's New York insurance subsidiary.
State insurance departments conduct periodic examinations of the books and records, financial reporting, policy filings and market conduct of insurance companies domiciled in their states, generally once every three to five years. Examinations are generally carried out in cooperation with the insurance departments of other states under guidelines promulgated by the National Association of Insurance Commissioners (NAIC). In 2016, full-scope, risk-focused financial examinations were conducted by the NDOI, New York Department of Financial Services (NYDFS), and the South Carolina Department of Insurance (SCDOI) on their state domiciled insurance entities Aflac, Aflac New York, and CAIC, respectively. There were no material findings contained in the final exam reports. CAIC redomiciled to Nebraska as of December 2016 and TOIC redomiciled to Nebraska effective March 11, 2019. The NDOI and NYDFS are scheduled to conduct a full-scope comprehensive financial examination covering years 2016-2019 in 2020.
NAIC Risk-Based Capital The NAIC continually reviews regulatory matters, such as risk-based capital (RBC) modernization, group capital calculations, liquidity risk assessment and principle-based reserving. The NAIC has adopted a valuation manual containing a principle-based approach to calculation of life insurance reserves. The valuation manual became effective January 1, 2017. There is a three-year transition period, beginning January 1, 2017, during which companies can choose on a product by product basis to implement principle-based reserving for new business. The Company anticipates that the adoption of this manual will not cause a material impact on the statutory reserves of Aflac, Aflac New York, CAIC or TOIC. The NAIC uses an RBC formula relating to insurance risk, business risk, asset risk and interest rate risk to facilitate identification by insurance regulators of inadequately capitalized insurance companies based upon the types and mix of risk inherent in the insurer's operations. The formulas for determining the amount of RBC specify various weighting factors that are applied to financial balances or various levels of activity based on the perceived degree of risk. Regulatory compliance is determined by a ratio of a company's regulatory total adjusted capital to its authorized control level RBC as defined by the NAIC. Companies below specific trigger points or ratios are classified within certain levels, each of which requires specified corrective action. The levels are company action, regulatory action, authorized control, and mandatory control. As of December 31, 2019, based on year-end statutory accounting results, Aflac's company action level RBC ratio was 539%. The 2018 RBC as filed is lower than Aflac U.S. stand-alone RBC due to the inclusion of Aflac Japan for the first quarter of 2018. The RBC charge reflects the business risk without any total adjusted capital (TAC). Aflac's NAIC RBC ratio remains high and reflects a very strong capital and surplus position.
Guaranty Association and Similar Arrangements Under state insurance guaranty association laws and similar laws in international jurisdictions, the Company is subject to assessments, based on the share of business the Company writes in the relevant jurisdiction, for certain obligations of insolvent insurance companies to policyholders and claimants. In the U.S., some states permit member insurers to recover assessments paid through full or partial premium tax offsets. The Company's policy is to accrue assessments when the entity for which the insolvency relates has met its state of domicile's statutory
definition of insolvency, the amount of the loss is reasonably estimable and the related premium upon which the assessment is based is written. In most states, the definition is met with a declaration of financial insolvency by a court of competent jurisdiction.
Federal Initiatives Federal legislation and administrative policies in several areas, including health care reform legislation, financial services reform legislation, securities regulation, pension regulation, privacy, tort reform legislation and taxation, can significantly and adversely affect insurance companies. Federal regulations applicable to Aflac U.S. are outlined below.
| • | Affordable Care Act (ACA) |
The ACA, federal health care reform legislation, gave the U.S. federal government direct regulatory authority over the business of health insurance. The reform included major changes to the U.S. health care insurance marketplace. The ACA, as enacted, does not require material changes in the design of the Company's insurance products. However, indirect consequences of the legislation and regulations could present challenges that could potentially have an impact on the Company's sales model, financial condition and results of operations. The U.S. Congress has considered and may continue to consider legislation that would repeal and replace key provisions of the ACA. There can be no assurance that any legislation affecting the ACA will be passed by Congress, nor as to the ultimate timing or provisions of any such legislation, nor as to the effect of any such legislation on the design or marketability of the Company's insurance products. Further, certain provisions of the ACA have been and may continue to be subject to challenge through litigation, the ultimate effects of which on the ACA are uncertain.
| • | Dodd-Frank Act |
Title VII of the Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010 (Dodd-Frank) and regulations issued thereunder, in particular rules to require central clearing for certain types of derivatives, may have an impact on the Company's derivative activity, including activity on behalf of Aflac Japan. In addition, in 2015 and 2016, six U.S. financial regulators, including the U.S. Commodity Futures Trading Commission (CFTC), issued final rules regarding the exchange of initial margin (IM) and variation margin (VM) for uncleared swaps that impose greater obligations on swap dealers regarding uncleared swaps with certain counterparties, such as the Company. The requirements of such rules with respect to IM are currently being phased in and will be fully implemented by September 1, 2020, although an extension to September 1, 2021 is expected for covered entities with an aggregate average notional amount below $50 billion. The margin requirements are expected to result in more stringent collateral requirements and to affect other aspects of the Company's derivative activity.
The Dodd-Frank Act also established a Federal Insurance Office (FIO) under the U.S. Treasury Department to monitor all aspects of the insurance industry and of lines of business other than certain health insurance, certain long-term care insurance and crop insurance. Traditionally, U.S. insurance companies have been regulated primarily by state insurance departments. The FIO does not directly regulate the insurance industry, but under Dodd-Frank it has the power to preempt state insurance regulations that are inconsistent with international agreements reached by the federal government, subject to certain requirements and restrictions. The FIO and certain federal agencies must achieve consensus positions with the state insurance regulators when taking positions on insurance proposals by certain international forums. The President and Congress have stated proposals to reform or repeal certain provisions of the Dodd-Frank Act, some of which have been implemented. The Company cannot predict with any degree of certainty what impact, if any, such proposals might have on Aflac's business, financial condition, or results of operations.
| • | Privacy and Cybersecurity |
The collection, maintenance, use, protection, disclosure and disposal of individually identifiable data by the Company's businesses are regulated at the international, federal and state levels. These laws and rules are subject to change by legislation or administrative or judicial interpretation. Various state laws address the unauthorized access and acquisition of personal information and the use and disclosure of individually identifiable health data to the extent they are more restrictive than those contained in the privacy and security provisions in the federal Gramm-Leach-Bliley Act of 1999 (GLBA) and in the Health Insurance Portability and Accountability Act of 1996 (HIPAA). For example, the California Consumer Privacy Act became effective January 1, 2020 and requires businesses to provide California consumers rights to access, delete, and restrict certain uses of their personal information. Under the law, the California Attorney General may not bring an enforcement action prior to July 1, 2020. HIPAA also requires that the Company imposes privacy and security requirements on its business associates (as such term is defined in the HIPAA regulations).
Cybersecurity also continues to be an area of evolving focus for U.S. legislation and regulatory activity. In March 2017, new cybersecurity regulation issued by the NYDFS went into effect that requires covered entities, including Aflac New York, to maintain an information security program meeting certain security, data disposal, audit, activity
monitoring, and data encryption requirements. In October 2017, the NAIC adopted an Insurance Data Security Model Law that may be adopted in whole or in part by U.S. states in which the Company’s subsidiaries are licensed. Other states have adopted and, the Company expects, will continue to pass legislation and issue regulations related to cybersecurity. The Company anticipates, assesses and if necessary modifies its information security program to accommodate such changes.
For further information concerning Aflac U.S. operations, see the "Aflac U.S. Segment" subsection of the MD&A and Notes 2 and 13 of the Notes to the Consolidated Financial Statements in this report.
CORPORATE AND OTHER
The Company's other operations include the Parent Company, asset management subsidiaries, results of reinsurance retrocession activities and a printing subsidiary. For additional information on the Company's other operations, see the "Corporate and Other" subsection of the MD&A and Note 8 in the Notes to the Consolidated Financial Statements.
EMPLOYEES
As of December 31, 2019, Aflac Japan had 6,178 employees, Aflac U.S. had 4,799 employees, and the Company's other operations had 752 employees.
Information about the Company's Executive Officers
| NAME | PRINCIPAL OCCUPATION*(1)* | AGE | |
| Daniel P. Amos | Chairman, Aflac Incorporated and Aflac, since 2001; Chief Executive Officer, Aflac Incorporated and Aflac, since 1990; President, Aflac, since 2017; President, Aflac Incorporated, from 2018 until 2020 | 68 | |
| Koji Ariyoshi | Executive Vice President, Director of Sales and Marketing, Aflac Japan, since 2012 | 66 | |
| Steven K. Beaver | Senior Vice President, Chief Financial Officer, Aflac U.S., since 2019; Senior Vice President, Financial Planning and Analysis, Aflac Incorporated, from 2018 until 2019; Senior Vice President, Global Strategic Projects, Corporate Financial Planning and Analysis, Aflac Incorporated, from 2017 until 2018; Vice President, Deputy Chief Accounting Officer, Tax Department, Aflac Incorporated, from 2015 until 2016; Vice President, Corporate Tax, Aflac Incorporated, from 2012 until 2014 | 55 | |
| Max K. Broden | Executive Vice President, Chief Financial Officer, Aflac Incorporated, since 2020; Senior Vice President and Treasurer, Aflac Incorporated, from 2017 until 2020; Senior Portfolio Manager, Norges Bank, from 2007 until 2017 | 41 | |
| Frederick J. Crawford | President and Chief Operating Officer, Aflac Incorporated, since 2020; Executive Vice President, Chief Financial Officer, Aflac Incorporated, from 2015 until 2020; Executive Vice President, Chief Financial Officer, CNO Financial Group, from 2012 until 2015 | 56 | |
| J. Todd Daniels | Executive Vice President, Chief Financial Officer, Aflac Japan, since 2018; Executive Vice President, Global Chief Risk Officer and Chief Actuary, Aflac Incorporated, from 2016 until 2018; Senior Vice President, Global Chief Risk Officer and Chief Actuary, Aflac, from 2015 until 2016; Senior Vice President, Deputy Corporate Actuary and Global Chief Risk Officer, Aflac, from 2014 until 2015; Senior Vice President, Deputy Corporate Actuary, Aflac, from 2012 until 2014 | 49 | |
| June Howard | Chief Accounting Officer, Aflac Incorporated and Aflac, since 2010; Senior Vice President, Financial Services, Aflac Incorporated and Aflac, since 2010; Treasurer, Aflac, from 2011 until 2015 | 53 | |
| Eric M. Kirsch | Executive Vice President, Global Chief Investment Officer, Aflac, since 2012; President, Aflac Asset Management LLC, since 2017 | 59 | |
| Masatoshi Koide | President and Chief Operating Officer, Aflac Japan since 2017; Deputy President, Aflac Japan from 2016 until 2017; Executive Vice President, Aflac Japan from 2015 until 2016; First Senior Vice President, Aflac Japan, from 2013 until 2015 | 59 | |
| Charles D. Lake, II | President, Aflac International, since 2014; Chairman, Aflac Japan, since 2008 | 58 | |
| Albert A. Riggieri | Senior Vice President, Global Chief Risk Officer and Chief Actuary, Aflac Incorporated, since 2018; Senior Vice President, Corporate Actuary, Aflac, from 2016 until 2018; Group Chief Actuary, Unum Group, until 2016 | 64 | |
| Audrey B. Tillman | Executive Vice President, General Counsel, Aflac Incorporated and Aflac, since 2014; Executive Vice President, Corporate Services, Aflac Incorporated, from 2008 until 2014 | 55 | |
| Teresa L. White | President, Aflac U.S., since 2014 | 53 | |
| Richard L. Williams Jr. | Executive Vice President and Chief Distribution Officer, Aflac since 2017; Senior Vice President and General Manager, Stop Loss, Unum, U.S. in 2017; Senior Vice President, Growth Markets, Colonial Life and Accident Insurance Company from 2013 until 2017 | 48 |
*(1)*Unless specifically noted, the respective executive officer has held the occupation(s) set forth in the table for at least the last five years. Each executive officer is appointed annually by the board of directors and serves until his or her successor is chosen and qualified, or until his or her death, resignation or removal.
Previous: Cover and table of contents · Next: Item 1A. RISK FACTORS