 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
100K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion and analysis of our financial condition and results of operations should be read together with “Selected Consolidated Financial Data” and our consolidated financial statements and related notes included elsewhere in this Annual Report on Form 10-K.
Overview
Align Technology, Inc. is a global medical device company that advanced the invisible orthodontics market with the introduction of the Invisalign System in 1999. Today, we are focused on designing, manufacturing and marketing innovative technology-rich products to help dental professionals achieve the clinical results they expect and deliver effective, convenient cutting-edge dental treatment options to their patients. Align Technology was founded in March 1997 and is headquartered in San Jose, California with offices worldwide. Our international headquarters are located in Amsterdam, the Netherlands. We have two operating segments: (1) Clear Aligner, known as the Invisalign System; and (2) Scanner and Services ("Scanner"), known as the iTero intra-oral scanners and OrthoCAD services (which we previously referred to as Scanner and CAD/CAM Services ("SCCS")).
We received FDA clearance in 1998 and began our first commercial sales of Invisalign to U.S. orthodontists in 1999 followed by U.S. General Practitioner Dentists ("GPs") in 2002. Over the next decade, we introduced Invisalign to the European market and Japan, added distribution partners in Asia Pacific, Latin America, and Europe Middle East and Africa ("EMEA"), and introduced a full range of treatment options including Invisalign Express 10, Invisalign Teen, Invisalign Assist, and Vivera Retainers. By 2011, we launched significant new aligner and software features across all Invisalign products that make it easier for doctors to use Invisalign on more complex cases, and introduced Invisalign to the People’s Republic of China. In 2013, we launched SmartTrack, the next generation of Invisalign clear aligner material, which became the new standard aligner material for Invisalign products in North America, Europe and other international markets where we have obtained regulatory approval. Over the last several years’ we have continued to build upon our technology and expertise to deliver enhanced clinical innovations aimed at helping our customers treat some of the most challenging cases. These innovations, both launched in early 2014, include Invisalign G5, specifically designed for treatment of deep bite malocclusion, as well as ClinCheck Pro, the next generation Invisalign treatment software tool designed to help Invisalign providers achieve their treatment goals. Most recently, in November 2014, we announced the upcoming release of Invisalign G6 clinical innovations for first premolar extraction.
We also sell iTero intra-oral scanners and provide computer-aided design and computer-aided manufacturing ("CAD/CAM") services. Intra-oral scanners provide a dental “chair-side” platform for accessing valuable digital diagnosis and treatment tools, with potential for enhancing accuracy of records, treatment efficiency, and the overall patient experience. We believe there are numerous benefits for customers and the opportunity to accelerate the adoption of Invisalign through interoperability with our intra-oral scanners. The use of digital technologies such as CAD/CAM for restorative dentistry or in-office restorations has been growing rapidly and intra-oral scanning is a critical part of enabling these new digital technologies and procedures in dental practices. In late 2012, we commercially launched the Invisalign Outcome Simulator, the first Invisalign chair-side application powered by the iTero scanner. The interactive application provides dentists and orthodontists an enhanced platform for patient education and is designed to increase treatment acceptance by helping patients visualize the benefits possible with Invisalign treatment. In January 2014, we announced that the 3M™ True Definition scanner was qualified for use with Invisalign case submissions. This qualification enables Invisalign providers with a True Definition scanner to submit a digital impression in place of a traditional PVS impression as part of the Invisalign case submission process. The 3M True Definition scanner is currently the only third-party scanner that has been qualified for use with Invisalign treatment. We continue to believe in an open systems approach to digital impressions, and are committed to working with other intra-oral scanning companies interested in developing interoperability for use with Invisalign treatment.
The Invisalign System is offered in more than 80 countries and has been used to treat more than 3.0 million patients. Our iTero intra-oral scanner, which is primarily sold in North America, provides dental professionals with an open choice to send digital impressions to any laboratory-based CAD/CAM system or to any of the more than 2,400 dental labs worldwide.
Our goal is to establish Invisalign clear aligners as the standard method for treating malocclusion and to establish the iTero intra-oral scanner as the preferred scanning device for 3D digital scans, ultimately driving increased product adoption by dental professionals. We intend to achieve this by continued focus and execution of our strategic growth drivers set forth in the Business Strategy section in our Annual Report on Form 10-K.
The successful execution of our business strategy and our results in 2014 and beyond may be affected by a number of other factors, which are updated below:
| • | New Products, Feature Enhancements and Technology Innovation. Product innovation drives greater treatment predictability and clinical applicability, and ease of use for our customers, which supports adoption of Invisalign in their practices. Increasing applicability and treating more complex cases requires that we move away from individual features to more comprehensive solutions so that Invisalign providers can more predictably treat the whole case, such as with Invisalign G5 for deep bite treatment. Launched in February 2014, Invisalign G5 was engineered to help doctors achieve even better clinical outcomes when treating patients with deep bites - a prevalent orthodontic problem. In North America, in February 2014, we also launched ClinCheck Pro, the next generation Invisalign treatment software tool, designed to provide more precise control over final tooth position and to help Invisalign providers achieve their treatment goals. We intend to launch ClinCheck Pro in our other country markets in the first quarter of 2015. Most recently, in November 2014, we announced the upcoming release of Invisalign G6 clinical innovations for first premolar extraction. Invisalign G6 is engineered to improve clinical outcomes for orthodontic treatment of severe crowding and bimaxillary protrusion. Invisalign G6 clinical innovations will be available to Invisalign-trained providers beginning in the first quarter of 2015 with limited commercialization, followed by full commercialization in Asia Pacific, Europe, Middle East and Africa ("EMEA"), and Latin America geographies throughout 2015 and North America in early 2016. We believe that over the long-term, clinical solutions and treatment tools will increase adoption of Invisalign; however, it is difficult to predict the rate of adoption which may vary by region and channel. |
| • | Invisalign Utilization rates. Our goal is to establish Invisalign as the treatment of choice for treating malocclusion ultimately driving increased product adoption and frequency of use by dental professionals, also known as "utilization rates." Our quarterly utilization rates for the previous 9 quarters are as follows: |
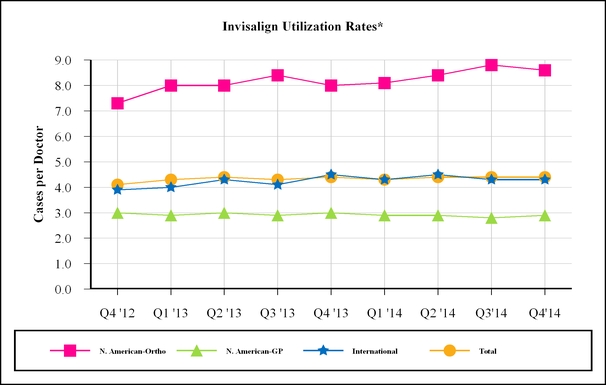
- Invisalign Utilization rates = # of cases shipped divided by # of doctors cases were shipped to
Total utilization in the fourth quarter of 2014 was 4.4 cases per doctor which is flat when compared to the third quarter of 2014; however, in the fourth quarter of 2013, utilization rates increased for our International doctors which was offset by a decrease in utilization by our North American orthodontic doctors. The decrease by our North American orthodontic doctors reflects a seasonal decline in the number of teen-aged cases shipped as summer is typically the busiest season for orthodontists with practices that have a high percentage of adolescent and teenage patients as many parents want to get their teenagers started in treatment before the start of the school year. On a year-over-year basis, total utilization of 4.4 cases per doctor in the fourth quarter of 2014 remained flat compared to the
fourth quarter of 2013. We expect that over the long-term our utilization rates will gradually improve as a result of advancements in product and technology, which continue to strengthen our doctors’ clinical confidence in the use of Invisalign, along with the implementation of our Go-To-Market strategy (as discussed below). However, we expect that our utilization rates may fluctuate from period to period.
| • | Number of new Invisalign doctors trained. We continue to expand our Invisalign customer base through the training of new doctors. In 2014, Invisalign growth was driven primarily by increased utilization by our North American orthodontist doctors and International doctors as well as by the continued expansion of our customer base as we trained a total of 9,440 new Invisalign doctors, of which 56% were trained internationally. GPs are one of the keys to driving growth in the adult segment, and, in 2014, we launched Invisalign Fundamentals, a new training course, designed to improve practice integration and increase utilization for newly trained doctors. We have implemented this new Invisalign Fundamentals program across North America and will look for opportunities to adjust our international training programs as we work to help our GP practices worldwide more successfully adopt Invisalign into their practices. We believe that this new training approach has the potential to increase the number of doctors submitting cases 90-days post-training, as well as the number of cases submitted per doctor. |
| • | International Clear Aligner. We will continue to focus our efforts towards increasing adoption of our products by dental professionals in our direct international markets. International volume increased 28.6% in 2014 from 2013 driven primarily by growth in Europe as well as by strong performance in the Asia Pacific region. In 2015, we are continuing to expand in our existing markets through targeted investments in sales coverage and professional marketing and education programs, along with consumer marketing in selected country markets. We expect international revenues to continue to grow at a faster rate than North America for the foreseeable future due to our continued investment in international market expansion, the size of the market opportunity, and our relatively low market penetration in this region. |
| • | Go-To-Market Evolution. In order to provide more comprehensive sales and service coverage, we are currently implementing an updated go-to-market strategy with an expanded team and new structure in North America. In order to ensure our North America sales and marketing team can increase time in-office and help each practice become more successful, we are in the process of adding approximately 50 sales team members in 2015, the majority of which are in place as of the date of this Form 10-K. We believe that these investments in a refined go-to-market strategy and the strategic deployment of more people will improve adoption and utilization of Invisalign by our customers. |
| • | Operating Expenses. We expect operating expenses to increase in 2015 compared to 2014 due in part to: |
| ▪ | the increase in North American sales force coverage discussed above, as well as additions to our sales force in EMEA and Asia Pacific regions |
| ▪ | infrastructure investments, including a project to implement a new enterprise resource planning system which we started in late 2014 with expected "go-live" for various modules and subsidiaries throughout 2016; and |
| ▪ | investments in new products and markets like our recently announced intention to develop new products for dentists who treat mild to moderate obstructive sleep apnea with oral appliance therapy. |
We believe that these investments will position us to increase our revenue and continue to grow our market share.
| • | Increase in Invisalign Selling Price. We have historically invested in research and development and continuous product innovation. In order to continue and even accelerate this product innovation cycle, we recently announced a price increase of $50 per treatment, or approximately 3%, on Invisalign Full and Invisalign Teen products, effective April 1, 2015 in North America. The prices for Invisalign Assist, Invisalign Express 10 and Invisalign Express 5 products will remain unchanged. |
| • | Foreign exchange rates. Although the U.S. dollar is our reporting currency, a portion of our net revenues and income are generated in foreign currencies. Net revenues and income generated by subsidiaries operating outside of the U.S. are translated into U.S. dollars using exchange rates effective during the respective period and as a result are affected by changes in exchange rates. We have generally accepted the exposure to exchange rate movements without using derivative financial instruments to manage this risk; therefore, both positive and negative movements in currency exchange rates against the U.S. dollar will continue to affect the reported amount of net revenues and income in our consolidated financial statements. In the third and fourth quarter of 2014 combined, our net revenues were negatively impacted by $3.1 million, and we incurred foreign currency translation net losses of $4.1 million in Interest and Other Income (Expense) net, primarily due to the weakening of the Euro and other foreign currencies relative to the |
U.S. Dollar. If the U.S. Dollar continues to strengthen compared to other foreign currencies, including the Euro, our reported amount of net revenues and income will be negatively impacted compared to the same period last year.
| • | Medical Device Excise Tax. During March 2014, Align had extensive discussions with the IRS and they informed us that our aligners are not subject to the medical device excise tax ("MDET") which we had been paying and expensing in general and administrative expenses in the consolidated statements of operations since January 1, 2013; however, our scanners are still subject to the MDET. As a result of these discussions, beginning in March 2014, we ceased expensing and paying the MDET for aligners. In June 2014, we received a $1.2 million refund for MDET paid in 2014 related to our aligners which reduced general and administrative expenses for the three months ended June 30, 2014. For the year ended December 31, 2014, MDET expense was lower by approximately $6.8 million compared to the prior year. Additionally, we are in process of claiming a $6.8 million refund of MDET paid in 2013 related to our aligners; however, because this claim is subject to review and approval by the IRS, we have not recorded a receivable as the outcome of the audit is uncertain. Any future changes in the applicability of the MDET as it applies to us or refunds of amounts previously paid will be recorded as an additional expense or a credit to the consolidated statement of operations in the period in which it becomes probable and reasonably estimable. |
| • | Stock Repurchase Authorization. On April 23, 2014, we announced that our Board of Directors had authorized a stock repurchase program pursuant to which we may purchase up to $300.0 million of our common stock over the next three years, with $100.0 million of that amount authorized to be purchased over the first twelve months. Any purchases under this stock repurchase program may be made, from time-to-time, pursuant to open market purchases (including pursuant to Rule 10b5-1 plans), privately-negotiated transactions, accelerated stock repurchases, block trades or derivative contracts or otherwise in accordance with applicable federal securities laws, including Rule 10b-18 of the Securities Exchange Act of 1934. The program does not obligate Align to acquire any particular amount of common stock and depending on market conditions or other factors these purchases may be commenced or suspended at any time, or from time-to-time without prior notice. The authorization or continuance of any repurchases under stock repurchase programs is contingent on a variety of factors, including our financial condition, results of operations, business requirements, and our Board of Directors' continuing determination that such stock repurchases are in the best interests of our stockholders and in compliance with all laws and applicable agreements. Additionally, there can be no assurance that our stock repurchase program will have a beneficial impact on our stock price. As of December 31, 2014, there is approximately $201.8 million remaining under the April 2014 stock repurchase program, of which $1.8 million was repurchased in January 2015. In addition, in January 2015, our Board of Directors has authorized the next $100.0 million under the program to be repurchased which we anticipate completing within twelve months. We expect to finance future stock repurchases with current cash on hand. |
Results of Operations
Net revenues by Reportable Segment Comparison for Year Ended December 31, 2014, 2013 and 2012:
We group our operations into two reportable segments: Clear Aligner segment and Scanner and Services segment.
| • | Our Clear Aligner segment consists of our Invisalign system which includes Invisalign Full, Teen and Assist ("Full Products"), Express/Lite ("Express Products"),Vivera retainers, along with our training and ancillary products for treating malocclusion. |
| • | Our Scanner and Services segment consists of intra-oral scanning systems and additional services available with the intra-oral scanners that provide digital alternatives to the traditional cast models. This segment includes our iTero scanner and OrthoCAD services. |
Net revenues for our Clear Aligner segment by region and product and our Scanner segment by region for the year ended December 31, 2014, 2013 and 2012 is as follows (in millions):
| Year Ended | Year Ended | ||||||||||||||||||||||||||||
| December 31, 2014 | December 31, 2013 | Change | December 31, 2013 | December 31, 2012 | Change | ||||||||||||||||||||||||
| Clear Aligner | |||||||||||||||||||||||||||||
| Region and Channel | |||||||||||||||||||||||||||||
| North America | $ | 446.6 | $ | 408.2 | $ | 38.4 | 9.4 | % | $ | 408.2 | $ | 361.1 | $ | 47.1 | 13.0 | % | |||||||||||||
| International | 219.7 | 161.7 | $ | 58.0 | 35.9 | % | 161.7 | 124.8 | 36.9 | 29.6 | % | ||||||||||||||||||
| Invisalign non-case net revenues | 46.2 | 44.7 | $ | 1.5 | 3.4 | % | 44.7 | 30.7 | 14.0 | 45.6 | % | ||||||||||||||||||
| Total Clear Aligner net revenues 1 | $ | 712.5 | $ | 614.6 | $ | 97.9 | 15.9 | % | $ | 614.6 | $ | 516.6 | $ | 98.0 | 19.0 | % | |||||||||||||
| Product | |||||||||||||||||||||||||||||
| Invisalign Full Products | $ | 585.7 | $ | 497.5 | $ | 88.2 | 17.7 | % | $ | 497.5 | $ | 434.4 | $ | 63.1 | 14.5 | % | |||||||||||||
| Invisalign Express Products | 80.6 | 72.4 | 8.2 | 11.3 | % | 72.4 | 51.5 | 20.9 | 40.6 | % | |||||||||||||||||||
| Invisalign non-case net revenues | 46.2 | 44.7 | 1.5 | 3.4 | % | 44.7 | 30.7 | 14.0 | 45.6 | % | |||||||||||||||||||
| Total Clear Aligner net revenues | $ | 712.5 | $ | 614.6 | $ | 97.9 | 15.9 | % | $ | 614.6 | $ | 516.6 | $ | 98.0 | 19.0 | % | |||||||||||||
| Scanner: | |||||||||||||||||||||||||||||
| Region | |||||||||||||||||||||||||||||
| North America | $ | 48.7 | $ | 45.3 | $ | 3.4 | 7.5 | % | $ | 45.3 | $ | 42.2 | $ | 3.1 | 7.3 | % | |||||||||||||
| International | 0.4 | 0.3 | 0.1 | 33.3 | % | 0.3 | 1.2 | (0.9 | ) | (75.0 | )% | ||||||||||||||||||
| Total Scanner net revenues | $ | 49.1 | $ | 45.6 | $ | 3.5 | 7.7 | % | $ | 45.6 | $ | 43.4 | $ | 2.2 | 5.1 | % | |||||||||||||
| Total net revenues | $ | 761.6 | $ | 660.2 | $ | 101.4 | 15.4 | % | $ | 660.2 | $ | 560.0 | $ | 100.2 | 17.9 | % |
Changes and percentages are based on actual values. Certain tables may not sum or recalculate due to rounding.
| 1 | In the fourth quarter of 2012, we identified an error that the actual case refinement usage rate was lower than our estimate and, as a result, we recorded a net revenue release of $4.9 million previously deferred for case refinement of which $5.2 million was a correction of an error of which $4.5 million related to the first three quarters for the fiscal year 2012 and $0.7 million related to the fiscal year 2011. The adjustment was not material to any quarter within 2012. The net amount of $4.9 million is not material to the results of operations for twelve months ended December 31, 2012. |
Clear Aligner Case Volume by Channel and Product
Case volume data which represents Invisalign case shipments by region and product, for the year ended December 31, 2014, 2013 and 2012 as follows (in millions):
| Year Ended | Year Ended | ||||||||||||||||||||||
| Region and Channel | December 31, 2014 | December 31, 2013 | Change | December 31, 2013 | December 31, 2012 | Change | |||||||||||||||||
| North American Invisalign | 338.5 | 313.9 | 24.6 | 7.8 | % | 313.9 | 276.7 | 37.2 | 13.4 | % | |||||||||||||
| International Invisalign | 139.5 | 108.5 | 31.0 | 28.6 | % | 108.5 | 86.8 | 21.7 | 25.0 | % | |||||||||||||
| Total Invisalign case volume | 478.0 | 422.4 | 55.6 | 13.2 | % | 422.4 | 363.5 | 58.9 | 16.2 | % | |||||||||||||
| Product | |||||||||||||||||||||||
| Invisalign Full Product Group | 395.1 | 343.4 | 51.7 | 15.1 | % | 343.4 | 304.8 | 38.6 | 12.7 | % | |||||||||||||
| Invisalign Express Product Group | 82.9 | 79.0 | 3.9 | 4.9 | % | 79.0 | 58.7 | 20.3 | 34.6 | % | |||||||||||||
| Total Invisalign case volume | 478.0 | 422.4 | 55.6 | 13.2 | % | 422.4 | 363.5 | 58.9 | 16.2 | % |
Changes and percentages are based on actual values. Certain tables may not sum or recalculate due to rounding.
Fiscal Year 2014 compared to Fiscal Year 2013
Total net revenues increased by $101.4 million in 2014 as compared to 2013 primarily as a result of Invisalign case volume growth across all regions and products as well as increased Invisalign non-case revenue.
Clear Aligner
Clear Aligner North America net revenues increased by $38.4 million, or 9.4%, in 2014 compared to 2013 primarily due to Invisalign case volume growth of approximately $32.1 million across all channels and products, and, to a lesser extent, higher average selling prices ("ASP") which contributed approximately $6.3 million to the increase in net revenues. The increase in ASP was primarily a result of increased mid-course correction revenue from higher usage as well as a product mix shift towards higher priced Invisalign products in 2014 compared to 2013. This increase was offset in part by higher promotional discounts in 2014 as compared to 2013.
Clear Aligner international net revenues increased by $58.0 million, or 35.9%, in 2014 compared to 2013 primarily driven by Invisalign case volume growth of $46.2 million along with higher ASP which contributed approximately $11.8 million to the increase in net revenues. The increase in ASP was primarily due to the impact from acquiring our distributor in the Asia Pacific region on April 30, 2013 when we began recognizing direct sales of Invisalign products sold in that region at our full ASP rather than the discounted ASP under the distributor agreement, as well as the price increases which were effective July 2013 along with a favorable impact from foreign exchange rates. Foreign exchange rates had a favorable impact to revenues in 2014 as compared to 2013, despite the weakening of the Euro to the U.S. dollar in the last six months of 2014.
Invisalign non-case net revenues, consisting of training fees and ancillary product revenues, increased by $1.5 million in 2014 as compared to 2013 primarily due to the consolidation of our Vivera product shipments in North America from four shipments per year to one shipment along with increased Vivera volume both in North America and international.
Scanner and Services
Scanner and Services net revenues increased by $3.5 million, or 7.7%, in 2014 compared to 2013 due to an increase in both services revenue as well as scanner revenue.
The increase in services revenue was primarily due to an increase in the volume of CAD/CAM services resulting from a larger installed base of scanners. The increase in scanner revenue was primarily due to an increase in the number of scanners recognized offset in part by lower scanner ASP as a result of promotional discounts as well as permanent price reductions. The increase was partially offset as 2013 had higher net revenues due to the release of $1.4 million of revenue previously reserved for the iTero upgrade program which was completed in the first quarter of 2013.
Fiscal Year 2013 compared to Fiscal Year 2012
Total net revenues increased by $100.2 million in 2013 as compared to 2012 primarily as a result of Invisalign case volume growth across all regions and products as well as increased Invisalign non-case revenue.
Clear Aligner
Clear Aligner North America net revenues increased by $47.1 million, or 13.0%, in 2013 compared to 2012 primarily due to Invisalign case volume growth of approximately $48.5 million across all channels and products, offset in part, by lower average selling prices ("ASP") which decreased net revenues by approximately $1.4 million. The decrease in ASP was a result of product mix shift towards lower priced Invisalign Express products combined with the revenue deferral for free mid-course correction as a result of our policy change in June 2013. Beginning June 15, 2013, we included up to three free mid-course correction orders in our list prices for Invisalign Full and Invisalign Teen.
Clear Aligner international net revenues increased by $36.9 million, or 29.6%, in 2013 compared to 2012 primarily driven by Invisalign case volume growth of $31.1 million along with higher ASP, which resulted in approximately $5.8 million increase in net revenues. The increase in ASP was primarily due to the impact from acquiring our distributor in the APAC region on April 30, 2013, as well as a favorable impact of foreign exchange rates. By bringing the APAC region direct, we began to recognize
direct sales of Invisalign products sold in that region at our full ASP rather than the discounted ASP under the distributor agreement. The increase in ASP was offset in part due to a product mix shift towards lower priced Invisalign Lite products.
Invisalign non-case net revenues, consisting of training fees and ancillary product revenues, increased by $14.0 million, or 45.6%, in 2013 as compared to 2012 primarily due to the consolidation of our Vivera product shipments in North America from four shipments per year to one shipment along with increased Vivera volume both in North America and international.
Scanner and Services
Scanner and Services net revenues increased by $2.2 million, or 5.1%, in 2013 compared to 2012 primarily due to an increase in scanner revenues, partially offset by a decrease in CAD/CAM services net revenues as a result of the discontinuation of the OrthoCAD iQ services during the fourth quarter of 2012. The increase in scanner revenues in 2013 was as a result of the increase in number of scanners sales recognized in 2013 as compared to 2012 as well as the release of $1.4 million of revenue previously reserved for the new iTero upgrade program which was completed in the first quarter of 2013.
Cost of net revenues and gross profit (in millions):
| Year Ended | Year Ended | ||||||||||||||||||||||
| December 31, 2014 | December 31, 2013 | Change | December 31, 2013 | December 31, 2012 | Change | ||||||||||||||||||
| Clear Aligner | |||||||||||||||||||||||
| Cost of net revenues | $ | 149.7 | $ | 129.8 | $ | 19.9 | $ | 129.8 | $ | 110.6 | $ | 19.2 | |||||||||||
| % of net segment revenues | 21.0 | % | 21.1 | % | 21.1 | % | 21.4 | % | |||||||||||||||
| Gross profit | $ | 562.9 | $ | 484.8 | $ | 78.1 | $ | 484.8 | $ | 406.0 | $ | 78.8 | |||||||||||
| Gross margin % | 79.0 | % | 78.9 | % | 78.9 | % | 78.6 | % | |||||||||||||||
| Scanner | |||||||||||||||||||||||
| Cost of net revenues | $ | 33.6 | $ | 32.3 | $ | 1.3 | $ | 32.3 | $ | 33.0 | $ | (0.7 | ) | ||||||||||
| % of net segment revenues | 68.3 | % | 70.9 | % | 70.9 | % | 75.9 | % | |||||||||||||||
| Gross profit | $ | 15.6 | $ | 13.3 | $ | 2.3 | $ | 13.3 | $ | 10.4 | $ | 2.9 | |||||||||||
| Gross margin % | 31.7 | % | 29.1 | % | 29.1 | % | 24.1 | % | |||||||||||||||
| Total cost of net revenues | $ | 183.2 | $ | 162.1 | $ | 21.1 | $ | 162.1 | $ | 143.6 | $ | 18.5 | |||||||||||
| % of net revenues | 24.1 | % | 24.6 | % | 24.6 | % | 25.7 | % | |||||||||||||||
| Gross profit | $ | 578.4 | $ | 498.1 | $ | 80.3 | $ | 498.1 | $ | 416.4 | $ | 81.7 | |||||||||||
| Gross margin % | 75.9 | % | 75.4 | % | 75.4 | % | 74.3 | % |
Changes and percentages are based on actual values. Certain tables may not sum or recalculate due to rounding.
Cost of net revenues for our Clear Aligner and Scanner segments includes salaries for staff involved in the production process, the cost of materials, packaging, shipping costs, depreciation on capital equipment used in the production process, amortization of acquired intangible assets from Cadent, training costs and stock-based compensation.
Fiscal Year 2014 compared to Fiscal Year 2013
Clear Aligner
The gross margin percentage improved slightly in 2014 compared to 2013 due to higher ASP. The ASP improvement was mostly offset by increased manufacturing costs in 2014 when compared to 2013 which benefited from an out of period adjustment (see Note 1 in the Financial Statements).
Scanner
The gross margin percentage increased in 2014 compared to 2013 due to increased absorption of manufacturing spend from higher production volumes, lower product costs due to product mix and lower inventory reserves. These were partially offset by a lower ASP as a result of price reductions.
Fiscal Year 2013 compared to Fiscal Year 2012
Clear Aligner
The gross margin percentage improved slightly in 2013 compared to 2012 primarily due to lower warranty costs as a result of reduced warranty claims corresponding with the change in our mid-course correction policy in June 2013. In addition, gross margins benefited to a lessor extent from an out of period adjustment (see Note 1 in the Financial Statements) which was partially offset by increased material costs, primarily related to our new SmartTrack material. In addition, we incurred higher inventory reserves for our prior aligner material which has been substantially replaced by our new SmartTrack aligner material.
Scanner
The gross margin percentage increased in 2013 compared to 2012 primarily as a result of the release of revenue for amounts previously reserved in 2012 for the new 2.9 iTero scanner upgrade program which was completed in the first quarter of 2013. In addition, we had lower manufacturing costs as a result of the closure of our New Jersey facility, which was completed by October 2012, and a reduction in training costs; however, these savings were partially offset by higher third party labor service costs and lower manufacturing cost absorption.
Sales and marketing (in millions):
| Year Ended | Year Ended | ||||||||||||||||||||||
| December 31, 2014 | December 31, 2013 | Change | December 31, 2013 | December 31, 2012 | Change | ||||||||||||||||||
| Sales and marketing | $ | 217.3 | $ | 180.0 | $ | 37.3 | $ | 180.0 | $ | 152.0 | $ | 28.0 | |||||||||||
| % of net revenues | 28.5 | % | 27.3 | % | 27.3 | % | 27.1 | % |
Changes and percentages are based on actual values. Certain tables may not sum or recalculate due to rounding.
Sales and marketing expense includes sales force and marketing compensation (including travel-related costs), media and advertising, clinical education, trade shows and industry events, product marketing, stock-based compensation and allocations of corporate overhead expenses including facilities and IT.
Sales and marketing expense increased in 2014 compared to 2013 primarily due to higher compensation costs of $19.4 million due to increased headcount, including the additional headcount from the acquisition of our APAC distributor. In addition, we incurred higher advertising and marketing expenses as a result of increased advertising production and marketing campaigns combined with higher costs for trade shows and our Europe and APAC Summits.
Sales and marketing expense increased in 2013 compared to 2012 due primarily to higher compensation costs of $16.4 million largely related to increased headcount, including additional employees as a result of the acquisition of our APAC distributor, higher sales commissions and stock-based compensation. In addition, we incurred higher advertising and media costs primarily related to network and television media campaigns.
General and administrative (in millions):
| Year Ended | Year Ended | ||||||||||||||||||||||
| December 31, 2014 | December 31, 2013 | Change | December 31, 2013 | December 31, 2012 | Change | ||||||||||||||||||
| General and administrative | $ | 114.8 | $ | 112.8 | $ | 2.0 | $ | 112.8 | $ | 99.3 | $ | 13.5 | |||||||||||
| % of net revenues | 15.1 | % | 17.1 | % | 17.1 | % | 17.7 | % |
Changes and percentages are based on actual values. Certain tables may not sum or recalculate due to rounding.
General and administrative expense primarily includes administrative personnel compensation costs including stock-based compensation, outside consulting services, legal expenses, depreciation and amortization expense, the medical device excise tax ("MDET") effective January 2013 and allocations of corporate overhead expenses including facilities and IT.
General and administrative expense for 2014 increased compared to 2013 primarily due to higher stock-based compensation of $4.7 million as well as increases in consulting expenses and credit card processing fees; however, these increases were offset
by lower MDET of $6.8 million as our aligners are no longer subject to the excise tax in 2014 as well as lower outside litigation costs. As previously noted, in March 2014, the IRS informed us that our aligners are not subject to the MDET, which we had been paying and expensing in general and administrative expenses in the consolidated statements of operations since January 1, 2013; however, our scanners are still subject to the MDET but are not material. There is no expense in the current year period for MDET related to our aligners. Additionally, we are in process of claiming a $6.8 million refund of MDET paid in 2013 related to our aligners; however, because this claim is subject to review and approval by the IRS, we have not recorded a receivable as the outcome of the audit is uncertain. Any future changes in the applicability of the MDET as it applies to us or refunds of amounts previously paid will be recorded as an additional expense or a credit to the consolidated statement of operations in the period in which is becomes probable and reasonably estimable.
General and administrative expense for 2013 increased compared to 2012 primarily due to higher compensation related costs of $7.6 million as a result of higher stock-based compensation expense and increased salaries. Additionally we incurred $7.1 million of medical device excise tax as a result of new tax regulations effective January 1, 2013. These costs were partially offset by lower outside legal expenses.
Research and development (in millions):
| Year Ended | Year Ended | ||||||||||||||||||||||
| December 31, 2014 | December 31, 2013 | Change | December 31, 2013 | December 31, 2012 | Change | ||||||||||||||||||
| Research and development | $ | 52.8 | $ | 44.1 | $ | 8.7 | $ | 44.1 | $ | 42.9 | $ | 1.2 | |||||||||||
| % of net revenues | 6.9 | % | 6.7 | % | 6.7 | % | 7.7 | % |
Changes and percentages are based on actual values. Certain tables may not sum or recalculate due to rounding.
Research and development expense includes the personnel-related costs and outside consulting expenses associated with the research and development of new products and enhancements to existing products, corporate allocations, facility and facility related costs and stock-based compensation expense.
Research and development expense increased during 2014 compared to 2013 almost entirely due to higher compensation costs as a result of higher bonuses, stock-based compensation and salaries primarily due to additional headcount.
Research and development expense increased slightly during 2013 compared to 2012 due to higher facilities related expenses primarily related to our Russia research and development facility and compensation costs offset in part by lower clinical and product innovation research program costs.
Impairment of goodwill (in millions):
| Year Ended | Year Ended | ||||||||||||||||||||||
| December 31, 2014 | December 31, 2013 | Change | December 31, 2013 | December 31, 2012 | Change | ||||||||||||||||||
| Impairment of goodwill | $ | — | $ | 40.7 | $ | (40.7 | ) | $ | 40.7 | $ | 36.6 | $ | 4.1 | ||||||||||
| % of net revenues | — | % | 6.2 | % | 6.2 | % | 6.5 | % |
Changes and percentages are based on actual values. Certain tables may not sum or recalculate due to rounding.
There was no impairment of goodwill charge recorded in the year ended December 31, 2014.
During the first quarter of 2013, we determined that the goodwill for our Scanner and Services reporting unit should be tested for impairment between annual tests due to changes in the competitive environment for intra-oral scanners which included announcements of new low-priced scanners targeted at orthodontist and GP dentist in North America. As a result, this caused us to lower our expectations for growth and profitability for our Scanner and Services reporting unit that would more likely than not reduce the fair value of our Scanner and Services reporting unit below its carrying amount. As a result of our analysis, we recorded a goodwill impairment charge of $40.7 million in the first quarter of 2013, none of which was deductible for tax purposes. Refer to Note 5 for details of the impairment analysis.
During the third quarter of 2012, we determined that the goodwill for our Scanner and Services reporting unit should be tested for impairment between annual tests since an event occurred or circumstances changed that would more likely than not reduce the fair value of our Scanner and Services reporting unit below its carrying amount. As a result of our analysis, we recorded a preliminary goodwill impairment charge during the third quarter of 2012 of $24.7 million and an additional $11.9 million during
the fourth quarter of 2012, representing a change in estimate upon finalizing our 2013 annual budget process, for a total impairment charge of $36.6 million. None of the goodwill impairment charge was deductible for tax purposes, and there was no additional impairment that resulted from our annual goodwill impairment test during the fourth quarter of 2012. Refer to Note 5 for details of the impairment analysis.
Impairment of long-lived assets (in millions):
| Year Ended | Year Ended | |||||||||||||||||||||
| December 31, 2014 | December 31, 2013 | Change | December 31, 2013 | December 31, 2012 | Change | |||||||||||||||||
| Impairment of long-lived assets | $ | — | $ | 26.3 | $ | (26.3 | ) | $ | 26.3 | — | $ | 26.3 | ||||||||||
| % of net revenues | — | % | 4.0 | % | 4.0 | % | — | % |
Changes and percentages are based on actual values. Certain tables may not sum or recalculate due to rounding.
There was no impairment of long-lived assets charge recorded in the year ended December 31, 2014.
The impairment of our long-lived assets in 2013 was the result of changes in the competitive environment for intra-oral scanners which included announcements of new low-priced scanners targeted at orthodontist and GP dentist in North America that caused us to lower our expectations for growth and profitability for our Scanner and Services reporting unit. As a result, we determined that the carrying value of the long-lived assets was not recoverable and therefore recorded an impairment charge of $26.3 million. Refer to Note 5 for details of the impairment analysis.
Interest and Other income (expense), net (in millions):
| Year Ended | Year Ended | ||||||||||||||||||||||
| December 31, 2014 | December 31, 2013 | Change | December 31, 2013 | December 31, 2012 | Change | ||||||||||||||||||
| Interest and other income (expense), net | $ | (3.2 | ) | $ | (1.1 | ) | $ | (2.1 | ) | $ | (1.1 | ) | $ | (1.3 | ) | $ | 0.2 |
Interest and other income (expense), net, includes foreign currency translation gains and losses, interest income earned on cash, cash equivalents and investment balances and other miscellaneous charges.
Interest and Other income (expense), net, in 2014 decreased due to higher foreign exchange losses primarily as a result of the weakening of the Euro to the U.S. dollar offset slightly by increased interest income earned on higher balances of cash, cash equivalents and investments.
Interest and Other income (expense), net, in 2013 increased slightly due to increased interest income earned on higher balances of cash, cash equivalents and investments offset slightly by higher foreign exchange losses.
Provision for income taxes (in millions):
| Year Ended | Year Ended | ||||||||||||||||||||||
| December 31, 2014 | December 31, 2013 | Change | December 31, 2013 | December 31, 2012 | Change | ||||||||||||||||||
| Provision for income taxes | $ | 44.5 | $ | 28.8 | $ | 15.7 | $ | 28.8 | $ | 25.6 | $ | 3.2 | |||||||||||
| Effective tax rates | 23.4 | % | 31.0 | % | 31.0 | % | 30.4 | % |
Changes and percentages are based on actual values. Certain tables may not sum or recalculate due to rounding.
Our provision for income taxes was $44.5 million, $28.8 million and $25.6 million for the year ended December 31, 2014, 2013 and 2012, respectively. This represents effective tax rates of 23.4%, 31.0% and 30.4%, respectively. Our effective tax rates in these fiscal years differ from the statutory federal income tax rate of 35% due to certain foreign earnings, primarily from Costa Rica, which are subject to a lower tax rate, partially offset by higher state income tax expense, the tax impact of certain stock-based compensation charges and unrecognized tax benefits. Our provision for income taxes for the year ended December 31, 2014 also reflects a negative impact from a $1.8 million adjustment related to prior years, which was recorded during the three months ended June 30, 2014. The effective tax rate for the year ended December 31, 2013 and 2012 also reflects a non-deductible goodwill impairment charge of $40.7 million and $36.6 million, respectively.
As of December 31, 2014, approximately $260.9 million of undistributed earnings from non-U.S. operations held by our foreign subsidiaries are designated as indefinitely reinvested outside the U.S. Accordingly, no additional U.S. income taxes or
additional foreign withholding taxes have been provided thereon. We have sufficient cash reserves in the U.S. and do not intend to repatriate our foreign earnings. We intend to use the undistributed earnings for local operating expansions and to meet local operating working capital needs. If these earnings were distributed in the form of dividends or otherwise, or if the shares of the relevant foreign subsidiaries were sold or otherwise transferred, we would be subject to additional U.S. income taxes subject to an adjustment for foreign tax credits and foreign withholding taxes. Determination of the amount of unrecognized deferred tax liability related to these earnings is not practicable.
We assess the likelihood that we will be able to realize our deferred tax assets quarterly. Should there be a change in our ability to realize our deferred tax assets, our tax provision would increase in the period in which we determine that it is more likely than not that we cannot realize our deferred tax assets. We consider all available evidence, both positive and negative, including historical levels of income, expectations and risks associated with estimates of future taxable income and ongoing prudent and feasible tax planning strategies in assessing the need for a valuation allowance. If it is more likely than not that we do not expect to realize our deferred tax assets, we will increase our provision for taxes by recording a valuation allowance against the deferred tax assets that we estimate will not ultimately be realizable. The available positive evidence at December 31, 2014 included historical operating profits, a projection of future income and other objectively verifiable evidence. As of December 31, 2014, we believed, except for the items noted in the subsequent paragraph, that is was more likely than not that the amount of deferred tax assets recorded on the balance sheet will be realized.
As of December 31, 2014, we had a valuation allowance of $32.5 million against our deferred tax assets which primarily relates to foreign net operating loss and capital loss carryforwards. The valuation allowance decreased from December 31, 2013 by $2.6 million due to $1.8 million related to foreign net operating loss carryforwards and $0.8 million related to the release of the valuation allowance related to Japan and China deferred tax assets.
At December 31, 2014, we have California net operating loss carryforwards of approximately $37.3 million, which, if not used, will begin to expire in 2015. These net operating loss carryforwards are subject to an annual limitation under Internal Revenue Code §382, but are expected to be fully realized. At December 31, 2014, we had California research credit carryforwards of approximately $3.8 million that can be carried forward indefinitely.
We account for uncertain tax positions pursuant to authoritative guidance based on a two-step approach to recognize and measure uncertain tax positions taken or expected to be taken in a tax return. We first determine whether it is more likely than not that a tax position will be sustained upon audit based on its technical merits. If a tax position meets the more-likely-than-not recognition threshold it is then measured to determine the amount of benefit to recognize in the financial statements. The tax position is measured as the largest amount of benefit that is more than 50 percent likely to be realized upon ultimate settlement. We adjust our uncertain tax positions due to changing facts and circumstances, such as the closing of a tax audit, or refinement of estimates due to new information. To the extent the final outcome of these matters is different than the amounts recorded, such differences will impact our tax provision in our Consolidated Statements of Operations in the period in which such determination is made.
During fiscal year 2014, the amount of gross unrecognized tax benefits increased by $6.4 million. The total amount of unrecognized tax benefits was $33.1 million as of December 31, 2014, all of which would impact our effective tax rate if recognized. We have elected to recognize interest and penalties related to unrecognized tax benefits as a component of income tax expense. The penalties and interest accrued as of December 31, 2014 and 2013 are immaterial. We do not expect any significant changes to the amount of unrecognized tax benefits within the next twelve months.
During the first quarter of 2014, we adopted ASU 2013-11, "Presentation of an Unrecognized Tax Benefit when a Net Operating Loss Carryforward, a Similar Tax Loss, or a Tax Credit Carryforward Exists (a consensus of the FASB Emerging Issues Task Force)." The adoption of this standard had the effect of reducing our accruals for uncertain tax positions by $8.4 million, with an offsetting reduction in our long term deferred tax assets, but had no effect on net income.
We file U.S. federal, U.S. state, and non-U.S. tax returns. Our major tax jurisdictions are U.S. federal and the State of California. For U.S. federal and state tax returns, we are no longer subject to tax examinations for years before 2000. With few exceptions, we are no longer subject to examination by foreign tax authorities for years before 2007.
Liquidity and Capital Resources
We fund our operations from product sales and the proceeds from the sale of our common stock. As of December 31, 2014 and 2013, we had the following cash and cash equivalents, and short-term and long-term investments (in thousands):
| Year Ended December 31, | |||||||
| 2014 | 2013 | ||||||
| Cash and cash equivalents | $ | 199,871 | $ | 242,953 | |||
| Short-term investments | 254,787 | 127,040 | |||||
| Long-term investments | 147,892 | 101,978 | |||||
| Total | $ | 602,550 | $ | 471,971 |
Cash flows (in thousands):
| Year Ended December 31, | |||||||||||
| 2014 | 2013 | 2012 | |||||||||
| Net cash flow provided by (used in): | |||||||||||
| Operating activities | $ | 226,899 | $ | 185,976 | $ | 133,778 | |||||
| Investing activities | (201,627 | ) | (210,734 | ) | (78,300 | ) | |||||
| Financing activities | (66,420 | ) | (38,171 | ) | 10,205 | ||||||
| Effects of exchange rate changes on cash and cash equivalents | (1,934 | ) | (504 | ) | 28 | ||||||
| Net increase (decrease) in cash and cash equivalents | $ | (43,082 | ) | $ | (63,433 | ) | $ | 65,711 |
As of December 31, 2014, we had $602.6 million in cash, cash equivalents, and short-term and long-term marketable securities. Cash equivalents and marketable securities are comprised of money market funds and highly liquid debt instruments which primarily include commercial paper, corporate bonds, U.S. dollar denominated foreign corporate bonds, U.S. government agency bonds, municipal bonds and asset-backed securities.
As of December 31, 2014, approximately $338.2 million of cash, cash equivalents and short-term and long-term marketable securities was held by our foreign subsidiaries. Amounts held by foreign subsidiaries are generally subject to U.S. income taxation on repatriation to the U.S. The costs to repatriate our foreign earnings to the U.S. would likely be material; however, our intent is to permanently reinvest our earnings from foreign operations, and our current plans do not require us to repatriate them to fund our U.S. operations as we generate sufficient domestic operating cash flow and have access to external funding under our current revolving line of credit.
On April 23, 2014, we announced that our Board of Directors had authorized a stock repurchase program pursuant to which we may purchase up to $300.0 million of our common stock over the next three years, with $100.0 million of that amount authorized to be purchased over the next twelve months. Any purchases under this stock repurchase program may be made, from time-to-time, pursuant to open market purchases (including pursuant to Rule 10b5-1 plans), privately-negotiated transactions, accelerated stock repurchases, block trades or derivative contracts or otherwise in accordance with applicable federal securities laws, including Rule 10b-18 of the Securities Exchange Act of 1934. As part of this repurchase program, on April 28, 2014, we entered into an accelerated share repurchase agreement ("ASR") with Goldman, Sachs & Co. to repurchase $70.0 million of our common stock. Under the terms of the ASR, we agreed to repurchase in total $70.0 million of our common stock and received an initial delivery of approximately 1.0 million shares based on the then current market price, which were retired. The ASR was completed on July 29, 2014 with a final delivery of approximately 0.4 million shares. We received a total of 1.4 million shares under the ASR for an average purchase price per share of $51.46. The final number of shares repurchased was based on our volume-weighted average stock price during the term of the transaction, less an agreed upon discount. In addition, during 2014, we repurchased on the open market approximately 0.6 million shares of our common stock at an average price of $50.93 per share, including commissions, for an aggregate purchase price of approximately $28.2 million. All repurchased shares were retired. As of December 31, 2014, we have $201.8 million remaining under the April 2014 stock repurchase program, $1.8 million of which we expect to purchase over the next three months. In addition, in January 2015, our Board of Directors has authorized the next $100.0 million under the program to be repurchased which we anticipate completing within twelve months. We expect to finance future stock repurchases with current cash on hand.
On March 22, 2013, we entered into a credit facility with Wells Fargo Bank. The credit facility provides for a $50.0 million revolving line of credit, with a $10.0 million letter of credit sublimit, and has a maturity date on March 22, 2016. The credit facility also requires us to maintain a minimum unrestricted cash balance of $50.0 million and comply with specific financial conditions and performance requirements. The loan bears interest, at our option, at a fluctuating rate per annum equal to the daily one-month adjusted LIBOR rate plus a spread of 1.75% or an adjusted LIBOR rate (based on one, three, six or twelve-month interest periods) plus a spread of 1.75%. As of December 31, 2014, we had no outstanding borrowings under this credit facility and were in compliance with the conditions and performance requirements.
We believe that our current cash and cash equivalents and marketable securities combined with our positive cash flows from operations will be sufficient to fund our operations and stock repurchases for at least the next 12 months. If we are unable to generate adequate operating cash flows, we may need to suspend our stock repurchase program or seek additional sources of capital through equity or debt financing, collaborative or other arrangements with other companies, bank financing and other sources in order to realize our objectives and to continue our operations. There can be no assurance that we will be able to obtain additional debt or equity financing on terms acceptable to us, or at all. If adequate funds are not available, we may need to make business decisions that could adversely affect our operating results such as modifications to our pricing policy, business structure or operations. Accordingly, the failure to obtain sufficient funds on acceptable terms when needed could have a material adverse effect on our business, results of operations and financial condition.
Operating Activities
For the year ended December 31, 2014, cash flows from operations of $226.9 million resulted primarily from our net income of approximately $145.8 million as well as the following:
Significant non-cash activities
| • | Stock-based compensation was $39.8 million related to our equity incentive compensation granted to employees and directors. |
| • | Deferred taxes of $25.5 million primarily due to the utilization of deferred tax assets. |
| • | Excess tax benefits from our share-based compensation arrangements of $21.4 million. |
| • | Depreciation and amortization of $17.9 million related to our fixed assets and acquired intangible assets. |
Significant changes in working capital
| • | an increase of $27.2 million in accounts receivable which is a result of the increase in net revenues, |
| • | an increase of $22.7 million in accrued and other long-term liabilities primarily due to an increase in income tax payable along with other accruals due to timing of payment, and |
| • | an increase of $15.8 million in deferred revenues corresponding to the increases in revenues. |
For the year ended December 31, 2013, cash flows from operations of $186.0 million resulted primarily from our net income of approximately $64.3 million as well as the following:
Significant non-cash activities
| • | Impairment of goodwill related to our Scanner and Services reporting unit was $40.7 million. |
| • | Impairment of long-lived assets related to our Scanner and Services reporting unit was $26.3 million. |
| • | Excess tax benefits from our share-based compensation arrangements of $27.1 million. |
| • | Stock-based compensation was $26.4 million related to our equity incentive compensation granted to employees and directors. |
| • | Depreciation and amortization of $16.8 million related to our fixed assets and acquired intangible assets. |
| • | Deferred taxes of $21.2 million primarily due to the utilization of deferred tax assets. |
Significant changes in working capital
| • | an increase of $12.0 million in accounts receivable due to the increase in net revenues, |
| • | an increase of $9.7 million in accrued and other long-term liabilities due to compensation and bonuses accruals along with higher sales rebates, and |
| • | an increase of $14.9 million in deferred revenue primarily due to higher product sales along with additional deferrals as a result of our mid-course correction policy change in June 2013. |
For the year ended December 31, 2012, cash flows from operations of $133.8 million resulted primarily from our net income of approximately $58.7 million and the following reasons:
Significant non-cash activities
| • | Impairment of goodwill related to our Scanner and Services reporting unit was $36.6 million. |
| • | Stock-based compensation was $21.5 million related to our equity incentive compensation granted to employees and directors. |
| • | Depreciation and amortization of $17.8 million related to our fixed assets and acquired intangible assets. |
| • | Deferred taxes of $17.8 million primarily due to the utilization of deferred tax assets. |
| • | Excess tax benefits from our share-based payments were $17.2 million. |
Significant changes in working capital
| • | an increase of $11.7 million in accounts receivable due to the increase in revenues during 2012, |
| • | an increase of $5.7 million in inventories primarily due to increased production volumes for our intra-oral scanner products in anticipation of the move to our new facility in Israel as well as procuring the new SmartTrack material for our clear aligners, |
| • | an increase of $3.9 million in prepaid expenses and other assets primarily due to the timing of software license and insurance policy renewals, |
| • | an increase of $2.9 million in accrued and other long-term liabilities primarily due to higher deferred tax liabilities, and |
| • | an increase of $12.4 million in deferred revenue primarily due to higher sales with deferred revenue components in 2012. |
Investing Activities
Net cash used in investing activities was $201.6 million for the year ended December 31, 2014, primarily consisted of purchases of marketable securities of $437.2 million and property, plant and equipment purchases of $24.1 million. These uses were partially offset by $259.8 million of maturities and sales of our marketable securities.
For 2015, we expect to invest $70.0 million to $80.0 million on capital expenditures primarily for additional manufacturing capacity and infrastructure including a project to implement a new enterprise resource planning system which we started in late 2014 with expected go-live for various modules and subsidiaries throughout 2016. Although we believe our current investment portfolio has little risk of impairment, we cannot predict future market conditions or market liquidity and can provide no assurance that our investment portfolio will remain unimpaired.
Net cash used in investing activities was $210.7 million for the year ended December 31, 2013, primarily consisted of our purchase of marketable securities of $303.9 million and property and equipment purchases of $19.4 million along with $7.7 million for the acquisition of our Asia Pacific distributor in April 2013. These uses were partially offset by $122.7 million of maturities and sales of our marketable securities.
Net cash used in investing activities was $78.3 million for the year ended December 31, 2012, primarily consisted of our purchase of marketable securities of $67.5 million and property and equipment purchases of $38.3 million. These costs were partially offset by maturities and sales of marketable securities of $25.2 million and the release of $2.5 million of funds related to unclaimed merger consideration for the acquisition of Cadent on April 29, 2011 included in Other Investing Activities.
Financing Activities
Net cash used by financing activities was $66.4 million for the year ended December 31, 2014 resulting from repurchases of our common stock of $98.2 million and $7.6 million of payroll taxes paid for our employees' vesting of restricted stock units
through share withholdings, partially off-set by proceeds from issuance of common stock of $18.0 million and $21.4 million from excess tax benefit from our share-based compensation arrangements.
Net cash used by financing activities was $38.2 million for the year ended December 31, 2013 resulting from repurchases of our common stock of $95.1 million and $4.4 million of payroll taxes paid for our employees' vesting of restricted stock units through share withholdings, partially off-set by proceeds from issuance of common stock of $34.2 million and $27.1 million from excess tax benefit from our share-based compensation arrangements.
Net cash provided by financing activities was $10.2 million for the year ended December 31, 2012 resulting from approximately $42.3 million in proceeds from the issuance of our common stock and approximately $17.2 million from excess tax benefit from our share-based compensation arrangements. These proceeds were partially offset by approximately $47.2 million common stock repurchases and $2.1 million of payroll taxes paid for our employees’ vesting of restricted stock units through share withholdings.
Net proceeds from the issuance of our common stock related to the exercise of employee stock options have historically been a significant component of our liquidity; however, in 2006, we began granting restricted stock units (“RSUs”) which, unlike stock options, do not generate cash from exercises. As a result, we will continue to generate less cash from the proceeds of the sale of our common stock in future periods. In addition, because restricted stock units are taxable to the individuals when they vest, the number of shares we issue to each of our employees will be net of applicable withholding taxes which will be paid by us on their behalf. During 2014, 2013 and 2012, we paid $7.6 million, $4.4 million and $2.1 million, respectively, for taxes related to restricted stock units that vested during the periods.
Stock Repurchase
On October 27, 2011, we announced that our Board of Directors approved a stock repurchase program pursuant to which we may repurchase up to $150.0 million of common stock. Purchases under the stock repurchase program may be made from time to time in the open market.
During 2012, we repurchased approximately 1.7 million shares of common stock at an average price of $27.28 per share for an aggregate purchase price of approximately $47.2 million, including commissions. The common stock repurchases reduced additional paid-in capital by approximately $15.4 million and increased accumulated deficit by $31.8 million. During 2013, we repurchased approximately 2.7 million shares of our common stock at an average price of $34.95 per share, including commissions, for an aggregate purchase price of approximately $95.1 million. The common stock repurchases reduced additional paid-in capital by approximately $24.5 million and increased accumulated deficit by $70.6 million. All repurchased shares were retired. The October 2011 program was complete as of December 31, 2013.
On April 23, 2014, we announced that our Board of Directors had authorized a stock repurchase program pursuant to which we may purchase up to $300.0 million of our common stock over the next three years, with $100.0 million of that amount authorized to be purchased over the first twelve months. Any purchases under this stock repurchase program may be made, from time-to-time, pursuant to open market purchases (including pursuant to Rule 10b5-1 plans), privately-negotiated transactions, accelerated stock repurchases, block trades or derivative contracts or otherwise in accordance with applicable federal securities laws, including Rule 10b-18 of the Securities Exchange Act of 1934.
As part of our $300.0 million stock repurchase program, we entered into an accelerated share repurchase agreement ("ASR") with Goldman, Sachs & Co. on April 28, 2014 to repurchase $70.0 million of our common stock. We paid $70.0 million on April 29, 2014 and received an initial delivery of approximately 1.0 million shares. The ASR was completed on July 29, 2014 with a final delivery of approximately 0.4 million shares. We received a total of approximately 1.4 million shares under the ASR for an average purchase price per share of $51.46, which all shares were retired. The final number of shares repurchased was based on our volume-weighted average stock price during the term of the transaction, less an agreed upon discount.
During 2014, we repurchased on the open market approximately 0.6 million shares of our common stock at an average price of $50.93 per share, including commissions, for an aggregate purchase price of approximately $28.2 million. All repurchased shares were retired. As of December 31, 2014, we have $201.8 million remaining under the April 2014 stock repurchase program, of which $1.8 million was repurchased in January 2015. In addition, in January 2015, our Board of Directors has authorized the next $100.0 million under the program to be repurchased which we anticipate completing within twelve months. We expect to finance future stock repurchases with current cash on hand.
Contractual Obligations/Off Balance Sheet Arrangements
The impact that our contractual obligations as of December 31, 2014 are expected to have on our liquidity and cash flows in future periods is as follows (in thousands):
| Payments Due by Period | |||||||||||||||||||
| Total | Less than 1 Year | 1-3 Years | 3-5 Years | More than 5 Years | |||||||||||||||
| Operating lease obligations | $ | 24,046 | $ | 9,130 | $ | 12,952 | 1,754 | 210 | |||||||||||
| Unconditional purchase obligations | 49,802 | 49,802 | — | — | — | ||||||||||||||
| Total contractual cash obligations | $ | 73,848 | $ | 58,932 | $ | 12,952 | $ | 1,754 | $ | 210 |
Our contractual obligations table above excludes approximately $33.1 million of non-current uncertain tax benefits which are included in other long-term obligations and deferred tax assets on our balance sheet as of December 31, 2014. We have not included this amount because we cannot make a reasonably reliable estimate regarding the timing of settlements with taxing authorities, if any.
We had no off-balance sheet arrangements as defined in Regulation S-K Item 303(a) (4) as of December 31, 2014.
We believe that our current cash and cash equivalents and marketable debt securities combined with our positive cash flows from operations will be sufficient to fund our operations for at least the next 12 months. If we are unable to generate adequate operating cash flows, we may need to seek additional sources of capital through equity or debt financing, collaborative or other arrangements with other companies, bank financing and other sources in order to realize our objectives and to continue our operations. There can be no assurance that we will be able to obtain additional debt or equity financing on terms acceptable to us, or at all. If adequate funds are not available, we may need to make business decisions that could adversely affect our operating results such as modifications to our pricing policy, business structure or operations. Accordingly, the failure to obtain sufficient funds on acceptable terms when needed could have a material adverse effect on our business, results of operations and financial condition.
Indemnification Provisions
In the normal course of business to facilitate transactions in our services and products, we indemnify customers, vendors, lessors, and other parties with respect to certain matters, including, but not limited to, services to be provided by us and intellectual property infringement claims made by third parties. In addition, we have entered into indemnification agreements with our directors and certain of our officers that will require us, among other things, to indemnify them against certain liabilities that may arise by reason of their status or service as directors or officers. Several of these agreements limit the time within which an indemnification claim can be made and the amount of the claim.
It is not possible to make a reasonable estimate of the maximum potential amount under these indemnification agreements due to the unique facts and circumstances involved in each particular agreement. Additionally, we have a limited history of prior indemnification claims and the payments we have made under such agreements have not had a material adverse effect on our results of operations, cash flows, or financial position. However, to the extent that valid indemnification claims arise in the future, future payments by us could be significant and could have a material adverse effect on our results of operations or cash flows in a particular period. As of December 31, 2014, we did not have any material indemnification claims that were probable or reasonably possible.
Critical Accounting Policies and Estimates
Management’s discussion and analysis of our financial condition and results of operations is based upon our consolidated financial statements, which have been prepared in accordance with accounting principles generally accepted in the United States of America. The preparation of financial statements requires management to make estimates and judgments that affect the reported amounts of assets and liabilities, revenues and expenses and disclosures at the date of the financial statements. We evaluate our estimates on an on-going basis, including those related to revenue recognition, stock-based compensation, goodwill and finite-lived assets and related impairment, and income taxes. We use authoritative pronouncements, historical experience and other assumptions as the basis for making estimates. Actual results could differ from those estimates.
We believe the following critical accounting policies and estimates affect our more significant judgments used in the preparation of our consolidated financial statements.
Revenue Recognition
We measure and allocate revenue according to the accounting guidance for multiple-deliverable revenue arrangements in Accounting Standards Update (“ASU”) 2009-13, Multiple-Deliverable Revenue Arrangements-a consensus of the Financial Accounting Standard Board (“FASB”) Emerging Issues Task Force.
Multiple-Element Arrangements (“MEAs”): Arrangements with customers may include multiple deliverables, including any combination of products/equipment and services. The deliverables included in the MEAs are separated into more than one unit of accounting when (i) the delivered product/equipment has value to the customer on a stand-alone basis, and (ii) delivery of the undelivered service element(s) is probable and substantially in our control. Arrangement consideration is then allocated to each unit, delivered or undelivered, based on the relative selling price (“RSP”) of each unit of accounting based first on vendor-specific objective evidence (“VSOE”) if it exists, second on third-party evidence (“TPE”) if it exists, and on best estimated selling price (“BESP”) if neither VSOE or TPE exist.
| • | VSOE – In most instances, products are sold separately in stand-alone arrangements. Services are also sold separately through renewals of contracts with varying periods. We determine VSOE based on pricing and discounting practices for the specific product or service when sold separately, considering geographical, customer, and other economic or marketing variables, as well as renewal rates or stand-alone prices for the service element(s). |
| • | TPE – If we cannot establish VSOE of selling price for a specific product or service included in a multiple-element arrangement, we use third-party evidence of selling price. We determine TPE based on sales of comparable amount of similar products or service offered by multiple third parties considering the degree of customization and similarity of product or service sold. |
| • | BESP – The best estimated selling price represents the price at which we would sell a product or service if it were sold on a stand-alone basis. When VSOE or TPE do not exist for all elements, we determine BESP for the arrangement element based on sales, cost and margin analysis, as well as other inputs based on our pricing practices. Adjustments for other market and Company-specific factors are made as deemed necessary in determining BESP. |
Provisions for discounts and rebates to customers are provided for in the same period that the related product sales are recorded based upon historical discounts and rebates.
Clear Aligner
We enter into arrangements (“treatment plans”) that involve multiple future product deliverables. Invisalign Full, Invisalign Teen, and Invisalign Assist products include up to three optional case refinements. Case refinement is a finishing tool used to adjust a patient's teeth to the desired final position. Case refinement may be elected by the dental professional at any time during treatment however it is generally ordered in the last stages of orthodontic treatment. Beginning June 15, 2013, Invisalign Full and Invisalign Teen products also include up to three optional mid-course corrections. Mid-course correction is a treatment adjustment during active treatment if the case is not tracking to the original treatment plan or goals. Mid-course correction gives doctors the ability to "adjust course" based on the needs of the individual patient. Invisalign Teen also includes up to six optional replacement aligners in the price of the product and may be ordered any time throughout treatment.
We determined that our treatment plans, except Invisalign Assist with progress tracking, comprise the following deliverables which also represent separate units of accounting: single-batched aligners, case refinement mid-course correction and replacement aligners. We allocate revenue for each treatment plan based on each unit's relative selling price based on BESP and recognize the revenue upon the delivery of each unit in the treatment plan. We regularly review our estimates of selling price and maintain internal controls over the establishment and update of these estimates.
For Invisalign Assist with the progress tracking feature, aligners and services are provided to the dental professional every nine stages (“a batch”). Beginning January 1, 2011, we were able to reliably estimate the number of batches which are expected to be shipped for each case based upon our historical experience. The amounts allocated to this deliverable are recognized on a prorated basis as each batch is shipped.
Prior to 2013, the Vivera Retainer included four shipments per year, and revenue was recognized ratably as each shipment occurred. In the first quarter of 2013, we consolidated Vivera Retainer product shipments down to one shipment per year.
Scanners and Services
We recognize revenues from the sales of iTero intra-oral scanners and CAD/CAM services. CAD/CAM services include scanning services, extended warranty for the intra-oral scanners, a range of iTero restorative services, and OrthoCAD services such as OrthoCAD iRecord. We sell intra-oral scanners and services through both our direct sales force and distribution partners. The intra-oral scanner sales price includes one year of warranty, and for additional fees, the customer may select an unlimited scanning service agreement over a fixed period of time or extended warranty periods. Revenue is recognized when persuasive evidence of the arrangement exists, the price is fixed or determinable, collectability is reasonably assured, title and risk of loss has passed to customers based on the shipping terms, no significant obligations remain, and allowances for discounts, returns, and customer incentives can be reliably estimated. When intra-oral scanners are sold with either an unlimited scanning service agreement and/or extended warranty, we allocate revenue based on each element's relative selling price. We estimate the selling price of each element, as if it is sold on a stand-alone basis, taking into consideration historical prices as well as our discounting strategies. Scanner revenue, net of related discounts and allowances, is recognized when products or equipment have been shipped, installed and on-site training completed. For certain distributors who provide installation and training to the customer, we recognize scanner revenue when the intra-oral scanner is shipped to the distributor assuming all of the other revenue recognition criteria have been met.
Discounts are deducted from revenue at the time of sale or when the discount is offered, whichever is later and free cases or training is included as a deliverable in the multiple-element arrangement assessment. Returns of products, excluding warranty related returns, are infrequent and insignificant.
Service revenue, including iTero restorative and all OrthoCAD services are recognized upon delivery or ratably over the contract term as the specified services are performed. If a customer selects a pay per use basis for scanning service fees, the revenue is recognized as the service is provided.
We offer customers an option to purchase extended warranties on certain products. We recognize revenue on these extended warranty contracts ratably over the life of the contract. The costs associated with these extended warranty contracts are recognized when incurred.
Stock-based Compensation Expense
We recognize stock-based compensation cost for only those shares ultimately expected to vest on a straight-line basis over the requisite service period of the award. We use the Black-Scholes option pricing model to determine the fair value of stock options and employee stock purchase plan shares. We estimate the fair value of market-performance based restricted stock units using a Monte Carlo simulation model which requires the input of assumptions, including expected term, stock price volatility and the risk-free rate of return. In addition, judgment is required in estimating the number of stock-based awards that are expected to be forfeited. Forfeitures are estimated based on historical experience at the time of grant and revised, if necessary, in subsequent periods if actual forfeitures differ from those estimates. The assumptions used in calculating the fair value of share-based payment awards represent management’s best estimates, but these estimates involve inherent uncertainties and the application of management’s judgment. As a result, if factors change and we use different assumptions, our stock-based compensation expense could be materially different in the future.
Goodwill and finite-lived acquired intangible assets
Goodwill represents the excess of the purchase price paid over the fair value of tangible and identifiable intangible net assets acquired in business combinations and is allocated to the reporting units based on relative synergies generated.
Our intangible assets primarily consist of intangible assets acquired as part of acquisitions and are amortized using the straight-line method over their estimated useful lives, reflecting the period in which the economic benefits of the assets are expected to be realized.
Impairment of goodwill, finite-lived acquired intangible assets and long-lived assets
Goodwill
We evaluate goodwill for impairment at least annually on November 30th or more frequently if indicators are present, an event occurs or circumstances changes that suggest an impairment may exist and that it would more likely than not reduce the fair
value of a reporting unit below its carrying amount. The allocation of goodwill to the respective reporting unit is based on relative synergies generated as a result of an acquisition.
We perform an initial assessment of qualitative factors to determine whether the existence of events and circumstances leads to a determination that it is more likely than not that the fair value of a reporting unit is less than its carrying amount. In performing the qualitative assessment, we identify and consider the significance of relevant key factors, events, and circumstances that affect the fair value of our reporting units. These factors include external factors such as macroeconomic, industry, and market conditions, as well as entity-specific factors, such as our actual and planned financial performance. We also give consideration to the difference between the reporting unit fair value and carrying value as of the most recent date a fair value measurement was performed. If, after assessing the totality of relevant events and circumstances, we determine that it is more likely than not that the fair value of the reporting unit exceeds its carrying value and there is no indication of impairment, no further testing is performed; however, if we conclude otherwise, the first step of the two-step impairment test is performed by estimating the fair value of the reporting unit and comparing it with its carrying value, including goodwill.
Step one of the goodwill impairment test consists of a comparison of the fair value of a reporting unit against its carrying amount, including the goodwill allocated to each reporting unit. We determine the fair value of our reporting units based on the present value of estimated future cash flows under the income approach of the reporting units as well as various price or market multiples applied to the reporting unit's operating results along with the appropriate control premium under the marketing approach, both of which are classified as level 3 within the fair value hierarchy (as described in Note 2 in our consolidated financial statements). If the carrying amount of the reporting unit is in excess of its fair value, step two requires the comparison of the implied fair value of the reporting unit’s goodwill against the carrying amount of the reporting unit’s goodwill. Any excess of the carrying value of the reporting unit’s goodwill over the implied fair value of the reporting unit’s goodwill is recorded as an impairment loss.
During March 2013, changes in the competitive environment for intra-oral scanners, including announcements from our competitors of new low-priced scanners targeted at orthodontists and general practitioner dentists in North America, caused us to lower our expectations for growth and profitability for our Scanner and Services reporting unit. The impairment analysis performed for goodwill requires several estimates in computing the estimated fair value of a reporting unit. We use a discounted cash flow (“DCF”) approach to estimate the fair value of a reporting unit, utilizing harvest model, which we believe is the most reliable indicator of fair value of this business, and is most consistent with the approach a market place participant would use. As a result, we determined that goodwill related only to our Scanner and Services reporting unit should be tested for impairment as of March 31, 2013 due to these facts and circumstances which would more likely than not reduce the fair value of our Scanner and Services reporting unit below its carrying amount. Based on our analysis, there was no implied goodwill for the Scanner and Services reporting unit; therefore, we recorded a goodwill impairment charge of $40.7 million in the three months ended March 31, 2013, which represented the entire goodwill balance in the Scanner and Services reporting unit. There was no triggering event related to the Clear Aligner goodwill. Refer to Note 5 for details of the impairment analysis.
The remaining goodwill is entirely attributable to our Clear Aligner reporting unit. During the fourth quarter of fiscal 2014, we performed the annual goodwill impairment testing using the qualitative approach discussed above and found no impairment as the fair value of our Clear Aligner reporting unit was significantly in excess of the carrying value.
Finite-lived intangible assets and long-lived assets
We evaluate long-lived assets (including finite-lived intangible assets) for impairment whenever events or changes in circumstances indicate that the carrying amount of an asset group may not be recoverable. An asset or asset group is considered impaired if its carrying amount exceeds the future undiscounted net cash flows the asset or asset group is expected to generate. If an asset or asset group is considered to be impaired, the impairment to be recognized is calculated as the amount by which the carrying amount of the asset or asset group exceeds its fair market value. Our estimates of future cash flows attributable to our long-lived assets require significant judgment based on our historical and anticipated results and are subject to many factors. Factors we consider important which could trigger an impairment review include significant negative industry or economic trends, significant loss of customers and changes in the competitive environment. In 2013, we used a DCF approach to estimate the fair value of a reporting unit, utilizing harvest model, which we believe is the most reliable indicator of fair value of a business, and is most consistent with the approach of a marketplace participant would use. The estimation of fair value utilizing a DCF approach includes numerous uncertainties which require our significant judgment when making assumptions of expected growth rates and the selection of discount rates, as well as assumptions regarding general economic and business conditions, and the structure that would yield the highest economic value, among other factors. Key assumptions used in measuring the fair values of Scanner and Services reporting unit included the discount rate (based on the weighted-average cost of capital) and revenue growth. The fair value of Scanner and Services trademark was determined using a risk-adjusted DCF model under the relief-from-royalty method. The royalty rate used was based on a consideration of market rates. The fair value of Scanner and Services finite-lived customer
relationships was determined using a DCF model under the multi-period excess earnings method. We recorded a long-lived asset impairment in the quarter ended March 31, 2013 due to changes in the competitive environment for our intra-oral scanners, including announcements from our competitors of new low-priced scanners targeted at orthodontists and general practitioner dentists in North America. There was no triggering event related to the Clear Aligner asset group. Refer to Note 5 for details of the impairment analysis.
Accounting for Income Taxes
We make certain estimates and judgments in determining income tax expense for financial statement purposes. These estimates and judgments occur in the calculation of certain tax assets and liabilities, which arise from differences in the timing of recognition of revenue and expense for tax and financial statement purposes.
As part of the process of preparing our Consolidated Financial Statements, we are required to estimate our income taxes in each of the jurisdictions in which we operate. This process involves us estimating our current tax exposure under the applicable tax laws and assessing temporary differences resulting from differing treatment of items for tax and accounting purposes. These differences result in deferred tax assets and liabilities, which are included in our Consolidated Balance Sheet.
We account for uncertainty in income taxes pursuant to authoritative guidance based on a two-step approach to recognize and measure uncertain tax positions taken or expected to be taken in a tax return. The first step is to determine if the weight of available evidence indicates that it is more likely than not that the tax position will be sustained on audit based on its technical merits, including resolution of any related appeals or litigation processes. The second step is to measure the tax benefit as the largest amount that is more than 50% likely to be realized upon ultimate settlement. We adjust reserves for our uncertain tax positions due to changing facts and circumstances, such as the closing of a tax audit, or refinement of estimates due to new information. To the extent that the final outcome of these matters is different than the amounts recorded, such differences will impact our tax provision in our Consolidated Statements of Operations in the period in which such determination is made.
We assess the likelihood that we will be able to realize our deferred tax assets. Should there be a change in our ability to realize our deferred tax assets, our tax provision would increase in the period in which we determine that it is more likely than not that we cannot realize our deferred tax assets. We consider all available evidence, both positive and negative, including historical levels of income, expectations and risks associated with estimates of future taxable income and ongoing prudent and feasible tax planning strategies in assessing the need for a valuation allowance. If it is more likely than not that we will not realize our deferred tax assets, we will increase our provision for taxes by recording a valuation allowance against the deferred tax assets that we estimate will not ultimately be realized. The available positive evidence at December 31, 2014 included historical operating profits and a projection of future income sufficient to realize most of our remaining deferred tax assets. As of December 31, 2014, it was considered more likely than not that our deferred tax assets would be realized with the exception of certain foreign loss carryovers as we are unable to forecast sufficient future profits to realize the deferred tax assets.
Accounting guidance for stock-based compensation prohibits recognition of a deferred income tax asset for excess tax benefits due to stock option exercises that have not yet been realized through a reduction in income taxes payable. Such unrecognized deferred tax benefits totaled $1.4 million as of December 31, 2014 and will be accounted for as a credit to additional paid-in capital, if and when realized through a reduction in income taxes payable. We follow the tax law ordering method to determine when excess tax benefits have been realized and consider only the direct impacts of awards when calculating the amount of windfalls or shortfalls.
As of December 31, 2014, U.S. income taxes and foreign withholding taxes associated with the repatriation of undistributed earnings of foreign subsidiaries were not provided for on a cumulative total of $260.9 million. We intend to reinvest these earnings indefinitely in our foreign subsidiaries. If these earnings were distributed in the form of dividends or otherwise, or if the shares of the relevant foreign subsidiaries were sold or otherwise transferred, we would be subject to additional U.S. income taxes subject to an adjustment for foreign tax credits, and foreign withholding taxes. Determination of the amount of unrecognized deferred income tax liability related to these earnings is not practicable.
Recent Accounting Pronouncements
See Note 1 “Summary of Significant Accounting Policies” in the Notes to our Consolidated Financial Statements in Item 8 for a full description of recent accounting pronouncements, including the expected dates of adoption and estimated effects on results of operations and financial condition, which is incorporated herein.
Previous: Item 6. SELECTED CONSOLIDATED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK