 filings.tools
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations
187K characters. Original on sec.gov · Markdown
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations
Overview
The following discussion highlights significant factors influencing the consolidated financial position and results of operations of The Allstate Corporation (referred to in this document as “we,” “our,” “us,” the “Company” or “Allstate”). It should be read in conjunction with the condensed consolidated financial statements and related notes thereto found under Part I. Item 1. contained herein, and with the discussion, analysis, consolidated financial statements and notes thereto in Part I. Item 1. and Part II. Item 7. and Item 8. of The Allstate Corporation annual report on Form 10-K for 2021, filed February 18, 2022.
Further analysis of our insurance segments is provided in the Property-Liability Operations and Segment Results sections, including Allstate Protection and Run-off Property-Liability, Protection Services and Allstate Health and Benefits, of Management’s Discussion and Analysis (“MD&A”). The segments are consistent with the way in which the chief operating decision maker reviews financial performance and makes decisions about the allocation of resources.
The Novel Coronavirus Pandemic or COVID-19 (“Coronavirus”)
The Coronavirus resulted in governments worldwide enacting emergency measures to combat the spread of the virus, including travel restrictions, government-imposed shelter-in-place orders, quarantine periods, social distancing, and restrictions on large gatherings. These measures have moderated, but there is no way of predicting with certainty how long the pandemic might last. We continue to closely monitor and proactively adapt to developments and changing conditions. Currently, it is not possible to reliably estimate the impact to our operations, but the effects have been and could be material.
Certain growth and profitability comparisons to the prior year were impacted, in part, by the effects the Coronavirus had on our prior year results. Beginning in March 2020, when shelter-in-place orders and other restrictions were initiated, and throughout 2021, we experienced lower auto accident claim frequency and different claim patterns than historically experienced. Total auto claim frequency has increased through the first six months of 2022 and during 2021, but remains below pre-pandemic levels.
The Coronavirus has affected our operations and may continue to significantly affect our results of operations, financial condition and liquidity. The impact from the pandemic should be considered when comparing the current period to the prior period, including:
-
Sales of new and retention of existing policies
-
Rate increases and average gross premiums
-
Supply chain disruptions and labor shortages increasing the cost of settling claims
-
Premium for transportation network products
-
Driving behavior and auto accident frequency
-
Hospital and outpatient claim costs
-
Investment valuations and returns
-
Bad debt and credit allowance exposure
-
Consumer utilization of Milewise®, our pay-per-mile insurance product
-
Retail sales in Allstate Protection Plans
This list is not inclusive of all potential impacts and should not be treated as such. Within the MD&A we have included further disclosures related to the impacts of the Coronavirus on our 2022 results.
Russia/Ukraine Conflict
The Russia-Ukraine war and related sanctions imposed as a result of this conflict have increased global economic and political uncertainty, including inflationary pressures and an increased risk of cybersecurity incidents. Allstate does not have operations or direct investments in Russia, Belarus or Ukraine. The conflict is evolving, but we have not experienced significant impacts to date on our investment portfolio, financial position, or results of operations.
Corporate Strategy
Our strategy has two components: increase personal property-liability market share and expand protection offerings by leveraging the Allstate brand, customer base and other core capabilities.
Transformative Growth is about creating a business model, capabilities and culture that continually transform to better serve customers. This is done by providing affordable, simple and connected protection through multiple distribution partners. The ultimate objective is to create continuous transformative growth in all businesses.
In the personal property-liability businesses this has five key components:
-
Expanding customer access
-
Improving customer value
-
Increasing customer acquisition sophistication
-
Modernizing the technology ecosystem
-
Enhancing organizational capabilities
The protection businesses are being expanded by leveraging enterprise capabilities and resources such as distribution, brand, analytics, claims, investment expertise, talent and capital.
Acquisitions and Dispositions
Acquisitions On January 4, 2021, we completed the acquisition of National General Holdings Corp. (“National General”), significantly enhancing our strategic position in the independent agency channel. The transaction increased our market share in personal property-liability by over one percentage point and enhanced our independent agent-facing technology.
Second Quarter 2022 Form 10-Q 45
Discontinued operations and held for sale On October 1, 2021, we closed the sale of Allstate Life Insurance Company of New York (“ALNY”) to Wilton Reassurance Company for $400 million. On November 1, 2021, we closed the sale of Allstate Life Insurance Company (“ALIC”) and certain affiliates to entities managed by Blackstone for total proceeds of $4 billion, including a pre-close dividend of $1.25 billion paid by ALIC.
In 2021 and prior periods, the assets and liabilities of the businesses were reclassified as held for sale and results were presented as discontinued operations.
See Note 3 of the condensed consolidated financial statements for further information on acquisitions and dispositions.
Measuring segment profit or loss
The measure of segment profit or loss used in evaluating performance is underwriting income for the Allstate Protection and Run-off Property-Liability segments and adjusted net income for the Protection Services, Allstate Health and Benefits and Corporate and Other segments.
Underwriting income is calculated as premiums earned and other revenue, less claims and claims expense (“losses”), amortization of deferred policy acquisition costs (“DAC”), operating costs and expenses, amortization or impairment of purchased intangibles and restructuring and related charges, as determined using accounting principles generally accepted in the United States of America (“GAAP”). We use this measure in our evaluation of results of operations to analyze profitability.
Adjusted net income is net income (loss) applicable to common shareholders, excluding:
| • | Net gains and losses on investments and derivatives | ||||
| • | Pension and other postretirement remeasurement gains and losses | ||||
| • | Business combination expenses and the amortization or impairment of purchased intangibles | ||||
| • | Income or loss from discontinued operations | ||||
| • | Gain or loss on disposition of operations | ||||
| • | Adjustments for other significant non-recurring, infrequent or unusual items, when (a) the nature of the charge or gain is such that it is reasonably unlikely to recur within two years, or (b) there has been no similar charge or gain within the prior two years | ||||
| • | Income tax expense or benefit on reconciling items |
Highlights
| Consolidated net income | ||||||||||||||
| ($ in millions) | ||||||||||||||
| Q1 | Q2 |
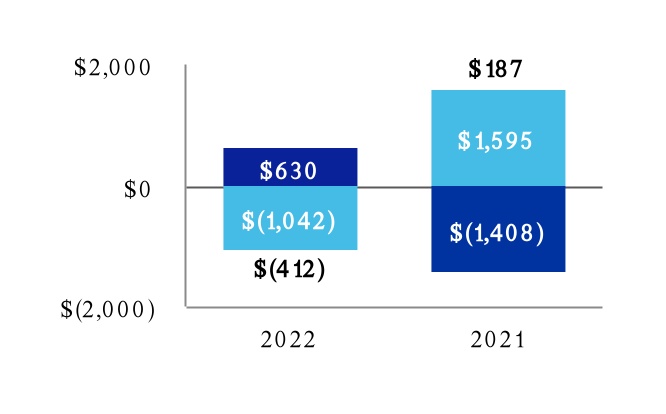
| Consolidated net loss applicable to common shareholders was $1.04 billion and $412 million in the second quarter and first six months of 2022, respectively, compared to income of $1.60 billion and $187 million in the second quarter and first six months of 2021 primarily due to higher non-catastrophe losses and equity valuation decreases, partially offset by increased Property-Liability premiums earned and the loss from discontinued operations in the first six months of 2021. For the twelve months ended June 30, 2022, return on Allstate common shareholders’ equity was 4.0%, a decrease of 11.3 points from 15.3% for the twelve months ended June 30, 2021. | ||
| Total revenue | ||||||||||||||
| ($ in millions) |
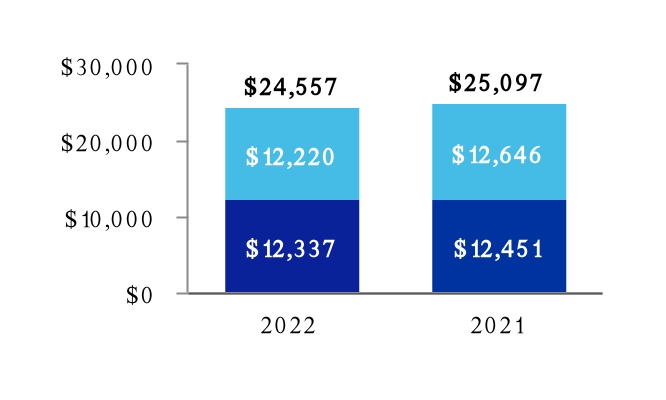
| Total revenue decreased 3.4% to $12.22 billion and decreased 2.2% to $24.56 billion in the second quarter and first six months of 2022, respectively, compared to the same periods of 2021, driven by net losses on investments and derivatives in 2022 compared to net gains in 2021 and decreases in net investment income, partially offset by 8.8% and 7.7% increases in property and casualty insurance premiums earned in the second quarter and first six months of 2022, respectively. Insurance premiums earned increased for Property-Liability and Protection Services. |
| Net investment income | ||||||||||||||
| ($ in millions) |
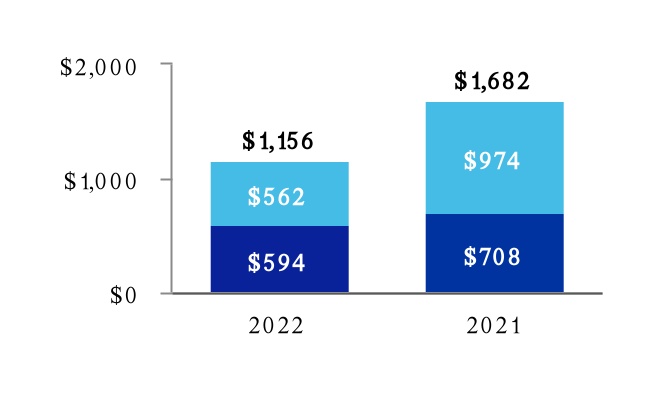
| Net investment income decreased $412 million to $562 million in the second quarter of 2022 and decreased $526 million to $1.16 billion in the first six months of 2022 compared to the same periods of 2021. The decrease in both periods was primarily due to lower performance-based investment results, mainly from limited partnerships. The decrease in the second quarter was slightly offset by higher market-based fixed income portfolio yields. |
Second Quarter 2022 Form 10-Q 47
Financial highlights
Investments totaled $61.06 billion as of June 30, 2022, decreasing from $64.70 billion as of December 31, 2021.
Allstate shareholders’ equity As of June 30, 2022, Allstate shareholders’ equity was $20.12 billion.
Book value per common share (ratio of Allstate common shareholders’ equity to total common shares outstanding and dilutive potential common shares outstanding) was $66.15, a decrease of 23.4% from $86.33 as of June 30, 2021, and a decrease of 18.9% from $81.52 as of December 31, 2021.
Return on average Allstate common shareholders’ equity For the twelve months ended June 30, 2022, return on Allstate common shareholders’ equity was 4.0%, a decrease of 11.3 points from 15.3% for the twelve months ended June 30, 2021. The decrease was primarily due to lower net income applicable to common shareholders for the trailing twelve-month period ending June 30, 2022.
Pension and other postretirement remeasurement gains and losses We recorded pension and other postretirement remeasurement losses of $259 million and $12 million in the second quarter and first six months of 2022, respectively, primarily related to unfavorable asset performance compared to expected return on plan assets, partially offset by a reduction in the projected benefit obligation due to an increase in the liability discount rate and changes in other assumptions.
Summarized consolidated financial results
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| Revenues | ||||||||||||||||||||||||||
| Property and casualty insurance premiums | $ | 11,362 | $ | 10,444 | $ | 22,343 | $ | 20,751 | ||||||||||||||||||
| Accident and health insurance premiums and contract charges | 466 | 447 | 935 | 902 | ||||||||||||||||||||||
| Other revenue | 563 | 494 | 1,123 | 1,049 | ||||||||||||||||||||||
| Net investment income | 562 | 974 | 1,156 | 1,682 | ||||||||||||||||||||||
| Net gains (losses) on investments and derivatives | (733) | 287 | (1,000) | 713 | ||||||||||||||||||||||
| Total revenues | 12,220 | 12,646 | 24,557 | 25,097 | ||||||||||||||||||||||
| Costs and expenses | ||||||||||||||||||||||||||
| Property and casualty insurance claims and claims expense | (9,367) | (7,207) | (17,189) | (13,250) | ||||||||||||||||||||||
| Shelter-in-Place Payback expense | — | (29) | — | (29) | ||||||||||||||||||||||
| Accident, health and other policy benefits | (269) | (252) | (538) | (494) | ||||||||||||||||||||||
| Amortization of deferred policy acquisition costs | (1,619) | (1,545) | (3,231) | (3,068) | ||||||||||||||||||||||
| Operating, restructuring and interest expenses | (1,934) | (1,845) | (3,931) | (3,713) | ||||||||||||||||||||||
| Pension and other postretirement remeasurement gains (losses) | (259) | 134 | (12) | 444 | ||||||||||||||||||||||
| Amortization of purchased intangibles | (87) | (105) | (174) | (158) | ||||||||||||||||||||||
| Total costs and expenses | (13,535) | (10,849) | (25,075) | (20,268) | ||||||||||||||||||||||
| (Loss) income from operations before income tax expense | (1,315) | 1,797 | (518) | 4,829 | ||||||||||||||||||||||
| Income tax benefit (expense) | 291 | (362) | 140 | (988) | ||||||||||||||||||||||
| Net (loss) income from continuing operations | (1,024) | 1,435 | (378) | 3,841 | ||||||||||||||||||||||
| Income (loss) from discontinued operations, net of tax | — | 196 | — | (3,597) | ||||||||||||||||||||||
| Net (loss) income | (1,024) | 1,631 | (378) | 244 | ||||||||||||||||||||||
| Less: Net (loss) income attributable to noncontrolling interest | (9) | 6 | (19) | — | ||||||||||||||||||||||
| Net (loss) income attributable to Allstate | (1,015) | 1,625 | (359) | 244 | ||||||||||||||||||||||
| Preferred stock dividends | (27) | (30) | (53) | (57) | ||||||||||||||||||||||
| Net (loss) income applicable to common shareholders | $ | (1,042) | $ | 1,595 | $ | (412) | $ | 187 |
Segment highlights
Allstate Protection underwriting loss was $861 million in the second quarter of 2022, compared to underwriting income of $431 million in the second quarter of 2021. Underwriting loss totaled $579 million in the first six months of 2022 compared to underwriting income of $2.09 billion in the first six months of 2021. The decrease in both periods was primarily due to higher non-catastrophe losses, primarily in auto, and unfavorable non-catastrophe reserve reestimates, partially offset by increased premiums. We are executing a comprehensive plan to improve profitability, including broadly raising auto and home insurance rates, reducing expenses, advertising and growth investments, implementing underwriting restrictions in underperforming states and executing claims operating actions to manage loss costs.
Catastrophe losses were $1.11 billion and $1.57 billion in the second quarter and first six months of 2022, respectively, compared to $952 million and $1.54 billion in the second quarter and first six months of 2021, respectively.
Premiums written increased 11.5% to $11.51 billion and 10.8% to $22.27 billion in the second quarter and first six months of 2022, respectively, compared to the same periods of 2021, reflecting higher premiums in both Allstate and National General brands.
Protection Services adjusted net income was $43 million in the second quarter of 2022 compared to $56 million in the second quarter of 2021. Adjusted net income was $96 million in the first six months of 2022 compared to $105 million in the first six months of 2021. The decrease in both periods was due to investments in geographic and product expansion at Allstate Protection Plans and increased severity at Allstate Roadside.
Premiums and other revenue increased 10.7% or $56 million in the second quarter of 2022 and 12.9% or $132 million in the first six months of 2022 compared to the same periods of 2021, primarily due to Allstate Protection Plans.
Allstate Health and Benefits adjusted net income was $65 million in the second quarter of 2022 compared to $62 million in the second quarter 2021, primarily due to an increase in group health revenues, partially offset by an increase in individual health claims. Adjusted net income was $118 million in the first six months of 2022 compared to $127 million in the first six months of 2021, primarily due to increases in individual and group health claims, partially offset by lower employer voluntary benefits claim utilization.
Premiums and contract charges increased 4.3% to $466 million in the second quarter of 2022 and 3.7% to $935 million in the first six months of 2022 compared to the same periods of 2021, primarily due to growth in individual and group health.
Second Quarter 2022 Form 10-Q 49
Property-Liability Operations
Property-Liability Operations
Overview Property-Liability operations consist of two reportable segments: Allstate Protection and Run-off Property-Liability. These segments are consistent with the groupings of financial information that management uses to evaluate performance and to determine the allocation of resources.
We do not allocate Property-Liability investment income, net gains and losses on investments and derivatives, or assets to the Allstate Protection and Run-off Property-Liability segments. Management reviews assets at the Property-Liability level for decision-making purposes.
GAAP operating ratios are used to measure our profitability to enhance an investor’s understanding of our financial results and are calculated as follows:
*•*Loss ratio: the ratio of claims and claims expense (loss adjustment expenses), to premiums earned. Loss ratios include the impact of catastrophe losses and prior year reserve reestimates.
*•*Expense ratio: the ratio of amortization of DAC, operating costs and expenses, amortization or impairment of purchased intangibles and restructuring and related charges and Shelter-in-Place Payback expense, less other revenue to premiums earned.
*•*Combined ratio: the sum of the loss ratio and the expense ratio.
We have also calculated the following impacts of specific items on the GAAP operating ratios because of the volatility of these items between periods. The impacts are calculated by taking the specific items noted below divided by Property-Liability premiums earned:
*•*Effect of catastrophe losses on combined ratio: includes catastrophe losses and prior year reserve reestimates of catastrophe losses, included in claims and claims expense
*•*Effect of prior year reserve reestimates on combined ratio
*•*Effect of amortization of purchased intangibles on combined ratio
*•*Effect of restructuring and related charges on combined ratio
*•*Effect of Shelter-in-Place Payback expense on combined and expense ratios.
*•*Effect of Run-off Property-Liability business on combined ratio: includes claims and claims expense, restructuring and related charges and operating costs and expenses in the Run-off Property-Liability segment
Premium measures and statistics are used to analyze our premium trends and are calculated as follows:
*•*PIF: policy counts are based on items rather than customers. A multi-car customer would generate multiple item (policy) counts, even if all cars were
insured under one policy. Commercial lines PIF counts for shared economy agreements typically reflect contracts that cover multiple rather than individual drivers.
*•*New issued applications: item counts of automobile or homeowner insurance applications for insurance policies that were issued during the period, regardless of whether the customer was previously insured by another Allstate brand.
*•*Average premium-gross written (“average premium”): gross premiums written divided by issued item count. Gross premiums written include the impacts from discounts, surcharges and ceded reinsurance premiums and exclude the impacts from mid-term premium adjustments and premium refund accruals. Average premiums represent the appropriate policy term for each line.
*•*Renewal ratio: renewal policy item counts issued during the period, based on contract effective dates, divided by the total policy item counts issued generally 6 months prior for auto or 12 months prior for homeowners.
*•*Implemented rate changes: represents the impact in the locations (U.S. states, the District of Columbia or Canadian provinces) where rate changes were implemented during the period as a percentage of total brand prior year-end premiums written.
Frequency and severity statistics, which are influenced by driving patterns, inflation and other factors, are provided to describe the trends in loss costs. Our reserving process incorporates changes in loss patterns, operational statistics and changes in claims reporting processes to determine our best estimate of recorded reserves. We use the following statistics to evaluate losses:
*•*Gross claim frequency is calculated as annualized notice counts, excluding counts associated with catastrophe events, received in the period divided by the average of PIF with the applicable coverage during the period. Gross claim frequency includes all actual notice counts, regardless of their current status (open or closed) or their ultimate disposition (closed with a payment or closed without payment).
*•*Report year incurred claim severity is calculated by dividing the sum of recorded estimated incurred losses and allocated loss adjustment expenses, excluding catastrophes, by the reported notice counts during that report year. Report year incurred claim severity does not include incurred but not reported (“IBNR”) losses or benefits from subrogation and salvage.
*•*Paid claim severity is calculated by dividing the sum of paid losses and loss expenses by claims closed with a payment during the period.
*•*Percent change in frequency or paid claim severity statistics is calculated as the amount of increase or decrease in gross claim frequency or paid claim
Property-Liability Operations
severity in the current period compared to the same period in the prior year, divided by the prior year gross claim frequency or paid claim severity.
*•*Percent change in report year incurred claim severity statistic is calculated as the amount of
increase or decrease in report year incurred claim severity recorded in the year-to-date period divided by the current estimate of the prior report year incurred claim severity.
| Underwriting results | ||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| ($ in millions, except ratios) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| Premiums written | $ | 11,509 | $ | 10,323 | $ | 22,270 | $ | 20,091 | ||||||||||||||||||
| Premiums earned | $ | 10,874 | $ | 10,009 | $ | 21,372 | $ | 19,905 | ||||||||||||||||||
| Other revenue | 355 | 321 | 702 | 706 | ||||||||||||||||||||||
| Claims and claims expense | (9,231) | (7,103) | (16,933) | (13,048) | ||||||||||||||||||||||
| Shelter-in-Place Payback expense | — | (29) | — | (29) | ||||||||||||||||||||||
| Amortization of DAC | (1,355) | (1,319) | (2,703) | (2,622) | ||||||||||||||||||||||
| Other costs and expenses | (1,450) | (1,313) | (2,895) | (2,638) | ||||||||||||||||||||||
| Restructuring and related charges (1) | 2 | (66) | (10) | (98) | ||||||||||||||||||||||
| Amortization of purchased intangibles | (59) | (71) | (117) | (90) | ||||||||||||||||||||||
| Underwriting (loss) income | $ | (864) | $ | 429 | $ | (584) | $ | 2,086 | ||||||||||||||||||
| Catastrophe losses | ||||||||||||||||||||||||||
| Catastrophe losses, excluding reserve reestimates | $ | 1,057 | $ | 915 | $ | 1,532 | $ | 1,748 | ||||||||||||||||||
| Catastrophe reserve reestimates (2) | 51 | 37 | 38 | (206) | ||||||||||||||||||||||
| Total catastrophe losses | $ | 1,108 | $ | 952 | $ | 1,570 | $ | 1,542 | ||||||||||||||||||
| Non-catastrophe reserve reestimates (2) | 411 | (20) | 569 | (18) | ||||||||||||||||||||||
| Prior year reserve reestimates (2) | 462 | 17 | 607 | (224) | ||||||||||||||||||||||
| GAAP operating ratios | ||||||||||||||||||||||||||
| Loss ratio | 84.9 | 71.0 | 79.2 | 65.5 | ||||||||||||||||||||||
| Expense ratio (3) | 23.0 | 24.7 | 23.5 | 24.0 | ||||||||||||||||||||||
| Combined ratio | 107.9 | 95.7 | 102.7 | 89.5 | ||||||||||||||||||||||
| Effect of catastrophe losses on combined ratio | 10.2 | 9.5 | 7.3 | 7.7 | ||||||||||||||||||||||
| Effect of prior year reserve reestimates on combined ratio | 4.2 | 0.2 | 2.9 | (1.1) | ||||||||||||||||||||||
| Effect of catastrophe losses included in prior year reserve reestimates on combined ratio | 0.4 | 0.4 | 0.2 | (1.0) | ||||||||||||||||||||||
| Effect of restructuring and related charges on combined ratio (1) | — | 0.6 | — | 0.5 | ||||||||||||||||||||||
| Effect of amortization of purchased intangibles on combined ratio | 0.5 | 0.7 | 0.5 | 0.5 | ||||||||||||||||||||||
| Effect of Shelter-in-Place Payback expense on combined and expense ratios | — | 0.3 | — | 0.1 | ||||||||||||||||||||||
| Effect of Run-off Property-Liability business on combined ratio | — | — | — | — |
(1)Restructuring and related charges for the second quarter and first six months of 2022 primarily related to future work environment. See Note 11 of the condensed consolidated financial statements for additional details.
(2)Favorable reserve reestimates are shown in parentheses.
(3)Other revenue is deducted from operating costs and expenses in the expense ratio calculation.
Second Quarter 2022 Form 10-Q 51
Segment Results Allstate Protection
Allstate Protection Segment

| Underwriting results | ||||||||||||||||||||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||||||||||||||||||||
| Premiums written | $ | 11,509 | $ | 10,323 | $ | 22,270 | $ | 20,091 | ||||||||||||||||||||||||||||||||||||
| Premiums earned | $ | 10,874 | $ | 10,009 | $ | 21,372 | $ | 19,905 | ||||||||||||||||||||||||||||||||||||
| Other revenue | 355 | 321 | 702 | 706 | ||||||||||||||||||||||||||||||||||||||||
| Claims and claims expense | (9,228) | (7,102) | (16,929) | (13,046) | ||||||||||||||||||||||||||||||||||||||||
| Shelter-in-Place Payback expense | — | (29) | — | (29) | ||||||||||||||||||||||||||||||||||||||||
| Amortization of DAC | (1,355) | (1,319) | (2,703) | (2,622) | ||||||||||||||||||||||||||||||||||||||||
| Other costs and expenses | (1,450) | (1,313) | (2,894) | (2,636) | ||||||||||||||||||||||||||||||||||||||||
| Restructuring and related charges | 2 | (65) | (10) | (97) | ||||||||||||||||||||||||||||||||||||||||
| Amortization of purchased intangibles | (59) | (71) | (117) | (90) | ||||||||||||||||||||||||||||||||||||||||
| Underwriting (loss) income | $ | (861) | $ | 431 | $ | (579) | $ | 2,091 | ||||||||||||||||||||||||||||||||||||
| Catastrophe losses | $ | 1,108 | $ | 952 | $ | 1,570 | $ | 1,542 | ||||||||||||||||||||||||||||||||||||
Underwriting loss was $861 million and $579 million in the second quarter and first six months of 2022, respectively, compared to underwriting income of $431 million and $2.09 billion in the second quarter and first six months of 2021, respectively, primarily due to higher non-catastrophe losses, primarily in auto, and unfavorable non-catastrophe reserve reestimates, partially offset by increased premiums. We are executing a comprehensive plan to improve profitability, including broadly raising auto and home insurance rates, reducing expenses, advertising and growth investments, implementing underwriting restrictions in underperforming states and executing claims operating actions to manage loss costs.
| Change in underwriting results from the prior period - three months ended | ||||||||||||||
| ($ in millions) |

| Change in underwriting results from the prior period - six months ended | ||||||||||||||
| ($ in millions) |

Allstate Protection Segment Results
| Underwriting income (loss) by brand and by line of business | ||||||||||||||||||||||||||||||||||||||
| Allstate brand | National General | Allstate Protection | ||||||||||||||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||||||||||||
| Three months ended June 30, | ||||||||||||||||||||||||||||||||||||||
| Auto (1) | $ | (578) | $ | 364 | $ | — | $ | 30 | $ | (578) | $ | 394 | ||||||||||||||||||||||||||
| Homeowners (2) | (132) | 7 | (54) | (14) | (186) | (7) | ||||||||||||||||||||||||||||||||
| Other personal lines | 5 | 40 | 6 | (1) | 11 | 39 | ||||||||||||||||||||||||||||||||
| Commercial lines | (145) | (25) | 10 | — | (135) | (25) | ||||||||||||||||||||||||||||||||
| Other business lines (3) | 25 | 28 | — | — | 25 | 28 | ||||||||||||||||||||||||||||||||
| Answer Financial | — | — | — | — | 2 | 2 | ||||||||||||||||||||||||||||||||
| Total | $ | (825) | $ | 414 | $ | (38) | $ | 15 | $ | (861) | $ | 431 | ||||||||||||||||||||||||||
| Six months ended June 30, | ||||||||||||||||||||||||||||||||||||||
| Auto (1) | $ | (715) | $ | 1,567 | $ | (10) | $ | 154 | $ | (725) | $ | 1,721 | ||||||||||||||||||||||||||
| Homeowners (2) | 236 | 269 | (12) | (8) | 224 | 261 | ||||||||||||||||||||||||||||||||
| Other personal lines | 23 | 65 | 6 | 7 | 29 | 72 | ||||||||||||||||||||||||||||||||
| Commercial lines | (164) | (27) | 7 | — | (157) | (27) | ||||||||||||||||||||||||||||||||
| Other business lines (3) | 46 | 55 | — | — | 46 | 55 | ||||||||||||||||||||||||||||||||
| Answer Financial | — | — | — | — | 4 | 9 | ||||||||||||||||||||||||||||||||
| Total | $ | (574) | $ | 1,929 | $ | (9) | $ | 153 | $ | (579) | $ | 2,091 |
(1)2021 results include certain National General commercial lines insurance products.
(2)2021 results include National General packaged policies, which include auto, and commercial lines insurance products.
(3)Other business lines represents commissions earned and other costs and expenses for Ivantage and non-proprietary life and annuity products.
Premium measures and statistics include PIF, new issued applications, average premiums and renewal ratio to analyze our premium trends. Premiums written is the amount of premiums charged for policies issued during a fiscal period. Premiums are considered earned and are included in the financial results on a pro-rata basis over the policy period. The portion of premiums written applicable to the unexpired term of the policies is recorded as unearned premiums on our Condensed Consolidated Statements of Financial Position.
| Premiums written by brand and by line of business | ||||||||||||||||||||||||||||||||||||||
| Allstate brand | National General | Allstate Protection | ||||||||||||||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||||||||||||
| Three months ended June 30, | ||||||||||||||||||||||||||||||||||||||
| Auto | $ | 6,374 | $ | 5,952 | $ | 1,096 | $ | 866 | $ | 7,470 | $ | 6,818 | ||||||||||||||||||||||||||
| Homeowners | 2,665 | 2,313 | 468 | 409 | 3,133 | 2,722 | ||||||||||||||||||||||||||||||||
| Other personal lines | 576 | 539 | 33 | 40 | 609 | 579 | ||||||||||||||||||||||||||||||||
| Commercial lines | 247 | 204 | 50 | — | 297 | 204 | ||||||||||||||||||||||||||||||||
| Total premiums written | $ | 9,862 | $ | 9,008 | $ | 1,647 | $ | 1,315 | $ | 11,509 | $ | 10,323 | ||||||||||||||||||||||||||
| Six months ended June 30, | ||||||||||||||||||||||||||||||||||||||
| Auto | $ | 12,682 | $ | 12,012 | $ | 2,350 | $ | 1,818 | $ | 15,032 | $ | 13,830 | ||||||||||||||||||||||||||
| Homeowners | 4,685 | 4,040 | 849 | 765 | 5,534 | 4,805 | ||||||||||||||||||||||||||||||||
| Other personal lines | 1,045 | 976 | 68 | 79 | 1,113 | 1,055 | ||||||||||||||||||||||||||||||||
| Commercial lines | 485 | 401 | 106 | — | 591 | 401 | ||||||||||||||||||||||||||||||||
| Total premiums written | $ | 18,897 | $ | 17,429 | $ | 3,373 | $ | 2,662 | $ | 22,270 | $ | 20,091 |
Second Quarter 2022 Form 10-Q 53
Segment Results Allstate Protection
| Premiums earned by brand and by line of business | ||||||||||||||||||||||||||||||||||||||
| Allstate brand | National General | Allstate Protection | ||||||||||||||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||||||||||||
| Three months ended June 30, | ||||||||||||||||||||||||||||||||||||||
| Auto | $ | 6,253 | $ | 6,036 | $ | 1,095 | $ | 847 | $ | 7,348 | $ | 6,883 | ||||||||||||||||||||||||||
| Homeowners | 2,281 | 2,032 | 405 | 379 | 2,686 | 2,411 | ||||||||||||||||||||||||||||||||
| Other personal lines | 510 | 482 | 35 | 37 | 545 | 519 | ||||||||||||||||||||||||||||||||
| Commercial lines | 244 | 196 | 51 | — | 295 | 196 | ||||||||||||||||||||||||||||||||
| Total premiums earned | $ | 9,288 | $ | 8,746 | $ | 1,586 | $ | 1,263 | $ | 10,874 | $ | 10,009 | ||||||||||||||||||||||||||
| Six months ended June 30, | ||||||||||||||||||||||||||||||||||||||
| Auto | $ | 12,326 | $ | 12,050 | $ | 2,103 | $ | 1,642 | $ | 14,429 | $ | 13,692 | ||||||||||||||||||||||||||
| Homeowners | 4,491 | 4,040 | 798 | 763 | 5,289 | 4,803 | ||||||||||||||||||||||||||||||||
| Other personal lines | 1,006 | 951 | 70 | 73 | 1,076 | 1,024 | ||||||||||||||||||||||||||||||||
| Commercial lines | 476 | 386 | 102 | — | 578 | 386 | ||||||||||||||||||||||||||||||||
| Total premiums earned | $ | 18,299 | $ | 17,427 | $ | 3,073 | $ | 2,478 | $ | 21,372 | $ | 19,905 |
| Reconciliation of premiums written to premiums earned | ||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| Total premiums written | $ | 11,509 | $ | 10,323 | $ | 22,270 | $ | 20,091 | ||||||||||||||||||
| (Increase) decrease in unearned premiums | (599) | (312) | (857) | (592) | ||||||||||||||||||||||
| Other | (36) | (2) | (41) | 406 | ||||||||||||||||||||||
| Total premiums earned | $ | 10,874 | $ | 10,009 | $ | 21,372 | $ | 19,905 |
| Policies in force by brand and by line of business | ||||||||||||||||||||||||||||||||||||||
| Allstate brand | National General | Allstate Protection | ||||||||||||||||||||||||||||||||||||
| PIF (thousands) | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||||||||||||
| Auto | 21,979 | 21,920 | 4,213 | 3,694 | 26,192 | 25,614 | ||||||||||||||||||||||||||||||||
| Homeowners | 6,566 | 6,459 | 631 | 652 | 7,197 | 7,111 | ||||||||||||||||||||||||||||||||
| Other personal lines | 4,632 | 4,525 | 287 | 291 | 4,919 | 4,816 | ||||||||||||||||||||||||||||||||
| Commercial lines | 206 | 213 | 105 | 109 | 311 | 322 | ||||||||||||||||||||||||||||||||
| Total | 33,383 | 33,117 | 5,236 | 4,746 | 38,619 | 37,863 |
Auto insurance premiums written increased 9.6% or $652 million in the second quarter of 2022 compared to the second quarter of 2021 and 8.7% or $1.2 billion in the first six months of 2022 compared to the first six months of 2021, primarily due to the following factors:
-
Increased average premiums driven by rate increases. In the six months ended June 30, 2022, rate increases of 9.5% were taken for Allstate brand in 48 locations, resulting in total Allstate brand insurance premium impact of 6.1%, and 9.0% were taken for National General brand in 29 locations, resulting in total National General brand insurance premium impact of 4.7%, to improve underwriting results. Rate increases may accelerate in the second half of 2022
-
Renewal ratio increased 0.4 and 0.6 points in the second quarter and first six months of 2022, respectively, compared to the second quarter and first six months of 2021 and remains flat compared to prior quarter
-
PIF increased 2.3% or 578 thousand to 26,192 thousand as of June 30, 2022 compared to June 30, 2021 due to growth in National General, including SafeAuto acquisition, and Allstate brand
-
The impact of the ongoing rate actions may have an adverse effect on the renewal ratio and future PIF growth
-
Increased new issued applications driven by direct channel, including the acquisition of SafeAuto, and growth in the independent agency channel
Allstate Protection Segment Results
| Auto premium measures and statistics | ||||||||||||||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | Change | 2022 | 2021 | Change | |||||||||||||||||||||||||||||||||
| New issued applications (thousands) | ||||||||||||||||||||||||||||||||||||||
| Allstate Protection by brand | ||||||||||||||||||||||||||||||||||||||
| Allstate brand | 959 | 926 | 3.6 | % | 1,923 | 1,855 | 3.7 | % | ||||||||||||||||||||||||||||||
| National General | 672 | 495 | 35.8 | % | 1,390 | 1,037 | 19.0 | % | ||||||||||||||||||||||||||||||
| Total new issued applications | 1,631 | 1,421 | 14.8 | % | 3,313 | 2,892 | 14.6 | % | ||||||||||||||||||||||||||||||
| Allstate Protection by channel | ||||||||||||||||||||||||||||||||||||||
| Exclusive agency channel | 619 | 620 | (0.2) | % | 1,218 | 1,233 | (1.2) | % | ||||||||||||||||||||||||||||||
| Direct channel | 571 | 435 | 31.3 | % | 1,202 | 890 | 35.1 | % | ||||||||||||||||||||||||||||||
| Independent agency channel | 441 | 366 | 20.5 | % | 893 | 769 | 16.1 | % | ||||||||||||||||||||||||||||||
| Total new issued applications | 1,631 | 1,421 | 14.8 | % | 3,313 | 2,892 | 14.6 | % | ||||||||||||||||||||||||||||||
| Allstate brand average premium | $ | 644 | $ | 600 | 7.3 | % | $ | 635 | $ | 604 | 5.1 | % | ||||||||||||||||||||||||||
| Allstate brand renewal ratio (%) | 87.5 | 87.1 | 0.4 | 87.5 | 86.9 | 0.6 | ||||||||||||||||||||||||||||||||
Homeowners insurance premiums written increased 15.1% or $411 million in the second quarter of 2022 compared to the second quarter of 2021 and increased 15.2% or $729 million in the first six months of 2022 compared to the first six months of 2021, primarily due to the following factors:
-
Higher Allstate brand average premiums from approved rate increases and inflation adjustments to premium due to higher insured home valuations
-
Increased new issued applications driven by growth in the independent agency and direct channels
| Homeowners premium measures and statistics | ||||||||||||||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | Change | 2022 | 2021 | Change | |||||||||||||||||||||||||||||||||
| New issued applications (thousands) | ||||||||||||||||||||||||||||||||||||||
| Allstate Protection by brand | ||||||||||||||||||||||||||||||||||||||
| Allstate brand | 263 | 258 | 1.9 | % | 498 | 478 | 4.2 | % | ||||||||||||||||||||||||||||||
| National General | 40 | 27 | 48.1 | % | 67 | 49 | 36.7 | % | ||||||||||||||||||||||||||||||
| Total new issued applications | 303 | 285 | 6.3 | % | 565 | 527 | 7.2 | % | ||||||||||||||||||||||||||||||
| Allstate Protection by channel | ||||||||||||||||||||||||||||||||||||||
| Exclusive agency channel | 222 | 226 | (1.8) | % | 423 | 421 | 0.5 | % | ||||||||||||||||||||||||||||||
| Direct channel | 27 | 22 | 22.7 | % | 50 | 38 | 31.6 | % | ||||||||||||||||||||||||||||||
| Independent agency channel | 54 | 37 | 45.9 | % | 92 | 68 | 35.3 | % | ||||||||||||||||||||||||||||||
| Total new issued applications | 303 | 285 | 6.3 | % | 565 | 527 | 7.2 | % | ||||||||||||||||||||||||||||||
| Allstate brand average premium | $ | 1,590 | $ | 1,404 | 13.2 | % | $ | 1,574 | $ | 1,384 | 13.7 | % | ||||||||||||||||||||||||||
| Allstate brand renewal ratio (%) | 86.9 | 87.3 | (0.4) | 86.6 | 87.2 | (0.6) | ||||||||||||||||||||||||||||||||
Other personal lines premiums written increased 5.2% or $30 million in the second quarter of 2022 compared to the second quarter of 2021 and increased 5.5% or $58 million in the first six months of 2022 compared to the first six months of 2021, primarily due to increases in condominiums, landlords and personal umbrella premiums for Allstate brand.
Commercial lines premiums written increased 45.6% or $93 million in the second quarter of 2022 compared to the second quarter of 2021 and increased 47.4% or $190 million in the first six months of 2022 compared to the first six months of 2021, primarily due to increased average premium and higher miles driven in our shared economy business.
Second Quarter 2022 Form 10-Q 55
Segment Results Allstate Protection
GAAP operating ratios include loss ratio, expense ratio and combined ratio to analyze our profitability trends. Frequency and severity statistics are used to describe the trends in loss costs.
| Combined ratios by line of business | ||||||||||||||||||||||||||||||||||||||
| Loss ratio | Expense ratio (1) | Combined ratio | ||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||
| Three months ended June 30, | ||||||||||||||||||||||||||||||||||||||
| Auto | 84.9 | 68.7 | 23.0 | 25.6 | 107.9 | 94.3 | ||||||||||||||||||||||||||||||||
| Impact of Shelter-in-Place Payback expense | — | — | — | 0.4 | — | 0.4 | ||||||||||||||||||||||||||||||||
| Homeowners | 82.3 | 76.3 | 24.6 | 24.0 | 106.9 | 100.3 | ||||||||||||||||||||||||||||||||
| Other personal lines | 74.9 | 68.0 | 23.1 | 24.5 | 98.0 | 92.5 | ||||||||||||||||||||||||||||||||
| Commercial lines | 127.1 | 90.8 | 18.7 | 22.0 | 145.8 | 112.8 | ||||||||||||||||||||||||||||||||
| Total | 84.9 | 71.0 | 23.0 | 24.7 | 107.9 | 95.7 | ||||||||||||||||||||||||||||||||
| Impact of amortization of purchased intangibles | — | — | 0.5 | 0.7 | 0.5 | 0.7 | ||||||||||||||||||||||||||||||||
| Impact of Shelter-in-Place Payback expense | — | — | — | 0.3 | — | 0.3 | ||||||||||||||||||||||||||||||||
| Impact of restructuring and related charges | — | — | — | 0.6 | — | 0.6 | ||||||||||||||||||||||||||||||||
| Impact of Allstate Special Payment plan bad debt expense | — | — | — | (0.1) | — | (0.1) | ||||||||||||||||||||||||||||||||
| Six months ended June 30, | ||||||||||||||||||||||||||||||||||||||
| Auto | 81.3 | 63.0 | 23.7 | 24.4 | 105.0 | 87.4 | ||||||||||||||||||||||||||||||||
| Impact of Shelter-in-Place Payback expense | — | — | — | 0.2 | — | 0.2 | ||||||||||||||||||||||||||||||||
| Homeowners | 71.6 | 70.6 | 24.2 | 24.0 | 95.8 | 94.6 | ||||||||||||||||||||||||||||||||
| Other personal lines | 73.5 | 68.1 | 23.8 | 24.9 | 97.3 | 93.0 | ||||||||||||||||||||||||||||||||
| Commercial lines | 107.6 | 84.7 | 19.6 | 22.3 | 127.2 | 107.0 | ||||||||||||||||||||||||||||||||
| Total | 79.2 | 65.5 | 23.5 | 24.0 | 102.7 | 89.5 | ||||||||||||||||||||||||||||||||
| Impact of amortization of purchased intangibles | — | — | 0.5 | 0.5 | 0.5 | 0.5 | ||||||||||||||||||||||||||||||||
| Impact of Shelter-in-Place Payback expense | — | — | — | 0.1 | — | 0.1 | ||||||||||||||||||||||||||||||||
| Impact of restructuring and related charges | — | — | — | 0.5 | — | 0.5 | ||||||||||||||||||||||||||||||||
| Impact of Allstate Special Payment plan bad debt expense | — | — | — | (0.1) | — | (0.1) |
(1)Other revenue is deducted from operating costs and expenses in the expense ratio calculation.
| Loss ratios by line of business | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Loss ratio | Effect of catastrophe losses (1) | Effect of prior year reserve reestimates | Effect of catastrophe losses included in prior year reserve reestimates | |||||||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||||||||||
| Three months ended June 30, | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Auto | 84.9 | 68.7 | 1.5 | 2.2 | 3.3 | (0.5) | (0.5) | (0.1) | ||||||||||||||||||||||||||||||||||||||||||
| Homeowners | 82.3 | 76.3 | 34.3 | 30.3 | 4.9 | 1.2 | 3.2 | 1.5 | ||||||||||||||||||||||||||||||||||||||||||
| Other personal lines | 74.9 | 68.0 | 13.0 | 11.9 | (0.4) | 0.2 | 0.5 | 0.7 | ||||||||||||||||||||||||||||||||||||||||||
| Commercial lines | 127.1 | 90.8 | 2.7 | 3.6 | 31.2 | 9.2 | 0.4 | — | ||||||||||||||||||||||||||||||||||||||||||
| Total | 84.9 | 71.0 | 10.2 | 9.5 | 4.2 | 0.2 | 0.4 | 0.4 | ||||||||||||||||||||||||||||||||||||||||||
| Six months ended June 30, | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Auto | 81.3 | 63.0 | 1.0 | 1.3 | 2.6 | (0.5) | (0.3) | (0.2) | ||||||||||||||||||||||||||||||||||||||||||
| Homeowners | 71.6 | 70.6 | 24.7 | 25.5 | 2.3 | (3.6) | 1.5 | (3.6) | ||||||||||||||||||||||||||||||||||||||||||
| Other personal lines | 73.5 | 68.1 | 9.8 | 11.7 | (0.8) | (1.6) | 0.7 | (1.4) | ||||||||||||||||||||||||||||||||||||||||||
| Commercial lines | 107.6 | 84.7 | 1.4 | 3.9 | 19.2 | 8.5 | — | 0.5 | ||||||||||||||||||||||||||||||||||||||||||
| Total | 79.2 | 65.5 | 7.3 | 7.7 | 2.9 | (1.1) | 0.2 | (1.0) |
(1) The ten-year average effect of catastrophe losses on the total combined ratio was 11.4 points in the second quarter of 2022.
Allstate Protection Segment Results
Auto loss ratio increased 16.2 and 18.3 points in the second quarter and first six months of 2022, respectively, compared to the same periods of 2021, primarily due to:
-
Higher gross claim frequency in all coverages, as miles driven has rebounded toward pre-pandemic levels. While total frequency increased relative to the prior year quarter, it remains below pre-pandemic levels
-
Increased severity for all coverages, driven by inflationary pressures and medical service utilization for bodily injury claims
-
Unfavorable non-catastrophe prior year reserve reestimates in both physical damage and bodily injury coverages
The impacts of the Coronavirus affect frequency and severity statistics including:
-
Supply chain disruptions and labor shortages
-
Value of total losses due to higher used car prices
-
Labor and part cost increases
-
Unemployment levels
-
Changes in commuting activity
-
Driving behavior (e.g., speed, time of day) impacting mix of claim types
Property damage gross claim frequency for Allstate brand increased 7.1% and 12.3% in the second quarter and first six months of 2022, respectively, compared to the same periods of 2021 due to factors including:
-
Increases in miles driven compared to 2021 which was impacted by the pandemic
-
While gross claim frequency has rebounded from the low in 2020, it is 15.5% below pre-pandemic levels of 2019 as auto miles driven, particularly during peak commuting hours, remains lower than pre-pandemic levels
Collision gross claim frequency for Allstate brand increased 5.1% and 9.8% in the second quarter and first six months of 2022, respectively, compared to the same periods of 2021. While gross claim frequency has rebounded from the low in 2020, it is 9.4% below pre-pandemic levels of 2019.
Property damage estimated report year 2022 incurred claim severity for Allstate brand, excluding Esurance and Canada, increased approximately 12% compared to report year 2021 and also increased approximately 22% compared to the 2021 recorded severity as of June 30, 2021.
Collision estimated report year 2022 incurred claim severity for Allstate brand, excluding Esurance and Canada, increased approximately 16% compared to report year 2021 and also increased approximately 22% compared to the 2021 recorded severity as of June 30, 2021.
The increase in estimated report year 2022 incurred claim severity for both coverages is geographically widespread and is due to rising inflationary factors that began in the second quarter of
2021 impacting both repairable vehicles and total losses, including higher used car values, replacement part costs and labor rates, and higher costs to repair more sophisticated newer model vehicles.
Bodily injury estimated report year 2022 incurred claim severity for Allstate brand, excluding Esurance and Canada, increased approximately 9% compared to report year 2021 and also increased approximately 16% compared to the 2021 recorded severity as of June 30, 2021. The increase is due to more severe auto accidents, higher consumption of medical treatment, increased severity of claims with attorney representation and higher medical care inflation.
Homeowners loss ratio increased 6.0 points in the second quarter compared to the same period of 2021 primarily due to higher catastrophe losses and severity, partially offset by increased premiums earned. Homeowners loss ratio increased 1.0 point in the first six months of 2022, compared to the same period of 2021, primarily due to higher severity and unfavorable reserve reestimates compared to favorable reserve reestimates in 2021, partially offset by increased premiums earned.
| Allstate brand homeowners frequency and severity statistics (excluding catastrophe losses) | ||||||||||||||
| (% change year-over-year) | ||||||||||||||
| Three months ended June 30, 2022 | ||||||||||||||
| Gross claim frequency | (0.8) | % | ||||||||||||
| Paid claim severity | 22.6 | |||||||||||||
| Six months ended June 30, 2022 | ||||||||||||||
| Gross claim frequency | (2.7) | % | ||||||||||||
| Paid claim severity | 24.0 |
Gross claim frequency decreased in the second quarter and first six months of 2022 compared to the same periods of 2021 primarily due to a decline in the wind/hail peril. Paid claim severity increased in the second quarter and first six months of 2022 compared to the same periods of 2021 due to inflationary loss cost pressure driven by increases in labor and materials costs. Homeowner paid claim severity can be impacted by both the mix of perils and the magnitude of specific losses paid during the quarter.
Other personal lines loss ratio increased 6.9 and 5.4 points in the second quarter and first six months of 2022, respectively, compared to the same periods of 2021, primarily due to higher non-catastrophe losses, partially offset by increased premiums earned.
Commercial lines loss ratio increased 36.3 and 22.9 points in the second quarter and first six months of 2022, respectively, compared to the same periods of 2021, primarily due to higher auto severity and higher unfavorable non-catastrophe prior year reserve reestimates in the shared economy business, partially offset by increased premiums earned.
Second Quarter 2022 Form 10-Q 57
Segment Results Allstate Protection
Catastrophe losses increased 16.4% or $156 million in the second quarter of 2022 compared to the second quarter of 2021. Catastrophe losses increased 1.8% or $28 million in the first six months of 2022 compared to the first six months of 2021. Reinsurance recoveries in 2021 related to the Nationwide Aggregate Reinsurance Program for aggregate catastrophe losses occurring between April 1, 2020 and December 31, 2020, which primarily impacted homeowners reestimates.
We define a “catastrophe” as an event that produces pre-tax losses before reinsurance in excess of $1 million and involves multiple first party policyholders, or a winter weather event that produces a number of claims in excess of a preset, per-event threshold of average claims in a specific area, occurring within a certain amount of time following the event. Catastrophes are caused by various natural events including high winds, winter storms and freezes, tornadoes, hailstorms, wildfires, tropical storms, tsunamis, hurricanes, earthquakes and volcanoes.
We are also exposed to man-made catastrophic events, such as certain types of terrorism, civil unrest or industrial accidents. The nature and level of catastrophes in any period cannot be reliably predicted.
Loss estimates are generally based on claim adjuster inspections and the application of historical loss development factors. Our loss estimates are calculated in accordance with the coverage provided by our policies. Auto policyholders generally have coverage for physical damage due to flood if they have purchased optional auto comprehensive coverage. Our homeowners policies specifically exclude coverage for losses caused by flood.
Over time, we have limited our aggregate insurance exposure to catastrophe losses in certain regions of the country that are subject to high levels of natural catastrophes, limited by our participation in various state facilities.
| Catastrophe losses by the type of event | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | Number of events | 2022 | Number of events | 2021 | Number of events | 2022 | Number of events | 2021 | ||||||||||||||||||||||||||||||||||||||||||
| Hurricanes/Tropical storms | — | $ | — | 1 | $ | 6 | — | $ | — | 1 | $ | 6 | ||||||||||||||||||||||||||||||||||||||
| Tornadoes | 2 | 93 | — | — | 3 | 158 | 1 | 17 | ||||||||||||||||||||||||||||||||||||||||||
| Wind/Hail | 32 | 966 | 22 | 877 | 46 | 1,328 | 33 | 1,166 | ||||||||||||||||||||||||||||||||||||||||||
| Wildfires | 4 | 28 | — | — | 4 | 28 | — | — | ||||||||||||||||||||||||||||||||||||||||||
| Freeze/other events | — | — | — | — | 1 | 18 | 1 | 613 | ||||||||||||||||||||||||||||||||||||||||||
| Prior year reserve reestimates | 61 | 84 | 48 | (7) | ||||||||||||||||||||||||||||||||||||||||||||||
| Prior year aggregate reinsurance recoveries | (10) | (47) | (10) | (199) | ||||||||||||||||||||||||||||||||||||||||||||||
| Current year aggregate reinsurance recoveries | — | (11) | — | (54) | ||||||||||||||||||||||||||||||||||||||||||||||
| Prior quarter reserve reestimates | (30) | 43 | — | — | ||||||||||||||||||||||||||||||||||||||||||||||
| Total catastrophe losses | 38 | $ | 1,108 | 23 | $ | 952 | 54 | $ | 1,570 | 36 | $ | 1,542 |
Catastrophe reinsurance Our current catastrophe reinsurance program supports our risk tolerance framework which utilizes a modeled 1-in-100 annual aggregate limit for catastrophe losses from hurricanes, earthquakes and wildfires of $2.5 billion, net of reinsurance.
These reinsurance agreements are part of our catastrophe management strategy, which is intended to provide our shareholders with an acceptable return on the risks assumed in our property business, and to reduce variability of earnings, while providing protection to our customers.
During the second quarter of 2022, we completed the placement of our 2022-2023 Florida Excess Catastrophe Reinsurance Program (“Florida program”), National General Lender Services Standalone Program and the National General Reciprocal Excess Catastrophe Reinsurance Contract.
Florida program updates Our 2022 Florida program provides coverage up to $1.83 billion of loss less a $40 million retention. The Florida program includes reinsurance agreements placed in the traditional market, the Florida Hurricane Catastrophe Fund
(“FHCF”), and the Insurance-Linked Securities (“ILS”) market as follows:
-
Traditional market placements comprise reinsurance limits for losses to personal lines property in Florida arising out of multiple perils. These contracts provide a combined $1.30 billion of limits, with a portion of the traditional market placements providing coverage for perils not covered by the FHCF contracts, which only cover hurricanes.
-
Two FHCF contracts provide $394 million of limits for qualifying losses to personal lines property in Florida caused by storms the National Hurricane Center declares to be hurricanes. The two contracts are 90% placed.
-
ILS placements provide $488 million of reinsurance limits for qualifying losses to personal lines property in Florida caused by a named storm event, a severe weather event, an earthquake event, a fire event, a volcanic eruption event, or a meteorite impact event.
Allstate Protection Segment Results
National General Lender Services Standalone Program is placed in the traditional market and provides $225 million of coverage, subject to a $50 million retention, with one reinstatement of limits.
National General Reciprocal Excess Catastrophe Reinsurance Contracts are placed in the traditional market and provides $690 million of coverage, subject to a $20 million retention, with one reinstatement of limits.
Canada Catastrophe Excess of Loss Reinsurance Contract is placed in the traditional market and provides CAD 175 million of coverage, subject to a CAD 50 million retention, with one reinstatement of limits.
For a complete summary of the 2022 reinsurance placement, please read this in conjunction with the discussion and analysis in Part I. Item 2. Management’s Discussion and Analysis - Allstate Protection Segment Results, Catastrophe Reinsurance of The Allstate Corporation Form 10-Q for the quarterly period ended March 31, 2022.
The total cost of our property catastrophe reinsurance programs, excluding reinstatement premiums, during the second quarter and first six months of 2022 was $173 million and $317 million, respectively, compared to $128 million and $241 million in the second quarter and first six months of 2021, respectively. Catastrophe placement premiums reduce
net written and earned premium with approximately 73% related to homeowners.
Reserve reestimates Unfavorable reserve reestimates were $459 million and $603 million in the second quarter and first six months of 2022, respectively, primarily due to strengthening of non-catastrophe reserves in personal auto, primarily from physical damage and bodily injury coverages. Increases in physical damage reflect the ongoing inflationary factors and supply chain shortages impacting used vehicle and parts prices, labor rates and length of claim resolution, which contributed to the adverse development of claims reported in prior years but settled in 2022. Increases in injury coverages reflect the ongoing impacts of more severe auto accidents, increased medical inflation, higher consumption of medical treatment and the increased prevalence and severity of claims with attorney representation.
Unfavorable reserve reestimates for homeowners were driven by catastrophe and non-catastrophe losses. Unfavorable reserve reestimates for commercial auto during the second quarter are primarily from shared economy business written in states which Allstate has exited.
For a more detailed discussion on reinsurance and reserve reestimates, see Note 9 of the condensed consolidated financial statements.
| Reserve reestimates | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||||||||||||||||||||||||||
| Reserve reestimates (1) | Effect on combined ratio (2) | Reserve reestimates (1) | Effect on combined ratio (2) | |||||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions, except ratios) | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||||||||||||||||||||||
| Auto | $ | 237 | $ | (33) | 2.2 | (0.3) | $ | 379 | $ | (69) | 1.8 | (0.3) | ||||||||||||||||||||||||||||||||||||||
| Homeowners | 132 | 30 | 1.2 | 0.3 | 122 | (173) | 0.6 | (0.9) | ||||||||||||||||||||||||||||||||||||||||||
| Other personal lines | (2) | 1 | — | — | (9) | (17) | — | (0.1) | ||||||||||||||||||||||||||||||||||||||||||
| Commercial lines | 92 | 18 | 0.8 | 0.2 | 111 | 33 | 0.5 | 0.2 | ||||||||||||||||||||||||||||||||||||||||||
| Total Allstate Protection | $ | 459 | $ | 16 | 4.2 | 0.2 | $ | 603 | $ | (226) | 2.9 | (1.1) | ||||||||||||||||||||||||||||||||||||||
| Allstate brand | $ | 442 | $ | 12 | 4.1 | 0.2 | $ | 590 | $ | (216) | 2.8 | (1.0) | ||||||||||||||||||||||||||||||||||||||
| National General | 17 | 4 | 0.1 | — | 13 | (10) | 0.1 | (0.1) | ||||||||||||||||||||||||||||||||||||||||||
| Total Allstate Protection | $ | 459 | $ | 16 | 4.2 | 0.2 | $ | 603 | $ | (226) | 2.9 | (1.1) |
(1)Favorable reserve reestimates are shown in parentheses.
(2)Ratios are calculated using Allstate Protection premiums earned.
Second Quarter 2022 Form 10-Q 59
Segment Results Allstate Protection
Expense ratio decreased 1.7 and 0.5 points in the second quarter and first six months of 2022, respectively, compared to the second quarter and first six months of 2021, primarily due to lower advertising costs, restructuring and related charges and the impact of amortization of DAC, partially offset by higher operating costs. Higher operating costs are primarily due to employee-related costs.
| Impact of specific costs and expenses on the expense ratio | ||||||||||||||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||||||||||||||
| ($ in millions, except ratios) | 2022 | 2021 | Change | 2022 | 2021 | Change | ||||||||||||||||||||||||||||||||
| Amortization of DAC | $ | 1,355 | $ | 1,319 | $ | 36 | $ | 2,703 | $ | 2,622 | $ | 81 | ||||||||||||||||||||||||||
| Advertising expense | 253 | 312 | (59) | 596 | 624 | (28) | ||||||||||||||||||||||||||||||||
| Amortization of purchased intangibles | 59 | 71 | (12) | 117 | 90 | 27 | ||||||||||||||||||||||||||||||||
| Other costs and expenses, net of other revenue | 842 | 694 | 148 | 1,596 | 1,325 | 271 | ||||||||||||||||||||||||||||||||
| Restructuring and related charges | (2) | 65 | (67) | 10 | 97 | (87) | ||||||||||||||||||||||||||||||||
| Shelter-in-Place Payback expense | — | 29 | (29) | — | 29 | (29) | ||||||||||||||||||||||||||||||||
| Allstate Special Payment plan bad debt expense | — | (14) | 14 | — | (19) | 19 | ||||||||||||||||||||||||||||||||
| Total underwriting expenses | $ | 2,507 | $ | 2,476 | $ | 31 | $ | 5,022 | $ | 4,768 | $ | 254 | ||||||||||||||||||||||||||
| Premiums earned | $ | 10,874 | $ | 10,009 | $ | 865 | $ | 21,372 | $ | 19,905 | $ | 1,467 | ||||||||||||||||||||||||||
| Expense ratio | ||||||||||||||||||||||||||||||||||||||
| Amortization of DAC | 12.5 | 13.2 | (0.7) | 12.7 | 13.2 | (0.5) | ||||||||||||||||||||||||||||||||
| Advertising expense | 2.3 | 3.1 | (0.8) | 2.8 | 3.1 | (0.3) | ||||||||||||||||||||||||||||||||
| Other costs and expenses | 7.7 | 6.9 | 0.8 | 7.5 | 6.7 | 0.8 | ||||||||||||||||||||||||||||||||
| Subtotal | 22.5 | 23.2 | (0.7) | 23.0 | 23.0 | — | ||||||||||||||||||||||||||||||||
| Amortization of purchased intangibles | 0.5 | 0.7 | (0.2) | 0.5 | 0.5 | — | ||||||||||||||||||||||||||||||||
| Restructuring and related charges | — | 0.6 | (0.6) | — | 0.5 | (0.5) | ||||||||||||||||||||||||||||||||
| Shelter-in-Place Payback expense | — | 0.3 | (0.3) | — | 0.1 | (0.1) | ||||||||||||||||||||||||||||||||
| Allstate Special Payment plan bad debt expense | — | (0.1) | 0.1 | — | (0.1) | 0.1 | ||||||||||||||||||||||||||||||||
| Total expense ratio | 23.0 | 24.7 | (1.7) | 23.5 | 24.0 | (0.5) |
Run-off Property-Liability Segment Results
Run-off Property-Liability Segment
| Underwriting results | ||||||||||||||||||||||||||
| ($ in millions) | Three months ended June 30, | Six months ended June 30, | ||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||
| Claims and claims expense | $ | (3) | $ | (1) | $ | (4) | $ | (2) | ||||||||||||||||||
| Operating costs and expenses | — | (1) | (1) | (3) | ||||||||||||||||||||||
| Underwriting loss | $ | (3) | $ | (2) | $ | (5) | $ | (5) |
| Reserves for asbestos, environmental and other run-off claims before and after the effects of reinsurance | ||||||||||||||
| ($ in millions) | June 30, 2022 | December 31, 2021 | ||||||||||||
| Asbestos claims | ||||||||||||||
| Gross reserves | $ | 1,185 | $ | 1,210 | ||||||||||
| Reinsurance | (373) | (382) | ||||||||||||
| Net reserves | 812 | 828 | ||||||||||||
| Environmental claims | ||||||||||||||
| Gross reserves | 267 | 273 | ||||||||||||
| Reinsurance | (46) | (47) | ||||||||||||
| Net reserves | 221 | 226 | ||||||||||||
| Other run-off claims | ||||||||||||||
| Gross reserves | 424 | 433 | ||||||||||||
| Reinsurance | (65) | (66) | ||||||||||||
| Net reserves | 359 | 367 | ||||||||||||
| Total | ||||||||||||||
| Gross reserves | 1,876 | 1,916 | ||||||||||||
| Reinsurance | (484) | (495) | ||||||||||||
| Net reserves | $ | 1,392 | $ | 1,421 |
| Reserves by type of exposure before and after the effects of reinsurance | ||||||||||||||
| ($ in millions) | June 30, 2022 | December 31, 2021 | ||||||||||||
| Direct excess commercial insurance | ||||||||||||||
| Gross reserves | $ | 1,023 | $ | 1,050 | ||||||||||
| Reinsurance | (354) | (363) | ||||||||||||
| Net reserves | 669 | 687 | ||||||||||||
| Assumed reinsurance coverage | ||||||||||||||
| Gross reserves | 607 | 617 | ||||||||||||
| Reinsurance | (56) | (56) | ||||||||||||
| Net reserves | 551 | 561 | ||||||||||||
| Direct primary commercial insurance | ||||||||||||||
| Gross reserves | 164 | 168 | ||||||||||||
| Reinsurance | (73) | (75) | ||||||||||||
| Net reserves | 91 | 93 | ||||||||||||
| Other run-off business | ||||||||||||||
| Gross reserves | 1 | 1 | ||||||||||||
| Reinsurance | — | — | ||||||||||||
| Net reserves | 1 | 1 | ||||||||||||
| Unallocated loss adjustment expenses | ||||||||||||||
| Gross reserves | 81 | 80 | ||||||||||||
| Reinsurance | (1) | (1) | ||||||||||||
| Net reserves | 80 | 79 | ||||||||||||
| Total | ||||||||||||||
| Gross reserves | 1,876 | 1,916 | ||||||||||||
| Reinsurance | (484) | (495) | ||||||||||||
| Net reserves | $ | 1,392 | $ | 1,421 | ||||||||||
Second Quarter 2022 Form 10-Q 61
Segment Results Run-off Property-Liability
| Percentage of gross and ceded reserves by case and IBNR | ||||||||||||||||||||||||||
| June 30, 2022 | December 31, 2021 | |||||||||||||||||||||||||
| Case | IBNR | Case | IBNR | |||||||||||||||||||||||
| Direct excess commercial insurance | ||||||||||||||||||||||||||
| Gross reserves (1) | 70 | % | 30 | % | 61 | % | 39 | % | ||||||||||||||||||
| Ceded (2) | 80 | 20 | 67 | 33 | ||||||||||||||||||||||
| Assumed reinsurance coverage | ||||||||||||||||||||||||||
| Gross reserves | 35 | 65 | 33 | 67 | ||||||||||||||||||||||
| Ceded | 36 | 64 | 38 | 62 | ||||||||||||||||||||||
| Direct primary commercial insurance | ||||||||||||||||||||||||||
| Gross reserves | 53 | 47 | 53 | 47 | ||||||||||||||||||||||
| Ceded | 71 | 29 | 71 | 29 |
(1)Approximately 63% of gross case reserves as of June 30, 2022 are subject to settlement agreements.
(2)Approximately 69% of ceded case reserves as of June 30, 2022 are subject to settlement agreements.
| Gross payments from case reserves by type of exposure | ||||||||||||||||||||||||||
| ($ in millions) | Three months ended June 30, | Six months ended June 30, | ||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||
| Direct excess commercial insurance | ||||||||||||||||||||||||||
| Gross (1) | $ | 10 | $ | 16 | 28 | $ | 34 | |||||||||||||||||||
| Ceded (2) | (3) | (7) | (10) | (15) | ||||||||||||||||||||||
| Assumed reinsurance coverage | ||||||||||||||||||||||||||
| Gross | 5 | 11 | 11 | 22 | ||||||||||||||||||||||
| Ceded | — | (1) | (1) | (3) | ||||||||||||||||||||||
| Direct primary commercial insurance | ||||||||||||||||||||||||||
| Gross | 2 | 2 | 3 | 6 | ||||||||||||||||||||||
| Ceded | (1) | (2) | (1) | (3) | ||||||||||||||||||||||
| Other run-off business | ||||||||||||||||||||||||||
| Gross | — | — | — | — | ||||||||||||||||||||||
| Ceded | — | — | — | — |
(1) In the second quarter and first six months of 2022, 77% and 84% of payments related to settlement agreements.
(2) In the second quarter and first six months of 2022, 85% and 91% of payments related to settlement agreements.
Total net reserves as of June 30, 2022, included $652 million or 47% of estimated IBNR reserves compared to $733 million or 52% of estimated IBNR reserves as of December 31, 2021.
Total gross payments were $16 million and $41 million for the second quarter and first six months of 2022, respectively. Payments for the second quarter and first six months of 2022 primarily related to settlement agreements reached with several insureds
on large claims, mainly asbestos claims, where the scope of coverages has been agreed upon. The claims associated with these settlement agreements are expected to be substantially paid out over the next several years as qualified claims are submitted by these insureds. Reinsurance collections were $11 million and $21 million for the second quarter and first six months of 2022, respectively.
Protection Services Segment Results
Protection Services Segment

| Summarized financial information | ||||||||||||||||||||||||||
| ($ in millions) | Three months ended June 30, | Six months ended June 30, | ||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||
| Premiums written | $ | 670 | $ | 692 | $ | 1,300 | $ | 1,275 | ||||||||||||||||||
| Revenues | ||||||||||||||||||||||||||
| Premiums | $ | 488 | $ | 435 | $ | 971 | $ | 846 | ||||||||||||||||||
| Other revenue | 91 | 88 | 185 | 178 | ||||||||||||||||||||||
| Intersegment insurance premiums and service fees (1) | 38 | 46 | 79 | 87 | ||||||||||||||||||||||
| Net investment income | 12 | 12 | 21 | 22 | ||||||||||||||||||||||
| Costs and expenses | ||||||||||||||||||||||||||
| Claims and claims expense | (128) | (109) | (251) | (212) | ||||||||||||||||||||||
| Amortization of DAC | (228) | (194) | (449) | (375) | ||||||||||||||||||||||
| Operating costs and expenses | (213) | (203) | (431) | (401) | ||||||||||||||||||||||
| Restructuring and related charges | — | (4) | — | (13) | ||||||||||||||||||||||
| Income tax expense on operations | (16) | (15) | (28) | (27) | ||||||||||||||||||||||
| Less: noncontrolling interest | 1 | — | 1 | — | ||||||||||||||||||||||
| Adjusted net income | $ | 43 | $ | 56 | $ | 96 | $ | 105 | ||||||||||||||||||
| Allstate Protection Plans | $ | 36 | $ | 42 | $ | 79 | $ | 87 | ||||||||||||||||||
| Allstate Dealer Services | 8 | 10 | 17 | 18 | ||||||||||||||||||||||
| Allstate Roadside | 1 | 2 | 3 | 6 | ||||||||||||||||||||||
| Arity | (1) | 1 | (2) | 3 | ||||||||||||||||||||||
| Allstate Identity Protection | (1) | 1 | (1) | (9) | ||||||||||||||||||||||
| Adjusted net income | $ | 43 | $ | 56 | $ | 96 | $ | 105 | ||||||||||||||||||
| Allstate Protection Plans | 137,292 | 139,453 | ||||||||||||||||||||||||
| Allstate Dealer Services | 3,921 | 4,013 | ||||||||||||||||||||||||
| Allstate Roadside | 519 | 539 | ||||||||||||||||||||||||
| Allstate Identity Protection | 2,961 | 3,041 | ||||||||||||||||||||||||
| Policies in force as of June 30 (in thousands) | 144,693 | 147,046 |
(1)Primarily related to Arity and Allstate Roadside and are eliminated in our condensed consolidated financial statements.
Adjusted net income decreased 23.2% or $13 million in the second quarter of 2022 and decreased 8.6% or $9 million in the first six months of 2022 compared to the same periods of 2021, primarily driven by investments in geographic and product expansion at Allstate Protection Plans and increased severity at Allstate Roadside.
Premiums written decreased 3.2% or $22 million in the second quarter of 2022 primarily due to a decline in sales at Allstate Dealer Services and Allstate Protection Plans. Premiums written increased 2.0% or $25 million in the first six months of 2022, compared to the same periods of 2021, primarily due to growth at Allstate Roadside and Allstate Protection Plans.
PIF decreased 1.6% or 2 million as of June 30, 2022 compared to June 30, 2021 due to a decline in Allstate Protection Plans.
Other revenue increased 3.4% or $3 million in the second quarter of 2022 and increased 3.9% or $7 million in the first six months of 2022 compared to the same periods of 2021, reflecting growth at Allstate Identity Protection.
Intersegment premiums and service fees decreased 17.4% or $8 million in the second quarter of 2022 and decreased 9.2% or $8 million in the first six months of 2022, compared to the same periods of 2021 driven by decreased Arity device sales due to a shift from Drivewise® devices to a mobile program.
Claims and claims expense increased 17.4% or $19 million in the second quarter 2022 and increased 18.4% or $39 million in the first six months of 2022 compared to the same periods of 2021, primarily due to higher levels of claims at Allstate Protection Plans driven by growth of the business and increased claims cost at Allstate Roadside due to higher severity and rescue volumes.
Second Quarter 2022 Form 10-Q 63
Segment Results Protection Services
Amortization of DAC increased 17.5% or $34 million in the second quarter of 2022 and increased 19.7% or $74 million in the first six months of 2022 compared to the same periods of 2021, driven by Allstate Protection Plans and Allstate Dealer Services business growth.
Operating costs and expenses increased 4.9% or $10 million in the second quarter of 2022 and increased 7.5% or $30 million in the first six months of 2022 compared to the same periods of 2021, primarily due to investments in geographic and product expansion at Allstate Protection Plans and Allstate Identity Protection.
Restructuring and related charges decreased $4 million in the second quarter of 2022 and decreased $13 million in the first six months of 2022 compared to the same periods of 2021, primarily due to a facility closure at Allstate Identity Protection in the first quarter of 2021.
Allstate Health and Benefits Segment Results
Allstate Health and Benefits Segment
| Summarized financial information | ||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| Revenues | ||||||||||||||||||||||||||
| Accident and health insurance premiums and contract charges | $ | 466 | $ | 447 | $ | 935 | $ | 902 | ||||||||||||||||||
| Other revenue | 92 | 83 | 187 | 163 | ||||||||||||||||||||||
| Net investment income | 16 | 19 | 33 | 38 | ||||||||||||||||||||||
| Costs and expenses | ||||||||||||||||||||||||||
| Accident, health and other policy benefits | (269) | (252) | (538) | (494) | ||||||||||||||||||||||
| Amortization of DAC | (36) | (32) | (79) | (71) | ||||||||||||||||||||||
| Operating costs and expenses | (185) | (186) | (387) | (376) | ||||||||||||||||||||||
| Restructuring and related charges | (2) | (1) | (2) | (1) | ||||||||||||||||||||||
| Income tax expense on operations | (17) | (16) | (31) | (34) | ||||||||||||||||||||||
| Adjusted net income | $ | 65 | $ | 62 | $ | 118 | $ | 127 | ||||||||||||||||||
| Benefit ratio (1) | 55.8 | 54.6 | 55.7 | 52.9 | ||||||||||||||||||||||
| Employer voluntary benefits (2) | 3,832 | 3,913 | ||||||||||||||||||||||||
| Group health (3) | 115 | 120 | ||||||||||||||||||||||||
| Individual health (4) | 421 | 419 | ||||||||||||||||||||||||
| Policies in force as of June 30 (in thousands) | 4,368 | 4,452 |
(1)Benefit ratio is calculated as accident, health and other policy benefits less interest credited to contractholder funds of $9 million and $8 million for the three months ended June 30, 2022 and 2021, respectively, and $17 million for both the six months ended June 30, 2022 and 2021, divided by premiums and contract charges.
(2)Employer voluntary benefits include supplemental life and health products offered through workplace enrollment.
(3)Group health includes health products and administrative services sold to employers.
(4)Individual health includes short-term medical and other health products sold directly to individuals.
Adjusted net income increased $3 million in the second quarter of 2022 compared to the second quarter of 2021, primarily due to an increase in group health revenues, partially offset by an increase in individual health claims. Adjusted net income decreased $9 million in the first six months of 2022, compared to the same period of 2021, primarily due to increases in individual and group health claims, partially offset by lower employer voluntary benefits claim utilization.
Premiums and contract charges increased 4.3% or $19 million in the second quarter of 2022 and increased 3.7% or $33 million in the first six months of 2022 compared to the same periods of 2021, primarily due to growth in individual and group health.
| Premiums and contract charges by line of business | ||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| Employer voluntary benefits | $ | 257 | $ | 255 | $ | 523 | $ | 518 | ||||||||||||||||||
| Group health | 95 | 87 | 189 | 170 | ||||||||||||||||||||||
| Individual health | 114 | 105 | 223 | 214 | ||||||||||||||||||||||
| Premiums and contract charges | $ | 466 | $ | 447 | $ | 935 | $ | 902 |
Other revenue increased $9 million and $24 million in the second quarter and first six months of 2022, respectively, compared to the same periods of 2021, primarily due to an increase in group health administrative fees.
Accident, health and other policy benefits increased 6.7% or $17 million in the second quarter of 2022 and increased 8.9% or $44 million in the first six months of 2022 compared to the same periods of 2021, primarily due to increased benefits utilization for
individual health and group health, partially offset by lower utilization for employer voluntary benefits.
Benefit ratio increased to 55.8 and 55.7 in the second quarter and the first six months of 2022, respectively, compared to 54.6 and 52.9 in the same periods of 2021, primarily due to an increase in individual and group health claims, partially offset by a lower benefit ratio for employer voluntary benefits products due to lower accident and health claim
Second Quarter 2022 Form 10-Q 65
Segment Results Allstate Health and Benefits
experience and lower life mortality compared to the prior year.
Amortization of DAC increased 12.5% or $4 million in the second quarter of 2022 and increased 11.3% or
$8 million in the first six months of 2022 compared to the same periods of 2021, primarily related to employer voluntary benefits.
| Operating costs and expenses | ||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| Non-deferrable commissions | $ | 72 | $ | 77 | $ | 153 | $ | 151 | ||||||||||||||||||
| General and administrative expenses | 113 | 109 | 234 | 225 | ||||||||||||||||||||||
| Total operating costs and expenses | $ | 185 | $ | 186 | $ | 387 | $ | 376 |
Operating costs and expenses decreased $1 million in the second quarter of 2022 compared to the second quarter of 2021, primarily due to a decrease in employer voluntary benefits. Operating costs and expenses increased $11 million in the first six months of 2022 compared to the same period of 2021, primarily due to growth in group health.
Analysis of reserves
| Reserve for future policy benefits | ||||||||||||||
| ($ in millions) | June 30, 2022 | December 31, 2021 | ||||||||||||
| Traditional life insurance and other | $ | 326 | $ | 313 | ||||||||||
| Accident and health insurance | 969 | 960 | ||||||||||||
| Reserve for future policy benefits | $ | 1,295 | $ | 1,273 |
Investments
Investments
| Portfolio composition and strategy by reporting segment (1) | ||||||||||||||||||||||||||||||||
| June 30, 2022 | ||||||||||||||||||||||||||||||||
| ($ in millions) | Property-Liability | Protection Services | Allstate Health and Benefits | Corporate and Other | Total | |||||||||||||||||||||||||||
| Fixed income securities (2) | $ | 33,984 | $ | 1,637 | $ | 1,660 | $ | 4,001 | $ | 41,282 | ||||||||||||||||||||||
| Equity securities (3) | 3,910 | 139 | 66 | 566 | 4,681 | |||||||||||||||||||||||||||
| Mortgage loans, net | 748 | — | 100 | — | 848 | |||||||||||||||||||||||||||
| Limited partnership interests | 7,935 | — | — | 8 | 7,943 | |||||||||||||||||||||||||||
| Short-term investments (4) | 3,748 | 89 | 41 | 506 | 4,384 | |||||||||||||||||||||||||||
| Other investments, net | 1,770 | — | 145 | 2 | 1,917 | |||||||||||||||||||||||||||
| Total | $ | 52,095 | $ | 1,865 | $ | 2,012 | $ | 5,083 | $ | 61,055 | ||||||||||||||||||||||
| Percent to total | 85.3 | % | 3.1 | % | 3.3 | % | 8.3 | % | 100.0 | % | ||||||||||||||||||||||
| Market-based | $ | 43,243 | $ | 1,865 | $ | 2,012 | $ | 5,081 | $ | 52,201 | ||||||||||||||||||||||
| Performance-based | 8,852 | — | — | 2 | 8,854 | |||||||||||||||||||||||||||
| Total | $ | 52,095 | $ | 1,865 | $ | 2,012 | $ | 5,083 | $ | 61,055 |
(1) Balances reflect the elimination of related party investments between segments.
(2) Fixed income securities are carried at fair value. Amortized cost, net for these securities was $36.37 billion, $1.76 billion, $1.81 billion, $4.09 billion and $44.03 billion for Property-Liability, Protection Services, Allstate Health and Benefits, Corporate and Other, and in total, respectively.
(3) Equity securities are carried at fair value. The fair value of equity securities held as of June 30, 2022, was $271 million in excess of cost. These net gains were primarily concentrated in the technology, consumer goods and banking sectors. Equity securities include $1.08 billion of funds with underlying investments in fixed income securities as of June 30, 2022.
(4) Short-term investments are carried at fair value.
Investments totaled $61.06 billion as of June 30, 2022, decreasing from $64.70 billion as of December 31, 2021, primarily due to lower fixed income and equity valuations, common share repurchases and dividends paid to shareholders, partially offset by positive operating cash flows.
Portfolio composition by investment strategy We utilize two primary strategies to manage risks and returns and to position our portfolio to take advantage of market opportunities while attempting to mitigate adverse effects. As strategies and market conditions evolve, the asset allocation may change.
Market-based strategy seeks to deliver predictable earnings aligned to business needs and take advantage of short-term opportunities primarily through public and private fixed income investments and public equity securities.
Performance-based strategy seeks to deliver attractive risk-adjusted returns and supplement market risk with idiosyncratic risk primarily through investments in private equity, including infrastructure
investments, and real estate, most of which were limited partnerships. These investments include investee level expenses, reflecting asset level operating expenses on directly held real estate and other consolidated investments.
Macroeconomic impacts Future investment results will be influenced by the magnitude and duration of the global pandemic and the impact of actions taken by governmental authorities, businesses and consumers, which creates significant uncertainty. Supply chain disruptions, labor shortages and other macroeconomic factors have increased inflation, which may have an adverse impact on investment valuations and returns.
Investments in Russia and Ukraine As of June 30, 2022, we do not have any direct investments in Russia, Belarus or Ukraine. We have indirect exposure of less than $1 million in Russia and Ukraine through broad-based, global funds managed by external asset managers.
Second Quarter 2022 Form 10-Q 67
Investments
| Portfolio composition by investment strategy | ||||||||||||||||||||
| June 30, 2022 | ||||||||||||||||||||
| ($ in millions) | Market- based | Performance-based | Total | |||||||||||||||||
| Fixed income securities | $ | 41,181 | $ | 101 | $ | 41,282 | ||||||||||||||
| Equity securities | 4,259 | 422 | 4,681 | |||||||||||||||||
| Mortgage loans, net | 848 | — | 848 | |||||||||||||||||
| Limited partnership interests | 437 | 7,506 | 7,943 | |||||||||||||||||
| Short-term investments | 4,384 | — | 4,384 | |||||||||||||||||
| Other investments, net | 1,092 | 825 | 1,917 | |||||||||||||||||
| Total | $ | 52,201 | $ | 8,854 | $ | 61,055 | ||||||||||||||
| Percent to total | 85.5 | % | 14.5 | % | 100.0 | % | ||||||||||||||
| Unrealized net capital gains and losses | ||||||||||||||||||||
| Fixed income securities | $ | (2,744) | $ | (1) | $ | (2,745) | ||||||||||||||
| Limited partnership interests | — | 7 | 7 | |||||||||||||||||
| Other | (3) | — | (3) | |||||||||||||||||
| Total | $ | (2,747) | $ | 6 | $ | (2,741) |
Fixed income securities
| Fixed income securities by type | ||||||||||||||||||||||||||
| Fair value as of | ||||||||||||||||||||||||||
| ($ in millions) | June 30, 2022 | December 31, 2021 | ||||||||||||||||||||||||
| U.S. government and agencies | $ | 8,745 | $ | 6,273 | ||||||||||||||||||||||
| Municipal | 5,911 | 6,393 | ||||||||||||||||||||||||
| Corporate | 24,092 | 27,330 | ||||||||||||||||||||||||
| Foreign government | 972 | 985 | ||||||||||||||||||||||||
| Asset-backed securities (“ABS”) | 1,562 | 1,155 | ||||||||||||||||||||||||
| Total fixed income securities | $ | 41,282 | $ | 42,136 |
Fixed income securities are rated by third-party credit rating agencies or are internally rated. The Securities Valuation Office (“SVO”) of the National Association of Insurance Commissioners (“NAIC”) evaluates the fixed income securities of insurers for regulatory reporting and capital assessment purposes. The NAIC assigns securities to one of six credit quality categories defined as “NAIC designations.” In general, securities with NAIC designations of 1 and 2 are considered investment grade and securities with NAIC designations of 3 through 6 are considered below investment grade. The rating is either received from the SVO based on availability of applicable ratings from rating agencies on the NAIC Nationally Recognized Statistical Rating Organizations (“NRSRO”) provider list, including Moody’s Investors Service (“Moody’s”), S&P Global Ratings (“S&P”), Fitch Ratings (“Fitch”), or a comparable internal rating.
As a result of time lags between the funding of investments, the finalization of legal documents, and the completion of the SVO filing process, the portfolio includes certain securities that have not yet been designated by the SVO as of each balance sheet date and the categorization of these securities is based on the expected ratings indicated by internal analysis.
As of June 30, 2022, 88.8% of the consolidated fixed income securities portfolio was rated investment grade. Credit ratings below these designations are considered lower credit quality or below investment grade, which includes high yield bonds.
Market prices for certain securities may have credit spreads which imply higher or lower credit quality than the current third-party rating. Our initial investment decisions and ongoing monitoring procedures for fixed income securities are based on a due diligence process which includes, but is not limited to, an assessment of the credit quality, sector, structure, and liquidity risks of each issuer.
Fixed income portfolio monitoring is a comprehensive process to identify and evaluate each fixed income security that may require a credit loss allowance. The process includes a quarterly review of all securities to identify instances where the fair value of a security compared to its amortized cost is below internally established thresholds. For further detail on our fixed income portfolio monitoring process, see Note 5 of the condensed consolidated financial statements.
Investments
The following table presents total fixed income securities by the applicable NAIC designation and comparable S&P rating.
| Fair value and unrealized net capital gains (losses) for fixed income securities by credit rating | ||||||||||||||||||||||||||||||||||||||
| June 30, 2022 | ||||||||||||||||||||||||||||||||||||||
| NAIC 1 | NAIC 2 | NAIC 3 | ||||||||||||||||||||||||||||||||||||
| A and above | BBB | BB | ||||||||||||||||||||||||||||||||||||
| ($ in millions) | Fair value | Unrealized gain (loss) | Fair value | Unrealized gain (loss) | Fair value | Unrealized gain (loss) | ||||||||||||||||||||||||||||||||
| U.S. government and agencies | $ | 8,745 | $ | (133) | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||||||
| Municipal | 5,587 | (245) | 309 | (23) | — | — | ||||||||||||||||||||||||||||||||
| Corporate | ||||||||||||||||||||||||||||||||||||||
| Public | 4,346 | (246) | 10,271 | (846) | 1,139 | (156) | ||||||||||||||||||||||||||||||||
| Privately placed | 1,543 | (97) | 3,397 | (296) | 1,749 | (290) | ||||||||||||||||||||||||||||||||
| Total corporate | 5,889 | (343) | 13,668 | (1,142) | 2,888 | (446) | ||||||||||||||||||||||||||||||||
| Foreign government | 971 | (49) | 1 | — | — | — | ||||||||||||||||||||||||||||||||
| ABS | 1,490 | (47) | 11 | (1) | 9 | (1) | ||||||||||||||||||||||||||||||||
| Total fixed income securities | $ | 22,682 | $ | (817) | $ | 13,989 | $ | (1,166) | $ | 2,897 | $ | (447) | ||||||||||||||||||||||||||
| NAIC 4 | NAIC 5-6 | Total | ||||||||||||||||||||||||||||||||||||
| B | CCC and lower | |||||||||||||||||||||||||||||||||||||
| Fair value | Unrealized gain (loss) | Fair value | Unrealized gain (loss) | Fair value | Unrealized gain (loss) | |||||||||||||||||||||||||||||||||
| U.S. government and agencies | $ | — | $ | — | $ | — | $ | — | $ | 8,745 | $ | (133) | ||||||||||||||||||||||||||
| Municipal | 9 | — | 6 | 2 | 5,911 | (266) | ||||||||||||||||||||||||||||||||
| Corporate | ||||||||||||||||||||||||||||||||||||||
| Public | 132 | (22) | 3 | — | 15,891 | (1,270) | ||||||||||||||||||||||||||||||||
| Privately placed | 1,337 | (255) | 175 | (35) | 8,201 | (973) | ||||||||||||||||||||||||||||||||
| Total corporate | 1,469 | (277) | 178 | (35) | 24,092 | (2,243) | ||||||||||||||||||||||||||||||||
| Foreign government | — | — | — | — | 972 | (49) | ||||||||||||||||||||||||||||||||
| ABS | — | — | 52 | (5) | 1,562 | (54) | ||||||||||||||||||||||||||||||||
| Total fixed income securities | $ | 1,478 | $ | (277) | $ | 236 | $ | (38) | $ | 41,282 | $ | (2,745) |
Municipal bonds, including tax-exempt and taxable securities, include general obligations of state and local issuers and revenue bonds.
Corporate bonds include publicly traded and privately placed securities. Privately placed securities primarily consist of corporate issued senior debt securities that are negotiated with the borrower or are issued by public entities in unregistered form.
ABS includes collateralized debt obligations, consumer and other ABS. Credit risk is managed by monitoring the performance of the underlying collateral. Many of the securities in the ABS portfolio have credit enhancement with features such as overcollateralization, subordinated structures, reserve funds, guarantees or insurance. ABS also includes residential mortgage-backed securities and commercial mortgage back securities.
Equity securities of $4.68 billion primarily include common stocks, exchange traded and mutual funds, non-redeemable preferred stocks and real estate investment trust (“REIT”) equity investments. Certain exchange traded and mutual funds have fixed income securities as their underlying investments.
Mortgage loans of $848 million mainly comprise loans secured by first mortgages on developed commercial real estate. Key considerations used to manage our exposure include property type and geographic diversification. For further detail on our mortgage loan portfolio, see Note 5 of the condensed consolidated financial statements.
Limited partnership interests include $6.58 billion of interests in private equity funds, $928 million of interests in real estate funds and $437 million of interests in other funds as of June 30, 2022. We have commitments to invest additional amounts in limited partnership interests totaling $2.64 billion as of June 30, 2022.
Other investments include $868 million of bank loans, net, and $741 million of direct investments in real estate as of June 30, 2022.
Second Quarter 2022 Form 10-Q 69
Investments
| Unrealized net capital gains (losses) | ||||||||||||||
| June 30, | December 31, | |||||||||||||
| ($ in millions) | 2022 | 2021 | ||||||||||||
| U.S. government and agencies | $ | (133) | $ | (14) | ||||||||||
| Municipal | (266) | 263 | ||||||||||||
| Corporate | (2,243) | 496 | ||||||||||||
| Foreign government | (49) | 3 | ||||||||||||
| ABS | (54) | 12 | ||||||||||||
| Fixed income securities | (2,745) | 760 | ||||||||||||
| Short-term investments | — | — | ||||||||||||
| Derivatives | (3) | (3) | ||||||||||||
| Equity method of accounting (“EMA”) limited partnerships | 7 | (1) | ||||||||||||
| Unrealized net capital gains and losses, pre-tax | $ | (2,741) | $ | 756 |
Investments
| Gross unrealized gains (losses) on fixed income securities by type and sector | ||||||||||||||||||||||||||
| June 30, 2022 | ||||||||||||||||||||||||||
| ($ in millions) | Amortized cost, net | Gross unrealized | Fair value | |||||||||||||||||||||||
| Gains | Losses | |||||||||||||||||||||||||
| Corporate | ||||||||||||||||||||||||||
| Consumer goods (cyclical and non-cyclical) | $ | 6,217 | $ | 4 | $ | (588) | $ | 5,633 | ||||||||||||||||||
| Technology | 2,978 | 1 | (263) | 2,716 | ||||||||||||||||||||||
| Banking | 4,092 | 1 | (259) | 3,834 | ||||||||||||||||||||||
| Capital goods | 2,276 | 1 | (226) | 2,051 | ||||||||||||||||||||||
| Communications | 2,190 | — | (221) | 1,969 | ||||||||||||||||||||||
| Utilities | 2,215 | 2 | (170) | 2,047 | ||||||||||||||||||||||
| Financial services | 2,015 | 1 | (169) | 1,847 | ||||||||||||||||||||||
| Energy | ||||||||||||||||||||||||||
| Midstream | 1,328 | 1 | (101) | 1,228 | ||||||||||||||||||||||
| Independent/upstream | 333 | 1 | (32) | 302 | ||||||||||||||||||||||
| Integrated | 93 | — | (4) | 89 | ||||||||||||||||||||||
| Other | 215 | — | (13) | 202 | ||||||||||||||||||||||
| Total energy | 1,969 | 2 | (150) | 1,821 | ||||||||||||||||||||||
| Basic industry | 1,102 | 1 | (83) | 1,020 | ||||||||||||||||||||||
| Transportation | 892 | 1 | (67) | 826 | ||||||||||||||||||||||
| Other | 389 | — | (61) | 328 | ||||||||||||||||||||||
| Total corporate fixed income portfolio | 26,335 | 14 | (2,257) | 24,092 | ||||||||||||||||||||||
| U.S. government and agencies | 8,878 | 8 | (141) | 8,745 | ||||||||||||||||||||||
| Municipal | 6,177 | 18 | (284) | 5,911 | ||||||||||||||||||||||
| Foreign government | 1,021 | — | (49) | 972 | ||||||||||||||||||||||
| ABS | 1,616 | 3 | (57) | 1,562 | ||||||||||||||||||||||
| Total fixed income securities | $ | 44,027 | $ | 43 | $ | (2,788) | $ | 41,282 |
| December 31, 2021 | ||||||||||||||||||||||||||
| ($ in millions) | Amortized cost, net | Gross unrealized | Fair value | |||||||||||||||||||||||
| Gains | Losses | |||||||||||||||||||||||||
| Corporate | ||||||||||||||||||||||||||
| Consumer goods (cyclical and non-cyclical) | $ | 6,817 | $ | 176 | $ | (42) | $ | 6,951 | ||||||||||||||||||
| Technology | 2,947 | 80 | (23) | 3,004 | ||||||||||||||||||||||
| Banking | 3,975 | 54 | (31) | 3,998 | ||||||||||||||||||||||
| Capital goods | 2,615 | 75 | (12) | 2,678 | ||||||||||||||||||||||
| Communications | 2,077 | 58 | (21) | 2,114 | ||||||||||||||||||||||
| Utilities | 2,009 | 43 | (28) | 2,024 | ||||||||||||||||||||||
| Financial services | 1,936 | 41 | (14) | 1,963 | ||||||||||||||||||||||
| Energy | ||||||||||||||||||||||||||
| Midstream | 1,132 | 37 | (4) | 1,165 | ||||||||||||||||||||||
| Independent/upstream | 312 | 18 | (1) | 329 | ||||||||||||||||||||||
| Integrated | 119 | 6 | — | 125 | ||||||||||||||||||||||
| Other | 224 | 6 | (1) | 229 | ||||||||||||||||||||||
| Total energy | 1,787 | 67 | (6) | 1,848 | ||||||||||||||||||||||
| Basic industry | 1,249 | 56 | (6) | 1,299 | ||||||||||||||||||||||
| Transportation | 976 | 35 | (5) | 1,006 | ||||||||||||||||||||||
| Other | 446 | 3 | (4) | 445 | ||||||||||||||||||||||
| Total corporate fixed income portfolio | 26,834 | 688 | (192) | 27,330 | ||||||||||||||||||||||
| U.S. government and agencies | 6,287 | 12 | (26) | 6,273 | ||||||||||||||||||||||
| Municipal | 6,130 | 279 | (16) | 6,393 | ||||||||||||||||||||||
| Foreign government | 982 | 9 | (6) | 985 | ||||||||||||||||||||||
| ABS | 1,143 | 14 | (2) | 1,155 | ||||||||||||||||||||||
| Total fixed income securities | $ | 41,376 | $ | 1,002 | $ | (242) | $ | 42,136 |
In general, the gross unrealized losses are related to an increase in market yields which may include increased risk-free interest rates and wider credit spreads since the time of initial purchase. Similarly, gross unrealized gains reflect a decrease in market yields since the time of initial purchase.
Second Quarter 2022 Form 10-Q 71
Investments
| Equity securities by sector | ||||||||||||||||||||||||||||||||||||||
| June 30, 2022 | December 31, 2021 | |||||||||||||||||||||||||||||||||||||
| ($ in millions) | Cost | Over (under) cost | Fair value | Cost | Over (under) cost | Fair value | ||||||||||||||||||||||||||||||||
| Capital Goods | 198 | (9) | 189 | 376 | 37 | 413 | ||||||||||||||||||||||||||||||||
| Basic Industry | $ | 64 | $ | 8 | $ | 72 | $ | 119 | $ | 30 | $ | 149 | ||||||||||||||||||||||||||
| Utilities | 76 | 13 | 89 | 122 | 23 | 145 | ||||||||||||||||||||||||||||||||
| Transportation | 49 | 13 | 62 | 74 | 22 | 96 | ||||||||||||||||||||||||||||||||
| Energy | ||||||||||||||||||||||||||||||||||||||
| Midstream | 38 | 2 | 40 | 39 | 7 | 46 | ||||||||||||||||||||||||||||||||
| Independent/upstream | 32 | 10 | 42 | 44 | 5 | 49 | ||||||||||||||||||||||||||||||||
| Integrated | 41 | 18 | 59 | 62 | 8 | 70 | ||||||||||||||||||||||||||||||||
| Other | 7 | 5 | 12 | 14 | 3 | 17 | ||||||||||||||||||||||||||||||||
| Total energy | 118 | 35 | 153 | 159 | 23 | 182 | ||||||||||||||||||||||||||||||||
| Other (1) | 1,803 | 346 | 2,149 | 3,413 | 811 | 4,224 | ||||||||||||||||||||||||||||||||
| Funds | ||||||||||||||||||||||||||||||||||||||
| Fixed income | 1,164 | (82) | 1,082 | 1,108 | 24 | 1,132 | ||||||||||||||||||||||||||||||||
| Equities | 918 | (53) | 865 | 645 | 75 | 720 | ||||||||||||||||||||||||||||||||
| Other | 20 | — | 20 | — | — | — | ||||||||||||||||||||||||||||||||
| Total funds | 2,102 | (135) | 1,967 | 1,753 | 99 | 1,852 | ||||||||||||||||||||||||||||||||
| Total equity securities | $ | 4,410 | $ | 271 | $ | 4,681 | $ | 6,016 | $ | 1,045 | $ | 7,061 |
(1)Other is comprised of communications, REITs, financial services, banking, technology and consumer goods sectors.
| Net investment income | ||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| Fixed income securities | $ | 299 | $ | 290 | $ | 566 | $ | 591 | ||||||||||||||||||
| Equity securities | 34 | 13 | 70 | 27 | ||||||||||||||||||||||
| Mortgage loans | 9 | 12 | 17 | 22 | ||||||||||||||||||||||
| Limited partnership interests | 224 | 651 | 516 | 1,029 | ||||||||||||||||||||||
| Short-term investments | 10 | 1 | 12 | 2 | ||||||||||||||||||||||
| Other investments | 42 | 48 | 82 | 89 | ||||||||||||||||||||||
| Investment income, before expense | 618 | 1,015 | 1,263 | 1,760 | ||||||||||||||||||||||
| Investment expense | ||||||||||||||||||||||||||
| Investee level expenses | (14) | (11) | (30) | (24) | ||||||||||||||||||||||
| Securities lending expense | (3) | — | (3) | — | ||||||||||||||||||||||
| Operating costs and expenses | (39) | (30) | (74) | (54) | ||||||||||||||||||||||
| Total investment expense | (56) | (41) | (107) | (78) | ||||||||||||||||||||||
| Net investment income | $ | 562 | $ | 974 | $ | 1,156 | $ | 1,682 | ||||||||||||||||||
| Property-Liability | $ | 506 | $ | 931 | $ | 1,064 | $ | 1,604 | ||||||||||||||||||
| Protection Services | 12 | 12 | 21 | 22 | ||||||||||||||||||||||
| Allstate Health and Benefits | 16 | 19 | 33 | 38 | ||||||||||||||||||||||
| Corporate and Other | 28 | 12 | 38 | 18 | ||||||||||||||||||||||
| Net investment income | $ | 562 | $ | 974 | $ | 1,156 | $ | 1,682 | ||||||||||||||||||
| Market-based | $ | 369 | $ | 356 | $ | 694 | $ | 711 | ||||||||||||||||||
| Performance-based | 249 | 659 | 569 | 1,049 | ||||||||||||||||||||||
| Investment income, before expense | $ | 618 | $ | 1,015 | $ | 1,263 | $ | 1,760 |
Net investment income decreased $412 million and $526 million in the second quarter and first six months of 2022, respectively, compared to the same periods of 2021, primarily due to lower performance-based results, mainly from limited partnerships. The decrease in the second quarter was slightly offset by higher market-based fixed income portfolio yields.
Investments
| Performance-based investment income | ||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| Private equity | $ | 129 | $ | 552 | $ | 377 | $ | 882 | ||||||||||||||||||
| Real estate | 120 | 107 | 192 | 167 | ||||||||||||||||||||||
| Total performance-based income before investee level expenses | $ | 249 | $ | 659 | $ | 569 | $ | 1,049 | ||||||||||||||||||
| Investee level expenses (1) | (13) | (10) | (27) | (22) | ||||||||||||||||||||||
| Total performance-based income | $ | 236 | $ | 649 | $ | 542 | $ | 1,027 |
(1)Investee level expenses include asset level operating expenses reported in investment expense.
Performance-based investment income decreased $413 million and $485 million in the second quarter and first six months of 2022, respectively, compared to strong results in the same periods of 2021, primarily due to lower valuation increases and net gains on the sale of underlying investments.
Performance-based investment results and income can vary significantly between periods and are
influenced by economic conditions, equity market performance, comparable public company earnings multiples, capitalization rates, operating performance of the underlying investments and the timing of asset sales. The company typically employs a lag in recording and recognizing changes in valuations of limited partnership interests due to the availability of investee financial statements.
| Components of net gains (losses) on investments and derivatives and the related tax effect | ||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| Sales | $ | (303) | $ | 115 | $ | (430) | $ | 361 | ||||||||||||||||||
| Credit losses | (13) | 12 | (24) | 14 | ||||||||||||||||||||||
| Valuation change of equity investments - appreciation (decline): | ||||||||||||||||||||||||||
| Equity securities | (508) | 138 | (855) | 319 | ||||||||||||||||||||||
| Equity fund investments in fixed income securities | (128) | 14 | (128) | (3) | ||||||||||||||||||||||
| Limited partnerships (1) | (53) | 11 | (153) | 14 | ||||||||||||||||||||||
| Total valuation of equity investments | (689) | 163 | (1,136) | 330 | ||||||||||||||||||||||
| Valuation change and settlements of derivatives | 272 | (3) | 590 | 8 | ||||||||||||||||||||||
| Net gains (losses) on investments and derivatives, pre-tax | (733) | 287 | (1,000) | 713 | ||||||||||||||||||||||
| Income tax benefit (expense) | 160 | (64) | 216 | (158) | ||||||||||||||||||||||
| Net gains (losses) on investments and derivatives, after-tax | $ | (573) | $ | 223 | $ | (784) | $ | 555 | ||||||||||||||||||
| Property-Liability | $ | (517) | $ | 207 | $ | (678) | $ | 521 | ||||||||||||||||||
| Protection Services | (23) | 4 | (33) | 12 | ||||||||||||||||||||||
| Allstate Health and Benefits | (10) | 3 | (15) | 5 | ||||||||||||||||||||||
| Corporate and Other | (23) | 9 | (58) | 17 | ||||||||||||||||||||||
| Net gains (losses) on investments and derivatives, after-tax | $ | (573) | $ | 223 | $ | (784) | $ | 555 | ||||||||||||||||||
| Market-based | $ | (778) | $ | 248 | $ | (1,082) | $ | 585 | ||||||||||||||||||
| Performance-based | 45 | 39 | 82 | 128 | ||||||||||||||||||||||
| Net gains (losses) on investments and derivatives, pre-tax | $ | (733) | $ | 287 | $ | (1,000) | $ | 713 |
(1)Relates to limited partnerships where the underlying assets are predominately public equity securities.
Net losses on investments and derivatives in the second quarter and first six months of 2022 related primarily to lower valuation on equity investments and losses on sales, partially offset by increased valuation change and settlements of derivatives.
Sales in the second quarter and first six months of 2022 related primarily to sales of fixed income securities in connection with ongoing portfolio management.
Valuation change and settlements of derivatives of $272 million and $590 million in the second quarter and first six months of 2022, respectively, primarily comprised of gains on interest rate futures used as part of an interest rate risk reduction strategy to mitigate the impact of increases in interest rates and gains on equity futures and options used to mitigate the impact of declining equity markets.
Second Quarter 2022 Form 10-Q 73
Investments
| Net gains (losses) on performance-based investments and derivatives | ||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| ($ in millions) | 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||||
| Sales | $ | 27 | $ | 25 | $ | 50 | $ | 84 | ||||||||||||||||||
| Credit losses | (3) | — | (7) | — | ||||||||||||||||||||||
| Valuation change of equity investments | (16) | 17 | (5) | 37 | ||||||||||||||||||||||
| Valuation change and settlements of derivatives | 37 | (3) | 44 | 7 | ||||||||||||||||||||||
| Total performance-based | $ | 45 | $ | 39 | $ | 82 | $ | 128 | ||||||||||||||||||
Net gains on performance-based investments and derivatives in the second quarter and first six months of 2022 primarily related to increased valuation change and settlements of derivatives and gains on sales, partially offset by decreased valuation of equity investments.
Capital Resources and Liquidity
Capital Resources and Liquidity
Capital resources consist of shareholders’ equity and debt, representing funds deployed or available to be deployed to support business operations or for general corporate purposes.
| Capital resources | ||||||||||||||
| ($ in millions) | June 30, 2022 | December 31, 2021 | ||||||||||||
| Preferred stock, common stock, treasury stock, retained income and other shareholders’ equity items | $ | 22,273 | $ | 24,524 | ||||||||||
| Accumulated other comprehensive (loss) income | (2,158) | 655 | ||||||||||||
| Total Allstate shareholders’ equity | 20,115 | 25,179 | ||||||||||||
| Debt | 7,970 | 7,976 | ||||||||||||
| Total capital resources | $ | 28,085 | $ | 33,155 | ||||||||||
| Ratio of debt to Allstate shareholders’ equity | 39.6 | % | 31.7 | % | ||||||||||
| Ratio of debt to capital resources | 28.4 | 24.1 | ||||||||||||
Allstate shareholders’ equity decreased in the first six months of 2022, primarily due to net unrealized capital losses on investments in 2022 compared to gains at December 31, 2021, common share repurchases, dividends paid to shareholders and a net loss. In the six months ended June 30, 2022, we paid dividends of $466 million and $53 million related to our common and preferred shares, respectively.
Debt maturities We do not have any scheduled debt maturities in 2022.
| Debt maturities for each of the next five years and thereafter (excluding issuance costs and other) | ||||||||
| ($ in millions) | ||||||||
| 2023 | $ | 750 | ||||||
| 2024 | 350 | |||||||
| 2025 | 600 | |||||||
| 2026 | 550 | |||||||
| 2027 | — | |||||||
| Thereafter | 5,741 | |||||||
| Total long-term debt principal | $ | 7,991 |
Common share repurchases As of June 30, 2022, there was $1.82 billion remaining in the $5.00 billion common share repurchase program that is expected to be completed by March 31, 2023.
During the first six months of 2022, we repurchased 11.6 million common shares, or 4.1% of total common shares outstanding at December 31, 2021, for $1.48 billion.
Common shareholder dividends On January 3, 2022 and April 1, 2022, we paid a common shareholder dividend of $0.81 and $0.85, respectively. On May 23, 2022, we declared a common shareholder dividend of $0.85 payable on July 1, 2022.
Financial ratings and strength Our ratings are influenced by many factors including our operating and financial performance, asset quality, liquidity, overall portfolio mix, financial leverage (i.e., debt), exposure to risks such as catastrophes and the current level of operating leverage. The preferred stock and subordinated debentures are viewed as having a common equity component by certain rating agencies and are given equity credit up to a pre-determined limit in our capital structure as determined by their respective methodologies. These respective
methodologies consider the existence of certain terms and features in the instruments such as the noncumulative dividend feature in the preferred stock.
In May 2022, Moody’s affirmed The Allstate Corporation’s (the “Corporation’s”) debt and short-term issuer ratings of A3 and P-2, respectively, and the insurance financial strength rating of Aa3 for Allstate Insurance Company (“AIC”). The outlook for the ratings is stable.
In June 2022, S&P affirmed the Corporation’s debt and short-term issuer ratings of A- and A-2, respectively, and the insurance financial strength rating of AA- for AIC. The outlook for the ratings is stable.
There have been no changes to our ratings for A.M. Best since December 31, 2021.
Liquidity sources and uses We actively manage our financial position and liquidity levels in light of changing market, economic and business conditions. Liquidity is managed at both the entity and enterprise level across the Company and is assessed on both base and stressed level liquidity needs. We believe we have sufficient liquidity to meet these needs. Additionally, we have existing intercompany agreements in place that facilitate liquidity management across the Company to enhance flexibility.
The Corporation is party to an Amended and Restated Intercompany Liquidity Agreement (“Liquidity Agreement”) with certain subsidiaries, which includes, but is not limited to AIC. The Liquidity Agreement allows for short-term advances of funds to be made between parties for liquidity and other general corporate purposes. The Liquidity Agreement does not establish a commitment to advance funds on the part of any party. AIC serves as a lender and borrower, certain other subsidiaries serve only as borrowers, and the Corporation serves only as a lender. The maximum amount of potential funding under each of these agreements is $1.00 billion.
In addition to the Liquidity Agreement, the Corporation also has an intercompany loan agreement with certain of its subsidiaries, which includes, but is not limited to, AIC. The amount of intercompany loans available to the Corporation’s subsidiaries is at the
Second Quarter 2022 Form 10-Q 75
Capital Resources and Liquidity
discretion of the Corporation. The maximum amount of loans the Corporation will have outstanding to all its eligible subsidiaries at any given point in time is limited to $1.00 billion. The Corporation may use commercial paper borrowings, bank lines of credit and securities lending to fund intercompany borrowings.
Parent company capital capacity Parent holding company deployable assets totaled $5.13 billion as of June 30, 2022, primarily comprised of cash and investments that are generally saleable within one quarter. The earnings capacity of the operating subsidiaries is the primary source of capital generation for the Corporation.
As of June 30, 2022, we held $13.52 billion of cash, U.S. government and agencies fixed income securities, and public equity securities which we would expect to be able to liquidate within one week.
Intercompany dividends were paid in the first six months of 2022 between the following companies: AIC, Allstate Insurance Holdings, LLC (“AIH”), the Corporation, American Heritage Life Insurance Company (“AHL”) and Allstate Financial Insurance Holdings Corporation (“AFIHC”).
| Intercompany dividends | ||||||||
| ($ in millions) | ||||||||
| AIC to AIH | $ | 3,949 | ||||||
| AIH to the Corporation | 3,949 | |||||||
| AHL to AFIHC | 50 | |||||||
Based on the greater of 2021 statutory net income or 10% of statutory surplus, the maximum amount of dividends that AIC will be able to pay, without prior Illinois Department of Insurance approval, at a given point in time through February 2023 is estimated at $5.51 billion, less dividends paid during the preceding twelve months measured at that point in time. As of June 30, 2022, we paid dividends of $3.95 billion.
Dividends may not be paid or declared on our common stock and shares of common stock may not be repurchased unless the full dividends for the latest completed dividend period on our preferred stock have been declared and paid or provided for. We are prohibited from declaring or paying dividends on our Series G preferred stock if we fail to meet specified capital adequacy, net income or shareholders’ equity levels, except out of the net proceeds of common stock issued during the 90 days prior to the date of declaration. As of June 30, 2022, we satisfied all the requirements with no current restrictions on the payment of preferred stock dividends.
The terms of our outstanding subordinated debentures also prohibit us from declaring or paying any dividends or distributions on our common or preferred stock or redeeming, purchasing, acquiring, or making liquidation payments on our common stock or preferred stock if we have elected to defer interest payments on the subordinated debentures, subject to certain limited exceptions. In the first six months of 2022, we did not defer interest payments on the subordinated debentures.
Additional resources to support liquidity are as follows:
-
The Corporation and AIC have access to a $750 million unsecured revolving credit facility that is available for short-term liquidity requirements. The maturity date of this facility is November 2026. The facility is fully subscribed among 11 lenders with the largest commitment being $95 million. The commitments of the lenders are several and no lender is responsible for any other lender’s commitment if such lender fails to make a loan under the facility. This facility contains an increase provision that would allow up to an additional $500 million of borrowing, subject to the lenders’ commitment. This facility has a financial covenant requiring that we not exceed a 37.5% debt to capitalization ratio as defined in the agreement. This ratio was 20.5% as of June 30, 2022. Although the right to borrow under the facility is not subject to a minimum rating requirement, the costs of maintaining the facility and borrowing under it are based on the ratings of our senior unsecured, unguaranteed long-term debt. There were no borrowings under the credit facility during 2022.
-
To cover short-term cash needs, the Corporation has access to a commercial paper facility with a borrowing capacity limited to any undrawn credit facility balance up to $750 million.
-
As of June 30, 2022, there were no balances outstanding for the credit facility or the commercial paper facility and therefore the remaining borrowing capacity was $750 million.
-
The Corporation has access to a universal shelf registration statement with the Securities and Exchange Commission that expires in 2024. We can use this shelf registration to issue an unspecified amount of debt securities, common stock (including 629 million shares of treasury stock as of June 30, 2022), preferred stock, depositary shares, warrants, stock purchase contracts, stock purchase units and securities of trust subsidiaries. The specific terms of any securities we issue under this registration statement will be provided in the applicable prospectus supplements.
Recent Developments
The following updates the regulation disclosures included in Part I, Item 1. Regulation in our annual report on Form 10-K for the year ended December 31, 2021.
Securities and Exchange Commission (“SEC”) proposed rule changes
Climate disclosures. In March 2022, the SEC released its climate-related proposed regulation, requiring registrants to provide certain climate-related information in their registration statements and annual reports. The proposed rule would require information about a registrant’s climate-related risks that are reasonably likely to have a material impact on its business, results of operations, or financial condition. The required information about climate-related risks would also include disclosure of a registrant’s greenhouse gas emissions, which have become a commonly used metric to assess a registrant’s exposure to such risks. In addition, under the proposed rule, certain climate-related financial metrics would be required in a registrant’s audited financial statements. The Company is evaluating the anticipated impacts of the proposed guidance to its disclosures.
Cybersecurity risk management. The SEC issued a proposed rule in March 2022 to mandate cybersecurity disclosures, including information such as: management's and the board’s role and oversight of cybersecurity risks, policies and procedures and how risks and incidents are likely to impact the financial statements. Additionally, certain incidents would have mandatory reporting on a Form 8-K. The Company is evaluating the anticipated impacts of the proposed guidance to its disclosures.
Share repurchase disclosure modernization. The SEC issued two proposed amendments in December 2021 that could impact both the administration of 10b5-1 plans used in part to execute the Company’s stock repurchases and disclosure of activity under those plans. The proposals involve potential daily reporting of share repurchase activity, cooling off periods for both individual and corporate 10b5-1 plans (120 and 30 days, respectively) and a number of new 10Q and 10K disclosures that would be subject to SOX Section 302 Certifications. The Company is evaluating the anticipated impacts of the proposed guidance to its disclosures.
Second Quarter 2022 Form 10-Q 77
Forward-Looking Statements
This report contains “forward-looking statements” that anticipate results based on our estimates, assumptions and plans that are subject to uncertainty. These statements are made subject to the safe-harbor provisions of the Private Securities Litigation Reform Act of 1995. Forward-looking statements do not relate strictly to historical or current facts and may be identified by their use of words like “plans,” “seeks,” “expects,” “will,” “should,” “anticipates,” “estimates,” “intends,” “believes,” “likely,” “targets” and other words with similar meanings. These statements may address, among other things, our strategy for growth, catastrophe, exposure management, product development, investment results, regulatory approvals, market position, expenses, financial results, litigation, and reserves. We believe that these statements are based on reasonable estimates, assumptions and plans. Forward-looking statements speak only as of the date on which they are made, and we assume no obligation to update any forward-looking statements as a result of new information or future events or developments. In addition, forward-looking statements are subject to certain risks or uncertainties that could cause actual results to differ materially from those communicated in these forward-looking statements. Factors that could cause actual results to differ materially from those expressed in, or implied by, the forward-looking statements include risks related to:
Insurance and Financial Services (1) unexpected increases in claim frequency and severity; (2) catastrophes and severe weather events; (3) limitations in analytical models used for loss cost estimates; (4) price competition and changes in regulation and underwriting standards; (5) actual claims costs exceeding current reserves; (6) market risk and declines in credit quality of our investment portfolio; (7) our subjective determination of fair value and amount of credit losses for investments; (8) our participation in indemnification programs, including state industry pools and facilities; (9) inability to mitigate the impact associated with changes in capital requirements; (10) a downgrade in financial strength ratings;
Business, Strategy and Operations (11) competition in the industries in which we compete and new or changing technologies; (12) implementation of our transformative growth strategy; (13) our catastrophe management strategy; (14) restrictions on our subsidiaries’ ability to pay dividends; (15) restrictions under terms of certain of our securities on our ability to pay dividends or repurchase our stock; (16) the availability of reinsurance at current levels and prices; (17) counterparty risk related to reinsurance; (18) acquisitions and divestitures of businesses; (19) intellectual property infringement, misappropriation and third-party claims;
Macro, Regulatory and Risk Environment (20) conditions in the global economy and capital markets, including the economic impacts from the recent military conflict between Russia and Ukraine; (21) a large-scale pandemic, the occurrence of terrorism, military actions or social unrest; (22) the failure in cyber or other information security controls, as well as the occurrence of events unanticipated in our disaster recovery processes and business continuity planning; (23) changing climate and weather conditions; (24) restrictive regulations and regulatory reforms, including limitations on rate increases and requirements to underwrite business and participate in loss sharing arrangements; (25) losses from legal and regulatory actions; (26) changes in or the application of accounting standards; (27) loss of key vendor relationships or failure of a vendor to protect our data, confidential and proprietary information, or personal information of our customers, claimants or employees; (28) our ability to attract, develop and retain talent; and (29) misconduct or fraudulent acts by employees, agents and third parties.
Additional information concerning these and other factors may be found in our filings with the Securities and Exchange Commission, including the “Risk Factors” section in our most recent annual report on Form 10-K.
Previous: Item 1. Financial Statements · Next: Item 4. Controls and Procedures