 filings.tools
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
360K characters. Original on sec.gov · Markdown
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Forward-looking statements
Certain information and statements included in this quarterly report on Form 10-Q, including, without limitation, statements containing the words “forecast,” “guidance,” “goals,” “projects,” “estimates,” “anticipates,” “believes,” “expects,” “intends,” “may,” “plans,” “seeks,” “should,” “targets,” or “will,” or the negative of those words or similar words, constitute “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements involve inherent risks and uncertainties regarding events, conditions, and financial trends that may affect our future plans of operations, business strategy, results of operations, and financial position. A number of important factors could cause actual results to differ materially from those included within or contemplated by the forward-looking statements, including, but not limited to, the following:
-
Operating factors such as a failure to operate our business successfully in comparison to market expectations or in comparison to our competitors, our inability to obtain capital when desired or refinance debt maturities when desired, and/or a failure to maintain our status as a REIT for federal tax purposes.
-
Market and industry factors such as adverse developments concerning the life science, agtech, and technology industries and/or our tenants.
-
Government factors such as any unfavorable effects resulting from federal, state, local, and/or foreign government policies, laws, and/or funding levels.
-
Global factors such as negative economic, political, financial, credit market, and/or banking conditions.
-
Uncertain global, national, and local impacts of the ongoing COVID-19 pandemic.
-
Other factors such as climate change, cyber intrusions, and/or changes in laws, regulations, and financial accounting standards.
This list of risks and uncertainties is not exhaustive. Additional information regarding risk factors that may affect us is included under “Item 1A. Risk factors” and “Item 7. Management’s discussion and analysis of financial condition and results of operations” of our annual report on Form 10-K for the year ended December 31, 2020, and respective sections within this quarterly report on Form 10-Q. Readers of this quarterly report on Form 10-Q should also read our other documents filed publicly with the SEC for further discussion regarding such factors.
Overview
We are a Maryland corporation formed in October 1994 that has elected to be taxed as a REIT for federal income tax purposes. We are an S&P 500® urban office REIT and the first, longest-tenured, and pioneering owner, operator, and developer uniquely focused on collaborative life science, agtech, and technology campuses in AAA innovation cluster locations, with a total market capitalization of $38.6 billion and an asset base in North America of 63.9 million SF as of September 30, 2021. The asset base in North America includes 38.7 million RSF of operating properties and 4.3 million RSF of Class A properties undergoing construction, 8.9 million RSF of near-term and intermediate-term development and redevelopment projects, and 12.0 million SF of future development projects. Founded in 1994, we pioneered this niche and have since established a significant market presence in key locations, including Greater Boston, the San Francisco Bay Area, New York City, San Diego, Seattle, Maryland, and Research Triangle. We have a longstanding and proven track record of developing Class A properties clustered in urban life science, agtech, and technology campuses that provide our innovative tenants with highly dynamic and collaborative environments that enhance their ability to successfully recruit and retain world-class talent and inspire productivity, efficiency, creativity, and success. Alexandria also provides strategic capital to transformative life science, agtech, and technology companies through our venture capital platform. We believe these advantages result in higher occupancy levels, longer lease terms, higher rental income, higher returns, and greater long-term asset value.
As of September 30, 2021:
-
Investment-grade or publicly traded large cap tenants represented 53% of our total annual rental revenue;
-
Approximately 95% of our leases (on an RSF basis) contained effective annual rent escalations that were either fixed (generally ranging from approximately 3.0% to 3.5%) or indexed based on a consumer price index or other index;
-
Approximately 92% of our leases (on an RSF basis) were triple net leases, which require tenants to pay substantially all real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses (including increases thereto) in addition to base rent; and
-
Approximately 94% of our leases (on an RSF basis) provided for the recapture of capital expenditures (such as heating, ventilation, and air conditioning systems maintenance and/or replacement, roof replacement, and parking lot resurfacing) that we believe would typically be borne by the landlord in traditional office leases.
Our primary business objective is to maximize stockholder value by providing our stockholders with the greatest possible total return and long-term asset value based on a multifaceted platform of internal and external growth. A key element of our strategy is our unique focus on Class A properties clustered in urban campuses. These key urban campus locations are characterized by high barriers to entry for new landlords, high barriers to exit for tenants, and a limited supply of available space. They generally represent highly desirable locations for tenancy by life science, agtech, and technology entities because of their close proximity to concentrations of specialized skills, knowledge, institutions, and related businesses. Our strategy also includes drawing upon our deep and broad real estate, life science, agtech, and technology relationships in order to identify and attract new and leading tenants and to source additional value-creation real estate.
Executive summary
Operating results
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||
| Net income attributable to Alexandria’s common stockholders – diluted: | |||||||||||||||||||||||
| In millions | $ | 101.3 | $ | 79.3 | $ | 490.6 | $ | 324.2 | |||||||||||||||
| Per share | $ | 0.67 | $ | 0.63 | $ | 3.38 | $ | 2.61 | |||||||||||||||
| Funds from operations attributable to Alexandria’s common stockholders – diluted, as adjusted: | |||||||||||||||||||||||
| In millions | $ | 296.0 | $ | 230.7 | $ | 841.3 | $ | 677.1 | |||||||||||||||
| Per share | $ | 1.95 | $ | 1.83 | $ | 5.80 | $ | 5.46 |
The operating results shown above include certain items related to corporate-level investing and financing decisions. Refer to the tabular presentation of these items at the beginning of the “Results of operations” section within this Item 2 for additional information.
Strategic relationship with Moderna, Inc. leads to new HQ and R&D facility at 325 Binney Street, representing largest life science lease executed in Company history
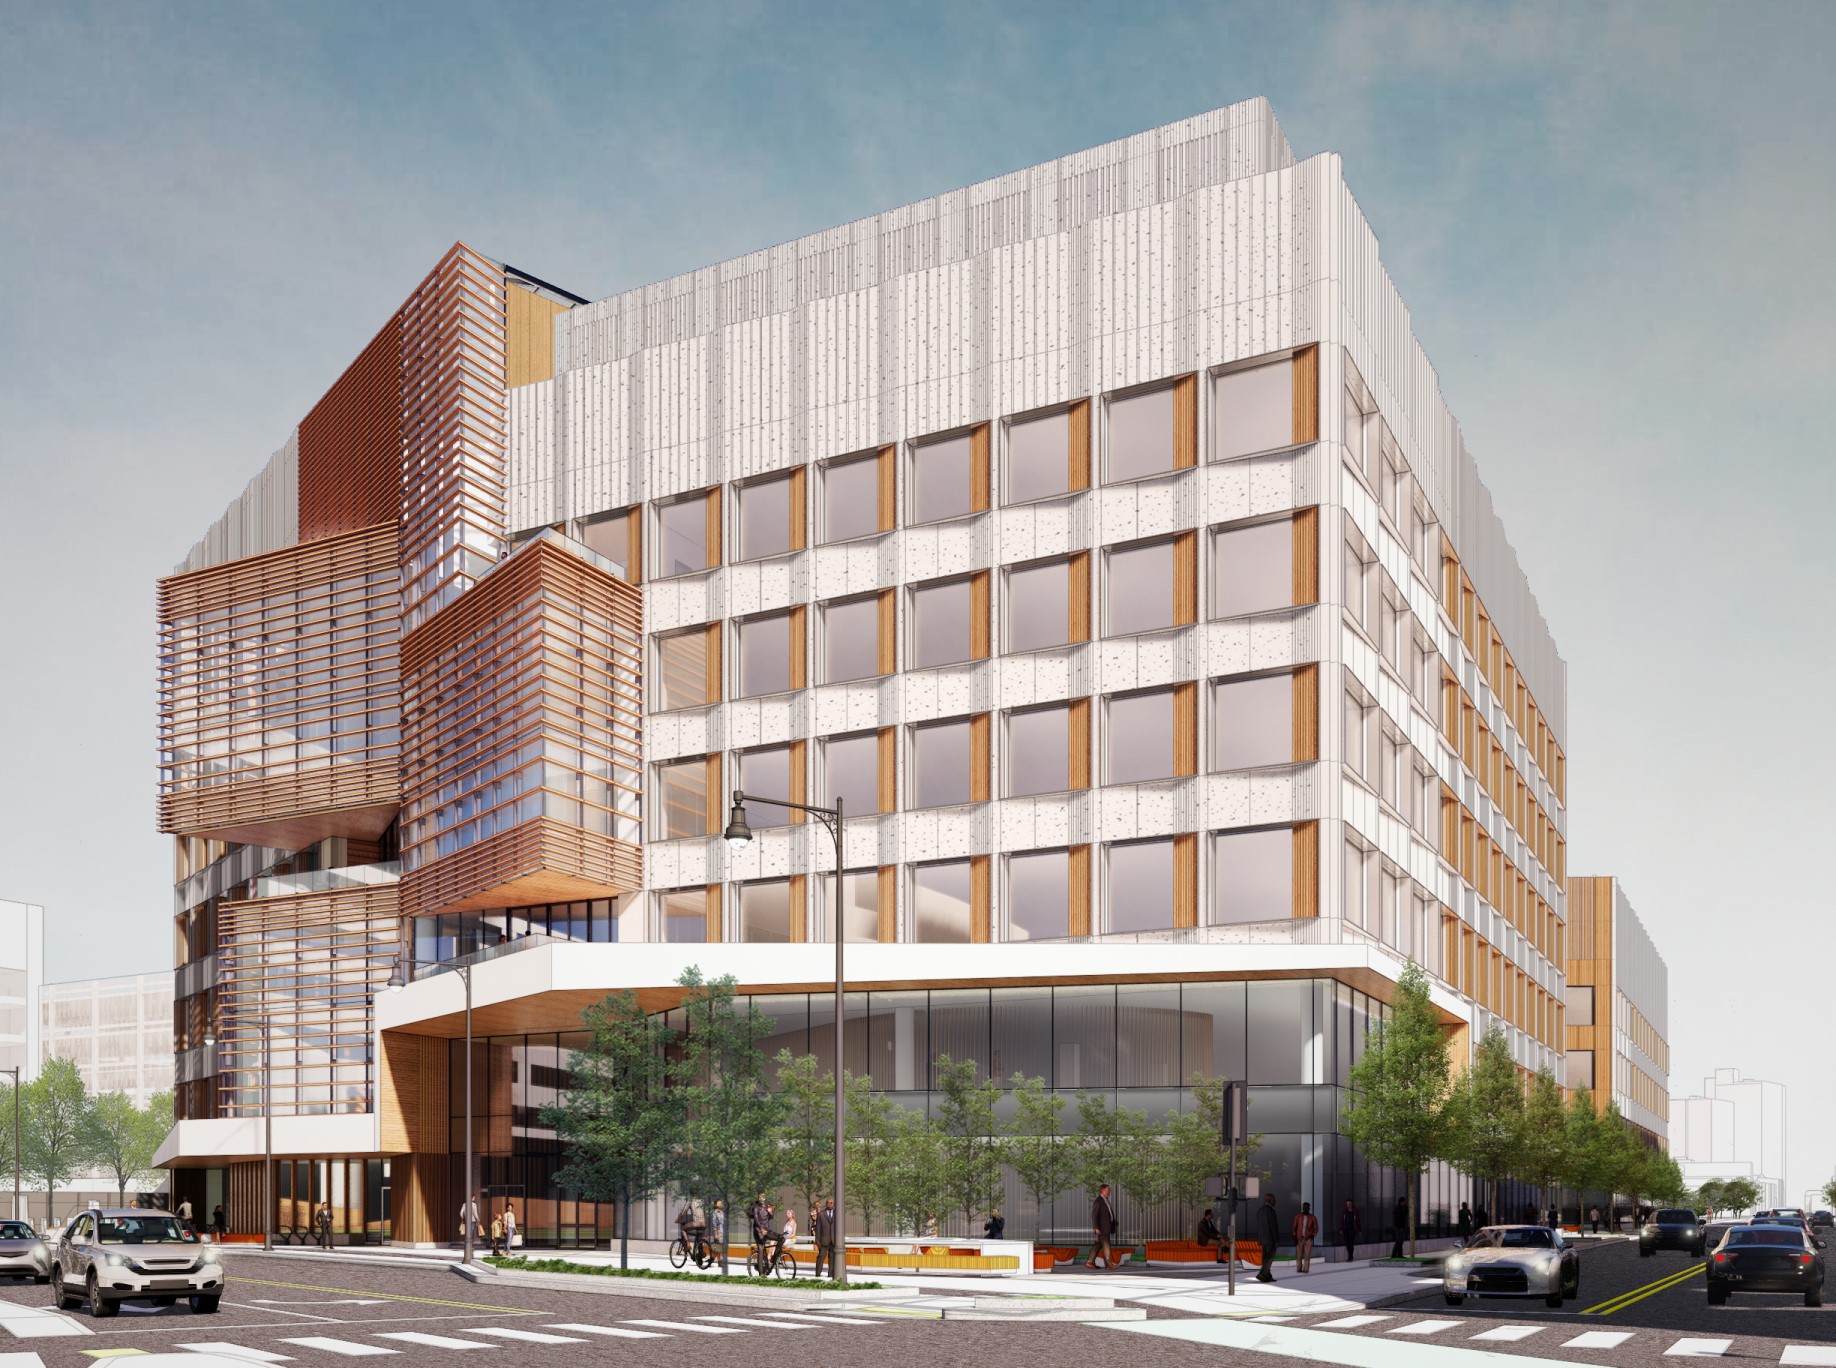
In September 2021, we signed a 15-year full-building lease with Moderna, Inc. to develop, construct, and operate its new headquarters and core R&D facility at 325 Binney Street, a leading-edge 462,100 RSF property designed to be the most sustainable laboratory building in Cambridge, representing the largest life science lease in Company history.
Historic-high year-to-date leasing volume and continued strong rental rate growth
*•*During the nine months ended September 30, 2021, historic demand for our high-quality office/laboratory space translated into 5.4 million RSF of leasing activity in only nine months, representing the highest leasing activity in Company history, surpassing our record annual leasing of 5.1 million RSF in 2019.
- Continued strong leasing activity and rental rate growth during the three and nine months ended September 30, 2021, over expiring rates on renewed and re-leased space:
| September 30, 2021 | |||||||||||||||||
| Three Months Ended | Nine Months Ended | ||||||||||||||||
| Total leasing activity – RSF | 1,810,630 | 5,422,127 | |||||||||||||||
| Leasing of development and redevelopment space – RSF | 1,005,890 | (1) | 2,071,750 | ||||||||||||||
| Lease renewals and re-leasing of space: | |||||||||||||||||
| RSF (included in total leasing activity above) | 671,775 | 2,666,313 | |||||||||||||||
| Rental rate increases | 35.3% | 39.4% | |||||||||||||||
| Rental rate increases (cash basis) | 19.3% | 22.3% | |||||||||||||||
| (1)Represents the second highest leasing quarter of development and redevelopment square footage in Company history. |
Continued strong net operating income and internal growth
-
Total revenues:
-
$547.8 million, up 0.5%, for the three months ended September 30, 2021, compared to $545.0 million for the three months ended September 30, 2020.
-
$1.5 billion, up 8.1%, for the nine months ended September 30, 2021, compared to $1.4 billion for the nine months ended September 30, 2020.
-
Revenues for the three and nine months ended September 30, 2020, included a termination fee of $89.5 million. Excluding this termination fee, growth for the three and nine months ended September 30, 2021, was 20.2% and 15.4%, respectively.
-
Net operating income (cash basis) of $1.3 billion for the three months ended September 30, 2021, annualized, increased by $234.3 million, or 21.2%, compared to the three months ended September 30, 2020, annualized, excluding the effect of income recognized during the three months ended September 30, 2020, aggregating $86.2 million, which comprised a termination fee of $89.5 million and related expenses of $3.3 million.
-
95% of our leases contain contractual annual rent escalations approximating 3%.
-
Same property net operating income growth:
-
3.0% and 7.1% (cash basis) for the three months ended September 30, 2021, over the three months ended September 30, 2020.
-
4.1% and 7.3% (cash basis) for the nine months ended September 30, 2021, over the nine months ended September 30, 2020.
A REIT industry-leading high-quality tenant roster with high-quality revenues and cash flows, strong margins, and operational excellence
| Percentage of annual rental revenue in effect from investment-grade or publicly traded large cap tenants | 53 | % | ||||||||||||
| Occupancy of operating properties in North America | 94.4 | % | ||||||||||||
| Occupancy of operating properties in North America (excluding vacancy at recently acquired properties) | 98.5 | % | (1) | |||||||||||
| Operating margin | 70 | % | ||||||||||||
| Adjusted EBITDA margin | 68 | % | ||||||||||||
| Weighted-average remaining lease term: | ||||||||||||||
| All tenants | 7.4 | years | ||||||||||||
| Top 20 tenants | 10.6 | years | ||||||||||||
(1)Excludes 1.6 million RSF, or 4.1%, of vacancy at recently acquired properties, representing lease-up opportunities that are expected to provide incremental annual rental revenues in excess of $59 million upon full lease-up. Excluding acquired vacancies, occupancy was 98.5% as of September 30, 2021, up 80 bps from 97.7% as of December 31,2020. Refer to the “Summary of occupancy percentages in North America” section within this Item 2 for additional information regarding vacancy at recently acquired properties.
Credit rating outlook improvement
In October 2021, S&P Global Ratings raised our corporate issuer credit rating outlook to BBB+/Positive from BBB+/Stable.
Strong and flexible balance sheet with significant liquidity
-
Investment-grade credit ratings ranked in the top 10% among all publicly traded U.S. REITs as of September 30, 2021.
-
Net debt and preferred stock to Adjusted EBITDA of 5.8x and fixed-charge coverage ratio of 5.1x for the three months ended September 30, 2021, annualized.
-
Net debt to gross assets of 28% as of September 30, 2021.
-
$4.0 billion of liquidity as of September 30, 2021.
Continued dividend strategy to share growth in cash flows with stockholders
Common stock dividend declared for the three months ended September 30, 2021, of $1.12 per common share, aggregating $4.42 per common share for the twelve months ended September 30, 2021, up 24 cents, or 6%, over the twelve months ended September 30, 2020. Our FFO payout ratio of 58% for the three months ended September 30, 2021, allows us to continue to share growth in cash flows from operating activities with our stockholders while also retaining a significant portion for reinvestment.
Sustained strength in tenant collections
-
Tenant collections remain consistently high, with 99.6% of October 2021 billings collected as of the date of this report.
-
As of September 30, 2021, our tenant receivables balance of $7.7 million continues to be near historic lows.
Alexandria at the vanguard of innovation for over 750 tenants, with a focus to accommodate current tenant needs plus a path for their future growth
During the three months ended September 30, 2021, we completed acquisitions in our key life science cluster submarkets aggregating 5.6 million SF, comprising 4.9 million RSF of value-creation opportunities and 0.7 million RSF of operating space, for an aggregate purchase price of $989.7 million.
Robust leasing activity of development and redevelopment projects
Historically high demand for our value-creation development and redevelopment projects of high-quality office/laboratory space, as well as continued operational excellence at our world-class, sophisticated laboratory facilities, and strong execution by our team, has translated into record lease executed in the nine months ended September 30, 2021, aggregating 2.1 million RSF, related to our development and redevelopment projects.
Value-creation development and redevelopment projects expected to generate significant growth in rental revenues and cash flows
Our highly leased value-creation pipeline of current and near-term projects that are under construction or will commence construction in the next six quarters is expected to generate significant incremental revenues, as follows:
| Under Construction | Key Projects Expected to Commence Construction in the Next Six Quarters(1) | Incremental Projected Annual Rental Revenues | ||||||||||||||||||
| 4.3 Million RSF | 3.4 Million RSF | > $615 Million | ||||||||||||||||||
| 37 Properties | + | 20 Properties | = | |||||||||||||||||
| 79% Leased/Negotiating | 80% Leased/Negotiating | |||||||||||||||||||
| (1)We expect to commence construction of other projects in 2022. |
*•*Approximately 93% of leased/negotiating activity related to the 7.7 million RSF of projects under construction or expected to commence construction in the next six quarters, is from existing relationships.
- In October 2021, our Alexandria Center® for Life Science – Fenway campus received entitlement rights to develop 450,000 SF of office/laboratory space.
Delivery of fully leased value-creation projects
- During the three months ended September 30, 2021, we placed into service development and redevelopment projects aggregating 238,163 RSF that are 100% leased across four submarkets.
*•*Commencement of three value-creation projects aggregating 1.1 million RSF during the three months ended September 30, 2021, including a 462,100 RSF development project at 325 Binney Street in our Cambridge submarket and a 229,000 RSF development project at 751 Gateway Boulevard in our South San Francisco submarket, which are 100% leased and 100% negotiating, respectively.
- Annual net operating income (cash basis) is expected to increase by $45 million upon the burn-off of initial free rent from recently delivered projects.
Key strategic transactions that generated capital for investment into our highly leased value-creation pipeline and acquisitions with development and redevelopment opportunities
-
During the three months ended September 30, 2021, we completed dispositions of and sales of partial interests in real estate assets aggregating $339.4 million in our key life science cluster submarkets.
-
In October 2021, we completed the recapitalization of two consolidated real estate joint ventures in our Mission Bay submarket:
| 409 and 499 Illinois Street | 1500 Owens Street | ||||||||||||||||||||||||||||
| (Dollars in thousands) | Alexandria | JV Partner | Alexandria | JV Partner | |||||||||||||||||||||||||
| Previous ownership | 60 | % | 40 | % | 50.1 | % | 49.9 | % | |||||||||||||||||||||
| Recapitalization in October 2021 | 25 | % | 75 | % | 25 | % | 75 | % | |||||||||||||||||||||
| Sale of ownership interest | 35 | % | 25.1 | % | |||||||||||||||||||||||||
| Sales price (our share) | $274,681 | ||||||||||||||||||||||||||||
| Capitalization rate | 5.0% | ||||||||||||||||||||||||||||
| Capitalization rate (cash) | 4.2% |
We retained control over these joint ventures and continue to consolidate them in our financial statements. Refer to Note 4 – “Consolidated and unconsolidated real estate joint ventures” to our unaudited consolidated financial statements under Item 1 of this report for further discussion.
Balance sheet management
Key metrics as of September 30, 2021
-
$38.6 billion of total market capitalization.
-
$29.3 billion of total equity capitalization.
-
No debt maturing prior to 2024.
-
11.9 years weighted-average remaining term of debt as of September 30, 2021.
-
Investment-grade credit ratings ranked in the top 10% among all publicly traded U.S. REITs as of September 30, 2021.
| September 30, 2021 | Goal for Fourth Quarter of 2021, Annualized | |||||||||||||||||||||||||
| Quarter Annualized | Trailing 12 Months | |||||||||||||||||||||||||
| Net debt and preferred stock to Adjusted EBITDA | 5.8x | 6.2x | Less than or equal to 5.2x | |||||||||||||||||||||||
| Fixed-charge coverage ratio | 5.1x | 4.8x | Greater than or equal to 5.0x | |||||||||||||||||||||||
| Value-creation pipeline of new Class A development and redevelopment projects as a percentage of gross assets | September 30, 2021 | ||||||||||||||||||||||
| Under construction projects | 7% | ||||||||||||||||||||||
| Pre-leased/negotiating near-term projects and key pending acquisition | 2% | ||||||||||||||||||||||
| Income-producing/potential cash flows/covered land play(1) | 5% | ||||||||||||||||||||||
| Land | 2% | ||||||||||||||||||||||
(1)Includes projects that have existing buildings that are generating or can generate operating cash flows. Also includes development rights associated with existing operating campuses.
Key capital events
-
During the three months ended September 30, 2021, we issued 2.5 million shares under our ATM program at a price of $200.73 per share (before underwriting discounts) and received net proceeds of $492.3 million. As of September 30, 2021, we have no amounts remaining under our ATM program. We expect to establish a new ATM program during the three months ending December 31, 2021.
-
As of September 30, 2021, we had outstanding forward equity sales agreements aggregating $771.9 million to sell 4.6 million shares of our common stock. We expect to settle these forward equity sales agreements during the three months ending December 31, 2021.
Investments
-
As of September 30, 2021, our investments aggregated $2.0 billion, including unrealized gains of $929.8 million.
-
Investment income of $67.1 million for the three months ended September 30, 2021, consisted of $81.5 million of realized gains and $14.4 million of unrealized losses.
Industry and ESG leadership: catalyzing and leading the way for positive change to benefit human health and society
*•*In October 2021, our ESG commitment and leadership was recognized in the 2021 Global Real Estate Sustainability Benchmark (“GRESB”) Real Estate Assessment, including the following achievements: (i) Global Sector Leader and a 5 Star rating — GRESB’s highest rating — in the Diversified Listed sector for buildings in development, (ii) #2 ranking in the U.S. in the Science & Technology sector for buildings in operation, and (iii) fourth consecutive “A” disclosure score.
-
In October 2021, Alexandria received an ESG Rating of A from MSCI as a result of our continued advancement of green building opportunities, recognition of talent management programs, and below-industry-average turnover rate, among other achievements. Our MSCI ESG Rating of A is currently ranked in the top 10% among all publicly traded U.S. equity REITs. An MSCI ESG Rating is designed to measure a company’s resilience to long-term industry-material ESG risks.
-
In September 2021, Alexandria achieved the Fitwel Viral Response Certification With Distinction, the highest certification level within the Fitwel Viral Response module, for the second consecutive year. This evidence-based, third-party certification recognizes the Company's comprehensive and rigorous approach to protecting the health of its building occupants.
-
In September 2021, the National September 11 Memorial & Museum honored Joel S. Marcus, our executive chairman and founder, for Distinction in Civic Engagement and Renewal, recognizing his meaningful contributions to and unwavering support of the 9/11 Memorial & Museum and its mission. As an active supporter of the Memorial & Museum since it opened in 2014, Mr. Marcus has served as a member of its board of trustees since his appointment in 2018 by former New York City Mayor Michael Bloomberg.
-
In September 2021, OneFifteen, an innovative non-profit healthcare ecosystem dedicated to the full and sustained recovery of people living with addiction, received an honorable mention in Fast Company’s 2021 Innovation by Design Awards in the Impact category. Alexandria led the design and development of the pioneering OneFifteen campus in Dayton, Ohio, which houses a unique, evidence-based model encompassing a full continuum of care in one location, from intake, medication-assisted treatment, and residential living to family reunification, job training, and community transition.
-
In July 2021, Alexandria Venture Investments, our strategic venture capital platform, was recognized by Silicon Valley Bank in its Healthcare Investments and Exits: Mid-Year 2021 Report as the most active biopharma corporate investor by new deal volume from 2020 to 1H 2021, for the fourth consecutive year and as the most active new Series A investor in biopharma from 2020 to 1H 2021. Alexandria’s venture activity provides us with, among other things, mission-critical data and knowledge on innovations and trends.
Operating summary
| Historical Same Property Net Operating Income Growth | Favorable Lease Structure**(1)** | |||||||||||||||||||||||||||||||
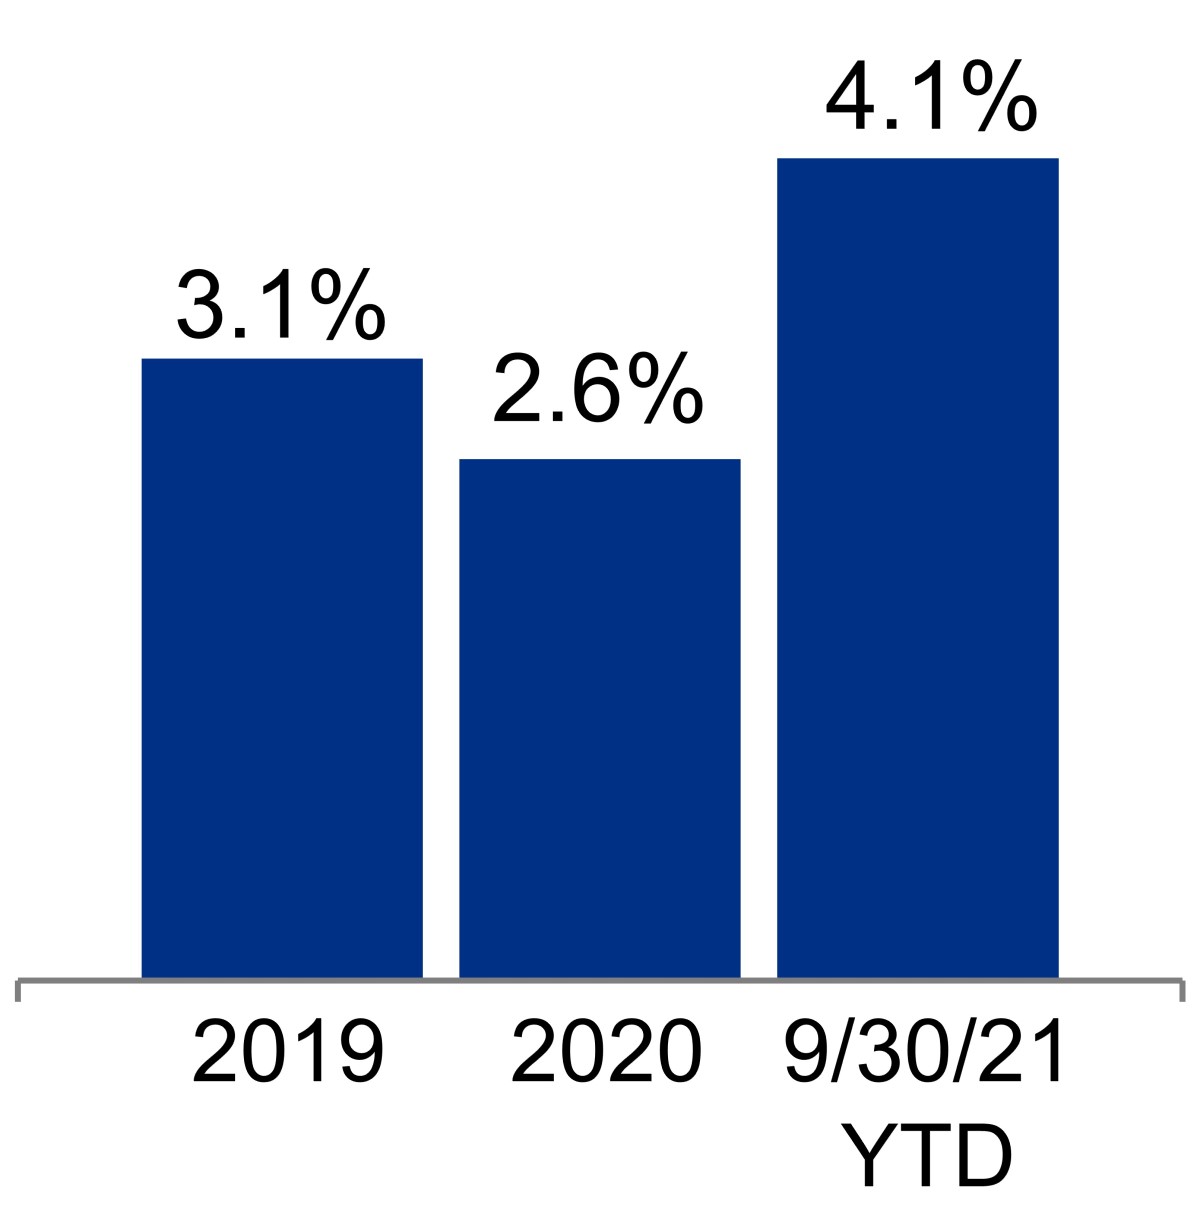 | 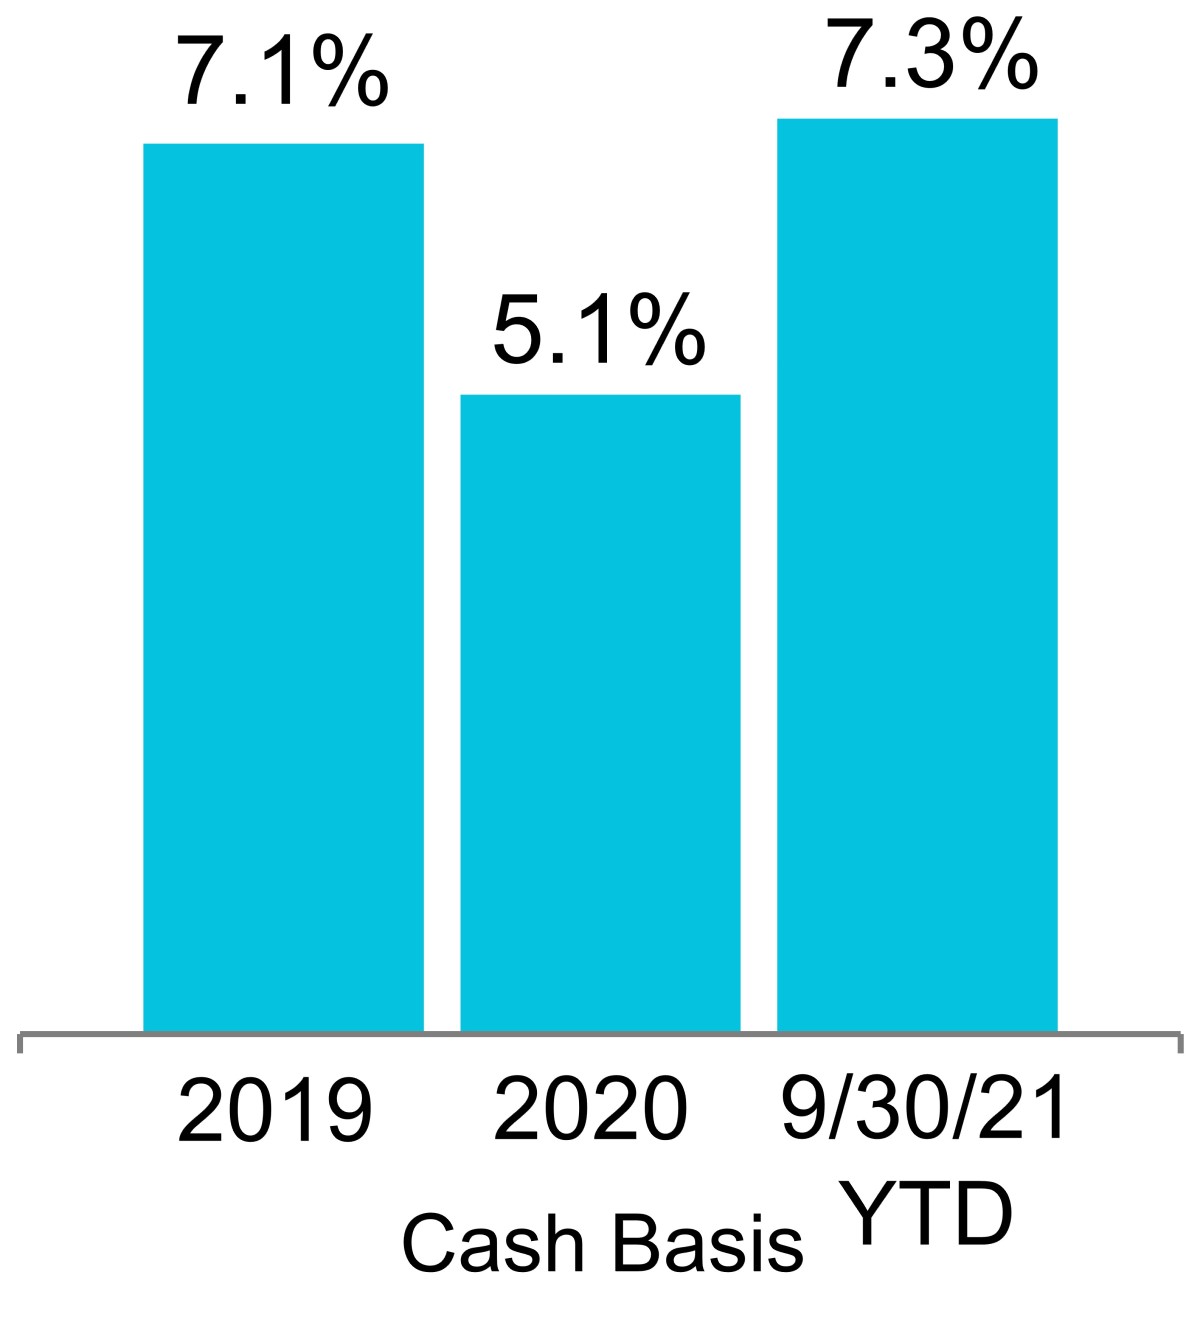 | Strategic Lease Structure by Owner and Operator of Collaborative Life Science, Agtech, and Technology Campuses | ||||||||||||||||||||||||||||||
| Increasing cash flows | ||||||||||||||||||||||||||||||||
| Percentage of leases containing annual rent escalations | 95% | |||||||||||||||||||||||||||||||
| Stable cash flows | ||||||||||||||||||||||||||||||||
| Percentage of triple net leases | 92% | (2) | ||||||||||||||||||||||||||||||
| Lower capex burden | ||||||||||||||||||||||||||||||||
| Percentage of leases providing for the recapture of capital expenditures | 94% | |||||||||||||||||||||||||||||||
| Historical Rental Rate Growth: Renewed/Re-Leased Space | Margins**(3)** | |||||||||||||||||||||||||||||||
 | 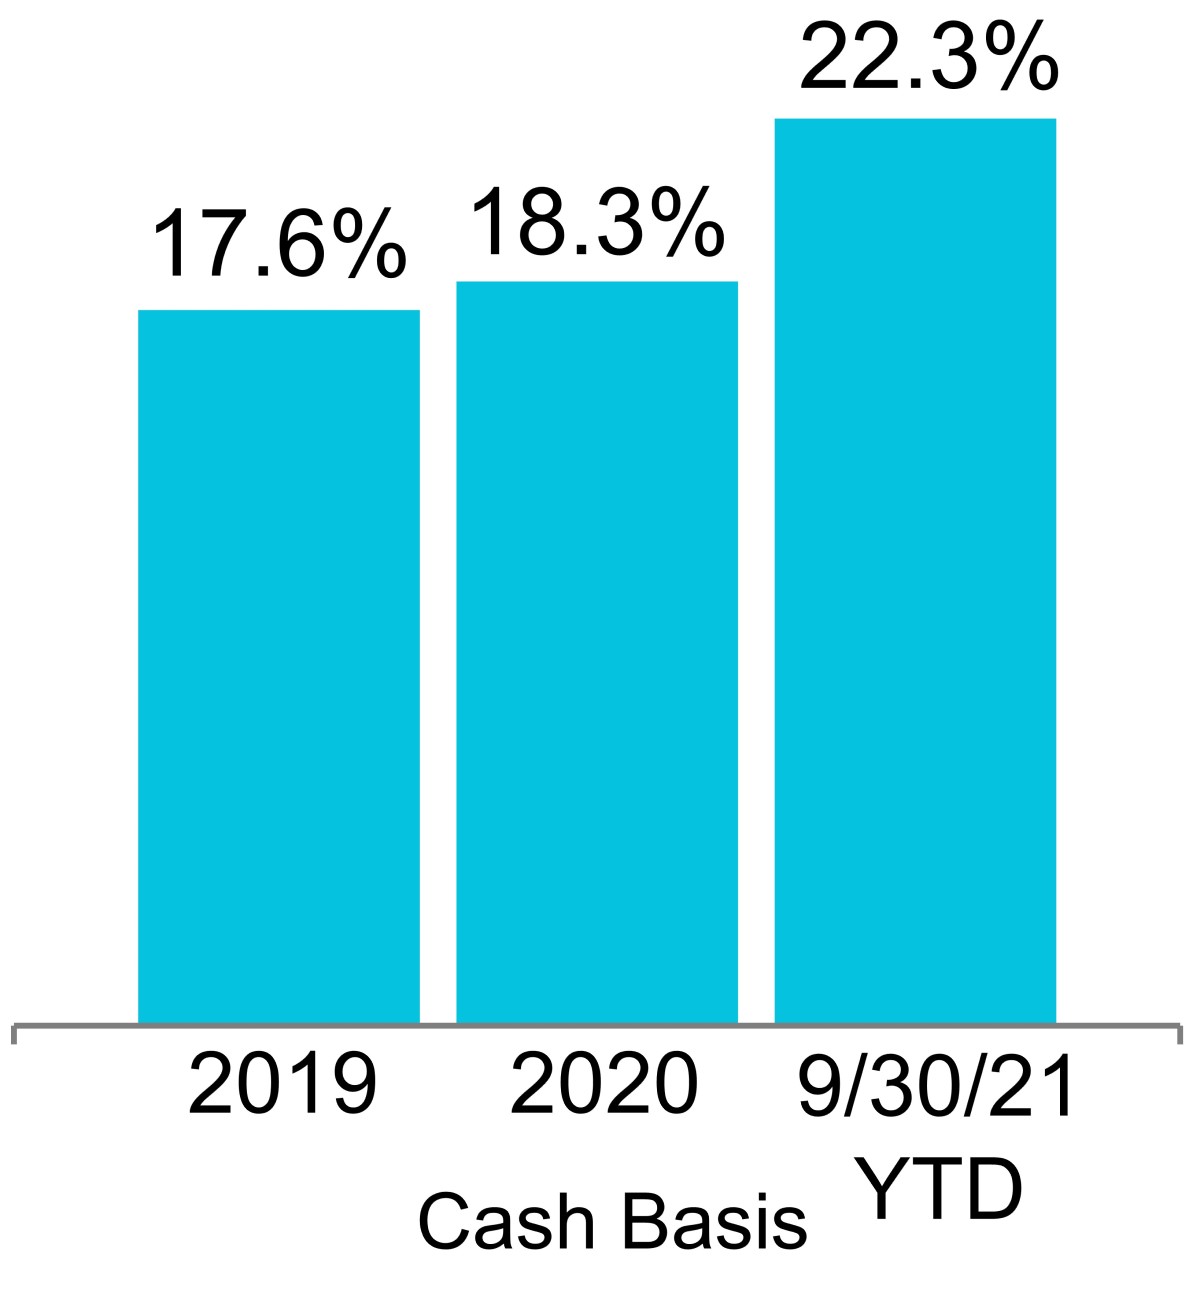 | |||||||||||||||||||||||||||||||
| Operating | Adjusted EBITDA | |||||||||||||||||||||||||||||||
| 70% | 68% | |||||||||||||||||||||||||||||||
(1)Percentages calculated based on RSF as of September 30, 2021.
(2)Decline to 92% from 94% as of June 30, 2021, related to non-triple net leases in place at operating properties with future development or redevelopment opportunities acquired during the three months ended September 30, 2021. We expect to transition these properties to our triple net lease structure, in conjunction with our future development or redevelopment activities.
(3)Represents percentages for the three months ended September 30, 2021.
| Long-Duration Cash Flows From High-Quality, Diverse, and Innovative Tenants | ||||||||
| Investment-Grade or Publicly Traded Large Cap Tenants | Long-Duration Lease Terms | |||||||
| 53% | 7.4 Years | |||||||
| of ARE’s | Weighted-Average | |||||||
| Annual Rental Revenue(1) | Remaining Term(2) | |||||||
| Tenant Mix | ||||||||
 | ||||||||
| Percentage of ARE’s Annual Rental Revenue(1) | ||||||||
(1)Represents annual rental revenue in effect as of September 30, 2021. Refer to the “Non-GAAP measures and definitions” section within this Item 2 for additional information.
(2)Based on aggregate annual rental revenue in effect as of September 30, 2021. Refer to definition of “Annual rental revenue” in the “Non-GAAP measures and definitions” section within this Item 2 for additional information on our methodology on annual rental revenue for unconsolidated real estate joint ventures.
(3)Represents annual rental revenue currently generated from office space that is targeted for a future change in use. The weighted-average remaining term of these leases is 3.2 years.
(4)Represents annual rental revenue from publicly traded technology tenants with an average daily market capitalization greater than $200 billion for the twelve months ended September 30, 2021.
(5)Our other tenants, aggregating 5.0% of our annual rental revenue, comprise 4.0% of annual rental revenue from technology, professional services, finance, telecommunications, and construction/real estate companies and only 1.0% from retail-related tenants.
| High-Quality Cash Flows From High-Quality Tenants and Class A Properties in AAA Locations | |||||||||||
| Industry-Leading Tenant Roster | AAA Locations | ||||||||||
 | |||||||||||
| 89% | |||||||||||
| of ARE’s Top 20 Tenants’ Annual Rental Revenue(1) Is From Investment-Grade or Publicly Traded Large Cap Tenants | |||||||||||
| Percentage of ARE’s Annual Rental Revenue(1) | |||||||||||
| Solid Historical Occupancy**(2)** | Occupancy Across Key Locations**(3)** | ||||||||||
 | |||||||||||
| 96% | |||||||||||
| Over 10 Years |
(1)Represents annual rental revenue in effect as of September 30, 2021. Refer to the “Non-GAAP measures and definitions” section within this Item 2 for additional information.
(2)Represents average occupancy of operating properties in North America as of each December 31 for the last 10 years and as of September 30, 2021.
(3)As of September 30, 2021.
(4)Refer to the “Summary of occupancy percentages in North America” section within this Item 2 for additional information.
Leasing
The following table summarizes our leasing activity at our properties:
| Three Months Ended | Nine Months Ended | Year Ended | |||||||||||||||||||||||||||||||||||||||||||||
| September 30, 2021 | September 30, 2021 | December 31, 2020 | |||||||||||||||||||||||||||||||||||||||||||||
| Including Straight-Line Rent | Cash Basis | Including Straight-Line Rent | Cash Basis | Including Straight-Line Rent | Cash Basis | ||||||||||||||||||||||||||||||||||||||||||
| (Dollars per RSF) | |||||||||||||||||||||||||||||||||||||||||||||||
| Leasing activity: | |||||||||||||||||||||||||||||||||||||||||||||||
| Renewed/re-leased space(1) | |||||||||||||||||||||||||||||||||||||||||||||||
| Rental rate changes | 35.3% | 19.3% | 39.4% | 22.3% | 37.6% | 18.3% | |||||||||||||||||||||||||||||||||||||||||
| New rates | $54.66 | $52.90 | $57.47 | $55.08 | $49.51 | $46.53 | |||||||||||||||||||||||||||||||||||||||||
| Expiring rates | $40.39 | $44.34 | $41.23 | $45.05 | $35.99 | $39.32 | |||||||||||||||||||||||||||||||||||||||||
| RSF | 671,775 | 2,666,313 | 2,556,833 | ||||||||||||||||||||||||||||||||||||||||||||
| Tenant improvements/leasing commissions | $24.00 | $29.96 | $35.08 | ||||||||||||||||||||||||||||||||||||||||||||
| Weighted-average lease term | 4.4 years | 5.7 years | 6.0 years | ||||||||||||||||||||||||||||||||||||||||||||
| Developed/redeveloped/ previously vacant space leased(2) | |||||||||||||||||||||||||||||||||||||||||||||||
| New rates | $103.29 | $88.46 | $72.94 | $64.67 | $56.67 | $53.61 | |||||||||||||||||||||||||||||||||||||||||
| RSF | 1,138,855 | 2,755,814 | 1,802,013 | ||||||||||||||||||||||||||||||||||||||||||||
| Weighted-average lease term | 11.2 years | 10.4 years | 9.0 years | ||||||||||||||||||||||||||||||||||||||||||||
| Leasing activity summary (totals): | |||||||||||||||||||||||||||||||||||||||||||||||
| New rates | $85.25 | $75.27 | $65.33 | $59.96 | $52.47 | $49.46 | |||||||||||||||||||||||||||||||||||||||||
| RSF | 1,810,630 | 5,422,127 | (3)(4) | 4,358,846 | |||||||||||||||||||||||||||||||||||||||||||
| Weighted-average lease term | 8.7 years | 8.1 years | 7.3 years | ||||||||||||||||||||||||||||||||||||||||||||
| Lease expirations*(1)* | |||||||||||||||||||||||||||||||||||||||||||||||
| Expiring rates | $40.74 | $42.61 | $40.38 | $43.16 | $36.03 | $39.01 | |||||||||||||||||||||||||||||||||||||||||
| RSF | 870,283 | 3,329,865 | 3,560,188 |
Leasing activity includes 100% of results for each property in which we have an investment in North America.
(1)Excludes month-to-month leases aggregating 94,202 RSF and 96,383 RSF as of September 30, 2021, and December 31, 2020, respectively.
(2)Refer to “New Class A development and redevelopment properties: summary of pipeline” section within this Item 2 for additional information on total project costs.
(3)Represents the highest leasing activity in Company history, surpassing our record annual leasing volume of 5.1 million RSF during the year ended December 31, 2019.
(4)During the nine months ended September 30, 2021, we granted tenant concessions/free rent averaging 2.5 months with respect to the 5,422,127 RSF leased. Approximately 52% of the leases executed during the nine months ended September 30, 2021, did not include concessions for free rent.
Summary of contractual lease expirations
The following table summarizes information with respect to the contractual lease expirations at our properties as of September 30, 2021:
| Year | RSF | Percentage of Occupied RSF | Annual Rental Revenue (per RSF)(1) | Percentage of Total Annual Rental Revenue | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2021 | (2) | 669,501 | 1.8 | % | $ | 42.01 | 1.6 | % | ||||||||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2,514,927 | 6.9 | % | $ | 43.75 | 6.4 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2023 | 3,593,276 | 9.9 | % | $ | 40.09 | 8.4 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2024 | 3,220,392 | 8.9 | % | $ | 43.27 | 8.1 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2025 | 2,894,465 | 8.0 | % | $ | 50.51 | 8.5 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2,282,272 | 6.3 | % | $ | 45.40 | 6.0 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2027 | 2,264,684 | 6.2 | % | $ | 48.00 | 6.3 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2028 | 3,046,238 | 8.4 | % | $ | 49.97 | 8.9 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2029 | 2,333,448 | 6.4 | % | $ | 53.34 | 7.3 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 2030 | 2,282,456 | 6.3 | % | $ | 53.32 | 7.1 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Thereafter | 11,285,360 | 30.9 | % | $ | 47.44 | 31.4 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
(1)Represents amounts in effect as of September 30, 2021.
(2)Excludes month-to-month leases aggregating 94,202 RSF as of September 30, 2021.
The following tables present information by market with respect to our lease expirations in North America as of September 30, 2021, for the remainder of 2021, and all of 2022:
| 2021 Contractual Lease Expirations (in RSF) | Annual Rental Revenue (per RSF)(2) | |||||||||||||||||||||||||||||||||||||
| Market | Leased | Negotiating/ Anticipating | Targeted for Development/ Redevelopment | Remaining Expiring Leases | Total(1) | |||||||||||||||||||||||||||||||||
| Greater Boston | 91,284 | 16,674 | 202,428 | 5,807 | 316,193 | $ | 37.23 | |||||||||||||||||||||||||||||||
| San Francisco Bay Area | 63,831 | 18,223 | — | 60,904 | 142,958 | 63.31 | ||||||||||||||||||||||||||||||||
| New York City | — | 130 | — | 1,191 | 1,321 | N/A | ||||||||||||||||||||||||||||||||
| San Diego | 38,201 | — | 32,774 | 62,175 | 133,150 | 29.54 | ||||||||||||||||||||||||||||||||
| Seattle | — | — | — | 17,883 | 17,883 | 16.09 | ||||||||||||||||||||||||||||||||
| Maryland | 7,268 | — | — | 3,125 | 10,393 | 37.63 | ||||||||||||||||||||||||||||||||
| Research Triangle | 21,215 | 6,871 | — | 10,747 | 38,833 | 37.78 | ||||||||||||||||||||||||||||||||
| Canada | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||
| Non-cluster/other markets | — | — | — | 8,770 | 8,770 | 104.46 | ||||||||||||||||||||||||||||||||
| Total | 221,799 | 41,898 | 235,202 | 170,602 | 669,501 | $ | 42.01 | |||||||||||||||||||||||||||||||
| Percentage of expiring leases | 33 | % | 6 | % | 35 | % | 26 | % | 100 | % | ||||||||||||||||||||||||||||
| 2022 Contractual Lease Expirations (in RSF) | Annual Rental Revenue (per RSF)(2) | |||||||||||||||||||||||||||||||||||||
| Market | Leased | Negotiating/ Anticipating | Targeted for Development/ Redevelopment(3) | Remaining Expiring Leases(4) | Total | |||||||||||||||||||||||||||||||||
| Greater Boston | 57,663 | 158,561 | — | 267,256 | 483,480 | $ | 57.99 | |||||||||||||||||||||||||||||||
| San Francisco Bay Area | — | 60,075 | 490,127 | 180,190 | 730,392 | 51.78 | ||||||||||||||||||||||||||||||||
| New York City | 14,891 | — | — | 3,464 | 18,355 | N/A | ||||||||||||||||||||||||||||||||
| San Diego | 103,730 | 6,196 | 354,123 | 160,226 | 624,275 | 35.26 | ||||||||||||||||||||||||||||||||
| Seattle | — | 15,177 | 51,255 | 124,951 | 191,383 | 32.79 | ||||||||||||||||||||||||||||||||
| Maryland | 35,789 | 35,144 | — | 9,966 | 80,899 | 26.81 | ||||||||||||||||||||||||||||||||
| Research Triangle | — | 7,591 | 62,490 | 149,202 | 219,283 | 24.76 | ||||||||||||||||||||||||||||||||
| Canada | — | 26,426 | — | 2,197 | 28,623 | 22.49 | ||||||||||||||||||||||||||||||||
| Non-cluster/other markets | — | 10,430 | — | 127,807 | 138,237 | 35.21 | ||||||||||||||||||||||||||||||||
| Total | 212,073 | 319,600 | 957,995 | 1,025,259 | 2,514,927 | $ | 43.75 | |||||||||||||||||||||||||||||||
| Percentage of expiring leases | 8 | % | 13 | % | 38 | % | 41 | % | 100 | % |
(1)Excludes month-to-month leases aggregating 94,202 RSF as of September 30, 2021.
(2)Represents amounts in effect as of September 30, 2021.
(3)Represents RSF targeted for development or redevelopment upon expiration of existing in-place leases primarily related to recently acquired properties with an average contractual lease expiration date, weighted by annual rental revenue, of April 26, 2022. Refer to “Investments in real estate – value-creation square footage currently in rental properties” in the “Non-GAAP measures and definitions” section within this Item 2 for additional details on value-creation square feet currently included in rental properties.
(4)The largest remaining contractual expiration is 113,555 RSF in our Cambridge/Inner Suburbs submarket.
Top 20 tenants
89% of Top 20 Annual Rental Revenue From Investment-Grade
or Publicly Traded Large Cap Tenants**(1)**
Our properties are leased to a high-quality and diverse group of tenants, with no individual tenant accounting for more than 3.1% of our annual rental revenue in effect as of September 30, 2021. The following table sets forth information regarding leases with our 20 largest tenants in North America based upon annual rental revenue in effect as of September 30, 2021 (dollars in thousands, except average market cap):
| Remaining Lease Term(1) (in Years) | Aggregate RSF | Annual Rental Revenue(1) | Percentage of Aggregate Annual Rental Revenue (1) | Investment-Grade Credit Ratings | Average Market Cap(1) (in billions) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Tenant | Moody’s | S&P | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1 | Bristol-Myers Squibb Company | 7.0 | 916,234 | $ | 53,085 | 3.1 | % | A2 | A+ | $ | 142.8 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2 | Takeda Pharmaceutical Company Ltd. | 7.9 | 606,249 | 39,416 | 2.3 | Baa2 | BBB+ | $ | 54.7 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 3 | Moderna, Inc. | 11.0 | 855,458 | 39,341 | 2.3 | — | — | $ | 79.5 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 4 | Facebook, Inc. | 10.3 | 903,786 | 38,795 | 2.3 | — | — | $ | 869.2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 5 | Eli Lilly and Company | 7.5 | 602,874 | 37,755 | 2.2 | A2 | A+ | $ | 189.7 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 6 | Sanofi | 7.7 | 553,693 | 36,952 | 2.2 | A1 | AA | $ | 126.3 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 7 | Illumina, Inc. | 8.9 | 891,495 | 36,141 | 2.1 | Baa3 | BBB | $ | 60.2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 8 | Novartis AG | 6.8 | 447,820 | 30,595 | 1.8 | A1 | AA- | $ | 219.2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 9 | Uber Technologies, Inc. | 61.2 | (2) | 1,009,188 | 27,477 | 1.6 | — | — | $ | 91.0 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 10 | Roche | 2.5 | (3) | 546,893 | 26,077 | 1.5 | Aa3 | AA | $ | 308.2 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 11 | bluebird bio, Inc. | 5.7 | 312,805 | 23,140 | 1.4 | — | — | $ | 2.3 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 12 | Maxar Technologies | 4.0 | (4) | 478,000 | 21,803 | 1.3 | — | — | $ | 2.4 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 13 | Massachusetts Institute of Technology | 7.2 | 257,626 | 21,165 | 1.2 | Aaa | AAA | $ | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 14 | United States Government | 13.5 | 918,516 | 20,276 | 1.2 | Aaa | AA+ | $ | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 15 | The Children’s Hospital Corporation | 15.1 | 269,816 | 20,066 | 1.2 | Aa2 | AA | $ | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 16 | New York University | 10.0 | 204,691 | 19,531 | 1.2 | Aa2 | AA- | $ | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 17 | Merck & Co., Inc. | 12.4 | 311,015 | 19,392 | 1.1 | A1 | AA- | $ | 196.5 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 18 | Pfizer Inc. | 3.4 | 416,896 | 17,760 | 1.0 | A2 | A+ | $ | 218.2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 19 | FibroGen, Inc. | 7.2 | 234,249 | 16,896 | 1.0 | — | — | $ | 2.8 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 20 | Amgen Inc. | 2.5 | 407,369 | 16,838 | 1.0 | Baa1 | A- | $ | 136.3 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total/weighted-average | 10.6 | (2) | 11,144,673 | $ | 562,501 | 33.0 | % |
(1)Based on aggregate annual rental revenue in effect as of September 30, 2021. Refer to the definitions of “Annual rental revenue” and “Investment-grade or publicly traded large cap tenants” in the “Non-GAAP measures and definitions” section within this Item 2 for our methodologies on annual rental revenue from unconsolidated real estate joint ventures and average market capitalization.
(2)Includes (i) ground leases for land at 1455 and 1515 Third Street (two buildings aggregating 422,980 RSF) and (ii) leases at 1655 and 1725 Third Street (two buildings aggregating 586,208 RSF) owned by our unconsolidated real estate joint venture in which we have an ownership interest of 10%. Annual rental revenue is presented using 100% of the annual rental revenue of our consolidated properties and our share of annual rental revenue for our unconsolidated real estate joint ventures. Refer to footnote 1 for additional details. Excluding the ground lease, the weighted-average remaining lease term for our top 20 tenants was 8.1 years as of September 30, 2021.
(3)Includes 197,787 RSF expiring in 2022 at our recently acquired property at 651 Gateway Boulevard in our South San Francisco submarket. Upon expiration of the lease, 651 Gateway Boulevard will be redeveloped into a Class A office/laboratory building. Excluding this 197,787 RSF, the weighted-average remaining term of space leased to Roche is 3.1 years.
(4)Represents remaining lease term at two recently acquired properties with future redevelopment and development opportunities. The leases with this tenant were in place when we acquired the property during the year ended December 31, 2019.
Locations of properties
The locations of our properties are diversified among a number of life science, agtech, and technology cluster markets. The following table sets forth the total RSF, number of properties, and annual rental revenue in effect as of September 30, 2021, in each of our markets in North America (dollars in thousands, except per RSF amounts):
| RSF | Number of Properties | Annual Rental Revenue | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Market | Operating | Development | Redevelopment | Total | % of Total | Total | % of Total | Per RSF | ||||||||||||||||||||||||||||||||||||||||||||||||
| Greater Boston | 10,163,050 | 972,216 | 885,001 | 12,020,267 | 28 | % | 82 | $ | 590,125 | 35 | % | $ | 61.58 | |||||||||||||||||||||||||||||||||||||||||||
| San Francisco Bay Area | 8,385,438 | 535,373 | 48,722 | 8,969,533 | 21 | 68 | 419,550 | 25 | 59.92 | |||||||||||||||||||||||||||||||||||||||||||||||
| New York City | 1,165,060 | — | 104,959 | 1,270,019 | 3 | 5 | 82,964 | 5 | 72.43 | |||||||||||||||||||||||||||||||||||||||||||||||
| San Diego | 7,932,982 | 341,891 | 117,212 | 8,392,085 | 19 | 103 | 284,665 | 17 | 38.23 | |||||||||||||||||||||||||||||||||||||||||||||||
| Seattle | 2,734,010 | — | 213,976 | 2,947,986 | 7 | 42 | 109,681 | 6 | 41.70 | |||||||||||||||||||||||||||||||||||||||||||||||
| Maryland | 3,594,657 | 84,264 | 344,226 | 4,023,147 | 9 | 50 | 96,652 | 6 | 26.97 | |||||||||||||||||||||||||||||||||||||||||||||||
| Research Triangle | 3,202,145 | 363,688 | 325,936 | 3,891,769 | 9 | 36 | 77,270 | 5 | 25.64 | |||||||||||||||||||||||||||||||||||||||||||||||
| Canada | 322,159 | — | — | 322,159 | 1 | 4 | 6,638 | — | 24.90 | |||||||||||||||||||||||||||||||||||||||||||||||
| Non-cluster/other markets | 1,128,223 | — | — | 1,128,223 | 3 | 16 | 28,311 | 1 | 32.95 | |||||||||||||||||||||||||||||||||||||||||||||||
| Properties held for sale | 79,007 | — | — | 79,007 | — | 1 | 707 | — | 24.12 | |||||||||||||||||||||||||||||||||||||||||||||||
| North America | 38,706,731 | 2,297,432 | 2,040,032 | 43,044,195 | 100 | % | 407 | $ | 1,696,563 | 100 | % | $ | 47.73 | |||||||||||||||||||||||||||||||||||||||||||
| 4,337,464 |
Summary of occupancy percentages in North America
The following table sets forth the occupancy percentages for our operating properties and our operating and redevelopment properties in each of our North America markets, excluding properties held for sale, as of the following dates:
| Operating Properties | Operating and Redevelopment Properties | |||||||||||||||||||||||||||||||||||||
| Market | 9/30/21 | 6/30/21 | 9/30/20 | 9/30/21 | 6/30/21 | 9/30/20 | ||||||||||||||||||||||||||||||||
| Greater Boston | 94.3 | % | (1) | 95.5 | % | 98.3 | % | 86.7 | % | 91.0 | % | 95.0 | % | |||||||||||||||||||||||||
| San Francisco Bay Area | 94.5 | (1) | 94.0 | 95.3 | 94.0 | 92.9 | 94.2 | |||||||||||||||||||||||||||||||
| New York City | 98.3 | 99.4 | 95.5 | 90.2 | 90.1 | 84.8 | ||||||||||||||||||||||||||||||||
| San Diego | 93.9 | (1) | 93.8 | 93.7 | 92.5 | 92.3 | 92.7 | |||||||||||||||||||||||||||||||
| Seattle | 96.2 | 97.6 | 91.0 | 89.2 | 90.2 | 91.0 | ||||||||||||||||||||||||||||||||
| Maryland | 99.7 | 98.9 | 96.0 | 91.0 | 90.3 | 96.0 | ||||||||||||||||||||||||||||||||
| Research Triangle | 94.1 | (1) | 92.8 | 90.5 | 85.4 | 84.1 | 73.4 | |||||||||||||||||||||||||||||||
| Subtotal | 95.0 | 95.2 | 95.2 | 90.1 | 90.9 | 91.5 | ||||||||||||||||||||||||||||||||
| Canada | 82.8 | 77.0 | 90.0 | 82.8 | 77.0 | 90.0 | ||||||||||||||||||||||||||||||||
| Non-cluster/other markets | 76.2 | 46.0 | 69.8 | 76.2 | 46.0 | 69.8 | ||||||||||||||||||||||||||||||||
| North America | 94.4 | % | (1) | 94.3 | % | 94.9 | % | 89.6 | % | 90.1 | % | 91.3 | % | |||||||||||||||||||||||||
(1)Includes 1.6 million RSF, or 4.1%, of vacancy at recently acquired properties, representing lease-up opportunities that are expected to generate incremental annual rental revenues in excess of $59 million upon full lease-up. Approximately 41% of the vacant 1.6 million RSF is currently leased/negotiating, with occupancy expected primarily over the next two quarters. Excluding acquired vacancies, occupancy of operating properties in North America was 98.5% as of September 30, 2021, up 80 bps from 97.7% as of December 31, 2020. The following table provides vacancy detail for our recent acquisitions:
| As of September 30, 2021 | Percentage of Vacancy Leased/Negotiating | Incremental Projected Annual Rental Revenue Upon Full Lease-Up | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Vacant | Occupancy Impact | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Property | Market/Submarket | RSF | Region | Consolidated | |||||||||||||||||||||||||||||||||||||||||||||||||
| 601, 611, and 651 Gateway Boulevard | San Francisco Bay Area/South San Francisco | 314,991 | 3.8 | % | 0.8 | % | 45 | % | >$59 million | ||||||||||||||||||||||||||||||||||||||||||||
| 275 Grove Street | Greater Boston/Route 128 | 180,648 | 1.8 | % | 0.5 | 65 | |||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Durham | Research Triangle/Research Triangle | 150,337 | 4.7 | % | 0.4 | 94 | |||||||||||||||||||||||||||||||||||||||||||||||
| Other | Greater Boston/Other | 95,501 | 0.9 | % | 0.2 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| SD Tech by Alexandria | San Diego/Sorrento Mesa | 92,768 | 1.2 | % | 0.2 | 13 | |||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Fenway | Greater Boston/Fenway | 81,538 | 0.8 | % | 0.2 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Other acquisitions | Various | 674,471 | N/A | 1.8 | 36 | ||||||||||||||||||||||||||||||||||||||||||||||||
| 1,590,254 | 4.1 | % | 41 | % |
Investments in real estate
A key component of our business model is our disciplined allocation of capital to the development and redevelopment of new Class A properties located in collaborative life science, agtech, and technology campuses in AAA innovation clusters. These projects are focused on providing high-quality, generic, and reusable spaces that meet the real estate requirements of, and are reusable by, a wide range of tenants. Upon completion, each value-creation project is expected to generate a significant increase in rental income, net operating income, and cash flows. Our development and redevelopment projects are generally in locations that are highly desirable to high-quality entities, which we believe results in higher occupancy levels, longer lease terms, higher rental income, higher returns, and greater long-term asset value. Our pre-construction activities are undertaken in order to get the property ready for its intended use and include entitlements, permitting, design, site work, and other activities preceding commencement of construction of aboveground building improvements.
Our investments in real estate consisted of the following as of September 30, 2021 (dollars in thousands):
| Development and Redevelopment | ||||||||||||||||||||||||||||||||||||||||||||
| Operating | Under Construction | Near Term | Intermediate Term | Future | Subtotal | Total | ||||||||||||||||||||||||||||||||||||||
| Investments in real estate | ||||||||||||||||||||||||||||||||||||||||||||
| Book value as of September 30, 2021(1) | $ | 21,499,872 | $ | 2,240,891 | $ | 1,190,570 | $ | 605,848 | $ | 1,130,464 | $ | 5,167,773 | $ | 26,667,645 | ||||||||||||||||||||||||||||||
| Square footage | ||||||||||||||||||||||||||||||||||||||||||||
| Operating | 38,706,731 | — | — | — | — | — | 38,706,731 | |||||||||||||||||||||||||||||||||||||
| New Class A development and redevelopment properties | — | 4,337,464 | 6,392,194 | (2) | 4,047,611 | 14,790,048 | 29,567,317 | 29,567,317 | ||||||||||||||||||||||||||||||||||||
| Value-creation square feet currently included in rental properties(3) | — | — | (1,235,727) | (372,991) | (2,806,550) | (4,415,268) | (4,415,268) | |||||||||||||||||||||||||||||||||||||
| Total square footage | 38,706,731 | 4,337,464 | 5,156,467 | 3,674,620 | 11,983,498 | 25,152,049 | 63,858,780 |
(1)Balances exclude our share of the cost basis associated with our properties held by our unconsolidated real estate joint ventures, which is classified as investments in unconsolidated real estate joint ventures in our consolidated balance sheets.
(2)Includes 3,366,117 RSF, currently 80% leased/negotiating, expected to commence construction in the next six quarters. Refer to “New Class A development and redevelopment properties: current projects” within this Item 2 for additional details.
(3)Refer to the definition of “Investments in real estate – value-creation square footage currently in rental properties” in the “Non-GAAP measures and definitions” section within this Item 2 for additional details on value-creation square feet currently included in rental properties.
Acquisitions
Our real estate asset acquisitions for the nine months ended September 30, 2021, consisted of the following (dollars in thousands):
| Property | Submarket/Market | Date of Purchase | Number of Properties | Operating Occupancy | Square Footage | Purchase Price | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Acquisitions With Development and Redevelopment Opportunities(1) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Future Development | Active Development/Redevelopment | Operating With Future Development/ Redevelopment | Operating(2) | Operating | Total | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Nine months ended September 30, 2021: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 550 Arsenal Street | Cambridge/Inner Suburbs/Greater Boston | 4/21/21 | 1 | 98 | % | 775,000 | — | 260,867 | — | — | 775,000 | (3) | $ | 130,000 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Fenway | Fenway/Greater Boston | 1/29/21 | 2 | 90 | (4) | 305,000 | 510,116 | 311,066 | 662,079 | — | 1,788,261 | 1,483,200 | (4) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| One Investors Way | Route 128/Greater Boston | 4/6/21 | 1 | 100 | 350,000 | — | — | 240,000 | (5) | — | 590,000 | 105,000 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
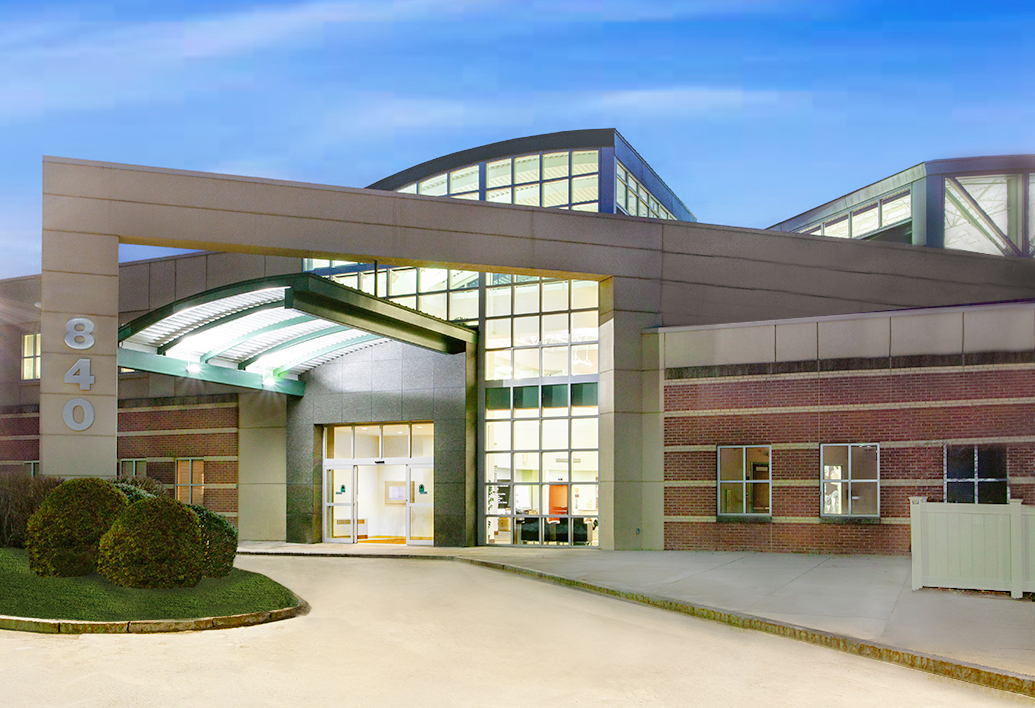
| 840 Winter Street | Route 128/Greater Boston | 1/20/21 | 1 | 100 | — | 130,000 | — | 30,009 | — | 160,009 | 58,126 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | Other/Greater Boston | 8/24/21 | 4 | 45 | 440,992 | 453,869 | 173,276 | — | — | 1,068,137 | 192,000 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1122 El Camino Real | South San Francisco/San Francisco Bay Area | 9/14/21 | 1 | 100 | 700,000 | — | 223,232 | — | — | 700,000 | (3) | 105,250 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1501-1599 Industrial Road | Greater Stanford/ San Francisco Bay Area | 6/22/21 | 6 | 88 | — | — | 103,063 | — | — | 103,063 | 112,000 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2475 Hanover Street | Greater Stanford/San Francisco Bay Area | 4/28/21 | 1 | 100 | — | — | 83,980 | — | — | 83,980 | 105,000 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 6260, 6290, 6310, 6340, and 6350 Sequence Drive | Sorrento Mesa/San Diego | 6/10/21 | 5 | 100 | 887,000 | — | 487,023 | — | — | 887,000 | (3) | 298,476 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Pacific Technology Park (50% interest in consolidated JV) | Sorrento Mesa/San Diego | 8/5/21 | 5 | 100 | — | — | 228,871 | 315,481 | — | 544,352 | 85,750 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | Other/San Diego | 7/21/21 | 9 | 77 | 64,235 | — | 211,440 | 98,428 | — | 374,103 | 135,484 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 9601, 9605, 9609, 9613, and 9615 Medical Center Drive(6) | Rockville/Maryland | 5/12/21 | 5 | 100 | 258,000 | 94,256 | — | 595,381 | — | 947,637 | 80,382 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 3029 East Cornwallis Road | Research Triangle/Research Triangle | 7/30/21 | — | N/A | 1,055,000 | — | — | — | — | 1,055,000 | 91,000 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | Various | Various | 35 | 94 | 3,110,894 | 246,562 | 740,269 | 859,663 | 238,948 | (7) | 5,196,336 | 960,234 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 76 | 93 | % | 7,946,121 | 1,434,803 | 2,823,087 | 2,801,041 | 238,948 | 14,272,878 | $ | 3,941,902 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
(1)We expect to provide total estimated costs and related yields for development and redevelopment projects in the future, subsequent to the commencement of construction. Refer to “New Class A development and redevelopment properties: current projects” within this Item 2 for additional information on active development and redevelopment projects.
(2)Represents the operating component of our value-creation acquisitions that is not expected to undergo development or redevelopment.
(3)Represents total square footage upon completion of development or redevelopment of a new Class A property. Square footage presented includes RSF of buildings currently in operations with future development or redevelopment opportunities. We intend to demolish and develop or redevelop the existing properties upon expiration of the existing in-place leases. Refer to the definition of “Investments in real estate – value-creation square footage currently in rental properties” in the “Non-GAAP measures and definitions” section within this Item 2 for additional information.
(4)The campus includes an operating property with future redevelopment opportunities at 401 Park Drive, a development project at 201 Brookline Avenue, and a future development opportunity. 401 Park Drive, aggregating 973,145 RSF, is 90% occupied, with an additional 3% of leased space that is under renovation, and has initial stabilized yields of 5.7% and 4.5% (cash basis). We expect to provide total estimated costs and related yields for the development projects at 201 Brookline Avenue and the future development/redevelopment opportunities in the future, subsequent to the commencement of construction. Refer to “New Class A development and redevelopment properties: current projects” within this Item 2 for additional information.
(5)Upon acquisition of this property, we entered into a 12-year lease with Moderna, Inc.
(6)We acquired land subject to two ground leases aggregating 595,381 RSF at 9609, 9613, and 9615 Medical Center Drive. We also acquired the land at 9605 Medical Center Drive, where we had previously acquired the building subject to a ground lease during the three months ended March 31, 2020.
(7)Includes the acquisition of our partner’s 43.2% ownership interest in our previously unconsolidated real estate joint venture at 704 Quince Orchard Road for $9.4 million. We completed the redevelopment of this stabilized property during the three months ended June 30, 2019.
Dispositions and sales of partial interest
Our completed dispositions of and sales of partial interest in real estate assets during the nine months ended September 30, 2021, consisted of the following (dollars in thousands, except for sales price per RSF):
| Property | Submarket/Market | Date of Sale | Interest Sold | RSF | Capitalization Rate | Capitalization Rate (Cash Basis) | Sales Price(1) | Sales Price per RSF | Consideration in Excess of Book Value(2) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Nine months ended September 30, 2021: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 213 East Grand Avenue | South San Francisco/ San Francisco Bay Area | 4/22/21 | 70% | 300,930 | 4.5 | % | 4.0 | % | $ | 301,000 | $ | 1,429 | $ | 103,679 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 400 Dexter Avenue North | Lake Union/Seattle | 7/23/21 | 70% | 290,111 | 4.1 | % | 4.2 | % | 254,814 | $ | 1,255 | 95,467 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 260 Townsend Street | SoMa/San Francisco Bay Area | 7/30/21 | 100% | 66,682 | N/A | N/A | 49,000 | (3) | $ | 735 | (3) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 220 and 240 2nd Avenue South | SoDo/Seattle | 7/29/21 | 100% | 80,160 | N/A | N/A | 24,100 | $ | 301 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Land | Other/San Diego | 3/12/21 | 100% | 185,000 | N/A | N/A | 22,900 | N/A | (4) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 9444 Waples Street | Sorrento Mesa/San Diego | 8/5/21 | 50% | 88,380 | N/A | N/A | 11,469 | $ | 260 | — | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1,011,263 | $ | 663,283 | $ | 199,146 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
(1)For sales of partial interests, represents the contractual sales price for the percentage interest of the property sold by us.
(2)For each partial interest sale, we control the newly formed real estate joint venture and therefore continue to consolidate this property. We accounted for the difference between the consideration received and the book value of the interest sold as an equity transaction, with no gain or loss recognized in earnings.
(3)The sales price includes the assumption by the buyer of a secured loan for $28.2 million. Upon completion of the sale, we recognized a loss on sale of real estate aggregating $435 thousand.
(4)During the three months ended March 31, 2021, we recognized $2.8 million of gains on sales of real estate related to the completion of two real estate dispositions.
Sustainability

(1)Source: Barron’s, “The 10 Most Sustainable REITs, According to Calvert,” February 19, 2021.
(2)Relative to a 2015 baseline for buildings in operation that Alexandria directly manages.
(3)For buildings in operation that Alexandria indirectly and directly manages.
(4)Reflects sum of annual like-for-like progress from 2015 to 2020.
(5)Reflects progress for all buildings in operation in 2020 that Alexandria indirectly and directly manages.
Social Responsibility

New Class A development and redevelopment properties
We continue to execute our unique and differentiated life science strategy at an accelerated pace and expand our collaborative campuses and asset base in each of our key life science cluster submarkets, and we remain strategically positioned to take maximum advantage of historic tenant demand.
Demand for our value-creation development and redevelopment projects of high-quality office/laboratory space, as well as continued operational excellence at our world-class, sophisticated laboratory facilities and strong execution by our team, has translated into record leasing activity.
| Under Construction | Key Projects Expected to Commence Construction in the Next Six Quarters**(1)** | Incremental Projected Annual Rental Revenues | ||||||||||||
| 4.3 Million RSF | 3.4 Million RSF | > $615 Million | ||||||||||||
| 37 Properties | + | 20 Properties | = | |||||||||||
| 79% Leased/Negotiating | 80% Leased/Negotiating |
(1)We also expect other projects to commence construction in 2022.
New Class A development and redevelopment properties: recent deliveries
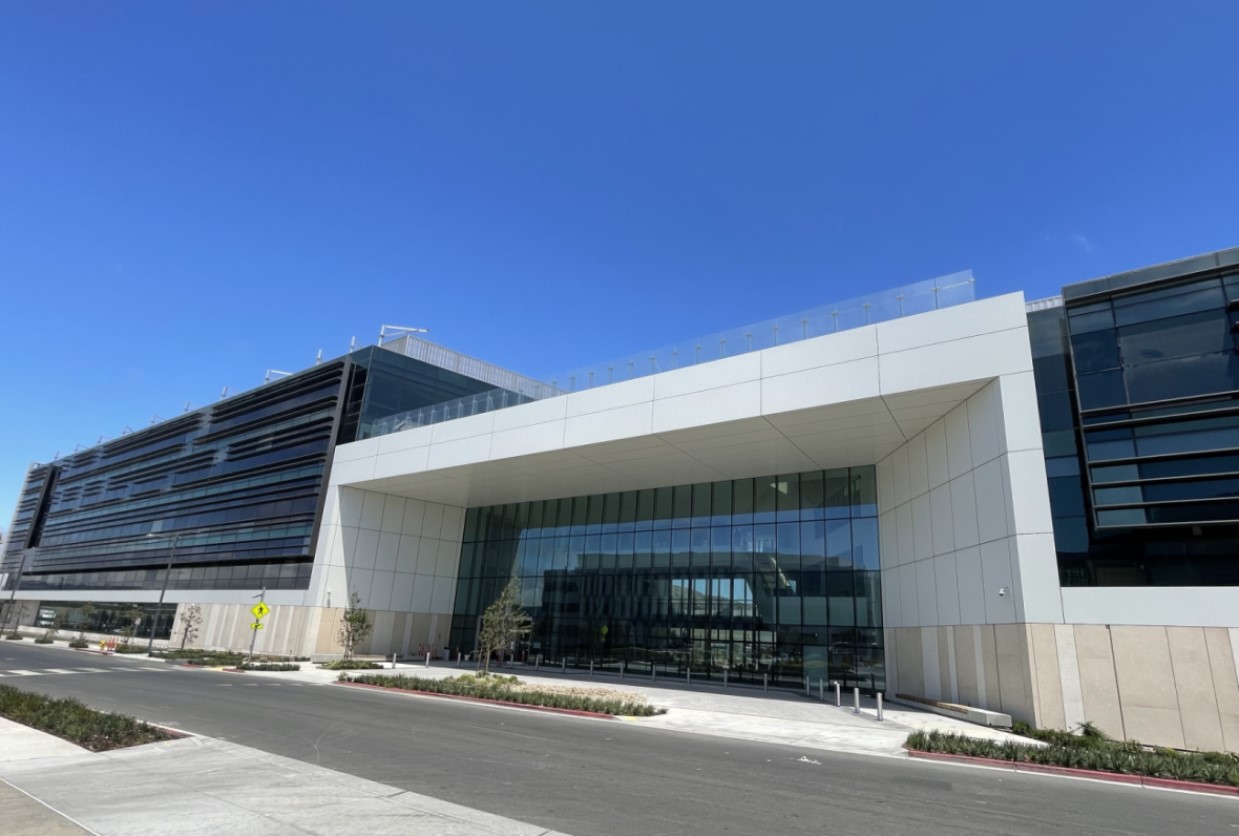
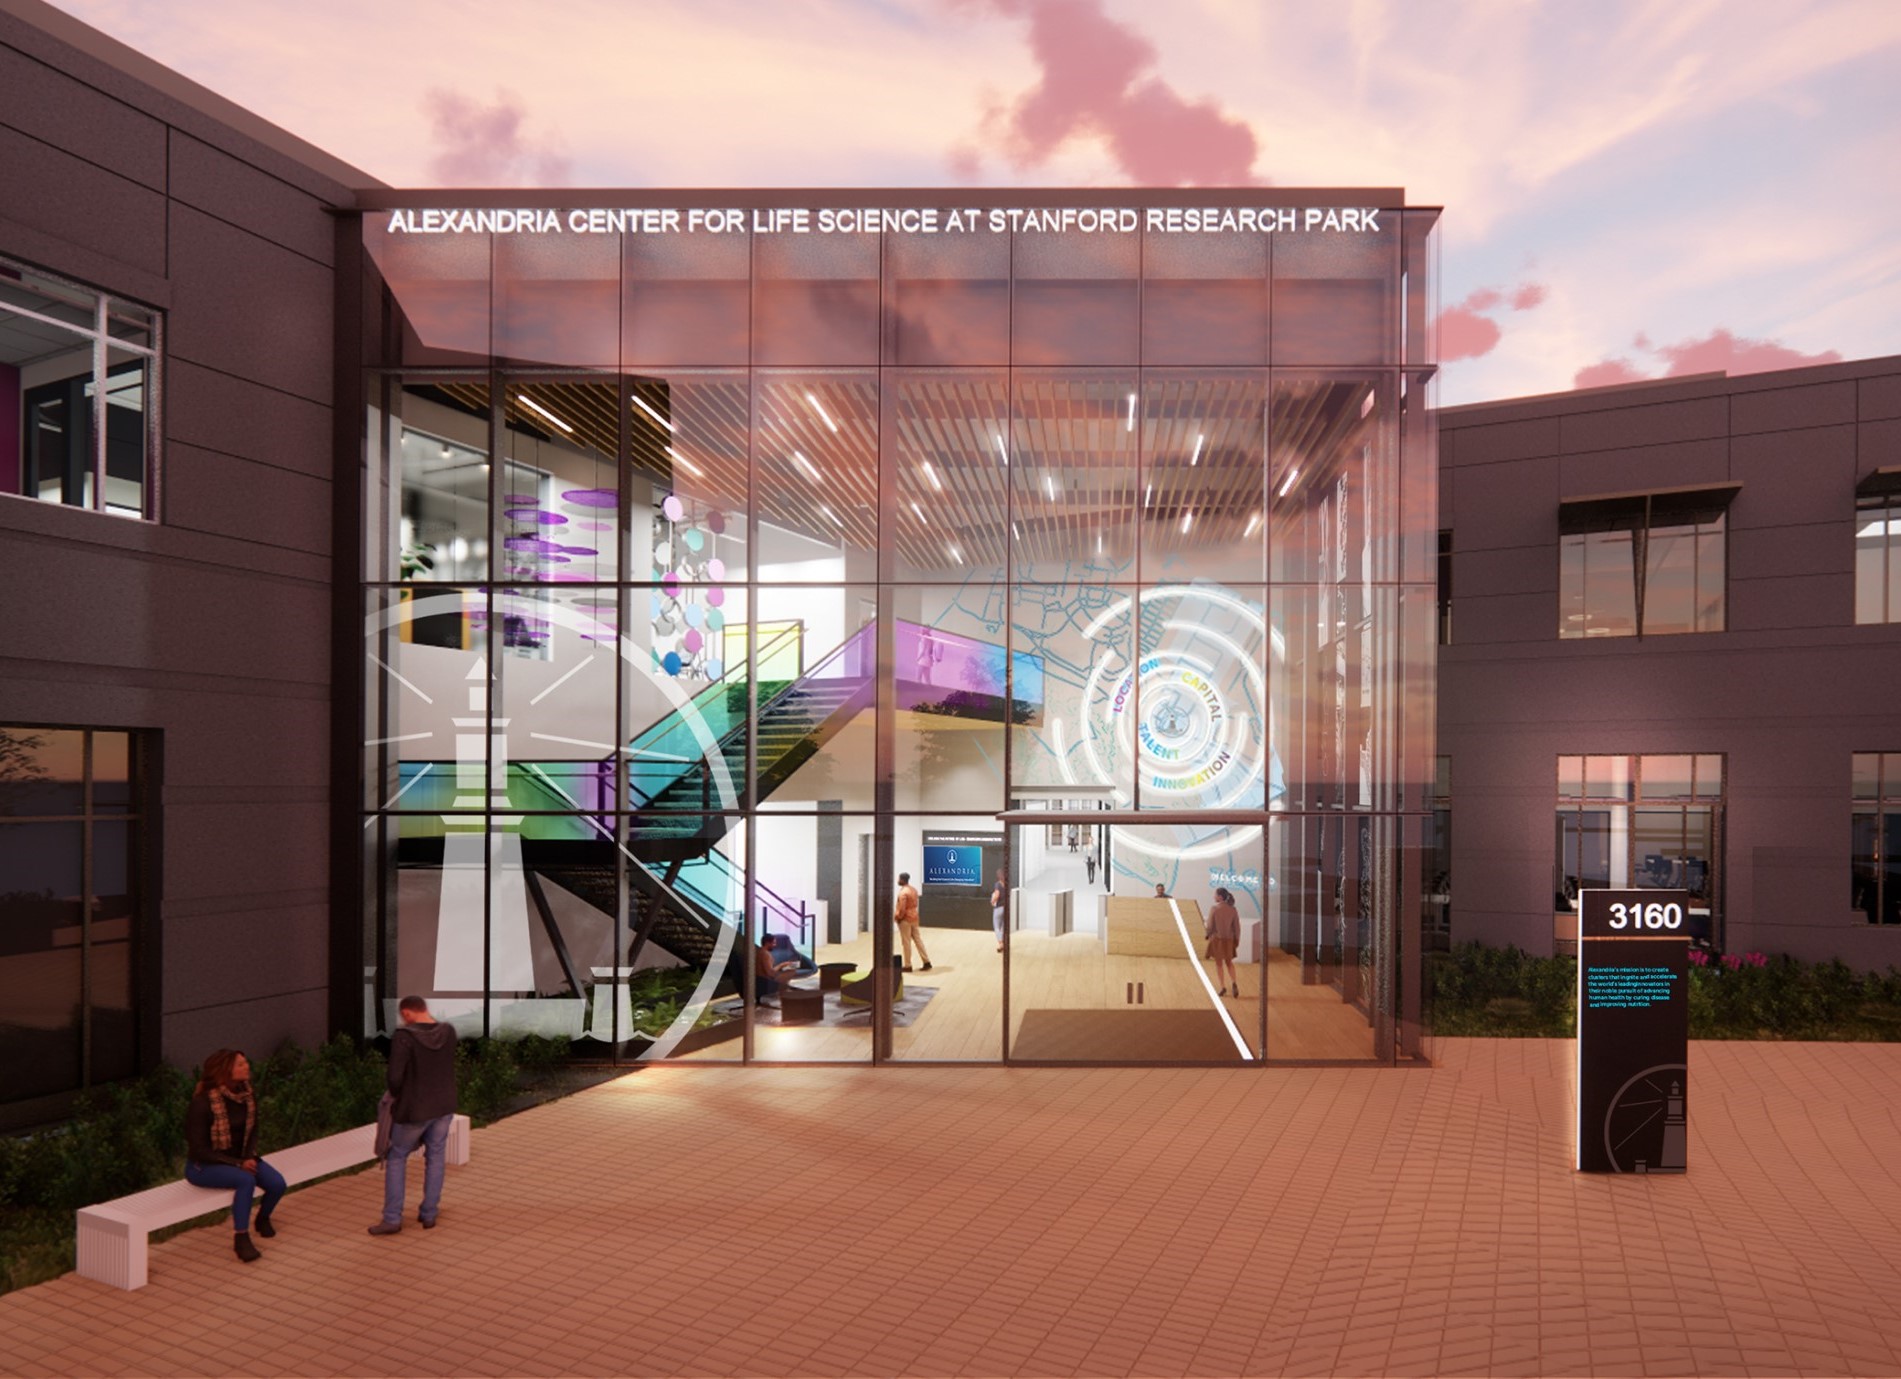
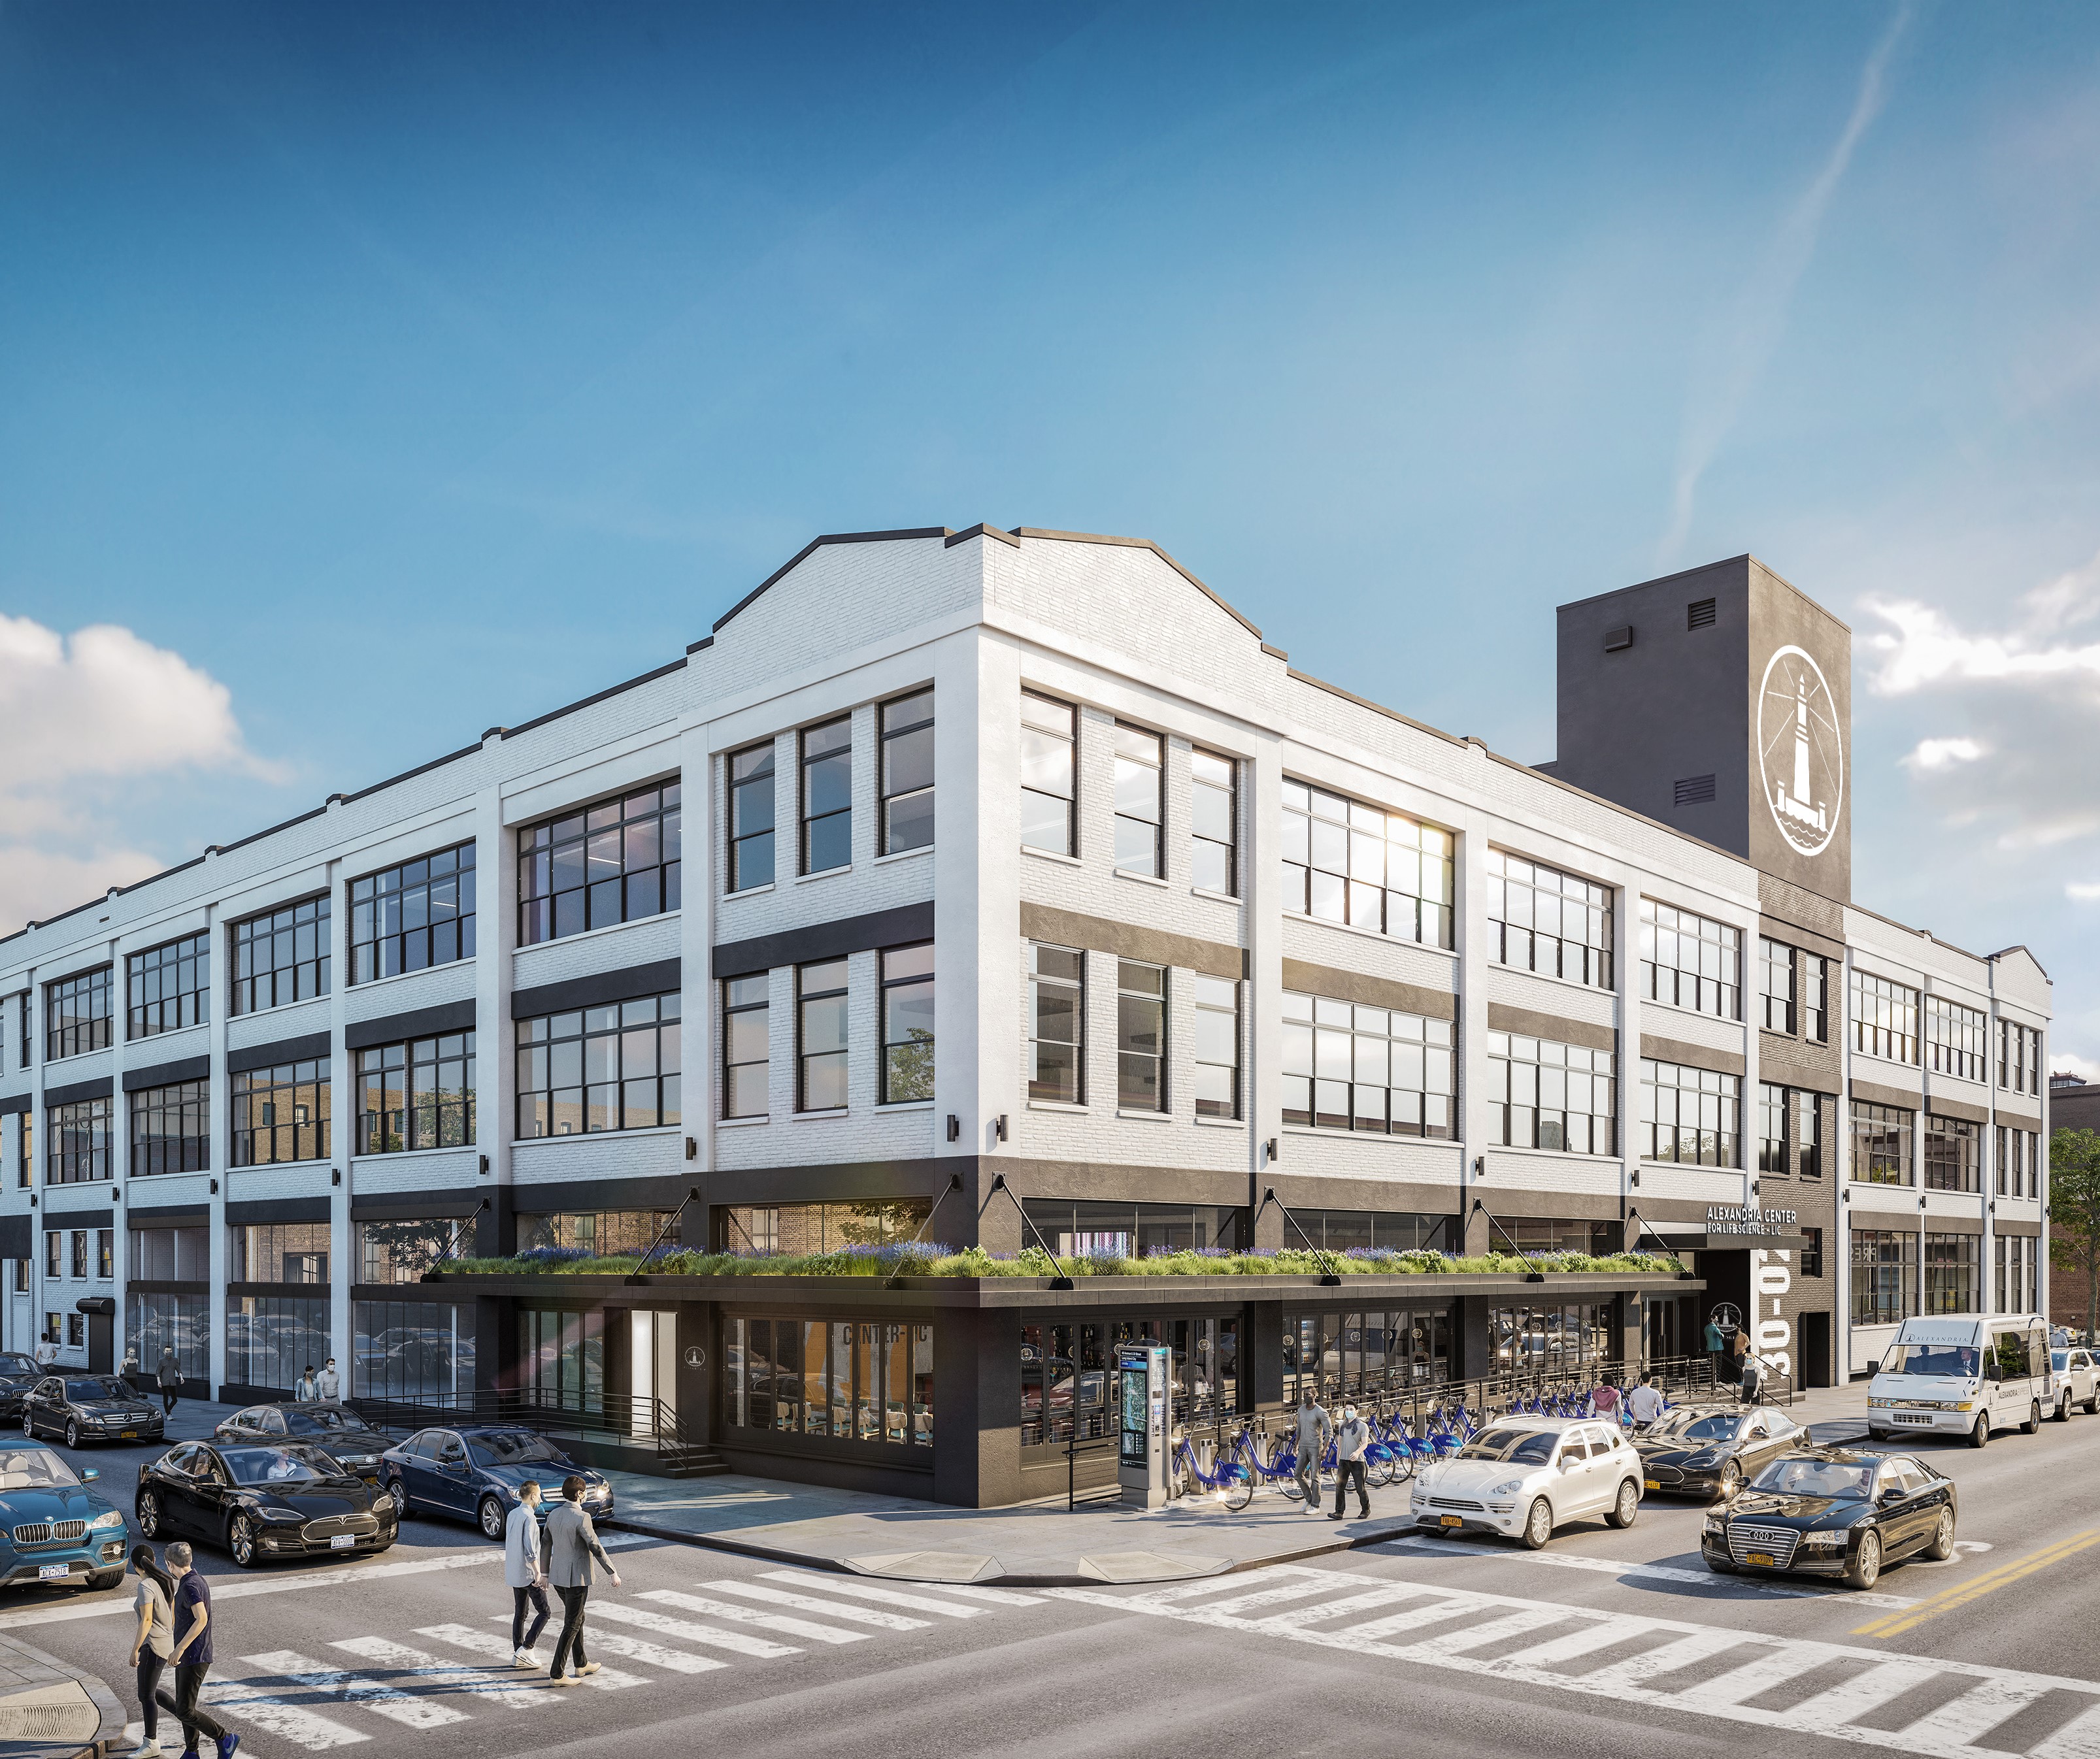
| The Arsenal on the Charles | Alexandria Center**®** for Life Science – South San Francisco**(1)** | Alexandria Center**®** for Life Science – San Carlos**(2)** | 3160 Porter Drive | Alexandria Center**®** for Life Science – Long Island City**(3)** | ||||||||||||||||||||||||||||
| Greater Boston/ Cambridge/Inner Suburbs | San Francisco Bay Area/ South San Francisco | San Francisco Bay Area/ Greater Stanford | San Francisco Bay Area/ Greater Stanford | New York City/New York City | ||||||||||||||||||||||||||||
| 86,546 RSF | 226,400 RSF | 316,546 RSF | 43,578 RSF | 32,892 RSF | ||||||||||||||||||||||||||||
| 100% Occupancy | 100% Occupancy | 100% Occupancy | 100% Occupancy | 100% Occupancy | ||||||||||||||||||||||||||||
 |  |  |  |  |
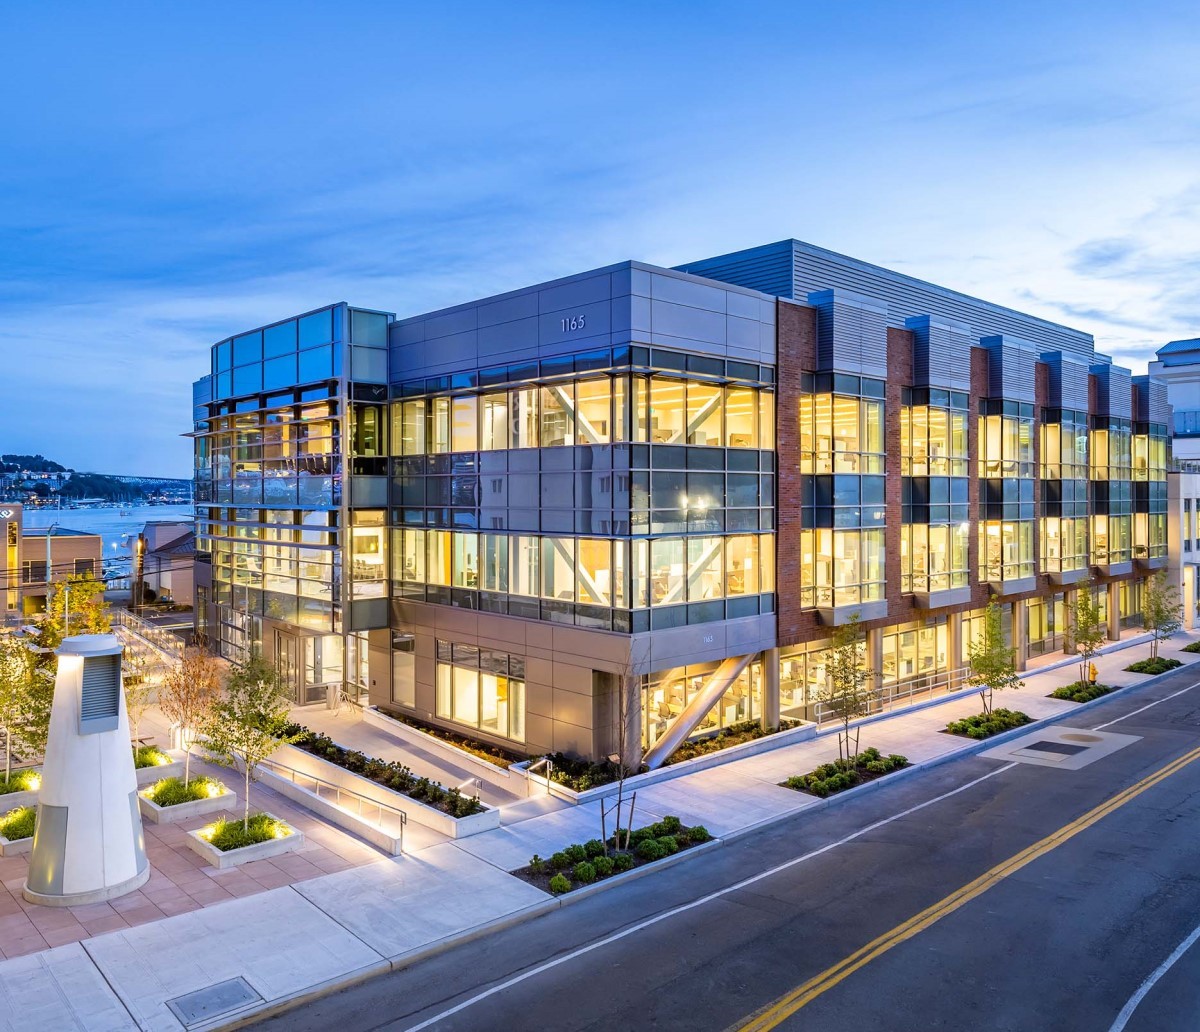
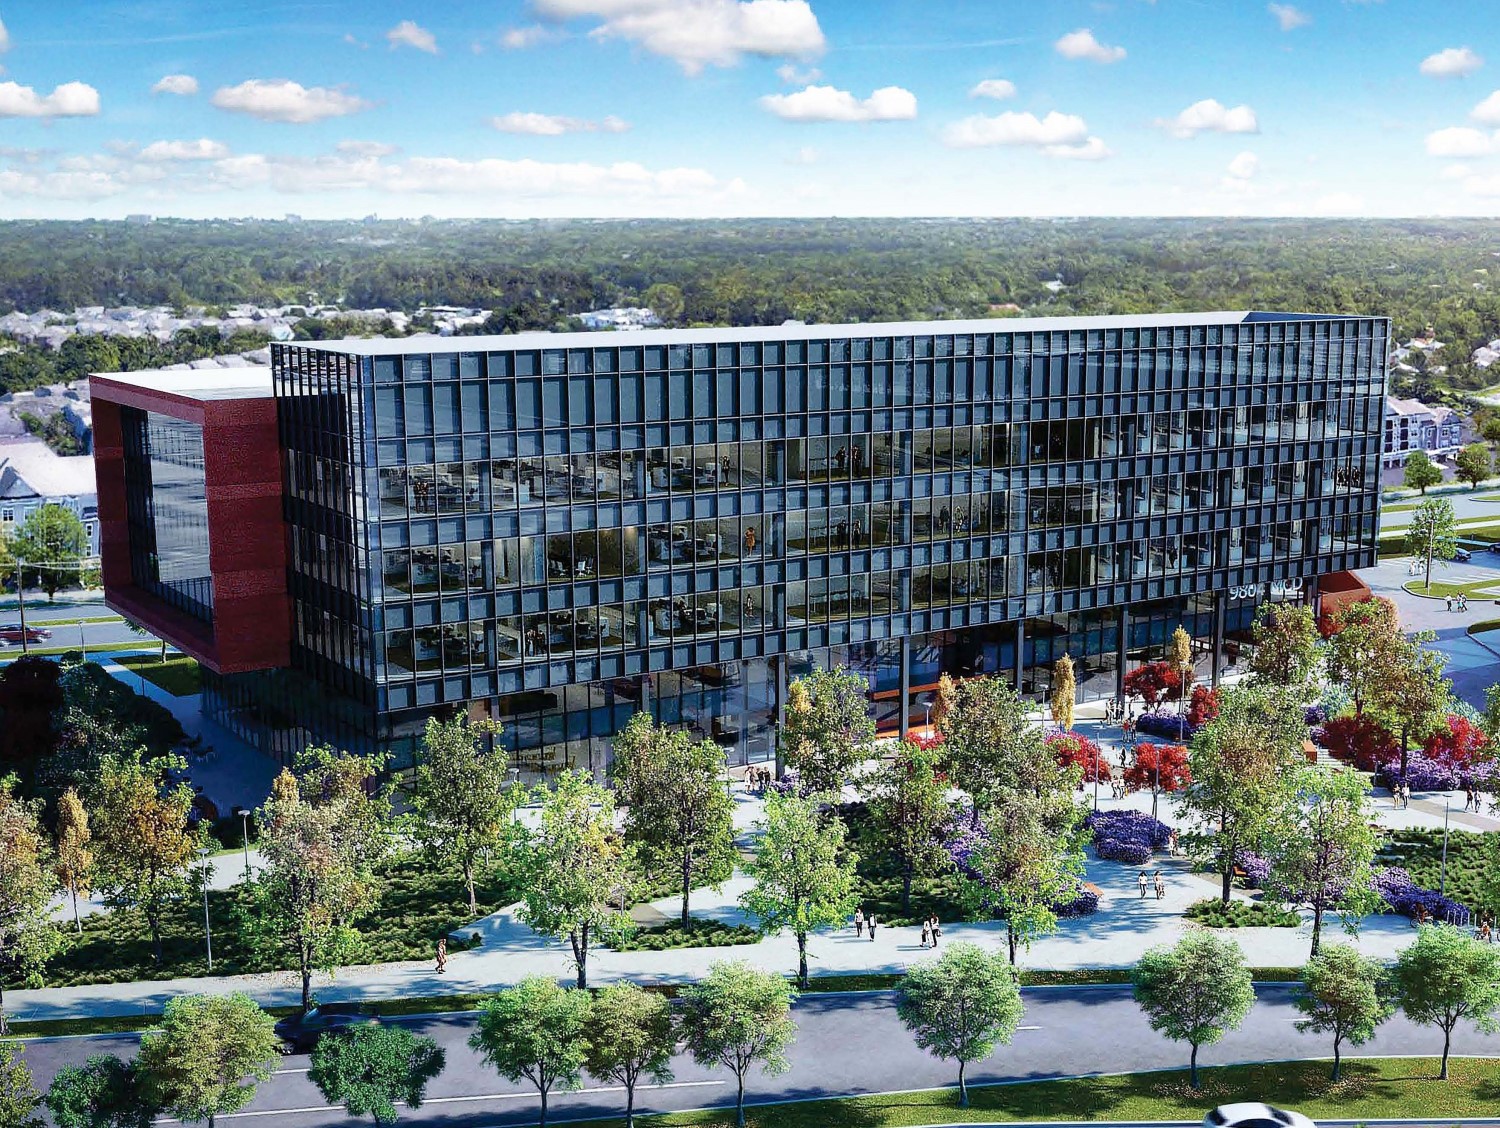
| 1165 Eastlake Avenue East | 9804 Medical Center Drive | Alexandria Center**®** for Life Science – Durham**(4)** | Alexandria Center**®** for AgTech**(5)** | Alexandria Center**®** for Advanced Technologies**(6)** | ||||||||||||||||||||||||||||
| Seattle/Lake Union | Maryland/Rockville | Research Triangle/Research Triangle | Research Triangle/Research Triangle | Research Triangle/Research Triangle | ||||||||||||||||||||||||||||
| 100,086 RSF | 176,832 RSF | 326,445 RSF | 25,812 RSF | 20,500 RSF | ||||||||||||||||||||||||||||
| 100% Occupancy | 100% Occupancy | 100% Occupancy | 100% Occupancy | 100% Occupancy | ||||||||||||||||||||||||||||
 |  |  |  |  |
(1)Image represents 201 Haskins Way in our Alexandria Center® for Life Science – South San Francisco campus.
(2)Image represents 825 and 835 Industrial Road in our Alexandria Center® for Life Science – San Carlos campus.
(3)Image represents 30-02 48th Avenue in our Alexandria Center® for Life Science – Long Island City campus.
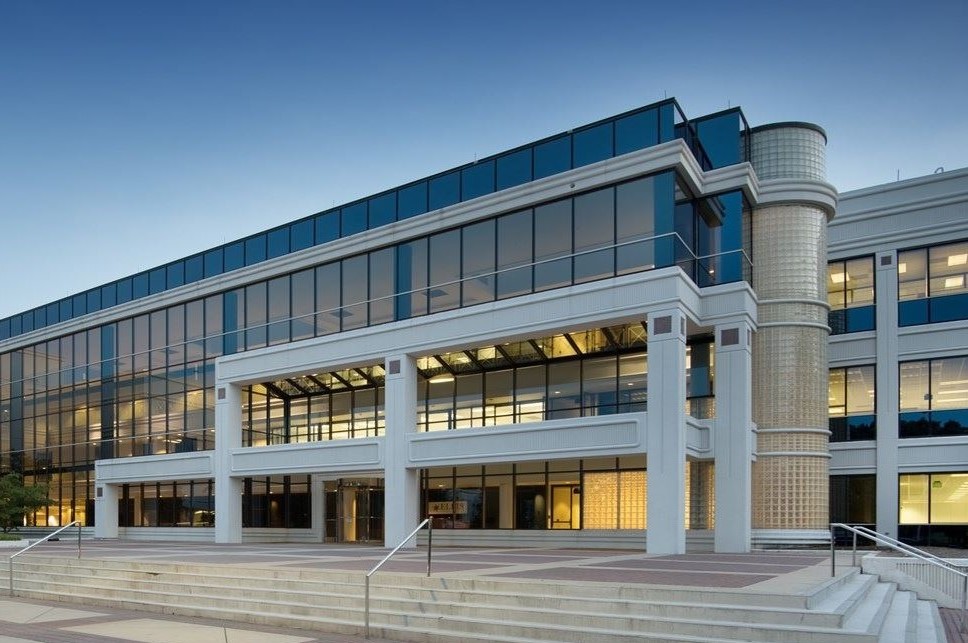
(4)Image represents 2400 Ellis Road in our Alexandria Center® for Life Science – Durham campus.
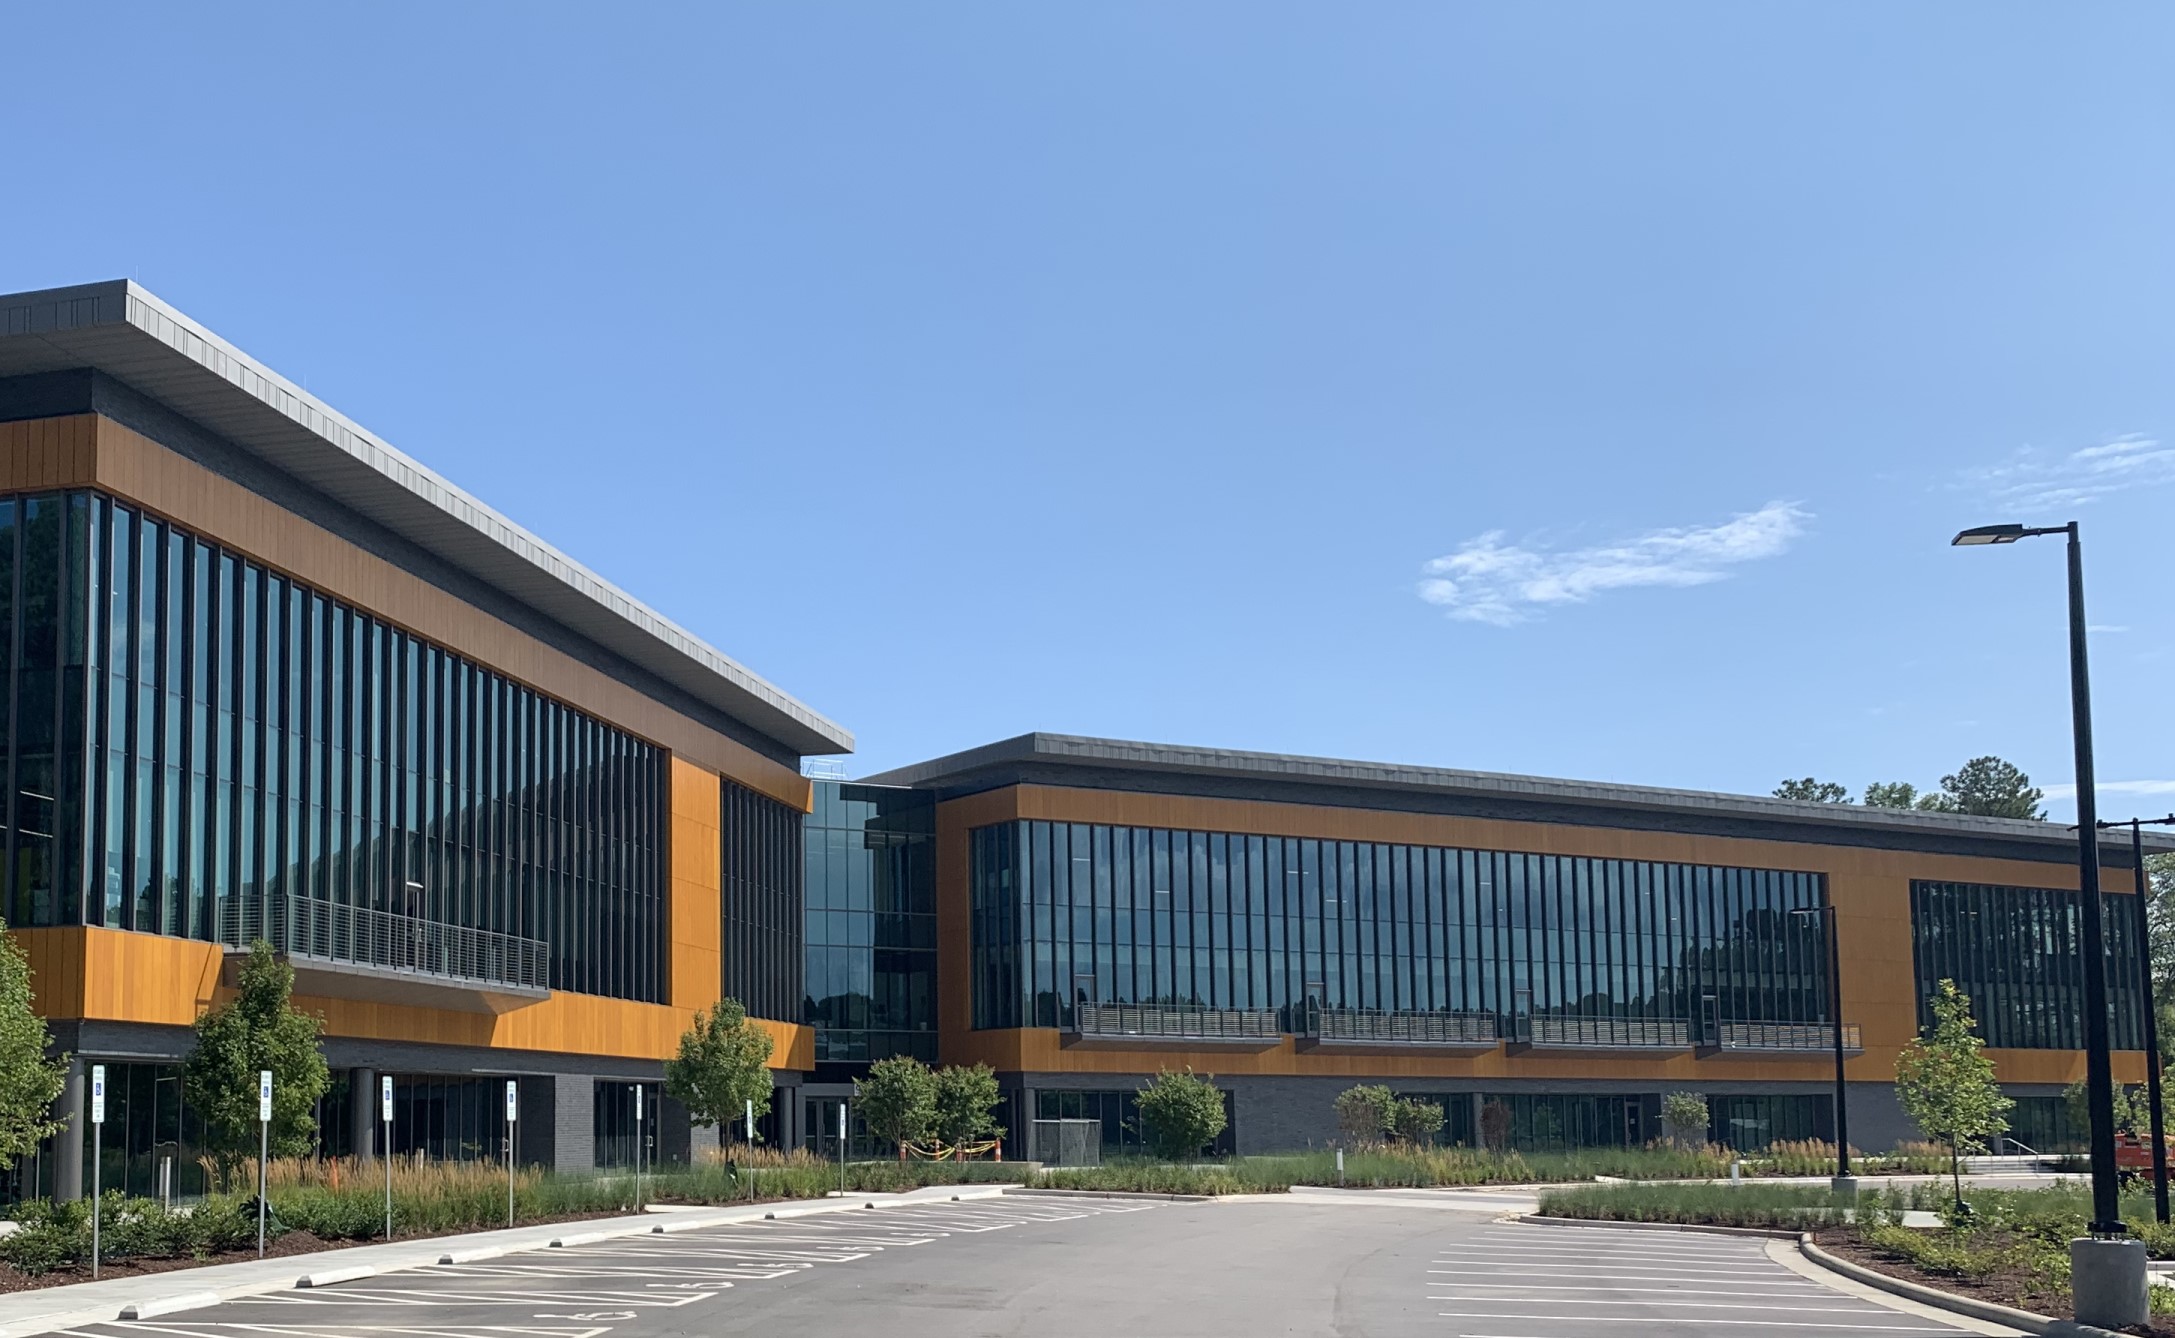
(5)Image represents 9 Laboratory Drive in our Alexandria Center® for AgTech campus.
(6)Image represents 10 Davis Drive in our Alexandria Center® for Advanced Technologies campus.
New Class A development and redevelopment properties: recent deliveries (continued)
The following table presents value-creation development and redevelopment of new Class A properties placed into service during the three months ended September 30, 2021 (dollars in thousands):
| Property/Market/Submarket | 3Q21 Delivery Date**(1)** | Our Ownership Interest | RSF Placed in Service | Occupancy Percentage**(2)** | Total Project | Unlevered Yields | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 4Q20 | 1Q21 | 2Q21 | 3Q21 | Total | Initial Stabilized | Initial Stabilized (Cash Basis) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| RSF | Investment | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Development projects | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – South San Francisco/San Francisco Bay Area/ South San Francisco | 8/4/21 | 100% | — | — | 171,042 | 55,358 | 226,400 | 100% | 323,190 | $ | 370,000 | 6.4 | % | 6.2 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – San Carlos/San Francisco Bay Area/Greater Stanford | 7/9/21 | 100% | 96,463 | 99,557 | 114,157 | 6,369 | 316,546 | 100% | 526,129 | 630,000 | 6.4 | 6.1 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1165 Eastlake Avenue East/Seattle/Lake Union | N/A | 100% | — | 100,086 | — | — | 100,086 | 100% | 100,086 | 138,000 | 6.3 | (3) | 6.4 | (3) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 9804 Medical Center Drive/Maryland/Rockville | N/A | 100% | — | 176,832 | — | — | 176,832 | 100% | 176,832 | 89,300 | 8.3 | 8.0 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for AgTech/Research Triangle/Research Triangle | 7/22/21 | 100% | — | — | — | 25,812 | 25,812 | 100% | 340,400 | 193,000 | 7.1 | 7.0 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Advanced Technologies/Research Triangle/Research Triangle | 9/24/21 | 100% | — | — | — | 20,500 | 20,500 | 100% | 250,000 | 151,000 | 7.5 | 7.3 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Redevelopment projects | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| The Arsenal on the Charles/Greater Boston/Cambridge/Inner Suburbs | 9/4/21 | 100% | — | — | — | 86,546 | 86,546 | 100% | 872,665 | 772,000 | 6.2 | 5.5 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 3160 Porter Drive/San Francisco Bay Area/ Greater Stanford | 8/19/21 | 100% | — | — | — | 43,578 | 43,578 | 100% | 92,300 | 107,000 | 5.2 | 5.0 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Long Island City/New York City/New York City | N/A | 100% | 17,716 | — | 15,176 | — | 32,892 | 100% | 179,100 | 224,000 | 5.8 | 5.8 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 9877 Waples Street/San Diego/Sorrento Mesa | N/A | 100% | 63,774 | — | — | — | 63,774 | 100% | 63,774 | 31,000 | 8.8 | 8.1 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other/San Diego | N/A | 100% | — | — | 128,745 | — | 128,745 | 100% | 128,745 | 47,000 | 8.0 | (4) | 8.0 | (4) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Durham/Research Triangle/Research Triangle | N/A | 100% | — | — | 326,445 | — | 326,445 | 100% | 652,381 | 245,000 | 7.5 | 6.7 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total | 8/22/21 | 177,953 | 376,475 | 755,565 | 238,163 | 1,548,156 | 3,705,602 | $ | 2,997,300 | 6.6 | % | 6.2 | % |
(1)Represents the average delivery date during the current quarter, weighted by annual rental revenue.
(2)Relates to total operating RSF placed in service as of the most recent delivery.
(3)Unlevered yields represent aggregate returns for 1165 Eastlake Avenue East, an amenity-rich research headquarters for Adaptive Biotechnologies Corporation, and 1208 Eastlake Avenue East, an adjacent multi-tenant office/laboratory building.
(4)We achieved yields greater than 8.0%.
New Class A development and redevelopment properties: current projects
| 325 Binney Street | The Arsenal on the Charles | 201 Brookline Avenue | 840 Winter Street | Alexandria Center**®** for Life Science – South San Francisco**(1)** | ||||||||||||||||||||||||||||
| Greater Boston/Cambridge | Greater Boston/ Cambridge/Inner Suburbs | Greater Boston/Fenway | Greater Boston/Route 128 | San Francisco Bay Area/ South San Francisco | ||||||||||||||||||||||||||||
| 462,100 RSF | 301,132 RSF | 510,116 RSF | 130,000 RSF | 96,790 RSF | ||||||||||||||||||||||||||||
| 100% Leased | 92% Leased/Negotiating | 96% Leased/Negotiating | 18% Leased/Negotiating | 100% Leased | ||||||||||||||||||||||||||||
 | |  |  | |
| 751 Gateway Boulevard | Alexandria Center**®** for Life Science – San Carlos**(2)** | 3160 Porter Drive | Alexandria Center**®** for Life Science – Long Island City**(3)** | 3115 Merryfield Row | ||||||||||||||||||||||
| San Francisco Bay Area/ South San Francisco | San Francisco Bay Area/ Greater Stanford | San Francisco Bay Area/ Greater Stanford | New York City/New York City | San Diego/Torrey Pines | ||||||||||||||||||||||
| 229,000 RSF | 209,583 RSF | 48,722 RSF | 104,959 RSF | 146,456 RSF | ||||||||||||||||||||||
| 100% Leased/Negotiating | 100% Leased | 88% Leased/Negotiating | 52% Leased/Negotiating | 100% Leased | ||||||||||||||||||||||
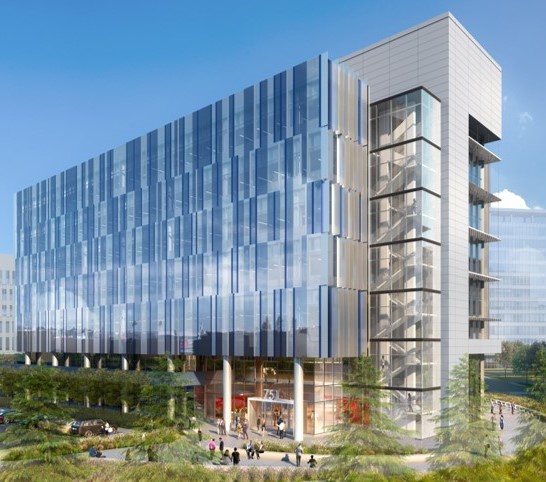 | | | |  |
(1)Image represents 201 Haskins Way in our Alexandria Center® for Life Science – South San Francisco campus.
(2)Image represents 825 and 835 Industrial Road in our Alexandria Center® for Life Science – San Carlos campus.
(3)Image represents 30-02 48th Avenue in our Alexandria Center® for Life Science – Long Island City campus.
New Class A development and redevelopment properties: current projects (continued)
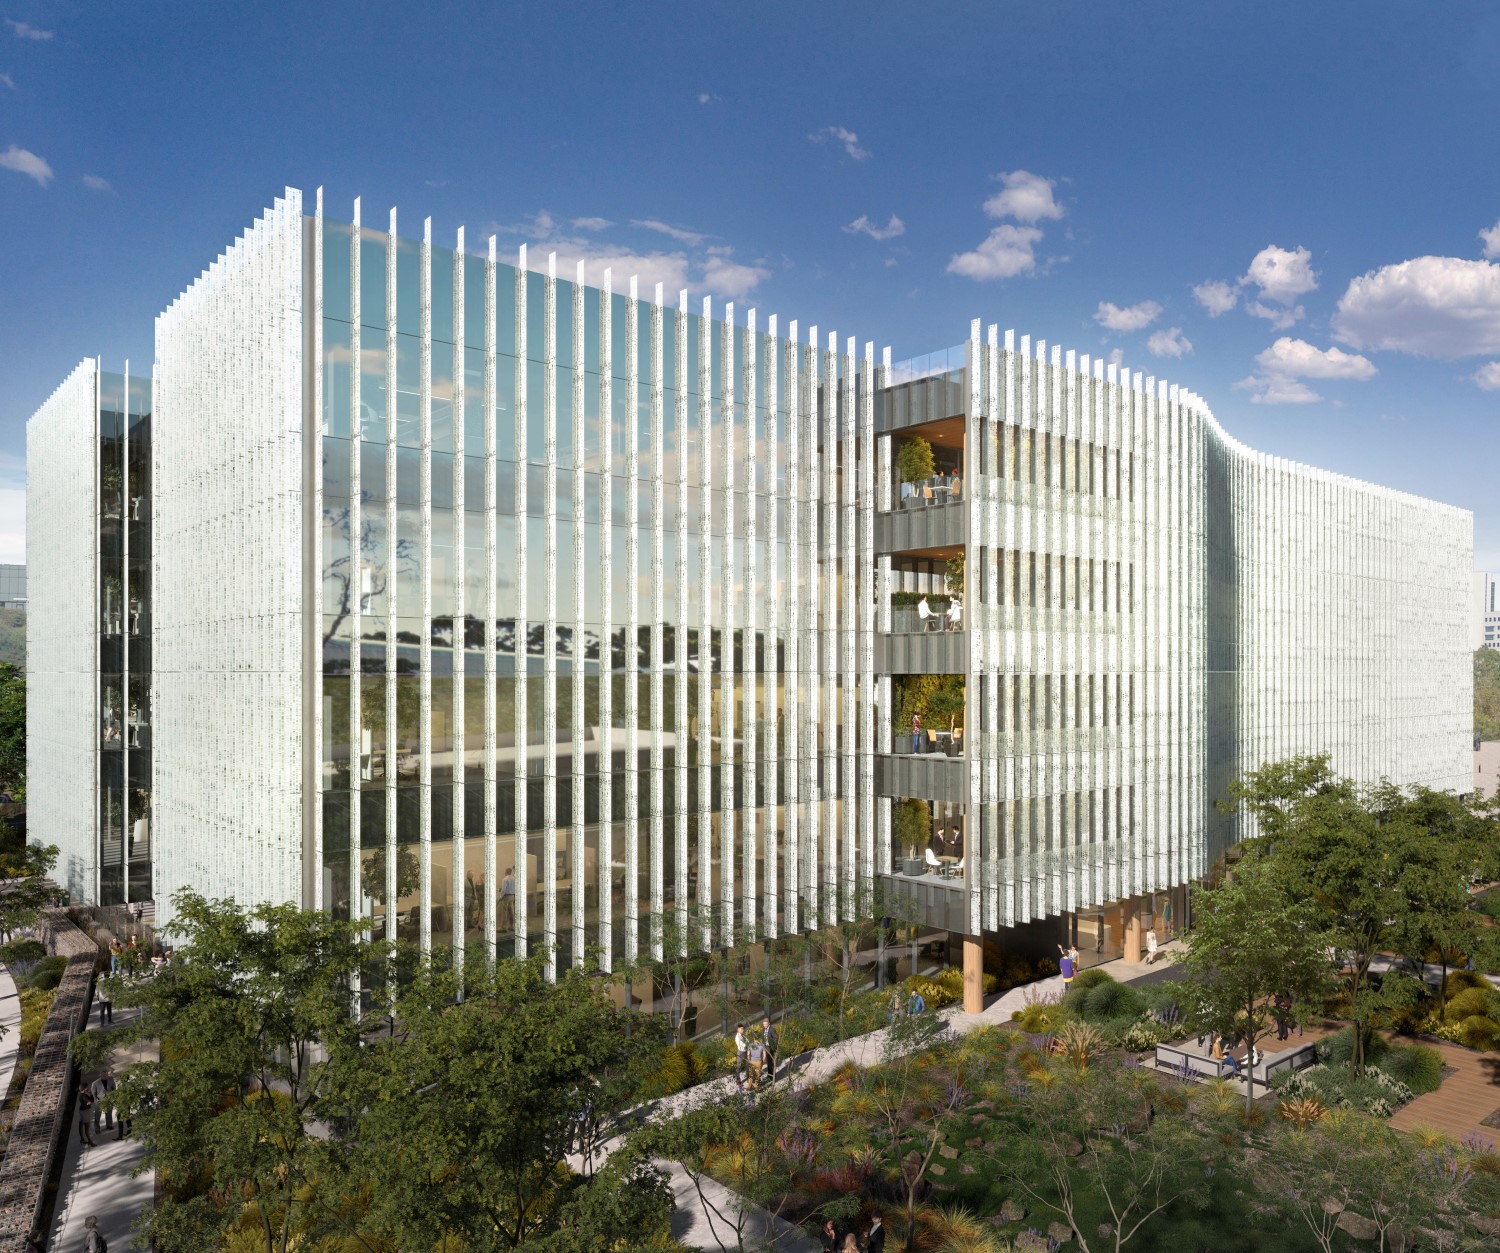
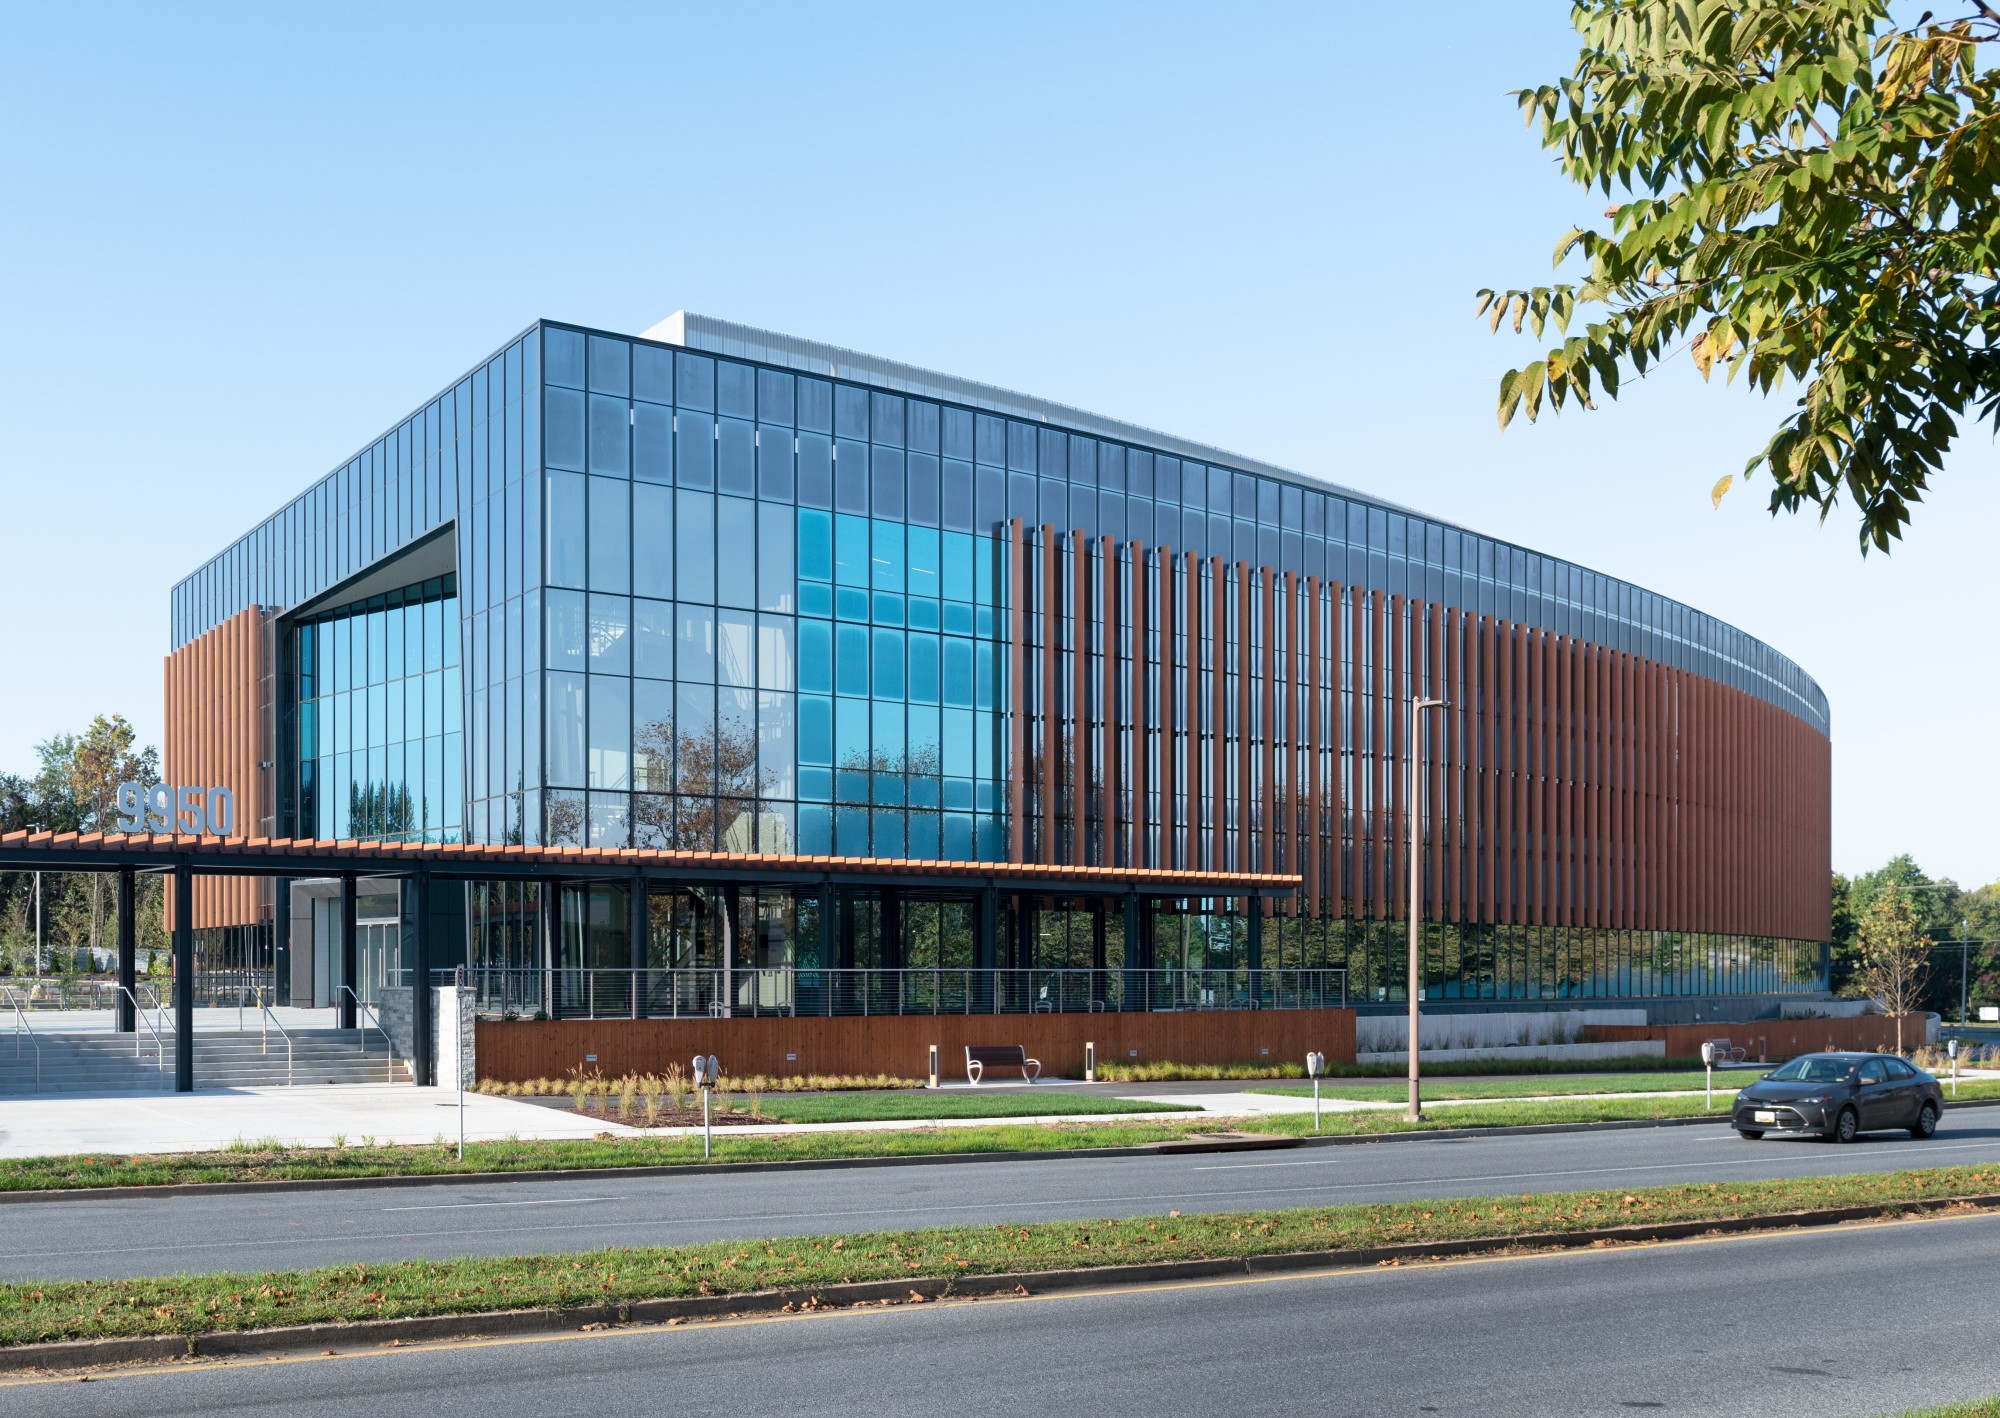
| SD Tech by Alexandria**(1)** | 5505 Morehouse Drive | 10277 Scripps Ranch Boulevard | 9601 and 9603 Medical Center Drive | 9950 Medical Center Drive | ||||||||||||||||||||||
| San Diego/Sorrento Mesa | San Diego/Sorrento Mesa | San Diego/Other | Maryland/Rockville | Maryland/Rockville | ||||||||||||||||||||||
| 195,435 RSF | 79,945 RSF | 37,267 RSF | 94,256 RSF | 84,264 RSF | ||||||||||||||||||||||
| 100% Leased | 100% Leased | 47% Leased/Negotiating | 51% Leased/Negotiating | 100% Leased | ||||||||||||||||||||||
 |  |  |  |  |
| 700 Quince Orchard Road | 20400 Century Boulevard | Alexandria Center**®** for Life Science – Durham**(2)** | Alexandria Center**®** for AgTech**(3)** | Alexandria Center**®** for Advanced Technologies**(4)** | ||||||||||||||||||||||
| Maryland/Gaithersburg | Maryland/Gaithersburg | Research Triangle/Research Triangle | Research Triangle/Research Triangle | Research Triangle/Research Triangle | ||||||||||||||||||||||
| 169,420 RSF | 80,550 RSF | 325,936 RSF | 134,188 RSF | 229,500 RSF | ||||||||||||||||||||||
| 100% Leased | 40% Leased/Negotiating | 77% Leased/Negotiating | 87% Leased/Negotiating | 83% Leased/Negotiating | ||||||||||||||||||||||
 |  |  | | |
(1)Image represents 10055 Barnes Canyon Road in our SD Tech by Alexandria campus.
(2)Image represents 14 TW Alexander Drive in our Alexandria Center® for Life Science – Durham campus.
(3)Image represents 9 Laboratory Drive in our Alexandria Center® for AgTech campus.
(4)Image represents 10 Davis Drive in our Alexandria Center® for Advanced Technologies campus.
New Class A development and redevelopment properties: current projects (continued)
The following tables set forth a summary of our new Class A development and redevelopment properties under construction, pre-leased/negotiating near-term projects, and key pending acquisition as of September 30, 2021 (dollars in thousands):
| Market Property/Submarket | Square Footage | Percentage | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dev/Redev | In Service | CIP | Total | Leased | Leased/Negotiating | Initial Occupancy**(1)** | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Under construction | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Greater Boston | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 325 Binney Street/Cambridge | Dev | — | 462,100 | 462,100 | 100 | % | 100 | % | 2023 | |||||||||||||||||||||||||||||||||||||||||||||||
| The Arsenal on the Charles/Cambridge/Inner Suburbs | Redev | 571,533 | 301,132 | 872,665 | 85 | 92 | 3Q21 | |||||||||||||||||||||||||||||||||||||||||||||||||
| 201 Brookline Avenue/Fenway | Dev | — | 510,116 | 510,116 | 59 | 96 | 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||
| 840 Winter Street/Route 128 | Redev | 30,009 | 130,000 | 160,009 | 18 | 18 | 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other | Redev | — | 453,869 | 453,869 | — | — | 2023/2024 | |||||||||||||||||||||||||||||||||||||||||||||||||
| San Francisco Bay Area | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – South San Francisco/South San Francisco | Dev | 226,400 | 96,790 | 323,190 | 100 | 100 | 2Q21 | |||||||||||||||||||||||||||||||||||||||||||||||||
| 751 Gateway Boulevard/South San Francisco | Dev | — | 229,000 | 229,000 | — | 100 | 2023 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – San Carlos/Greater Stanford | Dev | 316,546 | 209,583 | 526,129 | 100 | 100 | 4Q20 | |||||||||||||||||||||||||||||||||||||||||||||||||
| 3160 Porter Drive/Greater Stanford | Redev | 43,578 | 48,722 | 92,300 | 86 | 88 | 3Q21 | |||||||||||||||||||||||||||||||||||||||||||||||||
| New York City | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Long Island City/New York City | Redev | 74,141 | 104,959 | 179,100 | 49 | 52 | 4Q20 | |||||||||||||||||||||||||||||||||||||||||||||||||
| San Diego | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 3115 Merryfield Row/Torrey Pines | Dev | — | 146,456 | 146,456 | 100 | 100 | 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||
| SD Tech by Alexandria/Sorrento Mesa | Dev | — | 195,435 | 195,435 | 100 | 100 | 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||
| 5505 Morehouse Drive/Sorrento Mesa | Redev | — | 79,945 | 79,945 | 100 | 100 | 2021 | |||||||||||||||||||||||||||||||||||||||||||||||||
| 10277 Scripps Ranch Boulevard/Other | Redev | 32,774 | 37,267 | 70,041 | 47 | 47 | 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Seattle | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | Redev | 246,647 | 213,976 | 460,623 | 53 | 61 | 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Maryland | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 9601 and 9603 Medical Center Drive/Rockville | Redev | — | 94,256 | 94,256 | — | 51 | 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||
| 9950 Medical Center Drive/Rockville | Dev | — | 84,264 | 84,264 | 100 | 100 | 1H22 | |||||||||||||||||||||||||||||||||||||||||||||||||
| 700 Quince Orchard Road/Gaithersburg | Redev | — | 169,420 | 169,420 | 100 | 100 | 2021 | |||||||||||||||||||||||||||||||||||||||||||||||||
| 20400 Century Boulevard/Gaithersburg | Redev | — | 80,550 | 80,550 | 27 | 40 | 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Research Triangle | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Durham/Research Triangle(2) | Redev | 326,445 | 325,936 | 652,381 | 77 | 77 | 2Q21/2022 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for AgTech/Research Triangle(3) | Redev/Dev | 206,212 | 134,188 | 340,400 | 83 | 87 | 3Q21 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Advanced Technologies/Research Triangle | Dev | 20,500 | 229,500 | 250,000 | (4) | 80 | (4) | 83 | (4) | 3Q21/2022 | ||||||||||||||||||||||||||||||||||||||||||||||
| 2,094,785 | 4,337,464 | 6,432,249 | 70 | 79 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Pre-leased/negotiating near-term projects and key pending acquisition | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Charles Park/Greater Boston/Cambridge(5) | Redev | — | 400,000 | 400,000 | — | 100 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 4150 Campus Point Court/San Diego/University Town Center | Dev | — | 171,102 | 171,102 | 100 | 100 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other near-term projects expected to commence construction in the next six quarters (17 properties) | Dev/Redev | — | 2,795,015 | 2,795,015 | 4 | 76 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| — | 3,366,117 | 3,366,117 | 9 | % | 80 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 2,094,785 | 7,703,581 | 9,798,366 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
(1)Initial occupancy dates are subject to leasing and/or market conditions. Multi-tenant projects may have occupancy by tenants over a period of time. Stabilized occupancy may vary depending on single tenancy versus multi-tenancy.
(2)The recently acquired Alexandria Center® for Life Science – Durham campus redevelopment project includes three properties at 40 Moore Drive, 2400 Ellis Road, and 14 TW Alexander Drive. 2400 Ellis Road is 100% leased and was delivered during the three months ended June 30, 2021. We expect stabilized occupancy for the remaining buildings in 2022.
(3)The strategic collaborative agtech campus consists of Phase I at 5 Laboratory Drive, including campus amenities, which was previously delivered, and Phase II at 9 Laboratory Drive.
(4)Represents 150,000 RSF that is 71% leased/negotiating at 8 Davis Drive and 100,000 RSF that is 100% leased at 10 Davis Drive.
(5)We expect to complete this acquisition in December 2021.
New Class A development and redevelopment properties: current projects (continued)
| Our Ownership Interest | Unlevered Yields | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Market Property/Submarket | In Service | CIP | Cost to Complete | Total at Completion | Initial Stabilized | Initial Stabilized (Cash Basis) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Under construction | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Greater Boston | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 325 Binney Street/Cambridge | 100 | % | $ | — | $ | 198,031 | $ | 582,969 | $ | 781,000 | 8.6 | % | 7.2 | % | |||||||||||||||||||||||||||||||||||||||||||||
| The Arsenal on the Charles/Cambridge/Inner Suburbs | 100 | % | 454,061 | 236,242 | 81,697 | 772,000 | 6.2 | % | 5.5 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 201 Brookline Avenue/Fenway | 98.2 | % | — | 446,219 | 287,781 | 734,000 | 6.8 | % | 6.0 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 840 Winter Street/Route 128 | 100 | % | 12,981 | 56,926 | TBD | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 100 | % | — | 113,389 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| San Francisco Bay Area | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – South San Francisco/South San Francisco | 100 | % | 254,933 | 92,551 | 22,516 | 370,000 | 6.4 | % | 6.2 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 751 Gateway Boulevard/South San Francisco | 48.1 | % | — | 59,657 | TBD | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – San Carlos/Greater Stanford | 100 | % | 391,681 | 202,346 | 35,973 | 630,000 | 6.4 | % | 6.1 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 3160 Porter Drive/Greater Stanford | 100 | % | 44,537 | 50,469 | 11,994 | 107,000 | 5.2 | % | 5.0 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| New York City | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Long Island City/New York City | 100 | % | 52,470 | 120,664 | 50,866 | 224,000 | 5.8 | % | 5.8 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| San Diego | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 3115 Merryfield Row/Torrey Pines | 100 | % | — | 104,535 | 47,465 | 152,000 | 6.2 | % | 6.2 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| SD Tech by Alexandria/Sorrento Mesa | 50.0 | % | — | 71,291 | 109,709 | 181,000 | 7.2 | % | 6.6 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 5505 Morehouse Drive/Sorrento Mesa | 100 | % | — | 41,784 | 25,216 | 67,000 | 6.9 | % | 7.0 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 10277 Scripps Ranch Boulevard/Other | 100 | % | 11,850 | 13,727 | TBD | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Seattle | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 100 | % | 54,500 | 68,259 | TBD | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Maryland | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 9601 and 9603 Medical Center Drive/Rockville | 100 | % | — | 28,724 | TBD | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 9950 Medical Center Drive/Rockville | 100 | % | — | 41,813 | 17,787 | 59,600 | 8.6 | % | 7.7 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 700 Quince Orchard Road/Gaithersburg | 100 | % | — | 62,156 | 17,344 | 79,500 | 8.6 | % | 7.3 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| 20400 Century Boulevard/Gaithersburg | 100 | % | — | 12,391 | TBD | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Research Triangle | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Durham/Research Triangle | 100 | % | 89,443 | 74,138 | 81,419 | 245,000 | 7.5 | % | 6.7 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for AgTech/Research Triangle | 100 | % | 111,803 | 73,184 | 8,013 | 193,000 | 7.1 | % | 7.0 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Advanced Technologies/Research Triangle | 100 | % | 10,622 | 72,395 | 67,983 | 151,000 | 7.5 | % | 7.3 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| $ | 1,488,881 | $ | 2,240,891 | $ | 2,210,000 | (1)(2) | $ | 5,940,000 | (1) | ||||||||||||||||||||||||||||||||||||||||||||||||||
(1)Amounts rounded to the nearest $10 million.
(2)Based on our current target of net debt and preferred stock to adjusted EBITDA of less than or equal to 5.2x, we expect the net operating income to be generated upon stabilization of these projects will require $1.6 billion of debt and approximately $600 million of incremental equity funding on a leverage-neutral basis. Actual debt and equity capital funding until stabilization of these projects will vary from these estimates.
New Class A development and redevelopment properties: summary of pipeline
The following table summarizes the key information for all our development and redevelopment projects in North America as of September 30, 2021 (dollars in thousands):
| Market Property/Submarket | Our Ownership Interest | Book Value | Square Footage | |||||||||||||||||||||||||||||||||||||||||||||||
| Development and Redevelopment | Total**(1)** | |||||||||||||||||||||||||||||||||||||||||||||||||
| Under Construction | Near Term | Intermediate Term | Future | |||||||||||||||||||||||||||||||||||||||||||||||
| Greater Boston | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 325 Binney Street/Cambridge | 100 | % | $ | 198,031 | 462,100 | — | — | — | 462,100 | |||||||||||||||||||||||||||||||||||||||||
| The Arsenal on the Charles/Cambridge/Inner Suburbs | 100 | % | 269,802 | 301,132 | 200,000 | — | 12,502 | 513,634 | ||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Fenway/Fenway | (2) | 572,449 | 510,116 | — | 450,000 | — | 960,116 | |||||||||||||||||||||||||||||||||||||||||||
| 840 Winter Street/Route 128 | 100 | % | 56,926 | 130,000 | — | — | — | 130,000 | ||||||||||||||||||||||||||||||||||||||||||
| 99 Coolidge Avenue/Cambridge/Inner Suburbs | 75.0 | % | 56,152 | — | 275,000 | — | — | 275,000 | ||||||||||||||||||||||||||||||||||||||||||
| 15 Necco Street/Seaport Innovation District | 90.0 | % | 211,324 | — | 350,000 | — | — | 350,000 | ||||||||||||||||||||||||||||||||||||||||||
| Reservoir Woods/Route 128 | 100 | % | 47,762 | — | 515,273 | — | 440,000 | 955,273 | ||||||||||||||||||||||||||||||||||||||||||
| 10 Necco Street/Seaport Innovation District | 100 | % | 93,586 | — | — | 175,000 | — | 175,000 | ||||||||||||||||||||||||||||||||||||||||||
| 215 Presidential Way/Route 128 | 100 | % | 6,808 | — | — | 112,000 | — | 112,000 | ||||||||||||||||||||||||||||||||||||||||||
| Alexandria Technology Square®/Cambridge | 100 | % | 7,881 | — | — | — | 100,000 | 100,000 | ||||||||||||||||||||||||||||||||||||||||||
| 550 Arsenal Street/Cambridge/Inner Suburbs | 100 | % | 54,853 | — | — | — | 775,000 | 775,000 | ||||||||||||||||||||||||||||||||||||||||||
| 380 and 420 E Street/Seaport Innovation District | 100 | % | 119,517 | — | — | — | 1,000,000 | 1,000,000 | ||||||||||||||||||||||||||||||||||||||||||
| 99 A Street/Seaport Innovation District | 94.8 | % | 46,597 | — | — | — | 235,000 | 235,000 | ||||||||||||||||||||||||||||||||||||||||||
| One Upland Road, 100 Tech Drive, and One Investors Way/Route 128 | 100 | % | 14,081 | — | — | — | 1,100,000 | 1,100,000 | ||||||||||||||||||||||||||||||||||||||||||
| 231 Second Avenue/Route 128 | 100 | % | 1,093 | — | — | — | 32,000 | 32,000 | ||||||||||||||||||||||||||||||||||||||||||
| Other value-creation projects | 100 | % | 161,182 | 453,869 | 190,992 | — | 434,504 | 1,079,365 | ||||||||||||||||||||||||||||||||||||||||||
| 1,918,044 | 1,857,217 | 1,531,265 | 737,000 | 4,129,006 | 8,254,488 | |||||||||||||||||||||||||||||||||||||||||||||
| San Francisco Bay Area | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Technology Center® – Gateway/South San Francisco | 48.1 | % | 82,176 | 229,000 | 300,010 | — | 291,000 | 820,010 | ||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – South San Francisco/ South San Francisco | 100 | % | 92,551 | 96,790 | — | — | — | 96,790 | ||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – San Carlos/Greater Stanford | 100 | % | 481,720 | 209,583 | — | 700,000 | 587,000 | 1,496,583 | ||||||||||||||||||||||||||||||||||||||||||
| 3160 Porter Drive/Greater Stanford | 100 | % | 50,469 | 48,722 | — | — | — | 48,722 | ||||||||||||||||||||||||||||||||||||||||||
| 1450 Owens Street/Mission Bay | 100 | % | 65,685 | — | 191,000 | — | — | 191,000 | ||||||||||||||||||||||||||||||||||||||||||
| 901 California Avenue/Greater Stanford | 100 | % | 2,694 | — | 56,924 | — | — | 56,924 | ||||||||||||||||||||||||||||||||||||||||||
| 3450 and 3460 Hillview Avenue/Greater Stanford | 100 | % | — | — | 42,340 | 34,611 | — | 76,951 | ||||||||||||||||||||||||||||||||||||||||||
| 88 Bluxome Street/SoMa | 100 | % | 318,656 | — | 1,070,925 | — | — | 1,070,925 | ||||||||||||||||||||||||||||||||||||||||||
| 3825 and 3875 Fabian Way/Greater Stanford | 100 | % | — | — | — | 250,000 | 228,000 | 478,000 | ||||||||||||||||||||||||||||||||||||||||||
| 1122 El Camino Real/South San Francisco | 100 | % | 105,053 | — | — | — | 700,000 | 700,000 | ||||||||||||||||||||||||||||||||||||||||||
| East Grand Avenue/South San Francisco | 30.0 | % | 6,113 | — | — | — | 90,000 | 90,000 | ||||||||||||||||||||||||||||||||||||||||||
| 2475 Hanover Street/Greater Stanford | 100 | % | — | — | — | — | 83,980 | 83,980 | ||||||||||||||||||||||||||||||||||||||||||
| Other value-creation projects | 100 | % | (3) | 38,137 | — | — | — | 223,188 | 223,188 | |||||||||||||||||||||||||||||||||||||||||
| $ | 1,243,254 | 584,095 | 1,661,199 | 984,611 | 2,203,168 | 5,433,073 | ||||||||||||||||||||||||||||||||||||||||||||
| (1)Represents total square footage upon completion of development or redevelopment of a new Class A property. Square footage presented includes RSF of buildings currently in operation at properties that also have inherent future development or redevelopment opportunities. Upon expiration of existing in-place leases, we have the intent to demolish or redevelop the existing property and commence future construction. Refer to the definition of “Investments in real estate – value-creation square footage currently in rental properties” in the “Non-GAAP measures and definitions” section within this Item 2 for additional information. (2)We have a 98.2% ownership interest in 201 Brookline Avenue, aggregating 510,116 RSF, and is currently under construction. We have a 100% ownership interest in the intermediate-term development project, aggregating 450,000 RSF. (3)Includes a future development project at Alexandria Center® for Life Science – Millbrae Station where we have a 37.6% ownership interest. | ||||||||||||||||||||||||||||||||||||||||||||||||||
New Class A development and redevelopment properties: summary of pipeline (continued)
| Market Property/Submarket | Our Ownership Interest | Book Value | Square Footage | |||||||||||||||||||||||||||||||||||||||||||||||
| Development and Redevelopment | Total**(1)** | |||||||||||||||||||||||||||||||||||||||||||||||||
| Under Construction | Near Term | Intermediate Term | Future | |||||||||||||||||||||||||||||||||||||||||||||||
| New York City | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Long Island City/New York City | 100 | % | $ | 120,664 | 104,959 | — | — | — | 104,959 | |||||||||||||||||||||||||||||||||||||||||
| 47-50 30th Street/New York City | 100 | % | 30,639 | — | 135,938 | — | — | 135,938 | ||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – New York City/New York City | 100 | % | 74,894 | — | — | 550,000 | (2) | — | 550,000 | |||||||||||||||||||||||||||||||||||||||||
| 219 East 42nd Street/New York City | 100 | % | — | — | — | — | 579,947 | 579,947 | ||||||||||||||||||||||||||||||||||||||||||
| 226,197 | 104,959 | 135,938 | 550,000 | 579,947 | 1,370,844 | |||||||||||||||||||||||||||||||||||||||||||||
| San Diego | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 3115 Merryfield Row/Torrey Pines | 100 | % | 104,535 | 146,456 | — | — | — | 146,456 | ||||||||||||||||||||||||||||||||||||||||||
| SD Tech by Alexandria/Sorrento Mesa | 50.0 | % | 159,088 | 195,435 | 190,074 | 160,000 | 333,845 | 879,354 | ||||||||||||||||||||||||||||||||||||||||||
| 5505 Morehouse Drive/Sorrento Mesa | 100 | % | 41,784 | 79,945 | — | — | — | 79,945 | ||||||||||||||||||||||||||||||||||||||||||
| 10277 Scripps Ranch Boulevard/Other | 100 | % | 13,727 | 37,267 | 32,774 | — | — | 70,041 | ||||||||||||||||||||||||||||||||||||||||||
| 11255 and 11355 North Torrey Pines Road/Torrey Pines | 100 | % | 111,760 | — | 288,956 | — | — | 288,956 | ||||||||||||||||||||||||||||||||||||||||||
| 10931 and 10933 North Torrey Pines Road/Torrey Pines | 100 | % | — | — | 242,000 | — | — | 242,000 | ||||||||||||||||||||||||||||||||||||||||||
| Alexandria Point/University Town Center | 55.0 | % | 112,895 | — | 596,102 | — | 324,445 | 920,547 | ||||||||||||||||||||||||||||||||||||||||||
| Sequence District by Alexandria/Sorrento Mesa | 100 | % | 37,758 | — | 200,000 | 509,000 | 1,089,915 | 1,798,915 | ||||||||||||||||||||||||||||||||||||||||||
| University District/University Town Center | 100 | % | 66,108 | — | — | 600,000 | (3) | — | 600,000 | |||||||||||||||||||||||||||||||||||||||||
| 9444 Waples Street/Sorrento Mesa | 50.0 | % | 18,809 | — | — | 149,000 | — | 149,000 | ||||||||||||||||||||||||||||||||||||||||||
| 10975 and 10995 Torreyana Road/Torrey Pines | 100 | % | 49,009 | — | — | — | 125,280 | 125,280 | ||||||||||||||||||||||||||||||||||||||||||
| 5200 Illumina Way/University Town Center | 51.0 | % | 13,313 | — | — | — | 451,832 | 451,832 | ||||||||||||||||||||||||||||||||||||||||||
| 4025, 4031, 4045, and 4075 Sorrento Valley Boulevard/Sorrento Valley | 100 | % | 7,765 | — | — | — | 247,000 | 247,000 | ||||||||||||||||||||||||||||||||||||||||||
| Other value-creation projects | 100 | % | 13,734 | — | 54,000 | — | 114,235 | 168,235 | ||||||||||||||||||||||||||||||||||||||||||
| 750,285 | 459,103 | 1,603,906 | 1,418,000 | 2,686,552 | 6,167,561 | |||||||||||||||||||||||||||||||||||||||||||||
| Seattle | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 1150 Eastlake Avenue East/Lake Union | 100 | % | 102,305 | — | 311,631 | — | — | 311,631 | ||||||||||||||||||||||||||||||||||||||||||
| 701 Dexter Avenue North/Lake Union | 100 | % | 67,509 | — | 217,000 | — | — | 217,000 | ||||||||||||||||||||||||||||||||||||||||||
| 601 Dexter Avenue North/Lake Union | 100 | % | 37,827 | — | — | — | 188,400 | 188,400 | ||||||||||||||||||||||||||||||||||||||||||
| 1010 4th Avenue South/SoDo | 100 | % | 50,969 | — | — | — | 544,825 | 544,825 | ||||||||||||||||||||||||||||||||||||||||||
| 830 4th Avenue South/SoDo | 100 | % | — | — | — | — | 52,488 | 52,488 | ||||||||||||||||||||||||||||||||||||||||||
| Other value-creation projects | 100 | % | 80,172 | 213,976 | 51,255 | — | 230,000 | 495,231 | ||||||||||||||||||||||||||||||||||||||||||
| $ | 338,782 | 213,976 | 579,886 | — | 1,015,713 | 1,809,575 | ||||||||||||||||||||||||||||||||||||||||||||
| (1)Represents total square footage upon completion of development or redevelopment of a new Class A property. Square footage presented includes RSF of buildings currently in operation at properties that also have inherent future development or redevelopment opportunities. Upon expiration of existing in-place leases, we have the intent to demolish or redevelop the existing property and commence future construction. Refer to the definition of “Investments in real estate – value-creation square footage currently in rental properties” in the “Non-GAAP measures and definitions” section within this Item 2 for additional information. (2)Pursuant to an option agreement, we are currently negotiating a long-term ground lease with the City of New York for the future site of a new building approximating 550,000 RSF. (3)Includes our recently acquired property at 4555 Executive Drive and 9363, 9373, and 9393 Towne Centre Drive in our University Town Center submarket, which are currently under evaluation for development, subject to future market conditions. | ||||||||||||||||||||||||||||||||||||||||||||||||||
New Class A development and redevelopment properties: summary of pipeline (continued)
| Market Property/Submarket | Our Ownership Interest | Book Value | Square Footage | |||||||||||||||||||||||||||||||||||||||||||||||
| Development and Redevelopment | Total**(1)** | |||||||||||||||||||||||||||||||||||||||||||||||||
| Under Construction | Near Term | Intermediate Term | Future | |||||||||||||||||||||||||||||||||||||||||||||||
| Maryland | ||||||||||||||||||||||||||||||||||||||||||||||||||
| 9601 and 9603 Medical Center Drive and Excess Land/Rockville | 100 | % | $ | 43,073 | 94,256 | — | 258,000 | — | 352,256 | |||||||||||||||||||||||||||||||||||||||||
| 9950 Medical Center Drive/Rockville | 100 | % | 41,813 | 84,264 | — | — | — | 84,264 | ||||||||||||||||||||||||||||||||||||||||||
| 700 Quince Orchard Road/Gaithersburg | 100 | % | 62,156 | 169,420 | — | — | — | 169,420 | ||||||||||||||||||||||||||||||||||||||||||
| 20400 Century Boulevard/Gaithersburg | 100 | % | 12,391 | 80,550 | — | — | — | 80,550 | ||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® at Traville Gateway/Rockville | 100 | % | 33,091 | — | 410,000 | — | 70,000 | 480,000 | ||||||||||||||||||||||||||||||||||||||||||
| 9808 Medical Center Drive/Rockville | 100 | % | 9,986 | — | 90,000 | — | — | 90,000 | ||||||||||||||||||||||||||||||||||||||||||
| 202,510 | 428,490 | 500,000 | 258,000 | 70,000 | 1,256,490 | |||||||||||||||||||||||||||||||||||||||||||||
| Research Triangle | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Life Science – Durham/Research Triangle | 100 | % | 117,469 | 325,936 | 100,000 | — | 885,000 | 1,310,936 | ||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for Advanced Technologies/Research Triangle | 100 | % | 112,762 | 229,500 | 180,000 | — | 990,000 | 1,399,500 | ||||||||||||||||||||||||||||||||||||||||||
| Alexandria Center® for AgTech, Phase II/Research Triangle | 100 | % | 73,184 | 134,188 | — | — | — | 134,188 | ||||||||||||||||||||||||||||||||||||||||||
| 3029 East Cornwallis Road/Research Triangle | 100 | % | 94,958 | — | 100,000 | 100,000 | 855,000 | 1,055,000 | ||||||||||||||||||||||||||||||||||||||||||
| Other value-creation projects | 100 | % | 4,185 | — | — | — | 76,262 | 76,262 | ||||||||||||||||||||||||||||||||||||||||||
| 402,558 | 689,624 | 380,000 | 100,000 | 2,806,262 | 3,975,886 | |||||||||||||||||||||||||||||||||||||||||||||
| Other value-creation projects | 100 | % | 86,143 | — | — | — | 1,299,400 | 1,299,400 | ||||||||||||||||||||||||||||||||||||||||||
| Total pipeline as of September 30, 2021 | $ | 5,167,773 | (2) | 4,337,464 | 6,392,194 | 4,047,611 | 14,790,048 | 29,567,317 | (1) | |||||||||||||||||||||||||||||||||||||||||
| Key pending acquisitions | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Charles Park/Cambridge(3) | — | 400,000 | — | — | 400,000 | |||||||||||||||||||||||||||||||||||||||||||||
| Mercer Mega Block/Lake Union | — | 800,000 | — | — | 800,000 | |||||||||||||||||||||||||||||||||||||||||||||
| 4,337,464 | 7,592,194 | 4,047,611 | 14,790,048 | 30,767,317 |
(1)Total square footage includes 4,415,268 RSF of buildings currently in operation that will be redeveloped or replaced with new development RSF upon commencement of future construction. Refer to the definition of “Investments in real estate – value-creation square footage currently in rental properties” in the “Non-GAAP measures and definitions” section within this Item 2 for additional information.
(2)Total book value includes $2.2 billion of projects currently under construction that are 79% leased/negotiating. We also expect to commence construction on pre-leased/negotiating near-term projects and a key pending acquisition aggregating $624.5 million in the next six quarters that are 80% leased/negotiating.
(3)We expect to complete this acquisition in December 2021.
Results of operations
We present a tabular comparison of items, whether gain or loss, that may facilitate a high-level understanding of our results and provide context for the disclosures included in our annual report on Form 10-K for the year ended December 31, 2020, and our subsequent quarterly reports on Form 10-Q. We believe such tabular presentation promotes a better understanding for investors of the corporate-level decisions made and activities performed that significantly affect comparison of our operating results from period to period. We also believe this tabular presentation will supplement for investors an understanding of our disclosures and real estate operating results. Gains or losses on sales of real estate and impairments of held for sale assets are related to corporate-level decisions to dispose of real estate. Gains or losses on early extinguishment of debt are related to corporate-level financing decisions focused on our capital structure strategy. Significant realized and unrealized gains or losses on non-real estate investments, impairments of real estate and non-real estate investments, and significant termination fees are not related to the operating performance of our real estate assets as they result from strategic, corporate-level decisions and external market conditions. Impairments of non-real estate investments are not related to the operating performance of our real estate as they represent the write-down of non-real estate investments when their fair values decrease below their respective carrying values due to changes in general market or other conditions outside of our control. Significant items, whether a gain or loss, included in the tabular disclosure for current periods are described in further detail within this Item 2. Key items included in net income attributable to Alexandria’s common stockholders for the three and nine months ended September 30, 2021 and 2020, were as follows (in millions, except per share amounts):
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||||||||
| Amount | Per Share – Diluted | Amount | Per Share – Diluted | ||||||||||||||||||||||||||||||||||||||||||||
| Unrealized (losses) gains on non-real estate investments | $ | (14.4) | $ | (14.0) | $ | (0.10) | $ | (0.11) | $ | 183.3 | $ | 140.5 | $ | 1.26 | $ | 1.13 | |||||||||||||||||||||||||||||||
| Significant realized gains on non-real estate investments | 52.4 | (1) | — | 0.35 | — | 110.1 | — | 0.76 | — | ||||||||||||||||||||||||||||||||||||||
| (Loss) gain on sales of real estate | (0.4) | 1.6 | — | 0.01 | 2.3 | 1.6 | 0.02 | 0.01 | |||||||||||||||||||||||||||||||||||||||
| Impairment of real estate | (42.6) | (1) | (7.7) | (0.28) | (0.06) | (52.7) | (30.5) | (0.37) | (0.24) | ||||||||||||||||||||||||||||||||||||||
| Impairment of non-real estate investments | — | — | — | — | — | (24.5) | — | (0.20) | |||||||||||||||||||||||||||||||||||||||
| Loss on early extinguishment of debt | — | (52.8) | — | (0.42) | (67.3) | (52.8) | (0.46) | (0.42) | |||||||||||||||||||||||||||||||||||||||
| Termination fee(1) | — | 86.2 | — | 0.69 | — | 86.2 | — | 0.69 | |||||||||||||||||||||||||||||||||||||||
| Acceleration of stock compensation expense due to executive officer resignation | — | (4.5) | — | (0.04) | — | (4.5) | — | (0.04) | |||||||||||||||||||||||||||||||||||||||
| Total | $ | (5.0) | $ | 8.8 | $ | (0.03) | $ | 0.07 | $ | 175.7 | $ | 116.0 | $ | 1.21 | $ | 0.93 | |||||||||||||||||||||||||||||||
(1)Refer to “Funds from operations and funds from operations, as adjusted, attributable to Alexandria Real Estate Equities, Inc.’s common stockholders” in the “Non-GAAP measures and definitions” section within this Item 2 for additional information.
Same properties
We supplement an evaluation of our results of operations with an evaluation of operating performance of certain of our properties, referred to as Same Properties. For additional information on the determination of our Same Properties portfolio, refer to the definition of “Same property comparisons” in the “Non-GAAP measures and definitions” section within this Item 2. The following table presents information regarding our Same Properties for the three and nine months ended September 30, 2021:
| September 30, 2021 | ||||||||||||||||||||
| Three Months Ended | Nine Months Ended | |||||||||||||||||||
| Percentage change in net operating income over comparable period from prior year | 3.0% | 4.1% | ||||||||||||||||||
| Percentage change in net operating income (cash basis) over comparable period from prior year | 7.1% | 7.3% | ||||||||||||||||||
| Operating margin | 71% | 72% | ||||||||||||||||||
| Number of Same Properties | 259 | 249 | ||||||||||||||||||
| RSF | 25,493,710 | 23,701,101 | ||||||||||||||||||
| Occupancy – current-period average | 94.8% | 96.5% | ||||||||||||||||||
| Occupancy – same-period prior-year average | 95.1% | 96.2% |
The following table reconciles the number of Same Properties to total properties for the nine months ended September 30, 2021:
| Development – under construction | Properties | |||||||
| 9950 Medical Center Drive | 1 | |||||||
| The Alexandria Center® for Life Science – San Carlos | 2 | |||||||
| 3115 Merryfield Row | 1 | |||||||
| Alexandria Center® for Life Science – South San Francisco | 1 | |||||||
| Alexandria Center® for AgTech | 2 | |||||||
| Alexandria Center® for Advanced Technologies | 2 | |||||||
| 201 Brookline Avenue | 1 | |||||||
| SD Tech by Alexandria | 1 | |||||||
| 751 Gateway Boulevard | 1 | |||||||
| 325 Binney Street | 1 | |||||||
| 13 | ||||||||
| Development – placed into service after January 1, 2020 | Properties | |||||||
| 9804 Medical Center Drive | 1 | |||||||
| 1165 Eastlake Avenue East | 1 | |||||||
| 2 | ||||||||
| Redevelopment – under construction | Properties | |||||||
| 5505 Morehouse Drive | 1 | |||||||
| Alexandria Center® for Life Science – Long Island City | 1 | |||||||
| 3160 Porter Drive | 1 | |||||||
| The Arsenal on the Charles | 11 | |||||||
| 700 Quince Orchard Road | 1 | |||||||
| Alexandria Center® for Life Science – Durham | 3 | |||||||
| 840 Winter Street | 1 | |||||||
| 20400 Century Boulevard | 1 | |||||||
| 10277 Scripps Ranch Boulevard | 1 | |||||||
| 9601 and 9603 Medical Center Drive | 2 | |||||||
| Other | 8 | |||||||
| 31 | ||||||||
| Redevelopment – placed into service after January 1, 2020 | Properties | |||||||
| 9877 Waples Street | 1 | |||||||
| Other | 1 | |||||||
| 2 | ||||||||
| Acquisitions after January 1, 2020 | Properties | ||||||||||
| 3181 Porter Drive | 1 | ||||||||||
| 275 Grove Street | 1 | ||||||||||
| 601, 611, and 651 Gateway Boulevard | 3 | ||||||||||
| 3330, 3412, 3450, and 3460 Hillview Avenue | 4 | ||||||||||
| 9605, 9609, 9613, and 9615 Medical Center Drive | 4 | ||||||||||
| 9808 and 9868 Scranton Road | 2 | ||||||||||
| Alexandria Center® for Life Science – Durham | 13 | ||||||||||
| Reservoir Woods | 3 | ||||||||||
| One Upland Road | 1 | ||||||||||
| 830 4th Avenue South | 1 | ||||||||||
| 11255 and 11355 North Torrey Pines Road | 2 | ||||||||||
| Sequence District by Alexandria | 7 | ||||||||||
| 380 and 420 E Street | 2 | ||||||||||
| Alexandria Center® for Life Science – Fenway | 1 | ||||||||||
| 550 Arsenal Street | 1 | ||||||||||
| 1501-1599 Industrial Road | 6 | ||||||||||
| One Investors Way | 1 | ||||||||||
| 2475 Hanover Street | 1 | ||||||||||
| 10975 and 10995 Torreyana Road | 2 | ||||||||||
| Pacific Technology Park | 6 | ||||||||||
| 1122 El Camino Real | 1 | ||||||||||
| 12 Davis Drive | 1 | ||||||||||
| 7360 Carroll Road | 1 | ||||||||||
| Other | 39 | ||||||||||
| 104 | |||||||||||
| Unconsolidated real estate JVs | 5 | ||||||||||
| Properties held for sale | 1 | ||||||||||
| Total properties excluded from Same Properties | 158 | ||||||||||
| Same Properties | 249 | ||||||||||
| Total properties in North America as of September 30, 2021 | 407 | ||||||||||
Comparison of results for the three months ended September 30, 2021, to the three months ended September 30, 2020
The following table presents a comparison of the components of net operating income for our Same Properties and Non-Same Properties for the three months ended September 30, 2021, compared to the three months ended September 30, 2020. Refer to the “Non-GAAP measures and definitions” section within this Item 2 for definitions of “Tenant recoveries” and “Net operating income” and their reconciliations from the most directly comparable financial measures presented in accordance with GAAP, income from rentals and net income (loss), respectively.
Refer to “Item 1A. Risk factors” in our annual report on Form 10-K for the year ended December 31, 2020, for a discussion about risks that COVID-19 directly or indirectly may pose to our business.
| Three Months Ended September 30, | |||||||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2020 | $ Change | % Change | |||||||||||||||||||||||||
| Income from rentals: | |||||||||||||||||||||||||||||
| Same Properties | $ | 323,383 | $ | 313,015 | $ | 10,368 | 3.3 | % | |||||||||||||||||||||
| Non-Same Properties | 92,535 | 125,378 | (32,843) | (26.2) | |||||||||||||||||||||||||
| Rental revenues | 415,918 | 438,393 | (22,475) | (5.1) | |||||||||||||||||||||||||
| Same Properties | 108,958 | 98,749 | 10,209 | 10.3 | |||||||||||||||||||||||||
| Non-Same Properties | 21,651 | 6,270 | 15,381 | 245.3 | |||||||||||||||||||||||||
| Tenant recoveries | 130,609 | 105,019 | 25,590 | 24.4 | |||||||||||||||||||||||||
| Income from rentals | 546,527 | 543,412 | 3,115 | 0.6 | |||||||||||||||||||||||||
| Same Properties | 178 | 126 | 52 | 41.3 | |||||||||||||||||||||||||
| Non-Same Properties | 1,054 | 1,504 | (450) | (29.9) | |||||||||||||||||||||||||
| Other income | 1,232 | 1,630 | (398) | (24.4) | |||||||||||||||||||||||||
| Same Properties | 432,519 | 411,890 | 20,629 | 5.0 | |||||||||||||||||||||||||
| Non-Same Properties | 115,240 | 133,152 | (17,912) | (13.5) | |||||||||||||||||||||||||
| Total revenues | 547,759 | 545,042 | 2,717 | 0.5 | |||||||||||||||||||||||||
| Same Properties | 125,661 | 113,969 | 11,692 | 10.3 | |||||||||||||||||||||||||
| Non-Same Properties | 40,334 | 26,474 | 13,860 | 52.4 | |||||||||||||||||||||||||
| Rental operations | 165,995 | 140,443 | 25,552 | 18.2 | |||||||||||||||||||||||||
| Same Properties | 306,858 | 297,921 | 8,937 | 3.0 | |||||||||||||||||||||||||
| Non-Same Properties | 74,906 | 106,678 | (31,772) | (29.8) | |||||||||||||||||||||||||
| Net operating income | $ | 381,764 | $ | 404,599 | $ | (22,835) | (5.6 | %) | |||||||||||||||||||||
| Net operating income – Same Properties | $ | 306,858 | $ | 297,921 | $ | 8,937 | 3.0 | % | |||||||||||||||||||||
| Straight-line rent revenue | (16,654) | (25,852) | 9,198 | (35.6) | |||||||||||||||||||||||||
| Amortization of acquired below-market leases | (4,201) | (4,965) | 764 | (15.4) | |||||||||||||||||||||||||
| Net operating income – Same Properties (cash basis) | $ | 286,003 | $ | 267,104 | $ | 18,899 | 7.1 | % |
Income from rentals
Total income from rentals for the three months ended September 30, 2021, increased by $3.1 million, or 0.6%, to $546.5 million, compared to $543.4 million for the three months ended September 30, 2020, as a result of increases in tenant recoveries, as discussed below.
Rental revenues
Total rental revenues for the three months ended September 30, 2021, decreased by $22.5 million, or 5.1%, to $415.9 million, compared to $438.4 million for the three months ended September 30, 2020. Excluding a termination fee of $89.5 million recognized during the three months ended September 30, 2020, our total rental revenues increased by $67.0 million, or 19.2%, which was primarily due to an increase in rental revenues from our Non-Same Properties related to 1.5 million RSF of development and redevelopment projects placed into service subsequent to July 1, 2020, and 94 operating properties aggregating 9.2 million RSF acquired subsequent to July 1, 2020.
Rental revenues from our Same Properties for the three months ended September 30, 2021, increased by $10.4 million, or 3.3%, to $323.4 million, compared to $313.0 million for the three months ended September 30, 2020. The increase was primarily due to rental rate increases on lease renewals and re-leasing of space since July 1, 2020.
Tenant recoveries
Tenant recoveries for the three months ended September 30, 2021, increased by $25.6 million, or 24.4%, to $130.6 million, compared to $105.0 million for the three months ended September 30, 2020. The increase was primarily from our Non-Same Properties related to our development and redevelopment projects placed into service and properties acquired subsequent to July 1, 2020, as discussed above under “Rental revenues.”
Same Properties’ tenant recoveries for the three months ended September 30, 2021, increased by $10.2 million, or 10.3%, primarily due to an increase in property tax expenses resulting from higher assessed values of our properties, higher contract services expenses, higher utilities expenses, and higher property insurance during the three months ended September 30, 2021, as discussed under “Rental operations” below. As of September 30, 2021, 92% of our leases (on an RSF basis) were triple net leases, which require tenants to pay substantially all real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses (including increases thereto) in addition to base rent.
Rental operations
Total rental operating expenses for the three months ended September 30, 2021, increased by $25.6 million, or 18.2%, to $166.0 million, compared to $140.4 million for the three months ended September 30, 2020. The increase was primarily due to incremental expenses related to our Non-Same Properties, which consist of development and redevelopment projects placed into service and acquired properties, as discussed above under “Income from rentals.”
Same Properties’ rental operating expenses increased by $11.7 million, or 10.3%, to $125.7 million during the three months ended September 30, 2021, compared to $114.0 million for the three months ended September 30, 2020. The increase was primarily the result of an increase in recoverable property tax expenses resulting from higher assessed values of our properties, higher utility expenses, and higher contract services expenses.
General and administrative expenses
General and administrative expenses for the three months ended September 30, 2021, increased by $1.0 million, or 2.8%, to $37.9 million, compared to $36.9 million for the three months ended September 30, 2020. The increase was primarily due to costs related to the continued growth in the depth and breadth of our operations in multiple markets, including development and redevelopment projects placed into service and properties acquired, as discussed above under “Income from rentals.” As a percentage of net operating income, our general and administrative expenses for the trailing twelve months ended September 30, 2021 and 2020, were 10.1% and 9.9%, respectively.
Interest expense
Interest expense for the three months ended September 30, 2021 and 2020, consisted of the following (dollars in thousands):
| Three Months Ended September 30, | ||||||||||||||||||||
| Component | 2021 | 2020 | Change | |||||||||||||||||
| Gross interest | $ | 78,863 | $ | 75,874 | $ | 2,989 | ||||||||||||||
| Capitalized interest | (43,185) | (32,556) | (10,629) | |||||||||||||||||
| Interest expense | $ | 35,678 | $ | 43,318 | $ | (7,640) | ||||||||||||||
| Average debt balance outstanding(1) | $ | 9,257,859 | $ | 8,070,031 | $ | 1,187,828 | ||||||||||||||
| Weighted-average annual interest rate(2) | 3.4 | % | 3.8 | % | (0.4) | % | ||||||||||||||
(1)Represents the average debt balance outstanding during the respective periods.
(2)Represents annualized total interest incurred divided by the average debt balance outstanding during the respective periods.
The net change in interest expense during the three months ended September 30, 2021, compared to the three months ended September 30, 2020, resulted from the following (dollars in thousands):
| Component | Interest Rate(1) | Effective Date | Change | ||||||||||||||||||||||||||
| Increases in interest incurred due to: | |||||||||||||||||||||||||||||
| Issuances of debt: | |||||||||||||||||||||||||||||
| $1.0 billion unsecured senior notes payable due 2033 | 1.97 | % | August 2020 | $ | 1,785 | ||||||||||||||||||||||||
| $900 million unsecured senior notes payable due 2032 – green bond | 2.12 | % | February 2021 | 4,557 | |||||||||||||||||||||||||
| $850 million unsecured senior notes payable due 2051 | 3.08 | % | February 2021 | 6,395 | |||||||||||||||||||||||||
| Other increase in interest | 323 | ||||||||||||||||||||||||||||
| Total increases | 13,060 | ||||||||||||||||||||||||||||
| Decreases in interest incurred due to: | |||||||||||||||||||||||||||||
| Repayments of debt: | |||||||||||||||||||||||||||||
| Secured notes payable | Various | December 2020 | (985) | ||||||||||||||||||||||||||
| $500 million unsecured senior notes payable due 2023 | 4.04 | % | September 2020 | (2,659) | |||||||||||||||||||||||||
| $650 million unsecured senior notes payable due 2024 – green bond | 4.03 | % | March 2021 | (6,290) | |||||||||||||||||||||||||
| Fluctuations in interest rate and average balance: | |||||||||||||||||||||||||||||
| Unsecured senior line of credit | (198) | ||||||||||||||||||||||||||||
| $1.5 billion commercial paper program | 61 | ||||||||||||||||||||||||||||
| Total decreases | (10,071) | ||||||||||||||||||||||||||||
| Change in gross interest | 2,989 | ||||||||||||||||||||||||||||
| Increase in capitalized interest | (10,629) | ||||||||||||||||||||||||||||
| Total change in interest expense | $ | (7,640) |
(1)Represents the weighted-average interest rate as of the end of the applicable period, including amortization of loan fees, amortization of debt premiums (discounts), and other bank fees.
Depreciation and amortization
Depreciation and amortization expense for the three months ended September 30, 2021, increased by $34.0 million, or 19.2%, to $210.8 million, compared to $176.8 million for the three months ended September 30, 2020. The increase was primarily due to additional depreciation from 1.5 million RSF of development and redevelopment projects placed into service subsequent to July 1, 2020, and 94 operating properties aggregating 9.2 million RSF acquired subsequent to July 1, 2020.
Impairments of real estate
During the three months ended September 30, 2021, we recognized impairment charges aggregating $42.6 million, primarily consisting of the following:
-
Impairment charge of $22.5 million to reduce the carrying amount of an option to purchase a land parcel in our SoMa submarket for the development of an office property to its estimated fair value less costs to sell, upon classification of the option as held for sale.
-
Impairment charge of $18.6 million to reduce the carrying amount of a property located in a non-core submarket to its estimated fair value less costs to sell, upon our review of the current local market conditions.
Loss on early extinguishment of debt
During the three months ended September 30, 2020, we refinanced our 3.90% unsecured senior notes payable due in 2023 aggregating $500.0 million and recognized a loss on early extinguishment of debt of $50.8 million, including the write-off of unamortized loan fees. Additionally, we recognized a loss on early extinguishment of debt of $1.9 million due to the termination of our $750.0 million unsecured senior line of credit.
Investment income
During the three months ended September 30, 2021, we recognized investment income aggregating $67.1 million, which consisted of $81.5 million of realized gains and $14.4 million of unrealized losses. Realized gains primarily related to sales of investments and distributions received. Unrealized losses of $14.4 million primarily consisted of decreases in fair values of our investments in publicly traded companies and investments in privately held entities that do not report NAV, partially offset by increases in fair values of our investments in privately held entities that report NAV and our share of unrealized gains reported by our equity method investees.
During the three months ended September 30, 2020, we recognized investment income aggregating $3.3 million, which consisted of $17.4 million of realized gains and $14.0 million of unrealized losses.
For more information about our investments, refer to Note 7 – “Investments” to our unaudited consolidated financial statements under Item 1 of this report. For our impairments accounting policy, refer to the “Investments” section of Note 2 – “Summary of significant accounting policies” to our unaudited consolidated financial statements under Item 1 of this report.
(Loss) gain on sales of real estate
During the three months ended September 30, 2021, we completed the sales of three office properties located in our San Francisco Bay Area and Seattle markets for the aggregate purchase price of $73.1 million and recognized a loss on sale of real estate aggregating $435 thousand.
Comparison of results for the nine months ended September 30, 2021, to the nine months ended September 30, 2020
The following table presents a comparison of the components of net operating income for our Same Properties and Non-Same Properties for the nine months ended September 30, 2021, compared to the nine months ended September 30, 2020. Refer to the “Non-GAAP measures and definitions” section within this Item 2 for definitions of “Tenant recoveries” and “Net operating income” and their reconciliations from the most directly comparable financial measures presented in accordance with GAAP, income from rentals and net income, respectively.
Refer to “Item 1A. Risk factors” in our annual report on Form 10-K for the year ended December 31, 2020, for a discussion about risks that COVID-19 directly or indirectly may pose to our business.
| Nine Months Ended September 30, | |||||||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2020 | $ Change | % Change | |||||||||||||||||||||||||
| Income from rentals: | |||||||||||||||||||||||||||||
| Same Properties | $ | 915,884 | $ | 884,359 | $ | 31,525 | 3.6 | % | |||||||||||||||||||||
| Non-Same Properties | 267,071 | 233,531 | 33,540 | 14.4 | |||||||||||||||||||||||||
| Rental revenues | 1,182,955 | 1,117,890 | 65,065 | 5.8 | |||||||||||||||||||||||||
| Same Properties | 298,955 | 275,953 | 23,002 | 8.3 | |||||||||||||||||||||||||
| Non-Same Properties | 51,683 | 23,030 | 28,653 | 124.4 | |||||||||||||||||||||||||
| Tenant recoveries | 350,638 | 298,983 | 51,655 | 17.3 | |||||||||||||||||||||||||
| Income from rentals | 1,533,593 | 1,416,873 | 116,720 | 8.2 | |||||||||||||||||||||||||
| Same Properties | 382 | 237 | 145 | 61.2 | |||||||||||||||||||||||||
| Non-Same Properties | 3,252 | 4,807 | (1,555) | (32.3) | |||||||||||||||||||||||||
| Other income | 3,634 | 5,044 | (1,410) | (28.0) | |||||||||||||||||||||||||
| Same Properties | 1,215,221 | 1,160,549 | 54,672 | 4.7 | |||||||||||||||||||||||||
| Non-Same Properties | 322,006 | 261,368 | 60,638 | 23.2 | |||||||||||||||||||||||||
| Total revenues | 1,537,227 | 1,421,917 | 115,310 | 8.1 | |||||||||||||||||||||||||
| Same Properties | 336,317 | 316,028 | 20,289 | 6.4 | |||||||||||||||||||||||||
| Non-Same Properties | 111,521 | 77,429 | 34,092 | 44.0 | |||||||||||||||||||||||||
| Rental operations | 447,838 | 393,457 | 54,381 | 13.8 | |||||||||||||||||||||||||
| Same Properties | 878,904 | 844,521 | 34,383 | 4.1 | |||||||||||||||||||||||||
| Non-Same Properties | 210,485 | 183,939 | 26,546 | 14.4 | |||||||||||||||||||||||||
| Net operating income | $ | 1,089,389 | $ | 1,028,460 | $ | 60,929 | 5.9 | % | |||||||||||||||||||||
| Net operating income – Same Properties | $ | 878,904 | $ | 844,521 | $ | 34,383 | 4.1 | % | |||||||||||||||||||||
| Straight-line rent revenue | (47,713) | (65,899) | 18,186 | (27.6) | |||||||||||||||||||||||||
| Amortization of acquired below-market leases | (9,844) | (13,166) | 3,322 | (25.2) | |||||||||||||||||||||||||
| Net operating income – Same Properties (cash basis) | $ | 821,347 | $ | 765,456 | $ | 55,891 | 7.3 | % |
Income from rentals
Total income from rentals for the nine months ended September 30, 2021, increased by $116.7 million, or 8.2%, to $1.5 billion, compared to $1.4 billion for the nine months ended September 30, 2020, as a result of increases in rental revenues and tenant recoveries, as discussed below.
Rental revenues
Total rental revenues for the nine months ended September 30, 2021, increased by $65.1 million, or 5.8%, to $1.2 billion, compared to $1.1 billion for the nine months ended September 30, 2020. Excluding a termination fee of $89.5 million recognized during the nine months ended September 30, 2020, our total rental revenues increased by $154.6 million, or 15.0%, which was primarily due to an increase in rental revenues from our Non-Same Properties related to 1.5 million RSF of development and redevelopment projects placed into service subsequent to January 1, 2020, and 104 operating properties aggregating 11.0 million RSF acquired subsequent to January 1, 2020.
Rental revenues from our Same Properties for the nine months ended September 30, 2021, increased by $31.5 million, or 3.6%, to $915.9 million, compared to $884.4 million for the nine months ended September 30, 2020. The increase was primarily due to rental rate increases on lease renewals and re-leasing of space since January 1, 2020.
Tenant recoveries
Tenant recoveries for the nine months ended September 30, 2021, increased by $51.7 million, or 17.3%, to $350.6 million, compared to $299.0 million for the nine months ended September 30, 2020. This increase was primarily from our Non-Same Properties related to our development and redevelopment projects placed into service and properties acquired subsequent to January 1, 2020, as discussed above under “Rental revenues.”
Same Properties’ tenant recoveries for the nine months ended September 30, 2021, increased by $23.0 million, or 8.3%, primarily due to an increase in property tax expenses resulting from higher assessed values of our properties, higher contract services expenses, higher utilities expenses, and higher property insurance during the nine months ended September 30, 2021, as discussed under “Rental operations” below. As of September 30, 2021, 92% of our leases (on an RSF basis) were triple net leases, which require tenants to pay substantially all real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses (including increases thereto) in addition to base rent.
Other income
Other income for the nine months ended September 30, 2021 and 2020, was $3.6 million and $5.0 million, respectively, which primarily consisted of construction management fees and interest income earned during each respective period.
Rental operations
Total rental operating expenses for the nine months ended September 30, 2021, increased by $54.4 million, or 13.8%, to $447.8 million, compared to $393.5 million for the nine months ended September 30, 2020. The increase was primarily due to incremental expenses related to our Non-Same Properties, which consist of development and redevelopment projects placed into service and acquired properties, as discussed above under “Income from rentals.”
Same Properties’ rental operating expenses increased by $20.3 million, or 6.4%, to $336.3 million during the nine months ended September 30, 2021, compared to $316.0 million for the nine months ended September 30, 2020. The increase was primarily the result of increased recoverable property tax expenses driven by higher assessed values of our properties, higher contract services expenses, higher utilities expenses, and higher property insurance.
General and administrative expenses
General and administrative expenses for the nine months ended September 30, 2021, increased by $9.2 million, or 9.1%, to $109.8 million, compared to $100.7 million for the nine months ended September 30, 2020. The increase was primarily due to the costs related to our corporate responsibility efforts, as well as the continued growth in the depth and breadth of our operations in multiple markets, including development and redevelopment projects placed into service and properties acquired, as discussed above under “Income from rentals.” As a percentage of net operating income, our general and administrative expenses for the trailing twelve months ended September 30, 2021 and 2020, were 10.1% and 9.9%, respectively.
Interest expense
Interest expense for the nine months ended September 30, 2021 and 2020, consisted of the following (dollars in thousands):
| Nine Months Ended September 30, | ||||||||||||||||||||
| Component | 2021 | 2020 | Change | |||||||||||||||||
| Gross interest | $ | 233,866 | $ | 222,100 | $ | 11,766 | ||||||||||||||
| Capitalized interest | (126,563) | (88,029) | (38,534) | |||||||||||||||||
| Interest expense | $ | 107,303 | $ | 134,071 | $ | (26,768) | ||||||||||||||
| Average debt balance outstanding(1) | $ | 8,960,600 | $ | 7,626,396 | $ | 1,334,204 | ||||||||||||||
| Weighted-average annual interest rate(2) | 3.5 | % | 3.9 | % | (0.4) | % | ||||||||||||||
(1)Represents the average debt balance outstanding during the respective periods.
(2)Represents annualized total interest incurred divided by the average debt balance outstanding during the respective periods.
The net change in interest expense during the nine months ended September 30, 2021, compared to the nine months ended September 30, 2020, resulted from the following (dollars in thousands):
| Component | Interest Rate(1) | Effective Date | Change | ||||||||||||||||||||||||||
| Increases in interest incurred due to: | |||||||||||||||||||||||||||||
| Issuances of debt: | |||||||||||||||||||||||||||||
| $700 million unsecured senior notes payable | 5.05 | % | March 2020 | $ | 8,109 | ||||||||||||||||||||||||
| $1.0 billion unsecured senior notes payable | 1.97 | % | August 2020 | 11,230 | |||||||||||||||||||||||||
| $900 million unsecured senior notes payable - green bond | 2.12 | % | February 2021 | 11,291 | |||||||||||||||||||||||||
| $850 million unsecured senior notes payable | 3.08 | % | February 2021 | 15,844 | |||||||||||||||||||||||||
| Other increase in interest | 1,059 | ||||||||||||||||||||||||||||
| Total increases | 47,533 | ||||||||||||||||||||||||||||
| Decreases in interest incurred due to: | |||||||||||||||||||||||||||||
| Repayments of debt: | |||||||||||||||||||||||||||||
| Secured notes payable | Various | December 2020 | (2,964) | ||||||||||||||||||||||||||
| $500 million unsecured senior notes payable | 4.04 | % | September 2020 | (12,489) | |||||||||||||||||||||||||
| $650 million unsecured senior notes payable – green bond | 4.03 | % | March 2021 | (15,930) | |||||||||||||||||||||||||
| Fluctuations in interest rate and average balance: | |||||||||||||||||||||||||||||
| Unsecured senior line of credit | (1,743) | ||||||||||||||||||||||||||||
| $1.5 billion commercial paper program | (2,641) | ||||||||||||||||||||||||||||
| Total decreases | (35,767) | ||||||||||||||||||||||||||||
| Change in gross interest | 11,766 | ||||||||||||||||||||||||||||
| Increase in capitalized interest | (38,534) | ||||||||||||||||||||||||||||
| Total change in interest expense | $ | (26,768) |
(1)Represents the weighted-average interest rate as of the end of the applicable period, including amortization of loan fees, amortization of debt premiums (discounts), and other bank fees.
Depreciation and amortization
Depreciation and amortization expense for the nine months ended September 30, 2021, increased by $61.5 million, or 11.8%, to $581.8 million, compared to $520.4 million for the nine months ended September 30, 2020. The increase was primarily due to additional depreciation from 1.5 million RSF of development and redevelopment projects placed into service subsequent to January 1, 2020, and 104 operating properties aggregating 11.0 million RSF acquired subsequent to January 1, 2020.
Impairment of real estate
During the nine months ended September 30, 2021, we recognized impairment charges aggregating $52.7 million, primarily consisting of the following:
-
Impairment charge of $22.5 million during the three months ended September 30, 2021, upon classification as held for sale of an option to purchase a land parcel in our SoMa submarket for the development of an office property, to reduce the option’s carrying amount to its estimated fair value less costs to sell.
-
Impairment charge of $18.6 million during the three months ended September 30, 2021, to reduce the carrying amount of a property located in a non-core submarket to its estimated fair value less costs to sell, upon our review of the current local market conditions.
-
Impairment charges aggregating $6.9 million during the six months ended June 30, 2021, to reduce the carrying amounts of three office properties located in our San Francisco Bay Area and Seattle markets to their estimated fair values less costs to sell, based on the sales price negotiated for each property during this period. We completed the sales of these properties during the three months ended September 30, 2021.
Loss on early extinguishment of debt
During the nine months ended September 30, 2021, we recognized a loss on early extinguishment of debt of $67.3 million, including the write-off of unamortized loan fees primarily related to the refinancing of our 4.00% unsecured senior notes payable aggregating $650.0 million due in 2024 pursuant to a partial cash tender offer completed on February 10, 2021, and a subsequent call for redemption for the remaining outstanding amounts completed on March 12, 2021.
During the nine months ended September 30, 2020, we refinanced our 3.90% unsecured senior notes payable due in 2023 aggregating $500.0 million and recognized a loss on early extinguishment of debt of $50.8 million, including the write-off of unamortized loan fees. Additionally, we recognized a loss on early extinguishment of debt of $1.9 million due to the termination of our $750.0 million unsecured senior line of credit.
Equity in earnings of unconsolidated real estate joint ventures
During the nine months ended September 30, 2021, we recognized equity in earnings of unconsolidated real estate joint ventures of $9.2 million.
During the nine months ended September 30, 2020, we recognized equity in earnings of unconsolidated real estate joint ventures aggregating $4.6 million. This balance consisted of earnings from our unconsolidated real estate joint ventures of approximately $12.2 million, partially offset by an impairment charge on one of our unconsolidated joint ventures. In March 2020, the impact of COVID-19 pandemic led to the temporary closure of a retail center owned by our 1401/1413 Research Boulevard joint venture. We evaluated the recoverability of our investment in this joint venture and recognized a $7.6 million impairment charge to lower the carrying amount of our investment balance, which primarily consisted of real estate, to zero.
Refer to Note 4 – “Consolidated and unconsolidated real estate joint ventures” to our unaudited consolidated financial statements under Item 1 of this report for additional information.
Investment income
During the nine months ended September 30, 2021, we recognized investment income aggregating $372.4 million, which consisted of $189.0 million of realized gains and $183.3 million of unrealized gains. Realized gains of $189.0 million primarily consisted of sales of investments and distributions received. Unrealized gains of $183.3 million during the nine months ended September 30, 2021, primarily consisted of increases in fair values of our investments in publicly traded companies and investments in privately held entities that report NAV.
During the nine months ended September 30, 2020, we recognized investment income aggregating $166.2 million, which consisted of $25.7 million of realized gains and $140.5 million of unrealized gains.
For more information about our investments, refer to Note 7 – “Investments” to our unaudited consolidated financial statements under Item 1 of this report. For our impairments accounting policy, refer to the “Investments” section of Note 2 – “Summary of significant accounting policies” to our unaudited consolidated financial statements under Item 1 of this report.
Gain on sales of real estate
During the nine months ended September 30, 2021, we recognized gain on sales of real estate aggregating $2.3 million, which included $2.8 million of gains related to the completion of two real estate dispositions and a loss of $435 thousand related to the sale of an office property located in our San Francisco Bay Area market. The net gains were classified in (loss) gain on sales of real estate within our consolidated statements of operations for the nine months ended September 30, 2021.
Summary of capital expenditures
Our construction spending for the nine months ended September 30, 2021, consisted of the following (in thousands):
| Construction Spending | Nine Months Ended September 30, 2021 | ||||||||||
| Additions to real estate – consolidated projects | $ | 1,542,210 | |||||||||
| Investments in unconsolidated real estate joint ventures | 739 | ||||||||||
| Contributions from noncontrolling interests | (56,669) | ||||||||||
| Construction spending (cash basis) | 1,486,280 | ||||||||||
| Change in accrued construction | 69,551 | ||||||||||
| Construction spending for the nine months ended September 30, 2021 | 1,555,831 | ||||||||||
| Projected construction spending for the three months ending December 31, 2021 | 554,169 | ||||||||||
| Guidance midpoint | $ | 2,110,000 |
The following table summarizes the total projected construction spending for the year ending December 31, 2021, which includes interest, property taxes, insurance, payroll, and other indirect project costs (in thousands):
| Projected Construction Spending | Year Ending December 31, 2021 | |||||||||||||||||||
| Development, redevelopment, and pre-construction projects | $ | 1,990,000 | ||||||||||||||||||
| Contributions from noncontrolling interests (consolidated real estate joint ventures) | (100,000) | |||||||||||||||||||
| Revenue-enhancing and repositioning capital expenditures | 155,000 | |||||||||||||||||||
| Non-revenue-enhancing capital expenditures | 65,000 | |||||||||||||||||||
| Guidance midpoint | $ | 2,110,000 | ||||||||||||||||||
Projected results
We present updated guidance for EPS attributable to Alexandria’s common stockholders – diluted, funds from operations per share attributable to Alexandria’s common stockholders – diluted, and funds from operations per share attributable to Alexandria’s common stockholders – diluted, as adjusted, based on our current view of existing market conditions and other assumptions for the year ending December 31, 2021, as set forth, in the tables below. The tables below also provide a reconciliation of EPS attributable to Alexandria’s common stockholders – diluted, the most directly comparable GAAP measure, to funds from operations per share and funds from operations per share, as adjusted, non-GAAP measures, and other key assumptions included in our updated guidance for the year ending December 31, 2021. There can be no assurance that actual amounts will not be materially higher or lower than these expectations. Refer to our discussion of “Forward-looking statements” within this Item 2.
| Projected 2021 Earnings per Share and Funds From Operations per Share Attributable to Alexandria’s Common Stockholders – Diluted | As of 10/25/21 | As of 7/26/21 | ||||||||||||||||||||||||
| Earnings per share(1) | $3.91 to $3.93 | $3.46 to $3.54 | ||||||||||||||||||||||||
| Depreciation and amortization of real estate assets | 5.05 | 5.50 | ||||||||||||||||||||||||
| Gain on sales of real estate | (0.02) | (0.02) | ||||||||||||||||||||||||
| Impairment of real estate – rental properties(2) | 0.18 | 0.05 | ||||||||||||||||||||||||
| Allocation of unvested restricted stock awards | (0.04) | (0.04) | ||||||||||||||||||||||||
| Funds from operations per share(2) | $9.08 to $9.10 | $8.95 to $9.03 | ||||||||||||||||||||||||
| Unrealized gains on non-real estate investments | (1.26) | (1.39) | ||||||||||||||||||||||||
| Significant realized gains on non-real estate investments(2) | (0.76) | (0.41) | ||||||||||||||||||||||||
| Impairment of real estate(2) | 0.19 | 0.02 | ||||||||||||||||||||||||
| Loss on early extinguishment of debt | 0.46 | 0.47 | ||||||||||||||||||||||||
| Allocation to unvested restricted stock awards | 0.02 | 0.01 | ||||||||||||||||||||||||
| Other | 0.01 | 0.06 | ||||||||||||||||||||||||
| Funds from operations per share, as adjusted(2) | $7.74 to $7.76 | $7.71 to $7.79 | ||||||||||||||||||||||||
| Midpoint | $7.75 | $7.75 | ||||||||||||||||||||||||
(1)Excludes unrealized gains or losses after September 30, 2021, that are required to be recognized in earnings and are excluded from funds from operations per share, as adjusted.
(2)Refer to the definition of “Funds from operations and funds from operations, as adjusted, attributable to Alexandria Real Estate Equities, Inc.’s common stockholders” in the “Non-GAAP measures and definitions” section within this Item 2 for additional information.
| Key Assumptions**(1)** (Dollars in millions) | 2021 Guidance | |||||||||||||||||||||||||
| Low | High | |||||||||||||||||||||||||
| Occupancy percentage for operating properties in North America as of December 31, 2021(2) | 93.3% | 93.9% | ||||||||||||||||||||||||
| Lease renewals and re-leasing of space: | ||||||||||||||||||||||||||
| Rental rate increases | 33.0% | 36.0% | ||||||||||||||||||||||||
| Rental rate increases (cash basis) | 19.0% | 22.0% | ||||||||||||||||||||||||
| Same property performance: | ||||||||||||||||||||||||||
| Net operating income increase | 2.0% | 4.0% | ||||||||||||||||||||||||
| Net operating income increase (cash basis) | 4.7% | 6.7% | ||||||||||||||||||||||||
| Straight-line rent revenue | $ | 119 | $ | 129 | ||||||||||||||||||||||
| General and administrative expenses | $ | 146 | $ | 151 | ||||||||||||||||||||||
| Capitalization of interest | $ | 172 | $ | 182 | ||||||||||||||||||||||
| Interest expense | $ | 128 | $ | 138 | ||||||||||||||||||||||
(1)Our assumptions presented in the table above are subject to a number of variables and uncertainties, including those discussed as “Forward-looking statements” under Part I; “Item 1A. Risk factors”; and “Item 7. Management’s discussion and analysis of financial condition and results of operations” of our annual report on Form 10-K for the year ended December 31, 2020, as well as in “Item 1A. Risk factors” within “Part II – Other information” of this quarterly report on Form 10-Q.
(2)Updated guidance for occupancy percentage in North America as of December 31, 2021, reflects vacancy at one recently acquired property that closed in the third quarter of 2021, and two pending acquisitions expected to close in the fourth quarter of 2021, representing lease-up opportunities that will contribute to growth in cash flows. One of the two pending acquisitions includes value-creation opportunities while the other pending acquisition is 50% under lease negotiation. Excluding vacancy at recently acquired properties, we expect occupancy for properties in North America as of December 31, 2021 to increase by approximately 100 bps compared to December 31, 2020. Refer to “Summary of occupancy percentages in North America” within this Item 2 for additional information.
| Key Credit Metrics | 2021 Guidance | |||||||||||||
| Net debt and preferred stock to Adjusted EBITDA – fourth quarter of 2021, annualized | Less than or equal to 5.2x | |||||||||||||
| Fixed-charge coverage ratio – fourth quarter of 2021, annualized | Greater than or equal to 5.0x | |||||||||||||
Consolidated and unconsolidated real estate joint ventures
We present components of balance sheet and operating results information for the noncontrolling interest share of our consolidated real estate joint ventures and for our share of investments in unconsolidated real estate joint ventures to help investors estimate balance sheet and operating results information related to our partially owned entities. These amounts are estimated by computing, for each joint venture that we consolidate in our financial statements, the noncontrolling interest percentage of each financial item to arrive at the cumulative noncontrolling interest share of each component presented. In addition, for our real estate joint ventures that we do not control and do not consolidate, we apply our economic ownership percentage to the unconsolidated real estate joint ventures to arrive at our proportionate share of each component presented. Refer to Note 4 – “Consolidated and unconsolidated real estate joint ventures” to our unaudited consolidated financial statements under Item 1 of this report for further discussion.
| Consolidated Real Estate Joint Ventures | ||||||||||||||||||||||||||
| Property/Market/Submarket | Noncontrolling(1) Interest Share | Operating RSF at 100% | ||||||||||||||||||||||||
| 75/125 Binney Street/Greater Boston/Cambridge/Inner Suburbs | 60.0 | % | 388,270 | |||||||||||||||||||||||
| 225 Binney Street/Greater Boston/Cambridge/Inner Suburbs | 70.0 | % | 305,212 | |||||||||||||||||||||||
| 99 Coolidge Avenue/Greater Boston/Cambridge/Inner Suburbs | 25.0 | % | — | (2) | ||||||||||||||||||||||
| 409 and 499 Illinois Street/San Francisco Bay Area/Mission Bay | 40.0 | % | (3) | 455,069 | ||||||||||||||||||||||
| 1500 Owens Street/San Francisco Bay Area/Mission Bay | 49.9 | % | (3) | 158,267 | ||||||||||||||||||||||
| Alexandria Technology Center® – Gateway/San Francisco Bay Area/South San Francisco(4) | 51.9 | % | 1,089,852 | |||||||||||||||||||||||
| 213 East Grand Avenue/San Francisco Bay Area/South San Francisco | 70.0 | % | 300,930 | |||||||||||||||||||||||
| 500 Forbes Boulevard/San Francisco Bay Area/South San Francisco | 90.0 | % | 155,685 | |||||||||||||||||||||||
| Alexandria Center® for Life Science – Millbrae Station/San Francisco Bay Area/South San Francisco | 62.4 | % | — | |||||||||||||||||||||||
| Alexandria Point/San Diego/University Town Center(5) | 45.0 | % | 1,337,916 | |||||||||||||||||||||||
| 5200 Illumina Way/San Diego/University Town Center | 49.0 | % | 792,687 | |||||||||||||||||||||||
| 9625 Towne Centre Drive/San Diego/University Town Center | 49.9 | % | 163,648 | |||||||||||||||||||||||
| SD Tech by Alexandria/San Diego/Sorrento Mesa(6) | 50.0 | % | 679,801 | |||||||||||||||||||||||
| Pacific Technology Park/San Diego/Sorrento Mesa | 50.0 | % | 632,732 | |||||||||||||||||||||||
| The Eastlake Life Science Campus by Alexandria/Seattle/Lake Union(7) | 70.0 | % | 321,218 | |||||||||||||||||||||||
| 400 Dexter Avenue North/Seattle/Lake Union | 70.0 | % | 290,111 | |||||||||||||||||||||||
| Unconsolidated Real Estate Joint Ventures | ||||||||||||||||||||||||||
| Property/Market/Submarket | Our Ownership Share(8) | Operating RSF at 100% | ||||||||||||||||||||||||
| 1655 and 1725 Third Street/San Francisco Bay Area/Mission Bay | 10.0 | % | 586,208 | |||||||||||||||||||||||
| Menlo Gateway/San Francisco Bay Area/Greater Stanford | 49.0 | % | 772,983 | |||||||||||||||||||||||
| 1401/1413 Research Boulevard/Maryland/Rockville | 65.0 | % | (9) | (10) |
(1)In addition to the consolidated real estate joint ventures listed, various partners hold insignificant noncontrolling interests in five other real estate joint ventures in North America.
(2)We expect to commence vertical construction of 275,000 RSF during 2021.
(3)Refer to “Real estate dispositions and partial interest sales” in the “Sources of capital” section within this Item 2 for additional information.
(4)Includes 601, 611, 651, 681, 685, 701, and 751 Gateway Boulevard in our South San Francisco submarket. Noncontrolling interest share is anticipated to be 49% as we make further contributions into the joint venture over time.
(5)Includes 10210, 10260, 10290, and 10300 Campus Point Drive and 4161, 4224, and 4242 Campus Point Court in our University Town Center submarket.
(6)Includes 9605, 9645, 9675, 9685, 9725, 9735, 9808, 9855, and 9868 Scranton Road and 10055 and 10065 Barnes Canyon Road in our Sorrento Mesa submarket.
(7)Includes 1201 and 1208 Eastlake Avenue East and 199 East Blaine Street in our Lake Union submarket.
(8)In addition to the unconsolidated real estate joint ventures listed, we hold an interest in one other insignificant unconsolidated real estate joint venture in North America.
(9)Represents our ownership interest; our voting interest is limited to 50%.
(10)Represents a joint venture with a distinguished retail real estate developer for an approximate 90,000 RSF retail shopping center.
The following table presents key terms related to our unconsolidated real estate joint ventures’ secured loans as of September 30, 2021 (dollars in thousands):
| Maturity Date | Stated Rate | Interest Rate(1) | Debt Balance at 100%(2) | ||||||||||||||||||||||||||||||||||||||||||||
| Unconsolidated Joint Venture | Our Share | ||||||||||||||||||||||||||||||||||||||||||||||
| 1401/1413 Research Boulevard | 65.0% | 5/17/22 | L+2.50% | 3.50 | % | (3) | $ | 27,145 | |||||||||||||||||||||||||||||||||||||||
| 1655 and 1725 Third Street | 10.0% | 3/10/25 | 4.50% | 4.57 | % | 598,550 | |||||||||||||||||||||||||||||||||||||||||
| Menlo Gateway, Phase II | 49.0% | 5/1/35 | 4.53% | 4.59 | % | 154,992 | |||||||||||||||||||||||||||||||||||||||||
| Menlo Gateway, Phase I | 49.0% | 8/10/35 | 4.15% | 4.18 | % | 137,578 | |||||||||||||||||||||||||||||||||||||||||
| $ | 918,265 |
(1)Includes interest expense and amortization of loan fees.
(2)Represents outstanding principal, net of unamortized deferred financing costs, as of September 30, 2021.
(3)This loan is subject to a fixed floor rate of 3.50%.
The following tables present information related to the operating results and financial positions of our consolidated and unconsolidated real estate joint ventures for the three and nine months ended September 30, 2021 (in thousands):
| Noncontrolling Interest Share of Consolidated Real Estate Joint Ventures | Our Share of Unconsolidated Real Estate Joint Ventures | ||||||||||||||||||||||
| September 30, 2021 | September 30, 2021 | ||||||||||||||||||||||
| Three Months Ended | Nine Months Ended | Three Months Ended | Nine Months Ended | ||||||||||||||||||||
| Total revenues | $ | 54,419 | $ | 147,534 | $ | 10,876 | $ | 33,595 | |||||||||||||||
| Rental operations | (15,217) | (39,845) | (1,785) | (5,610) | |||||||||||||||||||
| 39,202 | 107,689 | 9,091 | 27,985 | ||||||||||||||||||||
| General and administrative | (267) | (599) | (31) | (185) | |||||||||||||||||||
| Interest | — | — | (2,504) | (7,887) | |||||||||||||||||||
| Depreciation and amortization | (17,871) | (49,615) | (3,465) | (10,676) | |||||||||||||||||||
| Fixed returns allocated to redeemable noncontrolling interests(1) | 222 | 659 | — | — | |||||||||||||||||||
| $ | 21,286 | $ | 58,134 | $ | 3,091 | $ | 9,237 | ||||||||||||||||
| Straight-line rent and below-market lease revenue | $ | 1,377 | $ | 3,459 | $ | 809 | $ | 2,924 | |||||||||||||||
| Funds from operations(2) | $ | 39,157 | $ | 107,749 | $ | 6,556 | $ | 19,913 |
(1)Represents an allocation of joint venture earnings to redeemable noncontrolling interests primarily in one property in our South San Francisco submarket. These redeemable noncontrolling interests earn a fixed return on their investment rather than participate in the operating results of the property.
(2)Refer to the definition of “Funds from operations and funds from operations, as adjusted, attributable to Alexandria Real Estate Equities, Inc.’s common stockholders” in the “Non-GAAP measures and definitions” section within this Item 2 for the definition and the reconciliation from the most directly comparable GAAP measure.
| As of September 30, 2021 | |||||||||||
| Noncontrolling Interest Share of Consolidated Real Estate Joint Ventures | Our Share of Unconsolidated Real Estate Joint Ventures | ||||||||||
| Investments in real estate | $ | 2,048,838 | $ | 475,982 | |||||||
| Cash, cash equivalents, and restricted cash | 70,786 | 9,492 | |||||||||
| Other assets | 235,407 | 63,397 | |||||||||
| Secured notes payable | — | (219,245) | |||||||||
| Other liabilities | (106,148) | (7,889) | |||||||||
| Redeemable noncontrolling interests | (11,681) | — | |||||||||
| $ | 2,237,202 | $ | 321,737 |
During the nine months ended September 30, 2021 and 2020, our consolidated real estate joint ventures distributed an aggregate of $81.9 million and $64.6 million, respectively, to our joint venture partners. Refer to our consolidated statements of cash flows and Note 4 – “Consolidated and unconsolidated real estate joint ventures” to our unaudited consolidated financial statements under Item 1 of this report for additional information.
Investments
We hold investments in publicly traded companies and privately held entities primarily involved in the life science, agtech, and technology industries. The tables below summarize components of our non-real estate investments and investment income. For additional information, refer to Note 7 – “Investments” to our unaudited consolidated financial statements under Item 1 of this report.
| September 30, 2021 | |||||||||||||||||||||||||||||
| (In thousands) | Three Months Ended | Nine Months Ended | Year Ended December 31, 2020 | ||||||||||||||||||||||||||
| Realized gains | $ | 81,516 | (1) | $ | 189,013 | (2) | $ | 47,288 | (3) | ||||||||||||||||||||
| Unrealized (losses) gains | (14,432) | 183,348 | 374,033 | ||||||||||||||||||||||||||
| Investment income | $ | 67,084 | $ | 372,361 | $ | 421,321 | |||||||||||||||||||||||
| September 30, 2021 | |||||||||||||||||||||||||||||
| Investments (In thousands) | Cost | Unrealized Gains | Carrying Amount | ||||||||||||||||||||||||||
| Publicly traded companies | $ | 282,816 | $ | 374,515 | (4) | $ | 657,331 | ||||||||||||||||||||||
| Entities that report NAV | 355,400 | 480,412 | 835,812 | ||||||||||||||||||||||||||
| Entities that do not report NAV: | |||||||||||||||||||||||||||||
| Entities with observable price changes | 54,562 | 74,906 | 129,468 | ||||||||||||||||||||||||||
| Entities without observable price changes | 349,100 | — | 349,100 | ||||||||||||||||||||||||||
| $ | 1,041,878 | (5) | $ | 929,833 | 1,971,711 | ||||||||||||||||||||||||
| Investments accounted for under the equity method of accounting | 75,167 | ||||||||||||||||||||||||||||
| Total investments | $ | 2,046,878 |
(1)Includes three separate significant realized gains aggregating $52.4 million related to the following transactions: (i) the sale of shares in an investment in a publicly traded biotechnology company, (ii) a distribution received from a limited partnership investment, and (iii) the acquisition of one of our privately held biotechnology investments by a publicly traded biotechnology company.
(2)Includes six separate significant realized gains aggregating $110.1 million related to the following transactions: (i) the sales of investments in three publicly traded biotechnology companies, (ii) a distribution received from a limited partnership investment, and (iii) the acquisition of two of our privately held non-real estate investments in a biopharmaceutical company and biotechnology company.
(3)Includes impairments of $24.5 million related to investments in privately held entities that do not report NAV.
(4)Includes gross unrealized gains and losses of $400.0 million and $25.5 million, respectively, as of September 30, 2021.
(5)Represents 3.2% of gross assets as of September 30, 2021.
| Public/Private Mix (Cost) | ||||||||
 | ||||||||
| Tenant/Non-Tenant Mix (Cost) | ||||||||
 |
Liquidity
| Liquidity | Minimal Outstanding Borrowings and Significant Availability on Unsecured Senior Line of Credit | ||||||||||||||||
| $4.0B | (in millions) | ||||||||||||||||
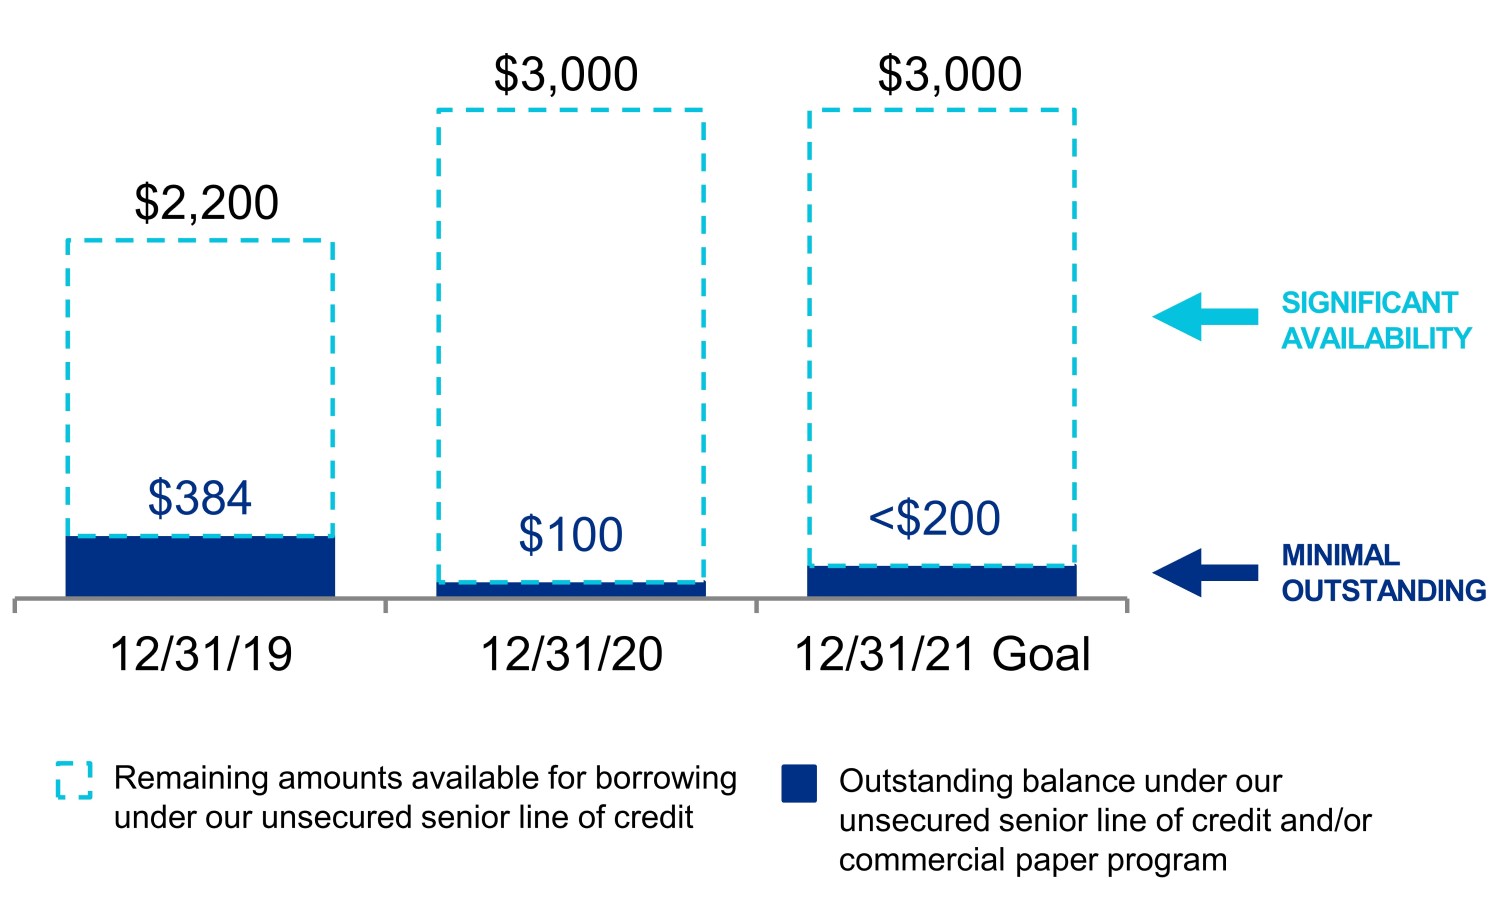 | |||||||||||||||||
| (In millions) | |||||||||||||||||
| Availability under our unsecured senior line of credit, net of amounts outstanding under our commercial paper program | $ | 2,250 | |||||||||||||||
| Outstanding forward equity sales agreements(1) | 772 | ||||||||||||||||
| Cash, cash equivalents, and restricted cash | 368 | ||||||||||||||||
| Investments in publicly traded companies | 657 | ||||||||||||||||
| Liquidity as of September 30, 2021 | $ | 4,047 | |||||||||||||||
| Net Debt and Preferred Stock to Adjusted EBITDA**(2)** | Fixed-Charge Coverage Ratio**(2)** | ||||||||||||||||
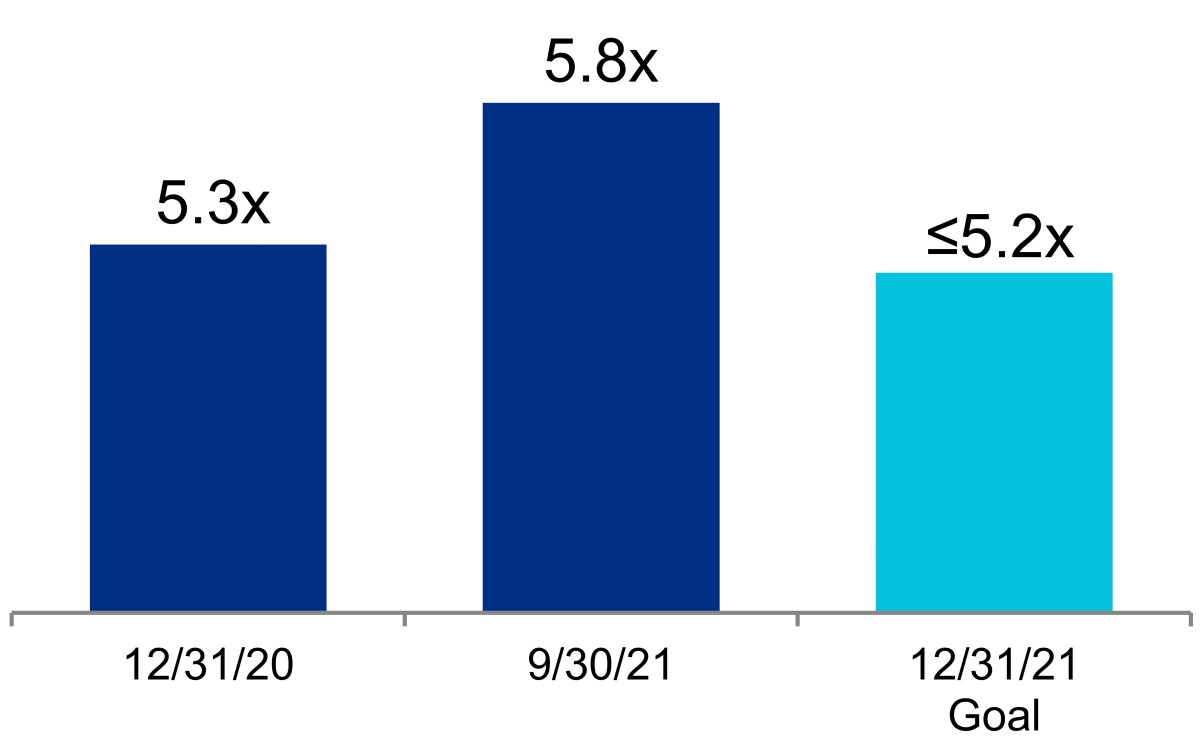 |  | ||||||||||||||||
(1)Represents expected net proceeds from the future settlement of the remaining 4.6 million shares outstanding under our forward equity sales agreements as of September 30, 2021.
(2)Quarter annualized. Refer to the definitions of “Net debt and preferred stock to Adjusted EBITDA” and “Fixed-charge coverage ratio” in the “Non-GAAP measures and definitions” section within this Item 2 for additional details.
We expect to meet certain long-term liquidity requirements, such as requirements for development, redevelopment, other construction projects, capital improvements, tenant improvements, property acquisitions, leasing costs, non-revenue-enhancing capital expenditures, scheduled debt maturities, distributions to noncontrolling interests, and payment of dividends through net cash provided by operating activities, periodic asset sales, strategic real estate joint venture capital, long-term secured and unsecured indebtedness, borrowings under our unsecured senior line of credit, issuances under our commercial paper program, and issuances of additional debt and/or equity securities.
We expect to continue meeting our short-term liquidity and capital requirements, as further detailed in this section, generally through our working capital and net cash provided by operating activities. We believe that the net cash provided by operating activities will continue to be sufficient to enable us to make the distributions necessary to continue qualifying as a REIT.
Over the next several years, our balance sheet, capital structure, and liquidity objectives are as follows:
-
Retain positive cash flows from operating activities after payment of dividends and distributions to noncontrolling interests for investment in development and redevelopment projects and/or acquisitions;
-
Improve credit profile and relative long-term cost of capital;
-
Maintain diverse sources of capital, including sources from net cash provided by operating activities, unsecured debt, secured debt, selective real estate asset sales, partial interest sales, non-real estate investment sales, and common stock;
-
Maintain commitment to long-term capital to fund growth;
-
Maintain prudent laddering of debt maturities;
-
Maintain solid credit metrics;
-
Maintain significant balance sheet liquidity;
-
Mitigate variable-rate debt exposure through the reduction of short-term and medium-term variable-rate debt;
-
Maintain a large unencumbered asset pool to provide financial flexibility;
-
Fund common stock dividends and distributions to noncontrolling interests from net cash provided by operating activities;
-
Manage a disciplined level of value-creation projects as a percentage of our gross investments in real estate; and
-
Maintain high levels of pre-leasing and percentage leased in value-creation projects.
The following table presents the availability under our unsecured senior line of credit, net of amounts outstanding under our commercial paper program; outstanding forward equity sales agreements; cash, cash equivalents, and restricted cash; and investments in publicly traded companies as of September 30, 2021 (dollars in thousands):
| Description | Stated Rate | Aggregate Commitments | Outstanding Balance | Remaining Commitments/Liquidity | ||||||||||||||||||||||
| Availability under our unsecured senior line of credit, net of amounts outstanding under our commercial paper program | L+0.815 | % | $ | 3,000,000 | $ | 750,000 | $ | 2,250,000 | ||||||||||||||||||
| Outstanding forward equity sales agreements(1) | 771,852 | |||||||||||||||||||||||||
| Cash, cash equivalents, and restricted cash | 368,054 | |||||||||||||||||||||||||
| Investments in publicly traded companies | 657,331 | |||||||||||||||||||||||||
| Total liquidity as of September 30, 2021 | $ | 4,047,237 |
(1)Represents expected net proceeds from the future settlement of the remaining 4.6 million shares outstanding under our forward equity sales agreements as of September 30, 2021.
Cash, cash equivalents, and restricted cash
As of September 30, 2021, and December 31, 2020, we had $368.1 million and $597.7 million, respectively, of cash, cash equivalents, and restricted cash. We expect existing cash, cash equivalents, and restricted cash, net cash from operating activities, proceeds from real estate asset sales and partial interest sales, non-real estate investment sales, borrowings under our unsecured senior line of credit, issuances under our commercial paper program, issuances of unsecured notes payable, and issuances of common stock to continue to be sufficient to fund our operating activities and cash commitments for investing and financing activities, such as regular quarterly dividends, distributions to noncontrolling interests, scheduled debt repayments, acquisitions, and certain capital expenditures, including expenditures related to construction activities.
Cash flows
We report and analyze our cash flows based on operating activities, investing activities, and financing activities. The following table summarizes changes in our cash flows for the nine months ended September 30, 2021 and 2020 (in thousands):
| Nine Months Ended September 30, | |||||||||||||||||
| 2021 | 2020 | Change | |||||||||||||||
| Net cash provided by operating activities | $ | 760,637 | $ | 708,941 | $ | 51,696 | |||||||||||
| Net cash used in investing activities | $ | (5,433,393) | $ | (2,865,016) | $ | (2,568,377) | |||||||||||
| Net cash provided by financing activities | $ | 4,442,763 | $ | 2,398,781 | $ | 2,043,982 |
Operating activities
Cash flows provided by operating activities are primarily dependent upon the occupancy level of our asset base, the rental rates of our leases, the collectibility of rent and recovery of operating expenses from our tenants, the timing of completion of development and redevelopment projects, and the timing of acquisitions and dispositions of operating properties. Net cash provided by operating activities for the nine months ended September 30, 2021, increased to $760.6 million, compared to $708.9 million for the nine months ended September 30, 2020. This increase was primarily attributable to (i) cash flows generated from our highly leased development and redevelopment projects recently placed into service, (ii) income-producing acquisitions since January 1, 2020, and (iii) increases in rental rates on lease renewals and re-leasing of space since January 1, 2020.
Investing activities
Cash used in investing activities for the nine months ended September 30, 2021 and 2020, consisted of the following (in thousands):
| Nine Months Ended September 30, | Increase (Decrease) | ||||||||||||||||
| 2021 | 2020 | ||||||||||||||||
| Sources of cash from investing activities: | |||||||||||||||||
| Sales of and distributions from non-real estate investments | $ | 278,554 | $ | 103,670 | $ | 174,884 | |||||||||||
| Proceeds from sales of real estate | 65,245 | 199,537 | (134,292) | ||||||||||||||
| Return of capital from unconsolidated real estate joint ventures | — | 20,225 | (20,225) | ||||||||||||||
| 343,799 | 323,432 | 20,367 | |||||||||||||||
| Uses of cash for investing activities: | |||||||||||||||||
| Purchases of real estate | 3,758,704 | 1,989,648 | 1,769,056 | ||||||||||||||
| Additions to real estate | 1,542,210 | 1,072,102 | 470,108 | ||||||||||||||
| Acquisition of interest in unconsolidated real estate joint ventures | 9,048 | — | 9,048 | ||||||||||||||
| Investments in unconsolidated real estate joint ventures | 739 | 3,291 | (2,552) | ||||||||||||||
| Change in escrow deposits | 147,414 | 7,041 | 140,373 | ||||||||||||||
| Additions to non-real estate investments | 319,077 | 116,366 | 202,711 | ||||||||||||||
| 5,777,192 | 3,188,448 | 2,588,744 | |||||||||||||||
| Net cash used in investing activities | $ | 5,433,393 | $ | 2,865,016 | $ | 2,568,377 |
The increase in net cash used in investing activities for the nine months ended September 30, 2021, was primarily due to an increased use of cash for property acquisitions, additions to real estate, and additions to non-real estate investments, partially offset by increased proceeds from sales of and distributions from non-real estate investments. Refer to Note 3 – “Investments in real estate” to our unaudited consolidated financial statements under Item 1 of this report for additional information.
Financing activities
Cash flows provided by financing activities for the nine months ended September 30, 2021 and 2020, consisted of the following (in thousands):
| Nine Months Ended September 30, | |||||||||||||||||
| 2021 | 2020 | Change | |||||||||||||||
| Repayments of borrowings from secured notes payable | $ | (17,108) | $ | (4,741) | $ | (12,367) | |||||||||||
| Proceeds from issuance of unsecured senior notes payable | 1,743,716 | 1,697,651 | 46,065 | ||||||||||||||
| Repayments of unsecured senior notes payable | (650,000) | (500,000) | (150,000) | ||||||||||||||
| Premium paid for early extinguishment of debt | (66,829) | (48,653) | (18,176) | ||||||||||||||
| Borrowings from unsecured senior line of credit | 2,101,000 | 2,700,000 | (599,000) | ||||||||||||||
| Repayments of borrowings from unsecured senior line of credit | (2,101,000) | (3,084,000) | 983,000 | ||||||||||||||
| Proceeds from issuance under commercial paper program | 21,850,000 | 18,818,900 | 3,031,100 | ||||||||||||||
| Repayments of borrowings from commercial paper program | (21,200,000) | (18,568,900) | (2,631,100) | ||||||||||||||
| Payments of loan fees | (16,870) | (16,990) | 120 | ||||||||||||||
| Changes related to debt | 1,642,909 | 993,267 | 649,642 | ||||||||||||||
| Contributions from and sales of noncontrolling interests | 629,138 | 64,207 | 564,931 | ||||||||||||||
| Distributions to and redemption of noncontrolling interests | (81,926) | (66,095) | (15,831) | ||||||||||||||
| Proceeds from the issuance of common stock | 2,758,545 | 1,813,573 | 944,972 | ||||||||||||||
| Dividend payments | (482,408) | (389,940) | (92,468) | ||||||||||||||
| Taxes paid related to net settlement of equity awards | (23,495) | (16,231) | (7,264) | ||||||||||||||
| Net cash provided by financing activities | $ | 4,442,763 | $ | 2,398,781 | $ | 2,043,982 |
Capital resources
We expect that our principal liquidity needs for the year ending December 31, 2021, will be satisfied by the multiple sources of capital shown in the table below. There can be no assurance that our sources and uses of capital will not be materially higher or lower than these expectations.
| Key Sources and Uses of Capital (In millions) | As of 10/25/21 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Range | Midpoint | Certain Completed Items | ||||||||||||||||||||||||||||||||||||||||||||||||
| Sources of capital: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net cash provided by operating activities after dividends | $ | 210 | $ | 250 | $ | 230 | ||||||||||||||||||||||||||||||||||||||||||||
| Incremental debt | 1,415 | 575 | 995 | |||||||||||||||||||||||||||||||||||||||||||||||
| 2020 debt capital proceeds held in cash | 150 | 250 | 200 | |||||||||||||||||||||||||||||||||||||||||||||||
| Real estate dispositions and partial interest sales (refer to the “Dispositions and sales of partial interest” section within Item 2 for additional information) | 1,670 | 2,670 | 2,170 | $ | 938 | |||||||||||||||||||||||||||||||||||||||||||||
| Common equity | 2,975 | 3,975 | 3,475 | $ | 3,533 | (1) | ||||||||||||||||||||||||||||||||||||||||||||
| Total sources of capital | $ | 6,420 | $ | 7,720 | $ | 7,070 | ||||||||||||||||||||||||||||||||||||||||||||
| Uses of capital: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Construction (refer to the “Summary of capital expenditures” section within Item 2 for additional information)(2) | $ | 1,960 | $ | 2,260 | $ | 2,110 | ||||||||||||||||||||||||||||||||||||||||||||
| Acquisitions (refer to the “Acquisitions” section within Item 2 for additional information) | 4,460 | 5,460 | 4,960 | $ | 4,146 | |||||||||||||||||||||||||||||||||||||||||||||
| Total uses of capital | $ | 6,420 | $ | 7,720 | $ | 7,070 | ||||||||||||||||||||||||||||||||||||||||||||
| Incremental debt (included above): | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of unsecured senior notes payable | $ | 1,750 | $ | 1,750 | $ | 1,750 | $ | 1,750 | ||||||||||||||||||||||||||||||||||||||||||
| Principal repayments of unsecured senior notes payable | (650) | (650) | (650) | $ | (650) | |||||||||||||||||||||||||||||||||||||||||||||
| Unsecured senior line of credit, commercial paper, and other | 315 | (525) | (105) | |||||||||||||||||||||||||||||||||||||||||||||||
| Incremental debt | $ | 1,415 | $ | 575 | $ | 995 | ||||||||||||||||||||||||||||||||||||||||||||
(1)During the nine months ended September 30, 2021, we issued 16.2 million shares of common stock and received net proceeds of $2.8 billion. We expect to issue 4.6 million shares during the three months ending December 31, 2021, to settle our remaining outstanding forward equity sales agreements and receive net proceeds of approximately $771.9 million. Refer to Note 13 – “Stockholders’ equity” to our unaudited consolidated financial statements under Item 1 of this report for additional details.
(2)Increase in construction guidance was primarily driven by recent pre-leasing/negotiating activity, which has provided additional visibility and accelerated our spending requirements on our active and near-term value-creation projects.
The key assumptions behind the sources and uses of capital in the table above include a favorable capital market environment, performance of our core operating properties, lease-up and delivery of current and future development and redevelopment projects, and leasing activity. Our expected sources and uses of capital are subject to a number of variables and uncertainties, including those discussed as “Forward-looking statements” under Part I; “Item 1A. Risk factors”; and “Item 7. Management’s discussion and analysis of financial condition and results of operations” of our annual report on Form 10-K for the year ended December 31, 2020; as well as “Item 1A. Risk factors” within “Part II – Other information” of this quarterly report on Form 10-Q. We expect to update our forecast of sources and uses of capital on a quarterly basis.
Sources of capital
Net cash provided by operating activities after dividends
We expect to retain $210.0 million to $250.0 million of net cash flows from operating activities after payment of common stock dividends, and distributions to noncontrolling interests for the year ending December 31, 2021. For purposes of this calculation, changes in operating assets and liabilities are excluded as they represent timing differences. We also exclude significant contract termination fees that represent an ancillary source of cash that is not associated with any ongoing activity at any of our operating properties. For the year ending December 31, 2021, we expect our recently delivered projects, our highly pre-leased value-creation projects expected to be completed and along with contributions from Same Properties and recently acquired properties, to contribute significant increases in income from rentals, net operating income, and cash flows. We anticipate significant contractual near-term growth in annual cash rents of $45 million related to the commencement of contractual rents on the projects recently placed into service that are near the end of their initial free rent period. Refer to the “Cash flows” subsection of the “Liquidity” section within this Item 2 for a discussion of cash flows provided by operating activities for the nine months ended September 30, 2021.
Debt
We expect to fund a portion of our capital needs for the remainder of 2021 from the real estate dispositions and partial interest sales, settlement of our outstanding forward equity sales agreements, sales of our common stock under our ATM program, issuances under our commercial paper program discussed below, and borrowings under our unsecured senior line of credit.
As of September 30, 2021, we have no outstanding balance on our unsecured senior line of credit. Our unsecured senior line of credit bears an interest rate of LIBOR plus 0.825% with a 0% LIBOR floor and is subject to certain annual sustainability measures entitling us to a temporary reduction in the interest rate margin of one basis point, but not below zero percent per year. During the year ended December 31, 2020, we achieved certain sustainability measures, as described in our unsecured senior line of credit agreement, which reduced our borrowing rate to LIBOR plus 0.815% for a one-year period. In addition to the cost of borrowing, the unsecured senior line of credit is subject to an annual facility fee of 0.15% based on the aggregate commitments outstanding.
We use our unsecured senior line of credit to fund working capital, construction activities, and, from time to time, acquisition of properties. Borrowings under the unsecured senior line of credit bear interest at a “Eurocurrency Rate,” a “LIBOR Floating Rate,” or a “Base Rate” specified in the unsecured senior line of credit agreement plus, in any case, the Applicable Margin. The Eurocurrency Rate specified in the unsecured senior line of credit agreement is, as applicable, the rate per annum equal to either (i) the LIBOR or a successor rate thereto as agreed to by the administrative agent and the Company for loans denominated in a LIBOR quoted currency (i.e., U.S. dollars, euro, sterling, or yen), (ii) the average annual yield rates applicable to Canadian dollar bankers’ acceptances for loans denominated in Canadian dollars, (iii) the Bank Bill Swap Reference Bid rate for loans denominated in Australian dollars, or (iv) the rate designated with respect to the applicable alternative currency for loans denominated in a non-LIBOR quoted currency (other than Canadian or Australian dollars). The LIBOR Floating Rate means, for any day, one-month LIBOR, or a successor rate thereto as agreed to by the administrative agent and the Company for loans denominated in U.S. dollars. The Base Rate means, for any day, a fluctuating rate per annum equal to the highest of (i) the federal funds rate plus 1/2 of 1.00%, (ii) the rate of interest in effect for such day as publicly announced from time to time by the Administrative Agent as its “prime rate,” and (iii) the Eurocurrency Rate plus 1.00%. Our unsecured senior line of credit contains a feature that allows lenders to competitively bid on the interest rate for borrowings under the facility. This may result in an interest rate that is below the stated rate.
We established a commercial paper program that provides us with the ability to issue up to $1.5 billion of commercial paper notes with a maturity of generally 30 days or less and with a maximum maturity of 397 days from the date of issuance. Our commercial paper program is backed by our unsecured senior line of credit, and at all times we expect to retain a minimum undrawn amount of borrowing capacity under our unsecured senior line of credit equal to any outstanding balance on our commercial paper program. We use borrowings under the program to fund short-term capital needs. The notes issued under our commercial paper program are sold under customary terms in the commercial paper market. They are typically issued at a discount to par, representing a yield to maturity dictated by market conditions at the time of issuance. In the event we are unable to issue commercial paper notes or refinance outstanding commercial paper notes under terms equal to or more favorable than those under the unsecured senior line of credit, we expect to borrow under the unsecured senior line of credit at LIBOR plus 0.815%. The commercial paper notes sold during the three months ended September 30, 2021, were issued at a weighted-average yield to maturity of 0.21%. As of September 30, 2021, we had an aggregate of $750.0 million of notes outstanding under our commercial paper program.
In February 2021, we opportunistically issued $1.75 billion of unsecured senior notes payable with a weighted-average interest rate of 2.49% and a weighted-average maturity of 20.4 years. The unsecured senior notes consisted of $900.0 million of 2.00% unsecured senior notes due 2032 (“2.00% Unsecured Senior Notes”) and $850.0 million of 3.00% unsecured senior notes due 2051. The proceeds from our 2.00% Unsecured Senior Notes are expected to be allocated to eligible green projects and were initially used to refinance $650.0 million of our 4.00% unsecured senior notes payable due in 2024, pursuant to a partial cash tender offer completed on February 10, 2021, and a subsequent call for redemption for the remaining outstanding amounts that settled on March 12, 2021.
Proactive management of transition away from LIBOR
LIBOR has been used extensively in the U.S. and globally as a reference rate for various commercial and financial contracts, including variable-rate debt and interest rate swap contracts. However, based on an announcement made by the Financial Conduct Authority (“FCA”) on March 5, 2021, all LIBOR settings will effectively cease after June 30, 2023, and it is expected that LIBOR will no longer be used after this date. To address the impending discontinuation of LIBOR, in the U.S. the Alternative Reference Rates Committee (“ARRC”) was established to help ensure the successful transition from LIBOR. In June 2017, the ARRC selected SOFR, a new index calculated by reference to short-term repurchase agreements backed by U.S. Treasury securities, as its preferred replacement for U.S. dollar LIBOR. We have been closely monitoring developments related to the transition away from LIBOR and have implemented numerous proactive measures to minimize the potential impact of the transition to the Company, specifically:
-
We have proactively eliminated outstanding LIBOR-based borrowings under our unsecured senior bank term loans and secured construction loans through repayments. From January 2017 through September 2021, we retired approximately $1.5 billion of all such debt.
-
During 2020, we increased the aggregate amount of our commercial paper program to $1.5 billion from $750.0 million. This program provides us with ability to issue commercial paper notes bearing interest at short-term fixed rates, with a maturity of generally 30 days or less and with a maximum maturity of 397 days from the date of issuance. Our commercial paper program is not subject to LIBOR and is used for funding short-term working capital needs. As of September 30, 2021, we had an aggregate of $750.0 million of notes outstanding under our commercial paper program.
-
We continue to prudently manage outstanding borrowings under our unsecured senior line of credit. As of September 30, 2021, we had no borrowings outstanding under our unsecured senior line of credit. Our unconsolidated real estate joint venture at 1401/1413 Research Boulevard holds a LIBOR-based construction loan with an outstanding balance of $27.1 million that matures in May 2022. We hold a 65.0% interest in this unconsolidated real estate joint venture.
-
Our unsecured senior line of credit contains fallback language generally consistent with the ARRC’s Amendment Approach, which provides a streamlined amendment approach for negotiating a benchmark replacement.
-
We continue to monitor developments by the FCA, the ARRC, and other governing bodies involved in LIBOR transition.
Refer to Note 10 – “Secured and unsecured senior debt” and Note 4 – “Consolidated and unconsolidated real estate joint ventures” to our unaudited consolidated financial statements under Item 1 of this quarterly report on Form 10-Q and “Item 1A. Risk factors” of our annual report on Form 10-K for the year ended December 31, 2020, for additional information about our management of risks related to the transition away from LIBOR.
Real estate dispositions and partial interest sales
We expect to continue the disciplined execution of select sales of operating assets. Future sales will provide an important source of capital to fund a portion of pending and recently completed opportunistic acquisitions and our highly leased value-creation development and redevelopment projects, and also provide significant capital for growth. We may also consider additional sales of partial interests in core Class A properties and/or development projects. For 2021, we expect real estate dispositions and partial interest sales ranging from $1.7 billion to $2.7 billion. The amount of asset sales necessary to meet our forecasted sources of capital will vary depending upon the amount of EBITDA associated with the assets sold.
During the nine months ended September 30, 2021, we completed dispositions for an aggregate sales price $663.3 million. Refer to the “Dispositions and sales of partial interest” section of “Investments in real estate” within this Item 2 for additional information on these transaction. In addition, in October 2021 we completed sales of partial interests in two consolidated real estate joint ventures, as described below.
409 and 499 Illinois Street
In October 2021, an investor acquired a 75% interest in our consolidated joint venture at 409 and 499 Illinois Street located in our Mission Bay submarket, which consisted of a 35% partial interest sold by us and a 40% interest held by our previous joint venture partner, for an aggregate sales price of $495.6 million. Our portion of the sales price was $231.0 million, representing $92.4 million of consideration in excess of the book value of our 35% interest sold. Upon completion of the sale, our ownership interest in the joint venture is 25%. We retained control over the newly formed real estate joint venture and therefore will continue to consolidate these properties. Accordingly, we accounted for the difference between the consideration received and the book value of our interest sold as an equity transaction, with no gain or loss recognized in earnings.
1500 Owens Street
In October 2021, an investor acquired a 75% interest in our consolidated joint venture at 1500 Owens Street located in our Mission Bay submarket, which consisted of a 25.1% partial interest sold by us and a 49.9% interest held by our previous joint venture partner, for an aggregate sales price of $130.5 million. Our portion of the sales price was $43.7 million, representing $21.3 million of consideration in excess of the book value of our 25.1% interest sold. Upon completion of the sale, our ownership interest in the joint venture is 25%. We retained control over the newly formed real estate joint venture and therefore will continue to consolidate this property. Accordingly, we accounted for the difference between the consideration received and the book value of our interest sold as an equity transaction, with no gain or loss recognized in earnings.
As a REIT, we are generally subject to a 100% tax on the net income from real estate asset sales that the IRS characterizes as “prohibited transactions.” We do not expect our sales will be categorized as prohibited transactions. However, unless we meet certain “safe harbor” requirements, whether a real estate asset sale is a “prohibited transaction” will be based on the facts and circumstances of the sale. Our real estate asset sales may not always meet such “safe harbor” requirements. Refer to “Item 1A. Risk factors” of our annual report on Form 10-K for the year ended December 31, 2020, for additional information about the “prohibited transaction” tax.
Common equity transactions
During the nine months ended September 30, 2021, our common equity transactions included the following:
-
In January 2021, we entered into forward equity sales agreements to sell 6.9 million shares of our common stock (including the exercise of underwriters’ option) aggregating $1.1 billion at a public offering price of $164.00 per share, before underwriting discounts and commissions.
-
During the three months ended March 31, 2021, we settled a portion of our forward equity sales agreements by issuing 5.4 million shares and received proceeds of $850.5 million.
-
As of September 30, 2021, 1.5 million shares representing net proceeds of approximately $228.5 million remain outstanding under our forward equity sales agreements.
-
In February 2021, we entered into a new ATM common stock offering program, which allowed us to sell up to an aggregate of $1.0 billion of our common stock.
-
During the three months ended March 31, 2021, we issued 3.1 million shares under our ATM program at a price of $163.26 per share (before underwriting discounts) and received net proceeds of $492.3 million.
-
During the three months ended September 31, 2021, we issued 2.5 million shares under our ATM program at a price of $200.73 per share (before underwriting discounts) and received net proceeds of $492.3 million.
-
As of September 30, 2021, we have no amounts remaining under our ATM program. We expect to establish a new ATM program during three months ended December 31, 2021.
-
In March 2021, we issued the remaining 362 thousand shares of common stock to settle our forward equity sales agreements that were outstanding as of December 31, 2020, and received net proceeds of $56.2 million.
-
In June 2021, we entered into forward equity sales agreements to sell 8.1 million shares of our common stock (including the exercise of underwriters’ option) aggregating $1.5 billion at a public offering price of $184.00 per share, before underwriting discounts and commissions.
-
During the three months ended June 30, 2021, we settled a portion of our forward equity sales agreements by issuing 4.9 million shares and received net proceeds of $870.3 million.
-
As of September 30, 2021, 3.1 million shares representing net proceeds of approximately $543.4 million remain outstanding under our forward equity sales agreements.
Other sources
Under our current shelf registration statement filed with the SEC, we may offer common stock, preferred stock, debt, and other securities. These securities may be issued, from time to time, at our discretion based on our needs and market conditions, including, as necessary, to balance our use of incremental debt capital.
Additionally, we hold interests, together with joint venture partners, in real estate joint ventures that we consolidate in our financial statements. These joint venture partners may contribute equity into these entities primarily related to their share of funds for construction and financing-related activities. During the nine months ended September 30, 2021, we received $629.1 million of contributions from and sales of noncontrolling interests.
Uses of capital
Summary of capital expenditures
One of our primary uses of capital relates to the development, redevelopment, pre-construction, and construction of properties. We currently have projects in our growth pipeline aggregating 4.3 million RSF of Class A office/laboratory and tech office space undergoing construction, 8.9 million RSF of near-term and intermediate-term development and redevelopment projects, and 12.0 million SF of future development projects in North America. We incur capitalized construction costs related to development, redevelopment, pre-construction, and other construction activities. We also incur additional capitalized project costs, including interest, property taxes, insurance, and other costs directly related and essential to the development, redevelopment, pre-construction, or construction of a project, during periods when activities necessary to prepare an asset for its intended use are in progress. Refer to the “New Class A development and redevelopment properties: current projects” and “Summary of capital expenditures” subsections of the “Investments in real estate” section within this Item 2 for more information on our capital expenditures.
We capitalize interest cost as a cost of the project only during the period for which activities necessary to prepare an asset for its intended use are ongoing, provided that expenditures for the asset have been made and interest cost has been incurred. Capitalized interest for the nine months ended September 30, 2021 and 2020, of $126.6 million and $88.0 million, respectively, was classified in investments in real estate. Indirect project costs, including construction administration, legal fees, and office costs that clearly relate to projects under development or construction, are capitalized as incurred during the period an asset is undergoing activities to prepare it for its intended use. We capitalized payroll and other indirect project costs related to development, redevelopment, pre-construction, and construction projects, which aggregated $51.2 million and $47.6 million for the nine months ended September 30, 2021 and 2020, respectively. The increase in capitalized payroll and other indirect project costs for the nine months ended September 30, 2021, compared to the same period in 2020 was primarily due to an increase in our value-creation pipeline projects undergoing construction and pre-construction activities in 2021 over 2020. Pre-construction activities include entitlements, permitting, design, site work, and other activities preceding commencement of construction of aboveground building improvements. The advancement of pre-construction efforts is focused on reducing the time required to deliver projects to prospective tenants. These critical activities add significant value for future ground-up development and are required for the vertical construction of buildings. Should we cease activities necessary to prepare an asset for its intended use, the interest, taxes, insurance, and certain other direct project costs related to this asset would be expensed as incurred. Expenditures for repairs and maintenance are expensed as incurred.
Fluctuations in our development, redevelopment, and construction activities could result in significant changes to total expenses and net income. For example, had we experienced a 10% reduction in development, redevelopment, and construction activities without a corresponding decrease in indirect project costs, including interest and payroll, total expenses would have increased by approximately $17.8 million for the nine months ended September 30, 2021.
We use third-party brokers to assist in our leasing activity, who are paid on a contingent basis upon successful leasing. We are required to capitalize initial direct costs related to successful leasing transactions that result directly from and are essential to the lease transaction and would not have been incurred had that lease transaction not been successfully executed. During the nine months ended September 30, 2021, we capitalized total initial direct leasing costs of $93.7 million. Costs that we incur to negotiate or arrange a lease regardless of its outcome, such as fixed employee compensation, tax, or legal advice to negotiate lease terms, and other costs, are expensed as incurred.
Acquisitions
Refer to the “Acquisitions” section of Note 3 – “Investments in real estate” and to Note 4 – “Consolidated and unconsolidated real estate joint ventures” to our unaudited consolidated financial statements under Item 1 of this report, and the “Acquisitions” subsection of the “Investments in real estate” section within this Item 2 for information on our acquisitions.
Dividends
During the nine months ended September 30, 2021 and 2020, we paid common stock dividends of $482.4 million and $389.9 million, respectively. The increase of $92.5 million in dividends paid on our common stock during the nine months ended September 30, 2021, compared to the nine months ended September 30, 2020, was primarily due to an increase in number of common shares outstanding subsequent to January 1, 2020, as a result of issuances of common stock under our ATM program and settlement of forward equity sales agreements, and partially due to the increase in the related dividends to $3.30 per common share paid during the nine months ended September 30, 2021, from $3.12 per common share paid during the nine months ended September 30, 2020.
Contractual obligations and commitments
Contractual obligations as of September 30, 2021, consisted of the following (in thousands):
| Payments by Period | |||||||||||||||||||||||||||||
| Total | 2021 | 2022–2023 | 2024–2025 | Thereafter | |||||||||||||||||||||||||
| Secured and unsecured debt(1)(2) | $ | 9,317,381 | $ | 870 | $ | 7,364 | $ | 783,593 | $ | 8,525,554 | |||||||||||||||||||
| Estimated interest payments on fixed-rate debt(3) | 3,745,352 | 71,007 | 593,550 | 566,400 | 2,514,395 | ||||||||||||||||||||||||
| Ground lease obligations – operating leases | 846,455 | 4,607 | 37,150 | 37,514 | 767,184 | ||||||||||||||||||||||||
| Operating office leases | 26,303 | 864 | 5,253 | 4,682 | 15,504 | ||||||||||||||||||||||||
| Total | $ | 13,935,491 | $ | 77,348 | $ | 643,317 | $ | 1,392,189 | $ | 11,822,637 |
(1)Amounts represent principal amounts due and exclude unamortized premiums (discounts) and deferred financing costs reflected in the consolidated balance sheets under Item 1 of this report.
(2)Payment dates reflect any extension options that we control.
(3)Amounts are based upon contractual interest rates, including interest payment dates and scheduled maturity dates.
During the three months ended September 30, 2021, we acquired four properties in our Greater Boston market aggregating 1,068,137 RSF, including 453,869 RSF under active development or redevelopment, 173,276 RSF of operating properties with development and redevelopment opportunities, and 440,992 RSF with future development opportunities, for an aggregate purchase price of $192.0 million, to be paid in two installments. We paid $32.0 million of the $192.0 million in August 2021, with the remaining $160.0 million to be paid in December 2021.
Secured notes payable
Secured notes payable as of September 30, 2021, consisted of three notes secured by eight properties. Our secured notes payable typically require monthly payments of principal and interest and had a weighted-average interest rate of approximately 3.41%. As of September 30, 2021, the total book value of our investments in real estate securing debt was approximately $861.3 million. Additionally, as of September 30, 2021, our entire secured notes payable balance of $198.8 million, including unamortized discounts and deferred financing costs, was fixed-rate debt.
Unsecured senior notes payable and unsecured senior line of credit
The requirements of, and our actual performance with respect to, the key financial covenants under our unsecured senior notes payable as of September 30, 2021, were as follows:
| Covenant Ratios(1) | Requirement | September 30, 2021 | ||||||||||||
| Total Debt to Total Assets | Less than or equal to 60% | 31% | ||||||||||||
| Secured Debt to Total Assets | Less than or equal to 40% | 1% | ||||||||||||
| Consolidated EBITDA(2) to Interest Expense | Greater than or equal to 1.5x | 11.5x | ||||||||||||
| Unencumbered Total Asset Value to Unsecured Debt | Greater than or equal to 150% | 299% |
(1)All covenant ratio titles utilize terms as defined in the respective debt agreements.
(2)The calculation of consolidated EBITDA is based on the definitions contained in our loan agreements and is not directly comparable to the computation of EBITDA as described in Exchange Act Release No. 47226.
In addition, the terms of the indentures, among other things, limit the ability of the Company, Alexandria Real Estate Equities, L.P., and the Company’s subsidiaries to (i) consummate a merger, or consolidate or sell all or substantially all of the Company’s assets, and (ii) incur certain secured or unsecured indebtedness.
The requirements of, and our actual performance with respect to, the key financial covenants under our unsecured senior line of credit as of September 30, 2021, were as follows:
| Covenant Ratios(1) | Requirement | September 30, 2021 | |||||||||||||||
| Leverage Ratio | Less than or equal to 60.0% | 28.7% | |||||||||||||||
| Secured Debt Ratio | Less than or equal to 45.0% | 0.6% | |||||||||||||||
| Fixed-Charge Coverage Ratio | Greater than or equal to 1.50x | 4.34x | |||||||||||||||
| Unsecured Interest Coverage Ratio | Greater than or equal to 1.75x | 9.15x |
(1)All covenant ratio titles utilize terms as defined in the credit agreement.
Estimated interest payments
Estimated interest payments on our fixed-rate debt were calculated based upon contractual interest rates, including interest payment dates and scheduled maturity dates. As of September 30, 2021, 92% of our debt was fixed-rate debt. For additional information regarding our debt, refer to Note 10 – “Secured and unsecured senior debt” to our unaudited consolidated financial statements under Item 1 of this report.
Ground lease obligations
Operating lease agreements
Ground lease obligations as of September 30, 2021, included leases for 38 of our properties, which accounted for approximately 9% of our total number of properties. Excluding one ground lease that expires in 2036 related to one operating property with a net book value of $7.0 million as of September 30, 2021, our ground lease obligations have remaining lease terms ranging from approximately 32 to 93 years, including available extension options that we are reasonably certain to exercise.
As of September 30, 2021, the remaining contractual payments under ground and office lease agreements in which we are the lessee aggregated $846.5 million and $26.3 million, respectively. We are required to recognize a right-of-use asset and a related liability to account for our future obligations under operating lease arrangements in which we are the lessee. The operating lease liability is measured based on the present value of the remaining lease payments, including payments during the term under our extension options that we are reasonably certain to exercise. The right-of-use asset is equal to the corresponding operating lease liability, adjusted for the initial direct leasing cost and any other consideration exchanged with the landlord prior to the commencement of the lease, as well as adjustments to reflect favorable or unfavorable terms of an acquired lease when compared with market terms at the time of acquisition. As of September 30, 2021, the present value of the remaining contractual payments aggregating $872.8 million under our operating lease agreements, including our extension options that we are reasonably certain to exercise, was $371.5 million, which was classified in accounts payable, accrued expenses, and other liabilities in our consolidated balance sheets. As of September 30, 2021, the weighted-average remaining lease term of operating leases in which we are the lessee was approximately 43 years, and the weighted-average discount rate was 4.78%. Our corresponding operating lease right-of-use assets, adjusted for initial direct leasing costs and other consideration exchanged with the landlord prior to the commencement of the lease, aggregated $395.9 million. We classify the right-of-use asset in other assets in our consolidated balance sheets. Refer to the “Lease accounting” section of Note 2 – “Summary of significant accounting policies” to our unaudited consolidated financial statements under Item 1 of this report for additional information.
Commitments
As of September 30, 2021, remaining aggregate costs under contract for the construction of properties undergoing development, redevelopment, and improvements under the terms of leases approximated $1.7 billion. We expect payments for these obligations to occur over one to three years, subject to capital planning adjustments from time to time. We may have the ability to cease the construction of certain properties, which would result in the reduction of our commitments. In addition, we have letters of credit and performance obligations aggregating $81.8 million primarily related to construction projects, including one $77.5 million letter of credit we issued during the three months ended June 30, 2021. The $77.5 million letter of credit serves to secure our performance under the purchase and sale agreement of our acquisition of Charles Park in our Cambridge submarket for a purchase price of $815.0 million. We expect to complete this acquisition in December 2021, and the letter of credit will expire in January 2022.
We are committed to funding approximately $362.0 million related to our non-real estate investments. These funding commitments are primarily associated with our investments in privately held entities that report NAV, which expire at various dates over the next 12 years, with a weighted-average expiration of 8.9 years as of September 30, 2021.
Exposure to environmental liabilities
In connection with the acquisition of all of our properties, we have obtained Phase I environmental assessments to ascertain the existence of any environmental liabilities or other issues. The Phase I environmental assessments of our properties have not revealed any environmental liabilities that we believe would have a material adverse effect on our financial condition or results of operations taken as a whole, nor are we aware of any material environmental liabilities that have occurred since the Phase I environmental assessments were completed. In addition, we carry a policy of pollution legal liability insurance covering exposure to certain environmental losses at substantially all of our properties.
Foreign currency translation gains and losses
The following table presents the change in accumulated other comprehensive loss attributable to Alexandria Real Estate Equities, Inc.’s stockholders during the nine months ended September 30, 2021, due to the changes in the foreign exchange rates for our real estate investments in Canada and Asia. We reclassify unrealized foreign currency translation gains and losses into net income (loss) as we dispose of these holdings.
| (In thousands) | Total | |||||||||||||||||||
| Balance as of December 31, 2020 | $ | (6,625) | ||||||||||||||||||
| Other comprehensive income before reclassifications | 596 | |||||||||||||||||||
| Net other comprehensive income | 596 | |||||||||||||||||||
| Balance as of September 30, 2021 | $ | (6,029) |
Inflation
As of September 30, 2021, approximately 92% of our leases (on an RSF basis) were triple net leases, which require tenants to pay substantially all real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses (including increases thereto) in addition to base rent. Approximately 95% of our leases (on an RSF basis) contained effective annual rent escalations that were either fixed (generally ranging from 3.0% to 3.5%) or indexed based on a consumer price index or other indices. Accordingly, we do not believe that our cash flows or earnings from real estate operations are subject to significant risks from inflation. A period of inflation, however, could cause an increase in the cost of our variable-rate borrowings, including borrowings related to our unsecured senior line of credit, commercial paper program, and secured loans held by our unconsolidated real estate joint ventures.
In addition, refer to “Item 1A. Risk factors” within “Part II – Other information” of this quarterly report on Form 10-Q for a discussion about risks that inflation directly or indirectly may pose to our business.
Issuer and guarantor subsidiary summarized financial information
Alexandria Real Estate Equities, Inc. (the “Issuer”) has sold certain debt securities registered under the Securities Act of 1933, as amended, that are fully and unconditionally guaranteed by Alexandria Real Estate Equities, L.P. (the “LP” or the “Guarantor Subsidiary”), an indirectly 100% owned subsidiary of the Issuer. The Issuer’s other subsidiaries, including, but not limited to, the subsidiaries that own substantially all of its real estate (collectively, the “Combined Non-Guarantor Subsidiaries”), will not provide a guarantee of such securities, including the subsidiaries that are partially or 100% owned by the LP. The following summarized financial information presents on a combined basis for the Issuer and the Guarantor Subsidiary balance sheet financial information as of September 30, 2021, and December 31, 2020, and results of operations and comprehensive income for the nine months ended September 30, 2021, and year ended December 31, 2020. The information presented below excludes eliminations necessary to arrive at the information on a consolidated basis. In presenting the summarized financial statements, the equity method of accounting has been applied to (i) the Issuer’s interests in the Guarantor Subsidiary, (ii) the Guarantor Subsidiary’s interests in the Combined Non-Guarantor Subsidiaries, and (iii) the Combined Non-Guarantor Subsidiaries’ interests in the Guarantor Subsidiary, where applicable, even though all such subsidiaries meet the requirements to be consolidated under GAAP. All assets and liabilities have been allocated to the Issuer and the Guarantor Subsidiary generally based on legal entity ownership.
The following tables present combined summarized financial information as of September 30, 2021, and December 31, 2020, and for the nine months ended September 30, 2021, and the year ended December 31, 2020, for the Issuer and Guarantor Subsidiary. Amounts provided do not represent our total consolidated amounts (in thousands):
| September 30, 2021 | December 31, 2020 | |||||||||||||
| Assets: | ||||||||||||||
| Cash, cash equivalents, and restricted cash | $ | 145,162 | $ | 404,802 | ||||||||||
| Other assets | 104,408 | 100,689 | ||||||||||||
| Total assets | $ | 249,570 | $ | 505,491 | ||||||||||
| Liabilities: | ||||||||||||||
| Unsecured senior notes payable | $ | 8,314,851 | $ | 7,232,370 | ||||||||||
| Unsecured senior line of credit and commercial paper | 749,978 | 99,991 | ||||||||||||
| Other liabilities | 378,793 | 341,621 | ||||||||||||
| Total liabilities | $ | 9,443,622 | $ | 7,673,982 | ||||||||||
| Nine Months Ended September 30, 2021 | Year Ended December 31, 2020 | |||||||||||||
| Total revenues | $ | 19,492 | $ | 22,946 | ||||||||||
| Total expenses | (289,930) | (355,370) | ||||||||||||
| Net loss | (270,438) | (332,424) | ||||||||||||
| Net income attributable to unvested restricted stock awards | (5,750) | (10,168) | ||||||||||||
| Net loss attributable to Alexandria Real Estate Equities, Inc.’s common stockholders | $ | (276,188) | $ | (342,592) | ||||||||||
Critical accounting policies
Refer to our annual report on Form 10-K for the year ended December 31, 2020, for a discussion of our critical accounting policies related to REIT compliance, investments in real estate, impairment of long-lived assets, equity investments, liability and right-of-use assets related to operating leases in which we are the lessee, monitoring of tenant credit quality, and allowance for credit losses.
Non-GAAP measures and definitions
This section contains additional information of certain non-GAAP financial measures and the reasons why we use these supplemental measures of performance and believe they provide useful information to investors, as well as the definitions of other terms used in this report.
Funds from operations and funds from operations, as adjusted, attributable to Alexandria Real Estate Equities, Inc.’s common stockholders
GAAP-basis accounting for real estate assets utilizes historical cost accounting and assumes that real estate values diminish over time. In an effort to overcome the difference between real estate values and historical cost accounting for real estate assets, the Nareit Board of Governors established funds from operations as an improved measurement tool. Since its introduction, funds from operations has become a widely used non-GAAP financial measure among equity REITs. We believe that funds from operations is helpful to investors as an additional measure of the performance of an equity REIT. Moreover, we believe that funds from operations, as adjusted, allows investors to compare our performance to the performance of other real estate companies on a consistent basis, without having to account for differences recognized because of real estate acquisition and disposition decisions, financing decisions, capital structure, capital market transactions, variances resulting from the volatility of market conditions outside of our control, or other corporate activities that may not be representative of the operating performance of our properties.
The 2018 White Paper published by the Nareit Board of Governors (the “Nareit White Paper”) defines funds from operations as net income (computed in accordance with GAAP), excluding gains or losses on sales of real estate, and impairments of real estate, plus depreciation and amortization of operating real estate assets, and after adjustments for our share of consolidated and unconsolidated partnerships and real estate joint ventures. Impairments represent the write-down of assets when fair value over the recoverability period is less than the carrying value due to changes in general market conditions and do not necessarily reflect the operating performance of the properties during the corresponding period.
We compute funds from operations, as adjusted, as funds from operations calculated in accordance with the Nareit White Paper, excluding significant gains, losses, and impairments realized on non-real estate investments, unrealized gains or losses on non-real estate investments, gains or losses on early extinguishment of debt, significant termination fees, acceleration of stock compensation expense due to the resignation of an executive officer, deal costs, the income tax effect related to such items, and the amount of such items that is allocable to our unvested restricted stock awards. Neither funds from operations nor funds from operations, as adjusted, should be considered as alternatives to net income (determined in accordance with GAAP) as indications of financial performance, or to cash flows from operating activities (determined in accordance with GAAP) as measures of liquidity, nor are they indicative of the availability of funds for our cash needs, including our ability to make distributions.
The following table reconciles net income to funds from operations for the share of consolidated real estate joint ventures attributable to noncontrolling interests and our share of unconsolidated real estate joint ventures for the three and nine months ended September 30, 2021 (in thousands):
| Noncontrolling Interest Share of Consolidated Real Estate Joint Ventures | Our Share of Unconsolidated Real Estate Joint Ventures | ||||||||||||||||||||||
| September 30, 2021 | September 30, 2021 | ||||||||||||||||||||||
| Three Months Ended | Nine Months Ended | Three Months Ended | Nine Months Ended | ||||||||||||||||||||
| Net income | $ | 21,286 | $ | 58,134 | $ | 3,091 | $ | 9,237 | |||||||||||||||
| Depreciation and amortization | 17,871 | 49,615 | 3,465 | 10,676 | |||||||||||||||||||
| Funds from operations | $ | 39,157 | $ | 107,749 | $ | 6,556 | $ | 19,913 | |||||||||||||||
The following tables present a reconciliation of net income attributable to Alexandria Real Estate Equities, Inc.’s common stockholders, the most directly comparable financial measure presented in accordance with GAAP, including our share of amounts from consolidated and unconsolidated real estate joint ventures, to funds from operations attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted, and funds from operations attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted, as adjusted, and the related per share amounts for the three and nine months ended September 30, 2021 and 2020. Per share amounts may not add due to rounding.
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| (In thousands) | 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||||
| Net income attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – basic and diluted | $ | 101,264 | $ | 79,326 | $ | 490,602 | $ | 324,171 | ||||||||||||||||||
| Depreciation and amortization of real estate assets | 205,436 | 173,622 | 569,654 | 511,290 | ||||||||||||||||||||||
| Noncontrolling share of depreciation and amortization from consolidated real estate JVs | (17,871) | (15,256) | (49,615) | (46,901) | ||||||||||||||||||||||
| Our share of depreciation and amortization from unconsolidated real estate JVs | 3,465 | 2,936 | 10,676 | 8,437 | ||||||||||||||||||||||
| Loss (gain) on sales of real estate | 435 | (1,586) | (2,344) | (1,586) | ||||||||||||||||||||||
| Impairment of real estate – rental properties | 18,602 | (1) | 7,680 | 25,485 | 15,324 | |||||||||||||||||||||
| Allocation to unvested restricted stock awards | (1,472) | (1,261) | (6,574) | (5,692) | ||||||||||||||||||||||
| Funds from operations attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted(2) | 309,859 | 245,461 | 1,037,884 | 805,043 | ||||||||||||||||||||||
| Unrealized losses (gains) on non-real estate investments | 14,432 | 14,013 | (183,348) | (140,495) | ||||||||||||||||||||||
| Significant realized gains on non-real estate investments | (52,427) | (3) | — | (110,119) | — | |||||||||||||||||||||
| Impairment of real estate | 24,018 | (4) | — | 27,190 | 15,221 | |||||||||||||||||||||
| Impairment of non-real estate investments | — | — | — | 24,482 | ||||||||||||||||||||||
| Loss on early extinguishment of debt | — | 52,770 | 67,253 | 52,770 | ||||||||||||||||||||||
| Termination fee | — | (86,179) | (5) | — | (86,179) | |||||||||||||||||||||
| Acceleration of stock compensation expense due to executive officer resignation | — | 4,499 | — | 4,499 | ||||||||||||||||||||||
| Allocation to unvested restricted stock awards | 149 | 179 | 2,400 | 1,804 | ||||||||||||||||||||||
| Funds from operations attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted, as adjusted | $ | 296,031 | $ | 230,743 | $ | 841,260 | $ | 677,145 |
(1)Related to a property in a non-core submarket to reduce the carrying amount of the property to its estimated fair value less costs to sell, upon our review of the current local market conditions.
(2)Calculated in accordance with standards established by the Nareit Board of Governors.
(3)Includes three separate significant realized gains from the following transactions: (i) the sale of shares in an investment in a publicly traded biotechnology company, (ii) a distribution received from a limited partnership investment, and (iii) the acquisition of one of our privately held biotechnology investments by a publicly traded biotechnology company.
(4)Primarily related to an impairment charge of $22.5 million to reduce the carrying amount of an option to purchase a land parcel in our SoMa submarket for the development of an office property to its estimated fair value less costs to sell, upon our classification of the option as held for sale in September 2021.
(5)Represents termination fee of $89.5 million and related expenses of $3.3 million recognized during the three months ended September 30, 2020, upon termination of our contract with Pinterest, Inc. related to a lease at 88 Bluxome Street in our SoMa submarket.
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| (Per share) | 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||||
| Net income per share attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted | $ | 0.67 | $ | 0.63 | $ | 3.38 | $ | 2.61 | ||||||||||||||||||
| Depreciation and amortization of real estate assets | 1.26 | 1.28 | 3.66 | 3.81 | ||||||||||||||||||||||
| Loss (gain) on sales of real estate | — | (0.01) | (0.02) | (0.01) | ||||||||||||||||||||||
| Impairment of real estate – rental properties | 0.12 | 0.06 | 0.18 | 0.12 | ||||||||||||||||||||||
| Allocation to unvested restricted stock awards | (0.01) | (0.01) | (0.05) | (0.04) | ||||||||||||||||||||||
| Funds from operations per share attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted | 2.04 | 1.95 | 7.15 | 6.49 | ||||||||||||||||||||||
| Unrealized losses (gains) on non-real estate investments | 0.10 | 0.11 | (1.26) | (1.13) | ||||||||||||||||||||||
| Significant realized gains on non-real estate investments | (0.35) | — | (0.76) | — | ||||||||||||||||||||||
| Impairment of real estate | 0.16 | — | 0.19 | 0.12 | ||||||||||||||||||||||
| Impairment of non-real estate investments | — | — | — | 0.20 | ||||||||||||||||||||||
| Loss on early extinguishment of debt | — | 0.42 | 0.46 | 0.42 | ||||||||||||||||||||||
| Termination fee | — | (0.69) | — | (0.69) | ||||||||||||||||||||||
| Acceleration of stock compensation expense due to executive officer resignation | — | 0.04 | — | 0.04 | ||||||||||||||||||||||
| Allocation to unvested restricted stock awards | — | — | 0.02 | 0.01 | ||||||||||||||||||||||
| Funds from operations per share attributable to Alexandria Real Estate Equities, Inc.’s common stockholders – diluted, as adjusted | $ | 1.95 | $ | 1.83 | $ | 5.80 | $ | 5.46 | ||||||||||||||||||
| Weighted-average shares of common stock outstanding – diluted | 151,561 | 125,828 | 145,153 | 124,027 |
Adjusted EBITDA and Adjusted EBITDA margin
We use Adjusted EBITDA as a supplemental performance measure of our operations, for financial and operational decision-making, and as a supplemental means of evaluating period-to-period comparisons on a consistent basis. Adjusted EBITDA is calculated as earnings before interest, taxes, depreciation, and amortization (“EBITDA”), excluding stock compensation expense, gains or losses on early extinguishment of debt, gains or losses on sales of real estate, impairments of real estate, and significant termination fees. Adjusted EBITDA also excludes unrealized gains or losses and significant realized gains or losses and impairments that result from our non-real estate investments. These non-real estate investment amounts are classified in our consolidated statements of operations outside of total revenues.
We believe Adjusted EBITDA provides investors with relevant and useful information as it allows investors to evaluate the operating performance of our business activities without having to account for differences recognized because of investing and financing decisions related to our real estate and non-real estate investments, our capital structure, capital market transactions, and variances resulting from the volatility of market conditions outside of our control. For example, we exclude gains or losses on the early extinguishment of debt to allow investors to measure our performance independent of our indebtedness and capital structure. We believe that adjusting for the effects of impairments and gains or losses on sales of real estate, significant impairments and realized gains or losses on non-real estate investments, and significant termination fees allows investors to evaluate performance from period to period on a consistent basis without having to account for differences recognized because of investing and financing decisions related to our real estate and non-real estate investments or other corporate activities that may not be representative of the operating performance of our properties.
In addition, we believe that excluding charges related to stock compensation and unrealized gains or losses facilitates for investors a comparison of our business activities across periods without the volatility resulting from market forces outside of our control. Adjusted EBITDA has limitations as a measure of our performance. Adjusted EBITDA does not reflect our historical expenditures or future requirements for capital expenditures or contractual commitments. While Adjusted EBITDA is a relevant measure of performance, it does not represent net income (loss) or cash flows from operations calculated and presented in accordance with GAAP, and it should not be considered as an alternative to those indicators in evaluating performance or liquidity.
In order to calculate Adjusted EBITDA margin, we also make comparable adjustments to our revenues. We adjust our total revenues by realized gains, losses, and impairments related to our non-real estate investments and significant termination fees to arrive at revenues, as adjusted. Our calculation of Adjusted EBITDA margin divides Adjusted EBITDA by our revenues, as adjusted. We believe that consistent application of these comparable adjustments to both components of Adjusted EBITDA margin provides a more useful calculation for the comparison across periods.
The following table reconciles net income (loss) and revenues, the most directly comparable financial measures calculated and presented in accordance with GAAP, to Adjusted EBITDA and revenues, as adjusted, respectively, for the three and nine months ended September 30, 2021 and 2020 (dollars in thousands):
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||
| Net income | $ | 124,433 | $ | 95,799 | $ | 554,486 | $ | 370,038 | |||||||||||||||
| Interest expense | 35,678 | 43,318 | 107,303 | 134,071 | |||||||||||||||||||
| Income taxes | 3,672 | 2,430 | 7,898 | 5,177 | |||||||||||||||||||
| Depreciation and amortization | 210,842 | 176,831 | 581,807 | 520,354 | |||||||||||||||||||
| Stock compensation expense | 9,728 | 12,994 | 34,416 | 32,108 | |||||||||||||||||||
| Loss on early extinguishment of debt | — | 52,770 | 67,253 | 52,770 | |||||||||||||||||||
| Loss (gain) on sales of real estate | 435 | (1,586) | (2,344) | (1,586) | |||||||||||||||||||
| Significant realized gains on non-real estate investments | (52,427) | (1) | — | (110,119) | (1) | — | |||||||||||||||||
| Unrealized losses (gains) on non-real estate investments | 14,432 | 14,013 | (183,348) | (140,495) | |||||||||||||||||||
| Impairment of real estate | 42,620 | 7,680 | 52,675 | 30,545 | |||||||||||||||||||
| Impairment of non-real estate investments | — | — | — | 24,482 | |||||||||||||||||||
| Termination fee | — | (86,179) | — | (86,179) | |||||||||||||||||||
| Adjusted EBITDA | $ | 389,413 | $ | 318,070 | $ | 1,110,027 | $ | 941,285 | |||||||||||||||
| Revenues | $ | 547,759 | $ | 545,042 | $ | 1,537,227 | $ | 1,421,917 | |||||||||||||||
| Total realized gains on non-real estate investments | 81,516 | (1) | 17,361 | 189,013 | (1) | 25,689 | |||||||||||||||||
| Significant realized gains on non-real estate investments | (52,427) | — | (110,119) | — | |||||||||||||||||||
| Impairment of non-real estate investments | — | — | — | 24,482 | |||||||||||||||||||
| Termination fee | — | (86,179) | — | (86,179) | |||||||||||||||||||
| Revenues, as adjusted | $ | 576,848 | $ | 476,224 | $ | 1,616,121 | $ | 1,385,909 | |||||||||||||||
| Adjusted EBITDA margin | 68% | 67% | 69% | 68% |
(1)Refer to “Investments” section within this Item 2 of this report for additional information.
Annual rental revenue
Annual rental revenue represents the annualized fixed base rental obligations, calculated in accordance with GAAP, for leases in effect as of the end of the period, related to our operating RSF. Annual rental revenue is presented using 100% of the annual rental revenue of our consolidated properties and our share of annual rental revenue for our unconsolidated real estate joint ventures. Annual rental revenue per RSF is computed by dividing annual rental revenue by the sum of 100% of the RSF of our consolidated properties and our share of the RSF of properties held in unconsolidated real estate joint ventures. As of September 30, 2021, approximately 92% of our leases (on an RSF basis) were triple net leases, which require tenants to pay substantially all real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses (including increases thereto) in addition to base rent. Annual rental revenue excludes these operating expenses recovered from our tenants. Amounts recovered from our tenants related to these operating expenses, along with base rent, are classified in income from rentals in our consolidated statements of operations.
Capitalization rates
Capitalization rates are calculated based upon net operating income and net operating income (cash basis) annualized for the quarter preceding the date on which the property is sold, or near term prospective net operating income.
Cash interest
Cash interest is equal to interest expense calculated in accordance with GAAP plus capitalized interest, less amortization of loan fees and debt premiums (discounts). Refer to the definition of “Fixed-charge coverage ratio” within this section of this Item 2 for a reconciliation of interest expense, the most directly comparable financial measure calculated and presented in accordance with GAAP, to cash interest.
Class A properties and AAA locations
Class A properties are properties clustered in AAA locations that provide innovative tenants with highly dynamic and collaborative environments that enhance their ability to successfully recruit and retain world-class talent and inspire productivity, efficiency, creativity, and success. Class A properties generally command higher annual rental rates than other classes of similar properties.
AAA locations are in close proximity to concentrations of specialized skills, knowledge, institutions, and related businesses. Such locations are generally characterized by high barriers to entry for new landlords, high barriers to exit for tenants, and a limited supply of available space.
Development, redevelopment, and pre-construction
A key component of our business model is our disciplined allocation of capital to the development and redevelopment of new Class A properties, and property enhancements identified during the underwriting of certain acquired properties, located in collaborative life science, agtech, and technology campuses in AAA innovation clusters. These projects are generally focused on providing high-quality, generic, and reusable spaces that meet the real estate requirements of, and are reusable by, a wide range of tenants. Upon completion, each value-creation project is expected to generate a significant increase in rental income, net operating income, and cash flows. Our development and redevelopment projects are generally in locations that are highly desirable to high-quality entities, which we believe results in higher occupancy levels, longer lease terms, higher rental income, higher returns, and greater long-term asset value.
Development projects generally consist of the ground-up development of generic and reusable facilities. Redevelopment projects consist of the permanent change in use of office, warehouse, and shell space into office/laboratory, agtech, or tech office space. We generally will not commence new development projects for aboveground construction of new Class A office/laboratory, agtech, and tech office space without first securing significant pre-leasing for such space, except when there is solid market demand for high-quality Class A properties.
Pre-construction activities include entitlements, permitting, design, site work, and other activities preceding commencement of construction of aboveground building improvements. The advancement of pre-construction efforts is focused on reducing the time required to deliver projects to prospective tenants. These critical activities add significant value for future ground-up development and are required for the vertical construction of buildings. Ultimately, these projects will provide high-quality facilities and are expected to generate significant revenue and cash flows.
Development, redevelopment, and pre-construction spending also includes the following costs: (i) certain tenant improvements and renovations that will be reimbursed, (ii) amounts to bring certain acquired properties up to market standard and/or other costs identified during the acquisition process (generally within two years of acquisition), and (iii) permanent conversion of space for highly flexible, move-in-ready office/laboratory space to foster the growth of promising early- and growth-stage life science companies.
Revenue-enhancing and repositioning capital expenditures represent spending to reposition or significantly change the use of a property, including through improvement in the asset quality from Class B to Class A.
Non-revenue-enhancing capital expenditures represent costs required to maintain the current revenues of a stabilized property, including the associated costs for renewed and re-leased space.
Fixed-charge coverage ratio
Fixed-charge coverage ratio is a non-GAAP financial measure representing the ratio of Adjusted EBITDA to fixed charges. We believe this ratio is useful to investors as a supplemental measure of our ability to satisfy fixed financing obligations and preferred stock dividends. Cash interest is equal to interest expense calculated in accordance with GAAP plus capitalized interest, less amortization of loan fees and debt premiums (discounts).
The following table reconciles interest expense, the most directly comparable financial measure calculated and presented in accordance with GAAP, to cash interest and fixed charges for the three and nine months ended September 30, 2021 and 2020 (dollars in thousands):
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||||||
| Adjusted EBITDA | $ | 389,413 | $ | 318,070 | $ | 1,110,027 | $ | 941,285 | ||||||||||||||||||
| Interest expense | $ | 35,678 | $ | 43,318 | $ | 107,303 | $ | 134,071 | ||||||||||||||||||
| Capitalized interest | 43,185 | 32,556 | 126,563 | 88,029 | ||||||||||||||||||||||
| Amortization of loan fees | (2,854) | (2,605) | (8,530) | (7,589) | ||||||||||||||||||||||
| Amortization of debt premiums | 498 | 910 | 1,539 | 2,686 | ||||||||||||||||||||||
| Cash interest and fixed charges | $ | 76,507 | $ | 74,179 | $ | 226,875 | $ | 217,197 | ||||||||||||||||||
| Fixed-charge coverage ratio: | ||||||||||||||||||||||||||
| – period annualized | 5.1x | 4.3x | 4.9x | 4.3x | ||||||||||||||||||||||
| – trailing 12 months | 4.8x | 4.3x | 4.8x | 4.3x |
Gross assets
Gross assets is calculated as total assets plus accumulated depreciation (in thousands):
| September 30, 2021 | December 31, 2020 | |||||||||||||
| Total assets | $ | 28,558,718 | $ | 22,827,878 | ||||||||||
| Accumulated depreciation | 3,614,440 | 3,182,438 | ||||||||||||
| Gross assets | $ | 32,173,158 | $ | 26,010,316 | ||||||||||
Initial stabilized yield (unlevered)
Initial stabilized yield is calculated as the estimated amounts of net operating income at stabilization divided by our investment in the property. Our initial stabilized yield excludes the benefit of leverage. Our cash rents related to our value-creation projects are generally expected to increase over time due to contractual annual rent escalations. Our estimates for initial stabilized yields, initial stabilized yields (cash basis), and total costs at completion represent our initial estimates at the commencement of the project. We expect to update this information upon completion of the project, or sooner if there are significant changes to the expected project yields or costs.
-
Initial stabilized yield reflects rental income, including contractual rent escalations and any rent concessions over the term(s) of the lease(s), calculated on a straight-line basis.
-
Initial stabilized yield (cash basis) reflects cash rents at the stabilization date after initial rental concessions, if any, have elapsed and our total cash investment in the property.
Investment-grade or publicly traded large cap tenants
Investment-grade or publicly traded large cap tenants represent tenants that are investment-grade rated or publicly traded companies with an average daily market capitalization greater than $10 billion for the twelve months ended September 30, 2021, as reported by Bloomberg Professional Services. Credit ratings from Moody’s Investors Service and S&P Global Ratings reflect credit ratings of the tenant’s parent entity, and there can be no assurance that a tenant’s parent entity will satisfy the tenant’s lease obligation upon such tenant’s default. We monitor the credit quality and related material changes of our tenants. Material changes that cause a tenant’s market capitalization to decrease below $10 billion, which are not immediately reflected in the twelve-month average, may result in their exclusion from this measure.
Investments in real estate – value-creation square footage currently in rental properties
The square footage presented in the table below includes RSF of buildings in operation as of September 30, 2021, primarily representing lease expirations at recently acquired properties that also have inherent future development or redevelopment opportunities, for which we have the intent to demolish or redevelop the existing property upon expiration of the existing in-place leases and commencement of future construction:
| Dev/Redev | RSF of Lease Expirations Targeted for Development and Redevelopment | |||||||||||||||||||||||||||||||
| Property/Submarket | 2021 | 2022 | Thereafter | Total | ||||||||||||||||||||||||||||
| Near-term projects: | ||||||||||||||||||||||||||||||||
| Reservoir Woods/Route 128 | Redev | 202,428 | — | 312,845 | 515,273 | |||||||||||||||||||||||||||
| 651 Gateway Boulevard/South San Francisco | Redev | — | 197,787 | 102,223 | (1) | 300,010 | ||||||||||||||||||||||||||
| 3450 Hillview Avenue/Greater Stanford | Redev | — | 42,340 | — | 42,340 | |||||||||||||||||||||||||||
| 11255 and 11355 North Torrey Pines Road/Torrey Pines | Dev | — | 139,135 | — | 139,135 | |||||||||||||||||||||||||||
| 10931 and 10933 North Torrey Pines Road/Torrey Pines | Dev | — | 92,450 | — | 92,450 | |||||||||||||||||||||||||||
| 10277 Scripps Ranch Boulevard/Other San Diego | Redev | 32,774 | — | — | 32,774 | |||||||||||||||||||||||||||
| Other/Seattle | Redev | — | 51,255 | — | 51,255 | |||||||||||||||||||||||||||
| 41 Moore Drive/Research Triangle | Redev | — | 62,490 | — | 62,490 | |||||||||||||||||||||||||||
| 235,202 | 585,457 | 415,068 | 1,235,727 | |||||||||||||||||||||||||||||
| Intermediate-term projects: | ||||||||||||||||||||||||||||||||
| 3825 Fabian Way/Greater Stanford | Redev | — | 250,000 | — | 250,000 | |||||||||||||||||||||||||||
| 3460 Hillview Avenue/Greater Stanford | Redev | — | — | 34,611 | 34,611 | |||||||||||||||||||||||||||
| 9444 Waples Street/Sorrento Mesa | Dev | — | 39,944 | 48,436 | (2) | 88,380 | ||||||||||||||||||||||||||
| — | 289,944 | 83,047 | 372,991 | |||||||||||||||||||||||||||||
| Future projects: | ||||||||||||||||||||||||||||||||
| 550 Arsenal Street/Cambridge/Inner Suburbs | Dev | — | — | 260,867 | 260,867 | |||||||||||||||||||||||||||
| 380 and 420 E Street/Seaport Innovation District | Dev | — | — | 195,506 | 195,506 | |||||||||||||||||||||||||||
| Other/Greater Boston | Redev | — | — | 167,549 | (3) | 167,549 | ||||||||||||||||||||||||||
| 1122 El Camino Real/South San Francisco | Dev | — | — | 223,232 | 223,232 | |||||||||||||||||||||||||||
| 3875 Fabian Way/Greater Stanford | Redev | — | — | 228,000 | 228,000 | |||||||||||||||||||||||||||
| 960 Industrial Road/Greater Stanford | Dev | — | — | 110,000 | 110,000 | |||||||||||||||||||||||||||
| 2475 Hanover Street/Greater Stanford | Redev | — | — | 83,980 | 83,980 | |||||||||||||||||||||||||||
| 219 East 42nd Street/New York City | Dev | — | — | 349,947 | 349,947 | |||||||||||||||||||||||||||
| 10975 and 10995 Torreyana Road/Torrey Pines | Dev | — | — | 84,829 | 84,829 | |||||||||||||||||||||||||||
| 4161 Campus Point Court/University Town Center | Dev | — | — | 159,884 | 159,884 | |||||||||||||||||||||||||||
| 10260 Campus Point Drive/University Town Center | Dev | — | — | 109,164 | 109,164 | |||||||||||||||||||||||||||
| Sequence District by Alexandria/Sorrento Mesa | Dev/Redev | — | — | 689,938 | 689,938 | |||||||||||||||||||||||||||
| 4025, 4031, 4045, and 4075 Sorrento Valley Boulevard/Sorrento Valley | Dev | — | 82,594 | — | 82,594 | |||||||||||||||||||||||||||
| 601 Dexter Avenue North/Lake Union | Dev | — | — | 18,680 | 18,680 | |||||||||||||||||||||||||||
| 830 4th Avenue South/SoDo | Dev | — | — | 42,380 | 42,380 | |||||||||||||||||||||||||||
| — | 82,594 | 2,723,956 | 2,806,550 | |||||||||||||||||||||||||||||
| 235,202 | 957,995 | 3,222,071 | 4,415,268 |
(1)Represents vacant square footage as of September 30, 2021.
(2)Includes 43,690 of vacant square footage as of September 30, 2021.
(3)Includes 89,774 of vacant square footage as of September 30, 2021.
Joint venture financial information
We present components of balance sheet and operating results information related to our real estate joint ventures, which are not presented, or intended to be presented, in accordance with GAAP. We present the proportionate share of certain financial line items as follows: (i) for each real estate joint venture that we consolidate in our financial statements, which are controlled by us through contractual rights or majority voting rights, but of which we own less than 100%, we apply the noncontrolling interest economic ownership percentage to each financial item to arrive at the amount of such cumulative noncontrolling interest share of each component presented; and (ii) for each real estate joint venture that we do not control and do not consolidate, and are instead controlled jointly or by our joint venture partners through contractual rights or majority voting rights, we apply our economic ownership percentage to each financial item to arrive at our proportionate share of each component presented.
The components of balance sheet and operating results information related to our real estate joint ventures do not represent our legal claim to those items. For each entity that we do not wholly own, the joint venture agreement generally determines what equity holders can receive upon capital events, such as sales or refinancing, or in the event of a liquidation. Equity holders are normally entitled to their respective legal ownership of any residual cash from a joint venture only after all liabilities, priority distributions, and claims have been repaid or satisfied.
We believe this information can help investors estimate the balance sheet and operating results information related to our partially owned entities. Presenting this information provides a perspective not immediately available from consolidated financial statements and one that can supplement an understanding of the joint venture assets, liabilities, revenues, and expenses included in our consolidated results.
The components of balance sheet and operating results information related to our real estate joint ventures are limited as an analytical tool as the overall economic ownership interest does not represent our legal claim to each of our joint ventures’ assets, liabilities, or results of operations. In addition, joint venture financial information may include financial information related to the unconsolidated real estate joint ventures that we do not control. We believe that in order to facilitate for investors a clear understanding of our operating results and our total assets and liabilities, joint venture financial information should be examined in conjunction with our consolidated statements of operations and balance sheets. Joint venture financial information should not be considered an alternative to our consolidated financial statements, which are presented and prepared in accordance with GAAP.
Net cash provided by operating activities after dividends
Net cash provided by operating activities after dividends includes the deduction for distributions to noncontrolling interests. For purposes of this calculation, changes in operating assets and liabilities are excluded as they represent timing differences.
Net debt and preferred stock to Adjusted EBITDA
Net debt and preferred stock to Adjusted EBITDA is a non-GAAP financial measure that we believe is useful to investors as a supplemental measure of evaluating our balance sheet leverage. Net debt and preferred stock is equal to the sum of total consolidated debt less cash, cash equivalents, and restricted cash, plus preferred stock outstanding as of the end of the period. Refer to the definition of “Adjusted EBITDA and Adjusted EBITDA margin” within this section of this Item 2 for further information on the calculation of Adjusted EBITDA.
The following table reconciles debt to net debt and preferred stock and computes the ratio to Adjusted EBITDA as of September 30, 2021, and December 31, 2020 (dollars in thousands):
| September 30, 2021 | December 31, 2020 | ||||||||||
| Secured notes payable | $ | 198,758 | $ | 230,925 | |||||||
| Unsecured senior notes payable | 8,314,851 | 7,232,370 | |||||||||
| Unsecured senior line of credit and commercial paper | 749,978 | 99,991 | |||||||||
| Unamortized deferred financing costs | 65,112 | 56,312 | |||||||||
| Cash and cash equivalents | (325,872) | (568,532) | |||||||||
| Restricted cash | (42,182) | (29,173) | |||||||||
| Preferred stock | — | — | |||||||||
| Net debt and preferred stock | $ | 8,960,645 | $ | 7,021,893 | |||||||
| Adjusted EBITDA: | |||||||||||
| – quarter annualized | $ | 1,557,652 | $ | 1,331,608 | |||||||
| – trailing 12 months | $ | 1,442,929 | $ | 1,274,187 | |||||||
| Net debt and preferred stock to Adjusted EBITDA: | |||||||||||
| – quarter annualized | 5.8 | x | 5.3 | x | |||||||
| – trailing 12 months | 6.2 | x | 5.5 | x |
Net operating income, net operating income (cash basis), and operating margin
The following table reconciles net income to net operating income and to net operating income (cash basis) for the three and nine months ended September 30, 2021 and 2020 (dollars in thousands):
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||||||
| Net income | $ | 124,433 | $ | 95,799 | $ | 554,486 | $ | 370,038 | ||||||||||||||||||
| Equity in earnings of unconsolidated real estate joint ventures | (3,091) | (3,778) | (9,237) | (4,555) | ||||||||||||||||||||||
| General and administrative expenses | 37,931 | 36,913 | 109,807 | 100,651 | ||||||||||||||||||||||
| Interest expense | 35,678 | 43,318 | 107,303 | 134,071 | ||||||||||||||||||||||
| Depreciation and amortization | 210,842 | 176,831 | 581,807 | 520,354 | ||||||||||||||||||||||
| Impairment of real estate | 42,620 | 7,680 | 52,675 | 22,901 | ||||||||||||||||||||||
| Loss on early extinguishment of debt | — | 52,770 | 67,253 | 52,770 | ||||||||||||||||||||||
| Loss (gain) on sales of real estate | 435 | (1,586) | (2,344) | (1,586) | ||||||||||||||||||||||
| Investment income | (67,084) | (3,348) | (372,361) | (166,184) | ||||||||||||||||||||||
| Net operating income | 381,764 | 404,599 | 1,089,389 | 1,028,460 | ||||||||||||||||||||||
| Straight-line rent revenue | (33,918) | (28,822) | (89,203) | (72,786) | ||||||||||||||||||||||
| Amortization of acquired below-market leases | (13,664) | (13,979) | (39,043) | (43,730) | ||||||||||||||||||||||
| Net operating income (cash basis) | $ | 334,182 | $ | 361,798 | $ | 961,143 | $ | 911,944 | ||||||||||||||||||
| Net operating income (cash basis) – annualized | $ | 1,336,728 | $ | 1,447,192 | $ | 1,281,524 | $ | 1,215,925 | ||||||||||||||||||
| Net operating income (from above) | $ | 381,764 | $ | 404,599 | $ | 1,089,389 | $ | 1,028,460 | ||||||||||||||||||
| Total revenues | $ | 547,759 | $ | 545,042 | $ | 1,537,227 | $ | 1,421,917 | ||||||||||||||||||
| Operating margin(1) | 70% | 74% | 71% | 72% |
(1)Includes the effect of a termination fee recognized during the three months ended September 30, 2020. Refer to the definition of “Funds from operations and funds from operations, as adjusted, attributable to Alexandria Real Estate Equities, Inc.’s common stockholders” within this section for additional details. Excluding this effect, our operating margin for the three and nine months ended September 30, 2020, would have been 70% and 71%, respectively.
Net operating income is a non-GAAP financial measure calculated as net income, the most directly comparable financial measure calculated and presented in accordance with GAAP, excluding equity in the earnings of our unconsolidated real estate joint ventures, general and administrative expenses, interest expense, depreciation and amortization, impairments of real estate, gains or losses on early extinguishment of debt, gains or losses on sales of real estate, and investment income or loss. We believe net operating income provides useful information to investors regarding our financial condition and results of operations because it primarily reflects those income and expense items that are incurred at the property level. Therefore, we believe net operating income is a useful measure for investors to evaluate the operating performance of our consolidated real estate assets. Net operating income on a cash basis is net operating income adjusted to exclude the effect of straight-line rent and amortization of acquired above- and below-market lease revenue adjustments required by GAAP. We believe that net operating income on a cash basis is helpful to investors as an additional measure of operating performance because it eliminates straight-line rent revenue and the amortization of acquired above- and below-market leases.
Furthermore, we believe net operating income is useful to investors as a performance measure of our consolidated properties because, when compared across periods, net operating income reflects trends in occupancy rates, rental rates, and operating costs, which provide a perspective not immediately apparent from net income or loss. Net operating income can be used to measure the initial stabilized yields of our properties by calculating net operating income generated by a property divided by our investment in the property. Net operating income excludes certain components from net income in order to provide results that are more closely related to the results of operations of our properties. For example, interest expense is not necessarily linked to the operating performance of a real estate asset and is often incurred at the corporate level rather than at the property level. In addition, depreciation and amortization, because of historical cost accounting and useful life estimates, may distort comparability of operating performance at the property level. Impairments of real estate have been excluded in deriving net operating income because we do not consider impairments of real estate to be property-level operating expenses. Impairments of real estate relate to changes in the values of our assets and do not reflect the current operating performance with respect to related revenues or expenses. Our impairments of real estate represent the write-down in the value of the assets to the estimated fair value less cost to sell. These impairments result from investing decisions or a deterioration in market conditions. We also exclude realized and unrealized investment gain or loss, which results from investment decisions that occur at the corporate level related to non-real estate investments in publicly traded companies and certain privately held entities. Therefore, we do not consider these activities to be an indication of operating performance of our real estate assets at the property level. Our calculation of net operating income also excludes charges incurred from changes in certain financing decisions, such as losses on early extinguishment of debt, as these charges often relate to corporate strategy. Property operating expenses included in determining net operating income primarily consist of costs that are related to our operating properties, such as utilities, repairs, and maintenance; rental expense related to ground leases; contracted services, such as janitorial, engineering, and landscaping; property taxes and insurance; and property-level salaries. General and administrative expenses consist primarily of accounting and corporate compensation, corporate insurance, professional fees, office rent, and office supplies that are incurred as part of corporate office management. We calculate operating margin as net operating income divided by total revenues.
We believe that in order to facilitate for investors a clear understanding of our operating results, net operating income should be examined in conjunction with net income or loss as presented in our consolidated statements of operations. Net operating income should not be considered as an alternative to net income or loss as an indication of our performance, nor as an alternative to cash flows as a measure of our liquidity or our ability to make distributions.
Operating statistics
We present certain operating statistics related to our properties, including number of properties, RSF, occupancy percentage, leasing activity, and contractual lease expirations as of the end of the period. We believe these measures are useful to investors because they facilitate an understanding of certain trends for our properties. We compute the number of properties, RSF, occupancy percentage, leasing activity, and contractual lease expirations at 100% for all properties in which we have an investment, including properties owned by our consolidated and unconsolidated real estate joint ventures. For operating metrics based on annual rental revenue, refer to the definition of “Annual rental revenue” within this section of this Item 2.
Same property comparisons
As a result of changes within our total property portfolio during the comparative periods presented, including changes from assets acquired or sold, properties placed into development or redevelopment, and development or redevelopment properties recently placed into service, the consolidated total income from rentals, as well as rental operating expenses in our operating results, can show significant changes from period to period. In order to supplement an evaluation of our results of operations over a given quarterly or annual period, we analyze the operating performance for all consolidated properties that were fully operating for the entirety of the comparative periods presented, referred to as same properties. We separately present quarterly and year-to-date same property results to align with the interim financial information required by the SEC in our management’s discussion and analysis of our financial condition and results of operations. These same properties are analyzed separately from properties acquired subsequent to the first day in the earliest comparable quarterly or year-to-date period presented, properties that underwent development or redevelopment at any time during the comparative periods, unconsolidated real estate joint ventures, properties classified as held for sale, and corporate entities (legal entities performing general and administrative functions), which are excluded from same property results. Additionally, termination fees, if any, are excluded from the results of same properties. Refer to the “Same properties” subsection in the “Results of operations” section within this Item 2 for additional information.
Stabilized occupancy date
The stabilized occupancy date represents the estimated date on which the project is expected to reach occupancy of 95% or greater.
Tenant recoveries
Tenant recoveries represent revenues comprising reimbursement of real estate taxes, insurance, utilities, repairs and maintenance, common area expenses, and other operating expenses and earned in the period during which the applicable expenses are incurred and the tenant’s obligation to reimburse us arises.
We classify rental revenues and tenant recoveries generated through the leasing of real estate assets within revenue in income from rentals in our consolidated statements of operations. We provide investors with a separate presentation of rental revenues and tenant recoveries in the “Comparison of results for the three months ended September 30, 2021, to the three months ended September 30, 2020” subsection of the “Results of operations” section within this Item 2 because we believe it promotes investors’ understanding of our operating results. We believe that the presentation of tenant recoveries is useful to investors as a supplemental measure of our ability to recover operating expenses under our triple net leases, including recoveries of utilities, repairs and maintenance, insurance, property taxes, common area expenses, and other operating expenses, and of our ability to mitigate the effect to net income for any significant variability to components of our operating expenses.
The following table reconciles income from rentals to tenant recoveries for the three and nine months ended September 30, 2021 and 2020 (in thousands):
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||||||
| Income from rentals | $ | 546,527 | $ | 543,412 | $ | 1,533,593 | $ | 1,416,873 | ||||||||||||||||||
| Rental revenues | (415,918) | (438,393) | (1,182,955) | (1,117,890) | ||||||||||||||||||||||
| Tenant recoveries | $ | 130,609 | $ | 105,019 | $ | 350,638 | $ | 298,983 | ||||||||||||||||||
Total market capitalization
Total market capitalization is equal to the outstanding shares of common stock at the end of the period multiplied by the closing price on the last trading day of the period (i.e., total equity capitalization), plus total debt outstanding at period-end.
Unencumbered net operating income as a percentage of total net operating income
Unencumbered net operating income as a percentage of total net operating income is a non-GAAP financial measure that we believe is useful to investors as a performance measure of the results of operations of our unencumbered real estate assets as it reflects those income and expense items that are incurred at the unencumbered property level. Unencumbered net operating income is derived from assets classified in continuing operations, which are not subject to any mortgage, deed of trust, lien, or other security interest, as of the period for which income is presented.
The following table summarizes unencumbered net operating income as a percentage of total net operating income for the three and nine months ended September 30, 2021 and 2020 (dollars in thousands):
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||
| Unencumbered net operating income | $ | 371,026 | $ | 388,575 | $ | 1,054,290 | $ | 979,934 | |||||||||||||||
| Encumbered net operating income | 10,738 | 16,024 | 35,099 | 48,526 | |||||||||||||||||||
| Total net operating income | $ | 381,764 | $ | 404,599 | $ | 1,089,389 | $ | 1,028,460 | |||||||||||||||
| Unencumbered net operating income as a percentage of total net operating income | 97% | 96% | 97% | 95% |
Weighted-average shares of common stock outstanding – diluted
From time to time, we enter into capital market transactions, including forward equity sales agreements (“Forward Agreements”), to fund acquisitions, to fund construction of our highly leased development and redevelopment projects, and for general working capital purposes. We are required to consider the potential dilutive effect of our forward equity sales agreements under the treasury stock method while the forward equity sales agreements are outstanding. As of September 30, 2021, we had Forward Agreements outstanding to sell an aggregate of 4.6 million shares of common stock. Refer to Note 13 – “Stockholders’ equity” to our unaudited consolidated financial statements under Item 1 of this report for additional information.
The weighted-average shares of common stock outstanding used in calculating EPS – diluted, funds from operations per share – diluted, and funds from operations per share – diluted, as adjusted, for the three and nine months ended September 30, 2021 and 2020, are calculated as follows (in thousands):
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||
| Weighted-average shares of common stock outstanding – basic | 150,854 | 124,901 | 144,716 | 123,561 | |||||||||||||||||||
| Outstanding forward equity sales agreements | 707 | 927 | 437 | 466 | |||||||||||||||||||
| Weighted-average shares of common stock outstanding – diluted | 151,561 | 125,828 | 145,153 | 124,027 |
Previous: Item 1. FINANCIAL STATEMENTS (UNAUDITED) · Next: Item 3. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK