 filings.tools
Item 1. Business
135K characters. Original on sec.gov · Markdown
Item 1. Business
BUSINESS
Overview
Ares is a leading global alternative investment manager with $352.0 billion of assets under management and over 2,550 employees in over 30 offices in more than 15 countries. We offer our investors a range of investment strategies and seek to deliver attractive performance to an investor base that includes over 1,900 direct institutional relationships and a significant retail investor base across our public and sub-advised funds. Since our inception in 1997, we have adhered to a disciplined investment philosophy that focuses on delivering strong risk-adjusted investment returns through market cycles. Ares believes each of its distinct but complementary investment groups in Credit, Private Equity, Real Assets, Secondaries and Strategic Initiatives is a market leader based on assets under management and investment performance. We believe we create value for our stakeholders not only through our investment performance, but also by expanding our product offering, enhancing our distribution channels, increasing our global presence, investing in our non-investment functions, securing strategic partnerships and completing strategic acquisitions and portfolio purchases.
Our AUM has grown to $352.0 billion as of December 31, 2022 from $60.0 billion a decade earlier. As shown in the chart below, over the past five and 10 years, our assets under management have achieved a compound annual growth rate (“CAGR”) of 27% and 19%, respectively ($ in billions):

We have an established track record of delivering strong risk-adjusted returns through market cycles. We believe our consistent and strong performance in a broad range of alternative investments has been shaped by several distinguishing features of our platform:
-
Comprehensive Multi-Asset Class Expertise and Flexible Capital: Our proficiency at evaluating every level of the capital structure, from senior debt to common equity, across companies, structured assets, real estate projects, and infrastructure and energy assets enables us to effectively assess relative value. This proficiency is complemented by our flexibility in deploying capital in a range of structures and different market environments to maximize risk-adjusted returns.
-
Differentiated Market Intelligence: Our proprietary research on over 55 industries and insights from a broad, global investment portfolio enable us to more effectively diligence and structure our products and investments.
-
Consistent Investment Approach: We believe our rigorous, credit-oriented investment approach across each of our investment groups is a key contributor to our strong investment performance and ability to expand our product offering.
-
Robust Sourcing Model: Our investment professionals’ local market presence and ability to effectively cross-source for other investment groups generates a robust pipeline of high-quality investment opportunities across our platform.
-
Talented and Committed Professionals: We attract, develop and retain highly accomplished professionals who not only demonstrate deep and broad investment and non-investment expertise but also have a strong sense of commitment to our firm.
-
Collaborative Culture: We share ideas, relationships and information across our investment groups, which enables us to more effectively source, evaluate and manage investments. We also leverage our operations management group to help drive the efficiencies across the platforms and support our investment process.
Integrated Investment Platform and Process
We operate our firm as an integrated investment platform with a collaborative culture that emphasizes sharing of knowledge and expertise. We believe the exchange of information enhances our ability to analyze investments, deploy capital and improve the performance of our funds and portfolio companies. We have established deep and sophisticated independent research capabilities in over 55 industries and insights from active investments in over 1,750 companies, over 1,100 alternative credit investments, over 510 properties and over 875 limited partnership interests.
Our investment process leverages the power of the Ares platform and an extensive network of professionals across our investment areas to identify and source attractive risk adjusted return opportunities while emphasizing capital preservation. We utilize our collective market and company knowledge, proprietary internal industry and company research, third party information and financial modeling to drive fundamental credit analysis and investment selection. We are able to invest up and down a company’s capital structure, which we believe helps us capitalize on out-performance opportunities and assess relative value for a particular investment. The investment committees of our investment groups review and evaluate investment opportunities in a framework that includes a qualitative and quantitative assessment of the key risks of each investment. We do not have a centralized investment committee and instead our investment committees are structured with overlapping membership from different investment groups to ensure consistency of approach, shared investment experience and collaboration across our platform. Our extensive network of investment professionals includes local and other individuals based in our markets with the knowledge, experience and relationships that enable them to identify and take advantage of a wide range of investment opportunities. In addition, our investment vehicles have investment policies and procedures that generally contain requirements and limitations, such as concentrations of securities, industries, and geographies in which such investment vehicle will invest, as well as other limitations required by law.
-
Credit**: Our experienced team takes a value-oriented approach which, among other factors, considers industry and market analysis, technical analysis, fundamental credit analysis and in-house research to identify investments that offer attractive value in comparison to the perceived credit risk profile. We use our longstanding relationships, considerable scale, research, industry knowledge, structuring expertise and often our self-origination capabilities to invest actively across capital structures with a focus on selecting the best risk-adjusted returns for our investors, while also seeking to provide our borrowers a valued capital solution. Each investment decision involves an intensive due diligence process that is generally focused on evaluating the target company and its current and future prospects, its management team and industry, its ability to withstand adverse conditions and its capital structure, sponsorship and structural protection, among others.
-
Private Equity**: Our private equity professionals have demonstrated the ability to deploy capital across various market environments at attractive rates of return through control and non-control transactions. At the center of our investment process is a systematic approach that emphasizes rigorous due diligence at company and market levels in addition to assessing attractive relative value. We seek to be a private equity partner of choice and believe our partnership mentality well-positions our investments for long-term success, whereby management teams gain access to our expertise and extensive internal and external networks from diligence to exit. In addition to focusing on generating strong returns for our investors, we are simultaneously focused on driving positive change by helping to promote diversity, inclusivity and social responsibility in the companies in which we invest, which we believe benefits the businesses as a whole in addition to its employees, communities and stakeholders.
- Real Assets**: With our experienced team, along with our expansive network of relationships, our Real Assets Group manages equity and debt strategies across real estate and infrastructure investments. Across our real estate equity and debt investment strategies, our team differentiates itself through its cycle-tested leadership, demonstrated performance across market cycles, access to real-time property market and corporate trends, and proven ability to create value through a disciplined investment process. Our real estate activities are managed by dedicated equity and debt teams in the U.S. and Europe, along with our vertically integrated operating platform. These individuals collaborate frequently within and across strategies to enhance sourcing, exchange information to inform underwriting and leverage relationships to drive pricing power. Our real estate equity team focuses on core/core-plus, value-add and opportunistic investing, while our real estate debt team focuses on directly originated commercial mortgage loans across the risk spectrum. Ares completed the acquisition of the Black Creek Group on July 1, 2021 (the “Black Creek Acquisition”) and the acquired business is presented within the Real Assets Group.
The infrastructure strategy focuses on debt and equity in essential infrastructure assets and companies with stable cash flow profiles through long-term contracts and high-barriers to entry, and may demonstrate a lower correlation to public markets and potential for inflation projection. Across our infrastructure opportunities and debt investment strategies, we have a long-tenured global team utilizing deep local sourcing capabilities and extensive sector experience to originate and manage diverse, high quality investments in private infrastructure assets across the globe. We have dedicated direct infrastructure opportunities and debt teams that collaborate to share market insights, support underwriting and enhance origination. Our infrastructure opportunities strategy focuses on value-add equity with a flexible mandate in climate infrastructure. The infrastructure debt strategy was formed during the first quarter of 2022 in connection with the acquisition of AMP Capital’s Infrastructure Debt Platform (the “Infrastructure Debt Acquisition”). The infrastructure debt strategy targets global assets and businesses with defensive characteristics across the digital, transport, energy and utility sectors. Leveraging the established long standing relationships, the strategy seeks to generate exclusive deal flow and high-quality investment opportunities.
-
Secondaries:** The Secondaries Group was formed during the second quarter of 2021 in connection with the acquisition of Landmark Partners, LLC (the “Landmark Acquisition”). Our Secondaries team invests in secondary markets across a range of alternative asset class strategies, including private equity, real estate and infrastructure. The secondary funds acquire interests across a range of partnership vehicles, including funds, multi-asset portfolios and single asset joint ventures. These strategies involve the acquisition of interests from investors in existing funds as well as recapitalizing and restructuring the funds, including transactions that can address pending fund maturity, strategy change or the need for additional equity capital. The private equity secondaries strategy targets opportunities in non-competitive channels and makes investments involving durable, performing assets with attractive capital structures, as well as opportunities in traditional diversified limited partner portfolios. In the real estate secondaries strategy, the team seeks broad diversification by property sector and geography and to drive investment results through underwriting, transaction structuring and portfolio construction. In the infrastructure secondaries strategy, the team focuses on achieving diversification through building a portfolio that provides inflation protection and exposure to uncorrelated assets.
-
Strategic Initiatives:** Our strategic initiatives team executes investment strategies that expand our reach and scale in new and existing global markets. Strategic Initiatives includes the Ares SSG platform, which includes a majority interest in Ares SSG Capital Holdings Limited and its operating subsidiaries (“Ares SSG”). Ares SSG makes credit and special situations investments through its local originating presence across Asia-Pacific on behalf of its institutional client base. Strategic Initiatives also includes Ares Insurance Solutions (“AIS”), our dedicated in-house team that provides solutions to insurance clients including asset management, capital solutions and corporate development, and Ares Acquisition Corporation (NYSE: AAC) (“AAC”), our first sponsored SPAC.
We also recognize the importance of considering environmental, social and governance (“ESG”) factors in our investment process and have adopted an ESG policy for the conduct of our business. We work collaboratively with our various underwriting, asset management, legal and compliance teams to appropriately integrate relevant ESG considerations into our investment process.
In addition, as part of our growth strategy, we may from time to time engage in discussions with counterparties with respect to various potential strategic transactions, including potential investments in, and acquisitions of, other companies or assets. In connection with evaluating potential strategic transactions and assets, we may incur significant expenses for the evaluation and due diligence investigation and negotiation of any potential transaction.
Breadth, Depth and Tenure of our Senior Management
Ares was built upon the fundamental principle that each of our distinct but complementary investment groups benefits from being part of our broader platform. We believe that our strong performance, consistent growth and high talent retention through economic cycles is due largely to the effective application of this principle across our broad organization of over 2,550 employees. The management of our operating businesses is currently overseen by our Executive Management Committee which meets frequently to discuss strategy and operational matters, and includes as representatives Holdco Members and other senior leadership from our investment groups and business operations team. We also have a Partners Committee comprised of senior leadership from across the firm that meets periodically to discuss our business, including investment and operating performance, fundraising, market conditions, strategic initiatives and other firm matters. Each of our investment groups is led by its own deep leadership team of highly accomplished investment professionals, who average approximately 25 years of investment experience in managing, advising, underwriting and restructuring companies. While primarily focused on managing strategies within their own investment group, these senior professionals are integrated within our platform through economic, cultural and structural measures. Our senior professionals have the opportunity to participate in the incentive programs of multiple investment groups to reward collaboration across our investment activities. This collaboration takes place on a daily basis and is formally promoted through internal systems and widely attended weekly or monthly meetings.
Human Capital
We believe that our people and our culture are the most critical strategic drivers of our success as a firm. Creating a welcoming and inclusive work environment with opportunities for growth and development is essential to attracting and retaining a high-performance team, which in turn is necessary to drive differentiated outcomes. We believe that our unique culture, which centers upon values of collaboration, responsibility, entrepreneurialism, self-awareness and trustworthiness makes Ares a preferred place for top talent at all levels to build a long-term career within the alternative asset management industry. To foster this culture, we invest heavily in our human capital efforts, including:
Talent Management: As of December 31, 2022, we had over 2,550 full-time employees, comprised of approximately 900 professionals in our investment groups and over 1,650 operations management professionals, located in over 30 offices in more than 15 countries. We provide a comprehensive set of programs, policies and benefits to enable team members to thrive, grow and contribute to their highest potential.
-
Governance and Policies:** Ares is committed to providing a work environment in which all individuals are treated with respect and dignity. While our culture is the foundation of our work environment, our equal opportunity employment, diversity, and anti-harassment/anti-discrimination policies reinforce a professional atmosphere.
-
Recruiting and Onboarding:** We pursue several strategic paths to hire top talent, including campus and lateral recruiting efforts, and focus on diversity. We prioritize making all new team members feel welcome and seek to set them up for success through onboarding training, ongoing touchpoints, and connecting them with our employee resource groups (“ERGs”), which are grassroots, employee-led, executive-sponsored groups and open to all team members.
-
Internship Training Program:** Ares offers a formal analyst internship program for students between their sophomore and senior years of college with the possibility of full-time hire into our analyst program upon graduation for those who intern between their junior and senior years. Available roles span our investment and operations management teams.
-
Mentoring, Training and Employee Engagement:** We provide formal and informal mentoring, learning and development, and employee engagement opportunities. We host frequent townhall meetings hosted by senior leadership and events to foster belonging. We also conduct anonymous firmwide surveys at least annually to evaluate employee morale, productivity and overall well-being.
-
Education Sponsorship Program:** Employees are encouraged to participate in degree programs, business-related seminars, workshops, ad-hoc academic courses, continued education seminars to maintain job-related licenses and other outside training courses to facilitate professional development, the cost of which is reimbursed to the employee by Ares.
-
I****nternal Training and Development Programs:** We continue to foster an environment that cultivates company and employee growth through educational programs focused on professional development, mandated training and other
learning opportunities. Our team is focused on the training and development of our employees and has invested in a learning management system to facilitate this initiative.
-
Performance Management:** We take a continuous feedback approach to performance management, encouraging leaders and team members to participate in goal setting and ongoing feedback discussions throughout the year. Our formal, firm-wide annual review process includes a self-assessment, a 360-degree feedback component and/or round table discussions, and management appraisals. In addition to the annual review, we also conduct mid-year performance reviews that are less formal and serve to evaluate progress against goals and as an opportunity to discuss specific career development objectives that were identified in the annual assessment. Training is provided for each phase of our performance assessment process.
-
Retention, Rewards and Recognition:** We provide competitive compensation and benefits to (i) attract and retain talent, (ii) align the incentives of our employees with our investors and stakeholders and (iii) support our employees across many aspects of their lives. We also have programs that seek to recognize significant team member contributions at the firm level.
Environmental, Social and Governance: We believe that ESG is an integral part of what will drive long-term success for our investments, clients, shareholders, employees and other stakeholders. We pursue an ESG strategy that is designed to address the most material issues to our business, starting with our corporate sustainability program that focuses on how we lead by example through our own corporate operations and then scaling through a responsible investment program that focuses on how we amplify our impact through our investment platform.
-
In order to continuously improve our ESG integration processes, we have defined three tiers of roles and responsibilities for oversight and implementation: (i) Oversight Responsibility, (ii) Defining Implementation and (iii) Driving Implementation. The Oversight Responsibility tier consists of our most-senior managers and decision-making bodies, including our Executive Management Committee and board of directors, to whom our Global Head of ESG periodically presents. Next, our ESG team is responsible for Defining Implementation steps and processes in partnership with ESG champions embedded within each business line to adapt the Ares firmwide approach to strategy-specific implementation steps. Specific to climate, we also have a cross-functional Climate Action Group that facilitates the collaboration on climate-related issues across investment strategies and climate-relevant corporate functions. We focus on Driving Implementation with ESG champions across our investment strategies and corporate functions and are able to integrate our ESG goals across the firm and collect feedback that could improve our approach over time.
-
We look to support ESG initiatives where we can provide a leadership role. Ares is the Chair of the UN Principles for Responsible Investing Private Debt Advisory Committee and is committed to collaborating with other industry leaders to manage the risks and capture the opportunities related to climate change. Ares is also a public supporter of the Financial Stability Board Taskforce on Climate-related Financial Disclosures (“TCFD”). We believe the TCFD recommendations provide a useful framework to increase transparency on climate-related risks and opportunities within financial markets. In line with broader environmental and climate change regulations, we are committed to measuring and reporting on Scope 1, 2 and 3 categories and minimizing our footprint with attention to high-impact, high-quality offsets. We will also look to opportunistically incorporate in-suite energy savings mechanisms, where possible, into our office suite buildouts, such as smart meters that help to identify energy drains, automatic light shut-offs and HVAC system best practices. We continue to invest in people, processes and systems to allow us to drive positive ESG progress throughout our company and industry.
Diversity, Equity and Inclusion: We invest heavily in diversity, equity and inclusion (“DEI”) as a strategic pillar that integrates with all talent processes and global business practices. Our human resources function, our global DEI Council and team led by our Chief Diversity, Equity, and Inclusion officer and business leaders across the Ares platform work in partnership to implement a strategic framework to attract, engage, develop and advance diverse talent within an inclusive and welcoming environment, as well as to amplify DEI best practices across our investment portfolios and through our broader involvement in our communities.
- People and Culture:** We focus on conducting reviews with business leadership to continuously assess our people, progress, metrics and strategies to enable the long-term success of diverse talent at Ares. In addition, as part of our commitment to equitable pay for all employees, we monitor and assess total compensation to ensure we have alignment with role responsibilities and contributions. As part of our ongoing effort to foster an inclusive culture built on apprenticeship, we support the growth and advancement of talent through various mentorship and professional
development programs. In line with our continued commitment to seek to provide an environment where all team members experience a genuine sense of belonging, we hold educational and employee engagement events in partnership with our seven ERGs that help to drive our DEI strategy and enhance the employee experience for historically underrepresented groups and diverse talent more broadly.
-
Business Processes and Investment Platform:** We seek to embed DEI best practices into our business and investment diligence processes as both a reflection of our values and to drive innovation and returns. We have identified DEI champions within each investment group to develop bespoke strategies focused on representation, DEI governance, equitable access and employee engagement/equity ownership, which will be integrated into our business plans each year. In addition, we are focused on increasing vendor and supplier diversity in our procurement practices. In 2022, we also introduced sustainability-linked pricing to our Credit Facility, tying a portion of our borrowing costs to certain ESG and DEI-related targets. We also partner with select Ares private equity portfolio companies to understand the current state of their DEI efforts, as well as to share best practices and establish mutually agreed strategies and targets for driving DEI improvements in parallel with our internal efforts.
-
Communities:** We partner with organizations to foster diversity within our communities and promote corporate citizenship through charity and volunteerism, much of which targets historically underrepresented and economically disadvantaged populations. We also participate in DEI-focused industry groups in an effort to identify and advance best practices more broadly within alternative asset management. In partnership with our ERGs, we donated to various community organizations that support diverse communities.
Health and Wellness: We believe that healthy team members are more productive, and we invest heavily in benefits and initiatives to support our working families. In addition to medical, dental, vision, life insurance, disability insurance and retirement benefits, we provide generous primary and non-primary caregiver leave, domestic partner health and life insurance, adoption and reproductive assistance, family care resources (including back-up care benefits and baby baskets for new parents) and mental health benefits. We also provide employees with access to a medical advisory team and concierge service at no cost to help them navigate complex health situations and concerns. We also host several wellness-related events throughout the year on topics such as nutrition and stress management.
Flexibility: We believe that our culture benefits from people collaborating in-person in our offices, while also recognizing the value of flexibility. We are committed to providing flexibility to our employees, and in 2022, we piloted business group flexibility frameworks, which included shared days onsite to promote togetherness. We also piloted a program in late summer 2022, in which we supported people working virtually for up to a maximum of three weeks. We will continue to offer a flexible work structure in 2023, while evaluating ongoing effectiveness and evolving as we continue to learn more about what works best for our organization.
Philanthropy: Philanthropy at Ares is comprised of the Ares Charitable Foundation, our Ares In Motion volunteerism program and our corporate giving program.
-
The Ares Charitable Foundation (the “Ares Foundation”) awards grants to nonprofit organizations globally to accelerate equality of economic opportunity through funding priorities in career preparation, reskilling, entrepreneurship and personal finance. Examples of signature initiatives include a $25.0 million grant for Climate-Resilient Employees for a Sustainable Tomorrow (“CREST”) to help prepare and reskill people for climate-resilient jobs in the U.S. and India and a $30.0 million grant for AltFinance, which helps prepare Historically Black College and University students for careers in the alternative investment industry. These grants are in addition to employee-directed grants that, for example, better enable low-income women to transition out of poverty, identify barriers to young people’s successful workforce entry, explore disability workforce inclusion strategies and encourage intergenerational entrepreneurship. The Ares Foundation has awarded approximately $57.6 million since it launched in June 2021.
-
We and certain of our portfolio managers have committed to donating a percentage of our carried interest allocations to charitable organizations. For example, Ares has committed to donate a minimum of 10% of the carried interest generated from Ares Pathfinder Fund, L.P. ("Pathfinder") and from our open-end core alternative credit fund to global health and education charities with 5% of the contributions being made directly from each fund and the difference contributed by us and our employees. We believe Pathfinder is the first institutional private investment fund to utilize a predefined structure to make a substantial commitment to charitable activities. In addition, we donate up to 5% of annual realized net performance income from a growing pool of over 20 funds to charitable organizations through the Ares Foundation.
-
Ares in Motion (“AIM”) is our signature platform for employee engagement, volunteerism, and matching gifts. We have launched initiatives to benefit our employees, including sponsoring a training and placement program for non-profit board of directors and hosting a series of community conversations between our professionals and non-profit leaders of organizations such as the American Heart Association and World Central Kitchen.
-
Our corporate giving program focuses on sponsorships and support of charitable causes in our communities, including initiatives that are outside the scope of funding priorities of the Ares Foundation. These initiatives include sponsoring the Center for Workforce Inclusion Equity Summit 2022, which examined how best to include older Americans in current workforce development programs, especially older women of color who seek to enter the labor market, in addition to supporting Ukrainian relief efforts, family mental health programming and social justice initiatives.
2022 Highlights
Fundraising
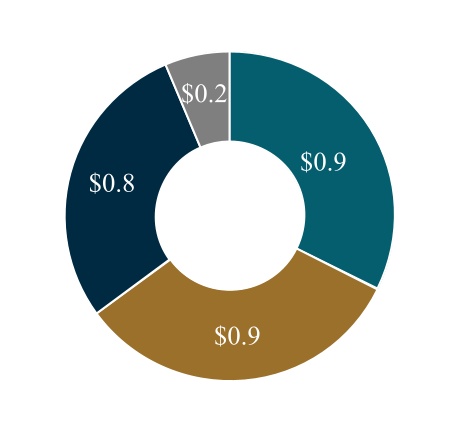
In 2022, we raised $56.8 billion in gross new capital for more than 135 different investment vehicles. Of the $56.8 billion, $44.0 billion was raised directly from 353 institutional investors (243 existing and 110 new to Ares) and $12.8 billion was raised through intermediaries. The charts below summarize our gross new capital commitments by investment group and strategy ($ in billions):
| Credit: $32.1 | Private Equity: $2.2 |
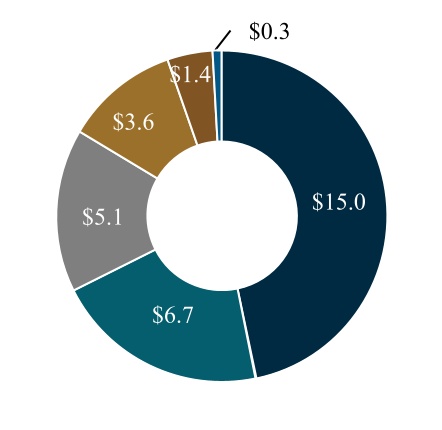
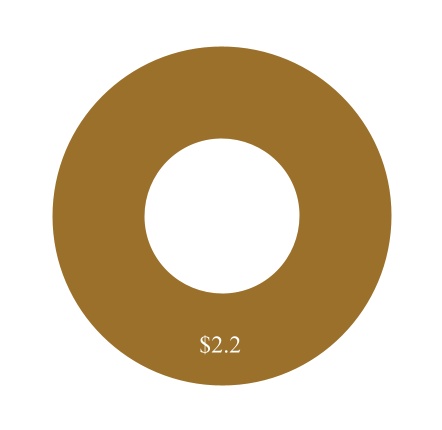
| U.S. Direct Lending | Alternative Credit | Syndicated Loans | Special Opportunities | ||||||||||||||||||||||||||||||||||||||
| European Direct Lending | Multi-Asset Credit | High Yield |
| Real Assets: $13.9 | Secondaries: $2.5 |

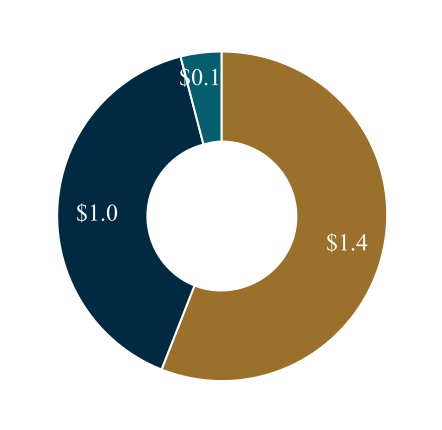
| U.S. Real Estate Equity | European Real Estate Equity | Real Estate Debt | Real Estate Secondaries | Private Equity Secondaries | Infrastructure Secondaries | ||||||||||||||||||||||||||||||||||||||||||
| Infrastructure Debt | Infrastructure Opportunities |
| Strategic Initiatives: $6.1 |
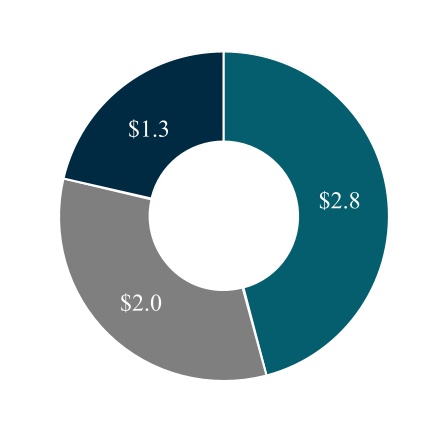
| Insurance | APAC Direct Lending | Asian Special Situations |
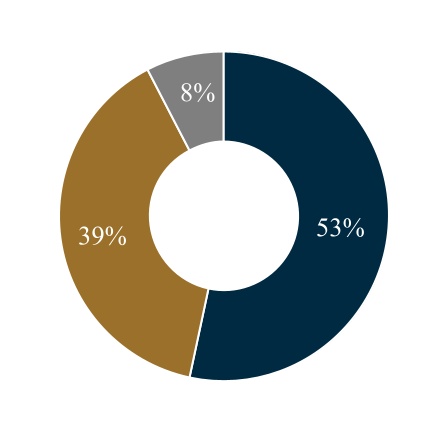
The chart below summarizes gross new capital raised from existing and new direct institutional investors for the year ended December 31, 2022:
| Existing - Re-Up | Existing - New Product | New |
In 2022, 92% of our fundraising from direct institutional investors was from existing investors that either committed to a new product or re-upped their commitment to a subsequent fund vintage within the same product. We believe the fundraising from existing investors demonstrates our investors’ satisfaction with our performance, disciplined management of their capital and diverse product offering.
Capital Deployment
We took advantage of our diverse global platform to invest approximately $79.8 billion globally in 2022 as shown in the following charts ($ in billions):
| Credit $56.9 | Private Equity: $5.2 |
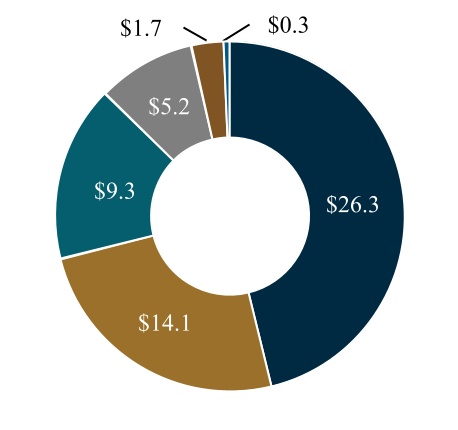
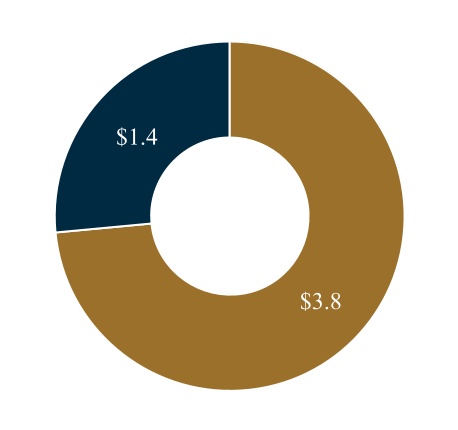
| U.S. Direct Lending | European Direct Lending | Alternative Credit | Special Opportunities | Corporate Private Equity | |||||||||||||||||||||||||||||||
| Syndicated Loans | Multi-Asset Credit | High Yield |
| Real Assets: $12.0 | Secondaries: $2.9 |
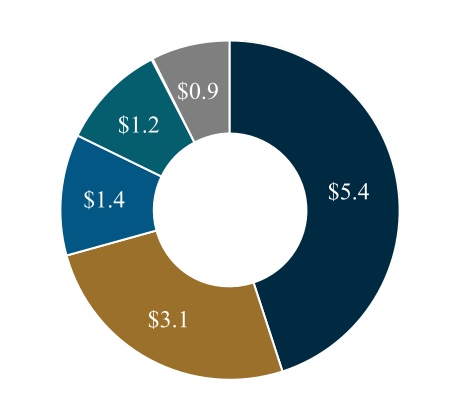
| U.S. Real Estate Equity | Real Estate Debt | Infrastructure Debt | Private Equity Secondaries | Real Estate Secondaries | Infrastructure Secondaries | ||||||||||||||||||||||||||||||||||||
| European Real Estate Equity | Infrastructure Opportunities |
| Strategic Initiatives: $2.8 |
| Insurance | Asian Secured Lending | Asian Special Situations | APAC Direct Lending |
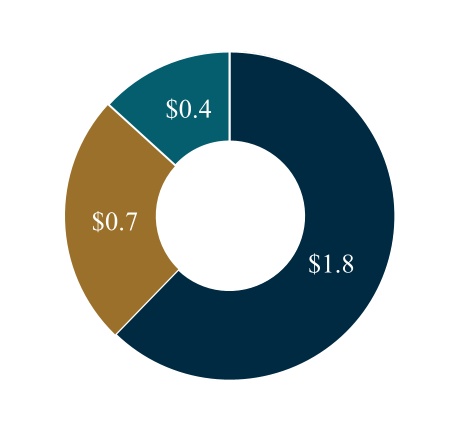
Of the $79.8 billion invested, $51.5 billion was tied to our drawdown funds. Our capital deployment in drawdown funds comprised of the following ($ in billions):

| Credit | Private Equity | Real Assets | Secondaries | Strategic Initiatives |
Investment Groups
Each of our investment groups employs a disciplined, credit-oriented investment philosophy and is managed by a seasoned leadership team of senior professionals with extensive experience investing in, advising and underwriting assets held by our funds.
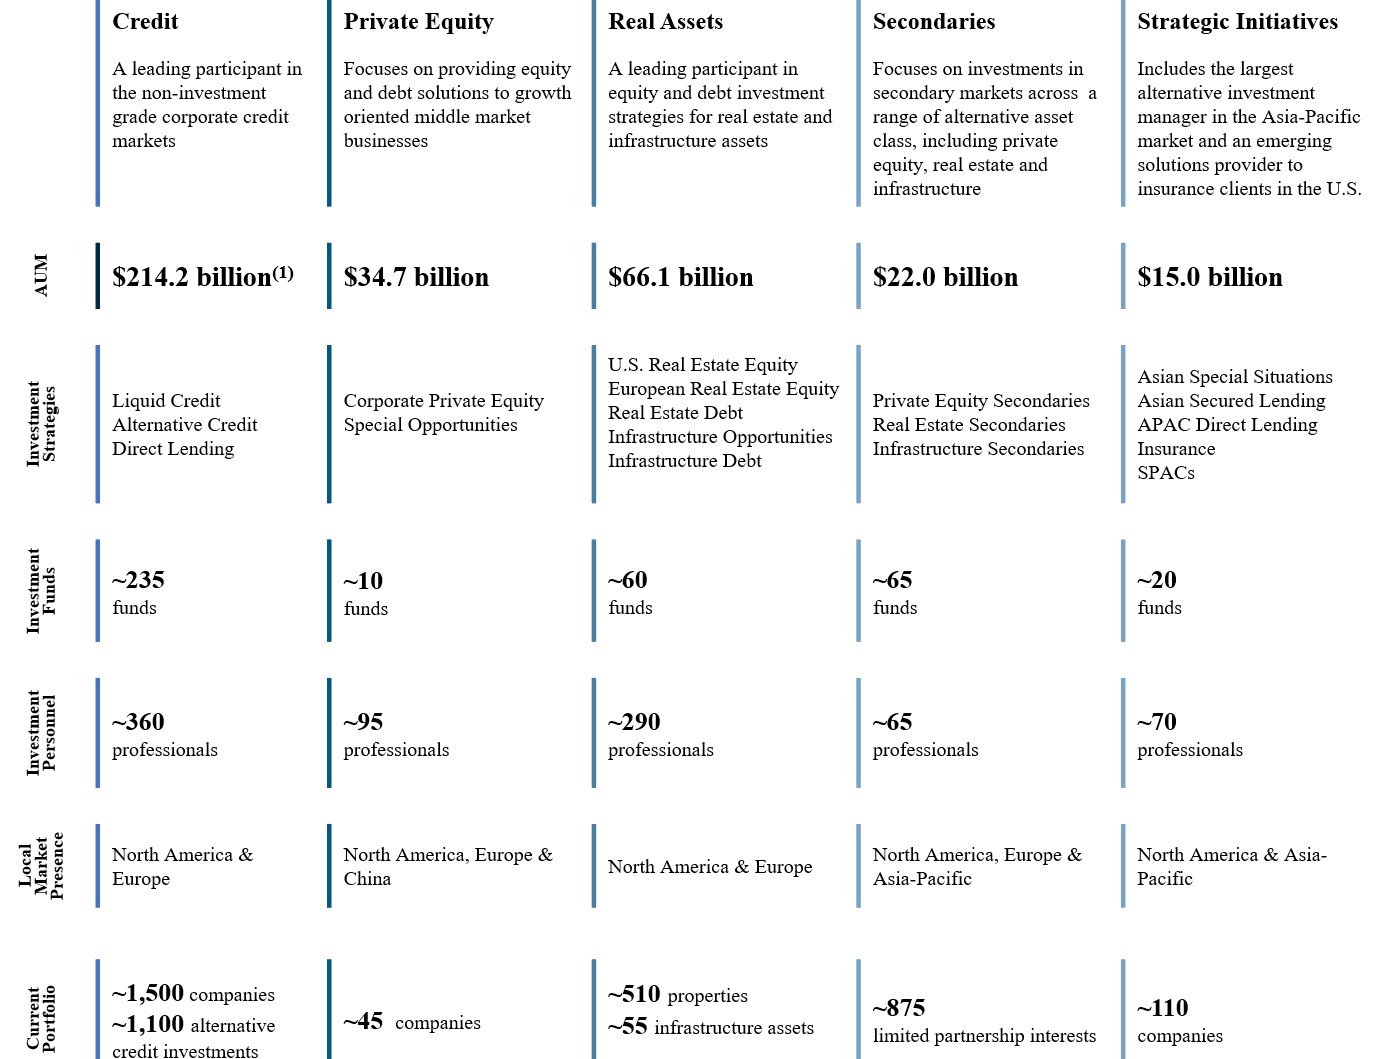
(1)As of December 31, 2022, AUM amounts include vehicles managed by Ivy Hill Asset Management, L.P., a wholly owned portfolio company of ARCC and an SEC-registered investment adviser (“IHAM”).
Cr****edit Group
Our Credit Group is one of the largest managers of credit strategies across the non-investment grade credit universe, with $214.2 billion of AUM and over 235 funds as of December 31, 2022. The Credit Group provides solutions for investors seeking to access a wide range of credit assets, including liquid credit, alternative credit and direct lending products. The Credit Group capitalizes on opportunities across traded and non-traded corporate and consumer debt across the U.S. and European markets, providing investors access to directly originated fixed and floating rate credit assets along with the ability to capitalize on illiquidity premiums across the credit spectrum. Our U.S. and European direct lending strategies are among the largest in their respective markets. We are also a leading global manager of syndicated bank loans.
The Credit Group offers the following credit strategies across the liquid and illiquid spectrum:
Liquid Credit: Our liquid credit investment solutions help investors access the syndicated loan and high yield bond markets, among other asset categories. We focus on capitalizing on opportunities across traded corporate credit. As of December 31, 2022, our liquid credit team managed $43.9 billion of AUM in over 100 funds and separately managed accounts (“SMAs”).
- Syndicated Loans: Our syndicated loans strategy delivers a diversified portfolio of liquid, traded non-investment grade secured loans to corporate issuers in North America and Europe. We focus on evaluating individual credit opportunities related primarily to non-investment grade senior secured loans and primarily target first lien secured debt, with a secondary focus on second lien secured loans and subordinated and other unsecured loans. These capabilities have supported our long history as leading manager and issuer of CLOs which hold syndicated loans.
*•*High Yield Bonds: Our high yield bonds strategy employs a value-driven philosophy, utilizing fundamental research to identify non-investment grade corporate issuers. We primarily seek a diversified portfolio of liquid, traded non-investment grade corporate bonds. This approach incorporates secured, unsecured and subordinated debt instruments of issuers in both North America and Europe.
- Multi-Asset Credit: Our multi-asset credit strategy combines both syndicated loans and high yield bonds, as well as other asset categories including structured credit, special situations and related credit instruments into a single portfolio. These portfolios are designed to offer investors a flexible solution to global credit investing by allowing us to tactically allocate between multiple asset classes in various market conditions. This strategy invests globally, can be highly customized, and is designed to “go anywhere” within the liquid, non-investment grade credit universe.
Alternative Credit: Our alternative credit strategy seeks to capitalize on asset-focused investment opportunities that fall outside of traditional, well-defined markets such as corporate debt, real estate and private equity. As of December 31, 2022, our dedicated team of over 55 professionals managed $21.4 billion of AUM in over 30 private funds and SMAs for a global investor base. Our alternative credit strategy emphasizes downside protection and capital preservation through a focus on investments that tend to share the following key attributes: asset security, covenants, cash flow velocity and other features designed to capture value and minimize risk to principal. Our investment approach is designed to capture and create value by leveraging our firm’s platform insights to assess risk and relative value.
Direct Lending: Our direct lending strategy is one of the largest self-originating direct lenders to the U.S. and European markets, with $148.9 billion of AUM in over 100 funds and investment vehicles as of December 31, 2022. We manage various types of direct lending vehicles within our U.S. and European direct lending teams including commingled funds, SMAs for large institutional investors seeking tailored investment solutions and joint venture lending programs. As of December 31, 2022, we managed over 50 SMAs across our direct lending strategy.
Our direct lending team has a multi-channel origination strategy designed to address a broad set of investment opportunities in the middle market. We focus on being the lead or sole lender to our portfolio companies which we believe allows us to exert greater influence over deal terms, capital structure, documentation, fees and pricing, while securing our position as a preferred source of financing for our transaction partners. The team maintains a flexible investment strategy with the capability to invest in first lien senior secured loans (including “unitranche” loans which are loans that combine senior and subordinated debt, generally in a first lien position), second lien senior secured loans, subordinated debt, preferred equity and non-control equity co-investments in private middle market companies.
U.S. Direct Lending: Our leading U.S. team is comprised of over 170 investment professionals that cover more than 635 financial sponsors and provide a wide range of financing solutions to middle market companies that typically range from $10 million to over $500 million in earnings before interest, tax, depreciation and amortization (“EBITDA”). As of December 31, 2022, our U.S. direct lending team and its affiliates managed $98.3 billion of AUM in over 65 funds and investment vehicles. Our U.S. team manages corporate lending activities through our inaugural vehicle and publicly-traded business development company (“BDC”), ARCC, our non-traded BDC, ASIF, as well as private commingled funds and SMAs. Primary areas of focus for our U.S. direct lending teams include:
-
Ares Capital Corporation: ARCC is a leading specialty finance company focused on providing direct loans to and making other investments in private middle market companies in the U.S. ARCC has elected to be regulated as a BDC and was the largest publicly-traded BDC by market capitalization in the U.S. as of December 31, 2022.
-
Ares Strategic Income Fund: ASIF is a closed-end investment company focused primarily on providing direct loans to private middle market companies in the U.S., and to a lesser extent, broadly syndicated loans and other more liquid credit opportunities, including in publicly-traded debt instruments. ASIF has elected to be regulated as a BDC.
•U.S. Commingled Funds and SMAs: Outside of ARCC, U.S. direct lending also generates fees from other funds, including: Ares Private Credit Solutions, L.P. (“PCS”) and Ares Private Credit Solutions II, L.P. (“PCS II”), which focus on junior debt investments in upper middle market companies; Ares Senior Direct Lending Fund, L.P. (“SDL”) and Ares Senior Direct Lending Fund II, L.P. (“SDL II”), which focus on first lien senior secured loans to North American middle market companies; Ares Commercial Finance, which focuses on asset-based and cash flow loans to middle market and specialty finance companies; and SMAs for large institutional investors.
European Direct Lending: Our leading European team is comprised of over 85 investment professionals that cover over 395 financial sponsors and is one of the most active participants in the European middle market. The team offers a wide range of financing opportunities to middle market companies with EBITDA typically ranging from €10 million to over €300 million. As of December 31, 2022, our European direct lending team managed $50.6 billion of AUM in over 30 funds, including our commingled funds and SMAs.
The following charts present the Credit Group’s AUM and FPAUM as of December 31, 2022 by investment strategy ($ in billions):
| AUM: $214.2 | FPAUM: $145.2 |
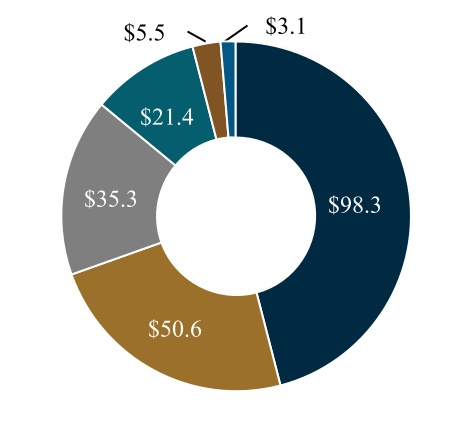
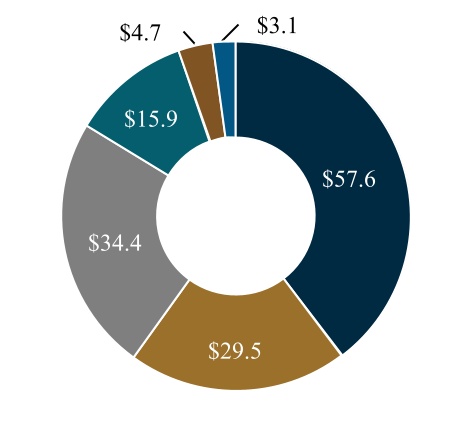
| U.S. Direct Lending | European Direct Lending | Syndicated Loans | Alternative Credit | Multi-Asset Credit | High Yield | ||||||||||||||||||||||||||||||
Private Equity Group
Our Private Equity Group has achieved compelling investment returns for its limited partners and, as of December 31, 2022, managed $34.7 billion of AUM in over 10 funds. The group broadly categorizes its investment strategies into corporate
private equity and special opportunities. Our private equity professionals have demonstrated ability to deploy capital across market environments, which allows them to stay both active and disciplined in their assessment of the best relative value opportunities. The group manages funds focused primarily on investing in North America and Europe.
Corporate Private Equity: Our team consists of approximately 75 investment professionals based primarily in Los Angeles and London. Our flagship funds are private equity leaders in the North American and European middle market, where they focus on growth buyouts, with the ability to flex into distressed investing during periods of market volatility and dislocation. We seek to invest in high-quality middle market companies in the core industries of healthcare, services, industrials, and consumer; across North America and Europe, where we can utilize the team’s extensive growth-oriented investing experience, dedicated value creation system and ability to flex into distressed to target attractive returns across market environments. This differentiated strategy, together with the broad resources of the Ares platform, widens our universe of potential investment opportunities and allows us to remain active across various market environments and to be highly selective in making investments by identifying the most attractive relative value opportunities.
Special Opportunities: Our special opportunities team consists of approximately 25 investment professionals and employs an “all weather” flexible capital strategy to finance debt and non-control equity solutions in healthy, stressed and distressed middle market companies undergoing transformational change. Our team partners with companies in North America and Europe to enhance enterprise values, filling the void between for-control private equity and traditional private debt. The strategy seeks to consistently invest in a range of private, special-situation opportunities and flex into distressed public market debt when attractive. We believe the special opportunities team benefits from (i) advantaged sourcing, (ii) private equity integration, with an ability to leverage the deep industry experience of the corporate private equity professionals, (iii) an extensive network and information edge and (iv) an experienced team utilizing a consistent and repeatable investment process.
The following charts present the Private Equity Group’s AUM and FPAUM as of December 31, 2022 by investment strategy ($ in billions):
| AUM: $34.7 | FPAUM: $18.5 |
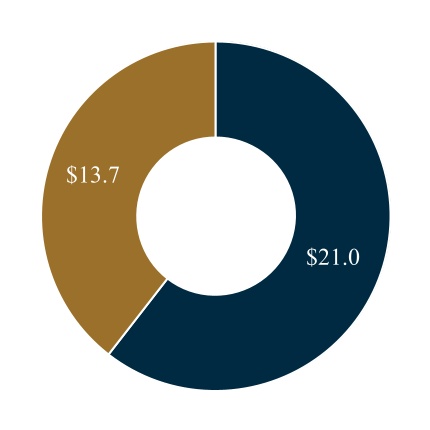
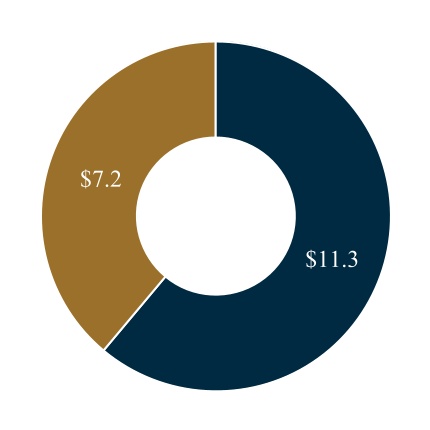
| Corporate Private Equity | Special Opportunities |
Real Assets Group
Our Real Assets Group manages comprehensive public and private equity and debt strategies with $66.1 billion of AUM in over 60 investment vehicles as of December 31, 2022. With our experienced team, along with our expansive network of relationships, our Real Assets Group capitalizes on opportunities in equity and debt investing across real estate and infrastructure investment strategies.
Real Estate: Our real estate equity investments focus on implementing hands-on value creation initiatives to mismanaged and capital-starved assets, platform-level investments, as well as new developments, ultimately selling stabilized assets back into the market. Our real estate debt strategies utilize diverse sources of capital to directly originate and manage commercial mortgage loans on properties that range from stabilized to those requiring hands-on value creation. Our real estate platform has achieved significant scale over time through both organic fundraising efforts as well as various acquisitions. Today, we provide investors access to our real estate investment capabilities through several vehicles: U.S. and European real estate equity closed-end funds, diversified commingled funds, a U.S. real estate equity, open-end industrial-focused commingled fund, U.S. real estate debt open-end commingled funds, real estate equity and real estate debt SMAs, our non-
traded REITs, Ares Real Estate Income Trust, Inc. (“AREIT”) and Ares Industrial REIT, Inc. (“AIREIT”), and our publicly-traded commercial mortgage REIT, ACRE. The group’s activities are managed by dedicated equity and debt teams in the U.S. and Europe.
Real Estate Equity: Our real estate equity team, with over 205 investment professionals, has extensive real estate private equity experience in the U.S. and Europe. Our team primarily acquires standing assets and improves them through renovating, repositioning and retenanting and selectively developing assets in supply-constrained markets. As of December 31, 2022, our real estate equity team managed $40.1 billion of AUM in over 40 investment vehicles. Primary areas of focus for our real estate equity teams include:
- Real Estate Core/Core-Plus: Our U.S. core/core-plus real estate strategy focuses on the acquisition of assets with strong long-term cash flow potential and durable tenancy diversified across end-user industries and geographies. We predominately target industrial real estate in top-tier primary and regional distribution markets with an additional focus on other major sectors including multifamily, office, necessity-based retail and other select property types across major metropolitan economies in the U.S.
•Real Estate Value-Add:** Our U.S. and European value-add investment activities focus on undermanaged and under-funded income-producing assets, including multifamily, office, hotel, industrial, and mixed-use retail properties and adjacent sectors across the U.S. and Western Europe. The strategy seeks to create value and generate stable and growing distributions to investors by buying properties at attractive valuations, implementing asset management initiatives to increase income and by identifying multiple exit strategies upfront.
- Real Estate Opportunistic**:** Our U.S. and European opportunistic real estate investment activities capitalize on increased investor demand for developed and stabilized assets by focusing on the repositioning of assets, capitalization of distressed and special situations, and development of core-quality assets across all major property types including multifamily, industrial, office, hotel, and retail properties and adjacent sectors throughout the U.S. and Europe.
Real Estate Debt: Our real estate debt team, with over 30 professionals, primarily focuses on directly originating a wide range of financing opportunities in the U.S. and Europe. As of December 31, 2022, our real estate debt team managed $11.1 billion of AUM in five investment vehicles. In addition to managing private commingled funds and SMAs, our real estate debt team also invests through our publicly traded commercial mortgage REIT, ACRE, which invests in a diversified portfolio of commercial real estate debt-related investments. By investing through multiple investment vehicles, our real estate debt team has the ability to provide flexible financing across the capital structure. While our real estate debt strategies focus predominantly on directly originated transactions, we also selectively pursue secondary market acquisitions and syndicated transactions.
Infrastructure: Our long-tenured global infrastructure team utilizes deep local sourcing capabilities and extensive sector experience to seek to originate and manage diverse, high-quality investments in private infrastructure assets across the globe and, as of December 31, 2022, managed $14.9 billion of AUM in over 15 investment vehicles.
-
Infrastructure Opportunities: Our infrastructure opportunities team consists of over 25 investment professionals and managed $5.2 billion of AUM in over 10 investment vehicles as of December 31, 2022. We utilize a broad origination strategy, flexible investment approach, and leverage industry relationships and the Ares platform to seek attractive risk-adjusted returns across the climate infrastructure market. We believe our experience as value-add investors, flexible approach, and broad infrastructure experience positions us well to take advantage of the transitioning infrastructure industry.
-
Infrastructure Debt: Our global infrastructure debt team consists of over 25 investment professionals and sources global assets and businesses with defensive characteristics across the digital, transport, energy and utility sectors. As of December 31, 2022, our global infrastructure debt team managed $9.7 billion of AUM in five investment vehicles. We aim to deliver attractive risk adjusted returns focused on cash yield by targeting infrastructure debt investments with defensive characteristics that have the potential to perform across different market cycles. Our structuring experience helps enhance cash yield and reduce downside risks in a core asset class.
The following charts present the Real Assets Group’s AUM and FPAUM as of December 31, 2022 by investment strategy ($ in billions):
| AUM: $66.1 | FPAUM: $41.6 |
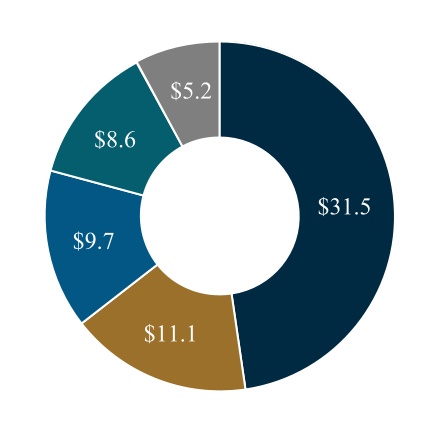

| U.S. Real Estate Equity | Real Estate Debt | Infrastructure Debt | European Real Estate Equity | Infrastructure Opportunities | |||||||||||||||||||||||||
Secondaries Group
Our Secondaries Group invests in secondary markets across a range of alternative asset class strategies, including private equity, real estate and infrastructure, with $22.0 billion of AUM in over 65 funds as of December 31, 2022. The team has extensive experience investing across the secondaries market primarily in North America. We have established ourselves among the most active secondary investors engaged in recapitalizing and restructuring existing limited partnership interests in funds with a focus on transactions that can address pending fund maturity, strategy change or the need for additional equity capital.
Private Equity Secondaries**:** Our private equity secondaries team has an established track record of providing customized private equity transaction solutions to institutional limited partners and general partners. As of December 31, 2022, our private equity secondaries team of approximately 35 investment professionals managed $12.8 billion of AUM in over 35 funds and open-end accounts. Our private equity secondaries team acquires interests across a range of partnership vehicles, including private equity funds, multi-asset portfolios, as well as single asset joint ventures. We continue to maintain a differentiated investment strategy that utilizes our internal research process to provide customized transaction solutions and seeks to generate strong risk-adjusted returns.
Real Estate Secondaries**:** Our real estate secondaries team has a track record of innovation through customized transaction solutions tailored to meet the needs of limited partners and general partners. As of December 31, 2022, our real estate secondaries team of approximately 20 investment professionals managed $7.6 billion of AUM in over 25 funds and related co-investment vehicles. Our real estate secondaries team acquires interests across a range of partnership vehicles, including private real estate funds, multi-asset portfolios and single property joint ventures.
Infrastructure Secondaries: Our infrastructure secondaries team acquires interests across a range of partnership vehicles, including private infrastructure funds, multi-asset portfolios and single asset joint ventures. As of December 31, 2022, our infrastructure secondaries team of 10 investment professionals managed $1.6 billion of AUM in over five funds and related co-investment vehicles.
The following charts present the Secondaries Group’s AUM and FPAUM as of December 31, 2022 by investment strategy ($ in billions):
| AUM: $22.0 | FPAUM: $17.7 |
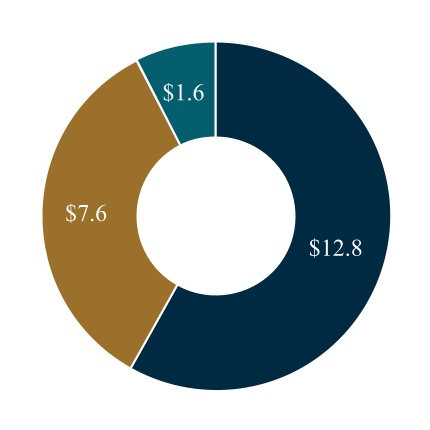

| Private Equity Secondaries | Real Estate Secondaries | Infrastructure Secondaries | ||||||||||||||||||
Strategic Initiatives
Strategic Initiatives represents operating segments and strategic investments that seek to expand the Company’s reach and its scale in new and existing global markets and include Ares SSG, AIS and our SPACs.
Ares SSG: Ares SSG is a highly differentiated investment manager making credit, special situations and private equity investments in the Asia-Pacific region. The team of over 55 investment professionals has an extensive history of investing in Asian markets. Ares SSG benefits from having an on-the-ground presence in offices across Asia-Pacific and a comprehensive range of local market licenses and entities to provide our clients with an extensive regional investment platform. Ares SSG has $11.4 billion of AUM in over 15 funds and related co-investment vehicles as of December 31, 2022 and primarily employs a direct origination model and aims to provide flexible capital solutions to its investee companies and compelling risk-reward investment opportunities to our investors.
- Asian Special Situations: Our Asian special situations strategy focuses on primary and secondary special situation across the Asia-Pacific region. Our team primarily targets restructuring-related situations, deep value acquisitions and last-mile financing.
*•*Asian Secured Lending: Our Asian secured lending strategy targets high quality, privately sourced direct lending loans that do not exhibit financial strain. Our team primarily targets investments in secured loans, growth capital financing and acquisition financing, leveraging our deep set of relationships and coverage to enable direct origination across the Asia-Pacific region.
- Asia-Pacific (“APAC”) Direct Lending: Our APAC direct lending team manages a portfolio of debt obligations, unitranche securities and any other credit instruments which generate fixed income returns with a significant cash coupon component and are issued by portfolio companies that are primarily based in Australia and New Zealand.
Ares Insurance Solutions: AIS is Ares Management’s dedicated, in-house team that provides solutions to insurance clients including asset management, capital solutions and corporate development. AIS strives to provide insurers with attractive risk and capital adjusted return profiles that fit within regulatory, rating agency and other counterparty guidelines. Leveraging approximately 900 investment professionals across the firm’s investment groups, AIS creates tailored investment solutions that meet the unique objectives of our insurance clients. AIS is overseen by an experienced management team with direct insurance industry experience in many areas directly applicable to AIS and our insurance company clients. Members of the Ares team have previously held senior positions at leading insurers. AIS acts as the dedicated investment manager, capital solutions and corporate development partner to Aspida Life Insurance Company (“Aspida Life”) and Aspida Life Re Ltd. (“Aspida Re”). Aspida Life and Aspida Re are insurance companies that focus on the U.S. life and annuity insurance and reinsurance markets.
Ares Acquisition Corporation: AAC is a SPAC sponsored by Ares and formed in 2020 for the purpose of effecting a merger, share exchange, asset acquisition, share purchase, reorganization or similar business combination. On December 5, 2022, AAC entered into a business combination agreement by and among AAC, X-Energy Reactor Company, LLC, a Delaware limited liability company, and additional parties thereto. The business combination is expected to close in the second quarter of 2023, following the receipt of the required approval by AAC’s shareholders and the fulfillment of other customary closing conditions.
The following charts present Strategic Initiatives’ AUM and FPAUM as of December 31, 2022 by investment strategy ($ in billions):
| AUM: $15.0 | FPAUM: $8.1 |
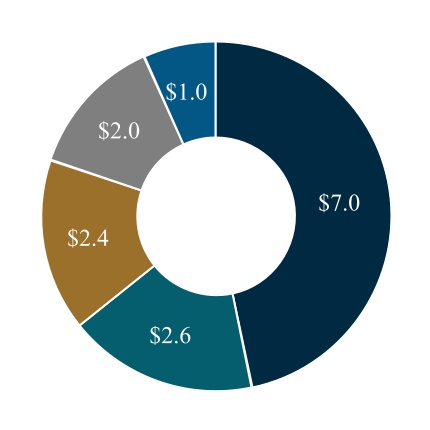
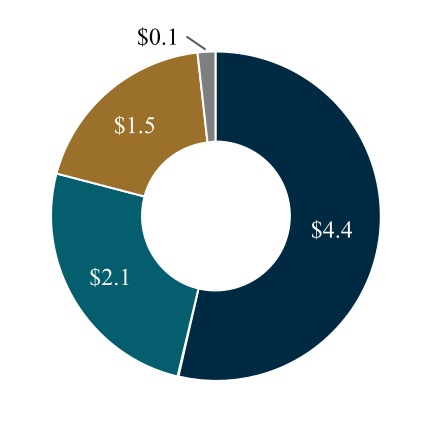
| Asian Special Situations | Insurance | Asian Secured Lending | APAC Direct Lending | SPACs | |||||||||||||||||||||||||
Product Offering
To meet investors’ growing demand for alternative investments, we manage investments in an increasingly comprehensive range of funds across a spectrum of compelling and complementary strategies. We have demonstrated an ability to consistently generate attractive and differentiated investment returns across these investment strategies and through various market environments. We believe the breadth of our product offering, our expertise in various investment strategies and our proficiency in attracting and satisfying our growing institutional and retail client base has enabled and will continue to enable us to increase our AUM across each of our investment groups.
Investor Base and Fundraising
Our diverse investor base includes direct institutional relationships and a significant number of retail investors. Our high-quality institutional investor base includes corporate and public pension funds, insurance companies, sovereign wealth funds, banks, investment managers, endowments and foundations. We have grown the number of these relationships from approximately 780 in 2017 to over 1,900 in 2022.
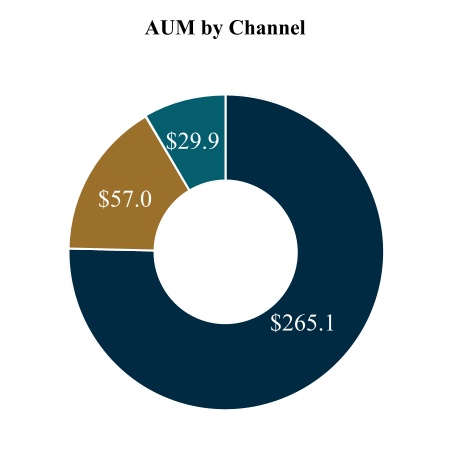
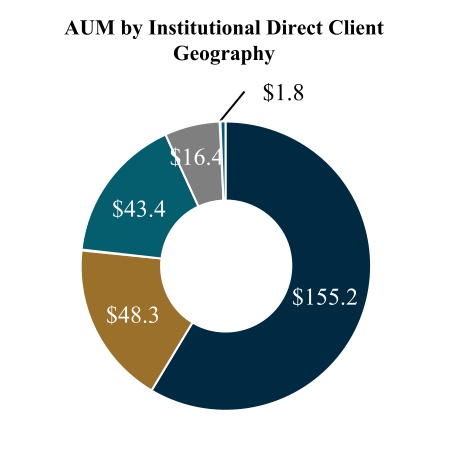
As of December 31, 2022, $265.1 billion, or 75% of our $352.0 billion of AUM, was attributable to our direct institutional relationships. As of December 31, 2022, our total AUM was divided by channel, and further our institutional direct AUM by client type and geographic origin as follows ($ in billions):

| Institutional Direct | Public Entities and Related | Institutional Intermediaries | Pension | Insurance | Bank | North America | Europe | Asia-Pacific | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Sovereign Wealth Fund | High Net Worth and Private Bank | Investment Manager | Middle East & Africa | Other | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other |
The following chart presents the AUM of investors committed to more than one of our funds as of December 31, 2022 compared to December 31, 2017 ($ in billions):
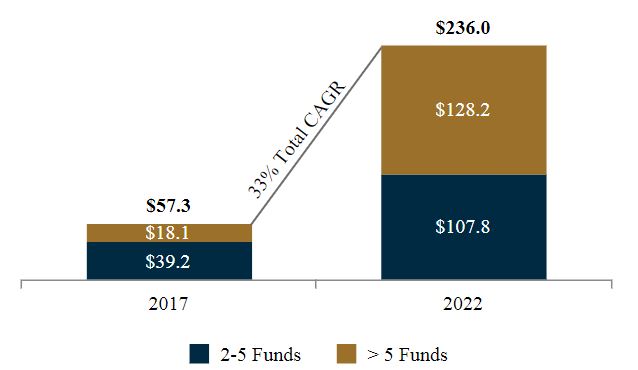
We believe that the AUM of multi-fund investors demonstrates our investors’ satisfaction with our performance, disciplined management of their capital and diverse product offering. Their loyalty has facilitated the growth of our existing businesses and we believe improves our ability to raise new funds and successor funds in existing strategies in the future.
Institutional investors continue to demonstrate interest in SMAs, which include contractual arrangements and single investor vehicles and funds, because these accounts can provide investors with greater levels of transparency, liquidity and control over their investments as compared to more traditional commingled funds. As of December 31, 2022, $73.2 billion, or 28%, of our direct institutional AUM was managed through SMAs. Our public entities and their affiliates, including ARCC, ACRE, ARDC, ASIF, APMF, CADC, AREIT and AIREIT account for $48.6 billion, or 14%, of our AUM. We have over 920 institutional investors and hundreds of thousands of retail investor accounts across our public vehicles.
We believe that client relationships are fundamental to our business and that our performance across our investment groups coupled with our focus on client service has resulted in strong relationships with our investors. Our dedicated and extensive in-house relationship management team, comprised of over 55 professionals located in North America, Europe and Asia-Pacific, is dedicated to raising capital globally across all of our funds, servicing existing fund investors and tailoring offerings to meet their needs, developing products to complement our existing offerings, and deepening existing relationships to expand them across our platform. We also have a strategic joint venture with Fidante Partners focused on expanding our presence in Australia. Our senior relationship management team maintains an active and transparent dialogue with an expansive list of investors. This team is supported by product managers and investor relations professionals with deep experience in each of our complementary investment groups that are dedicated to servicing our existing and prospective investors.
In addition to our expansive relationships with institutional investors, we have further diversified our investor base with our retail distribution channel. AWMS, our wholly owned subsidiary, facilitates the product development, distribution, marketing and client management activities for investment offerings in the global wealth management channel with over 70 professionals.
Operations Management Group
The OMG consists of shared resource groups to support our operating segments by providing infrastructure and administrative support in the areas of accounting/finance, operations, information technology, legal, compliance, human resources, strategy and relationship management and distribution. Our clients seek to partner with investment management firms that not only have compelling investment track records across multiple investment products but also possess seasoned infrastructure support functions. As such, significant investments have been made to develop the OMG. The OMG also includes AWMS to facilitate our investment offerings in the global wealth management channel. We have successfully launched new business lines, integrated acquired businesses into the operations and created scale within the OMG to support a much larger platform in the future.
Organizational Structure
The simplified diagram below (which omits certain intermediate holding companies) depicts our legal organizational structure. Ownership information in the diagram below is presented as of December 31, 2022. Ares Management Corporation (“AMC”) is a holding company and through subsidiaries is the general partner of the Ares Operating Group entity and operates and controls the business and affairs of the Ares Operating Group. AMC consolidates the financial results of the Ares Operating Group, its consolidated subsidiaries and certain consolidated funds.
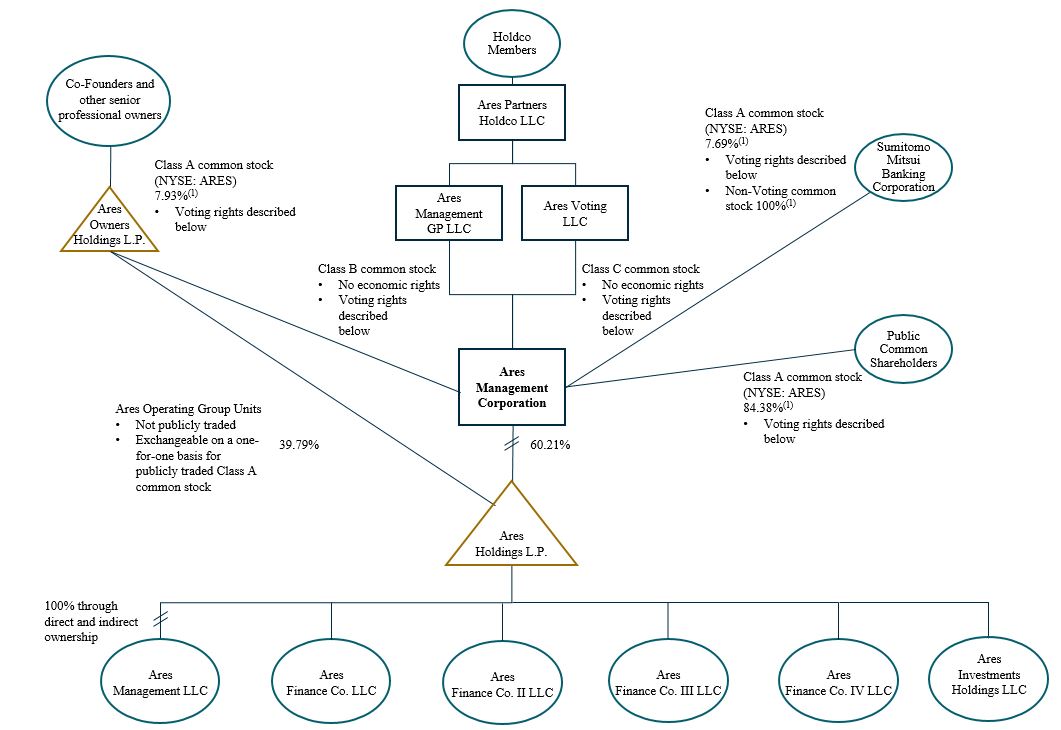
(1)Assuming the full exchange of Ares Operating Group Units for shares of our Class A common stock, as of December 31, 2022, Ares Owners Holdings L.P. would hold 44.48%, Sumitomo Mitsui Banking Corporation (“SMBC”) holds 5.72% and the public would hold 49.80% of AMC. Inclusive of Class A common stock held directly by Ares employees and assuming the full exchange of Ares Operating Group Units for shares of our Class A common stock, Ares employee ownership would represent 48.30% of all outstanding shares.
Holding Company Structure
Our common stockholders are entitled to vote on all matters on which stockholders of a corporation are generally entitled to vote under the Delaware General Corporation Law (the “DGCL”), including the election of our board of directors. Holders of shares of our Class A common stock are entitled to one vote per share of our Class A common stock. On any date on which the Ares Ownership Condition (as defined in the Certificate of Incorporation) is satisfied, holders of shares of our Class B common stock are, in the aggregate, entitled to a number of votes equal to (x) four times the aggregate number of votes attributable to our Class A common stock minus (y) the aggregate number of votes attributable to our Class C common stock. On any date on which the Ares Ownership Condition is not satisfied, holders of shares of our Class B common stock are not entitled to vote on any matter submitted to a vote of our stockholders. The holder of shares of our Class C common stock is generally entitled to a number of votes equal to the number of Ares Operating Group Units (as defined in the Certificate of Incorporation) held of record by each Ares Operating Group Limited Partner (as defined in the Certificate of Incorporation) other than the Company and its subsidiaries. Ares Management GP LLC is the sole holder of shares of our Class B common stock and Ares Voting LLC is the sole holder of shares of our Class C common stock. Our Class B common stock and our Class C common stock are non-economic and holders thereof shall not be entitled to (i) dividends from the Company or (ii) receive any assets of the Company in the event of any dissolution, liquidation or winding up of the Company. Ares Management GP LLC and Ares Voting LLC are both wholly owned by Ares Partners Holdco LLC. As a result, the Company is a “controlled company” within the meaning of the corporate governance standards of the New York Stock Exchange (“NYSE”) and qualifies for exceptions from certain corporate governance rules of the NYSE. The Company also has non-voting common stock solely held by SMBC, which has the same economic rights as the Class A common stock.
Accordingly, AMC and any direct subsidiaries of AMC that are treated as corporations for U.S. federal income tax purposes and that are the holders of AOG Units are subject to U.S. federal, state and local income taxes in respect of their interests in the Ares Operating Group. The Ares Operating Group entity is treated as a partnership for U.S. federal income tax purposes. An entity that is treated as a partnership for U.S. federal income tax purposes generally incurs no U.S. federal income tax liability at the entity level. Instead, each partner is required to take into account its allocable share of items of income, gain, loss, deduction and credit of the partnership in computing its U.S. federal, state and local income tax liability each taxable year, whether or not cash distributions are made.
AMC holds through subsidiaries a number of AOG Units equal to the number of shares of Class A common stock that AMC has issued. The AOG Units held by AMC and its subsidiaries are economically identical in all respects to the AOG Units that are not held by AMC and its subsidiaries. Accordingly, AMC receives the distributive share of income of the Ares Operating Group from its equity interest in the Ares Operating Group.
Structure and Operation of our Funds
We conduct the management of our funds and other similar private vehicles primarily through organizing a limited partnership or other limited liability structure in which entities organized by us accept commitments and/or funds for investment from institutional investors and other investors. Such commitments are generally drawn down from investors on an as needed basis to fund investments over a specified term. Our Credit Group funds also include structured funds in which the investor’s capital is fully funded upon or soon after the subscription for interests in the fund. The CLOs that we manage are structured investment vehicles that are generally private limited liability companies. Our drawdown funds are generally organized as limited partnerships or limited liability companies. However, there are non-U.S. funds that are structured as corporate or non-partnership entities under applicable law. We also advise a number of investors through SMA relationships structured as contractual arrangements or single investor vehicles. In the case of our SMAs that are not structured as single investor vehicles, the investor, rather than us, generally controls custody of the investments with respect to which we advise. We also manage closed-end interval funds (CADC and APMF) that allow for periodic redemptions of the various share classes, four publicly-traded corporations (AAC, ACRE, ARCC and ARDC), two non-traded REITs (AREIT and AIREIT) and a non-traded BDC (ASIF). ACRE, ARDC and ARCC do not have redemption provisions or a requirement to return capital to investors upon exiting the investments made with such capital, except as required by applicable law (including distribution requirements that must be met to maintain RIC or REIT status). However, ACRE’s charter includes certain limitations relating to the ownership or purported transfer of its common stock in violation of the REIT ownership requirements. In addition, Class A ordinary shares issued by AAC are redeemable for cash by the public shareholders in the event that AAC does not complete a business combination or tender offer associated with stockholder approval provisions.
Our funds are generally advised by Ares Management LLC, which is registered under the Investment Advisers Act of 1940, as amended (the “Investment Advisers Act”), a wholly owned subsidiary thereof or subsidiary controlled by Ares Management LLC. Responsibility for the day-to-day operations of each investment vehicle is typically delegated to the Ares entity serving as investment adviser pursuant to an investment advisory, management or similar agreement. Generally, the
material terms of our investment advisory agreements relate to the scope of services to be rendered by the investment adviser to the applicable vehicle, the calculation of management fees to be borne by investors in our investment vehicles and certain rights of termination with respect to our investment advisory agreements. With the exception of certain of the publicly-traded investment vehicles, the investment vehicles themselves do not generally register as investment companies under the Investment Company Act of 1940, as amended (the “Investment Company Act”), in reliance on applicable exemptions thereunder.
The governing agreements of many of our funds provide that, subject to certain conditions, third-party investors in those funds have the right to terminate the investment period or the fund without cause. The governing agreements of some of our funds provide that, subject to certain conditions, third-party investors have the right to remove the general partner. In addition, the governing agreements of certain of our funds provide that upon the occurrence of certain events, the investment period will be suspended or the investors have the right to vote to terminate the investment period in accordance with specified procedures. Such events may include certain “key persons” in our funds that engage in bad acts or depart the firm.
Fee Structure
See “Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations—Components of Consolidated Results of Operations” for an overview of our fee structure, including management fee, incentive fee and carried interest arrangements with our funds.
Capital Invested In and Through Our Funds
To further align our interests with those of investors in our funds, we have invested the firm’s capital and that of our professionals in the funds we sponsor and manage. General partner capital commitments to our funds are determined separately with respect to our funds and, generally, are less than 5% of the total commitments of any particular fund. We determine the general partner capital commitments based on a variety of factors, including regulatory requirements, investor requirements, estimates regarding liquidity over the estimated time period during which commitments will be funded, estimates regarding the amounts of capital that may be appropriate for other opportunities or other funds we may be in the process of raising or are considering raising, prevailing industry standards with respect to sponsor commitments and our general working capital requirements. Our general partner capital commitments are typically funded with cash and not with carried interest or deferral of management fees. We generally offer a portion of the general partner commitments to our eligible professionals in accordance with the Investment Company Act. Ares employees had capital commitments of $2.0 billion in Ares-managed funds as of December 31, 2022. For more information, see “Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations—Liquidity and Capital Resources—Sources and Uses of Liquidity.”
Regulatory and Compliance Matters
Our businesses, as well as the financial services industry, generally are subject to extensive regulation, including periodic examinations, by governmental agencies and self-regulatory organizations or exchanges in the U.S. and foreign jurisdictions in which we operate relating to, among other things, antitrust laws, anti-money laundering laws, anti-bribery laws relating to foreign officials, tax laws and privacy laws with respect to client and other information, and some of our funds invest in businesses that operate in highly regulated industries. Each of the regulatory bodies with jurisdiction over us has regulatory powers dealing with many aspects of financial services, including the authority to grant, and in specific circumstances to cancel, permissions to carry on particular activities. Any failure to comply with these rules and regulations could expose us to liability and/or reputational damage. Additional legislation, increasing global regulatory oversight of fundraising activities, changes in rules promulgated by self-regulatory organizations or exchanges or changes in the laws or rules, or interpretation or enforcement of existing laws and rules, either in the United States (“U.S.”) or elsewhere, may directly affect our mode of operation and profitability. See “Item 1A. Risk Factors—Risks Related to Regulation—Extensive regulation affects our activities, increases the cost of doing business and creates the potential for significant liabilities and penalties that could adversely affect our businesses and results of operations,” “—Failure to comply with “pay to play” regulations implemented by the SEC and certain states, and changes to the “pay to play” regulatory regimes, could adversely affect our businesses,” “—Regulatory changes in jurisdictions outside the U.S. could adversely affect our businesses,” “—Adverse incidents with respect to ESG activities could impact our or our portfolio companies’ reputation, the cost of our or their operations, or result in investors ceasing to allocate their capital to us, all of which could adversely affect our business and results of operations,” and “—Regulations governing ARCC’s operation as a business development company affect its ability to raise, and the way in which it raises, additional capital.”
Rigorous legal and compliance analysis of our businesses and investments is important to our culture. We strive to maintain a culture of compliance through the use of policies and procedures such as oversight compliance, codes of ethics,
compliance systems, communication of compliance guidance and employee education and training. All employees must annually certify their understanding of, compliance with and adherence to key global Ares policies, procedures and code of ethics. We maintain a compliance group, supervised by our Chief Compliance Officer, that is responsible for monitoring our compliance with the regulatory and legal requirements to which we are subject and managing our compliance policies and procedures. Our compliance policies and procedures seek to address a variety of regulatory and compliance risks such as the handling of material non-public information, position reporting, personal securities trading, valuation of investments on a fund-specific basis, document retention, potential conflicts of interest and the allocation of investment opportunities.
Many jurisdictions in which we operate have laws and regulations relating to data privacy, cybersecurity and protection of personal information, including the General Data Protection Regulation (“GDPR”), a European Union (“EU”) regulation designed to protect privacy rights of individuals residing in the European Economic Area (the “EEA”), the GDPR as it forms part of the laws of England and Wales, Scotland and Northern Ireland by virtue of Section 3 of the European Union Withdrawal Act 2018 (“U.K. GDPR”) with respect to individuals residing in the United Kingdom (the “U.K.”), and various privacy laws applicable to individuals residing in the U.S., including the California Consumer Privacy Act (the “CCPA”), as amended by the California Privacy Rights Act. Any failure to comply with such laws or regulations could result in fines, penalties and/or sanctions, which could be substantial, litigation as well as reputational harm. Moreover, to the extent that these laws and regulations or the enforcement of the same become more stringent, or if new laws or regulations or enacted, our financial performance or plans for growth may be adversely impacted.
U.S.
The SEC oversees the activities of our subsidiaries that are registered investment advisers under the Investment Advisers Act. The Financial Industry Regulatory Authority (“FINRA”) and the SEC oversee the activities of our wholly owned subsidiaries, AWMS and Ares Management Capital Markets LLC (formerly known as Ares Investor Services LLC) (“AMCM”), as registered broker-dealers. In connection with certain investments made by funds in our Private Equity Group, certain of our subsidiaries and funds are subject to audits by the Defense Security Service to determine whether we are under foreign ownership, control or influence. In addition, we regularly rely on exemptions from various requirements of the Securities Act of 1933, as amended (the “Securities Act”), the Securities Exchange Act of 1934, as amended (the “Exchange Act”), the Investment Company Act, the Commodity Exchange Act and the U.S. Employee Retirement Income Security Act of 1974, as amended (“ERISA”). These exemptions are sometimes highly complex and may in certain circumstances depend on compliance by third parties who we do not control.
Additionally, the SEC and various self-regulatory organizations have in recent years increased their regulatory activities in respect of investment management firms. See “Item 1A. Risk Factors—Risks Related to Regulation—Extensive regulation affects our activities, increases the cost of doing business and creates the potential for significant liabilities and penalties that could adversely affect our businesses and results of operations.” Effective September 2019, the SEC adopted a rule that requires a broker-dealer, or a natural person who is an associated person of a broker-dealer, to act in the best interest of a retail customer when making a recommendation of any securities transaction or investment strategy involving securities, without placing the financial or other interest of the broker, dealer or natural person who is an associated person of a broker-dealer making the recommendation ahead of the interest of the retail customer (“Regulation Best Interest”). The term “retail customer” is defined as a natural person who uses such a recommendation primarily for personal, family or household purposes, without reference to investor sophistication or net worth. The “best interest” standard is satisfied through compliance with certain disclosure, duty of care, conflict of interest mitigation and compliance obligations. Under Regulation Best Interest, high cost, high risk and complex products may be subject to greater scrutiny by broker-dealers and their salespersons. The impact of Regulation Best Interest and state fiduciary standards on broker-dealers cannot be determined at this time, as no administrative or case law currently exists under Regulation Best Interest and the full scope of its applicability is uncertain. However, it may negatively impact whether broker-dealers and their associated persons are willing to recommend investment products, including our funds, to retail customers. As such, Regulation Best Interest may reduce the ability of our funds to raise capital, which would adversely affect our business and results of operations.
Funds and Portfolio Companies of our Funds
All of our funds are advised by SEC registered investment advisers (or wholly owned subsidiaries thereof). Registered investment advisers are subject to more stringent requirements and regulations under the Investment Advisers Act than unregistered investment advisers. Such requirements relate to, among other things, fiduciary duties to clients, maintaining an effective compliance program, managing conflicts of interest and general anti-fraud prohibitions. In addition, the SEC requires investment advisers registered or required to register with the SEC under the Investment Advisers Act that advise one or more private funds and have at least $150 million in private fund assets under management to periodically file reports on Form PF. We have filed, and will continue to file, quarterly reports on Form PF, which has resulted in increased administrative costs and
a significant amount of attention and time to be spent by our personnel. The SEC has recently proposed changes to Form PF which, among other proposed requirements, would require reporting within one business day upon the occurrence of certain fund-level events, which, if enacted, could further increase related administrative costs and burdens.
Further, the SEC has highlighted valuation practices as one of its areas of focus in investment adviser examinations and has instituted enforcement actions against advisers for misleading investors about valuation. If the SEC were to investigate and find errors in our methodologies or procedures, we and/or members of our management could be subject to penalties and fines, which could harm our reputation and our business, financial condition and results of operations could be materially and adversely affected.
ARCC and ASIF are registered investment companies that have each elected to be treated as a business development company under the Investment Company Act. ARDC and certain other funds are registered investment companies under the Investment Company Act. Each of the registered investment companies has elected, for U.S. federal tax purposes, to be treated as a regulated investment company (“RIC”) under Subchapter M of the U.S. Internal Revenue Code of 1986, as amended (the “Code”). To maintain its RIC status under the Code, a RIC must timely distribute an amount equal to at least 90% of its investment company taxable income (as defined by the Code, which generally includes net ordinary income and net short term capital gains) to its stockholders. In addition, a RIC generally will be required to pay an excise tax equal to 4% on certain undistributed taxable income unless it distributes in a timely manner an amount at least equal to the sum of (i) 98% of its ordinary income recognized during a calendar year, (ii) 98.2% of its capital gain net income, as defined by the Code, recognized during the one-year period ending on October 31 of the calendar year, and (iii) any income recognized, but not distributed, in preceding years. The taxable income on which a RIC pays excise tax is generally distributed to its stockholders in the next tax year. Depending on the level of taxable income earned in a tax year, a RIC may choose to carry forward such taxable income for distribution in the following year, and pay any applicable excise tax. In addition, as a business development company, ARCC must not acquire any assets other than “qualifying assets” specified in the Investment Company Act unless, at the time the acquisition is made, at least 70% of ARCC’s total assets are qualifying assets (with certain limited exceptions). Qualifying assets include investments in “eligible portfolio companies.” ARCC is also generally prohibited from issuing and selling its common stock at a price below net asset value per share and from incurring indebtedness (including for this purpose, preferred stock), if ARCC’s asset coverage, as calculated pursuant to the Investment Company Act, equals less than 150% after such incurrence.
ACRE, AREIT and AIREIT have each elected and qualified to be taxed as a real estate investment trust, or REIT, under the Code. To maintain its qualification as a REIT, each must distribute at least 90% of its taxable income to its stockholders and meet, on a continuing basis, certain other complex requirements under the Code.
AWMS and AMCM, our wholly owned subsidiaries, are registered as broker-dealers with the SEC, maintain licenses in many states, and are members of FINRA. As a broker-dealer, each subsidiary is subject to regulation and oversight by the SEC and state securities regulators. In addition, FINRA promulgates and enforces rules governing the conduct of, and examines the activities of, its member firms. Due to the limited authority granted to each of our subsidiaries in its capacity as broker-dealers, they are not required to comply with certain regulations covering trade practices among broker-dealers and the use and safekeeping of customers’ funds and securities. As registered broker-dealers and members of a self-regulatory organization, AWMS and AMCM are, however, subject to the SEC’s uniform net capital rule. Rule 15c3-1 of the Exchange Act, which specifies the minimum level of net capital a broker-dealer must maintain and also requires that a significant part of a broker-dealer’s assets be kept in relatively liquid form. See “Item 1A. Risk Factors—Risks Related to Our Businesses—Political and regulatory conditions, including the effects of negative publicity surrounding the financial industry in general and proposed legislation, could adversely affect our businesses.”
Other Jurisdictions
Certain of our subsidiaries operate outside the U.S. In Luxembourg, Ares Management Luxembourg (“AM Lux”) is subject to authorization and regulation by the Commission de Surveillance du Secteur Financier (“CSSF”). In the U.K., Ares Management Limited (“AML”) and Ares Management U.K. Limited (“AMUKL”) are subject to regulation and authorization by the U.K. Financial Conduct Authority (the “FCA”). Ares European Loan Management LLP (“AELM”), which is not a subsidiary, but in which we are indirectly invested and which procures certain services from AML, is also subject to regulation by the FCA. In some circumstances, AML, AMUKL, AELM (the “U.K. Regulated Entities”) and other Ares entities are or may become subject to U.K. or EU laws, for instance in relation to marketing our funds to investors in the EEA.
The U.K. exited the EU on January 31, 2020. The withdrawal agreement which provided for a transitional period to allow for the terms of the U.K.’s future relationship with the EU to be negotiated, ended on December 31, 2020. EEA passporting rights are no longer available to the relevant U.K. entities following the end of the transitional period. Various EU laws were “on-shored” into domestic U.K. legislation and certain transitional regimes and deficiency-correction powers exist to
ease the transition. The Trade and Cooperation Agreement (the “TCA”) between the U.K. and the EU formally came into force on May 1, 2021 and since its effectiveness, the TCA has governed certain matters between the U.K. and the EU. In addition, the Temporary Marketing Permission Regime (the “TMPR”) allows our alternative investment fund managers (“AIFMs”) to continue to market those funds in the U.K. that were in existence on December 31, 2020, on broadly the same terms as previously applied. Unless extended, the TMPR lasts until December 31, 2025. Any marketing of a new fund coming into existence after December 31, 2020 must comply with the U.K.’s national private placement regime. Notwithstanding the TCA and the TMPR, there remains considerable uncertainty as to the nature of the U.K.’s future relationship with the EU, creating continuing uncertainty as to the full extent to which the businesses of the U.K. Regulated Entities and our businesses generally could be adversely affected by Brexit. See “Item 1A. Risk Factors—Risks Related to Regulation—The U.K.’s exit from the EU (“Brexit”) could adversely affect our business and our operations.” Despite the U.K.’s departure from the EU, new and existing EU legislation is expected to continue to impact our business in the U.K. (whether because its effect is preserved in the U.K. as a matter of domestic policy or because compliance with such legislation (whether in whole or part) is a necessary condition for market access into the EEA) and other EEA member states where we have operations. The U.K.’s departure has the potential to change the U.K. legislative and regulatory frameworks within which the U.K. Regulated Entities operate, which could adversely affect our businesses or cause a material increase in our tax liability.
AM Lux operates under the EU legislative frameworks. Notwithstanding the U.K.’s withdrawal from the EU, the U.K. Regulated Entities generally continue to be regulated under these frameworks to the extent they were preserved in U.K. law. In some circumstances other Ares entities are or may become subject to EU laws or the law of EEA member states, including with respect to marketing our funds to investors in the EEA.
AM Lux and AMUKL are both AIFMs. Their operations are primarily governed by Directive 2011/61/EU on Alternative Investment Fund Managers and other associated legislation, rules and guidance (“AIFMD”). The U.K. implemented AIFMD while it was still a member of the EU and similar requirements therefore continue to apply in the U.K. notwithstanding Brexit. The AIFMD imposes significant regulatory requirements on AIFMs established in the EEA. AIFMD regulates fund managers by, amongst other things, prescribing authorization conditions for an AIFM, restricting the activities that can be undertaken by an AIFM and prescribing the organizational requirements, operating conditions, and regulatory standards relating to such things as initial capital, remuneration, conflicts, risk management, leverage, liquidity management, delegation of duties, transparency and reporting requirements.
In the EU (but not the U.K.), AIFMD is currently under review. On November 25, 2021, the European Commission published draft legislation, commonly referred to as “AIFMD II”. On May 16, 2022, the European Parliament issued its draft report on the European Commission’s proposals, and on June 21, 2022, the Council of the EU published its compromise text. Subject to the EU ordinary legislative process involving the European Parliament and the Council of the EU, this is expected to result in certain amendments to AIFMD, which will affect firms two years after the legislation comes into force, possibly in 2025. It is not yet clear to what extent (if any) the U.K. will seek to reflect AIFMD II in its domestic rules implementing AIFMD.
AML and AELM are both investment firms within the meaning of Directive 2014/65/EU on Markets in Financial Instruments (“MiFID II”). Notwithstanding Brexit, the U.K.’s rules implementing MiFID II continue to have effect and the accompanying Markets in Financial Instruments Regulation 600/2014/EU (“MiFIR”) has been on-shored into U.K. law in connection with this withdrawal. The operations of AML and AELM are primarily governed by U.K. laws and regulatory rules implementing MiFID II, MiFIR and other associated legislation, rules and guidance. AMUKL is subject to certain provisions of U.K.-retained MiFID II because it has top-up permissions to provide certain U.K.-retained MiFID investment services. AM Lux is subject to certain provisions of EU MiFID II because it has top-up permissions to provide certain MIFID investment services. The main business of AM Lux and the U.K. Regulated Entities is to provide asset management services to clients in Europe.
MiFID II and MiFIR extended the Markets and Financial Instruments Directive (“MiFID”) requirements in a number of areas with more prescriptive and onerous obligations with respect to costs and charges disclosure, product design and governance, the receipt and payment of inducements, the receipt of and payment for investment research, suitability and appropriateness assessments, conflicts of interest, record-keeping, best execution, transaction and trade reporting, remuneration, training and competence and corporate governance. Certain aspects of MIFID II and MiFIR are subject to review and change in both the EU and the U.K.
Effective January 1, 2022, the U.K. introduced a new prudential regulatory framework for U.K. investment firms (the “Investment Firm Prudential Regime” or “IFPR”). IFPR applies to AML and AELM as U.K. MiFID investment firms as well as to AMUKL, as a U.K. AIFM with MiFID “top-up” permissions. Under IFPR, among other requirements, AML, AMUKL and AELM will be required to maintain a more onerous policy on the way in which it remunerates its staff, to set an appropriate ratio between the variable and fixed components of total remuneration and to meet requirements on the structure of variable remuneration. AML and AMUKL are considered to be part of the same “prudential consolidation group”, and many of the
requirements of IFPR (including but not limited to capital, liquidity and remuneration) will apply at the consolidated group level. Importantly, the broad discretion that previously exempted U.K. firms from certain remuneration rules on the basis of “proportionality” does not apply in relation to IFPR. Under IFPR, each of AML, AMUKL and AELM will have to make public disclosures on its website in relation to its: (i) own funds, own funds requirements and governance structures; (ii) risk management; and (iii) remuneration. The new public disclosure requirements mandate more detail, including quantitative information on remuneration paid to staff, split in between classes of employees, and confirmation of the highest severance payment awarded to an individual material risk taker. As a new regime, operating the relevant requirements may lead to additional operational and compliance complexity in the short to medium term and possibly higher regulatory capital requirements for the affected firms.
The U.K. is introducing an important and substantial regime, the Consumer Duty, designed to improve outcomes for retail investors, aspects of which will begin to apply from July 31, 2023. Although Ares entities do not generally deal with consumers in the ordinary sense, the regime will apply to certain of our funds. On December 2, 2022, the FCA published a consultation proposal which would, if implemented, remove an important exemption that is currently available to asset managers of investment funds and potentially make the impact of the Consumer Duty more significant. This could have important implications for Ares entities that are unable to rely on another exemption.
Our operations and our investment activities worldwide are subject to a variety of regulatory regimes that vary by country. These include operating subsidiaries of Ares SSG Capital Holdings Limited, which are subject to regulation by various regulatory authorities, including the Securities and Futures Commission of Hong Kong and Monetary Authority of Singapore. In addition, as the ultimate parent of the controlling entity of Aspida Re, a Bermuda Class E insurance company, we are considered its “shareholder controller” (as defined in the Bermuda Insurance Act) by the Bermuda Monetary Authority (the “BMA”).
Competition
The investment management industry is intensely competitive, and we expect it to remain so. We compete globally and on a regional, industry and asset basis.
We face competition both in the pursuit of fund investors and investment opportunities. Generally, our competition varies across business lines, geographies and financial markets. We compete for outside investors based on a variety of factors, including investment performance, investor perception of investment managers’ drive, focus and alignment of interest, quality of service provided to and duration of relationship with investors, breadth of our product offering, business reputation and the level of fees and expenses charged for services. We compete for investment opportunities both at our funds and for strategic acquisitions by us based on a variety of factors, including breadth of market coverage and relationships, access to capital, transaction execution skills, the range of products and services offered, innovation and price.
We face competition in our direct lending, trading, acquisitions and other investment activities primarily from traditional asset managers, business development companies, specialized funds, investment managers and other financial institutions, and we expect that competition will continue to increase. Many of these competitors in some of our businesses are substantially larger and have considerably greater financial, technical and marketing resources than are available to us. Many of these competitors have similar investment objectives to us, which may create additional competition for investment opportunities. Some of these competitors may also have a lower cost of capital and access to funding sources that are not available to us, which may create competitive disadvantages for us with respect to investment opportunities. In addition, some of these competitors may have higher risk tolerances, different risk assessments or lower return thresholds, which could allow them to consider a wider variety of investments and to bid more aggressively than us for investments that we want to make. Corporate buyers may be able to achieve synergistic cost savings with regard to an investment that may provide them with a competitive advantage in bidding for an investment. Lastly, institutional and individual investors are allocating increasing amounts of capital to alternative investment strategies. Several large institutional investors have announced a desire to consolidate their investments in a more limited number of managers. We expect that this will cause competition in our industry to intensify and could lead to a reduction in the size and duration of pricing inefficiencies that many of our funds seek to exploit.
Competition is also intense for the attraction and retention of qualified employees. Our ability to continue to compete effectively in our businesses will depend upon our ability to attract new employees and retain and motivate our existing employees.
For additional information concerning the competitive risks that we face, see “Item 1A. Risk Factors—Risks Related to Our Businesses—The investment management business is intensely competitive.”
Available Information
Ares Management Corporation is a Delaware corporation. Our principal executive offices are located at 2000 Avenue of the Stars, 12th Floor, Los Angeles, California 90067, and our telephone number is (310) 201-4100.
Our website address is http://www.aresmgmt.com. Information on our website is not a part of this report and is not incorporated by reference herein. We make available free of charge on our website or provide a link on our website to our Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K, proxy statements and any amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act, as soon as reasonably practicable after those reports are electronically filed with, or furnished to, the SEC. To access these filings, go to the “Investor Resources” section of our website and then click on “SEC Filings.” In addition, these reports and the other documents we file with the SEC are available at a website maintained by the SEC at http://www.sec.gov.
Previous: Cover and table of contents · Next: Item 1A. Risk Factors