 filings.tools
Item 1. BUSINESS
78K characters. Original on sec.gov · Markdown
Item 1. BUSINESS
Our Company
With a history dating back to 1886, American Water is the largest and most geographically diverse, publicly-traded water and wastewater utility company in the United States, as measured by both operating revenues and population served. A holding company originally incorporated in Delaware in 1936, we employ approximately 6,900 professionals who provide drinking water, wastewater and other related services to an estimated 15 million people in 46 states, the District of Columbia and Ontario, Canada. The largest component of the Company’s business includes rate regulated subsidiaries that provide water and wastewater services, collectively presented as our “Regulated Businesses.” We conduct the majority of our business through the Regulated Businesses segment. We also operate several market-based businesses that provide a broad range of related and complementary water and wastewater services within four operating segments that individually do not meet the criteria of a reportable segment in accordance with generally accepted accounting principles in the United States (“GAAP”). These four, non-reportable operating segments are collectively presented as our “Market-Based Businesses,” which is consistent with how management assesses the results of these businesses.
Throughout this Annual Report on Form 10-K (this “Form 10-K”), unless the context otherwise requires, references to “we,” “us,” “our,” the “Company,” and “American Water” mean American Water Works Company, Inc. and its subsidiaries, taken together as a whole. References to “parent company” mean American Water Works Company, Inc., without its subsidiaries.
Regulated Businesses
Our primary business involves the ownership of utilities that provide water and wastewater services to residential, commercial, industrial, public authority, fire service and sale for resale customers. Our utilities operate in approximately 1,600 communities in 16 states in the United States, with approximately 3.4 million active customer connections to our water and wastewater networks. Services provided by our utilities are generally subject to economic regulation by certain state utility commissions or other entities engaged in utility regulation, collectively referred to as Public Utility Commissions (“PUCs” or “Regulators”). Certain federal, state and local governments also regulate environmental, health and safety, and water quality matters. We report the results of the services provided by our utilities in our Regulated Businesses segment. Operating revenues for our Regulated Businesses were $2,958 million for 2017, $2,871 million for 2016 and $2,743 million for 2015, accounting for 88%, 87% and 87%, respectively, of the Company’s total operating revenues for the same periods.
The following table geographically summarizes our Regulated Businesses’ operating revenues and the number of customers we serve by type of service, each as of and for the year ended December 31, 2017:
| Operating Revenues (In millions) | Number of Customers (In thousands) | |||||||||||||||||||||||||
| Water (a) | Wastewater | Total | % of Total | Water | Wastewater | Total | % of Total | |||||||||||||||||||
| New Jersey | $ | 698 | $ | 41 | $ | 739 | 25.0 | % | 639 | 48 | 687 | 20.5 | % | |||||||||||||
| Pennsylvania | 617 | 44 | 661 | 22.3 | % | 658 | 64 | 722 | 21.5 | % | ||||||||||||||||
| Illinois | 284 | 20 | 304 | 10.3 | % | 284 | 33 | 317 | 9.5 | % | ||||||||||||||||
| Missouri | 280 | 9 | 289 | 9.8 | % | 466 | 13 | 479 | 14.3 | % | ||||||||||||||||
| Indiana | 222 | — | 222 | 7.5 | % | 302 | — | 302 | 9.0 | % | ||||||||||||||||
| California | 219 | 3 | 222 | 7.5 | % | 175 | 3 | 178 | 5.3 | % | ||||||||||||||||
| West Virginia | 143 | 1 | 144 | 4.9 | % | 166 | 1 | 167 | 5.0 | % | ||||||||||||||||
| Total - Top Seven States (b) | 2,463 | 118 | 2,581 | 87.3 | % | 2,690 | 162 | 2,852 | 85.1 | % | ||||||||||||||||
| Other states (c) | 353 | 24 | 377 | 12.7 | % | 470 | 31 | 501 | 14.9 | % | ||||||||||||||||
| Total Regulated Businesses | $ | 2,816 | $ | 142 | $ | 2,958 | 100.0 | % | 3,160 | 193 | 3,353 | 100.0 | % |
| (a) | Includes Other operating revenues, consisting primarily of fees, miscellaneous service charges and rents. |
| (b) | Our “Top Seven States” are determined based upon operating revenues. |
| (c) | Includes our utilities in the following states: Georgia, Hawaii, Iowa, Kentucky, Maryland, Michigan, New York, Tennessee and Virginia. |
See Item 7—Management’s Discussion and Analysis of Financial Condition and Results of Operations and Note 19—Segment Information in the Notes to Consolidated Financial Statements for additional information.
Customers
Our Regulated Businesses have a large and geographically diverse customer base. A customer is defined as a person, business, municipality or any other entity that purchases our water or wastewater services as of the last business day of a reporting period. One single customer may purchase our services for use by multiple individuals or businesses, as is the case in many homes, apartment complexes, businesses and governmental entities.
The vast majority of our regulated water customers are metered, which allows us to measure and bill for our customers’ water usage, typically on a monthly basis. We employ a variety of methods of customer meter reading to monitor consumption. These methods range from meters with mechanical registers where consumption is manually recorded by meter readers, to meters with electronic registers capable of transmitting consumption data to proximity devices (touch read) or via radio frequency to mobile or fixed network data collectors. Our wastewater customers are billed either a flat rate or based upon their water consumption.
Residential customers make up a substantial portion of our customer base in all of the states in which we operate. We also serve: (i) commercial customers, such as hospitals, food and beverage providers and energy suppliers; (ii) industrial customers, such as large-scale manufacturers, mining and production operations; and (iii) public authorities, such as government buildings and other public sector facilities, including schools. In addition, we supply water through our distribution systems to public fire hydrants for firefighting purposes, to private fire customers for use in fire suppression systems in office buildings and other facilities, and to other water utilities and community water systems in the form of bulk water supplies for distribution to their own customers.
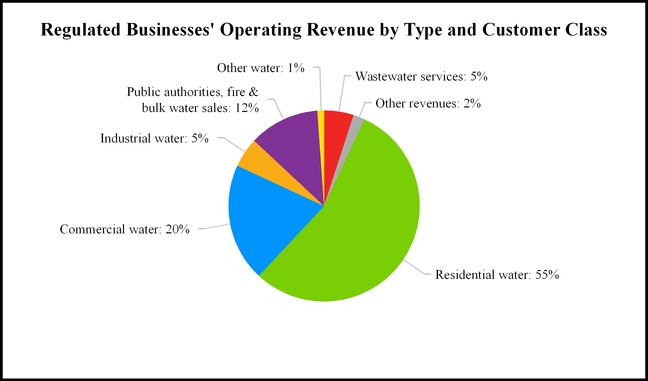
The following chart depicts the allocation of our Regulated Businesses’ operating revenue by type, including a breakout of the total water services revenues by class of customer, for the year ended December 31, 2017:
The following table summarizes the number of water and wastewater customers we served by class as of December 31:
| 2017 | 2016 | 2015 | |||||||||||||||
| (In thousands) | Water | Wastewater (a) | Water | Wastewater | Water | Wastewater | |||||||||||
| Residential | 2,872 | 182 | 2,846 | 171 | 2,829 | 133 | |||||||||||
| Commercial | 221 | 11 | 220 | 10 | 219 | 8 | |||||||||||
| Industrial | 4 | — | 4 | — | 4 | — | |||||||||||
| Public & other | 63 | — | 61 | — | 60 | — | |||||||||||
| Total | 3,160 | 193 | 3,131 | 181 | 3,112 | 141 |
| (a) | In 2017, we acquired substantially all of the wastewater collection and treatment system assets of the Municipal Authority of the City of McKeesport, Pennsylvania (the “McKeesport system”). This acquisition included approximately 22,000 customer equivalents in total; comprised of 11,000 customer connections, which are reflected in the 2017 residential customer count in the table above, as well as service to an additional 11,000 customers under bulk contracts to 13 municipalities in Allegheny County, Pennsylvania. |
Customer growth in our Regulated Businesses is primarily driven by: (i) adding new customers to our customer base through acquisitions of water and/or wastewater utility systems; (ii) organic population growth (or decline) in our authorized service areas; and (iii) sale of water to other water utilities and community water systems.
Capital Investment
On an annual basis, approximately 2 trillion gallons of treated water are lost in the United States through more than 240,000 main breaks at an estimated cost of $2.6 billion. This represents approximately 20% of all treated water in the country. In addition, every year approximately 900 billion gallons of untreated sewage is discharged into the country’s rivers and streams. The aging water and wastewater infrastructure in the United States is in need of replacement and modernization. In 2017, the American Society of Civil Engineers published its Report Card for America’s Infrastructure, in which it gave the drinking water industry a grade of “D” and the wastewater infrastructure a grade of “D+,” primarily because much of the infrastructure is nearing the end of its useful life. As documented in the American Water Works Association’s (the “AWWA”) Buried No Longer: Confronting America’s Water Infrastructure Challenge, restoring the country’s existing water systems as they reach the end of their useful lives and expanding them to serve a growing population will cost at least $1 trillion between 2011 and 2035, if we are to maintain current levels of water service. In addition, increased regulation related to water quality and the management of water and wastewater residuals’ discharges, which began with the passage of the Clean Water Act in 1972 and the Safe Drinking Water Act in 1974, is also a primary driver for the need to modernize.
To address the growing infrastructure needs in the areas we serve, we plan to invest $7.2 billion over the next five years, including a range of $1.4 billion to $1.5 billion in 2018, for capital improvements to our Regulated Businesses’ water and wastewater infrastructure, largely aimed for pipe replacement and upgrading aging water and wastewater treatment facilities. We have proactively doubled our pipe renewal rate over a five year period, from 2011 to 2016, from a 250 year replacement cycle to a 120 year replacement cycle, which we anticipate will enable us to replace nearly 2,000 miles of mains and collection pipes over the next five years. In addition, during this same five year period, capital investment in treatment plants, storage tanks and other key, above-ground facilities has increased over 10%, further addressing aging infrastructure and emerging regulatory compliance needs.
Economic Regulation and Rate Making
Our Regulated Businesses operate under a regulatory compact whereby, in exchange for exclusive rights to provide water and wastewater services in defined service territories, we have an obligation to serve customers within those territories requesting service, within reasonable limits. In return for agreeing to invest capital into our water and wastewater systems, we are given the opportunity to recover our costs of doing business and earn a reasonable rate of return on our investments.
The operations of our Regulated Businesses are generally subject to economic regulation by PUCs in the state in which they operate, with the primary responsibility of the PUCs to promote the overall public interest by balancing the interest of customers and utility investors. Specific authority might differ from state to state, but in most states PUCs approve rates charged to customers, accounting treatments, long-term financing programs and cost of capital, capital expenditures, O&M expenses, taxes, transactions and affiliate relationships, reorganizations and mergers and acquisitions. Regulatory policies vary from state to state and could potentially change over time. These policies will affect the timing, as well as the extent, of recovery of expenses and the realized return on invested capital.
The process to obtain approval for a change in rates generally occurs by way of a rate case filed by the utility with the PUC on a periodic basis. The timing of rate case filings is typically determined by either periodic requirements in the regulatory jurisdiction or by the utility’s need to increase its revenue to recover capital investment costs, changes in operating revenues, operating costs or other market conditions. Our rate case management program is guided by the principles of obtaining timely recovery of capital investment costs, recognition of declining sales resulting from reduced consumption and appropriate recovery of utility operating and maintenance costs, including costs incurred for compliance with environmental regulations. The program attempts to minimize “regulatory lag,” the time between the occurrence of an event that triggers a change in the utility’s revenue requirement and its recognition in rates. It is, for example, the time between when an investment in plant is placed into service for the benefit of the customer and when the Company can begin earning a return of and on the investment through the ratemaking process. It also applies to the lag in the recognition in rate recovery of changes in expenses and revenues.
Our Regulated Businesses support regulatory practices at the PUCs and state legislatures that mitigate the adverse impact of regulatory lag. Examples of approved regulatory practices include:
| Regulatory Practices | Description | States Allowed | ||
| Infrastructure replacement surcharges | Allows rates to change periodically, outside a general rate proceeding, to reflect recovery of investments made to replace infrastructure necessary to sustain safe, reliable services for our customers. These mechanisms typically involve periodic filings and reviews, to ensure transparency. | IA, IL, IN, MO, NJ, NY, PA, TN, VA, WV | ||
| Future test year | A test period used for setting rates, that begins with the date new rates are effective. This allows current or projected revenues, expenses and investments to be collected on a timelier basis. | CA, HI, IL, IN, KY, NY, PA, TN, VA | ||
| Hybrid test year | Allows an update to historical data for “known and measurable” changes that occur subsequent to the historical test year. | IA, MD, MO, NJ, WV | ||
| Utility plant recovery mechanisms | Allows recovery of the full return on utility plant costs during the construction period, instead of capitalizing an allowance for funds used during construction. In addition, some states allow the utility to seek pre-approval of certain capital projects and associated costs. In this pre-approval process, the PUC may assess the prudency of such projects. | CA, IL, KY, NY, PA, TN, VA | ||
| Expense mechanisms | Allows changes in certain operating expenses, which may fluctuate based on conditions beyond the utility’s control, to be recovered outside of a general rate proceeding or deferred until the next general rate proceeding. | CA, IL, MD, MO, NJ, NY, PA, TN, VA, WV | ||
| Revenue stability mechanisms | Separates a water utility’s cost recovery from the amount of water it sells to recover its fixed costs and on-going infrastructure investment needs. Such a mechanism adjusts rates periodically to ensure that a utility’s revenue will be sufficient to cover its costs regardless of sales volume, including recognition of declining sales resulting from reduced consumption, while providing an incentive for customers to use water more efficiently. | CA, IL, NY | ||
| Consolidated tariffs | Use of a unified rate structure for water systems owned and operated by a single utility, which may or may not be physically interconnected. The consolidated tariff pricing structure may be used fully or partially in a state and is generally used to prioritize capital investments and moderate the impact of periodic fluctuations in local costs while lowering administrative costs for customers. Pennsylvania also permits a blending of water and wastewater revenue requirements. | IA, IL, IN, KY, MD, MO, NJ, PA, VA, WV |
We pursue or seek enhancement to these regulatory practices to facilitate efficient recovery of our costs and investments in order to continue to provide safe, reliable and affordable services to our customers. The ability to seek regulatory treatment as described above does not guarantee that the state PUCs will accept our proposal in the context of a particular rate case, and these practices may reduce, but not eliminate, regulatory lag associated with traditional rate making processes. It is also our strategy to expand their use in areas where they may not currently apply.
Acquisitions and Strategic Growth
The U.S. water and wastewater industries include investor-owned systems as well as municipal systems that are owned and operated by local governments or governmental subdivisions. Both industries are highly fragmented. According to the Environmental Protection Agency (“EPA”), approximately 84% of the United States water market is served by municipal systems and approximately 98% of the country’s wastewater systems are government owned. The EPA also estimates that there are approximately 50,000 community water systems and approximately 20,000 community wastewater systems in the United States, with over half of the community water systems serving a population of 500 or less. This large number of relatively small, fragmented water and wastewater systems may result in inefficiencies in the marketplace, since such utilities may not have the operating expertise, financial and technological capability or economies of scale to provide services or raise capital as efficiently as larger utilities. Larger utilities that have greater access to capital are generally more capable of making mandated and other necessary infrastructure upgrades to their water and wastewater systems. In addition, water and wastewater utilities with large customer bases, spread across broad geographic regions, may more easily absorb the impact of significant variations in precipitation and temperatures, such as droughts, excessive rain and cool or warm temperatures in specific areas. Larger utilities generally are able to spread support services over a larger customer base, thereby reducing the costs to serve each customer. Since many administrative and support activities can be efficiently centralized to gain economies of scale, companies that participate in industry consolidation have the potential to improve operating efficiencies, lower costs per unit and improve service at the same time.
A fundamental aspect of our growth strategy is to pursue acquisitions of small and medium water and/or wastewater systems of between 1,000 and 30,000 customer connections, in close geographic proximity to areas where we operate our Regulated Businesses. The close proximity of acquisition opportunities to our regulated footprint allows us to integrate and manage the acquired systems and operations primarily using our existing management and to achieve operational efficiencies and prioritize capital investment needs. Our current customer mix of 94% water and 6% wastewater also presents strategic opportunities for wastewater growth and systems consolidation, adding wastewater customers where we already serve water customers. We intend to continue to expand our regulated footprint geographically by acquiring water and wastewater systems in our existing markets and, if appropriate, pursue acquisition opportunities in certain domestic markets where we do not currently operate our Regulated Businesses. Before entering new regulated markets, we will evaluate the business and regulatory climates to ensure that we will have the opportunity to achieve an appropriate rate of return on our investment while maintaining our high standards for providing safe, reliable and affordable services to our customers, as well as a line of sight to grow our base customers to a significant level to attain efficiencies after entering the new market.
More stringent environmental, health and safety, and water quality regulations, the amount of infrastructure in need of significant capital investment and financial challenges are driving more municipalities to consider selling their water and wastewater assets. For example, in 2015, New Jersey enacted the Water Infrastructure Protection Act, which allows municipalities with a water or wastewater system that meets certain emergent conditions, to allow it to sell the system on an expedited basis without a referendum. Also, in 2017, New Jersey enacted the Water Quality Accountability Act, which sets new operational standards for all water utilities in New Jersey, including municipal and investor-owned utilities. This law imposes new requirements in areas such as cybersecurity, asset management, water quality reporting, remediation of notices of violation, and hydrant and valve maintenance.
We also support full optionality for municipalities, including state legislation that enables the consolidation of the largely fragmented water and wastewater industries through fair market valuations of purchased property and the consolidation of water and wastewater rates. Our Regulated Businesses in California, Illinois, Indiana, Missouri, New Jersey and Pennsylvania have access to fair market value legislation for private sector investment in public sector systems. Fair market value assessment of water and wastewater systems is an alternative to the traditional depreciated original cost method of valuation, providing municipalities with a fair and objective purchase price that is more reflective of the assets’ value, while the utility has increased assurance of recovering investment over the life of the assets. Ultimately, we believe that many communities could benefit from receiving safe and reliable water and wastewater service from an experienced utility with proven access to capital and financial, technical, and managerial resources.
Consolidated tariffs use a unified rate structure for systems owned and operated by a single utility, which may or may not be physically interconnected. Consolidated tariff pricing moderates the impact of periodic fluctuations in local costs and promotes a more universal water infrastructure investment in the state. As a result, consolidated tariffs can make it easier to incorporate new systems into an existing utility and can ensure economies of scale for even the smallest of systems and prioritize capital needs across the state. Overall, this brings cost-effective, higher quality services to a larger number of citizens. Ten of our regulated subsidiaries currently have some form of consolidated tariff pricing, including Illinois, Indiana, Iowa, Kentucky, Maryland, Missouri, New Jersey, Pennsylvania, Virginia, and West Virginia.
Competition
In our Regulated Businesses, we generally do not face direct competition in our existing markets because: (i) we operate in those markets pursuant to certificates of public convenience and necessity (or similar authorizations) issued by state PUCs; and (ii) the high cost of constructing a new water and wastewater system in an existing market creates a high barrier to market entry. However, our Regulated Businesses do face competition from governmental agencies, other investor-owned utilities, large industrial customers with the ability to provide their own water supply/treatment process and strategic buyers that are entering new markets and/or making strategic acquisitions. When pursuing acquisitions, our largest investor-owned competitors, based on a comparison of operating revenues and population served, are Aqua America, Inc., Suez North America, American States Water Company and California Water Service Group. From time to time, we also face competition from infrastructure funds, multi-utility companies and others, such as Algonquin Power and Utilities Corp. and Corix.
Condemnation and Eminent Domain
All or portions of our Regulated Businesses’ utility assets could be acquired by state, municipal or other government entities through one or more of the following methods: (i) eminent domain (also known as condemnation); (ii) the right of purchase given or reserved by a municipality or political subdivision when the original certificate of public convenience and necessity was granted; and (iii) the right of purchase given or reserved under the law of the state in which the utility subsidiary was incorporated or from which it received its certificate. The acquisition consideration related to such a proceeding initiated by a local government may be determined consistent with applicable eminent domain law, or may be negotiated or fixed by appraisers as prescribed by the law of the state or in the particular franchise or charter.
Furthermore, the law in certain jurisdictions in which our Regulated Businesses operate, including, for example, California, provides for eminent domain rights allowing private property owners to seek just compensation against a public utility, if a public utility’s infrastructure has been determined to be a substantial cause of damage to that property. In these actions, the plaintiff would not have to prove that the public utility acted negligently. These actions have occurred in connection with events such as floods, mudslides and debris flow, broken water mains, landslides and wild and brush fires.
Water Supply and Wastewater Services
Our Regulated Businesses generally own the physical assets used to store, pump, treat and deliver water to our customers and collect, treat, transport and recycle wastewater. Typically, we do not own the water itself, which is held in public trust and is allocated to us through contracts, permits and allocation rights granted by federal and state agencies or through the ownership of water rights pursuant to local law. We are dependent on defined sources of water supply and obtain our water supply from surface water sources such as reservoirs, lakes, rivers and streams; from groundwater sources, such as wells and aquifers; and water purchased from third party water suppliers. The level of treatment we apply to the water varies significantly depending upon the quality of the water source and customer stipulations. Surface water sources typically generally require significant treatment, while groundwater sources require chemical treatment only.
The following chart depicts our sources of water supply as of December 31, 2017:
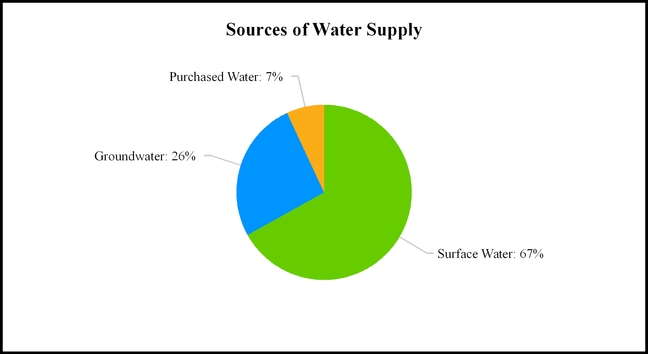
The percentages of water supply by source type for our top seven states for 2017 were as follows:
| Surface Water | Ground Water | Purchased Water | |||
| New Jersey | 72% | 24% | 4% | ||
| Pennsylvania | 91% | 7% | 2% | ||
| Illinois | 53% | 36% | 11% | ||
| Missouri | 80% | 19% | 1% | ||
| Indiana | 44% | 56% | — | ||
| California | — | 65% | 35% | ||
| West Virginia | 100% | — | — |
Our ability to meet the existing and future water demands of our customers depends on an adequate water supply. Drought, governmental restrictions, overuse of sources of water, the protection of threatened species or habitats, contamination or other factors may limit the availability of ground and surface water. We employ a variety of measures in an effort to obtain adequate sources of water supply, both in the short-term and over the long-term. The geographic diversity of our service areas may mitigate some of the economic effects on the water supply associated with weather extremes we might encounter in any particular service territory. For example, in any given summer, some areas may experience drier than average weather, which may reduce the amount of source water available, while other areas we serve may experience wetter than average weather.
In our long-term planning, we evaluate quality, quantity, growth needs and alternate sources of water supply as well as transmission and distribution capacity. Water supply is seasonal in nature and weather conditions can have a pronounced effect on supply. In order to ensure that we have adequate water supply, we use long-term planning processes and maintain contingency plans to minimize the potential impact on service caused by climate variability and a wide range of weather fluctuations. In connection with supply planning for most surface or groundwater sources, we employ models to determine safe yields under different rainfall and drought conditions. Surface and ground water levels are routinely monitored so that supply capacity deficits may, to the extent possible, be predicted and mitigated through demand management and additional supply development. An example of our use of long-term planning to ensure that we have adequate water supply is our involvement in the Monterey Peninsula Water Supply Project (the “Water Supply Project”) in California. The Water Supply Project includes the construction of a desalination plant, owned by California-American Water Company (“Cal Am”), our wholly owned subsidiary, and the construction of wells that would supply water to the desalination plant. In addition, the Water Supply Project also includes Cal Am’s purchase of water from a groundwater replenishment project between the Monterey Regional Water Pollution Control Agency and the Monterey Peninsula Water Management District (the “MPWMD”). The Water Supply Project is intended, among other things, to fulfill obligations of Cal Am to eliminate unauthorized diversions from the Carmel River as required under orders of the California State Water Resources Control Board (the “SWRCB”).
Wastewater services involve the collection of wastewater from customers’ premises through sewer lines. The wastewater is then transported through a sewer network to a treatment facility, where it is treated to meet required regulatory standards for wastewater before being returned to the environment. The solid waste by-product of the treatment process is disposed of or recycled in accordance with applicable standards and regulations.
Seasonality
Customer demand for our water service is affected by weather and tends to vary with temperature, rainfall levels and the frequency of rainfall. Customer demand is generally greater during the warmer months, primarily due to increased water usage for irrigation systems and other outdoor water use. As such, we typically expect our operating revenues to be the highest in the third quarter of each year. Weather that is hotter and drier than average generally increases operating revenues whereas, weather that is cooler and/or wetter than average generally serves to suppress customer water demand and can reduce water operating revenues. Three of our jurisdictions, California, Illinois and New York, have adopted revenue stability mechanisms which permit us to collect state PUC-authorized revenue for a given period which is not tied to the volume of water sold during that period, thereby lessening the impact of weather variability. See “Economic Regulation and Rate Making” for additional information regarding revenue stability mechanisms.
Market-Based Businesses
Through our Market-Based Businesses, we provide a broad range of related and complementary water and wastewater services to military bases, municipalities, gas exploration and production companies, as well as commercial, industrial and residential customers. These businesses are not subject to economic regulation by state PUCs and the services provided do not require significant capital investment. Operating revenues for our Market-Based Businesses were $422 million for 2017, $451 million for 2016 and $434 million for 2015, accounting for 13%, 14% and 14%, respectively, of the Company’s total operating revenues for the same periods. Included within our Market-Based Businesses’ results is operating revenues attributed to Canadian operations of $5 million for 2017 and $6 million for both 2016 and 2015, respectively.
Our Market-Based Businesses are comprised of four operating segments:
| • | Military Services Group, which enters into long-term contracts with the U.S. government to provide water and wastewater services on various military bases; |
| • | Homeowner Services Group, which provides warranty-type services to homeowners and smaller commercial customers to protect against the cost of repairing broken or leaking water pipes and clogged or blocked sewer pipes on their premises, and other services; |
| • | Contract Operations Group, which enters into contracts with municipal, commercial and industrial customers, primarily to operate and manage water and wastewater facilities and other related services; and |
| • | Keystone Clearwater Solutions, LLC (“Keystone”), which provides customized water service and management solutions for natural gas exploration and production companies and customers in the municipal water services market. |
Military Services Group
Our Military Services Group has been granted contracts to operate on 13 military bases under 50-year contracts with the U.S. government as part of its Utility Privatization Program. See Item 7—Management’s Discussion and Analysis of Financial Condition and Results of Operations—Strategic Focus and 2017 Achievements—Growth for additional information. The scope of these contracts generally includes the O&M of the bases’ water and wastewater systems and a capital program focused on asset replacement and, in certain instances, systems expansion. The replacement of assets assumed when a contract is awarded to the Company is funded from the contract fee. At times, new assets are required to support the base’s mission and the construction of these assets are funded by the U.S. government as additional work under the contract. The current capital program does not use the Company’s equity or debt borrowings; however, we may make limited short-term working capital investments under these contracts and some working capital is used to fund work-in-process until paid by the U.S. government.
The contract price for nine of our contracts with the U.S. government is subject to redetermination two years after commencement of operations, and every three years thereafter. Price redetermination is a contract mechanism to periodically adjust the service fee in the next period to reflect changes in contract obligations and anticipated market conditions. The remaining four contracts with the U.S. government are subject to annual price adjustments under a mechanism similar to price redetermination, called “Economic Price Adjustment.” All of these contracts may be terminated, in whole or in part, prior to the end of the 50-year term for convenience of the U.S. government or as a result of default or non-performance by the subsidiary performing the contract. In either event, pursuant to termination provisions applicable to these contracts, we would be entitled to recover allowable costs that we may have incurred under the contract, plus the contract profit margin on incurred costs. Our backlog of revenue associated with our contracts with the U.S. government is approximately $3.6 billion, with an average remaining contract term of 42 years.
Homeowner Services Group
Our Homeowner Services Group, through our various protection programs, provides services to domestic homeowners and smaller commercial customers to protect against repair costs for interior and external water and sewer lines, interior electric lines, heating and cooling systems and water heaters, as well as power surge protection and other related services. Our LineSaver™ program involves partnering with utilities, municipalities and other organizations to offer our protection programs to customers serviced by or affiliated with those municipalities and organizations. Terms of these partnership agreements are typically three to five years in length, with optional renewals. As of December 31, 2017, our Homeowner Services Group had approximately 1.7 million customer contracts in 43 states and the District of Columbia, and 10 LineSaver™ partnership agreements with municipalities and other organizations.
Contract Operations Group
Our Contract Operations Group enters into contracts to provide O&M services, including the delivery of design-build-operate projects and the provision of water and wastewater operations, maintenance and management services, to municipal and regional governmental entities through public-private partnerships, as well as industrial customers who possess a wide range of water quality and regulatory compliance needs. Historically, we have made minimal long-term capital investment under these contracts; instead we perform our services for a fee. Occasionally, we provide our customers with financing for capital projects as part of a long-term O&M partnership. As of December 31, 2017, our Contract Operations Group had 33 contracts across the United States and Canada, varying in size and scope, with an average remaining contract term of 3 years. In the course of pursuing our long-term strategy and growth initiatives for our Market-Based Businesses, we will concentrate on optimizing the portfolio of contracts in our Contract Operations Group, which will involve strategic decisions around the pursuit of renewals of our current contracts approaching expiration, as well as the sale of certain contracts that fall outside of our strategic focus.
Keystone
In July 2015, we acquired a 95% interest in Water Solutions Holdings, LLC, including its wholly owned subsidiary, Keystone. Keystone is a water service and management solutions company that serves natural gas exploration and production customers in the Appalachian Basin, as well as customers in the municipal water services market. Keystone is primarily focused on customized water transfer, sourcing, recycling and storage services, along with pipeline construction and related O&M services. Keystone operates under master service agreements that are generally shorter term in nature. When the initial term of these agreements expire, they typically renew automatically on an annual basis and generally are cancelable by either party with 30 days prior notice. As of December 31, 2017, Keystone serves approximately 35 customers.
Competition
We face competition in our Market-Based Businesses from a number of service providers, including American States Water Company, Suez North America, and Veolia Environnement S.A. in our Military Services Group, and Pivotal Home Solutions (owned by Southern Company Gas) and HomeServe USA in our Homeowner Services Group. Our Contract Operations Group competes in a highly competitive market in order to secure new O&M contracts, as these contracts are awarded based on a combination of customer relationships, service levels, competitive pricing, references and technical expertise. We also face competition in maintaining existing O&M contracts to which we are a party, as the municipal and industrial fixed term contracts frequently come up for renegotiation and are subject to an open bidding process. Competitors of our Contract Operations Group include Suez North America, Veolia Environnement S.A., Inframark, LLC and Woodard & Curran. Keystone currently faces competition from water service providers that typically provide particular segments of the water management cycle, such as Select Energy Services, Inc., TETRA Technologies, Inc. and Fluid Delivery Solutions, LLC.
Environmental, Health and Safety, and Water Quality Regulation
Our water and wastewater operations, including the services provided by both our Regulated Businesses and Market-Based Businesses, are subject to extensive federal, state and local laws and regulations, and in the case of our Canadian operations, Canadian laws and regulations governing the protection of the environment, health and safety, the provision of water and wastewater services, particularly with respect to the quality of water we deliver to our customers, and the manner in which we collect, treat, discharge, recycle and dispose of wastewater. These regulations include the Safe Drinking Water Act, the Lead and Copper Rule (“LCR”), the Reduction of Lead in Drinking Water Act and the Clean Water Act. We are subject to various federal, state, local and Canadian laws and regulations governing the storage of hazardous materials, the management and disposal of hazardous and solid wastes, discharges to air and water, the cleanup of contaminated sites, dam safety and other matters relating to the protection of the environment and health and safety. State PUCs also set conditions and standards for the water and wastewater services we deliver.
Environmental, health and safety, and water quality regulations are complex and change frequently. For example, in 2017, the New Jersey Department of Environmental Protection announced that it would seek to adopt more stringent maximum contaminant levels for perfluorooctoanic acid, or PFOA, and perfluorononanoic acid, or PFNA. The overall trend has been that they have become increasingly stringent over time. As newer or stricter standards are introduced, our capital and operating costs could increase. We incur substantial costs associated with compliance with the environmental, health and safety, and water quality standards to which our operations are subject. In the past, our Regulated Businesses have generally been able to recover the costs associated with compliance; however, this recovery is affected by regulatory lag and the corresponding uncertainties surrounding rate recovery. We estimate that we will make capital expenditures of $96 million during 2018 and $138 million during 2019 for environmental control facilities, which we define for this purpose as any project (or portion thereof) that involves the preservation of air, water or land. We also maintain an environmental program that includes responsible business practices, compliance with environmental laws and regulations, and effective use of natural resources. We believe that our operations are materially in compliance with, and in many cases surpass, minimum standards required by applicable environmental laws and regulations.
Our operations also involve the use, storage and disposal of hazardous substances and wastes. For example, our water and wastewater treatment facilities store and use chlorine and other chemicals that generate wastes that require proper handling and disposal under applicable environmental requirements. We also could incur remedial costs in connection with any contamination relating to our operations or facilities or our off-site disposal of wastes. The Comprehensive Environmental Response, Compensation, and Liability Act of 1980 (“CERCLA”), authorizes the EPA, and comparable state laws authorize state environmental authorities, to issue orders and bring enforcement actions to compel responsible parties to investigate and take remedial actions at any site that is determined to present an actual or potential threat to human health or the environment because of an actual or threatened release of one or more hazardous substances. Parties that generated or transported hazardous substances to such sites, as well as the owners and operators of such sites, may be deemed liable, without regard to fault, under CERCLA or comparable state laws. Although we are not aware of any material cleanup or decontamination obligations, the discovery of contamination or the imposition of such obligations in the future could result in additional costs. Our facilities and operations are also subject to requirements under the U.S. Occupational Safety and Health Act and inspections thereunder. Certain of our subsidiaries are involved in pending legal proceedings relating to environmental matters. See Item 3—Legal Proceedings for additional information.
Safe Drinking Water Act
The Safe Drinking Water Act and related regulations establish national quality standards for drinking water. The EPA has issued rules governing the levels of numerous, naturally occurring and man-made chemical and microbial contaminants and radionuclides allowable in drinking water, and continues to propose new rules. These rules also prescribe testing requirements for detecting regulated contaminants, the treatment systems that may be used for removing those contaminants, and other requirements. To date, the EPA has set standards for approximately 90 contaminants and indicators for drinking water, and there is a process in place to make a regulatory determination on at least five additional compounds every five years.
To help formulate the basis for future regulations, the EPA has the authority to require monitoring for additional, unregulated contaminants under the Unregulated Contaminant Monitoring Rule (the “Rule”). Our laboratory and many of our treatment systems are preparing for the fourth round of testing under the Rule, which will begin in 2018. There are thousands of other chemical compounds that are not regulated, many of which are lacking a testing methodology, occurrence data, health effects information and/or treatment technology. The process of developing new drinking water standards is long and complex, but we actively participate with the EPA and other water industry groups by sharing research and water quality operational knowledge. See Item 1—Business—Research and Development—Emerging Containments for further discussion.
To effect the removal or inactivation of microbial organisms, the EPA has established various rules to improve the disinfection and filtration of drinking water and to reduce consumers’ exposure to disinfectants and by-products of the disinfection process. In 2006, the EPA issued the Long-Term 2 Enhanced Surface Water Treatment Rule and the Stage 2 Disinfectants and Disinfection Byproduct Rule and, later in 2006, finalized the Ground Water Rule, applicable to systems providing water from underground sources. In 2016, the revised Total Coliform Rule implemented a “find and fix” process where exceeding bacterial trigger levels requires an assessment to correct any sanitary defects. We are within the EPA’s time frame for compliance of these standards, which includes sample collection, data analysis, engineering planning and system implementation. Recent monitoring under the Long-Term 2 Rule has resulted in the need for more than 30 of our surface water systems to provide additional protection against cryptosporidium. In most cases, this will involve installing UV disinfection at an estimated cost ranging from $150 million to $250 million. Further, the EPA is actively considering regulations for a number of contaminants, including strontium, hexavalent chromium, fluoride, nitrosamines, perchlorate, some pharmaceuticals and certain volatile organic compounds. We do not anticipate that any such regulations, if enacted, will require implementation in 2018.
Across the Company, we conduct over one million water quality tests each year at our laboratory facilities and plant operations, including continuous on-line instrumentations such as monitoring turbidity levels, disinfectant residuals and adjustments to chemical treatment based on changes in incoming water. We participate in the Partnership for Safe Water, the EPA’s voluntary program to meet more stringent goals for reducing microbial contaminants. With 68 of our 72 surface water treatment plants receiving the EPA program’s “Director” award, which recognizes utilities that: (i) have completed a comprehensive self-assessment report; (ii) created an action plan for continuous improvement; and (iii) produced high quality drinking water, we account for approximately one-third of the plants receiving such awards nationwide. In addition, 66 of our surface water treatment plants have received the “Five-Year Phase III” award, 61 plants have received the “Ten-Year Phase III” award and 54 plants have received the “Fifteen-Year Phase III” award; these awards recognize plants that have met the Director award status for five, 10 and 15 years, respectively. Further, nine of our surface water plants have received the “Presidents” award, which recognizes treatment plants that achieve the Partnership’s rigorous individual filter effluent turbidity standards.
Although it is difficult to project the ultimate costs of complying with the above or other pending or future requirements, we expect current requirements under the Safe Drinking Water Act and other similar laws to be recoverable through the regulatory process and therefore compliance costs are not expected to have a material impact on our operations or financial condition. In addition, capital expenditures and operating costs to comply with environmental mandates have been traditionally recognized by the state PUCs as appropriate for inclusion in establishing rates. As a result, we expect to recover the operating and capital costs resulting from these pending or future requirements.
Lead and Copper Rule and Lead in Drinking Water Act
Across the country, there is a renewed focus on the potential risk of lead in drinking water. In 1991, the EPA published the LCR to control lead and copper in drinking water and, since that time, has issued minor revisions in 2000, 2004 and 2007, enhancing monitoring, reporting and public education requirements. In 2011, Congress enacted the Reduction of Lead in Drinking Water Act regarding the use and introduction into commerce of lead pipes, plumbing fittings for fixtures, solder and flux. While these advances have made an impact in reducing lead exposure in drinking water, legacy lead plumbing materials, primarily in building plumbing, still remain in many communities. The EPA is currently working to develop long-term revisions to the LCR, with a revised draft likely in 2018. It is currently estimated that approximately 5% of our service lines contain lead. We have reviewed our related practices and are working with stakeholders to develop feasible solutions to remove legacy lead from service lines in older neighborhoods. A fundamental step in this effort is the ongoing project to inventory lead service lines across our footprint. Our goal is to replace our lead service lines in most areas over an approximate 10 year time frame, at an estimated cost ranging from $600 million to $1.2 billion. In cases where we are replacing an American Water owned lead service line, our standard approach will be to replace the company-owned portion of the service line, and work with the customer to replace the customer-owned portion of the service line. Replacing the full service line is considered a best practice as advised by the Lead Service Line Replacement Collaborative, an association of leading water industry organizations. The prioritization of this work will depend on several factors, including our planned water main and service line renewal projects, adjacent projects by municipalities or other utilities, LCR compliance monitoring results and cooperation with our customers with respect to the customer-owned portion of the service line.
Clean Water Act
The Clean Water Act regulates discharges from drinking water and wastewater treatment facilities into lakes, rivers, streams and groundwater. In addition to requirements applicable to our wastewater collection systems, our operations require discharge permits under the National Pollutant Discharge Elimination System (“NPDES”) permit program established under the Clean Water Act, which must be renewed every five years. Pursuant to the NPDES permit program, the EPA and implementing states set maximum discharge limits for wastewater effluents and overflows from wastewater collection systems. Discharges that exceed the limits specified under NPDES permits can lead to the imposition of penalties, and persistent non-compliance could lead to significant penalties and compliance costs. In addition, the difficulty of obtaining and complying with NPDES permits, and renewing expiring permits, may impose time and cost burdens on our operations. From time to time, discharge violations occur at our facilities, some of which result in fines. We do not expect any such violations or fines to have a material impact on our results of operations or financial condition.
Environmental, Social Responsibility and Governance
Integrating environmental, social responsibility and governance (“ESG”) policies and practices into our daily operations emphasizes our belief that the only way to do business is to do it responsibly, by delivering value to our customers, building strong communities, leveraging innovation to develop our industry and supporting the expertise and dedication of our people. This focus is derived from our vision statement, “clean water for life”, and our core values: (i) safety; (ii) trust; (iii) environmental leadership; (iv) teamwork; and (v) high performance, the principles by which we work and live. Our vision and values drive our company strategy, which is centered on five central themes:
| • | Customers—Our customers are at the center of everything we do, helping us to shape our strategic priorities. We challenge ourselves so that if our regulated utility customers had a choice of providers, we would want them to choose us. |
| • | Safety—The safety of our employees and our customers is the number one focus for American Water. |
| • | People—Maintaining an environment which is open, diverse and inclusive, and where our people feel valued, included and accountable is critical to our ability to serve our customers every day. |
| • | Technology and Operational Efficiency—Our technology and operational efficiency strategy helps us to continually find better and more efficient ways to do business and provide the best services at affordable costs for our customers. |
| • | Growth—We believe that when companies grow, they can invest more in creating stable jobs, training, benefits, infrastructure and our communities. Growth, in turn, benefits all stakeholders. |
In 2017, we issued our fourth biennial Corporate Responsibility Report, covering our performance in 2015 to 2016. Our first report was issued in 2011, making us the first large water services company to measure its performance against the Global Reporting Index. In addition, our sustainability practices have supported our inclusion in the Dow Jones Sustainability North America Index in 2012, 2013 and 2015, and we have also maintained our position in the Euronext Vigeo® U.S. 50 index, which includes the 50 most advanced companies in the nation with respect to their environmental, social and governance performance, based on a review of hundreds of indicators.
Highlights of our commitment to our ESG policies and practices, many of which are detailed in our most recent Corporate Responsibility Report, are summarized below:
Environmental
| • | Expect to spend between $8.0 billion and $8.6 billion on capital investments from 2018 to 2022, including: |
| • | $7.2 billion for regulated capital expenditures to address aging infrastructure, reduce/eliminate leaks, improve cyber/physical security, and increase resiliency of critical assets to climate variability; |
| • | $600 million to $1.2 billion to acquire financially distressed municipal water and wastewater systems which tend to have a strong need for capital investment; and |
| • | $200 million for strategic capital investments with approximately $164 million focused on construction of our new corporate headquarters in Camden, New Jersey, as part of the revitalization effort in this community. |
| • | Lowered our greenhouse gas emissions by approximately 26% since our base year of 2007. |
| • | Reduced water use by 3.5 billion gallons year over year, through our conservation efforts and programs. |
| • | Recycled over 2 billion gallons of water annually and produced reuse water at 30 of our facilities. |
Social Responsibility
| • | On average, more than 60,000 hours of safety training given annually to our employees. |
| • | Achieved top quartile in the water industry for customer satisfaction. |
| • | Increased our annual spend with Tier 1 diverse suppliers to over $385 million. |
| • | More than 4,000 hours of Company-sponsored community service performed annually by our employees. |
| • | Company-sponsored workplace giving campaigns with the United Way and Water For People, as well annual contributions from the American Water Charitable Foundation, focused on supporting employees in their own charitable endeavors, providing support for disaster relief efforts, and providing funding for initiatives related to clean water, conservation, education and community sustainability. |
| • | Over 85% of our job requisitions had a diverse candidate pool, with more than 50% of transfers or promotions filled by minority, female, veteran or disabled individuals. |
Governance
| • | Our Board of Directors is led by an independent, non-executive chairman, and has an average director tenure, including our two new directors, of approximately 6 years. |
| • | Including our two new directors, we have achieved gender parity among the members of the Board of Directors. |
| • | Stock ownership guidelines and retention requirements that align equity ownership of executives and directors with the long-term interests of our stockholders. |
Research and Development
Our Research and Development Program
We maintain an industry-leading Research and Development (“R&D”) program that is designed to enhance our services, help ensure compliance, and improve quality and operational effectiveness. Our R&D personnel are located in New Jersey and Illinois, the latter housing our quality control and testing laboratory, which supports our R&D activities through testing and analysis. Approximately one-third of our research budget is funded by competitively awarded outside research grants. Such grants reduce the cost of research and allow collaboration with leading national and international researchers. In 2017, we spent $3 million on research in total, including $1 million funded by grants. Spending on research amounted to $4 million, including $1 million funded by grants, in each of 2016 and 2015.
We continue to leverage the Company’s expertise and collaborate with the EPA to help establish effective environmental, health and safety, and water quality standards and regulation. This relationship includes the sharing of our research, such as our treatment and distribution system optimization research and our and national water quality monitoring data. Our engagement with the EPA provides us with early insight into emerging regulatory issues and initiatives, thereby allowing us to anticipate and to accommodate our future compliance requirements. We also frequently engage with the Centers for Disease Control and other state environmental agencies. We believe that continued R&D activities are critical for providing safe, reliable and affordable services, as well as maintaining our leadership position in the industry, which provides us with a competitive advantage as we seek additional business with new and existing customers.
Emerging Contaminants
Emerging contaminants include chemicals such as pharmaceuticals, personal care products, pesticides, herbicides and endocrine disrupting compounds, which have been detected in drinking water supplies, for which the risk to the public’s health is not fully understood and/or has not been quantified. While these contaminants have been present in our drinking water for as long as they have been in use, technological advances have only recently made it possible to detect many of them. The ability to detect contaminants, even at trace levels, has raised questions among regulators and government agencies, further affecting the public’s perception of drinking water quality.
The Chemicals Abstract Service Registry contains over 130 million registered chemicals, with a new substance being produced approximately every 3 seconds from chemical breakdown and reformation. We are continually investigating new substances and contaminants, employing a team of scientists, engineers and public health professionals to identify threats to our water supply, to act on emerging regulations and new health advisories, and to research the influx of advanced treatment technologies. We maintain state-of-the-art water quality testing equipment and implement new and emerging technologies to help predict and manage potential water supply contamination issues. Examples of our efforts include:
| • | using our research findings to communicate information to our customers (via a web site) on the actions they can take to manage Legionella (the Centers for Disease Control statistics indicate that water-associated disease from Legionella is on the rise, with exposure typically associated with plumbing systems in large buildings); |
| • | aerial drone testing to detect harmful algal blooms and ultrasonic technology testing to help prevent taste and odor events and to eliminate cyanotoxins before they get to the water treatment plant; |
| • | the implementation of water source assessment tools, including sensors and analytics, to evaluate and track chemical storage and transport through watersheds and to detect source water contamination events; and |
| • | the implementation of activated carbon and biofiltration for the control of emerging contaminants. |
Support Services
American Water Works Service Company, Inc. (the “Service Company”) is our wholly owned subsidiary that provides support and operational services to the Company’s operating subsidiaries. These services are predominantly provided to our Regulated Businesses under contracts that have been approved by PUCs, where necessary, and are also provided to (i) our three Market-Based Businesses organized under American Water Enterprises, Inc., our wholly owned subsidiary (“AWE”), and (ii) Keystone as requested or may be necessary. Services provided by the Service Company may include accounting and finance, administration, business development, communications, compliance, education and training, engineering, health and safety, human resources, information systems, internal audit, investor relations, legal and governance, operations, procurement, rates and regulatory support, security, risk management, treasury, water quality and R&D. The Service Company also operates two national customer service centers located in Alton, Illinois and Pensacola, Florida, which provide customer relations, field service and operational support to our Regulated Businesses. Services are provided by the Service Company at cost, enabling our operating subsidiaries to fulfill their responsibilities in a cost-effective manner, while providing them access to in-depth, functional expertise.
Our security team provides oversight and policy guidance on physical, cyber and information security, as well as business continuity, throughout our operations. It is responsible for designing, implementing, monitoring and supporting effective physical and technical security controls for our physical assets, business systems and operational technologies. Risk assessments are conducted periodically to evaluate the effectiveness of existing security controls and serve as the basis for additional safeguards, security controls and measures. Operational and technical security controls are deployed and integrated as safeguards against unauthorized access to the Company’s information systems. These controls: (i) are aimed at assuring the continuity of business processes that are dependent upon automation; (ii) seek to maintain the integrity of our data; (iii) support regulatory and legislative compliance requirements; and (iv) are aimed at maintaining safe and reliable service to our customers. We engage in partnerships with U.S. federal, state and local law enforcement agencies to coordinate and improve the security of our water delivery systems and to safeguard our water supply and operations.
Employee Matters
As of December 31, 2017, approximately 46% of our workforce was represented by unions, which include 76 collective bargaining agreements with 19 different unions. Additionally, as of December 31, 2017 we had one collective bargaining agreement beyond expiration, affecting approximately 180 employees, all of which are actively working under the terms of the existing agreement, and another collective bargaining agreement in the process of being implemented, affecting approximately 20 employees. During 2018, 20 of our collective bargaining agreements, and our national benefits agreement with most of the labor unions representing employees in our Regulated Businesses, will be expiring in accordance with their terms.
Executive Officers
The following table summarizes the name, age, offices held and business experience for each of our executive officers, as of February 20, 2018:
| Name | Age | Office and Experience | ||
| Susan N. Story | 58 | President and Chief Executive Officer. Ms. Story has served as President and Chief Executive Officer of the Company since May 2014. Ms. Story served as Senior Vice President and Chief Financial Officer of the Company from April 2013 until May 2014. Prior to joining American Water, she served as President and Chief Executive Officer of Southern Company Services, a subsidiary of Southern Company, from January 2011 until March 2013 and President and Chief Executive Officer of Gulf Power Company, also a subsidiary of Southern Company, from 2003 until December 2010. Since 2008, Ms. Story has served as a member of the board of directors of Raymond James Financial, Inc., a diversified financial services company, and as lead director since 2016. Since January 2017, Ms. Story has also served on the board of directors of Dominion Energy, Inc., a producer and transporter of energy. | ||
| Brian Chin | 44 | Senior Vice President, Planning and Strategy Integration. Mr. Chin joined the Company as its Senior Vice President, Planning and Strategy Integration on June 20, 2017. Prior to joining the Company, from May 2013 to April 2017, Mr. Chin served as the lead utility analyst for the North America research function at Bank of America Merrill Lynch. From 2001 to 2013, Mr. Chin worked in Electric Utilities Research at Citigroup. Within that period, Mr. Chin was the global head of Electric Utilities Research for Citigroup. | ||
| Deborah A. Degillio | 46 | President, AWE. Ms. Degillio has been President of AWE since May 2016. From January 2015 to May 2016, Ms. Degillio served as the Company’s Vice President and Treasurer. Prior to that time, Ms. Degillio served as Vice President of Finance of AWE from November 2013 to February 2015, as a Vice President in the Company’s Finance team for its Eastern Division from June 2009 until October 2013, and as Director of Financial Planning and Analysis for American Water’s then Western states, from April 2007 until May 2009. |
| Name | Age | Office and Experience | ||
| Melanie M. Kennedy | 44 | Senior Vice President, Human Resources. Since March 1, 2017, Ms. Kennedy has served as the Company’s Senior Vice President, Human Resources. From August 2014 until February 2017, Ms. Kennedy served as Vice President, Human Resources of the Company, and from August 2012 to August 2014, she served as Director, Human Resources in our Northeast Division. Ms. Kennedy initially joined the Company in 2007, and before that time, she practiced law for nine years. | ||
| Walter J. Lynch | 55 | Executive Vice President and Chief Operating Officer. Mr. Lynch has over 20 years of experience in the water and wastewater industry. Mr. Lynch has served as the Company’s Executive Vice President and Chief Operating Officer since January 2016, as Chief Operating Officer of Regulated Operations from February 2010 to December 2015, and President of Regulated Operations from July 2008 to December 2015. Mr. Lynch joined us in 2001. Mr. Lynch is on the Board of Directors of the National Association of Water Companies and serves on its Executive Committee. In addition, Mr. Lynch also serves on the Water Research Foundation Board of Trustees. | ||
| Bradley A. Okoniewski | 51 | Vice President, Safety and Environmental Leadership. Mr. Okoniewski joined the Company on May 1, 2017 as its Vice President, Safety and Environmental Leadership. Prior to that, from April 2016 to May 2017, Mr. Okoniewski served as the global environmental, occupational health and safety director for Campbell Soup Company, a publicly-traded consumer products company based in Camden, New Jersey. Prior to that, Mr. Okoniewski served as the global director, safety, health and environmental affairs for Carpenter Technology Company, a publicly-traded specialty metals company based in Philadelphia, Pennsylvania, from February 2013 to March 2016. | ||
| Michael A. Sgro | 59 | Executive Vice President, General Counsel and Secretary. Mr. Sgro has over 20 years of experience in the water and wastewater industry. He has served as the Company’s Executive Vice President, General Counsel and Secretary since January 1, 2016 and its Senior Vice President, General Counsel and Secretary from February 2015 to January 2016. Prior to that, he served as the Company’s Interim General Counsel and Secretary from January 2015 until February 2015 and as Vice President, General Counsel and Secretary of American Water’s Northeast Division beginning in 2002. | ||
| Linda G. Sullivan | 54 | Executive Vice President and Chief Financial Officer. Ms. Sullivan has served as the Company’s Executive Vice President and Chief Financial Officer since January 1, 2016 and the Company’s Senior Vice President and Chief Financial Officer from May 2014 to December 31, 2015. Prior to joining American Water, Ms. Sullivan served as the Senior Vice President and Chief Financial Officer of Southern California Edison Company, a subsidiary of Edison International, from July 2009 until May 2014, and Vice President and Controller of both Edison International and Southern California Edison Company, from July 2004 until July 2009. Ms. Sullivan is a Certified Public Accountant (inactive) and a Certified Management Accountant. On April 27, 2017, Ms. Sullivan was elected to the Board of Directors of NorthWestern Corp. and serves on its Audit Committee. In addition, Ms. Sullivan serves on the board of directors of University of Maryland University College Ventures and on its Audit & Finance Committee and is a member of the EPA’s Finance Advisory Board. | ||
| Radhakrishnan Swaminathan | 56 | Senior Vice President, Chief Technology and Information Officer. Mr. Swaminathan has served as Senior Vice President, Chief Technology and Innovation Officer of the Company since November 1, 2017. Mr. Swaminathan joined the Company in March 2016 as our Chief Technology and Innovation Officer. Prior to that, from October 2012 through February 2016, he served as Vice President and Chief Technology Officer, Energy, Natural Resources and Utilities, of WIPRO Technologies. Prior to that, he served as the Director of Smart Grid Technologies at NextEra Energy, Inc. from January 2009 through September 2012. | ||
| Loyd “Aldie” Warnock | 58 | Senior Vice President of External Affairs and Business Development. Mr. Warnock has served as the Company’s Senior Vice President of External Affairs and Business Development since August 1, 2017. From April 2014 to July 31, 2017, Mr. Warnock served as the Company’s Senior Vice President of External Affairs, Communications and Public Policy. Prior to joining the Company, he served as Senior Vice President of External Affairs at Midwest Independent System Operator, Inc., a non-profit, self-governing organization, from March 2011 to April 2014. Prior to that, he served as Vice President of External Affairs for Allegheny Energy, Inc. from December 2005 to February 2011 and Senior Vice President of Governmental and Regulatory Affairs at Mirant Corporation from July 2004 to November 2005. Mr. Warnock serves on the Board of Directors of the National Association of Water Companies and on the Executive Advisory Board of the Mississippi State University College of Business. | ||
| Melissa K. Wikle | 52 | Vice President and Controller. Ms. Wikle joined the Company in July 2016 as its Vice President and Controller, and assumed the duties of the Company’s principal accounting officer in August 2016. Prior to joining the Company, Ms. Wikle served as Corporate Controller and Chief Accounting Officer of Columbus McKinnon Corporation, a publicly-traded worldwide designer, manufacturer and marketer of material handling products, systems and services, since April 2011. Ms. Wikle is a Certified Public Accountant. | ||
| Charles Witherspoon | 50 | Vice President and Treasurer. Mr. Witherspoon has served as the Company’s Vice President and Treasurer since February 14, 2018 and has over 24 years of collective experience in corporate treasury, marketing, finance and audit roles. Mr. Witherspoon joined the Company in January 2016 as its Assistant Treasurer. Prior to joining the Company, Mr. Witherspoon served as Vice President of Finance and Corporate Treasurer of Church & Dwight Co., Inc., a publicly-traded packaged goods company, from December 2007 to January 2016. Before that, Mr. Witherspoon held finance and treasury roles for Johnson & Johnson and FMC Corporation. Mr. Witherspoon is a Certified Public Accountant and a Certified Treasury Professional. |
Each executive officer is elected annually by the Board of Directors and serves until his or her respective successor has been elected and qualified or his or her earlier death, resignation or removal.
Available Information
We are subject to the reporting requirements of the Exchange Act. We file or furnish annual, quarterly and current reports, proxy statements and other information with the SEC. You may obtain a copy of our annual reports on Form 10-K, our quarterly reports on Form 10-Q or our current reports on Form 8-K, or any amendments to them, that are filed with or furnished to the SEC, free of charge, from the Investor Relations section of our website, http://ir.amwater.com, as soon as reasonably practicable after we file or furnish the information to the SEC. Information contained on our website shall not be deemed incorporated into, or to be a part of, this report, and any website references included herein are not intended to be made through active hyperlinks. We recognize our website as a key channel of distribution to reach public investors and as a means of disclosing material non-public information to comply with our disclosure obligations under SEC Regulation FD.
The American Water corporate governance guidelines and the charters for each of the standing committees of the Board of Directors, together with the American Water Code of Ethics and additional information regarding our corporate governance, are available on our Investor Relations website, http://ir.amwater.com, and will be made available, without charge, in print to any stockholder who requests such documents from our Investor Relations Department, American Water Works Company, Inc., 1025 Laurel Oak Road, Voorhees, NJ, 08043.
Previous: Cover and table of contents · Next: Item 1A. RISK FACTORS