 filings.tools
AutoZone (AZO) 10-K risk factor changes: FY2021 vs FY2020
The 2021-08-28 10-K against the 2020-08-29 one, compared heading by heading and sentence by sentence.
Item 1A44 rewritten31 added18 removed145 unchanged
All filing items800 rewritten382 added444 removed1,387 unchanged
Summary
counted, not written
- Item 1A lists 19 risk factor headings: 1 new, 3 reworded and 15 unchanged since FY2020. 2 headings from FY2020 no longer appear.
- Sentence by sentence, 382 added, 444 removed, 800 rewritten and 1,387 unchanged across 22 items that differ.
- New this year: Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections.
New Item 1A headings (1)
- We may be adversely affected by legal, regulatory or market responses to global climate change.
Removed Item 1A headings (2)
- Consolidation among our competitors may negatively impact our business.
- We rely heavily on our information technology systems for our key business processes. Any failure or interruption in these systems could have a material adverse impact on our business.
Reworded Item 1A headings (3)
- The
[removed: ongoing outbreak of]COVID-19[removed: has been declared a]pandemic[removed: by the World Health Organization, continues to spread within][added: persists in] the[removed: United States][added: U.S.] and many other parts of the world and may have a material adverse effect on our business operations, financial condition, liquidity and cash flow. - Our ability to grow depends in part on new
[removed: location][added: store] openings, existing[removed: location][added: store] remodels and expansions and effective utilization of our existing supply chain and hub network. - Business interruptions may negatively impact our
[removed: location][added: operating] hours, operability of our computer and other systems, availability of merchandise and otherwise have a material negative effect on our sales and our business.
A heading is new when no FY2020 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2021; struck-through words were in FY2020. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
44 rewritten, 31 added, 18 removed, 145 unchanged
The [removed: ongoing outbreak of] COVID-19 [removed: has been declared a] pandemic [removed: by the World Health Organization, continues to spread within] [added: persists in] the [removed: United States] [added: U.S.] and many other parts of the world and may have a material adverse effect on our business operations, financial condition, liquidity and cash flow.
[removed: We are unable] [added: This is due] to [removed: accurately predict] the [removed: impact] [added: numerous uncertainties] that [removed: COVID-19 will] have [removed: on our business and financial condition due to numerous uncertainties,] [added: risen from the pandemic,] including the severity of the disease, the duration of the outbreak, the likelihood of [removed: a resurgence] [added: resurgences] of the outbreak, [added: including due to the emergence and spread of variants,] actions that may be taken by governmental authorities in response to the [removed: disease] [added: disease, the timing, distribution, efficacy] and [added: public acceptance of vaccines, and] unintended consequences of the foregoing.
[removed: Continued] [added: While we have added safety measures to protect our employees and customers, continued] business disruption caused by COVID-19 may require [added: further] significant actions to mitigate the impact, including but not limited to employee furloughs, reductions in store hours and store closings as well as ongoing increases in expenses.
Further, the continuing pandemic and related economic uncertainty may result in prolonged disruption [added: and volatility] to our business, [added: cause] additional negative impacts of which we are not currently aware and [removed: may] also magnify other risks associated with our business and operations, including risks associated with sourcing quality merchandise domestically and outside the U.S.; our ability to promptly adjust inventory levels to meet fluctuations in customer demand; our ability to comply with complex and evolving laws and regulations related to customers’ and AutoZoners’ health and safety; our ability to open new store locations and expand or remodel existing stores; and our ability to hire and train qualified employees to address temporary or sustained labor shortages.
| | • | | the weather. Milder weather conditions may lower the failure rates of automotive parts, while extended periods of rain and winter precipitation may cause our customers to defer maintenance and repair on their vehicles. Extremely hot or cold conditions may enhance demand for our products due to increased failure rates of our customers’ automotive parts. [added: Additionally, global warming trends and other significant climate changes can create more variability in the short term or lead to other weather conditions that could impact our business.] |
[removed: We] [added: We] believe that we compete effectively on the basis of merchandise availability as a result of investments in inventory available for immediate sale, the development of a robust hub and mega hub distribution network providing efficient access to obtain products required on-demand, options to order products online or by telephone and pick them up in stores and options for special orders directly from our vendors.
In addition, we believe that customers value the personal interaction with a salesperson [removed: that] [added: who] is qualified to offer trustworthy advice and provide other free services such as parts testing.
We have increased our store count in the past five fiscal years, growing from [removed: 5,609] [added: 5,814] stores at August [removed: 29, 2015,] [added: 27, 2016,] to [removed: 6,549] [added: 6,767] stores at August [removed: 29, 2020, an average store increase per year] [added: 28, 2021, a compounded annual growth rate] of three percent.
Additionally, we have increased annual revenues in the past five fiscal years from [removed: $10.187] [added: $10.636] billion in fiscal [removed: 2015] [added: 2016] to [removed: $12.632] [added: $14.630] billion in fiscal [removed: 2020, an average increase per year] [added: 2021, with a compounded annual growth rate] of [removed: five] [added: seven] percent.
We believe [removed: that] much of our brand value lies in the quality of the approximately 100,000 AutoZoners employed in our stores, distribution centers, store support centers and ALLDATA.
Our [removed: workforce costs represent our largest operating expense, and our] business is [added: also] subject to employment laws and regulations, including requirements related to minimum wage, benefits and scheduling requirements.
If we are unable to hire, properly train and retain qualified employees, we could experience higher employment costs, reduced sales, [removed: regulatory noncompliance,] losses of customers and diminution of our brand or company culture, which could adversely affect our earnings.
If our merchandise offerings do not meet our customers’ expectations regarding [removed: quality] [added: quality, innovation] and safety, we could experience lost sales, increased costs and exposure to legal and reputational risk.
Events that give rise to actual, potential or perceived product safety concerns could expose us to government enforcement action or private [removed: litigation and] [added: litigation,] result in costly product recalls and other [removed: liabilities.][added: liabilities and lead to reputational harm and loss of customer confidence.]
Credit market and other macroeconomic [removed: conditions, including disruption to the global supply chain,] [added: conditions] could [added: also] have a material adverse effect on the ability of our [added: global and domestic] suppliers to finance and operate their [removed: businesses, resulting in increased product costs and difficulties in meeting our inventory demands.][added: businesses.]
We directly imported approximately 13% of our purchases in fiscal [removed: 2020,] [added: 2021,] but many of our domestic vendors directly import their products or components of their products.
Changes to the price or flow of these goods for any reason, such as civil unrest or acts of war, currency fluctuations, disruptions in maritime lanes, port labor [removed: disputes and] [added: disputes,] economic conditions and instability in the countries in which foreign suppliers are located, the financial instability of suppliers, [added: suppliers’] failure to meet our standards, issues with labor practices of our suppliers or labor problems they may experience (such as strikes, stoppages or slowdowns, which could also increase labor costs during and following the disruption), the availability and cost of raw materials to suppliers, increased import duties or tariffs, merchandise quality or safety issues, [added: shipping and] transport availability and cost, increases in wage rates and taxes, transport security, inflation and other factors relating to the suppliers and the countries in which they are located or from which they import, often are beyond our control and could adversely affect our operations and profitability.
Our ability to grow depends in part on new [removed: location] [added: store] openings, existing [removed: location] [added: store] remodels and expansions and effective utilization of our existing supply chain and hub network.
Our continued growth and success will depend in part on our ability to open and operate new [removed: locations] [added: stores] and expand and remodel existing [removed: locations] [added: stores] to meet customers’ needs on a timely and profitable basis.
Accomplishing our new and existing [removed: location] [added: store] expansion goals will depend upon a number of factors, including the ability to partner with developers and landlords to obtain suitable sites for new and expanded [removed: locations] [added: stores] at acceptable costs, the hiring and training of qualified personnel and the integration of new [removed: locations] [added: stores] into existing operations.
There can be no assurance we will be able to achieve our [removed: location] [added: store] expansion goals, manage our growth effectively, successfully integrate the planned new [removed: locations] [added: stores] into our operations or operate our new, remodeled and expanded [removed: locations] [added: stores] profitably.
In addition, we extensively utilize our hub network, our supply chain and logistics management techniques to efficiently stock our [removed: locations.][added: stores.]
If we fail to effectively utilize our existing hubs and/or supply chains or if our investments in our supply chain initiatives, including directly sourcing some products from outside the U.S., do not provide the anticipated benefits, we could experience sub-optimal inventory levels in our [removed: locations] [added: stores] or increases in our operating costs, which could adversely affect our sales volume and/or our margins.
Any negative publicity about these [added: or other] areas [added: involving our business, including our response or lack thereof to external events involving civil unrest, social justice, and political issues, whether or not based in fact,] could damage our reputation and may result in reduced demand for our merchandise.
Failure to protect or effectively respond to a breach of the privacy and security of customers’, suppliers’, AutoZoners’ or Company information could damage our reputation, subject us to [removed: litigation,] [added: litigation] and cause us to incur substantial costs.
Failure to protect the security of our customers’, suppliers’, [removed: employees’] [added: AutoZoners’] and Company information could subject us to costly regulatory enforcement actions, expose us to litigation and impair our reputation, which may have a negative impact on our sales.
We believe [removed: that] our preventative actions provide adequate measures of protection against security breaches and generally reduce our cyber-security risks.
As the regulatory environment related to information security, data collection and use, and privacy becomes increasingly [removed: rigorous,] [added: rigorous and complex,] compliance with these requirements could also result in significant additional costs.
To the extent [removed: that] any cyber-attack or intrusion in our or one of our third-party service provider’s information systems results in the loss, damage or misappropriation of information, we may be materially adversely affected by claims from customers, financial institutions, regulatory authorities, payment card networks and others.
In certain circumstances, payment card association rules and obligations to which we are subject under our contracts with payment card processors make us liable to payment card issuers if information in connection with payment cards and payment card transactions [removed: that] we hold is compromised, which liabilities could be substantial.
We have invested in [removed: information-technology] [added: information technology] risk management and disaster recovery plans.
[removed: We] [added: We] rely heavily on our information technology systems for our key business processes.
If our systems are damaged or fail to function properly, we may incur substantial costs to repair or replace them, and [added: we] may experience loss of critical data and interruptions or delays in our ability to manage inventories or process transactions, which could result in lost sales, inability to process purchase orders and/or a potential loss of customer loyalty, which could adversely affect our results of operations.
These technological changes will require significant investment of human and financial resources, and we may experience significant delays, [removed: costs] [added: cost] increases and other obstacles with these projects.
Business interruptions may negatively impact our [removed: location] [added: operating] hours, operability of our computer and other systems, availability of merchandise and otherwise have a material negative effect on our sales and our business.
War or acts of terrorism, political or civil unrest, unusual weather conditions, [added: including due to the impacts of climate change,] hurricanes, tornadoes, windstorms, fires, [removed: earthquakes,] [added: earthquakes and] floods, global health epidemics (such as COVID-19) and other natural or other disasters or the threat of any of them, may result in certain of our [removed: locations] [added: stores, distribution centers, store support centers or sourcing offices] being closed for a period of time or permanently or have a negative impact on our ability to obtain merchandise available for sale in our [removed: locations.][added: stores.]
In the event [removed: that] commercial transportation is curtailed or substantially delayed, our business may be adversely impacted, as we may have difficulty transporting merchandise to our distribution centers and [removed: locations] [added: stores] resulting in lost sales and/or a potential loss of customer loyalty.
Our reserves are established using historical trends [removed: and] [added: and,] where appropriate, using a third party [removed: actuary,] [added: actuary] to estimate costs to settle reported claims and claims incurred but not yet reported.
[removed: Our business,] [added: Our business,] results of operations, financial condition and cash flows may be adversely affected by the adoption of new laws, changes to existing laws, increased enforcement activity or other governmental actions.
These include laws governing employment and labor, wage and hour, environmental matters, proper handling and disposal of hazardous materials and waste, healthcare, data privacy, cybersecurity, the pricing and sale of goods, import and export [removed: compliance and] [added: compliance,] transportation and logistics, [added: consumer protection and advertising,] among others.
Strategic and Operational Risks
The COVID-19 pandemic continues to impact numerous aspects of our business, and the long-term impact to our business remains unknown.
Conversely, if the unprecedented levels of customer demand we have experienced during the pandemic revert or subside, we may be unable to reduce expenses or otherwise react quickly and effectively to such changes.
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
| | | | |
See “Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations” for further discussion of same store sales.
Additionally, the unprecedented levels of customer demand we have experienced for our products during the COVID-19 pandemic has resulted in significant increases in same store sales growth during fiscal 2020 and fiscal 2021.
Therefore, we may not be able to sustain these growth trends if customer demand returns to pre-pandemic levels.
Our workforce costs represent our largest operating expense, and our ability to meet our labor needs while controlling labor costs is subject to numerous external factors, including market pressures with respect to prevailing wage rates and unemployment levels.
We compete with other retail businesses for many of our associates in hourly positions, and these positions have historically had high turnover rates, which can lead to increased training and retention costs, particularly in a competitive labor market.
Furthermore, our vendors are impacted by global economic conditions which in turn impact our ability to source merchandise at competitive prices.
For example, the recent surges in consumer demand, shortages of raw materials and disruption to the global supply chain have negatively impacted costs and inventory availability and may continue to have a negative impact on future results and profitability.
Cyber-security and Data Privacy Risks
In particular, in connection with the COVID-19 pandemic, there has been a spike in cyber-security attacks as shelter in place orders and work from home measures have led businesses to increase reliance on virtual environments and communications systems, which have been subjected to increasing third-party vulnerabilities and security risks.
Indebtedness, Financial and Market Risks
Legal and Regulatory Risks
We may be adversely affected by legal, regulatory or market responses to global climate change.
Growing concern over climate change has led policy makers in the U.S. to consider the enactment of legislative and regulatory proposals that would impose mandatory requirements on greenhouse gas emissions.
Such laws, if enacted, are likely to impact our business in a number of ways.
For example, significant increases in fuel economy requirements, new federal or state restrictions on emissions of carbon dioxide or new federal or state incentive programs that may be imposed on vehicles and automobile fuels could adversely affect demand for vehicles, annual miles driven or the products we sell.
We may not be able to accurately predict, prepare for and respond to new kinds of technological innovations with respect to electric vehicles and other technologies that minimize emissions.
Compliance with any new or more stringent laws or regulations, or stricter interpretations of existing laws, could require additional expenditures by us or our suppliers.
Our inability to appropriately respond to such changes could adversely impact our business, financial condition, results of operations or cash flows.
General Risks
While the unemployment rate has improved, the rate has not returned to pre-pandemic levels.
As the outbreak of COVID-19 continues to grow both in the U.S. and globally, there has been significant volatility in financial market indices and the adoption of emergency legislation aimed to address the negative impacts of the pandemic.
While sales were initially negatively impacted and we have incurred significant expenses, following the U.S. federal government stimulus, our sales rebounded, reaching record levels.
| --- | --- | --- | --- |
We cannot provide any assurance that we will continue to open stores at historical rates or continue to achieve increases in same store sales.
Consolidation among our competitors may negatively impact our business.
Historically some of our competitors have merged.
Consolidation among our competitors could enhance their market share and financial position, provide them with the ability to achieve better purchasing terms and provide more competitive prices to customers for whom we compete, and allow them to utilize merger synergies and cost savings to increase advertising and marketing budgets to more effectively compete for customers.
Consolidation by our competitors could also increase their access to local market parts assortment.
These consolidated competitors could take sales volume away from us in certain markets, could achieve greater market penetration, could cause us to change our pricing with a negative impact on our margins or could cause us to spend more money to maintain customers or seek new customers, all of which could negatively impact our business.
Moreover, our vendors are impacted by global economic conditions.
Failure to comply with applicable laws and regulations, to maintain an effective system of internal controls or to provide accurate and timely financial statement information could also hurt our reputation.
If we fail to comply with existing or future laws or regulations, we may be subject to governmental or judicial fines or sanctions, while incurring substantial legal fees and costs.
In addition, our capital and operating expenses could increase due to implementation of and compliance with existing and future laws and regulations or remediation measures that may be required if we are found to be noncompliant with any existing or future laws or regulations.
The inability to pass through any increased expenses through higher prices would have an adverse effect on our results of operations.
**
General Risk Factors
While in recent years, the unemployment rate has improved to below pre-recession levels, unemployment has again reached historically high levels due to COVID-19.
An excerpt. Shown here: 40 of 44 rewritten, all 31 added and all 18 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2021 filing and the FY2020 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
172 rewritten, 117 added, 50 removed, 179 unchanged
We began operations in 1979 and at August [removed: 29, 2020,] [added: 28, 2021,] operated [removed: 5,885] [added: 6,051] stores in the U.S., [removed: 621] [added: 664] stores in Mexico and [removed: 43] [added: 52] stores in Brazil.
At August [removed: 29, 2020,] [added: 28, 2021,] in [removed: 5,007] [added: 5,179] of our domestic stores, we also had a commercial sales program that provides commercial credit and prompt delivery of parts and other products to local, regional and national repair garages, dealers, service stations and public sector accounts.
We also sell the ALLDATA brand automotive [removed: diagnostic and] [added: diagnostic,] repair [added: and shop management] software through [removed: www.alldata.com and www.alldatadiy.com.][added: www.alldata.com.]
[removed: We have also taken numerous measures] [added: Our main priority continues] to [removed: ensure] [added: be] the health, safety and well-being of our customers and [removed: employees.][added: AutoZoners.]
[removed: However,] [added: The long-term impact to our business remains unknown as] we are unable to accurately predict the impact that COVID-19 will have due to numerous uncertainties, including the severity of the disease, the duration of the outbreak, [added: the likelihood of additional variants and resurgences of the outbreak,] actions that may be taken by governmental authorities [removed: intended] [added: in response] to [removed: minimize] the [removed: spread of the pandemic or to stimulate] [added: disease,] the [removed: economy or other] [added: timing, distribution, efficacy and public acceptance of vaccines, and] unintended [removed: consequences.][added: consequences of the foregoing.]
Our business is impacted by various factors within the economy that affect both our consumer and our industry, including but not limited to fuel costs, wage [removed: rates] [added: rates, supply chain disruptions, hiring] and other economic conditions, including for fiscal [added: 2021 and] 2020, [added: the effects of, and responses to,] COVID-19.
For fiscal [removed: 2020,] [added: 2021,] we achieved record net income of [removed: $1.733] [added: $2.170] billion, a [removed: 7.2%] [added: 25.2%] increase over the prior year, and sales growth of [removed: $768.2 million,] [added: $1.998 billion,] a [removed: 6.5%] [added: 15.8%] increase over the prior year.
Domestic commercial sales increased [removed: 6.4%,] [added: 22.6%,] which represents [removed: 21.6%] [added: approximately 23%] of our total sales.
Both our retail sales and commercial sales grew this past year as we continue to [added: experience unprecedented demand for our products during the COVID-19 pandemic and] make progress on our initiatives [removed: that are] aimed at improving our ability to say “Yes” to our customers more frequently, drive traffic to our stores and accelerate our commercial growth.
One macroeconomic factor affecting our customers and our industry during fiscal [removed: 2020] [added: 2021] was gas prices.
During fiscal [removed: 2020,] [added: 2021,] the average price per gallon of unleaded gasoline in the U.S. was [removed: $2.32 per gallon,] [added: $2.62,] compared to [removed: $2.63 per gallon] [added: $2.32] during fiscal [removed: 2019.][added: 2020.]
With approximately [removed: 12] [added: 10] billion gallons of unleaded gas consumption each month across the U.S., each $1 decrease at the pump contributes approximately [removed: $12] [added: $10] billion of additional spending capacity to consumers each month.
We have also experienced continued accelerated pressure on wages in the U.S. during fiscal [removed: 2020.][added: 2021.]
Some of this is attributed to regulatory changes in certain states and municipalities, while the larger portion is being driven by general market pressures and some specific actions taken [removed: in recent years] [added: recently] by other retailers.
During fiscal [removed: 2020,] [added: 2021,] failure and maintenance related categories represented the largest portion of our sales mix, at approximately [removed: 84%] [added: 83%] of total sales, with failure related categories continuing to comprise our largest set of categories.
While we have not experienced any fundamental shifts in our category sales mix as compared to previous years, in our domestic stores we [removed: did experience] [added: continue to see] a slight increase in mix of sales of the discretionary category as compared to last year.
We believe the improvement in this sales category resulted from the pandemic as many of our customers [removed: had] [added: continue to have] more time to work on [added: discretionary] projects.
We believe [removed: that] as the number of miles driven increases, consumers’ vehicles are more likely to need service and maintenance, resulting in an increase in the need for automotive hard parts and maintenance items.
Since the beginning of the fiscal year and through July [removed: 2020] [added: 2021] (latest publicly available information), miles driven in the U.S. decreased by [removed: 8.8%] [added: 5.2%] compared to the same period in the prior year.
We believe this decrease is a result of the pandemic, but we are unable to predict if this decline will continue and are uncertain [removed: if it continues] [added: of] the impact it will have to our business.
According to the latest data provided by the Auto Care Association, as of January 1, [removed: 2020,] [added: 2021,] the average age of [added: light] vehicles on the road was [removed: 11.9] [added: 12.1] years.
[removed: For the ninth consecutive year, the] [added: The] average age of [added: light] vehicles has exceeded 11 [removed: years.][added: years since 2012.]
For the fiscal year ended August [removed: 29, 2020,] [added: 28, 2021,] we reported net sales of [removed: $12.632] [added: $14.630] billion compared with [removed: $11.864] [added: $12.632] billion for the year ended August [removed: 31, 2019,] [added: 29, 2020,] a [removed: 6.5%] [added: 15.8%] increase from fiscal [removed: 2019.][added: 2020.]
This growth was driven primarily by a domestic same store sales increase of [removed: 7.4%] [added: 13.6%] and net sales of [removed: $244.7] [added: $215.8] million from new stores.
Domestic commercial sales increased [removed: $164.9] [added: $617.7] million, or [removed: 6.4%,] [added: 22.6%,] over domestic commercial sales for fiscal [removed: 2019.][added: 2020.]
At August [removed: 29, 2020,] [added: 28, 2021,] we operated [removed: 5,885] [added: 6,051] domestic stores, [removed: 621] [added: 664] in Mexico and [removed: 43] [added: 52] in Brazil, compared with [removed: 5,772] [added: 5,885] domestic stores, [removed: 604] [added: 621] in Mexico and [removed: 35] [added: 43] in Brazil at August [removed: 31, 2019.][added: 29, 2020.]
We reported a total auto parts segment (domestic, Mexico and Brazil) sales increase of [removed: 6.5%] [added: 15.9%] for fiscal [removed: 2020.][added: 2021.]
Gross profit for fiscal [removed: 2020] [added: 2021] was [removed: $6.771] [added: $7.718] billion, or [removed: 53.6%] [added: 52.8%] of net sales, [removed: a 5] [added: an 85] basis point decrease compared with [removed: $6.365] [added: $6.771] billion, or [removed: 53.7%] [added: 53.6%] of net sales for fiscal [removed: 2019.][added: 2020.]
Operating, selling, general and administrative expenses for fiscal [removed: 2020] [added: 2021] increased to [removed: $4.353] [added: $4.773] billion, or [removed: 34.5%] [added: 32.6%] of net sales, from [removed: $4.149] [added: $4.353] billion, or [removed: 35.0%] [added: 34.5%] of net sales for fiscal [removed: 2019.][added: 2020.]
Interest expense, net for fiscal [removed: 2020] [added: 2021] was [removed: $201.2] [added: $195.3] million compared with [removed: $184.8] [added: $201.2] million during fiscal [removed: 2019.][added: 2020.]
Average borrowings for fiscal [removed: 2020] [added: 2021] were [removed: $5.393] [added: $5.401] billion, compared with [removed: $5.097] [added: $5.393] billion for fiscal [removed: 2019.][added: 2020.]
Weighted average borrowing rates were [removed: 3.3% for fiscal 2020] [added: 3.28%] and [removed: 3.2%] [added: 3.26%] for fiscal [removed: 2019.][added: 2021 and 2020, respectively.]
Our effective income tax rate was [removed: 21.8%] [added: 21.1%] of pre-tax income for fiscal [removed: 2020] [added: 2021] compared to [removed: 20.4%] [added: 21.8%] for fiscal [removed: 2019.][added: 2020.]
The [removed: increase] [added: decrease] in the tax rate was primarily attributable to [removed: a reduced] [added: an increased] benefit from stock options exercised during fiscal [removed: 2020] [added: 2021] compared to fiscal [removed: 2019.][added: 2020.]
The benefit of stock options exercised for fiscal [removed: 2020] [added: 2021] was [removed: $20.9] [added: $56.4] million compared to [removed: $46.0] [added: $20.9] million for fiscal [removed: 2019] [added: 2020] (see “Note D – Income Taxes” in the Notes to Consolidated Financial Statements).
Net income for fiscal [removed: 2020] [added: 2021] increased by [removed: 7.2%] [added: 25.2%] to [removed: $1.733] [added: $2.170] billion, and diluted earnings per share increased [removed: 13.4%] [added: 32.3%] to [removed: $71.93] [added: $95.19] from [removed: $63.43] [added: $71.93] in fiscal [removed: 2019.][added: 2020.]
The impact on the fiscal [removed: 2020] [added: 2021] diluted earnings per share from stock repurchases was an increase of [removed: $1.59.][added: $5.13.]
Fiscal [removed: 2019] [added: 2021] Compared with Fiscal [removed: 2018][added: 2020]
A discussion of changes in our results of operations from fiscal [removed: 2018] [added: 2019] to fiscal [removed: 2019] [added: 2020] has been omitted from this [added: Annual Report on] Form 10-K, but may be found in “Item 7.
Management’s Discussion and Analysis of Financial Condition and Results of Operations” of our [added: Annual Report on] Form 10-K for the fiscal year ended August [removed: 31, 2019,] [added: 29, 2020,] filed with the SEC on October [removed: 28, 2019,] [added: 26, 2020,] which is available free of charge on the SECs website at www.sec.gov and at www.autozone.com, by clicking “Investor Relations” located at the bottom of the page.
COVID-19 continues to impact numerous aspects of our business.
Our sales remain at record levels as we have experienced unprecedented customer demand for our products during the COVID-19 pandemic, as we believe that many of our customers have benefitted from pandemic-related government stimulus and benefits.
We continue to invest in supplies for the protection of our employees and customers and increased the frequency of cleaning and disinfecting our stores.
For fiscal 2021, we incurred approximately $43.0 million in pandemic related expenses, including Emergency Time-Off benefit enhancements for both full-time and part-time employees as compared to approximately $83.9 million in the comparable prior year period.
Furthermore, the continuing pandemic and related economic uncertainty may result in prolonged disruption and volatility to our business and magnify certain risks, including risks associated with sourcing quality merchandise domestically and outside the U.S.; our ability to promptly adjust inventory levels to meet fluctuations in customer demand; our ability to comply with complex and evolving laws and regulations related to customers’ and AutoZoners’ health and safety; our ability to open new store locations and expand or remodel existing stores; and our ability to hire and train qualified employees to address temporary or sustained labor shortages.
According to the latest data provided by the U.S. Bureau of Economic Analysis, new light vehicle sales for the year ended August 2021 increased 11.5% as compared to the comparable prior year period.
Additionally, there is increased demand for used vehicles as a result of new vehicle inventory shortages during the COVID-19 pandemic.
The following table highlights selected financial information over the last 5 years:
| _(in thousands, except per share data, same store sales and selected operating data)_ | | 2021(1) | | | 2020(1) | | | 2019(2) | | | 2018(3) | | | 2017 | | |
| Income Statement Data | | | | | | | | | | | | | | | | |
| Net sales | | $ | 14,629,585 | | $ | 12,631,967 | | $ | 11,863,743 | | $ | 11,221,077 | | $ | 10,888,676 | |
| Cost of sales, including warehouse and delivery expenses | | | 6,911,800 | | | 5,861,214 | | | 5,498,742 | | | 5,247,331 | | | 5,149,056 | |
| Gross profit | | | 7,717,785 | | | 6,770,753 | | | 6,365,001 | | | 5,973,746 | | | 5,739,620 | |
| Operating, selling, general and administrative expenses | | | 4,773,258 | | | 4,353,074 | | | 4,148,864 | | | 4,162,890 | | | 3,659,551 | |
| Operating profit | | | 2,944,527 | | | 2,417,679 | | | 2,216,137 | | | 1,810,856 | | | 2,080,069 | |
| Interest expense, net | | | 195,337 | | | 201,165 | | | 184,804 | | | 174,527 | | | 154,580 | |
| Income before income taxes | | | 2,749,190 | | | 2,216,514 | | | 2,031,333 | | | 1,636,329 | | | 1,925,489 | |
| Diluted earnings per share(4) | | $ | 95.19 | | $ | 71.93 | | $ | 63.43 | | $ | 48.77 | | $ | 44.07 | |
| Weighted average shares for diluted earnings per share(4) | | | 22,799 | | | 24,093 | | | 25,498 | | | 27,424 | | | 29,065 | |
| Same Store Sales | | | | | | | | | | | | | | | | |
| Increase in domestic comparable store net sales(5) | | | 13.6 | % | | 7.4 | % | | 3.0 | % | | 1.8 | % | | 0.5 | % |
| Balance Sheet Data | | | | | | | | | | | | | | | | |
| Current assets | | $ | 6,415,303 | | $ | 6,811,872 | | $ | 5,028,685 | | $ | 4,635,869 | | $ | 4,611,255 | |
| Operating lease right-of-use assets(6) | | | 2,718,712 | | | 2,581,677 | | | — | | | — | | | — | |
| Working capital (deficit) | | | (954,451) | | | 528,781 | | | (483,456) | | | (392,812) | | | (155,046) | |
| Total assets | | | 14,516,199 | | | 14,423,872 | | | 9,895,913 | | | 9,346,980 | | | 9,259,781 | |
| Current liabilities | | | 7,369,754 | | | 6,283,091 | | | 5,512,141 | | | 5,028,681 | | | 4,766,301 | |
| Finance lease liabilities, less current portion(6) | | | 186,122 | | | 155,855 | | | 123,659 | | | 102,013 | | | 102,322 | |
| Operating lease liabilities, less current portion(6) | | | 2,632,842 | | | 2,501,560 | | | — | | | — | | | — | |
| Stockholders’ deficit | | | (1,797,536) | | | (877,977) | | | (1,713,851) | | | (1,520,355) | | | (1,428,377) | |
| Selected Operating Data | | | | | | | | | | | | | | | | |
| Number of locations at beginning of year | | | 6,549 | | | 6,411 | | | 6,202 | | | 6,029 | | | 5,814 | |
| Sold locations(7) | | | — | | | — | | | — | | | 26 | | | — | |
| New locations | | | 219 | | | 138 | | | 209 | | | 201 | | | 215 | |
| Closed locations | | | 1 | | | — | | | — | | | 2 | | | — | |
| Net new locations | | | 218 | | | 138 | | | 209 | | | 199 | | | 215 | |
| Relocated locations | | | 12 | | | 5 | | | 2 | | | 7 | | | 5 | |
| Number of locations at end of year | | | 6,767 | | | 6,549 | | | 6,411 | | | 6,202 | | | 6,029 | |
| AutoZone domestic commercial programs | | | 5,179 | | | 5,007 | | | 4,893 | | | 4,741 | | | 4,592 | |
| Inventory per location (in thousands) | | $ | 686 | | $ | 683 | | $ | 674 | | $ | 636 | | $ | 644 | |
The outbreak of a novel strain of the coronavirus (“COVID-19”), which was declared a global pandemic on March 11, 2020 by the World Health Organization, has led to adverse impacts on the national and global economy.
We have been able to keep our stores open and operating in the U.S. Initially, we reduced the hours of operation in most stores, but subsequently have returned to more normal operating hours.
We provided new Emergency Time-Off benefit enhancements for both full-time and part-time eligible hourly employees in the U.S. We invested in supplies for the protection of our employees and customers, increased the frequency of cleaning and disinfecting, and introduced new service options for customers, such as curbside pickup, among other things.
These expanded benefits, supply costs and other COVID-19 related costs resulted in approximately $83.9 million of expense included in Operating, selling, general and administrative expenses in the Condensed Consolidated Statements of Income for the year ended August 29, 2020.
In March 2020, we issued $1.250 billion in Senior Notes and closed on a new 364-day Senior unsecured revolving credit facility to strengthen our financial position and our ability to be responsive during this ever-changing environment.
We have also experienced challenges in recruiting and hiring employees in certain of our retail stores and distribution centers.
While sales were initially negatively impacted, they have since increased to record levels.
Accordingly, continued business disruption related to the COVID-19 outbreak may continue to cause significant fluctuations in our business, unusually impacting demand for our products, our store hours and our workforce availability and magnify risks associated with sourcing quality merchandise domestically and outside the U.S. at competitive prices, some of which would adversely impact our business and results of operations.
Further, a resurgence of the outbreak or other unforeseen developments may impede our ability to complete construction and open new stores at our desired pace.
Given the nature of these macroeconomic factors, we cannot predict whether or for how long certain trends will continue, nor can we predict to what degree these trends will impact us in the future.
Fiscal 2020 consisted of 52 weeks whereas fiscal 2019 consisted of 53 weeks.
Our business is impacted by various factors within the economy that affect both our consumer and our industry, including but not limited to fuel costs, wage rates and other economic conditions, including for fiscal 2020, the effects of, and responses to, COVID-19.
New vehicles sales decreased 0.8% during 2020 as compared to the prior calendar year.
The decrease in gross margin was primarily attributable to lower merchandise margins driven primarily by a shift in mix.
The decrease in operating expenses, as a percentage of sales, was primarily due to leverage from higher sales growth, partially offset by $83.9 million of costs incurred in response to COVID-19.
This increase was primarily due to higher debt levels.
Net income and diluted earnings per share for fiscal 2019 benefitted from an additional week of sales.
Income Taxes
On December 22, 2017, the Tax Cuts and Jobs Act (“Tax Reform”) was enacted into law.
Tax Reform significantly revises the U.S. federal corporate income tax by, among other things, lowering the statutory federal corporate rate from 35% to 21%, eliminating certain deductions, imposing a mandatory one-time transition tax on accumulated earnings of foreign subsidiaries, and changing how foreign earnings are subject to U.S. federal tax.
Also, in December 2017, the SEC issued Staff Accounting Bulletin No. 118 (“SAB 118”) to address the application of GAAP in situations when the registrant does not have the necessary information available, prepared or analyzed in reasonable detail to complete the accounting for certain income tax effects of Tax Reform.
During the year ended August 25, 2018, we recorded provisional tax benefit of $131.5 million related to Tax Reform, comprised of $157.3 million remeasurement of its net Deferred Tax Asset (“DTA”), offset by $25.8 million of transition tax.
During the year ended August 31, 2019, we completed our analysis of Tax Reform and recorded adjustments to the previously-recorded provisional amounts, resulting in an $8.8 million tax benefit, primarily related to transition tax on accumulated earnings of foreign subsidiaries.
Beginning with the year ending August 31, 2019, we are subject to a new tax on global intangible low-taxed income (“GILTI”) that is imposed on foreign earnings.
We have made the election to record this tax as a period cost and therefore, have not adjusted the deferred tax assets or liabilities of our foreign subsidiaries for the new tax.
Net impacts for GILTI are included in the provision for income taxes for the years ended August 29, 2020 and August 31, 2019.
The decrease in capital expenditures from fiscal 2019 to fiscal 2020 was attributable to delayed store openings in response to COVID-19.
In fiscal 2018, we used commercial paper borrowings to repay our $250 million Senior Notes due in August 2018.
Net repayments of commercial paper and short term borrowings for fiscal 2019 were $295.3 million and net proceeds from the issuance of commercial paper and short-term borrowings for fiscal 2018 were $170.2 million.
Our investments are expected to be directed primarily to new locations, supply chain infrastructure, enhancements to existing locations and investments in technology.
The increase from fiscal 2019 was primarily due to accelerated sales growth.
For fiscal 2020, ROIC was presented net of average excess cash of $374.2 million.
For fiscal 2020, debt was presented net of excess cash, which ended the year at $1.6 billion.
| Debt(1) | | $ | 5,550,000 | | $ | 250,000 | | $ | 1,300,000 | | $ | 1,200,000 | | $ | 2,800,000 |
| Interest payments(2) | | | 1,093,138 | | | 181,275 | | | 327,238 | | | 255,175 | | | 329,450 |
| Operating leases(3) | | | 3,534,369 | | | 302,890 | | | 632,719 | | | 543,395 | | | 2,055,365 |
| Finance leases(4) | | | 251,380 | | | 69,013 | | | 102,565 | | | 35,037 | | | 44,765 |
| Self-insurance reserves(5) | | | 249,273 | | | 87,209 | | | 85,529 | | | 36,532 | | | 40,003 |
| | | $ | 10,729,023 | | $ | 941,250 | | $ | 2,448,051 | | $ | 2,070,139 | | $ | 5,269,583 |
An excerpt. Shown here: 40 of 172 rewritten, 40 of 117 added and 40 of 50 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2021 filing and the FY2020 filing.
Item 7A. Quantitative and Qualitative Disclosures about Market Risk
8 rewritten, 1 added, 2 removed, 23 unchanged
The fair value of our debt was estimated at [removed: $6.081] [added: $5.683] billion as of August [removed: 29, 2020,] [added: 28, 2021,] and [removed: $5.419] [added: $6.081] billion as of August [removed: 31, 2019,] [added: 29, 2020,] based on the quoted market prices for the same or similar debt issues or on the current rates available to us for debt having the same remaining maturities.
Such fair value is greater than the carrying value of debt by [added: $413.1 million and] $567.5 million at August [added: 28, 2021 and August] 29, 2020, [added: respectively,] which reflects its face amount, adjusted for any unamortized debt issuance costs and discounts.
We had no variable rate debt outstanding at August [removed: 29, 2020,] [added: 28, 2021] and [removed: $1.030 billion of variable rate debt outstanding at] August [removed: 31, 2019.][added: 29, 2020.]
We had outstanding fixed rate debt of [removed: $5.513] [added: $5.270] billion, net of unamortized debt issuance costs of [removed: $36.6] [added: $30.2] million, at August [removed: 29, 2020,] [added: 28, 2021,] and [removed: $4.176] [added: $5.513] billion, net of unamortized debt issuance costs of [removed: $23.7] [added: $36.6] million, at August [removed: 31, 2019.][added: 29, 2020.]
A one percentage point increase in interest rates would have reduced the fair value of our fixed rate debt by approximately [removed: $318.7] [added: $258.3] million at August [removed: 29, 2020.][added: 28, 2021.]
The net asset exposure in the Mexican subsidiaries translated into U.S. dollars using the year-end exchange rates was [removed: $293.1] [added: $310.1] million at August [removed: 29, 2020] [added: 28, 2021] and [removed: $328.8] [added: $293.1] million at August [removed: 31, 2019.][added: 29, 2020.]
The year-end exchange rates with respect to the Mexican peso [removed: decreased] [added: increased] by approximately 10% [removed: and approximately 7%] with respect to the U.S. dollar during fiscal [removed: 2020] [added: 2021] and [added: decreased by approximately 10% with respect to the U.S. dollar during] fiscal [removed: 2019, respectively.][added: 2020.]
The [added: potential] loss in value of our net assets in the Mexican subsidiaries resulting from a hypothetical 10 percent adverse change in quoted foreign currency exchange rates at August [removed: 29, 2020] [added: 28, 2021] and August [removed: 31, 2019,] [added: 29, 2020,] would have been approximately [removed: $26.6] [added: $28.2] million and approximately [removed: $29.9] [added: $26.6] million, respectively.
As of August 28, 2021 and August 29, 2020 no such interest rate swaps were outstanding.
At August 31, 2019, the fair value was greater than the carrying value of debt by $212.7 million.
Item 1. Business
103 rewritten, 89 added, 48 removed, 163 unchanged
We began operations in 1979 and at August [removed: 29, 2020,] [added: 28, 2021,] operated [removed: 5,885] [added: 6,051] stores in the United States (“U.S.”), [removed: 621] [added: 664] stores in Mexico and [removed: 43] [added: 52] stores in Brazil.
At August [removed: 29, 2020,] [added: 28, 2021,] in [removed: 5,007] [added: 5,179] of our domestic stores, we also had a commercial sales program that provides commercial credit and prompt delivery of parts and other products to local, regional and national repair garages, dealers, service stations and public sector accounts.
We also sell the ALLDATA brand automotive [removed: diagnostic and] [added: diagnostic,] repair [added: and shop management] software through [removed: www.alldata.com and www.alldatadiy.com.][added: www.alldata.com.]
At August [removed: 29, 2020,] [added: 28, 2021,] our stores were in the following locations:
| Arkansas | | [removed: 67] [added: 70] |
| Colorado | | [removed: 93] [added: 95] |
| Connecticut | | [removed: 49] [added: 53] |
| Delaware | | [removed: 16] [added: 17] |
| Idaho | | [removed: 31] [added: 32] |
| Iowa | | [removed: 32] [added: 36] |
| Maryland | | [removed: 81] [added: 88] |
| Massachusetts | | [removed: 82] [added: 83] |
| Minnesota | | [removed: 58] [added: 60] |
| Mississippi | | [removed: 95] [added: 98] |
| Nebraska | | [removed: 23] [added: 24] |
| New Jersey | | [removed: 111] [added: 117] |
| New York | | [removed: 204] [added: 211] |
| North Carolina | | [removed: 226] [added: 228] |
| Oklahoma | | [removed: 82] [added: 85] |
| Oregon | | [removed: 50] [added: 53] |
| Puerto Rico | | [removed: 48] [added: 50] |
| South Carolina | | [removed: 95] [added: 101] |
| Utah | | [removed: 61] [added: 70] |
| Washington | | [removed: 95] [added: 97] |
| Wisconsin | | [removed: 75] [added: 77] |
| Total Domestic stores | | [removed: 5,885] [added: 6,051] |
| Brazil | | [removed: 43] [added: 52] |
| Total stores | | [removed: 6,549] [added: 6,767] |
We emphasize that our AutoZoners [removed: (employees)] should always put customers first by providing prompt, courteous service and trustworthy advice.
Our electronic parts catalog assists in the selection of parts as well as identifying any associated warranties [removed: that are] offered by us or our vendors.
We sell automotive hard parts, maintenance items, accessories and non-automotive parts through www.autozone.com, for pick-up in store or to be shipped directly to a customer’s home or business, with next day delivery covering approximately [removed: 80%] [added: 82%] of the U.S. population.
Additionally, we offer a smartphone application that provides customers with store locations, driving directions, operating hours, product [removed: availability and] [added: availability,] the ability to purchase [removed: products.][added: products and other information.]
We believe [removed: that] customer satisfaction is often impacted by our ability to promptly provide specific automotive products as requested.
We are constantly updating the products we offer to ensure [removed: that] our inventory matches the products our customers need or desire.
We are constantly working to understand our customers’ wants and needs so [removed: that] we can build long-lasting, loyal relationships.
We utilize in-store signage, [removed: in-store circulars, and] creative product placement and promotions to help educate customers about products that they need.
As a part of the domestic store program, we offer credit and delivery to our customers, as well as online ordering through [removed: www.autozonepro.com.][added: www.autozonepro.com or through the AutoZone Pro smartphone application.]
[removed: Store Formats][added: _Store Formats_]
We believe [removed: that] our stores are “destination stores,” generating their own traffic rather than relying on traffic created by adjacent stores.
| | | [added: 2021 | |] 2020 | | 2019 | | 2018 | | 2017 | [removed: | 2016 |]
Human Capital Resources
We believe the foundation of our success is our culture, which defines how our employees (“AutoZoners”) take care of customers.
Each AutoZoner works hard to Live the Pledge, share their passion for WOW!
Customer Service and Go the Extra Mile every day to continue building and growing AutoZone for our customers.
**
_Training & Development_
We have a number of different types of jobs and career opportunities.
While many of our AutoZoners follow more traditional career paths (e.g., part-time to full-time sales, store manager, district manager, regional manager, vice president), we encourage cross-functional development and support of AutoZoners as they expand their career into other departments and fields of interest.
Many members of our senior leadership team have held positions in two or more areas of the business.
**
_Recognition_
The AutoZone Pledge and Values drive our success and foster a strong, unique culture of teamwork and customer service.
We encourage the recognition of AutoZoners for a variety of accomplishments, such as going above and beyond to deliver Trustworthy Advice and WOW!
Customer Service, taking initiative to prevent incidents and injuries, making contributions to help detect or report internal or external theft or providing significant service to help others.
Whether they work in our stores, distribution centers, support centers or travel to support our customers and business, we believe AutoZoners everywhere should be recognized for their efforts and outstanding performance.
We also recognize AutoZoners for their years of service to the organization and our customers.
**
_Diversity, Equity and Inclusion (“DEI”)_
“Embraces Diversity” is one of our Values, and we have made great strides to lay a proper foundation for our DEI initiatives.
With the oversight and support of a cross-functional Diversity Council and DEI Steering Committee, our DEI efforts influence and inform many parts of our human capital management function including talent acquisition, retention, professional development and workforce management.
Our first business resource group (“BRG”) was established in 2014 (AutoZone Women’s Initiative).
Since then, four other BRGs now support AutoZoners who share common interests or backgrounds and have a mission to contribute their voices, time and talent to helping AutoZoners succeed and grow in their careers.
_Health and Safety_
We are committed to providing a safe working and shopping environment for our AutoZoners and customers.
Aligned with our values, we strive to continually monitor our working and shopping environment to keep our AutoZoners and customers as safe as possible.
In response to the COVID-19 pandemic, we continue to invest in supplies for the protection of our AutoZoners and our customers and increased the frequency of cleaning and disinfecting our stores.
We also provided Emergency Time-Off benefit enhancements for both full-time and part-time AutoZoners and a one-time financial incentive for receiving the COVID-19 vaccine.
As the effects of COVID-19 continue to evolve, we are closely monitoring the changing situation and complying with public health guidance.
Additional information about our human capital resources can be found in our most recent Corporate Social Responsibility (“CSR”) Report, which is available on our website.
Our CSR Report is not, and will not be deemed to be, a part of this Annual Report on Form 10-K or incorporated by reference into any of our other filings with the Securities and Exchange Commission (“the SEC”).
| Alabama | | 120 |
| Arizona | | 162 |
| California | | 641 |
| Florida | | 397 |
| Georgia | | 209 |
| Illinois | | 243 |
| Indiana | | 160 |
| Kentucky | | 102 |
| Louisiana | | 129 |
| Michigan | | 214 |
| Alabama | | 118 |
| Arizona | | 159 |
| California | | 631 |
| Florida | | 379 |
| Georgia | | 204 |
| Illinois | | 241 |
| Indiana | | 158 |
| Kentucky | | 100 |
| Louisiana | | 127 |
| Michigan | | 203 |
| Missouri | | 116 |
| Ohio | | 274 |
| Pennsylvania | | 205 |
| Tennessee | | 169 |
| Texas | | 637 |
| Virginia | | 141 |
| Mexico | | 621 |
Employees
William T.
Giles was named Chief Financial Officer during May 2006 and has notified the Company of his intent to retire, effective December 31, 2020.
He has also held other responsibilities at various times including Executive Vice President of Finance, Information Technology, ALLDATA and Store Development.
From 1991 to May 2006, he held several positions with Linens N’ Things, Inc., most recently as the Executive Vice President and Chief Financial Officer.
Prior to 1991, he was with Melville, Inc. and PricewaterhouseCoopers.
Mr. Giles is a member of the Board of Directors for Brinker International.
_Jamere Jackson, 51—Chief Financial Officer and Executive Vice President – Finance and Store Development-Elect, Customer Satisfaction_
Hertz Global Holdings, Inc. filed Chapter 11 bankruptcy on May 22, 2020.
Prior thereto, he served in various capacities within the Company.
Daniele was elected Senior Vice President – Commercial during November 2015.
From 1993 until 2008, Mr. Daniele served in various capacities within the Company.
Previously, he was Vice President, Internal Audit from 2010 to 2015.
From 2006 to 2010, Mr. Frazer served in various capacities within the Company.
Ronald B.
Prior to that, he was Senior Vice President, Global Information Technology at Hewlett-Packard Company.
During his tenure at Hewlett-Packard Company, he also served as the Chief Information Officer for the Enterprise Business Division.
Prior to that, Mr. Griffin was Executive Vice President and Chief Information Officer for Fleming Companies, Inc. He also spent over 12 years with The Home Depot, Inc., with the last eight years in the role of Chief Information Officer.
Mr. Griffin also served at Deloitte & Touche LLP and Delta Air Lines, Inc.
_William R.
William R.
An excerpt. Shown here: 40 of 103 rewritten, 40 of 89 added and 40 of 48 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2021 filing and the FY2020 filing.
Item 3. Legal Proceedings
0 rewritten, 2 added, 11 removed, 2 unchanged
Item 103 of Regulation S-K requires disclosure of certain environmental matters when a governmental authority is a party to the proceedings and such proceedings involve potential monetary sanctions that we reasonably believe will exceed an applied threshold of $1 million.
Applying this threshold, there are no environmental matters to disclose for this period.
In 2004, we acquired a store site in Mount Ephraim, New Jersey that had previously been the site of a gasoline service station and contained evidence of groundwater contamination.
Upon acquisition, we voluntarily reported the groundwater contamination issue to the New Jersey Department of Environmental Protection (“NJDEP”) and entered into a Voluntary Remediation Agreement providing for the remediation of the contamination associated with the property.
We have conducted and paid for (at an immaterial cost to us) remediation of contamination on the property.
We have also voluntarily investigated and addressed potential vapor intrusion impacts in downgradient residences and businesses.
The NJDEP has asserted, in a Directive and Notice to Insurers dated February 19, 2013 and again in an Amended Directive and Notice to Insurers dated January 13, 2014 (collectively the “Directives”), that we are liable for the downgradient impacts under a joint and severable liability theory.
By letter dated April 23, 2015, NJDEP has demanded payment from us, and other parties, in the amount of approximately $296 thousand for costs incurred by NJDEP in connection with contamination downgradient of the property.
By letter dated January 29, 2016, we were informed that NJDEP has filed a lien against the property in connection with approximately $355 thousand in costs incurred by NJDEP in connection with contamination downgradient of the property.
We have contested, and will continue to contest, any such assertions due to the existence of other entities/sources of contamination, some of which are named in the Directives and the April 23, 2015 demand letter, in the area of the property.
Pursuant to the Voluntary Remediation Agreement, upon completion of all remediation required by the agreement, we believe we should be eligible to be reimbursed up to 75% of qualified remediation costs by the State of New Jersey.
We have asked the state for clarification that the agreement applies to off-site work.
Although the aggregate amount of additional costs that we may incur pursuant to the remediation cannot currently be ascertained, we do not currently believe that fulfillment of our obligations under the agreement or otherwise will result in costs that are material to our financial condition, results of operations or cash flows.
Cover and table of contents
33 rewritten, 4 added, 4 removed, 77 unchanged
| For the fiscal year ended August [removed: 29, 2020.] [added: 28, 2021.] | |
[removed: ][added: ]
Indicate by [removed: checkmark] [added: check mark] if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act.
The aggregate market value of the voting and non-voting common equity held by non-affiliates computed by reference to the price at which the common equity was last sold, or the average bid and asked price of such common equity, as of the last business day of the registrant’s most recently completed second fiscal quarter was [removed: $24,661,503,822.][added: $24,697,255,765.]
The number of shares of Common Stock outstanding as of October [removed: 19, 2020,] [added: 18, 2021,] was [removed: 23,175,554.][added: 20,967,962.]
Portions of the definitive Proxy Statement to be filed within 120 days of August [removed: 29, 2020,] [added: 28, 2021,] pursuant to Regulation 14A under the Securities Exchange Act of 1934 for the Annual Meeting of Stockholders to be held December [removed: 16, 2020,] [added: 15, 2021,] are incorporated by reference into Part III.
| | [Marketing and Merchandising [removed: Strategy](#MarketingandMerchandisingStrategy_311942)] [added: Strategy](#MarketingandMerch)] | [removed: 6] [added: 8] |
| | [Store [removed: Operations](#StoreOperations_66614)] [added: Operations](#_Store_Operations)] | [removed: 7] [added: 6] |
| | [Purchasing and Supply Chain](#PurchasingandSupplyChain_301199) | [removed: 9] [added: 10] |
| | [Competition](#Competition_974800) | [removed: 9] [added: 10] |
| | [Trademarks and Patents](#TrademarksandPatents_374286) | [removed: 10] [added: 11] |
| | [Seasonality](#Seasonality_291101) | [removed: 10] [added: 11] |
| | [AutoZone Websites](#AutoZoneWebsites_139280) | [removed: 10] [added: 11] |
| | [Information about our Executive Officers](#InformationaboutourExecutiveOfficers_691) | [removed: 10] [added: 11] |
| [Item 1A.](#Item1ARiskFactors_38338) | [Risk Factors](#Item1ARiskFactors_38338) | [removed: 13] [added: 14] |
| [Item 1B.](#Item1BUnresolvedStaffComments_805543) | [Unresolved Staff Comments](#Item1BUnresolvedStaffComments_805543) | [removed: 22] [added: 23] |
| [Item 3.](#Item3LegalProceedings_756426) | [Legal Proceedings](#Item3LegalProceedings_756426) | [removed: 23] [added: 24] |
| [Item 4.](#Item4MineSafetyDisclosures_520665) | [Mine Safety Disclosures](#Item4MineSafetyDisclosures_520665) | [removed: 23] [added: 24] |
| [Item 7.](#Item7ManagementsDiscussionandAnalysisofF) | [Management’s Discussion and Analysis of Financial Condition and Results of Operations](#Item7ManagementsDiscussionandAnalysisofF) | [removed: 28] [added: 26] |
| [Item 9.](#Item9ChangesInandDisagreementswithAccoun) | [Changes In and Disagreements with Accountants on Accounting and Financial Disclosure](#Item9ChangesInandDisagreementswithAccoun) | [removed: 79] [added: 77] |
| [Item 9A.](#Item9AControlsandProcedures_188492) | [Controls and Procedures](#Item9AControlsandProcedures_188492) | [removed: 79] [added: 77] |
| [Item 9B.](#Item9BOtherInformation_172860) | [Other Information](#Item9BOtherInformation_172860) | [removed: 79] [added: 77] |
| [PART III](#PARTIII_203734) | | [removed: 80] [added: 78] |
| [Item 10.](#Item10DirectorsExecutiveOfficersandCorpo) | [Directors, Executive Officers and Corporate Governance](#Item10DirectorsExecutiveOfficersandCorpo) | [removed: 80] [added: 78] |
| [Item 11.](#Item11ExecutiveCompensation_791654) | [Executive Compensation](#Item11ExecutiveCompensation_791654) | [removed: 80] [added: 78] |
| [Item 12.](#Item12SecurityOwnershipofCertainBenefici) | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#Item12SecurityOwnershipofCertainBenefici) | [removed: 80] [added: 78] |
| [Item 13.](#Item13CertainRelationshipsandRelatedTran) | [Certain Relationships and Related Transactions, and Director Independence](#Item13CertainRelationshipsandRelatedTran) | [removed: 80] [added: 78] |
| [Item 14.](#Item14PrincipalAccountingFeesandServices) | [Principal Accounting Fees and Services](#Item14PrincipalAccountingFeesandServices) | [removed: 80] [added: 78] |
| [PART IV](#PARTIV_397719) | | [removed: 81] [added: 79] |
| [Item 15.](#Item15ExhibitsandFinancialStatementSched) | [Exhibits and Financial Statement Schedules](#Item15ExhibitsandFinancialStatementSched) | [removed: 81] [added: 79] |
| [Item 16.](#Item16Form10KSummary_196381) | [Form 10-K Summary](#Item16Form10KSummary_196381) | [removed: 86] [added: 84] |
These forward-looking statements are subject to a number of risks and uncertainties, including without limitation: product demand; energy prices; weather; competition; credit market conditions; cash flows; access to available and feasible financing; future stock repurchases; the impact of recessionary conditions; consumer debt levels; changes in laws or regulations; risks associated with self-insurance; war and the prospect of war, including terrorist activity; the impact of public health issues, such as the ongoing global [removed: pandemic of a novel strain of the] coronavirus [removed: (“COVID-19”);] [added: (“COVID-19”) pandemic;] inflation; the ability to hire, train and retain qualified employees; construction delays; the compromising of confidentiality, availability or integrity of information, including [added: due to] cyber-attacks; historic growth rate sustainability; downgrade of our credit ratings; [removed: damages] [added: damage] to our reputation; challenges in international markets; failure or interruption of our information technology systems; origin and raw material costs of suppliers; [added: inventory availability;] disruption in our supply [removed: chain, due to public health epidemics or otherwise;] [added: chain;] impact of tariffs; anticipated impact of new accounting standards; and business interruptions.
Certain of these risks and uncertainties are discussed in more detail in the “Risk Factors” section contained in Item 1A under Part 1 of this Annual Report on Form [removed: 10 K] [added: 10-K] for the year ended August [removed: 29, 2020,] [added: 28, 2021,] and these Risk Factors should be read carefully.
| | [Human Capital Resources](#HumanCapitalResources) | 4 |
| | [Government Relations](#GovernmentRelations) | 10 |
| [Item 6.](#Reserved) | [Reserved](#Reserved) | 25 |
| [Item 9C.](#Item9CDisclosureRegardingForeignJurisdic) | [Disclosure Regarding Foreign Jurisdictions that Prevent Inspections](#Item9CDisclosureRegardingForeignJurisdic) | 77 |
Yes ⌧ No ◻
| | [Employees](#Employees_668167) | 10 |
| [Item 6.](#Item6SelectedFinancialData_301078) | [Selected Financial Data](#Item6SelectedFinancialData_301078) | 26 |
Item 1B. Unresolved Staff Comments
0 rewritten, 0 added, 1 removed, 1 unchanged
Item 2. Properties
4 rewritten, 5 added, 3 removed, 7 unchanged
The following table reflects the square footage and number of leased and owned properties for our stores as of August [removed: 29, 2020:][added: 28, 2021:]
| | | Stores | | [removed: Footage] [added: Footage(1)] |
We have approximately 5.9 million square feet in distribution centers servicing our stores, of which approximately [removed: 1.9] [added: 1.8] million square feet is leased and the remainder is owned.
The ALLDATA headquarters in Elk Grove, California is leased, and we also own or lease other properties [removed: that] [added: which] are not material in the aggregate.
| Leased | | 3,641 | | 23,911,656 |
| Owned | | 3,126 | | 21,145,587 |
| Total | | 6,767 | | 45,057,243 |
| (1) | _Square footage excludes store support centers, regional offices, distribution centers and the areas that hold the local mega hub and hub expanded assortment._ |
| --- | --- |
| Leased | | 3,489 | | 22,811,306 |
| Owned | | 3,060 | | 20,690,477 |
| Total | | 6,549 | | 43,501,783 |
Item 4. Mine Safety Disclosures
0 rewritten, 0 added, 1 removed, 2 unchanged
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
11 rewritten, 10 added, 2 removed, 7 unchanged
[removed: Our] [added: The principal market on which our] common stock is [removed: listed on] [added: traded is] the New York Stock Exchange under the symbol “AZO.” On October [removed: 19, 2020,] [added: 18, 2021,] there were [removed: 2,021] [added: 1,936] stockholders of record, which does not include the number of beneficial owners whose shares were represented by security position listings.
The program was most recently amended on October [removed: 7, 2019,] [added: 5, 2021,] to increase the repurchase authorization by [removed: $1.250] [added: $1.5] billion, bringing [added: the] total value of authorized share repurchases to [removed: $23.15] [added: $27.65] billion.
[removed: During] [added: Beginning in the first quarter of] fiscal [removed: 2020,] [added: 2021,] we [removed: temporarily ceased] [added: restarted our] share repurchases under our share repurchase [removed: program to conserve liquidity] [added: program, which had been temporarily suspended during fiscal 2020] in response to the uncertainty [removed: related to COVID-19.][added: surrounding the COVID-19 pandemic.]
[removed: While we have restarted share repurchases during the first quarter of fiscal year 2021, we] [added: We] will continue to evaluate current and expected business conditions and adjust the level of share repurchases under our share repurchase program as we deem appropriate.
The Company also repurchased, at market value, an additional [removed: 8,287, 17,201] [added: 7,611, 8,287] and [removed: 11,816] [added: 17,201] shares in fiscal years [removed: 2020, 2019] [added: 2021, 2020] and [removed: 2018,] [added: 2019,] respectively, from employees electing to sell their stock under the Company’s Sixth Amended and Restated Employee Stock Purchase Plan (the “Employee Plan”), qualified under Section 423 of the Internal Revenue Code, under which all eligible employees may purchase AutoZone’s common stock at 85% of the lower of the market price of the common stock on the first day or last day of each calendar quarter through payroll deductions.
Under the Employee Plan, [removed: 10,525, 11,011] [added: 8,479, 10,525] and [removed: 14,523] [added: 11,011] shares were sold to employees in fiscal [removed: 2020, 2019] [added: 2021, 2020] and [removed: 2018,] [added: 2019,] respectively.
At August [removed: 29, 2020, 142,241] [added: 28, 2021, 133,762] shares of common stock were reserved for future issuance under the Employee Plan.
Purchases by executives under the Executive Plan were [removed: 1,204, 1,483] [added: 997, 1,204] and [removed: 1,840] [added: 1,483] shares in fiscal [removed: 2020, 2019] [added: 2021, 2020] and [removed: 2018,] [added: 2019,] respectively.
At August [removed: 29, 2020, 235,361] [added: 28, 2021, 234,364] shares of common stock were reserved for future issuance under the Executive Plan.
The graph below presents changes in the value of AutoZone’s stock as compared to Standard & Poor’s 500 Composite Index (“S&P 500”) and to Standard & Poor’s Retail Index (“S&P Retail Index”) for the five-year period beginning August [removed: 29, 2015] [added: 27, 2016] and ending August [removed: 29, 2020.][added: 28, 2021.]
[removed: 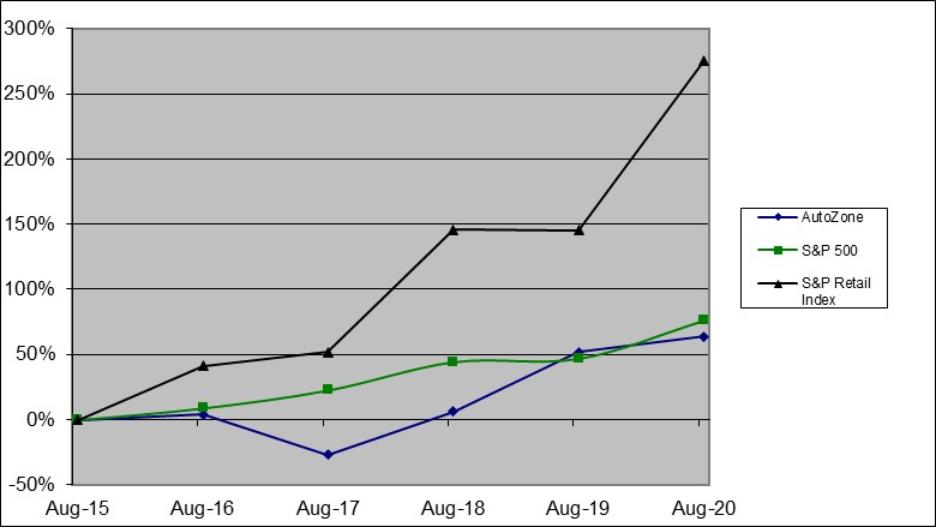][added: Description automatically generated](https://www.sec.gov/Archives/edgar/data/866787/000155837021013446/azo-20210828x10k002.jpg)]
Shares of common stock repurchased by the Company during the quarter ended August 28, 2021 were as follows:
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Period | Total Number of Shares Purchased | | | Average Price Paid per Share | | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | | | Maximum Dollar Value that May Yet Be Purchased Under the Plans or Programs |
| May 9, 2021 to June 5, 2021 | 119,391 | | $ | 1,463.82 | | 119,391 | | $ | 1,142,800,316 |
| June 6, 2021 to July 3, 2021 | 179,195 | | | 1,420.00 | | 179,195 | | | 888,343,302 |
| July 4, 2021 to July 31, 2021 | 164,072 | | | 1,580.00 | | 164,072 | | | 629,109,159 |
| August 1, 2021 to August 28, 2021 | 129,802 | | | 1,629.71 | | 129,802 | | | 417,569,204 |
| Total | 592,460 | | $ | 1,519.09 | | 592,460 | | $ | 417,569,204 |
] | 45 |
Management, with the participation of our principal executive and financial officers, assessed our internal control over financial reporting as of August [removed: 29, 2020,] [added: 28, 2021,] the end of our fiscal year.
Based on this assessment, management has concluded that our internal control over financial reporting was effective as of August [removed: 29, 2020.][added: 28, 2021.]
Ernst & Young LLP’s attestation report on the Company’s internal control over financial reporting as of August [removed: 29, 2020] [added: 28, 2021] is included in this Annual Report on Form 10-K.
To the [added: Stockholders and the] Board of Directors [removed: and Stockholders] of AutoZone, Inc.
We have audited AutoZone Inc.’s internal control over financial reporting as of August [removed: 29, 2020,] [added: 28, 2021,] based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria).
In our opinion, AutoZone, Inc. (the Company) maintained, in all material respects, effective internal control over financial reporting as of August [removed: 29, 2020,] [added: 28, 2021,] based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of August [removed: 29, 2020] [added: 28, 2021] and August [removed: 31, 2019,] [added: 29, 2020,] and the related consolidated statements of income, comprehensive income, stockholders’ deficit, and cash flows for each of the three years in the period ended August [removed: 29, 2020,] [added: 28, 2021,] and the related notes and our report dated October [removed: 26, 2020] [added: 25, 2021] expressed an unqualified opinion thereon.
We have audited the accompanying consolidated balance sheets of AutoZone, Inc. (the Company) as of August [removed: 29, 2020] [added: 28, 2021] and August [removed: 31, 2019,] [added: 29, 2020,] the related consolidated statements of income, comprehensive income, stockholders' deficit, and cash flows for each of the three years in the period ended August [removed: 29, 2020,] [added: 28, 2021,] and the related notes (collectively referred to as the “consolidated financial statements”).
In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at August [removed: 29, 2020] [added: 28, 2021] and August [removed: 31, 2019,] [added: 29, 2020,] and the results of its operations and its cash flows for each of the three years in the period ended August [removed: 29, 2020,] [added: 28, 2021,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of August [removed: 29, 2020,] [added: 28, 2021,] based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated October [removed: 26, 2020,] [added: 25, 2021,] expressed an unqualified opinion thereon.
| Description of the Matter | At August [removed: 29, 2020,] [added: 28, 2021,] the Company’s self-insurance reserve estimate was [removed: $289] [added: $284] million. As more fully described in Note A of the consolidated financial statements, the Company retains a significant portion of the risks associated with workers’ compensation, general liability, product liability, property and vehicle insurance. Accordingly, the Company utilizes various methods, including analyses of historical trends and actuarial methods, to estimate the costs of these risks. |
| | | August [removed: 29,] [added: 28,] | | | August [removed: 31,] [added: 29,] | | | August [removed: 25,] [added: 31,] | |
| | | [removed: 2020] [added: 2021] | | | [removed: 2019] [added: 2020] | | | [removed: 2018] [added: 2019] | |
| _(in thousands, except per share data)_ | | (52 weeks) | | | [removed: (53] [added: (52] weeks) | | | [removed: (52] [added: (53] weeks) | |
| Net sales | | $ | [removed: 12,631,967] [added: 14,629,585] | | $ | [removed: 11,863,743] [added: 12,631,967] | | $ | [removed: 11,221,077] [added: 11,863,743] |
| Cost of sales, including warehouse and delivery expenses | | | [removed: 5,861,214] [added: 6,911,800] | | | [removed: 5,498,742] [added: 5,861,214] | | | [removed: 5,247,331] [added: 5,498,742] |
| Gross profit | | | [removed: 6,770,753] [added: 7,717,785] | | | [removed: 6,365,001] [added: 6,770,753] | | | [removed: 5,973,746] [added: 6,365,001] |
| Operating, selling, general and administrative expenses | | | [removed: 4,353,074] [added: 4,773,258] | | | [removed: 4,148,864] [added: 4,353,074] | | | [removed: 4,162,890] [added: 4,148,864] |
| Operating profit | | | [removed: 2,417,679] [added: 2,944,527] | | | [removed: 2,216,137] [added: 2,417,679] | | | [removed: 1,810,856] [added: 2,216,137] |
| Interest expense, net | | | [removed: 201,165] [added: 195,337] | | | [removed: 184,804] [added: 201,165] | | | [removed: 174,527] [added: 184,804] |
| Income before income taxes | | | [removed: 2,216,514] [added: 2,749,190] | | | [removed: 2,031,333] [added: 2,216,514] | | | [removed: 1,636,329] [added: 2,031,333] |
| Income tax expense | | | [removed: 483,542] [added: 578,876] | | | [removed: 414,112] [added: 483,542] | | | [removed: 298,793] [added: 414,112] |
| Net income | | $ | [removed: 1,732,972] [added: 2,170,314] | | $ | [removed: 1,617,221] [added: 1,732,972] | | $ | [removed: 1,337,536] [added: 1,617,221] |
| Weighted average shares for basic earnings per share | | | [removed: 23,540] [added: 22,237] | | | [removed: 24,966] [added: 23,540] | | | [removed: 26,970] [added: 24,966] |
| Effect of dilutive stock equivalents | | | [removed: 553] [added: 562] | | | [removed: 532] [added: 553] | | | [removed: 454] [added: 532] |
| Weighted average shares for diluted earnings per share | | | [removed: 24,093] [added: 22,799] | | | [removed: 25,498] [added: 24,093] | | | [removed: 27,424] [added: 25,498] |
| Basic earnings per share | | $ | [removed: 73.62] [added: 97.60] | | $ | [removed: 64.78] [added: 73.62] | | $ | [removed: 49.59] [added: 64.78] |
| Diluted earnings per share | | $ | [removed: 71.93] [added: 95.19] | | $ | [removed: 63.43] [added: 71.93] | | $ | [removed: 48.77] [added: 63.43] |
| | [removed: |] August [removed: 29,] [added: 28,] | | | August [removed: 31,] [added: 29,] | | | August [removed: 25,] [added: 31,] | |
| | [removed: | 2020] [added: 2021] | | | [removed: 2019] [added: 2020] | | | [removed: 2018] [added: 2019] | |
| _(in thousands)_ | [removed: |] (52 weeks) | | | [removed: (53] [added: (52] weeks) | | | [removed: (52] [added: (53] weeks) | |
| Other comprehensive [removed: loss: | ] [added: gain (loss) income:] | | | | | | | | |
| Foreign currency translation adjustments | [removed: ] | [removed: | (66,723)] [added: 44,683] | | | [removed: (36,699)] [added: (66,723)] | | | [removed: (53,085)] [added: (36,699)] |
| Unrealized [removed: gains] (losses) [added: gains] on marketable debt securities, net of [removed: taxes(3) | ] [added: taxes] | | [removed: 1,254] [added: (1,256)] | | | [removed: 1,464] [added: 1,254] | | | [removed: (862)] [added: 1,464] |
| Net derivative activities, net of [removed: taxes(4) | ] [added: taxes] | | [removed: (19,461)] [added: 2,839] | | | [removed: 1,718] [added: (19,461)] | | | [removed: 323] [added: 1,718] |
| Total other comprehensive [removed: (loss)] income [removed: | ] [added: (loss)] | | [removed: (84,930)] [added: 46,266] | | | [removed: (33,517)] [added: (84,930)] | | | [removed: 18,752] [added: (33,517)] |
| Comprehensive income | [removed: |] $ | [removed: 1,648,042] [added: 2,216,580] | | $ | [removed: 1,583,704] [added: 1,648,042] | | $ | [removed: 1,356,288] [added: 1,583,704] |
| ** | | August [removed: 29,] [added: 28,] | | | August [removed: 31,] [added: 29,] | |
| _(in thousands)_ | [removed: ] [added: ] | [added: 2021 | | |] 2020 | | [removed: ] [added: ] | 2019 | |
October 25, 2021
To the Stockholders and the Board of Directors of AutoZone, Inc.
October 25, 2021
| | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | |
| Net income | $ | 2,170,314 | | $ | 1,732,972 | | $ | 1,617,221 |
| (1) | |
| _(in thousands)_ | | 2021 | | | 2020 | |
| Cash and cash equivalents | | $ | 1,171,335 | | $ | 1,750,815 |
| | | | 4,856,891 | | | 4,509,221 |
| | | | 3,244,005 | | | 3,102,779 |
| Total assets | | $ | 14,516,199 | | $ | 14,423,872 |
| Total liabilities and stockholders' deficit | | $ | 14,516,199 | | $ | 14,423,872 |
| _(in thousands)_ | | | (52 weeks) | | | (52 weeks) | | | (53 weeks) |
| Net income | | $ | 2,170,314 | | $ | 1,732,972 | | $ | 1,617,221 |
| Net income | | — | | | — | | | — | | | 2,170,314 | | | — | | | — | | | 2,170,314 |
| Retirement of treasury shares | | (1,044) | | | (10) | | | (60,005) | | | (1,139,173) | | | — | | | 1,199,188 | | | — |
| Balance at August 28, 2021 | | 23,007 | | $ | 230 | | $ | 1,465,669 | | $ | (419,829) | | $ | (307,986) | | $ | (2,535,620) | | $ | (1,797,536) |
Accounts Receivable: Effective in fiscal 2021, the Company adopted ASU 2016-13, _Financial Instruments - Credit Losses (Topic 326)_, which requires the Company to estimate all expected credit losses for financial assets measured at amortized cost basis, including trade receivables, based on historical experience, current market conditions and supportable forecasts.
The Company’s accounts receivable primarily consists of receivables from commercial customers.
The Company routinely grants credit to certain commercial customers on a short-term basis consisting primarily of daily, weekly or monthly terms.
Receivables are presented net of an allowance for credit losses.
The Company will apply adjustments for specific factors and current economic conditions as needed at each reporting date.
The Company’s allowance for credit losses are included in “Accounts receivable” on the accompanying Consolidated Balance Sheets as of August 28, 2021 and August 29, 2020.
Vendor Receivables: The Company’s vendor receivables primarily consist of balances arising from its vendors through a variety of programs and arrangements, including rebates, allowances, promotional funds and reimbursement of specific, incremental, identifiable costs incurred by the Company in selling the vendors’ products.
The amounts to be received are prescribed by the terms of the vendor agreements and therefore collection of such amounts is generally not at risk.
The Company regularly reviews vendor receivables for collectability and assesses the need for an allowance for credit losses based on an evaluation of the vendors’ financial positions and corresponding abilities to meet financial obligations.
Management does not believe there is a reasonable likelihood that the Company will be unable to collect the receivables from vendors and did not record a reserve for expected credit losses from vendors in the Consolidated Financial Statements as of August 28, 2021 and August 29, 2020.
The Company adopted the new guidance on a prospective basis in the first quarter of fiscal 2021.
The adoption of this guidance did not have a material impact on the Company’s Consolidated Financial Statements and related disclosures.
The adoption of this new guidance did not have a material impact on the Company’s Consolidated Financial Statements and related disclosures.
_AutoZone, Inc. 2020 Omnibus Incentive Award Plan_
On December 16, 2020, the Company’s stockholders approved the AutoZone, Inc. 2020 Omnibus Incentive Award Plan (the “2020 Omnibus Plan”), which serves as the successor to the Amended 2011 Equity Plan.
The 2020 Omnibus Plan provides equity-based compensation to our non-employee directors and employees for their service to AutoZone or our subsidiaries or affiliates.
Under the 2020 Omnibus Plan, participants may receive equity-based compensation in the form of stock options, stock appreciation rights, restricted stock, restricted stock units, dividend equivalents, deferred stock, stock payments, performance based awards, cash based awards and other incentive awards structured by the Compensation Committee and the Board within parameters set forth in the 2020 Omnibus Plan.
| Granted | | 202,820 | | | 1,152.54 | | | | | |
| Exercised | | (349,592) | | | 541.80 | | | | | |
| Cancelled | | (30,160) | | | 906.26 | | | | | |
| Outstanding – August 28, 2021 | | 1,208,054 | | | 790.41 | | 5.95 | | $ | 915,807 |
| --- | --- |
October 26, 2020
Adoption of ASU 2016-02
As discussed in Note A to the consolidated financial statements, the Company changed its method of accounting for leases on September 1, 2019 due to the adoption of Accounting Standards Update (ASU) No. 2016-02, _Leases_ (Topic 842), and related amendments.
| Pension liability adjustments, net of taxes(1)(2) | | | — | | | — | | | 72,376 |
| (1) | _Pension liability adjustments are presented net of taxes of_ _$46,523_ _in 2018, which includes_ _$13,122_ _related to the adoption of ASU 2018-02 - Income Statement - Reporting Comprehensive Income: Reclassification of Certain Tax effects from Accumulated Other Comprehensive Income (ASU 2018-02)._ |
| (2) | _On December 19, 2017, the Board approved a resolution to terminate both of the Company’s pension plans, effective March 15, 2018. During the fourth quarter of 2018, the Company completed the termination and no longer has any remaining defined benefit pension obligation._ |
| (3) | _Unrealized gains on marketable debt securities are presented net of taxes of_ _$336_ _and_ _$389_ _in 2020 and 2019, respectively. Unrealized losses on marketable debt securities are presented net of tax benefit of_ _$234_ _in 2018._ |
| (4) | _Net derivative activities are presented net of tax benefit of_ _$6,164_ _in 2020. Net derivative activities are presented net of taxes of_ _$530_ _in 2019 and_ _$1,882_ _in 2018, which includes_ _$1,367_ _related to the adoption of ASU 2018-02._ |
| | | | 4,509,221 | | | 4,398,751 |
| | | | 3,102,779 | | | 468,477 |
| Pension plan contributions | | | — | | | — | | | (11,596) |
| Pension termination charges (refund) | | | — | | | (6,796) | | | 130,263 |
| Asset impairment | | | — | | | — | | | 193,162 |
| Proceeds from sale of assets | | | — | | | — | | | 35,279 |
| Cash and cash equivalents at beginning of period | | | 176,300 | | | 217,824 | | | 293,270 |
**
| Balance at August 26, 2017 | | 28,735 | | | $ 287 | | | $ 1,086,671 | | | $ (1,642,387) | | | $ (254,557) | | | $ (618,391) | | | $ (1,428,377) |
| Net income | | — | | | — | | | — | | | 1,337,536 | | | — | | | — | | | 1,337,536 |
| Retirement of treasury shares | | (1,512) | | | (15) | | | (60,500) | | | (918,462) | | | — | | | 978,977 | | | — |
| Adoption of ASU 2018-02 | | — | | | — | | | — | | | 14,489 | | | — | | | — | | | 14,489 |
Accounts Receivable: Accounts receivable consists of receivables from commercial customers and vendors, and is presented net of an allowance for uncollectible accounts.
AutoZone routinely grants credit to certain of its commercial customers.
Intangible Assets: Intangible assets consist of customer relationships purchased relating to ALLDATA operations.
Amortizing intangible assets are amortized over periods ranging from 3 to 10 years.
The exercise of lease renewal options is at the Company’s sole discretion.
The Company’s lease agreements do not contain any material residual value guarantees or material restrictive covenants.
Effective in fiscal 2020, the Company adopted Accounting Standards Update (“ASU”) 2016-02, Leases (Topic 842).
Refer to “Note A – Recently Adopted Accounting Pronouncements”.
Prior to the adoption of Topic 842, the Company accounted for leases under Topic 840 and recognized rent expense on a straight-line basis over the course of the lease term, which included any reasonably assured renewal periods, beginning on the date the Company took physical possession of the property.
Differences between the calculated expense and cash payments was recorded as a liability within the Accrued expenses and other and Other long-term liabilities captions in the accompanying Consolidated Balance Sheets, based on the terms of the lease.
Deferred rent approximated $159.9 million as of August 31, 2019.
Refer to Note O – Leases for additional disclosures regarding the Company’s leases.
A discussion of the carrying values and fair values of the Company’s debt is included in “Note I – Financing,” marketable debt securities is included in “Note F – Marketable Debt Securities,” and derivatives is included in “Note H – Derivative Financial Instruments.”
Refer to “Note D – Income Taxes” for additional disclosures regarding the Company’s income taxes.
See “Note R – Revenue Recognition” for further discussion.
| --- | --- | --- |
In February 2016, the Financial Accounting Standards Board (“FASB”) issued ASU 2016-02, _Leases (Topic 842)_, and subsequently amended this update by issuing additional ASU’s that provided clarification and further guidance for areas identified as potential implementation issues.
ASU 2016-02 requires a two-fold approach for lessee accounting, under which a lessee will account for leases as finance leases or operating leases.
An excerpt. Shown here: 40 of 385 rewritten, 40 of 106 added and 40 of 212 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data in the FY2021 filing and the FY2020 filing.
Item 9A. Controls and Procedures
5 rewritten, 0 added, 0 removed, 4 unchanged
As of August [removed: 29, 2020,] [added: 28, 2021,] an evaluation was performed under the supervision and with the participation of AutoZone’s management, including the Chief Executive Officer and the Chief Financial Officer, of the effectiveness of the design and operation of our disclosure controls and procedures, as defined in Rules 13a-15(e) and 15d-15(e) under the Exchange Act, as amended.
Based on that evaluation, our management, including the Chief Executive Officer and the Chief Financial Officer, concluded that our disclosure controls and procedures were effective as of August [removed: 29, 2020.][added: 28, 2021.]
A report of AutoZone’s management on our internal control over financial reporting (as such term defined in Rule 13a-15(f) under the Exchange Act) [removed: as] [added: and] a report of Ernst & Young, LLP, an independent registered public accounting firm, on the effectiveness of AutoZone’s internal control over financial reporting are included in Part I, Item 8 of this document and is incorporated herein by reference.
There were no changes in our internal control over financial reporting that occurred during the quarter ended August [removed: 29, 2020] [added: 28, 2021] that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Our internal control over financial reporting as of August [removed: 29, 2020] [added: 28, 2021] has been audited by Ernst & Young, LLP, an independent registered public accounting firm, which also audited our Consolidated Financial Statements for the year ended August [removed: 29, 2020,] [added: 28, 2021,] as stated in their report included herein, which expresses an unqualified opinion on the effectiveness of our internal control over financial reporting as of August [removed: 29, 2020.][added: 28, 2021.]
Item 9B. Other Information
0 rewritten, 0 added, 2 removed, 1 unchanged
PART III
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
0 rewritten, 2 added, 0 removed, 0 unchanged
New section this year
Not applicable.
PART III
Item 10. Directors, Executive Officers and Corporate Governance
1 rewritten, 0 added, 0 removed, 3 unchanged
Additionally, the information contained in AutoZone, Inc.’s Proxy Statement dated October [removed: 26, 2020,] [added: 25, 2021,] in the sections entitled “Corporate Governance Matters,” “Proposal 1 – Election of Directors” and “Delinquent Section 16(a) Reports,” is incorporated herein by reference in response to this item.
Item 11. Executive Compensation
1 rewritten, 0 added, 0 removed, 0 unchanged
The information contained in AutoZone, Inc.’s Proxy Statement dated October [removed: 26, 2020,] [added: 25, 2021,] in the section entitled “Executive Compensation,” is incorporated herein by reference in response to this item.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
1 rewritten, 0 added, 0 removed, 0 unchanged
The information contained in AutoZone, Inc.’s Proxy Statement dated October [removed: 26, 2020,] [added: 25, 2021,] in the sections entitled “Security Ownership of Management and Board of Directors,” “Security Ownership of Certain Beneficial Owners” and “Equity Compensation Plans” is incorporated herein by reference in response to this item.
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 0 unchanged
The information contained in AutoZone, Inc’s Proxy Statement dated October [removed: 26, 2020,] [added: 25, 2021,] in the sections entitled “Related Party Transactions” and “Corporate Governance Matters – Independence” is incorporated herein by reference in response to this item.
Item 14. Principal Accounting Fees and Services
1 rewritten, 0 added, 1 removed, 1 unchanged
The information contained in AutoZone, Inc.’s Proxy Statement dated October [removed: 26, 2020,] [added: 25, 2021,] in the section entitled “Proposal 2 – Ratification of Independent Registered Public Accounting Firm,” is incorporated herein by reference in response to this item.
Item 15. Exhibits and Financial Statement Schedules
16 rewritten, 12 added, 2 removed, 147 unchanged
| [Reports of Independent Registered Public Accounting [removed: Firm](#ReportOfIndependentRegisteredPublicAcct)] [added: Firm](#Report_Of_Independent)] |
| [Consolidated Statements of Income for the fiscal years ended August [removed: 29, 2020,] [added: 28, 2021,] August [removed: 31, 2019,] [added: 29, 2020] and August [removed: 25, 2018](#StatementsofIncome_880869)] [added: 31, 2019](#StatementsofIncome_880869)] |
| [Consolidated Statements of Comprehensive Income for the fiscal years ended August [removed: 29, 2020,] [added: 28, 2021,] August [removed: 31, 2019,] [added: 29, 2020] and August [removed: 25, 2018](#StatementsofComprehensiveIncome_464381)] [added: 31, 2019](#StatementsofComprehensiveIncome_464381)] |
| [Consolidated Balance Sheets as of August [removed: 29, 2020,] [added: 28, 2021] and August [removed: 31, 2019](#ConsolidatedBalanceSheets_880763)] [added: 29, 2020](#ConsolidatedBalanceSheets_880763)] |
| [Consolidated Statements of Cash Flows for the fiscal years ended August [removed: 29, 2020,] [added: 28, 2021,] August [removed: 31, 2019,] [added: 29, 2020] and August [removed: 25, 2018](#ConsolidatedStatementsofCashFlows_609202)] [added: 31, 2019](#ConsolidatedStatementsofCashFlows_609202)] |
| [Consolidated Statements of Stockholders’ Deficit for the fiscal years ended August [removed: 29, 2020,] [added: 28, 2021,] August [removed: 31, 2019,] [added: 29, 2020] and August [removed: 25, 2018](#StatementsofStockholdersDeficit_845379)] [added: 31, 2019](#StatementsofStockholdersDeficit_845379)] |
| 4.28 | | [Description of Securities of AutoZone, [removed: Inc.](https://www.sec.gov/Archives/edgar/data/866787/000119312519276201/d771460dex424.htm)] [added: Inc. Incorporated by reference to Exhibit 4.24 to the Annual Report on Form 10-K dated October 28, 2019.](https://www.sec.gov/Archives/edgar/data/0000866787/000119312519276201/d771460dex424.htm)] |
| *10.22 | | [AutoZone, Inc. Director Compensation Program effective January 1, [removed: 2020.](https://www.sec.gov/Archives/edgar/data/866787/000155837020011748/azo-20200829xex10d22.htm)] [added: 2020. Incorporated by reference to Exhibit 10.5 to the Quarterly Report on Form 10-Q date March 19, 2021.](https://www.sec.gov/Archives/edgar/data/866787/000155837021003264/azo-20210213xex10d5.htm)] |
| 10.26 | | [Master Extension, New Commitment and Amendment Agreement dated as of November 18, 2017 among AutoZone, Inc. as Borrower; Bank of America, N.A. as Administrative Agent and Swingline Lender; JPMorgan Chase Bank, N.A. as Syndication Agent; Merrill Lynch, Pierce, Fenner & Smith Incorporated and J.P. Morgan Chase Bank, N.A. as Joint Lead Arrangers; Merrill Lynch, Pierce, Fenner & Smith Incorporated, J.P. Morgan Chase Bank, N.A., SunTrust Robinson Humphrey, Inc., U.S. Bank National Association, Wells Fargo Securities, LLC and Barclay’s Capital as Joint Book Runners; SunTrust Bank, U.S. Bank National Association, Wells Fargo Bank, National Association and Barclay’s Bank PLC as Documentation Agents; and the several lenders party [removed: thereto.](https://www.sec.gov/Archives/edgar/data/866787/000119312517350673/d457659dex101.htm)] [added: thereto. Incorporated by reference to Exhibit 10.1 to the Current Report on the Form 8-K dated November 22, 2017.](https://www.sec.gov/Archives/edgar/data/866787/000119312517350673/d457659dex101.htm)] |
| *10.28 | | [364-Day Credit [removed: Agreement,] [added: Agreement] dated April 3, 2020, by and among the Company, as borrower, the several lenders from time to time party thereto, and U.S. Bank, National Association., as administrative agent for the lenders. Incorporated by reference to Exhibit 10.1 of the Current Report on Form 8-K dated April 7, 2020.](https://www.sec.gov/Archives/edgar/data/866787/000114036120008175/ex10_1.htm) |
| 21.1 | | [Subsidiaries of the [removed: Registrant.](https://www.sec.gov/Archives/edgar/data/866787/000155837020011748/azo-20200829xex21d1.htm)] [added: Registrant.](https://www.sec.gov/Archives/edgar/data/866787/000155837021013446/azo-20210828xex21d1.htm)] |
| 23.1 | | [Consent of Independent Registered Public Accounting [removed: Firm.](https://www.sec.gov/Archives/edgar/data/866787/000155837020011748/azo-20200829xex23d1.htm)] [added: Firm.](https://www.sec.gov/Archives/edgar/data/866787/000155837021013446/azo-20210828xex23d1.htm)] |
| 31.1 | | [Certification of Principal Executive Officer Pursuant to Rules 13a-14(a) and 15d-14(a) under the Securities Exchange Act of 1934, as Adopted Pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/866787/000155837020011748/azo-20200829xex31d1.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/866787/000155837021013446/azo-20210828xex31d1.htm)] |
| 31.2 | | [Certification of Principal Financial Officer Pursuant to Rules 13a-14(a) and 15d-14(a) under the Securities Exchange Act of 1934, as Adopted Pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/866787/000155837020011748/azo-20200829xex31d2.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/866787/000155837021013446/azo-20210828xex31d2.htm)] |
| 32.1 | | [Certification of Principal Executive Officer Pursuant to 18 U.S.C. Section 1350 as adopted Pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/866787/000155837020011748/azo-20200829xex32d1.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/866787/000155837021013446/azo-20210828xex32d1.htm)] |
| 32.2 | | [Certification of Principal Financial Officer Pursuant to 18 U.S.C. Section 1350 as adopted Pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002.](https://www.sec.gov/Archives/edgar/data/866787/000155837020011748/azo-20200829xex32d2.htm)] [added: 2002.](https://www.sec.gov/Archives/edgar/data/866787/000155837021013446/azo-20210828xex32d2.htm)] |
| *10.17 | | Reserved. |
| *10.29 | | [AutoZone, Inc. 2020 Omnibus Incentive Award Plan. Incorporated by reference to Exhibit 10.1 to the Current Report on Form 8-K dated December 17, 2020.](https://www.sec.gov/Archives/edgar/data/0000866787/000155837020014451/azo-20201216xex10d1.htm) |
| *10.30 | | [Form of Grant Notice and Award Agreement for Stock Options granted to Officers under the AutoZone, Inc. 2020 Omnibus Incentive Award Plan. Incorporated by reference to Exhibit 10.2 to the Current Report on Form 8-K dated December 17, 2020.](https://www.sec.gov/Archives/edgar/data/866787/000155837020014451/azo-20201216xex10d2.htm) |
| *10.31 | | [Form of Grant Notice and Award Agreement for Restricted Stock Units granted to Officers under the AutoZone, Inc. 2020 Omnibus Incentive Award Plan. Incorporated by reference to Exhibit 10.3 to the Current Report on Form 8-K dated December 17, 2020.](https://www.sec.gov/Archives/edgar/data/866787/000155837020014451/azo-20201216xex10d3.htm) |
| *10.32 | | [Form of Grant Notice and Award Agreement for Restricted Stock Units granted to Directors under the AutoZone, Inc. 2020 Omnibus Incentive Award Plan. Incorporated by reference to Exhibit 10.4 to the Current Report on Form 8-K dated December 17, 2020.](https://www.sec.gov/Archives/edgar/data/866787/000155837020014451/azo-20201216xex10d4.htm) |
| *10.33 | | [AutoZone, Inc. Director Compensation Program. Incorporated by reference to Exhibit 10.5 to the Current Report on Form 10-Q dated March 19, 2021.](https://www.sec.gov/Archives/edgar/data/866787/000155837021003264/azo-20210213xex10d5.htm) |
| *10.34 | | [Amendment No. 1 to the AutoZone, Inc. 2020 Omnibus Incentive Award Plan](https://www.sec.gov/Archives/edgar/data/866787/000155837021013446/azo-20210828xex10d34.htm). |
| | | |
| | | |
| | | |
| | | |
| | | |
| *10.17 | | [Form of Stock Option Agreement under the 2011 Equity Incentive Award Plan for officers effective September 27, 2011. Incorporated by reference to Exhibit 10.37 to the Annual Report on Form 10-K for the fiscal year ended August 27, 2011.](https://www.sec.gov/Archives/edgar/data/866787/000095012311091540/c22621exv10w37.htm) |
Item 16. Form 10-K Summary
14 rewritten, 1 added, 2 removed, 41 unchanged
| Dated: October [removed: 26, 2020] [added: 25, 2021] | | | |
| /s/ WILLIAM C. RHODES, III | | Chairman, President and Chief Executive Officer | | October [removed: 26, 2020] [added: 25, 2021] |
| /s/ [removed: WILLIAM T. GILES] [added: JAMERE JACKSON] | | Chief Financial Officer and Executive Vice | | October [removed: 26, 2020] [added: 25, 2021] |
| | | [removed: Store Development] (Principal Financial Officer) | | |
| /s/ CHARLIE PLEAS, III | | Senior Vice President and Controller | | October [removed: 26, 2020] [added: 25, 2021] |
| /s/ DOUGLAS H. BROOKS | | Director | | October [removed: 26, 2020] [added: 25, 2021] |
| /s/ MICHAEL M. CALBERT | | Director | | October [removed: 26, 2020] [added: 25, 2021] |
| /s/ LINDA A. GOODSPEED | | Director | | October [removed: 26, 2020] [added: 25, 2021] |
| /s/ EARL G. GRAVES, JR. | | Director | | October [removed: 26, 2020] [added: 25, 2021] |
| /s/ ENDERSON GUIMARAES | | Director | | October [removed: 26, 2020] [added: 25, 2021] |
| /s/ D. BRYAN JORDAN | | Director | | October [removed: 26, 2020] [added: 25, 2021] |
| /s/ GALE V. KING | | Director | | October [removed: 26, 2020] [added: 25, 2021] |
| /s/ GEORGE R. MRKONIC, JR. | | Director | | October [removed: 26, 2020] [added: 25, 2021] |
| /s/ JILL A. SOLTAU | | Director | | October [removed: 26, 2020] [added: 25, 2021] |
| Jamere Jackson | | President – Finance and Store Development | | |
| William T. Giles | | President – Finance, Information Technology and | | |