 filings.tools
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations
112K characters. Original on sec.gov · Markdown
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations
The following discussion should be read in conjunction with our unaudited condensed consolidated financial statements (condensed consolidated financial statements) and the accompanying notes beginning on page 5 of this quarterly report on Form 10-Q and our audited consolidated financial statements and the accompanying notes included in our Annual Report on Form 10-K for the year ended December 31, 2020 (2020 Form 10-K).
Executive Summary
Introduction
Biogen is a global biopharmaceutical company focused on discovering, developing and delivering worldwide innovative therapies for people living with serious neurological and neurodegenerative diseases as well as related therapeutic adjacencies. Our core growth areas include multiple sclerosis (MS) and neuroimmunology; Alzheimer’s disease and dementia; neuromuscular disorders, including spinal muscular atrophy (SMA) and amyotrophic lateral sclerosis (ALS); movement disorders, including Parkinson's disease; ophthalmology; and neuropsychiatry. We are also focused on discovering, developing and delivering worldwide innovative therapies in our emerging growth areas of immunology; acute neurology; and neuropathic pain. In addition, we commercialize biosimilars of advanced biologics. We support our drug discovery and development efforts through the commitment of significant resources to discovery, research and development programs and business development opportunities.
Our marketed products include TECFIDERA, VUMERITY, AVONEX, PLEGRIDY, TYSABRI and FAMPYRA for the treatment of MS; SPINRAZA for the treatment of SMA; ADUHELM for the treatment of Alzheimer's disease; and FUMADERM for the treatment of severe plaque psoriasis. We have certain business and financial rights with respect to RITUXAN for the treatment of non-Hodgkin's lymphoma, chronic lymphocytic leukemia (CLL) and other conditions; RITUXAN HYCELA for the treatment of non-Hodgkin's lymphoma and CLL; GAZYVA for the treatment of CLL and follicular lymphoma; OCREVUS for the treatment of primary progressive MS and relapsing MS (RMS); and other potential anti-CD20 therapies pursuant to our collaboration arrangements with Genentech, Inc. (Genentech), a wholly-owned member of the Roche Group. For additional information on our collaboration arrangements with Genentech, please read Note 18, Collaborative and Other Relationships, to our
consolidated financial statements included in our 2020 Form 10-K.
Our innovative drug development and commercialization activities are complemented by our biosimilar business that expands access to medicines and reduces the cost burden for healthcare systems. Through our agreements with Samsung Bioepis Co., Ltd. (Samsung Bioepis), our joint venture with Samsung BioLogics Co., Ltd. (Samsung BioLogics), we market and sell BENEPALI, an etanercept biosimilar referencing ENBREL, IMRALDI, an adalimumab biosimilar referencing HUMIRA, and FLIXABI, an infliximab biosimilar referencing REMICADE, in certain countries in Europe. For additional information on our collaboration arrangements with Samsung Bioepis, please read Note 16, Collaborative and Other Relationships, to our condensed consolidated financial statements included in this report.
We seek to ensure an uninterrupted supply of our medicines to patients around the world. To that end, we continually review our manufacturing capacity, capabilities, processes and facilities. In order to support our future growth and drug development pipeline, we are expanding our large molecule production capacity by building a large-scale biologics manufacturing facility in Solothurn, Switzerland. In the second quarter of 2021 a portion of the facility received a Good Manufacturing Practice (GMP) multi-product license from the Swiss Agency for Therapeutic Products (SWISSMEDIC). We believe that the Solothurn facility will support our anticipated near-term needs for the manufacturing of ADUHELM and other biologic assets. In addition, we believe that the Solothurn site may provide us with the ability to further expand if we need additional large scale manufacturing capacity to support future clinical and commercial manufacturing requirements.
Our revenue depends upon continued sales of our products as well as the financial rights we have in our anti-CD20 therapeutic programs, and, unless we develop, acquire rights to and/or commercialize new products and technologies, we will be substantially dependent on sales from our products and our financial rights in our anti-CD20 therapeutic programs for many years.
In the longer term, our revenue growth will depend upon the successful clinical development, regulatory approval and launch of new commercial products as well as additional indications for our existing products, our ability to obtain and maintain patents and other rights related to our marketed products, assets originating from our research and development efforts and/or successful execution of external business development opportunities.
Business Environment
The biopharmaceutical industry and the markets in which we operate are intensely competitive. Many of our competitors are working to develop or have commercialized products similar to those we market or are developing and have considerable experience in undertaking clinical trials and in obtaining regulatory approval to market pharmaceutical products. In addition, the commercialization of certain of our own approved products, products of our collaborators and pipeline product candidates may negatively impact future sales of our existing products.
Our products and revenue streams continue to face increasing competition in many markets from generic versions, prodrugs and biosimilars of existing products as well as products approved under abbreviated regulatory pathways. Such products are likely to be sold at substantially lower prices than branded products. Accordingly, the introduction of such products as well as other lower-priced competing products may significantly reduce both the price that we are able to charge for our products and the volume of products we sell, which will negatively impact our revenue. In addition, in some markets, when a generic or biosimilar version of one of our products is commercialized, it may be automatically substituted for our product and significantly reduce our revenue in a short period of time.
Sales of our products depend, to a significant extent, on the availability and extent of adequate coverage, pricing and reimbursement from government health administration authorities, private health insurers and other organizations. When a new pharmaceutical product is approved, the availability of government and private reimbursement for that product may be uncertain, as is the pricing and amount for which that product will be reimbursed.
Drug prices are under significant scrutiny in the markets in which our products are prescribed. We expect drug pricing and other health care costs to continue to be subject to intense political and societal pressures on a global basis.
Our failure to obtain or maintain adequate coverage, pricing or reimbursement for our products could have an adverse effect on our business, reputation, revenue and results of operations, could curtail or eliminate our ability to adequately fund research and development programs for the discovery and commercialization of new products or could cause a decline or volatility in our stock price.
In addition to the impact of competition, pricing actions and other measures being taken worldwide designed to reduce healthcare costs and limit the overall level of government expenditures, our sales and operations could also be affected by other risks of doing business internationally, including the impact
of public health epidemics, such as the COVID-19 pandemic, on employees, the global economy and the delivery of healthcare treatments, foreign currency exchange fluctuations, changes in intellectual property legal protections and changes in trade regulations and procedures.
For additional information on our competition and pricing risks that could negatively impact our product sales, please read Item 3. Quantitative and Qualitative Disclosures About Market Risk and Item 1A. Risk Factors included in this report.
ADUHELM (aducanumab)
U.S.
In June 2021 the U.S. Food and Drug Administration (FDA) granted accelerated approval of ADUHELM, which we are developing in collaboration with Eisai Co., Ltd. (Eisai), based on reduction in amyloid beta plaques observed in patients treated with ADUHELM. As part of the accelerated approval, we will conduct a confirmatory trial to verify the clinical benefit of ADUHELM in patients with Alzheimer’s disease. The FDA may withdraw approval if, among other things, the confirmatory trial fails to verify clinical benefit, ADUHELM's benefit-risk is no longer positive or we fail to comply with the conditions of the accelerated approval.
The U.S. ADUHELM product label states that treatment with ADUHELM should be initiated in patients with mild cognitive impairment or mild dementia stage of disease, the population which was studied in clinical trials. We expect patient uptake will be gradual and we do not expect all eligible patients will be treated with ADUHELM for a variety of reasons, including appropriate patient selection criteria, a complex diagnostic and care pathway, the lack of readiness of healthcare providers and institutions to initiate treatment, concern regarding the accelerated approval of ADUHELM and its data and the ability to obtain and maintain adequate reimbursement for ADUHELM. We expect a Medicare National Coverage Determination by the second quarter of 2022, which should clarify Medicare reimbursement for the class of antibodies directed against amyloid.
Under our collaboration agreement with Eisai (ADUHELM Collaboration Agreement), we and Eisai will co-promote ADUHELM with a region-based profit split, with Eisai reimbursing us for 45.0% of development and commercialization costs incurred by the collaboration for the advancement of ADUHELM in the U.S. Shipments of ADUHELM commenced during the second quarter of 2021.
We have made, and will continue to make, commercial, medical and infrastructure investments in support of activities associated with the launch of ADUHELM in the U.S., including the adding of
headcount and the manufacture of pre-launch inventory.
Rest of World
In October 2020 the European Medicines Agency (EMA) accepted for review the Marketing Authorization Application for aducanumab and in December 2020 the Ministry of Health, Labor and Welfare accepted for review the Japanese New Drug Application (NDA) for aducanumab.
If we do not receive regulatory approval or are unable to successfully commercialize aducanumab in other jurisdictions, our financial condition, business and operations may be adversely affected.
TECFIDERA
In June 2020 and September 2020 judgments were entered in favor of the defendants in the patent infringement proceedings relating to TECFIDERA Orange-Book listed patents pursuant to the Drug Price Competition and Patent Term Restoration Act of 1984, commonly known as the Hatch-Waxman Act, in West Virginia and Delaware. We have appealed the judgments in both actions.
Multiple TECFIDERA generic entrants are now in the U.S. market and have deeply discounted prices compared to TECFIDERA. The generic competition for TECFIDERA has significantly reduced our TECFIDERA revenue and is expected to have a substantial negative impact on our TECFIDERA revenue for as long as there is generic competition.
On May 5, 2021, the European General Court annulled the EMA's non-validation decision with respect to a generic application related to TECFIDERA in the European Union (E.U.). This generic application is now before the EMA, which is reassessing TECFIDERA's regulatory data protection by performing a scientific assessment pursuant to the European General Court's decision. The result of the scientific assessment of the EMA is expected in the fourth quarter of 2021. We have appealed the European General Court's decision to the European Court of Justice and the appeal is pending.
We will face TECFIDERA generic competition in the E.U. if regulatory data protection is not upheld and we expect that this would have an adverse impact on our TECFIDERA sales and our results of operations.
For additional information, please read Note 18, Litigation, to our condensed consolidated financial statements included in this report and the discussion under Results of Operations - Product Revenue - Multiple Sclerosis (MS) - Fumarate below.
Business Update Regarding COVID-19
The COVID-19 pandemic continues to present a substantial public health and economic challenge around the world. The length of time and full extent to which the COVID-19 pandemic directly or indirectly impacts our business, results of operations and financial condition, including sales, expenses, reserves and allowances, the supply chain, manufacturing, clinical trials, research and development costs and employee-related costs, depends on future developments that are highly uncertain, subject to change and are difficult to predict, including as a result of new information that may emerge concerning COVID-19 and the actions taken to contain or treat COVID-19 as well as the economic impact on local, regional, national and international customers and markets.
We are monitoring the demand for our products, including the duration and degree to which we may see delays in starting new patients on a product due to hospitals diverting the resources that are necessary to administer certain of our products to care for COVID-19 patients, including products, such as TYSABRI and SPINRAZA, that are administered in a physician's office or hospital setting. We may also see reduced demand for immunosuppressant therapies during the COVID-19 pandemic.
While we are currently continuing the clinical trials we have underway in sites across the globe, COVID-19 precautions have impacted the timeline for some of our clinical trials and these precautions may, directly or indirectly, have a further impact on timing in the future. For example, our Phase 3 study of BIIB093 (glibenclamide IV) for large hemispheric infarction (LHI), a severe form of ischemic stroke, has been delayed as this study involves administration of BIIB093 in an acute hospital setting. To help mitigate the impact of the COVID-19 pandemic to our clinical trials, we are pursuing innovative approaches such as remote monitoring, remote patient visits and supporting home infusions. These alternative measures have resulted in an immaterial increase to the cost of the clinical trials underway.
Factors such as the COVID-19 pandemic, adverse weather events, labor or raw material shortages and other supply chain disruptions could result in product shortages or other difficulties and delays in manufacturing our products.
For additional information on the various risks posed by the COVID-19 pandemic, please read Item 3. Quantitative and Qualitative Disclosures About Market Risk and Item 1A. Risk Factors included in this report.
Financial Highlights
Diluted earnings per share attributable to Biogen Inc. was $2.22 for the three months ended September 30, 2021, representing a decrease of 50.2% compared to $4.46 in the same period in 2020.
As described below under Results of Operations, our net income and diluted earnings per share attributable to Biogen Inc. for the three months ended September 30, 2021, compared to the three months ended September 30, 2020, reflects the following:
Revenue
-
Total revenue was $2,778.9 million for the third quarter of 2021, representing a $597.2 million, or 17.7%, decrease compared to $3,376.1 million in the same period in 2020.
-
Product revenue, net totaled $2,205.7 million for the third quarter of 2021, representing a $484.6 million, or 18.0%, decrease compared to $2,690.3 million in the same period in 2020. This decrease was primarily due to a $428.9 million, or 21.6%, decrease in MS product revenue as well as a $50.3 million, or 10.2%, decrease in SPINRAZA product revenue.
◦The decrease in MS product revenue was primarily due to a decrease in U.S. TECFIDERA demand as a result of multiple TECFIDERA generic entrants in the U.S. market.
◦The decrease in SPINRAZA revenue was primarily due to a decrease in demand as a result of increased competition in the U.S.
-
Revenue from anti-CD20 therapeutic programs totaled $415.4 million for the third quarter of 2021, representing a $144.7 million, or 25.8%, decrease compared to $560.1 million in the same period in 2020. This decrease was primarily due to a $136.2 million, or 51.7%, decrease in RITUXAN revenue. Sales of RITUXAN have been adversely affected by the onset of biosimilars competition.
-
Other revenue totaled $157.8 million for the third quarter of 2021, representing a 25.5% increase from $125.7 million in the same period in 2020.
Expense
- Total cost and expense was $1,984.9 million for the third quarter of 2021, representing a $304.8 million, or 13.3%, decrease compared to $2,289.7 million in the same period in
- This decrease was primarily due to a $438.5 million decrease in research and development expense.
**◦**The decrease in research development expense for the third quarter of 2021 was primarily due to $601.3 million in upfront payments recognized in connection with our collaboration with Denali Therapeutics Inc. (Denali) in the third quarter of 2020.
As described below under Financial Condition, Liquidity and Capital Resources:
-
We generated $2,801.6 million of net cash flows from operations for the nine months ended September 30, 2021.
-
Cash, cash equivalents and marketable securities totaled approximately $3,923.4 million as of September 30, 2021.
-
We repurchased and retired approximately 2.2 million shares of our common stock at a cost of approximately $750.0 million during the third quarter of 2021 under a program authorized by our Board of Directors in October 2020 to repurchase up to $5.0 billion of our common stock (2020 Share Repurchase Program). Approximately $2.8 billion remained available under our 2020 Share Repurchase Program as of September 30, 2021.
Acquisitions and Collaborative and Other Relationships
InnoCare Pharma Limited
In July 2021 we entered into a license and collaboration agreement with InnoCare Pharma Limited (InnoCare) for orelabrutinib, an oral small molecule Bruton's tyrosine kinase inhibitor for the potential treatment of MS.
For additional information on our proposed collaboration with InnoCare, please read Note 16, Collaborative and Other Relationships, to our condensed consolidated financial statements included in this report.
Other Key Developments
Exchange Offer
In February 2021 we completed a private offer to exchange (Exchange Offer) our tendered 5.200% Senior Notes due September 15, 2045 (2045 Senior Notes) for a new series of 3.250% Senior Notes due February 15, 2051 (2051 Senior Notes) and cash, and an offer to purchase our tendered 2045 Senior Notes for cash.
For additional information on our Exchange Offer, please read Note 10, Indebtedness, to our condensed consolidated financial statements included in this report.
North Carolina Gene Therapy Manufacturing Facility
In March 2021 we announced our plans to build a new gene therapy manufacturing facility in Research Triangle Park, North Carolina to support our growing gene therapy pipeline across multiple therapeutic areas. The new facility will be 175,000 square feet and is expected to be operational by 2023, with an estimated total investment of approximately $200.0 million.
Solothurn, Switzerland Manufacturing Facility
In May 2021 we announced that a portion of our Solothurn manufacturing facility received a GMP multi-product license from SWISSMEDIC.
For additional information on our Solothurn manufacturing facility, please read Note 9, Property, Plant and Equipment, to our condensed consolidated financial statements included in this report.
BIIB125 (zuranolone)
In June 2021 we and Sage Therapeutics, Inc. (Sage) announced positive Phase 3 results for BIIB125 (zuranolone) for the potential treatment of major depressive disorder (MDD) and postpartum depression (PPD). In October 2021 we and Sage announced our plan to submit an NDA to the FDA for zuranolone in the second half of 2022, with rolling
submission expected to start in early 2022. The planned initial submission package will seek approval of zuranolone for MDD, and an additional filing for PPD is anticipated in the first half of 2023.
For additional information on our collaboration arrangement with Sage, please read Note 16, Collaborative and Other Relationships, to our condensed consolidated financial statements included in this report.
Lecanemab (BAN2401)
In June 2021 the FDA granted Breakthrough Therapy designation for lecanemab, an anti-amyloid antibody for the potential treatment of Alzheimer's disease, which we are developing in collaboration with Eisai. In September 2021 Eisai initiated a rolling submission to the FDA of a Biologics License Application (BLA) for lecanemab. The BLA is being submitted under the accelerated approval pathway and is primarily based on clinical, biomarker and safety data from the Phase 2b clinical trial in people with early Alzheimer's disease and confirmed amyloid pathology.
BYOOVIZ (ranibizumab-nuna)
In September 2021 we and Samsung Bioepis announced that the FDA has approved BYOOVIZ (ranibizumab-nuna), a biosimilar referencing LUCENTIS for the treatment of neovascular (wet) age-related macular degeneration, macular edema following retinal vein occlusion, and myopic choroidal neovascularization. In addition to the U.S. approval, BYOOVIZ was approved in Europe in August 2021.
BIIB067 (tofersen)
In October 2021 we announced topline results from our pivotal Phase 3 VALOR study of BIIB067 (tofersen), an investigational antisense drug being evaluated for people with superoxide dismutase 1 (SOD1) amyotrophic lateral sclerosis (ALS), indicating that the primary endpoint was not met. We are engaging with regulators and other key stakeholders to determine potential next steps.
Results of Operations
Revenue
Revenue is summarized as follows:
| For the Three Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||
| (In millions, except percentages) | 2021 | 2020 | $ Change | % Change | ||||||||||||||||||||||||||||||||||
| Product revenue, net: | ||||||||||||||||||||||||||||||||||||||
| United States | $ | 973.5 | 35.0 | % | $ | 1,498.2 | 44.4 | % | $ | (524.7) | (35.0) | % | ||||||||||||||||||||||||||
| Rest of world | 1,232.2 | 44.4 | 1,192.1 | 35.3 | 40.1 | 3.4 | ||||||||||||||||||||||||||||||||
| Total product revenue, net | 2,205.7 | 79.4 | 2,690.3 | 79.7 | (484.6) | (18.0) | ||||||||||||||||||||||||||||||||
| Revenue from anti-CD20 therapeutic programs | 415.4 | 14.9 | 560.1 | 16.6 | (144.7) | (25.8) | ||||||||||||||||||||||||||||||||
| Other revenue | 157.8 | 5.7 | 125.7 | 3.7 | 32.1 | 25.5 | ||||||||||||||||||||||||||||||||
| Total revenue | $ | 2,778.9 | 100.0 | % | $ | 3,376.1 | 100.0 | % | $ | (597.2) | (17.7) | % |
| For the Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||
| (In millions, except percentages) | 2021 | 2020 | $ Change | % Change | ||||||||||||||||||||||||||||||||||
| Product revenue, net: | ||||||||||||||||||||||||||||||||||||||
| United States | $ | 2,850.7 | 34.6 | % | $ | 4,803.1 | 45.3 | % | $ | (1,952.4) | (40.6) | % | ||||||||||||||||||||||||||
| Rest of world | 3,802.7 | 46.1 | 3,587.5 | 33.9 | 215.2 | 6.0 | ||||||||||||||||||||||||||||||||
| Total product revenue, net | 6,653.4 | 80.7 | 8,390.6 | 79.2 | (1,737.2) | (20.7) | ||||||||||||||||||||||||||||||||
| Revenue from anti-CD20 therapeutic programs | 1,244.4 | 15.1 | 1,558.8 | 14.7 | (314.4) | (20.2) | ||||||||||||||||||||||||||||||||
| Other revenue | 350.1 | 4.2 | 642.6 | 6.1 | (292.5) | (45.5) | ||||||||||||||||||||||||||||||||
| Total revenue | $ | 8,247.9 | 100.0 | % | $ | 10,592.0 | 100.0 | % | $ | (2,344.1) | (22.1) | % |
Product Revenue
Product revenue is summarized as follows:
| For the Three Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||
| (In millions, except percentages) | 2021 | 2020 | $ Change | % Change | ||||||||||||||||||||||||||||||||||
| Multiple Sclerosis: | ||||||||||||||||||||||||||||||||||||||
| Fumarate* | $ | 619.5 | 28.1 | % | $ | 967.5 | 36.0 | % | $ | (348.0) | (36.0) | % | ||||||||||||||||||||||||||
| Interferon** | 387.5 | 17.6 | 474.1 | 17.6 | (86.6) | (18.3) | ||||||||||||||||||||||||||||||||
| TYSABRI | 522.8 | 23.7 | 516.5 | 19.2 | 6.3 | 1.2 | ||||||||||||||||||||||||||||||||
| FAMPYRA | 26.2 | 1.2 | 26.8 | 1.0 | (0.6) | (2.2) | ||||||||||||||||||||||||||||||||
| Subtotal: MS product revenue | 1,556.0 | 70.5 | 1,984.9 | 73.8 | (428.9) | (21.6) | ||||||||||||||||||||||||||||||||
| Spinal Muscular Atrophy: | ||||||||||||||||||||||||||||||||||||||
| SPINRAZA | 444.1 | 20.1 | 494.4 | 18.4 | (50.3) | (10.2) | ||||||||||||||||||||||||||||||||
| Alzheimer's disease: | ||||||||||||||||||||||||||||||||||||||
| ADUHELM*** | 0.3 | — | — | — | 0.3 | nm | ||||||||||||||||||||||||||||||||
| Biosimilars: | ||||||||||||||||||||||||||||||||||||||
| BENEPALI | 120.8 | 5.5 | 124.2 | 4.6 | (3.4) | (2.7) | ||||||||||||||||||||||||||||||||
| IMRALDI | 57.4 | 2.6 | 56.2 | 2.1 | 1.2 | 2.1 | ||||||||||||||||||||||||||||||||
| FLIXABI | 24.6 | 1.1 | 27.5 | 1.0 | (2.9) | (10.5) | ||||||||||||||||||||||||||||||||
| Subtotal: Biosimilar product revenue | 202.8 | 9.2 | 207.9 | 7.7 | (5.1) | (2.5) | ||||||||||||||||||||||||||||||||
| Other: | ||||||||||||||||||||||||||||||||||||||
| FUMADERM | 2.5 | 0.1 | 3.1 | 0.1 | (0.6) | (19.4) | ||||||||||||||||||||||||||||||||
| Total product revenue, net | $ | 2,205.7 | 100.0 | % | $ | 2,690.3 | 100.0 | % | $ | (484.6) | (18.0) | % |
*Fumarate includes TECFIDERA and VUMERITY.
**Interferon includes AVONEX and PLEGRIDY.
***In June 2021 the FDA granted accelerated approval of ADUHELM, which became commercially available in the U.S. during the second quarter of 2021. For additional information, please read Note 16, Collaborative and Other Relationships - Eisai Co., Ltd. - ADUHELM Collaboration Agreement, to our condensed consolidated financial statements included in this report.
nm Not meaningful
| For the Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||
| (In millions, except percentages) | 2021 | 2020 | $ Change | % Change | ||||||||||||||||||||||||||||||||||
| Multiple Sclerosis: | ||||||||||||||||||||||||||||||||||||||
| Fumarate* | $ | 1,750.9 | 26.3 | % | $ | 3,258.6 | 38.9 | % | $ | (1,507.7) | (46.3) | % | ||||||||||||||||||||||||||
| Interferon** | 1,188.4 | 17.9 | 1,421.5 | 17.0 | (233.1) | (16.4) | ||||||||||||||||||||||||||||||||
| TYSABRI | 1,550.4 | 23.3 | 1,470.9 | 17.5 | 79.5 | 5.4 | ||||||||||||||||||||||||||||||||
| FAMPYRA | 78.8 | 1.2 | 78.1 | 0.9 | 0.7 | 0.9 | ||||||||||||||||||||||||||||||||
| Subtotal: MS product revenue | 4,568.5 | 68.7 | 6,229.1 | 74.3 | (1,660.6) | (26.7) | ||||||||||||||||||||||||||||||||
| Spinal Muscular Atrophy: | ||||||||||||||||||||||||||||||||||||||
| SPINRAZA | 1,464.4 | 22.1 | 1,554.0 | 18.5 | (89.6) | (5.8) | ||||||||||||||||||||||||||||||||
| Alzheimer's disease: | ||||||||||||||||||||||||||||||||||||||
| ADUHELM*** | 2.0 | — | — | — | 2.0 | nm | ||||||||||||||||||||||||||||||||
| Biosimilars: | ||||||||||||||||||||||||||||||||||||||
| BENEPALI | 363.9 | 5.5 | 363.9 | 4.3 | — | — | ||||||||||||||||||||||||||||||||
| IMRALDI | 170.9 | 2.6 | 162.6 | 1.9 | 8.3 | 5.1 | ||||||||||||||||||||||||||||||||
| FLIXABI | 75.4 | 1.1 | 71.8 | 0.9 | 3.6 | 5.0 | ||||||||||||||||||||||||||||||||
| Subtotal: Biosimilar product revenue | 610.2 | 9.2 | 598.3 | 7.1 | 11.9 | 2.0 | ||||||||||||||||||||||||||||||||
| Other: | ||||||||||||||||||||||||||||||||||||||
| FUMADERM | 8.3 | 0.1 | 9.2 | 0.1 | (0.9) | (9.8) | ||||||||||||||||||||||||||||||||
| Total product revenue, net | $ | 6,653.4 | 100.0 | % | $ | 8,390.6 | 100.0 | % | $ | (1,737.2) | (20.7) | % |
*Fumarate includes TECFIDERA and VUMERITY.
**Interferon includes AVONEX and PLEGRIDY.
***In June 2021 the FDA granted accelerated approval of ADUHELM, which became commercially available in the U.S. during the second quarter of 2021. For additional information, please read Note 16, Collaborative and Other Relationships - Eisai Co., Ltd. - ADUHELM Collaboration Agreement, to our condensed consolidated financial statements included in this report.
nm Not meaningful
Multiple Sclerosis (MS)
Fumarate

Fumarate revenue includes sales from TECFIDERA and VUMERITY. In October 2019 the FDA approved VUMERITY for the treatment of RMS and VUMERITY became commercially available in the U.S. in November 2019.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases of 56% and 66%, respectively, in U.S. Fumarate revenue were primarily due to a decrease in TECFIDERA demand as a result of multiple TECFIDERA generic entrants in the U.S. market. The decrease was partially offset by an increase in VUMERITY sales volume.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the increases of 13% and 8%, respectively, in rest of world Fumarate revenue were primarily due to increases in TECFIDERA sales volumes of 10% and 7%, respectively.
In June 2020 and September 2020 judgments were entered in favor of the defendants in the patent
infringement proceedings relating to TECFIDERA Orange-Book listed patents pursuant to the Hatch-Waxman Act in West Virginia and Delaware. We have appealed the judgments in both actions.
Multiple TECFIDERA generic entrants are now in the U.S. market and have deeply discounted prices compared to TECFIDERA. The generic competition for TECFIDERA has significantly reduced our TECFIDERA revenue and is expected to have a substantial negative impact on our TECFIDERA revenue for as long as there is generic competition.
We anticipate an increase in TECFIDERA sales volume in rest of world in 2021, compared to 2020, notwithstanding the increasing competition from additional treatments for MS and potential disruptions due, directly or indirectly, to the COVID-19 pandemic.
On May 5, 2021, the European General Court annulled the EMA's non-validation decision with respect to a generic application related to TECFIDERA in the E.U. This generic application is now before the EMA, which is reassessing TECFIDERA's regulatory data protection by performing a scientific assessment pursuant to the European General Court's decision. The result of the scientific assessment of the EMA is expected in the fourth quarter of 2021. We have appealed the European General Court's decision to the European Court of Justice and the appeal is pending.
We will face TECFIDERA generic competition in the E.U. if regulatory data protection is not upheld and we expect that this would have an adverse impact on our TECFIDERA sales and our results of operations.
For additional information, please read Note 18, Litigation, to our condensed consolidated financial statements included in this report.
We expect an increase in VUMERITY sales volume driven by demand growth.
Interferon

For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases of 23% and 22%, respectively, in U.S. Interferon revenue were primarily due to decreases in Interferon sales volumes of 19% and 19%, respectively. The net declines in sales volumes reflect the continued decline of the Interferon market as patients transition to other higher efficacy and oral MS therapies.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases of 8% and 4%, respectively, in rest of world Interferon revenue were primarily due to decreases in Interferon sales volumes of 11% and 5%, respectively.
We expect that Interferon revenue will continue to decline in both the U.S. and rest of world markets in 2021, compared to 2020, as a result of increasing competition from our other MS products as well as other treatments for MS, including biosimilars, and pricing reductions in certain European markets.
TYSABRI

For the three months ended September 30, 2021, compared to the same period in 2020, the decrease of 8% in U.S. TYSABRI revenue was primarily due to a decrease in sales volume of 13%, partially offset by an increase in pricing.
For the nine months ended September 30, 2021, compared to the same period in 2020, the increase of 3% in U.S. TYSABRI revenue was primarily due to an increase in pricing, partially offset by a decrease in sales volume.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the increases of 14% and 8%, respectively, in rest of world TYSABRI revenue were primarily due to favorable volume impacts, partially offset by decreases in pricing.
We anticipate TYSABRI sales volume to modestly increase on a global basis in 2021, compared to 2020, despite increasing competition from additional treatments for MS, including OCREVUS. We expect to continue to face price reductions in certain European markets.
Spinal Muscular Atrophy
SPINRAZA

For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases of 23% and 30%, respectively, in U.S. SPINRAZA revenue were primarily due to decreases in sales volumes resulting from increased competition.
For the three months ended September 30, 2021, compared to the same period in 2020, the decrease of 2% in rest of world SPINRAZA revenue was primarily due to a decrease in sales volume resulting from increased competition as well as a decrease in pricing.
For the nine months ended September 30, 2021, compared to the same period in 2020, the increase of 11% in rest of world SPINRAZA revenue was primarily due to an increase in sales volume of 10% due in part to the timing of shipments in developing markets and increases in patients. The increase was also due to the favorable impact of foreign currency exchange of 4%.
In 2021 we expect that SPINRAZA revenue will be subject to increased competition resulting in higher discontinuations and a lower rate of new patient starts combined with the impact of loading dose dynamics, as patients transition to dosing once every four months, and lower prices in certain rest of world countries.
We face competition from a gene therapy product and an oral product. We expect that we will experience competition from both products in additional jurisdictions in the future, which may adversely affect our sales of SPINRAZA.
For additional information on our collaboration arrangements with Ionis Pharmaceuticals, Inc. (Ionis), please read Note 18, Collaborative and Other
Relationships, to our consolidated financial statements included in our 2020 Form 10-K.
Alzheimer's Disease
ADUHELM
In June 2021 the FDA granted accelerated approval of ADUHELM, which became commercially available in the U.S. during the second quarter of 2021. For the three and nine months ended September 30, 2021, U.S. ADUHELM revenue was approximately $0.3 million and $2.0 million, respectively.
In 2021 we expect minimal sales of ADUHELM in the U.S.
For additional information on our collaboration arrangements with Eisai, please read Note 16, Collaborative and Other Relationships, to our condensed consolidated financial statements included in this report.
Biosimilars
BENEPALI, IMRALDI and FLIXABI

For the three months ended September 30, 2021, compared to the same period in 2020, the decrease of 2% in biosimilar revenue was primarily due to decreases in pricing, partially offset by the favorable impact of higher volumes.
For the nine months ended September 30, 2021, compared to the same period in 2020, the increase of 2% in biosimilar revenue was primarily due to the favorable impact of higher volumes and foreign currency exchange, partially offset by decreases in pricing.
In 2021 we expect revenue for our biosimilars business to be flat as compared to 2020. We expect to continue to face price reductions in certain European countries.
For additional information on our collaboration arrangements with Samsung Bioepis, please read Note 16, Collaborative and Other Relationships, to our condensed consolidated financial statements included in this report.
Revenue from Anti-CD20 Therapeutic Programs
Genentech (Roche Group)
Our share of RITUXAN, including RITUXAN HYCELA, and GAZYVA collaboration operating profits in the U.S. and other revenue from anti-CD20 therapeutic programs are summarized in the table below. For purposes of this discussion, we refer to RITUXAN and RITUXAN HYCELA collectively as RITUXAN.

Biogen’s Share of Pre-tax Profits in the U.S. for RITUXAN and GAZYVA
The following tables provide a summary of amounts comprising our share of pre-tax profits in the U.S. for RITUXAN and GAZYVA:
| For the Three Months Ended September 30, | ||||||||||||||
| (In millions) | 2021 | 2020 | ||||||||||||
| Product revenue, net | $ | 457.0 | $ | 814.4 | ||||||||||
| Cost and expense | 70.8 | 81.1 | ||||||||||||
| Pre-tax profits in the U.S. | 386.2 | 733.3 | ||||||||||||
| Biogen's share of pre-tax profits | $ | 145.8 | $ | 275.0 |
| For the Nine Months Ended September 30, | ||||||||||||||
| (In millions) | 2021 | 2020 | ||||||||||||
| Product revenue, net | $ | 1,562.5 | $ | 2,700.5 | ||||||||||
| Cost and expense | 222.9 | 350.0 | ||||||||||||
| Pre-tax profits in the U.S. | 1,339.6 | 2,350.5 | ||||||||||||
| Biogen's share of pre-tax profits | $ | 498.7 | $ | 873.8 |
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases in U.S. product revenue, net were primarily due to decreases in sales volumes of RITUXAN in the U.S. of 43.3% and 41.0%, respectively, primarily due to the onset of competition from multiple biosimilar products.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, product revenue, net also reflected increases in GAZYVA sales volume of 5.1% and 10.5%, respectively.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases in collaboration costs and expense were primarily due to lower cost of sales on RITUXAN.
We are aware of several other anti-CD20 molecules, including biosimilar products, that have recently been approved and are competing with RITUXAN and GAZYVA in the oncology and other markets. In November 2019, January 2020 and January 2021 biosimilar products referencing RITUXAN were launched in the U.S. and are being offered at lower prices. This competition has had a significant adverse impact on the pre-tax profits of our collaboration arrangements with Genentech, as the sales of RITUXAN have decreased substantially compared to prior periods. We expect that biosimilar competition will continue to increase as these products capture additional market share and that this will have a significant adverse impact on our co-promotion profits in the U.S. in future years.
Other Revenue from Anti-CD20 Therapeutic Programs
Other revenue from anti-CD20 therapeutic programs consists of royalty revenue on sales of OCREVUS and our share of pre-tax co-promotion profits from RITUXAN in Canada.
For the nine months ended September 30, 2021, compared to the same period in 2020, the increase in other revenue from anti-CD20 therapeutic programs was primarily due to sales growth of OCREVUS. Royalty revenue recognized on sales of OCREVUS for the three and nine months ended September 30, 2021, totaled $264.2 million and $730.5 million, respectively, compared to $272.5
million and $643.0 million, respectively, in the prior year comparative periods.
OCREVUS royalty revenue is based on our estimates from third party and market research data of OCREVUS sales occurring during the corresponding period. Differences between actual and estimated royalty revenue will be adjusted for in the period in which they become known, which is generally expected to be the following quarter.
For additional information on our collaboration arrangements with Genentech, including information regarding the pre-tax profit-sharing formula and its impact on future revenue from anti-CD20 therapeutic programs, please read Note 18, Collaborative and Other Relationships, to our consolidated financial statements included in our 2020 Form 10-K.
Other Revenue
Other revenue is summarized as follows:
| For the Three Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||
| (In millions, except percentages) | 2021 | 2020 | % Change | $ Change | ||||||||||||||||||||||||||||||||||
| Revenue from collaborative and other relationships | $ | 6.3 | 4.0 | % | $ | 5.4 | 4.3 | % | 16.7 | % | $ | 0.9 | ||||||||||||||||||||||||||
| Other royalty and corporate revenue | 151.5 | 96.0 | 120.3 | 95.7 | 25.9 | 31.2 | ||||||||||||||||||||||||||||||||
| Total other revenue | $ | 157.8 | 100.0 | % | $ | 125.7 | 100.0 | % | 25.5 | % | $ | 32.1 |
| For the Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (In millions, except percentages) | 2021 | 2020 | % Change | $ Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Revenue from collaborative and other relationships | $ | 15.7 | 4.5 | % | $ | 14.3 | 2.2 | % | 9.8 | % | $ | 1.4 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other royalty and corporate revenue | 334.4 | 95.5 | 628.3 | 97.8 | (46.8) | (293.9) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total other revenue | $ | 350.1 | 100.0 | % | $ | 642.6 | 100.0 | % | (45.5) | % | $ | (292.5) |
Revenue from Collaborative and Other Relationships
Revenue from collaborative and other relationships primarily includes royalty revenue on biosimilar products from Samsung Bioepis.
For additional information on our collaborative arrangements with Samsung Bioepis, please read Note 16, Collaborative and Other Relationships, to our condensed consolidated financial statements included in this report.
Other Royalty and Corporate Revenue

We receive royalties from net sales on products related to patents that we have out-licensed and we
record other corporate revenue primarily from amounts earned under contract manufacturing agreements.
For the three months ended September 30, 2021, compared to the same period in 2020, the increase in other corporate revenue was primarily due to higher revenue related to contract manufacturing agreements.
For the nine months ended September 30, 2021, compared to the same period in 2020, the decrease in other corporate revenue was primarily due to higher contract manufacturing revenue during the second quarter of 2020, resulting from $329.4 million in revenue related to the delivery of a license for certain of our manufacturing-related intellectual property to a contract manufacturing customer.
Reserves for Discounts and Allowances
Revenue from product sales is recorded net of reserves established for applicable discounts and allowances, including those associated with the implementation of pricing actions in certain international markets where we operate.
These reserves are based on estimates of the amounts earned or to be claimed on the related sales and are classified as reductions of accounts receivable (if the amount is payable to our customer) or a liability (if the amount is payable to a party other than our customer). These estimates reflect our historical experience, current contractual and statutory requirements, specific known market events and trends, industry data and forecasted customer buying and payment patterns. Actual amounts may ultimately differ from our estimates. If actual results vary, we adjust these estimates, which could have an effect on earnings in the period of adjustment.
Reserves for discounts, contractual adjustments and returns that reduced gross product revenue are summarized as follows:

For the three and nine months ended September 30, 2021, reserves for discounts and allowances as a percentage of gross product revenue were 26.5% and 27.9%, respectively, compared to 27.3% and 26.3%, respectively, in the prior year comparative periods.
Discounts
Discounts include trade term discounts and wholesaler incentives.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases in discounts were primarily driven by a decrease in gross sales.
Contractual Adjustments
Contractual adjustments primarily relate to Medicaid and managed care rebates, pharmacy rebates, co-payment (copay) assistance, Veterans Administration, 340B discounts, specialty pharmacy program fees and other government rebates or applicable allowances.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases in contractual adjustments were primarily caused by lower TECFIDERA sales in the U.S., resulting in lower Medicaid and managed care rebates, partially offset by pharmacy rebates.
Returns
Product return reserves are established for returns made by wholesalers. In accordance with contractual terms, wholesalers are permitted to return product for reasons such as damaged or expired product. The majority of wholesaler returns are due to product expiration. Provisions for product returns are recognized in the period the related revenue is recognized, resulting in a reduction to product sales.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, return reserves were relatively consistent.
For additional information on our revenue reserves, please read Note 3, Revenue, to our condensed consolidated financial statements included in this report.
Cost and Expense
A summary of total cost and expense is as follows:
| For the Three Months Ended September 30, | ||||||||||||||||||||||||||
| (In millions, except percentages) | 2021 | 2020 | % Change | $ Change | ||||||||||||||||||||||
| Cost of sales, excluding amortization and impairment of acquired intangible assets | $ | 511.8 | $ | 449.1 | 14.0 | % | $ | 62.7 | ||||||||||||||||||
| Research and development | 702.4 | 1,140.9 | (38.4) | (438.5) | ||||||||||||||||||||||
| Selling, general and administrative | 654.1 | 573.1 | 14.1 | 81.0 | ||||||||||||||||||||||
| Amortization and impairment of acquired intangible assets | 111.0 | 82.6 | 34.4 | 28.4 | ||||||||||||||||||||||
| Collaboration profit sharing | 21.2 | 73.0 | (71.0) | (51.8) | ||||||||||||||||||||||
| (Gain) loss on fair value remeasurement of contingent consideration | (15.6) | (29.0) | (46.2) | 13.4 | ||||||||||||||||||||||
| Acquired in-process research and development | — | — | nm | — | ||||||||||||||||||||||
| Total cost and expense | $ | 1,984.9 | $ | 2,289.7 | (13.3) | % | $ | (304.8) |
| For the Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||||||||
| (In millions, except percentages) | 2021 | 2020 | % Change | $ Change | ||||||||||||||||||||||||||||||||||||||||
| Cost of sales, excluding amortization and impairment of acquired intangible assets | $ | 1,449.6 | $ | 1,314.6 | 10.3 | % | $ | 135.0 | ||||||||||||||||||||||||||||||||||||
| Research and development | 1,801.7 | 2,264.8 | (20.4) | (463.1) | ||||||||||||||||||||||||||||||||||||||||
| Selling, general and administrative | 1,886.4 | 1,698.3 | 11.1 | 188.1 | ||||||||||||||||||||||||||||||||||||||||
| Amortization and impairment of acquired intangible assets | 813.2 | 215.6 | 277.2 | 597.6 | ||||||||||||||||||||||||||||||||||||||||
| Collaboration profit sharing | 74.5 | 166.5 | (55.3) | (92.0) | ||||||||||||||||||||||||||||||||||||||||
| (Gain) loss on fair value remeasurement of contingent consideration | (49.1) | (23.5) | 108.9 | (25.6) | ||||||||||||||||||||||||||||||||||||||||
| Acquired in-process research and development | 18.0 | 75.0 | (76.0) | (57.0) | ||||||||||||||||||||||||||||||||||||||||
| Total cost and expense | $ | 5,994.3 | $ | 5,711.3 | 5.0 | % | $ | 283.0 |
nm Not meaningful
Cost of Sales, Excluding Amortization and Impairment of Acquired Intangible Assets

Product Cost of Sales
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the increases in product cost of sales were primarily due to product mix and higher cost of sales associated with contract manufacturing agreements.
Royalty Cost of Sales
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the increases in royalty cost of sales were primarily due to higher royalties payable on higher sales of TYSABRI and VUMERITY.
Research and Development
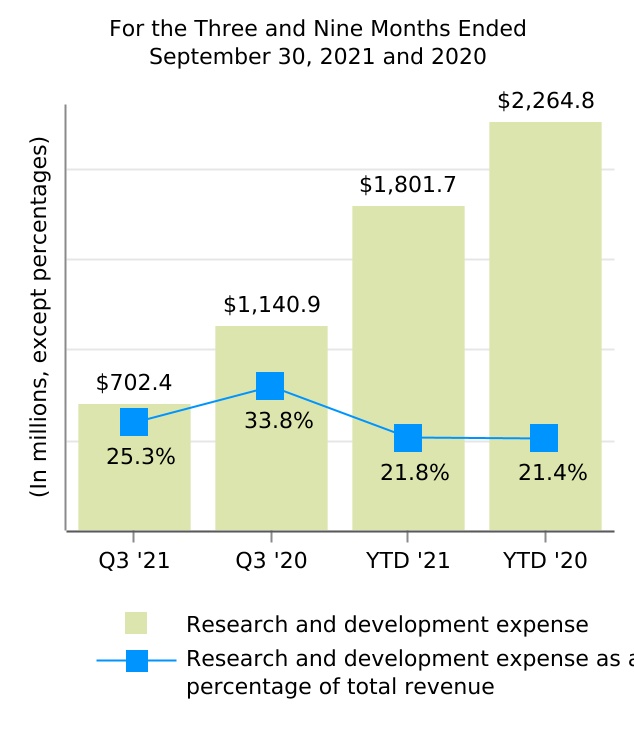

We support our drug discovery and development efforts through the commitment of significant resources to discovery, research and development programs and business development opportunities.
A significant amount of our research and development costs consists of indirect costs incurred in support of overall research and development activities and non-specific programs, including activities that benefit multiple programs, such as
management costs, as well as depreciation, information technology and facility-based expenses. These costs are considered other research and development costs in the table above and are not allocated to a specific program or stage.
Research and development expense incurred in support of our marketed products includes costs associated with product lifecycle management activities including, if applicable, costs associated with the development of new indications for existing products. Late stage programs are programs in Phase 3 development or in registration stage. Early stage programs are programs in Phase 1 or Phase 2 development. Research and discovery represents costs incurred to support our discovery research and translational science efforts. Costs are reflected in the development stage based upon the program status when incurred. Therefore, the same program could be reflected in different development stages in the same year. For several of our programs, the research and development activities are part of our collaborative and other relationships. Our costs reflect our share of the total costs incurred.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases in research and development expense were primarily due to $601.3 million in upfront payments recognized upon the closing of our collaboration with Denali in the third quarter of 2020, partially offset by a $125.0 million upfront payment recognized upon closing of our collaboration with InnoCare in the third quarter of 2021, the development of zuranolone for the potential treatment of MDD and PPD, the development of BIIB124 (SAGE-324) for the potential treatment of essential tremor, which we are developing in collaboration with Sage, and closeout costs associated with BIIB111 (timrepigene emparvovec) and BIIB112 (cotoretigene toliparvovec).
Early Stage Programs
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases in spending related to our early stage programs were primarily due to decreases in costs associated with:
-
the discontinuation of opicinumab (anti-LINGO) in MS;
-
the discontinuation of BIIB054 (cinpanemab) in Parkinson's disease and the discontinuation of gosuranemab (BIIB092) in Alzheimer's disease;
-
the advancement of dapirolizumab pego, an anti-CD40L pegylated Fab that we are developing in collaboration with UCB, for the
potential treatment of systemic lupus erytheatosus (SLE) into late stage; and
- the advancement of BIIB059 (anti-BDCA2) for the potential treatment of SLE into late stage.
These decreases were partially offset by increases in costs associated with:
-
an increase in spending in the development of BIIB124 for the potential treatment of essential tremor;
-
an increase in spending in the development of BIIB122 (DNL151) for the potential treatment of Parkinson's disease, which we are developing in collaboration with Denali;
-
close out costs related to the discontinuation of gosuranemab (BIIB092) in Alzheimer's disease;
-
an increase in spending in the development of BIIB135 (Orelabrutinib) for the potential treatment of MS; and
-
closeout costs related to BIIB112.
Late Stage Programs
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the increases in spending associated with our late stage programs were primarily due to:
-
an increase in spending in the development of zuranolone for the potential treatment of MDD and PPD;
-
the advancement of dapirolizumab pegol for the potential treatment of SLE into late stage;
-
the advancement of BIIB059 for the potential treatment of SLE into late stage;
-
an increase in spending related to lecanemab; and
-
closeout costs related to BIIB111.
In March 2019 Eisai initiated a global Phase 3 trial for the development of lecanemab in early Alzheimer's disease. Under our collaboration arrangement, Eisai serves as the global operational and regulatory lead for lecanemab and all costs, including research, development, sales and marketing expense, are shared equally between us and Eisai.
For additional information on our collaboration arrangements with Eisai, please read Note 16, Collaborative and Other Relationships, to our condensed consolidated financial statements included in this report.
Selling, General and Administrative

For the three and nine months ended September 30, 2021, compared to the same periods in 2020, selling, general and administrative expense increased 14.1% and 11.1%, respectively, primarily due to increases in personnel in support of the launch of ADUHELM in the U.S. Beginning in the second quarter of 2021, reimbursement from Eisai for its share of U.S. ADUHELM selling, general and administrative expense is reflected within collaboration profit sharing.
Amortization and Impairment of Acquired Intangible Assets

Our amortization expense is based on the economic consumption and impairment of intangible assets. Our most significant amortizable intangible assets are related to our TYSABRI, AVONEX, SPINRAZA, VUMERITY and TECFIDERA (rest of world)
products and other programs acquired through business combinations.
For the three and nine months ended September 30, 2021, amortization and impairment of acquired intangible assets reflects charges of $15.0 million and $365.0 million, respectively, related to BIIB111 for the potential treatment of choroideremia, and charges of $28.4 million and $220.0 million, respectively, related to BIIB112 for the potential treatment of X-linked retinitis pigmentosa.
For the nine months ended September 30, 2021, amortization and impairment of acquired intangible assets reflects the impact of a $44.3 million impairment charge related to vixotrigine (BIIB074) for the potential treatment of trigeminal neuralgia (TGN).
For the three and nine months ended September 30, 2020, amortization and impairment of acquired intangible assets reflects the impact of a $19.3 million impairment charge related to one of our in-process research and development (IPR&D) intangible assets.
We monitor events and expectations regarding product performance. If new information indicates that the assumptions underlying our most recent analysis are substantially different than those utilized in our current estimates, our analysis would be updated and may result in a significant change in the anticipated lifetime revenue of the relevant products. The occurrence of an adverse event could substantially increase the amount of amortization expense related to our acquired intangible assets as compared to previous periods or our current expectations, which may result in a significant negative impact on our future results of operations.
IPR&D Related to Business Combinations
IPR&D represents the fair value assigned to research and development assets that we acquired as part of a business combination and had not yet reached technological feasibility at the date of acquisition. We review amounts capitalized as acquired IPR&D for impairment annually, as of October 31, and whenever events or changes in circumstances indicate to us that the carrying value of the assets might not be recoverable.
Overall, the value of our acquired IPR&D assets is dependent upon several variables, including estimates of future revenue and the effects of competition, our ability to secure sufficient pricing in a competitive market, our ability to confirm safety and efficacy based on data from clinical trials and regulatory feedback, the level of anticipated development costs and the probability and timing of successfully advancing a particular research program from one clinical trial phase to the next. We are
continually reevaluating our estimates concerning these and other variables, including our life cycle management strategies, research and development priorities and development risk, changes in program and portfolio economics and related impact of foreign currency exchange rates and economic trends and evaluating industry and company data regarding the productivity of clinical research and the development process. Changes in our estimates may result in a significant change to our valuation of our IPR&D assets.
Vixotrigine
In the periods since we acquired vixotrigine, there have been numerous delays in the initiation of Phase 3 studies for the potential treatment of TGN and for the potential treatment of diabetic painful neuropathy (DPN), another form of neuropathic pain. We have engaged with the FDA regarding the design of the Phase 3 studies of vixotrigine for the potential treatment of TGN and DPN and are now performing an additional clinical trial of vixotrigine.
The performance of this additional clinical trial delayed the initiation of the Phase 3 studies of vixotrigine for the potential treatment of TGN, and, as a result, we recognized an impairment charge of $44.3 million related to vixotrigine for the potential treatment of TGN during the first quarter of 2021. As of September 30, 2021, the carrying value associated with the remaining vixotrigine IPR&D asset for DPN was $132.0 million.
BIIB111 and BIIB112
During the fourth quarter of 2020 we recognized an impairment charge of $115.0 million related to BIIB111 as a result of third-party manufacturing delays that impacted the timing and increased the costs associated with advancing BIIB111 through Phase 3 development.
During the second quarter of 2021 we announced that our Phase 3 STAR study of BIIB111 and our Phase 2/3 XIRIUS study of BIIB112 did not meet their primary endpoints. In the third quarter of 2021 we suspended further development on these programs based on the decision by management as part of its strategic review process. For the three and nine months ended September 30, 2021, we recorded impairment charges of $15.0 million and $365.0 million, respectively, related to BIIB111, and charges of $28.4 million and $220.0 million, respectively, related to BIIB112. As a result, the remaining book values associated with these programs were reduced to zero.
In addition, for the three months ended September 30, 2021, as a result of our decision to suspend further development of BIIB111 and BIIB112, we recorded charges of approximately $39.1 million related to our manufacturing arrangements and
other costs that we expect to incur as a result of suspending these programs.
Collaboration Profit Sharing
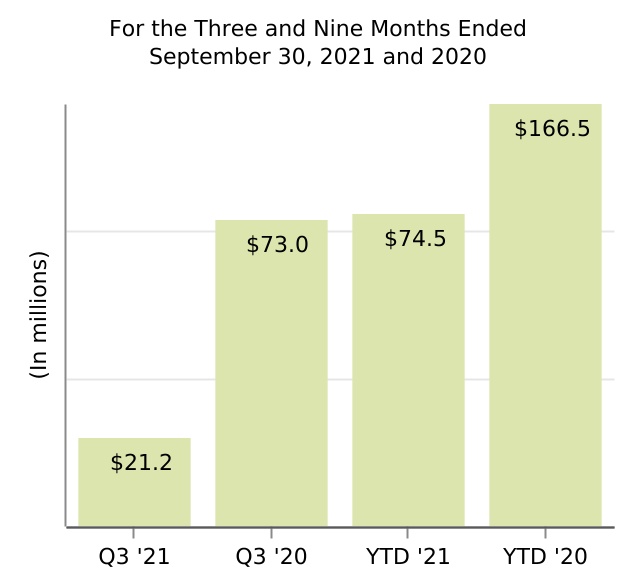
Collaboration profit sharing primarily includes Samsung Bioepis' 50.0% share of the profit or loss related to our biosimilars commercial agreement with Samsung Bioepis and, beginning in the second quarter of 2021, Eisai's 45.0% share of income and expenses in the U.S. related to the ADUHELM Collaboration Agreement.
For the three and nine months ended September 30, 2021, we recognized net profit-sharing expense of $71.8 million and $210.2 million, respectively, to reflect Samsung Bioepis' 50.0% sharing of the net collaboration profits compared to a net profit sharing expense of $72.9 million and $200.1 million, respectively, in the prior year comparative periods.
For the three and nine months ended September 30, 2021, we recognized net profit-sharing income of $50.6 million and $90.7 million, respectively, to reflect Eisai's 45.0% share of loss related to the ADUHELM Collaboration Agreement. For the nine months ended September 30, 2021, we also recognized net profit-sharing income of $45.0 million to reflect Eisai's 45.0% share of the $100.0 million milestone payment made to Neurimmune related to the launch of ADUHELM in the U.S.
For the nine months ended September 30, 2020, we also recognized net profit-sharing income of $33.8 million to reflect Eisai's 45.0% share of the $75.0 million milestone payment made to Neurimmune related to the submission of the BLA for the approval of ADUHELM to the FDA.
For additional information on our collaboration arrangements with Samsung Bioepis and Eisai, please read Note 16, Collaborative and Other Relationships, to
our condensed consolidated financial statements included in this report.
(Gain) Loss on Fair Value Remeasurement of Contingent Consideration

Consideration payable for certain of our business combinations includes future payments that are contingent upon the occurrence of a particular event or events. We record an obligation for such contingent consideration payments at fair value on the acquisition date. We then revalue our contingent consideration obligations each reporting period. Changes in the fair value of our contingent consideration obligations, other than changes due to payments, are recognized as a (gain) loss on fair value remeasurement of contingent consideration in our condensed consolidated statements of income.
For the three and nine months ended September 30, 2021, the decrease in the fair value of our contingent consideration obligations was primarily due to reductions in the probability of technical and regulatory success and delays in the expected timing of the achievement of certain remaining developmental milestones related to our vixotrigine programs.
Acquired In-Process Research and Development

BIIB118 Acquisition
In March 2020 we acquired BIIB118 (CK1 inhibitor) for the potential treatment of patients with behavioral and neurological symptoms across various psychiatric and neurological diseases from Pfizer Inc. (Pfizer). In connection with this acquisition, we made an upfront payment of $75.0 million to Pfizer, which was accounted for as an asset acquisition and recorded as acquired IPR&D in our condensed consolidated statements of income as BIIB118 has not yet reached technological feasibility.
For additional information on our acquisition of BIIB118, please read Note 2, Acquisitions, to our condensed consolidated financial statements included in this report.
Other Income (Expense), Net

For the three months ended September 30, 2021, compared to the same period in 2020, the
change in other income (expense), net primarily reflects net unrealized losses on our holdings in equity securities.
For the nine months ended September 30, 2021, compared to the same period in 2020, the change in other income (expense), net primarily reflects net unrealized losses on our holdings in equity securities.
For the three months ended September 30, 2021, net unrealized losses and realized gains on our holdings in equity securities were approximately $426.9 million and $2.7 million, respectively, compared to net unrealized losses and realized gains (losses) of $82.3 million and zero, respectively, in the prior year comparative period. The net unrealized losses recognized during the three months ended September 30, 2021, primarily reflect decreases in the aggregate fair value of our investments in Denali, Ionis, Sage and Sangamo common stock of approximately $424.3 million.
For the nine months ended September 30, 2021, net unrealized losses and realized gains on our holdings in equity securities were approximately $715.2 million and $9.3 million, respectively, compared to net unrealized losses and realized gains (losses) of $40.3 million and zero, respectively, in the prior year comparative period. The net unrealized losses recognized during the nine months ended September 30, 2021, primarily reflect decreases in the aggregate fair value of our investments in Denali, Ionis, Sage and Sangamo common stock of approximately $709.1 million.
We expect a moderate increase in interest expense for 2021, compared to 2020, primarily due to lower interest being capitalized as a result of assets being placed into service during 2021.
Income Tax (Benefit) Provision
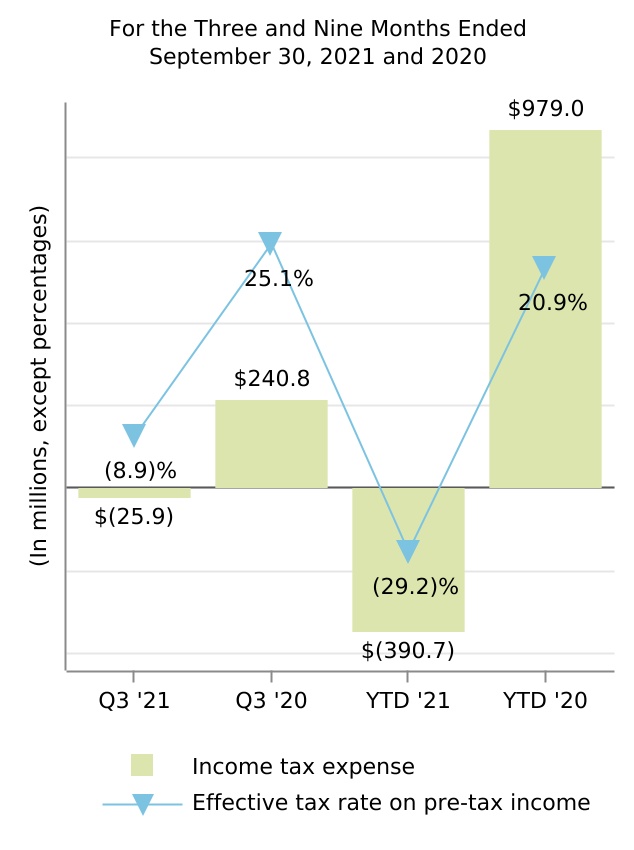
Our effective tax rate fluctuates from year to year due to the global nature of our operations. The factors that most significantly impact our effective tax rate include changes in tax laws, variability in the allocation of our taxable earnings among multiple jurisdictions, the amount and characterization of our research and development expense, the levels of certain deductions and credits, acquisitions and licensing transactions.
For the three and nine months ended September 30, 2021, compared to the same periods in 2020, the decreases in our effective tax rate, excluding the impact of the Neurimmune deferred tax asset discussed below, were primarily due to the change in the territorial mix of our profitability, which included the adverse effect of generic competition for TECFIDERA in the U.S. market; the tax impacts of the BIIB111 and BIIB112 impairment charges; and the impact of the non-cash tax effects of changes in the value of our equity investments, where we recorded unrealized losses in 2021. The tax effects of this change in value of our equity investments were recorded in the current period, as the changes in value of equity investments cannot be reliably forecasted. Our 2020 effective tax rate also reflected an income tax expense related to the establishment of a valuation allowance against certain deferred tax assets, the realization of which is dependent on future sales of TECFIDERA in the U.S.
In addition, for the nine months ended September 30, 2021, compared to the same period in 2020, the decrease in our effective tax rate was primarily due to a current year deferred tax benefit in Switzerland resulting from the accelerated approval of ADUHELM by the FDA in the U.S. recognized during the second quarter of 2021. We recorded a net deferred tax asset of approximately $500.0 million. The net deferred tax asset is comprised of approximately $875.0 million of gross deferred tax asset, reduced by approximately $375.0 million of unrecognized tax benefit discussed below. The deferred tax benefit relates to Neurimmune's tax basis in ADUHELM, the realization of which is dependent on future sales of ADUHELM and approval of the Swiss cantonal tax authorities, with an equal and offsetting amount assigned to net income (loss) attributable to noncontrolling interests, net of tax in our condensed consolidated statements of income, resulting in a zero net impact to net income attributable to Biogen Inc.
For additional information on our collaboration arrangement with Neurimmune, please read Note 17, Investments in Variable Interest Entities, to our condensed consolidated financial statements included in this report
For additional information on our income taxes please read Note 14, Income Taxes, to our condensed consolidated financial statements included in this report.
Equity in (Income) Loss of Investee, Net of Tax

In February 2012 we entered into a joint venture agreement with Samsung BioLogics establishing an entity, Samsung Bioepis, to develop, manufacture and market biosimilar products.
In June 2018 we exercised our option under our joint venture agreement to increase our ownership
percentage in Samsung Bioepis from approximately 5.0% to approximately 49.9%. The share purchase transaction was completed in November 2018. As of September 30, 2021, our ownership percentage remained at approximately 49.9%.
We recognize our share of the results of operations related to our investment in Samsung Bioepis under the equity method of accounting one quarter in arrears when the results of the entity become available, which is reflected as equity in (income) loss of investee, net of tax in our condensed consolidated statements of income. We recognize amortization on certain basis differences resulting from our November 2018 investment.
Certain officers and affiliates of our joint venture partner, Samsung BioLogics, are currently subject to ongoing criminal proceedings that we continue to monitor. While these proceedings could impact the operations of Samsung Bioepis and its business, we have assessed the value of our investment in Samsung Bioepis and continue to believe that the fair value of the investment is in excess of its net book value.
For the three and nine months ended September 30, 2021, we recognized net income on our investment of $1.1 million and $17.2 million, respectively, reflecting our share of Samsung Bioepis' operating results and amortization of basis differences, net of tax, compared to net losses on our investment of $13.1 million and $12.7 million, respectively, in the prior year comparative periods.
Net income on our investment for the nine months ended September 30, 2021, reflects a $31.2 million benefit related to the release of a valuation allowance on deferred tax assets associated with Samsung Bioepis. The valuation allowance was released in the second quarter of 2021 based on a consideration of the positive and negative evidence, including the historic earnings of Samsung Bioepis.
For additional information on our collaboration arrangements with Samsung Bioepis, please read Note 16, Collaborative and Other Relationships, to our condensed consolidated financial statements included in this report.
Noncontrolling Interests

For the nine months ended September 30, 2021, compared to the same period in 2020, the increase is due to the recognition of a current year deferred tax benefit associated with the accelerated approval of ADUHELM by the FDA in the U.S. During the second quarter of 2021, we recorded a net deferred tax asset of approximately $500.0 million related to Neurimmune's tax basis in ADUHELM, the realization of which is dependent on future sales of ADUHELM and approval of the Swiss cantonal tax authorities, with an equal and offsetting amount assigned to net income (loss) attributable to noncontrolling interests, net of tax in our condensed consolidated statements of income, resulting in a zero net impact to net income attributable to Biogen Inc.
For the nine months ended September 30, 2021, compared to the same period in 2020, the change in net income (loss) attributable to noncontrolling interests, net of tax was also due to the $100.0 million milestone payment to Neurimmune related to the launch of ADUHELM in the U.S. during the second quarter of 2021.
For the nine months ended September 30, 2020, net income (loss) attributable to noncontrolling interests, net of tax was primarily related to the $75.0 million milestone payment to Neurimmune related to the submission of the BLA for the approval of ADUHELM to the FDA.
For additional information on our collaboration agreement with Neurimmune, please read Note 17, Investments in Variable Interest Entities, to our condensed consolidated financial statements included in this report.
For additional information on our income taxes please read Note 14, Income Taxes, to our condensed consolidated financial statements included in this report.
Financial Condition, Liquidity and Capital Resources
Our financial condition is summarized as follows:
| (In millions, except percentages) | As of September 30, 2021 | As of December 31, 2020 | Change % | |||||||||||||||||
| Financial assets: | ||||||||||||||||||||
| Cash and cash equivalents | $ | 1,541.8 | $ | 1,331.2 | 15.8 | % | ||||||||||||||
| Marketable securities — current | 1,413.3 | 1,278.9 | 10.5 | |||||||||||||||||
| Marketable securities — non-current | 968.3 | 772.1 | 25.4 | |||||||||||||||||
| Total cash, cash equivalents and marketable securities | $ | 3,923.4 | $ | 3,382.2 | 16.0 | % | ||||||||||||||
| Borrowings: | ||||||||||||||||||||
| Current portion of notes payable | $ | 998.8 | $ | — | — | % | ||||||||||||||
| Notes payable | $ | 6,272.3 | $ | 7,426.2 | (15.5) | % | ||||||||||||||
| Total borrowings | $ | 7,271.1 | $ | 7,426.2 | (2.1) | % | ||||||||||||||
| Working capital: | ||||||||||||||||||||
| Current assets | $ | 7,162.3 | $ | 6,887.1 | 4.0 | % | ||||||||||||||
| Current liabilities | (4,211.6) | (3,742.2) | 12.5 | |||||||||||||||||
| Total working capital | $ | 2,950.7 | $ | 3,144.9 | (6.2) | % |
For the nine months ended September 30, 2021, certain significant cash flows were as follows:
-
$2,801.6 million in net cash flow provided by operating activities, which reflected an upfront payment of $125.0 million made in connection with entering into our collaboration with InnoCare and recognized as research and development expense;
-
$1,800.0 million used for share repurchases;
-
$170.0 million used in connection with our Exchange Offer;
-
$206.5 million used for purchases of property, plant and equipment;
-
$100.1 million in total net payments of income taxes; and
-
$100.0 million milestone payment to Neurimmune.
Overview
We have historically financed our operating and capital expenditures primarily through cash flow earned through our operations. We expect our operating expenditures, particularly those related to research and development, clinical trials, commercialization of new products and international expansion to continue to grow. However, we expect to continue funding our current and planned operating requirements primarily through our cash flow earned from our operations as well as our existing cash resources. We believe generic competition for TECFIDERA in the U.S. will continue to reduce our cash flow from operations in 2021 and will have a
significant adverse impact on our future cash flow from operations. We believe that our existing funds, when combined with cash generated from operations and our access to additional financing resources, if needed, are sufficient to satisfy our operating, working capital, strategic alliance, milestone payment, capital expenditure and debt service requirements for the foreseeable future. In addition, we may choose to opportunistically return cash to shareholders and pursue other business initiatives, including acquisition and licensing activities. We may, from time to time, also seek additional funding through a combination of new collaborative agreements, strategic alliances and additional equity and debt financings or from other sources should we identify a significant new opportunity**.**
For additional information on certain risks that could negatively impact our financial position or future results of operations, please read Item 3. Quantitative and Qualitative Disclosures About Market Risk and Item 1A. Risk Factors included in this report.
Cash, Cash Equivalents and Marketable Securities
Until required for another use in our business, we typically invest our cash reserves in bank deposits, certificates of deposit, commercial paper, corporate notes, U.S. and foreign government instruments, overnight reverse repurchase agreements and other interest-bearing marketable debt instruments in accordance with our investment policy. It is our policy to mitigate credit risk in our cash reserves and marketable securities by maintaining a well-diversified portfolio that limits the amount of exposure as to institution, maturity and investment type.
As of September 30, 2021, we had cash, cash equivalents and marketable securities totaling approximately $3.9 billion compared to approximately $3.4 billion as of December 31, 2020. The change in cash, cash equivalents and marketable securities at September 30, 2021, from December 31, 2020, was primarily due to net cash flow provided by operating activities, partially offset by cash used for share repurchases and capital expenditures, cash payments made in connection with our Exchange Offer and a milestone payment made to Neurimmune.
Investments and other assets in our condensed consolidated balance sheets as of September 30, 2021 and December 31, 2020, include the carrying value of our investment in Samsung Bioepis of $586.1 million and $620.2 million, respectively. As Samsung Bioepis is a privately-held entity, our ability to liquidate our investment may be limited and we may realize significantly less than the value of such investment. This investment is also subject to foreign currency exchange fluctuations.
In connection with our collaboration with Sangamo, we purchased approximately 24 million shares of Sangamo common stock in April 2020. As of September 30, 2021 and December 31, 2020, the fair value of this investment was $210.5 million and $333.7 million, respectively.
In connection with our collaboration with Denali, we purchased approximately 13 million shares of Denali common stock in September 2020. As of September 30, 2021 and December 31, 2020, the fair value of this investment was $612.9 million and $935.7 million, respectively.
In connection with our collaboration with Sage, we purchased approximately 6.2 million shares of Sage common stock in December 2020. As of September 30, 2021 and December 31, 2020, the fair value of this investment was $236.9 million and $433.9 million, respectively.
Our investment in Ionis common stock had a fair value of $96.4 million and $249.1 million as of September 30, 2021 and December 31, 2020, respectively. The decrease was partially due to the sale of a portion of our investment in Ionis common stock during the first quarter of 2021.
For additional information on our collaboration arrangements with Samsung Bioepis, Sangamo, Denali and Sage, please read Note 16, Collaborative and Other Relationships, to our condensed consolidated financial statements included in this report*.*
For additional information on our collaboration arrangements with Ionis, please read Note 18, Collaborative and Other Relationships, to our
consolidated financial statements included in our 2020 Form 10-K.
Borrowings
In February 2021 we completed our Exchange Offer, consisting of the following:
-
$624.6 million aggregate principal amount of our 2045 Senior Notes was exchanged for $700.7 million aggregate principal amount of our 2051 Senior Notes and approximately $151.8 million of aggregate cash payments; and
-
$8.9 million aggregate principal amount of our 2045 Senior Notes was redeemed for approximately $12.1 million of aggregate cash payments, excluding accrued and unpaid interest.
In April 2020 we issued senior unsecured notes for an aggregate principal amount of $3.0 billion (2020 Senior Notes), consisting of the following:
-
$1.5 billion aggregate principal amount of 2.25% Senior Notes due May 1, 2030; and
-
$1.5 billion aggregate principal amount of 3.15% Senior Notes due May 1, 2050.
The following is a summary of our currently outstanding senior unsecured notes issued in 2015 (2015 Senior Notes):
-
$1.0 billion aggregate principal amount of 3.625% Senior Notes due September 15, 2022;
-
$1.75 billion aggregate principal amount of 4.05% Senior Notes due September 15, 2025; and
-
$1.12 billion aggregate principal amount of 5.20% Senior Notes due September 15, 2045.
Our 2020 Senior Notes and our 2015 Senior Notes were issued at a discount, which are amortized as additional interest expense over the period from issuance through maturity.
For a summary of the fair and carrying values of our outstanding borrowings as of September 30, 2021 and December 31, 2020, please read Note 6, Fair Value Measurements, to our condensed consolidated financial statements included in this report.
Credit Facility
In January 2020 we entered into a $1.0 billion, five-year senior unsecured revolving credit facility under which we are permitted to draw funds for working capital and general corporate purposes. The terms of the revolving credit facility include a financial covenant that requires us not to exceed a maximum consolidated leverage ratio. As of September 30,
2021, we had no outstanding borrowings and were in compliance with all covenants under this facility.
Working Capital
Working capital is defined as current assets less current liabilities. Total working capital decreased by $194.2 million, or 6.2%, primarily driven by an increase in current liabilities, partially offset by an increase in current liabilities.
The increase in current liabilities was primarily due to the reclassification of our $1.0 billion aggregate principal amount of 3.625% Senior Notes due September 15, 2022 from long-term to short-term, partially offset by a reduction in accounts payable as well as accrued expense and other, which was primarily related to decreases in the accrual of contingent payments, the accrual for employee compensation and benefits and the fair values of derivative liabilities.
The increase in total current assets was primarily driven by an increase in net cash, cash equivalents and marketable securities, due to $2,801.6 million of cash generated from operations, partially offset by cash used for share repurchases, capital expenditures and a Neurimmune milestone payment as well as cash payments made in conjunction with our Exchange Offer.
Share Repurchase Programs
In October 2020 our Board of Directors authorized our 2020 Share Repurchase Program, which is a program to repurchase up to $5.0 billion of our common stock. Our 2020 Share Repurchase Program does not have an expiration date. All share
repurchases under our 2020 Share Repurchase Program will be retired. Under our 2020 Share Repurchase Program, we repurchased and retired approximately 2.2 million and 6.0 million shares of our common stock at a cost of approximately $750.0 million and $1.8 billion during the three and nine months ended September 30, 2021, respectively. Approximately $2.8 billion remained available under our 2020 Share Repurchase Program as of September 30, 2021.
In December 2019 our Board of Directors authorized a program to repurchase up to $5.0 billion of our common stock (December 2019 Share Repurchase Program), which was completed as of September 30, 2020. All shares repurchased under our December 2019 Share Repurchase Program were retired. Under our December 2019 Share Repurchase Program, we repurchased and retired approximately 4.5 million and 16.7 million shares of our common stock at a cost of approximately $1.3 billion and $5.0 billion during the three and nine months ended September 30, 2020, respectively.
In March 2019 our Board of Directors authorized a program to repurchase up to $5.0 billion of our common stock (March 2019 Share Repurchase Program), which was completed as of March 31, 2020. All shares repurchased under our March 2019 Share Repurchase Program were retired. Under our March 2019 Share Repurchase Program, we repurchased and retired approximately 4.1 million shares of our common stock at a cost of approximately $1.3 billion during the nine months ended September 30, 2020.
Cash Flow
The following table summarizes our cash flow activity:
| For the Nine Months Ended September 30, | ||||||||||||||||||||
| (In millions, except percentages) | 2021 | 2020 | % Change | |||||||||||||||||
| Net cash flow provided by operating activities | $ | 2,801.6 | $ | 4,596.9 | (39.1) | % | ||||||||||||||
| Net cash flow used in investing activities | (451.0) | (442.2) | (2.0) | |||||||||||||||||
| Net cash flow used in financing activities | (2,096.0) | (4,871.6) | 57.0 |
Operating Activities
Cash flow from operating activities represents the cash receipts and disbursements related to all of our activities other than investing and financing activities. We expect cash provided from operating activities will continue to be our primary source of funds to finance operating needs and capital expenditures for the foreseeable future.
Operating cash flow is derived by adjusting our net income for:
-
non-cash operating items such as depreciation and amortization, impairment charges, unrealized gain (loss) on strategic investments, acquired IPR&D and share-based compensation;
-
changes in operating assets and liabilities, which reflect timing differences between the receipt and payment of cash associated with transactions and when they are recognized in results of operations; and
- changes in the fair value of contingent payments associated with our acquisitions of businesses and payments related to collaborations.
For the nine months ended September 30, 2021, compared to the same period in 2020, the decrease in net cash flow provided by operating activities was primarily due to lower net income.
Investing Activities
For the nine months ended September 30, 2021, compared to the same period in 2020, the increase in net cash flow used in investing activities was primarily due to higher net proceeds received from the sale of marketable securities in 2020 as compared to the current year, partially offset by higher capital expenditures and acquisitions of IPR&D and other intangible assets in 2020 as well as the upfront payments made to Sangamo and Denali.
Financing Activities
For the nine months ended September 30, 2021, compared to the same period in 2020, the decrease in net cash flow used in financing activities was primarily due to the greater number of shares repurchased in 2020 as compared to the comparative period in 2021, partially offset by cash used in connection with our Exchange Offer and a milestone payment to Neurimmune in 2021.
Contractual Obligations and Off-Balance Sheet Arrangements
Contractual Obligations
Our contractual obligations primarily consist of our obligations under non-cancellable operating leases, long-term debt obligations and defined benefit and other purchase obligations, excluding amounts related to uncertain tax positions, funding commitments, contingent development, regulatory and commercial milestone payments, contingent payments and contingent consideration related to our business combinations, as described below.
There have been no material changes in our contractual obligations since December 31, 2020.
Royalty Payments
TYSABRI
We are obligated to make contingent payments of 18.0% on annual worldwide net sales of TYSABRI up to $2.0 billion and 25.0% on annual worldwide net sales of TYSABRI that exceed $2.0 billion. Royalty payments are recognized as cost of sales in our condensed consolidated statements of income.
SPINRAZA
We make royalty payments on annual worldwide net sales of SPINRAZA using a tiered royalty rate between 11.0% and 15.0%, which are recognized as cost of sales in our condensed consolidated statements of income.
VUMERITY
In October 2019 the FDA approved VUMERITY for the treatment of RMS. Under our agreement with Alkermes Pharma Ireland Limited, a subsidiary of Alkermes plc (Alkermes), we make royalty payments to Alkermes on worldwide net sales of VUMERITY using a royalty rate of 15.0%, which are recorded as cost of sales in our condensed consolidated statements of income.
In October 2019 we entered into a new supply agreement and amended our license and collaboration agreement with Alkermes. We have elected to initiate a technology transfer and, following a transition period, to manufacture VUMERITY or have VUMERITY manufactured by a third party we have engaged in exchange for paying an increased royalty rate to Alkermes on any portion of future worldwide net sales of VUMERITY that is manufactured by us or our designee. For additional information on our collaboration arrangement with Alkermes, please read Note 18, Collaborative and Other Relationships, to our consolidated financial statements included in our 2020 Form 10-K.
Contingent Consideration related to Business Combinations
In connection with our acquisition of Convergence Pharmaceuticals Holdings Ltd., we agreed to make additional payments based upon the achievement of certain milestone events.
We recognized the contingent consideration liabilities associated with this acquisition at its fair value on the acquisition date and revalue this obligation each reporting period. We may pay up to approximately $400.0 million in remaining milestones related to this acquisition.
Contingent Development, Regulatory and Commercial Milestone Payments
Based on our development plans as of September 30, 2021, we could trigger potential future milestone payments to third parties of up to approximately $10.9 billion, including approximately $2.1 billion in development milestones, approximately $1.2 billion in regulatory milestones and approximately $7.6 billion in commercial milestones, as part of our various collaborations, including licensing and development programs. Payments under these agreements generally become due and payable
upon achievement of certain development, regulatory or commercial milestones. Because the achievement of these milestones was not considered probable as of September 30, 2021, such contingencies have not been recorded in our financial statements. Amounts related to contingent milestone payments are not considered contractual obligations as they are contingent on the successful achievement of certain development, regulatory or commercial milestones.
If certain clinical and commercial milestones are met, we may pay up to $20.5 million in milestones in 2021 under our current agreements. In addition, if aducanumab receives regulatory approval in the jurisdictions where we have submitted filings, we may pay up to $100.0 million in additional milestones to Neurimmune, which includes $50.0 million if launched in three or more countries in the E.U. and $50.0 million if launched in Japan. Milestones payable to Neurimmune are shared expenses under the ADUHELM Collaboration Agreement.
For additional information on our collaboration arrangements with Eisai, please read Note 16, Collaborative and Other Relationships, to our condensed consolidated financial statements included in this report.
For additional information on our collaboration arrangement with Neurimmune, please read Note 17, Investments in Variable Interest Entities, to our condensed consolidated financial statements included in this report.
Other Funding Commitments
As of September 30, 2021, we have several ongoing clinical studies in various clinical trial stages. Our most significant clinical trial expenditures are to contract research organizations (CROs). The contracts with CROs are generally cancellable, with notice, at our option. We recorded accrued expense of approximately $47.0 million in our condensed consolidated balance sheet for expenditures incurred by CROs as of September 30, 2021. We have approximately $644.1 million in cancellable future commitments based on existing CRO contracts as of September 30, 2021.
As part of the sale of our Hillerød, Denmark manufacturing operations to FUJIFILM Corporation (FUJIFILM), we provided FUJIFILM with certain minimum batch production commitment guarantees. There is a risk that the minimum contractual batch production commitments will not be met. Based upon current estimates we do not expect to incur an adverse commitment obligation associated with such guarantees. We developed this estimate using a probability-weighted estimate of future manufacturing activity and may further adjust this estimate based upon changes in business conditions, which may
result in the increase or reduction of this adverse commitment obligation in subsequent periods.
For additional information on the divestiture of our Hillerød, Denmark manufacturing operations, please read Note 3, Divestitures, to our consolidated financial statements included in our 2020 Form 10-K.
Tax Related Obligations
We exclude liabilities pertaining to uncertain tax positions from our summary of contractual obligations as we cannot make a reliable estimate of the period of cash settlement with the respective taxing authorities. As of September 30, 2021, we have approximately $102.4 million of liabilities associated with uncertain tax positions.
As of September 30, 2021 and December 31, 2020, we have accrued income tax liabilities of approximately $633.0 million and $697.0 million, respectively, under a one-time mandatory deemed repatriation tax on accumulated foreign subsidiaries' previously untaxed foreign earnings (the Transition Toll Tax). Of the amounts accrued as of September 30, 2021, approximately $72.7 million is expected to be paid within one year. The Transition Toll Tax will be paid in installments over an eight-year period, which started in 2018, and will not accrue interest.
Other Off-Balance Sheet Arrangements
We do not have any relationships with entities often referred to as structured finance or special purpose entities that were established for the purpose of facilitating off-balance sheet arrangements. As such, we are not exposed to any financing, liquidity, market or credit risk that could arise if we had engaged in such relationships. We consolidate variable interest entities if we are the primary beneficiary.
New Accounting Standards
For a discussion of new accounting standards please read Note 1, Summary of Significant Accounting Policies, to our condensed consolidated financial statements included in this report.
Critical Accounting Estimates
The preparation of our condensed consolidated financial statements, which have been prepared in accordance with accounting principles generally accepted in the U.S., requires us to make estimates, judgments and assumptions that may affect the reported amounts of assets, liabilities, equity, revenue and expense and related disclosure of contingent assets and liabilities. On an ongoing basis we evaluate our estimates, judgments and assumptions. We base our estimates on historical
experience and on various other assumptions that we believe are reasonable, the results of which form the basis for making judgments about the carrying values of assets, liabilities and equity and the amount of revenue and expense. Actual results may differ from these estimates.
For a discussion of our critical accounting estimates, please read Part II, Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in our 2020 Form 10-K. There have been no material changes to our critical accounting estimates since our 2020 Form 10-K.
Previous: Cover and table of contents · Next: Item 3. Quantitative and Qualitative Disclosures About Market Risk