 filings.tools
Item 2. Management's Discussion and Analysis of Financial Condition and Results of Operations
96K characters. Original on sec.gov · Markdown
Item 2. Management's Discussion and Analysis of Financial Condition and Results of Operations
The following discussion should be read in conjunction with our Annual Report on Form 10-K for the year ended December 31, 2021, including Part I, Item 1A "Risk Factors," as well as our Unaudited Consolidated Financial Statements and accompanying notes and the Section entitled "Special Note Regarding Forward-Looking Statements" in this Quarterly Report on Form 10-Q. The information on our websites is not a part of this Quarterly Report and is not incorporated herein by reference.
We evaluate certain operating and financial measures on both an as-reported and constant-currency basis. We calculate constant currency by converting our current-year period operating and financial results for transactions recorded in currencies other than U.S. Dollars using the corresponding prior-year period monthly average exchange rates rather than the current-year period monthly average exchange rates.
Overview
Our mission is to make it easier for everyone to experience the world. We connect consumers who wish to make travel reservations with travel service providers around the world through our online platforms. Consumers can also use our meta-search services to easily compare travel reservation information from hundreds of online travel platforms at once. We also offer various other services to consumers and partners, such as travel-related insurance products and restaurant management services to restaurants.
We offer these services through six primary consumer-facing brands: Booking.com, Priceline, agoda, Rentalcars.com, KAYAK, and OpenTable. We continue to increase the collaboration, cooperation, and interdependency among our brands to provide consumers with the most comprehensive services.
The results of our business outside of the U.S. consist of the results of Booking.com, agoda, and Rentalcars.com in their entirety and the parts of the KAYAK and OpenTable businesses located outside of the U.S. This classification is independent of where the consumer resides, where the consumer is physically located while using our services, or the location of the travel service provider or restaurant. For example, a reservation made through Booking.com (which is domiciled in the Netherlands) at a hotel in New York by a consumer in the U.S. is part of the results of our businesses outside of the U.S. In 2021, the revenues from our businesses outside of the U.S. (the substantial majority of which is generated by Booking.com through facilitating accommodation reservations) represented approximately 87% of our consolidated revenues. See Note 2 to the Unaudited Consolidated Financial Statements for more geographic information.
We derive substantially all of our revenues from enabling consumers to make travel service reservations. We also earn revenues from advertising services, restaurant reservations and restaurant management services, and various other services, such as travel-related insurance revenues.
Trends
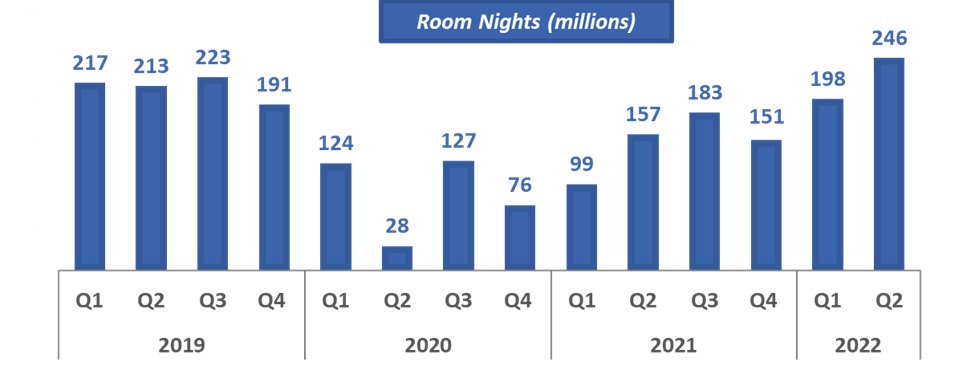
The COVID-19 pandemic and the resulting implementation of travel restrictions by governments around the world resulted in a significant decline in travel activities and consumer demand for related services. Accommodation room nights, which include the impact of cancellations, declined rapidly as the COVID-19 pandemic spread in 2020. Since the beginning of the second quarter of 2020 and through 2021, accommodation room night declines versus the comparable period in 2019 have generally improved as government-imposed travel restrictions have eased, vaccines and other medical interventions have become more widespread, and consumer demand for travel has started to rebound. However, there have been periods of worsening trends due to spikes in COVID-19 cases and newly implemented travel restrictions, primarily related to new variants. In the first quarter of 2022, many countries in Europe and some countries in Asia relaxed COVID-19 related travel restrictions, which we believe positively impacted room night trends in those regions in the quarter. For the first quarter of 2022 compared to the first quarter of 2019, room nights were down 9%, an improvement from the 21% room night decline in the fourth quarter of 2021 compared to the fourth quarter of 2019.
In early March 2022 following Russia's invasion of Ukraine, we suspended the booking of travel services in Russia and Belarus. This led to the loss of new bookings from bookers in these countries, although we do not believe this impact to be material at this time. Additionally, we saw some slowdown in booking trends across Europe as travelers took in the news of the invasion. Excluding room nights from bookers in Russia, Ukraine, and Belarus in both the first quarter of 2022 and the first quarter of 2019, our overall room nights were down about 6% for the full first quarter.
For the second quarter of 2022 compared to the second quarter of 2019, room nights were up 16%, an improvement from the 9% room night decline in the first quarter of 2022 compared to the first quarter of 2019. Excluding room nights from bookers in Russia, Ukraine, and Belarus in both the second quarter of 2022 and the second quarter of 2019, our overall room nights were up about 21% for the full second quarter. Within the second quarter of 2022, room night growth improved from 10% in April 2022 to about 22% in May 2022 relative to April 2019 and May 2019, respectively, driven by improving room night trends in all our regions, but primarily in Europe. Room night growth in June 2022 was about 14% relative to June 2019, which was above the growth rate in April 2022 but below the level of growth in May 2022. We saw a moderation in the room night growth rate from June 2022 to July 2022 with room nights growing about 4% versus July 2019, with the moderation in growth relative to June observed across all of our major regions. North America showed the smallest change in growth rate relative to June.
The comparison of room nights in 2021 and 2022 to the comparable period in 2019 avoids the distortion created from comparing to a prior year period that was significantly impacted by the COVID-19 pandemic.
Quarterly Room Nights and Change versus 2019

We have observed an improvement in cancellation rates since the high in April 2020, though we have seen periods of elevated cancellation rates typically coinciding with significant increases in COVID-19 cases and newly imposed travel restrictions. The cancellation rate in the first quarter of 2022 was about in line with the first quarter of 2019 and improved compared to the first quarter of 2021. The cancellation rate in the second quarter of 2022 improved compared to the second quarters of 2019 and 2021. In the first and second quarters of 2022, a higher share of our room nights was booked with flexible cancellation policies, as compared to the first and second quarters of 2019 and 2021, which could result in higher cancellation rates in future quarters.
Because we recognize revenue from bookings when the traveler checks in, our reported revenue is not at risk of being reversed due to cancellations. Increases in cancellation rates can negatively impact our marketing efficiency as a result of incurring performance marketing expense at the time a booking is made even though that booking could be canceled in the future if it was booked under a flexible cancellation policy. There are many factors in addition to cancellation rates that contribute to marketing efficiency including average daily rates ("ADRs"), costs per click, foreign currency exchange rates, our ability to convert paid traffic to booking customers, the timing and effectiveness of our brand marketing campaigns, and the extent to which consumers come directly to our platforms for bookings. Finally, we may see increased customer service costs during periods with significant increases in cancellation rates, which we have not observed since the second quarter of 2020.
Since the second quarter of 2020, government-imposed travel restrictions have generally limited international travel (travelers booking a stay at a property located outside their own country) more than domestic travel (travelers booking a stay within their own country). We believe the continued easing of government-imposed travel restrictions in many countries throughout the world in the second quarter of 2022 helped drive an increase in the share of room nights booked for international travel versus the second quarter of 2021, however, the share remained below 2019 levels.
We saw an increase in the share of room nights booked on a mobile device and mobile app bookings in the second quarter of 2022 compared to the second quarter of 2019. We saw a decrease in the share of room nights booked on a mobile device in the second quarter of 2022 compared to the second quarter of 2021, due to a year-over-year increase in the share of room nights booked for international travel and a year-over-year expansion of the booking window. Room nights booked on a mobile device generally have a lower mix of international travel and a shorter booking window than room nights booked on a desktop. The share of mobile app bookings in the second quarter of 2022 was slightly above the second quarter of 2021. We continue to see favorable repeat direct booking behavior from consumers in our apps which allow us more opportunities to engage directly with consumers. The revenue earned on a mobile transaction may be less than a typical desktop transaction due to different consumer purchasing patterns. For example, accommodation reservations made on a mobile device typically are for shorter lengths of stay and have lower accommodation ADRs.
Our global ADRs increased approximately 25%, on a constant currency basis, in the second quarter of 2022 as compared to the second quarter of 2019, due primarily to higher ADRs in Europe and North America as compared to the second quarter of 2019, driven by rate increases across many destination types with notable strength in leisure destinations. In addition, we estimate that our global ADRs in the second quarter of 2022, as compared to the second quarter of 2019, benefited by approximately two percentage points from changes in the geographical mix of our business driven primarily by weaker room night performance in Asia, which is a low ADR region. Our global ADRs increased approximately 12%, on a constant currency basis, in the second quarter of 2022 as compared to the second quarter of 2021. Prior to the COVID-19 outbreak, we observed a trend of declining constant-currency accommodation ADRs partially driven by the negative impact of the changing geographical mix of our business (e.g., lower ADR regions like Asia were generally growing faster than higher ADR regions like Western Europe and North America) as well as pricing pressures within local markets from time to time. Those declining ADR trends resulted in and could in the future result in gross bookings growing less than room nights. As the travel market continues to recover from the impact of the COVID-19 pandemic and with some regions experiencing general inflation in prices, we have seen travel industry ADRs generally increasing from pandemic lows in 2020. While our ADRs have continued to increase in the second quarter of 2022 as compared to the second quarter of 2019, it remains highly uncertain what the trend in industry ADRs will look like going forward.
We are constantly innovating to grow our business by, among other things, providing a best-in-class user experience with intuitive, easy-to-use online platforms to ensure that we are meeting the needs of online consumers while aiming to exceed their expectations. As part of these ongoing efforts, we have a long-term strategy to build a more integrated offering of multiple elements of travel connected by a payment platform, which we refer to as the "Connected Trip," and we expect these efforts to increase room night growth and revenue growth over time. We may see a negative impact on our operating margins in the near term as we incur the expenses associated with Connected Trip-related investments. Further, to the extent our non-accommodation services (e.g., airline ticket reservation services) have lower margins and increase as a percentage of our total business, our operating margins may be negatively affected.
As part of our strategy to provide more payment options to consumers and travel service providers, increase the number and variety of accommodations available on Booking.com, and enable our long-term Connected Trip strategy, Booking.com is increasingly processing transactions on a merchant basis, where it facilitates payments from travelers for the services provided. This allows Booking.com to process transactions for travel service providers and to increase its ability to offer secure and flexible transaction terms to consumers, such as the form and timing of payment. We believe that adding these types of service offerings will benefit consumers and travel service providers, as well as our gross bookings, room night, and earnings growth rates. However, this results in additional expenses for personnel, payment processing, chargebacks (including those related to fraud), and other expenses related to these transactions, which are recorded in "Personnel" and "Sales and other
expenses" in our Consolidated Statements of Operations, as well as associated incremental revenues (e.g., credit card rebates), which are recorded in "Merchant revenues." To the extent more of our business is generated on a merchant basis, we incur a greater level of these merchant-related expenses, which negatively impacts our operating margins despite increases in associated incremental revenues.
We have established widely used and recognized e-commerce brands through marketing and promotional campaigns. Our marketing expenses, which are substantially variable in nature and are comprised of performance marketing and brand marketing expenses, increased significantly in 2021 from 2020 as a result of the improving demand environment and our own efforts to invest in marketing, but remained below 2019 levels. Total marketing expenses in the first half of 2022 were $2.9 billion, 99% above the first half of 2021 and 13% above the first half of 2019. Our performance marketing expense, which represents a substantial majority of our marketing expense, is primarily related to the use of online search engines (primarily Google), meta-search and travel research services, and affiliate marketing to generate traffic to our platforms. Our brand marketing expense is primarily related to costs associated with producing and airing television advertising, online video advertising (for example, on YouTube and Facebook), online display advertising, and other brand marketing.
Marketing efficiency, expressed as marketing expense as a percentage of gross bookings, and performance marketing returns on investment ("ROIs") are impacted by a number of factors that are subject to variability and are in some cases outside of our control, including ADRs, costs per click, cancellation rates, foreign currency exchange rates, our ability to convert paid traffic to booking customers, and the timing and effectiveness of our brand marketing campaigns. Marketing efficiency can also be impacted by the extent to which consumers come directly to our platforms for bookings. In the second quarter of 2022, the share of room nights booked by consumers coming directly to our platforms increased as compared to the second quarters of 2021 and 2019, which benefits marketing efficiency.
In recent years, we observed periods of stable or increasing ROIs. In the second quarter of 2022, ROIs increased versus the second quarter of 2019, but were down compared to the second quarter of 2021. We expect volatility in our ROIs as the pandemic continues to affect travel, and that ROIs could be negatively impacted in the future by increased levels of competition and other factors. When evaluating our performance marketing spend, we typically consider several factors for each channel, such as the customer experience on the advertising platform, the incremental traffic we receive, and anticipated repeat rates.
Historically, our growth has primarily been generated by the worldwide accommodation reservation business of our most significant brand, Booking.com, due in part to the availability of a large number of properties through Booking.com. Booking.com included over 2.5 million properties on its website at June 30, 2022, consisting of over 400,000 hotels, motels, and resorts and over 2.1 million alternative accommodation properties (including homes, apartments, and other unique places to stay), and representing an increase from approximately 2.4 million properties on its website at June 30, 2021. The year-over-year increase in total properties was driven by an increase in alternative accommodation properties.
The share of Booking.com’s room nights booked for alternative accommodation properties in the second quarter of 2022 was approximately 32%, up versus the second quarter of 2019 and in line with the second quarter of 2021. We have observed an overall longer-term trend of an increasing share of room nights booked for alternative accommodation properties as consumer demand for these types of properties has grown, and as we have increased the number and variety of alternative accommodation properties available to consumers on Booking.com. We may experience lower profit margins due to certain additional costs, such as increased customer service costs, related to offering alternative accommodations on our platforms. As our alternative accommodation business has grown, these different characteristics have negatively impacted our profit margins and this trend may continue.
Although we believe that providing an extensive collection of properties, excellent customer service, and an intuitive, easy-to-use consumer experience are important factors influencing a consumer's decision to make a reservation, for many consumers, particularly in certain markets, the price of the travel service is the primary factor determining whether a consumer will book a reservation. Discounting and couponing coupled with a high degree of consumer shopping behavior is particularly common in Asian markets. In some cases, our competitors are willing to make little or no profit on a transaction, or offer travel services at a loss, in order to gain market share. As a result, it is increasingly important to offer travel services, such as accommodation reservations, at a competitive price, whether through discounts, coupons, closed-user group rates or loyalty programs, increased flexibility in cancellation policies, or otherwise. These initiatives have resulted and, in the future, may result in lower ADRs and lower revenue as a percentage of gross bookings.
Many taxing authorities are increasingly focused on ways to increase tax revenues and have targeted large multinational technology companies in these efforts. As a result, many countries and some U.S. states have implemented or are considering the adoption of a digital services tax or similar tax that imposes a tax on revenue earned from digital advertisements
or the use of online platforms, even when there is no physical presence in the jurisdiction. Currently, rates for this tax range from 1.5% to 10% of revenue deemed generated in the jurisdiction. The digital services taxes currently in effect, which we record in "General and administrative" expense in the Unaudited Consolidated Statements of Operations, have negatively impacted our results of operations. While the Organisation for Economic Co-operation and Development has been working on multinational tax changes that could require all member parties to remove all digital services taxes, the timing and details are not yet known.
Many national governments have conducted or are conducting investigations into competitive practices within the online travel industry, and we may be involved or affected by such investigations and their results. Some countries have adopted or proposed legislation that could also affect business practices within the online travel industry. For example, France, Italy, Belgium, and Austria have passed legislation prohibiting parity contract clauses in their entirety. Also, a number of governments are investigating or conducting information-gathering exercises with respect to compliance by online travel companies ("OTCs") with consumer protection laws, including practices related to the display of search results and search ranking algorithms, claims regarding discounts, disclosure of charges and availability, and similar messaging. In July 2022, the European Parliament and the Council of the European Union adopted the Digital Markets Act ("DMA") and voted to adopt the Digital Services Act ("DSA"), which will likely be formally adopted in September 2022. Both Acts are expected to enter into force in the second half of 2022 and will give regulators more instruments to investigate and regulate digital businesses and impose new rules on certain digital platforms determined to be "gatekeepers" (under the DMA) or online platforms more generally, with separate rules for "Very Large Online Platforms" ("VLOPs") (under the DSA). If regulators were to determine that we are a gatekeeper under the DMA or a VLOP under the DSA, we could be subject to additional rules and regulations not applicable to our competitors and our business could be harmed. Any designation as a "gatekeeper" under the DMA or VLOP under the DSA is not expected to take place until 2023 at the earliest, and any such designation may be subject to a further implementation and review process under the relevant legislation. The requirements for "gatekeepers" and VLOPs are also subject to further interpretation and regulatory engagement, including as to when these requirements would become effective. For more information on these matters and their potential effects on our business, see Note 13 to our Unaudited Consolidated Financial Statements. In general, increased regulatory focus on online businesses, including online travel businesses like ours, could result in increased compliance costs or otherwise adversely affect our business.
Our businesses outside of the U.S. represent a substantial majority of our financial results, but because we report our results in U.S. Dollars, we face exposure to movements in foreign currency exchange rates as the financial results and the financial condition of our businesses outside of the U.S. are translated from local currency (principally Euros and British Pounds Sterling) into U.S. Dollars. As a result, both the absolute amounts of and percentage changes in our foreign-currency-denominated net assets, gross bookings, revenues, operating expenses and net income as expressed in U.S. Dollars are affected by foreign currency exchange rate changes. For example, total revenues from our businesses outside of the U.S. increased by 109% for the three months ended June 30, 2022 as compared to the three months ended June 30, 2021, but without the impact of changes in foreign currency exchange rates, increased year-over-year on a constant-currency basis by approximately 131%. Since our expenses are generally denominated in foreign currencies on a basis similar to our revenues, our operating margins have not been significantly impacted by currency fluctuations. We designate certain portions of the aggregate principal value of our Euro-denominated debt as a hedge of the foreign currency exposure of the net investment in certain Euro functional currency subsidiaries. Foreign currency transaction gains or losses on the Euro-denominated debt that is not designated as a hedging instrument for accounting purposes are recognized in "Other income (expense), net" in the Unaudited Consolidated Statements of Operations (see Note 9 to our Unaudited Consolidated Financial Statements). Such foreign currency transaction gains or losses are dependent on the amount of net assets of the Euro functional currency subsidiaries, the amount of the Euro-denominated debt that is designated as a hedge, and fluctuations in foreign currency exchange rates.
We generally enter into derivative instruments to minimize the impact of foreign currency exchange rate fluctuations. We will continue to evaluate the use of derivative instruments in the future. See Note 6 to our Unaudited Consolidated Financial Statements for additional information related to our derivative contracts.
Outlook
In July 2022, across all of our major regions we saw a moderation in the room night growth rate relative to June 2022, with room nights growing about 4% versus July 2019. Given the continued uncertainty in the near-term environment, we cannot accurately predict the number of room nights that will be booked in the third quarter of 2022. Following from the above, and assuming room night growth for the third quarter of 2022 remains in line with the levels we saw in July 2022, for the third quarter of 2022 we currently expect:
- the change in gross bookings relative to the third quarter of 2019 will be slightly less than 20 percentage points better than the change in room nights relative to the same period, primarily due to an increase in constant currency
accommodation ADRs, partially offset by the negative impact of foreign exchange rate fluctuations, which we expect to be higher than they were in the second quarter of 2022;
-
revenues as a percentage of gross bookings will be lower than it was in the third quarter of 2019; and
-
operating profit will be slightly higher than the third quarter of 2019, including the negative impact of foreign exchange rate fluctuations.
Seasonality and Other Timing Factors
Prior to the COVID-19 pandemic, our gross bookings were generally similar in the first three quarters of the year and higher than in the fourth quarter. We generally recognize our marketing activities as the expense is incurred, which is typically in the quarter when the gross bookings for the associated reservations are recognized. However, we would generally recognize revenue from these bookings when the travel begins (at "check-in"), and accommodation check-ins in Europe and North America are generally highest in the third quarter during those regions' peak summer travel season and lowest in the first quarter. As a result of this timing difference between when we record marketing expense and when we generally recognize associated revenue, we typically experience our highest levels of profitability in the third quarter and our lowest level of profitability in the first quarter. In addition to the typical seasonality effects on our business, our quarterly results and quarterly year-over-year growth rates can be impacted by:
-
the length of the booking window (the average time between the booking of a travel reservation and when the travel begins), which impacts the relationship between our gross bookings (recognized at the time of booking) and our revenues (recognized at the time of check-in);
-
the level of acceleration or deceleration in the gross bookings growth rate. For example, our operating margins are typically negatively impacted in the near term from gross bookings and related variable marketing expense growth acceleration, as revenue growth is typically less impacted by accelerating gross bookings growth in the near term. Any such acceleration would positively impact revenue growth in subsequent periods as a portion of the revenue recognized from such gross bookings will occur in future quarters. Conversely, in periods where our gross bookings growth rate substantially decelerates, our operating margins typically benefit; and
-
the date on which certain holidays (e.g., Easter and Ramadan) fall.
The COVID-19 pandemic has impacted the booking window and seasonality of our business since its onset in 2020. For example, in the second quarter of 2022, we saw a shorter booking window than we saw in the second quarter of 2019, as an increased percentage of bookings were made for travel that was to occur close to the time of booking. However, in the second quarter of 2022, we saw the booking window expand compared to the second quarter of 2021. It is difficult to accurately predict travel patterns given the COVID-19 pandemic, and we may not experience typical seasonality effects on our business throughout the duration of the pandemic, and potentially for some time thereafter. As the travel market recovers from the impact of the COVID-19 pandemic, we expect to see periods of gross bookings growth rate acceleration, which will likely result in periods where our operating margins are negatively impacted due to the timing difference of when marketing expense is recorded and when revenue is recognized.
Other Factors
We believe that our future success depends in large part on our ability to continue to profitably grow our brands worldwide, and, over time, to offer other travel and travel-related services. Factors beyond our control, such as terrorist attacks, extreme weather or natural disasters, travel-related health concerns including pandemics and epidemics such as COVID-19, wars and regional hostilities, travel-related accidents, or increased focus on the environmental impact of travel, can disrupt travel, limit the ability or willingness of travelers to visit certain locations, or otherwise result in declines in travel demand, negatively affecting our business and results of operations.
The extent of the effects of the COVID-19 pandemic on our business, results of operations, cash flows, and growth prospects, are highly uncertain and will ultimately depend on future developments. While we have seen a recovery in travel demand in most parts of the world, we continue to expect that our business could be adversely impacted by surges of COVID-19 case counts, including those driven by variants of COVID-19, as well as any government-imposed travel restrictions in reaction to COVID-19 outbreaks, which could remain a risk for an extended period of time.
Over the long term, we intend to continue to invest in marketing and promotion, technology, and personnel within parameters consistent with attempts to improve long-term operating results, even if those expenditures create pressure on operating margins. In recent years, we have experienced pressure on operating margins as we invested in initiatives to drive future growth. We also intend to broaden the scope of our business, including exploring strategic alternatives such as acquisitions.
The competition for technology talent in our industry has intensified, including among established technology companies, startups, and companies transitioning to digital. The competition for talent is exacerbated by an increased willingness of certain companies to offer flexible and remote working policies, which expands the pool of candidates from which our competitors may attract talent. This could continue in the future due to an actual or perceived slower pace of recovery of the travel industry as a result of the COVID-19 pandemic than other industries and other factors beyond our control. As a result of the highly competitive labor market and inflationary pressure on compensation, our personnel expenses to attract and retain key talent are increasing, which may adversely affect our results of operations.
Critical Accounting Estimates
Management's Discussion and Analysis of Financial Condition and Results of Operations is based upon our Unaudited Consolidated Financial Statements, which have been prepared in accordance with accounting principles generally accepted in the United States of America ("U.S. GAAP"). Certain of our accounting estimates are particularly important to our financial position and results of operations and require us to make difficult and subjective judgments, often due to the need to make estimates of matters that are inherently uncertain. We use our judgment to determine the appropriate assumptions to be used in the determination of certain estimates and we evaluate our estimates on an ongoing basis. Estimates are based on historical experience, terms of existing contracts, our observance of trends in the travel industry, and on various other assumptions that we believe to be reasonable under the circumstances. Our actual results may differ from these estimates under different assumptions or conditions. For a complete discussion of our critical accounting estimates, see the "Critical Accounting Estimates" section of the Management's Discussion and Analysis of Financial Condition and Results of Operations in our Form 10-K for the year ended December 31, 2021.
Valuation of Investments in Private Companies
See Note 5 to our Unaudited Consolidated Financial Statements for additional information related to the Company's investments in private companies. The fair value of these investments are measured using unobservable inputs when little or no market data is available ("Level 3 inputs"). See Note 6 to our Unaudited Consolidated Financial Statements for additional information.
Our investments measured using Level 3 inputs primarily consist of investments in privately-held companies that are classified as equity securities without readily determinable fair values. Fair values of privately held securities are estimated using a variety of valuation methodologies, including both market and income approaches. We use valuation techniques appropriate for the type of investment and the information available about the investee as of the valuation date to determine fair value. Recent financing transactions in the investee, such as new investments in preferred stock, are generally considered the best indication of the enterprise value and therefore used as a basis to estimate fair value. However, based on a number of factors, such as the proximity in timing to the valuation date or the volume or other terms of these financing transactions, we may also use other valuation techniques to supplement this data, including the income approach. When a recent financing transaction occurs and represents fair value, we also use the calibration process, as appropriate, when estimating fair value on subsequent measurement dates. Calibration is the process of using observed transactions in the investee company's own instruments to ensure that the valuation techniques that will be employed to value the investee company investment on subsequent measurement dates begin with assumptions that are consistent with the original observed transaction as well as any more recent observed transactions in the instruments issued by the investee company.
In July 2021, Yanolja announced a new round of funding which was completed in October 2021 along with certain other transactions. As a result of these observable transactions, we increased the carrying value of our investment in Yanolja to $306 million as of December 31, 2021. Considering the recent significant adverse changes in the market valuations of companies in the travel and technology industries, we evaluated our investment in Yanolja for impairment and recognized an impairment charge of $184 million during the three months ended June 30, 2022, resulting in an adjusted carrying value of $122 million at June 30, 2022. As discussed below, we used unobservable inputs to determine fair value. We used a combination of the market approach and the income approach in estimating the fair value of our investment in Yanolja as of June 30, 2022. The market approach estimates value using prices and other relevant information generated by market transactions involving identical or comparable companies. The income approach estimates value based on the expectation of future cash flows that a company will generate. These future cash flows are discounted to their present values using a discount
rate based on a company’s weighted-average cost of capital, and is adjusted to reflect the risks inherent in its cash flows. The key unobservable inputs and ranges used include, for the market approach, percentage decrease in the calibrated EBITDA multiple (36%) and for the income approach, the weighted average cost of capital (10%-14%) and terminal EBITDA multiple (14x-16x). Significant changes in any of these inputs in isolation would result in significantly different fair value measurements. Generally, a change in the assumption used for EBITDA multiples would result in a directionally similar change in the fair value and a change in the assumption used for weighted average cost of capital would result in a directionally opposite change in the fair value.
The determination of the fair values of investments where we are a minority shareholder and have access to limited information from the investee reflects numerous assumptions that are subject to various risks and uncertainties, including key assumptions regarding the investee’s expected growth rates and operating margin, as well as other key assumptions with respect to matters outside of our control, such as discount rates and market comparables. It requires significant judgments and estimates and actual results could be materially different than those judgments and estimates utilized in the fair value estimate. Future events and changing market conditions may lead us to re-evaluate the assumptions reflected in the valuation which may result in a need to recognize an additional impairment charge that could have a material adverse effect on our results of operations.
Recent Accounting Pronouncements
See Note 1 to the Unaudited Consolidated Financial Statements, which is incorporated by reference into this Item 2, for details regarding recent accounting pronouncements.
Results of Operations
Three and Six Months Ended June 30, 2022 compared to the Three and Six Months Ended June 30, 2021
We evaluate certain operating and financial measures on both an as-reported and constant-currency basis. We calculate constant currency by converting our current-year period operating and financial results for transactions recorded in currencies other than U.S. Dollars using the corresponding prior-year period monthly average exchange rates rather than the current-year period monthly average exchange rates.
Operating and Statistical Metrics
Our financial results are driven by certain operating metrics that encompass the booking and other business activity generated by our travel and travel-related services. Specifically, reservations of room nights, rental car days, and airline tickets capture the volume of units booked through our OTC brands by our travel reservation services customers. Gross bookings is an operating and statistical metric that captures the total dollar value, generally inclusive of taxes and fees, of all travel services booked through our OTC brands by our customers, net of cancellations, and is widely used in the travel business. Our non-OTC brands (KAYAK and OpenTable) have different business metrics from those of our OTC brands, so search queries through KAYAK and restaurant reservations through OpenTable do not contribute to our gross bookings.
Room nights, rental car days, and airline tickets reserved through our services for the three and six months ended June 30, 2022 and 2021 were as follows:
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Room nights | 246 | 157 | 56.3 | % | 444 | 257 | 73.0 | % | ||||||||||||||||||||||||||||||
| Rental car days | 16 | 13 | 22.4 | % | 32 | 23 | 35.4 | % | ||||||||||||||||||||||||||||||
| Airline tickets | 6 | 4 | 31.4 | % | 10 | 7 | 46.4 | % |
Room nights, rental car days, and airline tickets reserved through our services increased significantly for the three and six months ended June 30, 2022, compared to the three and six months ended June 30, 2021, due primarily to the continued improvement in travel demand trends as the impact of the COVID-19 pandemic has lessened in the first half of 2022 versus the first half of 2021.
Gross bookings resulting from reservations of room nights, rental car days, and airline tickets made through our agency and merchant categories for the three and six months ended June 30, 2022 and 2021 were as follows (numbers may not total due to rounding):
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Agency gross bookings | $ | 19,448 | $ | 15,290 | 27.2 | % | $ | 35,734 | $ | 23,994 | 48.9 | % | ||||||||||||||||||||||||||
| Merchant gross bookings | 15,097 | 6,665 | 126.5 | % | 26,104 | 9,897 | 163.8 | % | ||||||||||||||||||||||||||||||
| Total gross bookings | $ | 34,545 | $ | 21,956 | 57.3 | % | $ | 61,838 | $ | 33,891 | 82.5 | % |
Agency gross bookings are derived from travel-related transactions where we do not facilitate payments from travelers for the services provided, while merchant gross bookings are derived from services where we facilitate payments. Agency and merchant gross bookings increased for the three and six months ended June 30, 2022, compared to the three and six months ended June 30, 2021 due primarily to the continued improvement in travel demand trends. Merchant gross bookings increased more than agency gross bookings due to the expansion of merchant accommodation reservation services at Booking.com.
The year-over-year increase in gross bookings during the three months ended June 30, 2022 was due primarily to the increase in room nights and the increase in accommodation ADRs of approximately 12% on a constant-currency basis, partially offset by the negative impact of foreign exchange rate fluctuations. The year-over-year increase in gross bookings during the six months ended June 30, 2022 was due primarily to the increase in room nights and the increase in accommodation ADRs of approximately 15% on a constant-currency basis, partially offset by the negative impact of foreign exchange rate fluctuations.
Gross bookings resulting from reservations of airline tickets increased year-over-year during the three and six months ended June 30, 2022 due to higher unit growth and ticket price increases. Gross bookings resulting from reservations of rental car days increased year-over-year during the three and six months ended June 30, 2022 due primarily to higher unit growth.
Revenues
Online travel reservation services
Substantially all of our revenues are generated by providing online travel reservation services, which facilitate online travel purchases between travel service providers and travelers.
Revenues from online travel reservation services are classified into two categories:
-
Agency. Agency revenues are derived from travel-related transactions where we do not facilitate payments from travelers for the services provided. Agency revenues consist almost entirely of travel reservation commissions from our accommodation, rental car, and airline reservation services. Substantially all of our agency revenue is from Booking.com agency accommodation reservations.
-
Merchant. Merchant revenues are derived from travel-related transactions where we facilitate payments from travelers for the services provided, generally at the time of booking. Merchant revenues are derived from transactions where travelers book accommodation, rental car, and airline reservations. Merchant revenues include:
◦travel reservation commissions and transaction net revenues (i.e., the amount charged to travelers less the amount owed to travel service providers) in connection with our merchant reservation services;
◦credit card processing rebates and customer processing fees; and
◦ancillary fees, including travel-related insurance revenues.
Advertising and other revenues
Advertising and other revenues are derived primarily from:
-
revenues earned by KAYAK for (a) sending referrals to OTCs and travel service providers and (b) advertising placements on its platforms; and
-
revenues earned by OpenTable for (a) restaurant reservation services (fees paid by restaurants for diners seated through OpenTable's online reservation service) and (b) subscription fees for restaurant management services.
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Agency revenues | $ | 2,301 | $ | 1,328 | 73.3 | % | $ | 3,751 | $ | 2,045 | 83.5 | % | ||||||||||||||||||||||||||
| Merchant revenues | 1,749 | 661 | 164.8 | % | 2,799 | 1,034 | 170.8 | % | ||||||||||||||||||||||||||||||
| Advertising and other revenues | 244 | 171 | 41.6 | % | 439 | 222 | 96.8 | % | ||||||||||||||||||||||||||||||
| Total revenues | $ | 4,294 | $ | 2,160 | 98.7 | % | $ | 6,989 | $ | 3,301 | 111.7 | % |
Agency, merchant, and advertising and other revenues increased for the three and six months ended June 30, 2022, compared to the three and six months ended June 30, 2021, due primarily to the continued improvement in travel demand as the impact of the COVID-19 pandemic lessened in the first half of 2022 versus the first half of 2021. Merchant revenues for the three and six months ended June 30, 2022 increased more than agency revenues due to the expansion of merchant accommodation reservation services at Booking.com. For the six months ended June 30, 2022, advertising and other revenues year-over-year growth benefited from fees for diners seated through OpenTable's online reservation service and subscription fees for restaurant management services, as the program that waived those fees ended in March 2021.
Total revenues as a percentage of gross bookings were 12.4% and 11.3% for the three and six months ended June 30, 2022, an increase from 9.8% and 9.7% for the three and six months ended June 30, 2021. The three and six months ended June 30, 2022 were less negatively impacted from the timing of booking versus travel than the three and six months ended June 30, 2021, due to a year-over-year increase in the portion of gross bookings made in the first half of 2022 that were related to travel in the first half of 2022, which is when we recognized the associated revenue.
Operating Expenses
Marketing Expenses
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Marketing expenses | $ | 1,737 | $ | 988 | 75.8 | % | $ | 2,884 | $ | 1,449 | 99.0 | % | ||||||||||||||||||||||||||
| % of Total gross bookings | 5.0 | % | 4.5 | % | 4.7 | % | 4.3 | % | ||||||||||||||||||||||||||||||
| % of Total revenues | 40.5 | % | 45.8 | % | 41.3 | % | 43.9 | % |
Marketing expenses consist primarily of the costs of:
-
search engine keyword purchases;
-
referrals from meta-search and travel research websites;
-
affiliate programs;
-
offline and online brand marketing; and
-
other performance-based marketing and incentives.
We adjust our marketing spend based on our growth and profitability objectives, as well as the travel demand and expected ROIs in our marketing channels. We rely on our marketing channels to generate a significant amount of traffic to our websites. For the three and six months ended June 30, 2022, our marketing expenses, which are substantially variable in nature, increased significantly compared to the three and six months ended June 30, 2021, due primarily to the continued improvement in travel demand as the impact of the COVID-19 pandemic has lessened in the first half of 2022 versus the first half of 2021. Marketing expenses as a percentage of total gross bookings increased in the first half of 2022 compared to the first half of 2021 due to year-over-year decreases in performance marketing ROIs, partly offset by favorable changes in the share of traffic by channel.
Sales and Other Expenses
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Sales and other expenses | $ | 465 | $ | 206 | 124.7 | % | $ | 804 | $ | 318 | 152.5 | % | ||||||||||||||||||||||||||
| % of Total gross bookings | 1.3 | % | 0.9 | % | 1.3 | % | 0.9 | % | ||||||||||||||||||||||||||||||
| % of Total revenues | 10.8 | % | 9.6 | % | 11.5 | % | 9.6 | % |
Sales and other expenses consist primarily of:
-
credit card and other payment processing fees associated with merchant transactions;
-
fees paid to third parties that provide call center, website content translations, and other services;
-
chargeback provisions and fraud prevention expenses associated with merchant transactions;
-
provisions for expected credit losses, primarily related to accommodation commission receivables and prepayments to certain customers; and
-
customer relations and other costs.
For the three and six months ended June 30, 2022, sales and other expenses, which are substantially variable in nature, increased compared to the three and six months ended June 30, 2021, due primarily to increased merchant transaction costs of $173 million and $310 million, respectively, and increased third-party call center costs of $58 million and $105 million, respectively. Merchant transactions increased year-over-year in the first half of 2022 due to the continued improvement in travel demand trends as the impact of the COVID-19 pandemic has lessened in the first half of 2022 versus the first half of 2021, as well as the expansion of merchant accommodation reservation services at Booking.com.
Personnel
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Personnel | $ | 635 | $ | 686 | (7.5) | % | $ | 1,231 | $ | 1,238 | (0.6) | % | ||||||||||||||||||||||||||
| % of Total revenues | 14.8 | % | 31.8 | % | 17.6 | % | 37.5 | % |
Personnel expenses consist primarily of:
-
salaries;
-
bonuses;
-
stock-based compensation;
-
payroll taxes; and
-
employee health and other benefits.
Personnel expenses excluding stock-based compensation decreased for the three and six months ended June 30, 2022, compared to the three and six months ended June 30, 2021, principally due to the $136 million expense associated with the return of government assistance received through various government aid programs which was recorded in the second quarter of 2021. Personnel expenses, excluding stock-based compensation and the expense associated with the return of government assistance in the second quarter of 2021, increased 14% for the three and six months ended June 30, 2022 compared to the three and six months ended June 30, 2021 due to increased salary expense of $36 million and $61 million, respectively, and increased bonus expense accruals of $25 million and $52 million, respectively. Employee headcount of approximately 19,450 as of June 30, 2022 was about in line with June 30, 2021. Employee headcount as of June 30, 2022 decreased by 7% versus March 31, 2022 due primarily to the transfer of certain customer service operations of Booking.com to Majorel, partially offset by hiring in the second quarter of 2022. Subsequent to the transfer of these customer service operations to Majorel, the related costs are recognized as third-party call center costs in "Sales and other expenses".
Stock-based compensation expense was $108 million and $201 million for the three and six months ended June 30, 2022, respectively, compared to $90 million and $199 million for the three and six months ended June 30, 2021, respectively.
General and Administrative
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| General and administrative | $ | 207 | $ | 134 | 55.8 | % | $ | 365 | $ | 253 | 45.1 | % | ||||||||||||||||||||||||||
| % of Total revenues | 4.8 | % | 6.1 | % | 5.2 | % | 7.6 | % |
General and administrative expenses consist primarily of:
-
occupancy and office expenses;
-
fees for outside professionals;
-
indirect taxes such as travel transaction taxes and digital services taxes; and
-
personnel-related expenses such as travel, relocation, recruiting, and training expenses.
General and administrative expenses increased for the three and six months ended June 30, 2022, compared to the three and six months ended June 30, 2021, due to increases of $37 million and $48 million, respectively, for indirect taxes (primarily digital services taxes), driven by the improvement in revenue, as well as higher personnel-related expenses and higher fees for professional services.
Information Technology
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Information technology | $ | 137 | $ | 93 | 46.6 | % | $ | 271 | $ | 180 | 50.2 | % | ||||||||||||||||||||||||||
| % of Total revenues | 3.2 | % | 4.3 | % | 3.9 | % | 5.5 | % |
Information technology expenses consist primarily of:
-
software license and system maintenance fees;
-
payments to contractors;
-
outsourced data center and cloud computing costs; and
-
data communications and other expenses associated with operating our services.
Information technology expenses increased during the three and six months ended June 30, 2022, compared to the three and six months ended June 30, 2021, due to increased payments to contractors, cloud computing costs, and software license fees, some of which relate to cybersecurity and data privacy.
Depreciation and Amortization
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Depreciation and amortization | $ | 107 | $ | 108 | (0.5) | % | $ | 218 | $ | 221 | (1.4) | % | ||||||||||||||||||||||||||
| % of Total revenues | 2.5 | % | 5.0 | % | 3.1 | % | 6.7 | % |
Depreciation and amortization expenses consist of:
-
amortization of intangible assets with determinable lives;
-
amortization of internally-developed and purchased software;
-
depreciation of computer equipment; and
-
depreciation of leasehold improvements, furniture and fixtures, and office equipment.
Depreciation and amortization expenses decreased during the three and six months ended June 30, 2022, compared to the three and six months ended June 30, 2021, due to decreased depreciation of computer equipment and leasehold improvements, partially offset by increased amortization expense related to the acquisition of Getaroom.
Restructuring, Disposal, and Other Exit Costs
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Restructuring, disposal, and other exit costs | $ | 6 | $ | 1 | 386.7 | % | $ | 42 | $ | 9 | 364.0 | % | ||||||||||||||||||||||||||
| % of Total revenues | 0.1 | % | 0.1 | % | 0.6 | % | 0.3 | % |
Restructuring, disposal, and other exit costs for the three and six months ended June 30, 2021 principally relate to the restructuring charges as a result of restructuring actions taken in 2020. These restructuring charges are primarily related to employee severance and other termination benefits at Booking.com. Restructuring, disposal, and other exit costs for the three and six months ended June 30, 2022 relate to the loss on transfer of certain customer service operations of Booking.com to Majorel. See Note 15 to the Unaudited Consolidated Financial Statements.
Interest Expense
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Interest expense | $ | 76 | $ | 81 | (5.0) | % | $ | 144 | $ | 179 | (19.2) | % | ||||||||||||||||||||||||||
Interest expense decreased for the three months ended June 30, 2022, compared to the three months ended June 30, 2021, primarily due to the adoption on January 1, 2022 of the new accounting standards for convertible instruments, and the maturity in, September 2021, of convertible senior notes. Interest expense decreased for the six months ended June 30, 2022, compared to the six months ended June 30, 2021, primarily due to the adoption of the new accounting standards update for convertible instruments, the issuance of senior notes with lower interest rates in March 2021, the redemption of senior notes with higher interest rates in April 2021, and the maturity in September 2021 of convertible senior notes. The amortization of debt discount on convertible debt was recorded in Interest expense. With the adoption of the new accounting standards update, such amortization is not recorded in the financial statements for periods after January 1, 2022 (see Note 1 to our Unaudited Consolidated Financial Statements).
Other Income (Expense), Net
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Other income (expense), net | $ | 220 | $ | 96 | 129.5 | % | $ | (735) | $ | 227 | (423.5) | % | ||||||||||||||||||||||||||
The following table sets forth the breakdown of "Other income (expense), net" for the six months ended June 30, 2022 and 2021:
| Three Months Ended June 30, (in millions) | Six Months Ended June 30, (in millions) | |||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||
| Interest and dividend income | $ | 24 | $ | 4 | $ | 27 | $ | 8 | ||||||||||||||||||
| Net gains (losses) on equity securities | 181 | 391 | $ | (806) | $ | 427 | ||||||||||||||||||||
| Foreign currency transaction gains (losses) | 16 | (41) | 46 | 47 | ||||||||||||||||||||||
| Loss on early extinguishment of debt | — | (242) | — | (242) | ||||||||||||||||||||||
| Other | (1) | (16) | (2) | (13) | ||||||||||||||||||||||
| Other income (expense), net | $ | 220 | $ | 96 | $ | (735) | $ | 227 |
Net gains (losses) on equity securities for the three and six months ended June 30, 2022 are principally related to our equity investments in Meituan, Yanolja, Grab Holdings Limited ("Grab"), and DiDi Global Inc. ("DiDi"). Net gains on equity securities for the three and six months ended June 30, 2021 are principally related to our equity investments in Meituan and DiDi. See Note 5 to our Unaudited Consolidated Financial Statements for additional information.
Foreign currency transaction gains for the three and six months ended June 30, 2022 include gains of $38 million and $68 million, respectively, related to our Euro-denominated debt and accrued interest that were not designated as net investment hedges offset by losses of $40 million and $56 million, respectively, on derivative contracts. Foreign currency transaction (losses) gains for the three and six months ended June 30, 2021 include losses of $37 million and gains of $54 million, respectively, related to our Euro-denominated debt and accrued interest that were not designated as net investment hedges and for the six months ended June 30, 2021, losses of $8 million on derivative contracts.
Loss on early extinguishment of debt is related to our Senior Notes due April 2025 (the "April 2025 Notes") and our Senior Notes due April 2027 (the "April 2027 Notes") that were redeemed in April 2021 (see Note 9 to our Unaudited Consolidated Financial Statements).
Income Taxes
| Three Months Ended June 30, (in millions) | Increase (Decrease) | Six Months Ended June 30, (in millions) | Increase (Decrease) | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | $ | 287 | $ | 126 | 126.9 | % | $ | 138 | $ | (97) | (243.4) | % | ||||||||||||||||||||||||||
| % of Income (loss) before income taxes | 25.1 | % | (311.7) | % | 46.8 | % | 30.3 | % |
Our 2021 and 2022 effective tax rates differ from the U.S. federal statutory tax rate of 21%, primarily due to higher international tax rates, the benefit of the Netherlands Innovation Box Tax (discussed below), certain non-deductible expenses, and, in 2022, valuation allowance related to certain unrealized losses on equity securities.
We incurred a pre-tax loss and recorded an income tax provision during the three months ended June 30, 2021, which resulted in a negative effective tax rate. The difference in our effective tax rate for the three months ended June 30, 2022 compared to the three months ended June 30, 2021, is primarily due to a decrease in the benefit of the Netherlands Innovation Box Tax, higher U.S. Federal and state tax associated with the our international earnings, and higher discrete tax expenses, partially offset by lower international tax rates and certain lower non-deductible expenses.
Our effective tax rate for the six months ended June 30, 2022 was higher than the six months ended June 30, 2021, primarily due to valuation allowance related to certain unrealized losses on equity securities, a decrease in the benefit of the Netherlands Innovation Box Tax, and higher U.S. Federal and state tax associated with our international earnings, partially offset by lower international tax rates and certain lower non-deductible expenses.
During the three and six months ended June 30, 2022 and 2021, a majority of our income was reported in the Netherlands, where Booking.com is based. Under Dutch corporate income tax law, income generated from qualifying innovative activities is taxed at a rate of 9% ("Innovation Box Tax") rather than the Dutch statutory rate. Effective January 1, 2022, the Netherlands corporate income tax rate increased from 25% to 25.8%. A portion of Booking.com's earnings during the three and six months ended June 30, 2022 and 2021 qualified for Innovation Box Tax treatment, which had a beneficial impact on the effective tax rates for these periods. While we expect Booking.com to continue to qualify for Innovation Box Tax treatment with respect to a portion of its earnings for the foreseeable future, the loss of the Innovation Box Tax benefit, whether due to a change in tax law, a determination by the Dutch government that Booking.com's activities are not innovative, or for any other reason, could substantially increase our effective tax rate and adversely impact our results of operations and cash flows in future periods.
Liquidity and Capital Resources
Our financial results and prospects are almost entirely dependent on the sale of travel-related services. The COVID-19 pandemic and the resulting implementation of restrictive measures resulted in a significant decline in travel activities and consumer demand for related services, in 2020 in particular.
Marketing expenses and personnel expenses are the most significant operating expenses for our business. We rely on marketing channels to generate a significant amount of traffic to our websites. See our Unaudited Consolidated Statements of Operations and "Trends" and "Results of Operations" within Management's Discussion and Analysis of Financial Condition and Results of Operations for additional information on marketing expenses and personnel expenses including stock-based compensation expenses.
Our continued access to sources of liquidity depends on multiple factors, including global economic conditions, the condition of global financial markets, the availability of sufficient amounts of financing, our ability to meet debt covenant requirements, our operating performance, our credit ratings, and the ongoing effects of the COVID-19 pandemic. If our credit ratings were to be downgraded, or financing sources were to ascribe higher risk to our rating levels or our industry, our access to capital and the cost of any financing would be negatively impacted. There is no guarantee that additional debt financing will be available in the future to fund our obligations, or that it will be available on commercially reasonable terms, in which case we may need to seek other sources of funding. In addition, the terms of future debt agreements could include more restrictive covenants than those we are currently subject to, which could restrict our business operations.
At June 30, 2022, we had $14.2 billion in cash, cash equivalents, and short-term and long-term investments, of which approximately $9.9 billion is held by our international subsidiaries. Cash, cash equivalents, and long-term investments held by our international subsidiaries are denominated primarily in Euros, Hong Kong Dollars, and British Pounds Sterling. Cash equivalents and short-term and long-term investments are principally comprised of money market funds, time deposits and certificates of deposit, equity securities of Meituan, Grab, and DiDi, and our investments in private companies (see Notes 5 and 6 to the Unaudited Consolidated Financial Statements).
Deferred merchant bookings of $4.4 billion and $906 million at June 30, 2022 and December 31, 2021, respectively, represent cash payments received from travelers in advance of us completing our performance obligations and are comprised principally of amounts estimated to be payable to travel service providers as well as our estimated future revenue for our commission or margin and fees. The amounts are subject to refunds for cancellations.
At June 30, 2022, we had a remaining transition tax liability of $811 million as a result of the Tax Cuts and Jobs Act (the "Tax Act"), which included $711 million reported as "Long-term U.S. transition tax liability" and $100 million included in "Accrued expenses and other current liabilities" in the Consolidated Balance Sheet. This liability will be paid over the next four years. In accordance with the Tax Act, generally, future repatriation of our international cash will not be subject to a U.S. federal income tax liability as a dividend, but will be subject to U.S. state income taxes and international withholding taxes, which have been accrued by us.
In August 2019, we entered into a $2.0 billion five-year unsecured revolving credit facility with a group of lenders. The revolving credit facility provides for the issuance of up to $80 million of letters of credit as well as borrowings of up to $100 million on same-day notice, referred to as swingline loans. The proceeds of loans made under the facility can be used for working capital and general corporate purposes, including acquisitions, share repurchases and debt repayments. At June 30, 2022, there were no borrowings outstanding and $9 million of letters of credit issued under the facility. The revolving credit facility contains a maximum leverage ratio covenant, compliance with which is a condition to our ability to borrow thereunder. After a 2020 amendment to the revolving credit facility, the permitted maximum leverage ratio is increased through and including the three months ending March 31, 2023 and we may not declare or make any cash distribution or repurchase any of our shares (with certain exceptions including in connection with tax withholding related to shares issued to employees) unless we are in compliance on a pro forma basis with the maximum leverage ratio covenant then in effect. Such restriction ends upon delivery of financial statements required for the three months ending June 30, 2023, or we have the ability to terminate this restriction earlier if we demonstrate compliance with the original maximum leverage ratio covenant in the revolving credit facility. At June 30, 2022, we were in compliance with the relevant financial covenant. There can be no assurance that we will be able to meet the maximum leverage ratio covenant at any particular time, and our ability to borrow under the revolving credit facility depends on compliance with the covenant. Further, the lenders have the right to require repayment of any amounts borrowed under the facility if we are not in compliance with the covenant.
In March 2022, we repaid $1.1 billion on the maturity of senior notes with an interest rate of 0.8% and aggregate principal amount of 1.0 billion Euros. In September 2021, in connection with the maturity of Convertible Senior Notes due September 2021, we paid $1.0 billion to satisfy the aggregate principal amount due and an additional $86 million conversion premium in excess of the principal amount.
In March 2021, we issued Senior Notes due March 2025 with an interest rate of 0.1% for an aggregate principal amount of 950 million Euros and Senior Notes due March 2028 with an interest rate of 0.5% for an aggregate principal amount of 750 million Euros. The proceeds from the senior notes issued in March 2021 were used to redeem the Senior Notes due April 2025 and the Senior Notes due April 2027, which we paid $2.0 billion to redeem in April 2021.
See Note 9 to the Unaudited Consolidated Financial Statements for additional information related to our debt arrangements, including principal amounts, interest rates and maturity dates.
During the six months ended June 30, 2022, we repurchased 1,100,068 shares of our common stock for an aggregate cost of $2.4 billion. At June 30, 2022, we had a remaining aggregate amount of $8.2 billion authorized by our Board of Directors to repurchase our common stock. We expect to complete repurchases under the authorization in about two years from when we resumed repurchases in January 2022, assuming the travel recovery continues and we remain in compliance with the maximum leverage ratio covenant then in effect under the credit facility amendment. See Note 9 to the Unaudited Consolidated Financial Statements for a description of the impact of the 2020 credit facility amendment on our ability to repurchase shares. In July 2022, we repurchased approximately $840 million of our common stock.
In November 2021, we entered into an agreement to acquire global flight booking provider Etraveli Group for approximately 1.6 billion Euros ($1.7 billion). Completion of the acquisition is subject to certain closing conditions, including regulatory approvals.
As of June 30, 2022, we had a remaining obligation of 5 million Euros ($5 million) related to the turnkey agreement for the construction of Booking.com's future headquarters in the Netherlands, which will be paid through 2022, when we anticipate construction will be complete. In addition to the turnkey agreement, we have a remaining obligation at June 30, 2022 to pay 67 million Euros ($70 million) over the remaining initial term of the acquired land lease, which expires in 2065. We have made and will continue to make additional capital expenditures to fit out and furnish the office space. At June 30, 2022, we had 16 million Euros ($17 million) of outstanding commitments to vendors to fit out and furnish the office space.
At June 30, 2022 and December 31, 2021, we had lease obligations of $509 million and $561 million, respectively. Additionally, at June 30, 2022 and December 31, 2021, we had, in the aggregate, $146 million and $154 million, respectively, of non-cancellable purchase obligations individually greater than $10 million.
At June 30, 2022 and December 31, 2021, there were $812 million and $511 million, respectively, of standby letters of credit and bank guarantees issued on our behalf. These are obtained primarily for regulatory purposes.
See Note 13 to the Unaudited Consolidated Financial Statements for additional information related to our commitments and contingencies.
We believe that our existing cash balances and liquid resources will be sufficient to fund our operating activities, capital expenditures, and other obligations through at least the next twelve months. However, if we are not successful in generating sufficient cash flow from operations or in raising additional capital when required in sufficient amounts and on terms acceptable to us, we may be required to reduce our planned capital expenditures and scale back the scope of our business plans, either of which could have a material adverse effect on our business, our ability to compete or our future growth prospects, financial condition, and results of operations. If additional funds were raised through the issuance of equity securities, the percentage ownership of our then current stockholders would be diluted. We may not generate sufficient cash flow from operations in the future, revenue growth or sustained profitability may not be realized, and future borrowings or equity sales may not be available in amounts sufficient to make anticipated capital expenditures, finance our strategies, or repay our indebtedness.
Cash Flow Analysis
Net cash provided by operating activities for the six months ended June 30, 2022 was $4.4 billion, resulting from net income of $157 million, a favorable net change in working capital and long-term assets and liabilities of $3.0 billion, and a favorable impact from adjustments for non-cash items of $1.2 billion. Non-cash items were principally associated with net losses on equity securities, depreciation and amortization, stock-based compensation expense and other stock-based payments, deferred income tax benefit, provision for expected credit losses and chargebacks, and operating lease amortization. For the six months ended June 30, 2022, deferred merchant bookings and other current liabilities increased by $4.9 billion, and accounts receivable increased by $1.1 billion, primarily due to increases in business volumes.
Net cash provided by operating activities for the six months ended June 30, 2021 was $945 million, resulting from net loss of $222 million, a favorable net change in working capital and other long-term assets and liabilities of $926 million, and a favorable impact from adjustments for non-cash items of $241 million. Non-cash items were principally associated with net gains on equity securities, loss on early extinguishment of debt, depreciation and amortization, stock-based compensation expense and other stock-based payments, deferred income tax benefit, and operating lease amortization. For the six months ended June 30, 2021, prepaid expenses and other current assets increased by $173 million, primarily related to the prepayment of Netherlands income taxes of $175 million. For the six months ended June 30, 2021, accounts receivable increased by $820 million, and deferred merchant bookings and other current liabilities increased by $2.0 billion, primarily due to increases in business volumes.
Net cash used in investing activities for the six months ended June 30, 2022 and 2021 was $243 million and $136 million, respectively, principally resulting from purchase of property and equipment.
Net cash used in financing activities for the six months ended June 30, 2022 was $3.4 billion, almost entirely resulting from payments for the repurchase of common stock of $2.3 billion and the repayment of debt of $1.1 billion. Net cash used in financing activities for the six months ended June 30, 2021 was $138 million, principally resulting from payments for redemption of debt of $2.0 billion and payments for the repurchase of common stock of $150 million, partially offset by the proceeds from the issuance of long-term debt of $2.0 billion.
Contingencies
French tax authorities conducted audits of Booking.com for the years 2003 through 2012, 2013 through 2015, and 2016 through 2018. In December 2015, the French tax authorities issued Booking.com assessments for unpaid income and value added taxes ("VAT") related to tax years 2006 through 2012 for approximately 356 million Euros ($372 million), the majority of which represents penalties and interest. The assessments assert that Booking.com had a permanent establishment in France. In December 2019, the French tax authorities issued an additional assessment of 70 million Euros ($73 million), including interest and penalties, for the 2013 tax year asserting that Booking.com had taxable income attributable to a permanent establishment in France. The French tax authorities also have issued assessments totaling 39 million Euros ($41 million), including interest and penalties, for certain tax years between 2011 and 2015 on Booking.com's French subsidiary asserting that the subsidiary did not receive sufficient compensation for the services it rendered to Booking.com in the Netherlands. In December 2021, the French tax authorities issued assessments on Booking.com’s French subsidiary totaling 78 million Euros ($81 million), including interest and penalties, for the tax years 2016 through 2018 asserting that the subsidiary did not receive sufficient compensation for the services it rendered to Booking.com. As a result of a formal demand from the French tax authorities for payment of the amounts assessed against Booking.com for the years 2006 through 2012, in January 2019, we paid the assessments of approximately 356 million Euros ($372 million) in order to preserve our right to contest those assessments in court. The payment, which is included in "Other assets, net" in the Consolidated Balance Sheets at June 30, 2022 and December 31, 2021, does not constitute an admission that we owe the taxes and will be refunded (with interest) to us to the extent we prevail. On February 8, 2022, the French Tax Court issued a decision in favor of Booking.com’s French subsidiary regarding the assessments of 3 million Euros ($3 million) for the tax years 2011 and 2012. In April 2022, the French tax authorities refunded the 3 million Euros ($3 million) deposit related to those assessments, plus interest and filed their notice of appeal of the decision. In October 2020, we initiated court proceedings with respect to the 2003-2012 permanent establishment assessments. That case is still pending in the French Tax Court. Although we believe that Booking.com has been, and continues to be, in compliance with French tax law, and we are contesting the assessments, during the three months ended September 30, 2020, we contacted the French tax authorities regarding the potential to achieve resolution of the matter through a settlement. After assessing several potential outcomes and potential settlement amounts and terms, an expense for unrecognized tax benefit in the amount of 50 million Euros ($59 million) was recorded during the year ended December 31, 2020, of which the majority was included as a partial reduction to the tax payment recorded in "Other assets, net" in the Consolidated Balance Sheets at June 30, 2022 and December 31, 2021. In December 2020, the French Administrative Court (Conseil d’Etat) delivered a decision in the "ValueClick" case that could have an impact on the outcome in our case. After considering the potential adverse impact of the new decision on the potential outcomes for the Booking.com assessments, we currently estimate that the reasonably possible loss related to VAT is approximately 20 million Euros ($21 million). For additional information related to the French and other tax assessments and other tax matters, see Note 13 to our Unaudited Consolidated Financial Statements and Part I, Item IA, Risk Factors - "We may have exposure to additional tax liabilities" in our Annual Report on Form 10-K for the year ended December 31, 2021.
Beginning in 2014, Booking.com received several letters from the Netherlands Pension Fund for the Travel Industry (Reiswerk) ("BPF") claiming that Booking.com is required to participate in the mandatory pension scheme of the BPF with retroactive effect to 1999, which has a higher contribution rate than the pension scheme in which Booking.com is currently participating. BPF instituted legal proceedings against Booking.com and in 2016 the District Court of Amsterdam rejected all of
BPF's claims. BPF appealed the decision to the Court of Appeal, and, in May 2019, the Court of Appeal also rejected all of BPF's claims, in each case by ruling that Booking.com does not meet the definition of a travel intermediary for purposes of the mandatory pension scheme. BPF then appealed to the Netherlands Supreme Court. In April 2021, the Supreme Court overturned the previous decision of the Court of Appeal and held that Booking.com meets the definition of a travel intermediary for the purposes of the mandatory pension scheme. The Supreme Court ruled only on the qualification of Booking.com as a travel intermediary for the purposes of the mandatory pension scheme and did not rule on the various other defenses we brought forward against BPF's claims. The Supreme Court referred the matter to another Court of Appeal that will have to assess the other defenses we brought forward. We intend to pursue a number of defenses in the subsequent proceedings and may ultimately prevail in whole or in part. While we continue to believe that Booking.com is in compliance with its pension obligations and that the Court of Appeal could ultimately rule in favor of Booking.com, given the Supreme Court’s decision, we believe it is probable that we have incurred a loss related to this matter. We are not able to reasonably estimate a loss or a range of loss because there are significant factual and legal questions yet to be determined in the subsequent proceedings. As a result, as of June 30, 2022, we have not recorded a liability in connection with a potential adverse ultimate outcome to this litigation. However, if Booking.com were to ultimately lose and all of BPF's claims were to be accepted (including with retroactive effect to 1999), we estimate that as of June 30, 2022, the maximum loss, not including any potential interest or penalties, would be approximately 313 million Euros ($328 million). Such estimated potential loss increases as Booking.com continues not to contribute to the BPF and depends on Booking.com's applicable employee compensation after June 30, 2022. For additional information related to the pension matter and our other contingent liabilities, see Note 13 to our Unaudited Consolidated Financial Statements.
SPECIAL NOTE REGARDING FORWARD-LOOKING STATEMENTS
This Form 10-Q contains forward-looking statements. These forward-looking statements reflect our views regarding current expectations and projections about future events and conditions and are based on currently available information. These forward-looking statements are not guarantees of future performance and are subject to risks, uncertainties, and assumptions that are difficult to predict including the Risk Factors identified in Part I, Item 1A of our Annual Report on Form 10-K for the year ended December 31, 2021; therefore, our actual results could differ materially from those described in the forward-looking statements.
Expressions of future goals and expectations and similar expressions, including "may," "will," "should," "could," "aims," "seeks," "expects," "plans," "anticipates," "intends," "believes," "estimates," "predicts," "potential," "targets," and "continue," reflecting something other than historical fact are intended to identify forward-looking statements. Unless required by law, we undertake no obligation to update publicly any forward-looking statements, whether as a result of new information, future events or otherwise. However, readers should carefully review the reports and documents we file or furnish from time to time with the Securities and Exchange Commission, particularly our Annual Report on Form 10-K for the year ended December 31, 2021, our subsequent Quarterly Reports on Form 10-Q, and our Current Reports on Form 8-K.
Previous: Item 1. Financial Statements · Next: Item 3. Quantitative and Qualitative Disclosures About Market Risk