 filings.tools
Brown & Brown 10-K 2014-12-31
Filed 2015-03-02. 21 sections, 393K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 d847767d10k.htm 10-K
Table of Contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| x | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the fiscal year ended December 31, 2014
OR
| ¨ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15 (d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the transition period from to
Commission file number 001-13619
BROWN & BROWN, INC.
(Exact name of registrant as specified in its charter)
| Florida (State or other jurisdiction of incorporation or organization) |  | 59-0864469 (I.R.S. Employer Identification Number) | ||
| 220 South Ridgewood Avenue, Daytona Beach, FL | 32114 | |
| (Address of principal executive offices) | (Zip Code) |
Registrant’s telephone number, including area code: (386) 252-9601
Registrant’s Website: www.bbinsurance.com
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Name of each exchange on which registered | |
| COMMON STOCK, $0.10 PAR VALUE | NEW YORK STOCK EXCHANGE |
Securities registered pursuant to Section 12(g) of the Act:
None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes x No ¨
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ¨ No x
NOTE: Checking the box above will not relieve any registrant required to file reports pursuant to Section 13 or 15(d) of the Exchange Act from their obligations under those Sections.
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes x No ¨
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Website, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes x No ¨
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§ 229.405 of this chapter) is not contained herein, and will not be contained, to the best of the registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. ¨
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer,” and “smaller reporting company” in Rule 12b-2 of the Exchange Act:
| Large accelerated filer | x | Accelerated filer | ¨ | |||
| Non-accelerated filer | ¨ (Do not check if a smaller reporting company) | Smaller reporting company | ¨ |
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act.): Yes ¨ No x
The aggregate market value of the voting common stock held by non-affiliates of the registrant, computed by reference to the price at which the stock was last sold on June 30, 2014 (the last business day of the registrant’s most recently completed second fiscal quarter) was $3,374,535,891.
The number of outstanding shares of the registrant’s Common Stock, $0.10 par value, as of February 19, 2015 was 143,520,097.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of Brown & Brown, Inc.’s Proxy Statement for the 2015 Annual Meeting of Shareholders are incorporated by reference into Part III of this Report.
Table of Contents
BROWN & BROWN, INC.
ANNUAL REPORT ON FORM 10-K
FOR THE FISCAL YEAR ENDED DECEMBER 31, 2014
INDEX
Table of Contents
Disclosure Regarding Forward-Looking Statements
Brown & Brown, Inc., together with its subsidiaries (collectively, “we,” “Brown & Brown” or the “Company”), makes “forward-looking statements” within the “safe harbor” provision of the Private Securities Litigation Reform Act of 1995, as amended, throughout this report and in the documents we incorporate by reference into this report. You can identify these statements by forward-looking words such as “may,” “will,” “should,” “expect,” “anticipate,” “believe,” “intend,” “estimate,” “plan” and “continue” or similar words. We have based these statements on our current expectations about potential future events. Although we believe the expectations expressed in the forward-looking statements included in this Form 10-K and the reports, statements, information and announcements incorporated by reference into this report are based on reasonable assumptions within the bounds of our knowledge of our business, a number of factors could cause actual results to differ materially from those expressed in any forward-looking statements, whether oral or written, made by us or on our behalf. Many of these factors have previously been identified in filings or statements made by us or on our behalf. Important factors which could cause our actual results to differ materially from the forward-looking statements in this report include but are not limited to the following items, in addition to those matters described in Part I, Item 1A “Risk Factors” and Part I, Item 7 “Management’s Discussion and Analysis of Financial Condition and Results of Operations”:
| • | Future prospects; |
|---|
| • | Material adverse changes in economic conditions in the markets we serve and in the general economy; |
|---|
| • | Future regulatory actions and conditions in the states in which we conduct our business; |
|---|
| • | The occurrence of adverse economic conditions, an adverse regulatory climate, or a disaster in California, Florida, Georgia, Illinois, Indiana, Kansas, Massachusetts, Michigan, New Jersey, New York, North Carolina, Oregon, Pennsylvania, Texas, Virginia and Washington, because a significant portion of business written by us is for customers located in these states; |
|---|
| • | The integration of our operations with those of businesses or assets we have acquired, including our May 2014 acquisition of The Wright Insurance Group, LLC (“Wright”), or may acquire in the future, and the failure to realize the expected benefits of such acquisitions and integration; |
|---|
| • | Our ability to attract, retain and enhance qualified personnel; |
|---|
| • | Competition from others in the insurance agency, wholesale brokerage, insurance programs and service business; |
|---|
| • | Risks that could negatively affect our acquisition strategy, including continuing consolidation among insurance intermediaries and the increasing presence of private equity investors driving up valuations; |
|---|
| • | Exposure units, and premium rates set by insurance companies which have traditionally varied and are difficult to predict; |
|---|
| • | Our ability to forecast liquidity needs through at least the end of 2015; |
|---|
| • | Our ability to renew or replace expiring leases; |
|---|
| • | Outcomes of existing or future legal proceedings and governmental investigations, as well as future regulatory actions and conditions in the states in which we conduct our business; |
|---|
| • | Policy cancellations, which can be unpredictable; |
|---|
| • | Potential changes to the tax rate that would affect the value of deferred tax assets and liabilities; |
|---|
| • | The inherent uncertainty in making estimates, judgments, and assumptions in the preparation of financial statements in accordance with generally accepted accounting principles in the United States of America (“U.S. GAAP”); |
|---|
| • | Our ability to effectively apply technology in providing improved value for our customers as well as applying effective internal controls and efficiencies in operations; and |
|---|
| • | Other risks and uncertainties as may be detailed from time to time in our public announcements and Securities and Exchange Commission (“SEC”) filings. |
|---|
Table of Contents
Assumptions as to any of the foregoing and all statements are not based on historical fact, but rather reflect our current expectations concerning future results and events. Forward-looking statements that we make or that are made by others on our behalf are based on a knowledge of our business and the environment in which we operate, but because of the factors listed above, among others, actual results may differ from those in the forward-looking statements. Consequently, these cautionary statements qualify all of the forward-looking statements we make herein. We cannot assure you that the results or developments anticipated by us will be realized or, even if substantially realized, that those results or developments will result in the expected consequences for us or affect us, our business or our operations in the way we expect. We caution readers not to place undue reliance on these forward-looking statements, which speak only as of their dates. We assume no obligation to update any of the forward-looking statements.
Table of Contents
PART I
Item 1. Business.
| --- | --- |
General
Brown & Brown is a diversified insurance agency, wholesale brokerage, insurance programs and service organization with origins dating from 1939, headquartered in Daytona Beach, Florida. We market and sell to our customers insurance products and services, primarily in the property, casualty and employee benefits areas. As an agent and broker, we do not assume underwriting risks with the exception of the activity in Wright, which was acquired in May 2014. We provide our customers with quality, non-investment insurance contracts, as well as other targeted, customized risk management products and services. Within Wright, we operate a write-your-own flood insurance carrier, Wright National Flood Insurance Company (“WNFIC”), which is a Wright subsidiary. WNFIC’s entire business consists of policies written pursuant to the National Flood Insurance Program (“NFIP”), the program administered by the Federal Emergency Management Agency (“FEMA”) and excess flood insurance policies which are fully reinsured substantially eliminating WNFIC’s exposure to underwriting risk, given that these policies are backed by either FEMA or a reinsurance carrier with an AM Best Company rating of “A” or better.
The Company is compensated for our services primarily by commissions paid by insurance companies and to a lesser extent, by fees paid directly by customers for certain services. Commission revenues are usually a percentage of the premium paid by the insured and generally depend upon the type of insurance, the particular insurance company and the nature of the services provided by us. In some cases, we share commissions with other agents or brokers who have acted jointly with us in a transaction. We may also receive from an insurance company a “profit-sharing contingent commission,” which is a profit-sharing commission based primarily on underwriting results, but may also contain considerations for volume, growth and/or retention. Fee revenues are generated primarily by: (1) our Services Segment, which provides insurance-related services, including third-party claims administration and comprehensive medical utilization management services in both the workers’ compensation and all-lines liability arenas, as well as Medicare set-aside services, Social Security disability and Medicare benefits advocacy services, and catastrophe claims adjusting services, (2) our National Programs and Wholesale Brokerage Segments, which earn fees primarily for the issuing of insurance policies on behalf of insurance carriers, and (3) our Retail Segment for fees received in lieu of commissions, primarily since our July 1, 2013 acquisition of Beecher Carlson Holdings, Inc. (“Beecher Carlson”) which services many larger fee-based accounts. The amount of our revenues from commissions and fees is a function of, among other factors, continued new business production, retention of existing customers, acquisitions and fluctuations in insurance premium rates and “insurable exposure units,” which are units that insurance companies use to measure or express insurance exposed to risk (such as property values, sales and payroll levels) to determine what premium to charge the insured. Insurance companies establish these premium rates based upon many factors, including reinsurance rates paid by such insurance companies, none of which we control.
As of December 31, 2014, our activities were conducted in 232 locations in 41 states as follows, as well as in London, England, Hamilton, Bermuda, and George Town, Cayman Islands:
| Florida | 41 | Oklahoma | 5 | Missouri | 2 | |||||||
| California | 24 | Connecticut | 4 | New Hampshire | 2 | |||||||
| New York | 17 | Minnesota | 4 | Delaware | 1 | |||||||
| Texas | 13 | Virginia | 4 | Maryland | 1 | |||||||
| Washington | 12 | Arizona | 3 | Mississippi | 1 | |||||||
| Georgia | 11 | Arkansas | 3 | Montana | 1 | |||||||
| New Jersey | 10 | Kentucky | 3 | Nevada | 1 | |||||||
| Louisiana | 7 | Indiana | 3 | North Carolina | 1 | |||||||
| Pennsylvania | 7 | New Mexico | 3 | Rhode Island | 1 | |||||||
| Illinois | 7 | Ohio | 3 | Utah | 1 | |||||||
| Colorado | 6 | South Carolina | 3 | Vermont | 1 | |||||||
| Massachusetts | 6 | Tennessee | 3 | West Virginia | 1 | |||||||
| Oregon | 6 | Hawaii | 2 | Wisconsin | 1 | |||||||
| Michigan | 5 | Kansas | 2 |
Table of Contents
Industry Overview
Premium pricing within the property and casualty insurance underwriting (risk-bearing) industry has historically been cyclical in nature, and has varied widely based on market conditions. For example, in late 2003, after three years of a “hard” market in which premium rates were stable or increasing, the insurance industry experienced the return of a “soft” market, characterized by flat or reduced premium rates in many lines and geographic areas. In 2004, as general premium rates continued to moderate, the southeastern United States experienced the worst hurricane season since 1992 (when Hurricane Andrew hit south Florida), and the following year brought that region the worst hurricane season ever recorded. As a result of the significant losses incurred by insurance companies due to these hurricanes, property and casualty insurance premium rates increased on coastal property, primarily in the southeastern United States, in 2006, while otherwise generally declining during 2006 and 2007.
To counter the higher property insurance rates in Florida, the State of Florida directed its property “insurer of last resort,” “Citizens Property Insurance Corporation” (“Citizens”), to significantly reduce its rates beginning in January 2007 and extending through January 1, 2010. As a result, several of our Florida-based operations lost significant amounts of revenue to Citizens in this period. Since that time, Citizens’ impact on our operations has declined each year as Citizens has slowly increased its rates in an effort to reduce its insured exposures. Our commission revenues from Citizens for 2014, 2013 and 2012 were approximately $3.8 million, $5.7 million, and $6.4 million, respectively.
Although property and casualty insurance premium rates generally continued to decline from 2008 through 2011 in most lines of coverage, the rates of decline were slowing. However, from the second half of 2008 through 2011, insurable exposure units, such as sales and payroll expenditures, decreased significantly, primarily in the southeastern and western regions of the United States, due to the economic recession, and this decrease had a greater adverse impact on our commissions and fees revenue than did declining insurance premium rates in this period.
From the first quarter of 2012 through 2013, insurance premium rates gradually increased for most lines of coverage, and insurable exposure units began to flatten and in certain cases, increase. As a result, in 2012, the Company achieved positive internal organic core commissions and fees revenue growth for the first time since 2006. In 2013, these rate and exposure unit increases, along with new business growth, generated positive internal organic revenue growth for each of our four reportable business segments in each quarter, with the single exception of the fourth quarter for our Services Segment, which experienced a record fourth quarter in 2012 as a result of the significant flood claims activity from Superstorm Sandy that was not replicated in 2013.
During 2014, changes in rates and exposure units varied by geography and line of business with rates and units for employee benefits increasing as a result of general improvements in the economy. We have experienced a downward trend in coverage for employers with less than 50 employees, due to the implementation of the Affordable Care Act that has driven more employees to state healthcare exchanges. Rates for property and casualty coverage were under pressure, especially in the coastal areas, as a long period without significant storm activity and low interest rates have driven significant loss reserves and alternative capital sources.
SEGMENT INFORMATION
Our business is divided into four reportable segments: (1) the Retail Segment; (2) the National Programs Segment; (3) the Wholesale Brokerage Segment; and (4) the Services Segment. The Retail Segment provides a broad range of insurance products and services to commercial, public and quasi-public entities, and to professional and individual customers. The National Programs Segment provides professional liability and related package products for certain professionals delivered through nationwide networks of independent agents and also through our Brown & Brown retail offices, markets targeted products and services designed for specific industries, trade groups, public and quasi-public entities, and market niches and provides flood coverage. The Wholesale Brokerage Segment markets and sells excess and surplus commercial and personal lines insurance, primarily through independent agents and brokers. The Services Segment provides insurance-related services, including third-party claims administration and comprehensive medical utilization management services in both the workers’ compensation and all-lines liability arenas, as well as Medicare set-aside services, Social Security disability and Medicare benefits advocacy services and catastrophe claims adjusting services.
Table of Contents
The following table summarizes (1) the commissions and fees revenue generated by each of our reportable operating segments for 2014, 2013 and, 2012, and (2) the percentage of our total commissions and fees revenue represented by each segment for each such period:
| (in thousands, except percentages) | 2014 | % | 2013 | % | 2012 | % | ||||||||||||||||||
| Retail Segment | $ | 809,880 | 51.7 | % | $ | 725,159 | 53.5 | % | $ | 639,708 | 53.7 | % | ||||||||||||
| National Programs Segment | 387,858 | 24.7 | % | 291,014 | 21.5 | % | 251,929 | 21.2 | % | |||||||||||||||
| Wholesale Brokerage Segment | 234,294 | 14.9 | % | 209,493 | 15.4 | % | 182,822 | 15.4 | % | |||||||||||||||
| Services Segment | 136,482 | 8.7 | % | 131,033 | 9.7 | % | 116,247 | 9.8 | % | |||||||||||||||
| Other | (1,054 | ) | (0.0 | )% | (1,196 | ) | (0.1 | )% | (1,625 | ) | (0.1 | )% | ||||||||||||
| Total | $ | 1,567,460 | 100.0 | % | $ | 1,355,503 | 100.0 | % | $ | 1,189,081 | 100.0 | % | ||||||||||||
We conduct all of our operations within the United States of America, except for one wholesale brokerage operation based in London, England, and retail operations based in Hamilton, Bermuda and George Town, Cayman Islands. These operations generated $13.3 million, $12.2 million and $9.7 million of revenues for the years ended December 31, 2014, 2013 and 2012, respectively. We do not have any material foreign long-lived assets.
See Note 15 to the Consolidated Financial Statements and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” for additional segment financial data relating to our business.
Retail Segment
As of December 31, 2014, our Retail Segment employed 3,684 people. Our retail insurance agency business provides a broad range of insurance products and services to commercial, public and quasi-public entity, professional and individual customers. The categories of insurance we principally sell include: property insurance relating to physical damage to property and resultant interruption of business or extra expense caused by fire, windstorm or other perils; casualty insurance relating to legal liabilities, workers’ compensation, commercial and private passenger automobile coverages; and fidelity and surety bonds. We also sell and service group and individual life, accident, disability, health, hospitalization, medical and dental insurance.
No material part of our retail business is attributable to a single customer or a few customers. During 2014, commissions and fees from our largest single Retail Segment customer represented less than four tenths of one percent (0.4%) of the Retail Segment’s total commissions and fees revenue.
In connection with the selling and marketing of insurance coverages, we provide a broad range of related services to our customers, such as risk management and loss control surveys and analysis, consultation in connection with placing insurance coverages and claims processing.
National Programs Segment
As of December 31, 2014, our National Programs Segment employed 1,750 people. Our National Programs Segment can be grouped into five broad categories; (1) Professional Programs; (2) Arrowhead Insurance Programs; (3) Commercial Programs; (4) Public Entity-Related Programs; and (5) the National Flood Program:
Professional Programs. Professional Programs provide professional liability and related package insurance products tailored to the needs of specific professional groups. Professional Programs negotiates policy forms and coverage options with their specific insurance carriers. Securing endorsements of these products from a professional association or sponsoring company is also an integral part of their function. Professional Programs affiliate with professional groups, including but not limited to, dentists, oral surgeons, hygienists, lawyers, CPA’s, optometrists, opticians, ophthalmologists, insurance agents, financial advisors, registered representatives, securities broker-dealers, benefit administrators, real estate brokers, real estate title agents and escrow agents. In addition, Professional Programs encompasses supplementary insurance related products to include weddings, events, medical facilities and cyber liability.
Table of Contents
Below are brief descriptions of the Professional programs.
| • | Allied Protector Plan®: Allied Protector Plan® (“APP®”) specializes in customized professional liability and business insurance programs for individual practitioners and businesses in the healthcare industry. The APP program offers liability insurance coverage for, among others, dental hygienists and dental assistants, home health agencies, physical therapy clinics, and medical directors. Also available through the APP program is cyber/data breach insurance offering a solution to privacy breaches and information security exposures tailored to the needs of healthcare organizations. |
|---|
| • | Certified Public Accountants: The CPA Protector Plan® is a specialty insurance program offering comprehensive professional liability insurance solutions and risk management services to CPA practitioners and their firms nationwide. Optional coverage enhancements allow the insured to round out their policy and coverage needs, including: Employment Practices Liability, Employee Dishonesty, Non-Profit Directors and Officers, as well as Network Security and Privacy Protection Coverage. |
|---|
| • | Dentists: First initiated in 1969, the Professional Protector Plan® (“PPP®”) for Dentists provides dental professionals insurance products including professional and general liability, property, employment practices liability, workers’ compensation, claims and risk management. The PPP recognized the importance of policyholder and customer service and developed a customized, proprietary, web-based rating and policy issuance system which in turn provides a seamless policy delivery resource and access to policy information on a real time basis. Obtaining endorsements from state and local dental societies and associations plays an integral role in the PPP partnership. The PPP is offered in all 50 states, the District of Columbia, Puerto Rico and the Virgin Islands. |
|---|
| • | Financial Professionals: CalSurance® and CITA Insurance Services® have specialized in this niche since 1980 and offer professional liability programs designed for insurance agents, financial advisors, registered representatives, securities broker-dealers, benefit administrators, real estate brokers and real estate title agents. An important aspect of CalSurance is Lancer Claims Services, which provides specialty claims administration for insurance companies underwriting CalSurance product lines. |
|---|
| • | Lawyers: The Lawyer’s Protector Plan® (“LPP®”), for over 30 years, has been providing professional liability insurance with a niche focus on law firms with 1-20 attorneys. The LPP program handles all aspects of insurance operations including underwriting, distribution management, policy issuance and claims. The LPP is offered in 44 states and the District of Columbia. |
|---|
| • | Optometrists, Opticians, and Ophthalmologists: Since 1973 the Optometric Protector Plan® (“OPP®”), has continually provided professional liability, general liability, property, workers’ compensation insurance and risk management programs for eye care professionals nationwide. Our carrier partners offer specialty insurance products tailored to the eye care profession, and our agents and brokers are chosen for their expertise. The OPP is offered in all 50 states and the District of Columbia. Through our strategic carrier partnerships, we have diversified our demographic and also offer professional liability coverage to Chiropractors, Podiatrists and Physicians nationwide. |
|---|
| • | Professional Risk Specialty Group: Professional Risk Specialty Group (“PRSG”) has been providing Errors & Omissions/Professional Liability/Malpractice Insurance for over 22 years both in a direct retail sales and brokering capacity. PRSG has been an exclusive State Administrator for a Lawyers Professional Liability Program since 1994 in Florida, Louisiana, and Puerto Rico, as well as state appointments in 23 other states. The admitted Lawyers Program focuses on 1-19 attorney firms and the non-admitted program is for firms with 20+ attorneys and is available for primary or excess coverage. PRSG is also involved in direct sales and brokering for other professional lines, such as Accountants, Architects & Engineers, Medical Malpractice, Directors & Officers, Employment Practices Liability, Title Agency E&O and Miscellaneous E&O. |
|---|
| • | Real Estate Title Professionals: TitlePac® provides professional liability products and services designed for real estate title agents and escrow agents in 47 states and the District of Columbia. |
|---|
| • | Wedding Protector Plan® and Protector Plan® for Events provide an online wedding/private event cancellation and postponement insurance policy that offers financial protection if certain unfortunate, unforeseen events should occur during the period leading up to and including the wedding/event date. Liability and liquor liability is available as an option. Both the Wedding Protector Plan and Protector Plan for Events are offered in 47 states. |
|---|
Table of Contents
The Professional Protector Plan® for Dentists and the Lawyer’s Protector Plan® are marketed and sold primarily through a national network of independent agencies and also through our Brown & Brown retail offices; however, certain professional liability programs, CalSurance® and TitlePac®, are principally marketed and sold directly to our insured customers. Under our agency agreements with the insurance companies that underwrite these programs, we often have authority to bind coverages (subject to established guidelines), to bill and collect premiums and, in some cases, to adjust claims. For the programs that we market through independent agencies, we receive a wholesale commission or “override,” which is then shared with these independent agencies.
Arrowhead Programs. Arrowhead is a Managing General Agent (“MGA”), General Agent (“GA”), and Program Administrator (“PA”) to the property and casualty insurance industry. Arrowhead acts as a virtual insurer providing outsourced product development, marketing, underwriting, actuarial, compliance and claims and other administrative services to insurance carrier partners. As an MGA, Arrowhead has the authority to underwrite, bind insurance carriers, issue policies, collect premiums and provide administrative and claims services.
Below are brief descriptions of the Arrowhead Programs:
| • | Architects and Engineering, operating as Arrowhead Design Insurance (“ADI”), is a leading writer of professional liability insurance for architects, engineers and environmental consultants. ADI is a national program writing in all 50 states. |
|---|
| • | Automotive Aftermarket is a new program launched in 2012 in conjunction with Zurich American Insurance Company’s transfer of selected assets and employees to Arrowhead. The Automotive Aftermarket program writes commercial package insurance for non-dealership automotive services such as auto recyclers, brake shops, equipment dealers, mechanical repairs, oil and lube shops, parts retailers and wholesalers, tire retailers and wholesalers and transmission mechanics. |
|---|
| • | Commercial is a program that offers three distinct products to commercial operations, primarily in California: commercial auto, commercial package and general liability. |
|---|
| • | Earthquake and DIC is a Differences-in-Conditions (“DIC”) Program, writing notably earthquake, flood, and the “All Risk” insurance coverages to commercial property owners. The Earthquake and DIC program writes insurance on both a primary and excess layer basis. |
|---|
| • | Marine is a national program manager and wholesale producer of marine insurance products including yachts and high performance boats, small boats, commercial marine and marine artisan contractors. |
|---|
| • | OnPoint is an MGA with underwriting programs for tribal nations, manufactured housing, contractors’ equipment and various affinity programs. The largest program is the Tribal business, which provides tailored risk management and insurance solutions for U.S. tribal nations. |
|---|
| • | Personal Property provides a variety of coverages for homeowners and renters in numerous states. |
|---|
| • | Real Estate Errors & Omissions writes errors and omissions insurance for small to medium-sized residential real estate agents and brokers in California. Coverage includes real estate brokerage, property management, escrow, appraisal, leasing and consulting services. |
|---|
| • | Residential Earthquake specializes in monoline residential earthquake coverage for California home and condominium owners. |
|---|
| • | Wheels provides private passenger automobile and motorcycle coverage for a range of drivers. Arrowhead’s auto program offers two personal auto coverage types: one traditional non-standard auto product offering minimum state required liability limits and another targeting full coverage, multi-vehicle risks. The auto product is written in several states including California, Georgia, Michigan, and Alabama. |
|---|
| • | Workers’ Compensation provides workers’ compensation insurance coverage primarily for California-based insureds. Arrowhead’s workers’ compensation program targets industry segments such as agriculture, contractors, food services, horticulture and manufacturing. |
|---|
Commercial Programs. Commercial Programs markets targeted products and services to specific industries, trade groups, and market niches. Most of these products and services are marketed and sold primarily through independent agents, including certain of our retail offices. However, a number of these products and services are also marketed and sold directly to insured customers. Under agency agreements with the insurance companies that underwrite these programs, we often have authority to bind coverages (subject to established guidelines), to bill and collect premiums and, in some cases, to adjust claims.
Table of Contents
| • | Acumen RE Management Corporation (“Acumen RE”) has been active in the facultative reinsurance casualty market since 1993, providing outsourced technical expertise in workers’ compensation, general liability and professional liability (directors and officers along with errors and omissions) reinsurance accounts. Acumen RE’s territory encompasses the entire United States, and this entity accesses insureds via approved reinsurance intermediaries strategically located throughout the country. |
|---|
| • | AFC Insurance, Inc. (“AFC”)(“Humanity Plus Program”) is a Program Administrator specializing in niche Property & Casualty products for a wide range of For-Profit and Nonprofit Human & Social Service organizations. Eligible risks include Addiction Treatment Centers, Adult Day Care Centers, Group Homes, Services for the Developmentally Disabled and more. AFC’s nationwide comprehensive program offers all lines of coverage. AFC also has a separate program for independent pizza/deli restaurants. |
|---|
| • | American Specialty Insurance & Risk Services, Inc. provides insurance and risk management services for customers in professional sports, motor sports, amateur sports, and the entertainment industry. |
|---|
| • | Fabricare: Irving Weber Associates, Inc. (“IWA”) has specialized in this niche since 1946, providing package insurance including workers’ compensation to dry cleaners, linen supply and uniform rental operations. IWA also offers insurance programs for independent grocery stores and restaurants. |
|---|
| • | Florida Intracoastal Underwriters, Limited Company (“FIU”) is a managing general agency that specializes in providing insurance coverage for coastal and inland high-value condominiums and apartments. FIU has developed a specialty insurance facility to support the underwriting activities associated with these risks. |
|---|
| • | Industry Consulting Group, Inc. (“ICG”) is a complete property tax service provider, and works with Proctor Financial, Inc., one of our subsidiaries, in providing solutions to the financial institutions industry. ICG provides a full range of property tax processing solutions, property valuations and appeals, and other services to the real estate, oil and gas, and financial institution industries. ICG features full electronic interfaces, sophisticated and flexible reporting and systems that are customized to individual specifications. This business was sold effective November 30, 2014. |
|---|
| • | Parcel Insurance Plan® is a specialty insurance agency providing insurance coverage to commercial and private shippers for small packages and parcels with insured values of less than $25,000 each. |
|---|
| • | Proctor Financial, Inc. (“Proctor”) provides insurance programs and compliance solutions for financial institutions that service mortgage loans. Proctor’s products include lender-placed hazard and flood insurance, full insurance outsourcing, mortgage impairment, and blanket equity insurance. Proctor acts as a wholesaler and writes surplus lines property business for its financial institution customers. Proctor receives payments for insurance compliance tracking as well as commissions on lender-placed insurance. |
|---|
| • | Railroad Protector Plan® (“RRPP®”) provides insurance products for contractors, manufacturers and wholesalers supporting the railroad industry (not the railroads) in 47 states. The RRPP insurance coverages include general liability, property, commercial auto, umbrella and inland marine. |
|---|
| • | Towing Operators Protector Plan® (“TOPP®”) serves 21 states providing insurance coverage including general liability, commercial auto, garage keeper’s legal liability, property and motor truck cargo coverage. |
|---|
| • | Wright Specialty Insurance Agency, LLC provides insurance products for specialty programs such as food, grocery, and franchise programs that are offered throughout the U.S. |
|---|
Public Entity-Related Programs. Public Entity-Related Programs administers various insurance trusts specifically created for cities, counties, municipalities, school boards, special taxing districts and quasi-governmental agencies. These insurance coverages can range from providing fully insured programs to establishing risk retention insurance pools to excess and facultative specific coverages.
| • | Public Risk Underwriters of Indiana, LLC, dba Downey Insurance is a program administrator of insurance trusts offering tailored property and casualty insurance products, risk management consulting, third-party administration and related services designed for cities, counties, municipalities, schools, special taxing districts, and other public entities in the State of Indiana. |
|---|
| • | Public Risk Underwriters of The Northwest, Inc., dba Canfield & Associates is a program administrator of insurance trusts offering tailored property and casualty insurance products, risk management consulting, third-party administration and related services designed for cities, counties, municipalities, school boards and non-profit organizations in the State of Washington. |
|---|
Table of Contents
| • | Public Risk Underwriters of Illinois, LLC, dba Ideal Insurance Agency is a program administrator offering tailored property and casualty insurance products, risk management consulting, third-party administration and related services designed for municipalities, schools, fire districts and other public entities in the State of Illinois. |
|---|
| • | Public Risk Underwriters of New Jersey, Inc. provides administrative services and insurance procurement for the Statewide Insurance Fund (“Statewide”). Statewide is a municipal joint insurance fund comprised of counties, municipalities, utility authorities, community colleges and emergency services entities in New Jersey. |
|---|
| • | Public Risk Underwriters of Florida, Inc. is the program administrator for the Preferred Governmental Insurance Trust offering tailored property and casualty insurance products, risk management consulting, third-party administration and related services designed for cities, counties, municipalities, schools, special taxing districts and other public entities in the State of Florida. |
|---|
| • | Wright Risk Management Company, LLC, is a program administrator for the New York Schools Insurance Reciprocal and the New York Municipal Insurance Reciprocal offering tailored property and casualty insurance products, risk management consulting, third-party administration and related services designed for cities, counties, municipalities, schools, special taxing districts and other public entities in the State of New York. |
|---|
National Flood Program. Wright, which was acquired in May 2014, operates a flood insurance carrier, WNFIC, which is a Wright subsidiary. WNFIC’s entire business consists of policies written pursuant to the National Flood Insurance Program (“NFIP”), the program administered by FEMA and excess flood insurance policies, which are fully reinsured, substantially eliminating WNFIC’s exposure to underwriting risk, given that these policies are backed by either FEMA or a reinsurance carrier with an AM Best Company rating of “A” or better.
Wholesale Brokerage Segment
At December 31, 2014, our Wholesale Brokerage Segment employed 1,067 people. Our Wholesale Brokerage Segment markets and sells excess and surplus commercial insurance products and services to retail insurance agencies (including our retail offices). The Wholesale Brokerage Segment offices represent various U.S. and U.K. surplus lines insurance companies. Additionally, certain offices are also Lloyd’s of London correspondents. The Wholesale Brokerage Segment also represents admitted insurance companies for purposes of affording access to such companies for smaller agencies that otherwise do not have access to large insurance company representation. Excess and surplus insurance products encompass many insurance coverages, including personal lines, homeowners, yachts, jewelry, commercial property and casualty, commercial automobile, garage, restaurant, builder’s risk and inland marine lines. Difficult-to-insure general liability and products liability coverages are a specialty, as is excess workers’ compensation coverage. Wholesale brokers solicit business through mailings and direct contact with retail agency representatives. During 2014, commissions and fees from our largest Wholesale Brokerage Segment customer represented approximately 0.7% of the Wholesale Brokerage Segment’s total commissions and fees revenue.
Services Segment
At December 31, 2014, our Services Segment employed 895 people and provided a wide-range of insurance-related services.
Below are brief descriptions of the programs offered by the Services Segment.
| • | The Advocator Group assists individuals throughout the United States who are seeking to establish eligibility for coverage under the federal Social Security Disability program and provides health plan selection and enrollment assistance for Medicare beneficiaries. The Advocator Group works closely with employer-sponsored group life, disability and health plan participants to assist disabled employees in receiving the education, advocacy and benefit coordination assistance necessary to achieve the fastest possible benefit approvals. In addition, The Advocator Group also provides second injury fund recovery services to the workers’ compensation insurance market. |
|---|
| • | American Claims Management (“ACM”) provides third-party administration (“TPA”) services to both the commercial and personal property and casualty insurance markets on a nationwide basis, and provides claims adjusting, administration, subrogation, litigation and data management services to insurance companies, self-insureds, public municipalities, insurance brokers and corporate entities. ACM services also include managed care, claim investigations, field adjusting and audit services. Approximately 71.5% of ACM’s 2014 net revenues were derived from the various Arrowhead programs in our National Programs Segment, with the remainder generated from third parties. |
|---|
Table of Contents
| • | Colonial Claims provides insurance claims adjusting and related services, including education and training services, throughout the United States. Colonial Claims handles property and casualty insurers’ multi-line and catastrophic claims needs, including auto, earthquake, flood, hail, homeowners and wind claims. Colonial Claims’ adjusters are approved by the NFIP and are certified in each classification of loss, which includes dwelling, mobile home, condominium association, commercial and large losses. |
|---|
| • | ICA provides comprehensive claims management solutions for both personal and commercial lines of insurance. ICA is a national service provider for daily and catastrophe claims, vendor management, TPA operations and staff augmentation. ICA offers training and educational opportunities to independent adjusters nationwide in ICA’s regional training facilities. Additional claims services offered by ICA include first notice of loss, fast track, field appraisals, quality control and consulting. |
|---|
| • | NuQuest/Bridge Pointe and Protocols provide a full spectrum of Medicare Secondary Payer (“MSP”) statutory compliance services, from MSA Allocation through Professional Administration to over 250 insurance carriers, third-party administrators, self-insured employers, attorneys, brokers and related claims professionals nationwide. Specialty services include medical projections, life care plans, Medicare set-aside analysis, allocation and administration. |
|---|
| • | Preferred Governmental Claims Solutions (“PGCS”) provides TPA services for insurance entities and self-funded or fully-insured workers’ compensation and liability plans. PGCS’ services include claims administration, cost containment consulting, services for secondary disability and subrogation recoveries. |
|---|
| • | USIS provides TPA services for insurance entities and self-funded or fully-insured workers’ compensation and liability plans. USIS’ services include claims administration, access to major reinsurance markets, cost containment consulting, services for secondary disability, and subrogation recoveries and risk management services such as loss control. USIS’ services also include managed care services, including medical networks, case management and utilization review services certified by the American Accreditation Health Care Commission. |
|---|
In 2014, our three largest workers’ compensation contracts represented approximately 12.3% of our Services Segment’s fees revenues.
Employees
At December 31, 2014, we had 7,591 full-time equivalent employees. We have agreements with our sales employees and certain other employees that include provisions: (1) protecting our confidential information and trade secrets; (2) restricting their ability post-employment to solicit the business of our customers; and (3) preventing the hiring of our employees for a period of time after separation from employment with us. The enforceability of such agreements varies from state to state depending upon applicable law and factual circumstances. The majority of our employment relationships are at-will and terminable by either party at any time; however, the covenants regarding confidential information and non-solicitation of our customers and employees generally extend for a period of at least two years after cessation of employment.
None of our employees are represented by a labor union, and we consider our relations with our employees to be good.
Competition
The insurance intermediary business is highly competitive, and numerous firms actively compete with us for customers and insurance markets. Competition in the insurance business is largely based on innovation, quality of service and price. A number of firms and banks with substantially greater resources and market presence compete with us.
A number of insurance companies directly sell insurance, primarily to individuals, and do not pay commissions to third-party agents and brokers. In addition, the Internet continues to be a source for direct placement of personal lines business. To date, such direct sales efforts have had little effect on our operations, primarily because our Retail Segment is mostly commercially oriented rather than individually oriented.
In addition, the Gramm-Leach-Bliley Financial Services Modernization Act of 1999 and regulations enacted thereunder permit banks, securities firms and insurance companies to affiliate. As a result, the financial services industry has experienced and may continue to experience consolidation, which in turn has resulted and could continue to result in increased competition from diversified financial institutions, including competition for acquisition prospects.
Table of Contents
Regulation, Licensing and Agency Contracts
We and/or our designated employees must be licensed to act as agents, brokers, intermediaries or third-party administrators by state regulatory authorities in the states in which we conduct business. Regulations and licensing laws vary by individual state and are often complex.
The applicable licensing laws and regulations in all states are subject to amendment or reinterpretation by state regulatory authorities, and such authorities are vested in most cases with relatively broad discretion as to the granting, revocation, suspension and renewal of licenses. The possibility exists that we and/or our employees could be excluded or temporarily suspended from carrying on some or all of our activities in, or could otherwise be subjected to penalties by, a particular state.
Available Information
We are subject to the reporting requirements of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), and its rules and regulations. The Exchange Act requires us to file reports, proxy statements and other information with the Securities and Exchange Commission (“SEC”). We make available free of charge on our website, at www.bbinsurance.com, our annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act and the rules promulgated thereunder, as soon as reasonably practicable after electronically filing or furnishing such material to the SEC. These documents are posted on our website at www.bbinsurance.com—select the “Investor Relations” link and then the “SEC Filings” link.
Copies of these reports, proxy statements and other information can be read and copied at:
SEC Public Reference Room
100 F Street NE
Washington, D.C. 20549
Information on the operation of the Public Reference Room may be obtained by calling the SEC at 1-800-732-0330. Also, the SEC maintains a website that contains reports, proxy statements and other information regarding issuers that file electronically with the SEC. These materials may be obtained electronically by accessing the SEC’s website at www.sec.gov.
The charters of the Audit, Compensation and Nominating/Governance Committees of our Board of Directors as well as our Corporate Governance Principles, Code of Business Conduct and Ethics and Code of Ethics—CEO and Senior Financial Officers (including any amendments to, or waivers of any provision of any of these charters, principles or codes) are also available on our website or upon request. Requests for copies of any of these documents should be directed in writing to: Corporate Secretary, Brown & Brown, Inc., 220 South Ridgewood Avenue, Daytona Beach, Florida 32114, or by telephone to (386)-252-9601.
Item 1A. Risk Factors
| --- | --- |
OUR BUSINESS, AND THEREFORE OUR RESULTS OF OPERATIONS AND FINANCIAL CONDITION, MAY BE ADVERSELY AFFECTED BY ECONOMIC CONDITIONS THAT RESULT IN REDUCED INSURER CAPACITY.
Our results of operations depend on the continued capacity of insurance carriers to underwrite risk and provide coverage, which depends in turn on those insurance companies’ ability to procure reinsurance. Capacity could also be reduced by insurance companies failing or withdrawing from writing certain coverages that we offer our clients. We have no control over these matters. To the extent that reinsurance becomes less widely available, we may not be able to procure the amount or types of coverage that our customers desire and the coverage we are able to procure may be more expensive or limited.
Table of Contents
OUR GROWTH STRATEGY DEPENDS IN PART ON THE ACQUISITION OF OTHER INSURANCE INTERMEDIARIES, WHICH MAY NOT BE AVAILABLE ON ACCEPTABLE TERMS IN THE FUTURE AND WHICH, IF CONSUMMATED, MAY NOT BE ADVANTAGEOUS TO US.
Our growth strategy includes the acquisition of other insurance intermediaries. Our ability to successfully identify suitable acquisition candidates, complete acquisitions, integrate acquired businesses into our operations, and expand into new markets requires us to implement and improve our operations and our financial and management information systems. Integrated, acquired businesses may not achieve levels of revenues or profitability comparable to our existing operations, or otherwise perform as expected. In addition, we compete for acquisition and expansion opportunities with firms and banks that have substantially greater resources than we do. Acquisitions also involve a number of special risks, such as: diversion of management’s attention; difficulties in the integration of acquired operations and retention of personnel; increase in expenses and working capital requirements, which could reduce our return on invested capital; entry into unfamiliar markets; unanticipated problems or legal liabilities; estimation of the acquisition earn-out payables; and tax and accounting issues, some or all of which could have a material adverse effect on the results of our operations, financial condition and cash flows. Post-acquisition deterioration of targets could also result in lower or negative earnings contribution and/or goodwill impairment charges.
INFLATION MAY ADVERSELY AFFECT OUR BUSINESS OPERATIONS IN THE FUTURE.
Given the current macroeconomic environment, it is possible that U.S. government actions, in the form of a monetary stimulus, a fiscal stimulus, or both, to the U.S. economy, could lead to inflationary conditions that would adversely affect our cost base, resulting in an increase in our employee compensation and benefits and our other operating expenses. This could harm our margins and profitability if we are unable to increase revenues or cut costs enough to offset the effects of inflation on our cost base.
BECAUSE OUR BUSINESS IS HIGHLY CONCENTRATED IN CALIFORNIA, FLORIDA, GEORGIA, ILLINOIS, INDIANA, KANSAS, MASSACHUSETTS, MICHIGAN, NEW JERSEY, NEW YORK, NORTH CAROLINA, OREGON, PENNSYLVANIA, TEXAS, VIRGINIA AND WASHINGTON, ADVERSE ECONOMIC CONDITIONS, NATURAL DISASTERS, OR REGULATORY CHANGES IN THESE STATES COULD ADVERSELY AFFECT OUR FINANCIAL CONDITION.
A significant portion of our business is concentrated in California, Florida, Georgia, Illinois, Indiana, Kansas, Massachusetts, Michigan, New Jersey, New York, North Carolina, Oregon, Pennsylvania, Texas, Virginia and Washington. For the years ended December 31, 2014, 2013 and 2012, we derived $1,361.5 million or 86.4%, $1,163.8 million or 85.4% and $1,016.5 million or 84.8%, of our revenues, respectively, from our operations located in these states. We believe that these revenues are attributable predominately to customers in these states. We believe the current regulatory environment for insurance intermediaries in these states is no more restrictive than in other states. The insurance business is primarily a state-regulated industry, and therefore, state legislatures may enact laws that adversely affect the insurance industry. Because our business is concentrated in the states identified above, we face greater exposure to unfavorable changes in regulatory conditions in those states than insurance intermediaries whose operations are more diversified through a greater number of states. In addition, the occurrence of adverse economic conditions, natural or other disasters, or other circumstances specific to or otherwise significantly impacting these states could adversely affect our financial condition, results of operations and cash flows. We are susceptible to losses and interruptions caused by hurricanes (particularly in Florida, where our headquarters are located and we maintain several offices), earthquakes (including California, where we maintain a relatively large number of offices), power shortages, telecommunications failures, water shortages, floods, fire, extreme weather conditions, geopolitical events such as terrorist acts and other natural or manmade disasters. Our insurance coverage with respect to natural disasters is limited and is subject to deductibles and coverage limits. Such coverage may not be adequate, or may not continue to be available at commercially reasonable rates and terms.
WE DERIVE A SIGNIFICANT PORTION OF OUR COMMISSION REVENUES FROM A LIMITED NUMBER OF INSURANCE COMPANIES, THE LOSS OF WHICH COULD RESULT IN ADDITIONAL EXPENSE AND LOSS OF MARKET SHARE.
For the year ended December 31, 2014, no insurance company accounted for more than 7.0% of our total core commissions. For the year ended December 31, 2013 and 2012, approximately 8.0% and 5.0% respectively, of our total core commissions were derived from insurance policies underwritten by one insurance company. Should this insurance company seek to terminate their arrangements with us, we believe that other insurance companies are available to underwrite the business, and we could likely move our business to one of these other insurance companies, although some additional expense and loss of market share could possibly result.
Table of Contents
OUR CURRENT MARKET SHARE MAY DECREASE AS A RESULT OF INCREASED COMPETITION FROM INSURANCE COMPANIES AND THE FINANCIAL SERVICES INDUSTRY.
The insurance intermediary business is highly competitive and we actively compete with numerous firms for customers and insurance companies, many of which have relationships with insurance companies or have a significant presence in niche insurance markets that may give them an advantage over us. Other competitive concerns may include the quality of our products and services, our pricing and the ability of some of our customers to self-insure. A number of insurance companies are engaged in the direct sale of insurance, primarily to individuals, and do not pay commissions to agents and brokers. In addition, and to the extent that banks, securities firms and insurance companies affiliate, the financial services industry may experience further consolidation, and we therefore may experience increased competition from insurance companies and the financial services industry, as a growing number of larger financial institutions increasingly, and aggressively, offer a wider variety of financial services, including insurance intermediary services.
QUARTERLY AND ANNUAL VARIATIONS IN OUR COMMISSIONS THAT RESULT FROM THE TIMING OF POLICY RENEWALS AND THE NET EFFECT OF NEW AND LOST BUSINESS PRODUCTION MAY HAVE UNEXPECTED EFFECTS ON OUR RESULTS OF OPERATIONS.
Our commission income (including profit-sharing contingent commissions and override commissions) can vary quarterly or annually due to the timing of policy renewals and the net effect of new and lost business production. We do not control the factors that cause these variations. Specifically, customers’ demand for insurance products can influence the timing of renewals, new business and lost business (which includes policies that are not renewed), and cancellations. In addition, as discussed, we rely on insurance companies for the payment of certain commissions. Because these payments are processed internally by these insurance companies, we may not receive a payment that is otherwise expected from a particular insurance company in a particular quarter or year until after the end of that period, which can adversely affect our ability to forecast these revenues and therefore budget for significant future expenditures. Quarterly and annual fluctuations in revenues based on increases and decreases associated with the timing of policy renewals may adversely affect our financial condition, results of operations and cash flows.
Profit-sharing contingent commissions are special revenue-sharing commissions paid by insurance companies based upon the profitability, volume and/or growth of the business placed with such companies during the prior year. We primarily receive these commissions in the first and second quarters of each year. These commissions generally have accounted for 4.3% to 4.4% of our previous year’s total annual revenues over the last three years. Due to, among other things, potentially poor macroeconomic conditions, the inherent uncertainty of loss in our industry and changes in underwriting criteria due in part to the high loss ratios experienced by insurance companies, we cannot predict the payment of these profit-sharing contingent commissions. Further, we have no control over the ability of insurance companies to estimate loss reserves, which affects our ability to make profit-sharing calculations. Override commissions are paid by insurance companies based on the volume of business that we place with them and are generally paid over the course of the year. Because profit-sharing contingent commissions and override commissions materially affect our revenues, any decrease in their payment to us could adversely affect the results of our operations and our financial condition.
CONSOLIDATION IN THE INDUSTRIES THAT WE SERVE COULD ADVERSELY AFFECT OUR BUSINESS.
Companies that we serve may seek to achieve economies of scale and other synergies by combining with or acquiring other companies. If two or more of our current customers merge or consolidate and combine their operations, it may decrease the overall amount of work that we perform for these customers. If one of our current customers merges or consolidates with a company that relies on another provider for its services, we may lose work from that customer or lose the opportunity to gain additional work. The increased market power of larger companies could also increase pricing and competitive pressures on us. Any of these possible results of industry consolidation could adversely affect our business.
WE COULD INCUR SUBSTANTIAL LOSSES FROM OUR CASH AND INVESTMENT ACCOUNTS IF ONE OF THE FINANCIAL INSTITUTIONS THAT WE USE FAILS OR IS TAKEN OVER BY THE U.S. FEDERAL DEPOSIT INSURANCE CORPORATION (“FDIC”).
We maintain cash and investment balances, including restricted cash held in premium trust accounts, at various depository institutions in amounts that are significantly in excess of the limits insured by the FDIC. If one or more of the depository institutions with which we maintain significant cash balances were to fail, our ability to access these funds might be temporarily or permanently limited, and we could face material liquidity problems and potential material financial losses.
Table of Contents
OUR BUSINESS PRACTICES AND COMPENSATION ARRANGEMENTS ARE SUBJECT TO UNCERTAINTY DUE TO INVESTIGATIONS BY GOVERNMENTAL AUTHORITIES AND POTENTIAL RELATED PRIVATE LITIGATION.
The business practices and compensation arrangements of the insurance intermediary industry, including our practices and arrangements, are subject to uncertainty due to investigations by various governmental authorities. As disclosed in prior years, certain of our offices are parties to profit-sharing contingent commission agreements with certain insurance companies, including agreements providing for potential payment of revenue-sharing commissions by insurance companies based primarily on the overall profitability of the aggregate business written with those insurance companies and/or additional factors such as retention ratios and the overall volume of business that an office or offices place with those insurance companies. Additionally, to a lesser extent, some of our offices are parties to override commission agreements with certain insurance companies, which provide for commission rates in excess of standard commission rates to be applied to specific lines of business, such as group health business, and which are based primarily on the overall volume of business that such office or offices placed with those insurance companies. The Company has not chosen to discontinue receiving profit-sharing contingent commissions or override commissions. The legislatures of various states may adopt new laws addressing contingent commission arrangements, including laws prohibiting such arrangements, and addressing disclosure of such arrangements to insureds. Various state departments of insurance may also adopt new regulations addressing these matters. While we cannot predict the outcome of the governmental inquiries and investigations into the insurance industry’s commission payment practices or the responses by the market and government regulators, any unfavorable resolution of these matters could adversely affect our results of operations. Further, if such resolution included a material decrease in our profit-sharing contingent commissions and override commissions, it would likely adversely affect our results of operations.
WE COMPETE IN A HIGHLY-REGULATED INDUSTRY, WHICH MAY RESULT IN INCREASED EXPENSES OR RESTRICTIONS ON OUR OPERATIONS.
We conduct business in most states and are subject to comprehensive regulation and supervision by government agencies in the states in which we do business. The primary purpose of such regulation and supervision is to provide safeguards for policyholders rather than to protect the interests of our stockholders. As a result, such regulation and supervision could reduce our profitability or growth by increasing compliance costs, restricting the products or services we may sell, the markets we may enter, the methods by which we may sell our products and services, or the prices we may charge for our services and the form of compensation we may accept from our clients, carriers and third parties. The laws of the various state jurisdictions establish supervisory agencies with broad administrative powers with respect to, among other things, licensing of entities to transact business, licensing of agents, admittance of assets, regulating premium rates, approving policy forms, regulating unfair trade and claims practices, establishing reserve requirements and solvency standards, requiring participation in guarantee funds and shared market mechanisms, and restricting payment of dividends. Also, in response to perceived excessive cost or inadequacy of available insurance, states have from time to time created state insurance funds and assigned risk pools, which compete directly, on a subsidized basis, with private insurance providers. We act as agents and brokers for such state insurance funds and assigned risk pools in California and certain other states. These state funds and pools could choose to reduce the sales or brokerage commissions we receive. Any such reductions, in a state in which we have substantial operations, such as Florida, California or New York, could substantially affect the profitability of our operations in such state, or cause us to change our marketing focus. Further, state insurance regulators and the National Association of Insurance Commissioners continually re-examine existing laws and regulations, and such re-examination may result in the enactment of insurance-related laws and regulations, or the issuance of interpretations thereof, that adversely affect our business. Although we believe that we are in compliance in all material respects with applicable local, state and federal laws, rules and regulations, there can be no assurance that more restrictive laws, rules or regulations will not be adopted in the future that could make compliance more difficult or expensive. Specifically, recently adopted federal financial services modernization legislation could lead to additional federal regulation of the insurance industry in the coming years, which could result in increased expenses or restrictions on our operations.
PROPOSED TORT REFORM LEGISLATION, IF ENACTED, COULD DECREASE DEMAND FOR LIABILITY INSURANCE, THEREBY REDUCING OUR COMMISSION REVENUES.
Legislation concerning tort reform has been considered, from time to time, in the United States Congress and in several state legislatures. Among the provisions considered in such legislation have been limitations on damage awards, including punitive damages, and various restrictions applicable to class action lawsuits. Enactment of these or similar provisions by Congress, or by states in which we sell insurance, could reduce the demand for liability insurance policies or lead to a decrease in policy limits of such policies sold, thereby reducing our commission revenues.
Table of Contents
CHANGES IN LAWS AND REGULATIONS MAY INCREASE OUR COSTS.
The Sarbanes-Oxley Act of 2002, as amended (“Sarbanes-Oxley”) and the Dodd-Frank Act enacted in 2010 have required changes in some of our corporate governance, securities disclosure and compliance practices. In response to the requirements of these Acts, the SEC and the New York Stock Exchange have promulgated and will likely continue to promulgate new rules on a variety of subjects. These developments have increased (and may increase in the future) our compliance costs, may make it more difficult and more expensive for us to obtain director and officer liability insurance, and may make it more difficult for us to attract and retain qualified members of our Board of Directors or qualified executive officers.
From time to time new regulations are enacted, or existing requirements are changed, and it is difficult to anticipate how such regulations and changes will be implemented and enforced. We continue to evaluate the necessary steps for compliance with regulations as they are enacted. Legislative developments that could adversely affect us include: changes in our business compensation model as a result of regulatory developments (for example, the 2010 Health Care Reform Legislation); and federal and state governments establishing programs to provide health insurance or, in certain cases, property insurance in catastrophe-prone areas or other alternative market types of coverage, that compete with, or completely replace, insurance products offered by insurance carriers. Also, as climate change issues become more prevalent, the U.S. and foreign governments are beginning to respond to these issues. This increasing governmental focus on climate change may result in new environmental regulations that may negatively affect us and our customers. This could cause us to incur additional direct costs in complying with any new environmental regulations, as well as increased indirect costs resulting from our customers incurring additional compliance costs that get passed on to us. These costs may adversely impact our operations and financial condition.
HEALTHCARE REFORM AND INCREASED COSTS OF CURRENT EMPLOYEES’ MEDICAL AND OTHER BENEFITS COULD HAVE A MATERIALLY ADVERSE EFFECT ON OUR BUSINESS.
Our profitability is affected by the cost of current employees’ medical and other benefits. In recent years, we have experienced significant increases in these costs as a result of economic factors beyond our control. Although we have actively sought to contain increases in these costs, there can be no assurance we will succeed in limiting future cost increases, and continued upward pressure in these costs could reduce our profitability.
In addition, we believe that increased health care costs resulting from the 2010 health care reform bill could have a material adverse impact on our business, cash flows, financial condition or results of operations.
WE ARE SUBJECT TO LITIGATION WHICH, IF DETERMINED UNFAVORABLY TO US, COULD HAVE A MATERIAL ADVERSE EFFECT ON OUR BUSINESS, RESULTS OF OPERATIONS OR FINANCIAL CONDITION.
We are and may be subject to a number of claims, regulatory actions and other proceedings that arise in the ordinary course of business. We cannot, and likely will not be able to, predict the outcome of these claims, actions and proceedings with certainty. An adverse outcome in connection with one or more of these matters could have a material adverse effect on our business, results of operations or financial condition in any given quarterly or annual period. In addition, regardless of monetary costs, these matters could have a material adverse effect on our reputation and cause harm to our carrier, customer or employee relationships, or divert personnel and management resources.
While we currently have insurance coverage for some of these potential liabilities, other potential liabilities may not be covered by insurance, insurers may dispute coverage or the amount of our insurance may not be enough to cover the damages awarded. In addition, some types of damages, like punitive damages, may not be covered by insurance. Insurance coverage for all or some forms of liability may become unavailable or prohibitively expensive in the future.
OUR BUSINESS, AND THEREFORE OUR RESULTS OF OPERATIONS AND FINANCIAL CONDITION, MAY BE ADVERSELY AFFECTED BY FURTHER CHANGES IN THE U.S.-BASED CREDIT MARKETS.
Although we are not currently experiencing any limitation of access to our revolving credit facility (which matures in 2019) and are not aware of any issues impacting the ability or willingness of our lenders under such facility to honor their commitments to extend us credit, the failure of a lender could adversely affect our ability to borrow on that facility, which over time could negatively impact our ability to consummate significant acquisitions or make other significant capital expenditures. Tightening conditions in the credit markets in future years could adversely affect the availability and terms of future borrowings or renewals or refinancing.
We also have a significant amount of trade accounts receivable from some insurance companies with which we place insurance. If those insurance companies were to experience liquidity problems or other financial difficulties, we could encounter delays or defaults in payments owed to us, which could have a significant adverse impact on our financial condition and results of operations.
Table of Contents
IF WE FAIL TO COMPLY WITH THE COVENANTS CONTAINED IN CERTAIN OF OUR AGREEMENTS, OUR LIQUIDITY, RESULTS OF OPERATIONS AND FINANCIAL CONDITION MAY BE ADVERSELY AFFECTED.
The credit agreements that govern our debt contain various covenants and other limitations with which we must comply. At December 31, 2014, we were in compliance with the financial covenants and other limitations contained in each of these agreements. However, failure to comply with material provisions of our covenants in these agreements or other credit or similar agreements to which we may become a party could result in a default, rendering them unavailable to us and causing a material adverse effect on our liquidity, results of operations and financial condition. In the event of certain defaults, the lenders thereunder would not be required to lend any additional amounts to or purchase any additional notes from us and could elect to declare all borrowings outstanding, together with accrued and unpaid interest and fees, to be due and payable. If the indebtedness under these agreements or our other indebtedness, including the notes, were to be accelerated, there can be no assurance that our assets would be sufficient to repay such indebtedness in full.
CERTAIN OF OUR AGREEMENTS CONTAIN VARIOUS COVENANTS THAT LIMIT THE DISCRETION OF OUR MANAGEMENT IN OPERATING OUR BUSINESS AND COULD PREVENT US FROM ENGAGING IN CERTAIN POTENTIALLY BENEFICIAL ACTIVITIES.
The restrictive covenants in our debt agreements may impact how we operate our business and prevent us from engaging in certain potentially beneficial activities. In particular, among other covenants, the Credit Facility requires us to maintain a minimum ratio of consolidated EBITDA (earnings before interest, taxes, depreciation and amortization), adjusted for certain transaction-related items (“Consolidated EBITDA”), to consolidated interest expense and a maximum ratio of consolidated net indebtedness to Consolidated EBITDA. Our compliance with these covenants limits our management’s discretion in operating our business and could prevent us from engaging in certain potentially beneficial activities.
OUR CREDIT RATINGS ARE SUBJECT TO CHANGE.
Our credit ratings are an assessment by rating agencies of our ability to pay our debts when due. Consequently, real or anticipated changes in our credit ratings will generally affect the market value of our securities. Agency ratings are not a recommendation to buy, sell or hold any security, and may be revised or withdrawn at any time by the issuing agency. Each agency’s rating should be evaluated independently of any other agency’s rating.
OUR BUSINESS, RESULTS OF OPERATIONS, FINANCIAL CONDITION OR LIQUIDITY MAY BE MATERIALLY ADVERSELY AFFECTED BY ERRORS AND OMISSIONS AND THE OUTCOME OF CERTAIN ACTUAL AND POTENTIAL CLAIMS, LAWSUITS AND PROCEEDINGS.
We are subject to various actual and potential claims, lawsuits and other proceedings relating principally to alleged errors and omissions in connection with the placement or servicing of insurance and/or the provision of services in the ordinary course of business. Because we often assist customers with matters involving substantial amounts of money, including the placement of insurance and the handling of related claims that customers may assert, errors and omissions claims against us may arise alleging potential liability for all or part of the amounts in question. Also, the failure of an insurer with whom we place business could result in errors and omissions claims against us by our clients, which could adversely affect our results of operations and financial condition. Claimants may seek large damage awards, and these claims may involve potentially significant legal costs, including punitive damages. Such claims, lawsuits and other proceedings could, for example, include claims for damages based on allegations that our employees or sub-agents improperly failed to procure coverage, report claims on behalf of customers, provide insurance companies with complete and accurate information relating to the risks being insured or appropriately apply funds that we hold for our customers on a fiduciary basis. In addition, given the long-tail nature of professional liability claims, errors and omissions matters can relate to matters dating back many years. We have established provisions against these potential matters that we believe to be adequate in the light of current information and legal advice, and we adjust such provisions from time to time according to developments.
While most of the errors and omissions claims made against us (subject to our self-insured deductibles) have been covered by our professional indemnity insurance, our business, results of operations, financial condition and liquidity may be adversely affected if, in the future, our insurance coverage proves to be inadequate or unavailable, or if there is an increase in liabilities for which we self-insure. Our ability to obtain professional indemnity insurance in the amounts and with the deductibles we desire in the future may be adversely impacted by general developments in the market for such insurance or our own claims experience. In addition, claims, lawsuits and other proceedings may harm our reputation or divert management resources away from operating our business.
Table of Contents
WE HAVE OPERATIONS INTERNATIONALLY, WHICH MAY RESULT IN A NUMBER OF ADDITIONAL RISKS AND REQUIRE MORE MANAGEMENT TIME AND EXPENSE THAN OUR DOMESTIC OPERATIONS TO ACHIEVE OR MAINTAIN PROFITABILITY.
We have operations in the United Kingdom, Hamilton, Bermuda and George Town, Cayman Islands. In the future, we intend to continue to consider additional international expansion opportunities. Our international operations may be subject to a number of risks, including:
| • | Difficulties in staffing and managing foreign operations; |
|---|
| • | Less flexible employee relationships, which may make it difficult and expensive to terminate employees and which limits our ability to prohibit employees from competing with us after their employment ceases; |
|---|
| • | Political and economic instability (including acts of terrorism and outbreaks of war); |
|---|
| • | Coordinating our communications and logistics across geographic distances and multiple time zones; |
|---|
| • | Unexpected changes in regulatory requirements and laws; |
|---|
| • | Adverse trade policies, and adverse changes to any of the policies of either the U.S. or any of the foreign jurisdictions in which we operate; |
|---|
| • | Adverse changes in tax rates; |
|---|
| • | Legal or political constraints on our ability to maintain or increase prices; |
|---|
| • | Governmental restrictions on the transfer of funds to us from our operations outside the United States; and |
|---|
| • | Burdens of complying with a wide variety of labor practices and foreign laws, including those relating to export and import duties, environmental policies and privacy issues. |
|---|
OUR INABILITY TO RETAIN OR HIRE QUALIFIED EMPLOYEES, AS WELL AS THE LOSS OF ANY OF OUR EXECUTIVE OFFICERS, COULD NEGATIVELY IMPACT OUR ABILITY TO RETAIN EXISTING BUSINESS AND GENERATE NEW BUSINESS.
Our success depends on our ability to attract and retain skilled and experienced personnel. There is significant competition from within the insurance industry and from businesses outside the industry for exceptional employees, especially in key positions. If we are not able to successfully attract, retain and motivate our employees, our business, financial results and reputation could be materially and adversely affected.
Losing employees who manage or support substantial customer relationships or possess substantial experience or expertise could adversely affect our ability to secure and complete customer engagements, which would adversely affect our results of operations. Also, if any of our key professionals were to join an existing competitor or form a competing company, some of our customers could choose to use the services of that competitor instead of our services. While our key personnel are prohibited by contract from soliciting our employees and customers for a period of years following separation from employment with us, they are not prohibited from competing with us.
In addition, we could be adversely affected if we fail to adequately plan for the succession of our Senior Leaders and key executives. While we have succession plans in place and we have employment arrangements with certain key executives, these do not guarantee that the services of these executives will continue to be available to us. Although we operate with a decentralized management system, the loss of our senior managers or other key personnel, or our inability to continue to identify, recruit and retain such personnel, could materially and adversely affect our business, operating results and financial condition.
WE ARE EXPOSED TO INTANGIBLE ASSET RISK; SPECIFICALLY, OUR GOODWILL MAY BECOME IMPAIRED IN THE FUTURE.
As of the date of the filing of our Annual Report on Form 10-K for the 2014 fiscal year, we have $2,460,610,929 of goodwill recorded on our Consolidated Balance Sheet. We perform a goodwill impairment test on an annual basis and whenever events or changes in circumstances indicate that the carrying value of our goodwill may not be recoverable from estimated future cash flows. We completed our most recent evaluation of impairment for goodwill as of November 30, 2014 and determined that the fair value of goodwill exceeded the carrying value of such assets. A significant and sustained decline in our stock price and market capitalization, a significant decline in our expected future cash flows, a significant adverse change in the business climate or slower growth rates could result in the need to perform an additional impairment analysis prior to the next annual goodwill impairment test. If we were to conclude that a future write-down of our goodwill is necessary, we would then record the appropriate charge, which could result in material charges that are adverse to our operating results and financial position. See Note 1—“Summary of Significant Accounting Policies” and Note 3—“Goodwill” to the Consolidated Financial Statements and “Management’s Report on Internal Control Over Financial Reporting.”
Table of Contents
Additionally, the carrying value of amortizable intangible assets attributable to each business or asset group comprising Brown & Brown is periodically reviewed by management to determine if there are events or changes in circumstances that would indicate that its carrying amount may not be recoverable. Accordingly, if there are any such circumstances that occur during the year, Brown & Brown assesses the carrying value of its amortizable intangible assets by considering the estimated future undiscounted cash flows generated by the corresponding business or asset group. Any impairment identified through this assessment may require that the carrying value of related amortizable intangible assets be adjusted; however, no impairments have been recorded for the years ended December 31, 2014, 2013 and 2012.
CURRENT U.S. ECONOMIC CONDITIONS AND THE SHIFT AWAY FROM TRADITIONAL INSURANCE MARKETS MAY CONTINUE TO ADVERSELY AFFECT OUR BUSINESS.
From late 2007 through 2011, global consumer confidence had eroded amidst concerns over declining asset values, volatility in energy costs, geopolitical issues, the availability and cost of credit, high unemployment, and the stability and solvency of financial institutions, financial markets, businesses, and sovereign nations. Those concerns slowed economic growth and resulted in a recession in the United States. Economic conditions had a negative impact on our results of operations during the years 2008 through 2011 due to reduced customer demand. In 2012, the economic conditions in the middle-market economy appeared to stabilize, and a gradual improvement continued through 2013 and 2014. However, if these economic conditions worsen, a number of negative effects on our business could result, including declines in values of insurable exposure units, declines in insurance premium rates, and the financial insolvency, or reduced ability to pay, of certain of our customers. Also, if general economic conditions are poor, some of our clients may cease operations completely or be acquired by other companies, which could have an adverse effect on our results of operations and financial condition. If these clients are affected by poor economic conditions but yet remain in existence, they may face liquidity problems or other financial difficulties which could result in delays or defaults in payments owed to us, which could have a significant adverse impact on our consolidated financial condition and results of operations. Any of these effects could decrease our net revenues and profitability.
In addition, there has been an increase in alternative insurance markets, such as self-insurance, captives, risk retention groups and non-insurance capital markets. While we compete in these segments on a fee-for-service basis, we cannot be certain that such alternative markets will provide the same level of profitability as traditional insurance markets.
THERE ARE INHERENT UNCERTAINTIES INVOLVED IN ESTIMATES, JUDGMENTS AND ASSUMPTIONS USED IN THE PREPARATION OF FINANCIAL STATEMENTS IN ACCORDANCE WITH U.S. GAAP. ANY CHANGES IN ESTIMATES, JUDGMENTS AND ASSUMPTIONS COULD HAVE A MATERIAL ADVERSE EFFECT ON OUR BUSINESS, FINANCIAL POSITION AND RESULTS OF OPERATIONS.
The consolidated and Condensed Consolidated Financial Statements included in the periodic reports we file with the SEC are prepared in accordance with U.S. GAAP. The preparation of financial statements in accordance with U.S. GAAP involves making estimates, judgments and assumptions that affect reported amounts of assets (including intangible assets), liabilities and related reserves, revenues, expenses and income. Estimates, judgments and assumptions are inherently subject to change in the future, and any such changes could result in corresponding changes to the amounts of assets, liabilities, revenues, expenses and income, and could have a material adverse effect on our financial position, results of operations and cash flows.
WE HAVE NOT DETERMINED THE AMOUNT OF RESOURCES AND THE TIME THAT MAY BE NECESSARY TO ADEQUATELY RESPOND TO RAPID TECHNOLOGICAL CHANGE IN OUR INDUSTRY, WHICH MAY ADVERSELY AFFECT OUR BUSINESS AND OPERATING RESULTS.
Frequent technological changes, new products and services and evolving industry standards are influencing the insurance business. The Internet, for example, is increasingly used to securely transmit benefits and related information to customers and to facilitate business-to-business information exchange and transactions. We believe that the development and implementation of new technologies will require additional investment of our capital resources in the future. We have not determined, however, the amount of resources and the time that this development and implementation may require, which may result in short-term, unexpected interruptions to our business, or may result in a competitive disadvantage in price and/or efficiency, as we develop or implement new technologies.
Table of Contents
OUR ABILITY TO CONDUCT BUSINESS WOULD BE NEGATIVELY IMPACTED IN THE EVENT OF AN INTERRUPTION IN INFORMATION TECHNOLOGY AND/OR DATA SECURITY AND/OR OUTSOURCING RELATIONSHIPS.
Our business relies on information systems to provide effective and efficient service to our customers, process claims, and timely and accurately report results to carriers. An interruption of our access to, or an inability to access, our information technology, telecommunications or other systems could significantly impair our ability to perform such functions on a timely basis. If sustained or repeated, such a business interruption, system failure or service denial could result in a deterioration of our ability to write and process new and renewal business, provide customer service, pay claims in a timely manner or perform other necessary business functions.
Computer viruses, hackers and other external hazards could expose our data systems to security breaches. These increased risks, and expanding regulatory requirements regarding data security, could expose us to data loss, monetary and reputational damages and significant increases in compliance costs. While we have taken, and continue to take, actions to protect the security and privacy of our information, entirely eliminating all risk of improper access to private information is not possible.
We are taking steps to upgrade and expand our information systems capabilities. Maintaining, protecting and enhancing these capabilities to keep pace with evolving industry and regulatory standards, and changing customer preferences, requires an ongoing commitment of significant resources. If the information we rely upon to run our businesses was found to be inaccurate or unreliable or if we fail to maintain effectively our information systems and data integrity, we could experience operational disruptions, regulatory or other legal problems, increases in operating expenses, loss of existing customers, difficulty in attracting new customers, or suffer other adverse consequences.
Our technological development projects may not deliver the benefits we expect once they are completed, or may be replaced or become obsolete more quickly than expected, which could result in the accelerated recognition of expenses. If we do not effectively and efficiently manage and upgrade our technology portfolio, or if the costs of doing so are higher than we expect, our ability to provide competitive services to new and existing customers in a cost-effective manner and our ability to implement our strategic initiatives could be adversely impacted.
IMPROPER DISCLOSURE OF CONFIDENTIAL INFORMATION COULD NEGATIVELY IMPACT OUR BUSINESS.
We are responsible for maintaining the security and privacy of our customers’ confidential and proprietary information and the personal data of their employees. We have put in place policies, procedures and technological safeguards designed to protect the security and privacy of this information, however, we cannot guarantee that this information will not be improperly disclosed or accessed. Disclosure of this information could harm our reputation and subject us to liability under our contracts and laws that protect personal data, resulting in increased costs or loss of revenues.
Further, privacy laws and regulations are continuously changing and often are inconsistent among the states in which we operate. Our failure to adhere to or successfully implement procedures to respond to these requirements could result in legal liability or impairment to our reputation.
CERTAIN OF OUR EXISTING STOCKHOLDERS HAVE SIGNIFICANT CONTROL OF THE COMPANY.
At December 31, 2014, our executive officers, directors and certain of their family members collectively beneficially owned approximately 17.8% of our outstanding common stock, of which J. Hyatt Brown, our Chairman, and his family members, which include his sons, J. Powell Brown, our President and Chief Executive Officer and P. Barrett Brown, one of our Senior Vice Presidents, beneficially owned approximately 16.0%. As a result, our executive officers, directors and certain of their family members have significant influence over (1) the election of our Board of Directors, (2) the approval or disapproval of any other matters requiring stockholder approval, and (3) our affairs and policies.
Table of Contents
DUE TO INHERENT LIMITATIONS, THERE CAN BE NO ASSURANCE THAT OUR SYSTEM OF DISCLOSURE AND INTERNAL CONTROLS AND PROCEDURES WILL BE SUCCESSFUL IN PREVENTING ALL ERRORS OR FRAUD, OR IN INFORMING MANAGEMENT OF ALL MATERIAL INFORMATION IN A TIMELY MANNER.
Our management, including our Chief Executive Officer and Chief Financial Officer, does not expect that our disclosure controls and internal controls and procedures will prevent all error and all fraud. A control system, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. Further, the design of a control system reflects that there are resource constraints, and the benefits of controls must be considered relative to their costs. Because of the inherent limitations in all control systems, no evaluation of controls can provide absolute assurance that all control issues and instances of fraud, if any, within the company have been detected. These inherent limitations include the realities that judgments in decision-making can be faulty and that breakdowns can occur simply because of error or mistake. Additionally, controls can be circumvented by the individual acts of some persons, by collusion of two or more people, or by management override of a control.
The design of any system of controls also is based in part upon certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions; over time, a control may become inadequate because of changes in conditions, or the degree of compliance with the policies or procedures may deteriorate. Because of the inherent limitations in a cost-effective control system, misstatements due to error or fraud may occur and may not be detected.
IF WE RECEIVE OTHER THAN AN UNQUALIFIED OPINION ON THE ADEQUACY OF OUR INTERNAL CONTROL OVER FINANCIAL REPORTING AS OF DECEMBER 31, 2014 AND FUTURE YEAR-ENDS AS REQUIRED BY SECTION 404 OF SARBANES-OXLEY, INVESTORS COULD LOSE CONFIDENCE IN THE RELIABILITY OF OUR FINANCIAL STATEMENTS, WHICH COULD RESULT IN A DECREASE IN THE VALUE OF OUR SHARES.
As directed by Section 404 of Sarbanes-Oxley, the SEC adopted rules requiring public companies to include an annual report on internal control over financial reporting on Form 10-K that contains an assessment by management of the effectiveness of our internal control over financial reporting. We continuously conduct a rigorous review of our internal control over financial reporting in order to assure compliance with the Section 404 requirements. However, if our independent auditors interpret the Section 404 requirements and the related rules and regulations differently than we do, or if our independent auditors are not satisfied with our internal control over financial reporting or with the level at which it is documented, operated or reviewed, they may issue a report other than an unqualified opinion. A report other than an unqualified opinion could result in an adverse reaction in the financial markets due to a loss of confidence in the reliability of our financial statements.
WE MAY EXPERIENCE VOLATILITY IN OUR STOCK PRICE THAT COULD AFFECT YOUR INVESTMENT.
The market price of our common stock may be subject to significant fluctuations in response to various factors, including: quarterly fluctuations in our operating results; changes in securities analysts’ estimates of our future earnings; changes in securities analysts’ predictions regarding the short-term and long-term future of our industry; and our loss of significant customers or significant business developments relating to us or our competitors. Our common stock’s market price also may be affected by our ability to meet stock analysts’ earnings and other expectations. Any failure to meet such expectations, even if minor, could cause the market price of our common stock to decline. In addition, stock markets have generally experienced a high level of price and volume volatility, and the market prices of equity securities of many listed companies have experienced wide price fluctuations not necessarily related to the operating performance of such companies. These broad market fluctuations may adversely affect our common stock’s market price. In the past, securities class action lawsuits frequently have been instituted against companies following periods of volatility in the market price of such companies’ securities. If any such litigation is initiated against us, it could result in substantial costs and a diversion of management’s attention and resources, which could have a material adverse effect on our business, results of operations, financial condition and cash flows.
Item 1B. Unresolved Staff Comments.
Item 2. Properties.
| --- | --- |
We lease our executive offices, which are located at 220 South Ridgewood Avenue, Daytona Beach, Florida 32114. We lease offices at each of our 235 locations, with the exception of Jamestown, New York, where we own the building in which our office is located. We also own an airplane hangar in Daytona Beach, Florida, which sits upon land leased from Volusia Country, Florida. There are no outstanding mortgages on our owned properties. Our operating leases expire on various dates. These leases generally contain renewal options and rent escalation clauses based on increases in the lessors’ operating expenses and other charges. We expect that most leases will be renewed or replaced upon expiration. We believe that our facilities are suitable and adequate for present purposes, and that the productive capacity in such facilities is substantially being utilized. From time to time, we may have unused space and seek to sublet such space to third parties, depending on the demand for office space in the locations involved. In the future, we may need to purchase, build or lease additional facilities to meet the requirements projected in our long-term business plan. See Note 13 to the Consolidated Financial Statements for additional information on our lease commitments.
Item 3. Legal Proceedings.
| --- | --- |
We are subject to numerous litigation claims that arise in the ordinary course of business. We do not believe any of these are, or are likely to become, material to our business.
Item 4. Mine Safety Disclosures.
| --- | --- |
Not applicable.
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
| --- | --- |
Our common stock is listed on the New York Stock Exchange (“NYSE”) under the symbol “BRO.” The table below sets forth, for the quarterly periods indicated, the intra-day high and low sales prices for our common stock as reported on the NYSE Composite Tape, and the cash dividends declared on our common stock.
| High | Low | Cash Dividends Per Common Share | ||||||||||
| 2013 | ||||||||||||
| First Quarter | $ | 32.08 | $ | 25.31 | $ | 0.09 | ||||||
| Second Quarter | $ | 33.24 | $ | 30.00 | $ | 0.09 | ||||||
| Third Quarter | $ | 35.13 | $ | 30.55 | $ | 0.09 | ||||||
| Fourth Quarter | $ | 33.69 | $ | 27.76 | $ | 0.10 | ||||||
| 2014 | ||||||||||||
| First Quarter | $ | 32.88 | $ | 27.77 | $ | 0.10 | ||||||
| Second Quarter | $ | 31.29 | $ | 28.27 | $ | 0.10 | ||||||
| Third Quarter | $ | 33.46 | $ | 30.02 | $ | 0.10 | ||||||
| Fourth Quarter | $ | 33.40 | $ | 30.96 | $ | 0.11 |
On February 19, 2015, there were 143,520,097 shares of our common stock outstanding, held by approximately 1,178 shareholders of record.
We intend to continue to pay quarterly dividends, subject to continued capital availability and determination by our Board of Directors that cash dividends continue to be in the best interests of our stockholders. Our dividend policy may be affected by, among other items, our views on potential future capital requirements, including those relating to the creation and expansion of sales distribution channels and investments and acquisitions, legal risks, stock repurchase programs and challenges to our business model.
Table of Contents
Equity Compensation Plan Information
The following table sets forth information as of December 31, 2014, with respect to compensation plans under which the Company’s equity securities are authorized for issuance:
| Plan Category | Number of securities to be issued upon exercise of outstanding options, warrants and rights(a)(1) | Weighted-average exercise price of outstanding options, warrants and rights(b)(2) | Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column (a))(c)(3) | |||||||||
| Equity compensation plans approved by shareholders: | ||||||||||||
| Brown & Brown, Inc. 2000 Incentive Stock Option Plan | 470,356 | $ | 18.57 | — | ||||||||
| Brown & Brown, Inc. 2010 Stock Incentive Plan | N/A | N/A | 2,309,929 | |||||||||
| Brown & Brown, Inc. 1990 Employee Stock Purchase Plan | N/A | N/A | 734,317 | |||||||||
| Brown & Brown, Inc. Performance Stock Plan | N/A | N/A | — | |||||||||
| Total | 470,356 | $ | 18.57 | 3,044,246 | ||||||||
| Equity compensation plans not approved by shareholders | — | — | — | |||||||||
| (1) | In addition to the number of securities listed in this column, 2,964,103 shares are issuable upon the vesting of restricted stock granted under the Brown & Brown, Inc. Performance Stock Plan and the Brown & Brown, Inc. 2010 Stock Incentive Plan, which represents the maximum number of shares that can vest based on the achievement of certain performance criteria. |
|---|
| (2) | The weighted-average exercise price excludes outstanding restricted stock as there is no exercise price associated with these equity awards. |
|---|
| (3) | All of the shares available for future issuance under the Brown & Brown, Inc. 2000 Incentive Stock Option Plan, the Brown & Brown, Inc. Performance Stock Plan, and the Brown & Brown, Inc. 2010 Stock Incentive Plan may be issued in connection with options, warrants, rights, restricted stock, or other stock-based awards. |
|---|
Sales of Unregistered Securities
We did not sell any unregistered securities during 2014.
Issuer Purchases of Equity Securities
On July 18, 2014, our Board of Directors approved a common stock repurchase plan to authorize the repurchase of up to $200.0 million worth of shares of the Company’s common stock during the period running from the July 18, 2014 approval date to December 31, 2015. As of December 31, 2014, we have repurchased $50.0 million worth of shares of our common stock under the repurchase plan.
Table of Contents
The following table presents information with respect to our purchases of our common stock during the three months ended December 31, 2014.
| Period | Total Number of Shares Purchased(1) | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Approximate Dollar Value of Shares that May Yet Be Purchased Under the Plans or Programs | ||||||||||||
| October 1, 2014 to October 31, 2014 | 246,740 | $ | 30.49 | 246,000 | $ | 150,000,000 | ||||||||||
| November 1, 2014 to November 30, 2014 | — | — | — | $ | — | |||||||||||
| December 1, 2014 to December 31, 2014 | 4,701 | $ | 32.50 | — | $ | — | ||||||||||
| Total | 251,441 | $ | 30.53 | 246,000 | $ | 150,000,000 | ||||||||||
| (1) | With the exception of the 246,000 shares purchased in October 2014 as part of the final settlement of an accelerated share repurchase program initiated in September 2014, all of the shares reported above as purchased are attributable to shares withheld for employees’ payroll taxes and withholding taxes pertaining to the vesting of restricted shares awarded under our Performance Stock Plan and Incentive Stock Option Plan. |
|---|
Table of Contents
PERFORMANCE GRAPH
The following graph is a comparison of five-year cumulative total stockholder returns for our common stock as compared with the cumulative total stockholder return for the NYSE Composite Index, and a group of peer insurance broker and agency companies (Aon plc, Arthur J. Gallagher & Co, Marsh & McLennan Companies, and Willis Group Holdings plc). The returns of each company have been weighted according to such companies’ respective stock market capitalizations as of December 31, 2009 for the purposes of arriving at a peer group average. The total return calculations are based upon an assumed $100 investment on December 31, 2009, with all dividends reinvested.
| 12/09 | 12/10 | 12/11 | 12/12 | 12/13 | 12/14 | |||||||||||||||||||
| Brown & Brown, Inc. | 100.00 | 135.33 | 129.79 | 148.04 | 184.72 | 196.27 | ||||||||||||||||||
| NYSE Composite | 100.00 | 113.76 | 109.70 | 127.54 | 161.21 | 172.27 | ||||||||||||||||||
| Peer Group | 100.00 | 127.85 | 143.75 | 159.43 | 232.33 | 265.77 |
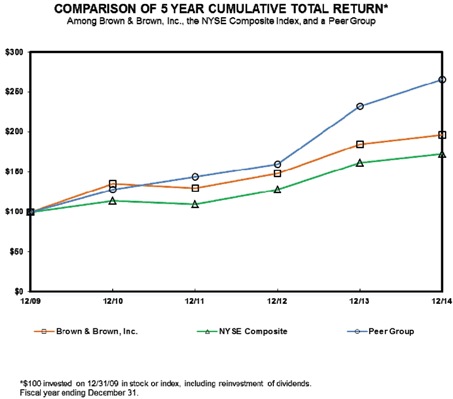
Table of Contents
Item 6. Selected Financial Data.
| --- | --- |
The following selected Consolidated Financial Data for each of the five fiscal years in the period ended December 31, 2014 have been derived from our Consolidated Financial Statements. Such data should be read in conjunction with Management’s Discussion and Analysis of Financial Condition and Results of Operations in Item 7 of Part II of this Annual Report and with our Consolidated Financial Statements and related Notes thereto in Item 8 of Part II of this Annual Report.
| Year Ended December 31 | ||||||||||||||||||||
| (in thousands, except per share data, number of employees and percentages | 2014 | 2013 | 2012 | 2011 | 2010 | |||||||||||||||
| REVENUES | ||||||||||||||||||||
| Commissions and fees | $ | 1,567,460 | $ | 1,355,503 | $ | 1,189,081 | $ | 1,005,962 | $ | 966,917 | ||||||||||
| Investment income | 747 | 638 | 797 | 1,267 | 1,326 | |||||||||||||||
| Other income, net | 7,589 | 7,138 | 10,154 | 6,313 | 5,249 | |||||||||||||||
| Total revenues | 1,575,796 | 1,363,279 | 1,200,032 | 1,013,542 | 973,492 | |||||||||||||||
| EXPENSES | ||||||||||||||||||||
| Employee compensation and benefits | 791,749 | 683,000 | 608,506 | 508,675 | 487,820 | |||||||||||||||
| Non-cash stock-based compensation | 19,363 | 22,603 | 15,865 | 11,194 | 6,845 | |||||||||||||||
| Other operating expenses | 235,328 | 195,677 | 174,389 | 144,079 | 135,851 | |||||||||||||||
| Loss on disposal | 47,425 | — | — | — | — | |||||||||||||||
| Amortization | 82,941 | 67,932 | 63,573 | 54,755 | 51,442 | |||||||||||||||
| Depreciation | 20,895 | 17,485 | 15,373 | 12,392 | 12,639 | |||||||||||||||
| Interest | 28,408 | 16,440 | 16,097 | 14,132 | 14,471 | |||||||||||||||
| Change in estimated acquisition earn-out payables | 9,938 | 2,533 | 1,418 | (2,206 | ) | (1,674 | ) | |||||||||||||
| Total expenses | 1,236,047 | 1,005,670 | 895,221 | 743,021 | 707,394 | |||||||||||||||
| Income before income taxes | 339,749 | 357,609 | 304,811 | 270,521 | 266,098 | |||||||||||||||
| Income taxes | 132,853 | 140,497 | 120,766 | 106,526 | 104,346 | |||||||||||||||
| Net income | $ | 206,896 | $ | 217,112 | $ | 184,045 | $ | 163,995 | $ | 161,752 | ||||||||||
| EARNINGS PER SHARE INFORMATION | ||||||||||||||||||||
| Net income per share — diluted | $ | 1.41 | $ | 1.48 | $ | 1.26 | $ | 1.13 | $ | 1.12 | ||||||||||
| Weighted average number of shares outstanding — diluted | 142,891 | 142,624 | 142,010 | 140,264 | 139,318 | |||||||||||||||
| Dividends declared per share | $ | 0.41 | $ | 0.37 | $ | 0.35 | $ | 0.33 | $ | 0.31 | ||||||||||
| YEAR-END FINANCIAL POSITION | ||||||||||||||||||||
| Total assets | $ | 4,956,458 | $ | 3,649,508 | $ | 3,128,058 | $ | 2,607,011 | $ | 2,400,814 | ||||||||||
| Long-term debt(1) | $ | 1,152,846 | $ | 380,000 | $ | 450,000 | $ | 250,033 | $ | 250,067 | ||||||||||
| Total shareholders’ equity | $ | 2,113,745 | $ | 2,007,141 | $ | 1,807,333 | $ | 1,643,963 | $ | 1,506,344 | ||||||||||
| Total shares outstanding at year-end | 143,486 | 145,419 | 143,878 | 143,352 | 142,795 | |||||||||||||||
| OTHER INFORMATION | ||||||||||||||||||||
| Number of full-time equivalent employees at year-end | 7,591 | 6,992 | 6,438 | 5,557 | 5,286 | |||||||||||||||
| Total revenues per average number of employees(2) | $ | 216,114 | $ | 203,020 | $ | 191,729 | (3) | $ | 186,949 | $ | 185,568 | |||||||||
| Stock price at year-end | $ | 32.91 | $ | 31.39 | $ | 25.46 | $ | 22.63 | $ | 23.94 | ||||||||||
| Stock price earnings multiple at year-end(4) | 23.3 | 21.2 | 20.2 | 20.0 | 21.4 | |||||||||||||||
| Return on beginning shareholders’ equity(5) | 10 | % | 12 | % | 11 | % | 11 | % | 12 | % |
| (1) | Represents the incremental new debt associated with the acquisition of Wright and evolution of our capital structure. Please refer to Part I, Item 7 “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and Note 8 “Long-Term Debt” for more details. |
|---|
| (2) | Represents total revenues divided by the average of the number of full-time equivalent employees at the beginning of the year and the number of full-time equivalent employees at the end of the year. |
|---|
| (3) | Of the 881 increase in the number of full-time equivalent employees from 2011 to 2012, 523 employees related to the January 9, 2012 acquisition of Arrowhead, and therefore, are considered to be full-time equivalent as of January 1, 2012. Thus, the average number of full-time equivalent employees for 2012 is considered to be 6,259. |
|---|
| (4) | Stock price at year-end divided by net income per share-diluted. |
|---|
| (5) | Represents net income divided by total shareholders’ equity as of the beginning of the year. |
|---|
Table of Contents
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
| --- | --- |
General
The following discussion should be read in conjunction with our Consolidated Financial Statements and the related Notes to those Consolidated Financial Statements included elsewhere in this Annual Report.
We are a diversified insurance agency, wholesale brokerage, insurance programs and services organization headquartered in Daytona Beach, Florida. As an insurance intermediary, our principal sources of revenue are commissions paid by insurance companies and, to a lesser extent, fees paid directly by customers. Commission revenues generally represent a percentage of the premium paid by an insured and are materially affected by fluctuations in both premium rate levels charged by insurance companies and the insureds’ underlying “insurable exposure units,” which are units that insurance companies use to measure or express insurance exposed to risk (such as property values, or sales and payroll levels) to determine what premium to charge the insured. Insurance companies establish these premium rates based upon many factors, including reinsurance rates paid by such insurance companies, none of which we control.
The volume of business from new and existing customers, fluctuations in insurable exposure units and changes in general economic and competitive conditions all affect our revenues. For example, level rates of inflation or a general decline in economic activity could limit increases in the values of insurable exposure units. Conversely, the increasing costs of litigation settlements and awards have caused some customers to seek higher levels of insurance coverage. Historically, our revenues have typically grown as a result of our focus on net new business growth and acquisitions.
We foster a strong, decentralized sales culture with a goal of consistent, sustained growth over the long term.
We increased revenues every year from 1993 to 2014, with the exception of 2009, when our revenues dropped 1.0%. Our revenues grew from $95.6 million in 1993 to $1.6 billion in 2014, reflecting a compound annual growth rate of 14.2%. In the same 21 year period, we increased net income from $8.1 million to $206.9 million in 2014, a compound annual growth rate of 16.7%.
The years 2007 through 2011 posed significant challenges for us and for our industry in the form of a prevailing decline in insurance premium rates, commonly referred to as a “soft market” and increased significant governmental involvement in the Florida insurance marketplace which resulted in a substantial loss of revenues for us. Additionally, beginning in the second half of 2008 and throughout 2011, there was a general decline in insurable exposure units as the consequence of the general weakening of the economy in the United States. As a result, from the first quarter of 2007 through the fourth quarter of 2011 we experienced negative internal revenue growth each quarter. The continued declining exposure units during 2010 and 2011 had a greater negative impact on our commissions and fees revenues than declining insurance premium rates.
Beginning in the first quarter of 2012, many insurance premium rates began to slightly increase. Additionally, in the second quarter of 2012, the general declines in insurable exposure units started to flatten and these exposures units subsequently began to gradually increase during the year. As a result, we recorded positive internal revenue growth for each quarter of 2012 for each of our four segments with two exceptions; the first quarter for the Retail Segment and the third quarter for the National Programs Segment, in which declines of only 0.7% and 3.3%, respectively, were experienced.
This growth trend has continued into 2014 with our consolidated internal revenue growth rate of 2.0%. Additionally, each of our four segments recorded positive internal revenue growth for each quarter in 2014 except for the Services Segment in the first quarter. The decline in the core organic commissions and fees revenues in the first quarter of 2014 for the Services Segment was the result of the significant revenue recorded at our Colonial Claims operation in the first quarter of 2013 attributable to Superstorm Sandy, for which no comparable revenues occurred in the first quarter of 2014. In the first quarter of 2013, Colonial Claims earned claims fees of $16.2 million as a direct result of the continued significant claims activity from Superstorm Sandy.
Table of Contents
We also earn “profit-sharing contingent commissions,” which are profit-sharing commissions based primarily on underwriting results, but which may also reflect considerations for volume, growth and/or retention. These commissions are primarily received in the first and second quarters of each year, based on the aforementioned considerations for the prior year(s). Over the last three years, profit-sharing contingent commissions have averaged approximately 4.3% of the previous year’s total commissions and fees revenue. Profit-sharing contingent commissions are included in our total commissions and fees in the Consolidated Statements of Income in the year received. The term “core commissions and fees” excludes profit-sharing contingent commissions and guaranteed supplemental commissions, and therefore represents the revenues earned directly from specific insurance policies sold, and specific fee-based services rendered. In contrast, the term “core organic commissions and fees” is our core commissions and fees less (i) the core commissions and fees earned for the first twelve months by newly-acquired operations and (ii) divested business (core commissions and fees generated from offices, books of business or niches sold or terminated during the comparable period). “Core organic commissions and fees” are reported in this manner in order to express the current year’s core commissions and fees on a comparable basis with the prior year’s core commissions and fees. The resulting net change reflects the aggregate changes attributable to (i) net new and lost accounts, (ii) net changes in our clients’ exposure units, and (iii) net changes in insurance premium rates.
Certain insurance companies offer guaranteed fixed-base agreements, referred to as “Guaranteed Supplemental Commissions” (“GSCs”) in lieu of profit –sharing contingent commissions. Since GSCs are not subject to the uncertainty of loss ratios, they are accrued throughout the year based on actual premiums written. As of December 31, 2014, we had $7.6 million of GSC revenue accrued and had earned $9.9 million of GSCs during 2014, most of which will be collected in the first quarter of 2015. For the twelve-month periods ended December 31, 2014, 2013 and 2012, we earned GSCs of $9.9 million, $8.3 million and $9.1 million, respectively.
Fee revenues relate to fees negotiated in lieu of commissions, which are recognized as services are rendered. Fee revenues have historically been generated primarily by: (1) our Services Segment, which provides insurance-related services, including third-party claims administration and comprehensive medical utilization management services in both the workers’ compensation and all-lines liability arenas, as well as Medicare set-aside services, Social Security disability and Medicare benefits advocacy services, and catastrophe claims adjusting services, and (2) our National Programs and Wholesale Brokerage Segments, which earn fees primarily for the issuance of insurance policies on behalf of insurance companies. These services are provided over a period of time, typically one year. However, in conjunction with our July 1, 2013 acquisition of Beecher Carlson, which has a primary focus on large retail customers that generally pay us fees directly, the fee revenues in our Retail Segment for 2014 have increased by $44.8 million to $117.8 million. Also, with the acquisition of Wright, which primarily receives income in the form of fees, fee revenue in our National Programs Segment increa
Showing the first 8K of 96K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
| --- | --- |
Market risk is the potential loss arising from adverse changes in market rates and prices, such as interest rates and equity prices. We are exposed to market risk through our investments, revolving credit line and term loan agreements.
Our invested assets are held as cash and cash equivalents, restricted cash and investments, available-for-sale equity securities, equity securities and certificates of deposit. These investments are subject to interest rate risk and equity price risk. The fair values of our cash and cash equivalents, restricted cash and investments, and certificates of deposit at December 31, 2014 and 2013 approximated their respective carrying values due to their short-term duration and, therefore, such market risk is not considered to be material.
We do not actively invest or trade in equity securities.
Table of Contents
Item 8. Financial Statements and Supplementary Data.
| --- | --- |
Index to Consolidated Financial Statements
Table of Contents
BROWN & BROWN, INC.
CONSOLIDATED STATEMENTS OF INCOME
| Year Ended December 31, | ||||||||||||
| (in thousands, except per share data) | 2014 | 2013 | 2012 | |||||||||
| REVENUES | ||||||||||||
| Commissions and fees | $ | 1,567,460 | $ | 1,355,503 | $ | 1,189,081 | ||||||
| Investment income | 747 | 638 | 797 | |||||||||
| Other income, net | 7,589 | 7,138 | 10,154 | |||||||||
| Total revenues | 1,575,796 | 1,363,279 | 1,200,032 | |||||||||
| EXPENSES | ||||||||||||
| Employee compensation and benefits | 791,749 | 683,000 | 608,506 | |||||||||
| Non-cash stock-based compensation | 19,363 | 22,603 | 15,865 | |||||||||
| Other operating expenses | 235,328 | 195,677 | 174,389 | |||||||||
| Loss on disposal | 47,425 | — | — | |||||||||
| Amortization | 82,941 | 67,932 | 63,573 | |||||||||
| Depreciation | 20,895 | 17,485 | 15,373 | |||||||||
| Interest | 28,408 | 16,440 | 16,097 | |||||||||
| Change in estimated acquisition earn-out payables | 9,938 | 2,533 | 1,418 | |||||||||
| Total expenses | 1,236,047 | 1,005,670 | 895,221 | |||||||||
| Income before income taxes | 339,749 | 357,609 | 304,811 | |||||||||
| Income taxes | 132,853 | 140,497 | 120,766 | |||||||||
| Net income | $ | 206,896 | $ | 217,112 | $ | 184,045 | ||||||
| Net income per share: | ||||||||||||
| Basic | $ | 1.43 | $ | 1.50 | $ | 1.28 | ||||||
| Diluted | $ | 1.41 | $ | 1.48 | $ | 1.26 | ||||||
| Weighted average number of shares outstanding: | ||||||||||||
| Basic | 140,944 | 141,033 | 139,364 | |||||||||
| Diluted | 142,891 | 142,624 | 142,010 | |||||||||
| Dividends declared per share | $ | 0.41 | $ | 0.37 | $ | 0.35 | ||||||
See accompanying notes to consolidated financial statements.
Table of Contents
BROWN & BROWN, INC.
CONSOLIDATED BALANCE SHEETS
| At December 31, | ||||||||
| (in thousands, except per share data) | 2014 | 2013 | ||||||
| ASSETS | ||||||||
| Current Assets: | ||||||||
| Cash and cash equivalents | $ | 470,048 | $ | 202,952 | ||||
| Restricted cash and investments | 259,769 | 250,009 | ||||||
| Short-term investments | 11,157 | 10,624 | ||||||
| Premiums, commissions and fees receivable | 424,547 | 395,915 | ||||||
| Reinsurance recoverable | 13,028 | — | ||||||
| Prepaid reinsurance premiums | 320,586 | — | ||||||
| Deferred income taxes | 25,431 | 29,276 | ||||||
| Other current assets | 45,542 | 39,260 | ||||||
| Total current assets | 1,570,108 | 928,036 | ||||||
| Fixed assets, net | 84,668 | 74,733 | ||||||
| Goodwill | 2,460,611 | 2,006,173 | ||||||
| Amortizable intangible assets, net | 784,642 | 618,888 | ||||||
| Investments | 19,862 | 16 | ||||||
| Other assets | 36,567 | 21,662 | ||||||
| Total assets | $ | 4,956,458 | $ | 3,649,508 | ||||
| LIABILITIES AND SHAREHOLDERS’ EQUITY | ||||||||
| Current Liabilities: | ||||||||
| Premiums payable to insurance companies | $ | 568,184 | $ | 534,360 | ||||
| Losses and loss adjustment reserve | 13,028 | — | ||||||
| Unearned premiums | 320,586 | — | ||||||
| Premium deposits and credits due customers | 83,313 | 80,959 | ||||||
| Accounts payable | 57,261 | 34,158 | ||||||
| Accrued expenses and other liabilities | 181,156 | 157,400 | ||||||
| Current portion of long-term debt | 45,625 | 100,000 | ||||||
| Total current liabilities | 1,269,153 | 906,877 | ||||||
| Long-term debt | 1,152,846 | 380,000 | ||||||
| Deferred income taxes, net | 341,497 | 291,704 | ||||||
| Other liabilities | 79,217 | 63,786 | ||||||
| Commitments and contingencies (Note 13) | ||||||||
| Shareholders’ Equity: | ||||||||
| Common stock, par value $0.10 per share; authorized 280,000 shares; issued 145,871 and outstanding 143,486 at 2014; and issued and outstanding 145,419 at 2013 | 14,587 | 14,542 | ||||||
| Additional paid-in capital | 405,982 | 371,960 | ||||||
| Treasury stock, at cost 2,385 and 0 shares at 2014 and 2013, respectively | (75,025 | ) | — | |||||
| Retained earnings | 1,768,201 | 1,620,639 | ||||||
| Total shareholders’ equity | 2,113,745 | 2,007,141 | ||||||
| To |
Showing the first 8K of 150K characters. Open the full section
Item 9. Changes in and Disagreements With Accountants on Accounting and Financial Disclosure.
| --- | --- |
There were no changes in or disagreements with accountants on accounting and financial disclosure in 2014.
Item 9A. Controls and Procedures.
| --- | --- |
Evaluation of Disclosure Controls and Procedures
We carried out an evaluation required by Rules 13a-15 and 15d-15 under the Exchange Act (the “Evaluation”), under the supervision and with the participation of our Chief Executive Officer (“CEO”) and Chief Financial Officer (“CFO”), of the effectiveness of our disclosure controls and procedures as defined in Rule 13a-15 and 15d-15 under the Exchange Act (“Disclosure Controls”) as of December 31, 2014. Based on the Evaluation, our CEO and CFO concluded that the design and operation of our Disclosure Controls were effective to ensure that information required to be disclosed by us in reports that we file or submit under the Exchange Act is (i) recorded, processed, summarized and reported within the time periods specified in SEC rules and forms and (ii) accumulated and communicated to our senior management, including our CEO and CFO, to allow timely decisions regarding required disclosure.
Changes in Internal Controls
We are in the process of integrating Pacific Resources Benefits Advisors, LLC, and The Wright Insurance Group, LLC into our overall internal control over financial reporting processes.
Except as described above, there have been no change in our internal control over financial reporting identified in connection with the Evaluation that occurred during the quarter ended December 31, 2014 that has materially affected, or is reasonably likely to materially affect, those controls.
Inherent Limitations of Internal Control Over Financial Reporting
Our management, including our principal executive officer and principal financial officer, does not expect that our Disclosure Controls and internal controls will prevent all error and all fraud. A control system, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. Further, the design of a control system must reflect the fact that there are resource constraints, and the benefits of controls must be considered relative to their costs. Because of the inherent limitations in all control systems, no evaluation of controls can provide absolute assurance that all control issues and instances of fraud, if any, within the company have been detected. These inherent limitations include the realities that judgments in decision-making can be faulty, and that breakdowns can occur because of simple error or mistake. Additionally, controls can be circumvented by the individual acts of some persons, by collusion of two or more people, or by management override of the control.
The design of any system of controls also is based in part upon certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions; over time, a control may become inadequate because of changes in conditions, or the degree of compliance with the policies or procedures may deteriorate. Because of the inherent limitations in a cost-effective control system, misstatements due to error or fraud may occur and not be detected.
CEO and CFO Certifications
Exhibits 31.1 and 31.2 are the Certifications of the acting CEO and the CFO, respectively. The Certifications are required in accordance with Section 302 of Sarbanes-Oxley (the “Section 302 Certifications”). This Item 9A is the information concerning the evaluation referred to in the Section 302 Certifications and this information should be read in conjunction with the Section 302 Certifications for a more complete understanding of the topics presented.
Table of Contents
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Board of Directors and Shareholders of
Brown & Brown, Inc.
Daytona Beach, Florida
We have audited the internal control over financial reporting of Brown & Brown, Inc. and subsidiaries (the “Company”) as of December 31, 2014, based on criteria established in Internal Control—Integrated Framework (1992) issued by the Committee of Sponsoring Organizations of the Treadway Commission. As described in Management’s Report on Internal Control Over Financial Reporting, management excluded from its assessment the internal control over financial reporting at The Wright Insurance Group, LLC and Pacific Resources Benefits Advisors, LLC (collectively the “2014 Excluded Acquisitions”), which were acquired during 2014 and whose financial statements constitute 23.5% of total assets, 6.8% of revenues, and (1.8)% of net income of the consolidated financial statement amounts as of and for the year ended December 31, 2014. Accordingly, our audit did not include the internal control over financial reporting of the 2014 Excluded Acquisitions. The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company’s internal control over financial reporting is a process designed by, or under the supervision of, the company’s principal executive and principal financial officers, or persons performing similar functions, and effected by the company’s board of directors, management, and other personnel to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of the inherent limitations of internal control over financial reporting, including the possibility of collusion or improper management override of controls, material misstatements due to error or fraud may not be prevented or detected on a timely basis. Also, projections of any evaluation of the effectiveness of the internal control over financial reporting to future periods are subject to the risk that the controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2014, based on the criteria established in Internal Control—Integrated Framework (1992) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated financial statements as of and for the year ended December 31, 2014 of the Company and our report dated February 27, 2015 expressed an unqualified opinion on those financial statements.
| /s/ DELOITTE & TOUCHE LLP |
| Certified Public Accountants |
| Miami, Florida |
| February 27, 2015 |
Table of Contents
Management’s Report on Internal Control Over Financial Reporting
The management of Brown & Brown, Inc. and its subsidiaries (“Brown & Brown”) is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Securities Exchange Act Rule 13a-15(f). Under the supervision and with the participation of management, including Brown & Brown’s principal executive officer and principal financial officer, Brown & Brown conducted an evaluation of the effectiveness of internal control over financial reporting based on the framework in Internal Control—Integrated Framework (1992) issued by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”).
In conducting Brown & Brown’s evaluation of the effectiveness of its internal control over financial reporting, Brown & Brown has excluded the following acquisitions completed during 2014: Pacific Resources Benefits Advisors, LLC, and The Wright Insurance Group, LLC (collectively the “2014 Excluded Acquisitions”), which were acquired during 2014 and whose financial statements constitute 23.5% of total assets, 6.8% of revenues, and (1.8%) of net income of the consolidated financial statement amounts as of and for the year ended December 31, 2014. Refer to Note 2 to the Consolidated Financial Statements for further discussion of these acquisitions and their impact on Brown & Brown’s Consolidated Financial Statements.
Based on Brown & Brown’s evaluation under the framework in Internal Control—Integrated Framework (1992) issued by the Committee of Sponsoring Organizations of the Treadway Commission_,_ management concluded that internal control over financial reporting was effective as of December 31, 2014. Management’s internal control over financial reporting as of December 31, 2014 has been audited by Deloitte & Touche LLP, an independent registered public accounting firm, as stated in their report which is included herein.
Brown & Brown, Inc.
Daytona Beach, Florida
February 27, 2015
| /s/ J. Powell Brown | /s/ R. Andrew Watts | |||
| J. Powell Brown Chief Executive Officer | R. Andrew Watts Executive Vice President, Chief Financial Officer and Treasurer |
Table of Contents
Item 9B. Other Information.
| --- | --- |
None
PART III
Item 10. Directors, Executive Officers and Corporate Governance.
| --- | --- |
The information required by this item regarding directors and executive officers is incorporated herein by reference to our definitive Proxy Statement to be filed with the SEC in connection with the Annual Meeting of Shareholders to be held in 2015 (the “2015 Proxy Statement”) under the headings “Management” and “Section 16(a) Beneficial Ownership Reporting.” We have adopted a code of ethics that applies to our principal executive officer, principal financial officer, and controller. A copy of our Code of Ethics for our Chief Executive Officer and our Senior Financial Officers and a copy of our Code of Business Conduct and Ethics applicable to all employees are posted on our Internet website, at www.bbinsurance.com, and are also available upon written request directed to Corporate Secretary, Brown & Brown, Inc., 220 South Ridgewood Avenue, Daytona Beach, Florida 32114, or by telephone to (386)-239-5752. Any approved amendments to, or waiver of, any provision of the Code of Business Conduct and Ethics will be posted on our website at the above address.
Item 11. Executive Compensation.
| --- | --- |
The information required by this item is incorporated herein by reference to the 2015 Proxy Statement under the heading “Executive Compensation.”
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
| --- | --- |
The information required by this item is incorporated herein by reference to the 2015 Proxy Statement under the heading “Security Ownership of Management and Certain Beneficial Owners.”
Information regarding equity compensation plans required by this item is included in Item 5 of Part II of this report and is incorporated into this item by reference.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
| --- | --- |
The information required by this item is incorporated herein by reference to the 2015 Proxy Statement under the heading “Management—Certain Relationships and Related Transactions.”
Item 14. Principal Accounting Fees and Services.
| --- | --- |
The information required by this item is incorporated herein by reference to the 2015 Proxy Statement under the heading “Fees Paid to Deloitte & Touche LLP.”
Table of Contents
PART IV
Item 15. Exhibits and Financial Statement Schedules.
| --- | --- |
The following documents are filed as part of this Report:
- Financial statements
Reference is made to the information set forth in Part II, Item 8 of this Report, which information is incorporated by reference.
- Consolidated Financial Statement Schedules.
All required Financial Statement Schedules are included in the Consolidated Financial Statements or the Notes to Consolidated Financial Statements.
- Exhibits
The following exhibits are filed as a part of this Report:
| 3.1 | Articles of Amendment to Articles of Incorporation (adopted April 24, 2003) (incorporated by reference to Exhibit 3a to Form 10-Q for the quarter ended March 31, 2003), and Amended and Restated Articles of Incorporation (incorporated by reference to Exhibit 3a to Form 10-Q for the quarter ended March 31, 1999). | |
| 3.2 | Bylaws (incorporated by reference to Exhibit 3.2 to Form 8-K filed on March 2, 2012). | |
| 4.1 | Indenture, dated as of September 18, 2014, between the Registrant and U.S. Bank National Association (incorporated by reference to Exhibit 4.1 to Form 8-K filed on September 18, 2014). | |
| 4.2 | First Supplemental Indenture, dated as of September 18, 2014, between the Registrant and U.S. Bank National Association (incorporated by reference to Exhibit 4.2 to Form 8-K filed on September 18, 2014). | |
| 4.3 | Form of the Registrant’s 4.200% Notes due 2024 (incorporated by reference to Exhibit 4.3 to Form 8-K filed on September 18, 2014). | |
| 10.1 | Lease of the Registrant for office space at 220 South Ridgewood Avenue, Daytona Beach, Florida dated August 15, 1987 (incorporated by reference to Exhibit 10a(3) to Form 10-K for the year ended December 31,1993), as amended by Letter Agreement dated June 26, 1995; First Amendment to Lease dated August 2, 1999; Second Amendment to Lease dated December 11, 2001; Third Amendment to Lease dated August 8, 2002; Fourth Amendment to Lease dated October 26, 2004 (incorporated by reference to Exhibit 10.2(a) to Form 10-K for the year ended December 31, 2005); Fifth Amendment to Lease dated 2006 (incorporated by reference to Exhibit 10.1(a) to Form 10-K for the year ended December 31, 2010); Sixth Amendment to Lease dated August 17, 2009 (incorporated by reference to Exhibit 10.1(a) to Form 10-K for the year ended December 31, 2010); Seventh Amendment to Lease dated March 25, 2011 (incorporated by reference to Exhibit 10.1(a) to Form 10-K for the year ended December 31, 2012); Eighth Amendment to Lease dated April 16, 2012 (incorporated by reference to Exhibit 10.1(a) to Form 10-K for the year ended December 31, 2012); and Ninth Amendment to Lease dated December 5, 2012 (incorporated by reference to Exhibit 10.1(a) to Form 10-K for the year ended December 31, 2012). | |
| 10.2 | Indemnity Agreement dated January 1, 1979, among the Registrant, Whiting National Management, Inc., and Pennsylvania Manufacturers’ Association Insurance Company (incorporated by reference to Exhibit 10g to Registration Statement No. 33-58090 on Form S-4). | |
| 10.3 | Agency Agreement dated January 1, 1979 among the Registrant, Whiting National Management, Inc., and Pennsylvania Manufacturers’ Association Insurance Company (incorporated by reference to Exhibit 10h to Registration Statement No.33-58090 on Form S-4). | |
| 10.4(a) | Employment Agreement, dated and effective as of July 1, 2009 between the Registrant and J. Hyatt Brown (incorporated by reference to Exhibit 10.1 to Form 10-Q for the quarter ended June 30, 2009). | |
| 10.4(b) | Employment Agreement, dated as of October 8, 1996, between the Registrant and J. Powell Brown (incorporated by reference to Exhibit 10.4(c) to Form 10-K for the year ended December 31, 2007). |
Table of Contents
| 10.4(c) | Employment Agreement, dated as of August 1, 1994, between the Registrant and Cory T. Walker (incorporated by reference to Exhibit 10.4(f) to Form 10-K for the year ended December 31, 2009). | |
| 10.4(d) | Employment Agreement, dated as of October 27, 1997, between the Registrant and Charles H. Lydecker (incorporated by reference to Exhibit 10.4(g) to Form 10-K for the year ended December 31, 2012). | |
| 10.4(e) | Employment Agreement, dated as of June 1, 2009, between the Registrant and Anthony Strianese (incorporated by reference to Exhibit 10.4(h) to Form 10-K for the year ended December 31, 2012). | |
| 10.4(f) | Transition Agreement, dated as of November 7, 2013, between the Registrant and Cory T. Walker (incorporated by reference to Exhibit 10.4(i) to Form 10-K for the year ended December 31, 2013). | |
| 10.4(g) | Executive Employment Agreement, effective as of February 17, 2014, between the Registrant and R. Andrew Watts (incorporated by reference to Exhibit 10.2 to Form 10-Q for the quarter ended March 31, 2014). | |
| 10.4(h) | Transition Equity Bonus Performance-Triggered Stock Grant Agreement, effective as of February 17, 2014, between the Registrant and R. Andrew Watts (incorporated by reference to Exhibit 10.3 to the Form 10-Q for the quarter ended March 31, 2014). | |
| 10.4(i) | Form of Employment Agreement (incorporated by reference to Exhibit 10.2 to Form 10-Q for the quarter ended September 30, 2014). | |
| 10.5 | Registrant’s 2000 Incentive Stock Option Plan for Employees (incorporated by reference to Exhibit 4 to Registration Statement No. 333-43018 on Form S-8 filed on August 3, 2000). | |
| 10.6(a) | Registrant’s Stock Performance Plan (incorporated by reference to Exhibit 4 to Registration Statement No. 333-14925 on Form S-8 filed on October 28, 1996). | |
| 10.6(b) | Registrant’s Stock Performance Plan as amended, effective January 23, 2008 (incorporated by reference to Exhibit 10.6(b) to Form 10-K for the year ended December 31, 2007). | |
| 10.6(c) | Registrant’s Stock Performance Plan as amended, effective July 21, 2009 (incorporated by reference to Exhibit 10.1 to Form 10-Q for the quarter ended September 30, 2009). | |
| 10.7 | Registrant’s 2010 Stock Incentive Plan (incorporated by reference to Exhibit 10.1 to Form 10-Q for the quarter ended March 31, 2010). | |
| 10.8(a) | Form of Performance-Based Stock Grant Agreement under 2010 Stock Incentive Plan (incorporated by reference to Exhibit 10.16 to Form 10-K for the year ended December 31, 2010). | |
| 10.8(b) | Form of Performance-Triggered Stock Grant Agreement under 2010 Stock Incentive Plan (incorporated by reference to Exhibit 10.1 to Form 8-K filed on July 8, 2013). | |
| 10.9 | Amended and Restated Revolving and Term Loan Credit Agreement dated as of January 9, 2012 by and between the Registrant and SunTrust Bank (incorporated by reference to Exhibit 10.17 to Form 10-K for the year ended December 31, 2011). | |
| 10.10 | Promissory Note dated January 9, 2012, by and between Registrant and JPMorgan Chase Bank, N.A (incorporated by reference to Exhibit 10.18 to Form 10-K for the year ended December 31, 2011). | |
| 10.11 | Letter Agreement dated January 9, 2012 by and between Registrant and JPMorgan Chase Bank, N.A (incorporated by reference to Exhibit 10.19 to Form 10-K for the year ended December 31, 2011). | |
| 10.12 | Term Loan Agreement dated as of January 26, 2012 by and between the Registrant and JPMorgan Chase Bank, N.A (incorporated by reference to Exhibit 10.20 to Form 10-K for the year ended December 31, 2011). | |
| 10.13 | Merger Agreement, dated December 15, 2011, among the Registrant, Pacific Merger Corp., a wholly-owned subsidiary of the Registrant, Arrowhead General Insurance Agency Superholding Corporation, and Spectrum Equity Investors V, L.P. (incorporated by reference to Exhibit 10.16 to Form 10-K for the year ended December 31, 2011). | |
| 10.14 | Merger Agreement, dated May 21, 2013, among Brown & Brown, Inc., Brown & Brown Merger Co., Beecher Carlson Holdings, Inc., and BC Sellers’ Representative LLC, solely in its capacity as the representative of Beecher’s shareholders (incorporated by reference to Exhibit 10.1 to Form 10-Q for the quarter ended June 30, 2013). |
Table of Contents
| 10.15 | Agreement and Plan of Merger by and among The Wright Insurance Group, LLC, the Registrant, Brown & Brown Acquisition Group, LLC and Teiva Securityholders Representative, LLC, solely in its capacity as the Representative dated January 15, 2014 (incorporated by reference to Exhibit 10.1 to Form 10-Q for the quarter ended March 31, 2014). | |
| 10.16 | Credit Agreement dated as of April 16, 2014, among the Registrant, JPMorgan Chase Bank, N.A., Bank of America, N.A., Royal Bank of Canada and SunTrust Bank (incorporated by reference to Exhibit 10.4 to Form 10-Q for the quarter ended March 31, 2014). | |
| 21 | Subsidiaries of the Registrant. | |
| 23 | Consent of Deloitte & Touche LLP. | |
| 24 | Powers of Attorney. | |
| 31.1 | Rule 13a-14(a)/15d-14(a) Certification by the Chief Executive Officer of the Registrant. | |
| 31.2 | Rule 13a-14(a)/15d-14(a) Certification by the Chief Financial Officer of the Registrant. | |
| 32.1 | Section 1350 Certification by the Chief Executive Officer of the Registrant. | |
| 32.2 | Section 1350 Certification by the Chief Financial Officer of the Registrant. | |
| 101.INS | XBRL Instance Document. | |
| 101.SCH | XBRL Taxonomy Extension Schema Document. | |
| 101.CAL | XBRL Taxonomy Extension Calculation Linkbase Document. | |
| 101.DEF | XBRL Taxonomy Extension Definition Linkbase Document. | |
| 101.LAB | XBRL Taxonomy Extension Label Linkbase Document. | |
| 101.PRE | XBRL Taxonomy Extension Presentation Linkbase Document. |
Table of Contents
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| BROWN & BROWN, INC. Registrant | ||||
| Date: February 27, 2015 | By: | /s/ J. Powell Brown | ||
| J. Powell Brown | ||||
| Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the date indicated.
| Signature | Title | Date | ||
| /s/ J. Powell Brown J. Powell Brown | Director; President and Chief Executive Officer (Principal Executive Officer) | February 27, 2015 | ||
| /s/ R. Andrew Watts R. Andrew Watts | Executive Vice President, Chief Financial Officer and Treasurer (Principal Financial and Accounting Officer) | February 27, 2015 | ||
| * J. Hyatt Brown | Chairman of the Board | February 27, 2015 | ||
| * Samuel P. Bell, III | Director | February 27, 2015 | ||
| * Hugh M. Brown | Director | February 27, 2015 | ||
| * Bradley Currey, Jr. | Director | February 27, 2015 | ||
| * Theodore J. Hoepner | Director | February 27, 2015 | ||
| * James S. Hunt | Director | February 27, 2015 | ||
| * Toni Jennings | Director | February 27, 2015 | ||
| * Timothy R.M. Main | Director | February 27, 2015 | ||
| * H. Palmer Proctor, Jr. | Director | February 27, 2015 | ||
| * Wendell Reilly | Director | February 27, 2015 | ||
| * Chilton D. Varner | Director | February 27, 2015 |
| *By: | /s/ Robert W. Lloyd | |
| Robert W. Lloyd Attorney-in-Fact |