 filings.tools
Item 1. Business.
35K characters. Original on sec.gov · Markdown
Item 1. Business.
General
Brown & Brown is a diversified insurance agency, wholesale brokerage, insurance programs and service organization with origins dating from 1939 and is headquartered in Daytona Beach, Florida. The Company markets and sells insurance products and services, primarily in the property, casualty and employee benefits areas. We provide our customers with quality, non-investment insurance contracts, as well as other targeted, customized risk management products and services. As an agent and broker, we do not assume underwriting risks with the exception of the activity in The Wright Insurance Group, LLC (“Wright”). Within Wright, we operate a write-your-own flood insurance carrier, Wright National Flood Insurance Company (“WNFIC”). WNFIC’s underwriting business consists entirely of policies written pursuant to the National Flood Insurance Program (“NFIP”), the program administered by the Federal Emergency Management Agency (“FEMA”), and excess flood policies which are fully reinsured, thereby substantially eliminating WNFIC’s exposure to underwriting risk, as these policies are backed by either FEMA or a reinsurance carrier with an AM Best Company rating of “A” or better.
The Company is compensated for its services primarily by commissions paid by insurance companies and to a lesser extent, by fees paid directly by customers for certain services. Commission revenues are usually a percentage of the premium paid by the insured and generally depend upon the type of insurance, the particular insurance company and the nature of the services provided by us. In some limited cases, we share commissions with other agents or brokers who have acted jointly with us in a transaction. We may also receive from an insurance company a “profit-sharing contingent commission,” which is a profit-sharing commission based primarily on underwriting results, but may also contain considerations for volume, growth and/or retention. Fee revenues are generated primarily by: (1) our Services Segment, which provides insurance-related services, including third-party claims administration and comprehensive medical utilization management services in both the workers’ compensation and all-lines liability arenas, as well as Medicare Set-aside services, Social Security disability and Medicare benefits advocacy services, and other claims adjusting services, (2) our National Programs and Wholesale Brokerage Segments, which earn fees primarily for the issuing of insurance policies on behalf of insurance carriers, and (3) our Retail Segment for fees received in lieu of commissions. The amount of our revenues from commissions and fees is a function of several factors, including continued new business production, retention of existing customers, acquisitions and fluctuations in insurance premium rates and “insurable exposure units,” which are units that insurance companies use to measure or express insurance exposed to risk (such as property values, sales and payroll levels) to determine what premium to charge the insured. Insurance companies establish these premium rates based upon many factors, including loss experience, risk profile and reinsurance rates paid by such insurance companies, none of which we control.
As of December 31, 2020, our activities were conducted in 332 domestic locations in 43 states, and 9 international locations in Canada, England, Bermuda, and the Cayman Islands.
Industry Overview
Premium pricing within the property and casualty insurance underwriting (risk-bearing) industry has historically been cyclical in nature and has varied widely based upon market conditions with a “hard” market in which premium rates are increasing or a “soft” market, characterized by stable or declining premium rates in many lines and geographic areas. Premium pricing is influenced by many factors including loss experience, interest rates and the availability of capital being deployed into the insurance market in search of returns.
Segment Information
Our business is divided into four reportable segments: (1) the Retail Segment, (2) the National Programs Segment, (3) the Wholesale Brokerage Segment and (4) the Services Segment. The Retail Segment provides a broad range of insurance products and services to commercial, public and quasi-public entities, and to professional and individual customers, as well as non-insurance warranty services and products through our automobile dealer services (“F&I”) businesses. The National Programs Segment, which acts as a managing general agent (“MGA”), provides professional liability and related package products for certain professionals, a range of insurance products for individuals, flood coverage, and targeted products and services designated for specific industries, trade groups, governmental entities and market niches, all of which are delivered through a nationwide network of independent agents, including Brown & Brown retail agents. The Wholesale Brokerage Segment markets and sells excess and surplus commercial and personal lines insurance, primarily through independent agents and brokers, as well as Brown & Brown retail agents. The Services Segment provides insurance-related services, including third-party claims administration and adjusting services, comprehensive medical utilization management services in both the workers’ compensation and all-lines liability arenas, as well as Medicare Set-aside services and Social Security disability benefits advocacy services.
The following table summarizes (1) the commissions and fees generated by each of our reportable operating segments for 2020, 2019 and 2018, and (2) the percentage of our total commissions and fees represented by each segment for each such period:
| (in thousands, except percentages) | 2020 | % | 2019 | % | 2018 | % | ||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Retail Segment | $ | 1,471,352 | 56.5 | % | $ | 1,366,016 | 57.3 | % | $ | 1,041,691 | 51.8 | % | ||||||||||||
| National Programs Segment | 609,842 | 23.4 | % | 516,915 | 21.7 | % | 493,878 | 24.6 | % | |||||||||||||||
| Wholesale Brokerage Segment | 352,161 | 13.5 | % | 309,426 | 13.0 | % | 286,364 | 14.2 | % | |||||||||||||||
| Services Segment | 174,012 | 6.7 | % | 193,641 | 8.1 | % | 189,041 | 9.4 | % | |||||||||||||||
| Other | (1,259 | ) | (0.1 | )% | (1,261 | ) | (0.1 | )% | (1,117 | ) | (0.0 | )% | ||||||||||||
| Total | $ | 2,606,108 | 100.0 | % | $ | 2,384,737 | 100.0 | % | $ | 2,009,857 | 100.0 | % |
We conduct all of our operations within the United States of America, except for one Wholesale Brokerage operation based in England, one National Programs operation in Canada and Retail operations based in Bermuda and The Cayman Islands. These operations generated $35.1 million, $17.7 million and $15.2 million of revenues for the years ended December 31, 2020, 2019 and 2018, respectively. We do not have any material foreign long-lived assets.
See Note 17 to the Consolidated Financial Statements and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” for additional segment financial data relating to our business.
Retail Segment
The Retail Segment provides a broad range of insurance products and services to commercial, public and quasi-public, professional and individual insured customers, and non-insurance services and products through our automobile dealer services (“F&I”) businesses. Significant lines of coverage and capabilities are:
| Builders Risk | Group Medical & Pharmaceutical | Property |
| Commercial Auto | Homeowners | Reinsurance |
| Crop & Hail | Inland Marine | Retirement Benefit |
| Cyber | Long Term Disability | Risk Mitigating Warranty Products |
| Directors & Officers | Management Liability | Short Term Disability |
| Errors & Omissions | Medical Stop Loss | Term Life |
| Excess Liability | Personal Auto | Umbrella |
| General Liability | Prescription Drug | Workers Compensation |
| Group Dental |
No material part of our retail business is attributable to a single customer or a few customers. During 2020, commissions and fees from our largest single Retail Segment customer represented four tenths of one percent (0.4%) of the Retail Segment’s total commissions and fees.
As of December 31, 2020, our Retail Segment employed 5,764 employees. Our Retail Segment has physical locations in 39 states and Bermuda and is licensed to do business in all 50 states. In connection with the selling and marketing of insurance coverages, we provide a broad range of related services to our customers, such as risk management strategies, loss control surveys and analysis, consultation in connection with placing insurance coverages and claims processing.
National Programs Segment
As of December 31, 2020, our National Programs Segment employed 2,508 employees. The National Programs Segment specializes in the development and management of insurance program business, often designed for niche, underserved markets. We offer program management expertise for insurance carrier partners across numerous lines of business, which can be grouped into five broad categories: (1) Professional Programs, (2) Personal Lines Programs, (3) Commercial Programs, (4) Public Entity-Related Programs, and (5) Specialty Lines Program:
Professional Programs. Professional liability and related package insurance products are tailored to the needs of professionals in the following areas: dentistry, legal, eyecare, insurance, financial, physicians, and real estate title professionals. Professional liability programs also offer supplementary insurance-related products to include weddings, events, medical facilities, and cyber liability.
Personal Lines Programs. Personal lines programs offer a variety of insurance products to personal lines consumers including homeowners and personal property policies; residential earthquake; as well as private passenger automobile and motorcycle coverage.
Commercial Lines Programs. Commercial programs serve a broad segment of industries with our Core Commercial offering. Specific industries and market niches are served by our specialty programs including automotive aftermarket, professional and amateur sports, motorsports, special events, and the entertainment industry; commercial transportation and trucking; forestry; manufactured housing; and workers’ compensation.
Public Entity Programs. Public entity programs range from providing fully insured programs to establishing risk retention insurance pools, and excess and facultative specific coverages, including administration of various insurance trusts for cities, counties, municipalities, school boards, special taxing districts, and quasi-governmental agencies.
Specialty Programs. Specialty programs include flood insurance, commercial difference-in-conditions (earthquake), all-risk commercial property, coastal property programs including wind, lender-placed solutions, sovereign Indian nations, and parcel insurance.
Wholesale Brokerage Segment
As of December 31, 2020, our Wholesale Brokerage Segment employed 1,578 employees. Our Wholesale Brokerage Segment markets and sells excess and surplus commercial insurance products and services to retail insurance agencies (including Brown & Brown retail offices). The Wholesale Brokerage Segment offices represent various U.S. and U.K. surplus lines insurance companies. Additionally, certain offices are also Lloyd’s of London correspondents. The Wholesale Brokerage Segment also represents admitted insurance companies for purposes of affording access to such companies for smaller agencies that otherwise do not have access to large insurance company representation. Excess and surplus insurance products encompass many insurance coverages, including personal lines, homeowners, yachts, jewelry, commercial property and casualty, commercial automobile, garage, restaurant, builder’s risk and inland marine lines. Difficult-to-insure general liability and products liability coverages are a specialty, as is excess workers’ compensation coverage. Wholesale brokers solicit business through mailings and direct contact with retail agency representatives. During 2020, commissions and fees from our largest Wholesale Brokerage Segment customer represented approximately 1.3% of the Wholesale Brokerage Segment’s total commissions and fees.
Services Segment
As of December 31, 2020, our Services Segment employed 936 employees and provided a wide range of insurance-related services.
Below are brief descriptions of the capabilities within the Services Segment.
Social Security Advocacy - assists individuals throughout the United States who are seeking to establish eligibility for coverage under the federal Social Security Disability program and provides health plan selection and enrollment assistance for Medicare beneficiaries. We work closely with employer sponsored group life, disability and health plan participants to assist disabled individuals in receiving the education, advocacy and benefit coordination assistance necessary to achieve the fastest possible benefit approvals. In addition, we provide second injury fund recovery services to the workers’ compensation insurance market.
Claims Administration - provides third-party administration (“TPA”) services for commercial and personal property and casualty, medical, vocational, and professional liability insurance markets on a nationwide basis, providing claims adjusting, administration, subrogation, litigation and data management, claims investigations services, claim investigations, and audit services to insurance companies, self-insureds, public municipalities, insurance brokers and corporate entities. We source claims activity from various Arrowhead programs in our National Programs Segment, as well as from third parties.
Medicare Secondary Payer compliance and Medicare Set-Aside – provides statutory compliance services, conditional payment negotiation and resolution, structured settlements/annuity funding, professional administration, and a post-settlement durable medical equipment and pharmacy program administration.
Self-Insured Trust Administration - provides TPA services for government entities and self-funded or fully-insured workers’ compensation and liability plans and trusts including claims administration and a dedicated subrogation recovery department.
Workers’ Compensation and Liability Plan Administration - provides claims administration, cost containment consulting services for secondary disability and subrogation recoveries, certified and non-certified medical management programs, access to medical networks, case management, utilization review services and risk management services such as loss control.
In 2020, our five largest contracts represented approximately 20.0% of fees revenues in our Services Segment.
Competition
The insurance intermediary business is highly competitive, and numerous firms actively compete with us for customers and insurance markets. Competition in the insurance business is largely based upon innovation, knowledge, understanding of terms and conditions of coverage, quality of service and price. A number of firms and banks with substantially greater resources and market presence compete with us.
A number of insurance companies directly sell insurance, primarily to individuals or small enterprises, and do not pay commissions to third-party agents and brokers. In addition, the internet and start-up technology companies continue to be a source for direct placement of personal lines or small business insurance. We have our own technology capabilities to also serve single-line and small businesses. While it is difficult to quantify the impact on our business from individuals or small businesses purchasing insurance over the Internet, we believe this risk would generally be isolated to personal lines customers with single-line coverage, or small businesses that do not have a complex insurance program, which represent a small portion of our overall Retail or National Programs segments.
Regulation, Licensing and Agency Contracts
We and/or our designated employees must be licensed to act as agents, brokers, intermediaries or third-party administrators by state regulatory authorities in the locations in which we conduct business. Regulations and licensing laws vary by individual state and international location and are often complex.
The applicable licensing laws and regulations in all states and international jurisdictions are subject to amendment or reinterpretation by regulatory authorities, and such authorities are vested in most cases with relatively broad discretion as to the granting, revocation, suspension and renewal of licenses. We endeavor to monitor the licensing of our employees, but the possibility exists that we and/or our employees could be excluded or temporarily suspended from carrying on some or all of our activities in a particular jurisdiction in addition to being subjected to fines.
Human Capital
At December 31, 2020, the Company had 11,136 employees. We have agreements with our sales employees and certain other employees that include provisions: (1) protecting our confidential information and trade secrets, (2) restricting their ability post-employment to solicit the business of our customers, and (3) preventing the hiring of our employees for a period of time after separation from employment with us. The enforceability of such agreements varies from state to state depending upon applicable law and factual circumstances. The majority of our employment relationships are at-will and terminable by either party at any time; however, the covenants regarding confidential information and non-solicitation of our customers and employees generally extend for a period of at least two years after cessation of employment.
None of our employees are subject to a collective bargaining agreement and we consider our relations with our employees to be good.
Our Guiding Principles
Every successful team thrives on the diversity of talent, thought, experience, character, and work ethic. Our continued success depends on the full and effective recruitment and enhancement of the most qualified teammates. Put simply, Brown & Brown is a Meritocracy®—our people rise according to their merits. We pride ourselves on creating an open, diverse, performance-driven, and transparent culture that celebrates and recognizes teammates at all levels.
Culture
Our unique culture drives our results and is a key component of the Company’s strategy. Brown & Brown is a lean, decentralized, highly competitive, profit-oriented sales and service organization composed of people of the highest integrity and quality, bound together by clearly defined goals and prideful relationships. We consider ourselves teammates, not “employees,” and our success is guided by leaders, not managers. Our Company believes our teammates are far more than ordinary, and we know they achieve extraordinary results because they are challenged, empowered, and rewarded for doing so.
Soliciting Feedback.
We regularly solicit anonymous feedback from our teammates, and we are proud that 94% of our teammates say Brown & Brown is a Great Place to Work®. We know these results stem from the fact that we view the personal health and well-being of our teammates and their families as paramount. As an organization, we value, encourage, and support these priorities, and by doing so, we cultivate a productive and highly engaged team that drives our Company to thrive and succeed.
Human Capital Credentials
Nearly a quarter of our Company is owned by our teammates, which we believe cultivates a unique ownership culture. We strive to provide multiple opportunities for teammates to share in the ownership of Brown & Brown and to create personal wealth, including through our employee stock purchase program, our 401(k) plan, and long-term equity grants. We estimate that more than 60% of our teammates own stock in our Company, establishing an ownership mindset that we believe demonstrates the strongest vote of confidence from our teammates. This ownership mindset also influences how we operate, including how we invest in our business, and the work we do for our customers. In addition to being a Great Place to Work® certified company, Brown & Brown, Inc. was recognized as a Best Workplace for Women and Millennials in 2020.
Our Workforce.
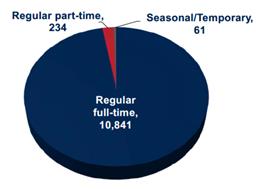
The vast majority of our teammates are regular full-time employees. Our goal is to provide our teammates with careers, not jobs. In addition to our regular full-time teammates, we also employ regular part-time teammates and seasonal/temporary teammates. The following chart illustrates the categorical breakdown of our teammate population, which includes all persons who receive wages or salaries through the Company’s payroll:
| • | Regular full-time teammates: Teammates who work at least a 32-hour workweek for an indefinite period of time. All regular full-time teammates are generally eligible for all employment benefits provided by the Company to its teammates. |
|---|
| • | Regular part-time teammates: Teammates working less than a 32-hour workweek for an indefinite period of time. Depending on the average hours worked per week, regular part-time teammates may be eligible for limited employment benefits as specified in the terms of the particular employment benefit plan or policy. |
|---|
| • | Seasonal/temporary teammates: A teammate who is hired as an interim replacement, to temporarily supplement our workforce, or to assist on the completion of a specific project, other than those supplied under contract by an outside agency. Employment assignments in this category are typically of a limited duration. |
|---|
Recruitment; Education and Development
A critical part of the Company’s strategy revolves around the recruitment and development of our teammates; to drive our growth by offering innovative risk management solutions to our customers, we often think of ourselves as being in the people recruiting and enhancing business. We actively recruit in all of our offices and at all levels of our organization. We have been particularly successful at building our talented workforce by hiring recent college graduates, mid-level professionals with experience outside of the insurance industry, and seasoned insurance professionals with a desire to elevate their careers. We also recruit and develop talent through our college internship program, which leverages our strong relationships with a number of key colleges and universities.
We also build our team by completing high-quality acquisitions that fit culturally and make sense financially. In 2020, we added approximately 796 new teammates through 25 strategic acquisitions.
We invest heavily in our teammates' education and development because we believe it improves their capabilities, engagement, satisfaction, and productivity, which, in turn, positively impacts how we serve our customers and, ultimately, our Company’s performance and results. One of the pillars of our educational program is “Brown & Brown University,” a rigorous training program we believe distinguishes us from our industry peers, offering comprehensive sales, technical, and other courses for new producers, office leaders, and other teams within the organization. In addition, the Company recently established the Brown & Brown Education Assistance Program, which provides tuition reimbursement and student loan repayment assistance, as well as the National Merit Brown & Brown Scholarship.
The Company recently launched a “Peer Partnership Program” designed to connect individuals from across our organization and support them in building new partnerships, expanding their networks, and experiencing our Company culture through different perspectives.
Diversity, Inclusion, and Belonging
The Company believes diversity of thought and experiences results in better outcomes and empowers our teammates to make more meaningful contributions to our customers, our Company, and the communities in which we live. Accordingly, as part of our strategy, we recently announced the formation of the Brown & Brown Diversity, Inclusion, and Belonging Task Force. This task force is composed of individuals with diverse experience and expertise, and it seeks to collect ideas, thoughts, and stories from our teammates across our operating segments and locations. Our goal is to ensure a wide range of perspectives are considered as we develop a strategic framework around promoting diversity, inclusion, and belonging throughout the Company. To this end, the task force has already undertaken the following initiatives to understand the Company’s current strengths and areas for development, which will drive our go-forward priorities:
| • | launched a Company-wide teammate survey on diversity, inclusion, and belonging that allows us to gather baseline metrics; |
|---|
| • | conducted focus group sessions, as well as one-on-one outreach and conversations, that foster meaningful discussions on our future strategy; |
|---|
| • | completed an assessment to analyze the strategies, programs, and messaging of companies with similar size and composition, as well as peers across the insurance industry; |
|---|
| • | launched an external listening campaign involving interviews with peer corporations with a range of experiences and approaches, as well as engaging sector experts with knowledge of diversity and inclusion program design, training modalities, and cross-company comparisons; and |
|---|
| • | provided a dedicated mailbox for teammates to submit suggestions, thoughts, and stories. |
|---|
Brown & Brown does not tolerate discrimination in any form with respect to any aspect of employment. The Company has an established policy that recruitment, hiring, transfers, promotions, terminations, compensation, and benefits practices be without regard to race, color, religion, absence of religious affiliation, national origin, ethnicity, age, disability, perception of disability, sex, sexual orientation, gender identity/expression, gender orientation, marital status, service in our armed forces, veteran status in our armed forces, political activity, or political party affiliation.
The Company tracks the representation of women and underrepresented racial and ethnic minorities because we know diversity helps us build better teams and improve our customer experience. Our gender and minority data are presented periodically to our Board. We are proud of our efforts in this area to date and continue to strive to further diversify our workforce and strengthen our culture of inclusion and belonging.
Health and Safety
The safety and well-being of all Brown & Brown teammates are of utmost importance. Brown & Brown intends to provide a safe environment for teammates and visitors to our offices.
In 2020, the Company had no work-related fatalities and 29 injuries or occupational diseases, as determined based on the number of claims made under our workers’ compensation policy, other than claims that were closed and for which no payment was made.
Focus on Health and Wellness
The Company is uniquely focused on our teammates' physical, mental, spiritual, and financial health and wellness. We recognize that healthy employees are better positioned to support their families, their communities, and our customers and, in turn, to deliver strong results for the Company and our shareholders. Individuals are encouraged to exercise regularly, and our offices routinely sponsor local races and other events to encourage our teammates to stay active. We also encourage our teammates to pursue interests outside of work by taking vacation or personal time, volunteering in their communities, and pursuing their hobbies.
Our new headquarters in Daytona Beach, Florida, was designed with open floorplans to encourage regular movement and interaction among our teammates, which we believe facilitates a better and more productive work environment. Substantially all offices and workstations in our new headquarters have been equipped with ergonomic furniture and standing desks to support the physical health of our teammates.
The remote working environment resulting from the COVID-19 pandemic has underscored the importance we place on our teammates' health and wellness. During the pandemic, our Chief Executive Officer appeared in weekly check-in videos to our teammates focused on personal stories about grit, resiliency, and maintaining mental and physical well-being. In addition, during the pandemic, the Company launched a series of 30-minute “Small Bites” sessions on a wide range of topics, including meditation, yoga, nutrition, fitness, and home office ergonomics.
Safety Guidelines
The Company has formal workplace safety guidelines that apply to all of our teammates and facilities, with some offices establishing even more specific guidelines for conduct. These guidelines cover, among other things, hazardous and unsafe work areas and conditions, cell phone usage, travel, attire, communication protocols for closures and emergencies, and our workers’ compensation benefits. Our teammates are expected to conduct themselves in a manner that will foster and maintain cooperative working relationships, ensure safety, and promote effectiveness. Teammates are expected to perform their duties professionally, to the best of their ability, and in accordance with all established standards, and to exercise sound judgment and conduct themselves in a professional, courteous manner at all times.
Driving for Business Policy
The Company has a formal Driving for Business policy prohibiting teammates from using mobile devices for calls, texting, or email while driving, except when using a hands-free device. Under our policy, teammates routinely driving for business purposes are required to maintain an acceptable motor vehicle record (“MVR”) and be subject to the MVR being reviewed at the time of hire and periodically after that. Teammates must have a valid driver’s license, obtain supervisory approval, and show proof of minimum required insurance before using their personal vehicle for business purposes.
Violence in the Workplace Policy
The Company has a formal policy against violence in the workplace. This policy prohibits any form of weapon from being carried or maintained in the Company’s offices and prohibits teammates from making threats or engaging in violent activities. Under our policy, any teammate who believes he or she has been a victim of violence, threats of violence, intimidating conduct, or has heard jokes or offensive comments about a violent occurrence must report such actions immediately to their team leader or another member of the Company’s leadership. In addition, any teammate who believes he, she, or another teammate may be in imminent danger of violence must notify local law enforcement officials immediately.
Mental Health
We are particularly passionate about mental health, and we believe leadership in that area starts at the top. Our Chief Executive Officer regularly addresses the importance of mental health in his communications with our teammates. Individuals are encouraged to engage in activities that promote good mental health and, when needed, to seek out help from friends, co-workers, and medical professionals. To foster a sense of connection during the COVID-19 pandemic and to help our teammates better recognize and address mental health issues, the Company curated weekly videos featuring teammates from across our organization sharing their personal experiences related to stress, anxiety, loneliness, acts of kindness and service, and navigating work from home with spouses, partners, pets, and children.
Through the Company’s Employee Assistance Program (“EAP”), the Company has contracted with a third-party service provider to offer all teammates and their dependents no-cost, confidential employee assistance on a 24/7 basis. Under the EAP, teammates and their dependents can get help for emotional concerns, marital or family difficulties, alcohol or drug dependency, stress, compulsive gambling, and legal or financial problems.
Available Information
We are subject to the reporting requirements of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), and its rules and regulations. The Exchange Act requires us to file reports, proxy statements and other information with the SEC. We make available free of charge on our website, at www.bbinsurance.com, our Annual Report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act and the rules promulgated thereunder, as soon as reasonably practicable after electronically filing or furnishing such material to the SEC. These documents are posted on our website at www.bbinsurance.com and may be accessed by selecting the “Investor Relations” link and then the “SEC Filings” link.
The SEC maintains a website that contains reports, proxy statements and other information regarding issuers that file electronically with the SEC. These materials may be obtained electronically by accessing the SEC’s website at www.sec.gov.
The charters of the Audit, Compensation and Nominating/Governance Committees of our Board of Directors as well as our Corporate Governance Principles, Code of Business Conduct and Ethics and Code of Ethics-CEO and Senior Financial Officers (including any amendments to, or waivers of any provision of any of these charters, principles or codes) are also available on our website or upon request. Requests for copies of any of these documents should be directed in writing to: Corporate Secretary, Brown & Brown, Inc., 300 North Beach Street, Daytona Beach, Florida 32114, or by telephone to (386)-252-9601.
Previous: Cover and table of contents · Next: Item 1A. Risk Factors.