 filings.tools
Brown & Brown (BRO) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A36 rewritten41 added26 removed207 unchanged
All filing items920 rewritten407 added472 removed1,716 unchanged
Summary
counted, not written
- Item 1A lists 29 risk factor headings: 1 new, 5 reworded and 23 unchanged since FY2022. 3 headings from FY2022 no longer appear.
- Sentence by sentence, 407 added, 472 removed, 920 rewritten and 1,716 unchanged across 19 items that differ.
- New this year: Item 1C. Cybersecurity..
New Item 1A headings (1)
- Our F&I businesses may be negatively impacted by a slowdown in vehicles sales in the united states or by regulatory changes, including tax-related changes, affecting the sale of f&I products by vehicle dealers changes in, or the termination of, certain programs administered by the U.s. federal government from which we derive revenues could adversely impact our results of operations.
Removed Item 1A headings (3)
- Our F&I businesses may be negatively impacted by a slowdown in vehicles sales in the united states or by regulatory changes, including tax-related changes, affecting the sale of f&I products by vehicle dealers
- We face a variety of risks in our services segment, including our third-party claims administration operations, that are distinct from those we face in our insurance intermediary operations.
- WE ARE SUBJECT TO RISKS ASSOCIATED WITH THE CURRENT INTEREST RATE ENVIRONMENT AND TO THE EXTENT WE USE DEBT TO FINANCE OUR INVESTMENTS, CHANGES IN INTEREST RATES WILL AFFECT OUR COST OF CAPITAL AND NET INVESTMENT INCOME.
Reworded Item 1A headings (5)
- OUR INABILITY TO [added: HIRE,] RETAIN
[removed: OR HIRE][added: AND DEVELOP] QUALIFIED EMPLOYEES, AS WELL AS THE LOSS OF ANY OF OUR EXECUTIVE OFFICERS OR OTHER KEY EMPLOYEES, COULD NEGATIVELY IMPACT OUR ABILITY TO RETAIN EXISTING BUSINESS AND GENERATE NEW BUSINESS. - BECAUSE A SIGNIFICANT PORTION OF OUR BUSINESSES ARE CONCENTRATED IN FLORIDA, CALIFORNIA, MASSACHUSETTS, GEORGIA, [added: MICHIGAN, AND] NEW YORK,
[removed: AND MICHIGAN,]AS WELL AS IN THE UNITED KINGDOM, ADVERSE ECONOMIC CONDITIONS, NATURAL DISASTERS, OR REGULATORY CHANGES IN THESE JURISDICTIONS COULD ADVERSELY AFFECT OUR FINANCIAL CONDITION. - SIGNIFICANT [added: OR SUSTAINED] INFLATION COULD ADVERSELY AFFECT OUR BUSINESS, RESULTS OF OPERATIONS AND FINANCIAL CONDITION.
- INCREASING SCRUTINY AND CHANGING [added: LAWS AND] EXPECTATIONS FROM [added: REGULATORS,] INVESTORS AND CUSTOMERS WITH RESPECT TO OUR ENVIRONMENTAL, SOCIAL AND GOVERNANCE (“ESG”) PRACTICES [added: AND DISCLOSURE] MAY IMPOSE ADDITIONAL COSTS ON US OR EXPOSE US TO REPUTATIONAL OR OTHER RISKS.
[removed: THE COVID-19 PANDEMIC, AS WELL AS]FUTURE PANDEMICS, EPIDEMICS OR OUTBREAKS OF INFECTIOUS DISEASE, AND THE RESULTING GOVERNMENTAL AND SOCIETAL RESPONSES MAY MATERIALLY AND ADVERSELY AFFECT THE COMPANY’S BUSINESS, LIQUIDITY, CUSTOMERS, INSURANCE CARRIERS AND THIRD PARTIES.
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
24 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors.
36 rewritten, 41 added, 26 removed, 207 unchanged
OUR INABILITY TO [added: HIRE,] RETAIN [removed: OR HIRE] [added: AND DEVELOP] QUALIFIED EMPLOYEES, AS WELL AS THE LOSS OF ANY OF OUR EXECUTIVE OFFICERS OR OTHER KEY EMPLOYEES, COULD NEGATIVELY IMPACT OUR ABILITY TO RETAIN EXISTING BUSINESS AND GENERATE NEW BUSINESS.
Our success depends on our ability to [removed: attract and] [added: attract,] retain [added: and develop] skilled and experienced personnel.
If we are not able to successfully attract, [removed: retain] [added: retain, develop] and motivate our employees, our business, financial results and reputation could be materially and adversely affected.
Additionally, we are an acquisitive organization and the process of integrating the information systems of the businesses we acquire is complex and exposes us to additional risk as we might not adequately identify weaknesses in the targets’ information systems, which could [added: expose us to unexpected liabilities or make our own systems more vulnerable to attack.]
[removed: As] these threats evolve, cybersecurity incidents will be more difficult to detect, defend against and remediate.
We have substantial operations in the United Kingdom, as well as operations in Belgium, Bermuda, Canada, Cayman Islands, [added: France, Germany, Hong Kong, Republic of] Ireland, [removed: Italy] [added: Italy, Malaysia, the Netherlands] and [removed: Northern Ireland.][added: United Arab Emirates.]
Difficulties in staffing and managing [removed: foreign] [added: international] operations;
Political and economic instability (including acts of terrorism and outbreaks of [removed: war);][added: war) either in the United States or globally;]
Adverse trade policies, and adverse changes to any of the policies of either the U.S. or any of the [removed: foreign] [added: international] jurisdictions in which we operate;
Burdens of complying with a wide variety of labor practices and [removed: foreign] [added: international] laws, including those relating to export and import duties, environmental policies and privacy issues.
SIGNIFICANT [added: OR SUSTAINED] INFLATION COULD ADVERSELY AFFECT OUR BUSINESS, RESULTS OF OPERATIONS AND FINANCIAL CONDITION.
Any [added: sustained inflation or] significant increases in inflation, such as the wage inflation experienced during the fiscal year ended December 31, 2022, and interest rates could have an adverse effect on our business, results of operations and financial condition.
For the year ended December 31, [removed: 2022, 2021,] [added: 2023, 2022] and [removed: 2020,] [added: 2021,] no more than 5.0% of our total core commissions was derived from insurance policies underwritten by one insurance company.
BECAUSE A SIGNIFICANT PORTION OF OUR BUSINESSES ARE CONCENTRATED IN FLORIDA, CALIFORNIA, MASSACHUSETTS, GEORGIA, [added: MICHIGAN, AND] NEW YORK, [removed: AND MICHIGAN,] AS WELL AS IN THE UNITED KINGDOM, ADVERSE ECONOMIC CONDITIONS, NATURAL DISASTERS, OR REGULATORY CHANGES IN THESE JURISDICTIONS COULD ADVERSELY AFFECT OUR FINANCIAL CONDITION.
A significant portion of our businesses are concentrated in Florida, California, Massachusetts, Georgia, Michigan, and New York, where for the year ended December 31, [removed: 2022,] [added: 2023,] we derived approximately [removed: 19%, 9%, 9%,] [added: 20%, 8%, 8%,] 7%, [removed: 6%,] [added: 7%,] and [removed: 6%] [added: 5%] of our annual revenue, respectively.
We also derived approximately [removed: 4.7%] [added: 10%] of our annual revenue from our businesses located in the United Kingdom.
We are susceptible to losses and interruptions caused by hurricanes (particularly in Florida, where we have [removed: 55] [added: 54] offices and our headquarters, as well as in Texas, where we have [removed: 21] [added: 17] offices), earthquakes (including in California, where we have [removed: 28] [added: 23] offices), power shortages, telecommunications failures, water shortages, floods, fire, extreme weather conditions, geopolitical events such as terrorist acts and other natural or human-made disasters.
As we grow, including from the integration of employees and businesses acquired in connection with previous or future acquisitions, we may find it difficult to maintain important aspects of our corporate culture, which could negatively affect our profitability and/or our ability to retain and recruit people of the highest integrity and quality who are essential to our [added: future success.]
Remote and hybrid work arrangements [removed: as a result of the COVID-19 pandemic] may also negatively impact our ability to maintain our culture.
In addition, as our organization grows and we are required [added: (either by new regulations or otherwise)] to implement more complex organizational structures, or if we experience a significant change in management, management philosophy or business strategy, we may find it increasingly difficult to maintain the beneficial aspects of our corporate culture, such as our decentralized sales and service operating model, which could negatively impact our future success.
For the year ended December 31, [removed: 2022,] [added: 2023,] we derived less than [removed: 10%] [added: 4%] of our annual total revenues from our F&I businesses.
[removed: If there were a slowdown in vehicle] sales in the United States or regulatory changes, including tax-related changes, affecting the sale of non-insurance warranty services and products by vehicle dealers, our F&I businesses may be negatively impacted, which may impact our results of operation.
At December 31, [removed: 2022,] [added: 2023,] our executive officers, directors and certain of their family members collectively beneficially owned approximately [removed: 16.5%] [added: 16.3%] of our outstanding common stock, of which J.
Significant uncertainty exists as privacy and data protection laws [added: evolve and] may be interpreted and applied differently from country to country and may create inconsistent or conflicting requirements.
In addition, legislators and regulators in the U.S. have enacted and are proposing new and more robust privacy and cybersecurity laws and regulations in light of the recent broad-based cyber-attacks at a number of companies, including but not limited to the New York State Department of Financial Services Cybersecurity Requirements for Financial Services [removed: Companies and] [added: Companies,] the California Consumer Privacy Act of [removed: 2018.][added: 2018 and the California Privacy Rights Act.]
In 2022, the Company acquired GRP (Jersey) Holdco Limited and its business and the general insurance operating companies of BdB Limited companies [added: and in 2023 Kentro Capital Limited] (the “Acquisitions”).
Other legislative developments that could adversely affect us include: changes in our business compensation model as a result of regulatory developments (for example, the Affordable Care Act); and federal and state governments establishing programs to provide health insurance or, in certain cases, property [added: insurance in catastrophe-prone areas or other alternative market types of coverage that compete with or completely replace, insurance products offered by insurance carriers.]
INCREASING SCRUTINY AND CHANGING [added: LAWS AND] EXPECTATIONS FROM [added: REGULATORS,] INVESTORS AND CUSTOMERS WITH RESPECT TO OUR ENVIRONMENTAL, SOCIAL AND GOVERNANCE (“ESG”) PRACTICES [added: AND DISCLOSURE] MAY IMPOSE ADDITIONAL COSTS ON US OR EXPOSE US TO REPUTATIONAL OR OTHER RISKS.
There is increased focus, including from governmental organizations, [added: regulators (including the SEC),] investors and customers, on ESG issues such as environmental stewardship, climate change, [added: greenhouse gas emissions,] diversity and inclusion, [added: human rights,] racial justice and workplace conduct.
At December 31, [removed: 2022,] [added: 2023,] we believe we were in compliance with the financial covenants and other limitations contained in each of the credit agreements that govern out debt.
Over the last three years our profit-sharing contingent commissions generally have been in the range of 3.0% to [removed: 3.5%] [added: 3.6%] of our previous year’s total core commissions and fees.
As of the date of the filing of our Annual Report on Form 10-K for the [removed: 2022] [added: 2023] fiscal year, we have [removed: $6.7] [added: $7.3] billion of goodwill recorded on our Consolidated Balance Sheet.
We completed our most recent evaluation of impairment for goodwill as of November 30, [removed: 2022] [added: 2023] and determined that the fair value of goodwill exceeded the carrying value of each reporting unit.
There have been no impairments recorded to either goodwill or amortizable intangibles for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020.][added: 2021.]
[removed: THE COVID-19 PANDEMIC, AS WELL AS FUTURE] [added: FUTURE] PANDEMICS, EPIDEMICS OR OUTBREAKS OF INFECTIOUS DISEASE, AND THE RESULTING GOVERNMENTAL AND SOCIETAL RESPONSES MAY MATERIALLY AND ADVERSELY AFFECT THE COMPANY’S BUSINESS, LIQUIDITY, CUSTOMERS, INSURANCE CARRIERS AND THIRD PARTIES.
We cannot predict the impact that [removed: COVID-19, or] future pandemics, epidemics or outbreaks of infectious disease, will have in the future on our customers, insurance carriers, suppliers and other third-party contractors, and each of their financial conditions; however, any material effect on these parties could adversely impact us.
Our success and future performance depends in part upon the continued services of our executive officers, senior management, and other highly skilled personnel.
This risk may be increased by remote or hybrid working arrangements, which may make our employees more vulnerable to solicitations by competing firms.
In addition, regulation or legislation impacting the workforce or the ability to enforce employment-related restrictive covenants (due to state or federal laws or regulations), may lead to increased uncertainty and competition for talent.
The risk of such cybersecurity breaches may be increased by our increased reliance on work-from-home or other remote work technologies.
As
If we are unable to identify appropriate acquisition targets, or if our competitors are more successful in identifying acquisition targets at favorable valuations, we may fail to achieve desired strategic goals and capabilities, and our results of operations may be adversely affected.
Difficulties in maintaining, or resistance to, our corporate culture;
OUR COMMISSION REVENUE COULD FLUCTUATE AS A RESULT OF FACTORS OUTSIDE OF OUR CONTROL
We derive significant revenue from commissions, but do not determine the insurance premiums on which our commissions are generally based.
Commission levels generally follow the same trend as premium levels, as they are a percentage of the premiums paid by the insureds.
Fluctuations in the premiums charged by the insurance carriers can therefore have a direct and potentially material impact on our results of operations.
Due to the cyclical nature of the insurance market and the impact of other market conditions on insurance premiums, commission levels may vary widely between accounting periods.
A period of low or declining premium rates, generally known as a “soft” or “softening” market, generally leads to downward pressure on commission revenue and can have a material adverse impact on our commission revenue and operating margins.
We could be negatively impacted by soft market conditions across certain sectors and geographic regions.
In addition, insurance carriers may seek to reduce their expenses by reducing the commission rates payable to insurance agents or brokers such as us.
The reduction of these commission rates, along with general volatility and/or declines in premiums, may significantly undermine our profitability.
Because we do not determine the timing or extent of premium pricing changes, it is difficult to accurately forecast our commission revenue, including whether they will significantly decline.
As a result, we may have to adjust our plans for future acquisitions, capital expenditures, dividend payments, loan repayments and other expenditures to account for unexpected changes in revenue, and any decreases in premium rates may adversely affect the results of our operations.
In addition to movements in premium rates, our ability to generate premium-based commission revenue may be challenged by disintermediation and the growing availability of alternative methods for clients to meet their risk-protection needs.
This trend includes a greater willingness on the part of corporations to self-insure, the use of captive insurers, and the presence of capital markets-based solutions for traditional insurance and reinsurance needs.
Further, the profitability of our risk and broking businesses depends in part on our ability to be compensated for the analytical services and other advice that we provide, including the consulting and analytics services that we provide to insurers.
If we are unable to achieve and maintain adequate billing rates for all of our services, our margins and profitability could decline.
If there were a slowdown in vehicle
changes in, or the termination of, certain programs administered by the U.s. federal government from which we derive revenues could adversely impact our results of operations.
We face the risk that the U.S. federal government modifies, discontinues, or otherwise limits our ability to derive revenues from certain federal programs, including failure by United States Congress to appropriate funding for any such programs.
These programs include the National Flood Insurance Program, the Social Security disability benefits program or the federal crop insurance program, from which in the aggregate we derive less than 5% of our annual total revenues.
Many statutory requirements, both in the United States and abroad, include obligations for companies to notify individuals of security breaches involving certain personal information, which could result from breaches experienced by us or our vendors.
In addition to government regulation, privacy advocates and industry groups have and may in the future propose self-regulatory standards from time to time.
These and other industry standards may legally or contractually apply to us, or we may elect to comply with such standards.
We expect that there will
continue to be new proposed laws and regulations concerning data privacy and security, and we cannot yet determine the impact such future laws, regulations and standards may have on our business.
Data protection laws also include strict notification requirements for organizations related to confirmed or suspected breaches.
With such a limited time available to validate indicators, there is an increased risk of reporting a false alarm or immaterial breach, which may lead to reputational damage despite there not being an actual data breach.
Additionally, there has been increased regulatory focus on ESG and sustainability.
For example, laws and regulations related to ESG issues continue to evolve, including in the U.S., the U.K. and the EU.
New regulations may impose additional compliance or disclosure obligations on us.
In particular, heightened demand for, and scrutiny of, ESG and sustainable-related strategies and advice has increased the risk that we could be perceived as, or accused of, making inaccurate or misleading statements, commonly referred to as “greenwashing” or that
we have otherwise run afoul of regulation.
Such perceptions or accusations could damage our reputation, result in litigation or regulatory enforcement actions, and adversely affect our business.
Furthermore, perceptions of our efforts to achieve ESG goals or advance ESG and sustainable-related strategies may differ widely among stakeholders and could present risks to our reputation and business.
expose us to unexpected liabilities or make our own systems more vulnerable to attack.
future success.
We face a variety of risks in our services segment, including our third-party claims administration operations, that are distinct from those we face in our insurance intermediary operations.
Our Services segment, including our third-party claims administration operations, face a variety of risks distinct from those faced by our insurance intermediary operations, including the risks that:
The favorable trend among both insurance companies and self-insured entities toward outsourcing various types of claims administration and risk management services may reverse or slow, causing our revenues or revenue growth to decline;
Concentration of large amounts of revenue with certain customers may result in greater exposure to the potential negative effects of lost business due to changes in management of such customers or for other reasons;
Contracting terms will become less favorable or the margins on our services may decrease due to increased competition, regulatory constraints or other developments;
Our revenue is impacted by claims volumes, which are dependent upon a number of factors and difficult to forecast accurately;
Economic weakness or a slowdown in economic activity could lead to a reduction in the number of claims we process;
The U.S. Federal government modifies, discontinues, or otherwise limits our ability to derive revenues from the Social Security disability benefits program, Medicare, or any other program or type of coverage from which our business derives revenue;
We may be unable to develop further efficiencies in our claims-handling business and may be unable to obtain or retain certain customers if we fail to make adequate improvements in technology or operations; and
Insurance companies or certain large self-insured entities may create in-house servicing capabilities that compete with our services.
insurance in catastrophe-prone areas or other alternative market types of coverage that compete with or completely replace, insurance products offered by insurance carriers.
WE ARE SUBJECT TO RISKS ASSOCIATED WITH THE CURRENT INTEREST RATE ENVIRONMENT AND TO THE EXTENT WE USE DEBT TO FINANCE OUR INVESTMENTS, CHANGES IN INTEREST RATES WILL AFFECT OUR COST OF CAPITAL AND NET INVESTMENT INCOME.
As of July 2017, the UK Financial Conduct Authority (“FCA”) has urged banks and institutions to discontinue their use of the London Interbank Offered Rate (“LIBOR”) benchmark rate for floating rate debt, and other financial instruments tied to the rate after 2021.
To help with the transition, the Federal Reserve Board and New York Fed have commissioned the Alternative Reference Rates Committee (“ARRC”), composed of a diverse set of private-sector entities that have an important presence in markets affected by USD LIBOR and a wide array of official-sector entities, including banking and financial sector regulators, as ex-officio members.
The ARRC has recommended the Secured Overnight Financing Rate (“SOFR”) as the best alternative rate to LIBOR post discontinuance and has proposed a transition plan and timeline designed to encourage the adoption of SOFR from LIBOR.
On March 5, 2021, the ICE Benchmark Administration, which administers LIBOR, and the FCA announced that all LIBOR settings will either cease to be provided by any administrator, or no longer be representative immediately after December 31, 2021, for all non-U.S. dollar LIBOR settings and one-week and two-month U.S. dollar LIBOR settings, and immediately after June 30, 2023 for the remaining U.S. dollar LIBOR settings.
As of December 31, 2022, the Company’s primary exposures are debt instruments referencing LIBOR-based rates, which include the Second Amended and Restated Credit Agreement (the “Second Amended and Restated Credit Agreement”) term loan balance of $234.4 million outstanding and matures in October 2026, as well as the term loan credit agreement (the “Term Loan Credit Agreement”) which had an outstanding balance of $210.0 million and matures in December 2023.
As such, any potential effect of any such event on our cost of capital, interest rate exposure and net investment income cannot yet be determined.
In addition, any further changes or reforms to the determination or supervision of LIBOR may result in a sudden or prolonged increase or decrease in reported LIBOR, which could have an adverse impact on the market value for or value of any LIBOR-linked securities, loans, and other financial obligations or extensions of credit held by or due to us and could have a material adverse effect on our business, financial condition and results of operations.
The Company entered into the Second Amended and Restated Credit Agreement in October 2021, which includes provisions regarding the transition from LIBOR to SOFR.
The new benchmark for our USD borrowings will be SOFR, in which the Company is taking active measures to transition and replace LIBOR.
The shift to SOFR from LIBOR is complex and may adversely affect our business, financial condition, results of operations, liquidity and cash flows.
The extent to which COVID-19 impacts our business will depend on future developments, which are highly uncertain and cannot be predicted with confidence.
In addition, if COVID-19 creates disruptions or turmoil in the credit or financial markets in the future, or impacts our credit ratings, it could adversely affect our ability to access capital on favorable terms and continue to meet our liquidity needs, all of which are highly uncertain and cannot be predicted.
An excerpt. Shown here: all 36 rewritten, 40 of 41 added and all 26 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors. in the FY2023 filing and the FY2022 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
243 rewritten, 95 added, 76 removed, 295 unchanged
The following discussion should be read in conjunction with our Consolidated Financial Statements and the related Notes to those Financial Statements included elsewhere in this Annual Report on Form [removed: 10-K.][added: 10-K, which are prepared in accordance with accounting principles generally accepted in the United States of America ("GAAP").]
In addition, [removed: please] see “Information Regarding Non-GAAP Financial Measures” below regarding important information on non-GAAP financial measures contained in our discussion and analysis.
We also participate in capitalized captive insurance facilities (the "Captives") for the purpose of having additional capacity to place coverage, drive additional revenues and to participate in [removed: underwriting.][added: underwriting results.]
The Captives focus on property insurance for earthquake and wind exposed properties underwritten by certain [removed: managing general agents.][added: of our MGUs.]
The Captives [added: focus on property insurance for earthquake and wind exposed properties underwritten by certain of our MGUs and] limit the Company's exposure to claims expenses [removed: either] through reinsurance or by only participating in certain tranches of the underwriting.
We have increased revenues every year from 1993 to [removed: 2022,] [added: 2023,] with the exception of 2009, when our revenues declined 1.0%.
Our revenues grew from $95.6 million in 1993 to [removed: $3.6] [added: $4.3] billion in [removed: 2022,] [added: 2023,] reflecting a compound annual growth rate of [removed: 13.3%.][added: 13.5%.]
In the same [removed: 29-year] [added: 30-year] period, we increased net income from $8.1 million to [removed: $671.8] [added: $870.5] million in [removed: 2022,] [added: 2023,] a [removed: 16.5%] [added: 16.9%] compound annual growth rate.
The volume of business from new and existing customers, fluctuations in insurable exposure units, changes in premium rate levels, changes in general economic and competitive conditions, a [removed: health pandemic or a] reduction of purchased limits [added: or] the occurrence of catastrophic weather events all affect our revenues.
For example, higher levels of inflation, an increase the value of insurable exposure units, or a general decline in economic activity, could [added: increase or] decrease the value of insurable exposure units.
The net change in core commissions and fees reflects the aggregate changes attributable to: (i) net new and lost accounts; (ii) net changes in our customers’ exposure [removed: units;] [added: units, deductibles or insured limits;] (iii) net changes in insurance premium rates or the commission rate paid to us by our carrier partners; (iv) the net change in fees paid to us by our customers; and (v) any businesses acquired or disposed of.
These commissions, which are included in our commissions and fees in the Consolidated Statements of Income, are [added: estimated and] accrued throughout the year based on actual premiums written and [removed: are primarily received in] [added: knowledge, to] the [removed: first and second quarters] [added: extent it is available,] of [removed: each subsequent year, based upon the aforementioned considerations for the prior year(s).][added: losses incurred.]
Over the last three years, profit-sharing contingent commissions have averaged approximately [removed: 3.0%] [added: 3.3%] of commissions and fees revenue.
Fee revenues primarily relate to services other than securing coverage for our customers, and [removed: to a lesser extent as] [added: for] fees negotiated in lieu of commissions.
Fee revenues are generated by: (i) our Services segment, which is primarily a fee-based business that provides insurance-related services, including third-party claims administration and comprehensive medical utilization management services in both the workers’ compensation and all-lines liability arenas, as well as Medicare Set-aside services, Social Security disability and Medicare benefits advocacy services, and claims adjusting services; (ii) our National Programs and Wholesale Brokerage segments, which earn fees primarily for the issuance of insurance policies on behalf of insurance companies; and (iii) our Retail segment in our large-account customer base, where we primarily earn fees for securing insurance for our customers, and in our automobile dealer services (“F&I”) businesses where we earn fees for [added: assisting our customers]
[removed: assisting our customers] with creating and selling warranty and service risk management programs.
Fee revenues as a percentage of our total commissions and fees, represented [removed: 25.8%] [added: 23.9%] in [removed: 2022] [added: 2023] and [removed: 27.4%] [added: 25.8%] in [removed: 2021.][added: 2022.]
For the year ended December 31, [removed: 2022,] [added: 2023,] our commissions and fees growth rate was [removed: 16.9%] [added: 17.9%] and our consolidated Organic Revenue growth rate was [removed: 8.1%.][added: 10.2%.]
Other income primarily reflects [removed: legal settlements and] other [added: miscellaneous] revenues.
Income before income taxes for the year ended December 31, [removed: 2022] [added: 2023] increased by [removed: $113.3] [added: $270.0] million, or [removed: 14.9%] [added: 30.8%] over [removed: 2021,] [added: 2022,] driven by [added: net] new [removed: business and] [added: business,] growth from existing customers, acquisitions we completed in the last [removed: twelve] [added: 12] months and [removed: the year-over-year change] [added: an increase] in [removed: estimated acquisition earn-out payables,] [added: the (gain)/loss on disposal primarily associated with the divestiture of certain businesses within the Services segment during the fourth quarter of 2023,] which were partially offset by incremental operating costs, increased amortization expense as a result of [removed: our recent acquisitions] [added: acquisitions,] along with [removed: increased] [added: higher] interest expense associated with [removed: higher average debt balances from debt issued and bank financing] [added: an increase] in the [removed: first quarter of 2022 to fund] [added: reference rate associated with] the [removed: acquisitions] [added: portion] of [removed: GRP (Jersey) Holdco Limited and its businesses ("GRP"), Orchid Underwriters Agency and CrossCover Insurance Services ("Orchid") and BdB Limited companies ("BdB") as well as increases in the floating-rate benchmark used on] our [removed: adjustable rate] debt [added: that carries a floating rate,] and [added: an increase in] the [removed: net] change in [removed: any gain or loss associated with the sales of businesses or books of business.][added: estimated acquisition earn-out payables.]
We present these measures because we believe such information is of interest to the investment community and because we believe it provides additional meaningful methods to evaluate the Company’s operating performance from period to period on a basis that may not be otherwise apparent on a GAAP basis due to the impact of certain items that have a high degree of [removed: variability and] [added: variability,] that we believe are not indicative of ongoing [removed: performance.][added: performance and that are not easily comparable from period to period.]
This non-GAAP financial information should be considered in addition to, not in lieu of, the Company’s consolidated income statements [added: and balance sheets] as of the relevant date.
Consistent with Regulation G, a description of such information is provided below and tabular reconciliations of this supplemental non-GAAP financial information to our most comparable GAAP information are contained in this Annual Report on Form 10-K under “Results of Operations - Segment [removed: Information.”][added: Information.]
We view Organic Revenue and Organic Revenue growth as important indicators when assessing and evaluating our performance on a consolidated basis and for each of our four segments, because they allow us to determine a comparable, but non-GAAP, measurement of revenue growth that is associated with the revenue sources that were a part of our business in both the current and prior [removed: year.][added: year and that are expected to continue in the future.]
As disclosed in our most recent proxy statement, we use Organic Revenue [added: growth,] and EBITDAC Margin [added: - Adjusted] as key performance metrics for our short-term and long-term incentive compensation plans for executive officers and other key employees.
“Acquisition/Integration [removed: Costs,” which represent] [added: Costs” means] the acquisition and integration costs (e.g., costs associated with regulatory filings, legal/accounting services, due diligence and the costs of integrating our information technology systems) arising out of our acquisitions of [removed: GRP,] [added: GRP (Jersey) Holdco Limited and its business ("GRP"),] Orchid [added: Underwriters Agency] and [removed: BdB,] [added: CrossCover Insurance Services ("Orchid"), and BdB Limited companies ("BdB"),] which are not [removed: expected] [added: considered] to [removed: occur on an ongoing basis in] [added: be normal, recurring or part of] the [removed: future.][added: ongoing operations.]
[removed: The] [added: “Foreign Currency Translation” means the] period-over-period impact of foreign currency [removed: translation (“Foreign Currency Translation”),] [added: translation,] which is calculated by applying current-year foreign exchange rates to the various functional currencies in our business to our reporting currency of U.S. dollars for the same period in the prior year.
Total Revenues - Adjusted is our total revenues, excluding [removed: the period-over-period impact of] Foreign Currency [removed: Translation.][added: Translation (as defined below).]
Organic Revenue is our core commissions and fees less: (i) the core commissions and fees earned for the first [removed: twelve] [added: 12] months by newly acquired operations; (ii) divested business (core commissions and fees generated from offices, books of business or niches sold or terminated during the comparable period); and (iii) [removed: the period-over-period impact of] Foreign Currency [removed: Translation.][added: Translation (as defined below).]
EBITDAC - Adjusted is defined as EBITDAC, excluding (i) (gain)/loss on disposal, (ii) Acquisition/Integration Costs [removed: and] [added: (as defined below),] (iii) [added: for 2023,] the [removed: period-over-period impact of] [added: 1Q23 Nonrecurring Cost (as defined below) and (iv)] Foreign Currency [removed: Translation.][added: Translation (as defined below).]
From 1993 through the fourth quarter of [removed: 2022,] [added: 2023,] we acquired [removed: 610] [added: 644] insurance intermediary operations.
When we are paid a fee for service, however, the associated revenue is recognized over a period of time that coincides with when the customer simultaneously receives and consumes the benefit of our work, which characterizes [added: most of our claims processing arrangements and various services performed in our property and casualty, and employee benefits practices.]
To a much lesser extent, the Company [removed: earned] [added: earns] revenues [removed: starting] in [removed: 2022 in] the form of net retained earned premiums in connection with the Captives.
[removed: Please see] [added: See] Note 2 [removed: “Revenues” in the “Notes] to [added: our] Consolidated Financial [removed: Statements”] [added: Statements] for additional information regarding the nature and timing of our revenues.
Their value primarily represents the present value of the underlying [added: net] cash flows expected to be received over the estimated future duration of the acquired customer relationships.
Fair value is estimated based upon multiples of [removed: EBITDAC,] [added: earnings,] or on a discounted cash flow basis.
We completed our most recent evaluation of impairment for goodwill as of November 30, [removed: 2022] [added: 2023] and determined that the fair value of goodwill exceeded the carrying value of such assets.
Additionally, there have been no impairments recorded for amortizable intangible assets for the years ended December 31, [removed: 2022] [added: 2023] and [removed: 2021.][added: 2022.]
During the performance measurement period, we review the probable outcome of the performance conditions associated with our performance awards [added: quarterly] and adjust the expense recognition accruals with the expected performance outcome.
During the first quarter of [removed: 2021,] [added: 2024,] the performance conditions for approximately [removed: 1.2 million] [added: 1,200,000] shares of the Company’s common stock granted under the [removed: Company’s 2010 SIP and approximately 22,000 shares of the Company’s common stock granted] under the Company’s 2019 SIP were determined by the Compensation Committee to have been satisfied relative to the performance-based grants issued in [removed: 2018] [added: 2021] and [removed: 2020.][added: 2023.]
Payments are primarily received in the first and second quarters of each subsequent year, based upon the aforementioned considerations for the prior year(s), but may differ from the amount estimated and accrued due to the lack of complete loss information until paid.
Definitions Related to Certain Components of Non-GAAP Measures
“1Q23 Nonrecurring Cost” means approximately $11.0 million expensed and substantially paid in the first quarter of 2023 to resolve a business matter, which is not considered to be normal, recurring or part of the ongoing operations.
| Amortization | | | 166.0 | | | | 13.2 | % | | | 146.6 | |
| Depreciation | | | 40.0 | | | | 2.0 | % | | | 39.2 | |
| Interest | | | 190.0 | | | | 34.6 | % | | | 141.2 | |
| EBITDAC - Adjusted (2) | | $ | 1,444.7 | | | | 23.1 | % | | $ | 1,173.8 | |
Other income consists primarily of miscellaneous income and therefore can fluctuate between comparable periods.
in 2023 we recorded a gain on disposal of $134.6 million in our Services segment associated with the sale of certain third-party claims administration and adjusting services businesses in the fourth quarter of 2023.
Amortization expense for 2023 increased $19.4 million to $166.0 million, or 13.2% over 2022.
Depreciation expense for 2023 increased $0.8 million to $40.0 million, or 2.0% over 2022.
Interest expense for 2023 increased $48.8 million to $190.0 million, or 34.6%, from 2022.
Likewise, other income consists primarily of miscellaneous income and therefore can fluctuate between comparable periods.
| Commissions and fees | | $ | 2,433.0 | | | $ | 2,080.4 | | | $ | 1,064.3 | | | $ | 858.1 | | | $ | 539.0 | | | $ | 452.8 | | | $ | 163.1 | | | $ | 171.9 | | | $ | 4,199.4 | | | $ | 3,563.2 | |
| Total change | | $ | 352.6 | | | | | | | $ | 206.2 | | | | | | | $ | 86.2 | | | | | | | $ | (8.8 | ) | | | | | | $ | 636.2 | | | | | |
| Total growth % | | | 16.9 | % | | | | | | | 24.0 | % | | | | | | | 19.0 | % | | | | | | | (5.1 | )% | | | | | | | 17.9 | % | | | | |
| Profit-sharing contingent commissions | | | (49.9 | ) | | | (48.8 | ) | | | (65.2 | ) | | | (27.6 | ) | | | (14.8 | ) | | | (12.3 | ) | | | — | | | | — | | | | (129.9 | ) | | | (88.7 | ) |
| Core commissions and fees | | $ | 2,383.1 | | | $ | 2,031.6 | | | $ | 999.1 | | | $ | 830.5 | | | $ | 524.2 | | | $ | 440.5 | | | $ | 163.1 | | | $ | 171.9 | | | $ | 4,069.5 | | | $ | 3,474.5 | |
| Acquisitions | | | (203.5 | ) | | | — | | | | (47.1 | ) | | | — | | | | (34.4 | ) | | | — | | | | — | | | | — | | | | (285.0 | ) | | | — | |
| Dispositions | | | — | | | | (20.2 | ) | | | — | | | | (18.0 | ) | | | — | | | | (5.0 | ) | | | — | | | | (7.8 | ) | | | — | | | | (51.0 | ) |
| Organic Revenue(2) | | $ | 2,179.6 | | | $ | 2,020.2 | | | $ | 952.0 | | | $ | 812.5 | | | $ | 489.8 | | | $ | 436.6 | | | $ | 163.1 | | | $ | 164.1 | | | $ | 3,784.5 | | | $ | 3,433.4 | |
| Organic Revenue growth(2) | | $ | 159.4 | | | | | | | $ | 139.5 | | | | | | | $ | 53.2 | | | | | | | $ | (1.0 | ) | | | | | | $ | 351.1 | | | | | |
Excluding the amounts from the "Other" column the growth in commissions and fees was 17.0%.
| Total Revenues | | $ | 2,440.0 | | | $ | 1,077.3 | | | $ | 540.7 | | | $ | 163.1 | | | $ | 36.0 | | | $ | 4,257.1 | |
| Total Revenues - Adjusted(2) | | | 2,440.0 | | | | 1,077.3 | | | | 540.7 | | | | 163.1 | | | | 36.0 | | | | 4,257.1 | |
| Income before income taxes | | | 528.4 | | | | 405.5 | | | | 125.8 | | | | 153.8 | | | | (67.4 | ) | | | 1,146.1 | |
| Income Before Income Taxes Margin(1) | | | 21.7 | % | | | 37.6 | % | | | 23.3 | % | | | 94.3 | % | | NMF | | | | | 26.9 | % |
| Amortization | | | 108.5 | | | | 41.2 | | | | 11.2 | | | | 5.1 | | | | — | | | | 166.0 | |
| Depreciation | | | 18.0 | | | | 11.8 | | | | 2.6 | | | | 1.4 | | | | 6.2 | | | | 40.0 | |
| Interest | | | 83.4 | | | | 35.6 | | | | 11.9 | | | | 1.3 | | | | 57.8 | | | | 190.0 | |
| EBITDAC(2) | | $ | 739.8 | | | $ | 494.0 | | | $ | 171.9 | | | $ | 161.6 | | | $ | (3.4 | ) | | $ | 1,563.9 | |
| EBITDAC Margin(2) | | | 30.3 | % | | | 45.9 | % | | | 31.8 | % | | | 99.1 | % | | NMF | | | | | 36.7 | % |
| Acquisition/Integration Costs | | | 10.3 | | | | 0.2 | | | | 0.5 | | | | — | | | | 2.1 | | | | 13.1 | |
| 1Q23 Nonrecurring Cost | | | | | | | | | | | | | | | | | | | 11.0 | | | | 11.0 | |
| EBITDAC - Adjusted(2) | | $ | 747.6 | | | $ | 488.0 | | | $ | 172.4 | | | $ | 27.0 | | | $ | 9.7 | | | $ | 1,444.7 | |
| EBITDAC Margin - Adjusted(2) | | | 30.6 | % | | | 45.3 | % | | | 31.9 | % | | | 16.6 | % | | NMF | | | | | 33.9 | % |
| Foreign Currency Translation | | | 10.6 | | | | 0.2 | | | | 1.3 | | | | — | | | | — | | | | 12.1 | |
| Total Revenues - Adjusted(2) | | | 2,094.9 | | | | 859.7 | | | | 454.7 | | | | 171.9 | | | | 4.3 | | | | 3,585.5 | |
| Foreign Currency Translation | | | 3.0 | | | | — | | | | 0.1 | | | | — | | | | (0.2 | ) | | | 2.9 | |
| EBITDAC - Adjusted(2) | | $ | 646.4 | | | $ | 345.2 | | | $ | 145.7 | | | $ | 32.9 | | | $ | 3.6 | | | $ | 1,173.8 | |
The Company has traditionally participated in underwriting profits through profit-sharing contingent commissions.
These Captives give us another way to deliver incremental revenue growth and continue to participate in underwriting results while limiting exposure to claims expenses.
Beginning January 1, 2022, we include guaranteed supplemental commissions ("GSCs") as part of core commissions and fees and, therefore, GSCs are a component of Organic Revenue.
All current and prior periods contained within this Annual Report on Form 10-K have been adjusted for this treatment.
GSCs are a stable source of revenue that are highly correlated to core commissions, so isolating them separately provided no meaningful incremental value in evaluating our revenue.
Beginning January 1, 2022, the following, in addition to the change in estimated acquisition earn-out payables, are excluded from certain non-GAAP measures, as we believe these amounts are not indicative of the ongoing operating performance of the business and are not easily comparable from period-to-period:
“(Gain)/loss on disposal,” a caption on our consolidated statements of income which reflects net proceeds received as compared to net book value related to sales of books of business and other divestiture transactions, such as the disposal of a business through sale or closure.
We are presenting EBITDAC - Adjusted and EBITDAC Margin - Adjusted for the current and prior year periods contained within this Annual Report on Form 10-K so these non-GAAP financial measures compare both periods on the same basis.
most of our claims processing arrangements and various services performed in our property and casualty, and employee benefits practices.
| Amortization | | | 146.6 | | | | 22.6 | % | | | 119.6 | |
| Depreciation | | | 39.2 | | | | 17.7 | % | | | 33.3 | |
| Interest | | | 141.2 | | | | 117.2 | % | | | 65.0 | |
| EBITDAC - Adjusted (2) | | $ | 1,170.9 | | | | 15.9 | % | | $ | 1,010.1 | |
Amortization expense for 2022 increased $27.0 million to $146.6 million, or 22.6% over 2021.
Depreciation expense for 2022 increased $5.9 million to $39.2 million, or 17.7% over 2021.
Interest expense for 2022 increased $76.2 million to $141.2 million, or 117.2%, from 2021.
Likewise, other revenues in each segment reflects net gains primarily from legal settlements and miscellaneous income.
| Commissions and fees | | $ | 1,764.9 | | | $ | 1,470.1 | | | $ | 701.1 | | | $ | 609.8 | | | $ | 402.6 | | | $ | 352.2 | | | $ | 178.9 | | | $ | 174.0 | | | $ | 3,047.5 | | | $ | 2,606.1 | |
| Total change | | $ | 294.8 | | | | | | | $ | 91.3 | | | | | | | $ | 50.4 | | | | | | | $ | 4.9 | | | | | | | $ | 441.4 | | | | | |
| Total growth % | | | 20.1 | % | | | | | | | 15.0 | % | | | | | | | 14.3 | % | | | | | | | 2.8 | % | | | | | | | 16.9 | % | | | | |
| Profit-sharing contingent commissions | | | (38.9 | ) | | | (35.8 | ) | | | (35.3 | ) | | | (27.3 | ) | | | (8.0 | ) | | | (7.9 | ) | | | — | | | | — | | | | (82.2 | ) | | | (71.0 | ) |
| Core commissions and fees | | $ | 1,726.0 | | | $ | 1,434.3 | | | $ | 665.8 | | | $ | 582.5 | | | $ | 394.6 | | | $ | 344.3 | | | $ | 178.9 | | | $ | 174.0 | | | $ | 2,965.3 | | | $ | 2,535.1 | |
| Acquisitions | | | (139.0 | ) | | | — | | | | (8.2 | ) | | | — | | | | (23.0 | ) | | | — | | | | — | | | | — | | | | (170.2 | ) | | | — | |
| Dispositions | | | — | | | | (4.4 | ) | | | — | | | | (0.5 | ) | | | — | | | | — | | | | — | | | | (0.4 | ) | | | — | | | | (5.3 | ) |
| Organic Revenue(2) | | $ | 1,587.0 | | | $ | 1,429.9 | | | $ | 657.6 | | | $ | 583.2 | | | $ | 371.6 | | | $ | 344.3 | | | $ | 178.9 | | | $ | 173.6 | | | $ | 2,795.1 | | | $ | 2,531.0 | |
| Organic Revenue growth(2) | | $ | 157.1 | | | | | | | $ | 74.4 | | | | | | | $ | 27.3 | | | | | | | $ | 5.3 | | | | | | | $ | 264.1 | | | | | |
| Total Revenues - Adjusted(2) | | | 2,084.3 | | | | 859.5 | | | | 453.4 | | | | 171.9 | | | | 4.3 | | | | 3,573.4 | |
| EBITDAC - Adjusted(2) | | $ | 643.4 | | | $ | 345.2 | | | $ | 145.6 | | | $ | 32.9 | | | $ | 3.8 | | | $ | 1,170.9 | |
| Total Revenues | | $ | 1,767.9 | | | $ | 701.9 | | | $ | 403.4 | | | $ | 178.9 | | | $ | (0.7 | ) | | $ | 3,051.4 | |
| Foreign Currency Translation | | | (4.1 | ) | | | (0.7 | ) | | | — | | | | — | | | | — | | | | (4.8 | ) |
| Total Revenues - Adjusted(2) | | | 1,763.8 | | | | 701.2 | | | | 403.4 | | | | 178.9 | | | | (0.7 | ) | | | 3,046.6 | |
| Income before income taxes | | | 334.4 | | | | 242.3 | | | | 94.8 | | | | 28.3 | | | | 63.0 | | | | 762.8 | |
| Income Before Income Taxes Margin(1) | | | 18.9 | % | | | 34.5 | % | | | 23.5 | % | | | 15.8 | % | | NMF | | | | | 25.0 | % |
| Amortization | | | 77.8 | | | | 27.4 | | | | 9.1 | | | | 5.3 | | | | — | | | | 119.6 | |
| Depreciation | | | 11.2 | | | | 9.8 | | | | 2.6 | | | | 1.5 | | | | 8.2 | | | | 33.3 | |
| Interest | | | 91.4 | | | | 11.4 | | | | 16.0 | | | | 2.9 | | | | (56.7 | ) | | | 65.0 | |
| EBITDAC(2) | | $ | 555.6 | | | $ | 283.2 | | | $ | 129.8 | | | $ | 38.0 | | | $ | 14.5 | | | $ | 1,021.1 | |
| 'EBITDAC Margin(2) | | | 31.4 | % | | | 40.3 | % | | | 32.2 | % | | | 21.2 | % | | NMF | | | | | 33.5 | % |
| Acquisition/Integration Costs | | | — | | | | — | | | | — | | | | — | | | | — | | | | — | |
| Foreign Currency Translation | | | (1.0 | ) | | | (0.4 | ) | | | — | | | | — | | | | — | | | | (1.4 | ) |
An excerpt. Shown here: 40 of 243 rewritten, 40 of 95 added and 40 of 76 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2023 filing and the FY2022 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
5 rewritten, 1 added, 10 removed, 7 unchanged
Our invested assets are held primarily as cash and cash equivalents, [removed: restricted] [added: fiduciary] cash, available-for-sale marketable debt securities, non-marketable debt securities, certificates of deposit, U.S. treasury securities, and professionally managed short duration fixed income funds.
The fair value of our invested assets at December 31, [removed: 2022] [added: 2023] and December 31, [removed: 2021,] [added: 2022,] approximated their respective carrying values due to their short-term duration and therefore, such market risk is not considered to be material.
In addition, we generally dispose of any [removed: significant] equity securities received in conjunction with an acquisition shortly after the acquisition date.
We are subject to translational exchange rate risk having businesses operating outside of the U.S. in the following functional currencies, British pounds, Canadian dollar and [removed: euros.][added: euros and other currencies to a lesser extent.]
Based upon our foreign currency rate exposure as of December 31, [removed: 2022,] [added: 2023,] an immediate 10% hypothetical change of foreign currency exchange rates would not have a material effect on our Consolidated Financial Statements.
As of December 31, 2023, we had $1,075.0 million outstanding under the Second Amended and Restated Credit Agreement and the Loan Agreement tied to SOFR.
As of December 31, 2022, we had $781.2 million outstanding under the Loan Agreement tied to the Secured Overnight Financing Rate (“SOFR”) and $444.4 million of borrowings outstanding under certain credit agreements tied to the overnight London Interbank Offered Rate (“LIBOR”).
As of July 2017, the UK Financial Conduct Authority (“FCA”) has urged banks and institutions to discontinue their use of the LIBOR benchmark rate for floating-rate debt, and other financial instruments tied to the rate after 2021.
However, on November 30, 2020, the ICE Benchmark Administration Limited (“IBA”), announced that it would consult in early December 2020 on its intention to cease the publication of the one-week and two-month U.S. dollar LIBOR settings immediately following the LIBOR publication on December 31, 2021, and the remaining U.S. dollar LIBOR settings (overnight and one, three, six and twelve months) immediately following the LIBOR publication on June 30, 2023.
In connection to the released statement from the IBA, on December 4, 2020, the FCA released a similar statement in support of the continuation of the LIBOR rate beyond 2021.
The Alternative Reference Rates Committee (“ARRC”) has recommended the Secured Overnight Financing Rate (“SOFR”) as the best alternative rate to LIBOR post discontinuance and has proposed a transition plan and timeline designed to encourage the adoption of SOFR from LIBOR.
Post consultation on March 5, 2021, IBA confirmed its proposed dates to stop publishing the London interbank offered rate for dollars ("USD LIBOR") on a representative basis.
When the Company entered into the Second Amended and Restated Credit on October 27, 2021, it included provisions regarding transition from LIBOR to SOFR in preparation of the LIBOR cessation.
On March 31, 2022, the Company entered into the Loan Agreement which bears interest tied to the annual rate for the adjusted Secured Overnight Financing Rate ("Adjusted Term SOFR").
In the coming periods,
the Company will assess any other current agreements with benchmark rates tied to LIBOR with an expectation that the Company will be prepared for a termination of LIBOR benchmarks prior to June 30, 2023 when typical rate settings will no longer be available.
Item 1. Business.
61 rewritten, 22 added, 11 removed, 237 unchanged
[removed: WNFIC’s underwriting business consists of policies written pursuant to the National Flood Insurance Program (“NFIP”), the program administered by the Federal Emergency Management Agency (“FEMA”),] [added: We also sell] excess flood [removed: and private flood] policies which are fully reinsured, thereby substantially eliminating WNFIC’s exposure to underwriting risk, as these policies are backed by either FEMA or a reinsurance carrier with an AM Best Company rating of “A” or better.
The Captives give us another way to continue to participate in underwriting [removed: results] [added: results,] while limiting exposure to underwriting claim costs.
The Captives focus on property insurance for earthquake and wind exposed properties underwritten by certain [added: of our] managing general [removed: agents.][added: underwriters (“MGUs”).]
As of December 31, [removed: 2022,] [added: 2023,] our activities were conducted in [removed: 345] [added: 322] domestic locations in 46 states, and [removed: 150] [added: 177] international locations in Belgium, Bermuda, Canada, Cayman Islands, [added: France, Germany, Hong Kong Special Administrative Region of the People's Republic of China (“Hong Kong”), Republic of] Ireland, [removed: Italy] [added: Italy, Malaysia, the Netherlands, United Arab Emirates] and the United Kingdom.
The National Programs segment, which acts as [removed: a managing general agent (“MGA”),] [added: an MGU,] provides professional liability and related package products for certain professionals, a range of insurance products for individuals, flood coverage, and targeted products and services designated for specific industries, trade groups, governmental entities and market niches, all of which are delivered through a nationwide network of independent agents, including Brown & Brown retail agents, as well as affinity groups, wholesale entities and sold direct to consumers.
The following table summarizes (i) the commissions and fees generated by each of our reportable operating segments for [added: 2023,] 2022, [removed: 2021,] and [removed: 2020] [added: 2021] and (ii) the percentage of our total commissions and fees represented by each segment for each such period:
| (in millions, except percentages) | | [removed: 2022] [added: 2023] | | | | % | | | | [removed: 2021] [added: 2022] | | | | % | | | | [removed: 2020] [added: 2021] | | | | % | | |
| Retail segment | | $ | [removed: 2,081.6] [added: 2,434.7] | | | | [removed: 58.4] [added: 58.0] | % | | $ | [removed: 1,766.6] [added: 2,081.6] | | | | [removed: 58.0] [added: 58.4] | % | | $ | [removed: 1,471.4] [added: 1,766.6] | | | | [removed: 56.5] [added: 58.0] | % |
| National Programs segment | | | [removed: 858.1] [added: 1,064.3] | | | | [removed: 24.1] [added: 25.3] | % | | | [removed: 701.1] [added: 858.1] | | | | [removed: 23.0] [added: 24.1] | % | | | [removed: 609.8] [added: 701.1] | | | | [removed: 23.4] [added: 23.0] | % |
| Wholesale Brokerage segment | | | [removed: 452.8] [added: 539.0] | | | | [removed: 12.7] [added: 12.8] | % | | | [removed: 402.6] [added: 452.8] | | | | [removed: 13.2] [added: 12.7] | % | | | [removed: 352.2] [added: 402.6] | | | | [removed: 13.5] [added: 13.2] | % |
| Services segment | | | [removed: 171.9] [added: 163.1] | | | | [removed: 4.8] [added: 3.9] | % | | | [removed: 178.9] [added: 171.9] | | | | [removed: 5.9] [added: 4.8] | % | | | [removed: 174.0] [added: 178.9] | | | | [removed: 6.7] [added: 5.9] | % |
| Other | | | [removed: (1.2] [added: (1.7] | ) | | | (— | )% | | | [removed: (1.7] [added: (1.2] | ) | | | [removed: (0.1] [added: (—] | )% | | | [removed: (1.3] [added: (1.7] | ) | | | (0.1 | )% |
| Total | | $ | [removed: 3,563.2] [added: 4,199.4] | | | | 100.0 | % | | $ | [removed: 3,047.5] [added: 3,563.2] | | | | 100.0 | % | | $ | [removed: 2,606.1] [added: 3,047.5] | | | | 100.0 | % |
Outside of the United States we have retail operations based in Bermuda, [added: Canada,] Cayman Islands, [removed: Ireland,] [added: Republic of Ireland] and the United Kingdom, [removed: wholesale brokerage] [added: managing general underwriter] operations [removed: based] in [added: Canada, France, Germany, Hong Kong, Italy, Malaysia,] the [removed: Belgium, Italy] [added: Netherlands, United Arab Emirates] and the United [removed: Kingdom] [added: Kingdom;] and [removed: a managing general agent operation] [added: wholesale brokerage operations based] in [removed: Canada] [added: Belgium, Hong Kong, Italy] and the United Kingdom.
These operations generated [removed: $240.6] [added: $527.0] million, [removed: $78.0] [added: $240.6] million and [removed: $35.1] [added: $78.0] million of revenues for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020,] [added: 2021,] respectively.
No material part of our [removed: retail business] [added: Retail segment] is attributable to a single customer or a few customers.
During [removed: 2022,] [added: 2023,] commissions and fees from our largest single Retail segment customer represented [removed: 0.5%] [added: 0.8%] of the Retail segment’s total commissions and fees.
As of December 31, [removed: 2022,] [added: 2023,] our Retail segment employed [removed: 9,185] [added: 9,705] employees.
Our Retail segment has physical locations in 42 states [removed: and] [added: plus] Bermuda, [added: Canada,] Cayman Islands, [added: Republic of] Ireland and the United Kingdom.
[removed: In connection with selling and marketing of insurance] coverages, we provide a broad range of related services to our customers, such as risk management strategies, loss control surveys and analysis, consultation in connection with placing insurance coverages and claims processing.
As of December 31, [removed: 2022,] [added: 2023,] our National Programs segment employed [removed: 3,008] [added: 3,743] employees.
The National Programs segment specializes in the [removed: development] [added: development, underwriting] and management of insurance program business, often designed for niche, underserved markets and distributes these coverages to retail [removed: insurance] agencies (including Brown & Brown retail offices), as well as affinity groups, wholesale entities and sold direct to consumers.
Our largest National Programs segment customer represented approximately [removed: 7.6%] [added: 8.1%] of the segment's total commissions and fees.
As of December 31, [removed: 2022,] [added: 2023,] our Wholesale Brokerage segment employed [removed: 1,687] [added: 1,918] employees.
The Wholesale Brokerage segment [removed: represent] [added: represents] various U.S., U.K., and European surplus lines insurance companies.
During [removed: 2022,] [added: 2023,] commissions and fees from our largest Wholesale Brokerage segment customer represented approximately [removed: 1.4%] [added: 1.3%] of the Wholesale Brokerage segment’s total commissions and fees.
As of December 31, [removed: 2022,] [added: 2023,] our Services segment employed [removed: 991] [added: 398] employees and provided a [removed: wide range] [added: variety] of insurance-related services.
In [removed: 2022,] [added: 2023,] our five largest contracts represented approximately [removed: 22.4%] [added: 38.8%] of [removed: fees] [added: fee] revenues in our Services segment.
We and/or our designated employees must [added: generally] be licensed to act as agents, brokers, intermediaries or third-party administrators by regulatory authorities in the locations in which we conduct business.
At December 31, [removed: 2022,] [added: 2023,] the Company had [removed: 15,201] [added: 16,152] employees globally.
[removed: None] [added: Except for certain] of our employees [added: in Canada, none of our employees] are subject to a collective bargaining agreement and we consider our relations with our employees to be good.
We [removed: view ourselves as a team and refer to our employees as “teammates.” We] believe in always doing what is best for our customers, communities, teammates, carrier partners and shareholders.
With more than 60% of our [added: U.S.] teammates owning stock in our Company, we operate with an ownership mindset that influences how we invest in our business and the work we do for our customers.
Full-time teammates work at least a [removed: 30-hours] [added: 30 hours] per week for an indefinite period of time and are generally eligible for all employment benefits provided by the Company.
In [removed: 2022,] [added: 2023,] we grew our team by almost [removed: 2,800] [added: 900] new teammates through the acquisition of [removed: 30] [added: 33] companies.
In [removed: 2022,] [added: 2023,] there were no widespread layoffs or pay reductions as a result of external factors, such as the [removed: economy, the COVID-19 pandemic] [added: economy] or natural disasters.
Additionally, [removed: teammates] [added: teammates, their families and others] affected [removed: in 2022] by [removed: the COVID-19 pandemic or natural disasters, including Hurricane Ian and Hurricane Nicole, had] [added: disasters have] the opportunity to apply for financial assistance through our Brown & Brown Disaster Relief Foundation.
We are committed to actively listening and amplifying our teammates' well-being, satisfaction and engagement at work, and are proud that in [removed: 2022,] [added: 2023,] 93% of our teammates say Brown & Brown is a Great Place to Work®.
As part of our strategy, we continue to evolve and augment our Diversity, Inclusion and Belonging ("DIB") [removed: task force,] [added: advisory council,] which [removed: was established in 2020.][added: is composed of numerous teammates and leaders with different backgrounds, work experiences and skill sets.]
The [removed: task force] [added: DIB advisor council] is overseen and guided by our chief people officer.
WNFIC’s underwriting business consists of policies written pursuant to the National Flood Insurance Program (“NFIP”), the program administered by the Federal Emergency Management Agency (“FEMA”).
As announced on October 31, 2023 and completed in the fourth quarter of 2023, the Company sold certain third-party claims administration and adjusting services businesses representing approximately 50% of the total revenues of the Services segment to Davies Group Ltd. As a result, beginning in fiscal year 2024 the Company will operate three segments: Retail, Programs (formerly National Programs), and Wholesale.
Historical results will be recast to align with the three-segment structure with the remaining businesses to be included as part of the Retail segment.
The Company performed an evaluation to determine if the sold businesses should be reported as
discontinued operations.
However, with the sold businesses representing, as a percentage of total Company, approximately 3% of the total revenue, 2% of the total assets and 2% of net income, the Company determined that treating the sale as discontinued operations was not appropriate.
In connection with selling and marketing of insurance
Our National Programs segment has physical locations in 20 states plus Canada, France, Germany, Hong Kong, Italy, Malaysia, the Netherlands, United Arab Emirates and the United Kingdom.
Our Wholesale Brokerage segment has physical locations in 22 states plus Belgium, Hong Kong, Italy and the United Kingdom.
The two businesses listed below were not part of the sale of certain businesses to Davies Group Ltd. in the fourth quarter of 2023.
In 2024, the financial results of these businesses, along with their historical financial results, will be included in the Retail segment.
The following businesses were sold to Davies Group Ltd. in the fourth quarter of 2023.
In 2024 the historical results associated with these businesses will be included within the Programs (formerly National Programs) segment.
The Company performed an evaluation to determine if the sold businesses should be reported as discontinued operations.
However, with the sold businesses representing, as a percentage of total Company, approximately 3% of the total revenue, 2% of the total assets and 2% of net income, the Company determined that treating the sale as discontinued operations was not appropriate.
We view ourselves as a team and refer to our employees as “teammates,” and our team is characterized by a common framework of behaviors, skills, and characteristics that create a link between what we do and how we do it – our cultural DNA.
We believe our own teammates are the best stewards of our culture and have invested in building our internal recruiting capabilities to attract and onboard high-quality talent companywide.
Each year we have a robust process to evaluate the benefits of our medical and well being plans.
We incorporate feedback from our teammates into the design of our benefits.
The mission of the DIB advisory council is assist with recruiting and development of inclusive relationships.
We offer specialized training related to a hybrid work environment for our leaders.
Barrett Brown, are employed by us as
Below are brief descriptions of the capabilities within the Services segment.
The DIB team is composed of numerous teammates and leaders with different backgrounds, work experiences and skill sets.
The mission of the task force is to provide an environment to foster the collection of ideas, thoughts and stories that help further develop a strategic framework of promoting diversity, inclusion and belonging.
We are proud of our efforts in this area and continue to strive to further diversify our workforce and strengthen our culture.
During the COVID-19 pandemic, we navigated the pandemic by carefully executing our business continuity plan.
We prioritized the health and well-being of our teammates to support the welfare of our customers, carrier partners and shareholders.
The Brown & Brown team demonstrated resiliency in a time of uncertainty, and through “The Power of WE,” navigated this uncharted territory with minimal interruption to our business.
We know we must remain prepared to deal with future pandemics.
Our response has formed the basis for preparedness if another dangerous and contagious disease should arise.
We continue to engage our team of employed health care professionals to provide critical and timely guidance on the physiological and psychological implications of COVID-19.
We also provide access to public COVID-19 resources through our website portal to benefit individuals and businesses coping with challenges resulting from the pandemic.
An excerpt. Shown here: 40 of 61 rewritten, all 22 added and all 11 removed. The counts are complete. For every sentence, read Item 1. Business. in the FY2023 filing and the FY2022 filing.
Cover and table of contents
38 rewritten, 3 added, 2 removed, 114 unchanged
For the fiscal year ended December 31, [removed: 2022][added: 2023]
| 300 North Beach Street, Daytona Beach, FL | | [removed: ] [added: ] | | 32114 |
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive [removed: officers] [added: officers] during the relevant recovery period pursuant to §240.10D-1(b).
The aggregate market value of the voting common stock held by non-affiliates of the registrant, computed by reference to the price at which the stock was last sold on June 30, [removed: 2022] [added: 2023] (the last business day of the registrant’s most recently completed second fiscal quarter) was [removed: $15,295,411,331.][added: $16,289,316,561.]
The number of shares of the Registrant’s common stock, $0.10 par value, outstanding as of February [removed: 23, 2023] [added: 19, 2024] was [removed: 284,294,500.][added: 285,801,863.]
Portions of Brown & Brown, Inc.’s Proxy Statement for the [removed: 2023] [added: 2024] Annual Meeting of Shareholders are incorporated by reference into Part III of this Report.
FOR THE FISCAL YEAR ENDED DECEMBER 31, [removed: 2022][added: 2023]
| Item 1B. | [Unresolved Staff [removed: Comments](#item_2_properties)] [added: Comments](#item_1b_unresolved_staff_comments)] | 22 |
| Item 2. | [Properties](#item_2_properties) | [removed: 22] [added: 24] |
| Item 3. | [Legal Proceedings](#item_3_legal_proceedings) | [removed: 22] [added: 24] |
| Item 4. | [Mine Safety Disclosures](#item_4_mine_safety_disclosures) | [removed: 22] [added: 24] |
| [Part II](#part_ii) | | [removed: 23] [added: 25] |
| Item 5. | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities](#item_5_market_for_registrants_common_equ) | [removed: 23] [added: 25] |
| Item 6. | Reserved | [removed: 25] [added: 27] |
| Item 7. | [Management’s Discussion and Analysis of Financial Condition and Results of Operations](#item_7_managements_discussion_analysis_f) | [removed: 26] [added: 28] |
| Item 7A. | [Quantitative and Qualitative Disclosures About Market Risk](#item_7a_quantitative_qualitative_disclos) | [removed: 42] [added: 45] |
| Item 8. | [Financial Statements and Supplementary Data](#item_8_financial_statements_supplementar) | [removed: 44] [added: 46] |
| Item 9. | [Changes in and Disagreements With Accountants on Accounting and Financial Disclosure](#item_9_changes_in_disagreements_with_acc) | [removed: 93] [added: 86] |
| Item 9A. | [Controls and Procedures](#item_9a_controls_procedures) | [removed: 93] [added: 86] |
| Item 9B. | [Other Information](#item_9b_or_information) | [removed: 93] [added: 86] |
| Item 9C. | [Disclosure Regarding Foreign Jurisdictions that Prevent Inspections](#item_9b_or_information) | [removed: 93] [added: 86] |
| [Part III](#part_iii) | | [removed: 94] [added: 87] |
| Item 10. | [Directors, Executive Officers and Corporate Governance](#item_10_directors_executive_ficers_corpo) | [removed: 94] [added: 87] |
| Item 11. | [Executive Compensation](#item_11_executive_compensation) | [removed: 94] [added: 87] |
| Item 12. | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#item_12_security_ownership_certain_benef) | [removed: 95] [added: 88] |
| Item 13. | [Certain Relationships and Related Transactions, and Director Independence](#item_13_certain_relationships_related_tr) | [removed: 95] [added: 88] |
| Item 14. | [Principal Accounting Fees and Services](#item_14_principal_accounting_fees_servic) | [removed: 95] [added: 88] |
| [Part IV](#part_iv) | | [removed: 96] [added: 89] |
| Item 15. | [Exhibits, Financial Statement Schedules](#item_15_exhibits_financial_statements_sc) | [removed: 96] [added: 89] |
| Item 16. | [Form 10-K Summary](#item_16_form_10k_summary) | [removed: 98] [added: 91] |
| [Signatures](#signatures) | | [removed: 99] [added: 92] |
The inability to [added: hire,] retain [removed: or hire] [added: and develop] qualified employees, as well as the loss of any of our executive officers or other key employees;
The effects of [removed: inflation;][added: sustained inflation or higher interest rates;]
The effect of natural disasters on our profit-sharing contingent commissions, insurer capacity [removed: and] [added: or] claims expenses [removed: from] [added: within] our capitalized captive insurance facilities;
Adverse economic conditions, [removed: natural] [added: political conditions, outbreaks of war,] disasters, or regulatory changes in states or countries where we have a concentration of our business;
Regulatory changes that could reduce our profitability or growth by increasing compliance costs, technology compliance, restricting the products or services we may sell, the markets we may enter, the methods by which we may sell our products and services, or the prices we may charge for our services and the form of compensation we may accept from our customers, carriers and [removed: third-parties;][added: third parties;]
Increasing scrutiny and changing [added: laws and] expectations from [added: regulators,] investors and customers with respect to our environmental, social and governance [removed: practices;][added: practices and disclosure;]
[removed: The COVID-19 pandemic (“COVID-19”), as well as future] [added: Future] pandemics, epidemics or outbreaks of infectious diseases, and the resulting governmental and societal responses;
| Item 1C. | [Cybersecurity](#item_1c_cybersecurity) | 22 |
Fluctuations in our commission revenue as a result of factors outside of our control;
Changes in, or the termination of, certain programs administered by the U.S. federal government from which we derive revenues;
Risks facing us in our Services segment, including our third-party claims administration operations, that are distinct from those we face in our insurance intermediary operations;
Risks associated with the current interest rate environment, and to the extent we use debt to finance our investments, changes in interest rates will affect our cost of capital and net investment income;
Item 1C. Cybersecurity.
0 rewritten, 30 added, 0 removed, 0 unchanged
New section this year
The Company relies on our internal Technology Solutions team and third-party vendors to provide effective and efficient service to our customers, process claims and timely and accurately report information to carriers, which often involves secure processing of confidential, sensitive, proprietary and other types of information.
We monitor the risks presented by the possibility of cybersecurity breaches of any of these systems.
Accordingly, we have significantly invested, and will continue to invest, in technology security initiatives, information technology policies and resources, and teammate training to mitigate the risk of improper access to private information.
The Audit Committee, composed entirely of independent directors, is responsible for organization-wide oversight regarding information security and reports to the full Board.
All directors typically attend our committee meetings, which we believe creates transparency and a more
collaborative and informed Board.
The Audit Committee receives reports on at least a quarterly basis from the Company’s chief information security officer, who is typically accompanied by the Company’s chief security officer and chief information officer, on the Company’s latest information security risks and mitigation strategies.
Assessing, identifying and managing cybersecurity related risks are integrated into our overall enterprise risk management (ERM) program.
As part of the Company’s ERM program, the Board receives a report at least annually from the Company’s chief executive officer and chief legal officer concerning the Company’s risks, which include cybersecurity risks.
The Company’s chief information security officer, under the direction of our chief security officer, is responsible for developing and implementing our information security program.
Our chief information security officer and our chief security officer each has more than 35 years of experience in technology, operations, information risk and security.
Our chief information security officer has deep experience developing comprehensive information security programs for large and complex financial services and insurance organizations.
Our chief security officer brings extensive experience in both the military and the private sector and is a specialist in attack surface reduction, incident response and recovery, targeted threat hunting, forensics/malware analysis and threat group analysis.
Our Information Security team has deployed a structured and measured vulnerability management program that proactively identifies vulnerabilities across our platforms and processes.
The program is composed of the following:
Internal persistent scans and external monthly scans;
Static and dynamic software custom code to develop scans for secure code development;
Periodic third-party executed penetration tests and risk assessments; and
A model to comply with SOC 2 Type II standards or other industry certifications at certain offices based on an office’s contractual agreements with carrier partners or other third parties.
In addition, external partners and products are submitted through a security risk assessment process facilitated through our security scorecard tool for data security risk and vulnerability maturity rating, and our teammates undertake a yearly security and compliance online training with test certification.
Our teammates are also subject to security awareness communications and random simulated phishing campaigns.
Teammates are also required to complete Health Insurance Portability and Accountability Act of 1996 (HIPAA) training every one or two years, depending on location.
In 2023, substantially all Brown & Brown teammates completed ethical conduct training; cybersecurity awareness training; the California Consumer Privacy Act (CCPA) Survey; and the Annual Certification for Insurance Licensees training as a reminder of the regulatory obligation to report certain changes to the jurisdictions in which they are licensed.
We have also established a structured incident response process driven by the severity and type of issue.
This process, which engages our Security Operations Center (SOC) for incident identification, our internal security team for incident analysis and assignment, our Technology Solutions teams for isolation/remediation and our third-party business partner for continuity awareness and escalations.
These teams operate at the direction of our Legal Department when we identify potentially impactful information security incidents, which, among other things, directs external and internal reporting, including escalation to other functional areas within the Company and the Board of Directors.
We have adopted an in-depth defense approach that includes intrusion detection systems and intrusion prevention systems, endpoint protection, endpoint detection and response and a log management platform.
Additionally, to defray the costs of any future data breach, we have a cyber liability insurance policy.
We face a number of cybersecurity risks in connection with our business and have from time-to-time experienced cybersecurity incidents, such as malware infections, phishing campaigns and vulnerability exploit attempts, which to date have not had a material impact on our business strategy, results of operations, or financial condition.
For more information about the cybersecurity risks we face, see the risk factor entitled “A cybersecurity attack, or any other interruption in information technology and/or data security that may impact our operations or the operations of third parties that support us, could adversely affect our business, financial condition and reputation” in Item 1A - Risk Factors.
Item 2. Properties.
2 rewritten, 0 added, 0 removed, 6 unchanged
We own our executive offices, which are located at 300 North Beach Street, Daytona Beach, Florida 32114, as well as certain other [added: vacant land and] office buildings in the Daytona Beach area.
We lease offices at each of our other [removed: 492] [added: 499] locations.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
11 rewritten, 8 added, 14 removed, 14 unchanged
On February [removed: 23, 2023,] [added: 19, 2024,] there were [removed: 284,294,500] [added: 285,801,863] shares of our common stock outstanding, held by approximately [removed: 1,804] [added: 1,564] shareholders of record.
During [removed: 2022,] [added: 2023,] the Company issued [removed: 252,802] [added: 261,614] shares of the Company's common stock to the owners of the businesses acquired in connection with the acquisition of [removed: GRP.][added: Kentro Capital Limited.]
During [removed: 2022,] [added: 2023,] the Company repurchased [removed: 1,164,009] [added: 2,100] shares at an average price of [removed: $63.62] [added: $53.84] for a total cost of [removed: $74.1] [added: $0.1] million under the current share repurchase authorization.
At December 31, [removed: 2022,] [added: 2023,] the remaining amount authorized by our board of directors for share repurchases was [removed: $249.6] [added: $249.5] million.
Under the authorized repurchase programs, the Company has repurchased approximately 19.7 million shares for an aggregate cost of approximately [removed: $748.0] [added: $748.1] million between 2014 and [removed: 2022.][added: 2023.]
The following table presents information with respect to our purchases of our common stock during the three months ended December 31, [removed: 2022.][added: 2023.]
| Period | | Total number of shares [removed: purchased(1)] [added: purchased] | | | | Average price paid per share | | | | Total number of shares purchased as part of publicly announced plans or programs | | | | Approximate dollar value of shares that may yet be purchased under the plans or programs | | |
The following graph is a comparison of five-year cumulative total shareholder returns for our common stock as compared with the cumulative total shareholder return for the S&P 500 Composite Index, [removed: the NYSE Composite Index,] and a group of peer insurance broker and agency companies (Aon plc, Arthur J.
The returns of each company have been weighted according to such companies’ respective stock market capitalizations as of December 31, [removed: 2017] [added: 2018] for the purposes of arriving at a peer group average.
The total return calculations are based upon an assumed $100.00 investment on December 31, [removed: 2017,] [added: 2018,] with all dividends reinvested.
[removed: 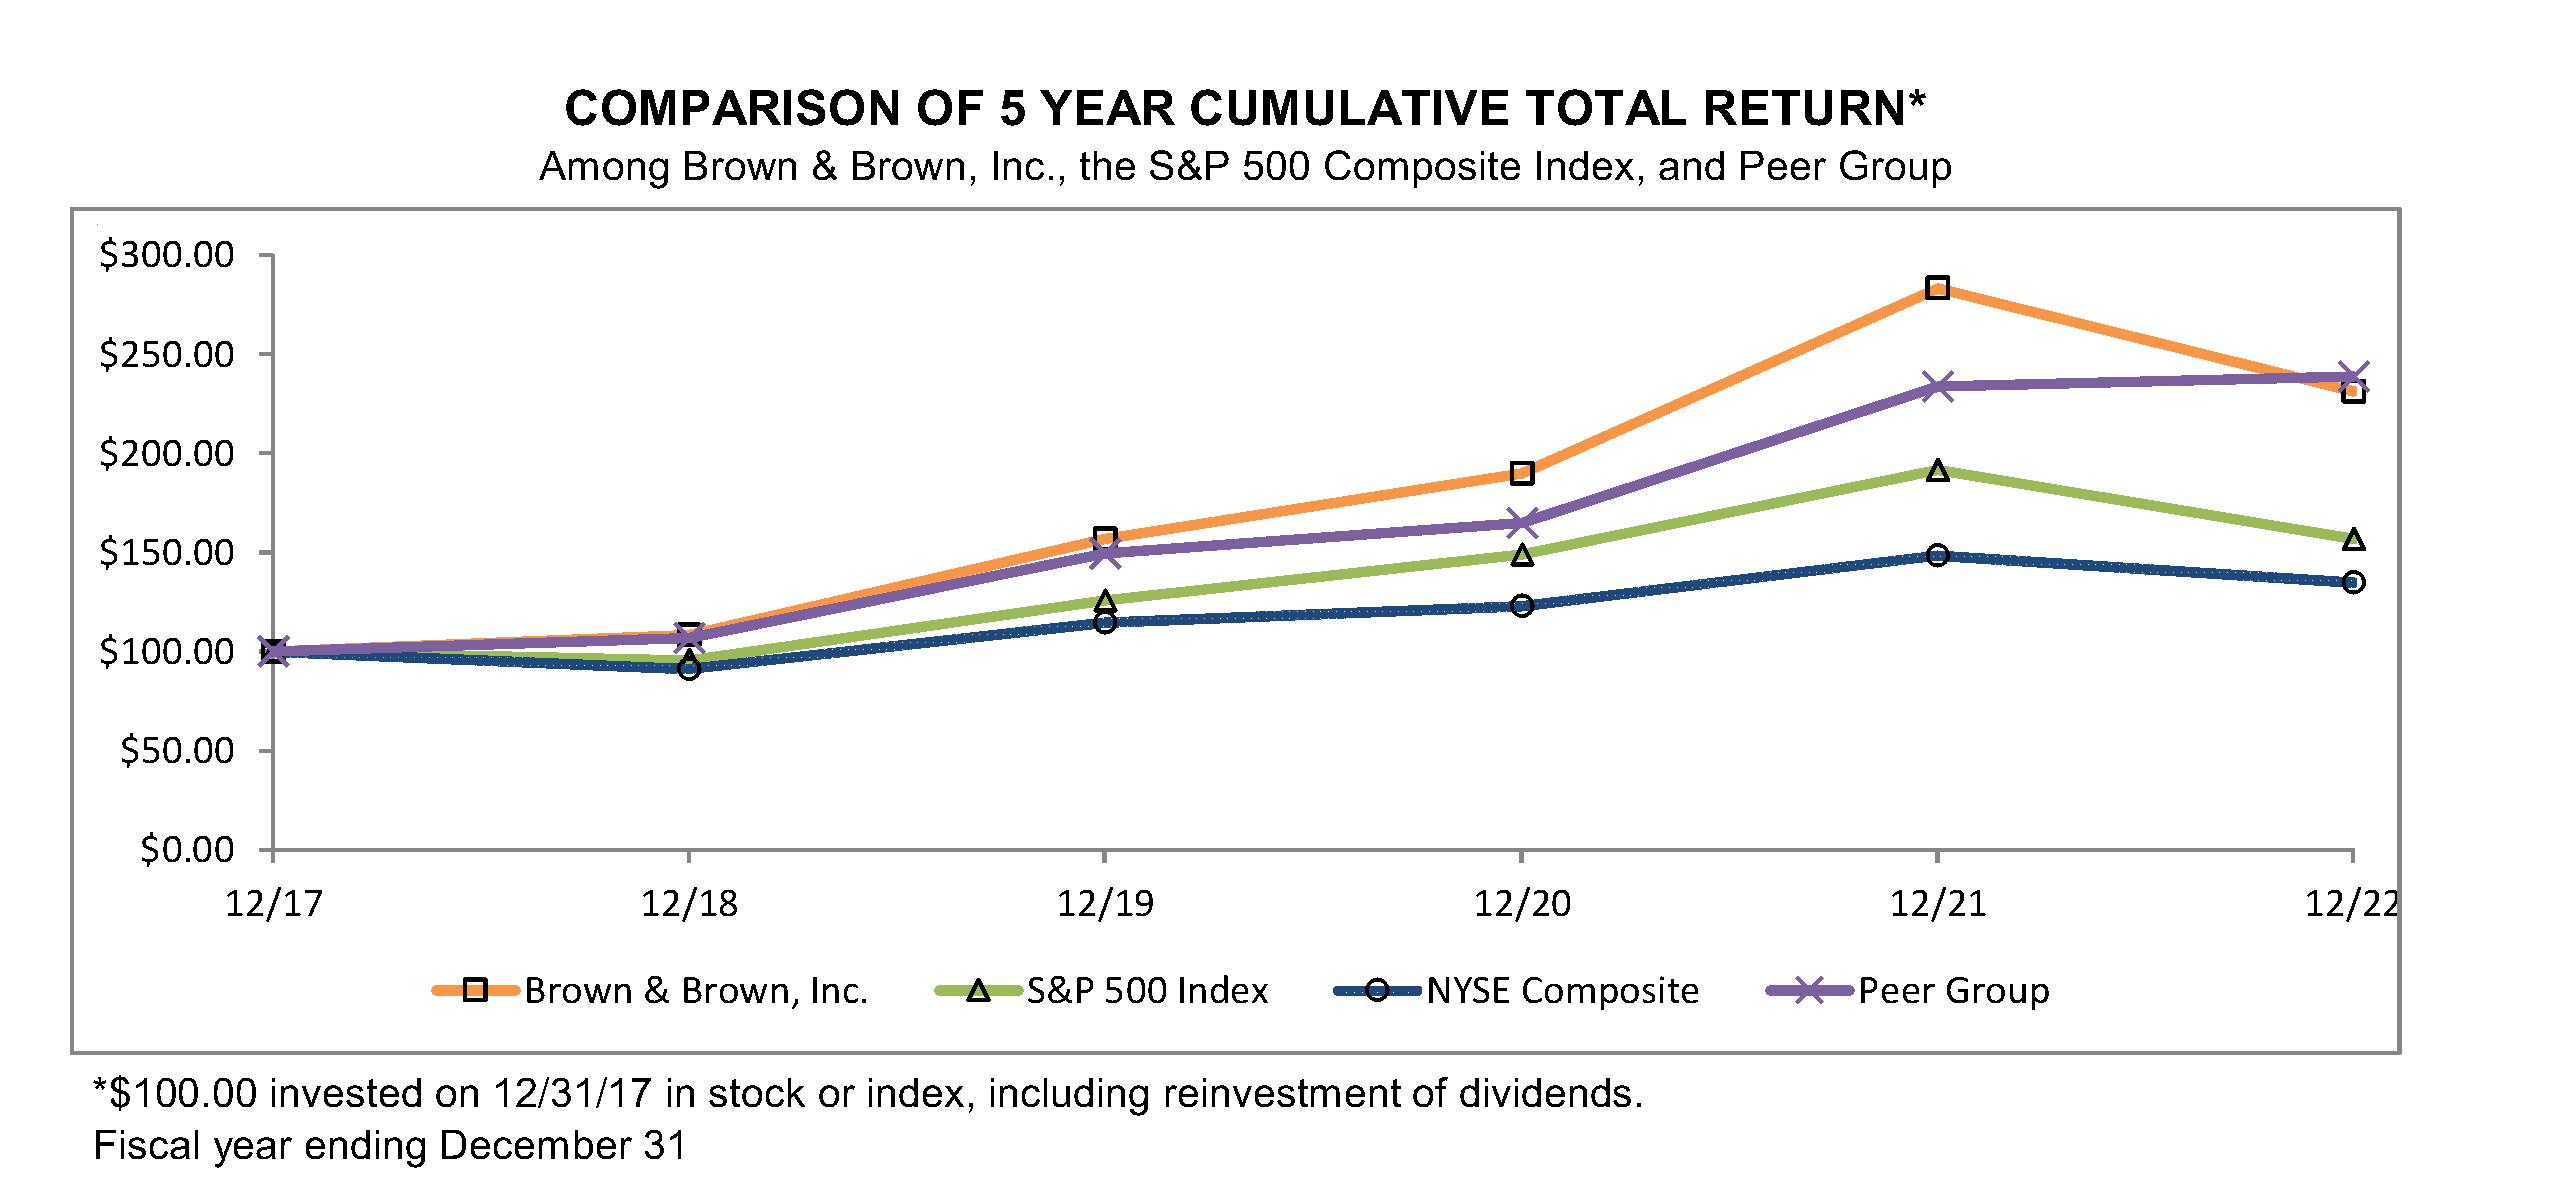][added: ]
| October 1, 2023 to October 31, 2023 | | | — | | | $ | — | | | | — | | | $ | 249.5 | |
| November 1, 2023 to November 30, 2023 | | | — | | | | — | | | | — | | | | 249.5 | |
| December 1, 2023 to December 31, 2023 | | | — | | | | — | | | | — | | | | 249.5 | |
| Total | | | — | | | $ | — | | | | — | | | $ | 249.5 | |
| | | 12/18 | | | | 12/19 | | | | 12/20 | | | | 12/21 | | | | 12/22 | | | | 12/23 | | |
| Brown & Brown, Inc. | | | 100.00 | | | | 144.66 | | | | 175.13 | | | | 261.47 | | | | 213.40 | | | | 268.29 | |
| S&P 500 Composite | | | 100.00 | | | | 131.47 | | | | 155.65 | | | | 200.29 | | | | 163.98 | | | | 207.04 | |
| Peer Group | | | 100.00 | | | | 140.40 | | | | 151.85 | | | | 213.43 | | | | 216.03 | | | | 234.74 | |
| October 1, 2022 to October 31, 2022 | | | 12 | | | $ | 62.89 | | | | — | | | $ | 249.6 | |
| November 1, 2022 to November 30, 2022 | | | 548 | | | | 56.31 | | | | — | | | | 249.6 | |
| December 1, 2022 to December 31, 2022 | | | — | | | | — | | | | — | | | | 249.6 | |
| Total | | | 560 | | | $ | 56.45 | | | | — | | | $ | 249.6 | |
(1)
Of the shares reported in this column, no shares were purchased in open market transactions and all shares reported in this column are attributable to shares withheld for taxes in connection with the vesting of restricted shares awarded under our Performance Stock Plan and 2010 Stock Incentive Plan.
In previous years, we compared our cumulative total shareholder return with the NYSE Composite Index.
We have replaced the NYSE Composite Index with the S&P 500 Composite Index as required by SEC rules.
In this transition year, the stock performance graph below includes the comparative performance of the new index and the previously reported index.
| | | 12/17 | | | | 12/18 | | | | 12/19 | | | | 12/20 | | | | 12/21 | | | | 12/22 | | |
| Brown & Brown, Inc. | | | 100.00 | | | | 108.29 | | | | 156.66 | | | | 189.64 | | | | 283.14 | | | | 231.09 | |
| S&P 500 Composite | | | 100.00 | | | | 95.61 | | | | 125.70 | | | | 148.81 | | | | 191.48 | | | | 156.77 | |
| NYSE Composite | | | 100.00 | | | | 91.21 | | | | 114.70 | | | | 122.83 | | | | 148.42 | | | | 134.76 | |
| Peer Group | | | 100.00 | | | | 106.73 | | | | 149.32 | | | | 164.77 | | | | 233.57 | | | | 238.65 | |
Item 8. Financial Statements and Supplementary Data.
492 rewritten, 183 added, 330 removed, 651 unchanged
| [Consolidated Statements of Income for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_income)] [added: 2021](#consolidated_statements_income)] | [removed: 45] [added: 47] |
| [Consolidated Statements of Comprehensive Income for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_of_comp_income)] [added: 2021](#consolidated_statements_of_comp_income)] | [removed: 46] [added: 48] |
| [Consolidated Balance Sheets as of December 31, [removed: 2022] [added: 2023] and [removed: 2021](#consolidated_balance_sheets)] [added: 2022](#consolidated_balance_sheets)] | [removed: 47] [added: 49] |
| [Consolidated Statements of Shareholders’ Equity for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_shareholders_equ)] [added: 2021](#consolidated_statements_shareholders_equ)] | [removed: 48] [added: 50] |
| [Consolidated Statements of Cash Flows for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_cash_flows)] [added: 2021](#consolidated_statements_cash_flows)] | [removed: 50] [added: 52] |
| [Notes to Consolidated Financial Statements for the years ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#notes_to_consolidated_financial_statemen)] [added: 2021](#notes_to_consolidated_financial_statemen)] | [removed: 53] [added: 55] |
| [Note 1: Summary of Significant Accounting Policies](#note_1_summary_significant_accounting_po) | [removed: 53] [added: 55] |
| [Note 2: Revenues](#note_2_revenues) | [removed: 59] [added: 60] |
| [Note 3: Business Combinations](#note_3_business_combinations) | [removed: 61] [added: 62] |
| [Note 4: Goodwill](#note_4_goodwill) | [removed: 70] [added: 65] |
| [Note 5: Amortizable Intangible Assets](#note_5_amortizable_intangible_assets) | [removed: 70] [added: 65] |
| [Note 6: Investments](#note_6_investments) | [removed: 70] [added: 65] |
| [Note 7: Fixed Assets](#note_7_fixed_assets) | [removed: 73] [added: 68] |
| [Note 8: Accrued Expenses and Other Liabilities](#note_8_accrued_expenses_or_current_liabi) | [removed: 73] [added: 68] |
| [Note 9: Long-Term Debt](#note_9_longterm_debt) | [removed: 74] [added: 69] |
| [Note 10: Income Taxes](#note_10_income_taxes) | [removed: 76] [added: 71] |
| [Note 11: Employee Savings Plan](#note_11_employee_savings_plan) | [removed: 79] [added: 73] |
| [Note 12: Stock-Based Compensation](#note_12_stockbased_compensation) | [removed: 79] [added: 73] |
| [Note 13: Supplemental Disclosures of Cash Flow Information and Non-Cash Financing and Investing Activities](#note_13_supplemental_disclosures_cash_f) | [removed: 82] [added: 76] |
| [Note 14: Commitments and Contingencies](#note_14_commitments_contingencies) | [removed: 83] [added: 77] |
| [Note 15: Leases](#note_15_leases) | [removed: 84] [added: 78] |
| [Note 16: Segment Information](#note_16_segment_information) | [removed: 86] [added: 80] |
| [Note 17: Insurance Company Subsidiary Operations](#note_17_reinsurance) | [removed: 87] [added: 81] |
| [Note 18: Shareholders’ Equity](#note_20_shareholders_equity) | [removed: 88] [added: 82] |
| [Reports of Independent Registered Public Accounting Firm](#report_of_independant_registered_public) | [removed: 88] [added: 82] |
| (in millions, except per share data) | | [removed: 2022] [added: 2023] | | | | [removed: 2021] [added: 2022] | | | | [removed: 2020] [added: 2021] | | |
| Commissions and fees | | $ | [removed: 3,563.2] [added: 4,199.4] | | | $ | [removed: 3,047.5] [added: 3,563.2] | | | $ | [removed: 2,606.1] [added: 3,047.5] | |
| Investment income | | | [removed: 6.5] [added: 52.4] | | | | [removed: 1.1] [added: 6.5] | | | | [removed: 2.8] [added: 1.1] | |
| Other income, net | | | [removed: 3.7] [added: 5.3] | | | | [removed: 2.8] [added: 3.7] | | | | [removed: 4.5] [added: 2.8] | |
| Total revenues | | | [removed: 3,573.4] [added: 4,257.1] | | | | [removed: 3,051.4] [added: 3,573.4] | | | | [removed: 2,613.4] [added: 3,051.4] | |
| Employee compensation and benefits | | | [removed: 1,816.9] [added: 2,186.6] | | | | [removed: 1,636.9] [added: 1,816.9] | | | | [removed: 1,436.4] [added: 1,636.9] | |
| Other operating expenses | | | [removed: 596.8] [added: 649.9] | | | | [removed: 403.0] [added: 596.8] | | | | [removed: 366.0] [added: 403.0] | |
| (Gain)/loss on disposal | | | [removed: (4.5] [added: (143.3] | ) | | | [removed: (9.6] [added: (4.5] | ) | | | [removed: (2.4] [added: (9.6] | ) |
| Amortization | | | [removed: 146.6] [added: 166.0] | | | | [removed: 119.6] [added: 146.6] | | | | [removed: 108.5] [added: 119.6] | |
| Depreciation | | | [removed: 39.2] [added: 40.0] | | | | [removed: 33.3] [added: 39.2] | | | | [removed: 26.3] [added: 33.3] | |
| Interest | | | [removed: 141.2] [added: 190.0] | | | | [removed: 65.0] [added: 141.2] | | | | [removed: 59.0] [added: 65.0] | |
| Change in estimated acquisition earn-out payables | | | [removed: (38.9] [added: 21.8] | [removed: )] | | | [removed: 40.4] [added: (38.9] | [added: )] | | | [removed: (4.5] [added: 40.4] | [removed: )] |
| Total expenses | | | [removed: 2,697.3] [added: 3,111.0] | | | | [removed: 2,288.6] [added: 2,697.3] | | | | [removed: 1,989.3] [added: 2,288.6] | |
| Income before income taxes | | | [removed: 876.1] [added: 1,146.1] | | | | [removed: 762.8] [added: 876.1] | | | | [removed: 624.1] [added: 762.8] | |
| Income taxes | | | [removed: 204.3] [added: 275.6] | | | | [removed: 175.7] [added: 204.3] | | | | [removed: 143.6] [added: 175.7] | |
| Net income | | $ | 870.5 | | | $ | 671.8 | | | $ | 587.1 | |
| Foreign currency translation | | | | | | | | | | | (0.2 | ) | | | | | | | 128.6 | | | | | | | | 128.4 | |
| Stock incentive plans | | | 1,034 | | | | 0.1 | | | | 75.5 | | | | | | | | | | | | | | | | 75.6 | |
| Agency acquisition | | | 262 | | | | | | | | 18.3 | | | | | | | | | | | | | | | | 18.3 | |
| Directors | | | 16 | | | | | | | | 1.1 | | | | | | | | | | | | | | | | 1.1 | |
| Balance at December 31, 2023 | | | 284,579 | | | $ | 30.4 | | | $ | 1,027.1 | | | $ | (748.1 | ) | | $ | (19.1 | ) | | $ | 5,288.5 | | | $ | 5,578.8 | |
| Net income | | $ | 870.5 | | | $ | 671.8 | | | $ | 587.1 | |
| Amortization | | | 166.0 | | | | 146.6 | | | | 119.6 | |
| Depreciation | | | 40.0 | | | | 39.2 | | | | 33.3 | |
| Change in estimated acquisition earn-out payables | | | 21.8 | | | | (38.9 | ) | | | 40.4 | |
As announced on October 31, 2023 and completed in the third quarter of 2023, the Company sold certain third-party claims administration and adjusting services businesses representing approximately 50% of the total revenues of the Services segment.
The Company performed an evaluation to determine if the sold businesses should be reported as discontinued operations.
However, with the sold businesses representing, as a percentage of total Company, approximately 3% of the total revenue, 2% of the total assets and 2% of net income, the Company determined that treating the sale as discontinued operations was not appropriate.
On November 27, 2023, the Financial Accounting Standards Board ("FASB") issued Accounting Standards Update ("ASU") 2023-07, "Improvements to Reportable Segment Disclosures." This ASU requires additional reportable segment disclosures, primarily through enhanced disclosures about significant segment expenses.
In addition, the ASU enhances interim disclosure requirements effectively making the current annual requirements a requirement for interim reporting.
This ASU is effective for fiscal years beginning after December 15, 2023, and interim periods within fiscal years beginning after December 15, 2024.
Early adoption is permitted.
The Company is currently evaluating these new disclosure requirements.
On December 14, 2023, the FASB issued ASU 2023-09, "Improvements to Income Tax Disclosures." This ASU improves the transparency of income tax disclosures by requiring consistent categories and greater disaggregation of information in the rate reconciliation and income taxes paid disaggregated by jurisdiction.
This ASU is effective for annual periods beginning after December 15, 2024.
Early adoption is permitted.
The Company is currently evaluating these new disclosure requirements.
The Company adopted ASU 2020-04 on February 10, 2023 in connection with enacting the transition provision in our Second Amended and Restated Credit Agreement dated October 27, 2021.
Under the allowable expedients, a modification of a debt contract that is only a replacement of the reference rate is accounted for as a non-substantial modification.
Adoption of this guidance had no impact on the Company's financial statements.
Uncollected premiums are presented as fiduciary receivables.
The Company’s investment holdings include U.S. Government securities, municipal
Gain or Loss on Disposal
From time to time the Company will sell individual books of business or entire businesses when it aligns with our strategic priorities.
When a business is sold, goodwill along with identified tangible and intangible assets and liabilities are netted against the agreed transaction price net of transaction costs to determine the associated gain or loss on disposal.
Goodwill is apportioned to the disposed business using the relative fair value of the disposed business to the associated reporting unit to which it was a member.
In the fourth quarter of 2023, the Company completed the sale of certain third-party claims administration and adjusting services businesses from its Services segment and recognized a pre-tax gain on the sale of businesses totaling $134.6 million.
The Company is entitled
to future consideration payments upon achievement of certain conditions in accordance with the terms of the sale agreement.
Any future consideration payments will be recognized as the condition for achievement is satisfied.
For the years ending December 31, 2023, 2022 and 2021, total gains recognized on sales of businesses and books of business totaled $143.3 million, $4.5 million, and $9.6 million, respectively.
| Net income | | $ | 870.5 | | | $ | 671.8 | | | $ | 587.1 | |
| Basic | | $ | 3.07 | | | $ | 2.38 | | | $ | 2.08 | |
| Diluted | | $ | 3.05 | | | $ | 2.37 | | | $ | 2.07 | |
As of December 31, 2023 the carrying value of our fixed-rate borrowings was $2,739.6 million and we approximate their values using market quotes of notes with the similar terms as ours and calculate a fair value of $2,487.4 million.
| | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Balance at January 1, 2020 | | | 281,655 | | | $ | 29.7 | | | $ | 716.0 | | | $ | (536.2 | ) | | $ | \- | | | $ | 3,140.9 | | | $ | 3,350.4 | |
| Stock incentive plans | | | 1,895 | | | | 0.2 | | | | 50.9 | | | | | | | | | | | | | | | | 51.1 | |
| Agency acquisition | | | 723 | | | | 0.1 | | | | 30.0 | | | | | | | | | | | | | | | | 30.1 | |
| Directors | | | 16 | | | | | | | | 0.6 | | | | | | | | | | | | | | | | 0.6 | |
We are currently evaluating our contracts and the available expedients provided by the new standard; however, the Company can assert there is no impact to any carrying value of assets or liabilities aside from our floating-rate debt instruments that are indexed to LIBOR and are carried at amortized cost.
Any further impact of adoption will be in determining the new periodic floating interest rate indexed to our floating-rate debt instruments with no impact on the balance sheet upon adoption.
In December 2019, the FASB issued ASU 2019-12, “Income Taxes (Topic 740): Simplifying the Accounting for Income Taxes.” The standard removes specific exceptions in the current rules and eliminates the need for an organization to analyze whether the following apply in a given period: (a) exception to the incremental approach for intra-period tax allocation; (b) exceptions to accounting for basis differences when there are ownership changes in foreign investments and (c) exception in interim period income tax accounting for year-to-date losses that exceed anticipated losses.
The standard also is designed to improve financial statement preparers’ application of income tax-related guidance and simplify GAAP for (a) franchise taxes that are partially based on income; (b) transactions with a government that result in a step-up in the tax basis of goodwill; (c) separate financial statements of legal entities that are not subject to tax and (d) enacted changes in tax laws in interim periods.
The Company adopted ASU 2019-12 effective January 1, 2021.
The impact of adopting this standard was not material to the presentation of the Consolidated Financial Statements.
Uncollected premiums are no longer presented in the same caption with commissions, fees and other receivables, but rather represented in a separate caption as fiduciary receivables.
Previously the net change in cash balances held to remit to insurance carriers or to return to customers was presented as cash flows from operating activities.
All prior periods included in these financial statements have been recast to conform to this basis of presentation.
The relevant balance sheet captions and how the December 31, 2021 balances as presented under the prior method relate to the current presentation are reflected in the tables below.
Certain liabilities reported as premiums payable to insurance companies or within premiums deposits and credits due customers were deemed not to be fiduciary in nature and have been included within accounts payable in the current presentation.
Likewise, a small component of accounts payable was deemed to be fiduciary in nature and is now included within fiduciary liabilities.
| | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| December 31, 2021 | | | | | | | | | | | |
| (in millions) | As reported | | | | Change in presentation | | | | As revised | | |
| Cash and cash equivalents | $ | 887.0 | | | $ | (193.8 | ) | | $ | 693.2 | |
| Restricted cash and investments | | 583.2 | | | | (583.2 | ) | | | — | |
| Total | | 1,470.2 | | | | — | | | | 1,470.2 | |
| Premiums, commissions and fees receivables | | 1,216.3 | | | | (1,216.3 | ) | | | — | |
| Commissions, fees and other receivables | | — | | | | 522.6 | | | | 522.6 | |
| Fiduciary receivables | | — | | | | 693.7 | | | | 693.7 | |
| Total | | 1,216.3 | | | | — | | | | 1,216.3 | |
| Premium payable to insurance companies | | 1,384.6 | | | | (1,384.6 | ) | | | — | |
| Premium deposits and credits due customers | | 122.4 | | | | (122.4 | ) | | | — | |
| Accounts payable | | 206.4 | | | | 36.3 | | | | 242.7 | |
| Fiduciary liabilities | | — | | | | 1,470.7 | | | | 1,470.7 | |
| Total | $ | 1,713.4 | | | $ | — | | | $ | 1,713.4 | |
| Premiums, commissions and fees receivable (1) | $ | (72.8 | ) | | $ | 10.9 | | | $ | (61.9 | ) |
| Premiums payable to insurance companies | | 128.0 | | | | (128.0 | ) | | | — | |
| Premium deposits and credits due customers | | 19.6 | | | | (19.6 | ) | | | — | |
| Accounts payable | | 51.4 | | | | 3.0 | | | | 54.4 | |
An excerpt. Shown here: 40 of 492 rewritten, 40 of 183 added and 40 of 330 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data. in the FY2023 filing and the FY2022 filing.
Item 9. Changes in and Disagreements with Accountants and Financial Disclosure.
1 rewritten, 0 added, 0 removed, 0 unchanged
There were no changes in or disagreements with accountants on accounting and financial disclosure in [removed: 2022.][added: 2023.]
Item 9A. Controls and Procedures.
2 rewritten, 0 added, 0 removed, 16 unchanged
We carried out an evaluation (the “Evaluation”) required by Rules 13a-15 and 15d-15 under the Securities Exchange Act of 1934, as amended (the “Exchange Act”), under the supervision and with the participation of our chief executive officer (“CEO”) and chief financial officer (“CFO”), of the effectiveness of our disclosure controls and procedures as defined in Rule 13a-15 and 15d-15 under the Exchange Act (“Disclosure Controls”) as of December 31, [removed: 2022.][added: 2023.]
There has not been any change in our internal control over financial reporting identified in connection with the Evaluation that occurred during the quarter ended December 31, [removed: 2022] [added: 2023] that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. Other Information.
0 rewritten, 2 added, 1 removed, 0 unchanged
During the fourth quarter of 2023, none of the Company’s officers or directors adopted or terminated any “Rule 10b5-1 trading
arrangement” or any “non-Rule 10b5-1 trading arrangement,” as each term is defined in Item 408 of Regulation S-K.
None
Item 10. Directors, Executive Officers and Corporate Governance.
1 rewritten, 0 added, 0 removed, 3 unchanged
The additional information required by this item regarding directors and executive officers is incorporated herein by reference to our definitive Proxy Statement to be filed with the SEC in connection with the Annual Meeting of Shareholders to be held in [removed: 2023] [added: 2024] (the [removed: “2023] [added: “2024] Proxy Statement”) under the headings “Board and Corporate Governance Matters” and “Other Important Information.” We have adopted a code of ethics that applies to our principal executive officer, principal financial officer and controller.
Item 11. Executive Compensation.
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference to the [removed: 2023] [added: 2024] Proxy Statement under the heading “Compensation Matters.”
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholders Matters.
5 rewritten, 1 added, 1 removed, 12 unchanged
The following table sets forth information as of December 31, [removed: 2022,] [added: 2023,] with respect to compensation plans under which the Company’s equity securities are authorized for issuance:
| Brown & Brown, Inc. 2019 Stock Incentive Plan | | | [removed: 6,088,438] [added: 4,238,212] | | (2) |
| Brown & Brown, Inc. 1990 Employee Stock Purchase Plan | | | [removed: 3,735,669] [added: 2,991,813] | | |
The number of securities remaining available of [removed: 6,088,438] [added: 4,238,212] has been reduced by [removed: 1,198,548] [added: 1,422,486] to reflect the maximum shares potentially distributed subject to the level of performance obtained for outstanding performance-based grants which may be increased up to 200% of the target or decreased to zero.
The other information required by this item is incorporated herein by reference to the [removed: 2023] [added: 2024] Proxy Statement under the heading “Security Ownership of Management and Certain Beneficial Owners.”
| Total | | | 7,230,025 | | |
| Total | | | 9,824,107 | | |
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is incorporated herein by reference to the [removed: 2023] [added: 2024] Proxy Statement under the headings “Director Independence,” “Related Party Transactions Policy” and “Relationships and Transactions with Affiliated Parties.”
Item 14. Principal Accounting Fees and Services.
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required by this item is incorporated herein by reference to the [removed: 2023] [added: 2024] Proxy Statement under the heading “Fees Paid to Deloitte & Touche LLP.”
Item 15. Exhibits and Financial Statements Schedules.
14 rewritten, 4 added, 0 removed, 99 unchanged
| 10.4(j)* | | [Form of Performance Stock [added: Unit] Award Agreement under the 2019 Stock Incentive Plan (incorporated by reference to Exhibit 10.1 to Form 8-K filed on February 23, 2022).](https://www.sec.gov/Archives/edgar/data/79282/000095017022001657/bro-ex10_1.htm) |
| [removed: 10.6] [added: 10.7] | | [Term Loan Credit Agreement, dated December 21, 2018, by and among the Company, Wells Fargo Bank, National Association, as administrative agent, Bank of America, N.A., BMO Harris Bank N.A. and SunTrust Bank as co-syndication agents, and Wells Fargo Securities, LLC, Merrill Lynch, Pierce, Fenner & Smith Incorporated, BMO Capital Markets Corp. and SunTrust Robinson Humphrey, Inc. as joint lead arrangers and joint bookrunners (incorporated by reference to Exhibit 10.10 to Form 10-K for the year ended December 31, 2019).](https://www.sec.gov/Archives/edgar/data/79282/000007928219000006/exhibit1010q42018.htm) |
| [removed: 10.7] [added: 10.8] | | [Majority Share Purchase Agreement, dated March 7, 2022, between the Company, Brown & Brown UK Holdco Limited, GRP (Jersey) Topco Limited and certain other parties named therein (incorporated by reference to Exhibit 10.1 to Form 10-Q for the quarter ended March 31, 2022).](https://www.sec.gov/Archives/edgar/data/79282/000095017022008555/bro-ex10_1.htm) |
| [removed: 10.8] [added: 10.9] | | [Amendment Agreement, dated July 1, 2022, to Majority Share Purchase Agreement, dated March 7, 2022, between the Company Brown & Brown UK Holdco Limited, GRP (Jersey) Topco Limited and certain other parties named therein (incorporated by referenced to Exhibit 10.1 to Form 10-Q for the quarter ended September 30, 2022).](https://www.sec.gov/Archives/edgar/data/79282/000095017022021976/bro-ex10_1.htm) |
| [removed: 10.9] [added: 10.10] | | [Loan Agreement, dated March 31, 2022, between the Company and the lenders named therein, BMO Harris Bank N.A., as administrative agent, Fifth Third Bank, National Association, PNC Bank, National Association, U.S. Bank National Association and Wells Fargo Bank, National Association, as co-syndication agents, BMO Capital Markets Corp., BofA Securities, Inc., JPMorgan Chase Bank, N.A. and Truist Securities, Inc., as joint bookrunners and joint lead arrangers (incorporated by reference to Exhibit 10.2 to Form 10-Q for the quarter ended March 31, 2022).](https://www.sec.gov/Archives/edgar/data/79282/000095017022008555/bro-ex10_2.htm) |
| 21 | | [Subsidiaries of the [removed: Registrant.](https://www.sec.gov/Archives/edgar/data/79282/000095017023004717/bro-ex21.htm)] [added: Registrant.](https://www.sec.gov/Archives/edgar/data/79282/000095017024018890/bro-ex21.htm)] |
| 23 | | [Consent of Deloitte & Touche [removed: LLP.](https://www.sec.gov/Archives/edgar/data/79282/000095017023004717/bro-ex23.htm)] [added: LLP.](https://www.sec.gov/Archives/edgar/data/79282/000095017024018890/bro-ex23.htm)] |
| 24 | | [Powers of [removed: Attorney.](https://www.sec.gov/Archives/edgar/data/79282/000095017023004717/bro-ex24.htm)] [added: Attorney.](https://www.sec.gov/Archives/edgar/data/79282/000095017024018890/bro-ex24.htm)] |
| 31.1 | | [Rule 13a-14(a)/15d-14(a) Certification by the Chief Executive Officer of the [removed: Registrant.](https://www.sec.gov/Archives/edgar/data/79282/000095017023004717/bro-ex31_1.htm)] [added: Registrant.](https://www.sec.gov/Archives/edgar/data/79282/000095017024018890/bro-ex31_1.htm)] |
| 31.2 | | [Rule 13a-14(a)/15d-14(a) Certification by the Chief Financial Officer of the [removed: Registrant.](https://www.sec.gov/Archives/edgar/data/79282/000095017023004717/bro-ex31_2.htm)] [added: Registrant.](https://www.sec.gov/Archives/edgar/data/79282/000095017024018890/bro-ex31_2.htm)] |
| 32.1 | | [Section 1350 Certification by the Chief Executive Officer of the [removed: Registrant.](https://www.sec.gov/Archives/edgar/data/79282/000095017023004717/bro-ex32_1.htm)] [added: Registrant.](https://www.sec.gov/Archives/edgar/data/79282/000095017024018890/bro-ex32_1.htm)] |
| 32.2 | | [Section 1350 Certification by the Chief Financial Officer of the [removed: Registrant.](https://www.sec.gov/Archives/edgar/data/79282/000095017023004717/bro-ex32_2.htm)] [added: Registrant.](https://www.sec.gov/Archives/edgar/data/79282/000095017024018890/bro-ex32_2.htm)] |
| 101 | | The following financial statements from the Company’s Annual Report on Form 10-K for the period ended December 31, [removed: 2022,] [added: 2023,] formatted in inline XBRL, include: (i) Consolidated Statements of Income, (ii) Consolidated Balance Sheets, (iii) Consolidated Statements of Shareholders’ Equity, (iv) Consolidated Statements of Cash Flows and (v) the Notes to the Consolidated Financial Statements. |
| 104 | | Cover Page Interactive Data File for the Registrant’s Annual Report on Form 10-K for the fiscal year ended December 31, [removed: 2022,] [added: 2023,] formatted Inline XBRL (included as Exhibit 101). |
| 10.6 | | [Amendment No. 1, dated February 10, 2023, to the Second Amended and Restated Credit Agreement dated October 27, 2021, among the Registrant, JPMorgan Chase Bank, N.A. and the lenders named therein (incorporated by reference to Exhibit 10.1 to Form 10-Q filed on April 27, 2023).](https://www.sec.gov/Archives/edgar/data/79282/000095017023015456/bro-ex10_1.htm) |
| 97 | | [Policy Regarding the Mandatory Recovery of Compensation](https://www.sec.gov/Archives/edgar/data/79282/000095017024018890/bro-ex97.htm) |
| | | |
| | | |
Item 16. Form 10-K Summary.
6 rewritten, 17 added, 1 removed, 47 unchanged
[removed: SIGNATURE][added: SIGNATURES]
| Date: February [removed: 27, 2023] [added: 22, 2024] | | By: | /s/ J. Powell Brown | |
| /s/ J. Powell Brown | | Director; president and chief executive officer (principal executive officer) | | February [removed: 27, 2023] [added: 22, 2024] |
| /s/ R. Andrew Watts | | Executive vice president, chief financial officer and treasurer (principal financial and accounting officer) | | February [removed: 27, 2023] [added: 22, 2024] |
| * | | Chairman of the board | | February [removed: 27, 2023] [added: 22, 2024] |
| * | | Director | | February [removed: 27, 2023] [added: 22, 2024] |
| * | | Director | | February 22, 2024 |
| * | | Director | | February 22, 2024 |
| * | | Director | | February 22, 2024 |
| * | | Director | | February 22, 2024 |
| * | | Director | | February 22, 2024 |
| Paul Krump | | | | |
| * | | Director | | February 22, 2024 |
| * | | Director | | February 22, 2024 |
| Bronek Masojada | | | | |
| * | | Director | | February 22, 2024 |
| * | | Director | | February 22, 2024 |
| * | | Director | | February 22, 2024 |
| * | | Director | | February 22, 2024 |
| Kathleen A. Savio | | | | |
| * | | Director | | February 22, 2024 |
| | | | | |
| | | | | |
| Hugh M. Brown | | | | |