 filings.tools
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
256K characters. Original on sec.gov · Markdown
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
| --- | --- |
The following discussion and analysis should be read in conjunction with The Blackstone Group Inc.’s consolidated financial statements and the related notes included within this Annual Report on
Form 10-K.
This section of this
Form 10-K
generally discusses 2020 and 2019 items and year to year comparisons between 2020 and 2019. For the discussion of 2019 compared to 2018 see “Part II. Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations” of Blackstone’s Annual Report on
Form 10-K
for the year ended December 31, 2019, which specific discussion is incorporated herein by reference.
Effective July 1, 2019, The Blackstone Group L.P. (the “Partnership”) converted from a Delaware limited partnership to a Delaware corporation, The Blackstone Group Inc. (the “Conversion”). This report includes the results for the Partnership prior to the Conversion and The Blackstone Group Inc. following the Conversion. In this report, references to “Blackstone,” the “Company,” “we,” “us” or “our” refer to (a) The Blackstone Group Inc. and its consolidated subsidiaries following the Conversion and (b) the Partnership and its consolidated subsidiaries prior to the Conversion. All references to shares or per share amounts prior to the Conversion refer to units or per unit amounts. Unless otherwise noted, all references to shares or per share amounts following the Conversion refer to shares or per share amounts of common stock. All references to dividends prior to the Conversion refer to distributions. See “— Organizational Structure.”
Effective January 1, 2020, the Credit segment was renamed Credit & Insurance. There was no change to the composition of the segment or historical results.
Effective February 26, 2021, Blackstone effectuated changes to rename its Class A common stock as “common stock,” and to reclassify its Class B and Class C common stock into a new “Series I preferred stock” and “Series II preferred stock,” respectively. Each new stock has the same rights and powers of its predecessor. See “Part II. Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations — Organizational Structure” and “Part II. Item 9B. Other Information.”
Our Business
Blackstone is one of the world’s leading investment firms. Our business is organized into four segments:
| • | Real Estate. Our real estate business is a global leader in real estate investing. Our Real Estate segment operates as one globally integrated business, with investments in the Americas, Europe and Asia. Our real estate investment teams seek to utilize our global expertise and presence to generate attractive risk-adjusted returns for our investors and to make a positive impact on the communities in which we invest. |
|---|
Our Blackstone Real Estate Partners (“BREP”) funds are geographically diversified and target a broad range of “opportunistic” real estate and real estate-related investments. The BREP funds include global funds as well as funds focused specifically on Europe or Asia investments. BREP seeks to invest thematically in high-quality assets, focusing where we see outsized growth potential driven by global economic and demographic trends. BREP has made significant investments in logistics, office, rental housing, hospitality and retail properties around the world, as well as a variety of real estate operating companies.
Our Blackstone Real Estate Debt Strategies (“BREDS”) vehicles primarily target real estate-related debt investment opportunities. BREDS’ scale and investment mandates enable it to provide a variety of lending and investment options including commercial real estate and mezzanine loans, residential mortgage loan pools and liquid real estate-related debt securities. The BREDS platform includes a number of high-yield real estate debt funds, liquid real estate debt funds and BXMT, a NYSE-listed real estate investment trust (“REIT”).
Blackstone Real Estate began its Core+ strategy in 2013. Blackstone’s Core+ strategy invests in substantially stabilized real estate globally through regional open-ended funds focused on high-quality assets, the Blackstone Property Partners funds (“BPP”), and Blackstone Real Estate Income Trust, Inc. (“BREIT”), a non-listed REIT which was launched in 2017 and invests in U.S. income-generating assets. In November 2020, we launched Blackstone BioMed Life Science Real Estate L.P. (“BPP Life Sciences”), a long-term, perpetual capital, core+ return fund that owns BioMed Realty and is focused on life science office investments primarily across the U.S.
| • | Private Equity. Our Private Equity segment includes our corporate private equity business, which consists of (a) our flagship private equity funds (Blackstone Capital Partners (“BCP”) funds), (b) our sector-focused private equity funds, including our energy-focused funds (Blackstone Energy Partners (“BEP”) funds), (c) our Asia-focused fund (Blackstone Capital Partners Asia (“BCP Asia”) fund) and (d) our core private equity funds, Blackstone Core Equity Partners (“BCEP”). In addition, our Private Equity segment includes (a) our opportunistic investment platform that invests globally across asset classes, industries and geographies, Blackstone Tactical Opportunities (“Tactical Opportunities”), (b) our secondary fund of funds business, Strategic Partners Fund Solutions (“Strategic Partners”), (c) our infrastructure-focused funds, Blackstone Infrastructure Partners (“BIP”), (d) our life sciences private investment platform, Blackstone Life Sciences (“BXLS”), (e) our growth equity investment platform, Blackstone Growth (“BXG”), (f) our multi-asset investment program for eligible high net worth investors offering exposure to certain of Blackstone’s key illiquid investment strategies through a single commitment, Blackstone Total Alternatives Solution (“BTAS”) and (g) our capital markets services business, Blackstone Capital Markets (“BXCM”). |
|---|
We are a global leader in private equity investing. Our corporate private equity business, established in 1987, pursues transactions across industries in both established and growth-oriented businesses across the globe. It strives to create value by investing in great businesses where our capital, strategic insight, global relationships and operational support can drive transformation. Our core private equity funds target control-oriented investments in high-quality companies with durable businesses and seeks to offer a lower level of risk and a longer hold period than traditional private equity.
Tactical Opportunities invests globally across asset classes, industries and geographies, seeking to identify and execute on attractive, differentiated investment opportunities, leveraging the intellectual capital across our various businesses while continuously optimizing its approach in the face of ever-changing market conditions. Strategic Partners is a total fund solutions provider that acquires interests in high-quality private funds from original holders seeking liquidity, makes primary investments and
co-investments
with financial sponsors and provides investment advisory services to clients investing in primary and secondary investments in private funds and
co-investments.
BIP focuses on investments across all infrastructure sectors, including energy infrastructure, transportation, digital infrastructure, and water and waste with a primary focus in the U.S. BXLS is our private investment platform with capabilities to invest across the life cycle of companies and products within the life sciences sector. BXG seeks to deliver attractive risk-adjusted returns by investing in dynamic, growth-stage businesses, with a focus on the consumer, enterprise solutions, financial services and healthcare sectors.
| • | Hedge Fund Solutions. The principal component of our Hedge Fund Solutions segment is Blackstone Alternative Asset Management (“BAAM”). BAAM is the world’s largest discretionary allocator to hedge funds, managing a broad range of commingled and customized fund solutions since its inception in 1990. The Hedge Fund Solutions segment also includes investment platforms that seed new hedge fund businesses, purchase minority interests in more established general partners and management companies of funds, invest in special situation opportunities, create alternative solutions in the form of daily liquidity products and invest directly. |
|---|
| • | Credit & Insurance. The principal component of our Credit & Insurance segment is Blackstone Credit (“BXC”), formerly known as GSO Capital Partners LP. BXC is one of the largest credit-oriented managers in the world and is the largest manager of collateralized loan obligations (“CLOs”) globally. The investment portfolios of the funds BXC manages or sub-advises predominantly consist of loans and securities of non-investment grade companies spread across the capital structure including senior debt, subordinated debt, preferred stock and common equity. |
|---|
BXC is organized into two overarching strategies: private credit and liquid credit. Private credit strategies include mezzanine lending funds, middle market direct lending funds (including Blackstone Secured Lending Fund (“BXSL”) and Blackstone Private Credit Fund (“BCRED”), both of which are business development companies (“BDCs”)), our structured products group, stressed/distressed strategies (including stressed/distressed funds and credit alpha strategies) and energy strategies. Liquid credit strategies consist of CLOs, closed-ended funds, open-ended funds and separately managed accounts. In December 2020, BXC acquired DCI LLC (“DCI”), a San Francisco based systematic credit investment firm. As part of the transaction, DCI will be integrated into BXC as systematic strategies within its liquid credit strategies unit.
Our Credit & Insurance segment includes our insurer-focused platform, Blackstone Insurance Solutions (“BIS”). BIS focuses on providing full investment management services for insurers’ general accounts, delivering customized and diversified portfolios that include allocations to Blackstone managed products and strategies across asset classes and Blackstone’s private credit origination capabilities. BIS provides its clients tailored portfolio construction and strategic asset allocation, seeking to generate risk-managed, capital-efficient returns, diversification and capital preservation that meets clients’ objectives. BIS also provides similar services to clients through separately managed accounts or by
sub-managing
assets for certain insurance-dedicated funds and special purpose vehicles.
Our Credit & Insurance segment also includes our publicly traded midstream energy infrastructure and master limited partnership (“MLP”) investment platform, which is managed by Harvest Fund Advisors LLC (“Harvest”). Harvest primarily invests capital raised from institutional investors in separately managed accounts and pooled vehicles, investing in publicly traded energy infrastructure and MLPs holding primarily midstream energy assets in North America.
We generate revenue from fees earned pursuant to contractual arrangements with funds, fund investors and fund portfolio companies (including management, transaction and monitoring fees), and from capital markets services. We also invest in the funds we manage and we are entitled to a
pro-rata
share of the results of the fund (a
“pro-rata
allocation”). In addition to a
pro-rata
allocation, and assuming certain investment returns are achieved, we are entitled to a disproportionate allocation of the income otherwise allocable to the limited partners, commonly referred to as carried interest (“Performance Allocations”). In certain structures, we receive a contractual incentive fee from an investment fund in the event that specified cumulative investment returns are achieved (an “Incentive Fee,” and together with Performance Allocations, “Performance Revenues”). The composition of our revenues will vary based on market conditions and the cyclicality of the different businesses in which we operate. Net investment gains and investment income generated by the Blackstone Funds are driven by value created by our operating and strategic initiatives as well as overall market conditions. Fair values are affected by changes in the fundamentals of our portfolio company and other investments, the industries in which they operate, the overall economy and other market conditions.
Our Response to
COVID-19
As the global response to novel coronavirus
(“COVID-19”)
continues to evolve, our primary focus has been the safety and wellbeing of our employees and their families, as well as the seamless functioning of the firm in serving our limited partner investors who have entrusted us with their capital, and our shareholders. In accordance with local government guidance and social distancing recommendations, the majority of our employees globally have been working remotely. Our technology infrastructure has proven to be robust and capable of supporting this model. We have implemented rigorous protocols for remote work across the firm, including increased cadence of group calls and updates, and frequent communication across leadership and working levels. We are leveraging technology to ensure our teams stay connected and productive, and that our culture remains strong even in these unusual circumstances. While we are generally not meeting with our clients in person, we continue to actively communicate with our clients through videoconference, teleconference and email. Investment committees continue to convene as needed, and the firm continues to operate across investment, asset management and corporate support functions.
Since July 2020, employees in our U.S. and European offices began returning to the office on a voluntary basis, consistent with local government guidelines, with testing, contact-tracing and social distancing and other safety protocols in place. We continue to closely monitor applicable public health and government guidance.
Business Environment
Blackstone’s businesses are materially affected by conditions in the financial markets and economic conditions in the U.S., Europe, Asia and, to a lesser extent, elsewhere in the world.
Global economic conditions in 2020 were significantly impacted by the
COVID-19
pandemic. Following dramatic declines in global equity and credit markets in the first quarter of the year coupled with certain liquidity issues, markets generally experienced sharp recoveries later in the year as governments around the world implemented fiscal and monetary stimulus to counter the economic impacts of the pandemic. The recovery has been more recently aided by progress on
COVID-19
vaccine production and distribution. The global economy has, with certain setbacks, begun reopening and wider distribution of vaccines will likely encourage greater economic activity. Nonetheless, the recovery could remain uneven, particularly given uncertainty with respect to the distribution and acceptance of the vaccines.
In the U.S., the S&P 500 increased 18% in 2020, with positive returns across most sectors and particular strength in technology stocks, which were up 44%. The S&P energy, real estate and financial sectors posted negative returns in 2020, with energy in particular down 34% as commodity prices remained suppressed. Despite rising during the second half of 2020, the price of West Texas ended the year at $48.52 per barrel, 21% below the 2019
year-end
price of $61. The Bloomberg Commodity Index finished the year down 4%.
Volatility increased sharply during the year, with the CBOE Volatility index averaging 29 in 2020, up 89% from the prior-year average of 15. Global equity issuance increased 60% in 2020. Merger and acquisition activity decreased slightly in 2020, with announced volumes down 4% compared to 2019.
Debt markets largely retraced their declines from early in 2020, with U.S. leveraged loans declining 0.5% overall in 2020 and high yield bonds increasing 5.5%. High yield spreads ended the year roughly in line with
pre-COVID
levels and issuance increased 51% year-over-year. The Federal Reserve maintained the federal funds target range at
0.0%-0.25%
and expanded its balance sheet since
mid-March
2020 by more than $3 trillion to support new credit and liquidity facilities. The Federal Reserve expects to maintain the current pace of purchasing in the coming months. Three-month LIBOR ended the year at 0.24%, near historical lows. The U.S. Treasury yield curve steepened towards the end of 2020, with
ten-year
yields rising 41 basis points from their trough in August to 0.91% by the end of 2020.
Two-year
U.S. Treasury yields remained relatively stable since their decline in the first quarter of 2020, ending the year at 0.12%.
The U.S. unemployment rate was 6.7% at the end of 2020, representing a decline from 11.1% at the end of June, although it remains at an elevated level. Wages grew, with average hourly earnings increasing 5.1% year-over-year based on the three-month average for production and nonsupervisory employees. New orders for durable goods in December increased for the eighth consecutive month, while U.S. retail sales increased 3.2% in 2020 compared to 2019. The industrial sector continued to show mixed signals, as industrial production declined 3.6% in the fourth quarter from the
year-ago
period. However, the Institute for Supply Management Purchasing Managers’ Index increased in the fourth quarter, rising to 60.7 from 55.4 in the third quarter, signaling moderate expansion in the U.S. manufacturing sector.
Countries around the world continue to grapple with the economic impacts of the
COVID-19
pandemic. Although a recovery is partially underway, it continues to be gradual, uneven and characterized by meaningful dispersion across sectors and regions, and could be hindered by persistent or resurgent infection rates. A potential next round of U.S. fiscal stimulus could provide meaningful support, along with continued accommodative monetary policy and wider distribution of vaccines. Issues with respect to the distribution and acceptance of vaccines or the spread of new variants of the virus could adversely impact the recovery. Overall, there remains significant uncertainty regarding the timing and duration of the economic recovery, which precludes any prediction as to the ultimate adverse impact of
COVID-19
on economic and market conditions.
Notable Transactions
On September 29, 2020, Blackstone issued $500 million aggregate principal amount of 1.600% senior notes due March 30, 2031 (the “2031 Notes”) and $400 million aggregate principal amount of 2.800% senior notes due September 30, 2050 (the “2050 Notes”).
On November 24, 2020, Blackstone entered into an amended and restated $2.25 billion revolving credit facility. The amendment and restatement to the credit facility, among other things, increased the amount of available borrowings and extended the maturity date from September 21, 2023 to November 24, 2025.
For additional information see Note 13. “Borrowings” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data.”
In December 2020, Blackstone acquired DCI, a San Francisco based systematic credit investment firm. As part of the transaction, DCI will be integrated into BXC as systematic strategies within its liquid credit strategies unit.
On January 26, 2021, Pátria completed its IPO, pursuant to which we sold a portion of our interest. For additional information, see “Part I. Item 1. Business — Pátria Investments” and Note 4. “Investments — Equity Method Investments” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing.
Effective February 26, 2021, Blackstone effectuated changes to its common stock as described in the immediately following section “Organizational Structure.”
Organizational Structure
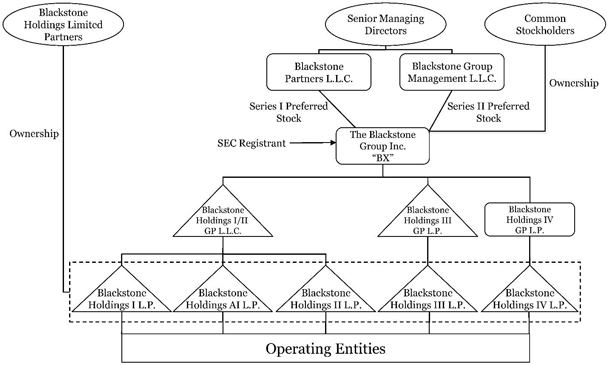
Effective July 1, 2019, The Blackstone Group L.P. converted from a Delaware limited partnership to a Delaware corporation, The Blackstone Group Inc.
Effective February 26, 2021, Blackstone effectuated changes to rename its Class A common stock as “Common Stock,” and to reclassify its Class B and Class C common stock into a new “Series I Preferred Stock” and “Series II Preferred Stock,” respectively. Each new stock has the same rights and powers of its predecessor. For additional information, see Note 1. “Organization” and Note 16. “Earnings Per Share and Stockholder’s Equity — Stockholder’s Equity” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing and “— Item 9B. Other Information.”
The simplified diagram below depicts our current organizational structure. The diagram does not depict all of our subsidiaries, including intermediate holding companies through which certain of the subsidiaries depicted are held.
Key Financial Measures and Indicators
We manage our business using certain financial measures and key operating metrics since we believe these metrics measure the productivity of our investment activities. We prepare our Consolidated Financial Statements in accordance with GAAP. See “— Item 8. Financial Statements and Supplementary Data — Notes to Consolidated Financial Statements — Note 2. Summary of Significant Accounting Policies” and “— Critical Accounting Policies.” Our key
non-GAAP
financial measures and operating indicators and metrics are discussed below.
Distributable Earnings
Distributable Earnings is derived from Blackstone’s segment reported results. Distributable Earnings is used to assess performance and amounts available for dividends to Blackstone shareholders, including Blackstone personnel and others who are limited partners of the Blackstone Holdings Partnerships. Distributable Earnings is the sum of Segment Distributable Earnings plus Net Interest Income (Loss) less Taxes and Related Payables. Distributable Earnings excludes unrealized activity and is derived from and reconciled to, but not equivalent to, its most directly comparable GAAP measure of Income (Loss) Before Provision (Benefit) for Taxes. See “—
Non-GAAP
Financial Measures” for our reconciliation of Distributable Earnings.
Net Interest Income (Loss) is presented on a segment basis and is equal to Interest and Dividend Revenue less Interest Expense, adjusted for the impact of consolidation of Blackstone Funds, and interest expense associated with the Tax Receivable Agreement.
Taxes and Related Payables represent the total GAAP tax provision adjusted to include only the current tax provision (benefit) calculated on Income (Loss) Before Provision (Benefit) for Taxes and including the Payable under the Tax Receivable Agreement. Further, the current tax provision utilized when calculating Taxes and Related Payables and Distributable Earnings reflects the benefit of deductions available to the company on certain expense items that are excluded from the underlying calculation of Segment Distributable Earnings and Total Segment Distributable Earnings, such as equity-based compensation charges and certain Transaction-Related Charges where there is a current tax provision or benefit. The economic assumptions and methodologies that impact the implied income tax provision are the same as those methodologies and assumptions used in calculating the current income tax provision for Blackstone’s consolidated statements of operations under GAAP, excluding the impact of divestitures and accrued tax contingencies and refunds which are reflected when paid or received. Management believes that including the amount payable under the tax receivable agreement and utilizing the current income tax provision adjusted as described above when calculating Distributable Earnings is meaningful as it increases comparability between periods and more accurately reflects earnings that are available for distribution to shareholders.
Segment Distributable Earnings
Segment Distributable Earnings is Blackstone’s segment profitability measure used to make operating decisions and assess performance across Blackstone’s four segments. Segment Distributable Earnings represents the net realized earnings of Blackstone’s segments and is the sum of Fee Related Earnings and Net Realizations for each segment. Blackstone’s segments are presented on a basis that deconsolidates Blackstone Funds, eliminates
non-controlling
ownership interests in Blackstone’s consolidated operating partnerships, removes the amortization of intangible assets and removes Transaction-Related Charges. Transaction-Related Charges arise from corporate actions including acquisitions, divestitures and Blackstone’s initial public offering. They consist primarily of equity-based compensation charges, gains and losses on contingent consideration arrangements, changes in the balance of the Tax Receivable Agreement resulting from a change in tax law or similar event, transaction costs and any gains or losses associated with these corporate actions. Segment Distributable Earnings excludes unrealized activity and is derived from and reconciled to, but not equivalent to, its most directly comparable GAAP measure of Income (Loss) Before Provision (Benefit) for Taxes. See “—
Non-GAAP
Financial Measures” for our reconciliation of Segment Distributable Earnings.
Net Realizations is presented on a segment basis and is the sum of Realized Principal Investment Income and Realized Performance Revenues (which refers to Realized Performance Revenues excluding Fee Related Performance Revenues), less Realized Performance Compensation (which refers to Realized Performance Compensation excluding Fee Related Performance Compensation and Equity-Based Performance Compensation).
Fee Related Earnings
Fee Related Earnings is a performance measure used to assess Blackstone’s ability to generate profits from revenues that are measured and received on a recurring basis and not subject to future realization events. Fee Related Earnings equals management and advisory fees (net of management fee reductions and offsets) plus Fee Related Performance Revenues, less (a) Fee Related Compensation on a segment basis, and (b) Other Operating Expenses. Fee Related Earnings is derived from and reconciled to, but not equivalent to, its most directly comparable GAAP measure of Income (Loss) Before Provision (Benefit) for Taxes. See “—
Non-GAAP
Financial Measures” for our reconciliation of Fee Related Earnings.
Fee Related Compensation is presented on a segment basis and refers to the compensation expense, excluding Equity-Based Compensation, directly related to (a) Management and Advisory Fees, Net and (b) Fee Related Performance Revenues, referred to as Fee Related Performance Compensation.
Fee Related Performance Revenues refers to the realized portion of Performance Revenues from Perpetual Capital that are (a) measured and received on a recurring basis, and (b) not dependent on realization events from the underlying investments.
Other Operating Expenses is presented on a segment basis and is equal to General, Administrative and Other Expenses, adjusted to (a) remove the amortization of transaction-related intangibles, (b) remove certain expenses reimbursed by the Blackstone Funds which are netted against Management and Advisory Fees, Net in Blackstone’s segment presentation, and (c) give effect to an administrative fee collected on a quarterly basis from certain holders of Blackstone Holdings Partnership Units. The administrative fee is accounted for as a capital contribution under GAAP, but is reflected as a reduction of Other Operating Expenses in Blackstone’s segment presentation.
Adjusted Earnings Before Interest, Taxes and Depreciation and Amortization
Adjusted Earnings Before Interest, Taxes and Depreciation and Amortization (“Adjusted EBITDA”), is a supplemental measure used to assess performance derived from Blackstone’s segment results and may be used to assess its ability to service its borrowings. Adjusted EBITDA represents Distributable Earnings plus the addition of (a) Interest Expense on a segment basis, (b) Taxes and Related Payables, and (c) Depreciation and Amortization. Adjusted EBITDA is derived from and reconciled to, but not equivalent to, its most directly comparable GAAP measure of Income (Loss) Before Provision (Benefit) for Taxes. See “—
Non-GAAP
Financial Measures” for our reconciliation of Adjusted EBITDA.
Operating Metrics
The alternative asset management business is primarily based on managing third party capital and does not require substantial capital investment to support rapid growth. Since our inception, we have developed and used various key operating metrics to assess and monitor the operating performance of our various alternative asset management businesses in order to monitor the effectiveness of our value creating strategies.
Assets Under Management.
Assets Under Management refers to the assets we manage. Our Assets Under Management equals the sum of:
| (a) | the fair value of the investments held by our carry funds and our side-by-side and co-investment entities managed by us plus the capital that we are entitled to call from investors in those funds and entities pursuant to the terms of their respective capital commitments, including capital commitments to funds that have yet to commence their investment periods, |
|---|
| (b) | the net asset value of (1) our hedge funds, real estate debt carry funds, BPP, certain co-investments managed by us, certain credit-focused funds, and our Hedge Fund Solutions drawdown funds (plus, in each case, the capital that we are entitled to call from investors in those funds, including commitments yet to commence their investment periods), and (2) our funds of hedge funds, our Hedge Fund Solutions registered investment companies, and BREIT, |
|---|
| (c) | the invested capital, fair value or net asset value of assets we manage pursuant to separately managed accounts, |
|---|
| (d) | the amount of debt and equity outstanding for our CLOs during the reinvestment period, |
|---|
| (e) | the aggregate par amount of collateral assets, including principal cash, for our CLOs after the reinvestment period, |
|---|
| (f) | the gross or net amount of assets (including leverage where applicable) for our credit-focused registered investment companies, |
|---|
| (g) | the fair value of common stock, preferred stock, convertible debt, term loans or similar instruments issued by BXMT, and |
|---|
| (h) | borrowings under and any amounts available to be borrowed under certain credit facilities of our funds. |
|---|
Our carry funds are commitment-based drawdown structured funds that do not permit investors to redeem their interests at their election. Our funds of hedge funds, hedge funds, funds structured like hedge funds and other open-ended funds in our Real Estate, Hedge Fund Solutions and Credit & Insurance segments generally have structures that afford an investor the right to withdraw or redeem their interests on a periodic basis (for example, annually or quarterly), typically with 30 to 95 days’ notice, depending on the fund and the liquidity profile of the underlying assets. Investment advisory agreements related to certain separately managed accounts in our Hedge Fund Solutions and Credit & Insurance segments, excluding our BIS separately managed accounts, may generally be terminated by an investor on 30 to 90 days’ notice.
Fee-Earning
Assets Under Management
.
Fee-Earning
Assets Under Management refers to the assets we manage on which we derive management fees and/or performance revenues. Our
Fee-Earning
Assets Under Management equals the sum of:
| (a) | for our Private Equity segment funds and Real Estate segment carry funds, including certain BREDS and Hedge Fund Solutions funds, the amount of capital commitments, remaining invested capital, fair value, net asset value or par value of assets held, depending on the fee terms of the fund, |
|---|
| (b) | for our credit-focused carry funds, the amount of remaining invested capital (which may include leverage) or net asset value, depending on the fee terms of the fund, |
|---|
| (c) | the remaining invested capital or fair value of assets held in co-investment vehicles managed by us on which we receive fees, |
|---|
| (d) | the net asset value of our funds of hedge funds, hedge funds, BPP, certain co-investments managed by us, certain registered investment companies, BREIT, and certain of our Hedge Fund Solutions drawdown funds, |
|---|
| (e) | the invested capital, fair value of assets or the net asset value we manage pursuant to separately managed accounts, |
|---|
| (f) | the net proceeds received from equity offerings and accumulated distributable earnings of BXMT, subject to certain adjustments, |
|---|
| (g) | the aggregate par amount of collateral assets, including principal cash, of our CLOs, and |
|---|
| (h) | the gross amount of assets (including leverage) or the net assets (plus leverage where applicable) for certain of our credit-focused registered investment companies. |
|---|
Each of our segments may include certain
Fee-Earning
Assets Under Management on which we earn performance revenues but not management fees.
Our calculations of assets under management and
fee-earning
assets under management may differ from the calculations of other asset managers, and as a result this measure may not be comparable to similar measures presented by other asset managers. In addition, our calculation of assets under management includes commitments to, and the fair value of, invested capital in our funds from Blackstone and our personnel, regardless of whether such commitments or invested capital are subject to fees. Our definitions of assets under management and
fee-earning
assets under management are not based on any definition of assets under management and
fee-earning
assets under management that is set forth in the agreements governing the investment funds that we manage.
For our carry funds, total assets under management includes the fair value of the investments held and uncalled capital commitments, whereas
fee-earning
assets under management may include the total amount of capital commitments or the remaining amount of invested capital at cost depending on whether the investment period has expired or as specified by the fee terms of the fund. As such, in certain carry funds
fee-earning
assets under management may be greater than total assets under management when the aggregate fair value of the remaining investments is less than the cost of those investments.
Perpetual Capital
. Perpetual Capital refers to the component of assets under management with an indefinite term, that is not in liquidation, and for which there is no requirement to return capital to investors through redemption requests in the ordinary course of business, except where funded by new capital inflows. Perpetual Capital includes
co-investment
capital with an investor right to convert into Perpetual Capital.
Dry Powder
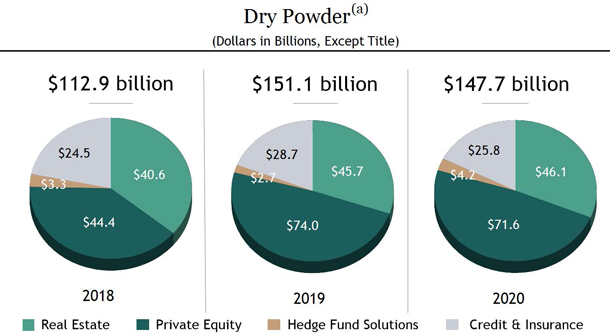
. Dry Powder represents the amount of capital available for investment or reinvestment, including general partner and employee capital, and is an indicator of the capital we have available for future investments.
Performance Eligible Assets Under Management
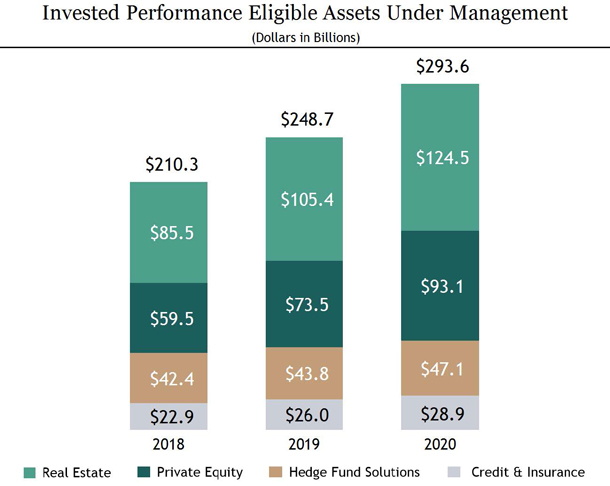
. Performance Eligible Assets Under Management represents invested and to be invested capital at fair value, including capital closed for funds whose investment period has not yet commenced, on which performance revenues could be earned if certain hurdles are met.
Consolidated Results of Operations
Following is a discussion of our consolidated results of operations for each of the years in the three-year period ended December 31, 2020. For a more detailed discussion of the factors that affected the results of our four business segments (which are presented on a basis that deconsolidates the investment funds we manage) in these periods, see “—Segment Analysis” below.
The following table sets forth information regarding our consolidated results of operations and certain key operating metrics for the years ended December 31, 2020, 2019 and 2018:
| Year Ended December 31, | 2020 vs. 2019 | 2019 vs. 2018 | ||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | ||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||
| Revenues | ||||||||||||||||||||||||||||
| Management and Advisory Fees, Net | $ | 4,092,549 | $ | 3,472,155 | $ | 3,027,796 | $ | 620,394 | 18% | $ | 444,359 | 15% | ||||||||||||||||
| Incentive Fees | 138,661 | 129,911 | 57,540 | 8,750 | 7% | 72,371 | 126% | |||||||||||||||||||||
| Investment Income (Loss) | ||||||||||||||||||||||||||||
| Performance Allocations | ||||||||||||||||||||||||||||
| Realized | 2,106,000 | 1,739,000 | 1,876,507 | 367,000 | 21% | (137,507 | ) | -7% | ||||||||||||||||||||
| Unrealized | (384,393 | ) | 1,126,332 | 561,373 | (1,510,725 | ) | N/M | 564,959 | 101% | |||||||||||||||||||
| Principal Investments | ||||||||||||||||||||||||||||
| Realized | 391,628 | 393,478 | 415,862 | (1,850 | ) | — | (22,384 | ) | -5% | |||||||||||||||||||
| Unrealized | (114,607 | ) | 215,003 | 49,917 | (329,610 | ) | N/M | 165,086 | 331% | |||||||||||||||||||
| Total Investment Income | 1,998,628 | 3,473,813 | 2,903,659 | (1,475,185 | ) | -42% | 570,154 | 20% | ||||||||||||||||||||
| Interest and Dividend Revenue | 125,231 | 182,398 | 171,947 | (57,167 | ) | -31% | 10,451 | 6% | ||||||||||||||||||||
| Other | (253,142 | ) | 79,993 | 672,317 | (333,135 | ) | N/M | (592,324 | ) | -88% | ||||||||||||||||||
| Total Revenues | 6,101,927 | 7,338,270 | 6,833,259 | (1,236,343 | ) | -17% | 505,011 | 7% | ||||||||||||||||||||
| Expenses | ||||||||||||||||||||||||||||
| Compensation and Benefits | ||||||||||||||||||||||||||||
| Compensation | 1,855,619 | 1,820,330 | 1,609,957 | 35,289 | 2% | 210,373 | 13% | |||||||||||||||||||||
| Incentive Fee Compensation | 44,425 | 44,300 | 33,916 | 125 | — | 10,384 | 31% | |||||||||||||||||||||
| Performance Allocations Compensation | ||||||||||||||||||||||||||||
| Realized | 843,230 | 662,942 | 711,076 | 180,288 | 27% | (48,134 | ) | -7% | ||||||||||||||||||||
| Unrealized | (154,516 | ) | 540,285 | 319,742 | (694,801 | ) | N/M | 220,543 | 69% | |||||||||||||||||||
| Total Compensation and Benefits | 2,588,758 | 3,067,857 | 2,674,691 | (479,099 | ) | -16% | 393,166 | 15% | ||||||||||||||||||||
| General, Administrative and Other | 711,782 | 679,408 | 594,873 | 32,374 | 5% | 84,535 | 14% | |||||||||||||||||||||
| Interest Expense | 166,162 | 199,648 | 163,990 | (33,486 | ) | -17% | 35,658 | 22% | ||||||||||||||||||||
| Fund Expenses | 12,864 | 17,738 | 78,486 | (4,874 | ) | -27% | (60,748 | ) | -77% | |||||||||||||||||||
| Total Expenses | 3,479,566 | 3,964,651 | 3,512,040 | (485,085 | ) | -12% | 452,611 | 13% | ||||||||||||||||||||
| Other Income (Loss) | ||||||||||||||||||||||||||||
| Change in Tax Receivable Agreement Liability | (35,383 | ) | 161,567 | — | (196,950 | ) | N/M | 161,567 | N/M | |||||||||||||||||||
| Net Gains from Fund Investment Activities | 30,542 | 282,829 | 191,722 | (252,287 | ) | -89% | 91,107 | 48% | ||||||||||||||||||||
| Total Other Income (Loss) | (4,841 | ) | 444,396 | 191,722 | (449,237 | ) | N/M | 252,674 | 132% | |||||||||||||||||||
| Income Before Provision (Benefit) for Taxes | 2,617,520 | 3,818,015 | 3,512,941 | (1,200,495 | ) | -31% | 305,074 | 9% | ||||||||||||||||||||
| Provision (Benefit) for Taxes | 356,014 | (47,952 | ) | 249,390 | 403,966 | N/M | (297,342 | ) | N/M | |||||||||||||||||||
| Net Income | 2,261,506 | 3,865,967 | 3,263,551 | (1,604,461 | ) | -42% | 602,416 | 18% | ||||||||||||||||||||
| Net Loss Attributable to Redeemable Non-Controlling Interests in Consolidated Entities | (13,898 | ) | (121 | ) | (2,104 | ) | (13,777 | ) | N/M | 1,983 | -94% | |||||||||||||||||
| Net Income Attributable to Non-Controlling Interests in Consolidated Entities | 217,117 | 476,779 | 358,878 | (259,662 | ) | -54% | 117,901 | 33% | ||||||||||||||||||||
| Net Income Attributable to Non-Controlling Interests in Blackstone Holdings | 1,012,924 | 1,339,627 | 1,364,989 | (326,703 | ) | -24% | (25,362 | ) | -2% | |||||||||||||||||||
| Net Income Attributable to The Blackstone Group Inc. | $ | 1,045,363 | $ | 2,049,682 | $ | 1,541,788 | $ | (1,004,319 | ) | -49% | $ | 507,894 | 33% | |||||||||||||||
N/M Not meaningful.
Year Ended December 31, 2020 Compared to Year Ended December 31, 2019
Revenues
Revenues were $6.1 billion for the year ended December 31, 2020, a decrease of $1.2 billion compared to $7.3 billion for the year ended December 31, 2019. The decrease in Revenues was primarily attributable to decreases of $1.5 billion in Investment Income (Loss) and $333.1 million in Other Revenue, partially offset by an increase of $620.4 million in Management and Advisory Fees, Net.
The decrease in Investment Income (Loss) was primarily driven by the impacts of
COVID-19.
Investment Income (Loss) in our Real Estate and Credit & Insurance segments decreased $1.7 billion and $287.7 million, respectively, partially offset by an increase in our Private Equity segment of $494.2 million. The decrease in our Real Estate segment was primarily attributable to lower net unrealized appreciation of investment holdings in BREP opportunistic funds and lower realized gains in the year ended December 31, 2020 compared to the year ended December 31, 2019. BREP opportunistic funds’ carrying value increased 3.4% in the year ended December 31, 2020 compared to 17.6% in the year ended December 31, 2019. The decrease in our Credit & Insurance segment was primarily attributable to net unrealized depreciation of investments in our private credit strategies in the year ended December 31, 2020 compared to net unrealized appreciation in the year ended December 31, 2019. The increase in our Private Equity segment was primarily attributable to higher realized gains and higher net unrealized appreciation of investment holdings in corporate private equity in the year ended December 31, 2020 compared to the year ended December 31, 2019. Corporate private equity carrying value increased 11.9% in the year ended December 31, 2020 compared to 10.3% in the year ended December 31, 2019.
The decrease in Other Revenue was primarily due to foreign exchange losses on our euro denominated bonds and cross-currency swaps.
The increase in Management and Advisory Fees, Net was primarily due to increases in our Real Estate and Private Equity segments of $373.5 million and $205.5 million, respectively. The increase in our Real Estate segment was primarily due to the end of BREP IX’s fee holiday in 2019, the commencement of BREP Europe VI’s investment period in the fourth quarter of 2019 along with the end of its fee holiday in the first quarter of 2020 and
Fee-Earning
Assets Under Management growth in core+ real estate. The increase in our Private Equity segment was primarily due to the end of BCP VIII, BEP III and BXLS V’s fee holiday during the third quarter of 2020 and a full year of Base Management Fees from Strategic Partners VIII.
Expenses
Expenses were $3.5 billion for the year ended December 31, 2020, a decrease of $485.1 million, compared to $4.0 billion for the year ended December 31, 2019. The decrease was primarily attributable to a decrease of $479.1 million in Total Compensation and Benefits, which was primarily due to a decrease of $514.5 million in Performance Allocations Compensation. The decrease in Performance Allocations Compensation was primarily due to the decrease in Investment Income (Loss) – Performance Allocations, on which the compensation is based.
Other Income (Loss)
Year Ended December 31, 2020 Compared to Year Ended December 31, 2019
Other Income (Loss) was $(4.8) million for the year ended December 31, 2020, a decrease of $449.2 million, compared to $444.4 million for the year ended December 31, 2019. The decrease in Other Income (Loss) was due to decreases of $252.3 million in Net Gains (Losses) from Fund Investment Activities and $197.0 million in Change in Tax Receivable Agreement Liability.
The decrease in Net Gain (Losses) from Fund Investment Activities was primarily due to decreases of $188.9 million in our Credit & Insurance segment and $86.2 million in our Real Estate segment, partially offset by an increase of $19.0 million in our Private Equity segment. The decrease in our Credit & Insurance segment was primarily driven by depreciation of consolidated CLOs and other vehicles during the first six months of 2020 and the deconsolidation of nine CLO vehicles during the third quarter of 2020. See Note 9. “Variable Interest Entities” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing. The decrease in our Real Estate segment was primarily driven by depreciation of investments in our consolidated Real Estate segment funds. The increase in our Private Equity segment was primarily due to appreciation of investments in our consolidated Private Equity segment funds.
The decrease in Change in Tax Receivable Agreement Liability was primarily due to the reduction of the estimated cash savings to be realized by Blackstone recorded in relation to the Conversion during the year ended December 31, 2019.
Provision (Benefit) for Taxes
The following table summarizes Blackstone’s tax position:
| Year Ended December 31, | ||||||||||||
| 2020 | 2019 | 2018 | ||||||||||
| (Dollars in Thousands) | ||||||||||||
| Income Before Provision (Benefit) for Taxes | $ | 2,617,520 | $ | 3,818,015 | $ | 3,512,941 | ||||||
| Provision (Benefit) for Taxes | $ | 356,014 | $ | (47,952 | ) | $ | 249,390 | |||||
| Effective Income Tax Rate | 13.6 | % | -1.3 | % | 7.1 | % |
The following table reconciles the effective income tax rate to the U.S. federal statutory tax rate:
| Year Ended December 31, | 2020 vs. | 2019 vs. | ||||||||||||||||||
| 2020 | 2019 | 2018 | 2019 | 2018 | ||||||||||||||||
| Statutory U.S. Federal Income Tax Rate | 21.0 | % | 21.0 | % | 21.0 | % | — | — | ||||||||||||
| Income Passed Through to Common Shareholders and Non-Controlling Interest Holders (a) | -8.6 | % | -13.5 | % | -15.5 | % | 4.9 | % | 2.0 | % | ||||||||||
| State and Local Income Taxes | 2.4 | % | 1.6 | % | 1.8 | % | 0.8 | % | -0.2 | % | ||||||||||
| Foreign Income Taxes | -1.2 | % | -0.6 | % | -0.3 | % | -0.6 | % | -0.3 | % | ||||||||||
| Change to a Taxable Corporation | 1.4 | % | -10.3 | % | — | 11.7 | % | -10.3 | % | |||||||||||
| Change in Valuation Allowance (b) | -2.8 | % | -0.8 | % | — | -2.0 | % | -0.8 | % | |||||||||||
| Other | 1.4 | % | 1.3 | % | 0.1 | % | 0.1 | % | 1.2 | % | ||||||||||
| Effective Income Tax Rate | 13.6 | % | -1.3 | % | 7.1 | % | 14.9 | % | -8.4 | % | ||||||||||
| (a) | Includes income that was not taxable to Blackstone and its subsidiaries. Such income was directly taxable to shareholders of Blackstone’s common stock for the period prior to the Conversion and remains taxable to Blackstone’s non-controlling interest holders. |
|---|
| (b) | The Change in Valuation Allowance for the year ended December 31, 2019 represents the change from July 1, 2019 to December 31, 2019, following the change to a taxable corporation. |
|---|
Blackstone’s Provision (Benefit) for Taxes for the years ended December 31, 2020 and 2019 was $356.0 million and $(48.0) million, respectively. This resulted in an effective tax rate of 13.6% and
-1.3%,
respectively, based on our Income Before Provision (Benefit) for Taxes of $2.6 billion and $3.8 billion, respectively.
The increase in Blackstone’s effective tax rate for the year ended December 31, 2020, compared to the year ended December 31, 2019, resulted primarily from the Conversion in 2019. For the year ended December 31, 2020, Blackstone was a corporation subject to federal and state corporate income taxes while for the first six months of the year ended December 31, 2019, The Blackstone Group L.P. was a publicly traded partnership with income directly taxable to common unitholders. The estimated tax benefit recorded on the date of the Conversion was reflected in the year ended December 31, 2019. Upon finalization of the 2019 tax returns, an adjustment was made to the tax basis step up related to the Conversion, resulting in an increase to the effective tax rate for the period ended December 31, 2020. In addition, the effective tax rate for the year ended December 31, 2020 benefited from a reduction in Blackstone’s valuation allowance, due to the tax basis utilization attributable to asset dispositions during the year.
Additional information regarding our income taxes can be found in “— Item 8. Financial Statements and Supplementary Data — Notes to Consolidated Financial Statements — Note 15. Income Taxes” of this filing.
Non-Controlling
Interests in Consolidated Entities
The Net Income Attributable to Redeemable
Non-Controlling
Interests in Consolidated Entities and Net Income Attributable to
Non-Controlling
Interests in Consolidated Entities is attributable to the consolidated Blackstone Funds. The amounts of these items vary directly with the performance of the consolidated Blackstone Funds and largely eliminate the amount of Other Income (Loss) — Net Gains (Losses) from Fund Investment Activities from the Net Income (Loss) Attributable to The Blackstone Group Inc.
Net Income Attributable to
Non-Controlling
Interests in Blackstone Holdings is derived from the Income Before Provision (Benefit) for Taxes at the Blackstone Holdings level, excluding the Net Gains (Losses) from Fund Investment Activities and the percentage allocation of the income between Blackstone personnel and others who are limited partners of Blackstone Holdings and Blackstone after considering any contractual arrangements that govern the allocation of income such as fees allocable to Blackstone.
For the years ended December 31, 2020 and 2019, the Net Income Before Taxes allocated to Blackstone personnel and others who are limited partners of Blackstone Holdings was 42.7% and 43.9%, respectively. The decrease of 1.2% was primarily due to conversions of Blackstone Holdings Partnership Units to shares of common stock and the vesting of shares of common stock.
The Other Income (Loss) — Change in Tax Receivable Agreement Liability was entirely allocated to The Blackstone Group Inc.
Operating Metrics
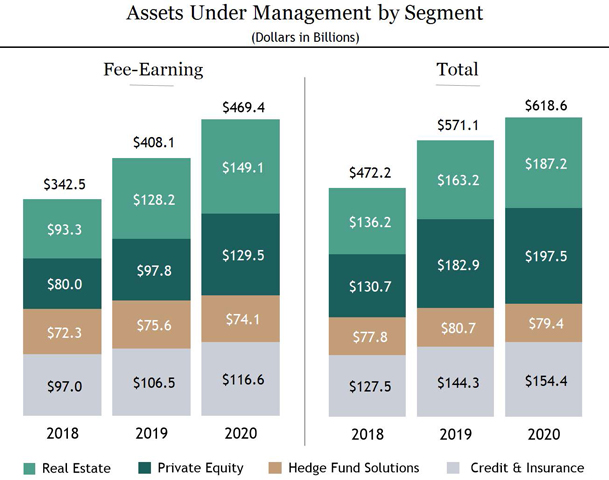
The following graphs and tables summarize the
Fee-Earning
Assets Under Management by Segment and Total Assets Under Management by Segment, followed by a rollforward of activity for the years ended December 31, 2020, 2019 and 2018. For a description of how Assets Under Management and
Fee-Earning
Assets Under Management are determined, please see “—Key Financial Measures and Indicators — Operating Metrics — Assets Under Management and
Fee-Earning
Assets Under Management.”
Note: Totals may not add due to rounding.
| Year Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | |||||||||||||||||||||||||||||||||||||||
| Real Estate | Private Equity | Hedge Fund Solutions | Credit & Insurance | Total | Real Estate | Private Equity | Hedge Fund Solutions | Credit & Insurance | Total | |||||||||||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||||||||||||||
| Fee-Earning Assets Under Management | ||||||||||||||||||||||||||||||||||||||||
| Balance, Beginning of Period | $ | 128,214,137 | $ | 97,773,964 | $ | 75,636,004 | $ | 106,450,747 | $ | 408,074,852 | $ | 93,252,724 | $ | 80,008,166 | $ | 72,280,606 | $ | 96,986,011 | $ | 342,527,507 | ||||||||||||||||||||
| Inflows (a) | 28,071,474 | 45,359,946 | 9,712,930 | 26,035,009 | 109,179,359 | 52,424,662 | 27,260,480 | 11,488,234 | 21,069,189 | 112,242,565 | ||||||||||||||||||||||||||||||
| Outflows (b) | (3,517,881 | ) | (5,956,364 | ) | (12,538,753 | ) | (9,417,126 | ) | (31,430,124 | ) | (9,690,143 | ) | (2,352,716 | ) | (11,928,940 | ) | (9,067,554 | ) | (33,039,353 | ) | ||||||||||||||||||||
| Net Inflows (Outflows) | 24,553,593 | 39,403,582 | (2,825,823 | ) | 16,617,883 | 77,749,235 | 42,734,519 | 24,907,764 | (440,706 | ) | 12,001,635 | 79,203,212 | ||||||||||||||||||||||||||||
| Realizations (c) | (9,007,492 | ) | (7,290,931 | ) | (1,346,147 | ) | (5,506,288 | ) | (23,150,858 | ) | (11,353,675 | ) | (7,212,993 | ) | (1,153,785 | ) | (5,629,089 | ) | (25,349,542 | ) | ||||||||||||||||||||
| Market Activity (d)(g) | 5,361,223 | (346,985 | ) | 2,662,576 | (916,929 | ) | 6,759,885 | 3,580,569 | 71,027 | 4,949,889 | 3,092,190 | 11,693,675 | ||||||||||||||||||||||||||||
| Balance, End of Period (e) | $ | 149,121,461 | $ | 129,539,630 | $ | 74,126,610 | $ | 116,645,413 | $ | 469,433,114 | $ | 128,214,137 | $ | 97,773,964 | $ | 75,636,004 | $ | 106,450,747 | $ | 408,074,852 | ||||||||||||||||||||
| Increase (Decrease) | $ | 20,907,324 | $ | 31,765,666 | $ | (1,509,394 | ) | $ | 10,194,666 | $ | 61,358,262 | $ | 34,961,413 | $ | 17,765,798 | $ | 3,355,398 | $ | 9,464,736 | $ | 65,547,345 | |||||||||||||||||||
| Increase (Decrease) | 16 | % | 32 | % | -2 | % | 10 | % | 15 | % | 37 | % | 22 | % | 5 | % | 10 | % | 19 | % | ||||||||||||||||||||
| Annualized Base Management Fee Rate (f) | 1.14 | % | 1.00 | % | 0.81 | % | 0.57 | % | 0.91 | % | 1.02 | % | 1.08 | % | 0.75 | % | 0.57 | % | 0.86 | % |
| Year Ended December 31, | ||||||||||||||||||||
| 2018 | ||||||||||||||||||||
| Private | Hedge Fund | Credit & | ||||||||||||||||||
| Real Estate | Equity | Solutions | Insurance | Total | ||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||
| Fee-Earning Assets Under Management | ||||||||||||||||||||
| Balance, Beginning of Period | $ | 83,984,824 | $ | 70,140,883 | $ | 69,914,061 | $ | 111,304,230 | $ | 335,343,998 | ||||||||||
| Inflows (a) | 17,961,223 | 16,096,543 | 12,354,410 | 24,587,957 | 71,000,133 | |||||||||||||||
| Outflows (b) | (2,000,367 | ) | (1,888,223 | ) | (10,278,403 | ) | (27,640,908 | ) | (41,807,901 | ) | ||||||||||
| Net Inflows (Outflows) | 15,960,856 | 14,208,320 | 2,076,007 | (3,052,951 | ) | 29,192,232 | ||||||||||||||
| Realizations (c) | (8,781,140 | ) | (4,729,843 | ) | (429,912 | ) | (6,672,539 | ) | (20,613,434 | ) | ||||||||||
| Market Activity (d)(g) | 2,088,184 | 388,806 | 720,450 | (4,592,729 | ) | (1,395,289 | ) | |||||||||||||
| Balance, End of Period (e) | $ | 93,252,724 | $ | 80,008,166 | $ | 72,280,606 | $ | 96,986,011 | $ | 342,527,507 | ||||||||||
| Increase (Decrease) | $ | 9,267,900 | $ | 9,867,283 | $ | 2,366,545 | $ | (14,318,219 | ) | $ | 7,183,509 | |||||||||
| Increase (Decrease) | 11 | % | 14 | % | 3 | % | -13 | % | 2 | % | ||||||||||
| Annualized Base Management Fee Rate (f) | 1.11 | % | 1.04 | % | 0.72 | % | 0.54 | % | 0.84 | % |
| Year Ended December 31, | ||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | |||||||||||||||||||||||||||||||||||||||
| Real Estate | Private Equity | Hedge Fund Solutions | Credit & Insurance | Total | Real Estate | Private Equity | Hedge Fund Solutions | Credit & Insurance | Total | |||||||||||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||||||||||||||
| Total Assets Under Management | ||||||||||||||||||||||||||||||||||||||||
| Balance, Beginning of Period | $ | 163,156,064 | $ | 182,886,109 | $ | 80,738,112 | $ | 144,342,178 | $ | 571,122,463 | $ | 136,247,229 | $ | 130,665,286 | $ | 77,814,516 | $ | 127,515,286 | $ | 472,242,317 | ||||||||||||||||||||
| Inflows (a) | 33,426,600 | 23,030,463 | 10,415,356 | 28,141,077 | 95,013,496 | 34,190,566 | 56,836,570 | 12,242,855 | 31,107,288 | 134,377,279 | ||||||||||||||||||||||||||||||
| Outflows (b) | (3,836,842 | ) | (2,707,863 | ) | (13,353,437 | ) | (9,380,391 | ) | (29,278,533 | ) | (2,664,717 | ) | (1,065,445 | ) | (13,433,702 | ) | (11,629,269 | ) | (28,793,133 | ) | ||||||||||||||||||||
| Net Inflows (Outflows) | 29,589,758 | 20,322,600 | (2,938,081 | ) | 18,760,686 | 65,734,963 | 31,525,849 | 55,771,125 | (1,190,847 | ) | 19,478,019 | 105,584,146 | ||||||||||||||||||||||||||||
| Realizations (c) | (16,256,579 | ) | (17,304,777 | ) | (1,392,894 | ) | (7,670,738 | ) | (42,624,988 | ) | (18,097,899 | ) | (13,540,914 | ) | (1,271,968 | ) | (7,291,045 | ) | (40,201,826 | ) | ||||||||||||||||||||
| Market Activity (d)(h)(i) | 10,702,004 | 11,645,290 | 3,015,732 | (1,038,536 | ) | 24,324,490 | 13,480,885 | 9,990,612 | 5,386,411 | 4,639,918 | 33,497,826 | |||||||||||||||||||||||||||||
| Balance, End of Period (e) | $ | 187,191,247 | $ | 197,549,222 | $ | 79,422,869 | $ | 154,393,590 | $ | 618,556,928 | $ | 163,156,064 | $ | 182,886,109 | $ | 80,738,112 | $ | 144,342,178 | $ | 571,122,463 | ||||||||||||||||||||
| Increase (Decrease) | $ | 24,035,183 | $ | 14,663,113 | $ | (1,315,243 | ) | $ | 10,051,412 | $ | 47,434,465 | $ | 26,908,835 | $ | 52,220,823 | $ | 2,923,596 | $ | 16,826,892 | $ | 98,880,146 | |||||||||||||||||||
| Increase (Decrease) | 15 | % | 8 | % | -2 | % | 7 | % | 8 | % | 20 | % | 40 | % | 4 | % | 13 | % | 21 | % |
| Year Ended December 31, | ||||||||||||||||||||
| 2018 | ||||||||||||||||||||
| Private | Hedge Fund | Credit & | ||||||||||||||||||
| Real Estate | Equity | Solutions | Insurance | Total | ||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||
| Total Assets Under Management | ||||||||||||||||||||
| Balance, Beginning of Period | $ | 115,340,363 | $ | 105,560,576 | $ | 75,090,834 | $ | 138,136,470 | $ | 434,128,243 | ||||||||||
| Inflows (a) | 31,478,431 | 26,639,963 | 13,278,327 | 29,578,890 | 100,975,611 | |||||||||||||||
| Outflows (b) | (2,162,958 | ) | (1,617,585 | ) | (10,780,055 | ) | (28,057,658 | ) | (42,618,256 | ) | ||||||||||
| Net Inflows | 29,315,473 | 25,022,378 | 2,498,272 | 1,521,232 | 58,357,355 | |||||||||||||||
| Realizations (c) | (14,675,095 | ) | (10,396,611 | ) | (471,931 | ) | (8,516,996 | ) | (34,060,633 | ) | ||||||||||
| Market Activity (d)(h)(i) | 6,266,488 | 10,478,943 | 697,341 | (3,625,420 | ) | 13,817,352 | ||||||||||||||
| Balance, End of Period (e) | $ | 136,247,229 | $ | 130,665,286 | $ | 77,814,516 | $ | 127,515,286 | $ | 472,242,317 | ||||||||||
| Increase (Decrease) | $ | 20,906,866 | $ | 25,104,710 | $ | 2,723,682 | $ | (10,621,184 | ) | $ | 38,114,074 | |||||||||
| Increase (Decrease) | 18 | % | 24 | % | 4 | % | -8 | % | 9 | % |
| (a) | Inflows represent contributions, capital raised, other increases in available capital (recallable capital, increased side-by-side commitments), purchases, inter-segment allocations and acquisitions. |
|---|
| (b) | Outflows represent redemptions, client withdrawals and decreases in available capital (expired capital, expense drawdowns and decreased side-by-side commitments). |
|---|
| (c) | Realizations represent realization proceeds from the disposition or other monetization of assets, current income or capital returned to investors from CLOs. |
|---|
| (d) | Market activity includes realized and unrealized gains (losses) on portfolio investments and the impact of foreign exchange rate fluctuations. |
|---|
| (e) | Assets Under Management are reported in the segment where the assets are managed. |
|---|
| (f) | Effective January 1, 2020, Blackstone updated its calculation methodology as follows: annualized year to date Base Management Fee divided by the average of the beginning of year and each quarter end’s Fee-Earning Assets Under Management in the reporting period. Prior periods have been recast for this update |
|---|
| (g) | For the year ended December 31, 2020, the impact to Fee-Earning Assets Under Management due to foreign exchange rate fluctuations was $2.4 billion, $1.0 billion and $3.5 billion for the Real Estate, Credit & Insurance and Total segments, respectively. For the year ended December 31, 2019, the impact to Fee-Earning Assets Under Management due to foreign exchange rate fluctuations was $(94.9) million, $(280.6) million and $(375.5) million for the Real Estate, Credit & Insurance and Total segments, respectively. For the year ended December 31, 2018, such impact was $(904.2) million, $(626.6) million and $(1.5) billion for the Real Estate, Credit & Insurance and Total segments, respectively. |
|---|
| (h) | For the year ended December 31, 2020, the impact to Total Assets Under Management due to foreign exchange rate fluctuations was $4.2 billion, $642.6 million, $1.2 billion and $6.1 billion for the Real Estate, Private Equity, Credit & Insurance and Total segments, respectively. For the year ended December 31, 2019, the impact to Total Assets Under Management due to foreign exchange rate fluctuations was $(908.4) million, $238.8 million, $(233.0) million and $(902.6) million for the Real Estate, Private Equity, Credit & Insurance and Total segments, respectively. For the year ended December 31, 2018, such impact was $(2.1) billion, $(354.1) million, $(821.9) million and $(3.3) billion for the Real Estate, Private Equity, Credit & Insurance and Total segments, respectively. |
|---|
| (i) | Effective in the three months ended December 31, 2020, the methodology for Total Assets Under Management was updated with respect to the relevant segment for certain real estate, secondaries and credit funds to include permanent fund level leverage (as this represents additional capital the fund is managing), to include uncalled capital commitments until they are legally expired and to exclude certain uncalled capital commitments where the investors have complete discretion over investment. Funds without an adjustment were either already applying that methodology in reporting Total Assets Under Management or the updates were not applicable. Additional detail on these adjustments is included below: |
|---|
| Year Ended December 31, 2020 | ||||||||||||||||||||
| Private | Hedge Fund | Credit & | ||||||||||||||||||
| Real Estate | Equity | Solutions | Insurance | Total | ||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||
| Market Activity | $ | 6,923,489 | $ | 9,776,454 | $ | 3,015,732 | $ | 475,847 | $ | 20,191,522 | ||||||||||
| One-Time Methodology Adjustment | 3,778,515 | 1,868,836 | — | (1,514,383 | ) | 4,132,968 | ||||||||||||||
| Reported Market Activity | $ | 10,702,004 | $ | 11,645,290 | $ | 3,015,732 | $ | (1,038,536 | ) | $ | 24,324,490 | |||||||||
Subsequent to December 31, 2020, increases/decreases in permanent fund level leverage and uncalled capital commitments that have not legally expired where investors do not have complete discretion over investment for the aforementioned funds will be reflected as inflows, outflows, realization and/or market activity, as the case may be.
Fee-Earning
Assets Under Management
Fee-Earning
Assets Under Management were $469.4 billion at December 31, 2020, an increase of $61.4 billion, or 15%, compared to $408.1 billion at December 31, 2019. The net increase was due to:
| • | Inflows of $109.2 billion related to: |
|---|
| o | $45.4 billion in our Private Equity segment driven by $29.5 billion from corporate private equity, primarily related to the commencement of BCP VIII and BEP III’s investment periods, $4.9 billion from BXLS, related to the commencement of BXLS V’s investment period, $4.6 billion from Strategic Partners, $3.3 billion from BXG, $2.6 billion from Tactical Opportunities and $504.1 million from multi-asset products, |
|---|
| o | $28.1 billion in our Real Estate segment driven by $9.5 billion from BREIT, $6.9 billion from the launch of a new perpetual capital vehicle, BPP Life Sciences, $5.9 billion from BREDS, $2.1 billion from BREP opportunistic funds and co-investment, $1.3 billion from BPP Europe and co-investment, $1.2 billion from BPP Asia and co-investment and $1.1 billion from BPP U.S. and co-investment, |
|---|
| o | $26.0 billion in our Credit & Insurance segment driven by $13.0 billion from certain liquid credit and MLP strategies (including $7.8 billion related to the DCI acquisition), $4.7 billion from direct lending, $4.3 billion from our structured products group, $4.2 billion of capital raised from CLOs, $2.5 billion from BIS, $1.6 billion from mezzanine funds, $1.3 billion from stressed/distressed strategies and $525.8 million from energy strategies, all partially offset by $6.6 billion of allocations to various strategies and other segments, and |
|---|
| o | $9.7 billion in our Hedge Fund Solutions segment driven by $6.5 billion from individual investor and specialized solutions, $1.9 billion from customized solutions and $1.2 billion from commingled products. |
|---|
| • | Market activity of $6.8 billion primarily attributable to: |
|---|
| o | $5.4 billion of market appreciation in our Real Estate segment driven by $4.5 billion from core+ real estate (including $1.3 billion from foreign exchange appreciation) and $1.1 billion from BREP opportunistic and co-investment, |
|---|
| o | $2.7 billion of market appreciation in our Hedge Fund Solutions segment driven by returns from BAAM’s Principal Solutions Composite of 5.5% gross and 4.6% net, and |
|---|
| o | Partially offset by $916.9 million of market depreciation in our Credit & Insurance segment driven by depreciation of $1.1 billion from certain liquid credit and MLP strategies, $1.0 billion from stressed/distressed strategies, partially offset by $534.5 million of market appreciation from CLOs, $388.9 million from direct lending and $360.3 million from BIS, all of which included $1.0 billion of foreign exchange appreciation across the segment. |
|---|
Offsetting these increases were:
| • | Outflows of $31.4 billion primarily attributable to: |
|---|
| o | $12.5 billion in our Hedge Fund Solutions segment driven by $5.7 billion from individual investor and specialized solutions, $4.0 billion from customized solutions and $2.8 billion from commingled products, |
|---|
| o | $9.4 billion in our Credit & Insurance segment driven by $6.8 billion from certain liquid credit and MLP strategies, $1.1 billion from direct lending and $809.9 million from stressed/distressed strategies, |
|---|
| o | $6.0 billion in our Private Equity segment driven by $4.6 billion from corporate private equity primarily due to the end of BCP VII and BEP II’s investment periods, $706.8 million from Strategic Partners, $497.5 million from BXLS due to the end of Clarus IV’s investment period and $237.2 million from multi-asset products, and |
|---|
| o | $3.5 billion in our Real Estate segment driven by $1.5 billion from BREIT, $1.5 billion from BREDS, $336.0 million from BPP U.S. and co-investment and $160.3 million from BPP Europe. |
|---|
| • | Realizations of $23.2 billion primarily driven by: |
|---|
| o | $9.0 billion in our Real Estate segment driven by $3.2 billion from BREP opportunistic funds and co-investment, $3.1 billion from core+ real estate and $2.7 billion from BREDS, |
|---|
| o | $7.3 billion in our Private Equity segment driven by $3.7 billion from Tactical Opportunities, $1.9 billion from corporate private equity and $1.7 billion from Strategic Partners, and |
|---|
| o | $5.5 billion in our Credit & Insurance segment driven by $1.2 billion from direct lending, $1.2 billion from stressed/distressed strategies, $1.0 billion from CLOs, $978.6 million from mezzanine funds, $583.8 million from energy strategies and $551.7 million from certain liquid credit and MLP strategies. |
|---|
Total Assets Under Management
Total Assets Under Management were $618.6 billion at December 31, 2020, an increase of $47.4 billion, compared to $571.1 billion at December 31, 2019. The net increase was due to:
| • | Inflows of $95.0 billion related to: |
|---|
| o | $33.4 billion in our Real Estate segment driven by $9.5 billion from BREIT, $8.8 billion from BREDS, $8.0 billion from the launch of a new perpetual capital vehicle, BPP Life Sciences, $2.3 billion from BREP opportunistic funds and co-investment, $1.9 billion from BPP Asia and co-investment, $1.8 billion from BPP Europe and co-investment and $1.1 billion from BPP U.S. and co-investment, |
|---|
| o | $28.1 billion in our Credit & Insurance segment driven by $14.1 billion from certain liquid credit and MLP strategies (including $7.8 billion related to the DCI acquisition), $7.3 billion from our structured products group, $5.1 billion from direct lending, $4.2 billion of capital raised from CLOs, $3.5 billion from mezzanine funds and $2.7 billion from BIS, all partially offset by $9.6 billion of allocations to various strategies and other segments, |
|---|
| o | $23.0 billion in our Private Equity segment driven by $10.3 billion from corporate private equity, including $8.2 billion capital raised from the second core private equity fund, $4.1 billion from Strategic Partners, $3.5 billion from BXG, $2.1 billion from Tactical Opportunities, $2.1 billion from BXLS and $888.0 million from BIP, and |
|---|
| o | $10.4 billion in our Hedge Fund Solutions segment driven by $6.6 billion from individual investor and specialized solutions, $2.3 billion from customized solutions and $1.6 billion from commingled products. |
|---|
| • | Market activity of $24.3 billion primarily driven by: |
|---|
| o | $11.6 billion of market appreciation in our Private Equity segment driven by carrying value increases in corporate private equity and Tactical Opportunities of 11.9% and 14.1%, respectively, which includes $642.6 million of foreign exchange appreciation across the segment, |
|---|
| o | $10.7 billion of market appreciation in our Real Estate segment driven by carrying value increases in opportunistic and core+ real estate of 3.4% and 7.9%, during the year, respectively, which includes $4.2 billion of foreign exchange appreciation across the segment, |
|---|
| o | $3.0 billion of market appreciation in our Hedge Fund Solutions segment driven by reasons noted above in Fee-Earning Assets Under Management, and |
|---|
| o | Partially offset by $1.0 billion of market depreciation in our Credit & Insurance segment driven by depreciation of $1.2 billion from certain liquid credit and MLP strategies, $816.5 million from energy strategies and $616.7 million from stressed/distressed strategies, partially offset by market appreciation of $1.2 billion from direct lending and $554.8 million from CLOs, all of which included $1.2 billion of foreign exchange appreciation across the segment. |
|---|
Total Assets Under Management market activity in our Real Estate and Private Equity segments generally represents the change in fair value of the investments held and typically exceeds the
Fee-Earning
Assets Under Management market activity.
Offsetting these increases were:
| • | Realizations of $42.6 billion primarily driven by: |
|---|
| o | $17.3 billion in our Private Equity segment driven by $8.3 billion from corporate private equity, $6.1 billion from Tactical Opportunities, $2.5 billion from Strategic Partners and $446.6 million from BXLS, |
|---|
| o | $16.3 billion in our Real Estate segment driven by $11.1 billion from BREP opportunistic and co-investment, $3.2 billion from core+ real estate and $1.9 billion from BREDS, and |
|---|
| o | $7.7 billion in our Credit & Insurance segment driven by $2.2 billion from direct lending, $1.9 billion from mezzanine funds, $1.3 billion from stressed/distressed strategies, $1.0 billion from CLOs, $638.5 million from energy strategies and $617.3 million from certain liquid credit and MLP strategies. |
|---|
Total Assets Under Management realizations in our Real Estate and Private Equity segments generally represents the total proceeds and typically exceeds the
Fee-Earning
Assets Under Management realizations which generally represents only the invested capital.
| • | Outflows of $29.3 billion primarily attributable to: |
|---|
| o | $13.4 billion in our Hedge Fund Solutions segment driven by $5.8 billion from individual investor and specialized solutions, $4.1 billion from customized solutions and $3.4 billion from commingled products, |
|---|
| o | $9.4 billion in our Credit & Insurance segment driven by $7.3 billion from certain liquid credit and MLP strategies, $1.1 billion from direct lending and $508.5 million from CLOs, |
|---|
| o | $3.8 billion in our Real Estate segment driven by $2.1 billion from core+ real estate, $1.3 billion from BREP opportunistic funds and co-investment and $467.2 million from BREDS, and |
|---|
| o | $2.7 billion in our Private Equity segment driven by $824.8 million from multi-asset products, $705.9 million from Strategic Partners, $658.1 million from corporate private equity, $337.2 million from Tactical Opportunities and $171.7 million from BXLS. |
|---|
Dry Powder
The following presents our Dry Powder as of December 31 of each year:
Note: Totals may not add due to rounding.
| (a) | Represents illiquid drawdown funds, a component of Perpetual Capital and fee-paying co-investments; includes fee-paying third party capital as well as general partner and employee capital that does not earn fees. Amounts are reduced by outstanding capital commitments, for which capital has not yet been invested. |
|---|
Net Accrued Performance Revenues
The following table presents the Accrued Performance Revenues, net of performance compensation, of the Blackstone Funds as of December 31, 2020 and 2019. Net Accrued Performance Revenues presented do not include clawback amounts, if any, which are disclosed in Note 19. “Commitments and Contingencies — Contingencies — Contingent Obligations (Clawback)” in the “Notes to Consolidated Financial Statements” in “—Item 8. Financial Statements and Supplementary Data” of this filing. See
“— Non-GAAP
Financial Measures” for our reconciliation of Net Accrued Performance Revenues.
| December 31, | ||||||||
| 2020 | 2019 | |||||||
| (Dollars in Millions) | ||||||||
| Real Estate | ||||||||
| BREP IV | $ | 9 | $ | 11 | ||||
| BREP V | 13 | 19 | ||||||
| BREP VI | 42 | 76 | ||||||
| BREP VII | 236 | 445 | ||||||
| BREP VIII | 475 | 674 | ||||||
| BREP IX | 137 | 6 | ||||||
| BREP Europe IV | 97 | 158 | ||||||
| BREP Europe V | 211 | 193 | ||||||
| BREP Asia I | 127 | 152 | ||||||
| BREP Asia II | — | 22 | ||||||
| BPP | 264 | 281 | ||||||
| BREDS | 23 | 33 | ||||||
| BTAS | 21 | 42 | ||||||
| Total Real Estate (a) | 1,656 | 2,112 | ||||||
| Private Equity | ||||||||
| BCP IV | 18 | 23 | ||||||
| BCP VI | 680 | 705 | ||||||
| BCP VII | 688 | 471 | ||||||
| BCP Asia | 72 | 17 | ||||||
| BEP I | 29 | 102 | ||||||
| BEP III | 16 | — | ||||||
| BCEP | 105 | 46 | ||||||
| Tactical Opportunities (b) | 204 | 157 | ||||||
| Strategic Partners | 105 | 144 | ||||||
| BXLS | 10 | 7 | ||||||
| BTAS/Other | 45 | 62 | ||||||
| Total Private Equity (a) | 1,971 | 1,735 | ||||||
| Hedge Fund Solutions | 29 | 15 | ||||||
| Credit & Insurance | 170 | 237 | ||||||
| Total Blackstone Net Accrued Performance Revenues | $ | 3,826 | $ | 4,099 | ||||
Note: Totals may not add due to rounding.
| (a) | Real Estate and Private Equity include Co-Investments, as applicable |
|---|
| (b) | Tactical Opportunities includes Blackstone Growth. |
|---|
For the year ended December 31, 2020 Net Accrued Performance Revenues receivable decreased due to net realized distributions of $1.4 billion in excess of Net Accrued Performance Revenues of $1.1 billion.
Invested Performance Eligible Assets Under Management
The following presents our Invested Performance Eligible Assets Under Management as of December 31 of each year:
Note: Totals may not add due to rounding.
Perpetual Capital
The following presents our Perpetual Capital Assets Under Management as of December 31 of each year:
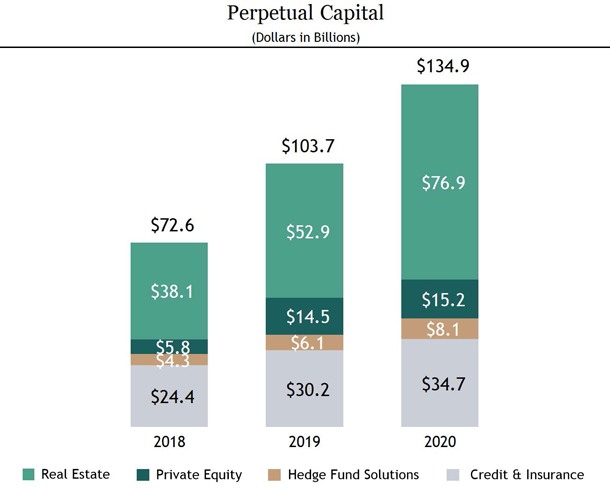
Note: Totals may not add due to rounding.
Investment Record
Fund returns information for our significant funds is included throughout this discussion and analysis to facilitate an understanding of our results of operations for the periods presented. The fund returns information reflected in this discussion and analysis is not indicative of the financial performance of Blackstone and is also not necessarily indicative of the future performance of any particular fund. An investment in Blackstone is not an investment in any of our funds. There can be no assurance that any of our funds or our other existing and future funds will achieve similar returns.
The following table presents the investment record of our significant drawdown funds from inception through December 31, 2020:
| Fund (Investment Period | Committed | Available | Unrealized Investments | Realized Investments | Total Investments | Net IRRs (d) | ||||||||||||||||||||||||||||||||||||||
| Beginning Date / Ending Date) (a) | Capital | Capital (b) | Value | MOIC (c) | % Public | Value | MOIC (c) | Value | MOIC (c) | Realized | Total | |||||||||||||||||||||||||||||||||
| (Dollars/Euros in Thousands, Except Where Noted) | ||||||||||||||||||||||||||||||||||||||||||||
| Real Estate | ||||||||||||||||||||||||||||||||||||||||||||
| Pre-BREP | $ | 140,714 | $ | — | $ | — | N/A | — | $ | 345,190 | 2.5x | $ | 345,190 | 2.5x | 33 | % | 33 | % | ||||||||||||||||||||||||||
| BREP I (Sep 1994 / Oct 1996) | 380,708 | — | — | N/A | — | 1,327,708 | 2.8x | 1,327,708 | 2.8x | 40 | % | 40 | % | |||||||||||||||||||||||||||||||
| BREP II (Oct 1996 / Mar 1999) | 1,198,339 | — | — | N/A | — | 2,531,614 | 2.1x | 2,531,614 | 2.1x | 19 | % | 19 | % | |||||||||||||||||||||||||||||||
| BREP III (Apr 1999 / Apr 2003) | 1,522,708 | — | — | N/A | — | 3,330,406 | 2.4x | 3,330,406 | 2.4x | 21 | % | 21 | % | |||||||||||||||||||||||||||||||
| BREP IV (Apr 2003 / Dec 2005) | 2,198,694 | — | 89,243 | 1.8x | 27 | % | 4,544,926 | 1.7x | 4,634,169 | 1.7x | 13 | % | 12 | % | ||||||||||||||||||||||||||||||
| BREP V (Dec 2005 / Feb 2007) (e) | 5,539,418 | 231,919 | 191,895 | 0.8x | 50 | % | 13,080,463 | 2.4x | 13,272,358 | 2.3x | 12 | % | 11 | % | ||||||||||||||||||||||||||||||
| BREP VI (Feb 2007 / Aug 2011) (e) | 11,060,444 | 550,734 | 512,439 | 2.3x | 77 | % | 27,223,779 | 2.5x | 27,736,218 | 2.5x | 13 | % | 13 | % | ||||||||||||||||||||||||||||||
| BREP VII (Aug 2011 / Apr 2015) | 13,496,823 | 1,525,946 | 5,584,753 | 1.2x | 6 | % | 23,030,962 | 2.1x | 28,615,715 | 1.8x | 22 | % | 14 | % | ||||||||||||||||||||||||||||||
| BREP VIII (Apr 2015 / Jun 2019) | 16,567,256 | 2,729,536 | 13,706,200 | 1.2x | — | 13,362,963 | 2.3x | 27,069,163 | 1.6x | 29 | % | 14 | % | |||||||||||||||||||||||||||||||
| *BREP IX (Jun 2019 / Dec 2024) | 20,891,658 | 14,175,042 | 8,173,444 | 1.2x | 6 | % | 1,204,084 | 1.4x | 9,377,528 | 1.3x | N/M | 20 | % | |||||||||||||||||||||||||||||||
| Total Global BREP | $ | 72,996,762 | $ | 19,213,177 | $ | 28,257,974 | 1.2x | 5 | % | $ | 89,982,095 | 2.3x | $ | 118,240,069 | 1.9x | 18 | % | 15 | % | |||||||||||||||||||||||||
| BREP Int’l (Jan 2001 / Sep 2005) | € | 824,172 | € | — | € | — | N/A | — | € | 1,373,170 | 2.1x | € | 1,373,170 | 2.1x | 23 | % | 23 | % | ||||||||||||||||||||||||||
| BREP Int’l II (Sep 2005 / Jun 2008) (f) | 1,629,748 | — | — | N/A | — | 2,576,670 | 1.8x | 2,576,670 | 1.8x | 8 | % | 8 | % | |||||||||||||||||||||||||||||||
| BREP Europe III (Jun 2008 / Sep 2013) (e) | 3,205,167 | 456,744 | 362,083 | 0.6x | — | 5,738,120 | 2.5x | 6,100,203 | 2.1x | 20 | % | 14 | % | |||||||||||||||||||||||||||||||
| BREP Europe IV (Sep 2013 / Dec 2016) | 6,710,146 | 1,308,972 | 2,441,555 | 1.3x | — | 9,045,059 | 2.0x | 11,486,614 | 1.8x | 22 | % | 14 | % | |||||||||||||||||||||||||||||||
| BREP Europe V (Dec 2016 / Oct 2019) | 7,949,959 | 1,563,722 | 8,006,708 | 1.3x | — | 853,905 | 2.8x | 8,860,613 | 1.4x | 51 | % | 9 | % | |||||||||||||||||||||||||||||||
| *BREP Europe VI (Oct 2019 / Apr 2025) | 9,786,439 | 7,021,025 | 2,670,641 | 1.1x | 3 | % | 4,800 | N/A | 2,675,441 | 1.1x | N/M | — | ||||||||||||||||||||||||||||||||
| Total BREP Europe | € | 30,105,631 | € | 10,350,463 | € | 13,480,987 | 1.2x | 1 | % | € | 19,591,724 | 2.1x | € | 33,072,711 | 1.6x | 16 | % | 12 | % | |||||||||||||||||||||||||
continued ...
| Fund (Investment Period | Committed | Available | Unrealized Investments | Realized Investments | Total Investments | Net IRRs (d) | ||||||||||||||||||||||||||||||||||||||
| Beginning Date / Ending Date) (a) | Capital | Capital (b) | Value | MOIC (c) | % Public | Value | MOIC (c) | Value | MOIC (c) | Realized | Total | |||||||||||||||||||||||||||||||||
| (Dollars/Euros in Thousands, Except Where Noted) | ||||||||||||||||||||||||||||||||||||||||||||
| Real Estate (continued) | ||||||||||||||||||||||||||||||||||||||||||||
| BREP Asia I (Jun 2013 / Dec 2017) | $ | 4,598,089 | $ | 1,277,077 | $ | 3,227,787 | 1.4x | 14 | % | $ | 4,422,796 | 1.9x | $ | 7,650,583 | 1.7x | 21 | % | 12 | % | |||||||||||||||||||||||||
| *BREP Asia II (Dec 2017 / Jun 2023) | 7,302,307 | 3,989,162 | 3,830,476 | 1.2x | 10 | % | 267,905 | 1.5x | 4,098,381 | 1.2x | 47 | % | 7 | % | ||||||||||||||||||||||||||||||
| BREP Co-Investment (g) | 7,055,974 | 52,499 | 556,811 | 1.4x | — | 14,780,923 | 2.2x | 15,337,734 | 2.2x | 16 | % | 16 | % | |||||||||||||||||||||||||||||||
| Total BREP | $ | 128,730,171 | $ | 37,176,041 | $ | 51,343,542 | 1.2x | 5 | % | $ | 134,129,927 | 2.2x | $ | 185,473,469 | 1.8x | 17 | % | 15 | % | |||||||||||||||||||||||||
| *Core+ BPP (Various) (h) | $ | N/A | $ | N/A | $ | 43,373,269 | N/A | — | $ | 7,884,244 | N/A | $ | 51,257,513 | N/A | N/M | 9 | % | |||||||||||||||||||||||||||
| *Core+ BREIT (Various) (i) | N/A | N/A | 21,046,096 | N/A | — | 706,600 | N/A | 21,752,696 | N/A | N/A | 9 | % | ||||||||||||||||||||||||||||||||
| *BREDS High-Yield (Various) (j) | 19,991,345 | 9,009,057 | 3,983,786 | 1.0x | — | 13,213,838 | 1.3x | 17,197,624 | 1.2x | 11 | % | 10 | % | |||||||||||||||||||||||||||||||
| Private Equity | ||||||||||||||||||||||||||||||||||||||||||||
| Corporate Private Equity | ||||||||||||||||||||||||||||||||||||||||||||
| BCP I (Oct 1987 / Oct 1993) | $ | 859,081 | $ | — | $ | — | N/A | — | $ | 1,741,738 | 2.6x | $ | 1,741,738 | 2.6x | 19 | % | 19 | % | ||||||||||||||||||||||||||
| BCP II (Oct 1993 / Aug 1997) | 1,361,100 | — | — | N/A | — | 3,256,819 | 2.5x | 3,256,819 | 2.5x | 32 | % | 32 | % | |||||||||||||||||||||||||||||||
| BCP III (Aug 1997 / Nov 2002) | 3,967,422 | — | — | N/A | — | 9,184,688 | 2.3x | 9,184,688 | 2.3x | 14 | % | 14 | % | |||||||||||||||||||||||||||||||
| BCOM (Jun 2000 / Jun 2006) | 2,137,330 | 24,575 | 12,891 | N/A | — | 2,953,649 | 1.4x | 2,966,540 | 1.4x | 6 | % | 6 | % | |||||||||||||||||||||||||||||||
| BCP IV (Nov 2002 / Dec 2005) | 6,773,182 | 188,664 | 161,420 | 2.0x | — | 21,417,821 | 2.9x | 21,579,241 | 2.9x | 36 | % | 36 | % | |||||||||||||||||||||||||||||||
| BCP V (Dec 2005 / Jan 2011) | 21,009,112 | 1,035,259 | 534,817 | 5.9x | 44 | % | 37,465,460 | 1.9x | 38,000,277 | 1.9x | 8 | % | 8 | % | ||||||||||||||||||||||||||||||
| BCP VI (Jan 2011 / May 2016) | 15,202,400 | 1,164,970 | 10,785,320 | 1.8x | 48 | % | 18,844,732 | 2.2x | 29,630,052 | 2.0x | 17 | % | 13 | % | ||||||||||||||||||||||||||||||
| BCP VII (May 2016 / Feb 2020) | 18,853,440 | 1,500,064 | 23,833,391 | 1.5x | 3 | % | 2,127,704 | 1.4x | 25,961,095 | 1.5x | 20 | % | 15 | % | ||||||||||||||||||||||||||||||
| *BCP VIII (Feb 2020 / Feb 2026) | 24,839,835 | 24,780,233 | 55,918 | N/A | 100 | % | — | N/A | 55,918 | N/A | N/A | N/A | ||||||||||||||||||||||||||||||||
| Energy I (Aug 2011 / Feb 2015) | 2,441,558 | 142,138 | 707,832 | 1.0x | 20 | % | 3,332,406 | 1.9x | 4,040,238 | 1.7x | 15 | % | 10 | % | ||||||||||||||||||||||||||||||
| Energy II (Feb 2015 / Feb 2020) | 4,913,589 | 452,250 | 3,542,696 | 0.9x | 8 | % | 538,308 | 0.8x | 4,081,004 | 0.9x | -18 | % | -9 | % | ||||||||||||||||||||||||||||||
| *Energy III (Feb 2020 / Feb 2026) | 4,230,317 | 3,659,611 | 740,313 | 1.5x | 87 | % | — | N/A | 740,313 | 1.5x | N/A | N/M | ||||||||||||||||||||||||||||||||
| *BCP Asia (Dec 2017 / Dec 2023) | 2,407,749 | 1,314,996 | 1,882,785 | 1.8x | 11 | % | 160,023 | 2.2x | 2,042,808 | 1.8x | 145 | % | 35 | % | ||||||||||||||||||||||||||||||
| *Core Private Equity I (Jan 2017 / Jul 2021) (k) | 4,756,127 | 1,704,858 | 5,140,800 | 1.6x | — | 1,007,863 | 1.9x | 6,148,663 | 1.7x | 33 | % | 20 | % | |||||||||||||||||||||||||||||||
| Core Private Equity II (TBD) (k) | 8,160,000 | 8,160,000 | — | N/A | — | — | N/A | — | N/A | N/A | N/A | |||||||||||||||||||||||||||||||||
| Total Corporate Private Equity | $ | 121,912,242 | $ | 44,127,618 | $ | 47,398,183 | 1.5x | 16 | % | $ | 102,031,211 | 2.1x | $ | 149,429,394 | 1.8x | 16 | % | 15 | % | |||||||||||||||||||||||||
continued ...
| Fund (Investment Period | Committed | Available | Unrealized Investments | Realized Investments | Total Investments | Net IRRs (d) | ||||||||||||||||||||||||||||||||||||||
| Beginning Date / Ending Date) (a) | Capital | Capital (b) | Value | MOIC (c) | % Public | Value | MOIC (c) | Value | MOIC (c) | Realized | Total | |||||||||||||||||||||||||||||||||
| (Dollars/Euros in Thousands, Except Where Noted) | ||||||||||||||||||||||||||||||||||||||||||||
| Private Equity (continued) | ||||||||||||||||||||||||||||||||||||||||||||
| Tactical Opportunities | ||||||||||||||||||||||||||||||||||||||||||||
| *Tactical Opportunities (Various) | $ | 23,059,743 | $ | 9,485,052 | $ | 13,781,064 | 1.3x | 11 | % | $ | 11,484,767 | 1.8x | $ | 25,265,831 | 1.4x | 17 | % | 11 | % | |||||||||||||||||||||||||
| *Tactical Opportunities Co-Investment and Other (Various) | 8,752,000 | 2,219,611 | 3,412,302 | 1.2x | 7 | % | 5,404,166 | 1.7x | 8,816,468 | 1.5x | 19 | % | 15 | % | ||||||||||||||||||||||||||||||
| Total Tactical Opportunities | $ | 31,811,743 | $ | 11,704,663 | $ | 17,193,366 | 1.3x | 10 | % | $ | 16,888,933 | 1.7x | $ | 34,082,299 | 1.4x | 18 | % | 12 | % | |||||||||||||||||||||||||
| *Blackstone Growth (Jul 2020 / Jul 2025) | $ | 3,378,427 | $ | 2,590,318 | $ | 480,643 | N/M | — | $ | — | N/A | $ | 480,643 | N/M | N/A | N/M | ||||||||||||||||||||||||||||
| Strategic Partners (Secondaries) | ||||||||||||||||||||||||||||||||||||||||||||
| Strategic Partners I-V (Various) (l) | 11,863,351 | 1,163,562 | 767,152 | N/M | — | 17,047,367 | N/M | 17,814,519 | 1.5x | N/A | 13 | % | ||||||||||||||||||||||||||||||||
| Strategic Partners VI (Apr 2014 / Apr 2016) (l) | 4,362,750 | 1,231,443 | 1,140,668 | N/M | — | 3,420,227 | N/M | 4,560,895 | 1.4x | N/A | 13 | % | ||||||||||||||||||||||||||||||||
| Strategic Partners VII (May 2016 / Mar 2019) (l) | 7,489,970 | 2,236,145 | 4,502,593 | N/M | — | 2,501,199 | N/M | 7,003,792 | 1.4x | N/A | 13 | % | ||||||||||||||||||||||||||||||||
| Strategic Partners Real Assets II (May 2017 / Jun 2020) (l) | 1,749,807 | 342,200 | 1,146,290 | N/M | — | 457,411 | N/M | 1,603,701 | 1.2x | N/A | 12 | % | ||||||||||||||||||||||||||||||||
| *Strategic Partners VIII (Mar 2019 / Jul 2023) (l) | 10,763,600 | 6,057,212 | 3,116,224 | N/M | — | 349,817 | N/M | 3,466,041 | 1.3x | N/A | 25 | % | ||||||||||||||||||||||||||||||||
| *Strategic Partners Real Estate, SMA and Other (Various) (l) | 7,678,498 | 2,637,711 | 2,721,040 | N/M | — | 1,515,801 | N/M | 4,236,841 | 1.2x | N/A | 12 | % | ||||||||||||||||||||||||||||||||
| *Strategic Partners Infra III (Jun 2020 / Jul 2024) (l) | 3,250,100 | 2,945,629 | 95,680 | N/M | — | — | N/A | 95,680 | 1.9x | N/A | N/M | |||||||||||||||||||||||||||||||||
| Total Strategic Partners (Secondaries) | $ | 47,158,076 | $ | 16,613,902 | $ | 13,489,647 | N/M | — | $ | 25,291,822 | N/M | $ | 38,781,469 | 1.4x | N/A | 13 | % | |||||||||||||||||||||||||||
| *Infrastructure (Various) | $ | 13,658,063 | $ | 10,643,283 | $ | 3,221,714 | 1.1x | 19 | % | $ | — | N/A | $ | 3,221,714 | 1.1x | N/A | — | |||||||||||||||||||||||||||
| Life Sciences | ||||||||||||||||||||||||||||||||||||||||||||
| Clarus IV (Jan 2018 / Jan 2020) | 910,000 | 376,877 | 620,930 | 1.3x | 3 | % | 25,626 | 1.3x | 646,556 | 1.3x | 15 | % | 11 | % | ||||||||||||||||||||||||||||||
| *BXLS V (Jan 2020 / Jan 2025) | 4,711,227 | 4,124,901 | 659,008 | 1.2x | 15 | % | — | N/A | 659,008 | 1.2x | N/A | N/M |
continued ...
| Fund (Investment Period Beginning Date / Ending Date) (a) | Committed Capital | Available Capital (b) | Unrealized Investments | Realized Investments | Total Investments | Net IRRs (d) | ||||||||||||||||||||||||||||||||||||||
| Value | MOIC (c) | % Public | Value | MOIC (c) | Value | MOIC (c) | Realized | Total | ||||||||||||||||||||||||||||||||||||
| (Dollars/Euros in Thousands, Except Where Noted) | ||||||||||||||||||||||||||||||||||||||||||||
| Credit | ||||||||||||||||||||||||||||||||||||||||||||
| Mezzanine / Opportunistic I (Jul 2007 / Oct 2011) | $ | 2,000,000 | $ | 97,114 | $ | 19,479 | 1.0x | — | $ | 4,774,747 | 1.6x | $ | 4,794,226 | 1.6x | N/A | 17 | % | |||||||||||||||||||||||||||
| Mezzanine / Opportunistic II (Nov 2011 / Nov 2016) | 4,120,000 | 1,033,222 | 837,744 | 0.6x | — | 5,741,374 | 1.6x | 6,579,118 | 1.3x | N/A | 10 | % | ||||||||||||||||||||||||||||||||
| *Mezzanine / Opportunistic III (Sep 2016 / Sep 2021) | 6,639,133 | 1,523,459 | 5,183,034 | 1.1x | — | 2,714,002 | 1.7x | 7,897,036 | 1.2x | N/A | 10 | % | ||||||||||||||||||||||||||||||||
| Stressed / Distressed I (Sep 2009 / May 2013) | 3,253,143 | 76,000 | — | N/A | — | 5,775,572 | 1.3x | 5,775,572 | 1.3x | N/A | 9 | % | ||||||||||||||||||||||||||||||||
| Stressed / Distressed II (Jun 2013 / Jun 2018) | 5,125,000 | 552,970 | 887,348 | 0.7x | — | 4,511,189 | 1.2x | 5,398,537 | 1.0x | N/A | -1 | % | ||||||||||||||||||||||||||||||||
| *Stressed / Distressed III (Dec 2017 / Dec 2022) | 7,356,380 | 3,913,986 | 2,167,831 | 0.9x | — | 1,502,127 | 1.4x | 3,669,958 | 1.1x | N/A | 2 | % | ||||||||||||||||||||||||||||||||
| Energy I (Nov 2015 / Nov 2018) | 2,856,867 | 999,173 | 1,459,608 | 0.9x | — | 1,236,203 | 1.7x | 2,695,811 | 1.2x | N/A | 4 | % | ||||||||||||||||||||||||||||||||
| *Energy II (Feb 2019 / Feb 2024) | 3,616,081 | 2,797,654 | 890,262 | 1.1x | — | 227,003 | 1.6x | 1,117,265 | 1.2x | N/A | 23 | % | ||||||||||||||||||||||||||||||||
| European Senior Debt I (Feb 2015 / Feb 2019) | € | 1,964,689 | € | 267,442 | € | 1,684,033 | 1.0x | 2 | % | € | 1,428,233 | 1.5x | € | 3,112,266 | 1.2x | N/A | 5 | % | ||||||||||||||||||||||||||
| *European Senior Debt II (Jun 2019 / Jun 2024) | € | 4,088,344 | € | 3,362,428 | € | 921,206 | 1.1x | — | € | 267,489 | 1.1x | € | 1,188,695 | 1.1x | N/A | 16 | % | |||||||||||||||||||||||||||
| Total Credit Drawdown Funds (m) | $ | 41,872,262 | $ | 15,434,919 | $ | 14,629,225 | 1.0x | — | $ | 28,421,511 | 1.4x | $ | 43,050,736 | 1.2x | N/A | 9 | % | |||||||||||||||||||||||||||
| *Direct Lending BDC BXSL (Various) (n) | $ | 3,926,295 | $ | 713,254 | $ | 3,267,808 | N/A | — | $ | 267,134 | N/A | $ | 3,534,942 | N/A | N/A | 9 | % |
The returns presented herein represent those of the applicable Blackstone Funds and not those of Blackstone.
| N/M | Not meaningful generally due to the limited time since initial investment. |
|---|
| N/A | Not applicable. |
|---|
| * | Represents funds that are currently in their investment period and open-ended funds. |
|---|
| (a) | Excludes investment vehicles where Blackstone does not earn fees. |
|---|
| (b) | Available Capital represents total investable capital commitments, including side-by-side, adjusted for certain expenses and expired or recallable capital and may include leverage, less invested capital. This amount is not reduced by outstanding commitments to investments. |
|---|
| (c) | Multiple of Invested Capital (“MOIC”) represents carrying value, before management fees, expenses and Performance Revenues, divided by invested capital. |
|---|
| (d) | Unless otherwise indicated, Net Internal Rate of Return (“IRR”) represents the annualized inception to December 31, 2020 IRR on total invested capital based on realized proceeds and unrealized value, as applicable, after management fees, expenses and Performance Revenues. IRRs are calculated using actual timing of limited partner cash flows. Initial inception date of cash flows may differ from the Investment Period Beginning Date. |
|---|
| (e) | Effective December 31, 2020, Available Capital was updated to include uncalled capital commitments until they are legally expired, which increased Available Capital. |
|---|
| (f) | The 8% Realized Net IRR and 8% Total Net IRR exclude investors that opted out of the Hilton investment opportunity. Overall BREP International II performance reflects a 7% Realized Net IRR and a 7% Total Net IRR. |
|---|
| (g) | BREP Co-Investment represents co-investment capital raised for various BREP investments. The Net IRR reflected is calculated by aggregating each co-investment’s realized proceeds and unrealized value, as applicable, after management fees, expenses and Performance Revenues. |
|---|
| (h) | BPP represents the core+ real estate funds which invest with a more modest risk profile and lower leverage. Committed Capital and Available Capital are not regularly reported to investors in our core+ strategy and are not applicable in the context of these funds. |
|---|
| (i) | Unrealized Investment Value reflects BREIT’s net asset value as of December 31, 2020. Realized Investment Value represents BREIT’s cash distributions, net of servicing fees. The BREIT net return reflects a per share blended return, assuming BREIT had a single share class, reinvestment of all dividends received during the period, and no upfront selling commission, net of all fees and expenses incurred by BREIT. These returns are not representative of the returns experienced by any particular investor or share class. Inception to date net returns are presented on an annualized basis and are from January 1, 2017. Committed Capital and Available Capital are not regularly reported to investors in our core+ strategy and are not applicable in the context of this vehicle. |
|---|
| (j) | BREDS High-Yield represents the flagship real estate debt drawdown funds only and excludes BREDS High-Grade. |
|---|
| (k) | Blackstone Core Equity Partners is a core private equity strategy which invests with a more modest risk profile and longer hold period than traditional private equity. |
|---|
| (l) | Realizations are treated as return of capital until fully recovered and therefore unrealized and realized MOICs are not meaningful. If information is not available on a timely basis, returns are calculated from results that are reported on a three month lag and therefore do not include the impact of economic and market activities in the quarter in which such events occur. |
|---|
| (m) | Funds presented represent the flagship credit drawdown funds only. The Total Credit Net IRR is the combined IRR of the credit drawdown funds presented. |
|---|
| (n) | Unrealized Investment Value reflects BXSL’s net asset value as of December 31, 2020. Realized Investment Value represents BXSL’s cash distributions. BXSL’s net return is annualized and calculated since inception starting on November 20, 2018, as the change in net asset value (“NAV”) per share during the period, plus distributions per share (assuming dividends and distributions are reinvested in accordance with the Company’s dividend reinvestment plan) divided by the beginning NAV per share. |
|---|
Segment Analysis
Discussed below is our Segment Distributable Earnings for each of our segments. This information is reflected in the manner utilized by our senior management to make operating decisions, assess performance and allocate resources. References to “our” sectors or investments may also refer to portfolio companies and investments of the underlying funds that we manage.
Real Estate
The following table presents the results of operations for our Real Estate segment:
| Year Ended December 31, | 2020 vs. 2019 | 2019 vs. 2018 | ||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | ||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||
| Management Fees, Net | ||||||||||||||||||||||||||||
| Base Management Fees | $ | 1,553,483 | $ | 1,116,183 | $ | 985,399 | $ | 437,300 | 39 | % | $ | 130,784 | 13 | % | ||||||||||||||
| Transaction and Other Fees, Net | 98,225 | 175,831 | 152,513 | (77,606 | ) | -44 | % | 23,318 | 15 | % | ||||||||||||||||||
| Management Fee Offsets | (13,020 | ) | (26,836 | ) | (11,442 | ) | 13,816 | -51 | % | (15,394 | ) | 135 | % | |||||||||||||||
| Total Management Fees, Net | 1,638,688 | 1,265,178 | 1,126,470 | 373,510 | 30 | % | 138,708 | 12 | % | |||||||||||||||||||
| Fee Related Performance Revenues | 338,161 | 198,237 | 124,502 | 139,924 | 71 | % | 73,735 | 59 | % | |||||||||||||||||||
| Fee Related Compensation | (618,105 | ) | (531,259 | ) | (459,430 | ) | (86,846 | ) | 16 | % | (71,829 | ) | 16 | % | ||||||||||||||
| Other Operating Expenses | (183,132 | ) | (168,332 | ) | (146,260 | ) | (14,800 | ) | 9 | % | (22,072 | ) | 15 | % | ||||||||||||||
| Fee Related Earnings | 1,175,612 | 763,824 | 645,282 | 411,788 | 54 | % | 118,542 | 18 | % | |||||||||||||||||||
| Realized Performance Revenues | 787,768 | 1,032,337 | 914,984 | (244,569 | ) | -24 | % | 117,353 | 13 | % | ||||||||||||||||||
| Realized Performance Compensation | (312,698 | ) | (374,096 | ) | (284,319 | ) | 61,398 | -16 | % | (89,777 | ) | 32 | % | |||||||||||||||
| Realized Principal Investment Income | 24,764 | 79,733 | 92,525 | (54,969 | ) | -69 | % | (12,792 | ) | -14 | % | |||||||||||||||||
| Net Realizations | 499,834 | 737,974 | 723,190 | (238,140 | ) | -32 | % | 14,784 | 2 | % | ||||||||||||||||||
| Segment Distributable Earnings | $ | 1,675,446 | $ | 1,501,798 | $ | 1,368,472 | $ | 173,648 | 12 | % | $ | 133,326 | 10 | % | ||||||||||||||
N/M Not meaningful.
Year Ended December 31, 2020 Compared to Year Ended December 31, 2019
Segment Distributable Earnings were $1.7 billion for the year ended December 31, 2020, an increase of $173.6 million, or 12%, compared to $1.5 billion for the year ended December 31, 2019. The increase in Segment Distributable Earnings was primarily attributable to an increase of $411.8 million in Fee Related Earnings, partially offset by a decrease of $238.1 million in Net Realizations.
Segment Distributable Earnings in our Real Estate segment in 2020 were higher compared to 2019. This was primarily driven by increased Fee Related Earnings due to the end of BREP IX’s fee holiday in 2019, the commencement of BREP Europe VI’s investment period in the fourth quarter of 2019 along with the end of its fee holiday in the first quarter of 2020 and growth in
Fee-Earning
Assets Under Management in core+ real estate, partially offset by decreased Net Realizations. The global economy has, with certain setbacks, continued to reopen following the onset of the
COVID-19
pandemic and the related shutdowns or limitations in the operations of certain
non-essential
businesses. Market rebounds across many asset classes have contributed to capital deployment, realization and fundraising activity. Progress on
COVID-19
vaccine production and distribution, together with continued support from previously implemented fiscal and monetary stimulus, have aided the continuing economic recovery and could potentially accelerate such recovery. Although certain investments in our real estate portfolio, such as those in the hospitality and retail sectors and in select office and residential assets in urban locations, have been materially impacted and could continue to be adversely affected, the majority of our aggregate global real estate portfolio in BREP and core+ real estate businesses is in sectors that we believe are more resilient to the impact of
COVID-19.
Nevertheless, the recovery could remain uneven and characterized by
meaningful dispersion across sectors and regions, particularly given uncertainty with respect to the distribution and acceptance of the vaccines. The resurgence in
COVID-19
infection levels in certain geographies and a potential resulting market downturn may pose material risks. These risks potentially create additional pressure for certain of our portfolio companies’ and investments’ liquidity needs and their ability to meet financial obligations, including by adversely impacting operational performance. We have not experienced a period of significant dislocation since the first quarter of 2020, during which the liquidity of certain assets traded in the credit markets was limited. Nonetheless, another period of such dislocation would impact the value of certain assets held by our funds, such funds’ ability to sell assets at attractive prices or in a timely manner in order to avoid losses and the likelihood of margin calls from credit providers. A continuing market recovery, however, could contribute to increased activity over the longer term.
We have also seen a continuing focus toward rent regulation as a means to address residential affordability caused by undersupply of housing in certain markets in the U.S. and Europe, as well as an increasing focus on the institution of eviction limitations in response to the
COVID-19
pandemic in the U.S. In addition, the new Presidential administration and the U.S. Congress may introduce new or enforce existing policies and regulations that may create uncertainty for our business and investment strategies and could have an adverse impact on us and our portfolio companies. Such conditions (which may be across industries, sectors or geographies) may contribute to adverse operating performance, including moderated rent growth in certain markets in our residential portfolio. See “Part I. Item 1A. Risk Factors – Risks Related to Our Business – The global outbreak of the novel coronavirus, or
COVID-19,
has caused severe disruptions in the U.S. and global economies and has adversely impacted, and may continue to adversely impact, our performance and results of operations”, “– Difficult market and geopolitical conditions can adversely affect our business in many ways, each of which could materially reduce our revenue, earnings and cash flow and adversely affect our financial prospects and condition” and “– A period of economic slowdown, which may be across one or more industries, sectors or geographies, has contributed and could in the future contribute to adverse operating performance for certain of our funds’ investments, which would adversely affect our operating results and cash flows.”
Fee Related Earnings
Fee Related Earnings were $1.2 billion for the year ended December 31, 2020, an increase of $411.8 million, or 54%, compared to $763.8 million for the year ended December 31, 2019. The increase in Fee Related Earnings was primarily attributable to increases of $373.5 million in Management Fees, Net and $139.9 million in Fee Related Performance Revenues, partially offset by an increase of $86.8 million in Fee Related Compensation.
Management Fees, Net were $1.6 billion for the year ended December 31, 2020, an increase of $373.5 million compared to $1.3 billion for the year ended December 31, 2019, primarily driven by an increase in Base Management Fees. Base Management Fees increased $437.3 million primarily due to the end of BREP IX’s fee holiday in 2019, the commencement of BREP Europe VI’s investment period in the fourth quarter of 2019 along with the end of its fee holiday in the first quarter of 2020 and
Fee-Earning
Assets Under Management growth in core+ real estate.
The annualized Base Management Fee Rate increased from 1.02% at December 31, 2019 to 1.14% at December 31, 2020. The increase was principally due to BREP IX, the majority of which was under a Base Management Fee holiday in 2019, and BREP Europe VI, which commenced its investment period in the fourth quarter of 2019 and came out of its fee holiday in the first quarter of 2020.
Fee Related Performance Revenues were $338.2 million for the year ended December 31, 2020, an increase of $139.9 million, compared to $198.2 million for the year ended December 31, 2019. The increase was primarily due to crystallization events in BPP Europe, a BPP U.S.
co-investment
and an increase in BREIT’s net asset value.
Fee Related Compensation was $618.1 million for the year ended December 31, 2020, an increase of $86.8 million, compared to $531.3 million for the year ended December 31, 2019. The increase was primarily due to increases in Management Fees, Net and Fee Related Performance Revenues, on which a portion of Fee Related Compensation is based.
Net Realizations
Net Realizations were $499.8 million for the year ended December 31, 2020, a decrease of $238.1 million, compared to $738.0 million for the year ended December 31, 2019. The decrease in Net Realizations was primarily attributable to decreases of $244.6 million in Realized Performance Revenues and $55.0 million in Realized Principal Investment Income, partially offset by a decrease of $61.4 million in Realized Performance Compensation.
Realized Performance Revenues were $787.8 million for the year ended December 31, 2020, a decrease of $244.6 million, compared to $1.0 billion for the year ended December 31, 2019. The decrease was due to lower realized gains as a result of market impacts of
COVID-19
in the year ended December 31, 2020 compared to the year ended December 31, 2019.
Realized Principal Investment Income was $24.8 million for the year ended December 31, 2020, a decrease of $55.0 million, compared to $79.7 million for the year ended December 31, 2019. The decrease was primarily due to redemptions in BREDS funds in the year ended December 31, 2019 and lower realized gains in BREP funds in the year ended December 31, 2020 compared to the year ended December 31, 2019.
Realized Performance Compensation was $312.7 million for the year ended December 31, 2020, a decrease of $61.4 million, compared to $374.1 million for the year ended December 31, 2019. The decrease was primarily due to the decrease in Realized Performance Revenues.
Fund Returns
Fund return information for our significant funds is included throughout this discussion and analysis to facilitate an understanding of our results of operations for the periods presented. The fund returns information reflected in this discussion and analysis is not indicative of the financial performance of Blackstone and is also not necessarily indicative of the future performance of any particular fund. An investment in Blackstone is not an investment in any of our funds. There can be no assurance that any of our funds or our other existing and future funds will achieve similar returns.
The following table presents the internal rates of return, except where noted, of our significant real estate funds:
| Year Ended December 31, | December 31, 2020 Inception to Date | |||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | Realized | Total | ||||||||||||||||||||||||||||||||||||
| Fund (a) | Gross | Net | Gross | Net | Gross | Net | Gross | Net | Gross | Net | ||||||||||||||||||||||||||||||
| BREP IV | 66 | % | 106 | % | 90 | % | 66 | % | -14 | % | -12 | % | 23 | % | 13 | % | 22 | % | 12 | % | ||||||||||||||||||||
| BREP V | -13 | % | -11 | % | 16 | % | 13 | % | -6 | % | -5 | % | 15 | % | 12 | % | 14 | % | 11 | % | ||||||||||||||||||||
| BREP VI | -16 | % | -15 | % | 34 | % | 28 | % | 7 | % | 5 | % | 18 | % | 13 | % | 17 | % | 13 | % | ||||||||||||||||||||
| BREP VII | -22 | % | -20 | % | 15 | % | 12 | % | 3 | % | 2 | % | 30 | % | 22 | % | 21 | % | 14 | % | ||||||||||||||||||||
| BREP VIII | 10 | % | 7 | % | 20 | % | 15 | % | 20 | % | 14 | % | 36 | % | 29 | % | 20 | % | 14 | % | ||||||||||||||||||||
| BREP IX | 35 | % | 21 | % | N/ | M | N/ | M | N/ | A | N/ | A | N/ | M | N/ | M | 35 | % | 20 | % | ||||||||||||||||||||
| BREP Europe III (b) | -14 | % | -11 | % | 1 | % | -1 | % | -18 | % | -15 | % | 30 | % | 20 | % | 22 | % | 14 | % | ||||||||||||||||||||
| BREP Europe IV (b) | -17 | % | -15 | % | 13 | % | 10 | % | 20 | % | 14 | % | 31 | % | 22 | % | 21 | % | 14 | % | ||||||||||||||||||||
| BREP Europe V (b) | 1 | % | — | 20 | % | 14 | % | 25 | % | 17 | % | 67 | % | 51 | % | 15 | % | 9 | % | |||||||||||||||||||||
| BREP Europe VI (b) | 14 | % | — | N/ | M | N/ | M | N/ | A | N | /A | N/ | M | N/ | M | 11 | % | — | ||||||||||||||||||||||
| BREP Asia I | -5 | % | -5 | % | 19 | % | 14 | % | 10 | % | 7 | % | 29 | % | 21 | % | 18 | % | 12 | % | ||||||||||||||||||||
| BREP Asia II | 8 | % | 4 | % | 27 | % | 16 | % | N/ | M | N/ | M | 74 | % | 47 | % | 14 | % | 7 | % | ||||||||||||||||||||
| BREP Co-Investment (c) | 33 | % | 32 | % | 20 | % | 13 | % | -1 | % | — | 18 | % | 16 | % | 18 | % | 16 | % | |||||||||||||||||||||
| BPP (d) | 7 | % | 6 | % | 10 | % | 8 | % | 11 | % | 10 | % | N/ | M | N/ | M | 11 | % | 9 | % | ||||||||||||||||||||
| BREDS High-Yield (e) | 5 | % | 1 | % | 17 | % | 13 | % | 9 | % | 4 | % | 15 | % | 11 | % | 14 | % | 10 | % | ||||||||||||||||||||
| BREDS High-Grade (e) | 2 | % | 1 | % | 8 | % | 7 | % | 7 | % | 5 | % | 8 | % | 6 | % | 5 | % | 4 | % | ||||||||||||||||||||
| BREDS Liquid (f) | -10 | % | -11 | % | 13 | % | 10 | % | 6 | % | 4 | % | N | /A | N | /A | 9 | % | 6 | % | ||||||||||||||||||||
| BXMT (g) | N | /A | -18 | % | N/ | A | 25 | % | N | /A | 7 | % | N | /A | N | /A | N | /A | 9 | % | ||||||||||||||||||||
| BREIT (h) | N | /A | 7 | % | N/ | A | 12 | % | N | /A | 8 | % | N | /A | N | /A | N | /A | 9 | % |
The returns presented herein represent those of the applicable Blackstone Funds and not those of Blackstone.
| N/M | Not meaningful generally due to the limited time since initial investment. |
|---|
| N/A | Not applicable. |
|---|
| (a) | Net returns are based on the change in carrying value (realized and unrealized) after management fees, expenses and Performance Revenues. |
|---|
| (b) | Euro-based internal rates of return. |
|---|
| (c) | BREP Co-Investment represents co-investment capital raised for various BREP investments. The Net IRR reflected is calculated by aggregating each co-investment’s realized proceeds and unrealized value, as applicable, after management fees, expenses and Performance Revenues. |
|---|
| (d) | BPP represents the core+ real estate funds which invest with a more modest risk profile and lower leverage. |
|---|
| (e) | BREDS High-Yield represents the flagship real estate debt drawdown funds and excludes the BREDS High-Grade drawdown fund, which has a different risk-return profile. Inception to date returns are from July 1, 2009 and July 1, 2017 for BREDS High-Yield and BREDS High-Grade, respectively. |
|---|
| (f) | BREDS Liquid represents BREDS funds that invest in liquid real estate debt securities, except funds in liquidation and insurance mandates with specific investment objectives. The returns presented represent summarized asset-weighted gross and net rates of return from August 1, 2008. Inception to Date returns are presented on an annualized basis. |
|---|
| (g) | Reflects annualized return of a shareholder invested in BXMT as of the beginning of each period presented, assuming reinvestment of all dividends received during the period, and net of all fees and expenses incurred by BXMT. Return incorporates the closing NYSE stock price as of each period end. Inception to date returns are from May 22, 2013. |
|---|
| (h) | Reflects a per share blended return for each respective period, assuming BREIT had a single share class, reinvestment of all dividends received during the period, and no upfront selling commission, net of all fees and expenses incurred by BREIT. These returns are not representative of the returns experienced by any particular investor or share class. Inception to date returns are presented on an annualized basis and are from January 1, 2017. |
|---|
Funds With Closed Investment Periods
The Real Estate segment has eleven funds with closed investment periods as of December 31, 2020: BREP VIII, BREP VII, BREP VI, BREP V, BREP IV, BREP Europe V, BREP Europe IV, BREP Europe Ill, BREP Asia I, BREDS Ill and BREDS II. As of December 31, 2020, BREP VII, BREP VI, BREP V, BREP IV, BREP Europe IV, BREP Europe Ill and BREDS II were above their carried interest thresholds and would have been above their carried interest thresholds even if all remaining investments were valued at zero. BREP VIII, BREP Europe V, BREP Asia I and BREDS III were above their carried interest thresholds.
Private Equity
The following table presents the results of operations for our Private Equity segment:
| Year Ended December 31, | 2020 vs. 2019 | 2019 vs. 2018 | ||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | ||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||
| Management and Advisory Fees, Net | ||||||||||||||||||||||||||||
| Base Management Fees | $ | 1,232,028 | $ | 986,482 | $ | 785,223 | $ | 245,546 | 25 | % | $ | 201,259 | 26 | % | ||||||||||||||
| Transaction, Advisory and Other Fees, Net | 82,440 | 115,174 | 58,165 | (32,734 | ) | -28 | % | 57,009 | 98 | % | ||||||||||||||||||
| Management Fee Offsets | (44,628 | ) | (37,327 | ) | (13,504 | ) | (7,301 | ) | 20 | % | (23,823 | ) | 176 | % | ||||||||||||||
| Total Management and Advisory Fees, Net | 1,269,840 | 1,064,329 | 829,884 | 205,511 | 19 | % | 234,445 | 28 | % | |||||||||||||||||||
| Fee Related Compensation | (455,538 | ) | (423,752 | ) | (375,446 | ) | (31,786 | ) | 8 | % | (48,306 | ) | 13 | % | ||||||||||||||
| Other Operating Expenses | (195,213 | ) | (160,010 | ) | (133,096 | ) | (35,203 | ) | 22 | % | (26,914 | ) | 20 | % | ||||||||||||||
| Fee Related Earnings | 619,089 | 480,567 | 321,342 | 138,522 | 29 | % | 159,225 | 50 | % | |||||||||||||||||||
| Realized Performance Revenues | 877,493 | 468,992 | 757,406 | 408,501 | 87 | % | (288,414 | ) | -38 | % | ||||||||||||||||||
| Realized Performance Compensation | (366,949 | ) | (192,566 | ) | (318,167 | ) | (174,383 | ) | 91 | % | 125,601 | -39 | % | |||||||||||||||
| Realized Principal Investment Income | 72,089 | 90,249 | 109,731 | (18,160 | ) | -20 | % | (19,482 | ) | -18 | % | |||||||||||||||||
| Net Realizations | 582,633 | 366,675 | 548,970 | 215,958 | 59 | % | (182,295 | ) | -33 | % | ||||||||||||||||||
| Segment Distributable Earnings | $ | 1,201,722 | $ | 847,242 | $ | 870,312 | $ | 354,480 | 42 | % | $ | (23,070 | ) | -3 | % | |||||||||||||
N/M Not meaningful.
Year Ended December 31, 2020 Compared to Year Ended December 31, 2019
Segment Distributable Earnings were $1.2 billion for the year ended December 31, 2020, an increase of $354.5 million, or 42%, compared to $847.2 million for the year ended December 31, 2019. The increase in Segment Distributable Earnings was primarily attributable to increases of $138.5 million in Fee Related Earnings and $216.0 million in Net Realizations.
Segment Distributable Earnings in our Private Equity segment in 2020 were higher compared to 2019. This was primarily driven by an increase in Fee Related Earnings from growth in
Fee-Earning
Assets Under Management and an increase in Net Realizations due to higher Realized Performance Revenue, partially offset by an increase in Realized Performance Compensation. The global economy has, with certain setbacks, continued to reopen following the onset of the
COVID-19
pandemic and the related shutdowns or limitations in the operations of certain
non-essential
businesses. Market rebounds across many asset classes have contributed to capital deployment, realization and fundraising activity. Progress on
COVID-19
vaccine production and distribution,
together with continued support from previously implemented fiscal and monetary stimulus, have aided the continuing economic recovery and could potentially accelerate such recovery. Although certain investments in our private equity portfolio, such as those in the travel, leisure and events sectors, have experienced material reductions in value and could continue to be adversely impacted, the majority of our aggregate
non-energy
portfolio in our corporate private funds is in sectors that we believe are more resilient to the impact of
COVID-19.
Nevertheless, the recovery could remain uneven and characterized by meaningful dispersion across sectors and regions, particularly given uncertainty with respect to the distribution and acceptance of the vaccines. The resurgence in
COVID-19
infection levels in certain geographies and a potential resulting market downturn may pose material risks. These risks potentially create additional pressure for certain of our portfolio companies’ liquidity needs and their ability to meet financial obligations. A continuing market recovery, however, could contribute to increased activity over the longer term.
In energy, oil prices have stabilized since the significant declines experienced in the first quarter of 2020. Nonetheless, weakened market fundamentals continue to pose challenges, particularly in upstream energy, which represents 3% of the Private Equity segment’s investment portfolio and less than 2% of Blackstone’s aggregate investment portfolio. An increased focus on energy sustainability due to concerns about climate change and the impact of carbon emissions, including potential alternatives to fossil fuels, has also exacerbated the impact of such weakened market fundamentals. The persistence of these weakened market fundamentals would further negatively impact the performance of certain investments in our energy and corporate private equity funds.
In addition, the new Presidential administration and the U.S. Congress may introduce new or enforce existing policies and regulations that may create uncertainty for our business and investment strategies and could have an adverse impact on us and our portfolio companies. For example, new policies seeking to increase the corporate tax rate or raise the minimum wage could adversely affect our business and the profitability of our portfolio companies. See “Part I. Item 1A. Risk Factors – Risks Related to Our Business – The global outbreak of the novel coronavirus, or
COVID-19,
has caused severe disruptions in the U.S. and global economies and has adversely impacted, and may continue to adversely impact, our performance and results of operations”, “– Difficult market and geopolitical conditions can adversely affect our business in many ways, each of which could materially reduce our revenue, earnings and cash flow and adversely affect our financial prospects and condition” and “– A period of economic slowdown, which may be across one or more industries, sectors or geographies, has contributed and could in the future contribute to adverse operating performance for certain of our funds’ investments, which would adversely affect our operating results and cash flows.”
Fee Related Earnings
Fee Related Earnings were $619.1 million for the year ended December 31, 2020, an increase of $138.5 million, or 29%, compared to $480.6 million for the year ended December 31, 2019. The increase in Fee Related Earnings was primarily attributable to an increase of $205.5 million in Management and Advisory Fees, Net, partially offset by increases of $35.2 million in Other Operating Expenses and $31.8 million in Fee Related Compensation.
Management and Advisory Fees, Net were $1.3 billion for the year ended December 31, 2020, an increase of $205.5 million compared to $1.1 billion for the year ended December 31, 2019, primarily driven by an increase in Base Management Fees. Base Management Fees increased $245.5 million primarily due to the end of BCP VIII, BEP III and BXLS V’s fee holidays during the third quarter of 2020 and a full year of Base Management Fees from Strategic Partners VIII.
Other Operating Expenses were $195.2 million for the year ended December 31, 2020, an increase of $35.2 million, compared to $160.0 million for the year ended December 31, 2019. The increase was primarily due to growth in our BIP, Tactical Opportunities and BXLS businesses, partially offset by less travel and entertainment expenses in the year ended December 31, 2020 due to
COVID-19.
Fee Related Compensation was $455.5 million for the year ended December 31, 2020, an increase of $31.8 million, compared to $423.8 million for the year ended December 31, 2019. The increase was primarily due to an increase in Management and Advisory Fees, Net on which a portion of Fee Related Compensation is based.
Net Realizations
Net Realizations were $582.6 million for the year ended December 31, 2020, an increase of $216.0 million, or 59%, compared to $366.7 million for the year ended December 31, 2019. The increase in Net Realizations was primarily attributable to an increase of $408.5 million in Realized Performance Revenues, partially offset by an increase of $174.4 million in Realized Performance Compensation and a decrease of $18.2 million in Realized Principal Investment Income.
Realized Performance Revenues were $877.5 million for the year ended December 31, 2020, an increase of $408.5 million, compared to $469.0 million for the year ended December 31, 2019. The increase was primarily due to higher Realized Performance Revenues in corporate private equity and Tactical Opportunities.
Realized Performance Compensation was $366.9 million for the year ended December 31, 2020, an increase of $174.4 million, compared to $192.6 million for the year ended December 31, 2019. The increase was primarily due to the increase in Realized Performance Revenues.
Realized Principal Investment Income was $72.1 million for the year ended December 31, 2020, a decrease of $18.2 million, compared to $90.2 million for the year ended December 31, 2019. The decrease was primarily due to a decrease of Realized Principal Investment Income in corporate private equity.
Fund Returns
Fund returns information for our significant funds is included throughout this discussion and analysis to facilitate an understanding of our results of operations for the periods presented. The fund returns information reflected in this discussion and analysis is not indicative of the financial performance of Blackstone and is also not necessarily indicative of the future performance of any particular fund. An investment in Blackstone is not an investment in any of our funds. There can be no assurance that any of our funds or our other existing and future funds will achieve similar returns.
The following table presents the internal rates of return of our significant private equity funds:
| Year Ended December 31, | December 31, 2020 Inception to Date | |||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | Realized | Total | ||||||||||||||||||||||||||||||||||||
| Fund (a) | Gross | Net | Gross | Net | Gross | Net | Gross | Net | Gross | Net | ||||||||||||||||||||||||||||||
| BCP IV | -15 | % | -15 | % | 68 | % | 51 | % | 6 | % | 5 | % | 50 | % | 36 | % | 50 | % | 36 | % | ||||||||||||||||||||
| BCP V | 14 | % | 5 | % | -14 | % | -4 | % | -6 | % | -5 | % | 10 | % | 8 | % | 10 | % | 8 | % | ||||||||||||||||||||
| BCP VI | 18 | % | 16 | % | 4 | % | 3 | % | 17 | % | 14 | % | 22 | % | 17 | % | 17 | % | 13 | % | ||||||||||||||||||||
| BCP VII | 11 | % | 9 | % | 24 | % | 18 | % | 43 | % | 28 | % | 32 | % | 20 | % | 23 | % | 15 | % | ||||||||||||||||||||
| BCP Asia | 56 | % | 42 | % | 43 | % | 24 | % | N/ | M | N/ | M | 292 | % | 145 | % | 56 | % | 35 | % | ||||||||||||||||||||
| BEP I | -19 | % | -18 | % | — | — | 18 | % | 15 | % | 19 | % | 15 | % | 13 | % | 10 | % | ||||||||||||||||||||||
| BEP II | -31 | % | -31 | % | -5 | % | -3 | % | 32 | % | 20 | % | -8 | % | -18 | % | -5 | % | -9 | % | ||||||||||||||||||||
| BCOM | -4 | % | -5 | % | -22 | % | -23 | % | 3 | % | 2 | % | 13 | % | 6 | % | 13 | % | 6 | % | ||||||||||||||||||||
| BCEP I (b) | 33 | % | 29 | % | 24 | % | 20 | % | N/ | M | N/ | M | 37 | % | 33 | % | 23 | % | 20 | % | ||||||||||||||||||||
| BIP | 6 | % | 1 | % | N/ | M | N/ | M | N/ | A | N/ | A | N/ | A | N/ | A | 6 | % | — | |||||||||||||||||||||
| Clarus IV | 3 | % | — | 68 | % | 46 | % | N/ | M | N/ | M | 26 | % | 15 | % | 24 | % | 11 | % | |||||||||||||||||||||
| Tactical Opportunities | 19 | % | 15 | % | 10 | % | 6 | % | 13 | % | 9 | % | 21 | % | 17 | % | 15 | % | 11 | % | ||||||||||||||||||||
| Tactical Opportunities Co-Investment and Other | 14 | % | 11 | % | 15 | % | 14 | % | 13 | % | 11 | % | 21 | % | 19 | % | 18 | % | 15 | % | ||||||||||||||||||||
| Strategic Partners I-V (c) | -4 | % | -5 | % | — | -1 | % | 9 | % | 6 | % | N/ | A | N/ | A | 16 | % | 13 | % | |||||||||||||||||||||
| Strategic Partners VI (c) | -9 | % | -9 | % | -4 | % | -5 | % | 18 | % | 15 | % | N/ | A | N/ | A | 18 | % | 13 | % | ||||||||||||||||||||
| Strategic Partners VII (c) | -7 | % | -8 | % | 12 | % | 10 | % | 32 | % | 26 | % | N/ | A | N/ | A | 18 | % | 13 | % | ||||||||||||||||||||
| Strategic Partners Real Assets II (c) | 10 | % | 6 | % | 21 | % | 17 | % | 33 | % | 22 | % | N/ | A | N/ | A | 18 | % | 12 | % | ||||||||||||||||||||
| Strategic Partners VIII (c) | 6 | % | 2 | % | N/ | M | N/ | M | N/ | A | N/ | A | N/ | A | N/ | A | 38 | % | 25 | % | ||||||||||||||||||||
| Strategic Partners RE, SMA and Other (c) | 2 | % | 2 | % | 19 | % | 18 | % | 15 | % | 13 | % | N/ | A | N/ | A | 16 | % | 12 | % |
The returns presented herein represent those of the applicable Blackstone Funds and not those of Blackstone.
| N/M | Not meaningful generally due to the limited time since initial investment. |
|---|
| N/A | Not applicable. |
|---|
| (a) | Net returns are based on the change in carrying value (realized and unrealized) after management fees, expenses and Performance Revenues. |
|---|
| (b) | BCEP is a core private equity strategy which invests with a more modest risk profile and longer hold period than traditional private equity. |
|---|
| (c) | Realizations are treated as return of capital until fully recovered and therefore inception to date realized returns are not applicable. If information is not available on a timely basis, returns are calculated from results that are reported on a three month lag and therefore do not include the impact of economic and market activities in the quarter in which such events occur. |
|---|
Funds With Closed Investment Periods
The corporate private equity funds within the Private Equity segment have seven funds with closed investment periods: BCP IV, BCP V, BCP VI, BCP VII, BCOM, BEP I and BEP II. As of December 31, 2020, BCP IV was above its carried interest threshold (i.e., the preferred return payable to its limited partners before the general partner is eligible to receive carried interest) and would still be above its carried interest threshold even if all remaining investments were valued at zero. BCP V is comprised of two fund classes based on the timings of fund closings, the BCP V “main fund” and
BCP V-AC
fund. Within these fund classes, the general partner is subject to equalization such that (a) the general partner accrues carried interest when the respective carried interest for
either fund class is positive and (b) the general partner realizes carried interest so long as clawback obligations, if any, for either of the respective fund classes are fully satisfied. As of December 31, 2020, BCP V was below its carried interest threshold, while
BCP V-AC
was above its carried interest threshold. BCP VI, BCP VII, BCOM and BEP I were above their respective carried interest thresholds. We are entitled to retain previously realized carried interest up to 20% of BCOM’s net gains. As a result, Performance Revenues are recognized from BCOM on current period gains and losses. BEP II was below its carried interest threshold.
Hedge Fund Solutions
The following table presents the results of operations for our Hedge Fund Solutions segment:
| Year Ended December 31, | 2020 vs. 2019 | 2019 vs. 2018 | ||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | ||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||
| Management Fees, Net | ||||||||||||||||||||||||||||
| Base Management Fees | $ | 582,830 | $ | 556,730 | $ | 519,782 | $ | 26,100 | 5% | $ | 36,948 | 7% | ||||||||||||||||
| Transaction and Other Fees, Net | 5,899 | 3,533 | 3,180 | 2,366 | 67% | 353 | 11% | |||||||||||||||||||||
| Management Fee Offsets | (650 | ) | (138 | ) | (93 | ) | (512 | ) | 371% | (45 | ) | 48% | ||||||||||||||||
| Total Management Fees, Net | 588,079 | 560,125 | 522,869 | 27,954 | 5% | 37,256 | 7% | |||||||||||||||||||||
| Fee Related Compensation | (161,713 | ) | (151,960 | ) | (162,172 | ) | (9,753 | ) | 6% | 10,212 | -6% | |||||||||||||||||
| Other Operating Expenses | (79,758 | ) | (81,999 | ) | (77,772 | ) | 2,241 | -3% | (4,227 | ) | 5% | |||||||||||||||||
| Fee Related Earnings | 346,608 | 326,166 | 282,925 | 20,442 | 6% | 43,241 | 15% | |||||||||||||||||||||
| Realized Performance Revenues | 179,789 | 126,576 | 42,419 | 53,213 | 42% | 84,157 | 198% | |||||||||||||||||||||
| Realized Performance Compensation | (31,224 | ) | (24,301 | ) | (21,792 | ) | (6,923 | ) | 28% | (2,509 | ) | 12% | ||||||||||||||||
| Realized Principal Investment Income | 54,110 | 21,707 | 17,039 | 32,403 | 149% | 4,668 | 27% | |||||||||||||||||||||
| Net Realizations | 202,675 | 123,982 | 37,666 | 78,693 | 63% | 86,316 | 229% | |||||||||||||||||||||
| Segment Distributable Earnings | $ | 549,283 | $ | 450,148 | $ | 320,591 | $ | 99,135 | 22% | $ | 129,557 | 40% | ||||||||||||||||
N/M Not meaningful.
Year Ended December 31, 2020 Compared to Year Ended December 31, 2019
Segment Distributable Earnings were $549.3 million for the year ended December 31, 2020, an increase of $99.1 million, or 22%, compared to $450.1 million for the year ended December 31, 2019. The increase in Segment Distributable Earnings was primarily attributable to increases of $20.4 million in Fee Related Earnings and $78.7 million in Net Realizations.
Segment Distributable Earnings in our Hedge Fund Solutions segment in 2020 were higher compared to 2019. This increase was primarily driven by increased Realized Performance Revenues and Realized Principal Investment Income, partially offset by increased Realized Performance Compensation. The global economy has, with certain setbacks, continued to reopen following the onset of the
COVID-19
pandemic and the related shutdowns or limitations in the operations of certain
non-essential
businesses. Following a more muted period since the onset of the
COVID-19
pandemic, the market has experienced rebounds across many asset classes, and our Hedge Fund Solutions segment largely recovered from the losses in composite returns experienced in the first quarter of 2020. The segment has also benefited from the recovery of liquidity in the market during the second half of 2020. Progress on
COVID-19
vaccine production and distribution, together with continued support from previously implemented fiscal and monetary stimulus, have aided the continuing economic recovery and could potentially accelerate such recovery. Nevertheless, the recovery could remain uneven and characterized by meaningful dispersion across sectors and regions, particularly given uncertainty with respect to the distribution and acceptance of the vaccines. The resurgence in
COVID-19
infection levels in certain geographies and a potential resulting market downturn may pose material risks to our Hedge Fund Solutions segment, including by potentially causing investors to seek liquidity in the form of redemptions from our funds and adversely impacting management fees. We have not experienced a period of significant dislocation since the first quarter of 2020,
during which the liquidity of certain assets traded in the credit markets was limited. Nonetheless, another period of such dislocation would impact the value of certain assets held by our funds, such funds’ ability to sell such assets at attractive prices or in a timely manner in order to avoid losses and the likelihood of margin calls from credit providers. In addition, future market uncertainty could slow the pace of fundraising in our Hedge Fund Solutions segment, which may result in a delay in management fees. A continuing market recovery, however, could contribute to increased activity over the longer term.
In an equity market environment that generally has been characterized by relatively low volatility, investors may choose to reallocate capital away from traditional hedge fund strategies. Our Hedge Fund Solutions segment operates multiple business lines, manages strategies that are both long and short asset classes and generates a majority of its revenue through management fees. In that regard, the segment’s revenues will depend in part on our ability to successfully grow such existing diverse business lines and strategies, and identify new ones to meet evolving investor appetites. Over time we expect an increasing change in the mix of our product offerings to products whose performance-based fees represent a more significant proportion of the fees than has historically been the case for such products.
In addition, the new Presidential administration and the U.S. Congress may introduce new or enforce existing policies and regulations that may create uncertainty for our business and investment strategies and may adversely affect the profitability of certain of our investments. See “Part I. Item 1A. Risk Factors – Risks Related to Our Business – The global outbreak of the novel coronavirus, or
COVID-19,
has caused severe disruptions in the U.S. and global economies and has adversely impacted, and may continue to adversely impact, our performance and results of operations”, “– Difficult market and geopolitical conditions can adversely affect our business in many ways, each of which could materially reduce our revenue, earnings and cash flow and adversely affect our financial prospects and condition” and “– A period of economic slowdown, which may be across one or more industries, sectors or geographies, has contributed and could in the future contribute to adverse operating performance for certain of our funds’ investments, which would adversely affect our operating results and cash flows.”
Fee Related Earnings
Fee Related Earnings were $346.6 million for the year ended December 31, 2020, an increase of $20.4 million, compared to $326.2 million for the year ended December 31, 2019. The increase in Fee Related Earnings was primarily attributable to an increase of $28.0 million in Management Fees, Net, partially offset by an increase of $9.8 million in Fee Related Compensation.
Management Fees, Net were $588.1 million for the year ended December 31, 2020, an increase of $28.0 million, compared to $560.1 million for the year ended December 31, 2019, primarily driven by an increase in Base Management Fees. Base Management Fees increased $26.1 million primarily driven by
Fee-Earning
Assets Under Management growth in our individual investor and specialized solutions platform.
Fee Related Compensation was $161.7 million for the year ended December 31, 2020, an increase of $9.8 million, compared to $152.0 million for the year ended December 31, 2019. The increase was primarily due to an increase in Management Fees, Net, on which a portion of Fee Related Compensation is based.
Net Realizations
Net Realizations were $202.7 million for the year ended December 31, 2020, an increase of $78.7 million, or 63%, compared to $124.0 million for the year ended December 31, 2019. The increase in Net Realizations was primarily attributable to increases of $53.2 million in Realized Performance Revenues and $32.4 million in Realized Principal Investment Income, partially offset by an increase of $6.9 million in Realized Performance Compensation.
Realized Performance Revenues were $179.8 million for the year ended December 31, 2020, an increase of $53.2 million, compared to $126.6 million for the year ended December 31, 2019. The increase was primarily driven by higher returns in our individual investor and specialized solutions platform compared to the year ended December 31, 2019.
Realized Principal Investment Income was $54.1 million for the year ended December 31, 2020, an increase of $32.4 million, compared to $21.7 million for the year ended December 31, 2019. The increase was primarily due to the realized gains on our corporate treasury investments allocated to the segment.
Realized Performance Compensation was $31.2 million for the year ended December 31, 2020, an increase of $6.9 million, compared to $24.3 million for the year ended December 31, 2019. The increase was primarily due to the increase in Realized Performance Revenues.
Composite Returns
Composite returns information is included throughout this discussion and analysis to facilitate an understanding of our results of operations for the periods presented. The composite returns information reflected in this discussion and analysis is not indicative of the financial performance of Blackstone and is also not necessarily indicative of the future results of any particular fund or composite. An investment in Blackstone is not an investment in any of our funds or composites. There can be no assurance that any of our funds or composites or our other existing and future funds or composites will achieve similar returns.
The following table presents the return information of the BAAM Principal Solutions Composite:
| Average Annual Returns (a) | ||||||||||||||||||||||||||||||||
| Periods Ended December 31, 2020 | ||||||||||||||||||||||||||||||||
| One Year | Three Year | Five Year | Historical | |||||||||||||||||||||||||||||
| Composite | Gross | Net | Gross | Net | Gross | Net | Gross | Net | ||||||||||||||||||||||||
| BAAM Principal Solutions Composite (b) | 5 | % | 5 | % | 5 | % | 4 | % | 5 | % | 5 | % | 7 | % | 6 | % |
The returns presented herein represent those of the applicable Blackstone Funds and not those of Blackstone.
| (a) | Composite returns present a summarized asset-weighted return measure to evaluate the overall performance of the applicable class of Blackstone Funds. |
|---|
| (b) | BAAM’s Principal Solutions (“BPS”) Composite covers the period from January 2000 to present, although BAAM’s inception date is September 1990. The BPS Composite includes only BAAM-managed commingled and customized multi-manager funds and accounts. None of the other platforms/strategies managed through the Blackstone Hedge Fund Solutions Group are included in the composite (except for investments by BPS funds/accounts directly into those platforms/strategies). BAAM-managed funds in liquidation and non-fee-paying assets (in the case of net returns) are excluded from the composite. The funds/accounts that comprise the BPS Composite are not managed within a single fund or account and are managed with different mandates. There is no guarantee that BAAM would have made the same mix of investments in a standalone fund/account. The BPS Composite is not an investible product and, as such, the performance of the BPS Composite does not represent the performance of an actual fund or account. The historical return is from January 1, 2000. |
|---|
Operating Metrics
The following table presents information regarding our Invested Performance Eligible Assets Under Management:
| Invested Performance Eligible Assets Under Management | Estimated % Above High Water Mark/Benchmark (a) | |||||||||||||||||||||||
| December 31, | December 31, | |||||||||||||||||||||||
| 2020 | 2019 | 2018 | 2020 | 2019 | 2018 | |||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||
| Hedge Fund Solutions Managed Funds (b) | $ | 47,088,501 | $ | 43,789,081 | $ | 42,393,275 | 75 | % | 91 | % | 46 | % |
| (a) | Estimated % Above High Water Mark/Benchmark represents the percentage of Invested Performance Eligible Assets Under Management that as of the dates presented would earn performance fees when the applicable Hedge Fund Solutions managed fund has positive investment performance relative to a benchmark, where applicable. Incremental positive performance in the applicable Blackstone Funds may cause additional assets to reach their respective High Water Mark or clear a benchmark return, thereby resulting in an increase in Estimated % Above High Water Mark/Benchmark. |
|---|
| (b) | For the Hedge Fund Solutions managed funds, at December 31, 2020, the incremental appreciation needed for the 25% of Invested Performance Eligible Assets Under Management below their respective High Water Marks/Benchmarks to reach their respective High Water Marks/Benchmarks was $622.9 million, an increase of $118.6 million, compared to $504.3 million at December 31, 2019. Of the Invested Performance Eligible Assets Under Management below their respective High Water Marks/ Benchmarks as of December 31, 2020, 49% were within 5% of reaching their respective High Water Mark. |
|---|
Credit & Insurance
The following table presents the results of operations for our Credit & Insurance segment:
| Year Ended December 31, | 2020 vs. 2019 | 2019 vs. 2018 | ||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | ||||||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||||||
| Management Fees, Net | ||||||||||||||||||||||||||||
| Base Management Fees | $ | 603,713 | $ | 586,535 | $ | 553,921 | $ | 17,178 | 3% | $ | 32,614 | 6% | ||||||||||||||||
| Transaction and Other Fees, Net | 21,311 | 19,882 | 15,640 | 1,429 | 7% | 4,242 | 27% | |||||||||||||||||||||
| Management Fee Offsets | (10,466 | ) | (11,813 | ) | (12,332 | ) | 1,347 | -11% | 519 | -4% | ||||||||||||||||||
| Total Management Fees, Net | 614,558 | 594,604 | 557,229 | 19,954 | 3% | 37,375 | 7% | |||||||||||||||||||||
| Fee Related Performance Revenues | 40,515 | 13,764 | (666 | ) | 26,751 | 194% | 14,430 | N/M | ||||||||||||||||||||
| Fee Related Compensation | (261,214 | ) | (229,607 | ) | (219,098 | ) | (31,607 | ) | 14% | (10,509 | ) | 5% | ||||||||||||||||
| Other Operating Expenses | (165,114 | ) | (160,801 | ) | (131,200 | ) | (4,313 | ) | 3% | (29,601 | ) | 23% | ||||||||||||||||
| Fee Related Earnings | 228,745 | 217,960 | 206,265 | 10,785 | 5% | 11,695 | 6% | |||||||||||||||||||||
| Realized Performance Revenues | 20,943 | 32,737 | 96,962 | (11,794 | ) | -36% | (64,225 | ) | -66% | |||||||||||||||||||
| Realized Performance Compensation | (3,476 | ) | (12,972 | ) | (53,863 | ) | 9,496 | -73% | 40,891 | -76% | ||||||||||||||||||
| Realized Principal Investment Income | 7,970 | 32,466 | 16,763 | (24,496 | ) | -75% | 15,703 | 94% | ||||||||||||||||||||
| Net Realizations | 25,437 | 52,231 | 59,862 | (26,794 | ) | -51% | (7,631 | ) | -13% | |||||||||||||||||||
| Segment Distributable Earnings | $ | 254,182 | $ | 270,191 | $ | 266,127 | $ | (16,009 | ) | -6% | $ | 4,064 | 2% | |||||||||||||||
N/M Not meaningful.
Year Ended December 31, 2020 Compared to Year Ended December 31, 2019
Segment Distributable Earnings were $254.2 million for the year ended December 31, 2020, a decrease of $16.0 million, compared to $270.2 million for the year ended December 31, 2019. The decrease in Segment Distributable Earnings was primarily attributable to a decrease of $26.8 million in Net Realizations, partially offset by an increase of $10.8 million in Fee Related Earnings.
Segment Distributable Earnings in our Credit & Insurance segment in 2020 were lower compared to 2019, driven by lower Net Realizations due to lower Realized Principal Investment Income and Realized Performance Revenues. The global economy has, with certain setbacks, continued to reopen following the onset of the
COVID-19
pandemic and the related shutdowns or limitations in the operations of certain
non-essential
businesses. Although the pandemic has adversely impacted and could continue to adversely impact the performance of our Credit & Insurance segment, the majority of the segment’s portfolio is in sectors that we believe are more resilient to the impact of
COVID-19.
The market has experienced rebounds across many asset classes, and our Credit & Insurance segment largely recovered from the losses in composite returns experienced in the first quarter of 2020. The segment has also benefited from the recovery of liquidity in the market during the second half of 2020. The continuing recovery has also contributed to capital deployment, realization and fundraising activity. Progress on
COVID-19
vaccine production and distribution, together with continued support from previously implemented fiscal and monetary stimulus, have also aided the continuing recovery and could potentially accelerate such recovery. Nevertheless, the recovery could remain uneven and characterized by meaningful dispersion across sectors and regions, particularly given uncertainty with respect to the distribution and acceptance of the vaccines. The resurgence in
COVID-19
infection levels in certain geographies and a potential resulting market downturn may pose material risks, which potentially create additional pressure for borrowers with respect to their ability to meet their debt payment obligations or increase their focus on deleveraging. Our Credit & Insurance funds have, however, continued to actively manage their portfolios in order to limit downside and protect capital. Further, we have not experienced a period of significant dislocation since the first quarter of 2020, during which the liquidity of certain assets traded in the credit markets was limited. Nonetheless, another period of such dislocation would impact the value of certain assets held by our funds and such funds’ ability to sell such assets at attractive prices or in a timely manner, each of which would adversely impact performance revenues in our Credit & Insurance segment. A continuing market recovery, however, could contribute to increased activity over the longer term.
In energy, oil prices have stabilized since the significant declines experienced in the first quarter of 2020. Nonetheless, weakened market fundamentals continue to pose challenges, particularly in upstream energy, which represents 3% of the Credit & Insurance segment’s investment portfolio and less than 2% of Blackstone’s aggregate investment portfolio. An increased focus on energy sustainability due to concerns about climate change and the impact of carbon emissions, including potential alternatives to fossil fuels, has also exacerbated the impact of such weakened market fundamentals. The persistence of these weakened market fundamentals in the energy sector or in the credit markets more broadly would further negatively impact the performance of certain investments in our credit funds.
In addition, the new Presidential administration and the U.S. Congress may introduce new or enforce existing policies and regulations that may create uncertainty for our business and investment strategies and may adversely affect the profitability of certain of our investments. See “Part I. Item 1A. Risk Factors – Risks Related to Our Business – The global outbreak of the novel coronavirus, or
COVID-19,
has caused severe disruptions in the U.S. and global economies and has adversely impacted, and may continue to adversely impact, our performance and results of operations”, “– Difficult market and geopolitical conditions can adversely affect our business in many ways, each of which could materially reduce our revenue, earnings and cash flow and adversely affect our financial prospects and condition” and “– A period of economic slowdown, which may be across one or more industries, sectors or geographies, has contributed and could in the future contribute to adverse operating performance for certain of our funds’ investments, which would adversely affect our operating results and cash flows.”
Fee Related Earnings
Fee Related Earnings were $228.7 million for the year ended December 31, 2020, an increase of $10.8 million, compared to $218.0 million for the year ended December 31, 2019. The increase in Fee Related Earnings was primarily attributable to increases of $26.8 million in Fee Related Performance Revenues and $20.0 million in Management Fees, Net, partially offset by an increase of $31.6 million in Fee Related Compensation.
Fee Related Performance Revenues were $40.5 million for the year ended December 31, 2020, an increase of $26.8 million, compared to $13.8 million for the year ended December 31, 2019. The increase was primarily due to performance and growth in assets in our BDC.
Management Fees, Net were $614.6 million for the year ended December 31, 2020, an increase of $20.0 million, compared to $594.6 million for the year ended December 31, 2019, primarily driven by an increase in Base Management Fees. Base Management Fees increased $17.2 million primarily due to increased capital deployed in our most recently launched credit funds and vehicles, including our BDC, and inflows in our liquid credit business, partially offset by a decrease in Harvest.
Fee Related Compensation was $261.2 million for the year ended December 31, 2020, an increase of $31.6 million, compared to $229.6 million for the year ended December 31, 2019. The increase was primarily due to increases in Management Fees, Net and Fee Related Performance Revenues, on which a portion of Fee Related Compensation is based.
Net Realizations
Net Realizations were $25.4 million for the year ended December 31, 2020, a decrease of $26.8 million, compared to $52.2 million for the year ended December 31, 2019. The decrease in Net Realizations was primarily attributable to decreases of $24.5 million in Realized Principal Investment Income and $11.8 million in Realized Performance Revenues, partially offset by a decrease of $9.5 million in Realized Performance Compensation.
Realized Principal Investment Income was $8.0 million for the year ended December 31, 2020, a decrease of $24.5 million, compared to $32.5 million for the year ended December 31, 2019. The decrease was primarily due to higher realized gains in our corporate treasury investments in the year ended December 31, 2019 compared to the year ended December 31, 2020.
Realized Performance Revenues were $20.9 million for the year ended December 31, 2020, a decrease of $11.8 million, compared to $32.7 million for the year ended December 31, 2019. The decrease was primarily attributable to a decrease in realized carry compared to the year ended December 31, 2019.
Realized Performance Compensation was $3.5 million for the year ended December 31, 2020, a decrease of $9.5 million, compared to $13.0 million for the year ended December 31, 2019. The decrease was primarily due to the decrease in Realized Performance Revenues.
Composite Returns
Composite returns information is included throughout this discussion and analysis to facilitate an understanding of our results of operations for the periods presented. The composite returns information reflected in this discussion and analysis is not indicative of the financial performance of Blackstone and is also not necessarily indicative of the future results of any particular fund or composite. An investment in Blackstone is not an investment in any of our funds or composites. There can be no assurance that any of our funds or composites or our other existing and future funds or composites will achieve similar returns.
The following table presents the return information for the Credit Composite:
| Year Ended December 31, | Inception to December 31, 2020 | |||||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | Total | |||||||||||||||||||||||||||||
| Composite (a) | Gross | Net | Gross | Net | Gross | Net | Gross | Net | ||||||||||||||||||||||||
| Credit Composite (b) | 4 | % | 3 | % | 9 | % | 8 | % | 2 | % | 1 | % | 9 | % | 6 | % |
The returns presented herein represent those of the applicable Blackstone Funds and not those of Blackstone.
| (a) | Net returns are based on the change in carrying value (realized and unrealized) after management fees, expenses and Performance Allocations, net of tax advances. |
|---|
| (b) | Effective January 1, 2020, Credit returns have been redefined to present a composite return instead of separate returns for performing credit strategies and distressed strategies. The Credit Composite now also includes the liquid credit strategy. The Credit Composite return is a weighted-average of (a) the return based on the combined quarterly cash flows of the private credit fee-earning funds and (b) the weighted-average quarterly return of all liquid credit strategy fee-earning funds. Only fee-earning funds exceeding $100 million of fair value at the beginning of each respective quarter end are included and funds in liquidation are excluded. Credit returns exclude Blackstone Funds that were contributed to BXC as part of Blackstone’s acquisition of BXC in March 2008 and the pre-acquisition date performance for funds and vehicles acquired by BXC subsequent to March 2008. The inception to date returns are from December 31, 2005. Prior periods have been updated to reflect this presentation. |
|---|
Operating Metrics
The following table presents information regarding our Invested Performance Eligible Assets Under Management:
| Invested Performance Eligible Assets Under Management | Estimated % Above High Water Mark/Hurdle | |||||||||||||||||||||||
| December 31, | December 31, | |||||||||||||||||||||||
| 2020 | 2019 | 2018 | 2020 | 2019 | 2018 | |||||||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||||||
| Credit & Insurance | $ | 28,944,333 | $ | 26,004,779 | $ | 22,943,261 | 58 | % | 72 | % | 67 | % |
Non-GAAP
Financial Measures
These
non-GAAP
financial measures are presented without the consolidation of any Blackstone Funds that are consolidated into the Consolidated Financial Statements. Consequently, all
non-GAAP
financial measures exclude the assets, liabilities and operating results related to the Blackstone Funds. See “— Key Financial Measures and Indicators” for our definitions of Distributable Earnings, Segment Distributable Earnings, Fee Related Earnings and Adjusted EBITDA.
The following table is a reconciliation of Net Income Attributable to The Blackstone Group Inc. to Distributable Earnings, Total Segment Distributable Earnings, Fee Related Earnings and Adjusted EBITDA:
| Year Ended December 31, | ||||||||||||
| 2020 | 2019 | 2018 | ||||||||||
| (Dollars in Thousands) | ||||||||||||
| Net Income Attributable to The Blackstone Group Inc. | $ | 1,045,363 | $ | 2,049,682 | $ | 1,541,788 | ||||||
| Net Income Attributable to Non-Controlling Interests in Blackstone Holdings | 1,012,924 | 1,339,627 | 1,364,989 | |||||||||
| Net Income Attributable to Non-Controlling Interests in Consolidated Entities | 217,117 | 476,779 | 358,878 | |||||||||
| Net Loss Attributable to Redeemable Non-Controlling Interests in Consolidated Entities | (13,898 | ) | (121 | ) | (2,104 | ) | ||||||
| Net Income | 2,261,506 | 3,865,967 | 3,263,551 | |||||||||
| Provision (Benefit) for Taxes | 356,014 | (47,952 | ) | 249,390 | ||||||||
| Net Income Before Provision (Benefit) for Taxes | 2,617,520 | 3,818,015 | 3,512,941 | |||||||||
| Transaction-Related Charges (a) | 240,729 | 208,613 | (261,916 | ) | ||||||||
| Amortization of Intangibles (b) | 65,984 | 65,931 | 59,994 | |||||||||
| Impact of Consolidation (c) | (203,219 | ) | (476,658 | ) | (356,774 | ) | ||||||
| Unrealized Performance Revenues (d) | 384,758 | (1,126,668 | ) | (561,163 | ) | |||||||
| Unrealized Performance Allocations Compensation (e) | (154,516 | ) | 540,285 | 319,742 | ||||||||
| Unrealized Principal Investment (Income) Loss (f) | 101,742 | (113,327 | ) | 65,851 | ||||||||
| Other Revenues (g) | 253,693 | (79,447 | ) | (89,468 | ) | |||||||
| Equity-Based Compensation (h) | 333,767 | 230,194 | 158,220 | |||||||||
| Administrative Fee Adjustment (i) | 5,265 | — | — | |||||||||
| Taxes and Related Payables (j) | (304,127 | ) | (196,159 | ) | (153,865 | ) | ||||||
| Distributable Earnings | 3,341,596 | 2,870,779 | 2,693,562 | |||||||||
| Taxes and Related Payables (j) | 304,127 | 196,159 | 153,865 | |||||||||
| Net Interest (Income) Loss (k) | 34,910 | 2,441 | (21,925 | ) | ||||||||
| Total Segment Distributable Earnings | 3,680,633 | 3,069,379 | 2,825,502 | |||||||||
| Realized Performance Revenues (l) | (1,865,993 | ) | (1,660,642 | ) | (1,811,771 | ) | ||||||
| Realized Performance Compensation (m) | 714,347 | 603,935 | 678,141 | |||||||||
| Realized Principal Investment Income (n) | (158,933 | ) | (224,155 | ) | (236,058 | ) | ||||||
| Fee Related Earnings | $ | 2,370,054 | $ | 1,788,517 | $ | 1,455,814 | ||||||
| Adjusted EBITDA Reconciliation | ||||||||||||
| Distributable Earnings | $ | 3,341,596 | $ | 2,870,779 | $ | 2,693,562 | ||||||
| Interest Expense (o) | 165,022 | 195,034 | 159,838 | |||||||||
| Taxes and Related Payables (j) | 304,127 | 196,159 | 153,865 | |||||||||
| Depreciation and Amortization | 35,136 | 26,350 | 23,882 | |||||||||
| Adjusted EBITDA | $ | 3,845,881 | $ | 3,288,322 | $ | 3,031,147 | ||||||
| (a) | This adjustment removes Transaction-Related Charges, which are excluded from Blackstone’s segment presentation. Transaction-Related Charges arise from corporate actions including acquisitions, divestitures, and Blackstone’s initial public offering. They consist primarily of equity-based compensation charges, gains and losses on contingent consideration arrangements, changes in the balance of the Tax Receivable Agreement resulting from a change in tax law or similar event, transaction costs and any gains or losses associated with these corporate actions. |
|---|
| (b) | This adjustment removes the amortization of transaction-related intangibles, which are excluded from Blackstone’s segment presentation. This amount includes amortization of intangibles associated with Blackstone’s investment in Pátria, which is accounted for under the equity method. |
|---|
| (c) | This adjustment reverses the effect of consolidating Blackstone Funds, which are excluded from Blackstone’s segment presentation. This adjustment includes the elimination of Blackstone’s interest in these funds and the removal of amounts associated with the ownership of Blackstone consolidated operating partnerships held by non-controlling interests. |
|---|
| (d) | This adjustment removes Unrealized Performance Revenues on a segment basis. The Segment Adjustment represents the add back of performance revenues earned from consolidated Blackstone Funds which have been eliminated in consolidation. |
|---|
| Year Ended December 31, | ||||||||||||
| 2020 | 2019 | 2018 | ||||||||||
| (Dollars in Thousands) | ||||||||||||
| GAAP Unrealized Performance Allocations | $ | (384,393 | ) | $ | 1,126,332 | $ | 561,373 | |||||
| Segment Adjustment | (365 | ) | 336 | (210 | ) | |||||||
| Unrealized Performance Revenues | $ | (384,758 | ) | $ | 1,126,668 | $ | 561,163 | |||||
| (e) | This adjustment removes Unrealized Performance Allocations Compensation. |
|---|
| (f) | This adjustment removes Unrealized Principal Investment Income (Loss) on a segment basis. The Segment Adjustment represents (1) the add back of Principal Investment Income, including general partner income, earned from consolidated Blackstone Funds which have been eliminated in consolidation, and (2) the removal of amounts associated with the ownership of Blackstone consolidated operating partnerships held by non-controlling interests. |
|---|
| Year Ended December 31, | ||||||||||||
| 2020 | 2019 | 2018 | ||||||||||
| (Dollars in Thousands) | ||||||||||||
| GAAP Unrealized Principal Investment Income (Loss) | $ | (114,607 | ) | $ | 215,003 | $ | 49,917 | |||||
| Segment Adjustment | 12,865 | (101,676 | ) | (115,768 | ) | |||||||
| Unrealized Principal Investment Income (Loss) | $ | (101,742 | ) | $ | 113,327 | $ | (65,851 | ) | ||||
| (g) | This adjustment removes Other Revenues on a segment basis. The Segment Adjustment represents (1) the add back of Other Revenues earned from consolidated Blackstone Funds which have been eliminated in consolidation, and (2) the removal of certain Transaction-Related Charges. For the year ended December 31, 2018, Transaction-Related Charges included $580.9 million of Other Revenues received upon the conclusion of Blackstone’s investment sub-advisory relationship with FS Investments’ funds. |
|---|
| Year Ended December 31, | ||||||||||||
| 2020 | 2019 | 2018 | ||||||||||
| (Dollars in Thousands) | ||||||||||||
| GAAP Other Revenue | $ | (253,142 | ) | $ | 79,993 | $ | 672,317 | |||||
| Segment Adjustment | (551 | ) | (546 | ) | (582,849 | ) | ||||||
| Other Revenues | $ | (253,693 | ) | $ | 79,447 | $ | 89,468 | |||||
| (h) | This adjustment removes Equity-Based Compensation on a segment basis. |
|---|
| (i) | This adjustment adds an amount equal to an administrative fee collected on a quarterly basis from certain holders of Blackstone Holdings Partnership Units. The administrative fee is accounted for as a capital contribution under GAAP, but is reflected as a reduction of Other Operating Expenses in Blackstone’s segment presentation. |
|---|
| (j) | Taxes represent the total GAAP tax provision adjusted to include only the current tax provision (benefit) calculated on Income (Loss) Before Provision (Benefit) for Taxes and adjusted to exclude the tax impact of any divestitures. Related Payables represent tax-related payables including the amount payable under the Tax Receivable Agreement. See “— Key Financial Measures and Indicators — Distributable Earnings” for the full definition of Taxes and Related Payables. |
|---|
| Year Ended December 31, | ||||||||||||
| 2020 | 2019 | 2018 | ||||||||||
| (Dollars in Thousands) | ||||||||||||
| Taxes | $ | 260,569 | $ | 140,416 | $ | 90,022 | ||||||
| Related Payables | 43,558 | 55,743 | 63,843 | |||||||||
| Taxes and Related Payables | $ | 304,127 | $ | 196,159 | $ | 153,865 | ||||||
| (k) | This adjustment removes Interest and Dividend Revenue less Interest Expense on a segment basis. The Segment Adjustment represents (1) the add back of Interest and Dividend Revenue earned from consolidated Blackstone Funds which have been eliminated in consolidation, and (2) the removal of interest expense associated with the Tax Receivable Agreement. |
|---|
| Year Ended December 31, | ||||||||||||
| 2020 | 2019 | 2018 | ||||||||||
| (Dollars in Thousands) | ||||||||||||
| GAAP Interest and Dividend Revenue | $ | 125,231 | $ | 182,398 | $ | 171,947 | ||||||
| Segment Adjustment | 4,881 | 10,195 | 9,816 | |||||||||
| Interest and Dividend Revenue | 130,112 | 192,593 | 181,763 | |||||||||
| GAAP Interest Expense | 166,162 | 199,648 | 163,990 | |||||||||
| Segment Adjustment | (1,140 | ) | (4,614 | ) | (4,152 | ) | ||||||
| Interest Expense | 165,022 | 195,034 | 159,838 | |||||||||
| Net Interest Income (Loss) | $ | (34,910 | ) | $ | (2,441 | ) | $ | 21,925 | ||||
| (l) | This adjustment removes the total segment amount of Realized Performance Revenues. |
|---|
| (m) | This adjustment removes the total segment amount of Realized Performance Compensation. |
|---|
| (n) | This adjustment removes the total segment amount of Realized Principal Investment Income. |
|---|
| (o) | This adjustment adds back Interest Expense on a segment basis, excluding interest expense related to the Tax Receivable Agreement. |
|---|
The following tables are a reconciliation of Total GAAP Investments to Net Accrued Performance Revenues. Total GAAP Investments and Net Accrued Performance Revenues consist of the following:
| December 31, | ||||||||
| 2020 | 2019 | |||||||
| (Dollars in Thousands) | ||||||||
| Investments of Consolidated Blackstone Funds | $ | 1,455,008 | $ | 8,380,698 | ||||
| Equity Method Investments | ||||||||
| Partnership Investments | 4,353,234 | 4,035,675 | ||||||
| Accrued Performance Allocations | 6,891,262 | 7,180,449 | ||||||
| Corporate Treasury Investments | 2,579,716 | 2,419,587 | ||||||
| Other Investments | 337,922 | 265,273 | ||||||
| Total GAAP Investments | $ | 15,617,142 | $ | 22,281,682 | ||||
| Accrued Performance Allocations - GAAP | $ | 6,891,262 | $ | 7,180,449 | ||||
| Impact of Consolidation (a) | 1 | 384 | ||||||
| Due From Affiliates - GAAP (b) | 165,678 | 154,980 | ||||||
| Less: Net Realized Performance Revenues (c) | (313,610 | ) | (214,662 | ) | ||||
| Less: Accrued Performance Compensation - GAAP (d) | (2,917,609 | ) | (3,021,899 | ) | ||||
| Net Accrued Performance Revenues | $ | 3,825,722 | $ | 4,099,252 | ||||
| (a) | This adjustment adds back investments in consolidated Blackstone Funds which have been eliminated in consolidation. |
|---|
| (b) | Represents GAAP accrued performance revenue recorded within Due from Affiliates. |
|---|
| (c) | Represents Performance Revenues realized but not yet distributed as of the reporting date and are included in Distributable Earnings in the period they are realized. |
|---|
| (d) | Represents GAAP accrued performance compensation associated with Accrued Performance Allocations and is recorded within Accrued Compensation and Benefits and Due to Affiliates. |
|---|
Liquidity and Capital Resources
General
Blackstone’s business model derives revenue primarily from third party assets under management. Blackstone is not a capital or balance sheet intensive business and targets operating expense levels such that total management and advisory fees exceed total operating expenses each period. As a result, we require limited capital resources to support the working capital or operating needs of our businesses. We draw primarily on the long-term committed capital of our limited partner investors to fund the investment requirements of the Blackstone Funds and use our own realizations and cash flows to invest in growth initiatives, make commitments to our own funds, where our minimum general partner commitments are generally less than 5% of the limited partner commitments of a fund, and pay dividends to shareholders.
Fluctuations in our statement of financial condition result primarily from activities of the Blackstone Funds that are consolidated as well as business transactions, such as the issuance of senior notes described below. The majority economic ownership interests of the Blackstone Funds are reflected as Redeemable
Non-Controlling
Interests in Consolidated Entities, and
Non-Controlling
Interests in Consolidated Entities in the Consolidated Financial Statements. The consolidation of these Blackstone Funds has no net effect on Blackstone’s Net Income or Partners’ Capital. Additionally, fluctuations in our statement of financial condition also include appreciation or depreciation in Blackstone investments in the Blackstone Funds, additional investments and redemptions of such interests in the Blackstone Funds and the collection of receivables related to management and advisory fees.
During the year ended December 31, 2020, Blackstone deconsolidated nine CLO vehicles. See Note 9. “Variable Interest Entities” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data” of this filing for additional details.
Total assets were $26.3 billion as of December 31, 2020, a decrease of $6.3 billion, from December 31, 2019. The decrease in total assets was principally due to a decrease of $7.3 billion in total assets attributable to the consolidated Blackstone funds. The decrease in total assets attributable to the consolidated Blackstone funds was primarily due to a decrease of $6.9 billion in Investments which was primarily due to the deconsolidation of nine CLO vehicles. The other net variances of the assets attributable to the consolidated operating partnerships were relatively unchanged.
Total liabilities were $11.7 billion as of December 31, 2020, a decrease of $5.8 billion, from December 31, 2019. The decrease in total liabilities was principally due to a decrease of $7.3 billion in total liabilities attributable to the consolidated Blackstone funds, partially offset by an increase of $1.1 billion in total liabilities attributable to consolidated operating partnerships. The decrease in total liabilities attributable to consolidated Blackstone funds was primarily due to a decrease of $6.5 billion in Loans Payable. The decrease in Loans Payable was primarily due to the deconsolidation of nine CLO vehicles. The increase in total liabilities attributable to the consolidated operating partnerships was primarily due to an increase of $1.0 billion in Loans Payable. The increase in Loans Payable was primarily due to the issuance of $900 million of notes on September 29, 2020. The other net variances of the liabilities attributable to the consolidated operating partnerships were relatively unchanged.
We have multiple sources of liquidity to meet our capital needs as described in “— Sources and Uses of Liquidity.” While our liquidity has not been materially impacted by the
COVID-19
pandemic to date, we continue to closely monitor developments in the impact of the
COVID-19
pandemic and actively evaluate our sources and uses of liquidity in light of such developments. See “Part I. Item IA. Risk Factors — The global outbreak of the novel coronavirus, or
COVID-19,
has caused severe disruptions in the U.S. and global economies and has adversely impacted, and may continue to adversely impact, our performance and results of operations.”
Sources and Uses of Liquidity
We have multiple sources of liquidity to meet our capital needs, including annual cash flows, accumulated earnings in our businesses, the proceeds from our issuances of senior notes, liquid investments we hold on our balance sheet and access to our $2.25 billion committed revolving credit facility. On November 24, 2020, Blackstone amended and restated its revolving credit facility to, among other things, increase the amount of the revolving credit facility from $1.6 billion to $2.25 billion and to extend the maturity date of the revolving credit facility from September 21, 2023 to November 24, 2025. As of December 31, 2020, Blackstone had $2.0 billion in cash and cash equivalents, $2.6 billion invested in corporate treasury investments, against $5.7 billion in borrowings from our bond issuances, and no borrowings outstanding under our revolving credit facility.
On September 29, 2020, Blackstone issued $500 million aggregate principal amount of 1.600% senior notes due March 30, 2031 and $400 million aggregate principal amount of 2.800% senior notes due September 30, 2050. Blackstone intends to use the net proceeds from the sale of the notes for general corporate purposes. For additional information see Note 13. “Borrowings” in the “Notes to Consolidated Financial Statements” in “— Item 8. Financial Statements and Supplementary Data.”
In addition to the cash we received from our notes offerings and availability under our revolving credit facility, we expect to receive (a) cash generated from operating activities, (b) Performance Allocations and Incentive Fee realizations, and (c) realizations on the fund investments that we make. The amounts received from these three sources in particular may vary substantially from year to year and quarter to quarter depending on the frequency and size of realization events or net returns experienced by our investment funds. Our available capital could be adversely affected if there are prolonged periods of few substantial realizations from our investment funds accompanied by substantial capital calls for new investments from those investment funds. Therefore, Blackstone’s commitments to our funds are taken into consideration when managing our overall liquidity and cash position.
We expect that our primary liquidity needs will be cash to (a) provide capital to facilitate the growth of our existing businesses, which principally includes funding our general partner and
co-investment
commitments to our funds, (b) provide capital to facilitate our expansion into new businesses, (c) pay operating expenses, including cash compensation to our employees, and other obligations as they arise, (d) fund modest capital expenditures, (e) repay borrowings and related interest costs, (f) pay income taxes, (g) repurchase share of our common stock and Blackstone Holdings Partnership Units pursuant to our repurchase program and (h) pay dividends to our shareholders and distributions to the holders of Blackstone Holdings Partnership Units.
Our own capital commitments to our funds, the funds we invest in and our investment strategies as of December 31, 2020 consisted of the following:
| Blackstone and General Partner | Senior Managing Directors and Certain Other Professionals (a) | |||||||||||||||
| Fund | Original Commitment | Remaining Commitment | Original Commitment | Remaining Commitment | ||||||||||||
| (Dollars in Thousands) | ||||||||||||||||
| Real Estate | ||||||||||||||||
| BREP V (b) | $ | 52,545 | $ | 2,185 | $ | — | $ | — | ||||||||
| BREP VI (b) | 750,000 | 36,809 | 150,000 | 12,270 | ||||||||||||
| BREP VII | 300,000 | 33,652 | 100,000 | 11,217 | ||||||||||||
| BREP VIII | 300,000 | 51,159 | 100,000 | 17,053 | ||||||||||||
| BREP IX | 300,000 | 205,693 | 100,000 | 68,564 | ||||||||||||
| BREP Europe III (b) | 100,000 | 13,231 | 35,000 | 4,410 | ||||||||||||
| BREP Europe IV | 130,000 | 24,074 | 43,333 | 8,025 | ||||||||||||
| BREP Europe V | 150,000 | 33,779 | 43,333 | 9,758 | ||||||||||||
| BREP Europe VI | 130,000 | 97,024 | 43,333 | 32,341 | ||||||||||||
| BREP Asia I | 50,000 | 10,335 | 16,667 | 3,445 | ||||||||||||
| BREP Asia II | 70,707 | 39,063 | 23,569 | 13,021 | ||||||||||||
| BREDS II | 50,000 | 6,227 | 16,667 | 2,076 | ||||||||||||
| BREDS III | 50,000 | 17,659 | 16,667 | 5,886 | ||||||||||||
| BREDS IV | 50,000 | 40,894 | — | — | ||||||||||||
| BPP | 176,226 | 17,639 | — | — | ||||||||||||
| Other (c) | 23,199 | 15,054 | — | — | ||||||||||||
| Total Real Estate | 2,682,677 | 644,477 | 688,569 | 188,066 | ||||||||||||
| Private Equity | ||||||||||||||||
| BCP V | 629,356 | 30,642 | — | — | ||||||||||||
| BCP VI | 719,718 | 82,829 | 250,000 | 28,771 | ||||||||||||
| BCP VII | 500,000 | 41,787 | 225,000 | 18,804 | ||||||||||||
| BCP VIII | 500,000 | 500,000 | 225,000 | 225,000 | ||||||||||||
| BEP I | 50,000 | 4,728 | — | — | ||||||||||||
| BEP II | 80,000 | 8,259 | 26,667 | 2,753 | ||||||||||||
| BEP III | 80,000 | 69,798 | 26,667 | 23,266 | ||||||||||||
| BCEP I | 120,000 | 42,944 | 18,992 | 6,797 | ||||||||||||
| BCEP II | 160,000 | 160,000 | 32,640 | 32,640 | ||||||||||||
| BCP Asia | 40,000 | 21,962 | 13,333 | 7,321 | ||||||||||||
| Tactical Opportunities | 409,661 | 161,546 | 136,554 | 53,849 | ||||||||||||
| Strategic Partners | 770,838 | 475,641 | 118,907 | 71,733 | ||||||||||||
| BIP | 168,632 | 113,140 | — | — | ||||||||||||
| BXLS | 110,000 | 85,376 | 26,667 | 23,752 | ||||||||||||
| BXG | 64,638 | 59,326 | 21,546 | 19,775 | ||||||||||||
| Other (c) | 273,139 | 31,438 | — | — | ||||||||||||
| Total Private Equity | 4,675,982 | 1,889,416 | 1,121,973 | 514,461 | ||||||||||||
continued...
| Blackstone and General Partner | Senior Managing Directors and Certain Other Professionals (a) | |||||||||||||||
| Fund | Original Commitment | Remaining Commitment | Original Commitment | Remaining Commitment | ||||||||||||
| (Dollars in Thousands) | ||||||||||||||||
| Hedge Fund Solutions | ||||||||||||||||
| Strategic Alliance I | $ | 50,000 | $ | 2,033 | $ | — | $ | — | ||||||||
| Strategic Alliance II | 50,000 | 1,482 | — | — | ||||||||||||
| Strategic Alliance III | 22,000 | 1,193 | — | — | ||||||||||||
| Strategic Holdings I | 154,610 | 63,159 | — | — | ||||||||||||
| Strategic Holdings II | 50,000 | 43,617 | — | — | ||||||||||||
| Other (c) | 18,178 | 9,646 | — | — | ||||||||||||
| Total Hedge Fund Solutions | 344,788 | 121,130 | — | — | ||||||||||||
| Credit & Insurance | ||||||||||||||||
| Mezzanine / Opportunistic II | 120,000 | 30,217 | 110,101 | 27,725 | ||||||||||||
| Mezzanine / Opportunistic III | 130,783 | 41,513 | 31,081 | 9,866 | ||||||||||||
| Mezzanine / Opportunistic IV | 122,000 | 122,000 | 33,333 | 33,333 | ||||||||||||
| European Senior Debt I | 63,000 | 16,521 | 56,955 | 14,936 | ||||||||||||
| European Senior Debt II | 93,350 | 78,168 | 24,142 | 20,030 | ||||||||||||
| Stressed / Distressed I | 50,000 | 4,869 | 27,666 | 2,694 | ||||||||||||
| Stressed / Distressed II | 125,000 | 51,695 | 121,050 | 50,061 | ||||||||||||
| Stressed / Distressed III | 151,000 | 113,042 | 31,840 | 23,836 | ||||||||||||
| Energy I | 80,000 | 38,026 | 75,555 | 35,913 | ||||||||||||
| Energy II | 150,000 | 139,722 | 25,423 | 23,681 | ||||||||||||
| Credit Alpha Fund | 52,102 | 19,752 | 50,624 | 19,192 | ||||||||||||
| Credit Alpha Fund II | 25,500 | 11,396 | 6,034 | 2,696 | ||||||||||||
| BXSL | 80,000 | 8,000 | — | — | ||||||||||||
| Other (c) | 149,315 | 53,607 | 21,583 | 4,472 | ||||||||||||
| Total Credit & Insurance | 1,392,050 | 728,528 | 615,387 | 268,435 | ||||||||||||
| Other | ||||||||||||||||
| Treasury (d) | 801,580 | 387,753 | — | — | ||||||||||||
| $ 9,897,077 | $ 3,771,304 | $ 2,425,929 | $ 970,962 | |||||||||||||
| (a) | For some of the general partner commitments shown in the table above, we require our senior managing directors and certain other professionals to fund a portion of the commitment even though the ultimate obligation to fund the aggregate commitment is ours pursuant to the governing agreements of the respective funds. The amounts of the aggregate applicable general partner original and remaining commitment are shown in the table above. In addition, certain senior managing directors and other professionals may be required to fund a de minimis amount of the commitment in certain carry funds. We expect our commitments to be drawn down over time and to be funded by available cash and cash generated from operations and realizations. Taking into account prevailing market conditions and both the liquidity and cash or liquid investment balances, we believe that the sources of liquidity described above will be more than sufficient to fund our working capital requirements. |
|---|
| (b) | Effective December 31, 2020, Available Capital was updated to include uncalled capital commitments until they are legally expired, which increased Remaining Commitments. |
|---|
| (c) | Represents capital commitments to a number of other funds in each respective segment. |
|---|
| (d) | Represents loan origination commitments, revolver commitments and capital market commitments. |
|---|
As of December 31, 2020, Blackstone Holdings Finance Co. L.L.C. (the “Issuer”), an indirect subsidiary of Blackstone, had issued and outstanding the following senior notes (collectively the “Notes”):
| Senior Notes (a) | Aggregate Principal Amount (Dollars/Euros in Thousands) | |||
| 4.750%, Due 2/15/2023 | $ | 400,000 | ||
| 2.000%, Due 5/19/2025 | € | 300,000 | ||
| 1.000%, Due 10/5/2026 | € | 600,000 | ||
| 3.150%, Due 10/2/2027 | $ | 300,000 | ||
| 1.500%, Due 4/10/2029 | € | 600,000 | ||
| 2.500%, Due 1/10/2030 | $ | 500,000 | ||
| 1.600%, Due 3/30/2031 | $ | 500,000 | ||
| 6.250%, Due 8/15/2042 | $ | 250,000 | ||
| 5.000%, Due 6/15/2044 | $ | 500,000 | ||
| 4.450%, Due 7/15/2045 | $ | 350,000 | ||
| 4.000%, Due 10/2/2047 | $ | 300,000 | ||
| 3.500%, Due 9/10/2049 | $ | 400,000 | ||
| 2.800%, Due 9/30/2050 | $ | 400,000 | ||
| $ | 5,732,400 | |||
| (a) | The Notes are unsecured and unsubordinated obligations of the Issuer and are fully and unconditionally guaranteed, jointly and severally, by The Blackstone Group Inc. and each of the Blackstone Holdings Partnerships. The Notes contain customary covenants and financial restrictions that, among other things, limit the Issuer and the guarantors’ ability, subject to certain exceptions, to incur indebtedness secured by liens on voting stock or profit participating equity interests of their subsidiaries or merge, consolidate or sell, transfer or lease assets. The Notes also contain customary events of default. All or a portion of the Notes may be redeemed at our option, in whole or in part, at any time and from time to time, prior to their stated maturity, at the make-whole redemption price set forth in the Notes. If a change of control repurchase event occurs, the Notes are subject to repurchase at the repurchase price as set forth in the Notes. |
|---|
Blackstone, through its indirect subsidiary Blackstone Holdings Finance Co. L.L.C., has a $2.25 billion unsecured revolving credit facility (the “Credit Facility”) with Citibank, N.A., as administrative agent with a maturity date of November 24, 2025. Borrowings may also be made in U.K. sterling, euros, Swiss francs, Japanese yen or Canadian dollars, in each case subject to certain
sub-limits.
The Credit Facility contains customary representations, covenants and events of default. Financial covenants consist of a maximum net leverage ratio and a requirement to keep a minimum amount of
fee-earning
assets under management, each tested quarterly.
On July 16, 2019, our board of directors authorized the repurchase of up to $1.0 billion of common stock and Blackstone Holdings Partnership Units. Under the repurchase program, repurchases may be made from time to time in open market transactions, in privately negotiated transactions or otherwise. The timing and the actual number repurchased will depend on a variety of factors, including legal requirements, price and economic and market conditions. The repurchase program may be changed, suspended or discontinued at any time and does not have a specified expiration date.
During the year ended December 31, 2020, we repurchased 9.0 million shares of common stock as part of the repurchase program at a total cost of $474.0 million. As of December 31, 2020, the amount remaining available for repurchases under the program was $307.2 million.
Dividends
Our intention is to pay to holders of common stock a quarterly dividend representing approximately 85% of The Blackstone Group Inc.’s share of Distributable Earnings, subject to adjustment by amounts determined by our board of directors to be necessary or appropriate to provide for the conduct of our business, to make appropriate investments in our business and funds, to comply with applicable law, any of our debt instruments or other agreements, or to provide for future cash requirements such as
tax-related
payments, clawback obligations and dividends to shareholders for any ensuing quarter. The dividend amount could also be adjusted upward in any one quarter.
For Blackstone’s definition of Distributable Earnings, see “— Key Financial Measures and Indicators.”
All of the foregoing is subject to the qualification that the declaration and payment of any dividends are at the sole discretion of our board of directors, and our board of directors may change our dividend policy at any time, including, without limitation, to reduce such quarterly dividends or even to eliminate such dividends entirely.
Because the publicly traded entity and/or its wholly owned subsidiaries must pay taxes and make payments under the tax receivable agreements, the amounts ultimately paid as dividends by The Blackstone Group Inc. to common shareholders in respect of each fiscal year are generally expected to be less, on a per share or per unit basis, than the amounts distributed by the Blackstone Holdings Partnerships to the Blackstone personnel and others who are limited partners of the Blackstone Holdings Partnerships in respect of their Blackstone Holdings Partnership Units. Following the Conversion, we expect to pay more corporate income taxes than we would have as a limited partnership, which will increase this difference between the per share dividend and per unit distribution amounts.
Dividends are treated as qualified dividends to the extent of Blackstone’s current and accumulated earnings and profits, with any excess dividends treated as a return of capital to the extent of the shareholder’s basis.
The following graph shows fiscal quarterly and annual per common shareholder dividends for 2020, 2019 and 2018. Dividends are declared and paid in the quarter subsequent to the quarter in which they are earned.
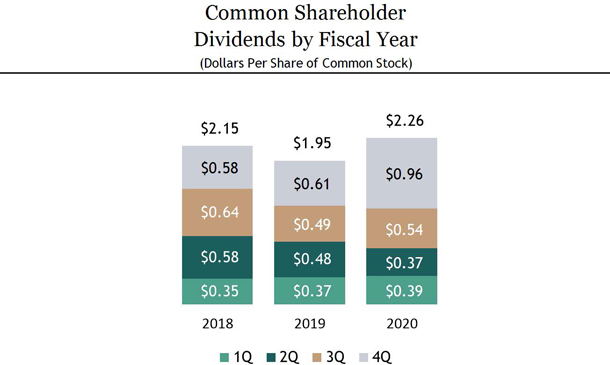
With respect to fiscal year 2020, we paid to shareholders of our common stock a dividend of $0.39, $0.37, $0.54 and $0.96 per share in respect of the first, second, third and fourth quarters, respectively, aggregating $2.26 per share. With respect to fiscal years 2019 and 2018, we paid shareholders of our common stock aggregate dividends of $1.95 per share and $2.15 per share, respectively. The dividend for each of the second, third and fourth quarter of 2018 was $0.58, $0.64 and $0.58, respectively, and in each case included a $0.10 per share dividend from a portion of the
after-tax
proceeds received in connection with the conclusion of Blackstone’s
sub-advisory
relationship with FS Investments.
Leverage
We may under certain circumstances use leverage opportunistically and over time to create the most efficient capital structure for Blackstone and our shareholders. In addition to the borrowings from our notes issuances and our revolving credit facility, we may use reverse repurchase agreements, repurchase agreements and securities sold, not yet purchased. All of these positions are held in a separately managed portfolio. Reverse repurchase agreements are entered into primarily to take advantage of opportunistic yields otherwise absent in the overnight markets and also to use the collateral received to cover securities sold, not yet purchased. Repurchase agreements are entered into primarily to opportunistically yield higher spreads on purchased securities. The balances held in these financial instruments fluctuate based on Blackstone’s liquidity needs, market conditions and investment risk profiles.
The following table presents information regarding these financial instruments in our Consolidated Statements of Financial Condition:
| Repurchase Agreements | Securities Sold, Not Yet Purchased | |||||||
| (Dollars in Millions) | ||||||||
| Balance, December 31, 2020 | $ | 76.8 | $ | 51.0 | ||||
| Balance, December 31, 2019 | $ | 154.1 | $ | 75.5 | ||||
| Year Ended December 31, 2020 | ||||||||
| Average Daily Balance | $ | 94.2 | $ | 56.1 | ||||
| Maximum Daily Balance | $ | 152.8 | $ | 75.7 |
Critical Accounting Policies
We prepare our Consolidated Financial Statements in accordance with GAAP. In applying many of these accounting principles, we need to make assumptions, estimates and/or judgments that affect the reported amounts of assets, liabilities, revenues and expenses in our Consolidated Financial Statements. We base our estimates and judgments on historical experience and other assumptions that we believe are reasonable under the circumstances. These assumptions, estimates and/or judgments, however, are often subjective. Actual results may be affected negatively based on changing circumstances. If actual amounts are ultimately different from our estimates, the revisions are included in our results of operations for the period in which the actual amounts become known. We believe the following critical accounting policies could potentially produce materially different results if we were to change underlying assumptions, estimates and/or judgments. For a description of our accounting policies, see Note 2. “Summary of Significant Accounting Policies” in the “Notes to Consolidated Financial Statements” in “—Item 8. Financial Statements and Supplementary Data” of this filing.
Principles of Consolidation
For a description of our accounting policy on consolidation, see Note 2. “Summary of Significant Accounting Policies—Consolidation” and Note 9. “Variable Interest Entities” in the “Notes to Consolidated Financial Statements” in “—Item 8. Financial Statements and Supplementary Data” for detailed information on Blackstone’s involvement with VIEs. The following discussion is intended to provide supplemental information about how the application of consolidation principles impact our financial results, and management’s process for implementing those principles including areas of significant judgment.
The determination that Blackstone holds a controlling financial interest in a Blackstone Fund or investment vehicle significantly changes the presentation of our consolidated financial statements. In our Consolidated Statements of Financial Position included in this filing, we present 100% of the assets and liabilities of consolidated VIEs along with a
non-controlling
interest which represents the portion of the consolidated vehicle’s interests held by third parties. However, assets of our consolidated VIEs can only be used to settle obligations of the consolidated VIE and are not available for general use by Blackstone. Further, the liabilities of our consolidated VIEs do not have recourse to the general credit of Blackstone. In the Consolidated Statements of Operations, we eliminate any management fees, Incentive Fees, or Performance Allocations received or accrued from consolidated VIEs as they are considered intercompany transactions. We recognize 100% of the consolidated VIE’s investment income (loss) and allocate the portion of that income (loss) attributable to third party ownership to
non-controlling
interests in arriving at Net Income Attributable to The Blackstone Group Inc.
The assessment of whether we consolidate a Blackstone Fund or investment vehicle we manage requires the application of significant judgment. These judgments are applied both at the time we become involved with the VIE and on an ongoing basis and include, but are not limited to:
| • | Determining whether our management fees, Incentive Fees or Performance Allocations represent variable interests – We make judgments as to whether the fees we earn are commensurate with the level of effort required for those fees and at market rates. In making this judgment, we consider, among other things, the extent of third party investment in the entity and the terms of any other interests we hold in the VIE. |
|---|
| • | Determining whether kick-out rights are substantive – We make judgments as to whether the third party investors in a partnership entity have the ability to remove the general partner, the investment manager or its equivalent, or to dissolve (liquidate) the partnership entity, through a simple majority vote. This includes an evaluation of whether barriers to exercise these rights exist. |
|---|
| • | Concluding whether Blackstone has an obligation to absorb losses or the right to receive benefits that could potentially be significant to the VIE – As there is no explicit threshold in GAAP to define “potentially significant,” management must apply judgment and evaluate both quantitative and qualitative factors to conclude whether this threshold is met. |
|---|
Revenue Recognition
For a description of our accounting policy on revenue recognition, see Note 2. “Summary of Significant Accounting Policies—Revenue Recognition” in the “Notes to Consolidated Financial Statements” in “—Item 8. Financial Statements and Supplementary Data.” For additional description of the nature of our revenue arrangements, including how management fees, Incentive Fees, and Performance Allocations are generated, please refer to “Part I. Item 1. Business — Fee Structure/Incentive Arrangements.” The following discussion is intended to provide supplemental information about how the application of revenue recognition principles impact our financial results, and management’s process for implementing those principles including areas of significant judgment.
Management and Advisory Fees, Net
— Blackstone earns base management fees from the investors in its managed funds and investment vehicles, at a fixed percentage of a calculation base which is typically assets under management, net asset value, total assets, committed capital or invested capital. The range of management fee rates and the calculation base from which they are earned, generally, are as follows:
On private equity, real estate, and certain of our hedge fund solutions and credit-focused funds:
| • | 0.25% to 1.75% of committed capital or invested capital during the investment period, |
|---|
| • | 0.25% to 1.50% of invested capital, committed capital or investment fair value subsequent to the investment period for private equity and real estate funds, and |
|---|
| • | 0.75% to 1.50% of invested capital or net asset value subsequent to the investment period for certain of our hedge fund solutions and credit-focused funds. |
|---|
On real estate, credit and
MLP-focused
funds structured like hedge funds:
| • | 0.24% to 1.50% of net asset value. |
|---|
On credit and
MLP-focused
separately managed accounts:
| • | 0.24% to 1.50% of net asset value or total assets. |
|---|
On real estate separately managed accounts:
| • | 0.65% to 2.00% of invested capital, net operating income or net asset value. |
|---|
On funds of hedge funds, certain hedge funds and separately managed accounts invested in hedge funds:
| • | 0.25% to 1.50% of net asset value. |
|---|
On CLO vehicles:
| • | 0.40% to 0.50% of the aggregate par amount of collateral assets, including principal cash. |
|---|
On credit-focused registered and
non-registered
investment companies:
| • | 0.25% to 1.20% of total assets or net asset value. |
|---|
The investment adviser of BXMT receives annual management fees based on 1.50% of BXMT’s net proceeds received from equity offerings and accumulated “distributable earnings” (which is generally equal to its GAAP net income excluding certain
non-cash
and other items), subject to certain adjustments. The investment adviser of BREIT receives a management fee of 1.25% per annum of net asset value, payable monthly.
Management fee calculations based on committed capital or invested capital are mechanical in nature and therefore do not require the use of significant estimates or judgments. Management fee calculations based on net asset value, total assets, or investment fair value depend on the fair value of the underlying investments within the funds. Estimates and assumptions are made when determining the fair value of the underlying investments within the funds and could vary depending on the valuation methodology that is used as well as economic conditions. See “—Fair Value” below for further discussion of the judgment required for determining the fair value of the underlying investments.
Investment Income (Loss)
— Performance Allocations are made to the general partner based on cumulative fund performance to date, subject to a preferred return to limited partners. Blackstone has concluded that investments made alongside its limited partners in a partnership which entitle Blackstone to a Performance Allocation represent equity method investments that are not in the scope of the GAAP guidance on accounting for revenues from contracts with customers. Blackstone accounts for these arrangements under the equity method of accounting. Under the equity method, Blackstone’s share of earnings (losses) from equity method investments is determined using a balance sheet approach referred to as the hypothetical liquidation at book value (“HLBV”) method. Under the HLBV method, at the end of each reporting period Blackstone calculates the accrued Performance Allocations that would be due to Blackstone for each fund pursuant to the fund agreements as if the fair value of the underlying investments were realized as of such date, irrespective of whether such amounts have been realized. Performance Allocations are subject to clawback to the extent that the Performance Allocation received to date exceeds the amount due to Blackstone based on cumulative results.
The change in the fair value of the investments held by certain Blackstone Funds is a significant input into the accrued Performance Allocation calculation and accrual for potential repayment of previously received Performance Allocations. Estimates and assumptions are made when determining the fair value of the underlying investments within the funds. See “—Fair Value” below for further discussion related to significant estimates and assumptions used for determining fair value of the underlying investments.
Fair Value
Blackstone uses fair value throughout the reporting process. For a description of our accounting policies related to valuation, see Note 2. “Summary of Significant Accounting Policies—Fair Value of Financial Instruments” and “Summary of Significant Accounting Policies—Investments at Fair Value” in the “Notes to Consolidated Financial Statements” in “—Item 8. Financial Statements and Supplementary Data” of this filing. The following discussion is intended to provide supplemental information about how the application of fair value principles impact our financial results, and management’s process for implementing those principles including areas of significant judgment.
The fair value of the investments held by Blackstone Funds is the primary input to the calculation of certain of our management fees, Incentive Fees, Performance Allocations and the related Compensation we recognize. The Blackstone Funds are accounted for as investment companies under the American Institute of Certified Public Accountants Accounting and Auditing Guide,
Investment Companies
, and in accordance with the GAAP guidance on investment companies and reflect their investments, including majority-owned and controlled investments (the
“Portfolio Companies”), at fair value. In the absence of observable market prices, we utilize valuation methodologies applied on a consistent basis and assumptions that we believe market participants would use to determine the fair value of the investments. For investments where little market activity exists management’s determination of fair value is based on the best information available in the circumstances, which may incorporate management’s own assumptions and involves a significant degree of judgment, and the consideration of a combination of internal and external factors, including the appropriate risk adjustments for
non-performance
and liquidity risks.
Blackstone has also elected the fair value option for certain instruments it owns directly, including loans and receivables and investments in private debt securities, the assets of consolidated CLO vehicles and other proprietary investments. Blackstone is required to measure certain financial instruments at fair value, including debt instruments, equity securities and freestanding derivatives.
Fair Value of Investments or Instruments that are Publicly Traded
Securities that are publicly traded and for which a quoted market exists will be valued at the closing price of such securities in the principal market in which the security trades, or in the absence of a principal market, in the most advantageous market on the valuation date. When a quoted price in an active market exists, no block discounts or control premiums are permitted regardless of the size of the public security held. In some cases, securities will include legal and contractual restrictions limiting their purchase and sale for a period of time, such as may be required under SEC Rule 144. A discount to publicly traded price may be appropriate in those cases; the amount of the discount, if taken, shall be determined based on the time period that must pass before the restricted security becomes unrestricted or otherwise available for sale.
Fair Value of Investments or Instruments that are not Publicly Traded
Investments for which market prices are not observable include private investments in the equity or debt of operating companies or real estate properties. Our primary methodology for determining the fair values of such investments is generally the income approach which provides an indication of fair value based on the present value of cash flows that a business, security, or property is expected to generate in the future. The most widely used methodology under the income approach is the discounted cash flow method which includes significant assumptions about the underlying investment’s projected net earnings or cash flows, discount rate, capitalization rate and exit multiple. Our secondary methodology, generally used to corroborate the results of the income approach, is typically the market approach. The most widely used methodology under the market approach relies upon valuations for comparable public companies, transactions, or assets, and includes making judgments about which companies, transactions, or assets are comparable. Depending on the facts and circumstances associated with the investment, different primary and secondary methodologies may be used including option value, contingent claims or scenario analysis, yield analysis, projected cash flow through maturity or expiration, probability weighted methods or recent round of financing.
In certain cases debt and equity securities are valued on the basis of prices from an orderly transaction between market participants provided by reputable dealers or pricing services. In determining the value of a particular investment, pricing services may use certain information with respect to transactions in such investments, quotations from dealers, pricing matrices and market transactions in comparable investments and various relationships between investments.
Management Process on Fair Value
Due to the importance of fair value throughout the consolidated financial statements and the significant judgment required to be applied in arriving at those fair values, we have developed a process around valuation that incorporates several levels of approval and review from both internal and external sources. Investments held by Blackstone Funds and investment vehicles are valued on at least a quarterly basis by our internal valuation or asset management teams, which are independent from our investment teams.
For investments valued utilizing the income method and where Blackstone has information rights, we generally have a direct line of communication with each of the Portfolio Company finance teams and collect financial data used to support projections used in a discounted cash flow analysis. The respective business unit’s valuation team then analyzes the data received and updates the valuation models reflecting any changes in the underlying cash flow projections, weighted-average cost of capital, exit multiple, and any other valuation input relevant economic conditions.
The results of all valuations of investments held by Blackstone Fund and investment vehicles are reviewed and approved by the relevant business unit’s valuation
sub-committee,
which is comprised of key personnel from the business unit, typically the chief investment officer, chief operating officer, chief financial officer, chief compliance officer (or their respective equivalents where applicable) and other senior managing directors in the business. To further corroborate results, each business unit also generally obtains either a positive assurance opinion or a range of value from an independent valuation party, at least annually for internally prepared valuations for investments that have been held by Blackstone Funds and investment vehicles for greater than a year and quarterly for certain investments. Our firmwide valuation committee, chaired by our Chief Financial Officer and comprised of senior members of our businesses and representatives from corporate functions, including legal and finance, reviews the valuation process for investments held by us and our investment vehicles, including the application of appropriate valuation standards on a consistent basis. Each quarter, the valuation process is also reviewed by the audit committee of our board of directors, which is comprised of our employee directors.
The global outbreak of COVID-19 required management to make significant judgments about the ultimate adverse impact of COVID-19 on financial markets and economic conditions, which is uncertain and may change over time. These judgments and estimates were incorporated into the valuation process outlined herein. Management’s policies were unchanged and critical processes were executed in a remote working environment.
Income Tax
For a description of our accounting policy on taxes and additional information on taxes see Note 2. “Summary of Significant Accounting Policies” and Note 15. “Income Taxes,” respectively, in the “Notes to Consolidated Financial Statements” in “—Item 8. Financial Statements and Supplementary Data” of this filing.
Our provision for income taxes is composed of current and deferred taxes. Current income taxes approximate taxes to be paid or refunded for the current period. Deferred income taxes reflect the net tax effects of temporary differences between the financial reporting and tax bases of assets and liabilities and are measured using the applicable enacted tax rates and laws that will be in effect when such differences are expected to reverse. During the year ended December 31, 2019, the Conversion resulted in a
step-up
in the tax basis of certain assets that will be recovered as those assets are sold or the basis is amortized.
Additionally, significant judgment is required in estimating the provision for (benefit from) income taxes, current and deferred tax balances (including valuation allowance), accrued interest or penalties and uncertain tax positions. In evaluating these judgments, we consider, among other items, projections of taxable income (including the character of such income), beginning with historic results and incorporating assumptions of the amount of future pretax operating income. These assumptions about future taxable income require significant judgment and are consistent with the plans and estimates that Blackstone uses to manage its business. A portion of the deferred tax assets are not considered to be more likely than not to be realized due to the character of income necessary for recovery. For that portion of the deferred tax assets, a valuation allowance has been recorded.
Revisions in estimates and/or actual costs of a tax assessment may ultimately be materially different from the recorded accruals and unrecognized tax benefits, if any.
Off-Balance
Sheet Arrangements
In the normal course of business, we engage in
off-balance
sheet arrangements, including transactions in derivatives, guarantees, commitments, indemnifications and potential contingent repayment obligations. We do not have any
off-balance
sheet arrangements that would require us to fund losses or guarantee target returns to investors in our funds.
Further disclosure on our
off-balance
sheet arrangements is presented in the “Notes to Consolidated Financial Statements” in “—Item 8. Financial Statements and Supplementary Data” of this filing as follows:
| • | Note 9. “Variable Interest Entities,” and |
|---|
| • | Note 19. “Commitments and Contingencies — Commitments — Investment Commitments” and “— Contingencies — Guarantees.” |
|---|
Recent Accounting Developments
Information regarding recent accounting developments and their impact on Blackstone can be found in Note 2. “Summary of Significant Accounting Policies” in the “Notes to Consolidated Financial Statements” in “—Item 8. Financial Statements and Supplementary Data” of this filing.
Interbank Offered Rates Transition
Certain jurisdictions are currently reforming or phasing out their Interbank Offered Rates (“IBORs”), including, without limitation, the London Interbank Offered Rates, Euro Interbank Offered Rate, Tokyo Interbank Offered Rate, Hong Kong Interbank Offered Rate and Singapore Interbank Offered Rate. The timing of the anticipated reforms or phase-outs vary by jurisdiction, with most of the reforms or phase-outs currently scheduled to take effect at the end of calendar year 2021. Blackstone is evaluating the operational impact of such changes on existing transactions and contractual arrangements and managing transition efforts. See “Part I. Item 1A. Risk Factors — Risks Related to Our Business — Interest rates on our and our portfolio companies’ outstanding financial instruments might be subject to change based on regulatory developments, which could adversely affect our revenue, expenses and the value of those financial instruments.”
Contractual Obligations, Commitments and Contingencies
The following table sets forth information relating to our contractual obligations as of December 31, 2020 on a consolidated basis and on a basis deconsolidating the Blackstone Funds:
| Contractual Obligations | 2021 | 2022-2023 | 2024-2025 | Thereafter | Total | |||||||||||||||
| (Dollars in Thousands) | ||||||||||||||||||||
| Operating Lease Obligations (a) | $ | 93,815 | $ | 212,647 | $ | 185,136 | $ | 186,710 | $ | 678,308 | ||||||||||
| Purchase Obligations | 63,708 | 45,157 | 8,736 | — | 117,601 | |||||||||||||||
| Blackstone Issued Notes and Revolving Credit Facility (b) | — | 400,000 | 366,480 | 4,965,920 | 5,732,400 | |||||||||||||||
| Interest on Blackstone Issued Notes and Revolving Credit Facility (c) | 168,004 | 326,507 | 298,007 | 2,090,082 | 2,882,600 | |||||||||||||||
| Blackstone Funds Debt Obligations Payable | 99 | — | — | — | 99 | |||||||||||||||
| Blackstone Funds Capital Commitments to Investee Funds (d) | 140,185 | — | — | — | 140,185 | |||||||||||||||
| Due to Certain Non-Controlling Interest Holders in Connection with Tax Receivable Agreements (e) | 51,366 | 98,321 | 89,940 | 617,848 | 857,475 | |||||||||||||||
| Unrecognized Tax Benefits, Including Interest and Penalties (f) | 1,055 | — | — | — | 1,055 | |||||||||||||||
| Blackstone Operating Entities Capital Commitments to Blackstone Funds and Other (g) | 3,771,304 | — | — | — | 3,771,304 | |||||||||||||||
| Consolidated Contractual Obligations | 4,289,536 | 1,082,632 | 948,299 | 7,860,560 | 14,181,027 | |||||||||||||||
| Blackstone Funds Debt Obligations Payable | (99 | ) | — | — | — | (99 | ) | |||||||||||||
| Blackstone Funds Capital Commitments to Investee Funds (d) | (140,185 | ) | — | — | — | (140,185 | ) | |||||||||||||
| Blackstone Operating Entities Contractual Obligations | $ | 4,149,252 | $ | 1,082,632 | $ | 948,299 | $ | 7,860,560 | $ | 14,040,743 | ||||||||||
| (a) | We lease our primary office space and certain office equipment under agreements that expire through 2030. Occupancy lease agreements, in addition to contractual rent payments, generally include additional payments for certain costs incurred by the landlord, such as building expenses, and utilities. To the extent these are fixed or determinable they are included in the table above. The table above includes operating leases that are recognized as Operating Lease Liabilities, short-term leases that are not recorded as Operating Lease Liabilities and leases that have been signed but not yet commenced which are not recorded as Operating Lease Liabilities. The amounts in this table are presented net of contractual sublease commitments. |
|---|
| (b) | Represents the principal amount due on the senior notes we issued. As of December 31, 2020, we had no outstanding borrowings under our revolver. |
|---|
| (c) | Represents interest to be paid over the maturity of our senior notes and borrowings under our revolving credit facility which has been calculated assuming no pre-payments are made and debt is held until its final maturity date. These amounts exclude commitment fees for unutilized borrowings under our revolver. |
|---|
| (d) | These obligations represent commitments of the consolidated Blackstone Funds to make capital contributions to investee funds and portfolio companies. These amounts are generally due on demand and are therefore presented in the less than one year category. |
|---|
| (e) | Represents obligations by Blackstone’s corporate subsidiary to make payments under the Tax Receivable Agreements to certain non-controlling interest holders for the tax savings realized from the taxable purchases of their interests in connection with the reorganization at the time of Blackstone’s IPO in 2007 and subsequent purchases. The obligation represents the amount of the payments currently expected to be made, which are dependent on the tax savings actually realized as determined annually without discounting for the timing of the payments. As required by GAAP, the amount of the obligation included in the Consolidated Financial Statements and shown in Note 18. “Related Party Transactions” (see “—Item 8. Financial Statements and Supplementary Data”) differs to reflect the net present value of the payments due to certain non-controlling interest holders. |
|---|
| (f) | The total represents gross unrecognized tax benefits of $0.5 million and interest and penalties of $0.5 million. In addition, Blackstone is not able to make a reasonably reliable estimate of the timing of payments in individual years in connection with gross unrecognized benefits of $32.4 million and interest of $3.4 million; therefore, such amounts are not included in the above contractual obligations table. |
|---|
| (g) | These obligations represent commitments by us to provide general partner capital funding to the Blackstone Funds, limited partner capital funding to other funds and Blackstone principal investment commitments. These amounts are generally due on demand and are therefore presented in the less than one year category; however, a substantial amount of the capital commitments are expected to be called over the next three years. We expect to continue to make these general partner capital commitments as we raise additional amounts for our investment funds over time. |
|---|
Guarantees
Blackstone and certain of its consolidated funds provide financial guarantees. The amounts and nature of these guarantees are described in Note 19. “Commitments and Contingencies — Contingencies — Guarantees” in the “Notes to Consolidated Financial Statements” in “—Item 8. Financial Statements and Supplementary Data” of this filing.
Indemnifications
In many of its service contracts, Blackstone agrees to indemnify the third party service provider under certain circumstances. The terms of the indemnities vary from contract to contract and the amount of indemnification liability, if any, cannot be determined and has not been included in the table above or recorded in our Consolidated Financial Statements as of December 31, 2020.
Clawback Obligations
Performance Allocations are subject to clawback to the extent that the Performance Allocations received to date with respect to a fund exceeds the amount due to Blackstone based on cumulative results of that fund. The actual clawback liability, however, generally does not become realized until the end of a fund’s life except for certain Blackstone real estate funds, multi-asset class investment funds and credit-focused funds, which may have an interim clawback liability. The lives of the carry funds, including available contemplated extensions, for which a liability for potential clawback obligations has been recorded for financial reporting purposes, are currently anticipated to expire at various points through 2029. Further extensions of such terms may be implemented under given circumstances.
For financial reporting purposes, when applicable, the general partners record a liability for potential clawback obligations to the limited partners of some of the carry funds due to changes in the unrealized value of a fund’s remaining investments and where the fund’s general partner has previously received Performance Allocation distributions with respect to such fund’s realized investments.
As of December 31, 2020, the total clawback obligations were $108.6 million, of which $83.9 million was related to Blackstone Holdings and $24.6 million was related to current and former Blackstone personnel. The split of clawback between Blackstone Holdings and current and former personnel is based on the performance of individual investments held by a fund rather than on a fund by fund basis.
If, at December 31, 2020, all of the investments held by our carry funds were deemed worthless, a possibility that management views as remote, the amount of Performance Allocations subject to potential clawback would be $4.0 billion, on an
after-tax
basis where applicable, of which Blackstone Holdings is potentially liable for $3.8 billion if current and former Blackstone personnel default on their share of the liability, a possibility that management also views as remote. See Note 18. “Related Party Transactions” and Note 19. “Commitments and Contingencies” in the “Notes to Consolidated Financial Statements” in “—Item 8. Financial Statements and Supplementary Data” of this filing.
Previous: Item 6. (Removed and Reserved) · Next: Item 7A. Quantitative and Qualitative Disclosures About Market Risk