 filings.tools
Item 1. Business
127K characters. Original on sec.gov · Markdown
Item 1. Business
The following description of the business should be read in conjunction with the information included elsewhere in this Annual Report on Form 10-K for the year ended December 31, 2023. This description contains forward-looking statements that involve risks and uncertainties. Actual results could differ significantly from the results discussed in the forward-looking statements due to the factors set forth in “Risk Factors” and elsewhere in this Annual Report on Form 10-K.
Overview
Cboe Global Markets, Inc., the world's leading derivatives and securities exchange network, delivers cutting-edge trading, clearing and investment solutions to people around the world. Cboe provides trading solutions and products in multiple asset classes, including equities, derivatives, FX, and digital assets, across North America, Europe, and Asia Pacific. Above all, the Company is committed to building a trusted, inclusive global marketplace that enables people to pursue a sustainable financial future.
Cboe’s subsidiaries include the largest options exchange and the third largest stock exchange operator in the U.S. In addition, the Company operates Cboe Europe, one of the largest stock exchanges by value traded in Europe, and owns Cboe Clear Europe, a leading pan-European equities and derivatives clearinghouse, BIDS Holdings, which owns a leading block-trading ATS by volume in the U.S., and provides block-trading services with Cboe market operators in Europe, Canada, Australia, and Japan, Cboe Australia, an operator of trading venues in Australia, Cboe Japan, an operator of trading venues in Japan, Cboe Digital, an operator of a U.S. based digital asset spot market and a regulated futures exchange, Cboe Clear Digital, an operator of a regulated clearinghouse, and Cboe Canada Inc., a recognized Canadian securities exchange. Cboe subsidiaries also serve collectively as a leading market globally for exchange-traded products (“ETPs”) listings and trading.
The graphic below provides a brief overview of Cboe’s history:
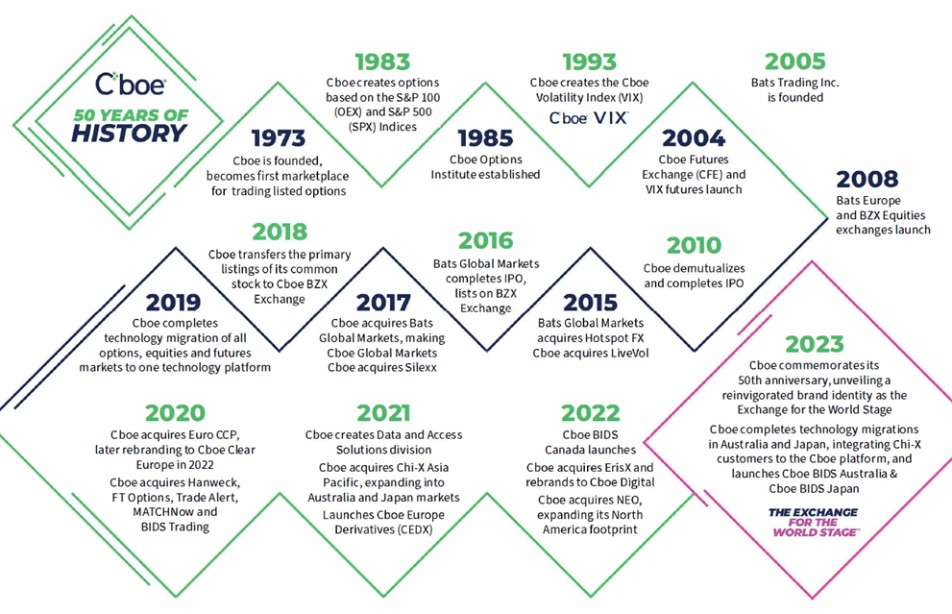
Our Business
Cboe reports on the following six business segments:
| ● | Options. The Options segment includes options on market indices (“index options”), as well as on the stocks of individual corporations (“equity options”) and on ETPs such as exchange-traded funds (“ETFs”) and exchange-traded notes (“ETNs”), which are “multi-listed” options and listed on a non-exclusive basis. These options are eligible to trade, as applicable, on Cboe Options, C2, BZX, EDGX, and/or other U.S. national security exchanges. Cboe Options is the Company’s primary options market and offers trading in listed options through a single system that integrates electronic trading and traditional open outcry trading on the Cboe Options trading floor in Chicago. C2 Options, BZX Options, and EDGX Options are all-electronic options exchanges, and typically operate with different market models and fee structures than Cboe Options. The Options segment also includes applicable market data fees revenues generated from the consolidated tape plans, the licensing of proprietary options market data, index licensing, routing services, and access and capacity services. |
|---|
| ● | North American Equities. The North American Equities segment includes U.S. equities and ETP transaction services that occur on fully electronic exchanges owned and operated by BZX, BYX, EDGX, and EDGA, equities transactions that occur on the BIDS Trading platform in the U.S. and Canada, and Canadian equities and other transaction services that occur on or through Cboe Canada Inc.’s order books. The North American Equities segment also includes listing services on Cboe Canada Inc., corporate and ETP listings on BZX, applicable market data fees revenues generated from the consolidated tape plans, the licensing of proprietary equities market data, routing services, and access and capacity services. |
|---|
| ● | Europe and Asia Pacific. The Europe and Asia Pacific segment includes the pan-European listed equities and derivatives transaction services, ETPs, exchange-traded commodities, and international depository receipts that are hosted on MTFs operated by Cboe Europe Equities (Cboe Europe and Cboe NL equities exchanges) and Cboe Europe Derivatives (“CEDX”). It also includes the ETP listings business on RMs and clearing activities of Cboe Clear Europe, as well as the equities transaction services of Cboe Australia and Cboe Japan, operators of trading venues in Australia and Japan, respectively, along with equities transactions that occur on the BIDS Trading platform in Australia and Japan. Cboe Europe operates lit and dark books, a periodic auctions book, and Cboe BIDS Europe, a Large-in-Scale (“LIS”) trading negotiation facility for UK symbols. Cboe NL, launched in October 2019 and based in Amsterdam, operates similar business functionality to that offered by Cboe Europe, and provides for trading only in European Economic Area (“EEA”) symbols. Cboe Europe Derivatives, a pan-European derivatives platform launched in September 2021, offers futures and options based on Cboe Europe equity indices, and single stock options. This segment also includes Cboe Europe, Cboe NL, CEDX, Cboe Australia and Cboe Japan revenue generated from the licensing of proprietary market data and from access and capacity services. |
|---|
| ● | Futures. The Futures segment includes transaction services provided by CFE, a fully electronic futures exchange, which includes offerings for trading of VIX futures and other futures products, the licensing of proprietary market data, as well as access and capacity services. |
|---|
| ● | Global FX. The Global FX segment includes institutional FX trading services that occur on the Cboe FX fully electronic trading platform, non-deliverable forward FX transactions (“NDFs”) offered for execution on Cboe SEF, as well as revenue generated from the licensing of proprietary market data and from access and capacity services. The segment includes transaction services for U.S. government securities executed on the Cboe Fixed Income fully electronic trading platform. |
|---|
| ● | Digital. The Digital segment includes a U.S. based digital asset spot market, a regulated futures exchange, and a regulated clearinghouse, as well as revenue generated from the licensing of proprietary market data and from access and capacity services. |
|---|
See “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and Note 16 (“Segment Reporting”) in the notes to our consolidated financial statements for discussion of revenues and certain operational and financial metrics, and operating income (or loss) by business segment. Certain activities within our segments operate globally. For information regarding risks related to our international operations see “Risk Factors.”
Executive Transitions
On July 6, 2023, Brian Schell, former Executive Vice President, Chief Financial Officer and Treasurer, announced his departure from the Company to pursue a new professional opportunity outside of the exchange industry. Jill Griebenow, Senior Vice President, Chief Accounting Officer, was appointed to serve as Executive Vice President, Chief Financial Officer, Treasurer and Chief Accounting Officer effective July 10, 2023, and currently serves as Executive Vice President, Chief Financial Officer.
On September 18, 2023 (the “Effective Date”), Edward T. Tilly, former Chief Executive Officer of the Company, resigned and voluntarily terminated his employment with the Company. Mr. Tilly also resigned as Chairman of the Company’s Board of Directors, effective as of the Effective Date. Mr. Tilly’s resignation followed the conclusion of an investigation led by the Board of Directors and outside independent counsel that was launched in late August 2023. The Board of Directors determined that Mr. Tilly did not disclose personal relationships with colleagues, which violated the Company’s policies and stands in stark contrast to the Company’s values. The conduct was not related to and does not impact the Company’s strategy, financial performance, technology and market operations, financial reporting or internal controls over financial reporting. Following Mr. Tilly’s resignation, Fredric J. Tomczyk, an existing director of the Company, was appointed as Chief Executive Officer of the Company, effective as of the Effective Date. As a result of Mr. Tomczyk’s appointment as Chief Executive Officer, Mr. Tomczyk stepped down from the Board of Directors’ Compensation Committee and Finance and Strategy Committee as of the Effective Date. Also as of the Effective Date, William M. Farrow III was appointed as non-executive Chairman of the Board of Directors (in substitution of his prior role as Lead Director of the Board of Directors).
Competitive Strengths
Cboe is a leading provider of market infrastructure and tradable products across cash and spot markets, derivatives markets, and data and access solutions. Cboe delivers cutting-edge trading, clearing and investment solutions across the globe through a comprehensive ecosystem that helps drive innovation and growth.

Key Growth Strategy Initiatives
Our strategy is to build one of the world’s largest global derivatives and securities networks to create value and drive growth by:
| ● | Innovating to capture growing demand for trading products and data services, globally. We plan to increase access to data products and trading solutions, provide unrivaled transaction capabilities, and have a global presence in the highest value markets. In 2023, we delivered on this initiative by expanding the use of zero days to expiry (0-DTE) products, expanding Cboe Global Indices to Europe, launching the 1-Day Volatility Index (VIX1D), designed to measure volatility over the current trading day, launching the Cboe S&P 500 Dispersion Index (DSPX), a volatility index designed to measure expected dispersion in the S&P 500 Index, launching new options on futures on two corporate bond index products, and launching four new Credit VIX Indices, designed to provide a VIX Index-like measures for credit market volatility. |
|---|
| ● | Unlocking the value capabilities of our ecosystems to increase efficiency and better serve customers. We aim to unlock the value, capabilities, and efficiencies of our ecosystems to increase efficiency and utilize our client coordination model to better serve our customers. We leverage industry-leading technology, apply a non-siloed integration approach to expand ecosystems and fuel our flywheel and generate strong free cash flow as we improve operating efficiency. In 2023, we delivered on this initiative by completing the migration of Cboe Australia and Cboe Japan to the Cboe technology platform, launching BIDS in Australia and Japan, successfully integrating Cboe Canada (which was the trade name of the former Aequitas Innovations Inc. and Neo Exchange Inc.) and the MATCHNow ATS into Cboe Canada Inc., a recognized Canadian securities exchange, and launching the Cboe Theoretical Options Pricing Service. |
|---|
| ● | Growing by accessing untapped addressable markets. We are expanding and diversifying our revenue opportunity set through organic investment and merger and acquisition activity. In 2023, we delivered on this initiative by expanding into pan-European single stock options and completing phase 1 of our initiative to offer options on leading European companies, adding extended trading hours for corporate bond index futures, developing plans to introduce a clearing service for securities financing transactions through Cboe Clear Europe, announcing and then launching in January 2024 margined futures on Bitcoin and Ether, Cboe FX successfully trading U.S. Treasury products, and launching Cboe Global Listings, the first-of-its-kind, global listing network facilitating worldwide access to capital and secondary liquidity for companies and ETFs, and successfully attracting its first intralisted corporate issuer to the global platform. |
|---|
Proprietary Products
In addition to operating cash and spot markets and derivative markets, and providing data and access solutions, we are a leader in the volatility space with the proprietary products we offer for trading. These proprietary products are built through Cboe Labs, a dedicated team centered on the creation, development, and implementation of new ideas and our strategic relationships and license agreements with index providers, which are both described below in further detail. Our most frequently traded proprietary products include SPX options and VIX options and futures.
SPX Options
The S&P 500 Index is an index comprised of 500 large-cap U.S. listed companies. It is one of the most commonly followed indices and is considered a bellwether for the U.S. economy. The SPX options we offer on the S&P 500 Index are exclusive to Cboe and contribute substantially to our volumes and transaction fees. Because of the S&P 500 Index’s status as a bellwether, SPX options are used in many different trading strategies by customers with different goals, including pension funds hedging their equity exposure by buying put options, asset managers seeking enhanced returns by selling covered call options and hedge funds using risk-managed strategies to capture so-called “risk premia” embedded in option prices. We also offer zero days to expiry (0-DTE) products, Mini- and Nano-SPX options, FLEX- and FLEX micro-SPX options, and SPX Weeklys options, which have settlements on Mondays, Tuesdays, Wednesdays, Thursdays, Fridays and on the last trading day of each month and 24x5 trading in SPX options. We believe these additional expirations provide customers with more precision when hedging overall portfolio risk.
Volatility Trading
Cboe pioneered the trading of exchange-traded volatility products with its introduction of VIX futures in 2004 and VIX options in 2006. The VIX Index (as defined below), although not directly tradable, is based on the mid-point of real-time
quotes of SPX options and is designed to reflect investors’ consensus view of future 30-day expected stock market volatility. The VIX Index methodology provides the basis for the creation of VIX options and futures. The final settlement value of VIX options and futures is determined on their expiration date through a Special Opening Quotation (“SOQ”) of the VIX Index. The SOQ calculation uses opening trade prices of selected options; unless there is no opening price, in which case the opening price used in the SOQ calculation is the midpoint of the highest bid and lowest offer at the time of the opening. Since we started offering these products, we have seen trading from a number of different customer segments utilizing a number of different trading strategies, including hedging extreme stock market declines, also known as “tail risk” hedging, and risk-managed strategies that seek to capture the relative price changes of expected volatility at different times in the future. We also offer the 1-Day Volatility Index (VIX1D), VIX Weeklys options and futures, mini VIX futures, and 24x5 trading in VIX options and futures to provide investors with additional tools to trade volatility.
Proprietary Indices
We also calculate and disseminate proprietary indices that are licensed for use by third parties or are used as the basis for Cboe proprietary products. These proprietary indices are built both through our in-house research and development staff of the Data and Access Solutions business and our strategic relationships and license agreements with index providers, which are both described below in further detail. Our proprietary indices include:
| ● | volatility indices based on broad-based market indices, such as the S&P 500 and the Russell 2000, |
|---|
| ● | volatility indices based on ETFs, and |
|---|
| ● | options strategy benchmark indices, such as the Cboe BuyWrite, PutWrite and Collar indices based on the S&P 500 and Russell 2000, BuyWrite and PutWrite indices based on MSCI EAFE and MSCI Emerging Markets indices, and BuyWrite indices based on other broad-based market indices. |
|---|
In addition to any transaction fee revenue generated from trading of products based on these indices on Cboe exchanges, we distribute these indices through the Cboe Global Index Feed index data subscription service and, together with index providers with whom we have strategic relationships, we license proprietary indices for third parties to use to create third-party indices and products. Accordingly, we generate revenue from proprietary indices by distributing them for reference purposes, using them as the basis for proprietary products and licensing them for use for third-party indices and products.
Strategic Index Provider Relationships
The Company has long-term business relationships with several providers of market indices. We license their indices, including on an exclusive basis, as the foundation for indices, index options and other products. The Company also agrees to work jointly with key providers to develop new products and services that are expected to capitalize on our core competencies and diversify our sources of revenue. Of particular note are the following:
| ● | S&P Global. We have the following licensing arrangements with S&P Global, Inc. subsidiaries: |
|---|
| o | S&P Dow Jones Indices. We have the exclusive right to offer exchange-listed options contracts in the United States on the S&P 500 Index, the S&P 100 Index, the S&P 500 ESG Index, and the S&P Select Sector Indices as a result of a licensing arrangement with S&P Dow Jones Indices, LLC (“S&P”). Our license from S&P is through December 31, 2033, with an exclusive license to trade options on the S&P 500 Index through December 31, 2032. We use the market data from the trading of options on the S&P 500 Index and S&P 100 Index for the creation of Cboe volatility indices, such as the Cboe Volatility Index (“VIX Index”), and to create tradable products on those volatility indices**.** |
|---|
| o | IHS Markit. Under our licensing agreement with IHS Markit Ltd. (acquired by S&P Global in 2022), we have a worldwide license through August 23, 2025 to offer options and futures on indices designed to reflect values of investment grade and high-yield U.S. corporate bonds. Unless either party elects otherwise, this agreement auto-renews for successive two-year periods. We offer futures and options on futures on high yield and investment grade corporate bond indices. |
|---|
| o | DJI Opco. We have the exclusive right during standard U.S. trading hours to offer listed options contracts in the United States on the Dow Jones Industrial Average (“DJIA”) and Dow 10 Index, and |
|---|
| non-exclusive rights to offer listed options on several other Dow Jones indices including the Dow Jones Utilities Average and Dow Jones Transportation Average. This licensing arrangement with DJI Opco, LLC (acquired by S&P in 2012) extends through December 31, 2033. We use market data from the trading of options on these indices to create Cboe volatility indices, variance indicators and BuyWrite indices, and we trade options and other products on these indices. |
|---|
| ● | FTSE Russell. Under our license agreement with the London Stock Exchange Group’s (“LSEG”) leading global index franchises, Frank Russell Company and FTSE International Limited (together “FTSE Russell”), we have the exclusive or first right in the United States to offer listed options on more than two dozen FTSE Russell indices, which represent a diverse group of domestic and global equities with international appeal. Our exclusive license from FTSE Russell is through April 1, 2030. We offer options on the Russell 2000, Russell 1000, Russell 1000 Value and Russell 1000 Growth indices and mini-options on the Russell 2000 Index. |
|---|
| ● | MSCI**.** We have an agreement with MSCI Inc. (“MSCI”) until December 31, 2031 in which we have the right to offer U.S.-listed options on several of MSCI’s indices including the MSCI EAFE and MSCI Emerging Markets indices. We use market data from the trading of the MSCI EAFE and MSCI Emerging Markets index options (among other inputs) to calculate volatility indices and several versions of BuyWrite and PutWrite strategy indices. |
|---|
Data and Access Solutions
The Data and Access Solutions business provides an offering of market data and information solutions products across multiple asset classes and geographic regions that are designed to suit our customers’ diverse needs. The Data and Access Solutions business consists of three product groups:
| ● | Market Data and Access Services. Data products include real-time depth of book quotation information, auction and complex option information, top of book quotes and trades, last sale information, and consolidated equity feeds. In addition to market data, access services include all access and capacity products including connectivity, terminal and other equipment rights, maintenance services, trading floor space and permits for the opportunity to trade. |
|---|
| ● | Cboe Global Indices. Services include index creation, calculation, licensing, and data dissemination. In addition to index data dissemination, through Cboe’s Global Indices platform, we distribute real-time cryptocurrency prices and indicative net asset values. See above for additional information regarding our proprietary indices. |
|---|
| ● | Risk and Market Analytics. Services include analytics and historical data with three areas of focus: |
|---|
| o | Data and Market Analytics. Services include aggregated equity and derivative market statistics, theoretical values, trading indicators, portfolio and margin risk, scenarios, and historical data from Cboe’s markets as well as third-party consolidated data. |
|---|
| o | Front-End Platforms. Cboe provides multiple trading solutions and services including Cboe Silexx, LiveVol Pro, FT Options and Trade Alert. |
|---|
| o | Connectivity. Services include FIX Order Routing, Trade Drop Copy Network, consolidated audit trail (“CAT”) reporting, and broker connectivity. |
|---|
We provide data services to market participants globally through a number of distribution channels including direct, via our vendor partners and Cboe Global Cloud, which is our global cloud data distribution service.
U.S. Tape Plans
We also derive a portion of our revenue from market data fees from U.S. tape plans, including Unlisted Trading Privileges (“UTPs”), the Consolidated Tape Association (“CTA”) and OPRA. Fees, net of plan costs, from UTP, CTA, and OPRA are allocated and distributed to plan participants like us according to their share of tape fees based on a formula, required by Regulation NMS, which may take into account both trading and quoting activity.
Our Market Models
We operate a variety of derivatives and cash and spot markets. Our markets use a combination of pricing and market models to differentiate them from each other and from our competitors.
For our U.S. derivatives options markets, Cboe Options is a hybrid market combining open outcry floor trading with electronic trading. For multi-listed products, we utilize public customer priority, market turner in certain products, participation rights and pro-rata allocation market models, combined with the “classic” pricing model. Under the classic pricing model, professional participants pay transaction fees, public customers generally do not pay transaction fees and market makers compensate brokers for sending order flow to the exchange (known as payment for order flow). For proprietary products, we use price-time or pro-rata allocation, sometimes with public customer priority, and market turner market models, combined with a pricing model where all market participants generally pay fees. Our other three options markets are fully electronic. BZX options utilizes a price-time market model, combined with a “maker-taker” pricing model. Under the maker-taker pricing model, market participants who make the market (a “maker”) generally receive a rebate, while market participants who trade against those markets (a “taker”) pay a transaction fee. EDGX options utilizes customer priority, participation rights and pro-rata allocation market models, combined with the classic pricing model. C2 options utilizes a pro-rata allocation market model, combined with the maker-taker pricing model.
For CFE’s U.S. derivatives futures market, which is fully electronic, CFE utilizes a price-time market model, combined with a pricing model where all market participants generally pay fees, subject to specified exceptions.
For our U.S. cash and spot markets, the U.S. equities exchanges, which are fully electronic, offer various market models. BZX equities utilizes a price-time market model, combined with the maker-taker pricing model. EDGX equities utilizes a price-time with retail priority market model, combined with the maker-taker pricing model. BYX equities utilizes a price-time with price improvement for retail customers market model, combined with the “taker-maker” pricing model. Under the taker-maker pricing model, market participants who make the market pay a transaction fee, while market participants who trade against those markets receive a rebate. EDGA equities utilizes a price-time market model, combined with a taker-maker pricing model. In addition to these market models, each of the U.S. equity exchanges provides numerous specific order types that are designed to enhance their respective market models.
For our cash and spot markets, BIDS Trading, the U.S. equities ATS market, which is fully electronic and is an independently managed and operated trading venue, separate from and not integrated with the Exchanges, utilizes a sponsored access model to provide anonymous executions in NMS stocks. BIDS Trading provides numerous order types, including both firm and conditional orders. All orders matched within BIDS Trading are executed at or better than the National Best Bid and Offer (“NBBO”). BIDS Trading charges fees based on disclosed, objective criteria: (i) means of access; (ii) the type of order; and (iii) the total volume of executions during the calendar month. Cboe and BIDS Trading collaborate in operating similar venues with our cash and spot markets in Australia, Canada, Europe, and Japan.
In Canada, for our cash and spot markets, Cboe Canada Inc., a recognized Canadian securities exchange, which is fully electronic, offers four order books: NEO-L, which provides resting orders with priority over high-frequency orders and combines a maker-taker pricing model with a NEO trader priority; NEO-N, which prioritizes larger resting orders over smaller orders, imposes a speed bump, and displays volume aggregate by price, with a taker-maker pricing model; NEO-D, which allows participants to submit marketable and resting orders with specified parameters and NEO trader priority with size-time priority, with a taker-maker pricing model; and MATCHNow, which combines frequent call matches and continuous execution opportunities in a confidential trading book, using real-time quotes for protected transparent Canadian markets, accepting both firm and conditional orders, and matching firm orders at three levels of price improvement. Trading fees are typically calculated as a function of trade volume and share price.
In Europe, we operate a number of market models, including continuous Lit orderbooks, periodic auction orderbooks, dark midpoint orderbooks, a post-closing cross, as well as BIDS Europe. Fees are typically charged on an ad valorem basis based on traded notional value, and are differentiated by orderbook, by order type, by monthly value traded, and in the case of Lit orderbooks by liquidity providing/taking orders where (on a subset of orderbooks) a rebate may be paid to the provider of passive liquidity. Following the implementation of the Directive on Markets in Financial Instruments (Directive 2014/65/EU) (“MiFID II”), for the derivatives and cash and spot markets, rebates are generally available if they are tied to a market making scheme or specific service.
In Australia, for our derivatives and cash and spot markets, Cboe Australia, a regulated stock exchange, which is fully electronic, utilizes a model that charges a different ad valorem fee rate depending on whether a participant is making or
taking liquidity. Fee waivers are also provided to participants registered as market makers, but payments for order flow are prohibited.
In Japan, for our cash and spot markets, Cboe Japan, offers two fully electronic displayed markets, Cboe-Alpha, which utilizes a price-time market model, combined with the “maker-taker” pricing model and Cboe-Select, which utilizes a price-time retail customers focused market model, combined with the “taker-maker” pricing model. Cboe Japan also offers two fully electronic non-displayed markets, Cboe-Match, which matches volume-weighted average price (“VWAP”) orders during pre-market hours and Cboe BIDS Japan, which utilizes a price-time market model aiming for primary market mid-point trades.
For our FX spot markets, the Cboe FX platform utilizes a price-firmness-time priority market model, combined with a pricing model where users are charged either a flat or tiered commission rate based upon the notional amount traded on the platform. For our FX NDF markets, Cboe SEF utilizes a price-firmness-time priority market model and charge a flat commission based upon the notional amount traded on the platform and the capacity in which a participant is trading. Cboe Digital, which is fully electronic, for our digital asset spot and futures markets, utilizes a price-time priority model.
Our markets also charge fees for the opportunity to trade or access our markets, including fees for trading-related functionality. To facilitate trading, we also charge fees for certain technology services, terminal and other equipment rights, maintenance services, trading floor space and telecommunications services.
Listing
Cboe operates five listing venues across the globe that are structured and designed, in the U.S. and Canada, for all types of equity instruments, such as ETPs, corporate securities, warrants and depositary receipts, while in the UK and EU they support ETPs only. In Australia, both ETPs and warrants are supported. Over the course of 2023, Cboe added approximately 800 listings across the globe and had approximately 2,080 listings for the year ended December 31, 2023. Cboe also launched Cboe Global Listings in June of 2023, the first-of-its-kind, global listing network facilitating worldwide access to capital and secondary liquidity for companies and ETFs, and successfully attracted its first intralisted corporate issuer to the global platform.
Clearing
Our subsidiary Cboe Clear Europe, a European central counterparty (“CCP”), provides post-trade clearing services, to stock exchanges, multilateral trading facilities and for over-the-counter equities trades and exchange-traded derivatives trades. Cboe Clear Europe acts as a central counterparty that, for its clearing participants, becomes the buyer to every seller and the seller to every buyer. As a result, it guarantees the timely performance of the settlement obligations of buyers and sellers and takes on the risk of the performance of the transactions that it clears. Additionally, as a Financial Market Infrastructure, Cboe Clear Europe is subject to strict business continuity requirements and regulatory oversight. In 2023, Cboe Clear Europe provided CCP protection for an average of €44 billion of cleared value on a daily basis. Through the process of netting, in 2023, Cboe Clear Europe eliminated 71%, or €31 billion of the average daily cleared value, leaving an average daily settlement value of €13 billion. In 2022, Cboe Clear Europe provided CCP protection for an average of €48 billion of cleared value on a daily basis. Through the process of netting, in 2022, Cboe Clear Europe eliminated 71%, or €34 billion of the average daily cleared value, leaving an average daily settlement value of €14 billion.
Cboe Clear Digital is a digital asset clearinghouse and central counterparty that provides clearing and settlement of digital asset trades for its affiliate, Cboe Digital Exchange. Cboe Clear Digital clears cryptocurrencies from 50 U.S. jurisdictions authorized by license or not subject to licensing. In 2023, Cboe Clear Digital cleared $18 billion in notional volume. In 2022, for the period subsequent to the acquisition, Cboe Clear Digital cleared $4 billion in notional volume.
Customers
Our customers generally include financial institutions, trading platforms, institutional and individual investors, and professional traders. Our equities and options customers in the United States include trading permit holders and members (as applicable) of Cboe Options, C2, BZX, BYX, EDGX, and EDGA, which are SEC-registered broker-dealers, and the customers of those broker-dealers. Our Canadian equities customers include members of Cboe Canada Inc., which are Canadian registered investment dealers. Our Australian customers include trading participants of Cboe Australia, which are Australian registered investment dealers, and certain clients of those dealers. Our Japanese customers include participants of Cboe-Alpha, Cboe-Select, Cboe-Match and Cboe BIDS Japan, which are Japanese registered broker-dealers, and certain clients of those dealers. Our ATS equities participants in the United States include subscribers of
BIDS Trading, which are SEC-registered broker-dealers, and certain customers of those broker-dealers. Our futures customers include banks, futures commission merchants and their customers, hedge funds, asset managers, proprietary trading firms, and Commodity Trading Advisors. Similarly, our equities’ customers in Europe are European Union (“EU”) regulated brokerage and proprietary trading firms, as well as sponsored access clients of these brokerage firms and certain non-EU regulated and unregulated direct access participants. Cboe Clear Europe clears equities, equity like instruments traded on 47 European trading segments. Cboe Clear Europe also clears equity derivative instruments traded on Cboe NL. Cboe Clear Europe clearing participants include EEA regulated banks and brokerage trading firms. Our institutional global FX customers include banks, broker-dealers, hedge funds, asset managers, proprietary trading firms, Commodity Trading Advisors, and corporates. Our digital asset customers in the U.S. include SEC-registered broker-dealers, the customers of those broker-dealers, financial institutions, trading platforms, institutional and individual investors, futures commission merchants, introducing brokers, and professional traders. Access to our markets and trading rights and privileges depend upon the nature of the customer, such as whether the individual or firm is (or is eligible to become) a trading permit holder, trading privilege holder, member, participant, or subscriber of one of our markets.
Competition
The industry in which we operate is intensely competitive. We believe we face competition on a number of factors, including:
| ● | price, quality and speed of our trade and clearing execution; |
|---|
| ● | functionality and ease of use of our trading and clearing platforms; |
|---|
| ● | reliability, integrity, range and functionality of our products and services; |
|---|
| ● | integrity of our marketplaces; |
|---|
| ● | technological innovation and adaption; |
|---|
| ● | our brand awareness; and |
|---|
| ● | our reputation. |
|---|
We believe that we compete favorably with respect to these factors through a variety of methods, including:
| ● | offering access to a broad array of products and services, including proprietary products and market data; |
|---|
| ● | offering fee schedules and pricing models that both attract order flow and provide incentives to liquidity providers; |
|---|
| ● | providing advanced technology that offers broad functionality, low latency, fast execution, ease of use, scalability, reliability and security; |
|---|
| ● | offering efficient, transparent and liquid marketplaces; |
|---|
| ● | offering deep and liquid markets with opportunities for price improvement; |
|---|
| ● | offering broad trading platform access in the EU; |
|---|
| ● | offering efficient and transparent clearing services designed to help maximize netting opportunities; |
|---|
| ● | maintaining close relationships with customers; and |
|---|
| ● | providing customers with a comprehensive source of information on options and ETPs as well as extensive options education. |
|---|
In our proprietary products, we compete against other futures exchanges and swap execution facilities that offer similar products, as well as against financial market participants that offer similar over-the-counter derivatives. We also compete against certain multi-listed options products, such as SPY options and cash settled index options, which may offer similar market exposure of our proprietary products, such as SPX options.
The multi-listed options industry is extremely competitive. We expect this trend to continue. As of December 31, 2023, our four options exchanges compete with 13 other U.S. options exchanges, in large part due to existing exchange holding companies opening new exchanges that offer different markets and pricing models on existing technology. Most of the equity and ETP options listed and traded on our exchanges are also listed and traded on the other exchanges. In addition, the options exchanges that we compete with set fees and rebates to attract multi-listed options business to their exchanges, which has historically reduced the net revenue per contract that we generate from multi-listed options, and the options exchanges that we compete with structure their options businesses in partnership with established market participants, such as consolidators, and other order flow providers, to increase their volume traded.
Our U.S. equities and the BIDS Trading ATS compete against 12 other equities exchanges as of December 31, 2023, and over 25 other ATSs and single dealer platforms. Market participants have multiple venues for the execution of orders, including national securities exchanges and numerous off-exchange venues, including other ATSs and broker-dealers that internalize orders off-exchange. Additionally, corporate and ETP issuers have multiple venues they can choose from in the listing of their products. In Canada, our recognized Canadian securities exchange, Cboe Canada Inc., competes with several Canadian exchanges and ATSs. In Australia, our exchange, Cboe Australia, competes with other Australian exchanges and ATSs. In Japan, our equities exchanges and ATSs, compete with several Japanese exchanges and other ATSs.
The market for execution and clearing services in Europe became more competitive following the introduction of MiFID II and the Regulation on Markets in Financial Instruments (Regulation (EU) No 600/2014) (“MiFIR”). Our major competitors in Europe include national stock exchanges, other pan-European MTFs, systematic internalizers, and other European clearinghouses.
The global FX market remains severely fragmented, with transparent automated marketplaces such as Cboe FX challenging a small number of similarly situated competitors. While the global FX market has experienced a shift from competing interbank platforms to ECNs, the electronification of the spot and NDF FX market may encounter resistance from customers that still prefer to utilize the phone, instant chats, terminals and key banking relationships for price discovery and trading. Furthermore, electronification of the FX market appears to be experiencing more resistance outside the U.S. The electronic spot FX market is also intensely competitive, with over 10 other venues competing for market share as of December 31, 2023. Cboe measures and reports on market share against a narrower set of competitors, included in those venues.
Our digital asset spot market, regulated futures exchange, and regulated clearinghouse, compete against other spot trading platforms, futures exchanges, and decentralized trading platforms that offer similar instruments.
In addition, our data and access solutions face competition from other securities exchanges, technology companies, third-party market data providers, and information and software vendors, which have their own substantial market data distribution capabilities that serve as alternative means for receiving open market data feeds instead of connecting directly to our exchanges or trading venues. The sale of our proprietary data products is also under competitive threat from ATSs and trading venues that offer similar products. Distributors and consumers of our market data may also use our market data as an input into a product that competes against one of our traded or cleared products.
Technology
Cboe Trading Technology
The trading platform for our equities, options, and futures markets is developed, owned, and operated in-house and is designed to optimize reliability, speed, scalability, and versatility. Our exchanges provide different market models, appealing to different user bases, and the trading technologies support all of them. Further, the technologies are designed to support many specialized features for each of the markets, such as: dark pools, trade reporting facility, systematic internalizer, Large-in-Scale, smart order routing, FLEX options, 24x5 trading, and hybrid trading (combining electronic and open outcry). In addition, Cboe and its applicable subsidiaries operate separate trading and/or clearing platforms, as applicable, for BIDS Trading, certain Cboe Canada Inc. order books, Cboe Digital, Cboe Clear Europe, and Global FX.
Our trading platforms have generally experienced very low operational downtime and low latency. The trading platforms use readily available hardware, thereby minimizing capital outlays required for each new market entry. Also, in order to continue to implement new enhancements to our trading platforms, new releases of software are generally deployed routinely in all of the applicable markets.
Disaster Recovery
We operate and maintain geographically diverse disaster recovery facilities for all of our markets. We expect that the disaster recovery facilities can be up and running in a short period of time and in certain instances we work with our market participants to try to quickly reopen marketplaces. We regularly test our data center recovery plans and periodically carry out weekend tests using our back-up data centers, as well as an annual test with our U.S. trading participants. In Canada, as required by local regulations, Cboe Canada Inc. conducts internal testing of its disaster recovery data processing capabilities at least annually, and it participates in the bi-annual testing coordinated by CIRO. Cboe Australia and Cboe Japan conduct internal testing of their disaster recovery data processing capabilities at least annually. In Europe, we also regularly test our data center recovery plans and periodically carry out weekend tests which
use our back-up data center, as well as an annual test with our European trading participants. We continue to work to improve both the availability of our technology and our disaster recovery facilities.
Emerging Technologies
We are exploring the potential use of new technologies, such as artificial intelligence (“AI”), machine learning, blockchain, distributed ledger technology, quantum computing, tokenization, the cloud, and other emerging technologies to potentially help drive new products, increase productivity, improve our self-regulatory oversight responsibilities, and increase automation of tasks.
Routing and Clearing
OCC is the sole provider of clearing on all of our U.S. options exchanges and CFE. National Securities Clearing Corporation (“NSCC”), a subsidiary of the Depository Trust and Clearing Corporation (“DTC”), is the sole provider of clearing on our U.S. listed equity exchanges. The Canadian Depository for Securities (“CDS”) is the sole provider of clearing on all equities transactions occurring on Cboe Canada Inc. With respect to Australian equities and derivatives, Cboe Australia delivers matched trades of its customers to ASX Clear Pty Ltd and ASX Settlement Pty Ltd. ASX Clear Pty Ltd acts as a central counterparty on all transactions occurring on Cboe Australia. The Japan Securities Clearing Corporation (“JSCC”) is the sole provider of clearing on all equities transactions occurring on Cboe Japan’s Cboe-Alpha, Cboe-Select, Cboe-Match and Cboe BIDS Japan. BofA Securities, Inc. (“BOA”) is the sole provider of clearing on all equities transactions occurring on BIDS Trading. Cboe Europe Equities relies on LCH Limited and LCH SA (“LCH”), Cboe Clear Europe, and SIX x-clear Ltd (“SIX x-clear”) to clear trades in European listed equity securities and exchange traded products as part of an interoperable clearing model. For derivatives, Cboe NL relies on Cboe Clear Europe to clear both index and single stock derivative contracts. Cboe Clear Digital is the sole provider of clearing and settlement of all digital asset transactions occurring on Cboe Digital Exchange.
Cboe Trading is a routing broker-dealer used by our four U.S. equities exchanges and our four U.S. options exchanges, including the electronic platform portion of Cboe Options. Cboe Trading’s clearing firms are Wedbush Securities, Inc. (“Wedbush”) and Morgan Stanley & Co. LLC (“Morgan Stanley”).
Digital Assets and Recent Developments
Cboe Digital is an operator of a U.S. based digital asset spot market, a regulated futures exchange, and a regulated clearinghouse. As described in further detail below, Cboe Digital does not engage in proprietary trading activities and does not maintain a trading entity. Cboe Digital does not itself trade digital assets, does not trade on its own exchange, and does not maintain an affiliate trading entity for purposes of trading, market making, or liquidity provision on its exchange. Cboe Clear Digital maintains its own operating funds in separate bank accounts from its customer funds. Each bank account and digital wallet is appropriately titled in accordance with applicable regulatory requirements thus helping to ensure that customer assets are clearly denoted as such.
Cboe Digital takes several steps to isolate the digital assets held for customers from its own assets and to structure customer accounts in a way that reinforces customer ownership of digital assets. Primarily, Cboe Digital holds customer digital assets separate from its own assets in customer accounts, referred to as wallets, with long-term storage by a third party custody provider and licensed trust company. When Cboe Digital temporarily holds digital asset for customers to enable the inbound receipt and outbound transmittal of virtual currencies, customer digital assets are held in omnibus wallets titled for the benefit of customers of Cboe Digital. Digital assets of customers (but not those of Cboe Digital) are held together in the omnibus wallets, and Cboe Digital maintains the records of the amount and type of digital asset owned by each of its customers in the omnibus wallets. Cboe Digital does not hold its own corporate assets together with the customer digital assets in the omnibus wallets, other than corporate assets that are held in omnibus wallets to facilitate customer transactions relating to the digital assets contained in the omnibus wallet, including in order to pay customary transaction fees and expenses. Because Cboe Digital does not have a trading entity for proprietary or liquidity trading purposes, Cboe Digital maintains its own digital assets only to facilitate customer trading. Cboe Digital does not currently pledge, rehypothecate, or invest customer digital assets, although its customer agreements and rulebook permit it to do so in the future. Additionally, Cboe Digital does not otherwise use customer digital assets for its own corporate or business purposes.
Further, Cboe Digital holds customer digital clearing assets through accounts with third party custodians and, in the case of hot and warm wallets, through self-custody. Cboe Digital’s custody strategy is designed to maximize liquidity and efficient access to assets by making those assets readily available. Cboe Digital monitors its cash and the digital asset balances it maintains with custodians. Digital assets require control of one or more unique public and private keys relating
to the local or online digital wallet in which the digital assets are held. The networks require one or more private keys relating to a digital wallet to authorize a spending transaction. If private keys are lost or destroyed, this could prevent the ability to transfer the corresponding digital asset. Security breaches, computer malware, and computer hacking attacks have been a prevalent concern in digital asset markets. Cboe Digital has committed to securely store digital assets it holds on behalf of users. As such, Cboe Digital may be liable to its users for losses arising from theft or loss of user private keys. Cboe Digital has no reason to believe it will incur any expense associated with such potential liability because (i) it has no known or historical experience of claims to use as a basis of measurement, (ii) it accounts for and continually verifies the amount of digital assets within its control, and (iii) it has established security around custodial private keys to minimize the risk of theft or loss.
Also, Cboe Digital is exposed to risk with respect to digital asset prices and valuations which are largely based on the supply and demand for those digital assets in financial markets. Cboe Digital’s valuation governance framework includes numerous controls and other procedural safeguards that are intended to maximize the quality of fair value measurements. New products and valuation techniques are reviewed and approved by senior management. Cboe Digital’s valuation process for digital assets are fair value estimates that are also validated by the finance control function independently. Independent price verification is performed by finance control through benchmarking fair value estimates with observable market prices or other independent sources. Reasonably designed controls and governance framework are in place and are intended to help ensure quality third-party pricing sources were used.
Cboe Clear Digital clears cryptocurrencies from 50 U.S. jurisdictions authorized by license or not subject to licensing. Cboe Clear Digital performs a guarantee function whereby Cboe Clear Digital helps to ensure that the obligations of the transactions it clears are fulfilled. Spot trading is either cleared on a fully funded basis or by providing non-material daily trading limits to certain well-qualified institutional clearing members. In order to help mitigate the impact of any potential default by such a clearing member, extension of any trading limits is accompanied by performing credit due diligence, requiring posting of collateral or other forms of financial guarantee and hard pre-trade limits. Cboe Digital does not allow access from unauthorized or impermissible jurisdictions, and has taken active steps to help prevent such access and to help prevent circumvention of our controls. To help ensure an orderly market, Cboe Digital maintains digital assets to support its clearing operations which may be subject to significant changes in value and therefore exposed to market risk with the fluctuation in market prices. Cboe Digital monitors this risk on a daily, weekly and monthly basis. The business model is such that Cboe Digital earns digital assets and at times may accumulate positions that are subject to market risk. Customer positions do have market risk based on daily activity and settlement prices.
While Cboe Digital and its vendors have experienced cybersecurity threats and events of varying degrees, we are not aware of any of these threats or events having a material impact on Cboe Digital’s business, financial condition or operating results to date. However, there can be no assurance that we or our vendors and custodians will not experience future threats or events that may be material. If any such threats or events materialize, we may be subject to contractual restrictions, liability and damages, loss of business, penalties, unfavorable publicity, and increased scrutiny by regulators, which may have an adverse effect on our business.
The bankruptcy of FTX and the bankruptcies of other digital asset platforms has brought increased scrutiny to the digital asset industry. FTX’s bankruptcy and the bankruptcies of other digital asset platforms did not have a direct material effect on Cboe’s overall business or financial condition in 2023.
Cboe Digital launched trading and clearing in margin futures on Bitcoin and Ether on January 11, 2024. With this launch, Cboe Digital became the first U.S. regulated crypto native exchange and clearinghouse to enable both spot and leveraged derivatives trading on a single platform.
See “Risk Factors” for more information regarding Cboe Digital.
Regulatory Environment and Compliance
Various aspects of our business are subject to regulation by the SEC, CFTC, FINRA, the New York Department of Financial Services (“NYDFS”), various state regulators, CIRO, the Canadian Securities Administrators (and, in particular, the Ontario Securities Commission or “OSC”), the Australian Securities & Investments Commission (“ASIC”), JFSA, JSDA, ESMA, FCA, the Central Bank of the Netherlands (“DNB”), AFM, Bank of England, and other international regulatory authorities where our exchanges or Cboe Clear Europe may be authorized to act as foreign exchanges or provide clearing services, and market participants may be subject to regulation by the SEC, CFTC, FINRA, National Futures Association (“NFA”), FCA, Board of Governors of the Federal Reserve, U.S. Department of the Treasury and/or
foreign regulators. The following is a discussion of the more significant areas of regulation of us by the SEC, the CFTC, and certain European regulators.
Recent Developments
Laws and regulations regarding our business are frequently modified or changed to address perceived problems, new products, or competition or at the request of market participants. The following is a brief discussion of recent regulatory developments that may significantly impact our business.
United States
Equity Market Structure
In December 2022, the SEC released four proposals that could impact equity market structure: (1) Disclosure of Order Execution Information (Rule 605); (2) Regulation NMS Amendments: Tick Size, Access Fees, and Transparency; (3) Regulation Best Execution; and (4) Proposed Rule to Enhance Order Competition. These proposals have been noticed for public comment. If adopted as-is, final implementation of these equity market structure proposals could occur in late 2024 and 2025 and could result in market technology changes and additional compliance costs to Cboe. Further, it is possible that additional proposals or changes to the existing equity market structure, which could have a negative impact on our operations. In addition, bills are sometimes introduced in the U.S. Congress that could also potentially impact equity market structure and adversely impact our volumes and operations. See “Risk Factors” for more information.
Volume Based Pricing Proposal
On October 18, 2023, the SEC released a proposed rule that would impact the way in which volume based discounts are applied (“Volume Based Proposal”). If adopted, this Volume Based Proposal would prohibit national securities exchanges, including Cboe’s equities exchanges, BZX, BYX, EDGX, and EDGA, from offering volume-based transaction pricing in connection with the execution of agency or riskless principal orders in NMS stocks. Although the new rules do not appear likely to have a near term material impact, the new rules may have a long term material impact on our business, financial condition and operating results if, for example, there is a reduction of overall volumes, liquidity, or market share on Cboe’s equities exchanges, BZX, BYX, EDGX, and EDGA. See “Risk Factors” for more information.
Digital Asset Legislation
Members of U.S. Congress have introduced various bills related to the regulation of digital assets, however no legislation has been passed and the details of any potential legislation remain to be discussed and agreed. While some of these contemplated changes could reduce regulatory uncertainty, increase transparency, and promote investor protection, which could be beneficial for Cboe Digital’s volumes and liquidity, the implementation of certain changes could result in a reduction in overall volumes and liquidity or require additional resources to comply with any new rules included as part of the legislation, which could have a negative impact on our operations. See “Risk Factors” for more information.
Europe
Capital Markets Union
The European Council (“E.C.”) has highlighted one of its top priorities as being the establishment of a fully functioning, well-regulated Capital Markets Union (“CMU”). An Action Plan of concrete steps was set out in September 2015, and an update of the list of initiatives was published in September 2016. In November 2019, the E.C. set up a High Level Forum on CMU, resulting in a final report published in June 2020. On September 24, 2020, the E.C. published a new CMU Action Plan, and on November 25, 2021, published a set of legislative proposals in furtherance of the CMU, including proposals to amend the Markets in Financial Instruments Regulation (“MiFIR”) described in the EU Transparency Rules section below. This therefore remains an ongoing project for the E.C., which may result in additional regulation or legislation. In November 2021 the EU Commission published an update regarding progress against the CMU Action Plan alongside a number of new legislative proposals designed to contribute to the objectives of CMU.
These included proposals to:
| ● | Create a European Single Access Point (“ESAP”) which will be a common source of public, free information about EU companies and investment products, regardless of where in the EU they are located or originated. |
|---|
| ● | Amend the ELTIF framework to promote long-term investments through European Long-Term Investment Funds (“ELTIFs”). |
|---|
| ● | Make funding more diversified for companies by reviewing the Alternative Investment Fund Managers Directive (“AIFMD”). |
|---|
| ● | Enhance market transparency by reviewing the Markets in Financial Instruments Regulation (“MiFIR”). |
|---|
| ● | Create a binding, comprehensive information and communication technology risk management framework for the EU financial sector through the Digital Operational Resilience Act (“DORA”). |
|---|
Many of the above initiatives have been legislated for and are now in the process of being implemented. Further detail on the MiFIR review is provided below.
OTC Derivatives, Central Counterparties and Trade Repositories
Regulation (EU) No 648/2012 of the European Parliament and of the Council of July 4, 2012 on OTC derivatives, central counterparties and trade repositories (the “European Market Infrastructure Regulation” or “EMIR”) sets out rules relating to over-the-counter (“OTC”) derivatives markets, central counterparties and trade repositories. EMIR was enhanced and amended by EMIR REFIT and EMIR 2.2. In December 2022, the EU Commission published a proposal to further amend EMIR with the primary goal of making EU clearing services more attractive to market participants. This proposal is currently going through the usual legislative procedure.
In addition, regulation governing the authorization and supervision of Central Securities Depositories (“CSDR”) was approved in September 2014, with the publication of most “Level 2” Regulatory Technical Standards in March 2017, with implementation in March 2019. Rules in relation to the calculation and collection of cash penalties have come in to force in February 2022. In November 2022, ESMA published a proposal to amend CSDR to simplify the cash penalties process for cleared transactions. This proposal has since been adopted and will come into force in September 2024. Furthermore, CSDR Refit has been adopted and will come into force from the 1st of May 2024 onwards depending on the specific articles.
The Central Counterparty Recovery and Resolution Regulation (“R&R Regulation”) was published in the Official Journal of the EU on January 22, 2021, which resulted in an increase in the amount of prefunded capital Cboe Clear Europe is required to maintain. This additional prefunded capital is required to be drawn before any recovery measures can be taken by the CCP. On July 12, 2021, and November 18, 2021, ESMA proposed a set of level 2 and level 3 guidance pursuant to the R&R Regulation, which have been adopted by the European Commission and, except for one regulation, have been published in the Official Journal of the EU.
EU Transparency Rules
On November 11, 2021, the European Council (“E.C.”) published its proposal for a review of EU market structure legislation, including proposed amendments to Markets in Financial Instruments Regulation (“MiFiR”) and Directive 2014/65/EU on markets in financial instruments (“MiFID II”). The legislative phase of the review is now almost complete. The final text includes, among other provisions, provision for a consolidated tape for the EU and changes to the transparency regime for equities. These provisions are expected to be implemented in 2025. The legislation, as drafted, does not appear likely to have a material adverse effect on our business, financial condition and operating results. However, there are review clauses contained in the legislation which provide a further opportunity to review the effectiveness of the transparency regime, at which point, potential changes may have a material adverse effect on our business, financial condition and operating results. See “Risk Factors” for more information.
Compliance
U.S. Securities Industry
Federal securities laws have established a two-tiered system for the regulation of securities exchanges and market participants. The first tier consists of the SEC, which has primary responsibility for enforcing federal securities laws. The second tier consists of self-regulatory organizations (“SROs”), which are non-governmental entities that must register with and are regulated by the SEC. The Exchanges are SROs, each registered under Section 6 of the Exchange Act of 1934, as amended (“Exchange Act”) as a “national securities exchange,” and are subject to oversight by the SEC.
SROs are an essential component of the regulatory scheme of the Exchange Act for providing fair and orderly markets and protecting investors. To be registered as a national securities exchange, an exchange must successfully undergo an application and review process with the SEC prior to beginning operations. Among other things, the SEC must determine that the SRO has the ability to comply with the Exchange Act and to enforce compliance by its members and persons associated with its members with the provisions of the Exchange Act, the rules and regulations thereunder and the rules of the exchange.
In general, an exchange SRO is responsible for operating its trading platforms consistent with its rules, and regulating its members through the adoption and enforcement of rules governing the business conduct of its members. The rules of the exchange must also assure fair representation of its members in the selection of its directors and administration of its affairs and, among other things, provide that one or more directors be representative of issuers or investors and not be associated with a member of the exchange or with a broker or dealer. Additionally, the rules of the exchange must be adequate to ensure fair dealing and to protect investors and may not impose any burden on competition not necessary or appropriate in furtherance of the purposes of the Exchange Act.
As registered national securities exchanges, virtually all facets of our Exchange operations are subject to the SEC’s oversight, as prescribed by the Exchange Act. The Exchange Act and the rules thereunder impose on us many regulatory and operational responsibilities, including record keeping and the day-to-day responsibilities for market operations and broker-dealer oversight. Furthermore, as SROs, the Exchanges are potentially subject to regulatory or legal action by the SEC or other interested parties. The SEC also has broad enforcement powers to censure, fine, issue cease-and-desist orders, prohibit us from engaging in some of our businesses, suspend or revoke our designation as a registered securities exchange or remove or censure any of our officers or directors who violate applicable laws or regulations. For example, in the past we have entered into consent orders with the SEC, under which our subsidiaries were censured, ordered to cease and desist from violating certain sections of the Exchange Act, paid fines and completed certain undertakings.
As part of its regulatory oversight, the SEC conducts periodic reviews and inspections of exchanges, and the Exchanges have been subject to such routine reviews and inspections. To the extent such reviews and inspections result in regulatory or other changes, we may be required to modify the manner in which we conduct our business, which may adversely affect our business. We collect certain fees to cover Section 31 fees charged to the Exchanges by the SEC and certain fees derived from our regulatory function and fines in connection with our disciplinary proceedings. The Exchanges are responsible for the ultimate payment of Section 31 fees to the SEC. Additionally, under the rules of each of our exchanges, as required by the SEC, any revenue derived from the regulatory fees and fines cannot be used for non-regulatory purposes.
Section 19 of the Exchange Act also provides that we must submit to the SEC proposed changes to any of the Exchanges’ rules, including revisions of their certificates of incorporation, bylaws, or other governing documents of the SROs or their parent companies. The SEC will typically publish the proposal for public comment, following which the SEC may approve or disapprove the proposal, as it deems appropriate. Certain categories of rule changes, like fee changes, can be effective on filing, but the SEC retains the ability to suspend or reject such filings within a prescribed period of time.
Canadian Securities Industry
Cboe Canada Inc. is subject to comprehensive regulation and oversight by its primary provincial securities regulatory authority, the OSC. In addition, Cboe Canada Inc. is a Marketplace Member of, and subject to a regulation services agreement with, CIRO. The regulations applicable to Cboe Canada Inc. cover a wide array of areas, including, but not limited to, marketplace operations (which include corporate governance, fair access, systems compliance and integrity, and conflict management requirements), trading rules, electronic trading risk management, and financial viability.
Australian Securities Industry
Cboe Australia is subject to comprehensive regulation and oversight by ASIC. The regulations applicable to Cboe Australia cover a wide array of areas, including, but not limited to, marketplace operations (which include corporate governance, fair access, systems compliance and integrity, and conflict management requirements), trading rules, electronic trading risk management, and financial viability.
Japanese Securities Industry
Cboe Japan is subject to comprehensive regulation and oversight by the JFSA and the JSDA. The regulations applicable to Cboe Japan cover a wide array of areas, including, but not limited to, marketplace operations (which include corporate governance, fair access, systems compliance and integrity, and conflict management requirements), trading rules, electronic trading risk management, and financial viability.
Futures and Swaps Industry-CFE and Cboe SEF
The operations of each of CFE and Cboe SEF are subject to regulation by the CFTC under the Commodity Exchange Act (“CEA”). The CEA generally requires that futures trading in the United States be conducted on a designated contract market and, in some cases, requires swaps trading to be conducted on a swap execution facility (“SEF”) or designated contract market (“DCM”). The CEA and CFTC regulations establish criteria for an exchange to be designated as a contract market on which futures and futures options contracts may be traded, and for a trading platform to be designated as a swap execution facility on which certain swaps may be traded. Designation as a contract market or swap execution facility for the trading of specified futures or swaps contracts is non-exclusive. This means that the CFTC may permit additional exchanges or trading platforms to be contract markets or swap execution facilities for trading the same or similar contracts.
CFE is a designated contract market, and Cboe SEF is a swap execution facility, each of which is subject to the oversight of the CFTC and to a variety of ongoing regulatory and reporting responsibilities under the CEA. As a designated contract market, CFE is required to comply with the applicable core principles and regulations under the CEA, as is Cboe SEF as a swap execution facility. Each of CFE and Cboe SEF has surveillance and regulatory operations and procedures to monitor and enforce compliance by trading privilege holders with CFE rules, and by participants with Cboe SEF rules, as applicable. If CFE or Cboe SEF fails to comply with applicable laws, rules or regulations, it may be subject to censure, fines, cease-and-desist orders, suspension of its business, removal of personnel or other sanctions, including revocation of CFE’s designation as a contract market or Cboe SEF’s designation as a swap execution facility.
Digital Assets
Cboe Digital Exchange is a designated contract market, and Cboe Clear Digital is a derivatives clearing organization, each of which is subject to the oversight of the CFTC and to a variety of ongoing regulatory and reporting responsibilities under the CEA. As a designated contract market, Cboe Digital Exchange is required to comply with the applicable core principles and regulations under the CEA, as is Cboe Clear Digital as a derivatives clearing organization. Each of Cboe Digital Exchange and Cboe Clear Digital has surveillance and regulatory operations and procedures to monitor and enforce compliance by trading privilege holders with Cboe Digital Exchange rules, and by participants with Cboe Clear Digital rules. If Cboe Digital Exchange or Cboe Clear Digital fails to comply with applicable laws, rules or regulations, it may be subject to censure, fines, cease-and-desist orders, suspension of its business, removal of personnel or other sanctions, including revocation of Cboe Digital Exchange’s designation as a contract market or Cboe Clear Digital’s designation as a derivatives clearing organization.
Cboe Clear Digital also maintains a license to operate as a money transmitter in the states where such licenses or equivalent are required to conduct business. In addition, Cboe Clear Digital has a BitLicense from the NYDFS. As a licensed money transmitter and an entity subject to the BitLicense regulatory regime, Cboe Clear Digital is subject to, among other things, the Bank Secrecy Act, restrictions and requirements with respect to the investment of customer funds and use and safeguarding of customer funds and crypto assets, and bonding, net worth, customer notice and disclosure, reporting and recordkeeping requirements applicable to the company and control persons, and inspection and examination by state regulatory agencies.
Europe
Cboe Europe is located in London and is subject to regulation in the UK and to certain European regulations. The current UK regulatory system was established by the Financial Services Act 2012 (“FSA12”), which amended the Financial Services and Markets Act 2000. The legislation replaced the previous financial services regulator, the Financial Services Authority, with three new bodies: The Financial Policy Committee (“FPC”), The Prudential Regulation Authority, and the FCA. Financial conduct of markets, including activity on, and the operation of, markets is regulated by the FCA, which is an independent non-governmental body, given statutory powers by the FSA12. The FCA has three statutory objectives: to secure an appropriate degree of protection for consumers; to protect and enhance the integrity of the UK financial system; and to promote effective competition in the interests of consumers in the markets for financial services. The FCA is accountable to His Majesty’s Treasury Ministers and, through them, to Parliament.
Cboe Clear Europe and Cboe NL are located in Amsterdam and subject to Dutch law and regulation. The current Dutch regulatory system was established by the Act on Financial Supervision. Financial conduct of markets, including activity on, and the operation of, markets is regulated by the AFM. Financial conduct of CCPs, including clearing activity is regulated by the AFM and DNB. The AFM is an independent non-governmental body, given statutory powers by the Act on Financial Supervision. The AFM has three strategic objectives: to promote the fair and conscientious provision of financial services, to promote the fair and efficient operation of the capital markets and to contribute to the stability of the financial system. The AFM is accountable to the Minister of Finance. The DNB is the Dutch central bank, financial sector supervisor and resolution authority. The DNB is committed to a stable financial system: stable prices, solid financial institutions and properly functioning payment transfers. Cboe Clear Europe is recognized as a non-UK CCP in the United Kingdom, which allows it to provide services to UK Clearing Participants and UK trading venues. Cboe Clear Europe is also recognized as a foreign central counterparty in Switzerland, which allows it to provide services to Swiss Clearing Participants and SIX Swiss Exchange AG.
Much of the UK and Dutch financial services regulation originates from the EU. Such regulation includes organizational requirements, capital resources requirements and the specific requirements for RMs and MTFs and are applicable to both Cboe Europe and Cboe NL. MiFID II and MiFIR set out requirements for RMs and MTFs with respect to the establishment of transparent and non-discretionary rules and procedures governing access and for fair and orderly trading and the efficient execution of orders, as well as to facilitate the efficient settlement of transactions conducted on RMs and MTFs and monitoring compliance with the rules. EMIR governs the CCPs operating in the EU and requires them to meet common risk management, governance and capital adequacy standards. The regulatory functions required of Cboe Europe Equities and Derivatives, including Cboe Clear Europe and Cboe NL, by MiFID II, MiFIR, EMIR and other relevant legislation and regulations are performed by in-house staff. Cboe Europe Equities and Derivatives utilizes the same state-of-the-art, real-time surveillance system is used on the U.S. to monitor trading and market activities on BZX, BYX, EDGA, and EDGX. Cboe Clear Europe utilizes proprietary risk management software to monitor settlement and funding flows.
Global FX
While the global institutional spot FX market remains largely unregulated, the enactment of the Dodd Frank Act and its related regulations in the United States and the ongoing implementation of MiFID II and MiFIR in Europe have impacted the regulatory landscape for currency derivative products. For example, certain standardized currency derivative products are required to trade on an organized trading venue such as a SEF or DCM in the United States or on an MTF or organized trading facility in Europe. Moreover, even in the largely unregulated spot FX market, this movement towards additional trading standards and norms is highlighted by the publication of the FX Global Code in 2017 by the Global Foreign Exchange Committee, reflecting principles of good conduct for the wholesale FX market, and whose publication may lead to additional oversight in the global FX market. Cboe FX issued a Statement of Commitment declaring its commitment to conduct its FX market activities in a manner consistent with the principles of the FX Global Code. Following the publication of the FX Global Code regulators are taking a new look at the spot FX market, and any decision to impose new regulations may affect our spot FX business line.
Broker-Dealers
Cboe Trading, BIDS Trading, and Cboe Fixed Income are registered broker-dealers regulated by the SEC, FINRA, other SROs of which they are members and various state securities regulators. Cboe Trading currently operates as a routing broker-dealer for sending orders from the Exchanges to other venues for execution, including routing orders among the Exchanges. Cboe Trading is considered a facility of each of the Exchanges and is subject to the rules of the Exchanges. The Exchanges are responsible for enforcing Cboe Trading’s compliance with their rules, including to ensure
Cboe Trading is not given preferential treatment. BIDS Trading currently operates an ATS, which is designed to bring counterparties together to anonymously trade large blocks of U.S. equities. BIDS Trading is not a member of any of the U.S. national securities exchanges and is not subject to exchange rules. Cboe Fixed Income, a registered broker-dealer and member of FINRA, operates an electronic trading system for U.S. government securities targeted at the institutional inter-dealer market for trading on-the-run U.S. Treasury bonds and notes in the secondary OTC markets. Cboe Fixed Income’s participants are SEC registered broker-dealers that are members of The Depository Trust and Clearing Corporation’s Fixed Income Clearing Corporation.
Cboe Trading, BIDS Trading, and Cboe Fixed Income are subject to SEC and SRO rules, as applicable, and, as registered broker-dealers, regulations concerning all aspects of their businesses, including trading practices, order handling, best execution, anti-money laundering, handling of material non-public information, safeguarding data, reporting, capital adequacy, record retention, market access and the conduct of their officers, employees and other associated persons. The SEC, SROs and state securities commissions may conduct proceedings which can result in injunctions or other sanctions, censures, fines, the issuance of cease and desist orders or the suspension or expulsion of a broker-dealer, its officers or employees. The SEC and FINRA impose certain minimum capital requirement rules that require notification when a broker-dealer’s net capital falls below certain predefined criteria, dictate the ratio of debt to equity in the regulatory capital composition of a broker-dealer, constrain the ability of a broker-dealer to expand its business under certain circumstances and impose certain requirements that may have the effect of prohibiting a broker-dealer from distributing or withdrawing capital.
In addition, the ATS operated by BIDS Trading is not a registered national securities exchange or a facility thereof, as such, Cboe intends to maintain the BIDS ATS as an independently managed and operated trading venue, separate from and not integrated with the Exchanges. The Chief Executive Officer of BIDS Trading is expected to lead BIDS Trading as an independent business within Cboe, reporting into an independent committee of the board of Cboe Global Markets. Further, Cboe Trading will not route orders to BIDS Trading on behalf of the Exchanges.
Cboe Global Markets
Certain aspects of Cboe Global Markets are also subject to SEC, FCA and AFM oversight, including certain ownership and voting restrictions on its stockholders. The focus of the SEC’s regulation of Cboe Global Markets is to assure fair representation of members in the selection of the directors of the Exchanges, public participation in the governance of the Exchanges and that the Exchanges can satisfy their regulatory responsibilities under the Exchange Act. Furthermore, the SEC requires that Cboe Global Markets give due regard to the preservation of the independence of the self-regulatory function of the Exchanges and to Cboe Global Markets’ obligations to investors and the general public. The SEC also requires that Cboe Global Markets not take any actions that would interfere with the effectuation of any decisions by the Board of Directors of any of the Exchanges relating to its regulatory functions or the structure of the market that it regulates or that would interfere with the ability of such Exchange to carry out its responsibilities under the Exchange Act. To the extent that Cboe Global Markets’ business activities involve or relate to the Exchanges, the officers and directors of Cboe Global Markets may be deemed to be officers and directors of the exchanges for purposes of and subject to oversight under the federal securities laws. Accordingly, the SEC may exercise direct supervision and disciplinary authority over certain Cboe Global Markets’ activities and those activities may be subject to SEC approval and, in some cases, public notice and comment.
In addition, Cboe Global Markets indirectly holds all of the issued share capital and voting rights in Cboe Europe and its wholly-owned subsidiaries, Cboe Chi-X Europe and Cboe NL. As a result, we and any person who holds, or has voting power with respect to, 10% or more of the outstanding shares of Cboe Global Markets common stock may be subject to certain regulatory requirements under UK and Dutch law.
U.S. Regulatory Responsibilities
Our U.S.-based exchanges are responsible for assessing the compliance of their TPHs or members, including Cboe Trading, with the respective exchange’s rules and the applicable rules of the SEC and/or CFTC. The main activities that the exchanges, as applicable, are required to monitor for the purpose of compliance with these rules include:
| ● | surveillance designed to detect violations of exchange trading rules; |
|---|
| ● | surveillance designed to detect violations of SEC and/or CFTC rules; |
|---|
| ● | investigation of matters involving potential rule violations; |
|---|
| ● | the investigation of complaints about possible rule violations brought by customers, TPHs, members or other SROs; and |
|---|
| ● | the examination of TPHs or members for compliance with rules such as those related to net capital, books and records, market access and other matters related to the TPHs’ or members’ exchange business functions. |
|---|
In order to ensure market integrity, we regulate and monitor our TPHs’ and members’ trading activities by using both our employees and/or third parties under regulatory services agreements (“RSAs”). See “U.S. Regulatory Agreements” below. Providing effective regulation is important for attracting and retaining the confidence and participation of market-makers, broker-dealers and institutional and retail investors.
We expend considerable time, financial resources and effort to ensure that the exchanges’ rules and regulations conform to regulatory best practices within the securities and futures exchange industries and within the regulatory regime overseen by the SEC and CFTC, our primary U.S. regulators. In order to support our efforts and those of our market participants to comply with applicable law and our exchange rules, we developed a regulatory program to monitor market activity on our exchanges.
All of our Exchanges, CFE, and Cboe Digital Exchange are participants in various cooperative and regulatory information sharing agreements, including in the Intermarket Surveillance Group (“ISG”). ISG is an international information-sharing cooperative governed by a written agreement that provides for a comprehensive surveillance sharing arrangement. In addition to the agreement for confidential information sharing, the ISG provides a framework for the coordination of regulatory efforts among exchanges trading securities, commodity futures and related products to address potential intermarket manipulations and trading abuses.
CFE and Cboe Digital Exchange are also members of the Joint Audit Committee (“JAC”), which is a representative committee of the U.S. futures exchanges and regulatory organizations which participate in a joint audit and financial surveillance program that has been approved and is overseen by the CFTC. The JAC’s primary responsibility is to oversee the implementation and functioning of all terms and conditions of the Joint Audit Agreement and to determine the practices and procedures to be followed by each designated self-regulatory organization in the conduct of regulatory examinations and financial reviews of FCMs.
As part of the regulatory program, each of our Exchanges and CFE have rules pertaining to their respective disciplinary processes.
U.S. Regulatory Agreements
The Exchanges and CFE have entered into agreements under which third parties have agreed to perform regulatory functions on behalf of our markets (e.g., RSAs). As discussed below, in addition, in certain other instances for our Exchanges, a third party has been allocated the regulatory responsibility under Rule 17d-1 or Rule 17d-2 under the Exchange Act, while in others, we retain the regulatory responsibility for the activities.
Regulatory Services Agreement with FINRA
The Exchanges have entered into agreements with FINRA under which FINRA has agreed to provide regulatory services to the Exchanges. Under these agreements, FINRA performs certain regulatory functions on behalf of the Exchanges and, to avoid any potential conflicts of interest concerning the regulation and oversight of Cboe Trading, certain regulatory services specific to Cboe Trading. The Exchanges remain responsible for the regulation of their TPHs, members and marketplaces, and retain the authority for bringing disciplinary actions against their TPHs and members, although FINRA performs certain functions on behalf of the Exchanges. The Exchanges also perform certain regulatory and disciplinary-related functions in-house.
Regulatory Services Agreement with OCC
While CFE also performs most regulatory and disciplinary-related functions in-house, OCC has performed and continues to perform certain regulatory functions on behalf of CFE pursuant to an RSA with CFE. Whether performed under an RSA or in-house, CFE retains overall responsibility for the regulation of its marketplace and for bringing disciplinary actions.
Rule 17d-1 Designations and Rule 17d-2 Agreements
Section 17(d) of the Exchange Act and the related Exchange Act rules permit SROs to allocate certain regulatory responsibilities to avoid duplicative oversight and regulation. Under Exchange Act Rule 17d-1, the SEC designates one SRO to be the designated examining authority (“DEA”) for each broker-dealer that is a member of more than one SRO. The DEA is responsible for the regulatory oversight of applicable financial responsibility rules pertaining to that broker-dealer. Cboe Options is the DEA for several of its TPHs. Cboe Trading’s assigned DEA is FINRA.
Exchange Act Rule 17d-2 permits SROs to enter into agreements, commonly called Rule 17d-2 agreements, which are approved by the SEC and concern the allocation of regulatory responsibility for rules applicable to TPHs and members that those SROs have in common. The Exchanges have entered into certain bi-lateral Rule 17d-2 agreements under which FINRA is allocated responsibility for enforcing certain federal securities laws and certain exchange rules that are common with FINRA rules. The Exchanges have entered into certain other multi-party Rule 17d-2 agreements that allocate responsibility among the participating SROs, which may include the Exchanges, for oversight of their allocated common members compliance with certain rules governing, among other items, options related sales practices, options related market surveillance, insider trading, NMS and consolidated audit trail (“CAT”) NMS plan compliance.
National Market System Plans
We are member participants of several NMS plans including, but not limited to, the following: Cboe Options, C2, BZX, and EDGX are member exchanges in OPRA, which is the designated securities information processor for market information that is generated through the trading of exchange-listed securities options in the United States, and it disseminates certain core trading information, such as last sale reports and quotations. Cboe Options, BZX, BYX, EDGA, and EDGX also participate in the CTA/CQ and the UTP Plans, which perform analogous services for the U.S. equities market. Securities Information Automation Corporation (“SIAC”) acts as the “processor” for OPRA and the CTA/QC Plans. Nasdaq Stock Market, LLC acts as the processor for the Nasdaq Unlisted Trading Privileges Plan. Also, see “Risk Factors” for more information regarding the consolidated data plan order.
Cboe Options, C2, BZX, and EDGX are also parties to the Options Order Protection and Locked/Crossed Market Plan, which is designed to prohibit trade-throughs and avoid locked/crossed markets. Cboe Options, C2, BZX, and EDGX are also parties to the Options Listing Procedures Plan, which sets forth the procedures that the options exchanges must follow to list new options. Cboe Options, BZX, BYX, EDGA, and EDGX are also parties to the NMS plan for the selection and reservation of securities symbols.
Under the Options Regulatory Surveillance Authority Plan (“ORSA Plan”), U.S. securities options exchanges are permitted to act jointly in the administration, operation and maintenance of a regulatory system for the surveillance, investigation and detection of the unlawful use of undisclosed, material information in trading in one or more of their markets. The ORSA Plan is intended to enhance the effectiveness and efficiency with which the exchanges regulate their respective markets and to avoid duplication of certain regulatory efforts. FINRA operates the ORSA Plan facility for options insider trading.
The Consolidated Audit Trail Plan (“CAT Plan”) involves the creation of a consolidated audit trail that tracks orders throughout their lifecycle, which strives to enhance regulators’ ability to efficiently monitor trading activity in Eligible Securities in the U.S. securities markets. Eligible Securities currently include NMS Stocks, Listed Options and OTC Equities. Order and trade data is required to be reported to the CAT central repository the following day by each SRO (a “Plan Participant”) and broker-dealer (an “Industry Member”), along with certain customer and account information by each Industry Member. On November 15, 2016, the SEC approved the CAT Plan and a phased implementation was originally required to begin in November 2017; however, there were some delays. The first phase of CAT (“Phase 1”) ultimately went live in November 2018, at which time we and other SROs/Plan Participants began initial reporting of order and trade file submissions to the CAT. The second phase of CAT (“Phase 2”) for Industry Members began with order and trade file submissions in June 2020. The final Phase 2 implementation sub-phase (Phase 2e), related to Industry Member submissions to the customer and account information submissions system (“CAIS”) has been live in production since April 2022, but its completion has been delayed. The Industry Member full CAIS compliance reporting requirements are currently scheduled to go into effect May 31, 2024.
On May 15, 2020, the SEC adopted amendments to the CAT to establish financial accountability provisions to achieve full CAT implementation, including a financial accountability milestone requiring full implementation of the CAT requirements by December 30, 2022. If the SEC were to determine any financial accountability milestone was not met, it may limit the SROs’/Plan Participants’ recovery of certain costs. Due to the delayed completion of CAIS, the SROs/Plan
Participants have submitted to the SEC requests to extend the timeline for the completion of Phase 2e and the deadline for the final financial accountability milestone and additional requests may be submitted. If the SEC does not grant extensions and finds that the SROs/Plan Participants did not satisfy the related last financial accountability milestone, it could result in the SROs/Plan Participants not being able to recover certain costs associated with this final sub-phase, which amount of unrecoverable costs may increase for additional delays.
On September 6, 2023, the SEC issued an order approving an amendment to the CAT national market system plan to implement a revised funding model (“CAT Funding Model”) for Consolidated Audit Trail, LLC (“CATLLC”) to fund the CAT. The approved CAT Funding Model contemplates two categories of CAT fees calculated based on the “executed equivalent shares” of transactions in eligible securities: (i) CAT fees assessed by CATLLC to Industry Members who are CAT Executing Brokers (the brokers responsible for executing each side of the transaction) to recover a portion of historical CAT costs previously paid to CATLLC by the Plan Participants; and (ii) CAT fees assessed by CATLLC to CAT Executing Brokers and Plan Participants to fund prospective CAT costs. To date, the funding of the CAT has solely been provided by the SROs/Plan Participants has been done in exchange for promissory notes. The funds generated from the assessment of CAT fees to recover a portion of historical CAT costs will be used by CATLLC to repay a portion of these promissory notes to the Plan Participants.
The Plan Participants submitted fee filings during the first week of January 2024 with the SEC to implement the applicable transaction-based fee rates that are to be assessed by CATLLC to CAT Executing Brokers to recover a portion of historical CAT costs incurred prior to 2022. Additional CAT fees related to other historical CAT costs and to prospective CAT costs are planned to be introduced at a later time through separate fee filings submitted by the Plan Participants. Once the CAT fee related to ongoing prospective CAT costs becomes effective through fee filings submitted by the Plan Participants, it is anticipated there will no longer be any need for Plan Participants to fund CATLLC in exchange for promissory notes. On January 17, 2024, the SEC issued orders suspending each Plan Participant’s fee filing and instituting proceedings to determine whether to approve or disapprove the fees, which orders were published in the Federal Register on February 13, 2024. Comments are due March 5, 2024, and rebuttal comments are due March 19, 2024.
A challenge to the SEC’s September 6, 2023 order was filed by the American Securities Association and Citadel Securities, LLC against SEC before the U.S. Court of Appeals for the 11th Circuit on October 17, 2023. This challenge or any other challenge to the SEC order approving the CAT Funding Model and/or Plan Participant(s) fee filings may significantly delay implementation efforts. As a result, the Plan Participants may continue to incur additional significant costs, and/or it may result in them not being able to collect on the promissory notes related to the funding of the implementation and operation of the CAT.
CATLLC, as well as the Cboe U.S. Securities Exchanges, and certain other exchanges/Plan Participants filed motions to intervene in the aforementioned matter on November 16, 2023 and are waiting the Court’s ruling on the motions. CATLLC also determined to move forward with implementing its first fee under the SEC-approved CAT Funding Model. As a result, the Cboe U.S. Securities Exchanges and other Plan Participants submitted fee filings on or near January 2, 2024 to implement the CAT fee on behalf of CATLLC related to a portion of historical CAT costs incurred prior to 2022 the discussed above. Although the fee filings were submitted as “immediately effective” filings, the CATLLC fee will be assessed beginning with trades occurring on March 1, 2024 (with the first monthly invoice for the month of March being issued in April 2024 and first monthly payment due in May 2024).
Until the fees for historical CAT costs that are associated with the promissory notes are collected from CAT Executing Brokers and remitted by CATLLC to the Plan Participants, and until CAT fees assessed by CATLLC to CAT Executing Brokers and Plan Participants to fund prospective CAT costs are implemented, the Plan Participants may continue to incur additional significant costs, including additional promissory notes to fund CAT. Additionally, portions of promissory notes related to the funding of the implementation and operation of the CAT may not be collectible, including if the SEC finds that the SROs/Plan Participants did not satisfy any of the financial accountability milestones. The allowance for notes receivable credit losses associated with the CAT is calculated using a methodology that is primarily based on the structure of the notes and various potential outcomes under the CAT Funding Model. See Note 23 (“Commitments, Contingencies, and Guarantees”) for more information.
Intellectual Property
We own or have rights to a number of intellectual property assets, including trademarks, service marks, domain names, trade names, copyrights, trade secrets and patents. While the majority of our intellectual property is protected under U.S. law, we have many intellectual property assets protected by laws in Europe, Asia and other parts of the world.
We license some intellectual property assets to other entities. We attempt to protect our intellectual property rights, while respecting the legitimate intellectual property rights of others.
Human Capital Management
Cboe has a robust human capital management program in place focused on equal opportunities including diversity, equity and inclusion (“DEI”), performance and career development, health and well-being, comprehensive benefits, training, talent acquisition, and succession planning. Additional information on our approach to human capital and environmental, social, and governance (“ESG”) issues can be found in the Cboe Global Markets, Inc. Environmental, Social and Governance Report located in the Corporate Social Responsibility section of our website at https://markets.cboe.com/about/corporate-social-responsibility, which does not form a part of this Form 10-K.
Equal Opportunity, Diversity, and Pay Equity
Cboe believes in a culture of diversity and inclusion that promotes creativity, collaboration and innovation, which is critical to the success of our business and defining the markets of tomorrow. Cboe is an equal opportunity employer and provides equal employment opportunities to all qualified persons without regard to sex, gender, race, color, ethnicity, creed, religion, national origin, ancestry, citizenship status, age, veteran or military status, disability, marital status, domestic partnership or civil union status, pregnancy, sexual orientation, genetic status, gender identity or expression, and any other characteristic protected by applicable law (a “Protected Characteristic”). Cboe is committed to applying our Equal Employment Opportunity Policy to all employment practices that impact the terms and conditions of employment including, but not limited to, hiring, evaluation, discipline, promotion, training, compensation, transfer, and termination. Actively nurturing and maintaining a diverse and inclusive culture at Cboe is a core imperative. We believe that our collective and unique perspectives fuel our capabilities, enhance our team spirit and enable us to attract and retain top talent as we define the markets of the future. Our commitment and responsibility in this regard starts at the top, with leadership and support from the full Cboe Board of Directors and executive team.
To maintain and strengthen our pledge to equity, diversity and inclusion and to keep a level playing field, we regularly review key touchpoints across the employee journey with Cboe., from the talent selection, promotion, compensation, leadership development, and succession planning processes and make adjustments, as necessary, to help ensure opportunity parity across the Company. Our goal is to ensure that fair pay and equal opportunity for all that results in a collaborative, high performing organization bringing new innovations to market and providing superior service to our customers.
We also have associate resource groups, including the Cboe Women’s Initiative, the Diversity Leadership Council, the Veterans Initiative, PRISM+ (People Respecting Individuality and Sexuality in Markets), Cboe UNIDOS, Asian and Pacific Islanders Network (APIN) and Black Equity and Allyship in Markets (BEAM).
| ● | The Cboe Women’s Initiative works toward its mission: to increase representation, strengthen voices, and build a culture of opportunity and advancement for the women of Cboe. The Women’s Initiative is led by an associate board and engages women throughout the Company on a variety of programs. More specifically, the Women’s Initiative is comprised of three committees that target areas where its membership strives to promote change, such as networking events, mentorship, and building an advocacy group aimed at gathering input on topics of importance for its membership. Networking events include the “Trailblazers” events where senior women share their success stories through personal accounts of career growth and impact and speakers on Male Allyship in the workplace. |
|---|
| ● | The Diversity Leadership Council focuses on unlocking the potential of a variety of perspectives, capabilities and cultural experiences. We believe in a culture of diversity and inclusion that promotes creativity, collaboration and innovation, which is critical to the success of our business and defining the markets of tomorrow. To reinforce this belief, this council is a collective voice on how Cboe strives to create a diverse workforce that reflects the world in which we operate. Further, they are charged with oversight on how we build an inclusive culture where every employee feels welcome, safe and empowered. |
|---|
| ● | The Cboe Veterans Initiative operates based on four main pillars: recruiting, mentorship, service, and networking. The vision for the Cboe Veterans Initiative is to actively seek Veteran talent, provide mentorship to veterans within and outside of the Company, commit to giving back to the Veteran community through financial and non-monetary support, and encourage outreach to Cboe Veterans. |
|---|
| ● | PRISM+ is focused on celebrating the LGBTQIA+ community through education and allyship. |
|---|
| ● | Cboe UNIDOS is committed to increasing and sustaining the visibility of Hispanic/Latinos/Latinx associates at Cboe by improving opportunities through education, mentorship and networking. |
|---|
| ● | The Asian and Pacific Islanders Network (APIN) is committed to empower, support and advocate for Asian and Pacific Islander associates at Cboe. We strive to foster an inclusive and supportive environment that values the diverse backgrounds, perspectives and contributions of APIN associates. |
|---|
| ● | Black Equity and Allyship in Markets (BEAM) unites Allies and Black professionals to address the unique challenges to opportunity, entry, and advancement in financial markets and create a workplace where equity is reimagined, equal opportunities are accessible and associates from all backgrounds can ascend to leadership roles and contribute to the strategy and achievements of Cboe. |
|---|
To reinforce our commitment to organization wide education and commitment to diversity and inclusion we also provide harassment and unconscious bias training for employees.
We also have a community engagement program, Cboe Empowers, that provides mentorship, scholarship and guidance to under-resourced students throughout their educational journey through access to Cboe’s associates, resources, work environment and other learning and experience opportunities. Initially launched in Chicago, the vision for Cboe Empowers is to support students through all stages of education from elementary or primary school to career by providing mentorship, learning and experience opportunities, professional development and scholarships to students within the Chicago Public School system and graduates pursuing higher education. Cboe Empowers expects to supplement its own programs by collaborating with local partners, including the Greenwood Project and Working in the Schools, to help create maximum impact for its participants. In 2023, Cboe Empowers awarded seven full-ride college scholarships to under-resourced high school students to attend the school of their choice, expanding the program to include students from Kansas City. Five of the scholarships were awarded to students from Chicago and two were awarded to students from Kansas City.
Performance and Career Development
Cboe expects employees to perform their duties to the best of their ability and to develop their competencies for career growth. We recognize the need to provide ongoing, timely, and constructive performance feedback. Cboe has designed a Performance Management Program that drives the professional development of our employees while also providing fair and equitable rewards and recognition.
The principles of performance management include:
| ● | align performance expectations with strategy and goals of the business, |
|---|
| ● | ongoing open dialogue regarding performance and development, |
|---|
| ● | foster accountability for behaviors and actions which contribute to a positive culture, and |
|---|
| ● | commitment to deliver results which drive our business. |
|---|
To help promote career development, among other items, Cboe offers a formal mentorship program among its associates. The mentorship program was originally developed by the Cboe Women’s Initiative. In 2023, the mentorship program paired over 60 mentors with mentees across the Company.
Employee Health and Well-Being and Comprehensive Benefits Program
Cboe’s vision is to support the overall wellness of employees and their families through education and activities that encourage a healthy lifestyle, resulting in improved health and productivity. Our programs and benefit plans provide a corporate atmosphere of collective well-being and incorporate strategies for physical, emotional, mental and financial wellness. Our programs include enhanced employee assistance programs, wellness programs and challenges (which address both mental and physical well-being), and webinars and classes through our retirement vendor to support the financial health of our employees.
With the global pandemic in 2020 and 2021, there was further focus on our Employee Assistance program, which was strengthened across the globe with a diverse set of mental health resources aimed at supporting our employees during a unique and challenging time.
Employee Engagement and Pulse Surveys, Town Halls and an Open-Door Policy
In 2023, Cboe conducted our sixth annual employee engagement survey and has implemented career, leadership, and culture focused programs in response to the survey findings. Our participation rate exceeds standard benchmarks and a significant majority of our employees would recommend Cboe as a great place to work.
Our senior management team continues to hold the commitment to an open-door policy and encourages the free flow of information and communication in furtherance of active transparency. With the recent executive transitions, our ability to tap into the voice of our employees was critically important and we conducted a pulse survey to gauge sentiment. Our CEO also issues weekly letters to help connect with our employees. Human Resources also provided ongoing regular resources and tips to help support the variety of challenges, from the new reality of hybrid work to childcare and elder care, that our employees faced throughout 2023.
Cboe also continues to create an open and frank atmosphere in which any grievance, complaint, suggestion or question receives a timely response. Cboe offers a whistleblower hotline for complaints, which can be made anonymously. Additionally, employees can raise questions and suggestions to the Cboe Human Resources team either in-person or via a group email address and are either responded to individually or addressed at our Global Town Hall meetings. The objective of these town halls is to provide employees an update on Company news, share updates from major business lines, as well as provide a forum to ask questions and offer feedback. Town halls can include updates on anything from legislation that may impact our business to ESG topics. Employees are encouraged to participate in free flow of information and communication and to offer positive and constructive feedback in furtherance of active transparency.
Training and Succession Planning
We believe that the development of all Cboe employees helps drive our collective success. Through skill and competency development we signal our investment in all while also enabling enhanced productivity. Through our tuition reimbursement program, our employees receive financial support in their pursuit of specialized university courses and degrees. In addition to our ongoing offering of online courses on diverse topics through our corporate university, CboeU, employees can participate in the CboeLearns hybrid program focused on virtual classroom instruction combined with work application and CboeLive, which is focused on business topics to foster organizational-wide knowledge sharing and education.
Leadership is another critical element of our success at Cboe. The Board of Directors of Cboe and global senior leaders participated in a Clifton StrengthsFinder assessment and workshop to learn about their leadership style and how to empower Cboe associates based on their natural strengths. Leaders can participate in Lead the Way, Cboe’s leadership development hybrid program focused on virtual classroom instruction combined with in-person facilitated workshops and exercises, and individual development plans leveraging insights for a 360-feedback process. This leadership training program has helped to expand on the development of our high potential leaders, further strengthening the leadership bench and accelerating readiness of this key talent pool.
Cboe has held several succession planning discussions with the Compensation Committee and Board of Directors to plan for the fulfillment of essential roles, such as the CEO and other senior officers. This process includes investments in advanced development planning for targeted successors to accelerate their readiness through key internal projects and assignments as well as tailored training. Diversity and inclusion are a formal part of Cboe’s succession planning process as we work to identify and advance internal diverse talent and, in parallel, continually scan external talent pools for successors. Following the recent executive transitions, one of the new CEO’s top areas of focus is to develop talent and spend time on succession planning.
Employees
As of December 31, 2023, we employed 1,647 individuals in the following locations:
| | | |
|---|---|---|
| Location | | Number of Employees |
| United States | | 1,107 |
| United Kingdom | | 186 |
| Netherlands | | 125 |
| Canada | | 80 |
| Australia | | 78 |
| Philippines | | 30 |
| Japan | | 26 |
| Singapore | | 9 |
| Hong Kong | | 5 |
| Switzerland | | 1 |
Of these employees, 595 were involved in technology operations and 185 were involved in direct support of trading operations. The remaining 867 employees provide business development, financial, regulation, human resources, compliance, legal, planning and research, administrative, and managerial support.
We have three building engineers that are covered by a collective bargaining agreement, which expires on March 31, 2024, with the International Union of Operating Engineers Local 399, AFL-CIO. Management believes that we have strong relationships with our employees, and we have never experienced a work stoppage.
Information about our Executive Officers
Set forth below is information regarding our executive officers:
| Name | Age | Position | ||
| Fredric J. Tomczyk | | 68 | | Chief Executive Officer |
| Catherine R. Clay | | 56 | | Executive Vice President, Global Head of Derivatives |
| Stephanie Foley | | 42 | | Executive Vice President, Chief Human Resources Officer |
| Jill M. Griebenow | | 44 | | Executive Vice President, Chief Financial Officer |
| David Howson | | 47 | | Executive Vice President, Global President |
| Adam Inzirillo | | 47 | | Executive Vice President, Global Head of Data and Access Solutions |
| Christopher A. Isaacson | | 45 | | Executive Vice President, Chief Operating Officer |
| Patrick Sexton | | 59 | | Executive Vice President, General Counsel and Corporate Secretary |
| Allen Wilkinson | | 36 | | Senior Vice President, Chief Accounting Officer |
Fredric J. Tomczyk. Mr. Tomczyk is our current Chief Executive Officer and director. He has served as our CEO since September 2023. Mr. Tomczyk served on our Board as an independent director from July 2019 to September 2023. He is the retired President and Chief Executive Officer of TD Ameritrade Holding Corporation, a position he held from October 2008 to October 2016. Prior to this position, he held positions of increasing responsibility and leadership with the TD organization from 1999. Mr. Tomczyk was also a member of the TD Ameritrade board of directors from 2006 to 2007 and 2008 to 2016. Prior to joining the TD organization in 1999, Mr. Tomczyk was President and Chief Executive Officer of London Life. He currently serves on the board of Willis Towers Watson PLC, a publicly traded company, and is a member of the Cornell University Athletic Alumni Advisory Council. Mr. Tomczyk also previously served as the lead independent director of Sagen MI Canada Inc., a publicly traded company, and of its operating subsidiary Sagen Mortgage Insurance Company Canada, as a director of Knight Capital Group, Inc. and a trustee of Liberty Property Trust, both formerly publicly traded companies, and as a director of the Securities Industry and Financial Markets Association. Mr. Tomczyk holds a B.S. degree in Applied Economics & Business Management from Cornell University and is a Fellow of the Institute of Chartered Accountants of Ontario.
Catherine R. Clay. Ms. Clay is our Executive Vice President, Global Head of Derivatives, a position she has held since October 2023. Previously, she was Executive Vice President, Global Head of Data and Access Solutions from March 2021 to October 2023, Senior Vice President, Global Head of Information Solutions of the Company’s subsidiary Cboe Exchange, Inc. from February 2019 to March 2021, and she has held other various senior leadership positions since 2015, including Vice President Business Development, a position she was appointed to upon the Company’s acquisition of Livevol, Inc. Prior to that, she served as Chief Executive Officer of Livevol, Inc. from 2013 to 2015 and as its
Chief Strategy Officer from 2010 to 2013. Prior to that, she served as Founder of Thales LLC from 2006 through 2010. Ms. Clay holds a B.S. degree from University of Colorado-Boulder.
Stephanie Foley. Ms. Foley is our Executive Vice President, Chief Human Resources Officer, a position she has held since October 2023. Previously, she served as Senior Vice President, Chief Human Resources Officer of the Company’s subsidiary Cboe Exchange, Inc. from June 2022 to October 2023. Prior to joining Cboe in 2022, Ms. Foley was Chief Human Resources Officer, Americas, of Kearney Holdings Limited from August 2016 to May 2022. Ms. Foley holds a bachelor’s degree in psychology and sociology from the University at Albany, SUNY, and a master’s degree in industrial organizational psychology from New York University.
Jill M. Griebenow. Ms. Griebenow is our Executive Vice President, Chief Financial Officer, a position she has held since July 2023. Previously, she served as Executive Vice President, Chief Accounting Officer from July 2023 to February 2024, Treasurer from July 2023 to October 2023 and as Senior Vice President, Chief Accounting Officer from August 2018 to July 2023. She also previously served as Chief Financial Officer of Cboe Europe from 2014 to 2018 and was employed by Bats in the financial area since 2011. Prior to that, she held various positions at Ernst & Young LLP from 2001 to 2011. Ms. Griebenow is a certified public accountant and holds a bachelor’s degree in accounting from the University of Northern Iowa.
David Howson. Mr. Howson is our Executive Vice President, Global President, a position he has held since May 2022. Previously, he was our Executive Vice President, President Europe and Asia Pacific, from July 2021 to May 2022, Executive Vice President, President Europe from January 2020 to July 2021 and Chief Operating Officer of Cboe Europe from 2013 to 2019. Prior to that, he served as Founder, Chief Technology Officer of Equiduct from April 2006 through June 2013. Prior to that he held various international Financial Services consulting roles between 1998 and 2006 for TIBCO Finance Technology and Thomson Reuters. Mr. Howson serves as the Chairman of the Boards of Directors of the Exchanges, and of CFE, Cboe SEF, and Cboe Canada Inc. Mr. Howson holds a First Class Honours bachelor's degree from the University of Newcastle-upon-Tyne.
Adam Inzirillo. Mr. Inzirillo is our Executive Vice President, Global Head of Data and Access Solutions, a position he has held since October 2023. Previously, he served as Senior Vice President, Head of North American Equities since 2020, and Senior Vice President, Head of U.S. Equities since September 2019. Prior to joining Cboe, Mr. Inzirillo was Managing Director, Head of Order Routing and Execution Products at Bank of America Merrill Lynch, where he worked for nearly a decade. Previously, he was Executive Director, Head of Broker Dealer Business Development at UBS Securities LLC from 2005 through 2010. Mr. Inzirillo also serves on the Board of Directors of Cboe Canada Inc. Mr. Inzirillo holds a bachelor’s degree in economics from Bucknell University and a M.B.A. degree from Dowling College.
Christopher A. Isaacson. Mr. Isaacson is our Executive Vice President, Chief Operating Officer, a position he has held since January 2019. Previously he was our Executive Vice President, Chief Information Officer, a position he was appointed to upon the Company’s acquisition of Bats. Prior to that, he served as Bats' Executive Vice President and Global Chief Information Officer since February 2014, he served as Bats' Senior Vice President, Chief Operation Officer from 2007 to 2014 and he has held other various senior leadership positions since 2005. Prior to being one of the founders of Bats, Mr. Isaacson was a software developer at Tradebot Systems, Inc. from 2003 to 2005. Mr. Isaacson serves as the Chairman of the Board of Directors of Cboe Digital and previously served as the Chairman of the Boards of Directors of CFE and Cboe SEF and on the Boards of Directors of Cboe Japan, Cboe Australia, and OCC. Mr. Isaacson holds a bachelor’s degree in information systems with a minor in math from Nebraska Wesleyan University and an M.B.A. degree from the University of Nebraska-Lincoln.
Patrick Sexton. Mr. Sexton is our Executive Vice President, General Counsel and Corporate Secretary, a position he has held since March 2018. Previously, he was Deputy General Counsel of the Company’s subsidiary Cboe Exchange, Inc. He served in that capacity from July 2013 to March 2018 and has acted as legal, regulatory and compliance counsel with increasing responsibility and oversight since joining the Company in 1997. Mr. Sexton holds a bachelor’s degree from the University of Notre Dame and a J.D. degree with honors from Notre Dame Law School.
Allen Wilkinson. Mr. Wilkinson is our Senior Vice President, Chief Accounting Officer, a position he has held since February 2024. Previously, he served as Vice President, Controller of the Company, from June 2021 to February 2024 and has been employed in the financial area in various roles since April 2018. Prior to that, he also held various positions at PricewaterhouseCoopers LLP from January 2011 to April 2018. Mr. Wilkinson is a certified public accountant and holds master’s and bachelor's degrees in accounting from the University of Missouri – Columbia.
Corporate Social Responsibility
The Company recognizes that operating in a socially responsible manner helps promote the long-term interests of our investors, associates, customers, community members, and all other stakeholders with whom we live and work. We are actively engaged with policymakers on behalf of our customers to promote fairness, innovation, trust, and confidence in our markets, and we continuously seek to further our corporate social responsibility efforts through:
| ● | Industry Leadership – As an industry leader, we are deeply committed to building trusted markets for participants. |
|---|
| ● | Diversity and Associate Engagement – We strive to create a diverse workforce that reflects the world in which we operate, and to build an inclusive culture where every associate feels welcome, safe and empowered. |
|---|
| ● | Corporate Governance – Corporate governance is embedded in the operations of our company. The Company’s Board of Directors recognizes that operating in a socially responsible manner helps promote the long-term interests of our organization, stockholders, associates, industry and community. |
|---|
| ● | Promoting Transparency and Efficient Capital Markets – We maintain a comprehensive regulatory program in support of providing trusted markets and integrity in the marketplace. |
|---|
| ● | Environmental Performance – We recognize the need to do our part in supporting the environment. |
|---|
We believe being a good citizen means that we hold ourselves accountable for the integrity of the markets and to the communities we serve, seek to help resolve conflicts and build consensus, inform those impacted before taking action, lead by example and serve as part of the solution. We also seek to be good citizens to the communities we serve by being committed to being environmentally conscious. Additionally, being good citizens also means that we strive to support our associates and better serve our industry and community through our human capital development, volunteerism and policies. See “Human Capital Management” subsection above for more information.
Additional information on our approach to ESG can be found in the 2023 Cboe Global Markets, Inc. Environmental, Social and Governance Report located in the Corporate Social Responsibility section of our website at https://www.cboe.com/about/esg/, which does not form a part of this Form 10-K.
Available Information
Our website is www.cboe.com. The Company files annual, quarterly and current reports, proxy statements and other information with the SEC under the Exchange Act. The Company makes available, free of charge, on its website its annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act, as soon as reasonably practicable after such reports are electronically filed with, or furnished to, the SEC. The Company's reports filed with, or furnished to, the SEC are also available on the SEC's website at www.sec.gov.
In addition, we have posted on our website the charters for our (i) Audit Committee, (ii) Compensation Committee, and (iii) Nominating and Governance Committee, as well as our Code of Business Conduct and Ethics and Corporate Governance Guidelines. We will provide a copy of these documents without charge to stockholders upon written request to Investor Relations, Cboe Global Markets, Inc., 433 West Van Buren Street, Chicago, Illinois 60607. Our website and information included in or linked to our website are not part of this Form 10-K.
Previous: Cover and table of contents · Next: Item 1A. Risk Factors.