 filings.tools
Citizens Financial Group 10-K 2022-12-31
Filed 2023-02-17. 23 sections, 760K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
☒ ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d)
OF THE SECURITIES EXCHANGE ACT OF 1934
For the Fiscal Year Ended
December 31, 2022
☐ TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d)
OF THE SECURITIES EXCHANGE ACT OF 1934
For the Transition Period From
(Not Applicable)
Commission File Number 001-36636
(Exact name of the registrant as specified in its charter)
| Delaware | 05-0412693 | |||||||
| (State or Other Jurisdiction of Incorporation or Organization) | (I.R.S. Employer Identification Number) |
One Citizens Plaza, Providence, RI 02903
(Address of principal executive offices, including zip code)
(203) 900-6715
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading symbol(s) | Name of each exchange on which registered | ||||||
| Common stock, $0.01 par value per share | CFG | New York Stock Exchange | ||||||
| Depositary Shares, each representing a 1/40th interest in a share of 6.350% Fixed-to-Floating Rate Non-Cumulative Perpetual Preferred Stock, Series D | CFG PrD | New York Stock Exchange | ||||||
| Depositary Shares, each representing a 1/40th interest in a share of 5.000% Fixed-Rate Non-Cumulative Perpetual Preferred Stock, Series E | CFG PrE | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act:
None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. ☑ Yes ☐ No
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. ☐ Yes ☑ No
Indicate by check mark whether the Registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports) and (2) has been subject to such filing requirements for the past 90 days. ☑ Yes ☐ No
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). ☑ Yes ☐ No
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company” and “emerging growth company” in Rule 12b-2 of the Exchange Act:
| Large accelerated filer | ☑ | Accelerated filer | ☐ | ||||||||
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ | ||||||||
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☑
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements. ☐
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b). ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). ☐ Yes ☑ No
The aggregate market value of voting stock held by non-affiliates of the registrant was $17,591,222,864 (based on the June 30, 2022 closing price of Citizens Financial Group, Inc. common shares of $35.69 as reported on the New York Stock Exchange). There were 484,106,460 shares of the registrant’s common stock ($0.01 par value) outstanding on January 31, 2023.
Documents incorporated by reference
Portions of Citizens Financial Group, Inc.’s proxy statement to be filed with the United States Securities and Exchange Commission in connection with Citizens Financial Group, Inc.’s 2023 annual meeting of stockholders (the “Proxy Statement”) are incorporated by reference into Part III hereof. Such Proxy Statement will be filed within 120 days of Citizens Financial Group, Inc.’s fiscal year ended December 31, 2022.
| Citizens Financial Group, Inc. | 1 |
GLOSSARY OF ACRONYMS AND TERMS
The following is a list of common acronyms and terms we regularly use in our financial reporting:
| AACL | Adjusted Allowance for Credit Losses | |||||||
| ACL | Allowance for Credit Losses: Allowance for Loan and Lease Losses plus Allowance for Unfunded Lending Commitments | |||||||
| AFS | Available for Sale | |||||||
| ALLL | Allowance for Loan and Lease Losses | |||||||
| ALM | Asset and Liability Management | |||||||
| AOCI | Accumulated Other Comprehensive Income (Loss) | |||||||
| ARRC | Alternative Reference Rates Committee | |||||||
| ASU | Accounting Standards Update | |||||||
| ATM | Automated Teller Machine | |||||||
| Bank Holding Company Act | The Bank Holding Company Act of 1956 | |||||||
| BHC | Bank Holding Company | |||||||
| Board or Board of Directors | The Board of Directors of Citizens Financial Group, Inc. | |||||||
| bps | Basis Points | |||||||
| Capital Plan Rule | Federal Reserve Regulation Y Capital Plan Rule | |||||||
| CARES Act | Coronavirus Aid, Relief, and Economic Security Act | |||||||
| CBNA | Citizens Bank, National Association | |||||||
| CCAR | Comprehensive Capital Analysis and Review | |||||||
| CCB | Capital Conservation Buffer | |||||||
| CCMI | Citizens Capital Markets, Inc. | |||||||
| CECL | Current Expected Credit Losses (ASU 2016-13, Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments) | |||||||
| CET1 | Common Equity Tier 1 | |||||||
| CEO | Chief Executive Officer | |||||||
| CET1 capital ratio | Common Equity Tier 1 capital divided by total risk-weighted assets as defined under the U.S. Basel III Standardized approach | |||||||
| CFPB | Consumer Financial Protection Bureau | |||||||
| CFTC | Commodity Futures Trading Commission | |||||||
| Citizens, CFG, the Company, we, us, or our | Citizens Financial Group, Inc. and its Subsidiaries | |||||||
| CLO | Collateralized Loan Obligation | |||||||
| CLTV | Combined Loan-to-Value | |||||||
| CMO | Collateralized Mortgage Obligation | |||||||
| COVID | Coronavirus Disease | |||||||
| CRA | Community Reinvestment Act | |||||||
| CRE | Commercial Real Estate | |||||||
| DE&I | Diversity, Equity and Inclusion | |||||||
| DH Capital | DH Capital, LLC | |||||||
| DIF | Deposit Insurance Fund | |||||||
| Dodd-Frank Act | The Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010 | |||||||
| EAD | Exposure at Default | |||||||
| EPS | Earnings Per Share | |||||||
| ERISA | Employee Retirement Income Security Act of 1974 | |||||||
| ESG | Environmental, Social, and Governance | |||||||
| ESPP | Employee Stock Purchase Program |
| Citizens Financial Group, Inc. | 2 |
| EVE | Economic Value of Equity | |||||||
| Exchange Act | The Securities Exchange Act of 1934, as amended | |||||||
| Fannie Mae (FNMA) | Federal National Mortgage Association | |||||||
| FASB | Financial Accounting Standards Board | |||||||
| FCA | Financial Conduct Authority | |||||||
| FDIA | Federal Deposit Insurance Act | |||||||
| FDIC | Federal Deposit Insurance Corporation | |||||||
| Federal Banking Regulators | Board of Governors of the Federal Reserve System, Federal Deposit Insurance Corporation and Office of the Comptroller of the Currency | |||||||
| FFIEC | Federal Financial Institutions Examination Council | |||||||
| FHA | Federal Housing Administration | |||||||
| FHC | Financial Holding Company | |||||||
| FHLB | Federal Home Loan Bank | |||||||
| FICO | Fair Isaac Corporation (credit rating) | |||||||
| FINRA | Financial Industry Regulation Authority | |||||||
| FRB or Federal Reserve | Board of Governors of the Federal Reserve System and, as applicable, Federal Reserve Bank(s) | |||||||
| Freddie Mac (FHLMC) | Federal Home Loan Mortgage Corporation | |||||||
| FTE | Fully Taxable Equivalent | |||||||
| FTP | Funds Transfer Pricing | |||||||
| GAAP | Accounting Principles Generally Accepted in the United States of America | |||||||
| GDP | Gross Domestic Product | |||||||
| GLBA | Gramm-Leach-Bliley Act of 1999 | |||||||
| Ginnie Mae (GNMA) | Government National Mortgage Association | |||||||
| GSE | Government Sponsored Entity | |||||||
| HSBC | HSBC Bank U.S.A., N.A. | |||||||
| HSBC transaction | Acquisition of HSBC East Coast branches and national online deposit business | |||||||
| HTM | Held To Maturity | |||||||
| ICE | Intercontinental Exchange | |||||||
| Investors | Investors Bancorp, Inc. and its subsidiaries | |||||||
| JMP | JMP Group LLC | |||||||
| Last-of-Layer | Last-of-layer is a fair value hedge of the interest rate risk of a portfolio of similar prepayable assets whereby the last dollar amount within the portfolio of assets is identified as the hedged item | |||||||
| LHFS | Loans Held for Sale | |||||||
| LGD | Loss Given Default | |||||||
| LIBOR | London Interbank Offered Rate | |||||||
| LIHTC | Low Income Housing Tax Credit | |||||||
| LTV | Loan to Value | |||||||
| MD&A | Management’s Discussion and Analysis of Financial Condition and Results of Operations | |||||||
| Mid-Atlantic | District of Columbia, Delaware, Maryland, New Jersey, New York, Pennsylvania, Virginia, and West Virginia | |||||||
| Midwest | Illinois, Indiana, Michigan, and Ohio | |||||||
| Modified AACL Transition | The Day-1 CECL adoption entry booked to ACL plus 25% of subsequent CECL ACL reserve build | |||||||
| Modified CECL Transition | The Day-1 CECL adoption entry booked to retained earnings plus 25% of subsequent CECL ACL reserve build | |||||||
| MSRs | Mortgage Servicing Rights |
| Citizens Financial Group, Inc. | 3 |
| NCOs | Net charge-offs | |||||||
| New England | Connecticut, Maine, Massachusetts, New Hampshire, Rhode Island, and Vermont | |||||||
| NM | Not meaningful | |||||||
| NSFR | Net Stable Funding Ratio | |||||||
| OCC | Office of the Comptroller of the Currency | |||||||
| OCI | Other Comprehensive Income (Loss) | |||||||
| OFAC | Office of Foreign Assets Control | |||||||
| Operating Leverage | Period-over-period percent change in total revenue, less the period-over-period percent change in noninterest expense | |||||||
| OTC | Over the Counter | |||||||
| Parent Company | Citizens Financial Group, Inc. (the Parent Company of Citizens Bank, National Association and other subsidiaries) | |||||||
| PCD | Purchased Credit Deteriorated | |||||||
| PD | Probability of Default | |||||||
| peers or peer regional banks | Comerica, Fifth Third, Huntington, KeyCorp, M&T, PNC, Regions, Truist and U.S. Bancorp | |||||||
| PPP | The U.S. Small Business Administration’s Paycheck Protection Program | |||||||
| REIT | Real estate investment trust | |||||||
| ROTCE | Return on Average Tangible Common Equity | |||||||
| RPA | Risk Participation Agreement | |||||||
| RWA | Risk-Weighted Assets | |||||||
| SBA | United States Small Business Administration | |||||||
| SCB | Stress Capital Buffer | |||||||
| SEC | United States Securities and Exchange Commission | |||||||
| SOFR | Secured Overnight Financing Rate | |||||||
| SVaR | Stressed Value at Risk | |||||||
| Tailoring Rules | Rules establishing risk-based categories for determining prudential standards for large U.S. and foreign banking organizations, consistent with the Dodd-Frank Act, as amended by the Economic Growth, Regulatory Relief and Consumer Protection Act | |||||||
| TBAs | To-Be-Announced Mortgage Securities | |||||||
| TDR | Troubled Debt Restructuring | |||||||
| Tier 1 capital ratio | Tier 1 capital, which includes Common Equity Tier 1 capital plus non-cumulative perpetual preferred equity that qualifies as additional tier 1 capital, divided by total risk-weighted assets as defined under the U.S. Basel III Standardized approach | |||||||
| Tier 1 leverage ratio | Tier 1 capital, which includes Common Equity Tier 1 capital plus non-cumulative perpetual preferred equity that qualifies as additional tier 1 capital, divided by quarterly adjusted average assets as defined under the U.S. Basel III Standardized approach | |||||||
| TOP | Tapping Our Potential | |||||||
| Total capital ratio | Total capital, which includes Common Equity Tier 1 capital, tier 1 capital and allowance for credit losses and qualifying subordinated debt that qualifies as tier 2 capital, divided by total risk-weighted assets as defined under the U.S. Basel III Standardized approach | |||||||
| USDA | United States Department of Agriculture | |||||||
| VA | United States Department of Veterans Affairs | |||||||
| VaR | Value at Risk | |||||||
| VIE | Variable Interest Entities |
| Citizens Financial Group, Inc. | 4 |
FORWARD-LOOKING STATEMENTS
This document contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Any statement that does not describe historical or current facts is a forward-looking statement. These statements often include the words “believes,” “expects,” “anticipates,” “estimates,” “intends,” “plans,” “goals,” “targets,” “initiatives,” “potentially,” “probably,” “projects,” “outlook,” “guidance” or similar expressions or future conditional verbs such as “may,” “will,” “should,” “would,” and “could.”
Forward-looking statements are based upon the current beliefs and expectations of management, and on information currently available to management. Our statements speak as of the date hereof, and we do not assume any obligation to update these statements or to update the reasons why actual results could differ from those contained in such statements in light of new information or future events. We caution you, therefore, against relying on any of these forward-looking statements. They are neither statements of historical fact nor guarantees or assurances of future performance. While there is no assurance that any list of risks and uncertainties or risk factors is complete, important factors that could cause actual results to differ materially from those in the forward-looking statements include the following, without limitation:
-
Negative economic, business and political conditions, including as a result of the interest rate environment, supply chain disruptions, inflationary pressures and labor shortages, that adversely affect the general economy, housing prices, the job market, consumer confidence and spending habits;
-
The rate of growth in the economy and employment levels, as well as general business and economic conditions, and changes in the competitive environment;
-
Our ability to implement our business strategy, including the cost savings and efficiency components, and achieve our financial performance goals, including through the integration of Investors and the HSBC branches;
-
The effects of geopolitical instability, including as a result of Russia’s invasion of Ukraine and the imposition of sanctions on Russia and other actions in response, on economic and market conditions, inflationary pressures and the interest rate environment, commodity price and foreign exchange rate volatility, and heightened cybersecurity risks;
-
Our ability to meet heightened supervisory requirements and expectations;
-
Liabilities and business restrictions resulting from litigation and regulatory investigations;
-
Our capital and liquidity requirements under regulatory capital standards and our ability to generate capital internally or raise capital on favorable terms;
-
The effect of changes in interest rates on our net interest income, net interest margin and our mortgage originations, mortgage servicing rights and mortgages held for sale;
-
Changes in interest rates and market liquidity, as well as the magnitude of such changes, which may reduce interest margins, impact funding sources and affect the ability to originate and distribute financial products in the primary and secondary markets;
-
The effect of changes in the level of checking or savings account deposits on our funding costs and net interest margin;
-
Financial services reform and other current, pending or future legislation or regulation that could have a negative effect on our revenue and businesses;
-
Environmental risks, such as physical or transitional risks associated with climate change, and social and governance risks, that could adversely affect our reputation, operations, business, and customers;
-
A failure in or breach of our operational or security systems or infrastructure, or those of our third-party vendors or other service providers, including as a result of cyber-attacks; and
-
Management’s ability to identify and manage these and other risks.
| Citizens Financial Group, Inc. | 5 |
In addition to the above factors, we also caution that the actual amounts and timing of any future common stock dividends or share repurchases will be subject to various factors, including our capital position, financial performance, capital impacts of strategic initiatives, market conditions, receipt of required regulatory approvals and other regulatory considerations, as well as any other factors that our Board of Directors deems relevant in making such a determination. Therefore, there can be no assurance that we will repurchase shares from or pay any dividends to holders of our common stock, or as to the amount of any such repurchases or dividends.
More information about factors that could cause actual results to differ materially from those described in the forward-looking statements can be found under Item 1A “Risk Factors”.
PART I
Item 1. BUSINESS
Citizens Financial Group, Inc. is headquartered in Providence, Rhode Island. We offer a broad range of retail and commercial banking products and services to individuals, small businesses, middle-market companies, large corporations and institutions. Our products and services are offered through more than 1,100 branches in 14 states and the District of Columbia and 123 retail and commercial non-branch offices, though certain lines of business serve national markets. At December 31, 2022, we had total assets of $226.7 billion, total deposits of $180.7 billion and total stockholders’ equity of $23.7 billion.
We are a BHC incorporated under Delaware state law in 1984 and our primary federal regulator is the FRB. CBNA is our banking subsidiary, whose primary federal regulator is the OCC.
Business Segments
We manage our business through two business segments: Consumer Banking and Commercial Banking. For additional information regarding our business segments see the “Business Operating Segments” section of Item 7 and Note 26 in Item 8. Our activities outside these segments are classified as “Other” and include treasury activities, wholesale funding activities, the securities portfolio, community development assets, and other unallocated assets, liabilities, capital, revenues, provision for credit losses and expenses, including income tax expense.
Consumer Banking Segment
Consumer Banking serves retail customers and small businesses with annual revenues of up to $25 million, with products and services that include deposit products, mortgage and home equity lending, credit cards, business loans, wealth management and investment services largely across our 14-state traditional banking footprint. We also offer auto, education and point-of-sale finance loans in addition to select digital deposit products nationwide.
Consumer Banking operates a multi-channel distribution network with a workforce of approximately 5,780 branch colleagues, approximately 1,100 branches, including 220 in-store locations, and approximately 3,400 ATMs. Our network includes approximately 1,250 specialists covering lending, savings and investment needs as well as a broad range of small business products and services. We serve customers on a national basis through telephone service centers as well as through our online and mobile platforms where we offer customers the convenience of depositing funds, paying bills and transferring money between accounts and from person to person, as well as a host of other everyday transactions.
Commercial Banking Segment
Commercial Banking primarily serves companies and institutions with annual revenues of over $25 million to more than $3.0 billion and strives to be our clients’ trusted advisor and preferred provider for their banking needs. We offer a broad complement of financial products and solutions, including lending and leasing, deposit and treasury management services, foreign exchange, interest rate and commodity risk management solutions, as well as syndicated loans, corporate finance, mergers and acquisitions, and debt and equity capital markets capabilities.
Commercial Banking is structured along business lines and product groups. The business lines, Corporate Banking and Commercial Real Estate, and the product groups, Corporate Finance & Capital Markets, and Treasury Solutions work in teams to understand client needs and provide comprehensive solutions to meet those needs. We acquire new clients through a coordinated approach to the market, leveraging deep industry knowledge in specialized banking groups and a geographic coverage model.
| Citizens Financial Group, Inc. | 6 |
Corporate Banking serves middle market commercial and industrial clients with annual gross revenues of $25 million to $500 million, and mid-corporate clients with annual revenues of $500 million to more than $3.0 billion in the United States. In several areas, such as Aerospace, Defense and Government Services, Communications, Transportation and Logistics, Franchise, Human Capital Management, and Gaming we offer a more dedicated and tailored approach to better meet the unique needs of these client segments.
Commercial Real Estate provides customized debt capital solutions for middle market operators, institutional developers, investors, and REITs. Commercial Real Estate provides financing for projects primarily in the multi-family, co-op, office, industrial, retail, healthcare and hospitality sectors.
Corporate Finance & Capital Markets serves clients through key product groups including Corporate Finance, Capital Markets, and Global Markets. Corporate Finance provides advisory services to middle market and mid-corporate clients, including mergers and acquisitions and capital structure advice. The team works closely with industry-sector specialists within capital markets to advise our clients. Corporate Finance also provides acquisition and follow-on financing for new and recapitalized portfolio companies of key sponsors, with services meeting the unique and time-sensitive needs of private equity firms, management companies and funds, and underwriting and portfolio management expertise for leveraged transactions and relationships. Capital Markets originates, structures and underwrites credit and equity facilities targeting middle market, mid-corporate and private equity sponsors. They focus on offering value-added ideas to optimize their capital structures, including advising on and facilitating mergers and acquisitions, valuations, tender offers, financial restructurings, bond and equity underwriting, asset sales, divestitures and other corporate reorganizations and business combinations. Capital Markets also provides sales and trading across loan, fixed income and equity products, as well as other brokerage services including equity research. Global Markets provides foreign exchange, interest rate and commodities risk management services.
The Treasury Solutions product group supports Commercial Banking and certain small business clients with treasury management solutions, including domestic and international products and services related to receivables, payables, information reporting and liquidity management, as well as commercial credit cards and trade finance.
Business Strategy
Our mission is to help our customers, colleagues and communities reach their potential, and our vision is to become a top-performing bank distinguished by our customer-centric culture, mindset of continuous improvement, and excellent capabilities. We strive to understand customer and client needs, so we can tailor advice and solutions to help make them more successful. Our business strategy is designed to maximize the full potential of our businesses, drive sustainable growth and enhance profitability. Our success rests on our ability to distinguish ourselves as follows:
Maintain a high-performing, customer-centric organization: We continually strive to enhance our “customer-first” culture by emphasizing the “voice of the customer” to deliver the best possible banking experience. In addition, we are taking talent management to the next level, with a goal of attracting, developing and retaining great people, while ensuring strong leadership, teamwork, and a sense of empowerment, accountability and urgency.
Develop differentiated value propositions to acquire, deepen, and retain core customer segments: Our focus is on select customer segments where we believe we are well positioned to compete. In Consumer Banking, we focus on serving mass affluent and affluent customers, and small businesses customers nationally. In Commercial Banking, we focus on serving customers in the middle market, mid-corporate, and select industry verticals. By developing differentiated and targeted value propositions, building our fee-based businesses and developin
Showing the first 8K of 71K characters. Open the full section
Item 1A. RISK FACTORS
We are subject to a number of risks potentially impacting our business, financial condition, results of operations and cash flows. As we are a financial services organization, certain elements of risk are inherent in our transactions and operations and are present in the business decisions we make. We, therefore, encounter risk as part of the normal course of our business and we design risk management processes to help manage these risks. Our success is dependent on our ability to identify, understand and manage the risks presented by our business activities so that we can appropriately balance revenue generation and profitability. These risks include, but are not limited to, credit risk, market risk, liquidity risk, operational risk, model risk, technology, regulatory and legal risk and strategic and reputational risk. We discuss our principal risk management processes and, in appropriate places, related historical performance in the “Risk Governance” section in Item 7.
You should carefully consider the following risk factors that may affect our business, financial condition and results of operations. Other factors that could affect our business, financial condition and results of operation are discussed in the “Forward-Looking Statements” section above. However, there may be additional risks that are not presently material or known, and factors besides those discussed below, or in this or other reports that we file or furnish with the SEC, that could also adversely affect us.
| Citizens Financial Group, Inc. | 20 |
Risks Related to Our Business
We may not be able to successfully execute our business strategy.
Our business strategy is designed to maximize the full potential of our business and drive sustainable growth and enhanced profitability, and our success rests on our ability to maintain a high-performing, customer-centric organization; develop differentiated value propositions to acquire, deepen, and retain core customer segments; build excellent capabilities designed to help us stand out from our competitors; operate with financial discipline and a mindset of continuous improvement to self-fund investments; prudently grow and optimize our balance sheet; modernize our technology and operational models to improve delivery, organizational agility and speed to market; and embed risk management within our culture and our operations. Our future success and the value of our stock will depend, in part, on our ability to effectively implement our business strategy, including the cost savings and efficiency components, and achieve our financial performance goals, including through the integration of Investors and the HSBC branches. There are risks and uncertainties, many of which are not within our control, associated with each element of our strategy. If we are not able to successfully execute our business strategy, we may never achieve our financial performance goals and any shortfall may be material. See the “Business Strategy” section in Item 1 for further information.
Supervisory requirements and expectations on us as a financial holding company and a bank holding company and any regulator-imposed limits on our activities could adversely affect our ability to implement our strategic plan, expand our business, continue to improve our financial performance and make capital distributions to our stockholders.
Our operations are subject to extensive regulation, supervision and examination by the federal banking agencies (the FRB, the OCC and the FDIC), as well as the CFPB. As part of the supervisory and examination process, if we are unsuccessful in meeting the supervisory requirements and expectations that apply to us, regulatory agencies may from time to time take supervisory actions against us that may not be publicly disclosed. Such actions may include restrictions on our activities or the activities of our subsidiaries, informal (nonpublic) or formal (public) supervisory actions or public enforcement actions, including the payment of civil money penalties, which could increase our costs and limit our ability to implement our strategic plans and expand our business, and as a result could have a material adverse effect on our business, financial condition or results of operations. See the “Regulation and Supervision” section in Item 1 for further information.
Difficult economic conditions, including inflationary pressures or volatility in the financial markets would likely have an adverse effect on our business, financial position and results of operations.
Robust demand, labor shortages and supply chain constraints have led to persistent inflationary pressures throughout the economy. In response to these inflationary pressures, the FRB has raised benchmark interest rates in recent months and may continue to raise interest rates in response to economic conditions, particularly a continued high rate of inflation. Amidst these uncertainties, including potential recessionary economic conditions, financial markets have continued to experience volatility. Changes in interest rates can affect numerous aspects of our business and may impact our future performance. See risk factor headed “Changes in interest rates may have an adverse effect on our profitability” below for more information on the risks associated with changes in interest rates.
Prolonged periods of inflation may impact our profitability by negatively impacting our costs and expenses, including increasing funding costs and expense related to talent acquisition and retention, and negatively impacting consumer demand and client purchasing power for our products and services. If significant inflation continues, our business could be negatively affected by, among other things, increased default rates leading to credit losses which could adversely impact our earnings and capital.
Any of the effects of these adverse economic conditions would likely have an adverse impact on our earnings, with the significance of the impact generally depending on the nature and severity of the adverse economic conditions.
| Citizens Financial Group, Inc. | 21 |
Changes in interest rates may have an adverse effect on our profitability.
Net interest income historically has been, and we anticipate that it will remain, a significant component of our total revenue. This is due to the fact that a high percentage of our assets and liabilities have been and will likely continue to be in the form of interest-bearing or interest-related instruments. Changes in interest rates can have a material effect on many areas of our business, including net interest income, deposit costs, loan volume and delinquency, and the value of our mortgage servicing rights. Interest rates are highly sensitive to many factors that are beyond our control, including general economic conditions and policies of various governmental and regulatory agencies and, in particular, the Federal Open Market Committee. Changes in monetary policy, including changes in interest rates, could influence not only the interest we receive on loans and securities and the amount of interest we pay on deposits and borrowings, but such changes could also affect our ability to originate loans and obtain deposits and the fair value of our financial assets and liabilities. If the interest rates on our interest-bearing liabilities increase at a faster pace than the interest rates on our interest earning assets, our net interest income may decline and, with it, a decline in our earnings may occur. Our net interest income and our earnings would be similarly affected if the interest rates on our interest earning assets declined at a faster pace than the interest rates on our interest-bearing liabilities.
We ca
Showing the first 8K of 74K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
We lease seven operations centers in Boston, Medford, and Westwood, Massachusetts; Pittsburgh, Pennsylvania; Franklin, Tennessee; Irving, Texas and Glen Allen, Virginia. We own two principal operations centers in Johnston and East Providence, Rhode Island. At December 31, 2022, our subsidiaries owned and operated a total of 59 facilities and leased an additional 1,293 facilities. We believe our current facilities are adequate to meet our needs. See Note 7 and Note 9 in Item 8 for more information regarding our premises and equipment, and leases, respectively.
Item 3. LEGAL PROCEEDINGS
Information required by this item is presented in Note 19 in Item 8 and is incorporated herein by reference.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Our common stock is traded on the New York Stock Exchange under the symbol “CFG.” As of January 31, 2023, our common stock was owned by 7,306 holders of record (including Cede & Co.) and approximately 525,000 beneficial shareholders whose shares were held in “street name” through a broker or bank. Information relating to compensation plans under which our equity securities are authorized for issuance is presented in Item 12.
The following graph compares the cumulative total stockholder returns for our performance during the five-year period ended December 31, 2022 relative to the performance of the Standard & Poor’s 500® index, a commonly referenced U.S. equity benchmark consisting of leading companies from diverse economic sectors; the KBW Nasdaq Bank Index (“BKX”), composed of 24 leading national money centers, regional banks and thrifts; and a group of other banks that constitute our peer regional banks. The graph assumes a $100 investment at the closing price on December 31, 2017 in each of CFG common stock, the S&P 500 index, the BKX and the peer market-capitalization weighted average and assumes all dividends were reinvested on the date paid. The points on the graph represent the fiscal quarter-end amounts based on the last trading day in each subsequent fiscal quarter.
| Citizens Financial Group, Inc. | 35 |
This graph shall not be deemed “soliciting material” or be filed with the Securities and Exchange Commission for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (“Exchange Act”), or otherwise subject to the liabilities under that Section, and shall not be deemed to be incorporated by reference into any filing of Citizens Financial Group, Inc. under the Securities Act of 1933, as amended, or the Exchange Act.
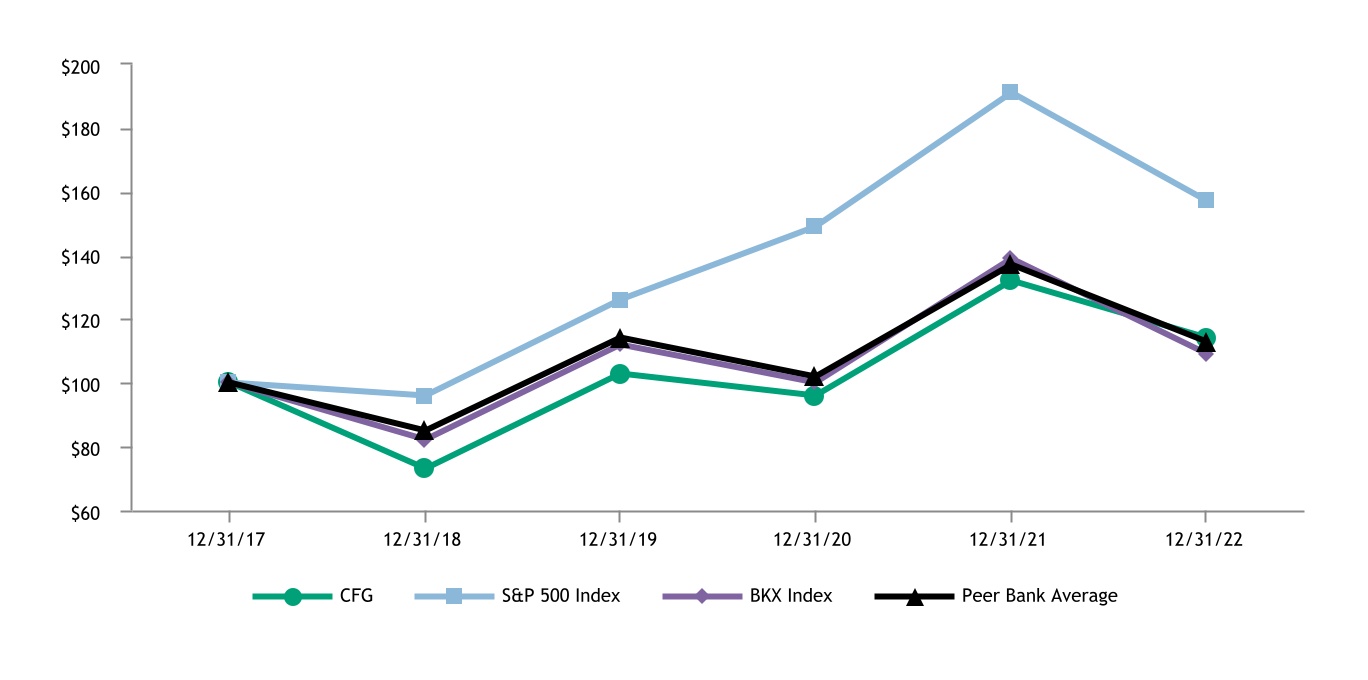
| 12/31/2022 | 12/31/2021 | 12/31/2020 | 12/31/2019 | 12/31/2018 | 12/31/2017 | |||||||||||||||
| CFG | $114 | $132 | $96 | $103 | $73 | $100 | ||||||||||||||
| S&P 500 Index | 157 | 191 | 149 | 126 | 96 | 100 | ||||||||||||||
| KBW BKX Index | 109 | 139 | 100 | 112 | 82 | 100 | ||||||||||||||
| Peer Regional Bank Average | 113 | 137 | 102 | 114 | 85 | 100 |
Issuer Purchase of Equity Securities
Details of the repurchases of the Company’s common stock during the three months ended December 31, 2022 are included below:
| Period | Total Number of Shares Repurchased**(1)** | Average Price Paid Per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs**(2)** | Maximum Dollar Amount of Shares That May Yet Be Purchased as Part of Publicly Announced Plans or Programs**(2)** | ||||||||||
| October 1, 2022 - October 31, 2022 | 3,366,139 | $40.18 | 3,360,569 | $864,930,346 | ||||||||||
| November 1, 2022 - November 30, 2022 | 5,597 | $39.49 | — | $864,930,346 | ||||||||||
| December 1, 2022 - December 31, 2022 | 373,120 | $40.02 | 371,471 | $850,000,000 |
(1) Includes shares repurchased to satisfy applicable tax withholding obligations in connection with an employee share-based compensation plan and the forfeiture of unvested restricted stock awards.
(2) On June 27, 2022, the Company announced that its Board of Directors increased the authorization of common share repurchases to $1.0 billion, which was an increase of $545 million above the $455 million of capacity remaining under the $750 million authorization on January 20, 2021.
On February 17, 2023, the Company announced that its Board of Directors increased the capacity under its common share repurchase program by an additional $1.15 billion. This is incremental to the $850 million of capacity remaining as of December 31, 2022 under the prior June 2022 authorization.
| Citizens Financial Group, Inc. | 36 |
Common stock share repurchases may be executed in the open market or in privately negotiated transactions, including under Rule 10b5-1 plans and accelerated share repurchase and other structured transactions. The timing and exact amount of future share repurchases will be subject to various factors, including the Company’s capital position, financial performance, capital impacts of strategic initiatives, market conditions, receipt of required regulatory approvals and other regulatory considerations.
Item 6. RESERVED
Not applicable.
| Citizens Financial Group, Inc. | 37 |
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
| Citizens Financial Group, Inc. | 38 |
INTRODUCTION
Citizens Financial Group, Inc. is one of the nation’s oldest and largest financial institutions, with $226.7 billion in assets as of December 31, 2022. Headquartered in Providence, Rhode Island, we offer a broad range of retail and commercial banking products and services to individuals, small businesses, middle-market companies, large corporations and institutions. We help our customers reach their potential by listening to them and by understanding their needs in order to offer tailored advice, ideas and solutions. In Consumer Banking, we provide an integrated experience that includes mobile and online banking, a full-service customer contact center and the convenience of approximately 3,400 ATMs and more than 1,100 branches in 14 states and the District of Columbia. Consumer Banking products and services include a full range of banking, lending, savings, wealth management and small business offerings. In Commercial Banking, we offer a broad complement of financial products and solutions, including lending and leasing, deposit and treasury management services, foreign exchange, interest rate and commodity risk management solutions, as well as loan syndication, corporate finance, merger and acquisition, and debt and equity capital markets capabilities. More information is available at www.citizensbank.com.
On February 18, 2022, CBNA completed the acquisition of the HSBC East Coast branches and national online deposit business. The transaction extends our physical presence and adds customers in several attractive markets, accelerating our national expansion strategy. The transaction includes 66 branches in the New York City metropolitan area, 9 branches in the Mid-Atlantic/Washington D.C. area, and 5 branches in Southeast Florida.
On April 6, 2022, Citizens completed the acquisition of all outstanding shares of Investors for a combination of stock and cash. The acquisition enhances Citizens’ banking franchise, adding an attractive middle market, small business and consumer customer base while building our physical presence in the Mid-Atlantic region with the addition of 154 branches located in the greater New York City and Philadelphia metropolitan areas and across New Jersey.
On June 8, 2022, Citizens completed the acquisition of DH Capital, a private investment banking firm serving companies in the internet infrastructure, software, IT services and communications sectors. This acquisition further strengthens our growing corporate advisory capabilities.
For additional information regarding these acquisitions see Note 2.
The following MD&A is intended to assist readers in their analysis of the accompanying Consolidated Financial Statements and supplemental financial information. It should be read in conjunction with the Consolidated Financial Statements and Notes to Consolidated Financial Statements in Item 8, as well as other information contained in this document.
Non-GAAP Financial Measures
This document contains non-GAAP financial measures denoted as “Underlying” results. Underlying results for any given reporting period exclude certain items that may occur in that period which management does not consider indicative of our on-going financial performance. We believe these non-GAAP financial measures provide useful information to investors because they are used by management to evaluate our operating performance and make day-to-day operating decisions. In addition, we believe our Underlying results in any given reporting period reflect our on-going financial performance in that period and, accordingly, are useful to consider in addition to our GAAP financial results. We further believe the presentation of Underlying results increases comparability of period-to-period results.
Other companies may use similarly titled non-GAAP financial measures that are calculated differently from the way we calculate such measures. Accordingly, our non-GAAP financial measures may not be comparable to similar measures used by such companies. We caution investors not to place undue reliance on such non-GAAP financial measures, but to consider them with the most directly comparable GAAP measures. Non-GAAP financial measures have limitations as analytical tools and should not be considered in isolation or as a substitute for our results reported under GAAP.
Non-GAAP measures are denoted throughout our MD&A by the use of the term Underlying. Where there
Showing the first 8K of 182K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
Quantitative and qualitative disclosures about market risk are presented in the “Market Risk” section of Part II, Item 7 and is incorporated herein by reference.
| Citizens Financial Group, Inc. | 78 |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
| Citizens Financial Group, Inc. | 79 |
REPORT OF MANAGEMENT ON INTERNAL CONTROL OVER FINANCIAL REPORTING
Management is responsible for establishing and maintaining an adequate system of internal control over financial reporting as defined in Rule 13a-15(f) of the Securities Exchange Act of 1934. The Company’s system of internal control over financial reporting is designed, under the supervision of the Chief Executive Officer and the Chief Financial Officer, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with accounting principles generally accepted in the United States of America.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect all misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions or that the degree of compliance with the policies or procedures may deteriorate.
Management assessed the effectiveness of the Company’s system of internal control over financial reporting as of December 31, 2022 based on the framework set forth by the Committee of Sponsoring Organizations of the Treadway Commission in Internal Control — Integrated Framework (2013). Based on that assessment, management concluded that, as of December 31, 2022, the Company’s internal control over financial reporting is effective.
The Company’s internal control over financial reporting as of December 31, 2022 has been audited by Deloitte & Touche LLP, an independent registered public accounting firm, as stated in their accompanying report appearing on page 85, which ex
Showing the first 8K of 359K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
| Citizens Financial Group, Inc. | 153 |
Item 9A. CONTROLS AND PROCEDURES
The Company maintains a set of disclosure controls and procedures designed to ensure that information required to be disclosed by the Company in reports that it files or submits under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in SEC rules and forms. The design of any disclosure controls and procedures is based in part upon certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions. Any controls and procedures, no matter how well designed and operated, can provide only reasonable, not absolute, assurance of achieving the desired control objectives. In accordance with Rule 13a-15(b) of the Exchange Act, as of the end of the period covered by this Annual Report on Form 10-K, an evaluation was carried out under the supervision and with the participation of the Company’s management, including its Chief Executive Officer and Chief Financial Officer, of the effectiveness of its disclosure controls and procedures. Based on that evaluation, the Company’s Chief Executive Officer and Chief Financial Officer concluded that the Company’s disclosure controls and procedures, as of the end of the period covered by this Annual Report on Form 10-K, were effective to provide reasonable assurance that information required to be disclosed by the Company in reports that it files or submits under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in SEC rules and forms and is accumulated and communicated to the Company’s management, including the Chief Executive Officer and Chief Financial Officer, as appropriate, to allow timely decisions regarding required disclosure.
There were no changes in our internal control over financial reporting identified in management's evaluation pursuant to Rules 13a-15(d) or 15d-15(d) of the Exchange Act during the period covered by this Annual Report on Form 10-K that materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
Management’s Annual Report on Internal Control over Financial Reporting, the Report of the Independent Registered Public Accounting Firm on the Consolidated Financial Statements and the Report of the Independent Registered Public Accounting Firm on Internal Control over Financial Reporting are included in Item 8.
Item 9B. OTHER INFORMATION
Effective February 16, 2023, the Company’s Board of Directors approved and adopted an amendment and restatement of the Company’s Bylaws (as so amended and restated, the “Bylaws”).
The Board of Directors approved the Bylaws as part of its periodic review of the Company’s corporate governance documents. The Bylaws include amendments that:
-
revise provisions regarding adjournment of stockholder meetings in light of recent amendments to the Delaware General Corporation Law (the “DGCL”);
-
update the Company’s bylaws in connection with the new SEC rules relating to universal proxy cards (the “Universal Proxy Rules”), including requiring stockholders providing notice pursuant to Rule 14a-19(b) under the Exchange Act, to certify to the Company that they have complied with certain requirements under the Universal Proxy Rules no later than 7 business days prior to the applicable stockholder meeting;
-
refine and clarify the advance notice provisions for stockholder nominations and proposals, including provisions regarding (1) the information to be provided by proposing stockholders, proposed nominees and other persons related to a stockholder’s solicitation of proxies and (2) the questionnaire, representation and agreement to be completed by proposing stockholders and proposed nominees in connection with a stockholder nomination; and
-
require any stockholder directly or indirectly soliciting proxies from other stockholders to use a proxy card color other than white.
The Bylaws also implement certain other administrative, technical and conforming changes, including changes to align with the language used in certain provisions of the DGCL and the Universal Proxy Rules.
The foregoing description of the changes implemented by the Bylaws does not purport to be complete and is qualified in its entirety by reference to the Bylaws that are attached hereto as Exhibit 3.2 and incorporated by reference herein.
Item 9C. DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS
Not applicable.
| Citizens Financial Group, Inc. | 154 |
PART III
In Part III of this Report we refer to relevant sections of our 2023 Proxy Statement for the 2023 annual meeting of shareholders, which will be filed with the SEC pursuant to Regulation 14A within 120 days of the close of our 2022 fiscal year. Portions of our 2023 Proxy Statement, including the sections we refer to in this Report, are incorporated by reference into this Report.
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
Information required by this item is presented under the captions “Corporate Governance Matters” — “Proposal One — Election of Directors” and “Board Governance and Oversight — “Corporate Governance Guidelines, Committee Charters and Code of Business Conduct and Ethics” of our 2023 Proxy Statement, which is incorporated by reference into this item.
Item 11. EXECUTIVE COMPENSATION
Information required by this item is presented under the captions “Compensation Matters” — “Compensation Discussion and Analysis,” “Compensation and Human Resources Committee Report,” “Executive Compensation,” “Termination of Employment and Change of Control,” “Director Compensation,” “Role of Risk Management in Compensation,” “Dodd Frank Compensation Disclosure” — “CEO Pay Ratio” and “Pay Versus Performance” of our 2023 Proxy Statement, which is incorporated by reference into this item.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
The information required by this item regarding security ownership of certain beneficial owners and management is presented under the caption “Security Ownership of Certain Beneficial Owners and Management” in our 2023 Proxy Statement and is incorporated herein by reference.
Information regarding our compensation plans under which CFG equity securities are authorized for issuance is included in the table below. Additional information regarding these plans is included in Note 18 in Item 8.
Equity Compensation Plan Information
At December 31, 2022
| Plan Category | Number of securities to be issued upon exercise of outstanding options, warrants and rights (#)****(3) | Weighted-average exercise price of outstanding options, warrants and rights ($)****(4) | Number of securities remaining available (excluding securities reflected in first column) (#)****(5) | ||||||||
| Equity compensation plans approved by security holders | 3,864,001 | — | 47,080,139 | ||||||||
| Equity compensation plans not approved by security holders | — | — | — | ||||||||
| Total(1)(2) | 3,864,001 | — | 47,080,139 |
(1) Excludes securities subject to the Investors Bancorp, Inc. 2006 Equity Incentive Plan and the Investors Bancorp, Inc. 2015 Equity Incentive Plan (“Investors Plans”). Although equity-based awards granted under the Investors Plans were converted into CFG awards and assumed in connection with the Investors acquisition, CFG does not intend to grant any awards under the Investors Plans. As of December 31, 2022, 1,114,324 stock options with a weighted-average exercise price of $38.21 and 71,413 restricted shares were outstanding under the Investors Plans.
(2) Excludes securities subject to the JMP Group LLC Amended and Restated Equity Incentive Plan (“JMP Plan”). Although equity-based awards granted under the JMP Plan were converted into CFG awards and assumed in connection with the JMP acquisition in 2021, CFG does not intend to grant any awards under the JMP Plan. As of December 31, 2022, 245,861 stock options with a weighted-average exercise price of $19.45 and 12,600 restricted stock units were outstanding under the JMP Plan.
(3) Represents the number of shares of common stock associated with outstanding time-based and performance-based restricted stock units.
(4) Other than the stock options assumed in connection with the JMP and Investors acquisitions, CFG had no outstanding stock options.
(5) Represents the number of shares remaining available for future issuance under the Citizens Financial Group, Inc. 2014 Omnibus Incentive Plan (41,887,596 shares), the Citizens Financial Group, Inc. 2014 Employee Stock Repurchase Plan (3,903,590 shares), and the Citizens Financial Group, Inc. 2014 Non-Employee Directors Compensation Plan (1,288,953 shares).
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
Information required by this item is set forth under the captions “Corporate Governance Matters” — “Board Governance and Oversight — Director Independence” and “Related Person Transactions” of our 2023 Proxy Statement, which is incorporated by reference into this item.
| Citizens Financial Group, Inc. | 155 |
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
Information required by this item is presented under the captions “Audit Matters” — “Pre-approval of Independent Auditor Services” and “Independent Registered Public Accounting Firm Fees” of our 2023 Proxy Statement, which is incorporated by reference into this item.
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
(a)(1) Financial Statements of Citizens Financial Group, Inc., included in this Report:
-
Report of Independent Registered Public Accounting Firm on the Consolidated Financial Statements;
-
Consolidated Balance Sheets as of December 31, 2022 and 2021;
-
Consolidated Statements of Operations for the Years Ended December 31, 2022, 2021 and 2020;
-
Consolidated Statements of Comprehensive Income for the Years Ended December 31, 2022, 2021 and 2020;
-
Consolidated Statements of Changes in Stockholders’ Equity for the Years Ended December 31, 2022, 2021 and 2020;
-
Consolidated Statements of Cash Flows for the Years Ended December 31, 2022, 2021 and 2020; and
-
Notes to Consolidated Financial Statements.
(a)(2) Financial Statement Schedules
All financial statement schedules for the Registrant have been included in the audited Consolidated Financial Statements or the related footnotes in Item 8, or are either inapplicable or not required.
(a)(3) Exhibits
3.2 Amended and Restated Bylaws of the Registrant (as amended and restated on February 16, 2023)*
4.6 Description of the Securities Registered Pursuant to Section 12 of the Securities Act of 1934*
| Citizens Financial Group, Inc. | 156 |
10.6 Citizens Financial Group, Inc. 2014 Omnibus Incentive Plan Form of Performance Stock Unit Award Agreement†*
10.7 Citizens Financial Group, Inc. 2014 Omnibus Incentive Plan Performance Stock Unit Award Agreement for Bruce Van Saun Relating to Annual Awards (incorporated herein by reference to Exhibit 10.15 of the Annual Report on Form 10-K, Filed February 24, 2017)†
10.11 Citizens Financial Group, Inc. Non-Employee Directors Compensation Policy, amended and effective April 28, 2022 (incorporated herein by reference to Exhibit 10.1 of the Quarterly Report on Form 10-Q, filed August 3, 2022)†
10.13 Amended and Restated Citizens Financial Group, Inc. 2014 Non-Employee Directors Compensation Plan as of June 23, 2016 (incorporated herein by reference to Exhibit 10.1 of the Quarterly Report on Form 10-Q, filed August 5, 2016)†
10.14 Citizens Financial Group, Inc. 2014 Non-Employee Directors Compensation Plan Form of Restricted Stock Unit Award Agreement (incorporated herein by reference to Exhibit 10.19 of the Annual Report on Form 10-K, filed February 26, 2016)†
10.15 Citizens Financial Group, Inc. 2014 Non-Employee Directors Compensation Plan Form of Restricted Stock Unit Award Agreement (incorporated herein by reference to Exhibit 10.2 of the Quarterly Report on Form 10-Q, Filed August 3, 2017)†
| Citizens Financial Group, Inc. | 157 |
10.16 Amended and Restated Deferred Compensation Plan for Directors of Citizens Financial Group, Inc., effective January 1, 2009 (incorporated herein by reference to Exhibit 10.19 of Amendment No. 2 to Registration Statement on Form S-1, filed August 15, 2014)†
10.17 Form of Indemnification Agreement (incorporated herein by reference to Exhibit 10.5 of Amendment No. 3 to Registration Statement on Form S-1, filed September 8, 2014)†
10.18 Amended and Restated CFG Voluntary Executive Deferred Compensation Plan, effective January 1, 2009 and amended and restated on September 1, 2014 (incorporated herein by reference to Exhibit 10.21 of the Annual Report on Form 10-K, filed March 3, 2015)†
10.19 First Amendment to the CFG Voluntary Executive Deferred Compensation Plan dated March 1, 2019 (incorporated herein by reference to Exhibit 10.26 of the Annual Report on Form 10-K, filed February 24, 2020)†
10.20 Second Amendment to the CFG Voluntary Executive Deferred Compensation Plan dated December 9, 2019 (incorporated herein by reference to Exhibit 10.27 of the Annual Report on Form 10-K, filed February 24, 2020)†
10.21 Third Amendment to the CFG Voluntary Executive Deferred Compensation Plan dated March 4, 2020 (incorporated herein by reference to Exhibit 10.27 of the Annual Report on Form 10-K, filed February 23, 2021)†
10.22 Fourth Amendment to the CFG Voluntary Executive Deferred Compensation Plan dated January 1, 2022 (incorporated herein by reference to Exhibit 10.21 of the Annual Report on Form 10-K, filed February 23, 2022)†
10.23 Amended and Restated Citizens Financial Group, Inc. Deferred Compensation Plan, effective January 1, 2009 (incorporated herein by reference to Exhibit 10.20 of Amendment No. 2 to Registration Statement on Form S-1, filed August 15, 2014)†
10.24 Citizens Financial Group, Inc. Form of Deferred Cash Award Agreement†*
10.25 Citizens Financial Group, Inc. Executive Severance Practice (incorporated herein by reference to Exhibit 10.21 of Amendment No. 2 to Registration Statement on Form S-1, filed August 15, 2014)†
10.26 Amended and Restated Executive Employment Agreement, dated May 5, 2016, between the Registrant and Bruce Van Saun (incorporated herein by reference to Exhibit 10.5 of the Quarterly Report on Form 10-Q, filed May 9, 2016)†
10.27 Addendum to Amended and Restated Executive Employment Agreement, dated as of June 25, 2021 between the Registrant and Bruce Van Saun (incorporated herein by reference to Exhibit 10.2 of the Quarterly Report on Form 10-Q filed August 3, 2021)†
10.28 Executive Employment Agreement, dated March 23, 2015, between the Registrant and Donald H. McCree III and subsequent addendum dated August 2, 2017 (incorporated herein by reference to Exhibit 10.7 of the Quarterly Report on Form 10-Q, filed August 3, 2017)†
10.29 Executive Employment Agreement, dated September 6, 2014, between the Registrant and Malcolm Griggs and subsequent addendum dated August 14, 2017 (incorporated herein by reference to Exhibit 10.41 of the Annual Report on Form 10-K, filed February 21, 2019)†
10.30 Executive Employment Agreement, dated December 13, 2016, between the Registrant and John F. Woods and subsequent addendum dated August 2, 2017 (incorporated herein by reference to Exhibit 10.8 of the Quarterly Report on Form 10-Q, filed August 3, 2017)†
| Citizens Financial Group, Inc. | 158 |
10.31 Executive Employment Agreement, dated August 25, 2011, between the Registrant and Susan LaMonica and subsequent addenda dated July 15, 2014 and August 11, 2017 (incorporated herein by reference to Exhibit 10.39 of the Annual Report on Form 10-K, filed February 23, 2021)†
10.32 Amended and Restated Executive Employment Agreement, dated December 20, 2021, between the Registrant and Brendan Coughlin (incorporated herein by reference to Exhibit 10.32 of the Annual Report on Form 10-K, filed February 23, 2022)†
10.33 Supplemental Retirement Agreement, dated October 31, 1995, as amended, between Charter One Financial, Inc. and, Charles J. Koch (incorporated herein by reference to Exhibit 10.37 of Amendment No. 3 to Registration Statement on Form S-1, filed September 8, 2014)†
10.34 Investors Bancorp, Inc. 2015 Equity Incentive Plan (incorporated herein by reference to Exhibit 4.3 of the Registration Statement on Form S-8, filed April 7, 2022)†
10.35 Investors Bancorp, Inc. 2015 Equity Incentive Plan Form of Stock Option Agreement†*
21.1 Subsidiaries of Registrant*
23.1 Consent of Independent Registered Public Accounting Firm*
24.1 Power of Attorney (contained herein on signature pages)
101 The following materials from the Registrant's Annual Report on Form 10-K for the fiscal year ended December 31, 2022, formatted in XBRL: (i) the Consolidated Balance Sheets, (ii) the Consolidated Statements of Operations, (iii) the Consolidated Statements of Comprehensive Income, (iv) the Consolidated Statements of Changes in Stockholders’ Equity, (v) the Consolidated Statements of Cash Flows and (vi) the Notes to Consolidated Financial Statements*
104 Cover page interactive data file in inline XBRL format, included in Exhibit 101 to this report*
† Indicates management contract or compensatory plan or arrangement.
- Filed herewith.
Item 16. FORM 10-K SUMMARY
Not applicable.
| Citizens Financial Group, Inc. | 159 |
SIGNATURES
Pursuant to the requirements of the Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this Report to be signed on its behalf by the undersigned, thereunto duly authorized on February 17, 2023.
| CITIZENS FINANCIAL GROUP, INC. | |||||
| (Registrant) | |||||
| By: | /s/ Bruce Van Saun | ||||
| Name: Bruce Van Saun | |||||
| Title: Chairman of the Board and Chief Executive Officer | |||||
| (Principal Executive Officer) | |||||
| Citizens Financial Group, Inc. | 160 |
SIGNATURES
KNOW ALL PERSONS BY THESE PRESENTS, that each of the undersigned, being a director or officer of Citizens Financial Group, Inc., a Delaware corporation (the "Company"), hereby constitutes and appoints Bruce Van Saun, John F. Woods, Polly N. Klane, and C. Jack Read, and each of them, his or her true and lawful attorney-in-fact and agent, with full power of substitution and resubstitution, for him or her and in his or her name, place and stead in any and all capacities, to sign one or more Annual Reports for the Company's fiscal year ended December 31, 2022 on Form 10-K under the Securities Exchange Act of 1934, as amended, or such other form as any such attorney-in-fact may deem necessary or desirable, any amendments thereto, and all additional amendments thereto, each in such form as they or any one of them may approve, and to file the same with all exhibits thereto and other documents in connection therewith with the Securities and Exchange Commission, granting unto said attorneys-in-fact and agents, and each of them, full power and authority to do and perform each and every act and thing requisite and necessary to be done so that such Annual Report shall comply with the Securities Exchange Act of 1934, as amended, and the applicable Rules and Regulations adopted or issued pursuant thereto, as fully and to all intents and purposes as he or she might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact and agents, or any of them or their substitute or resubstitute, may lawfully do or cause to be done by virtue hereof.
Pursuant to the requirements of the Securities Exchange Act of 1934, this Report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the date indicated.
| Signature | Title | Date | |||||||||||||||
| /s/ Bruce Van Saun | |||||||||||||||||
| Bruce Van Saun | Chairman of the Board and Chief Executive Officer | February 17, 2023 | |||||||||||||||
| (Principal Executive Officer and Director) | |||||||||||||||||
| /s/ John F. Woods | |||||||||||||||||
| John F. Woods | Vice Chairman and Chief Financial Officer | February 17, 2023 | |||||||||||||||
| (Principal Financial Officer) | |||||||||||||||||
| /s/ C. Jack Read | |||||||||||||||||
| C. Jack Read | Executive Vice President, Chief Accounting Officer and Controller | February 17, 2023 | |||||||||||||||
| (Principal Accounting Officer) | |||||||||||||||||
| /s/ Lee Alexander | |||||||||||||||||
| Lee Alexander | Director | February 17, 2023 | |||||||||||||||
| /s/ Christine M. Cumming | |||||||||||||||||
| Christine M. Cumming | Director | February 17, 2023 | |||||||||||||||
| /s/ Kevin Cummings | |||||||||||||||||
| Kevin Cummings | Director | February 17, 2023 | |||||||||||||||
| /s/ William P. Hankowsky | |||||||||||||||||
| William P. Hankowsky | Director | February 17, 2023 | |||||||||||||||
| /s/ Edward J. Kelly III | |||||||||||||||||
| Edward J. Kelly III | Director | February 17, 2023 | |||||||||||||||
| /s/ Robert G. Leary | |||||||||||||||||
| Robert G. Leary | Director | February 17, 2023 | |||||||||||||||
| /s/ Terrance J. Lillis | |||||||||||||||||
| Terrance J. Lillis | Director | February 17, 2023 | |||||||||||||||
| /s/ Michele N. Siekerka | |||||||||||||||||
| Michele N. Siekerka | Director | February 17, 2023 | |||||||||||||||
| /s/ Shivan S. Subramaniam | |||||||||||||||||
| Shivan S. Subramaniam | Director | February 17, 2023 | |||||||||||||||
| /s/ Christopher J. Swift | |||||||||||||||||
| Christopher J. Swift | Director | February 17, 2023 | |||||||||||||||
| /s/ Wendy A. Watson | |||||||||||||||||
| Wendy A. Watson | Director | February 17, 2023 | |||||||||||||||
| /s/ Marita Zuraitis | |||||||||||||||||
| Marita Zuraitis | Director | February 17, 2023 |
| Citizens Financial Group, Inc. | 161 |