 filings.tools
Citizens Financial Group (CFG) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A105 rewritten45 added77 removed206 unchanged
All filing items2,115 rewritten1,100 added901 removed2,672 unchanged
Summary
counted, not written
- Item 1A lists 36 risk factor headings: 3 new, 5 reworded and 28 unchanged since FY2022. 4 headings from FY2022 no longer appear.
- Sentence by sentence, 1,100 added, 901 removed, 2,115 rewritten and 2,672 unchanged across 21 items that differ.
- New this year: Item 1C. CYBERSECURITY.
New Item 1A headings (3)
- Our financial performance may be adversely affected by deterioration in borrower credit quality.
- The preparation of our financial statements requires us to make subjective determinations and use estimates that may vary from actual results and materially impact our financial condition and results of operations.
- Our regulators may impose restrictions or limitations on our operations.
Removed Item 1A headings (4)
- Changes in the method pursuant to which the LIBOR and other benchmark rates are calculated and their planned discontinuance could adversely impact our business operations and financial results.
- Our financial performance may be adversely affected by deterioration in borrower credit quality, particularly in the New England, Mid-Atlantic and Midwest regions, where our operations are predominately concentrated.
- The preparation of our financial statements requires the use of estimates that may vary from actual results. Particularly, various factors may cause our Allowance for Credit Losses to increase.
- We may be unable to disclose some restrictions or limitations on our operations imposed by our regulators.
Reworded Item 1A headings (5)
- Difficult economic conditions, including inflationary
[removed: pressures or volatility in the financial markets][added: pressures,] would likely have an adverse effect on our business, financial position and results of operations. - Changes in interest rates may have an adverse effect on our [added: liquidity and] profitability.
- A reduction in our credit
[removed: ratings, which are based on a number of factors,][added: ratings] could have a material adverse effect on our business, financial condition and results of operations. - The financial services industry, including the banking sector,
[removed: is undergoing rapid][added: continues to make] technological[removed: change as a result of changes in][added: enhancements to meet] customer[removed: behavior, competition and changes in the][added: preferences, as well as meet] legal and regulatory[removed: framework,][added: requirements,] and we may not be able to compete effectively as a result of these changes. - The effects of geopolitical
[removed: instability, such as Russia’s invasion of Ukraine,][added: instability] may adversely affect us and create significant risks and uncertainties for our business, with the ultimate impact dependent on future developments, which are highly uncertain and unpredictable.
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
24 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
105 rewritten, 45 added, 77 removed, 206 unchanged
As [removed: we are] a financial services organization, certain elements of risk are inherent in our transactions and operations and [removed: are present in] the business decisions we make.
[removed: We, therefore,] [added: Therefore, we] encounter risk as part of the normal course of our business and [removed: we] design [added: a] risk management [added: framework and associated] processes to help manage these risks.
Our success is dependent on our ability to identify, understand and manage the risks presented by our business activities so that we can appropriately balance [added: risk taking with] revenue generation and profitability.
We discuss [added: the primary risks we face and] our [removed: principal] risk management [added: framework and associated] processes [removed: and, in appropriate places, related historical performance] [added: and strategies] in the “Risk Governance” section in Item 7.
You should carefully consider the following risk factors that may affect our business, financial [removed: condition and] [added: condition,] results of [removed: operations.][added: operations or cash flows.]
Other factors that could affect [removed: our business, financial condition and results of operation] [added: us] are discussed in the “Forward-Looking Statements” section above.
However, there may be additional risks that are not [removed: presently] [added: currently] material or known, and factors besides those discussed below, or in this or other reports that we file or furnish with the SEC, that could [removed: also] adversely affect us.
Our future success and the value of our stock [removed: will depend,] [added: depends,] in part, on our ability to effectively implement our business strategy, including the cost savings and efficiency components, and achieve our financial performance goals, including [removed: through] the [removed: integration] [added: anticipated benefits] of [removed: Investors and] the [removed: HSBC branches.][added: Private Bank start-up investment and Investors acquisition.]
If we are not able to successfully execute our business strategy, we may [removed: never] [added: not] achieve our financial performance goals and any shortfall may be material.
Our operations are subject to extensive regulation, supervision and examination by the federal banking [removed: agencies (the FRB, the OCC and the FDIC),] [added: regulators,] as well as the CFPB.
As part of the supervisory and examination process, if we are unsuccessful in meeting the [removed: supervisory] requirements and expectations that apply to us, regulatory agencies may from time to time take supervisory actions against us that may not be publicly disclosed.
Difficult economic conditions, including inflationary [removed: pressures or volatility in the financial markets] [added: pressures,] would likely have an adverse effect on our business, financial position and results of operations.
[removed: Amidst these uncertainties,] [added: Financial markets remain volatile amidst the uncertainty of economic conditions,] including potential recessionary [removed: economic conditions, financial markets have continued to experience volatility.][added: conditions.]
[removed: See risk factor headed] [added: Also, see] “Changes in interest rates may have an adverse effect on our profitability” below for more information on the risks associated with changes in interest rates.
Any of the effects of these adverse economic conditions would likely have an adverse impact on our earnings, with the significance of the impact generally depending on the nature and severity of the [removed: adverse] economic conditions.
Changes in interest rates may have an adverse effect on our [added: liquidity and] profitability.
Interest rates [added: and the yield curve] are highly sensitive to many factors that are beyond our control, including general economic conditions and [added: the] policies of various governmental and regulatory agencies and, in particular, the Federal Open Market Committee.
Although we have policies and procedures designed to manage [removed: the risks associated with changes in market] [added: our] interest [removed: rates,] [added: rate risks,] as further discussed [removed: under] [added: in] the “Risk Governance” section in Item 7, [removed: changes] [added: there can be no assurance that these policies and procedures will be effective] in [removed: interest rates still may have an] [added: avoiding material] adverse [removed: effect] [added: effects] on our profitability.
For more information [removed: on] [added: regarding] our [removed: LIBOR transition,] [added: credit ratings,] see the [removed: “Market Risk”] [added: “Liquidity”] section in Item 7.
We could fail to attract, retain or motivate [removed: highly skilled] [added: highly-skilled] and qualified personnel, including our senior management, other key employees or members of our Board, which could impair our ability to successfully execute our strategic plan and otherwise adversely affect our business.
[removed: Accordingly, our] [added: Our] ability to implement our strategic plan and our future success depends on our ability to attract, retain and motivate [removed: highly skilled] [added: highly-skilled] and qualified personnel, including our senior management and other key employees and directors.
The marketplace for skilled personnel [removed: is becoming more] [added: continues to be] competitive, which means the cost of hiring, incentivizing and retaining skilled personnel may continue to [removed: increase.][added: rise.]
The failure to attract [removed: or retain, including as a result of an untimely death or illness of key personnel, or replace a sufficient number of appropriately] [added: and retain highly] skilled and [removed: key] [added: qualified] personnel could place us at a significant competitive disadvantage and [removed: prevent us from successfully implementing our strategy, which could] impair our ability to implement our strategic plan [removed: successfully,] [added: successfully and] achieve our performance [removed: targets and otherwise] [added: targets, which could] have a material adverse effect on our business, financial condition and results of operations.
Limitations on the manner in which regulated financial institutions, such as us, can compensate their officers and employees, including those contained in pending rule proposals implementing [added: the] requirements of Section 956 of the Dodd-Frank Act, may make it more difficult for such institutions to compete for talent with financial institutions and other companies not subject to these or similar limitations.
Liquidity risk is the risk [removed: that we will not be able] [added: arising from the inability] to meet our [removed: obligations, including funding commitments, as] [added: obligations when] they come due.
A reduction in our credit [removed: ratings, which are based on a number of factors,] [added: ratings] could have a material adverse effect on our business, financial condition and results of operations.
Rating agencies regularly evaluate us, and their ratings are based on a number of factors, including our financial [removed: strength.][added: strength and conditions affecting the financial services industry generally.]
Any downgrade in our ratings would likely increase our borrowing [removed: costs,] [added: costs and] could limit our access to capital markets, [removed: and otherwise] [added: which would] adversely affect our business.
For example, a ratings downgrade could adversely affect our ability to sell or market [removed: certain of] our securities, including long-term debt, engage in certain longer-term derivatives transactions and retain our customers, particularly corporate customers who may require a minimum rating threshold in order to place funds with us.
In addition, under the terms of [removed: certain of] our derivatives contracts, we may be required to maintain a minimum credit [removed: rating or have to] [added: rating,] post additional collateral or terminate such contracts.
Any of these results of a [removed: rating] [added: ratings] downgrade could increase our cost of funding, reduce our liquidity and have adverse effects on our business, financial condition and results of operations.
[removed: We have exposure to many different industries and risks] [added: Risks] arising from actual or perceived changes in credit quality and uncertainty over the recoverability of amounts due from borrowers is inherent in our businesses.
The credit quality of our borrowers may deteriorate for a number of reasons that are outside our control, including [removed: as a result of] prevailing economic and market conditions and [removed: asset valuation.][added: collateral valuations.]
The trends and risks affecting borrower credit [removed: quality, particularly in the New England, Mid-Atlantic and Midwest regions,] [added: quality] have caused, and in the future may cause, us to experience [added: credit losses,] impairment charges, increased repurchase demands, higher [added: recovery] costs, [removed: additional write-downs] and [removed: losses and] an inability to engage in routine funding transactions, which could have a material adverse effect on our business, financial condition and results of operations.
An important feature of our credit risk management system is to employ an internal credit risk control system through which we identify, measure, monitor and mitigate [added: the] existing and emerging credit risk of our customers.
[removed: As this] [added: This] process involves [added: a] detailed [removed: analyses] [added: analysis] of the customer or credit risk, taking into account both quantitative and qualitative factors, [removed: it] [added: and] is [added: inherently] subject to human error.
In addition, we have undertaken certain actions to enhance our credit policies and guidelines to address potential risks associated with particular industries or types of [removed: customers, as discussed in more detail under the “Risk Governance” and “Market Risk” sections in Item 7.][added: customers.]
[removed: From time to time, the] [added: The] FASB and SEC [added: periodically] change the financial accounting and reporting standards that govern the accounting for our financial results and the preparation of our [added: consolidated] financial statements.
These changes can be [removed: operationally complex] [added: hard] to [removed: implement] [added: predict] and can materially impact how we record and report our financial condition and results of operations.
The processes we use to estimate [removed: our inherent] loan [removed: losses and to] [added: losses,] measure the fair value of financial [removed: instruments, as well as the processes used to] [added: instruments and] estimate the effects of changing interest rates and other market measures on our financial condition and results of [removed: operations, depends] [added: operations are reliant] upon the use of analytical and forecasting models.
Therefore, the risks described in the risk factors below should not be considered a complete list of risks that we may encounter.
Our business strategy is designed to maximize the full potential of our business and drive sustainable growth and enhanced profitability, with our success resting on our ability to distinguish ourselves.
From March 2022 to July 2023, the FRB raised its benchmark interest rate eleven times in response to inflationary pressures throughout the economy.
We must maintain adequate funding to meet current and future obligations, including customer loan requests, customer deposit maturities and withdrawals, debt service, equipment and premises leases, and other cash commitments, under both normal operating conditions and under periods of company-specific and/or market stress.
We primarily rely on customer deposits to be a relatively stable and low-cost source of funding.
In addition to customer deposits, our funding sources also include our ability to securitize loans in secondary markets, raise funds in the debt and equity capital markets, pledge loans and/or securities for borrowing from the FHLB, pledge securities as collateral for borrowing under repurchase agreements, and sell AFS securities.
Our ability to meet our obligations and support our operations could be materially affected by a variety of conditions, including market-wide illiquidity or disruption, a loss of market or customer confidence in the financial services industry generally or in the Company specifically, or reductions in one or more of our credit ratings.
This could limit our ability to retain our deposits, securitize or sell assets, access the debt or equity capital markets, or otherwise borrow money at a reasonable cost.
Additionally, these conditions, among others, if severe enough, could create unanticipated material outflows of cash due to, among other factors, draws on unfunded commitments or deposit attrition, which could have significant adverse impact on our liquidity.
Further, changes to the FHLB’s or the FRB’s underwriting guidelines for wholesale borrowings or lending policies may limit or restrict our ability to borrow, and therefore could have a significant adverse impact on our liquidity.
Changes in interest rates can have a material impact on the value of our securities, a primary objective of which is to provide a ready source of contingent liquidity.
An increase in rates could lower the collateral value of these securities, reducing the amount we could borrow, and lead to losses in the event of their sale.
Since our earning assets are primarily in the form of loans and debt securities, changes in interest rates can have a material impact our net interest income, net interest margin, fee income, and credit costs.
Changes in interest rates can affect our net interest income and margin as our asset yields and funding costs may not rise or fall in parallel, causing our net interest income to increase or decrease and our margin to expand or contract.
If our funding costs rise faster than our asset yields, or if our asset yields fall faster than our funding costs, our net interest income could decrease, and our margin could contract.
An increase in interest rates could cause lower demand for loans by customers, reducing our net interest income due to lower loan balances and origination-related fee income due to lower production volume, and could also have an adverse impact on our credit costs, as borrowers may have difficulty in making higher interest payments.
Additionally, an increase in rates could cause recognition of losses on the debt securities in our AFS portfolio if the securities needed to be sold.
Similarly, a decrease in interest rates could lower our net interest income, net interest margin and fee income.
We may be adversely affected by a prolonged period of low interest rates as it may result in us holding lower yielding loans and securities should rates rise rapidly after the period of low interest rates.
Changes in the spread between short-term and long-term interest rates (i.e., the yield curve) can also have a material impact on our net interest income and net interest margin.
Typically, the yield curve is upward sloping, with short-term rates being lower than long-term rates.
When the yield curve flattens or inverts, our net interest income and net interest margin may decrease if the cost of our short-term funding increases relative to the yield we can earn on our long-term assets.
Our financial performance may be adversely affected by deterioration in borrower credit quality.
If the economic environment were to deteriorate, more of our borrowers may have difficulty in repaying their loans which could result in higher credit losses and increased loan loss provision expense.
Further, our credit risk and credit losses may increase to the extent our loans are concentrated by loan type, industry segment, collateral type, borrower type, or location of the collateral or borrower.
A significant portion of our earnings assets are in the form of loans to borrowers across the U.S., primarily for residential, commercial and industrial, commercial real estate, education, auto and other retail purposes.
A deterioration in economic conditions or changes in consumer or business behavior that negatively impacts home property or commercial property values could, in event of the borrower’s default, result in materially higher credit losses.
Similarly, higher unemployment levels and higher interest rates can adversely affect our customers’ ability to repay their loans, which can negatively impact our credit performance.
In some cases, we could be required to apply a new or revised standard retroactively, which would result in the recasting of our prior period financial statements.
Our accounting policies and methods are fundamental to how we record and report our financial condition and results of operations and, at times, require management to exercise judgment in their application so as to report our financial condition and results of operations in the most appropriate manner.
Certain accounting policies are critical because they require management to make difficult, subjective or complex judgments about matters that are inherently uncertain and the likelihood that materially different estimates would result under different conditions or through the utilization of different assumptions.
Our critical accounting estimates include the ACL, estimations of fair value and review of goodwill for impairment.
If our estimates are inaccurate or need to be adjusted periodically, our financial condition and results of operations could be materially impacted.
Employee error, failure to follow security procedures, or malfeasance also present these risks.
Also, our customers are routinely the target of fraudulent schemes.
Cybercriminals can use fraudulent schemes directly targeting our customers or our own systems to compromise and directly extract funds from a customer’s account or access sensitive customer data.
The occurrence of catastrophic events, including pandemics, terrorists attacks, extreme weather events, such as hurricanes, tropical storms, or tornadoes, and other large-scale catastrophes could adversely affect our business, financial condition or results of operations.
While the U.S. economy has generally recovered since the onset of the COVID disruption, a resurgence of pandemic conditions could reintroduce, or intensify, these impacts and adversely affect our business, financial condition and results of operations, as well as our liquidity and capital profile.
These changes could materially and negatively impact our or our customers’ business, results of operations, financial condition and reputation.
Concerns about, or a default by, one institution could lead to significant market and customer perception of the risk of similar problems at other institutions.
These risks include, but are not limited to, credit risk, market risk, liquidity risk, operational risk, model risk, technology, regulatory and legal risk and strategic and reputational risk.
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
Our business strategy is designed to maximize the full potential of our business and drive sustainable growth and enhanced profitability, and our success rests on our ability to maintain a high-performing, customer-centric organization; develop differentiated value propositions to acquire, deepen, and retain core customer segments; build excellent capabilities designed to help us stand out from our competitors; operate with financial discipline and a mindset of continuous improvement to self-fund investments; prudently grow and optimize our balance sheet; modernize our technology and operational models to improve delivery, organizational agility and speed to market; and embed risk management within our culture and our operations.
Robust demand, labor shortages and supply chain constraints have led to persistent inflationary pressures throughout the economy.
In response to these inflationary pressures, the FRB has raised benchmark interest rates in recent months and may continue to raise interest rates in response to economic conditions, particularly a continued high rate of inflation.
Net interest income historically has been, and we anticipate that it will remain, a significant component of our total revenue.
This is due to the fact that a high percentage of our assets and liabilities have been and will likely continue to be in the form of interest-bearing or interest-related instruments.
Changes in interest rates can have a material effect on many areas of our business, including net interest income, deposit costs, loan volume and delinquency, and the value of our mortgage servicing rights.
Changes in monetary policy, including changes in interest rates, could influence not only the interest we receive on loans and securities and the amount of interest we pay on deposits and borrowings, but such changes could also affect our ability to originate loans and obtain deposits and the fair value of our financial assets and liabilities.
If the interest rates on our interest-bearing liabilities increase at a faster pace than the interest rates on our interest earning assets, our net interest income may decline and, with it, a decline in our earnings may occur.
Our net interest income and our earnings would be similarly affected if the interest rates on our interest earning assets declined at a faster pace than the interest rates on our interest-bearing liabilities.
We cannot control or predict with certainty changes in interest rates.
Global, national, regional and local economic conditions, competitive pressures and the policies of regulatory authorities, including monetary policies of the FRB, affect interest income and interest expense.
If our ongoing assumptions regarding borrower or depositor behavior or overall economic conditions are significantly different than we anticipate, then our risk mitigation may be insufficient to protect against interest rate risk and our net income would be adversely affected.
Changes in the method pursuant to which the LIBOR and other benchmark rates are calculated and their planned discontinuance could adversely impact our business operations and financial results.
Many of our lending products, securities, derivatives, and other financial transactions utilize a benchmark rate, such as LIBOR, to determine the applicable interest rate or payment amount.
The U.K. Financial Conduct Authority and the ICE Benchmark Administration have announced that the publication of the most commonly used U.S. Dollar LIBOR tenors will cease to be provided or cease to be representative after June 30, 2023.
The publication of all other LIBOR settings ceased to be provided or ceased to be representative as of December 31, 2021.
The Adjustable Interest Rate (LIBOR) Act (LIBOR Act), enacted in March 2022, provides a statutory framework to replace U. S. Dollar LIBOR with a benchmark rate based on the Secured Overnight Financing Rate (SOFR) for contracts governed by U.S. law that have no fallbacks or fallbacks that would require the use of a poll or LIBOR-based rate, and in December 2022, the FRB adopted rules which identify different SOFR-based replacement rates for derivative contracts, for cash instruments such as floating-rate notes and preferred stock, for consumer loans, for certain government-sponsored enterprise contracts and for certain asset-backed securities.
We continue to monitor market developments and regulatory updates related to the cessation of LIBOR, as well as collaborate with regulators and industry groups on the transition.
As the transition from LIBOR is ongoing, there continues to be uncertainty as to the ultimate effect of the transition on the financial markets for LIBOR-linked financial instruments.
The discontinuation of a benchmark rate, changes in a benchmark rate, or changes in market perceptions of the acceptability of a benchmark rate, including LIBOR, could, among other things, adversely affect the value of and return on certain of our financial instruments or products, result in changes to our risk exposures, or require renegotiation of previous transactions.
In addition, any such discontinuation or changes, whether actual or anticipated, could result in market volatility, increased compliance, legal and operational costs, and risks associated with customer disclosures and contract negotiations.
Although the LIBOR Act includes safe harbors if the FRB-identified SOFR-based replacement rate is selected, these safe harbors are untested.
As a result, and despite the enactment of the LIBOR Act, for the most commonly used U.S. Dollar LIBOR settings, the use or selection of a successor rate could also expose us to risks associated with disputes with customers and other market participants in connection with implementing LIBOR fallback provisions.
A cornerstone of our strategic plan involves the hiring of highly skilled and qualified personnel.
For example, the increase in remote and hybrid work arrangements has also increased competition for skilled personnel, and our current or future approach to in-office and remote-work arrangements may not meet the needs or expectations of current or prospective employees or may not be perceived as favorable as compared to the arrangements offered by other companies, which could adversely affect our ability to attract and retain skilled and qualified personnel.
This risk is inherent in our operations and can be heightened by a number of factors, including an over-reliance on a particular source of funding (including, for example, secured FHLB advances), changes in credit ratings or market-wide phenomena such as market dislocation and major disasters.
Like many banking groups, our reliance on customer deposits to meet a considerable portion of our funding has grown over recent years, and we continue to seek to increase the proportion of our funding represented by customer deposits.
However, these deposits are subject to fluctuation due to certain factors outside our control, such as increasing competitive pressures for retail or corporate customer deposits, changes in interest rates and returns on other investment classes, or a loss of confidence by customers in us or in the banking sector generally which could result in a significant outflow of deposits within a short period of time.
To the extent there is heightened competition among U.S. banks for retail customer deposits, this competition may increase the cost of procuring new deposits and/or retaining existing deposits, and otherwise negatively affect our ability to grow our deposit base.
An inability to grow, or any material decrease in, our deposits could have a material adverse effect on our ability to satisfy our liquidity needs.
Maintaining a diverse and appropriate funding strategy for our assets consistent with our wider strategic risk appetite and plan remains challenging, and any tightening of credit markets could have a material adverse impact on us.
In particular, there is a risk that corporate and financial institution counterparties may seek to reduce their credit exposures to banks and other financial institutions (for example, reductions in unsecured deposits supplied by these counterparties), which may cause funding from these sources to no longer be available.
Under these circumstances, we may need to seek funds from alternative sources, potentially at higher costs than has previously been the case, or may be required to consider disposals of other assets not previously identified for disposal, in order to reduce our funding commitments.
Other factors considered by rating agencies include conditions affecting the financial services industry generally.
Our financial performance may be adversely affected by deterioration in borrower credit quality, particularly in the New England, Mid-Atlantic and Midwest regions, where our operations are predominately concentrated.
Our exposure may be exacerbated by the geographic concentration of our operations, which are predominately located in the New England, Mid-Atlantic and Midwest regions.
For example, in June 2016, the FASB issued Accounting Standards Update 2016-13, *Measurement of Credit Losses on Financial Instruments* (“CECL”), that substantially changed the accounting for credit losses on loans and other financial assets held by banks, financial institutions and other organizations.
An excerpt. Shown here: 40 of 105 rewritten, 40 of 45 added and 40 of 77 removed. The counts are complete. For every sentence, read Item 1A. RISK FACTORS in the FY2023 filing and the FY2022 filing.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
571 rewritten, 376 added, 333 removed, 530 unchanged
| [Financial [removed: Performance](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_52)] [added: Performance](#i51f41e5d525741dd9c933046ddb6d1a8_52)] | | | | | | [removed: [40](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_52)] [added: [39](#i51f41e5d525741dd9c933046ddb6d1a8_52)] | | |
| [Results of Operations - 2022 compared with [removed: 2021](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_55)] [added: 2021](#i51f41e5d525741dd9c933046ddb6d1a8_76)] | | | | | | [removed: [41](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_55)] [added: [44](#i51f41e5d525741dd9c933046ddb6d1a8_76)] | | |
| [Net Interest [removed: Income](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_58)] [added: Income](#i51f41e5d525741dd9c933046ddb6d1a8_58)] | | | | | | [removed: [41](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_58)] [added: [40](#i51f41e5d525741dd9c933046ddb6d1a8_58)] | | |
| [Noninterest [removed: Income](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_61)] [added: Income](#i51f41e5d525741dd9c933046ddb6d1a8_61)] | | | | | | [removed: [44](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_61)] [added: [42](#i51f41e5d525741dd9c933046ddb6d1a8_61)] | | |
| [Noninterest [removed: Expense](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_64)] [added: Expense](#i51f41e5d525741dd9c933046ddb6d1a8_64)] | | | | | | [removed: [44](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_64)] [added: [42](#i51f41e5d525741dd9c933046ddb6d1a8_64)] | | |
| [Provision for Credit [removed: Losses](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_67)] [added: Losses](#i51f41e5d525741dd9c933046ddb6d1a8_67)] | | | | | | [removed: [45](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_67)] [added: [43](#i51f41e5d525741dd9c933046ddb6d1a8_67)] | | |
| [Income Tax [removed: Expense](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_70)] [added: Expense](#i51f41e5d525741dd9c933046ddb6d1a8_70)] | | | | | | [removed: [45](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_70)] [added: [43](#i51f41e5d525741dd9c933046ddb6d1a8_70)] | | |
| [Business Operating [removed: Segments](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_73)] [added: Segments](#i51f41e5d525741dd9c933046ddb6d1a8_73)] | | | | | | [removed: [45](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_73)] [added: [43](#i51f41e5d525741dd9c933046ddb6d1a8_73)] | | |
[removed: | [Results of Operations - 2021] [added: RESULTS OF OPERATIONS — 2023] compared with [removed: 2020](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_76) | | | | | | [46](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_76) | | |][added: 2022]
| [Analysis of Financial [removed: Condition](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_79)] [added: Condition](#i51f41e5d525741dd9c933046ddb6d1a8_79)] | | | | | | [removed: [47](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_79)] [added: [45](#i51f41e5d525741dd9c933046ddb6d1a8_79)] | | |
| [Loans and [removed: Leases](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_85)] [added: Leases](#i51f41e5d525741dd9c933046ddb6d1a8_85)] | | | | | | [removed: [48](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_85)] [added: [46](#i51f41e5d525741dd9c933046ddb6d1a8_85)] | | |
| [removed: [Allowance] [added: Allowance] for [removed: Credit Losses and Nonaccrual Loans] [added: credit losses to nonaccrual loans] and [removed: Leases](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_88)] [added: leases] | | | [added: 170] | | | [removed: [50](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_88)] | | | [added: 237 | | | | | | (67 | | %) | | | | | | |]
| [Borrowed [removed: Funds](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_94)] [added: Funds](#i51f41e5d525741dd9c933046ddb6d1a8_94)] | | | | | | [removed: [55](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_94)] [added: [53](#i51f41e5d525741dd9c933046ddb6d1a8_94)] | | |
| [Capital and Regulatory [removed: Matters](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_97)] [added: Matters](#i51f41e5d525741dd9c933046ddb6d1a8_97)] | | | | | | [removed: [56](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_97)] [added: [54](#i51f41e5d525741dd9c933046ddb6d1a8_97)] | | |
| [removed: [Liquidity](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_100)] [added: [Liquidity](#i51f41e5d525741dd9c933046ddb6d1a8_100)] | | | | | | [removed: [59](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_100)] [added: [58](#i51f41e5d525741dd9c933046ddb6d1a8_100)] | | |
| [Critical Accounting [removed: Estimates](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_103)] [added: Estimates](#i51f41e5d525741dd9c933046ddb6d1a8_103)] | | | | | | [removed: [62](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_103)] [added: [61](#i51f41e5d525741dd9c933046ddb6d1a8_103)] | | |
| [Accounting and Reporting [removed: Developments](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_106)] [added: Developments](#i51f41e5d525741dd9c933046ddb6d1a8_106)] | | | | | | [removed: [64](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_106)] [added: [63](#i51f41e5d525741dd9c933046ddb6d1a8_106)] | | |
| [Risk [removed: Governance](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_109)] [added: Governance](#i51f41e5d525741dd9c933046ddb6d1a8_109)] | | | | | | [removed: [65](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_109)] [added: [64](#i51f41e5d525741dd9c933046ddb6d1a8_109)] | | |
| [Market [removed: Risk](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_112)] [added: Risk](#i51f41e5d525741dd9c933046ddb6d1a8_112)] | | | | | | [removed: [67](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_112)] [added: [66](#i51f41e5d525741dd9c933046ddb6d1a8_112)] | | |
| [Non-GAAP Financial Measures and [removed: Reconciliations](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_115)] [added: Reconciliations](#i51f41e5d525741dd9c933046ddb6d1a8_115)] | | | | | | [removed: [76](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_115)] [added: [75](#i51f41e5d525741dd9c933046ddb6d1a8_115)] | | |
Citizens Financial Group, Inc. is one of the nation’s oldest and largest financial institutions, with [removed: $226.7] [added: $222.0] billion in assets as of December 31, [removed: 2022.][added: 2023.]
In Consumer Banking, we provide an integrated experience that includes mobile and online banking, a full-service customer contact center and the convenience of approximately [removed: 3,400] [added: 3,200] ATMs and more than 1,100 branches in 14 states and the District of Columbia.
For additional information regarding [removed: these acquisitions] [added: the ACL,] see Note [removed: 2.][added: 6.]
[added: This document contains non-GAAP financial measures denoted as “Underlying” results and “including AOCI impact.”] Underlying results for any given reporting period exclude certain items that may occur in that period which management does not consider indicative of our on-going financial performance.
Other companies may use similarly titled non-GAAP financial measures that [removed: are] [added: may be] calculated differently from the way we calculate such measures.
Non-GAAP measures are denoted throughout our MD&A by the use of the term [removed: Underlying.][added: “Underlying.” Where there is a reference to these metrics in that paragraph, all measures that follow are on the same basis when applicable.]
For more information on the computation of non-GAAP financial measures, see [removed: “—Non-GAAP] [added: “Non-GAAP] Financial Measures and Reconciliations.”
Net income decreased [removed: $246] [added: $465] million, with earnings per diluted common share down [removed: $1.06] [added: $0.97] to [removed: $4.10] [added: $3.13] compared to [removed: 2021.][added: 2022.]
Results reflect notable items of [removed: $352] [added: $357] million or [removed: $0.74] [added: $0.75] per diluted common share, net of tax benefit, compared to [removed: $78] [added: $352] million or [removed: $0.18] [added: $0.74] per diluted common share, net of tax benefit, in [removed: 2021.][added: 2022.]
| Table 1: Notable Items | | | | | | | | | | | | | | | | | | [added: | | |]
| | | | Year Ended December 31, 2022 | | | | | | | | | | | | | | | [added: | | |]
| | | | | | | Less: notable items | | | | | | | | | | | | [added: | | |]
| [removed: (in] [added: (dollars in] millions) | | | Reported results (GAAP) | | | Integration related costs(1) | | | TOP and other(2) | | | [removed: Provision(3)] [added: FDIC special assessment(3)] | | | [added: Provision | | |] Underlying results (non-GAAP) | | |
| Provision [removed: (benefit)] for credit losses | | | $474 | | | $— | | | $— | | | [added: $— | | |] $169 | | | $305 | | |
| Noninterest income | | | 2,009 | | | (31) | | | — | | | — | | | [added: — | | |] 2,040 | | |
| Noninterest expense | | | 4,892 | | | 213 | | | 49 | | | — | | | [added: — | | |] 4,630 | | |
| Income tax expense | | | 582 | | | (58) | | | (9) | | | [added: — | | |] (43) | | | 692 | | |
| | | | Year Ended December [removed: 31, 2021] [added: 31,] | | | | | | | | | | | | [added: Year Ended December 31,] | | | [added: | | | | | | | | | Year Ended December 31, | | | | | | | | |]
| [removed: (in] [added: (dollars in] millions) | | | Reported results (GAAP) | | | Integration related costs(1) | | | TOP and other(2) | | | [removed: Provision] [added: FDIC special assessment] | | | [added: Provision(4) | | |] Underlying results (non-GAAP) | | |
| Provision (benefit) for credit losses [removed: | | | ($411)] [added: (GAAP)] | | | [removed: $—] | | | [removed: $—] [added: $687] | | | [removed: $—] | | | [removed: ($411)] [added: $474] | | |
| [Introduction](#i51f41e5d525741dd9c933046ddb6d1a8_49) | | | | | | [38](#i51f41e5d525741dd9c933046ddb6d1a8_49) | | |
| [Securities](#i51f41e5d525741dd9c933046ddb6d1a8_82) | | | | | | [45](#i51f41e5d525741dd9c933046ddb6d1a8_82) | | |
| [Credit Quality](#i51f41e5d525741dd9c933046ddb6d1a8_88) | | | | | | [48](#i51f41e5d525741dd9c933046ddb6d1a8_88) | | |
| [Deposits](#i51f41e5d525741dd9c933046ddb6d1a8_91) | | | | | | [53](#i51f41e5d525741dd9c933046ddb6d1a8_91) | | |
| | | | Year Ended December 31, 2023 | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | |
| Noninterest expense | | | $5,507 | | | $104 | | | $177 | | | $225 | | | $— | | | $5,001 | | |
| | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
(3) Represents an industry-wide FDIC special assessment.
For more information, see “Regulation and Supervision - Deposit Insurance” in Item 1.
◦On an Underlying basis, earnings per diluted common share of $3.88 compared to $4.84 in 2022.
| Commercial real estate | | | 29,206 | | | 1,804 | | | 6.09 | | | | | | 24,746 | | | 1,026 | | | 4.09 | | | | | | 4,460 | | | 200 | | |
| Leases | | | 1,305 | | | 46 | | | 3.53 | | | | | | 1,521 | | | 46 | | | 3.00 | | | | | | (216) | | | 53 | | |
| Total commercial | | | 79,204 | | | 4,806 | | | 5.99 | | | | | | 76,269 | | | 3,014 | | | 3.90 | | | | | | 2,935 | | | 209 | | |
| Residential mortgages | | | 30,660 | | | 1,052 | | | 3.43 | | | | | | 27,759 | | | 876 | | | 3.16 | | | | | | 2,901 | | | 27 | | |
| Home Equity | | | 14,475 | | | 1,092 | | | 7.54 | | | | | | 13,057 | | | 555 | | | 4.25 | | | | | | 1,418 | | | 329 | | |
| Automobile | | | 10,374 | | | 429 | | | 4.13 | | | | | | 13,729 | | | 507 | | | 3.69 | | | | | | (3,355) | | | 44 | | |
| Education | | | 12,333 | | | 621 | | | 5.04 | | | | | | 13,047 | | | 560 | | | 4.29 | | | | | | (714) | | | 75 | | |
| Other retail | | | 5,171 | | | 489 | | | 9.46 | | | | | | 5,483 | | | 456 | | | 8.31 | | | | | | (312) | | | 115 | | |
| Total retail | | | 73,013 | | | 3,683 | | | 5.04 | | | | | | 73,075 | | | 2,954 | | | 4.04 | | | | | | (62) | | | 100 | | |
| Interest-earning assets | | | 201,686 | | | 10,204 | | | 5.02 | | | | | | 194,136 | | | 7,060 | | | 3.61 | | | | | | 7,550 | | | 141 | | |
| Total assets | | | $222,221 | | | | | | | | | | | | $215,061 | | | | | | | | | | | | $7,160 | | | | | |
| Money market | | | 51,178 | | | 1,494 | | | 2.92 | | | | | | 48,410 | | | 320 | | | 0.66 | | | | | | 2,768 | | | 226 | | |
| Savings | | | 29,266 | | | 433 | | | 1.48 | | | | | | 27,524 | | | 100 | | | 0.37 | | | | | | 1,742 | | | 111 | | |
| Term | | | 19,320 | | | 772 | | | 4.00 | | | | | | 8,330 | | | 89 | | | 1.07 | | | | | | 10,990 | | | 293 | | |
Average total borrowed funds increased $2.9 billion compared to 2022, driven by an increase in FHLB advances and secured borrowings collateralized by auto loans.
| Taxable investment securities | | | 91 | | | 231 | | | 322 | | |
| Total investment securities | | | 91 | | | 231 | | | 322 | | |
| Commercial and industrial | | | (49) | | | 1,063 | | | 1,014 | | |
| Total commercial | | | 126 | | | 1,666 | | | 1,792 | | |
| Total retail | | | (29) | | | 758 | | | 729 | | |
| Total interest income | | | $171 | | | $2,973 | | | $3,144 | | |
| Money market | | | 19 | | | 1,155 | | | 1,174 | | |
| Savings | | | 7 | | | 326 | | | 333 | | |
| Term | | | 117 | | | 566 | | | 683 | | |
| Long-term borrowed funds | | | 128 | | | 273 | | | 401 | | |
| Total borrowed funds | | | 116 | | | 305 | | | 421 | | |
| Total interest expense | | | 250 | | | 2,665 | | | 2,915 | | |
| [Introduction](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_49) | | | | | | [39](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_49) | | |
| [Securities](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_82) | | | | | | [47](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_82) | | |
| [Deposits](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_91) | | | | | | [55](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_91) | | |
On February 18, 2022, CBNA completed the acquisition of the HSBC East Coast branches and national online deposit business.
The transaction extends our physical presence and adds customers in several attractive markets, accelerating our national expansion strategy.
The transaction includes 66 branches in the New York City metropolitan area, 9 branches in the Mid-Atlantic/Washington D.C. area, and 5 branches in Southeast Florida.
On April 6, 2022, Citizens completed the acquisition of all outstanding shares of Investors for a combination of stock and cash.
The acquisition enhances Citizens’ banking franchise, adding an attractive middle market, small business and consumer customer base while building our physical presence in the Mid-Atlantic region with the addition of 154 branches located in the greater New York City and Philadelphia metropolitan areas and across New Jersey.
On June 8, 2022, Citizens completed the acquisition of DH Capital, a private investment banking firm serving companies in the internet infrastructure, software, IT services and communications sectors.
This acquisition further strengthens our growing corporate advisory capabilities.
This document contains non-GAAP financial measures denoted as “Underlying” results.
Where there is a reference to these metrics in that paragraph, all measures that follow are on the same basis when applicable.
| | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Noninterest income | | | 2,135 | | | — | | | — | | | — | | | 2,135 | | |
| Noninterest expense | | | 4,081 | | | 35 | | | 70 | | | — | | | 3,976 | | |
◦On an Underlying basis, earnings per diluted common share of $4.84 compared to $5.34 in 2021, driven primarily by $305 million in provision expense in 2022 versus a $411 million provision benefit in 2021.
| Commercial real estate | | | 24,746 | | | 1,026 | | | 4.09 | | | | | | 14,515 | | | 380 | | | 2.58 | | | | | | 10,231 | | | 151 | | |
| Leases | | | 1,521 | | | 46 | | | 3.00 | | | | | | 1,742 | | | 49 | | | 2.79 | | | | | | (221) | | | 21 | | |
| Total commercial | | | 76,269 | | | 3,014 | | | 3.90 | | | | | | 59,769 | | | 1,828 | | | 3.02 | | | | | | 16,500 | | | 88 | | |
| Residential mortgages | | | 27,759 | | | 876 | | | 3.16 | | | | | | 20,636 | | | 613 | | | 2.97 | | | | | | 7,123 | | | 19 | | |
| Home Equity | | | 13,057 | | | 555 | | | 4.25 | | | | | | 11,901 | | | 370 | | | 3.11 | | | | | | 1,156 | | | 114 | | |
| Automobile | | | 13,729 | | | 507 | | | 3.69 | | | | | | 12,972 | | | 506 | | | 3.90 | | | | | | 757 | | | (21) | | |
| Education | | | 13,047 | | | 560 | | | 4.29 | | | | | | 12,666 | | | 536 | | | 4.23 | | | | | | 381 | | | 6 | | |
| Other retail | | | 5,483 | | | 456 | | | 8.31 | | | | | | 5,607 | | | 400 | | | 7.15 | | | | | | (124) | | | 116 | | |
| Total retail | | | 73,075 | | | 2,954 | | | 4.04 | | | | | | 63,782 | | | 2,425 | | | 3.80 | | | | | | 9,293 | | | 24 | | |
| Interest-earning assets | | | 194,136 | | | 7,060 | | | 3.61 | | | | | | 166,511 | | | 4,851 | | | 2.90 | | | | | | 27,625 | | | 71 | | |
| Total assets | | | $215,061 | | | | | | | | | | | | $185,106 | | | | | | | | | | | | $29,955 | | | | | |
| Money market | | | 48,410 | | | 320 | | | 0.66 | | | | | | 49,148 | | | 78 | | | 0.16 | | | | | | (738) | | | 50 | | |
| Savings | | | 27,524 | | | 100 | | | 0.37 | | | | | | 20,276 | | | 19 | | | 0.10 | | | | | | 7,248 | | | 27 | | |
| Term | | | 8,330 | | | 89 | | | 1.07 | | | | | | 6,802 | | | 39 | | | 0.58 | | | | | | 1,528 | | | 49 | | |
Average interest-earning asset yields increased 71 basis points to 3.61%, while average interest-bearing liability costs increased 48 basis points to 0.78% compared to 2021.
Average interest-earning assets increased $27.6 billion, or 17%, compared to 2021.
Growth in commercial and industrial, commercial real estate, residential mortgage, home equity, and investments was partially offset by a decrease in cash held in interest-bearing deposits reflecting the deployment of elevated liquidity.
Average total borrowed funds increased $6.2 billion compared to 2021, given an increase in long-term and short-term FHLB borrowings driven by advances acquired from Investors and the funding of loan and security growth, partially offset by a decrease in senior debt.
| | | | | | | | | | | | |
| Total investment securities | | | 142 | | | 211 | | | 353 | | |
| Commercial and industrial | | | 203 | | | 340 | | | 543 | | |
| Commercial real estate | | | 265 | | | 381 | | | 646 | | |
| Total commercial | | | 462 | | | 724 | | | 1,186 | | |
An excerpt. Shown here: 40 of 571 rewritten, 40 of 376 added and 40 of 333 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2023 filing and the FY2022 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
1 rewritten, 0 added, 0 removed, 3 unchanged
| | | | | | | Citizens Financial Group, Inc. \| [removed: 78] [added: 77] | | |
Item 1. BUSINESS
131 rewritten, 103 added, 99 removed, 211 unchanged
Our products and services are offered through more than 1,100 branches in 14 states and the District of Columbia and [removed: 123] [added: 105] retail and commercial non-branch offices, though certain lines of business serve national markets.
At December 31, [removed: 2022,] [added: 2023,] we had total assets of [removed: $226.7] [added: $222.0] billion, total deposits of [removed: $180.7] [added: $177.3] billion and total stockholders’ equity of [removed: $23.7] [added: $24.3] billion.
We manage our business through two [added: primary] business segments: Consumer Banking and Commercial Banking.
[removed: Our activities outside these segments are classified as “Other” and include] [added: Other includes] treasury activities, wholesale [removed: funding activities,] [added: funding,] the securities portfolio, community development assets, and other unallocated assets, liabilities, capital, revenues, provision [added: (benefit)] for credit losses and expenses, including income tax expense.
Consumer Banking serves [removed: retail] [added: consumer] customers and small businesses with annual revenues of up to $25 million, with products and services that include [removed: deposit products,] [added: deposits,] mortgage and home equity lending, credit cards, [added: small] business loans, wealth management and investment services largely across our 14-state traditional banking footprint.
We also offer [removed: auto,] education and point-of-sale finance loans in addition to select digital deposit products nationwide.
Consumer Banking operates a multi-channel distribution network with a workforce of approximately [removed: 5,780] [added: 5,300] branch colleagues, approximately 1,100 branches, including [removed: 220] [added: 187] in-store locations, and approximately [removed: 3,400] [added: 3,200] ATMs.
Our network includes approximately [removed: 1,250] [added: 1,100] specialists covering lending, savings and investment needs as well as a broad range of small business products and services.
Commercial Banking primarily serves companies and institutions with annual revenues of [removed: over] $25 million to more than $3.0 billion and strives to be [removed: our clients’] [added: a] trusted advisor [added: to our clients] and preferred provider for their banking needs.
[removed: The business lines,] Corporate [removed: Banking and] [added: Banking,] Commercial Real Estate, [removed: and the product groups, Corporate Finance &] Capital [removed: Markets,] [added: Markets] and [added: Advisory, and] Treasury Solutions work [removed: in teams] [added: together] to understand client needs and provide comprehensive solutions to meet those needs.
Corporate Banking serves [removed: middle market] commercial and industrial clients with annual gross revenues of $25 million to $500 million, and [removed: mid-corporate] [added: corporate] clients with annual revenues of $500 million to more than $3.0 billion in the United States.
In several areas, such as Aerospace, Defense and Government Services, Communications, Transportation and Logistics, [removed: Franchise,] [added: Food and Restaurants,] Human Capital Management, and Gaming we offer a more dedicated and tailored approach to better meet the unique needs of these client segments.
Commercial Real Estate provides customized debt capital solutions for [removed: middle market] [added: middle-market] operators, institutional developers, investors, and REITs.
Commercial Real Estate provides financing for projects primarily in the multi-family, [removed: co-op,] office, industrial, retail, healthcare and hospitality sectors.
[removed: Corporate Finance &] Capital Markets [added: and Advisory] serves clients through key product groups including Corporate Finance, Capital Markets, and Global Markets.
Corporate Finance provides advisory services to [removed: middle market] [added: middle-market] and mid-corporate clients, including mergers and acquisitions and capital structure advice.
Capital Markets originates, structures and underwrites credit and equity facilities targeting [removed: middle market,] [added: middle-market,] mid-corporate and private equity sponsors.
Our mission is to help our customers, colleagues and communities reach their potential, and our vision is to become a top-performing bank distinguished by our customer-centric culture, mindset of continuous improvement, [added: product innovation,] and excellent capabilities.
In Consumer Banking, we focus on serving mass affluent and affluent customers, [removed: and] small businesses [removed: customers nationally.][added: and high-net-worth individuals and families.]
In Commercial Banking, we focus on serving customers in the [removed: middle market,] [added: middle-market,] mid-corporate, and select industry verticals.
By developing differentiated and targeted value propositions, building our fee-based businesses and developing innovative [added: product] solutions, we believe we can attract new customers, deepen relationships with existing customers and deliver an enhanced customer experience.
We [removed: are accelerating the] [added: strive to] use [removed: of] advanced data analytics and artificial intelligence for personalization and to provide timely, insight-driven, tailored advice in order to deliver solutions to consumer and [removed: business] [added: commercial] customers throughout their lifecycles.
Our TOP [removed: 7] [added: 8] program was completed in [removed: 2022,] [added: 2023,] and we [removed: are launching] [added: launched] a TOP [removed: 8] [added: 9] program to allow us to continue to self-fund investments.
Within these [removed: markets] [added: markets,] we face competition from community banks, super-regional and national financial institutions, credit unions, savings and loan associations, mortgage banking firms, consumer finance companies, securities brokerage firms, insurance companies, money market funds, hedge funds and private equity firms.
In Consumer Banking, the industry has become increasingly dependent on and oriented toward technology-driven delivery systems, permitting transactions to be conducted through [removed: telephone,] online and mobile channels.
In Commercial Banking, [removed: there is] [added: we face] competition [removed: for quality loan originations] [added: in all our client segments] from [added: a variety of industry participants including] traditional banking institutions, particularly large regional banks, as well as commercial finance companies, leasing companies, other non-bank lenders, and institutional [removed: investors] [added: investors,] including collateralized loan obligation managers, hedge funds and private equity firms.
Some larger competitors, including certain national banks that compete in our market area, may offer a broader array of products and, due to their asset size, may [removed: sometimes] be in a position to hold more exposure on their balance sheet.
As of December 31, [removed: 2022,] [added: 2023,] Citizens [removed: and its subsidiaries] had [removed: 18,889] [added: 17,570] full-time equivalent employees, primarily across New England and the Mid-Atlantic.
Our Board of Directors and [removed: the] [added: its] Compensation and Human Resources Committee are responsible for overseeing our human capital management strategy, with senior management providing regular updates to facilitate that oversight.
[removed: To deepen critical skills, we have] [added: We] expanded our learning academies [added: as well as badging and bootcamp programs] focusing on [added: critical skills such as] Innovation, Agile, Next Gen Tech, Banking and Credit, and Data & Analytics.
[removed: Through our development programs, we] [added: We] aim to equip [added: all] colleagues with the skills necessary to excel in their current roles and to build [removed: competencies] [added: capabilities] that will enable them to be highly valuable contributors in the future.
As part of our ongoing efforts to develop a high performing workforce and make Citizens a great place to work and build a career, we [removed: have used McKinsey & Company’s Organizational Health Index (“OHI”) since our 2014 initial public offering to understand colleagues’ viewpoints about Citizens on a range of topics.][added: conduct an annual organizational health survey (“OHS”).]
[removed: OHI] [added: Survey] results are used to refine our focus, address gaps, and strengthen efforts to improve our organizational effectiveness and colleague experience.
The results of our [removed: OHI surveys have been] [added: survey are] instrumental in helping management prioritize areas of change that are most important to colleagues.
[removed: To] [added: We acknowledge] that [removed: end,] [added: there are opportunities to further increase the representation of women and people of color, particularly in leadership roles, and] we [removed: have continued] [added: continue] to develop strong partnerships with business and community organizations to help identify [removed: qualified] diverse candidates for roles within every segment of our organization.
[removed: Internal diversity scorecards are] [added: An internal dashboard is] used to [removed: measure] [added: monitor] our progress across multiple DE&I metrics.
We also partner with external organizations to offer additional resources for reskilling and upskilling [added: colleagues, including] diverse colleagues.
We also offer education programs focused on embedding inclusive behaviors in our culture [removed: to] [added: designed for colleagues at] all [removed: colleagues.][added: levels of leadership.]
[removed: We use various] [added: Various] resources [added: are used by management] to understand what drives a sense of inclusion and belonging and to identify what actions will be effective in attracting and retaining diverse colleagues.
Analytics are used to help prioritize initiatives, including [removed: answers] [added: responses] to [removed: OHI survey items,] [added: our OHS,] which we segment by various colleague populations to provide additional insights.
Our activities outside these segments are classified as Non-Core or Other.
Non-Core includes our indirect auto and certain purchased consumer loan portfolios that we discontinued the origination of as part of our recently announced balance sheet optimization strategy.
Citizens Private Bank, launched during 2023, integrates wealth management and banking services to serve high net-worth individuals and families, as well as businesses.
Commercial Banking is organized around client segments and their banking needs.
We seek to deepen relationships with our customers by offering a full suite of products designed to meet their unique needs.
In 2023, we launched the Private Bank, which seeks to serve high-net-worth individuals and families, as well as commercial clients, to integrate our wealth management and banking services.
We have integrated the Investors acquisition and HSBC transaction and are focused on improving branch productivity and deepening relationships with those customers.
In addition, some of our competitors may not be subject to the same regulatory requirements as we are and, therefore, may have lower costs they can pass on to customers in the form of more favorable terms.
During 2023, we continued tailored leadership training and coaching for senior management following the detailed talent assessments conducted the prior year.
The talent market remains competitive, particularly in emerging skill areas, and we implemented a strategy to fill critical gaps that utilizes a combination of external hiring in critical areas (e.g., technology, digital, cyber, risk, marketing, and data), a strong internal mobility program made possible by the expanded learning and development offerings provided to colleagues, and reliance on temporary workers for short-term or technical projects.
Between our initial public offering and 2022, we had a 19-point increase in our overall survey score and achieved top quartile status within McKinsey’s global benchmarks.
In 2023, with an eye toward continuing to evolve our strategy and culture, we transitioned to a new OHS tool.
In 2023, 87% of colleagues participated in the OHS, which is our all-time highest participation rate.
Development programs are designed to build a strong pipeline of emerging talent, including diverse talent, internally, and have been effective in increasing the development of our overall colleague base as well as increasing the number of women and people of color in senior leader roles.
In addition, we ensure that interview slates for senior openings include candidates with diverse backgrounds and perspectives.
Information regarding our workforce demographics can be found in our Environmental Social Governance Report and on our website, which includes a link to our most recently filed EEO-1 report.
In an effort to greater support each colleague’s unique journey, we enhanced our partnership with our BRGs by providing subject matter experts to share their experience and expertise with all BRG members, as well as increasing awareness of available tools and resources.
In 2023, we increased paid bereavement leave, added several mental health resources, and provided each colleague an extra day of paid time-off to be used as a wellness day.
We continue to embrace flexibility and manage our hybrid workforce in a manner that ensures colleagues are working in ways that best support our customers, foster engagement and innovation, and maintain our company culture.
Sustainability
Our efforts relative to ESG matters are aligned with the needs, interests, and expectations of our stakeholders and are divided into four focus areas: Leading with Robust Corporate Governance, Driving Positive Climate Impact, Building the Workforce of the Future, and Fostering Strong Communities.
These areas speak to the strengths of our company, align with our business priorities, and define how we can have an outsized impact on our business, society, and the planet.
In 2023, we announced a $50 billion Sustainable Finance Target, including $5 billion in green financing, by 2030.
As part of this announcement, we committed to engage corporate clients in high-emitting sectors on climate-related topics, beginning with a target to engage 100% of our Oil & Gas clients by the end of 2024.
In addition, we committed to achieving carbon neutrality by 2035.
Enhanced Prudential Standards and Regulatory Tailoring Rules
As a BHC with over $100 billion in total consolidated assets, we are currently subject to enhanced prudential standards and associated capital and liquidity rules (“Tailoring Rules”).
The Tailoring Rules assign each BHC, including its bank subsidiaries, to one of four categories based on its size and certain risk-based indicators.
CFG and CBNA are each subject to Category IV standards, the least restrictive of the requirements under the Tailoring Rules.
As discussed in greater detail in “Capital and Stress Testing Requirements” and “Long-Term Debt Requirements”, the federal banking regulators proposed sweeping changes to the regulatory capital and liquidity rules that would significantly impact the application of those rules to the Company.
We calculate RWA using the standardized approach and have made the AOCI opt-out election, permitting us to exclude components of AOCI from regulatory capital.
- Tier 1 capital ratio of 6.0%;
- Total capital ratio of 8.0%; and
- Tier 1 leverage ratio of 4.0%.
On July 27, 2023, the federal banking regulators issued a proposal to implement the Basel Committee on Banking Supervision’s finalization of the post-crisis bank regulatory capital reforms.
The proposal, commonly referred to as Basel III “Endgame,” would significantly revise the capital requirements applicable to large banking organizations with total assets of $100 billion or more, including the Company.
Under the proposal, Category III and IV firms, including the Company as a Category IV firm, would become subject to the same capital treatment regarding the inclusion of AOCI, deductions, and rules for minority interest as Category I and II firms.
The proposal would also replace the existing models-based approaches for credit and operational risk, which currently apply only to Category I and II firms, with two new approaches applicable to Category I through IV firms.
The first would use the existing standardized approach and a proposed revised market risk capital rule.
The second would use a new expanded risk-based approach, consisting of new non-models-based approaches for credit risk, operational risk and credit valuation adjustment risk, as well as the proposed revised market risk capital rule.
Commercial Banking is structured along business lines and product groups.
We are integrating recent transactions in the NYC Metro market area and are improving the productivity of those acquired branches and deepening relationships with those customers.
During 2022, we conducted a detailed assessment of the current state of our culture and leadership to inform future areas of focus.
As we continue to prepare colleagues for the future, we are building capabilities by upskilling and reskilling colleagues to support new ways of working and operating models.
We offer programs that include technical and skills-based programs as well as resources aligned with our leadership competencies.
We continue to expand recruiting efforts across the different levels of the organization, with the goal of building a strong pipeline of future leaders.
This includes strengthening opportunities for internal mobility within Citizens through rotational programs and our academies, as well as external partnerships to support our ability to hire critical talent in areas such as technology, digital, cyber, marketing and data.
Since our inaugural survey, our overall OHI score has increased nearly 20 points to 77 in 2022 and is now within the first quartile of McKinsey’s global benchmarks.
In 2023, we are transitioning to a new listening platform, which will include a colleague survey tool aimed at providing additional insights as we continue to evolve our strategy and culture.
We are committed to increasing the representation of women and people of color, particularly in leadership roles.
In addition, through our diverse hiring commitment, we aim to have at least 50% of candidates interviewed for mid-to-senior openings be women or people of color.
As of December 31, 2022, approximately 58% of our colleagues were women and approximately 32% were people of color.
In addition, approximately 31% of the members of our Board of Directors are women and approximately 15% are people of color.
More detail regarding our workforce demographics can be found on our website and in our Corporate Responsibility Report.
Development programs are designed to build a strong pipeline of diverse emerging talent internally.
Development efforts have been effective in increasing the number of women and people of color considered “ready now” succession candidates.
We require all colleagues to attend inclusion training and there is additional targeted inclusion training specifically for colleagues in manager roles.
We implemented a return to office strategy which incorporates flexibility for colleagues.
As part of that strategy, non-branch roles have been assigned to various categories including fully remote, hybrid, or fully in the office, based on the responsibilities of each role.
This approach has allowed us to balance colleague flexibility with in-person collaboration, which we believe is key to maintaining our Company values and culture.
Environmental, Social and Governance
Investors have begun to consider how corporations are addressing ESG matters when making investment decisions.
Specifically, certain investors are beginning to incorporate the business risks of climate change and the adequacy of a company’s response to climate change as part of their investment strategy.
In 2021, we announced targets to reduce our Scope 1 and 2 greenhouse gas emissions 30% by 2025 and 50% by 2035, based on our 2016 baseline.
These reductions align with the recommendations of the Paris Agreement, which aims to limit average global temperature increase to well below 2 degrees Celsius compared to pre-industrial levels.
In 2022, we published our fifth annual Corporate Responsibility Report and completed the CDP’s Climate Change Questionnaire for the seventh time.
We also issued our inaugural Task Force on Climate-related Financial Disclosures (“TCFD”) report and expanded our climate commitment by:
- joining the Partnership for Carbon Accounting Financials (“PCAF”), a collaboration among worldwide financial institutions working to develop and implement a harmonized approach to assess and disclose greenhouse gas (“GHG”) emissions associated with loans and investments;
- participating in the Risk Management Association Climate Risk Consortium, a financial industry group dedicated to advancing best practices in climate risk management; and
- entering into a virtual power purchase agreement with Ørsted, supporting the construction of the Sunflower Wind Project in Kansas, which will offset 100% of our power consumption across our entire operational footprint with renewable energy credits.
We are a BHC under the Bank Holding Company Act.
Tailoring of Prudential Requirements
The FRB and the other federal banking regulators have enacted rules that tailor the application of the enhanced prudential standards to BHCs and depository institutions to implement the Economic Growth, Regulatory Relief, and Consumer Protection Act of 2018 amendments to the Dodd-Frank Act (“Tailoring Rules”).
Under the Tailoring Rules, we are subject to “Category IV standards,” which apply to banking organizations with at least $100 billion in total consolidated assets that do not meet any of the thresholds specified for Categories I through III.
We discuss other elements of the Tailoring Rules where relevant below.
If a BHC fails to meet these regulatory standards, the FRB could place limitations on its ability to conduct the broader financial activities permissible for FHCs or impose limitations or conditions on the conduct or activities of the BHC or its affiliates.
Capital
The U.S. Basel III rules apply to us.
We calculate RWA using the standardized approach and have made the one-time election to opt-out of recognizing in regulatory capital the impacts of net unrealized gains and losses included within AOCI for debt securities that are available for sale or held to maturity, accumulated net gains and losses on cash flow hedges and certain defined benefit pension plan assets.
- 6.0% tier 1 capital (that is, CET1 capital plus additional tier 1 capital) to risk-weighted assets;
An excerpt. Shown here: 40 of 131 rewritten, 40 of 103 added and 40 of 99 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2023 filing and the FY2022 filing.
Cover and table of contents
55 rewritten, 10 added, 12 removed, 208 unchanged
[removed: ][added: ]
The aggregate market value of voting stock held by non-affiliates of the registrant was [removed: $17,591,222,864] [added: $12,304,245,801] (based on the June 30, [removed: 2022] [added: 2023] closing price of Citizens Financial Group, Inc. common shares of [removed: $35.69] [added: $26.08] as reported on the New York Stock Exchange).
There were [removed: 484,106,460] [added: 458,756,723] shares of the registrant’s common stock ($0.01 par value) outstanding on [removed: January 31, 2023.][added: February 1, 2024.]
Portions of Citizens Financial Group, Inc.’s proxy statement to be filed with the United States Securities and Exchange Commission in connection with Citizens Financial Group, Inc.’s [removed: 2023] [added: 2024] annual meeting of stockholders (the “Proxy Statement”) are incorporated by reference into Part III hereof.
Such Proxy Statement will be filed within 120 days of Citizens Financial Group, Inc.’s fiscal year ended December 31, [removed: 2022.][added: 2023.]
| | | | [removed: ] [added: ] | | | | | | | | | | | |
| | | | [Glossary of Acronyms and [removed: Terms](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_10)] [added: Terms](#i51f41e5d525741dd9c933046ddb6d1a8_10)] | | | | | | [removed: [2](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_10)] [added: [2](#i51f41e5d525741dd9c933046ddb6d1a8_10)] | | | | | |
| | | | [Forward-looking [removed: Statements](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_13)] [added: Statements](#i51f41e5d525741dd9c933046ddb6d1a8_13)] | | | | | | [removed: [5](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_13)] [added: [5](#i51f41e5d525741dd9c933046ddb6d1a8_13)] | | | | | |
| | | | [Item 1. [removed: Business](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_19)] [added: Business](#i51f41e5d525741dd9c933046ddb6d1a8_19)] | | | | | | [removed: [6](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_19)] [added: [6](#i51f41e5d525741dd9c933046ddb6d1a8_19)] | | | | | |
| | | | [Item 1A. Risk [removed: Factors](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_22)] [added: Factors](#i51f41e5d525741dd9c933046ddb6d1a8_22)] | | | | | | [removed: [20](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_22)] [added: [20](#i51f41e5d525741dd9c933046ddb6d1a8_22)] | | | | | |
| | | | [Item 1B. Unresolved Staff [removed: Comments](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_25)] [added: Comments](#i51f41e5d525741dd9c933046ddb6d1a8_25)] | | | | | | [removed: [35](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_25)] [added: [33](#i51f41e5d525741dd9c933046ddb6d1a8_25)] | | | | | |
| | | | [Item 2. [removed: Properties](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_28)] [added: Properties](#i51f41e5d525741dd9c933046ddb6d1a8_28)] | | | | | | [removed: [35](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_28)] [added: [34](#i51f41e5d525741dd9c933046ddb6d1a8_28)] | | | | | |
| | | | [Item 3. Legal [removed: Proceedings](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_31)] [added: Proceedings](#i51f41e5d525741dd9c933046ddb6d1a8_31)] | | | | | | [removed: [35](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_31)] [added: [34](#i51f41e5d525741dd9c933046ddb6d1a8_31)] | | | | | |
| | | | [Item 4. Mine Safety [removed: Disclosures](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_34)] [added: Disclosures](#i51f41e5d525741dd9c933046ddb6d1a8_34)] | | | | | | [removed: [35](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_34)] [added: [34](#i51f41e5d525741dd9c933046ddb6d1a8_34)] | | | | | |
| | | | [removed: Part II.] [added: [Part II.](#i51f41e5d525741dd9c933046ddb6d1a8_37)] | | | | | | | | | | | |
| | | | [Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_40)] [added: Securities](#i51f41e5d525741dd9c933046ddb6d1a8_40)] | | | | | | [removed: [35](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_40)] [added: [34](#i51f41e5d525741dd9c933046ddb6d1a8_40)] | | | | | |
| | | | [Item 6. [removed: Reserved](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_43)] [added: Reserved](#i51f41e5d525741dd9c933046ddb6d1a8_43)] | | | | | | [removed: [37](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_43)] [added: [36](#i51f41e5d525741dd9c933046ddb6d1a8_43)] | | | | | |
| | | | [Item 7. Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_46)] [added: Operations](#i51f41e5d525741dd9c933046ddb6d1a8_46)] | | | | | | [removed: [38](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_46)] [added: [37](#i51f41e5d525741dd9c933046ddb6d1a8_46)] | | | | | |
| | | | [Item 7A. Quantitative and Qualitative Disclosures about Market [removed: Risk](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_118)] [added: Risk](#i51f41e5d525741dd9c933046ddb6d1a8_118)] | | | | | | [removed: [78](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_118)] [added: [77](#i51f41e5d525741dd9c933046ddb6d1a8_118)] | | | | | |
| | | | [Item 8. Financial Statements and Supplementary [removed: Data](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_121)] [added: Data](#i51f41e5d525741dd9c933046ddb6d1a8_121)] | | | | | | [removed: [79](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_121)] [added: [78](#i51f41e5d525741dd9c933046ddb6d1a8_121)] | | | | | |
| | | | [Consolidated Balance [removed: Sheets](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_133)] [added: Sheets](#i51f41e5d525741dd9c933046ddb6d1a8_133)] | | | | | | [removed: [86](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_133)] [added: [84](#i51f41e5d525741dd9c933046ddb6d1a8_133)] | | | | | |
| | | | [Consolidated Statements of [removed: Operations](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_136)] [added: Operations](#i51f41e5d525741dd9c933046ddb6d1a8_136)] | | | | | | [removed: [87](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_136)] [added: [85](#i51f41e5d525741dd9c933046ddb6d1a8_136)] | | | | | |
| | | | [Consolidated Statements of Comprehensive [removed: Income](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_139)] [added: Income](#i51f41e5d525741dd9c933046ddb6d1a8_139)] | | | | | | [removed: [88](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_139)] [added: [86](#i51f41e5d525741dd9c933046ddb6d1a8_139)] | | | | | |
| | | | [Consolidated Statements of Changes in Stockholders’ [removed: Equity](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_142)] [added: Equity](#i51f41e5d525741dd9c933046ddb6d1a8_142)] | | | | | | [removed: [89](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_142)] [added: [87](#i51f41e5d525741dd9c933046ddb6d1a8_142)] | | | | | |
| | | | [Consolidated Statements of Cash [removed: Flows](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_145)] [added: Flows](#i51f41e5d525741dd9c933046ddb6d1a8_145)] | | | | | | [removed: [90](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_145)] [added: [88](#i51f41e5d525741dd9c933046ddb6d1a8_145)] | | | | | |
| | | | [Notes to Consolidated Financial [removed: Statements](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_148)] [added: Statements](#i51f41e5d525741dd9c933046ddb6d1a8_148)] | | | | | | [removed: [92](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_148)] [added: [90](#i51f41e5d525741dd9c933046ddb6d1a8_148)] | | | | | |
| | | | [Item 9. Changes in and Disagreements With Accountants on Accounting and Financial [removed: Disclosure](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_247)] [added: Disclosure](#i51f41e5d525741dd9c933046ddb6d1a8_247)] | | | | | | [removed: [153](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_247)] [added: [153](#i51f41e5d525741dd9c933046ddb6d1a8_247)] | | | | | |
| | | | [Item 9A. Controls and [removed: Procedures](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_250)] [added: Procedures](#i51f41e5d525741dd9c933046ddb6d1a8_250)] | | | | | | [removed: [154](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_250)] [added: [153](#i51f41e5d525741dd9c933046ddb6d1a8_250)] | | | | | |
| | | | [Item 9B. Other [removed: Information](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_253)] [added: Information](#i51f41e5d525741dd9c933046ddb6d1a8_253)] | | | | | | [removed: [154](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_253)] [added: [154](#i51f41e5d525741dd9c933046ddb6d1a8_253)] | | | | | |
| | | | [Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent [removed: Inspections](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_256)] [added: Inspections](#i51f41e5d525741dd9c933046ddb6d1a8_256)] | | | | | | [removed: [154](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_256)] [added: [154](#i51f41e5d525741dd9c933046ddb6d1a8_256)] | | | | | |
| | | | [Part [removed: III.](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_259)] [added: III.](#i51f41e5d525741dd9c933046ddb6d1a8_259)] | | | | | | | | | | | |
| | | | [Item 10. Directors, Executive Officers and Corporate [removed: Governance](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_262)] [added: Governance](#i51f41e5d525741dd9c933046ddb6d1a8_262)] | | | | | | [removed: [155](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_262)] [added: [154](#i51f41e5d525741dd9c933046ddb6d1a8_262)] | | | | | |
| | | | [Item 11. Executive [removed: Compensation](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_265)] [added: Compensation](#i51f41e5d525741dd9c933046ddb6d1a8_265)] | | | | | | [removed: [155](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_265)] [added: [154](#i51f41e5d525741dd9c933046ddb6d1a8_265)] | | | | | |
| | | | [Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_268)] [added: Matters](#i51f41e5d525741dd9c933046ddb6d1a8_268)] | | | | | | [removed: [155](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_268)] [added: [155](#i51f41e5d525741dd9c933046ddb6d1a8_268)] | | | | | |
| | | | [Item 13. Certain Relationships and Related Transactions, and Director [removed: Independence](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_271)] [added: Independence](#i51f41e5d525741dd9c933046ddb6d1a8_271)] | | | | | | [removed: [155](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_271)] [added: [155](#i51f41e5d525741dd9c933046ddb6d1a8_271)] | | | | | |
| | | | [Item 14. Principal Accountant Fees and [removed: Services](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_274)] [added: Services](#i51f41e5d525741dd9c933046ddb6d1a8_274)] | | | | | | [removed: [156](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_274)] [added: [155](#i51f41e5d525741dd9c933046ddb6d1a8_274)] | | | | | |
| | | | [Part [removed: IV.](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_277)] [added: IV.](#i51f41e5d525741dd9c933046ddb6d1a8_277)] | | | | | | | | | | | |
| | | | [Item 15. Exhibits and Financial Statement [removed: Schedules](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_280)] [added: Schedules](#i51f41e5d525741dd9c933046ddb6d1a8_280)] | | | | | | [removed: [156](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_280)] [added: [155](#i51f41e5d525741dd9c933046ddb6d1a8_280)] | | | | | |
| | | | [Item 16. Form 10-K [removed: Summary](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_283)] [added: Summary](#i51f41e5d525741dd9c933046ddb6d1a8_283)] | | | | | | [removed: [159](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_283)] [added: [159](#i51f41e5d525741dd9c933046ddb6d1a8_283)] | | | | | |
| | | | [removed: [Signatures](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_286)] [added: [Signatures](#i51f41e5d525741dd9c933046ddb6d1a8_286)] | | | | | | [removed: [160](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_286)] [added: [160](#i51f41e5d525741dd9c933046ddb6d1a8_286)] | | | | | |
December 31, 2023
| | | | [Part I.](#i51f41e5d525741dd9c933046ddb6d1a8_16) | | | | | | | | | | | |
| | | | [Item 1C. Cybersecurity](#i51f41e5d525741dd9c933046ddb6d1a8_2321) | | | | | | [33](#i51f41e5d525741dd9c933046ddb6d1a8_2321) | | | | | |
| EEO-1 report | | | | | | Mandatory report on workforce demographics submitted annually to the U.S. Equal Employment Opportunity Commission | | |
| FDM | | | | | | Financially Distressed Modification | | |
| IDI | | | | | | Insured Depository Institution | | |
| IPO | | | | | | Initial Public Offering of Citizens Financial Group, Inc. in 2014 | | |
| M&A | | | | | | Merger and Acquisition | | |
| NMTC | | | | | | New Markets Tax Credit | | |
- The effect of changes in our credit ratings on our cost of funding, access to capital markets, ability to market our securities, and overall liquidity position;
December 31, 2022
| | | | [Part I.](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_16) | | | | | | | | | | | |
| ARRC | | | | | | Alternative Reference Rates Committee | | |
| CARES Act | | | | | | Coronavirus Aid, Relief, and Economic Security Act | | |
| CCMI | | | | | | Citizens Capital Markets, Inc. | | |
| CFTC | | | | | | Commodity Futures Trading Commission | | |
| CLO | | | | | | Collateralized Loan Obligation | | |
| DH Capital | | | | | | DH Capital, LLC | | |
| ERISA | | | | | | Employee Retirement Income Security Act of 1974 | | |
| ICE | | | | | | Intercontinental Exchange | | |
| NCOs | | | | | | Net charge-offs | | |
| Tailoring Rules | | | | | | Rules establishing risk-based categories for determining prudential standards for large U.S. and foreign banking organizations, consistent with the Dodd-Frank Act, as amended by the Economic Growth, Regulatory Relief and Consumer Protection Act | | |
An excerpt. Shown here: 40 of 55 rewritten, all 10 added and all 12 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2023 filing and the FY2022 filing.
Item 1C. CYBERSECURITY
0 rewritten, 35 added, 0 removed, 0 unchanged
New section this year
Risk Management and Strategy
The Company’s Cybersecurity Program (“CSP”) drives an end-to-end, continuous process that protects our customers, colleagues, assets, premises, systems, and information (electronic and non-electronic), and is designed to ensure compliance with current and emerging federal and state laws and regulations.
The CSP is designed to ensure the effective implementation of the Corporate Security and Resilience Operating Model across all business lines of the Company and is under the supervision of the Chief Security Officer (“CSO”).
Non-Financial Risk Management coordinates the development, maintenance, and day-to-day oversight of the Company’s Enterprise Risk Management Governance Framework (“the Framework”), which defines an integrated enterprise-wide approach to risk management.
This centrally managed program is designed to ensure that all business lines play a role in the successful implementation of the CSP.
The CSP aligns with the Framework, enabling the CSO to provide risk oversight to and drive accountability from the business lines.
The CSP is designed to assess and mitigate threats and risks to the Company.
New and emerging threats are assessed through an intelligence lifecycle, which includes threat modeling.
In addition, risk assessment processes drive risk identification and measurement related to security.
Once risks are identified and measured, the Framework is leveraged to track and mitigate them.
Control testing is utilized to demonstrate that risks are managed effectively, identify gaps in expected control operation, and develop appropriate remediation plans, in order to manage risk to the Company within tolerable limits.
As part of the Company’s Third Party Risk Management Program and in support of the CSP, reviews for cybersecurity, business continuity, fraud, and other policy-related topics are performed for the onboarding of new vendors and ongoing monitoring of existing vendors.
Ratings assigned to a vendor determine review frequency and scope.
Results are reported to key stakeholders and identified issues are tracked and monitored.
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | Citizens Financial Group, Inc. \| 33 | | |
The Company regularly reviews the nature of its business activities and modifies the CSP as appropriate.
Many of the elements of the CSP are cyber defense related and are in place to reduce our risk to a wide range of potential cyber threats that may target our assets and information daily.
The effectiveness of the CSP is assessed and measured periodically by various lines of defense within the Company and is conducted primarily through risk assessments, assurance testing, and an independent audit.
External organizations are also routinely engaged to assess our CSP and test our perimeter defenses.
The effectiveness of the CSP is reported periodically to the appropriate governance committees.
Governance
Under the guidance of our CSO, we maintain a comprehensive CSP designed to protect our employees, customers, assets, premises, systems, and information against unauthorized access, misuse, alteration, or destruction that could result in substantial harm or inconvenience to our customers, and loss or reputational damage.
The CSP incorporates all of our security policies and covers the core elements of access control, infrastructure security, cybersecurity event and incident management, data protection, third-party vendor cyber risk oversight, payment security, and training and awareness.
Independent assessment and benchmarking of the CSP are regularly completed, and the CSP is reviewed and assessed by federal regulators.
While we look to numerous frameworks to ensure the CSP is maintained in line with regulatory expectations and industry best practices, the National Institute of Standards and Technology cybersecurity framework is the primary standard against which we benchmark ourselves.
Both the Risk and Audit Committees have oversight of the management of our cybersecurity risk.
The Audit Committee is responsible for overseeing the CSP under its risk oversight responsibilities as it relates to financial controls.
The Risk Committee is responsible for oversight of the management of cybersecurity risk consistent with the Framework.
The CSP is presented by the CSO to the Risk Committee annually for approval in conjunction with an annual cybersecurity briefing.
This briefing provides an overall assessment of the effectiveness of the CSP and an outlook for the upcoming year.
In addition to the annual cybersecurity briefing, the CSO provides updates on cybersecurity to the Risk Committee at each of its meetings.
The Audit Committee and Board also receive regular cybersecurity updates as part of the reporting provided by the Technology/Cyber Oversight Committee, a management committee chaired by the CEO which provides executive oversight, guidance and transparency to key transformative initiatives designed to enhance our technology stability, cyber defenses and risk management capabilities.
Further, to ensure the Board maintains the appropriate knowledge for providing effective oversight, it is provided with relevant cybersecurity training on an annual basis, with any additional training provided as requested.
Item 2. PROPERTIES
2 rewritten, 0 added, 0 removed, 3 unchanged
We lease [removed: seven] [added: five] operations centers in Boston, Medford, and Westwood, Massachusetts; Pittsburgh, Pennsylvania; [removed: Franklin, Tennessee; Irving, Texas] and Glen Allen, Virginia.
At December 31, [removed: 2022,] [added: 2023,] our subsidiaries owned and operated a total of [removed: 59] [added: 60] facilities and leased an additional [removed: 1,293] [added: 1,193] facilities.
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
11 rewritten, 7 added, 9 removed, 14 unchanged
Our common stock is traded on the New York Stock Exchange under the symbol “CFG.” As of [removed: January 31, 2023,] [added: February 1, 2024,] our common stock was owned by [removed: 7,306] [added: 7,086] holders of record (including Cede & Co.) and approximately [removed: 525,000] [added: 445,000] beneficial shareholders whose shares were held in “street name” through a broker or bank.
The following graph compares the cumulative total stockholder returns for our performance during the five-year period ended December 31, [removed: 2022] [added: 2023] relative to the performance of the Standard & Poor’s 500® index, a commonly referenced U.S. equity benchmark consisting of leading companies from diverse economic sectors; the KBW Nasdaq Bank Index (“BKX”), composed of 24 leading national money centers, regional banks and thrifts; and a group of other banks that constitute our peer regional banks.
The graph assumes a $100 investment at the closing price on December 31, [removed: 2017] [added: 2018] in each of CFG common stock, the S&P 500 index, the BKX and the peer market-capitalization weighted average and assumes all dividends were reinvested on the date paid.
This graph shall not be deemed “soliciting material” or be filed with the Securities and Exchange Commission for purposes of Section 18 of the [removed: Securities] Exchange [removed: Act of 1934, as amended (“Exchange Act”),] [added: Act,] or otherwise subject to the liabilities under that Section, and shall not be deemed to be incorporated by reference into any filing of Citizens Financial Group, Inc. under the Securities Act of 1933, as amended, or the Exchange Act.
[removed: 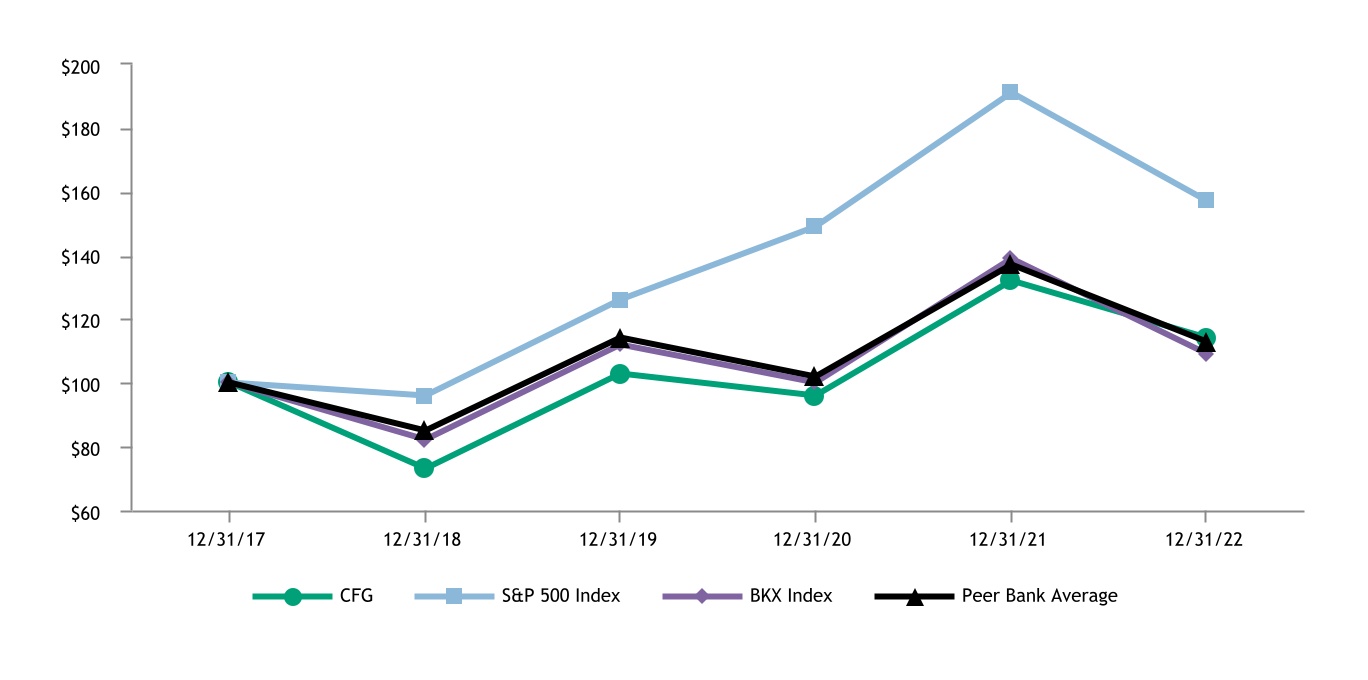][added: ]
| | | | [added: 12/31/2023 | | |] 12/31/2022 | | | 12/31/2021 | | | 12/31/2020 | | | 12/31/2019 | | | 12/31/2018 | | | [removed: 12/31/2017 | | |]
Details of the repurchases of the Company’s common stock during the three months ended December 31, [removed: 2022] [added: 2023] are included below:
(1) [removed: Includes] [added: Reflects] shares repurchased to satisfy applicable tax withholding obligations in connection with an employee share-based compensation plan and the forfeiture of unvested restricted stock awards.
(2) On [removed: June 27, 2022,] [added: February 17, 2023,] the Company announced that its Board of Directors increased the [removed: authorization of] [added: capacity under its] common share [removed: repurchases to $1.0] [added: repurchase program by an additional $1.15] billion, which was [removed: an increase of $545 million above] [added: incremental to] the [removed: $455] [added: $850] million of capacity remaining [added: as of December 31, 2022] under the [removed: $750 million authorization on January 20, 2021.][added: prior June 2022 authorization.]
| | | | | | | Citizens Financial Group, Inc. \| [removed: 36] [added: 34] | | |
The timing and exact amount of future share repurchases will be subject to various factors, including the Company’s capital position, financial performance, capital impacts of strategic initiatives, market conditions, [removed: receipt of required regulatory approvals] and [removed: other] regulatory considerations.
| CFG | | | $140 | | | $157 | | | $181 | | | $132 | | | $142 | | | $100 | | |
| S&P 500 Index | | | 207 | | | 164 | | | 200 | | | 156 | | | 131 | | | 100 | | |
| KBW BKX Index | | | 132 | | | 133 | | | 169 | | | 122 | | | 136 | | | 100 | | |
| Peer Regional Bank Average | | | 133 | | | 134 | | | 162 | | | 120 | | | 134 | | | 100 | | |
| October 1, 2023 - October 31, 2023 | | | 329 | | | $16.82 | | | — | | | $1,094,000,058 | | |
| November 1, 2023 - November 30, 2023 | | | 335 | | | $23.43 | | | — | | | $1,094,000,058 | | |
| December 1, 2023 - December 31, 2023 | | | 691 | | | $12.41 | | | — | | | $1,094,000,058 | | |
| CFG | | | $114 | | | $132 | | | $96 | | | $103 | | | $73 | | | $100 | | |
| S&P 500 Index | | | 157 | | | 191 | | | 149 | | | 126 | | | 96 | | | 100 | | |
| KBW BKX Index | | | 109 | | | 139 | | | 100 | | | 112 | | | 82 | | | 100 | | |
| Peer Regional Bank Average | | | 113 | | | 137 | | | 102 | | | 114 | | | 85 | | | 100 | | |
| October 1, 2022 - October 31, 2022 | | | 3,366,139 | | | $40.18 | | | 3,360,569 | | | $864,930,346 | | |
| November 1, 2022 - November 30, 2022 | | | 5,597 | | | $39.49 | | | — | | | $864,930,346 | | |
| December 1, 2022 - December 31, 2022 | | | 373,120 | | | $40.02 | | | 371,471 | | | $850,000,000 | | |
On February 17, 2023, the Company announced that its Board of Directors increased the capacity under its common share repurchase program by an additional $1.15 billion.
This is incremental to the $850 million of capacity remaining as of December 31, 2022 under the prior June 2022 authorization.
Item 6. RESERVED
1 rewritten, 0 added, 0 removed, 3 unchanged
| | | | | | | Citizens Financial Group, Inc. \| [removed: 37] [added: 36] | | |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
1,162 rewritten, 508 added, 348 removed, 1,378 unchanged
| [Report of Management on Internal Control Over Financial [removed: Reporting](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_124)] [added: Reporting](#i51f41e5d525741dd9c933046ddb6d1a8_124)] | | | | | | [removed: [80](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_124)] [added: [79](#i51f41e5d525741dd9c933046ddb6d1a8_124)] | | |
| [Report of Independent Registered Public Accounting Firm on the Consolidated Financial Statements (PCAOB ID [removed: No.](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_127) 34[)](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_127)] [added: No.](#i51f41e5d525741dd9c933046ddb6d1a8_127) 34)] | | | | | | [removed: [81](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_127)] [added: [80](#i51f41e5d525741dd9c933046ddb6d1a8_127)] | | |
| [Report of Independent Registered Public Accounting Firm on Internal Control Over Financial [removed: Reporting](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_130)] [added: Reporting](#i51f41e5d525741dd9c933046ddb6d1a8_130)] | | | | | | [removed: [85](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_130)] [added: [83](#i51f41e5d525741dd9c933046ddb6d1a8_130)] | | |
| [Consolidated Balance [removed: Sheets](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_133)] [added: Sheets](#i51f41e5d525741dd9c933046ddb6d1a8_133)] | | | | | | [removed: [86](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_133)] [added: [84](#i51f41e5d525741dd9c933046ddb6d1a8_133)] | | |
| [Consolidated Statements of [removed: Operations](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_136)] [added: Operations](#i51f41e5d525741dd9c933046ddb6d1a8_136)] | | | | | | [removed: [87](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_136)] [added: [85](#i51f41e5d525741dd9c933046ddb6d1a8_136)] | | |
| [Consolidated Statements of Comprehensive [removed: Income](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_139)] [added: Income](#i51f41e5d525741dd9c933046ddb6d1a8_139)] | | | | | | [removed: [88](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_139)] [added: [86](#i51f41e5d525741dd9c933046ddb6d1a8_139)] | | |
| [Consolidated Statements of Changes in Stockholders’ [removed: Equity](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_142)] [added: Equity](#i51f41e5d525741dd9c933046ddb6d1a8_142)] | | | | | | [removed: [89](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_142)] [added: [87](#i51f41e5d525741dd9c933046ddb6d1a8_142)] | | |
| [Consolidated Statements of Cash [removed: Flows](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_145)] [added: Flows](#i51f41e5d525741dd9c933046ddb6d1a8_145)] | | | | | | [removed: [90](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_145)] [added: [88](#i51f41e5d525741dd9c933046ddb6d1a8_145)] | | |
| [Notes to Consolidated Financial [removed: Statements](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_148)] [added: Statements](#i51f41e5d525741dd9c933046ddb6d1a8_148)] | | | | | | [removed: [92](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_148)] [added: [90](#i51f41e5d525741dd9c933046ddb6d1a8_148)] | | |
[removed: | [Note 1 - Basis] [added: Basis] of [removed: Presentation](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_151) | | | | | | [92](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_151) | | |][added: Presentation]
| [Note 3 - Cash and Due from [removed: Banks](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_157)] [added: Banks](#i51f41e5d525741dd9c933046ddb6d1a8_157)] | | | | | | [removed: [97](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_157)] [added: [96](#i51f41e5d525741dd9c933046ddb6d1a8_157)] | | |
| [Note 4 - [removed: Securities](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_160)] [added: Securities](#i51f41e5d525741dd9c933046ddb6d1a8_160)] | | | | | | [removed: [97](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_160)] [added: [96](#i51f41e5d525741dd9c933046ddb6d1a8_160)] | | |
| [Note 5 - Loans and [removed: Leases](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_163)] [added: Leases](#i51f41e5d525741dd9c933046ddb6d1a8_163)] | | | | | | [removed: [101](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_163)] [added: [100](#i51f41e5d525741dd9c933046ddb6d1a8_163)] | | |
| [Note 7 - Premises, Equipment and [removed: Software](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_172)] [added: Software](#i51f41e5d525741dd9c933046ddb6d1a8_172)] | | | | | | [removed: [116](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_172)] [added: [116](#i51f41e5d525741dd9c933046ddb6d1a8_172)] | | |
| [Note 8 - Mortgage Banking and [removed: Other](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_175)] [added: Other](#i51f41e5d525741dd9c933046ddb6d1a8_175)] | | | | | | [removed: [117](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_175)] [added: [117](#i51f41e5d525741dd9c933046ddb6d1a8_175)] | | |
| [Note 9 - [removed: Leases](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_178)] [added: Leases](#i51f41e5d525741dd9c933046ddb6d1a8_178)] | | | | | | [removed: [119](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_178)] [added: [118](#i51f41e5d525741dd9c933046ddb6d1a8_178)] | | |
| [Note 10 - Goodwill and Intangible [removed: Assets](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_184)] [added: Assets](#i51f41e5d525741dd9c933046ddb6d1a8_181)] | | | | | | [removed: [120](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_184)] [added: [120](#i51f41e5d525741dd9c933046ddb6d1a8_181)] | | |
| [Note 11 - Variable Interest [removed: Entities](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_187)] [added: Entities](#i51f41e5d525741dd9c933046ddb6d1a8_184)] | | | | | | [removed: [122](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_187)] [added: [121](#i51f41e5d525741dd9c933046ddb6d1a8_184)] | | |
| [Note 12 - [removed: Deposits](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_190)] [added: Deposits](#i51f41e5d525741dd9c933046ddb6d1a8_187)] | | | | | | [removed: [124](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_190)] [added: [124](#i51f41e5d525741dd9c933046ddb6d1a8_187)] | | |
| [Note 14 - [removed: Derivatives](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_196)] [added: Derivatives](#i51f41e5d525741dd9c933046ddb6d1a8_193)] | | | | | | [removed: [126](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_196)] [added: [126](#i51f41e5d525741dd9c933046ddb6d1a8_193)] | | |
| [Note 16 - Accumulated Other Comprehensive Income [removed: (Loss)](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_202)] [added: (Loss)](#i51f41e5d525741dd9c933046ddb6d1a8_199)] | | | | | | [removed: [131](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_202)] [added: [131](#i51f41e5d525741dd9c933046ddb6d1a8_199)] | | |
| [Note 18 - Share-Based [removed: Compensation](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_211)] [added: Compensation](#i51f41e5d525741dd9c933046ddb6d1a8_208)] | | | | | | [removed: [133](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_211)] [added: [133](#i51f41e5d525741dd9c933046ddb6d1a8_208)] | | |
| [Note 19 - Commitments and [removed: Contingencies](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_214)] [added: Contingencies](#i51f41e5d525741dd9c933046ddb6d1a8_214)] | | | | | | [removed: [134](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_214)] [added: [134](#i51f41e5d525741dd9c933046ddb6d1a8_214)] | | |
| [Note 20 - Fair Value [removed: Measurements](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_217)] [added: Measurements](#i51f41e5d525741dd9c933046ddb6d1a8_217)] | | | | | | [removed: [135](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_217)] [added: [136](#i51f41e5d525741dd9c933046ddb6d1a8_217)] | | |
| [Note 21 - Noninterest [removed: Income](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_220)] [added: Income](#i51f41e5d525741dd9c933046ddb6d1a8_220)] | | | | | | [removed: [142](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_220)] [added: [142](#i51f41e5d525741dd9c933046ddb6d1a8_220)] | | |
| [Note 22 - Other Operating [removed: Expense](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_223)] [added: Expense](#i51f41e5d525741dd9c933046ddb6d1a8_223)] | | | | | | [removed: [144](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_223)] [added: [144](#i51f41e5d525741dd9c933046ddb6d1a8_223)] | | |
| [Note 23 - Income [removed: Taxes](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_226)] [added: Taxes](#i51f41e5d525741dd9c933046ddb6d1a8_226)] | | | | | | [removed: [144](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_226)] [added: [144](#i51f41e5d525741dd9c933046ddb6d1a8_226)] | | |
| [Note 24 - Earnings Per [removed: Share](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_229)] [added: Share](#i51f41e5d525741dd9c933046ddb6d1a8_232)] | | | | | | [removed: [147](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_229)] [added: [147](#i51f41e5d525741dd9c933046ddb6d1a8_232)] | | |
| [Note 26 - Business Operating [removed: Segments](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_235)] [added: Segments](#i51f41e5d525741dd9c933046ddb6d1a8_238)] | | | | | | [removed: [149](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_235)] [added: [149](#i51f41e5d525741dd9c933046ddb6d1a8_238)] | | |
| [Note 27 - Parent Company [removed: Financials](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_241)] [added: Financials](#i51f41e5d525741dd9c933046ddb6d1a8_241)] | | | | | | [removed: [152](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_241)] [added: [152](#i51f41e5d525741dd9c933046ddb6d1a8_241)] | | |
Management assessed the effectiveness of the Company’s system of internal control over financial reporting as of December 31, [removed: 2022] [added: 2023] based on the framework set forth by the Committee of Sponsoring Organizations of the Treadway Commission in *Internal Control — Integrated Framework (2013)*.
Based on that assessment, management concluded that, as of December 31, [removed: 2022,] [added: 2023,] the Company’s internal control over financial reporting is effective.
The Company’s internal control over financial reporting as of December 31, [removed: 2022] [added: 2023] has been audited by Deloitte & Touche LLP, an independent registered public accounting firm, as stated in their accompanying report appearing on page [removed: [85](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_130),] [added: [83](#i51f41e5d525741dd9c933046ddb6d1a8_130),] which expresses an unqualified opinion on the effectiveness of the Company’s internal control over financial reporting.
We have audited the accompanying consolidated balance sheets of Citizens Financial Group, Inc. and its subsidiaries (the "Company") as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] the related consolidated statements of operations, comprehensive income, changes in stockholders' equity, and cash flows, for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] and the related notes (collectively referred to as the "consolidated financial statements").
In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of their operations and their cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control* *—* *Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February [removed: 17, 2023,] [added: 16, 2024,] expressed an unqualified opinion on the Company's internal control over financial reporting.
[removed: *Critical] [added: Critical] Audit Matter [removed: Description*][added: Description]
[removed: Management’s] [added: The Company’s] estimate of expected credit losses in [removed: the Company’s] [added: its] loan and lease portfolios is recorded in the [removed: ALLL and the allowance for unfunded lending commitments (collectively the ACL).][added: ACL.]
The ACL is maintained at a level the Company believes to be appropriate to absorb expected lifetime credit losses over the contractual life of [removed: the] [added: a] loan [removed: and] [added: or] lease [removed: portfolios] and on the unfunded lending commitments.
The determination of the ACL is based on periodic evaluation of the loan and lease portfolios and unfunded lending commitments that are not unconditionally [removed: cancellable considering a number of relevant underlying factors, including key assumptions and evaluation of quantitative and qualitative information.][added: cancellable.]
| [Note 1 - Significant Accounting Policies](#i51f41e5d525741dd9c933046ddb6d1a8_151) | | | | | | [90](#i51f41e5d525741dd9c933046ddb6d1a8_151) | | |
| [Note 2 - Acquisitions](#i51f41e5d525741dd9c933046ddb6d1a8_2406) | | | | | | [92](#i51f41e5d525741dd9c933046ddb6d1a8_2406) | | |
| [Note 6 - Credit Quality and the Allowance for Credit Losses](#i51f41e5d525741dd9c933046ddb6d1a8_166) | | | | | | [102](#i51f41e5d525741dd9c933046ddb6d1a8_166) | | |
| [Note 13 - Borrowed Funds](#i51f41e5d525741dd9c933046ddb6d1a8_190) | | | | | | [125](#i51f41e5d525741dd9c933046ddb6d1a8_190) | | |
| [Note 15 - Employee Benefit Plans](#i51f41e5d525741dd9c933046ddb6d1a8_196) | | | | | | [129](#i51f41e5d525741dd9c933046ddb6d1a8_196) | | |
| [Note 17 - Stockholders’ Equity](#i51f41e5d525741dd9c933046ddb6d1a8_202) | | | | | | [132](#i51f41e5d525741dd9c933046ddb6d1a8_202) | | |
| [Note 25 - Regulatory Matters](#i51f41e5d525741dd9c933046ddb6d1a8_235) | | | | | | [148](#i51f41e5d525741dd9c933046ddb6d1a8_235) | | |
| | | | | | | Citizens Financial Group, Inc. \| 78 | | |
A number of relevant underlying factors, including key assumptions and evaluation of quantitative and qualitative information, are considered.
Known and estimated data include current PD, LGD and EAD for commercial loans, timing and amount of expected draws for unfunded lending commitments, FICO, LTV, and term for retail loans.
Critical Audit Matter Description
Management has identified and assigned goodwill to two reporting units, Consumer Banking and Commercial Banking.
Management reviews the goodwill of each reporting unit for impairment on an annual basis as of October 31st or more frequently if events or circumstances change that indicate an impairment may exist.
Management performed a quantitative goodwill impairment test due to a triggering event in the third quarter of 2023 in addition to performing a quantitative impairment test associated with its annual assessment date.
In both instances, the fair value of the Company’s reporting units was determined using a combination of income and market-based approaches.
Under the income approach, key assumptions included cash flow projections based on multi-year forecasts, long-term earnings growth rate, and discount rates.
Under the market-based approach, key assumptions included determination of comparable public companies, valuation multiples, and utilization of a market control premium associated with cost synergies and other cash flow benefits that arise from obtaining control over a reporting unit, and guideline transactions, when applicable.
How the Critical Audit Matter Was Addressed in the Audit
- We tested the completeness and accuracy of the data used in the valuation of the commercial and consumer reporting units.
- We tested the reasonableness of Management’s forecast used in the valuation of the commercial and consumer reporting units.
February 16, 2024
| (dollars in millions, except par value) | | | 2023 | | | | | | 2022 | | |
(1) Includes amounts in consolidated VIEs.
See Note 11 for additional information.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Share repurchase excise tax | | | — | | | — | | | | | | — | | | — | | | — | | | — | | | (9) | | | — | | | (9) | | |
| Balance at December 31, 2023 | | | 2 | | | $2,014 | | | | | | 466 | | | $6 | | | $22,250 | | | $9,816 | | | ($5,986) | | | ($3,758) | | | $24,342 | | |
| Transfer of loans from portfolio to LHFS | | | $2,617 | | | $— | | | $— | | |
| Transfer of securities from AFS to HTM | | | — | | | 8,563 | | | — | | |
NOTE 1 - SIGNIFICANT ACCOUNTING POLICIES
Nature of Operations
The Company is a regional bank holding company organized under Delaware law and headquartered in Providence, Rhode Island.
Through its bank subsidiary, CBNA, the Company provides a broad range of retail and commercial banking products and services to individuals, small businesses, middle-market companies, large corporations and institutions.
The Company’s retail branch network is primarily located in the New England, Mid-Atlantic and Midwest regions, with certain lines of business serving national markets.
Investments in VIEs in which the Company does not have the ability to exercise significant influence are not consolidated.
During the third quarter of 2023, the Company’s indirect auto and certain purchased consumer loan portfolios were transferred from the Consumer Banking segment into a new Non-Core segment to reflect the manner in which management is currently assessing performance and allocating resources.
Prior period results have been revised to conform to the new segment presentation.
See Note 26 for additional information.
| [Note 2 - Acquisitions](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_154) | | | | | | [93](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_154) | | |
| [Note 6 - Allowance for Credit Losses, Nonaccrual Loans and Leases, and Concentrations of Credit Risk](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_166) | | | | | | [103](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_166) | | |
| [Note 13 - Borrowed Funds](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_193) | | | | | | [124](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_193) | | |
| [Note 15 - Employee Benefits](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_199) | | | | | | [129](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_199) | | |
| [Note 17 - Stockholders’ Equity](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_205) | | | | | | [131](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_205) | | |
| [Note 25 - Regulatory Matters](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_232) | | | | | | [147](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_232) | | |
| [N](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_244)[ote 28 - Subsequent Events](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_244) | | | | | | [153](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_244) | | |
Pursuant to the terms of the agreement, Investors merged with Citizens, with Citizens as the surviving corporation, and Investors Bank, a New Jersey state-chartered bank and wholly-owned subsidiary of Investors, merged with CBNA, with CBNA as the surviving bank.
The Investors acquisition was accounted for as a business combination.
The determination of fair value requires management to make estimates about discount rates, future expected cash flows, market conditions and other future events that are highly subjective in nature and are subject to change.
Fair values for loans and leases are based on a discounted cash flow methodology that considered factors including type of loan and lease and related collateral, fixed or variable interest rate, term, amortization status, credit loss and prepayment expectations, market interest rates and other market factors (e.g., liquidity) from the perspective of a market participant.
Loans and leases were grouped together according to similar characteristics when applying various valuation techniques.
The discount rates used are based on current market rates for new originations of comparable loans and leases and include adjustments for liquidity.
The probability of default, loss given default, exposure at default and prepayment assumptions are the key factors driving credit losses which are embedded into the estimated cash flows.
Fair value of core deposit intangible represents the value of certain client deposit relationships, estimated utilizing the favorable source of funds method.
Appropriate consideration was given to deposit costs including servicing costs, client retention and alternative funding source costs at the time of acquisition.
The discount rate used was derived taking into account the estimated cost of equity, risk-free return rate and risk premium for the market, and specific risk related to the asset’s cash flows.
The core deposit intangible is being amortized over 10 years using an accelerated depreciation methodology.
- We tested the completeness and accuracy of the source information used in the valuation of the loans and leases and valuation of the core deposit intangible asset.
February 17, 2023
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Balance at December 31, 2019 | | | 2 | | | $1,570 | | | | | | 433 | | | $6 | | | $18,891 | | | $6,498 | | | ($4,353) | | | ($411) | | | $22,201 | | |
| Preferred stock issued | | | — | | | 395 | | | | | | — | | | — | | | — | | | — | | | — | | | — | | | 395 | | |
| Payments of employee tax withholding for share-based compensation | | | (25) | | | (22) | | | (16) | | |
| Transfer of securities from available for sale to held to maturity | | | $8,563 | | | $— | | | $813 | | |
| Loans securitized and transferred to securities held to maturity | | | — | | | — | | | 111 | | |
| Stock issued for share-based compensation plans | | | 77 | | | 43 | | | 30 | | |
| Stock issued for Employee Stock Purchase Plan | | | 24 | | | 22 | | | 19 | | |
See Note 2 for more detailed information regarding these acquisitions.
NOTE 1 - BASIS OF PRESENTATION
The accounting and reporting policies of Citizens Financial Group, Inc. conform to GAAP.
The Company’s principal business activity is banking, conducted through its subsidiary CBNA.
The Company also provides M&A, capital raising and other financial advisory services to middle market companies across a focused set of industry verticals through its broker-dealers.
The Company has evaluated its unconsolidated entities and does not believe that any entity in which it has an interest, but does not currently consolidate, meets the requirements to be consolidated as a variable interest entity.
| Leases | | | [9](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_178) | | | [119](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_178) | | |
| Variable Interest Entities | | | [11](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_187) | | | [122](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_187) | | |
| Treasury Stock | | | [17](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_205) | | | [131](#ie7b3d7e1d2b740b6a1d0b50b0b3a564c_205) | | |
| Reference Rate Reform - Deferral of the Sunset Date *December 2022* | | | •This standard was effective upon issuance. •Deferred the sunset date of the temporary relief provided by ASU 2020-04, *Reference Rate Reform (Topic 848): Facilitation of the Effects of Reference Rate Reform on Financial Reporting* from December 31, 2022 to December 31, 2024. | | | •The Company adopted this standard upon issuance. •Adoption did not have a material impact on the Company’s Consolidated Financial Statements. | | |
On April 6, 2022, Citizens completed its previously announced Investors acquisition pursuant to an agreement and plan of merger entered into on July 28, 2021.
Citizens considers its valuation of certain other assets and other liabilities to be preliminary as of December 31, 2022.
An excerpt. Shown here: 40 of 1,162 rewritten, 40 of 508 added and 40 of 348 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2023 filing and the FY2022 filing.
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
0 rewritten, 0 added, 3 removed, 1 unchanged
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | Citizens Financial Group, Inc. \| 153 | | |
Item 9A. CONTROLS AND PROCEDURES
0 rewritten, 3 added, 0 removed, 7 unchanged
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | Citizens Financial Group, Inc. \| 153 | | |
Item 9B. OTHER INFORMATION
0 rewritten, 1 added, 9 removed, 0 unchanged
None.
Effective February 16, 2023, the Company’s Board of Directors approved and adopted an amendment and restatement of the Company’s Bylaws (as so amended and restated, the “Bylaws”).
The Board of Directors approved the Bylaws as part of its periodic review of the Company’s corporate governance documents.
The Bylaws include amendments that:
- revise provisions regarding adjournment of stockholder meetings in light of recent amendments to the Delaware General Corporation Law (the “DGCL”);
- update the Company’s bylaws in connection with the new SEC rules relating to universal proxy cards (the “Universal Proxy Rules”), including requiring stockholders providing notice pursuant to Rule 14a-19(b) under the Exchange Act, to certify to the Company that they have complied with certain requirements under the Universal Proxy Rules no later than 7 business days prior to the applicable stockholder meeting;
- refine and clarify the advance notice provisions for stockholder nominations and proposals, including provisions regarding (1) the information to be provided by proposing stockholders, proposed nominees and other persons related to a stockholder’s solicitation of proxies and (2) the questionnaire, representation and agreement to be completed by proposing stockholders and proposed nominees in connection with a stockholder nomination; and
- require any stockholder directly or indirectly soliciting proxies from other stockholders to use a proxy card color other than white.
The Bylaws also implement certain other administrative, technical and conforming changes, including changes to align with the language used in certain provisions of the DGCL and the Universal Proxy Rules.
The foregoing description of the changes implemented by the Bylaws does not purport to be complete and is qualified in its entirety by reference to the Bylaws that are attached hereto as Exhibit 3.2 and incorporated by reference herein.
Item 9C. DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS
2 rewritten, 0 added, 3 removed, 2 unchanged
In Part III of this Report we refer to relevant sections of our [removed: 2023] [added: 2024] Proxy Statement for the [removed: 2023] [added: 2024] annual meeting of shareholders, which will be filed with the SEC pursuant to Regulation 14A within 120 days of the close of our [removed: 2022] [added: 2023] fiscal year.
Portions of our [removed: 2023] [added: 2024] Proxy Statement, including the sections we refer to in this Report, are incorporated by reference into this Report.
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | Citizens Financial Group, Inc. \| 154 | | |
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
1 rewritten, 0 added, 0 removed, 0 unchanged
Information required by this item is presented under the captions “Corporate Governance Matters” — [removed: “Proposal One — Election of Directors”] [added: “Director Nominees”] and “Board [removed: Governance] [added: Structure] and Oversight [added: Responsibilities”] — “Corporate Governance [removed: Guidelines, Committee Charters and Code] [added: Guidelines”, “Committees] of [added: the Board”, “Code of] Business Conduct and Ethics” [added: and “Other Items” - “Delinquent Section 16(a) Reporting”] of our [removed: 2023] [added: 2024] Proxy Statement, which is incorporated by reference into this item.
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 3 added, 0 removed, 0 unchanged
Information required by this item is presented under the captions [removed: “Compensation] [added: “Executive Compensation] Matters” — “Compensation Discussion and Analysis,” “Compensation and [removed: Human Resources] [added: HR] Committee [removed: Report,”] [added: Report”,] “Executive [removed: Compensation,”] [added: Compensation Tables”,] “Termination of Employment and Change of [removed: Control,” “Director Compensation,”] [added: Control”,] “Role of Risk Management in [removed: Compensation,”] [added: Compensation”,] “Dodd Frank Compensation Disclosure” — “CEO Pay Ratio” and “Pay Versus [removed: Performance”] [added: Performance”, and “Corporate Governance Matters” - “Director Compensation”] of our [removed: 2023] [added: 2024] Proxy Statement, which is incorporated by reference into this item.
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | Citizens Financial Group, Inc. \| 154 | | |
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
6 rewritten, 2 added, 2 removed, 12 unchanged
The information required by this item regarding security ownership of certain beneficial owners and management is presented under the caption [added: “Other Items” -] “Security Ownership of Certain Beneficial Owners and Management” in our [removed: 2023] [added: 2024] Proxy [removed: Statement and] [added: Statement, which] is incorporated [removed: herein] by [removed: reference.][added: reference into this item.]
| Equity compensation plans approved by security holders | | | [removed: 3,864,001] [added: 4,567,994] | | | — | | | [removed: 47,080,139] [added: 43,741,366] | | |
Although equity-based awards granted under the Investors Plans were converted into CFG awards and assumed in connection with the Investors [removed: acquisition,] [added: acquisition in 2022,] CFG does not intend to grant any awards under the Investors Plans.
As of December 31, [removed: 2022, 1,114,324] [added: 2023, 393,426] stock options with a weighted-average exercise price of [removed: $38.21] [added: $38.35] and [removed: 71,413] [added: 18,509] restricted shares were outstanding under the Investors Plans.
As of December 31, [removed: 2022, 245,861] [added: 2023, 214,601] stock options with a weighted-average exercise price of $19.45 and [removed: 12,600] [added: 5,663] restricted stock units were outstanding under the JMP Plan.
(5) Represents the number of shares remaining available for future issuance under the Citizens Financial Group, Inc. 2014 Omnibus Incentive Plan [removed: (41,887,596] [added: (39,532,535] shares), the Citizens Financial Group, Inc. 2014 Employee Stock [removed: Repurchase] [added: Purchase] Plan [removed: (3,903,590] [added: (2,991,009] shares), and the Citizens Financial Group, Inc. 2014 Non-Employee Directors Compensation Plan [removed: (1,288,953] [added: (1,217,822] shares).
At December 31, 2023
| Total(1)(2) | | | 4,567,994 | | | — | | | 43,741,366 | | |
At December 31, 2022
| Total(1)(2) | | | 3,864,001 | | | — | | | 47,080,139 | | |
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 3 removed, 0 unchanged
Information required by this item is set forth under the captions “Corporate Governance Matters” — “Board Governance and [removed: Oversight] [added: Oversight”] — [removed: Director] [added: “Director Nominees” - “Director] Independence” and “Related Person Transactions” of our [removed: 2023] [added: 2024] Proxy Statement, which is incorporated by reference into this item.
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | Citizens Financial Group, Inc. \| 155 | | |
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
1 rewritten, 0 added, 0 removed, 1 unchanged
Information required by this item is presented under the captions “Audit Matters” — “Pre-approval of Independent Auditor Services” and “Independent Registered Public Accounting Firm Fees” of our [removed: 2023] [added: 2024] Proxy Statement, which is incorporated by reference into this item.
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
47 rewritten, 7 added, 3 removed, 29 unchanged
[removed: *(a)(1) Financial Statements of] [added: | | | | | | |] Citizens Financial Group, [removed: Inc., included in this Report:*][added: Inc. \| 155 | | |]
- Consolidated Balance Sheets as of December 31, [removed: 2022] [added: 2023] and [removed: 2021;][added: 2022;]
- Consolidated Statements of Operations for the Years Ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020;][added: 2021;]
- Consolidated Statements of Comprehensive Income for the Years Ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020;][added: 2021;]
- Consolidated Statements of Changes in Stockholders’ Equity for the Years Ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020;][added: 2021;]
- Consolidated Statements of Cash Flows for the Years Ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020;] [added: 2021;] and
All [added: required] financial statement schedules for the Registrant [removed: have been] [added: are] included in the audited Consolidated Financial Statements or [removed: the] related footnotes in Item [removed: 8, or are either inapplicable or not required.][added: 8.]
[removed: [3.2 Amended] [added: [3.2](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit32-2023.htm) [Amended] and Restated Bylaws of the Registrant (as amended and restated on February [removed: 16,](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit32-2023.htm) [](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit32-2023.htm)[2023](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit32-2023.htm)[)](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit32-2023.htm)[*](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit32-2023.htm)[](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit32-2023.htm)][added: 16, 2023) (incorporated herein by reference to Exhibit 3.2 of the Annual Report on Form 10-K, filed February 17, 2023)](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit32-2023.htm)]
[removed: [4.3 Form] [added: [4.3](http://www.sec.gov/Archives/edgar/data/759944/000119312518173169/d592114dex42.htm) [](http://www.sec.gov/Archives/edgar/data/759944/000119312518173169/d592114dex42.htm)[Form] of Certificate representing the Series B Preferred Stock (incorporated herein by reference to Exhibit 4.2 of the Current Report on Form 8-K, filed May 24, 2018)](http://www.sec.gov/Archives/edgar/data/759944/000119312518173169/d592114dex42.htm)
[removed: [4.6 Description] [added: [4.6](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit46-q42023.htm) [](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit46-q42023.htm)[Description] of the Securities Registered Pursuant to Section 12 of the Securities Act of [removed: 1934*](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit462022.htm)][added: 1934*](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit46-q42023.htm)]
[removed: [4.7 Agreement] [added: [4.7](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit47-q42023.htm) [Agreement] to furnish to the SEC upon request a copy of instruments defining the rights of holders of certain long-term debt of the registrant and consolidated [removed: subsidiaries*](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit472022.htm)][added: subsidiaries*](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit47-q42023.htm)]
[10.4 Citizens Financial Group, Inc. 2014 Omnibus Incentive Plan Form of Restricted Stock Unit Award [removed: Agreement†*](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit104-2023.htm)][added: Agreement†*](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit104-rsuagmt.htm)]
[removed: [10.5 Citizens] [added: [10.5](http://www.sec.gov/Archives/edgar/data/759944/000075994417000012/exhibit1011bvsrsu2017grant.htm) [Citizens] Financial Group, Inc. 2014 Omnibus Incentive Plan Restricted Stock Unit Award Agreement for Bruce Van Saun Relating to Annual Awards (incorporated herein by reference to Exhibit 10.11 of the Annual Report on Form 10-K, Filed February 24, 2017)†](http://www.sec.gov/Archives/edgar/data/759944/000075994417000012/exhibit1011bvsrsu2017grant.htm)
[10.6 Citizens Financial Group, Inc. 2014 Omnibus Incentive Plan Form of Performance Stock Unit Award [removed: Agreement](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit106-2023.htm)[†](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit106-2023.htm)[*](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit106-2023.htm)][added: Agreement†*](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit106-psuagmt.htm)]
[10.7 Citizens Financial Group, Inc. 2014 Omnibus Incentive Plan Performance Stock Unit Award Agreement for Bruce Van Saun [removed: Relat](http://www.sec.gov/Archives/edgar/data/759944/000075994417000012/exhibit1015bvspsu2017grant.htm)[ing] [added: Relating] to Annual Awards (incorporated herein by reference to Exhibit 10.15 of the Annual Report on Form 10-K, Filed February 24, 2017)†](http://www.sec.gov/Archives/edgar/data/759944/000075994417000012/exhibit1015bvspsu2017grant.htm)
[removed: [10.8 Citizens] [added: [10.8](http://www.sec.gov/Archives/edgar/data/759944/000095010314006651/dp49578_ex9903.htm) [Citizens] Financial Group, Inc. 2014 Employee Stock Purchase Plan (incorporated herein by reference to Exhibit 99.3 of the Registration Statement on Form S-8, filed September 26, 2014)†](http://www.sec.gov/Archives/edgar/data/759944/000095010314006651/dp49578_ex9903.htm)
[removed: [10.11](https://www.sec.gov/Archives/edgar/data/759944/000075994422000120/exhibit101q22022.htm) [Citizens] [added: [10.11 Citizens] Financial Group, Inc. Non-Employee Directors Compensation Policy, amended and effective April 28, 2022 (incorporated herein by reference to Exhibit 10.1 of the Quarterly Report on Form 10-Q, filed August 3, 2022)†](https://www.sec.gov/Archives/edgar/data/759944/000075994422000120/exhibit101q22022.htm)
[removed: [10.12 Citizens] [added: [10.13](https://www.sec.gov/Archives/edgar/data/759944/000095010314006651/dp49578_ex9902.htm) [Citizens] Financial Group, Inc. 2014 Non-Employee Directors Compensation Plan (incorporated herein by reference to Exhibit 99.2 of the Registration Statement on Form S-8, filed September 26, 2014)†](https://www.sec.gov/Archives/edgar/data/759944/000095010314006651/dp49578_ex9902.htm)
[removed: [10.1](https://www.sec.gov/Archives/edgar/data/759944/000075994416000143/exhbit101.htm)[3](https://www.sec.gov/Archives/edgar/data/759944/000075994416000143/exhbit101.htm)] [added: [10.1](https://www.sec.gov/Archives/edgar/data/759944/000075994416000143/exhbit101.htm)[4](https://www.sec.gov/Archives/edgar/data/759944/000075994416000143/exhbit101.htm)] [Amended and Restated Citizens Financial Group, Inc. 2014 Non-Employee Directors Compensation Plan as of June 23, 2016 (incorporated herein by reference to Exhibit 10.1 of the Quarterly Report on Form 10-Q, filed August 5, 2016)†](https://www.sec.gov/Archives/edgar/data/759944/000075994416000143/exhbit101.htm)
[removed: [10.1](http://www.sec.gov/Archives/edgar/data/759944/000075994416000099/formofdirector2016rsuagmt.htm)[4](http://www.sec.gov/Archives/edgar/data/759944/000075994416000099/formofdirector2016rsuagmt.htm) [Citizens] [added: [10.1](http://www.sec.gov/Archives/edgar/data/759944/000075994416000099/formofdirector2016rsuagmt.htm)[5](http://www.sec.gov/Archives/edgar/data/759944/000075994416000099/formofdirector2016rsuagmt.htm) [](http://www.sec.gov/Archives/edgar/data/759944/000075994416000099/formofdirector2016rsuagmt.htm)[Citizens] Financial Group, Inc. 2014 Non-Employee Directors Compensation Plan Form of Restricted Stock Unit Award Agreement (incorporated herein by reference to Exhibit 10.19 of the Annual Report on Form 10-K, filed February 26, 2016)†](http://www.sec.gov/Archives/edgar/data/759944/000075994416000099/formofdirector2016rsuagmt.htm)
[removed: [10.1](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-2.htm)[5](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-2.htm) [Citizens] [added: [10.1](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-2.htm)[6](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-2.htm) [](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-2.htm)[Citizens] Financial Group, Inc. 2014 Non-Employee Directors Compensation Plan Form of Restricted Stock Unit Award Agreement (incorporated herein by reference to Exhibit 10.2 of the Quarterly Report on Form 10-Q, Filed August 3, 2017)†](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-2.htm)
[removed: [10.1](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1019.htm)[6](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1019.htm) [Amended] [added: [10.1](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1019.htm)[7](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1019.htm) [](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1019.htm)[Amended] and Restated Deferred Compensation Plan for Directors of Citizens Financial Group, Inc., effective January 1, 2009 (incorporated herein by reference to Exhibit 10.19 of Amendment No. 2 to Registration Statement on Form S-1, filed August 15, 2014)†](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1019.htm)
[removed: [10.1](http://www.sec.gov/Archives/edgar/data/759944/000119312514334394/d723158dex105.htm)[7](http://www.sec.gov/Archives/edgar/data/759944/000119312514334394/d723158dex105.htm)] [added: [10.1](http://www.sec.gov/Archives/edgar/data/759944/000119312514334394/d723158dex105.htm)[8](http://www.sec.gov/Archives/edgar/data/759944/000119312514334394/d723158dex105.htm)] [Form of Indemnification Agreement (incorporated herein by reference to Exhibit 10.5 of Amendment No. 3 to Registration Statement on Form S-1, filed September 8, 2014)†](http://www.sec.gov/Archives/edgar/data/759944/000119312514334394/d723158dex105.htm)
[removed: [10.1](http://www.sec.gov/Archives/edgar/data/759944/000075994415000016/exhibit10-21.htm)[8](http://www.sec.gov/Archives/edgar/data/759944/000075994415000016/exhibit10-21.htm)] [added: [10.1](http://www.sec.gov/Archives/edgar/data/759944/000075994415000016/exhibit10-21.htm)[9](http://www.sec.gov/Archives/edgar/data/759944/000075994415000016/exhibit10-21.htm)] [Amended and Restated CFG Voluntary Executive Deferred Compensation Plan, effective January 1, 2009 and amended and restated on September 1, 2014 (incorporated herein by reference to Exhibit 10.21 of the Annual Report on Form 10-K, filed March 3, 2015)†](http://www.sec.gov/Archives/edgar/data/759944/000075994415000016/exhibit10-21.htm)
[removed: [10.1](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1026.htm)[9](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1026.htm) [First] [added: [10.](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1026.htm)[20](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1026.htm) [](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1026.htm)[First] Amendment to the CFG Voluntary Executive Deferred Compensation Plan dated March 1, 2019 (incorporated herein by reference to Exhibit 10.26 of the Annual Report on Form 10-K, filed February 24, 2020)†](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1026.htm)
[removed: [10.](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1027.htm)[20](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1027.htm)] [added: [10.2](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1027.htm)[1](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1027.htm)] [Second Amendment to the CFG Voluntary Executive Deferred Compensation Plan dated December 9, 2019 (incorporated herein by reference to Exhibit 10.27 of the Annual Report on Form 10-K, filed February 24, 2020)†](https://www.sec.gov/Archives/edgar/data/759944/000075994420000030/exhibit1027.htm)
[removed: [10.2](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1027.htm)[1](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1027.htm) [Third] [added: [10.2](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1027.htm)[2](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1027.htm) [](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1027.htm)[Third] Amendment to the CFG Voluntary Executive Deferred Compensation Plan dated March 4, 2020 (incorporated herein by reference to Exhibit 10.27 of the Annual Report on Form 10-K, filed February 23, 2021)†](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1027.htm)
[removed: [10.22 Fourth] [added: [10.2](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit1021.htm)[3](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit1021.htm) [](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit1021.htm)[Fourth] Amendment to the CFG Voluntary Executive Deferred Compensation Plan dated January 1, 2022 (incorporated herein by reference to Exhibit [removed: 10.](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit1021.htm)[21](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit1021.htm) [of] [added: 10.21 of] the Annual Report on Form 10-K, filed February 23, [removed: 2022)](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit1021.htm)[†](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit1021.htm)][added: 2022)†](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit1021.htm)]
[removed: [10.2](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm)[3](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm) [Amended and] [added: [10.2](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm)[5](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm) [](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm)[Amend](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm)[e](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm)[d](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm) [](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm)[and] Restated Citizens Financial Group, Inc. Deferred Compensation Plan, [removed: effective January] [added: effective](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm) [January] 1, [removed: 2009 (incorporated] [added: 20](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm)[0](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm)[9](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm) [(incorporated] herein by reference to Exhibit 10.20 of Amendment No. 2 to Registration Statement on Form S-1, filed August 15, 2014)†](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1020.htm)
[removed: [10.24](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit1024-2023.htm) [Citizens] [added: [10.26 Citizens] Financial Group, Inc. Form of Deferred Cash Award [removed: Agreement](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit1024-2023.htm)[†](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit1024-2023.htm)[*](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit1024-2023.htm)][added: Agreement†*](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit1026-deferredcashag.htm)]
[removed: [10.2](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1021.htm)[5](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1021.htm) [Citizens] [added: [10.2](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1021.htm)[7](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1021.htm) [](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1021.htm)[Citizens] Financial Group, Inc. Executive Severance Practice (incorporated herein by reference to [removed: Exhibit 10.21] [added: Exhibit](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1021.htm) [10.21] of Amendment No. 2 to Registration Statement on Form S-1, filed August 15, 2014)†](http://www.sec.gov/Archives/edgar/data/759944/000119312514311183/d723158dex1021.htm)
[removed: [10.2](http://www.sec.gov/Archives/edgar/data/759944/000075994416000137/ceocontract-5516xexecution.htm)[6](http://www.sec.gov/Archives/edgar/data/759944/000075994416000137/ceocontract-5516xexecution.htm) [Amended] [added: [10.2](http://www.sec.gov/Archives/edgar/data/759944/000075994416000137/ceocontract-5516xexecution.htm)[8](http://www.sec.gov/Archives/edgar/data/759944/000075994416000137/ceocontract-5516xexecution.htm) [](http://www.sec.gov/Archives/edgar/data/759944/000075994416000137/ceocontract-5516xexecution.htm)[Amended] and Restated Executive Employment Agreement, dated May 5, 2016, between the Registrant and Bruce Van Saun (incorporated herein by reference to Exhibit 10.5 of the Quarterly Report on Form 10-Q, filed May 9, 2016)†](http://www.sec.gov/Archives/edgar/data/759944/000075994416000137/ceocontract-5516xexecution.htm)
[removed: [10.2](https://www.sec.gov/Archives/edgar/data/759944/000075994421000108/exhibit102.htm)[7](https://www.sec.gov/Archives/edgar/data/759944/000075994421000108/exhibit102.htm)] [added: [10.29](https://www.sec.gov/Archives/edgar/data/759944/000075994421000108/exhibit102.htm)] [Addendum to Amended and Restated Executive Employment Agreement, dated as of June 25, 2021 between the Registrant and Bruce Van Saun (incorporated herein by reference to Exhibit 10.2 of the Quarterly Report on Form [removed: 10-Q] [added: 10-Q,] filed August 3, 2021)†](https://www.sec.gov/Archives/edgar/data/759944/000075994421000108/exhibit102.htm)
[removed: [10.2](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-7.htm)[8](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-7.htm)] [added: [10.](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-7.htm)[30](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-7.htm)] [Executive Employment Agreement, dated March 23, 2015, between the Registrant and Donald H.
[removed: [10.](http://www.sec.gov/Archives/edgar/data/759944/000075994419000024/exhibit10_41.htm)[29](http://www.sec.gov/Archives/edgar/data/759944/000075994419000024/exhibit10_41.htm)] [added: [10.](http://www.sec.gov/Archives/edgar/data/759944/000075994419000024/exhibit10_41.htm)[3](http://www.sec.gov/Archives/edgar/data/759944/000075994419000024/exhibit10_41.htm)[1](http://www.sec.gov/Archives/edgar/data/759944/000075994419000024/exhibit10_41.htm)] [Executive Employment Agreement, dated September 6, 2014, between the Registrant and Malcolm Griggs and subsequent addendum dated August 14, 2017 (incorporated herein by reference to Exhibit 10.41 of the Annual Report on Form 10-K, filed February 21, 2019)†](http://www.sec.gov/Archives/edgar/data/759944/000075994419000024/exhibit10_41.htm)
[removed: [10.3](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-8.htm)[0](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-8.htm)] [added: [10.3](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-8.htm)[2](http://www.sec.gov/Archives/edgar/data/759944/000075994417000047/exhibit10-8.htm)] [Executive Employment Agreement, dated December 13, 2016, between the Registrant and John F.
[removed: [10.3](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1039.htm)[1](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1039.htm) [Executive] [added: [10.3](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit10322021.htm)[3](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit10322021.htm) [](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit10322021.htm)[Amended and Restated Executive] Employment Agreement, dated [removed: August 25, 2011,] [added: December 20, 2021,] between the Registrant and [removed: Susan LaMonica and subsequent](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1039.htm) [addend](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1039.htm)[a](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1039.htm) [dated July 15, 2014 and August 11, 2017] [added: Brendan Coughlin] (incorporated herein by reference to Exhibit [removed: 10.39] [added: 10.32] of the Annual Report on Form 10-K, filed February 23, [removed: 2021)†](https://www.sec.gov/Archives/edgar/data/759944/000075994421000034/exhibit1039.htm)][added: 2022)†](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit10322021.htm)]
[removed: [10.34](https://www.sec.gov/Archives/edgar/data/759944/000119312522098321/d348985dex43.htm)] [added: [10.3](https://www.sec.gov/Archives/edgar/data/759944/000119312522098321/d348985dex43.htm)[4](https://www.sec.gov/Archives/edgar/data/759944/000119312522098321/d348985dex43.htm)] [](https://www.sec.gov/Archives/edgar/data/759944/000119312522098321/d348985dex43.htm)[Investors Bancorp, Inc. 2015 Equity Incentive Plan (incorporated herein by reference to Exhibit 4.3 of the Registration Statement on Form S-8, filed April 7, [removed: 2022)](https://www.sec.gov/Archives/edgar/data/759944/000119312522098321/d348985dex43.htm)[†](https://www.sec.gov/Archives/edgar/data/759944/000119312522098321/d348985dex43.htm)][added: 2022)†](https://www.sec.gov/Archives/edgar/data/759944/000119312522098321/d348985dex43.htm)]
[removed: [10.35 Investors] [added: [10.3](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit1035-2022.htm)[5](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit1035-2022.htm) [](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit1035-2022.htm)[Investors] Bancorp, Inc. 2015 Equity Incentive Plan Form of Stock Option [removed: Agreement†*](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit1035-2022.htm)][added: Agreement (incorporated herein by reference to Exhibit 10.35 of the Annual Report on Form 10-K, filed February 17, 2023)†](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit1035-2022.htm)]
[21.1 Subsidiaries of [removed: Registrant*](https://www.sec.gov/Archives/edgar/data/759944/000075994423000029/exhibit211-2022.htm)][added: Registrant*](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit211-q42023.htm)]
*(a)(1) Financial Statements*
The following report of our independent registered public accounting firm and the consolidated financial statements of Citizens Financial Group, Inc. are included in Item 8 of this Form 10-K:
[10.12 Citizens Financial Group, Inc. Non-Employee Directors Compensation Policy, amended and effective April 27, 2023 (incorporated herein by reference to Exhibit 10.1 of the Quarterly Report on Form 10-Q, filed August 8, 2023)†](https://www.sec.gov/Archives/edgar/data/759944/000075994423000124/a2q23non-employeedirectors.htm)
[10.24 Fifth Amendment to the CFG Voluntary Executive Deferred Compensation Plan dated January 1, 2024†*](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit1024-voluntaryexecu.htm)
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
[97.1 Citizens Financial Group, Inc. Clawback Policy, effective December 1, 2023*](https://www.sec.gov/Archives/edgar/data/759944/000075994424000039/exhibit971-cfgxclawbackpol.htm)
[10.3](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit10322021.htm)[2](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit10322021.htm) [Amended and Restated Executive Employment Agreement, dated December 20, 2021, between the Registrant and Brendan Coughlin (incorporated herein by reference to Exhibit 10.32 of the Annual Report on Form 10-K, filed February 23, 2022)†](https://www.sec.gov/Archives/edgar/data/759944/000075994422000025/exhibit10322021.htm)
[10.3](http://www.sec.gov/Archives/edgar/data/759944/000119312514334394/d723158dex1037.htm)[3](http://www.sec.gov/Archives/edgar/data/759944/000119312514334394/d723158dex1037.htm) [Supplemental Retirement Agreement, dated October 31, 1995, as amended, between Charter One Financial, Inc. and, Charles J.
Koch (incorporated herein by reference to Exhibit 10.37 of Amendment No. 3 to Registration Statement on Form S-1, filed September 8, 2014)†](http://www.sec.gov/Archives/edgar/data/759944/000119312514334394/d723158dex1037.htm)
An excerpt. Shown here: 40 of 47 rewritten, all 7 added and all 3 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES in the FY2023 filing and the FY2022 filing.
Item 16. FORM 10-K SUMMARY
17 rewritten, 0 added, 0 removed, 60 unchanged
Pursuant to the requirements of [removed: the] Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this [removed: Report] [added: report] to be signed on its behalf by the undersigned, thereunto duly authorized on February [removed: 17, 2023.][added: 16, 2024.]
Jack Read, and each of them, his or her true and lawful attorney-in-fact and agent, with full power of substitution and resubstitution, for him or her and in his or her name, place and stead in any and all capacities, to sign one or more Annual Reports for the Company's fiscal year ended December 31, [removed: 2022] [added: 2023] on Form 10-K under the Securities Exchange Act of 1934, as amended, or such other form as any such attorney-in-fact may deem necessary or desirable, any amendments thereto, and all additional amendments thereto, each in such form as they or any one of them may approve, and to file the same with all exhibits thereto and other documents in connection therewith with the Securities and Exchange Commission, granting unto said attorneys-in-fact and agents, and each of them, full power and authority to do and perform each and every act and thing requisite and necessary to be done so that such Annual Report shall comply with the Securities Exchange Act of 1934, as amended, and the applicable Rules and Regulations adopted or issued pursuant thereto, as fully and to all intents and purposes as he or she might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact and agents, or any of them or their substitute or resubstitute, may lawfully do or cause to be done by virtue hereof.
| Bruce Van Saun | | | | | | | | | Chairman of the Board and Chief Executive Officer | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| John F. Woods | | | | | | | | | Vice [removed: Chairman] [added: Chair] and Chief Financial Officer | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| C. Jack Read | | | | | | | | | Executive Vice President, Chief Accounting Officer and Controller | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Lee Alexander | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Christine M. Cumming | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Kevin Cummings | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| William P. Hankowsky | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Edward J. Kelly III | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Robert G. Leary | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Terrance J. Lillis | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Michele N. Siekerka | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Shivan S. Subramaniam | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Christopher J. Swift | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Wendy A. Watson | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |
| Marita Zuraitis | | | | | | | | | Director | | | | | | February [removed: 17, 2023] [added: 16, 2024] | | |