 filings.tools
Item 16. FORM 10-K SUMMARY
192K characters. Original on sec.gov · Markdown
Item 16. FORM 10-K SUMMARY
None.
COLGATE-PALMOLIVE COMPANY
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| Colgate-Palmolive Company (Registrant) | ||||||||
| Date: February 17, 2022 | By | /s/ Noel R. Wallace | ||||||
| Noel R. Wallace Chairman of the Board, President and Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below on February 17, 2022, by the following persons on behalf of the registrant and in the capacities indicated.
| (a) Principal Executive Officer | (d) Directors: | |||||||
| /s/ Noel R. Wallace | /s/ Noel R. Wallace | |||||||
| Noel R. Wallace Chairman of the Board, President and Chief Executive Officer | Noel R. Wallace | |||||||
| (b) Principal Financial Officer | John P. Bilbrey, John T. Cahill, Lisa M. Edwards, C. Martin Harris, Martina Hund-Mejean, Kimberly A. Nelson, Lorrie M. Norrington, Michael B. Polk, Stephen I. Sadove* | |||||||
| /s/ Stanley J. Sutula III | *By: /s/ Jennifer M. Daniels | |||||||
| Stanley J. Sutula III Chief Financial Officer | Jennifer M. Daniels As Attorney-in-Fact | |||||||
| (c) Principal Accounting Officer | ||||||||
| /s/ Philip G. Shotts | ||||||||
| Philip G. Shotts Vice President and Controller |
Index to Financial Statements
| Page | |||||
| Consolidated Financial Statements | |||||
| Report of Independent Registered Public Accounting Firm (PCAOB ID 238) | 67 | ||||
| Consolidated Statements of Income for the years ended December 31, 2021, 2020 and 2019 | 70 | ||||
| Consolidated Statements of Comprehensive Income for the years ended December 31, 2021, 2020 and 2019 | 71 | ||||
| Consolidated Balance Sheets as of December 31, 2021 and 2020 | 72 | ||||
| Consolidated Statements of Changes in Shareholders’ Equity for the years ended December 31, 2021, 2020 and 2019 | 73 | ||||
| Consolidated Statements of Cash Flows for the years ended December 31, 2021, 2020 and 2019 | 74 | ||||
| Notes to Consolidated Financial Statements | 75 | ||||
| Financial Statement Schedule | |||||
| Schedule II - Valuation and Qualifying Accounts for the years ended December 31, 2021, 2020 and 2019 | 122 | ||||
| Selected Financial Data | |||||
| Market Information | 123 | ||||
All other financial statements and schedules not listed have been omitted since the required information is included in the financial statements or the notes thereto or is not applicable or required.
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Shareholders of Colgate-Palmolive Company
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the consolidated financial statements, including the related notes and financial statement schedule, of Colgate-Palmolive Company and its subsidiaries (the “Company”) as listed in the accompanying index (collectively referred to as the “consolidated financial statements”). We also have audited the Company's internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, 2021 and 2020, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2021 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
Basis for Opinions
The Company's management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in Management’s Annual Report on Internal Control Over Financial Reporting appearing under Item 9A. Our responsibility is to express opinions on the Company’s consolidated financial statements and on the Company's internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and whether effective internal control over financial reporting was maintained in all material respects.
Our audits of the consolidated financial statements included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Critical Audit Matters
The critical audit matter communicated below is a matter arising from the current period audit of the consolidated financial statements that was communicated or required to be communicated to the audit committee and that (i) relates to accounts or disclosures that are material to the consolidated financial statements and (ii) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
Goodwill and Indefinite-Lived Intangible Asset Impairment Assessments - Filorga
As described in Notes 2 and 5 to the consolidated financial statements, the Company’s consolidated balance of goodwill and indefinite-lived intangible assets was $3.3 billion and $1.6 billion, respectively, as of December 31, 2021. Goodwill and indefinite-lived intangible assets are subject to impairment tests at least annually or when events or changes in circumstances indicate that an asset may be impaired. Given the impact of the COVID-19 pandemic on the Filorga skin health business, during the fourth quarter of 2021, the Company concluded that the changes in circumstances in this reporting unit triggered the need for an interim impairment review of its indefinite-lived trademark and goodwill. Accordingly, the Company performed an interim impairment test for the trademark as of December 31, 2021. The Company concluded that the carrying value of the trademark exceeded its estimated fair value, and recorded an impairment charge of $204 million, reducing the carrying value to approximately $588 million. After adjusting the carrying value of the trademark, the Company completed a quantitative impairment test for goodwill and recorded a goodwill impairment charge of $367 million in the Filorga reporting unit, reducing the carrying value of goodwill to approximately $577 million. The fair value of the Filorga reporting unit and indefinite-lived trademark were determined using an income approach. This method incorporates significant judgments and estimates by management regarding several key inputs, including future cash flows, sales growth rates, discount rate, and the selection of royalty rates, among others.
The principal considerations for our determination that performing procedures relating to the goodwill and indefinite-lived intangible asset impairment assessments of Filorga is a critical audit matter are (i) the significant judgment by management when developing the fair value of the reporting unit and indefinite-lived intangible asset; (ii) a high degree of auditor judgment, subjectivity, and effort in performing procedures and evaluating management’s significant assumptions related to the sales growth rates and discount rate for the goodwill and indefinite-lived intangible asset, and the royalty rate for the indefinite-lived intangible asset; and (iii) the audit effort involved the use of professionals with specialized skill and knowledge.
Addressing the matter involved performing procedures and evaluating audit evidence in connection with forming our overall opinion on the consolidated financial statements. These procedures included testing the effectiveness of controls relating to management’s goodwill and indefinite-lived intangible asset impairment assessments, including controls over the valuation of the Filorga reporting unit and indefinite-lived intangible asset. These procedures also included, among others (i) testing management’s process for developing the fair value of the reporting unit and indefinite-lived intangible asset; (ii) evaluating the appropriateness of the income approach; (iii) testing the completeness and accuracy of underlying data used in the income approach; and (iv) evaluating the reasonableness of significant assumptions used by management related to the sales growth rates and discount rate for the goodwill and indefinite-lived intangible asset, and the royalty rate for the indefinite-lived intangible asset. Evaluating management’s significant assumptions related to the sales growth rates and discount rate for the goodwill and indefinite-lived intangible asset and the royalty rate for the indefinite-lived intangible asset involved evaluating whether the significant assumptions used by management were reasonable considering (i) the current and past performance of the reporting unit; (ii) the consistency with external market and industry data, and (iii) whether these assumptions were consistent with evidence obtained in other areas of the audit. Professionals with specialized skill and knowledge were used to assist in evaluating the appropriateness of the income approach and the reasonableness of the discount rate and royalty rate significant assumptions.
| /s/ PricewaterhouseCoopers LLP | |||||
| New York, New York February 17, 2022 | |||||
| We have served as the Company’s auditor since 2002. |
COLGATE-PALMOLIVE COMPANY
Consolidated Statements of Income
For the years ended December 31,
(Dollars in Millions Except Per Share Amounts)
| 2021 | 2020 | 2019 | |||||||||||||||
| Net sales | $ | 17,421 | $ | 16,471 | $ | 15,693 | |||||||||||
| Cost of sales | 7,046 | 6,454 | 6,368 | ||||||||||||||
| Gross profit | 10,375 | 10,017 | 9,325 | ||||||||||||||
| Selling, general and administrative expenses | 6,407 | 6,019 | 5,575 | ||||||||||||||
| Other (income) expense, net | 65 | 113 | 196 | ||||||||||||||
| Goodwill and indefinite-lived intangible impairment charges | 571 | — | — | ||||||||||||||
| Operating profit | 3,332 | 3,885 | 3,554 | ||||||||||||||
| Non-service related postretirement costs | 70 | 74 | 108 | ||||||||||||||
| Interest (income) expense, net | 175 | 164 | 145 | ||||||||||||||
| Income before income taxes | 3,087 | 3,647 | 3,301 | ||||||||||||||
| Provision for income taxes | 749 | 787 | 774 | ||||||||||||||
| Net income including noncontrolling interests | 2,338 | 2,860 | 2,527 | ||||||||||||||
| Less: Net income attributable to noncontrolling interests | 172 | 165 | 160 | ||||||||||||||
| Net income attributable to Colgate-Palmolive Company | $ | 2,166 | $ | 2,695 | $ | 2,367 | |||||||||||
| Earnings per common share, basic | $ | 2.56 | $ | 3.15 | $ | 2.76 | |||||||||||
| Earnings per common share, diluted | $ | 2.55 | $ | 3.14 | $ | 2.75 |
See Notes to Consolidated Financial Statements.
COLGATE-PALMOLIVE COMPANY
Consolidated Statements of Comprehensive Income
For the years ended December 31,
(Dollars in Millions)
| 2021 | 2020 | 2019 | |||||||||||||||
| Net income including noncontrolling interests | $ | 2,338 | $ | 2,860 | $ | 2,527 | |||||||||||
| Other comprehensive income (loss), net of tax: | |||||||||||||||||
| Cumulative translation adjustments | (193) | (24) | 25 | ||||||||||||||
| Retirement plan and other retiree benefit adjustments | 134 | (40) | (100) | ||||||||||||||
| Gains (losses) on cash flow hedges | 16 | (2) | (12) | ||||||||||||||
| Total Other comprehensive income (loss), net of tax | (43) | (66) | (87) | ||||||||||||||
| Total Comprehensive income including noncontrolling interests | 2,295 | 2,794 | 2,440 | ||||||||||||||
| Less: Net income attributable to noncontrolling interests | 172 | 165 | 160 | ||||||||||||||
| Less: Cumulative translation adjustments attributable to noncontrolling interests | (2) | 6 | (2) | ||||||||||||||
| Total Comprehensive income attributable to noncontrolling interests | 170 | 171 | 158 | ||||||||||||||
| Total Comprehensive income attributable to Colgate-Palmolive Company | $ | 2,125 | $ | 2,623 | $ | 2,282 |
See Notes to Consolidated Financial Statements.
COLGATE-PALMOLIVE COMPANY
Consolidated Balance Sheets
As of December 31,
(Dollars in Millions Except Share and Per Share Amounts)
| 2021 | 2020 | ||||||||||
| Assets | |||||||||||
| Current Assets | |||||||||||
| Cash and cash equivalents | $ | 832 | $ | 888 | |||||||
| Receivables (net of allowances of $78 and $89, respectively) | 1,297 | 1,264 | |||||||||
| Inventories | 1,692 | 1,673 | |||||||||
| Other current assets | 576 | 513 | |||||||||
| Total current assets | 4,397 | 4,338 | |||||||||
| Property, plant and equipment, net | 3,730 | 3,716 | |||||||||
| Goodwill | 3,284 | 3,824 | |||||||||
| Other intangible assets, net | 2,462 | 2,894 | |||||||||
| Deferred income taxes | 193 | 291 | |||||||||
| Other assets | 974 | 857 | |||||||||
| Total assets | $ | 15,040 | $ | 15,920 | |||||||
| Liabilities and Shareholders’ Equity | |||||||||||
| Current Liabilities | |||||||||||
| Notes and loans payable | $ | 39 | $ | 258 | |||||||
| Current portion of long-term debt | 12 | 9 | |||||||||
| Accounts payable | 1,479 | 1,393 | |||||||||
| Accrued income taxes | 436 | 403 | |||||||||
| Other accruals | 2,085 | 2,341 | |||||||||
| Total current liabilities | 4,051 | 4,404 | |||||||||
| Long-term debt | 7,194 | 7,334 | |||||||||
| Deferred income taxes | 395 | 426 | |||||||||
| Other liabilities | 2,429 | 2,655 | |||||||||
| Total liabilities | 14,069 | 14,819 | |||||||||
| Commitments and contingent liabilities | — | — | |||||||||
| Shareholders’ Equity | |||||||||||
| Common stock, $1 par value (2,000,000,000 shares authorized, 1,465,706,360 shares issued) | 1,466 | 1,466 | |||||||||
| Additional paid-in capital | 3,269 | 2,969 | |||||||||
| Retained earnings | 24,350 | 23,699 | |||||||||
| Accumulated other comprehensive income (loss) | (4,386) | (4,345) | |||||||||
| Unearned compensation | (1) | (1) | |||||||||
| Treasury stock, at cost | (24,089) | (23,045) | |||||||||
| Total Colgate-Palmolive Company shareholders’ equity | 609 | 743 | |||||||||
| Noncontrolling interests | 362 | 358 | |||||||||
| Total equity | 971 | 1,101 | |||||||||
| Total liabilities and equity | $ | 15,040 | $ | 15,920 |
See Notes to Consolidated Financial Statements.
COLGATE-PALMOLIVE COMPANY
Consolidated Statements of Changes in Shareholders’ Equity
(Dollars in Millions)
| Colgate-Palmolive Company Shareholders’ Equity | |||||||||||||||||||||||||||||||||||||||||
| Common Stock | Additional Paid-In Capital | Unearned Compensation | Treasury Stock | Retained Earnings | Accumulated Other Comprehensive Income (Loss) | Noncontrolling Interests | |||||||||||||||||||||||||||||||||||
| Balance, January 1, 2019 | $ | 1,466 | $ | 2,204 | $ | (3) | $ | (21,196) | $ | 21,615 | $ | (4,188) | $ | 299 | |||||||||||||||||||||||||||
| Net income | 2,367 | 160 | |||||||||||||||||||||||||||||||||||||||
| Other comprehensive income (loss), net of tax | (85) | (2) | |||||||||||||||||||||||||||||||||||||||
| Dividends ($1.71)/per share* | (1,472) | (141) | |||||||||||||||||||||||||||||||||||||||
| Stock-based compensation expense | 100 | ||||||||||||||||||||||||||||||||||||||||
| Shares issued for stock options | 210 | 305 | |||||||||||||||||||||||||||||||||||||||
| Shares issued for restricted stock awards | (29) | 29 | |||||||||||||||||||||||||||||||||||||||
| Noncontrolling interests assumed through acquisition | 125 | ||||||||||||||||||||||||||||||||||||||||
| Treasury stock acquired | (1,202) | ||||||||||||||||||||||||||||||||||||||||
| Other | 3 | 1 | 1 | (9) | |||||||||||||||||||||||||||||||||||||
| Balance, December 31, 2019 | $ | 1,466 | $ | 2,488 | $ | (2) | $ | (22,063) | $ | 22,501 | $ | (4,273) | $ | 441 | |||||||||||||||||||||||||||
| Net income | 2,695 | 165 | |||||||||||||||||||||||||||||||||||||||
| Other comprehensive income (loss), net of tax | (72) | 6 | |||||||||||||||||||||||||||||||||||||||
| Dividends ($1.75)/per share* | (1,502) | (152) | |||||||||||||||||||||||||||||||||||||||
| Stock-based compensation expense | 107 | ||||||||||||||||||||||||||||||||||||||||
| Shares issued for stock options | 400 | 462 | |||||||||||||||||||||||||||||||||||||||
| Shares issued for restricted stock awards | (31) | 31 | |||||||||||||||||||||||||||||||||||||||
| Noncontrolling interests acquired | (99) | ||||||||||||||||||||||||||||||||||||||||
| Treasury stock acquired | (1,476) | ||||||||||||||||||||||||||||||||||||||||
| Other | 5 | 1 | 1 | 5 | (3) | ||||||||||||||||||||||||||||||||||||
| Balance, December 31, 2020 | $ | 1,466 | $ | 2,969 | $ | (1) | $ | (23,045) | $ | 23,699 | $ | (4,345) | $ | 358 | |||||||||||||||||||||||||||
| Net income | 2,166 | 172 | |||||||||||||||||||||||||||||||||||||||
| Other comprehensive income (loss), net of tax | (41) | (2) | |||||||||||||||||||||||||||||||||||||||
| Dividends ($1.79)/per share* | (1,515) | (166) | |||||||||||||||||||||||||||||||||||||||
| Stock-based compensation expense | 135 | ||||||||||||||||||||||||||||||||||||||||
| Shares issued for stock options | 188 | 248 | |||||||||||||||||||||||||||||||||||||||
| Shares issued for restricted stock awards | (27) | 27 | |||||||||||||||||||||||||||||||||||||||
| Treasury stock acquired | (1,320) | ||||||||||||||||||||||||||||||||||||||||
| Other | 4 | — | 1 | — | — | ||||||||||||||||||||||||||||||||||||
| Balance, December 31, 2021 | $ | 1,466 | $ | 3,269 | $ | (1) | $ | (24,089) | $ | 24,350 | $ | (4,386) | $ | 362 |
- Two dividends were declared in each of the first quarters of 2021, 2020 and 2019.
See Notes to Consolidated Financial Statements.
COLGATE-PALMOLIVE COMPANY
Consolidated Statements of Cash Flows
For the years ended December 31,
(Dollars in Millions)
| 2021 | 2020 | 2019 | |||||||||||||||
| Operating Activities | |||||||||||||||||
| Net income including noncontrolling interests | $ | 2,338 | $ | 2,860 | $ | 2,527 | |||||||||||
| Adjustments to reconcile net income including noncontrolling interests to net cash provided by operations: | |||||||||||||||||
| Depreciation and amortization | 556 | 539 | 519 | ||||||||||||||
| Restructuring and termination benefits, net of cash | (21) | (71) | 18 | ||||||||||||||
| Stock-based compensation expense | 135 | 107 | 100 | ||||||||||||||
| Goodwill and indefinite-lived intangible impairment charges | 571 | — | — | ||||||||||||||
| Loss on early extinguishment of debt | 75 | 23 | — | ||||||||||||||
| Deferred income taxes | (132) | (120) | 17 | ||||||||||||||
| Voluntary benefit plan contributions | — | — | (113) | ||||||||||||||
| Cash effects of changes in: | |||||||||||||||||
| Receivables | (84) | 138 | 19 | ||||||||||||||
| Inventories | (72) | (251) | (77) | ||||||||||||||
| Accounts payable and other accruals | 14 | 520 | 36 | ||||||||||||||
| Other non-current assets and liabilities | (55) | (26) | 87 | ||||||||||||||
| Net cash provided by operations | 3,325 | 3,719 | 3,133 | ||||||||||||||
| Investing Activities | |||||||||||||||||
| Capital expenditures | (567) | (410) | (335) | ||||||||||||||
| Purchases of marketable securities and investments | (141) | (143) | (184) | ||||||||||||||
| Proceeds from sale of marketable securities and investments | 141 | 124 | 131 | ||||||||||||||
| Payment for acquisitions, net of cash acquired | — | (353) | (1,711) | ||||||||||||||
| Other investing activities | (25) | 3 | — | ||||||||||||||
| Net cash used in investing activities | (592) | (779) | (2,099) | ||||||||||||||
| Financing Activities | |||||||||||||||||
| Short-term borrowing (repayment) less than 90 days, net | (171) | 488 | 296 | ||||||||||||||
| Principal payments on debt (1) | (703) | (1,085) | (1,441) | ||||||||||||||
| Proceeds from issuance of debt | 699 | — | 2,578 | ||||||||||||||
| Dividends paid | (1,679) | (1,654) | (1,614) | ||||||||||||||
| Purchases of treasury shares | (1,320) | (1,476) | (1,202) | ||||||||||||||
| Proceeds from exercise of stock options | 424 | 874 | 498 | ||||||||||||||
| Purchases of non-controlling interests in subsidiaries | — | (99) | — | ||||||||||||||
| Other financing activities | (24) | 33 | 15 | ||||||||||||||
| Net cash used in financing activities | (2,774) | (2,919) | (870) | ||||||||||||||
| Effect of exchange rate changes on Cash and cash equivalents | (15) | (16) | (7) | ||||||||||||||
| Net (decrease) increase in Cash and cash equivalents | (56) | 5 | 157 | ||||||||||||||
| Cash and cash equivalents at beginning of year | 888 | 883 | 726 | ||||||||||||||
| Cash and cash equivalents at end of year | $ | 832 | $ | 888 | $ | 883 | |||||||||||
| Supplemental Cash Flow Information | |||||||||||||||||
| Income taxes paid | $ | 890 | $ | 845 | $ | 803 | |||||||||||
| Interest paid | $ | 194 | $ | 188 | $ | 185 |
(1) For the years ended December 31, 2021 and 2020, Principal payments on debt includes cash charges of $75 and $20, respectively, related to the extinguishment of debt prior to maturity. See Note 6, Long-Term Debt and Credit Facilities for additional information.
See Notes to Consolidated Financial Statements.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements
(Dollars in Millions Except Share and Per Share Amounts)
1. Nature of Operations
The Company manufactures and markets a wide variety of products in the U.S. and around the world in two product segments: Oral, Personal and Home Care; and Pet Nutrition. Oral, Personal and Home Care products include toothpaste, toothbrushes, mouthwash, bar and liquid hand soaps, shower gels, shampoos, conditioners, deodorants and antiperspirants, skin health products, dishwashing detergents, fabric conditioners, household cleaners and other similar items. These products are sold primarily to a variety of traditional and eCommerce retailers, wholesalers and distributors worldwide. Pet Nutrition products include specialty pet nutrition products manufactured and marketed by Hill’s Pet Nutrition. The principal customers for Pet Nutrition products are authorized pet supply retailers, veterinarians and eCommerce retailers. Some of our products are also sold direct-to-consumer. Principal global and regional trademarks include Colgate, Palmolive, elmex, hello, meridol, Sorriso, Tom’s of Maine, EltaMD, Filorga, Irish Spring, Lady Speed Stick, PCA SKIN, Protex, Sanex, Softsoap, Speed Stick, Ajax, Axion, Fabuloso, Murphy, Soupline and Suavitel, as well as Hill’s Science Diet and Hill’s Prescription Diet.
The Company’s principal classes of products accounted for the following percentages of worldwide Net sales for the past three years:
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Oral Care | 44 | % | 44 | % | 46 | % | ||||||||||||||
| Personal Care | 20 | % | 21 | % | 20 | % | ||||||||||||||
| Home Care | 17 | % | 18 | % | 18 | % | ||||||||||||||
| Pet Nutrition | 19 | % | 17 | % | 16 | % | ||||||||||||||
| Total | 100 | % | 100 | % | 100 | % |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
2. Summary of Significant Accounting Policies
Principles of Consolidation
The Consolidated Financial Statements include the accounts of Colgate-Palmolive Company and its majority-owned or controlled subsidiaries. Intercompany transactions and balances have been eliminated. The Company’s investments in consumer products companies with interests ranging between 20% and 50%, where the Company has significant influence over the investee, are accounted for using the equity method. Net income (loss) from such investments is recorded in Other (income) expense, net in the Consolidated Statements of Income. As of December 31, 2021 and 2020, equity method investments included in Other assets in the Consolidated Balance Sheets were $64 and $56, respectively. Unrelated third parties hold the remaining ownership interests in these investments. Investments with less than a 20% interest are recorded at cost and periodically adjusted based on observable price changes or quoted market prices in active markets, if applicable.
Use of Estimates
The preparation of financial statements in accordance with accounting principles generally accepted in the United States of America requires management to use judgment and make estimates that affect the reported amounts of assets and liabilities and disclosure of contingent gains and losses at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. The level of uncertainty in estimates and assumptions increases with the length of time until the underlying transactions are completed. As such, the most significant uncertainty in the Company’s assumptions and estimates involved in preparing the financial statements includes pension and other retiree benefit cost assumptions, stock-based compensation, asset impairments, uncertain tax positions, tax valuation allowances and legal and other contingency reserves. Additionally, the Company uses available market information and other valuation methodologies in assessing the fair value of financial instruments and retirement plan assets. Judgment is required in interpreting market data to develop the estimates of fair value and, accordingly, changes in assumptions or the estimation methodologies may affect the fair value estimates. Actual results could ultimately differ from those estimates.
Revenue Recognition
The Company’s revenue contracts represent a single performance obligation to sell its products to trade customers. Sales are recorded at the time control of the products is transferred to trade customers, in an amount that reflects the consideration the Company expects to be entitled to in exchange for the products. Control is the ability of trade customers to “direct the use of” and “obtain” the benefit from our products. In evaluating the timing of the transfer of control of products to trade customers, the Company considers several control indicators, including significant risks and rewards of products, the Company’s right to payment and the legal title of the products. Based on the assessment of control indicators, sales are generally recognized when products are delivered to trade customers.
Net sales reflect the transaction prices for contracts, which include units shipped at selling list prices reduced by variable consideration. Variable consideration includes expected sales returns and the cost of current and continuing promotional programs. Current promotional programs primarily include product listing allowances and co-operative advertising arrangements. Continuing promotional programs are predominantly consumer coupons and volume-based sales incentive arrangements. The cost of promotional programs is estimated using the expected value method considering all reasonably available information, including the Company’s historical experience and its current expectations, and is reflected in the transaction price when sales are recorded. Adjustments to the cost of promotional programs in subsequent periods are generally not material, as the Company’s promotional programs are typically of short duration, thereby reducing the uncertainty inherent in such estimates.
Sales returns are generally accepted at the Company’s discretion and are not material to the Company’s Consolidated Financial Statements. The Company’s contracts with trade customers do not have significant financing components or non-cash consideration and the Company does not have unbilled revenue or significant amounts of prepayments from customers. The Company records Net sales excluding taxes collected on its sales to its trade customers. Shipping and handling activities are accounted for as contract fulfillment costs and classified as Selling, general and administrative expenses.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Shipping and Handling Costs
Shipping and handling costs are classified as Selling, general and administrative expenses and were $1,687, $1,392 and $1,275 for the years ended December 31, 2021, 2020 and 2019, respectively.
Marketing Costs
The Company markets its products through advertising and other promotional activities. Advertising costs are included in Selling, general and administrative expenses and are expensed as incurred. Certain consumer and trade promotional programs, such as consumer coupons, are recorded as a reduction of sales.
Cash and Cash Equivalents
The Company considers all highly liquid investments with original maturities of three months or less at the time of purchase to be cash equivalents.
Inventories
The cost of approximately 75% of inventories is determined using the FIFO method, which is stated at the lower of cost or net realizable value. The cost of all other inventories, in the U.S. and Mexico, is determined using the LIFO method, which is stated at the lower of cost or market. Inventories in excess of one year of forecasted sales are classified in the Consolidated Balance Sheets as non-current “Other assets.”
Property, Plant and Equipment
Land, buildings and machinery and equipment are stated at cost. Depreciation is provided, primarily using the straight-line method, over-estimated useful lives ranging from 3 to 15 years for machinery and equipment and up to 40 years for buildings. Depreciation attributable to manufacturing operations is included in Cost of sales. The remaining component of depreciation is included in Selling, general and administrative expenses.
Goodwill and Other Intangibles
Goodwill and indefinite-life intangible assets, such as the Company’s global brands, are subject to impairment tests at least annually or when events or changes in circumstances indicate that an asset may be impaired. Other intangible assets with finite lives, such as local brands and trademarks, customer relationships and non-compete agreements, are amortized over their estimated useful lives, generally ranging from 5 to 40 years. Amortization expense related to intangible assets is included in Other (income) expense, net, which is included in Operating profit.
Income Taxes
The provision for income taxes is determined using the asset and liability method. Under this method, deferred tax assets and liabilities are recognized based upon the differences between the financial statement and tax bases of assets and liabilities using enacted tax rates that will be in effect at the time such differences are expected to reverse. Deferred tax assets are reduced by a valuation allowance when, in the opinion of management, it is more likely than not that some portion or all of the deferred tax assets will not be realized.
The Company uses a comprehensive model to recognize, measure, present and disclose in its financial statements uncertain tax positions that the Company has taken or expects to take on an income tax return. The Company recognizes interest expense and penalties related to unrecognized tax benefits within Provision for income taxes.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Financial Instruments
Derivative instruments are recorded as assets and liabilities at estimated fair value based on available market information. The Company’s derivative instruments that qualify for hedge accounting are designated as either fair value hedges, cash flow hedges or net investment hedges. For fair value hedges, changes in the fair value of the derivative, as well as the offsetting changes in the fair value of the hedged item, are recognized in earnings each period. For cash flow hedges, changes in the fair value of the derivative are recorded in Other comprehensive income (loss) and are recognized in earnings when the offsetting effect of the hedged item is also recognized in earnings. For hedges of the net investment in foreign subsidiaries, changes in the fair value of the derivative are recorded in Other comprehensive income (loss) to offset the change in the value of the net investment being hedged. Cash flows related to hedges are classified in the same category as the cash flows from the hedged item in the Consolidated Statements of Cash Flows.
The Company may also enter into certain foreign currency and interest rate instruments that economically hedge certain of its risks but do not qualify for hedge accounting. Changes in fair value of these derivative instruments, based on quoted market prices, are recognized in earnings each period. The Company’s derivative instruments and other financial instruments are more fully described in Note 7, Fair Value Measurements and Financial Instruments along with the related fair value measurement considerations.
Stock-Based Compensation
The Company recognizes the cost of employee services received in exchange for awards of equity instruments, such as stock options and restricted stock units (both performance-based and time-vested), based on the fair value of those awards at the date of grant over the requisite service period. The Company uses the Black-Scholes-Merton (“Black-Scholes”) option pricing model to estimate the fair value of stock option awards. In addition to performance conditions, performance-based restricted stock units also include a total shareholder return modifier. Because the total shareholder return modifier is considered a market condition, the Company uses a Monte-Carlo simulation model to determine the fair value of performance-based restricted stock units. The fair value of time-vested restricted stock units is determined based on the closing market price of the Company’s stock at the date of grant. Stock-based compensation plans, related expenses and assumptions used in the Black-Scholes option pricing model are more fully described in Note 8, Capital Stock and Stock-Based Compensation Plans.
Currency Translation
The assets and liabilities of foreign subsidiaries, other than those operating in highly inflationary environments, are translated into U.S. dollars at year-end exchange rates with resulting translation gains and losses accumulated in a separate component of shareholders’ equity. Income and expense items are translated into U.S. dollars at average rates of exchange prevailing during the year.
For subsidiaries operating in highly inflationary environments, local currency-denominated non-monetary assets, including inventories, goodwill and property, plant and equipment, are remeasured at their historical exchange rates, while local currency-denominated monetary assets and liabilities are remeasured at year-end exchange rates. Remeasurement adjustments for these operations are included in Net income attributable to Colgate-Palmolive Company.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Recent Accounting Pronouncements
In November 2021, the Financial Accounting Standards Board (the “FASB”) issued Accounting Standards Update (“ASU”) No. 2021-10, “Government Assistance (Topic 832).” This ASU requires increased disclosure on an annual basis about transactions with domestic, foreign, local, regional and national governments, including entities related to those governments and intergovernmental organizations, that are accounted for by applying a grant or contribution accounting model by analogy to other accounting guidance. This guidance is effective for the Company beginning on January 1, 2022 and is not expected to have a material impact on the Company’s Consolidated Financial Statements.
In October 2021, the FASB issued ASU No. 2021-08, “Business Combinations (Topic 805): Accounting for Contract Assets and Contract Liabilities from Contracts with Customers.” This ASU requires contract assets and contract liabilities acquired in a business combination to be recognized and measured by the acquirer on the acquisition date in accordance with ASU No. 2016-10, “Revenue from Contracts with Customers (Topic 606).” This guidance is effective for the Company beginning on January 1, 2023 and is not expected to have a material impact on the Company’s Consolidated Financial Statements.
In January 2021, the FASB issued ASU No. 2021-01, “Reference Rate Reform (Topic 848): Scope.” This ASU clarifies that certain optional expedients and exceptions in Topic 848 apply to derivatives that are affected by the discounting transition. This guidance was effective upon issuance for the Company and is not expected to have a material impact on the Company’s Consolidated Financial Statements.
In October 2020, the FASB issued ASU No. 2020-10, “Codification Improvements.” This ASU improves the consistency of the codification topics by including all disclosure guidance in the appropriate disclosure section and also clarifies the application of various provisions in the codification. This guidance was effective for the Company beginning on January 1, 2021 and did not have a material impact on the Company’s Consolidated Financial Statements.
In March 2020, the FASB issued ASU No. 2020-04, “Reference Rate Reform (Topic 848): Facilitation of the Effects of Reference Rate Reform on Financial Reporting.” The ASU provides optional expedients and exceptions for applying generally accepted accounting principles (“GAAP”) to contracts, hedging relationships and other transactions that reference LIBOR or another reference rate expected to be discontinued because of reference rate reform. This guidance was effective upon issuance of this ASU for contract modifications and hedging relationships on a prospective basis and is not expected to have a material impact on the Company’s Consolidated Financial Statements.
In January 2020, the FASB issued ASU No. 2020-01, “Investments-Equity Securities (Topic 321), Investments-Equity Method and Joint Ventures (Topic 323), and Derivatives and Hedging (Topic 815)-Clarifying the Interactions between Topic 321, Topic 323, and Topic 815.” The guidance provides clarification of the interaction of rules for equity securities, the equity method of accounting and forward contracts and purchase options on certain types of securities. This guidance was effective for the Company beginning on January 1, 2021 and did not have a material impact on the Company’s Consolidated Financial Statements.
In December 2019, the FASB issued ASU No. 2019-12, “Income taxes (Topic 740): Simplifying the Accounting for Income Taxes.” This ASU simplifies the accounting for income taxes by removing certain exceptions to the general principles in ASC 740 and also clarifies and amends existing guidance to improve consistent application. This guidance was effective for the Company beginning on January 1, 2021 and did not have a material impact on the Company’s Consolidated Financial Statements.
Reclassifications
Certain prior year amounts have been reclassified to conform to the current year presentation.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
3. Acquisitions
Hello Products LLC (“hello”)
On January 31, 2020, the Company acquired hello, an oral care business, for cash consideration of $351. The acquisition was financed with a combination of debt and cash. This acquisition is part of the Company’s strategy to focus on high growth segments within its Oral Care, Personal Care and Pet Nutrition businesses.
The total purchase price consideration of $351 has been allocated to the net assets acquired based on their respective estimated fair values as follows:
| Receivables | $ | 11 | |||
| Inventories | 13 | ||||
| Other assets and liabilities, net | (4) | ||||
| Other intangible assets | 160 | ||||
| Goodwill | 171 | ||||
| Fair value of net assets acquired | $ | 351 |
Other intangible assets acquired include trademarks, valued at $115, which are considered to have a finite useful life of 25 years, and customer relationships valued at $45, which are considered to have a finite useful life of 17 years. Goodwill of $171 was allocated to the North America segment and is deductible for tax purposes.
Pro forma results of operations have not been presented as the impact on the Company’s Consolidated Financial Statements is not material.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
4. Restructuring and Related Implementation Charges
2022 Global Productivity Initiative
On January 27, 2022, the Board approved a targeted productivity program (the “2022 Global Productivity Initiative”). The program is intended to reallocate resources towards the Company’s strategic priorities and faster growth businesses, drive efficiencies in the Company’s operations and streamline the Company’s supply chain to reduce structural costs.
Implementation of the 2022 Global Productivity Initiative, which is expected to be substantially completed by December 31, 2022, is projected to result in cumulative pre-tax charges, once all phases are approved and implemented, totaling between $200 and $240, which are currently estimated to be comprised of the following: employee-related costs, including severance, pension and other termination benefits (80%); asset-related costs, primarily accelerated depreciation and asset write-downs (10%); and other charges (10%), which include contract termination costs, consisting primarily of implementation-related charges resulting directly from exit activities and the implementation of new strategies. It is estimated that approximately 90% of the charges will result in cash expenditures.
Global Growth and Efficiency Program
The Global Growth and Efficiency Program, which commenced in the fourth quarter of 2012, concluded on December 31, 2019. Initiatives under the Global Growth and Efficiency Program fit within the program’s three focus areas of expanding commercial hubs, extending shared business services and streamlining global functions and optimizing the global supply chain and facilities. Substantially all initiatives under the Global Growth and Efficiency Program had been implemented as of December 31, 2019.
In the third quarter of 2020, the Company adjusted the accrual balances related to certain projects approved prior to the conclusion of the Global Growth and Efficiency Program to reflect its revised estimate of remaining liabilities. This adjustment resulted in a reduction of $16 ($13 aftertax), of which a benefit of $3 was recorded in Selling, general and administrative expenses and $13 was recorded in Other (income) expense, net.
For the year ended December 31, 2019, restructuring and related implementation charges are reflected in the Consolidated Statements of Income as follows:
| 2019 | |||||||||||||||||
| Cost of sales | $ | 8 | |||||||||||||||
| Selling, general and administrative expenses | 60 | ||||||||||||||||
| Other (income) expense, net | 57 | ||||||||||||||||
| Non-service related postretirement costs | 7 | ||||||||||||||||
| Total Global Growth and Efficiency Program charges, pretax | $ | 132 | |||||||||||||||
| Total Global Growth and Efficiency Program charges, aftertax | $ | 102 |
Restructuring and related implementation charges in the preceding table and the adjustment recorded in the third quarter of 2020 were recorded in the Corporate segment as these initiatives were predominantly centrally directed and controlled and were not included in internal measures of segment operating performance.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Total charges incurred for the Global Growth and Efficiency Program related to initiatives undertaken by the following reportable operating segments:
| Total Program | |||||||||||||||||||||||
| 2019 | Charges | ||||||||||||||||||||||
| North America | 4 | % | 17 | % | |||||||||||||||||||
| Latin America | 12 | % | 5 | % | |||||||||||||||||||
| Europe | 4 | % | 19 | % | |||||||||||||||||||
| Asia Pacific | 6 | % | 4 | % | |||||||||||||||||||
| Africa/Eurasia | (1) | % | 5 | % | |||||||||||||||||||
| Hill’s Pet Nutrition | 2 | % | 8 | % | |||||||||||||||||||
| Corporate | 73 | % | 42 | % | |||||||||||||||||||
| Total | 100 | % | 100 | % |
Over the course of the Global Growth and Efficiency Program, the Company incurred total pretax charges of $1,854 ($1,380 aftertax) in connection with the implementation of various projects as follows:
| Total Program Charges | |||||
| as of December 31, 2019 | |||||
| Employee-Related Costs | $ | 706 | |||
| Incremental Depreciation | 128 | ||||
| Asset Impairments | 58 | ||||
| Other | 962 | ||||
| Total | $ | 1,854 |
Over the course of the Global Growth and Efficiency Program, the majority of the costs incurred related to the following projects: the implementation of the Company’s overall hubbing strategy; the consolidation of facilities; the extension of shared business services and streamlining of global functions; the closing of the Morristown, New Jersey personal care facility; the simplification and streamlining of the Company’s research and development capabilities and oral care supply chain, both in Europe; redesigning the European commercial organization; restructuring how the Company will provide future retirement benefits to substantially all of the U.S.-based employees participating in the Company’s defined benefit retirement plan by shifting them to the Company’s defined contribution plan; and the implementation of a Corporate efficiencies program.
Employee-Related Costs primarily included severance and other termination benefits and were calculated based on long-standing benefit practices, local statutory requirements and, in certain cases, voluntary termination arrangements. Employee-Related Costs also included pension and other retiree benefit enhancements.
Incremental Depreciation was recorded to reflect changes in useful lives and estimated residual values for long-lived assets that will be taken out of service prior to the end of their normal service period. Asset Impairments were recorded to write down inventories and assets held for sale or disposal to their fair value based on amounts expected to be realized. Charges against assets within Asset Impairments are net of cash proceeds pertaining to the sale of certain assets.
Other charges consisted primarily of charges resulting directly from exit activities and the implementation of new strategies as a result of the Global Growth and Efficiency Program.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
5. Goodwill and Other Intangible Assets
The net carrying value of Goodwill as of December 31, 2021 and 2020 by segment was as follows:
| 2021 | 2020 | |||||||||||||
| Oral, Personal and Home Care | ||||||||||||||
| North America | $ | 912 | $ | 912 | ||||||||||
| Latin America | 159 | 171 | ||||||||||||
| Europe | 1,902 | 2,415 | ||||||||||||
| Asia Pacific | 182 | 190 | ||||||||||||
| Africa/Eurasia | 114 | 121 | ||||||||||||
| Total Oral, Personal and Home Care | 3,269 | 3,809 | ||||||||||||
| Pet Nutrition | 15 | 15 | ||||||||||||
| Total Goodwill | $ | 3,284 | $ | 3,824 |
The change in the amount of Goodwill during 2021 is due to the goodwill impairment charge related to the Filorga reporting unit as more fully described below, and foreign currency translation.
Other intangible assets as of December 31, 2021 and 2020 were comprised of the following:
| 2021 | 2020 | |||||||||||||||||||||||||||||||||||||
| Gross Carrying Amount | Accumulated Amortization | Net | Gross Carrying Amount | Accumulated Amortization | Net | |||||||||||||||||||||||||||||||||
| Trademarks - finite life | $ | 891 | $ | (445) | $ | 446 | $ | 902 | $ | (422) | $ | 480 | ||||||||||||||||||||||||||
| Other finite life intangible assets | 744 | (289) | 455 | 786 | (237) | 549 | ||||||||||||||||||||||||||||||||
| Indefinite life intangible assets | 1,561 | — | 1,561 | 1,865 | — | 1,865 | ||||||||||||||||||||||||||||||||
| Total Other intangible assets | $ | 3,196 | $ | (734) | $ | 2,462 | $ | 3,553 | $ | (659) | $ | 2,894 |
The change in the net carrying amounts of Other intangible assets during 2021 was primarily due to the impact of impairment charge related to the Filorga indefinite-lived trademark as more fully described below, foreign currency translation and amortization expense of $89. Annual estimated amortization expense for each of the next five years is expected to be approximately $77.
The Company made revisions to the internal forecasts relating to its Filorga reporting unit during the fourth quarter of 2021 due primarily to the impact of the COVID-19 pandemic on the Filorga skin health business as a result of government restrictions and reduced consumer mobility, which negatively impacted consumption in the duty-free, travel retail and pharmacy channels. The Company concluded that the changes in circumstances in this reporting unit triggered the need for an interim impairment review of its indefinite-lived trademark and goodwill and, accordingly, performed an interim impairment test for the trademark as of December 31, 2021. The Company concluded that the carrying value of the trademark exceeded its estimated fair value, and recorded an impairment charge of $204, reducing the carrying value to approximately $588. After adjusting the carrying value of the trademark, the Company completed a quantitative impairment test for goodwill and recorded a goodwill impairment charge of $367 in the Filorga reporting unit, reducing the carrying value of goodwill to approximately $577. The goodwill and trademark impairment charges are presented as a separate line item in the Consolidated Statements of Income.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
The Company used the income approach to determine the fair value of the Filorga reporting unit and indefinite-lived trademark that required significant judgments and estimates by management regarding several key inputs, including future cash flows consistent with management’s strategic plans, sales growth rates and the selection of royalty rate and a discount rate, among others. Estimating sales growth rates requires significant judgment by management in areas such as future economic conditions, category and industry growth rates, product pricing, consumer tastes and preferences and future expansion expectations.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
6. Long-Term Debt and Credit Facilities
Long-term debt consisted of the following at December 31:
| Weighted Average Interest Rate | Maturities | 2021 | 2020 | |||||||||||||||||||||||||||||
| Notes | 1.9% | 2022 | - | 2078 | $ | 5,958 | $ | 6,170 | ||||||||||||||||||||||||
| Commercial paper | (0.4)% | 2022 | 1,204 | 1,139 | ||||||||||||||||||||||||||||
| Finance Lease Obligations | Various | Various | 44 | 34 | ||||||||||||||||||||||||||||
| 7,206 | 7,343 | |||||||||||||||||||||||||||||||
| Less: Current portion of long-term debt | (12) | (9) | ||||||||||||||||||||||||||||||
| Total | $ | 7,194 | $ | 7,334 |
The weighted-average interest rate on short-term borrowings included in Notes and loans payable in the Consolidated Balance Sheets as of December 31, 2021 and 2020 was 0.7% and 4.8%, respectively.
The Company classifies commercial paper and notes maturing within the next twelve months as long-term debt when it has the intent and ability to refinance such obligations on a long-term basis. Excluding such obligations, scheduled maturities of long-term debt and finance leases outstanding as of December 31, 2021, were as follows:
| Years Ended December 31, | |||||
| 2022 | $ | 456 | |||
| 2023 | 908 | ||||
| 2024 | 506 | ||||
| 2025 | 135 | ||||
| 2026 | 566 | ||||
| Thereafter | 3,431 |
The Company has entered into interest rate swap agreements and foreign exchange contracts related to certain of these debt instruments. See Note 7, Fair Value Measurements and Financial Instruments for further information about the Company’s financial instruments.
The Company’s debt issuances and redemptions support its capital structure strategy objectives of funding its business and growth initiatives while minimizing its risk-adjusted cost of capital. During the fourth quarter of 2021, the Company issued €500 of eight-year notes at a fixed coupon rate of 0.300%. The debt issuance was under the Company’s shelf registration statement. An amount equal to the net proceeds of the notes will be used to finance or refinance, in part or in full, new and existing projects and programs with distinct environmental or social benefits.
During the fourth quarter of 2021, the Company redeemed prior to maturity all of its outstanding 0.000% notes due 2021 with a principal amount of €500, originally issued on November 12, 2019. The redemption was financed with commercial paper borrowings. The redemption price was equal to the carrying amount of the debt extinguished.
In 1990, the Company’s Canadian subsidiary (“CP Canada”), issued C$145 of Canadian dollar-denominated unsecured unsubordinated 12.85% guaranteed notes due October 4, 2030 (the “Canada notes”). During the third quarter of 2021, CP Canada redeemed the Canada notes and recorded a loss on the early extinguishment of debt of $75, which is included in Interest (income) expense, net in the Consolidated Statements of Income, representing the difference between the redemption price and the carrying amount of the debt extinguished.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
During the fourth quarter of 2020, the Company redeemed prior to maturity all of its outstanding 2.450% notes due 2021 with a principal amount $300, originally issued on November 8, 2011, and all of its outstanding 2.300% notes due 2022 with a principal amount of $500, originally issued on May 3, 2012. These redemptions were financed with commercial paper borrowings and cash. The Company recorded a loss on the early extinguishment of debt of $23, which is included in Interest (income) expense, net in the Consolidated Statements of Income, representing the difference between the redemption price and the carrying amount of the debt extinguished.
At December 31, 2021, the Company had access to unused domestic and foreign lines of credit of $3,457 (including under the facility discussed below) and could also issue long-term debt pursuant to an effective shelf registration statement. In August 2021, the Company entered into a new $3,000 five-year revolving credit facility with a syndicate of banks for a five-year term expiring August 2026, which replaced, on substantially similar terms, the Company’s $2,650 revolving credit facility that was scheduled to expire in November 2024. Commitment fees related to the credit facility are not material. The Company’s $1,500 364-day credit facility with a syndicate of banks expired in August 2021 and was not renewed.
Certain agreements with respect to the Company’s bank borrowings contain financial and other covenants as well as cross-default provisions. Noncompliance with these requirements could ultimately result in the acceleration of amounts owed. The Company is in full compliance with all such requirements and believes the likelihood of noncompliance is remote.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
7. Fair Value Measurements and Financial Instruments
The Company uses available market information and other valuation methodologies in assessing the fair value of financial instruments. Judgment is required in interpreting market data to develop the estimates of fair value and, accordingly, changes in assumptions or the estimation methodologies may affect the fair value estimates. The Company is exposed to the risk of credit loss in the event of nonperformance by counterparties to financial instrument contracts; however, nonperformance is considered unlikely and any nonperformance is unlikely to be material, as it is the Company’s policy to contract only with diverse, credit-worthy counterparties based upon both strong credit ratings and other credit considerations.
The Company is exposed to market risk from foreign currency exchange rates, interest rates and commodity price fluctuations. Volatility relating to these exposures is managed on a global basis by utilizing a number of techniques, including working capital management, sourcing strategies, selling price increases, selective borrowings in local currencies and entering into selective derivative instrument transactions, issued with standard features, in accordance with the Company’s treasury and risk management policies, which prohibit the use of derivatives for speculative purposes and leveraged derivatives for any purpose. It is the Company’s policy to enter into derivative instrument contracts with terms that match the underlying exposure being hedged. Provided below are details of the Company’s exposures by type of risk and derivative instruments by type of hedge designation.
Valuation Considerations
The Company’s derivative instruments include interest rate swap contracts, forward-starting interest rate swaps, foreign currency contracts and commodity contracts. The Company utilizes interest rate swap contracts to manage its targeted mix of fixed and floating rate debt, and these swaps are classified as follows:
Level 1: Based upon quoted market prices in active markets for identical assets or liabilities.
Level 2: Based upon observable market-based inputs or unobservable inputs that are corroborated by market data.
Level 3: Based upon unobservable inputs reflecting the reporting entity’s own assumptions.
Foreign Exchange Risk
As the Company markets its products in over 200 countries and territories, it is exposed to currency fluctuations related to manufacturing and selling its products in currencies other than the U.S. dollar. The Company manages its foreign currency exposures through a combination of cost containment measures, sourcing strategies, selling price increases and the hedging of certain costs in an effort to minimize the impact on earnings of foreign currency rate movements.
The Company primarily utilizes foreign currency contracts, including forward and swap contracts, option contracts, foreign and local currency deposits and local currency borrowings to hedge portions of its foreign currency purchases, assets and liabilities arising in the normal course of business and the net investment in certain foreign subsidiaries. The duration of foreign currency contracts generally does not exceed 12 months and the contracts are valued using observable market rates (Level 2 valuation).
Interest Rate Risk
The Company manages its targeted mix of fixed and floating rate debt with debt issuances and by entering into interest rate swaps in order to mitigate fluctuations in earnings and cash flows that may result from interest rate volatility. The Company utilizes forward-starting interest rate swaps to mitigate the risk of variability in interest rate for future debt issuances. The notional amount, interest payment and maturity date of the swaps generally match the principal, interest payment and maturity date of the related debt, and the swaps are valued using observable benchmark rates (Level 2 valuation).
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Commodity Price Risk
The Company is exposed to price volatility related to raw materials used in production, such as essential oils, resins, tropical oils, pulp, tallow, corn, poultry and soybeans. The Company manages its raw material exposures through a combination of cost containment measures, sourcing strategies, ongoing productivity initiatives and the limited use of commodity hedging contracts. Futures contracts are used on a limited basis, primarily in the Hill’s Pet Nutrition segment, to manage volatility related to raw material inventory purchases of certain traded commodities, and these contracts are measured using quoted commodity exchange prices (Level 1 valuation). The duration of the commodity contracts generally does not exceed 12 months.
Credit Risk
The Company is exposed to the risk of credit loss in the event of nonperformance by counterparties to financial instrument contracts; however, nonperformance is considered unlikely and any nonperformance is unlikely to be material as it is the Company’s policy to contract with diverse, credit-worthy counterparties based upon both strong credit ratings and other credit considerations.
The following table summarizes the fair value of the Company’s derivative instruments and other financial instruments which are carried at fair value in the Company’s Consolidated Balance Sheets as of December 31, 2021 and December 31, 2020:
| Assets | Liabilities | ||||||||||||||||||||||||||||||||||
| Account | Fair Value | Account | Fair Value | ||||||||||||||||||||||||||||||||
| Designated derivative instruments | December 31, 2021 | December 31, 2020 | December 31, 2021 | December 31, 2020 | |||||||||||||||||||||||||||||||
| Interest rate swap contracts | Other current assets | $ | 5 | $ | — | Other accruals | $ | — | $ | — | |||||||||||||||||||||||||
| Interest rate swap contracts | Other assets | — | 14 | Other liabilities | — | — | |||||||||||||||||||||||||||||
| Forward-starting interest rate swaps | Other assets | 20 | 5 | Other liabilities | 21 | — | |||||||||||||||||||||||||||||
| Foreign currency contracts | Other current assets | 22 | 7 | Other accruals | 6 | 93 | |||||||||||||||||||||||||||||
| Commodity contracts | Other current assets | 2 | 3 | Other accruals | — | — | |||||||||||||||||||||||||||||
| Total designated | $ | 49 | $ | 29 | $ | 27 | $ | 93 | |||||||||||||||||||||||||||
| Other financial instruments | |||||||||||||||||||||||||||||||||||
| Marketable securities | Other current assets | 34 | 37 | ||||||||||||||||||||||||||||||||
| Total other financial instruments | $ | 34 | $ | 37 |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
The carrying amount of cash, cash equivalents, accounts receivable and short-term debt approximated fair value as of December 31, 2021 and 2020. The estimated fair value of the Company’s long-term debt, including the current portion, as of December 31, 2021 and 2020, was $7,651 and $8,175, respectively, and the related carrying value was $7,206 and $7,343, respectively. The estimated fair value of long-term debt was derived principally from quoted prices on the Company’s outstanding fixed-term notes (Level 2 valuation).
The following amounts were recorded on the Consolidated Balance Sheet related to cumulative basis adjustment for fair value hedges as of:
| December 31, 2021 | December 31, 2020 | ||||||||||
| Long-term debt: | |||||||||||
| Carrying amount of hedged item | $ | 405 | $ | 413 | |||||||
| Cumulative hedging adjustment included in the carrying amount | $ | 5 | $ | 14 |
The following tables present the notional values as of:
| December 31, 2021 | |||||||||||||||||||||||||||||||||||
| Foreign Currency Contracts | Foreign Currency Debt | Interest Rate Swaps | Forward-Starting Interest Rate Swaps | Commodity Contracts | Total | ||||||||||||||||||||||||||||||
| Fair Value Hedges | $ | 566 | $ | — | $ | 400 | $ | — | $ | — | $ | 966 | |||||||||||||||||||||||
| Cash Flow Hedges | 873 | — | — | 700 | 24 | 1,597 | |||||||||||||||||||||||||||||
| Net Investment Hedges | 173 | 4,600 | — | — | — | 4,773 |
| December 31, 2020 | |||||||||||||||||||||||||||||||||||
| Foreign Currency Contracts | Foreign Currency Debt | Interest Rate Swaps | Forward-Starting Interest Rate Swaps | Commodity Contracts | Total | ||||||||||||||||||||||||||||||
| Fair Value Hedges | $ | 589 | $ | — | $ | 400 | $ | — | $ | — | $ | 989 | |||||||||||||||||||||||
| Cash Flow Hedges | 854 | — | — | 300 | 17 | 1,171 | |||||||||||||||||||||||||||||
| Net Investment Hedges | 528 | 4,523 | — | — | — | 5,051 |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
The following table presents the location and amount of gains (losses) on hedges recognized on the Company’s Consolidated Statements of Income:
| Twelve Months Ended December 31, | |||||||||||||||||||||||||||||||||||
| 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| Cost of sales | Selling, general and administrative expenses | Interest (income) expense, net | Cost of sales | Selling, general and administrative expenses | Interest (income) expense, net | ||||||||||||||||||||||||||||||
| Gain (loss) on hedges recognized in income: | |||||||||||||||||||||||||||||||||||
| Interest rate swaps designated as fair value hedges: | |||||||||||||||||||||||||||||||||||
| Derivative instrument | $ | — | $ | — | $ | 8 | $ | — | $ | — | $ | (10) | |||||||||||||||||||||||
| Hedged items | — | — | (8) | — | — | 10 | |||||||||||||||||||||||||||||
| Foreign currency contracts designated as fair value hedges: | |||||||||||||||||||||||||||||||||||
| Derivative instrument | — | 6 | — | — | 29 | — | |||||||||||||||||||||||||||||
| Hedged items | — | (6) | — | — | (29) | — | |||||||||||||||||||||||||||||
| Foreign currency contracts designated as cash flow hedges: | |||||||||||||||||||||||||||||||||||
| Amount reclassified from OCI | (12) | — | — | 1 | — | — | |||||||||||||||||||||||||||||
| Commodity contracts designated as cash flow hedges: | |||||||||||||||||||||||||||||||||||
| Amount reclassified from OCI | 5 | — | — | (1) | — | — | |||||||||||||||||||||||||||||
| Total gain (loss) on hedges recognized in income | $ | (7) | $ | — | $ | — | $ | — | $ | — | $ | — |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
The following table presents the location and amount of unrealized gains (losses) on hedges included in OCI:
| Twelve Months Ended | |||||||||||
| December 31, | |||||||||||
| 2021 | 2020 | ||||||||||
| Foreign currency contracts designated as cash flow hedges: | |||||||||||
| Gain (loss) recognized in OCI | $ | 16 | $ | (11) | |||||||
| Forward-starting interest rate swaps designated as cash flow hedges: | |||||||||||
| Gain (loss) recognized in OCI | (6) | 5 | |||||||||
| Commodity contracts designated as cash flow hedges: | |||||||||||
| Gain (loss) recognized in OCI | 3 | 3 | |||||||||
| Foreign currency contracts designated as net investment hedges: | |||||||||||
| Gain (loss) on instruments | 30 | (52) | |||||||||
| Gain (loss) on hedged items | (30) | 52 | |||||||||
| Foreign currency debt designated as net investment hedges: | |||||||||||
| Gain (loss) on instruments | 370 | (356) | |||||||||
| Gain (loss) on hedged items | (370) | 356 | |||||||||
| Total unrealized gain (loss) on hedges recognized in OCI | $ | 13 | $ | (3) |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
8. Capital Stock and Stock-Based Compensation Plans
Preference Stock
The Company has the authority to issue 50,262,150 shares of preference stock.
Stock Repurchases
On June 18, 2018, the Board authorized the repurchase of shares of the Company’s common stock having an aggregate purchase price of up to $5 billion under a new share repurchase program (the “2018 Program”), which replaced a previously authorized share repurchase program. The Company commenced repurchases of shares of the Company’s common stock under the 2018 Program beginning June 19, 2018. The Board also has authorized share repurchases on an ongoing basis to fulfill certain requirements of the Company’s compensation and benefit programs. The shares are repurchased from time to time in open market or privately negotiated transactions at the Company’s discretion, subject to market conditions, customary blackout periods and other factors. The Company repurchased its common stock at a cost of $1,320 during 2021 under the 2018 Program.
The Company may use either authorized and unissued shares or treasury shares to meet share requirements resulting from the exercise of stock options and the vesting of restricted stock unit awards.
A summary of common stock and treasury stock activity for the three years ended December 31 is as follows:
| Common Stock Outstanding | Treasury Stock | |||||||||||||
| Balance, January 1, 2019 | 862,912,792 | 602,793,568 | ||||||||||||
| Common stock acquired | (17,219,642) | 17,219,642 | ||||||||||||
| Shares issued for stock options | 8,145,777 | (8,145,777) | ||||||||||||
| Shares issued for restricted stock units and other | 862,852 | (862,852) | ||||||||||||
| Balance, December 31, 2019 | 854,701,779 | 611,004,581 | ||||||||||||
| Common stock acquired | (18,701,843) | 18,701,843 | ||||||||||||
| Shares issued for stock options | 13,018,354 | (13,018,354) | ||||||||||||
| Shares issued for restricted stock units and other | 875,311 | (875,311) | ||||||||||||
| Balance, December 31, 2020 | 849,893,601 | 615,812,759 | ||||||||||||
| Common stock acquired | (16,518,163) | 16,518,163 | ||||||||||||
| Shares issued for stock options | 6,357,793 | (6,357,793) | ||||||||||||
| Shares issued for restricted stock units and other | 747,053 | (747,053) | ||||||||||||
| Balance, December 31, 2021 | 840,480,284 | 625,226,076 |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Stock-Based Compensation
The Company recognizes the cost of employee services received in exchange for awards of equity instruments, such as stock options and restricted stock units, based on the fair value of those awards at the date of grant. The fair value of restricted stock units, generally based on market prices, is amortized on a straight-line basis over the requisite service period. The estimated fair value of stock options on the date of grant is amortized on a straight-line basis over the requisite service period for each separately vesting portion of the award. Awards to employees eligible for retirement prior to the award becoming fully vested are recognized as compensation cost from the grant date through the date that the employee first becomes eligible to retire and is no longer required to provide service to earn the award.
The Company has one incentive compensation plan pursuant to which it issues restricted stock units (both performance-based and time-vested) and stock options to employees and shares of common stock and stock options to non-employee directors. The Personnel and Organization Committee of the Board of Directors, which is comprised entirely of independent directors, administers the incentive compensation plan. The total stock-based compensation expense charged against pretax income for this plan was $135, $107 and $100 for the years ended December 31, 2021, 2020 and 2019, respectively. The total income tax benefit recognized on stock-based compensation, excluding excess tax benefits, was approximately $25, $20 and $20 for the years ended December 31, 2021, 2020 and 2019, respectively.
Stock-based compensation expense is recorded within Selling, general and administrative expenses in the Corporate segment as these amounts are not included in internal measures of segment operating performance.
The Company uses the Black-Scholes option pricing model to estimate the fair value of stock option awards. The weighted-average estimated fair value of stock options granted in the years ended December 31, 2021, 2020 and 2019 was $11.11, $11.26 and $10.48, respectively. Fair value is estimated using the Black-Scholes option pricing model with the assumptions summarized in the following table:
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Expected term of options | 6 years | 6 years | 6 years | |||||||||||||||||
| Expected volatility rate | 20.3 | % | 21.8 | % | 19.2 | % | ||||||||||||||
| Risk-free interest rate | 1.0 | % | 0.5 | % | 1.5 | % | ||||||||||||||
| Expected dividend yield | 2.3 | % | 2.3 | % | 2.3 | % |
The weighted-average expected term of options granted each year was determined with reference to historical exercise and post-vesting cancellation experience, the vesting period of the awards and the contractual term of the awards, among other factors. Expected volatility incorporates implied share-price volatility derived from exchange traded options on the Company’s common stock. The risk-free interest rate for the expected term of the option is based on the yield of a zero-coupon U.S. Treasury bond with a maturity period equal to the option’s expected term.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Performance-based Restricted Stock Units
In 2019, the Company evolved its approach to granting long-term incentive compensation from granting time-vested restricted stock units following the conclusion of a three-year performance cycle to granting officers and other key employees a target number of unearned performance-based restricted stock units at the beginning of each three-year performance cycle. Awards are earned and vest following the conclusion of the performance period on the basis of achievement of performance goals established at the commencement of each three-year performance period.
A summary of performance-based restricted stock unit activity for the year ended December 31, 2021 is presented below:
| Shares (in thousands) | Weighted Average Grant Date Fair Value Per Award | |||||||||||||
| Performance-based restricted stock units as of January 1, 2021 | 860 | $ | 73 | |||||||||||
| Activity: | ||||||||||||||
| Granted | 355 | 70 | ||||||||||||
| Forfeited | (189) | 81 | ||||||||||||
| Performance-based restricted stock units as of December 31, 2021 | 1,026 | $ | 70 |
As of December 31, 2021, there was $26 of total unrecognized compensation expense related to unvested performance-based restricted stock unit awards, which will be recognized ratably over the remaining performance period.
The Company uses a Monte-Carlo simulation model to estimate the fair value of performance-based restricted stock units at the date of grant.
Time-Vested Restricted Stock Units
The Company also grants time-vested restricted stock unit awards. As described above, under the Company’s previous long-term incentive program, time-vested restricted stock unit awards were granted to officers and other key employees following a three-year performance period. Awards vest at the end of the restriction period, which is three years from the date of grant. Awards for the 2018-2020 performance period were granted in 2021. No awards were granted in 2019 or 2020 for the 2016-2018 or 2017-2019 performance periods. As of December 31, 2021, approximately 10,990,000 shares of common stock were available for future restricted stock unit awards.
A summary of restricted stock unit activity during 2021 is presented below:
| Shares (in thousands) | Weighted Average Grant Date Fair Value Per Award | |||||||||||||
| Restricted stock units as of January 1, 2021 | 1,897 | $ | 73 | |||||||||||
| Activity: | ||||||||||||||
| Granted | 749 | 78 | ||||||||||||
| Vested | (674) | 70 | ||||||||||||
| Forfeited | (56) | 74 | ||||||||||||
| Restricted stock units as of December 31, 2021 | 1,916 | $ | 76 |
As of December 31, 2021, there was $56 of total unrecognized compensation expense related to unvested time-vested restricted stock unit awards, which will be recognized over a weighted-average period of 2 years. The total fair value of time-vested restricted stock units vested during the years ended December 31, 2021, 2020 and 2019 was $47, $58 and $53, respectively.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Stock Options
The Company issues non-qualified stock options to non-employee directors, officers and other employees. Beginning in 2019, stock options have a contractual term of eight years. Prior to 2019, stock options generally had a contractual term of six years. Stock options generally vest ratably over three years. As of December 31, 2021, approximately 26,038,000 shares of common stock were available for future stock option grants.
A summary of stock option activity during 2021 is presented below:
| Shares (in thousands) | Weighted Average Exercise Price | Weighted Average Remaining Contractual Life (in years) | Intrinsic Value of Unexercised In-the-Money Options | |||||||||||||||||||||||
| Options outstanding, January 1, 2021 | 27,530 | $ | 71 | |||||||||||||||||||||||
| Granted | 5,120 | 77 | ||||||||||||||||||||||||
| Exercised | (6,358) | 68 | ||||||||||||||||||||||||
| Forfeited | (173) | 75 | ||||||||||||||||||||||||
| Expired | (24) | 73 | ||||||||||||||||||||||||
| Options outstanding, December 31, 2021 | 26,095 | 72 | 5 | $ | 309 | |||||||||||||||||||||
| Options exercisable, December 31, 2021 | 16,725 | $ | 72 | 3 | $ | 223 |
As of December 31, 2021, there was $32 of total unrecognized compensation expense related to unvested options, which will be recognized over a weighted-average period of 1.5 years. The total intrinsic value of options exercised during the years ended December 31, 2021, 2020 and 2019 was $83, $136 and $84, respectively.
The benefits of tax deductions in excess of grant date fair value resulting from the exercise of stock options and vesting of restricted stock unit awards for the years ended December 31, 2021, 2020 and 2019 were $9, $8 and $6, respectively, and are recognized in the provision for income taxes as a discrete item in the quarterly period in which they occur and classified as an operating cash flow. Cash proceeds received from options exercised for the years ended December 31, 2021, 2020 and 2019 were $424, $874 and $498, respectively.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
9. Employee Stock Ownership Plan
In 1989, the Company expanded its Employee Stock Ownership Plan (“ESOP”) through the introduction of a leveraged ESOP that funds certain benefits for employees who have met eligibility requirements. As of December 31, 2021 and 2020, there were 10,290,667 and 11,545,950 shares of common stock, respectively, outstanding and issued to the Company’s ESOP.
During 2000, the ESOP entered into a loan agreement with the Company under which the benefits of the ESOP may be extended through 2035. As of December 31, 2021, the ESOP had outstanding borrowings from the Company of $1, which represents unearned compensation shown as a reduction in Shareholders’ equity.
Dividends on stock held by the ESOP are paid to the ESOP trust and, together with cash contributions from the Company, are (a) used by the ESOP to repay principal and interest, (b) credited to participant accounts, (c) used for contributions to the Company’s defined contribution plans or (d) used to pay the Company’s defined contribution plan expenses. Stock is allocated to participants based upon the ratio of the current year’s debt service to the sum of total outstanding principal and interest payments over the life of the debt. As of December 31, 2021, 9,559,255 shares of common stock had been released and allocated to participant accounts and 731,412 shares of common stock were available for future release and allocation to participant accounts.
Dividends on the stock used to repay principal and interest or credited to participant accounts are deductible for income tax purposes and, accordingly, are reflected net of their tax benefit in the Consolidated Statements of Changes in Shareholders’ Equity.
Annual expense related to the ESOP was $0 in 2021, 2020 and 2019.
The Company paid dividends on the shares held by the ESOP of $20 in 2021, $23 in 2020 and $25 in 2019. The Company did not make any contributions to the ESOP in 2021, 2020 or 2019.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
10. Retirement Plans and Other Retiree Benefits
Retirement Plans
The Company and certain of its U.S. and foreign subsidiaries maintain defined benefit retirement plans. Benefits under these plans are based primarily on years of service and employees’ earnings.
In the U.S., effective January 1, 2014, the Company provides virtually all future retirement benefits through the Company’s defined contribution plan. As a result, service after December 31, 2013 is not considered for participants in the Company’s principal U.S. defined benefit retirement plan. Participants in the Company’s principal U.S. defined benefit retirement plan whose retirement benefit was determined under the cash balance formula continue to earn interest credits on their vested balances as of December 31, 2013 but no longer receive pay credits. Participants whose retirement benefit was determined under the final average earnings formula or career average earnings formula continue to have their accrued benefit adjusted for pay increases until termination of employment.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
In the Company’s principal U.S. plans and certain funded foreign plans, funds are contributed to trusts in accordance with regulatory limits to provide for current service and for any unfunded projected benefit obligation over a reasonable period. The target asset allocation for the Company’s defined benefit plans is as follows:
| United States | International | |||||||||||||
| Asset Category | ||||||||||||||
| Equity securities | 21 | % | 22 | % | ||||||||||
| Fixed income securities | 76 | % | 63 | % | ||||||||||
| Real estate and other investments | 3 | % | 15 | % | ||||||||||
| Total | 100 | % | 100 | % |
At December 31, 2021, the allocation of the Company’s plan assets and the level of valuation input, as applicable, for each major asset category were as follows:
| Level of Valuation Input | Pension Plans | |||||||||||||||||||||||||
| United States | International | Other Retiree Benefit Plans | ||||||||||||||||||||||||
| Cash and cash equivalents | Level 1 | $ | 38 | $ | 9 | $ | — | |||||||||||||||||||
| U.S. common stocks | Level 1 | — | 2 | — | ||||||||||||||||||||||
| International common stocks | Level 1 | — | 13 | — | ||||||||||||||||||||||
| Pooled funds(1) | Level 1 | 48 | 116 | — | ||||||||||||||||||||||
| Fixed income securities(2) | Level 2 | 905 | 67 | — | ||||||||||||||||||||||
| Guaranteed investment contracts(3) | Level 2 | 1 | 51 | — | ||||||||||||||||||||||
| 992 | 258 | — | ||||||||||||||||||||||||
| Investments valued using NAV per share(4) | ||||||||||||||||||||||||||
| Domestic, developed and emerging markets equity funds | 361 | 97 | — | |||||||||||||||||||||||
| Fixed income funds(5) | 469 | 328 | — | |||||||||||||||||||||||
| Hedge funds(6) | — | 8 | — | |||||||||||||||||||||||
| Multi-asset funds(7) | 26 | 2 | — | |||||||||||||||||||||||
| Real estate funds(8) | — | 30 | — | |||||||||||||||||||||||
| 856 | 465 | — | ||||||||||||||||||||||||
| Other assets and liabilities, net(9) | (14) | — | — | |||||||||||||||||||||||
| Total Investments | $ | 1,834 | $ | 723 | $ | — | ||||||||||||||||||||
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
At December 31, 2020, the allocation of the Company’s plan assets and the level of valuation input, as applicable, for each major asset category were as follows:
| Level of Valuation Input | Pension Plans | |||||||||||||||||||||||||
| United States | International | Other Retiree Benefit Plans | ||||||||||||||||||||||||
| Cash and cash equivalents | Level 1 | $ | 50 | $ | 12 | $ | — | |||||||||||||||||||
| U.S. common stocks | Level 1 | — | 1 | — | ||||||||||||||||||||||
| International common stocks | Level 1 | — | 8 | — | ||||||||||||||||||||||
| Pooled funds(1) | Level 1 | 65 | 117 | — | ||||||||||||||||||||||
| Fixed income securities(2) | Level 2 | 1,117 | 59 | 2 | ||||||||||||||||||||||
| Guaranteed investment contracts(3) | Level 2 | 1 | 55 | — | ||||||||||||||||||||||
| 1,233 | 252 | 2 | ||||||||||||||||||||||||
| Investments valued using NAV per share(4) | ||||||||||||||||||||||||||
| Domestic, developed and emerging markets equity funds | 456 | 183 | 1 | |||||||||||||||||||||||
| Fixed income funds(5) | 136 | 225 | — | |||||||||||||||||||||||
| Hedge funds(6) | — | 6 | — | |||||||||||||||||||||||
| Multi-asset funds(7) | 77 | 2 | — | |||||||||||||||||||||||
| Real estate funds(8) | 34 | 30 | — | |||||||||||||||||||||||
| 703 | 446 | 1 | ||||||||||||||||||||||||
| Other assets and liabilities, net(9) | (15) | — | — | |||||||||||||||||||||||
| Total Investments | $ | 1,921 | $ | 698 | $ | 3 |
(1)Pooled funds primarily invest in U.S. and foreign equity securities, debt and money market securities.
(2)The fixed income securities are traded over-the-counter and certain of these securities lack daily pricing or liquidity and as such are classified as Level 2. As of December 31, 2021, approximately 40% of the U.S. pension plan fixed income portfolio was invested in U.S. treasury or agency securities, with the remainder invested in other government bonds and corporate bonds, compared to approximately 50% as of December 31, 2020.
(3)The guaranteed investment contracts (“GICs”) represent contracts with insurance companies measured at the cash surrender value of each contract. The Level 2 valuation reflects that the cash surrender value is based principally on a referenced pool of investment funds with active redemption.
(4)Investments that are measured at fair value using net asset value (“NAV”) per share as a practical expedient have not been classified in the fair value hierarchy. The NAV is based on the value of the underlying investments owned, minus its liabilities, divided by the number of shares outstanding. There are no unfunded commitments related to these investments. Redemption notice period primarily ranges from 0-3 months and redemption frequency windows range from daily to quarterly.
(5)Fixed income funds primarily invest in U.S. government and investment grade corporate bonds.
(6)Consists of investments in underlying hedge fund strategies that are primarily implemented through the use of long and short equity and fixed income securities and derivative instruments such as futures and options.
(7)Multi-asset funds primarily invest across a variety of asset classes, including global stocks and bonds, as well as alternative strategies.
(8)Real estate is valued using the NAV per unit of funds that are invested in real estate property. The investment value of the real estate property is determined quarterly using independent market appraisals as determined by the investment manager.
(9)This category primarily includes unsettled trades for investments purchased and sold and dividend receivables.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Equity securities in the U.S. plans did not include any investment in the Company’s common stock at either December 31, 2021 or December 31, 2020. In 2020, the U.S. plans sold 739,869 shares of the Company’s common stock to the Company to take the number of shares of the Company’s stock in the U.S. plans to zero as of December 31, 2020. No shares of the Company’s stock were purchased by the U.S. plans in 2021 or 2020. The plans received no dividends on the Company’s common stock in either 2021 or 2020.
Other Retiree Benefits
The Company and certain of its subsidiaries provide health care and life insurance benefits for retired employees to the extent not provided by government-sponsored plans.
The Company uses a December 31 measurement date for its defined benefit and other retiree benefit plans. Summarized information for the Company’s defined benefit and other retiree benefit plans is as follows:
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
| Pension Plans | Other Retiree Benefit Plans | |||||||||||||||||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||||||||||
| United States | International | |||||||||||||||||||||||||||||||||||||
| Change in Benefit Obligations | ||||||||||||||||||||||||||||||||||||||
| Benefit obligations at beginning of year | $ | 2,363 | $ | 2,272 | $ | 1,013 | $ | 876 | $ | 1,112 | $ | 1,050 | ||||||||||||||||||||||||||
| Service cost | — | 1 | 19 | 17 | 26 | 20 | ||||||||||||||||||||||||||||||||
| Interest cost | 61 | 74 | 20 | 21 | 35 | 37 | ||||||||||||||||||||||||||||||||
| Participants’ contributions | — | — | 6 | 5 | — | — | ||||||||||||||||||||||||||||||||
| Acquisitions/plan amendments | (2) | — | — | 30 | — | — | ||||||||||||||||||||||||||||||||
| Actuarial loss (gain) | (52) | 171 | (39) | 65 | (50) | 61 | ||||||||||||||||||||||||||||||||
| Foreign exchange impact | — | — | (38) | 46 | (8) | (9) | ||||||||||||||||||||||||||||||||
| Termination benefits | — | 3 | — | — | — | — | ||||||||||||||||||||||||||||||||
| Curtailments and settlements | (5) | (3) | (4) | (7) | — | — | ||||||||||||||||||||||||||||||||
| Benefit payments | (158) | (155) | (40) | (40) | (35) | (47) | ||||||||||||||||||||||||||||||||
| Other | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||
| Benefit obligations at end of year | $ | 2,207 | $ | 2,363 | $ | 937 | $ | 1,013 | $ | 1,080 | $ | 1,112 | ||||||||||||||||||||||||||
| Change in Plan Assets | ||||||||||||||||||||||||||||||||||||||
| Fair value of plan assets at beginning of year | $ | 1,921 | $ | 1,806 | $ | 698 | $ | 586 | $ | 3 | $ | 37 | ||||||||||||||||||||||||||
| Actual return on plan assets | 46 | 243 | 45 | 59 | — | 2 | ||||||||||||||||||||||||||||||||
| Company contributions | 28 | 30 | 33 | 36 | 32 | 11 | ||||||||||||||||||||||||||||||||
| Participants’ contributions | — | — | 6 | 5 | — | — | ||||||||||||||||||||||||||||||||
| Foreign exchange impact | — | — | (14) | 26 | — | — | ||||||||||||||||||||||||||||||||
| Settlements and acquisitions | (3) | (3) | (5) | 26 | — | — | ||||||||||||||||||||||||||||||||
| Benefit payments | (158) | (155) | (40) | (40) | (35) | (47) | ||||||||||||||||||||||||||||||||
| Other | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||
| Fair value of plan assets at end of year | $ | 1,834 | $ | 1,921 | $ | 723 | $ | 698 | $ | — | $ | 3 | ||||||||||||||||||||||||||
| Funded Status | ||||||||||||||||||||||||||||||||||||||
| Benefit obligations at end of year | $ | 2,207 | $ | 2,363 | $ | 937 | $ | 1,013 | $ | 1,080 | $ | 1,112 | ||||||||||||||||||||||||||
| Fair value of plan assets at end of year | 1,834 | 1,921 | 723 | 698 | — | 3 | ||||||||||||||||||||||||||||||||
| Net amount recognized | $ | (373) | $ | (442) | $ | (214) | $ | (315) | $ | (1,080) | $ | (1,109) | ||||||||||||||||||||||||||
| Amounts Recognized in Balance Sheet | ||||||||||||||||||||||||||||||||||||||
| Noncurrent assets | $ | 70 | $ | 20 | $ | 72 | $ | 18 | $ | — | $ | — | ||||||||||||||||||||||||||
| Current liabilities | (27) | (30) | (13) | (14) | (47) | (45) | ||||||||||||||||||||||||||||||||
| Noncurrent liabilities | (416) | (432) | (273) | (319) | (1,033) | (1,064) | ||||||||||||||||||||||||||||||||
| Net amount recognized | $ | (373) | $ | (442) | $ | (214) | $ | (315) | $ | (1,080) | $ | (1,109) | ||||||||||||||||||||||||||
| Amounts Recognized in Accumulated Other Comprehensive Income (Loss) | ||||||||||||||||||||||||||||||||||||||
| Actuarial loss | $ | 866 | $ | 902 | $ | 179 | $ | 255 | $ | 356 | $ | 429 | ||||||||||||||||||||||||||
| Transition/prior service cost | — | 1 | 9 | 7 | — | — | ||||||||||||||||||||||||||||||||
| $ | 866 | $ | 903 | $ | 188 | $ | 262 | $ | 356 | $ | 429 | |||||||||||||||||||||||||||
| Accumulated benefit obligation | $ | 2,171 | $ | 2,325 | $ | 872 | $ | 946 | $ | — | $ | — |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
| Pension Plans | Other Retiree Benefit Plans | |||||||||||||||||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||||||||||
| United States | International | |||||||||||||||||||||||||||||||||||||
| Weighted-Average Assumptions Used to Determine Benefit Obligations | ||||||||||||||||||||||||||||||||||||||
| Discount rate | 2.98 | % | 2.65 | % | 2.10 | % | 1.61 | % | 3.06 | % | 2.88 | % | ||||||||||||||||||||||||||
| Expected long-term rate of return on plan assets | 5.70 | % | 5.70 | % | 2.72 | % | 2.93 | % | N/A | 5.70 | % | |||||||||||||||||||||||||||
| Long-term rate of compensation increase | 3.50 | % | 3.50 | % | 2.89 | % | 2.62 | % | 3.50 | % | 3.50 | % | ||||||||||||||||||||||||||
| ESOP growth rate | — | % | — | % | — | % | — | % | 6.00 | % | 10.00 | % | ||||||||||||||||||||||||||
| Medical cost trend rate of increase | — | % | — | % | — | % | — | % | 6.00 | % | 6.00 | % | ||||||||||||||||||||||||||
| Interest Crediting Rate | 2.85 | % | 2.48 | % | 0.84 | % | 0.83 | % | — | % | — | % |
The actuarial gains recorded during 2021 for both the U.S. pension and other retiree benefit plans were primarily a result of an increase in discount rates applied against future estimated benefit payments that resulted in a decrease in the benefit obligation for both the U.S. pension and Other retiree benefit plans. The actuarial losses incurred during 2020 were primarily driven by a decrease in discount rates applied against future expected benefit payments that resulted in an increase in the benefit obligation for both the U.S. pension and Other retiree benefit plans.
The overall investment objective of the plans is to balance risk and return so that obligations to employees are met. The Company evaluates its expected long-term rate of return on plan assets on an annual basis. In determining the expected long-term rate of return, the Company considers the nature of the plans’ investments and the historical rates of return. The assumed expected long-term rate of return on plan assets as of December 31, 2021 for the U.S. plans was 5.70%. Average annual rates of return for the U.S. plans for the most recent 1-year, 5-year, 10-year, 15-year and 25-year periods were 3%, 8%, 8%, 6% and 7%, respectively. Similar assessments were performed in determining rates of return on international pension plan assets to arrive at the Company’s 2021 weighted-average expected long-term rate of return on plan assets of 2.72%.
The medical cost trend rate of increase assumed in measuring the expected cost of benefits is projected to decrease from 6.00% in 2022 to 4.75% by 2026, remaining at 4.75% for the years thereafter.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Pension plans with projected benefit obligations in excess of plan assets and plans with accumulated benefit obligations in excess of plan assets as of December 31 consisted of the following:
| 2021 | 2020 | |||||||||||||
| Benefit Obligation Exceeds Fair Value of Plan Assets | ||||||||||||||
| Projected benefit obligation | $ | 805 | $ | 1,092 | ||||||||||
| Fair value of plan assets | 82 | 299 | ||||||||||||
| Accumulated benefit obligation | 771 | 882 | ||||||||||||
| Fair value of plan assets | 81 | 134 |
Other Retiree Benefit plans with accumulated postretirement benefit obligation in excess of plan assets as of December 31 consisted of the following:
| 2021 | 2020 | |||||||||||||
| Benefit Obligation Exceeds Fair Value of Plan Assets | ||||||||||||||
| Accumulated postretirement benefit obligation | $ | 1,080 | $ | 1,112 | ||||||||||
| Fair value of plan assets | — | 3 |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Summarized information regarding the net periodic benefit costs for the Company’s defined benefit and other retiree benefit plans is as follows:
| Pension Plans | Other Retiree Benefit Plans | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2021 | 2020 | 2019 | 2021 | 2020 | 2019 | 2021 | 2020 | 2019 | ||||||||||||||||||||||||||||||||||||||||||||||||
| United States | International | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Components of Net Periodic Benefit Cost | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Service cost | $ | — | $ | 1 | $ | 1 | $ | 19 | $ | 17 | $ | 14 | $ | 26 | $ | 20 | $ | 15 | ||||||||||||||||||||||||||||||||||||||
| Interest cost | 61 | 74 | 90 | 20 | 21 | 22 | 35 | 37 | 41 | |||||||||||||||||||||||||||||||||||||||||||||||
| Expected return on plan assets | (106) | (111) | (103) | (20) | (22) | (19) | — | (2) | (3) | |||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of transition and prior service costs (credits) | — | — | — | 1 | — | 1 | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Amortization of actuarial loss | 47 | 46 | 51 | 11 | 9 | 9 | 23 | 18 | 11 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net periodic benefit cost | $ | 2 | $ | 10 | $ | 39 | $ | 31 | $ | 25 | $ | 27 | $ | 84 | $ | 73 | $ | 64 | ||||||||||||||||||||||||||||||||||||||
| Other postretirement charges | (3) | 4 | 7 | 1 | — | 1 | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Total pension cost | $ | (1) | $ | 14 | $ | 46 | $ | 32 | $ | 25 | $ | 28 | $ | 84 | $ | 73 | $ | 64 | ||||||||||||||||||||||||||||||||||||||
| Weighted-Average Assumptions Used to Determine Net Periodic Benefit Cost | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Discount rate | 2.65 | % | 3.40 | % | 4.38 | % | 1.61 | % | 2.06 | % | 2.80 | % | 2.88 | % | 3.56 | % | 4.43 | % | ||||||||||||||||||||||||||||||||||||||
| Expected long-term rate of return on plan assets | 5.70 | % | 6.30 | % | 6.60 | % | 2.93 | % | 3.38 | % | 4.06 | % | 5.70 | % | 6.30 | % | 6.60 | % | ||||||||||||||||||||||||||||||||||||||
| Long-term rate of compensation increase | 3.50 | % | 3.50 | % | 3.50 | % | 2.62 | % | 2.83 | % | 2.86 | % | — | % | — | % | — | % | ||||||||||||||||||||||||||||||||||||||
| ESOP growth rate | — | % | — | % | — | % | — | % | — | % | — | % | 10.00 | % | 10.00 | % | 10.00 | % | ||||||||||||||||||||||||||||||||||||||
| Medical cost trend rate of increase | — | % | — | % | — | % | — | % | — | % | — | % | 6.00 | % | 6.00 | % | 6.00 | % | ||||||||||||||||||||||||||||||||||||||
| Interest Crediting Rate | 2.48 | % | 3.21 | % | 4.26 | % | 0.83 | % | 0.85 | % | 0.85 | % | — | % | — | % | — | % |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
The service related component of pension and other postretirement benefit costs is included in Operating profit. The non-service related components (interest cost, expected return on assets and amortization of actuarial gains and losses) are included in the line item “Non-service related postretirement costs,” which is below Operating profit.
The Company made no voluntary contributions in 2021 and 2020, and made voluntary contributions of $113 in 2019, to its U.S. retirement plans.
Expected Contributions and Benefit Payments
The Company does not expect to make any voluntary contributions to its U.S. postretirement plans for the year ending December 31, 2022. Actual funding may differ from current estimates depending on the variability of the market value of the assets as compared to the obligation and other market or regulatory conditions.
Benefit payments expected to be paid from the Company’s assets to participants in unfunded plans are estimated to be approximately $89 for the year ending December 31, 2022.
Total benefit payments expected to be paid to participants in both funded and unfunded plans are estimated as follows:
| Pension Plans | ||||||||||||||||||||||||||
| Years Ended December 31, | United States | International | Other Retiree Benefit Plans | Total | ||||||||||||||||||||||
| 2022 | $ | 147 | $ | 43 | $ | 47 | $ | 237 | ||||||||||||||||||
| 2023 | 146 | 40 | 48 | 234 | ||||||||||||||||||||||
| 2024 | 147 | 45 | 49 | 241 | ||||||||||||||||||||||
| 2025 | 144 | 44 | 50 | 238 | ||||||||||||||||||||||
| 2026 | 147 | 46 | 51 | 244 | ||||||||||||||||||||||
| 2027-2031 | 692 | 246 | 267 | 1,205 |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
11. Income Taxes
The components of Income before income taxes are as follows for the years ended December 31:
| 2021 | 2020 | 2019 | ||||||||||||||||||
| United States | $ | 1,256 | $ | 1,317 | $ | 1,050 | ||||||||||||||
| International | 1,831 | 2,330 | 2,251 | |||||||||||||||||
| Total Income before income taxes | $ | 3,087 | $ | 3,647 | $ | 3,301 |
The Provision for income taxes consists of the following for the years ended December 31:
| 2021 | 2020 | 2019 | ||||||||||||||||||
| United States | $ | 228 | $ | 259 | $ | 180 | ||||||||||||||
| International | 521 | 528 | 594 | |||||||||||||||||
| Total Provision for income taxes | $ | 749 | $ | 787 | $ | 774 |
Temporary differences between accounting for financial statement purposes and accounting for tax purposes result in the current provision for taxes being higher (lower) than the total provision for income taxes as follows:
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Goodwill and intangible assets | $ | 50 | $ | 1 | $ | 34 | ||||||||||||||
| Property, plant and equipment | (19) | 12 | 12 | |||||||||||||||||
| Pension and other retiree benefits | (4) | 10 | (13) | |||||||||||||||||
| Stock-based compensation | 11 | (7) | (1) | |||||||||||||||||
| Right-of-use assets/lease liabilities | (2) | (1) | — | |||||||||||||||||
| Tax credits and tax loss carryforwards | (2) | (1) | 3 | |||||||||||||||||
| Deferred withholding tax | (16) | 111 | (21) | |||||||||||||||||
| Other, net | 19 | 18 | (33) | |||||||||||||||||
| Total deferred tax benefit (provision) | $ | 37 | $ | 143 | $ | (19) |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
The difference between the statutory U.S. federal income tax rate and the Company’s global effective tax rate as reflected in the Consolidated Statements of Income is as follows:
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Percentage of Income before income taxes | ||||||||||||||||||||
| Tax at United States statutory rate | 21.0 | % | 21.0 | % | 21.0 | % | ||||||||||||||
| State income taxes, net of federal benefit | 1.1 | 1.0 | 0.6 | |||||||||||||||||
| Earnings taxed at other than United States statutory rate | 2.7 | 3.3 | 4.6 | |||||||||||||||||
| Benefit for foreign tax matters(1) | — | (2.0) | (0.9) | |||||||||||||||||
| Non-deductible goodwill impairment charges | 2.2 | — | — | |||||||||||||||||
| Foreign-derived intangible income benefit | (2.2) | (1.6) | (1.3) | |||||||||||||||||
| Other, net | (0.5) | (0.1) | (0.6) | |||||||||||||||||
| Effective tax rate | 24.3 | % | 21.6 | % | 23.4 | % |
(1)In 2020, the provision for income taxes includes $71 of income tax benefits recorded on a discrete period basis, of which $45 relates to previously recorded foreign withholding taxes and $26 relates to a previously recorded valuation allowance against a deferred tax asset. As part of a previously recorded charge for the Tax Cuts and Jobs Act of 2017 (the “TCJA”), the Company has provided for foreign withholding taxes expected to be paid on the remittance of earnings from certain overseas subsidiaries no longer deemed indefinitely reinvested. As a result of a recent reorganization of the ownership structure of certain foreign subsidiaries, the Company determined that no withholding taxes will be due on the remittance by certain subsidiaries of earnings previously deemed reinvested and, accordingly, reversed $45 of previously recorded foreign withholding taxes. Also as part of the previously recorded charge for the TCJA, the Company provided a valuation allowance against a deferred tax asset related to the foreign tax credit carryforwards that the Company did not expect to be able to use due to changes made by the TCJA. As a result of a new operating structure being implemented within one of the Company’s divisions, the Company believes the use of these foreign tax credit carryforwards will not be limited in the future and, accordingly, reversed the previously recorded valuation allowance of $26. In 2019, the provision for income taxes includes a net benefit of $29 related to changes enacted by the Swiss government to its corporate tax regime, which included, among other items, the repeal of certain preferential tax regimes and an increase to the cantonal tax rate for future periods. Additionally, the government provided transition rules which allowed companies to record goodwill for tax purposes, partially offsetting the impact on cash taxes of the higher cantonal rate over the next ten years.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
The components of deferred tax assets (liabilities) are as follows at December 31:
| 2021 | 2020 | |||||||||||||
| Deferred tax liabilities: | ||||||||||||||
| Goodwill and intangible assets | $ | (523) | $ | (603) | ||||||||||
| Property, plant and equipment | (301) | (281) | ||||||||||||
| Right-of-use assets | (125) | (131) | ||||||||||||
| Deferred withholding tax | (111) | (95) | ||||||||||||
| Other | (35) | (52) | ||||||||||||
| Total deferred tax liabilities | (1,095) | (1,162) | ||||||||||||
| Deferred tax assets: | ||||||||||||||
| Pension and other retiree benefits | 344 | 404 | ||||||||||||
| Tax credits and tax loss carryforwards | 152 | 127 | ||||||||||||
| Lease liabilities | 138 | 144 | ||||||||||||
| Accrued liabilities | 234 | 250 | ||||||||||||
| Stock-based compensation | 76 | 73 | ||||||||||||
| Other | 69 | 125 | ||||||||||||
| Total deferred tax assets | 1,013 | 1,123 | ||||||||||||
| Valuation Allowance | $ | (120) | $ | (96) | ||||||||||
| Net deferred tax assets | $ | 893 | $ | 1,027 | ||||||||||
| Net deferred income taxes | $ | (202) | $ | (135) |
Applicable U.S. income and foreign withholding taxes have been provided on substantially all of the Company’s accumulated earnings of foreign subsidiaries.
Net tax expense of $(146) was recorded directly through equity in 2021, and net tax benefits of $101 and $13 were recorded directly through equity in 2020 and 2019, respectively. The net tax expense or benefit in each year predominantly includes current and future tax impacts related to benefit plans and the impact of currency translation adjustments.
The Company uses a comprehensive model to recognize, measure, present and disclose in its financial statements uncertain tax positions that the Company has taken or expects to take on an income tax return.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Unrecognized tax benefits activity for the years ended December 31, 2021, 2020 and 2019 is summarized below:
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Unrecognized tax benefits: | ||||||||||||||||||||
| Balance, January 1 | $ | 227 | $ | 173 | $ | 190 | ||||||||||||||
| Increases as a result of tax positions taken during the current year | 26 | 18 | 14 | |||||||||||||||||
| Decreases of tax positions taken during prior years | (20) | (5) | (21) | |||||||||||||||||
| Increases of tax positions taken during prior years | 40 | 57 | 20 | |||||||||||||||||
| Decreases as a result of settlements with taxing authorities and the expiration of statutes of limitations | (23) | (19) | (30) | |||||||||||||||||
| Effect of foreign currency rate movements | (5) | 3 | — | |||||||||||||||||
| Balance, December 31 | $ | 245 | $ | 227 | $ | 173 |
If all of the unrecognized tax benefits for 2021 above were recognized, approximately $235 would impact the effective tax rate. Although it is possible that the amount of unrecognized benefits with respect to our uncertain tax positions will increase or decrease in the next twelve months, the Company does not expect material changes.
The Company recognized expense of approximately $10, $9 and $0 for interest and penalties related to the above unrecognized tax benefits within income tax expense in 2021, 2020 and 2019, respectively. The Company had accrued interest and penalties of approximately $35, $24 and $23 as of December 31, 2021, 2020 and 2019, respectively.
The Company and its subsidiaries file U.S. federal income tax returns as well as income tax returns in many state and foreign jurisdictions. All U.S. federal income tax returns through December 31, 2013 have been audited by the IRS and there are limited matters which the Company plans to appeal for years 2010 through 2013, the settlement of which is not expected to have a material effect on the Company’s results of operations, cash flows or financial condition. With a few exceptions, the Company is no longer subject to U.S. state and local income tax examinations for income tax returns through December 31, 2016. In addition, the Company has subsidiaries in various foreign jurisdictions that have statutes of limitations for tax audits generally ranging from three to six years.
The Company has made an accounting policy election to treat Global Intangible Low-Taxed Income taxes as a current period expense rather than including these amounts in the measurement of deferred taxes.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
12. Earnings Per Share
For the years ended December 31, 2021, 2020 and 2019, earnings per share were as follows:
| 2021 | 2020 | 2019 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Net income attributable to Colgate-Palmolive Company | Shares (millions) | Per Share | Net income attributable to Colgate-Palmolive Company | Shares (millions) | Per Share | Net income attributable to Colgate-Palmolive Company | Shares (millions) | Per Share | |||||||||||||||||||||||||||||||||||||||||||||
| Basic EPS | $ | 2,166 | 845.0 | $ | 2.56 | $ | 2,695 | 856.8 | $ | 3.15 | $ | 2,367 | 859.1 | $ | 2.76 | ||||||||||||||||||||||||||||||||||||||
| Stock options and restricted stock units | 3.3 | 2.5 | 2.0 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Diluted EPS | $ | 2,166 | 848.3 | $ | 2.55 | $ | 2,695 | 859.3 | $ | 3.14 | $ | 2,367 | 861.1 | $ | 2.75 |
Basic earnings per common share is computed by dividing net income available for common stockholders by the weighted-average number of shares of common stock outstanding for the period.
Diluted earnings per common share is computed using the treasury stock method on the basis of the weighted-average number of shares of common stock plus the dilutive effect of potential common shares outstanding during the period. Dilutive potential common shares include outstanding stock options and restricted stock units.
As of December 31, 2021, 2020 and 2019, the average number of stock options that were anti-dilutive and not included in diluted earnings per share calculations were 2,495,393, 3,257,310 and 19,901,202, respectively. As of December 31, 2021, 2020 and 2019, the average number of restricted stock units that were anti-dilutive and not included in diluted earnings per share calculations were 126,378, 25,381 and 4,516, respectively.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
13. Commitments and Contingencies
As of December 31, 2021, the Company has various contractual commitments for future multi-year purchases of raw, packaging and other materials totaling approximately $724.
As a global company serving consumers in more than 200 countries and territories, the Company is routinely subject to a wide variety of legal proceedings. These include disputes relating to intellectual property, contracts, product liability, marketing, advertising, foreign exchange controls, antitrust and trade regulation, as well as labor and employment, pension, data privacy and security, environmental and tax matters and consumer class actions. Management proactively reviews and monitors the Company’s exposure to, and the impact of, environmental matters. The Company is party to various environmental matters and, as such, may be responsible for all or a portion of the cleanup, restoration and post-closure monitoring of several sites.
The Company establishes accruals for loss contingencies when it has determined that a loss is probable and that the amount of loss, or range of loss, can be reasonably estimated. Any such accruals are adjusted thereafter as appropriate to reflect changes in circumstances.
The Company also determines estimates of reasonably possible losses or ranges of reasonably possible losses in excess of related accrued liabilities, if any, when it has determined that a loss is reasonably possible and it is able to determine such estimates. For those matters disclosed below for which the amount of any potential losses can be reasonably estimated, the Company currently estimates that the aggregate range of reasonably possible losses in excess of any accrued liabilities is $0 to approximately $425 (based on current exchange rates). The estimates included in this amount are based on the Company’s analysis of currently available information and, as new information is obtained, these estimates may change. Due to the inherent subjectivity of the assessments and the unpredictability of outcomes of legal proceedings, any amounts accrued or included in this aggregate range may not represent the ultimate loss to the Company. Thus, the Company’s exposure and ultimate losses may be higher or lower, and possibly significantly so, than the amounts accrued or the range disclosed above.
Based on current knowledge, management does not believe that the ultimate resolution of loss contingencies arising from the matters discussed herein will have a material effect on the Company’s consolidated financial position or its ongoing results of operations or cash flows. However, in light of the inherent uncertainties noted above, an adverse outcome in one or more matters could be material to the Company’s results of operations or cash flows for any particular quarter or year.
Brazilian Matters
There are certain tax and civil proceedings outstanding, as described below, related to the Company’s 1995 acquisition of the Kolynos oral care business from Wyeth (the “Seller”).
The Brazilian internal revenue authority has disallowed interest deductions and foreign exchange losses taken by the Company’s Brazilian subsidiary for certain years in connection with the financing of the Kolynos acquisition. The tax assessments with interest, penalties and any court-mandated fees, at the current exchange rate, are approximately $106. This amount includes additional assessments received from the Brazilian internal revenue authority in April 2016 relating to net operating loss carryforwards used by the Company’s Brazilian subsidiary to offset taxable income that had also been deducted from the authority’s original assessments. The Company has been disputing the disallowances by appealing the assessments since October 2001.
In each of September 2015, February 2017, June 2018, April 2019 and September 2020, the Company lost an administrative appeal and subsequently filed an appeal in Brazilian federal court. Currently, there are five appeals pending in the Brazilian federal court. Although there can be no assurances, management believes, based on the opinion of its Brazilian legal counsel, that the disallowances are without merit and that the Company should ultimately prevail. The Company is challenging these disallowances vigorously.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
In July 2002, the Brazilian Federal Public Attorney filed a civil action against the federal government of Brazil, Laboratorios Wyeth-Whitehall Ltda. (the Brazilian subsidiary of the Seller) and the Company, as represented by its Brazilian subsidiary, in the 6th. Lower Federal Court in the City of São Paulo, seeking to annul an April 2000 decision by the Brazilian Board of Tax Appeals that found in favor of the Seller’s Brazilian subsidiary on the issue of whether it had incurred taxable capital gains as a result of the divestiture of Kolynos. The action seeks to make the Company’s Brazilian subsidiary jointly and severally liable for any tax due from the Seller’s Brazilian subsidiary. The case has been pending since 2002, and the Lower Federal Court has not issued a decision. Although there can be no assurances, management believes, based on the opinion of its Brazilian legal counsel, that the Company should ultimately prevail in this action. The Company is challenging this action vigorously.
In December 2005, the Brazilian internal revenue authority issued to the Company’s Brazilian subsidiary a tax assessment with interest, penalties and any court-mandated fees of approximately $47, at the current exchange rate, based on a claim that certain purchases of U.S. Treasury bills by the subsidiary and their subsequent disposition during the period 2000 to 2001 were subject to a tax on foreign exchange transactions. The Company had been disputing the assessment within the internal revenue authority’s administrative appeals process. However, in November 2015, the Superior Chamber of Administrative Tax Appeals denied the Company’s final administrative appeal, and the Company has filed a lawsuit in the Brazilian federal court. In the event the Company is unsuccessful in this lawsuit, further appeals are available within the Brazilian federal courts. Although there can be no assurances, management believes, based on the opinion of its Brazilian legal counsel, that the tax assessment is without merit and that the Company should ultimately prevail. The Company is challenging this assessment vigorously.
Competition Matter
Certain of the Company’s subsidiaries were historically subject to actions and, in some cases, fines, by governmental authorities in a number of countries related to alleged competition law violations. Substantially all of these matters also involved other consumer goods companies and/or retail customers. The Company’s policy is to comply with antitrust and competition laws and, if a violation of any such laws is found, to take appropriate remedial action and to cooperate fully with any related governmental inquiry. The status as of December 31, 2021 of such competition law matters pending against the Company during the year ended December 31, 2021 is set forth below.
▪In July 2014, the Greek competition law authority issued a statement of objections alleging a restriction of parallel imports into Greece. The Company responded to this statement of objections. In July 2017, the Company received the decision from the Greek competition law authority in which the Company was fined $11. The Company appealed the decision to the Greek courts. In April 2019, the Greek courts affirmed the judgment against the Company’s Greek subsidiary, but reduced the fine to $10.5 and dismissed the case against Colgate-Palmolive Company. The Company’s Greek subsidiary and the Greek competition authority have appealed the decision to the Greek Supreme Court.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Talcum Powder Matters
The Company has been named as a defendant in civil actions alleging that certain talcum powder products that were sold prior to 1996 were contaminated with asbestos and/or caused mesothelioma and other cancers. Many of these actions involve a number of co-defendants from a variety of different industries, including suppliers of asbestos and manufacturers of products that, unlike the Company’s products, were designed to contain asbestos. As of December 31, 2021, there were 171 individual cases pending against the Company in state and federal courts throughout the United States, as compared to 136 cases as of December 31, 2020. During the year ended December 31, 2021, 74 new cases were filed and 39 cases were resolved by voluntary dismissal, settlement or dismissal by the court. The value of the settlements in the years presented was not material, either individually or in the aggregate, to each such period’s results of operations.
A significant portion of the Company’s costs incurred in defending and resolving these claims has been, and the Company believes that a portion of the costs will continue to be, covered by insurance policies issued by several primary, excess and umbrella insurance carriers, subject to deductibles, exclusions, retentions, policy limits and insurance carrier insolvencies.
While the Company and its legal counsel believe that these cases are without merit and intend to challenge them vigorously, there can be no assurances regarding the ultimate resolution of these matters.
ERISA Matter
In June 2016, a putative class action claiming that residual annuity payments made to certain participants in the Colgate-Palmolive Company Employees’ Retirement Income Plan (the “Plan”) did not comply with the Employee Retirement Income Security Act was filed against the Plan, the Company and certain individuals (the “Company Defendants”) in the United States District Court for the Southern District of New York (the “Court”). The relief sought includes recalculation of benefits, pre- and post-judgment interest and attorneys’ fees. This action was certified as a class action in July 2017. In July 2020, the Court granted in part and denied in part the Company Defendants’ motion for summary judgment and dismissed certain claims on consent of the parties. In August 2020, the Court granted the plaintiffs’ motion for summary judgment on the remaining claims. The Company and the Plan are contesting this action vigorously and, in September 2020, appealed to the United States Court of Appeals for the Second Circuit. The appeal is currently pending.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
14. Segment Information
The Company operates in two product segments: Oral, Personal and Home Care; and Pet Nutrition.
The operations of the Oral, Personal and Home Care product segment are managed geographically in five reportable operating segments: North America, Latin America, Europe, Asia Pacific and Africa/Eurasia.
The Company evaluates segment performance based on several factors, including Operating profit. The Company uses Operating profit as a measure of operating segment performance because it excludes the impact of Corporate-driven decisions related to interest expense and income taxes.
The accounting policies of the operating segments are generally the same as those described in Note 2, Summary of Significant Accounting Policies. Intercompany sales have been eliminated. Corporate operations include costs related to stock options and restricted stock units, research and development costs, Corporate overhead costs, restructuring and related implementation charges and gains and losses on sales of non-core product lines and assets. The Company reports these items within Corporate operations as they relate to Corporate-based responsibilities and decisions and are not included in the internal measures of segment operating performance used by the Company to measure the underlying performance of the operating segments.
Approximately 70% of the Company’s Net sales are generated from markets outside the U.S., with approximately 45% of the Company’s Net sales coming from emerging markets (which consist of Latin America, Asia (excluding Japan), Africa/Eurasia and Central Europe). Oral, Personal and Home Care sales to Walmart, Inc. and its affiliates represent approximately 12%, 12% and 11% of the Company’s Net sales in 2021, 2020 and 2019, respectively. No other customer represented more than 10% of Net sales in any period presented.
In 2021, Corporate Operating profit included goodwill and indefinite-lived intangible impairment charges of $571, and a benefit of $26 related to a value-added tax matter in Brazil. In 2020, Corporate Operating profit included benefits of $16 resulting from the Global Growth and Efficiency Program and a charge of $6 for acquisition-related costs. In 2019, Corporate Operating profit included charges of $125 resulting from the Global Growth and Efficiency Program, a charge of $24 for acquisition-related costs and a benefit of $30 from a value-added tax matter in Brazil.
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Net sales | ||||||||||||||||||||
| Oral, Personal and Home Care | ||||||||||||||||||||
| North America(1) | $ | 3,694 | $ | 3,741 | $ | 3,424 | ||||||||||||||
| Latin America | 3,663 | 3,418 | 3,606 | |||||||||||||||||
| Europe | 2,841 | 2,747 | 2,450 | |||||||||||||||||
| Asia Pacific | 2,867 | 2,701 | 2,707 | |||||||||||||||||
| Africa/Eurasia | 1,045 | 981 | 981 | |||||||||||||||||
| Total Oral, Personal and Home Care | 14,110 | 13,588 | 13,168 | |||||||||||||||||
| Pet Nutrition(2) | 3,311 | 2,883 | 2,525 | |||||||||||||||||
| Total Net sales | $ | 17,421 | $ | 16,471 | $ | 15,693 |
(1) Net sales in the U.S. for Oral, Personal and Home Care were $3,391, $3,447 and $3,166 in 2021, 2020 and 2019, respectively.
(2) Net sales in the U.S. for Pet Nutrition were $2,018, $1,712 and $1,441 in 2021, 2020 and 2019, respectively.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Operating profit | ||||||||||||||||||||
| Oral, Personal and Home Care | ||||||||||||||||||||
| North America | $ | 754 | $ | 988 | $ | 982 | ||||||||||||||
| Latin America | 1,012 | 975 | 963 | |||||||||||||||||
| Europe | 682 | 652 | 624 | |||||||||||||||||
| Asia Pacific | 844 | 773 | 749 | |||||||||||||||||
| Africa/Eurasia | 203 | 206 | 187 | |||||||||||||||||
| Total Oral, Personal and Home Care | 3,495 | 3,594 | 3,505 | |||||||||||||||||
| Pet Nutrition | 901 | 793 | 703 | |||||||||||||||||
| Corporate | (1,064) | (502) | (654) | |||||||||||||||||
| Total Operating profit | $ | 3,332 | $ | 3,885 | $ | 3,554 |
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Capital expenditures | ||||||||||||||||||||
| Oral, Personal and Home Care | ||||||||||||||||||||
| North America | $ | 87 | $ | 65 | $ | 43 | ||||||||||||||
| Latin America | 118 | 104 | 90 | |||||||||||||||||
| Europe | 44 | 41 | 42 | |||||||||||||||||
| Asia Pacific | 50 | 51 | 40 | |||||||||||||||||
| Africa/Eurasia | 33 | 13 | 8 | |||||||||||||||||
| Total Oral, Personal and Home Care | 332 | 274 | 223 | |||||||||||||||||
| Pet Nutrition | 147 | 56 | 41 | |||||||||||||||||
| Corporate | 88 | 79 | 71 | |||||||||||||||||
| Total Capital expenditures | $ | 567 | $ | 409 | $ | 335 |
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Depreciation and amortization | ||||||||||||||||||||
| Oral, Personal and Home Care | ||||||||||||||||||||
| North America | $ | 104 | $ | 101 | $ | 94 | ||||||||||||||
| Latin America | 88 | 81 | 84 | |||||||||||||||||
| Europe | 98 | 94 | 72 | |||||||||||||||||
| Asia Pacific | 96 | 95 | 100 | |||||||||||||||||
| Africa/Eurasia | 9 | 9 | 8 | |||||||||||||||||
| Total Oral, Personal and Home Care | 395 | 380 | 358 | |||||||||||||||||
| Pet Nutrition | 62 | 58 | 55 | |||||||||||||||||
| Corporate | 99 | 101 | 106 | |||||||||||||||||
| Total Depreciation and amortization | $ | 556 | $ | 539 | $ | 519 |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Identifiable assets | ||||||||||||||||||||
| Oral, Personal and Home Care | ||||||||||||||||||||
| North America | $ | 4,058 | $ | 4,132 | $ | 3,576 | ||||||||||||||
| Latin America | 2,369 | 2,251 | 2,384 | |||||||||||||||||
| Europe | 4,432 | 5,386 | 5,104 | |||||||||||||||||
| Asia Pacific | 2,161 | 2,272 | 2,155 | |||||||||||||||||
| Africa/Eurasia | 599 | 605 | 590 | |||||||||||||||||
| Total Oral, Personal and Home Care | 13,619 | 14,646 | 13,809 | |||||||||||||||||
| Pet Nutrition | 1,342 | 1,210 | 1,175 | |||||||||||||||||
| Corporate(1) | 79 | 64 | 50 | |||||||||||||||||
| Total Identifiable assets | $ | 15,040 | $ | 15,920 | $ | 15,034 |
(1)In 2021, Corporate identifiable assets primarily consisted of investments in equity securities (87%) and derivative instruments (10%). In 2020, Corporate identifiable assets primarily consisted of investments in equity securities (95%). In 2019, Corporate identifiable assets primarily consisted of investments in equity securities (92%) and derivative instruments (2%).
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Long-lived assets**(1)** | ||||||||||||||||||||
| United States | $ | 1,981 | $ | 1,889 | $ | 1,895 | ||||||||||||||
| International | 2,275 | 2,348 | 2,359 | |||||||||||||||||
| Total Long-lived assets | $ | 4,256 | $ | 4,237 | $ | 4,254 |
(1)Long-lived assets include Property, plant and equipment, net and lease right-of-use assets.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
15. Leases
The Company enters into leases for land, office space, warehouses and equipment. A number of the leases include one or more options to renew the lease terms, purchase the leased property or terminate the lease. The exercise of these options is at the Company’s discretion and is therefore recognized on the balance sheet when it is reasonably certain the Company will exercise such options. As the Company’s leases typically do not contain a readily determinable implicit rate, the Company determines the present value of the lease liability using its incremental borrowing rate at the lease commencement date.
Substantially all of the Company’s leases are considered operating leases. Finance leases were not material as of December 31, 2021 and 2020.
As of December 31, 2021 and 2020, the Company’s right-of use assets and liabilities for operating leases were as follows:
| 2021 | 2020 | |||||||||||||
| Other assets | $ | 527 | $ | 521 | ||||||||||
| Other accruals | 137 | 137 | ||||||||||||
| Other liabilities | 451 | 476 | ||||||||||||
| Total operating lease liabilities | $ | 588 | $ | 613 |
Lease liabilities for operating leases as of December 31, 2021 were as follows:
| 2022 | $ | 156 | |||||||||
| 2023 | 109 | ||||||||||
| 2024 | 76 | ||||||||||
| 2025 | 61 | ||||||||||
| 2026 | 48 | ||||||||||
| Thereafter | 235 | ||||||||||
| Total lease commitments | $ | 685 | |||||||||
| Less: Interest | (97) | ||||||||||
| Present value of lease liabilities | $ | 588 |
The components of the Company’s operating lease cost for the twelve months ended December 31, 2021 and 2020 were as follows:
| 2021 | 2020 | |||||||||||||
| Operating lease cost | $ | 142 | $ | 155 | ||||||||||
| Short-term lease cost | 7 | 3 | ||||||||||||
| Variable lease cost | 20 | 20 | ||||||||||||
| Sublease Income | (1) | — | ||||||||||||
| Total lease cost | $ | 168 | $ | 178 |
Short-term lease cost represents the Company’s cost with respect to leases with a duration of 12 months or less and is not reflected on the Company’s Consolidated Balance Sheets. Variable lease costs are comprised of costs, such as the Company’s proportionate share of actual costs for utilities, common area maintenance, property taxes and insurance, that are not included in the lease liability and are recognized in the period in which they are incurred.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
Supplemental cash flow information related to operating leases for the twelve months ended December 31, 2021 and 2020 was as follows:
▪Payments against amounts included in the measurement of lease liabilities: $173 and $193, respectively
▪Lease assets obtained in exchange for lease liabilities: $197 and $163, respectively.
As of December 31, 2021 and 2020, the weighted-average remaining lease term for operating leases was 8 and 8 years, respectively, and the weighted-average discount rate for operating leases was 4.0% and 4.2%, respectively.
There were no material operating leases that the Company had entered into and that were yet to commence as of December 31, 2021.
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
16. Supplemental Income Statement Information
| Other (income) expense, net | 2021 | 2020 | 2019 | |||||||||||||||||
| Global Growth and Efficiency Program | $ | — | $ | (13) | $ | 57 | ||||||||||||||
| Amortization of intangible assets | 89 | 88 | 62 | |||||||||||||||||
| Equity income | (12) | (12) | (9) | |||||||||||||||||
| Value-added tax matter in Brazil | (26) | — | (30) | |||||||||||||||||
| Write-off of certain investments and fixed assets | 10 | — | 51 | |||||||||||||||||
| Acquisition-related costs | — | 2 | 21 | |||||||||||||||||
| Charges for a change in go-to-market strategy in certain countries | — | — | 15 | |||||||||||||||||
| Other, net | 4 | 48 | 29 | |||||||||||||||||
| Total Other (income) expense, net | $ | 65 | $ | 113 | $ | 196 |
| Interest (income) expense, net | 2021 | 2020 | 2019 | |||||||||||||||||
| Interest incurred | $ | 195 | $ | 184 | $ | 193 | ||||||||||||||
| Interest capitalized | (3) | (1) | (1) | |||||||||||||||||
| Interest income | (17) | (19) | (47) | |||||||||||||||||
| Total Interest (income) expense, net | $ | 175 | $ | 164 | $ | 145 |
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Research and development | $ | 307 | $ | 290 | $ | 281 | ||||||||||||||
| Advertising | $ | 2,021 | $ | 1,948 | $ | 1,694 |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
17. Supplemental Balance Sheet Information
Inventories by major class are as follows at December 31:
| Inventories | 2021 | 2020 | ||||||||||||
| Raw materials and supplies | $ | 505 | $ | 454 | ||||||||||
| Work-in-process | 39 | 45 | ||||||||||||
| Finished goods | 1,248 | 1,256 | ||||||||||||
| Total Inventories, net | $ | 1,792 | $ | 1,755 | ||||||||||
| Non-current inventory, net | (100) | (82) | ||||||||||||
| Current Inventories, net | $ | 1,692 | $ | 1,673 |
Inventories valued under LIFO amounted to $410 and $439 at December 31, 2021 and 2020, respectively. The excess of current cost over LIFO cost at the end of each year was $60 and $65, respectively. The liquidations of LIFO inventory quantities had no material effect on income in 2021, 2020 and 2019. Inventory classified as non-current at December 31, 2021 was recorded on the Consolidated Balance Sheets as “Other assets.”
| Property, plant and equipment, net | 2021 | 2020 | ||||||||||||
| Land | $ | 163 | $ | 166 | ||||||||||
| Buildings | 1,603 | 1,623 | ||||||||||||
| Manufacturing machinery and equipment | 5,527 | 5,409 | ||||||||||||
| Other equipment | 1,606 | 1,553 | ||||||||||||
| 8,899 | 8,751 | |||||||||||||
| Accumulated depreciation | (5,169) | (5,035) | ||||||||||||
| Total Property, plant and equipment, net | $ | 3,730 | $ | 3,716 |
| Other accruals | 2021 | 2020 | ||||||||||||
| Accrued advertising and coupon redemption | $ | 709 | $ | 728 | ||||||||||
| Accrued payroll and employee benefits | 353 | 401 | ||||||||||||
| Accrued taxes other than income taxes | 118 | 116 | ||||||||||||
| Restructuring accrual | 7 | 21 | ||||||||||||
| Pension and other retiree benefits | 87 | 89 | ||||||||||||
| Lease liabilities due in one year | 137 | 137 | ||||||||||||
| Accrued interest | 38 | 39 | ||||||||||||
| Derivatives | 6 | 93 | ||||||||||||
| Other | 630 | 717 | ||||||||||||
| Total Other accruals | $ | 2,085 | $ | 2,341 |
| Other liabilities | 2021 | 2020 | ||||||||||||
| Pension and other retiree benefits | $ | 1,722 | $ | 1,815 | ||||||||||
| Restructuring accrual | 2 | 10 | ||||||||||||
| Long-term lease liabilities | 451 | 476 | ||||||||||||
| Other | 254 | 354 | ||||||||||||
| Total Other liabilities | $ | 2,429 | $ | 2,655 |
COLGATE-PALMOLIVE COMPANY
Notes to Consolidated Financial Statements (continued)
(Dollars in Millions Except Share and Per Share Amounts)
18. Supplemental Other Comprehensive Income (Loss) Information
Other comprehensive income (loss) components attributable to Colgate-Palmolive Company before tax and net of tax during the years ended December 31 were as follows:
| 2021 | 2020 | 2019 | |||||||||||||||||||||||||||
| Pretax | Net of Tax | Pretax | Net of Tax | Pretax | Net of Tax | ||||||||||||||||||||||||
| Cumulative translation adjustments | $ | (99) | $ | (191) | $ | (119) | $ | (30) | $ | 49 | $ | 27 | |||||||||||||||||
| Pension and other benefits: | |||||||||||||||||||||||||||||
| Net actuarial gain (loss), prior service costs and settlements during the period | 102 | 71 | (125) | (97) | (204) | (154) | |||||||||||||||||||||||
| Amortization of net actuarial loss, transition and prior service costs(1) | 82 | 63 | 74 | 57 | 72 | 54 | |||||||||||||||||||||||
| Retirement Plan and other retiree benefit adjustments | 184 | 134 | (51) | (40) | (132) | (100) | |||||||||||||||||||||||
| Cash flow hedges: | |||||||||||||||||||||||||||||
| Unrealized gains (losses) on cash flow hedges | 13 | 10 | (3) | (2) | (9) | (7) | |||||||||||||||||||||||
| Reclassification of (gains) losses into net earnings on cash flow hedges(2) | 7 | 6 | — | — | (6) | (5) | |||||||||||||||||||||||
| Gains (losses) on cash flow hedges | 20 | 16 | (3) | (2) | (15) | (12) | |||||||||||||||||||||||
| Total Other comprehensive income (loss) | $ | 105 | $ | (41) | $ | (173) | $ | (72) | $ | (98) | $ | (85) |
(1)These components of Other comprehensive income (loss) are included in the computation of total pension cost. See Note 10, Retirement Plans and Other Retiree Benefits for additional details.
(2)These (gains) losses are reclassified into Cost of sales. See Note 7, Fair Value Measurements and Financial Instruments for additional details.
There were no tax impacts on Other comprehensive income (loss) attributable to Noncontrolling interests.
Accumulated Other Comprehensive Income (Loss)
Accumulated other comprehensive income (loss) is comprised of cumulative foreign currency translation gains and losses, unrecognized pension and other retiree benefit costs and unrealized gains and losses from derivative instruments designated as cash flow hedges. At December 31, 2021 and 2020, Accumulated other comprehensive income (loss) consisted primarily of aftertax unrecognized pension and other retiree benefit costs of $1,044 and $1,178, respectively, and cumulative foreign currency translation adjustments of $3,349 and $3,158, respectively. Foreign currency translation adjustments in 2021 primarily reflect losses from the euro, Brazilian real, Thailand bhat and Turkish lira. Foreign currency translation adjustments in 2020 primarily reflect loss from the Brazilian real and the Mexican peso.
COLGATE-PALMOLIVE COMPANY
SCHEDULE II - VALUATION AND QUALIFYING ACCOUNTS
(Dollars in Millions)
| Additions | ||||||||||||||||||||||||||||||||
| Balance at Beginning of Period | Charged to Costs and Expenses | Other | Deductions | Balance at End of Period | ||||||||||||||||||||||||||||
| Year Ended December 31, 2021 | ||||||||||||||||||||||||||||||||
| Allowance for doubtful accounts and estimated returns | $ | 89 | $ | 35 | $ | — | $ | 46 | $ | 78 | ||||||||||||||||||||||
| Valuation allowance for deferred tax assets | $ | 96 | $ | 27 | $ | — | $ | 3 | $ | 120 | ||||||||||||||||||||||
| Year Ended December 31, 2020 | ||||||||||||||||||||||||||||||||
| Allowance for doubtful accounts and estimated returns | $ | 76 | $ | 16 | $ | — | $ | 3 | $ | 89 | ||||||||||||||||||||||
| Valuation allowance for deferred tax assets | $ | 115 | $ | 31 | $ | — | $ | 50 | $ | 96 | ||||||||||||||||||||||
| Year Ended December 31, 2019 | ||||||||||||||||||||||||||||||||
| Allowance for doubtful accounts and estimated returns | $ | 82 | $ | 6 | $ | — | $ | 12 | $ | 76 | ||||||||||||||||||||||
| Valuation allowance for deferred tax assets | $ | 54 | $ | 68 | $ | — | $ | 7 | $ | 115 |
COLGATE-PALMOLIVE COMPANY
Market Information
The Company’s common stock is listed on the New York Stock Exchange, and its trading symbol is CL.
Stock Price Performance Graphs
The following graphs compare cumulative total shareholder returns on Colgate-Palmolive Company common stock against the S&P Composite-500 Stock Index and a peer company index for the twenty-year, ten-year and five-year periods each ended December 31, 2021. The peer company index is comprised of consumer products companies that have both domestic and international businesses. For 2021, the peer company index consisted of Campbell Soup Company, The Clorox Company, The Coca-Cola Company, ConAgra Brands, Inc., The Estee Lauder Companies, Inc., General Mills, Inc., Johnson & Johnson, Kellogg Company, Kimberly-Clark Corporation, The Kraft Heinz Company, Mondelez International, Inc., PepsiCo, Inc., The Procter & Gamble Company, Reckitt Benckiser Group plc and Unilever PLC.
These performance graphs do not constitute soliciting material, are not deemed filed with the SEC and are not incorporated by reference in any of the Company’s filings under the Securities Act of 1933 or the Securities Exchange Act of 1934, as amended, whether made before or after the date of this Annual Report on Form 10-K and irrespective of any general incorporation language in any such filing, except to the extent the Company specifically incorporates these performance graphs by reference therein.

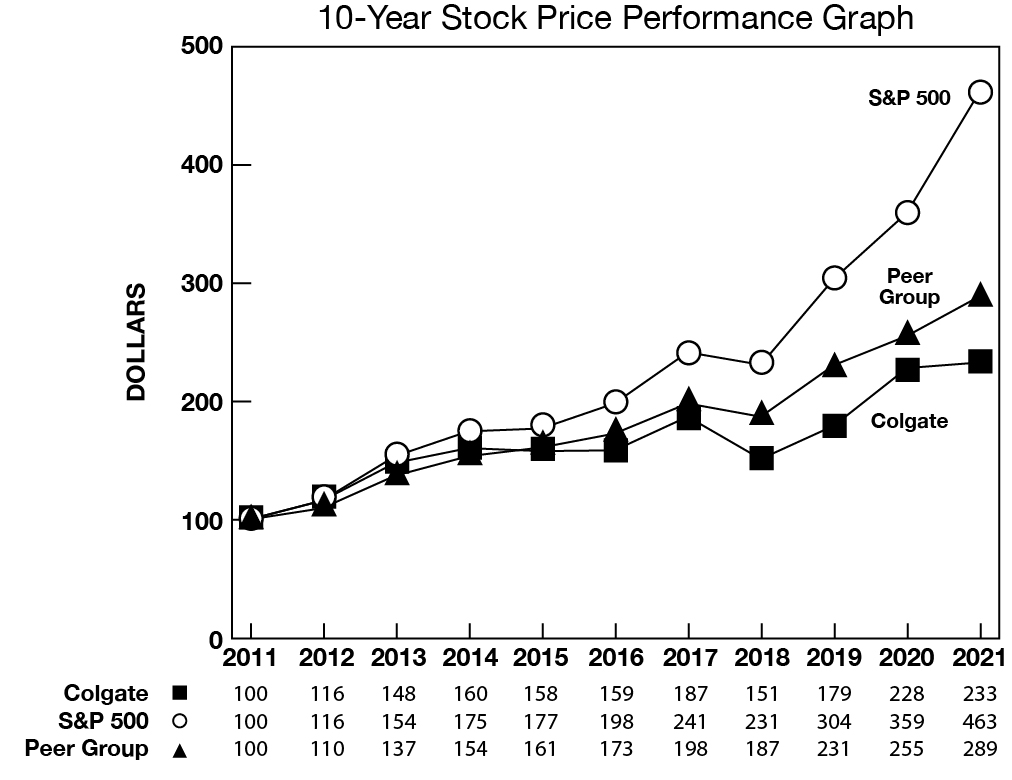
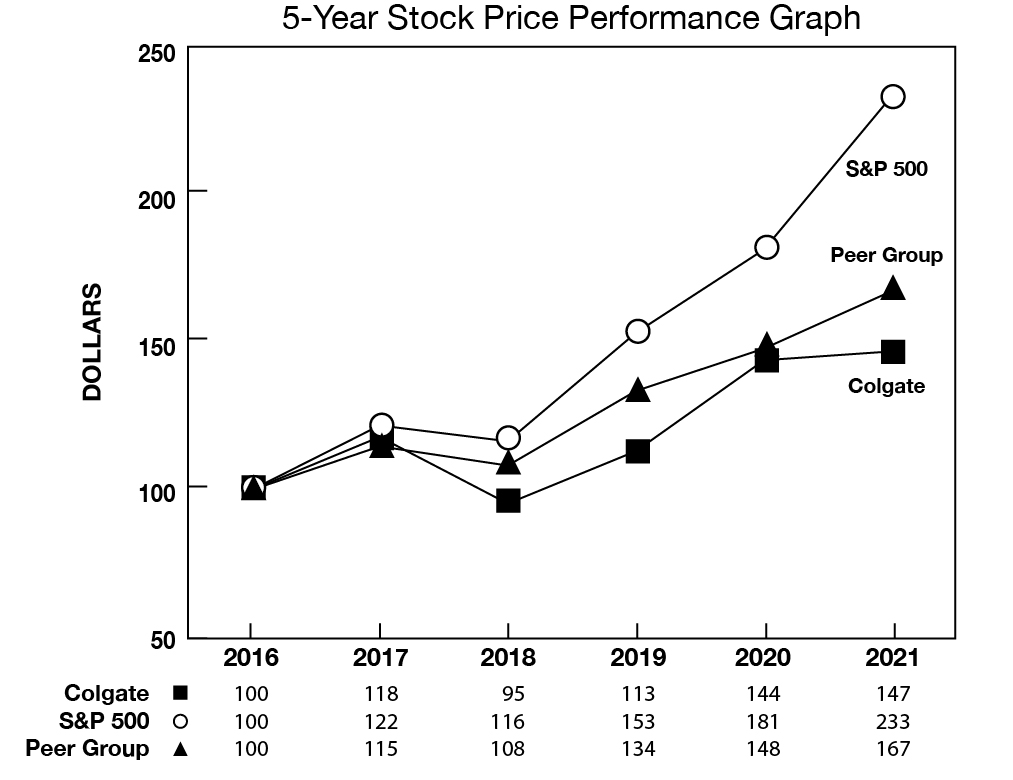
Previous: Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES