 filings.tools
Capital One Financial 10-K 2022-12-31
Filed 2023-02-24. 22 sections, 1082K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2022
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the transition period from to
Commission File No. 001-13300
CAPITAL ONE FINANCIAL CORPORATION
(Exact name of registrant as specified in its charter)
| Delaware | 54-1719854 | ||||||||||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | ||||||||||
| 1680 Capital One Drive, | |||||||||||
| McLean, | Virginia | 22102 | |||||||||
| (Address of principal executive offices) | (Zip Code) |
Registrant’s telephone number, including area code: (703) 720-1000
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbol(s) | Name of Each Exchange on Which Registered | ||||||
| Common Stock (par value $.01 per share) | COF | New York Stock Exchange | ||||||
| Depositary Shares, Each Representing a 1/40th Interest in a Share of Fixed Rate Non-Cumulative Perpetual Preferred Stock, Series I | COF PRI | New York Stock Exchange | ||||||
| Depositary Shares, Each Representing a 1/40th Interest in a Share of Fixed Rate Non-Cumulative Perpetual Preferred Stock, Series J | COF PRJ | New York Stock Exchange | ||||||
| Depositary Shares, Each Representing a 1/40th Interest in a Share of Fixed Rate Non-Cumulative Perpetual Preferred Stock, Series K | COF PRK | New York Stock Exchange | ||||||
| Depositary Shares, Each Representing a 1/40th Interest in a Share of Fixed Rate Non-Cumulative Perpetual Preferred Stock, Series L | COF PRL | New York Stock Exchange | ||||||
| Depositary Shares, Each Representing a 1/40th Interest in a Share of Fixed Rate Non-Cumulative Perpetual Preferred Stock, Series N | COF PRN | New York Stock Exchange | ||||||
| 0.800% Senior Notes Due 2024 | COF24 | New York Stock Exchange | ||||||
| 1.650% Senior Notes Due 2029 | COF29 | New York Stock Exchange |
Securities registered pursuant to section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒ Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☒ | Accelerated filer | ☐ | |||||||||||||||||
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ | |||||||||||||||||
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C.7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements.☐
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b).☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☒
The aggregate market value of the voting and non-voting stock held by non-affiliates of the registrant as of the close of business on June 30, 2022 was approximately $39.6 billion. As of January 31, 2023, there were 381,079,743 shares of the registrant’s Common Stock outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
**1.**Portions of the Proxy Statement for the annual meeting of stockholders to be held on May 4, 2023, are incorporated by reference into Part III.
TABLE OF CONTENTS
| 1 | Capital One Financial Corporation (COF) |
| 2 | Capital One Financial Corporation (COF) |
INDEX OF MD&A AND SUPPLEMENTAL TABLES
| 3 | Capital One Financial Corporation (COF) |
PART I
Item 1. Business
| OVERVIEW |
General
Capital One Financial Corporation, a Delaware corporation established in 1994 and headquartered in McLean, Virginia, is a diversified financial services holding company with banking and non-banking subsidiaries. Capital One Financial Corporation and its subsidiaries (the “Company” or “Capital One”) offer a broad array of financial products and services to consumers, small businesses and commercial clients through digital channels, branch locations, cafés and other distribution channels.
As of December 31, 2022, Capital One Financial Corporation’s principal operating subsidiary was Capital One, National Association (“CONA”). On October 1, 2022, the Company completed the merger of Capital One Bank (USA), National Association (“COBNA”), with and into CONA, with CONA as the surviving entity (the “Bank Merger”). The Company is hereafter collectively referred to as “we,” “us” or “our.” References to the “Bank” shall mean and refer to (i) CONA from and after the Bank Merger and (ii) CONA and COBNA collectively prior to the Bank Merger.
References to “this Report” or our “2022 Form 10-K” or “2022 Annual Report” are to our Annual Report on Form 10-K for the fiscal year ended December 31, 2022. All references to 2022, 2021 and 2020, refer to our fiscal years ended, or the dates, as the context requires, December 31, 2022, December 31, 2021 and December 31, 2020, respectively. Certain business terms used in this document are defined in the “MD&A—Glossary and Acronyms” and should be read in conjunction with the Consolidated Financial Statements included in this Report.
We were the third largest issuer of Visa® (“Visa”) and MasterCard® (“MasterCard”) credit cards in the U.S. based on the outstanding balance of credit card loans as of December 31, 2022. In addition to credit cards, we also offer debit cards, bank lending, treasury management and depository services, auto loans and other consumer lending products in markets across the U.S. As one of the nation’s largest banks based on deposits as of December 31, 2022, we service banking customer accounts through digital channels and our network of branch locations, cafés, call centers and automated teller machines (“ATMs”).
We also offer products and services outside of the U.S. principally through Capital One (Europe) plc (“COEP”), an indirect subsidiary of CONA organized and located in the United Kingdom (“U.K.”), and through a branch of CONA in Canada. Both COEP and our Canadian branch of CONA have the authority to provide credit card loans.
Business Developments
We regularly explore and evaluate opportunities to acquire financial products and services as well as financial assets, including credit card and other loan portfolios, and enter into strategic partnerships as part of our growth strategy. We also explore opportunities to acquire technology companies and related assets to improve our information technology infrastructure and to deliver on our digital strategy. We may issue equity or debt to fund our acquisitions. In addition, we regularly consider the potential disposition of certain of our assets, branches, partnership agreements or lines of business.
| 4 | Capital One Financial Corporation (COF) |
Additional Information
Our common stock trades on the New York Stock Exchange (“NYSE”) under the symbol “COF” and is included in the Standard & Poor’s (“S&P”) 100 Index. We maintain a website at www.capitalone.com. Documents available under “Governance & Leadership” in the Investor Relations section of our website include:
-
our Certificate of Incorporation, Bylaws, Corporate Governance Guidelines, and Code of Conduct; and
-
charters for the Audit, Compensation, Governance and Nominating, and Risk Committees of the Board of Directors.
These documents also are available in print to any stockholder who requests a copy. We intend to disclose any future amendments to, or waivers from, our Code of Conduct on the website following the date of any such amendment or waiver.
In addition, we make available free of charge through our website all of our U.S. Securities and Exchange Commission (“SEC”) filings, including our Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K and amendments to those reports, as soon as reasonably practicable after electronically filing or furnishing such material to the SEC at www.sec.gov.
| 5 | Capital One Financial Corporation (COF) |
| OPERATIONS AND BUSINESS SEGMENTS |
Our consolidated total net revenues are derived primarily from lending to consumer and commercial customers net of funding costs associated with our deposits, long-term debt and other borrowings. We also earn non-interest income which primarily consists of interchange income, net of reward expenses, service charges and other customer-related fees. Our expenses primarily consist of the provision for credit losses, operating expenses, marketing expenses and income taxes.
Our principal operations are organized for management reporting purposes into three major business segments, which are defined primarily based on the products and services provided or the types of customers served: Credit Card, Consumer Banking and Commercial Banking. The operations of acquired businesses have been integrated into or managed as a part of our existing business segments. Certain activities that are not part of a segment, such as management of our corporate investment portfolio and asset/liability management by our centralized Corporate Treasury group, are included in the Other category. The Other category also includes unallocated corporate expenses that do not directly support the operations of the business segments or for which the business segments are not considered financially accountable in evaluating their performance, such as certain restructuring charges, as well as residual tax expense or benefit to arrive at the consolidated effective tax rate that is not assessed to our primary business segments.
-
Credit Card: Consists of our domestic consumer and small business card lending, and international card businesses in the United Kingdom and Canada.
-
Consumer Banking: Consists of our deposit gathering and lending activities for consumers and small businesses, and national auto lending.
-
Commercial Banking: Consists of our lending, deposit gathering, capital markets and treasury management services to commercial real estate and commercial and industrial customers. Our customers typically include companies with annual revenues between $20 million and $2 billion.
Customer usage and payment patterns, estimates of future expected credit losses, levels of marketing expense and operating efficiency all affect our profitability. In our Credit Card business, we generally experience fluctuations in purchase volume and the level of outstanding loan receivables from seasonal variances in consumer spending and payment patterns which, for example, have historically been the highest around the winter holiday season. Net charge-off rates for our credit card loan portfolio also have historically exhibited seasonal patterns as well and generally tend to be the highest in the first quarter of the year.
For additional information on our business segments, including the financial performance of each business, see “Part II—Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (“MD&A”)—Executive Summary,” “Part II—Item 7. MD&A—Business Segment Financial Performance” and “Part II—Item 8. Financial Statements and Supplementary Data—Note 17—Business Segments and Revenue from
Showing the first 8K of 74K characters. Open the full section
Item 1A. Risk Factors
The following discussion sets forth what management currently believes could be the material risks and uncertainties that could impact our businesses, results of operations and financial condition. The events and consequences discussed in these risk factors could, in circumstances we may not be able to accurately predict, recognize, or control, have a material adverse effect on our business, growth, reputation, prospects, financial condition, operating results, cash flows, liquidity, and stock price. These risk factors do not identify all risks that we face; our operations could also be affected by factors, events, or uncertainties that are not presently known to us or that we currently do not consider to present significant risks to our operations. In addition, the global economic and political climate may amplify many of these risks.
Summary of Risk Factors
The following is a summary of the Risk Factors disclosure in this Item 1A. This summary does not address all of the risks that we face. Additional discussion of the risks summarized in this risk factor summary, and other risks that we face, can be found below and should be carefully considered, together with other information in this Form 10-K and our other filings with the SEC, before making an investment decision regarding our securities.
-
Changes and instability in the macroeconomic environment, consumer confidence and customer behavior may adversely affect our business.
-
Fluctuations in market interest rates or volatility in the capital markets could adversely affect our business.
-
Our results of operations may be adversely affected by the effects of the COVID-19 pandemic.
| 21 | Capital One Financial Corporation (COF) |
-
We may experience increases or fluctuations in delinquencies and credit losses, inaccurate estimates and inadequate reserves.
-
We may not be able to maintain adequate capital or liquidity levels or may become subject to revised capital or liquidity requirements, which could have a negative impact on our financial results and our ability to return capital to our stockholders.
-
Limitations on our ability to receive dividends from our subsidiaries could affect our liquidity and ability to pay dividends and repurchase common stock.
-
We face risks related to our operational, technological and organizational infrastructure.
*•*A cyber-attack or other security incident, including one that results in the theft, loss, manipulation or misuse of information (including personal information), or the disabling of systems and access to information critical to business operations, may result in increased costs, reductions in revenue, reputational damage, legal exposure and business disruptions.
-
Our required compliance with applicable laws and regulations related to privacy, data protection and data security may increase our costs, reduce our revenue, increase our legal exposure and limit our ability to pursue business opportunities.
-
We face risks resulting from the extensive use of models and data.
-
Compliance with new and existing laws, regulations and regulatory expectations is costly and complex.
-
Our businesses are subject to the risk of increased litigation, government investigations and regulatory enforcement.
-
We face intense competition in all of our markets.
-
Our business, financial condition and results of operations may be adversely affected by merchants’ increasing focus on the fees charged by credit and debit card networks and by legislation and regulation impacting such fees.
-
If we are not able to invest successfully in and introduce digital and other technological developments across all our businesses, our financial performance may suffer.
-
We may fail to realize the anticipated benefits of our mergers, acquisitions and strategic partnerships.
-
Reputational risk and social factors may impact our results and damage our brand.
-
If we are not able to protect our intellectual property, our revenue and profitability could be negatively affected.
-
Our risk management strategies may not be fully effective in mitigating our risk exposures in all market environments or against all types of risk.
-
The transition away from London Interbank Offered Rate may adversely affect our business.
-
Our business could be negatively affected if we are unable to attract, retain and motivate key senior leaders and skilled employees.
-
We face risks from catastrophic events.
-
Climate change manifesting as physical or transition risks could adversely affect our businesses, operations and customers.
-
We face risks from the use of or changes to assumptions or estimates in our financial statements.
-
The soundness of other financial institutions and other third parties could adversely affect us.
| 22 | Capital One Financial Corporation (COF) |
General Economic and Market Risks
Changes and instability in the macroeconomic environment, consumer confidence and customer behavior may adversely affect our business.
We offer a broad array of financial products and services to consumers, small businesses and commercial clients. A prolonged period of economic volatility, slow growth, or a significant deterioration in economic conditions, in the U.S., Canada or the U.K., could have a material adverse effect on our financial condition and results of operations as customers default on their loans, maintain lower deposit levels or, in the case of credit card accounts, carry lower balances and reduce credit card purchase activity.
Some of the risks we face in connection with adverse changes and instability in the macroeconomic environment and changes in consumer confidence levels and behavior, include the following:
-
Monetary policies and actions taken by the Federal Reserve and other central banks or governmental authorities;
-
Economic deterioration due to escalation of military hostilities or other geopolitical instabilities;
-
Changes in payment patterns, increases or fluctuations in delinquencies and default rates, decreased consumer spending, inflation, fluctuation in interest rates, lower demand for credit and shifts in consumer behavior, including deposits and payments;
-
Increases in our charge-off rate caused by bankruptcies and reduced ability to recover debt that we have previously charged-off;
-
Recent changes in usage of commercial real estate, which may have a sustained negative impact on utilization rates and values;
-
Decreased reliability of the process and models, including those we use to estimate our allowance for credit losses, particularly if unexpected variations in key inputs and assumptions cause actual losses to diverge from the projections of our models and our estimates become increasingly subject to management’s judgment. See “We face risks resulting from the extensive use of models and data.”
The U.K. and the EU agreed to a free trade deal at the end of 2020 relating to the U.K.’s exit from the EU. Although this deal has provided greater near-term stability, there is still some degree of uncertainty as to the relationship between the U.K and the EU, which may increase volatility in the regional and global financial markets. In addition, the global economy, including economic conditions in the U.K., has been negatively impacted by the war between Russia and Ukraine. Continued escalation of geopolitical tensions related to the war, including increased trade barriers or restrictions on global trade, could further deteriorate international economic conditions. We continue to consider and monitor the potential impacts of the relationship between the U.K. and EU, as well as the war between Russia and Ukraine.
**Fluctuations in market interest rate
Showing the first 8K of 104K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
Our corporate and banking real estate portfolio consists of approximately 11.9 million square feet of owned or leased office and retail space, which is used to support our business. Of this overall portfolio, approximately 9.9 million square feet of space is dedicated for various corporate office uses and approximately 2.0 million square feet of space is for bank branches and cafés.
Our 9.9 million square feet of corporate office space consists of approximately 6.0 million square feet of owned space and 3.9 million square feet of leased space. We maintain corporate office space primarily in Virginia, Texas and New York, including our headquarters located in McLean, Virginia.
Our 2.0 million square feet for bank branches and cafés is located primarily across New York, Louisiana, Texas, Maryland, and Virginia and consists of approximately 1.3 million square feet of leased space and 0.7 million square feet of owned space. See “Part II—Item 8. Financial Statements and Supplementary Data—Note 7—Premises, Equipment and Leases” for information about our premises.
Item 3. Legal Proceedings
The information required by Item 103 of Regulation S-K is included in “Part II—Item 8. Financial Statements and Supplementary Data —Note 18—Commitments, Contingencies, Guarantees and Others.”
Item 4. Mine Safety Disclosures
Not applicable.
| 40 | Capital One Financial Corporation (COF) |
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Market Information
Our common stock is listed on the NYSE and is traded under the symbol “COF.” As of January 31, 2023, there were 8,963 holders of record of our common stock.
Securities Authorized for Issuance Under Equity Compensation Plans
Information relating to compensation plans under which our equity securities are authorized for issuance is presented in this Report under “Part III—Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.”
| 41 | Capital One Financial Corporation (COF) |
Common Stock Performance Graph
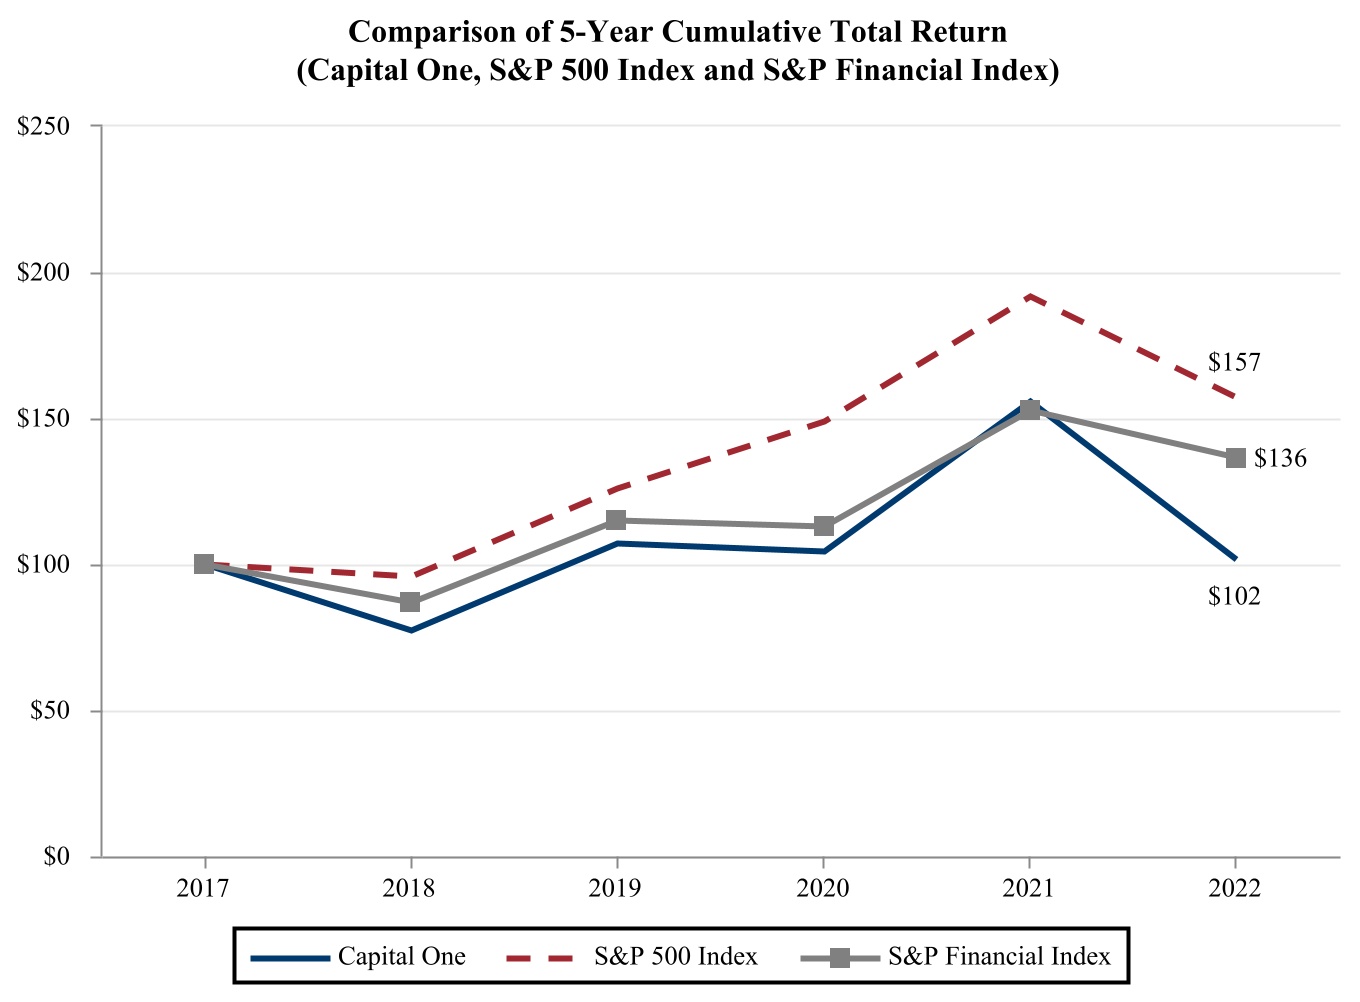
The following graph shows the cumulative total stockholder return on our common stock compared to an overall stock market index, the S&P Composite 500 Stock Index (“S&P 500 Index”), and a published industry index, the S&P Financial Composite Index (“S&P Financial Index”), over the five-year period commencing December 31, 2017 and ended December 31, 2022. The stock performance graph assumes that $100 was invested in our common stock and each index and that all dividends were reinvested. The stock price performance on the graph below is not necessarily indicative of future performance.
| December 31, | ||||||||||||||||||||||||||||||||||||||
| 2017 | 2018 | 2019 | 2020 | 2021 | 2022 | |||||||||||||||||||||||||||||||||
| Capital One | $ | 100.00 | $ | 77.22 | $ | 107.05 | $ | 104.19 | $ | 155.53 | $ | 101.65 | ||||||||||||||||||||||||||
| S&P 500 Index | 100.00 | 95.62 | 125.72 | 148.85 | 191.58 | 156.88 | ||||||||||||||||||||||||||||||||
| S&P Financial Index | 100.00 | 86.97 | 114.91 | 112.96 | 152.54 | 136.48 | ||||||||||||||||||||||||||||||||
| 42 | Capital One Financial Corporation (COF) |
Recent Sales of Unregistered Securities
We did not have any sales of unregistered equity securities in 2022.
Issuer Purchases of Equity Securities
The following table presents information related to repurchases of shares of our common stock for each calendar month in the fourth quarter of 2022. Commission costs are excluded from the amounts presented below.
| Total Number of Shares Purchased**(1)** | Average Price per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans**(1)** | Maximum Amount That May Yet be Purchased Under the Plan or Program**(1)** (in millions) | |||||||||||||||||||||||
| October | 509,142 | $ | 98.20 | 509,142 | $ | 5,286 | ||||||||||||||||||||
| November | 502,840 | 105.07 | 442,263 | 5,240 | ||||||||||||||||||||||
| December | 567,076 | 94.50 | 567,076 | 5,186 | ||||||||||||||||||||||
| Total | 1,579,058 | 99.06 | 1,518,481 |
(1) In January 2022, our Board of Directors authorized the repurchase of up to $5.0 billion of shares of our common stock. In April 2022, our Board of Directors authorized the repurchase of up to an additional $5.0 billion of shares of our common stock. There were 60,577 shares withheld in November to cover taxes on restricted stock awards whose restrictions have lapsed. See “Part II—Item 7. MD&A—Capital Management—Dividend Policy and Stock Purchases” for more information.
| 43 | Capital One Financial Corporation (COF) |
Item 6. [Reserved]
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (“MD&A”)
This discussion contains forward-looking statements that are based upon management’s current expectations and are subject to significant uncertainties and changes in circumstances. Please review “Part I—Item 1.Business—Forward-Looking Statements” for more information on the forward-looking statements in this Report. All statements that address operating performance, events or developments that we expect or anticipate will occur in the future are forward-looking statements. Our actual results may differ materially from those included in these forward-looking statements due to a variety of factors including, but not limited to, those described in “Part I—Item 1A. Risk Factors” in this Report. Unless otherwise specified, references to notes to our consolidated financial statements refer to the notes to our consolidated financial statements as of December 31, 2022 included in this Report.
Management monitors a variety of key indicators to evaluate our business results and financial condition. The following MD&A is intended to provide the reader with an understanding of our results of operations and financial condition, including capital and liquidity management, by focusing on changes from year to year in certain key measures used by management to evaluate performance, such as profitability, growth and credit quality metrics. MD&A is provided as a supplement to, and should be read in conjunction with, our audited consolidated financial statements as of and for the year ended December 31, 2022 and accompanying notes. MD&A is organized in the following sections:
| • Executive Summary | • Capital Management | |||||||
| • Consolidated Results of Operations | • Risk Management | |||||||
| • Consolidated Balance Sheets Analysis | • Credit Risk Profile | |||||||
| • Off-Balance Sheet Arrangements | • Liquidity Risk Profile | |||||||
| • Business Segment Financial Performance | • Market Risk Profile | |||||||
| • Critical Accounting Policies and Estimates | • Supplemental Tables | |||||||
| • Accounting Changes and Developments | • Glossary and Acronyms |
| 44 | Capital One Financial Corporation (COF) |
Selected Financial Data
The following table presents selected consolidated financial data and performance metrics for the three-year period ended December 31, 2022, 2021 and 2020. We also provide selected key metrics we use in evaluating our performance, including certain metrics that are computed using non-GAAP measures. We consider these metrics to be key financial measures that management uses in assessing our operating performance, capital adequacy and the level of returns generated. We believe these non-GAAP metrics provide useful insight to investors and users of our financial information as they provide an alternate measurement of our performance and assist in assessing our capital adequacy and the level of return generated. These non-GAAP measures should not be viewed as a substitute for reported results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP measures that may be presented by other companies.
Three-Year Summary of Selected Financial Data
| (Dollars in millions, except per share data and as noted) | 2022 | 2021 | 2020 | 2022 vs. 2021 | 2021 vs. 2020 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Income statement | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest income | $ | 31,237 | $ | 25,769 | $ | 26,033 | 21% | (1)% | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest expense | 4,123 | 1,598 | 3,120 | 158 | (49) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 27,114 | $ | 24,171 | $ | 22,913 | 12 | 5 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest income | 7,136 | 6,264 | 5,610 | 14 | 12 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total net revenue | 34,250 | 30,435 | 28,523 | 13 | 7 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Provision (benefit) for credit losses | 5,847 | (1,944) | 10,264 | ** | ** | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest expense: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Marketing | 4,017 | 2,871 | 1,610 | 40 | 78 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Operating expense | 15,146 | 13,699 | 13,446 | 11 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total non-interest expense | 19,163 | 16,570 | 15,056 | 16 | 10 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Income from continuing operations before income taxes | 9,240 | 15,809 | 3,203 | (42) | ** | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Income tax provision | 1,880 | 3,415 | 486 | (45) | ** | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Income from continuing operations, net of tax | 7,360 | 12,394 | 2,717 | (41) | ** | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Income (loss) from discontinued operations, net of tax |
Showing the first 8K of 341K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures about Market Risk
For a discussion of the quantitative and qualitative disclosures about market risk, see “Part II—Item 7. MD&A—Market Risk Profile.”
| 111 | Capital One Financial Corporation (COF) |
| 112 | Capital One Financial Corporation (COF) |
MANAGEMENT’S REPORT ON INTERNAL CONTROL OVER FINANCIAL REPORTING
The management of Capital One Financial Corporation (the “Company” or “Capital One”) is responsible for establishing and maintaining adequate internal control over financial reporting and for the assessment of the effectiveness of internal control over financial reporting. Internal control over financial reporting is a process designed by, or under the supervision of, the Company’s principal executive and principal financial officers, or persons performing similar functions, and effected by the Company’s Board of Directors, management and other personnel, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external reporting purposes in accordance with U.S. generally accepted accounting principles.
Capital One’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the Company’s assets; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that the Company’s receipts and expenditures are being made only in accordance with authorizations of the Company’s management and directors; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use or disposition of the Company’s assets that could have a material effect on its financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Management conducted an assessment of the effectiveness
Showing the first 8K of 485K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
Overview
We are required under applicable laws and regulations to maintain controls and procedures, which include disclosure controls and procedures as well as internal control over financial reporting, as further described below.
(a) Disclosure Controls and Procedures
Disclosure controls and procedures refer to controls and other procedures designed to provide reasonable assurance that information required to be disclosed in our financial reports is recorded, processed, summarized and reported within the time periods specified by SEC rules and forms and that such information is accumulated and communicated to management, including our Chief Executive Officer and Chief Financial Officer, as appropriate, to allow timely decisions regarding our required disclosure. In designing and evaluating our disclosure controls and procedures, we recognize that any controls and procedures, no matter how well designed and operated, can provide only reasonable assurance of achieving the desired control objectives, and we must apply judgment in evaluating and implementing possible controls and procedures.
Evaluation of Disclosure Controls and Procedures
As required by Rule 13a-15 of the Securities Exchange Act of 1934 (“Exchange Act”), our management, including the Chief Executive Officer and Chief Financial Officer, conducted an evaluation of the effectiveness of our disclosure controls and procedures (as that term is defined in Rules 13a-15(e) and 15d-15(e) of the Exchange Act) as of December 31, 2022, the end of the period covered by this Annual Report on Form 10-K. Based upon that evaluation, the Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures were effective as of December 31, 2022, at a reasonable level of assurance, in recording, processing, summarizing and reporting information required to be disclosed within the time periods specified by the SEC rules and forms.
(b) Changes in Internal Control Over Financial Reporting
We regularly review our disclosure controls and procedures and make changes intended to ensure the quality of our financial reporting. There have been no changes in internal control over financial reporting that occurred in the fourth quarter of 2022 which have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
(c) Management’s Report on Internal Control Over Financial Reporting
Management’s Report on Internal Control Over Financial Reporting is included in “Part II—Item 8. Financial Statements and Supplementary Data” and is incorporated herein by reference. The Report of Independent Registered Public Accounting Firm on Internal Control Over Financial Reporting also is included in “Part II—Item 8. Financial Statements and Supplementary Data” and incorporated herein by reference.
Item 9B. Other Information
None.
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
Not applicable.
| 207 | Capital One Financial Corporation (COF) |
PART III
Item 10. Directors, Executive Officers and Corporate Governance
The information required by Item 10 will be included in our Proxy Statement for the 2023 Annual Stockholder Meeting (“Proxy Statement”) under the heading “Election of Directors,” “Executive Officers,” “Process for Stockholder Recommendations of Director Candidates,” “Board Committees,” and “Delinquent Section 16(a) Reports,” and is incorporated herein by reference. The Proxy Statement will be filed with the Securities and Exchange Commission pursuant to Regulation 14A within 120 days of the end of our 2022 fiscal year. In addition, please see “Part I—Item 1. Business—Overview.”
Item 11. Executive Compensation
The information required by Item 11 will be included in the Proxy Statement under the headings “Director Compensation,” “Compensation Discussion and Analysis,” “Named Executive Officer Compensation” and “Compensation Committee Report,” and is incorporated herein by reference.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information required by Item 12 will be included in the Proxy Statement under the headings “Security Ownership” and “Equity Compensation Plans,” and is incorporated herein by reference.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information required by Item 13 will be included in the Proxy Statement under the headings “Related Person Transactions” and “Director Independence,” and is incorporated herein by reference.
Item 14. Principal Accountant Fees and Services
The information required by Item 14 will be included in the Proxy Statement under the heading “Ratification of Selection of Our Independent Registered Public Accounting Firm,” and is incorporated herein by reference.
| 208 | Capital One Financial Corporation (COF) |
PART IV
Item 15. Exhibits and Financial Statement Schedules
(a) Financial Statement Schedules
The following documents are filed as part of this Annual Report in Part II, Item 8 and are incorporated herein by reference.
(1) Management’s Report on Internal Control Over Financial Reporting
Report of Independent Registered Public Accounting Firm on Internal Control Over Financial Reporting
Report of Independent Registered Public Accounting Firm on the Consolidated Financial Statements
Consolidated Financial Statements:
Consolidated Statements of Income for the years ended December 31, 2022, 2021 and 2020
Consolidated Statements of Comprehensive Income for the years ended December 31, 2022, 2021 and 2020
Consolidated Balance Sheets as of December 31, 2022 and 2021
Consolidated Statements of Changes in Stockholders’ Equity for the years ended December 31, 2022, 2021 and 2020
Consolidated Statements of Cash Flows for the years ended December 31, 2022, 2021 and 2020
Notes to Consolidated Financial Statements
(2) Schedules
None.
(b) Exhibits
An index to exhibits has been filed as part of this Report and is incorporated herein by reference.
Item 16. Form 10-K Summary
Not applicable.
| 209 | Capital One Financial Corporation (COF) |
ANNUAL REPORT ON FORM 10-K
DATED DECEMBER 31, 2022
Commission File No. 001-13300
The following exhibits are incorporated by reference or filed herewith. References to (i) the “2002 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2002, filed on March 17, 2003; (ii) the “2003 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2003, filed on March 5, 2004; (iii) the “2011 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2011, filed on February 28, 2012; (iv) the “2012 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2012, filed on February 28, 2013; (v) the “2013 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2013, filed on February 27, 2014; (vi) the “2014 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2014, filed on February 24, 2015; (vii) the “2015 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2015, filed on February 25, 2016; (viii) the “2016 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2016, filed on February 23, 2017; (ix) the “2018 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2018, filed on February 20, 2019; (x) the “2019 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2019, filed on February 20, 2020; (xi) the “2020 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2020, filed on February 25, 2021; and (xii) the “2021 Form 10-K” are to the Company’s Annual Report on Form 10-K for the year ended December 31, 2021, filed on February 25, 2022.
| 210 | Capital One Financial Corporation (COF) |
| 211 | Capital One Financial Corporation (COF) |
| 212 | Capital One Financial Corporation (COF) |
| 104 | The cover page of Capital One Financial Corporation’s Annual Report on Form 10-K for the year ended December 31, 2022, formatted in Inline XBRL (included within the Exhibit 101 attachments). |
| + | Represents a management contract or compensatory plan or arrangement. | ||||
| * | Indicates a document being filed with this Form 10-K. | ||||
| ** | Indicates a document being furnished with this Form 10-K. Information in this Form 10-K furnished herewith shall not be deemed to be “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of that Section. Such exhibit shall not be deemed incorporated by reference into any filing under the Securities Act of 1933, as amended, or the Securities Exchange Act of 1934. |
| 213 | Capital One Financial Corporation (COF) |
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| CAPITAL ONE FINANCIAL CORPORATION | ||||||||||||||
| Date: February 24, 2023 | By: | /s/ RICHARD D. FAIRBANK | ||||||||||||
| Richard D. Fairbank | ||||||||||||||
| Chair and Chief Executive Officer |
| 214 | Capital One Financial Corporation (COF) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Signature | Title | Date | ||||||||||||
| /s/ RICHARD D. FAIRBANK | Chair and Chief Executive Officer | February 24, 2023 | ||||||||||||
| Richard D. Fairbank | (Principal Executive Officer) | |||||||||||||
| /s/ ANDREW M. YOUNG | Chief Financial Officer | February 24, 2023 | ||||||||||||
| Andrew M. Young | (Principal Financial Officer) | |||||||||||||
| /s/ TIMOTHY P. GOLDEN | Controller | February 24, 2023 | ||||||||||||
| Timothy P. Golden | (Principal Accounting Officer) | |||||||||||||
| /s/ IME ARCHIBONG | Director | February 24, 2023 | ||||||||||||
| Ime Archibong | ||||||||||||||
| /s/ CHRISTINE DETRICK | Director | February 24, 2023 | ||||||||||||
| Christine Detrick | ||||||||||||||
| /s/ ANN FRITZ HACKETT | Director | February 24, 2023 | ||||||||||||
| Ann Fritz Hackett | ||||||||||||||
| /s/ PETER THOMAS KILLALEA | Director | February 24, 2023 | ||||||||||||
| Peter Thomas Killalea | ||||||||||||||
| /s/ C.P.A.J. (ELI) LEENAARS | Director | February 24, 2023 | ||||||||||||
| C.P.A.J. (Eli) Leenaars | ||||||||||||||
| /s/ FRANÇOIS LOCOH-DONOU | Director | February 24, 2023 | ||||||||||||
| François Locoh-Donou | ||||||||||||||
| /s/ PETER E. RASKIND | Director | February 24, 2023 | ||||||||||||
| Peter E. Raskind | ||||||||||||||
| /s/ EILEEN SERRA | Director | February 24, 2023 | ||||||||||||
| Eileen Serra | ||||||||||||||
| /s/ MAYO A. SHATTUCK III | Director | February 24, 2023 | ||||||||||||
| Mayo A. Shattuck III | ||||||||||||||
| /s/ BRADFORD H. WARNER | Director | February 24, 2023 | ||||||||||||
| Bradford H. Warner | ||||||||||||||
| /s/ CRAIG WILLIAMS | Director | February 24, 2023 | ||||||||||||
| Craig Williams |
| 215 | Capital One Financial Corporation (COF) |