 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND
131K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND
MANAGEMENT’S DISCUSSION AND
ANALYSIS OF FINANCIAL CONDITION AND
RESULTS OF OPERATIONS
Management’s
Discussion and Analysis is the company’s analysis of its financial performance and of
significant trends that may affect future performance.
It should be read in conjunction with the financial
statements and notes, and supplemental oil
and gas disclosures included elsewhere in this report.
It contains
forward-looking statements including, without limitation, statements
relating to the company’s
plans,
strategies, objectives, expectations and intentions
that are made pursuant to the “safe harbor” provisions of
the Private Securities Litigation Reform Act of
The words “anticipate,” “estimate,” “believe,”
“budget,” “continue,” “could,” “intend,” “may,” “plan,” “potential,”
“predict,” “seek,” “should,” “will,”
“would,” “expect,” “objective,” “projection,” “forecast,” “goal,” “guidance,”
“outlook,” “effort,” “target”
and similar expressions identify forward-looking statements.
The company does not undertake to update,
revise or correct any of the forward-looking information unless required to do so under the federal securities
laws.
Readers are cautioned that such forward-looking statements should be read in conjunction with
the
company’s
disclosures under the heading: “CAUTIONARY STATEMENT FOR THE PURPOSES OF THE
‘SAFE HARBOR’ PROVISIONS OF THE PRIVATE SECURITIES LITIGATION REFORM ACT OF 1995,”
beginning on page
The terms “earnings” and “loss” as used in Management’s Discussion and Analysis refer to net income (loss)
attributable to ConocoPhillips.
BUSINESS ENVIRONMENT AND EXECUTIVE
OVERVIEW
ConocoPhillips is an independent E&P company
with operations and activities in 17 countries.
Our diverse,
low cost of supply portfolio includes resource-rich
unconventional plays in North America;
conventional
assets in North America, Europe, Asia and
Australia; LNG developments; oil sands in
Canada; and an
inventory of global conventional and unconventional
exploration prospects.
Headquartered in Houston, Texas,
at December 31, 2019, we employed approximately
10,400 people worldwide and had total
assets of
$71 billion.
Overview
Global oil prices continued
to be volatile in 2019.
Optimism about worldwide economic growth during
the
first quarter turned to pessimism in the second quarter
as trade disputes dampened growth forecasts.
At the
end of the second quarter, geopolitical tensions in the Middle East,
threatening the safe passage of supertankers
carrying crude oil through the Persian Gulf, revived
oil prices.
Worldwide economic growth concerns returned
in the third quarter to depress prices, only to be
reversed again by geopolitical tensions in the
Middle East, as
oilfield infrastructure in Saudi Arabia was attacked,
temporarily disrupting approximately
five percent of the
world’s oil supply.
Production was restored relatively quickly, and prices settled in the fourth
quarter.
Brent
crude averaged $64
per barrel in 2019, down nine percent
from the prior year.
Our business strategy
anticipates prices will remain volatile and is designed
to be resilient in lower price environments, while
retaining upside during periods of higher prices.
Portfolio diversification and optimization, a strong
balance
sheet and disciplined capital investment have positioned
our company to navigate through volatile energy
cycles.
Our value proposition principles, namely, to focus on financial returns, maintain
a strong balance sheet, deliver
compelling returns of capital,
and expand cash flow through disciplined capital
investments, are being
executed in accordance with our priorities for
allocating cash flows from the business.
These priorities are:
invest capital to sustain
production and pay our existing dividend;
grow our existing dividend; maintain debt at
a level we believe is sufficient to maintain a strong investment
grade credit rating through price cycles; allocate
greater than 30 percent of our net cash provided
by operating activities to share repurchases
and dividends;
and, invest capital in a disciplined fashion to grow
our cash from operations.
We believe our commitment to
our value proposition, as evidenced by the results
discussed below, positions us for success in an environment
of price uncertainty and ongoing volatility.
In 2019, we successfully delivered on our priorities.
We achieved production growth of five percent on a total
BOE basis compared with the prior year, with higher value oil
volumes growing eight percent.
Cash provided
by operating activities of $11.1 billion exceeded capital expenditures
and
investments of $6.6 billion.
After
repurchasing $3.5 billion of our common stock
and paying $1.5 billion of dividends to shareholders,
we ended
the year with cash, cash equivalents and restricted
cash totaling $5.4 billion and $3.0 billion
of short-term
investments.
In October, we announced an increase to our quarterly dividend
of 38 percent to $0.42 per share
and announced planned 2020 share buybacks of
$3 billion.
In February 2020, we announced 2020 operating
plan capital of $6.5 billion to $6.7 billion.
The plan includes
funding for ongoing development drilling
programs, major projects, exploration and appraisal
activities, as
well as base maintenance.
Capital spend is expected to be higher in the first
quarter largely from winter
construction and exploration and appraisal drilling
in Alaska.
This guidance does not include capital for
acquisitions.
Key Operating and Financial Summary
Significant items
during 2019 included the following:
●
Net cash provided by operating activities was $11.1 billion and exceeded capital
expenditures and
investments of $6.6 billion.
●
Repurchased $3.5 billion of shares and paid $1.5 billion in dividends,
representing 45 percent of net cash
provided by operating activities.
●
Increased the quarterly dividend by 38 percent to $0.42 per share
.
●
Achieved 100 percent total reserve replacement and 117
percent organic replacement.
●
Underlying production, which excludes Libya and the net volume impact
from closed dispositions and
acquisitions of 51 MBOED in 2019 and 47 MBOED in 2018, grew 5 percent
.
●
Increased production from the Lower 48 Big 3 unconventionals—Eagle
Ford, Bakken and Permian
Unconventional—by 22 percent year-over-year.
●
Executed successful Alaska appraisal program; conducted appraisal drilling
and commissioned
infrastructure at Montney in Canada.
●
Completed Lower 48, Alaska and Argentina acquisitions;
awarded a 20-year extension of the Indonesia
Corridor Block PSC, with new terms.
●
Generated $3 billion in disposition proceeds; entered into agreements to
sell Australia-West
assets for $1.4
billion and Niobrara for $0.4 billion, both subject to customary closing
adjustments, as well as regulatory
and other approvals.
●
Reduced asset retirement obligations and accrued environmental costs by $2.3
billion, primarily due to
closed and pending dispositions.
●
Ended the year with cash, cash equivalents and restricted cash totaling $
5.4 billion and short-term
investments of $3.0 billion.
●
Recognized a $296 million after-tax impairment related
to the sale of our Niobrara interests in the Lower
48 segment.
●
Discontinued exploration activities in the Central Louisiana Austin Chalk trend
and recognized $197
million after-tax in leasehold impairment and dry hole expenses.
Operationally, we remain focused on safely executing our operating plan and maintaining
capital and cost
discipline.
Production of 1,348 MBOED increased 5 percent
or 65 MBOED in 2019 compared with 2018.
Production, excluding Libya, of 1,305 MBOED
increased 5 percent or 63 MBOED.
Underlying production,
which excludes Libya and the net volume impact
from closed dispositions and acquisitions
of 51 MBOED in
2019 and 47 MBOED in 2018, is used to measure
our ability to grow production organically.
Our underlying
production grew 5 percent in 2019 to 1,254 MBOED
from 1,195 MBOED in 2018.
On September 30, 2019, we completed the sale of
two ConocoPhillips U.K. subsidiaries to
Chrysaor E&P
Limited for proceeds of $2.2 billion after interest
and customary adjustments.
In 2019, we recorded a $1.7
billion before-tax and $2.1 billion after-tax
gain associated with this transaction.
Together the subsidiaries
sold our indirectly held exploration and production
assets in the U.K., including $1.8 billion
of ARO.
Annualized average production associated with the
U.K. assets sold was 50 MBOED in 2019.
Reserves
associated with the U.K. assets sold were 84 MMBOE
at the time of disposition.
Results of operations for the
U.K. are reported within our Europe and North
Africa segment.
In the second quarter of 2019, we completed the sale
of our 30 percent interest in the Greater Sunrise
Fields to
the government of Timor-Leste for $350 million and recognized
an after-tax gain of $52 million.
No
production or reserve impacts were associated
with the sale.
The Greater Sunrise Fields were included in
our
Asia Pacific and Middle East segment.
In October 2019, we entered into an agreement to sell
the subsidiaries that hold our Australia-West assets and
operations to Santos for $1.39 billion, plus customary
adjustments, with an effective date of January 1, 2019.
In addition, we will receive a payment of $75 million
upon final investment decision of the Barossa
development project.
These subsidiaries hold our 37.5 percent interest
in the Barossa Project and Caldita
Field, our 56.9 percent interest in the Darwin LNG
Facility and Bayu-Undan Field, our 40 percent
interest in
the Greater Poseidon Fields, and our 50 percent
interest in the Athena Field.
This transaction is expected to be
completed in the first quarter of 2020, subject to regulatory
approvals and the satisfaction of other specific
conditions precedent.
In 2019, production associated with the Australia-West assets to be sold was 48
MBOED.
Year
-end 2019
reserves associated with these assets were 17
MMBOE.
We will retain our 37.5
percent interest in the Australia Pacific LNG project
and operatorship of that project’s LNG facility.
Results
of operations for the subsidiaries to be sold are reported
within our Asia Pacific and Middle East segment.
In the fourth quarter of 2019, we signed an agreement
to sell our interests in the Niobrara shale play
for $380
million, plus customary adjustments,
and overriding royalty interests in certain
future wells.
We recorded an
after-tax impairment
of $296 million in the fourth quarter of 2019 to reduce
the carrying value to fair value.
In
2019, production from Niobrara was 11 MBOED.
Year
-end 2019 reserves associated with the
Niobrara assets
to be sold were 14 MMBOE.
This transaction is subject to regulatory approval
and other conditions precedent
and is expected to close in the first quarter
of 2020.
The Niobrara results of operations are reported
within our
Lower 48 segment.
For more information regarding the accounting impacts
of these transactions, see Note 5—Asset Acquisitions
and Dispositions,
in the Notes to Consolidated Financial
Statements.
Business Environment
Brent crude oil prices averaged $64 per barrel in 2019,
ranging from a low of $53 per barrel in January
to a
high of almost $75 per barrel in April.
The energy industry has periodically experienced
this type of volatility
due to fluctuating supply-and-demand conditions
and such volatility may persist for the foreseeable
future.
Commodity prices are the most significant
factor impacting our profitability and related reinvestment
of
operating cash flows into our business.
Our strategy is to create value through price cycles
by delivering on
the foundational principles that underpin our value
proposition;
focus on financial returns through cash flow
expansion, maintain balance sheet strength and
deliver peer-leading distributions.
Operational and Financial Factors Affecting
Profitability
The focus areas we believe will drive our success
through the price cycles include:
●
Maintain a relentless focus on safety and environmental
stewardship.
Safety and environmental
stewardship, including the operating integrity
of our assets, remain our highest priorities,
and we are
committed to protecting the health and safety of
everyone who has a role in our operations
and the
communities in which we operate.
We strive to conduct our business with respect and care for both
the local and global environment and systematically
manage risk to drive sustainable business growth.
Demonstrating our commitment to sustainability
and environmental stewardship, on November 2017,
we announced our intention to target a 5 to 15 percent reduction
in our GHG emission
intensity by 2030.
In December 2018, we became a founding
member of the Climate Leadership
Council (CLC), an international policy institute
founded in collaboration with business and
environmental interests to develop a carbon dividend
plan.
Participation in the CLC provides another
opportunity for ongoing dialogue about carbon
pricing and framing the issues in alignment
with our
public policy principles.
We also belong to and fund Americans For Carbon Dividends, the education
and advocacy branch of the CLC.
In early 2019, we issued our first stand-alone
Climate-related Risk
Report and incorporated this into our website
during our annual Sustainability Report update.
Our
sustainability efforts continued through 2019 with a focus
on advancing our action plans for climate
change, biodiversity, water and human rights.
We are committed to building a learning organization
using human performance principles as we relentlessly
pursue improved HSE and operational
performance.
●
Focus on financial returns.
This is a core principle of our value proposition.
Our goal is to achieve
strong financial returns by exercising capital
discipline,
controlling our costs, and continually
optimizing our portfolio.
o
Maintain capital allocation discipline.
We participate in a commodity price-driven and
capital-intensive industry, with varying lead times from when an investment
decision is made
to the time an asset is operational and generates cash
flow.
As a result, we must invest
significant capital dollars to explore for new oil
and gas fields, develop newly discovered
fields, maintain existing fields, and construct pipelines
and LNG facilities.
We allocate
capital across a geographically diverse, low cost
of supply resource base, which combined
with legacy assets results in low production decline.
Cost of supply is the WTI equivalent
price that generates a 10 percent after-tax return
on a point-forward and fully burdened basis.
Fully burdened includes capital infrastructure,
foreign exchange, price related inflation and
G&A.
In setting our capital plans, we exercise a rigorous
approach that evaluates projects
using this cost of supply criteria, which should
lead to value maximization and cash flow
expansion using an optimized investment pace,
not production growth for growth’s sake.
Additional capital may be allocated toward growth,
but discipline will be maintained.
Our
cash allocation priorities call for the investment
of sufficient capital to sustain production and
pay the existing dividend.
In February 2020, we announced 2020 operating
plan capital of $6.5 billion to $6.7 billion.
The plan includes funding for ongoing development
drilling programs, major projects,
exploration and appraisal activities, as
well as base maintenance.
Capital spend is expected to
be higher in the first quarter largely from winter construction
and exploration and appraisal
drilling in Alaska.
This guidance does not include capital
for acquisitions.
o
Control costs and expenses.
Controlling operating and overhead costs,
without compromising
safety and environmental stewardship, is a high priority.
We monitor these costs using
various methodologies that are reported to senior management
monthly, on both an absolute-
dollar basis and a per-unit basis.
Managing operating and overhead costs is critical
to
maintaining a competitive position in our industry, particularly in a low commodity
price
environment.
The ability to control our operating and overhead
costs impacts our ability to
deliver strong cash from operations.
In 2019, our production and operating expenses
were
two percent higher than 2018, primarily due to costs
associated with higher production
volumes, which grew five percent during the same
period.
o
Optimize our portfolio.
We continue to optimize our asset portfolio to focus on low cost of
supply assets that support our strategy.
In 2019, we continued to dispose of or market
certain
non-core assets, including the U.K., Australia-West and our Niobrara assets
in the Lower 48.
Additions to the portfolio were made in the Lower
48 with bolt-on interests and acreage
acquisitions,
in Alaska with the Nuna discovery acreage acquisition,
and internationally with
entrance into Argentina’s Neuquén and Austral Basins.
We will continue to evaluate our
assets to determine whether they compete for capital
within our portfolio and will optimize
the portfolio as necessary, directing capital towards the most competitive investments.
●
Maintain balance sheet strength.
We believe balance sheet strength is critical in a cyclical business
such as ours.
Our strong operating performance buffered by a solid
balance sheet enables us to deliver
on our priorities through the price cycles.
Our priorities include execution of our development
plans,
maintaining a growing dividend,
and repurchasing shares on a dollar cost
average basis.
●
Return value to shareholders.
We believe in delivering value to our shareholders via a growing,
sustainable dividend supplemented by share repurchases.
In 2019, we paid dividends on our common
stock of approximately $1.5 billion and repurchased
$3.5 billion of our common stock.
Combined,
our dividend and repurchases represented 45 percent
of our net cash provided by operating
activities.
Since we initiated our current share repurchase
program in late 2016, we have repurchased $9.6
billion
of shares.
Additionally, as of December 31, 2019, $5.4 billion of repurchase authority
remained of the
$15 billion share repurchase program our Board
of Directors had authorized.
In February 2020, we
announced that the Board of Directors approved
an increase to our repurchase authorization
from $15
billion to $25 billion, to support our plan for future
share repurchases.
Whether we undertake these
additional repurchases is ultimately subject to numerous
considerations, including market conditions
and other factors.
See Risk Factors “Our ability to declare and
pay dividends and repurchase shares is
subject to certain considerations.”
In October 2019, we announced that our Board
of Directors approved an increase to our quarterly
dividend of 38 percent to $0.42 per share.
●
Add to our proved reserve base.
We primarily add to our proved reserve base in three ways:
o
Successful exploration, exploitation and development
of new and existing fields.
o
Application of new technologies and processes
to improve recovery from existing fields.
o
Purchases of increased interests in existing
fields and bolt-on acquisitions.
Proved reserve estimates require economic production
based on historical 12-month, first-of-month,
average prices and current costs.
Therefore, our proved reserves generally increase
as prices rise and
decrease as prices decline.
Reserve replacement represents the net change in
proved reserves, net of
production, divided by our current year production,
as shown in our supplemental reserve table
disclosures.
In 2019, our reserve replacement, which included
a net decrease of 0.1 billion BOE from
sales and purchases, was 100 percent.
Increased crude oil reserves accounted for approximately
percent of the total change in reserves. Our organic reserve
replacement, which excludes the impact of
sales and purchases, was 117 percent in 2019.
Approximately 50 percent of organic reserve additions
were from Lower 48 unconventional assets.
The remaining additions were evenly distributed
across
the other operating segments.
In the five years ended December 31, 2019, our reserve
replacement was negative 34 percent,
reflecting the impact of asset dispositions and lower
prices during that period.
Our organic reserve
replacement during the five years ended December
31, 2019, which excludes a decrease of 2.0 billion
BOE related to sales and purchases, was 40 percent,
reflecting development activities as
well as lower
prices during that period.
Historically, our reserve replacement has varied considerably year to year contingent
upon the timing
of major projects which may have long lead times
between capital investment and production.
In the
last several years, more of our capital has been
allocated to short cycle time, onshore,
unconventional
plays.
Accordingly, we believe our recent success in replacing reserves can be viewed
on a trailing
three-year basis.
In the three years ended December 31, 2019, our reserve
replacement was 23 percent, reflecting the
impact of asset dispositions during that period.
Our organic reserve replacement during the three
years ended December 31, 2019, which excludes a
decrease of 1.8 billion BOE related to sales
and
purchases, was 143 percent, reflecting reserve
additions from development activities.
Access to additional resources may become increasingly
difficult as commodity prices can make
projects uneconomic or unattractive.
In addition, prohibition of direct investment
in some nations,
national fiscal terms, political instability, competition from national oil companies,
and lack of access
to high-potential areas due to environmental or other
regulation may negatively impact our
ability to
increase our reserve base.
As such, the timing and level at which we add
to our reserve base may, or
may not, allow us to replace our production
over subsequent years.
●
Apply technical capability.
We leverage our knowledge and technology to create value and safely
deliver on our plans.
Technical strength is part of our heritage and allows us to economically
convert
additional resources to reserves, achieve greater
operating efficiencies and reduce our environmental
impact.
Companywide, we continue to evaluate potential
solutions to leverage knowledge of
technological successes across our operations.
We have embraced the digital transformation and are using digital innovations to
work and operate
more efficiently.
Predictive analytics have been adopted in our operations
and planning process.
Artificial intelligence, machine learning and
deep learning are being used for seismic
advancements.
●
Attract, develop and retain a talented work force.
We strive to attract, develop and retain individuals
with the knowledge and skills to implement
our business strategy and who support our values
and
ethics.
We offer university internships across multiple disciplines to attract the best early career
talent.
We also recruit experienced hires to fill critical skills and maintain a broad range
of expertise
and experience.
We promote continued learning, development and technical training through
structured development programs designed to enhance
the technical and functional skills
of our
employees.
Other Factors Affecting Profitability
Other significant factors that can affect our profitability
include:
●
Energy commodity prices.
Our earnings and operating cash flows generally
correlate with industry
price levels for crude oil and natural gas.
Industry price levels are subject to factors external
to the
company and over which we have no control, including
but not limited to global economic health,
supply disruptions or fears thereof caused by civil
unrest or military conflicts, actions taken by
OPEC,
environmental laws, tax regulations, governmental
policies and weather-related disruptions.
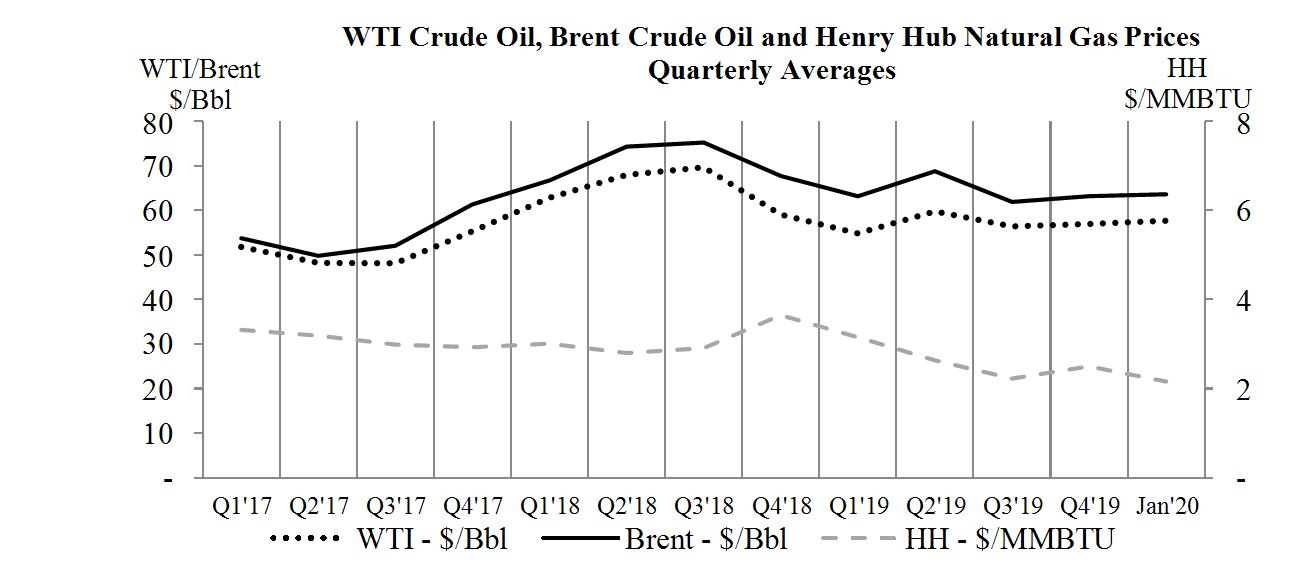
The
following graph depicts the average benchmark
prices for WTI crude oil, Brent crude oil
and U.S.
Henry Hub natural gas:
Brent crude oil prices averaged $64.30 per barrel
in 2019, a decrease of 9 percent compared
with
$71.04 per barrel in 2018.
Similarly, WTI crude oil prices decreased 12 percent from $64.92 per
barrel in 2018 to $57.02 per barrel in 2019.
Crude oil prices weakened year over year primarily
due to
ample global supplies and a decelerating global
economy.
Henry Hub natural gas price averages decreased
15 percent from $3.09 per MMBTU in 2018 to
$2.63
per MMBTU in 2019.
Natural gas prices weakened in 2019 versus the
prior year due to strong
production, while demand growth was dampened
by mild weather.
Our realized NGL prices decreased 34 percent from
$30.48 per barrel in 2018 to $20.09 per barrel
in
NGL prices weakened year over year due to
strong supply growth with only moderate demand
growth.
Our realized bitumen price increased 42 percent
from $22.29 per barrel in 2018 to $31.72 per
barrel in
Curtailment orders imposed by the Alberta
Government, which limited production from
the
province starting January 2019, provided strength
to the WCS differential to WTI at Hardisty.
We
continue to optimize bitumen price realizations
through the utilization of downstream transportation
solutions and implementation of alternate blend capability
which results in lower diluent costs.
Our worldwide annual average realized price decreased
9 percent from $53.88
per BOE in 2018 to
$48.78
per BOE in 2019 due to lower realized oil,
natural gas and NGL prices.
North America’s energy supply landscape has been transformed from one of resource
scarcity to one
of abundance.
In recent years, the use of hydraulic fracturing
and horizontal drilling in
unconventional formations has led to increased industry
actual and forecasted crude oil and natural
gas production in the U.S.
Although providing significant short-
and long-term growth opportunities
for our company, the increased abundance of crude oil and natural gas due to development
of
unconventional plays could also have adverse
financial implications to us, including: an extended
period of low commodity prices; production curtailments;
and delay of plans to develop areas such as
unconventional fields.
Should one or more of these events occur, our revenues would
be reduced, and
additional asset impairments might be possible.
●
Impairments.
We participate in a capital-intensive industry.
At times, our PP&E and investments
become impaired when, for example, commodity
prices decline significantly for long
periods of time,
our reserve estimates are revised downward, or a
decision to dispose of an asset leads to
a write-down
to its fair value.
We may also invest large amounts of money in exploration which, if exploratory
drilling proves unsuccessful, could lead to a material
impairment of leasehold values.
As we optimize
our assets in the future, it is reasonably possible
we may incur future losses upon sale or
impairment
charges to long-lived assets used in operations, investments
in nonconsolidated entities accounted for
under the equity method, and unproved properties.
A sustained decline in the current and long-term
outlook on gas price could affect the carrying value
of certain Lower 48 non-core gas assets and it
is
reasonably possible this could result in a future
non-cash impairment.
For additional information on
our impairments in 2019, 2018 and 2017, see
Note 9—Impairments, in the Notes to Consolidated
Financial Statements.
●
Effective tax rate.
Our operations are in countries with different tax rates
and fiscal structures.
Accordingly, even in a stable commodity price and fiscal/regulatory environment,
our overall
effective tax rate can vary significantly between periods
based on the “mix” of before-tax earnings
within our global operations.
●
Fiscal and regulatory environment.
Our operations can be affected by changing economic,
regulatory
and political environments in the various countries
in which we operate, including the U.S.
Civil
unrest or strained relationships with governments
may impact our operations or investments.
These
changing environments could negatively impact our
results of operations, and further changes to
increase government fiscal take could have a
negative impact on future operations.
Our management
carefully considers the fiscal and regulatory
environment when evaluating projects or
determining the
levels and locations of our activity.
Outlook
Full-year 2020 production is expected to be 1,230
MBOED to 1,270 MBOED, including the impact
of a recent
third-party pipeline outage on the Kebabangan
Field in Malaysia.
First-quarter 2020 production is expected to
be 1,240 MBOED to 1,280 MBOED.
Production guidance for 2020 excludes Libya.
Operating Segments
We manage our operations through six operating segments, which are primarily
defined by geographic region:
Alaska, Lower 48, Canada, Europe and North
Africa, Asia Pacific and Middle East, and Other
International.
Corporate and Other represents costs not directly
associated with an operating segment, such as most
interest
expense, premiums incurred on the early retirement
of debt, corporate overhead, certain technology
activities,
as well as licensing revenues.
Our key performance indicators, shown in the statistical
tables provided at the beginning of the operating
segment sections that follow, reflect results from our operations, including commodity
prices and production.
RESULTS OF OPERATIONS
This section of the Form 10-K
discusses year-to-year comparisons between 2019
and 2018.
For discussion of
year-to-year comparisons between 2018 and 2017, see
"Management's Discussion and Analysis
of Financial
Condition and Results of Operations" in Part II, Item
7 of our 2018 10-K.
Consolidated Results
A summary of the company’s net income (loss) attributable to ConocoPhillips
by business segment follows:
Millions of Dollars
Years Ended December 31
2019
2018
2017
Alaska
$
1,520
1,814
1,466
Lower 48
1,747
(2,371)
Canada
2,564
Europe and North Africa
2,724
1,866
Asia Pacific and Middle East
1,929
2,070
(1,098)
Other International
Corporate and Other
(1,667)
(2,136)
Net income (loss) attributable to ConocoPhillips
$
7,189
6,257
(855)
2019 vs. 2018
Net income attributable to ConocoPhillips
increased $932 million in 2019.
The increase was mainly due to:
●
A $2.1 billion after-tax gain associated with the
completion of the sale of two ConocoPhillips
U.K.
subsidiaries to Chrysaor E&P Limited.
●
An unrealized gain of $649 million after-tax
on our Cenovus Energy (CVE) common shares in 2019,
as compared to a $436 million after-tax unrealized
loss on those shares in 2018.
●
Higher crude oil sales volumes due to growth in the
Lower 48 unconventionals and from the
acquisition of incremental interests in operated
assets in Alaska during the second and
fourth quarters
of 2018.
●
The absence of premiums on early debt retirements
totaling $195 million after-tax.
●
A $164 million income tax benefit related to
deepwater incentive tax credits recognized for
Malaysia
Block G.
●
A $151
million income tax benefit related to the
revaluation of deferred tax assets following
finalization of rules relating to the 2017 Tax Cuts and Jobs Act.
These increases in net income were partly offset by:
●
Lower realized crude oil, natural gas and NGL
prices.
●
The absence of a $774 million after-tax gain on the
Clair disposition in the U.K.
●
A $296
million after-tax impairment related to
the sale of our Lower 48 Niobrara interests.
●
Lower equity in earnings of affiliates due to $120 million
of impairments to equity method
investments in our Lower 48 segment and a $118 million reduction
in equity earnings at QG3 in our
Asia Pacific and Middle East segment due to a deferred
tax adjustment.
●
Higher exploration expenses, primarily in
our Lower 48 segment due to $197 million after-tax
of
leasehold impairment and dry hole costs associated
with our decision to discontinue exploration
activities in the Central Louisiana Austin
Chalk trend.
Income Statement Analysis
2019 vs. 2018
Sales and other operating revenues decreased 11 percent in 2019,
mainly due to lower realized crude oil,
natural gas and NGL prices, partly offset by higher sales
volumes of crude oil in the Lower 48 and Alaska.
Equity in earnings of affiliates decreased $295 million
in 2019, primarily due to impairments of equity
method
investments in our Lower 48 segment totaling
$155 million.
Additionally, equity earnings decreased $118
million resultant from a deferred tax adjustment
at QG3,
reported in our Asia Pacific and Middle East segment.
For more information related to these items,
see Note 3—Variable Interest Entities and Note 5—Asset
Acquisitions and Dispositions, in the Notes to
Consolidated Financial Statements.
Gain on dispositions increased $903 million
in 2019, primarily due to a $1.7
billion before-tax gain associated
with the completion of the sale of two ConocoPhillips
U.K. subsidiaries to Chrysaor E&P Limited.
Partly
offsetting this increase, was the absence of a $715 million
before-tax gain on the sale of a ConocoPhillips
subsidiary to BP in 2018,
which held 16.5 percent of our 24 percent interest
in the BP-operated Clair Field in
the U.K.
For additional information related to these dispositions,
see Note 5—Asset Acquisitions and
Dispositions, in the Notes to Consolidated Financial
Statements.
Other income increased $1,185 million in 2019, primarily
due to an unrealized gain of $649 million before-tax
on our CVE common shares in 2019, and the absence
of a $437 million before-tax unrealized loss
on those
shares in 2018.
For discussion of our CVE shares, see Note
7—Investment in Cenovus Energy, in the Notes to
Consolidated Financial Statements.
Purchased commodities decreased 17 percent in
2019, primarily due to lower natural gas
and crude oil prices.
Selling, general and administrative expenses increased
$155 million in 2019, primarily due to higher
costs
associated with compensation and benefits,
including mark to market impacts of certain
key employee
compensation programs, and increased facility
costs.
Exploration expenses increased $374 million
in 2019, primarily due to higher leasehold impairment
and dry
hole costs,
mainly in our Lower 48 segment,
and higher exploration G&A expenses.
In 2019, we recorded a
$141 million before-tax leasehold impairment
expense due to our decision to discontinue
exploration activities
in the Central Louisiana Austin Chalk trend and
expensed $111 million of dry hole costs related to this play.
Impairments increased $378 million in
2019, mainly due to a $379 million before-tax impairment
related to the
sale of our Niobrara interests in the Lower 48 segment.
For additional information, see Note 5—Asset
Acquisitions and Dispositions and Note 9—Impairments,
in the Notes to Consolidated Financial Statements.
Other expenses decreased $310 million in
2019, primarily due to the absence of a $206
million before-tax
expense for premiums on early debt retirements
and lower pension settlement expense.
See Note 19—Income Taxes, in the Notes to Consolidated Financial Statements,
for information regarding our
income tax provision (benefit) and effective tax rate.
Summary Operating Statistics
2019
2018
2017
Average Net Production
Crude oil (MBD)
Natural gas liquids (MBD)
Bitumen (MBD)
Natural gas (MMCFD)
2,805
2,774
3,270
Total Production
(MBOED)
1,348
1,283
1,377
Dollars Per Unit
Average Sales Prices
Crude oil (per bbl)
$
60.99
68.13
51.96
Natural gas liquids (per bbl)
20.09
30.48
25.22
Bitumen (per bbl)
31.72
22.29
22.66
Natural gas (per mcf)
5.03
5.65
4.07
Millions of Dollars
Worldwide Exploration Expenses
General and administrative; geological and geophysical,
lease rental, and other
$
Leasehold impairment
Dry holes
$
We explore for, produce, transport and market crude oil, bitumen, natural gas, LNG and NGLs on
a worldwide
basis.
At December 31, 2019, our operations were
producing in the U.S., Norway, Canada, Australia, Timor-
Leste, Indonesia, China, Malaysia, Qatar and
Libya.
2019 vs. 2018
Total production, including Libya, of 1,348 MBOED increased 65 MBOED
or 5 percent in 2019 compared
with 2018,
primarily due to:
●
New wells online in the Lower 48.
●
An increased interest in the Western North Slope (WNS) and Greater Kuparuk Area
(GKA) of Alaska
following acquisitions closed in 2018.
●
Higher production in Norway due to drilling activity
and the startup of Aasta Hansteen in December
The increase in production during 2019 was
partly offset by:
●
Normal field decline.
●
Disposition impacts from the U.K. and non-core
asset sales in the Lower 48.
Production excluding Libya was 1,305 MBOED in
2019 compared with 1,242 MBOED in 2018,
an increase of
63 MBOED or 5 percent.
Underlying production, which excludes Libya and
the net volume impact from
closed dispositions and acquisitions of 51 MBOED
in 2019 and 47 MBOED in 2018, is used to measure
our
ability to grow production organically.
Our underlying production grew 5 percent to 1,254
MBOED in 2019
from 1,195 MBOED in 2018.
Alaska
2019
2018
2017
Net Income Attributable to ConocoPhillips
(millions of dollars)
$
1,520
1,814
1,466
Average Net Production
Crude oil (MBD)
Natural gas liquids (MBD)
Natural gas (MMCFD)
Total Production
(MBOED)
Average Sales Prices
Crude oil (per bbl)
$
64.12
70.86
53.33
Natural gas (per mcf)
3.19
2.48
2.72
The Alaska segment primarily explores for, produces, transports
and markets crude oil, NGLs and natural gas.
In 2019, Alaska contributed 25 percent of our
worldwide liquids production and less than 1 percent
of our
natural gas production.
2019 vs. 2018
Alaska reported earnings of $1,520 million in
2019, compared with earnings of $1,814 million
in 2018.
The
decrease in earnings was mainly due to lower
realized crude oil prices and higher production
and operating and
DD&A expenses associated with incremental volumes
from acquisitions completed during 2018.
Additionally, earnings were lower due to the absence of a $98 million tax valuation
allowance reduction,
the
absence of a $79 million after-tax benefit resulting
from an accrual reduction due to a transportation
cost ruling
by the FERC,
and $62 million less in enhanced oil recovery
credits.
Partly offsetting these decreases in
earnings, were higher crude oil sales volumes
due to the GKA and WNS acquisitions completed
in 2018.
Average production increased 32 MBOED in 2019 compared with 2018, primarily
due to acquisitions at GKA
and WNS in 2018, which provided an incremental
38 MBOED of production in 2019, as well as volumes
from
new wells online.
These production increases were partly offset by normal
field decline.
Acquisition Update
In the third quarter of 2019, we completed the
Nuna discovery acreage acquisition for approximately
$100
million, expanding the Kuparuk River Unit by
21,000 acres and leveraging legacy infrastructure.
Lower 48
2019
2018
2017
Net Income (Loss) Attributable to ConocoPhillips
(millions of dollars)
$
1,747
(2,371)
Average Net Production
Crude oil (MBD)
Natural gas liquids (MBD)
Natural gas (MMCFD)
Total Production
(MBOED)
Average Sales Prices
Crude oil (per bbl)
$
55.30
62.99
47.36
Natural gas liquids (per bbl)
16.83
27.30
22.20
Natural gas (per mcf)
2.12
2.82
2.73
The Lower 48 segment consists of operations located
in the contiguous U.S. and the Gulf of Mexico.
During
2019, the Lower 48 contributed 39 percent of our
worldwide liquids production and 22 percent
of our natural
gas production.
2019 vs. 2018
Lower 48 reported earnings of $436 million in
2019, compared with $1,747 million in 2018.
Earnings
decreased primarily due to lower realized crude oil,
NGL and natural gas prices; higher DD&A due to
increased production volumes; a $301 million after-tax
impairment of our Niobrara assets;
higher exploration
expenses, primarily due to a combined $197 million
after-tax of leasehold impairment and dry
hole costs
associated with our decision to discontinue exploration
activities in the Central Louisiana Austin
Chalk; and
lower earnings in equity
affiliates due to a combined $120 million after-tax
of impairments associated with a
fair value reduction of our investment in MWCC
and the disposition of our interests in the
Golden Pass LNG
Terminal and Golden Pass Pipeline.
Partly offsetting the decrease in earnings were increased
crude oil and
NGL sales volumes in the Eagle Ford, Bakken
and Permian Unconventional.
For additional information related to our impairment
of MWCC, see Note 3—Variable Interest Entities in the
Notes to Consolidated Financial Statements.
For more information related to the sale of our interests
in
Golden Pass LNG Terminal and Golden Pass Pipeline, see Note 5—Asset
Acquisitions and Dispositions in the
Notes to Consolidated Financial Statements.
Total average production increased 54 MBOED in 2019 compared with 2018.
The increase was primarily due
to new production from unconventional assets in
Eagle Ford, Bakken and the Permian Basin,
partly offset by
normal field decline.
Additionally, production decreased by 10 MBOED due to non-core dispositions
in 2018.
Asset Dispositions
Update
In January 2019, we entered into agreements to
sell our 12.4 percent ownership interests
in the Golden Pass
LNG Terminal and Golden Pass Pipeline.
We have also entered into agreements to amend our contractual
obligations for retaining use of the facilities.
As a result of entering into these agreements, we recognized
a
before-tax impairment of $60 million in the
first quarter of 2019 which is included in the “Equity
in earnings
of affiliates” line on our consolidated income statement.
We completed the sale in the second quarter of 2019.
See Note 15—Fair Value Measurement in the Notes to Consolidated Financial Statements, for
additional
information.
In the fourth quarter of 2019, we sold our interests
in the Magnolia field and platform and recognized
an after-
tax gain of $63 million.
Production from Magnolia in 2019 was less
than one MBOED.
In the fourth quarter of 2019, we signed an agreement
to sell our interests in the Niobrara shale
play for $380
million, plus customary adjustments,
and overriding royalty interests in certain
future wells.
We recorded an
after-tax impairment of $301 million in
the fourth quarter to reduce the carrying value to
fair value.
Production from Niobrara was approximately 11 MBOED in 2019.
This transaction is subject to regulatory
approval and other conditions precedent and
is expected to close in the first quarter
of 2020.
In January 2020, we entered into an agreement to
sell our interests in certain non-core properties
in the Lower
48 segment for $186 million, plus customary
adjustments.
The assets met the held for sale criteria
in January
2020 and the transaction is expected to be completed
in the first quarter of 2020.
No gain or loss is anticipated
on the sale.
This disposition will not have a significant
impact on Lower 48 production.
For additional information on these transactions,
see Note 5—Asset Acquisitions and Dispositions,
in the
Notes to Consolidated Financial Statements.
Canada
2019
2018
2017
Net Income Attributable to ConocoPhillips
(millions of dollars)
$
2,564
Average Net Production
Crude oil (MBD)
Natural gas liquids (MBD)
-
Bitumen (MBD)
Consolidated operations
Equity affiliates
-
-
Total bitumen
Natural gas (MMCFD)
Total Production
(MBOED)
Average Sales Prices
Crude oil (per bbl)
$
40.87
48.73
43.69
Natural gas liquids (per bbl)
19.87
43.70
21.51
Bitumen (dollars per bbl)*
Consolidated operations
31.72
22.29
21.43
Equity affiliates
-
-
23.83
Total bitumen
31.72
22.29
22.66
Natural gas (per mcf)
0.49
1.00
1.93
*Average prices for sales of bitumen produced during 2018 and 2019 excludes additional value realized from the purchase and sale of third-
party volumes for optimization of our pipeline capacity between Canada
and the U.S. Gulf Coast.
Our Canadian operations consist of the Surmont
oil sands development in Alberta and the liquids-rich
Montney unconventional play in British Columbia.
In 2019, Canada contributed 7 percent of our
worldwide
liquids production and less than one percent of
our worldwide natural gas production.
2019 vs. 2018
Canada operations reported earnings of $279 million
in 2019 compared with $63 million in 2018.
Earnings
increased mainly due to higher realized bitumen
prices,
a $68 million tax benefit primarily comprised
of a
previously unrecognizable tax basis related to
a tax settlement,
lower DD&A expense due to lower rates from
reserve additions,
lower production and operating expenses,
and a $25 million tax benefit due to a four year
phased four percent reduction in Alberta’s corporate income tax rate.
Partly offsetting the increase in earnings
were lower sales volumes due to a planned turnaround
at Surmont, lower production due to a mandated
production curtailment imposed by the Alberta
government in January 2019, and the absence of
an $80 million
tax restructuring benefit.
Total average production decreased 7 MBOED in 2019 compared with 2018.
The production decrease was
primarily due to a turnaround at Surmont, which
had an annualized average impact of 3 MBOED,
and a
mandated production curtailment imposed by the
Alberta government,
which also impacted production by 3
MBOED.
The curtailment program is established and administered
by the Alberta Energy Regulator under the
Curtailment Rules regulation, which is currently
set to expire on December 31, 2020.
This program is
intended to strengthen the WCS differential to WTI at
Hardisty.
Asset Disposition
On May 17, 2017, we completed the sale of our
50 percent nonoperated interest in the FCCL
Partnership, as
well as the majority of our western Canada gas
assets to Cenovus Energy.
Consideration for the transaction
was $11.0 billion in cash after customary adjustments, 208 million
Cenovus Energy common shares and a five
year uncapped contingent payment.
The contingent payment, calculated and paid
on a quarterly basis, is $6
million CAD for every $1 CAD by which the WCS
quarterly average crude
price exceeds $52 CAD per barrel.
During 2019 and 2018, we recorded after-tax gains
on dispositions for these contingent payments of
$84
million and $68 million,
respectively.
See Note 5—Asset Acquisitions and Dispositions
in the Notes to
Consolidated Financial Statements, for additional
information.
Europe and North Africa
2019
2018
2017
Net Income Attributable to ConocoPhillips
(millions of dollars)
$
2,724
1,866
Average Net Production
Crude oil (MBD)
Natural gas liquids (MBD)
Natural gas (MMCFD)
Total Production
(MBOED)
Average Sales Prices
Crude oil (dollars per bbl)
$
64.94
70.71
54.21
Natural gas liquids (per bbl)
29.37
36.87
34.07
Natural gas (per mcf)
4.92
7.65
5.70
The Europe and North Africa segment consisted
of operations principally located in the Norwegian
and U.K.
sectors of the North Sea, the Norwegian Sea and
Libya.
In 2019, our Europe and North Africa operations
contributed 16 percent of our worldwide liquids production
and 17 percent of our natural gas production.
2019 vs. 2018
Earnings for Europe and North Africa operations
of $2,724 million increased $858 million
in 2019 compared
with 2018.
The increase in earnings was primarily
due to a $2.1 billion after-tax gain associated with
the
completion of the sale of two ConocoPhillips
U.K. subsidiaries to Chrysaor E&P Limited.
Earnings also
increased due to the cessation of DD&A in the second
quarter of 2019 for our disposed U.K. subsidiaries
when
these assets became held-for-sale.
Partly offsetting the increase in earnings were the absence
of a $774 million
after-tax gain related to the sale of a ConocoPhillips
subsidiary to BP, which held 16.5 percent of our 24
percent interest in the BP-operated Clair Field
in the U.K.; lower sales volumes primarily
due to the U.K.
disposition to Chrysaor completed September 30,
2019; and lower realized natural gas and crude
oil prices.
Average production decreased 17 MBOED in 2019, compared with 2018.
The decrease was mainly due to
normal field decline and a 20 MBOED disposition
impact from the sale of our U.K. assets to Chrysaor
completed September 30, 2019.
Partly offsetting these production decreases were volumes
from new wells
online in Norway,
including the Aasta Hansteen Field which
achieved first production in December of 2018.
Asset Disposition Update
On September 30, 2019, we completed the sale of
two ConocoPhillips U.K. subsidiaries to
Chrysaor E&P
Limited for proceeds of $2.2 billion after interest
and customary adjustments.
In 2019, we recorded a $1.7
billion before-tax and $2.1 billion after-tax
gain associated with this transaction.
Together the subsidiaries
sold indirectly held our exploration and production
assets in the U.K., including $1.8 billion
of ARO.
Annualized average production associated with the
U.K. assets sold was 50 MBOED in 2019.
Reserves
associated with the U.K. assets sold were 84 MMBOE
at the time of disposition.
For additional information,
see Note 5—Asset Acquisitions and Dispositions
in the Notes to Consolidated Financial
Statements.
Asia Pacific and Middle East
2019
2018
2017
Net Income (Loss) Attributable to ConocoPhillips
(millions of dollars)
$
1,929
2,070
(1,098)
Average Net Production
Crude oil (MBD)
Consolidated operations
Equity affiliates
Total crude oil
Natural gas liquids (MBD)
Consolidated operations
Equity affiliates
Total natural gas liquids
Natural gas (MMCFD)
Consolidated operations
Equity affiliates
1,052
1,031
1,007
Total natural gas
1,689
1,657
1,694
Total Production
(MBOED)
Average Sales Prices
Crude oil (dollars per bbl)
Consolidated operations
$
65.02
70.93
54.38
Equity affiliates
61.32
72.49
54.76
Total crude oil
64.52
71.14
54.43
Natural gas liquids (dollars per bbl)
Consolidated operations
37.85
47.20
41.37
Equity affiliates
36.70
45.69
38.74
Total natural gas liquids
37.10
46.13
39.75
Natural gas (dollars per mcf)
Consolidated operations
5.91
6.15
4.98
Equity affiliates
6.29
6.06
4.27
Total natural gas
6.15
6.09
4.55
The Asia Pacific and Middle East segment has
operations in China, Indonesia, Malaysia,
Australia, Timor-Leste
and Qatar.
During 2019,
Asia Pacific and Middle East contributed 13 percent
of our worldwide liquids
production and 60 percent of our natural gas production.
2019 vs. 2018
Asia Pacific and Middle East reported earnings
of $1,929 million in 2019, compared with
$2,070 million in
The decrease in earnings was mainly due to
lower realized crude oil, NGL and natural gas
prices;
lower
LNG and crude oil sales volumes; and lower equity
in earnings of affiliates, primarily due to a deferred
tax
adjustment at QG3 that resulted in a $118 million reduction to equity
earnings.
Partly offsetting this decrease in
earnings was a $164 million income tax benefit
related to deepwater incentive tax credits
from the Malaysia
Block G and a $52 million after-tax gain on disposition
of our interest in the Greater Sunrise Fields.
Average production increased 1 percent in 2019, compared with 2018.
The increase was primarily due to new
production from Malaysia, including first gas
supply from KBB to PFLNG1 in the second quarter
of 2019 and
first oil from Gumusut Phase 2 in the third quarter
of 2019;
and new wells online in China, including
Bohai
Phase 3.
Partly offsetting this production increase was normal
field decline.
Asset Dispositions Update
In the second quarter of 2019, we recognized an
after-tax gain of $52 million upon completion
of the sale of our
30 percent interest in the Greater Sunrise Fields
to the government of Timor-Leste for $350 million.
No
production or reserve impacts were associated
with the sale.
In October 2019, we entered into an agreement to sell
the subsidiaries that hold our Australia-West assets and
operations to Santos for $1.39 billion, plus customary
adjustments, with an effective date of January 1, 2019.
In
addition, we will receive a payment of $75 million
upon final investment decision of the Barossa development
project.
These subsidiaries hold our 37.5 percent interest
in the Barossa Project and Caldita Field, our 56.9
percent interest in the Darwin LNG Facility
and Bayu-Undan Field, our 40 percent interest
in the Greater
Poseidon Fields, and our 50 percent interest in
the Athena Field.
This transaction is expected to be completed in
the first quarter of 2020, subject to regulatory approvals
and the satisfaction of other specific conditions
precedent.
In 2019, production associated with the
Australia-West assets to be sold was 48 MBOED.
Year
-end
2019 reserves associated with these assets were
17 MMBOE.
We will retain our 37.5 percent interest in the
Australia Pacific LNG project and operatorship
of that project’s LNG facility.
See Note 5—Asset Acquisitions and Dispositions
in the Notes to Consolidated Financial
Statements, for
additional information related to these dispositions.
Other International
2019
2018
2017
Net Income Attributable to ConocoPhillips
(millions of dollars)
$
The Other International segment includes exploration
activities in Colombia, Chile and Argentina and
contingencies associated with prior operations.
2019 vs. 2018
Other International operations reported earnings
of $263 million in 2019, compared with
earnings of $364
million in 2018.
The decrease in earnings was primarily due
to the recognition of $417 million after-tax
in
other income related to a settlement agreement
with PDVSA in 2018, compared with $317 million
after-tax
associated with this settlement agreement in 2019.
In 2018 and 2019, we collected approximately
$0.8 billion of the $2.0 billion settlement with
PDVSA.
PDVSA has defaulted on its remaining payment obligations
under this agreement, we are therefore now forced
to incur additional costs as we seek to recover
any unpaid amounts under the agreement.
For additional
information, see Note 13—Contingencies and Commitments
in the Notes to Consolidated Financial
Statements.
Argentina
In January 2019,
we secured a 50 percent nonoperated interest
in the El Turbio Este Block, within the Austral
Basin in southern Argentina.
In 2019, we acquired and processed 3-D
seismic covering 500 square miles,
with
evaluation of the data ongoing.
In November 2019, we acquired interests in
two nonoperated blocks in the Neuquén Basin
targeting the Vaca
Muerta play.
We have a 50 percent interest in the Bandurria Norte Block and a 45 percent interest
in the
Aguada Federal Block.
In Bandurria Norte, 1 vertical and 4 horizontal
wells were tested and shut-in during
In Aguada Federal, 2 horizontal wells
were being tested at the end of the year.
Corporate and Other
Millions of Dollars
2019
2018
2017
Net Income (Loss) Attributable to ConocoPhillips
Net interest
$
(604)
(680)
(739)
Corporate general and administrative expenses
(252)
(91)
(193)
Technology
Other
(1,005)
(1,224)
$
(1,667)
(2,136)
2019 vs. 2018
Net interest consists of interest and financing expense,
net of interest income and capitalized interest.
Net
interest decreased $76 million in 2019 compared
with 2018,
primarily due to lower capitalized interest
on
projects; increased interest income from holding
higher cash balances; and lower interest on debt expense
resultant from the retirement of $4.7 billion of
debt in 2018; partly offset by the absence of an accrual
reduction due to a transportation cost ruling
by the FERC.
Corporate G&A expenses include compensation
programs and staff costs.
These costs increased by $161
million in 2019 compared with 2018, primarily
due to higher costs associated with compensation
and benefits,
including certain key employee compensation
programs and higher facility costs.
Technology includes our investment in new technologies or businesses, as well as licensing
revenues.
Activities are focused on both conventional and tight
oil reservoirs, shale gas, heavy oil, oil
sands, enhanced
oil recovery and LNG.
Earnings from Technology increased by $14 million in 2019 compared with
2018,
primarily due to higher licensing revenues.
The category “Other” includes certain foreign currency
transaction gains and losses, environmental costs
associated with sites no longer in operation, other
costs not directly associated with an operating
segment,
premiums incurred on the early retirement
of debt, unrealized holding gains or losses
on equity securities, and
pension settlement expense.
Earnings in “Other” increased by $1,776 million
in 2019 compared with 2018,
primarily due to an unrealized gain of $649 million
after-tax on our CVE common shares in
2019, and the
absence of a $436
million after-tax unrealized loss on those
shares in 2018.
Additionally, earnings increased
due to the absence of $195 million in
premiums on the early retirement of debt, lower pension
settlement
expense, and a $151 million tax benefit related
to the revaluation of deferred tax assets following
finalization
of rules related to the 2017 Tax Cuts and Jobs Act.
See Note 19—Income Taxes, in the Notes to Consolidated
Financial Statements, for additional information
related to the 2017 Tax Cuts and Jobs Act.
CAPITAL RESOURCES AND LIQUIDITY
Financial Indicators
Millions of Dollars
Except as Indicated
2019
2018
2017
Net cash provided by operating activities
$
11,104
12,934
7,077
Cash and cash equivalents
5,088
5,915
6,325
Short-term debt
2,575
Total debt
14,895
14,968
19,703
Total equity
35,050
32,064
30,801
Percent of total debt to capital*
%
Percent of floating-rate debt to total debt
%
*Capital includes total debt and total equity.
To meet our short-
and long-term liquidity requirements, we look
to a variety of funding sources, including
cash generated from operating activities,
proceeds from asset sales, our commercial paper
and credit facility
programs and our ability to sell securities
using our shelf registration statement.
In 2019, the primary uses of
our available cash were $6,636 million to support
our ongoing capital expenditures and investments
program;
$3,500 million to repurchase our common stock;
$2,910 million net purchases of investments,
and $1,500
million to pay dividends on our common stock.
During 2019, cash and cash equivalents decreased
by $827
million to $5,088 million.
We believe current cash balances and cash generated by operations, together with
access to external sources of
funds as described below in the “Significant Changes
in Capital” section, will be sufficient to meet our
funding
requirements in the near and long term, including
our capital spending program, share repurchases,
dividend
payments and required debt payments.
Our commitment to disciplined execution of these
funding requirements includes cash
investment strategies
that position us for success in an environment
of short-term price volatility as well as
extended downturns in
commodity prices.
The primary objectives of these cash investment
strategies in priority order are to protect
principal, maintain liquidity, and provide yield and total returns.
Funds for short-term needs to support our
operating plan and provide resiliency to react
to short-term price volatility are invested in
highly liquid
instruments with maturities within the year.
Funds we consider available to maintain
resiliency in longer term
price downturns and to capture opportunities outside
a given operating plan may be invested in
instruments
with maturities greater than one year.
For additional information, see Note 1–Accounting
Policies and Note
14–Derivative and Financial Instruments.
Significant Changes in Capital
Operating Activities
During 2019, cash provided by operating activities
was $11,104 million, a 14 percent decrease from 2018.
The
decrease was primarily due to lower prices, lower
collections related to settlements reached with
Ecuador and
PDVSA, and a pension contribution made in conjunction
with the sale of two U.K. subsidiaries, partially
offset
by higher volumes.
While the stability of our cash flows from operating
activities benefits from geographic diversity, our short-
and long-term operating cash flows are highly
dependent upon prices for crude oil, bitumen,
natural gas, LNG
and NGLs.
Prices and margins in our industry have historically
been volatile and are driven by market
conditions over which we have no control.
Absent other mitigating factors, as these
prices and margins
fluctuate, we would expect a corresponding
change in our operating cash flows.
The level of absolute production volumes, as
well as product and location mix, impacts our cash flows.
Full-
year production averaged 1,348 MBOED in 2019.
Full-year production excluding Libya averaged
1,305
MBOED in 2019
and is expected to be 1,230 to 1,270 MBOED
in 2020.
Future production is subject to
numerous uncertainties, including, among others,
the volatile crude oil and natural gas price
environment,
which may impact investment decisions; the
effects of price changes on production sharing and variable-
royalty contracts; acquisition and disposition of fields;
field production decline rates; new technologies;
operating efficiencies; timing of startups and major turnarounds;
political instability; weather-related
disruptions; and the addition of proved reserves through
exploratory success and their timely
and cost-effective
development.
While we actively manage these factors, production
levels can cause variability in cash flows,
although generally this variability has not been as significant
as that caused by commodity prices.
To maintain or grow our production volumes on an ongoing basis, we must continue
to add to our proved
reserve base.
Our proved reserves generally increase as prices
rise and decrease as prices decline.
In 2019,
our reserve replacement, which included a net decrease
of 0.1 billion BOE from sales and purchases,
was 100
percent.
Increased crude oil reserves accounted for approximately
55 percent of the total change in reserves.
Our organic reserve replacement, which excludes the
impact of sales and purchases, was 117 percent
in 2019.
Approximately 51 percent of organic reserve additions
are from Lower 48, 13 percent from Alaska,
12 percent
from Canada, 12 percent from Europe and North
Africa and 12 percent from Asia Pacific and Middle
East.
In the five years ended December 31, 2019, our reserve
replacement, which included a decrease
of 2.0 billion
BOE from sales and purchases, was negative 34
percent, reflecting the impact of asset dispositions
and lower
prices during that period.
Our organic reserve replacement during the five years
ended December 31, 2019,
was 40
percent, reflecting development activities
as well as lower prices during that period.
Historically our reserve replacement has varied
considerably year to year contingent upon the timing
of major
projects which may have long lead times between
capital investment and production.
In the last several years,
more of our capital has been allocated to short cycle
time, onshore, unconventional plays.
Accordingly, we
believe our recent success in replacing reserves can
be viewed on a trailing three-year basis.
In the three years ended December 31, 2019, our reserve
replacement was 23 percent, reflecting the impact
of
asset dispositions during that period.
Our organic reserve replacement during the three years
ended December
31, 2019, which excludes a decrease of 1.8 billion
BOE related to sales and purchases, was 143 percent,
reflecting reserve additions from development activities.
Reserve replacement represents the net change in
proved reserves, net of production, divided
by our current
year production, as shown in our supplemental reserve
table disclosures. For additional information about
our
2020 capital budget, see the “2020 Capital Budget”
section within “Capital Resources and Liquidity”
and for
additional information on proved reserves, including
both developed and undeveloped reserves, see the
“Oil
and Gas Operations” section of this report.
As discussed in the “Critical Accounting Estimates”
section, engineering estimates of proved
reserves are
imprecise; therefore, each year reserves may be revised
upward or downward due to the impact of changes
in
commodity prices or as more technical data becomes
available on reservoirs.
We have reported revisions as
increases to reserves in the current period, however
in prior periods,
reported revisions as decreases to
reserves. It is not possible to reliably predict
how revisions will impact reserve quantities
in the future.
Investing Activities
Proceeds from asset sales in 2019 were $3.0 billion.
We
completed the sale of two ConocoPhillips U.K.
subsidiaries to Chrysaor E&P Limited for $2.2
billion.
We also completed the sale of several assets including
our 30 percent interest in the Greater Sunrise Fields
for $350 million and received $106 million
of contingent
payments from Cenovus Energy.
In the fourth quarter of 2019, we entered into an
agreement to sell the subsidiaries that hold
our Australia-West
assets and operations to Santos for $1.39 billion,
plus customary adjustments.
In addition, we will receive a
payment of $75 million upon final investment
decision of the Barossa development project.
Also in the fourth
quarter of 2019, we signed an agreement to sell
our interests in the Niobrara shale play
for $380 million, plus
customary adjustments,
and overriding royalty interests in certain
future wells.
Both transactions are subject to
regulatory approval and other conditions precedent
and expected to close in the first quarter of 2020.
Investing activities in 2019 also included net purchases
of $2.9 billion of investments in short-term
and long-
term financial instruments. These investments include
time deposits, commercial paper as well as debt
securities classified as available for sale.
The investment in short-term instruments
was $2.8 billion, the
remaining $0.1 billion was invested in long-term
debt securities.
For additional information, see Note 14–
Derivative and Financial Instruments.
Proceeds from asset sales in 2018 were $1.1 billion.
We completed several undeveloped acreage transactions
in our Lower 48 segment for a total of $267 million
after customary adjustments and another transaction
in our
Lower 48 segment for $112 million after customary adjustments.
We completed the sale of our interests in the
Barnett to Lime Rock Resources for $196 million
after customary adjustments.
We also completed the sale of
a ConocoPhillips subsidiary to BP and received
$253 million net proceeds.
The subsidiary held 16.5 percent
of our 24 percent interest in the BP-operated
Clair Field in the U.K.
During 2018, we received $95 million of
contingent payments from Cenovus Energy.
For additional information on our dispositions,
see Note 5—Asset Acquisitions and Dispositions
in the Notes
to Consolidated Financial Statements.
Commercial Paper and Credit Facilities
We have a revolving credit facility totaling $6.0 billion, expiring in May 2023.
Our revolving credit facility
may be used for direct bank borrowings, the issuance
of letters of credit totaling up to $500 million, or
as
support for our commercial paper program.
The revolving credit facility is broadly syndicated
among financial
institutions and does not contain any material
adverse change provisions or any covenants
requiring
maintenance of specified financial ratios or credit
ratings.
The facility agreement contains a cross-default
provision relating to the failure to pay principal or interest
on other debt obligations of $200 million or more
by ConocoPhillips, or any of its consolidated subsidiaries.
Credit facility borrowings may bear interest at
a margin above rates offered by certain designated banks in the
London interbank market or at a margin above the overnight
federal funds rate or prime rates offered by
certain designated banks in the U.S.
The agreement calls for commitment fees
on available, but unused,
amounts.
The agreement also contains early termination
rights if our current directors or their approved
successors cease to be a majority of the Board
of Directors.
The revolving credit facility supports the ConocoPhillips
Company $6.0 billion commercial paper program,
which is primarily a funding source for short-term
working capital needs.
Commercial paper maturities are
generally limited to 90 days.
We had no commercial paper outstanding in programs in place at December 31,
2019 or December 31, 2018.
We had no direct outstanding borrowings or letters of credit under the revolving
credit facility at December 31, 2019 and December
31, 2018.
Since we had no commercial paper outstanding
and had issued no letters of credit, we had access to
$6.0 billion in borrowing capacity under our revolving
credit facility at December 31, 2019.
Our current long-term debt ratings remained
unchanged in 2019 and are as follows:
Fitch - “A” with a “stable”
outlook; Moody’s Investors Services - “A3” with a “stable” outlook; and
Standard & Poor’s - “A” with a
stable outlook.
We do not have any ratings triggers on any of our corporate debt that would
cause an
automatic default, and thereby impact our access
to liquidity, in the event of a downgrade of our credit rating.
If our credit rating were downgraded, it could
increase the cost of corporate debt available
to us and restrict our
access to the commercial paper markets.
If our credit rating were to deteriorate to
a level prohibiting us from
accessing the commercial paper market, we
would still be able to access funds under our revolving
credit
facility.
Certain of our project-related contracts, commercial
contracts and derivative instruments contain
provisions
requiring us to post collateral.
Many of these contracts and instruments permit
us to post either cash or letters
of credit as collateral.
At December 31, 2019 and 2018, we had direct
bank letters of credit of $277 million
and $323 million, respectively, which secured performance obligations related to
various purchase
commitments incident to the ordinary conduct of business.
In the event of credit ratings downgrades, we may
be required to post additional letters of
credit.
Shelf Registration
We have a universal shelf registration statement on file with the SEC under which
we, as a well-known
seasoned issuer, have the ability to issue and sell an indeterminate
amount of various types of debt and equity
securities.
Off-Balance Sheet Arrangements
As part of our normal ongoing business operations
and consistent with normal industry practice,
we enter into
numerous agreements with other parties to pursue
business opportunities, which share costs
and apportion
risks among the parties as governed by the agreements.
For information about guarantees, see Note 12—Guarantees,
in the Notes to Consolidated Financial
Statements, which is incorporated herein by reference.
Capital Requirements
For information about our capital expenditures
and investments, see the “Capital Expenditures”
section.
Our debt balance at December 31, 2019, was $14,895
million, a decrease of $73 million from the balance
at
December 31, 2018.
For more information on Debt, see Note 11—Debt, in the Notes
to Consolidated
Financial Statements.
On January 30, 2019, we announced a quarterly
dividend of $0.305 per share.
The dividend was paid on
March 1, 2019, to stockholders of record at the close
of business on February 11, 2019.
On May 1, 2019, we
announced a quarterly dividend of $0.305 per share.
The dividend was paid on June 3, 2019, to stockholders
of record at the close of business on May 13,
On July 11, 2019, we announced a quarterly dividend of
$0.305 per share.
The dividend was paid on September 3, 2019, to
stockholders of record at the close of
business on July 22, 2019.
On October 7, 2019, we announced a 38 percent increase
in the quarterly dividend
to $0.42 per share.
The dividend was paid on December 2, 2019, to
stockholders of record at the close of
business on October 17, 2019.
In February 2020, we announced a quarterly dividend
of $0.42 per share,
payable March 2, 2020, to stockholders of record
at the close of business on February 14, 2020.
In late 2016, we initiated our current share repurchase
program.
As of December 31, 2019, we had announced
a total authorization to repurchase $15 billion
of our common stock.
We repurchased $3 billion in 2017, $3
billion in 2018 and $3.5 billion in 2019.
Of the remaining authorization, we expect to
repurchase $3 billion in
In February 2020, we announced that the
Board of Directors approved an increase to
our authorization
from $15 billion to $25 billion, to support our
plan for future share repurchases.
Whether we undertake these
additional repurchases is ultimately subject to numerous
considerations, market conditions and other factors.
See Risk Factors -“Our ability to declare and pay
dividends and repurchase shares is subject to certain
considerations.”
Since our share repurchase program began
in November 2016, we have repurchased 169
million shares at a cost of $9.6 billion through
December 31, 2019.
Contractual Obligations
The table below summarizes our aggregate contractual
fixed and variable obligations as of December
31, 2019:
Millions of Dollars
Payments Due by Period
Up to 1
Years
Years
After
Total
Year
2–3
4–5
5 Years
Debt obligations (a)
$
14,175
1,018
12,534
Finance lease obligations (b)
Total debt
14,895
1,175
12,869
Interest on debt
11,339
1,671
1,603
7,209
Operating lease obligations (c)
1,050
Purchase obligations (d)
8,671
3,237
1,745
1,327
2,362
Other long-term liabilities
Pension and postretirement benefit
contributions (e)
1,375
-
Asset retirement obligations (f)
6,206
4,618
Accrued environmental costs (g)
Unrecognized tax benefits (h)
(h)
(h)
(h)
Total
$
43,789
6,124
5,823
4,546
27,296
(a)
Includes $204 million of net unamortized premiums,
discounts and debt issuance costs.
See Note 11—
Debt, in the Notes to Consolidated Financial Statements,
for additional information.
(b)
See Note 17—Non-Mineral Leases, in the Notes to
Consolidated Financial Statements, for
additional
information.
(c)
Includes $31 million of short-term leases that
are not recorded on our consolidated balance
sheet.
See
Note 17—Non-Mineral Leases, in the Notes to
Consolidated Financial Statements, for
additional
information.
(d)
Represents any agreement to purchase goods
or services that is enforceable and legally binding
and that
specifies all significant terms, presented on an undiscounted
basis.
Does not include purchase
commitments for jointly owned fields and facilities
where we are not the operator.
The majority of the purchase obligations are market-based
contracts related to our commodity business.
Product purchase commitments with third parties
totaled $2,426 million.
Purchase obligations of $5,111 million are related to agreements to access and
utilize the capacity of
third-party equipment and facilities, including
pipelines and LNG and product terminals, to
transport,
process, treat and store commodities.
The remainder is primarily our net share of purchase
commitments for materials and services for jointly
owned fields and facilities where we are the
operator.
(e)
Represents contributions to qualified and nonqualified
pension and postretirement benefit plans
for the
years 2020 through 2024.
For additional information related to expected
benefit payments subsequent to
2024, see Note 18—Employee Benefit Plans,
in the Notes to Consolidated Financial
Statements.
(f)
Represents estimated discounted costs to retire
and remove long-lived assets at the end of their
operations.
(g)
Represents estimated costs for accrued environmental
expenditures presented on a discounted basis
for
costs acquired in various business combinations
and an undiscounted basis for all other accrued
environmental costs.
(h)
Excludes unrecognized tax benefits of $1,095
million because the ultimate disposition and timing
of any
payments to be made with regard to such amounts
are not reasonably estimable.
Although unrecognized
tax benefits are not a contractual obligation,
they are presented in this table because they
represent
potential demands on our liquidity.
Capital Expenditures and Investments
Millions of Dollars
2019
2018
2017
Alaska
$
1,513
1,298
Lower 48
3,394
3,184
2,136
Canada
Europe and North Africa
Asia Pacific and Middle East
Other International
Corporate and Other
Capital Program
$
6,636
6,750
4,591
Our capital expenditures and investments
for the three-year period ended December 31,
2019, totaled $18.0
billion.
The 2019 expenditures supported key exploration
and developments, primarily:
●
Development, appraisal and exploration activities
in the Lower 48, including Eagle Ford, Permian
Unconventional, and Bakken.
●
Appraisal and development activities
in Alaska related to the Western North Slope; development
activities in the Greater Kuparuk Area and the
Greater Prudhoe Area; leasehold acquisition
in the
Greater Kuparuk Area.
●
Development activities across assets in Norway, as well as for assets in the U.K. that
recently have
been sold.
●
Optimization of oil sands development and appraisal
activities in liquids-rich plays in Canada.
●
Signature bonus for Indonesia Corridor Block
production sharing contract, as well as continued
development in China, Malaysia, Australia, and
Indonesia.
2020 CAPITAL BUDGET
In February 2020, we announced 2020 operating
plan capital of $6.5 billion to $6.7 billion.
The plan includes
funding for ongoing development drilling
programs, major projects, exploration and appraisal
activities, as
well as base maintenance.
Capital spend is expected to be higher in the first
quarter largely from winter
construction and exploration and appraisal drilling
in Alaska.
This guidance does not include capital for
acquisitions.
For information on PUDs and the associated costs
to develop these reserves, see the “Oil and
Gas Operations”
section in this report.
Contingencies
A number of lawsuits involving a variety of claims
arising in the ordinary course of business
have been filed
against ConocoPhillips.
We also may be required to remove or mitigate the effects on the environment of the
placement, storage, disposal or release of certain
chemical, mineral and petroleum substances
at various active
and inactive sites.
We regularly assess the need for accounting recognition or disclosure of these
contingencies.
In the case of all known contingencies (other
than those related to income taxes), we accrue
a
liability when the loss is probable and the amount
is reasonably estimable.
If a range of amounts can be
reasonably estimated and no amount within the range
is a better estimate than any other amount,
then the
minimum of the range is accrued.
We do not reduce these liabilities for potential insurance or third-party
recoveries.
If applicable, we accrue receivables for probable
insurance or other third-party recoveries.
With
respect to income tax-related contingencies,
we use a cumulative probability-weighted loss
accrual in cases
where sustaining a tax position is less than certain.
Based on currently available information, we believe
it is remote that future costs related to known
contingent
liability exposures will exceed current accruals by
an amount that would have a material
adverse impact on our
consolidated financial statements.
For information on other contingencies, see
“Critical Accounting
Estimates” and Note 13—Contingencies and
Commitments, in the Notes to Consolidated
Financial Statements.
Legal and Tax Matters
We are subject to various lawsuits and claims including but not limited to matters
involving oil and gas royalty
and severance tax payments, gas measurement and
valuation methods, contract disputes,
environmental
damages, climate change, personal injury, and property damage.
Our primary exposures for such matters
relate to alleged royalty and tax underpayments
on certain federal, state and privately owned
properties and
claims of alleged environmental contamination
from historic operations.
We will continue to defend ourselves
vigorously in these matters.
Our legal organization applies its knowledge, experience
and professional judgment to the specific
characteristics of our cases, employing a litigation
management process to manage and monitor the
legal
proceedings against us.
Our process facilitates the early evaluation and
quantification of potential exposures in
individual cases.
This process also enables us to track those cases that
have been scheduled for trial and/or
mediation.
Based on professional judgment and experience
in using these litigation management tools and
available information about current developments
in all our cases, our legal organization regularly assesses
the
adequacy of current accruals and determines if
adjustment of existing accruals, or establishment
of new
accruals, is required.
See Note 19—Income Taxes, in the Notes to Consolidated Financial Statements,
for
additional information about income tax-related
contingencies.
Environmental
We are subject to the same numerous international, federal, state and local environmental
laws and regulations
as other companies in our industry.
The most significant of these environmental
laws and regulations include,
among others, the:
●
U.S. Federal Clean Air Act, which governs
air emissions.
●
U.S. Federal Clean Water Act, which governs discharges to water bodies.
●
European Union Regulation for Registration, Evaluation,
Authorization and Restriction of Chemicals
(REACH).
●
U.S. Federal Comprehensive Environmental
Response, Compensation and Liability Act
(CERCLA or
Superfund), which imposes liability on generators,
transporters and arrangers of hazardous substances
at sites where hazardous substance releases have
occurred or are threatening to occur.
●
U.S. Federal Resource Conservation and Recovery
Act (RCRA), which governs the treatment,
storage
and disposal of solid waste.
●
U.S. Federal Oil Pollution Act of 1990 (OPA90), under which owners and operators
of onshore
facilities and pipelines, lessees or permittees
of an area in which an offshore facility is located, and
owners and operators of vessels are liable for
removal costs and damages that result from
a discharge
of oil into navigable waters of the U.S.
●
U.S. Federal Emergency Planning and Community Right-to-Know
Act (EPCRA), which requires
facilities to report toxic chemical inventories
with local emergency planning committees and response
departments.
●
U.S. Federal Safe Drinking Water Act, which governs the disposal of wastewater
in underground
injection wells.
●
U.S. Department of the Interior regulations, which
relate to offshore oil and gas operations in U.S.
waters and impose liability for the cost of pollution
cleanup resulting from operations, as well as
potential liability for pollution damages.
●
European Union Trading Directive resulting in European
Emissions Trading Scheme.
These laws and their implementing regulations
set limits on emissions and, in the case of discharges to
water,
establish water quality limits and establish standards
and impose obligations for the remediation of
releases of
hazardous substances and hazardous wastes.
They also, in most cases, require permits in
association with new
or modified operations.
These permits can require an applicant to
collect substantial information in connection
with the application process, which can be expensive
and time consuming.
In addition, there can be delays
associated with notice and comment periods and
the agency’s processing of the application.
Many of the
delays associated with the permitting process
are beyond the control of the applicant.
Many states and foreign countries where
we operate also have, or are developing, similar
environmental laws
and regulations governing these same types of
activities.
While similar, in some cases these regulations may
impose additional, or more stringent, requirements
that can add to the cost and difficulty of marketing
or
transporting products across state and international
borders.
The ultimate financial impact arising from
environmental laws and regulations is neither
clearly known nor
easily determinable as new standards, such as
air emission standards and water quality standards,
continue to
evolve.
However, environmental laws and regulations, including those that
may arise to address concerns
about global climate change, are expected to continue
to have an increasing impact on our operations
in the
U.S. and in other countries in which we operate.
Notable areas of potential impacts include air emission
compliance and remediation obligations in
the U.S. and Canada.
An example is the use of hydraulic fracturing,
an essential completion technique that facilitates
production of
oil and natural gas otherwise trapped in lower
permeability rock formations.
A range of local, state, federal or
national laws and regulations currently govern
hydraulic fracturing operations, with hydraulic
fracturing
currently prohibited in some jurisdictions.
Although hydraulic fracturing has been conducted
for many
decades, a number of new laws, regulations
and permitting requirements are under consideration
by various
state environmental agencies, and others which
could result in increased costs, operating restrictions,
operational delays and/or limit the ability
to develop oil and natural gas resources.
Governmental restrictions
on hydraulic fracturing could impact the overall
profitability or viability of certain of our oil
and natural gas
investments.
We have adopted operating principles that incorporate established industry standards
designed to
meet or exceed government requirements.
Our practices continually evolve as technology improves
and
regulations change.
We also are subject to certain laws and regulations relating to environmental remediation
obligations
associated with current and past operations.
Such laws and regulations include CERCLA
and RCRA and their
state equivalents.
Longer-term expenditures are subject to considerable
uncertainty and may fluctuate
significantly.
We occasionally receive requests for information or notices of potential liability
from the EPA and state
environmental agencies alleging we are a potentially
responsible party under CERCLA or an equivalent
state
statute.
On occasion, we also have been made a party
to cost recovery litigation by those agencies
or by
private parties.
These requests, notices and lawsuits assert
potential liability for remediation costs at various
sites that typically are not owned by us, but allegedly
contain wastes attributable to our past operations.
As of
December 31, 2019, there were 15 sites around
the U.S. in which we were identified as a potentially
responsible party under CERCLA and comparable
state laws.
For most Superfund sites, our potential liability
will be significantly less than the total site
remediation costs
because the percentage of waste attributable
to us, versus that attributable to all other
potentially responsible
parties, is relatively low.
Although liability of those potentially
responsible is generally joint and several for
federal sites and frequently so for state sites,
other potentially responsible parties at sites where
we are a party
typically have had the financial strength to
meet their obligations, and where they have
not, or where
potentially responsible parties could not be located,
our share of liability has not increased materially.
Many of
the sites at which we are potentially responsible
are still under investigation by the EPA or the state agencies
concerned.
Prior to actual cleanup, those potentially responsible
normally assess site conditions, apportion
responsibility and determine the appropriate remediation.
In some instances, we may have no liability
or attain
a settlement of liability.
Actual cleanup costs generally occur after the parties
obtain EPA or equivalent state
agency approval.
There are relatively few sites where we
are a major participant, and given the timing
and
amounts of anticipated expenditures, neither
the cost of remediation at those sites nor
such costs at all
CERCLA sites, in the aggregate, is expected to
have a material adverse effect on our competitive
or financial
condition.
Expensed environmental costs were $511 million in 2019 and are expected
to be about $545 million per year
in 2020 and 2021.
Capitalized environmental costs were $194 million
in 2019 and are expected to be about
$225 million per year in 2020 and 2021.
Accrued liabilities for remediation activities
are not reduced for potential recoveries from insurers
or other
third parties and are not discounted (except those
assumed in a purchase business combination,
which we do
record on a discounted basis).
Many of these liabilities result from CERCLA,
RCRA and similar state or international
laws that require us to
undertake certain investigative and remedial
activities at sites where we conduct, or once
conducted,
operations or at sites where ConocoPhillips-generated
waste was disposed.
The accrual also includes a number
of sites we identified that may require environmental
remediation, but which are not currently the
subject of
CERCLA, RCRA or other agency enforcement
activities.
The laws that require or address environmental
remediation may apply retroactively and regardless
of fault, the legality of the original activities
or the current
ownership or control of sites.
If applicable, we accrue receivables for probable
insurance or other third-party
recoveries.
In the future, we may incur significant costs
under both CERCLA and RCRA.
Remediation activities vary substantially
in duration and cost from site to site, depending on the
mix of unique
site characteristics, evolving remediation technologies,
diverse regulatory agencies and enforcement
policies,
and the presence or absence of potentially liable
third parties.
Therefore, it is difficult to develop reasonable
estimates of future site remediation costs.
At December 31, 2019, our balance sheet included
total accrued environmental costs of
$171 million,
compared with $178 million at December 31,
2018, for remediation activities in the
U.S. and Canada.
We
expect to incur a substantial amount of these expenditures
within the next 30 years.
Notwithstanding any of the foregoing, and as
with other companies engaged in similar businesses,
environmental costs and liabilities are inherent
concerns in our operations and products, and there
can be no
assurance that material costs and liabilities
will not be incurred.
However, we currently do not expect any
material adverse effect upon our results of operations or financial
position as a result of compliance with
current environmental laws and regulations.
Climate Change
Continuing political and social attention to the
issue of global climate change has resulted in
a broad range of
proposed or promulgated state, national and international
laws focusing on GHG reduction.
These proposed or
promulgated laws apply or could apply in countries
where we have interests or may have interests
in the future.
Laws in this field continue to evolve, and
while it is not possible to accurately estimate either
a timetable for
implementation or our future compliance costs
relating to implementation, such laws, if
enacted, could have a
material impact on our results of operations and
financial condition.
Examples of legislation or precursors for
possible regulation that do or could affect our operations
include:
●
European Emissions Trading Scheme (ETS), the program through
which many of the EU member
states are implementing the Kyoto Protocol.
Our cost of compliance with the EU ETS in 2019
was
approximately $8 million before-tax.
●
The Alberta Carbon Competitiveness Incentive
Regulation (CCIR) requires any existing facility
with
emissions equal to or greater than 100,000 metric
tonnes of carbon dioxide, or equivalent,
per year to
meet an industry benchmark intensity.
The total cost of these regulations in 2019
was approximately
$4 million.
●
The U.S. Supreme Court decision in Massachusetts
v. EPA,
549 U.S. 497, 127 S.Ct. 1438 (2007),
confirmed that the EPA has the authority to regulate carbon dioxide as an “air pollutant”
under the
Federal Clean Air Act.
●
The U.S. EPA’s
announcement on March 29, 2010 (published
as “Interpretation of Regulations that
Determine Pollutants Covered by Clean Air Act
Permitting Programs,” 75 Fed. Reg. 17004 (April
2,
2010)), and the EPA’s
and U.S. Department of Transportation’s joint promulgation of a Final Rule on
April 1, 2010, that triggers regulation of GHGs
under the Clean Air Act, may trigger
more climate-
based claims for damages, and may result in longer
agency review time for development projects.
●
The U.S. EPA’s
announcement on January 14, 2015, outlining
a series of steps it plans to take to
address methane and smog-forming volatile organic compound
emissions from the oil and gas
industry.
The former U.S. administration established
a goal of reducing the 2012 levels in methane
emissions from the oil and gas industry by 40
to 45 percent by 2025.
●
Carbon taxes in certain jurisdictions.
Our cost of compliance with Norwegian carbon
tax legislation
in 2019 was approximately $30 million (net
share before-tax).
We also incur a carbon tax for
emissions from fossil fuel combustion in our
British Columbia and Alberta Operations
totaling just
over $0.8 million (net share before-tax).
●
The agreement reached in Paris in December 2015
at the 21
st
Conference of the Parties to the United
Nations Framework on Climate Change, setting
out a new process for achieving global
emission
reductions.
While the U.S. announced its intention
to withdraw from the Paris Agreement, there
is no
guarantee that the commitments made by the
U.S. will not be implemented, in whole or
in part, by
U.S. state and local governments or by major corporations
headquartered in the U.S.
In the U.S., some additional form of regulation
may be forthcoming in the future at the
federal and state levels
with respect to GHG emissions.
Such regulation could take any of several
forms that may result in the creation
of additional costs in the form of taxes, the restriction
of output, investments of capital to maintain
compliance
with laws and regulations, or required acquisition
or trading of emission allowances.
We are working to
continuously improve operational and energy efficiency through
resource and energy conservation throughout
our operations.
Compliance with changes in laws and regulations
that create a GHG tax, emission trading scheme
or GHG
reduction policies could significantly increase
our costs, reduce demand for fossil energy derived
products,
impact the cost and availability of capital
and increase our exposure to litigation.
Such laws and regulations
could also increase demand for less carbon intensive
energy sources, including natural gas.
The ultimate
impact on our financial performance, either positive
or negative, will depend on a number of factors,
including
but not limited to:
●
Whether and to what extent legislation or
regulation is enacted.
●
The timing of the introduction of such legislation
or regulation.
●
The nature of the legislation (such as a cap and
trade system or a tax on emissions) or
regulation.
●
The price placed on GHG emissions (either
by the market or through a tax).
●
The GHG reductions required.
●
The price and availability of offsets.
●
The amount and allocation of allowances.
●
Technological and scientific developments leading to new products or services.
●
Any potential significant physical effects of climate
change (such as increased severe weather events,
changes in sea levels and changes in temperature).
●
Whether, and the extent to which, increased compliance costs are
ultimately reflected in the prices of
our products and services.
The company has responded by putting in place
a Sustainable Development Risk Management Standard
covering the assessment and registering of significant
and high sustainable development risks based
on their
consequence and likelihood of occurrence.
We have developed a company-wide Climate Change Action Plan
with the goal of tracking mitigation activities
for each climate-related risk included in the corporate
Sustainable Development Risk Register.
The risks addressed in our Climate Change Action
Plan fall into four broad categories:
●
GHG-related legislation and regulation.
●
GHG emissions management.
●
Physical climate-related impacts.
●
Climate-related disclosure and reporting.
Emissions are categorized into different scopes.
Scope 1 and Scope 2 GHG emissions
help us understand
climate transition risk.
Scope 1 emissions are direct GHG emissions from sources
that we own or control.
Scope 2 emissions are GHG emissions from
the generation of purchased electricity or
steam that we consume.
Our corporate authorization process requires all
qualifying projects to run a GHG pricing
sensitivity using a
corporate price of $40 per tonne of carbon
dioxide equivalent, plus annual inflation, for
all Scope 1 and Scope
2 GHG emissions produced in 2024 and later.
Projects in jurisdictions with existing GHG pricing
regimes
must incorporate that existing GHG price and its
forecast into their base case economics.
Where the existing
GHG price is below the corporate price, the
$40 per tonne of carbon dioxide equivalent
sensitivity must also be
run from 2024 onward.
Thus, both existing and emerging regulatory requirements
are considered in our
decision-making.
The company does not use an estimated market
cost of GHG emissions when assessing
reserves in jurisdictions without existing GHG regulations.
In December 2018, we became a founding member
of the CLC, an international policy institute
founded in
collaboration with business and environmental
interests to develop a carbon dividend plan.
Participation in the
CLC provides another opportunity for ongoing
dialogue about carbon pricing and framing the
issues in
alignment with our public policy principles.
We also belong to and fund Americans For Carbon Dividends,
the education and advocacy branch of the CLC.
In 2017 and 2018, cities, counties, and a state
government in California, New York, Washington, Rhode Island
and Maryland, as well as the Pacific Coast Federation
of Fishermen’s Association, Inc., have filed lawsuits
against oil and gas companies, including ConocoPhillips,
seeking compensatory damages and equitable
relief
to abate alleged climate change impacts.
ConocoPhillips is vigorously defending against
these lawsuits.
The
lawsuits brought by the Cities of San Francisco,
Oakland and New York have been dismissed by the district
courts and appeals are pending.
Lawsuits filed by other cities and counties
in California and Washington are
currently stayed pending resolution of the appeals
brought by the Cities of San Francisco and
Oakland to the
U.S. Court of Appeals for the Ninth Circuit.
Lawsuits filed in Maryland and Rhode Island
are proceeding in
state court while rulings in those matters, on the
issue of whether the matters should proceed
in state or federal
court, are on appeal to the U.S. Court of Appeals
for the Fourth Circuit and First Circuit,
respectively.
Several Louisiana parishes and individual landowners
have filed lawsuits against oil and gas companies,
including ConocoPhillips, seeking compensatory
damages in connection with historical oil
and gas operations
in Louisiana.
All parish lawsuits are stayed pending an appeal
to the Fifth Circuit Court of Appeals on the
issue of whether they will proceed in federal or
state court.
ConocoPhillips will vigorously defend against
these lawsuits.
Other
We have deferred tax assets related to certain accrued liabilities, loss carryforwards
and credit carryforwards.
Valuation
allowances have been established to reduce
these deferred tax assets to an amount that
will, more
likely than not, be realized.
Based on our historical taxable income, our expectations
for the future, and
available tax-planning strategies, management
expects the net deferred tax assets will be realized
as offsets to
reversing deferred tax liabilities.
CRITICAL ACCOUNTING ESTIMATES
The preparation of financial statements in
conformity with GAAP requires management
to select appropriate
accounting policies and to make estimates
and assumptions that affect the reported amounts of assets,
liabilities, revenues and expenses.
See Note 1—Accounting Policies, in the Notes
to Consolidated Financial
Statements, for descriptions of our major accounting
policies.
Certain of these accounting policies involve
judgments and uncertainties to such an extent there
is a reasonable likelihood materially different amounts
would have been reported under different conditions, or if
different assumptions had been used.
These critical
accounting estimates are discussed with the Audit
and Finance Committee of the Board of Directors at
least
annually.
We believe the following discussions of critical accounting estimates, along
with the discussion of
deferred tax asset valuation allowances in this
report, address all important accounting
areas where the nature
of accounting estimates or assumptions is material
due to the levels of subjectivity and judgment necessary
to
account for highly uncertain matters or the
susceptibility of such matters to change.
Oil and Gas Accounting
Accounting for oil and gas exploratory activity
is subject to special accounting rules unique
to the oil and gas
industry.
The acquisition of geological and geophysical
seismic information, prior to the discovery
of proved
reserves, is expensed as incurred, similar to
accounting for research and development
costs.
However,
leasehold acquisition costs and exploratory well
costs are capitalized on the balance sheet
pending
determination of whether proved oil and gas reserves
have been recognized.
Property Acquisition
Costs
For individually significant leaseholds, management
periodically assesses for impairment based on
exploration
and drilling efforts to date.
For relatively small individual leasehold acquisition
costs, management exercises
judgment and determines a percentage probability
that the prospect ultimately will fail to find
proved oil and
gas reserves and pools that leasehold information
with others in the geographic area.
For prospects in areas
with limited, or no, previous exploratory drilling,
the percentage probability of ultimate failure
is normally
judged to be quite high.
This judgmental percentage is multiplied
by the leasehold acquisition cost, and that
product is divided by the contractual period
of the leasehold to determine a periodic leasehold
impairment
charge that is reported in exploration expense.
This judgmental probability percentage is reassessed
and
adjusted throughout the contractual period of the
leasehold based on favorable or unfavorable
exploratory
activity on the leasehold or on adjacent leaseholds,
and leasehold impairment amortization expense is
adjusted
prospectively.
At year-end 2019, the remaining $3.5 billion of net capitalized
unproved property costs consisted primarily
of
individually significant leaseholds, mineral rights
held in perpetuity by title ownership, exploratory
wells
currently being drilled, suspended exploratory
wells, and capitalized interest.
Of this amount, approximately
$2.1 billion is concentrated in 10 major development
areas, the majority of which are not expected to
move to
proved properties in 2020,
and $0.6 billion is held for sale.
Management periodically assesses individually
significant leaseholds for impairment based on
the results of exploration and drilling efforts and the outlook
for
commercialization.
Exploratory Costs
For exploratory wells, drilling costs are temporarily
capitalized, or “suspended,” on the balance sheet,
pending
a determination of whether potentially economic
oil and gas reserves have been discovered by the
drilling
effort to justify development.
If exploratory wells encounter potentially economic
quantities of oil and gas, the well costs
remain capitalized
on the balance sheet as long as sufficient progress assessing
the reserves and the economic and operating
viability of the project is being made.
The accounting notion of “sufficient progress” is
a judgmental area, but
the accounting rules do prohibit continued capitalization
of suspended well costs on the expectation
future
market conditions will improve or new technologies
will be found that would make the development
economically profitable.
Often, the ability to move into the development
phase and record proved reserves is
dependent on obtaining permits and government
or co-venturer approvals, the timing of which is
ultimately
beyond our control.
Exploratory well costs remain suspended as long
as we are actively pursuing such
approvals and permits, and believe they will be obtained.
Once all required approvals and permits have
been
obtained, the projects are moved into the development
phase, and the oil and gas reserves are designated
as
proved reserves.
For complex exploratory discoveries, it
is not unusual to have exploratory wells remain
suspended on the balance sheet for several
years while we perform additional appraisal
drilling and seismic
work on the potential oil and gas field or while
we seek government or co-venturer approval of development
plans or seek environmental permitting.
Once a determination is made the well did not
encounter potentially
economic oil and gas quantities, the well costs
are expensed as a dry hole and reported in
exploration expense.
Management reviews suspended well balances quarterly, continuously monitors
the results of the additional
appraisal drilling and seismic work, and expenses
the suspended well costs as a dry hole when
it determines
the potential field does not warrant further
investment in the near term.
Criteria utilized in making this
determination include evaluation of the reservoir
characteristics and hydrocarbon properties,
expected
development costs, ability to apply existing technology
to produce the reserves, fiscal terms,
regulations or
contract negotiations, and our expected return
on investment.
At year-end 2019,
total suspended well costs were $1,020 million,
compared with $856 million at year-end
For additional information on suspended wells,
including an aging analysis, see Note 8—Suspended
Wells and Other Exploration Expenses, in the Notes to Consolidated Financial
Statements.
Proved Reserves
Engineering estimates of the quantities of proved reserves
are inherently imprecise and represent only
approximate amounts because of the judgments involved
in developing such information.
Reserve estimates
are based on geological and engineering assessments
of in-place hydrocarbon volumes, the production
plan,
historical extraction recovery and processing yield
factors, installed plant operating capacity
and approved
operating limits.
The reliability of these estimates at any point
in time depends on both the quality and
quantity of the technical and economic data
and the efficiency of extracting and processing the
hydrocarbons.
Despite the inherent imprecision in these engineering
estimates, accounting rules require disclosure
of
“proved” reserve estimates due to the importance
of these estimates to better understand the perceived
value
and future cash flows of a company’s operations.
There are several authoritative guidelines
regarding the
engineering criteria that must be met before estimated
reserves can be designated as “proved.”
Our
geosciences and reservoir engineering organization
has policies and procedures in place consistent
with these
authoritative guidelines.
We have trained and experienced internal engineering personnel who estimate our
proved reserves held by consolidated companies, as
well as our share of equity affiliates.
Proved reserve estimates are adjusted annually
in the fourth quarter and during the year
if significant changes
occur, and take into account recent production and subsurface
information about each field.
Also, as required
by current authoritative guidelines, the estimated
future date when an asset will be permanently
shut down for
economic reasons is based on 12-month average
prices and current costs.
This estimated date when production
will end affects the amount of estimated reserves.
Therefore, as prices and cost levels change from
year to
year, the estimate of proved reserves also changes.
Generally, our proved reserves decrease as prices decline
and increase as prices rise.
Our proved reserves include estimated quantities
related to PSCs, reported under the “economic interest”
method, as well as variable-royalty regimes,
and are subject to fluctuations in commodity
prices; recoverable
operating expenses; and capital costs.
If costs remain stable, reserve quantities
attributable to recovery of costs
will change inversely to changes in commodity
prices.
We would expect reserves from these contracts to
decrease when product prices rise and increase
when prices decline.
The estimation of proved developed reserves also
is important to the income statement because the
proved
developed reserve estimate for a field serves as the
denominator in the unit-of-production
calculation of the
DD&A of the capitalized costs for that asset.
At year-end 2019, the net book value of productive PP&E
subject to a unit-of-production calculation was
approximately $35 billion and the DD&A recorded
on these
assets in 2019 was approximately $5.8 billion.
The estimated proved developed reserves for
our consolidated
operations were 3.3 billion BOE at the end
of 2018 and 3.2
billion BOE at the end of 2019.
If the estimates of
proved reserves used in the unit-of-production
calculations had been lower by 10 percent
across all
calculations, before-tax DD&A in 2019
would have increased by an estimated $642
million.
Impairments
Long-lived assets used in operations are assessed
for impairment whenever changes in facts
and circumstances
indicate a possible significant deterioration
in future cash flows expected to be generated
by an asset group and
annually in the fourth quarter following updates
to corporate planning assumptions.
If there is an indication
the carrying amount of an asset may not be recovered,
the asset is monitored by management through
an
established process where changes to significant
assumptions such as prices, volumes and future
development
plans are reviewed.
If, upon review, the sum of the undiscounted before-tax cash flows is
less than the
carrying value of the asset group, the carrying
value is written down to estimated fair
value.
Individual assets
are grouped for impairment purposes based on a
judgmental assessment of the lowest level
for which there are
identifiable cash flows that are largely independent of the
cash flows of other groups of assets—generally on
a
field-by-field basis for E&P assets.
Because there usually is a lack of quoted market
prices for long-lived
assets, the fair value of impaired assets is
typically determined based on the present values
of expected future
cash flows using discount rates believed to be
consistent with those used by principal market
participants, or
based on a multiple of operating cash flow validated
with historical market transactions of similar
assets where
possible.
The expected future cash flows used for impairment
reviews and related fair value calculations are
based on judgmental assessments of future production
volumes, commodity prices, operating
costs and capital
decisions, considering all available information
at the date of review.
Differing assumptions could affect the
timing and the amount of an impairment
in any period.
See Note 9—Impairments, in the Notes to
Consolidated Financial Statements, for additional
information.
Investments in nonconsolidated entities
accounted for under the equity method are reviewed
for impairment
when there is evidence of a loss in value and annually
following updates to corporate planning assumptions.
Such evidence of a loss in value might include
our inability to recover the carrying amount,
the lack of
sustained earnings capacity which would justify
the current investment amount, or a current
fair value less than
the investment’s carrying amount.
When it is determined such a loss in value
is other than temporary, an
impairment charge is recognized for the difference between the
investment’s carrying value and its estimated
fair value.
When determining whether a decline in
value is other than temporary, management considers
factors such as the length of time and extent of
the decline, the investee’s financial condition and near-term
prospects, and our ability and intention to retain
our investment for a period that will be sufficient
to allow for
any anticipated recovery in the market value
of the investment.
Since quoted market prices are usually not
available, the fair value is typically based on the
present value of expected future cash flows using
discount
rates believed to be consistent with those used by
principal market participants, plus market analysis
of
comparable assets owned by the investee, if appropriate.
Differing assumptions could affect the timing and the
amount of an impairment of an investment in any
period.
See the “APLNG” section of Note 6—Investments,
Loans and Long-Term Receivables,
in the Notes to Consolidated Financial Statements,
for additional
information.
Asset Retirement Obligations and Environmental Costs
Under various contracts, permits and regulations,
we have material legal obligations to remove
tangible
equipment and restore the land or seabed at the
end of operations at operational sites.
Our largest asset
removal obligations involve plugging and abandonment
of wells, removal and disposal of offshore oil and
gas
platforms around the world, as well as oil and gas
production facilities and pipelines in Alaska.
The fair values
of obligations for dismantling and removing these
facilities are recorded as a liability and
an increase to PP&E
at the time of installation of the asset based on estimated
discounted costs.
Estimating future asset removal
costs is difficult.
Most of these removal obligations are many years,
or decades, in the future and the contracts
and regulations often have vague descriptions
of what removal practices and criteria
must be met when the
removal event actually occurs.
Asset removal technologies and costs, regulatory
and other compliance
considerations, expenditure timing, and other inputs
into valuation of the obligation, including discount
and
inflation rates, are also subject to change.
Normally, changes in asset removal obligations are reflected in the income statement
as increases or decreases
to DD&A over the remaining life of the assets.
However, for assets at or nearing the end of their operations, as
well as previously sold assets for which we
retained the asset removal obligation, an increase
in the asset
removal obligation can result in an immediate
charge to earnings, because any increase in PP&E
due to the
increased obligation would immediately be subject
to impairment, due to the low fair value of these
properties.
In addition to asset removal obligations, under the
above or similar contracts, permits and regulations,
we have
certain environmental-related projects.
These are primarily related to remediation
activities required by
Canada and various states
within the U.S. at exploration and production sites.
Future environmental
remediation costs are difficult to estimate because they are
subject to change due to such factors as the
uncertain magnitude of cleanup costs, the unknown
time and extent of such remedial actions
that may be
required, and the determination of our liability
in proportion to that of other responsible parties.
See Note
10—Asset Retirement Obligations and Accrued
Environmental Costs, in the Notes to Consolidated
Financial
Statements, for additional information.
Projected Benefit Obligations
Determination of the projected benefit obligations
for our defined benefit pension and postretirement
plans are
important to the recorded amounts for such obligations
on the balance sheet and to the amount of benefit
expense in the income statement.
The actuarial determination of projected benefit
obligations and company
contribution requirements involves judgment about
uncertain future events, including estimated
retirement
dates, salary levels at retirement, mortality
rates, lump-sum election rates, rates of return on plan
assets, future
health care cost-trend rates, and rates of utilization
of health care services by retirees.
Due to the specialized
nature of these calculations, we engage outside actuarial
firms to assist in the determination of these
projected
benefit obligations and company contribution requirements.
For Employee Retirement Income Security Act-
governed pension plans, the actuary exercises fiduciary
care on behalf of plan participants in the
determination
of the judgmental assumptions used in determining
required company contributions into the
plans.
Due to
differing objectives and requirements between financial
accounting rules and the pension plan funding
regulations promulgated by governmental agencies,
the actuarial methods and assumptions
for the two
purposes differ in certain important respects.
Ultimately, we will be required to fund all vested benefits under
pension and postretirement benefit plans not
funded by plan assets or investment returns,
but the judgmental
assumptions used in the actuarial calculations
significantly affect periodic financial statements and funding
patterns over time.
Projected benefit obligations are particularly
sensitive to the discount rate assumption.
A
100 basis-point decrease in the discount rate assumption
would increase projected benefit obligations
by
$1,000 million.
Benefit expense is sensitive to the discount rate
and return on plan assets assumptions.
A
100 basis-point decrease in the discount rate assumption
would increase annual benefit expense by
$100 million, while a 100 basis-point decrease
in the return on plan assets assumption
would increase annual
benefit expense by $60 million.
In determining the discount rate, we use yields
on high-quality fixed income
investments matched to the estimated benefit
cash flows of our plans.
We are also exposed to the possibility
that lump sum retirement benefits taken from pension
plans during the year could exceed the total of
service
and interest components of annual pension expense
and trigger accelerated recognition of a portion
of
unrecognized net actuarial losses and gains.
These benefit payments are based on decisions
by plan
participants and are therefore difficult to predict.
In the event there is a significant reduction in the
expected
years of future service of present employees or the
elimination of the accrual of defined benefits
for some or all
of their future services for a significant number
of employees, we could recognize a curtailment
gain or loss.
See Note 18—Employee Benefit Plans, in the
Notes to Consolidated Financial Statements,
for additional
information.
Contingencies
A number of claims and lawsuits are made against
the company arising in the ordinary course of
business.
Management exercises judgment related to accounting
and disclosure of these claims which includes
losses,
damages, and underpayments associated with environmental
remediation, tax, contracts, and other legal
disputes.
As we learn new facts concerning contingencies,
we reassess our position both with respect to
amounts recognized and disclosed considering
changes to the probability of additional
losses and potential
exposure.
However, actual losses can and do vary from estimates
for a variety of reasons including legal,
arbitration, or other third-party decisions; settlement
discussions; evaluation of scope of damages;
interpretation of regulatory or contractual terms;
expected timing of future actions; and proportion
of liability
shared with other responsible parties.
Estimated future costs related to contingencies
are subject to change as
events evolve and as additional information becomes
available during the administrative and litigation
processes.
For additional information on contingent
liabilities, see the “Contingencies” section
within “Capital
Resources and Liquidity” and Note 13—Contingencies
and Commitments.
CAUTIONARY STATEMENT
FOR THE PURPOSES OF THE “SAFE HARBOR”
PROVISIONS OF
THE PRIVATE
SECURITIES LITIGATION REFORM ACT OF 1995
This report includes forward-looking statements
within the meaning of Section 27A of the Securities
Act of
1933 and Section 21E of the Securities Exchange
Act of 1934.
All statements other than statements of
historical fact included or incorporated by reference in
this report, including, without limitation,
statements
regarding our future financial position, business
strategy, budgets, projected revenues, projected costs and
plans, and objectives of management for future operations,
are forward-looking statements.
Examples of
forward-looking statements contained in this report
include our expected production growth and
outlook on the
business environment generally, our expected capital budget and capital expenditures,
and discussions
concerning future dividends.
You can often identify our forward-looking statements by the words “anticipate,”
“estimate,” “believe,” “budget,” “continue,” “could,”
“intend,” “may,” “plan,” “potential,” “predict,” “seek,”
“should,” “will,” “would,” “expect,” “objective,”
“projection,” “forecast,” “goal,” “guidance,” “outlook,”
“effort,” “target” and similar expressions.
We based the forward-looking statements on our current expectations, estimates
and projections about
ourselves and the industries in which we operate in
general.
We caution you these statements are not
guarantees of future performance as they involve
assumptions that, while made in good faith,
may prove to be
incorrect, and involve risks and uncertainties
we cannot predict.
In addition, we based many of these forward-
looking statements on assumptions about future events
that may prove to be inaccurate.
Accordingly, our
actual outcomes and results may differ materially from
what we have expressed or forecast in the forward-
looking statements.
Any differences could result from a variety of factors,
including, but not limited to, the
following:
●
Fluctuations in crude oil, bitumen, natural gas,
LNG and NGLs prices, including a prolonged
decline
in these prices relative to historical or future
expected levels.
●
The impact of significant declines in prices for
crude oil, bitumen, natural gas, LNG and NGLs,
which
may result in recognition of impairment costs
on our long-lived assets, leaseholds and
nonconsolidated equity investments.
●
Potential failures or delays in achieving expected
reserve or production levels from existing
and future
oil and gas developments, including due to operating
hazards, drilling risks and the inherent
uncertainties in predicting reserves and reservoir
performance.
●
Reductions in reserves
replacement rates, whether as a result
of the significant declines in commodity
prices or otherwise.
●
Unsuccessful exploratory drilling activities
or the inability to obtain access to exploratory acreage.
●
Unexpected changes in costs or technical requirements
for constructing, modifying or operating E&P
facilities.
●
Legislative and regulatory initiatives
addressing environmental concerns, including initiatives
addressing the impact of global climate change or further
regulating hydraulic fracturing, methane
emissions, flaring or water disposal.
●
Lack of, or disruptions in, adequate and reliable
transportation for our crude oil, bitumen, natural
gas,
LNG and NGLs.
●
Inability to timely obtain or maintain permits,
including those necessary for construction, drilling
and/or development, or inability to make capital
expenditures required to maintain compliance
with
any necessary permits or applicable laws or regulations.
●
Failure to complete definitive agreements and feasibility
studies for, and to complete construction of,
announced and future exploration and production
and LNG development in a timely manner
(if at all)
or on budget.
●
Potential disruption or interruption of our operations
due to accidents, extraordinary weather
events,
civil unrest, political events, war, global health epidemics, terrorism,
cyber attacks, and information
technology failures, constraints or disruptions.
●
Changes in international monetary conditions and
foreign currency exchange rate fluctuations.
●
Changes in international trade relationships,
including the imposition of trade restrictions
or tariffs
relating to crude oil, bitumen, natural gas,
LNG, NGLs and any materials or products (such
as
aluminum and steel) used in the operation of our
business.
●
Substantial investment in and development use
of, competing or alternative energy sources, including
as a result of existing or future environmental
rules and regulations.
●
Liability for remedial actions, including removal
and reclamation obligations, under existing
or future
environmental regulations and litigation.
●
Significant operational or investment changes imposed
by existing or future environmental
statutes
and regulations, including international agreements
and national or regional legislation and regulatory
measures to limit or reduce GHG emissions.
●
Liability resulting from litigation or our failure
to comply with applicable laws and regulations.
●
General domestic and international economic and
political developments, including armed
hostilities;
expropriation of assets; changes in governmental
policies relating to crude oil, bitumen, natural
gas,
LNG and NGLs pricing, regulation or taxation;
the impact of and uncertainty surrounding the
U.K.’s
decision to withdraw from the EU; and other political,
economic or diplomatic developments.
●
Volatility
in the commodity futures markets.
●
Changes in tax and other laws, regulations (including
alternative energy mandates), or royalty rules
applicable to our business, including changes
resulting from the implementation and interpretation
of
the Tax Cuts and Jobs Act.
●
Competition and consolidation in the oil and gas
E&P industry.
●
Any limitations on our access to capital or increase
in our cost of capital, including as a result
of
illiquidity or uncertainty in domestic or international
financial markets.
●
Our inability to execute, or delays in the completion,
of any asset dispositions or acquisitions
we elect
to pursue.
●
Potential failure to obtain, or delays in obtaining,
any necessary regulatory approvals for
asset
dispositions or acquisitions, or that such approvals
may require modification to the terms of the
transactions or the operation of our remaining business.
●
Potential disruption of our operations as a result
of asset dispositions or acquisitions, including
the
diversion
of management time and attention.
●
Our inability to deploy the net proceeds from any
asset dispositions we undertake in the manner
and
timeframe we currently anticipate, if at all.
●
Our inability to liquidate the common stock issued
to us by Cenovus Energy as part of our sale of
certain assets in western Canada at prices we deem
acceptable, or at all.
●
The operation and financing of our joint ventures.
●
The ability of our customers and other contractual
counterparties to satisfy their obligations to
us,
including our ability to collect payments
when due from the government of Venezuela or PDVSA.
●
Our inability to realize anticipated cost savings
and expenditure reductions.
●
The factors generally described in Item 1A—Risk
Factors in this 2019 Annual Report on Form 10-K
and any additional risks described in our other filings
with the SEC.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE