 filings.tools
Item 14. Principal Accounting Fees and Services
406K characters. Original on sec.gov · Markdown
Item 14. Principal Accounting Fees and Services
The information required by Item 9(e) of Schedule 14A and contained under the heading “Board Proposal to Ratify PricewaterhouseCoopers LLP as the Independent Registered Public Accounting Firm for 2020” in the 2020 Proxy Statement is incorporated by reference into this Annual Report on Form 10-K.
THIS PAGE INTENTIONALLY LEFT BLANK
Financial Table of Contents
Management's Discussion and Analysis of Financial Condition and Results of Operations
Key Financial Results
| Millions of dollars, except per-share amounts | 2019 | 2018 | 2017 | ||||||||
| Net Income (Loss) Attributable to Chevron Corporation | $ | 2,924 | $ | 14,824 | $ | 9,195 | |||||
| Per Share Amounts: | |||||||||||
| Net Income (Loss) Attributable to Chevron Corporation | |||||||||||
| – Basic | $ | 1.55 | $ | 7.81 | $ | 4.88 | |||||
| – Diluted | $ | 1.54 | $ | 7.74 | $ | 4.85 | |||||
| Dividends | $ | 4.76 | $ | 4.48 | $ | 4.32 | |||||
| Sales and Other Operating Revenues | $ | 139,865 | $ | 158,902 | $ | 134,674 | |||||
| Return on: | |||||||||||
| Capital Employed | 2.0 | % | 8.2 | % | 5.0 | % | |||||
| Stockholders’ Equity | 2.0 | % | 9.8 | % | 6.3 | % | |||||
| Earnings by Major Operating Area | |||||||||||
| Millions of dollars | 2019 | 2018 | 2017 | ||||||||
| Upstream | |||||||||||
| United States | $ | (5,094 | ) | $ | 3,278 | $ | 3,640 | ||||
| International | 7,670 | 10,038 | 4,510 | ||||||||
| Total Upstream | 2,576 | 13,316 | 8,150 | ||||||||
| Downstream | |||||||||||
| United States | 1,559 | 2,103 | 2,938 | ||||||||
| International | 922 | 1,695 | 2,276 | ||||||||
| Total Downstream | 2,481 | 3,798 | 5,214 | ||||||||
| All Other | (2,133 | ) | (2,290 | ) | (4,169 | ) | |||||
| Net Income (Loss) Attributable to Chevron Corporation****1,2 | $ | 2,924 | $ | 14,824 | $ | 9,195 | |||||
| 1 Includes foreign currency effects: | $ | (304 | ) | $ | 611 | $ | (446 | ) | |||
| 2 Income net of tax, also referred to as “earnings” in the discussions that follow. |
Refer to the “Results of Operations” section beginning on page 32 for a discussion of financial results by major operating area for the three years ended December 31, 2019.
Business Environment and Outlook
Chevron is a global energy company with substantial business activities in the following countries: Angola, Argentina, Australia, Azerbaijan, Bangladesh, Brazil, Canada, China, Colombia, Indonesia, Kazakhstan, Myanmar, Mexico, Nigeria, the Partitioned Zone between Saudi Arabia and Kuwait, the Philippines, Republic of Congo, Singapore, South Korea, Thailand, the United Kingdom, the United States, and Venezuela.
Earnings of the company depend mostly on the profitability of its upstream business segment. The most significant factor affecting the results of operations for the upstream segment is the price of crude oil, which is determined in global markets outside of the company’s control. In the company’s downstream business, crude oil is the largest cost component of refined products. It is the company’s objective to deliver competitive results and stockholder value in any business environment. Periods of sustained lower prices could result in the impairment or write-off of specific assets in future periods and cause the company to adjust operating expenses and capital and exploratory expenditures, along with other measures intended to improve financial performance. Similarly, impairments or write-offs may occur as a result of managerial decisions not to progress certain projects in the company's portfolio.
The effective tax rate for the company can change substantially during periods of significant earnings volatility. This is due to the mix effects that are impacted both by the absolute level of earnings or losses and whether they arise in higher or lower tax rate jurisdictions. As a result, a decline or increase in the effective income tax rate in one period may not be indicative of expected results in future periods. Note 15 provides the company’s effective income tax rate for the last three years.
Refer to the “Cautionary Statements Relevant to Forward-Looking Information” on page 2 and to “Risk Factors” in Part I, Item 1A, on pages 18 through 21 for a discussion of some of the inherent risks that could materially impact the company’s results of operations or financial condition.
The company continually evaluates opportunities to dispose of assets that are not expected to provide sufficient long-term value or to acquire assets or operations complementary to its asset base to help augment the company’s financial performance and value growth. Asset dispositions and restructurings may result in significant gains or losses in future periods. The company’s
Management's Discussion and Analysis of Financial Condition and Results of Operations
asset sale program for 2018 through 2020 is targeting before-tax proceeds of $5-10 billion. Proceeds related to asset sales were $2.0 billion in 2018 and $2.8 billion in 2019.
The company closely monitors developments in the financial and credit markets, the level of worldwide economic activity, and the implications for the company of movements in prices for crude oil and natural gas. Management takes these developments into account in the conduct of daily operations and for business planning.
Comments related to earnings trends for the company’s major business areas are as follows:
Upstream Earnings for the upstream segment are closely aligned with industry prices for crude oil and natural gas. Crude oil and natural gas prices are subject to external factors over which the company has no control, including product demand connected with global economic conditions, industry production and inventory levels, technology advancements, production quotas or other actions imposed by the Organization of Petroleum Exporting Countries (OPEC) or other producers, actions of regulators, weather-related damage and disruptions, competing fuel prices, and regional supply interruptions or fears thereof that may be caused by military conflicts, civil unrest or political uncertainty. Any of these factors could also inhibit the company’s production capacity in an affected region. The company closely monitors developments in the countries in which it operates and holds investments, and seeks to manage risks in operating its facilities and businesses. The longer-term trend in earnings for the upstream segment is also a function of other factors, including the company’s ability to find or acquire and efficiently produce crude oil and natural gas, changes in fiscal terms of contracts, and changes in tax and other applicable laws and regulations.
The company continues to actively manage its schedule of work, contracting, procurement, and supply-chain activities to effectively manage costs and support operational goals. Price levels for capital, exploratory costs, and operating expenses associated with the production of crude oil and natural gas can be subject to external factors beyond the company’s control including, but not limited to: the general level of inflation, tariffs or other taxes imposed on goods or services, and commoditized prices charged by the industry’s material and service providers. The spot markets for many services and materials fell as overall industry drilling activity in North America declined in 2019, particularly onshore. However, as industry activity contracts, financial pressure on suppliers has increased, which may limit further de-escalation and/or lead to consolidation across the supplier community impacting costs. The international and offshore rig markets are also showing some signs of weaknesses as activity has pulled back; however, pricing for some products and services remains resilient as many suppliers have reset expectations of higher industry spend and instead are looking to higher pricing and margins on a more limited scope of work. Chevron utilizes contracts with various pricing mechanisms, so there may be a delay in when the company’s costs reflect the changes in market trends.
Capital and exploratory expenditures and operating expenses could also be affected by damage to production facilities caused by severe weather or civil unrest, delays in construction, or other factors.
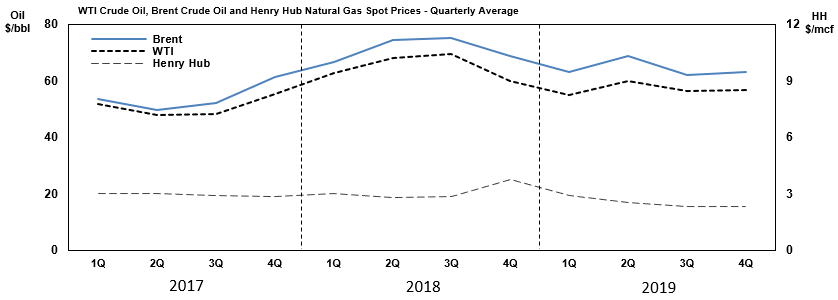
The chart above shows the trend in benchmark prices for Brent crude oil, West Texas Intermediate (WTI) crude oil and U.S. Henry Hub natural gas. The majority of the company’s equity crude production is priced based on the Brent benchmark. The Brent price averaged $64 per barrel for the full-year 2019, compared to $71 in 2018. Brent prices increased through the first half of 2019 due to OPEC production cuts and U.S. sanctions on Iran and Venezuela. Prices then started to decline due to heightened concerns about a slowing macro economy and weakening oil demand growth amid trade tensions between the
Management's Discussion and Analysis of Financial Condition and Results of Operations
U.S. and China. OPEC announced additional production cuts in December 2019, leading to a price increase with Brent prices at $67 at the end of the year. As of mid-February 2020, the Brent price was $57 per barrel, having declined more than 10 percent since December 2019, primarily due to concerns about demand erosion following the coronavirus outbreak.
The WTI price averaged $57 per barrel for the full-year 2019, compared to $65 in 2018. WTI traded at a discount to Brent throughout 2019. Differentials to Brent have ranged between $4 to $10 in 2019, primarily due to pipeline infrastructure constraints which have restricted flows of inland crude to export outlets on the Gulf Coast. Variability in other factors impacting supply and demand of each benchmark crude also affect price differential. As of mid-February 2020, the WTI price was $52 per barrel.
Chevron has interests in the production of heavy crude oil in California, Indonesia, the Partitioned Zone between Saudi Arabia and Kuwait, Venezuela and in certain fields in Angola and China. (See page 37 for the company’s average U.S. and international crude oil sales prices.)
In contrast to price movements in the global market for crude oil, price changes for natural gas are more closely aligned with seasonal supply-and-demand and infrastructure conditions in local markets. In the United States, prices at Henry Hub averaged $2.53 per thousand cubic feet (MCF) during 2019, compared with $3.12 during 2018. As of mid-February 2020, the Henry Hub spot price was $1.84 per MCF. Increased production in the Permian Basin has resulted in insufficient gas pipeline and fractionation capacity in the near-term, and over-supply conditions, leading to depressed natural gas and natural gas liquids prices in West Texas. A sizable portion of Chevron’s U.S. natural gas production comes from the Permian Basin, resulting in natural gas realizations that are significantly lower than the Henry Hub price.
Outside the United States, price changes for natural gas depend on a wide range of supply, demand and regulatory circumstances. Chevron sells natural gas into the domestic pipeline market in many locations. In some locations, Chevron has invested in long-term projects to produce and liquefy natural gas for transport by tanker to other markets. The company’s long-term contract prices for liquefied natural gas (LNG) are typically linked to crude oil prices. Most of the equity LNG offtake from the operated Australian LNG projects is committed under binding long-term contracts, with the remainder to be sold in the Asian spot LNG market. The Asian spot market reflects the supply and demand for LNG in the Pacific Basin and is not directly linked to crude oil prices. International natural gas realizations averaged $5.83 per MCF during 2019, compared with $6.29 per MCF during 2018. (See page 37 for the company’s average natural gas realizations for the U.S. and international regions.)
The company’s worldwide net oil-equivalent production in 2019 averaged 3.058 million barrels per day. About 15 percent of the company’s net oil-equivalent production in 2019 occurred in the OPEC-member countries of Angola, Nigeria, Republic of Congo and Venezuela. OPEC quotas had no material effect on the company’s net crude oil production in 2019 or 2018.
The company estimates that net oil-equivalent production in 2020 will grow up to 3 percent compared to 2019, assuming a Brent crude oil price of $60 per barrel and excluding the impact of anticipated 2020 asset sales. This estimate is subject to many factors and uncertainties, including quotas or other actions that may be imposed by OPEC; tariffs and trade sanctions; price effects on entitlement volumes; changes in fiscal terms or restrictions on the scope of company operations; delays in construction; reservoir performance; greater-than-expected declines in production from mature fields; start-up or ramp-up of projects; fluctuations in demand for natural gas in various markets; weather conditions that may shut in production; civil unrest; changing geopolitics; delays in completion of maintenance turnarounds; or other disruptions to operations. The outlook for future production levels is also affected by the size and number of economic investment opportunities and the time lag between initial exploration and the beginning of production. The company has increased its investment emphasis on short-cycle projects.
In the Partitioned Zone between Saudi Arabia and Kuwait, production was shut-in beginning in May 2015 as a result of difficulties in securing work and equipment permits. Net oil-equivalent production in the Partitioned Zone in 2014 was 81,000 barrels per day. During 2015, net oil-equivalent production averaged 28,000 barrels per day. In December 2019, the governments of Saudi Arabia and Kuwait signed a memorandum of understanding to resolve the dispute and allow production to restart in the Partitioned Zone. In mid-February 2020, pre-startup activities commenced. The financial effects from the loss of production in 2019 were not significant and are not expected to be significant in 2020.
Chevron has interests in Venezuelan crude oil production assets operated by independent equity affiliates. While the operating environment in Venezuela has been deteriorating for some time, the equity affiliates have continued to operate consistent with the authorization provided pursuant to general licenses issued by the United States government. It remains uncertain when the environment in Venezuela will stabilize, but the company remains committed to its personnel and operations in
Management's Discussion and Analysis of Financial Condition and Results of Operations
Venezuela. Refer to Note 22 on page 88 under the heading “Other Contingencies” for more information on the company’s activities in Venezuela.
 |
Net proved reserves for consolidated companies and affiliated companies totaled 11.4 billion barrels of oil-equivalent at year-end 2019, a decrease of 5 percent from year-end 2018. The reserve replacement ratio in 2019 was 44 percent. The 5 and 10 year reserve replacement ratios were 106 percent and 101 percent, respectively. Refer to Table V beginning on page 96 for a tabulation of the company’s proved net oil and gas reserves by geographic area, at the beginning of 2017 and each year-end from 2017 through 2019, and an accompanying discussion of major changes to proved reserves by geographic area for the three-year period ending December 31, 2019.
Refer to the “Results of Operations” section on pages 32 through 34 for additional discussion of the company’s upstream business.
Downstream Earnings for the downstream segment are closely tied to margins on the refining, manufacturing and marketing of products that include gasoline, diesel, jet fuel, lubricants, fuel oil, fuel and lubricant additives, and petrochemicals. Industry margins are sometimes volatile and can be affected by the global and regional supply-and-demand balance for refined products and petrochemicals, and by changes in the price of crude oil, other refinery and petrochemical feedstocks, and natural gas. Industry margins can also be influenced by inventory levels, geopolitical events, costs of materials and services, refinery or chemical plant capacity utilization, maintenance programs, and disruptions at refineries or chemical plants resulting from unplanned outages due to severe weather, fires or other operational events.
Other factors affecting profitability for downstream operations include the reliability and efficiency of the company’s refining, marketing and petrochemical assets, the effectiveness of its crude oil and product supply functions, and the volatility of tanker-charter rates for the company’s shipping operations, which are driven by the industry’s demand for crude oil and product tankers. Other factors beyond the company’s control include the general level of inflation and energy costs to operate the company’s refining, marketing and petrochemical assets and changes in tax laws and regulations.
The company’s most significant marketing areas are the West Coast and Gulf Coast of the United States and Asia. Chevron operates or has significant ownership interests in refineries in each of these areas.
Refer to the “Results of Operations” section on pages 32 through 34 for additional discussion of the company’s downstream operations.
All Other consists of worldwide cash management and debt financing activities, corporate administrative functions, insurance operations, real estate activities and technology companies.
Management's Discussion and Analysis of Financial Condition and Results of Operations
Operating Developments
Key operating developments and other events during 2019 and early 2020 included the following:
Upstream
Azerbaijan Signed an agreement to sell the company’s interest in the Azeri-Chirag-Gunashli fields and Baku-Tbilisi-Ceyhan pipeline.
Brazil Completed the sale of an interest in the Frade field.
Denmark Completed the sale of Denmark upstream interests.
Philippines Signed an agreement to sell the company’s interest in the Malampaya field in late October.
United Kingdom Completed the sale of interest in the Rosebank field.
United Kingdom Completed the sale of Central North Sea assets.
United States Announced the sanction of a waterflood project in the St. Malo field in the Gulf of Mexico.
United States Announced final investment decision for the Anchor field in the Gulf of Mexico.
Downstream
United States Completed the acquisition of a refinery in Pasadena, Texas.
Australia Signed an agreement to acquire a network of terminals and service stations.
CPChem Announced agreements to jointly develop petrochemical complexes in Qatar and the U.S. Gulf Coast.
Other
Common Stock Dividends The 2019 annual dividend was $4.76 per share, making 2019 the 32nd consecutive year that the company increased its annual per share dividend payout. In January 2020, the company’s Board of Directors approved a $0.10 per share increase in the quarterly dividend to $1.29 per share, payable in March 2020, representing an increase of 8.4 percent.
Common Stock Repurchase Program The company purchased $4 billion of its common stock in 2019 under its stock repurchase programs. The company currently expects to repurchase $5 billion of its common stock in 2020.
Results of Operations
The following section presents the results of operations and variances on an after-tax basis for the company’s business segments – Upstream and Downstream – as well as for “All Other.” Earnings are also presented for the U.S. and international geographic areas of the Upstream and Downstream business segments. Refer to Note 12, beginning on page 68, for a discussion of the company’s “reportable segments.” This section should also be read in conjunction with the discussion in “Business Environment and Outlook” on pages 28 through 32. Refer to the “Selected Operating Data” table on page 37 for a three-year comparison of production volumes, refined product sales volumes, and refinery inputs. A discussion of variances between 2018 and 2017 can be found in the “Results of Operations” section on pages 32 through 34 of the company’s 2018 Annual Report on Form 10-K filed with the SEC on February 22, 2019.
Management's Discussion and Analysis of Financial Condition and Results of Operations
 |
U.S. Upstream
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Earnings | $ | (5,094 | ) | $ | 3,278 | $ | 3,640 |
U.S. upstream recorded a loss of $5.09 billion in 2019, compared with earnings of $3.28 billion in 2018. The decrease in earnings was largely due to $8.17 billion in 2019 impairment charges primarily associated with Appalachia shale and Big Foot, partially offset by the absence of 2018 write-offs and impairments of $660 million, largely due to the Tigris Project in the Gulf of Mexico. Also contributing to the decrease was lower crude oil and natural gas prices of $1.72 billion, higher operating expenses of $260 million and the absence of several 2018 asset sale gains totaling $220 million, partially offset by higher crude oil and natural gas production of $1.33 billion.
The company’s average realization for U.S. crude oil and natural gas liquids in 2019 was $48.54 per barrel compared with $58.17 in 2018. The average natural gas realization was $1.09 per thousand cubic feet in 2019, compared with $1.86 in 2018.
Net oil-equivalent production in 2019 averaged 929,000 barrels per day, up 17 percent from 2018. The production increase was largely due to shale and tight properties in the Permian Basin in Texas and New Mexico.
The net liquids component of oil-equivalent production for 2019 averaged 724,000 barrels per day, up 17 percent from 2018. Net natural gas production averaged 1.23 billion cubic feet per day in 2019, up 18 percent from 2018.
International Upstream
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Earnings***** | $ | 7,670 | $ | 10,038 | $ | 4,510 | ||||||
| *Includes foreign currency effects: | $ | (323 | ) | $ | 545 | $ | (456 | ) |
International upstream earnings were $7.67 billion in 2019, compared with $10.04 billion in 2018. Lower crude oil and natural gas realizations of $1.4 billion and $830 million, respectively, were partially offset by lower depreciation and tax expenses of $560 million and $280 million, respectively. There were also a number of special items that largely offset each other in 2019 and 2018. Included in 2019 earnings were items totaling $800 million for write-offs and impairment charges of $2.2 billion associated with Kitimat LNG and other gas projects partially offset by a gain of $1.2 billion on the sale of the U.K. Central North Sea assets and a benefit of $180 million related to a reduction in the corporate income tax rate in Alberta, Canada. Offsetting these items were the absence of 2018 special items of $920 million associated with impairments, write-offs, a receivable write-down and a contractual settlement. Foreign currency effects had an unfavorable impact on earnings of $868 million between periods.
Management's Discussion and Analysis of Financial Condition and Results of Operations
The company’s average realization for international crude oil and natural gas liquids in 2019 was $58.14 per barrel compared with $64.25 in 2018. The average natural gas realization was $5.83 per thousand cubic feet in 2019 compared with $6.29 in 2018.
International net oil-equivalent production was 2.13 million barrels per day in 2019, essentially unchanged from 2018. Production increases from Wheatstone and major capital projects were offset by normal field declines and the impact of asset sales in 2019.
The net liquids component of international oil-equivalent production was 1.14 million barrels per day in 2019, down 2 percent from 2018. International net natural gas production of 5.93 billion cubic feet per day in 2019 increased 1 percent from 2018.
U.S. Downstream
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Earnings | $ | 1,559 | $ | 2,103 | $ | 2,938 |
U.S. downstream earned $1.56 billion in 2019, compared with $2.10 billion in 2018. The decrease was primarily due to lower margins on refined product sales of $300 million, lower equity earnings from the 50 percent-owned CPChem of $140 million and higher depreciation expense of $100 million following first production at the new hydrogen plant at the Richmond refinery.
Total refined product sales of 1.25 million barrels per day in 2019 were up 3 percent from 2018.
International Downstream
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Earnings***** | $ | 922 | $ | 1,695 | $ | 2,276 | ||||||
| *Includes foreign currency effects: | $ | 17 | $ | 71 | $ | (90 | ) |
International downstream earned $922 million in 2019, compared with $1.70 billion in 2018. The decrease in earnings was due to lower margins on refined product sales of $570 million, lower gains on asset sales of $300 million, primarily due to the absence of the 2018 gains from the southern Africa asset sale, partially offset by favorable tax items of $100 million. Foreign currency effects had an unfavorable impact on earnings of $54 million between periods.
Total refined product sales of 1.33 million barrels per day in 2019 were down 8 percent from 2018, primarily due to the sale of the southern Africa refining and marketing business in third quarter 2018.
All Other
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Net charges***** | $ | (2,133 | ) | $ | (2,290 | ) | $ | (4,169 | ) | |||
| *Includes foreign currency effects: | $ | 2 | $ | (5 | ) | $ | 100 |
All Other consists of worldwide cash management and debt financing activities, corporate administrative functions, insurance operations, real estate activities, and technology companies.
Net charges in 2019 decreased $157 million from 2018. The change between periods was mainly due to receipt of the Anadarko merger termination fee, partially offset by higher tax items. Foreign currency effects decreased net charges by $7 million between periods.
Consolidated Statement of Income
Comparative amounts for certain income statement categories are shown below. A discussion of variances between 2018 and 2017 can be found in the “Consolidated Statement of Income” section on pages 34 through 36 of the company’s 2018 Annual Report on Form 10-K.
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Sales and other operating revenues | $ | 139,865 | $ | 158,902 | $ | 134,674 |
Sales and other operating revenues decreased in 2019 mainly due to lower refined product, crude oil and natural gas prices, and lower crude oil and refined product volumes.
Management's Discussion and Analysis of Financial Condition and Results of Operations
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Income from equity affiliates | $ | 3,968 | $ | 6,327 | $ | 4,438 |
Income from equity affiliates decreased in 2019 mainly due to lower upstream-related earnings from Tengizchevroil in Kazakhstan, Petroboscan and Petropiar in Venezuela, and lower downstream-related earnings from GS Caltex in South Korea. In addition, two upstream affiliates were written-down in 2019.
Refer to Note 13, beginning on page 71, for a discussion of Chevron’s investments in affiliated companies.
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Other income | $ | 2,683 | $ | 1,110 | $ | 2,610 |
Other income increased in 2019 mainly due to the receipt of the Anadarko merger termination fee and higher gains from asset sales, partially offset by unfavorable swings in foreign currency effects.
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Purchased crude oil and products | $ | 80,113 | $ | 94,578 | $ | 75,765 |
Crude oil and product purchases decreased $14.5 billion in 2019, primarily due to lower crude oil volumes and prices, and lower product prices and volumes.
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Operating, selling, general and administrative expenses | $ | 25,528 | $ | 24,382 | $ | 23,237 |
Operating, selling, general and administrative expenses increased $1.1 billion in 2019. The increase is mainly due to higher services and fees, materials and supplies expense and higher transportation expense, partially offset by the absence of a 2018 receivable write-down and contractual settlement.
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Exploration expense | $ | 770 | $ | 1,210 | $ | 864 |
Exploration expenses in 2019 decreased primarily due to lower charges for well write-offs, partially offset by higher geological and geophysical expenses.
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Depreciation, depletion and amortization | $ | 29,218 | $ | 19,419 | $ | 19,349 |
Depreciation, depletion and amortization expenses increased in 2019 mainly due to higher impairments, production and well write-offs, partially offset by lower rates.
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Taxes other than on income | $ | 4,136 | $ | 4,867 | $ | 12,331 |
Taxes other than on income decreased in 2019 mainly due to lower local and municipal taxes and licenses as a result of the company’s divestment of its downstream interest in southern Africa in third quarter 2018, partially offset by higher U.S. state carbon emissions regulatory expenses.
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Interest and debt expense | $ | 798 | $ | 748 | $ | 307 |
Interest and debt expenses increased in 2019 mainly due to lower capitalized interest, partially offset by lower interest expense resulting from lower debt balances.
| Millions of dollars | 2019 | 2018 | 2017 | |||||||||
| Income tax expense (benefit) | $ | 2,691 | $ | 5,715 | $ | (48 | ) |
The decrease in income tax expense in 2019 of $3.02 billion is due to the decrease in total income before tax for the company of $15.04 billion. The decrease in income before taxes for the company is primarily the result of the upstream impairment and project write-off charges along with lower commodity prices, partially offset by higher gains on asset sales.
U.S. income before tax decreased from a profit of $4.73 billion in 2018 to a loss of $5.48 billion in 2019. This decrease in earnings before tax was primarily driven by the effect of upstream impairments and lower crude oil and natural gas prices,
Management's Discussion and Analysis of Financial Condition and Results of Operations
partially offset by the Anadarko merger termination fee and higher production. The U.S. tax decreased from a tax charge of $724 million in 2018 to a tax benefit of $1.17 billion in 2019 primarily due to the before-tax loss.
International income before tax decreased from $15.84 billion in 2018 to $11.02 billion in 2019. This decrease was primarily driven by the effects of upstream project write-off and impairment charges and lower crude oil and natural gas prices, partially offset by gains on asset sales. The lower before-tax income primarily drove the $1.13 billion decrease in international income tax expense, from $4.99 billion in 2018 to $3.86 billion in 2019.
Refer also to the discussion of the effective income tax rate in Note 15 beginning on page 74.
Management's Discussion and Analysis of Financial Condition and Results of Operations
Selected Operating Data****1,2
| 2019 | 2018 | 2017 | |||||||||
| U.S. Upstream | |||||||||||
| Net Crude Oil and Natural Gas Liquids Production (MBPD) | 724 | 618 | 519 | ||||||||
| Net Natural Gas Production (MMCFPD)3 | 1,225 | 1,034 | 970 | ||||||||
| Net Oil-Equivalent Production (MBOEPD) | 929 | 791 | 681 | ||||||||
| Sales of Natural Gas (MMCFPD) | 4,016 | 3,481 | 3,331 | ||||||||
| Sales of Natural Gas Liquids (MBPD) | 130 | 110 | 30 | ||||||||
| Revenues from Net Production | |||||||||||
| Liquids ($/Bbl) | $ | 48.54 | $ | 58.17 | $ | 44.53 | |||||
| Natural Gas ($/MCF) | $ | 1.09 | $ | 1.86 | $ | 2.10 | |||||
| International Upstream | |||||||||||
| Net Crude Oil and Natural Gas Liquids Production (MBPD)4 | 1,141 | 1,164 | 1,204 | ||||||||
| Net Natural Gas Production (MMCFPD)3 | 5,932 | 5,855 | 5,062 | ||||||||
| Net Oil-Equivalent Production (MBOEPD)4 | 2,129 | 2,139 | 2,047 | ||||||||
| Sales of Natural Gas (MMCFPD) | 5,869 | 5,604 | 5,081 | ||||||||
| Sales of Natural Gas Liquids (MBPD) | 34 | 34 | 29 | ||||||||
| Revenues from Liftings | |||||||||||
| Liquids ($/Bbl) | $ | 58.14 | $ | 64.25 | $ | 49.46 | |||||
| Natural Gas ($/MCF) | $ | 5.83 | $ | 6.29 | $ | 4.62 | |||||
| Worldwide Upstream | |||||||||||
| Net Oil-Equivalent Production (MBOEPD)4 | |||||||||||
| United States | 929 | 791 | 681 | ||||||||
| International | 2,129 | 2,139 | 2,047 | ||||||||
| Total | 3,058 | 2,930 | 2,728 | ||||||||
| U.S. Downstream | |||||||||||
| Gasoline Sales (MBPD)5 | 667 | 627 | 625 | ||||||||
| Other Refined Product Sales (MBPD) | 583 | 591 | 572 | ||||||||
| Total Refined Product Sales (MBPD) | 1,250 | 1,218 | 1,197 | ||||||||
| Sales of Natural Gas Liquids (MBPD) | 101 | 74 | 109 | ||||||||
| Refinery Input (MBPD)6 | 947 | 905 | 901 | ||||||||
| International Downstream | |||||||||||
| Gasoline Sales (MBPD)5 | 289 | 336 | 365 | ||||||||
| Other Refined Product Sales (MBPD) | 1,038 | 1,101 | 1,128 | ||||||||
| Total Refined Product Sales (MBPD)7 | 1,327 | 1,437 | 1,493 | ||||||||
| Sales of Natural Gas Liquids (MBPD) | 72 | 62 | 64 | ||||||||
| Refinery Input (MBPD)8 | 617 | 706 | 760 | ||||||||
| 1 Includes company share of equity affiliates. | |||||||||||
| 2 MBPD – thousands of barrels per day; MMCFPD – millions of cubic feet per day; MBOEPD – thousands of barrels of oil-equivalents per day; Bbl – barrel; MCF – thousands of cubic feet. Oil-equivalent gas (OEG) conversion ratio is 6,000 cubic feet of natural gas = 1 barrel of crude oil. | |||||||||||
| 3 Includes natural gas consumed in operations (MMCFPD): | |||||||||||
| United States | 36 | 35 | 37 | ||||||||
| International | 602 | 584 | 528 | ||||||||
| 4 Includes net production of synthetic oil: | |||||||||||
| Canada | 53 | 53 | 51 | ||||||||
| Venezuela affiliate | 3 | 24 | 28 | ||||||||
| 5 Includes branded and unbranded gasoline. | |||||||||||
| 6 In May 2019, the company acquired the Pasadena Refinery in Pasadena, Texas, which has an operable capacity of 110,000 barrels per day. | |||||||||||
| 7 Includes sales of affiliates (MBPD): | 379 | 373 | 366 | ||||||||
| 8 In September 2018, the company sold its interest in the Cape Town Refinery in Cape Town, South Africa, which had an operable capacity of 110,000 barrels per day. |
Management's Discussion and Analysis of Financial Condition and Results of Operations
Liquidity and Capital Resources
Sources and uses of cash
The strength of the company’s balance sheet enabled it to fund any timing differences throughout the year between cash inflows and outflows.
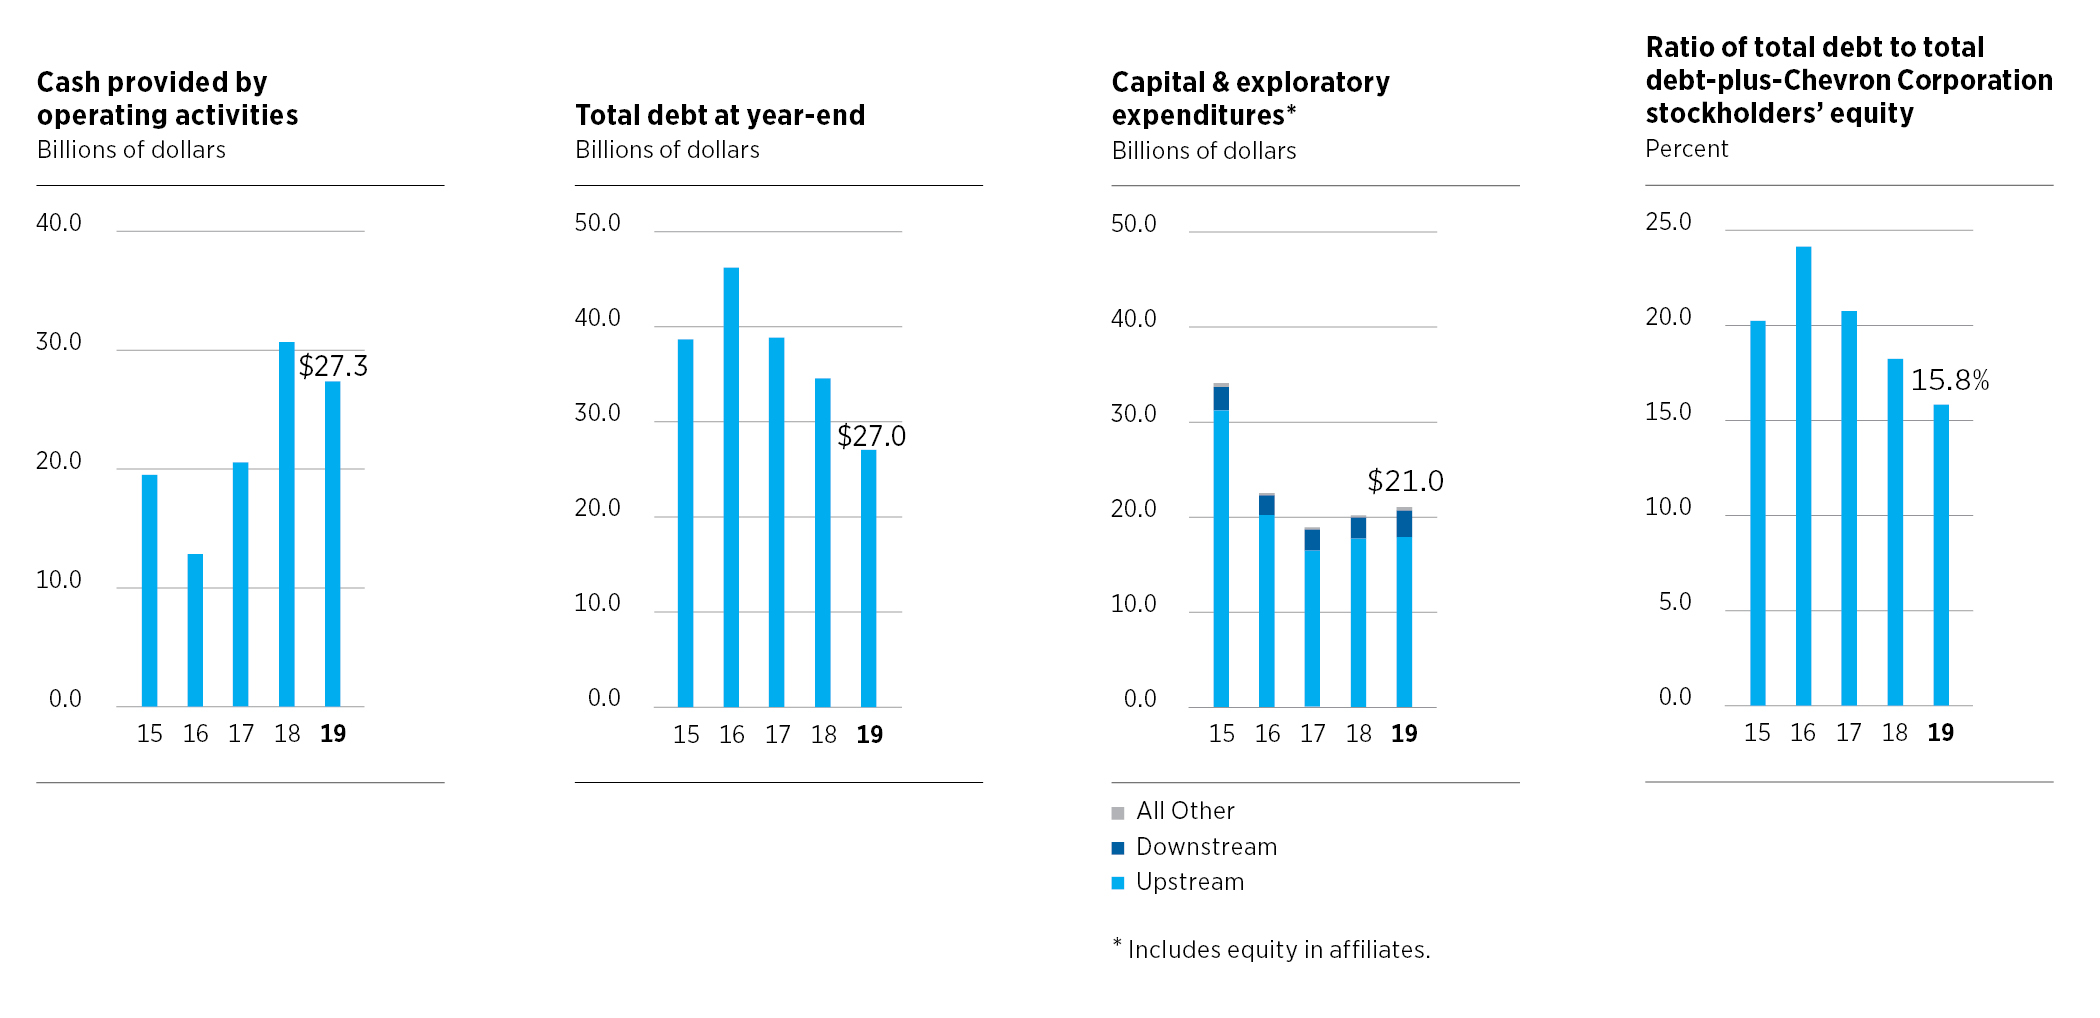
Cash, Cash Equivalents, Marketable Securities and Time Deposits Total balances were $5.7 billion and $10.3 billion at December 31, 2019 and 2018, respectively. Cash provided by operating activities in 2019 was $27.3 billion, compared to $30.6 billion in 2018, primarily due to lower crude oil prices. Cash provided by operating activities was net of contributions to employee pension plans of approximately $1.4 billion in 2019 and $1.0 billion in 2018. Cash provided by investing activities included proceeds and deposits related to asset sales of $2.8 billion in 2019 and $2.0 billion in 2018.
Restricted cash of $1.2 billion and $1.1 billion at December 31, 2019 and 2018, respectively, was held in cash and short-term marketable securities and recorded as “Deferred charges and other assets” and “Prepaid expenses and other current assets” on the Consolidated Balance Sheet. These amounts are generally associated with upstream decommissioning activities, tax payments, funds held in escrow for tax-deferred exchanges and refundable deposits related to pending asset sales.
Dividends Dividends paid to common stockholders were $9.0 billion in 2019 and $8.5 billion in 2018.
Debt and Finance Lease Liabilities Total debt and finance lease liabilities were $27.0 billion at December 31, 2019, down from $34.5 billion at year-end 2018.
The $7.5 billion decrease in total debt and finance lease liabilities during 2019 was primarily due to the repayment of long-term notes totaling $5.0 billion as they matured during 2019, and a reduction in commercial paper. The company’s debt and finance lease liabilities due within one year, consisting primarily of commercial paper, redeemable long-term obligations and the current portion of long-term debt, totaled $13.0 billion at December 31, 2019, compared with $15.6 billion at year-end 2018. Of these amounts, $9.75 billion and $9.9 billion were reclassified to long-term debt at the end of 2019 and 2018, respectively.
At year-end 2019, settlement of these obligations was not expected to require the use of working capital in 2020, as the company had the intent and the ability, as evidenced by committed credit facilities, to refinance them on a long-term basis.
Chevron has an automatic shelf registration statement that expires in May 2021 for an unspecified amount of nonconvertible debt securities issued or guaranteed by the company.
 |
The major debt rating agencies routinely evaluate the company’s debt, and the company’s cost of borrowing can increase or decrease depending on these debt ratings. The company has outstanding public bonds issued by Chevron Corporation and Texaco Capital Inc. All of these securities are the obligations of, or guaranteed by, Chevron Corporation and are rated AA by
Management's Discussion and Analysis of Financial Condition and Results of Operations
Standard and Poor’s Corporation and Aa2 by Moody’s Investors Service. The company’s U.S. commercial paper is rated A-1+ by Standard and Poor’s and P-1 by Moody’s. All of these ratings denote high-quality, investment-grade securities.
The company’s future debt level is dependent primarily on results of operations, cash that may be generated from asset dispositions, the capital program and shareholder distributions. Based on its high-quality debt ratings, the company believes that it has substantial borrowing capacity to meet unanticipated cash requirements. During extended periods of low prices for crude oil and natural gas and narrow margins for refined products and commodity chemicals, the company can also modify capital spending plans and discontinue or curtail the stock repurchase program to provide flexibility to continue paying the common stock dividend and also remain committed to retaining the company’s high-quality debt ratings.
Committed Credit Facilities Information related to committed credit facilities is included in Note 17, Short-Term Debt, on page 78.
Common Stock Repurchase Program In January 2019, the company purchased shares for $0.3 billion under the July 2010 stock repurchase program. On February 1, 2019, the company announced that the Board of Directors authorized a new stock repurchase program with a maximum dollar limit of $25 billion and no set term limits. As of December 31, 2019, the company had purchased a total of 31.1 million shares for $3.7 billion, resulting in $21.3 billion remaining under the program authorized in February 2019. The company currently expects to repurchase $5 billion of its common stock in 2020. Repurchases may be made from time to time in the open market, by block purchases, in privately negotiated transactions or in such other manner as determined by the company. The timing of the repurchases and the actual amount repurchased will depend on a variety of factors, including the market price of the company’s shares, general market and economic conditions, and other factors. The stock repurchase program does not obligate the company to acquire any particular amount of common stock, and it may be suspended or discontinued at any time.
Capital and Exploratory Expenditures
Capital and exploratory expenditures by business segment for 2019, 2018 and 2017 are as follows:
| 2019 | 2018 | 2017 | |||||||||||||||||||||||||||||
| Millions of dollars | U.S. | Int’l. | Total | U.S. | Int’l. | Total | U.S. | Int’l. | Total | ||||||||||||||||||||||
| Upstream | $ | 8,197 | $ | 9,627 | $ | 17,824 | $ | 7,128 | $ | 10,529 | $ | 17,657 | $ | 5,145 | $ | 11,243 | $ | 16,388 | |||||||||||||
| Downstream | 1,868 | 920 | 2,788 | 1,582 | 611 | 2,193 | 1,656 | 534 | 2,190 | ||||||||||||||||||||||
| All Other | 365 | 17 | 382 | 243 | 13 | 256 | 239 | 4 | 243 | ||||||||||||||||||||||
| Total | $ | 10,430 | $ | 10,564 | $ | 20,994 | $ | 8,953 | $ | 11,153 | $ | 20,106 | $ | 7,040 | $ | 11,781 | $ | 18,821 | |||||||||||||
| Total, Excluding Equity in Affiliates | $ | 10,062 | $ | 4,820 | $ | 14,882 | $ | 8,651 | $ | 5,739 | $ | 14,390 | $ | 6,295 | $ | 7,783 | $ | 14,078 |
Total expenditures for 2019 were $21.0 billion, including $6.1 billion for the company’s share of equity-affiliate expenditures, which did not require cash outlays by the company. In 2018, expenditures were $20.1 billion, including the company’s share of affiliates’ expenditures of $5.7 billion.
Of the $21.0 billion of expenditures in 2019, 85 percent, or $17.8 billion, related to upstream activities. Approximately 88 percent was expended for upstream operations in 2018. International upstream accounted for 54 percent of the worldwide upstream investment in 2019 and 60 percent in 2018.
The company estimates that 2020 organic capital and exploratory expenditures will be $20 billion, including $6.2 billion of spending by affiliates. This is in line with 2019 expenditures, and reflects a robust portfolio of upstream and downstream investments, highlighted by the company’s Permian Basin position, and additional shale and tight development in other basins. Approximately 84 percent of the total, or $16.8 billion, is budgeted for exploration and production activities. Approximately $11 billion of planned upstream capital spending relates to base producing assets, including $4 billion for the Permian and $1 billion for other shale and tight rock investments. Approximately $5 billion of the upstream program is planned for major capital projects underway, including $4 billion associated with the Future Growth and Wellhead Pressure Management Project at the Tengiz field in Kazakhstan. Global exploration funding is expected to be about $1 billion. Remaining upstream spend is budgeted for early stage projects supporting potential future developments. The company monitors crude oil market conditions and is able to adjust future capital outlays should oil price conditions deteriorate.
Worldwide downstream spending in 2020 is estimated to be $2.8 billion, with $1.6 billion estimated for projects in the United States.
Investments in technology businesses and other corporate operations in 2020 are budgeted at $0.4 billion.
Management's Discussion and Analysis of Financial Condition and Results of Operations
Noncontrolling Interests The company had noncontrolling interests of $1.0 billion at December 31, 2019 and $1.1 billion at December 31, 2018. Distributions to noncontrolling interests totaled $18 million and $91 million in 2019 and 2018, respectively.
Pension Obligations Information related to pension plan contributions is included beginning on page 82 in Note 21, Employee Benefit Plans, under the heading “Cash Contributions and Benefit Payments.”
Financial Ratios and Metrics
The following represent several metrics the company believes are useful measures to monitor the financial health of the company and its performance over time:
Current Ratio Current assets divided by current liabilities, which indicates the company’s ability to repay its short-term liabilities with short-term assets. The current ratio in all periods was adversely affected by the fact that Chevron’s inventories are valued on a last-in, first-out basis. At year-end 2019, the book value of inventory was lower than replacement costs, based on average acquisition costs during the year, by approximately $4.5 billion.
| At December 31 | |||||||||||||||
| Millions of dollars | 2019 | 2018 | 2017 | ||||||||||||
| Current assets | $ | 28,329 | $ | 34,021 | $ | 28,560 | |||||||||
| Current liabilities | 26,530 | 27,171 | 27,737 | ||||||||||||
| Current Ratio | 1.1 | 1.3 | 1.0 |
Interest Coverage Ratio Income before income tax expense, plus interest and debt expense and amortization of capitalized interest, less net income attributable to noncontrolling interests, divided by before-tax interest costs. This ratio indicates the company’s ability to pay interest on outstanding debt. The company’s interest coverage ratio in 2019 was lower than 2018 due to lower income.
| Year ended December 31 | |||||||||||||||
| Millions of dollars | 2019 | 2018 | 2017 | ||||||||||||
| Income (Loss) Before Income Tax Expense | $ | 5,536 | $ | 20,575 | $ | 9,221 | |||||||||
| Plus: Interest and debt expense | 798 | 748 | 307 | ||||||||||||
| Plus: Before-tax amortization of capitalized interest | 240 | 280 | 197 | ||||||||||||
| Less: Net income attributable to noncontrolling interests | (79 | ) | 36 | 74 | |||||||||||
| Subtotal for calculation | 6,653 | 21,567 | 9,651 | ||||||||||||
| Total financing interest and debt costs | $ | 817 | $ | 921 | $ | 902 | |||||||||
| Interest Coverage Ratio | 8.1 | 23.4 | 10.7 |
Free Cash Flow The cash provided by operating activities less cash capital expenditures, which represents the cash available to creditors and investors after investing in the business.
| Year ended December 31 | |||||||||||||||
| Millions of dollars | 2019 | 2018 | 2017 | ||||||||||||
| Net cash provided by operating activities | $ | 27,314 | $ | 30,618 | $ | 20,338 | |||||||||
| Less: Capital expenditures | 14,116 | 13,792 | 13,404 | ||||||||||||
| Free Cash Flow | $ | 13,198 | $ | 16,826 | $ | 6,934 |
Debt Ratio Total debt as a percentage of total debt plus Chevron Corporation Stockholders’ Equity, which indicates the company’s leverage. The company’s debt ratio was 15.8 percent at year-end 2019, compared with 18.2 percent at year-end 2018.
| At December 31 | |||||||||||||||
| Millions of dollars | 2019 | 2018 | 2017 | ||||||||||||
| Short-term debt | $ | 3,282 | $ | 5,726 | $ | 5,192 | |||||||||
| Long-term debt | 23,691 | 28,733 | 33,571 | ||||||||||||
| Total debt | 26,973 | 34,459 | 38,763 | ||||||||||||
| Total Chevron Corporation Stockholders’ Equity | 144,213 | 154,554 | 148,124 | ||||||||||||
| Total debt plus total Chevron Corporation Stockholders’ Equity | $ | 171,186 | $ | 189,013 | $ | 186,887 | |||||||||
| Debt Ratio | 15.8 | % | 18.2 | % | 20.7 | % |
Management's Discussion and Analysis of Financial Condition and Results of Operations
Net Debt Ratio Total debt less cash and cash equivalents, time deposits, and marketable securities as a percentage of total debt less cash and cash equivalents, time deposits, and marketable securities, plus Chevron Corporation Stockholders’ Equity, which indicates the company’s leverage, net of its cash balances.
| At December 31 | |||||||||||||||
| Millions of dollars | 2019 | 2018 | 2017 | ||||||||||||
| Short-term debt | $ | 3,282 | $ | 5,726 | $ | 5,192 | |||||||||
| Long-term debt | 23,691 | 28,733 | 33,571 | ||||||||||||
| Total Debt | 26,973 | 34,459 | 38,763 | ||||||||||||
| Less: Cash and cash equivalents | 5,686 | 9,342 | 4,813 | ||||||||||||
| Less: Time deposits | — | 950 | — | ||||||||||||
| Less: Marketable securities | 63 | 53 | 9 | ||||||||||||
| Total adjusted debt | 21,224 | 24,114 | 33,941 | ||||||||||||
| Total Chevron Corporation Stockholders’ Equity | 144,213 | 154,554 | 148,124 | ||||||||||||
| Total adjusted debt plus total Chevron Corporation Stockholders’ Equity | $ | 165,437 | $ | 178,668 | $ | 182,065 | |||||||||
| Net Debt Ratio | 12.8 | % | 13.5 | % | 18.6 | % |
Capital Employed The sum of Chevron Corporation Stockholders’ Equity, total debt and noncontrolling interests, which represents the net investment in the business.
| At December 31 | |||||||||||||||
| Millions of dollars | 2019 | 2018 | 2017 | ||||||||||||
| Chevron Corporation Stockholders’ Equity | $ | 144,213 | $ | 154,554 | $ | 148,124 | |||||||||
| Plus: Short-term debt | 3,282 | 5,726 | 5,192 | ||||||||||||
| Plus: Long-term debt | 23,691 | 28,733 | 33,571 | ||||||||||||
| Plus: Noncontrolling interest | 995 | 1,088 | 1,195 | ||||||||||||
| Capital Employed at December 31 | $ | 172,181 | $ | 190,101 | $ | 188,082 |
Return on Average Capital Employed (ROCE) Net income attributable to Chevron (adjusted for after-tax interest expense and noncontrolling interest) divided by average capital employed. Average capital employed is computed by averaging the sum of capital employed at the beginning and end of the year. ROCE is a ratio intended to measure annual earnings as a percentage of historical investments in the business.
| Year ended December 31 | |||||||||||||||
| Millions of dollars | 2019 | 2018 | 2017 | ||||||||||||
| Net income attributable to Chevron | $ | 2,924 | $ | 14,824 | $ | 9,195 | |||||||||
| Plus: After-tax interest and debt expense | 761 | 713 | 264 | ||||||||||||
| Plus: Noncontrolling interest | (79 | ) | 36 | 74 | |||||||||||
| Net income after adjustments | 3,606 | 15,573 | 9,533 | ||||||||||||
| Average capital employed | $ | 181,141 | $ | 189,092 | $ | 190,465 | |||||||||
| Return on Average Capital Employed | 2.0 | % | 8.2 | % | 5.0 | % |
Return on Stockholders’ Equity (ROSE) Net income attributable to Chevron divided by average Chevron Corporation Stockholders’ Equity. Average stockholder’s equity is computed by averaging the sum of stockholder’s equity at the beginning and end of the year. ROSE is a ratio intended to measure earnings as a percentage of shareholder investments.
| Year ended December 31 | |||||||||||||||
| Millions of dollars | 2019 | 2018 | 2017 | ||||||||||||
| Net income attributable to Chevron | $ | 2,924 | $ | 14,824 | $ | 9,195 | |||||||||
| Chevron Corporation Stockholders’ Equity at December 31 | 144,213 | 154,554 | 148,124 | ||||||||||||
| Average Chevron Corporation Stockholders’ Equity | 149,384 | 151,339 | 146,840 | ||||||||||||
| Return on Average Stockholders’ Equity | 2.0 | % | 9.8 | % | 6.3 | % |
Management's Discussion and Analysis of Financial Condition and Results of Operations
Off-Balance-Sheet Arrangements, Contractual Obligations, Guarantees and Other Contingencies
Long-Term Unconditional Purchase Obligations and Commitments, Including Throughput and Take-or-Pay Agreements Information related to these matters is included on page 87 in Note 22, Other Contingencies and Commitments.
The following table summarizes the company’s significant contractual obligations:
| Payments Due by Period | |||||||||||||||||||
| Millions of dollars | Total1 | 2020 | 2021-2022 | 2023-2024 | After 2024 | ||||||||||||||
| On Balance Sheet:2 | |||||||||||||||||||
| Short-Term Debt3, 4 | $ | 3,264 | $ | 3,264 | $ | — | $ | — | $ | — | |||||||||
| Long-Term Debt3, 4 | 23,426 | — | 16,072 | 4,003 | 3,351 | ||||||||||||||
| Leases | 4,662 | 1,409 | 1,693 | 613 | 947 | ||||||||||||||
| Interest4 | 3,040 | 565 | 903 | 554 | 1,018 | ||||||||||||||
| Off Balance Sheet: | |||||||||||||||||||
| Throughput and Take-or-Pay Agreements5 | 11,422 | 854 | 1,720 | 1,956 | 6,892 | ||||||||||||||
| Other Unconditional Purchase Obligations5 | 1,257 | 76 | 457 | 438 | 286 |
| 1 | Excludes contributions for pensions and other postretirement benefit plans. Information on employee benefit plans is contained in Note 21 beginning on page 82. |
| 2 | Does not include amounts related to the company’s income tax liabilities associated with uncertain tax positions. The company is unable to make reasonable estimates of the periods in which such liabilities may become payable. The company does not expect settlement of such liabilities to have a material effect on its consolidated financial position or liquidity in any single period. |
| 3 | $9.75 billion of short-term debt that the company expects to refinance is included in long-term debt. The repayment schedule above reflects the projected repayment of the entire amounts in the 2021–2022 period. The amounts represent only the principal balance. |
| 4 | Excludes finance lease liabilities. |
| 5 | Does not include commodity purchase obligations that are not fixed or determinable. These obligations are generally monetized in a relatively short period of time through sales transactions or similar agreements with third parties. Examples include obligations to purchase LNG, regasified natural gas and refinery products at indexed prices. |
Direct Guarantees
| Commitment Expiration by Period | |||||||||||||||||||
| Millions of dollars | Total | 2020 | 2021-2022 | 2023-2024 | After 2024 | ||||||||||||||
| Guarantee of nonconsolidated affiliate or joint-venture obligations | $ | 704 | $ | 314 | $ | 214 | $ | 77 | $ | 99 |
Additional information related to guarantees is included on page 87 in Note 22, Other Contingencies and Commitments.
Indemnifications Information related to indemnifications is included on page 87 in Note 22, Other Contingencies and Commitments.
Financial and Derivative Instrument Market Risk
The market risk associated with the company’s portfolio of financial and derivative instruments is discussed below. The estimates of financial exposure to market risk do not represent the company’s projection of future market changes. The actual impact of future market changes could differ materially due to factors discussed elsewhere in this report, including those set forth under the heading “Risk Factors” in Part I, Item 1A.
Derivative Commodity Instruments Chevron is exposed to market risks related to the price volatility of crude oil, refined products, natural gas, natural gas liquids, liquefied natural gas and refinery feedstocks. The company uses derivative commodity instruments to manage these exposures on a portion of its activity, including firm commitments and anticipated transactions for the purchase, sale and storage of crude oil, refined products, natural gas, natural gas liquids and feedstock for company refineries. The company also uses derivative commodity instruments for limited trading purposes. The results of these activities were not material to the company’s financial position, results of operations or cash flows in 2019.
The company’s market exposure positions are monitored on a daily basis by an internal Risk Control group in accordance with the company’s risk management policies. The company’s risk management practices and its compliance with policies are reviewed by the Audit Committee of the company’s Board of Directors.
Derivatives beyond those designated as normal purchase and normal sale contracts are recorded at fair value on the Consolidated Balance Sheet with resulting gains and losses reflected in income. Fair values are derived principally from published market quotes and other independent third-party quotes. The change in fair value of Chevron’s derivative commodity instruments in 2019 was not material to the company’s results of operations.
The company uses the Monte Carlo simulation method as its Value-at-Risk (VaR) model to estimate the maximum potential loss in fair value, at the 95% confidence level with a one-day holding period, from the effect of adverse changes in market
Management's Discussion and Analysis of Financial Condition and Results of Operations
conditions on derivative commodity instruments held or issued. Based on these inputs, the VaR for the company’s primary risk exposures in the area of derivative commodity instruments at December 31, 2019 and 2018 was not material to the company’s cash flows or results of operations.
Foreign Currency The company may enter into foreign currency derivative contracts to manage some of its foreign currency exposures. These exposures include revenue and anticipated purchase transactions, including foreign currency capital expenditures and lease commitments. The foreign currency derivative contracts, if any, are recorded at fair value on the balance sheet with resulting gains and losses reflected in income. There were no open foreign currency derivative contracts at December 31, 2019.
Interest Rates The company may enter into interest rate swaps from time to time as part of its overall strategy to manage the interest rate risk on its debt. Interest rate swaps, if any, are recorded at fair value on the balance sheet with resulting gains and losses reflected in income. At year-end 2019, the company had no interest rate swaps.
Transactions With Related Parties
Chevron enters into a number of business arrangements with related parties, principally its equity affiliates. These arrangements include long-term supply or offtake agreements and long-term purchase agreements. Refer to “Other Information” on page 71, in Note 13, Investments and Advances, for further discussion. Management believes these agreements have been negotiated on terms consistent with those that would have been negotiated with an unrelated party.
Litigation and Other Contingencies
MTBE Information related to methyl tertiary butyl ether (MTBE) matters is included on page 72 in Note 14 under the heading “MTBE.”
Ecuador Information related to Ecuador matters is included in Note 14 under the heading “Ecuador,” beginning on page 72.
Environmental The following table displays the annual changes to the company’s before-tax environmental remediation reserves, including those for federal Superfund sites and analogous sites under state laws.
| Millions of dollars | 2019 | 2018 | 2017 | ||||||||
| Balance at January 1 | $ | 1,327 | $ | 1,429 | $ | 1,467 | |||||
| Net Additions | 200 | 197 | 323 | ||||||||
| Expenditures | (293 | ) | (299 | ) | (361 | ) | |||||
| Balance at December 31 | $ | 1,234 | $ | 1,327 | $ | 1,429 |
The company records asset retirement obligations when there is a legal obligation associated with the retirement of long-lived assets and the liability can be reasonably estimated. These asset retirement obligations include costs related to environmental issues. The liability balance of approximately $12.8 billion for asset retirement obligations at year-end 2019 related primarily to upstream properties.
For the company’s other ongoing operating assets, such as refineries and chemicals facilities, no provisions are made for exit or cleanup costs that may be required when such assets reach the end of their useful lives unless a decision to sell or otherwise decommission the facility has been made, as the indeterminate settlement dates for the asset retirements prevent estimation of the fair value of the asset retirement obligation.
Refer to the discussion below for additional information on environmental matters and their impact on Chevron, and on the company’s 2019 environmental expenditures. Refer to Note 22 on page 87 for additional discussion of environmental remediation provisions and year-end reserves. Refer also to Note 23 on page 89 for additional discussion of the company’s asset retirement obligations.
Suspended Wells Information related to suspended wells is included in Note 19, Accounting for Suspended Exploratory Wells, beginning on page 79.
Income Taxes Information related to income tax contingencies is included on pages 74 through 76 in Note 15 and page 87 in Note 22 under the heading “Income Taxes.”
Other Contingencies Information related to other contingencies is included on page 88 in Note 22 to the Consolidated Financial Statements under the heading “Other Contingencies.”
Management's Discussion and Analysis of Financial Condition and Results of Operations
Environmental Matters
The company is subject to various international, federal, state and local environmental, health and safety laws, regulations and market-based programs. These laws, regulations and programs continue to evolve and are expected to increase in both number and complexity over time and govern not only the manner in which the company conducts its operations, but also the products it sells. For example, international agreements and national, regional, and state legislation and regulatory measures that aim to limit or reduce greenhouse gas (GHG) emissions are currently in various stages of implementation. Consideration of GHG issues and the responses to those issues through international agreements and national, regional or state legislation or regulations are integrated into the company’s strategy and planning, capital investment reviews and risk management tools and processes, where applicable. They are also factored into the company’s long-range supply, demand and energy price forecasts. These forecasts reflect long-range effects from renewable fuel penetration, energy efficiency standards, climate-related policy actions, and demand response to oil and natural gas prices. In addition, legislation and regulations intended to address hydraulic fracturing also continue to evolve at the national, state and local levels. Refer to “Risk Factors” in Part I, Item 1A, on pages 18 through 21 for a discussion of some of the inherent risks of increasingly restrictive environmental and other regulation that could materially impact the company’s results of operations or financial condition.
Most of the costs of complying with existing laws and regulations pertaining to company operations and products are embedded in the normal costs of doing business. However, it is not possible to predict with certainty the amount of additional investments in new or existing technology or facilities or the amounts of increased operating costs to be incurred in the future to: prevent, control, reduce or eliminate releases of hazardous materials or other pollutants into the environment; remediate and restore areas damaged by prior releases of hazardous materials; or comply with new environmental laws or regulations. Although these costs may be significant to the results of operations in any single period, the company does not presently expect them to have a material adverse effect on the company’s liquidity or financial position.
Accidental leaks and spills requiring cleanup may occur in the ordinary course of business. The company may incur expenses for corrective actions at various owned and previously owned facilities and at third-party-owned waste disposal sites used by the company. An obligation may arise when operations are closed or sold or at non-Chevron sites where company products have been handled or disposed of. Most of the expenditures to fulfill these obligations relate to facilities and sites where past operations followed practices and procedures that were considered acceptable at the time but now require investigative or remedial work or both to meet current standards.
Using definitions and guidelines established by the American Petroleum Institute, Chevron estimated its worldwide environmental spending in 2019 at approximately $2.0 billion for its consolidated companies. Included in these expenditures were approximately $0.6 billion of environmental capital expenditures and $1.4 billion of costs associated with the prevention, control, abatement or elimination of hazardous substances and pollutants from operating, closed or divested sites, and the decommissioning and restoration of sites.
For 2020, total worldwide environmental capital expenditures are estimated at $0.4 billion. These capital costs are in addition to the ongoing costs of complying with environmental regulations and the costs to remediate previously contaminated sites.
Critical Accounting Estimates and Assumptions
Management makes many estimates and assumptions in the application of accounting principles generally accepted in the United States of America (GAAP) that may have a material impact on the company’s consolidated financial statements and related disclosures and on the comparability of such information over different reporting periods. Such estimates and assumptions affect reported amounts of assets, liabilities, revenues and expenses, as well as disclosures of contingent assets and liabilities. Estimates and assumptions are based on management’s experience and other information available prior to the issuance of the financial statements. Materially different results can occur as circumstances change and additional information becomes known.
The discussion in this section of “critical” accounting estimates and assumptions is according to the disclosure guidelines of the Securities and Exchange Commission (SEC), wherein:
| 1. | the nature of the estimates and assumptions is material due to the levels of subjectivity and judgment necessary to account for highly uncertain matters, or the susceptibility of such matters to change; and |
| 2. | the impact of the estimates and assumptions on the company’s financial condition or operating performance is material. |
The development and selection of accounting estimates and assumptions, including those deemed “critical,” and the associated disclosures in this discussion have been discussed by management with the Audit Committee of the Board of Directors. The areas of accounting and the associated “critical” estimates and assumptions made by the company are as follows:
Management's Discussion and Analysis of Financial Condition and Results of Operations
Oil and Gas Reserves Crude oil and natural gas reserves are estimates of future production that impact certain asset and expense accounts included in the Consolidated Financial Statements. Proved reserves are the estimated quantities of oil and gas that geoscience and engineering data demonstrate with reasonable certainty to be economically producible in the future under existing economic conditions, operating methods and government regulations. Proved reserves include both developed and undeveloped volumes. Proved developed reserves represent volumes expected to be recovered through existing wells with existing equipment and operating methods. Proved undeveloped reserves are volumes expected to be recovered from new wells on undrilled proved acreage, or from existing wells where a relatively major expenditure is required for recompletion. Variables impacting Chevron’s estimated volumes of crude oil and natural gas reserves include field performance, available technology, commodity prices, and development and production costs.
The estimates of crude oil and natural gas reserves are important to the timing of expense recognition for costs incurred and to the valuation of certain oil and gas producing assets. Impacts of oil and gas reserves on Chevron’s Consolidated Financial Statements, using the successful efforts method of accounting, include the following:
| 1. | Amortization - Capitalized exploratory drilling and development costs are depreciated on a unit-of-production (UOP) basis using proved developed reserves. Acquisition costs of proved properties are amortized on a UOP basis using total proved reserves. During 2019, Chevron’s UOP Depreciation, Depletion and Amortization (DD&A) for oil and gas properties was $14.2 billion, and proved developed reserves at the beginning of 2019 were 6.3 billion barrels for consolidated companies. If the estimates of proved reserves used in the UOP calculations for consolidated operations had been lower by 5 percent across all oil and gas properties, UOP DD&A in 2019 would have increased by approximately $700 million. |
| 2. | Impairment - Oil and gas reserves are used in assessing oil and gas producing properties for impairment. A significant reduction in the estimated reserves of a property would trigger an impairment review. Proved reserves (and, in some cases, a portion of unproved resources) are used to estimate future production volumes in the cash flow model. For a further discussion of estimates and assumptions used in impairment assessments, see Impairment of Properties, Plant and Equipment and Investments in Affiliates below. |
Refer to Table V, “Reserve Quantity Information,” beginning on page 96, for the changes in proved reserve estimates for the three years ended December 31, 2019, and to Table VII, “Changes in the Standardized Measure of Discounted Future Net Cash Flows From Proved Reserves” on page 103 for estimates of proved reserve values for each of the three years ended December 31, 2019.
This Oil and Gas Reserves commentary should be read in conjunction with the Properties, Plant and Equipment section of Note 1, beginning on page 57, which includes a description of the “successful efforts” method of accounting for oil and gas exploration and production activities.
Impairment of Properties, Plant and Equipment and Investments in Affiliates The company assesses its properties, plant and equipment (PP&E) for possible impairment whenever events or changes in circumstances indicate that the carrying value of the assets may not be recoverable. If the carrying value of an asset exceeds the future undiscounted cash flows expected from the asset, an impairment charge is recorded for the excess of carrying value of the asset over its estimated fair value.
Determination as to whether and how much an asset is impaired involves management estimates on highly uncertain matters, such as future commodity prices, operating expenses, production profiles, and the outlook for global or regional market supply-and-demand conditions for crude oil, natural gas, commodity chemicals and refined products. However, the impairment reviews and calculations are based on assumptions that are generally consistent with the company’s business plans and long-term investment decisions. Refer also to the discussion of impairments of properties, plant and equipment in Note 16 on page 77 and to the section on Properties, Plant and Equipment in Note 1, “Summary of Significant Accounting Policies,” beginning on page 57.
The company routinely performs impairment reviews when triggering events arise to determine whether any write-down in the carrying value of an asset or asset group is required. For example, when significant downward revisions to crude oil and natural gas reserves are made for any single field or concession, an impairment review is performed to determine if the carrying value of the asset remains recoverable. Similarly, a significant downward revision in the company’s crude oil or natural gas price outlook would trigger impairment reviews for impacted upstream assets. In addition, impairments could occur due to changes in national, state or local environmental regulations or laws, including those designed to stop or impede the development or production of oil and gas. Also, if the expectation of sale of a particular asset or asset group in any period has been deemed more likely than not, an impairment review is performed, and if the estimated net proceeds exceed the carrying value of the asset or asset group, no impairment charge is required. Such calculations are reviewed each period until the asset or asset group is
Management's Discussion and Analysis of Financial Condition and Results of Operations
disposed. Assets that are not impaired on a held-and-used basis could possibly become impaired if a decision is made to sell such assets. That is, the assets would be impaired if they are classified as held-for-sale and the estimated proceeds from the sale, less costs to sell, are less than the assets’ associated carrying values.
Investments in common stock of affiliates that are accounted for under the equity method, as well as investments in other securities of these equity investees, are reviewed for impairment when the fair value of the investment falls below the company’s carrying value. When this occurs, a determination must be made as to whether this loss is other-than-temporary, in which case the investment is impaired. Because of the number of differing assumptions potentially affecting whether an investment is impaired in any period or the amount of the impairment, a sensitivity analysis is not practicable.
In 2019, the company recorded impairments and write-offs for certain oil and gas properties following the review and approval of its business plan and capital expenditure program. As a result of the company’s disciplined approach to capital allocation and a downward revision in its longer-term commodity price outlook, the company will reduce funding to various natural gas-related upstream opportunities including Appalachia shale, Kitimat LNG and other international projects. In addition, the revised long-term oil price outlook resulted in an impairment of Big Foot. No individually material impairments of PP&E or Investments were recorded for 2018 or 2017. A sensitivity analysis of the impact on earnings for these periods if other assumptions had been used in impairment reviews and impairment calculations is not practicable, given the broad range of the company’s PP&E and the number of assumptions involved in the estimates. That is, favorable changes to some assumptions might have avoided the need to impair any assets in these periods, whereas unfavorable changes might have caused an additional unknown number of other assets to become impaired, or resulted in larger impacts on impaired assets.
Asset Retirement Obligations In the determination of fair value for an asset retirement obligation (ARO), the company uses various assumptions and judgments, including such factors as the existence of a legal obligation, estimated amounts and timing of settlements, discount and inflation rates, and the expected impact of advances in technology and process improvements. A sensitivity analysis of the ARO impact on earnings for 2019 is not practicable, given the broad range of the company’s long-lived assets and the number of assumptions involved in the estimates. That is, favorable changes to some assumptions would have reduced estimated future obligations, thereby lowering accretion expense and amortization costs, whereas unfavorable changes would have the opposite effect. Refer to Note 23 on page 89 for additional discussions on asset retirement obligations.
Pension and Other Postretirement Benefit Plans Note 21, beginning on page 82, includes information on the funded status of the company’s pension and other postretirement benefit (OPEB) plans reflected on the Consolidated Balance Sheet; the components of pension and OPEB expense reflected on the Consolidated Statement of Income; and the related underlying assumptions.
The determination of pension plan expense and obligations is based on a number of actuarial assumptions. Two critical assumptions are the expected long-term rate of return on plan assets and the discount rate applied to pension plan obligations. Critical assumptions in determining expense and obligations for OPEB plans, which provide for certain health care and life insurance benefits for qualifying retired employees and which are not funded, are the discount rate and the assumed health care cost-trend rates. Information related to the company’s processes to develop these assumptions is included on page 84 in Note 21 under the relevant headings. Actual rates may vary significantly from estimates because of unanticipated changes beyond the company’s control.
For 2019, the company used an expected long-term rate of return of 6.75 percent and a discount rate for service costs of 4.4 percent and a discount rate for interest cost of 3.7 percent for U.S. pension plans. The actual return for 2019 was 18.3 percent. For the 10 years ended December 31, 2019, actual asset returns averaged 8.1 percent for these plans. Additionally, with the exception of three years within this 10-year period, actual asset returns for these plans equaled or exceeded 6.75 percent during each year.
Total pension expense for 2019 was $0.9 billion. An increase in the expected long-term return on plan assets or the discount rate would reduce pension plan expense, and vice versa. As an indication of the sensitivity of pension expense to the long-term rate of return assumption, a 1 percent increase in this assumption for the company’s primary U.S. pension plan, which accounted for about 59 percent of companywide pension expense, would have reduced total pension plan expense for 2019 by approximately $79 million. A 1 percent increase in the discount rates for this same plan would have reduced pension expense for 2019 by approximately $197 million.
The aggregate funded status recognized at December 31, 2019, was a net liability of approximately $5.2 billion. An increase in the discount rate would decrease the pension obligation, thus changing the funded status of a plan. At December 31, 2019, the company used a discount rate of 3.1 percent to measure the obligations for the U.S. pension plans. As an indication of the
Management's Discussion and Analysis of Financial Condition and Results of Operations
sensitivity of pension liabilities to the discount rate assumption, a 0.25 percent increase in the discount rate applied to the company’s primary U.S. pension plan, which accounted for about 62 percent of the companywide pension obligation, would have reduced the plan obligation by approximately $401 million, and would have decreased the plan’s underfunded status from approximately $2.5 billion to $2.1 billion.
For the company’s OPEB plans, expense for 2019 was $101 million, and the total liability, all unfunded at the end of 2019, was $2.5 billion. For the main U.S. OPEB plan, the company used a discount rate for service cost of 4.5 percent and a discount rate for interest cost of 3.9 percent to measure expense in 2019, and a 3.1 percent discount rate to measure the benefit obligations at December 31, 2019. Discount rate changes, similar to those used in the pension sensitivity analysis, resulted in an immaterial impact on 2019 OPEB expense and OPEB liabilities at the end of 2019. For information on the sensitivity of the health care cost-trend rate, refer to page 84 in Note 21 under the heading “Other Benefit Assumptions.”
Differences between the various assumptions used to determine expense and the funded status of each plan and actual experience are included in actuarial gain/loss. Refer to page 83 in Note 21 for a description of the method used to amortize the $6.5 billion of before-tax actuarial losses recorded by the company as of December 31, 2019, and an estimate of the costs to be recognized in expense during 2020. In addition, information related to company contributions is included on page 86 in Note 21 under the heading “Cash Contributions and Benefit Payments.”
Contingent Losses Management also makes judgments and estimates in recording liabilities for claims, litigation, tax matters and environmental remediation. Actual costs can frequently vary from estimates for a variety of reasons. For example, the costs for settlement of claims and litigation can vary from estimates based on differing interpretations of laws, opinions on culpability and assessments on the amount of damages. Similarly, liabilities for environmental remediation are subject to change because of changes in laws, regulations and their interpretation, the determination of additional information on the extent and nature of site contamination, and improvements in technology.
Under the accounting rules, a liability is generally recorded for these types of contingencies if management determines the loss to be both probable and estimable. The company generally reports these losses as “Operating expenses” or “Selling, general and administrative expenses” on the Consolidated Statement of Income. An exception to this handling is for income tax matters, for which benefits are recognized only if management determines the tax position is “more likely than not” (i.e., likelihood greater than 50 percent) to be allowed by the tax jurisdiction. For additional discussion of income tax uncertainties, refer to Note 22 beginning on page 87. Refer also to the business segment discussions elsewhere in this section for the effect on earnings from losses associated with certain litigation, environmental remediation and tax matters for the three years ended December 31, 2019.
An estimate as to the sensitivity to earnings for these periods if other assumptions had been used in recording these liabilities is not practicable because of the number of contingencies that must be assessed, the number of underlying assumptions and the wide range of reasonably possible outcomes, both in terms of the probability of loss and the estimates of such loss. For further information, refer to “Changes in management’s estimates and assumptions may have a material impact on the company’s consolidated financial statements and financial or operational performance in any given period” in “Risk Factors” in Part I, Item 1A, on page 21.
New Accounting Standards
Refer to Note 4 beginning on page 62 for information regarding new accounting standards.
Quarterly Results
Unaudited
| 2019 | 2018 | ||||||||||||||||||||||||||||||
| Millions of dollars, except per-share amounts | 4th Q | 3rd Q | 2nd Q | 1st Q | 4th Q | 3rd Q | 2nd Q | 1st Q | |||||||||||||||||||||||
| Revenues and Other Income | |||||||||||||||||||||||||||||||
| Sales and other operating revenues | $ | 34,574 | $ | 34,779 | $ | 36,323 | $ | 34,189 | $ | 40,338 | $ | 42,105 | $ | 40,491 | $ | 35,968 | |||||||||||||||
| Income from equity affiliates | 538 | 1,172 | 1,196 | 1,062 | 1,642 | 1,555 | 1,493 | 1,637 | |||||||||||||||||||||||
| Other income | 1,238 | 165 | 1,331 | (51 | ) | 372 | 327 | 252 | 159 | ||||||||||||||||||||||
| Total Revenues and Other Income | 36,350 | 36,116 | 38,850 | 35,200 | 42,352 | 43,987 | 42,236 | 37,764 | |||||||||||||||||||||||
| Costs and Other Deductions | |||||||||||||||||||||||||||||||
| Purchased crude oil and products | 19,693 | 19,882 | 20,835 | 19,703 | 23,920 | 24,681 | 24,744 | 21,233 | |||||||||||||||||||||||
| Operating expenses | 5,987 | 5,325 | 5,187 | 4,886 | 5,645 | 4,985 | 5,213 | 4,701 | |||||||||||||||||||||||
| Selling, general and administrative expenses | 1,129 | 954 | 1,076 | 984 | 1,080 | 1,018 | 1,017 | 723 | |||||||||||||||||||||||
| Exploration expenses | 272 | 168 | 141 | 189 | 250 | 625 | 177 | 158 | |||||||||||||||||||||||
| Depreciation, depletion and amortization | 16,429 | 4,361 | 4,334 | 4,094 | 5,252 | 5,380 | 4,498 | 4,289 | |||||||||||||||||||||||
| Taxes other than on income | 969 | 1,059 | 1,047 | 1,061 | 901 | 1,259 | 1,363 | 1,344 | |||||||||||||||||||||||
| Interest and debt expense | 178 | 197 | 198 | 225 | 190 | 182 | 217 | 159 | |||||||||||||||||||||||
| Other components of net periodic benefit costs | 98 | 121 | 97 | 101 | 216 | 158 | 102 | 84 | |||||||||||||||||||||||
| Total Costs and Other Deductions | 44,755 | 32,067 | 32,915 | 31,243 | 37,454 | 38,288 | 37,331 | 32,691 | |||||||||||||||||||||||
| Income (Loss) Before Income Tax Expense | (8,405 | ) | 4,049 | 5,935 | 3,957 | 4,898 | 5,699 | 4,905 | 5,073 | ||||||||||||||||||||||
| Income Tax Expense (Benefit) | (1,738 | ) | 1,469 | 1,645 | 1,315 | 1,175 | 1,643 | 1,483 | 1,414 | ||||||||||||||||||||||
| Net Income (Loss) | $ | (6,667 | ) | $ | 2,580 | $ | 4,290 | $ | 2,642 | $ | 3,723 | $ | 4,056 | $ | 3,422 | $ | 3,659 | ||||||||||||||
| Less: Net income attributable to noncontrolling interests | (57 | ) | — | (15 | ) | (7 | ) | (7 | ) | 9 | 13 | 21 | |||||||||||||||||||
| Net Income (Loss) Attributable to Chevron Corporation | $ | (6,610 | ) | $ | 2,580 | $ | 4,305 | $ | 2,649 | $ | 3,730 | $ | 4,047 | $ | 3,409 | $ | 3,638 | ||||||||||||||
| Per Share of Common Stock | |||||||||||||||||||||||||||||||
| Net Income (Loss) Attributable to Chevron Corporation | |||||||||||||||||||||||||||||||
| – Basic | $ | (3.51 | ) | $ | 1.38 | $ | 2.28 | $ | 1.40 | $ | 1.97 | $ | 2.13 | $ | 1.79 | $ | 1.92 | ||||||||||||||
| – Diluted | $ | (3.51 | ) | $ | 1.36 | $ | 2.27 | $ | 1.39 | $ | 1.95 | $ | 2.11 | $ | 1.78 | $ | 1.90 | ||||||||||||||
| Dividends | $ | 1.19 | $ | 1.19 | $ | 1.19 | $ | 1.19 | $ | 1.12 | $ | 1.12 | $ | 1.12 | $ | 1.12 | |||||||||||||||
| Management’s Responsibility for Financial Statements | ||||||
| To the Stockholders of Chevron Corporation Management of Chevron Corporation is responsible for preparing the accompanying consolidated financial statements and the related information appearing in this report. The statements were prepared in accordance with accounting principles generally accepted in the United States of America and fairly represent the transactions and financial position of the company. The financial statements include amounts that are based on management’s best estimates and judgments. As stated in its report included herein, the independent registered public accounting firm of PricewaterhouseCoopers LLP has audited the company’s consolidated financial statements in accordance with the standards of the Public Company Accounting Oversight Board (United States). The Board of Directors of Chevron has an Audit Committee composed of directors who are not officers or employees of the company. The Audit Committee meets regularly with members of management, the internal auditors and the independent registered public accounting firm to review accounting, internal control, auditing and financial reporting matters. Both the internal auditors and the independent registered public accounting firm have free and direct access to the Audit Committee without the presence of management. The company’s management has evaluated, with the participation of the Chief Executive Officer and Chief Financial Officer, the effectiveness of the company’s disclosure controls and procedures (as defined in the Exchange Act Rules 13a-15(e) and 15d-15(e)) as of December 31, 2019. Based on that evaluation, management concluded that the company’s disclosure controls are effective in ensuring that information required to be recorded, processed, summarized and reported, are done within the time periods specified in the U.S. Securities and Exchange Commission’s rules and forms. | ||||||
| Management’s Report on Internal Control Over Financial Reporting | ||||||
| The company’s management is responsible for establishing and maintaining adequate internal control over financial reporting, as defined in the Exchange Act Rules 13a-15(f) and 15d-15(f). The company’s management, including the Chief Executive Officer and Chief Financial Officer, conducted an evaluation of the effectiveness of the company’s internal control over financial reporting based on the Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). Based on the results of this evaluation, the company’s management concluded that internal control over financial reporting was effective as of December 31, 2019. The effectiveness of the company’s internal control over financial reporting as of December 31, 2019, has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in its report included herein. | ||||||
 |  |  | ||||
| Michael K. Wirth | Pierre R. Breber | David A. Inchausti | ||||
| Chairman of the Board | Vice President | Vice President | ||||
| and Chief Executive Officer | and Chief Financial Officer | and Comptroller | ||||
| February 21, 2020 | ||||||
| Report of Independent Registered Public Accounting Firm | ||
| To the Board of Directors and Shareholders of Chevron Corporation: | ||
| Opinions on the Financial Statements and Internal Control over Financial Reporting | ||
| We have audited the accompanying consolidated balance sheet of Chevron Corporation and its subsidiaries (the “Company”) as of December 31, 2019 and 2018, and the related consolidated statements of income, of comprehensive income, of equity and of cash flows for each of the three years in the period ended December 31, 2019, including the related notes and financial statement schedule listed in the index appearing under Item 15(a)(2) (collectively referred to as the “consolidated financial statements”). We also have audited the Company’s internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). | ||
| In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, 2019 and 2018, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2019 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO. | ||
| Basis for Opinions The Company’s management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Report on Internal Control Over Financial Reporting. Our responsibility is to express opinions on the Company’s consolidated financial statements and on the Company’s internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB. We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and whether effective internal control over financial reporting was maintained in all material respects. Our audits of the consolidated financial statements included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions. | ||
| Definition and Limitations of Internal Control over Financial Reporting A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements. Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate. | ||
| Critical Audit Matters The critical audit matter communicated below is a matter arising from the current period audit of the consolidated financial statements that was communicated or required to be communicated to the audit committee and that (i) relates to accounts or disclosures that are material to the consolidated financial statements and (ii) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates. | ||
| The Impact of Crude Oil and Natural Gas Reserves and Other Factors on Upstream Property, Plant, and Equipment, Net As described in Notes 1 and 16 to the consolidated financial statements, the Company’s upstream property, plant and equipment, net balance was $133.7 billion as of December 31, 2019, and related depreciation, depletion and amortization expense was $27.8 billion, including impairments of $10.8 billion for the year ended December 31, 2019. Management uses the successful efforts method for crude oil and natural gas exploration and production activities. Depreciation and depletion of all capitalized costs of proved crude oil and natural gas producing properties, except mineral interests, are expensed using the unit-of-production method, generally by individual field, as the proved developed reserves are produced. Depletion expenses for capitalized costs of proved mineral interests are recognized using the unit-of-production method by individual field as the related proved reserves are produced. Upstream property, plant, and equipment to be held and used, including proved crude oil and natural gas properties, are assessed for possible impairment by comparing their carrying values with their associated undiscounted, future net cash flows. Impaired assets are written down to their estimated fair values, generally their discounted, future net cash flows. As disclosed by management, determination as to whether and how much an asset is impaired involves management estimates on uncertain matters, such as future commodity prices, operating expenses, production profiles, and the outlook for global or regional market supply-and-demand conditions for crude oil, natural gas, commodity chemicals and refined products. Variables impacting Chevron’s estimated volumes of crude oil and natural gas reserves include field performance, available technology, commodity prices, and development and production costs. Reserves are estimated by Company asset teams composed of earth scientists and engineers. As part of the internal control process related to reserves estimation, the Company maintains a Reserves Advisory Committee (RAC) (the RAC is referred to as “management’s specialists”). The principal considerations for our determination that performing procedures relating to the impact of crude oil and natural gas reserves and other factors on upstream property, plant, and equipment, net is a critical audit matter are there was significant judgment by management, including the use of management’s specialists, when developing the estimates of proved crude oil and natural gas reserves and assessing upstream property, plant, and equipment to be held and used for impairment. This in turn led to a high degree of auditor judgment, subjectivity, and effort in performing procedures and evaluating audit evidence obtained related to the significant assumptions used by management, including future commodity prices, production profiles, development costs, and operating expenses. Addressing the matter involved performing procedures and evaluating audit evidence in connection with forming our overall opinion on the consolidated financial statements. These procedures included testing the effectiveness of controls relating to management’s calculation of upstream depreciation, depletion and amortization expense, assessment of upstream property, plant, and equipment to be held and used for impairment, and estimates of proved crude oil and natural gas reserves. These procedures also included, among others, (i) testing the unit-of-production rates used to calculate depreciation, depletion and amortization expense, (ii) testing the completeness, accuracy, and relevance of underlying data used in management’s estimates, and (iii) evaluating the significant assumptions used by management in developing these estimates, including future commodity prices, production profiles, development costs and operating expenses. Evaluating the significant assumptions relating to the estimates of crude oil and natural gas reserves also involved obtaining evidence to support the reasonableness of the assumptions, including whether the assumptions used were reasonable considering the past performance of the company, and whether they were consistent with evidence obtained in other areas of the audit. The work of management’s specialists was used in performing the procedures to evaluate the reasonableness of these estimates of proved crude oil and natural gas reserves. As a basis for using this work, the specialists’ qualifications and objectivity were understood, as well as the methods and assumptions used by the specialists. The procedures performed also included tests of the data used by the specialists and an evaluation of the specialists’ findings. | ||
 | ||
| San Francisco, California | ||
| February 21, 2020 | ||
| We have served as the Company’s auditor since 1935. |
Consolidated Statement of Income
Millions of dollars, except per-share amounts
| Year ended December 31 | ||||||||||||||
| 2019 | 2018 | 2017 | ||||||||||||
| Revenues and Other Income | ||||||||||||||
| Sales and other operating revenues1 | $ | 139,865 | $ | 158,902 | $ | 134,674 | ||||||||
| Income from equity affiliates | 3,968 | 6,327 | 4,438 | |||||||||||
| Other income | 2,683 | 1,110 | 2,610 | |||||||||||
| Total Revenues and Other Income | 146,516 | 166,339 | 141,722 | |||||||||||
| Costs and Other Deductions | ||||||||||||||
| Purchased crude oil and products | 80,113 | 94,578 | 75,765 | |||||||||||
| Operating expenses | 21,385 | 20,544 | 19,127 | |||||||||||
| Selling, general and administrative expenses | 4,143 | 3,838 | 4,110 | |||||||||||
| Exploration expenses | 770 | 1,210 | 864 | |||||||||||
| Depreciation, depletion and amortization | 29,218 | 19,419 | 19,349 | |||||||||||
| Taxes other than on income1 | 4,136 | 4,867 | 12,331 | |||||||||||
| Interest and debt expense | 798 | 748 | 307 | |||||||||||
| Other components of net periodic benefit costs | 417 | 560 | 648 | |||||||||||
| Total Costs and Other Deductions | 140,980 | 145,764 | 132,501 | |||||||||||
| Income (Loss) Before Income Tax Expense | 5,536 | 20,575 | 9,221 | |||||||||||
| Income Tax Expense (Benefit) | 2,691 | 5,715 | (48 | ) | ||||||||||
| Net Income (Loss) | 2,845 | 14,860 | 9,269 | |||||||||||
| Less: Net income (loss) attributable to noncontrolling interests | (79 | ) | 36 | 74 | ||||||||||
| Net Income (Loss) Attributable to Chevron Corporation | $ | 2,924 | $ | 14,824 | $ | 9,195 | ||||||||
| Per Share of Common Stock | ||||||||||||||
| Net Income (Loss) Attributable to Chevron Corporation | ||||||||||||||
| - Basic | $ | 1.55 | $ | 7.81 | $ | 4.88 | ||||||||
| - Diluted | $ | 1.54 | $ | 7.74 | $ | 4.85 | ||||||||
| 1 2017 include excise, value-added and similar taxes of $7,189, collected on behalf of third parties. Beginning in 2018, these taxes are netted in “Taxes other than on income” in accordance with Accounting Standards Update (ASU) 2014-09. Refer to Note 24, “Revenue” beginning on page 89. | ||||||||||||||
| See accompanying Notes to the Consolidated Financial Statements. | ||||||||||||||
Consolidated Statement of Comprehensive Income
Millions of dollars
| Year ended December 31 | |||||||||||||||
| 2019 | 2018 | 2017 | |||||||||||||
| Net Income (Loss) | $ | 2,845 | $ | 14,860 | $ | 9,269 | |||||||||
| Currency translation adjustment | |||||||||||||||
| Unrealized net change arising during period | (18 | ) | (19 | ) | 57 | ||||||||||
| Unrealized holding gain (loss) on securities | |||||||||||||||
| Net gain (loss) arising during period | 2 | (5 | ) | (3 | ) | ||||||||||
| Derivatives | |||||||||||||||
| Net derivatives loss on hedge transactions | (1 | ) | — | — | |||||||||||
| Reclassification to net income of net realized gain | — | — | — | ||||||||||||
| Income taxes on derivatives transactions | 3 | — | — | ||||||||||||
| Total | 2 | — | — | ||||||||||||
| Defined benefit plans | |||||||||||||||
| Actuarial gain (loss) | |||||||||||||||
| Amortization to net income of net actuarial loss and settlements | 519 | 792 | 817 | ||||||||||||
| Actuarial gain (loss) arising during period | (2,404 | ) | 85 | (571 | ) | ||||||||||
| Prior service credits (cost) | |||||||||||||||
| Amortization to net income of net prior service costs and curtailments | 4 | (13 | ) | (20 | ) | ||||||||||
| Prior service (costs) credits arising during period | (28 | ) | (26 | ) | (1 | ) | |||||||||
| Defined benefit plans sponsored by equity affiliates - benefit (cost) | (33 | ) | 23 | 19 | |||||||||||
| Income (taxes) benefit on defined benefit plans | 510 | (230 | ) | (44 | ) | ||||||||||
| Total | (1,432 | ) | 631 | 200 | |||||||||||
| Other Comprehensive Gain (Loss), Net of Tax | (1,446 | ) | 607 | 254 | |||||||||||
| Comprehensive Income | 1,399 | 15,467 | 9,523 | ||||||||||||
| Comprehensive loss (income) attributable to noncontrolling interests | 79 | (36 | ) | (74 | ) | ||||||||||
| Comprehensive Income (Loss) Attributable to Chevron Corporation | $ | 1,478 | $ | 15,431 | $ | 9,449 | |||||||||
| See accompanying Notes to the Consolidated Financial Statements. | |||||||||||||||
Consolidated Balance Sheet
Millions of dollars, except per-share amounts
| At December 31 | |||||||||
| 2019 | 2018 | ||||||||
| Assets | |||||||||
| Cash and cash equivalents | $ | 5,686 | $ | 9,342 | |||||
| Time deposits | — | 950 | |||||||
| Marketable securities | 63 | 53 | |||||||
| Accounts and notes receivable (less allowance: 2019 - $746; 2018 - $869) | 13,325 | 15,050 | |||||||
| Inventories: | |||||||||
| Crude oil and petroleum products | 3,722 | 3,383 | |||||||
| Chemicals | 492 | 487 | |||||||
| Materials, supplies and other | 1,634 | 1,834 | |||||||
| Total inventories | 5,848 | 5,704 | |||||||
| Prepaid expenses and other current assets | 3,407 | 2,922 | |||||||
| Total Current Assets | 28,329 | 34,021 | |||||||
| Long-term receivables, net | 1,511 | 1,942 | |||||||
| Investments and advances | 38,688 | 35,546 | |||||||
| Properties, plant and equipment, at cost | 326,722 | 340,244 | |||||||
| Less: Accumulated depreciation, depletion and amortization | 176,228 | 171,037 | |||||||
| Properties, plant and equipment, net | 150,494 | 169,207 | |||||||
| Deferred charges and other assets | 10,532 | 6,766 | |||||||
| Goodwill | 4,463 | 4,518 | |||||||
| Assets held for sale | 3,411 | 1,863 | |||||||
| Total Assets | $ | 237,428 | $ | 253,863 | |||||
| Liabilities and Equity | |||||||||
| Short-term debt | $ | 3,282 | $ | 5,726 | |||||
| Accounts payable | 14,103 | 13,953 | |||||||
| Accrued liabilities | 6,589 | 4,927 | |||||||
| Federal and other taxes on income | 1,554 | 1,628 | |||||||
| Other taxes payable | 1,002 | 937 | |||||||
| Total Current Liabilities | 26,530 | 27,171 | |||||||
| Long-term debt1 | 23,691 | 28,733 | |||||||
| Deferred credits and other noncurrent obligations | 20,445 | 19,742 | |||||||
| Noncurrent deferred income taxes | 13,688 | 15,921 | |||||||
| Noncurrent employee benefit plans | 7,866 | 6,654 | |||||||
| Total Liabilities****2 | $ | 92,220 | $ | 98,221 | |||||
| Preferred stock (authorized 100,000,000 shares; $1.00 par value; none issued) | — | — | |||||||
| Common stock (authorized 6,000,000,000 shares; $0.75 par value; 2,442,676,580 shares issued at December 31, 2019 and 2018) | 1,832 | 1,832 | |||||||
| Capital in excess of par value | 17,265 | 17,112 | |||||||
| Retained earnings | 174,945 | 180,987 | |||||||
| Accumulated other comprehensive losses | (4,990 | ) | (3,544 | ) | |||||
| Deferred compensation and benefit plan trust | (240 | ) | (240 | ) | |||||
| Treasury stock, at cost (2019 - 560,508,479 shares; 2018 - 539,838,890 shares) | (44,599 | ) | (41,593 | ) | |||||
| Total Chevron Corporation Stockholders’ Equity | 144,213 | 154,554 | |||||||
| Noncontrolling interests | 995 | 1,088 | |||||||
| Total Equity | 145,208 | 155,642 | |||||||
| Total Liabilities and Equity | $ | 237,428 | $ | 253,863 | |||||
| 1 Includes finance lease liabilities of $282 and $127 at December 31, 2019 and 2018, respectively. | |||||||||
| 2 Refer to Note 22, “Other Contingencies and Commitments” beginning on page 87. | |||||||||
| See accompanying Notes to the Consolidated Financial Statements. | |||||||||
Consolidated Statement of Cash Flows
Millions of dollars
| Year ended December 31 | |||||||||||||
| 2019 | 2018 | 2017 | |||||||||||
| Operating Activities | |||||||||||||
| Net Income (Loss) | $ | 2,845 | $ | 14,860 | $ | 9,269 | |||||||
| Adjustments | |||||||||||||
| Depreciation, depletion and amortization | 29,218 | 19,419 | 19,349 | ||||||||||
| Dry hole expense | 172 | 687 | 198 | ||||||||||
| Distributions less than income from equity affiliates | (2,073 | ) | (3,580 | ) | (2,380 | ) | |||||||
| Net before-tax gains on asset retirements and sales | (1,367 | ) | (619 | ) | (2,195 | ) | |||||||
| Net foreign currency effects | 272 | 123 | 131 | ||||||||||
| Deferred income tax provision | (1,966 | ) | 1,050 | (3,203 | ) | ||||||||
| Net decrease (increase) in operating working capital | 1,494 | (718 | ) | 520 | |||||||||
| Decrease (increase) in long-term receivables | 502 | 418 | (368 | ) | |||||||||
| Net decrease (increase) in other deferred charges | (69 | ) | — | (254 | ) | ||||||||
| Cash contributions to employee pension plans | (1,362 | ) | (1,035 | ) | (980 | ) | |||||||
| Other | (352 | ) | 13 | 251 | |||||||||
| Net Cash Provided by Operating Activities | 27,314 | 30,618 | 20,338 | ||||||||||
| Investing Activities | |||||||||||||
| Capital expenditures | (14,116 | ) | (13,792 | ) | (13,404 | ) | |||||||
| Proceeds and deposits related to asset sales and returns of investment | 2,951 | 2,392 | 5,096 | ||||||||||
| Net maturities of (investments in) time deposits | 950 | (950 | ) | — | |||||||||
| Net sales (purchases) of marketable securities | 2 | (51 | ) | 4 | |||||||||
| Net repayment (borrowing) of loans by equity affiliates | (1,245 | ) | 111 | (16 | ) | ||||||||
| Net Cash Used for Investing Activities | (11,458 | ) | (12,290 | ) | (8,320 | ) | |||||||
| Financing Activities | |||||||||||||
| Net borrowings (repayments) of short-term obligations | (2,821 | ) | 2,021 | (5,142 | ) | ||||||||
| Proceeds from issuances of long-term debt | — | 218 | 3,991 | ||||||||||
| Repayments of long-term debt and other financing obligations | (5,025 | ) | (6,741 | ) | (6,310 | ) | |||||||
| Cash dividends - common stock | (8,959 | ) | (8,502 | ) | (8,132 | ) | |||||||
| Distributions to noncontrolling interests | (18 | ) | (91 | ) | (78 | ) | |||||||
| Net sales (purchases) of treasury shares | (2,935 | ) | (604 | ) | 1,117 | ||||||||
| Net Cash Provided by (Used for) Financing Activities | (19,758 | ) | (13,699 | ) | (14,554 | ) | |||||||
| Effect of Exchange Rate Changes on Cash, Cash Equivalents and Restricted Cash | 332 | (91 | ) | 65 | |||||||||
| Net Change in Cash, Cash Equivalents and Restricted Cash | (3,570 | ) | 4,538 | (2,471 | ) | ||||||||
| Cash, Cash Equivalents and Restricted Cash at January 1 | 10,481 | 5,943 | 8,414 | ||||||||||
| Cash, Cash Equivalents and Restricted Cash at December 31 | $ | 6,911 | $ | 10,481 | $ | 5,943 | |||||||
| See accompanying Notes to the Consolidated Financial Statements. | |||||||||||||
Consolidated Statement of Equity
Amounts in millions of dollars
| Acc. Other | Treasury | Chevron Corp. | |||||||||||||||||||||
| Common | Retained | Comprehensive | Stock | Stockholders’ | Noncontrolling | Total | |||||||||||||||||
| Stock****1 | Earnings | Income (Loss) | (at cost) | Equity | Interests | Equity | |||||||||||||||||
| Balance at December 31, 2016 | $ | 18,187 | $ | 173,046 | $ | (3,843 | ) | $ | (41,834 | ) | $ | 145,556 | $ | 1,166 | $ | 146,722 | |||||||
| Treasury stock transactions | 253 | — | — | — | 253 | — | 253 | ||||||||||||||||
| Net income (loss) | — | 9,195 | — | — | 9,195 | 74 | 9,269 | ||||||||||||||||
| Cash dividends | — | (8,132 | ) | — | — | (8,132 | ) | (78 | ) | (8,210 | ) | ||||||||||||
| Stock dividends | — | (3 | ) | — | — | (3 | ) | — | (3 | ) | |||||||||||||
| Other comprehensive income | — | — | 254 | — | 254 | — | 254 | ||||||||||||||||
| Purchases of treasury shares | — | — | — | (1 | ) | (1 | ) | — | (1 | ) | |||||||||||||
| Issuances of treasury shares | — | — | — | 1,002 | 1,002 | — | 1,002 | ||||||||||||||||
| Other changes, net | — | — | — | — | — | 33 | 33 | ||||||||||||||||
| Balance at December 31, 2017 | $ | 18,440 | $ | 174,106 | $ | (3,589 | ) | $ | (40,833 | ) | $ | 148,124 | $ | 1,195 | $ | 149,319 | |||||||
| Treasury stock transactions | 264 | — | — | — | 264 | — | 264 | ||||||||||||||||
| Net income (loss) | — | 14,824 | — | — | 14,824 | 36 | 14,860 | ||||||||||||||||
| Cash dividends | — | (8,502 | ) | — | — | (8,502 | ) | (91 | ) | (8,593 | ) | ||||||||||||
| Stock dividends | — | (3 | ) | — | — | (3 | ) | — | (3 | ) | |||||||||||||
| Other comprehensive income | — | — | 607 | — | 607 | — | 607 | ||||||||||||||||
| Purchases of treasury shares | — | — | — | (1,751 | ) | (1,751 | ) | — | (1,751 | ) | |||||||||||||
| Issuances of treasury shares | — | — | — | 991 | 991 | — | 991 | ||||||||||||||||
| Other changes, net | — | 562 | (562 | ) | — | — | (52 | ) | (52 | ) | |||||||||||||
| Balance at December 31, 2018 | $ | 18,704 | $ | 180,987 | $ | (3,544 | ) | $ | (41,593 | ) | $ | 154,554 | $ | 1,088 | $ | 155,642 | |||||||
| Treasury stock transactions | 153 | — | — | — | 153 | — | 153 | ||||||||||||||||
| Net income (loss) | — | 2,924 | — | — | 2,924 | (79 | ) | 2,845 | |||||||||||||||
| Cash dividends | — | (8,959 | ) | — | — | (8,959 | ) | (18 | ) | (8,977 | ) | ||||||||||||
| Stock dividends | — | (3 | ) | — | — | (3 | ) | — | (3 | ) | |||||||||||||
| Other comprehensive income | — | — | (1,446 | ) | — | (1,446 | ) | — | (1,446 | ) | |||||||||||||
| Purchases of treasury shares | — | — | — | (4,039 | ) | (4,039 | ) | — | (4,039 | ) | |||||||||||||
| Issuances of treasury shares | — | — | — | 1,033 | 1,033 | — | 1,033 | ||||||||||||||||
| Other changes, net | — | (4 | ) | — | — | (4 | ) | 4 | — | ||||||||||||||
| Balance at December 31, 2019 | $ | 18,857 | $ | 174,945 | $ | (4,990 | ) | $ | (44,599 | ) | $ | 144,213 | $ | 995 | $ | 145,208 | |||||||
| Common Stock Share Activity | |||||||||||||||||||||||
| Issued****2 | Treasury | Outstanding | |||||||||||||||||||||
| Balance at December 31, 2016 | 2,442,676,580 | (551,170,158 | ) | 1,891,506,422 | |||||||||||||||||||
| Purchases | — | (10,237 | ) | (10,237 | ) | ||||||||||||||||||
| Issuances | — | 13,205,700 | 13,205,700 | ||||||||||||||||||||
| Balance at December 31, 2017 | 2,442,676,580 | (537,974,695 | ) | 1,904,701,885 | |||||||||||||||||||
| Purchases | — | (14,912,039 | ) | (14,912,039 | ) | ||||||||||||||||||
| Issuances | — | 13,047,844 | 13,047,844 | ||||||||||||||||||||
| Balance at December 31, 2018 | 2,442,676,580 | (539,838,890 | ) | 1,902,837,690 | |||||||||||||||||||
| Purchases | — | (33,955,300 | ) | (33,955,300 | ) | ||||||||||||||||||
| Issuances | — | 13,285,711 | 13,285,711 | ||||||||||||||||||||
| Balance at December 31, 2019 | 2,442,676,580 | (560,508,479 | ) | 1,882,168,101 | |||||||||||||||||||
| 1 Beginning and ending balances for all periods include capital in excess of par, common stock issued at par for $1,832, and $(240) associated with Chevron’s Benefit Plan Trust. Changes reflect capital in excess of par. | |||||||||||||||||||||||
| 2 Beginning and ending total issued share balances include 14,168 shares associated with Chevron’s Benefit Plan Trust. | |||||||||||||||||||||||
| See accompanying Notes to the Consolidated Financial Statements. | |||||||||||||||||||||||
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Note 1
Summary of Significant Accounting Policies
General The company’s Consolidated Financial Statements are prepared in accordance with accounting principles generally accepted in the United States of America. These require the use of estimates and assumptions that affect the assets, liabilities, revenues and expenses reported in the financial statements, as well as amounts included in the notes thereto, including discussion and disclosure of contingent liabilities. Although the company uses its best estimates and judgments, actual results could differ from these estimates as circumstances change and additional information becomes known.
Subsidiary and Affiliated Companies The Consolidated Financial Statements include the accounts of controlled subsidiary companies more than 50 percent-owned and any variable-interest entities in which the company is the primary beneficiary. Undivided interests in oil and gas joint ventures and certain other assets are consolidated on a proportionate basis. Investments in and advances to affiliates in which the company has a substantial ownership interest of approximately 20 percent to 50 percent, or for which the company exercises significant influence but not control over policy decisions, are accounted for by the equity method.
Investments in affiliates are assessed for possible impairment when events indicate that the fair value of the investment may be below the company’s carrying value. When such a condition is deemed to be other than temporary, the carrying value of the investment is written down to its fair value, and the amount of the write-down is included in net income. In making the determination as to whether a decline is other than temporary, the company considers such factors as the duration and extent of the decline, the investee’s financial performance, and the company’s ability and intention to retain its investment for a period that will be sufficient to allow for any anticipated recovery in the investment’s market value. The new cost basis of investments in these equity investees is not changed for subsequent recoveries in fair value.
Differences between the company’s carrying value of an equity investment and its underlying equity in the net assets of the affiliate are assigned to the extent practicable to specific assets and liabilities based on the company’s analysis of the various factors giving rise to the difference. When appropriate, the company’s share of the affiliate’s reported earnings is adjusted quarterly to reflect the difference between these allocated values and the affiliate’s historical book values.
Noncontrolling Interests Ownership interests in the company’s subsidiaries held by parties other than the parent are presented separately from the parent’s equity on the Consolidated Balance Sheet. The amount of consolidated net income attributable to the parent and the noncontrolling interests are both presented on the face of the Consolidated Statement of Income and Consolidated Statement of Equity.
Fair Value Measurements The three levels of the fair value hierarchy of inputs the company uses to measure the fair value of an asset or a liability are as follows. Level 1 inputs are quoted prices in active markets for identical assets or liabilities. Level 2 inputs are inputs other than quoted prices included within Level 1 that are directly or indirectly observable for the asset or liability. Level 3 inputs are inputs that are not observable in the market.
Derivatives The majority of the company’s activity in derivative commodity instruments is intended to manage the financial risk posed by physical transactions. For some of this derivative activity, generally limited to large, discrete or infrequently occurring transactions, the company may elect to apply fair value or cash flow hedge accounting. For other similar derivative instruments, generally because of the short-term nature of the contracts or their limited use, the company does not apply hedge accounting, and changes in the fair value of those contracts are reflected in current income. For the company’s commodity trading activity, gains and losses from derivative instruments are reported in current income. The company may enter into interest rate swaps from time to time as part of its overall strategy to manage the interest rate risk on its debt. Interest rate swaps related to a portion of the company’s fixed-rate debt, if any, may be accounted for as fair value hedges. Interest rate swaps related to floating-rate debt, if any, are recorded at fair value on the balance sheet with resulting gains and losses reflected in income. Where Chevron is a party to master netting arrangements, fair value receivable and payable amounts recognized for derivative instruments executed with the same counterparty are generally offset on the balance sheet.
Inventories Crude oil, petroleum products and chemicals inventories are generally stated at cost, using a last-in, first-out method. In the aggregate, these costs are below market. “Materials, supplies and other” inventories are primarily stated at cost or net realizable value.
Properties, Plant and Equipment The successful efforts method is used for crude oil and natural gas exploration and production activities. All costs for development wells, related plant and equipment, proved mineral interests in crude oil and natural gas properties, and related asset retirement obligation (ARO) assets are capitalized. Costs of exploratory wells are capitalized pending determination of whether the wells found proved reserves. Costs of wells that are assigned proved
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
reserves remain capitalized. Costs also are capitalized for exploratory wells that have found crude oil and natural gas reserves even if the reserves cannot be classified as proved when the drilling is completed, provided the exploratory well has found a sufficient quantity of reserves to justify its completion as a producing well and the company is making sufficient progress assessing the reserves and the economic and operating viability of the project. All other exploratory wells and costs are expensed. Refer to Note 19, beginning on page 79, for additional discussion of accounting for suspended exploratory well costs.
Long-lived assets to be held and used, including proved crude oil and natural gas properties, are assessed for possible impairment by comparing their carrying values with their associated undiscounted, future net cash flows. Events that can trigger assessments for possible impairments include write-downs of proved reserves based on field performance, significant decreases in the market value of an asset (including changes to the commodity price forecast), significant change in the extent or manner of use of or a physical change in an asset, and a more-likely-than-not expectation that a long-lived asset or asset group will be sold or otherwise disposed of significantly sooner than the end of its previously estimated useful life. Impaired assets are written down to their estimated fair values, generally their discounted, future net cash flows. For proved crude oil and natural gas properties, the company performs impairment reviews on a country, concession, PSC, development area or field basis, as appropriate. In Downstream, impairment reviews are performed on the basis of a refinery, a plant, a marketing/lubricants area or distribution area, as appropriate. Impairment amounts are recorded as incremental “Depreciation, depletion and amortization” expense.
Long-lived assets that are held for sale are evaluated for possible impairment by comparing the carrying value of the asset with its fair value less the cost to sell. If the net book value exceeds the fair value less cost to sell, the asset is considered impaired and adjusted to the lower value. Refer to Note 7, beginning on page 65, relating to fair value measurements. The fair value of a liability for an ARO is recorded as an asset and a liability when there is a legal obligation associated with the retirement of a long-lived asset and the amount can be reasonably estimated. Refer also to Note 23, on page 89, relating to AROs.
Depreciation and depletion of all capitalized costs of proved crude oil and natural gas producing properties, except mineral interests, are expensed using the unit-of-production method, generally by individual field, as the proved developed reserves are produced. Depletion expenses for capitalized costs of proved mineral interests are recognized using the unit-of-production method by individual field as the related proved reserves are produced. Impairments of capitalized costs of unproved mineral interests are expensed.
The capitalized costs of all other plant and equipment are depreciated or amortized over their estimated useful lives. In general, the declining-balance method is used to depreciate plant and equipment in the United States; the straight-line method is generally used to depreciate international plant and equipment and to amortize finance lease right-of-use assets.
Gains or losses are not recognized for normal retirements of properties, plant and equipment subject to composite group amortization or depreciation. Gains or losses from abnormal retirements are recorded as expenses, and from sales as “Other income.”
Expenditures for maintenance (including those for planned major maintenance projects), repairs and minor renewals to maintain facilities in operating condition are generally expensed as incurred. Major replacements and renewals are capitalized.
Goodwill Goodwill resulting from a business combination is not subject to amortization. The company tests such goodwill at the reporting unit level for impairment annually at December 31, or more frequently if an event occurs or circumstances change that would more likely than not reduce the fair value of the reporting unit below its carrying amount.
Environmental Expenditures Environmental expenditures that relate to ongoing operations or to conditions caused by past operations are expensed. Expenditures that create future benefits or contribute to future revenue generation are capitalized.
Liabilities related to future remediation costs are recorded when environmental assessments or cleanups or both are probable and the costs can be reasonably estimated. For crude oil, natural gas and mineral-producing properties, a liability for an ARO is made in accordance with accounting standards for asset retirement and environmental obligations. Refer to Note 23, on page 89, for a discussion of the company’s AROs.
For federal Superfund sites and analogous sites under state laws, the company records a liability for its designated share of the probable and estimable costs, and probable amounts for other potentially responsible parties when mandated by the regulatory agencies because the other parties are not able to pay their respective shares. The gross amount of environmental liabilities is based on the company’s best estimate of future costs using currently available technology and applying current
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
regulations and the company’s own internal environmental policies. Future amounts are not discounted. Recoveries or reimbursements are recorded as assets when receipt is reasonably assured.
Currency Translation The U.S. dollar is the functional currency for substantially all of the company’s consolidated operations and those of its equity affiliates. For those operations, all gains and losses from currency remeasurement are included in current period income. The cumulative translation effects for those few entities, both consolidated and affiliated, using functional currencies other than the U.S. dollar are included in “Currency translation adjustment” on the Consolidated Statement of Equity.
Revenue Recognition The company accounts for each delivery order of crude oil, natural gas, petroleum and chemical products as a separate performance obligation. Revenue is recognized when the performance obligation is satisfied, which typically occurs at the point in time when control of the product transfers to the customer. Payment is generally due within 30 days of delivery. The company accounts for delivery transportation as a fulfillment cost, not a separate performance obligation, and recognizes these costs as an operating expense in the period when revenue for the related commodity is recognized.
Revenue is measured as the amount the company expects to receive in exchange for transferring commodities to the customer. The company’s commodity sales are typically based on prevailing market-based prices and may include discounts and allowances. Until market prices become known under terms of the company’s contracts, the transaction price included in revenue is based on the company’s estimate of the most likely outcome.
Discounts and allowances are estimated using a combination of historical and recent data trends. When deliveries contain multiple products, an observable standalone selling price is generally used to measure revenue for each product. The company includes estimates in the transaction price only to the extent that a significant reversal of revenue is not probable in subsequent periods.
Excise, value-added and similar taxes assessed by a governmental authority on a revenue-producing transaction between a seller and a customer are presented on a net basis in “Taxes other than on income” on the Consolidated Statement of Income, on page 52. Purchases and sales of inventory with the same counterparty that are entered into in contemplation of one another (including buy/sell arrangements) are combined and recorded on a net basis and reported in “Purchased crude oil and products” on the Consolidated Statement of Income.
Prior to the adoption of ASC 606 on January 1, 2018, revenues associated with sales of crude oil, natural gas, petroleum and chemicals products, and all other sources were recorded when title passed to the customer, net of royalties, discounts and allowances, as applicable. Revenues from natural gas production from properties in which Chevron has an interest with other producers were generally recognized using the entitlement method. Excise, value-added and similar taxes assessed by a governmental authority on a revenue-producing transaction between a seller and a customer were presented on a gross basis on the Consolidated Statement of Income.
Stock Options and Other Share-Based Compensation The company issues stock options and other share-based compensation to certain employees. For equity awards, such as stock options, total compensation cost is based on the grant date fair value, and for liability awards, such as stock appreciation rights, total compensation cost is based on the settlement value. The company recognizes stock-based compensation expense for all awards over the service period required to earn the award, which is the shorter of the vesting period or the time period in which an employee becomes eligible to retain the award at retirement. The company’s Long-Term Incentive Plan (LTIP) awards include stock options and stock appreciation rights, which have graded vesting provisions by which one-third of each award vests on each of the first, second and third anniversaries of the date of grant. In addition, performance shares granted under the company’s LTIP will vest at the end of the three-year performance period. For awards granted under the company’s LTIP beginning in 2017, stock options and stock appreciation rights have graded vesting by which one third of each award vests annually on each January 31 on or after the first anniversary of the grant date. Standard restricted stock unit awards have cliff vesting by which the total award will vest on January 31 on or after the fifth anniversary of the grant date, subject to adjustment upon termination pursuant to the satisfaction of certain criteria. The company amortizes these awards on a straight-line basis.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Note 2
Changes in Accumulated Other Comprehensive Losses
The change in Accumulated Other Comprehensive Losses (AOCL) presented on the Consolidated Balance Sheet and the impact of significant amounts reclassified from AOCL on information presented in the Consolidated Statement of Income for the year ended December 31, 2019, are reflected in the table below.
| Currency Translation Adjustments | Unrealized Holding Gains (Losses) on Securities | Derivatives | Defined Benefit Plans | Total | |||||||||||||||
| Balance at December 31, 2016 | $ | (162 | ) | $ | (2 | ) | $ | (2 | ) | $ | (3,677 | ) | $ | (3,843 | ) | ||||
| Components of Other Comprehensive Income (Loss)1: | |||||||||||||||||||
| Before Reclassifications | 57 | (3 | ) | — | (310 | ) | (256 | ) | |||||||||||
| Reclassifications2 | — | — | — | 510 | 510 | ||||||||||||||
| Net Other Comprehensive Income (Loss) | 57 | (3 | ) | — | 200 | 254 | |||||||||||||
| Balance at December 31, 2017 | $ | (105 | ) | $ | (5 | ) | $ | (2 | ) | $ | (3,477 | ) | $ | (3,589 | ) | ||||
| Components of Other Comprehensive Income (Loss)1: | |||||||||||||||||||
| Before Reclassifications | (19 | ) | (5 | ) | — | 28 | 4 | ||||||||||||
| Reclassifications2 | — | — | — | 603 | 603 | ||||||||||||||
| Net Other Comprehensive Income (Loss) | (19 | ) | (5 | ) | — | 631 | 607 | ||||||||||||
| Stranded Tax Reclassification to Retained Earnings3 | — | — | — | (562 | ) | (562 | ) | ||||||||||||
| Balance at December 31, 2018 | $ | (124 | ) | $ | (10 | ) | $ | (2 | ) | $ | (3,408 | ) | $ | (3,544 | ) | ||||
| Components of Other Comprehensive Income (Loss)1: | |||||||||||||||||||
| Before Reclassifications | (18 | ) | 2 | (1 | ) | (1,838 | ) | (1,855 | ) | ||||||||||
| Reclassifications2 | — | — | 3 | 406 | 409 | ||||||||||||||
| Net Other Comprehensive Income (Loss) | (18 | ) | 2 | 2 | (1,432 | ) | (1,446 | ) | |||||||||||
| Balance at December 31, 2019 | $ | (142 | ) | $ | (8 | ) | $ | — | $ | (4,840 | ) | $ | (4,990 | ) |
| 1 | All amounts are net of tax. |
| 2 | Refer to Note 21 beginning on page 82, for reclassified components totaling $523 that are included in employee benefit costs for the year ended December 31, 2019. Related income taxes for the same period, totaling $117, are reflected in Income Tax Expense on the Consolidated Statement of Income. All other reclassified amounts were insignificant. |
| 3 | Stranded tax reclassification to retained earnings per ASU 2018-02. |
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Note 3
Information Relating to the Consolidated Statement of Cash Flows
| Year ended December 31 | ||||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| Net decrease (increase) in operating working capital was composed of the following: | ||||||||||||
| Decrease (increase) in accounts and notes receivable | $ | 1,852 | $ | 437 | $ | (915 | ) | |||||
| Decrease (increase) in inventories | 7 | (424 | ) | (267 | ) | |||||||
| Decrease (increase) in prepaid expenses and other current assets | (323 | ) | (149 | ) | 173 | |||||||
| Increase (decrease) in accounts payable and accrued liabilities | (109 | ) | (494 | ) | 998 | |||||||
| Increase (decrease) in income and other taxes payable | 67 | (88 | ) | 531 | ||||||||
| Net decrease (increase) in operating working capital | $ | 1,494 | $ | (718 | ) | $ | 520 | |||||
| Net cash provided by operating activities includes the following cash payments: | ||||||||||||
| Interest on debt (net of capitalized interest) | $ | 810 | $ | 736 | $ | 265 | ||||||
| Income taxes | 4,817 | 4,748 | 3,132 | |||||||||
| Proceeds and deposits related to asset sales and returns of investment consisted of the following gross amounts: | ||||||||||||
| Proceeds and deposits related to asset sales | $ | 2,809 | $ | 2,000 | $ | 4,930 | ||||||
| Returns of investment from equity affiliates | 142 | 392 | 166 | |||||||||
| Proceeds and deposits related to asset sales and returns of investment | $ | 2,951 | $ | 2,392 | $ | 5,096 | ||||||
| Net maturities (investments) of time deposits consisted of the following gross amounts: | ||||||||||||
| Investments in time deposits | $ | — | $ | (950 | ) | $ | — | |||||
| Maturities of time deposits | 950 | — | — | |||||||||
| Net maturities of (investments in) time deposits | $ | 950 | $ | (950 | ) | $ | — | |||||
| Net sales (purchases) of marketable securities consisted of the following gross amounts: | ||||||||||||
| Marketable securities purchased | $ | (1 | ) | $ | (51 | ) | $ | (3 | ) | |||
| Marketable securities sold | 3 | — | 7 | |||||||||
| Net sales (purchases) of marketable securities | $ | 2 | $ | (51 | ) | $ | 4 | |||||
| Net repayment (borrowing) of loans by equity affiliates: | ||||||||||||
| Borrowing of loans by equity affiliates | $ | (1,350 | ) | $ | — | $ | (142 | ) | ||||
| Repayment of loans by equity affiliates | 105 | 111 | 126 | |||||||||
| Net repayment (borrowing) of loans by equity affiliates | $ | (1,245 | ) | $ | 111 | $ | (16 | ) | ||||
| Net borrowings (repayments) of short-term obligations consisted of the following gross and net amounts: | ||||||||||||
| Proceeds from issuances of short-term obligations | $ | 2,586 | $ | 2,486 | $ | 5,051 | ||||||
| Repayments of short-term obligations | (1,430 | ) | (4,136 | ) | (8,820 | ) | ||||||
| Net borrowings (repayments) of short-term obligations with three months or less maturity | (3,977 | ) | 3,671 | (1,373 | ) | |||||||
| Net borrowings (repayments) of short-term obligations | $ | (2,821 | ) | $ | 2,021 | $ | (5,142 | ) | ||||
| Net sales (purchases) of treasury shares consists of the following gross and net amounts: | ||||||||||||
| Shares issued for share-based compensation plans | $ | 1,104 | $ | 1,147 | $ | 1,118 | ||||||
| Shares purchased under share repurchase and deferred compensation plans | (4,039 | ) | (1,751 | ) | (1 | ) | ||||||
| Net sales (purchases) of treasury shares | $ | (2,935 | ) | $ | (604 | ) | $ | 1,117 |
The Consolidated Statement of Cash Flows excludes changes to the Consolidated Balance Sheet that did not affect cash.
The “Other” line in the Operating Activities section includes changes in postretirement benefits obligations and other long-term liabilities.
The Consolidated Statement of Cash Flows excludes changes to the Consolidated Balance Sheet that did not affect cash. “Depreciation, depletion and amortization,” “Deferred income tax provision,” and “Dry hole expense” collectively include approximately $9.3 billion and $1.1 billion in non-cash reductions recorded in 2019 and 2018, respectively, relating to impairments and other non-cash charges.
Refer also to Note 23, on page 89, for a discussion of revisions to the company’s AROs that also did not involve cash receipts or payments for the three years ending December 31, 2019.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
The major components of “Capital expenditures” and the reconciliation of this amount to the reported capital and exploratory expenditures, including equity affiliates, are presented in the following table:
| Year ended December 31 | ||||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| Additions to properties, plant and equipment * | $ | 13,839 | $ | 13,384 | $ | 13,222 | ||||||
| Additions to investments | 140 | 65 | 25 | |||||||||
| Current-year dry hole expenditures | 124 | 344 | 157 | |||||||||
| Payments for other assets and liabilities, net | 13 | (1 | ) | — | ||||||||
| Capital expenditures | 14,116 | 13,792 | 13,404 | |||||||||
| Expensed exploration expenditures | 598 | 523 | 666 | |||||||||
| Assets acquired through finance leases and other obligations | 181 | 75 | 8 | |||||||||
| Payments for other assets and liabilities, net | (13 | ) | — | — | ||||||||
| Capital and exploratory expenditures, excluding equity affiliates | 14,882 | 14,390 | 14,078 | |||||||||
| Company’s share of expenditures by equity affiliates | 6,112 | 5,716 | 4,743 | |||||||||
| Capital and exploratory expenditures, including equity affiliates | $ | 20,994 | $ | 20,106 | $ | 18,821 |
| * | Excludes non-cash movements of $(239) in 2019, $25 in 2018 and $1,183 in 2017. |
The table below quantifies the beginning and ending balances of restricted cash and restricted cash equivalents in the Consolidated Balance Sheet:
| Year ended December 31 | ||||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| Cash and cash equivalents | $ | 5,686 | $ | 9,342 | $ | 4,813 | ||||||
| Restricted cash included in “Prepaid expenses and other current assets” | 452 | 341 | 405 | |||||||||
| Restricted cash included in “Deferred charges and other assets” | 773 | 798 | 725 | |||||||||
| Total cash, cash equivalents and restricted cash | $ | 6,911 | $ | 10,481 | $ | 5,943 |
Note 4
New Accounting Standards
Leases (Topic 842) Effective January 1, 2019, Chevron adopted Accounting Standards Update (ASU) 2016-02 and its related amendments. For additional information on the company’s leases, refer to Note 5 beginning on page 62.
Financial Instruments - Credit Losses (Topic 326) In June 2016, the FASB issued ASU 2016-13, which becomes effective for the company beginning January 1, 2020. The standard requires companies to use forward-looking information to calculate credit loss estimates. The company completed the accounting policy and work process changes necessary to meet the standard’s requirements. The company does not expect the implementation of the standard to have a material effect on its consolidated financial statements.
Note 5
Lease Commitments
Chevron implemented the new lease standard at the effective date of January 1, 2019. The cumulative-effect adjustment to the opening balance of 2019 retained earnings is de minimis. The company elected the option to apply the transition provisions at the adoption date instead of the earliest comparative period presented in the financial statements. By making this election, the company has not applied retrospective reporting for the comparable periods. The company elected the short-term lease exception provided for in the standard and therefore only recognizes right-of-use assets and lease liabilities for leases with a term greater than one year.
The company elected the package of practical expedients to not re-evaluate existing contracts as containing a lease or the lease classification unless it was not previously assessed against the lease criteria. In addition, the company did not reassess initial direct costs for any existing leases. The company applied the land easement practical expedient. The company has elected the practical expedient to not separate non-lease components from lease components for most asset classes except for certain asset classes that have significant non-lease (i.e., service) components. The company assessed some contracts, including those for drill ships, drilling rigs, and storage tanks, not previously assessed against the lease criteria, as operating leases under the new standard, increasing the lease commitments by approximately $2 billion.
The company enters into leasing arrangements as a lessee; any lessor arrangements are not significant. Leases are classified as operating or finance leases. Both operating and finance leases recognize lease liabilities and associated right-of-use assets. Operating lease arrangements mainly involve drill ships, drilling rigs, time chartered vessels, bareboat charters, terminals,
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
exploration and production equipment, office buildings and warehouses, and land. Finance leases primarily include facilities and vessels.
Chevron uses various assumptions and judgments in preparing the quantitative data and qualitative information that is material to the company’s overall lease population. Where leases are used in joint ventures, the company recognizes 100% of the right-of-use assets and lease liabilities when the company is the sole signatory for the lease (in most cases, where the company is the operator of a joint venture). Lease costs reflect only the costs associated with the operator’s working interest share. The lease term includes the committed lease term identified in the contract, taking into account renewal and termination options that management is reasonably certain to exercise. The company uses its incremental borrowing rate as a proxy for the discount rate based on the term of the lease unless the implicit rate is available.
Details of the right-of-use assets and lease liabilities for operating and finance leases, including the balance sheet presentation, are as follows:
| At December 31, 2019 | |||||||
| Operating Leases | Finance Leases | ||||||
| Deferred charges and other assets | $ | 4,074 | $ | — | |||
| Properties, plant and equipment, net | — | 329 | |||||
| Right-of-use assets****1, 2 | $ | 4,074 | $ | 329 | |||
| Accrued Liabilities | $ | 1,277 | $ | — | |||
| Short-term Debt | — | 18 | |||||
| Current lease liabilities | 1,277 | 18 | |||||
| Deferred credits and other noncurrent obligations | 2,608 | — | |||||
| Long-term Debt | — | 282 | |||||
| Noncurrent lease liabilities | 2,608 | 282 | |||||
| Total lease liabilities | $ | 3,885 | $ | 300 | |||
| Weighted-average remaining lease term (in years) | 5.2 | 16.0 | |||||
| Weighted-average discount rate | 3.2 | % | 4.7 | % |
1 Capitalized leased assets of $818 are primarily from the Upstream segment, with accumulated amortization of $617 at December 31, 2018.
2 Includes non-cash additions of $1,201 and $184 right-of-use assets obtained in exchange for new and modified lease liabilities in 2019 for operating and finance leases, respectively.
Total lease costs consist of both amounts recognized in the Consolidated Statement of Income during the period and amounts capitalized as part of the cost of another asset. Total lease costs incurred for operating and finance leases were as follows:
| Year Ended December 31, 2019 | ||||
| Operating lease costs1, 2 | $ | 2,621 | ||
| Finance lease costs | 66 | |||
| Total lease costs | $ | 2,687 |
1 Net rental expense of $816 and $721 for 2018 and 2017, respectively.
2 Includes variable and short-term lease costs.
Cash paid for amounts included in the measurement of lease liabilities was as follows:
| Year Ended December 31, 2019 | |||
| Operating cash flows from operating leases | $ | 1,574 | |
| Investing cash flows from operating leases | 1,047 | ||
| Operating cash flows from finance leases | 13 | ||
| Financing cash flows from finance leases | 24 |
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
At December 31, 2019, the estimated future undiscounted cash flows for operating and finance leases were as follows:
| At December 31, 2019 | ||||||||
| Operating Leases | Finance Leases | |||||||
| Year | 2020 | $ | 1,374 | $ | 35 | |||
| 2021 | 1,083 | 33 | ||||||
| 2022 | 546 | 31 | ||||||
| 2023 | 336 | 31 | ||||||
| 2024 | 216 | 30 | ||||||
| Thereafter | 696 | 251 | ||||||
| Total | $ | 4,251 | $ | 411 | ||||
| Less: Amounts representing interest | 366 | 111 | ||||||
| Total lease liabilities | $ | 3,885 | $ | 300 |
Additionally, the company has $790 in future undiscounted cash flows for operating leases not yet commenced. These leases are primarily for a drill ship, a facility, a bareboat charter, and a drilling rig. For those leasing arrangements where the underlying asset is not yet constructed, the lessor is primarily involved in the design and construction of the asset.
At December 31, 2018, the estimated future minimum lease payments (net of noncancelable sublease rentals) under operating and capital leases, which at inception had a noncancelable term of more than one year, were as follows:
| At December 31, 2018 | ||||||||
| Operating Leases | Capital Leases * | |||||||
| Year | 2019 | $ | 540 | $ | 30 | |||
| 2020 | 492 | 22 | ||||||
| 2021 | 378 | 17 | ||||||
| 2022 | 242 | 16 | ||||||
| 2023 | 166 | 16 | ||||||
| Thereafter | 341 | 132 | ||||||
| Total | $ | 2,159 | $ | 233 | ||||
| Less: Amounts representing interest and executory costs | (88 | ) | ||||||
| Net present values | 145 | |||||||
| Less: Capital lease obligations included in short-term debt | (18 | ) | ||||||
| Long-term capital lease obligations | $ | 127 |
- Excluded from the table is an executed but not-yet-commenced capital lease with payments of $14, $15, $22, $21, $21 and $219 for 2019, 2020, 2021, 2022, 2023 and thereafter, respectively.
Note 6
Summarized Financial Data – Chevron U.S.A. Inc.
Chevron U.S.A. Inc. (CUSA) is a major subsidiary of Chevron Corporation. CUSA and its subsidiaries manage and operate most of Chevron’s U.S. businesses. Assets include those related to the exploration and production of crude oil, natural gas and natural gas liquids and those associated with the refining, marketing, supply and distribution of products derived from petroleum, excluding most of the regulated pipeline operations of Chevron. CUSA also holds the company’s investment in the Chevron Phillips Chemical Company LLC joint venture, which is accounted for using the equity method. The summarized financial information for CUSA and its consolidated subsidiaries is as follows:
| Year ended December 31 | ||||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| Sales and other operating revenues | $ | 109,314 | $ | 125,076 | $ | 104,054 | ||||||
| Total costs and other deductions | 116,365 | 121,351 | 103,904 | |||||||||
| Net income (loss) attributable to CUSA | (5,061 | ) | 4,334 | 4,842 |
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
| At December 31 | ||||||||
| 2019 | 2018 | |||||||
| Current assets | $ | 13,059 | $ | 12,819 | ||||
| Other assets | 50,796 | 55,814 | ||||||
| Current liabilities | 18,291 | 16,376 | ||||||
| Other liabilities | 12,565 | 12,906 | ||||||
| Total CUSA net equity | $ | 32,999 | $ | 39,351 | ||||
| Memo: Total debt | $ | 3,222 | $ | 3,049 |
Note 7
Fair Value Measurements
The tables on the next page show the fair value hierarchy for assets and liabilities measured at fair value on a recurring and nonrecurring basis at December 31, 2019, and December 31, 2018.
Marketable Securities The company calculates fair value for its marketable securities based on quoted market prices for identical assets. The fair values reflect the cash that would have been received if the instruments were sold at December 31, 2019.
Derivatives The company records its derivative instruments – other than any commodity derivative contracts that are designated as normal purchase and normal sale – on the Consolidated Balance Sheet at fair value, with the offsetting amount to the Consolidated Statement of Income. Derivatives classified as Level 1 include futures, swaps and options contracts traded in active markets such as the New York Mercantile Exchange. Derivatives classified as Level 2 include swaps, options and forward contracts principally with financial institutions and other oil and gas companies, the fair values of which are obtained from third-party broker quotes, industry pricing services and exchanges. The company obtains multiple sources of pricing information for the Level 2 instruments. Since this pricing information is generated from observable market data, it has historically been very consistent. The company does not materially adjust this information.
Properties, Plant and Equipment The company reported impairments for certain upstream properties during 2019 primarily due to capital allocation decisions and a lower long-term commodity price outlook. The company did not have any individually material impairments in 2018.
Investments and Advances The company reported impairments for certain upstream equity companies during 2019 primarily due to capital allocation decisions and a lower long-term commodity price outlook. The company did not have any individually material impairments of investments and advances in 2018.
Assets and Liabilities Measured at Fair Value on a Recurring Basis
| At December 31, 2019 | At December 31, 2018 | |||||||||||||||||||||||
| Total | Level 1 | Level 2 | Level 3 | Total | Level 1 | Level 2 | Level 3 | |||||||||||||||||
| Marketable securities | $ | 63 | $ | 63 | $ | — | $ | — | $ | 53 | $ | 53 | $ | — | $ | — | ||||||||
| Derivatives | 11 | 1 | 10 | — | 283 | 185 | 98 | — | ||||||||||||||||
| Total assets at fair value | $ | 74 | $ | 64 | $ | 10 | $ | — | $ | 336 | $ | 238 | $ | 98 | $ | — | ||||||||
| Derivatives | 74 | 26 | 48 | — | 12 | — | 12 | — | ||||||||||||||||
| Total liabilities at fair value | $ | 74 | $ | 26 | $ | 48 | $ | — | $ | 12 | $ | — | $ | 12 | $ | — |
Assets and Liabilities Measured at Fair Value on a Nonrecurring Basis
| At December 31 | At December 31 | |||||||||||||||||||||||||||||
| Before-Tax Loss | Before-Tax Loss | |||||||||||||||||||||||||||||
| Total | Level 1 | Level 2 | Level 3 | Year 2019 | Total | Level 1 | Level 2 | Level 3 | Year 2018 | |||||||||||||||||||||
| Properties, plant and equipment, net (held and used) | $ | 2,177 | $ | — | $ | — | $ | 2,177 | $ | 2,095 | $ | 102 | $ | — | $ | 62 | $ | 40 | $ | 97 | ||||||||||
| Properties, plant and equipment, net (held for sale) | 1,412 | — | 1,412 | — | 8,702 | 1,694 | — | 1,273 | 421 | 638 | ||||||||||||||||||||
| Investments and advances | 52 | — | 30 | 22 | 594 | 81 | — | 20 | 61 | 69 | ||||||||||||||||||||
| Total nonrecurring assets at fair value | $ | 3,641 | $ | — | $ | 1,442 | $ | 2,199 | $ | 11,391 | $ | 1,877 | $ | — | $ | 1,355 | $ | 522 | $ | 804 |
Assets and Liabilities Not Required to Be Measured at Fair Value The company holds cash equivalents and time deposits in U.S. and non-U.S. portfolios. The instruments classified as cash equivalents are primarily bank time deposits with maturities of 90 days or less and money market funds. “Cash and cash equivalents” had carrying/fair values of $5,686 and $9,342 at
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
December 31, 2019, and December 31, 2018, respectively. The instruments held in “Time deposits” are bank time deposits with maturities greater than 90 days and had carrying/fair values of zero and $950 at December 31, 2019, and December 31, 2018, respectively. The fair values of cash, cash equivalents and bank time deposits are classified as Level 1 and reflect the cash that would have been received if the instruments were settled at December 31, 2019.
“Cash and cash equivalents” do not include investments with a carrying/fair value of $1,225 and $1,139 at December 31, 2019, and December 31, 2018, respectively. At December 31, 2019, these investments are classified as Level 1 and include restricted funds related to certain upstream decommissioning activities, refundable deposits held in escrow related to pending asset sales, tax payments and a financing program, which are reported in “Deferred charges and other assets” on the Consolidated Balance Sheet. Long-term debt, excluding finance lease liabilities, of $13,659 and $18,706 at December 31, 2019, and December 31, 2018, respectively, had estimated fair values of $14,326 and $18,729, respectively. Long-term debt primarily includes corporate issued bonds. The fair value of corporate bonds is $13,460 and classified as Level 1. The fair value of other long-term debt is $866 and classified as Level 2.
The carrying values of short-term financial assets and liabilities on the Consolidated Balance Sheet approximate their fair values. Fair value remeasurements of other financial instruments at December 31, 2019 and 2018, were not material.
Note 8
Financial and Derivative Instruments
Derivative Commodity Instruments The company’s derivative commodity instruments principally include crude oil, natural gas and refined product futures, swaps, options, and forward contracts. None of the company’s derivative instruments is designated as a hedging instrument, although certain of the company’s affiliates make such designation. The company’s derivatives are not material to the company’s financial position, results of operations or liquidity. The company believes it has no material market or credit risks to its operations, financial position or liquidity as a result of its commodity derivative activities.
The company uses derivative commodity instruments traded on the New York Mercantile Exchange and on electronic platforms of the Inter-Continental Exchange and Chicago Mercantile Exchange. In addition, the company enters into swap contracts and option contracts principally with major financial institutions and other oil and gas companies in the “over-the-counter” markets, which are governed by International Swaps and Derivatives Association agreements and other master netting arrangements. Depending on the nature of the derivative transactions, bilateral collateral arrangements may also be required.
Derivative instruments measured at fair value at December 31, 2019, December 31, 2018, and December 31, 2017, and their classification on the Consolidated Balance Sheet and Consolidated Statement of Income are below:
Consolidated Balance Sheet: Fair Value of Derivatives Not Designated as Hedging Instruments
| At December 31 | |||||||||
| Type of Contract | Balance Sheet Classification | 2019 | 2018 | ||||||
| Commodity | Accounts and notes receivable, net | $ | 11 | $ | 279 | ||||
| Commodity | Long-term receivables, net | — | 4 | ||||||
| Total assets at fair value | $ | 11 | $ | 283 | |||||
| Commodity | Accounts payable | $ | 74 | $ | 12 | ||||
| Commodity | Deferred credits and other noncurrent obligations | — | — | ||||||
| Total liabilities at fair value | $ | 74 | $ | 12 |
Consolidated Statement of Income: The Effect of Derivatives Not Designated as Hedging Instruments
| Gain/(Loss) | |||||||||||||
| Type of Derivative | Statement of | Year ended December 31 | |||||||||||
| Contract | Income Classification | 2019 | 2018 | 2017 | |||||||||
| Commodity | Sales and other operating revenues | $ | (291 | ) | $ | 135 | $ | (105 | ) | ||||
| Commodity | Purchased crude oil and products | (17 | ) | (33 | ) | (9 | ) | ||||||
| Commodity | Other income | (2 | ) | 3 | (2 | ) | |||||||
| $ | (310 | ) | $ | 105 | $ | (116 | ) |
The table below represents gross and net derivative assets and liabilities subject to netting agreements on the Consolidated Balance Sheet at December 31, 2019 and December 31, 2018.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Consolidated Balance Sheet: The Effect of Netting Derivative Assets and Liabilities
| Gross Amounts Recognized | Gross Amounts Offset | Net Amounts Presented | Gross Amounts Not Offset | Net Amounts | ||||||||||||||||
| At December 31, 2019 | ||||||||||||||||||||
| Derivative Assets | $ | 656 | $ | 645 | $ | 11 | $ | — | $ | 11 | ||||||||||
| Derivative Liabilities | $ | 719 | $ | 645 | $ | 74 | $ | — | $ | 74 | ||||||||||
| At December 31, 2018 | ||||||||||||||||||||
| Derivative Assets | $ | 3,685 | $ | 3,402 | $ | 283 | $ | — | $ | 283 | ||||||||||
| Derivative Liabilities | $ | 3,414 | $ | 3,402 | $ | 12 | $ | — | $ | 12 | ||||||||||
Derivative assets and liabilities are classified on the Consolidated Balance Sheet as accounts and notes receivable, long-term receivables, accounts payable, and deferred credits and other noncurrent obligations. Amounts not offset on the Consolidated Balance Sheet represent positions that do not meet all the conditions for “a right of offset.”
Concentrations of Credit Risk The company’s financial instruments that are exposed to concentrations of credit risk consist primarily of its cash equivalents, time deposits, marketable securities, derivative financial instruments and trade receivables. The company’s short-term investments are placed with a wide array of financial institutions with high credit ratings. Company investment policies limit the company’s exposure both to credit risk and to concentrations of credit risk. Similar policies on diversification and creditworthiness are applied to the company’s counterparties in derivative instruments.
The trade receivable balances, reflecting the company’s diversified sources of revenue, are dispersed among the company’s broad customer base worldwide. As a result, the company believes concentrations of credit risk are limited. The company routinely assesses the financial strength of its customers. When the financial strength of a customer is not considered sufficient, alternative risk mitigation measures may be deployed, including requiring pre-payments, letters of credit or other acceptable collateral instruments to support sales to customers.
Note 9
Assets Held for Sale
At December 31, 2019, the company classified $3,411 of net properties, plant and equipment as “Assets held for sale” on the Consolidated Balance Sheet. These assets are associated with upstream operations that are anticipated to be sold in the next 12 months. The revenues and earnings contributions of these assets in 2019 were not material.
Note 10
Equity
Retained earnings at December 31, 2019 and 2018, included $25,319 and $22,362, respectively, for the company’s share of undistributed earnings of equity affiliates.
At December 31, 2019, about 72 million shares of Chevron’s common stock remained available for issuance from the 260 million shares that were reserved for issuance under the Chevron Long-Term Incentive Plan. In addition, 688,303 shares remain available for issuance from the 1,600,000 shares of the company’s common stock that were reserved for awards under the Chevron Corporation Non-Employee Directors’ Equity Compensation and Deferral Plan.
Note 11
Earnings Per Share
Basic earnings per share (EPS) is based upon “Net Income (Loss) Attributable to Chevron Corporation” (“earnings”) and includes the effects of deferrals of salary and other compensation awards that are invested in Chevron stock units by certain officers and employees of the company. Diluted EPS includes the effects of these items as well as the dilutive effects of outstanding stock options awarded under the company’s stock option programs (refer to Note 20, “Stock Options and Other Share-Based Compensation,” beginning on page 80). The table on the following page sets forth the computation of basic and diluted EPS:
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
| Year ended December 31 | ||||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| Basic EPS Calculation | ||||||||||||
| Earnings available to common stockholders - Basic1 | $ | 2,924 | $ | 14,824 | $ | 9,195 | ||||||
| Weighted-average number of common shares outstanding2 | 1,882 | 1,897 | 1,882 | |||||||||
| Add: Deferred awards held as stock units | — | 1 | 1 | |||||||||
| Total weighted-average number of common shares outstanding | 1,882 | 1,898 | 1,883 | |||||||||
| Earnings per share of common stock - Basic | $ | 1.55 | $ | 7.81 | $ | 4.88 | ||||||
| Diluted EPS Calculation | ||||||||||||
| Earnings available to common stockholders - Diluted1 | $ | 2,924 | $ | 14,824 | $ | 9,195 | ||||||
| Weighted-average number of common shares outstanding2 | 1,882 | 1,897 | 1,882 | |||||||||
| Add: Deferred awards held as stock units | — | 1 | 1 | |||||||||
| Add: Dilutive effect of employee stock-based awards | 13 | 16 | 15 | |||||||||
| Total weighted-average number of common shares outstanding | 1,895 | 1,914 | 1,898 | |||||||||
| Earnings per share of common stock - Diluted | $ | 1.54 | $ | 7.74 | $ | 4.85 | ||||||
| 1 There was no effect of dividend equivalents paid on stock units or dilutive impact of employee stock-based awards on earnings. | ||||||||||||
| 2 Millions of shares. |
Note 12
Operating Segments and Geographic Data
Although each subsidiary of Chevron is responsible for its own affairs, Chevron Corporation manages its investments in these subsidiaries and their affiliates. The investments are grouped into two business segments, Upstream and Downstream, representing the company’s “reportable segments” and “operating segments.” Upstream operations consist primarily of exploring for, developing and producing crude oil and natural gas; liquefaction, transportation and regasification associated with liquefied natural gas (LNG); transporting crude oil by major international oil export pipelines; processing, transporting, storage and marketing of natural gas; and a gas-to-liquids plant. Downstream operations consist primarily of refining of crude oil into petroleum products; marketing of crude oil and refined products; transporting of crude oil and refined products by pipeline, marine vessel, motor equipment and rail car; and manufacturing and marketing of commodity petrochemicals, plastics for industrial uses, and fuel and lubricant additives. All Other activities of the company include worldwide cash management and debt financing activities, corporate administrative functions, insurance operations, real estate activities, and technology activities.
The company’s segments are managed by “segment managers” who report to the “chief operating decision maker” (CODM). The segments represent components of the company that engage in activities (a) from which revenues are earned and expenses are incurred; (b) whose operating results are regularly reviewed by the CODM, which makes decisions about resources to be allocated to the segments and assesses their performance; and (c) for which discrete financial information is available.
The company’s primary country of operation is the United States of America, its country of domicile. Other components of the company’s operations are reported as “International” (outside the United States).
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Segment Earnings The company evaluates the performance of its operating segments on an after-tax basis, without considering the effects of debt financing interest expense or investment interest income, both of which are managed by the company on a worldwide basis. Corporate administrative costs are not allocated to the operating segments. However, operating segments are billed for the direct use of corporate services. Nonbillable costs remain at the corporate level in “All Other.” Earnings by major operating area are presented in the following table:
| Year ended December 31 | ||||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| Upstream | ||||||||||||
| United States | $ | (5,094 | ) | $ | 3,278 | $ | 3,640 | |||||
| International | 7,670 | 10,038 | 4,510 | |||||||||
| Total Upstream | 2,576 | 13,316 | 8,150 | |||||||||
| Downstream | ||||||||||||
| United States | 1,559 | 2,103 | 2,938 | |||||||||
| International | 922 | 1,695 | 2,276 | |||||||||
| Total Downstream | 2,481 | 3,798 | 5,214 | |||||||||
| Total Segment Earnings | 5,057 | 17,114 | 13,364 | |||||||||
| All Other | ||||||||||||
| Interest expense | (761 | ) | (713 | ) | (264 | ) | ||||||
| Interest income | 181 | 137 | 60 | |||||||||
| Other | (1,553 | ) | (1,714 | ) | (3,965 | ) | ||||||
| Net Income (Loss) Attributable to Chevron Corporation | $ | 2,924 | $ | 14,824 | $ | 9,195 |
Segment Assets Segment assets do not include intercompany investments or receivables. Assets at year-end 2019 and 2018 are as follows:
| At December 31 | ||||||||
| 2019 | 2018 | |||||||
| Upstream | ||||||||
| United States | $ | 35,926 | $ | 42,594 | ||||
| International | 145,648 | 153,861 | ||||||
| Goodwill | 4,463 | 4,518 | ||||||
| Total Upstream | 186,037 | 200,973 | ||||||
| Downstream | ||||||||
| United States | 25,197 | 23,866 | ||||||
| International | 16,955 | 15,622 | ||||||
| Total Downstream | 42,152 | 39,488 | ||||||
| Total Segment Assets | 228,189 | 240,461 | ||||||
| All Other | ||||||||
| United States | 3,475 | 5,100 | ||||||
| International | 5,764 | 8,302 | ||||||
| Total All Other | 9,239 | 13,402 | ||||||
| Total Assets – United States | 64,598 | 71,560 | ||||||
| Total Assets – International | 168,367 | 177,785 | ||||||
| Goodwill | 4,463 | 4,518 | ||||||
| Total Assets | $ | 237,428 | $ | 253,863 |
Segment Sales and Other Operating Revenues Operating segment sales and other operating revenues, including internal transfers, for the years 2019, 2018 and 2017, are presented in the table on the next page. Products are transferred between operating segments at internal product values that approximate market prices.
Revenues for the upstream segment are derived primarily from the production and sale of crude oil and natural gas, as well as the sale of third-party production of natural gas. Revenues for the downstream segment are derived from the refining and marketing of petroleum products such as gasoline, jet fuel, gas oils, lubricants, residual fuel oils and other products derived from crude oil. This segment also generates revenues from the manufacture and sale of fuel and lubricant additives and the transportation and trading of refined products and crude oil. “All Other” activities include revenues from insurance operations, real estate activities and technology companies.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
| Year ended December 311 | ||||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| Upstream | ||||||||||||
| United States | $ | 23,358 | $ | 22,891 | $ | 13,242 | ||||||
| International | 35,628 | 37,822 | 28,680 | |||||||||
| Subtotal | 58,986 | 60,713 | 41,922 | |||||||||
| Intersegment Elimination — United States | (14,944 | ) | (13,965 | ) | (9,341 | ) | ||||||
| Intersegment Elimination — International | (12,335 | ) | (13,679 | ) | (11,471 | ) | ||||||
| Total Upstream | 31,707 | 33,069 | 21,110 | |||||||||
| Downstream | ||||||||||||
| United States | 55,271 | 59,376 | 53,140 | |||||||||
| International | 57,654 | 70,095 | 61,395 | |||||||||
| Subtotal | 112,925 | 129,471 | 114,535 | |||||||||
| Intersegment Elimination — United States | (3,924 | ) | (2,742 | ) | (14 | ) | ||||||
| Intersegment Elimination — International | (1,089 | ) | (1,132 | ) | (1,166 | ) | ||||||
| Total Downstream | 107,912 | 125,597 | 113,355 | |||||||||
| All Other | ||||||||||||
| United States | 1,064 | 1,022 | 1,022 | |||||||||
| International | 20 | 22 | 26 | |||||||||
| Subtotal | 1,084 | 1,044 | 1,048 | |||||||||
| Intersegment Elimination — United States | (818 | ) | (786 | ) | (814 | ) | ||||||
| Intersegment Elimination — International | (20 | ) | (22 | ) | (25 | ) | ||||||
| Total All Other | 246 | 236 | 209 | |||||||||
| Sales and Other Operating Revenues | ||||||||||||
| United States | 79,693 | 83,289 | 67,404 | |||||||||
| International | 93,302 | 107,939 | 90,101 | |||||||||
| Subtotal | 172,995 | 191,228 | 157,505 | |||||||||
| Intersegment Elimination — United States | (19,686 | ) | (17,493 | ) | (10,169 | ) | ||||||
| Intersegment Elimination — International | (13,444 | ) | (14,833 | ) | (12,662 | ) | ||||||
| Total Sales and Other Operating Revenues | $ | 139,865 | $ | 158,902 | $ | 134,674 |
1 Other than the United States, no other country accounted for 10 percent or more of the company’s Sales and Other Operating Revenues.
Segment Income Taxes Segment income tax expense for the years 2019, 2018 and 2017 is as follows:
| Year ended December 31 | ||||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| Upstream | ||||||||||||
| United States | $ | (1,550 | ) | $ | 811 | $ | (3,538 | ) | ||||
| International | 3,492 | 4,687 | 2,249 | |||||||||
| Total Upstream | 1,942 | 5,498 | (1,289 | ) | ||||||||
| Downstream | ||||||||||||
| United States | 392 | 534 | (419 | ) | ||||||||
| International | 170 | 328 | 650 | |||||||||
| Total Downstream | 562 | 862 | 231 | |||||||||
| All Other | 187 | (645 | ) | 1,010 | ||||||||
| Total Income Tax Expense (Benefit) | $ | 2,691 | $ | 5,715 | $ | (48 | ) |
Other Segment Information Additional information for the segmentation of major equity affiliates is contained in Note 13, on page 71. Information related to properties, plant and equipment by segment is contained in Note 16, on page 77.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Note 13
Investments and Advances
Equity in earnings, together with investments in and advances to companies accounted for using the equity method and other investments accounted for at or below cost, is shown in the following table. For certain equity affiliates, Chevron pays its share of some income taxes directly. For such affiliates, the equity in earnings does not include these taxes, which are reported on the Consolidated Statement of Income as “Income tax expense.”
| Investments and Advances | Equity in Earnings | ||||||||||||||||||
| At December 31 | Year ended December 31 | ||||||||||||||||||
| 2019 | 2018 | 2019 | 2018 | 2017 | |||||||||||||||
| Upstream | |||||||||||||||||||
| Tengizchevroil | $ | 20,214 | $ | 16,017 | $ | 3,067 | $ | 3,614 | $ | 2,581 | |||||||||
| Petropiar | 1,396 | 1,361 | 80 | 317 | 175 | ||||||||||||||
| Petroboscan | 1,139 | 1,315 | (11 | ) | 357 | 154 | |||||||||||||
| Caspian Pipeline Consortium | 883 | 1,022 | 155 | 170 | 155 | ||||||||||||||
| Angola LNG Limited | 2,423 | 2,496 | (26 | ) | 172 | 27 | |||||||||||||
| Other | 881 | 1,541 | (478 | ) | 19 | 104 | |||||||||||||
| Total Upstream | 26,936 | 23,752 | 2,787 | 4,649 | 3,196 | ||||||||||||||
| Downstream | |||||||||||||||||||
| Chevron Phillips Chemical Company LLC | 6,241 | 6,218 | 880 | 1,034 | 723 | ||||||||||||||
| GS Caltex Corporation | 3,796 | 3,924 | 13 | 373 | 290 | ||||||||||||||
| Other | 1,443 | 1,383 | 288 | 273 | 230 | ||||||||||||||
| Total Downstream | 11,480 | 11,525 | 1,181 | 1,680 | 1,243 | ||||||||||||||
| All Other | |||||||||||||||||||
| Other | (14 | ) | (16 | ) | — | (2 | ) | (1 | ) | ||||||||||
| Total equity method | $ | 38,402 | $ | 35,261 | $ | 3,968 | $ | 6,327 | $ | 4,438 | |||||||||
| Other non-equity method investments | 286 | 285 | |||||||||||||||||
| Total investments and advances | $ | 38,688 | $ | 35,546 | |||||||||||||||
| Total United States | $ | 7,203 | $ | 7,500 | $ | 641 | $ | 1,033 | $ | 788 | |||||||||
| Total International | $ | 31,485 | $ | 28,046 | $ | 3,327 | $ | 5,294 | $ | 3,650 |
Descriptions of major affiliates, including significant differences between the company’s carrying value of its investments and its underlying equity in the net assets of the affiliates, are as follows:
Tengizchevroil Chevron has a 50 percent equity ownership interest in Tengizchevroil (TCO), which operates the Tengiz and Korolev crude oil fields in Kazakhstan. At December 31, 2019, the company’s carrying value of its investment in TCO was about $110 higher than the amount of underlying equity in TCO’s net assets. This difference results from Chevron acquiring a portion of its interest in TCO at a value greater than the underlying book value for that portion of TCO’s net assets. Included in the investment is a loan to TCO to fund the development of the Future Growth and Wellhead Pressure Management Project with a balance of $3,350.
Petropiar Chevron has a 30 percent interest in Petropiar, a joint stock company which operates the heavy oil Huyapari Field and upgrading project in Venezuela’s Orinoco Belt. At December 31, 2019, the company’s carrying value of its investment in Petropiar was approximately $130 less than the amount of underlying equity in Petropiar’s net assets. The difference represents the excess of Chevron’s underlying equity in Petropiar’s net assets over the net book value of the assets contributed to the venture.
Petroboscan Chevron has a 39.2 percent interest in Petroboscan, a joint stock company which operates the Boscan Field in Venezuela. At December 31, 2019, the company’s carrying value of its investment in Petroboscan was approximately $90 higher than the amount of underlying equity in Petroboscan’s net assets. The difference reflects the excess of the net book value of the assets contributed by Chevron over its underlying equity in Petroboscan’s net assets. The company also has an outstanding long-term loan to Petroboscan of $566 at year-end 2019.
Caspian Pipeline Consortium Chevron has a 15 percent interest in the Caspian Pipeline Consortium, a variable interest entity, which provides the critical export route for crude oil from both TCO and Karachaganak. The company has investments and advances totaling $883, which includes long-term loans of $199 at year-end 2019. The loans were provided to fund 30 percent of the initial pipeline construction. The company is not the primary beneficiary of the consortium because it does not direct activities of the consortium and only receives its proportionate share of the financial returns.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Angola LNG Limited Chevron has a 36.4 percent interest in Angola LNG Limited, which processes and liquefies natural gas produced in Angola for delivery to international markets.
Chevron Phillips Chemical Company LLC Chevron owns 50 percent of Chevron Phillips Chemical Company LLC. The other half is owned by Phillips 66.
GS Caltex Corporation Chevron owns 50 percent of GS Caltex Corporation, a joint venture with GS Energy. The joint venture imports, refines and markets petroleum products, petrochemicals and lubricants, predominantly in South Korea.
Other Information “Sales and other operating revenues” on the Consolidated Statement of Income includes $8,006, $10,378 and $8,165 with affiliated companies for 2019, 2018 and 2017, respectively. “Purchased crude oil and products” includes $5,694, $6,598 and $4,800 with affiliated companies for 2019, 2018 and 2017, respectively.
“Accounts and notes receivable” on the Consolidated Balance Sheet includes $810 and $884 due from affiliated companies at December 31, 2019 and 2018, respectively. “Accounts payable” includes $506 and $631 due to affiliated companies at December 31, 2019 and 2018, respectively.
The following table provides summarized financial information on a 100 percent basis for all equity affiliates as well as Chevron’s total share, which includes Chevron’s net loans to affiliates of $4,331, $3,402 and $3,853 at December 31, 2019, 2018 and 2017, respectively.
| Affiliates | Chevron Share | |||||||||||||||||||||||
| Year ended December 31 | 2019 | 2018 | 2017 | 2019 | 2018 | 2017 | ||||||||||||||||||
| Total revenues | $ | 66,473 | $ | 84,469 | $ | 70,744 | $ | 32,628 | $ | 40,679 | $ | 33,460 | ||||||||||||
| Income before income tax expense | 13,197 | 16,693 | 13,487 | 5,954 | 6,755 | 5,712 | ||||||||||||||||||
| Net income attributable to affiliates | 9,809 | 13,321 | 10,751 | 4,366 | 6,384 | 4,468 | ||||||||||||||||||
| At December 31 | ||||||||||||||||||||||||
| Current assets | $ | 30,791 | $ | 32,657 | $ | 33,883 | $ | 12,998 | $ | 12,813 | $ | 13,568 | ||||||||||||
| Noncurrent assets | 97,177 | 87,614 | 82,261 | 41,531 | 36,369 | 32,643 | ||||||||||||||||||
| Current liabilities | 26,032 | 26,006 | 26,873 | 10,610 | 9,843 | 10,201 | ||||||||||||||||||
| Noncurrent liabilities | 21,593 | 20,000 | 21,447 | 5,068 | 4,446 | 4,224 | ||||||||||||||||||
| Total affiliates’ net equity | $ | 80,343 | $ | 74,265 | $ | 67,824 | $ | 38,851 | $ | 34,893 | $ | 31,786 |
Note 14
Litigation
MTBE Chevron and many other companies in the petroleum industry have used methyl tertiary butyl ether (MTBE) as a gasoline additive. Chevron is a party to six pending lawsuits and claims, the majority of which involve numerous other petroleum marketers and refiners. Resolution of these lawsuits and claims may ultimately require the company to correct or ameliorate the alleged effects on the environment of prior release of MTBE by the company or other parties. Additional lawsuits and claims related to the use of MTBE, including personal-injury claims, may be filed in the future. The company’s ultimate exposure related to pending lawsuits and claims is not determinable. The company no longer uses MTBE in the manufacture of gasoline in the United States.
Ecuador
Background Chevron is a defendant in civil litigation proceedings stemming from a lawsuit filed in the Superior Court for the province of Nueva Loja in Lago Agrio, Ecuador in May 2003 by plaintiffs who claim to be representatives of residents of an area where an oil production consortium formerly operated. The lawsuit alleged harm to the environment from the consortium’s oil production activities and sought monetary damages and other relief. Texaco Petroleum Company (Texpet), a subsidiary of Texaco Inc., was a minority member of the consortium from 1967 until 1992, with state-owned Petroecuador as the majority partner. Since 1992, Petroecuador has been the sole owner and operator in the concession area. After the termination of the consortium and following an independent third-party environmental audit of the concession area, in 1995, Texpet entered into a formal agreement with the Republic of Ecuador and Petroecuador under which Texpet agreed to remediate specific sites assigned by the government in proportion to Texpet’s minority share of the consortium. Pursuant to that agreement, Texpet conducted a three-year remediation program. After certifying that the assigned sites were properly remediated, in 1998, Ecuador granted Texpet and all related corporate entities a full release from any and all environmental liability arising from the consortium operations.
Chevron defended itself in the Lago Agrio lawsuit on the grounds that the claims lacked both legal and factual merit. As to matters of law, Chevron asserted that the court lacked jurisdiction, the plaintiffs sought to improperly apply a 1999 law
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
retroactively, the claims were time-barred, and the lawsuit was barred by releases signed by the Republic of Ecuador, Petroecuador, and the pertinent provincial and municipal governments. With regard to the facts, the company asserted that the evidence confirmed Texpet’s remediation was properly conducted and that any remaining environmental impacts reflected Petroecuador’s failure to timely fulfill its own legal obligation to remediate the concession area and Petroecuador’s conduct after it assumed control over operations. In February 2011, the provincial court rendered a judgment against Chevron, awarding approximately $8,600 in damages, plus approximately $900 for the plaintiffs’ representatives, and approximately $8,600 in additional punitive damages unless the company issued a public apology within 15 days, which Chevron did not do. In January 2012 an appellate panel affirmed the judgment and ordered that Chevron pay an additional 0.10% in attorneys’ fees. In November 2013, Ecuador’s National Court of Justice ratified the judgment but nullified the $8,600 punitive damage assessment, resulting in a judgment of $9,500. In December 2013, Chevron appealed the decision to Ecuador’s highest Constitutional Court, which rejected Chevron’s appeal in July 2018. No further appeals are available in Ecuador.
The Lago Agrio plaintiffs’ lawyers have sought to enforce the judgment in Ecuador and other jurisdictions. In May 2012, they filed a recognition and enforcement action against Chevron Corporation, Chevron Canada Limited and another subsidiary (which was later dismissed as a party) in the Superior Court of Justice in Ontario, Canada. In September 2015, the Supreme Court of Canada ruled that the Ontario Superior Court of Justice had jurisdiction over Chevron Corporation and Chevron Canada Limited for purposes of the action. In January 2017, the Superior Court ruled that Chevron Canada Limited and Chevron Corporation are separate legal entities with separate rights and obligations, and dismissed the action against Chevron Canada Limited. In May 2018, the Court of Appeal for Ontario upheld the dismissal of Chevron Canada Limited. The Supreme Court of Canada denied the plaintiffs’ application for leave to appeal in April 2019, rendering the dismissal of Chevron Canada Limited final. In July 2019, by consent of the parties, the Ontario Superior Court dismissed the recognition and enforcement action against Chevron Corporation with prejudice and with costs in favor of Chevron. In June 2012, the plaintiffs filed a recognition and enforcement action against Chevron Corporation in the Superior Court of Justice in Brasilia, Brazil. In May 2015, the Brazilian public prosecutor issued an opinion recommending that the court reject the plaintiffs’ action on grounds including that the Lago Agrio judgment was procured through fraud and corruption and violated Brazilian and international public order. In November 2017, the Superior Court of Justice dismissed the plaintiffs’ recognition and enforcement action on jurisdictional grounds, and in June 2018 the dismissal became final in Brazil. In October 2012, the provincial court in Ecuador issued an ex parte embargo order purporting to order the seizure of assets belonging to separate Chevron subsidiaries in Ecuador, Argentina and Colombia. In November 2012, at the request of the plaintiffs, a court in Argentina issued a freeze order against Chevron Argentina S.R.L. and another Chevron subsidiary. In January 2013, an appellate court upheld the freeze order, but in June 2013, the Supreme Court of Argentina revoked the freeze order in its entirety. In December 2013, Chevron was served with the plaintiffs’ complaint seeking recognition and enforcement of the judgment in Argentina. In April 2016, the public prosecutor in Argentina issued an opinion recommending rejection of the plaintiffs’ request to recognize the Ecuadorian judgment in Argentina. In November 2017, the National Court, First Instance, dismissed the complaint on jurisdictional grounds and the Federal Civil Court of Appeals affirmed the dismissal in July 2018. The plaintiffs’ appeal to the Supreme Court of Argentina remains pending. Chevron continues to believe the Ecuadorian judgment is illegitimate and unenforceable because it is the product of fraud and corruption, and contrary to the law and all legitimate scientific evidence. Chevron cannot predict the timing or outcome of any pending or threatened enforcement action, but expects to continue a vigorous defense against any imposition of liability and to contest and defend any and all enforcement actions.
In February 2011, Chevron filed a civil lawsuit in the U.S. District Court for the Southern District of New York against the Lago Agrio plaintiffs and several of their lawyers and supporters, asserting violations of the Racketeer Influenced and Corrupt Organizations (RICO) Act and state law. In March 2014, the District Court entered a judgment in favor of Chevron, finding that the Ecuadorian judgment had been procured through fraud, bribery and corruption, and prohibiting the RICO defendants from seeking to enforce the Lago Agrio judgment in the United States or profiting from their illegal acts. In August 2016, the U.S. Court of Appeals for the Second Circuit issued a unanimous decision affirming the New York judgment in full. In June 2017, the U.S. Supreme Court denied the RICO defendants’ petition for a Writ of Certiorari, rendering the New York judgment in favor of Chevron final.
Chevron and Texpet filed an arbitration claim in September 2009 against the Republic of Ecuador before an arbitral tribunal administered by the Permanent Court of Arbitration in The Hague, under the Rules of the United Nations Commission on International Trade Law. The claim alleged violations of Ecuador’s obligations under the United States-Ecuador Bilateral Investment Treaty (BIT) and breaches of the settlement and release agreements between Ecuador and Texpet. In January 2012, the Tribunal issued its First Interim Measures Award requiring Ecuador to take all measures at its disposal to suspend or cause to be suspended the enforcement or recognition within and outside of Ecuador of any judgment against Chevron in the Lago Agrio case pending further order of the Tribunal. In February 2012, the Tribunal issued a Second
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Interim Award mandating that Ecuador take all measures necessary to suspend or cause to be suspended enforcement and recognition proceedings within and outside of Ecuador. Also in February 2012, the Tribunal issued a Third Interim Award confirming its jurisdiction to hear Chevron and Texpet’s claims. In February 2013, the Tribunal issued its Fourth Interim Award in which it declared that Ecuador had violated the First and Second Interim Awards. The Tribunal divided the merits phase of the arbitration into three phases. In September 2013, after the conclusion of Phase One, the Tribunal issued its First Partial Award, finding that the settlement agreements between Ecuador and Texpet applied to both Texpet and Chevron and released them from public environmental claims arising from the consortium’s operations, but did not preclude individual claims for personal harm. In August 2018, the Tribunal issued its Phase Two award, again in favor of Chevron and Texpet. The Tribunal unanimously held that the Lago Agrio judgment was procured through fraud, bribery and corruption and was based on public claims that Ecuador had settled and released. According to the Tribunal, the Ecuadorian judgment “violates international public policy” and “should not be recognized or enforced by the courts of other States.” The Tribunal found that: (i) Ecuador breached its obligations under the settlement agreements releasing Texpet and its affiliates from public environmental claims; (ii) Ecuador committed a denial of justice under international law and violated the U.S.-Ecuador BIT due to the fraud and corruption in the Lago Agrio litigation; and (iii) Texpet satisfied its environmental remediation obligations through the remediation program that Ecuador supervised and approved. The Tribunal ordered Ecuador to: (a) take immediate steps to remove the status of enforceability from the Ecuadorian judgment; (b) take measures to “wipe out all the consequences” of Ecuador’s “internationally wrongful acts in regard to the Ecuadorian judgment;” and (c) compensate Chevron for any injuries resulting from the Ecuadorian judgment. The final Phase Three of the arbitration, at which damages for Chevron’s injuries will be determined, was set for hearing in March 2021. Ecuador filed in the District Court of The Hague a request to set aside the Tribunal’s Interim Awards and its First Partial Award, and in January 2016 that court denied Ecuador’s request. In July 2017, the Appeals Court of the Netherlands denied Ecuador’s appeal, and in April 2019, the Supreme Court of the Netherlands upheld the decision of the Appeals Court and finally rejected Ecuador’s challenges to the Tribunal’s Interim Awards and its First Partial Award. In December 2018, Ecuador filed in the District Court of The Hague a request to set aside the Tribunal’s Phase Two Award.
Management’s Assessment The ultimate outcome of the foregoing matters, including any financial effect on Chevron, remains uncertain. Management does not believe an estimate of a reasonably possible loss (or a range of loss) can be made in this case. Due to the defects associated with the Ecuadorian judgment, management does not believe the judgment has any utility in calculating a reasonably possible loss (or a range of loss). Moreover, the highly uncertain legal environment surrounding the case provides no basis for management to estimate a reasonably possible loss (or a range of loss).
Note 15
Taxes
| Income Taxes | Year ended December 31 | |||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| Income tax expense (benefit) | ||||||||||||
| U.S. federal | ||||||||||||
| Current | $ | (73 | ) | $ | (181 | ) | $ | (382 | ) | |||
| Deferred | (1,074 | ) | 738 | (2,561 | ) | |||||||
| State and local | ||||||||||||
| Current | 153 | 183 | (97 | ) | ||||||||
| Deferred | (172 | ) | (16 | ) | 66 | |||||||
| Total United States | (1,166 | ) | 724 | (2,974 | ) | |||||||
| International | ||||||||||||
| Current | 4,577 | 4,662 | 3,634 | |||||||||
| Deferred | (720 | ) | 329 | (708 | ) | |||||||
| Total International | 3,857 | 4,991 | 2,926 | |||||||||
| Total income tax expense (benefit) | $ | 2,691 | $ | 5,715 | $ | (48 | ) |
The reconciliation between the U.S. statutory federal income tax rate and the company’s effective income tax rate is detailed in the table on the following page:
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
| 2019 | 2018 | 2017 | ||||||||||
| Income (loss) before income taxes | ||||||||||||
| United States | $ | (5,483 | ) | $ | 4,730 | $ | (441 | ) | ||||
| International | 11,019 | 15,845 | 9,662 | |||||||||
| Total income (loss) before income taxes | 5,536 | 20,575 | 9,221 | |||||||||
| Theoretical tax (at U.S. statutory rate of 21% - 2019 & 2018, 35% - 2017) | 1,163 | 4,321 | 3,227 | |||||||||
| Effect of U.S. tax reform | 3 | (26 | ) | (2,020 | ) | |||||||
| Equity affiliate accounting effect | (687 | ) | (1,526 | ) | (1,373 | ) | ||||||
| Effect of income taxes from international operations* | 2,196 | 3,132 | (130 | ) | ||||||||
| State and local taxes on income, net of U.S. federal income tax benefit | (18 | ) | 162 | 39 | ||||||||
| Prior year tax adjustments, claims and settlements | 192 | (51 | ) | (39 | ) | |||||||
| Tax credits | (18 | ) | (163 | ) | (199 | ) | ||||||
| Other U.S.* | (140 | ) | (134 | ) | 447 | |||||||
| Total income tax expense (benefit) | $ | 2,691 | $ | 5,715 | $ | (48 | ) | |||||
| Effective income tax rate | 48.6 | % | 27.8 | % | (0.5 | )% |
- Includes one-time tax costs (benefits) associated with changes in uncertain tax positions and valuation allowances.
The 2019 decrease in income tax expense of $3,024 is a result of the year-over-year decrease in total income before income tax expense, which is primarily due to the impairment and project write-off charges in 2019. The company’s effective tax rate changed from 28 percent in 2018 to 49 percent in 2019. The change in effective tax rate is a consequence of mix effect resulting from the absolute level of earnings or losses and whether they arose in higher or lower tax rate jurisdictions, including a tax charge related to cash repatriation and the impact of asset sales and corporate rate reductions.
The company records its deferred taxes on a tax-jurisdiction basis. The reported deferred tax balances are composed of the following:
| At December 31 | ||||||||
| 2019 | 2018 | |||||||
| Deferred tax liabilities | ||||||||
| Properties, plant and equipment | $ | 17,251 | $ | 20,159 | ||||
| Investments and other* | 5,372 | 4,943 | ||||||
| Total deferred tax liabilities | 22,623 | 25,102 | ||||||
| Deferred tax assets | ||||||||
| Foreign tax credits | (9,840 | ) | (10,536 | ) | ||||
| Asset retirement obligations/environmental reserves | (4,329 | ) | (5,328 | ) | ||||
| Employee benefits | (3,454 | ) | (2,787 | ) | ||||
| Deferred credits | (1,083 | ) | (1,373 | ) | ||||
| Tax loss carryforwards | (5,262 | ) | (4,948 | ) | ||||
| Other accrued liabilities | (441 | ) | (595 | ) | ||||
| Inventory | (662 | ) | (505 | ) | ||||
| Operating leases * | (1,211 | ) | — | |||||
| Miscellaneous | (2,796 | ) | (3,481 | ) | ||||
| Total deferred tax assets | (29,078 | ) | (29,553 | ) | ||||
| Deferred tax assets valuation allowance | 15,965 | 15,973 | ||||||
| Total deferred taxes, net | $ | 9,510 | $ | 11,522 |
- Beginning in 2019, the deferred taxes that are the consequence of ASU 2016-02 are included in the “Investments and other” and “Operating lease” balances above. Refer to Note 5, “Lease Commitments” beginning on page 62.
Deferred tax liabilities at the end of 2019 decreased by approximately $2,500 from year-end 2018. The decrease was primarily related to property, plant and equipment temporary differences due to upstream asset impairments. Deferred tax assets were essentially unchanged from year-end 2018.
The overall valuation allowance relates to deferred tax assets for U.S. foreign tax credit carryforwards, tax loss carryforwards and temporary differences. The valuation allowance reduces the deferred tax assets to amounts that are, in management’s assessment, more likely than not to be realized. At the end of 2019, the company had tax loss carryforwards of approximately $13,419 and tax credit carryforwards of approximately $1,058, primarily related to various international tax jurisdictions. Whereas some of these tax loss carryforwards do not have an expiration date, others expire at various times from 2020 through 2034. U.S. foreign tax credit carryforwards of $9,840 will expire between 2020 and 2029.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
At December 31, 2019 and 2018, deferred taxes were classified on the Consolidated Balance Sheet as follows:
| At December 31 | ||||||||
| 2019 | 2018 | |||||||
| Deferred charges and other assets | $ | (4,178 | ) | $ | (4,399 | ) | ||
| Noncurrent deferred income taxes | 13,688 | 15,921 | ||||||
| Total deferred income taxes, net | $ | 9,510 | $ | 11,522 |
Income taxes are not accrued for unremitted earnings of international operations that have been or are intended to be reinvested indefinitely. The indefinite reinvestment assertion continues to apply for the purpose of determining deferred tax liabilities for U.S. state and foreign withholding tax purposes.
U.S. state and foreign withholding taxes are not accrued for unremitted earnings of international operations that have been or are intended to be reinvested indefinitely. Undistributed earnings of international consolidated subsidiaries and affiliates for which no deferred income tax provision has been made for possible future remittances totaled approximately $52,500 at December 31, 2019. This amount represents earnings reinvested as part of the company’s ongoing international business. It is not practicable to estimate the amount of state and foreign taxes that might be payable on the possible remittance of earnings that are intended to be reinvested indefinitely. The company does not anticipate incurring significant additional taxes on remittances of earnings that are not indefinitely reinvested.
Uncertain Income Tax Positions The company recognizes a tax benefit in the financial statements for an uncertain tax position only if management’s assessment is that the position is “more likely than not” (i.e., a likelihood greater than 50 percent) to be allowed by the tax jurisdiction based solely on the technical merits of the position. The term “tax position” in the accounting standards for income taxes refers to a position in a previously filed tax return or a position expected to be taken in a future tax return that is reflected in measuring current or deferred income tax assets and liabilities for interim or annual periods.
The following table indicates the changes to the company’s unrecognized tax benefits for the years ended December 31, 2019, 2018 and 2017. The term “unrecognized tax benefits” in the accounting standards for income taxes refers to the differences between a tax position taken or expected to be taken in a tax return and the benefit measured and recognized in the financial statements. Interest and penalties are not included.
| 2019 | 2018 | 2017 | ||||||||||
| Balance at January 1 | $ | 5,070 | $ | 4,828 | $ | 3,031 | ||||||
| Foreign currency effects | 1 | (6 | ) | 43 | ||||||||
| Additions based on tax positions taken in current year | 94 | 239 | 1,853 | |||||||||
| Additions for tax positions taken in prior years | 313 | 153 | 1,166 | |||||||||
| Reductions for tax positions taken in prior years | (194 | ) | (131 | ) | (90 | ) | ||||||
| Settlements with taxing authorities in current year | (78 | ) | (13 | ) | (1,173 | ) | ||||||
| Reductions as a result of a lapse of the applicable statute of limitations | (219 | ) | — | (2 | ) | |||||||
| Balance at December 31 | $ | 4,987 | $ | 5,070 | $ | 4,828 |
Approximately 81 percent of the $4,987 of unrecognized tax benefits at December 31, 2019, would have an impact on the effective tax rate if subsequently recognized. Certain of these unrecognized tax benefits relate to tax carryforwards that may require a full valuation allowance at the time of any such recognition.
Tax positions for Chevron and its subsidiaries and affiliates are subject to income tax audits by many tax jurisdictions throughout the world. For the company’s major tax jurisdictions, examinations of tax returns for certain prior tax years had not been completed as of December 31, 2019. For these jurisdictions, the latest years for which income tax examinations had been finalized were as follows: United States – 2013, Nigeria – 2000, Australia – 2009 and Kazakhstan – 2012.
The company engages in ongoing discussions with tax authorities regarding the resolution of tax matters in the various jurisdictions. Both the outcome of these tax matters and the timing of resolution and/or closure of the tax audits are highly uncertain. However, it is reasonably possible that developments on tax matters in certain tax jurisdictions may result in significant increases or decreases in the company’s total unrecognized tax benefits within the next 12 months. Given the number of years that still remain subject to examination and the number of matters being examined in the various tax jurisdictions, the company is unable to estimate the range of possible adjustments to the balance of unrecognized tax benefits.
On the Consolidated Statement of Income, the company reports interest and penalties related to liabilities for uncertain tax positions as “Income tax expense.” As of December 31, 2019, accruals of $30 for anticipated interest and penalty obligations were included on the Consolidated Balance Sheet, compared with accruals of $33 as of year-end 2018. Income tax expense (benefit) associated with interest and penalties was $(3), $8 and $(161) in 2019, 2018 and 2017, respectively.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
| Taxes Other Than on Income | ||||||||||||
| Year ended December 31 | ||||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| United States | ||||||||||||
| Excise and similar taxes on products and merchandise* | $ | 4,990 | $ | 4,830 | $ | 4,398 | ||||||
| Consumer excise taxes collected on behalf of third parties* | (4,990 | ) | (4,830 | ) | — | |||||||
| Import duties and other levies | 2 | 15 | 11 | |||||||||
| Property and other miscellaneous taxes | 1,785 | 1,577 | 1,824 | |||||||||
| Payroll taxes | 254 | 246 | 241 | |||||||||
| Taxes on production | 355 | 325 | 206 | |||||||||
| Total United States | 2,396 | 2,163 | 6,680 | |||||||||
| International | ||||||||||||
| Excise and similar taxes on products and merchandise* | 2,801 | 3,031 | 2,791 | |||||||||
| Consumer excise taxes collected on behalf of third parties* | (2,801 | ) | (3,031 | ) | — | |||||||
| Import duties and other levies | 35 | 37 | 45 | |||||||||
| Property and other miscellaneous taxes | 1,435 | 2,370 | 2,563 | |||||||||
| Payroll taxes | 125 | 132 | 137 | |||||||||
| Taxes on production | 145 | 165 | 115 | |||||||||
| Total International | 1,740 | 2,704 | 5,651 | |||||||||
| Total taxes other than on income | $ | 4,136 | $ | 4,867 | $ | 12,331 |
- Beginning in 2018, these taxes are netted in “Taxes other than on income” in accordance with ASU 2014-09. Refer to Note 24, “Revenue” beginning on page 89.
Note 16
Properties, Plant and Equipment1
| At December 31 | Year ended December 31 | ||||||||||||||||||||||||||||||||||||||
| Gross Investment at Cost | Net Investment | Additions at Cost2 | Depreciation Expense3 | ||||||||||||||||||||||||||||||||||||
| 2019 | 2018 | 2017 | 2019 | 2018 | 2017 | 2019 | 2018 | 2017 | 2019 | 2018 | 2017 | ||||||||||||||||||||||||||||
| Upstream | |||||||||||||||||||||||||||||||||||||||
| United States | $ | 82,117 | $ | 88,155 | $ | 84,602 | $ | 31,082 | $ | 39,526 | $ | 38,722 | $ | 7,751 | $ | 6,434 | $ | 4,995 | $ | 15,222 | $ | 5,328 | $ | 5,527 | |||||||||||||||
| International | 206,292 | 215,329 | 224,211 | 102,639 | 113,603 | 123,191 | 3,664 | 4,865 | 7,934 | 12,618 | 12,726 | 12,096 | |||||||||||||||||||||||||||
| Total Upstream | 288,409 | 303,484 | 308,813 | 133,721 | 153,129 | 161,913 | 11,415 | 11,299 | 12,929 | 27,840 | 18,054 | 17,623 | |||||||||||||||||||||||||||
| Downstream | |||||||||||||||||||||||||||||||||||||||
| United States | 25,968 | 24,685 | 23,598 | 11,398 | 10,838 | 10,346 | 1,452 | 1,259 | 907 | 869 | 751 | 753 | |||||||||||||||||||||||||||
| International | 7,480 | 7,237 | 7,094 | 3,114 | 3,023 | 3,074 | 355 | 278 | 306 | 256 | 282 | 282 | |||||||||||||||||||||||||||
| Total Downstream | 33,448 | 31,922 | 30,692 | 14,512 | 13,861 | 13,420 | 1,807 | 1,537 | 1,213 | 1,125 | 1,033 | 1,035 | |||||||||||||||||||||||||||
| All Other | |||||||||||||||||||||||||||||||||||||||
| United States | 4,719 | 4,667 | 4,798 | 2,236 | 2,186 | 2,341 | 324 | 224 | 218 | 243 | 320 | 677 | |||||||||||||||||||||||||||
| International | 146 | 171 | 182 | 25 | 31 | 38 | 9 | 6 | 4 | 10 | 12 | 14 | |||||||||||||||||||||||||||
| Total All Other | 4,865 | 4,838 | 4,980 | 2,261 | 2,217 | 2,379 | 333 | 230 | 222 | 253 | 332 | 691 | |||||||||||||||||||||||||||
| Total United States | 112,804 | 117,507 | 112,998 | 44,716 | 52,550 | 51,409 | 9,527 | 7,917 | 6,120 | 16,334 | 6,399 | 6,957 | |||||||||||||||||||||||||||
| Total International | 213,918 | 222,737 | 231,487 | 105,778 | 116,657 | 126,303 | 4,028 | 5,149 | 8,244 | 12,884 | 13,020 | 12,392 | |||||||||||||||||||||||||||
| Total | $ | 326,722 | $ | 340,244 | $ | 344,485 | $ | 150,494 | $ | 169,207 | $ | 177,712 | $ | 13,555 | $ | 13,066 | $ | 14,364 | $ | 29,218 | $ | 19,419 | $ | 19,349 |
| 1 | Other than the United States and Australia, no other country accounted for 10 percent or more of the company’s net properties, plant and equipment (PP&E) in 2019. Australia had PP&E of $51,359, $53,768 and $55,514 in 2019, 2018 and 2017, respectively. |
| 2 | Net of dry hole expense related to prior years’ expenditures of $124, $343 and $42 in 2019, 2018 and 2017, respectively. |
| 3 | Depreciation expense includes accretion expense of $628, $654 and $668 in 2019, 2018 and 2017, respectively, and impairments of $10,797, $735 and $1,021 in 2019, 2018 and 2017, respectively. |
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Note 17
Short-Term Debt
| At December 31 | ||||||||
| 2019 | 2018 | |||||||
| Commercial paper1 | $ | 4,654 | $ | 7,503 | ||||
| Notes payable to banks and others with originating terms of one year or less | 228 | 28 | ||||||
| Current maturities of long-term debt2 | 5,054 | 4,999 | ||||||
| Current maturities of long-term finance leases | 18 | 18 | ||||||
| Redeemable long-term obligations | ||||||||
| Long-term debt | 3,078 | 3,078 | ||||||
| Subtotal | 13,032 | 15,626 | ||||||
| Reclassified to long-term debt | (9,750 | ) | (9,900 | ) | ||||
| Total short-term debt | $ | 3,282 | $ | 5,726 | ||||
| 1 Weighted-average interest rates at December 31, 2019 and 2018, were 1.69 percent and 2.43 percent, respectively. | ||||||||
| 2 Net of unamortized discounts and issuance costs: $0 in 2019 and $1 in 2018. |
Redeemable long-term obligations consist primarily of tax-exempt variable-rate put bonds that are included as current liabilities because they become redeemable at the option of the bondholders during the year following the balance sheet date.
The company may periodically enter into interest rate swaps on a portion of its short-term debt. At December 31, 2019, the company had no interest rate swaps on short-term debt.
At December 31, 2019, the company had $9,750 in 364-day committed credit facilities with various major banks that enable the refinancing of short-term obligations on a long-term basis. The credit facilities allow the company to convert any amounts outstanding into a term loan for a period of up to one year. This supports commercial paper borrowing and can also be used for general corporate purposes. The company’s practice has been to continually replace expiring commitments with new commitments on substantially the same terms, maintaining levels management believes appropriate. Any borrowings under the facility would be unsecured indebtedness at interest rates based on the London Interbank Offered Rate or an average of base lending rates published by specified banks and on terms reflecting the company’s strong credit rating. No borrowings were outstanding under this facility at December 31, 2019.
The company classified $9,750 and $9,900 of short-term debt as long-term at December 31, 2019 and 2018, respectively. Settlement of these obligations is not expected to require the use of working capital within one year, and the company has both the intent and the ability, as evidenced by committed credit facilities, to refinance them on a long-term basis.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Note 18
Long-Term Debt
Total long-term debt including finance lease liabilities at December 31, 2019, was $23,691. The company’s long-term debt outstanding at year-end 2019 and 2018 was as follows:
| At December 31 | ||||||||
| 2019 | 2018 | |||||||
| Principal | Principal | |||||||
| 3.191% notes due 2023 | $ | 2,250 | $ | 2,250 | ||||
| 2.954% notes due 2026 | 2,250 | 2,250 | ||||||
| 2.355% notes due 2022 | 2,000 | 2,000 | ||||||
| 1.961% notes due 2020 | 1,750 | 1,750 | ||||||
| 2.100% notes due 2021 | 1,350 | 1,350 | ||||||
| 2.419% notes due 2020 | 1,250 | 1,250 | ||||||
| 2.427% notes due 2020 | 1,000 | 1,000 | ||||||
| 2.895% notes due 2024 | 1,000 | 1,000 | ||||||
| 2.566% notes due 2023 | 750 | 750 | ||||||
| 3.326% notes due 2025 | 750 | 750 | ||||||
| 2.498% notes due 2022 | 700 | 700 | ||||||
| 2.411% notes due 2022 | 700 | 700 | ||||||
| Floating rate notes due 2021 (2.599%)1 | 650 | 650 | ||||||
| Floating rate notes due 2022 (2.412%)1 | 650 | 650 | ||||||
| 1.991% notes due 2020 | 600 | 600 | ||||||
| Floating rate notes due 2020 (2.116%)2 | 400 | 400 | ||||||
| 3.400% loan3 | 218 | 218 | ||||||
| 8.625% debentures due 2032 | 147 | 147 | ||||||
| 8.625% debentures due 2031 | 108 | 108 | ||||||
| 8.000% debentures due 2032 | 75 | 75 | ||||||
| 9.750% debentures due 2020 | 54 | 54 | ||||||
| 8.875% debentures due 2021 | 40 | 40 | ||||||
| Medium-term notes, maturing from 2021 to 2038 (6.431%)1 | 38 | 38 | ||||||
| 4.950% notes due 2019 | — | 1,500 | ||||||
| 1.561% notes due 2019 | — | 1,350 | ||||||
| Floating rate notes due 2019 | — | 850 | ||||||
| 2.193% notes due 2019 | — | 750 | ||||||
| 1.686% notes due 2019 | — | 550 | ||||||
| Total including debt due within one year | 18,730 | 23,730 | ||||||
| Debt due within one year | (5,054 | ) | (5,000 | ) | ||||
| Reclassified from short-term debt | 9,750 | 9,900 | ||||||
| Unamortized discounts and debt issuance costs | (17 | ) | (24 | ) | ||||
| Finance lease liabilities4 | 282 | 127 | ||||||
| Total long-term debt | $ | 23,691 | $ | 28,733 |
| 1 | Weighted-average interest rate at December 31, 2019. |
| 2 | Interest rate at December 31, 2019. |
| 3 | Maturity date is conditional upon the occurrence of certain events. 2022 is the earliest period in which the loan may become payable. |
| 4 | For details on finance lease liabilities, see Note 5 beginning on page 62. |
Chevron has an automatic shelf registration statement that expires in May 2021. This registration statement is for an unspecified amount of nonconvertible debt securities issued or guaranteed by the company.
Long-term debt excluding finance lease liabilities with a principal balance of $18,730 matures as follows: 2020 – $5,054; 2021 – $2,054; 2022 – $4,268; 2023 – $3,003; 2024 – $1,000; and after 2024 – $3,351.
See Note 7, beginning on page 65, for information concerning the fair value of the company’s long-term debt.
Note 19
Accounting for Suspended Exploratory Wells
The company continues to capitalize exploratory well costs after the completion of drilling when the well has found a sufficient quantity of reserves to justify completion as a producing well, and the business unit is making sufficient progress assessing the reserves and the economic and operating viability of the project. If either condition is not met or if the company obtains information that raises substantial doubt about the economic or operational viability of the project, the exploratory well would be assumed to be impaired, and its costs, net of any salvage value, would be charged to expense.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
The following table indicates the changes to the company’s suspended exploratory well costs for the three years ended December 31, 2019:
| 2019 | 2018 | 2017 | |||||||
| Beginning balance at January 1 | $ | 3,563 | $ | 3,702 | $ | 3,540 | |||
| Additions to capitalized exploratory well costs pending the determination of proved reserves | 244 | 207 | 323 | ||||||
| Reclassifications to wells, facilities and equipment based on the determination of proved reserves | (500 | ) | (13 | ) | (113 | ) | |||
| Capitalized exploratory well costs charged to expense | (125 | ) | (333 | ) | (39 | ) | |||
| Other reductions* | (141 | ) | — | (9 | ) | ||||
| Ending balance at December 31 | $ | 3,041 | $ | 3,563 | $ | 3,702 |
- Represents property sales.
The following table provides an aging of capitalized well costs and the number of projects for which exploratory well costs have been capitalized for a period greater than one year since the completion of drilling.
| At December 31 | |||||||||
| 2019 | 2018 | 2017 | |||||||
| Exploratory well costs capitalized for a period of one year or less | $ | 214 | $ | 202 | $ | 307 | |||
| Exploratory well costs capitalized for a period greater than one year | 2,827 | 3,361 | 3,395 | ||||||
| Balance at December 31 | $ | 3,041 | $ | 3,563 | $ | 3,702 | |||
| Number of projects with exploratory well costs that have been capitalized for a period greater than one year* | 22 | 30 | 32 |
- Certain projects have multiple wells or fields or both.
Of the $2,827 of exploratory well costs capitalized for more than one year at December 31, 2019, $1,867 is related to 12 projects that had drilling activities underway or firmly planned for the near future. The $960 balance is related to 10 projects in areas requiring a major capital expenditure before production could begin and for which additional drilling efforts were not underway or firmly planned for the near future. Additional drilling was not deemed necessary because the presence of hydrocarbons had already been established, and other activities were in process to enable a future decision on project development.
The projects for the $960 referenced above had the following activities associated with assessing the reserves and the projects’ economic viability: (a) $256 (four projects) – undergoing front-end engineering and design with final investment decision expected within four years; (b) $704 (six projects) – development alternatives under review. While progress was being made on all 22 projects, the decision on the recognition of proved reserves under SEC rules in some cases may not occur for several years because of the complexity, scale and negotiations associated with the projects. More than half of these decisions are expected to occur in the next five years.
The $2,827 of suspended well costs capitalized for a period greater than one year as of December 31, 2019, represents 123 exploratory wells in 22 projects. The tables below contain the aging of these costs on a well and project basis:
| Aging based on drilling completion date of individual wells: | Amount | Number of wells | |||||
| 1998-2008 | $ | 244 | 27 | ||||
| 2009-2013 | 1,166 | 56 | |||||
| 2014-2018 | 1,417 | 40 | |||||
| Total | $ | 2,827 | 123 | ||||
| Aging based on drilling completion date of last suspended well in project: | Amount | Number of projects | |||||
| 2003-2011 | $ | 318 | 4 | ||||
| 2012-2015 | 1,653 | 11 | |||||
| 2016-2019 | 856 | 7 | |||||
| Total | $ | 2,827 | 22 |
Note 20
Stock Options and Other Share-Based Compensation
Compensation expense for stock options for 2019, 2018 and 2017 was $81 ($64 after tax), $105 ($83 after tax) and $137 ($89 after tax), respectively. In addition, compensation expense for stock appreciation rights, restricted stock, performance shares and restricted stock units was $313 ($266 after tax), $60 ($47 after tax) and $231 ($150 after tax) for 2019, 2018 and 2017, respectively. No significant stock-based compensation cost was capitalized at December 31, 2019, or December 31, 2018.
Cash received in payment for option exercises under all share-based payment arrangements for 2019, 2018 and 2017 was $1,090, $1,159 and $1,100, respectively. Actual tax benefits realized for the tax deductions from option exercises were $43, $43 and $48 for 2019, 2018 and 2017, respectively.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Cash paid to settle performance shares, restricted stock units and stock appreciation rights was $119, $157 and $187 for 2019, 2018 and 2017, respectively.
Awards under the Chevron Long-Term Incentive Plan (LTIP) may take the form of, but are not limited to, stock options, restricted stock, restricted stock units, stock appreciation rights, performance shares and nonstock grants. From April 2004 through May 2023, no more than 260 million shares may be issued under the LTIP. For awards issued on or after May 29, 2013, no more than 50 million of those shares may be in a form other than a stock option, stock appreciation right or award requiring full payment for shares by the award recipient. For the major types of awards issued before January 1, 2017, the contractual terms vary between three years for the performance shares and restricted stock units, and 10 years for the stock options and stock appreciation rights. For awards issued after January 1, 2017, contractual terms vary between three years for the performance shares and special restricted stock units, five years for standard restricted stock units and 10 years for the stock options and stock appreciation rights. Forfeitures for performance shares, restricted stock units, and stock appreciation rights are recognized as they occur. Forfeitures for stock options are estimated using historical forfeiture data dating back to 1990.
The fair market values of stock options and stock appreciation rights granted in 2019, 2018 and 2017 were measured on the date of grant using the Black-Scholes option-pricing model, with the following weighted-average assumptions:
| Year ended December 31 | |||||||||||||
| 2019 | 2018 | 2017 | |||||||||||
| Expected term in years1 | 6.6 | 6.5 | 6.3 | ||||||||||
| Volatility2 | 20.5 | % | 21.2 | % | 21.7 | % | |||||||
| Risk-free interest rate based on zero coupon U.S. treasury note | 2.6 | % | 2.6 | % | 2.2 | % | |||||||
| Dividend yield | 3.8 | % | 3.8 | % | 4.2 | % | |||||||
| Weighted-average fair value per option granted | $ | 15.82 | $ | 18.18 | $ | 15.31 |
1 Expected term is based on historical exercise and post-vesting cancellation data.
2 Volatility rate is based on historical stock prices over an appropriate period, generally equal to the expected term.
A summary of option activity during 2019 is presented below:
| Shares (Thousands) | Weighted-Average Exercise Price | Averaged Remaining Contractual Term (Years) | Aggregate Intrinsic Value | |||||||||
| Outstanding at January 1, 2019 | 94,724 | $ | 99.92 | |||||||||
| Granted | 5,771 | $ | 113.04 | |||||||||
| Exercised | (13,190 | ) | $ | 83.36 | ||||||||
| Forfeited | (664 | ) | $ | 111.57 | ||||||||
| Outstanding at December 31, 2019 | 86,641 | $ | 103.22 | 4.69 | $ | 1,518 | ||||||
| Exercisable at December 31, 2019 | 77,671 | $ | 101.63 | 4.25 | $ | 1,474 |
The total intrinsic value (i.e., the difference between the exercise price and the market price) of options exercised during 2019, 2018 and 2017 was $516, $506 and $407, respectively. During this period, the company continued its practice of issuing treasury shares upon exercise of these awards.
As of December 31, 2019, there was $55 of total unrecognized before-tax compensation cost related to nonvested share-based compensation arrangements granted under the plan. That cost is expected to be recognized over a weighted-average period of 1.8 years.
At January 1, 2019, the number of LTIP performance shares outstanding was equivalent to 3,669,730 shares. During 2019, 1,813,188 performance shares were granted, 684,620 shares vested with cash proceeds distributed to recipients and 411,514 shares were forfeited. At December 31, 2019, performance shares outstanding were 4,386,784. The fair value of the liability recorded for these instruments was $370, and was measured using the Monte Carlo simulation method.
At January 1, 2019, the number of restricted stock units outstanding was equivalent to 1,737,479 shares. During 2019, 1,054,556 restricted stock units were granted, 244,744 units vested with cash proceeds distributed to recipients and 120,332 units were forfeited. At December 31, 2019, restricted stock units outstanding were 2,426,959. The fair value of the liability recorded for the vested portion of these instruments was $192, valued at the stock price as of December 31, 2019. In addition, outstanding stock appreciation rights that were granted under LTIP totaled approximately 4.0 million equivalent shares as of December 31, 2019. The fair value of the liability recorded for the vested portion of these instruments was $82.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Note 21
Employee Benefit Plans
The company has defined benefit pension plans for many employees. The company typically prefunds defined benefit plans as required by local regulations or in certain situations where prefunding provides economic advantages. In the United States, all qualified plans are subject to the Employee Retirement Income Security Act (ERISA) minimum funding standard. The company does not typically fund U.S. nonqualified pension plans that are not subject to funding requirements under laws and regulations because contributions to these pension plans may be less economic and investment returns may be less attractive than the company’s other investment alternatives.
The company also sponsors other postretirement benefit (OPEB) plans that provide medical and dental benefits, as well as life insurance for some active and qualifying retired employees. The plans are unfunded, and the company and retirees share the costs. For the company’s main U.S. medical plan, the increase to the pre-Medicare company contribution for retiree medical coverage is limited to no more than 4 percent each year. Certain life insurance benefits are paid by the company.
The company recognizes the overfunded or underfunded status of each of its defined benefit pension and OPEB plans as an asset or liability on the Consolidated Balance Sheet.
The funded status of the company’s pension and OPEB plans for 2019 and 2018 follows:
| Pension Benefits | |||||||||||||||||||||||||
| 2019 | 2018 | Other Benefits | |||||||||||||||||||||||
| U.S. | Int’l. | U.S. | Int’l. | 2019 | 2018 | ||||||||||||||||||||
| Change in Benefit Obligation | |||||||||||||||||||||||||
| Benefit obligation at January 1 | $ | 11,726 | $ | 4,820 | $ | 13,580 | $ | 5,540 | $ | 2,430 | $ | 2,788 | |||||||||||||
| Service cost | 406 | 139 | 480 | 141 | 36 | 42 | |||||||||||||||||||
| Interest cost | 397 | 199 | 370 | 206 | 96 | 94 | |||||||||||||||||||
| Plan participants’ contributions | — | 4 | — | 4 | 72 | 71 | |||||||||||||||||||
| Plan amendments | — | 29 | — | 23 | — | 2 | |||||||||||||||||||
| Actuarial (gain) loss | 2,922 | 673 | (1,051 | ) | (239 | ) | 125 | (272 | ) | ||||||||||||||||
| Foreign currency exchange rate changes | — | 121 | — | (227 | ) | 2 | (9 | ) | |||||||||||||||||
| Benefits paid | (1,035 | ) | (302 | ) | (1,653 | ) | (432 | ) | (240 | ) | (237 | ) | |||||||||||||
| Divestitures/Acquisitions | 49 | — | — | (196 | ) | (1 | ) | (49 | ) | ||||||||||||||||
| Curtailment | — | (3 | ) | — | — | — | — | ||||||||||||||||||
| Benefit obligation at December 31 | 14,465 | 5,680 | 11,726 | 4,820 | 2,520 | 2,430 | |||||||||||||||||||
| Change in Plan Assets | |||||||||||||||||||||||||
| Fair value of plan assets at January 1 | 8,532 | 4,142 | 9,948 | 4,766 | — | — | |||||||||||||||||||
| Actual return on plan assets | 1,548 | 566 | (566 | ) | (9 | ) | — | — | |||||||||||||||||
| Foreign currency exchange rate changes | — | 115 | — | (221 | ) | — | — | ||||||||||||||||||
| Employer contributions | 1,096 | 266 | 803 | 232 | 168 | 166 | |||||||||||||||||||
| Plan participants’ contributions | — | 4 | — | 4 | 72 | 71 | |||||||||||||||||||
| Benefits paid | (1,035 | ) | (302 | ) | (1,653 | ) | (432 | ) | (240 | ) | (237 | ) | |||||||||||||
| Divestitures/Acquisitions | 36 | — | — | (198 | ) | — | — | ||||||||||||||||||
| Fair value of plan assets at December 31 | 10,177 | 4,791 | 8,532 | 4,142 | — | — | |||||||||||||||||||
| Funded status at December 31 | $ | (4,288 | ) | $ | (889 | ) | $ | (3,194 | ) | $ | (678 | ) | $ | (2,520 | ) | $ | (2,430 | ) |
Amounts recognized on the Consolidated Balance Sheet for the company’s pension and OPEB plans at December 31, 2019 and 2018, include:
| Pension Benefits | |||||||||||||||||||||||||
| 2019 | 2018 | Other Benefits | |||||||||||||||||||||||
| U.S. | Int’l. | U.S. | Int’l. | 2019 | 2018 | ||||||||||||||||||||
| Deferred charges and other assets | $ | 23 | $ | 413 | $ | 17 | $ | 412 | $ | — | $ | — | |||||||||||||
| Accrued liabilities | (239 | ) | (71 | ) | (180 | ) | (66 | ) | (174 | ) | (175 | ) | |||||||||||||
| Noncurrent employee benefit plans | (4,072 | ) | (1,231 | ) | (3,031 | ) | (1,024 | ) | (2,346 | ) | (2,255 | ) | |||||||||||||
| Net amount recognized at December 31 | $ | (4,288 | ) | $ | (889 | ) | $ | (3,194 | ) | $ | (678 | ) | $ | (2,520 | ) | $ | (2,430 | ) |
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Amounts recognized on a before-tax basis in “Accumulated other comprehensive loss” for the company’s pension and OPEB plans were $6,357 and $4,448 at the end of 2019 and 2018, respectively. These amounts consisted of:
| Pension Benefits | |||||||||||||||||||||||||
| 2019 | 2018 | Other Benefits | |||||||||||||||||||||||
| U.S. | Int’l. | U.S. | Int’l. | 2019 | 2018 | ||||||||||||||||||||
| Net actuarial loss | $ | 5,135 | $ | 1,269 | $ | 3,694 | $ | 955 | $ | 74 | $ | (56 | ) | ||||||||||||
| Prior service (credit) costs | 5 | 102 | 7 | 104 | (228 | ) | (256 | ) | |||||||||||||||||
| Total recognized at December 31 | $ | 5,140 | $ | 1,371 | $ | 3,701 | $ | 1,059 | $ | (154 | ) | $ | (312 | ) |
The accumulated benefit obligations for all U.S. and international pension plans were $12,781 and $5,203, respectively, at December 31, 2019, and $10,514 and $4,360, respectively, at December 31, 2018.
Information for U.S. and international pension plans with an accumulated benefit obligation in excess of plan assets at December 31, 2019 and 2018, was:
| Pension Benefits | ||||||||||||||||
| 2019 | 2018 | |||||||||||||||
| U.S. | Int’l. | U.S. | Int’l. | |||||||||||||
| Projected benefit obligations | $ | 14,401 | $ | 1,554 | $ | 11,667 | $ | 1,277 | ||||||||
| Accumulated benefit obligations | 12,718 | 1,268 | 10,456 | 1,062 | ||||||||||||
| Fair value of plan assets | 10,091 | 278 | 8,456 | 198 |
The components of net periodic benefit cost and amounts recognized in the Consolidated Statement of Comprehensive Income for 2019, 2018 and 2017 are shown in the table below:
| Pension Benefits | |||||||||||||||||||||||||||||||||
| 2019 | 2018 | 2017 | Other Benefits | ||||||||||||||||||||||||||||||
| U.S. | Int’l. | U.S. | Int’l. | U.S. | Int’l. | 2019 | 2018 | 2017 | |||||||||||||||||||||||||
| Net Periodic Benefit Cost | |||||||||||||||||||||||||||||||||
| Service cost | $ | 406 | $ | 139 | $ | 480 | $ | 141 | $ | 489 | $ | 151 | $ | 36 | $ | 42 | $ | 32 | |||||||||||||||
| Interest cost | 397 | 199 | 370 | 206 | 366 | 219 | 96 | 94 | 95 | ||||||||||||||||||||||||
| Expected return on plan assets | (565 | ) | (231 | ) | (636 | ) | (253 | ) | (597 | ) | (239 | ) | — | — | — | ||||||||||||||||||
| Amortization of prior service costs (credits) | 2 | 11 | 2 | 10 | (5 | ) | 13 | (28 | ) | (28 | ) | (28 | ) | ||||||||||||||||||||
| Recognized actuarial losses | 239 | 21 | 304 | 29 | 340 | 44 | (3 | ) | 15 | (5 | ) | ||||||||||||||||||||||
| Settlement losses | 259 | 3 | 411 | 33 | 436 | 2 | — | — | — | ||||||||||||||||||||||||
| Curtailment losses (gains) | — | 16 | — | 3 | — | — | — | — | — | ||||||||||||||||||||||||
| Total net periodic benefit cost | 738 | 158 | 931 | 169 | 1,029 | 190 | 101 | 123 | 94 | ||||||||||||||||||||||||
| Changes Recognized in Comprehensive Income | |||||||||||||||||||||||||||||||||
| Net actuarial (gain) loss during period | 1,939 | 338 | 151 | 12 | 381 | (94 | ) | 128 | (248 | ) | 284 | ||||||||||||||||||||||
| Amortization of actuarial loss | (498 | ) | (24 | ) | (715 | ) | (62 | ) | (776 | ) | (46 | ) | 3 | (15 | ) | 5 | |||||||||||||||||
| Prior service (credits) costs during period | — | 29 | — | 23 | — | 1 | (1 | ) | 3 | — | |||||||||||||||||||||||
| Amortization of prior service (costs) credits | (2 | ) | (30 | ) | (2 | ) | (13 | ) | 5 | (13 | ) | 28 | 28 | 28 | |||||||||||||||||||
| Total changes recognized in other comprehensive income | 1,439 | 313 | (566 | ) | (40 | ) | (390 | ) | (152 | ) | 158 | (232 | ) | 317 | |||||||||||||||||||
| Recognized in Net Periodic Benefit Cost and Other Comprehensive Income | $ | 2,177 | $ | 471 | $ | 365 | $ | 129 | $ | 639 | $ | 38 | $ | 259 | $ | (109 | ) | $ | 411 |
Net actuarial losses recorded in “Accumulated other comprehensive loss” at December 31, 2019, for the company’s U.S. pension, international pension and OPEB plans are being amortized on a straight-line basis over approximately 10, 12 and 14 years, respectively. These amortization periods represent the estimated average remaining service of employees expected to receive benefits under the plans. These losses are amortized to the extent they exceed 10 percent of the higher of the projected benefit obligation or market-related value of plan assets. The amount subject to amortization is determined on a plan-by-plan basis. During 2020, the company estimates actuarial losses of $385, $46 and $3 will be amortized from “Accumulated other comprehensive loss” for U.S. pension, international pension and OPEB plans, respectively. In addition, the company estimates an additional $320 will be recognized from “Accumulated other comprehensive loss” during 2020 related to lump-sum settlement costs from the main U.S. pension plans.
The weighted average amortization period for recognizing prior service costs (credits) recorded in “Accumulated other comprehensive loss” at December 31, 2019, was approximately 3 and 6 years for U.S. and international pension plans, respectively, and 8 years for OPEB plans. During 2020, the company estimates prior service (credits) costs of $2, $10 and
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
$(28) will be amortized from “Accumulated other comprehensive loss” for U.S. pension, international pension and OPEB plans, respectively.
Assumptions The following weighted-average assumptions were used to determine benefit obligations and net periodic benefit costs for years ended December 31:
| Pension Benefits | |||||||||||||||||||||||||
| 2019 | 2018 | 2017 | Other Benefits | ||||||||||||||||||||||
| U.S. | Int’l. | U.S. | Int’l. | U.S. | Int’l. | 2019 | 2018 | 2017 | |||||||||||||||||
| Assumptions used to determine benefit obligations: | |||||||||||||||||||||||||
| Discount rate | 3.1 | % | 3.2 | % | 4.2 | % | 4.4 | % | 3.5 | % | 3.9 | % | 3.2 | % | 4.4 | % | 3.8 | % | |||||||
| Rate of compensation increase | 4.5 | % | 4.0 | % | 4.5 | % | 4.0 | % | 4.5 | % | 4.0 | % | N/A | N/A | N/A | ||||||||||
| Assumptions used to determine net periodic benefit cost: | |||||||||||||||||||||||||
| Discount rate for service cost | 4.4 | % | 4.4 | % | 3.7 | % | 3.9 | % | 4.2 | % | 4.3 | % | 4.6 | % | 3.9 | % | 4.6 | % | |||||||
| Discount rate for interest cost | 3.7 | % | 4.4 | % | 3.0 | % | 3.9 | % | 3.0 | % | 4.3 | % | 4.2 | % | 3.5 | % | 3.8 | % | |||||||
| Expected return on plan assets | 6.8 | % | 5.6 | % | 6.8 | % | 5.5 | % | 6.8 | % | 5.5 | % | N/A | N/A | N/A | ||||||||||
| Rate of compensation increase | 4.5 | % | 4.0 | % | 4.5 | % | 4.0 | % | 4.5 | % | 4.5 | % | N/A | N/A | N/A |
Expected Return on Plan Assets The company’s estimated long-term rates of return on pension assets are driven primarily by actual historical asset-class returns, an assessment of expected future performance, advice from external actuarial firms and the incorporation of specific asset-class risk factors. Asset allocations are periodically updated using pension plan asset/liability studies, and the company’s estimated long-term rates of return are consistent with these studies.
For 2019, the company used an expected long-term rate of return of 6.75 percent for U.S. pension plan assets, which account for 68 percent of the company’s pension plan assets. In both 2018 and 2017, the company used a long-term rate of return of 6.75 percent for these plans.
The market-related value of assets of the main U.S. pension plan used in the determination of pension expense was based on the market values in the three months preceding the year-end measurement date. Management considers the three-month time period long enough to minimize the effects of distortions from day-to-day market volatility and still be contemporaneous to the end of the year. For other plans, market value of assets as of year-end is used in calculating the pension expense.
Discount Rate The discount rate assumptions used to determine the U.S. and international pension and OPEB plan obligations and expense reflect the rate at which benefits could be effectively settled, and are equal to the equivalent single rate resulting from yield curve analysis. This analysis considered the projected benefit payments specific to the company’s plans and the yields on high-quality bonds. The projected cash flows were discounted to the valuation date using the yield curve for the main U.S. pension and OPEB plans. The effective discount rates derived from this analysis at the end of 2019 were 3.1 percent for the main U.S. pension plan and 3.1 percent for the main U.S. OPEB plan. The discount rates for these plans at the end of 2018 were 4.2 and 4.3 percent, respectively, while in 2017 they were 3.5 and 3.6 percent for these plans, respectively.
Other Benefit Assumptions Assumed health care cost-trend rates can have a significant effect on the amounts reported for retiree health care costs. For the measurement of accumulated postretirement benefit obligation at December 31, 2019, for the main U.S. OPEB plan, the assumed health care cost-trend rates start with 6.8 percent in 2020 and gradually decline to 4.5 percent for 2025 and beyond. For this measurement at December 31, 2018, the assumed health care cost-trend rates started with 7.2 percent in 2019 and gradually declined to 4.5 percent for 2025 and beyond. A 1-percentage-point change in the assumed health care cost-trend rates would have the following effects on worldwide plans:
| 1 Percent Increase | 1 Percent Decrease | ||||||
| Effect on total service and interest cost components | $ | 20 | $ | (15 | ) | ||
| Effect on postretirement benefit obligation | $ | 224 | $ | (176 | ) |
Plan Assets and Investment Strategy
The fair value measurements of the company’s pension plans for 2019 and 2018 are on the following page:
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
| U.S. | Int’l. | |||||||||||||||||||||||||||||||||||||||
| Total | Level 1 | Level 2 | Level 3 | NAV | Total | Level 1 | Level 2 | Level 3 | NAV | |||||||||||||||||||||||||||||||
| At December 31, 2018 | ||||||||||||||||||||||||||||||||||||||||
| Equities | ||||||||||||||||||||||||||||||||||||||||
| U.S.1 | $ | 1,110 | $ | 1,110 | $ | — | $ | — | $ | — | $ | 520 | $ | 520 | $ | — | $ | — | $ | — | ||||||||||||||||||||
| International | 1,631 | 1,630 | 1 | — | — | 521 | 520 | — | 1 | — | ||||||||||||||||||||||||||||||
| Collective Trusts/Mutual Funds2 | 893 | 21 | — | — | 872 | 152 | 9 | — | — | 143 | ||||||||||||||||||||||||||||||
| Fixed Income | ||||||||||||||||||||||||||||||||||||||||
| Government | 225 | — | 225 | — | — | 254 | 97 | 157 | — | — | ||||||||||||||||||||||||||||||
| Corporate | 1,382 | — | 1,382 | — | — | 409 | — | 389 | 20 | — | ||||||||||||||||||||||||||||||
| Bank Loans | 119 | — | 114 | 5 | — | — | — | — | — | — | ||||||||||||||||||||||||||||||
| Mortgage/Asset Backed | 1 | — | 1 | — | — | 6 | — | 6 | — | — | ||||||||||||||||||||||||||||||
| Collective Trusts/Mutual Funds2 | 877 | — | — | — | 877 | 1,521 | 15 | — | — | 1,506 | ||||||||||||||||||||||||||||||
| Mixed Funds3 | — | — | — | — | — | 74 | 3 | 71 | — | — | ||||||||||||||||||||||||||||||
| Real Estate4 | 1,065 | — | — | — | 1,065 | 378 | — | — | 56 | 322 | ||||||||||||||||||||||||||||||
| Alternative Investments5 | 941 | — | — | — | 941 | — | — | — | — | — | ||||||||||||||||||||||||||||||
| Cash and Cash Equivalents | 212 | 208 | 4 | — | — | 287 | 277 | 2 | — | 8 | ||||||||||||||||||||||||||||||
| Other6 | 76 | (4 | ) | 31 | 44 | 5 | 20 | — | 17 | 3 | — | |||||||||||||||||||||||||||||
| Total at December 31, 2018 | $ | 8,532 | $ | 2,965 | $ | 1,758 | $ | 49 | $ | 3,760 | $ | 4,142 | $ | 1,441 | $ | 642 | $ | 80 | $ | 1,979 | ||||||||||||||||||||
| At December 31, 2019 | ||||||||||||||||||||||||||||||||||||||||
| Equities | ||||||||||||||||||||||||||||||||||||||||
| U.S.1 | $ | 1,769 | $ | 1,769 | $ | — | $ | — | $ | — | $ | 471 | $ | 471 | $ | — | $ | — | $ | — | ||||||||||||||||||||
| International | 1,958 | 1,958 | — | — | — | 422 | 421 | — | 1 | — | ||||||||||||||||||||||||||||||
| Collective Trusts/Mutual Funds2 | 1,079 | 52 | — | — | 1,027 | 184 | 6 | — | — | 178 | ||||||||||||||||||||||||||||||
| Fixed Income | ||||||||||||||||||||||||||||||||||||||||
| Government | 523 | — | 523 | — | — | 265 | 144 | 121 | — | — | ||||||||||||||||||||||||||||||
| Corporate | 1,444 | — | 1,444 | — | — | 493 | — | 490 | 3 | — | ||||||||||||||||||||||||||||||
| Bank Loans | 120 | — | 113 | 7 | — | — | — | — | — | — | ||||||||||||||||||||||||||||||
| Mortgage/Asset Backed | 1 | — | 1 | — | — | 4 | — | 4 | — | — | ||||||||||||||||||||||||||||||
| Collective Trusts/Mutual Funds2 | 963 | — | — | — | 963 | 2,230 | 5 | — | — | 2,225 | ||||||||||||||||||||||||||||||
| Mixed Funds3 | — | — | — | — | — | 84 | 7 | 77 | — | — | ||||||||||||||||||||||||||||||
| Real Estate4 | 1,089 | — | — | — | 1,089 | 277 | — | — | 55 | 222 | ||||||||||||||||||||||||||||||
| Alternative Investments5 | 924 | — | — | — | 924 | — | — | — | — | — | ||||||||||||||||||||||||||||||
| Cash and Cash Equivalents | 235 | 228 | 7 | — | — | 338 | 334 | 2 | — | 2 | ||||||||||||||||||||||||||||||
| Other6 | 72 | (5 | ) | 29 | 44 | 4 | 23 | — | 21 | 2 | — | |||||||||||||||||||||||||||||
| Total at December 31, 2019 | $ | 10,177 | $ | 4,002 | $ | 2,117 | $ | 51 | $ | 4,007 | $ | 4,791 | $ | 1,388 | $ | 715 | $ | 61 | $ | 2,627 |
| 1 | U.S. equities include investments in the company’s common stock in the amount of $6 at December 31, 2019, and $9 at December 31, 2018. |
| 2 | Collective Trusts/Mutual Funds for U.S. plans are entirely index funds; for International plans, they are mostly unit trust and index funds. |
| 3 | Mixed funds are composed of funds that invest in both equity and fixed-income instruments in order to diversify and lower risk. |
| 4 | The year-end valuations of the U.S. real estate assets are based on third-party appraisals that occur at least once a year for each property in the portfolio. |
| 5 | Alternative investments focus on market-neutral strategies that have a low expected correlation to traditional asset classes. |
| 6 | The “Other” asset class includes net payables for securities purchased but not yet settled (Level 1); dividends and interest- and tax-related receivables (Level 2); insurance contracts (Level 3); and investments in private-equity limited partnerships (NAV). |
The effects of fair value measurements using significant unobservable inputs on changes in Level 3 plan assets are outlined below:
| Equity | Fixed Income | |||||||||||||||||||||||||
| International | Corporate | Bank Loans | Real Estate | Other | Total | |||||||||||||||||||||
| Total at December 31, 2017 | $ | — | $ | 30 | $ | 11 | $ | 56 | $ | 46 | $ | 143 | ||||||||||||||
| Actual Return on Plan Assets: | ||||||||||||||||||||||||||
| Assets held at the reporting date | 4 | (2 | ) | — | 13 | — | 15 | |||||||||||||||||||
| Assets sold during the period | (4 | ) | — | — | — | — | (4 | ) | ||||||||||||||||||
| Purchases, Sales and Settlements | — | (7 | ) | (4 | ) | (13 | ) | — | (24 | ) | ||||||||||||||||
| Transfers in and/or out of Level 3 | 1 | — | (2 | ) | — | — | (1 | ) | ||||||||||||||||||
| Total at December 31, 2018 | $ | 1 | $ | 21 | $ | 5 | $ | 56 | $ | 46 | $ | 129 | ||||||||||||||
| Actual Return on Plan Assets: | ||||||||||||||||||||||||||
| Assets held at the reporting date | (1 | ) | 1 | — | — | (1 | ) | (1 | ) | |||||||||||||||||
| Assets sold during the period | — | — | — | — | — | — | ||||||||||||||||||||
| Purchases, Sales and Settlements | — | (19 | ) | — | (1 | ) | 1 | (19 | ) | |||||||||||||||||
| Transfers in and/or out of Level 3 | 1 | — | 2 | — | — | 3 | ||||||||||||||||||||
| Total at December 31, 2019 | $ | 1 | $ | 3 | $ | 7 | $ | 55 | $ | 46 | $ | 112 |
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
The primary investment objectives of the pension plans are to achieve the highest rate of total return within prudent levels of risk and liquidity, to diversify and mitigate potential downside risk associated with the investments, and to provide adequate liquidity for benefit payments and portfolio management.
The company’s U.S. and U.K. pension plans comprise 92 percent of the total pension assets. Both the U.S. and U.K. plans have an Investment Committee that regularly meets during the year to review the asset holdings and their returns. To assess the plans’ investment performance, long-term asset allocation policy benchmarks have been established.
For the primary U.S. pension plan, the company’s Investment Committee has established the following approved asset allocation ranges: Equities 30–60 percent, Fixed Income 20–40 percent, Real Estate 0–15 percent, Alternative Investments 0–15 percent and Cash 0–25 percent. For the U.K. pension plan, the U.K. Board of Trustees has established the following asset allocation guidelines: Equities 10–30 percent, Fixed Income 55–85 percent, Real Estate 5–15 percent, and Cash 0–5 percent. The other significant international pension plans also have established maximum and minimum asset allocation ranges that vary by plan. Actual asset allocation within approved ranges is based on a variety of factors, including market conditions and illiquidity constraints. To mitigate concentration and other risks, assets are invested across multiple asset classes with active investment managers and passive index funds.
The company does not prefund its OPEB obligations.
Cash Contributions and Benefit Payments In 2019, the company contributed $1,096 and $266 to its U.S. and international pension plans, respectively. In 2020, the company expects contributions to be approximately $1,250 to its U.S. plans and $250 to its international pension plans. Actual contribution amounts are dependent upon investment returns, changes in pension obligations, regulatory environments, tax law changes and other economic factors. Additional funding may ultimately be required if investment returns are insufficient to offset increases in plan obligations.
The company anticipates paying OPEB benefits of approximately $174 in 2020; $168 was paid in 2019.
The following benefit payments, which include estimated future service, are expected to be paid by the company in the next 10 years:
| Pension Benefits | Other | ||||||||||
| U.S. | Int’l. | Benefits | |||||||||
| 2020 | $ | 1,262 | $ | 280 | $ | 174 | |||||
| 2021 | $ | 1,176 | $ | 602 | $ | 170 | |||||
| 2022 | $ | 1,160 | $ | 224 | $ | 165 | |||||
| 2023 | $ | 1,150 | $ | 234 | $ | 161 | |||||
| 2024 | $ | 1,134 | $ | 255 | $ | 156 | |||||
| 2024-2028 | $ | 5,232 | $ | 1,434 | $ | 725 |
Employee Savings Investment Plan Eligible employees of Chevron and certain of its subsidiaries participate in the Chevron Employee Savings Investment Plan (ESIP). Compensation expense for the ESIP totaled $284, $270 and $316 in 2019, 2018 and 2017, respectively.
Benefit Plan Trusts Prior to its acquisition by Chevron, Texaco established a benefit plan trust for funding obligations under some of its benefit plans. At year-end 2019, the trust contained 14.2 million shares of Chevron treasury stock. The trust will sell the shares or use the dividends from the shares to pay benefits only to the extent that the company does not pay such benefits. The company intends to continue to pay its obligations under the benefit plans. The trustee will vote the shares held in the trust as instructed by the trust’s beneficiaries. The shares held in the trust are not considered outstanding for earnings-per-share purposes until distributed or sold by the trust in payment of benefit obligations.
Prior to its acquisition by Chevron, Unocal established various grantor trusts to fund obligations under some of its benefit plans, including the deferred compensation and supplemental retirement plans. At December 31, 2019 and 2018, trust assets of $35 and $34, respectively, were invested primarily in interest-earning accounts.
Employee Incentive Plans The Chevron Incentive Plan is an annual cash bonus plan for eligible employees that links awards to corporate, business unit and individual performance in the prior year. Charges to expense for cash bonuses were $826, $1,048 and $936 in 2019, 2018 and 2017, respectively. Chevron also has the LTIP for officers and other regular salaried employees of the company and its subsidiaries who hold positions of significant responsibility. Awards under the LTIP consist of stock options and other share-based compensation that are described in Note 20, beginning on page 80.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Note 22
Other Contingencies and Commitments
Income Taxes The company calculates its income tax expense and liabilities quarterly. These liabilities generally are subject to audit and are not finalized with the individual taxing authorities until several years after the end of the annual period for which income taxes have been calculated. Refer to Note 15, beginning on page 74, for a discussion of the periods for which tax returns have been audited for the company’s major tax jurisdictions and a discussion for all tax jurisdictions of the differences between the amount of tax benefits recognized in the financial statements and the amount taken or expected to be taken in a tax return.
Settlement of open tax years, as well as other tax issues in countries where the company conducts its businesses, are not expected to have a material effect on the consolidated financial position or liquidity of the company and, in the opinion of management, adequate provisions have been made for all years under examination or subject to future examination.
Guarantees The company has two guarantees to equity affiliates totaling $704. Of this amount, $412 is associated with a financing arrangement with an equity affiliate. Over the approximate 2-year remaining term of this guarantee, the maximum amount will be reduced as payments are made by the affiliate. The remaining amount of $292 is associated with certain payments under a terminal use agreement entered into by an equity affiliate. Over the approximate 8-year remaining term of this guarantee, the maximum guarantee amount will be reduced as certain fees are paid by the affiliate. There are numerous cross-indemnity agreements with the affiliate and the other partners to permit recovery of amounts paid under the guarantee. Chevron has recorded no liability for either guarantee.
Indemnifications In the acquisition of Unocal, the company assumed certain indemnities relating to contingent environmental liabilities associated with assets that were sold in 1997. The acquirer of those assets shared in certain environmental remediation costs up to a maximum obligation of $200, which had been reached at December 31, 2009. Under the indemnification agreement, after reaching the $200 obligation, Chevron is solely responsible until April 2022, when the indemnification expires. The environmental conditions or events that are subject to these indemnities must have arisen prior to the sale of the assets in 1997.
Although the company has provided for known obligations under this indemnity that are probable and reasonably estimable, the amount of additional future costs may be material to results of operations in the period in which they are recognized. The company does not expect these costs will have a material effect on its consolidated financial position or liquidity.
Long-Term Unconditional Purchase Obligations and Commitments, Including Throughput and Take-or-Pay Agreements The company and its subsidiaries have certain contingent liabilities with respect to long-term unconditional purchase obligations and commitments, including throughput and take-or-pay agreements, some of which may relate to suppliers’ financing arrangements. The agreements typically provide goods and services, such as pipeline and storage capacity, utilities, and petroleum products, to be used or sold in the ordinary course of the company’s business. The aggregate approximate amounts of required payments under these various commitments are: 2020 – $900; 2021 – $1,100; 2022 – $1,100; 2023 – $1,200; 2024 – $1,200; 2025 and after – $7,200. A portion of these commitments may ultimately be shared with project partners. Total payments under the agreements were approximately $800 in 2019, $1,400 in 2018 and $1,300 in 2017.
As part of the implementation of ASU 2016-02, the company assessed some contracts, previously incorporated into the unconditional purchase obligations disclosure, as operating leases in 2019.
Environmental The company is subject to loss contingencies pursuant to laws, regulations, private claims and legal proceedings related to environmental matters that are subject to legal settlements or that in the future may require the company to take action to correct or ameliorate the effects on the environment of prior release of chemicals or petroleum substances, including MTBE, by the company or other parties. Such contingencies may exist for various operating, closed and divested sites, including, but not limited to, federal Superfund sites and analogous sites under state laws, refineries, chemical plants, marketing facilities, crude oil fields, and mining sites.
Although the company has provided for known environmental obligations that are probable and reasonably estimable, it is likely that the company will continue to incur additional liabilities. The amount of additional future costs are not fully determinable due to such factors as the unknown magnitude of possible contamination, the unknown timing and extent of the corrective actions that may be required, the determination of the company’s liability in proportion to other responsible parties, and the extent to which such costs are recoverable from third parties. These future costs may be material to results of operations in the period in which they are recognized, but the company does not expect these costs will have a material effect on its consolidated financial position or liquidity.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Chevron’s environmental reserve as of December 31, 2019, was $1,234. Included in this balance was $266 related to remediation activities at approximately 145 sites for which the company had been identified as a potentially responsible party under the provisions of the federal Superfund law or analogous state laws which provide for joint and several liability for all responsible parties. Any future actions by regulatory agencies to require Chevron to assume other potentially responsible parties’ costs at designated hazardous waste sites are not expected to have a material effect on the company’s results of operations, consolidated financial position or liquidity.
Of the remaining year-end 2019 environmental reserves balance of $968, $667 is related to the company’s U.S. downstream operations, $28 to its international downstream operations, $272 to upstream operations and $1 to other businesses. Liabilities at all sites were primarily associated with the company’s plans and activities to remediate soil or groundwater contamination or both.
The company manages environmental liabilities under specific sets of regulatory requirements, which in the United States include the Resource Conservation and Recovery Act and various state and local regulations. No single remediation site at year-end 2019 had a recorded liability that was material to the company’s results of operations, consolidated financial position or liquidity.
Refer to Note 23 on page 89 for a discussion of the company’s asset retirement obligations.
Other Contingencies Governmental and other entities in California and other jurisdictions have filed legal proceedings against fossil fuel producing companies, including Chevron, purporting to seek legal and equitable relief to address alleged impacts of climate change. Further such proceedings are likely to be filed by other parties. The unprecedented legal theories set forth in these proceedings entail the possibility of damages liability and injunctions against the production of all fossil fuels that, while we believe remote, could have a material adverse effect on the company’s results of operations and financial condition. Management believes that these proceedings are legally and factually meritless and detract from constructive efforts to address the important policy issues presented by climate change, and will vigorously defend against such proceedings.
Chevron has interests in Venezuelan crude oil production assets operated by independent equity affiliates. During 2019, net oil equivalent production in Venezuela averaged 35,000 barrels per day, 3,000 barrels per day of which was upgraded to synthetic crude. Synthetic crude production in 2019 was impacted by operating conditions, including a shutdown of the Petropiar heavy oil upgrader for part of the year. The operating environment in Venezuela has been deteriorating for some time. In January 2019, the United States government issued sanctions against the Venezuelan national oil company, Petroleos de Venezuela, S.A. (PdVSA), which is the company’s partner in the equity affiliates. The company is conducting its business pursuant to general licenses and guidance issued coincident with the sanctions. In late July 2019, the United States government renewed General License 8A with the issuance of General License 8B, subsequently superseded by General License 8C issued on August 5, 2019. The authorization provided to Chevron under General License 8C was extended by General License 8D on October 21, 2019 and General License 8E issued by the United States government on January 17, 2020. General License 8E enables the company to continue to meet its contractual obligations in Venezuela with PdVSA and is effective until April 22, 2020.
At December 31, 2019, the carrying value of the company’s investments was approximately $2,650 and for the year ended December 31, 2019, the company recognized losses of $54 for its share of net income from the equity affiliates, and for demurrage, foreign exchange losses and other costs incurred in support of the company’s operations in Venezuela. Future events could result in the environment in Venezuela becoming more challenged, which could lead to increased business disruption and volatility in the associated financial results. The company continues to evaluate the carrying value of its Venezuelan investments in line with its accounting policies. Future events related to the company’s activities in Venezuela may result in significant impacts on the company’s results of operation in subsequent periods. Please see Note 13, “Investments and Advances”, on page 71 for further information on the company’s investments in equity affiliates in Venezuela.
Chevron receives claims from and submits claims to customers; trading partners; joint venture partners; U.S. federal, state and local regulatory bodies; governments; contractors; insurers; suppliers; and individuals. The amounts of these claims, individually and in the aggregate, may be significant and take lengthy periods to resolve, and may result in gains or losses in future periods.
The company and its affiliates also continue to review and analyze their operations and may close, retire, sell, exchange, acquire or restructure assets to achieve operational or strategic benefits and to improve competitiveness and profitability. These activities, individually or together, may result in significant gains or losses in future periods.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
Note 23
Asset Retirement Obligations
The company records the fair value of a liability for an asset retirement obligation (ARO) both as an asset and a liability when there is a legal obligation associated with the retirement of a tangible long-lived asset and the liability can be reasonably estimated. The legal obligation to perform the asset retirement activity is unconditional, even though uncertainty may exist about the timing and/or method of settlement that may be beyond the company’s control. This uncertainty about the timing and/or method of settlement is factored into the measurement of the liability when sufficient information exists to reasonably estimate fair value. Recognition of the ARO includes: (1) the present value of a liability and offsetting asset, (2) the subsequent accretion of that liability and depreciation of the asset, and (3) the periodic review of the ARO liability estimates and discount rates.
AROs are primarily recorded for the company’s crude oil and natural gas producing assets. No significant AROs associated with any legal obligations to retire downstream long-lived assets have been recognized, as indeterminate settlement dates for the asset retirements prevent estimation of the fair value of the associated ARO. The company performs periodic reviews of its downstream long-lived assets for any changes in facts and circumstances that might require recognition of a retirement obligation.
The following table indicates the changes to the company’s before-tax asset retirement obligations in 2019, 2018 and 2017:
| 2019 | 2018 | 2017 | ||||||||||
| Balance at January 1 | $ | 14,050 | $ | 14,214 | $ | 14,243 | ||||||
| Liabilities incurred | 32 | 96 | 684 | |||||||||
| Liabilities settled | (1,694 | ) | (830 | ) | (1,721 | ) | ||||||
| Accretion expense | 628 | 654 | 668 | |||||||||
| Revisions in estimated cash flows | (184 | ) | (84 | ) | 340 | |||||||
| Balance at December 31 | $ | 12,832 | $ | 14,050 | $ | 14,214 |
In the table above, the amount associated with “Revisions in estimated cash flows” in 2019 reflects decreased cost estimates to decommission wells, equipment and facilities. The long-term portion of the $12,832 balance at the end of 2019 was $11,592.
Note 24
Revenue
Revenue from contracts with customers is presented in “Sales and other operating revenue” along with some activity that is accounted for outside the scope of Accounting Standard Codification (ASC) 606, which is not material to this line, on the Consolidated Statement of Income. Purchases and sales of inventory with the same counterparty that are entered into in contemplation of one another (including buy/sell arrangements) are combined and recorded on a net basis and reported in “purchased crude oil and products” on the Consolidated Statement of Income. Refer to Note 12 beginning on page 68 for additional information on the company’s segmentation of revenue.
Receivables related to revenue from contracts with customers are included in “Accounts and notes receivable, net” on the Consolidated Balance Sheet, net of the allowance for doubtful accounts. The net balance of these receivables was $9,247 and $10,046 at December 31, 2019 and December 31, 2018, respectively. Other items included in “Accounts and notes receivable, net” represent amounts due from partners for their share of joint venture operating and project costs and amounts due from others, primarily related to derivatives, leases, buy/sell arrangements and product exchanges, which are accounted for outside the scope of ASC 606*.*
Contract assets and related costs are reflected in “Prepaid expenses and other current assets” and contract liabilities are reflected in “Accrued liabilities” and “Deferred credits and other noncurrent obligations” on the Consolidated Balance Sheet. Amounts for these items are not material to the company’s financial position.
Note 25
Other Financial Information
Earnings in 2019 included after-tax gains of approximately $1,500 relating to the sale of certain properties. Of this amount, approximately $50 and $1,450 related to downstream and upstream, respectively. Earnings in 2018 included after-tax gains of approximately $630 relating to the sale of certain properties, of which approximately $365 and $265 related to downstream and upstream assets, respectively. Earnings in 2019 included after-tax charges of approximately $10,400 for impairments and other asset write-offs related to upstream. Earnings in 2018 included after-tax charges of approximately $2,000 for impairments and other asset write-offs related to upstream.
Notes to the Consolidated Financial Statements
Millions of dollars, except per-share amounts
| Other financial information is as follows: | ||||||||||||
| Year ended December 31 | ||||||||||||
| 2019 | 2018 | 2017 | ||||||||||
| Total financing interest and debt costs | $ | 817 | $ | 921 | $ | 902 | ||||||
| Less: Capitalized interest | 19 | 173 | 595 | |||||||||
| Interest and debt expense | $ | 798 | $ | 748 | $ | 307 | ||||||
| Research and development expenses | $ | 500 | $ | 453 | $ | 433 | ||||||
| Excess of replacement cost over the carrying value of inventories (LIFO method) | $ | 4,513 | $ | 5,134 | $ | 3,937 | ||||||
| LIFO profits (losses) on inventory drawdowns included in earnings | $ | (9 | ) | $ | 26 | $ | (5 | ) | ||||
| Foreign currency effects* | $ | (304 | ) | $ | 611 | $ | (446 | ) |
- Includes $(28), $416 and $(45) in 2019, 2018 and 2017, respectively, for the company’s share of equity affiliates’ foreign currency effects.
The company has $4,463 in goodwill on the Consolidated Balance Sheet, all of which is in the upstream segment and primarily related to the 2005 acquisition of Unocal. The company tested this goodwill for impairment during 2019, and no impairment was required.
Note 26
Summarized Financial Data – Chevron Phillips Chemical Company LLC
Chevron has a 50 percent equity ownership interest in Chevron Phillips Chemical Company LLC (CPChem). Refer to Note 13, on page 72, for a discussion of CPChem operations. Summarized financial information for 100 percent of CPChem is presented in the table below:
| Year ended December 31 | |||||||||||
| 2019 | 2018 | 2017 | |||||||||
| Sales and other operating revenues | $ | 9,333 | $ | 11,310 | $ | 9,063 | |||||
| Costs and other deductions | 7,863 | 9,812 | 8,126 | ||||||||
| Net income attributable to CPChem | 1,760 | 2,069 | 1,446 |
| At December 31 | |||||||
| 2019 | 2018 | ||||||
| Current assets | $ | 2,554 | $ | 2,820 | |||
| Other assets | 14,314 | 13,790 | |||||
| Current liabilities | 1,247 | 1,281 | |||||
| Other liabilities | 3,174 | 2,892 | |||||
| Total CPChem net equity | $ | 12,447 | $ | 12,437 |
Five-Year Financial Summary
Unaudited
| Millions of dollars, except per-share amounts | 2019 | 2018 | 2017 | 2016 | 2015 | |||||||||||||||||
| Statement of Income Data | ||||||||||||||||||||||
| Revenues and Other Income | ||||||||||||||||||||||
| Total sales and other operating revenues* | $ | 139,865 | $ | 158,902 | $ | 134,674 | $ | 110,215 | $ | 129,925 | ||||||||||||
| Income from equity affiliates and other income | 6,651 | 7,437 | 7,048 | 4,257 | 8,552 | |||||||||||||||||
| Total Revenues and Other Income | 146,516 | 166,339 | 141,722 | 114,472 | 138,477 | |||||||||||||||||
| Total Costs and Other Deductions | 140,980 | 145,764 | 132,501 | 116,632 | 133,635 | |||||||||||||||||
| Income Before Income Tax Expense (Benefit) | 5,536 | 20,575 | 9,221 | (2,160 | ) | 4,842 | ||||||||||||||||
| Income Tax Expense (Benefit) | 2,691 | 5,715 | (48 | ) | (1,729 | ) | 132 | |||||||||||||||
| Net Income | 2,845 | 14,860 | 9,269 | (431 | ) | 4,710 | ||||||||||||||||
| Less: Net income attributable to noncontrolling interests | (79 | ) | 36 | 74 | 66 | 123 | ||||||||||||||||
| Net Income (Loss) Attributable to Chevron Corporation | $ | 2,924 | $ | 14,824 | $ | 9,195 | $ | (497 | ) | $ | 4,587 | |||||||||||
| Per Share of Common Stock | ||||||||||||||||||||||
| Net Income (Loss) Attributable to Chevron | ||||||||||||||||||||||
| – Basic | $ | 1.55 | $ | 7.81 | $ | 4.88 | $ | (0.27 | ) | $ | 2.46 | |||||||||||
| – Diluted | $ | 1.54 | $ | 7.74 | $ | 4.85 | $ | (0.27 | ) | $ | 2.45 | |||||||||||
| Cash Dividends Per Share | $ | 4.76 | $ | 4.48 | $ | 4.32 | $ | 4.29 | $ | 4.28 | ||||||||||||
| Balance Sheet Data (at December 31) | ||||||||||||||||||||||
| Current assets | $ | 28,329 | $ | 34,021 | $ | 28,560 | $ | 29,619 | $ | 34,430 | ||||||||||||
| Noncurrent assets | 209,099 | 219,842 | 225,246 | 230,459 | 230,110 | |||||||||||||||||
| Total Assets | 237,428 | 253,863 | 253,806 | 260,078 | 264,540 | |||||||||||||||||
| Short-term debt | 3,282 | 5,726 | 5,192 | 10,840 | 4,927 | |||||||||||||||||
| Other current liabilities | 23,248 | 21,445 | 22,545 | 20,945 | 20,540 | |||||||||||||||||
| Long-term debt | 23,691 | 28,733 | 33,571 | 35,286 | 33,622 | |||||||||||||||||
| Other noncurrent liabilities | 41,999 | 42,317 | 43,179 | 46,285 | 51,565 | |||||||||||||||||
| Total Liabilities | 92,220 | 98,221 | 104,487 | 113,356 | 110,654 | |||||||||||||||||
| Total Chevron Corporation Stockholders’ Equity | $ | 144,213 | $ | 154,554 | $ | 148,124 | $ | 145,556 | $ | 152,716 | ||||||||||||
| Noncontrolling interests | 995 | 1,088 | 1,195 | 1,166 | 1,170 | |||||||||||||||||
| Total Equity | $ | 145,208 | $ | 155,642 | $ | 149,319 | $ | 146,722 | $ | 153,886 | ||||||||||||
| * Includes excise, value-added and similar taxes: | $ | — | $ | — | $ | 7,189 | $ | 6,905 | $ | 7,359 | ||||||||||||
Supplemental Information on Oil and Gas Producing Activities - Unaudited
In accordance with FASB and SEC disclosure requirements for oil and gas producing activities, this section provides supplemental information on oil and gas exploration and producing activities of the company in seven separate tables. Tables I through IV provide historical cost information pertaining to costs incurred in exploration, property acquisitions and development; capitalized costs; and results of operations. Tables V through VII present information on the company’s estimated net proved reserve quantities, standardized measure of estimated discounted future net cash flows related to proved reserves,
Table I - Costs Incurred in Exploration, Property Acquisitions and Development****1
| Consolidated Companies | Affiliated Companies | |||||||||||||||||||||||||||
| Other | Australia/ | |||||||||||||||||||||||||||
| Millions of dollars | U.S. | Americas | Africa | Asia | Oceania | Europe | Total | TCO4 | Other | |||||||||||||||||||
| Year Ended December 31, 2019 | ||||||||||||||||||||||||||||
| Exploration | ||||||||||||||||||||||||||||
| Wells | $ | 571 | $ | 44 | $ | 9 | $ | 2 | $ | 4 | $ | 4 | $ | 634 | $ | — | $ | — | ||||||||||
| Geological and geophysical | 82 | 118 | 21 | 5 | 11 | 1 | 238 | — | — | |||||||||||||||||||
| Other | 140 | 52 | 35 | 29 | 44 | 6 | 306 | — | 8 | |||||||||||||||||||
| Total exploration | 793 | 214 | 65 | 36 | 59 | 11 | 1,178 | — | 8 | |||||||||||||||||||
| Property acquisitions2 | ||||||||||||||||||||||||||||
| Proved | 81 | 34 | — | 93 | — | — | 208 | — | — | |||||||||||||||||||
| Unproved | 68 | 150 | — | 17 | 1 | — | 236 | — | — | |||||||||||||||||||
| Total property acquisitions | 149 | 184 | — | 110 | 1 | — | 444 | — | — | |||||||||||||||||||
| Development3 | 7,072 | 1,216 | 279 | 1,020 | 518 | 199 | 10,304 | 5,112 | 158 | |||||||||||||||||||
| Total Costs Incurred****5 | $ | 8,014 | $ | 1,614 | $ | 344 | $ | 1,166 | $ | 578 | $ | 210 | $ | 11,926 | $ | 5,112 | $ | 166 | ||||||||||
| Year Ended December 31, 2018 | ||||||||||||||||||||||||||||
| Exploration | ||||||||||||||||||||||||||||
| Wells | $ | 508 | $ | 74 | $ | 25 | $ | 55 | $ | — | $ | 14 | $ | 676 | $ | — | $ | — | ||||||||||
| Geological and geophysical | 84 | 41 | 4 | 5 | 7 | 1 | 142 | — | — | |||||||||||||||||||
| Other | 190 | 46 | 35 | 33 | 49 | 23 | 376 | — | — | |||||||||||||||||||
| Total exploration | 782 | 161 | 64 | 93 | 56 | 38 | 1,194 | — | — | |||||||||||||||||||
| Property acquisitions2 | ||||||||||||||||||||||||||||
| Proved | 160 | — | 7 | 117 | — | — | 284 | — | — | |||||||||||||||||||
| Unproved | 52 | 494 | 2 | 27 | — | — | 575 | — | — | |||||||||||||||||||
| Total property acquisitions | 212 | 494 | 9 | 144 | — | — | 859 | — | — | |||||||||||||||||||
| Development3 | 6,245 | 856 | 711 | 1,095 | 845 | 278 | 10,030 | 4,963 | 200 | |||||||||||||||||||
| Total Costs Incurred****5 | $ | 7,239 | $ | 1,511 | $ | 784 | $ | 1,332 | $ | 901 | $ | 316 | $ | 12,083 | $ | 4,963 | $ | 200 | ||||||||||
| Year Ended December 31, 2017 | ||||||||||||||||||||||||||||
| Exploration | ||||||||||||||||||||||||||||
| Wells | $ | 479 | $ | 3 | $ | 1 | $ | 36 | $ | — | $ | 15 | $ | 534 | $ | — | $ | — | ||||||||||
| Geological and geophysical | 93 | 46 | 4 | 3 | 33 | 5 | 184 | — | — | |||||||||||||||||||
| Other | 157 | 32 | 52 | 60 | 46 | 128 | 475 | — | — | |||||||||||||||||||
| Total exploration | 729 | 81 | 57 | 99 | 79 | 148 | 1,193 | — | — | |||||||||||||||||||
| Property acquisitions2 | ||||||||||||||||||||||||||||
| Proved | 64 | — | — | 93 | — | — | 157 | — | — | |||||||||||||||||||
| Unproved | 77 | — | 40 | 18 | 1 | — | 136 | — | — | |||||||||||||||||||
| Total property acquisitions | 141 | — | 40 | 111 | 1 | — | 293 | — | — | |||||||||||||||||||
| Development3 | 4,346 | 944 | 1,136 | 1,324 | 2,580 | 121 | 10,451 | 3,683 | 147 | |||||||||||||||||||
| Total Costs Incurred****5 | $ | 5,216 | $ | 1,025 | $ | 1,233 | $ | 1,534 | $ | 2,660 | $ | 269 | $ | 11,937 | $ | 3,683 | $ | 147 |
| 1 | Includes costs incurred whether capitalized or expensed. Excludes general support equipment expenditures. Includes capitalized amounts related to asset retirement obligations. See Note 23, “Asset Retirement Obligations,” on page 89. | ||||||||||||
| 2 | Does not include properties acquired in nonmonetary transactions. | ||||||||||||
| 3 | Includes $246, $114 and $84 of costs incurred on major capital projects prior to assignment of proved reserves for consolidated companies in 2019, 2018, and 2017, respectively. | ||||||||||||
| 4 | 2017 and 2018 conformed to 2019 presentation | ||||||||||||
| 5 | Reconciliation of consolidated and affiliated companies total cost incurred to Upstream capital and exploratory (C&E) expenditures - $ billions: | ||||||||||||
| 2019 | 2018 | 2017 | |||||||||||
| Total cost incurred | $ | 17.2 | $ | 17.2 | $ | 15.7 | |||||||
| Non-oil and gas activities | 0.3 | 0.6 | 1.3 | (Primarily; LNG and transportation activities.) | |||||||||
| ARO reduction/(build) | 0.3 | (0.1 | ) | (0.6 | ) | ||||||||
| Upstream C&E | $ | 17.8 | $ | 17.7 | $ | 16.4 | Reference page 39 Upstream total |
Supplemental Information on Oil and Gas Producing Activities - Unaudited
and changes in estimated discounted future net cash flows. The amounts for consolidated companies are organized by geographic areas including the United States, Other Americas, Africa, Asia, Australia/Oceania and Europe. Amounts for affiliated companies include Chevron’s equity interests in Tengizchevroil (TCO) in the Republic of Kazakhstan and in other affiliates, principally in Venezuela and Angola. Refer to Note 13, beginning on page 71, for a discussion of the company’s major equity affiliates.
| Table II - Capitalized Costs Related to Oil and Gas Producing Activities | ||||||||||||||||||||||||||||
| Consolidated Companies | Affiliated Companies | |||||||||||||||||||||||||||
| Other | Australia/ | |||||||||||||||||||||||||||
| Millions of dollars | U.S. | Americas | Africa | Asia | Oceania | Europe | Total | TCO* | Other | |||||||||||||||||||
| At December 31, 2019 | ||||||||||||||||||||||||||||
| Unproved properties | $ | 4,620 | $ | 2,492 | $ | 151 | $ | 1,081 | $ | 1,986 | $ | — | $ | 10,330 | $ | 108 | $ | — | ||||||||||
| Proved properties and related producing assets | 82,199 | 24,189 | 45,756 | 56,648 | 22,032 | 2,082 | 232,906 | 10,757 | 4,311 | |||||||||||||||||||
| Support equipment | 2,287 | 311 | 1,098 | 2,075 | 18,610 | — | 24,381 | 1,981 | — | |||||||||||||||||||
| Deferred exploratory wells | 533 | 147 | 405 | 513 | 1,322 | 121 | 3,041 | — | — | |||||||||||||||||||
| Other uncompleted projects | 5,080 | 505 | 1,176 | 926 | 1,023 | 15 | 8,725 | 16,503 | 743 | |||||||||||||||||||
| Gross Capitalized Costs | 94,719 | 27,644 | 48,586 | 61,243 | 44,973 | 2,218 | 279,383 | 29,349 | 5,054 | |||||||||||||||||||
| Unproved properties valuation | 3,964 | 1,271 | 120 | 842 | 109 | — | 6,306 | 65 | — | |||||||||||||||||||
| Proved producing properties – Depreciation and depletion | 56,911 | 12,644 | 33,613 | 44,871 | 6,064 | 404 | 154,507 | 6,018 | 1,912 | |||||||||||||||||||
| Support equipment depreciation | 1,635 | 226 | 772 | 1,605 | 2,272 | — | 6,510 | 1,053 | — | |||||||||||||||||||
| Accumulated provisions | 62,510 | 14,141 | 34,505 | 47,318 | 8,445 | 404 | 167,323 | 7,136 | 1,912 | |||||||||||||||||||
| Net Capitalized Costs | $ | 32,209 | $ | 13,503 | $ | 14,081 | $ | 13,925 | $ | 36,528 | $ | 1,814 | $ | 112,060 | $ | 22,213 | $ | 3,142 | ||||||||||
| At December 31, 2018 | ||||||||||||||||||||||||||||
| Unproved properties | $ | 4,687 | $ | 2,463 | $ | 201 | $ | 1,299 | $ | 1,986 | $ | — | $ | 10,636 | $ | 108 | $ | — | ||||||||||
| Proved properties and related producing assets | 75,013 | 21,796 | 44,876 | 57,168 | 22,047 | 12,634 | 233,534 | 9,892 | 4,336 | |||||||||||||||||||
| Support equipment | 2,216 | 317 | 1,096 | 2,149 | 17,712 | 124 | 23,614 | 1,858 | — | |||||||||||||||||||
| Deferred exploratory wells | 782 | 160 | 405 | 632 | 1,323 | 261 | 3,563 | — | — | |||||||||||||||||||
| Other uncompleted projects | 4,730 | 3,704 | 1,744 | 1,292 | 1,462 | 300 | 13,232 | 12,311 | 605 | |||||||||||||||||||
| Gross Capitalized Costs | 87,428 | 28,440 | 48,322 | 62,540 | 44,530 | 13,319 | 284,579 | 24,169 | 4,941 | |||||||||||||||||||
| Unproved properties valuation | 820 | 694 | 164 | 623 | 107 | — | 2,408 | 61 | — | |||||||||||||||||||
| Proved producing properties – Depreciation and depletion | 45,712 | 12,984 | 31,102 | 43,735 | 4,631 | 10,014 | 148,178 | 5,276 | 1,730 | |||||||||||||||||||
| Support equipment depreciation | 1,466 | 220 | 738 | 1,674 | 1,531 | 119 | 5,748 | 947 | — | |||||||||||||||||||
| Accumulated provisions | 47,998 | 13,898 | 32,004 | 46,032 | 6,269 | 10,133 | 156,334 | 6,284 | 1,730 | |||||||||||||||||||
| Net Capitalized Costs | $ | 39,430 | $ | 14,542 | $ | 16,318 | $ | 16,508 | $ | 38,261 | $ | 3,186 | $ | 128,245 | $ | 17,885 | $ | 3,211 | ||||||||||
| At December 31, 2017 | ||||||||||||||||||||||||||||
| Unproved properties | $ | 6,466 | $ | 2,314 | $ | 240 | $ | 1,420 | $ | 1,986 | $ | 23 | $ | 12,449 | $ | 108 | $ | — | ||||||||||
| Proved properties and related producing assets | 66,390 | 20,696 | 43,656 | 55,616 | 21,544 | 10,697 | 218,599 | 8,956 | 4,346 | |||||||||||||||||||
| Support equipment | 2,248 | 337 | 1,104 | 2,050 | 15,599 | 132 | 21,470 | 1,731 | — | |||||||||||||||||||
| Deferred exploratory wells | 969 | 181 | 406 | 562 | 1,323 | 261 | 3,702 | — | — | |||||||||||||||||||
| Other uncompleted projects | 8,333 | 3,624 | 2,528 | 1,889 | 3,238 | 1,966 | 21,578 | 8,408 | 457 | |||||||||||||||||||
| Gross Capitalized Costs | 84,406 | 27,152 | 47,934 | 61,537 | 43,690 | 13,079 | 277,798 | 19,203 | 4,803 | |||||||||||||||||||
| Unproved properties valuation | 977 | 855 | 162 | 535 | 107 | 23 | 2,659 | 58 | — | |||||||||||||||||||
| Proved producing properties – Depreciation and depletion | 43,286 | 11,795 | 27,916 | 40,234 | 3,193 | 9,306 | 135,730 | 4,674 | 1,468 | |||||||||||||||||||
| Support equipment depreciation | 1,359 | 227 | 712 | 1,584 | 870 | 123 | 4,875 | 846 | — | |||||||||||||||||||
| Accumulated provisions | 45,622 | 12,877 | 28,790 | 42,353 | 4,170 | 9,452 | 143,264 | 5,578 | 1,468 | |||||||||||||||||||
| Net Capitalized Costs | $ | 38,784 | $ | 14,275 | $ | 19,144 | $ | 19,184 | $ | 39,520 | $ | 3,627 | $ | 134,534 | $ | 13,625 | $ | 3,335 |
- 2017 and 2018 conformed to 2019 presentation
Supplemental Information on Oil and Gas Producing Activities - Unaudited
Table III - Results of Operations for Oil and Gas Producing Activities****1
The company’s results of operations from oil and gas producing activities for the years 2019, 2018 and 2017 are shown in the following table. Net income (loss) from exploration and production activities as reported on page 69 reflects income taxes computed on an effective rate basis.
Income taxes in Table III are based on statutory tax rates, reflecting allowable deductions and tax credits. Interest income and expense are excluded from the results reported in Table III and from the net income amounts on page 69.
| Consolidated Companies | Affiliated Companies | |||||||||||||||||||||||||||
| Other | Australia/ | |||||||||||||||||||||||||||
| Millions of dollars | U.S. | Americas | Africa | Asia | Oceania | Europe | Total | TCO2 | Other | |||||||||||||||||||
| Year Ended December 31, 2019 | ||||||||||||||||||||||||||||
| Revenues from net production | ||||||||||||||||||||||||||||
| Sales | $ | 2,259 | $ | 863 | $ | 668 | $ | 7,410 | $ | 4,332 | $ | 592 | $ | 16,124 | $ | 5,603 | $ | 780 | ||||||||||
| Transfers | 11,043 | 2,160 | 6,534 | 1,311 | 2,596 | 655 | 24,299 | — | — | |||||||||||||||||||
| Total | 13,302 | 3,023 | 7,202 | 8,721 | 6,928 | 1,247 | 40,423 | 5,603 | 780 | |||||||||||||||||||
| Production expenses excluding taxes | (3,567 | ) | (1,020 | ) | (1,460 | ) | (2,703 | ) | (616 | ) | (343 | ) | (9,709 | ) | (475 | ) | (247 | ) | ||||||||||
| Taxes other than on income | (595 | ) | (64 | ) | (101 | ) | (16 | ) | (221 | ) | (2 | ) | (999 | ) | (57 | ) | (10 | ) | ||||||||||
| Proved producing properties: | ||||||||||||||||||||||||||||
| Depreciation and depletion | (11,659 | ) | (1,380 | ) | (2,548 | ) | (3,165 | ) | (2,192 | ) | (85 | ) | (21,029 | ) | (870 | ) | (211 | ) | ||||||||||
| Accretion expense3 | (191 | ) | (21 | ) | (148 | ) | (133 | ) | (53 | ) | (37 | ) | (583 | ) | (5 | ) | (8 | ) | ||||||||||
| Exploration expenses | (293 | ) | (211 | ) | (73 | ) | (93 | ) | (60 | ) | (10 | ) | (740 | ) | — | (8 | ) | |||||||||||
| Unproved properties valuation | (3,268 | ) | (591 | ) | (2 | ) | (388 | ) | (2 | ) | — | (4,251 | ) | (4 | ) | — | ||||||||||||
| Other income (expense)4 | (51 | ) | (44 | ) | (121 | ) | 413 | 53 | 1,373 | 1,623 | 1 | (157 | ) | |||||||||||||||
| Results before income taxes | (6,322 | ) | (308 | ) | 2,749 | 2,636 | 3,837 | 2,143 | 4,735 | 4,193 | 139 | |||||||||||||||||
| Income tax (expense) benefit | 1,311 | (27 | ) | (1,731 | ) | (1,212 | ) | (1,161 | ) | (311 | ) | (3,131 | ) | (1,261 | ) | (73 | ) | |||||||||||
| Results of Producing Operations | $ | (5,011 | ) | $ | (335 | ) | $ | 1,018 | $ | 1,424 | $ | 2,676 | $ | 1,832 | $ | 1,604 | $ | 2,932 | $ | 66 | ||||||||
| Year Ended December 31, 2018 | ||||||||||||||||||||||||||||
| Revenues from net production | ||||||||||||||||||||||||||||
| Sales | $ | 2,162 | $ | 1,008 | $ | 829 | $ | 5,880 | $ | 4,229 | $ | 619 | $ | 14,727 | $ | 5,987 | $ | 1,369 | ||||||||||
| Transfers | 11,645 | 1,808 | 7,829 | 3,206 | 3,413 | 1,071 | 28,972 | — | — | |||||||||||||||||||
| Total | 13,807 | 2,816 | 8,658 | 9,086 | 7,642 | 1,690 | 43,699 | 5,987 | 1,369 | |||||||||||||||||||
| Production expenses excluding taxes | (3,203 | ) | (1,009 | ) | (1,564 | ) | (2,653 | ) | (557 | ) | (424 | ) | (9,410 | ) | (447 | ) | (295 | ) | ||||||||||
| Taxes other than on income | (540 | ) | (70 | ) | (112 | ) | (22 | ) | (250 | ) | (2 | ) | (996 | ) | 160 | (210 | ) | |||||||||||
| Proved producing properties: | ||||||||||||||||||||||||||||
| Depreciation and depletion | (4,583 | ) | (998 | ) | (3,368 | ) | (3,714 | ) | (2,103 | ) | (411 | ) | (15,177 | ) | (711 | ) | (306 | ) | ||||||||||
| Accretion expense3 | (186 | ) | (26 | ) | (149 | ) | (146 | ) | (50 | ) | (52 | ) | (609 | ) | (4 | ) | (3 | ) | ||||||||||
| Exploration expenses | (777 | ) | (191 | ) | (52 | ) | (58 | ) | (56 | ) | (41 | ) | (1,175 | ) | (3 | ) | (6 | ) | ||||||||||
| Unproved properties valuation | (516 | ) | (42 | ) | (3 | ) | (135 | ) | — | — | (696 | ) | — | — | ||||||||||||||
| Other income (expense)4 | 336 | 4 | 97 | (33 | ) | 31 | (161 | ) | 274 | 70 | (280 | ) | ||||||||||||||||
| Results before income taxes | 4,338 | 484 | 3,507 | 2,325 | 4,657 | 599 | 15,910 | 5,052 | 269 | |||||||||||||||||||
| Income tax (expense) benefit | (886 | ) | (400 | ) | (2,131 | ) | (1,088 | ) | (1,415 | ) | (233 | ) | (6,153 | ) | (1,519 | ) | 341 | |||||||||||
| Results of Producing Operations | $ | 3,452 | $ | 84 | $ | 1,376 | $ | 1,237 | $ | 3,242 | $ | 366 | $ | 9,757 | $ | 3,533 | $ | 610 |
| 1 | The value of owned production consumed in operations as fuel has been eliminated from revenues and production expenses, and the related volumes have been deducted from net production in calculating the unit average sales price and production cost. This has no effect on the results of producing operations. |
| 2 | 2017 and 2018 conformed to 2019 presentation. |
| 3 | Represents accretion of ARO liability. Refer to Note 23, “Asset Retirement Obligations,” on page 89. |
| 4 | Includes foreign currency gains and losses, gains and losses on property dispositions and other miscellaneous income and expenses. |
Supplemental Information on Oil and Gas Producing Activities - Unaudited
Table III - Results of Operations for Oil and Gas Producing Activities1, continued
| Consolidated Companies | Affiliated Companies | |||||||||||||||||||||||||||
| Other | Australia/ | |||||||||||||||||||||||||||
| Millions of dollars | U.S. | Americas | Africa | Asia | Oceania | Europe | Total | TCO2 | Other | |||||||||||||||||||
| Year Ended December 31, 2017 | ||||||||||||||||||||||||||||
| Revenues from net production | ||||||||||||||||||||||||||||
| Sales | $ | 1,548 | $ | 999 | $ | 487 | $ | 5,381 | $ | 2,061 | $ | 372 | $ | 10,848 | $ | 4,509 | $ | 1,218 | ||||||||||
| Transfers | 7,610 | 1,371 | 6,533 | 2,966 | 937 | 1,246 | 20,663 | — | — | |||||||||||||||||||
| Total | 9,158 | 2,370 | 7,020 | 8,347 | 2,998 | 1,618 | 31,511 | 4,509 | 1,218 | |||||||||||||||||||
| Production expenses excluding taxes | (3,160 | ) | (1,021 | ) | (1,521 | ) | (2,670 | ) | (304 | ) | (415 | ) | (9,091 | ) | (425 | ) | (306 | ) | ||||||||||
| Taxes other than on income | (403 | ) | (85 | ) | (115 | ) | (11 | ) | (183 | ) | (3 | ) | (800 | ) | 118 | (121 | ) | |||||||||||
| Proved producing properties: | ||||||||||||||||||||||||||||
| Depreciation and depletion | (5,092 | ) | (1,046 | ) | (3,531 | ) | (4,134 | ) | (1,176 | ) | (668 | ) | (15,647 | ) | (645 | ) | (365 | ) | ||||||||||
| Accretion expense3 | (212 | ) | (23 | ) | (144 | ) | (155 | ) | (40 | ) | (60 | ) | (634 | ) | (3 | ) | (16 | ) | ||||||||||
| Exploration expenses | (299 | ) | (126 | ) | (65 | ) | (108 | ) | (85 | ) | (149 | ) | (832 | ) | — | — | ||||||||||||
| Unproved properties valuation | (204 | ) | (259 | ) | (3 | ) | (52 | ) | — | — | (518 | ) | (3 | ) | — | |||||||||||||
| Other income (expense)4 | 580 | (87 | ) | 259 | 273 | 170 | (170 | ) | 1,025 | 25 | (14 | ) | ||||||||||||||||
| Results before income taxes | 368 | (277 | ) | 1,900 | 1,490 | 1,380 | 153 | 5,014 | 3,576 | 396 | ||||||||||||||||||
| Income tax (expense) benefit | (88 | ) | (64 | ) | (1,199 | ) | (616 | ) | (413 | ) | (174 | ) | (2,554 | ) | (1,076 | ) | 20 | |||||||||||
| Results of Producing Operations | $ | 280 | $ | (341 | ) | $ | 701 | $ | 874 | $ | 967 | $ | (21 | ) | $ | 2,460 | $ | 2,500 | $ | 416 |
| 1 | The value of owned production consumed in operations as fuel has been eliminated from revenues and production expenses, and the related volumes have been deducted from net production in calculating the unit average sales price and production cost. This has no effect on the results of producing operations. |
| 2 | 2017 and 2018 conformed to 2019 presentation. |
| 3 | Represents accretion of ARO liability. Refer to Note 23, “Asset Retirement Obligations,” on page 89. |
| 4 | Includes foreign currency gains and losses, gains and losses on property dispositions and other miscellaneous income and expenses. |
Table IV - Results of Operations for Oil and Gas Producing Activities - Unit Prices and Costs****1
| Consolidated Companies | Affiliated Companies | |||||||||||||||||||||||||||
| Other | Australia/ | |||||||||||||||||||||||||||
| U.S. | Americas | Africa | Asia | Oceania | Europe | Total | TCO | Other | ||||||||||||||||||||
| Year Ended December 31, 2019 | ||||||||||||||||||||||||||||
| Average sales prices | ||||||||||||||||||||||||||||
| Liquids, per barrel | $ | 48.54 | $ | 54.85 | $ | 62.27 | $ | 59.53 | $ | 60.15 | $ | 61.80 | $ | 54.47 | $ | 49.14 | $ | 45.25 | ||||||||||
| Natural gas, per thousand cubic feet | 1.07 | 2.24 | 1.84 | 4.73 | 7.54 | 4.43 | 4.86 | 0.79 | 0.99 | |||||||||||||||||||
| Average production costs, per barrel2 | 10.48 | 15.97 | 11.90 | 12.74 | 4.08 | 14.28 | 10.62 | 3.53 | 7.93 | |||||||||||||||||||
| Year Ended December 31, 2018 | ||||||||||||||||||||||||||||
| Average sales prices | ||||||||||||||||||||||||||||
| Liquids, per barrel | $ | 58.17 | $ | 58.27 | $ | 69.75 | $ | 63.55 | $ | 68.78 | $ | 66.31 | $ | 62.45 | $ | 56.20 | $ | 56.41 | ||||||||||
| Natural gas, per thousand cubic feet | 1.86 | 2.62 | 2.55 | 4.48 | 8.78 | 7.54 | 5.54 | 0.77 | 3.19 | |||||||||||||||||||
| Average production costs, per barrel2 | 11.18 | 17.32 | 11.29 | 12.15 | 3.95 | 14.21 | 10.78 | 3.59 | 9.29 | |||||||||||||||||||
| Year Ended December 31, 2017 | ||||||||||||||||||||||||||||
| Average sales prices | ||||||||||||||||||||||||||||
| Liquids, per barrel | $ | 44.53 | $ | 51.26 | $ | 52.12 | $ | 48.45 | $ | 52.32 | $ | 51.15 | $ | 48.61 | $ | 41.47 | $ | 48.68 | ||||||||||
| Natural gas, per thousand cubic feet | 2.11 | 3.15 | 1.77 | 4.12 | 5.75 | 5.55 | 4.07 | 0.88 | 2.38 | |||||||||||||||||||
| Average production costs, per barrel2 | 12.83 | 18.64 | 10.88 | 11.30 | 3.60 | 11.95 | 11.41 | 3.34 | 8.51 |
| 1 | The value of owned production consumed in operations as fuel has been eliminated from revenues and production expenses, and the related volumes have been deducted from net production in calculating the unit average sales price and production cost. This has no effect on the results of producing operations. |
| 2 | Natural gas converted to oil-equivalent gas (OEG) barrels at a rate of 6 MCF = 1 OEG barrel. |
Supplemental Information on Oil and Gas Producing Activities - Unaudited
Table V Reserve Quantity Information
Summary of Net Oil and Gas Reserves
| 2019 | 2018 | 2017 | ||||||||||||||||||||||||
| Liquids in Millions of Barrels | ||||||||||||||||||||||||||
| Natural Gas in Billions of Cubic Feet | Crude Oil Condensate | SyntheticOil | NGL | Natural Gas | Crude Oil Condensate | SyntheticOil | NGL | Natural Gas | Crude Oil Condensate | SyntheticOil | NGL | Natural Gas | ||||||||||||||
| Proved Developed | ||||||||||||||||||||||||||
| Consolidated Companies | ||||||||||||||||||||||||||
| U.S. | 1,121 | — | 258 | 2,998 | 1,061 | — | 179 | 2,396 | 909 | — | 122 | 2,096 | ||||||||||||||
| Other Americas | 174 | 540 | 5 | 397 | 156 | 545 | 3 | 393 | 99 | 543 | 2 | 398 | ||||||||||||||
| Africa | 525 | — | 67 | 1,472 | 568 | — | 60 | 1,316 | 610 | — | 54 | 1,276 | ||||||||||||||
| Asia | 406 | — | — | 3,382 | 470 | — | — | 4,021 | 529 | — | — | 4,463 | ||||||||||||||
| Australia/Oceania | 136 | — | 4 | 10,697 | 127 | — | 5 | 10,084 | 121 | — | 5 | 9,907 | ||||||||||||||
| Europe | 21 | — | — | 8 | 81 | — | 3 | 205 | 80 | — | 3 | 215 | ||||||||||||||
| Total Consolidated | 2,383 | 540 | 334 | 18,954 | 2,463 | 545 | 250 | 18,415 | 2,348 | 543 | 186 | 18,355 | ||||||||||||||
| Affiliated Companies | ||||||||||||||||||||||||||
| TCO | 584 | — | 59 | 1,135 | 638 | — | 62 | 1,179 | 716 | — | 71 | 1,300 | ||||||||||||||
| Other | 114 | — | 10 | 308 | 65 | 55 | 11 | 308 | 74 | 66 | 10 | 270 | ||||||||||||||
| Total Consolidated and Affiliated Companies | 3,081 | 540 | 403 | 20,397 | 3,166 | 600 | 323 | 19,902 | 3,138 | 609 | 267 | 19,925 | ||||||||||||||
| Proved Undeveloped | ||||||||||||||||||||||||||
| Consolidated Companies | ||||||||||||||||||||||||||
| U.S. | 807 | — | 244 | 1,730 | 813 | — | 349 | 4,313 | 664 | — | 221 | 3,084 | ||||||||||||||
| Other Americas | 146 | — | 11 | 339 | 185 | — | 19 | 470 | 181 | — | 15 | 397 | ||||||||||||||
| Africa | 88 | — | 33 | 1,286 | 110 | — | 38 | 1,499 | 133 | — | 42 | 1,630 | ||||||||||||||
| Asia | 107 | — | — | 299 | 109 | — | — | 289 | 102 | — | — | 310 | ||||||||||||||
| Australia/Oceania | 30 | — | — | 3,961 | 29 | — | — | 3,647 | 32 | — | 1 | 3,652 | ||||||||||||||
| Europe | 48 | — | — | 18 | 65 | — | — | 100 | 62 | — | — | 86 | ||||||||||||||
| Total Consolidated | 1,226 | — | 288 | 7,633 | 1,311 | — | 406 | 10,318 | 1,174 | — | 279 | 9,159 | ||||||||||||||
| Affiliated Companies | ||||||||||||||||||||||||||
| TCO | 889 | — | 44 | 869 | 866 | — | 39 | 755 | 914 | — | 48 | 883 | ||||||||||||||
| Other | 45 | — | 5 | 558 | 2 | 72 | 5 | 601 | 9 | 93 | 11 | 769 | ||||||||||||||
| Total Consolidated and Affiliated Companies | 2,160 | — | 337 | 9,060 | 2,179 | 72 | 450 | 11,674 | 2,097 | 93 | 338 | 10,811 | ||||||||||||||
| Total Proved Reserves | 5,241 | 540 | 740 | 29,457 | 5,345 | 672 | 773 | 31,576 | 5,235 | 702 | 605 | 30,736 |
Reserves Governance The company has adopted a comprehensive reserves and resource classification system modeled after a system developed and approved by a number of organizations including the Society of Petroleum Engineers, the World Petroleum Congress and the American Association of Petroleum Geologists. The company classifies recoverable hydrocarbons into six categories based on their status at the time of reporting – three deemed commercial and three potentially recoverable. Within the commercial classification are proved reserves and two categories of unproved reserves: probable and possible. The potentially recoverable categories are also referred to as contingent resources. For reserves estimates to be classified as proved, they must meet all SEC and company standards.
Proved oil and gas reserves are the estimated quantities that geoscience and engineering data demonstrate with reasonable certainty to be economically producible in the future from known reservoirs under existing economic conditions, operating methods and government regulations. Net proved reserves exclude royalties and interests owned by others and reflect contractual arrangements and royalty obligations in effect at the time of the estimate.
Proved reserves are classified as either developed or undeveloped. Proved developed reserves are the quantities expected to be recovered through existing wells with existing equipment and operating methods. Proved undeveloped reserves are the quantities expected to be recovered from new wells on undrilled acreage or from existing wells where a relatively major expenditure is required for recompletion.
Due to the inherent uncertainties and the limited nature of reservoir data, estimates of reserves are subject to change as additional information becomes available.
Proved reserves are estimated by company asset teams composed of earth scientists and engineers. As part of the internal control process related to reserves estimation, the company maintains a Reserves Advisory Committee (RAC) that is chaired by the Manager of Global Reserves, an organization that is separate from the Upstream operating organization. The Manager
Supplemental Information on Oil and Gas Producing Activities - Unaudited
of Global Reserves has more than 30 years’ experience working in the oil and gas industry and holds both undergraduate and graduate degrees in geoscience. His experience includes various technical and management roles in providing reserve and resource estimates in support of major capital and exploration projects, and more than 10 years of overseeing oil and gas reserves processes. He has been named a Distinguished Lecturer by the American Association of Petroleum Geologists and is an active member of the American Association of Petroleum Geologists, the SEPM Society of Sedimentary Geologists and the Society of Petroleum Engineers.
All RAC members are degreed professionals, each with more than 10 years of experience in various aspects of reserves estimation relating to reservoir engineering, petroleum engineering, earth science or finance. The members are knowledgeable in SEC guidelines for proved reserves classification and receive annual training on the preparation of reserves estimates.
The RAC has the following primary responsibilities: establish the policies and processes used within the operating units to estimate reserves; provide independent reviews and oversight of the business units’ recommended reserves estimates and changes; confirm that proved reserves are recognized in accordance with SEC guidelines; determine that reserve volumes are calculated using consistent and appropriate standards, procedures and technology; and maintain the Chevron Corporation Reserves Manual, which provides standardized procedures used corporatewide for classifying and reporting hydrocarbon reserves.
During the year, the RAC is represented in meetings with each of the company’s upstream business units to review and discuss reserve changes recommended by the various asset teams. Major changes are also reviewed with the company’s senior leadership team including the Chief Executive Officer and the Chief Financial Officer. The company’s annual reserve activity is also reviewed with the Board of Directors. If major changes to reserves were to occur between the annual reviews, those matters would also be discussed with the Board.
RAC subteams also conduct in-depth reviews during the year of many of the fields that have large proved reserves quantities. These reviews include an examination of the proved-reserve records and documentation of their compliance with the Chevron Corporation Reserves Manual.
Technologies Used in Establishing Proved Reserves Additions In 2019, additions to Chevron’s proved reserves were based on a wide range of geologic and engineering technologies. Information generated from wells, such as well logs, wire line sampling, production and pressure testing, fluid analysis, and core analysis, was integrated with seismic data, regional geologic studies, and information from analogous reservoirs to provide “reasonably certain” proved reserves estimates. Both proprietary and commercially available analytic tools, including reservoir simulation, geologic modeling and seismic processing, have been used in the interpretation of the subsurface data. These technologies have been utilized extensively by the company in the past, and the company believes that they provide a high degree of confidence in establishing reliable and consistent reserves estimates.
Proved Undeveloped Reserves At the end of 2019, proved undeveloped reserves totaled 4.0 billion barrels of oil-equivalent (BOE), a decrease of 641 million BOE from year-end 2018. The decrease was due to 685 million BOE in revisions, the transfer of 593 million BOE to proved developed and 31 million BOE in sales, partially offset by 635 million BOE in extensions and discoveries, 26 million BOE in acquisitions and 7 million BOE in improved recovery. A major portion of the reserves revisions are attributed to the company’s decision to reduce planned developments and evaluate strategic alternatives, including divestment scenarios for it’s acreage in the Appalachian region.
During 2019, investments totaling approximately $10.5 billion in oil and gas producing activities and about $0.1 billion in non-oil and gas producing activities were expended to advance the development of proved undeveloped reserves. In Asia, expenditures during the year totaled approximately $5.3 billion, primarily related to development projects of the TCO affiliate in Kazakhstan. The United States accounted for about $3.3 billion related primarily to various development activities in the Gulf of Mexico and the Midland and Delaware basins. In Africa, about $0.5 billion was expended on various offshore development and natural gas projects in Nigeria, Angola and Republic of Congo. Development activities in Canada, Brazil and Argentina were primarily responsible for about $1.0 billion of expenditures in Other Americas.
Reserves that remain proved undeveloped for five or more years are a result of several factors that affect optimal project development and execution, such as the complex nature of the development project in adverse and remote locations, physical limitations of infrastructure or plant capacities that dictate project timing, compression projects that are pending reservoir pressure declines, and contractual limitations that dictate production levels.
At year-end 2019, the company held approximately 2.1 billion BOE of proved undeveloped reserves that have remained undeveloped for five years or more. The majority of these reserves are in three locations where the company has a proven track record of developing major projects. In Australia, approximately 700 million BOE have remained undeveloped for five years or more related to the Gorgon and Wheatstone projects. Further field development to convert the remaining proved
Supplemental Information on Oil and Gas Producing Activities - Unaudited
undeveloped reserves is scheduled to occur in line with operating constraints and infrastructure optimization. In Africa, approximately 300 million BOE have remained undeveloped for five years or more, primarily due to facility constraints at various fields and infrastructure associated with the Escravos gas projects in Nigeria. Affiliates account for about 1.2 billion BOE of proved undeveloped reserves with about 900 million BOE that have remained undeveloped for five years or more, with the majority related to the TCO affiliate in Kazakhstan. At TCO, further field development to convert the remaining proved undeveloped reserves is scheduled to occur in line with reservoir depletion and facility constraints.
Annually, the company assesses whether any changes have occurred in facts or circumstances, such as changes to development plans, regulations or government policies, that would warrant a revision to reserve estimates. In 2019, decreases in commodity prices negatively impacted the economic limits of oil and gas properties, resulting in proved reserve decreases, and positively impacted proved reserves due to entitlement effects. The year-end reserves quantities have been updated for these circumstances and significant changes have been discussed in the appropriate reserves sections. Over the past three years, the ratio of proved undeveloped reserves to total proved reserves has ranged between 35 percent and 38 percent.
Proved Reserve Quantities For the three years ending December 31, 2019, the pattern of net reserve changes shown in the following tables are not necessarily indicative of future trends. Apart from acquisitions, the company’s ability to add proved reserves can be affected by events and circumstances that are outside the company’s control, such as delays in government permitting, partner approvals of development plans, changes in oil and gas prices, OPEC constraints, geopolitical uncertainties, and civil unrest.
At December 31, 2019, proved reserves for the company were 11.4 billion BOE. The company’s estimated net proved reserves of liquids including crude oil, condensate and synthetic oil for the years 2017, 2018 and 2019 are shown in the table on page 99. The company’s estimated net proved reserves of natural gas liquids are shown on page 100 and the company’s estimated net proved reserves of natural gas are shown on page 101.
Noteworthy changes in crude oil, condensate and synthetic oil proved reserves for 2017 through 2019 are discussed below and shown in the table on the following page:
Revisions In 2017, improved field performance at various Gulf of Mexico fields, including Jack/St Malo and Tahiti, and in the Midland and Delaware basins were primarily responsible for the 209 million barrel increase in the United States. Improved field performance at various fields, including Agbami and Sonam in Nigeria, were responsible for the 73 million barrel increase in Africa. Synthetic oil reserves in Canada decreased by 42 million barrels, primarily due to entitlement effects. In the TCO affiliate in Kazakhstan, entitlement effects were mainly responsible for the 52 million barrel decrease.
In 2018, improved field performance at various Gulf of Mexico fields and in the Midland and Delaware basins were primarily responsible for the 121 million barrel increase in the United States. Improved field performance at various fields, including Agbami in Nigeria and Moho-Bilondo in the Republic of Congo, were responsible for the 61 million barrel increase in Africa. Reserves in Other Americas increased by 59 million barrels, primarily due to improved field performance at the Hebron field in Canada. In Asia, improved performance across numerous assets resulted in the 37 million barrel increase.
In 2019, portfolio optimizations, where future drilling in various fields in the Midland and Delaware basins is being targeted away from reservoirs with higher gas-to-oil ratios and lower execution efficiencies, and planned divestments in the Appalachian basin, were primarily responsible for the 153 million barrel decrease in the United States. Operational issues with the Petropiar upgrader in Venezuela resulted in a decrease in reserves of synthetic oil of 126 million barrels and an increase of crude oil and condensate reserves of 105 million barrels. Reservoir management and entitlement effects were mainly responsible for 75 million barrels increase in the TCO affiliate in Kazakhstan. Improved field performance at various fields, including Moho-Bilondo in the Republic of Congo, Mafumeria in Angola, and Sonam in Nigeria, were responsible for the 42 million barrel increase in Africa.
Extensions and Discoveries In 2017, extensions and discoveries in the Midland and Delaware basins and the Gulf of Mexico were primarily responsible for the 323 million barrel increase in the United States. Extensions and discoveries in the Duvernay Shale in Canada were primarily responsible for the 63 million barrel increase in Other Americas.
In 2018, extensions and discoveries in the Midland and Delaware basins were primarily responsible for the 359 million barrel increase in the United States. Extensions and discoveries in the Duvernay Shale in Canada and Loma Campana in Argentina were primarily responsible for the 31 million barrel increase in Other Americas.
Supplemental Information on Oil and Gas Producing Activities - Unaudited
In 2019, portfolio optimizations, where future drilling in various fields in the Midland and Delaware basins is being targeted towards liquids-rich reservoirs with higher execution efficiencies, and extensions and discoveries in the deepwater fields in the Gulf of Mexico, were primarily responsible for the 394 million barrel increase in the United States. Extensions and discoveries in Loma Campana in Argentina were primarily responsible for the 39 million barrel increase in Other Americas.
Purchases In 2017, purchases of 33 million barrels in Asia were due to contract extension in the Azeri-Chirag-Gunashli fields in Azerbaijan.
In 2018, purchases of 31 million barrels in the United States were primarily in the Midland and Delaware basins.
Sales In 2017, sales of 51 million barrels in the United States were primarily in the Gulf of Mexico shelf and in the Midland and Delaware basins.
In 2019, sales of 69 million barrels in Europe were in the United Kingdom and Denmark.
Net Proved Reserves of Crude Oil, Condensate and Synthetic Oil
| Consolidated Companies | Affiliated Companies | Total Consolidated | ||||||||||||||||||||||||
| Other | Australia/ | Synthetic | Synthetic | and Affiliated | ||||||||||||||||||||||
| Millions of barrels | U.S. | Americas1 | Africa | Asia | Oceania | Europe | Oil2 | Total | TCO | Oil | Other3 | Companies | ||||||||||||||
| Reserves at January 1, 2017 | 1,244 | 219 | 782 | 720 | 152 | 135 | 604 | 3,856 | 1,781 | 170 | 93 | 5,900 | ||||||||||||||
| Changes attributable to: | ||||||||||||||||||||||||||
| Revisions | 209 | 22 | 73 | (17 | ) | 10 | 29 | (42 | ) | 284 | (52 | ) | — | (4 | ) | 228 | ||||||||||
| Improved recovery | 9 | — | 7 | 1 | — | — | — | 17 | — | — | 3 | 20 | ||||||||||||||
| Extensions and discoveries | 323 | 63 | 4 | — | — | — | — | 390 | — | — | — | 390 | ||||||||||||||
| Purchases | 4 | — | 2 | 33 | — | — | — | 39 | — | — | — | 39 | ||||||||||||||
| Sales | (51 | ) | (1 | ) | — | (2 | ) | — | — | — | (54 | ) | — | — | — | (54 | ) | |||||||||
| Production | (165 | ) | (23 | ) | (125 | ) | (104 | ) | (9 | ) | (22 | ) | (19 | ) | (467 | ) | (99 | ) | (11 | ) | (9 | ) | (586 | ) | ||
| Reserves at December 31, 2017****4 | 1,573 | 280 | 743 | 631 | 153 | 142 | 543 | 4,065 | 1,630 | 159 | 83 | 5,937 | ||||||||||||||
| Changes attributable to: | ||||||||||||||||||||||||||
| Revisions | 121 | 59 | 61 | 37 | 17 | 19 | 21 | 335 | (28 | ) | (23 | ) | (7 | ) | 277 | |||||||||||
| Improved recovery | 5 | — | — | 1 | — | 4 | — | 10 | — | — | — | 10 | ||||||||||||||
| Extensions and discoveries | 359 | 31 | 1 | — | — | — | — | 391 | — | — | — | 391 | ||||||||||||||
| Purchases | 31 | — | — | — | — | — | — | 31 | — | — | — | 31 | ||||||||||||||
| Sales | (26 | ) | — | (5 | ) | — | — | — | — | (31 | ) | — | — | — | (31 | ) | ||||||||||
| Production | (189 | ) | (29 | ) | (122 | ) | (90 | ) | (14 | ) | (19 | ) | (19 | ) | (482 | ) | (98 | ) | (9 | ) | (9 | ) | (598 | ) | ||
| Reserves at December 31, 2018****4 | 1,874 | 341 | 678 | 579 | 156 | 146 | 545 | 4,319 | 1,504 | 127 | 67 | 6,017 | ||||||||||||||
| Changes attributable to: | ||||||||||||||||||||||||||
| Revisions | (153 | ) | (25 | ) | 42 | 19 | 25 | 6 | 14 | (72 | ) | 75 | (126 | ) | 105 | (18 | ) | |||||||||
| Improved recovery | 7 | — | — | — | — | — | — | 7 | — | — | — | 7 | ||||||||||||||
| Extensions and discoveries | 394 | 39 | 1 | 1 | 1 | 2 | — | 438 | — | — | — | 438 | ||||||||||||||
| Purchases | 19 | 2 | — | — | — | — | — | 21 | — | — | — | 21 | ||||||||||||||
| Sales | — | (4 | ) | — | — | — | (69 | ) | — | (73 | ) | — | — | — | (73 | ) | ||||||||||
| Production | (213 | ) | (33 | ) | (108 | ) | (86 | ) | (16 | ) | (16 | ) | (19 | ) | (491 | ) | (106 | ) | (1 | ) | (13 | ) | (611 | ) | ||
| Reserves at December 31, 2019****4 | 1,928 | 320 | 613 | 513 | 166 | 69 | 540 | 4,149 | 1,473 | — | 159 | 5,781 |
| 1 | Ending reserve balances in North America were 230, 269 and 217 and in South America were 90, 72 and 63 in 2019, 2018 and 2017, respectively. |
| 2 | Reserves associated with Canada. |
| 3 | Ending reserve balances in Africa were 3, 3 and 5 and in South America were 156, 64 and 78 in 2019, 2018 and 2017, respectively. |
| 4 | Included are year-end reserve quantities related to production-sharing contracts (PSC) (refer to page E-7 for the definition of a PSC). PSC-related reserve quantities are 11 percent, 14 percent and 16 percent for consolidated companies for 2019, 2018 and 2017, respectively. |
Supplemental Information on Oil and Gas Producing Activities - Unaudited
Noteworthy changes in natural gas liquids proved reserves for 2017 through 2019 are discussed and shown in the table below:
Revisions In 2017, improved field performance in the Midland and Delaware basins and at various Gulf of Mexico fields were primarily responsible for the 71 million barrel increase in the United States.
In 2018, improved field performance in the Midland and Delaware basins were primarily responsible for the 34 million barrel increase in the United States.
In 2019, portfolio optimizations and low price realizations in various fields in the Midland and Delaware basins and planned divestments in the Appalachian basin were mainly responsible for the 120 million barrel decrease in the United States.
Extensions and Discoveries In 2017, extensions and discoveries in the Midland and Delaware basins and the Appalachian region were primarily responsible for the 135 million barrel increase in the United States.
In 2018, extensions and discoveries in the Midland and Delaware basins were primarily responsible for the 173 million barrel increase in the United States.
In 2019, extensions and discoveries in the Midland and Delaware basins and deepwater fields in the Gulf of Mexico were primarily responsible for the 140 million barrel increase in the United States.
Net Proved Reserves of Natural Gas Liquids
| Consolidated Companies | Affiliated Companies | Total Consolidated | ||||||||||||||||||||
| Other | Australia/ | and Affiliated | ||||||||||||||||||||
| Millions of barrels | U.S. | Americas1 | Africa | Asia | Oceania | Europe | Total | TCO | Other2 | Companies | ||||||||||||
| Reserves at January 1, 2017 | 168 | 4 | 94 | — | 6 | 3 | 275 | 128 | 25 | 428 | ||||||||||||
| Changes attributable to: | ||||||||||||||||||||||
| Revisions | 71 | 3 | 6 | — | 1 | 1 | 82 | (1 | ) | (1 | ) | 80 | ||||||||||
| Improved recovery | — | — | — | — | — | — | — | — | — | — | ||||||||||||
| Extensions and discoveries | 135 | 11 | — | — | — | — | 146 | — | — | 146 | ||||||||||||
| Purchases | — | — | — | — | — | — | — | — | — | — | ||||||||||||
| Sales | (6 | ) | — | — | — | — | — | (6 | ) | — | — | (6 | ) | |||||||||
| Production | (25 | ) | (1 | ) | (4 | ) | — | (1 | ) | (1 | ) | (32 | ) | (8 | ) | (3 | ) | (43 | ) | |||
| Reserves at December 31, 2017****3 | 343 | 17 | 96 | — | 6 | 3 | 465 | 119 | 21 | 605 | ||||||||||||
| Changes attributable to: | ||||||||||||||||||||||
| Revisions | 34 | 1 | 7 | — | — | 1 | 43 | (11 | ) | (3 | ) | 29 | ||||||||||
| Improved recovery | — | — | — | — | — | — | — | — | — | — | ||||||||||||
| Extensions and discoveries | 173 | 5 | — | — | — | — | 178 | — | — | 178 | ||||||||||||
| Purchases | 19 | — | — | — | — | — | 19 | — | — | 19 | ||||||||||||
| Sales | (6 | ) | — | — | — | — | — | (6 | ) | — | — | (6 | ) | |||||||||
| Production | (35 | ) | (1 | ) | (5 | ) | — | (1 | ) | (1 | ) | (43 | ) | (7 | ) | (2 | ) | (52 | ) | |||
| Reserves at December 31, 2018****3 | 528 | 22 | 98 | — | 5 | 3 | 656 | 101 | 16 | 773 | ||||||||||||
| Changes attributable to: | ||||||||||||||||||||||
| Revisions | (120 | ) | (4 | ) | 6 | — | — | — | (118 | ) | 10 | 2 | (106 | ) | ||||||||
| Improved recovery | — | — | — | — | — | — | — | — | — | — | ||||||||||||
| Extensions and discoveries | 140 | — | — | — | — | — | 140 | — | — | 140 | ||||||||||||
| Purchases | 5 | — | — | — | — | — | 5 | — | — | 5 | ||||||||||||
| Sales | — | — | — | — | — | (2 | ) | (2 | ) | — | — | (2 | ) | |||||||||
| Production | (51 | ) | (2 | ) | (4 | ) | — | (1 | ) | (1 | ) | (59 | ) | (8 | ) | (3 | ) | (70 | ) | |||
| Reserves at December 31, 2019****3 | 502 | 16 | 100 | — | 4 | — | 622 | 103 | 15 | 740 |
| 1 | Reserves associated with North America. |
| 2 | Reserves associated with Africa. |
| 3 | Year-end reserve quantities related to production-sharing contracts (PSC) (refer to page E-7 for the definition of a PSC) are not material for 2019, 2018 and 2017, respectively. |
Supplemental Information on Oil and Gas Producing Activities - Unaudited
Net Proved Reserves of Natural Gas
| Consolidated Companies | Affiliated Companies | Total Consolidated | ||||||||||||||||||||
| Other | Australia/ | and Affiliated | ||||||||||||||||||||
| Billions of cubic feet (BCF) | U.S. | Americas1 | Africa | Asia | Oceania | Europe | Total | TCO | Other2 | Companies | ||||||||||||
| Reserves at January 1, 2017 | 3,676 | 647 | 2,827 | 5,533 | 12,515 | 234 | 25,432 | 2,242 | 1,086 | 28,760 | ||||||||||||
| Changes attributable to: | ||||||||||||||||||||||
| Revisions | 670 | 39 | 184 | 65 | 1,545 | 143 | 2,646 | 87 | 48 | 2,781 | ||||||||||||
| Improved recovery | 3 | — | — | — | — | — | 3 | — | — | 3 | ||||||||||||
| Extensions and discoveries | 1,361 | 319 | — | 2 | — | — | 1,682 | — | — | 1,682 | ||||||||||||
| Purchases | 1 | — | 2 | 46 | — | — | 49 | — | — | 49 | ||||||||||||
| Sales | (177 | ) | (129 | ) | — | (31 | ) | — | — | (337 | ) | — | — | (337 | ) | |||||||
| Production3 | (354 | ) | (81 | ) | (107 | ) | (842 | ) | (501 | ) | (76 | ) | (1,961 | ) | (146 | ) | (95 | ) | (2,202 | ) | ||
| Reserves at December 31, 2017****4 | 5,180 | 795 | 2,906 | 4,773 | 13,559 | 301 | 27,514 | 2,183 | 1,039 | 30,736 | ||||||||||||
| Changes attributable to: | ||||||||||||||||||||||
| Revisions | 258 | (3 | ) | 25 | 347 | 1,012 | 68 | 1,707 | (108 | ) | (38 | ) | 1,561 | |||||||||
| Improved recovery | 2 | 2 | — | — | 1 | — | 5 | — | — | 5 | ||||||||||||
| Extensions and discoveries | 1,627 | 138 | — | 5 | — | 1 | 1,771 | — | 3 | 1,774 | ||||||||||||
| Purchases | 144 | — | 1 | — | — | — | 145 | — | — | 145 | ||||||||||||
| Sales | (125 | ) | — | (5 | ) | — | — | — | (130 | ) | — | — | (130 | ) | ||||||||
| Production3 | (377 | ) | (69 | ) | (112 | ) | (815 | ) | (841 | ) | (65 | ) | (2,279 | ) | (141 | ) | (95 | ) | (2,515 | ) | ||
| Reserves at December 31, 2018****4 | 6,709 | 863 | 2,815 | 4,310 | 13,731 | 305 | 28,733 | 1,934 | 909 | 31,576 | ||||||||||||
| Changes attributable to: | ||||||||||||||||||||||
| Revisions | (2,565 | ) | (107 | ) | 46 | 165 | 1,732 | 3 | (726 | ) | 223 | 39 | (464 | ) | ||||||||
| Improved recovery | — | — | — | — | — | — | — | — | — | — | ||||||||||||
| Extensions and discoveries | 1,008 | 49 | — | 5 | 93 | 1 | 1,156 | — | 20 | 1,176 | ||||||||||||
| Purchases | 24 | — | — | — | — | — | 24 | — | — | 24 | ||||||||||||
| Sales | (1 | ) | (2 | ) | — | — | — | (240 | ) | (243 | ) | — | — | (243 | ) | |||||||
| Production3 | (447 | ) | (67 | ) | (103 | ) | (799 | ) | (898 | ) | (43 | ) | (2,357 | ) | (153 | ) | (102 | ) | (2,612 | ) | ||
| Reserves at December 31, 2019****4 | 4,728 | 736 | 2,758 | 3,681 | 14,658 | 26 | 26,587 | 2,004 | 866 | 29,457 |
| 1 | Ending reserve balances in North America and South America were 462, 582, 478 and 274, 281, 317 in 2019, 2018 and 2017, respectively. |
| 2 | Ending reserve balances in Africa and South America were 802, 799, 899 and 64, 110, 140 in 2019, 2018 and 2017, respectively. |
| 3 | Total “as sold” volumes are 2,379, 2,289 and 1,995 for 2019, 2018 and 2017, respectively. |
| 4 | Includes reserve quantities related to production-sharing contracts (PSC) (refer to page E-7 for the definition of a PSC). PSC-related reserve quantities are 10 percent, 10 percent and 12 percent for consolidated companies for 2019, 2018 and 2017, respectively. |
Noteworthy changes in natural gas proved reserves for 2017 through 2019 are discussed below and shown in the table above:
Revisions In 2017, reservoir performance and new seismic data in the greater Gorgon area were primarily responsible for the 1.5 TCF increase in Australia. Improved performance in the Midland and Delaware basins were primarily responsible for the 670 BCF increase in the United States. The Sonam Field in Nigeria was primarily responsible for the 184 BCF increase in Africa.
In 2018, reservoir performance, well test and surveillance data at Wheatstone and the greater Gorgon area were responsible for the 1.0 TCF increase in Australia. The Bibiyana Field in Bangladesh and the Pattani Field in Thailand were primarily responsible for the 347 BCF increase in Asia. Improved performance in the Midland and Delaware basins were primarily responsible for the 258 BCF increase in the United States.
In 2019, strong performances at Wheatstone and the greater Gorgon areas were mainly responsible for 1.7 TCF increase in Australia. In the TCO affiliate in Kazakhstan, reservoir management and entitlement effects were mainly responsible for 223 BCF increase. Portfolio optimizations and low price realizations in various fields of the Midland and Delaware basins and planned divestments in the Appalachian basin, were mainly responsible for the 2.6 TCF decrease in the United States.
Extensions and Discoveries In 2017, extensions and discoveries of 1.4 TCF in the United States were primarily in the Appalachian region and the Midland and Delaware basins. Extensions and discoveries in the Duvernay Shale in Canada were primarily responsible for the 319 BCF increase in Other Americas.
In 2018, extensions and discoveries of 1.6 TCF in the United States were primarily in the Appalachian region and the Midland and Delaware basins.
In 2019, extensions and discoveries of 1.0 TCF in the United States were primarily in the Midland and Delaware basins.
Supplemental Information on Oil and Gas Producing Activities - Unaudited
Sales In 2017, sales of 177 BCF in the United States were primarily from the Midland and Delaware basins. Sale of the company’s interests in Trinidad and Tobago was primarily responsible for the 129 BCF decrease in Other Americas.
In 2019, sales of 240 BCF in Europe were in the United Kingdom and Denmark.
Table VI - Standardized Measure of Discounted Future Net Cash Flows Related to Proved Oil and Gas Reserves
The standardized measure of discounted future net cash flows is calculated in accordance with SEC and FASB requirements. This includes using the average of first-day-of-the-month oil and gas prices for the 12-month period prior to the end of the reporting period, estimated future development and production costs assuming the continuation of existing economic conditions, estimated costs for asset retirement obligations (includes costs to retire existing wells and facilities in addition to those future wells and facilities necessary to produce proved undeveloped reserves), and estimated future income taxes based on appropriate statutory tax rates. Discounted future net cash flows are calculated using 10 percent mid-period discount factors. Estimates of proved-reserve quantities are imprecise and change over time as new information becomes available. Probable and possible reserves, which may become proved in the future, are excluded from the calculations. The valuation requires assumptions as to the timing and amount of future development and production costs. The calculations are made as of December 31 each year and do not represent management’s estimate of the company’s future cash flows or value of its oil and gas reserves. In the following table, the caption “Standardized Measure Net Cash Flows” refers to the standardized measure of discounted future net cash flows.
| Consolidated Companies | Affiliated Companies | Total Consolidated | ||||||||||||||||||||||||||||||
| Other | Australia/ | and Affiliated | ||||||||||||||||||||||||||||||
| Millions of dollars | U.S. | Americas | Africa | Asia | Oceania | Europe | Total | TCO | Other | Companies | ||||||||||||||||||||||
| At December 31, 2019 | ||||||||||||||||||||||||||||||||
| Future cash inflows from production | $ | 122,012 | $ | 45,701 | $ | 45,706 | $ | 43,386 | $ | 95,845 | $ | 4,466 | $ | 357,116 | $ | 85,179 | $ | 12,309 | $ | 454,604 | ||||||||||||
| Future production costs | (32,349 | ) | (18,324 | ) | (17,982 | ) | (14,646 | ) | (14,141 | ) | (1,428 | ) | (98,870 | ) | (22,302 | ) | (2,487 | ) | (123,659 | ) | ||||||||||||
| Future development costs | (15,987 | ) | (4,219 | ) | (3,643 | ) | (5,070 | ) | (5,458 | ) | (341 | ) | (34,718 | ) | (14,340 | ) | (705 | ) | (49,763 | ) | ||||||||||||
| Future income taxes | (15,780 | ) | (6,491 | ) | (17,562 | ) | (11,147 | ) | (22,874 | ) | (1,078 | ) | (74,932 | ) | (14,561 | ) | (3,855 | ) | (93,348 | ) | ||||||||||||
| Undiscounted future net cash flows | 57,896 | 16,667 | 6,519 | 12,523 | 53,372 | 1,619 | 148,596 | 33,976 | 5,262 | 187,834 | ||||||||||||||||||||||
| 10 percent midyear annual discount for timing of estimated cash flows | (26,422 | ) | (9,312 | ) | (1,629 | ) | (3,652 | ) | (26,536 | ) | (650 | ) | (68,201 | ) | (16,990 | ) | (2,096 | ) | (87,287 | ) | ||||||||||||
| Standardized Measure Net Cash Flows | $ | 31,474 | $ | 7,355 | $ | 4,890 | $ | 8,871 | $ | 26,836 | $ | 969 | $ | 80,395 | $ | 16,986 | $ | 3,166 | $ | 100,547 | ||||||||||||
| At December 31, 2018 | ||||||||||||||||||||||||||||||||
| Future cash inflows from production | $ | 132,512 | $ | 52,470 | $ | 56,856 | $ | 54,012 | $ | 109,116 | $ | 11,959 | $ | 416,925 | $ | 100,518 | $ | 16,928 | $ | 534,371 | ||||||||||||
| Future production costs | (34,679 | ) | (20,691 | ) | (18,850 | ) | (17,359 | ) | (16,296 | ) | (6,609 | ) | (114,484 | ) | (24,580 | ) | (4,665 | ) | (143,729 | ) | ||||||||||||
| Future development costs | (17,322 | ) | (5,106 | ) | (4,112 | ) | (5,494 | ) | (7,757 | ) | (1,393 | ) | (41,184 | ) | (14,069 | ) | (1,692 | ) | (56,945 | ) | ||||||||||||
| Future income taxes | (17,369 | ) | (7,553 | ) | (23,593 | ) | (14,514 | ) | (25,519 | ) | (1,676 | ) | (90,224 | ) | (18,561 | ) | (4,496 | ) | (113,281 | ) | ||||||||||||
| Undiscounted future net cash flows | 63,142 | 19,120 | 10,301 | 16,645 | 59,544 | 2,281 | 171,033 | 43,308 | 6,075 | 220,416 | ||||||||||||||||||||||
| 10 percent midyear annual discount for timing of estimated cash flows | (29,103 | ) | (11,136 | ) | (2,646 | ) | (4,822 | ) | (28,276 | ) | (419 | ) | (76,402 | ) | (22,025 | ) | (2,662 | ) | (101,089 | ) | ||||||||||||
| Standardized Measure Net Cash Flows | $ | 34,039 | $ | 7,984 | $ | 7,655 | $ | 11,823 | $ | 31,268 | $ | 1,862 | $ | 94,631 | $ | 21,283 | $ | 3,413 | $ | 119,327 | ||||||||||||
| At December 31, 2017 | ||||||||||||||||||||||||||||||||
| Future cash inflows from production | $ | 94,086 | $ | 43,175 | $ | 47,828 | $ | 47,809 | $ | 77,557 | $ | 8,800 | $ | 319,255 | $ | 80,090 | $ | 13,632 | $ | 412,977 | ||||||||||||
| Future production costs | (29,049 | ) | (20,044 | ) | (18,124 | ) | (18,640 | ) | (12,315 | ) | (6,345 | ) | (104,517 | ) | (22,050 | ) | (4,635 | ) | (131,202 | ) | ||||||||||||
| Future development costs | (10,849 | ) | (5,102 | ) | (3,808 | ) | (4,755 | ) | (6,682 | ) | (1,114 | ) | (32,310 | ) | (17,564 | ) | (1,760 | ) | (51,634 | ) | ||||||||||||
| Future income taxes | (10,803 | ) | (5,158 | ) | (17,845 | ) | (10,901 | ) | (17,568 | ) | (615 | ) | (62,890 | ) | (12,143 | ) | (3,250 | ) | (78,283 | ) | ||||||||||||
| Undiscounted future net cash flows | 43,385 | 12,871 | 8,051 | 13,513 | 40,992 | 726 | 119,538 | 28,333 | 3,987 | 151,858 | ||||||||||||||||||||||
| 10 percent midyear annual discount for timing of estimated cash flows | (19,781 | ) | (8,483 | ) | (2,058 | ) | (3,846 | ) | (19,730 | ) | 207 | (53,691 | ) | (16,310 | ) | (1,844 | ) | (71,845 | ) | |||||||||||||
| Standardized Measure Net Cash Flows | $ | 23,604 | $ | 4,388 | $ | 5,993 | $ | 9,667 | $ | 21,262 | $ | 933 | $ | 65,847 | $ | 12,023 | $ | 2,143 | $ | 80,013 |
Supplemental Information on Oil and Gas Producing Activities - Unaudited
Table VII - Changes in the Standardized Measure of Discounted Future Net Cash Flows From Proved Reserves
The changes in present values between years, which can be significant, reflect changes in estimated proved-reserve quantities and prices and assumptions used in forecasting production volumes and costs. Changes in the timing of production are included with “Revisions of previous quantity estimates.”
| Total Consolidated and | ||||||||||||||
| Millions of dollars | Consolidated Companies | Affiliated Companies | Affiliated Companies | |||||||||||
| Present Value at January 1, 2017 | $ | 42,355 | $ | 9,714 | $ | 52,069 | ||||||||
| Sales and transfers of oil and gas produced net of production costs | (21,505 | ) | (5,234 | ) | (26,739 | ) | ||||||||
| Development costs incurred | 9,417 | 3,721 | 13,138 | |||||||||||
| Purchases of reserves | 105 | — | 105 | |||||||||||
| Sales of reserves | (1,148 | ) | — | (1,148 | ) | |||||||||
| Extensions, discoveries and improved recovery less related costs | 3,716 | — | 3,716 | |||||||||||
| Revisions of previous quantity estimates | 11,132 | (1,085 | ) | 10,047 | ||||||||||
| Net changes in prices, development and production costs | 28,754 | 8,013 | 36,767 | |||||||||||
| Accretion of discount | 6,116 | 1,398 | 7,514 | |||||||||||
| Net change in income tax | (13,095 | ) | (2,361 | ) | (15,456 | ) | ||||||||
| Net Change for 2017 | 23,492 | 4,452 | 27,944 | |||||||||||
| Present Value at December 31, 2017 | $ | 65,847 | $ | 14,166 | $ | 80,013 | ||||||||
| Sales and transfers of oil and gas produced net of production costs | (33,535 | ) | (6,813 | ) | (40,348 | ) | ||||||||
| Development costs incurred | 9,723 | 5,044 | 14,767 | |||||||||||
| Purchases of reserves | 99 | — | 99 | |||||||||||
| Sales of reserves | (622 | ) | — | (622 | ) | |||||||||
| Extensions, discoveries and improved recovery less related costs | 5,503 | 14 | 5,517 | |||||||||||
| Revisions of previous quantity estimates | 15,480 | (2,255 | ) | 13,225 | ||||||||||
| Net changes in prices, development and production costs | 39,241 | 17,251 | 56,492 | |||||||||||
| Accretion of discount | 9,413 | 2,084 | 11,497 | |||||||||||
| Net change in income tax | (16,518 | ) | (4,795 | ) | (21,313 | ) | ||||||||
| Net Change for 2018 | 28,784 | 10,530 | 39,314 | |||||||||||
| Present Value at December 31, 2018 | $ | 94,631 | $ | 24,696 | $ | 119,327 | ||||||||
| Sales and transfers of oil and gas produced net of production costs | (29,436 | ) | (5,823 | ) | (35,259 | ) | ||||||||
| Development costs incurred | 10,497 | 5,120 | 15,617 | |||||||||||
| Purchases of reserves | 406 | — | 406 | |||||||||||
| Sales of reserves | (579 | ) | — | (579 | ) | |||||||||
| Extensions, discoveries and improved recovery less related costs | 5,697 | 43 | 5,740 | |||||||||||
| Revisions of previous quantity estimates | 621 | 2,122 | 2,743 | |||||||||||
| Net changes in prices, development and production costs | (25,056 | ) | (11,637 | ) | (36,693 | ) | ||||||||
| Accretion of discount | 13,538 | 3,584 | 17,122 | |||||||||||
| Net change in income tax | 10,077 | 2,046 | 12,123 | |||||||||||
| Net Change for 2019 | (14,235 | ) | (4,545 | ) | (18,780 | ) | ||||||||
| Present Value at December 31, 2019 | $ | 80,396 | $ | 20,151 | $ | 100,547 |
PART IV
Previous: Item 13. Certain Relationships and Related Transactions, and Director Independence · Next: Item 15. Exhibits and Financial Statement Schedules