 filings.tools
Delta Air Lines 10-K 2022-12-31
Filed 2023-02-10. 23 sections, 490K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
| ☑ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2022
| or | |||||
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
Commission File Number 001-5424

DELTA AIR LINES, INC.
(Exact name of registrant as specified in its charter)
| Delaware | 58-0218548 | ||||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | ||||
| Post Office Box 20706 | |||||
| Atlanta, Georgia | 30320-6001 | ||||
| (Address of principal executive offices) | (Zip Code) |
Registrant's telephone number, including area code: (404) 715-2600
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||||||||
| Common Stock, par value $0.0001 per share | DAL | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes þ No o
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Exchange Act. Yes o No þ
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports) and (2) has been subject to such filing requirements for the past 90 days. Yes þ No o
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes þ No o
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company or an emerging growth company. See the definitions of "large accelerated filer," "accelerated filer," "smaller reporting company" and "emerging growth company" in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☑ | Accelerated filer | ☐ | Non-accelerated filer | ☐ | ||||||||||||
| Smaller reporting company | ☐ | Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. o
Indicate by check mark whether the registrant has filed a report on and attestation to its management's assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☑
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements o
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant's executive officers during the relevant recovery period pursuant to §240.10D-1(b). o
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No þ
The aggregate market value of the voting and non-voting common equity held by non-affiliates of the registrant as of June 30, 2022 was approximately $18.6 billion.
On January 31, 2023, there were outstanding 641,238,655 shares of the registrant's common stock.
This document is also available on our website at http://ir.delta.com/.
Documents Incorporated By Reference
Part III of this Form 10-K incorporates by reference certain information from the registrant's definitive Proxy Statement for its 2022 Annual Meeting of Stockholders to be filed with the Securities and Exchange Commission.
Showing the first 8K of 64K characters. Open the full section
Item 1. Business
GHG Emissions. Aviation industry GHG emissions, particularly carbon emissions, and their impact on climate change have become a focus in the international community and within the U.S. In 2016, the International Civil Aviation Organization ("ICAO") formally adopted a global, market-based emissions offset program known as the Carbon Offsetting and Reduction Scheme for International Aviation ("CORSIA"). This program establishes a goal for the aviation industry to achieve carbon-neutral growth in international aviation beginning in 2021. Any growth above the baseline would need to be addressed using either eligible carbon offsets or a lower carbon fuel. The baseline for establishing airlines’ obligations under CORSIA was originally set as an average of 2019 and 2020 emissions. However, given the COVID-19 pandemic and resulting unprecedented reduction in international travel, in June 2020 ICAO removed 2020 from the baseline calculation for the first phase of CORSIA, from 2021 to 2023. In 2022, ICAO established a new, more stringent CORSIA baseline of 85% of 2019, which will apply starting in 2024 through 2035.
A pilot phase of the CORSIA program runs from 2021 through 2023, followed by a first phase of the program beginning in 2024 and a second phase beginning in 2027. Countries can voluntarily participate in the pilot and first phase, and the United States agreed to participate in these voluntary phases. Participation in the second phase is mandatory for certain countries, including the United States. The U.S. government has not yet enacted legislation to mandate that U.S. operators participate in CORSIA. Nonetheless, Delta has voluntarily submitted verified emissions reports on its annual international emissions.
Additionally, the EU requires its member states to implement regulations to include aviation in its Emissions Trading Scheme ("ETS"). Under these regulations, any airline with flights originating or landing in the European Economic Area ("EEA") is subject to the ETS and, beginning in 2012, was required to purchase emissions allowances if the airline exceeds the number of free allowances allocated to it under the ETS. The scope of the ETS has been narrowed so that it currently applies only to flights within the EEA through 2023 to align with the pilot phase of CORSIA. In late 2022, the EU agreed on legislative language that would extend the narrow scope of EU ETS through 2026. Extension beyond 2026 would be conditioned on the performance of CORSIA. The EU is expected to finalize this legislation in early 2023. As a result of the United Kingdom's ("UK") withdrawal from the EU, UK flights are no longer part of the EU ETS and are instead regulated under a separate UK ETS scheme. UK ETS is applicable to UK domestic flights and flights from the UK to EEA countries.
In 2017, ICAO also adopted aircraft certification standards to reduce carbon dioxide ("CO2") emissions from new aircraft. The new aircraft certification standards applied to new fleet types in 2020 and will apply to in-production aircraft starting in 2023 but no later than 2028. These standards will not apply to existing in-service aircraft.
In 2016, the EPA issued a final finding under the Clean Air Act that GHGs threaten the public health and welfare, and further determined that certain classes of aircraft engines cause or contribute to GHGs. The endangerment finding did not establish standards but triggered an obligation for the EPA to regulate GHG emissions from certain aircraft engines. In January 2021, the EPA finalized GHG emission standards for new aircraft engines designed to implement the ICAO standards on the same timeframe contemplated by ICAO. Like the ICAO standards, the final EPA standards would not apply to engines on in-service aircraft. The final standards have been challenged by several states and environmental groups. On November 15, 2021, the EPA announced that it would defend the current standards while simultaneously calling for ambitious new international CO2 standards at the ICAO negotiations. The outcome of the legal challenge cannot be predicted at this time.
The airline industry may face additional regulation of aircraft emissions in the U.S. and abroad and become subject to further taxes, charges or additional requirements to obtain permits or purchase allowances or emission credits for GHG emissions in various jurisdictions. For example, in 2023, the EU is expected to finalize a sustainable aviation fuel blending mandate for aviation fuel suppliers beginning in 2025. Individual EU member states have been developing their own requirements, including for example, separate SAF mandates in France and Sweden in 2022. In the United States, various exploratory discussions continue around approaches to address climate change, such as carbon pricing, without a clear legislative path forward. Additional regulation could result in taxation, regulatory or permitting requirements from multiple jurisdictions for the same operations and significant costs for us and the airline industry. In addition to direct costs, such regulation could result in increased fuel costs passed through from fuel suppliers affected by any such regulations. Certain airports have also adopted, and others could in the future adopt, GHG emission or climate-related goals and requirements that could impact our operations or require us to make changes or investments in our infrastructure. We are monitoring and evaluating the potential impact of such developments.
Delta Air Lines, Inc. | 2022 10-K 13
Item 1. Business
Noise. The Airport Noise and Capacity Act of 1990 recognizes the rights of operators of airports with noise problems to implement local noise abatement programs so long as such programs do not interfere unreasonably with interstate or foreign commerce or the national air transportation system. This statute generally provides that local noise restrictions on Stage 3 aircraft first effective after October 1, 1990, require FAA approval. While we have had sufficient scheduling flexibility to accommodate local noise restrictions in the past, our operations could be adversely impacted if locally imposed regulations become more restrictive or widespread. In addition, foreign governments may allow airports to enact similar restrictions, which could adversely impact our international operations or require significant expenditures in order for our aircraft to comply with the restrictions. For example, in 2022, to reduce noise, the Netherlands announced plans to reduce the maximum number of flights authorized annually at Amsterdam’s Schiphol Airport. Before implementing the new limitations, the Dutch government must assess alternatives, including noise impact and cost effectiveness. The outcome cannot be determined at this time.
Refinery Matters. Monroe's operation of the Trainer refinery is subject to numerous environmental laws and extensive regulations, including those relating to the discharge of materials into the environment, waste management, pollution prevention measures and greenhouse gas and other air emissions.
Under the Energy Policy Act of 2005, as expanded by the Energy Independence and Security Act of 2007, the Renewable Fuel Standard ("RFS") was created, setting up specific targets of renewable fuel to be used in the U.S. economy by mandating the blending of renewable fuels into gasoline and on-road diesel ("Transportation Fuels"). Renewable Identification Numbers ("RINs") are assigned to renewable fuels produced by or imported into the U.S. that are blended into Transportation Fuels to demonstrate compliance with this obligation. A refinery may meet its obligation under RFS by blending the necessary volumes of renewable fuels with Transportation Fuels, by purchasing RINs in the open market or through a combination of blending and purchasing RINs. Because Monroe is able to blend only a small amount of renewable fuels, it must purchase the majority of its RINs requir
Showing the first 8K of 61K characters. Open the full section
Item 1A. Risk Factors
The airline industry is subject to many forms of environmental regulation, including but not limited to increased regulation to reduce emissions and other risks associated with climate change. The cost of compliance with more stringent environmental regulations, failure to comply with existing or future regulations or failure to otherwise manage the risks of climate change effectively could have a material adverse effect on our business.
Many aspects of our operations are subject to evolving and increasingly stringent federal, state, local and international laws governing the protection of the environment. Compliance with existing and future environmental laws and regulations could require capital investment and increase operational costs, and violations can lead to significant fines and penalties and reputational harm.
For example, in 2022 the EPA proposed regulations to define certain per- and polyfluoroalkyl substances ("PFAS") as "hazardous substances" under CERCLA. Numerous states have adopted regulations governing these substances as well. PFAS are used in a wide variety of consumer and industrial products, including the firefighting foams used to extinguish fuel-based fires at airports and refineries. EPA's proposed rule, once finalized, could subject airports, airlines, and refineries, among others, to potential liability for cleanup of historical PFAS contamination associated with use of PFAS-containing firefighting foam. The ultimate impact and associated cost to Delta of this rulemaking cannot be predicted at this time.
Future regulatory action concerning climate change, aircraft emissions and noise emissions could have a significant effect on the airline industry. In order to address aircraft carbon dioxide emissions, the International Civil Aviation Organization, a United Nations specialized agency, formally adopted a global, market-based emission offset program known as CORSIA. This program establishes a goal for the aviation industry to achieve carbon-neutral growth in international aviation beginning in 2021 through the use of carbon offsets and/or lower carbon aviation fuel. The baseline for establishing airlines’ obligations under CORSIA was originally set as an average of 2019 and 2020 emissions. However, given the COVID-19 pandemic and resulting unprecedented reduction in international travel, in June 2020 ICAO removed 2020 from the baseline calculation for the first phase of CORSIA, from 2021 to 2023. In 2022, ICAO established a new, more stringent CORSIA baseline of 85% of 2019, which will apply starting in 2024 through 2035. Certain CORSIA program details remain to be developed and could potentially be affected by political developments in participating countries or the results of the pilot phase of the program, and thus the impact of CORSIA cannot be predicted at this time. However, CORSIA is expected to increase operating costs for airlines that operate internationally.
In addition to CORSIA, we may face a patchwork of regulation of aircraft emissions in the U.S. and abroad and could become subject to further taxes, charges or additional requirements to obtain permits or purchase allowances or emission credits for greenhouse gas emissions in various jurisdictions. For example, in 2021 the European Commission proposed legislation that would expand the reach of the EU ETS to include flights into and out of the European Economic Area beginning in 2027 under certain circumstances, increase the stringency of the program, and establish a sustainable aviation fuel blending mandate for aviation fuel suppliers, among other requirements. In 2022, the EU reached a deal on proposed legislation that would exclude extra-EU flights from the scope of EU ETS until 2027, however that deal has not yet been approved. The EU is expected to finalize a SAF mandate on fuel suppliers in 2023 and individual EU member states have been developing their own requirements, including for example, separate SAF mandates in France and Sweden in 2022. In the United States various exploratory discussions continue around approaches to address climate change, such as carbon pricing, without a clear legislative path forward. Additional regulation could result in taxation, regulatory or permitting requirements from multiple jurisdictions for the same operations and significant costs for the airline industry, including Delta. In addition to direct costs, such regulation could result in increased fuel costs passed through from fuel suppliers affected by any such regulations. While the specific nature of future actions is hard to predict, new laws or regulations related to environmental matters adopted in the U.S. or other countries could impose significant additional costs on or otherwise adversely affect our operations. Certain airports have also adopted, and others could in the future adopt, greenhouse gas emission or climate-related goals and requirements that could impact our operations or require us to make changes or investments in our infrastructure.
In addition to risks from potential changes to environmental regulation and policy, the transition to lower-carbon technologies, such as SAF, or changes in consumer preferences resulting from a negative perception of the environmental impact of air travel could materially adversely affect our business and financial results. For example, lower-carbon technologies such as SAF and direct air capture technologies are currently not available at scale and may take decades to develop, and the cost to transition to them could be prohibitively expensive without appropriate government policies and incentives in place. As more businesses have publicly announced environmental sustainability goals, the cost of carbon offsets has also increased significantly and will likely continue to do so.
Delta Air Lines, Inc. | 2022 10-K 26
Item 1A. Risk Factors
Because of the global nature of our business, unfavorable economic or political conditions in the markets in which we operate or volatility in currency exchange rates could have a material adverse effect on our business, financial condition and results of operations.
As a result of the discretionary nature of air travel, the airline industry has been cyclical and particularly sensitive to changes in economic conditions. Because we operate globally, our business is subject to economic and political conditions throughout the world. During periods of unfavorable or volatile economic conditions in the economy in the U.S. or abroad, including as a result of the COVID-19 pandemic and the worldwide response to it, demand for air travel can be significantly impacted as business and leisure travelers choose not to travel, seek alternative forms of transportation for short trips or conduct business using technological alternatives. If unfavorable economic conditions occur, particularly for an extended period, our business, financial condition and results of operations may be adversely affected. In addition, significant or volatile changes in exchange rates between the U.S. dollar and other currencies, and the imposition of exchange controls or other currency restrictions, may have a material adverse effect on our liquidity, financial conditions and results of operations.
Our international operations are an important part of our route network. Political disruptions and instability around the world can negatively impact the demand and network availability for air travel. Additionally, any deterioration in global trade relations, such as increased tariffs or other trade barriers, could result in a decrease in the demand for international air travel.
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Delta Air Lines, Inc. | 2022 10-K 27
Item 2. Properties
Item 2. PROPERTIES
Flight Equipment
Our operating aircraft fleet, purchase commitments and options at December 31, 2022 are summarized in the following table.
| Mainline aircraft information by fleet type | |||||||||||||||||||||||||||||
| Current Fleet**(1)** | Commitments | ||||||||||||||||||||||||||||
| Fleet Type | Owned | Finance Lease | Operating Lease | Total | Average Age (Years) | Purchase | Options | ||||||||||||||||||||||
| A220-100 | 41 | 4 | — | 45 | 3.0 | — | — | ||||||||||||||||||||||
| A220-300 | 14 | — | — | 14 | 1.5 | 60 | 26 | ||||||||||||||||||||||
| A319-100 | 57 | — | — | 57 | 20.9 | — | — | ||||||||||||||||||||||
| A320-200 | 61 | — | — | 61 | 27.3 | — | — | ||||||||||||||||||||||
| A321-200 | 69 | 22 | 36 | 127 | 4.0 | — | — | ||||||||||||||||||||||
| A321-200neo | 21 | — | — | 21 | 0.3 | 134 | 70 | ||||||||||||||||||||||
| A330-200 | 11 | — | — | 11 | 17.8 | — | — | ||||||||||||||||||||||
| A330-300 | 28 | — | 3 | 31 | 14.0 | — | — | ||||||||||||||||||||||
| A330-900neo | 12 | 3 | 5 | 20 | 1.6 | 18 | — | ||||||||||||||||||||||
| A350-900 | 17 | — | 11 | 28 | 4.1 | 16 | — | ||||||||||||||||||||||
| B-717-200 | 10 | 51 | 4 | 65 | 21.5 | — | — | ||||||||||||||||||||||
| B-737-800 | 73 | 4 | — | 77 | 21.3 | — | — | ||||||||||||||||||||||
| B-737-900ER | 112 | 2 | 49 | 163 | 7.0 | — | — | ||||||||||||||||||||||
| B-737-10 | — | — | — | — | — | 100 | 30 | ||||||||||||||||||||||
| B-757-200 | 100 | — | — | 100 | 25.4 | — | — | ||||||||||||||||||||||
| B-757-300 | 16 | — | — | 16 | 19.9 | — | — | ||||||||||||||||||||||
| B-767-300ER | 45 | — | — | 45 | 26.8 | — | — | ||||||||||||||||||||||
| B-767-400ER | 21 | — | — | 21 | 22.0 | — | — | ||||||||||||||||||||||
| Total | 708 | 86 | 108 | 902 | 14.4 | 328 | 126 |
(1)Includes both active and temporarily parked aircraft. Excludes certain aircraft we own or lease that are operated by regional carriers on our behalf shown in the table below.
The following table summarizes the aircraft operated by regional carriers on our behalf at December 31, 2022.
| Regional aircraft information by fleet type and carrier | ||||||||||||||||||||
| Fleet Type**(1)** | ||||||||||||||||||||
| Carrier | CRJ-200 | CRJ-700 | CRJ-900 | Embraer 170 | Embraer 175 | Total | ||||||||||||||
| Endeavor Air, Inc. (2) | 26 | 18 | 123 | — | — | 167 | ||||||||||||||
| SkyWest Airlines, Inc. | — | 6 | 38 | — | 84 | 128 | ||||||||||||||
| Republic Airways, Inc. | — | — | — | 11 | 46 | 57 | ||||||||||||||
| Total | 26 | 24 | 161 | 11 | 130 | 352 |
(1)Includes both active and temporarily parked aircraft. We own 231 and have operating leases for three of these regional aircraft. The remainder are owned or leased by SkyWest Airlines, Inc. or Republic Airways, Inc.
(2)Endeavor Air, Inc. is a wholly owned subsidiary of Delta.
Delta Air Lines, Inc. | 2022 10-K 28
Item 2. Properties
Aircraft Purchase Commitments
As part of a multi-year effort, we have been investing in new aircraft to provide an improved customer experience, greater fuel efficiency that results in reduced carbon emissions, better operating economics and more premium products. Our contractual purchase commitments for additional aircraft as of December 31, 2022 are detailed in the following table:
| Aircraft purchase commitments by fleet type | |||||||||||||||||
| Delivery in Calendar Years Ending | |||||||||||||||||
| Aircraft Purchase Commitments**(1)** | 2023 | 2024 | 2025 | After 2025 | Total | ||||||||||||
| A220-300 | 9 | 15 | 12 | 24 | 60 | ||||||||||||
| A321-200neo | 28 | 36 | 25 | 45 | 134 | ||||||||||||
| A330-900neo | 6 | 9 | 3 | — | 18 | ||||||||||||
| A350-900 | — | 7 | 6 | 3 | 16 | ||||||||||||
| B-737-10 | — | — | 20 | 80 | 100 | ||||||||||||
| Total | 43 | 67 | 66 | 152 | 328 |
(1)The timing of these commitments is based on our contractual agreements with the aircraft manufacturers and may be subject to change based on modifications to those agreements or changes in delivery schedules.
Ground Facilities
Airline Operations
We lease most of the land and buildings that we occupy. Our largest aircraft maintenance base, various equipment maintenance, cargo, flight kitchen and training facilities and most of our principal offices are located at or near the Atlanta airport on land leased from the City of Atlanta. We lease ticket counters, gate areas, operating facilities and other terminal space in most of the airports that we serve. At most airports, we have entered into use agreements which provide for the non-exclusive use of runways, taxiways and other improvements and facilities; landing fees under these agreements normally are based on the number of landings and weight of aircraft. These leases and use agreements generally run for periods of less than one year to 30 years or more, and often contain provisions for periodic adjustments of lease rates, landing fees and other charges applicable under that type of agreement. We also lease aircraft maintenance, equipment maintenance and air cargo facilities at several airports. Our facility leases generally require us to pay the cost of providing, operating and maintaining such facilities, including, in some cases, amounts necessary to pay debt service on special facility bonds issued to finance their construction. We also lease computer facilities, marketing offices, reservations offices and other off-airport facilities in certain locations for varying terms.
We own our Atlanta reservations center, other real property in Atlanta and reservations centers in Minot, North Dakota and Chisholm, Minnesota.
Refinery Operations
Our Monroe subsidiaries own and operate the Trainer refinery and related assets in Pennsylvania. The facilities include pipelines and terminal assets that allow the refinery to supply jet fuel to our airline operations throughout the Northeastern U.S., including our New York hubs at LaGuardia and JFK.
Delta Air Lines, Inc. | 2022 10-K 29
Item 3. Legal Proceedings
Item 3. LEGAL PROCEEDINGS
Capacity Antitrust Litigation
In July 2015, a number of purported class action antitrust lawsuits were filed alleging that Delta, American, United and Southwest had conspired to restrain capacity. The lawsuits were filed in the wake of media reports that the U.S. Department of Justice had served civil investigative demands upon these carriers seeking documents and information relating to this subject. The lawsuits have been consolidated into a single Multi-District Litigation proceeding in the U.S. District Court for the District of Columbia. Our summary judgment motion has been fully briefed and pending since May 2021. We believe the claims in these cases are without merit and have vigorously defended these lawsuits.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
Delta Air Lines, Inc. | 2022 10-K 30
Item 5. Market Information
Part II
ITEM 5. MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Market Information
Our common stock is listed on the New York Stock Exchange ("NYSE") under the trading symbol DAL.
Holders
As of January 31, 2023, there were approximately 2,200 holders of record of our common stock.
Dividends
While we have paid cash dividends to holders of our common stock on a quarterly basis, we suspended dividends in March 2020 due to the impact of the COVID-19 pandemic. The Coronavirus Aid, Relief, and Economic Security Act of 2020 (the "CARES Act") and payroll support program extensions restricted the payment of dividends through September 2022. Future dividend payments will be dependent upon our results of operations, financial condition, cash requirements, future prospects and other factors deemed relevant by the Board of Directors.
Stock Performance Graph
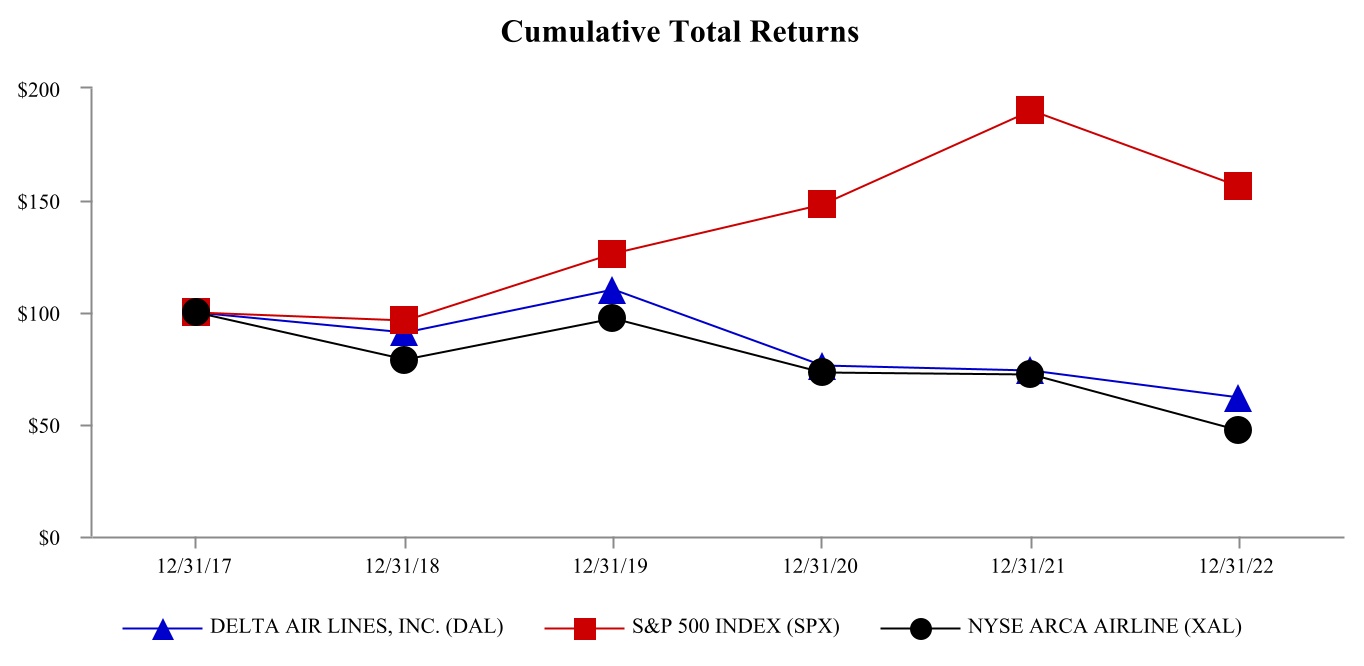
The following graph compares the cumulative total returns during the period from December 31, 2017 to December 31, 2022 of our common stock to the Standard & Poor's 500 Stock Index and the NYSE ARCA Airline Index. The comparison assumes $100 was invested on December 31, 2017 in each of our common stock and the indices and assumes that all dividends were reinvested.
Delta Air Lines, Inc. | 2022 10-K 31
Item 5. Market Information
Issuer Purchases of Equity Securities
The following table presents information with respect to purchases of common stock we made during the December 2022 quarter. The table reflects shares withheld from employees to satisfy certain tax obligations due in connection with grants of stock under the Delta Air Lines, Inc. Performance Compensation Plan (the "Plan"). The Plan provides for the withholding of shares to satisfy tax obligations but it does not specify a maximum number of shares that can be withheld for this purpose. The shares of common stock withheld to satisfy tax withholding obligations may be deemed to be "issuer purchases" of shares that are required to be disclosed pursuant to this Item.
| Shares purchased / withheld from employee awards during the December 2022 quarter | |||||||||||||||||
| Period | Total Number of Shares Purchased | Average Price Paid Per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Approximate Dollar Value (in millions) of Shares That May Yet Be Purchased Under the Plan or Programs | |||||||||||||
| October 2022 | 1,045 | $ | 28.62 | 1,045 | $ | — | |||||||||||
| November 2022 | 1,356 | $ | 34.54 | 1,356 | $ | — | |||||||||||
| December 2022 | 1,777 | $ | 34.74 | 1,777 | $ | — | |||||||||||
| Total | 4,178 | 4,178 |
Item 6. (RESERVED)
Delta Air Lines, Inc. | 2022 10-K 32
Item 7. MD&A
ITEM 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
During 2022, our recovery from the impact of the COVID-19 pandemic continued and is continuing into 2023. Given the drastic and unprecedented impact of the pandemic on our operating results in 2020 and 2021, we believe that a comparison of our results in 2022 to both 2021 and 2019 in this overview section allows for a better understanding of the full impact of the COVID-19 pandemic and the progress of our recovery.
This section of Form 10-K, however, does not address certain items regarding the year ended December 31, 2020. Discussion and analysis of 2020 and year-to-year comparisons between 2021 and 2020 not included in this Form 10-K can be found in "Item 7. Management's Discussion and Analysis" of our Annual Report on Form 10-K for the year ended December 31, 2021. The following discussion and analysis of our financial condition and results of operations should be read in conjunction with our audited Consolidated Financial Statements and the related notes and other financial information as well as the material risk factors included elsewhere in this Annual Report on Form 10-K.
The table below shows certain key financial measures for the years ended December 31, 2022, 2021 and 2019:
| Year Ended December 31, | 2022 vs 2021 % Increase (Decrease) | 2022 vs 2019 % Increase (Decrease) | |||||||||||||||||||||
| (in millions) | 2022 | 2021 | 2019 | ||||||||||||||||||||
| Total operating revenue | $ | 50,582 | $ | 29,899 | $ | 47,007 | 69 | % | 8 | % | |||||||||||||
| Total operating expense | 46,921 | 28,013 | 40,389 | 67 | % | 16 | % | ||||||||||||||||
| Operating income | 3,661 | 1,886 | 6,618 | 94 | % | (45) | % | ||||||||||||||||
| Available seat miles ("ASM" or "capacity") | 233,226 | 194,474 | 275,379 | 20 | % | (15) | % |
2022 Financial Overview
Our 2022 operating income was $3.7 billion, an improvement of $1.8 billion compared to 2021, while operating income, adjusted (a non-GAAP financial measure) which excludes restructuring charges and other items was $3.6 billion, an increase of $6.1 billion compared to 2021. The increases in operating income and operating income, adjusted were primarily due to the continued recovery in the demand for air travel during 2022, which resulted in a 69% increase in operating revenue on a 20% increase in system capacity. Operating income in 2021 included a benefit of $4.5 billion from the recognition of payroll support program ("PSP") grants, driving the smaller year-over-year increase than operating income, adjusted, which excluded the grants benefit in 2021.
Our 2022 operating income decreased $3.0 billion compared to 2019 primarily due to an increase in operating costs, including a 35% increase in fuel cost, and lower passenger revenue due to system capacity that was 15% lower as we continued to restore our operations from the effects of the COVID-19 pandemic. Operating income, adjusted (a non-GAAP financial measure) decreased $3.1 billion compared to 2019.
Revenue. Compared to 2021, our 2022 operating revenue increased $20.7 billion, or 69%, primarily due to continued recovery in travel demand from the COVID-19 pandemic and higher refinery sales to third parties. Improvement in premium products revenue resulted from both a shift in the mix of seats on our aircraft following the retirement of certain fleets in 2020 and delivery of new aircraft since that time, as well as incremental increase in demand, particularly from leisure customers.
Compared to 2019, our operating revenue increased $3.6 billion, or 8%, due primarily to higher refinery sales to third parties, partially offset by the revenue impact from 15% lower capacity. We are planning for our 2023 system capacity to fully recover to or exceed 2019 capacity levels.
Operating Expense. Total operating expense increased $18.9 billion, or 67%, compared to 2021, primarily resulting from higher fuel costs, due to both an increase in fuel price and increased consumption as capacity was restored, as well as higher salaries and related costs, higher volume-related expenses associated with the increase in capacity and demand and an increase in expenses related to refinery sales to third parties, reflected in ancillary business and refinery expense. The increase also resulted from $4.5 billion of PSP grants recognized during 2021, which reduced expenses in that year. Total operating expense, adjusted (a non-GAAP financial measure) which excludes expenses related to refinery sales to third parties, contra-expense from the recognition of PSP grants in 2021 and other items, increased $12.8 billion, or 44%, compared to 2021.
Delta Air Lines, Inc. | 2022 10-K 33
Item 7. MD&A - Financial Highlights
Our total operating cost per available seat mile ("CASM") increased 40% to 20.12 cents compared to 2021, primarily due to the higher costs discussed above. Non-fuel unit costs ("CASM-Ex", a non-GAAP financial measure), which excludes fuel, expenses related to refinery sales to third parties, contra-expense from the recognition of PSP grants in 2021 and other items, increased 6% to 12.87 cents.
Total operating expense increased $6.5 billion, or 16%, compared to 2019, primarily resulting from higher fuel costs and an increase in expenses related to refinery sales to third parties. Total operating expense, adjusted (a non-GAAP financial measure) increased $2.0 billion, or 5% compared to 2019.
Our CASM increased 37% compared to 2019, primarily due to the higher costs discussed above and a 15% decrease in capacity. CASM-Ex (a non-GAAP financial measure) increased 18% compared to 2019.
During 2023, we expect non-fuel unit costs to decrease compared to 2022 as we restore our network to pre-pandemic levels, better utilizing our assets. We expect to reduce our investments in rebuilding the network as we progress through the year while improving our operational efficiency and managing inflationary pressures including labor cost increases.
Non-Operating Results. Total non-operating expense was $1.7 billion in 2022, $259 million higher than 2021 primarily due to higher mark-to-market losses on certain of our equity investments, partially offset by reduced losses on our equity method investments, lower interest expense as a result of our debt reduction initiatives and lower losses on extinguishment of debt.
Total non-operating expense was $1.3 billion higher than 2019, primarily due to higher mark-to-market losses on certain of our equity investments and higher interest expense as a result of our increased debt balances due to the financing arrangements entered into during 2020.
Cash Flow. During 2022, operating activities provided cash flows of $6.4 billion, primarily on improving ticket sales, and incurred approximately $6.9 billion of net investing cash outflows, primarily for $6.4 billion of capital expenditures. After adjusting for strategic investments and certain other activities, these results generated $244 million of free cash flow (a non-GAAP financial measure) in 2022.
Also, during 2022 we had cash outflows of approximately $4.5 billion related to repayments of our debt and finance leases, including approximately $2.3 billion for early repayments and the remainder from scheduled maturities. Our cash, cash equivalents, short-term investments and aggregate principal amount committed and available to be drawn under our revolving credit facilities ("liquidity") at December 31, 2022 was $9.4 billion.
The non-GAAP financial measures operating income, adjusted, operating expense, adjusted, CASM-Ex and free cash flow used above are defined and reconciled in "Supplemental Information" below.
Delta Air Lines, Inc. | 2022 10-K 34
Item 7. MD&A - Results of Operations
Results of Operations
Operating Revenue
| Year Ended December 31, | Increase (Decrease) | % Increase (Decrease) | |||||||||||||||
| (in millions) (1) | 2022 | 2021 | |||||||||||||||
| Ticket - Main cabin | $ | 20,396 | $ | 11,393 | $ | 9,003 | 79 | % | |||||||||
| Ticket - Premium products | 15,230 | 7,946 | 7,284 | 92 | % | ||||||||||||
| Loyalty travel awards | 2,898 | 1,786 | 1,112 | 62 | % | ||||||||||||
| Travel-related services | 1,694 | 1,394 | 300 | 22 | % | ||||||||||||
| Total passenger revenue | $ | 40,218 | $ | 22,519 | $ | 17,699 | 79 | % | |||||||||
| Cargo | 1,050 | 1,032 | 18 | 2 | % | ||||||||||||
| Other | 9,314 | 6,348 | 2,966 | 47 | % | ||||||||||||
| Total operating revenue | $ | 50,582 | $ | 29,899 | $ | 20,683 | 69 | % | |||||||||
| TRASM (cents) | 21.69 | ¢ | 15.37 | ¢ | 6.32 | ¢ | 41 | % | |||||||||
| Third-party refinery sales (2) | (2.13) | (1.66) | (0.47) | 28 | % | ||||||||||||
| TRASM, adjusted (cents) | 19.55 | ¢ | 13.71 | ¢ | 5.84 | ¢ | 43 | % |
(1)Total amounts in the table above may not calculate exactly due to rounding.
(2)For additional information on adjustments to TRASM, see "Supplemental Information" below.
Operating Revenue
Our operating revenue increased $20.7 billion, or 69%, compared to the year ended December 31, 2021 due primarily to increased demand in 2022 as a result of the continued recovery from the COVID-19 pandemic and higher third-party refinery sales. The increase in operating revenue, on a 20% increase in system capacity, generated a 41% increase in total revenue per available seat mile ("TRASM") and a 43% increase in TRASM, adjusted (a non-GAAP financial measure) compared to 2021.
See "Refinery Segment" below for additional details on the refinery's operations, including third-party refinery sales recorded in other revenue, during each period.
Passenger Revenue by Geographic Region
| Increase (Decrease) vs. Year Ended December 31, 2021 | ||||||||||||||||||||||||||
| (in millions) | Year Ended December 31, 2022 | Passenger Revenue | RPMs (Traffic) | ASMs (Capacity) | Passenger Mile Yield | PRASM | Load Factor | |||||||||||||||||||
| Domestic | $ | 30,197 | 64 | % | 27 | % | 10 | % | 29 | % | 48 | % | 11 | pts | ||||||||||||
| Atlantic | 6,093 | 243 | % | 194 | % | 110 | % | 17 | % | 63 | % | 23 | pts | |||||||||||||
| Latin America | 2,889 | 54 | % | 24 | % | (5) | % | 25 | % | 62 | % | 19 | pts | |||||||||||||
| Pacific | 1,039 | 159 | % | 211 | % | 8 | % | (17) | % | 139 | % | 44 | pts | |||||||||||||
| Total passenger revenue | $ | 40,218 | 79 | % | 45 | % | 20 | % | 23 | % | 49 | % | 15 | pts |
Domestic
Domestic passenger unit revenue ("PRASM") for the year ended December 31, 2022 increased 48% compared to the year ended December 31, 2021 as a result of stronger demand and higher levels of traffic due to the ongoing recovery from the COVID-19 pandemic throughout 2022.
Domestic revenue in 2022 was above 2021 levels and near pre-pandemic levels, even though capacity was not fully restored, as consumers continue to return to travel. We believe spending patterns for services are returning to historical levels compared to spending on goods. We also experienced higher growth in premium product revenue (including Delta One, First Class, Delta Premium Select and Delta Comfort+) compared to main cabin with the delivery of new aircraft that include more premium seat capacity and an increase in premium product yield compared to main cabin, as we see more consumers choosing these premium offerings. In 2023, we expect domestic capacity to be restored to pre-pandemic levels through growth in our core hubs in Atlanta, Minneapolis-St. Paul, Detroit and Salt Lake City.
Delta Air Lines, Inc. | 2022 10-K 35
Item 7. MD&A - Results of Operations
International
International passenger revenue for the year ended December 31, 2022 increased 147% with capacity up 47% compared to the year ended December 31, 2021, with the Atlantic region experiencing the most significant improvement, as travel to many European destinations resumed or increased.
In November 2021, travel restrictions on most fully vaccinated foreign visitors to the United States were lifted. This action made travel to the U.S. by many foreign nationals possible for the first time in 18 months. Further, in June 2022, the United States lifted its testing requirement for international travel. Both of these changes have had a positive impact on international demand. Most countries in our network have removed or eased travel restrictions, resulting in revenue improvement across all international regions.
The Atlantic region showed strong demand improvement during 2022 as western European countries removed or eased travel restrictions in the first half of 2022. Revenue in this region was near pre-pandemic levels as travelers continue to show increased desire for transatlantic travel. This has been led by demand for leisure destinations such as Italy, Spain and Greece and improving business demand.
Latin America region revenue was also near pre-pandemic levels during 2022, due to continued strong demand for leisure destinations in Mexico, the Caribbean and Central America. Also, in 2022, final regulatory approval was granted for our trans-American joint venture agreement with LATAM. This agreement combines our highly complementary route networks between North and South America, with the goal of providing customers with a seamless travel experience and industry-leading connectivity. Beginning in the December 2022 quarter, we and LATAM began adding capacity on certain Latin America routes and introduced one new route between Los Angeles and São Paulo, Brazil.
The Pacific region continues to be the most impacted by travel restrictions, although we experienced demand improvement during 2022 following South Korea and Australia reopening to international travelers and the recent easing of travel restrictions to Japan. Throughout 2022, China still maintained international testing requirements and travel restrictions, which continued to restrain demand in the Pacific region.
We expect the increasing revenue trends in all international regions to continue into 2023 as demand for international locations continues to be strong and countries continue to reopen and remove or ease remaining travel restrictions. For example, in January 2023 China ended most of its pandemic-related travel restrictions and we expect to increase capacity based on demand during 2023.
Ticket Validity Flexibility
In order to provide our customers more flexibility and time to plan their travel, travel credit holders as of January 2022 and customers who purchased a ticket in 2022 are able to rebook their ticket through December 31, 2023 for travel throughout 2024.
Delta has eliminated change fees for tickets originating in the United States, Canada, Europe and Africa (excluding Basic Economy tickets). A change fee waiver continues to apply for travel originating in Asia and the Pacific. Starting in 2022, Basic Economy tickets may be cancelled for a charge to receive a partial ticket credit.
We estimate the value of ticket breakage and recognize revenue at the scheduled flight date. Our ticket breakage estimates are primarily based on historical experience, ticket contract terms and customers’ travel behavior. Given the impact of the COVID-19 pandemic on customer behavior and changes made in ticket validity terms, as well as the elimination of change fees for most tickets, our estimates of revenue that will be recognized from the air traffic liability for unused tickets may vary in future periods.
See Note 2 of the Notes to the Consolidated Financial Statements for additional information about passenger ticket sales.
Delta Air Lines, Inc. | 2022 10-K 36
Item 7. MD&A - Results of Operations
Other Revenue
| Year Ended December 31, | Increase (Decrease) | % Increase (Decrease) | |||||||||||||||
| (in millions) | 2022 | 2021 | |||||||||||||||
| Refinery | $ | 4,977 | $ | 3,229 | $ | 1,748 | 54 | % | |||||||||
| Loyalty program | 2,597 | 1,770 | 827 | 47 | % | ||||||||||||
| Ancillary businesses | 846 | 793 | 53 | 7 | % | ||||||||||||
| Miscellaneous | 894 | 556 | 338 | 61 | % | ||||||||||||
| Total other revenue | $ | 9,314 | $ | 6,348 | $ | 2,966 | 47 | % |
Refinery. This represents refinery sales to third parties. These sales increased $1.7 billion compared to 2021. The increase in third-party refinery sales resulted from higher pricing and production during 2022 compared to 2021. See "Refinery Segment" below for additional details on the refinery's operations, including third-party refinery sales recorded in other revenue, during each period.
Loyalty Program. This relates to brand usage by third parties and other performance obligations embedded in miles sold, including redemption of miles for non-travel awards. These revenues are mainly driven by customer spend on American Express cards and new cardholder acquisitions. On continued strength in co-brand card spend and card acquisitions, revenues from our relationship with American Express increased in 2022 compared to 2021.
Ancillary Businesses. This includes aircraft maintenance services we provide to third parties and our vacation wholesale operations.
Miscellaneous. This is primarily composed of lounge access, including access provided to certain American Express cardholders, and codeshare revenues. Compared to 2021, these transactions have increased due to the ongoing recovery of our business that continued to materialize in 2022. Our network of Delta Sky Club lounges was fully reopened by the end of July 2021 after some lounges temporarily closed at the onset of the pandemic in 2020.
Delta Air Lines, Inc. | 2022 10-K 37
Item 7. MD&A - Results of Operations
Operating Expense
| Year Ended December 31, | Increase (Decrease) | % Increase (Decrease) | |||||||||||||||
| (in millions) | 2022 | 2021 | |||||||||||||||
| Salaries and related costs | $ | 11,902 | $ | 9,728 | $ | 2,174 | 22 | % | |||||||||
| Aircraft fuel and related taxes | 11,482 | 5,633 | 5,849 | 104 | % | ||||||||||||
| Ancillary businesses and refinery | 5,756 | 3,957 | 1,799 | 45 | % | ||||||||||||
| Contracted services | 3,345 | 2,420 | 925 | 38 | % | ||||||||||||
| Landing fees and other rents | 2,181 | 2,019 | 162 | 8 | % | ||||||||||||
| Depreciation and amortization | 2,107 | 1,998 | 109 | 5 | % | ||||||||||||
| Regional carrier expense | 2,051 | 1,736 | 315 | 18 | % | ||||||||||||
| Aircraft maintenance materials and outside repairs | 1,982 | 1,401 | 581 | 41 | % | ||||||||||||
| Passenger commissions and other selling expenses | 1,891 | 953 | 938 | 98 | % | ||||||||||||
| Passenger service | 1,453 | 756 | 697 | 92 | % | ||||||||||||
| Profit sharing | 563 | 108 | 455 | 421 | % | ||||||||||||
| Aircraft rent | 508 | 430 | 78 | 18 | % | ||||||||||||
| Restructuring charges | (124) | (19) | (105) | 553 | % | ||||||||||||
| Government grant recognition | — | (4,512) | 4,512 | (100) | % | ||||||||||||
| Other | 1,824 | 1,405 | 419 | 30 | % | ||||||||||||
| Total operating expense | $ | 46,921 | $ | 28,013 | $ | 18,908 | 67 | % |
During 2021, travel demand began to recover from the low levels experienced during the height of the COVID-19 pandemic. This recovery in demand continued to accelerate during 2022. As a result, operating expenses increased in conjunction with the increases in demand and capacity discussed above. The continued restoration of our operations was the primary driver for the increases in most operating expense line items, particularly contracted services, aircraft maintenance materials and outside repairs, passenger commissions and other selling expenses and passenger service. Other year-over-year fluctuations are discussed below.
Salaries and Related Costs. We hired approximately 25,000 employees during 2022 principally in flight operations, in-flight service, reservations and customer care, TechOps and airport customer service, in order to support our operations as demand and capacity returned. These hiring actions and a 4% base pay increase effective May 1, 2022 for eligible employees resulted in the increase in salaries and related costs in 2022 compared to 2021. The increase also results from the ending of the voluntary unpaid leave of absence program we offered in response to the COVID-19 pandemic during 2021. During 2022, we no longer offered these leaves of absence as the program terminated in September 2021. In early 2023, we announced a 5% base pay increase for eligible employees effective April 1, 2023.
Delta and ALPA reached an Agreement in Principle on a new collective bargaining agreement in December 2022. In January 2023, a tentative agreement was ratified by ALPA’s Delta Master Executive Council ("MEC") and is subject to ratification by Delta’s pilots through a vote that is scheduled to close on March 1, 2023. In addition to various work rule changes and an 18% pay rate increase in 2023, the tentative agreement includes a provision for a one-time payment of approximately $700 million upon pilot ratification. As voting on the tentative agreement has not closed and there is significant uncertainty about the outcome of this process, we have not accrued for this one-time payment as of December 31, 2022.
Delta Air Lines, Inc. | 2022 10-K 38
Item 7. MD&A - Results of Operations
Aircraft Fuel and Related Taxes. Fuel expense increased $5.8 billion compared to 2021 primarily due to a 78% increase in the market price of jet fuel and a 23% increase in consumption as capacity was restored.
Additionally, during 2022, we purchased and retired $116 million of carbon offsets which relate to a portion of our airline segment's 2021 and March 2022 quarter carbon emissions. During 2021, we purchased and retired $95 million of carbon offsets, which related to a portion of our airline segment's 2020 and 2021 carbon emissions. In the table below, these costs are shown in the carbon offset costs line item. As we continue to work on accelerating our long-term, net-zero greenhouse gas emissions goal, our vision of the path forward will require multiple initiatives, centered on a long-term strategy of decarbonization; we therefore expect substantially all of our investment going forward will be focused on solutions other than carbon offsets.
| Fuel expense and average price per gallon | |||||||||||||||||||||||
| Average Price Per Gallon | |||||||||||||||||||||||
| Year Ended December 31, | Increase (Decrease) | Year Ended December 31, | Increase (Decrease) | ||||||||||||||||||||
| (in millions, except per gallon data) | 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||
| Fuel purchase cost (1) | $ | 12,114 | $ | 5,527 | $ | 6,587 | $ | 3.55 | $ | 1.99 | $ | 1.56 | |||||||||||
| Carbon offset costs | 116 | 95 | 21 | 0.03 | 0.03 | — | |||||||||||||||||
| Fuel hedge impact | 29 | 9 | 20 | 0.01 | — | 0.01 | |||||||||||||||||
| Refinery segment impact | (777) | 2 | (779) | (0.23) | — | (0.23) | |||||||||||||||||
| Total fuel expense | $ | 11,482 | $ | 5,633 | $ | 5,849 | $ | 3.36 | $ | 2.02 | $ | 1.34 | |||||||||||
(1)Market price for jet fuel at airport locations, including related taxes and transportation costs.
Ancillary Businesses and Refinery. Ancillary businesses and refinery includes expenses associated with refinery sales to third parties, aircraft maintenance services we provide to third parties and our vacation wholesale operations. Increased expenses were primarily related to refinery sales to third parties, which increased $1.7 billion compared to 2021. The increase compared to 2021 was driven by higher pricing and production during 2022. The cost of aircraft maintenance services we provide to third parties increased compared to 2021 due to the increase in flights and aircraft operated during 2022.
Regional Carrier Expense. Regional carrier expense increased compared to 2021 due to an increase in contract carrier rates and wages, while capacity was constrained due to a shortage of regional jet pilots.
Restructuring Charges. During 2020, we recorded restructuring charges of $8.2 billion for items such as fleet impairments and voluntary early retirement and separation programs following strategic business decisions in response to the COVID-19 pandemic. In the years ended December 31, 2022 and 2021, we recognized $124 million and $19 million, respectively, of adjustments to certain of those restructuring charges, representing changes in our estimates or the outcome of contract negotiations. See Note 15 of the Notes to the Consolidated Financial Statements for additional information about the restructuring charges recorded in 2020.
Profit Sharing. Profit sharing increased by $455 million during 2022 due to higher profit during the year. Our profit sharing program pays 10% to all eligible employees for the first $2.5 billion of annual profit, as defined by the terms of the program, and 20% of annual profit above $2.5 billion. For the year ended December 31, 2021, we recorded a special profit sharing expense of $108 million, based on the adjusted pre-tax profit earned during the second half of the year, to recognize the extraordinary efforts of our employees through the pandemic.
Government Grant Recognition. During the year ended December 31, 2021, we received a total of $6.4 billion under PSP agreements with the U.S. Department of the Treasury, which we were required to use exclusively for the payment of employee wages, salaries and benefits. The support payments included grants totaling $4.5 billion that were recognized as contra-expense in 2021 over the period that the funds were used.
Delta Air Lines, Inc. | 2022 10-K 39
Item 7. MD&A - Non-Operating Results
Non-Operating Results
| Year Ended December 31, | Favorable (Unfavorable) | |||||||||||||
| (in millions) | 2022 | 2021 | ||||||||||||
| Interest expense, net | $ | (1,029) | $ | (1,279) | $ | 250 | ||||||||
| Impairments and equity method results | (20) | (337) | 317 | |||||||||||
| Gain/(loss) on investments, net | (783) | 56 | (839) | |||||||||||
| Loss on extinguishment of debt | (100) | (319) | 219 | |||||||||||
| Pension and related benefit | 292 | 451 | (159) | |||||||||||
| Miscellaneous, net | (107) | (60) | (47) | |||||||||||
| Total non-operating expense, net | $ | (1,747) | $ | (1,488) | $ | (259) |
Interest expense, net. Interest expense, net includes interest expense and interest income. This decreased as compared to 2021 as a result of our debt reduction initiatives during 2021 and 2022. See Note 6 of the Notes to the Consolidated Financial Statements for additional information on our debt reduction initiatives. We are reducing the total amount of interest expense by pre-paying our debt in addition to periodic amortization payments and scheduled maturities. During 2021, we made payments of approximately $5.8 billion related to our debt and finance leases, which included approximately $3.8 billion for early repayments. We have continued to pay down our debt during 2022 with $4.5 billion of payments on debt and finance lease obligations, including early repayment activities of $1.5 billion of certain notes through a cash tender offer in the September 2022 quarter and $778 million in principal for the early repurchase of various secured and unsecured notes through repurchases on the open market. We will continue to seek opportunities to pre-pay our debt, in addition to periodic amortization payments and scheduled maturities, during 2023 and beyond.
Impairments and equity method results. Equity method results in 2022 consist of our share of Aeroméxico's net results and in 2021 reflected our share of Virgin Atlantic's net results. See Note 4 of the Notes to the Consolidated Financial Statements for additional information on our equity investments.
Gain/(loss) on investments, net. See Note 4 of the Notes to the Consolidated Financial Statements for additional information on our equity investments measured at fair value on a recurring basis.
Loss on extinguishment of debt. Loss on extinguishment of debt reflects the losses incurred in the early repayment of debt referenced above. See Note 6 of the Notes to the Consolidated Financial Statements for additional information on the early repayment of debt.
Pension and related benefit. Pension and related benefit reflects the net periodic benefit/(cost) of our pension and other postretirement and postemployment benefit plans. Based on our funded status as of December 31, 2021, we modified the strategic asset allocation mix in 2022 to reduce the investment risk of the portfolio. Based on the portfolio's risk profile, we lowered the weighted average expected long-term rate of return on our defined benefit pension plan assets for 2022 net periodic benefit cost to 7.00%. See Note 9 of the Notes to the Consolidated Financial Statements for additional information on our employee benefit plans.
Miscellaneous, net. Miscellaneous, net primarily includes charitable contributions and foreign exchange gains/(losses).
Delta Air Lines, Inc. | 2022 10-K 40
Item 7. MD&A - Income Taxes
Income Taxes
Our effective tax rate for 2022 was 31%. We expect our annual effective tax rate to be between 23% and 26% for 2023. Our effective tax rate in 2022 was impacted by mark-to-market adjustments on our equity investments which are considered capital assets for tax purposes. As of December 31, 2022, we had approximately $5.4 billion of U.S. federal pre-tax net operating loss carryforwards, of which $1.5 billion was generated prior to 2018 and will not begin to expire until 2029. Under current tax law, the remaining net operating loss carryforwards do not expire.
The Inflation Reduction Act ("IRA") was enacted into law on August 16, 2022. Included in the IRA was a provision to implement a 15% corporate alternative minimum tax on corporations whose average annual adjusted financial statement income during the most recently-completed three-year period exceeds $1.0 billion. This provision is effective for tax years beginning after December 31, 2022. We are in the process of evaluating the provisions of the IRA, but we do not currently believe the IRA will have a material impact on our reported results, cash flows or financial position.
For more information about our income taxes, see Note 11 of the Notes to the Consolidated Financial Statements.
Refinery Segment
The refinery operated by our wholly owned subsidiary Monroe primarily produces gasoline, diesel and jet fuel. Monroe has agreements in place to exchange the non-jet fuel products the refinery produces with third parties for jet fuel consumed in our airline operations. The jet fuel produced and procured through exchanging gasoline and diesel fuel produced by the refinery provided approximately 200,000 barrels per day, or approximately 75% of our pre-COVID-19 pandemic consumption, for use in our airline operations.
| Refinery segment financial information | |||||||||||
| Year Ended December 31, | |||||||||||
| (in millions, except per gallon data) | 2022 | 2021 | % Increase (Decrease) (1) | ||||||||
| Exchange products | $ | 3,475 | $ | 2,293 | 52 | % | |||||
| Sales of refined products | 278 | 40 | 595 | % | |||||||
| Sales to airline segment | 1,976 | 492 | 302 | % | |||||||
| Third-party refinery sales | 4,977 | 3,229 | 54 | % | |||||||
| Operating revenue | $ | 10,706 | $ | 6,054 | 77 | % | |||||
| Operating income (loss) | $ | 777 | $ | (2) | NM | ||||||
| Refinery segment impact on average price per fuel gallon | $ | (0.23) | $ | — | NM |
(1)Certain variances are labeled as not meaningful ("NM").
Refinery revenues increased from $6.1 billion in 2021 to $10.7 billion in 2022, primarily driven by the increase in third-party refinery sales and sales to the airline segment. The increase in third-party refinery sales resulted from higher pricing and production during 2022 compared to 2021. The refinery recorded an operating loss of $2 million in 2021 compared to operating income of $777 million in 2022 mainly due to the increased production and pricing, partially offset by higher Renewable Identification Numbers ("RINs") compliance costs discussed below.
A refinery is subject to annual Environmental Protection Agency ("EPA") requirements to blend renewable fuels into the gasoline and on-road diesel fuel it produces. Alternatively, a refinery may purchase RINs from third parties in the secondary market. The Monroe refinery purchases the majority of its RINs in the secondary market. Monroe incurred $576 million in RINs compliance costs during 2022, compared to $422 million incurred in 2021. Observable RINs prices increased through the first half of 2022 and remained at these higher rates through the second half of the year.
At December 31, 2022, we had a net fair value obligation related to RINs of $226 million. Our obligation as of December 31, 2022 was calculated using the U.S. EPA Renewable Fuel Standard ("RFS") volume requirements, which were finalized in the June 2022 quarter. During the December 2022 quarter, we retired our 2020 RINs assets to settle our 2020 obligations prior to the compliance deadline. We expect to settle our 2021 and 2022 obligations in the first half of 2023.
For more information regarding the refinery's results, see Note 14 of the Notes to the Consolidated Financial Statements.
Delta Air Lines, Inc. | 2022 10-K 41
Item 7. MD&A - Operating Statistics
Operating Statistics
| Year Ended December 31, | ||||||||||||||
| Consolidated (1) | 2022 | 2021 | 2019 | |||||||||||
| Revenue passenger miles (in millions) | 195,480 | 134,692 | 237,680 | |||||||||||
| Available seat miles (in millions) | 233,226 | 194,474 | 275,379 | |||||||||||
| Passenger mile yield | 20.57 | ¢ | 16.72 | ¢ | 17.79 | ¢ | ||||||||
| Passenger revenue per available seat mile ("PRASM") | 17.24 | ¢ | 11.58 | ¢ | 15.35 | ¢ | ||||||||
| Total revenue per available seat mile ("TRASM") | 21.69 | ¢ | 15.37 | ¢ | 17.07 | ¢ | ||||||||
| TRASM, adjusted (2) | 19.55 | ¢ | 13.71 | ¢ | 16.97 | ¢ | ||||||||
| Cost per available seat mile ("CASM") | 20.12 | ¢ | 14.40 | ¢ | 14.67 | ¢ | ||||||||
| CASM-Ex (2) | 12.87 | ¢ | 12.12 | ¢ | 10.88 | ¢ | ||||||||
| Passenger load factor | 84 | % | 69 | % | 86 | % | ||||||||
| Fuel gallons consumed (in millions) | 3,412 | 2,778 | 4,214 | |||||||||||
| Average price per fuel gallon (3) | $ | 3.36 | $ | 2.02 | $ | 2.02 | ||||||||
| Average price per fuel gallon, adjusted (2)(3) | $ | 3.36 | $ | 2.02 | $ | 2.01 | ||||||||
| Approximate full-time equivalent employees, end of period | 95,000 | 83,000 | 91,000 |
(1)Includes the operations of our regional carriers under capacity purchase agreements. Full-time equivalent employees exclude employees of regional carriers that we do not own.
(2)Non-GAAP financial measures are defined and reconciled to TRASM, CASM and average fuel price per gallon, respectively, in "Supplemental Information" below.
(3)Includes the impact of refinery segment results, carbon offset costs and fuel hedge activity.
Delta Air Lines, Inc. | 2022 10-K 42
Item 7. MD&A - Financial Condition and Liquidity
Financial Condition and Liquidity
As of December 31, 2022, we had $9.4 billion in cash, cash equivalents, short-term investments and aggregate principal amount committed and available to be drawn under our revolving credit facilities ("liquidity"). We expect to meet our liquidity needs for the next twelve months with cash and cash equivalents, short-term investments, restricted cash equivalents and cash flows from operations. We expect to meet our long-term liquidity needs with cash flows from operations and financing arrangements.
Sources and Uses of Liquidity
Operating Activities
Operating activities in 2022 provided $6.4 billion of cash flow compared to $3.3 billion in 2021. Operating activities in 2021 included $4.5 billion in funds received from payroll support program grants. We expect to continue generating positive cash flows from operations during 2023.
Our operating cash flow is impacted by the following factors:
Seasonality of Advance Ticket Sales. We sell tickets for air travel in advance of the customer's travel date. When we receive a cash payment at the time of sale, we record the cash received on advance sales as deferred revenue in air traffic liability. The air traffic liability typically increases during the winter and spring months as advanced ticket sales grow prior to the summer peak travel season and decreases during the summer and fall months.
Beginning with the COVID-19 pandemic in the March 2020 quarter through 2021, reduced demand for air travel resulted in a lower level of advance bookings and the associated cash received than we had historically experienced, which had been impacting the typical seasonal trend of air traffic liability. However, demand improved during 2022 as consumers regained confidence to travel and increased ticket purchases for travel further in advance. As a result, air traffic liability began returning to the usual seasonal trend in 2022.
Fuel. Fuel expense represented approximately 24% of our total operating expense during 2022. The market price for jet fuel is volatile, which can impact the comparability of our periodic cash flows from operations. The average fuel price per gallon increased substantially in 2022. While prices have recently moderated, we expect elevated jet fuel prices in comparison to historical levels to continue during the beginning of 2023 due to current market conditions, further exacerbated by geopolitical events. As capacity and demand increased throughout the year, fuel consumption was higher in 2022 than 2021 as well. We expect that fuel consumption will continue to increase throughout 2023 as we return to pre-pandemic levels of capacity, partially offset by increases in the fuel efficiency of our fleet.
We expect our commitment to environmental sustainability to depend on increased use of SAF, which is not presently available at scale or at prices competitive to jet fuel. While we do not expect a material adverse effect on our Consolidated Financial Statements in the near-term from the use of SAF, we are unable to predict the financial impact of increased use of SAF on our Consolidated Financial Statements over the longer term as government policies and incentives for, and sufficient third-party investment in, SAF are necessary to make its use in larger quantities commercially and economically feasible.
Employee Benefit Obligations. We sponsor defined benefit pension plans for eligible employees and retirees. These plans are closed to new entrants and are frozen for future benefit accruals. Our funding obligations for these plans are governed by the Employee Retirement Income Security Act ("ERISA") and any applicable legislation. We had no minimum funding requirements in 2021 or 2022, and have no such requirements in 2023. However, we voluntarily contributed $1.5 billion to these plans during 2021. At this level of funding, investment returns are expected to satisfy future benefit payments, which we believe would eliminate further material voluntary or required cash contributions to the plans under the terms of ERISA. Further, based on this level of funding, we have modified, and continue to evaluate, the asset allocation mix to reduce the investment risk of the portfolio. Estimates of future funding requirements are based on various assumptions and could vary materially from actual funding requirements. Assumptions include, among other things, the actual and projected market performance of assets, statutory requirements and demographic data for participants.
In addition, we have employee benefit obligations relating primarily to projected future benefit payments from our unfunded postretirement and postemployment plans. See Note 9 of the Notes to the Consolidated Financial Statements for more information on our employee benefit obligations.
Delta Air Lines, Inc. | 2022 10-K 43
Item 7. MD&A - Financial Condition and Liquidity
Voluntary Separation Programs. In 2020, we recorded a $3.4 billion charge associated with voluntary early retirement and separation programs and other employee benefit charges. Approximately $440 million, $575 million and $720 million was disbursed in cash payments to participants in the voluntary programs during 2022, 2021 and 2020 respectively. We anticipate that a total of approximately $300 million in cash payments will be made to participants in the voluntary separation programs in 2023 and the remaining payments in 2024 and beyond.
Profit Sharing. Our broad-based employee profit sharing program provides that, for each year in which we have an annual pre-tax profit, as defined by the terms of the program, we will pay a specified portion of that profit to employees. In determining the amount of profit sharing, the program defines profit as pre-tax profit adjusted for profit sharing and certain other items.
We pay profit sharing annually in February. To recognize the extraordinary efforts of our employees through the pandemic, we made a special profit-sharing payment of $108 million to eligible employees in February 2022, based on the adjusted pre-tax profit earned during the second half of 2021. During the year ended December 31, 2022, we recorded $563 million in profit sharing expense based on 2022 pre-tax profit, which we will pay to employees in February 2023.
Contract Carrier Obligations. We have certain estimated minimum fixed obligations under capacity purchase agreements with third-party regional carriers. These minimum amounts are based on the required minimum levels of flying by the regional carriers under the respective agreements and assumptions regarding the costs associated with such minimum levels of flying. As of December 31, 2022 the total of these minimum amounts was $10.6 billion and are approximately $1.6 billion on an annual basis over the next five years. See Note 10 of the Notes to the Consolidated Financial Statements for more information on our contract carrier obligations.
Operating Lease Obligations. As described further in Note 7 of the Notes to the Consolidated Financial Statements, as of December 31, 2022 we had a total of $9.8 billion of minimum operating lease obligations. These minimum lease payments range from approximately $800 million to $1.0 billion on an annual basis over the next five years.
New York-JFK Airport Expansion. We are enhancing and expanding our facilities at Terminal 4 of JFK to strengthen our competitive position and offer a premium travel experience for customers in New York City. Terminal 4 is operated by JFK International Air Terminal LLC ("IAT"), a private party, under its lease with the Port Authority of New York and New Jersey ("Port Authority"). We have a long-term agreement with IAT to sublease space in Terminal 4 through 2043 ("Sublease").
In 2021, the Port Authority approved plans to renovate and expand Terminal 4 in order to facilitate Delta's relocation from Terminal 2 and consolidation of its operations into Terminal 4. The project will add 10 new gates and other complementary facilities, including an additional Delta Sky Club and a new Delta One lounge. The project is estimated to cost approximately $1.6 billion and will be funded primarily with bonds issued in 2022 by the New York Transportation Development Corporation ("NYTDC") for which our landlord, IAT, is the obligor. The majority of project costs are being used to expand or modify Delta's leased premises. Construction started in late 2021 and Delta's portion of the project is estimated to be complete by early 2024.
In 2022, we amended our Sublease to provide for the expansion project, including the adjustment of our subleased space and rentals. We have recognized a right-of-use ("ROU") asset and lease liability representing the fixed component of the lease payments for this facility and as the majority of the project either expands or modifies Delta’s leased premises, our lease liability will increase upon completion. As of December 31, 2022, our lease liability related to this Sublease was $2.3 billion. See Note 7 of the Notes to the Consolidated Financial Statements for more information on our ROU assets and lease liabilities.
Other Obligations. We have certain purchase obligations under which we are required to make minimum payments for goods and services, including, but not limited to, aviation-related, maintenance, insurance, marketing, technology, sponsorships and other third-party services and products. As of December 31, 2022, we had approximately $8.6 billion of such obligations, which range from approximately $350 million to $900 million on an annual basis over the next five years.
Delta Air Lines, Inc. | 2022 10-K 44
Item 7. MD&A - Financial Condition and Liquidity
Investing Activities
Short-Term Investments. In 2022 we redeemed a net of $100 million in short-term investments. See Note 1 and Note 3 of the Notes to the Consolidated Financial Statements for further information on these investments.
Capital Expenditures. Our capital expenditures (i.e., property and equipment additions in our Consolidated Statements of Cash Flows ("cash flows statement")) were $6.4 billion and $3.2 billion in 2022 and 2021, respectively. Our capital expenditures are primarily related to the purchases of aircraft, airport construction projects, fleet modifications and technology enhancements.
We have committed to future aircraft purchases and have obtained, but are under no obligation to use, long-term financing commitments for a substantial portion of the purchase price of the aircraft. Excluding the New York-LaGuardia airport project discussed below, our expected 2023 capital spend of approximately $5.5 billion, which may vary depending on financing decisions, will be primarily for aircraft, including deliveries and advance deposit payments, as well as fleet modifications and technology enhancements. As described in Part I, Item 1. "Business - Environmental Sustainability," aircraft fleet renewal is an important component of our environmental sustainability strategy and the path to achievement of our ambitious climate goals, which will continue to require extensive capital investment in future periods. See Note 10 of the Notes to the Consolidated Financial Statements for additional information regarding our aircraft purchase commitments, which totaled approximately $19.0 billion as of December 31, 2022.
New York-LaGuardia Redevelopment. As part of the terminal redevelopment project at LaGuardia Airport, we are partnering with the Port Authority to replace Terminals C and D with a new state-of-the-art terminal facility consisting of 37 gates across four concourses connected to a central headhouse. The terminal will feature a new, larger Delta Sky Club, wider concourses, more gate seating and nearly double the amount of concessions space than the existing terminals. The facility will also offer direct access between the parking garage and terminal and improved roadways and drop-off/pick-up areas. Construction is underway and is being phased to limit passenger inconvenience. Due to an acceleration effort that commenced in 2020, completion is expected by 2025.
In 2019, we opened Concourse G, the first of four new concourses, housing seven of the 37 new gates. In 2022, we achieved a significant milestone by opening the headhouse (including the Delta Sky Club), the terminal roadways and Concourse E - the second of four new concourses to be built. Additionally, we opened four of 12 planned new gates on Concourse F.
In connection with the redevelopment, during 2017, we entered into an amended and restated terminal lease with the Port Authority with a term through 2050. Pursuant to the lease agreement, as amended to date, we will (1) fund (through debt issuance and existing cash) and undertake the design, management and construction of the terminal and certain off-premises supporting facilities, (2) receive a Port Authority contribution of approximately $500 million to facilitate construction of the terminal and other supporting infrastructure, (3) be responsible for all operations and maintenance during the term of the lease and (4) have preferential rights to all gates in the terminal subject to Port Authority requirements with respect to accommodation of designated carriers.
The project is expected to cost $4.3 billion. We currently expect our net project cost to be approximately $3.8 billion and we bear the risks of project construction, including any potential cost over-runs. We entered into loan agreements to fund a portion of the construction, which are recorded on our Consolidated Balance Sheets ("balance sheets") as debt with the proceeds reflected as restricted cash. Using funding primarily provided by these arrangements, we spent approximately $650 million, $950 million and $600 million during 2022, 2021 and 2020, respectively, bringing the total amount spent on the project to date to approximately $3.2 billion. We expect to spend approximately $500 million during 2023.
Los Angeles International Airport ("LAX") Construction. As part of the terminal redevelopment project at LAX, we are modernizing, upgrading, and providing post-security connection to Terminals 2 and 3. We announced this project and executed a modified lease agreement during 2016 with the City of Los Angeles (the "City"), which owns and operates LAX. This project includes a new centralized ticketing and arrival hall, a new security checkpoint, core infrastructure to support the City's planned airport people mover, ramp improvements and a post-security connector to the north side of the Tom Bradley International Terminal.
Delta Air Lines, Inc. | 2022 10-K 45
Item 7. MD&A - Financial Condition and Liquidity
The project is expected to cost approximately $2.4 billion. A substantial majority of the project costs are being funded through the Regional Airports Improvement Corporation ("RAIC"), a California public benefit corporation, using a revolving credit facility provided by a group of lenders. The credit facility was executed in 2017 and we have guaranteed the obligations of the RAIC under the credit facility. The revolving credit facility agreement was most recently amended in January 2023, decreasing the revolver capacity from $800 million to $700 million. Loans made under the credit facility are being repaid with the proceeds from the City’s purchase of completed project assets. Under the lease agreement and subsequent project component approvals by the City's Board of Airport Commissioners, the City has appropriated to date approximately $1.8 billion to purchase completed project assets, representing the maximum allowable reimbursement by the City. Costs incurred in excess of the $1.8 billion maximum will not be reimbursed by the City. We currently expect our net project costs to be approximately $600 million, of which approximately $350 million has been reflected as investing activities in our cash flows statement since the project started in 2017.
Given reduced passenger volumes resulting from the COVID-19 pandemic, we accelerated the construction schedule for this project in 2020. Additionally, we enhanced the project’s scope to include a more customer-friendly design of Terminal 3, an expanded Delta Sky Club and baggage system upgrades designed to increase the terminals’ operational efficiency going forward. In 2022, we opened a new consolidated headhouse for both terminals, which includes ticketing, security, baggage claim and a new Delta Sky Club lounge and have a total of 11 of 14 planned new gates now open in Terminal 3. Construction is expected to be completed in 2023.
Equity Investments. To support our international presence, during 2022 we invested an aggregate amount of $757 million in Grupo Aeroméxico and LATAM as each carrier emerged from restructuring processes. Upon completion of their respective processes, we received a 20% equity stake in Grupo Aeroméxico and a 10% equity stake in LATAM. See Note 4 of the Notes to the Consolidated Financial Statements for additional information on our equity investments
Financing Activities
Debt and Finance Leases. In 2022, we had cash outflows of approximately $4.5 billion related to repayments of our debt and finance leases, including approximately $2.3 billion for the early repayment of certain notes through a cash tender offer and other various secured and unsecured notes. We will continue to seek opportunities to pre-pay our debt, in addition to periodic amortization payments and scheduled maturities, during 2023 and beyond. See Note 6 of the Notes to the Consolidated Financial Statements for additional information on recent repayment activity.
The principal amount of our debt and finance leases was $23.2 billion at December 31, 2022.
Future Debt Obligations. As described further in Note 6 of the Notes to the Consolidated Financial Statements, as of December 31, 2022, scheduled maturities of our debt in 2023 and 2024 were $2.1 billion and $2.8 billion, respectively, with maturities from 2025 through 2027 ranging between $2.5 billion and $2.9 billion annually. As of December 31, 2022, scheduled maturities after 2027 aggregate to $8.4 billion. In addition, we are obligated to make periodic interest payments at fixed and variable rates, depending on the terms of the applicable debt agreements. Based on applicable interest rates and scheduled debt maturities as of December 31, 2022, these interest obligations total approximately $4.6 billion and range from approximately $350 million to $1.0 billion on an annual basis over the next five years. In addition to payment of scheduled debt maturities, we expect to continue paying down our debt in 2023, and therefore reduce our future interest obligations.
Finance Lease Obligations. As described further in Note 7 of the Notes to the Consolidated Financial Statements, as of December 31, 2022 we had a total of $1.8 billion of minimum finance lease obligations. These minimum lease payments range from approximately $200 million to $400 million on an annual basis over the next five years.
Undrawn Lines of Credit. As of December 31, 2022 we had approximately $2.9 billion undrawn and available under our revolving credit facilities. In addition, we had $400 million of outstanding letters of credit as of December 31, 2022 that did not affect the availability under our revolvers.
Covenants. We were in compliance with the covenants in our debt agreements at December 31, 2022. See Note 6 of the Notes to the Consolidated Financial Statements for more information on the covenants in our debt agreements.
Delta Air Lines, Inc. | 2022 10-K 46
Item 7. MD&A - Critical Accounting Estimates
Critical Accounting Estimates
Our critical accounting estimates are those estimates made in accordance with generally accepted accounting principles in the U.S. ("GAAP") that involve a significant level of estimation uncertainty and have had or are reasonably likely to have a material impact on our consolidated results of operations or financial condition. Accordingly, the actual results may differ materially from these estimates. For a discussion of our significant accounting policies, see Note 1 of the Notes to the Consolidated Financial Statements, unless otherwise noted below.
Loyalty Program
Our SkyMiles loyalty program generates customer loyalty by rewarding customers with incentives to travel on Delta. This program allows customers to earn mileage credits ("miles") by flying on Delta, Delta Connection carriers and other airlines that participate in the loyalty program. When traveling, customers earn miles primarily based on the passenger's loyalty program status, fare class and ticket price. Customers can also earn miles through participating companies such as credit card companies, hotels, car rental agencies and ridesharing companies. Miles are redeemable by customers in future periods for air travel on Delta and other participating airlines, access to our Sky Club and other program awards. To facilitate transactions with participating companies, we sell miles to non-airline businesses, customers and other airlines.
The loyalty program includes two types of transactions that are considered revenue arrangements with multiple performance obligations (1) passenger ticket sales earning miles and (2) sale of miles to participating companies.
Passenger Ticket Sales Earning Miles. Passenger ticket sales earning miles provide customers with (1) miles earned and (2) air transportation, which are each considered performance obligations. We value each performance obligation on a standalone basis. To value the miles earned, we consider the quantitative value a passenger receives by redeeming miles for a ticket rather than paying cash, which is referred to as equivalent ticket value ("ETV"). Our estimate of ETV is adjusted for miles that are not likely to be redeemed ("mileage breakage"). We use statistical models to estimate mileage breakage based on historical redemption patterns. A change in assumptions regarding the redemption activity for miles or the estimated fair value of miles expected to be redeemed could have a material impact on our revenue in the year in which the change occurs and in future years. We recognize mileage breakage proportionally during the period in which the remaining miles are actually redeemed.
At December 31, 2022, the aggregate deferred revenue balance associated with the SkyMiles program was $7.9 billion. A hypothetical 10% change in the number of outstanding miles estimated to be redeemed would result in an impact of less than 1% of total operating revenue recognized for the year ended December 31, 2022.
We defer revenue for the miles when earned and recognize loyalty travel awards in passenger revenue as the miles are redeemed and transportation is provided. We record the air transportation portion of the passenger ticket sales in air traffic liability and recognize passenger revenue when we provide transportation or if the ticket goes unused. A hypothetical 10% increase in our estimate of the ETV of a mile would have decreased total operating revenue by less than 1% for the year ended December 31, 2022, as a result of an increase in the amount of revenue deferred associated with the miles earned.
Sale of Miles to Participating Companies. Customers earn miles based on their spending with participating companies such as credit card companies, hotels, car rental agencies and ridesharing companies with which we have marketing agreements to sell miles. Our contracts to sell miles under these marketing agreements have multiple performance obligations. Payments are typically due to us monthly based on the volume of miles sold during the period, and the initial terms of our marketing contracts are from three to eleven years. During the years ended December 31, 2022, 2021 and 2020, total cash sales from marketing agreements related to our loyalty program were $5.7 billion, $4.1 billion and $2.9 billion, respectively, which are allocated to travel and other performance obligations, as discussed below.
Our most significant contract to sell miles relates to our co-brand credit card relationship with American Express. Our agreements with American Express provide for joint marketing, grant certain benefits to Delta-American Express co-branded credit card holders ("cardholders") and American Express Membership Rewards program participants, and allow American Express to market its services or products using our customer database. Cardholders earn miles for making purchases using co-branded cards, and certain cardholders may also check their first bag for free, are granted discounted access to Delta Sky Club lounges and receive priority boarding and other benefits while traveling on Delta. Additionally, participants in the American Express Membership Rewards program may exchange their points for miles under the loyalty program. We sell miles at agreed-upon rates to American Express which are then provided to their customers under the co-brand credit card program and the Membership Rewards program.
Delta Air Lines, Inc. | 2022 10-K 47
Item 7. MD&A - Critical Accounting Estimates
We account for marketing agreements, including those with American Express, by allocating the consideration to the individual products and services delivered. We allocate the value based on the relative selling prices of those products and services, which generally consist of award travel, priority boarding, baggage fee waivers, lounge access and the use of our brand. We determine our best estimate of the selling prices by using a discounted cash flow analysis using multiple inputs and assumptions, including (1) the expected number of miles awarded and number of miles redeemed, (2) ETV for the award travel obligation adjusted for mileage breakage, (3) published rates on our website for baggage fees, discounted access to Delta Sky Club lounges and other benefits while traveling on Delta, (4) brand value (using estimated royalties generated from the use of our brand) and (5) volume discounts provided to certain partners.
We defer the amount allocated to award travel as part of loyalty program deferred revenue and recognize loyalty travel awards in passenger revenue as the miles are redeemed and transportation is provided. Revenue allocated to services performed in conjunction with a passenger’s flight, such as baggage fee waivers, is recognized as travel-related services in passenger revenue when the related service is performed. Revenue allocated to access Delta Sky Club lounges is recognized as miscellaneous in other revenue as access is provided. Revenue allocated to the remaining performance obligations, primarily brand value, is recorded as loyalty program in other revenue as miles are delivered.
The timing of mile redemptions can vary widely; however, the majority of new miles have historically been redeemed within two years of being earned. The loyalty program deferred revenue classified as a current liability represents our estimate of revenue expected to be recognized in the next twelve months based on projected redemptions, while the balance classified as a noncurrent liability represents our estimate of revenue expected to be recognized beyond twelve months.
For additional information on our significant accounting policies related to the loyalty program, see Note 2 of the Notes to the Consolidated Financial Statements.
Passenger Ticket Sales
We defer sales of passenger tickets to be flown by us or that we sell on behalf of other airlines in our air traffic liability. Passenger revenue is recognized when we provide transportation or when the ticket expires unused ("ticket breakage"). For tickets that we sell on behalf of other airlines, we reduce the air traffic liability when consideration is remitted to those airlines. The air traffic liability primarily includes sales of passenger tickets with scheduled departure dates in the future and credits which can be applied as payment toward the cost of a ticket ("travel credits"). Travel credits are typically issued as a result of ticket cancellations prior to their expiration dates. We periodically evaluate the estimated air traffic liability and may record adjustments in our Consolidated Statement of Operations ("income statement"). These adjustments relate primarily to ticket breakage, refunds, exchanges, transactions with other airlines and other items for which final settlement occurs in periods subsequent to the sale of the related tickets at amounts other than the original sales price.
During the COVID-19 pandemic, we experienced significant ticket cancellations, particularly in the early months of 2020. Delta has eliminated change fees for tickets originating in the United States, Canada, Europe and Africa (excluding Basic Economy tickets). In order to provide our customers more flexibility and time to plan their travel, travel credit holders as of January 2022 and customers who purchased a ticket in 2022 are able to rebook their ticket through December 31, 2023 for travel throughout 2024.
We estimate the value of ticket breakage and recognize revenue at the scheduled flight date. Our ticket breakage estimates are primarily based on historical experience, ticket contract terms and customers’ travel behavior. Given the impact of the COVID-19 pandemic on customer behavior and changes made in ticket validity terms, as well as the elimination of change fees for most tickets, our estimates of revenue that will be recognized from the air traffic liability for unused tickets may vary in future periods. At December 31, 2022, the aggregate air traffic liability balance was $8.3 billion. A hypothetical 10% change in the amount of travel credits estimated to expire unused would result in an impact of less than 1% of total operating revenue for the year ended December 31, 2022.
For additional information on our significant accounting policies related to passenger ticket sales, see Note 2 of the Notes to the Consolidated Financial Statements.
Delta Air Lines, Inc. | 2022 10-K 48
Item 7. MD&A - Critical Accounting Estimates
Long-Lived Assets
Our long-lived lived assets, including flight equipment, which consists of aircraft and associated engines and parts, operating ROU assets and other long-lived assets, which have a recorded value of approximately $40.1 billion at December 31, 2022, are recorded in property and equipment, net and operating lease right-of-use assets on our balance sheets. This value is based on various factors, including the assets' acquisition costs, estimated useful lives, salvage values, discounted lease payments and lease terms. We review flight equipment, ROU assets and other long-lived assets used in operations for impairment losses when events and circumstances indicate the assets may be impaired. Factors which could be indicators of impairment include, but are not limited to (1) a decision to permanently remove flight equipment or other long-lived assets from operations, (2) significant changes in the estimated useful life, (3) significant changes in projected cash flows, (4) permanent and significant declines in fleet fair values and (5) changes to the regulatory environment. For long-lived assets held for sale, we discontinue depreciation and record impairment losses when the carrying amount of these assets is greater than the fair value less the cost to sell.
To determine whether impairments exist for aircraft used in operations, we group assets at the fleet type level or at the contract level for aircraft operated by third-party regional carriers (i.e., the lowest level for which there are identifiable cash flows) and then estimate future cash flows based on projections of capacity, passenger mile yield, fuel and labor costs and other relevant factors. If an asset group is impaired, the impairment loss recognized is the amount by which the asset group's carrying amount exceeds its estimated fair value. We estimate aircraft fair values using published sources, appraisals and bids received from third parties, as available.
As a result of the COVID-19 pandemic and our response, we made decisions to remove certain aircraft from active service and to early retire certain fleet types. We evaluated our fleet for impairment, determining that only certain fleet types were impaired, as the future cash flows from the operation of these fleet types through the respective retirement dates were lower than the carrying value. This resulted in impairment and other related charges of $4.4 billion during 2020, recorded in restructuring charges in our income statement. These charges were calculated using Level 3 fair value inputs based primarily upon recent market transactions and third-party bids, which were corroborated with published pricing guides and our assessment of existing market conditions based on industry knowledge. The effects of the COVID-19 pandemic created additional estimation uncertainty as there was a limited market for aircraft and limited data on how the COVID-19 pandemic affected the fair value of aircraft.
Due to the recovery in demand that we experienced throughout 2021 and 2022, we decided not to retire any additional aircraft and returned to service a majority of the aircraft that were temporarily parked in 2020. We recorded no further impairments during 2021 or 2022.
Following the impairment charges, the aggregate net book value of these aircraft as of December 31, 2022 and December 31, 2021 was approximately $220 million and $340 million, respectively, with the reduction in 2022 primarily due to aircraft sales. See Note 15 of the Notes to the Consolidated Financial Statements for additional details regarding these impairments and related charges.
Goodwill and Indefinite-Lived Intangible Assets
We apply a fair value-based impairment test to the carrying value of goodwill and indefinite-lived intangible assets on an annual basis (as of October 1) and, if certain events or circumstances indicate that an impairment loss may have been incurred, on an interim basis. We assess the value of our goodwill and indefinite-lived assets under either a qualitative or quantitative approach. Under a qualitative approach, we consider various market factors, including certain of the key assumptions listed below. We analyze these factors to determine if events and circumstances have affected the fair value of goodwill and indefinite-lived intangible assets. If we determine that it is more likely than not that the asset may be impaired, we use the quantitative approach to assess the asset's fair value and the amount of the impairment. Under a quantitative approach, we calculate the fair value of the asset incorporating the key assumptions listed below into our calculation.
When we evaluate goodwill for impairment using a quantitative approach, we estimate the fair value of the reporting unit by considering both comparable public company multiples (a market approach) and projected discounted future cash flows (an income approach). When we perform a quantitative impairment assessment of our indefinite-lived intangible assets, fair value is estimated based on (1) recent market transactions, where available, (2) the royalty method for the Delta tradename (which assumes hypothetical royalties generated from using our tradename) or (3) projected discounted future cash flows (an income approach).
Delta Air Lines, Inc. | 2022 10-K 49
Item 7. MD&A - Critical Accounting Estimates
Key Assumptions. The key assumptions in our impairment tests include (1) forecasted revenues, expenses and cash flows, including the duration and extent of impact to our business and our alliance partners from the COVID-19 pandemic, (2) current discount rates, (3) observable market transactions and (4) anticipated changes to the regulatory environment (e.g., changes in slot access and/or availability, additional Open Skies agreements or changes to antitrust approvals). These assumptions are consistent with those that hypothetical market participants would use. Because we are required to make estimates and assumptions when evaluating goodwill and indefinite-lived intangible assets for impairment, actual transaction amounts may differ materially from these estimates. In addition, when performing a qualitative valuation, we consider the amount by which the intangible assets' fair values exceeded their respective carrying values in the most recent fair value measurements calculated using a quantitative approach.
Changes in certain events and circumstances could result in impairment or a change from indefinite-lived to definite-lived. Factors which could cause impairment include, but are not limited to (1) negative trends in our market capitalization, (2) reduced profitability resulting from lower passenger mile yields or higher input costs (primarily related to fuel and employees), (3) lower passenger demand as a result of weakened U.S. and global economies, global pandemics or other factors, (4) interruption to our operations due to a prolonged employee strike, terrorist attack or other reasons, (5) changes to the regulatory environment (e.g., changes in slot access and/or availability, additional Open Skies agreements or changes to antitrust approvals), (6) competitive changes by other airlines and (7) strategic changes to our operations leading to diminished utilization of the intangible assets.
Goodwill. Our goodwill balance, which is related to the airline segment, was $9.8 billion at December 31, 2022.
Identifiable Intangible Assets. Our identifiable intangible assets, which are related to the airline segment, had a net carrying amount of $6.0 billion at December 31, 2022, of which $5.9 billion related to indefinite-lived intangible assets. Indefinite-lived assets are not amortized and consist of routes, slots, the Delta tradename and assets related to alliances and collaborative arrangements. Definite-lived assets consist primarily of marketing and maintenance service agreements.
In the September 2022 quarter, final regulatory approval was granted for our trans-American joint venture agreement with LATAM. This agreement combines our highly complementary route networks between North and South America, with the goal of providing customers with a seamless travel experience and industry-leading connectivity. Approval was granted for a 10-year period with a subsequent reassessment and extension process. This agreement supports our strategic partnership with LATAM and the value of our $1.2 billion alliance-related indefinite-lived intangible asset. We believe the LATAM joint venture agreement will generate growth opportunities, building upon Delta's and LATAM's global footprint.
We have classified our LATAM alliance intangible asset as indefinite-lived as we expect to indefinitely receive the economic benefits from the relationship, similar to other joint venture arrangements between U.S. and foreign carriers that have been cleared by competition authorities in relevant foreign jurisdictions and granted antitrust immunity from the U.S. Department of Transportation ("DOT"). Antitrust immunity grants are generally subject to reporting requirements and periodic reassessment processes administered by the DOT. We have determined that there are currently no material legal, regulatory, contractual, competitive, economic or other factors that limit the useful life of our LATAM alliance-related intangible asset.
In 2022, we performed qualitative assessments of our goodwill and indefinite-lived intangible assets, including applicable factors noted in "Key Assumptions" above, and determined that there was no indication that the assets were impaired. Our qualitative assessments include analyses and weighting of all relevant factors which impact the fair value of our indefinite-lived intangible assets.
For additional information on our goodwill and indefinite-lived intangible assets' significant accounting policies and the related fair values and book values, see Note 5 of the Notes to the Consolidated Financial Statements.
Defined Benefit Pension Plans
We sponsor defined benefit pension plans for eligible employees and retirees. These plans are closed to new entrants and frozen for future benefit accruals. As of December 31, 2022, the unfunded benefit obligation for these plans recorded on our balance sheets was $90 million. We had no minimum funding requirements in 2021 or 2022, and have no such requirements in 2023. However, we voluntarily contributed $1.5 billion to these plans during 2021. The most critical assumptions impacting our defined benefit pension plan obligations, plan assets and net periodic benefit cost are the discount rate, the expected long-term rate of return on plan assets and life expectancy of plan participants.
Delta Air Lines, Inc. | 2022 10-K 50
Item 7. MD&A - Critical Accounting Estimates
Weighted Average Discount Rate. We determine our weighted average discount rate on our measurement date primarily by reference to annualized rates earned on high-quality fixed income investments and yield-to-maturity analyses specific to our estimated future benefit payments. We used a weighted average discount rate to value the obligations of 5.62% and 2.97% at December 31, 2022 and 2021, respectively.
Expected Long-Term Rate of Return. Our expected long-term rate of return on plan assets is based primarily on plan-specific investment studies using historical market return and volatility data. Modest excess return expectations versus some public market indices are incorporated into the return projections based on the actively managed structure of the investment programs and their records of achieving such returns historically. We also expect to receive a premium for investing in less liquid private markets. We review our rate of return on plan assets assumptions annually.
The investment strategy for our defined benefit pension plan assets is to earn a long-term return that meets or exceeds our annualized return target while taking an acceptable level of risk and maintaining sufficient liquidity to pay current benefits and other cash obligations of the plan. Based on our funded status as of December 31, 2021, we modified the strategic asset allocation mix in 2022 to reduce the investment risk of the portfolio. Based on the portfolio's risk profile, we lowered the weighted average expected long-term rate of return on our defined benefit pension plan assets for 2022 net periodic benefit cost to 7.00%.
The impact of a 0.50% change in weighted average discount rate and 1.00% change in expected long-term rate of return on assets are shown in the table below:
| Benefit plan effects of change in assumptions used | ||||||||||||||
| Change in Assumption | Effect on 2023 Pension Benefit Cost | Effect on Accrued Pension Liability at December 31, 2022 | ||||||||||||
| 0.50% decrease in weighted average discount rate | $ | (5) | million | $ | 743 | million | ||||||||
| 0.50% increase in weighted average discount rate | $ | — | million | $ | (685) | million | ||||||||
| 1.00% decrease in expected long-term rate of return on assets | $ | 152 | million | $ | — | |||||||||
| 1.00% increase in expected long-term rate of return on assets | $ | (152) | million | $ | — |
Life Expectancy. Changes in life expectancy may significantly impact our benefit obligations and future net periodic benefit cost. We use the Society of Actuaries ("SOA") published mortality data and other publicly available information to develop our best estimate of life expectancy. The SOA publishes updated mortality tables for U.S. plans and updated improvement scales. Each year we consider updates by the SOA in setting our mortality assumptions for purposes of measuring pension and other postretirement and postemployment benefit obligations.
Funding. Our funding obligations for qualified defined benefit plans are governed by the Employee Retirement Income Security Act and any applicable legislation. Under the Pension Protection Act of 2006, we elected alternative funding rules so that the unfunded liability for a frozen defined benefit plan may be amortized over a fixed 17-year period and is calculated using an 8.85% discount rate until the 17-year period expires for all frozen defined benefit plans by the end of 2024. Upon expiration, under legislation passed in 2021, any required funding would be amortized over a rolling 15-year period and calculated using a discount rate of no less than 4.75% through 2030.
While this recent legislation makes our funding obligations for these plans more predictable, factors outside our control continue to have an impact on the funding requirements. Estimates of future funding requirements are based on various assumptions and can vary materially from actual funding requirements. Assumptions include, among other things, the actual and projected market performance of assets, statutory requirements and demographic data for participants.
Investments Valued at Net Asset Value ("NAV") Per Share. On an annual basis we assess the potential for adjustments to the fair value of all investments. These investments valued using NAV as a practical expedient are typically valued on a monthly or quarterly basis by third-party administrators, valuation agents or fund managers with an annual audit performed by an independent third-party, but certain of these investments have a lag in the availability of data. We solicit valuation updates from the investment fund managers and use their information and corroborating data from public markets to determine any needed fair value adjustments.
For additional information on our significant accounting policies related to defined benefit pension plans, see Note 9 of the Notes to the Consolidated Financial Statements.
Delta Air Lines, Inc. | 2022 10-K 51
Item 7. MD&A - Critical Accounting Estimates
Income Tax Valuation Allowance
We periodically assess whether it is more likely than not that we will generate sufficient taxable income to realize our deferred income tax assets. We establish valuation allowances if it is more likely than not that we will be unable to realize our deferred income tax assets. In making this determination, we consider available positive and negative evidence and make certain assumptions. We consider, among other things, projected future taxable income, scheduled reversals of deferred tax liabilities, the overall business environment, our historical financial results and tax planning strategies. In evaluating the likelihood of utilizing our net deferred income tax assets, the significant factors that we consider include (1) our recent history of significant profitability, (2) growth in the U.S. and global economies, (3) forecast of airline revenue trends, (4) estimate of future fuel prices and (5) future impact of taxable temporary differences.
At December 31, 2022 our net deferred tax asset balance was $301 million, including a $1.2 billion valuation allowance primarily related to certain net realized and unrealized capital losses and certain state net operating losses. Although we have cumulative losses since the onset of the pandemic, we have a history of significant earnings prior to the onset of the COVID-19 pandemic. During 2022, we returned to profitability, as our business continued to recover from the impact of the pandemic. We are expecting to generate sufficient taxable income to utilize our federal net operating loss carryforwards before any expire. However, the generation of future taxable income is dependent on many factors, including those which are out of our control, such as the demand for air travel and overall health of the economy. As such, there are no guarantees that a valuation allowance will not be required against some or all of our deferred tax assets in future periods.
Our federal net operating loss carryforwards generated before 2018 do not begin to expire until 2029. Under current tax law, federal net operating losses generated after 2017 do not expire. Therefore, we have not recorded a valuation allowance on our deferred tax assets other than the certain net realized and unrealized capital losses and certain state net operating losses that have short expiration periods.
For additional information on our significant accounting policies related to income taxes, see Note 11 of the Notes to the Consolidated Financial Statements.
Recent Accounting Standards
Standards Effective in Future Years
Fair Value of Equity Investments. In June 2022, the Financial Accounting Standards Board ("FASB") issued Accounting Standards Update ("ASU") No. 2022-03, "Fair Value Measurement (Topic 820): Fair Value Measurement of Equity Securities Subject to Contractual Sale Restrictions." Under this standard, a contractual restriction on the sale of an equity security is not considered in measuring the security's fair value. The standard also requires certain disclosures for equity securities that are subject to contractual restrictions. The ASU becomes effective January 1, 2024. Upon adoption, we do not believe it will have a material impact on the valuation of our equity investments; however, we may be required to include additional disclosures to the extent we have material equity investments subject to contractual sale restrictions.
Supplier Finance Program Obligations. In September 2022, the FASB issued ASU No. 2022-04, "Liabilities—Supplier Finance Programs (Subtopic 405-50)." This standard requires disclosure of the key terms of outstanding supplier finance programs and a rollforward of the related obligations. The new standard does not affect the recognition, measurement or financial statement presentation of supplier finance program obligations. The ASU becomes effective January 1, 2023, except for the rollforward requirement, which becomes effective January 1, 2024. Upon adoption, we may be required to include additional disclosures to the extent we have material supplier finance program obligations.
Delta Air Lines, Inc. | 2022 10-K 52
Item 7. MD&A - Supplemental Information
Supplemental Information
We sometimes use information ("non-GAAP financial measures") that is derived from the Consolidated Financial Statements, but that is not presented in accordance with GAAP. Under the U.S. Securities and Exchange Commission rules, non-GAAP financial measures may be considered in addition to results prepared in accordance with GAAP, but should not be considered a substitute for or superior to GAAP results.
Included below are reconciliations of non-GAAP measures used within this Form 10-K to the most directly comparable GAAP financial measures. These reconciliations include certain adjustments to GAAP measures, which are directly related to the impact of COVID-19 and our response. Reconciliations below may not calculate exactly due to rounding. These adjustments are made to provide comparability between the reported periods, if applicable, as indicated below:
-
Restructuring charges. During 2020, we recorded restructuring charges of $8.2 billion for items such as fleet impairments and voluntary early retirement and separation programs following strategic business decisions in response to the COVID-19 pandemic. In the years ended December 31, 2022 and 2021, we recognized $124 million and $19 million, respectively, of adjustments to certain of those restructuring charges, representing changes in our estimates or the outcome of contract negotiations.
-
Government grant recognition. We recognized $4.5 billion of the grant proceeds from the payroll support program extensions as a contra-expense during 2021. We recognized the grant proceeds as contra-expense based on the periods that the funds were intended to compensate and fully used all proceeds from the payroll support program extensions during that year.
*•*Special profit-sharing payment. This adjustment is exclusive to 2021. To recognize the extraordinary efforts of our employees through the pandemic, we made a special profit-sharing payment to eligible employees in February 2022, based on the adjusted pre-tax profit earned during the second half of 2021. This adjustment allows investors to better understand and analyze our recurring cost performance and provides a more meaningful comparison of our core operating costs to the airline industry.
We also regularly adjust certain GAAP measures for the following items, if applicable, for the reasons indicated below:
*•MTM adjustments and settlements on hedges. Mark-to-market ("*MTM") adjustments are defined as fair value changes recorded in periods other than the settlement period. Such fair value changes are not necessarily indicative of the actual settlement value of the underlying hedge in the contract settlement period, and therefore we remove this impact to allow investors to better understand and analyze our core performance. Settlements represent cash received or paid on hedge contracts settled during the applicable period.
*•*Delta Private Jets adjustment. Because we combined Delta Private Jets with Wheels Up in January 2020, we have excluded the impact of Delta Private Jets from 2019 results for comparability.
*•*Third-party refinery sales. Refinery sales to third parties, and related expenses, are not related to our airline segment. Excluding these sales therefore provides a more meaningful comparison of our airline operations to the rest of the airline industry.
*•*Aircraft fuel and related taxes. The volatility in fuel prices impacts the comparability of year-over-year financial performance. The adjustment for aircraft fuel and related taxes allows investors to better understand and analyze our non-fuel costs and year-over-year financial performance.
*•*Profit sharing. We adjust for profit sharing because this adjustment allows investors to better understand and analyze our recurring cost performance and provides a more meaningful comparison of our core operating costs to the airline industry.
Delta Air Lines, Inc. | 2022 10-K 53
Item 7. MD&A - Supplemental Information
| Operating income, adjusted reconciliation | ||||||||||||||||||||
| Year Ended December 31, | ||||||||||||||||||||
| (in millions) | 2022 | 2021 | 2019 | |||||||||||||||||
| Operating income | $ | 3,661 | $ | 1,886 | $ | 6,618 | ||||||||||||||
| Adjusted for: | ||||||||||||||||||||
| Restructuring charges | (124) | (19) | — | |||||||||||||||||
| Government grant recognition | — | (4,512) | — | |||||||||||||||||
| MTM adjustments and settlements on hedges | 29 | 9 | 14 | |||||||||||||||||
| Special profit sharing payment | — | 108 | — | |||||||||||||||||
| Delta Private Jets adjustment | — | — | 3 | |||||||||||||||||
| Operating income/(loss), adjusted | $ | 3,566 | $ | (2,527) | $ | 6,636 | ||||||||||||||
| Operating expense, adjusted reconciliation | ||||||||||||||
| Year Ended December 31, | ||||||||||||||
| (in millions) | 2022 | 2021 | 2019 | |||||||||||
| Operating expense | $ | 46,921 | $ | 28,013 | $ | 40,389 | ||||||||
| Adjusted for: | ||||||||||||||
| Restructuring charges | 124 | 19 | — | |||||||||||
| Government grant recognition | — | 4,512 | — | |||||||||||
| MTM adjustments and settlements on hedges | (29) | (9) | (14) | |||||||||||
| Special profit sharing payment | — | (108) | — | |||||||||||
| Third-party refinery sales | (4,977) | (3,229) | (97) | |||||||||||
| Delta Private Jets adjustment | — | — | (196) | |||||||||||
| Operating expense, adjusted | $ | 42,039 | $ | 29,197 | $ | 40,082 | ||||||||
| Fuel expense, adjusted and Average fuel price per gallon, adjusted reconciliations | |||||||||||||||||||||||||||||
| Average Price Per Gallon | |||||||||||||||||||||||||||||
| Year Ended December 31, | Year Ended December 31, | ||||||||||||||||||||||||||||
| (in millions, except per gallon data) | 2022 | 2021 | 2019 | 2022 | 2021 | 2019 | |||||||||||||||||||||||
| Total fuel expense | $ | 11,482 | $ | 5,633 | $ | 8,519 | $ | 3.36 | $ | 2.02 | $ | 2.02 | |||||||||||||||||
| Adjusted for: | |||||||||||||||||||||||||||||
| MTM adjustments and settlements on hedges | (29) | (9) | (14) | (0.01) | — | — | |||||||||||||||||||||||
| Delta Private Jets adjustment | — | — | (28) | — | — | (0.01) | |||||||||||||||||||||||
| Total fuel expense, adjusted | $ | 11,453 | $ | 5,625 | $ | 8,477 | $ | 3.36 | $ | 2.02 | $ | 2.01 |
| TRASM, adjusted reconciliation | |||||||||||||||||
| Year Ended December 31, | |||||||||||||||||
| (in cents) | 2022 | 2021 | 2019 | ||||||||||||||
| TRASM | 21.69 | ¢ | 15.37 | ¢ | 17.07 | ¢ | |||||||||||
| Adjusted for: | |||||||||||||||||
| Third-party refinery sales | (2.13) | (1.66) | (0.04) | ||||||||||||||
| Delta Private Jets adjustment | — | — | (0.07) | ||||||||||||||
| TRASM, adjusted | 19.55 | ¢ | 13.71 | ¢ | 16.97 | ¢ |
Delta Air Lines, Inc. | 2022 10-K 54
Item 7. MD&A - Supplemental Information
| CASM-Ex reconciliation | |||||||||||||||||
| Year Ended December 31, | |||||||||||||||||
| (in cents) | 2022 | 2021 | 2019 | ||||||||||||||
| CASM | 20.12 | ¢ | 14.40 | ¢ | 14.67 | ¢ | |||||||||||
| Adjusted for: | |||||||||||||||||
| Restructuring charges | 0.05 | 0.01 | — | ||||||||||||||
| Government grant recognition | — | 2.32 | — | ||||||||||||||
| Aircraft fuel and related taxes | (4.92) | (2.90) | (3.10) | ||||||||||||||
| Third-party refinery sales | (2.13) | (1.66) | (0.04) | ||||||||||||||
| Special profit sharing payment | — | (0.06) | — | ||||||||||||||
| Profit sharing | (0.24) | — | (0.60) | ||||||||||||||
| Delta Private Jets adjustment | — | — | (0.06) | ||||||||||||||
| CASM-Ex | 12.87 | ¢ | 12.12 | ¢ | 10.88 | ¢ | |||||||||||
Free Cash Flow
The following table shows a reconciliation of net cash provided by operating activities (a GAAP measure) to free cash flow (a non-GAAP financial measure). We present free cash flow because management believes this metric is helpful to investors to evaluate the company's ability to generate cash that is available for use for debt service or general corporate initiatives. Adjustments include:
- Net redemptions of short-term investments. Net redemptions of short-term investments represent the net purchase and sale activity of investments and marketable securities in the period, including gains and losses. We adjust for this activity to provide investors a better understanding of the company's free cash flow generated by our operations.
*•*Strategic investments and related. Cash flows related to our investments in and related transactions with other airlines are included in our GAAP investing activities. We adjust for this activity because it provides a more meaningful comparison to our airline industry peers.
*•*Net cash flows related to certain airport construction projects and other. Cash flows related to certain airport construction projects are included in our GAAP operating activities and capital expenditures. We have adjusted for these items because management believes investors should be informed that a portion of these capital expenditures from airport construction projects are either reimbursed by a third-party or funded with restricted cash specific to these projects.
- Financed aircraft acquisitions. This adjustment reflects aircraft deliveries that are leased as capital expenditures. The adjustment is based on their original contractual purchase price or an estimate of the aircraft's fair value and provides a more meaningful view of our investing activities.
| Free cash flow reconciliation | ||||||||||||||
| Year Ended December 31, | ||||||||||||||
| (in millions) | 2022 | |||||||||||||
| Net cash provided by operating activities | $ | 6,363 | ||||||||||||
| Net cash used in investing activities | (6,924) | |||||||||||||
| Adjusted for: | ||||||||||||||
| Net redemptions of short-term investments | (100) | |||||||||||||
| Strategic investments and related | 701 | |||||||||||||
| Net cash flows related to certain airport construction projects and other | 409 | |||||||||||||
| Financed aircraft acquisitions | (206) | |||||||||||||
| Free cash flow | $ | 244 | ||||||||||||
Delta Air Lines, Inc. | 2022 10-K 55
Item 7. MD&A - Glossary of Defined Terms
Glossary of Defined Terms
ASM - Available Seat Mile. A measure of capacity. ASMs equal the total number of seats available for transporting passengers during a reporting period multiplied by the total number of miles flown during that period.
CASM - (Total Operating) Cost per Available Seat Mile. The amount of operating cost incurred per ASM during a reporting period. CASM is also referred to as "unit cost."
CASM-Ex - The amount of operating cost incurred per ASM during a reporting period, adjusted for the items shown above in "Supplemental Information."
Free Cash Flow - A measure of net cash from operating and investing activities, adjusted for items shown above in "Supplemental Information." Represents the cash available for use for debt service or general corporate initiatives.
Liquidity - Includes our cash and cash-like assets, including cash equivalents, short-term investments and aggregate principal amount committed and available to be drawn under our revolving credit facilities.
Load Factor - A measure of utilized available seating capacity calculated by dividing RPMs by ASMs for a reporting period.
Passenger Mile Yield or Yield - The amount of passenger revenue earned per RPM during a reporting period.
PRASM - Passenger Revenue per ASM. The amount of passenger revenue earned per ASM during a reporting period. PRASM is also referred to as "passenger unit revenue."
RPM - Revenue Passenger Mile. One revenue-paying passenger transported one mile is one RPM. RPMs equal the number of revenue passengers during a reporting period multiplied by the number of miles flown by those passengers during that period. RPMs are also referred to as "traffic."
TRASM - Total Revenue per ASM. The amount of total revenue earned per ASM during a reporting period.
TRASM, adjusted - The amount of total revenue earned per ASM during a reporting period, adjusted for the item shown above in "Supplemental Information."
Delta Air Lines, Inc. | 2022 10-K 56
Item 7A. Market Risk
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
We have market risk exposure related to fuel prices, interest rates and foreign currency exchange rates. Market risk is the potential negative impact of adverse changes in these prices or rates on our Consolidated Financial Statements. In an effort to manage our exposure to these risks, we may enter into derivative contracts and may adjust our derivative portfolio as market conditions change. See Note 3 of the Notes to the Consolidated Financial Statements for further information on our derivative contracts. We expect adjustments to the fair value of financial instruments to result in ongoing volatility in earnings and stockholders' equity.
The following sensitivity analyses do not consider the effects of a change in demand for air travel, the economy as a whole or actions we may take to seek to mitigate our exposure to a particular risk. For these and other reasons, the actual results of changes in these prices or rates may differ materially from the following hypothetical results.
Fuel Price Risk
Changes in fuel prices materially impact our results of operations. A one cent increase in the cost of jet fuel would result in approximately $40 million of additional annual fuel expense based on annual pre-COVID-19 pandemic consumption of approximately four billion gallons of jet fuel. As a result of the reduced capacity from the COVID-19 pandemic, our jet fuel consumption during 2022 of 3.4 billion gallons was lower than our historical and expected future consumption. Our derivative contracts to hedge the financial risk from changing fuel prices are primarily related to Monroe’s inventory.
Interest Rate Risk
Our exposure to market risk from adverse changes in interest rates is primarily associated with our debt and lease obligations. Market risk associated with our fixed-rate debt relates to the potential reduction in fair value from an increase in interest rates. Market risk associated with our variable-rate debt and variable-rate leases relates to the potential negative impact to future earnings from an increase in interest rates.
At December 31, 2022, we had $17.9 billion of fixed-rate debt, $3.6 billion of variable-rate debt and $713 million of variable-rate leases. The rates used in our variable-rate debt are based on LIBOR, or another index rate, which in certain cases is subject to a floor. An increase of 100 basis points in average annual interest rates would have decreased the estimated fair value of our fixed-rate debt by $725 million at December 31, 2022 and would have increased the annual interest expense on our variable-rate debt and variable-rate leases by $43 million.
In March 2021, the administrator of LIBOR announced that the publication of certain LIBOR settings ceased after December 2021 and publication of the remainder of the LIBOR settings will cease after June 2023. At December 31, 2022, we had no exposure to the discontinued LIBOR settings and had approximately $1.4 billion of LIBOR-based debt and finance leases maturing after June 2023, all of which include mechanisms for replacing the applicable reference rate, which we do not expect to be materially different from LIBOR.
Foreign Currency Exchange Risk
We are subject to foreign currency exchange rate risk because we have revenue, expense and equity investments denominated in foreign currencies. To manage exchange rate risk, we execute both our international revenue and expense transactions in the same foreign currency to the extent practicable. From time to time, we may also enter into foreign currency option and forward contracts.
At December 31, 2022 we had no open foreign currency options or forward contracts.
Delta Air Lines, Inc. | 2022 10-K 57
Financial Statements
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
INDEX TO CONSOLIDATED FINANCIAL STATEMENTS
Delta Air Lines, Inc. | 2022 10-K 58
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Board of Directors and Stockholders of
Delta Air Lines, Inc.
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of Delta Air Lines, Inc. (the Company) as of December 31, 2022 and 2021, and the related consolidated statements of operations, comprehensive income/(loss), cash flows, and stockholders' equity for each of the three years in the period ended December 31, 2022, and the related notes (collectively referred to as the "consolidated financial statements"). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at December 31, 2022 and 2021, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2022, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, 2022, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework), and our report dated February 10, 2023 expressed an unqualified opinion thereon.
Basis for Opinion
These financial statements are the responsibility of the Company's management. Our responsibility is to express an opinion on the Company’s financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal secur
Showing the first 8K of 196K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Disclosure Controls and Procedures
Our management, including our Chief Executive Officer and Chief Financial Officer, performed an evaluation of our disclosure controls and procedures, which have been designed to permit us to record, process, summarize and report, within time periods specified by the SEC's rules and forms, information required to be disclosed. Our management, including our Chief Executive Officer and Chief Financial Officer, concluded that the controls and procedures were effective as of December 31, 2022 to ensure that material information was accumulated and communicated to our management, including our Chief Executive Officer and Chief Financial Officer, as appropriate to allow timely decisions regarding required disclosure.
Changes in Internal Control
During the three months ended December 31, 2022, we did not make any changes in our internal control over financial reporting that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Management's Annual Report on Internal Control Over Financial Reporting
Management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Rules 13a-15(f) and 15d-15(f) under the Securities Exchange Act of 1934. Our internal control over financial reporting is designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with accounting principles generally accepted in the United States of America.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies may deteriorate.
Management conducted an evaluation of the effectiveness of our internal control over financial reporting as of December 31, 2022 using the criteria issued by the Committee of Sponsoring Organizations of the Treadway Commission ("COSO") in the 2013 Internal Control-Integrated Framework. Based on that evaluation, management believes that our internal control over financial reporting was effective as of December 31, 2022.
The effectiveness of our internal control over financial reporting as of December 31, 2022 has been audited by Ernst & Young LLP, an independent registered public accounting firm, which also audited our Consolidated Financial Statements for the year ended December 31, 2022. Ernst & Young LLP's report on our internal control over financial reporting is set forth below.
Delta Air Lines, Inc. | 2022 10-K 103
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
The Board of Directors and Stockholders of
Delta Air Lines, Inc.
Opinion on Internal Control over Financial Reporting
We have audited Delta Air Lines, Inc.’s internal control over financial reporting as of December 31, 2022, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria). In our opinion, Delta Air Lines, Inc. (the Company) maintained, in all material respects, effective internal control over financial reporting as of December 31, 2022, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the 2022 consolidated financial statements of the Company and our report dated February 10, 2023 expressed an unqualified opinion thereon.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Annual Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects.
Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitation of Internal Control Over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
| Atlanta, Georgia | /s/ Ernst & Young LLP | ||||
| February 10, 2023 |
Delta Air Lines, Inc. | 2022 10-K 104
Item 9B. OTHER INFORMATION
None.
Item 9C. DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS
Not Applicable.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
Information required by this item is set forth under the headings "Governance - Board Matters" and "Proposal 1 - Election of Directors" in our Proxy Statement to be filed with the Commission related to our 2023 Annual Meeting of Stockholders ("Proxy Statement"), and is incorporated by reference. Certain information regarding Delta's executive officers is contained in Part I of this Form 10-K under the heading "Information About Our Executive Officers."
Item 11. EXECUTIVE COMPENSATION
Information required by this item is set forth under the headings "Executive Compensation" and "Director Compensation" in our Proxy Statement and is incorporated by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
Securities Authorized for Issuance Under Equity Compensation Plans
The following table provides information about the number of shares of common stock that may be issued under Delta's equity compensation plans as of December 31, 2022.
| Equity compensation plan information | |||||||||||
| Plan Category | (a) No. of Securities to be Issued Upon Exercise of Outstanding Options, Warrants and Rights**(1)** | (b) Weighted-Average Exercise Price of Outstanding Options, Warrants and Rights**(2)** | (c) No. of Securities Remaining Available for Future Issuance Under Equity Compensation Plans (Excluding Securities Reflected in Column (a))****(3) | ||||||||
| Equity compensation plans approved by securities holders | 8,162,240 | $ | 38.22 | 17,435,304 | |||||||
| Equity compensation plans not approved by securities holders | — | — | — | ||||||||
| Total | 8,162,240 | $ | 38.22 | 17,435,304 |
(1)Includes a maximum of 1,971,835 shares of common stock that may be issued upon the achievement of certain performance conditions under outstanding performance share awards as of December 31, 2022.
(2)Includes performance share awards, which do not have exercise prices. The weighted average exercise price of outstanding options at December 31, 2022 was $50.40.
(3)Reflects shares remaining available for issuance under Delta's Performance Compensation Plan. If any shares of our common stock are covered by an award under the Plan that expires, is canceled, forfeited or otherwise terminates without delivery of shares (including shares surrendered or withheld for payment of taxes related to an award), then such shares will again be available for issuance under the Plan except for (1) any shares tendered in payment of an option, (2) shares withheld to satisfy any tax withholding obligation with respect to the exercise of an option or stock appreciation right ("SAR") or (3) shares covered by a stock-settled SAR or other awards that were not issued upon the settlement of the award. Because 3,107,633 shares of restricted stock remained unvested and subject to forfeiture as of December 31, 2022, these shares could again be available for issuance.
Other information required by this item is set forth under the heading "Share Ownership - Beneficial Ownership of Securities" in our Proxy Statement and is incorporated by reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
Information required by this item is set forth under the headings "Governance - Board Matters" and "Proposal 1 - Election of Directors" in our Proxy Statement and is incorporated by reference.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
Information required by this item is set forth under the heading "Proposal 4 - Ratification of the Appointment of Independent Auditors" in our Proxy Statement and is incorporated by reference.
Delta Air Lines, Inc. | 2022 10-K 105
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
(a) (1). The following is an index of the financial statements required by this item that are included in this Form 10-K:
Report of Independent Registered Public Accounting Firm
Consolidated Balance Sheets—December 31, 2022 and 2021
Consolidated Statements of Operations for the years ended December 31, 2022, 2021 and 2020
Consolidated Statements of Comprehensive Income/(Loss) for the years ended December 31, 2022, 2021 and 2020
Consolidated Statements of Cash Flows for the years ended December 31, 2022, 2021 and 2020
Consolidated Statements of Stockholders' Equity for the years ended December 31, 2022, 2021 and 2020
Notes to the Consolidated Financial Statements
(2). Financial Statement Schedules. Financial statement schedules are not included herein as the required information is not applicable or is not present in amounts sufficient to require submission of the schedule, or because the information required is included in the Consolidated Financial Statements and accompanying notes included in this Form 10-K.
(3). Exhibit List.
The exhibits required by this item are listed below. The management contracts and compensatory plans or arrangements required to be filed as an exhibit to this Form 10-K are listed as Exhibits 10.12 through 10.21.
Note to Exhibits: Any representations and warranties of a party set forth in any agreement (including all exhibits and schedules thereto) filed with this Annual Report on Form 10-K have been made solely for the benefit of the other party to the agreement. Some of those representations and warranties were made only as of the date of the agreement or such other date as specified in the agreement, may be subject to a contractual standard of materiality different from what may be viewed as material to stockholders, or may have been used for the purpose of allocating risk between the parties rather than establishing matters as facts. Such agreements are included with this filing only to provide investors with information regarding the terms of the agreements, and not to provide investors with any other factual or disclosure information regarding the registrant or its business.
Delta is not filing any instruments evidencing any indebtedness because the total amount of securities authorized under any single such instrument does not exceed 10% of the total assets of Delta and its subsidiaries on a consolidated basis. Copies of such instruments will be furnished to the Securities and Exchange Commission upon request.
Delta Air Lines, Inc. | 2022 10-K 106
10.6(b) First Amendment to Term Loan Credit and Guaranty dated as of December 4, 2022 among SkyMiles IP Ltd., Delta Air Lines, Inc. and Barclays Bank PLC, as administrative agent.
Delta Air Lines, Inc. | 2022 10-K 107
10.7(b) Sixth Supplement to Anchor Tenant Agreement dated as of April 8, 2022 between JFK International Air Terminal LLC and Delta Air Lines, Inc. (Filed as Exhibit 10.1 to Delta's Quarterly Report on Form 10-Q for the quarter ended June 30, 2022).*
10.9(b) Amendment No. 3, dated May 10, 2017, to Airbus A330-900 Aircraft and A350-900 Aircraft Purchase Agreement dated as of November 24, 2014 between Airbus S.A.S. and Delta Air Lines, Inc. ("Amendment No. 3") (Filed as Exhibit 10.2(a) to Delta's Quarterly Report on Form 10-Q for the quarter ended June 30, 2017).*/**
10.9(d) Amendment No. 8, dated as of October 30, 2018, to Airbus A330-900 Aircraft and A350-900 Aircraft Purchase Agreement dated as of November 24, 2014 between Airbus S.A.S. and Delta Air Lines, Inc. ("Amendment No. 8") (Filed as Exhibit 10.7(d) to Delta’s Annual Report on Form 10-K for the year ended December 31, 2018).*/**
10.9(g) Amended and Restated Letter Agreement No. 1, dated as of July 30, 2020, relating to Airbus A330-900 Aircraft and A350-900 Aircraft Purchase Agreement dated as of November 24, 2014 (Filed as Exhibit 10.1(b) to Delta's Quarterly Report on Form 10-Q for the quarter ended September 30, 2020).*/**
10.10(b) Amendment No. 2, dated as of July 30, 2020 to Airbus A321neo Aircraft Purchase Agreement, dated as of December 15, 2017 between Delta and Airbus S.A.S. (Filed as Exhibit 10.2(a) to Delta's Quarterly Report on Form 10-Q for the quarter ended September 30, 2020).*/**
10.10(c) Amended and Restated Letter Agreement No. 3, dated as of July 30, 2020, relating to Airbus A321neo Aircraft Purchase Agreement, dated as of December 15, 2017 between Delta and Airbus S.A.S. (Filed as Exhibit 10.2(b) to Delta's Quarterly Report on Form 10-Q for the quarter ended September 30, 2020).*/**
10.10(d) Amendment No. 3, dated April 22, 2021, to Airbus A321neo Aircraft Purchase Agreement, dated as of December 15, 2017, between Airbus S.A.S. and Delta Air Lines, Inc. ("Amendment No. 3") (Filed as Exhibit 10.3(a) to Delta's Quarterly Report on Form 10-Q for the quarter ended June 30, 2021).*/**
Delta Air Lines, Inc. | 2022 10-K 108
10.10(f) Amendment No. 4, dated August 20, 2021, to Airbus A321neo Aircraft Purchase Agreement, dated as of December 15, 2017, between Airbus S.A.S. and Delta Air Lines, Inc. ("Amendment No. 4") (Filed as Exhibit 10.1 to Delta's Quarterly Report on Form 10-Q for the quarter ended September 30, 2021).*/**
10.14 Description of Certain Benefits of Members of the Board of Directors and Executive Officers (Filed as Exhibit 10.14 to Delta's Annual Report on Form 10-K for the year ended December 31, 2021).*
10.15(a) Delta Air Lines, Inc. 2020 Long-Term Incentive Program (Filed as Exhibit 10.14 to Delta’s Annual Report on Form 10-K for the year ended December 31, 2019).*
21.1 Subsidiaries of the Registrant.
23.1 Consent of Ernst & Young LLP.
31.1 Rule 13a-14(a)/15d-14(a) Certification of Chief Executive Officer.
31.2 Rule 13a-14(a)/15d-14(a) Certification of Chief Financial Officer.
Delta Air Lines, Inc. | 2022 10-K 109
101.INS XBRL Instance Document - The instance document does not appear in the interactive data file because its XBRL tags are embedded within the inline XBRL document.
101.SCH XBRL Taxonomy Extension Schema Document
101.CAL XBRL Taxonomy Extension Calculation Linkbase Document
101.DEF XBRL Taxonomy Extension Definition Linkbase Document
101.LAB XBRL Taxonomy Extension Labels Linkbase Document
101.PRE XBRL Taxonomy Extension Presentation Linkbase Document
104 The cover page from this Annual Report on Form 10-K for the year ended December 31, 2022 formatted in Inline XBRL (included in Exhibit 101)
- Incorporated by reference.
** Portions of this exhibit have been omitted as confidential information.
Item 16. FORM 10-K SUMMARY
Not applicable.
Delta Air Lines, Inc. | 2022 10-K 110
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized, on the 10th day of February, 2023.
| DELTA AIR LINES, INC. | |||||||||||
| By: | /s/ Edward H. Bastian | ||||||||||
| Edward H. Bastian | |||||||||||
| Chief Executive Officer |
Delta Air Lines, Inc. | 2022 10-K 111
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below on the 10th day of February, 2023 by the following persons on behalf of the registrant and in the capacities indicated.
| Signature | Title | |||||||
| /s/ Edward H. Bastian | Chief Executive Officer and Director (Principal Executive Officer) | |||||||
| Edward H. Bastian | ||||||||
| /s/ Daniel C. Janki | Executive Vice President and Chief Financial Officer (Principal Financial Officer) | |||||||
| Daniel C. Janki | ||||||||
| /s/ William C. Carroll | Senior Vice President - Controller (Principal Accounting Officer) | |||||||
| William C. Carroll | ||||||||
| /s/ Francis S. Blake | Chairman of the Board | |||||||
| Francis S. Blake | ||||||||
| /s/ Greg Creed | Director | |||||||
| Greg Creed | ||||||||
| /s/ David G. DeWalt | Director | |||||||
| David G. DeWalt | ||||||||
| /s/ William H. Easter III | Director | |||||||
| William H. Easter III | ||||||||
| /s/ Leslie D. Hale | Director | |||||||
| Leslie D. Hale | ||||||||
| /s/ Christopher A. Hazleton | Director | |||||||
| Christopher A. Hazleton | ||||||||
| /s/ Michael P. Huerta | Director | |||||||
| Michael P. Huerta | ||||||||
| /s/ Jeanne P. Jackson | Director | |||||||
| Jeanne P. Jackson | ||||||||
| /s/ George N. Mattson | Director | |||||||
| George N. Mattson | ||||||||
| /s/ Sergio A.L. Rial | Director | |||||||
| Sergio A.L. Rial | ||||||||
| /s/ David S. Taylor | Director | |||||||
| David S. Taylor | ||||||||
| /s/ Kathy N. Waller | Director | |||||||
| Kathy N. Waller |
Delta Air Lines, Inc. | 2022 10-K 112