 filings.tools
Item 1. Business
133K characters. Original on sec.gov · Markdown
Item 1. Business
Quest Diagnostics Incorporated is the world's leading provider of diagnostic information services. We empower people to take action to improve health outcomes. Derived from the world's largest database of clinical lab results, our diagnostic insights reveal new avenues to identify and treat disease, inspire healthy behaviors and improve health care management. In the right hands and with the right context, our diagnostic insights can inspire actions that transform lives.
Quest Diagnostics was incorporated in Delaware in 1990; its predecessor companies date back to 1967. In 2017, we celebrated 50 years of life-changing results. We conduct business through our headquarters in Secaucus, New Jersey, and our laboratories, patient service centers, offices and other facilities around the United States and in selected locations outside the United States. Unless the context otherwise requires, the terms “Quest Diagnostics,” the “Company,” “we” and “our” mean Quest Diagnostics Incorporated and its consolidated subsidiaries.
During 2017, we generated net revenues of $7.7 billion. Additional financial information concerning Quest Diagnostics, including our consolidated subsidiaries and businesses, for each of the years ended December 31, 2017, 2016 and 2015 is included in the consolidated financial statements and notes thereto in “Financial Statements and Supplementary Data” in Part II, Item 8.
The discussion below includes several tables. The index below is a guide to those tables.
| Index to Tables | |
| Table 1 - Vision, Goals and Values | 3 |
| Table 2 - Two Point Business Strategy | 3 |
| Table 3 - Portfolio Growth | 4 |
| Table 4 - Strategies to Accelerate Growth | 4 |
| Table 5 - Key Professional Laboratories Services Offerings | 5 |
| Table 6 - Clinical Franchises | 5 |
| Table 7 - Consumer-Centric Initiatives to Accelerate Growth | 6 |
| Table 8 - Recent Consumer-Centric Initiatives | 6 |
| Table 9 - Five Major Themes to Drive Operational Excellence | 7 |
| Table 10 - Invigorate Cost Excellence Program - Flagship Programs | 7 |
| Table 11 - Positioned to Grow and Continue to Lead | 7 |
| Table 12 - Assets and Capabilities | 9 |
| Table 13 - New or Enhanced Disease Area Solutions | 10 |
| Table 14 - Sample Collaborations | 12 |
| Table 15 - 2017 Medical and Scientific | 13 |
| Table 16 - 2017 Net Revenues | 14 |
| Table 17 - Quanum® Health Information Technology Solutions | 16 |
| Table 18 - U.S. Clinical Testing Industry | 17 |
| Table 19 - Key Trends | 18 |
| Table 20 - Contributing to Reducing Healthcare Costs and Improving Care | 22 |
| Table 21 - Customers | 23 |
| Table 22 - Factors Considered When Selecting a Diagnostics Information Services Provider | 25 |
| Table 23 - 2017 Medicare and Medicaid Revenues as % of Consolidated Net Revenues | 29 |
| Table 24 - Key Regulatory Schemes | 30 |
| Table 25 - Information Available at Our Corporate Governance Webpage | 32 |
| Table 26 - Executive Officers | 33 |
The discussion also uses the following defined terms:
ACA - Affordable Care Act
ACO - Accountable Care Organization
CAP - The College of American Pathologists
CLIA - Clinical Laboratory Improvement Act
CMS - Centers for Medicare and Medicaid Services
FDA - U.S. Food and Drug Administration
IDN - Independent Delivery Network (including hospital health systems)
IPA - Independent Physician Association
LDT - Laboratory-Developed Test
PAMA - The Protecting Access to Medicare Act of 2014
OUR STRATEGY AND STRENGTHS
In 2012, Quest Diagnostics launched a new vision, goals and strategy.
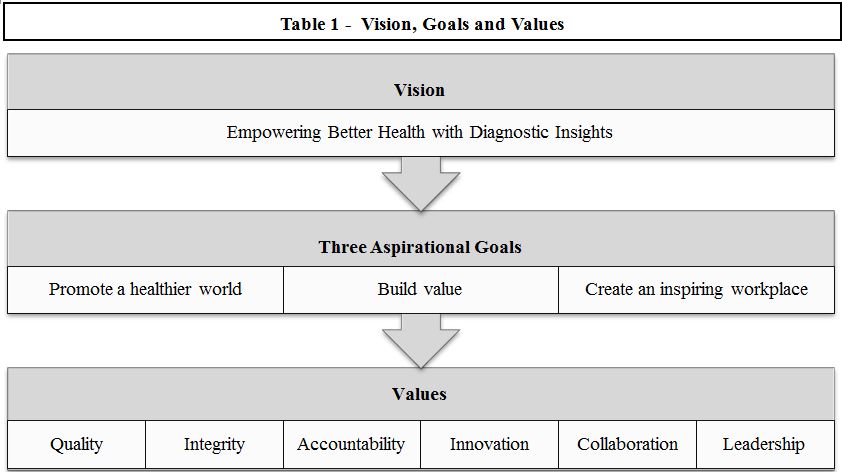
Our Strategy
In November 2012, we introduced a five-point business strategy to achieve our vision and our goals. We executed on this strategy, and at our Investor Day in November 2016, we updated our strategy to reflect our progress, narrowing our focus to two elements. Our Board of Directors has reviewed our strategy.
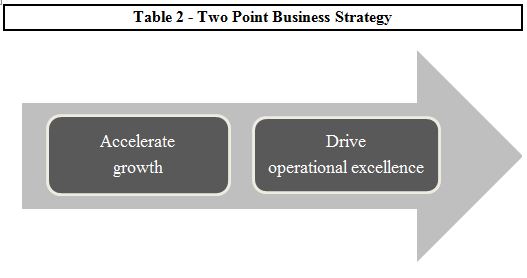
- Accelerate growth. Our strategy to accelerate revenue growth is based on a new way of looking at the Company’s portfolio of services. The Company's portfolio, from the perspective of growth, can be looked at as discussed in the following table.
| Table 3 - Portfolio Growth | |||
| Theme | Key Characteristics | At A Glance | Quest Value Proposition |
| General Diagnostics | Testing services generating strong cash flows and steady growth | Routine and non-routine testing services Largest revenue stream Essential portion of health care delivery | Scale Operational excellence Access and convenience |
| Advanced Diagnostics | Testing services providing faster growth through innovation testing model | Genetic and advanced molecular testing services An important part of precision medicine A growing set of unique, innovation-based competitors | Rich clinical, scientific and medical innovation expertise Quality and reliability of new assays Delivering on amplified customer expectations |
| Diagnostic Services | Laboratory and data-related healthcare opportunities providing faster growth | Enables partners to deliver health care more efficiently (e.g., risk assessment; Professional Laboratory Services; wellness) Services to support population health (e.g., data analytics; extended care services) | Extensive diagnostic capability Large and growing database and analytics expertise Partnerships with industry leaders across healthcare landscape |
The Company has identified five strategies to accelerate growth. They are set forth in the following table and discussed further below.
| Table 4 - Strategies to Accelerate Growth |
| Organic growth through: |
| 1. Partnerships with health plans, hospital systems and other risk bearing entities |
| 2. Offering the broadest access to diagnostic innovation |
| 3. Recognition as the consumer-friendly provider of diagnostic information services |
| 4. Supporting population health with data analytics and extended care services |
| Additionally: |
| 5. Grow 1-2% per year through accretive, strategic acquisitions |
The Company also plans to pursue strategic relationships to help accelerate growth. We believe that strategic relationships, including with healthcare providers, public health authorities, consumer-focused entities and others, can position us for growth at the center of healthcare and that healthcare companies that can partner effectively with others will be successful in the long term. The Company has maintained strategic partnerships over the years, and in recent years has pursued additional collaborations with leading partners. In 2017, the Company forged several new strategic relationships, including with Wal-Mart Stores, Inc., Cleveland Clinic, McKesson Specialty Health, U.S. Oncology Network and Texas Oncology. The Company's collaborations are discussed more fully below, in connection with table 14.
Growth through acquisitions. The Company has maintained a strategy, unchanged since November 2012, to grow 1-2% per year through accretive, strategic acquisitions. The Company's approach to acquisitions is discussed below on page 8, under the heading Deliver disciplined capital deployment.
Partner with health plans, independent delivery networks and other risk bearing entities. To help accelerate growth, we are focusing significant resources on large opportunities to partner with outside entities. We are deepening our relationships with health plans. This includes building an information platform to help health plans manage utilization and population health, and enhancing processes to help plans keep laboratory testing in network. We also are seeking to more effectively partner with IDNs, on their laboratory testing strategy. We have deployed a dedicated health systems team to strengthen our
relationships with IDNs, including with respect to their reference testing. We provide reference testing for approximately 50% of hospitals in the U.S., and are the leading provider of this testing in the country.
We have developed a full suite of solutions, our Professional Laboratory Services offerings, to help IDNs build and execute their laboratory strategy. Our industry-leading offering enables IDNs to improve quality, reduce the cost of care and focus on core competencies. We believe that market forces including continued price transparency, cost and utilization pressure, evolving healthcare payment models, capital needs, changing technology and limited resources will drive demand for our expertise. Our key Professional Laboratory Services offerings are highlighted in table 5 below. In 2017, we implemented new Professional Laboratory Services relationships with Montefiore Health System, a premier academic health system in the New York City area, and PeaceHealth Laboratories, in three Pacific Northwest states.
| Table 5 - Key Professional Laboratory Services Offerings | |
| Lab management outsourcing | Data diagnostics, consolidation and insights |
| Joint venture | Reference testing |
| Outreach acquisition | Supply chain management |
| Test menu management | Programs enabling effective patient care management |
Offer the broadest access to diagnostic innovation. Our diagnostic solutions deliver high clinical value to the medical community across the U.S. We plan to continue to create value through scientific and product innovation and solution delivery for major clinical opportunities. We are more than just a laboratory. Starting with a clinical focus on a specific disease state or clinical problem, we take advantage of advanced technology for more precise, comprehensive and actionable information, and deliver the information to the medical community in a meaningful way. We make innovative diagnostics solutions available to community physicians through our connectivity solutions, operational footprint and by making complex results actionable. The preferred provider relationship that we announced in 2017 with U.S. Oncology Network is an example of this. We plan to expand our innovative diagnostic solutions through research and development, as well as partnerships with academic institutions, other technology and healthcare leaders and public health agencies. Our collaboration with Cleveland Clinic, as well as our collaboration with McKesson Specialty Health, U.S. Oncology Network and Texas Oncology, are examples we announced in 2017 of our approach to such partnerships.
Our clinical franchises, working with our research and development team, focus on these opportunities and coordinate with our commercial organization to deliver new and improved solutions. Our franchises are designed to enable us to perform like a boutique service provider while maintaining the advantages of our scale, and to identify and access growing market segments so that we can more wisely deploy our resources and target opportunities to best serve our customers and patients.
| Table 6 - Clinical Franchises | |
| Cardiovascular, Metabolic and Endocrinology | Oncology |
| General Health and Wellness | Prescription Drug Monitoring and Toxicology |
| Infectious Diseases and Immunology | Sports Science and Human Performance |
| Neurology | Women’s and Reproductive Health |
Our 2017 introduction of QHerit genetic testing, non-fasting cholesterol testing with improved method for assessing heart disease risk and aiding treatment decisions, and our expanded Blueprint for Wellness® offering, as well as the continued growth of our prescription drug monitoring and toxicology and infectious diseases and immunology offerings, are recent examples of the power of our clinical franchises to deliver new solutions and foster organic growth.
Be recognized as the consumer-friendly provider of diagnostic information services. We plan to increase our retail presence, improve the consumer experience and offer consumers the ability to directly access our quality diagnostic information services. We have multiple consumer-centric initiatives, shown in the following table, focused on securing growth in today's changing healthcare landscape.
| Table 7 - Consumer-Centric Initiatives to Accelerate Growth | |
| Consistent and superior consumer experience | Retail consumer partnerships |
| Information and connectivity | Consumer testing offerings |
The Company has a long history of focusing on consumer interests, including being the first national diagnostic information services provider to offer on-line patient appointment scheduling and a patient connectivity solution. The Company has recently taken several actions in support of this strategy, including those set forth in the following table.
| Table 8 - Recent Consumer-Centric Initiatives | |
| Enhance patient experience | • Continued rollout of enhanced patient experience, including real-time payment determination for several major payors and electronic check-in. • Introduced for consumers lipid testing without the need for fasting. |
| Expand convenient access to testing services | • Partnership with Safeway to expand convenient access to testing services at select Safeway locations across the United States; the number of locations significantly increased in 2017. |
| Consumer-initiated testing service | • QuestDirectTM, our consumer-initiated testing service, available in Colorado and Missouri. Consumer-initiated testing also is available in Arizona and Oklahoma through our joint ventures in those states. |
| Expand consumer access to test results | • >4.8 million registered users in our MyQuest® health portal and mobile connectivity solution. Implemented MyQuest Advanced Access®, which enables patients to access their historical laboratory test results and trends. |
| Expand access to basic health care services | • Launched partnership with Wal-Mart Stores to expand access to basic health care services. |
| Expand sports diagnostics offering | • Continued enhancement and expansion of our Blueprint for Athletes® offerings. |
| Expand consumer awareness | • Multi-year global collaboration with AncestryDNA to provide genotyping test services. |
Support population health with data analytics and extended care services. We are working to accelerate growth by building offerings to support population health with data analytics and extended care services. We are accelerating our efforts to leverage the power of our information assets, to offer solutions using data information services and strategies that enable our customers to deliver the most effective healthcare to the right populations and individuals. We integrate our extensive clinical data to help manage populations and target health care solutions, and pursue opportunities to provide solutions centered on evidence-supported standards of care and guideline mandated testing. Currently the Company is developing additional solutions based on data insights, including pre- and post-market launch pharmaceutical data services as well as clinical trial patient recruitment solutions.
We also are developing extended care services, which will leverage our assets and capabilities (e.g., call centers, patient service centers and mobile workforce) and our collaborative approach. We anticipate that these services will include offerings designed to capture and document information to help healthcare providers, health plans, sponsors and IDNs deliver better care and identify and fill gaps in care for their patient populations. Our joint venture with Wal-Mart Stores, and our Chronic Care Management offering, both launched in 2017, are examples of our efforts to accelerate growth in this manner.
- Drive operational excellence. We strive to enhance operational excellence and improve our quality and efficiency across every portion of our value chain and supporting operations, from the time that we interact with a potential customer until the time we receive payment. Improving our operations will yield many benefits, including: enhancing customer experience; improving our quality and competitiveness; strengthening our foundation for growth; and increasing employee engagement and shareholder value.
We are building a superior experience, at lower cost, for all of our customers, including patients, health plans, IDNs and physicians. We endeavor to improve our processes and effectiveness at the same time. We are guided by a service dashboard that focuses throughout our operations on quality for patients, health care providers and employees, including medical quality, on-time delivery, competitive costs and employee safety. We are focusing on five major themes to drive operational excellence, highlighted in the following table.
| Table 9 - Five Major Themes to Drive Operational Excellence | |
| Increase digital enablement | Expand margins through cost excellence program |
| Inspire and engage employees | Transform platform for growth |
| Deliver quality and service with Quest Management System |
In 2017, we made strong progress on our initiatives. For example, we completed implementation of our new logistics system, have outfitted 60% of our patient service centers with electronic patient check-in and have reduced results-only call volume by nearly 20% compared to 2016 through increased adoption of our digital solutions.
Our cost excellence program, Invigorate, has included structured plans to drive savings and improve performance across the end-to-end value chain.
| Table 10 - Invigorate Cost Excellence Program - Flagship Programs | |
| Revenue services | Organizational design |
| Information technology | Procurement |
| Laboratory | Field and customer service |
Since 2014, we have been pursuing a goal of $600 million in additional run-rate savings exiting 2017, compared to 2011. We exited 2017 with total run-rate savings in excess of $1.3 billion, compared to 2011. The Company plans to continue to pursue opportunities to achieve additional cost savings.
Our Strengths
We offer high value diagnostic information services and diagnostic solutions that are attractive to our customers (discussed under the heading Customers beginning on page 22). We believe that our customers prefer providers that offer a comprehensive and innovative range of tests and services and convenient access to those services. We believe that, by offering such services, we strengthen our market offering, market position and reputation. Table 11 summarizes our strengths, which are discussed in greater detail below.
| Table 11 - Positioned to Grow and Continue to Lead | |
| A foundation of strong operating principles | Unmatched size, scale and capabilities |
| Leader in providing innovative solutions and diagnostic insights | Strong focus on quality and providing a superior customer experience |
| Strong collaborator, and strong relationships with healthcare stakeholders | Medical and scientific expertise |
| Deliver strong value |
Strong operating principles. We have a foundation of three strong operating principles: strengthen organizational capabilities; deliver disciplined capital deployment; and remain focused on diagnostic information services.
Strengthen organizational capabilities. We continuously strive to strengthen our organizational capabilities to support our strategy, enable growth and productivity, better focus on our customers, speed decision-making and empower employees. Highlights include:
| • | Starting in 2012, we have made changes to our senior management team and restructured our organization to eliminate organizational barriers in our core business, provide leadership in defined geographies, eliminate three unnecessary management layers and streamline regional operations. Our organization is designed to align around future growth opportunities, to coordinate upstream and downstream units in our business for seamless execution and to leverage our company-wide infrastructure to gain more capability, value and efficiency. |
| • | We established the Quest Management System to manage our Company. This system provides a foundation for day-to-day management, and includes a common set of best-in-class business performance tools to help us |
develop new capabilities to improve our Company. The system enables us to run the Company with a common language, approach and philosophy, and supports our efforts as we build a high-performance culture, with employees focused on behaviors to make us more agile, transparent, customer-focused, collaborative and performance oriented.
| • | We launched our new brand - Action from InsightTM - recommitting to a superior customer experience. |
| • | We implemented across our entire organization our Everyday Excellence program, which includes guiding principles to support a superior customer experience and to inspire our employees to be their best every day, with every person and with every customer interaction. |
| • | We (i) offer our Leading Quest Academy, which is designed to strengthen our more senior employee leaders through a highly experiential leadership development program focused on creating a high-performance culture and sharpening the capabilities needed to lead our organization, (ii) offer a leadership training program for our supervisor-level employees and (iii) in 2017 started a new leadership training program for our manager-level employees. |
| • | Reinforcing our commitment to integrity as one of our core values, we updated our Code of Ethics to better align with our brand, goals and vision. |
| • | Employees reported higher engagement levels compared to prior years. |
Remain focused on diagnostic information services. We maintain a sharp focus on providing diagnostic information services. In 2016, we completed our efforts to refocus on these services when we sold our Focus Diagnostics products business and concluded the disposition of our Celera® products business. Since 2012, we also have disposed of our OralDNA® salivary diagnostics business, our HemoCue® and Enterix® diagnostic products businesses and ibrutinib royalty rights. These dispositions collectively generated approximately $1 billion of proceeds. In 2015, we also contributed our business of central laboratory testing for clinical trials to a joint venture, Q2 SolutionsTM, in which we maintain a minority interest.
Deliver disciplined capital deployment. We focus on shareholder returns and returns on invested capital through a framework that encompasses improving operating performance and disciplined capital deployment.
Our disciplined capital deployment framework includes dividends, share repurchases and investment in our business. The framework is grounded in maintaining an investment grade credit rating. We expect to return a majority of our free cash flow to investors through a combination of dividends and share repurchases.
Consistent with that expectation, in February 2018 we announced that we increased our quarterly common stock dividend by over 11%, from $0.45 per common share to $0.50 per common share. This represents our seventh increase in the dividend since 2011. In December 2016, our Board of Directors approved a $1.0 billion increase in repurchase authority under our common stock repurchase program. Since the beginning of 2012, we have returned more than $2.6 billion to stockholders through repurchases of our common stock.
We expect to generate 1-2% revenue growth per year through value-creating, strategically-aligned acquisitions using disciplined investment criteria. We screen potential acquisitions using guidelines that assess strategic fit and financial considerations, including value creation, returns on invested capital and impact on our earnings. In 2017, we acquired:
| • | the outreach laboratory testing business of PeaceHealth Laboratories in the Pacific Northwest; |
| • | the Lewisville, Texas - based laboratory businesses Med Fusion and ClearPoint, which form the basis for our first national center of excellence in precision diagnostics for oncology. As part of that acquisition, we became a preferred provider of advanced oncology diagnostics for the U.S. Oncology Network, consisting of over 1,400 independent, community-based physicians, and a preferred provider of a full range of inpatient and outpatient diagnostic services for 12 hospitals of Baylor Scott & White Health in North Texas; |
| • | the Shiel Medical Laboratory business in the greater New York City area; |
| • | certain assets of California Laboratory Associates, a clinical lab network serving patients and providers in the greater Los Angeles area; and |
| • | Cleveland HeartLab, a leader in innovative diagnostics services for managing cardiovascular disease. We established our national cardiometabolic center of excellence at Cleveland HeartLab's laboratory facility in Cleveland. |
We will continue to invest in our business in a disciplined manner, including focusing on enhancing our solid foundation of strategic assets and capabilities, accelerating growth and driving operational excellence. Our near-term investments in growth are likely to focus on the strategies to accelerate growth set forth in Table 4 above. Our near-term investments to drive operational excellence are likely to focus on improving the customer experience and gaining efficiency, systems standardization, digital enablement of our processes and footprint optimization.
Our share repurchases, dividends and capital expenditures in each of the last five years are presented in the Selected Historical Financial Data of Our Company section beginning on page 54. Our acquisitions in each of the last three years are further discussed in Note 5 to the Consolidated Financial Statements (Part II, Item 8 of this Report).
Our assets and capabilities. We are the world's leading provider of diagnostic information services. We are the leading provider in the United States of clinical laboratory and anatomic pathology testing, and related services.
| Table 12 - Assets and Capabilities | |
| • Provide healthcare connectivity solutions to >300,000 clinician and hospital accounts and interface with >700 electronic health records systems | • Own or control approximately 880 issued and 590 pending patents worldwide in 2017 |
| • Strong logistics capabilities • make nearly 80,000 stops daily • >3,600 courier vehicles • 23 aircraft serving the U.S. | • One of the largest medical and scientific staffs in the industry to provide interpretive consultation • Approximately 650 M.D.s and Ph.D.s, many of whom are recognized leaders in their field • genetic counselors |
| • >20,000 phlebotomists, paramedics, nurses and other health and wellness professionals | • >6,200 patient access points, the most extensive network in the U.S., including phlebotomists in physician offices and >2,200 of our own patient service centers |
| • Access to approximately 80% of U.S. insured lives | • Processed approximately 164 million test requisitions in 2017 |
| • Industry-leading test menu | • Access to >40 billion patient data points from test results delivered over past decade |
Innovation. We are a leading innovator in diagnostic information services. We continue to introduce new tests, including many with a focus on personalized and targeted medicine, and new services. Our capabilities include discovery, technology development and clinical validation of diagnostic tests. We develop tests at our esoteric laboratories, such as Quest Diagnostics Nichols Institute®, Athena DiagnosticsTM, Med Fusion and Cleveland HeartLab.
We successfully transfer technical innovations to the market through our in-house expertise and our relationships with technology developers, including the academic community, pharmaceutical and biotechnology firms, emerging medical technology companies and others that develop and commercialize novel diagnostics, pharmaceutical and device technologies. We search for new opportunities and continue to build a robust pipeline of new solutions. Through our strengths in assay development and the commercialization of testing services, we believe that we are the partner of choice for developers of new technologies, services and tests to introduce their products to the marketplace.
We seek innovations and solutions that help healthcare providers care for their patients through better testing for predisposition, screening, monitoring, diagnosis, prognosis and treatment choices, and that will reduce the overall cost of healthcare. We seek to develop innovations and solutions that help to determine a patient's genotype or gene expression profile relative to a particular disease and its potential therapies, because they can help healthcare providers to determine a patient's susceptibility to disease or to tailor medical care to an individual's needs - such as determining if a medication might be an optimum choice for a particular person, or tailoring the right dosage once the proper medicine is prescribed. In addition, we aim to develop holistic solutions responsive to challenges that healthcare providers and patients face, by developing solutions of multiple tests, information and services focused on specific clinical challenges, and taking advantage of the latest informatics capabilities. We also look for innovations and solutions that are less invasive than currently available options, to increase the choices that healthcare providers and patients have for the collection of diagnostic samples. We additionally seek innovation in the ways we bring solutions to customers, and in the customer experience.
We have expertise with laboratory developed tests for companion and complementary diagnostics, and can offer an array of assets and services to support the development of companion diagnostics, including our robust data set and patient services network.
With these priorities in mind, during 2017 we introduced several new or enhanced disease area solutions, including those discussed below.
| Table 13 - New or Enhanced Disease Area Solutions | |
| Cardiovascular, Metabolic and Endocrinology | For all of our cholesterol test services that involve estimates of low-density lipoprotein cholesterol (LDL-C), we introduced a novel LDL-C calculation that improves accuracy of heart disease screening and helps personalize treatment with lipid-lowering medications. The method also does not require patients to fast from food for several hours before testing, enhancing the patient experience. Through our acquisition of Cleveland HeartLab, we are now offering novel biomarkers for cardiovascular risk assessment and management including MPO, Oxidized LDL and ADMA testing. We have also implemented a service for health plans, health systems and others that enables them to help close gaps in care for diabetes, using our Quanum® offering together with our testing solutions and access points (including patient service centers and mobile resources) to engage patients in their homes and places of employment. |
| General Health and Wellness | We launched our new Blueprint for Wellness® solution, which enables physician telemedicine consultation and referral into care. It also offers additional clinical solutions for participants, such as a diabetes prevention program, colon cancer testing and renal failure services. |
| Infectious Diseases and Immunology | We launched a new genetic marker, HLA-B*58:01, for evaluating risk of severe cutaneous adverse skin reactions to allopurinol, a drug used to treat gout. We introduced the Xpert® MTB/RIF test providing simultaneous detection of both mycobacterium tuberculosis and rifampin resistance mutations. This test can help physicians decide on whether to remove patients with suspected tuberculosis from isolation earlier. We introduced tree nut component testing, specific IgE blood tests that detect sensitization to specific allergens. Tree nut allergies may elicit severe and even life-threatening reactions in sensitized individuals. We launched a Systemic Sclerosis Antibody Panel and a Myositis Specific Antibody Panel, providing support for the diagnosis and management of these chronic, multisystem, heterogeneous autoimmune diseases. We updated our Anti-nuclear Antibody test offering to enable primary care physicians and specialists to order the right tests in sequence in order to enable diagnosis of rheumatologic disease. |
| Neurology | We introduced a novel mass spectrometry test for Alzheimer's biomarkers which offer the most specific assessment of established biomarkers (A Beta 40,42 and ApoE) in the cerebrospinal fluid to guide management, research and clinical trials. We began to offer a new epilepsy test using next generation sequencing, providing a high quality assessment of all genes known to be involved in the disease. We initiated implementation of an integrated dementia diagnostic solution based on our collaboration with University of California, San Francisco. This offering integrates laboratory testing, cognitive exam, MRI and clinical evaluation to help primary doctors assess and diagnose dementia to identify treatable cause, shorten time to diagnosis and eliminate waste. |
| Oncology | We updated our offering for assessment of DNA profiling of cancer - IBM Watson® Genomics from Quest Diagnostics - to improve performance on the variety of cancer sample types that are tested in the community setting. We introduced PDL1 testing to be used as a companion diagnostic for immunotherapy in cancer. We introduced EGFR testing of plasma in cancer patients. This offering enables evaluation of EFGR mutation status of a patient's lung cancer through a simple blood draw, without the need for a tissue biopsy. In collaboration with Veracyte, we introduced thyroid cancer molecular testing services. |
| Prescription Drug Monitoring and Toxicology | We implemented testing services for common drugs in several additional laboratories, to reduce test turnaround time in response to increasing demand based on the opioid / prescription drug crisis. We also validated an increased number of our Prescription Drug and Drugs of Abuse testing services on oral fluid samples, offering greater convenience and non-invasive testing for our patients. |
| Sports Science and Human Performance | We expanded and reconfigured the Blueprint for AthletesTM service, which gives athletes insights on their own biology to help improve fitness and performance. We added at-home collection options, including "concierge collection" and the Mitra® Microsampling device. We also added custom coaching, to help athletes create game plans to improve performance. We reconfigured the test services in "stacks" that feature panels of tests with results provided in easy to read action-oriented reports. The stacks include, among others, "Blueprint One" and "Endurance and Conditioning." |
| Women’s and Reproductive Health | We introduced QHerit, a new genetic pan-ethnic carrier screening panel aligned with new medical guidelines. It provides men and women with insights into the genetic risk of passing on heritable disorders to their offspring. We also introduced Creatine Biosynthesis testing to aid in the diagnosis of genetic disease. |
Relationships with healthcare stakeholders; collaboration. There are numerous stakeholders in healthcare, including insurers, employers, IDNs, physicians and other healthcare professionals, public health authorities, patients and innovators. We have relationships across the spectrum of healthcare. The patients we serve comprise approximately one-third of the adult population of the United States annually, and approximately one-half of the adult population in the United States over a three-year period. We estimate that annually we serve approximately half of the physicians and half of the hospitals in the United States.
We collaborate with partners that can help us to achieve our vision of empowering better health through diagnostic insights. Through our relationships, we believe that we are a leader in bringing to the market innovation and the ability to empower better health through diagnostic insights. As the industry leader with the largest and broadest U.S. network and a presence outside the United States, we believe we are the distribution channel of choice for developers of new solutions, including large commercial manufacturers, academic medical centers and pharmaceutical and biotechnology firms, to introduce their products to the marketplace. We maintain relationships with advisers and consultants who are leaders in key fields of science and medicine. We work with key groups and organizations, including world class healthcare and consumer-focused
leaders, to foster important advances in healthcare, including in precision medicine and healthcare delivery. Some examples of our collaborations include:
| Table 14 - Sample Collaborations | |
| Collaborator | Collaboration |
| IBM Watson® Health, Memorial Sloan Kettering Cancer Center and the Broad Institute of MIT and Harvard | IBM Watson® Genomics from Quest Diagnostics, a service that helps advance precision medicine by cognitive computing with genomic tumor sequencing. Memorial Sloan Kettering Cancer Center is supplementing Watson's corpus of scientific data with a precision oncology knowledge base to help inform precision treatment options for cancer patients, and the Broad Institute of MIT and Harvard is providing additional genome sequencing capabilities. |
| Optum | Our billing operations became part of Optum, helping us to reduce the complexity of our billing processes and fostering increased transparency of health care costs. Advance new technology services to digitize our customer orders and workflows, with the goals of reducing bad debt and payer denials and increasing operational efficiency and productivity. Increase the use of diagnostic information services, such as data analytics, population health insights and connectivity solutions, to help improve health care effectiveness and manage costs for health plans and care providers. We became Optum's primary partner for member biometric screening services that Optum provides to employers and health plans. |
| AncestryDNA | We provide testing to help meet the rapidly growing consumer demand for genetic tests that provide insights into genetic ethnicity, origins and other factors. |
| Safeway | We are providing diagnostic testing services in company-branded patient service centers in Safeway locations, enhancing convenient access to our services and diagnostic insights for patients. |
| Inovalon | Data Diagnostics®, a tool that provides real-time patient-specific data analysis that clinicians can order at the point of care to identify and help address gaps in quality, risk, utilization and medical history insights. |
| Perinatal Quality Foundation | The national initiative to advance clinically appropriate noninvasive prenatal screening. |
| University of California, San Francisco, the nation's leading university focused exclusively on health | To accelerate the translation of biomedical research into advanced diagnostics in the field of precision medicine. This collaboration has the overarching aim of enabling holistic and integrated diagnostic solutions that close gaps in care or enable new clinical value, with initial focus areas including autism, oncology, neurology and women's health. |
| U.S. Centers for Disease Control and Prevention ("CDC") | To improve public health analysis of hepatitis C screening, diagnosis and treatment, based on analysis of our database of national hepatitis C virus ("HCV") diagnostic information. With CDC and the American Medical Association, to assess the prevalence of pre-diabetes. |
| National Institutes of Health | We participate in studies they sponsor (e.g., NIH National Children Study). |
| IQVIA Holdings Inc. | Joint venture, Q2 SolutionsTM, providing central lab testing services for clinical trials. |
| Wal-Mart Stores, Inc. | Joint venture to provide expanded access to basic health care services. |
| American Diabetes Association® | To help identify people at risk for Type 2 diabetes, to share insights on how to lower the risk of developing diabetes and to share action steps that can be taken once a person is diagnosed with diabetes. |
| Cleveland Clinic | To speed the commercialization of biomarkers on inflammation and other disease areas discovered at Cleveland Clinic, including its Lerner Research Institute; Quest may independently develop test services for these biomarkers. To demonstrate the clinical and economic value of these and other biomarkers. |
| McKesson Specialty Health, U.S. Oncology Network and Texas Oncology | To enhance and nationally scale a model created by Med Fusion that standardizes clinical care pathways to ensure every patient receives the best possible cancer care. One example is highlighting available diagnostics, such as next-generation sequencing panels to aid therapy selection and monitoring for cancer. This approach guides the physician, according to guidelines and within an electronic health record, to a panel individualized to the patient's cancer type and stage of disease. |
| Arnold P. Gold Foundation | To advance humanism in healthcare. Quest is a founding member of the Gold Corporate Council. |
Medical and Scientific Expertise. Our medical and scientific experts publish research that demonstrates the clinical value and importance of diagnostic testing, including in connection with our research and development efforts. Our Quest Diagnostics Drug Testing IndexTM, which is a periodic report of trends derived from our aggregate drug testing results, is cited by employers, the federal government and the media to help identify and quantify drug abuse among the nation's workforce. The table below provides a further sample of the activities of our scientific and medical experts.
| Table 15 - 2017 Medical and Scientific | |
| Authored more than 145 publications, including approximately 85 articles in peer-reviewed journals | • Insights into diagnostic testing; introduce novel diagnostic approaches; provide latest thinking in lab testing and disease diagnosis - Addressed such topics as noninvasive prenatal screening, biomarkers for autoimmune diseases, concurrent use of opioids with other medications, and genetic testing for cancer and for cardiovascular disease risk |
| Authored textbooks or chapters | • Used by academic institutions to train healthcare providers |
| Participated on scientific committees determining guidelines for diagnostic usage | • Fields include personalized medicine, hormone testing and effective test utilization |
| Published Quest Diagnostics Health TrendsTM reports | • Identify trends in disease and wellness. - Recent reports focused on opioid use, HCV infection rates, vitamin D and misuse of prescription medications |
Health Information Technology Solutions and Information Assets. We have a history of providing leading information technology for diagnostic information services, including for patients, clinicians and healthcare organizations. We were the first national diagnostic information services provider to offer on-line patient appointment scheduling and a patient connectivity solution. We focus on protecting privacy in accordance with applicable regulatory requirements. Our MyQuest®patient healthcare portal enables patients to manage their healthcare and medical information and, among other things, use their smartphone or computer to receive and archive their Quest Diagnostics test results, find a Quest Diagnostics location and schedule appointments. At year end 2017, over 4.8 million consumers were registered on MyQuest®.
We also have significant information assets, including many years of test result data, and offer a robust portfolio of powerful analytics that inspire action and deliver value to an array of customers. With our Quanum® offerings, we are working on solutions designed to:
| • | enhance the customer experience, including ease of use and patient and provider engagement; |
| • | deliver more precise, comprehensive solutions and actionable information; |
| • | provide increased and interactive insights and analytics to patients and providers; |
| • | foster greater adherence to clinical and reimbursement guidelines; |
| • | promote population health solutions; |
| • | tap the potential of large amounts of clinical information; and |
| • | advance the development of precision medicine. |
Quality. Our goal is to provide every patient with services and products of superior quality. We strive to accomplish that through commitment, leadership, and establishing rigorous processes which we measure and continually seek to improve, and by using the Quest Management System, which provides best-in-class business performance tools to create and implement effective and sustainable quality processes. The Quest Diagnostics Quality Program includes policies and procedures to document, measure and monitor the effectiveness of our laboratory operations in providing and improving quality and meeting applicable regulatory requirements for clinical laboratory testing. The Quality Program is designed so that the quality of laboratory services is monitored objectively and evaluated systematically to deliver superior quality care, identify opportunities to improve patient care and resolve identified problems. To help achieve our goal of becoming recognized as the undisputed quality leader in the diagnostics information services industry, we have implemented our Quality System Framework, which serves as a reference guide for our employees and describes our Quality System Elements, which provide the structure for each laboratory to achieve and maintain quality processes.
Customer focus. The customer is at the center of everything we do. Customers have a choice when it comes to selecting a healthcare provider and we strive to give them reason to put their trust in us. We use customer insights in developing our approach and processes, listening to the voice of external and internal customers. Focusing on a thorough understanding of customer needs and requirements, we seek to identify and implement solutions and processes that will result in a superior customer experience. We strive to provide a superior experience for our customers because we believe that this will drive customer loyalty. Our brand -- Action from InsightTM -- reflects our commitment to a superior customer experience. We also maintain our Everyday Excellence program, which includes guiding principles to support a superior customer experience, inspiring our employees to be their best every day, with every person and with every customer interaction.
Deliver value. We are highly focused on delivering value to our customers. Diagnostic information services providers differ in the services they provide and the reimbursement they receive for their services. We believe that large diagnostic information services providers may be able to increase their share of the overall diagnostics information services industry due to their large networks and lower cost structures, including as a result of PAMA. We take advantage of our scale, and are aware of the stakeholder dynamics impacting the healthcare markets today, including the increased responsibility of patients for health care costs. Through the quality and breadth of services that we offer, the manner in which we offer them and the reimbursement that we receive for them, we strive to deliver value.
BUSINESS OPERATIONS
As of December 31, 2017, the Company was made up of two businesses: Diagnostic Information Services and Diagnostic Solutions. Our Diagnostic Information Services business develops and delivers diagnostic information services, providing insights that empower and enable a broad range of customers, including patients, clinicians, hospitals, IDNs, health plans, employers and ACOs. Our Diagnostic Solutions group includes our risk assessment services business, which offers solutions for insurers, and our healthcare information technology businesses, which offers solutions for healthcare providers.
We leverage our capabilities and assets to serve our multiple customer bases. Most of our services are provided in the United States. For the years ended December 31, 2017, 2016 and 2015, we derived approximately 1%, 1%, and 2%, respectively, of our net revenues from foreign operations. For the years ended December 31, 2017, 2016 and 2015, approximately 1% of our long-lived assets were held outside the United States. The following table shows the percentage of our 2017 net revenues generated by the activities identified.

Diagnostic Information Services
Background - clinical testing. Clinical testing is an essential element in the delivery of healthcare services. Clinicians use clinical testing for predisposition, screening, monitoring, diagnosis, prognosis and treatment choices of diseases and other medical conditions. Clinical testing is generally categorized as clinical laboratory testing and anatomic pathology services.
Clinical laboratory testing, which can be characterized as routine, non-routine or advanced, generally is performed on whole blood, serum, plasma and other body fluids, such as urine, and specimens such as microbiology samples. Clinical laboratory tests which can be performed by most clinical laboratories are considered routine. Routine testing measures various important bodily health parameters such as the functions of the kidney, heart, liver, thyroid and other organs. Commonly ordered routine tests include blood chemistries, urinalysis, allergy tests and complete blood cell counts. Non-routine tests may require professional “hands-on” attention from highly-skilled technical personnel, generally require more sophisticated informatics, technology, equipment or materials, may be performed less frequently than routine tests and may be reimbursed at higher levels than routine tests. It may be not practical, from a cost-effectiveness or infrastructure perspective, for many hospitals, IDNs, ACOs, commercial laboratories or physician office laboratories to develop and perform a broad menu of non-routine tests, or to perform low-volume non-routine testing in-house. Such tests generally are outsourced to a clinical testing laboratory which can perform these non-routine tests. Some non-routine tests are advanced. Advanced tests include procedures in the areas of molecular diagnostics (including next-generation sequencing), oncology, neurology, companion diagnostics and non-invasive pre-natal and other germline genetic testing.
Anatomic pathology services are performed on tissues, such as biopsies, and other samples, such as human cells. Anatomic pathology involves the diagnosis of cancer and other diseases and medical conditions through examination of tissue and cell samples taken from patients.
Our services. We are the world's largest provider of diagnostic information services. We provide information and insights based on the industry-leading menu of routine, non-routine and advanced clinical testing and anatomic pathology testing, and other diagnostic information services. We have built strong testing capabilities, including services for the predisposition, diagnosis, treatment and monitoring of cancers and other diseases, and offer advanced tests in many fields, including endocrinology, immunology, neurology and oncology. Increasingly, we are focused on providing solutions and insights to our customers, based on the testing that we perform, the data that we gather and our extensive medical, information and connectivity assets. We believe that offering services, solutions and insights based on a full range of tests, information assets and other capabilities strengthens our market offering, market position and reputation.
The value creation side of our business is organized by clinical franchise and focuses on customer solutions for the marketplace, including new test development and diagnostic insights. It also includes product and commercial marketing. The value delivery side includes sales, laboratory operations, field operations, logistics and client services. We offer the broadest access in the United States to diagnostic information services through our nationwide network of laboratories, patient service centers, phlebotomists in physician offices, and our connectivity resources, including call centers and mobile paramedics, nurses and other health and wellness professionals. We provide interpretive consultation to healthcare providers through one of the larger medical and scientific staffs in the industry. Our in-house experts, including medical directors, scientific directors, genetic counselors and board certified geneticists, provide medical and scientific consultation to healthcare providers regarding our tests and test results, and help them best utilize our services to improve patient outcomes and enhance patient satisfaction. Our experienced staff has a passion for providing the highest quality service to our customers.
We are a leading provider of infectious disease diagnostic information services and strive to be the first to provide diagnostic solutions for emerging infectious diseases, including our offerings for Zika, West Nile Virus, SARS and Influenza A H1N1. We have leading positions in prescription drug monitoring and toxicology, in the neurology diagnostics market, in advanced cardiovascular diagnostic information services, including our CardioIQ® and Cleveland HeartLab offerings, and in cancer diagnostics, including our QuestVantageTM and Med Fusion offerings. We are a leader in providing testing for the detection of employee use of drugs of abuse, offering a full range of solutions, including urine, hair, blood and oral fluid tests. We are the largest workplace drug testing provider certified by the U.S. Department of Health and Human Services to perform drug testing using electronic custody and control forms for federally-mandated, safety-sensitive workers.
We also are a leading provider of wellness services, including biometric wellness screenings, flu shots and related preventative services that leverage clinical data to improve population health outcomes and reduce healthcare spend. Our wellness solution, Blueprint for Wellness®, begins with biometric screenings conveniently offered at the worksite or through our patient service centers. The solution includes highly personalized reporting and incentive management services. We also offer intervention programs focused on connecting participants to the right care at the right time, such as a program designed to prevent diabetes and other chronic conditions, and another program that enables participants to speak with a board-certified physician about their results and to be guided about actions based on those results. These services are sold directly to employers and through reseller partnerships with many health plans.
We offer Quanum® health information technology solutions, including our products and national healthcare provider network, to help healthcare organizations and clinicians empower better health through diagnostic insights by leveraging the power of our significant information assets, including many years of test result data, and our technology prowess, including our history of providing leading information technology for diagnostic information services. We believe that the breadth and depth of our data, combined with our powerful analytics capabilities, enables us to take advantage of important data-based opportunities in diagnostics, and provides us a competitive advantage. With Inovalon, we also offer Data Diagnostics®, an award-winning point-of-care health analytic technology that is designed to help close costly gaps in care and improve health outcomes. Our portfolio of offerings is designed to address analytic, clinical and financial needs. The solutions help healthcare organizations and clinicians analyze and put in context data, and enable them to connect across the healthcare system and engage with their stakeholders. They can enter, share and access clinical information without costly information technology implementation or significant workflow disruption. Our Quanum® offerings are highlighted in the following table.
| Table 17 - Quanum® Health Information Technology | ||
| Health Systems | Healthcare Professionals & Practices | Health Plans |
| • Data Diagnostics | • eLabs | • Data Diagnostics |
| • Lab Utilization | • ePrescribing | • On Demand Informatics |
| • ChartMaxx | • Electronic Health Record | |
| • Practice Management | ||
| • Revenue Cycle Management | ||
| • Interactive Insights | ||
| • Data Diagnostics |
We offer extended care services that focus on extending the reach of physician offices beyond their traditional four walls, and doing so when and where it is convenient for consumers. These services include offerings designed to capture and document information to help healthcare providers, health plans and IDNs deliver better care, better assess their populations and identify and fill gaps in care for their patient populations. Once gaps are identified, our services engage patients in our retail sites, in home or by telephone, including through our call centers and our mobile base capabilities. We offer services focused on risk assessment, other examinations and chronic care management, and other services like post-hospital discharge visits, diabetic retinopathy and bone density examinations.
We maintain a nationwide network of laboratories, including our world renowned Quest Diagnostics Nichols Institute® and our rapid response laboratories, which are smaller facilities where we can quickly perform an abbreviated menu of routine tests for customers that require rapid turnaround times. We operate 24 hours a day, 365 days a year. We also provide testing services, inpatient anatomic pathology and medical director services at hospital laboratories.
We provide diagnostic information services in multiple markets outside the United States. We have laboratory facilities in Gurgaon, India; Mexico City, Mexico; and San Juan, Puerto Rico. We see opportunities to bring our experience and expertise in diagnostic information services to markets outside the United States, including by leveraging existing facilities to serve new markets.
Our services primarily are provided under the Quest Diagnostics brand, but we also provide services under other brands, including AmeriPath®, Dermpath Diagnostics®, Athena Diagnostics®, ExamOne®, and Quanum®.
Diagnostic Solutions
We are the leading provider of risk assessment services for the life insurance industry. In addition, we offer healthcare organizations and clinicians robust health information technology solutions.
Risk Assessment Services. ExamOne® is the largest provider of risk assessment services to the life insurance industry in North America. We also provide risk assessment services for insurance companies operating outside North America. Our risk assessment services comprise underwriting support services, including data gathering, paramedical examinations and clinical laboratory testing and analytics, designed to assist life insurance companies objectively to evaluate the mortality risks of applicants. Most specimen collections and paramedical examinations are performed by our network of paramedical examiners at the applicant's home or workplace, but they also are offered at approximately 575 company patient service centers in the United States and approximately 400 additional locations in North America. We also contract with third parties to coordinate providing these exams at more than 350 additional locations outside North America.
Healthcare Information Technology. Our healthcare information technology offerings include our Quanum® electronic health records system and our award-winning ChartMaxx® enterprise content management solution for hospitals and health systems. Healthcare organizations have contracted for the use of ChartMaxx® at more than 300 sites in North America. Our Quanum® electronic health records offering enables clinicians to generate a complete record of a clinical patient encounter, automates and streamlines the clinician's workflow, provides clinical decision support tools, captures patient encounter notes and lab and radiology results and enables secure communication with patients and other clinicians.
Other
Q2 SolutionsTM, a joint venture with IQVIA Holdings Inc. in which we own a minority interest, is the second largest central laboratory services company in the world and provides services to customers across all segments of the biopharmaceutical industry. Central laboratory testing services are critical to advances in genomics, precision medicine and drug development. Q2 SolutionsTM has helped develop many of the oncology precision medicine drugs approved by the U.S. Food and Drug Administration in recent years.
THE UNITED STATES CLINICAL TESTING INDUSTRY
The U.S. clinical testing industry consists of two segments. The following table discusses how we believe the industry is structured.
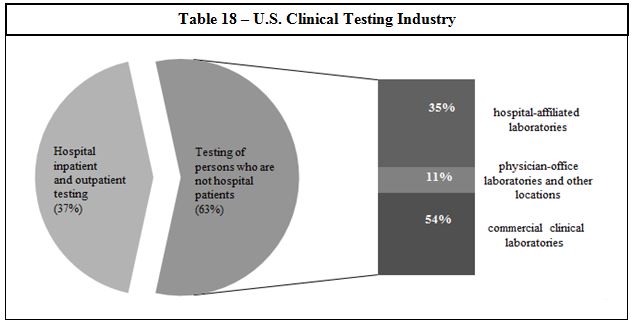
Key Trends
The healthcare system in the United States is evolving; significant change is taking place in the system. We expect that the evolution of the healthcare industry will continue, and that industry change is likely to be extensive. There are a number of key trends that are having, and that we expect will continue to have, a significant impact on the diagnostic information services business in the United States and on our business. These trends are discussed in the chart below; they present both opportunities and risks. We believe that several of the trends, including demographics, price transparency, consolidation, increased consumer involvement and value-based pricing, are favorable to our business. Because diagnostic information services is an essential healthcare service and because of the key trends discussed below, we believe that the industry will continue to grow over the long term and that we are well positioned to benefit from the long-term growth expected in the industry.
| Table 19 - Key Trends | |
| Demographics | As the population continues to grow and age, the burden of chronic diseases and unmet diagnostic needs may increase the demand for diagnostic information services. |
| Prevention and wellness | We believe that the value of detection, prevention, wellness and personalized care is well recognized. Consumers, employers, ACOs, IDNs, health plans and government agencies increasingly focus on helping the healthy stay healthy, detecting symptoms among those at risk and providing preventive insight and care that helps avoid disease. |
| Medical innovation | Medical advances allow for more accurate and earlier diagnosis and treatment of diseases. Continuing advances in genomics and proteomics are expected to yield new, more sophisticated and specialized diagnostic tests. These advances also are spurring interest in and demand for precision medicine, which relies on diagnostic and prognostic testing and in which data information services and strategies are used to deliver the most effective healthcare to the right populations and individuals. Pharmacogenomic testing increasingly is used as a parameter to help speed drug approval processes and to better focus therapy based on patient and tumor-specific genetic markers. Demand also is growing toward comprehensive care management solutions that serve patients, payers and healthcare providers by improving clinical decision support and access to patient data, and by increasing patient participation in care management and population health management. There is increasing focus on access to patient data and data-driven insights. |
| Customers and payers | Our customers and payers, including clinicians, health plans, IDNs, ACOs, employers and others, have been consolidating, converging and diversifying. For example, an increased number of hospital systems are considering establishing or have established health insurance plans, and health insurance plans are considering providing or are providing healthcare services. In addition, CVS Health, a leading provider of retail medical clinics and pharmacy benefits management services, has agreed to acquire Aetna, a leading health insurance provider. Consolidation is increasing pricing transparency and bargaining power, and may encourage internalization of clinical testing. Physicians frequently now are employed by hospital systems, IDNs, ACOs or large group practices integrated with healthcare systems, instead of organizing physician-owned practices, which is changing the dynamics for whether clinical testing is performed in or outside of a hospital. Physicians and other clinicians also increasingly are being employed by health plans or their affiliates. Value-based reimbursement is contributing to changes in the healthcare system. ACOs and patient-centered medical homes have grown as a means to deliver patient care. Healthcare services increasingly are being provided by non-traditional providers (e.g., physician assistants), in non-traditional venues (e.g., retail medical clinics, urgent care centers) and using new technologies (e.g., telemedicine). In addition, federal healthcare reform legislation adopted in 2010, the ACA, is resulting in changes in the way that some healthcare services are purchased and delivered in the United States. Patients are also our customers. Increasingly, patients are engaged in their own healthcare, being empowered to manage and understand their healthcare and are bearing responsibility for payment for the services provided to them. See also the discussion under the heading Patients in Table 21. |
| Pricing transparency | There has been a trend toward greater pricing transparency in the healthcare marketplace. This transparency, combined with increased patient financial responsibility for medical care, is enhancing purchasing sophistication and changes in behavior in the healthcare marketplace. |
| Competition | The diagnostic information services industry remains fragmented, is highly competitive and is subject to new competition. Competition is growing from non-traditional competitors. Increased hospital acquisitions of physician practices may enhance clinician ties to hospital-affiliated laboratories and may strengthen their competitive position. New industry entrants with extensive resources may make acquisitions or expand into our traditional areas of operations. |
| Reimbursement pressure; affordability | There is a strong focus in the United States on controlling the overall cost of healthcare. Healthcare market participants, including governments, are focused on controlling costs, including potentially by reducing reimbursement for healthcare services, changing reimbursement for healthcare services (e.g., shift from fee for service to capitation), changing medical coverage policies (e.g., healthcare benefits design), requiring preauthorization of laboratory testing, requiring co-pays, introducing laboratory spend management utilities and payment and patient care innovations such as ACOs and patient-centered medical homes. In light of continued pressure to reduce systemic healthcare costs, hospitals may change their approach to providing clinical testing services. The Health Transformation Alliance, a group of over 40 major U.S. companies, was formed to improve and reform the healthcare system in the United States. The rising cost of healthcare in the United States was a key driver for the formation of this alliance. In January 2018, Amazon.com Inc., Berkshire Hathaway Inc. and JPMorgan Chase &Co., citing rising health care costs, announced plans to reduce their workers' health care costs by forming a non-profit venture that would provide simplified, high-quality healthcare for their workers. Pursuant to PAMA, CMS has promulgated revised reimbursement schedules for clinical laboratory testing services provided under Medicare for 2018, 2019 and 2020. Under the revised Medicare Clinical Laboratory Fee Schedule, reimbursement for clinical laboratory testing is scheduled to be reduced in 2018, 2019 and 2020. PAMA calls for further revision of the Medicare Clinical Laboratory Fee Schedule for years after 2020, based on future surveys of market rates; further reduction in reimbursement may result from such revisions. The American Clinical Laboratory Association, of which the Company is a member, initiated a lawsuit charging that in implementing PAMA, CMS failed to follow a Congressional directive to implement a market-based laboratory payment system. The Company supports this lawsuit and also is pursuing a legislative solution from the revised Medicare Clinical Laboratory Fee Schedule implemented by CMS under PAMA, which the Company contends resulted from a flawed process and failed to protect access to laboratory services for Medicare beneficiaries. In 2017, CMS issued a draft national coverage policy for next-generation sequencing cancer panels. The draft policy, were it finalized without change, would effect a de facto requirement that each laboratory test using next generation sequencing technology would need to be approved or cleared by the FDA before it is covered by Medicare. Third parties, including health plans, have not announced any change in approach to coverage for next-generation sequencing cancer panels. While pressure to control healthcare costs poses a risk to our Company, it also creates opportunities, such as an opportunity for increased proper utilization of testing as an efficient means to manage the total cost of healthcare. We believe that it also creates greater opportunities for high value, low-cost providers, like our Company, as compared to other providers. |
| Healthcare utilization | In the past few years, healthcare utilization in the United States has fluctuated based on a number of factors. These factors include, without limitation, the economy, healthcare benefits design, patients delaying medical care and increased patient financial responsibility for medical care. The ACA contained provisions eliminating patient cost-sharing for preventive services, and additional provisions that we believe have increased the number of patients that have health insurance, including Medicaid, and thus better access to diagnostic testing. |
| Legislative, regulatory and policy environment | Government oversight of and attention to the healthcare industry in the United States is significant and increasing; healthcare payment reform is a top issue. The FDA previously announced guidance initiatives that may impact the clinical laboratory testing business, including by increasing regulation of LDTs. More recently, it has offered suggestions for legislation to address this issue. The ACA has created significant uncertainty as healthcare markets react to changes. For example, more than half of the states have opted in to Medicaid expansion and employers may discontinue offering group health insurance to their employees, shifting more people to exchange products. The President of the United States has announced that he favors repealing the ACA. In 2017, the federal legislature undertook efforts to repeal, revise or replace the ACA, and the individual mandate adopted as part of the ACA was repealed. In more recent legislation, some additional aspects of the ACA were modified: another two-year moratorium was implemented on the device tax imposed on the sellers of certain medical devices in the U.S., including those purchased and used by laboratories; the tax on health insurers was delayed for a year; and the "Cadillac tax" on certain employee benefit plans was also delayed for two years. As part of legislation enacted in early 2018, the Independent Payment Advisory Board, which under the ACA was to be responsible annually to submit proposals aimed at reducing Medicare cost growth while preserving quality, was repealed. The scope and timing of any further legislation to repeal, amend, replace, or reform the rest of the ACA is uncertain, but if such legislation were to become law, it could have a significant impact on the U.S. healthcare system. In addition, uncertainty regarding the ACA prior to any such repeal, amendment, replacement or reform could create uncertainty generally in the healthcare market. |
| Globalization | There is a growing demand for healthcare services in emerging market countries. Opportunities are arising to participate in the restructuring or growth of the healthcare systems outside the United States. Demographic changes globally also may create opportunities. |
| Informatics; technology | The increased availability of healthcare data, including data made available as a result of next generation DNA sequencing, and the increased ability to effectively analyze that data at population and patient levels, is impacting healthcare practices. It is anticipated that the increased use of data in healthcare, coupled with mobile healthcare IT solutions for doctors and patients, will help to improve patient outcomes and reduce overall healthcare costs. Informatics, including integrated diagnostic and decision support solutions, predictive analytics, use of population data and healthcare information technology, is spurring advances in precision medicine, including medical decision making and value, for populations and individuals. There is a need for technology solutions to harness these opportunities. In addition, new technology, social media and mobile technology are changing the way that healthcare markets interact with each other, and the expectations that they have about how services are provided, what services are provided, and other capabilities of healthcare market participants. These developments are creating new opportunities and new challenges and disrupting the healthcare environment. Healthcare market participants, including pharmaceutical companies, health plans, clinicians, ACOs and IDNs, are striving to leverage interoperability, informatics and analytics to positively influence the health of patient populations. |
| Chronic diseases and conditions; gaps in care | We believe that the cost and challenges of identifying, treating and controlling chronic diseases and conditions such as diabetes and heart disease are now well recognized. As a result of multiple factors, including increased focus on population health management and pressure to reduce the systemic costs associated with such diseases and conditions, there is increased focus on better identifying and attempting to reduce or eliminate the gaps in care historically associated with these diseases and conditions. Healthcare market participants are developing new approaches for this purpose. |
| Healthcare services delivery | Healthcare delivery is moving out of hospitals, doctor offices and other traditional locations in which it had been provided. Care is increasingly being provided in new settings, such as out-patient and home settings. For example, see the discussion of Emerging Retail Healthcare Providers in Table 21. This dynamic offers new opportunities and challenges for healthcare providers and reflects not only efforts to take advantage of new technologies, but also the focus, discussed in this table above under the heading Reimbursement pressure; affordability, on controlling the overall cost of healthcare. |
The Value of Diagnostic Information Services
As noted in Table 19, there is an increased focus on the affordability of healthcare. There also is increased focus on a disease-oriented approach to diagnostics, treatment and management. Healthcare providers, consumers and payers increasingly recognize the value of diagnostic information services as a means to improve health and reduce the overall cost of healthcare through early detection, prevention and treatment. Healthcare providers increasingly rely on diagnostic information services to help identify risk for a disease, to detect the symptoms of disease earlier, to aid in the choice of therapeutic regimen, to monitor patient compliance and to evaluate treatment results. The following table highlights how diagnostic information services can be an important contributor to reducing health care costs and improving care.
| Table 20 - Contributing to Reducing Healthcare Costs and Improving Care |
| • Identifying patients at risk for disease before they require urgent care, hospital treatment or expensive therapies |
| • Helping clinicians to target the right medicines for the right patients (those who will benefit from the medicines) |
| • Identifying treatment-related side effects |
| • Early assessment of the efficacy of a therapy, enabling changes or discontinuation of ineffective therapies |
| • Enabling population health management by utilizing diagnostic information, identifying gaps in proven care and delivering targeted solutions to individuals who need care |
| • Identification and proactive management of individuals at risk for developing chronic diseases, to decrease progression and associated costs and morbidity |
| • Providing telemedicine services along with laboratory testing to help individuals interpret and obtain appropriate advice and referrals into needed care |
Customers
We provide diagnostic information services to a broad range of customers, including those discussed below. As discussed in Table 19 above, customers are consolidating, converging and diversifying.
| Table 21 - Customers | |
| Health plans including managed care organizations and other health insurance providers | These customers typically reimburse us as a contracted (or out-of-network) provider on behalf of their members. In certain locations, health plans may delegate to IPAs or other alternative delivery systems (e.g., physician hospital organizations, ACOs, patient-centered medical homes) the ability to negotiate for diagnostic information services on behalf of certain members. Health plans and IPAs often require that diagnostic information services providers accept discounted fee structures or assume all or a portion of the financial risk associated with providing such services through capitated payment arrangements. Under capitated payment arrangements, we provide services at a predetermined monthly reimbursement rate for each covered member, generally regardless of the number or cost of services provided by us. Reimbursement under programs that do not provide for capitated payments is typically negotiated on a fee-for-service basis. Reimbursement from our five largest health plans totaled approximately 18%, and no one health plan accounted for 10%, of our consolidated net revenues in 2017. Health plans typically negotiate directly or indirectly with a number of diagnostic information services providers, and represent approximately one-half of our total clinical testing volumes and one-half of our net revenues from diagnostic information services. There has been a trend of consolidation among health plans. Some health plans also have narrowed their provider networks. We are also sometimes a member of a “complementary network.” A complementary network generally is a set of contractual arrangements that a third party will maintain with various providers that provide discounted fees for the benefit of its customers. A member of a health plan may choose to access a non-contracted provider that is a member of a complementary network; if so, the provider will be reimbursed at a rate negotiated by the complementary network. We attempt to strengthen our relationships with health plans and increase the volume of our services for their members by offering to health plans services and programs that leverage our Company's expertise and resources, including our superior access, extensive test menu, medical staff, data, IT solutions, and wellness and population health management capabilities. |
| Clinicians | Clinicians, including primary care physicians, specialists and physician assistants, requiring diagnostic information services for patients are the primary referral source for our services when patients choose their diagnostic information services provider. In recent years, there has been a marked increase in the number of physician practices owned by IDNs and hospital systems. There also has been a notable increase in some branches of medicine of the establishment of very large "rolled-up" specialty physician practice groups. Hospitals that own physician practices may require the practices to refer outreach testing to the hospital's affiliated laboratory. Large specialty physician groups may encourage their members to refer testing to other members of the group. In each case, referrals to independent diagnostic services providers may be reduced. Clinicians determine which laboratory to recommend or use based on a variety of factors, including those set forth in table 22. |
| Hospitals | We believe that we are the industry's leader in servicing hospitals. We provide services to hospitals throughout the United States, including advanced testing services, in some cases helping manage their laboratories and serving as the medical directors of the hospital's histology or clinical laboratory, including through our Professional Laboratory Services offerings. Hospitals generally maintain an on-site laboratory to perform the significant majority of clinical testing for their patients (inpatients and outpatients) and refer certain testing to outside service providers, which typically charge the hospitals on a negotiated fee-for-service basis. Fee schedules for hospital reference testing services often are negotiated on behalf of hospitals by group purchasing organizations. Hospitals also provide outreach testing, and historically were able to negotiate higher reimbursement rates with health plans than commercial clinical laboratories for comparable services. They may seek to leverage their relationships with community clinicians by encouraging the clinicians to send their outreach testing to the hospital's laboratory. Increased hospital acquisitions of physician practices may enhance clinician ties to hospital-affiliated laboratories and may strengthen their competitive position. We also have joint venture arrangements with leading hospitals or IDNs in several metropolitan areas. These joint venture arrangements, which provide diagnostic information services for affiliated hospitals as well as for unaffiliated clinicians and other local healthcare providers, serve as our principal facilities in their service areas. Typically, we have either a majority ownership interest in, or day-to-day management responsibilities for, our joint venture relationships. In light of continued pressure to reduce systemic healthcare costs, hospitals may change their approach to providing clinical testing services, including by seeking ways to improve profitability or to better utilize their laboratory capacity. We believe that our combination of services positions us to be an attractive partner for hospitals, offering a full range of strategic relationships. |
| ACOs and IDNs | An ACO is a network of providers and facilities that share financial risk in providing or arranging for the provision of healthcare. An IDN is a network of providers and facilities working together in providing or arranging for the provision of healthcare. ACOs and IDNs have increased in number; their impact on the provision of healthcare services to date has varied. ACOs and IDNs may exercise operational and financial control over providers across the continuum of care, and may function as a payer. Thus, they may be able to manage the health of a population group within a defined geography, and also may be able to influence the cost and quality of healthcare delivery, for example through owned entities and through ancillary services. ACOs may be encouraged to consider exclusive arrangements with healthcare providers that become part of the ACO, or to limit service providers to the ACO, since members of the ACO share financial risk. We are actively engaging with ACOs and IDNs to demonstrate the value of our services. |
| Employers | Employers use tests for drugs of abuse to determine an individual's employability and his or her “fitness for duty.” Companies with high employee turnover, safety conscious environments or regulatory testing requirements provide the highest volumes of testing. Factors such as the general economy and job market can impact the utilization of drugs-of-abuse testing. Employers also are investing in health and wellness services. We meet their needs by providing nationwide access to our customizable biometric and laboratory wellness testing, reporting and analytics, incentive management and flu shot services, and intervention solutions, directly and through health plan and health improvement providers. These services help employers, employees and others manage healthcare costs and capitalize on trends in personalized health. We seek to grow our employer business through offering new and innovative programs to help them with their goals of (1) maintaining a safe and productive workplace, (2) improving healthcare for employees and (3) lowering healthcare costs for employees and employers. |
| Patients | Patients are taking increased interest in and responsibility for their healthcare. Some patients are interested in ordering their own diagnostics tests, rather than relying upon a healthcare professional to order the tests. In addition, patients often are bearing increased financial responsibility for their healthcare (e.g., high deductible health plans). Patients are paying greater attention to their healthcare, are increasing their demands of healthcare providers, have increased expectations regarding their healthcare experiences and are becoming more sophisticated regarding healthcare. For example, in our experience, patients are more focused on transparency, ease of doing business and understanding diagnostics information services than they have been in the past. In addition, patients are seeking prompt, direct access to their test results. The changing expectations of patients about their healthcare and their healthcare transactions are influencing the way that we think about our business and the services that we provide. We are well positioned to provide information and insights to patients to help them take actions to improve their healthcare, and increasingly we are providing patients with tools to do this. |
| Emerging Retail Healthcare Providers | In recent years, as the healthcare sector changes, retail providers of healthcare services have emerged and are growing. These providers include "big-box" retailers, pharmacy chains, supermarkets, urgent care centers and Internet-based service providers. We are taking advantage of opportunities to work with these providers, not only to offer new access points for our services (e.g., our collaboration with Safeway), but also to grow our business by expanding our service offerings (e.g., our joint venture with Wal-Mart Stores). |
| Other Laboratories and Other Customers | We also provide services on a fee-for-service basis to federal, state and local governmental agencies and to other commercial clinical laboratories |
In many cases, the customer that orders our services is not responsible to pay for them. Depending on the billing arrangement and applicable law, the payer may be the patient or a third party, such as a health plan, Medicare or a Medicaid program. In light of healthcare reform, there is increased market activity regarding alternative payment models, including bundled payment models. Increasingly, patients are bearing responsibility for some portion of the payment for the services we provide to them, even if a third party is primarily responsible for payment.
GENERAL
Competition. While there has been significant consolidation in the diagnostic information services industry in recent years, our industry remains fragmented and highly competitive. We primarily compete with three types of clinical testing providers: commercial clinical laboratories, hospital-affiliated laboratories and physician-office laboratories. Our largest commercial clinical laboratory competitor is Laboratory Corporation of America Holdings, Inc. In addition, we compete with many smaller regional and local commercial clinical laboratories and specialized advanced laboratories. In anatomic pathology, we compete with anatomic pathology practices, including those in academic institutions and large physician group practices. There also has been a trend among specialty physician practices to establish their own histology laboratory capabilities and/or bring pathologists into their practices, thereby reducing referrals from these practices and increasing the competitive position of these practices.
We believe that healthcare providers consider a number of factors when selecting a diagnostic information services provider. Those factors include:
| Table 22 - Factors Considered When Selecting a Diagnostic Information Services Provider | |
| • Service capability and quality | • Reputation in the medical community |
| • Accuracy, timeliness and consistency in reporting test results | • Healthcare information technology solutions, including connectivity options |
| • Access to medical/scientific thought leaders for consultation | • Patient access, including the number, convenience and geographic coverage of patient service centers |
| • Patient insurance coverage and experience | • Ability to develop new and useful tests and services |
| • Number and type of tests performed | • Qualifications of its staff |
| • Pricing and overall value | • Provider office workflow |
| • Real time payment determination | • Capabilities to support population health initiatives |
We believe that providing the most attractive service offering in the industry, including the most comprehensive test menu, innovative test offerings, a positive customer experience, a staff including medical and scientific experts, strong quality, unparalleled access and distribution, and data-powered integrated information technology solutions provide us with a competitive advantage.
We believe that large diagnostic information services providers may be able to increase their share of the overall diagnostic information services industry due to their large networks and lower cost structures, including as a result of PAMA. These advantages should enable larger providers to more effectively serve customers. In addition, we believe that consolidation in the diagnostic information services industry will continue. However, a significant portion of clinical testing is likely to continue to be performed by hospitals, which generally have affiliations with community clinicians and may have more, or more convenient, locations in a market. As a result, we compete against hospital-affiliated laboratories primarily on the basis of service capability, quality and pricing. In addition, market activity may increase the competitive environment. For example, health plan actions to exclude large national providers from contracts may enhance the relative competitive position of regional providers. In addition, increased hospital acquisitions of physician practices may enhance the ties of the clinicians to hospital-affiliated laboratories, enhancing the competitive position of hospital-affiliated laboratories. The formation of ACOs and IDNs, and their approach to contracts with healthcare providers, in addition to the impact of informatics, also may impact competition to provide diagnostic information services.
The diagnostic information services industry is faced with changing technology and new product introductions. Competitors may compete using advanced technology, including technology that enables more convenient or cost-effective testing. Competitors also may offer testing to be performed outside of a commercial clinical laboratory, such as (1) point-of-care testing that can be performed by physicians in their offices; (2) testing that can be performed by hospitals in their own laboratories; and (3) home testing that can be carried out without requiring the services of outside providers.
The risk assessment and healthcare information technology industries are highly competitive. We have many competitors, some of which have much more extensive experience in these industries and some of which have greater resources. We compete in the risk assessment business by seeking to provide a superior applicant experience, faster services completion and a wider array of quality, integrated services than our competitors. We compete in the healthcare information technology industry by offering solutions that foster better patient care and improve performance for healthcare providers, including smaller and medium sized physician practices.
Sales and Marketing. Our Diagnostic Information Services business has a unified commercial organization focused on the sale of most of our services. It coordinates closely with our clinical franchises and marketing organization. The commercial organization is centrally led, and is organized regionally, in conjunction with our operations organization, to focus on local customer needs and to ensure aligned delivery for our customers. We have built excellence in our commercial organization, employing world-class processes and tools as well as strong management discipline. We continue to invest in talent, provide industry-leading training and development, focus on opportunities with IDNs and specialty physicians, and foster a customer-focused, performance-driven culture.
We also maintain sales and marketing organizations for our employer drugs-of-abuse testing services in Diagnostic Information Services and our offerings in Diagnostic Solutions.
Information Technology. We use information systems extensively in virtually all aspects of our business, including clinical testing, test ordering and reporting, billing, customer service, logistics and management of medical data. We endeavor to establish systems that create value and efficiencies for our Company and customers. The successful delivery of our services depends, in part, on the continued and uninterrupted performance of our information technology systems. We have taken precautionary measures to prevent problems that could affect our information technology systems.
Some of our historic growth has come through acquisitions and, as a result, we continue to use multiple information systems. We have implemented some common systems, and are planning to standardize laboratory information and billing systems across our operations. We expect that our standardization effort will take several more years to complete, and will result in significantly more centralized systems, improved operating efficiency, more positive customer experiences and enhanced control over our operational environment. Even after we complete our efforts to standardize our historic systems, acquisitions of other businesses in the future may create additional opportunities where we may conclude that system standardization would benefit our company.
Quality Assurance. As discussed further under the heading Quality beginning on page 14, our goal is to provide every patient with services and products of superior quality, and to meet that goal we have adopted the Quest Diagnostics
Quality Program. This program includes policies and procedures that document, measure and monitor the effectiveness of our laboratory operations in providing and improving quality and meeting applicable regulatory requirements for clinical laboratory testing. We use the Quest Management System, including standard frameworks and methodologies for project and change management, to manage our Company, and have a culture of continuous improvement. Employing root cause analysis, process improvements and rigorous tracking and measuring, we seek to enhance quality, continuously reduce defects, streamline processes, further increase the efficacy and efficiency of our operations and processes, eliminate waste and help standardize operations across our Company. We also have a robust Supplier Quality Program designed to ensure we have a high quality supplier network and to raise the bar of quality expectations across that network.
In our laboratory operations, our quality assurance efforts focus on pre-analytic, analytic and post-analytic processes, including positive patient identification of specimens, specimen tracking, analysis and report accuracy, proficiency testing, reference range relevance, process audits, statistical process control and personnel training for all of our laboratories and patient service centers. As part of our quality assurance program, we utilize internal proficiency testing, comprehensive quality control and rigorous process audits. For most clinical laboratory tests, quality control samples are processed in parallel with the analysis of patient specimens. The results of tests on these quality control samples are monitored to identify trends, biases or imprecision in our analytical processes. We also focus on the licensing, credentialing, training and competence of our professional and technical staff.
In addition, we participate in external proficiency testing and have accreditation or licenses for our clinical laboratory operations from various regulatory agencies or accrediting organizations, such as CMS, CAP and certain states. All of our laboratories participate in various external quality surveillance programs, including proficiency testing programs administered by CAP or states. CAP is an independent, nongovernmental organization of board-certified pathologists approved by CMS to inspect clinical laboratories to determine compliance with the standards required by CLIA. CAP offers an accreditation program to which clinical laboratories may voluntarily subscribe. All of our major laboratories, including our laboratories outside the U.S., and most of our rapid response laboratories, are accredited by CAP. Accreditation includes on-site inspections and participation in the CAP (or equivalent) proficiency testing program. Also, our cytotechnologists and pathologists participate in an internal peer-review evaluation and one or more external individual proficiency testing programs. In addition, some of our laboratories have achieved International Organization for Standardization certification for their quality management systems.
Intellectual Property Rights. We own significant intellectual property, including patents, patent applications, technology, trade secrets, know-how, copyrights and trademarks in the United States and other countries. From time to time, we also license U.S. and non-U.S. patents, patent applications, technology, trade secrets, know-how, copyrights or trademarks owned by others; we also may license our intellectual property to others. In the aggregate, our intellectual property assets and licenses are of material importance to our business. We believe, however, that no single patent, technology, trademark, intellectual property asset or license is material to our business as a whole.
Our approach is to manage our intellectual property assets, to safeguard them and to maximize their value to our enterprise. We actively defend our important intellectual property assets and pursue protection of our products, processes and other intellectual property where possible.
Our success in remaining a leading innovator in the diagnostic information services industry by continuing to introduce new tests, technology and services will depend, in part, on our ability to license new and improved technologies on favorable terms. Other companies or individuals, including our competitors, may obtain patents or other property rights on tests or processes that we may be performing, that could prevent, limit or interfere with our ability to develop, perform or sell our tests or operate our business.
Enterprise Risk Management Program. We maintain an enterprise risk management program designed to assure a culture of risk awareness throughout the Company's key business, operations and support functions. Our program, which is integrated with the Company’s governance, performance management and internal control frameworks, entails a formal continuous process that identifies, assesses, mitigates and manages both internal and external conditions that could significantly impact the Company and influence its business strategy and performance. The program is based on a framework issued by the Committee of Sponsoring Organizations of the Treadway Commission and focuses on the following risk types:
| • | Operational risk - risks arising from systems, processes, people and external events that affect the Company’s operational objectives or fundamental reason for its existence, including: product life-cycle and execution; service quality and performance; information management and data protection and security, including cybersecurity; supply chain and business disruption; and other risks, including human capital and reputation. |
| • | Financial risk - risks arising from the Company’s ability to meet its financial obligations pursuant to its strategic and operational objectives, including exposure to broad market and more specific industry risk that could impact liquidity, interest rate, credit, pricing and reimbursement, and also to internal and external financial reporting. |
| • | Legal and compliance risk - risks arising from government and regulatory environment and action, legal proceedings and compliance with integrity policies and procedures. |
| • | Strategic risk - risks that will impede the Company’s plan to achieve its mission and vision and apply its core values, including changes in the broad market and Company's industry, business development and restructuring activities, competitive threats and practices, technology and product innovation, and public policy. |
As part of our program, executive management routinely assesses our enterprise level risks, overall Company-level risk tolerance and the effectiveness of risk management, and monitors the progress of and resources applied to risk mitigation; our Board of Directors plays an active role in overseeing our program. Our primary risk factors are discussed in Risk Factors beginning on page 35.
Employees. At December 31, 2017, we employed approximately 45,000 people. This total excludes employees of the joint ventures where we do not have a majority ownership interest. We have no collective bargaining agreements with unions covering employees in the United States, and we believe that our overall relations with our employees are good.
BILLING AND REIMBURSEMENT
Billing. We generally bill for diagnostic information services on a fee-for-service basis under one of two types of fee schedules. These fees may be negotiated or discounted. The types of fee schedules are:
| • | “Client” fees charged to physicians, hospitals and institutions for which services are performed on a wholesale basis and which are billed on a monthly basis. |
| • | “Patient” fees charged to individual patients and certain third-party payers on a claim-by-claim basis. |
Billing for diagnostic information services is very complicated, and we maintain compliance policies and procedures for our billing. Patients, insurance companies, Medicare, Medicaid, physicians, hospitals, IDNs, ACOs and employer groups all have different billing requirements. Some billing arrangements require us to bill multiple payers, and there are several other factors that complicate billing (e.g., disparity in coverage and information requirements among various payers; and incomplete or inaccurate billing information provided by ordering clinicians). We incur additional costs as a result of our participation in Medicare and Medicaid programs because diagnostic testing services are subject to complex, stringent and frequently ambiguous federal and state laws and regulations, including those relating to coverage, billing and reimbursement. Additionally, auditing for compliance with applicable laws and regulations as well as internal compliance policies and procedures adds further cost and complexity to the billing process. Changes in laws and regulations could further complicate our billing and increase our billing costs. CMS establishes procedures and continuously evaluates and implements changes to the reimbursement process and requirements for coverage.
As an integral part of our billing compliance program, we investigate reported failures or suspected failures to comply with federal and state healthcare reimbursement requirements. Any Medicare or Medicaid overpayments resulting from non-compliance are reimbursed by us. As a result of these efforts, we have periodically identified and reported overpayments, reimbursed the payers for overpayments and taken appropriate corrective action.
Our bad debt expense is primarily the result of the failure of patients to pay the portion of the receivable that is their responsibility. Increased patient financial responsibility has adversely impacted our bad debt expense in recent years; additional increases in patient financial responsibility may further negatively impact our bad debt expense. The remainder of our bad debt expense is primarily due to missing or incorrect billing information on requisitions and Advance Beneficiary Notices received from healthcare providers. In general, due to the nature of our business, historically we have performed the requested testing and reported test results regardless of whether the billing information is correct or complete. We subsequently attempt to contact the healthcare provider or patient to obtain any missing information and to rectify incorrect billing information. Missing or incorrect information on requisitions complicates and slows down the billing process, creates backlogs of unbilled requisitions and generally increases the aging of accounts receivable and bad debt expense. We are taking, and plan to continue to take, steps to reduce our bad debt expense, including increasing use of electronic ordering, which reduces the incidence of missing or incorrect information, and real-time payment determination.
Government Coverage and Reimbursements. Government payers, such as Medicare and Medicaid, have taken steps and are expected to continue to take steps to control the cost, utilization and delivery of healthcare services, including clinical testing services. Historically, most Medicare and Medicaid beneficiaries were covered under the traditional Medicare and Medicaid programs administered by the federal government. Over the last several years, the federal government has continued to expand its contracts with private health insurance plans for Medicare beneficiaries and has encouraged such beneficiaries to switch from the traditional programs to the private programs, called “Medicare Advantage” programs. There has been growth of health insurance providers offering Medicare Advantage programs and of beneficiary enrollment in these programs. In recent years, in an effort to control costs, states also have mandated that Medicaid beneficiaries enroll in private managed care arrangements.
With regard to the clinical testing services performed on behalf of Medicare beneficiaries, we must bill Medicare directly and must accept the local Medicare carrier's fee schedule amount for covered services as payment in full. In addition, state Medicaid programs are prohibited from paying more (and in most instances, pay significantly less) than Medicare. Currently, Medicare does not require the beneficiary to pay a co-payment for diagnostic information services reimbursed under the Clinical Laboratory Fee Schedule, but generally does require a patient deductible for anatomic pathology services.
Part B of the Medicare program contains fee schedule payment methodologies for clinical testing services performed for covered patients, including a national ceiling on the amount that carriers could pay under their local Medicare clinical testing fee schedules. Historically, the Medicare Clinical Laboratory Fee Schedule and the Medicare Physician Fee Schedule established under that program have been subject to change, including each year. Pursuant to PAMA, which was implemented in 2018, CMS has revised the Medicare Clinical Laboratory Fee Schedule. Under the revised Medicare Clinical Laboratory Fee Schedule, reimbursement for clinical laboratory testing will be reduced in 2018, 2019 and 2020. PAMA calls for further revision of the Medicare Clinical Laboratory Fee Schedule for years after 2020, based on future surveys of market rates; further reduction in reimbursement may result from such revisions. The following table sets forth the percentage of our consolidated net revenues reimbursed under Medicare and Medicaid in 2017.
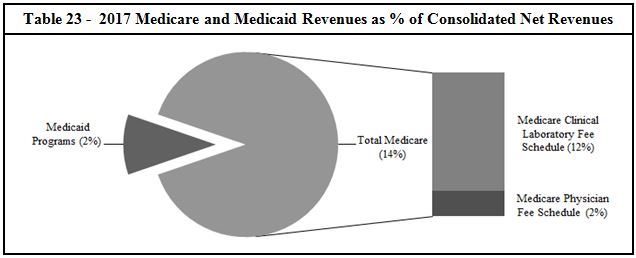
Violations of laws relating to billing government healthcare programs or federal and state fraud and abuse laws may result in: exclusion from participation in Medicare/Medicaid programs; civil and criminal fines and penalties; and the loss of various licenses, certificates and authorizations necessary to operate our business. Certain violations of these laws may also provide the basis for a civil remedy under the federal False Claims Act, including fines and damages of up to three times the amount claimed.
REGULATION
Our businesses are subject to or impacted by extensive and frequently changing laws and regulations in the United States (at both the federal and state levels) and the other jurisdictions in which we conduct business, including some particular to our business and others relating to conducting business generally (e.g., U.S. Foreign Corrupt Practices Act). We also are subject to inspections and audits by governmental agencies. The table below highlights the key regulatory schemes applicable to our businesses.
| Table 24 - Key Regulatory Schemes | |
| CLIA and State Clinical Laboratory Licensing | CLIA regulates the operations of virtually all clinical laboratories, requiring that they be certified by the federal government and that they comply with various technical, operational, personnel and quality requirements intended to ensure that the services provided are accurate, reliable and timely. State laws may require additional personnel qualifications or licenses, quality control, record maintenance, proficiency testing or detailed review of our scientific method validations and technical procedures for certain tests. Violations of these laws and regulations may result in monetary fines, criminal and civil penalties and/or suspension or exclusion from participation in Medicare, Medicaid and other federal or state healthcare programs. |
| Fraud and Abuse | Anti-kickback laws and regulations prohibit making payments or furnishing other benefits to influence the referral of tests billed to Medicare, Medicaid or certain other federal or state healthcare programs. In addition, federal and state anti-self-referral laws generally prohibit Medicare and Medicaid payments for clinical tests referred by physicians who have an ownership or investment interest in, or a compensation arrangement with, the testing laboratory. Some states have similar laws that are not limited to Medicare and Medicaid referrals and could also affect other tests referred by clinicians with investment or compensation arrangements with the testing laboratory. Violations of these laws and regulations may result in monetary fines, criminal and civil penalties and/or suspension or exclusion from participation in Medicare, Medicaid and other federal or state healthcare programs. |
| FDA | The FDA has regulatory responsibility over, among other areas, instruments, software, test kits, reagents and other devices used by clinical laboratories to perform diagnostic testing in the United States. The FDA also regulates drugs-of-abuse testing for employers and insurers, testing for blood bank purposes and testing of donors of human cells for purposes such as in vitro fertilization. A number of advanced tests we develop internally are offered as LDTs. The FDA has claimed regulatory authority over all LDTs, but has stated that it exercised enforcement discretion with regard to most LDTs performed by high complexity CLIA-certified laboratories. Pursuant to the 21st Century Cures Act, the FDA has issued guidance regarding the regulation of clinical decision support software, which may be used in, or in connection with, LDTs. The guidance has created uncertainty regarding whether FDA approval of certain tests is required. In 2017, the FDA published a "Discussion Document" providing its views on legislative alternatives to regulate LDTs. New legislation could significantly impact the clinical laboratory testing business, including by increasing or modifying the regulation of LDTs, hindering our ability to develop and market new services, causing an increase in the cost of our services, delaying our ability to introduce new tests or hindering our ability to perform testing. |
| Environmental, Health and Safety | We are subject to laws and regulations related to the protection of the environment, the health and safety of employees and the handling, transportation and disposal of medical specimens, infectious and hazardous waste and radioactive materials. For example, the U.S. Occupational Safety and Health Administration has established extensive requirements relating specifically to workplace safety for healthcare employers in the U.S. This includes requirements to develop and implement multi-faceted programs to protect workers from exposure to blood-borne pathogens, including preventing or minimizing any exposure through needle stick injuries. For purposes of transportation, some biological materials and laboratory supplies are classified as hazardous materials and are subject to regulation by one or more of the following agencies: the U.S. Department of Transportation, the U.S. Public Health Service, the U.S. Postal Service and the International Air Transport Association. |
| Physicians | Our pathologists are required to hold a valid license to practice medicine in the jurisdiction in which they practice. Many of our pathologists enter into an employment agreement. These agreements have varying terms, but generally can be terminated at any time, upon advance notice. Most of the agreements contain covenants generally limiting the activities of the pathologist within a defined geographic area for a limited period of time after termination of employment; the enforceability of these covenants may be limited under state law. Several jurisdictions, including some in which our businesses are located, prohibit business corporations from engaging in the practice of medicine. In certain jurisdictions, business corporations are prohibited from employing licensed healthcare professionals to provide services on behalf of the corporation; these laws vary. In some jurisdictions, anatomic pathology services are delivered through physician-owned entities that employ the practicing pathologists. The manner in which licensed physicians can be organized to perform medical services may be governed by the laws of the jurisdictions in which medical services are provided and by the medical boards or other entities authorized by these jurisdictions to oversee the practice of medicine. |
| Privacy and Security of Health and Personal Information | We are subject to laws and regulations regarding protecting the security and privacy of certain healthcare and personal information, including the federal Health Insurance Portability and Accountability Act and the regulations thereunder, which establish (i) a complex regulatory framework including requirements for safeguarding protected health information and (ii) comprehensive federal standards regarding the uses and disclosures of protected health information. In addition, in May 2018, the General Data Protection Regulation will supersede current European Union data protection legislation, impose more stringent European Union data protection requirements, and provide greater penalties for noncompliance. A healthcare provider may be required to notify individuals or the government if the provider discovers certain breaches of personal information or protected health information. |
| Drug Testing; Controlled Substances | All U.S. laboratories that perform drug testing for certain public sector employees and employees of certain federally regulated businesses are required to be certified as meeting the detailed performance and quality standards of the Substance Abuse and Mental Health Services Administration. To obtain access to controlled substances used to perform drugs-of-abuse testing in the United States, laboratories must be licensed by the Drug Enforcement Administration. |
Compliance. We strive to conduct our business in compliance with all applicable laws and regulations. All of our laboratories and, where applicable, patient service centers, are licensed and accredited as required by the appropriate federal and state agencies. We have a long-standing and well-established compliance program. The Quality, Safety and Compliance Committee of our Board of Directors oversees, and receives periodic management reports regarding, our compliance program. Our program includes detailed policies and procedures and training programs intended to ensure the implementation and observance of all applicable laws, regulations and Company policies. Further, we conduct in-depth reviews of procedures and facilities to assure regulatory compliance throughout our operations. We conduct annual training of our employees on these compliance policies and procedures.
Many of the laws and regulations applicable to us, including many of those relating to billing, reimbursement for tests and relationships with clinicians and hospitals, are vague or indefinite or have not been interpreted by the courts. The applicability or interpretation of laws and regulations also may not be clear in light of emerging changes in clinical testing science, healthcare technology and healthcare organizations. They may be interpreted or applied by a prosecutorial, regulatory or judicial authority in a manner that could require us to make changes in our operations, including our pricing and/or billing practices. Such occurrences, regardless of their outcome, could, among other things:
| • | increase our administrative, billing or other operating costs; |
| • | decrease the amount of reimbursement related to diagnostic information services performed; |
| • | damage our reputation; or |
| • | adversely affect important business relationships with third parties. |
If we fail to comply with applicable laws and regulations, we could suffer civil and criminal penalties, fines, exclusion from participation in governmental healthcare programs and the loss of various licenses, certificates and authorizations necessary to operate our business, as well as incur additional liabilities from third-party claims, all of which could have a material adverse effect on our business. Certain federal and state statutes, regulations and other laws, including the qui tam
provisions of federal and state false claims acts, allow private individuals to bring lawsuits against healthcare companies on behalf of government payers, private payers and/or patients alleging inappropriate billing practices.
The federal or state governments may bring claims based on our current practices, which we believe are lawful. The federal and state governments have substantial leverage in negotiating settlements since the amount of potential damages far exceeds the rates at which we are reimbursed, and the government has the remedy of excluding a non-compliant provider from participation in the Medicare and Medicaid programs. We believe that federal and state governments continue aggressive enforcement efforts against perceived healthcare fraud. Legislative provisions relating to healthcare fraud and abuse provide government enforcement personnel with substantial funding, powers, penalties and remedies to pursue suspected cases of fraud and abuse.
AVAILABLE INFORMATION
We file annual, quarterly and current reports, proxy statements and other information with the Securities and Exchange Commission (the “SEC”). You may read and copy any document that we file with the SEC at the SEC's public reference room at 100 F Street, NE, Washington, DC 20549 on official business days. Please call the SEC at 1-800-SEC-0330 for information regarding the public reference room. The SEC maintains an internet site that contains annual, quarterly and current reports, proxy and information statements and other information that issuers (including the Company) file electronically with the SEC. Our electronic SEC filings are available to the public at the SEC's internet site, www.sec.gov.
Our internet site is www.QuestDiagnostics.com. You can access our Investor Relations webpage at www.QuestDiagnostics.com/investor. The information on our website is not incorporated by reference into this Report. We make available free of charge, on or through our Investor Relations webpage, our proxy statements, Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K and any amendments to those reports filed or furnished pursuant to the Securities Exchange Act of 1934, as amended (the “Exchange Act”), as soon as reasonably practical after such material is filed with, or furnished to, the SEC.
We also have a corporate governance webpage, www.QuestDiagnostics.com/governance. You can access information regarding our corporate governance, including the information set forth below, at that page.
| Table 25 - Information Available at Our Corporate Governance Webpage | |
| • Directors | • Corporate Governance Guidelines |
| • Composition of the committees of our Board of Directors | • Code of Ethics |
| • Senior management | • Certificate of Incorporation |
| • Charters for the standing committees of our Board of Directors | • Bylaws |
| • Information about our corporate political contributions | • Values |
| • Statements of beneficial ownership of our equity securities filed by our directors, officers and others under Section 16 of the Exchange Act |
EXECUTIVE OFFICERS OF THE COMPANY
The following persons serve as executive officers of the Company.
| Table 26 - Executive Officers | |
| Name, Age, Title | Background |
| Stephen H. Rusckowski (60) Chairman of the Board, President and Chief Executive Officer | Mr. Rusckowski joined the Company in May 2012 as President and Chief Executive Officer and became Chairman of the Board on January 1, 2017. From October 2006 until he joined the Company, he was Chief Executive Officer of Philips Healthcare, the largest unit of Royal Philips Electronics, and a member of the Board of Management of Royal Philips Electronics and its Executive Committee. Previously, he was CEO of the Imaging Systems business of Royal Phillips Electronics. Before joining Philips in 2001, Mr. Rusckowski held numerous management positions with the healthcare division of Hewlett-Packard/Agilent Technologies. Mr. Rusckowski has been a director of the Company since May 2012. He has been a director of Xerox Corporation since February 2015, and was a director of Covidien plc from December 2013 to January 2015. Mr. Rusckowski served as Chairman of the American Clinical Laboratory Association from 2013-2016. |
| Jon R. Cohen, M.D. (63) Senior Vice President and Group Executive - Diagnostic Solutions | Dr. Cohen joined the company in March 2009 and served as Chief Medical Officer from then until January 2017. From May 2011 to January 2013, he also had responsibility for Hospital Services. In January 2013, Dr. Cohen assumed responsibility for anatomic pathology services, sports science and human performance and professional laboratory services, and he was responsible for the oncology clinical franchise from January 2013 until January 2017. From February 2014 to July 2015, he had responsibility for our clinical trials business. Dr. Cohen served as the Senior Adviser to New York Governor David Patterson from 2008 to 2009, where he was responsible for all policy and strategic planning. Previously, Dr. Cohen was a managing director, health industries advisory services, at PricewaterhouseCoopers LLP, and spent 21 years with North Shore-Long Island Jewish Health System, one of the nation's largest not-for-profit health systems, including serving as its Chief Medical Officer from 2000 to 2006. |
| Everett V. Cunningham (51) Senior Vice President, Commercial | Mr. Cunningham is responsible for the commercial organization for the Company's Diagnostic Information Services business. Prior to joining the Company in October 2012, he spent 21 years with Pfizer, Inc., where he served from June 2011 to October 2012 as Regional President, Established Products, Asia. From 2009 to 2011, Mr. Cunningham served as Regional President, West Business Unit, Primary Care. From 2007 to 2009, he served as Vice President, Human Resources, Corporate Groups. Before that Mr. Cunningham served Pfizer in a series of sales and leadership and general management roles. |
| James E. Davis (55) Executive Vice President, General Diagnostics | In January 2017, Mr. Davis became Executive Vice President, General Diagnostics; previously he was Senior Vice President and Group Executive - Regional Businesses. In January 2015, he assumed responsibility for the general management of the Company's regional Diagnostic Information Services business. Mr. Davis was responsible for our products business from February 2014 until 2016. From February 2014 to January 2015, he was responsible for operations for the Company's Diagnostic Information Services business. He joined Quest Diagnostics in April 2013 as Senior Vice President, Diagnostics Solutions, with responsibility for the healthcare information technology, risk assessment, clinical trials, diagnostic products and employer solutions businesses. Prior to joining Quest Diagnostics, from March 2012 to April 2013, Mr. Davis served as Lead Director, and then as Chief Executive Officer, of InSightec, Inc., a medical device company that designs and develops ultrasound ablation devices that are guided by magnetic resonance imaging systems. Previously, Mr. Davis held a number of senior positions in General Electric’s healthcare business, including from 2007 to 2012 as Vice President and General Manager of GE Healthcare’s magnetic resonance imaging business. Prior to joining GE Healthcare, Mr. Davis held leadership positions in GE’s aviation business and led the development of strategic and operational improvement initiatives for clients of McKinsey & Company, Inc. |
| Catherine T. Doherty (55) Senior Vice President and Group Executive - Clinical Franchise Solutions and Marketing | Since January 2013, Ms. Doherty has been responsible for overseeing the development of clinical franchise solutions in the areas of cardiovascular, general health and wellness, infectious disease and immunology, and prescription drug monitoring and toxicology, as well as enterprise-wide marketing. From January 2013 to January 2017, she also was responsible for clinical franchise solutions in the areas of neurology and women's health. In February 2014, Ms. Doherty assumed responsibility for the employer solutions and risk assessment businesses. From February 2014 to January 2017, she also was responsible for the healthcare information technology business. From May 2011 to December 2012, she served as Senior Vice President, Physician Services. Prior to May 2011, Ms. Doherty held a variety of positions of increasing responsibility since joining the Company in 1990, including Vice President, Hospital Services; Vice President, Office of the Chairman; Vice President, Finance and Administration for the Hospital business; Vice President, Communications and Investor Relations; and Chief Accounting Officer. |
| Carrie Eglinton Manner (43) Senior Vice President, Advanced Diagnostics | Ms. Eglinton Manner joined the Company in January 2017. She is responsible for the Company's advanced testing activities, including overseeing the development of clinical franchise solutions in the areas of neurology, oncology and women's health. Previously, Ms. Eglinton Manner spent over 20 years in various leadership roles in healthcare businesses at General Electric. From 2015 to 2016, she served as President and CEO of the Detection and Guidance Solutions business, delivering advanced x-ray technologies spanning the continuum of healthcare. From 2013 to 2015, Ms. Eglinton Manner served as President and CEO of OEC Surgical Mobile C-arm systems. She was President and CEO of General Electric's diagnostic pathology laboratory services business from 2012 to 2013, and President of the Maternal Infant Care Business from 2009 to 2012. |
| Mark J. Guinan (56) Executive Vice President and Chief Financial Officer | Mr. Guinan joined the Company in July 2013. From 2010 until joining Quest Diagnostics in 2013, he served as Chief Financial Officer for Hill-Rom Holdings Inc., a manufacturer and provider of medical technologies and related services for the health care industry. Previously, he had served in a number of finance and operations roles in a long career at Johnson & Johnson including 2009 to 2010 as Vice President, Chief Procurement Officer, and 2005 to 2009 as Vice President, Group Finance Pharmaceuticals. Before joining Johnson & Johnson in 1997, he held a number of financial roles at Procter & Gamble. |
| Michael E. Prevoznik (56) Senior Vice President and General Counsel | Mr. Prevoznik joined the Company as Vice President and General Counsel in August 1999. In 2003, he assumed responsibility for governmental affairs. From 1999 until April 2009, Mr. Prevoznik also had responsibility for the Company's Compliance Department. In addition, from April 2011 to January 2017, he had management responsibility for the Company's diagnostic information services activities outside the U.S., and from April 2011 to January 2013, he had management responsibility for the Company's clinical trials business. Prior to joining the Company, Mr. Prevoznik served in positions of increasing responsibility within the compliance organization at SmithKline Beecham, most recently as Vice President, Compliance, with responsibility for coordinating all SmithKline Beecham compliance activities worldwide. |
Previous: Cover and table of contents · Next: Item 1A. Risk Factors