 filings.tools
Digital Realty Trust 10-K 2022-12-31
Filed 2023-02-27. 23 sections, 696K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 10-K
| | |
|---|---|
| ☒ | Annual Report Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934 |
| | For the fiscal year ended December 31**, 2022** |
| ☐ | Transition Report Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934 |
| | For the Transition Period From to . |
| | | |
|---|---|---|
| | | |
| Commission file number | 001-32336 (Digital Realty Trust, Inc.) | |
| | | 000-54023 (Digital Realty Trust, L.P.) |
DIGITAL REALTY TRUST, INC.
DIGITAL REALTY TRUST, L.P.
(Exact name of registrant as specified in its charter)
| | |
|---|---|
| | |
| Maryland (Digital Realty Trust, Inc.) Maryland (Digital Realty Trust, L.P.) | 26-0081711 20-2402955 |
| (State or other jurisdiction of incorporation or organization) | (IRS employer identification number) |
| 5707 Southwest Parkway, Building 1, Suite 275 Austin**,** Texas | 78735 |
| (Address of principal executive offices) | (Zip Code) |
(737) 281-0101
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
| | | | | | | | |
|---|---|---|---|---|---|---|---|
| | Title of each class | | | Trading Symbols(s) | Name of each exchange on which registered | ||
| Digital Realty Trust, Inc. | | Common Stock, $0.01 par value per share | | | DLR | | New York Stock Exchange |
| | | | | | | | |
| | | Series J Cumulative Redeemable Preferred Stock, $0.01 par value per share | | | DLR Pr J | | New York Stock Exchange |
| | | Series K Cumulative Redeemable Preferred Stock, $0.01 par value per share | | | DLR Pr K | | New York Stock Exchange |
| | | Series L Cumulative Redeemable Preferred Stock, $0.01 par value per share | | | DLR Pr L | | New York Stock Exchange |
| Digital Realty Trust, L.P. | | None | | | None | | None |
Securities registered pursuant to Section 12(g) of the Act:
| | |
|---|---|
| Digital Realty Trust, Inc. | None |
| Digital Realty Trust, L.P. | Common Units of Partnership Interest |
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act.
| | |
|---|---|
| Digital Realty Trust, Inc. | Yes ⌧ No ◻ |
| Digital Realty Trust, L.P. | Yes ⌧ No ◻ |
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act.
| | |
|---|---|
| Digital Realty Trust, Inc. | Yes ◻ No ⌧ |
| Digital Realty Trust, L.P. | Yes ◻ No ⌧ |
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days.
| | |
|---|---|
| Digital Realty Trust, Inc. | Yes ⌧ No ◻ |
| Digital Realty Trust, L.P. | Yes ⌧ No ◻ |
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).
| | |
|---|---|
| Digital Realty Trust, Inc. | Yes ⌧ No ◻ |
| Digital Realty Trust, L.P. | Yes ⌧ No ◻ |
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
Digital Realty Trust, Inc.:
| | | | |
|---|---|---|---|
| Large accelerated filer | ⌧ | Accelerated filer | ◻ |
| Non-accelerated filer | ◻ | Smaller reporting company | ☐ |
| | | Emerging growth company | ☐ |
Digital Realty Trust, L.P.:
| | | | |
|---|---|---|---|
| Large accelerated filer | ◻ | Accelerated filer | ◻ |
| Non-accelerated filer | ⌧ | Smaller reporting company | ☐ |
| | | Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
| | |
|---|---|
| Digital Realty Trust, Inc. | ☐ |
| Digital Realty Trust, L.P. | ☐ |
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report.
| Digital Realty Trust, Inc. | ☒ |
| Digital Realty Trust, L.P. | ☐ |
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act).
| | |
|---|---|
| Digital Realty Trust, Inc. | Yes ☐ No ⌧ |
| Digital Realty Trust, L.P. | Yes ☐ No ⌧ |
The aggregate market value of the common equity held by non-affiliates of Digital Realty Trust, Inc. as of June 30, 2022 totaled approximately $37 billion based on the closing price for Digital Realty Trust, Inc.’s common stock on that day as reported by the New York Stock Exchange. Such value excludes common stock held by executive officers, directors and 10% or greater stockholders as of June 30, 2022. The identification of 10% or greater stockholders as of June 30, 2022 is based on Schedule 13G and amended Schedule 13G reports publicly filed before June 30, 2022. This calculation does not reflect a determination that such parties are affiliates for any other purposes.
There is no public trading market for the common units of Digital Realty Trust, L.P. As a result, the aggregate market value of the common units held by non-affiliates of Digital Realty Trust, L.P. cannot be determined.
Indicate the number of shares outstanding of each of the registrant’s classes of common stock, as of the latest practicable date.
Digital Realty Trust, Inc.:
| | | | |
|---|---|---|---|
| Class | Outstanding at February 21, 2023 | ||
| Common Stock, $.01 par value per share | | 291,157,152 | |
DOCUMENTS INCORPORATED BY REFERENCE
Part III incorporates by reference portions of Digital Realty Trust, Inc.’s Proxy Statement for its 2023 Annual Meeting of Stockholders which the registrants anticipate will be filed no later than 120 days after the end of their fiscal year pursuant to Regulation 14A.
EXPLANATORY NOTE
This report combines the annual reports on Form 10-K for the year ended December 31, 2022 of Digital Realty Trust, Inc., a Maryland corporation, and Digital Realty Trust, L.P., a Maryland limited partnership, of which Digital Realty Trust, Inc. is the sole general partner. Unless otherwise indicated or unless the context requires otherwise, all references in this report to “we,” “us,” “our,” “our Company”, or “the Company” refer to Digital Realty Trust, Inc. together with its consolidated subsidiaries, including Digital Realty Trust, L.P. In statements regarding qualification as a REIT, such terms refer solely to Digital Realty Trust, Inc. Unless otherwise, all references to the “Parent” refer to Digital Realty Trust, Inc., and all references to “our Operating Partnership,” “the Operating Partnership” or “the OP” refer to Digital Realty Trust, L.P. together with its consolidated subsidiaries.
The Parent is a real estate investment trust, or REIT, and the sole general partner of the OP. As of December 31, 2022, the Parent owned an approximate 97.9% common general partnership interest in Digital Realty Trust, L.P. The remaining approximate 2.1% of the common limited partnership interests of Digital Realty Trust, L.P. are owned by non-affiliated third parties and certain directors and officers of the Parent. As of December 31, 2022, the Parent owned all of the preferred limited partnership interests of Digital Realty Trust, L.P. As the sole general partner of Digital Realty Trust, L.P., the Parent has the full, exclusive and complete responsibility for the OP’s day-to-day management and control.
We believe combining the annual reports on Form 10-K of the Parent and the OP into this single report results in the following benefits:
| ● | enhancing investors’ understanding of the Parent and the OP by enabling investors to view the business as a whole in the same manner as management views and operates the business; |
|---|
| ● | eliminating duplicative disclosure and providing a more streamlined and readable presentation since a substantial portion of the disclosure applies to both the Parent and the OP; and |
|---|
| ● | creating time and cost efficiencies through the preparation of one combined report instead of two separate reports. |
|---|
It is important to understand the few differences between the Parent and the OP in the context of how we operate the Company. The Parent does not conduct business itself, other than acting as the sole general partner of the OP and issuing public equity from time to time and guaranteeing certain unsecured debt of the OP and certain of its subsidiaries and affiliates. The OP holds substantially all the assets of the business, directly or indirectly. The OP conducts the operations of the business and is structured as a partnership with no publicly traded equity. Except for net proceeds from equity issuances by the Parent, which are generally contributed to the OP in exchange for partnership units, the OP generates capital required by the business through the OP’s operations, incurrence of indebtedness and issuance of partnership units to third parties.
The presentation of noncontrolling interests, stockholders’ equity and partners’ capital are the main areas of difference between the consolidated financial statements of the Parent and those of the OP. The differences in the presentations between stockholders’ equity and partners’ capital result from the differences in the equity and capital issuances in the Parent and in the OP.
To highlight the differences between the Parent and the OP, separate sections in this report, as applicable, individually discuss the Parent and the OP, including separate financial statements and separate Exhibit 31 and 32 certifications. In the sections that combine disclosure of the Parent and the OP, this report refers to actions or holdings as being actions or holdings of the Company.
As general partner with control of the OP, the Parent consolidates the OP for financial reporting purposes, and it does not have significant assets other than its investment in the OP. Therefore, the assets and liabilities of the Parent and the OP are the same on their respective consolidated financial statements. The separate discussions of the Parent and the OP in this report should be read in conjunction with each other to understand the results of the Company on a consolidated basis and how management operates the Company.
In this report, “properties” and “buildings” refer to all or any of the buildings in our portfolio, including data centers and non-data centers, and “data centers” refers only to the properties or buildings in our portfolio that contain data center space.
DIGITAL REALTY TRUST, INC. AND DIGITAL REALTY TRUST, L.P.
FORM 10-K
FOR THE YEAR ENDED DECEMBER 31, 2022
TABLE OF CONTENTS
PART I
Item 1. BUSINESS
The Company
Digital Realty Trust, Inc. (the “Parent”), through its controlling interest in Digital Realty Trust, L.P. (the “Operating Partnership” or the “OP”) and the subsidiaries of the Operating Partnership, (collectively, “we”, “our”, “us” or the “Company”) is a leading global provider of data center, colocation and interconnection solutions for customers across a variety of industry verticals. The Parent operates as a REIT for U.S. federal income tax purposes. The OP is the entity through which the Parent conducts its business of owning, acquiring, developing and operating data centers. The Parent was incorporated in the state of Maryland on March 9, 2004. The OP was organized as a limited partnership in the state of Maryland on July 21, 2004.
As of December 31, 2022, our portfolio consisted of 316 data centers (including 59 data centers held as investments in unconsolidated entities), of which 132 are located in the United States, 114 are located in Europe, 34 are located in Latin America, 14 are located in Africa, 13 are located in Asia, six are located in Australia and three are located in Canada.
Our principal executive offices are located at 5707 Southwest Parkway, Building 1, Suite 275, Austin, Texas 78735. Our telephone number is (737) 281-0101. Our website is www.digitalrealty.com. The information found on, or otherwise accessible through, our website is not incorporated by reference into, nor does it form a part of, this Annual Report on Form 10-K.
Recent Acquisitions
On August 1, 2022, we completed the acquisition of 61.1% indirect controlling interest in Teraco Data Environments (Pty) Ltd., (“Teraco”), a leading carrier-neutral data center and interconnection services provider in South Africa. The total purchase price was $1.7 billion cash, funded by our global revolving credit facility and partial settlement of our forward equity sale agreements. Teraco’s financial information is included in our consolidated financial statements and associated notes to those financial statements.
Industry Background
The digital economy continues to grow and change how enterprises across all industries create and deliver value. Companies increasingly need to operate ubiquitously, on-demand and with real-time intelligence serving customers, partners and employees across multiple channels, business functions and points of business presence. Computational processing power requirements continue to advance, data traffic is growing, and the volume of data that enterprises generate, transmit, process, analyze, monitor and manage is expanding dramatically. The Internet of Things, 5G, autonomous vehicles and artificial intelligence, among other technological advancements, are driving this digital transformation.
We believe that enterprise data growth is accelerating due to the growing digital economy and emerging technological advances. As enterprises analyze and process this accelerating data mass, they create more data. As this mass of data continues to grow, it needs to be analyzed and processed: a task which we believe is becoming increasingly challenging to replicate and relocate. This phenomenon is called Data Gravity. We believe that enterprise decisionmakers will need to increasingly consider the impact of how Data Gravity impacts their enterprise IT architectures and, accordingly, we have developed the Data Gravity Index: a global forecast that measures the intensity and gravitational force of enterprise data growth.
As the largest global provider of cloud- and carrier-neutral data center, colocation and interconnection solutions, we believe the data center industry is poised for sustainable growth. The demand for data center infrastructure is being driven by this digital transformation which is contributing to the explosive growth of data, rapid growth of cloud adoption and greater demand for IT outsourcing. The power requirements and financial costs to support this growth in data, traffic and storage are substantial and growing accordingly. We believe data centers will continue to play a critical role in the digital economy and enabling business transformation strategies.
We believe cloud solutions and hybrid cloud solutions will remain significant drivers of demand for data center infrastructure. The hybrid cloud, which combines public and private cloud solutions, has gained traction because it enables corporate enterprises to achieve efficiencies and contain costs, as well as scale and secure their most sensitive information. In addition, the leading cloud service providers are generally mature, well-capitalized technology companies, and cloud platforms are among the fastest-growing business segments. Data center providers that can solve global coverage, capacity and connectivity needs, and coordinate and aggregate diverse customer and application demand, are poised to benefit from these cloud-specific industry drivers.
These diverse and secular industry dynamics are driving greater demand for data center capacity not only from global cloud service providers, but also from businesses across other industries, including IT service firms, social media, content providers and the financial services sector. As companies focus on their core competencies and rely on outsourcing to meet their IT infrastructure needs, they are prioritizing colocation for their data center solutions for various reasons, including to reduce latency in data transfer and increase global presence and connectivity. New technologies need a fast, reliable and flexible foundation to operate, and the importance of offering a full spectrum of power, space and connectivity solutions on a global platform continues to grow.
Our Business
We provide a global data center platform that supports our customers’ digital infrastructure and enables our customers to interconnect with their customers and partners. We solve global coverage, capacity and connectivity needs for companies of all sizes, including the world’s leading enterprises and services providers, through PlatformDIGITAL®, a global data center platform for scaling digital business which enables customers to deploy their critical infrastructure with a global data center provider.
PlatformDIGITAL® combines our global presence with our Pervasive Data Center Architecture (PDx®) solution methodology for scaling digital business and efficiently managing data gravity challenges. Our global data center footprint gives customers access to the connected data communities that matter to them with over 300 facilities in 54 metropolitan areas across 28 countries on six continents.
Fundamentally, we bring together foundational real estate and innovative technology expertise around the world to deliver a comprehensive, dedicated product suite to meet customers’ data and connectivity needs. We represent an important part of the digital economy that we believe will benefit from powerful, long-term growth drivers.
We believe that the growth trends in the data center market, technology, the cloud, internet traffic and internet-based services, combined with cost advantages in outsourcing data center requirements, provide attractive growth opportunities for us as a data center solutions provider. Leveraging deep expertise in technology and real estate, we have an expansive global footprint, impressive scale and a full-spectrum fit-for-purpose product offering in key metropolitan areas around the world. These advantages simplify the contracting process for multinational enterprises, eliminating their need to negotiate with multiple local data center solutions providers. In addition, in areas where high data center construction and operating costs and long time-to-market prohibit many of our customers from building their own data centers, our global footprint and scale allow us to meet our customers’ needs quickly and efficiently.
Showing the first 8K of 62K characters. Open the full section
Item 1A. RISK FACTORS
For purposes of this section, the term “stockholders” means the holders of shares of Digital Realty Trust, Inc.’s common stock and preferred stock. Set forth below are the risks that we believe are material to Digital Realty Trust, Inc.’s stockholders and Digital Realty Trust, L.P.’s unitholders. You should carefully consider the following factors in evaluating our Company, our properties and our business. The occurrence of any of the following risks might cause Digital Realty Trust, Inc.’s stockholders and Digital Realty Trust, L.P.’s unitholders to lose all or a part of their investment. Some statements in this report, including statements in the following risk factors, constitute forward-looking statements. Please refer to the section entitled “Forward-Looking Statements” starting on page 48.
Overview
Our business, operations and financial results are subject to various risks and uncertainties, including those described below, that could adversely affect our business, financial condition, results of operations, cash flows, and the trading price of our common stock and preferred stock. The following material factors, among others, could cause our actual results to differ materially from historical results and those expressed in forward-looking statements made by us or on our behalf in filings with the SEC, press releases, communications with investors and oral statements. The risks that we describe in our public filings are not the only risks that we face. Additional risks and uncertainties not presently known to us, or that we currently consider immaterial, also may materially adversely affect our business, financial condition, and results of operations.
Risk Factors Summary
The following is a summary of the principal risks that could adversely affect our business, operations and financial results.
Risk Related to Our Business and Operations
| ● | Our business depends upon the demand for data centers. |
|---|
| ● | We face significant competition, which may adversely affect the occupancy and rental rates of our data centers. |
|---|
| ● | Any failure of our physical or information technology or operational technology infrastructure or services could lead to significant costs and disruptions. |
|---|
| ● | We may be vulnerable to breaches, or unauthorized access to, or disruption of our physical and information technology and operational technology infrastructure and systems. |
|---|
| ● | We depend on significant customers, and many of our data centers are single-tenant properties or are currently occupied by single tenants. |
|---|
| ● | Failure to attract, grow and retain a diverse and balanced customer base, including key magnet customers, could harm our business and operating results. |
|---|
| ● | Our contracts with our customers could subject us to significant liability. |
|---|
| ● | Certain of our customer agreements may include restrictions on the sale of our properties to certain third parties, which could have a material adverse effect on us. |
|---|
| ● | Our data centers may not be suitable for re-leasing without significant expenditures or renovations. |
|---|
| ● | We may be unable to lease vacant or development space, renew leases, or re-lease space as leases expire. |
|---|
| ● | Even if we have additional space available for lease at any one of our data centers, our ability to lease this space to existing or new customers could be constrained by our ability to provide sufficient electrical power. |
|---|
| ● | Our portfolio depends upon local economic conditions and is geographically concentrated in certain locations. |
|---|
| ● | Our business and operations, and our customers, suppliers and business partners may be adversely affected by epidemics, pandemics or other outbreaks. |
|---|
| ● | We lease or sublease certain of our data center space from third parties and the ability to retain these leases or subleases could be a significant risk to our ongoing operations. |
|---|
| ● | We and our customers may experience supply chain or procurement disruptions, or increased supply chain costs, which may lead to delays. |
|---|
| ● | We may not be able to adapt to changing technologies and customer requirements, and our data center infrastructure may become obsolete. |
|---|
| ● | We depend upon third-party suppliers for power, and we are vulnerable to service failures and to price increases by such suppliers and to volatility in the supply and price of power in the open market. |
|---|
| ● | We depend on third parties to provide network connectivity to the customers in our data centers and any delays or disruptions in connectivity may materially adversely affect our operating results and cash flow. |
|---|
| ● | Our international activities, including acquisition, ownership and operation of data centers located outside of the United States, subject us to risks different than those we face in the United States and we may not be able to effectively manage our international business. |
|---|
| ● | Our recent acquisitions may not achieve the intended benefits or may disrupt our plans and operations. |
|---|
| ● | We may be subject to unknown or contingent liabilities related to our recent acquisitions, for which we may have no or limited recourse against the sellers. |
|---|
| ● | We may be unable to identify, including sourcing off-market deal flow, and complete acquisitions on favorable terms or at all. |
|---|
| ● | Joint venture (JV) investments could be adversely affected by our lack of sole decision-making authority, our reliance on our JV partners’ financial condition and disputes between us and our JV partners. |
|---|
| ● | Any delays or unexpected costs in the development of our existing space and developable land and new properties acquired for development may delay and harm our growth prospects, future operating results and financial condition. |
|---|
| ● | Many of our costs, such as operating and general and administrative expenses, interest expense and real estate acquisition and construction costs, could be adversely impacted by periods of heightened inflation. |
|---|
| ● | We have substantial debt and face risks associated with the use of debt to fund our business activities, including refinancing and interest rate risks. |
|---|
| ● | Our growth depends on external sources of capital which are outside of our control. |
|---|
| ● | Declining real estate valuations, impairment charges and illiquidity of real estate investments could adversely affect our earnings and financial condition. |
|---|
| ● | Our success depends on key personnel whose continued service is not guaranteed. |
|---|
| ● | We may have difficulty managing our growth. |
|---|
| ● | Potential losses may not be covered by insurance. |
|---|
| ● | We could incur significant costs related to environmental matters, including from government regulation, private litigation, and existing conditions at some of our properties. |
|---|
| ● | Our properties may contain or develop harmful mold or suffer from other air quality issues, which could lead to liability for adverse health effects and costs to remedy the problem. |
|---|
| | ● | We may incur significant costs complying with applicable laws and governmental regulations, including the Americans with
Showing the first 8K of 157K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
General
In addition to the information in this Item 2, certain information regarding our portfolio is contained in Schedule III (Financial Statement Schedule) under Part IV, Item 15(a)(2) and which is included in Part II, Item 8.
Our Portfolio
The following table presents an overview of our portfolio of properties, including the 59 data centers held as investments in unconsolidated entities and developable land, based on information as of December 31, 2022 (amounts in thousands). All data centers are held in fee simple except as otherwise indicated. Please refer to Note 11. “Debt of the Operating Partnership” in the Notes to the Consolidated Financial Statements included in Part II, Item 8 of this Annual Report on Form 10-K for a description of all applicable encumbrances as of December 31, 2022.
| | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|
| | | | | | | Space Under | | | | | |
| | | Data Center | | Net Rentable | | Active | | Space Held for | | Occupancy | |
| Metropolitan Area | | Buildings | | Square Feet (1) | | Development (Sq Ft) (2) | | Development (Sq Ft) (3) | | Percentage (4) | |
| | | | | | | | | | | | |
| North America | | | | | | | | | | | |
| Northern Virginia | | 25 | | 5,577 | | 1,774 | | 124 | | 93.8 | % |
| Chicago | | 10 | | 3,428 | | 35 | | 113 | | 91.7 | % |
| New York | | 13 | | 2,209 | | 73 | | 74 | | 80.6 | % |
| Dallas | | 22 | | 3,334 | | 327 | | 77 | | 83.0 | % |
| Silicon Valley | | 15 | | 1,590 | | — | | 131 | | 95.2 | % |
| Phoenix | | 2 | | 796 | | — | | — | | 70.0 | % |
| San Francisco | | 4 | | 843 | | — | | — | | 65.5 | % |
| Portland | | 3 | | 598 | | 553 | | — | | 97.4 | % |
| Atlanta | | 4 | | 526 | | 31 | | 314 | | 96.4 | % |
| Los Angeles | | 2 | | 611 | | 11 | | — | | 80.1 | % |
| Seattle | | 1 | | 399 | | — | | — | | 79.0 | % |
| Toronto | | 2 | | 367 | | 361 | | — | | 84.5 | % |
| Boston | | 3 | | 437 | | — | | 51 | | 45.9 | % |
| Houston | | 6 | | 393 | | — | | 14 | | 61.6 | % |
| Miami | | 2 | | 226 | | — | | — | | 84.2 | % |
| Austin | | 1 | | 86 | | — | | — | | 58.6 | % |
| Minneapolis/St. Paul | | 1 | | 329 | | — | | — | | 100.0 | % |
| Charlotte | | 3 | | 95 | | — | | — | | 90.0 | % |
| North America Total | | 119 | | 21,844 | | 3,165 | | 898 | | 86.3 | % |
| | | | | | | | | | | | |
| Europe | | | | | | | |||||
| London | | 16 | | 1,432 | | 64 | | 96 | | 65.8 | % |
| Frankfurt | | 29 | | 1,981 | | 1,759 | | — | | 87.9 | % |
| Amsterdam | | 13 | | 1,270 | | — | | 92 | | 79.5 | % |
| Paris | | 13 | | 760 | | 937 | | — | | 81.2 | % |
| Marseille | | 4 | | 436 | | 83 | | 38 | | 81.6 | % |
| Dublin | | 9 | | 475 | | 78 | | — | | 80.8 | % |
| Vienna | | 3 | | 355 | | 133 | | — | | 81.3 | % |
| Zurich | | 3 | | 285 | | 314 | | — | | 81.0 | % |
| Madrid | | 4 | | 220 | | 188 | | — | | 86.4 | % |
| Brussels | | 3 | | 163 | | 175 | | — | | 76.4 | % |
| Stockholm | | 6 | | 190 | | 116 | | — | | 71.0 | % |
| Copenhagen | | 3 | | 176 | | 149 | | — | | 77.6 | % |
| Dusseldorf | | 3 | | 116 | | 98 | | — | | 61.6 | % |
| Athens | | 4 | | 55 | | 159 | | — | | 87.1 | % |
| Zagreb | | 1 | | 22 | | 8 | | — | | 80.8 | % |
| Europe Total | | 114 | | 7,936 | | 4,261 | | 226 | | 79.3 | % |
| | | | | | | | | | | | |
| Asia Pacific | | | | | | | |||||
| Singapore | | 3 | | 883 | | — | | — | | 94.0 | % |
| Sydney | | 4 | | 362 | | — | | 88 | | 90.1 | % |
| Melbourne | | 2 | | 147 | | — | | — | | 62.3 | % |
| Seoul | | 1 | | 162 | | — | | — | | 4.3 | % |
| Hong Kong | | 1 | | 99 | | 186 | | — | | 0.6 | % |
| Osaka | | 1 | | — | | 236 | | — | | — | % |
| Asia Pacific Total | | 12 | | 1,653 | | 422 | | 88 | | 75.9 | % |
| | | | | | | | | | | | |
| Africa | | | | | | | | | | | |
| Johannesburg | | 5 | | 877 | | 742 | | — | | 71.7 | % |
| Cape Town | | 2 | | 194 | | 132 | | — | | 78.8 | % |
| Durban | | 1 | | 45 | | — | | — | | 73.1 | % |
| Nairobi | | 1 | | 16 | | — | | — | | 72.7 | % |
| Mombasa | | 2 | | 46 | | — | | 12 | | 12.2 | % |
| Maputo | | 1 | | 7 | | — | | — | | — | % |
| Africa Total | | 12 | | 1,185 | | 874 | | 12 | | 70.2 | % |
| | | | | | | | | | | | |
| Non-Data Center Properties | | — | | 51 | | — | | 212 | | 100.0 | % |
| | | | | | | | | | | | |
| Managed Unconsolidated Entities | | | | | | | |||||
| Northern Virginia | | 8 | | 1,482 | | — | | — | | 100.0 | % |
| Silicon Valley | | 4 | | 414 | | — | | — | | 100.0 | % |
| Hong Kong | | 1 | | 186 | | — | | — | | 87.4 | % |
| Toronto | | 1 | | 104 | | — | | — | | 87.1 | % |
| Los Angeles | | 2 | | 197 | | — | | — | | 100.0 | % |
| Lagos | | 1 | | 4 | | — | | — | | 100.0 | % |
| Abuja | | 1 | | 1 | | — | | — | | 73.0 | % |
| | | 18 | | 2,388 | | — | | — | | 98.4 | % |
| | | | | | | | | | | | |
| Non-Managed Unconsolidated Entities | | | | | | | |||||
| Sao Paulo | | 23 | | 1,103 | | 301 | | 1,067 | | 98.9 | % |
| Tokyo | | 3 | | 1,140 | | 160 | | — | | 71.8 | % |
| Osaka | | 3 | | 409 | | 56 | | 62 | | 88.5 | % |
| Queretaro | | 3 | | 108 | | 9 | | 391 | | 100.0 | % |
| Santiago | | 3 | | 96 | | — | | 198 | | 77.9 | % |
| Rio De Janeiro | | 2 | | 99 | | — | | — | | 100.0 | % |
| Fortaleza | | 1 | | 94 | | — | | — | | 100.0 | % |
| Seattle | | 1 | | 51 | | — | | — | | 100.0 | % |
| Bogota | | 2 | | — | | — | | 197 | | — | % |
| | | 41 | | 3,100 | | 526 | | 1,915 | | 87.1 | % |
| | | | | | | | | | | | |
| Total | | 316 | | 38,157 | | 9,248 | | 3,351 | | 84.7 | % |
| (1) | Net rentable square feet at a building represents the current square feet at that building under lease as specified in the lease agreements plus management’s estimate of space available for lease. We estimate the total net rentable square feet available for lease based on a number of factors in addition to contractually leased square feet, including available power, required support space and common area. Net rentable square feet includes tenants’ proportional share of common areas but excludes space held for development. |
|---|
| (2) | Space under active development includes current base building and data center projects in progress. |
|---|
| (3) | Space held for development includes space held for future data center development, and excludes space under active development and land held for development. |
|---|
| (4) | Excludes space held for development and space under active development. We estimate the total square feet available for lease based on a number of factors in addition to contractually leased square feet, including available power, required support space and common area. |
|---|
We lease space from third parties under noncancellable leases for: our corporate headquarters, several regional office locations, certain data centers, and certain equipment. In addition, we are subject to ground leases at certain data centers primarily in Europe and Singapore.
Customer Diversification
The following table sets forth information regarding the 20 largest customers in our portfolio based on annualized recurring revenue as of December 31, 2022 (dollar amounts in thousands).
| | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| | | | | Number | | Annualized | | % of Annualized | | Weighted Average | ||
| | | | | of | | Recurring | | Recurring | | Remaining Lease | ||
| | | Tenant | | Locations | | Revenue (1) | | Revenue | | Term in Years | ||
| 1 | Fortune 50 Software Company | 65 | $ | 370,954 | 10.2 | % | 8.2 | |||||
| 2 | IBM | 38 | 132,852 | 3.6 | % | 2.7 | ||||||
| 3 | Social Content Platform | 19 | 132,830 | 3.6 | % | 4.9 | ||||||
| 4 | Oracle Corporation | | 36 | 129,909 | 3.6 | % | 4.5 | |||||
| 5 | Global Cloud Provider | 54 | 125,132 | 3.4 | % | 3.1 | ||||||
| 6 | Fortune 25 Investment Grade-Rated Company | 29 | 111,130 | 3.0 | % | 3.9 | ||||||
| 7 | Equinix | 19 | 89,041 | 2.4 | % | 7.0 | ||||||
| 8 | LinkedIn Corporation | 9 | 85,374 | 2.3 | % | 2.1 | ||||||
| 9 | Meta Platforms, Inc. | 44 | 67,556 | 1.9 | % | 4.2 | ||||||
| 10 | Fortune 25 Tech Company | 49 | 65,285 | 1.8 | % | 3.6 | ||||||
| 11 | Fortune 500 SaaS Provider | 15 | 63,389 | 1.7 | % | 3.7 | ||||||
| 12 | Cyxtera | 15 | 61,469 | 1.7 | % | 9.4 | ||||||
| 13 | Social Media Platform | 8 | 61,277 | 1.7 | % | 8.4 | ||||||
| 14 | Rackspace | 24 | 53,225 | 1.5 | % | 9.8 | ||||||
| 15 | Lumen Technologies, Inc. | 130 | 51,005 | 1.4 | % | 10.1 | ||||||
| 16 | JPMorgan Chase & Co. | 17 | 43,223 | 1.2 | % | 1.8 | ||||||
| 17 | Verizon | 101 | 41,557 | 1.1 | % | 3.5 | ||||||
| 18 | Comcast Corporation | 39 | 40,821 | 1.1 | % | 5.0 | ||||||
| 19 | AT&T | 76 | 39,470 | 1.1 | % | 2.8 | ||||||
| 20 | Zayo | 125 | 35,380 | 1.0 | % | 1.7 | ||||||
| | Total / Weighted Average | | | $ | 1,800,879 | 49.3 | % | 5.9 |
Note: Represents consolidated portfolio in addition to our managed portfolio of unconsolidated entities based on our ownership percentage. Our direct customers may be the entities named in the table above or their subsidiaries or affiliates.
| (1) | Annualized recurring revenue represents the monthly contractual base rent (defined as cash base rent before abatements), and interconnection revenue under existing leases as of December 31, 2022 multiplied by 12. |
|---|
Lease Distribution
The following table sets forth information relating to the distribution of leases in the properties in our portfolio, based on size (in megawatts), excluding approximately 8.9 million square feet of space under active development and approximately 3.3 million square feet of space held for development at December 31, 2022, under lease as of December 31, 2022 (dollar and square feet amounts in thousands).
| | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|
| | | Total Net | | Percentage of Net | | | | | | ||
| | | Rentable Square | | Rentable Square | | Annualized | | Percentage of | |||
| Size | | Feet(1) | | Feet(1) | | Rent(2) | | Annualized Rent | |||
| Available | 5,278 | 16.0 | % | | — | — | | ||||
| 0 - 1 MW | 5,149 | 15.6 | % | $ | 1,132,142 | 34.7 | % | ||||
| > 1 MW | 14,285 | 43.5 | % | 1,860,237 | 57.0 | % | |||||
| Other (3) | 8,193 | 24.9 | % | 269,294 | 8.3 | % | |||||
| Total | 32,905 | 100.0 | % | $ | 3,261,673 | 100.0 | % |
Note: Represents consolidated portfolio in addition to our managed portfolio of unconsolidated entities based on our ownership percentage.
| (1) | We estimate the total net rentable square feet available for lease based on a number of factors in addition to contractually leased square feet, including available power, required support space and common area. |
|---|
| (2) | Annualized rent represents the monthly contractual base rent (defined as cash base rent before abatements) under existing leases as of December 31, 2022 multiplied by 12. |
|---|
| (3) | Other includes unimproved building shell capacity as well as storage and office space within fully improved data center facilities. |
|---|
Lease Expirations
The following table sets forth a summary schedule of the lease expirations for leases in place as of December 31, 2022 plus available space for ten calendar years at the properties in our portfolio. The table excludes space that is currently under active development or held for active development. Unless otherwise stated in the footnotes to the table below, the information set forth in the table assumes that tenants exercise no renewal options and all early termination rights (amounts in thousands, except per square foot amounts).
| | | | | | | | | | | | | | | | | | | | | |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| | | | | | | | | | | | | | | | | Annualized | | | | |
| | | | | | | | | | | | | | Annualized | | Rent Per | | | | ||
| | | | | Percentage | | | | | Percentage of | | Rent Per | | Occupied | | | | ||||
| | | Square Footage of | | of Net Rentable | | Annualized | | Annualized | | Occupied | | Square Foot | | Annualized Rent | ||||||
| Year | | Expiring Leases (1) | | Square Feet (1) | | Rent (2) | | Rent (2) | | Square Foot | | at Expiration | | at Expiration | ||||||
| Available | 5,278 | 16.0 | % | | | | | | | | ||||||||||
| Month to Month (3) | 366 | 1.1 | % | | $ | 68,654 | 2.1 | % | | $ | 187 | | $ | 188 | | $ | 69,016 | |||
| 2023 | 5,123 | 15.6 | % | | 894,353 | 27.4 | % | | 175 | | 175 | | 894,280 | |||||||
| 2024 | 2,581 | 7.8 | % | | 380,803 | 11.7 | % | | 148 | | 151 | | 388,675 | |||||||
| 2025 | 3,446 | 10.5 | % | | 428,658 | 13.0 | % | | 124 | | 130 | | 446,421 | |||||||
| 2026 | 2,904 | 8.8 | % | | 324,697 | 10.0 | % | | 112 | | 119 | | 346,166 | |||||||
| 2027 | 2,488 | 7.7 | % | | 309,596 | 9.5 | % | | 124 | | 136 | | 337,553 | |||||||
| 2028 | 1,130 | 3.4 | % | | 116,195 | 3.6 | % | | 103 | | 113 | | 127,333 | |||||||
| 2029 | 1,626 | 5.0 | % | | 149,820 | 4.6 | % | | 92 | | 104 | | 169,421 | |||||||
| 2030 | 1,314 | 4.0 | % | | 130,561 | 4.0 | % | | 99 | | 109 | | 143,164 | |||||||
| 2031 | 1,132 | 3.4 | % | | 129,092 | 4.0 | % | | 114 | | 129 | | 145,811 | |||||||
| 2032 | 901 | 2.7 | % | | 100,251 | 3.1 | % | | 111 | | 130 | | 117,396 | |||||||
| Thereafter | 4,615 | 14.0 | % | | 228,991 | 7.0 | % | | 50 | | 61 | | 279,960 | |||||||
| Portfolio Total / Weighted Average | 32,904 | 100.0 | % | | $ | 3,261,671 | 100.0 | % | | $ | 117 | | $ | 124 | | $ | 3,465,196 |
Note: Represents consolidated portfolio in addition to our managed portfolio of unconsolidated entities based on our ownership percentage.
| (1) | For some of our properties, we calculate square footage based on factors in addition to contractually leased square feet, including available power, required support space and common area. We estimate the total net rentable square feet available for lease based on a number of factors in addition to contractually leased square feet, including available power, required support space and common area. |
|---|
| (2) | Annualized rent represents the monthly contractual base rent (defined as cash base rent before abatements) under existing leases as of December 31, 2022 multiplied by 12. |
|---|
| (3) | Includes leases, licenses and similar agreements that upon expiration have been automatically renewed on a month-to-month basis. |
|---|
Item 3. LEGAL PROCEEDINGS
In the ordinary course of our business, we may become subject to various legal proceedings. As of December 31, 2022, we were not a party to any legal proceedings which we believe would have a material adverse effect on our operations or financial position.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Digital Realty Trust, Inc.
Digital Realty Trust, Inc.’s common stock has been listed, and is traded, on the New York Stock Exchange, or the NYSE, under the symbol “DLR” since October 29, 2004.
Subject to the distribution requirements applicable to REITs under the Code, Digital Realty Trust, Inc. intends, to the extent practicable, to invest substantially all of the proceeds from sales and refinancings of its assets in real estate-related assets and other assets. Digital Realty Trust, Inc. may, however, under certain circumstances, make a dividend of capital or of assets. Such dividends, if any, will be made at the discretion of Digital Realty Trust, Inc.’s Board of Directors.
As of February 21, 2023, there were approximately 68 holders of record of Digital Realty Trust, Inc.’s common stock. This figure does not reflect the beneficial ownership of shares held in nominee name.
Digital Realty Trust, L.P.
There is no established trading market for Digital Realty Trust, L.P.’s common units of limited partnership. As of February 21, 2023, there were 73 holders of record of common units, including Digital Realty Trust, L.P.’s general partner, Digital Realty Trust, Inc.
Digital Realty Trust, L.P. currently intends to continue to make regular quarterly distributions to holders of its common units. Any future distributions will be declared at the discretion of the Board of Directors of Digital Realty Trust, L.P.’s general partner, Digital Realty Trust, Inc., and will depend on our actual cash flow, financial condition, capital requirements, the annual distribution requirements under the REIT provisions of the Code, and such other factors as the Board of Directors may deem relevant.
STOCK PERFORMANCE GRAPH
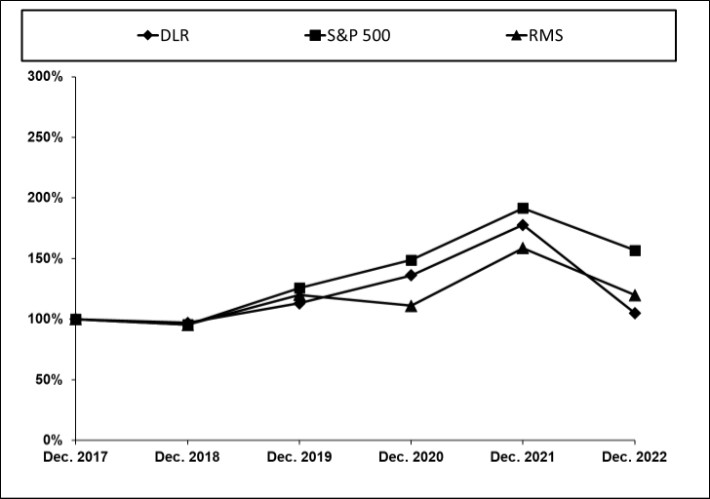
The following graph compares the yearly change in the cumulative total stockholder return on Digital Realty Trust, Inc.’s common stock during the period from December 31, 2017 through December 31, 2022, with the cumulative total returns on the MSCI US REIT Index (RMS) and the S&P 500 Market Index. The comparison assumes that $100 was invested on December 31, 2017 in Digital Realty Trust, Inc.’s common stock and in each of these indices and assumes reinvestment of dividends, if any.
COMPARISON OF CUMULATIVE TOTAL RETURNS
AMONG DIGITAL REALTY TRUST, INC., S&P 500 INDEX AND RMS INDEX
Assumes $100 invested on December 31, 2017 and
dividends reinvested
To fiscal year ending December 31, 2022
| | | | | | | |
|---|---|---|---|---|---|---|
| Pricing Date | DLR($) | S&P 500($) | RMS($) | |||
| December 31, 2017 | 100.0 | 100.0 | 100.0 | |||
| December 31, 2018 | 97.0 | 95.6 | 95.4 | |||
| December 31, 2019 | 113.0 | 125.7 | 120.1 | |||
| December 31, 2020 | 136.1 | 148.9 | 111.0 | |||
| December 31, 2021 | 177.8 | 191.6 | 158.8 | |||
| December 31, 2022 | 105.0 | 156.9 | 119.9 |
| ● | This graph and the accompanying text are not “soliciting material,” are not deemed filed with the SEC and are not to be incorporated by reference in any filing by us under the Securities Act of 1933, as amended, or the Securities Exchange Act of 1934, as amended, whether made before or after the date hereof and irrespective of any general incorporation language in any such filing. |
|---|
| ● | The stock price performance shown on the graph is not necessarily indicative of future price performance. |
|---|
| ● | The hypothetical investment in Digital Realty Trust, Inc.’s common stock presented in the stock performance graph above is based on the closing price of the common stock on December 31, 2017. |
|---|
SALES OF UNREGISTERED EQUITY SECURITIES
Digital Realty Trust, Inc.
None.
Digital Realty Trust, L.P.
During the year ended December 31, 2022, our Operating Partnership issued partnership units in private placements in reliance on the exemption from registration provided by Section 4(a)(2) of the Securities Act, in the amounts and for the consideration set forth below:
During the year ended December 31, 2022, Digital Realty Trust, Inc. issued an aggregate of 373,953 shares of its common stock in connection with restricted stock awards for no cash consideration. For each share of common stock issued by Digital Realty Trust, Inc. in connection with such awards, our Operating Partnership issued a restricted common unit to Digital Realty Trust, Inc. During the year ended December 31, 2022, our Operating Partnership issued an aggregate of 373,953 common units to Digital Realty Trust, Inc., as required by our Operating Partnership’s partnership agreement. During the year ended December 31, 2022, an aggregate of 65,854 shares of its common stock were forfeited to Digital Realty Trust, Inc. in connection with restricted stock awards for a net issuance of 308,099 shares of common stock.
All other issuances of unregistered equity securities of our Operating Partnership during the year ended December 31, 2022 have been disclosed previously in filings with the SEC. For all issuances of units to Digital Realty Trust, Inc., our Operating Partnership relied on Digital Realty Trust, Inc.’s status as a publicly traded NYSE-listed company with over $41 billion in total consolidated assets and as our Operating Partnership’s majority owner and general partner as the basis for the exemption under Section 4(a)(2) of the Securities Act.
REPURCHASES OF EQUITY SECURITIES
Digital Realty Trust, Inc.
None.
Digital Realty Trust, L.P.
None.
Item 6. [Reserved]
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion should be read in conjunction with the Consolidated Financial Statements and notes thereto included in Item 8. of this report and the matters described under Item 1A. Risk Factors. We make statements in this section that are forward-looking statements within the meaning of the federal securities laws. For a complete discussion of forward-looking statements, see the section in this report entitled “Forward-Looking Statements.”
A discussion regarding our financial condition and results of operations for 2022 as compared to 2021 is presented herein. Information on 2020 is presented in graphs and other tables only to show year-over-year trends in our results of operations and operating metrics. Our financial condition for 2020 and results of operations for 2020 – and also 2020 as compared to 2021 – can be found under Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations, of our Annual Report on form 10-K for the fiscal year ended 2021, filed with the SEC on February 25, 2022.
Business Overview and Strategy
Digital Realty Trust, Inc., through its controlling interest in Digital Realty Trust, L.P. and its subsidiaries, delivers comprehensive space, power, and interconnection solutions that enable its customers and partners to connect with each other and service their own customers on a global technology and real estate platform. We are a leading global provider of data center, colocation and interconnection solutions for customers across a variety of industry verticals. Digital Realty Trust, Inc. operates as a REIT for federal income tax purposes, and our Operating Partnership is the entity through which we conduct our business and own our assets.
Our primary business objectives are to maximize:
| (i) | sustainable long-term growth in earnings and funds from operations per share and unit; |
|---|
| (ii) | cash flow and returns to our stockholders and Digital Realty Trust, L.P.’s unitholders through the payment of distributions; and |
|---|
| (iii) | return on invested capital. |
|---|
We expect to accomplish our objectives by achieving superior risk-adjusted returns, prudently allocating capital, diversifying our product offerings, accelerating our global reach and scale, and driving revenue growth and operating efficiencies. A significant component of our current and future internal growth is anticipated through the development of our existing space held for development, acquisition of land for future development, and acquisition of new properties.
We target high-quality, strategically located properties containing the physical and connectivity infrastructure that supports the applications and operations of data center and technology industry customers and properties that may be developed for such use. Most of our data center properties contain fully redundant electrical supply systems, multiple power feeds, above-standard cooling systems, raised floor areas, extensive in-building communications cabling and high-level security systems. Fundamentally, we bring together foundational real estate and innovative technology expertise around the world to deliver a comprehensive, dedicated product suite to meet customers’ data and connectivity needs. We represent an important part of the digital economy that we believe will benefit from powerful, long-term growth drivers.
We have developed detailed, standardized procedures for evaluating new real estate investments to ensure that they meet our financial, technical and other criteria. We expect to continue to acquire additional assets as part of our growth strategy. We intend to aggressively manage and lease our assets to increase their cash flow. We may continue to build out our development portfolio when justified by anticipated demand and returns.
We may acquire properties subject to existing mortgage financing and other indebtedness or we may incur new indebtedness in connection with acquiring or refinancing these properties. Debt service on such indebtedness will have a priority over any cash dividends with respect to Digital Realty Trust, Inc.’s common stock and preferred stock. We are committed to maintaining a conservative capital structure. Our goal is to average through business cycles the following financial ratios: 1) a debt-to-Adjusted EBITDA ratio of 5.5x, 2) a fixed charge coverage of greater than three times, and 3) floating rate debt at less than 20% of total outstanding debt. In addition, we strive to maintain a well-laddered debt maturity schedule, and we seek to maximize the menu of our available sources of capital, while minimizing the cost.
Summary of 2022 Significant Activities
We completed the following significant activities in 2022 as described in the Notes to the Consolidated Financial Statements:
| ● | In January, we issued and sold €750.0 million aggregate principal amount of 1.375% Guaranteed Notes due 2032 (the “2032 Notes”). The 2032 Notes are senior unsecured obligations of Digital Intrepid Holding B.V. and are fully and unconditionally guaranteed by Digital Realty Trust, Inc. and Digital Realty Trust, L.P. Net proceeds from the offering were approximately €737.5 million (approximately $835.3 million based on the exchange rate on January 18, 2022) after deducting managers’ discounts and estimated offering expenses. |
|---|
| ● | In February, we redeemed $450.0 million of 4.750% Notes due 2025. As part of this redemption, we recorded a $51.1 million loss on extinguishment of debt. |
|---|
| ● | In March, we issued and sold CHF 100 million aggregate principal amount of 0.600% Guaranteed Notes due 2023 (the “2023 Notes”) and CHF 150 million aggregate principal amount of 1.700% Guaranteed Notes due 2027 (the “2027 Notes” and, together with the 2023 Notes, the “Swiss Franc Notes”). The Swiss Franc Notes are senior unsecured obligations of Digital Intrepid Holding B.V. and are fully and unconditionally guaranteed by Digital Realty Trust, Inc. and Digital Realty Trust, L.P. Net proceeds from the offering of the Swiss Franc Notes were approximately CHF 248.6 million (approximately $269.2 million based on the exchange rate on March 30, 2022) after deducting the managers’ commissions and certain offering expenses. |
|---|
| ● | In June, we announced the formation of a joint venture with Mivne Real Estate (K.D.). The joint venture will operate under the brand name Digital Realty Mivne and will develop a multi-tenant data center campus in Israel. |
|---|
| ● | In July, we partially settled the September 2021 forward sale agreements by issuing approximately 2.7 million shares, resulting in proceeds of approximately $400.0 million. |
|---|
| ● | In August, we closed the acquisition of 61.1% indirect controlling interest in Teraco, a leading carrier-neutral colocation provider in South Africa, for total cash consideration of $1.7 billion in a transaction valuing Teraco at approximately $3.3 billion. |
|---|
| ● | In August, we sold a non-core building in Dallas for net proceeds of $203 million resulting in a net gain on sale of $174 million. |
|---|
| ● | In August, we entered into a term loan agreement, comprised of a €375.0 million three-year senior unsecured term loan facility and a €375.0 million five-year senior unsecured term loan facility. The term loans were funded in August (€500.0 million) and in September (€250.0 million). The interest rate for borrowings under the term loans is based on EURIBO, plus a margin based on the corporate credit rating of our long-term senior unsecured debt. |
|---|
| | ● | In September, we completed an underwritten public offering of $550.0 million aggregate principal am
Showing the first 8K of 82K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
Our future income, cash flows and fair values relevant to financial instruments depend upon prevalent market interest rates. Market risk refers to the risk of loss from adverse changes in market prices and interest rates. We do not use derivatives for trading or speculative purposes and only enter into contracts with major financial institutions based on their credit ratings and other factors.
Analysis of Debt between Fixed and Variable Rate
We use interest rate swap agreements and fixed rate debt to reduce our exposure to interest rate movements. As of December 31, 2022, our consolidated debt was as follows (in millions):
| | | | | | | |
|---|---|---|---|---|---|---|
| | | | Estimated Fair | |||
| | | Carrying Value | Value | |||
| Fixed rate debt | | $ | 13,363.8 | | $ | 9,292.0 |
| Variable rate debt subject to interest rate swaps | | 157.3 | | 157.3 | ||
| Total fixed rate debt (including interest rate swaps) | | 13,521.1 | | 9,449.3 | ||
| Variable rate debt | | 3,202.8 | | 3,202.8 | ||
| Total outstanding debt | | $ | 16,723.9 | | $ | 12,652.1 |
Sensitivity to Changes in Interest Rates
The following table shows the effects if assumed changes in interest rates occurred, based on fair values and interest expense as of December 31, 2022:
| | | | |
|---|---|---|---|
| | Change | ||
| Assumed event | | ($ millions) | |
| Increase in fair value of interest rate swaps following an assumed 10% increase in interest rates | | $ | (0.2) |
| Decrease in fair value of interest rate swaps following an assumed 10% decrease in interest rates | | 0.2 | |
| Increase in annual interest expense on our debt that is variable rate and not subject to swapped interest following a 10% increase in interest rates | | 11.9 | |
| Decrease in annual interest expense on our debt that is variable rate and not subject to swapped interest following a 10% decrease in interest rates | | (11.9) | |
| Increase in fair value of fixed rate debt following a 10% decrease in interest rates | | 210.9 | |
| Decrease in fair value of fixed rate debt following a 10% increase in interest rates | | (201.0) |
Interest risk amounts were determined by considering the impact of hypothetical interest rates on our financial instruments. These analyses do not consider the effect of any change in overall economic activity that could occur in that environment. Further, in the event of a change of that magnitude, we may take actions to further mitigate our exposure to the change. However, due to the uncertainty of the specific actions that would be taken and their possible effects, these analyses assume no changes in our financial structure.
Foreign Currency Exchange Risk
We are subject to risk from the effects of exchange rate movements of a variety of foreign currencies, which may affect future costs and cash flows. Our primary currency exposures are to the Euro, Japanese yen, British pound sterling, Singapore dollar and South African rand. Our exposure to foreign exchange risk related to the Brazilian real is limited to the impact that currency has on our share of the Ascenty entity’s operations and financial position. We attempt to mitigate a portion of the risk of currency fluctuations by financing our investments in local currency denominations in order to reduce our exposure to any foreign currency transaction gains or losses resulting from transactions entered into in currencies other than the functional currencies of the associated entities. In addition, we may also hedge well-defined transactional exposures with foreign currency forwards or options, although there can be no assurances that these will be effective. As a result, changes in the relation of any such foreign currency to U.S. dollar may affect our revenues, operating margins and distributions and may also affect the book value of our assets and the amount of stockholders’ equity.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
INDEX TO THE CONSOLIDATED FINANCIAL STATEMENTS
Management’s Report on Internal Control over Financial Reporting
The management of Digital Realty Trust, Inc. (the Company) is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rules 13a-15(f) and 15(d)-15(f). Our internal control system was designed to provide reasonable assurance to the Company’s management and board of directors regarding the preparation and fair presentation of published financial statements.
All internal control systems, no matter how well designed, have inherent limitations. Therefore, even those systems determined to be effective can provide only reasonable assurance with respect to financial statement preparation and presentation.
Under the supervision and with the participation of management, including our Chief Executive Officer and Chief Financial Officer, we assessed the effectiveness of the Company’s internal control over financial reporting as of December 31, 2022. In making this assessment, we used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission in Internal Control—Integrated Framework (2013). We acquired a majority interest in Teraco during the year ended December 31, 2022. We have excluded from our overall assessment of the Company's internal control over financial reporting as of December 31, 2022, internal control over financial reporting associated with Teraco and its total assets of $4.1 billion and total revenues of $71.4 million. Based on our assessment, management concluded that as of December 31, 2022, the Company’s internal control over financial reporting was effective based on those criteria.
Our independent registered public accounting firm has issued an audit report on the Company’s internal control over financial reporting. This report appears on page 83.
Management’s Report on Internal Control over Financial Reporting
The management of Digital Realty Trust, L.P. (the Operating Partnership) is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rules 13a-15(f) and 15(d)-15(f). Our internal control system was designed to provide reasonable assurance to the Operating Partnership’s management regarding the preparation and fair presentation of published financial statements.
All internal control systems, no matter how well designed, have inherent limitations. Therefore, even those systems determined to be effective can provide only reasonable assurance with respect to financial statement preparation and presentation.
Under the supervision and with the participation of management, including the Chief Executive Officer and Chief Financial Officer of our general partner, we assessed the effectiveness of the Operating Partnership’s internal control over financial reporting as of December 31, 2022. In making this assessment, we used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission in Internal Control—Integrated Framework (2013). We acquired a majority interest in Teraco during the year ended December 31, 2022. We have excluded from our overall assessment of the Operating Partnership’s internal control over financial reporting as of December 31, 2022, internal control over financial reporting associated with Teraco and its total assets of $4.1 billion and total revenues of $71.4 million. Based on our assessment, management concluded that as of December 31, 2022, the Operating Partnership’s internal control over financial reporting was effective based on those criteria.
Report of Independent Registered Public Accounting Firm
To the Stockholders and Board of Directors
Digital Realty Trust, Inc.:
Opinion on the Consolidated Financial Statements
We have audited the accompanying consolidated balance sheets of Digital Realty Trust, Inc. and subsidiaries (the Company) as of December 31, 2022 and 2021, the related consolidated income statements, and statements of comprehensive income, equity, and cash flows for each of the years in the three-year period ended December 31, 2022, and the related notes and financial statement schedule III, properties and accumulated depreciation (collectively, the consolidated financial statements). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2022 and 2021, and the results of its operations and its cash flows for each of the years in the three-year period ended December 31, 2022, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of December 31, 2022, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission, and our report dated February 24, 2023 expressed an unqualified opinion on the effectiveness of the Company’s internal control over financial reporting.
Basis for Opinion
These consolidated financial statements are the responsibility of the Company’s manag
Showing the first 8K of 281K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Our Management’s Reports on Internal Control over Financial Reporting for Digital Realty Trust, Inc. and Digital Realty Trust, L.P. are included in Part II, Item 8, Financial Statements and Supplementary Data on page 79.
Evaluation of Disclosure Controls and Procedures (Digital Realty Trust, Inc.)
The Company maintains disclosure controls and procedures that are designed to ensure that information required to be disclosed in its reports filed under the Securities Exchange Act of 1934, as amended, is recorded, processed, summarized and reported within the time periods specified in the U.S. Securities and Exchange Commission’s rules and forms, and that such information is accumulated and communicated to its management, including its chief executive officer and chief financial officer, as appropriate, to allow timely decisions regarding required disclosure. In designing and evaluating the disclosure controls and procedures, the Company’s management recognizes that any controls and procedures, no matter how well designed and operated, can provide only reasonable assurance of achieving the desired control objectives, and its management is required to apply its judgment in evaluating the cost-benefit relationship of possible controls and procedures. Also, the Company has investments in certain unconsolidated entities, which are accounted for using the equity method of accounting. As the Company does not control or manage these entities, its disclosure controls and procedures with respect to such entities may be substantially more limited than those it maintains with respect to its consolidated subsidiaries.
As required by Rule 13a-15(b) or Rule 15d-15(b) of the Securities Exchange Act of 1934, as amended, management of the Company carried out an evaluation, under the supervision and with participation of its chief executive officer and chief financial officer, of the effectiveness of the design and operation of its disclosure controls and procedures that were in effect as of December 31, 2022. Based on the foregoing, the Company’s management concluded that its disclosure controls and procedures were effective at the reasonable assurance level.
Changes in Internal Control over Financial Reporting
There has not been any change in our internal control over financial reporting during the three months ended December 31, 2022, that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
Evaluation of Disclosure Controls and Procedures (Digital Realty Trust, L.P.)
The Operating Partnership maintains disclosure controls and procedures that are designed to ensure that information required to be disclosed in its reports filed under the Securities Exchange Act of 1934, as amended, is recorded, processed, summarized and reported within the time periods specified in the U.S. Securities and Exchange Commission’s rules and forms, and that such information is accumulated and communicated to its management, including the chief executive officer and chief financial officer of its general partner, as appropriate, to allow timely decisions regarding required disclosure. In designing and evaluating the disclosure controls and procedures, the Operating Partnership’s management recognizes that any controls and procedures, no matter how well designed and operated, can provide only reasonable assurance of achieving the desired control objectives, and its management is required to apply its judgment in evaluating the cost-benefit relationship of possible controls and procedures. Also, the Operating Partnership has investments in certain unconsolidated entities, which are accounted for using the equity method of accounting. As the Operating Partnership does not control or manage these entities, its disclosure controls and procedures with respect to such entities may be substantially more limited than those it maintains with respect to its consolidated subsidiaries.
As required by Rule 13a-15(b) or Rule 15d-15(b) of the Securities Exchange Act of 1934, as amended, management of the Operating Partnership carried out an evaluation, under the supervision and with participation of the chief executive officer and chief financial officer of its general partner, of the effectiveness of the design and operation of its disclosure controls and procedures that were in effect as of December 31, 2022. Based on the foregoing, the Operating Partnership’s management concluded that its disclosure controls and procedures were effective at the reasonable assurance level.
Changes in Internal Control over Financial Reporting
There has not been any change in our internal control over financial reporting during the three months ended December 31, 2022, that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. OTHER INFORMATION
None.
Item 9C. DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
The information concerning our directors, executive officers and corporate governance required by Item 10 will be included in the Proxy Statement to be filed relating to our 2023 Annual Meeting of Stockholders and is incorporated herein by reference.
We have filed, as exhibits to this Annual Report on Form 10-K for the year ended December 31, 2022, the certifications of our Chief Executive Officer and Chief Financial Officer required under Section 302 of the Sarbanes Oxley Act to be filed with the Securities and Exchange Commission regarding the quality of our public disclosure. We have furnished to the Securities and Exchange Commission as exhibits to this Annual Report on Form 10-K for the year ended December 31, 2022, the certifications of our Chief Executive Officer and Chief Financial Officer required under Section 906 of the Sarbanes Oxley Act. In addition, as required by Section 303A.12 of the NYSE Listed Company Manual, our Chief Executive Officer made his annual certification to the NYSE stating that he was not aware of any violation by the Company of the corporate governance listing standards of the NYSE.
Item 11. EXECUTIVE COMPENSATION
The information concerning our executive compensation required by Item 11 will be included in the Proxy Statement to be filed relating to our 2023 Annual Meeting of Stockholders and is incorporated herein by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
The information concerning the security ownership of certain beneficial owners and management and related stockholder matters (including equity compensation plan information) required by Item 12 will be included in the Proxy Statement to be filed relating to our 2023 Annual Meeting of Stockholders and is incorporated herein by reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS AND DIRECTOR INDEPENDENCE
The information concerning certain relationships, related transactions and director independence required by Item 13 will be included in the Proxy Statement to be filed relating to our 2023 Annual Meeting of Stockholders and is incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
The information concerning our principal accounting fees and services required by Item 14 will be included in the Proxy Statement to be filed relating to our 2023 Annual Meeting of Stockholders and is incorporated herein by reference.
PART IV
Item 15. EXHIBITS.
| | | |
|---|---|---|
| 31.3 | | Rule 13a-14(a)/15d-14(a) Certifications of Chief Executive Officer for Digital Realty Trust, L.P. |
| | | |
| 31.4 | | Rule 13a-14(a)/15d-14(a) Certifications of Chief Financial Officer for Digital Realty Trust, L.P. |
| | | |
| 32.1 | | 18 U.S.C. § 1350 Certifications of Chief Executive Officer for Digital Realty Trust, Inc. |
| | | |
| 32.2 | | 18 U.S.C. § 1350 Certifications of Chief Financial Officer for Digital Realty Trust, Inc. |
| | | |
| 32.3 | | 18 U.S.C. § 1350 Certifications of Chief Executive Officer for Digital Realty Trust, L.P. |
| | | |
| 32.4 | | 18 U.S.C. § 1350 Certifications of Chief Financial Officer for Digital Realty Trust, L.P. |
| | | |
| 101 | | The following financial statements from Digital Realty Trust, Inc.’s and Digital Realty Trust, L.P.’s Form 10-K for the year ended December 31, 2022, formatted in Inline XBRL interactive data files: (i) Consolidated Balance Sheets as of December 31, 2022 and December 31, 2021; (ii) Consolidated Income Statements for each of the years in the three-year period ended December 31, 2022; (iii) Consolidated Statements of Equity and Comprehensive Income/Statements of Capital and Comprehensive Income for each of the years in the three-year period ended December 31, 2022; (iv) Consolidated Statements of Cash Flows for each of the years in the three-year period ended December 31, 2022; and (v) Notes to Consolidated Financial Statements. |
| | | |
| 104 | | Cover Page Interactive Data File (formatted as Inline XBRL and contained in Exhibit 101). |
| † | Management contract or compensatory plan or arrangement. |
|---|
| * | Portions of this exhibit have been omitted because such portions (i) are not material and (ii) would be competitively harmful if publicly disclosed. |
|---|
Item 16. FORM 10-K SUMMARY
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| | | |
|---|---|---|
| | | DIGITAL REALTY TRUST, INC. |
| | | |
| | By: | /s/ ANDREW P. POWER |
| | | Andrew P. Power President & Chief Executive Officer |
| | | |
| | Date: | February 24, 2023 |
POWER OF ATTORNEY
KNOW ALL PERSONS BY THESE PRESENTS, that each person whose signature appears below constitutes and appoints Andrew P. Power, Jeannie Lee and Matthew R. Mercier, and each of them, with full power to act without the other, such person’s true and lawful attorneys-in-fact and agents, with full power of substitution and resubstitution, for him or her and in his or her name, place and stead, in any and all capacities, to sign this Form 10-K and any and all amendments thereto, and to file the same, with exhibits and schedules thereto, and other documents in connection therewith, with the Securities and Exchange Commission, granting unto said attorneys-in-fact and agents, and each of them, full power and authority to do and perform each and every act and thing necessary or desirable to be done in and about the premises, as fully to all intents and purposes as he or she might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact and agents, or any of them, or their or his or her substitute or substitutes, may lawfully do or cause to be done by virtue hereof.
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| NNIS | | | | | |||||||
|---|---|---|---|---|---|---|---|---|---|---|---|
| | | | | | |||||||
| Signature | Title | Date | |||||||||
| | | | | | |||||||
| /s/ MARY HOGAN PREUSSE | | Chairman of the Board | | February 24, 2023 | |||||||
| Mary Hogan Preusse | | | | | |||||||
| | | | | | |||||||
| /s/ ANDREW P. POWER | | President & Chief Executive Officer (Principal Executive Officer) | | February 24, 2023 | |||||||
| Andrew P. Power | | | | | |||||||
| | | | | | |||||||
| /s/ MATTHEW R. MERCIER | | Chief Financial Officer (Principal Financial Officer) | | February 24, 2023 | |||||||
| Matthew R. Mercier | | | | | |||||||
| | | | | | |||||||
| /s/ CAMILLA A. HARRIS | | Chief Accounting Officer (Principal Accounting Officer) | | February 24, 2023 | |||||||
| Camilla A. Harris | | | | | |||||||
| | | | | | |||||||
| /s/ ALEXIS BLACK BJORLIN | | Director | | February 24, 2023 | |||||||
| Alexis Black Bjorlin | | | | | |||||||
| | | | | | |||||||
| /s/ LAURENCE A. CHAPMAN | | Director | | February 24, 2023 | |||||||
| Laurence A. Chapman | | | | | |||||||
| | | | | | |||||||
| /s/ VeraLinn Jamieson | | Director | | February 24, 2023 | |||||||
| VeraLinn Jamieson | | | | |
| NNIS | | | | | |||||||
|---|---|---|---|---|---|---|---|---|---|---|---|
| | | | | | |||||||
| Signature | Title | Date | |||||||||
| | | | | | |||||||
| /s/ KEVIN J. KENNEDY | | Director | | February 24, 2023 | |||||||
| Kevin J. Kennedy | | | | | |||||||
| | | | | | |||||||
| /s/ WILLIAM G. LAPERCH | | Director | | February 24, 2023 | |||||||
| William G. LaPerch | | | | | |||||||
| | | | | | |||||||
| /s/ JEAN F.H.P. MANDEVILLE | | Director | | February 24, 2023 | |||||||
| Jean F.H.P. Mandeville | | | | | |||||||
| | | | | | |||||||
| /s/ AFSHIN MOHEBBI | | Director | | February 24, 2023 | |||||||
| Afshin Mohebbi | | | | | |||||||
| | | | | | |||||||
| /s/ MARK R. PATTERSON | | Director | | February 24, 2023 | |||||||
| Mark R. Patterson | | | | | |||||||
| | | | | | |||||||
| /s/ DENNIS E. SINGLETON | | Director | | February 24, 2023 | |||||||
| Dennis E. Singleton | | | | | |||||||
| | | | | | |||||||
| | | | | |
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| | | |
|---|---|---|
| | DIGITAL REALTY TRUST, L.P. | |
| | | |
| | By: | Digital Realty Trust, Inc., |
| | Its | General Partner |
| | | |
| | By: | /s/ ANDREW P. POWER |
| | | Andrew P. Power President & Chief Executive Officer |
| | | |
| | Date: | February 24, 2023 |
POWER OF ATTORNEY
KNOW ALL PERSONS BY THESE PRESENTS, that each person whose signature appears below constitutes and appoints Andrew P. Power, Jeannie Lee and Matthew R. Mercier, and each of them, with full power to act without the other, such person’s true and lawful attorneys-in-fact and agents, with full power of substitution and resubstitution, for him or her and in his or her name, place and stead, in any and all capacities, to sign this Form 10-K and any and all amendments thereto, and to file the same, with exhibits and schedules thereto, and other documents in connection therewith, with the Securities and Exchange Commission, granting unto said attorneys-in-fact and agents, and each of them, full power and authority to do and perform each and every act and thing necessary or desirable to be done in and about the premises, as fully to all intents and purposes as he or she might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact and agents, or any of them, or their or his or her substitute or substitutes, may lawfully do or cause to be done by virtue hereof.
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| NNIS | | | | | |||||||
|---|---|---|---|---|---|---|---|---|---|---|---|
| | | | | | |||||||
| Signature | Title | Date | |||||||||
| | | | | | |||||||
| /s/ MARY HOGAN PREUSSE | | Chairman of the Board | | February 24, 2023 | |||||||
| Mary Hogan Preusse | | | | | |||||||
| | | | | | |||||||
| /s/ ANDREW P. POWER | | President & Chief Executive Officer (Principal Executive Officer) | | February 24, 2023 | |||||||
| Andrew P. Power | | | | | |||||||
| | | | | | |||||||
| /s/ MATTHEW R. MERCIER | | Chief Financial Officer (Principal Financial Officer) | | February 24, 2023 | |||||||
| Matthew R. Mercier | | | | | |||||||
| | | | | | |||||||
| /s/ CAMILLA A. HARRIS | | Chief Accounting Officer (Principal Accounting Officer) | | February 24, 2023 | |||||||
| Camilla A. Harris | | | | | |||||||
| | | | | | |||||||
| /s/ ALEXIS BLACK BJORLIN | | Director | | February 24, 2023 | |||||||
| Alexis Black Bjorlin | | | | | |||||||
| | | | | | |||||||
| /s/ LAURENCE A. CHAPMAN | | Director | | February 24, 2023 | |||||||
| Laurence A. Chapman | | | | |
| NNIS | | | | | |||||||
|---|---|---|---|---|---|---|---|---|---|---|---|
| | | | | | |||||||
| Signature | Title | Date | |||||||||
| | | | | | |||||||
| /s/ VeraLinn Jamieson | | Director | | February 24, 2023 | |||||||
| VeraLinn Jamieson | | | | | |||||||
| | | | | | |||||||
| /s/ KEVIN J. KENNEDY | | Director | | February 24, 2023 | |||||||
| Kevin J. Kennedy | | | | | |||||||
| | | | | | |||||||
| /s/ WILLIAM G. LAPERCH | | Director | | February 24, 2023 | |||||||
| William G. LaPerch | | | | | |||||||
| | | | | | |||||||
| /s/ JEAN F.H.P. MANDEVILLE | | Director | | February 24, 2023 | |||||||
| Jean F.H.P. Mandeville | | | | | |||||||
| | | | | | |||||||
| /s/ AFSHIN MOHEBBI | | Director | | February 24, 2023 | |||||||
| Afshin Mohebbi | | | | | |||||||
| | | | | | |||||||
| /s/ MARK R. PATTERSON | | Director | | February 24, 2023 | |||||||
| Mark R. Patterson | | | | | |||||||
| | | | | | |||||||
| /s/ DENNIS E. SINGLETON | | Director | | February 24, 2023 | |||||||
| Dennis E. Singleton | | | | | |||||||
| | | | | | |||||||
| | | | | |