 filings.tools
Healthpeak Properties 10-K 2020-12-31
Filed 2021-02-10. 22 sections, 915K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
(Mark One)
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934. |
For the fiscal year ended December 31, 2020
or
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the transition period from to
Commission file number 001-08895
Healthpeak Properties, Inc.
(Exact name of registrant as specified in its charter)
| Maryland | 33-0091377 | |||||||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
5050 South Syracuse Street, Suite 800
Denver, CO 80237
(Address of principal executive offices) (Zip Code)
(949) 407-0700
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
| Common Stock, $1.00 par value | PEAK | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act:
None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See definitions of “large accelerated filer,” “accelerated filer”, “smaller reporting company,” and "emerging growth company" in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☒ | Accelerated filer | ☐ | ||||||||
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ | ||||||||
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management's assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
Indicate by check mark whether the registrant is a shell company (as defined by Rule 12b-2 of the Act.) Yes ☐ No ☒
State the aggregate market value of the voting and non-voting common equity held by non-affiliates computed by reference to the price at which the common equity was last sold, or the average bid and asked price of such common equity, as of the last business day of the registrant’s most recently completed second fiscal quarter: $12.5 billion.
As of February 8, 2021, there were 538,686,262 shares of the registrant's $1.00 par value common stock outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the definitive Proxy Statement for the registrant’s 2021 Annual Meeting of Stockholders have been incorporated by reference into Part III of this Report.
Healthpeak Properties, Inc.
Form 10-K
For the Fiscal Year Ended December 31, 2020
Table of Contents
All references in this report to “Healthpeak,” the “Company,” “we,” “us” or “our” mean Healthpeak Properties, Inc., together with its consolidated subsidiaries. Unless the context suggests otherwise, references to “Healthpeak Properties, Inc.” mean the parent company without its subsidiaries.
Cautionary Language Regarding Forward-Looking Statements
Statements in this Annual Report on Form 10-K that are not historical factual statements are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended (the “Exchange Act”). Forward-looking statements include, among other things, statements regarding our and our officers’ intent, belief or expectation as identified by the use of words such as “may,” “will,” “project,” “expect,” “believe,” “intend,” “anticipate,” “seek,” “target,” “forecast,” “plan,” “potential,” “estimate,” “could,” “would,” “should” and other comparable and derivative terms or the negatives thereof. Forward-looking statements reflect our current expectations and views about future events and are subject to risks and uncertainties that could cause actual results, including our future financial condition and results of operations, to differ materially from those expressed or implied by any forward-looking statements. You are urged to carefully review the disclosures we make concerning risks and uncertainties that may affect our business and future financial performance, including those made below under “Summary Risk Factors” and in “Item 1A, Risk Factors” in this report.
Forward-looking statements are based on certain assumptions and analysis made in light of our experience and perception of historical trends, current conditions and expected future developments as well as other factors that we believe are appropriate under the circumstances. While forward-looking statements reflect our good faith belief and assumptions we believe to be reasonable based upon current information, we can give no assurance that our expectations or forecasts will be attained. Further, we cannot guarantee the accuracy of any such forward-looking statement contained in this Annual Report. Except as required by law, we do not undertake, and hereby disclaim, any obligation to update any forward-looking statements, which speak only as of the date on which they are made.
Risk Factors Summary
Investors should consider the risks and uncertainties described below that may affect our business and future financial performance. These and other risks and uncertainties are more fully described in “Item 1A, Risk Factors” in this report. Additional risks not presently known to us or that we currently deem immaterial may also affect us. If any of these risks occur, our business, financial condition or results of operations could be materially and adversely affected.
As more fully set forth under “Item 1A, Risk Factors” in this report, principal risks and uncertainties that may affect our business, financial condition or results of operations include:
-
the COVID-19 pandemic and health and safety measures intended to reduce its spread;
-
operational risks associated with third party management contracts, including the additional regulation and liabilities of our RIDEA lease structures;
-
the ability of our existing and future tenants, operators and borrowers to conduct their respective businesses in a manner sufficient to maintain or increase their revenues and manage their expenses in order to generate sufficient income to make rent and loan payments to us and our ability to recover investments made, if applicable, in their operations;
-
increased competition, operating costs and market changes affecting our tenants, operators and borrowers;
-
the financial condition of our tenants, operators and borrowers, including potential bankruptcies and downturns in their businesses, and their legal and regulatory proceedings;
-
our concentration of investments in the healthcare property sector, which makes us vulnerable to a downturn in a specific sector than if we invested in multiple industries;
-
our ability to identify replacement tenants and operators and the potential renovation costs and regulatory approvals associated therewith;
-
our property development and redevelopment activity risks, including costs above original estimates, project delays and lower occupancy rates and rents than expected;
-
changes within the life science industry;
-
high levels of regulation, funding requirements, expense and uncertainty faced by our life science tenants;
-
the ability of the hospitals on whose campuses our MOBs are located and their affiliated healthcare systems to remain competitive or financially viable;
-
our ability to maintain our or expand our hospital and health system client relationships;
-
economic and other conditions that negatively affect geographic areas from which we recognize a greater percentage of our revenue;
-
uninsured or underinsured losses, which could result in significant losses and/or performance declines by us or our tenants and operators;
-
our investments in joint ventures and unconsolidated entities, including our lack of sole decision making authority and our reliance on our partners’ financial condition and continued cooperation;
-
our use of contingent rent provisions and/or rent escalators based on the Consumer Price Index;
-
competition for suitable healthcare properties to grow our investment portfolio;
-
our ability to make material acquisitions and successfully integrate them;
-
the potential impact on us and our tenants, operators and borrowers from litigation matters, including rising liability and insurance costs;
-
our ability to foreclose on collateral securing our real estate-related loans;
-
laws or regulations prohibiting eviction of our tenants;
-
the failure of our tenants and operators to comply with federal, state and local laws and regulations, including resident health and safety requirement, as well as licensure, certification and inspection requirements;
-
required regulatory approvals to transfer our healthcare properties;
-
compliance with the Americans with Disabilities Act and fire, safety and other health regulations;
-
the requirements of, or changes to, governmental reimbursement programs such as Medicare or Medicaid;
-
legislation to address federal government operations and administration decisions affecting the Centers for Medicare and Medicaid Services;
-
our participation in the CARES Act Provider Relief Program and other COVID-19 related stimulus and relief programs;
-
volatility or uncertainty in the capital markets, the availability and cost of capital as impacted by interest rates, changes in our credit ratings, and the value of our common stock, and other conditions that may adversely impact our ability to fund our obligations or consummate transactions, or reduce the earnings from potential transactions;
-
cash available for distribution to stockholders and our ability to make dividend distributions at expected levels;
-
our ability to manage our indebtedness level and covenants in and changes to the terms of such indebtedness;
-
changes in global, national and local economic and other conditions;
-
provisions of Maryland law and our charter that could prevent a transaction that may otherwise be in the interest of our stockholders;
-
environmental compliance costs and liabilities associated with our real-estate investments;
-
our ability to maintain our qualification as a real estate investment trust (“REIT”);
-
changes to U.S. federal income tax laws, and potential deferred and contingent tax liabilities from corporate acquisitions;
-
calculating non-REIT tax earnings and profits;
-
ownership limits in our charter that restrict ownership in our stock;
-
our reliance on information technology systems and the potential impact of system failures, disruptions or breaches;
-
unfavorable litigation resolution or disputes; and
-
the loss or limited availability of our key personnel.
Except as required by law, we do not undertake, and hereby disclaim, any obligation to update any forward-looking statements, which speak only as of the date on which they are made.
COVID-19 Infection Information
Information related to the number of our senior housing facilities with confirmed resident COVID-19 cases was provided to us by our operators, but has not been independently verified by us. We have no reason to believe that this information is inaccurate in any material respect, but cannot assure you it is accurate.
PART I
Item 1. Business
General Overview
Healthpeak Properties, Inc. is a Standard & Poor’s (“S&P”) 500 company that acquires, develops, owns, leases, and manages healthcare real estate across the United States (“U.S.”). Our company was originally founded in 1985. We are a Maryland corporation and qualify as a self-administered REIT. In November 2020, we moved our corporate headquarters from Irvine, CA to Denver, CO. With properties in nearly every state, the new headquarters provides a favorable mix of affordability and a centralized geographic location. Our Irvine, CA and Franklin, TN offices will continue to operate.
During 2020, we began the process of disposing of our senior housing triple-net portfolio and senior housing operating portfolio (“SHOP”). We have successfully disposed of a significant portion of both portfolios and will continue that process during 2021. Refer to a discussion of recent and upcoming dispositions in “Item 7, Management's Discussion and Analysis of Financial Condition and Results of Operations—2020 Transaction Overview” for the current status of transactions. As of December 31, 2020, we concluded the planned dispositions represented a strategic shift and therefore, the assets are classified as discontinued operations in all periods presented herein and prior periods have been recast to conform to the current period presentation. See Note 5 to the Consolidated Financial Statements for further information regarding discontinued operations.
In conjunction with the planned disposal of our senior housing triple-net and SHOP portfolios, we focused our strategy on investing in a diversified portfolio of high-quality healthcare properties across our three core asset classes of life science, medical office, and continuing care retirement community (“CCRC”) real estate. Under the life science and medical office segments, we invest through the acquisition, development and management of life science buildings, medical office buildings (“MOBs”), and hospitals. Under the CCRC segment, our properties are operated through RIDEA structures (see below for a description of RIDEA structures). We have other non-reportable segments that are comprised primarily of interests in an unconsolidated senior housing joint venture and debt investments.
At December 31, 2020, our portfolio of investments, including properties in our unconsolidated joint ventures and excluding investments classified as discontinued operations, consisted of interests in 457 properties. The following table summarizes information for our reportable segments, excluding discontinued operations, for the year ended December 31, 2020 (dollars in thousands):
| Segment | Total Portfolio Adjusted NOI**(1)(2)** | Percentage of Total Portfolio Adjusted NOI**(1)** | Number of Properties | |||||||||||||||||
| Life science | $ | 411,302 | 44 | % | 140 | |||||||||||||||
| Medical office | 390,174 | 42 | % | 281 | ||||||||||||||||
| CCRC | 113,423 | 12 | % | 17 | ||||||||||||||||
| Other non-reportable | 21,170 | 2 | % | 19 | ||||||||||||||||
| Totals | $ | 936,069 | 100 | % | 457 |
_______________________________________
(1) Total Portfolio metrics include results of operations from disposed properties through the disposition date. See “Item 7, Management's Discussion and Analysis of Financial Condition and Results of Operations—Results of Operations—Non-GAAP Financial Measures” for additional information regarding Adjusted NOI and see Note 16 to the Consolidated Financial Statements for a reconciliation of Adjusted NOI by segment to net income (loss).
(2) For the year ended December 31, 2020, Adjusted NOI for our senior housing triple-net and SHOP portfolios was $99 million and $105 million, respectively. Operating results for these portfolios are reported as discontinued operations for all periods presented herein.
For a description of our significant activities during 2020, see “Item 7, Management's Discussion and Analysis of Financial Condition and Results of Operations—2020 Transaction Overview” in this report.
Business Strategy
We invest in and manage our real estate portfolio for the long-term to maximize benefit to our stockholders and support the growth of our dividends. Our strategy consists of four core elements:
(i)Our real estate: Our portfolio is grounded in high-quality properties in desirable locations. We focus on three purposely selected private pay asset classes, life science, medical office, and continuing care retirement community, to provide stability through inevitable market cycles.
(ii)Our financials: We maintain a strong investment-grade balance sheet with ample liquidity as well as long-term fixed-rate debt financing with staggered maturities to reduce our exposure to interest-rate volatility and refinancing risk.
(iii)Our partnerships: We work with leading healthcare companies, operators, and service providers and are responsive to their space and capital needs. We provide high-quality management services to encourage tenants to renew, expand, and relocate into our properties, which drives increased occupancy, rental rates, and property values.
(iv)Our platform: We have a people-first culture that we believe attracts, develops, and retains top talent. We continually strive to create and maintain an industry-leading platform with systems and tools that allow us to effectively and efficiently manage our assets and investment activity.
Internal Growth Strategies
We believe our real estate portfolio holds the potential for increased future cash flows as it is well-maintained and in desirable locations. Our strategy for maximizing the benefits from these opportunities is to: (i) work with new or existing tenants and operators to address their space and capital needs and (ii) provide high-quality property management services in order to motivate tenants to renew, expand, or relocate into our properties.
We expect to continue our internal growth as a result of our ability to:
-
Build and maintain long-term leasing and management relationships with quality tenants and operators. In choosing locations for our properties, we focus on the physical environment, adjacency to established businesses (e.g., hospital systems) and educational centers, proximity to sources of business growth, and other local demographic factors.
-
Replace tenants and operators at the best available market terms and lowest possible transaction costs. We believe we are well-positioned to attract new tenants and operators and achieve attractive rental rates and operating cash flow as a result of the location, design, and maintenance of our properties, together with our reputation for high-quality building services and responsiveness to tenants, and our ability to offer space alternatives within our portfolio.
-
Extend and modify terms of existing leases prior to expiration. We structure lease extensions, early renewals, or modifications, which reduce the cost associated with lease downtime or the re-investment risk resulting from the exercise of tenants’ purchase options, while securing the tenancy and relationship of our high quality tenants and operators on a long-term basis.
Investment Strategies
The delivery of healthcare services requires real estate and, as a result, tenants and operators depend on real estate, in part, to maintain and grow their businesses. We believe the healthcare real estate market provides investment opportunities due to the: (i) compelling long-term demographics driving the demand for healthcare services; (ii) specialized nature of healthcare real estate investing; and (iii) ongoing consolidation of the fragmented healthcare real estate sector.
While we emphasize healthcare real estate ownership, we may also provide real estate secured financing to, or invest in equity or debt securities of, healthcare operators or other entities engaged in healthcare real estate ownership. We may also acquire all or substantially all of the securities or assets of other REITs, operating companies, or similar entities where such investments would be consistent with our investment strategies. We may co-invest alongside institutional or development investors through partnerships or limited liability companies.
We monitor, but do not limit, our investments based on the percentage of our total assets that may be invested in any one property type, investment vehicle, or geographic location, the number of properties that may be leased to a single tenant or operator, or loans that may be made to a single borrower. In allocating capital, we target opportunities with the most attractive risk/reward profile for our portfolio as a whole. We may take additional measures to mitigate risk, including diversifying our investments (by sector, geography, tenant, or operator), structuring transactions as master leases, requiring tenant or operator insurance and indemnifications, and/or obtaining credit enhancements in the form of guarantees, letters of credit, or security deposits.
We believe we are well-positioned to achieve external growth through acquisitions, financing, and development. Other factors that contribute to our competitive position include:
-
our reputation gained through over 30 years of successful operations and the strength of our existing portfolio of properties;
-
our relationships with leading healthcare operators and systems, investment banks and other market intermediaries, corporations, private equity firms, not-for-profit organizations, and public institutions seeking to monetize existing assets or develop new facilities;
-
our relationships with institutional buyers and sellers of high-quality healthcare real estate;
-
our track record and reputation for executing acquisitions responsively and efficiently, which provides confidence to domestic and foreign institutions and private investors who seek to sell healthcare real estate in our market areas;
-
our relationships with nationally recognized financial institutions that provide capital to the healthcare and real estate industries; and
-
our control of sites (including assets under contract with radius restrictions).
Financing Strategies
Our REIT qualification requires us to distribute at least 90% of our REIT taxable income (excluding net capital gains); therefore, we do not retain a significant amount of earnings. As a result, we regularly access the public equity and debt markets to raise the funds necessary to finance acquisitions and debt investments, develop and redevelop properties, and refinance maturing debt.
We may finance acquisitions and other investments primarily through the following vehicles:
-
cash flow from operations;
-
sale or exchange of ownership interests in properties or other investments;
-
borrowings under our credit facility or commercial paper program;
-
issuance of additional debt, including unsecured notes, term loans, and mortgage debt; and/or
-
issuance of common stock or preferred stock or its equivalent.
We maintain a disciplined balance sheet by actively managing our debt to equity levels and maintaining multiple sources of liquidity. Our debt obligations are primarily long-term fixed rate with staggered maturities.
We finance our investments based on our evaluation of available sources of funding. For short-term purposes, we may utilize our revolving line of credit facility or commercial paper program, arrange for other short-term borrowings from banks or other sources, or issue equity securities pursuant to our at-the-market equity offering program. We arrange for longer-term financing by offering debt and equity securities, placing mortgage debt, and obtaining capital from institutional lenders and joint venture partners.
Segments
Life science
Our life science properties, which contain laboratory and office space, are leased primarily to biotechnology, medical device and pharmaceutical companies, scientific research institutions, government agencies, and other organizations involved in the life science industry. While these properties have characteristics similar to commercial office buildings, they generally contain more advanced electrical, mechanical, heating, ventilating, and air conditioning systems. The facilities generally have specialty equipment including emergency generators, fume hoods, lab bench tops, and related amenities. In many instances, life science tenants make significant investments to improve their leased space, in addition to landlord improvements, to accommodate biology, chemistry, or medical device research initiatives.
Life science properties are primarily configured in business park or campus settings and include multiple buildings. The business park and campus settings allow us the opportunity to provide flexible, contiguous/adjacent expansion to accommodate the growth of existing tenants. Our properties are located in well-established geographical markets known for scientific research and drug discovery, including San Francisco (51%) and San Diego (24%), California, and Boston, Massachusetts (21%) (based on available square feet). At December 31, 2020, 91% of our life science properties were triple-net leased (based on leased square feet).
The following table provides information about our life science tenant concentration for the year ended December 31, 2020:
| Tenants | Percentage of Segment Revenues | Percentage of Total Revenues | ||||||||||||
| Amgen, Inc. | 10 | % | 3 | % | ||||||||||
Medical office
Our Medical Office segment includes Medical office buildings (“MOBs”) and hospitals. MOBs typically contain physicians’ offices and examination rooms, and may also include pharmacies, hospital ancillary service space, and outpatient services such as diagnostic centers, rehabilitation clinics, and day-surgery operating rooms. While these facilities are similar to commercial office buildings, they require additional plumbing, electrical, and mechanical systems to accommodate multiple exam rooms that may require sinks in every room and special equipment such as x-ray machines. In addition, MOBs are often built to accommodate higher structural loads for certain equipment and may contain vaults or other specialized construction. Our MOBs are typically multi-tenant properties leased to healthcare providers (hospitals and physician practices), with approximately 84% of our MOBs located on hospital campuses and 97% affiliated with hospital systems (based on available square feet). Occasionally, we invest in MOBs located on hospital campuses subject to ground leases. At December 31, 2020, approximately 61% of our MOBs were net leased (based on leased square feet) with the remaining leased under gross or modified gross leases.
The following table provides information about our medical office tenant concentration for the year ended December 31, 2020:
| Tenant | Percentage of Segment Revenues | Percentage of Total Revenues | ||||||||||||
| HCA Healthcare, Inc. (HCA) | 22 | % | 8 | % |
Our medical office segment also includes interests in 10 hospitals. Services provided by our tenants and operators in hospitals are paid for by private sources, third-party payors (e.g., insurance and HMOs) or through Medicare and Medicaid programs. Our hospital property types include acute care, long-term acute care, and specialty and rehabilitation hospitals. All of our hospitals are triple-net leased.
Continuing care retirement community, or CCRC
CCRCs are retirement communities that include independent living, assisted living, and skilled nursing units to provide a continuum of care in an integrated campus. Our CCRCs are owned through RIDEA structures, which is permitted by the Housing and Economic Recovery Act of 2008, and includes most of the provisions previously proposed in the REIT Investment Diversification and Empowerment Act of 2007 (commonly referred to as “RIDEA”). The services provided by our third-party manager-operators under a RIDEA structure at our properties are primarily paid for by the residents directly or through private insurance and are less reliant on government reimbursement programs such as Medicare and Medicaid.
A RIDEA structure allows us, through a taxable REIT subsidiary (“TRS”), to receive cash flow from the operations of a healthcare facility in compliance with REIT tax requirements. The criteria for operating a healthcare facility through a RIDEA structure require us to lease the facility to an affiliate TRS under a triple-net lease, and for such affiliate TRS to engage an independent qualifying management company (also known as an eligible independent contractor or third-party operator) to manage and operate the day-to-day business of the facility in exchange for a management fee. As a result, under a RIDEA structure, we are required to rely on a third-party operator to hire and train all facility employees, enter into third-party contracts for the benefit of the facility, including resident/patient agreements, comply with laws, including but not limited to healthcare laws, and provide resident care. We are substantially limited in our ability to control or influence day-to-day operations under a RIDEA structure, and thus rely on the third-party operator to manage and operate the business.
Through our TRS entities, we bear all operational risks and liabilities associated with the operation of these properties, with limited exceptions, such as a third-party operator’s gross negligence or willful misconduct. These operational risks and liabilities include those relating to any employment matters of our operator, compliance with healthcare and other laws and liabilities relating to personal injury-tort matters, resident-patient quality of care claims, and any governmental reimbursement matters, even though we have limited ability to control or influence our third-party operators’ management of these risks.
The management agreements we have in RIDEA structures related to CCRCs have terms ranging from 10 to 15 years, with mutual renewal options. There are base management fees and incentive management fees payable to our third-party operators if operating results of the RIDEA properties exceed pre-established thresholds. Conversely, there are also provisions in the management agreements that reduce management fees payable to our third-party operators if operating results do not meet certain pre-established thresholds.
CCRCs are different from other housing and care options for seniors because they typically provide written agreements or long-term contracts between residents and the communities (frequently lasting the term of the resident’s lifetime), which offer a continuum of housing, services and healthcare on one campus or site. CCRCs are appealing as they allow residents to “age in place” and typically require the individual to be independent and in relatively good health upon entry.
As third-party operators manage our RIDEA properties in exchange for the receipt of a management fee, we are not directly exposed to the credit risk of these operators in the same manner or to the same extent as a triple-net tenant.
Other non-reportable segment
At December 31, 2020, we had the following investments in our other non-reportable segments: (i) an interest in an unconsolidated joint venture that owns 19 senior housing assets, (ii) debt investments, and (iii) two preferred equity investments.
The properties in our unconsolidated senior housing joint venture are owned through RIDEA structures and include independent living facilities and assisted living facilities, which cater to different segments of the elderly population based upon their personal needs. These facilities are often in apartment-like buildings with private residences ranging from single rooms to large apartments.
Competition
Investing in real estate serving the healthcare industry is highly competitive. We face competition from other REITs, investment companies, pension funds, private equity investors, sovereign funds, healthcare operators, lenders, developers, and other institutional investors, some of whom may have greater flexibility (e.g., non-REIT competitors), greater resources, and lower costs of capital than we do. Increased competition makes it more challenging for us to identify and successfully capitalize on opportunities that meet our objectives. Our ability to compete may also be impacted by global, national, and local economic trends, availability of investment alternatives, availability and cost of capital, construction and renovation costs, existing laws and regulations, new legislation, and population trends.
Income from our investments depends on our tenants’ and operators’ ability to compete with other companies on multiple levels, including: (i) the quality of care provided, (ii) reputation, (iii) success of product or drug development, (iv) the physical appearance of a facility, (v) price and range of services offered, (vi) alternatives for healthcare delivery, (vii) the supply of competing properties, (viii) physicians, (ix) staff, (x) referral sources, (xi) location, (xii) the size and demographics of the population in surrounding areas, and (xiii) the financial condition of our tenants and operators. For a discussion of the risks associated with competitive conditions affecting our business, see “Item 1A, Risk Factors” in this report.
Government Regulation, Licensing and Enforcement
Overview
Our healthcare facility operators (which include our TRS entities when we use a RIDEA structure) and tenants are typically subject to extensive and complex federal, state, and local healthcare laws and regulations relating to quality of care, licensure and certificate of need, government reimbursement, fraud and abuse practices, and similar laws governing the operation of healthcare facilities, and we expect the healthcare industry, in general, will continue to face increased regulation and pressure in the areas of fraud, waste and abuse, cost control, healthcare management, and provision of services, among others. These regulations are wide ranging and can subject our tenants and operators to civil, criminal, and administrative sanctions. Affected tenants and operators may find it increasingly difficult to comply with this complex and evolving regulatory environment because of a relative lack of guidance in many areas as certain of our healthcare properties are subject to oversight from several government agencies, and the laws may vary from one jurisdiction to another. Changes in laws, regulations, reimbursement enforcement activity, and regulatory non-compliance by our tenants and operators can all have a significant effect on their operations and financial condition, which in turn may adversely impact us, as detailed below and set forth under “Item 1A, Risk Factors” in this report.
The following is a discussion of certain laws and regulations generally applicable to our operators, and in certain cases, to us.
Fraud and Abuse Enforcement
There are various extremely complex U.S. federal and state laws and regulations governing healthcare providers’ relationships and arrangements and prohibiting fraudulent and abusive practices by such providers. These laws include: (i) U.S. federal and state false claims acts, which, among other things, prohibit providers from filing false claims or making false statements to receive payment from Medicare, Medicaid, or other U.S. federal or state healthcare programs; (ii) U.S. federal and state anti-kickback and fee-splitting statutes, including the Medicare and Medicaid anti-kickback statute, which prohibit or restrict the payment or receipt of remuneration to induce referrals or recommendations of healthcare items or services; (iii) U.S. federal and state physician self-referral laws (commonly referred to as the “Stark Law”), which generally prohibit referrals by physicians to entities with which the physician or an immediate family member has a financial relationship; and (iv) the federal Civil Monetary Penalties Law, which prohibits, among other things, the knowing presentation of a false or fraudulent claim for certain healthcare services. Violations of U.S. healthcare fraud and abuse laws carry civil, criminal, and administrative sanctions, including punitive sanctions, monetary penalties, imprisonment, denial of Medicare and Medicaid reimbursement, and potential exclusion from Medicare, Medicaid or other federal or state healthcare programs. These laws are enforced by a variety of federal, state, and local agencies and in the U.S. can also be enforced by private litigants through, among other things, federal and state false claims acts, which allow private litigants to bring qui tam or “whistleblower” actions. Many of our tenants and operators are subject to these laws, and may become the subject of governmental enforcement actions or whistleblower actions if they fail to comply with applicable laws. Additionally, the licensed operators of our U.S. long-term care facilities that participate in government reimbursement programs are required to have compliance and ethics programs that meet the requirements of federal laws and regulations relating to the Social Security Act. Consistent with RIDEA, such responsibilities are delegated to our operating partners and we have developed a program to periodically monitor compliance with such obligations.
Laws and Regulations Governing Privacy and Security
There are various U.S. federal and state privacy laws and regulations, including the privacy and security rules contained in the Health Insurance Portability and Accountability Act of 1996 (commonly referred to as “HIPAA”), which provide for the privacy and security of personal health information. An increasing focus of the U. S. Federal Trade Commission’s (“FTC’s”) consumer protection regulation is the impact of technological change on protection of consumer privacy. The FTC, as well as state attorneys general, have taken enforcement action against companies that do not abide by their representations to consumers regarding electronic security and privacy. To the extent we or our affiliated operating entities are a covered entity or business associate under HIPAA and the Health Information Technology for Economic and Clinical Health Act (the “HITECH Act”), compliance with those requirements would require us to, among other things, conduct a risk analysis, implement a risk management plan, implement policies and procedures, and conduct employee training. In most cases, we are dependent on our tenants and management companies to fulfill our compliance obligations, and we have developed a program to periodically monitor compliance with such obligations. Because of the far reaching nature of these laws, there can be no assurance we would not be required to alter one or more of our systems and data security procedures to be in compliance with these laws. Our failure to protect health information could subject us to civil or criminal liability and adverse publicity, and could harm our business and impair our ability to attract new customers and residents. We may be required to notify individuals, as well as government agencies and the media, if we experience a data breach.
Reimbursement
Sources of revenue for some of our tenants and operators include, among others, governmental healthcare programs, such as the federal Medicare programs and state Medicaid programs, and non-governmental third-party payors, such as insurance carriers and HMOs. As federal and state governments focus on healthcare reform initiatives, and as the federal government and many states face significant current and future budget deficits, efforts to reduce costs by these payors will likely continue, which may result in reduced or slower growth in reimbursement for certain services provided by some of our tenants and operators. Additionally, new and evolving payor and provider programs in the U.S., including but not limited to Medicare Advantage, Dual Eligible, Accountable Care Organizations, and Bundled Payments could adversely impact our tenants’ and operators’ liquidity, financial condition, or results of operations.
Healthcare Licensure and Certificate of Need
Certain healthcare facilities in our portfolio are subject to extensive national, federal, state, and local licensure, certification, and inspection laws and regulations. A healthcare facility’s failure to comply with these laws and regulations could result in a revocation, suspension, restriction, or non-renewal of the facility’s license and loss of a certificate of need, which could adversely affect the facility’s operations and ability to bill for items and services provided at the facility. In addition, various licenses and permits are required to handle controlled substances (including narcotics), operate pharmacies, handle radioactive materials, and operate equipment. Many states in the U.S. require certain healthcare providers to obtain a certificate of need, which requires prior approval for the construction, expansion, or closure of certain healthcare facilities. The approval process related to state certificate of need laws may impact the ability of some of our tenants and operators to expand or change their businesses.
Product Approvals
While our life science tenants include some well-established companies, other tenants are less established and, in some cases, may not yet have a product approved by the Food and Drug Administration, or other regulatory authorities, for commercial sale. Creating a new pharmaceutical product or medical device requires substantial investments of time and capital, in part because of the extensive regulation of the healthcare industry. It also entails considerable risk of failure in demonstrating that the product is safe and effective and in gaining regulatory approval and market acceptance.
Senior Housing Entrance Fee Communities
Certain of our senior housing facilities, primarily our CCRCs, are operated as entrance fee communities. Generally, an entrance fee is an upfront fee or consideration paid by a resident, a portion of which may be refundable, in exchange for some form of long-term benefit, typically consisting of a right to receive certain personal or health care services. Some of the entrance fee communities are subject to significant state regulatory oversight, including, for example, oversight of each facility’s financial condition, establishment and monitoring of reserve requirements and other financial restrictions, the right of residents to cancel their contracts within a specified period of time, the right of residents to receive a refund of their entrance fees, lien rights in favor of the residents, restrictions on change of ownership, and similar matters.
Americans with Disabilities Act (“ADA”)
Our properties must comply with the ADA and any similar state or local laws to the extent that such properties are “public accommodations” as defined in those statutes. The ADA may require removal of barriers to access by persons with disabilities in certain public areas of our properties where such removal is readily achievable. To date, we have not received any notices of noncompliance with the ADA that have caused us to incur substantial capital expenditures to address ADA concerns. Should barriers to access by persons with disabilities be discovered at any of our properties, we may be directly or indirectly responsible for additional costs that may be required to make facilities ADA-compliant. Noncompliance with the ADA could result in the imposition of fines or an award of damages to private litigants. The obligation to make readily achievable accommodations pursuant to the ADA is an ongoing one, and we continue to assess our properties and make modifications as appropriate in this respect.
Environmental Matters
A wide variety of federal, state, and local environmental and occupational health and safety laws and regulations affect healthcare facility operations. These complex federal and state statutes, and their enforcement, involve a myriad of regulations, many of which involve strict liability on the part of the potential offender. Some of these federal and state statutes may directly impact us. Under various federal, state, and local environmental laws, ordinances, and regulations, an owner of real property or a secured lender, such as us, may be liable for the costs of removal or remediation of hazardous or toxic substances at, under or disposed of in connection with such property, as well as other potential costs relating to hazardous or toxic substances (including government fines and damages for injuries to persons and adjacent property). The cost of any required remediation, removal, fines or personal or property damages and any related liability therefore could exceed or impair the value of the property and/or the assets. In addition, the presence of such substances, or the failure to properly dispose of or remediate such substances, may adversely affect the value of such property and the owner’s ability to sell or rent such property or to borrow using such property as collateral which, in turn, could reduce our earnings. For a description of the risks associated with environmental matters, see “Item 1A, Risk Factors” in this report.
Insurance
We obtain various types of insurance to mitigate the impact of property, business interruption, liability, flood, windstorm, earthquake, fire, environmental, and terrorism-related losses. We attempt to obtain appropriate policy terms, conditions, limits, and deductibles considering the relative risk of loss, the cost of such coverage, and current industry practice. There are, however, certain types of extraordinary losses, such as those due to acts of war or other events that may be either uninsurable or not economically insurable. In addition, we have a large number of properties that are exposed to earthquake, flood, and windstorm occurrences which carry higher deductibles.
We maintain property insurance for all of our properties. Tenants under triple-net leases are required to provide primary property, business interruption, and liability insurance. We maintain separate general and professional liability insurance for our SHOP and CCRC facilities. Additionally, our corporate general liability insurance program also extends coverage for all of our properties beyond the aforementioned. We periodically review whether we or our RIDEA operators will bear responsibility for maintaining the required insurance coverage for the applicable SHOP and CCRC properties, but the costs of such insurance are facility expenses paid from the revenues of those properties, regardless of who maintains the insurance.
We also maintain directors and officers liability insurance which provides protection for claims against our directors and officers arising from their responsibilities as directors and officers. Such insurance also extends to us in certain situations.
Sustainability
We believe that environmental, social and governance (“ESG”) initiatives are a vital part of corporate responsibility, which supports our primary goal of increasing stockholder value through profitable growth. We continue to advance our commitment to sustainability, with a focus on achieving goals in each of the ESG dimensions.
Our environmental management programs strive to capture cost efficiencies that ultimately benefit our investors, tenants, operators, employees, and other stakeholders, while providing a positive impact on the communities in which we operate. We regularly assess the risks and financial impacts to our business posed by climate change, including potential business disruption and regulatory requirements. Our Compensation and Human Capital Committee of the Board oversees all human capital matters, including culture, diversity, inclusion, talent acquisition and development, compensation and succession planning, discussed below under “—Human Capital Matters.” In addition, our social responsibility committee leads our local philanthropic and volunteer activities. Our transparent corporate governance initiatives incorporate sustainability as a critical component in achieving our business objectives and properly managing risks.
Our numerous ESG recognitions in 2020 include:
-
Received Nareit’s Leader in the Light award for the ninth time, recognizing our top ESG performance among REITs
-
Nominated for Best Proxy Statement (large cap companies) by IR Magazine and Corporate Secretary in recognition of our leading proxy disclosure practices
-
Received a Green Star rating from the Global Real Estate Sustainability Benchmark (GRESB) for the ninth consecutive year
-
Named a constituent in the FTSE4Good Index for the ninth consecutive year
-
Named to CDP’s Leadership band for our climate disclosure for the eighth consecutive year
-
Listed in S&P Global’s North America Dow Jones Sustainability Index for the eighth consecutive year, recognizing top ESG performance in our sector
-
Named to the Sustainability Yearbook for the sixth consecutive year
-
Named to the Bloomberg Gender-Equality Index for the second consecutive year
-
Named to Corporate Responsibility Magazine’s 100 Best Corporate Citizens list for the second consecutive year
-
Named to Newsweek’s America’s Most Responsible Companies list for the second consecutive year
-
Received a rating of “Prime” by ISS ESG Corporate Rating for our excellence in ESG performance and disclosure within our industry
For additional information regarding our ESG initiatives and our approach to climate change, please visit our website at www.healthpeak.com/ESG.
Human Capital Matters
Our employees represent our greatest asset, and as of December 31, 2020, we had 217 full-time employees. Our Board of Directors, through its Compensation and Human Capital Committee, retains direct oversight of all human capital management, including corporate culture, diversity, inclusion, talent acquisition, retention, employee satisfaction, engagement, and succession planning. We report on human capital matters at each regularly scheduled Board of Directors meeting and periodically throughout the year. The most significant human capital measures or objectives that we focus on in managing our business and our related human capital initiatives include the following:
*•*Workforce Diversity: We believe we are a stronger organization when our workforce represents a diversity of ideas and experiences. We value and embrace diversity in our employee recruiting, hiring, and development practices. Our workforce was made up of 47% female employees and 38% racially or ethnically diverse employees as of December 31, 2020. In 2020, we launched our We Stand Together initiative, which is focused on enhancing racial diversity through education, awareness, and outreach throughout our company and communities.
-
Inclusion and Belonging**: We promote a work environment that emphasizes respect, fairness, inclusion, and dignity. We are committed to providing equal opportunity and fair treatment to all individuals based on merit, without discrimination, based on race, color, religion, national origin, citizenship, marital status, gender (including pregnancy), gender identity, gender expression, sexual orientation, age, disability, veteran status, or other characteristics protected by law. We do not tolerate discrimination or harassment.
-
Engagement:** High employee engagement and satisfaction are both critical to attracting and retaining top talent, and benefit our business in many ways. We conduct an annual employee engagement survey through an independent third party, measuring our progress on important employee issues and identifying opportunities for growth and improvement. Employee satisfaction increased for the fifth consecutive year in 2020. We also conducted 17 company-wide employee town halls in 2020 to provide employees with real-time updates on the business in light of the COVID-19 pandemic.
-
Training and Development:** We conduct annual employee training on our Code of Business Conduct and Ethics, as well as bi-annual training on unconscious bias and harassment prevention. We also provide training and development to all employees, focusing on career development, professional development, and REIT essentials.
-
Compensation and Benefits**: We aim to ensure merit-based, equitable compensation practices to attract, retain, and recognize talent. We provide competitive compensation and benefit packages to our employees.
-
Health, Safety, and Wellness**: The health, safety, and wellness of our employees are vital to our success. We are committed to protecting the well-being and safety of employees through special training and other measures. In 2020, in light of the COVID-19 pandemic, we shifted to a remote work environment ahead of mandatory stay-at-home orders and provided employees with resources, including virtual tools and ergonomic equipment, to maximize work-from-home efficiency.
-
Community Partnership**: Our Social Responsibility Committee is responsible for oversight of our charitable and volunteer activities. We partner with organizations that share our desire to support research, education, and other activities related to healthcare, senior communities, and disaster relief.
For additional information on human capital matters, please see our most recent proxy statement or ESG report, each of which is available on our website at www.healthpeak.com.
Available Information
Our website address is www.healthpeak.com. Our Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K and any amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act are available on our website, free of charge, as soon as reasonably practicable after we electronically file such materials with, or furnish them to, the U.S. Securities and Exchange Commission (“SEC”). Additionally, the SEC maintains a website that contains reports, proxy and information statements, and other information regarding issuers that file electronically with the SEC, including us, at www.sec.gov. References to our website throughout this Annual Report on Form 10-K are provided for convenience only and the content on our website does not constitute a part of this Annual Report on Form 10-K.
Item 1A. Risk Factors
The section below discusses the most significant risk factors that may materially adversely affect our business, results of operations and financial condition.
As set forth below, we believe that the risks we face generally fall into the following categories:
-
risks related to our business and operations;
-
risks related to the regulatory environment;
-
risks related to our capital structure and market conditions;
-
risks related to other events;
-
risks related to tax, including REIT-related risks; and
-
general risks.
Risks Related to Our Business and Operations
The COVID-19 pandemic and health and safety measures intended to reduce its spread have adversely affected, and may continue to adversely affect, our business, results of operations and financial condition.
Global health concerns and efforts to reduce the spread of COVID-19 resulted in travel bans, quarantines, “shelter-in-place” and similar orders restricting the activities of individuals outside of their homes, as well as business limitations and shutdowns of businesses deemed “non-essential.” Although some of these restrictions have been lifted or scaled back, ongoing resurgences of COVID-19 infections, including new strains, have resulted in the re-imposition of certain restrictions and may lead to other restrictions being re-implemented to reduce the spread of COVID-19. In many cases, these measures have limited and continue to limit the ability of our tenants, operators and borrowers to conduct their normal businesses operations and comply with their rent and other financial obligations to us and, because these restrictions may remain in place for a significant amount of time, we expect they will continue to place a substantial strain on the business operations of many of our tenants, operators and borrowers.
Senior housing facilities have been disproportionately impacted by COVID and COVID-related fatalities. Within our SHOP and CCRC properties, average occupancy declined from 83.2% and 85.6%, respectively, for the year ended December 31, 2019, to 75.3% and 81.4%, respectively, for the year ended December 31, 2020 and we expect occupancy rates will continue to decline for at least the duration of the COVID-19 pandemic due to a reduction in, or in some cases prohibitions on, new tenant move-ins due to “shelter-in-place” and local health department orders, stricter move-in criteria, lower inquiry volumes, and reduced in-person tours, as well as incidences of COVID-19 outbreaks at our facilities or the perception that outbreaks may occur. Outbreaks, which directly affect our residents and the employees at our senior housing facilities, have and could continue to materially and adversely disrupt operations. These outbreaks could cause significant reputational harm to us and our operators and could adversely affect demand for senior housing for an extended period. Our senior housing property operators are also facing material cost increases as a result of higher staffing hours and compensation, as well as increased usage and inventory of critical medical supplies and personal protective equipment. At our SHOP and CCRC facilities, we bear these material cost increases. The pandemic has also delayed the deployment of capital improvements and expenditures, which could adversely impact operations at our senior housing facilities.
We temporarily suspended development and redevelopment projects in the greater San Francisco and Boston areas as a result of the “shelter-in-place” orders and local, state and federal directives. Our operators also temporarily suspended development and redevelopment across our senior housing portfolio for the same reasons around the end of the first quarter of 2020, except for certain life safety and essential projects. Although these development and redevelopment projects restarted with infection control protocols in place, future local, state or federal orders could cause us to re-suspend the work. Furthermore, construction workers are following applicable guidelines, including appropriate social distancing, limitations on large group gatherings in close proximity, and increased sanitation efforts, which has slowed the pace of construction. These protective actions do not, however, eliminate the risk that outbreaks caused or spread by such activities may occur and impact our tenants, operators and residents. In addition, our planned dispositions may not occur within the expected time or at all because of buyer terminations or withdrawals related to the pandemic, capital constraints or other factors relating to the pandemic.
Within our medical office portfolio, many physician practices temporarily discontinued outpatient procedures and nonessential surgeries in 2020 due to health and safety measures, which negatively impacted their cash flows. During the second quarter of 2020, we implemented a deferred rent program primarily for May and June 2020 that was limited to certain non-health system and non-hospital tenants in good standing, which resulted in reduced cash flow in the periods in which such deferrals were granted, but increased our cash flow in the period in which such deferrals were repaid. We may also implement deferred rent programs for future periods. In 2020, we experienced a slowdown in new leasing during the government-mandated shutdown. We expect that overall leasing activity will be negatively impacted through the duration of the COVID-19 pandemic.
Within our life science portfolio, we may experience a decline in new leasing activity due to the COVID-19 pandemic. In addition, as a result of governmental restrictions on business activities, particularly in the greater San Francisco and Boston areas, we temporarily suspended development, redevelopment and tenant improvement projects at many of our life science properties around the end of the first quarter of 2020. Although we were able to restart these projects, future governmental restrictions may re-suspend them or suspend others. We are also experiencing time delays with our development, redevelopment, and tenant improvement projects due to the implementation of health and safety protocols related to social distancing and proper hygiene and sanitization.
The COVID-19 pandemic subjects our business and the businesses of our tenants and operators to various risks and uncertainties that have significantly adversely affected and could materially adversely affect our business, results of operations and financial condition for at least the pendency of the COVID-19 pandemic and possibly longer, including the following:
-
rent deferrals or delays in rent commencement for tenants may result in a significant decrease in our cash receipts during the period of the deferrals;
-
material cost increases at our SHOP and CCRC facilities, for which we are responsible;
-
non-payment of contractual obligations by our tenants or operators, and any limitations on our ability to enforce our lease agreements or management agreements with our tenants or operators, as applicable, as a result of any federal, state or local restrictions on tenant evictions for failure to make contractual rent payments, which may result in higher reserves for bad debt;
-
our tenants, operators or borrowers becoming insolvent or initiating bankruptcy or similar proceedings, which would adversely affect our ability to collect rent or interest payments from such tenants or borrowers, as applicable, and result in increased costs to us, as well as decreased revenues;
-
the complete or partial closures of, or other operational issues at, one or more of our properties resulting from government action or directives, which may intensify the risk of rent deferrals or non-payment of contractual obligations by our tenants or operators;
-
any possession taken of our properties, in whole or in part, by governmental authorities for public purposes in eminent domain proceedings or any government mandate or action that requ
Showing the first 8K of 114K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
We are organized to invest in income-producing healthcare-related facilities. In evaluating potential investments, we consider a multitude of factors, including:
-
location, construction quality, age, condition, and design of the property;
-
geographic area, proximity to other healthcare facilities, type of property, and demographic profile, including new competitive supply;
-
whether the expected risk-adjusted return exceeds the incremental cost of capital;
-
whether the rent or operating income provides a competitive market return to our investors;
-
duration, rental rates, tenant and operator quality, and other attributes of in-place leases, including master lease structures and coverage;
-
current and anticipated cash flow and its adequacy to meet our operational needs;
-
availability of security such as letters of credit, security deposits and guarantees;
-
potential for capital appreciation;
-
expertise and reputation of the tenant or operator;
-
occupancy and demand for similar healthcare facilities in the same or nearby communities;
-
availability of qualified operators or property managers and whether we can manage the property;
-
potential alternative uses of the facilities;
-
the regulatory and reimbursement environment in which the properties operate;
-
tax laws related to REITs;
-
prospects for liquidity through financing or refinancing; and
-
our access to and cost of capital.
Property and Direct Financing Lease Investments
The following table summarizes our consolidated property and direct financing lease ("DFL") investments, excluding investments classified as discontinued operations, as of and for the year ended December 31, 2020 (square feet and dollars in thousands):
| Facility Location | Number of Facilities | Capacity | Gross Asset Value**(1)** | Real Estate Revenues**(2)** | Operating Expenses | |||||||||||||||||||||||||||
| Life science: | (Sq. Ft.) | |||||||||||||||||||||||||||||||
| California | 118 | 7,536 | $ | 4,840,637 | $ | 454,506 | $ | (106,100) | ||||||||||||||||||||||||
| Massachusetts | 14 | 1,960 | 1,986,911 | 95,104 | (26,901) | |||||||||||||||||||||||||||
| Other (2 States) | 7 | 476 | 136,120 | 19,686 | (5,004) | |||||||||||||||||||||||||||
| Total life science | 139 | 9,972 | $ | 6,963,668 | $ | 569,296 | $ | (138,005) | ||||||||||||||||||||||||
| Medical office*(3)**:* | (Sq. Ft.) | |||||||||||||||||||||||||||||||
| Texas | 71 | 7,596 | $ | 1,353,419 | $ | 189,120 | $ | (64,811) | ||||||||||||||||||||||||
| California | 16 | 1,174 | 309,778 | 52,809 | (13,623) | |||||||||||||||||||||||||||
| Pennsylvania | 4 | 1,278 | 354,889 | 31,396 | (14,064) | |||||||||||||||||||||||||||
| South Carolina | 18 | 1,103 | 339,265 | 25,990 | (5,315) | |||||||||||||||||||||||||||
| Colorado | 18 | 1,315 | 288,488 | 41,179 | (15,377) | |||||||||||||||||||||||||||
| Florida | 25 | 1,398 | 275,240 | 35,231 | (12,419) | |||||||||||||||||||||||||||
| Other (27 States) | 126 | 8,769 | 1,850,004 | 246,673 | (78,399) | |||||||||||||||||||||||||||
| Total medical office | 278 | 22,633 | $ | 4,771,083 | $ | 622,398 | $ | (204,008) | ||||||||||||||||||||||||
| CCRC: | (Units) | |||||||||||||||||||||||||||||||
| Florida | 9 | 5,135 | $ | 1,261,321 | $ | 291,397 | $ | (301,849) | ||||||||||||||||||||||||
| Other (5 States) | 6 | 2,302 | 577,527 | 161,295 | (138,679) | |||||||||||||||||||||||||||
| Total CCRC | 15 | 7,437 | $ | 1,838,848 | $ | 452,692 | $ | (440,528) | ||||||||||||||||||||||||
| Other─non-reportable*(4)**:* | ||||||||||||||||||||||||||||||||
| Arizona | — | — | $ | — | $ | 134 | $ | — | ||||||||||||||||||||||||
| Total other non-reportable segments | — | — | $ | — | $ | 134 | $ | — | ||||||||||||||||||||||||
| Total properties in continuing operations | 432 | $ | 13,573,599 | $ | 1,644,520 | $ | (782,541) |
_______________________________________
(1)Represents gross real estate and the carrying value of DFLs. Gross real estate represents the carrying amount of real estate after adding back accumulated depreciation and amortization. Excludes gross real estate related to medical office assets held for sale of $133 million.
(2)Represents the combined amount of rental and related revenues, resident fees and services, income from DFLs, and government grant income.
(3)Includes one leased property that is classified as a DFL.
(4)Represents real estate revenues generated from a real estate asset that was sold in July 2020.
The following table summarizes our consolidated property investments classified as discontinued operations as of and for the year ended December 31, 2020 (square feet and dollars in thousands):
| Facility Location | Number of Facilities | Capacity | Gross Asset Value**(1)** | Real Estate Revenues**(2)** | Operating Expenses | |||||||||||||||||||||||||||
| Senior housing triple-net—real estate: | (Units) | |||||||||||||||||||||||||||||||
| Florida | 8 | 1,063 | $ | 172,890 | $ | 21,289 | $ | — | ||||||||||||||||||||||||
| Texas | 6 | 767 | 142,693 | 13,890 | — | |||||||||||||||||||||||||||
| New York | 2 | 201 | 76,333 | 2,513 | — | |||||||||||||||||||||||||||
| Oregon | 6 | 447 | 73,839 | 7,068 | (157) | |||||||||||||||||||||||||||
| Washington | 4 | 274 | 42,874 | 11,882 | (4) | |||||||||||||||||||||||||||
| Other (10 States) | 15 | 1,218 | 131,519 | 42,448 | (1,746) | |||||||||||||||||||||||||||
| Total senior housing triple-net | 41 | 3,970 | $ | 640,148 | $ | 99,090 | $ | (1,907) | ||||||||||||||||||||||||
| SHOP: | (Units) | |||||||||||||||||||||||||||||||
| California | 15 | 1,391 | $ | 658,523 | $ | 128,620 | $ | (100,201) | ||||||||||||||||||||||||
| Florida | 15 | 1,996 | 392,379 | 117,569 | (110,790) | |||||||||||||||||||||||||||
| Virginia | 9 | 865 | 206,958 | 41,985 | (35,889) | |||||||||||||||||||||||||||
| Texas | 15 | 1,685 | 199,018 | 53,126 | (41,036) | |||||||||||||||||||||||||||
| New Jersey | 5 | 562 | 182,408 | 58,896 | (49,551) | |||||||||||||||||||||||||||
| Maryland | 9 | 846 | 166,213 | 49,079 | (44,745) | |||||||||||||||||||||||||||
| Other (14 States) | 29 | 2,896 | 484,919 | 186,141 | (166,107) | |||||||||||||||||||||||||||
| Total SHOP | 97 | 10,241 | $ | 2,290,418 | $ | 635,416 | $ | (548,319) | ||||||||||||||||||||||||
| Total properties in discontinued operations | 138 | $ | 2,930,566 | $ | 734,506 | $ | (550,226) |
_______________________________________
(1)Represents gross real estate and the carrying value of DFLs. Gross real estate represents the carrying amount of real estate after adding back accumulated depreciation and amortization.
(2)Represents the combined amount of rental and related revenues, resident fees and services, income from DFLs, and government grant income.
Occupancy and Annual Rent Trends
The following table summarizes occupancy and average annual rent trends for our consolidated property and DFL investments for the years ended December 31 (average occupied square feet in thousands):
| 2020 | 2019 | 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| Continuing operations: | |||||||||||||||||||||||||||||
| Life science: | |||||||||||||||||||||||||||||
| Average occupancy percentage | 96 | % | 97 | % | 95 | % | 96 | % | 98 | % | |||||||||||||||||||
| Average annual rent per square foot(1) | $ | 63 | $ | 57 | $ | 54 | $ | 52 | $ | 48 | |||||||||||||||||||
| Average occupied square feet | 8,714 | 7,288 | 7,078 | 6,841 | 7,332 | ||||||||||||||||||||||||
| Medical office: | |||||||||||||||||||||||||||||
| Average occupancy percentage | 91 | % | 93 | % | 93 | % | 92 | % | 93 | % | |||||||||||||||||||
| Average annual rent per square foot(1) | $ | 30 | $ | 30 | $ | 29 | $ | 29 | $ | 28 | |||||||||||||||||||
| Average occupied square feet | 20,225 | 20,512 | 20,102 | 19,431 | 18,729 | ||||||||||||||||||||||||
| CCRC: | |||||||||||||||||||||||||||||
| Average occupancy percentage | 81 | % | 87 | % | — | % | — | % | — | % | |||||||||||||||||||
| Average annual rent per unit(1) | $ | 65,672 | $ | 62,856 | $ | — | $ | — | $ | — | |||||||||||||||||||
| Average capacity (available units) | 6,893 | 40 | — | — | — | ||||||||||||||||||||||||
| Other non-reportable segments: | |||||||||||||||||||||||||||||
| Average annual rent per unit (1) | $ | — | $ | 39,517 | $ | 44,091 | $ | 45,961 | $ | 40,757 | |||||||||||||||||||
| Average capacity (available units) | — | 4,178 | 4,304 | 4,308 | 4,316 | ||||||||||||||||||||||||
| Average annual rent per unit - U.K.(1) | — | — | — | 9,097 | 9,200 | ||||||||||||||||||||||||
| Average capacity (available units) - U.K. | — | — | — | 3,188 | 3,190 | ||||||||||||||||||||||||
| Average annual rent per bed - SNF(1) | — | — | 10,504 | 10,298 | 10,803 | ||||||||||||||||||||||||
| Average capacity (available beds) - SNF | — | — | 120 | 120 | 426 | ||||||||||||||||||||||||
| Discontinued operations: | |||||||||||||||||||||||||||||
| Senior housing triple-net: | |||||||||||||||||||||||||||||
| Average annual rent per unit(1) | $ | 17,042 | $ | 17,198 | $ | 16,187 | $ | 15,097 | $ | 14,467 | |||||||||||||||||||
| Average capacity (available units) | 5,910 | 10,551 | 15,859 | 20,481 | 27,089 | ||||||||||||||||||||||||
| SHOP: | |||||||||||||||||||||||||||||
| Average occupancy percentage | 75 | % | 80 | % | 80 | % | 84 | % | 86 | % | |||||||||||||||||||
| Average annual rent per unit(1) | $ | 53,255 | $ | 50,196 | $ | 40,786 | $ | 40,070 | $ | 43,533 | |||||||||||||||||||
| Average capacity (available units) | 11,940 | 11,635 | 9,823 | 9,505 | 13,079 |
_______________________________________
(1)Average annual rent is presented as a ratio of the sum of rental and related revenues, resident fees and services, income from DFLs, and government grant income divided by the average capacity or average occupied square feet of the facilities. Average annual rent for leased properties (including DFLs) excludes termination fees and non-cash revenue adjustments (i.e., straight-line rents, amortization of market lease intangibles, DFL non-cash interest, and the impact of deferred community fee income).
Tenant Lease Expirations
The following table shows tenant lease expirations, including those related to DFLs, for the next 10 years and thereafter at our consolidated properties, assuming that none of the tenants exercise any of their renewal or purchase options, unless otherwise noted below, and excludes properties in our CCRC segment, assets held for sale, and discontinued operations as of and for the year ended December 31, 2020 (dollars and square feet in thousands):
| Expiration Year | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Segment | Total | 2021**(1)** | 2022 | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | Thereafter | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Continuing operations: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Life science*:* | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Square feet | 9,600 | 468 | 762 | 780 | 436 | 1,321 | 612 | 1,081 | 502 | 1,287 | 1,260 | 1,091 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Base rent(2) | $ | 475,353 | $ | 27,302 | $ | 33,405 | $ | 47,999 | $ | 27,360 | $ | 57,615 | $ | 26,818 | $ | 51,569 | $ | 24,513 | $ | 68,160 | $ | 76,576 | $ | 34,036 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| % of segment base rent | 100 | 6 | 7 | 10 | 6 | 12 | 6 | 11 | 5 | 14 | 16 | 7 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Medical office: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Square feet | 20,025 | 2,834 | 2,661 | 1,920 | 2,147 | 4,327 | 821 | 762 | 1,672 | 628 | 1,012 | 1,241 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Base rent(2) | $ | 492,508 | $ | 77,019 | $ | 72,599 | $ | 51,712 | $ | 59,524 | $ | 86,889 | $ | 20,008 | $ | 19,388 | $ | 36,532 | $ | 15,378 | $ | 24,118 | $ | 29,341 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| % of segment base rent | 100 | 16 | 15 | 10 | 12 | 18 | 4 | 4 | 7 | 3 | 5 | 6 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Base rent(2) | $ | 967,861 | $ | 104,321 | $ | 106,004 | $ | 99,711 | $ | 86,884 | $ | 144,504 | $ | 46,826 | $ | 70,957 | $ | 61,045 | $ | 83,538 | $ | 100,694 | $ | 63,377 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| % of total base rent | 100 | 11 | 11 | 10 | 9 | 15 | 5 | 7 | 6 | 9 | 10 | 7 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
_______________________________________
(1)Includes month-to-month leases.
(2)The most recent month’s (or subsequent month’s, if acquired in the most recent month) base rent, including additional rent floors and cash income from DFLs, annualized for 12 months. Base rent does not include tenant recoveries, additional rents in excess of floors, and non-cash revenue adjustments (i.e., straight-line rents, amortization of market lease intangibles, DFL non-cash interest and deferred revenues).
See the “Tenant Purchase Options” section of Note 7 to the Consolidated Financial Statements for additional information on leases subject to purchase options. See Schedule III: Real Estate and Accumulated Depreciation, included in this report, which information is incorporated by reference in this Item 2.
Item 3. Legal Proceedings
See “Legal Proceedings” section of Note 12 to the Consolidated Financial Statements for information regarding legal proceedings, which information is incorporated by reference in this Item 3.
Item 4. Mine Safety Disclosures
None.
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Our common stock is listed on the New York Stock Exchange under the symbol “PEAK.”
At January 29, 2021, we had 7,949 stockholders of record, and there were 168,319 beneficial holders of our common stock.
Dividends (Distributions)
It has been our policy to declare quarterly dividends to common stockholders so as to comply with applicable provisions of the Code governing REITs. All distributions are made at the discretion of our Board of Directors in accordance with Maryland law. Distributions with respect to our common stock can be characterized for federal income tax purposes as ordinary dividends, capital gains, nondividend distributions, or a combination thereof. The following table shows the characterization of our annual common stock distributions per share:
| Year Ended December 31, | |||||||||||||||||
| 2020 | 2019 | 2018 | |||||||||||||||
| Ordinary dividends(1) | $ | 0.7139 | $ | 0.7633 | $ | 0.9578 | |||||||||||
| Capital gains(2) | 0.5298 | 0.2714 | 0.5222 | ||||||||||||||
| Nondividend distributions | 0.2363 | 0.4453 | — | ||||||||||||||
| $ | 1.4800 | $ | 1.4800 | $ | 1.4800 |
_______________________________________
(1)For the year ended December 31, 2020 all $0.7139 of ordinary dividends qualified as business income for purposes of Code Section 199A. For the year ended December 31, 2019 all $0.7633 of ordinary dividends qualified as business income for purposes of Code Section 199A. For the year ended December 31, 2018 the amount includes $0.9414 of qualified business income for purposes of Code Section 199A and $0.0164 of qualified dividend income for purposes of Code Section 1(h)(11).
(2)Pursuant to Treasury Regulation §1.1061-6(c), we are disclosing additional information related to the capital gain dividends for purposes of Section 1061 of the Internal Revenue Code (IRC). IRC Section 1061 is generally applicable to direct and indirect holders of “applicable partnership interests.” The “One Year Amounts” and “Three Year Amounts” required to be disclosed are both zero with respect to the 2020 distributions, since all capital gains relate to IRC Section 1231 gains.
On February 9, 2021, we announced that our Board of Directors declared a quarterly common stock cash dividend of $0.30 per share. The common stock dividend will be paid on March 5, 2021 to stockholders of record as of the close of business on February 22, 2021.
Issuer Purchases of Equity Securities
The table below sets forth the information with respect to purchases of our common stock made by or on our behalf during the quarter ended December 31, 2020.
| Period Covered | Total Number of Shares Purchased**(1)** | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Maximum Number (or Approximate Dollar Value) of Shares that May Yet be Purchased Under the Plans or Programs | ||||||||||||||||||||||
| October 1-31, 2020 | 5,267 | $ | 28.50 | — | — | |||||||||||||||||||||
| November 1-30, 2020 | 3,535 | 28.52 | — | — | ||||||||||||||||||||||
| December 1-31, 2020 | 179 | 28.86 | — | — | ||||||||||||||||||||||
| Total | 8,981 | $ | 28.52 | — | — |
_______________________________________
(1)Represents restricted shares withheld under our equity incentive plans to offset tax withholding obligations that occur upon vesting of restricted shares. The value of the shares withheld is based on the closing price of our common stock on the last trading day prior to the date the relevant transaction occurred.
Performance Graph
The graph and table below compare the cumulative total return of Healthpeak, the S&P 500 Index, and the Equity REIT Index of NAREIT, from January 1, 2016 to December 31, 2020. Total cumulative return is based on a $100 investment in Healthpeak common stock and in each of the indices at the close of trading on December 31, 2015 and assumes quarterly reinvestment of dividends before consideration of income taxes. Stockholder returns over the indicated periods should not be considered indicative of future stock prices or stockholder returns.
COMPARISON OF FIVE-YEAR CUMULATIVE TOTAL RETURN
AMONG S&P 500, EQUITY REITS AND HEALTHPEAK PROPERTIES, INC.
RATE OF RETURN TREND COMPARISON
JANUARY 1, 2016–DECEMBER 31, 2020
(JANUARY 1, 2016 = $100)
Performance Graph Total Stockholder Return
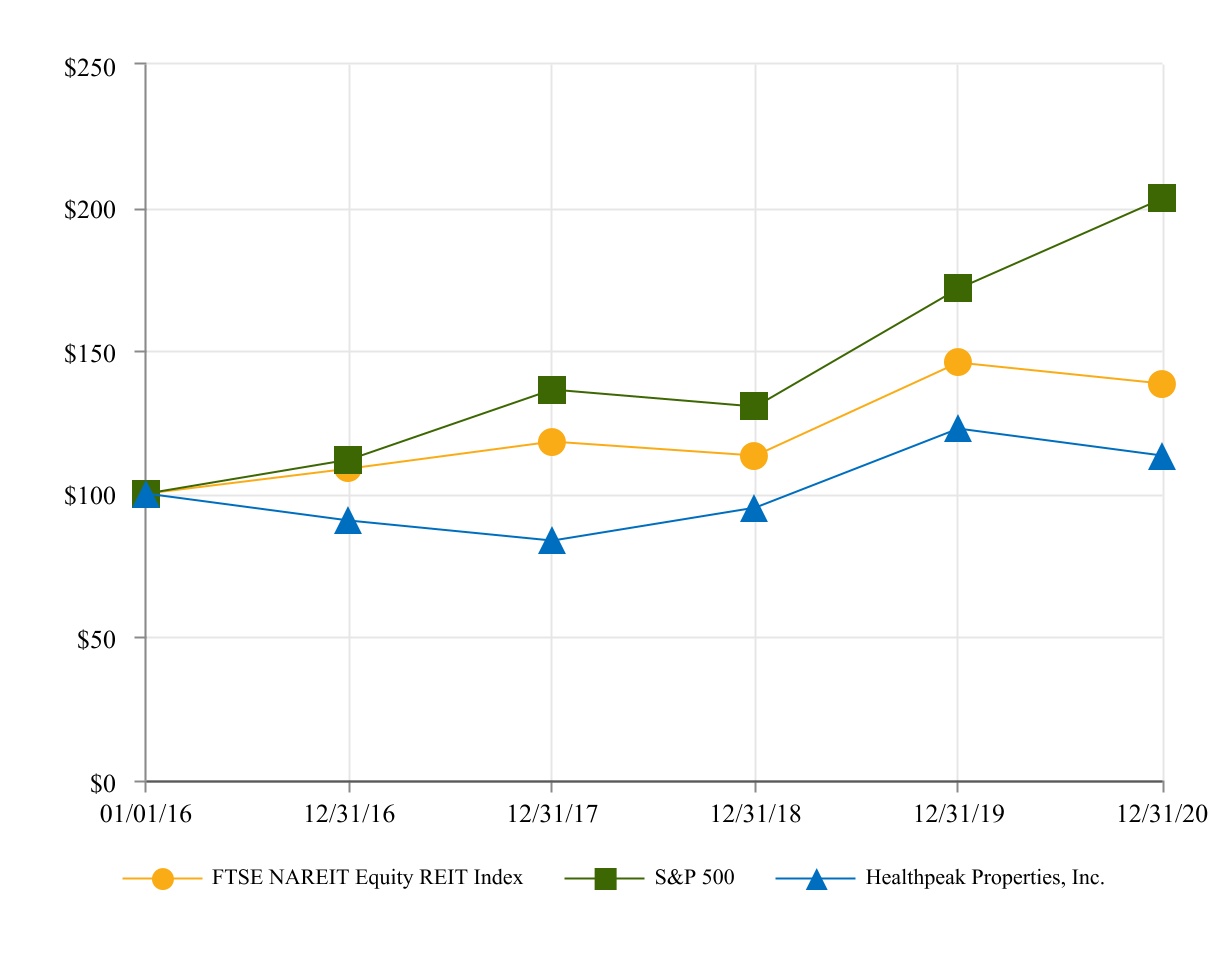
| December 31, | |||||||||||||||||||||||||||||
| 2016 | 2017 | 2018 | 2019 | 2020 | |||||||||||||||||||||||||
| FTSE NAREIT Equity REIT Index | $ | 108.63 | $ | 118.05 | $ | 113.28 | $ | 145.75 | $ | 138.28 | |||||||||||||||||||
| S&P 500 | 111.95 | 136.38 | 130.39 | 171.44 | 202.96 | ||||||||||||||||||||||||
| Healthpeak Properties, Inc. | 90.63 | 83.61 | 95.05 | 122.72 | 113.31 |
Item 6. Selected Financial Data
Set forth below is our selected financial data as of and for each of the years in the five-year period ended December 31 (dollars in thousands, except per share data):
| Year Ended December 31, | |||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | 2017 | 2016 | |||||||||||||||||||||||||
| Statement of operations data: | |||||||||||||||||||||||||||||
| Total revenues | $ | 1,644,875 | $ | 1,240,339 | $ | 1,191,320 | $ | 1,174,275 | $ | 1,160,152 | |||||||||||||||||||
| Income (loss) from continuing operations | 160,507 | 175,469 | 837,218 | (56,199) | 4,276 | ||||||||||||||||||||||||
| Income (loss) from discontinued operations | 267,746 | (115,408) | 236,256 | 478,833 | 635,650 | ||||||||||||||||||||||||
| Net income (loss) applicable to common shares | 411,147 | 43,987 | 1,058,424 | 413,013 | 626,549 | ||||||||||||||||||||||||
| Basic earnings per common share: | |||||||||||||||||||||||||||||
| Continuing operations | 0.27 | 0.33 | 1.75 | (0.15) | (0.02) | ||||||||||||||||||||||||
| Discontinued operations | 0.50 | (0.24) | 0.50 | 1.03 | 1.36 | ||||||||||||||||||||||||
| Net income (loss) applicable to common shares | 0.77 | 0.09 | 2.25 | 0.88 | 1.34 | ||||||||||||||||||||||||
| Diluted earnings per common share: | |||||||||||||||||||||||||||||
| Continuing operations | 0.27 | 0.33 | 1.74 | (0.15) | (0.02) | ||||||||||||||||||||||||
| Discontinued operations | 0.50 | (0.24) | 0.50 | 1.03 | 1.36 | ||||||||||||||||||||||||
| Net income (loss) applicable to common shares | 0.77 | 0.09 | 2.24 | 0.88 | 1.34 | ||||||||||||||||||||||||
| Balance sheet data: | |||||||||||||||||||||||||||||
| Total assets | 15,920,089 | 14,032,891 | 12,718,553 | 14,088,461 | 15,759,265 | ||||||||||||||||||||||||
| Debt obligations(1) | 6,297,979 | 6,002,252 | 5,352,424 | 7,656,944 | 8,667,637 | ||||||||||||||||||||||||
| Total equity | 7,344,572 | 6,667,474 | 6,512,591 | 5,594,938 | 5,941,308 | ||||||||||||||||||||||||
| Other data: | |||||||||||||||||||||||||||||
| Dividends paid | 787,072 | 720,123 | 696,913 | 694,955 | 979,542 | ||||||||||||||||||||||||
| Dividends paid per common share(2) | 1.480 | 1.480 | 1.480 | 1.480 | 2.095 | ||||||||||||||||||||||||
| Funds from operations (“NAREIT FFO”)(3) | 693,367 | 780,307 | 780,189 | 661,113 | 1,119,153 | ||||||||||||||||||||||||
| Diluted NAREIT FFO per common share(3) | 1.30 | 1.59 | 1.66 | 1.41 | 2.39 | ||||||||||||||||||||||||
| FFO as Adjusted(3) | 874,188 | 864,352 | 857,233 | 918,402 | 1,282,390 | ||||||||||||||||||||||||
| Diluted FFO as Adjusted per common share(3) | 1.64 | 1.76 | 1.82 | 1.95 | 2.74 | ||||||||||||||||||||||||
| Adjusted FFO (“AFFO”)(3) | 772,705 | 745,820 | 746,397 | 803,720 | 1,215,696 |
_______________________________________
(1)Includes bank line of credit, commercial paper, term loans, senior unsecured notes, and mortgage debt. Excludes mortgage debt on assets held for sale and discontinued operations.
(2)Represents cash dividends. Additionally, in October 2016 we issued $6.17 per common share of stock dividends related to the spin-off of Quality Care Properties, Inc.
(3)For a more detailed discussion and reconciliation of NAREIT FFO, FFO as Adjusted and AFFO, see "Results of Operations" and “Non-GAAP Financial Measure Reconciliations” in Item 7 of this report.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
The information set forth in this Item 7 is intended to provide readers with an understanding of our financial condition, changes in financial condition and results of operations. We will discuss and provide our analysis in the following order:
-
COVID-19 Update
-
2020 Transaction Overview
-
Dividends
-
Results of Operations
-
Liquidity and Capital Resources
-
Contractual Obligations
-
Off-Balance Sheet Arrangements
-
Inflation
-
Non-GAAP Financial Measure Reconciliations
-
Critical Accounting Policies
-
Recent Accounting Pronouncements
COVID-19 Update
Beginning in late 2019, a novel strain of Coronavirus (“COVID-19”) began to spread throughout the world, including the United States, ultimately being declared a pandemic by the World Health Organization. Global health concerns and increased efforts to reduce the spread of the COVID-19 pandemic have prompted federal, state, and local governments to restrict normal daily activities, and have resulted in travel bans, quarantines, school closings, “shelter-in-place” orders requiring individuals to remain in their homes other than to conduct essential services or activities, as well as business limitations and shutdowns, which resulted in closure of many businesses deemed to be non-essential. Although some of these restrictions have since been lifted or scaled back, certain restrictions remain in place and any future surges of COVID-19 may lead to other restrictions being re-implemented in response to efforts to reduce the spread. In addition, our tenants, operators and borrowers are facing significant cost increases as a result of increased health and safety measures, including increased staffing demands for patient care and sanitation, as well as increased usage and inventory of critical medical supplies and personal protective equipment. These health and safety measures, which may remain in place for a significant amount of time or be re-imposed from time to time, continue to place a substantial strain on the business operations of many of our tenants, operators, and borrowers.
Senior Housing
Within our SHOP and CCRC properties, occupancy rates have declined since the onset of the pandemic, a trend that may continue during the pandemic and for some period thereafter as a result of a reduction in, or in some cases prohibitions on, new tenant move-ins due to stricter move-in criteria, lower inquiry volumes, and reduced in-person tours, as well as incidences of COVID-19 outbreaks at our facilities or the perception that outbreaks may occur. Outbreaks, which directly affect our residents and the employees at our senior housing facilities, have and could continue to materially and adversely disrupt operations, as well as cause significant reputational harm to us, our operators, and our tenants. As of February 8, 2021, we had current confirmed resident COVID-19 cases at 85 of our 95 senior housing properties, since the beginning of the pandemic. Our senior housing property operators are also experiencing significant cost increases as a result of higher staffing hours and compensation, the implementation of increased health and safety measures and protocols, and increased usage and inventory of critical medical supplies and personal protective equipment. At our SHOP and CCRC facilities, we bear these significant cost increases.
We and/or our operators temporarily suspended redevelopment across our senior housing portfolio due to “shelter-in-place” orders and local, state, and federal directives, except for certain life safety and essential projects. Although some of these projects have been allowed to restart with infection control protocols in place, future local, state, or federal orders could cause us to re-suspend the work. Other projects remain suspended and we do not know when we will be able to restart construction. In locations where construction continues, construction workers are following applicable guidelines, including appropriate social distancing, limitations on large group gatherings in close proximity, and increased sanitation efforts, which has slowed the pace of construction. These protective actions do not, however, eliminate the risk that outbreaks caused or spread by such activities may occur and impact our tenants, operators and residents. In addition, our planned dispositions may not occur within the expected time or at all because of buyer terminations or withdrawals related to the pandemic, capital constraints, inability to tour properties, or other factors relating to the pandemic.
The ultimate impact of the pandemic on senior housing generally and the public perception of senior housing as a desirable residential setting depend on a number of factors that are unknown at this time, including, but not limited to: (i) the course and severity of the pandemic; (ii) responses of public and private health authorities; and (iii) the timing, distribution, and health effects of vaccines and other treatments.
Medical Office Portfolio
Within our medical office portfolio, many physician practices and affiliated hospitals initially delayed or discontinued nonessential surgeries and procedures due to “shelter-in-place” orders and other health and safety measures, which negatively impacted their cash flows during part of 2020. These restrictions have now been lifted in the majority of our markets and operations are at or near pre-pandemic levels. However, we expect that planned move-outs will be delayed during the COVID-19 pandemic, which is expected to slightly increase short-term retention in this portfolio.
We implemented a deferred rent program during the second and third quarters of 2020 that was limited to certain non-health system and non-hospital tenants in good standing, which reduced our cash collections during those months, although we required that the deferred rent be repaid ratably by the end of 2020. Under this program, we agreed to defer approximately $6 million of rent through December 31, 2020, substantially all of which had been collected as of December 31, 2020. We may also implement a deferred rent program for future periods.
Life Science Portfolio
Within our life science portfolio, we have numerous tenants that are working tirelessly to address critical research and testing needs in the fight against COVID-19. We are focused on providing our tenants with the necessary space to complete their critical work and are in continuous contact with our tenants regarding how we can help them meet their needs. Through December 31, 2020, we had provided approximately $1 million of rent deferrals to our life science tenants, all of which was required to be repaid by the end of 2020. As of December 31, 2020, all of the deferred rent had been collected.
However, within our life science portfolio, we may experience a decline in leasing activity at certain points during the COVID-19 pandemic. As a result of governmental restrictions on business activities in the greater San Francisco and Boston areas, we temporarily suspended development, redevelopment, and tenant improvement projects at many of our life science properties, resulting in delayed deliveries and project completions. Though we have been able to continue or re-start these projects, we remain subject to future governmental restrictions that may again suspend these projects. Even when these projects continue, we have been experiencing losses in efficiency as a result of the implementation of health and safety protocols related to social distancing and proper hygiene and sanitization.
Liquidity
We believe that we are well positioned to manage the short-term and long-term impacts of the COVID-19 pandemic and the measures to slow its spread while working closely with our tenants, operators, and borrowers as they navigate the pandemic. We had approximately $2.51 billion of liquidity available, including $2.26 billion borrowing capacity under our bank line of credit facility and $259 million of cash
Showing the first 8K of 149K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
We are exposed to various market risks, including the potential loss arising from adverse changes in interest rates. We use derivative and other financial instruments in the normal course of business to mitigate interest rate risk. We do not use derivative financial instruments for speculative or trading purposes. Derivatives are recorded on the consolidated balance sheets at fair value (see Note 22 to the Consolidated Financial Statements).
To illustrate the effect of movements in the interest rate markets, we performed a market sensitivity analysis on our hedging instruments. We applied various basis point spreads to the underlying interest rate curves of the derivative portfolio in order to determine the change in fair value. Assuming a one percentage point change in the underlying interest rate curve, the estimated change in fair value of each of the underlying derivative instruments would not be material.
Interest Rate Risk
At December 31, 2020, our exposure to interest rate risk is primarily on our variable rate debt. At December 31, 2020, $36 million of our variable-rate debt was hedged by interest rate swap transactions. The interest rate swaps are designated as cash flow hedges, with the objective of managing the exposure to interest rate risk by converting the interest rates on our variable-rate debt to fixed interest rates.
Interest rate fluctuations will generally not affect our future earnings or cash flows on our fixed rate debt and assets until their maturity or earlier prepayment and refinancing. If interest rates have risen at the time we seek to refinance our fixed rate debt, whether at maturity or otherwise, our future earnings and cash flows could be adversely affected by additional borrowing costs. Conversely, lower interest rates at the time of refinancing may reduce our overall borrowing costs. However, interest rate changes will affect the fair value of our fixed rate instruments. At December 31, 2020, a one percentage point increase or decrease in interest rates would change the fair value of our fixed rate debt by approximately $369 million and $401 million, respectively, and would not materially impact earnings or cash flows. Additionally, a one percentage point increase or decrease in interest rates would change the fair value of our fixed rate debt investments by approximately $2 million and would not materially impact earnings or cash flows. Conversely, changes in interest rates on variable rate debt and investments would change our future earnings and cash flows, but not materially impact the fair value of those instruments. Assuming a one percentage point change in the interest rate related to our variable-rate debt and variable-rate investments, and assuming no other changes in the outstanding balance at December 31, 2020, our annual interest expense and interest income would increase by approximately $3 million and $1 million, respectively.
Market Risk
We have investments in marketable debt securities classified as held-to-maturity because we have the positive intent and ability to hold the securities to maturity. Held-to-maturity securities are recorded at amortized cost and adjusted for the amortization of premiums and discounts through maturity. We consider a variety of factors in evaluating an other-than-temporary decline in value, such as: the length of time and the extent to which the market value has been less than our current adjusted carrying value, the issuer’s financial condition, capital strength and near-term prospects, any recent events specific to that issuer and economic conditions of its industry, and our investment horizon in relationship to an anticipated near-term recovery in the market value, if any. At December 31, 2020, both the fair value and carrying value of marketable debt securities was $20 million.
Item 8. Financial Statements and Supplementary Data
Healthpeak Properties, Inc.
Index to Consolidated Financial Statements
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the stockholders and the Board of Directors of Healthpeak Properties, Inc.
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of Healthpeak Properties, Inc. and subsidiaries. (the "Company") as of December 31, 2020 and 2019, the related consolidated statements of operations, comprehensive income (loss), equity, and cash flows, for each of the three years in the period ended December 31, 2020, and the related notes and the schedules listed in the Index at Item 15 (collectively referred to as the "financial statements"). In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2020 and 2019, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2020, in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, 2020, based on criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February 10, 2021, expressed an unqualified opinion on the Company's internal control over financial reporting.
Basis for Opinion
These financial statements are the responsibility of the Company's management. Our responsibility is to express an opinion on the Company's financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
Critical Audit Matters
The critical audit matters communicated below are matters arising from the current-period audit of the financial statements that were communicated or required to be communicated to the audit committee and that (1) relate to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating the critical audit matters below, providing separate opinions on the critical audit matters or on the accounts or disclosures to which they relate.
Impairments – Real Estate — Refer to Notes 2 and 6 to the consolidated financial statements
Critical Audit Matter Description
The Company’s evaluation of impairment of real estate involves an assessment of the carrying value of real estate assets and related intangibles (“real estate assets”) when events or changes in circumstances indicate that the carrying value may not be recoverable. If a real estate asset is classified as held for sale, individually or as part of a disposal group, the long-lived asset or disposal group shall be measured at the lower of its carrying value or fair value less costs to sell. If a real estate asset is held for use and its carrying value is not recoverable, the real estate asset shall be measured at the lower of its carrying value or fair value.
The determination of the fair value of real estate assets involves significant judgment. The fair value of the impaired assets was based on forecasted sales prices of the long-lived asset or disposal group, which are considered to be Level 3 measurements within the fair value hierarchy. Disposal groups were determined based on management’s intent, as of the measurement date, to sell two or more real estate assets as a portfolio. Forecasted sales prices were determined using an income approach and/or a market approach (comparable sales model), which rely on certain assumptions by the Company, including: (i) market capitalization rates, (ii) market prices per unit, and (iii) forecasted cash flow streams (lease-up periods, lease revenue rates, expense rates, growth rates, etc.). There are inherent uncertainties in these assumptions.
Given the Company’s evaluation of the forecasted sales price of a long lived asset or disposal group requires management to make significant estimates and assumptions related to market capitalization rates, market prices per unit, and forecasted cash flow streams, performing audit procedures to evaluate the reasonableness of management’s forecasted sales price required a high degree of auditor judgment and an increased extent of effort.
How the Critical Audit Matter Was Addressed in the Audit
Our audit procedures related to the forecasted sales price for certain real estate assets or disposal groups included the following, among others:
-
We tested the effectiveness of controls over impairment of real estate, including those over the forecasted sales price for real estate assets.
-
We evaluated the forecasted sales prices for a sample of real estate assets, which may have included estimates of market capitalization rates, market prices per unit, and/or forecasted cash flow streams used in the determination of fair value for each selected real estate asset by (1) evaluating the source information and assumptions used by management and (2) testing the mathematical accuracy of the discounted cash flow or direct capitalization model.
-
We performed a retrospective review of impairment charges and real estate assets that were classified as
Showing the first 8K of 516K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
Disclosure Controls and Procedures. We maintain disclosure controls and procedures that are designed to ensure that information required to be disclosed in our reports under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms and that such information is accumulated and communicated to our management, including our Principal Executive Officer and Principal Financial Officer, to allow for timely decisions regarding required disclosure. In designing and evaluating the disclosure controls and procedures, management recognizes that any controls and procedures, no matter how well designed and operated, can provide only reasonable assurance of achieving the desired control objectives, and management is required to apply its judgment in evaluating the cost-benefit relationship of possible controls and procedures.
As required by Rules 13a-15(b) and 15d-15(b) of the Exchange Act, we carried out an evaluation, under the supervision and with the participation of our management, including our Principal Executive Officer and Principal Financial Officer, of the effectiveness of the design and operation of our disclosure controls and procedures as of December 31, 2020. Based upon that evaluation, our Principal Executive Officer and Principal Financial Officer concluded that our disclosure controls and procedures were effective at the reasonable assurance level as of December 31, 2020.
Management’s Annual Report on Internal Control over Financial Reporting. Management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rules 13a-15(f) and 15d-15(f). Under the supervision and with the participation of our management, including our Principal Executive Officer and Principal Financial Officer, we conducted an evaluation of the effectiveness of our internal control over financial reporting based on the framework in Internal Control—Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on our evaluation under the framework in Internal Control—Integrated Framework (2013), our management concluded that our internal control over financial reporting was effective as of December 31, 2020.
The effectiveness of our internal control over financial reporting as of December 31, 2020 has been audited by Deloitte & Touche LLP, an independent registered public accounting firm, as stated in their report, which is included herein.
Changes in Internal Control Over Financial Reporting. There were no changes in our internal control over financial reporting (as such term is defined in Rules 13a-15(f) and 15d-15(f) under the Exchange Act) during the fourth quarter of 2020 that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the stockholders and the Board of Directors of Healthpeak Properties, Inc.
Opinion on Internal Control over Financial Reporting
We have audited the internal control over financial reporting of Healthpeak Properties, Inc. and subsidiaries (the “Company”) as of December 31, 2020, based on criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”). In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2020, based on criteria established in Internal Control — Integrated Framework (2013) issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements as of and for the year ended December 31, 2020, of the Company and our report dated February 10, 2021, expressed an unqualified opinion on those financial statements*.*
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Annual Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
| /s/ DELOITTE & TOUCHE LLP |
Costa Mesa, California
February 10, 2021
Item 9B. Other Information
None.
PART III
Item 10. Directors, Executive Officers and Corporate Governance
We have adopted a Code of Business Conduct and Ethics that applies to all of our directors and employees, including our Chief Executive Officer and all senior financial officers, including our principal financial officer, principal accounting officer and controller. We have also adopted a Vendor Code of Business Conduct and Ethics applicable to our vendors and business partners. Current copies of our Code of Business Conduct and Ethics and Vendor Code of Business Conduct and Ethics are posted on our website at www.healthpeak.com/corporate-responsibility/governance. In addition, waivers from, and amendments to, our Code of Business Conduct and Ethics that apply to our directors and executive officers, including our principal executive officer, principal financial officer, principal accounting officer, or persons performing similar functions, will be timely posted in the Investor Relations section of our website at www.healthpeak.com.
We hereby incorporate by reference the information appearing under the captions “Proposal No. 1 Election of Directors,” “Our Executive Officers,” “Board of Directors and Corporate Governance” and in our definitive proxy statement relating to our 2021 Annual Meeting of Stockholders to be held on April 28, 2021.
Item 11. Executive Compensation
We hereby incorporate by reference the information under the caption “Executive Compensation” in our definitive proxy statement to be filed with the SEC relating to our 2021 Annual Meeting of Stockholders to be held on April 28, 2021.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
We hereby incorporate by reference the information under the captions “Security Ownership of Principal Stockholders, Directors and Management” and “Equity Compensation Plan Information” in our definitive proxy statement to be filed with the SEC relating to our 2021 Annual Meeting of Stockholders to be held on April 28, 2021.
Item 13. Certain Relationships and Related Transactions, and Director Independence
We hereby incorporate by reference the information under the caption “Board of Directors and Corporate Governance” in our definitive proxy statement to be filed with the SEC relating to our 2021 Annual Meeting of Stockholders to be held on April 28, 2021.
Item 14. Principal Accounting Fees and Services
We hereby incorporate by reference under the caption “Audit and Non-Audit Fees” in our definitive proxy statement to be filed with the SEC relating to our 2021 Annual Meeting of Stockholders to be held on April 28, 2021.
PART IV
Item 15. Exhibits, Financial Statement Schedules
(a) 1. Financial Statement Schedules
The following Consolidated Financial Statements are included in Part II, Item 8-Financial Statements and Supplementary Data of this Annual Report on Form 10-K.
Report of Independent Registered Public Accounting Firm
Consolidated Balance Sheets - December 31, 2020 and 2019
Consolidated Statements of Operations - for the years ended December 31, 2020, 2019 and 2018
Consolidated Statements of Comprehensive Income (Loss) - for the years ended December 31, 2020, 2019 and 2018
Consolidated Statements of Equity - for the years ended December 31, 2020, 2019 and 2018
Consolidated Statements of Cash Flows - for the years ended December 31, 2020, 2019 and 2018
Notes to Consolidated Financial Statements
(a) 2. Financial Statement Schedules
The following Consolidated Financial Statements are included in Part II, Item 8-Financial Statements and Supplementary Data of this Annual Report on Form 10-K.
Schedule II: Valuation and Qualifying Accounts
Schedule III: Real Estate and Accumulated Depreciation
Schedule IV: Mortgage Loans on Real Estate
(a) 3. Exhibits
_______________________________________
- Management Contract or Compensatory Plan or Arrangement.
† Filed herewith.
†† Furnished herewith.
Item 16. Form 10-K Summary
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
Dated: February 10, 2021
| Healthpeak Properties, Inc. (Registrant) | |||||
| /s/ THOMAS M. HERZOG | |||||
| Thomas M. Herzog, Chief Executive Officer (Principal Executive Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the dates indicated.
| Signature | Title | Date | ||||||||||||
| /s/ THOMAS M. HERZOG | Chief Executive Officer | February 10, 2021 | ||||||||||||
| Thomas M. Herzog | (Principal Executive Officer), Director | |||||||||||||
| /s/ PETER A. SCOTT | Executive Vice President and Chief Financial Officer | February 10, 2021 | ||||||||||||
| Peter A. Scott | (Principal Financial Officer) | |||||||||||||
| /s/ SHAWN G. JOHNSTON | Executive Vice President and Chief Accounting Officer | February 10, 2021 | ||||||||||||
| Shawn G. Johnston | (Principal Accounting Officer) | |||||||||||||
| /s/ BRIAN G. CARTWRIGHT | Chairman of the Board | February 10, 2021 | ||||||||||||
| Brian G. Cartwright | ||||||||||||||
| /s/ CHRISTINE N. GARVEY | Director | February 10, 2021 | ||||||||||||
| Christine N. Garvey | ||||||||||||||
| /s/ R. KENT GRIFFIN, JR. | Director | February 10, 2021 | ||||||||||||
| R. Kent Griffin, Jr. | ||||||||||||||
| /s/ DAVID B. HENRY | Director | February 10, 2021 | ||||||||||||
| David B. Henry | ||||||||||||||
| /s/ LYDIA H. KENNARD | Director | February 10, 2021 | ||||||||||||
| Lydia H. Kennard | ||||||||||||||
| /s/ SARA GROOTWASSINK LEWIS | Director | February 10, 2021 | ||||||||||||
| Sara Grootwassink Lewis | ||||||||||||||
| /s/ KATHERINE M. SANDSTROM | Director | February 10, 2021 | ||||||||||||
| Katherine M. Sandstrom | ||||||||||||||