 filings.tools
Devon Energy 10-K 2014-12-31
Filed 2015-02-20. 19 sections, 462K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 d859923d10k.htm FORM 10-K
Table of Contents
UNITED STATES SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
Form 10-K
(Mark One)
| x | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the fiscal year ended December 31, 2014
or
| ¨ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
Commission File Number 001-32318
DEVON ENERGY CORPORATION
(Exact name of registrant as specified in its charter)
| Delaware | 73-1567067 | |
| (State of other jurisdiction of incorporation or organization) | (I.R.S. Employer identification No.) | |
| 333 West Sheridan Avenue, Oklahoma City, Oklahoma | 73102-5015 | |
| (Address of principal executive offices) | (Zip code) |
Registrant’s telephone number, including area code:
(405) 235-3611
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Name of each exchange on which registered | |
| Common stock, par value $0.10 per share | The New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act:
None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes x No ¨
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ¨ No x
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes x No ¨
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes x No ¨
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§ 229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. ¨
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act. (Check one):
Large accelerated filer x Accelerated filer ¨ Non-accelerated filer ¨ Smaller reporting company ¨
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ¨ No x
The aggregate market value of the voting common stock held by non-affiliates of the registrant as of June 30, 2014, was approximately $32.3 billion, based upon the closing price of $79.40 per share as reported by the New York Stock Exchange on such date. On February 11, 2015, 411.1 million shares of common stock were outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
Proxy statement for the 2015 annual meeting of stockholders – Part III
Table of Contents
DEVON ENERGY CORPORATION
FORM 10-K
TABLE OF CONTENTS
INFORMATION REGARDING FORWARD-LOOKING STATEMENTS
This report includes “forward-looking statements” as defined by the United States Securities and Exchange Commission (“SEC”). Such statements are those concerning strategic plans, our expectations and objectives for future operations, as well as other future events or conditions. Such forward-looking statements are based on our examination of historical operating trends, the information used to prepare our December 31, 2014 reserve reports and other data in our possession or available from third parties. Such statements are subject to a number of assumptions, risks and uncertainties, many of which are beyond our control. Consequently, actual future results could differ materially from our expectations due to a number of factors, such as changes in the supply of and demand for oil, natural gas and natural gas liquids (“NGLs”) and related products and services; exploration or drilling programs; our ability to successfully complete mergers, acquisitions and divestitures; political or regulatory events; general economic and financial market conditions; and other risks and factors discussed in this report.
All subsequent written and oral forward-looking statements attributable to Devon Energy Corporation, or persons acting on its behalf, are expressly qualified in their entirety by the cautionary statements above. We assume no duty to update or revise our forward-looking statements based on new information, future events or otherwise.
Table of Contents
PART I
Items 1 and 2. Business and Properties
General
Devon Energy Corporation (“Devon”) is a leading independent energy company engaged primarily in the exploration, development and production of oil, natural gas and natural gas liquids (NGLs). Our operations are concentrated in various North American onshore areas in the U.S. and Canada. Our portfolio of oil and gas properties provides stable, environmentally responsible production and a platform for future growth. We have doubled our onshore North American oil production since 2010 to more than 20
Showing the first 8K of 61K characters. Open the full section
Item 1A. Risk Factors
Our business activities, and our industry in general, are subject to a variety of risks. If any of the following risk factors should occur, our profitability, financial condition or liquidity could be materially impacted. As a result, holders of our securities could lose part or all of their investment in Devon.
Oil, Gas and NGL Prices are Volatile
Our financial results are highly dependent on the general supply and demand for oil, gas and NGLs, which impact the prices we ultimately realize on our sales of these commodities. A significant downward movement of the prices for these commodities could have a material adverse effect on our revenues, operating cash flows and profitability. Such a downward price movement could also have a material adverse effect on our estimated proved reserves, the carrying value of our oil and gas properties, the level of planned drilling activities and future growth. Historically, market prices and our realized prices have been volatile and are likely to continue to be volatile in the future due to numerous factors beyond our control. These factors include but are not limited to:
| • | supply of and consumer demand for oil, gas and NGLs; |
|---|
| • | conservation efforts; |
|---|
| • | OPEC production levels; |
|---|
| • | geopolitical risks; |
|---|
| • | weather; |
|---|
| • | regional pricing differentials; |
|---|
| • | differing quality of oil produced (i.e., sweet crude versus heavy or sour crude); |
|---|
| • | differing quality and NGL content of gas produced; |
|---|
| • | the level of imports and exports of oil, gas and NGLs; |
|---|
| • | the price and availability of alternative fuels; |
|---|
| • | the overall economic environment; and |
|---|
| • | governmental regulations and taxes. |
|---|
Estimates of Oil, Gas and NGL Reserves are Uncertain
The process of estimating oil, gas and NGL reserves is complex and requires significant judgment in the evaluation of available geological, engineering and economic data for each reservoir, particularly for new discoveries. Because of the high degree of judgment involved, different reserve engineers may develop different estimates of reserve quantities and related revenue based on the same data. In addition, the reserve estimates for a given reservoir may change substantially over time as a result of several factors including additional development activity, the viability of production under varying economic conditions and variations in production levels and associated costs. Consequently, material revisions to existing reserve estimates may occur as a result of changes in any of these factors. Such revisions to proved reserves could have a material adverse effect on our estimates of future net revenue, as well as our financial condition and profitability. Our policies and internal controls related to estimating and recording reserves are included in “Items 1 and 2. Business and Properties” of this report.
Discoveries or Acquisitions of Reserves are Needed to Avoid a Material Decline in Reserves and Production
The production rates from oil and gas properties generally decline as reserves are depleted, while related per unit production costs generally increase, due to decreasing reservoir pressures and other factors. Therefore, our estimated proved reserves and future oil, gas and NGL production will decline materially as reserves are produced
Table of Contents
unless we conduct successful exploration and development activities or, through engineering studies, identify additional producing zones in existing wells, utilize secondary or tertiary recovery techniques or acquire additional properties containing proved reserves. Consequently, our future oil, gas and NGL production and related per unit production costs are highly dependent upon our level of success in finding or acquiring additional reserves.
Future Exploration and Drilling Results are Uncertain and Involve Substantial Costs
Substantial costs are often required to locate and acquire properties and drill exploratory wells. Such activities are subject to numerous risks, including the risk that we will not encounter commercially productive oil or gas reservoirs. The costs of drilling and completing wells are often uncertain. In addition, oil and gas properties can become damaged or drilling operations may be curtailed, delayed or canceled as a result of a variety of factors including but not limited to:
| • | unexpected drilling conditions; |
|---|
| • | pressure or irregularities in reservoir formations; |
|---|
| • | equipment failures or accidents; |
|---|
| • | fires, explosions, blowouts and surface cratering; |
|---|
| • | adverse weather conditions; |
|---|
| • | lack of access to pipelines or other transportation methods; |
|---|
| • | environmental hazards or liabilities; and |
|---|
| • | shortages or delays in the availability of services or delivery of equipment. |
|---|
A significant occurrence of one of these factors could result in a partial or total loss of our investment in a particular property. In addition, drilling activities may not be successful in establishing proved reserves. Such a failure could have an adverse effect on our future results of operations and financial condition. While both exploratory and developmental drilling activities involve these risks, exploratory drilling involves greater risks of dry holes or failure to find commercial quantities of hydrocarbons.
Competition for Leases, Materials, People and Capital can be Significant
Strong competition exists in all sectors of the oil and gas industry. We compete with major integrated and independent oil and gas companies for the acquisition of oil and gas leases and properties. We also compete for the equipment and personnel required to explore, develop and operate properties. Competition is also prevalent in the marketing of oil, gas and NGLs. Typically, during times of high or rising commodity prices, drilling and operating costs will also increase. Higher prices will also generally increase the cost to acquire properties. Certain of our competitors have financial and other resources substantially larger than ours. They also may have established strategic long-term positions and relationships in areas in which we may seek new entry. As a consequence, we may be at a competitive disadvantage in bidding for drilling rights. In addition, many of our larger competitors may have a competitive advantage when responding to factors that affect demand for oil and gas production, such as changing worldwide price and production levels, the cost and availability of alternative fuels and the application of government regulations.
Midstream Capacity Constraints and Interruptions Impact Commodity Sales
We rely on midstream facilities and systems to process our natural gas production and to transport our oil, natural gas and NGL production to downstream markets. Such midstream systems include EnLink’s systems, as well as other systems operated by us or third parties. When possible, we gain access to midstream systems that provide the most advantageous downstream market prices available to us. Regardless of who operates the midstream systems we rely upon, a portion of our production in any region may be interrupted or shut in from time to time due to loss of access to plants, pipelines or gathering systems. Such access could be lost due to a
Table of Contents
number of factors, including, but not limited to, weather conditions, accidents, field labor issues or strikes. Additionally, we and third-parties may be subject to constraints that limit our ability to construct, maintain or repair midstream facilities needed to process and transport our production. Such interruptions or constraints could negatively impact our production and associated profitability.
Hedging Limits Participation in Commodity Price Increases and Increases Counterparty Credit Risk Exposure
We periodically enter into hedging activities with respect to a portion of our production to manage our exposure to oil, gas and NGL price volatility. To the extent that we engage in price risk management activities to protect ourselves from commodity price declines, we may be prevented from fully realizing the benefits of commodity price increases above the prices established by our hedging contracts. In addition, our hedging arrangements may expose us to the risk of financial loss in certain circumstances, including instances in which the contract counterparties fail to perform under the contracts.
Public Policy, which Includes Laws, Rules and Regulations, can Change
Our operations are generally subject to federal laws, rules and regulations in the United States and Canada. In addition, we are also subject to the laws and regulations of various states, provinces, tribal and local governments. Pursuant to public policy changes, numerous government departments and agencies have issued extensive rules and regulations binding on the oil and gas industry and its individual members, some of which require substantial compliance costs and carry substantial penalties for failure to comply. Changes in such public policy have affected, and at times in the future could affect, our operations. Political developments can restrict production levels, enact price controls, change environmental protection requirements and increase taxes, royalties and other amounts payable to governments or governmental agencies. Existing laws and regulations can also require us to incur substantial costs to maintain regulatory compliance. Our operating and other compliance costs could increase further if existing laws and regulations are revised or reinterpreted or if new laws and regulations become applicable to our operations. Although we are unable to predict changes to existing laws and regulations, such changes could significantly impact our profitability, financial condition and liquidity, particularly changes related to hydraulic fracturing, income taxes and climate change as discussed below.
Hydraulic Fracturing – Several proposals are before the U.S. Congress and other federal agencies that, if implemented, could either restrict the practice of hydraulic fracturing or subject the process to further regulation, including regulation of hydraulic fracturing on federal lands and tribal reservations; regulation of air emissions; regulation of wastewater discharges from unconventional oil and gas resources; and required disclosure of chemicals and mixtures used in hydraulic fracturing. Many states have already adopted and more states are considering adopting laws and/or regulations that require disclosure of chemicals used in hydraulic fracturing and impose stringent permitting, disclosure and well-construction requirements on hydraulic fracturing operations. Hydraulic fracturing of wells and subsurface water disposal are also under public and governmental scrutiny due to potential environmental and physical impacts. In addition, some states and municipalities have significantly limited drilling activities and/or hydraulic fracturing, or are considering doing so. Although it is not possible at this time to predict the final outcome of these proposals, any new federal, state or local restrictions on hydraulic fracturing that may be imposed in areas in which we conduct business could potentially result in increased compliance costs, delays in development or restrictions on our operations.
Income Taxes – We are subject to federal, state, provincial and local income taxes, and our operating cash flow is sensitive to the amount of income taxes we must pay. In the jurisdictions in which we operate, income taxes are assessed on our earnings after consideration of all allowable deductions and credits. Changes in the types of earnings that are subject to income tax, the types of costs that are considered allowable deductions or the rates assessed on our taxable earnings would all impact our income taxes and resulting operating cash flow. The United States President and other policy makers have proposed provisions that would, if enacted, make significant changes to United States tax laws applicable to us. The most significant change to our business would eliminate the immediate deduction for intangible drilling and development costs. Such a change could have a material adverse effect on our profitability, financial condition and liquidity.
Table of Contents
Climate Change – Policymakers in the United States and Canada are increasingly focusing on whether the emissions of greenhouse gases, such as carbon dioxide and methane, are contributing to harmful climatic changes. Policymakers at both the United States federal and state levels have introduced legislation and proposed new regulations that are designed to quantify and limit the emission of greenhouse gases through inventories, limitations and/or taxes on greenhouse gas emissions. Legislative initiatives and discussions to date have focused on the development of cap-and-trade and/or carbon tax programs. A cap-and-trade program generally would cap overall greenhouse gas emissions on an economy-wide basis and require major sources of greenhouse gas emissions or major fuel producers to acquire and surrender emission allowances. Cap-and-trade programs could be relevant to us and our operations in several ways. First, the equipment we use to explore for, develop, produce and process oil and natural gas emits greenhouse gases. We could therefore be subject to caps and penalties if emissions exceeded the caps. Second, the combustion of carbon-based fuels, such as the oil, gas and NGLs we sell, emits carbon dioxide and other greenhouse gases. Therefore, demand for our products could be reduced by imposition of caps and penalties on our customers. Carbon taxes could likewise affect us by being based on emissions from our equipment and/or emissions resulting from use of our products by our customers. Of overriding significance would be the point of regulation or taxation. Application of caps or taxes on companies such as Devon, based on carbon content of produced oil and gas volumes rather than on consumer emissions, could lead to penalties, fees or tax assessments for which there are no mechanisms to pass them through the distribution and consumption chain where fuel use or conservation choices are made. Moreover, because oil and natural gas are used as chemical feed stocks and not solely as fossil fuel, applying a carbon tax to oil and gas at the production stage would be excessive with respect to actual carbon emissions from petroleum fuels.
Environmental Matters and Costs can be Significant
As an owner, lessee or operator of oil and gas properties, we are subject to various federal, state, provincial, tribal and local laws and regulations relating to discharge of materials into, and protection of, the environment. These laws and regulations may, among other things, impose liability on us for the cost of pollution clean-up resulting from our operations in affected areas. Any future environmental costs of fulfilling our commitments to the environment are uncertain and will be governed by several factors, including future changes to regulatory requirements. Changes in or additions to public policy regarding the protection of the environment could have a significant impact on our operations and profitability.
Insurance Does Not Cover All Risks
Our business is hazardous and is subject to all of the operating risks normally associated with the exploration, development, production, processing and transportation of oil, natural gas and NGLs. Such risks include potential blowouts, cratering, fires, loss of well control, mishandling of fluids and chemicals and possible underground migration of hydrocarbons and chemicals. The occurrence of any of these risks could result in environmental pollution, damage to or destruction of our property, equipment and natural resources, injury to people or loss of life. Additionally, for our non-operated properties, we generally depend on the operator for operational safety and regulatory compliance.
To mitigate financial losses resulting from these operational hazards, we maintain comprehensive general liability insurance, as well as insurance coverage against certain losses resulting from physical damages, loss of well control, business interruption and pollution events that are considered sudden and accidental. We also maintain worker’s compensation and employer’s liability insurance. However, our insurance coverage does not provide 100 percent reimbursement of potential losses resulting from these operational hazards. Additionally, insurance coverage is generally not available to us for pollution events that are considered gradual, and we have limited or no insurance coverage for certain risks such as political risk, war and terrorism. Our insurance does not cover penalties or fines assessed by governmental authorities. The occurrence of a significant event against which we are not fully insured could have a material adverse effect on our profitability, financial condition and liquidity.
Table of Contents
Limited Control on Properties Operated by Others
Certain of the properties in which we have an interest are operated by other companies and involve third-party working interest owners. We have limited influence and control over the operation or future development of such properties, including compliance with environmental, health and safety regulations or the amount of required future capital expenditures. These limitations and our dependence on the operator and other working interest owners for these properties could result in unexpected future costs and adversely affect our financial condition and results of operations.
Cyber Attacks Targeting Our Systems and Infrastructure May Adversely Impact Our Operations
Our industry has become increasingly dependent on digital technologies to conduct daily operations. Concurrently, the industry has become the subject of increased levels of cyber attack activity. Cyber attacks often attempt to gain unauthorized access to digital systems for purposes of misappropriating assets or sensitive information, corrupting data or causing operational disruption and may be carried out by third parties or insiders. The techniques utilized range from highly sophisticated efforts to electronically circumvent network security to more traditional intelligence gathering and social engineering aimed at obtaining information necessary to gain access. Cyber attacks may also be carried out in a manner that does not require gaining unauthorized access, such as by causing denial-of-service attacks. We apply technical and process controls in line with the National Institute of Standards & Technology framework to secure corporate information assets. In addition, we participate in information sharing partnerships to collect relevant threat intelligence and pro-actively identify and mitigate targeted attacks. Although we have not suffered material losses related to cyber attacks, if we were successfully attacked, we may incur substantial remediation and other costs or suffer other negative consequences. As the sophistication of cyber attacks continues to evolve, we may be required to expend significant additional resources to further enhance our digital security or to remediate vulnerabilities.
Item 1B. Unresolved Staff Comments
Not applicable.
Item 3. Legal Proceedings
We are involved in various routine legal proceedings incidental to our business. However, to our knowledge as of the date of this report, there were no material pending legal proceedings to which we are a party or to which any of our property is subject.
Item 4. Mine Safety Disclosures
Item 5. Market for Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Our common stock is traded on the New York Stock Exchange (the “NYSE”). On February 11, 2015, there were 8,605 holders of record of our common stock. The following table sets forth the quarterly high and low sales prices for our common stock as reported by the NYSE during 2014 and 2013, as well as the quarterly dividends per share paid during 2014 and 2013. We began paying regular quarterly cash dividends on our common stock in the second quarter of 1993. We anticipate continuing to pay regular quarterly dividends in the foreseeable future.
| Price Range of Common Stock | Dividends | |||||||||||
| High | Low | Per Share | ||||||||||
| 2014: | ||||||||||||
| Quarter Ended December 31, 2014 | $ | 68.80 | $ | 51.76 | $ | 0.24 | ||||||
| Quarter Ended September 30, 2014 | $ | 80.01 | $ | 67.58 | $ | 0.24 | ||||||
| Quarter Ended June 30, 2014 | $ | 80.63 | $ | 66.75 | $ | 0.24 | ||||||
| Quarter Ended March 31, 2014 | $ | 66.95 | $ | 57.67 | $ | 0.22 | ||||||
| 2013: | ||||||||||||
| Quarter Ended December 31, 2013 | $ | 66.92 | $ | 57.58 | $ | 0.22 | ||||||
| Quarter Ended September 30, 2013 | $ | 60.38 | $ | 52.00 | $ | 0.22 | ||||||
| Quarter Ended June 30, 2013 | $ | 61.10 | $ | 50.81 | $ | 0.22 | ||||||
| Quarter Ended March 31, 2013 | $ | 61.80 | $ | 51.63 | $ | 0.20 |
Table of Contents
Performance Graph
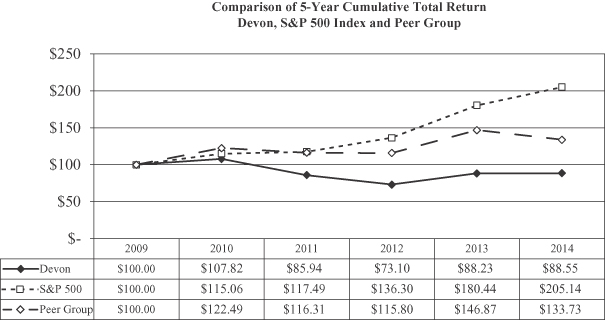
The following performance graph compares the yearly percentage change in the cumulative total shareholder return on Devon’s common stock with the cumulative total returns of the Standard & Poor’s 500 index (“the S&P 500 Index”) and a peer group of companies to which we compare our performance. The peer group includes Anadarko Petroleum Corporation, Apache Corporation, Chesapeake Energy Corporation, ConocoPhillips, Encana Corporation, EOG Resources, Inc., Hess Corporation, Marathon Oil Corporation, Murphy Oil Corporation, Newfield Exploration Company, Noble Energy, Inc., Occidental Petroleum Corporation, Pioneer Natural Resources Company and Talisman Energy, Inc. The graph was prepared assuming $100 was invested on December 31, 2009 in Devon’s common stock, the S&P 500 Index and the peer group and dividends have been reinvested subsequent to the initial investment.
The graph and related information shall not be deemed “soliciting material” or to be “filed” with the SEC, nor shall such information be incorporated by reference into any future filing under the Securities Act of 1933, as amended, or the Securities Exchange Act of 1934, as amended, except to the extent that we specifically incorporate such information by reference into such a filing. The graph and information is included for historical comparative purposes only and should not be considered indicative of future stock performance.
Issuer Purchases of Equity Securities
The following table provides information regarding purchases of our common stock that were made by us during the fourth quarter of 2014.
| Period | Total Number of Shares Purchased (1) | Average Price Paid per Share | ||||||
| October 1 – October 31 | 1,036 | $ | 60.00 | |||||
| November 1 – November 30 | 39 | $ | 57.07 | |||||
| December 1 – December 31 | 343,187 | $ | 59.94 | |||||
| Total | 344,262 | $ | 59.94 | |||||
| (1) | Share repurchases represent shares received by us from employees and directors for the payment of personal income tax withholding on restricted stock vesting and stock option exercises. |
|---|
Table of Contents
Under the Devon Energy Corporation Incentive Savings Plan (the “Plan”), eligible employees may purchase shares of our common stock through an investment in the Devon Stock Fund (the “Stock Fund”), which is administered by an independent trustee. Eligible employees purchased approximately 57,300 shares of our common stock in 2014, at then-prevailing stock prices, that they held through their ownership in the Stock Fund. We acquired the shares of our common stock sold under the Plan through open-market purchases.
Similarly, under the Devon Canada Corporation Savings Plan (the “Canadian Plan”), eligible Canadian employees may purchase shares of our common stock through an investment in the Canadian Plan, which is administered by an independent trustee, Sun Life Assurance Company of Canada. Shares sold under the Canadian Plan were acquired through open-market purchases. These shares and any interest in the Canadian Plan were offered and sold in reliance on the exemptions for offers and sales of securities made outside of the U.S., including under Regulation S for offers and sales of securities to employees pursuant to an employee benefit plan established and administered in accordance with the law of a country other than the U.S. In 2014, there were no shares purchased by Canadian employees.
Item 6. Selected Financial Data
The financial information below should be read in conjunction with “Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations” and “Item 8. Financial Statements and Supplementary Data” of this report.
| Year Ended December 31, | ||||||||||||||||||||
| 2014 | 2013 | 2012 | 2011 | 2010 | ||||||||||||||||
| (In millions, except per share amounts) | ||||||||||||||||||||
| Operating revenues | $ | 19,566 | $ | 10,397 | $ | 9,501 | $ | 11,445 | $ | 9,935 | ||||||||||
| Earnings (loss) from continuing operations (1) | $ | 1,691 | $ | (20 | ) | $ | (185 | ) | $ | 2,134 | $ | 2,333 | ||||||||
| Earnings (loss) from continuing operations attributable to Devon | $ | 1,607 | $ | (20 | ) | $ | (185 | ) | $ | 2,134 | $ | 2,333 | ||||||||
| Earnings (loss) from continuing operations per share attributable to Devon – Basic | $ | 3.93 | $ | (0.06 | ) | $ | (0.47 | ) | $ | 5.12 | $ | 5.31 | ||||||||
| Earnings (loss) from continuing operations per share attributable to Devon – Diluted | $ | 3.91 | $ | (0.06 | ) | $ | (0.47 | ) | $ | 5.10 | $ | 5.29 | ||||||||
| Cash dividends per common share | $ | 0.94 | $ | 0.86 | $ | 0.80 | $ | 0.67 | $ | 0.64 | ||||||||||
| Weighted average common shares outstanding – Basic | 409 | 406 | 404 | 417 | 440 | |||||||||||||||
| Weighted average common shares outstanding – Diluted | 411 | 406 | 404 | 418 | 441 | |||||||||||||||
| Total assets (1) | $ | 50,637 | $ | 42,877 | $ | 43,326 | $ | 41,117 | $ | 32,927 | ||||||||||
| Long-term debt | $ | 9,830 | $ | 7,956 | $ | 8,455 | $ | 5,969 | $ | 3,819 | ||||||||||
| Stockholders’ equity | $ | 26,341 | $ | 20,499 | $ | 21,278 | $ | 21,430 | $ | 19,253 |
| (1) | During 2014, 2013 and 2012, we recorded noncash asset impairments totaling $2.0 billion ($1.9 billion after income taxes), $2.0 billion ($1.4 billion after income taxes) and $2.0 billion ($1.3 billion after income taxes), respectively. |
|---|
Table of Contents
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
Introduction
The following discussion and analysis presents management’s perspective of our business, financial condition and overall performance. This information is intended to provide investors with an understanding of our past performance, current financial condition and outlook for the future and should be read in conjunction with “Item 8. Financial Statements and Supplementary Data” of this report.
Overview of 2014 Results
As an enterprise, we strive to optimize value for our shareholders by growing cash flow, earnings, production and reserves, all on a per debt-adjusted share basis. We accomplish this by executing our strategy, which is outlined in “Items 1 and 2. Business and Properties” of this report.
2014 was a year of strong execution and strengthening of the portfolio for Devon. We completed three strategic portfolio transformation initiatives that were focused on building value per share.
On February 28, 2014, we acquired certain of GeoSouthern’s Eagle Ford assets and operations in south Texas for approximately $6.0 billion. This acquisition included approximately 250 MMBoe of proved reserves. Additionally, since closing the transaction, we have produced approximately 24 MMBoe from our Eagle Ford development, with oil accounting for approximately 61% of our production from the play.
On March 7, 2014, we completed a transaction to combine substantially all of our U.S. midstream assets with Crosstex’s assets to form EnLink, a new midstream business that we control. This transaction is described more fully in Note 2 to the financial statements included in “Item 8. Financial Statements and Supplementary Data” in this report. Subsequent to the formation of EnLink’s midstream business, EnLink acquired additional oil and gas pipeline assets.
The results of operations from our assets contributed to EnLink are included in our consolidated financial statements for all periods presented. Additionally, the results of operations for all assets contributed to EnLink are included in our consolidated financial statements subsequent to the completion of the transaction. The portions of EnLink’s net earnings and stockholders’ equity not attributable to Devon’s controlling interest are shown separately as noncontrolling interests in our consolidated comprehensive statements of earnings and consolidated balance sheets.
Finally, we completed our asset divestitures of certain U.S. and Canadian properties through two significant transactions. On April 1, 2014, we sold Canadian conventional assets for $2.8 billion ($3.125 billion Canadian dollars), and on August 29, 2014, we sold certain U.S. assets for $2.2 billion.
Table of Contents
Key measures of our performance are summarized below.
| Year Ended December 31, | ||||||||||||||||||||
| 2014 | Change | 2013 | Change | 2012 | ||||||||||||||||
| ($ in millions, except per share and per Boe amounts) | ||||||||||||||||||||
| Net earnings (loss) attributable to Devon | $ | 1,607 | +8184 | % | $ | (20 | ) | +90 | % | $ | (206 | ) | ||||||||
| Core earnings attributable to Devon (1) | $ | 2,017 | +16 | % | $ | 1,734 | +33 | % | $ | 1,305 | ||||||||||
| Earnings (loss) from continuing operations per share attributable to Devon | $ | 3.91 | +6933 | % | $ | (0.06 | ) | +87 | % | $ | (0.47 | ) | ||||||||
| Core earnings per share attributable to Devon (1) | $ | 4.91 | +15 | % | $ | 4.26 | +32 | % | $ | 3.22 | ||||||||||
| Retained production (MBoe/d) | 622 | +15 | % | 541 | +6 | % | 511 | |||||||||||||
| Total production (MBoe/d) | 673 | -3 | % | 693 | +2 | % | 682 | |||||||||||||
| Realized price per Boe | $ | 40.33 | +20 | % | $ | 33.70 | +18 | % | $ | 28.65 | ||||||||||
| Core operating income per Boe (2) | $ | 27.28 | +27 | % | $ | 21.47 | +28 | % | $ | 16.78 | ||||||||||
| Operating cash flow – continuing operations | $ | 5,981 | +10 | % | $ | 5,436 | +10 | % | $ | 4,930 | ||||||||||
| Capitalized costs, including acquisitions | $ | 13,559 | +104 | % | $ | 6,643 | -22 | % | $ | 8,474 | ||||||||||
| Shareholder and noncontrolling interest distributions | $ | 621 | +78 | % | $ | 348 | +8 | % | $ | 324 | ||||||||||
| Reserves (MMBoe) | 2,754 | -7 | % | 2,963 | 0 | % | 2,963 |
| (1) | Core earnings and core earnings per share attributable to Devon are financial measures not prepared in accordance with accounting principles generally accepted in the U.S. (GAAP). For a description of core earnings and core earnings per share attributable to Devon, as well as reconciliations to the comparable GAAP measures, see “Non-GAAP Measures” in this Item 7. |
|---|
| (2) | Computed as revenues from commodity sales and marketing and midstream operations, less expenses for lease operations, marketing and midstream operations, cash-based general and administrative, production and property taxes and net financing costs, with the result divided by total production. |
|---|
Our 2014 net earnings attributable to Devon, core earnings, core earnings per share and core operating income per Boe all increased compared to 2013. The improved 2014 results were driven primarily by increases in production from our retained properties, particularly higher-margin liquids volumes, combined with higher gas and bitumen price realizations. EnLink’s earnings growth also contributed to improved 2014 results. These factors, along with our portfolio transformation, drove higher earnings and operating cash flow in 2014.
Business and Industry Outlook
North American crude oil and natural gas prices have historically been volatile based on supply and demand dynamics, and we expect this volatility to continue into 2015.
In the second half of 2014, crude oil prices began a rapid and significant decline as global supply outpaced demand. The decline increased further following OPEC’s announcement in late November 2014 that it would not reduce its production targets. This decline continued into 2015 but has started to stabilize with the West Texas Intermediate (“WTI”) benchmark generally ranging between $45-$50 per barrel throughout January and early February 2015. If WTI remained at this level throughout 2015, our realized crude price, excluding the effects of hedges, would decrease approximately 50% compared to 2014.
Although natural gas prices improved in 2014 compared to 2013, natural gas continues to be challenged due to an imbalance between supply and demand across North America. We expect most natural gas benchmark prices to be lower in 2015, as supply continues to surpass demand.
Our industry will be challenged by lower commodity prices. However, we have strategically positioned our company so that we can prudently continue investing in our portfolio of assets. First, following our 2014 asset divestitures our portfolio is more focused, and we will concentrate our capital programs on the highest return assets in our portfolio. We exited 2014 with a production profile comprised of roughly 35 percent oil, 20 percent natural gas liquids and 45 percent natural gas. Recognizing the relative value of crude oil, we are devoting the vast majority of our 2015 capital investment toward growing our oil production, particularly the sweet grades of oil found in the U.S.
Table of Contents
Second, we have hedged approximately 50 percent of our projected 2015 crude production at a floor price of $91 per barrel and approximate
Showing the first 8K of 105K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures about Market Risk
The primary objective of the following information is to provide forward-looking quantitative and qualitative information about our potential exposure to market risks. The term “market risk” refers to our risk of loss arising from adverse changes in oil, gas and NGL prices, interest rates and foreign currency exchange rates. The following disclosures are not meant to be precise indicators of expected future losses but rather indicators of reasonably possible losses. This forward-looking information provides indicators of how we view and manage our ongoing market risk exposures. All of our market risk sensitive instruments were entered into for purposes other than speculative trading.
Commodity Price Risk
Our major market risk exposure is the pricing applicable to our oil, gas and NGL production. Realized pricing is primarily driven by the prevailing worldwide price for crude oil and spot market prices applicable to our U.S. and Canadian gas production. Pricing for oil and gas production has been volatile and unpredictable as discussed in “Item 1A. Risk Factors” of this report. Consequently, we periodically enter into financial hedging activities with respect to a portion of our production through various financial transactions that hedge future prices received. The key terms to all our oil and gas derivative financial instruments as of December 31, 2014 are presented in Note 3 to the financial statements under “Item 8. Financial Statements and Supplementary Data” of this report.
The fair values of our commodity derivatives are largely determined by estimates of the forward curves of the relevant price indices. At December 31, 2014, a 10 percent increase or a 10 percent decrease in the forward curves associated with our commodity derivative instruments would have changed our net asset positions by the following amounts:
| 10% Increase | 10% Decrease | |||||||
| (In millions) | ||||||||
| Gain (loss): | ||||||||
| Gas derivatives | $ | (74 | ) | $ | 69 | |||
| Oil derivatives | $ | (282 | ) | $ | 279 | |||
| Processing and fractionation derivatives | $ | (2 | ) | $ | 2 |
Interest Rate Risk
At December 31, 2014, we had total debt of $11.3 billion. Of this amount, $9.3 billion bears fixed interest rates averaging 5.4 percent. Of the $11.3 billion of total debt, $2.0 billion is comprised of floating rate debt that bear interest rates averaging 0.74 percent. Our commercial paper borrowings typically have maturities between 1 and 90 days.
As of December 31, 2014, we had open interest rate swap positions that are presented in “Item 8. Financial Statements and Supplementary Data – Note 3” in this report. The fair values of our interest rate swaps are largely determined by estimates of the forward curves of the 3 month LIBOR rate. A 10 percent change in these forward curves would not have materially impacted our balance sheet at December 31, 2014.
Foreign Currency Risk
Our net assets, net earnings and cash flows from our Canadian subsidiaries are based on the U.S. dollar equivalent of such amounts measured in the Canadian dollar functional currency. Assets and liabilities of the Canadian subsidiaries are translated to U.S. dollars using the applicable exchange rate as of the end of a reporting period. Revenues, expenses and cash flow are translated using an average exchange rate during the reporting period. A 10 percent unfavorable change in the Canadian-to-U.S. dollar exchange rate would not materially impact our December 31, 2014 balance sheet.
Table of Contents
Our non-Canadian foreign subsidiaries have a U.S. dollar functional currency. However, one of these foreign subsidiaries holds Canadian-dollar cash and engages in intercompany loans with Canadian subsidiaries that are based in Canadian dollars. The value of the Canadian-dollar cash and intercompany loans increases or decreases from the remeasurement of the cash and loans into the U.S. dollar functional currency. Additionally, at December 31, 2014, we held foreign currency exchange forward contracts to hedge exposures to fluctuations in exchange rates on the Canadian-dollar cash and intercompany loans. The increase or decrease in the value of the forward contracts is offset by the increase or decrease to the U.S. dollar equivalent of the Canadian-dollar cash and intercompany loans. Based on the amount of the cash and intercompany loans as of December 31, 2014, a 10 percent change in the foreign currency exchange rates would not have materially impacted our balance sheet.
Table of Contents
Item 8. Financial Statements and Supplementary Data
INDEX TO CONSOLIDATED FINANCIAL STATEMENTS
AND CONSOLIDATED FINANCIAL STATEMENT SCHEDULES
All financial statement schedules are omitted as they are inapplicable or the required information has been included in the consolidated financial statements or notes thereto.
Table of Contents
Report of Independent Registered Public Accounting Firm
The Board of Directors and Stockholders
Devon Energy Corporation:
We have audited the accompanying consolidated balance sheets of Devon Energy Corporation and subsidiaries as of December 31, 2014 and 2013, and the related consolidated comprehensive statements of earnings, cash flows, and stockholders’ equity for each of the years in the three-year period ended December 31, 2014. We also have audited Devon Energy Corporation’s internal control over financial reporting as of December 31, 2014, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). Devon Energy Corporation’s management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in Management’s Annual Report contained in “Item 9A. Controls and Procedures” of Devon Energy Corporation’s Annual Report on Form 10-K. Our responsibility is to express an opinion on these consolidated financial statements and an opinion on the Company’s internal control over financial reporting based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the financial statements are free of material misstatement and whether effective internal control over financial reporting was maintained in all material respects. Our audits of the consolidated financial statements included examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements, assessing the accounting principles used and significant estimates made by management, and evaluating the overall financial statement presentation. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of Devon Energy Corporation and subsidiaries as of December 31, 2014 and 2013, and the results of its operations and its cash flows for each of the years in the three-year period ended December 31, 2014, in conformity with United States generally accepted accounting principles. Also in our opinion, Devon Energy Corporation maintained, in all material respects, effective internal control over financial reporting as of December 31, 2014, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
/s/ KPMG LLP
Oklahoma City, Oklahoma
February 20, 2015
Table of Contents
DEVON ENERGY CORPORATION AND SUBSIDIARIES
CONSOLIDATED COMPREHENSIVE STATEMENTS OF EARNINGS
| Year Ended December 31, | ||||||||||||
| 2014 | 2013 | 2012 | ||||||||||
| (In millions, except per share amounts) | ||||||||||||
| Oil, gas and NGL sales | $ | 9,910 | $ | 8,522 | $ | 7,153 | ||||||
| Oil, gas and NGL derivatives | 1,989 | (191 | ) | 693 | ||||||||
| Marketing and midstream revenues | 7,667 | 2,066 | 1,655 | |||||||||
| Total operating revenues | 19,566 | 10,397 | 9,501 | |||||||||
| Lease operating expenses | 2,332 | 2,268 | 2,074 | |||||||||
| Marketing and midstream operating expenses | 6,815 | 1,553 | 1,246 | |||||||||
| General and administrative expenses | 847 | 617 | 692 | |||||||||
| Production and property taxes | 535 | 461 | 414 | |||||||||
| Depreciation, depletion and amortization | 3,319 | 2,780 | 2,811 | |||||||||
| Asset impairments | 1,953 | 1,976 | 2,024 | |||||||||
| Restructuring costs | 46 | 54 | 74 | |||||||||
| Gains and losses on asset sales | (1,072 | ) | 9 | (13 | ) | |||||||
| Other operating items | 93 | 112 | 105 | |||||||||
| Total operating expenses | 14,868 | 9,830 | 9,427 | |||||||||
| Operating income | 4,698 | 567 | 74 | |||||||||
| Net financing costs | 526 | 417 | 370 | |||||||||
| Other nonoperating items | 113 | 1 | 21 | |||||||||
| Earnings (loss) from continuing operations before income taxes | 4,059 | 149 | (317 | ) | ||||||||
| Income tax expense (benefit) | 2,368 | 169 | (132 | ) | ||||||||
| Earnings (loss) from continuing operations | 1,691 | (20 |
Showing the first 8K of 228K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
Not Applicable.
Item 9A. Controls and Procedures
Disclosure Controls and Procedures
We have established disclosure controls and procedures to ensure that material information relating to Devon, including its consolidated subsidiaries, is made known to the officers who certify Devon’s financial reports and to other members of senior management and the Board of Directors.
Based on their evaluation, our principal executive and principal financial officers have concluded that our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934) were effective as of December 31, 2014 to ensure that the information required to be disclosed by Devon in the reports that it files or submits under the Securities Exchange Act of 1934 is recorded, processed, summarized and reported within the time periods specified in the SEC rules and forms.
Management’s Annual Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting for Devon, as such term is defined in Rules 13a-15(f) and 15d-15(f) under the Securities Exchange Act of 1934. Under the supervision and with the participation of Devon’s management, including our principal executive and principal financial officers, we conducted an evaluation of the effectiveness of our internal control over financial reporting based on the framework in Internal Control – Integrated Framework issued in 2013 by the Committee of Sponsoring Organizations of the Treadway Commission (the “2013 COSO Framework”). Based on this evaluation under the 2013 COSO Framework, which was completed on February 18, 2015, management concluded that its internal control over financial reporting was effective as of December 31, 2014.
The effectiveness of our internal control over financial reporting as of December 31, 2014 has been audited by KPMG LLP, an independent registered public accounting firm who audited our consolidated financial statements as of and for the year ended December 31, 2014, as stated in their report, which is included under “Item 8. Financial Statements and Supplementary Data” in this report.
Changes in Internal Control Over Financial Reporting
There was no change in our internal control over financial reporting during the fourth quarter of 2014 that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. Other Information
Item 10. Directors, Executive Officers and Corporate Governance
The information called for by this Item 10 is incorporated herein by reference to the definitive Proxy Statement to be filed by Devon pursuant to Regulation 14A of the General Rules and Regulations under the Securities Exchange Act of 1934 not later than April 30, 2015.
Item 11. Executive Compensation
The information called for by this Item 11 is incorporated herein by reference to the definitive Proxy Statement to be filed by Devon pursuant to Regulation 14A of the General Rules and Regulations under the Securities Exchange Act of 1934 not later than April 30, 2015.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information called for by this Item 12 is incorporated herein by reference to the definitive Proxy Statement to be filed by Devon pursuant to Regulation 14A of the General Rules and Regulations under the Securities Exchange Act of 1934 not later than April 30, 2015.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information called for by this Item 13 is incorporated herein by reference to the definitive Proxy Statement to be filed by Devon pursuant to Regulation 14A of the General Rules and Regulations under the Securities Exchange Act of 1934 not later than April 30, 2015.
Item 14. Principal Accountant Fees and Services
The information called for by this Item 14 is incorporated herein by reference to the definitive Proxy Statement to be filed by Devon pursuant to Regulation 14A of the General Rules and Regulations under the Securities Exchange Act of 1934 not later than April 30, 2015.
Table of Contents
PART IV
Item 15. Exhibits and Financial Statement Schedules
(a) The following documents are filed as part of this report:
- Consolidated Financial Statements
Reference is made to the Index to Consolidated Financial Statements and Consolidated Financial Statement Schedules appearing at “Item 8. Financial Statements and Supplementary Data” in this report.
- Consolidated Financial Statement Schedules
All financial statement schedules are omitted as they are inapplicable, or the required information has been included in the consolidated financial statements or notes thereto.
- Exhibits
| Exhibit No. | Description | |
| 2.1 | Agreement and Plan of Merger dated October 21, 2013, by and among Registrant, Devon Gas Services, L.P., Acacia Natural Gas Corp I, Inc., Crosstex Energy, Inc., New Public Rangers L.L.C., Boomer Merger Sub, Inc. and Rangers Merger Sub, Inc. (incorporated by reference to Exhibit 2.1 to Registrant’s Form 8-K filed October 22, 2013; File No. 001-32318). | |
| 2.2 | Contribution Agreement dated October 21, 2013, by and among Registrant, Devon Gas Corporation, Devon Gas Services, L.P., Southwestern Gas Pipeline, Inc., Crosstex Energy, L.P. and Crosstex Energy Services, L.P. (incorporated by reference to Exhibit 2.2 to Registrant’s Form 8-K filed October 22, 2013; File No. 001-32318). | |
| 2.3 | Purchase and Sale Agreement dated November 20, 2013, among GeoSouthern Intermediate Holdings, LLC, GeoSouthern Energy Corporation (solely with respect to certain sections specified therein), and Devon Energy Production Company, L.P. (incorporated by reference to Exhibit 10.1 to Registrant’s Form 8-K/A filed May 19, 2014; File No. 001-32318). | |
| 2.4 | Letter Agreement dated February 28, 2014 amending certain provisions of the Purchase and Sale Agreement dated November 20, 2013 among GeoSouthern Intermediate Holdings, LLC, GeoSouthern Energy Corporation and Devon Energy Production Company, L.P. | |
| 3.1 | Registrant’s Restated Certificate of Incorporation (incorporated by reference to Exhibit 3.1 of Registrant’s 10-K for the fiscal year ending December 31, 2012; File No. 001-32318). | |
| 3.2 | Registrant’s Bylaws (incorporated by reference to Exhibit 3.2 of Registrant’s Form 8-K filed June 8, 2012; File No. 001-32318). | |
| 3.3 | Amendment No. 1 to Registrant’s Bylaws (incorporated by reference to Exhibit 3.2 to Registrant’s Form 8-K filed September 16, 2013; File No. 001-32318). | |
| 4.1 | Indenture, dated as of July 12, 2011, between Registrant and UMB Bank, National Association, as Trustee (incorporated by reference to Exhibit 4.1 to Registrant’s Form 8-K filed July 12, 2011; File No. 001-32318). | |
| 4.2 | Supplemental Indenture No. 1, dated as of July 12, 2011, to Indenture dated as of July 12, 2011, between Registrant and UMB Bank, National Association, as Trustee, relating to the 4.00% Senior Notes due 2021 and the 5.60% Senior Notes due 2041 (incorporated by reference to Exhibit 4.2 to Registrant’s Form 8-K filed July 12, 2011; File No. 001-32318). |
Table of Contents
| Exhibit No. | Description | |
| 4.3 | Supplemental Indenture No. 2, dated as of May 14, 2012, to Indenture dated as of July 12, 2011, between Registrant and UMB Bank, National Association, as Trustee, relating to the 3.250% Senior Notes due 2022 and the 4.750% Senior Notes due 2042 (incorporated by reference to Exhibit 4.1 to Registrant’s Form 8-K filed May 14, 2012; File No. 001-32318). | |
| 4.4 | Supplemental Indenture No. 3, dated as of December 19, 2013, to Indenture dated as of July 12, 2011, between Registrant and UMB Bank, National Association, as Trustee, relating to the Floating Rate Senior Notes due 2015, the Floating Rate Senior Notes due 2016 and the 2.25% Senior Notes due 2018 (incorporated by reference to Exhibit 4.1 to Registrant’s Form 8-K filed December 19, 2013; File No. 001-32318). | |
| 4.5 | Indenture, dated as of March 1, 2002, between Registrant and The Bank of New York Mellon Trust Company, N.A., as Trustee (incorporated by reference to Exhibit 4.1 of Registrant’s Form 8-K filed April 9, 2002; File No. 000-30176). | |
| 4.6 | Supplemental Indenture No. 1, dated as of March 25, 2002, to Indenture dated as of March 1, 2002, between Registrant and The Bank of New York Mellon Trust Company, N.A., as Trustee, relating to the 7.95% Senior Debentures due 2032 (incorporated by reference to Exhibit 4.2 to Registrant’s Form 8-K filed April 9, 2002; File No. 000-30176). | |
| 4.7 | Supplemental Indenture No. 3, dated as of January 9, 2009, to Indenture dated as of March 1, 2002, between Registrant and The Bank of New York Mellon Trust Company, N.A., as Trustee, relating to the 6.30% Senior Notes due 2019 (incorporated by reference to Exhibit 4.1 to Registrant’s Form 8-K filed January 9, 2009; File No. 000-32318). | |
| 4.8 | Indenture dated as of October 3, 2001, by and among Devon Financing Corporation, U.L.C. as Issuer, Registrant as Guarantor, and The Bank of New York Mellon Trust Company, N.A., originally The Chase Manhattan Bank, as Trustee, relating to the 7.875% Debentures due 2031 (incorporated by reference to Exhibit 4.7 to Registrant’s Registration Statement on Form S-4 as filed October 31, 2001; File No. 333-68694). | |
| 4.9 | Indenture dated as of July 8, 1998 among Devon OEI Operating, Inc. (as successor by merger to Ocean Energy, Inc.), its Subsidiary Guarantors, and Wells Fargo Bank Minnesota, N.A., as Trustee, relating to the 8.25% Senior Notes due 2018 (incorporated by reference to Exhibit 10.24 to the Form 10-Q for the period ended June 30, 1998 of Ocean Energy, Inc.; File No. 001-14252). | |
| 4.10 | First Supplemental Indenture, dated March 30, 1999 to Indenture dated as of July 8, 1998 among Devon OEI Operating, Inc. (as successor by merger to Ocean Energy, Inc.), its Subsidiary Guarantors, and Wells Fargo Bank Minnesota, N.A., as Trustee, relating to the 8.25% Senior Notes due 2018 (incorporated by reference to Exhibit 4.5 to Ocean Energy, Inc.’s Form 10-Q for the period ended March 31, 1999; File No. 001-08094). | |
| 4.11 | Second Supplemental Indenture, dated as of May 9, 2001 to Indenture dated as of July 8, 1998 among Devon OEI Operating, Inc. (as successor by merger to Ocean Energy, Inc.), its Subsidiary Guarantors, and Wells Fargo Bank Minnesota, N.A., as Trustee, relating to the 8.25% Senior Notes due 2018 (incorporated by reference to Exhibit 99.2 to Ocean Energy, Inc.’s Form 8-K filed May 14, 2001; File No. 033-06444). | |
| 4.12 | Third Supplemental Indenture, dated January 23, 2006 to Indenture dated as of July 8, 1998 among Devon OEI Operating, Inc. as Issuer, Devon Energy Production Company, L.P. as Successor Guarantor, and Wells Fargo Bank Minnesota, N.A., as Trustee, relating to the 8.25% Senior Notes due 2018 (incorporated by reference to Exhibit 4.23 of Registrant’s Form 10-K for the year ended December 31, 2005; File No. 001-32318). |
Table of Contents
| Exhibit No. | Description | |
| 4.13 | Senior Indenture dated September 1, 1997, among Devon OEI Operating, Inc. (as successor by merger to Ocean Energy, Inc.) and The Bank of New York Mellon Trust Company, N.A., as Trustee, and Specimen of 7.50% Senior Notes (incorporated by reference to Exhibit 4.4 to Ocean Energy Inc.’s Form 10-K for the year ended December 31, 1997; File No. 001-08094). | |
| 4.14 | First Supplemental Indenture, dated as of March 30, 1999 to Senior Indenture dated as of September 1, 1997, among Devon OEI Operating, Inc. (as successor by merger to Ocean Energy, Inc.) and The Bank of New York Mellon Trust Company, N.A., as Trustee, relating to the 7.50% Senior Notes Due 2027 (incorporated by reference to Exhibit 4.10 to Ocean Energy’s Form 10-Q for the period ended March 31, 1999; File No. 001-08094). | |
| 4.15 | Second Supplemental Indenture, dated as of May 9, 2001 to Senior Indenture dated as of September 1, 1997, among Devon OEI Operating, Inc. (as successor by merger to Ocean Energy, Inc.), its Subsidiary Guarantors, and The Bank of New York Mellon Trust Company, N.A., as Trustee, relating to the 7.50% Senior Notes Due 2027 (incorporated by reference to Exhibit 99.4 to Ocean Energy, Inc.’s Form 8-K filed May 14, 2001; File No. 033-06444). | |
| 4.16 | Third Supplemental Indenture, dated December 31, 2005 to Senior Indenture dated as of September 1, 1997, among Devon OEI Operating, Inc. as Issuer, Devon Energy Production Company, L.P. as Successor Guarantor, and The Bank of New York Mellon Trust Company, N.A., as Trustee, relating to the 7.50% Senior Notes Due 2027 (incorporated by reference to Exhibit 4.27 of Registrant’s Form 10-K for the year ended December 31, 2005; File No. 001-32318). | |
| 4.17 | Registrant has not filed instruments defining the rights of holders of long-term indebtedness of Registrant’s majority owned subsidiary, EnLink Midstream Partners, LP, none of which exceeds ten percent of the total assets of Registrant and its subsidiaries on a consolidated basis. Registrant hereby agrees to furnish a copy of any such agreements to the Commission upon request. | |
| 10.1 | Credit Agreement dated October 24, 2012, among Registrant, as U.S. Borrower, Devon NEC Corporation and Devon Canada Corporation, as Canadian Borrowers, each lender from time to time party thereto, each L/C Issuer from time to time party thereto, and Bank of America, N.A., as Administrative Agent, Canadian Swing Line Lender and U.S. Swing Line Lender (incorporated by reference to Exhibit 10.1 of Registrant’s Form 8-K filed October 29, 2012; File No. 001-32318). | |
| 10.2 | Extension Agreement dated September 3, 2013 to the Credit Agreement dated October 24, 2012, among Registrant, as U.S. Borrower, Devon NEC Corporation and Devon Canada Corporation, as Canadian Borrowers, Devon Financing Company, L.L.C., the consenting lenders, and Bank of America, N.A., as Administrative Agent, Canadian Swing Line Lender and U.S. Swing Line Lender, with respect to Borrower’s extension of the Maturity Date from October 24, 2017 to October 24, 2018 (incorporated by reference to Exhibit 10.1 to Registrant’s Form 10-Q filed November 6, 2013; File No. 001-32318). | |
| 10.3 | First Amendment to Credit Agreement dated February 3, 2014, to the Credit Agreement dated October 24, 2012, among Registrant, as U.S. Borrower, Devon NEC Corporation and Devon Canada Corporation, as Canadian Borrowers, each lender from time to time party thereto, each L/C Issuer from time to time party thereto, and Bank of America, N.A., as Administrative Agent, Canadian Swing Line Lender and U.S. Swing Line Lender (incorporated by reference to Exhibit 10.1 of Registrant’s Form 8-K filed February 7, 2014; File No. 001-32318). |
Table of Contents
| Exhibit No. | Description | |
| 10.4 | Extension Agreement dated as of October 17, 2014, to the Credit Agreement dated October 24, 2012, among Registrant, as U.S. Borrower, Devon NEC Corporation and Devon Canada Corporation, as Canadian Borrowers, Devon Financing Company, L.L.C., the consenting lenders, and Bank of America, N.A., as Administrative Agent, Canadian Swing Line Lender and U.S. Swing Line Lender with respect to the extension of the maturity date from October 24, 2018 to October 24, 2019 (incorporated by reference to Exhibit 10.1 to Registrant’s Form 10-Q filed November 5, 2014; File No. 001-32318). | |
| 10.5 | Devon Energy Corporation 2009 Long-Term Incentive Plan (as amended and restated effective June 6, 2012)(incorporated by reference to Registrant’s Form S-8 Registration No. 333-182198, filed June 18, 2012).* | |
| 10.6 | Devon Energy Corporation 2013 Amendment (effective as of March 6, 2013) to the Devon Energy Corporation 2009 Long-Term Plan (as amended and restated effective June 6, 2012) (incorporated by reference to Exhibit 10.1 to Registrant’s Form 10-Q filed May 1, 2013; File No. 001-32318).* | |
| 10.7 | Devon Energy Corporation 2005 Long-Term Incentive Plan (incorporated by reference to Registrant’s Form S-8 Registration No. 333-127630, filed August 17, 2005).* | |
| 10.8 | First Amendment to Devon Energy Corporation 2005 Long-Term Incentive Plan (incorporated by reference to Appendix A to Registrant’s Proxy Statement for the 2006 Annual Meeting of Stockholders filed on April 28, 2006; File No. 001-32318).* | |
| 10.9 | Devon Energy Corporation Incentive Compensation Plan (incorporated by reference to Exhibit 10.1 to Registrant’s Form 8-K, filed June 8, 2012; File No. 001-32318).* | |
| 10.10 | Devon Energy Corporation Non-Qualified Deferred Compensation Plan Amended and Restated Effective as of April 15, 2014 (incorporated by reference to Exhibit 10.1 to Registrant’s Form 10-Q filed August 6, 2014; File No. 001-32318).* | |
| 10.11 | Devon Energy Corporation Amendment 2014-2, executed May 9, 2014, to the Devon Energy Corporation Non-Qualified Deferred Compensation Plan as amended effective April 15, 2014.* | |
| 10.12 | Devon Energy Corporation Benefit Restoration Plan (amended and restated effective January 1, 2012) (incorporated by reference to Exhibit 10.15 to Registrant’s Form 10-K, filed February 24, 2012; File No. 001-32318).* | |
| 10.13 | Devon Energy Corporation Amendment 2014-1, executed March 7, 2014, to the Devon Energy Corporation Benefit Restoration Plan (amended and restated effective January 1, 2012) (incorporated by reference to Exhibit 10.6 to Registrant’s Form 10-Q filed May 9, 2014; File No. 001-32318).* | |
| 10.14 | Devon Energy Corporation Defined Contribution Restoration Plan (amended and restated effective January 1, 2012) (incorporated by reference to Exhibit 10.16 to Registrant’s Form 10-K, filed February 24, 2012; File No. 001-32318).* | |
| 10.15 | Devon Energy Corporation Amendment 2014-1, executed March 7, 2014, to the Devon Energy Corporation Defined Contribution Restoration Plan (amended and restated effective January 1, 2012) (incorporated by reference to Exhibit 10.7 to Registrant’s Form 10-Q filed May 9, 2014; File No. 001-32318).* | |
| 10.16 | Devon Energy Corporation Supplemental Contribution Plan (amended and restated effective January 1, 2012) (incorporated by reference to Exhibit 10.17 to Registrant’s Form 10-K, filed February 24, 2012; File No. 001-32318).* | |
| 10.17 | Devon Energy Corporation Amendment 2014-1, executed March 7, 2014, to the Devon Energy Corporation Supplemental Contribution Plan (amended and restated effective January 1, 2012) (incorporated by reference to Exhibit 10.8 to Registrant’s Form 10-Q filed May 9, 2014; File No. 001-32318).* |
Table of Contents
| Exhibit No. | Description | |
| 10.18 | Devon Energy Corporation Supplemental Executive Retirement Plan (amended and restated effective January 1, 2012) (incorporated by reference to Exhibit 10.18 to Registrant’s Form 10-K, filed February 24, 2012; File No. 001-32318).* | |
| 10.19 | Devon Energy Corporation Supplemental Retirement Income Plan (amended and restated effective January 1, 2012) (incorporated by reference to Exhibit 10.19 to Registrant’s Form 10-K, filed February 24, 2012; File No. 001-32318).* | |
| 10.20 | Devon Energy Corporation Amendment 2014-1, executed March 7, 2014, to the Devon Energy Corporation Supplemental Retirement Income Plan (amended and restated effective January 1, 2012) (incorporated by reference to Exhibit 10.9 to Registrant’s Form 10-Q filed May 9, 2014; File No. 001-32318).* | |
| 10.21 | Devon Energy Corporation Incentive Savings Plan, as amended and restated effective January 1, 2014, executed September 22, 2014.* | |
| 10.22 | Amended and Restated Form of Employment Agreement between Registrant and Jeffrey A. Agosta, David A. Hager, R. Alan Marcum, John Richels, Frank W. Rudolph, Darryl G. Smette and Lyndon C. Taylor dated December 15, 2008 (incorporated by reference to Exhibit 10.19 to Registrant’s Form 10-K filed February 27, 2009; File No. 001-32318).* | |
| 10.23 | Form of Amendment No. 1 to the Amended and Restated Employment Agreement, between Registrant and Jeffrey A. Agosta, David A. Hager, R. Alan Marcum, John Richels, Frank W. Rudolph, Darryl G. Smette and Lyndon C. Taylor dated April 19, 2011. (incorporated by reference to Exhibit 10.1 to Registrant’s Form 8-K filed April 25, 2011; File No. 001-32318).* | |
| 10.24 | Form of Employment Agreement between Registrant and Tony D. Vaughn and Thomas L. Mitchell dated June 10, 2013 (Amended and Restated Form of Employment Agreement dated December 15, 2008 (Exhibit 10.22 above), as amended by Amendment No. 1 thereto dated April 19, 2011 (Exhibit 10.23 above)) (incorporated by reference to Exhibit 10.22 to Registrant’s Form 10-K filed February 28, 2014; File No. 001-32318).* | |
| 10.25 | Form of Notice of Grant of Performance Restricted Stock Award and Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and Jeffrey A. Agosta, David A. Hager, R. Alan Marcum, J. Larry Nichols, John Richels, Frank W. Rudolph, Darryl G. Smette and Lyndon C. Taylor for performance based restricted stock awarded (incorporated by reference to Exhibit 10.1 to Registrant’s Form 8-K filed December 7, 2011; File No. 001-32318).* | |
| 10.26 | Form of Notice of Grant of Performance Restricted Stock Award and Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and Jeffrey A. Agosta, David A. Hager, R. Alan Marcum, John Richels, Frank W. Rudolph, Darryl G. Smette, Lyndon C. Taylor and Tony D. Vaughn for performance based restricted stock awarded (incorporated by reference to Exhibit 10.16 to Registrant’s Form 10-K filed February 21, 2013; File No. 001-32318).* | |
| 10.27 | Form of Notice of Grant of Performance Restricted Stock Award and Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and David A. Hager, R. Alan Marcum, Thomas L. Mitchell, John Richels, Frank W. Rudolph, Darryl G. Smette, Lyndon C. Taylor and Tony D. Vaughn for performance based restricted stock awarded (incorporated by reference to Exhibit 10.25 to Registrant’s Form 10-K filed February 28, 2014; File No. 001-32318).* |
Table of Contents
| Exhibit No. | Description | |
| 10.28 | Form of Notice of Grant of Performance Share Unit Award and Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and Jeffrey A. Agosta, David A. Hager, R. Alan Marcum, John Richels, Frank W. Rudolph, Darryl G. Smette and Lyndon C. Taylor for performance based restricted share units awarded (incorporated by reference to Exhibit 10.1 to Registrant’s Form 8-K filed December 7, 2011); File No. 001-32318* | |
| 10.29 | Form of Notice of Grant of Performance Restricted Stock Award and Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and David A. Hager, R. Alan Marcum, Thomas L. Mitchell, John Richels, Frank W. Rudolph, Darryl G. Smette, Lyndon C. Taylor and Tony D. Vaughn for performance based restricted stock awarded.* | |
| 10.30 | Form of Notice of Grant of Performance Share Unit Award and Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and Jeffrey A. Agosta, David A. Hager, R. Alan Marcum, John Richels, Frank W. Rudolph, Darryl G. Smette, Lyndon C. Taylor and Tony D. Vaughn for performance based restricted share units awarded (incorporated by reference to Exhibit 10.17 to Registrant’s Form 10-K filed February 21, 2013; File No. 001-32318).* | |
| 10.31 | Form of Notice of Grant of Performance Share Unit Award and Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and David A. Hager, R. Alan Marcum, John Richels, Frank W. Rudolph, Darryl G. Smette, Lyndon C. Taylor and Tony D. Vaughn for performance based restricted share units awarded (incorporated by reference to Exhibit 10.28 to Registrant’s Form 10-K filed February 28, 2014; File No. 001-32318).* | |
| 10.32 | Form of Notice of Grant of Performance Share Unit Award and Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and David A. Hager, R. Alan Marcum, Thomas L. Mitchell, John Richels, Frank W. Rudolph, Darryl G. Smette, Lyndon C. Taylor and Tony D. Vaughn for performance based restricted share units awarded.* | |
| 10.33 | Form of Incentive Stock Option Award Agreement under the 2009 Long-Term Incentive Plan between Registrant and Jeffrey A. Agosta, David A. Hager, R. Alan Marcum, J. Larry Nichols, John Richels, Frank W. Rudolph, Darryl G. Smette, Lyndon C. Taylor and Tony D. Vaughn for incentive stock options granted (incorporated by reference to Exhibit 10.15 to Registrant’s Form 10-K filed February 25, 2011; File No. 001-32318).* | |
| 10.34 | Form of Employee Nonqualified Stock Option Award Agreement under the 2009 Long-Term Incentive Plan between Registrant and Jeffrey A. Agosta, David A. Hager, R. Alan Marcum, J. Larry Nichols, John Richels, Frank W. Rudolph, Darryl G. Smette, Lyndon C. Taylor and Tony D. Vaughn for nonqualified stock options granted (incorporated by reference to Exhibit 10.16 to Registrant’s Form 10-K filed February 25, 2011; File No. 001-32318).* | |
| 10.35 | Form of Non-Management Director Nonqualified Stock Option Award Agreement under the Devon Energy Corporation 2009 Long-Term Incentive Plan between Registrant and all Non-Management Directors for nonqualified stock options granted (incorporated by reference to Exhibit 10.20 to Registrant’s Form 10-K filed on February 25, 2010; File No. 001-32318).* | |
| 10.36 | Form of Restricted Stock Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and Thomas L. Mitchell for restricted stock awarded (incorporated by reference to Exhibit 10.18 to Registrant’s Form 10-K filed February 25, 2011; File No. 001-32318).* |
Table of Contents
| Exhibit No. | Description | |
| 10.37 | Form of Notice of Grant of Restricted Stock Award Agreement under the 2009 Long-Term Incentive Plan between Registrant and all Non-Management Directors for restricted stock awards (incorporated by reference to Exhibit 10.33 to Registrant’s Form 10-K filed February 28, 2014; File No. 001-32318).* | |
| 10.38 | Form of Letter Agreement amending the restricted stock award agreements and nonqualified stock option agreements under the 2009 Long-Term Incentive Plan and the 2005 Long-Term Incentive Plan between Registrant and J. Larry Nichols, John Richels and Darryl G. Smette (incorporated by reference to Exhibit 10.22 to Registrant’s Form 10-K filed February 25, 2011; File No. 001-32318).* | |
| 10.41 | Amendment to Incentive Stock Option Award Agreement between Registrant and J. Larry Nichols dated December 19, 2012, amending the Incentive Stock Option Agreements under the 2009 Long-Term Incentive Plan between Registrant and J. Larry Nichols (incorporated by reference to Exhibit 10.24 to Registrant’s Form 10-K filed February 21, 2013; File No. 001-32318). * | |
| 12 | Statement of computations of ratios of earnings to fixed charges. | |
| 21 | Registrant’s Significant Subsidiaries. | |
| 23.1 | Consent of KPMG LLP. | |
| 23.2 | Consent of LaRoche Petroleum Consultants, Ltd. | |
| 23.3 | Consent of Deloitte. | |
| 31.1 | Certification of principal executive officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002. | |
| 31.2 | Certification of principal financial officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002. | |
| 32.1 | Certification of principal executive officer pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. | |
| 32.2 | Certification of principal financial officer pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. | |
| 99.1 | Report of LaRoche Petroleum Consultants, Ltd. | |
| 99.2 | Report of Deloitte. | |
| 101.INS | XBRL Instance Document. | |
| 101.SCH | XBRL Taxonomy Extension Schema Document. | |
| 101.CAL | XBRL Taxonomy Extension Calculation Linkbase Document. | |
| 101.LAB | XBRL Taxonomy Extension Labels Linkbase Document. | |
| 101.PRE | XBRL Taxonomy Extension Presentation Linkbase Document. | |
| 101.DEF | XBRL Taxonomy Extension Definition Linkbase Document. |
| * | Compensatory plans or arrangements |
|---|
Table of Contents
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| DEVON ENERGY CORPORATION | ||||
| By: /s/ JOHN RICHELS | ||||
| John Richels | ||||
| President and Chief Executive Officer |
February 20, 2015
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the dates indicated.
| /s/ JOHN RICHELS | President, Chief Executive Officer and | February 20, 2015 | ||||
| John Richels | Director (Principal executive officer) | |||||
| /s/ THOMAS L. MITCHELL | Executive Vice President | February 20, 2015 | ||||
| Thomas L. Mitchell | and Chief Financial Officer (Principal financial officer) | |||||
| /s/ JEREMY D. HUMPHERS | Senior Vice President and Chief | February 20, 2015 | ||||
| Jeremy D. Humphers | Accounting Officer (Principal accounting officer) | |||||
| /s/ J. LARRY NICHOLS | Executive Chairman of the Board | February 20, 2015 | ||||
| J. Larry Nichols | ||||||
| /s/ BARBARA M. BAUMANN | Director | February 20, 2015 | ||||
| Barbara M. Baumann | ||||||
| /s/ JOHN E. BETHANCOURT | Director | February 20, 2015 | ||||
| John E. Bethancourt | ||||||
| /s/ ROBERT H. HENRY | Director | February 20, 2015 | ||||
| Robert H. Henry | ||||||
| /s/ JOHN A. HILL | Director | February 20, 2015 | ||||
| John A. Hill | ||||||
| /s/ MICHAEL M. KANOVSKY | Director | February 20, 2015 | ||||
| Michael M. Kanovsky | ||||||
| /s/ ROBERT A. MOSBACHER, JR. | Director | February 20, 2015 | ||||
| Robert A. Mosbacher, Jr. | ||||||
| /s/ DUANE C. RADTKE | Director | February 20, 2015 | ||||
| Duane C. Radtke | ||||||
| /s/ MARY P. RICCIARDELLO | Director | February 20, 2015 | ||||
| Mary P. Ricciardello |
Table of Contents
INDEX TO EXHIBITS
| Exhibit No. | Description | |
| 2.4 | Letter Agreement dated February 28, 2014 amending certain provisions of the Purchase and Sale Agreement dated November 20, 2013 among GeoSouthern Intermediate Holdings, LLC, GeoSouthern Energy Corporation and Devon Energy Production Company, L.P. | |
| 10.11 | Devon Energy Corporation Amendment 2014-2, executed May 9, 2014, to the Devon Energy Corporation Non-Qualified Deferred Compensation Plan as amended effective April 15, 2014.* | |
| 10.21 | Devon Energy Corporation Incentive Savings Plan, as amended and restated effective January 1, 2014, executed September 22, 2014.* | |
| 10.29 | Form of Notice of Grant of Performance Restricted Stock Award and Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and David A. Hager, R. Alan Marcum, Thomas L. Mitchell, John Richels, Frank W. Rudolph, Darryl G. Smette, Lyndon C. Taylor and Tony D. Vaughn for performance based restricted stock awarded.* | |
| 10.32 | Form of Notice of Grant of Performance Share Unit Award and Award Agreement under the 2009 Long-Term Incentive Plan (as amended and restated June 6, 2012) between Registrant and David A. Hager, R. Alan Marcum, Thomas L. Mitchell, John Richels, Frank W. Rudolph, Darryl G. Smette, Lyndon C. Taylor and Tony D. Vaughn for performance based restricted share units awarded.* | |
| 12 | Statement of computations of ratio of earnings to fixed charges. | |
| 21 | Registrant’s Significant Subsidiaries. | |
| 23.1 | Consent of KPMG LLP. | |
| 23.2 | Consent of LaRoche Petroleum Consultants., Ltd. | |
| 23.3 | Consent of Deloitte. | |
| 31.1 | Certification of principal executive officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002. | |
| 31.2 | Certification of principal financial officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002. | |
| 32.1 | Certification of principal executive officer pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. | |
| 32.2 | Certification of principal financial officer pursuant to Section 906 of the Sarbanes-Oxley Act of 2002. | |
| 99.1 | Report of LaRoche Petroleum Consultants, Ltd. | |
| 99.2 | Report of Deloitte. | |
| 101.INS | XBRL Instance Document. | |
| 101.SCH | XBRL Taxonomy Extension Schema Document. | |
| 101.CAL | XBRL Taxonomy Extension Calculation Linkbase Document. | |
| 101.LAB | XBRL Taxonomy Extension Labels Linkbase Document. | |
| 101.PRE | XBRL Taxonomy Extension Presentation Linkbase Document. | |
| 101.DEF | XBRL Taxonomy Extension Definition Linkbase Document. |
| * | Compensatory plans or arrangements |
|---|