 filings.tools
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
94K characters. Original on sec.gov · Markdown
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
Introduction
The following discussion and analysis presents management’s perspective of our business, financial condition and overall performance. This information is intended to provide investors with an understanding of our past performance, current financial condition and outlook for the future and should be read in conjunction with “Item 8. Financial Statements and Supplementary Data” of this report.
Overview of 2019 Results
During 2019, we completed our transformation to a U.S. oil growth company with our exit from Canada and pending sale of the Barnett Shale. These transactions accelerate efforts to focus exclusively on our resource-rich U.S. oil portfolio, which provides us with a strong foundation to grow returns, margin and profitability. By operating under a disciplined returns-driven strategy focused on delivering strong operational results, financial strength and value to our shareholders and continuing our commitment to environmental, social and governance excellence, we completed our transformation to “New Devon” and made significant progress toward our cost reduction objectives as evidenced by these 2019 highlights:
| • | Closed on the sale of our Canadian business for $2.6 billion ($3.4 billion Canadian dollars) in June 2019. |
|---|
| • | Announced the sale of our Barnett Shale assets for $770 million (expected closing in the second quarter of 2020). |
|---|
| • | Completed workforce reduction and other cost reduction initiatives, reaching approximately $240 million of annualized G&A savings. |
|---|
| • | Improved capital efficiency by reducing capital expenditures approximately 10% and increasing oil production 21% compared to 2018. |
|---|
| • | Retired $1.7 billion of senior notes, reducing annualized financing costs by $60 million. |
|---|
| • | Repurchased $4.8 billion of our total $5.8 billion share repurchase authorizations, representing an outstanding share count reduction of nearly 30% since the program’s inception. |
|---|
| • | Increased our quarterly common stock dividend 12.5% to $0.09 per share beginning in the second quarter of 2019. |
|---|
| • | Increased Delaware Basin and Powder River Basin production over 60% in 2019 compared to 2018. |
|---|
| • | Reduced methane emissions by nearly 20% over the last three years and established a target to further reduce methane intensity rates by 2025. |
|---|
| • | Exited 2019 with $1.8 billion of cash, inclusive of $380 million restricted for discontinued operations, $3.0 billion of available credit under our Senior Credit Facility and have no debt maturities until 2025. |
|---|
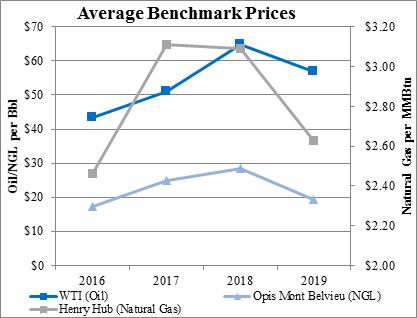 | As presented in the graph at the left, our operating achievements are subject to the volatility of commodity prices. Over the last four years, NYMEX WTI oil and NYMEX Henry Hub prices ranged from average highs of $64.79 per Bbl and $3.11 per MMBtu, respectively, to average lows of $43.36 per Bbl and $2.46 per MMBtu, respectively. | |
|---|---|---|
Trends of our annual earnings, operating cash flow, EBITDAX and capital expenditures are shown below. The annual earnings chart presents amounts pertaining to both Devon’s continuing and discontinued operations. The annual cash flow chart presents amounts pertaining to Devon’s continuing operations. “Core earnings” and “EBITDAX” are financial measures not prepared in accordance with GAAP. For a description of these measures, including reconciliations to the comparable GAAP measures, see “Non-GAAP Measures” in this Item 7.
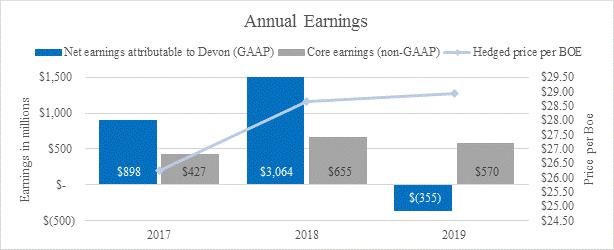
Our net earnings in recent years have been significantly impacted by divestiture transactions and temporary, noncash adjustments to the value of our commodity hedges. Net earnings in 2017 included a $0.1 billion gain on asset dispositions from continuing operations and a $0.2 billion hedge valuation gain, both net of taxes. Net earnings in 2018 included a $2.2 billion gain on our EnLink disposition, a $0.5 billion hedge valuation gain and a $0.2 billion gain on asset dispositions from continuing operations, all net of taxes. Net earnings in 2019 included a $0.4 billion hedge valuation loss, $0.2 billion net gains and charges related to our Canadian disposition and a $0.6 billion asset impairment related to our Barnett Shale disposition, all net of taxes. Excluding these amounts, our core earnings have been more stable over recent years but continue to be heavily influenced by commodity prices.
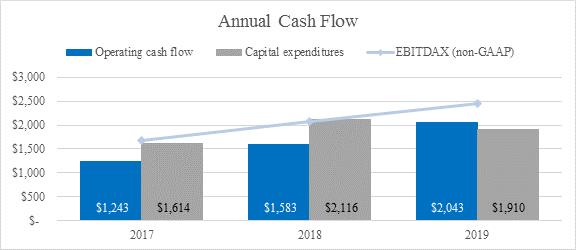
Like earnings, our operating cash flow is sensitive to volatile commodity prices. EBITDAX, which excludes financial amounts related to discontinued operations, has been increasing over the past three years as a result of our New Devon production growth and cost reductions. Regardless of cash flow fluctuations, we remain focused on managing our capital investment to generate free cash flow. As operating cash flow has declined, we have adjusted our capital development plans accordingly.
Business and Industry Outlook
Devon marked its 48th anniversary in the oil and gas business and its 31st year as a public company during 2019. As an established company with a strong leadership team, we have experience operating through periods of volatile commodity prices. With our focused strategy and portfolio of quality assets, we are committed to navigating the current environment while safeguarding our long-term financial strength.
Market prices for crude oil and natural gas are inherently volatile. In 2019, WTI oil prices averaged approximately $57.02/Bbl versus $64.79/Bbl in 2018. Despite price support in the first half of 2019 driven by supply tightness and geopolitical tensions, 2019 WTI oil prices overall were negatively impacted by trade concerns and economic slowdown fears, even with strong supply and demand fundamentals. Looking ahead, crude oil has experienced near term downward pressure as a result of softer demand from the growing impact of the coronavirus related crisis. Positive factors that could reduce these recent negative factors and create more demand for crude oil are the extension of OPEC cuts through 2020, as well as the International Maritime Organization 2020 regulations.
Henry Hub gas prices averaged approximately $2.63/MMBtu in 2019 versus $3.09/MMBtu in 2018. Mt. Belvieu Blended Index NGL prices averaged approximately $19.22/Bbl in 2019 versus $28.31/Bbl in 2018. Natural gas and NGL prices faced strong headwinds in 2019 due to U.S. supply growth far outpacing demand for both commodities domestically and internationally. These factors continue to weigh on current natural gas and NGL prices.
As discussed in our Critical Accounting Estimates, our STACK assets are susceptible to a material asset impairment should prices decrease from current levels. While such an impairment would materially impact our reported net earnings, it would not impact our operating cash flow or our current near-term drilling plans.
To mitigate our exposure to commodity price volatility and ensure our financial strength, we continue to execute a disciplined, risk-management hedging program. Our hedging program incorporates both systematic hedges added on a regular basis and discretionary hedges layered in on an opportunistic basis to take advantage of favorable market conditions. We are adding 2020 positions at desirable prices, and we currently have approximately 40% of our anticipated oil volumes and 25% of our anticipated gas volumes hedged. Additionally, we are actively adding attractive hedges for 2021. Further insulating our cash flow, we continue to examine and, when appropriate, execute attractive regional basis swap hedges in an effort to protect price realizations across our portfolio.
Throughout 2019, our operational efficiencies continued to accelerate. Our improved cost structure expanded margins, and we ended the year ahead of our multi-year cost savings initiative plan. As we carry our 2019 momentum into 2020, we will maintain our capital-efficiency focus and intensify our steadfast commitment to capital discipline. Our returns-driven strategy will be underpinned by our continued efforts to improve our cost structure and grow higher-margin oil production. As such, our 2020 capital program has been optimized for strong returns, high single-digit oil growth, free cash flow and enhanced per-share cash flow growth.
To achieve our 2020 capital program objectives, our capital allocation priorities are four-fold: maintain base production, fund dividends, invest in high-return growth projects and return excess cash to shareholders. Accordingly, over half of the 2020 spend will be focused in on our highest margin U.S. oil play, the Delaware Basin. As the most active program in Devon’s portfolio, capital activity in the Delaware Basin will be diversified across five core areas. Also accretive to our 2020 returns-focused capital program is our 2020 Rockies activity, where spend will be prioritized to our top-tier Powder River Basin development activity. In total, our 2020 operating plan is expected to deliver U.S. oil growth of approximately 7.5% to 9.0% on a retained asset basis.
Results of Operations
The following graphs, discussion and analysis are intended to provide an understanding of our results of operations and current financial condition. To facilitate the review, these numbers are being presented before consideration of earnings attributable to noncontrolling interests. Analysis of the change in net earnings from continuing operations is shown below and analysis of the change in net earnings from discontinued operations is shown on page 33.
| Continuing Operations |
|---|
2019 vs. 2018
Our 2019 net loss from continuing operations was $79 million and decreased $793 million compared to 2018. The graph below shows the change in net earnings from 2018 to 2019. The material changes are further discussed by category on the following pages. To facilitate the review, these numbers are being presented before consideration of earnings attributable to noncontrolling interests.

Production Volumes
| 2019 | % of Total | 2018 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Oil (MBbls/d) | ||||||||||||||||
| Delaware Basin | 70 | 47 | % | 42 | +67 | % | ||||||||||
| STACK | 31 | 20 | % | 32 | - 4 | % | ||||||||||
| Powder River Basin | 17 | 11 | % | 14 | +26 | % | ||||||||||
| Eagle Ford | 23 | 16 | % | 28 | - 17 | % | ||||||||||
| Other | 6 | 4 | % | 5 | +4 | % | ||||||||||
| New Devon | 147 | 98 | % | 121 | +21 | % | ||||||||||
| U.S. divest assets | 3 | 2 | % | 9 | - 70 | % | ||||||||||
| Total | 150 | 100 | % | 130 | +15 | % |
| 2019 | % of Total | 2018 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Gas (MMcf/d) | ||||||||||||||||
| Delaware Basin | 177 | 29 | % | 105 | +68 | % | ||||||||||
| STACK | 314 | 53 | % | 334 | - 6 | % | ||||||||||
| Powder River Basin | 24 | 4 | % | 16 | +55 | % | ||||||||||
| Eagle Ford | 79 | 13 | % | 79 | - 0 | % | ||||||||||
| Other | 1 | 0 | % | 1 | - 18 | % | ||||||||||
| New Devon | 595 | 99 | % | 535 | +11 | % | ||||||||||
| U.S. divest assets | 4 | 1 | % | 31 | - 87 | % | ||||||||||
| Total | 599 | 100 | % | 566 | +6 | % |
| 2019 | % of Total | 2018 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| NGLs (MBbls/d) | ||||||||||||||||
| Delaware Basin | 27 | 36 | % | 16 | +74 | % | ||||||||||
| STACK | 36 | 46 | % | 37 | - 5 | % | ||||||||||
| Powder River Basin | 2 | 3 | % | 1 | +53 | % | ||||||||||
| Eagle Ford | 11 | 14 | % | 13 | - 15 | % | ||||||||||
| Other | 1 | 1 | % | 1 | +12 | % | ||||||||||
| New Devon | 77 | 100 | % | 68 | +13 | % | ||||||||||
| U.S. divest assets | — | 0 | % | 3 | N/M | |||||||||||
| Total | 77 | 100 | % | 71 | +9 | % |
| 2019 | % of Total | 2018 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Combined (MBoe/d) | ||||||||||||||||
| Delaware Basin | 127 | 39 | % | 75 | +69 | % | ||||||||||
| STACK | 119 | 36 | % | 125 | - 5 | % | ||||||||||
| Powder River Basin | 23 | 7 | % | 17 | +34 | % | ||||||||||
| Eagle Ford | 47 | 15 | % | 54 | - 12 | % | ||||||||||
| Other | 7 | 2 | % | 7 | +5 | % | ||||||||||
| New Devon | 323 | 99 | % | 278 | +16 | % | ||||||||||
| U.S. divest assets | 4 | 1 | % | 18 | - 80 | % | ||||||||||
| Total | 327 | 100 | % | 296 | +11 | % |
From 2018 to 2019, an 11% increase in production volumes contributed to a $410 million increase in earnings. Continued development in the Delaware Basin and Powder River Basin drove a 16% production increase for New Devon which was slightly offset by decreased production associated with divested assets.
Field Prices
| 2019 | Realization | 2018 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Oil (per Bbl) | ||||||||||||||||
| WTI index | $ | 57.02 | $ | 64.79 | - 12 | % | ||||||||||
| Realized price, unhedged | $ | 54.73 | 96% | $ | 61.96 | - 12 | % | |||||||||
| Cash settlements | $ | 1.71 | $ | (8.01 | ) | |||||||||||
| Realized price, with hedges | $ | 56.44 | 99% | $ | 53.95 | +5 | % |
| 2019 | Realization | 2018 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Gas (per Mcf) | ||||||||||||||||
| Henry Hub index | $ | 2.63 | $ | 3.09 | - 15 | % | ||||||||||
| Realized price, unhedged | $ | 1.79 | 68% | $ | 2.34 | - 23 | % | |||||||||
| Cash settlements | $ | 0.14 | $ | 0.02 | ||||||||||||
| Realized price, with hedges | $ | 1.93 | 73% | $ | 2.36 | - 18 | % |
| 2019 | Realization | 2018 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| NGLs (per Bbl) | ||||||||||||||||
| Mont Belvieu blended index (1) | $ | 19.22 | $ | 28.31 | - 32 | % | ||||||||||
| Realized price, unhedged | $ | 15.21 | 79% | $ | 25.47 | - 40 | % | |||||||||
| Cash settlements | $ | 1.61 | $ | (1.75 | ) | |||||||||||
| Realized price, with hedges | $ | 16.82 | 88% | $ | 23.72 | - 29 | % |
| (1) | Based upon composition of our NGL barrel. |
|---|
| 2019 | 2018 | Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Combined (per Boe) | ||||||||||||
| Realized price, unhedged | $ | 31.93 | $ | 37.87 | - 16 | % | ||||||
| Cash settlements | $ | 1.43 | $ | (3.89 | ) | |||||||
| Realized price, with hedges | $ | 33.36 | $ | 33.98 | - 2 | % |
From 2018 to 2019, field prices contributed to a $686 million decrease in earnings. Unhedged realized oil, gas and NGL prices decreased primarily due to lower WTI, Henry Hub and Mont Belvieu index prices. These decreases were partially offset by favorable hedge cash settlements across each of our products.
Hedge Settlements
| 2019 | 2018 | Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Q | ||||||||||||
| Oil | $ | 93 | $ | (380 | ) | N/M | ||||||
| Natural gas | 31 | 5 | N/M | |||||||||
| NGL | 46 | (45 | ) | N/M | ||||||||
| Total cash settlements | $ | 170 | $ | (420 | ) | N/M |
Cash settlements as presented in the tables above represent realized gains or losses related to the instruments described in Note 3 in “Item 8. Financial Statements and Supplementary Data” of this report.
Production Expenses
| 2019 | 2018 | Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| LOE | $ | 462 | $ | 480 | - 4 | % | ||||||
| Gathering, processing & transportation | 463 | 407 | +14 | % | ||||||||
| Production taxes | 251 | 248 | +1 | % | ||||||||
| Property taxes | 21 | 18 | +17 | % | ||||||||
| Total | $ | 1,197 | $ | 1,153 | +4 | % | ||||||
| Per Boe: | ||||||||||||
| LOE | $ | 3.87 | $ | 4.45 | - 13 | % | ||||||
| Gathering, processing & transportation | $ | 3.88 | $ | 3.77 | +3 | % | ||||||
| Percent of oil, gas and NGL sales: | ||||||||||||
| Production taxes | 6.6 | % | 6.1 | % | +8 | % |
LOE per Boe decreased in 2019 compared to 2018 due to the impact of our cost reduction initiatives. Gathering, processing and transportation increased primarily due to increased activity in the Delaware Basin.
Field-Level Cash Margin
The table below presents the field-level cash margin for each of our operating areas. Field-level cash margin is computed as oil, gas and NGL revenues less production expenses and is not prepared in accordance with GAAP. A reconciliation to the comparable GAAP measures is found in “Non-GAAP Measures” in this Item 7. The changes in production volumes, field prices and production expenses, shown above, had the following impacts on our field-level cash margins by asset.
| 2019 | $ per BOE | 2018 | $ per BOE | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Field-level cash margin (non-GAAP) | ||||||||||||||||
| Delaware Basin | $ | 1,157 | $ | 25.00 | $ | 786 | $ | 28.65 | ||||||||
| STACK | 685 | $ | 15.81 | 992 | $ | 21.75 | ||||||||||
| Powder River Basin | 246 | $ | 28.64 | 249 | $ | 38.50 | ||||||||||
| Eagle Ford | 446 | $ | 25.80 | 717 | $ | 36.30 | ||||||||||
| Other | 65 | $ | 25.37 | 72 | $ | 28.59 | ||||||||||
| New Devon | 2,599 | $ | 22.02 | 2,816 | $ | 27.67 | ||||||||||
| U.S. divest assets | 13 | $ | 11.01 | 116 | $ | 19.15 | ||||||||||
| Total | $ | 2,612 | $ | 21.90 | $ | 2,932 | $ | 27.19 |
Depreciation, Depletion and Amortization
| 2019 | 2018 | Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Oil and gas per Boe | $ | 11.72 | $ | 10.51 | +11 | % | ||||||
| Oil and gas | $ | 1,398 | $ | 1,134 | +23 | % | ||||||
| Other property and equipment | 99 | 94 | +5 | % | ||||||||
| Total | $ | 1,497 | 1,228 | +22 | % |
Our oil and gas DD&A increased due to continued development in the Delaware Basin and Powder River Basin.
General and Administrative Expense
| 2019 | 2018 | Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Labor and benefits (net of reimbursements) | $ | 307 | $ | 365 | - 16 | % | ||||||
| Non-labor | 168 | 209 | - 20 | % | ||||||||
| Total Devon | $ | 475 | $ | 574 | - 17 | % |
From 2018 to 2019, G&A decreased $99 million primarily as a result of the workforce reduction and other cost-saving initiatives that occurred during 2019 as discussed in Note 6 in “Item 8. Financial Statements and Supplementary Data” of this report.
Other Items
| 2019 | 2018 | Change in earnings | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Commodity hedge valuation changes (1) | $ | (624 | ) | $ | 877 | $ | (1,501 | ) | ||||
| Marketing operations | 53 | 33 | 20 | |||||||||
| Exploration expenses | 58 | 128 | 70 | |||||||||
| Asset impairments | — | 156 | 156 | |||||||||
| Asset dispositions | (48 | ) | (278 | ) | (230 | ) | ||||||
| Net financing costs | 250 | 580 | 330 | |||||||||
| Restructuring and transaction costs | 84 | 97 | 13 | |||||||||
| Other expenses | 4 | (7 | ) | (11 | ) | |||||||
| $ | (1,153 | ) |
| (1) | Included as a component of upstream revenues on the consolidated statements of comprehensive earnings. |
|---|
We recognize fair value changes on our oil, gas and NGL derivative instruments in each reporting period. The changes in fair value resulted from new positions and settlements that occurred during each period, as well as the relationship between contract prices and the associated forward curves.
Exploration expense decreased primarily due to recognizing $95 million in unproved impairments related to certain non-core acreage in the U.S during 2018 compared to $18 million in 2019.
Asset impairments decreased due to recognizing $109 million of proved asset impairments and $47 million of non-oil and gas asset impairments during 2018 as discussed in Note 5 in “Item 8. Financial Statements and Supplementary Data” of this report.
Asset dispositions decreased primarily due to gains recognized in conjunction with certain of our U.S. asset dispositions in 2018. For additional information see Note 2 in “Item 8. Financial Statements and Supplementary Data” of this report.
Net financing costs decreased primarily due to $312 million of early retirement charges associated with our debt retirement in 2018 as discussed in Note 13 in “Item 8. Financial Statements and Supplementary Data” of this report.
Income Taxes
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Current benefit | $ | (5) | $ | (17) | ||||
| Deferred expense (benefit) | (25) | 247 | ||||||
| Total expense (benefit) | $ | (30) | $ | 230 | ||||
| Effective income tax rate | 28 | % | 24 | % |
For discussion on income taxes, see Note 7 in “Item 8. Financial Statements and Supplementary Data” of this report.
Results of Operations – 2018 vs. 2017
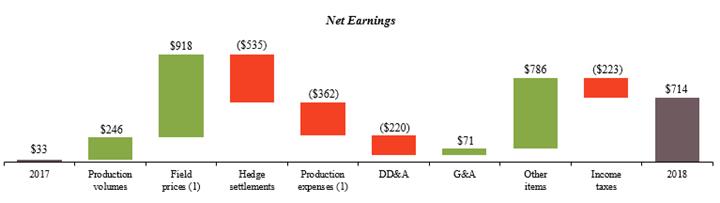
Our 2018 net earnings from continuing operations were $714 million and increased $681 million compared to 2017. The graph below shows the change in net earnings from 2017 to 2018. The material changes are further discussed by category on the following pages. To facilitate the review, these numbers are being presented before consideration of earnings attributable to noncontrolling interests.
| (1) | As further discussed in Note 1 in “Item 8. Financial Statements and Supplementary Data” of this report, the presentation of certain processing arrangements changed from a net to a gross presentation in 2018. The change resulted in an increase to our upstream revenues and production expenses by $191 million during 2018 with no impact to net earnings. |
|---|
Production Volumes
| 2018 | % of Total | 2017 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Oil (MBbls/d) | ||||||||||||||||
| Delaware Basin | 42 | 32 | % | 29 | +42 | % | ||||||||||
| STACK | 32 | 25 | % | 25 | +28 | % | ||||||||||
| Powder River Basin | 14 | 10 | % | 10 | +37 | % | ||||||||||
| Eagle Ford | 28 | 22 | % | 34 | - 17 | % | ||||||||||
| Other | 5 | 4 | % | 6 | - 6 | % | ||||||||||
| New Devon | 121 | 93 | % | 104 | +17 | % | ||||||||||
| U.S. divest assets | 9 | 7 | % | 11 | - 24 | % | ||||||||||
| Total | 130 | 100 | % | 115 | +13 | % |
| 2018 | % of Total | 2017 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Gas (MMcf/d) | ||||||||||||||||
| Delaware Basin | 105 | 19 | % | 86 | +22 | % | ||||||||||
| STACK | 334 | 59 | % | 294 | +13 | % | ||||||||||
| Powder River Basin | 16 | 3 | % | 8 | +85 | % | ||||||||||
| Eagle Ford | 79 | 14 | % | 95 | - 17 | % | ||||||||||
| Other | 1 | 0 | % | 1 | +6 | % | ||||||||||
| New Devon | 535 | 95 | % | 484 | +10 | % | ||||||||||
| U.S. divest assets | 31 | 5 | % | 35 | - 10 | % | ||||||||||
| Total | 566 | 100 | % | 519 | +9 | % |
| 2018 | % of Total | 2017 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| NGLs (MBbls/d) | ||||||||||||||||
| Delaware Basin | 16 | 22 | % | 10 | +53 | % | ||||||||||
| STACK | 37 | 53 | % | 30 | +24 | % | ||||||||||
| Powder River Basin | 1 | 2 | % | 1 | +75 | % | ||||||||||
| Eagle Ford | 13 | 18 | % | 13 | +2 | % | ||||||||||
| Other | 1 | 1 | % | 1 | - 4 | % | ||||||||||
| New Devon | 68 | 96 | % | 55 | +25 | % | ||||||||||
| U.S. divest assets | 3 | 4 | % | 3 | - 10 | % | ||||||||||
| Total | 71 | 100 | % | 58 | +23 | % |
| 2018 | % of Total | 2017 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Combined (MBoe/d) | ||||||||||||||||
| Delaware Basin | 75 | 26 | % | 54 | +39 | % | ||||||||||
| STACK | 125 | 42 | % | 104 | +20 | % | ||||||||||
| Powder River Basin | 17 | 6 | % | 12 | +43 | % | ||||||||||
| Eagle Ford | 54 | 18 | % | 62 | - 13 | % | ||||||||||
| Other | 7 | 2 | % | 7 | - 3 | % | ||||||||||
| New Devon | 278 | 94 | % | 239 | +16 | % | ||||||||||
| U.S. divest assets | 18 | 6 | % | 21 | - 14 | % | ||||||||||
| Total | 296 | 100 | % | 260 | +14 | % |
From 2017 to 2018, an increase in production volumes contributed to a $246 million increase in earnings. Focused development activities in the Delaware Basin, STACK and Powder River Basin drove production increases for New Devon and were partially offset by decreased activity in the Eagle Ford and lower production volumes associated with our U.S. divested assets.
Oil, Gas and NGL Prices
| 2018 | Realization | 2017 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Oil (per Bbl) | ||||||||||||||||
| WTI index | $ | 64.79 | $ | 50.99 | +27 | % | ||||||||||
| Realized price, unhedged | $ | 61.96 | 96% | $ | 49.41 | +25 | % | |||||||||
| Cash settlements | $ | (8.01 | ) | $ | 1.98 | |||||||||||
| Realized price, with hedges | $ | 53.95 | 83% | $ | 51.39 | +5 | % |
| 2018 | Realization | 2017 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Gas (per Mcf) | ||||||||||||||||
| Henry Hub index | $ | 3.09 | $ | 3.11 | - 1 | % | ||||||||||
| Realized price, unhedged | $ | 2.34 | 76% | $ | 2.57 | - 9 | % | |||||||||
| Cash settlements | $ | 0.02 | $ | 0.18 | ||||||||||||
| Realized price, with hedges | $ | 2.36 | 76% | $ | 2.75 | - 14 | % |
| 2018 | Realization | 2017 | Change | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| NGLs (per Bbl) | ||||||||||||||||
| Mont Belvieu blended index (1) | $ | 28.31 | $ | 24.77 | +14 | % | ||||||||||
| Realized price, unhedged | $ | 25.47 | 90% | $ | 16.74 | +52 | % | |||||||||
| Cash settlements | $ | (1.75 | ) | $ | (0.16 | ) | ||||||||||
| Realized price, with hedges | $ | 23.72 | 84% | $ | 16.58 | +43 | % |
| (1) | Based upon composition of average Devon NGL barrel. |
|---|
| 2018 | 2017 | Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Combined (per Boe) | ||||||||||||
| Realized price, unhedged | $ | 37.87 | $ | 30.80 | +23 | % | ||||||
| Cash settlements | $ | (3.89 | ) | $ | 1.21 | |||||||
| Realized price, with hedges | $ | 33.98 | $ | 32.01 | +6 | % |
Upstream revenues increased $918 million as a result of higher unhedged, realized prices for oil and NGLs. The increase in oil sales primarily resulted from higher average WTI crude index prices, which were 27% higher in 2018, resulting in an increase of approximately $600 million.
NGL sales increased $282 million as a result of 14% higher NGL prices at the Mont Belvieu, Texas hub, as well as improved realizations in our NGL price. These increases were partially offset by unfavorable hedge cash settlements for our oil and NGL hedges.
In 2018, the presentation of certain processing arrangements changed from a net to a gross presentation. The change resulted in an increase to our upstream revenues and production expenses by approximately $191 million with no impact to net earnings.
Hedge Settlements
| 2018 | 2017 | Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Q | ||||||||||||
| Oil | $ | (380 | ) | $ | 83 | N/M | ||||||
| Natural gas | 5 | 35 | N/M | |||||||||
| NGL | (45 | ) | (3 | ) | N/M | |||||||
| Total cash settlements | $ | (420 | ) | $ | 115 | N/M |
Production Expenses
| 2018 | 2017 | Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| LOE | $ | 480 | $ | 411 | +17 | % | ||||||
| Gathering, processing & transportation | 407 | 205 | +99 | % | ||||||||
| Production taxes | 248 | 161 | +54 | % | ||||||||
| Property taxes | 18 | 14 | +29 | % | ||||||||
| Total | $ | 1,153 | $ | 791 | +46 | % | ||||||
| Per Boe: | ||||||||||||
| LOE | $ | 4.45 | $ | 4.33 | +3 | % | ||||||
| Gathering, processing & transportation | $ | 3.77 | $ | 2.16 | +74 | % | ||||||
| Percent of oil, gas and NGL sales: | ||||||||||||
| Production taxes | 6.1 | % | 5.5 | % | +10 | % |
LOE increased $69 million primarily due to continued focus on growing our liquids-rich assets within the STACK and Delaware Basin, partially offset by our U.S. non-core divestitures.
In 2018, the presentation of certain processing arrangements changed from a net to a gross presentation. The change resulted in an increase to our upstream revenues and production expenses by approximately $191 million with no impact to net earnings.
Production taxes increased on an absolute dollar basis primarily due to the increase in our upstream revenues. Additionally, the increase in Oklahoma severance tax rates that became effective during the third quarter of 2018 also contributed to the increase on an absolute dollar basis and as a percentage of oil, gas and NGL sales.
Field-Level Cash Margin
The changes in production volumes, field prices and production expenses, shown above, had the following impact on our field-level cash margins by asset.
| 2018 | $ per BOE | 2017 | $ per BOE | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Field-level cash margin (non-GAAP) | ||||||||||||||||
| Delaware Basin | $ | 786 | $ | 28.65 | $ | 455 | $ | 23.04 | ||||||||
| STACK | 992 | $ | 21.75 | 683 | $ | 17.99 | ||||||||||
| Powder River Basin | 249 | $ | 38.50 | 128 | $ | 28.67 | ||||||||||
| Eagle Ford | 717 | $ | 36.30 | 667 | $ | 29.41 | ||||||||||
| Other | 72 | $ | 28.59 | 68 | $ | 26.21 | ||||||||||
| New Devon | 2,816 | $ | 27.67 | 2,001 | $ | 22.88 | ||||||||||
| U.S. divest assets | 116 | $ | 19.15 | 129 | $ | 17.47 | ||||||||||
| Total | $ | 2,932 | $ | 27.19 | $ | 2,130 | $ | 22.46 |
Depreciation, Depletion and Amortization
| 2018 | 2017 | Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Oil and gas per Boe | $ | 10.51 | $ | 9.58 | +10 | % | ||||||
| Oil and gas | $ | 1,134 | $ | 908 | +25 | % | ||||||
| Other property and equipment | 94 | 100 | - 5 | % | ||||||||
| Total | $ | 1,228 | $ | 1,008 | +22 | % |
Our oil and gas DD&A increased primarily due to continued development in the STACK, Delaware Basin and Powder River Basin properties.
General and Administrative Expense
| 2018 | 2017 | Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Labor and benefits (net of reimbursements) | $ | 365 | $ | 445 | - 18 | % | ||||||
| Non-labor | 209 | 200 | + 5 | % | ||||||||
| Total Devon | $ | 574 | $ | 645 | - 11 | % |
From 2017 to 2018, G&A decreased $71 million primarily as a result of the workforce reductions that occurred during 2018 as discussed in Note 6 in “Item 8. Financial Statements and Supplementary Data” of this report.
Other Items
| 2018 | 2017 | Change in earnings | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Commodity hedge valuation changes (1) | $ | 877 | $ | (48 | ) | $ | 925 | |||||
| Marketing operations | 33 | (46 | ) | 79 | ||||||||
| Exploration expenses | 128 | 346 | 218 | |||||||||
| Asset impairments | 156 | — | (156 | ) | ||||||||
| Asset dispositions | (278 | ) | (219 | ) | 59 | |||||||
| Net financing costs | 580 | 321 | (259 | ) | ||||||||
| Restructuring and transaction costs | 97 | — | (97 | ) | ||||||||
| Other expenses | (7 | ) | 10 | 17 | ||||||||
| $ | 786 |
| (1) | Included as a component of upstream revenues on the consolidated statements of comprehensive earnings. |
|---|
Marketing operations increased primarily due to improved commodity prices, which were partially offset by the impact of our downstream marketing commitments.
Exploration expense decreased due to recognizing $95 million in unproved impairments related to certain non-core acreage in the U.S during 2018 compared to $217 million in 2017. Additionally, geological and geophysical costs decreased $86 million primarily in the STACK and Delaware Basin.
Asset impairments increased due to recognizing $109 million of proved asset impairments and $47 million of non-oil and gas asset impairments during 2018. For additional information, see Note 5 in “Item 8. Financial Statements and Supplementary Data” of this report.
Asset dispositions increased primarily due to gains recognized in conjunction with certain of our U.S. asset dispositions in 2018. For additional information, see Note 2 in “Item 8. Financial Statements and Supplementary Data” of this report.
Net financing costs increased primarily due to $312 million of early retirement charges associated with our debt retirement in 2018 as discussed in Note 13 in “Item 8. Financial Statements and Supplementary Data” of this report.
Restructuring and transaction costs increased primarily as a result of our workforce reductions in 2018. See Note 6 in “Item 8. Financial Statements and Supplementary Data” of this report for additional information.
Income Taxes
| 2018 | 2017 | |||||||
|---|---|---|---|---|---|---|---|---|
| Current expense (benefit) | $ | (17 | ) | $ | 9 | |||
| Deferred expense (benefit) | 247 | (2 | ) | |||||
| Total expense | $ | 230 | $ | 7 | ||||
| Effective income tax rate | 24 | % | 18 | % |
For discussion on income taxes, see Note 7 in “Item 8. Financial Statements and Supplementary Data” of this report.
| Discontinued Operations |
|---|
The table below presents key components from discontinued operations for the time periods presented. Discontinued operations include our aggregate ownership interests in EnLink and the General Partner that Devon divested in July 2018 and the Canadian business that Devon sold in June 2019. Discontinued operations also include the Barnett Shale assets that Devon has contracted to sell and which is expected to close during the second quarter of 2020, as well as previously divested Barnett Shale properties located primarily in Johnson and Wise counties, Texas. For additional information on discontinued operations, see Note 18 in “Part I. Financial Information – Item 1. Financial Statements” of this report.
| 2019 | 2018 | 2017 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Upstream revenues | $ | 1,114 | $ | 1,742 | $ | 2,319 | ||||||
| Production expenses | $ | 599 | $ | 1,072 | $ | 1,031 | ||||||
| Marketing margin | $ | 20 | $ | 708 | $ | 958 | ||||||
| Gain on sale of Canadian operations | $ | (223 | ) | $ | — | $ | — | |||||
| Gain on sale of EnLink and General Partner interests | $ | — | $ | (2,607 | ) | $ | — | |||||
| Asset impairments | $ | 785 | $ | — | $ | 17 | ||||||
| Financing costs, net | $ | 87 | $ | 112 | $ | 177 | ||||||
| Restructuring and transaction costs | $ | 248 | $ | 17 | $ | — | ||||||
| Earnings (loss) from discontinued operations before income taxes | $ | (632 | ) | $ | 2,839 | $ | 856 | |||||
| Income tax expense (benefit) | $ | (358 | ) | $ | 329 | $ | (189 | ) | ||||
| Net earnings (loss) from discontinued operations, net of tax | $ | (274 | ) | $ | 2,510 | $ | 1,045 | |||||
| Production (MMBoe): | ||||||||||||
| Barnett Shale | 37 | 45 | 56 | |||||||||
| Canada | 19 | 42 | 48 | |||||||||
| Total production | 56 | 87 | 104 | |||||||||
| Realized price, unhedged (per Boe) - Barnett Shale | $ | 13.30 | $ | 17.36 | $ | 14.79 | ||||||
| Realized price, unhedged (per Boe) - Canada | $ | 38.98 | $ | 19.12 | $ | 29.39 |
2019 vs 2018
Net earnings from discontinued operations, net of tax decreased $2.8 billion as we recognized a $2.6 billion ($2.2 billion after-tax) gain on the sale of our aggregate ownership interests in EnLink and the General Partner during 2018. Net earnings from discontinued operations also decreased due to a $748 million asset impairment to our Barnett Shale assets in the fourth quarter of 2019.
2018 vs 2017
Net earnings from discontinued operations, net of tax increased $1.5 billion as we recognized a $2.6 billion ($2.2 billion after-tax) gain on the sale of our aggregate ownership interests in EnLink and the General Partner during 2018. The gain was partially offset by a decrease in upstream revenues, which was primarily driven by widening differentials for bitumen sales in Canada to the WTI index during the fourth quarter of 2018. Market forces widened Canadian heavy oil differentials beyond historical norms and negatively impacted the price we realized on our Canadian production. We had basis swaps for approximately half of our fourth quarter production to mitigate the effect of the lower market price. To further mitigate the effects of the lower price, we reduced our Jackfish production in November 2018 which impacted our fourth quarter production by approximately 8 MBbls/d. For discussion on discontinued operations, see Note 18 in “Item 8. Financial Statements and Supplementary Data” of this report.
Capital Resources, Uses and Liquidity
Sources and Uses of Cash
The following table presents the major changes in cash and cash equivalents for the time periods presented below.
| Year ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2019 | 2018 | 2017 | ||||||||||
| Operating cash flow from continuing operations | $ | 2,043 | $ | 1,583 | $ | 1,243 | ||||||
| Divestitures of property and equipment | 390 | 500 | 425 | |||||||||
| Capital expenditures | (1,910 | ) | (2,116 | ) | (1,614 | ) | ||||||
| Acquisitions of property and equipment | (31 | ) | (55 | ) | (44 | ) | ||||||
| Debt activity, net | (162 | ) | (1,226 | ) | — | |||||||
| Repurchases of common stock | (1,849 | ) | (2,956 | ) | — | |||||||
| Common stock dividends | (140 | ) | (149 | ) | (127 | ) | ||||||
| Contributions from noncontrolling interests | 116 | — | — | |||||||||
| Other | (26 | ) | (46 | ) | (46 | ) | ||||||
| Net change in cash, cash equivalents and restricted cash from discontinued operations | 967 | 4,227 | 888 | |||||||||
| Net change in cash, cash equivalents and restricted cash | $ | (602 | ) | $ | (238 | ) | $ | 725 | ||||
| Cash, cash equivalents and restricted cash at end of period | $ | 1,844 | $ | 2,446 | $ | 2,684 |
Operating Cash Flow – Continuing Operations
Net cash provided by operating activities continued to be a significant source of capital and liquidity in 2019. Our operating cash flow increased $460 million, or 29%, to $2.0 billion year over year. In 2019, our operating cash flow nearly funded the entirety of our capital expenditures program and dividends, allowing us to use available cash balances and net divestiture proceeds to fund other capital uses.
Our operating cash flow increased $340 million, or 27%, from 2017 to 2018. Our operating cash flow funded approximately 70% of our capital expenditures program and dividends in 2018 and 2017, respectively. As a result, we utilized available cash balances and divestiture proceeds to supplement our operating cash flows.
Divestitures of Property and Investments – Continuing Operations
During 2019, 2018 and 2017, as part of our announced divestiture programs, we sold non-core U.S. upstream assets for $390 million, $500 million and $425 million, respectively. For further discussion, see Note 2 in “Item 8. Financial Statements and Supplementary Data” of this report.
Capital Expenditures
The following table summarizes our capital expenditures and property acquisitions.
| Year ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2019 | 2018 | 2017 | ||||||||||
| Delaware Basin | $ | 912 | $ | 768 | $ | 394 | ||||||
| STACK | 396 | 827 | 742 | |||||||||
| Powder River Basin | 308 | 157 | 121 | |||||||||
| Eagle Ford | 194 | 215 | 115 | |||||||||
| Other | 36 | 110 | 155 | |||||||||
| Total oil and gas | 1,846 | 2,077 | 1,527 | |||||||||
| Midstream | 42 | 16 | 50 | |||||||||
| Other | 22 | 23 | 37 | |||||||||
| Total capital expenditures | $ | 1,910 | $ | 2,116 | $ | 1,614 | ||||||
| Acquisitions | $ | 31 | $ | 55 | $ | 44 |
Capital expenditures consist primarily of amounts related to our oil and gas exploration and development operations and other corporate activities. The vast majority of our capital expenditures are for the acquisition, drilling and development of oil and gas properties. Our capital program is designed to operate within or near operating cash flow and may fluctuate with changes to commodity prices and other factors impacting cash flow. This is evidenced by our operating cash flow fully funding capital expenditures in 2019 and funding approximately 75% and 77% of capital expenditures in 2018 and 2017, respectively. Our capital expenditures are lower in 2019 primarily due to our decreased spending in the STACK, partially offset by increased capital investment in higher margin assets in the Delaware and Powder River Basins.
Debt Activity, Net
During 2019, our debt decreased $162 million due to the repayment of our 6.30% senior notes at maturity.
During 2018, our debt decreased $922 million due to completed tender offers of certain long-term debt as well as the maturity of certain senior notes. In conjunction with the tender offers, we recognized a $312 million loss on the early retirement of debt, including $304 million of cash retirement costs and fees. For additional information, see Note 13 in “Item 8. Financial Statements and Supplementary Data” of this report.
Repurchases of Common Stock and Shareholder Distributions
We repurchased 68.6 million shares of common stock for $1.8 billion in 2019 and 78.1 million shares of common stock for $3.0 billion in 2018 under a share repurchase program authorized by our Board of Directors. For additional information, see Note 17 in “Item 8. Financial Statements and Supplementary Data” in this report.
Devon paid common stock dividends of $140 million, $149 million and $127 million during 2019, 2018 and 2017, respectively. During the second quarter of 2018, we increased our quarterly dividend 33% from $0.06 to $0.08 per share as part of our focus on returning cash to shareholders. In February 2019, we further increased our quarterly dividend 12.5% to $0.09 per share, beginning in the second quarter of 2019. For additional information, see Note 17 in “Item 8. Financial Statements and Supplementary Data” of this report.
Contributions from Noncontrolling Interests
During 2019, we received approximately $116 million in cash contributions from our partner in CDM.
Cash Flows from Discontinued Operations
All cash flows in the following table relate to activities from discontinued operations for the time periods presented. Discontinued operations include our aggregate ownership interests in EnLink and the General Partner that Devon divested in July 2018 and the Canadian business that Devon sold in June 2019. Discontinued operations also include the Barnett Shale assets that Devon has contracted to sell and which is expected to close during the second quarter of 2020, as well as previously divested Barnett Shale properties located primarily in Johnson and Wise counties, Texas.
| Year ended December 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2019 | 2018 | 2017 | ||||||||||
| Settlements of intercompany foreign denominated assets/liabilities | $ | (32 | ) | $ | (241 | ) | $ | 9 | ||||
| Other | 60 | 1,362 | 1,657 | |||||||||
| Operating activities | 28 | 1,121 | 1,666 | |||||||||
| Divestitures of property and equipment - Canadian operations | 2,608 | — | — | |||||||||
| Divestitures of investments - EnLink and General Partner | — | 3,104 | 190 | |||||||||
| Divestitures of property and equipment - Barnett Shale assets | — | 513 | — | |||||||||
| Capital expenditures and other | (136 | ) | (891 | ) | (1,156 | ) | ||||||
| Investing activities | 2,472 | 2,726 | (966 | ) | ||||||||
| Debt activity, net | (1,552 | ) | 347 | 2 | ||||||||
| Issuance of subsidiary units | — | 1 | 501 | |||||||||
| Distributions to noncontrolling interests | — | (217 | ) | (354 | ) | |||||||
| Other | (26 | ) | 43 | 33 | ||||||||
| Financing activities | (1,578 | ) | 174 | 182 | ||||||||
| Settlements of intercompany foreign denominated assets/liabilities | 32 | 241 | (9 | ) | ||||||||
| Other | 13 | (35 | ) | 15 | ||||||||
| Effect of exchange rate changes on cash | 45 | 206 | 6 | |||||||||
| Net change in cash, cash equivalents and restricted cash of discontinued operations | $ | 967 | $ | 4,227 | $ | 888 |
Operating cash flow in 2019 decreased $1.1 billion and $1.6 billion from 2018 and 2017, respectively, as a result of the divestitures referenced above. Additionally, operating cash flow was negatively affected in the first quarter of 2019 primarily due to realization impacts associated with the widening Canadian differentials in the fourth quarter of 2018. Foreign currency denominated intercompany loan activity resulted in a realized loss of $32 million and $241 million in 2019 and 2018, respectively, as a result of the strengthening of the U.S. dollar in relation to the Canadian dollar. Foreign currency denominated intercompany loan activity resulted in a realized gain of $9 million in 2017, as a result of the weakening of the U.S. dollar in relation to the Canadian dollar. There was an offset in the effect of exchange rate changes on cash line in the above table, resulting in no impact to the net change in cash, cash equivalents and restricted cash.
On June 27, 2019, Devon completed the sale of substantially all its oil and gas assets and operations in Canada for proceeds of $2.6 billion. In the second and fourth quarter of 2018, Devon completed the sale of a portion of its Barnett Shale assets, located primarily in Johnson and Wise counties, Texas for approximately $500 million in combined proceeds. On July 18, 2018, Devon completed the sale of its aggregate ownership interests in EnLink and the General Partner for $3.125 billion. During 2017, EnLink divested its ownership interest in Howard Energy Partners for approximately $190 million.
Cash flows from financing activities includes the $1.5 billion of senior notes retired prior to maturity in July 2019 and common and preferred units EnLink issued and sold during 2017 generating net proceeds of $501 million. Distributions to noncontrolling interests in the table above exclude the distributions EnLink and the General Partner paid to Devon, which have been eliminated in consolidation. Distributions EnLink and the General Partner paid to Devon were $134 million and $265 million during 2018 and 2017, respectively.
Liquidity
The business of exploring for, developing and producing oil and natural gas is capital intensive. Because oil, natural gas and NGL reserves are a depleting resource, we, like all upstream operators, must continually make capital investments to grow and even sustain production. Generally, our capital investments are focused on drilling and completing new wells and maintaining production
from existing wells. At opportunistic times, we also acquire operations and properties from other operators or land owners to enhance our existing portfolio of assets.
Historically, our primary sources of capital funding and liquidity have been our operating cash flow, cash on hand and asset divestiture proceeds. Additionally, we maintain a commercial paper program, supported by our revolving line of credit, which can be accessed as needed to supplement operating cash flow and cash balances. If needed, we can also issue debt and equity securities, including through transactions under our shelf registration statement filed with the SEC. We estimate the combination of our sources of capital will continue to be adequate to fund our planned capital requirements as discussed in this section.
Operating Cash Flow
Key inputs into determining our planned capital investment is the amount of cash we hold and operating cash flow we expect to generate over the next one to three or more years. At the end of 2019, we held approximately $1.8 billion of cash, inclusive of $380 million of cash restricted for discontinued operations. Our operating cash flow forecasts are sensitive to many variables and include a measure of uncertainty as these variables differ from our expectations.
Commodity Prices – The most uncertain and volatile variables for our operating cash flow are the prices of the oil, gas and NGLs we produce and sell. Prices are determined primarily by prevailing market conditions. Regional and worldwide economic activity, weather and other substantially variable factors influence market conditions for these products. These factors, which are difficult to predict, create volatility in prices and are beyond our control.
To mitigate some of the risk inherent in prices, we utilize various derivative financial instruments to protect a portion of our production against downside price risk. We hedge our production in a manner that systematically places hedges for several quarters in advance, allowing us to maintain a disciplined risk management program as it relates to commodity price volatility. We supplement the systematic hedging program with discretionary hedges that take advantage of favorable market conditions. The key terms to our oil, gas and NGL derivative financial instruments as of December 31, 2019 are presented in Note 3 in “Item 8. Financial Statements and Supplementary Data” of this report.
Further, when considering the current commodity price environment and our current hedge position, we expect to achieve our capital investment priorities. Should WTI drop closer to $45/Bbl for an extended period, we would shift our focus to preserving our financial strength and operational continuity. However, as WTI/Bbl rises above $50, our free cash flow will accelerate, providing additional capital allocation opportunities.
Operating Expenses – Commodity prices can also affect our operating cash flow through an indirect effect on operating expenses. Significant commodity price decreases can lead to a decrease in drilling and development activities. As a result, the demand and cost for people, services, equipment and materials may also decrease, causing a positive impact on our cash flow as the prices paid for services and equipment decline. However, the inverse is also generally true during periods of rising commodity prices.
In 2019, we aggressively optimized our cost structure in conjunction with our Canadian and Barnett Shale asset divestitures, as we focus on our remaining four U.S. oil plays, align our workforce with the retained business and reduce outstanding debt. These optimizations include cost reductions and efficiencies related to our capital programs, G&A, financing costs and production expenses.
Credit Losses – Our operating cash flow is also exposed to credit risk in a variety of ways. This includes the credit risk related to customers who purchase our oil, gas and NGL production, the collection of receivables from our joint interest partners for their proportionate share of expenditures made on projects we operate and counterparties to our derivative financial contracts. We utilize a variety of mechanisms to limit our exposure to the credit risks of our customers, partners and counterparties. Such mechanisms include, under certain conditions, requiring letters of credit, prepayments or collateral postings.
Divestitures of Property and Equipment
In December 2019, we announced the sale of our Barnett Shale assets for approximately $770 million. We expect this transaction to close in the second quarter of 2020.
Credit Availability
We have $3.0 billion of available borrowing capacity under our Senior Credit Facility at December 31, 2019. On December 13, 2019, we entered into an amendment and extension agreement to, among other things, (i) effect the extension of the maturity date of the Senior Credit Facility from October 5, 2023 to October 5, 2024 with respect to the consenting lenders and (ii) modify the maximum number of maturity extension requests during the term of the Senior Credit Facility from two to three. As a result of this amendment, the Senior Credit Facility matures on October 5, 2024, with the option to extend the maturity date by two additional one-year periods subject to lender consent. Subsequent to October 5, 2023, the borrowing capacity decreases to $2.8 billion. The Senior Credit Facility supports our $3.0 billion of short-term credit under our commercial paper program. As of December 31, 2019, there were no borrowings under our commercial paper program. See Note 13 in “Item 8. Financial Statements and Supplementary Data” of this report for further discussion.
The Senior Credit Facility contains only one material financial covenant. This covenant requires us to maintain a ratio of total funded debt to total capitalization, as defined in the credit agreement, of no more than 65%. As of December 31, 2019, we were in compliance with this covenant with a 19.1% debt-to-capitalization ratio.
Our access to funds from the Senior Credit Facility is not restricted under any “material adverse effect” clauses. It is not uncommon for credit agreements to include such clauses. These clauses can remove the obligation of the banks to fund the credit line if any condition or event would reasonably be expected to have a material and adverse effect on the borrower’s financial condition, operations, properties or business considered as a whole, the borrower’s ability to make timely debt payments or the enforceability of material terms of the credit agreement. While our credit facility includes covenants that require us to report a condition or event having a material adverse effect, the obligation of the banks to fund the credit facility is not conditioned on the absence of a material adverse effect.
As market conditions warrant and subject to our contractual restrictions, liquidity position and other factors, we may from time to time seek to repurchase or retire our outstanding debt through cash purchases and/or exchanges for other debt or equity securities in open market transactions, privately negotiated transactions, by tender offer or otherwise. Any such cash repurchases by us may be funded by cash on hand or incurring new debt. The amounts involved in any such transactions, individually or in the aggregate, may be material. Furthermore, any such repurchases or exchanges may result in our acquiring and retiring a substantial amount of such indebtedness, which would impact the trading liquidity of such indebtedness.
Debt Ratings
We receive debt ratings from the major ratings agencies in the U.S. In determining our debt ratings, the agencies consider a number of qualitative and quantitative items including, but not limited to, commodity pricing levels, our liquidity, asset quality, reserve mix, debt levels, cost structure, planned asset sales and production growth opportunities. Our credit rating from Standard and Poor’s Financial Services is BBB- with a stable outlook. Our credit rating from Fitch is BBB with a stable outlook. Our credit rating from Moody’s Investor Service is Ba1 with a positive outlook. Any rating downgrades may result in additional letters of credit or cash collateral being posted under certain contractual arrangements.
There are no “rating triggers” in any of our contractual debt obligations that would accelerate scheduled maturities should our debt rating fall below a specified level. However, a downgrade could adversely impact our interest rate on any credit facility borrowings and the ability to economically access debt markets in the future.
Share Repurchase Program
In December 2019, our Board of Directors approved a $1.0 billion share repurchase program that expires on December 31, 2020. This repurchase program was approved in conjunction with the announced divestiture of Devon’s assets in the Barnett Shale. Under this new program, $800 million of the $1.0 billion authorization is conditioned upon the closing of the pending Barnett Shale divestiture.
Capital Expenditures
Our 2020 exploration and development budget is expected to be approximately $1.7 billion to $1.85 billion.
In December 2019, we announced a partnership under which we will monetize half our working interest across 133 undrilled locations in the STACK for an approximate $100 million drilling carry spread over the next four years. Drilling operations under this agreement are expected to commence in mid-2020.
Contractual Obligations
The following table presents a summary of our contractual obligations as of December 31, 2019.
| Payments Due by Period | ||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Total | Less Than 1 Year | 1-3 Years | 3-5 Years | More Than 5 Years | ||||||||||||||||
| Continuing Operations | ||||||||||||||||||||
| Debt (1) | $ | 4,349 | $ | — | $ | — | $ | — | $ | 4,349 | ||||||||||
| Interest expense (2) | 4,513 | 259 | 518 | 518 | 3,218 | |||||||||||||||
| Operational agreements (3) | 1,468 | 320 | 431 | 301 | 416 | |||||||||||||||
| Asset retirement obligations (4) | 398 | 18 | 13 | 25 | 342 | |||||||||||||||
| Drilling and facility obligations (5) | 262 | 131 | 61 | 38 | 32 | |||||||||||||||
| Lease obligations (6) | 426 | 51 | 53 | 24 | 298 | |||||||||||||||
| Other (7) | 223 | 11 | 75 | 32 | 105 | |||||||||||||||
| Total | 11,639 | 790 | 1,151 | 938 | 8,760 | |||||||||||||||
| Discontinued Operations | ||||||||||||||||||||
| Barnett Shale obligations (8) | 271 | 35 | 63 | 46 | 127 | |||||||||||||||
| Canadian obligations (9) | 347 | 55 | 69 | 55 | 168 | |||||||||||||||
| Total | 618 | 90 | 132 | 101 | 295 | |||||||||||||||
| Total obligations | $ | 12,257 | $ | 880 | $ | 1,283 | $ | 1,039 | $ | 9,055 |
| (1) | Debt amounts represent scheduled maturities of debt obligations at December 31, 2019, excluding net discounts and debt issue costs included in the carrying value of debt. |
|---|
| (2) | Interest expense represents the scheduled cash payments on long-term fixed-rate debt. |
|---|
| (3) | Operational agreements represent commitments to transport or process certain volumes of oil, gas and NGLs for a fixed fee. We have entered into these agreements to aid the movement of our production to downstream markets. |
|---|
| (4) | Asset retirement obligations represent estimated discounted costs for future dismantlement, abandonment and rehabilitation costs. These obligations are recorded as liabilities on our December 31, 2019 balance sheet. |
|---|
| (5) | Drilling and facility obligations represent gross contractual agreements with third-party service providers to procure drilling rigs and other related services for developmental and exploratory drilling and facilities construction. |
|---|
| (6) | Lease obligations consist primarily of non-cancelable leases for office space and equipment. For additional information, see Note 14 in “Item 8. Financial Statements and Supplementary Data” of this report. |
|---|
| (7) | Other obligations primarily relate to various tax obligations. |
|---|
| (8) | Barnett Shale obligations primarily represent approximately $240 million of asset retirement obligations and firm transportation agreements which will be transferred to BKV when the divestiture of those assets close. The remainder of the Barnett Shale obligations relate to abandoned gas processing contracts which Devon retained in connection with the 2018 Barnett Shale divestitures. For additional information, see Note 18 in “Item 8. Financial Statements and Supplementary Data” of this report. |
|---|
| (9) | Canadian obligations are related to a firm transportation agreement and office lease abandonments that were retained after Devon’s sale of substantially all of its oil and gas assets and operations in Canada. For additional information, see Note 18 in “Item 8. Financial Statements and Supplementary Data” of this report. |
|---|
Contingencies and Legal Matters
For a detailed discussion of contingencies and legal matters, see Note 19 in “Item 8. Financial Statements and Supplementary Data” of this report.
Critical Accounting Estimates
The preparation of financial statements in conformity with accounting principles generally accepted in the U.S. requires us to make estimates, judgments and assumptions that affect the reported amounts of assets and liabilities and disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. Actual amounts could differ from these estimates, and changes in these estimates are recorded when known. We consider the following to be our most critical accounting estimates that involve judgment and have reviewed these critical accounting estimates with the Audit Committee of our Board of Directors.
Oil and Gas Assets Accounting, Classification, Reserves & Valuation
Successful Efforts Method of Accounting and Classification
We utilize the successful efforts method of accounting for our oil and natural gas exploration and development activities which requires management’s assessment of the proper designation of wells and associated costs as developmental or exploratory. This classification assessment is dependent on the determination and existence of proved reserves, which is a critical estimate discussed in the section below. The classification of developmental and exploratory costs has a direct impact on the amount of costs we initially recognize as exploration expense or capitalize, then subject to DD&A calculations and impairment assessments and valuations.
Once a well is drilled, the determination that proved reserves have been discovered may take considerable time and requires both judgment and application of industry experience. Development wells are always capitalized. Costs associated with drilling an exploratory well are initially capitalized, or suspended, pending a determination as to whether proved reserves have been found. At the end of each quarter, management reviews the status of all suspended exploratory drilling costs to determine whether the costs should continue to remain capitalized or shall be expensed. When making this determination, management considers current activities, near-term plans for additional exploratory or appraisal drilling and the likelihood of reaching a development program. If management determines future development activities and the determination of proved reserves are unlikely to occur, the associated suspended exploratory well costs are recorded as dry hole expense and reported in exploration expense in the consolidated statements of comprehensive earnings. Otherwise, the costs of exploratory wells remain capitalized. At December 31, 2019, all suspended well costs have been suspended for less than one year.
Similar to the evaluation of suspended exploratory well costs, costs for undeveloped leasehold, for which reserves have not been proven, must also be evaluated for continued capitalization or impairment. At the end of each quarter, management assesses undeveloped leasehold costs for impairment by considering future drilling plans, drilling activity results, commodity price outlooks, planned future sales or expiration of all or a portion of such projects. At December 31, 2019, Devon had approximately $250 million of undeveloped leasehold. Of the remaining undeveloped leasehold costs at December 31, 2019, approximately $6 million is scheduled to expire in 2020. The leasehold expiring in 2020 relates to areas in which Devon is actively drilling. If our drilling is not successful, this leasehold could become partially or entirely impaired.
Reserves
Our estimates of proved and proved developed reserves are a major component of DD&A calculations. Additionally, our proved reserves represent the element of these calculations that require the most subjective judgments. Estimates of reserves are forecasts based on engineering data, projected future rates of production and the timing of future expenditures. The process of estimating oil, gas and NGL reserves requires substantial judgment, resulting in imprecise determinations, particularly for new discoveries. Different reserve engineers may make different estimates of reserve quantities based on the same data. Our engineers prepare our reserve estimates. We then subject certain of our reserve estimates to audits performed by a third-party petroleum consulting firm. In 2019, 85% of our reserves were subjected to such audits.
The passage of time provides more qualitative information regarding estimates of reserves, when revisions are made to prior estimates to reflect updated information. In the past five years, annual performance revisions to our reserve estimates, which have been both increases and decreases in individual years, have averaged less than 5% of the previous year’s estimate. However, there can be no assurance that more significant revisions will not be necessary in the future. The data for a given reservoir may also change substantially over time as a result of numerous factors, including, but not limited to, additional development activity, evolving production history and continual reassessment of the viability of production under varying economic conditions.
Valuation of Long-Lived Assets
Long-lived assets used in operations, including proved and unproved oil and gas properties, are depreciated and assessed for impairment annually or whenever changes in facts and circumstances indicate a possible significant deterioration in future cash flows is expected to be generated by an asset group. For DD&A calculations and impairment assessments, management groups individual assets based on a judgmental assessment of the lowest level (“common operating field”) for which there are identifiable cash flows that are largely independent of the cash flows of other groups of assets. The determination of common operating fields is largely based on geological structural features or stratigraphic condition, which requires judgment. Management also considers the nature of production, common infrastructure, common sales points, common processing plants, common regulation and management oversight to make common operating field determinations. These determinations impact the amount of DD&A recognized each period and could impact the determination and measurement of a potential asset impairment.
Management evaluates assets for impairment through an established process in which changes to significant assumptions such as prices, volumes and future development plans are reviewed. If, upon review, the sum of the undiscounted pre-tax cash flows is less than the carrying value of the asset group, the carrying value is written down to estimated fair value. Because there usually is a lack of quoted market prices for long-lived assets, the fair value of impaired assets is typically determined based on the present values of expected future cash flows using discount rates believed to be consistent with those used by principal market participants. The expected future cash flows used for impairment reviews and related fair value calculations are typically based on judgmental assessments of future production volumes, commodity prices, operating costs and capital investment plans, considering all available information at the date of review. The expected future cash flows used for impairment reviews include future production volumes associated with proved producing and risk-adjusted proved undeveloped, probable and possible reserves. Besides the estimates of reserves and future production volumes, future commodity prices are the largest driver in the variability of undiscounted pre-tax cash flows. For our impairment determinations, we utilize the forward strip prices for the first five years and apply internally generated price forecasts for subsequent years. We estimate and escalate or de-escalate future capital and operating costs by using a method that correlates cost movements to price movements similar to recent history. Changes to any of these assumptions could result in lower undiscounted pre-tax cash flows and impact both the recognition and timing of impairments. Should management materially reduce planned capital investment and commodity prices remain depressed, recognition of material asset impairments could become more likely for certain of our assets.
As commodity prices decreased throughout 2019 and at year-end approximated the prices Devon used to determine and compute material asset impairments in 2019, management conducted a robust review of its assets for impairment as of December 31, 2019. Based on our recent impairment evaluations, our STACK asset’s sum of undiscounted pre-tax cash flows exceeds the carrying value by less than 10%. This cushion has narrowed significantly since the end of 2018 due primarily to approximately 30% and 5% declines in forward NGL and natural gas pricing, respectively, and negative non-price reserve revisions of approximately 40 MMBoe as discussed in Note 21 in “Item 8. Financial Statements and Supplementary Data” of this report. As of December 31, 2019, the difference between the STACK’s undiscounted pre-tax cash flows, which is used to determine whether an impairment exists, and the discounted pre-tax cash flows, which is used to measure an impairment, is approximately $2.0 billion. Therefore, if commodity prices deteriorate or we materially reduce future development plans, causing the capitalized costs to exceed the undiscounted pre-tax cash flows, our STACK asset would be subject to a material impairment of capitalized costs.
Income Taxes
The amount of income taxes recorded requires interpretations of complex rules and regulations of federal, state, provincial and foreign tax jurisdictions. We recognize current tax expense based on estimated taxable income for the current period and the applicable statutory tax rates. We routinely assess potential uncertain tax positions and, if required, estimate and establish accruals for such amounts. We have recognized deferred tax assets and liabilities for temporary differences, operating losses and other tax carryforwards. We routinely assess our deferred tax assets and reduce such assets by a valuation allowance if we deem it is more likely than not that some portion or all of the deferred tax assets will not be realized. Within continuing operations, Devon maintains only a valuation allowance against a portion of its deferred tax assets, including certain tax credits and state net operating losses. Devon also has recorded a valuation allowance in discontinued operations against certain Canadian deferred tax assets.
The accruals for deferred tax assets and liabilities are often based on assumptions that are subject to a significant amount of judgment by management. These assumptions and judgments are reviewed and adjusted as facts and circumstances change. Material changes to our income tax accruals may occur in the future based on the progress of ongoing audits, changes in legislation or resolution of pending matters.
Non-GAAP Measures
Core Earnings
We make reference to “core earnings (loss) attributable to Devon” and “core earnings (loss) per share attributable to Devon” in “Overview of 2019 Results” in this Item 7 that are not required by or presented in accordance with GAAP. These non-GAAP measures are not alternatives to GAAP measures and should not be considered in isolation or as a substitute for analysis of our results reported under GAAP. Core earnings (loss) attributable to Devon, as well as the per share amount, represent net earnings excluding certain noncash and other items that are typically excluded by securities analysts in their published estimates of our financial results. For more information on the results of discontinued operations for our Barnett Shale assets, Canadian operations and for EnLink and the General Partner, see Note 18 in “Item 8. Financial Statements and Supplementary Data” in this report. Our non-GAAP measures are typically used as a quarterly performance measure. Amounts excluded for 2019 relate to asset dispositions, the gain on the sale of Canadian operations, noncash asset impairments (including noncash Barnett Shale and unproved asset impairments), deferred tax asset valuation allowance, costs associated with early retirement of debt, fair value changes in derivative financial instruments and foreign currency, restructuring and transaction costs associated with the workforce reductions in 2019 and restructuring and transaction costs associated with the divestment of our Canadian operations in 2019.
Amounts excluded for 2018 relate to asset dispositions, the gain on the sale of Devon’s aggregate ownership interests in EnLink and the General Partner, noncash asset impairments (including noncash unproved asset impairments), deferred tax asset valuation allowance, costs associated with early retirement of debt, fair value changes in derivative financial instruments and foreign currency, restructuring and transaction costs associated with the workforce reductions in 2018.
Amounts excluded for 2017 relate to asset dispositions, noncash asset impairments (including noncash unproved asset impairments), U.S. tax reform changes, deferred tax asset valuation allowance, derivatives and financial instrument fair value changes, legal entity restructuring and costs associated with early retirement of debt.
We believe these non-GAAP measures facilitate comparisons of our performance to earnings estimates published by securities analysts. We also believe these non-GAAP measures can facilitate comparisons of our performance between periods and to the performance of our peers.
Below are reconciliations of our core earnings and earnings per share to their comparable GAAP measures.
| Before tax | After tax | After Noncontrolling Interests | Per Diluted Share | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2019 | |||||||||||||||
| Continuing Operations | |||||||||||||||
| Loss attributable to Devon (GAAP) | $ | (109 | ) | $ | (79 | ) | $ | (81 | ) | $ | (0.21 | ) | |||
| Adjustments: | |||||||||||||||
| Asset dispositions | (48 | ) | (37 | ) | (37 | ) | (0.09 | ) | |||||||
| Asset and exploration impairments | 20 | 15 | 15 | 0.04 | |||||||||||
| Fair value changes in financial instruments | 623 | 480 | 480 | 1.19 | |||||||||||
| Restructuring and transaction costs | 84 | 64 | 64 | 0.15 | |||||||||||
| Core earnings attributable to Devon (Non-GAAP) | $ | 570 | $ | 443 | $ | 441 | $ | 1.08 | |||||||
| Discontinued Operations | |||||||||||||||
| Loss attributable to Devon (GAAP) | $ | (632 | ) | $ | (274 | ) | $ | (274 | ) | $ | (0.68 | ) | |||
| Adjustments: | |||||||||||||||
| Gain on sale of Canadian operations | (223 | ) | (425 | ) | (425 | ) | (1.05 | ) | |||||||
| Asset and exploration impairments | 785 | 613 | 613 | 1.52 | |||||||||||
| Deferred tax asset valuation allowance | — | 24 | 24 | 0.06 | |||||||||||
| Early retirement of debt | 58 | 45 | 45 | 0.11 | |||||||||||
| Fair value changes in financial instruments and foreign currency and other | (33 | ) | (37 | ) | (37 | ) | (0.10 | ) | |||||||
| Restructuring and transaction costs | 248 | 183 | 183 | 0.45 | |||||||||||
| Core earnings attributable to Devon (Non-GAAP) | $ | 203 | $ | 129 | $ | 129 | $ | 0.31 | |||||||
| Total | |||||||||||||||
| Loss attributable to Devon (GAAP) | $ | (741 | ) | $ | (353 | ) | $ | (355 | ) | $ | (0.89 | ) | |||
| Adjustments: | |||||||||||||||
| Continuing Operations | 679 | 522 | 522 | 1.29 | |||||||||||
| Discontinued Operations | 835 | 403 | 403 | 0.99 | |||||||||||
| Core earnings attributable to Devon (Non-GAAP) | $ | 773 | $ | 572 | $ | 570 | $ | 1.39 | |||||||
| 2018 | |||||||||||||||
| Continuing Operations | |||||||||||||||
| Earnings attributable to Devon (GAAP) | $ | 944 | $ | 714 | $ | 714 | $ | 1.42 | |||||||
| Adjustments: | |||||||||||||||
| Asset dispositions | (278 | ) | (214 | ) | (214 | ) | (0.42 | ) | |||||||
| Asset and exploration impairments | 257 | 198 | 198 | 0.40 | |||||||||||
| Deferred tax asset valuation allowance | — | (4 | ) | (4 | ) | (0.01 | ) | ||||||||
| Early retirement of debt | 312 | 240 | 240 | 0.48 | |||||||||||
| Fair value changes in financial instruments | (938 | ) | (723 | ) | (723 | ) | (1.45 | ) | |||||||
| Restructuring and transaction costs | 97 | 76 | 76 | 0.15 | |||||||||||
| Core earnings attributable to Devon (Non-GAAP) | $ | 394 | $ | 287 | $ | 287 | $ | 0.57 | |||||||
| Discontinued Operations | |||||||||||||||
| Earnings attributable to Devon (GAAP) | $ | 2,839 | $ | 2,510 | $ | 2,350 | $ | 4.68 | |||||||
| Adjustments: | |||||||||||||||
| Asset dispositions | (2,593 | ) | (2,250 | ) | (2,250 | ) | (4.49 | ) | |||||||
| Fair value changes in financial instruments and foreign currency | 339 | 277 | 270 | 0.54 | |||||||||||
| Minimum volume commitment and restructuring and transaction costs | (31 | ) | (27 | ) | (2 | ) | (0.00 | ) | |||||||
| Core earnings attributable to Devon (Non-GAAP) | $ | 554 | $ | 510 | $ | 368 | $ | 0.73 | |||||||
| Total | |||||||||||||||
| Earnings attributable to Devon (GAAP) | $ | 3,783 | $ | 3,224 | $ | 3,064 | $ | 6.10 | |||||||
| Adjustments: | |||||||||||||||
| Continuing Operations | (550 | ) | (427 | ) | (427 | ) | (0.85 | ) | |||||||
| Discontinued Operations | (2,285 | ) | (2,000 | ) | (1,982 | ) | (3.95 | ) | |||||||
| Core earnings attributable to Devon (Non-GAAP) | $ | 948 | $ | 797 | $ | 655 | $ | 1.30 |
| Before tax | After tax | After Noncontrolling Interests | Per Diluted Share | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2017 | |||||||||||||||
| Continuing Operations | |||||||||||||||
| Earnings attributable to Devon (GAAP) | $ | 40 | $ | 33 | $ | 33 | $ | 0.06 | |||||||
| Adjustments: | |||||||||||||||
| Asset dispositions | (219 | ) | (140 | ) | (140 | ) | (0.27 | ) | |||||||
| Asset and exploration impairments | 217 | 138 | 138 | 0.26 | |||||||||||
| Deferred tax asset valuation allowance | — | (4 | ) | (4 | ) | (0.01 | ) | ||||||||
| Fair value changes in financial instruments | 70 | 45 | 45 | 0.09 | |||||||||||
| Core earnings attributable to Devon (Non-GAAP) | $ | 108 | $ | 72 | $ | 72 | $ | 0.13 | |||||||
| Discontinued Operations | |||||||||||||||
| Earnings attributable to Devon (GAAP) | $ | 856 | $ | 1,045 | $ | 865 | $ | 1.64 | |||||||
| Adjustments: | |||||||||||||||
| U.S. tax reform | — | (211 | ) | (112 | ) | (0.21 | ) | ||||||||
| Fair value changes in financial instruments and foreign currency | (289 | ) | (248 | ) | (248 | ) | (0.47 | ) | |||||||
| Asset dispositions, impairments and early retirement of debt | 11 | 9 | 7 | 0.01 | |||||||||||
| Legal entity restructuring and deferred tax asset valuation allowance | — | (157 | ) | (157 | ) | (0.29 | ) | ||||||||
| Core earnings attributable to Devon (Non-GAAP) | $ | 578 | $ | 438 | $ | 355 | $ | 0.68 | |||||||
| Total | |||||||||||||||
| Earnings attributable to Devon (GAAP) | $ | 896 | $ | 1,078 | $ | 898 | $ | 1.70 | |||||||
| Adjustments: | |||||||||||||||
| Continuing Operations | 68 | 39 | 39 | 0.07 | |||||||||||
| Discontinued Operations | (278 | ) | (607 | ) | (510 | ) | (0.96 | ) | |||||||
| Core earnings attributable to Devon (Non-GAAP) | $ | 686 | $ | 510 | $ | 427 | $ | 0.81 |
EBITDAX and Field-Level Cash Margin
To assess the performance of our assets, we use EBITDAX and Field-Level Cash Margin. We compute EBITDAX as net earnings from continuing operations before income tax expense; financing costs, net; exploration expenses; DD&A; asset impairments; asset disposition gains and losses; non-cash share-based compensation; non-cash valuation changes for derivatives and financial instruments; restructuring and transaction costs; accretion on discounted liabilities; and other items not related to our normal operations. Field-Level Cash Margin is computed as oil, gas and NGL revenues less production expenses. Production expenses consist of lease operating, gathering, processing and transportation expenses, as well as production and property taxes.
We exclude financing costs from EBITDAX to assess our operating results without regard to our financing methods or capital structure. Exploration expenses and asset disposition gains and losses are excluded from EBITDAX because they generally are not indicators of operating efficiency for a given reporting period. DD&A and impairments are excluded from EBITDAX because capital expenditures are evaluated at the time capital costs are incurred. We exclude share-based compensation, valuation changes, restructuring and transaction costs, accretion on discounted liabilities and other items from EBITDAX because they are not considered a measure of asset operating performance.
We believe EBITDAX and Field-Level Cash Margin provide information useful in assessing our operating and financial performance across periods. EBITDAX and Field-Level Cash Margin as defined by Devon may not be comparable to similarly titled measures used by other companies and should be considered in conjunction with net earnings from continuing operations.
Below are reconciliations of net earnings to EBITDAX and a further reconciliation to Field-Level Cash Margin.
| 2019 | 2018 | 2017 | |||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|
| Net earnings (loss) (GAAP) | $ | (353 | ) | $ | 3,224 | $ | 1,078 | ||||
| Net (earnings) loss from discontinued operations, net of tax | 274 | (2,510 | ) | (1,045 | ) | ||||||
| Financing costs, net | 250 | 580 | 321 | ||||||||
| Income tax expense (benefit) | (30 | ) | 230 | 7 | |||||||
| Exploration expenses | 58 | 128 | 346 | ||||||||
| Depreciation, depletion and amortization | 1,497 | 1,228 | 1,008 | ||||||||
| Asset impairments | — | 156 | — | ||||||||
| Asset dispositions | (48 | ) | (278 | ) | (219 | ) | |||||
| Share-based compensation | 83 | 104 | 121 | ||||||||
| Derivative and financial instrument non-cash valuation changes | 623 | (938 | ) | 70 | |||||||
| Restructuring and transaction costs | 84 | 97 | — | ||||||||
| Accretion on discounted liabilities and other | 5 | 54 | (12 | ) | |||||||
| EBITDAX (non-GAAP) | 2,443 | 2,075 | 1,675 | ||||||||
| Marketing revenues and expenses, net | (53 | ) | (33 | ) | 46 | ||||||
| Commodity derivative cash settlements | (170 | ) | 420 | (115 | ) | ||||||
| General and administration expenses, cash-based | 392 | 470 | 524 | ||||||||
| Field-level cash margin (non-GAAP) | $ | 2,612 | $ | 2,932 | $ | 2,130 |
Previous: Item 6. Selected Financial Data · Next: Item 7A. Quantitative and Qualitative Disclosures about Market Risk