 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
54K characters. Original on sec.gov ·
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
This document, including the following Management’s Discussion and Analysis of Financial Condition and Results of Operations, contains forward-looking statements that are not purely historical regarding Dexcom’s or its management’s intentions, beliefs, expectations and strategies for the future. These forward-looking statements fall within the meaning of the federal securities laws that relate to future events or our future financial performance. In some cases, you can identify forward-looking statements by terminology such as “may,” “will,” “expect,” “plan,” “anticipate,” “believe,” “estimate,” “intend,” “potential” or “continue” or the negative of these terms or other comparable terminology. Forward-looking statements are made as of the date of this report, deal with future events, are subject to various risks and uncertainties, and actual results could differ materially from those anticipated in those forward looking statements. The risks and uncertainties include, among other things, impacts on our business due to health pandemics or other contagious outbreaks, such as the current COVID-19 pandemic. The risks and uncertainties that could cause actual results to differ materially are more fully described under “Risk Factors” and elsewhere in this report and in our other reports filed with the SEC. We assume no obligation to update any of the forward-looking statements after the date of this report or to conform these forward-looking statements to actual results. You should read the following discussion and analysis together with our consolidated financial statements and related notes in Part II, Item 8 of this Annual Report.
| Overview |
| WHO WE ARE |  | ||||||||||
| We are a medical device company primarily focused on the design, development and commercialization of continuous glucose monitoring, or CGM, systems for the management of diabetes by patients, caregivers, and clinicians around the world. We received approval from the Food and Drug Administration, or FDA, and commercialized our first product in 2006. We launched our latest generation system, the Dexcom G6*®* integrated Continuous Glucose Monitoring System, or G6, in 2018. Unless the context requires otherwise, the terms “we,” “us,” “our,” the “company,” or “Dexcom” refer to DexCom, Inc. and its subsidiaries. | |||||||||||
 | Global Presence | |||||||
| We have built a direct sales organization in the United States, Australia, Canada, New Zealand, and certain countries in Europe to call on health care professionals, such as endocrinologists, physicians and diabetes educators, who can educate and influence patient adoption of continuous glucose monitoring. To complement our direct sales efforts, we have entered into distribution arrangements in the United States, and certain countries in Africa, Asia, Europe, Latin America, and the Middle East, as well as Australia, Canada, and New Zealand that allow distributors to sell our products. | ||||||||
 | ||||||||
 | Future Developments | |||||||
| Product Development: We plan to develop future generations of technologies that are focused on improved performance and convenience and that will enable intelligent insulin administration. Over the longer term, we plan to continue to develop and improve networked platforms with open architecture, connectivity and transmitters capable of communicating with other devices. We also intend to expand our efforts to accumulate CGM patient data and metrics and apply predictive modeling and machine learning to generate interactive CGM insights that can inform patient behavior. | ||||||||
| Partnerships: We also continue to pursue and support development partnerships with insulin pump companies and companies or institutions developing insulin delivery systems, including automated insulin delivery systems. | ||||||||
| New Opportunities: We are also exploring how to extend our offerings to other opportunities, including for people with Type 2 diabetes that are non-insulin using, people with pre-diabetes, people who are obese, people who are pregnant, and people in the hospital setting. Eventually, we may apply our technological expertise to products beyond glucose monitoring. | ||||||||
 | ||||||||||||||
 | Impact of COVID-19 Pandemic | |||||||||||||
| During 2020 and 2021, we have been subject to challenging social and economic conditions created as a result of the novel strain of coronavirus, SARS-CoV-2, or COVID-19. These conditions continue to create various financial impacts to our operations by necessitating precautions for our personnel to operate safely both in person as well as remotely. Costs incurred include items like incremental payroll costs, consulting support, IT infrastructure and facilities-related costs. | ||||||||||||||
| As the result of the COVID-19 pandemic, we made Dexcom CGM systems available for use in hospital settings and other healthcare facilities to assist frontline workers. The extent of the impact of the COVID-19 pandemic on our operational and financial performance will depend on certain developments, including the duration and spread of the outbreak, impact on our customers and our sales cycles, employee or industry events, and effect on our vendors, all of which are uncertain and cannot be predicted. The COVID-19 pandemic and its adverse effects have become more prevalent in the locations where we, our customers, suppliers or third-party business partners conduct business and as a result, we have experienced moderate disruptions in our global operations. We have experienced and may experience constrained supply or curtailed customer demand, including due to customer loss of private health insurance coverage for our products, that could materially adversely impact our business, results of operations and overall financial performance in future periods. We currently utilize third parties to, among other things, manufacture components and materials for our devices, and to provide services such as sterilization services and we purchase these materials and services from numerous suppliers worldwide. | ||||||||||||||
| The COVID-19 pandemic has and may continue to have an adverse impact on our manufacturing and distribution capabilities. Disruptions relating to the COVID-19 pandemic, including shelter-in-place orders in the U.S. and other countries, could prevent employees, suppliers, distributors, and others from accessing manufacturing facilities and from transporting our products or the components required to manufacture our products. For example, we have experienced some supply chain disruption due to the global restrictions resulting from the COVID-19 pandemic in the manufacturing of our next-generation CGM product. Further, worldwide supply chain disruption relating to the COVID-19 pandemic has resulted in product shortages that has and may continue to impact our ability to manufacture our devices. As of the filing date of this Annual Report, the extent to which COVID-19 may impact our financial condition or results of operations or guidance is uncertain. The effect of the COVID-19 pandemic will not be fully reflected in our results of operations and overall financial performance until future periods. See “Risk Factors” in Part I, Item 1A of this Annual Report for further discussion of the possible impact of the COVID-19 pandemic on our business. |
| Critical Accounting Estimates |
The discussion and analysis of our financial condition and results of operations are based on our consolidated financial statements, which we have prepared in accordance with U.S. GAAP. The preparation of these consolidated financial statements requires us to make estimates and assumptions that affect the reported amounts of assets and liabilities and the disclosure of contingent assets and liabilities at the date of the consolidated financial statements as well as the reported revenue and expenses during the reporting periods. On an ongoing basis, we evaluate our estimates and judgments. We base our estimates on historical experience and on various other factors that we believe are reasonable under the circumstances, the results of which form the basis for making judgments about the carrying value of assets and liabilities that are not readily apparent from other sources. Variability reflected in the sensitivity analysis presented below is based on our recent historical experience. Actual results may differ from these estimates under different assumptions or conditions.
While our significant accounting policies are described in Note 1 to the consolidated financial statements in Part II, Item 8 of this Annual Report, we believe that the following accounting estimates are most critical to a full understanding and evaluation of our reported financial results. Members of our senior management have discussed the development and selection of these critical accounting estimates and their disclosure in this Annual Report with the Audit Committee of our Board of Directors.
Pharmacy Rebates
We estimate provisions for pharmacy rebates based on contractual arrangements, estimates of products sold subject to rebate, known events or trends and channel inventory data. Estimates associated with rebates on products sold through our distributors under pharmacy benefits are the most significant component of our variable consideration estimates and most at risk for material adjustment because of the time delay between the recording of the accrual estimate and its ultimate settlement, an interval that generally ranges from 30 to 90 days, but can last up to one year. Due to this time lag, in any given period, our adjustments to reflect actual amounts can incorporate changes of estimates related to prior periods.
Historically, adjustments to these estimates to reflect actual results or updated expectations, have not been material to our overall business and generally have been less than 1% of revenue. An increase or decrease of 1% in our estimate of products sold subject to rebate during 2021, holding all other assumptions constant, would increase or decrease revenue by approximately $11.5 million.
For more information, see Revenue Recognition in Note 1 to the consolidated financial statements in Part II, Item 8 of this Annual Report.
Excess and Obsolete Inventory
We assess the value of our inventory on a quarterly basis and write down those inventories based on quality control testing data, obsolescence, or in excess of our forecasted demand to the lower of their cost or net realizable value. Our estimates of forecasted demand are based upon our analysis and assumptions including, but not limited to, expected product lifecycles, product development plans and historical usage by product. If actual market conditions are less favorable than our forecasts, or actual demand from our customers is lower than our estimates, we may be required to record additional inventory write-downs. If actual market conditions are more favorable than anticipated, inventory previously written down may be sold, resulting in lower cost of sales and higher income from operations than expected in that period.
Income Taxes
We estimate our income taxes based on the various jurisdictions where we conduct business. Significant judgment is required in determining our worldwide income tax provision. The calculation of our tax liabilities involves dealing with uncertainties in the application of complex tax laws and regulations and the potential for future adjustment of our uncertain tax positions by the Internal Revenue Service or other taxing jurisdictions. While we believe we have appropriate support for the positions taken on our tax returns, we regularly assess the potential outcomes of examinations by tax authorities in determining the adequacy of our provision for income taxes. We continually assess the likelihood and amount of potential adjustments and adjust the income tax provision, income taxes payable, and deferred taxes in the period in which the facts that give rise to a revision become known.
We use the asset and liability approach to recognize deferred tax assets and liabilities for the expected future tax consequences of temporary differences between the carrying amounts and the tax basis of assets and liabilities as described in Note 1 to the consolidated financial statements in Part II, Item 8 of this Annual Report. Significant judgment is required to evaluate the need for a valuation allowance against deferred tax assets. A valuation allowance is established when it is more likely than not that some or all of the deferred tax assets will not be realized. Realization of deferred tax assets is dependent upon future earnings in applicable tax jurisdictions. We maintain a valuation allowance on our California research and
development tax credits, foreign tax credits, and certain foreign intangible assets, as it is more likely than not that those deferred tax assets will not be realized.
We recognize and measure benefits for uncertain tax positions using a two-step approach as described in Note 1 to the consolidated financial statements in Part II, Item 8 of this Annual Report. Significant judgment is required to evaluate uncertain tax positions and is based upon a number of factors, including changes in facts or circumstances, changes in tax law, correspondence with tax authorities during the course of audits and effective settlement of audit issues. Changes in the recognition or measurement of uncertain tax positions could result in material increases or decreases in our income tax expense in the period in which we make the change, which could have a material impact on our effective tax rate and operating results.
Loss Contingencies
We are subject to certain legal proceedings, as well as demands, claims and threatened litigation that arise in the normal course of our business. We review the status of each significant matter quarterly and assess our potential financial exposure. Significant judgment is required in the determination of whether a potential loss is probable, reasonably possible, or remote as well as in the determination of whether a potential exposure is reasonably estimable. We base our judgments on the best information available at the time. As additional information becomes available, we reassess the potential liability related to our pending claims and litigation and may revise our estimates. Any revision of our estimates of potential liability could have a material impact on our financial position and operating results.
| Overview of Financial Results | ||||||||||||||||||||||||||||||||||||||
| The most important financial indicators that we use to assess our business are revenue growth, gross profit, operating income, net income, and cash flow from operations. | ||||||||||||||||||||||||||||||||||||||
| Key highlights for fiscal 2021 include the following: | ||||||||||||||||||||||||||||||||||||||
| Revenue | Gross Profit | Operating Income | Net Income | Operating Cash Flow | ||||||||||||||||||||||||||||||||||
| $2.45 billion | $1.68 billion | $265.8 million | $154.7 million | $442.5 million | ||||||||||||||||||||||||||||||||||
| up 27% from 2020 | up 31% from 2020 | down 11% from 2020 | down 69% from 2020 | down 7% from 2020 | ||||||||||||||||||||||||||||||||||
We ended fiscal 2021 with cash, cash equivalents and short-term marketable securities totaling $2.73 billion.
| Business Trends |
In addition to the general impacts of COVID-19 on our company as described in the Overview, looking ahead we expect our business could be affected by the following:
-
Increase in the worldwide incidence of people diagnosed with diabetes and costs related to the management and treatment of diabetes.
-
Changes in medical reimbursement policies and programs.
-
Growing demand for digital health technologies by both healthcare providers and consumers to reduce costs, empower consumers to make better-informed decisions about their own health and provide new options for facilitating prevention, early diagnosis of life-threatening diseases, and management of chronic conditions outside of traditional health care settings.
-
Continued product innovation and competition from other CGM device makers.
-
Our ability to scale efficiently with the construction of our production facility in Malaysia.
*•*Our ability to successfully develop, obtain regulatory approval of and commercialize the products within our pipeline, in particular, our next generation G7 CGM system.
| Results of Operations |
| Financial Overview |
For discussion related to the results of operations and changes in financial condition for fiscal 2020 compared to fiscal 2019 refer to “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in Part II, Item 7 of our 2020 Annual Report on Form 10-K, which was filed with the United States Securities and Exchange Commission on February 11, 2021.
| Twelve Months Ended December 31, 2021 Compared to Twelve Months Ended December 31, 2020 | |||||||||||||||||||||||||||||||||||
| Twelve Months Ended December 31, | 2021 - 2020 | ||||||||||||||||||||||||||||||||||
| (In millions, except per share amounts) | 2021 | % of Revenue (1) | 2020 | % of Revenue (1) | $ Change | % Change | |||||||||||||||||||||||||||||
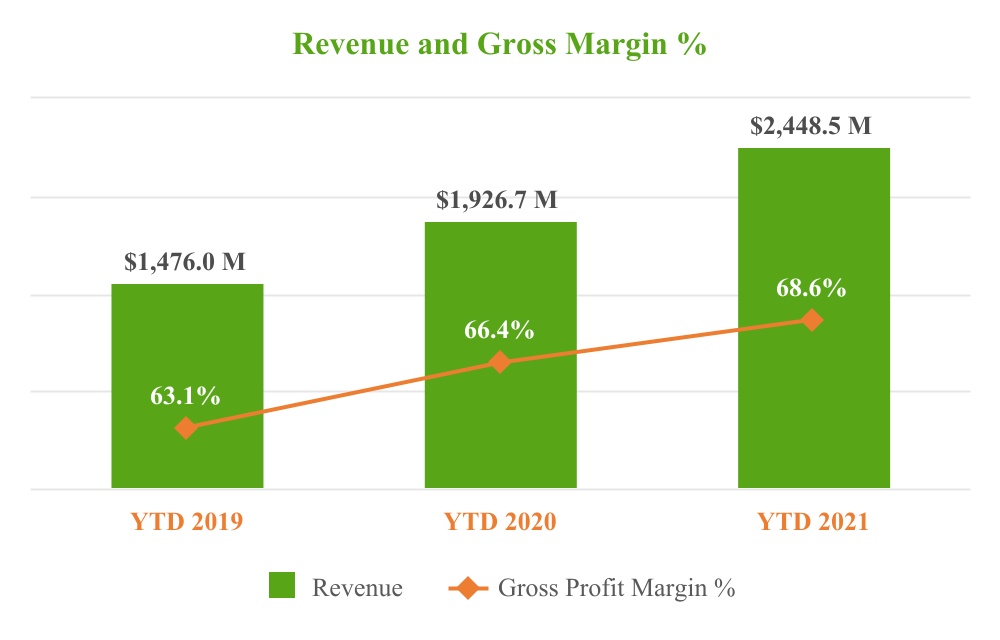
| Revenue | $ | 2,448.5 | 100 | % | $ | 1,926.7 | 100 | % | $ | 521.8 | 27 | % | |||||||||||||||||||||||
| Cost of sales | 768.0 | 31 | % | 646.6 | 34 | % | 121.4 | 19 | % | ||||||||||||||||||||||||||
| Gross profit | 1,680.5 | 68.6 | % | 1,280.1 | 66.4 | % | 400.4 | 31 | % | ||||||||||||||||||||||||||
| Operating expenses: | |||||||||||||||||||||||||||||||||||
| Research and development | 517.1 | 21 | % | 359.9 | 19 | % | 157.2 | 44 | % | ||||||||||||||||||||||||||
| Collaborative research and development fee | 87.1 | 4 | % | — | — | % | 87.1 | * | |||||||||||||||||||||||||||
| Selling, general and administrative | 810.5 | 33 | % | 620.7 | 32 | % | 189.8 | 31 | % | ||||||||||||||||||||||||||
| Total operating expenses | 1,414.7 | 58 | % | 980.6 | 51 | % | 434.1 | 44 | % | ||||||||||||||||||||||||||
| Operating income | 265.8 | 11 | % | 299.5 | 16 | % | (33.7) | (11) | % | ||||||||||||||||||||||||||
| Interest expense | (100.3) | (4) | % | (84.7) | (4) | % | (15.6) | 18 | % | ||||||||||||||||||||||||||
| Loss on extinguishment of debt | (1.5) | — | % | (5.9) | — | % | 4.4 | (75) | % | ||||||||||||||||||||||||||
| Income from equity investments | 11.6 | — | % | — | — | % | 11.6 | * | |||||||||||||||||||||||||||
| Interest and other income (expense), net | (1.7) | — | % | 16.1 | 1 | % | (17.8) | * | |||||||||||||||||||||||||||
| Income before income taxes | 173.9 | 7 | % | 225.0 | 12 | % | (51.1) | (23) | % | ||||||||||||||||||||||||||
| Income tax expense (benefit) | 19.2 | 1 | % | (268.6) | (14) | % | 287.8 | * | |||||||||||||||||||||||||||
| Net income | $ | 154.7 | 6 | % | $ | 493.6 | 26 | % | $ | (338.9) | (69) | % | |||||||||||||||||||||||
| (1) The sum of the individual percentages may not equal the total due to rounding. | |||||||||||||||||||||||||||||||||||
| * Not meaningful |
Revenue
We expect that revenue we generate from the sales of our products will fluctuate from quarter to quarter. We typically experience seasonality, with lower sales in the first quarter of each year compared to the immediately preceding fourth quarter. This seasonal sales pattern relates to U.S. annual insurance deductible resets and unfunded flexible spending accounts.
Cost of Sales
Cost of sales includes direct labor and materials costs related to each product sold or produced, including assembly, test labor and scrap, as well as factory overhead supporting our manufacturing operations. Factory overhead includes facilities, material procurement and control, manufacturing engineering, quality assurance, supervision and management. These costs are primarily salary, fringe benefits, share-based compensation, facility expense, supplies and purchased services. All of our manufacturing costs are included in cost of sales.
Research and Development
Our research and development expenses primarily consist of engineering and research expenses related to our continuous glucose monitoring technology, clinical trials, regulatory expenses, quality assurance programs, materials and products for clinical trials. Research and development expenses are primarily related to employee compensation, including salary, fringe benefits, share-based compensation, and temporary employee expenses. We also incur significant expenses to operate our clinical trials including clinical site reimbursement, clinical trial product and associated travel expenses. Our research and development expenses also include fees for design services, contractors and development materials.
Selling, General and Administrative
Our selling, general and administrative expenses primarily consist of salary, fringe benefits and share-based compensation for our executive, financial, sales, marketing, information technology and administrative functions. Other significant expenses include commissions, marketing and advertising, IT software license costs, insurance, professional fees for our outside legal counsel and independent auditors, litigation expenses, patent application expenses and consulting expenses.
| Twelve Months Ended December 31, 2021 Compared to Twelve Months Ended December 31, 2020 | ||||||||
| Revenue | The revenue increase was primarily driven by increased sales volume of our disposable sensors due to the continued growth of our worldwide customer base, partially offset by mix shift and price associated with the evolution of our channel strategy. Disposable sensor and other revenue comprised approximately 84% of total revenue and Reusable Hardware revenue comprised approximately 16% of total revenue for the twelve months ended December 31, 2021. Disposable sensor and other revenue comprised approximately 81% of total revenue and Reusable Hardware revenue comprised approximately 19% of total revenue for the twelve months ended December 31, 2020. | |||||||
| Cost of Sales & Gross Profit | Cost of sales increased primarily due to an increase in sales volume. The increase in gross profit and gross profit margin in 2021 compared to 2020 were primarily driven by increased revenue and cost savings associated with incremental improvements to product design, manufacturing efficiencies and economies of scale. | |||||||
| Research and Development Expense | Research and development expense increased primarily due to $62.7 million in additional third party and consulting fees primarily related to software development for new products and significant enhancements, $49.1 million in additional salaries, bonuses, and payroll-related costs primarily due to higher headcount, and $13.2 million in additional clinical trials costs related to pivotal trials. We continue to believe that focused investments in research and development are critical to our future growth and competitive position in the marketplace, and to the development of new and updated products and services that are central to our core business strategy. | |||||||
| Collaborative Research and Development Fee | Collaborative research and development fees of $87.1 million for the twelve months ended December 31, 2021 represents expense incurred in the fourth quarter of 2021 associated with a contingent milestone under the 2018 collaboration and license agreement with Verily. See Note 2 “Development and Other Agreements” to the consolidated financial statements in Part II, Item 8 of this Annual Report for more information. | |||||||
| Selling, General and Administrative Expense | Selling, general and administrative expense increased primarily due to $84.0 million in additional advertising and marketing costs due to an increase in worldwide marketing campaigns, $60.5 million in additional salaries, bonuses, and payroll-related costs primarily due to higher headcount primarily related to an expansion in our sales force, $16.3 million in additional legal expense related to litigation, $7.4 million of investments in customer experience, partially offset by $12.9 million in lower third party service provider fees due to a change in our channel strategy. | |||||||
| Loss on Extinguishment of Debt | The loss on extinguishment of debt of $1.5 million and $5.9 million is primarily related to the conversions and/or repurchases of our senior convertible notes for the twelve months ended December 31, 2021 and December 31, 2020, respectively. See Note 5 “Debt” to the consolidated financial statements in Part II, Item 8 of this Annual Report for more information about these transactions. | |||||||
| Income from Equity Investments | Income from equity investments of $11.6 million for the twelve months ended December 31, 2021 consisted solely of realized gains from the sale of an equity investment. | |||||||
| Interest Expense | Interest expense is comprised primarily of costs related to our senior convertible notes. Interest expense increased primarily due to the May 2020 issuance of our 2025 Notes. | |||||||
| Interest and Other Income (Expense), Net | Interest and other income (expense), net, consists primarily of interest income on our short-term marketable securities portfolio and foreign currency transaction gains and losses due to the effects of foreign currency fluctuations. The decrease in interest income was primarily related to a decline in market interest rates. | |||||||
| Income Tax Expense (Benefit) | We recorded pre-tax income for the twelve months ended December 31, 2021 and December 31, 2020. The income tax expense we recorded for 2021 is primarily attributable to income tax expense from normal, recurring operations offset by excess tax benefits recognized for employee share-based compensation, generation of research and development tax credits, and a one-time tax benefit related to tax law changes. The income tax benefit we recorded for 2020 is primarily attributable to the release of our valuation allowance on specific U.S. and foreign deferred tax assets. |
| Liquidity and Capital Resources |
| Overview, Capital Resources, and Capital Requirements |
Our principal sources of liquidity are our existing cash, cash equivalents and marketable securities, cash generated from operations, proceeds from our senior convertible notes issuances, and access to our Credit Facility. Our primary uses of cash have been for research and development programs, selling and marketing activities, capital expenditures, acquisitions of businesses, and debt service costs.
We expect that cash provided by our operations may fluctuate in future periods as a result of a number of factors, including fluctuations in our operating results, working capital requirements, and capital deployment decisions. We have historically invested our cash primarily in U.S. dollar-denominated, investment grade, highly liquid obligations of U.S. government agencies, commercial paper, corporate debt, and money market funds. Certain of these investments are subject to general credit, liquidity, and other market risks. The general condition of the financial markets and the economy may increase those risks and may affect the value and liquidity of investments and restrict our ability to access the capital markets.
Our future capital requirements will depend on many factors, including but not limited to:
| The evolution of the international expansion of our business and the revenue generated by sales of our approved products and other future products; | Our ability to efficiently scale our operations to meet demand for our current and any future products; | The success of our research and development efforts; | ||||||||||||||||||||||||
| The expenses we incur in manufacturing, developing, selling and marketing our products; | The costs, timing and risks of delays of additional regulatory approvals; | The costs of filing, prosecuting, defending and enforcing any patent claims and other intellectual property rights; | ||||||||||||||||||||||||
| The quality levels of our products and services; | The emergence of competing or complementary technological developments; | The terms and timing of any collaborative, licensing and other arrangements that we may establish; | ||||||||||||||||||||||||
| The third-party reimbursement of our products for our customers; | The rate of progress and cost of our clinical trials and other development activities; | The acquisition of businesses, products and technologies and our ability to integrate and manage any acquired businesses, products and technologies. |
We expect that existing cash and short-term investments and cash flows from our future operations will generally be sufficient to fund our ongoing core business. As current borrowing sources become due, we may be required to access the capital markets for additional funding. As we assess inorganic growth strategies, we may need to supplement our internally generated cash flow with outside sources. In the event that we are required to access the debt market, we believe that we will be able to secure reasonable borrowing rates. As part of our liquidity strategy, we will continue to monitor our current level of earnings and cash flow generation as well as our ability to access the market in light of those earning levels.
A substantial portion of our operations are located in the United States, and the majority of our sales since inception have been made in U.S. dollars. Accordingly, our assessment is that we have no material net exposure to foreign currency exchange rate fluctuations at this time. However, as our business in markets outside of the United States continues to increase, we will be exposed to foreign currency exchange risk related to our foreign operations. Fluctuations in the rate of exchange between the U.S. dollar and foreign currencies, primarily the Australian Dollar, the British Pound, the Canadian Dollar, the Euro and the Malaysian Ringgit, could adversely affect our financial results, including our revenues, revenue growth rates, gross margins, income and losses as well as assets and liabilities. We currently engage in hedging transactions to reduce foreign currency risks. We will continue to monitor and manage our financial exposures due to exchange rate fluctuations as an integral part of our overall risk management program.
Main Sources of Liquidity
Cash, cash equivalents and short-term marketable securities
Our cash, cash equivalents and short-term marketable securities totaled $2.73 billion as of December 31, 2021. None of those funds were restricted and approximately 95% of those funds were located in the United States.
Cash flow from Operations
For the twelve months ended December 31, 2021, we had positive cash inflows of $442.5 million from operating activities. We anticipate that we will continue to generate positive cash inflows for the foreseeable future.
Senior Convertible Notes
We received net proceeds of $836.6 million in November 2018 from the 2023 Notes offering and net proceeds of $1.19 billion in May 2020 from the 2025 Notes offering. We used $100.0 million of the net proceeds from the offering of the 2023 Notes to repurchase a portion of our common stock in 2018. We used $282.6 million of the net proceeds from the offering of the 2025 Notes to repurchase a portion of our senior convertible notes due 2022, or 2022 Notes. We intend to use the remainder of the net proceeds from the 2023 Notes and 2025 Notes offerings for general corporate purposes and capital expenditures, including working capital needs. We may also use the net proceeds to expand our current business through in-licensing or acquisitions of, or investments in, other businesses, products or technologies; however, we do not have any significant commitments with respect to any such acquisitions or investments at this time.
The 2023 Note Hedge is expected to reduce the potential equity dilution upon any conversion of the 2023 Notes and/or offset any cash payments we are required to make in excess of the principal amount of converted 2023 Notes. See Note 5 “Debt” to the consolidated financial statements in Part II, Item 8 of this Annual Report for conversion activity related to the 2023 Notes and shares received as the result of exercising a portion of the 2023 Note Hedge as well as for more information about the 2023 Notes and the 2025 Notes, the 2023 Note Hedge, and the 2023 Warrants.
Revolving Credit Agreement
As of December 31, 2021, we had no outstanding borrowings, $7.3 million in outstanding letters of credit, and a total available balance of $192.7 million under the Amended Credit Agreement. We monitor counterparty risk associated with the institutional lenders that are providing the Credit Facility. We currently believe that the Credit Facility will be available to us should we choose to borrow under it. Revolving loans will be available for general corporate purposes, including working capital and capital expenditures. See Note 5 “Debt” to the consolidated financial statements in Part II, Item 8 of this Annual Report for more details on the Revolving Credit Agreement.
Short-term Liquidity Requirements
Our short-term liquidity requirements primarily consist of regular operating costs, interest payments related to our senior convertible notes, capital expenditures for the development of our manufacturing facilities and office spaces, and short-term material cash requirements as described below. As of December 31, 2021, we had a working capital ratio of 5.11 and a quick ratio of 4.50, which indicates that our current assets are more than enough to cover our short-term liabilities. We expect to have significant capital expenditures for the next year to drive our strategic initiative of building out our manufacturing facility and equipment in Malaysia and the capacity scale-up in Mesa, Arizona.
We believe that our cash, cash equivalents, and marketable securities balances, projected cash contributions from our commercial operations, and borrowings under our Credit Facility will be sufficient to meet our anticipated seasonal working capital needs, all capital expenditure requirements, material cash requirements as described below, and other liquidity requirements associated with our operations for at least the next 12 months.
Long-term Liquidity Requirements
Our long-term liquidity requirements primarily consist of interest and principal payments related to our senior convertible notes, capital expenditures for the development of our manufacturing facilities and office spaces, and long-term material cash requirements as described below. As of December 31, 2021, we had a debt-to-assets ratio of 0.35, which indicates that our total assets are more than enough to cover our short-term and long-term debts. As demand grows for our products, we will continue to expand global operations to meet demand through investments in manufacturing and operations. We expect to meet our long-term liquidity requirements from our main sources of liquidity as described above to support our future operations, capital expenditures, acquisitions, and other liquidity requirements associated with our operations beyond the next 12 months.
As of December 31, 2021, we have outstanding senior convertible notes that will mature in December 2023 for the 2023 Notes and November 2025 for the 2025 Notes. However, the outstanding principal of our senior convertible notes could be converted into cash and/or shares of our common stock prior to maturity once certain conditions are met. See Note 5 “Debt” to
the consolidated financial statements in Part II, Item 8 of this Annual Report for information on conversion rights prior to maturity.
Material Cash Requirements
From time to time in the ordinary course of business, we enter into a variety of purchase arrangements including but not limited to, purchase arrangements related to capital expenditures, components used in manufacturing for the United States and Malaysia, and research and development activities. See Purchase Commitments in Note 6 to the consolidated financial statements in Part II, Item 8 of this Annual Report for more information.
We issued senior convertible notes in November 2018 and May 2020. The obligations presented above include both principal and interest for these notes. Although these notes mature in 2023 and 2025, they may be converted into cash and shares of our common stock prior to maturity if certain conditions are met. Any conversion prior to maturity can result in repayment of the principal amounts sooner than the scheduled repayment as indicated in the table. As of December 31, 2021, we had outstanding letters of credit of $7.3 million for which we cannot forecast with certainty the amount and timing of repayments. See Note 5 “Debt” to the consolidated financial statements in Part II, Item 8 of this Annual Report for further discussion of the terms of our senior convertible notes.
We are party to various leasing arrangements, primarily for office, manufacturing and warehouse space that expire at various times through December 2030, excluding any renewal options. We also have a land lease in Penang, Malaysia for the build-out of our international manufacturing facility lease that expires in 2080. We anticipate incurring significant expenditures related to the build-out of the Malaysia manufacturing facility and equipment in the next 24 months. See Leases in Note 6 to the consolidated financial statements in Part II, Item 8 of this Annual Report for more information.
Under our Restated Collaboration Agreement with Verily, upon the first regulatory approval of our next generation G7 CGM system, a regulatory approval milestone payment equivalent to 736,377 shares of our common stock, calculated based on the $100.0 million initial milestone amount divided by the volume-weighted average trading price during the 15 consecutive days ending on the date of the Restated Collaboration Agreement, will become payable. Additional sales-based milestone payments equivalent to 1,288,660 shares of our common stock, calculated based on the $175.0 million initial milestone amount divided by the volume-weighted average trading price during the 15 consecutive days ending on the date of the Restated Collaboration Agreement, may become due and payable by us upon achievement of certain sales-based milestones. All milestones may be paid in cash or shares of our common stock, at our election. If we elect to make these milestone payments in cash, any such cash payment would be equal to the number of shares that would otherwise be issued for the given milestone payment multiplied by the value of our stock on the date the relevant milestone is achieved, adjusted for stock splits, dividends, and the like. We intend to pay these milestones in shares of our common stock and as such we do not expect to have a material cash requirement for this agreement. See Note 2 “Development and Other Agreements” to the consolidated financial statements in Part II, Item 8 of this Annual Report for further discussion of the Collaboration Agreement with Verily.
| Cash Flows |
The following table sets forth a summary of our cash flows for the periods indicated. See the consolidated financial statements in Part II, Item 8 of this Annual Report for complete statements of cash flows for these periods.

As of December 31, 2021, we had $2.73 billion in cash, cash equivalents and short-term marketable securities, which is an increase of $23.5 million compared to $2.71 billion as of December 31, 2020.
The primary cash flows during the twelve months ended December 31, 2021 and 2020 are described below. See the consolidated financial statements in Part II, Item 8 of this Annual Report for complete consolidated statements of cash flows for these periods.
| Twelve Months Ended | ||||||||||||||||||||
| December 31, 2021 | December 31, 2020 | |||||||||||||||||||
| Operating Cash Flows | + | $154.7 million of net income and $419.8 million of net non-cash adjustments, partially offset by $132.0 million of net changes in working capital balances | + | $493.6 million of net income and $2.8 million of net non-cash adjustments, including $285.5 million of net benefit to tax expense associated with the release of the valuation allowance related to deferred tax assets, partially offset by $20.8 million of net changes in working capital balances | ||||||||||||||||
| Net non-cash adjustments were primarily related to collaborative research and development fees, share-based compensation, non-cash interest expense for our senior convertible notes, and depreciation and amortization. | Net non-cash adjustments were primarily related to a net benefit to tax expense associated with the release of the valuation allowance related to deferred tax assets, share-based compensation, non-cash interest expense for our senior convertible notes, and depreciation and amortization. | |||||||||||||||||||
| Investing Cash Flows | + | $193.2 million net proceeds from marketable securities | - | $807.7 million net purchases of marketable securities | ||||||||||||||||
| + | $15.7 million in proceeds from the sale of an equity investment | - | $199.0 million capital expenditures | |||||||||||||||||
| - | $389.2 million capital expenditures | |||||||||||||||||||
| - | $30.2 million in acquisitions, net of cash acquired | |||||||||||||||||||
| - | $5.0 million in purchases of equity investments | |||||||||||||||||||
| Financing Cash Flows | + | $20.3 million in proceeds from the issuance of common stock under our employee stock plans | + | $1.19 billion in proceeds from issuance of our 2025 Notes, net of issuance costs | ||||||||||||||||
| - | $9.9 million in payments for financing leases | + | $15.3 million in proceeds from the issuance of common stock under our employee stock plans | |||||||||||||||||
| - | $282.6 million cash outflow for repurchase of a portion of our 2022 Notes |
| Recent Accounting Guidance |
For a description of recently issued accounting guidance that is applicable to our financial statements, see Note 1 “Organization and Significant Accounting Policies” to the consolidated financial statements in Part II, Item 8 of this Annual Report.
Previous: Item 6. [RESERVED] · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK