 filings.tools
Item 1. BUSINESS
61K characters. Original on sec.gov · Markdown
Item 1. BUSINESS
OVERVIEW
Equifax Inc. is a leading global provider of information solutions and human resources business process outsourcing services for businesses, governments and consumers. We have a large and diversified group of clients, including financial institutions, corporations, governments and individuals. Our products and services are based on comprehensive databases of consumer and business information derived from numerous sources including credit, financial assets, telecommunications and utility payments, employment, income, demographic and marketing data. We use advanced statistical techniques and proprietary software tools to analyze all available data, creating customized insights, decision-making solutions and processing services for our clients. We help consumers understand, manage and protect their personal information and make more informed financial decisions. We also provide information, technology and services to support debt collections and recovery management. Additionally, we are a leading provider of payroll-related and human resource management business process outsourcing services in the United States of America, or U.S.
We currently operate in four global regions: North America (U.S. and Canada), Asia Pacific (Australia and New Zealand), Europe (the United Kingdom, or U.K., Spain and Portugal) and Latin America (Argentina, Chile, Costa Rica, Ecuador, El Salvador, Honduras, Mexico, Paraguay, Peru and Uruguay). We maintain support operations in the Republic of Ireland. We also offer Equifax branded credit services in Russia and India through joint ventures, have investments in consumer and/or commercial credit information companies through joint ventures in Cambodia, Malaysia and Singapore, and have an investment in a consumer and commercial credit information company in Brazil.
Equifax was originally incorporated under the laws of the State of Georgia in 1913, and its predecessor company dates back to 1899. As used herein, the terms Equifax, the Company, we, our and us refer to Equifax Inc., a Georgia corporation, and its consolidated subsidiaries as a combined entity, except where it is clear that the terms mean only Equifax Inc.
We are organized and report our business results in four operating segments, as follows:
| • | U.S. Information Solutions (USIS) — provides consumer and commercial information solutions to businesses in the U.S. including online information, decisioning technology solutions, fraud and identity management services, portfolio management services, mortgage reporting and financial marketing services. |
| • | International —which includes our Canada, Europe, Asia Pacific and Latin America business units, provides products and services similar to those available in the USIS operating segment but with variations by geographic region. In Europe, Asia and Latin America, we also provide information, technology and services to support debt collections and recovery management. |
| • | Workforce Solutions — provides services enabling clients to verify income and employment (Verification Services) as well as to outsource and automate the performance of certain payroll-related and human resources management business processes, including unemployment cost management, tax credits and incentives and I-9 management services and services to allow employers to ensure compliance with the Affordable Care Act (Employer Services). |
| • | Global Consumer Solutions — provides products to consumers in the United States, Canada, and the U.K., enabling them to understand and monitor their credit and monitor and help protect their identity. We also sell consumer and credit information to resellers who combine our information with other information to provide direct to consumer monitoring, reports and scores. |
2016 Acquisitions and Investments
On February 24, 2016, the Company completed the acquisition of 100% of the ordinary voting shares of Veda Group Limited ("Veda") for cash consideration plus debt assumed of approximately $1.9 billion. The acquisition provides a strong platform for Equifax to offer data and analytic services and further broaden the Company's geographic footprint. Veda stockholders received 2.825 Australian dollars in cash for each share of Veda common stock they owned. The Company financed the transaction with $1.7 billion of debt, consisting of commercial paper, an $800 million 364-Day revolving credit facility (the "364-Day Revolver"), and an $800 million three-year delayed draw term loan facility (the "Term Loan"). Refer to Note 5 for further discussion on debt. Additionally, we acquired two other smaller businesses in 2016.
Refer to Note 3 to the Consolidated Financial Statements for additional information on our acquisitions and investments for the year ended December 31, 2016.
Our revenue base and business mix are diversified among our four segments as depicted in the chart below.

OUR BUSINESS STRATEGY
Our strategic objective is to be the global leader in information solutions that creates unparalleled insights to solve customer challenges. Data is at the core of our value proposition. Leveraging our extensive resources, we deliver differentiated decisions through a broad and diverse set of data assets, sophisticated analytics and proprietary decisioning technology. Our long-term corporate growth strategy is driven by the following imperatives:
| • | Deliver consistently strong profitable growth and shareholder returns. We seek to meet or exceed our financial commitments on revenue growth and margins through disciplined execution of our strategic initiatives and by positioning ourselves as a premier provider of high value information solutions. |
| • | Develop unparalleled analytical insights leveraging Equifax unique data. We continue to invest in and acquire unique sources of credit and non-credit information to enhance the variety and quality of our services while increasing clients’ confidence in information-based business decisions. Areas of focus for investment in new sources of data include, among others, positive payment data, fraud and personal identification data, real estate data and new commercial business data. We also have developed unique capabilities to integrate customer and third-party data into our solution offerings to further enhance the decisioning solutions we develop for our customers. |
We continue to invest in and develop new technology to enhance the functionality, cost-effectiveness and security of the services we offer and further differentiate our products from those offered by our competitors. In addition to custom products for large clients, we develop software as a service based, decisioning and data access technology platforms that are more cost effective for clients of all sizes. We also develop predictive scores and analytics, some of which leverage multiple data assets, to help clients acquire new customers and manage their existing customer relationships. We develop a broad array of industry, risk management, cross-sell and account acquisition models to enhance the precision of our clients’ decisioning activities. We also develop custom and generic solutions that enable customers to more effectively manage their debt collection and recovery portfolios.
| • | Innovate for market leadership in key domains and verticals. We seek to increase our share of clients’ spend on information-related services through developing and introducing new products, pricing our services in accordance with the value they represent to our customers, increasing the range of current services utilized by our clients, and improving the quality and effectiveness of our sales organization and client support interactions with consumers. We are also helping clients address increased requirements to comply with emerging regulations and rules. |
We believe there are many opportunities to expand into emerging markets both in the U.S. and internationally. In the U.S., we have increased and broadened resources in key markets, including financial, mortgage, auto, insurance, telecommunications, healthcare and government, and we are delivering services ranging from identity authentication to risk management. We continue to invest in growing our ventures in Russia and India and leveraging our newer product offerings across all of our geographical business units and periodically enter new country markets through acquisitions or start-up operations.
| • | Serve as a trusted steward and advocate for our customers and consumers. This includes continuously improving the customer and consumer experience in our consumer and commercial offerings, anticipating and executing on regulatory initiatives, while simultaneously delivering security for our services. |
| • | Invest in talent to drive our strategy and foster a culture of innovation. We attract top talent by continuing to expand and diversify our talent pipeline. We regularly undertake various talent initiatives to engage, develop, and retain our top talent. |
MARKETS AND CLIENTS
Our products and services serve clients across a wide range of verticals, including financial services, mortgage, human resources, consumer, commercial, telecommunications, retail, automotive, utilities, brokerage, healthcare and insurance industries, as well as state and federal governments. We also serve consumers directly. Our revenue stream is highly diversified with our largest client providing less than 3% of total revenue. The following table summarizes the various end-user markets we serve:
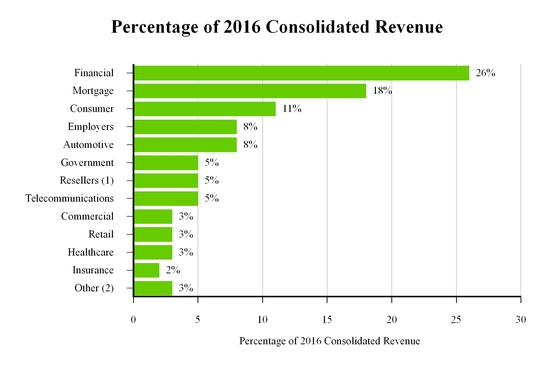
| (1) | Predominantly sold to companies who serve the direct to consumer market and includes other small end user markets. |
| (2) | Other includes revenue from other miscellaneous end user markets. |
We market our products and services primarily through our own direct sales organization that is structured around sales teams that focus on client segments typically aligned by vertical markets and geography. Sales groups are based in our headquarters in Atlanta, Georgia, and field offices located in the U.S. and in the countries where we have operations. We also market our products and services through indirect channels, including alliance partners, joint ventures and other resellers. In addition, we sell through direct mail and various websites, such as www.equifax.com.
Our largest geographic market segments are the U.S.; Asia Pacific (Australia and New Zealand); Europe (the U.K., Spain and Portugal); Canada; and Latin America (Argentina, Chile, Costa Rica, Ecuador, El Salvador, Honduras, Mexico, Paraguay, Peru and Uruguay). We maintain support operations in the Republic of Ireland. We also offer Equifax branded credit services in Russia and India through joint ventures, have investments in consumer and/or commercial credit information companies through joint ventures in Cambodia, Malaysia and Singapore, and have an investment in a consumer and commercial credit information company in Brazil. We also provide information, technology and services to support debt collections and recovery management in Europe, Asia Pacific, Canada and Latin America.
Revenue from international clients, including end users and resellers, amounted to 27% of our total revenue in 2016, 23% of our total revenue in 2015 and 26% of our total revenue in 2014.
PRODUCTS AND SERVICES
Our products and services help our clients make more informed decisions with higher levels of confidence by leveraging a broad array of data assets. Analytics are used to derive insights from the data that are most relevant for the client’s decisioning needs. The data and insights are then processed through proprietary software and transmitted to the client’s operating system to execute the decision.
The following chart summarizes the key products and services offered by each of the business units within our segments:
| USIS | International | Workforce Solutions | ||||||||||||||||||
| Online Information Solutions | Financial Marketing Services | Mortgage Services | Europe | Asia Pacific | Latin America | Canada | Verification Services | Employer Services | Global Consumer Solutions | |||||||||||
| Online data | X | X | X | X | X | X | X | X | ||||||||||||
| Portfolio management services | X | X | X | X | X | X | X | X | ||||||||||||
| Analytical services | X | X | X | X | X | X | X | X | X | X | ||||||||||
| Technology services | X | X | X | X | X | X | ||||||||||||||
| Identity management and fraud | X | X | X | X | X | X | X | |||||||||||||
| Marketing Services | X | X | X | X | X | |||||||||||||||
| Direct to consumer credit monitoring | X | X | ||||||||||||||||||
| Employment and income verification services | X | X | ||||||||||||||||||
| Business process outsourcing (BPO) | X | X | X | |||||||||||||||||
| Debt collection software, services and analytics | X | X | X | X | X |
Each of our operating segments is described more fully below.
USIS
USIS provides consumer and commercial information solutions to businesses in the U.S. through three product and service lines, as follows:
Online Information Solutions. Online Information Solutions’ products are derived from multiple large and comprehensive databases of consumer and commercial information that we maintain about individual consumers and businesses, including credit history, current credit status, payment history and address information. Our clients utilize the information and analytical insights we provide to make decisions for a broad range of financial and business purposes, such as whether, and on what terms, to approve auto loans or credit card applications, and whether to allow a consumer or a business to open a new utility or telephone account. In addition, this information is used by our clients for cross selling additional products to existing customers, improving their underwriting and risk management decisions, and authenticating and verifying consumer and business identities. We also sell consumer and credit information to resellers who combine our information with other information to provide services to the financial, mortgage, fraud and identity management, and other end-user markets. Our software platforms and analytical capabilities can integrate all types of information, including third-party and client information, to enhance the insights and decisioning process to help further mitigate the risk of granting credit, predict the risk
of bankruptcy, indicate the applicant’s risk potential for account delinquency, ensure the identity of the consumer, and reduce exposure to fraud. These risk management services enable our clients to monitor risks and opportunities and proactively manage their portfolios.
Online Information Solutions’ clients access products through a full range of electronic distribution mechanisms, including direct real-time access, which facilitates instant decisions. We also develop and host customized applications that enhance the decision-making process for our clients. These decisioning technology applications assist with a wide variety of decisioning activities, including determining pre-approved offers, cross-selling of various products, determining deposit amounts for telephone and utility companies, and verifying the identity of their customers. We have also compiled commercial databases regarding businesses in the U.S., which include loan, credit card, public records and leasing history data, trade accounts receivable performance, and Secretary of State and Securities and Exchange Commission registration information. We offer scoring and analytical services that provide additional information to help mitigate the credit risk assumed by our clients.
Mortgage Solutions. Our Mortgage Solutions products, offered in the U.S., consist of specialized credit reports that combine information from the three major consumer credit reporting agencies (Equifax, Experian Group and TransUnion LLC) into a single “merged” credit report in an online format, commonly referred to as a tri-merge report. Mortgage lenders use these tri-merge reports in making their mortgage underwriting decisions. Additionally, we offer various “triggering” services designed to alert lenders to changes in a consumer’s credit status during the underwriting period and securitized portfolio risk assessment services for evaluating inherent portfolio risk.
Financial Marketing Services. Our Financial Marketing Services products utilize consumer and commercial financial information enabling our clients to more effectively manage their marketing efforts, including targeting and segmentation; to identify and acquire new clients for their products and services; to develop portfolio strategies to minimize risk and maximize profitability; and to realize additional revenue from existing customers through more effective cross selling and upselling of additional products and services. These products utilize information derived from consumer and commercial information, including credit, income, asset, liquidity, net worth and spending activity, which also support many of our Online Information Solutions’ products. These data assets broaden the understanding of consumer and business financial potential and opportunity which can further drive high value decisioning and targeting solutions for our clients. We also provide account review services, which assist our clients in managing their existing customers and prescreen services that help our clients identify new opportunities with their customers. Clients for these products primarily include institutions in the banking, brokerage, retail, insurance and mortgage industries as well as companies primarily focused on digital and interactive marketing.
International
The International operating segment includes our Europe, Asia Pacific, Latin America and Canada business units. These business units offer products that are similar to those available in the USIS operating segment, although, in some jurisdictions, data sources tend to rely more heavily on government agencies than in the U.S. We also offer specialized services that help our customers better manage risk in their consumer portfolios. This operating segment’s products and services generate revenue in Argentina, Australia, Canada, Chile, Costa Rica, Ecuador, El Salvador, Honduras, Mexico, New Zealand, Paraguay, Peru, Portugal, Spain, the U.K. and Uruguay. We also maintain support operations in the Republic of Ireland, Chile and Costa Rica. We offer consumer credit services in Russia and India through our investment in joint ventures and have an investment in the second largest consumer and commercial credit information company in Brazil. We also provide information, technology and services to support debt collections and recovery management in Europe, Asia Pacific, Canada and Latin America.
Europe. Our European operation provides information solutions, marketing and personal solutions products. Information solutions and personal solutions products are generated from information that we maintain and include credit reporting and scoring, asset information, risk management, identity management and authentication services, fraud detection and modeling services. Most of these products are sold in the U.K. with a more limited set of information solutions products sold in Portugal and Spain. Our commercial products, such as business credit reporting and commercial risk management services, are available mostly in the U.K, with a more limited set of information solutions products sold in Portugal and Spain. Marketing products, which are similar to those offered in our Financial Marketing Services business unit, are primarily available in the U.K. and, to a lesser extent, in Spain. Beginning in 2014, we also provide information, technology and services to support debt collections and recovery management.
Asia Pacific. Our Asia Pacific operation provides consumer and commercial information solutions products, marketing products and personal solutions products. We offer a full range of products, generated from credit records, including credit reporting and scoring, decisioning technology, risk management, identity management, authentication and fraud detection services. Our consumer and commercial products are the primary source of revenue in each of the countries in which
we operate and include credit reporting, decisioning tools and risk management services, in the countries we serve. We also provide information, technology and services to support debt collections and recovery management. Additionally, we provide a variety of consumer and commercial marketing products generated from credit information databases, including business profile analysis, business prospect lists and database management. The countries in which we operate include Australia and New Zealand.
Latin America. Our Latin American operation provides consumer and commercial information solutions products, marketing products and personal solutions products. We offer a full range of products, generated from credit records that we maintain, including credit reporting and scoring, decisioning technology, risk management, identity management, authentication and fraud detection services. Our consumer products are the primary source of revenue in each of the countries in which we operate. We also offer various commercial products, which include credit reporting, decisioning tools and risk management services, in the countries we serve. Beginning in 2013, we also provide information, technology and services to support debt collections and recovery management. Additionally, we provide a variety of consumer and commercial marketing products generated from our credit information databases, including business profile analysis, business prospect lists and database management. The countries in which we operate include Argentina, Chile, Costa Rica, Ecuador, El Salvador, Honduras, Mexico, Paraguay, Peru and Uruguay.
Canada. Similar to Online Information Solutions, Mortgage Solutions and Financial Marketing Services business units, Canada offers products derived from the credit information that we maintain about individual consumers and businesses. We offer many products in Canada, including credit reporting and scoring, consumer and commercial marketing, risk management, fraud detection and modeling services, identity management and authentication services, together with certain of our decisioning products that facilitate pre-approved offers of credit and automate a variety of credit decisions. Beginning in 2016, we also provide information, technology and services to support debt collections and recovery management.
Workforce Solutions
Workforce Solutions operates in the U.S. through two business units:
Verification Services. Verification Services include employment, income and social security number verification services. Our online verification services enable direct third-party verifiers including various governmental agencies, mortgage originators, credit card and automotive lenders and pre-employment screeners to verify the employee’s employment status and income information. We also offer an offline research verification service, which expands employment verification to locate data outside our existing automated database.
The Work Number is our key repository of employment and income data serving our verifier business and enabling employer human resource services. We rely on payroll data received from over 7,100 organizations, including over three quarters of Fortune 500 companies, to regularly update the database. The updates occur as employers transmit data electronically to Equifax from their payroll systems. Employers contract to provide this data for specified periods under the terms of contracts which range from one to five years. We use this data to provide automated employment and income verification services to third-party verifiers as well as enabling employer services such as unemployment claims, I-9 and eVerify transactions and employer tax credits opportunities.
The fees we charge for these services are generally on a per transaction basis. We have not experienced significant turnover in the employer contributors to the database because we generally do not charge them to add their employment data to the database and the verification service we offer relieves them of the administrative burden and expense of responding to third-party employment verification requests. The database is approaching 300 million current and historic employment records at December 31, 2016.
Employer Services. These services are aimed at reducing the cost to the human resources function of businesses through a broad suite of services including assisting with employment tax matters designed to reduce the cost of unemployment claims through effective claims representation and management and efficient processing and to better manage the tax rate that employers are assessed for unemployment taxes; comprehensive services designed to research the availability of employment-related tax credits (e.g., the federal work opportunity and welfare to work tax credits and state tax credits), and to process the necessary filings and assist the client in obtaining the tax credit; W-2 management services (which include initial distribution, reissue and correction of W-2 forms); paperless pay services that enable employees to electronically receive pay statement information as well as review and change direct deposit account or W-4 information; integrated electronic time capture and reporting services; paperless new-hire services to bring new workers on board using electronic forms; I-9 management services designed to help clients electronically comply with the immigration laws that require employers to complete an I-9 form for each new hire; and onboarding services using online forms to complete the new hire process for employees of corporate and
government agencies. In addition we provide software and services to employers to assist in compliance with the Affordable Care Act ("ACA") through partnerships with government agencies.
Global Consumer Solutions
Our Global Consumer Solutions products give consumers information to enable them to understand and monitor their credit and monitor and help protect their identity primarily through our Equifax Complete, ID Patrol, Credit Watch and Score Watch monitoring products. Consumers can obtain credit file information about them and Equifax or FICO credit scores. Equifax products also offer monitoring features for consumers who are concerned about identity theft and data breaches, including credit report monitoring from all three bureaus, internet and bank account monitoring, lost wallet support, and the ability to lock and unlock the Equifax credit file. Our products are available to consumers in the United States, Canada, and the U.K. directly primarily over the internet and indirectly through relationships with business partners who distribute our products or provide these services to their employees or customers. We also sell consumer and credit information to resellers who combine our information with other information to provide direct to consumer monitoring, reports and scores.
COMPETITION
The market for our products and services is highly competitive and is subject to constant change. Our competitors vary widely in size and the nature of the products and services they offer. Sources of competition are numerous and include the following:
| • | Competition for our consumer credit information solutions and personal solutions products varies by both application and industry, but generally includes two global consumer credit reporting companies, Experian and TransUnion, both of which offer a product suite similar to our credit reporting solutions, and LifeLock, a national provider of personal identity theft protection products, as well as emerging competitors offering free credit scores including Credit Karma. There are also a large number of competitors who offer competing products in specialized areas (such as fraud prevention, risk management and application processing and decisioning solutions) and software companies offering credit modeling services or analytical tools. As a premier provider of information based insights and solutions, we believe that our products offer clients an advantage over those of our credit based competitors because of the depth and breadth of our consumer information files, which we believe to be superior in terms of accuracy, coverage and availability. Other differentiators include our decisioning technology and the features and functionality of our analytical capabilities. Our competitive strategy is to emphasize improved decision making and product quality while remaining competitive on price. Our marketing services products also compete with the foregoing companies and others who offer demographic information products, including Acxiom, Harte-Hanks and infoGROUP. We also compete with Fair Isaac Corporation with respect to certain of our analytical tools and solutions. |
| • | Competition for our commercial solutions products primarily includes Experian, Dun & Bradstreet and Cortera, and providers of these services in the international markets we serve. We believe our access to and knowledge of U.S. small business loan information from financial institutions combined with our consumer credit information in the case of small business owners enables more efficient and effective decision-making for the small business segment of that market. |
| • | Competition for our employment and income verification services includes large employers who serve their own needs through in-house systems to manage verification as well as regional online verification companies, such as Verify Jobs and First Advantage, who offer verification services along with other human resources ("HR") and tax services. Competition in the Employer Services market is diverse and includes in-house management of such services or the outsourcing of one or more of such services to HR consulting firms such as Mercer and Towers Watson, HR management services providers such as Oracle and Silk Road, payroll processors such as ADP and Ceridian, accounting firms such as PricewaterhouseCoopers and Ernst & Young, analytics companies such as Tableau and Visier and hundreds of smaller companies that provide one or multiple offerings that compete with our Employer Services business. Competition in the Verification Services market includes employers who manage verifications in-house, lenders who obtain verifications directly from employers, and online and offline verification companies, such as Verify Job System, Corporate Cost Control, Thomas & Thorngren and Employers Edge. |
| • | Competition for our debt collection and recovery management software, services and analytics is similar to the competition for our consumer credit information solutions. We believe that the breadth and depth of our data assets enable our clients to develop a more current and comprehensive view of consumers. In the category of platforms and analytics, we compete to some extent with entities that deploy collections platforms, account management systems or recovery solutions. |
While we believe that none of our competitors offers the same mix of products and services as we do, certain competitors may have a larger share of particular geographic or product markets or operate in geographic areas where we do not currently have a presence.
We assess the principal competitive factors affecting our markets to include: product attributes such as quality, depth, coverage, adaptability, scalability, interoperability, functionality and ease of use; product price; technical performance; access to unique proprietary databases; availability in application service provider, or ASP, format; quickness of response, flexibility and client services and support; effectiveness of sales and marketing efforts; existing market penetration; new product innovation; and our reputation as a trusted steward of information.
TECHNOLOGY AND INTELLECTUAL PROPERTY
We generally seek protection under federal, state and foreign laws for strategic or financially important intellectual property developed in connection with our business. Certain intellectual property, where appropriate, is protected by registration under applicable trademark laws or by prosecution of patent applications. We own a number of patents registered in the U.S. and several in foreign countries. We also have certain registered trademarks, service marks, logos and internet domain names in the U.S. and in many foreign countries, the most important of which are “Equifax,” “Decision360,” “The Work Number” and variations thereof. These marks are used in connection with many of our product lines and services. We believe that, in the aggregate, the rights under our patents and trademarks are generally important to our operations and competitive position, but we do not regard any of our businesses as being dependent upon any single patent or group of patents or trademark. However, certain Company trademarks, which contribute to our identity and the recognition of our products and services, including but not limited to the “Equifax” trademark, are an integral part of our business, and their loss could have a material adverse effect on us. We also protect certain of our confidential intellectual property and technology in compliance with trade secret laws and through the use of nondisclosure agreements.
We license other companies to use certain data, software, and other technology and intellectual property rights we own or control, primarily as core components of our products and services, on terms that are consistent with customary industry standards and that are designed to protect our interest in our intellectual property. Other companies license us to use certain data, technology and other intellectual property rights they own or control. For example, we license credit-scoring algorithms and the right to sell credit scores derived from those algorithms from third parties for a fee. We do not hold any franchises or concessions that are material to our business or results of operations.
GOVERNMENTAL REGULATION
We are subject to a number of U.S. federal, state, local and foreign laws and regulations that involve matters central to our business. These laws and regulations may involve privacy, data protection, intellectual property, competition, consumer protection, anti-corruption, anti-bribery, anti-money laundering, employment, health, taxation or other subjects. In particular, we are subject to federal, state and foreign laws regarding the collection, protection, dissemination and use of non-public personal information we have in our possession and to consumer financial protection. Foreign data and consumer protection, privacy and other laws and regulations are often more restrictive than those in the U.S. Failure to satisfy those legal and regulatory requirements, or the adoption of new laws or regulations, could have a material adverse effect on our results of operations, financial condition or liquidity.
U.S. federal and state and foreign laws and regulations are evolving and can be subject to significant change. In addition, the application and interpretation of these laws and regulations are often uncertain. These laws are enforced by federal, state and local regulatory agencies in the jurisdictions where we operate, and in some instances also through private civil litigation. There are also a number of legislative proposals pending before the U.S. Congress, various state legislative bodies, and foreign governments concerning consumer and data protection that could affect us.
Summary of U.S. Regulation Relating to Consumer and Data Protection
Our U.S. operations are subject to numerous laws and regulations governing the collection, protection and use of consumer credit and other information, and imposing sanctions for the misuse of such information or unauthorized access to data. Many of these provisions also affect our customers’ use of consumer credit or other data we furnish.
Examples of the most significant of these laws include, but are not limited to, the following:
Federal Laws and Regulation
| • | FCRA - The United States Fair Credit Reporting Act (“FCRA”) regulates consumer reporting agencies, including us, as well as data furnishers and users of consumer reports such as banks and other companies. FCRA provisions govern the accuracy, fairness and privacy of information in the files of consumer reporting agencies (“CRAs”) that engage in the practice of assembling or evaluating certain information relating to consumers for certain specified purposes. The FCRA limits the type of information that may be reported by CRAs, limits the distribution and use of consumer reports and establishes consumer rights to access and dispute their credit files. CRAs are required to follow reasonable procedures to assure maximum possible accuracy of the information concerning the individual about whom the report relates and if a consumer disputes the accuracy of any information in the consumer’s file, to conduct a reasonable reinvestigation. CRAs are required to make available to consumers a free annual credit report. The FCRA imposes many other requirements on CRAs, data furnishers and users of consumer report information. Violation of the FCRA can result in civil and criminal penalties. The FCRA contains an attorney fee shifting provision to provide an incentive for consumers to bring individual or class action lawsuits against a CRA for violations of the FCRA. Regulatory enforcement of the FCRA is under the purview of the United States Federal Trade Commission (“FTC”), the Consumer Financial Protection Bureau (“CFPB”), and state attorneys general, acting alone or in concert with one another. |
| • | The Dodd-Frank Act - One of the purposes of the Dodd-Frank Wall Street Reform and Consumer Protection Act (“Dodd-Frank Act”) is to protect consumers from abusive financial services practices. Title X of the Dodd-Frank Act created the CFPB. The Dodd-Frank Act transfers authority under certain existing laws to the CFPB and provides it with examination and supervisory authority. The Dodd-Frank Act also prohibits unfair, deceptive or abusive acts or practices (“UDAAP”) with respect to consumer finance and provides the CFPB with authority to enforce those provisions. We are subject to the examination and supervision of the CFPB. The CFPB may pursue administrative proceedings or litigation to enforce the laws and rules subject to its jurisdiction. In these proceedings the CFPB can obtain cease and desist orders, which can include orders for restitution to consumers or rescission of contracts, as well as other types of affirmative relief, and monetary penalties ranging from $5,000 per day for ordinary violations and up to $1 million per day for knowing violations. Also, the Dodd-Frank Act empowers state attorneys general and state regulators to bring civil actions in certain circumstances for the kind of cease and desist orders available to the CFPB (but not for civil penalties). |
| • | FTC Act - The Federal Trade Commission Act (“FTC Act”) prohibits unfair methods of competition and unfair or deceptive acts or practices. We must comply with the FTC Act when we market our services, such as consumer credit monitoring services offered through our Global Consumer Solutions unit. The security measures we employ to safeguard the personal data of consumers could also be subject to the FTC Act, and failure to safeguard data adequately may subject us to regulatory scrutiny or enforcement action. There is no private right of action under the FTC Act. |
| • | GLBA - The Financial Services Modernization Act of 1999, or Gramm-Leach-Bliley Act (“GLBA”) regulates, among other things, the use of non-public personal information of consumers that is held by financial institutions, including us. We are subject to various GLBA provisions, including rules relating to the use or disclosure of the underlying data and rules relating to the physical, administrative and technological protection of non-public personal financial information. Breach of the GLBA can result in civil and/or criminal liability and sanctions by regulatory authorities, such as fines of up to $100,000 per violation and up to five years’ imprisonment for individuals. Regulatory enforcement of the GLBA is under the purview of the FTC, the federal prudential banking regulators, the SEC and state attorneys general, acting alone or in concert with each other. |
| • | CROA - The Credit Repair Organizations Act (“CROA”) regulates companies that claim to be able to assist consumers in improving their credit standing. There have been efforts to apply the CROA to credit monitoring services offered by consumer reporting agencies and others. CROA allows for a private right of action and permits consumers to recover all money paid for alleged “credit repair” in the event of a violation. |
State Laws and Regulation Relating to Consumer and Data Protection
| • | A number of states have enacted requirements similar to the federal FCRA. Some of these state laws impose additional, or more stringent, requirements than the FCRA, especially in connection with the investigations and responses to reported inaccuracies in consumer reports. The FCRA preempts some of these state laws, but the scope of preemption continues to be defined by the courts. The state of Vermont is grandfathered under the original FCRA requirements and thus we are subject to additional requirements to comply with Vermont law. |
| • | Most states and the District of Columbia have passed laws that give consumers the right to place a security freeze on their credit reports to prevent others from opening new accounts or obtaining new credit in their name. These laws place differing requirements on credit reporting agencies with respect to how and when to respond to such credit file freeze requests and in the fees, if any, the agencies may charge for freeze-related actions. |
| • | A majority of states have adopted versions of data security breach laws that require notification of affected consumers in the event of a breach of personal information. Some of these laws require additional data protection measures which exceed the GLB Act data safeguarding requirements. If data within our system is compromised by a breach, we may be subject to provisions of various state security breach laws. |
| • | We are also subject to federal and state laws that are generally applicable to any U.S. business with national or international operations, such as antitrust laws, the Foreign Corrupt Practices Act, the Americans with Disabilities Act, state unfair or deceptive practices act and various employment laws. We continuously monitor federal and state legislative and regulatory activities that involve credit reporting, data privacy and security to identify issues in order to remain in compliance with all applicable laws and regulations. |
Summary of International Regulation Relating to Consumer and Data Protection
We are subject to various data protection, privacy and consumer credit laws and regulations in the foreign countries where we operate. Examples of the most significant of these laws include, but are not limited to, the following:
| • | In the U.K., we are subject to a regulatory framework which provides for primary regulation by the Financial Conduct Authority (the “FCA”). The FCA focuses on consumer protection and market regulation as well as prudential supervision of regulated financial institutions. The FCA has significant powers, including the power to regulate conduct related to the marketing of financial products, specify minimum standards and to place requirements on products, impose unlimited fines, and to investigate organizations and individuals. In addition, the FCA is able to ban financial products for up to a year while considering an indefinite ban; it has the power to instruct firms to immediately retract or modify promotions which it finds to be misleading, and to publish such decisions. Our core credit reporting (“credit reference”) and debt collections services and recovery management businesses in the U.K. are subject to FCA supervision and we are required to have certain corporate and “approved person” authorizations from the FCA to carry on such businesses. The license application for our collection business (TDX Group or "TDX") was approved in 2016, and our application for authorization in our capacity as a credit reference agency is under review. Although we do not currently anticipate any issues in receiving authorization, to the extent applicable approvals are not obtained in a timely manner, or at all, we may not conduct these businesses in the U.K. |
| • | In Europe, we are subject to the European Union (“EU”) Data Protection Regulation ("GDPR"), which will replace the comprehensive 1995 European Union Data Protection Directive. The GDPR establishes several obligations that organizations must follow with respect to use of personal data, including a prohibition on the transfer of personal information from the EU to other countries whose laws do not protect personal data to an “adequate” level of privacy or security. The new standards for adequacy are generally stricter and more comprehensive than that of the U.S. and most other countries where Equifax operates. In the U.K., regulatory limitations affect our use of the Electoral Roll, one of our key data sources in that jurisdiction. Generally, the data underlying the products offered by our U.K. Information Services and Global Consumer Solutions product lines, excluding our Commercial Services products, are subject to these regulations. In Spain and Portugal, privacy laws also regulate all credit bureau and personal solutions activities. The GDPR, among other things, will tighten data protection requirements and make enforcement more rigorous, for example, by streamlining enforcement at a European level, introducing data breach notification requirements and increasing penalties for non-compliance. The GDPR was passed by the EU Parliament in the spring of 2016 and will become fully effective in May 2018, following a two-year implementation period. |
| • | In Canada, federal and provincial laws govern how we collect, use or disclose personal information in the course of our commercial activities. The federal Personal Information Protection and Electronic Documents Act of 2000 gives individuals the right to access and request correction of their personal information collected by us, and requires compliance with the Canadian Standard Association Model Code for the Protection of Personal Information covering accountability and identifying purposes, consent, collection, use, disclosure, retention, accuracy, safeguards, individual access and compliance. The federal and provincial privacy regulators have powers of investigation and intervention, and provisions of Canadian law regarding civil liability apply in the event of unlawful processing which is prejudicial to the persons concerned. The EU recognizes Canada as having adequate levels of protection for personal data transfers and processing. |
| • | In Latin America, data protection and credit reporting laws and regulations vary considerably amongst Latin American countries. Some countries, such as El Salvador, Ecuador and Honduras, establish a constitutional right to privacy without general data protection standards or a data protection authority. These countries, however, have laws that govern the functioning of credit bureaus. Other countries, such as Argentina, Uruguay, Peru and Costa Rica, have enacted comprehensive data protection legislation similar to the EU Data Protection Regulation (GDPR). The EU recognizes Argentina and Uruguay as having adequate levels of protection for personal data transfers and processing. Peru also has a specific law for credit reporting. Paraguay and Chile have fewer comprehensive data protection laws in place, but do have rules regarding reporting periods, consent and data collection. |
| • | In Australia, we are subject to regulatory oversight by various agencies, but the Office of the Australian Information Commissioner (OAIC) is the agency with direct responsibility for administering the Australian Privacy Principles (which relate to the collection, holding, use and disclosure of personal information) and Part IIIA of the Privacy Act 1988 (which regulates credit reporting). The OAIC can investigate a complaint, conduct its own investigations, resolve/make binding determinations and seek civil penalties. Our Australian business is also a member of the Credit and Investments Ombudsman, an external dispute resolution scheme, which has been approved by the OAIC to handle privacy and credit reporting complaints and make binding determinations. The OAIC can register codes of practice under the Privacy Act 1988, and has registered the Privacy (Credit Reporting) Code 2014. The Australian Retail Credit Association (ARCA) is a credit and credit reporting industry self-regulatory body, which administers principles and standards for the exchange of credit data between industry participants. Corporate Scorecard Pty Limited (one of our Australian subsidiaries), holds an Australia Financial Services License (AFSL), which allows it to provide general advice to wholesale clients by issuing a credit rating. The Australian Securities and Investments Commission (ASIC) regulates that business, and has authority to investigate, prosecute, ban individuals, and to seek civil penalties. |
| • | In New Zealand, the regulatory framework provides for primary regulation under the Office of the Privacy Commissioner (OPC). The OPC investigates complaints relating to the collection, use, holding and disclosure of personal information, both credit-related and non-credit related. The OPC can make a finding that there has been an interference with privacy but cannot impose civil penalties. In extreme cases where there has been an interference with privacy it can refer these cases to the Director of Human Rights, for determination in the Human Rights Review Tribunal. The OPC can issue practice codes under the Privacy Act 1993, and has issued and subsequently amended, the Credit Reporting Privacy Code 2004. A self-regulatory body, the Retail Credit Association of New Zealand (RCANZ), addresses reciprocity of data issues relating to comprehensive credit reporting, and data standards. |
| • | In India, various legislation including the Information Technology Act 2000 and Rules framed thereunder and the Credit Information Companies (Regulation) Act of 2005 and Rules and Regulations framed thereunder, establishes a federal data protection framework. Entities that collect and maintain personal data and/or credit information must ensure that it is complete, accurate and safeguarded, and must adopt certain privacy principles with respect to collecting, processing, preserving, sharing and using such data and/or credit information. The Indian parliament has passed legislation that would allow individuals to sue for damages in the case of a data breach, if the entity negligently failed to implement reasonable security practices and procedures to protect personal data and/or credit information. Our Indian joint venture is subject to regulation by the Reserve Bank of India, which is India’s central banking institution. |
| • | In Russia, credit reporting activities are governed by the Federal Law on Credit Histories No.218-fz, dated December 30, 2004. The law regulates the contents of credit files, who may submit data to a credit bureau and who can receive credit reports. |
Tax Management Services
The Tax Management Services business within our Workforce Solutions segment is potentially impacted by changes in renewal or non-renewal of U.S. tax laws or interpretations, for example, those pertaining to work opportunity tax credits and unemployment compensation claims.
PERSONNEL
Equifax employed approximately 9,500 employees in 24 countries as of December 31, 2016. None of our U.S. employees are subject to a collective bargaining agreement and no work stoppages have been experienced. Pursuant to local laws, certain of our employees in Argentina and Spain are covered under government-mandated collective bargaining regulations that govern general salary and compensation matters, basic benefits and hours of work. In some of our non-U.S. subsidiaries, certain of our employees are represented by workers’ councils or statutory labor unions.
EXECUTIVE OFFICERS OF EQUIFAX
The executive officers of Equifax and their ages and titles are set forth below.
Richard F. Smith (57) has been Chairman and Chief Executive Officer since December 2005. He was named Chairman-Elect and Chief Executive Officer effective September 2005. Prior to that, Mr. Smith served as Chief Operating Officer, GE Insurance Solutions, from 2004 to September 2005 and President and Chief Executive Officer of GE Property and Casualty Reinsurance from 2003 to 2004.
John W. Gamble, Jr. (54) has been Corporate Vice President and Chief Financial Officer since May 2014. Prior to that, Mr. Gamble was Executive Vice President and Chief Financial Officer of Lexmark International, Inc., a global provider of document solutions, enterprise content management software and services, printers and multifunction printers, from September 2005 until May 2014.
John J. Kelley III (56) has been Corporate Vice President and Chief Legal Officer since January 2013. Responsibilities include legal services, sourcing, security and compliance, government and legislative relations, corporate governance and privacy functions. Mr. Kelley was a senior partner in the Corporate Practice Group of the law firm of King & Spalding LLP from January 1993 to December 2012.
Joseph M. Loughran, III (49) has been Chief Marketing Officer since March 2015. Prior thereto, he served as President, Global Consumer Solutions since January 4, 2010. Prior thereto, he was Senior Vice President - Corporate Development from April 2006 to December 2009. Prior to joining Equifax, he held various executive roles at BellSouth Corporation from May 2001 to April 2006, including most recently Managing Director-Corporate Strategy and Planning from May 2005 to April 2006.
Coretha M. Rushing (60) has been Corporate Vice President and Chief Human Resources Officer since 2006. Prior to joining Equifax, she served as an executive coach and HR Consultant with Atlanta-based Cameron Wesley LLC. Prior thereto, she was Senior Vice President of Human Resources at The Coca-Cola Company, where she was employed from 1996 until 2004.
David C. Webb (61) has been Chief Information Officer since January 2010. Prior thereto, he served as Chief Operations Officer for SVB Financial Corp. from 2008, and from 2004 to 2008 was Chief Information Officer. Mr. Webb was Vice President, Investment Banking Division at Goldman Sachs, a leading global investment banking, securities and investment management firm, from 1999 to 2004. He was Chief Information Officer at Bank One from 1997 to 1999.
Rodolfo O. Ploder (56) has been President, Workforce Solutions, since November 2015. Prior thereto, he served as President, U.S. Information Solutions, since April 2010. Prior thereto, he served as President, International, from January 2007 to April 2010. Prior thereto, he was Group Executive, Latin America from February 2004 to January 2007.
Paulino R. Barros (60) has been President, U.S. Information Solutions, since November 2015. Prior thereto, he served as President, International, since April 2010. Prior thereto, he served as President of PB&C Global Investments, LLC, an international consulting and investment firm. Prior thereto, he was President of Global Operations for AT&T.
John T. Hartman (57) has been President, International, since November 2015. Prior thereto, he served as Senior Vice President, Corporate Development, since July 2010. Prior thereto, he served as President of Growth Vector from 2009 to 2010. Prior thereto, he served as Executive Vice President and Chief Commercial Officer for Acuity Brands from 2004 to 2009.
J. Dann Adams (59) has been President, Global Consumer Solutions, since November 2015. Prior thereto, he served as President, Workforce Solutions, since July 2010. Prior thereto, he served as President, U.S. Information Solutions from 2007 to June 2010. Prior thereto, he served as Group Executive, North America Information Services from November 2003 until December 2006.
Nuala M. King (63) has been Senior Vice President and Controller since May 2006. Prior thereto, she was Vice President and Corporate Controller from March 2004 to April 2006. Prior to joining Equifax, Ms. King served as Corporate Controller for UPS Capital from March 2001 until March 2004.
FORWARD-LOOKING STATEMENTS
This report contains information that may constitute “forward-looking statements.” Generally, the words “believe,” “expect,” “intend,” “estimate,” “anticipate,” “project,” “will” and similar expressions identify forward-looking statements, which generally are not historical in nature. All statements that address operating performance, events or developments that we expect or anticipate will occur in the future are forward-looking statements. Management believes that these forward-looking statements are reasonable as and when made. However, forward-looking statements are subject to certain risks and uncertainties that could cause actual results to differ materially from our Company’s historical experience and our present expectations or projections, including without limitation our expectations regarding the Company’s outlook, long-term organic and inorganic growth, and customer acceptance of our business solutions referenced above under “Business” and below under “Business Environment and Company Outlook.” These risks and uncertainties include, but are not limited to, those described below in Item 1A. Risk Factors, and elsewhere in this report and those described from time to time in our future reports filed with the United States Securities and Exchange Commission, or SEC. As a result of such risks and uncertainties, we urge you not to place undue reliance on any such forward-looking statements. Forward-looking statements speak only as of the date when made. We undertake no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except as required by law.
AVAILABLE INFORMATION
Detailed information about us is contained in our annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, proxy statements and other reports, and amendments to those reports, that we file with, or furnish to, the SEC. These reports are available free of charge at our website, www.equifax.com, as soon as reasonably practicable after we electronically file such reports with or furnish such reports to the SEC. However, our website and any contents thereof should not be considered to be incorporated by reference into this document. We will furnish copies of such reports free of charge upon written request to Equifax Inc., Attn: Office of Corporate Secretary, P.O. Box 4081, Atlanta, Georgia, 30302.
Previous: Cover and table of contents · Next: Item 1A. RISK FACTORS