 filings.tools
Equifax 10-K 2019-12-31
Filed 2020-02-20. 22 sections, 684K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
☒ ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2019
OR
☐ TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the transition period from to
Commission File Number 001-06605
EQUIFAX INC.
(Exact name of registrant as specified in its charter)
| Georgia | 58-0401110 | |||||||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |||||||
| 1550 Peachtree Street | N.W. | Atlanta | Georgia | 30309 | ||||||||||||||||||||||
| (Address of principal executive offices) | (Zip Code) | |||||||||||||||||||||||||
Registrant’s telephone number, including area code: 404-885-8000
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||||||||
| Common Stock, $1.25 par value per share | EFX | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None.
Indicate by check mark if Registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Exchange Act (“Act”). ☒ Yes ☐ No
Indicate by check mark if Registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. ☐ Yes ☒ No
Indicate by check mark whether Registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the Registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. ☒ Yes ☐ No
Indicate by check mark whether the Registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the Registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the Registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company” and “emerging growth company” in Rule 12b-2 of the Exchange Act. (Check one):
| ☒ | Large accelerated filer | ☐ | Accelerated filer | ☐ | Non-accelerated filer | ☐ | Smaller reporting company | ☐ | Emerging growth company | ||||||||||||||||||||||||||||||||
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the Registrant is a shell company (as defined in Rule 12b-2 of the Act). ☐ YES ☒ NO
As of June 30, 2019, the aggregate market value of Registrant’s common stock held by non-affiliates of Registrant was approximately $16,348,175,266 based on the closing sale price as reported on the New York Stock Exchange. At January 31, 2020, there were 121,235,722 shares of Registrant’s common stock outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of Registrant’s definitive proxy statement for its 2020 annual meeting of shareholders are incorporated by reference in Part III of this Form 10-K.
TABLE OF CONTENTS
PART I
Item 1. BUSINESS
Overview
Equifax Inc. is a global data, analytics and technology company. We provide information solutions for businesses, governments and consumers, and we provide human resources business process outsourcing services for employers. We have a large and diversified group of clients, including financial institutions, corporations, government agencies and individuals. Our services are based on comprehensive databases of consumer and business information derived from numerous sources including credit, financial assets, telecommunications and utility payments, employment, income, demographic and marketing data. We use advanced statistical techniques, machine learning and proprietary software tools to analyze available data to create customized insights, decision-making solutions and processing services for our clients. We also provide information, technology and services to support debt collections and recovery management. Additionally, we are a leading provider of payroll-related and human resource management business process outsourcing services in the United States of America (“U.S.”). For consumers, we provide products and services to help people understand, manage and protect their personal information and make more informed financial decisions.
We currently operate in four global regions: North America (U.S. and Canada), Asia Pacific (Australia, New Zealand and India), Europe (the United Kingdom (“U.K.”), Spain and Portugal) and Latin America (Argentina, Chile, Costa Rica, Ecuador, El Salvador, Honduras, Mexico, Paraguay, Peru and Uruguay). We maintain support operations in the Republic of Ireland, Chile, Costa Rica and India. We also offer Equifax branded credit services in Russia through a joint venture, have investments in consumer and/or commercial credit information companies through joint ventures in Cambodia, Malaysia, Singapore and the United Arab Emirates, have an investment in a consumer and commercial credit information company in Brazil and have an investment in an identity authentication company in Canada.
Equifax was originally incorporated under the laws of the State of Georgia in 1913, and its predecessor company dates back to 1899. As used herein, the terms Equifax, the Company, we, our and us refer to Equifax Inc., a Georgia corporation, and its consolidated subsidiaries as a combined entity, except where it is clear that the terms mean only Equifax Inc.
We are organized and report our business results in four operating segments, as follows:
-
U.S. Information Solutions (“USIS”) — provides consumer and commercial information solutions to businesses in the U.S. including online information, decisioning technology solutions, fraud and identity management services, analytical services, portfolio management services, mortgage reporting and marketing services.
-
Workforce Solutions** — provides services enabling customers to verify income and employment (Verification Services) of people in the U.S., as well as providing our employer customers with services that assist them in complying with and automating certain payroll-related and human resource management processes throughout the entire cycle of the employment relationship, including unemployment cost management, employee onboarding, tax credits and incentives, I-9 management and compliance, tax form management services and Affordable Care Act management services (Employer Services). Workforce Solutions has recently established Verifications Service operations in Canada and is working toward a similar operation in Australia.
-
International** — provides products and services similar to those available in the USIS operating segment but with variations by geographic region. We also provide information, technology and services to support debt collections and recovery management. This operating segment is comprised of our Canada, Europe, Latin America and Asia Pacific business units.
-
Global Consumer Solutions** — provides products to consumers in the U.S., Canada and the U.K., enabling them to understand and monitor their credit and monitor and help protect their identity. We also sell consumer credit information to resellers who may combine our information with other information to provide direct-to-consumer monitoring, reports and scores.
2017 Cybersecurity Incident
In 2017, we experienced a cybersecurity incident following a criminal attack on our systems that involved the theft of certain personally identifiable information of U.S., Canadian and U.K. consumers. Criminals exploited a software vulnerability in a U.S. website application to gain unauthorized access to our network. In March 2017, the U.S. Department of Homeland
Security distributed a notice concerning the software vulnerability. We undertook efforts to identify and remediate vulnerable systems; however, the vulnerability in the website application that was exploited was not identified by our security processes. We discovered unusual network activity in late-July 2017 and upon discovery promptly investigated the activity. Once the activity was identified as potential unauthorized access, we acted to stop the intrusion and engaged a leading, independent cybersecurity firm to conduct a forensic investigation to determine the scope of the unauthorized access, including the specific information impacted. Based on our forensic investigation, the unauthorized access occurred from mid-May 2017 through July 2017. No evidence was found that the Company’s core consumer, employment and income, or commercial reporting databases were accessed. We continue to cooperate with law enforcement in connection with the criminal investigation into the actors responsible for the 2017 cybersecurity incident. On February 10, 2020, the U.S. Department of Justice announced that four members of the Chinese People’s Liberation Army were indicted on criminal charges for their involvement in the 2017 cybersecurity incident.
The Company has taken actions to provide consumers with tools to protect their credit data. Immediately following the announcement of the 2017 cybersecurity incident, the Company devoted substantial resources to notify people of the incident and to provide free services to assist people in monitoring their credit and identity information. Since then, the Company has been focused on implementing significant improvements to its data security systems, technology platforms and risk management processes, in an effort to underpin its business strategy.
Our Business Strategy
Our vision is to be a trusted global leader in data, advanced analytics and technology that creates innovative solutions and insights for our customers. Our business strategy is driven by the following imperatives:
-
Lead our industry in data security. We are focused on becoming a leader in our industry in the effectiveness of our data and technology security practices. This includes building an Equifax culture that considers data and technology security, and more broadly risk management, as a primary requirement in all decisions. This also includes the extensive use of advanced data and technology security tools, techniques, services and processes in order to enhance our ability to protect the information with which we are entrusted from fraudulent access.
-
Transform our technology. We are rebuilding our technology infrastructure, accelerating our migration to a public cloud environment, employing virtual private cloud deployment techniques, and rationalizing and rebuilding our application portfolio using cloud-native services. This technology transformation is a significant part of our goal of leading our industry in data and technology security capability. Our goal is to deliver market-leading capabilities to our customers in terms of speed of bringing new products and services to market; ease of customer and partner implementation and integration; ease of consumer access to and interaction with Equifax; system r
Showing the first 8K of 67K characters. Open the full section
Item 1A. RISK FACTORS
All of the risks and uncertainties described below and the other information included in this Form 10-K should be considered and read carefully. The risks described below are not the only ones facing us. The occurrence of any of the following risks or additional risks and uncertainties not presently known to us or that we currently believe to be immaterial could materially and adversely affect our business, financial condition or results of operations. This Form 10-K also contains forward-looking statements and estimates that involve risks and uncertainties. Our actual results could differ materially from those anticipated in the forward-looking statements as a result of specific factors, including the risks and uncertainties described below.
Security breaches and other disruptions to our information technology infrastructure could compromise Company, consumer and customer information, interfere with our operations, cause us to incur significant costs for remediation and enhancement of our IT systems and expose us to legal liability, all of which could have a substantial negative impact on our business and reputation.
We are a global data, analytics and technology company. In the ordinary course of business, we collect, process, transmit and store sensitive data, including intellectual property, proprietary business information and personally identifiable information of consumers, employees and strategic partners. The secure operation of our information technology networks and systems, and of the processing and maintenance of this information, is critical to our business operations and strategy. Despite our substantial investment in physical and technological security measures, employee training and contractual precautions, our information technology networks and infrastructure (or those of our third-party vendors and other service providers) are potentially vulnerable to unauthorized access to data or breaches of confidential information due to criminal conduct, attacks by hackers, employee or insider malfeasance and/or human error. For example, in 2017, we experienced a cybersecurity incident following a criminal attack on our systems that involved the theft of personally identifiable information of U.S., Canadian and U.K. consumers.
Following the 2017 cybersecurity incident, we began undertaking significant remediation efforts and other steps to enhance our data security infrastructure which are ongoing. In connection with these efforts, we have incurred significant costs and expect to incur additional significant costs as we continue to enhance our data security infrastructure and take further steps to prevent unauthorized access to our systems and the data we maintain. Despite these efforts, we cannot assure you that all potential causes of this incident have been identified and remediated and that similar cyber incidents will not occur in the future.
Because our products and services involve the storage and transmission of personal information of consumers, we will continue to routinely be the target of attempted cyber and other security threats by outside third parties, including technically sophisticated and well-resourced bad actors attempting to access or steal the data we store. We are in the process of transforming our applications and infrastructure technologies, transitioning to cloud-based technologies. As we transition to cloud-based technologies, we may be exposed to additional cyber threats as we migrate our data from our legacy systems to cloud-based solutions. Our increased dependence on third parties to store our cloud-based data systems may also subject us to further cyber threats. Insider or employee cyber and security threats are also a significant concern for all companies, including ours.
We must continuously plan, develop and monitor our information technology networks and infrastructure to identify, protect, detect, respond to and recover from the risk of unauthorized access, misuse, malware, phishing and other events that could have a security impact. Because the techniques used to obtain unauthorized access, disable or degrade service or sabotage systems change frequently and often are not recognized until launched against a target, or even some time after, we may be unable to anticipate these techniques, implement adequate preventative measures or remediate any intrusion on a timely or effective basis even if our security measures are appropriate, reasonable, and/or in accordance with applicable legal requirements. If we experience additional breaches of our security measures, including from incidents that we fail to detect for a period of time, sensitive data may be accessed, stolen, disclosed or lost. Any such access, disclosure or other loss of information could subject us to significant litigation, regulatory fines, penalties, losses of customers or reputational damage, any of which could have a material adverse effect on our cash flows, competitive position, financial condition or results of operations.
We cannot ensure that our insurance policies in the future will be adequate to cover losses from any future security breaches. Our $125.0 million cybersecurity insurance policy was not adequate to cover the losses we have incurred to date from the 2017 cybersecurity incident, and all future losses we incur as a result of the incident will not be covered by insurance. In addition, our insurance coverage will vary from time to time in both type and amount depending on availability, cost and our decisions with respect to risk retention.
As part of a global settlement, we entered into agreements with various parties to settle the U.S. Consumer MDL Litigation and certain federal and state government investigations arising out of the 2017 cybersecurity incident. If we are unable to comply with our obligations under these agreements, or if other lawsuits or investigations are filed or commenced, it could have a material adverse effect on our financial condition.
In July 2019, the Company entered into multiple agreements that resolve the U.S. consolidated consumer class action cases, captioned In re: Equifax, Inc. Customer Data Security Breach Litigation, MDL No. 2800 (Consumer Cases) (the “U.S. Consumer MDL Litigation”), and the investigations of the FTC, the CFPB, the Attorneys General of 48 states, the District of Columbia and Puerto Rico (the “MSAG Group”) and the NYDFS (collectively, the “Consumer Settlement”) relating to the 2017 cybersecurity incident. On January 13, 2020, the U.S. District Court for the Northern District of Georgia (the “Court”) entered an order granting final approval of the settlement in connection with the U.S. Consumer MDL Litigation, from which several objectors have appealed. Until the appeals are finally adjudicated or dismissed, we can provide no assurance that the U.S. Consumer MDL Litigation will be resolved as contemplated by the settlement agreement. If the Court’s order approving the settlement agreement were reversed by an appellate court, there is a risk that we would not be able to settle the U.S. Consumer MDL Litigation on acceptable terms or at all, which could have a material adverse effect on our financial condition.
In addition to the monetary payments and consumer redress, we also agreed as part of the Consumer Settlement to implement certain business practice commitments related to consumer assistance and our information security program, including third party assessments of our program. These business practice commitments are extensive and will require a significant amount of attention from management. We can provide no assurance that we will be able to comply with these business practice commitments. To the extent we were unable to comply or we are viewed as not being in compliance with these business practice commitments or other requirements of a relevant order, we could face an enforcement action or contempt proceeding that could potentially result in
Showing the first 8K of 61K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
Our executive offices are located at 1550 Peachtree Street, N.W., Atlanta, Georgia. Our other properties are geographically distributed to meet sales and operating requirements worldwide. We consider these properties to be both suitable and adequate to meet our current operating requirements. We ordinarily lease office space for conducting our business and are obligated under approximately 85 leases and other rental arrangements for our field locations. We owned 8 office buildings at December 31, 2019, including our executive offices, one campus which houses our Alpharetta, Georgia technology center, a building utilized by our Workforce Solutions operations located in St. Louis, Missouri, as well as three buildings utilized by our Latin America operations.
For additional information regarding our obligations under leases, see Note 6 of the Notes to Consolidated Financial Statements in this Form 10-K. We believe that suitable additional space will be available to accommodate our future needs.
Item 3. LEGAL PROCEEDINGS
Litigation and Investigations related to the 2017 Cybersecurity Incident
Following the 2017 cybersecurity incident, hundreds of class actions and other lawsuits were filed against us typically alleging harm from the 2017 cybersecurity incident and seeking various remedies, including monetary and injunctive relief. We were also subject to investigations and inquiries by federal, state and foreign governmental agencies and officials regarding the 2017 cybersecurity incident and related matters. As described below, most of these lawsuits and government investigations have concluded or been resolved, including pursuant to the settlement agreements described below, while others remain ongoing. The Company’s participation in these settlements does not constitute an admission by the Company of any fault or liability, and the Company does not admit fault or liability.
Consumer Settlement.
On July 19, 2019 and July 22, 2019, we entered into multiple agreements that resolve the U.S. consolidated consumer class action cases, captioned In re: Equifax, Inc. Customer Data Security Breach Litigation, MDL No. 2800 (Consumer Cases) (the “U.S. Consumer MDL Litigation”), and the investigations of the FTC, the CFPB, the MSAG Group and the NYDFS (collectively, the “Consumer Settlement”). Under the terms of the Consumer Settlement, the Company will contribute $380.5 million to a non-reversionary settlement fund (the “Consumer Restitution Fund”) to provide restitution for U.S. consumers identified by the Company whose personal information was compromised as a result of the 2017 cybersecurity incident.
The Consumer Restitution Fund will be used to (1) compensate affected consumers for certain unreimbursed costs or expenditures incurred by affected consumers that are fairly traceable to the 2017 cybersecurity incident, (2) provide affected consumers with an opportunity to enroll in at least four years of credit monitoring services provided by a third party unaffiliated with the Company or alternative compensation for affected consumers who already have other credit monitoring services, (3) provide affected consumers with additional benefits such as identity restoration services and (4) pay reasonable attorneys’ fees and reasonable costs and expenses for the plaintiffs’ counsel in the U.S. Consumer MDL Litigation (not to exceed $80.5 million) and administrative and notice costs.
The Company has agreed to contribute up to an additional $125.0 million to the Consumer Restitution Fund to cover unreimbursed costs and expenditures described in (1) above in the event the $380.5 million in the Consumer Restitution Fund is exhausted.
In accordance with the terms of the Consumer Settlement, in the third quarter of 2019, the Company paid $180.5 million to the MSAG Group and the following monetary penalties: (1) $100.0 million to the CFPB and (2) $10.0 million to the NYDFS. As part of the Consumer Settlement, the Company also agreed to implement certain business practice commitments related to consumer assistance and its information security program, including conducting third party assessments of its information security program.
In the third quarter of 2019, the agreements with the FTC and CFPB were approved by the U.S. District Court for the Northern District of Georgia. The settlement with the MSAG Group, which consists of substantially similar agreements with each of the participating jurisdictions, was approved by courts in the relevant jurisdiction also in the third quarter of 2019.
On January 13, 2020, the Northern District of Georgia, the U.S. District Court overseeing centralized pre-trial proceedings for the U.S. Consumer MDL Litigation and numerous other federal court actions relating to the 2017 cybersecurity incident (the “MDL Court”), entered an order granting final approval of the settlement in connection with the U.S. Consumer MDL Litigation, from which several objectors have appealed. Until the appeals are finally adjudicated or dismissed, we can provide no assurance that the U.S. Consumer MDL Litigation will be resolved as contemplated by the settlement agreement. If the MDL Court’s order approving the settlement were reversed by an appellate court, there is a risk that we would not be able to settle the U.S. Consumer MDL Litigation on acceptable terms or at all, which could have a material adverse effect on our financial condition.
Other Settlements.
Securities Class Action Litigation. A consolidated putative class action lawsuit alleging violations of certain federal securities laws in connection with statements and alleged omissions regarding our cybersecurity systems and controls was filed against us and our former Chairman and Chief Executive Officer in the U.S. District Court for the Northern District of Georgia. The consolidated complaint seeks certification of a class of all persons who purchased or otherwise acquired Equifax securities from February 25, 2016 through September 15, 2017 and unspecified monetary damages, costs and attorneys’ fees. The
Company moved to dismiss the complaint in its entirety. On January 28, 2019, the court dismissed claims against certain individual defendants and claims challenging certain statements, but allowed other claims against Equifax and our former Chairman and Chief Executive Officer to proceed.
On February 12, 2020, we entered into a settlement agreement to resolve the securities class action lawsuit in which the Company agreed to create a settlement fund for the benefit of class members. The settlement is subject to a number of conditions, including certification of a settlement class, notice, and preliminary and final court approvals. We can provide no assurance that all conditions will be satisfied or that the necessary court approvals will be obtained.
Shareholder Derivative Litigation. A consolidated putative shareholder derivative action naming certain of our current and former executives, officers and directors as defendants and naming us as a nominal defendant was filed in the U.S. District Court for the Northern District of Georgia. Among other things, the consolidated complaint alleges claims for breaches of fiduciary duties, unjust enrichment, corporate waste and insider selling by certain defendants, as well as certain claims under the federal securities laws. The complaint seeks unspecified damages on behalf of the Company, plus certain equitable relief. We appointed a committee of independent directors (the “Demand Review Committee”) empowered to evaluate and respond in our best interests to the claims and related litigation demands.
On February 12, 2020, the Company, by and through the Demand Review Committee, and individual defendants entered into a settlement agreement with the plaintiffs which, subject to court approval, will resolve the matter by agreeing to adopt certain governance changes and obtaining an insurance recovery for the Company. We can provide no assurance that the necessary court approvals will be obtained.
Government Lawsuits. Separate civil enforcement actions were filed against us in state court by the respective Attorneys General of Indiana and Massachusetts alleging violations of commonwealth/state consumer protection laws and seeking injunctive relief, civil penalties, restitution, costs and other relief. The Company filed motions to dismiss the actions which were denied. On December 26, 2019, we filed a motion asking the court in the Indiana action to certify its order denying our motion to dismiss for interlocutory appeal, and that motion was granted on February 6, 2019.
The Company has reached an agreement in principle with each of the Attorneys General of Massachusetts and Indiana to resolve their actions. These settlements, in which the Company has agreed to make a monetary payment and to injunctive relief consistent with the MSAG Group settlement, are subject to finalizing definitive settlement agreements and court approval in each respective jurisdiction.
Financial Institutions MDL Class Action. Certain class actions were filed by financial institutions and transferred to the MDL Court (the “Financial Institutions MDL Litigation”). These class actions allege that the financial institutions’ businesses have been placed at risk due to the 2017 cybersecurity incident, generally assert common law claims such as claims for negligence, as well as, in some cases, statutory claims and seek compensatory damages, injunctive relief and other related relief. The Company moved to dismiss the financial institutions’ consolidated class action complaint in its entirety, and the MDL Court dismissed certain claims, while allowing other claims to proceed. The financial institution plaintiffs filed a motion to amend their class action complaint which was granted in part and denied in part on December 18, 2019. The majority of the claims which the financial institutions sought to revive by amendment, however, remained dismissed.
The Company has reached an agreement in principle to enter into a class-wide settlement of the remaining financial institutions’ claims. Upon submission of the final settlement documents and necessary court approvals, the settlement will resolve any remaining claims that could be asserted by the financial institutions before the MDL Court. The settlement contemplates payment for claims up to a maximum amount and certain non-monetary relief. The settlement is subject to a number of conditions, including notice, and preliminary and final court approvals. We can provide no assurance that all conditions will be satisfied or that the necessary court approvals will be obtained.
Pennsylvania State Court Financial Institution Class Action. One of the initial named plaintiffs in Financial Institutions MDL Litigation filed a purported class action suit against us in the Court of Common Pleas of Lawrence County, Pennsylvania on behalf of financial institutions headquartered in Pennsylvania. The claims being asserted in this matter are substantially similar to claims that previously were dismissed in the MDL proceeding for lack of standing. We filed preliminary objections to the complaint on September 5, 2019, and a hearing on the preliminary objections is scheduled for June 29, 2020. The Company has reached an agreement in principle to resolve this matter. The settlement is subject to court approval, and we can provide no assurance that the necessary court approval will be obtained.
Indian Tribes Class Actions and City of Chicago Lawsuit. Three Indian Tribes and the City of Chicago filed separate suits with respect to the 2017 cybersecurity incident, which were subsequently transferred to the MDL Court. The Indian Tribes brought their claims purportedly on behalf of themselves and other similarly situated federally recognized Indian Tribes and
Nations. The Company has reached an agreement in principle to resolve the three Indian Tribes’ claims as well as an agreement in principle to resolve the City of Chicago’s lawsuit.
Other Matters.
We face other lawsuits and government investigations related to the 2017 cybersecurity incident that have not yet been concluded or resolved. These ongoing matters may result in judgments, fines or penalties, settlements or other relief. We dispute the allegations in the remaining lawsuits and intend to defend against such claims. Set forth below are descriptions of the main categories of these matters.
Georgia State Court Consumer Class Actions. Four putative class actions arising from the 2017 cybersecurity incident were filed against us in Fulton County Superior Court and Fulton County State Court in Georgia based on similar allegations and theories as alleged in the U.S. Consumer MDL Litigation and seek monetary damages, injunctive relief and other related relief on behalf of Georgia citizens. These cases were transferred to a single judge in the Fulton County Business Court and three of the cases were consolidated into a single action. On July 27, 2018, the Fulton County Business Court granted the Company’s motion to stay the remaining single case, and on August 17, 2018, the Fulton County Business Court granted the Company’s motion to stay the consolidated case. These cases remain stayed pending resolution of the U.S. Consumer MDL Litigation.
Canadian Class Actions. Eight Canadian class actions, six of which are on behalf of a national class of approximately 19,000 Canadian consumers, have been filed against us in Ontario, Saskatchewan, Quebec, British Columbia and Alberta. Each of the proposed Canadian class actions asserts a number of common law and statutory claims seeking monetary damages and other related relief in connection with the 2017 cybersecurity incident. The plaintiffs in each case seek class certification/authorization on behalf of Canadian consumers whose personal information was allegedly impacted by the 2017 cybersecurity incident. In some cases, plaintiffs also seek class certification on behalf of a larger group of Canadian consumers who had contracts for subscription products with Equifax around the time of the incident or earlier and were not impacted by the incident.
On October 21, 2019, the court in the Quebec case dismissed the plaintiff’s motion for authorization to institute a class action. On December 13, 2019, the court in the active Ontario case granted certification of a nationwide class that includes impacted Canadians as well as Canadians who had subscription products with Equifax between March 7, 2017 and July 30, 2017. We have sought leave to appeal this decision. All remaining purported class actions are at preliminary stages. In addition, one of the cases in Ontario as well as the Saskatchewan case have been stayed. The court’s order staying the Saskatchewan case is on appeal.
Individual Consumer Litigation. We have several hundred individual consumer actions pending against us in state (general jurisdiction and small claims) and federal courts across the U.S. related to the 2017 cybersecurity incident. The plaintiffs/claimants in these cases have generally claimed to have been harmed by alleged actions and/or omissions by Equifax in connection with the 2017 cybersecurity incident and assert a variety of common law and statutory claims seeking primarily monetary damages. Where possible, actions filed in or removed to federal court were noticed for transfer to the MDL Court. We believe that many of the remaining individual consumer actions will be subject to the settlement in the U.S. Consumer MDL Litigation discussed above, unless the individual consumers submitted a valid and timely request to be excluded from the settlement.
Government Investigations. We have cooperated with federal, state and foreign governmental agencies and officials investigating or otherwise seeking information, testimony and/or documents, regarding the 2017 cybersecurity incident and related matters.
The FCA opened an enforcement investigation against our U.K. subsidiary, Equifax Limited, in October 2017. The investigation by the FCA has involved a number of information requirements and interviews. We continue to respond to the information requirements and are cooperating with the investigation.
The New York State Attorney General Investor Protection Bureau (“IPB”) issued a subpoena in September 2017 relating to its investigation of whether there has been a violation of the Martin Act. We have cooperated with the IPB in its investigation, and the IPB has not contacted us regarding the investigation since January 2019.
Although we continue to cooperate in the above investigations and inquiries, an adverse outcome to any such investigations and inquiries could subject us to fines or other obligations, which may have an adverse effect on how we operate our business or our results of operations.
ACCC Investigation
In March 2017, the ACCC commenced an investigation to determine whether the Company has been or is engaged in unlawful acts or practices relating to advertising, marketing and sale of consumer reports, credit scores or credit monitoring products in violation of the Australian Consumer Law, which prohibits misleading or deceptive conduct and false representations. The ACCC issued a number of notices to produce documents and information. On March 16, 2018, the ACCC commenced proceedings against the Company. The proceedings were settled on October 2, 2018. Pursuant to the settlement, Equifax paid a monetary penalty and provided refunds to certain impacted consumers. As it was not possible to refund all impacted customers, Equifax has undertaken to the ACCC to refund those customers if and when their current address and/or bank account details become known. The proceedings formally concluded on November 30, 2019.
California Bankruptcy Litigation
In consolidated actions filed in the U.S. District Court for the Central District of California, captioned Terri N. White, et al. v. Equifax Information Services LLC, Jose Hernandez v. Equifax Information Services LLC, Kathryn L. Pike v. Equifax Information Services LLC, and Jose L. Acosta, Jr., et al. v. Trans Union LLC, et al., plaintiffs asserted that Equifax violated federal and state law (the FCRA, the California Credit Reporting Act and the California Unfair Competition Law) by failing to follow reasonable procedures to determine whether credit accounts are discharged in bankruptcy, including the method for updating the status of an account following a bankruptcy discharge. On August 20, 2008, the District Court approved a Settlement Agreement and Release providing for certain changes in the procedures used by defendants to record discharges in bankruptcy on consumer credit files. That settlement resolved claims for injunctive relief, but not plaintiffs’ claims for damages. On May 7, 2009, the District Court issued an order preliminarily approving an agreement to settle remaining class claims. The District Court subsequently deferred final approval of the settlement and required the settling parties to send a supplemental notice to those class members who filed a claim and objected to the settlement or opted out, with the cost for the re-notice to be deducted from the plaintiffs’ counsel fee award. Mailing of the supplemental notice was completed on February 15, 2011 and the deadline for this group of settling plaintiffs to provide additional documentation to support their damage claims or to opt-out of the settlement was March 31, 2011. On July 15, 2011, the District Court approved the settlement. Several objecting plaintiffs subsequently filed notices of appeal to the U.S. Court of Appeals for the Ninth Circuit, which, on April 22, 2013, issued an order vacating the settlement and remanding the case to the District Court for further proceedings. On January 21, 2014, the District Court denied the objecting plaintiffs’ motion to disqualify counsel for the settling plaintiffs and granted the motion of counsel for the settling plaintiffs to be appointed as interim lead class counsel. On March 28, 2016, the U.S. Court of Appeals for the Ninth Circuit affirmed the District Court’s lead counsel appointment. On January 9, 2017, the United States Supreme Court denied the objectors’ Petition for a Writ of Certiorari. The parties re-engaged in settlement discussions, including participation in mediations in August 2016 and November 2016, and reached an agreement to again settle the monetary claims. Settlement documents were filed with the District Court on April 14, 2017. On June 16, 2017, the Court granted preliminary approval of the proposed settlement, conditionally certified the settlement class, and appointed class counsel and administrator. A Final Fairness Hearing was held on December 11, 2017 and on April 6, 2018, the Court granted final approval. A Notice of Appeal was filed on May 7, 2018. Following the Notice of Appeal, the parties reached a Stipulation Regarding Attorneys’ Fees and Costs with the District Court subject to affirmance of the settlement with the U.S. Court of Appeals for the Ninth Circuit. On December 12, 2019, the Ninth Circuit affirmed the settlement and remanded to the District Court for recalculation of the attorneys’ fee award to class counsel. On January 10, 2020, the objecting plaintiffs filed a Petition for Rehearing and Rehearing En Banc which was denied.
Other
Equifax has been named as a defendant in various other legal actions, including administrative claims, regulatory matters, government investigations, class actions and other litigation arising in connection with our business. Some of the legal actions include claims for substantial compensatory or punitive damages or claims for indeterminate amounts of damages. We believe we have defenses to and, where appropriate, will contest, many of these matters. Given the number of these matters, some are likely to result in adverse judgments, penalties, injunctions, fines or other relief. We may explore potential settlements before a case is taken through trial because of the uncertainty and risks inherent in the litigation process.
For information regarding our accounting for legal contingencies, see Note 6 of the Notes to Consolidated Financial Statements in this Form 10-K.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
PART II
Item 5. MARKET FOR THE REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Equifax’s common stock is traded on the New York Stock Exchange under the symbol “EFX.” As of January 31, 2020, Equifax had approximately 3,121 holders of record; however, Equifax believes the number of beneficial owners of common stock exceeds this number.
Shareholder Return Performance Graph
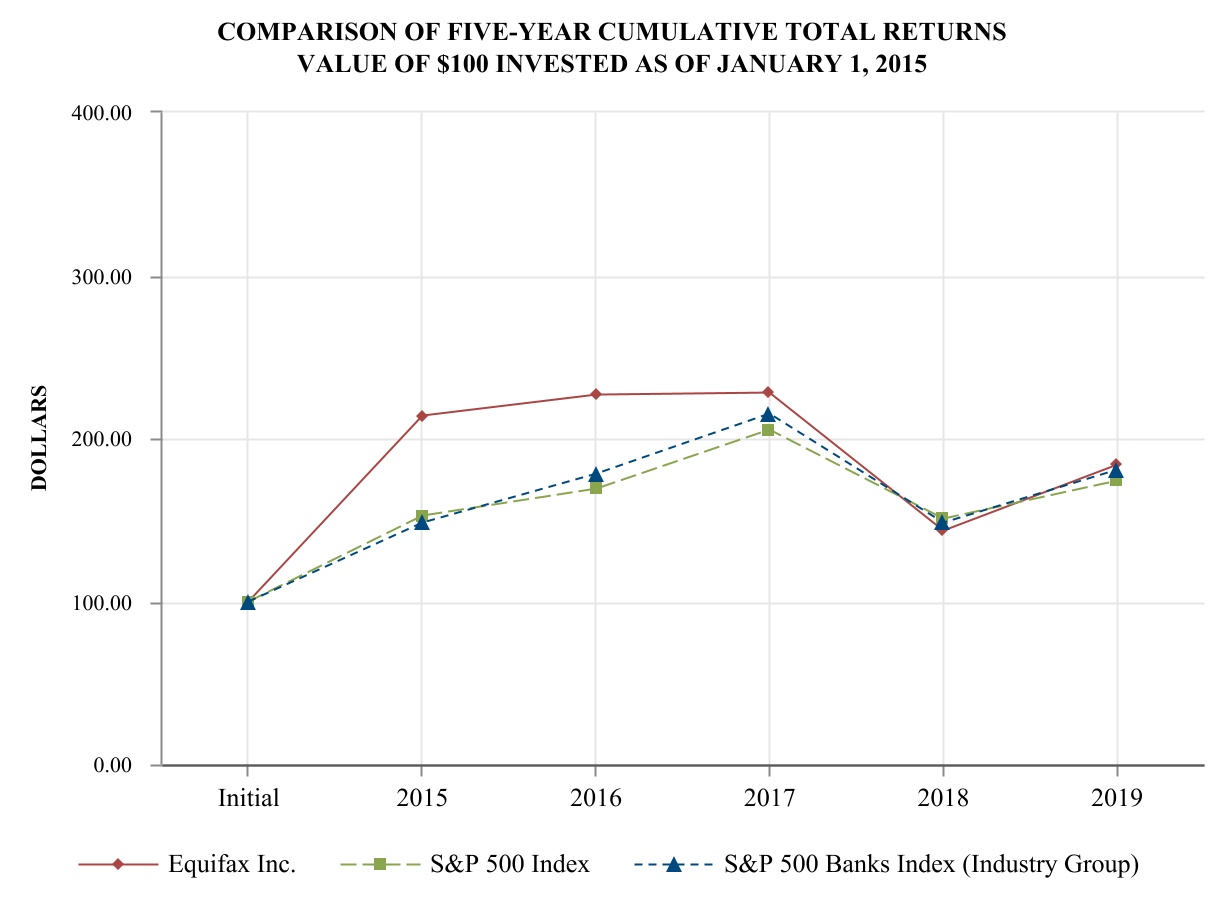
The graph below compares Equifax’s five-year cumulative total shareholder return with that of the Standard & Poor’s Composite Stock Index (S&P 500) and a peer group index, the S&P 500 Banks Index (Industry Group). The graph assumes that the value of the investment in our Common Stock and each index was $100 on the last trading day of 2014 and that all quarterly dividends were reinvested without commissions. Our past performance may not be indicative of future performance.
COMPARATIVE FIVE-YEAR CUMULATIVE TOTAL RETURN AMONG EQUIFAX INC., S&P 500 INDEX, AND S&P 500 BANKS INDEX (INDUSTRY GROUP)
| Fiscal Year Ended December 31, | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Initial | 2015 | 2016 | 2017 | 2018 | 2019 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equifax Inc. | 100.00 | 214.06 | 226.90 | 228.22 | 143.32 | 183.98 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| S&P 500 Index | 100.00 | 152.59 | 169.24 | 205.24 | 150.33 | 173.86 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| S&P 500 Banks Index (Industry Group) | 100.00 | 148.23 | 178.13 | 214.75 | 148.30 | 180.55 |
The table below contains information with respect to purchases made by or on behalf of Equifax of its common stock during the fourth quarter ended December 31, 2019:
Issuer Purchases of Equity Securities
| Period | Total Number of Shares Purchased (1) | Average Price Paid Per Share (2) | Total Number of Shares Purchased as Part of Publicly-Announced Plans or Programs | Maximum Number (or Approximate Dollar Value) of Shares that May Yet Be Purchased Under the Plans or Programs (3) | ||||||||||||||||||||||
| October 1 - October 31, 2019 | 1 | $ | — | — | $ | 590,092,166 | ||||||||||||||||||||
| November 1 - November 30, 2019 | 176 | $ | — | — | $ | 590,092,166 | ||||||||||||||||||||
| December 1 - December 31, 2019 | 4,970 | $ | — | — | $ | 590,092,166 | ||||||||||||||||||||
| Total | 5,147 | $ | — | — | $ | 590,092,166 |
(1) The total number of shares purchased includes, if applicable: (a) shares purchased pursuant to our publicly-announced share repurchase program, or Program; and (b) shares surrendered, or deemed surrendered, in satisfaction of the exercise price and/or to satisfy tax withholding obligations in connection with the exercise of employee stock options and vesting of restricted stock, totaling 1 share for the month of October 2019, 176 shares for the month of November 2019 and 4,970 shares for the month of December 2019.
(2) Average price paid per share for shares purchased as part of our Program (includes brokerage commissions).
(3) We did not repurchase any common shares during the twelve months ended December 31, 2019. At December 31, 2019, the amount authorized for future share repurchases under the Program was $590.1 million.
Information relating to compensation plans under which the Company’s equity securities are authorized for issuance is included in the section captioned “Equity Compensation Plan Information” in our 2020 Proxy Statement and is incorporated herein by reference.
Item 6. SELECTED FINANCIAL DATA
The table below summarizes our selected historical financial information for each of the last five years. The summary of operations data for the years ended December 31, 2019, 2018, and 2017, and the balance sheet data as of December 31, 2019 and 2018, have been derived from our audited Consolidated Financial Statements included in this report. The summary of operations data for the years ended December 31, 2016 and 2015, and the balance sheet data as of December 31, 2017, 2016 and 2015, have been derived from our audited Consolidated Financial Statements not included in this report. The historical selected financial information may not be indicative of our future performance and should be read in conjunction with the information contained in Management’s Discussion and Analysis of Financial Condition and Results of Operations, and the Consolidated Financial Statements and the accompanying Notes to the Consolidated Financial Statements in this report.
| Twelve Months Ended December 31, | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2019 (1) (2) | 2018 (2) (3) | 2017 (2) (4) | 2016 (5) | 2015 (3) (6) | |||||||||||||||||||||||||||||||||||||||||||||||||
| (In millions, except per share data) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Summary of Operations: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Operating revenue | $ | 3,507.6 | $ | 3,412.1 | $ | 3,362.2 | $ | 3,144.9 | $ | 2,663.6 | |||||||||||||||||||||||||||||||||||||||||||
| Operating expenses | 3,843.0 | 2,964.1 | 2,530.5 | 2,319.8 | 1,963.6 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Operating (loss) income | (335.4) | 448.0 | 831.7 | 825.1 | 700.0 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Consolidated (loss) income from continuing operations | (392.8) | 306.3 | 598.0 | 495.1 | 434.8 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Net (loss) income attributable to Equifax | $ | (398.8) | $ | 299.8 | $ | 587.3 | $ | 488.8 | $ | 429.1 | |||||||||||||||||||||||||||||||||||||||||||
| Dividends paid to Equifax shareholders | $ | 188.7 | $ | 187.9 | $ | 187.4 | $ | 157.6 | $ | 137.8 | |||||||||||||||||||||||||||||||||||||||||||
| Diluted earnings per share | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net (loss) income attributable to Equifax | $ | (3.27) | $ | 2.47 | $ | 4.83 | $ | 4.04 | $ | 3.55 | |||||||||||||||||||||||||||||||||||||||||||
| Cash dividends declared per share | $ | 1.56 | $ | 1.56 | $ | 1.56 | $ | 1.32 | $ | 1.16 | |||||||||||||||||||||||||||||||||||||||||||
| Weighted-average shares outstanding (diluted) | 122.0 | 121.4 | 121.5 | 121.1 | 120.9 |
| As of December 31, | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| 2019 (1) (2) | 2018 (2) (3) | 2017 (2) (4) | 2016 (5) | 2015 (3) (6) | |||||||||||||||||||||||||||||||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Balance Sheet Data: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 7,909.0 | $ | 7,153.2 | $ | 7,233.4 | $ | 6,664.0 | $ | 4,501.5 | |||||||||||||||||||||||||||||||||||||||||||
| Short-term debt and current maturities | 3.1 | 4.9 | 965.3 | 585.4 | 49.3 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Long-term debt, net of current portion | 3,379.5 | 2,630.6 | 1,739.0 | 2,086.8 | 1,138.4 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Total debt, net | 3,382.6 | 2,635.5 | 2,704.3 | 2,672.2 | 1,187.7 | ||||||||||||||||||||||||||||||||||||||||||||||||
| Total equity | 2,622.9 | 3,155.7 | 3,239.0 | 2,721.3 | 2,350.4 |
(1)During the year ended December 31, 2019, the Company recorded $800.9 million of losses, net of insurance recoveries, associated with certain legal proceedings and government investigations related to the 2017 cybersecurity incident, exclusive of our legal professional services expenses. For additional information, see Note 6 of the Notes to the Consolidated Financial Statements in this report.
(2)During the years ended December 31, 2019, 2018 and 2017, the Company recorded $337.3 million, $326.2 million, and $114.0 million, respectively, of pre-tax expenses, net of cybersecurity insurance recoveries, for costs related to the 2017 cybersecurity incident. Costs related to the 2017 cybersecurity incident are defined as incremental costs to transform our information technology infrastructure and data security; legal fees and professional services costs to investigate the 2017 cybersecurity incident and respond to legal, government and regulatory claims; as well as costs to provide free product
and related support to consumers. For additional information, see Note 6 of the Notes to the Consolidated Financial Statements in this report.
(3)During the fourth quarter of 2018 and the first quarter of 2015, we recorded a restructuring charge of $46.1 million and $20.7 million, respectively, all of which is recorded in selling, general, and administrative expenses in our Consolidated Statements of (Loss) Income. These restructuring charges primarily relate to a reduction in headcount to support the Company’s strategic objectives and increase the integration of our global operations. For additional information, see Note 11 of the Notes to the Consolidated Financial Statements in this report.
(4)The Tax Cuts and Jobs Act of 2017 (“Tax Act”), as signed by the President of the United States on December 22, 2017, significantly revised U.S. tax law. The legislation positively impacted the Company’s ongoing effective tax rate due to the reduction of the U.S. federal corporate tax rate from 35% to 21%. The Tax Act made major changes to the U.S. international tax system. Under previous law, foreign earnings were subject to U.S. tax when repatriated to the U.S. Under the Tax Act, foreign earnings are generally exempt from U.S. tax. Additionally, there is a one-time deemed repatriation tax on undistributed foreign earnings and profits. The Tax Act imposes other U.S. taxes on “global intangible low taxed income” and “base erosion anti-abuse transactions.” Other significant changes included limitations on the deductibility of interest expense and executive compensation, and repeal of the deduction for domestic production activities. As a result of the Tax Act, the Company recorded adjustments totaling a net tax benefit of $48.3 million in the fourth quarter of 2017 to provisionally account for the estimated impact. Refer to Note 7 of the Notes to the Consolidated Financial Statements in this Form 10-K for additional information. We also prospectively applied the provisions of ASU 2016-09 “Compensation - Stock Compensation (Topic 718),” related to the recognition of windfall tax benefits in the Consolidated Statement of Income which resulted in the recognition of $26.7 million of tax benefits for the year ended December 31, 2017.
(5)In the first quarter of 2016, we completed the acquisition of 100% of the ordinary voting shares of Veda Group Limited (“Veda”) for cash consideration plus debt assumed of approximately $1.9 billion. For the year ended December 31, 2016, we recorded $40.2 million ($28.2 million, net of tax) for Veda acquisition related amounts. Of this amount, $30.1 million relates to transaction and integration costs in operating income, $9.2 million is recorded in other income and is the impact of foreign currency changes on the transaction structure, including economic hedges, $0.2 million is recorded in depreciation and amortization, and $0.7 million is recorded in interest expense.
(6)During the second quarter of 2015, the management of Boa Vista Servicos S.A. (“BVS”), in which we hold a 15% cost method investment, updated the financial projections of BVS. The updated projections, along with the continued weakness in the Brazilian consumer and small commercial credit markets were considered indicators of impairment. As a result of these changes, and the associated near-term changes in cash flow expected from the business, we recorded a 46.0 million Brazilian Reais ($14.8 million) impairment of our investment.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
As used herein, the terms Equifax, the Company, we, our and us refer to Equifax Inc., a Georgia corporation, and its consolidated subsidiaries as a combined entity, except where it is clear that the terms mean only Equifax Inc.
All references to earnings per share data in Management’s Discussion and Analysis, or MD&A, are to diluted earnings per share, or EPS, unless otherwise noted. Diluted EPS is calculated to reflect the potential dilution that would occur if stock options or other contracts to issue common stock were exercised and resulted in additional common shares outstanding.
BUSINESS OVERVIEW
Equifax Inc. is a global data, analytics and technology company. We provide information solutions and human resources business process outsourcing services for businesses, governments and consumers. We have a large and diversified group of clients, including financial institutions, corporations, governments and individuals. Our services are based on comprehensive databases of consumer and business information derived from numerous sources including credit, financial assets, telecommunications and utility payments, employment, income, demographic and marketing data. We use advanced statistical techniques, machine learning and proprietary software tools to analyze available data to create customized insights, decision-making solutions and processing services for our clients. We also provide information, technology and services to support debt collections and recovery management. Additionally, we are a leading provider of payroll-related and human resource management business process outsourcing services in the United States of America, or U.S. For consumers, we provide products and services to help people understand, manage and protect their personal information and make more informed financial decisions.
We currently operate in four global regions: North America (U.S. and Canada), Asia Pacific (Australia, New Zealand and India), Europe (the United Kingdom, or U.K., Spain and Portugal) and Latin America (Argentina, Chile, Costa Rica, Ecuador, El Salvador, Honduras, Mexico, Paraguay, Peru and Uruguay). We maintain support operations in the Republic of Ireland, Chile, Costa Rica and India. We also offer Equifax branded credit services in Russia through a joint venture, have investments in consumer and/or commercial credit information companies through joint ventures in Cambodia, Malaysia, Singapore and the United Arab Emirates, have an investment in a consumer and commercial credit information company in Brazil and have an investment in an identity authentication company in Canada.
2017 Cybersecurity Incident
In 2017, we experienced a cybersecurity incident following a criminal attack on our systems that involved the theft of certain personally identifiable information of U.S., Canadian and U.K. consumers. Criminals exploited a software vulnerability in a U.S. website application to gain unauthorized access to our network. In March 2017, the U.S. Department of Homeland Security distributed a notice concerning the software vulnerability. We undertook efforts to identify and remediate vulnerable systems; however, the vulnerability in the website application that was exploited was not identified by our security processes. We discovered unusual network activity in late-July 2017 and upon discovery promptly investigated the activity. Once the activity was identified as potential unauthorized access, we acted to stop the intrusion and engaged a leading, independent cybersecurity firm to conduct a forensic investigation to determine the scope of the unauthorized access, including the specific information impacted. Based on our forensic investigation, the unauthorized access occurred from mid-May 2017 through July 2017. No evidence was found that the Company’s core consumer, employment and income, or commercial reporting databases were accessed. We continue to cooperate with law enforcement in connection with the criminal investigation into the actors responsible for the 2017 cybersecurity incident. On February 10, 2020, the U.S. Department of Justice announced that four members of the Chinese People’s Liberation Army were indicted on criminal charges for their involvement in the 2017 cybersecurity incident.
Product Liability. As a result of the 2017 cybersecurity incident, we offered TrustedID® Premier, a credit file monitoring and identity theft protection product, for free to all eligible U.S. consumers who signed up through January 31, 2018. In late 2018, the Company extended the free credit monitoring services for an additional twelve months for eligible consumers impacted by the 2017 cybersecurity incident by providing them the opportunity to enroll in Experian® IDNotify™ at no cost. We also provided free credit reports and scores, credit monitoring and identity theft protection for twenty four months to impacted consumers in Canada and the U.K. We have recorded the expenses necessary to provide this service to those who signed up. The remaining product liability balance at December 31, 2019 and 2018 was not material to the Consolidated Financial Statements.
Litigation, Claims and Government Investigations. As a result of the 2017 cybersecurity incident, we were subject to a significant number of proceedings and investigations as described in Part I, “Item 3. Legal Proceedings” in this Form 10-K. We recorded expenses, net of insurance recoveries, of $800.9 million in other current liabilities and selling, general, and administrative expenses in our Consolidated Balance Sheets and Statements of (Loss) Income, respectively, as of and for the twelve months ended December 31, 2019, exclusive of our legal and professional services expenses. The amount accrued represents our best estimate of the liability related to these matters. The Company will continue to evaluate information as it becomes known and adjust accruals for new information and further developments in accordance with ASC 450-20-25.
Future Costs. We are currently executing substantial initiatives in security and consumer support, and a company-wide transformation of our technology infrastructure, which we refer to as our technology transformation, and incurred substantial increased expenses and capital expenditures in 2019 related to these initiatives. We expect to continue to incur significant expenses and capital expenditures in 2020 related to these initiatives, at similar levels as those incurred in 2019.
We incurred significant legal and professional services expenses related to the lawsuits, claims and government investigations to which we were a party in 2019, and expect to continue to incur these expenses until all matters are fully resolved. However, we expect that the level of legal and professional service expenses related to these matters will be significantly lower in 2020 due to the settlement of all of the significant matters in the U.S.
We will recognize the expenses and capital expenditures referenced herein as they are incurred.
Insurance Coverage. At the time of the 2017 cybersecurity incident, we had $125.0 million of cybersecurity insurance coverage, above a $7.5 million deductible, to limit our exposure to losses such as those related to this incident. Since the announcement of the 2017 cybersecurity incident in September 2017, we have received the maximum reimbursement under the insurance policy of $125.0 million. We also maintained a directors and officers insurance policy of which we have recorded our estimated maximum recoveries as of December 31, 2019.
Segment and Geographic Information
Segments. The USIS segment, the largest of our four segments, consists of three service lines: Online Information Solutions, Mortgage Solutions, and Financial Marketing Services. Online Information Solutions and Mortgage Solutions revenue is principally transaction-based and is derived from our sales of products such as consumer and commercial c
Showing the first 8K of 144K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
In the normal course of our business, we are exposed to market risk, primarily from changes in foreign currency exchange rates and interest rates that could impact our results of operations and financial position. We manage our exposure to these market risks through our regular operating and financing activities, and, when deemed appropriate, through the use of derivative financial instruments, such as interest rate swaps, to hedge certain of these exposures. We use derivative financial instruments as risk management tools and not for speculative or trading purposes.
Foreign Currency Exchange Rate Risk
A substantial majority of our revenue, expense and capital expenditure activities are transacted in U.S. dollars. However, we do transact business in other currencies, primarily the British pound, the Australian dollar, the Canadian dollar, the Chilean peso, the Argentine peso and the Euro. For most of these foreign currencies, we are a net recipient, and, therefore, benefit from a weaker U.S. dollar and are adversely affected by a stronger U.S. dollar relative to the foreign currencies in which we transact significant amounts of business.
We are required to translate, or express in U.S. dollars, the assets and liabilities of our foreign subsidiaries that are denominated or measured in foreign currencies at the applicable year-end rate of exchange on our Consolidated Balance Sheets and income statement items of our foreign subsidiaries at the average rates prevailing during the year. We record the resulting translation adjustment, and gains and losses resulting from the translation of intercompany balances of a long-term investment nature within other comprehensive income, as a component of our shareholders’ equity. Foreign currency transaction gains and losses, which have historically been immaterial, are recorded on our Consolidated Statements of (Loss) Income. We generally do not mitigate the risks associated with fluctuating exchange rates, although we may from time to time through forward contracts or other derivative instruments hedge a portion of our translational foreign currency exposure or exchange rate risks associated with material transactions which are denominated in a foreign currency.
For the year ended December 31, 2019, a 10% weaker U.S. dollar against the currencies of all foreign countries in which we had operations during 2019 would have increased our revenue by $54.8 million and our pre-tax operating profit by $10.2 million. For the year ended December 31, 2018, a 10% weaker U.S. dollar against the currencies of all foreign countries in which we had operations during 2018 would have increased our revenue by $55.9 million and our pre-tax operating profit by $10.7 million. A 10% stronger U.S. dollar would have resulted in similar decreases to our revenue and pre-tax operating profit for 2019 and 2018.
On average across our mix of international businesses, foreign currencies at December 31, 2019 were weaker against the U.S. dollar than the average foreign exchange rates that prevailed across the full year 2019. As a result, if foreign exchange rates were unchanged throughout 2020, foreign exchange translation would reduce growth as reported in U.S. dollars. As foreign exchange rates change daily, there can be no assurance that foreign exchange rates will remain constant throughout 2020, and rates could go either higher or lower.
Interest Rate Risk
Our exposure to market risk for changes in interest rates relates to our variable-rate commercial paper, Revolver, and Floating Rate Notes borrowings. We attempt to achieve the lowest all-in weighted-average cost of debt while simultaneously taking into account the mix of our fixed- and floating-rate debt, and the average life and scheduled maturities of our debt. At December 31, 2019, our weighted average cost of debt was 3.8% and weighted-average life of debt was 4.54 years. At December 31, 2019, 91% of our debt was fixed rate, and the remaining 9% was variable rate. Occasionally we use derivatives to manage our exposure to changes in interest rates by entering into interest rate swaps. A 100 basis point increase in the weighted-average interest rate on our variable-rate debt would have increased our 2019 interest expense by $3.0 million.
Based on the amount of outstanding variable-rate debt, we have exposure to interest rate risk. In the future, if our mix of fixed-rate and variable-rate debt were to change due to additional borrowings under existing or new variable-rate debt, we could have additional exposure to interest rate risk. The nature and amount of our long-term and short-term debt, as well as the proportionate amount of fixed-rate and variable-rate debt, can be expected to vary as a result of future business requirements, market conditions and other factors.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
Report of Independent Registered Public Accounting Firm
To the Shareholders and the Board of Directors of Equifax Inc.
Opinion on Internal Control over Financial Reporting
We have audited Equifax Inc.’s internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (“2013 framework”) (the COSO criteria). In our opinion, Equifax Inc. (the Company) maintained, in all material respects, effective internal control over financial reporting as of December 31, 2019, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of December 31, 2019 and 2018, the related consolidated statements of (loss) income, comprehensive (loss) income, cash flows, and shareholders’ equity and other comprehensive income (loss) for each of the three years in the period ended December 31, 2019, and the related notes and financial statement schedule listed in the Index at Item 15(a)(2) (collectively referred to as the “consolidated financial statements”) and our report dated February 20, 2020 expressed an unqualified opinion thereon.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Annual Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects.
Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control Over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ Ernst & Young LLP
Atlanta, Georgia
February 20, 2020
Report of Independent Registered Public Accounting Firm
To the Shareholders and the Board of Directors of Equifax Inc.
Opinion on the Consolidated Financial Statements
We have audited the accompanying consolidated balance sheets of Equifax Inc. (the Company) as of December 31, 2019 and 2018, the related consolidated statements of (loss) income, comprehensive income (loss), cash flows, and shareholders’ equity and other comprehensive income (loss) for each of the three years in the period ended December 31, 2019, and the related notes and financial statement schedule listed in the Index at Item 15(a)(2) (collectively referred to as the “consolidated financial statements”). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at December 31, 2019 and 2018, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2019, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of December 31, 2019, based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated February 20, 2020 expressed an unqualified opinion thereon.
Basis for Opinion
These consolidated financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s consolidated financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risk of material misstatements of the consolidated financial statements, whether due to error or fraud, and perform
Showing the first 8K of 309K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Evaluation of Disclosure Controls and Procedures
Our management, with the participation of our Chief Executive Officer and Chief Financial Officer, evaluated the effectiveness of Equifax’s disclosure controls and procedures as of the end of the period covered by this report. Based on that evaluation, our Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures as of the end of the period covered by this report (i) were appropriately designed to provide reasonable assurance of achieving their objectives and (ii) were effective and provided reasonable assurance that the information required to be disclosed by Equifax in reports filed under the Exchange Act is (a) recorded, processed, summarized and reported within the time periods specified in the SEC’s rules and forms and (b) accumulated and communicated to Equifax’s management, including our Chief Executive Officer and Chief Financial Officer, as appropriate to allow timely decisions regarding required disclosure.
Management’s Annual Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting. Internal control over financial reporting is defined in Rules 13a-15(f) and 15d-15(f) under the Exchange Act as a process designed by, or under the supervision of, our Chief Executive Officer and Chief Financial Officer and effected by our Board of Directors, management and other personnel, to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles and includes those policies and procedures that:
-
pertain to the maintenance of records that in reasonable detail accurately and fairly reflect transactions and dispositions of our assets;
-
provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that our receipts and expenditures are being made only in accordance with authorizations of our management and directors; and
-
provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use or disposition of our assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Our management assessed the effectiveness of Equifax’s internal control over financial reporting as of December 31, 2019 using the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in Internal Control-Integrated Framework (2013 Framework). Based on this assessment using those criteria, our management concluded that, as of December 31, 2019, Equifax’s internal control over financial reporting was effective. Management reviewed the results of its assessment with the Audit Committee of its Board of Directors. The effectiveness of Equifax’s internal control over financial reporting as of December 31, 2019 has been audited by Ernst & Young LLP, Equifax’s independent registered public accounting firm, as stated in their report, which appears in “Item 8. Financial Statements and Supplementary Data” of this Form 10-K on page 59.
Changes in Internal Control Over Financial Reporting
There have been no changes in internal control over financial reporting identified in connection with the foregoing that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. OTHER INFORMATION
None.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
Except for the information about our executive officers shown below, the information required by this Item 10 is incorporated herein by reference from the information contained in our Proxy Statement to be filed with the SEC in connection with the solicitation of proxies for our 2020 Annual Meeting of Shareholders (the “2020 Proxy Statement”) under the sections entitled “Proposal 1 Election of Directors,” “Section 16(a) Beneficial Ownership Reporting Compliance” and “Board Leadership and Corporate Governance—Committees of the Board of Directors.”
We have adopted a written Code of Ethics and Business Conduct applicable to all our employees, including our principal executive officer, principal financial officer, and principal accounting officer and controller, and to members of our Board of Directors. Our Code of Ethics and Business Conduct is available on our investor relations website: www.equifax.com/about-equifax/corporate-governance. We will disclose amendments to certain provisions of our Code of Ethics and Business Conduct, or waivers of such provisions granted to executive officers and directors, on this website.
Executive Officers
Information regarding the executive officers of Equifax Inc. is set forth below.
Mark W. Begor (62) has been Chief Executive Officer and a member of the Board of Directors since April 2018. Prior thereto, he was a Managing Director in the Industrial and Business Services group at Warburg Pincus, a global private equity investment firm, since June 2016. Prior to Warburg Pincus, Mr. Begor spent 35 years at General Electric Company (“GE”), a global industrial and financial services company, in a variety of operating and financial roles. During his career at GE, Mr. Begor served in a variety of roles leading multibillion dollar units of the company, including President and CEO of GE Energy Management from 2014 to 2016, President and CEO of GE Capital Real Estate from 2011 to 2014, and President and CEO of GE Capital Retail Finance (Synchrony Financial) from 2002 to 2011. Mr. Begor served on the Fair Isaac Corporation (FICO) Board of Directors from 2016 to 2018.
Beverly Anderson (56) has been President, Global Consumer Solutions, since November 2019. Prior thereto, she served as Executive Vice President, Head of Card and Retail Services at Wells Fargo & Company, since March 2012. Prior to that, she served in roles of increasing responsibility at American Express from July 2004, ultimately serving as Vice President and General Manager, American Express Business Insights Americas - Global Merchant Services.
Carla Chaney (49) has been Corporate Vice President and Chief Human Resources Officer since April 2019. Prior thereto, she served as Executive Vice President, Human Resources of Graphic Packaging Holding Company and Graphic Packaging International, since July 2013. Prior thereto, she served as Executive Vice President, Human Resources and Communications, since February 2012. Prior thereto, she held a variety of leadership roles with Exide Technologies and Newell Rubbermaid, Inc., since 2004.
Prasanna Dhoré (58) has been Chief Data and Analytics Officer since August 2012. Prior thereto, Mr. Dhoré was Vice President, Global Customer Intelligence of Hewlett Packard from July 2007 to August 2012. Prior to that, he was Executive Vice President, Distribution, Customer Intelligence, and Marketing of Dreyfus Service Corporation from July 1996 to July 2007.
Jamil Farshchi (42) has been our Chief Information Security Officer since February 2018. Prior to joining Equifax, Mr. Farshchi served as Chief Information Security Officer at The Home Depot since April 2015. Prior thereto, he was the first Global Chief Information Security Officer at Time Warner Inc., from August 2014 to March 2015. Prior thereto, he was the Vice President of Global Information Security at Visa Inc. from August 2011 to August 2014. Mr. Farshchi has also held senior roles at Los Alamos National Laboratory, Sitel Corporation, Nextwave Broadband and NASA.
John W. Gamble, Jr. (57) has been Corporate Vice President and Chief Financial Officer since May 2014. Prior to that, Mr. Gamble was Executive Vice President and Chief Financial Officer of Lexmark International, Inc., a global provider of document solutions, enterprise content management software and services, printers and multifunction printers, from September 2005 until May 2014.
John T. Hartman (60) has been President, International, since November 2015. Prior thereto, he served as Senior Vice President, Corporate Development, since April 2010. Prior thereto, he served as President of Growth Vector from 2009 to 2010. Prior thereto, he served as Executive Vice President and Chief Commercial Officer for Acuity Brands from 2004 to 2009.
Julia A. Houston (49) has been Chief Transformation Officer since October 2017. Prior thereto, she was Senior Vice President, U.S. Legal, since October 2013. Prior to joining Equifax, Ms. Houston was Senior Vice President, General Counsel and Corporate Secretary at Convergys Corporation, from 2011 to 2013. Prior thereto, she served in roles of increasing responsibility at Mirant Corporation from 2004 to 2010, ultimately serving as Senior Vice President, General Counsel, Chief Compliance Officer and Corporate Secretary.
John J. Kelley III (59) has been Corporate Vice President and Chief Legal Officer since January 2013. Prior to joining Equifax, Mr. Kelley was a senior partner in the Corporate Practice Group of the law firm of King & Spalding LLP from January 1993 to December 2012.
Bryson Koehler (44) has been our Chief Technology Officer since June 2018. Prior to joining Equifax, Mr. Koehler served as Chief Technology Officer of IBM Watson and Cloud Platform since November 2016. Prior to that, Mr. Koehler was Chief Technology and Information Officer of The Weather Channel Companies, before it was acquired in 2015 by IBM. Before that, he served as Senior Vice President of Global Revenue & Guest Technology at the Intercontinental Hotels Group.
Rodolfo O. Ploder (59) has been President, Workforce Solutions, since November 2015. Prior thereto, he served as President, U.S. Information Solutions, since April 2010. Prior thereto, he served as President, International, from January 2007 to April 2010. Prior thereto, he was Group Executive, Latin America from February 2004 to January 2007.
Sid Singh (42) has been President, U.S. Information Solutions, since February 11, 2019. Mr. Singh served as group president of Integrated Solutions & Vertical Markets at Global Payments Inc., since February 2013. Prior thereto, he served as Senior Vice President, Global Product of Global Payments Inc. since 2010. Prior thereto, he served as Vice President and Regional Head, Asia Pacific of Global Payments Inc. since 2006. Prior thereto, he held senior management positions with HSBC and Citibank.
Item 11. EXECUTIVE COMPENSATION
The information required by this Item 11 is incorporated herein by reference from the information contained in our 2020 Proxy Statement under the sections entitled “Executive Compensation” and “Director Compensation.”
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
The information required by this Item 12 is incorporated herein by reference from the information contained in our 2020 Proxy Statement under the sections entitled “Security Ownership of Management and Certain Beneficial Owners” and “Executive Compensation Equity Compensation Plan Information.”
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS AND DIRECTOR INDEPENDENCE
The information required by this Item 13 is incorporated herein by reference from the information contained in our 2020 Proxy Statement under the sections entitled “Board Leadership and Corporate Governance Director Independence, ” “Related Person Transaction Policy” and “Certain Relationships and Related Person Transactions of Directors, Executive Officers, and 5 Percent Shareholders.”
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
The information required by this Item 14 is incorporated herein by reference from the information contained in our 2020 Proxy Statement under the section entitled “Proposal 3 Ratification of Appointment of Ernst & Young LLP as Independent Registered Public Accounting Firm for 2020.”
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
**(a)**List of Documents Filed as a Part of This Report:
(1) Financial Statements. The following financial statements are included in Item 8 of Part II:
-
Consolidated Balance Sheets — December 31, 2019 and 2018;
-
Consolidated Statements of (Loss) Income for the Years Ended December 31, 2019, 2018 and 2017;
-
Consolidated Statements of Comprehensive (Loss) Income for the Years Ended December 31, 2019, 2018 and 2017;
-
Consolidated Statements of Cash Flows for the Years Ended December 31, 2019, 2018 and 2017;
-
Consolidated Statements of Shareholders’ Equity and Other Comprehensive (Loss) Income for the Years Ended December 31, 2019, 2018 and 2017; and
-
Notes to Consolidated Financial Statements.
(2) Financial Statement Schedules.
- Schedule II — Valuation and Qualifying Accounts
All other schedules for which provision is made in the applicable accounting regulation of the SEC are not required under the related instructions or are inapplicable and, therefore, have been omitted.
(3) Exhibits. See exhibits listed under Part (b) below.
(b) Exhibits:
| 101.INS | Inline XBRL Instance Document. | |||||||
| 101.SCH | Inline XBRL Taxonomy Extension Schema Document. | |||||||
| 101.CAL | Inline XBRL Taxonomy Extension Calculation Linkbase. | |||||||
| 101.LAB | Inline XBRL Taxonomy Extension Label Linkbase. | |||||||
| 101.PRE | Inline XBRL Taxonomy Extension Presentation Linkbase. | |||||||
| 101.DEF | Inline XBRL Taxonomy Extension Definition Linkbase. | |||||||
| 104 | Cover Page Interactive Data File (formatted as Inline XBRL and contained in Exhibit 101) | |||||||
- Filed herewith
**Schedules and exhibits to this agreement have been omitted pursuant to Item 601(a)(5) of Regulation S-K. A copy of any omitted schedule and/or exhibit will be furnished as a supplement to the Securities and Exchange Commission upon request.
(c) Financial Statement Schedules. See Item 15(a)(2).
Item 16. FORM 10-K SUMMARY
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized, on February 20, 2020.
| EQUIFAX INC. | |||||
| (Registrant) | |||||
| By: | /s/ Mark W. Begor | ||||
| Mark W. Begor | |||||
| Chief Executive Officer |
We, the undersigned directors and executive officers of Equifax Inc., hereby severally constitute and appoint John W. Gamble, Jr. and James M. Griggs, and each of them singly, our true and lawful attorneys with full power to them and each of them to sign for us, and in our names in the capacities indicated below, any and all amendments to this Annual Report on Form 10-K filed with the SEC, hereby ratifying and confirming our signatures as they may be signed by our said attorneys to any and all amendments to said Annual Report on Form 10-K.
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities indicated on February 20, 2020.
| /s/ Mark W. Begor | |||||
| Mark W. Begor | |||||
| Chief Executive Officer | |||||
| (Principal Executive Officer) | |||||
| /s/ John W. Gamble, Jr. | |||||
| John W. Gamble, Jr. | |||||
| Corporate Vice President and Chief Financial Officer | |||||
| (Principal Financial Officer) | |||||
| /s/ James M. Griggs | |||||
| James M. Griggs | |||||
| Chief Accounting Officer and Corporate Controller | |||||
| (Principal Accounting Officer) | |||||
| /s/ Mark L. Feidler | |||||
| Mark L. Feidler | |||||
| Director and Non-Executive Chairman | |||||
| /s/ G. Thomas Hough | |||||
| G. Thomas Hough | |||||
| Director | |||||
| /s/ Robert D. Marcus | |||||
| Robert D. Marcus | |||||
| Director | |||||
| /s/ Siri S. Marshall | |||||
| Siri S. Marshall | |||||
| Director | |||||
| /s/ Scott A. McGregor | |||||
| Scott A. McGregor | |||||
| Director | |||||
| /s/ John A. McKinley | |||||
| John A. McKinley | |||||
| Director | |||||
| /s/ Robert W. Selander | |||||
| Robert W. Selander | |||||
| Director | |||||
| /s/ Elane B. Stock | |||||
| Elane B. Stock | |||||
| Director | |||||
| /s/ Heather Wilson | |||||
| Heather Wilson | |||||
| Director |
SCHEDULE II — VALUATION AND QUALIFYING ACCOUNTS
2019
| Column A | Column B | Column C | Column D | Column E | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Additions | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Description | Balance at Beginning of Period | Charged to Costs and Expenses | Charged to Other Accounts | Deductions | Balance at End of Period | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (In millions) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Reserves deducted in the balance sheet from the assets to which they apply: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Trade accounts receivable | $ | 10.9 | $ | 5.4 | $ | — | $ | (5.1) | $ | 11.2 | ||||||||||||||||||||||||||||||||||||||||||||||
| Deferred income tax asset valuation allowance | 431.9 | (61.9) | (2.0) | 11.8 | 379.8 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | 442.8 | $ | (56.5) | $ | (2.0) | $ | 6.7 | $ | 391.0 |
2018
| Column A | Column B | Column C | Column D | Column E | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Additions | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Description | Balance at Beginning of Period | Charged to Costs and Expenses | Charged to Other Accounts | Deductions | Balance at End of Period | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (In millions) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Reserves deducted in the balance sheet from the assets to which they apply: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Trade accounts receivable | $ | 9.1 | $ | 5.6 | $ | — | $ | (3.8) | $ | 10.9 | ||||||||||||||||||||||||||||||||||||||||||||||
| Deferred income tax asset valuation allowance | 401.8 | (164.0) | (12.3) | 206.4 | 431.9 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | 410.9 | $ | (158.4) | $ | (12.3) | $ | 202.6 | $ | 442.8 |
2017
| Column A | Column B | Column C | Column D | Column E | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Additions | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Description | Balance at Beginning of Period | Charged to Costs and Expenses | Charged to Other Accounts | Deductions | Balance at End of Period | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (In millions) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Reserves deducted in the balance sheet from the assets to which they apply: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Trade accounts receivable | $ | 7.8 | $ | 5.0 | $ | — | $ | (3.7) | $ | 9.1 | ||||||||||||||||||||||||||||||||||||||||||||||
| Deferred income tax asset valuation allowance | 307.3 | (6.1) | 8.1 | 92.5 | 401.8 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | 315.1 | $ | (1.1) | $ | 8.1 | $ | 88.8 | $ | 410.9 |