 filings.tools
Everest Group 10-K 2021-12-31
Filed 2022-02-28. 22 sections, 588K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
X Annual Report Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
For the fiscal year ended December 31, 2021
___ Transition Report Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Commission file number 1-15731
EVEREST RE GROUP, LTD.
(Exact name of registrant as specified in its charter)
| Bermuda | 98-0365432 | |
|---|---|---|
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
Seon Place – 4 Floor
141 Front Street
PO Box HM 845
HamiltonHM 19, Bermuda
441-295-0006
(Address, including zip code, and telephone number, including area code, of registrant’s principal executive office)
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act.
| YES | X | NO |
|---|
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act.
| YES | NO | X |
|---|
Indicate by check mark whether the registrant: (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days.
| YES | X | NO |
|---|
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit such files).
| YES | X | NO |
|---|
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of the registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. [ ]
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | X | Accelerated filer | ||
|---|---|---|---|---|
| Non-accelerated filer | Smaller reporting company | |||
| Emerging growth company |
Indicate by check mark if the registrant is an emerging growth company and has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange act.
| YES | NO | X |
|---|
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act).
| YES | NO | X |
|---|
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report.
| YES | x | NO |
|---|
The aggregate market value on June 30, 2021, the last business day of the registrant’s most recently completed second quarter, of the voting shares held by non-affiliates of the registrant was $10.1 billion.
Securities registered pursuant to Section 12(b) of the Act:
| Class | Trading Symbol | Name of Exchange where Registered | Number of Shares Outstanding At February 1, 2022 |
|---|---|---|---|
| Common Shares, $0.01 par value | RE | New York Stock Exchange | 39,271,864 |
DOCUMENTS INCORPORATED BY REFERENCE
Certain information required by Items 10, 11, 12, 13 and 14 of Form 10-K is incorporated by reference into Part III hereof from the registrant’s proxy statement for the 2022 Annual General Meeting of Shareholders, which will be filed with the Securities and Exchange Commission within 120 days of the close of the registrant’s fiscal year ended December 31, 2021.
EVEREST RE GROUP, LTD
TABLE OF CONTENTS
FORM 10-K
PART I
Unless otherwise indicated, all financial data in this document have been prepared using accounting principles generally accepted in the United States of America (“GAAP”). As used in this document, “Group” means Everest Re Group, Ltd.; “Holdings Ireland” means Everest Underwriting Group (Ireland) Limited; “Ireland Re” means Everest Reinsurance Company (Ireland), designated activity company; “Holdings” means Everest Reinsurance Holdings, Inc.; “Everest Re” means Everest Reinsurance Company and its subsidiaries (unless the context otherwise requires); and the “Company”, “we”, “us”, and “our” means Everest Re Group, Ltd. and its subsidiaries.
Item 1. BUSINESS
The Company.
Group, a Bermuda company, was established in 1999 as a wholly-owned subsidiary of Holdings. On February 24, 2000, a corporate restructuring was completed and Group became the new parent holding company of Holdings. Holdings continues to be the holding company for the Company’s U.S. based operations. Holders of shares of common stock of Holdings automatically became holders of the same number of common shares of Group. Prior to the restructuring, Group had no significant assets or capitalization and had not engaged in any business or prior activities other than in connection with the restructuring.
In connection with the February 24, 2000 restructuring, Group established a Bermuda-based reinsurance subsidiary, Everest Reinsurance (Bermuda), Ltd. (“Bermuda Re”), which commenced business in the second half of 2000. Group also formed Everest Global Services, Inc., a Delaware subsidiary, to perform administrative functions for Group and its U.S. based and non-U.S. based subsidiaries.
On December 30, 2008, Group contributed Holdings to its Irish holding company, Holdings Ireland. Holdings Ireland is a direct subsidiary of Group and was established to serve as a holding company for the U.S. and Irish reinsurance and insurance subsidiaries. Effective July 1, 2016, the Company established a new Irish holding company, Everest Dublin Insurance Holdings Limited (Ireland) (“Everest Dublin Holdings”) and contributed Ireland Re to Everest Dublin Holdings.
Holdings, a Delaware corporation, was established in 1993 to serve as the parent holding company of Everest Re, a Delaware property and casualty reinsurer formed in 1973. Until October 6, 1995, Holdings was an indirect wholly-owned subsidiary of The Prudential Insurance Company of America (“The Prudential”). On October 6, 1995, The Prudential sold its entire interest in Holdings in an initial public offering.
The Company’s principal business, conducted through its operating segments, is the underwriting of reinsurance and insurance in the U.S., Bermuda and international markets. The Company had gross written premiums, in 2021, of $13.0 billion with approximately 69.5% representing reinsurance and 30.5% representing insurance. Shareholders’ equity at December 31, 2021 was $10.1 billion. The Company underwrites reinsurance both through brokers and directly with ceding companies, giving it the flexibility to pursue business based on the ceding company’s preferred reinsurance purchasing method. The Company underwrites insurance principally through brokers, surplus lines brokers and general agent relationships. Group’s active operating subsidiaries are each rated A+ (“Superior”) by A.M. Best Company (“A.M. Best”), a leading provider of insurer ratings that assigns financial strength ratings to insurance companies based on their ability to meet their obligations to policyholders.
Following is a summary of the Company’s principal operating subsidiaries:
Bermuda Re, a Bermuda insurance company and a direct subsidiary of Group, is registered in Bermuda as a Class 4 insurer and long-term insurer and is authorized to write both reinsurance and insurance property and casualty and life and annuity business. Bermuda Re’s UK branch writes property and casualty reinsurance to the United Kingdom and European markets. At December 31, 2021, Bermuda Re had shareholder’s equity of $3.1 billion.
Everest International Reinsurance, Ltd. (“Everest International”), a Bermuda insurance company and a direct subsidiary of Group, is registered in Bermuda as a Class 4 insurer and is authorized to write property and casualty business. All of Everest International’s business has been inter-affiliate quota share reinsurance assumed from Everest Re, the UK branch of Bermuda Re, Ireland Re and Ireland Insurance. At December 31, 2021, Everest International had shareholder’s equity of $1.0 billion.
Ireland Re, an Ireland reinsurance company and an indirect subsidiary of Group, is licensed to write non-life reinsurance, both directly and through brokers, for the London and European markets.
Ireland Insurance, an Ireland insurance company and an indirect subsidiary of Group, is licensed to write insurance for the European markets.
Everest Re, a Delaware reinsurance company and a direct subsidiary of Holdings, is a licensed property and casualty insurer and/or reinsurer in all states, the District of Columbia, Puerto Rico and Guam and is authorized to conduct reinsurance business in Canada, Singapore and Brazil. Everest Re underwrites property and casualty reinsurance for insurance and reinsurance companies in the U.S. and international markets. At December 31, 2021, Everest Re had statutory surplus of $5.8 billion.
Everest Insurance Company of Canada (“Everest Canada”), a Canadian insurance company and direct subsidiary of Holdings Ireland, is licensed to write property and casualty insurance in all Canadian provinces.
Everest National Insurance Company (“Everest National”), a Delaware insurance company and a direct subsidiary of Everest Re, is licensed in 50 states, the District of Columbia and Puerto Rico and is authorized to write property and casualty insurance on an admitted basis in the jurisdictions in which it is licensed. The majority of Everest National’s business is reinsured by its parent, Everest Re.
Everest Indemnity Insurance Company (“Everest Indemnity”), a Delaware insurance company and a direct subsidiary of Everest Re, writes excess and surplus lines insurance business in the U.S. on a non-admitted basis. Excess and surplus lines insurance is specialty property and liability coverage that an insurer not licensed to write insurance in a particular jurisdiction is permitted to provide to insureds when the specific specialty coverage is unavailable from admitted insurers. Everest Indemnity is licensed in Delaware and is eligible to write business on a non-admitted basis in all other states, the District of Columbia and Puerto Rico. The majority of Everest Indemnity’s business is reinsured by its parent, Everest Re.
Everest Security Insurance Company (“Everest Security”), a Georgia insurance company and a direct subsidiary of Everest Re, writes property and casualty insurance on an admitted basis in Georgia and Alabama and is approved as an eligible surplus lines insurer in Delaware. The majority of Everest Security’s business is reinsured by its parent, Everest Re.
Everest International Assurance, Ltd. (“Everest Assurance”), a Bermuda company and a direct subsidiary of Holdings is registered in Bermuda as a Class 3A general business insurer and as a Class C long-term insurer. Everest Assurance has made a one-time election under section 953(d) of the U.S. Internal Revenue Code to be a U.S. income tax paying “Controlled Foreign Corporation.” By making this election, Everest Assurance is authorized to write life reinsurance and casualty reinsurance in both Bermuda and the U.S.
Everest Premier Insurance Company (“Everest Premier”), a Delaware insurance company and a direct subsidiary of Everest Re, is licensed to write property and casualty insurance in all 50 states and the District of Columbia.
Everest Denali Insurance Company (“Everest Denali”), a Delaware insurance company and a direct subsidiary of Everest Re, is licensed to write property and casualty insurance in all 50 states and the District of Columbia.
Reinsurance Industry Overview.
Reinsurance is an arrangement in which an insurance company, the reinsurer, agrees to indemnify another insurance or reinsurance company, the ceding company, against all or a portion of the insurance risks underwritten by the ceding company under one or more insurance contracts. Reinsurance can provide a ceding company with several benefits, including a reduction in its net liability on individual risks or classes of risks, catastrophe protection from large and/or multiple losses and/or a reduction in operating leverage as measured by t
Showing the first 8K of 95K characters. Open the full section
Item 1A. RISK FACTORS
In addition to the other information provided in this report, the following risk factors should be considered when evaluating an investment in our securities. If the circumstances contemplated by the individual risk factors materialize, our business, financial condition and results of operations could be materially and adversely affected and the trading price of our common shares could decline significantly.
RISKS RELATING TO OUR BUSINESS
Fluctuations in the financial markets could result in investment losses.
Prolonged and severe disruptions in the overall public and private debt and equity markets, such as occurred during 2008, or temporary disruption as occurred in early 2020 related to the COVID-19 pandemic, could result in significant realized and unrealized losses in our investment portfolio. Although financial markets have significantly improved since 2008, they could deteriorate in the future. There could also be disruption in individual market sectors, such as occurred in the energy sector in recent years. Such declines in the financial markets could result in significant realized and unrealized losses on investments and could have a material adverse impact on our results of operations, equity, business and insurer financial strength and debt ratings.
Our results could be adversely affected by catastrophic events.
We are exposed to unpredictable catastrophic events, including weather-related and other natural catastrophes, as well as acts of terrorism. The frequency and/or severity of catastrophic events may be impacted in the future by the continued effects of climate change. Any material reduction in our operating results caused by the occurrence of one or more catastrophes could inhibit our ability to pay dividends or to meet our interest and principal payment obligations. By way of illustration, during the past five calendar years, pre-tax catastrophe losses, net of reinsurance, were as follows:
| Calendar year: | Pre-tax catastrophe losses | |
|---|---|---|
| (Dollars in millions) | ||
| 2021 | $ | 1,135.0 |
| 2020 | 425.0 | |
| 2019 | 575.5 | |
| 2018 | 1,800.2 | |
| 2017 | 1,472.6 |
Our losses from future catastrophic events could exceed our projections.
We use projections of possible losses from future catastrophic events of varying types and magnitudes as a strategic underwriting tool. We use these loss projections to estimate our potential catastrophe losses in certain geographic areas and decide on the placement of retrocessional coverage or other actions to limit the extent of potential losses in a given geographic area. These loss projections are approximations, reliant on a mix of quantitative and qualitative processes, and actual losses may exceed the projections by a material amount, resulting in a material adverse effect on our financial condition and results of operations.
If our loss reserves are inadequate to meet our actual losses, our net income would be reduced or we could incur a loss.
We are required to maintain reserves to cover our estimated ultimate liability of losses and LAE for both reported and unreported claims incurred. These reserves are only estimates of what we believe the settlement and administration of claims will cost based on facts and circumstances known to us. In setting reserves for our reinsurance liabilities, we rely on claim data supplied by our ceding companies and brokers and we employ actuarial and statistical projections. The information received from our ceding companies is not always timely or accurate, which can contribute to inaccuracies in our loss projections. Because of the uncertainties that surround our estimates of loss and LAE reserves, we cannot be certain that ultimate losses and LAE payments will not exceed our estimates. If our reserves are deficient, we would be required to increase loss reserves in the period in which such deficiencies are identified which would cause a charge to our earnings and a reduction of capital. During the past five calendar years, the reserve re-estimation process resulted in an increase to our pre-tax net income in 2021, 2019 and 2017 and resulted in a decrease to our pre-tax net income in 2020 and 2018:
| Calendar year: | Effect on pre-tax net income | ||||
|---|---|---|---|---|---|
| (Dollars in millions) | |||||
| 2021 | $ | 9.1 | increase | ||
| 2020 | 401.4 | decrease | |||
| 2019 | 63.6 | increase | |||
| 2018 | 387.1 | decrease | |||
| 2017 | 293.4 | increase |
The difficulty in estimating our reserves is significantly more challenging as it relates to reserving for potential A&E liabilities. At year-end 2021, 0.9% of our gross reserves were comprised of A&E reserves. A&E liabilities are especially hard to estimate for many reasons, including the long delays between exposure and manifestation of any bodily injury or property damage, difficulty in identifying the source of the asbestos or environmental contamination, long reporting delays and difficulty in properly allocating liability for the asbestos or
environmental damage. Legal tactics and judicial and legislative developments affecting the scope of insurers’ liability, which can be difficult to predict, also contribute to uncertainties in estimating reserves for A&E liabilities.
The failure to accurately assess underwriting risk and establish adequate premium rates could reduce our net income or result in a net loss.
Our success depends on our ability to accurately assess the risks associated with the businesses on which the risk is retained. If we fail to accurately assess the risks we retain, we may fail to establish adequate premium rates to cover our losses and LAE. This could reduce our net income and even result in a net loss.
In addition, losses may arise from events or exposures that are not anticipated when the coverage is priced. In addition to unanticipated events, we also face the unanticipated expansion of our exposures, particularly in long-tail liability lines. An example of this is the expansion over time of the scope of insurers’ legal liability within the mass tort arena, particularly for A&E exposures discussed above.
Decreases in pricing for property and casualty reinsurance and insurance could reduce our net income.
The worldwide reinsurance and insurance businesses are highly competitive, as well as cyclical by product and market. These cycles, as well as other factors that influence aggregate supply and demand for property and casualty insurance and reinsurance products, are outside of our control. The supply of (re)insurance is driven by prevailing prices and levels of capacity that may fluctuate in response to a number of factors including large catastrophic losses and investment returns being realized in the insurance industry. Demand for (re)insurance is influenced by underwriting results of insurers and insureds, including catastrophe losses, and prevailing general economic conditions. If any of these factors were to result in a decline in the demand for (re)insurance or an overall increase in (re)insurance capacity, our net income could decrease.
If rating agencies downgrade the ratings of our insurance subsidiaries, future prospects for growth and profitability could be significantly and adversely affected.
Our active insurance company subsidiaries currently hold financial strength ratings assigned by third-party rating agencies which assess and rate the claims paying ability and financial strength of insurers and reinsurers. Financial strength ratings are used by cedents, agents and brokers to assess the financial strength and credit quality of reinsurers and insurers. A downgrade or withdrawal of any of these ratings could adversely affect our ability to market our reinsurance and insurance products, our ability to compete with other reinsurers and insurers, and could have a material and adverse effect on our ability to write new business that in turn could impact our profitability and operating results. In December 2021, S&P announced proposed changes to its rating methodologies. The proposed changes have not been finalized, so the impact, if any, that these changes may have on our financial strength ratings is unknown.
Consistent with market practice, much of our treaty reinsurance business allows the ceding company to terminate the contract or seek collateralization of our obligations in the event of a rating downgrade below a certain threshold. The termination provision would generally be triggered if a rating fell below A.M. Best’s A- rating level. To a lesser extent, Everest Re also has modest exposure to reinsurance contracts that contain provisions for obligatory funding of outstanding liabilities in the event of a rating agency downgrade. Those provisions would also generally be triggered if Everest Re’s rating fell below A.M. Best’s A- rating level.
The failure of our insureds, intermediaries and reinsurers to satisfy their obligations to us could reduce our income.
In accordance with industry practice, we have uncollateralized receivables from insureds, agents and brokers and/or rely on agents and brokers to process our payments. We may not be able to collect amounts due from insureds, agents and brokers, resulting in a reduction to net income.
We are subject to credit risk of reinsurers in connection with retrocessional arrangements because the transfer of risk to a reinsurer does not relieve us of our liability to the insured. In addition, reinsurers may be unwilling to pay us even though they are able to do so. The failure of one or more of our reinsurers to honor their obligations to us in a timely fashion would impact our cash flow and reduce our net income and could cause us to incur a significant loss.
If we are unable or choose not to purchase reinsurance and transfer risk to the reinsurance markets, our net income could be reduced or we could incur a net loss in the event of unusual loss experience.
We are generally less reliant on the purchase of reinsurance than many of our competitors, in part because of our strategic emphasis on underwriting discipline and management of the cycles inherent in our business. We try to separate our risk taking process from our risk mitigation process in order to avoid developing too great a reliance on reinsurance. With the expansion of the capital markets into insurance linked financial instruments, we increased our use of capital market products for catastrophe reinsurance. In addition, we have increased some of our quota share contracts with larger retrocessions. The percentage of business that we reinsure may vary considerably from year to year, depending on our view of the relationship between cost and expected benefit for the contract period.
| 2021 | 2020 | 2019 | 2018 | 2017 | |||||
|---|---|---|---|---|---|---|---|---|---|
| Percentage of ceded written premiums to gross written premiums | 12.3% | 13.0% | 14.3% | 12.5% | 13.0% |
Our industry is highly competitive and we may not be able to compete as successfully in the future.
Our industry is highly competitive and subject to pricing cycles that can be pronounced. We compete globally in the United States, Bermuda and international reinsurance and insurance markets with numerous competitors. Our competitors include independent reinsurance and insurance companies, subsidiaries or affiliates of established worldwide insurance companies, reinsurance departments of certain insurance companies and domestic and international underwriting operations, including underwriting syndicates at Lloyd’s of London.
According to S&P, Everest ranks among the top ten global property & casualty reinsurance groups, where more than two-thirds of the market share is concentrated. The worldwide net premium written by the Top 40 global reinsurance groups for both life and non-life business was estimated to be $274 billion in 2020 according to data compiled by S&P. In addition to competitors the entry of alternative capital market products and new company formations provide additional sources of reinsurance and insurance capacity.
We are dependent on our key personnel.
Our success has been, and will continue to be, dependent on our ability to retain the services of our Chairman, Joseph V. Taranto (age 72) and existing key executive officers and to attract and retain additional qualified personnel in the future. The loss of the services of any key executive officer or the inability to hire and retain other highly qualified personnel in the future could adversely affect our ability to conduct business. Generally, we consider key executive officers to be those individuals who have the greatest influence in setting overall policy and controlling operations: President and Chief Executive Officer, Juan C. Andrade (age 56); Executive Vice President and Chief Financial Officer, Mark Kociancic (age 52), Executive Vice President, Group, Chief Operating Officer and Head of Reinsurance Division, Jim Williamson (age 48), Executive Vice President, General Counsel, Chief Compliance Officer and Secretary, Sanjoy Mukherjee (age 55) and Executive Vice President, President and Chief Executive Officer of the Everest Insurance® Division, Mike Karmilowicz (age 53). We have employment contracts with all of our key officers, which contain automatic renewal provisions that provide for the contracts to continue indefinitely unless sooner terminated in accordance with the contract or as otherwise may be agreed.
Special considerations apply to our Bermuda operations. Under Bermuda law, non-Bermudians, other than spouses of Bermudians and individuals holding permanent or working resident certificates, are not permitted to
engage in any gainful occupation in Bermuda without a work permit issued by the Bermuda government. A work permit is only granted or extended if the employer can show that, after a proper public advertisement, no Bermudian, spouse of a Bermudian or individual holding a permanent or working resident certificate is available who meets the minimum standards reasonably required for the position. The Bermuda government places a six-year term limit on individuals with work permits, subject to specified exemptions for persons deemed to be key employees of businesses with a significant physical presence in Bermuda. Currently, all our Bermuda-based professional employees who require work permits have been granted permits by the Bermuda government that expire at various times between February 2024 and October 2027.
Our investment values and investment income could decline because they are exposed to interest rate, credit, and market risks.
A significant portion of our investment portfolio consists of fixed income securities and smaller portions consist of equity securities and other investments. Both the fair market value of our invested assets and associated investment income fluctuate depending on general economic and market conditions. For example, the fair market value of our predominant fixed income portfolio generally increases or decreases inversely to fluctuations in interest rates. The market value of our fixed income securities could also decrease as a result of a downturn in the business cycle that causes the credit quality of such securities to deteriorate. The net investment income that we realize from future investments in fixed income securities will generally increase or decrease with interest rates.
Interest rate fluctuations also can cause net investment income from fixed income investments that carry prepayment risk, such as mortgage-backed and other asset-backed securities, to differ from the income anticipated from those securities at the time of purchase. In addition, if issuers of individual investments are unable to meet their obligations, investment income will be reduced and realized capital losses may arise.
The majority of our fixed income securities are classified as available for sale and temporary changes in the market value of these investments are reflected as changes to our shareholders’ equity. Our actively managed equity security portfolios are fair valued and any changes in fair value are reflected as net realized capital gains or losses. As a result, a decline in the value of our securities reduces our capital or could cause us to incur a loss.
We have invested a portion of our investment portfolio in equity securities. The value of these assets fluctuates with changes in the markets. In times of economic weakness, the fair value of these assets may decline, and may negatively impact net income. We also invest in non-traditional investments which have different risk characteristics than traditional fixed income and equity securities. These alternative investments are comprised primarily of private equity limited partnerships. The changes in value and investment income/(loss) for these partnerships may be more volatile than over-the-counter securities.
We may experience foreign currency exchange losses that reduce our net income and capital levels.
Through our Bermuda and international operations, we conduct business in a variety of foreign (non-U.S.) currencies, principally the Euro, the British pound, the Canadian dollar, and the Singapore dollar. Assets, liabilities, revenues and expenses denominated in foreign currencies are exposed to changes in currency exchange rates. Our reporting currency is the U.S. dollar, and exchange rate fluctuations, especially relative to the U.S. dollar, may materially impact our results and financial position. In 2021, we wrote approximately 26.2% of our coverages in non-U.S. currencies; as of December 31, 2021, we maintained approximately 16.3% of our investment portfolio in investments denominated in non-U.S. currencies. During 2021 and 2020, the impact on our quarterly pre-tax net income from exchange rate fluctuations ranged from a loss of $45.2 million to a gain of $61.4 million.
In January 2020, the United Kingdom exited the European Union (commonly referred to as "Brexit"). The Company has a Lloyd’s of London Syndicate and Bermuda Re has a branch operation in the United Kingdom.
The nature and extent of the impact of Brexit on regulation, interest rates, currency exchange rates and financial markets is still uncertain and may adversely affect our operations.
Changes in the method for determining LIBOR and the potential replacement of LIBOR may affect our cost of capital and net investment income.
On July 27, 2017, the UK Financial Conduct Authority announced that it intends to stop persuading or compelling banks to submit LIBOR rates after 2021, which is expected to result in these widely used reference rates no longer being available. In 2020 it was announced that most LIBOR rates would continue to be published until June 2023. Potential changes to LIBOR, as well as uncertainty related to such potential changes and the establishment of any alternative reference rates, may adversely affect the market for LIBOR-based securities and could adversely impact the interest rate on our long term subordinate notes. In addition, the discontinuance of LIBOR or changes or reforms to the determination or supervision of LIBOR may result in a sudden or prolonged increase or decrease in reported LIBOR, which could have an adverse impact on the market for LIBOR-based securities or the value of our investment portfolio.
We are subject to cybersecurity risks that could negatively impact our business operations.
We are dependent upon our information technology platform, including our processing systems, data and electronic transmissions in our business operations. Security breaches could expose us to the loss or misuse of our information, litigation and potential liability. In addition, cyber incidents that impact the availability, reliability, speed, accuracy or other proper functioning of these systems could have a significant negative impact on our operations and possibly our results. An incident could also result in a violation of applicable privacy and other laws, damage our reputation, cause a loss of customers or give rise to monetary fines and other penalties, which could be significant. Management is not aware of a cybersecurity incident that has had a material impact on our operations.
The NAIC has adopted an Insurance Data Security Model Law, which, when adopted by the states will require insurers, insurance producers and other entities required to be licensed under state insurance laws to comply with certain requirements under state insurance laws, such as developing and maintaining a written information security program, conducting risk assessments and overseeing the data security practices of third-party vendors. In addition, certain state insurance regulators are developing or have developed regulations that may impose regulatory requirements relating to cybersecurity on insurance and reinsurance companies (potentially including insurance and reinsurance companies that are not domiciled, but are licensed, in the relevant state). For example, the New York State Department of Financial Services has adopted a regulation pertaining to cybersecurity for all banking and insurance entities under its jurisdiction, effective as of March 1, 2017, which applies to us. We cannot predict the impact these laws and regulations will have on our business, financial condition or results of operations, but our insurance and reinsurance companies could incur additional costs resulting from compliance with such laws and regulations.
The continuing COVID-19 pandemic has adversely affected, and may materially and adversely affect, our results of operations, financial position and liquidity in the future.
The ongoing COVID-19 pandemic, including the related impact on the U.S. and global economies, has adversely affected our results of operations. We expect the pandemic and its impact on our business to continue and potentially even worsen, but we cannot predict the magnitude or duration of its continued impact, particularly given the great uncertainties associated with COVID-19, including regarding the reopening of the U.S. and global economies and the recovery from its economic and other effects. The full impact of COVID-19 on our results of operations, financial position and liquidity is not yet known, and likely will not be known for some time, but includes the following:
Claim Losses Related to COVID-19 May Exceed Reserves: We have established reserves for COVID-19-related losses. Our reserves represent management’s best estimate of what the settlement and claims administration
will cost for claims that have occurred, whether reported or unreported. Given the great uncertainties associated with COVID-19 and its impact and the limited information upon which our current assumptions and assessments have been made, our preliminary reserves and the underlying estimated level of claim losses and costs arising from COVID-19 may materially change.
Adverse Legislative and Regulatory Action: Legislative and regulatory initiatives taken or which may be taken in response to COVID-19 may adversely affect us. For example, our business may be subject to, certain initiatives, including, but not limited to: legislative and regulatory action that seeks to retroactively mandate coverage for losses which our insurance policies would not otherwise cover and which were not priced to cover; actions prohibiting us from cancelling insurance policies in accordance with our policy terms or non-renewing policies at their natural expiration; and/or orders to provide premium refunds, grant extended grace periods for premium payments, and provide extended time to pay past due premiums. Any such action would likely increase both our underwriting losses and our expenses and any legal challenges to any such action could take years to resolve.
Reduction in Premiums: The demand for insurance is significantly influenced by general economic conditions. Consequently, reduced economic activity relating to the COVID-19 pandemic is likely to decrease demand for our insurance products and services and negatively impact our premium volumes (and, in certain cases, may result in return of premiums due to a decrease in exposures). This may continue for an indefinite period, with the magnitude of the impact impossible to predict.
Investments: Further disruptions in global financial markets due to the continuing impact of COVID-19 could cause us to incur additional unrealized and/or realized investment losses, including credit impairments in our fixed maturity portfolio. In addition, the economic uncertainty resulting from COVID-19 may result in a decline in interest rates, which may negatively impact our future net investment income.
Credit Risk: As credit risk is generally a function of the economy, we face greater credit risk from our policyholders, independent agents and brokers in connection with the payment and remittance of premiums as a result of the economic conditions caused by COVID-19. Similarly, our credit risk related to the reimbursement of deductibles from policyholders and in connection with reinsurance recoverables has increased.
Operational Disruptions and Costs: Our operations could be disrupted if key members of our senior management or a significant percentage of our workforce or the workforce of our agents, brokers, suppliers or other third party service providers are unable to continue to work because of illness, government directives or otherwise. In addition, our agents, brokers, suppliers and other third party service providers, which we rely on for key aspects of our operations, are subject to risks and uncertainties related to the COVID-19 pandemic, which may interfere with their ability to fulfill their respective commitments and responsibilities to us in a timely manner and in accordance with the agreed-upon terms. In response to the COVID-19 pandemic, we have implemented remote working policies which have resulted in disruptions to our business routines, heightened risk to cybersecurity attacks and data security incidents and a greater dependency on internet and telecommunication access and capabilities.
Risks Relating to Regulation
Insurance laws and regulations restrict our ability to operate and any failure to comply with those laws and regulations could have a material adverse effect on our business.
We are subject to extensive and increasing regulation under U.S., state and foreign insurance laws. These laws limit the amount of dividends that can be paid to us by our operating subsidiaries, impose restrictions on the amount and type of investments that we can hold, prescribe solvency, accounting and internal control standards that must be met and maintained and require us to maintain reserves. These laws also require disclosure of material inter-affiliate transactions and require prior approval of “extraordinary” transactions. Such “extraordinary” transactions include declaring dividends from operating subsidiaries that exceed statutory
thresholds. These laws also generally require approval of changes of control of insurance companies. The application of these laws could affect our liquidity and ability to pay dividends, interest and other payments on securities, as applicable, and could restrict our ability to expand our business operations through acquisitions of new insurance subsidiaries. We may not have or maintain all required licenses and approvals or fully comply with the wide variety of applicable laws and regulations or the relevant authority’s interpretation of the laws and regulations. If we do not have the requisite licenses and approvals or do not comply with applicable regulatory requirements, the insurance regulatory authorities could preclude or temporarily suspend us from carrying on some or all of our activities or monetarily penalize us. These types of actions could have a material adverse effect on our business. To date, no material fine, penalty or restriction has been imposed on us for failure to comply with any insurance law or regulation.
As a result of the previous dislocation of the financial markets, Congress and the previous Presidential administration in the United States implemented changes in the way the financial services industry is regulated. Some of these changes are also impacting the insurance industry. For example, the U.S. Treasury established the Federal Insurance Office with the authority to monitor all aspects of the insurance sector, monitor the extent to which traditionally underserved communities and consumers have access to affordable non-health insurance products, to represent the United States on prudential aspects of international insurance matters, to assist with administration of the Terrorism Risk Insurance Program and to advise on important national and international insurance matters. In addition, several European regulatory bodies are in process of updating existing or developing new capital adequacy directives for insurers and reinsurers. The future impact of such initiatives or new initiatives from the current Government Administration, if any, on our operation, net income (loss) or financial condition cannot be determined at this time.
Bermuda introduced new economic substance legislation in December 2018, which came into force on January 1, 2019. Based on the European Union guidelines, the legislation requires Bermuda companies to be locally managed and directed, to carry on their core income generating activities in Bermuda and to have an adequate level of local full time qualified employees, local accommodation and local expenditure. There is no experience yet as to how the Bermuda authorities will interpret and enforce these new rules, and, accordingly, we are not able to predict their impact on our operations and net income.
Regulatory challenges in the United States could adversely affect the ability of Bermuda Re to conduct business.
Bermuda Re does not intend to be licensed or admitted as an insurer or reinsurer in any U.S. jurisdiction. Under current law, Bermuda Re generally will be permitted to reinsure U.S. risks from its office in Bermuda without obtaining those licenses. However, the insurance and reinsurance regulatory framework is subject to periodic legislative review and revision. In the past, there have been congressional and other initiatives in the United States regarding increased supervision and regulation of the insurance industry, including proposals to supervise and regulate reinsurers domiciled outside the United States. If Bermuda Re were to become subject to any insurance laws of the United States or any U.S. state at any time in the future, it might be required to post deposits or maintain minimum surplus levels and might be prohibited from engaging in lines of business or from writing some types of policies. Complying with those laws could have a material adverse effect on our ability to conduct business in Bermuda and international markets.
Bermuda Re may need to be licensed or admitted in additional jurisdictions to develop its business.
As Bermuda Re’s business develops, it will monitor the need to obtain licenses in jurisdictions other than Bermuda and the U.K., where it has an authorized branch, in order to comply with applicable law or to be able to engage in additional insurance-related activities. In addition, Bermuda Re may be at a competitive disadvantage in jurisdictions where it is not licensed or does not enjoy an exemption from licensing relative to competitors that are so licensed or exempt from licensing. Bermuda Re may not be able to obtain any additional licenses that it determines are necessary or desirable. Furthermore, the process of obtaining those licenses is often costly and may take a long time.
Bermuda Re’s ability to write reinsurance may be severely limited if it is unable to arrange for security to back its reinsurance.
Many jurisdictions do not permit insurance companies to take credit for reinsurance obtained from unlicensed or non-admitted insurers on their statutory financial statements without appropriate security. Bermuda Re’s reinsurance clients typically require it to post a letter of credit or enter into other security arrangements. If Bermuda Re is unable to obtain or maintain a letter of credit facility on commercially acceptable terms or is unable to arrange for other types of security, its ability to operate its business may be severely limited. If Bermuda Re defaults on any letter of credit that it obtains, it may be required to prematurely liquidate a substantial portion of its investment portfolio and other assets pledged as collateral.
Risks Relating to Group’s Securities
Because of our holding company structure, our ability to pay dividends, interest and principal is dependent on our receipt of dividends, loan payments and other funds from our subsidiaries.
Group and Holdings are holding companies, each of whose most significant asset consists of the stock of its operating subsidiaries. As a result, each of Group’s and Holdings’ ability to pay dividends, interest or other payments on its securities in the future will depend on the earnings and cash flows of the operating subsidiaries and the ability of the subsidiaries to pay dividends or to advance or repay funds to it. This ability is subject to general economic, financial, competitive, regulatory and other factors beyond our control. Payment of dividends and advances and repayments from some of the operating subsidiaries are regulated by U.S., state and foreign insurance laws and regulatory restrictions, including minimum solvency and liquidity thresholds. Accordingly, the operating subsidiaries may not be able to pay dividends or advance or repay funds to Group and Holdings in the future, which could prevent us from paying dividends, interest or other payments on our securities.
Provisions in Group’s bye-laws could have an anti-takeover effect, which could diminish the value of its common shares.
Group’s bye-laws contain provisions that could delay or prevent a change of control that a shareholder might consider favorable. The effect of these provisions could be to prevent a shareholder from receiving the benefit from any premium over the market price of our common shares offered by a bidder in a potential takeover. Even in the absence of an attempt to effect a change in management or a takeover attempt, these provisions may adversely affect the prevailing market price of our common shares if they are viewed as discouraging takeover attempts in the future.
For example, Group’s bye-laws contain the following provisions that could have an anti-takeover effect:
the total voting power of any shareholder owning more than 9.9% of the common shares will be reduced to 9.9% of the total voting power of the common shares;
the board of directors may decline to register any transfer of common shares if it has reason to believe that the transfer would result in:
i.) any person that is not an investment company beneficially owning more than 5.0% of any class of the issued and outstanding share capital of Group,
ii.) any person holding controlled shares in excess of 9.9% of any class of the issued and outstanding share capital of Group, or
iii.) any adverse tax, regulatory or legal consequences to Group, any of its subsidiaries or any of its shareholders;
Group also has the option to redeem or purchase all or part of a shareholder’s common shares to the extent the board of directors determines it is necessary or advisable to avoid or cure any adverse or potential adverse consequences if:
i.) any person that is not an investment company beneficially owns more than 5.0% of any class of the issued and outstanding share capital of Group,
ii.) any person holds controlled shares in excess of 9.9% of any class of the issued and outstanding share capital of Group, or
iii.) share ownership by any person may result in adverse tax, regulatory or legal consequences to Group, any of its subsidiaries or any other shareholder.
The Board of Directors has indicated that it will apply these bye-law provisions in such manner that “passive institutional investors” will be treated similarly to investment companies. For this purpose, “passive institutional investors” include all persons who are eligible, pursuant to Rule 13d-1(b)(1) under the U.S. Securities Exchange Act of 1934, (“the Exchange Act”) to file a short-form statement on Schedule 13G, other than an insurance company or any parent holding company or control person of an insurance company.
Applicable insurance laws may also have an anti-takeover effect.
Before a person can acquire control of a U.S. insurance company, prior written approval must be obtained from the insurance commissioner of the state where that insurance company is domiciled or deemed commercially domiciled. Prior to granting approval of an application to acquire control of a domestic insurance company, a state insurance commissioner will consider such factors as the financial strength of the applicant, the integrity and competence of the applicant’s board of directors and executive officers, the acquiror’s plans for the future operations of the insurance company and any anti-competitive results that may arise from the consummation of the acquisition of control. Because any person who acquired control of Group would thereby acquire indirect control of its insurance company subsidiaries in the U.S., the insurance change of control laws of Delaware, California and Georgia would apply to such a transaction. This could have the effect of delaying or even preventing such a change of control.
The ownership of common shares of Group by Everest Preferred International Holdings, Ltd., (“Preferred Holdings”) a direct subsidiary of Group may have an impact on securing approval of shareholder proposals that Group’s management supports.
As of December 31, 2021, Everest Preferred owned 9,719,971 or 19.8% of the outstanding common shares of Group. Under Group’s bye-laws, the total voting power of any shareholder owning more than 9.9% of the common shares is reduced to 9.9% of the total voting power of the common shares. Nevertheless, Everest Preferred, which is controlled by Group, has the ability to vote 9.9% of the total voting power of Group’s common shares.
Investors in Group may have more difficulty in protecting their interests than investors in a U.S. corporation.
The Companies Act 1981 of Bermuda (the “Companies Act”), differs in material respects from the laws applicable to U.S. corporations and their shareholders. The following is a summary of material differences between the Companies Act, as modified in some instances by provisions of Group’s bye-laws, and Delaware corporate law that could make it more difficult for investors in Group to protect their interests than investors in a U.S. corporation. Because the following statements are summaries, they do not address all aspects of Bermuda law that may be relevant to Group and its shareholders.
Alternate Directors. Group’s bye-laws provide, as permitted by Bermuda law, that each director may appoint an alternate director, who shall have the power to attend and vote at any meeting of the board of directors or committee at which that director is not personally present and to sign written consents in place of that director. Delaware law permits a director to appoint another director as an alternate to attend any board committee meeting. However, Delaware law does not provide for the designation of alternate directors with authority to attend or vote at a meeting of the board of directors.
Committees of the Board of Directors. Group’s bye-laws provide, as permitted by Bermuda law, that the board of directors may delegate any of its powers to committees that the board appoints, and those committees may consist partly or entirely of non-directors. Delaware law allows the board of directors of a corporation to delegate many of its powers to committees, but those committees may consist only of directors.
Interested Directors. Bermuda law and Group’s bye-laws provide that if a director has a personal interest in a transaction to which the company is also a party and if the director discloses the nature of this personal interest at the first opportunity, either at a meeting of directors or in writing to the directors, then the company will not be able to declare the transaction void solely due to the existence of that personal interest and the director will not be liable to the company for any profit realized from the transaction. In addition, after a director has made the declaration of interest referred to above, he or she is allowed to be counted for purposes of determining whether a quorum is present and to vote on a transaction in which he or she has an interest, unless disqualified from doing so by the chairman of the relevant board meeting. Under Delaware law, an interested director could be held liable for a transaction in which that director derived an improper personal benefit. Additionally, under Delaware law, a corporation may be able to declare a transaction with an interested director to be void unless one of the following conditions is fulfilled:
the material facts as to the interested director’s relationship or interests are disclosed or are known to the board of directors and the board in good faith authorizes the transaction by the affirmative vote of a majority of the disinterested directors;
the material facts are disclosed or are known to the shareholders entitled to vote on the transaction and the transaction is specifically approved in good faith by the holders of a majority of the voting shares; or
the transaction is fair to the corporation as of the time it is authorized, approved or ratified.
Transactions with Significant Shareholders. As a Bermuda company, Group may enter into business transactions with its significant shareholders, including asset sales, in which a significant shareholder receives, or could receive, a financial benefit that is greater than that received, or to be received, by other shareholders with prior approval from Group’s board of directors but without obtaining prior approval from the shareholders. In the case of an amalgamation, in which two or more companies join together and continue as a single company, a resolution of shareholders approved by a majority of at least 75% of the votes cast is required in addition to the approval of the board of directors, except in the case of an amalgamation with and between wholly-owned subsidiaries. If Group was a Delaware corporation, any business combination with an interested shareholder (which, for this purpose, would include mergers and asset sales of greater than 10% of Group’s assets that would otherwise be considered transactions in the ordinary course of business) within a period of three years from the time the person became an interested shareholder would require prior approval from shareholders holding at least 66 2/3% of Group’s outstanding common shares not owned by the interested shareholder, unless the transaction qualified for one of the exemptions in the relevant Delaware statute or Group opted out of the statute. For purposes of the Delaware statute, an “interested shareholder” is generally defined as a person who together with that person’s affiliates and associates owns, or within the previous three years did own, 15% or more of a corporation’s outstanding voting shares.
Takeovers. Under Bermuda law, if an acquiror makes an offer for shares of a company and, within four months of the offer, the holders of not less than 90% of the shares that are the subject of the offer tender their shares, the acquiror may give the nontendering shareholders notice requiring them to transfer their shares on the terms
of the offer. Within one month of receiving the notice, dissenting shareholders may apply to the court objecting to the transfer. The burden is on the dissenting shareholders to show that the court should exercise its discretion to enjoin the transfer. The court will be unlikely to do this unless there is evidence of fraud or bad faith or collusion between the acquiror and the tendering shareholders aimed at unfairly forcing out minority shareholders. Under another provision of Bermuda law, the holders of 95% of the shares of a company (the “acquiring shareholders”) may give notice to the remaining shareholders requiring them to sell their shares on the terms described in the notice. Within one month of receiving the notice, dissenting shareholders may apply to the court for an appraisal of their shares. Within one month of the court’s appraisal, the acquiring shareholders are entitled either to acquire all shares involved at the price fixed by the court or cancel the notice given to the remaining shareholders. If shares were acquired under the notice at a price below the court’s appraisal price, the acquiring shareholders must either pay the difference in price or cancel the notice and return the shares thus acquired to the shareholder, who must then refund the purchase price. There are no comparable provisions under Delaware law.
Inspection of Corporate Records. Members of the general public have the right to inspect the public documents of Group available at the office of the Registrar of Companies and Group’s registered office, both in Bermuda. These documents include the memorandum of association, which describes Group’s permitted purposes and powers, any amendments to the memorandum of association and documents relating to any increase or reduction in Group’s authorized share capital. Shareholders of Group have the additional right to inspect Group’s bye-laws, minutes of general meetings of shareholders and audited financial statements that must be presented to the annual general meeting of shareholders. The register of shareholders of Group also is open to inspection by shareholders and to members of the public without charge. Group is required to maintain its share register at its registered office in Bermuda. Group also maintains a branch register in the offices of its transfer agent in the U.S., which is open for public inspection as required under the Companies Act. Group is required to keep at its registered office a register of its directors and officers that is open for inspection by members of the public without charge. However, Bermuda law does not provide a general right for shareholders to inspect or obtain copies of any other corporate records. Under Delaware law, any shareholder may inspect or obtain copies of a corporation’s shareholder list and its other books and records for any purpose reasonably related to that person’s interest as a shareholder.
Shareholder’s Suits. The rights of shareholders under Bermuda law are not as extensive as the rights of shareholders under legislation or judicial precedent in many U.S. jurisdictions. Class actions and derivative actions are generally not available to shareholders under the laws of Bermuda. However, the Bermuda courts ordinarily would be expected to follow English case law precedent, which would permit a shareholder to bring an action in the name of Group to remedy a wrong done to Group where the act complained of is alleged to be beyond the corporate power of Group or illegal or would result in the violation of Group’s memorandum of association or bye-laws. Furthermore, the court would give consideration to acts that are alleged to constitute a fraud against the minority shareholders or where an act requires the approval of a greater percentage of Group’s shareholders than actually approved it. The winning party in an action of this type generally would be able to recover a portion of attorneys’ fees incurred in connection with the action. Under Delaware law, class actions and derivative actions generally are available to stockholders for breach of fiduciary duty, corporate waste and actions not taken in accordance with applicable law. In these types of actions, the court has discretion to permit the winning party to recover its attorneys’ fees.
Limitation of Liability of Directors and Officers. Group’s bye-laws provide that Group and its shareholders waive all claims or rights of action that they might have, individually or in the right of the Company, against any director or officer for any act or failure to act in the performance of that director’s or officer’s duties. However, this waiver does not apply to claims or rights of action that arise out of fraud or dishonesty. This waiver may have the effect of barring claims arising under U.S. federal securities laws. Under Delaware law, a corporation may include in its certificate of incorporation provisions limiting the personal liability of its directors to the corporation or its stockholders for monetary damages for many types of breach of fiduciary duty. However, these provisions may not limit liability for any breach of the duty of loyalty, acts or omissions not in good faith or that involve intentional misconduct or a knowing violation of law, the authorization of unlawful dividends,
stock repurchases or stock redemptions, or any transaction from which a director derived an improper personal benefit. Moreover, Delaware provisions would not be likely to bar claims arising under U.S. federal securities laws.
Indemnification of Directors and Officers. Group’s bye-laws provide that Group shall indemnify its directors or officers to the full extent permitted by law against all actions, costs, charges, liabilities, loss, damage or expense incurred or suffered by them by reason of any act done, concurred in or omitted in the conduct of Group’s business or in the discharge of their duties. Under Bermuda law, this indemnification may not extend to any matter involving fraud or dishonesty of which a director or officer may be guilty in relation to the company, as determined in a final judgment or decree not subject to appeal. Under Delaware law, a corporation may indemnify a director or officer who becomes a party to an action, suit or proceeding because of his position as a director or officer if (1) the director or officer acted in good faith and in a manner he reasonably believed to be in or not opposed to the best interests of the corporation and (2) if the action or proceeding involves a criminal offense, the director or officer had no reasonable cause to believe his or her conduct was unlawful.
Enforcement of Civil Liabilities. Group is organized under the laws of Bermuda. Some of its directors and officers may reside outside the U.S. A substantial portion of our assets are or may be located in jurisdictions outside the U.S. As a result, a person may not be able to affect service of process within the U.S. on directors and officers of Group and those experts who reside outside the U.S. A person also may not be able to recover against them or Group on judgments of U.S. courts or to obtain original judgments against them or Group in Bermuda courts, including judgments predicated upon civil liability provisions of the U.S. federal securities laws.
Dividends. Bermuda law does not allow a company to declare or pay a dividend, or make a distribution out of contributed surplus, if there are reasonable grounds for believing that the company, after the payment is made, would be unable to pay its liabilities as they become due, or that the realizable value of the company’s assets would be less, as a result of the payment, than the aggregate of its liabilities and its issued share capital and share premium accounts. The share capital account represents the aggregate par value of issued shares, and the share premium account represents the aggregate amount paid for issued shares over and above their par value. Under Delaware law, subject to any restrictions contained in a company’s certificate of incorporation, a company may pay dividends out of the surplus or, if there is no surplus, out of net profits for the fiscal year in which the dividend is declared and/or the preceding fiscal year. Surplus is the amount by which the net assets of a corporation exceed its stated capital. Delaware law also provides that dividends may not be paid out of net profits at any time when stated capital is less than the capital represented by the outstanding stock of all classes having a preference upon the distribution of assets.
Risks Relating to Taxation
If international tax laws change, our net income may be impacted.
The Organization for Economic Co-operation and Development (“OECD”) and its member countries which includes the U.S., have been focusing for an extended period on issues related to the taxation of multinational corporations, such as the comprehensive plan set forth by the OECD to create an agreed set of international tax rules for preventing base erosion and profit shifting. Recently they agreed upon a broad framework for overhauling the taxation of multinational corporations that includes, among other things, profit reallocation rules and a 15% global minimum corporate income tax rate. These proposals, if implemented, could have an impact our net income and effective tax rate. Group and/or various Group companies may be subject to additional income taxes, which would reduce our net income.
If U.S. tax law changes, our net income may be impacted.
The 2017 TCJA addressed what some members of Congress had expressed concern about for several years, which was U.S. corporations moving their place of incorporation to low-tax jurisdictions to obtain a competitive advantage over domestic corporations that are subject to the U.S. corporate income tax rate of 21%.
Specifically, it addressed their concern over a perceived competitive advantage that foreign-controlled insurers and reinsurers may have had over U.S. controlled insurers and reinsurers resulting from the purchase of reinsurance by U.S. insurers from affiliates operating in some foreign jurisdictions, including Bermuda. Such affiliated reinsurance transactions may subject the U.S. ceding companies to a Base Erosion and Anti-abuse Tax (“BEAT”) of 10% from 2019 to 2025 and 12.5% thereafter which may exceed its regular income tax. In addition, new legislation as well as proposed and final regulations may further limit the ability of the Company to execute alternative capital balancing transactions with unrelated parties. This would further impact our net income and effective tax rate.
Group and/or Bermuda Re may be subject to U.S. corporate income tax, which would reduce our net income.
Bermuda Re. The income of Bermuda Re is a significant portion of our worldwide income from operations. We have established guidelines for the conduct of our operations that are designed to ensure that Bermuda Re is not engaged in the conduct of a trade or business in the U.S. Based on its compliance with those guidelines, we believe that Bermuda Re should not be required to pay U.S. corporate income tax, other than withholding tax on U.S. source dividend income. However, if the IRS were to successfully assert that Bermuda Re was engaged in a U.S. trade or business, Bermuda Re would be required to pay U.S. corporate income tax on all of its income and possibly the U.S. branch profits tax. However, if the IRS were to successfully assert that Bermuda Re was engaged in a U.S. trade or business, we believe the U.S.-Bermuda tax treaty would preclude the IRS from taxing Bermuda Re’s income except to the extent that its income was attributable to a U.S. permanent establishment maintained by that subsidiary. We do not believe that Bermuda Re has a permanent establishment in the U.S. If the IRS were to successfully assert that Bermuda Re did have income attributable to a permanent establishment in the U.S., Bermuda Re would be subject to U.S. tax only on that income. This would reduce our net income.
Group. We conduct our operations in a manner designed to minimize our U.S. tax exposures. Based on our compliance with guidelines designed to ensure that we generate only immaterial amounts, if any, of income that is subject to the taxing jurisdiction of the U.S., we believe that we should be required to pay only immaterial amounts, if any, of U.S. corporate income tax, other than withholding tax on U.S. source dividend income. However, if the IRS successfully asserted that we had material amounts of income that was subject to the taxing jurisdiction of the U.S., we would be required to pay U.S. corporate income tax on that income, and possibly the U.S. branch profits tax. The imposition of such tax would reduce our net income. If Bermuda Re became subject to U.S. income tax on its income, or if we became subject to U.S. income tax, our income could also be subject to the U.S. branch profits tax. In that event, Group and Bermuda Re would be subject to taxation at a higher combined effective rate than if they were organized as U.S. corporations. The combined effect of the 21% U.S. corporate income tax rate and the 30% branch profits tax rate is a net tax rate of 44.7%. The imposition of these taxes would reduce our net income.
Group and/or Bermuda Re may become subject to Bermuda tax, which would reduce our net income.
Group and Bermuda Re are not subject to income or profits tax, withholding tax or capital gains taxes in Bermuda. Both companies have received an assurance from the Bermuda Minister of Finance under The Exempted Undertakings Tax Protection Amendment Act of 2011 to the effect that if any legislation is enacted in Bermuda that imposes any tax computed on profits or income, or computed on any capital asset, gain or appreciation, or any tax in the nature of estate duty or inheritance tax, then that tax will not apply to us or to any of our operations or our shares, debentures or other obligations until March 31, 2035. This assurance does not prevent the application of any of those taxes to persons ordinarily resident in Bermuda and does not prevent the imposition of any tax payable in accordance with the provisions of The Land Tax Act 1967 of Bermuda or otherwise payable in relation to any land leased to Group or Bermuda Re.
Our net income will be reduced if U.S. excise and withholding taxes are increased.
Reinsurance and insurance premiums paid to Bermuda Re with respect to risks located in the U.S. are subject to a U.S. federal excise tax of one percent. In addition, Bermuda Re is subject to federal excise tax on reinsurance and insurance premiums with respect to risks located in the U.S. In addition, Bermuda Re is subject to withholding tax on dividend income from U.S. sources. These taxes could increase, and other taxes could be imposed in the future on Bermuda Re’s business, which would reduce our net income.
If U.S. tax law changes, our U.S. shareholders net income may be impacted.
U.S. shareholders. In January 2022, Treasury and the IRS released proposed regulations regarding the determination and inclusion of related-person insurance income (RPII). The regulations, if finalized without modifications, could cause RPII to be attributable to the Company’s U.S. shareholders prospectively and therefore additional income tax. The imposition of such tax could reduce our U.S. shareholders return on investment in the Company. Our U.S. shareholders net income and tax liabilities might be increased, reducing their net income.
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
Everest Re’s corporate offices are located in approximately 321,500 square feet of leased office space in Warren, New Jersey. Bermuda Re’s corporate offices are located in approximately 12,300 total square feet of leased office space in Hamilton, Bermuda. The Company’s other 23 locations occupy a total of approximately 254,000 square feet, all of which are leased.
Item 3. LEGAL PROCEEDINGS
In the ordinary course of business, the Company is involved in lawsuits, arbitrations and other formal and informal dispute resolution procedures, the outcomes of which will determine the Company’s rights and obligations under insurance and reinsurance agreements. In some disputes, the Company seeks to enforce its rights under an agreement or to collect funds owing to it. In other matters, the Company is resisting attempts by others to collect funds or enforce alleged rights. These disputes arise from time to time and are ultimately resolved through both informal and formal means, including negotiated resolution, arbitration and litigation. In all such matters, the Company believes that its positions are legally and commercially reasonable. The Company considers the statuses of these proceedings when determining its reserves for unpaid loss and loss adjustment expenses.
Aside from litigation and arbitrations related to these insurance and reinsurance agreements, the Company is not a party to any other material litigation or arbitration.
Item 4. MINE SAFETY DISCLOSURES
Not Applicable.
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED SHAREHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Market Information.
The common shares of Group trade on the New York Stock Exchange under the symbol, “RE”. The quarterly high and low closing market prices of Group’s common shares for the periods indicated were:
| 2021 | 2020 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|
| High | Low | High | Low | ||||||||
| First Quarter | $ | 255.97 | $ | 211.08 | $ | 291.78 | $ | 171.96 | |||
| Second Quarter | 276.95 | 236.21 | 231.07 | 161.72 | |||||||
| Third Quarter | 273.68 | 236.68 | 232.19 | 197.10 | |||||||
| Fourth Quarter | 286.62 | 250.41 | 241.54 | 196.20 |
Number of Holders of Common Shares.
The number of record holders of common shares as of February 1, 2022 was 630. That number does not include the beneficial owners of shares held in “street” name or held through participants in depositories, such as The Depository Trust Company.
Dividend History and Restrictions.
In 1995, the Board of Directors of the Company established a policy of declaring regular quarterly cash dividends and has paid a regular quarterly dividend in each quarter since the fourth quarter of 1995. The Company declared and paid its quarterly cash dividend of $1.55 per share for the four quarters of 2020. The Company declared and paid its quarterly cash dividend of $1.55 per share for the four quarters of 2021. On February 24, 2022, the Company’s Board of Directors declared a dividend of $1.55 per share, payable on or before March 30, 2022 to shareholders of record on March 16, 2022.
The declaration and payment of future dividends, if any, by the Company will be at the discretion of the Board of Directors and will depend upon many factors, including the Company’s earnings, financial condition, business needs and growth objectives, capital and surplus requirements of its operating subsidiaries, regulatory restrictions, rating agency considerations and other factors. As an insurance holding company, the Company is partially dependent on dividends and other permitted payments from its subsidiaries to pay cash dividends to its shareholders. The payment of dividends to Group by Holdings and to Holdings by Everest Re is subject to Delaware regulatory restrictions and the payment of dividends to Group by Bermuda Re is subject to Bermuda insurance regulatory restrictions. See “Regulatory Matters – Dividends” and ITEM 8, “Financial Statements and Supplementary Data” - Note 14 of Notes to Consolidated Financial Statements.
Purchases of Equity Securities by the Issuer and Affiliated Purchasers
| Issuer Purchases of Equity Securities | |||||||
|---|---|---|---|---|---|---|---|
| (a) | (b) | (c) | (d) | ||||
| Maximum Number (or | |||||||
| Total Number of | Approximate Dollar | ||||||
| Shares (or Units) | Value) of Shares (or | ||||||
| Purchased as Part | Units) that May Yet | ||||||
| Total Number of | of Publicly | Be Purchased Under | |||||
| Shares (or Units) | Average Price Paid | Announced Plans or | the Plans or | ||||
| Period | Purchased | per Share (or Unit) | Programs | Programs (1) | |||
| January 1 - 31, 2021 | — | $ | — | — | 2,357,803 | ||
| February 1 - 28, 2021 | 49,610 | $ | 241.4919 | 4,100 | 2,353,703 | ||
| March 1 - 31, 2021 | 93,362 | $ | 241.7088 | 93,362 | 2,260,341 | ||
| April 1 - 30, 2021 | — | $ | — | — | 2,260,341 | ||
| May 1 - 31, 2021 | 2,378 | $ | 267.0901 | — | 2,260,341 | ||
| June 1 - 30, 2021 | 68,100 | $ | 246.4414 | 68,100 | 2,192,241 | ||
| July 1 - 31, 2021 | 133,949 | $ | 248.8612 | 133,949 | 2,058,292 | ||
| August 1 - 31, 2021 | 191,560 | $ | 257.2113 | 191,560 | 1,866,732 | ||
| September 1 - 30, 2021 | 305,222 | $ | 257.1626 | 299,849 | 1,566,883 | ||
| October 1 - 31, 2021 | 2,062 | $ | 269.4910 | — | 1,566,883 | ||
| November 1 - 30, 2021 | 4,232 | $ | 274.4150 | — | 1,566,883 | ||
| December 1 - 31, 2021 | 97,186 | $ | 259.3518 | 96,702 | 1,470,181 | ||
| Total | 947,661 | $ | — | 887,622 | 1,470,181 |
(1)On May 22, 2020, the Company’s executive committee of the Board of Directors approved an amendment to the share repurchase program authorizing the Company and/or its subsidiary Holdings, to purchase up to a current aggregate of 32.0 million of the Company’s shares (recognizing that the number of shares authorized for repurchase has been reduced by those shares that have already been purchased) in open market transactions, privately negotiated transactions or both. Currently, the Company and/or its subsidiary Holdings have repurchased 30.5 million of the Company’s shares.
Recent Sales of Unregistered Securities.
None.
Performance Graph.
The following Performance Graph compares cumulative total shareholder returns on the Common Shares (assuming reinvestment of dividends) from December 31, 2016 through December 31, 2021, with the cumulative total return of the Standard & Poor’s 500 Index and the Standard & Poor’s Insurance (Property and Casualty) Index.
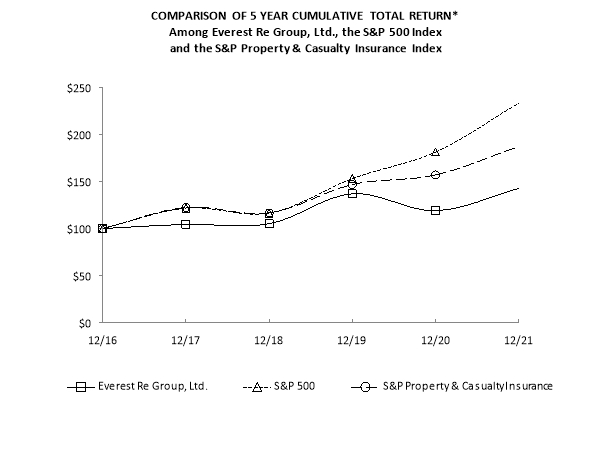
| 12/16 | 12/17 | 12/18 | 12/19 | 12/20 | 12/21 | ||||||
|---|---|---|---|---|---|---|---|---|---|---|---|
| Everest Re Group, Ltd. | 100.00 | 104.43 | 105.19 | 136.92 | 119.04 | 142.66 | |||||
| S&P 500 | 100.00 | 121.83 | 116.49 | 153.17 | 181.35 | 233.41 | |||||
| S&P Property & Casualty Insurance | 100.00 | 122.39 | 116.64 | 146.82 | 157.04 | 187.31 |
*$100 invested on 12/31/15 in stock or index, including reinvestment of dividends.
Fiscal year ending December 31.
Copyright© 2021 Standard & Poor's, a division of S&P Global. All rights reserved.
Item 6. SELECTED FINANCIAL DATA
The following selected consolidated GAAP financial data of the Company as of and for the years ended December 31, 2021, 2020, 2019, 2018 and 2017, were derived from the audited consolidated financial statements of the Company. The following financial data should be read in conjunction with the Consolidated Financial Statements and accompanying notes.
| Years Ended December 31, | ||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| (Dollars in millions, except per share amounts) | 2021 | 2020 | 2019 | 2018 | 2017 | |||||||||
| Operating data: | ||||||||||||||
| Gross written premiums | $ | 13,049.8 | $ | 10,482.4 | $ | 9,133.4 | $ | 8,475.2 | $ | 7,173.9 | ||||
| Net written premiums | 11,445.5 | 9,117.0 | 7,824.4 | 7,414.4 | 6,244.7 | |||||||||
| Premiums earned | 10,406.4 | 8,681.5 | 7,403.7 | 6,931.7 | 5,937.8 | |||||||||
| Net investment income | 1,164.9 | 642.5 | 647.1 | 581.2 | 542.9 | |||||||||
| Net realized capital gains (losses) | 257.9 | 267.6 | 185.0 | (127.1) | 153.2 | |||||||||
| Incurred losses and loss adjustment | ||||||||||||||
| expenses (including catastrophes) | 7,391.3 | 6,550.8 | 4,922.9 | 5,651.4 | 4,522.6 | |||||||||
| Net catastrophe losses (1) | 1,065.0 | 415.0 | 550.0 | 1,669.8 | 1,339.1 | |||||||||
| Commission, brokerage, taxes and fees | 2,208.8 | 1,873.3 | 1,703.7 | 1,519.0 | 1,304.0 | |||||||||
| Other underwriting expenses | 582.6 | 511.2 | 440.9 | 371.5 | 318.8 | |||||||||
| Corporate expenses | 67.8 | 41.1 | 33.0 | 30.7 | 25.9 | |||||||||
| Interest, fees and bond issue cost | ||||||||||||||
| amortization expense | 70.1 | 36.3 | 31.7 | 31.0 | 31.6 | |||||||||
| Income (loss) before taxes | 1,545.6 | 585.3 | 1,099.0 | (242.2) | 419.4 | |||||||||
| Income tax expense (benefit) | 166.5 | 71.2 | 89.5 | (331.2) | (63.4) | |||||||||
| Net income (loss) (2) | 1,379.1 | 514.2 | 1,009.5 | 89.0 | 482.8 | |||||||||
| EARNINGS PER COMMON SHARE: | ||||||||||||||
| Basic (3) | $ | 34.66 | $ | 12.81 | $ | 24.77 | $ | 2.18 | $ | 11.77 | ||||
| Diluted (4) | $ | 34.62 | $ | 12.78 | $ | 24.70 | $ | 2.17 | $ | 11.70 | ||||
| Dividends declared | $ | 6.20 | $ | 6.20 | $ | 5.75 | $ | 5.30 | $ | 5.05 | ||||
| Certain GAAP financial ratios: (5) | ||||||||||||||
| Loss ratio | 71.0% | 75.5% | 66.5% | 81.5% | 76.2% | |||||||||
| Other underwriting expense ratio | 26.8% | 27.4% | 29.0% | 27.3% | 27.3% | |||||||||
| Combined ratio (2) | 97.8% | 102.9% | 95.5% | 108.8% | 103.5% | |||||||||
| Balance sheet data (at end of period): | ||||||||||||||
| Total investments and cash | $ | 29,673.3 | $ | 25,461.6 | $ | 20,748.5 | $ | 18,433.1 | $ | 18,626.5 | ||||
| Total assets | 38,185.3 | 32,711.5 | 27,244.0 | 24,773.1 | 23,577.6 | |||||||||
| Loss and LAE reserves | 19,009.5 | 16,322.1 | 13,531.3 | 13,098.2 | 11,870.1 | |||||||||
| Total debt | 3,088.6 | 1,910.4 | 633.8 | 633.6 | 633.4 | |||||||||
| Total liabilities | 28,046.1 | 22,985.3 | 18,111.1 | 16,869.3 | 15,208.4 | |||||||||
| Shareholders' equity | 10,139.2 | 9,726.2 | 9,132.9 | 7,860.8 | 8,340.7 | |||||||||
| Book value per share (6) | 258.21 | 243.25 | 223.85 | 193.37 | 204.25 |
(1) Catastrophe losses are presented net of reinsurance and reinstatement premiums. Catastrophe insurance provides coverage for one event. When limits are exhausted, some contractual arrangements provide for the availability of additional coverage upon the payment of additional premium. This additional premium is referred to as reinstatement premium.
(2) Some amounts may not reconcile due to rounding.
(3) Based on weighted average basic common shares outstanding of 39.3 million, 39.7 million, 40.3 million, 40.4 million and 40.6 million for 2021, 2020, 2019, 2018 and 2017, respectively.
(4) Based on weighted average diluted common shares outstanding of 39.3 million, 39.7 million, 40.4 million, 40.6 million and 40.8 million for 2021, 2020, 2019, 2018 and 2017, respectively.
(5) Loss ratio is the GAAP losses and LAE incurred as a percentage of GAAP net premiums earned. Underwriting expense ratio is the GAAP commissions, brokerage, taxes, fees and other underwriting expenses as a percentage of GAAP net premiums earned. Combined ratio is the sum of the loss ratio and underwriting expense ratio.
(6) Based on 39.3 million, 40.0 million, 40.8 million, 40.7 million and 40.8 million common shares outstanding for December 31, 2021, 2020, 2019, 2018 and 2017, respectively.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operation
The following is a discussion and analysis of our results of operations and financial condition for the years ended December 31, 2021 and 2020. This discussion should be read in conjunction with the Consolidated Financial Statements and related Notes, under ITEM 8 of this Form 10-K. Pursuant to the FAST Act Modernization and Simplification of Regulation S-K, comparisons between 2020 and 2019 have been omitted from this Form 10-K but can be found in "Management's Discussion and Analysis of Financial Condition and Results of Operations" in Part II, Item 7 of our Form 10-K for the year ended December 31, 2020.
All comparisons in this discussion are to the corresponding prior year unless otherwise indicated.
Industry Conditions.
The worldwide reinsurance and insurance businesses are highly competitive, as well as cyclical by product and market. As such, financial results tend to fluctuate with periods of constrained availability, higher rates and stronger profits followed by periods of abundant capacity, lower rates and constrained profitability. Competition in the types of reinsurance and insurance business that we underwrite is based on many factors, including the perceived overall financial strength of the reinsurer or insurer, ratings of the reinsurer or insurer by A.M. Best and/or Standard & Poor’s, underwriting expertise, the jurisdictions where the reinsurer or insurer is licensed or otherwise authorized, capacity and coverages offered, premiums charged, other terms and conditions of the reinsurance and insurance business offered, services offered, speed of claims payment and reputation and experience in lines written. Furthermore, the market impact from these competitive factors related to reinsurance and insurance is generally not consistent across lines of business, domestic and international geographical areas and distribution channels.
We compete in the U.S., Bermuda and international reinsurance and insurance markets with numerous global competitors. Our competitors include independent reinsurance and insurance companies, subsidiaries or affiliates of established worldwide insurance companies, reinsurance departments of certain insurance companies, domestic and international underwriting operations, including underwriting syndicates at Lloyd’s of London and certain government sponsored risk transfer vehicles. Some of these competitors have greater financial resources than we do and have established long term and continuing business relationships, which can be a significant competitive advantage. In addition, the lack of strong barriers to entry into the reinsurance business and recently, the securitization of reinsurance and insurance risks through capital markets provide additional sources of potential reinsurance and insurance capacity and competition.
Worldwide insurance and reinsurance market conditions historically have been competitive. Generally, there was ample insurance and reinsurance capacity relative to demand, as well as additional capital from the capital markets through insurance linked financial instruments. These financial instruments such as side cars, catastrophe bonds and collateralized reinsurance funds, provided capital markets with access to insurance and reinsurance risk exposure. The capital markets demand for these products was being primarily driven by a low interest environment and the desire to achieve greater risk diversification and potentially higher returns on their investments. This increased competition was generally having a negative impact on rates, terms and conditions; however, the impact varies widely by market and coverage.
The industry continues to deal with the impacts of a global pandemic, COVID-19 and its subsequent variants. We activated our operational resiliency plan across our global footprint and all of our critical operations are functioning effectively from remote locations. We continue to service and meet the needs of our clients while ensuring the safety and health of our employees and customers.
Prior to the pandemic, there was a growing industry consensus that there was some firming of (re)insurance rates for the areas impacted by the recent catastrophes. The increased frequency of catastrophe losses in 2020 and 2021 appears to be further pressuring the increase of rates. As business activity continues to regain strength, rates also appear to be firming in most lines of business, particularly in the casualty lines that had seen
significant losses such as excess casualty and directors’ and officers’ liability. Other casualty lines are experiencing modest rate increase, while some lines such as workers’ compensation were experiencing softer market conditions. It is too early to tell what the impact on pricing conditions will be, but it is likely to change depending on the line of business and geography.
While we are unable to predict the full impact the pandemic will have on the insurance industry as it continues to have a negative impact on the global economy, we are well positioned to continue to service our clients. Our capital position remains a source of strength, with high quality invested assets, significant liquidity and a low operating expense ratio. Our diversified global platform with its broad mix of products, distribution and geography is resilient.
Financial Summary.
We monitor and evaluate our overall performance based upon financial results. The following table displays a summary of the consolidated net income (loss), ratios and shareholders’ equity for the periods indicated.
| Years Ended December 31, | Percentage Increase/(Decrease) | |||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| (Dollars in millions) | 2021 | 2020 | 2019 | 2021/2020 | 2020/2019 | |||||||
| Gross written premiums | $ | 13,049.8 | $ | 10,482.4 | $ | 9,133.4 | 24.5% | 14.8% | ||||
| Net written premiums | 11,445.5 | 9,117.0 | 7,824.4 | 25.5% | 16.5% | |||||||
| REVENUES: | ||||||||||||
| Premiums earned | $ | 10,406.4 | $ | 8,681.5 | $ | 7,403.7 | 19.9% | 17.3% | ||||
| Net investment income | 1,164.9 | 642.5 | 647.1 | 81.3% | (0.7)% | |||||||
| Net realized capital gains (losses) | 257.9 | 267.6 | 185.0 | (3.6)% | 44.7% | |||||||
| Other income (expense) | 37.0 | 6.5 | (4.6) | NM | (39.2)% | |||||||
| Total revenues | 11,866.3 | 9,598.1 | 8,231.2 | 23.6% | 16.6% | |||||||
| CLAIMS AND EXPENSES: | ||||||||||||
| Incurred losses and loss adjustment expenses | 7,391.3 | 6,550.8 | 4,922.9 | 12.8% | 33.1% | |||||||
| Commission, brokerage, taxes and fees | 2,208.8 | 1,873.3 | 1,703.7 | 17.9% | 10.0% | |||||||
| Other underwriting expenses | 582.6 | 511.2 | 440.9 | 14.0% | 16.0% | |||||||
| Corporate expenses | 67.8 | 41.1 | 33.0 | 65.0% | 24.7% | |||||||
| Interest, fees and bond issue cost amortization expense | 70.1 | 36.3 | 31.7 | 93.1% | 14.6% | |||||||
| Total claims and expenses | 10,320.6 | 9,012.8 | 7,132.2 | 14.5% | 26.4% | |||||||
| INCOME (LOSS) BEFORE TAXES | 1,545.6 | 585.3 | 1,099.0 | 164.1% | (46.7)% | |||||||
| Income tax expense (benefit) | 166.5 | 71.2 | 89.5 | 133.9% | (20.5)% | |||||||
| NET INCOME (LOSS) | $ | 1,379.1 | $ | 514.2 | $ | 1,009.5 | 168.2% | (49.1)% | ||||
| RATIOS: | Point Change | |||||||||||
| Loss ratio | 71.0% | 75.5% | 66.5% | (4.5) | 9.0 | |||||||
| Commission and brokerage ratio | 21.2% | 21.6% | 23.0% | (0.4) | (1.4) | |||||||
| Other underwriting expense ratio | 5.6% | 5.8% | 6.0% | (0.2) | (0.2) | |||||||
| Combi |
Showing the first 8K of 111K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
See “Market Sensitive Instruments” in ITEM 7.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
The financial statements and schedules listed in the accompanying Index to Financial Statements and Schedules on page F-1 are filed as part of this report.
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Disclosure Controls and Procedures.
As required by Rule 13a-15(b) of the Securities Exchange Act of 1934 (the “Exchange Act”), our management, including our Chief Executive Officer and Chief Financial Officer, has evaluated the effectiveness of our disclosure controls and procedures (as defined in Rule 13a-15(e) under the Exchange Act). Based on that evaluation, the Chief Executive Officer and Chief Financial Officer have concluded that our disclosure controls and procedures were effective as of the end of the period covered by this annual report.
Management’s Report on Internal Control Over Financial Reporting.
Our management is responsible for establishing and maintaining adequate internal controls over financial reporting. Our internal control over financial reporting is designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of our financial statements for external purposes in accordance with generally accepted accounting principles.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Management has assessed the effectiveness of our internal control over financial reporting as of December 31, 2021. In making this assessment, we used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in Internal Control – Integrated Framework (2013). Based on our assessment we concluded that, as of December 31, 2021, our internal control over financial reporting is effective based on those criteria.
The effectiveness of the Company’s internal control over financial reporting as of December 31, 2021, has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report, which appears herein.
Changes in Internal Control over Financial Reporting.
As required by Rule 13a-15(d) of the Exchange Act, our management, including our Chief Executive Officer and Chief Financial Officer, has evaluated our internal control over financial reporting to determine whether any changes occurred during the fourth fiscal quarter covered by this annual report that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting. Based on that evaluation, there has been no such change during the fourth quarter.
Item 9B. OTHER INFORMATION
None.
Item 9C. DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS
None.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
Reference is made to the sections captioned “Information Concerning Nominees”, “Information Concerning Continuing Directors and Executive Officers”, “Audit Committee”, “Nominating and Governance Committee”, “Code of Ethics for CEO and Senior Financial Officers” and “Section 16(a) Beneficial Ownership Reporting Compliance” in our proxy statement for the 2022 Annual General Meeting of Shareholders, which will be filed with the Commission within 120 days of the close of our fiscal year ended December 31, 2021 (the “Proxy Statement”), which sections are incorporated herein by reference.
Item 11. EXECUTIVE COMPENSATION
Reference is made to the sections captioned “Directors’ Compensation” and “Compensation of Executive Officers” in the Proxy Statement, which are incorporated herein by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED SHAREHOLDER MATTERS
Reference is made to the sections captioned “Common Share Ownership by Directors and Executive Officers”, “Principal Beneficial Owners of Common Shares” and “Securities Authorized for Issuance Under Equity Compensation Plans” in the Proxy Statement, which are incorporated herein by reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
Reference is made to the section captioned “Certain Transactions with Directors” in the Proxy Statement, which is incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
Reference is made to the section captioned “Audit Committee Report” in the Proxy Statement, which is incorporated herein by reference.
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
Financial Statements and Schedules.
The financial statements and schedules listed in the accompanying Index to Financial Statements and Schedules on page F-1 are filed as part of this report.
Exhibits.
The exhibits listed on the accompanying Index to Exhibits on page E-1 are filed as part of this report except that the certifications in Exhibit 32 are being furnished to the SEC, rather than filed with the SEC, as permitted under applicable SEC rules.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized on February 28, 2022.
| EVEREST RE GROUP, LTD. | |||
|---|---|---|---|
| By: | /S/ JUAN C. ANDRADE | ||
| Juan C. Andrade | |||
| (President and Chief Executive Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Signature | Title | Date | ||||
|---|---|---|---|---|---|---|
| /S/ JUAN C. ANDRADE | President and Chief Executive Officer (Principal Executive Officer) | February 28, 2022 | ||||
| Juan C. Andrade | ||||||
| /S/ MARK KOCIANCIC | Executive Vice President and Chief Financial Officer | February 28, 2022 | ||||
| Mark Kociancic | ||||||
| /S/ ROBERT J. FREILING | Senior Vice President and Chief | February 28, 2022 | ||||
| Robert J. Freiling | Accounting Officer | |||||
| /S/ JOSEPH V. TARANTO | Chairman | February 28, 2022 | ||||
| Joseph V. Taranto | ||||||
| /S/ JOHN J. AMORE | Director | February 28, 2022 | ||||
| John J. Amore | ||||||
| /S/ WILLIAM F. GALTNEY, JR. | Director | February 28, 2022 | ||||
| William F. Galtney, Jr. | ||||||
| /S/ JOHN A. GRAF | Director | February 28, 2022 | ||||
| John A. Graf | ||||||
| /S/ MERYL HARTZBAND | Director | February 28, 2022 | ||||
| Meryl Hartzband | ||||||
| /S/ GERALDINE LOSQUADRO | Director | February 28, 2022 | ||||
| Geraldine Losquadro | ||||||
| /S/ ROGER M. SINGER | Director | February 28, 2022 | ||||
| Roger M. Singer | ||||||
| /S/ JOHN A. WEBER | Director | February 28, 2022 | ||||
| John A. Weber | ||||||
E-1
| *10. | 5 | Form of Restricted Stock Award Agreement under the Everest Re Group, Ltd. 2003 Non-Employee Director Equity Compensation Plan, incorporated by reference to Exhibit 10.1 to Everest Re Group, Ltd. Form 8-K filed on September 22, 2005 | ||
|---|---|---|---|---|
| 10. | 6 | [Completion of Tender Offer relating to Everest Reinsurance Holdings, Inc. 6.60% Fixed to Floating Rate Long Term Subordinated Notes (LoTSSM) dated March 19, 2009, incorporated herein by reference to Exhibit 99.1 to Everest Re Group, Ltd. Form 8-K filed on March 31, 2009](http://www.sec.gov/Archives/edgar/data/ |
Showing the first 8K of 297K characters. Open the full section