 filings.tools
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
113K characters. Original on sec.gov · Markdown
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
The following commentary should be read in conjunction with the financial statements and related notes contained elsewhere in this Annual Report on Form 10-K. The information in this discussion contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Such statements are based upon current expectations that involve risks and uncertainties. Any statements contained herein that are not statements of historical fact may be deemed to be forward-looking statements. For example, the words "believes," "anticipates," "plans," "expects," "intends" and similar expressions are intended to identify forward-looking statements. Our actual results and the timing of certain events may differ significantly from the results discussed in the forward-looking statements. Factors that might cause such a discrepancy include, but are not limited to, those discussed in "Liquidity and Capital Resources" and "Risk Factors" elsewhere in this Annual Report on Form 10-K. All forward-looking statements in this document are based on information available to us as of the date hereof and we assume no obligation to update any such forward-looking statements.
Item 7 of this Form 10-K focuses on discussion of 2020 and 2019 items as well as 2020 results as compared to 2019 results. For the discussion of 2018 items and 2019 results as compared to 2018 results, please refer to Item 7 of our 2019 Form 10-K as filed with the SEC on February 21, 2020.
Our management's discussion and analysis of financial condition and results of operations is intended to assist readers in understanding our financial information from our management's perspective and is presented as follows:
-
Overview
-
Results of Operations
-
Non-GAAP Financial Measures
-
Liquidity and Capital Resources
-
Contractual Obligations and Off-Balance-Sheet Arrangements
-
Critical Accounting Policies and Estimates
-
Recent Accounting Pronouncements
Overview
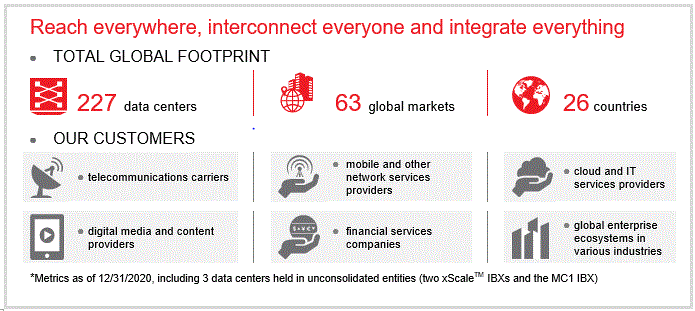
Equinix is a global digital infrastructure company, enabling digital leaders to harness a trusted platform to bring together and interconnect the foundational infrastructure that powers their success. Equinix enables today’s businesses to access all the right places, partners and possibilities they need to accelerate their advantage. Global enterprises, service providers and business ecosystems of industry partners rely on Equinix IBX data centers and
expertise around the world for the safe housing of their critical IT equipment and to protect and connect the world's most valued information assets. They also look to Platform Equinix® for the ability to directly and securely interconnect to the networks, clouds and content that enable today's information-driven global digital economy. Recent Equinix IBX data center openings and acquisitions, as well as xScaleTM data center investments, have expanded our total global footprint to 227 IBXs, including two xScaleTM data centers and the MC1 data center that were held in unconsolidated joint ventures, across 63 markets around the world. Equinix offers the following solutions:
-
premium data center colocation;
-
interconnection and data exchange solutions;
-
edge services for deploying networking, security and hardware; and
-
remote expert support and professional services.
Our interconnected data centers around the world allow our customers to increase information and application delivery performance to users, and quickly access distributed IT infrastructures and business and digital ecosystems, while significantly reducing costs. The Equinix global platform and the quality of our IBX data centers, interconnection offerings and edge services have enabled us to establish a critical mass of customers. As more customers choose Platform Equinix, for bandwidth cost and performance reasons it benefits their suppliers and business partners to colocate in the same data centers. This adjacency creates a “network effect” that enables our customers to capture the full economic and performance benefits of our offerings. These partners, in turn, pull in their business partners, creating a "marketplace" for their services. Our global platform enables scalable, reliable and cost-effective interconnection that increases data traffic exchange while lowering overall cost and increasing flexibility. Our focused business model is built on our critical mass of enterprise and service provider customers and the resulting "marketplace" effect. This global platform, combined with our strong financial position, continues to drive new customer growth and bookings.
Historically, our market was served by large telecommunications carriers who have bundled their products and services with their colocation offerings. The data center market landscape has evolved to include private and vendor-neutral MTDC providers, hyperscale cloud providers, managed infrastructure and application hosting providers, and systems integrators. It is estimated that Equinix is one of more than 1,200 companies that provide MTDC offerings around the world. Each of these data center solutions providers can bundle various colocation, interconnection and network offerings and outsourced IT infrastructure solutions. We are able to offer our customers a global platform that reaches 26 countries with the industry’s largest and most active ecosystem of partners in our sites, proven operational reliability, improved application performance and a highly scalable set of offerings.
The cabinet utilization rate represents the percentage of cabinet space billed versus total cabinet capacity, which is used to measure how efficiently we are managing our cabinet capacity. Our cabinet utilization rate varies from market to market among our IBX data centers across the Americas, EMEA and Asia-Pacific regions. Our cabinet utilization rates were approximately 79%, as of December 31, 2020 and 2019. Excluding the impact of our IBX data center expansion projects that have opened during the last 12 months, our cabinet utilization rate would have increased to approximately 80% as of December 31, 2020. We continue to monitor the available capacity in each of our selected markets. To the extent we have limited capacity available in a given market, it may limit our ability for growth in that market. We perform demand studies on an ongoing basis to determine if future expansion is warranted in a market. In addition, power and cooling requirements for most customers are growing on a per unit basis. As a result, customers are consuming an increasing amount of power per cabinet. Although we generally do not control the amount of power our customers draw from installed circuits, we have negotiated power consumption limitations with certain high power-demand customers. This increased power consumption has driven us to build out our new IBX data centers to support power and cooling needs twice that of previous IBX data centers. We could face power limitations in our IBX data centers, even though we may have additional physical cabinet capacity available within a specific IBX data center. This could have a negative impact on the available utilization capacity of a given IBX data center, which could have a negative impact on our ability to grow revenues, affecting our financial performance, results of operations and cash flows.
In 2019, we closed our EMEA Joint Venture with GIC to develop and operate xScaleTM data centers to serve the needs of the growing hyperscale data center market, including the world's largest cloud service providers. Upon closing, the EMEA Joint Venture acquired certain data center sites, including the London 10 data center, Paris 8 data center and few data center sites in London and Frankfurt, with the opportunity to add additional facilities in the future. In 2020, we sold the Paris 9 data center to the EMEA Joint Venture. In addition, we closed our Asia-Pacific Joint Venture with GIC in APAC to develop and operate xScaleTM data centers. Upon closing, the Asia-Pacific Joint
Venture acquired Osaka 2, Tokyo 12, and Tokyo 14 data center development sites in the APAC region, with the opportunity to add additional facilities in the future.
Strategically, we will continue to look at attractive opportunities to grow our market share and selectively improve our footprint and offerings. As was the case with our recent expansions and acquisitions, our expansion criteria will be dependent on a number of factors, including but not limited to demand from new and existing customers, quality of the design, power capacity, access to networks, clouds and software partners, capacity availability in the current market location, amount of incremental investment required by us in the targeted property, automation capabilities, developer talent pool, lead-time to break even on a free cash flow basis and in-place customers. Like our recent expansions and acquisitions, the right combination of these factors may be attractive to us. Depending on the circumstances, these transactions may require additional capital expenditures funded by upfront cash payments or through long-term financing arrangements in order to bring these properties up to Equinix standards. Property expansion may be in the form of purchases of real property, long-term leasing arrangements or acquisitions. Future purchases, construction or acquisitions may be completed by us or with partners or potential customers to minimize the outlay of cash, which can be significant.
Revenue:
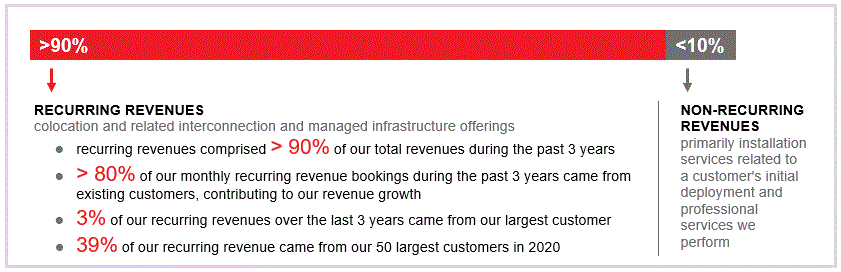
Our business is based on a recurring revenue model comprised of colocation and related interconnection and managed infrastructure offerings. We consider these offerings recurring because our customers are generally billed on a fixed and recurring basis each month for the duration of their contract, which is generally one to three years in length. Our recurring revenues have comprised more than 90% of our total revenues during the past three years. In addition, during the past three years, more than 80% of our monthly recurring revenue bookings came from existing customers, contributing to our revenue growth. Our largest customer accounted for approximately 3% of our recurring revenues for the years ended December 31, 2020, 2019 and 2018. Our 50 largest customers accounted for approximately 39%, 39% and 38%, respectively, of our recurring revenues for the years ended December 31, 2020, 2019 and 2018.
Our non-recurring revenues are primarily comprised of installation services related to a customer's initial deployment and professional services we perform. These services are considered to be non-recurring because they are billed typically once, upon completion of the installation or the professional services work performed. The majority of these non-recurring revenues are typically billed on the first invoice distributed to the customer in connection with their initial installation. However, revenues from installation services are deferred and recognized ratably over the period of the contract term. Additionally, revenue from contract settlements, when a customer wishes to terminate their contract early, is generally treated as a contract modification and recognized ratably over the remaining term of the contract, if any. As a percentage of total revenues, we expect non-recurring revenues to represent less than 10% of total revenues for the foreseeable future.
Operating Expenses:
Cost of Revenues. The largest components of our cost of revenues are depreciation, rental payments related to our leased IBX data centers, utility costs, including electricity, bandwidth access, IBX data center employees' salaries and benefits, including stock-based compensation, repairs and maintenance, supplies and equipment and security. A majority of our cost of revenues is fixed in nature and should not vary significantly from period to period,
unless we expand our existing IBX data centers or open or acquire new IBX data centers. However, there are certain costs that are considered more variable in nature, including utilities and supplies that are directly related to growth in our existing and new customer base. We expect the cost of our utilities, specifically electricity, will generally increase in the future on a per-unit or fixed basis, in addition to the variable increase related to the growth in consumption by our customers. In addition, the cost of electricity is generally higher in the summer months, as compared to other times of the year. To the extent we incur increased utility costs, such increased costs could materially impact our financial condition, results of operations and cash flows. Furthermore, to the extent we incur increased electricity or other costs as a result of either climate change policies or the physical effects of climate change, such increased costs could materially impact our financial condition, results of operations and cash flows.
Sales and Marketing. Our sales and marketing expenses consist primarily of compensation and related costs for sales and marketing personnel, including stock-based compensation, amortization of contract costs, marketing programs, public relations, promotional materials and travel, as well as bad debt expense and amortization of customer relationship intangible assets.
General and Administrative. Our general and administrative expenses consist primarily of salaries and related expenses, including stock-based compensation, accounting, legal and other professional service fees, and other general corporate expenses, such as our corporate regional headquarters office leases and some depreciation expense on back office systems.
Taxation as a REIT
We elected to be taxed as a REIT for U.S. federal income tax purposes beginning with our 2015 taxable year. As of December 31, 2020, our REIT structure included all of our data center operations in the U.S., Canada (with the exception of our data center in Ottawa), Mexico, Japan, Singapore and the data center operations in EMEA with the exception of Bulgaria, the United Arab Emirates, and the data center operations outside Amsterdam in the Netherlands. Our data center operations in other jurisdictions are operated as TRSs. We included our investment interest in the EMEA and Asia-Pacific Joint Ventures in our REIT structure.
As a REIT, we generally are permitted to deduct from our U.S. federal taxable income the dividends we pay to our stockholders. The income represented by such dividends is not subject to U.S. federal income taxes at the entity level but is taxed, if at all, at the stockholder level. Nevertheless, the income of our TRSs which hold our U.S. operations that may not be REIT compliant is subject to U.S. corporate federal and state income taxes, as applicable. Likewise, our foreign subsidiaries continue to be subject to foreign income taxes in jurisdictions in which they hold assets or conduct operations, regardless of whether held or conducted through TRSs or through QRSs. We are also subject to a separate U.S. federal corporate income tax on any gain recognized from a sale of a REIT asset where our basis in the asset is determined by reference to the basis of the asset in the hands of a C corporation (such as an asset held by us or a QRS following the liquidation or other conversion of a former TRS). This built-in-gains tax is generally applicable to any disposition of such an asset during the five-year period after the date we first owned the asset as a REIT asset to the extent of the built-in-gain based on the fair market value of such asset on the date we first held the asset as a REIT asset. If we fail to remain qualified for U.S. federal income taxation as a REIT, we will be subject to U.S. federal income taxes at regular corporate income tax rates. In addition, should we have net income from "prohibited transactions," we will be subject to tax on this income at a 100% rate. "Prohibited transactions," for this purpose, are defined as dispositions, at a gain, of inventory or property held primarily for sale to customers in the ordinary course of a trade or business other than dispositions of foreclosure property and other than dispositions excepted by statutory safe harbors. Even if we remain qualified for U.S. federal income taxation as a REIT, we may be subject to some federal, state, local and foreign taxes on our income and property in addition to taxes owed with respect to our TRSs' operations. In particular, while state income tax regimes often parallel the U.S. federal income tax regime for REITs, many states do not completely follow federal rules, and some may not follow them at all.
We continue to monitor our REIT compliance in order to maintain our qualification for U.S. federal income taxation as a REIT. For this and other reasons, as necessary, we may convert some of our data center operations in other countries into the REIT structure in future periods.
On each of March 18, June 17, September 23, and December 9, 2020 we paid quarterly cash dividends of $2.66 per share. We expect the amount of our applicable dividends and other applicable distributions to equal or exceed the REIT taxable income that we recognized in 2020.
The Impact of the ongoing COVID-19 pandemic on Our Results and Operations
In December 2019, a novel strain of coronavirus, referred to as Coronavirus disease 2019, or COVID-19, emerged. In February 2020, the World Health Organization (WHO) raised the COVID-19 threat from high to very high, and in March 2020, the WHO characterized COVID-19 as a global pandemic. The global pandemic and the efforts implemented to address the pandemic, including the issuance of “shelter-in-place” orders and social distancing guidelines, have impacted major economic and financial markets globally.
Many of our IBX data centers have been identified as "essential businesses" or "critical infrastructure" by local governments for purposes of remaining open during the COVID-19 pandemic. All of our IBX data centers remain operational at the time of filing of this Annual Report on Form 10-K. We have activated our business continuity plans globally with the goal of providing seamless operations throughout our facilities, including provisions for ensuring all data centers remain staffed and fully operational and that our IBXs are equipped with the necessary equipment and supplies. We have implemented precautionary measures to minimize the risk of operational impact and to protect the health and safety of our employees, customers, partners and communities. These include implementing tools such as an appointment-based system to control timing and frequency of visits while also encouraging our customers to leverage our IBX technicians via Smart Hands, our remote operational support service, in order to restrict visits and minimize the number of people and the amount of time spent in our IBX facilities.
Most of our corporate offices remain closed as a result of the pandemic and we instructed our non-IBX employees in these offices to work from home until further notice. We have announced a phased plan for return-to-office for non-IBX attached sites and have been following this plan to open certain offices with occupancy limits as local conditions allow. Additionally, we have decided to continue to limit employee travel and postpone or virtualize global events in response to the COVID-19 pandemic.
We are experiencing some construction delays, however, to date, the construction delays and additional costs are insignificant relative to the overall project duration and budget. Equipment for construction projects which are scheduled to be placed in the near future has been ordered, and is currently being manufactured or delivered with minimal delays. We are actively monitoring our vendors and suppliers to evaluate any anticipated changes in equipment availability or delivery timetables. We have redundancies built into our supply chain of vendors and, to the best of our ability, we keep a stock of critical items on site to ensure repairs can be completed. To date, we have not observed any significant disruption to our IBX data center operations due to supply chain impacts from the COVID-19 pandemic.
During the year ended December 31, 2020, the COVID-19 pandemic did not have a material impact on our results of operations. The majority of our revenue is derived from large companies across a diverse set of industries. Customers operating in sectors more drastically impacted by the COVID-19 pandemic, such as retail, travel, and energy, made up an insignificant percentage of our revenue. Smart Hands service revenues declined during the year ended December 31, 2020, as we waived Smart Hands service fees from the affected customers in certain circumstances during the first few months of the pandemic. We ceased to waive Smart Hands service fees for most customers as of June 30, 2020. We assessed realized and potential credit deterioration of our customers due to changes in the macroeconomic environment, considered the potential for payment term revision requests, and as a result, increased our allowance for credit losses for accounts receivable by an insignificant amount for the year ended December 31, 2020. We also incurred one-time cash bonuses and compensation expense of $8.6 million for our IBX employees as well as other employees to support their work-from-home requirements during the first quarter of 2020. We have experienced some travel expense savings during the year ended December 31, 2020 resulting from travel restrictions imposed in response to the COVID-19 pandemic.
Looking ahead, the full impact of the ongoing COVID-19 pandemic on our future financial condition or results of operations remains uncertain and will depend on a number of factors, including the duration and potential cyclicity of the health crisis and further public policy actions to be taken in response, as well as the continued impact of the pandemic on the global economy and our customers and vendors. Our past results may not be indicative of our future performance and historical trends may differ materially.
For additional details regarding the risks to our business from the ongoing COVID-19 pandemic, refer to Part I, Item 1A. Risk Factors included elsewhere in this Annual Report on Form 10-K.
2020 Highlights:
- In January, we redeemed the remaining $343.7 million principal amount of the 5.375% Senior Notes due 2022. See Note 11 within the Consolidated Financial Statements.
*•*In January, we completed the acquisition of three data centers in Mexico from Axtel for a total purchase consideration of approximately $189.0 million. See Note 3 within the Consolidated Financial Statements.
*•*In March, we completed the Packet Acquisition, a leading bare metal automation platform for a total purchase consideration of approximately $290.3 million. See Note 3 within the Consolidated Financial Statements.
-
In March, we borrowed a total of $250.0 million under our Revolving Facility, which was fully repaid in May. As of December 31, 2020, the amount available to borrow under the Revolving Facility was approximately $1.9 billion. See Note 11 within the Consolidated Financial Statements.
-
In April, we entered into a credit agreement which provided for senior unsecured 364-day term loan facilities in an aggregate principal amount of $750.0 million. On April 15, 2020, we borrowed $391.0 million, as well as €100.0 million or $109.8 million at the exchange rate in effect on that date. In May and June, we repaid all amounts outstanding under the 364-day term loan facilities. See Note 11 within the Consolidated Financial Statements.
-
In April, we entered into an agreement to form a second joint venture in the form of a limited liability partnership with GIC to develop and operate xScaleTM data centers in APAC. In the third quarter of 2020, we recorded an impairment charge of $7.3 million, reducing the carrying value of the three Japan development sites to be sold, Osaka 2, Tokyo 12, and Tokyo 14, to the estimated fair value less cost to sell. On December 17, 2020, we closed the Asia-Pacific Joint Venture transaction which included the sale of the three development sites in exchange for $209.8 million of cash proceeds and $15.6 million of receivables. We recognized an insignificant gain on the sale of these xScaleTM data center facilities to the Asia-Pacific Joint Venture. See Note 5 and Note 6 within the Consolidated Financial Statements.
-
In May, we issued and sold 2,587,500 shares of common stock in a public offering for net proceeds of approximately $1,683.1 million, after deducting underwriting discounts, commissions and offering expenses. See Note 12 within the Consolidated Financial Statements.
-
In June, we issued $2.6 billion in Senior Notes due 2025, 2027, 2030 and 2050. In July, using a portion of the proceeds, we redeemed all of our outstanding €750.0 million 2.875% Senior Notes due 2024 and $1.1 billion 5.875% Senior Notes due 2026. See Note 11 within the Consolidated Financial Statements.
-
In August, we entered into an agreement to purchase the India operations of GPX Global Systems, Inc. ("GPX India"), representing two data centers in Mumbai, India, for approximately $161.0 million in an all-cash transaction (the “GPX India Acquisition”). The GPX India Acquisition is expected to close in the second quarter of 2021, subject to customary closing conditions including regulatory approval. See Note 3 within the Consolidated Financial Statements.
-
In the fourth quarter, we completed the acquisition of 13 data center sites in Canada, and their operations from Bell, for a total combined purchase consideration of approximately C$931.7 million, or $702.0 million at the exchange rates in effect on the transaction dates. See Note 3 within the Consolidated Financial Statements.
-
In October, we issued $1.85 billion in Senior Notes due in 2025, 2028 and 2051. On October 23, 2020, using a portion of the net proceeds, we redeemed all of our outstanding €1.0 billion aggregate principal amount 2.875% Senior Notes due 2025, as well as €0.5 billion of our outstanding €1.0 billion aggregate principal amount 2.875% Senior Notes due 2026. See Note 11 within the Consolidated Financial Statements.
-
In September, we entered into an agreement to sell the Paris 9 ("PA9") data center to the EMEA Joint Venture. The assets and liabilities of the data center, which was included within our EMEA region, were classified as held for sale as of September 30, 2020. The transaction was completed on December 15, 2020 for a total consideration of $131.5 million, which is comprised of net cash proceeds of $124.6 million, a contract asset with a fair value of $5.6 million and an insignificant amount of contingent consideration that is receivable upon completion of certain performance milestones. See Note 5 and Note 6 within the Consolidated Financial Statements.
-
During 2020, we had sold 415,512 shares of our common stock for approximately $298.3 million in proceeds, net of payment of commissions and other offering expenses under the 2018 ATM Program, reaching the capacity of this program and subsequently closed. In October, we launched a new ATM program, under which we may offer and sell from time to time up to an aggregate of $1.5 billion of our common stock in "at the market" transactions (the "2020 ATM Program"). As of December 31, 2020 we had not sold any shares under the 2020 ATM Program. See Note 12 within the Consolidated Financial Statements.
Results of Operations
Our results of operations for the year ended December 31, 2020 include the results of operations from the acquisitions of 12 data center sites across Canada from Bell from October 1, 2020 and one additional data center acquired from Bell from November 2, 2020, Packet from March 2, 2020 and three data centers in Mexico from Axtel from January 8, 2020. Our results of operations for the year ended December 31, 2019 include the results of operations from the acquisition of the AM11 data center from April 18, 2019 within the EMEA region.
In order to provide a framework for assessing our performance excluding the impact of foreign currency fluctuations, we supplement the year-over-year actual change in results of operations with comparative changes on a constant currency basis. Presenting constant currency results of operations is a non-GAAP financial measure. See “Non-GAAP Financial Measures” below for further discussion.
Years ended December 31, 2020 and 2019
Revenues. Our revenues for the years ended December 31, 2020 and 2019 were generated from the following revenue classifications and geographic regions (dollars in thousands):
| Years Ended December 31, | % Change | ||||||||||||||||||||||||||||||||||
| 2020 | % | 2019 | % | Actual | Constant Currency | ||||||||||||||||||||||||||||||
| Americas: | |||||||||||||||||||||||||||||||||||
| Recurring revenues | $ | 2,582,800 | 43% | $ | 2,456,368 | 44% | 5% | 7% | |||||||||||||||||||||||||||
| Non-recurring revenues | 124,958 | 2% | 131,359 | 3% | (5)% | (4)% | |||||||||||||||||||||||||||||
| 2,707,758 | 45% | 2,587,727 | 47% | 5% | 6% | ||||||||||||||||||||||||||||||
| EMEA: | |||||||||||||||||||||||||||||||||||
| Recurring revenues | 1,864,720 | 31% | 1,680,746 | 30% | 11% | 12% | |||||||||||||||||||||||||||||
| Non-recurring revenues | 131,669 | 2% | 125,698 | 2% | 5% | 3% | |||||||||||||||||||||||||||||
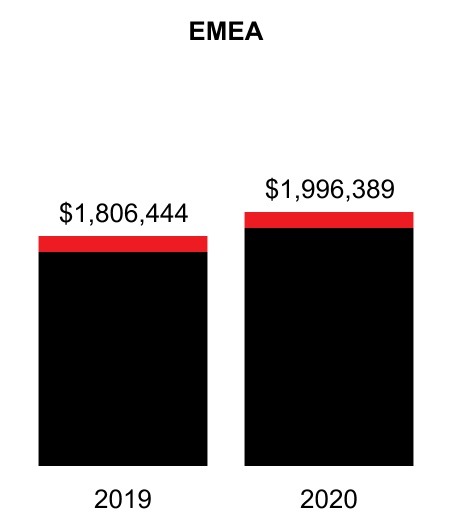
| 1,996,389 | 33% | 1,806,444 | 32% | 11% | 12% | ||||||||||||||||||||||||||||||
| Asia-Pacific: | |||||||||||||||||||||||||||||||||||
| Recurring revenues | 1,210,510 | 20% | 1,101,072 | 20% | 10% | 10% | |||||||||||||||||||||||||||||
| Non-recurring revenues | 83,888 | 2% | 66,897 | 1% | 25% | 24% | |||||||||||||||||||||||||||||
| 1,294,398 | 22% | 1,167,969 | 21% | 11% | 10% | ||||||||||||||||||||||||||||||
| Total: | |||||||||||||||||||||||||||||||||||
| Recurring revenues | 5,658,030 | 94% | 5,238,186 | 94% | 8% | 9% | |||||||||||||||||||||||||||||
| Non-recurring revenues | 340,515 | 6% | 323,954 | 6% | 5% | 4% | |||||||||||||||||||||||||||||
| $ | 5,998,545 | 100% | $ | 5,562,140 | 100% | 8% | 9% |
Revenues
(dollars in thousands)
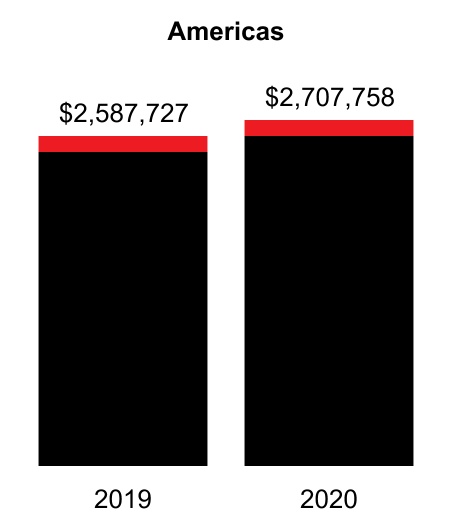
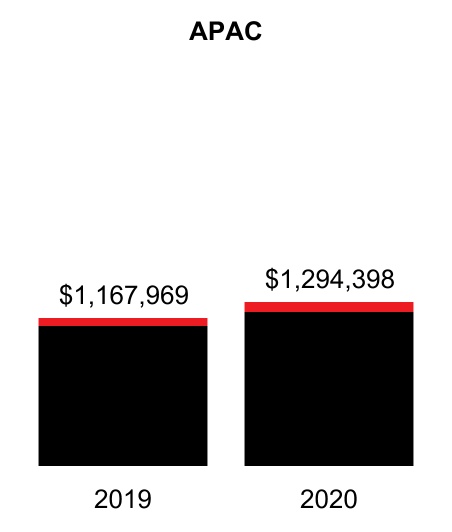
Americas Revenues. During the year ended December 31, 2020, Americas revenue increased by 5% (6% on a constant currency basis). Growth in Americas revenues was primarily due to:
-
approximately $78.0 million of incremental revenues from the Bell, Packet, and Axtel acquisitions;
-
$21.0 million of incremental revenues generated from our recently-opened IBX data centers or IBX data center expansions; and
-
an increase in orders from both our existing customers and new customers during the period.
The increase was partially offset by lower non-recurring revenues, primarily due to decreases in EIS products sales and lower revenues from Smart Hands products in 2020 as we restricted visits to our IBX facilities and waived certain Smart Hands service fees from the affected customers during the COVID-19 pandemic.
EMEA Revenues*.* During the year ended December 31, 2020, EMEA revenue increased by 11% (12% on a constant currency basis). Growth in EMEA revenues was primarily due to:
-
approximately $26.9 million of incremental revenues generated from our recently-opened IBX data centers or IBX data center expansions; and
-
an increase in orders from both our existing customers and new customers during the period.
The increase was partially offset by:
- a net decrease of $43.5 million of realized cash flow hedge gains from foreign currency forward contracts.
Asia-Pacific Revenues. During the year ended December 31, 2020, Asia-Pacific revenue increased by 11% (10% on a constant currency basis). Growth in Asia-Pacific revenue was primarily due to:
-
approximately $19.8 million of incremental revenues generated from our recently-opened IBX data centers or IBX data center expansions;
-
higher non-recurring revenues, primarily due to increases in EIS products sales; and
-
an increase in orders from both our existing customers and new customers during the period.
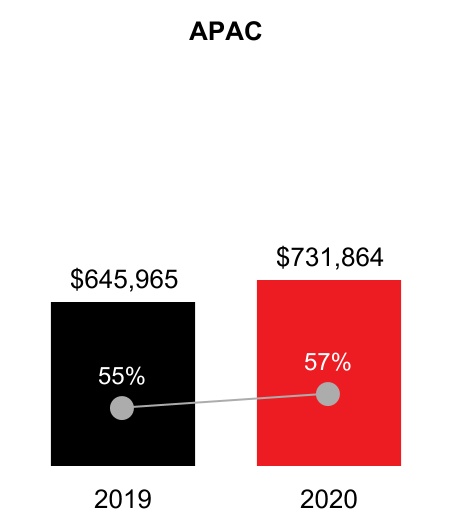
Cost of Revenues. Our cost of revenues for the years ended December 31, 2020 and 2019 were split among the following geographic regions (dollars in thousands):
| Years Ended December 31, | % Change | ||||||||||||||||||||||||||||||||||
| 2020 | % | 2019 | % | Actual | Constant Currency | ||||||||||||||||||||||||||||||
| Americas | $ | 1,248,141 | 41% | $ | 1,146,639 | 41% | 9% | 11% | |||||||||||||||||||||||||||
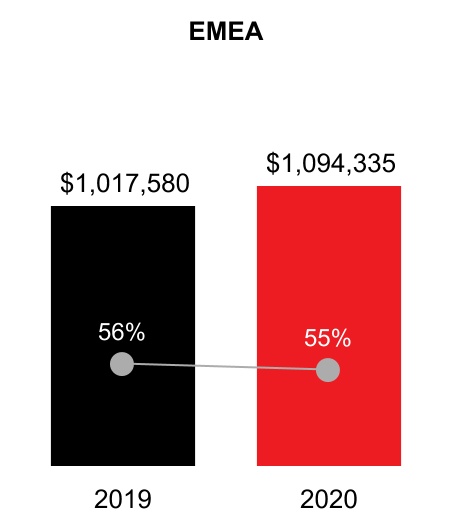
| EMEA | 1,094,335 | 36% | 1,017,580 | 36% | 8% | 8% | |||||||||||||||||||||||||||||
| Asia-Pacific | 731,864 | 23% | 645,965 | 23% | 13% | 13% | |||||||||||||||||||||||||||||
| Total | $ | 3,074,340 | 100% | $ | 2,810,184 | 100% | 9% | 10% |
Cost of Revenues
(dollars in thousands; percentages indicate expenses as a percentage of revenues)
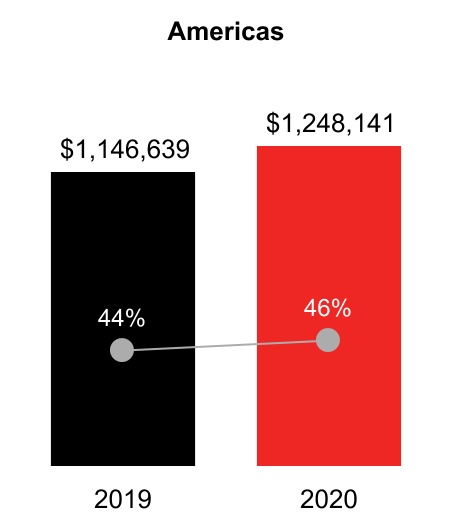
Americas Cost of Revenues. During the year ended December 31, 2020, Americas cost of revenues increased by 9% (11% on a constant currency basis). The increase in our Americas cost of revenues was primarily due to:
-
approximately $64.4 million of incremental cost of revenues from the Bell, Packet, and Axtel acquisitions;
-
$9.8 million of higher utilities cost driven by IBX data center expansions and integration, primarily in U.S.;
-
$9.6 million of higher compensation costs, including salaries, bonuses and stock-based compensation, primarily due to headcount growth and additional bonuses paid to IBX employees for supporting our business during the COVID-19 pandemic;
-
$7.9 million of higher property tax costs driven by IBX data center expansions;
-
$5.8 million of higher accretion and depreciation costs driven by IBX data center expansions; and
-
$5.2 million of higher consulting services and office expense, primarily due to project integration and additional spending on personal protective equipment for our IBX employees in response to the COVID-19 pandemic.
EMEA Cost of Revenues. During the year ended December 31, 2020, EMEA cost of revenues increased by 8% (and also 8% on a constant currency basis). The increase in our EMEA cost of revenues was primarily due to:
-
$42.8 million of higher depreciation expenses driven by IBX data center expansions in Germany, the United Kingdom, the Netherlands, United Arab Emirates, and France;
-
$25.9 million of higher compensation costs, including salaries, bonuses and stock-based compensation, primarily due to headcount growth and additional bonuses to IBX employees for supporting our business during the COVID-19 pandemic;
-
$17.7 million of higher utilities costs driven by increased utility usage to support IBX data center expansions and utility price increases, primarily in Germany and France;
-
$12.3 million of higher consulting services and office expense, primarily due to project integration and additional spending on personal protective equipment for our IBX employees in response to the COVID-19 pandemic; and
-
$9.4 million of higher rent and facilities costs and repairs and maintenance expense, primarily in the United Kingdom, Germany, France, and the Netherlands.
This increase was partially offset by:
- $15.5 million decrease in realized cash flow hedge losses from foreign currency forward contracts;
•$8.8 million of lower other expenses, as there was a general contractor bankruptcy during the year ended December 31, 2019, which resulted in incremental legal claim charges in the prior year; and
- $8.3 million of net decrease in other cost of revenue, primarily due to lower costs related to decreased EIS revenues in Germany and the United Kingdom.
Asia-Pacific Cost of Revenues. During the year ended December 31, 2020, Asia-Pacific cost of revenues increased by 13% (and also 13% on a constant currency basis). The increase in our Asia-Pacific cost of revenues was primarily due to:
-
$42.0 million of higher depreciation expense, primarily from IBX data center expansions in Australia, Singapore, Japan, and Hong Kong;
-
$14.6 million of higher utilities costs, primarily driven by expansions and higher utility usage in Hong Kong, Japan, and Singapore;
-
$9.0 million of higher costs from increased EIS revenues, primarily in Japan;
-
$8.4 million of higher compensation costs, including salaries, bonuses and stock-based compensation, primarily due to headcount growth and additional bonuses to IBX employees for supporting our business during the COVID-19 pandemic;
-
$6.6 million of higher taxes, licenses, and insurance, primarily driven by IBX data center expansions in Singapore, Australia, and Japan; and
-
$5.3 million of repairs and maintenance, primarily due to increases of maintenance projects in Japan and Australia.
This increase was partially offset by:
- $4.8 million of lower office, rent and facility expenses due to lower computer hardware costs and lower equipment lease activity in Japan.
We expect Americas, EMEA and Asia-Pacific cost of revenues to increase in line with the growth of our business, including from the impacts of acquisitions.
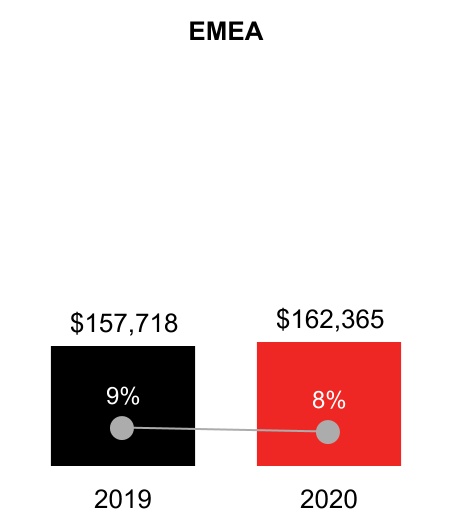
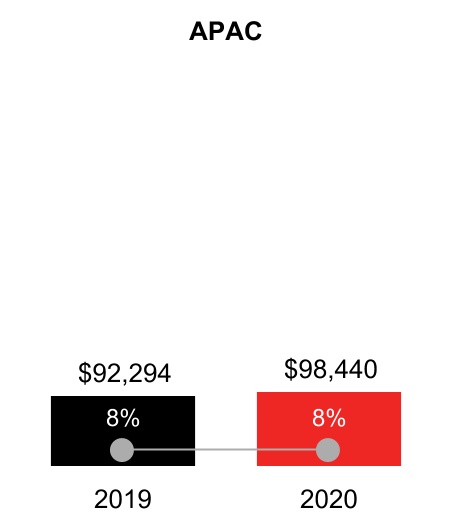
Sales and Marketing Expenses. Our sales and marketing expenses for the years ended December 31, 2020 and 2019 were split among the following geographic regions (dollars in thousands):
| Years ended December 31, | % Change | ||||||||||||||||||||||||||||||||||
| 2020 | % | 2019 | % | Actual | Constant Currency | ||||||||||||||||||||||||||||||
| Americas | $ | 457,551 | 64% | $ | 401,034 | 62% | 14% | 15% | |||||||||||||||||||||||||||
| EMEA | 162,365 | 23% | 157,718 | 24% | 3% | 4% | |||||||||||||||||||||||||||||
| Asia-Pacific | 98,440 | 13% | 92,294 | 14% | 7% | 6% | |||||||||||||||||||||||||||||
| Total | $ | 718,356 | 100% | $ | 651,046 | 100% | 10% | 11% |
Sales and Marketing Expenses
(dollars in thousands; percentages indicate expenses as a percentage of revenues)
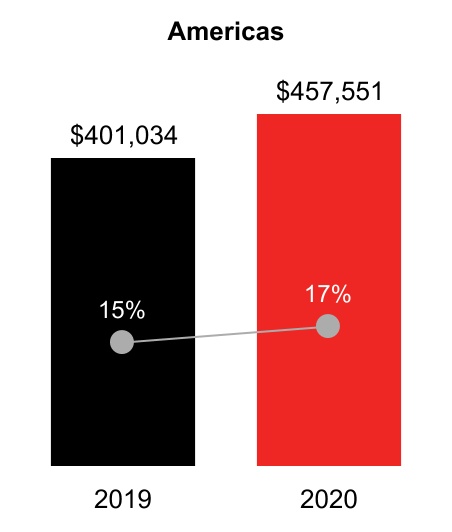
Americas Sales and Marketing Expenses. During the year ended December 31, 2020, Americas sales and marketing expenses increased by 14% (15% on a constant currency basis). The increase in our Americas sales and marketing expenses was primarily due to:
-
$42.9 million of higher compensation costs, including sales compensation, salaries and stock-based compensation, partially due to additional compensation expenses incurred related to our recent acquisitions and headcount growth;
-
$10.6 million of higher advertising and promotions expenses primarily due to higher spending in online advertising, digital marketing strategies and digital consultancy;
-
$5.4 million of higher consulting services primarily due to higher fees and an increase in business deals; and
-
$5.1 million of higher amortization expenses related to customer relationship intangibles acquired from our recent acquisitions.
This increase was partially offset by:
- $6.4 million decrease in travel and entertainment expenses resulting from travel restrictions imposed in response to the COVID-19 pandemic.
EMEA Sales and Marketing Expens**es. During the year ended December 31, 2020, EMEA sales and marketing increased by 3% (4% on a constant currency basis). The increase in our EMEA sales and marketing expenses was primarily due to:
- $16.1 million of higher compensation costs, including sales compensation, salaries and stock-based compensation, partially due to additional compensation expenses incurred related to headcount growth.
This increase was partially offset by:
-
$4.7 million decrease in amortization expense driven by certain intangibles being fully amortized in the current year;
-
$4.1 million decrease in travel and entertainment expenses resulting from travel restrictions imposed in response to the COVID-19 pandemic; and
-
$2.7 million decrease of realized cash flow hedge losses from foreign currency forward contracts.
Asia-Pacific Sales and Marketing Expenses. During the year ended December 31, 2020, Asia-Pacific sales and marketing increased by 7% (6% on a constant currency basis). The increase in our Asia-Pacific sales and marketing expenses was primarily due to:
- $9.8 million increase in compensation costs, including sales compensation, salaries and stock-based compensation and headcount growth.
This increase was partially offset by:
- $3.5 million decrease in travel and entertainment expenses resulting from travel restrictions imposed in response to the COVID-19 pandemic.
We anticipate that we will continue to invest in Americas, EMEA and Asia-Pacific sales and marketing initiatives and expect our Americas, EMEA and Asia-Pacific sales and marketing expenses to increase in line with the growth of our business. We also expect travel and entertainment expenses to increase once travel restrictions that were imposed in response to the COVID-19 pandemic are reduced. Additionally, given that certain global sales and marketing functions are located within the U.S., we expect Americas sales and marketing expenses as a percentage of revenues to be higher than our other regions.
General and Administrative Expenses. Our general and administrative expenses for the years ended December 31, 2020 and 2019 were split among the following geographic regions (dollars in thousands):
| Years Ended December 31, | % Change | ||||||||||||||||||||||||||||||||||
| 2020 | % | 2019 | % | Actual | Constant Currency | ||||||||||||||||||||||||||||||
| Americas | $ | 782,038 | 72% | $ | 641,261 | 69% | 22% | 23% | |||||||||||||||||||||||||||
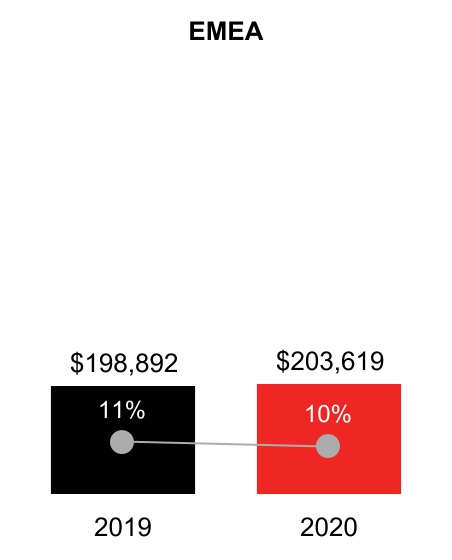
| EMEA | 203,619 | 19% | 198,892 | 21% | 2% | 3% | |||||||||||||||||||||||||||||
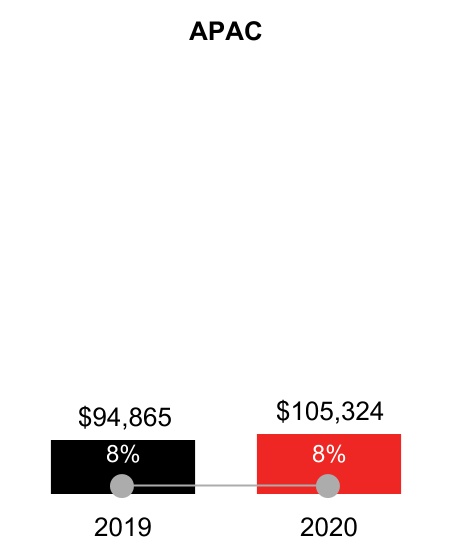
| Asia-Pacific | 105,324 | 9% | 94,865 | 10% | 11% | 11% | |||||||||||||||||||||||||||||
| Total | $ | 1,090,981 | 100% | $ | 935,018 | 100% | 17% | 17% |
General and Administrative Expenses
(dollars in thousands; percentages indicate expenses as a percentage of revenues)
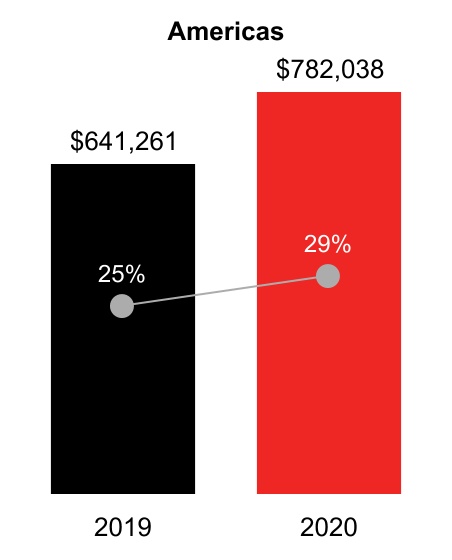
Americas General and Administrative Expense**s. During the year ended December 31, 2020, Americas general and administrative expenses increased by 22% (23% on a constant currency basis). The increase in our Americas general and administrative expenses was primarily due to:
-
$80.3 million of higher compensation costs, including salaries, bonuses, and stock-based compensation related to recent acquisitions and headcount growth;
-
$25.2 million of higher depreciation expense associated with the Axtel and Packet acquisitions and the implementation of certain systems to support the integration and growth of our business;
-
$20.2 million of higher consulting expenses in support of our business growth;
-
$16.9 million of higher office expenses due to additional computer software, hardware, and support services;
-
$4.6 million of higher third party services and other operating expenses due to higher project costs; and
-
$3.4 million of higher taxes, licenses, and insurance, primarily due to the Axtel and Packet acquisitions.
This increase was partially offset by:
- $12.1 million net decrease due to lower travel and entertainment expenses resulting from travel restrictions imposed in response to the COVID-19 pandemic.
EMEA General and Administrative Expenses. During the year ended December 31, 2020, EMEA general and administrative expenses increased by 2% (3% on a constant currency basis). The increase in our EMEA general and administrative expenses was primarily due to:
- $24.4 million of higher compensation costs, including salaries, bonuses, and stock-based compensation, primarily due to headcount growth.
This increase was partially offset by:
-
$6.0 million of lower travel and entertainment, resulting from travel restrictions imposed in response to the COVID-19 pandemic;
-
$5.5 million of lower other operating expenses, primarily due to the favorable determination of a legal claim;
-
$3.4 million of lower consulting expenses primarily related to lower accounting and tax fees; and
-
$3.2 million decrease of realized cash flow hedge losses from foreign currency forward contracts.
Asia-Pacific General and Administrative Expenses. During the year ended December 31, 2020, Asia-Pacific general and administrative expenses increased by 11% (and also 11% on a constant currency basis). The increase in our Asia-Pacific general and administrative expense was primarily due to:
-
$5.7 million of higher compensation costs, including salaries, bonuses, and stock-based compensation, primarily due to headcount growth;
-
$3.8 million of higher rent and facility costs, primarily due to additional rent expenses in Singapore; and
-
$3.5 million of higher office and consulting costs, primarily due to increase in hardware, software, supplies and fees resulting from the response to the COVID-19 pandemic.
This increase was partially offset by:
- $3.6 million of lower travel and entertainment expenses resulting from travel restrictions imposed in response to the COVID-19 pandemic.
Going forward, although we are carefully monitoring our spending, we expect Americas, EMEA and Asia-Pacific general and administrative expenses to increase as we continue to further scale our operations to support our growth, including investments in our back office systems and investments to maintain our qualification for taxation as a REIT and to integrate recent acquisitions. We also expect travel and entertainment expenses to increase once travel restrictions that were imposed in response to the COVID-19 pandemic are reduced. Additionally, given that our corporate headquarters is located within the U.S., we expect Americas general and administrative expenses as a percentage of revenues to continue to be higher than our other regions.
Transaction Costs. During the year ended December 31, 2020, we recorded transaction costs totaling $55.9 million primarily related to costs incurred in connection with the acquisitions of Bell, Packet, and Axtel, as well as the costs incurred in connection with the formation of the Asia-Pacific Joint Venture. During the year ended December 31, 2019, we recorded transaction costs totaling $24.8 million, primarily related to costs incurred in connection with the formation of the new EMEA Joint Venture.
Impairment Charges. During the year ended December 31, 2020, we recorded impairment charges totaling $7.3 million in the Asia-Pacific region as a result of the fair value adjustment of the Asia-Pacific Joint venture xScaleTM data centers, which were classified as held for sale assets before they were sold on December 17, 2020. During the year ended December 31, 2019, we recorded impairment charges totaling $15.8 million in the Americas region primarily as a result of the fair value adjustment for the New York 12 ("NY12") data center, which was classified as a held for sale asset before it was sold in October 2019.
Gain on Asset Sales. During the year ended December 31, 2020, we did not record a significant amount of gain on asset sales. During the year ended December 31, 2019, we recorded gain on asset sales of $44.3 million primarily relating to the sale of both the London 10 and Paris 8 data centers, as well as certain construction development and leases in London and Frankfurt, as part of the closing of the EMEA Joint Venture.
Income from Operations. Our income from operations for the years ended December 31, 2020 and 2019 was split among the following geographic regions (dollars in thousands):
| Years Ended December 31, | % Change | ||||||||||||||||||||||||||||||||||
| 2020 | % | 2019 | % | Actual | Constant Currency | ||||||||||||||||||||||||||||||
| Americas | $ | 178,454 | 17% | $ | 413,936 | 35% | (57)% | (54)% | |||||||||||||||||||||||||||
| EMEA | 531,530 | 50% | 421,786 | 36% | 26% | 32% | |||||||||||||||||||||||||||||
| Asia-Pacific | 342,944 | 33% | 333,909 | 29% | 3% | 5% | |||||||||||||||||||||||||||||
| Total | $ | 1,052,928 | 100% | $ | 1,169,631 | 100% | (10)% | (8)% |
Americas Income from Operations*.* During the year ended December 31, 2020, Americas income from operations decreased by 57% (54% on a constant currency basis). The decrease in our Americas income from operations was primarily due to higher operating expenses as a percentage of revenues and higher transaction costs in connection with the recent acquisitions. Namely, a large increase in general and administrative expenses was primarily driven by higher compensation costs and consulting expenses, which were in part related to recent acquisitions, higher office expenses and depreciation expense, and payments made in response to the COVID-19 pandemic.
EMEA Income from Operations. During the year ended December 31, 2020, EMEA income from operations increased by 26% (32% on a constant currency basis). The increase in our EMEA income from operations was
primarily due to higher revenues as a result of our IBX data center expansion activity and organic growth, as described above, as well as lower operating expenses as a percentage of revenues.
Asia-Pacific Income from Operations. During the year ended December 31, 2020, Asia-Pacific income from operations increased by 3% (5% on a constant currency basis). The increase in our Asia-Pacific income from operations was primarily due to higher revenues as a result of our IBX data center expansion activity, acquisition and organic growth as described above.
Interest Income. Interest income was $8.7 million and $27.7 million for the years ended December 31, 2020 and 2019, respectively. The average yield for the year ended December 31, 2020 was 0.43% versus 1.85% for the year ended December 31, 2019.
Interest Expense. Interest expense decreased to $406.5 million for the year ended December 31, 2020 from $479.7 million for the year ended December 31, 2019, primarily attributable to the redemption of legacy high yield Senior Notes due 2022, 2024, 2025, and 2026, partially offset by the issuance of new Senior Notes due 2025, 2027, 2028, 2030, 2050 and 2051. Due to the issuance and redemption of debt for the year ended December 31, 2020, the effective interest rate decreased from December 31, 2019. During the years ended December 31, 2020 and 2019, we capitalized $26.8 million and $32.2 million, respectively, of interest expense to construction in progress.
Other Income. We recorded net other income of $6.9 million and $27.8 million for the years ended December 31, 2020 and 2019, respectively. Other income is primarily comprised of foreign currency exchange gains and losses during the periods.
Loss on Debt Extinguishment. During the year ended December 31, 2020, we recorded $145.8 million of loss on debt extinguishment primarily related to the redemption of the Senior Notes due 2022, 2024, 2025, and 2026.
During the year ended December 31, 2019, we recorded $52.8 million of loss on debt extinguishment primarily related to the redemption of the Senior Notes due 2022, 2023 and 2025.
Income Taxes We operate as a REIT for U.S. federal income tax purposes. As a REIT, we are generally not subject to U.S. federal income taxes on our taxable income distributed to stockholders. We intend to distribute or have distributed the entire taxable income generated by the operations of our REIT and QRSs for the tax years ended December 31, 2020 and 2019, respectively. As such, other than tax attributable to built-in-gains recognized, state income taxes, and foreign income and withholding taxes, no provision for income taxes has been included for the REIT and its QRSs in the accompanying consolidated financial statements for the years ended December 31, 2020 and 2019.
We have made TRS elections for some of our subsidiaries in and outside the U.S. In general, a TRS may provide services that would otherwise be considered impermissible for REITs to provide and may hold assets that may not be REIT compliant.
U.S. income taxes for the TRS entities located in the U.S. and foreign income taxes for our foreign operations regardless of whether the foreign operations are operated as QRSs or TRSs have been accrued, as necessary, for the years ended December 31, 2020 and 2019.
For the years ended December 31, 2020 and 2019, we recorded $146.2 million and $185.4 million of income tax expenses, respectively. Our effective tax rates were 28.3% and 26.8%, respectively, for the years ended December 31, 2020 and 2019.
Adjusted EBITDA. Adjusted EBITDA is a key factor in how we assess the operating performance of our segments and develop regional growth strategies such as IBX data center expansion decisions. We define adjusted EBITDA as income or loss from operations excluding depreciation, amortization, accretion, stock-based compensation expense, restructuring charges, impairment charges, transaction costs and gain on asset sales. See "Non-GAAP Financial Measures" below for more information about adjusted EBITDA and a reconciliation of adjusted EBITDA to income or loss from operations. Our adjusted EBITDA for the years ended December 31, 2020 and 2019 was split among the following geographic regions (dollars in thousands):
| Years Ended December 31, | % Change | ||||||||||||||||||||||||||||||||||
| 2020 | % | 2019 | % | Actual | Constant Currency | ||||||||||||||||||||||||||||||
| Americas | $ | 1,186,022 | 42 | % | $ | 1,237,622 | 46 | % | (4) | % | (3) | % | |||||||||||||||||||||||
| EMEA | 974,246 | 34 | % | 827,980 | 31 | % | 18 | % | 19 | % | |||||||||||||||||||||||||
| Asia-Pacific | 692,630 | 24 | % | 622,125 | 23 | % | 11 | % | 11 | % | |||||||||||||||||||||||||
| Total | $ | 2,852,898 | 100 | % | $ | 2,687,727 | 100 | % | 6 | % | 7 | % |
Americas Adjusted EBITDA. During the year ended December 31, 2020, Americas adjusted EBITDA decreased by 4% (3% on a constant currency basis). The decrease in our Americas adjusted EBITDA was primarily due to the increase in compensation expenses, consulting expenses and office expenses.
EMEA Adjusted EBITDA. During the year ended December 31, 2020, EMEA adjusted EBITDA increased by 18% (19% on a constant currency basis). The increase in our EMEA adjusted EBITDA was primarily due to higher revenues as a result of our IBX data center expansion activity and organic growth, as described above.
Asia-Pacific Adjusted EBITDA. During the year ended December 31, 2020, Asia-Pacific adjusted EBITDA increased by 11% (and also 11% on a constant currency basis). The increase in our Asia-Pacific adjusted EBITDA was primarily due to higher revenues as a result of our IBX data center expansion activity and organic growth as described above.
Non-GAAP Financial Measures
We provide all information required in accordance with GAAP, but we believe that evaluating our ongoing operating results may be difficult if limited to reviewing only GAAP financial measures. Accordingly, we use non-GAAP financial measures to evaluate our operations.
Non-GAAP financial measures are not a substitute for financial information prepared in accordance with GAAP. Non-GAAP financial measures should not be considered in isolation, but should be considered together with the most directly comparable GAAP financial measures and the reconciliation of the non-GAAP financial measures to the most directly comparable GAAP financial measures. We have presented such non-GAAP financial measures to provide investors with an additional tool to evaluate our results of operations in a manner that focuses on what management believes to be our core, ongoing business operations. We believe that the inclusion of these non-GAAP financial measures provides consistency and comparability with past reports and provides a better understanding of the overall performance of the business and ability to perform in subsequent periods. We believe that if we did not provide such non-GAAP financial information, investors would not have all the necessary data to analyze Equinix effectively.
Investors should note that the non-GAAP financial measures used by us may not be the same non-GAAP financial measures, and may not be calculated in the same manner, as those of other companies. Investors should therefore exercise caution when comparing non-GAAP financial measures used by us to similarly titled non-GAAP financial measures of other companies.
Our primary non-GAAP financial measures, adjusted EBITDA and adjusted funds from operations ("AFFO"), exclude depreciation expense as these charges primarily relate to the initial construction costs of our IBX data centers and do not reflect our current or future cash spending levels to support our business. Our IBX data centers are long-lived assets and have an economic life greater than 10 years. The construction costs of an IBX data center do not recur with respect to such data center, although we may incur initial construction costs in future periods with respect to additional IBX data centers, and future capital expenditures remain minor relative to our initial investment. This is a trend we expect to continue. In addition, depreciation is also based on the estimated useful lives of our IBX data centers. These estimates could vary from actual performance of the asset, are based on historical costs incurred to build out our IBX data centers and are not indicative of current or expected future capital expenditures. Therefore, we exclude depreciation from our results of operations when evaluating our operations.
In addition, in presenting adjusted EBITDA and AFFO, we exclude amortization expense related to acquired intangible assets. Amortization expense is significantly affected by the timing and magnitude of our acquisitions and these charges may vary in amount from period to period. We exclude amortization expense to facilitate a more meaningful evaluation of our current operating performance and comparisons to our prior periods. We exclude accretion expense, both as it relates to asset retirement obligations as well as accrued restructuring charge liabilities, as these expenses represent costs which we believe are not meaningful in evaluating our current operations. We exclude stock-based compensation expense, as it can vary significantly from period to period based on share price, the timing, size and nature of equity awards. As such, we, and many investors and analysts, exclude stock-based compensation expense to compare our results of operations with those of other companies. We also exclude restructuring charges. The restructuring charges relate to our decisions to exit leases for excess space adjacent to several of our IBX data centers, which we did not intend to build out, or our decision to reverse such restructuring charges. We also exclude impairment charges related to certain long-lived assets. The impairment charges are related to expense recognized whenever events or changes in circumstances indicate that the carrying amount of long-lived assets are not recoverable. We also exclude gain or loss on asset sales as it represents profit or loss that is not meaningful in evaluating the current or future operating performance. Finally, we exclude transaction costs from AFFO and adjusted EBITDA to allow more comparable comparisons of our financial results to our historical operations. The transaction costs relate to costs we incur in connection with business combinations and the formation of joint ventures, including advisory, legal, accounting, valuation, and other professional or consulting fees. Such charges generally are not relevant to assessing the long-term performance of the company. In addition, the frequency and amount of such charges vary significantly based on the size and timing of the transactions. Management believes items such as restructuring charges, impairment charges, gain or loss on asset sales and transaction costs are non-core transactions; however, these types of costs may occur in future periods.
Adjusted EBITDA
The following table shows the reconciliation from income from operations to adjusted EBITDA (in thousands):
| Years Ended December 31, | |||||||||||||||||
| 2020 | 2019 | 2018 | |||||||||||||||
| Income from operations | $ | 1,052,928 | $ | 1,169,631 | $ | 977,383 | |||||||||||
| Depreciation, amortization, and accretion expense | 1,427,010 | 1,285,296 | 1,226,741 | ||||||||||||||
| Stock-based compensation expense | 311,020 | 236,539 | 180,716 | ||||||||||||||
| Transaction costs | 55,935 | 24,781 | 34,413 | ||||||||||||||
| Impairment charges | 7,306 | 15,790 | — | ||||||||||||||
| Gain on asset sales | (1,301) | (44,310) | (6,013) | ||||||||||||||
| Adjusted EBITDA | $ | 2,852,898 | $ | 2,687,727 | $ | 2,413,240 |
Our adjusted EBITDA results have improved each year in the EMEA and Asia-Pacific regions in total dollars due to the improved operating results discussed earlier in "Results of Operations", as well as the nature of our business model consisting of a recurring revenue stream. The increases in adjusted EBITDA results for the EMEA and Asia-Pacific regions were partially offset by the decrease in the AMER region, as noted above.
Funds from Operations ("FFO") and AFFO
We use FFO and AFFO, which are non-GAAP financial measures commonly used in the REIT industry. FFO is calculated in accordance with the standards established by the National Association of Real Estate Investment Trusts. FFO represents net income (loss), excluding gain (loss) from the disposition of real estate assets, depreciation and amortization on real estate assets and adjustments for unconsolidated joint ventures' and non-controlling interests' share of these items.
In presenting AFFO, we exclude certain items that we believe are not good indicators of our current or future operating performance. AFFO represents FFO excluding depreciation and amortization expense on non-real estate assets, accretion, stock-based compensation, restructuring charges, impairment charges, transaction costs, an installation revenue adjustment, a straight-line rent expense adjustment, a contract cost adjustment, amortization of deferred financing costs and debt discounts and premiums, gain (loss) on debt extinguishment, an income tax expense adjustment, recurring capital expenditures, net income (loss) from discontinued operations, net of tax, and adjustments from FFO to AFFO for unconsolidated joint ventures' and noncontrolling interests' share of these items. The adjustments for installation revenue, straight-line rent expense and contract costs are intended to isolate the
cash activity included within the straight-lined or amortized results in the consolidated statement of operations. We exclude the amortization of deferred financing costs and debt discounts and premiums as these expenses relate to the initial costs incurred in connection with debt financings that have no current or future cash obligations. We exclude gain (loss) on debt extinguishment since it generally represents the write-off of initial costs incurred in connection with debt financings or a cost that is incurred to reduce future interest costs and is not a good indicator of our current or future operating performance. We include an income tax expense adjustment, which represents the non-cash tax impact due to changes in valuation allowances, uncertain tax positions and deferred taxes that do not relate to current period's operations. We deduct recurring capital expenditures, which represent expenditures to extend the useful life of its IBX data centers or other assets that are required to support current revenues. We also exclude net income (loss) from discontinued operations, net of tax, which represents results that may not recur and are not a good indicator of our current future operating performance.
Our FFO and AFFO were as follows (in thousands):
| Years Ended December 31, | |||||||||||||||||
| 2020 | 2019 | 2018 | |||||||||||||||
| Net income | $ | 370,074 | $ | 507,245 | $ | 365,359 | |||||||||||
| Net gain (loss) attributable to non-controlling interests | (297) | 205 | — | ||||||||||||||
| Net income attributable to Equinix | 369,777 | 507,450 | 365,359 | ||||||||||||||
| Adjustments: | |||||||||||||||||
| Real estate depreciation | 924,064 | 845,798 | 883,118 | ||||||||||||||
| (Gain) loss on disposition of real estate property | 4,063 | (39,337) | 4,643 | ||||||||||||||
| Adjustments for FFO from unconsolidated joint ventures | 2,726 | 645 | — | ||||||||||||||
| FFO | $ | 1,300,630 | $ | 1,314,556 | $ | 1,253,120 |
| Years Ended December 31, | |||||||||||||||||
| 2020 | 2019 | 2018 | |||||||||||||||
| FFO | $ | 1,300,630 | $ | 1,314,556 | $ | 1,253,120 | |||||||||||
| Adjustments: | |||||||||||||||||
| Installation revenue adjustment | (125) | 11,031 | 10,858 | ||||||||||||||
| Straight-line rent expense adjustment | 10,787 | 8,167 | 7,203 | ||||||||||||||
| Contract cost adjustment | (35,675) | (40,861) | (20,358) | ||||||||||||||
| Amortization of deferred financing costs and debt discounts and premiums | 15,739 | 13,042 | 13,618 | ||||||||||||||
| Stock-based compensation expense | 311,020 | 236,539 | 180,716 | ||||||||||||||
| Non-real estate depreciation expense | 300,258 | 242,761 | 140,955 | ||||||||||||||
| Amortization expense | 199,047 | 196,278 | 203,416 | ||||||||||||||
| Accretion expense (adjustment) | 3,641 | 459 | (748) | ||||||||||||||
| Recurring capital expenditures | (160,637) | (186,002) | (203,053) | ||||||||||||||
| Loss on debt extinguishment | 145,804 | 52,825 | 51,377 | ||||||||||||||
| Transaction costs | 55,935 | 24,781 | 34,413 | ||||||||||||||
| Impairment charges | 7,306 | 15,790 | — | ||||||||||||||
| Income tax expense adjustment | 33,220 | 39,676 | (12,420) | ||||||||||||||
| Adjustments for AFFO from unconsolidated joint ventures | 2,195 | 2,080 | — | ||||||||||||||
| AFFO | $ | 2,189,145 | $ | 1,931,122 | $ | 1,659,097 |
Our AFFO results have improved due to the improved operating results discussed earlier in "Results of Operations," as well as due to the nature of our business model which consists of a recurring revenue stream and a cost structure which has a large base that is fixed in nature as discussed earlier in "Overview."
Constant Currency Presentation
Our revenues and certain operating expenses (cost of revenues, sales and marketing and general and administrative expenses) from our international operations have represented and will continue to represent a significant portion of our total revenues and certain operating expenses. As a result, our revenues and certain operating expenses have been and will continue to be affected by changes in the U.S. dollar against major international currencies. During the year ended December 31, 2020 as compared to the same period in 2019, the U.S. dollar was stronger relative to the Brazilian real, Singapore dollar and Australian dollar, which resulted in an unfavorable foreign currency impact on revenue, operating income and adjusted EBITDA, and a favorable foreign currency impact on operating expenses. During the year ended December 31, 2020 as compared to the same period in 2019, the U.S. dollar was weaker relative to the Japanese yen, Hong Kong dollar, Euro, and British pound, which resulted in a favorable foreign currency impact on revenue, operating income and adjusted EBITDA, and an unfavorable foreign currency impact on operating expenses. In order to provide a framework for assessing how each of our business segments performed excluding the impact of foreign currency fluctuations, we present period-over-period percentage changes in our revenues and certain operating expenses on a constant currency basis in addition to the historical amounts as reported. Our constant currency presentation excludes the impact of our foreign currency cash flow hedging activities. Presenting constant currency results of operations is a non-GAAP financial measure and is not meant to be considered in isolation or as an alternative to GAAP results of operations. However, we have presented this non-GAAP financial measure to provide investors with an additional tool to evaluate our results of operations. To present this information, our current period revenues and certain operating expenses from entities reporting in currencies other than the U.S. dollar are converted into U.S. dollars at constant exchange rates rather than the actual exchange rates in effect during the respective periods (i.e. average rates in effect for the year ended December 31, 2019 are used as exchange rates for the year ended December 31, 2020 when comparing the year ended December 31, 2020 with the year ended December 31, 2019).
Liquidity and Capital Resources
As of December 31, 2020, our total indebtedness was comprised of debt and lease obligations totaling approximately $12.6 billion (gross of debt issuance cost, debt discount, plus mortgage premium) consisting of:
-
approximately $9.3 billion of principal from our senior notes;
-
approximately $1.9 billion from our finance lease liabilities; and
-
$1.4 billion of principal from our loans payable and mortgage.
During 2020, we completed the following significant financing activities:
-
issued and sold 415,512 shares of common stock under our ATM Program, for proceeds of approximately $298.3 million, net of payment of commissions and other offering expenses;
-
issued and sold 2,587,500 shares of common stock for net proceeds of approximately $1.7 billion;
-
borrowed and repaid $0.8 billion under our revolving credit facility and the 364-day term loan facilities; and
-
issued $4.4 billion of our Senior Notes, net of debt discounts, and repaid $4.1 billion of legacy high yield Senior Notes and $300.0 million of Infomart Senior Notes.
As of December 31, 2020, we had $1.6 billion of cash, cash equivalents and short-term investments. In addition to our cash and investment portfolio, we had $1.9 billion of additional liquidity available to us from our $2.0 billion revolving facility and general access to both public and private debt and the equity capital markets. We also have additional liquidity available to us from our ATM programs, under which we may offer and sell from time to time our common stock in "at the market" transactions. As of December 31, 2020, we had completed sales under the ATM program that was previously launched in December 2018. On October 30, 2020, we launched a new ATM program allowing for aggregate sales of up to $1.5 billion (the "2020 ATM Program"). No sales have been made under the 2020 ATM Program to date.
Besides any further financing activity we may pursue, customer collections are our primary source of cash. We believe we have a strong customer base, and have continued to experience relatively strong collections. We believe we have sufficient cash, coupled with anticipated cash generated from operating activities and external financing sources, to meet our operating requirements, including repayment of the current portion of our debt as it becomes due, distribution of dividends and completion of our publicly-announced acquisition and expansion projects. We also believe that our financial resources will allow us to manage future possible impact of the ongoing COVID-19
pandemic on our business operations for the foreseeable future, which could include reductions in revenue and delays in payments from customers and partners.
As we continue to grow, we may pursue additional expansion opportunities, primarily the build out of new IBX data centers, in certain of our existing markets which are at or near capacity within the next year, as well as potential acquisitions and joint ventures. We may elect to access the equity or debt markets from time to time opportunistically, particularly if financing is available on attractive terms. We will continue to evaluate our operating requirements and financial resources in light of future developments, including those relating to the ongoing COVID-19 pandemic.
Sources and Uses of Cash
| Years Ended December 31, | |||||||||||
| 2020 | 2019 | ||||||||||
| (in thousands) | |||||||||||
| Net cash provided by operating activities | $ | 2,309,826 | $ | 1,992,728 | |||||||
| Net cash used in investing activities | (3,426,972) | (1,944,567) | |||||||||
| Net cash provided by financing activities | 815,526 | 1,202,082 |
Operating Activities
Our cash provided by our operations is generated by colocation, interconnection, managed infrastructure and other revenues. Our primary uses of cash from our operating activities include compensation and related costs, interest payments, other general corporate expenditures and taxes. The increase in net cash provided by operating activities during 2020 compared to 2019 was primarily due to improved results of operations offset by increases in cash paid for cost of revenues and operating expenses.
Investing Activities
The net cash used in investing activities for the year ended December 31, 2020 was primarily due to capital expenditures of $2.3 billion as a result of our expansion activity, purchases of real estate of $200.2 million, business acquisitions of Bell, Packet and Axtel for $1.2 billion, and purchases of investments of $127.8 million, partially offset by proceeds from the sale of assets to the Asia-Pacific and EMEA Joint Ventures of $334.4 million and proceeds from sales of investments of $29.4 million. The net cash used in investing activities for the year ended December 31, 2019 was primarily due to capital expenditures of $2.1 billion as a result of our expansion activity, purchases of real estate of $169.2 million, the AM11 data center acquisition of $34.1 million, and purchases of investments of $60.9 million, partially offset by proceeds from the sale of assets, primarily due to the sale of assets to the EMEA Joint Venture, of $358.8 million and proceeds from sales of investments of $40.4 million.
We anticipate our IBX data center expansion construction activity will be similar or increase from our 2020 levels. If the opportunity to expand is greater than planned and we have sufficient funding to pursue such expansion opportunities, we may further increase the level of capital expenditure to support this growth as well as pursue additional business and real estate acquisitions or joint ventures.
Financing Activities
Net cash provided by financing activities during 2020 was primarily due to:
-
the issuance of $4.4 billion in Senior Notes due 2025, 2027, 2028, 2030, 2050 and 2051;
-
the sale and issuance of 2,587,500 shares of common stock in a public offering for net proceeds of approximately $1.7 billion, net of underwriting discounts, commissions and offering expenses;
-
borrowings under the revolving credit facility of $250.0 million and the 364-Day term loan facilities of $500.8 million;
-
the sale of 415,512 shares of common stock under the ATM Program, for net proceeds of $298.3 million; and
-
proceeds from employee awards of $62.1 million.
The proceeds were partially offset by:
-
the redemption of $4.1 billion in Senior Notes due 2022, 2024, 2025 and 2026;
-
the repayment of $300.0 million of 5.0% Infomart Senior Notes according to the repayment terms;
-
dividend distributions of $947.9 million;
-
repayments of finance lease liabilities totaling $115.3 million;
-
repayments of mortgage and loans payable totaling $829.5 million, primarily from the repayments of the revolving credit facility and the 364-Day term loan facilities;
-
payments of debt extinguishment costs of $111.7 million, primarily related to redemption premium paid to redeem legacy high yield Senior Notes due 2022, 2024, 2025 and 2026; and
-
payments of debt issuance costs of $42.2 million.
Net cash provided by financing activities during 2019 was primarily due to:
-
the issuance of $2.8 billion in Senior Notes due 2024, 2026 and 2029;
-
the sale and issuance of 2,985,575 shares of common stock in a public equity offering and receipt of net proceeds of approximately $1.2 billion, net of underwriting discounts, commissions and offering expenses;
-
the sale of 903,555 shares under our ATM Program, for net proceeds of $447.5 million; and
-
proceeds from employee awards of $52.0 million.
The proceeds were partially offset by:
-
the redemption of $1.9 billion in Senior Notes due 2022, 2023 and 2025;
-
the repayment of $300.0 million of 5.0% Infomart Senior Notes according to the repayment terms;
-
dividend distributions of $836.2 million;
-
repayments of finance lease liabilities of $126.5 million;
-
repayments of mortgage and loans payable of $73.2 million;
-
payments of debt extinguishment costs of $43.3 million, primarily related to redemption premium paid to redeem Senior Notes due 2022, 2023 and 2025; and
-
payments of debt issuance costs of $23.3 million.
Contractual Obligations and Off-Balance-Sheet Arrangements
We lease a majority of our IBX data centers and certain equipment under long-term lease agreements. The following represents our debt maturities, financings, leases and other contractual commitments as of December 31, 2020 (in thousands):
| 2021 | 2022 | 2023 | 2024 | 2025 | Thereafter | Total | |||||||||||||||||||||||||||||||||||
| Term loans and other loans payable (1) | $ | 82,289 | $ | 1,253,106 | $ | 6,896 | $ | 6,395 | $ | 4,605 | $ | 19,540 | $ | 1,372,831 | |||||||||||||||||||||||||||
| Senior notes (1) | 150,000 | — | — | 1,000,000 | 1,200,000 | 6,911,050 | 9,261,050 | ||||||||||||||||||||||||||||||||||
| Interest (2) | 282,022 | 274,769 | 253,705 | 253,503 | 227,073 | 1,201,943 | 2,493,015 | ||||||||||||||||||||||||||||||||||
| Finance leases (3) | 232,415 | 221,058 | 215,909 | 213,186 | 209,424 | 1,928,094 | 3,020,086 | ||||||||||||||||||||||||||||||||||
| Operating leases (3) | 199,291 | 205,411 | 188,724 | 176,626 | 165,437 | 1,032,186 | 1,967,675 | ||||||||||||||||||||||||||||||||||
| Other contractual commitments (4) | 1,635,300 | 213,610 | 95,809 | 48,843 | 41,395 | 362,031 | 2,396,988 | ||||||||||||||||||||||||||||||||||
| Asset retirement obligations (5) | 3,993 | 14,013 | 5,986 | 7,436 | 8,243 | 74,098 | 113,769 | ||||||||||||||||||||||||||||||||||
| $ | 2,585,310 | $ | 2,181,967 | $ | 767,029 | $ | 1,705,989 | $ | 1,856,177 | $ | 11,528,942 | $ | 20,625,414 |
(1)Represents principal and unamortized mortgage premium only.
(2)Represents interest on mortgage payable, loans payable, senior notes and term loans based on their respective interest rates as of December 31, 2020, as well as the credit facility fee for the revolving credit facility.
(3)Represents lease payments under finance and operating lease arrangements, including renewal options that are certain to be exercised.
(4)Represents off-balance sheet arrangements. Other contractual commitments are described below.
(5)Represents liability, net of future accretion expense.
As of December 31, 2020, we were contractually committed for $1.1 billion of unaccrued capital expenditures, primarily for IBX equipment not yet delivered and labor not yet provided in connection with the work necessary to complete construction and open IBX data center expansion projects prior to making them available to customers for installation. This amount, which is expected to be paid during 2021 and thereafter, is reflected in the table above as "other contractual commitments."
We had other non-capital purchase commitments in place as of December 31, 2020, such as commitments to purchase power in select locations and other open purchase orders, which contractually bind us for goods, services or arrangements to be delivered or provided during 2021 and beyond. Such other purchase commitments as of December 31, 2020, which total $1.3 billion, are also reflected in the table above as "other contractual commitments."
Other commitments
In connection with certain of our leases and other contracts requiring deposits, we entered into 37 irrevocable letters of credit totaling $74.6 million under the revolving credit facility. These letters of credit were provided in lieu of cash deposits. If the landlords for these IBX leases decide to draw down on these letters of credit triggered by an event of default under the lease, we will be required to fund these letters of credit either through cash collateral or borrowing under the revolving credit facility. These contingent commitments are not reflected in the table above.
We had accrued liabilities related to uncertain tax positions totaling approximately $169.7 million as of December 31, 2020. These liabilities, which are reflected on our balance sheet, are not reflected in the table above since it is unclear when these liabilities will be paid.
In connection with the EMEA Joint Venture which closed in October 2019, we committed to make future equity contributions to the EMEA Joint Venture of €13.8 million and £6.6 million, or $25.8 million in total at the exchange rate in effect on December 31, 2020, to fund the EMEA Joint Venture’s future development until 2022, which are not reflected in the table above.
In connection with the sale of the PA9 data center, which closed in December 2020, we also has a commitment to the EMEA Joint Venture to complete a residual portion of the PA9 center for an estimated cost of €14.5 million or $17.7 million in total at the exchange rate in effect on December 31, 2020, which is reimbursable upon completion and is not reflected in the table above.
We also committed to make future equity contributions to the Asia-Pacific Joint Venture, which was closed on December 17, 2020. As of December 31, 2020, we had future equity contribution commitments of ¥6.3 billion, or $60.7 million in total at the exchange rate in effect on December 31, 2020, which is not reflected in the table above.
Additionally, we entered into lease agreements with various landlords primarily for data center spaces and ground leases which have not yet commenced as of December 31, 2020. These leases will commence between fiscal years 2021 and 2022 with lease terms of 10 to 49 years and a total lease commitment of approximately $684.1 million, which is not reflected in the table above.
Other Off-Balance-Sheet Arrangements
We have various guarantor arrangements with both our directors and officers and third parties, including customers, vendors and business partners. As of December 31, 2020, there were no significant liabilities recorded for these arrangements. For additional information, see "Guarantor Arrangements" in Note 15 within the Consolidated Financial Statements.
Critical Accounting Policies and Estimates
Our consolidated financial statements are prepared in accordance with U.S. GAAP. The preparation of our financial statements requires management to make estimates and assumptions about future events that affect the reported amounts of assets and liabilities and the disclosure of contingent assets and liabilities at the date of the financial statements and the reported amounts of revenues and expenses during the reporting period. On an ongoing basis, management evaluates the accounting policies, assumptions, estimates and judgments to ensure that our consolidated financial statements are presented fairly and in accordance with GAAP. Management bases its
assumptions, estimates and judgments on historical experience, current trends and various other factors that are believed to be reasonable under the circumstances, the results of which form the basis for making judgments about the carrying values of assets and liabilities that are not readily apparent from other sources. However, because future events and their effects cannot be determined with certainty, actual results may differ from these assumptions and estimates, and such differences could be material.
Our significant accounting policies are discussed in Note 1 to Consolidated Financial Statements in Item 8 of this Annual Report on Form 10-K. Management believes that the following accounting policies and estimates are the most critical to aid in fully understanding and evaluating our consolidated financial statements, and they require significant judgments, resulting from the need to make estimates about the effect of matters that are inherently uncertain:
-
Accounting for income taxes;
-
Accounting for business combinations;
-
Accounting for impairment of goodwill;
-
Accounting for property, plant and equipment; and
-
Accounting for leases.
| Description | Judgments and Uncertainties | Effect if Actual Results Differ from Assumptions | ||||||
| Accounting for Income Taxes. Deferred tax assets and liabilities are recognized based on the future tax consequences attributable to temporary differences that exist between the financial statement carrying value of assets and liabilities and their respective tax bases, and tax attributes such as operating loss, capital loss and tax credit carryforwards on a taxing jurisdiction basis. We measure deferred tax assets and liabilities using enacted tax rates that will apply in the years in which we expect the temporary differences to be recovered or settled. The accounting standard for income taxes requires a reduction of the carrying amounts of deferred tax assets by recording a valuation allowance if, based on the available evidence, it is more likely than not (defined by the accounting standard as a likelihood of more than 50%) that such assets will not be realized. A tax benefit from an uncertain income tax position may be recognized in the financial statements only if it is more likely than not that the position is sustainable, based solely on its technical merits and consideration of the relevant taxing authority's widely understood administrative practices and precedents. We recognize interest and penalties related to unrecognized tax benefits within income tax benefit (expense) in the consolidated statements of operations. | The valuation of deferred tax assets requires judgment in assessing the likely future tax consequences of events that have been recognized in our financial statements or tax returns. Our accounting for deferred tax consequences represents our best estimate of those future tax consequences. In assessing the need for a valuation allowance, we consider both positive and negative evidence related to the likelihood of realization of the deferred tax assets. If, based on the weight of that available evidence, it is more likely than not the deferred tax assets will not be realized, we record a valuation allowance. The weight given to the positive and negative evidence is commensurate with the extent to which the evidence may be objectively verified. This assessment, which is completed on a taxing jurisdiction basis, takes into account a number of types of evidence, including the following: 1) the nature, frequency and severity of current and cumulative financial reporting losses, 2) sources of future taxable income and 3) tax planning strategies. In assessing the tax benefit from an uncertain income tax position, the tax position that meets the more-likely-than-not recognition threshold is initially and subsequently measured as the largest amount of tax benefit that is greater than a 50% likelihood of being realized upon ultimate settlement with a taxing authority that has full knowledge of all relevant information. For purposes of the quarterly REIT asset tests, we estimate the fair market value of assets within our QRSs and TRSs using a discounted cash flow approach, by calculating the present value of forecasted future cash flows. We apply discount rates based on industry benchmarks relative to the market and forecasting risks. Other significant assumptions used to estimate the fair market value of assets in QRSs and TRSs include projected revenue growth, projected operating margins and projected capital expenditure. We revisit significant assumptions periodically to reflect any changes due to business or economic environment. | As of December 31, 2020 and 2019, we had net total deferred tax liabilities of $224.0 million and $211.4 million, respectively. As of December 31, 2020 and 2019, we had a total valuation allowance of $82.3 million and $57.8 million, respectively. If and when we increase or reduce our valuation allowances, it may have an unfavorable or favorable impact, respectively, to our financial position and results of operations in the periods when such determinations are made. We will continue to assess the need for our valuation allowances, by jurisdiction, in the future. During the year ended December 31, 2020, we provided full valuation allowances against certain deferred tax assets acquired in Canada and the Netherlands that are not expected to be realizable in the foreseeable future. During the year ended December 31, 2019, we released the full valuation allowances against the deferred tax assets of one of our Brazilian legal entities due to the evidence of achieving sustainable profitability. For the Metronode Acquisition, we increased the valuation allowance that was assessed in prior year as a result of finalizing the provisional estimates related to the realizability of certain deferred tax assets. As of December 31, 2020 and 2019, we had unrecognized tax benefits of $207.8 million and $173.7 million, respectively, exclusive of interest and penalties. During the year ended December 31, 2020, the unrecognized tax benefit increased by $34.1 million primarily due to integrations in the EMEA region, which was partially offset by the recognition of unrecognized tax benefits related to our tax positions in a few countries as a result of a lapse in statutes of limitations and the partial payment related to the UK integration. During the year ended December 31, 2019, the unrecognized tax benefit increased by $22.8 million primarily due to integrations, which was partially offset by the recognition of unrecognized tax benefits related to our tax positions in France as a result of a lapse in statutes of limitations and the partial payment of the Metronode pre-acquisition tax audit assessment which was fully indemnified by the seller. The unrecognized tax benefits of $207.8 million as of December 31, 2020, of which $33.8 million is subject to an indemnification agreement, if subsequently recognized, will affect our effective tax rate favorably at the time when such a benefit is recognized. |
| Description | Judgments and Uncertainties | Effect if Actual Results Differ from Assumptions | ||||||
| Accounting for Business Combinations In accordance with the accounting standard for business combinations, we allocate the purchase price of an acquired business to its identifiable assets and liabilities based on estimated fair values. The excess of the purchase price over the fair value of the assets acquired and liabilities assumed, if any, is recorded as goodwill. We use all available information to estimate fair values. We typically engage outside appraisal firms to assist in determining the fair value of identifiable intangible assets such as customer contracts, leases and any other significant assets or liabilities and contingent consideration, as well as the estimated useful life of intangible assets. We adjust the preliminary purchase price allocation, as necessary, up to one year after the acquisition closing date if we obtain more information regarding asset valuations and liabilities assumed. | Our purchase price allocation methodology contains uncertainties because it requires assumptions and management's judgment to estimate the fair value of assets acquired and liabilities assumed at the acquisition date. Key judgments used to estimate the fair value of intangible assets include projected revenue growth and operating margins, discount rates, customer attrition rates, as well as the estimated useful life of intangible assets. Management estimates the fair value of assets and liabilities based upon quoted market prices, the carrying value of the acquired assets and widely accepted valuation techniques, including discounted cash flows and market multiple analyses. Our estimates are inherently uncertain and subject to refinement. Unanticipated events or circumstances may occur which could affect the accuracy of our fair value estimates, including assumptions regarding industry economic factors and business strategies. | During the last three years, we have completed a number of business combinations, including the acquisition of Bell Data Centers in Canada in the fourth quarter of 2020, Packet in March 2020, Axtel in Mexico in January 2020, Switch Datacenters' AMS1 data center business in Amsterdam, Netherlands in April 2019, and the Metronode Acquisition and the Infomart Dallas Acquisition in April 2018. The purchase price allocation for these acquisitions has been finalized, except for the Bell acquisition. As of December 31, 2020 and 2019, we had net intangible assets of $2.2 billion and $2.1 billion, respectively. We recorded amortization expense for intangible assets of $199.0 million, $196.3 million and $203.4 million for the years ended December 31, 2020, 2019 and 2018, respectively. We do not believe there is a reasonable likelihood that there will be a material change in the estimates or assumptions we used to complete the purchase price allocations and the fair value of assets acquired and liabilities assumed. However, if actual results are not consistent with our estimates or assumptions, we may be exposed to losses or gains that could be material, which would be recorded in our consolidated statements of operations in 2020 or beyond. |
| Description | Judgments and Uncertainties | Effect if Actual Results Differ from Assumptions | ||||||
| Accounting for Impairment of Goodwill and Other Intangible Assets In accordance with the accounting standard for goodwill and other intangible assets, we perform goodwill and other intangible assets impairment reviews annually, or whenever events or changes in circumstances indicate that the carrying value of an asset may not be recoverable. We complete the annual goodwill impairment assessment for the Americas, EMEA and Asia-Pacific reporting units to determine if the fair values of the reporting units exceeded their carrying values. We perform a review of other intangible assets for impairment by assessing events or changes in circumstances that indicate the carrying amount of an asset may not be recoverable. | To perform annual goodwill impairment assessment, we elected to assess qualitative factors to determine whether it is more likely than not that the fair value of a reporting unit is less than its carrying value. This analysis requires assumptions and estimates before performing the quantitative goodwill impairment test, where the assessment requires assumptions and estimates derived from a review of our actual and forecasted operating results, approved business plans, future economic conditions and other market data. Additionally, we periodically review our assessment of our reporting units to determine if changes in facts and circumstances warrant changes to our conclusions. There were no specific factors present in 2020 or 2019 that indicated a potential goodwill impairment. We performed our annual review of other intangible assets by assessing if there were events or changes in circumstances indicating that the carrying amount of an asset may not be recoverable, such as a significant decrease in market price of an asset, a significant adverse change in the extent or manner in which an asset is being used, a significant adverse change in legal factors or business climate that could affect the value of an asset or a continuous deterioration of our financial condition. This assessment requires assumptions and estimates derived from a review of our actual and forecasted operating results, approved business plans, future economic conditions and other market data. There were no specific events in 2020 or 2019 that indicated a potential impairment. | As of December 31, 2020, goodwill attributable to the Americas, the EMEA and the Asia-Pacific reporting units was $2.2 billion, $2.6 billion and $0.6 billion, respectively. Future events, changing market conditions and any changes in key assumptions may result in an impairment charge. While we have not recorded an impairment charge against our goodwill to date, the development of adverse business conditions in our Americas, EMEA or Asia-Pacific reporting units, such as higher than anticipated customer churn or significantly increased operating costs, or significant deterioration of our market comparables that we use in the market approach, could result in an impairment charge in future periods. The balance of our other intangible assets, net, for the year ended December 31, 2020 and 2019 was $2.2 billion and $2.1 billion, respectively. While we have not recorded an impairment charge against our other intangible assets to date, future events or changes in circumstances, such as a significant decrease in market price of an asset, a significant adverse change in the extent or manner in which an asset is being used, a significant adverse change in legal factors or business climate, may result in an impairment charge in future periods. Any potential impairment charge against our goodwill and other intangible assets would not exceed the amounts recorded on our consolidated balance sheets. |
| Description | Judgments and Uncertainties | Effect if Actual Results Differ from Assumptions | ||||||
| Accounting for Property, Plant and Equipment We have a substantial amount of property, plant and equipment recorded on our consolidated balance sheet. The vast majority of our property, plant and equipment represent the costs incurred to build out or acquire our IBX data centers. Our IBX data centers are long-lived assets. We depreciate our property, plant and equipment using the straight-line method over the estimated useful lives of the respective assets (subject to the term of the lease in the case of leased assets or leasehold improvements and integral equipment located in leased properties). Accounting for property, plant and equipment includes determining the appropriate period in which to depreciate such assets, assessing such assets for potential impairment, capitalizing interest during periods of construction and assessing the asset retirement obligations required for certain leased properties that require us to return the leased properties back to their original condition at the time we decide to exit a leased property. | Judgments are required in arriving at the estimated useful life of an asset and changes to these estimates would have significant impact on our financial position and results of operations. When we lease a property for our IBX data centers, we generally enter into long-term arrangements with initial lease terms of at least 8-10 years and with renewal options generally available to us. In the next several years, a number of leases for our IBX data centers will come up for renewal. As we start approaching the end of these initial lease terms, we will need to reassess the estimated useful lives of our property, plant and equipment. In addition, we may find that our estimates for the useful lives of non-leased assets may also need to be revised periodically. We periodically review the estimated useful lives of certain of our property, plant and equipment and changes in these estimates in the future are possible. The assessment of long-lived assets for impairment requires assumptions and estimates of undiscounted and discounted future cash flows. These assumptions and estimates require significant judgment and are inherently uncertain. | As of December 31, 2020 and 2019, we had property, plant and equipment of $14.5 billion and $12.2 billion, respectively. During the years ended December 31, 2020, 2019 and 2018, we recorded depreciation expense of $1.2 billion, $1.1 billion, and $1.0 billion, respectively. While we evaluated the appropriateness, we did not revise the estimated useful lives of our property, plant and equipment during the years ended December 31, 2020, 2019 and 2018. Further changes in our estimated useful lives of our property, plant and equipment could have a significant impact on our results of operations. | ||||||
| Accounting for Leases A significant portion of our data center spaces, office spaces and equipment are leased. Each time we enter into a new lease or lease amendments, we analyze each lease or lease amendment for the proper accounting, including determining if an arrangement is or contains a lease at inception and making assessment of the leased properties to determine if they are operating or finance leases. | Determination of accounting treatment, including the result of the lease classification test for each new lease or lease amendment, is dependent on a variety of judgments, such as identification of lease and non-lease components, allocation of total consideration between lease and non-lease components, determination of lease term, including assessing the likelihood of lease renewals, valuation of leased property, and establishing the incremental borrowing rate to calculate the present value of the minimum lease payment for the lease test. The judgments used in the accounting for leases are inherently subjective; different assumptions or estimates could result in different accounting treatment for a lease. | Lease assumptions and estimates are determined and applied at the inception of the leases or at the lease modification date. As of both December 31, 2020 and 2019, operating right-of-use ("ROU") lease assets were at $1.5 billion and operating lease liabilities were at $1.5 billion . As of December 31, 2020 and 2019, finance ROU assets were $1.7 billion and $1.3 billion, respectively, and finance lease liabilities were $1.9 billion and $1.5 billion, respectively. For the years ended December 31, 2020, 2019 and 2018, we recorded the finance lease cost of $233.9 million and $193.6 million, respectively, and recorded rent expense of approximately $217.3 million, $219.0 million and $185.4 million, respectively. |
Recent Accounting Pronouncements
See "Recent Accounting Pronouncements" in Note 1 within the Consolidated Financial Statements.
Previous: Item 6. Selected Financial Data · Next: Item 7A. Quantitative and Qualitative Disclosures About Market Risk