 filings.tools
Erie Indemnity 10-K 2023-12-31
Filed 2024-02-26. 23 sections, 406K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 10-K
☒ ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
For the fiscal year ended December 31, 2023
OR
☐ TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
Commission File Number 0-24000
| ERIE INDEMNITY COMPANY | ||||||||
| (Exact name of registrant as specified in its charter) |
| Pennsylvania | 25-0466020 | |||||||||||||
| (State or other jurisdiction of | (IRS Employer | |||||||||||||
| incorporation or organization) | Identification No.) |
| 100 Erie Insurance Place, | Erie, | Pennsylvania | 16530 | |||||||||||||||||
| (Address of principal executive offices) | (Zip Code) |
| 814 | 870-2000 | ||||||||||
| (Registrant’s telephone number, including area code) |
Securities registered pursuant to Section 12(b) of the Act:
| Class A common stock, | stated value $0.0292 per share | ERIE | NASDAQ Stock Market, LLC | ||||||||||||||
| (Title of each class) | (Trading Symbol) | (Name of each exchange on which registered) |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, smaller reporting company, or an emerging growth company. See the definitions of "large accelerated filer," "accelerated filer," "smaller reporting company," and "emerging growth company" in Rule 12b-2 of the Exchange Act. (Check one):
| Large accelerated filer | ☒ | Accelerated filer | ☐ | Non-accelerated filer | ☐ | |||||||||||||||||||||
| Smaller reporting company | ☐ | Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements. ☐
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant's executive officers during the relevant recovery period pursuant to §240.10D-1 (b). ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☒
Aggregate market value of voting and non-voting common stock held by non-affiliates as of the last business day of the registrant's most recently completed second fiscal quarter: $5.3 billion of Class A non-voting common stock as of June 30, 2023. There is no active market for the Class B voting common stock. The Class B common stock is closely held by few shareholders.
Indicate the number of shares outstanding of each of the registrant's classes of common stock, as of the latest practicable date:
46,189,068 shares of Class A common stock and 2,542 shares of Class B common stock outstanding on February 20, 2024.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of Part III of this Form 10-K (Items 10, 11, 12, 13, and 14) are incorporated by reference to the information statement on Schedule 14C to be filed with the Securities and Exchange Commission no later than 120 days after December 31, 2023.
INDEX
PART I
Item 1. BUSINESS
General
Erie Indemnity Company ("Indemnity", "we", "us", "our") is a publicly held Pennsylvania business corporation that has since its incorporation in 1925 served as the attorney-in-fact for the subscribers (policyholders) at the Erie Insurance Exchange ("Exchange"). The Exchange, which also commenced business in 1925, is a Pennsylvania-domiciled reciprocal insurer that writes property and casualty insurance. The Exchange has wholly owned property and casualty subsidiaries including: Erie Insurance Company, Erie Insurance Company of New York, Erie Insurance Property & Casualty Company and Flagship City Insurance Company, and a wholly owned life insurance company, Erie Family Life Insurance Company ("EFL").
Our primary function as attorney-in-fact is to perform policy issuance and renewal services on behalf of the subscribers at the Exchange. We also act as attorney-in-fact on behalf of the subscribers at the Exchange with respect to all claims handling and investment management services, as well as the service provider for all claims handling, life insurance, and investment management services for the Exchange's insurance subsidiaries, collectively referred to as "administrative services". Acting as attorney-in-fact in these two capacities is done in accordance with a subscriber's agreement (a limited power of attorney) executed individually by each subscriber (policyholder), which appoints Indemnity as each subscriber's attorney-in-fact to transact certain business on their behalf. In accordance with the subscriber’s agreement for acting as attorney-in-fact in these two capacities, we retain a management fee calculated as a percentage, not to exceed 25%, of the direct and affiliated assumed premiums written by the Exchange. The management fee rate is set at least annually by our Board of Directors. The process of setting the management fee rate includes, but is not limited to, the evaluation of current year operating results compared to both prior year and industry estimated results for both Indemnity and the Exchange, and consideration of several factors for both entities including, but not limited to: their relative financial strength and capital position; projected revenue, expense and earnings for the subsequent year; future capital needs; as well as competitive position.
Services
The policy issuance and renewal services we provide on behalf of the subscribers at the Exchange are related to the sales, underwriting and issuance of policies. The sales related services we provide include agent compensation and certain sales and advertising support services. Agent compensation includes scheduled commissions to agents based upon premiums written as well as incentive compensation, which is earned by achieving targeted measures. Agent compensation comprised approximately 67% of our 2023 policy issuance and renewal expenses. The underwriting services we provide include underwriting and policy processing and comprised approximately 9% of our 2023 policy issuance and renewal expenses. The remaining services we provide include customer service and administrative support. We also provide information technology services that support all the functions listed above that comprised approximately 11% of our 2023 policy issuance and renewal expenses. Included in these expenses are allocations of costs for departments that support these policy issuance and renewal functions.
Consistent with its legal structure as a reciprocal insurer, the Exchange does not have any employees or officers. Therefore, it enters into contractual relationships by and through the subscribers' attorney-in-fact. Indemnity serves as the attorney-in-fact on behalf of the subscribers at the Exchange with respect to its administrative services as enumerated in the subscriber's agreement. The Exchange's insurance subsidiaries also utilize Indemnity for these services in accordance with the service agreements between each of the subsidiaries and Indemnity. Claims handling services include costs incurred in the claims process, including the adjustment, investigation, defense, recording and payment functions. Life insurance management services include costs incurred in the management and processing of life insurance business. Investment management services are related to investment trading activity, accounting and all other functions attributable to the investment of funds. Included in these expenses are allocations of costs for departments that support these administrative functions. The subscriber's agreement and service agreements provide for reimbursement of amounts incurred for these services to Indemnity. Reimbursements are settled at cost. State insurance regulations require that intercompany service agreements and any material amendments be approved in advance by the state insurance department.
Erie Insurance Exchange
As our primary purpose is to manage the affairs at the Exchange for the benefit of the subscribers (policyholders) through the policy issuance and renewal services and administrative services, the Exchange is our sole customer. Our earnings are largely generated from management fees based on the direct and affiliated assumed premiums written by the Exchange. We have no direct competition in providing these services to the Exchange.
The Exchange generates revenue by insuring preferred and standard risks, with personal lines comprising 70% of the 2023 direct and affiliated assumed written premiums and commercial lines comprising the remaining 30%. The principal personal
lines products are private passenger automobile and homeowners. The principal commercial lines products are commercial multi-peril, commercial automobile and workers compensation. Historically, due to policy renewal and sales patterns, the Exchange's direct and affiliated assumed written premiums tend to be greater in the second and third quarters than in the first and fourth quarters of the calendar year.
The Exchange is represented by independent agencies that serve as its sole distribution channel. In addition to their principal role as salespersons, the independent agents play a significant role as underwriting and service providers and are an integral part of the Exchange's success.
Our results of operations are tied to the growth and financial condition of the Exchange. If any events occurred that impaired the Exchange's ability to grow or sustain its financial condition, including but not limited to reduced financial strength ratings, disruption in the independent agency relationships, significant catastrophe losses, or products not meeting customer demands, the Exchange could find it more difficult to retain its existing business and attract new business. A decline in the business of the Exchange almost certainly could have as a consequence a decline in the total premiums paid and a correspondingly adverse effect on the amount of the management fees we receive. We also have an exposure to a concentration of credit risk related to the unsecured receivables due from the Exchange for net management fee and other reimbursements. See Part II, Item 8. "Financial Statements and Supplementary Data - Note 15, Concentrations of Credit Risk, of Notes to Financial Statements" contained within this report. See the risk factors related to our dependency on the growth and financial condition of the Exchange in Item 1A. "Risk Factors" contained within this report.
Competition
Our primary function as attorney-in-fact is to perform policy issuance and renewal services on behalf of the subscribers at the Exchange. We also act as attorney-in-fact on behalf of the subscribers at the Exchange, as well as the service provider for the Exchange's insurance subsidiaries, with respect to all administrative services. There are a limited number of companies that provide services under a reciprocal insurance exchange structure. We do not directly compete against other such companies, given we are appointed by the subscribers at the Exchange to provide these services.
The direct and affiliated assumed premiums written by the Exchange drive our management fee, which is our primary source of revenue. The property and casualty insurance industry is highly competitive. Property and casualty insurers generally compete on the basis of customer service, price, consumer recognition, coverages offered, claims handling, financial stability and geographic coverage. Vigorous competition, particularly in the personal lines automobile and homeowners lines of business, exists from large, well-capitalized national companies, some of which have broad distribution networks of employed or captive agents, by smaller regional insurers, and by large companies who market and sell personal lines products directly to consumers. Innovations by competitors or other market participants may also increase the level of competition in the industry. In addition, because the insurance products of the Exchange are marketed exclusively through independent insurance agents, the Exchange faces competition within its appointed agencies based upon ease of doing business, product, price, and service relationships.
Market competition bears directly on the price charged for insurance products and services subject to regulatory limitations. Industry capital levels can also significantly affect prices charged for coverage. Growth is driven by a company's ability to provide insurance services and competitive prices while maintaining target profit margins. Growth is a product of a company's ability to retain existing customers and to attract new customers, as well as movement in the average premium per policy.
The Exchange's business model is designed to provide the advantages of localized marketing and claims servicing with the economies of scale and low cost of operations from centralized support services. Indemnity, as part of its role managing and conducting the business and affairs of the Exchange, also carefully selects the independent agencies that represent the Exchange, which seeks to be the lead insurer with its agents in order to enhance the agency relationship and the likelihood of receiving the most desirable underwriting opportunities from its agents.
The Exchange’s strategic focus as a reciprocal insurer is to employ a disciplined underwriting philosophy and to leverage its strong surplus position to generate higher risk adjusted investment returns. The goal is to produce acceptable returns, on a long-term basis, through careful risk selection, appropriate pricing and superior investment returns. This focus allows the Exchange to accomplish its mission of providing as near perfect protection, as near perfect service as is humanly possible at the lowest possible cost.
See the risk factors related to our dependency on the growth and financial condition of the Exchange in Item 1A. "Risk Factors" contained within this report for further discussion on competition in the insurance industry.
Human Capital Management
Employee Value Proposition
Our human capital management strategy, including initiatives to shape our workforce and workplace, is designed to attract, retain, and develop talent to ensure we are well positioned for the future. Our partnership with our employees is one of the cornerstones of our success.
Our employee value proposition includes a culture that focuses on physical, financial, and emotional well-being. In 2023, we were Certified™ by Great Place To Work® for our positive employee experience. We offer competitive pay with a signature and affordable benefits package including options designed to meet the unique needs of our employees and their families. Employees have access to an employee assistance plan, emergency child and elder care providers, adoption assistance, and infertility assistance, among others. We hold a shared responsibility view of retirement planning whereby we provide tools and resources that employees are expected to use to achieve their retirement goals. We set ourselves apart by offering both a 401(k) savings plan and a noncontributory defined benefit pension plan. We encourage a work/life balance for all employees and recognize the need for employee flexibility by offering an allowance of remote work days to use throughout the year.
An engaged workforce is necessary for accomplishing organizational objectives and our portfolio of employee experience initiatives demonstrates our commitment to provide employees an engaging environment throughout all stages of their careers. We offer professional development opportunities that are designed to prepare employees for future career growth. Employees have access to skills enhancement training and programs as well as a generous tuition reimbursement program for higher education. We also grow and develop our employees by offering talent mobility opportunities such as expanded leadership experience, job shadowing, cross-training, stretch assignments, and formal career development programs.
Our employees also share in our values to give back and make a positive difference in their communities. We offer a volunteer program that provides employees with an allotment of paid hours annually to volunteer with eligible nonprofit organizations. We also offer a matching gifts program for donations to eligible nonprofit organizations.
Diversity, Equity & Inclusion
Diversity, equity, and inclusion ("DEI") is integral to our business success. Our DEI efforts are led by a Chief Diversity Officer who reports directly to the Chief Executive Officer, affirming our commitment to DEI from executive leadership. These efforts are further supported by a dedicated team of professionals including a Vice President of Diversity, Equity, and Inclusion.
We recognize the importance of diverse backgrounds and experiences. Our recruiting strategy includes access to multiple talent channels. We work to expand our pool of potential talent to include an array of skills, backgrounds, and experiences. We also offer a Future Focus internship program that provides opportunities for college students to gain relevant and real-world business experience in the insurance industry as well as an apprentice program to create a bridge for talent from high schools and community colleges into our workforce. We are also intentional about leveraging talent from the neuro diverse population, engaging individuals to support various enterprise initiatives.
We foster an inclusive workplace through the endorsement of nine affinity networks and five business resource groups. Affinity networks are employee-driven groups that focus on particular dimensions of diversity and are designed to foster greater awareness and a culture of inclusion. In support of our recruiting strategy, members of these networks engage with various colleges and universities throughout the country, including Historically Black Colleges and Universities. Business resource groups address business issues using a DEI lens. Through these groups, we are taking a broader approach to problem-solving and innovation by aligning cross-functional teams of employees to our business strategy.
Workforce Metrics
We used the following human capital metrics as part of managing our business for the years ended December 31:
| 2023 | 2022 | 2021 | ||||||||||||||||||
| Workforce size | ||||||||||||||||||||
| Full-time (1) | 6,481 | 5,970 | 5,805 | |||||||||||||||||
| Part-time | 24 | 23 | 30 | |||||||||||||||||
| Temporary (2) | 51 | 45 | 41 | |||||||||||||||||
| Turnover (3) | 9.0 | % | 11.2 | % | 8.0 | % | ||||||||||||||
| Voluntary | 4.8 | % | 6.9 | % | 4.8 | % | ||||||||||||||
| Retirements | 2.8 | % | 3.6 | % | 2.2 | % | ||||||||||||||
| Average tenure (4) | 10.4 | 11.7 | 12.6 |
(1) Includes 50% of employees who provide claims and life insurance management services exclusively for the Exchange and its subsidiaries for all periods presented. The Exchange and its subsidiaries reimburse us monthly for the cost of these services.
(2) Temporary employees are hired for short-term work and paid directly by us.
(3) Turnover is calculated using the number of employees who exited, divided by the average headcount of the period and represents the percentage of employees who left voluntarily or involuntarily, including retirements.
(4) Average tenure is calculated using the total number of years of employment, divided by average headcount of full-time and part-time employees for the period and represents the average number of years employees have been employed with the organization.
The largest portion of our turnover continues to be voluntary turnover, excluding retirements, and remains lower than industry benchmark data. We continue to monitor turnover trends to determine the appropriate actions to ensure we are well positioned for the future.
Government Regulation
Most states have enacted legislation that regulates insurance holding company systems, defined as two or more affiliated persons, one or more of which is an insurer. Indemnity and the Exchange, and its wholly owned subsidiaries, meet the definition of an insurance holding company system.
Each insurance company in the holding company system is required to register with the insurance supervisory authority of its state of domicile and furnish information regarding the operations of companies within the holding company system that may materially affect the operations, management, or financial condition of the insurers within the system. Pursuant to these laws, the respective insurance departments may examine us and the Exchange and its wholly owned subsidiaries at any time, and may require disclosure and/or prior approval of certain transactions with the insurers and us, as an insurance holding company.
All transactions within a holding company system affecting the member insurers of the holding company system must be fair and reasonable and any charges or fees for services performed must be reasonable. Approval by the applicable insurance commissioner is required prior to the consummation of transactions affecting the members within a holding company system.
Website Access
Our annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and any amendments to those reports are available free of charge on our website at www.erieinsurance.com as soon as reasonably practicable after such material is filed electronically with the Securities and Exchange Commission. Additionally, copies of our annual report on Form 10-K are available free of charge, upon written request, by contacting Investor Relations, Erie Indemnity Company, 100 Erie Insurance Place, Erie, PA 16530, or calling (800) 458-0811.
Item 1A. RISK FACTORS
Our business involves various risks and uncertainties, including, but not limited to those discussed in this section. The risks and uncertainties described in the risk factors below, or any additional risk outside of those discussed below, could have a material adverse effect on our business, financial condition, operating results, cash flows, or liquidity if they were to develop into actual events. This information should be considered carefully together with the other information contained in this report and in other reports and materials we file periodically with the Securities and Exchange Commission.
Our risks have been divided into the following categories:
Risks related to Erie Insurance Exchange – risks related to our dependence on our relationship with the Exchange associated with management fees, premium growth, and financial condition, as the Exchange is our sole customer and principal source of revenue
Operating risks – risks stemming from events or circumstances that directly or indirectly affect our operations, including our operations as attorney-in-fact for the subscribers at the Exchange
Market, Capital, and Liquidity risks – risks that may impact the values or results of our investment portfolio, ability to meet financial obligations or covenants, or obtain capital as necessary
Although we have organized risks generally according to these categories in the discussion below, risks may have impacts in more than one category and are included where the impact is most significant.
Risks related to Erie Insurance Exchange
If the management fee rate retained by Indemnity is reduced or if there is a significant decrease in the amount of direct and affiliated assumed premiums written by the Exchange, revenues and profitability could be materially adversely affected.
We are dependent upon management fees we retain, which represent our principal source of revenue. In accordance with the subscriber's agreement with the subscribers at the Exchange, we may retain up to 25% of all direct and affiliated assumed premiums written by the Exchange. Therefore, management fee revenue from the Exchange is calculated by multiplying the management fee rate by the direct and affiliated assumed premiums written by the Exchange. Accordingly, any reduction in direct and affiliated assumed premiums written by the Exchange and/or the management fee rate could have a negative effect on our revenues and net income.
The management fee rate is determined by our Board of Directors and may not exceed 25% of the direct and affiliated assumed premiums written by the Exchange. The Board of Directors sets the management fee rate each December for the following year. At their discretion, the rate can be changed at any time. The process of setting the management fee rate includes, but is not limited to, the evaluation of current year operating results compared to both prior year and industry estimated results for both Indemnity and the Exchange, and consideration of several factors for both entities including, but not limited to: their relative financial strength and capital position; projected revenue, expense and earnings for the subsequent year; future capital needs; as well as competitive position. The evaluation of these factors could result in a reduction to the management fee rate and our revenues and profitability could be materially adversely affected.
Serving as the attorney-in-fact for subscribers in the reciprocal insurance exchange structure with the Exchange being our sole customer, the growth of the Exchange could directly affect our operating revenue, which is largely generated from management fees based on the direct and affiliated assumed premiums written by the Exchange. If the Exchange's ability to grow or renew policies were adversely impacted, the premium revenue of the Exchange could be adversely affected, which could reduce our management fee revenue. The circumstances or events that might impair the Exchange's ability to grow include, but are not limited to, the items discussed below.
Unfavorable changes in macroeconomic conditions for any reason, including declining consumer confidence, inflation, high unemployment, lower demand for certain services, reduced personal income, and recession, among others, may lead the Exchange's customers to modify coverage, not renew policies, or even cancel policies, which could adversely affect the premium revenue of the Exchange, and consequently our management fee.
The Exchange faces significant competition from other regional and national insurance companies. The property and casualty insurance industry is highly competitive on the basis of product, price and service. If the Exchange's competitors offer property and casualty products with more coverage, offer lower rates, or introduce innovative services in response to evolving customer
preferences, and the Exchange is unable to implement product or service improvements quickly enough to keep pace, its ability to grow and renew its business may be adversely impacted. In addition, due to the Exchange's premium concentration in the automobile and homeowners insurance markets, it may be more sensitive to trends that could affect auto and home insurance coverages and rates over time, for example changing vehicle types or usage, usage-based methods of determining premiums, ownership and driving patterns such as ride sharing or remote work, advancements in vehicle or home technology or safety features such as accident and loss prevention technologies, the development of autonomous vehicles, or residential occupancy patterns, among other factors. Innovations, including the use of artificial intelligence and machine learning to support underwriting or other decisions, by competitors or other market participants may increase the level of competition in the industry. If the Exchange fails to respond to those innovations on a timely basis, its competitive position and results may be materially adversely affected.
The Exchange markets and sells its insurance products through independent, non-exclusive insurance agencies. These agencies are not obligated to sell only the Exchange's insurance products, and generally also sell products of the Exchange's competitors. If agencies do not maintain their current levels of marketing efforts, bind the Exchange to unacceptable risks, place business with competing insurers, or if the Exchange is unsuccessful in attracting or retaining agencies in its distribution system or maintaining its relationships with those agencies, the Exchange's ability to grow and renew its business may be adversely impacted. More broadly, if independent agents face challenges sustaining their own business operations due to unfavorable economic conditions or staffing constraints, it could result in the sale or closure of their businesses, thereby reducing the agency force of the Exchange. Additionally, shifting consumer behaviors toward increased digital interactions may cause the insurance industry as a whole to migrate to a delivery system other than independent agencies.
The Exchange maintains a brand recognized for customer service, which is the result of Indemnity's management of the Exchange in accordance with the subscriber's agreement. The perceived performance, actions, conduct and behaviors of employees, independent insurance agency representatives, and third-party service providers may result in reputational harm to the Exchange's brand. Specific incidents which may cause harm include but are not limited to disputes, long customer wait times, errors in processing a claim, failure to protect sensitive customer data, and negative or inaccurate social media or traditional media communications. Likewise, an inability to match or exceed the service provided by competitors, who are increasingly relying on digital delivery and enhanced distribution technology, may impede the Exchange’s ability to maintain and/or grow its customer base. If an extreme catastrophic event were to occur in a heavily concentrated geographic area of subscribers/policyholders, an extraordinarily high number of claims could have the potential to strain claims processing and affect the Exchange's ability to service its customers. If third-party service providers fail to perform as anticipated, the Exchange may experience operational difficulties, increased costs, and reputational damage. Similarly, the Exchange’s brand could be tarnished by reactions to business practices, adverse financial developments, perceptions of our corporate governance, how we address employee matters and concerns, environmental, social and governance (ESG) initiatives, or the conduct of our employees, officers and directors. Failure to satisfy expectations in these areas may result in negative publicity or other adverse outcomes, which could be aggravated as the expectations of consumers, regulators and other stakeholders evolve and as social media and other forms of modern communication rapidly magnify reactions. Any reputational harm to the Exchange could have the potential to impair its ability to grow and renew its business.
As the attorney-in-fact for subscribers in the reciprocal insurance exchange structure with the Exchange as our sole customer, we are dependent on the financial condition of the Exchange. If the Exchange were to fail to maintain acceptable financial strength ratings, its competitive position in the insurance industry could be adversely affected. If a rating downgrade led to customers not renewing or canceling policies, or impacted the Exchange's ability to attract new customers, the premium revenue of the Exchange could be adversely affected, which could reduce our management fee revenue. The circumstances or events that might impair the Exchange's financial condition include, but are not limited to, the items discussed below.
Financial strength ratings are an important factor in establishing the competitive position of insurance companies such as the Exchange. Higher ratings generally indicate greater financial stability and a stronger ability to meet ongoing obligations to policyholders. The Exchange's A.M. Best rating is currently A+ ("Superior"). A.M. Best periodically reviews the Exchange’s ratings and changes their rating criteria; therefore, the Exchange's current rating may not be maintained in the future. A significant downgrade in the A.M. Best rating could reduce the competitive position of the Exchange, making it more difficult to attract profitable business in the highly competitive property and casualty insurance market and potentially result in reduced sales of its products and lower premium revenue.
The performance of the Exchange's investment portfolio is subject to a variety of investment risks. The Exchange's investment portfolio is comprised principally of fixed income securities, equity securities and limited partnerships. The fixed income portfolio is subject to a number of risks including, but not limited to, interest rate risk, investment credit risk, sector/concentration risk and liquidity risk. The Exchange's common stock and preferred equity securities have exposure to price risk, the risk of potential loss in estimated fair value resulting from an adverse change in prices. Limited partnerships are
significantly less liquid and generally involve higher degrees of price risk than publicly traded securities. Limited partnerships, like publicly traded securities, have exposure to market volatility; but unlike fixed income securities, cash flows and return expectations are less predictable. Additionally, a portion of the Exchange’s common stock and limited partnership portfolios are exposed to foreign exchange rate risk, or the potential loss in estimated fair value resulting from adverse changes in foreign currency exchange rates. If any investments in the Exchange's investment portfolio were to suffer a substantial decrease in value, the Exchange's financial position could be materially adversely affected through increased unrealized losses or impairments. A significant decrease in the Exchange's portfolio could also put it, or its subsidiaries, at risk of failing to satisfy regulatory or rating agency minimum capital requirements.
Property and casualty insurers are subject to extensive regulatory supervision in the states in which they do business. This regulatory oversight includes, by way of example, matters relating to licensing, examination, rate setting, market conduct, policy forms, limitations on the nature and amount of certain investments, claims practices, mandated participation in involuntary markets and guaranty funds, reserve adequacy, insurer solvency, restrictions on underwriting standards, accounting standards, transactions between affiliates, risk management, cybersecurity and data privacy, and ESG practices. Such regulation and supervision are primarily for the benefit and protection of policyholders. Changes in applicable insurance laws, tax statutes, cyber, privacy, and other laws and regulations, or changes in the way regulators administer those laws, tax statutes, or regulations could adversely impact the Exchange's business, cash flows, results of operations, financial condition, or operating environment and increase its exposure to loss or put it at a competitive disadvantage, which could result in reduced sales of its products and lower premium revenue.
Property and casualty insurers face a significant risk of litigation and state and federal regulatory investigations, inquiries and actions in the ordinary course of operating their businesses, including the risk of class action lawsuits. The Exchange and its subsidiaries have also been named as defendants in a number of pandemic-related lawsuits and, therefore, are subject to the risks and uncertainties of such litigation. Plaintiffs in class action and other lawsuits against the Exchange may seek large or indeterminate amounts of damages, including punitive and treble damages, which may remain unknown for substantial periods of time.
The uncertainty of risks that emerge upon the occurrence of significant unexpected events, such as pandemics, or unexpected economic or social inflation caused by supply chain issues, societal trends, or otherwise, may cause additional challenges in the process of estimating loss and loss adjustment expense reserves or premiums to accommodate future claims and expenses. For example, the behavior of claimants and policyholders and the timing and amounts of claims settlements may change in unexpected ways. Furthermore, actions taken by governmental bodies, both legislative and regulatory, in reaction to significant unexpected events, and their related impacts, are hard to predict. Technology advancements, such as electric and autonomous vehicles, could impact frequency or severity of losses. The models that are used to determine appropriate premium levels, forecast future losses and expenses, estimate loss and loss adjustment expense reserves, and assess financial strength may be created or deployed in a manner that results in inaccurate predictions. This may result in changes to the Exchange's estimated level of loss and loss adjustment expense reserves or impact the adequacy of premiums to accommodate future claims and expenses.
As insurance industry practices and legal, judicial, social and other environmental conditions change, unexpected and unintended issues related to claims and coverage may emerge. In some instances, these emerging issues may not become apparent for some time after the Exchange has issued the affected insurance policies. As a result, the full extent of liability under the Exchange's insurance policies may not be known for many years after the policies are issued. These issues may adversely affect the Exchange's business by either extending coverage beyond its underwriting intent or by increasing the number or size of claims. If there were legislative action in response to a pandemic or other significant unexpected event that retroactively mandated coverage irrespective of terms, exclusions or other conditions included in policies, such as business interruption, that would otherwise preclude coverage, it could have a material impact on the financial condition, results of operations and cash flows of the Exchange.
The Exchange's insurance operations are exposed to claims arising out of catastrophes. Common natural catastrophic events include hurricanes, earthquakes, tornadoes, hail storms, and severe winter weather. The frequency and severity of these catastrophes is inherently unpredictable. Changing climate conditions have added to the unpredictability of the frequency and severity of natural disasters and have created additional uncertainty as to future trends and exposures. A single catastrophic occurrence or aggregation of multiple smaller occurrences within the geographical region of the Exchange or its assumed property reinsurance portfolio could adversely affect the financial condition of the Exchange. Man-made disasters such as terrorist attacks and riots could also cause losses from insurance claims related to the property and casualty insurance operations, which could adversely affect its financial condition.
Operating risks
If the costs of providing services to the Exchange are not controlled, our profitability could be materially adversely affected.
In accordance with the subscriber's agreement, we perform policy issuance and renewal services for the subscribers at the Exchange and we serve as the attorney-in-fact on behalf of the subscribers at the Exchange with respect to administrative services. The most significant costs we incur in providing policy issuance and renewal services are commissions, employee costs, and technology costs.
Commissions to independent agents are our largest expense. Commissions include scheduled commissions to agents based upon premiums written as well as incentive compensation, which is earned by achieving certain targeted measures. Changes to commission rates or incentive programs may result in increased future costs and lower profitability. Our agent incentive compensation includes a profitability component. If claims frequency and loss expenses were to decrease significantly as a result of an unexpected event, such as a pandemic, the profitability component of our agent incentive compensation would improve, and our agent compensation costs would increase. Our second largest expense is employee costs, including salaries, healthcare, pension, and other benefit costs. Regulatory developments, provider relationships, pandemics and demographic and economic factors that are beyond our control, such as inflation, are indicators that employee costs could increase, which could reduce our profitability. The defined benefit pension plan we offer to our employees is affected by variable factors such as the interest rate used to discount pension liabilities, asset performance, and changes in retirement patterns, which are beyond our control, and any related future cost increases could reduce our profitability.
Technological development is necessary to facilitate ease of doing business for employees, agents, and customers. Our technological developments are focused on simplifying and improving the employee, agent, and customer experiences, increasing efficiencies, redesigning products, and addressing other potentially disruptive changes in the insurance industry, including the use of artificial intelligence. As we continue to develop technology initiatives in order to remain competitive, our profitability could be negatively impacted as we invest in system development.
If we are unable to attract, develop, and retain talented executives, key managers, and employees our financial condition and results of operations could be adversely affected.
Our success is largely dependent upon our ability to attract and retain talented executives and other key management. Talent is defined as people with the right skills, knowledge, abilities, character, and motivation. The loss of the services and leadership of certain key officers and the failure to plan for turnover or retirement or to attract and develop talented new executives and managers could prevent us from successfully communicating, implementing, and executing business strategies.
Our success also depends on our ability to attract, develop, and retain a talented employee base. The inability to staff all functions of our business with employees possessing the appropriate talent could have an adverse effect on our business performance. Additionally, failure to recognize, evaluate, and respond to changing workforce trends including current labor market conditions and new ways of managing in hybrid work environments, or failure to execute proactive retention and replacement strategies could also have an adverse effect on our business performance. Furthermore, failure to instill appropriate cultural expectations and behavioral norms within our employees, particularly in a hybrid work environment, could damage our reputation. Staffing appropriately talented employees for the handling of claims and servicing of customers, rendering of disciplined underwriting, and effective sales and marketing are critical to the core functions of our business. In addition, talented employees in the actuarial, finance, human resources, information technology, law, and risk management areas are also essential to support our core functions.
If we are unable to effectively maintain system availability or manage technology initiatives, we may experience adverse financial consequences and/or may be unable to compete effectively.
Our business is highly dependent upon the effectiveness of our technology and information systems which support key functions of our core business operations, including processing applications and premium payments, providing customer support, performing actuarial and financial analysis, and maintaining key data. Additionally, the Exchange relies heavily on technology systems for processing claims. In order to support our business processes and strategic initiatives in a cost and resource efficient manner, we must maintain the effectiveness of existing technology systems and continue to identify and develop new, and enhance existing, technology systems. As we invest in the development of our systems, costs and completion times could exceed original estimates, and/or the project may not deliver the anticipated benefit or perform as expected. If we do not effectively and efficiently manage and upgrade our technology systems, or attract and retain qualified information technology employees and contract personnel to support those systems, our ability to serve our customers and implement our strategic initiatives could be adversely impacted.
Additionally, we depend on a large amount of data to price policies appropriately, track exposures, perform financial analysis, report to regulatory bodies, and ultimately make business decisions. Should this data be inaccurate or insufficient, risk exposure may be underestimated and/or poor business decisions may be made. This may in turn lead to adverse operational or financial performance and adverse customer or investor confidence.
If we experience difficulties with technology, data and network security, including those that could result from cyber attacks, third-party relationships or cloud-based relationships, our ability to conduct our business could be adversely impacted.
In the normal course of business, we collect, use, store and where appropriate, disclose data concerning individuals and businesses. We also conduct business using third parties who may provide software, data storage, cloud-based computing and other technology services. We have on occasion experienced, and will continue to experience, cyber threats to our data and systems. Cyber threats can create significant risks such as destruction of systems or data, denial or interruption of service, disruption of transaction execution, loss or exposure of customer data, theft or exposure of our intellectual property, theft of funds or disruption of other important business functions. Even with appropriate governance and controls, the use of artificial intelligence may increase our exposure to cyber threats. Our interactions with, and reliance upon, third parties may also expose us to increased risk related to data security, service disruptions or effectiveness of our control system, particularly as we increase our reliance on cloud-based computing and software-as-a-service from third parties to operate our business.
In addition, we are subject to numerous federal and state laws relating to the privacy and security of nonpublic personal information and other sensitive information of our customers, employees and others. The improper access, disclosure, misuse or mishandling of such information could result in legal liability, regulatory action and reputational damage. Third parties on whom we rely for certain business processing functions are also subject to these risks, and their failure to adhere to these laws and regulations could negatively impact us.
The number, complexity, and sophistication of cyber threats continue to increase over time. While we maintain cyber liability insurance to mitigate the financial risk around cyber incidents, such insurance may not cover all costs associated with the consequences of information or systems being compromised, and such insurance may become prohibitively expensive to maintain. Additionally, while we have dedicated resources with security incident response capabilities, our response process may not be adequate, may fail to accurately assess the severity of an incident, may not respond quickly enough or may fail to sufficiently remediate an incident. Similarly, if our third-party service providers experience a cyber incident, they may fail to report, or timely report, the incident to us. As a result, we may suffer significant legal, reputational, or financial losses, which could adversely affect our business, cash flows, financial condition or results of operations.
If events occurred causing interruption of our operations, facilities, systems or business functions, it could have a material adverse effect on our operations and financial results.
We have established business continuity and disaster recovery plans to provide for the continuation of core business operations in the event that normal business operations could not be performed due to catastrophic or other events, including pandemics. While we continue to test and assess our business continuity and disaster recovery plans to validate they meet the needs of our core business operations and address multiple business interruption events, there is no assurance that core business operations could be performed upon the occurrence of such an event. Employee absence, physical premises damage, systems failures or outages could compromise our ability to perform our business functions in a timely manner, which could harm our ability to conduct business and hurt our business and customer relationships. Our operational resiliency is also dependent on third-party personnel, infrastructure and systems on which we rely, including cloud-based technologies and software-as-a-service applications. Our operations and those of our third parties may become vulnerable to damage or disruption due to circumstances beyond our or their control, such as from catastrophic events, power anomalies or outages, natural disasters, pandemics, supply chain interruptions, network failures, and cyber attacks. Additionally, we are dependent on internet and telecommunications access and capabilities. Our workforce is largely concentrated in Erie, Pennsylvania. If a significant event affects the labor force in this area, it could impact the policy acquisition, underwriting, claims and/or support services provided to the policyholders and/or independent agents of the Exchange. Disruptions to our workforce or our operations for any reason could result in a material adverse effect on our business, cash flows, financial condition, or results of operations.
We are subject to applicable insurance laws, tax statutes, and numerous other federal and state laws and regulations, as well as claims and legal proceedings, which, if determined unfavorably, could have a material adverse effect on our business, results of operations, or financial condition.
Our activities are subject to extensive regulation under federal and state laws on matters as diverse as internal control over financial reporting and disclosure controls, securities regulation, data privacy and protection, cybersecurity, taxation, immigration, wage-and-hour standards and employment and labor relations. These laws and regulations are complex and
evolving, and compliance with these laws requires significant resources. In some cases, these laws and regulations may increase our costs, negatively impact revenues, or impose operational limitations on our business. Further, there can be no assurance that we, our third-party service providers and our independent agents are in full compliance with all applicable laws and regulations at all times. Efforts at compliance with all laws and regulations are further complicated by new and evolving regulations regarding cybersecurity, artificial intelligence and ESG matters.
We face a significant risk of litigation and regulatory investigations and actions in the ordinary course of operating our businesses including the risk of class action lawsuits. We are, have been, or may become subject to class actions and individual suits alleging breach of fiduciary or other duties, including our obligations to indemnify directors and officers in connection with certain legal matters. We are also subject to litigation arising out of our general business activities such as contractual and employment relationships and claims regarding the infringement of the intellectual property of others. Plaintiffs in class action and other lawsuits against us may seek large or indeterminate amounts of damages, including punitive and treble damages, which may remain unknown for substantial periods of time. We are also subject to various regulatory inquiries, such as information requests, subpoenas, and books and record examinations from state and federal regulators and authorities. In addition, changes in the way regulators administer applicable laws, tax statutes, or regulations could adversely impact our business, cash flows, results of operations, or financial condition. It is also possible that changes in economic conditions and steps taken by federal, state, and local governments in response to a pandemic or other significant events could cause an increase in taxes at the federal, state, and local levels, which could adversely impact our results of operations.
Market, Capital, and Liquidity risks
The performance of our investment portfolio is subject to a variety of investment risks, which may in turn have a material adverse effect on our results of operations or financial condition.
At December 31, 2023, our investment portfolio consisted of approximately 85% fixed maturity securities, with the remaining 15% invested in equity securities and other investments.
General economic conditions and other factors beyond our control can adversely affect the value of our investments and the realization of net investment income or result in realized investment losses. In addition, downward economic trends also may have an adverse effect on our investment results by negatively impacting the business conditions and impairing credit for the issuers of securities held in our respective investment portfolios. This could reduce fair values of investments and generate significant unrealized losses or impairment charges which may adversely affect our financial results.
The performance of the fixed income portfolio is subject to a number of risks including, but not limited to:
-
Interest rate risk - the risk of adverse changes in the value of fixed income securities as a result of increases in market interest rates.
-
Investment credit risk - the risk that the value of certain investments may decrease due to the deterioration in financial condition of, or the liquidity available to, one or more issuers of those securities or, in the case of structured securities, due to the deterioration of the loans or other assets that underlie the securities, which, in each case, also includes the risk of permanent loss.
-
Sector/Concentration risk - the risk that the portfolio may be too heavily concentrated in the securities of one or more issuers, sectors, or industries. Events or developments that have a negative impact on any particular industry, group of related industries, or geographic region may have a greater adverse effect on our investment portfolio to the extent that the portfolio is concentrated within those issuers, sectors, or industries.
-
Liquidity risk - the risk that we will not be able to convert investment securities into cash on favorable terms and on a timely basis, or that we will not be able to sell them at all, when desired. Disruptions in the financial markets or a lack of buyers for the specific securities that we are trying to sell could prevent us from liquidating securities or cause a reduction in prices to levels that are not acceptable to us.
-
Reinvestment risk - the possibility that the cash flows produced by an investment will have to be reinvested at a reduced rate of return. Approximately 36% of our fixed maturity portfolio is expected to mature over the next three years.
Our equity securities have exposure to price risk. Equity markets, sectors, industries, and individual securities may also be subject to some of the same risks that affect our fixed income portfolio, as discussed above.
All of our fixed income and equity securities are subject to market volatility. To the extent that future market volatility negatively impacts our investments, our financial condition will be negatively impacted. We review the fixed income portfolio on a periodic basis to evaluate positions that are in an unrealized loss position to determine whether impairments are a result of credit loss or other factors. Inherent in management's evaluation of a security are assumptions and estimates about the operations of the issuer and its future earnings potential. As the process for determining impairments is highly subjective, changes in our assessments may have a material effect on our operating results and financial condition. See also Part II, Item 7A. "Quantitative and Qualitative Disclosures about Market Risk".
Deteriorating capital and credit market conditions or a failure to accurately estimate capital needs may significantly affect our ability to meet liquidity needs and access capital.
Sufficient liquidity and capital levels are required to pay operating expenses, income taxes, and to provide the necessary resources to fund future growth opportunities, satisfy certain financial covenants, pay dividends on common stock, and repurchase common stock. Management estimates the appropriate level of capital necessary based upon current and projected results, which includes evaluating potential risks. Failure to accurately estimate our capital needs may have a material adverse effect on our financial condition until additional sources of capital can be obtained. Further, a deteriorating financial condition may create a negative perception of us by third parties, including investors, and financial institutions, which could impact our ability to access capital in the debt or equity markets. Volatility in the financial markets could also limit our ability to sell certain fixed income securities or cause such investments to sell at deep discounts.
Our primary sources of liquidity are management fee revenue and cash flows generated from our investment portfolio. In the event these traditional sources of liquidity are not available, we may have to seek additional financing. Our access to funds will depend upon a number of factors including current market conditions, the availability of credit, market liquidity, and the timing of obtaining credit ratings. In deteriorating market conditions, there can be no assurance that we will obtain additional financing, or, if available, that the cost of financing will not substantially increase and affect our overall profitability.
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 1C. CYBERSECURITY
Cybersecurity Risk Management
Our Privacy and Information Security Committee, comprised of officers and senior leaders, is responsible for overseeing the development and maintenance of information privacy and security policies and effective operation of our corporate information security and cybersecurity program in compliance with applicable state insurance regulations and other legal and regulatory requirements. This committee is sponsored by and reports directly to our Executive Council, which includes our Chief Executive Officer and executive vice presidents.
As part of our overall Enterprise Risk Management ("ERM") program, we employ a cybersecurity program of technical, administrative, and physical controls intended to reduce the risk of cyber threats and protect our information, as well as documented processes to determine and make appropriate disclosures regarding potential material threats and incidents. Our cybersecurity philosophy and approach align to the National Institute of Standards and Technology Cybersecurity Framework and its core elements to identify, protect, detect, respond, and recover from the various forms of cyber threats. Our practices include, but are not limited to, cybersecurity protocols and controls, system monitoring and detection, communication of incidents to appropriate management, third-party risk management, including assessments of emerging threats and vulnerabilities, and ongoing privacy and cybersecurity training for employees and contractors concerning cyber risk. A foundational element of our cybersecurity risk management processes is the annual Cybersecurity and Information Security Risk Assessment (CSRA), which includes an analysis of cybersecurity risks facing us and associated recommendations and action items to mitigate identified risks. We periodically utilize third parties to assess the effectiveness of our cybersecurity efforts through independent validations, verifications, and security assessments.
Our Board of Directors has a process in place to monitor management’s oversight of cybersecurity. This is done primarily through regular reports to its Risk Committee as well as the full Board of Directors. Management provides reports on our
cybersecurity risk management program, including our risk evaluation, the results of independent third-party security assessments, and our efforts to manage cyber related risks.
We have a core incident response team (Core Team) consisting of dedicated, skilled leadership representatives from our Information Security, Privacy and Law teams, responsible for analyzing and assessing cyber incidents and leading response efforts. Our Chief Information Security Officer (CISO), responsible for overseeing and managing information security incidents, has over 25 years of experience in information technology (IT), including over 20 years dedicated to practicing or leading cybersecurity functions. Our CISO is also a Certified Information Systems Security Professional (CISSP). Our Privacy leader, responsible for managing privacy incidents, has over 20 years of experience in IT risk management, including over 10 years in IT risk and control functions and the remaining time focused on privacy and cybersecurity related functions and holds several information privacy and risk certifications. Our Legal leader, responsible for providing guidance on legal and other regulatory obligations in the areas of privacy, cybersecurity, technology, data use and third-party risk management, holds a Juris Doctor degree, is licensed to practice law, and has over 20 years of legal experience, including 10 years focused on privacy and cybersecurity and holds several information security and privacy certifications, including the CISSP. The Core Team leaders are members of various organizations that support cybersecurity or privacy intelligence, education, information sharing and networking, including among others the Financial Services Information Sharing and Analysis Center (FS-ISAC), Domestic Security Alliance Council (DSAC), InfraGard, and International Association of Privacy Professionals (IAPP).
The Core Team members are augmented as needed by representatives from other internal groups, including subject matter experts from Information Security, Privacy, Finance and Law, as well as certain third parties that may need to participate in the incident response process. Depending on the severity and impact of the incident, third parties engaged may include outside counsel, forensics investigators, public relation firms, data breach resolution providers, and cyber insurance brokers and carriers. In conjunction with legal counsel, the Core Team evaluates notification requirements and as necessary will notify stakeholders depending on the nature and severity of the incident, including law enforcement, state attorneys general, regulators, external auditors, third party providers, and impacted individuals.
The Core Team is informed of cyber incidents from diverse sources, including for example, internal monitoring systems, information sharing organizations, employees, and other external information sources. Depending upon the levels of access to our information and/or information systems, third party service providers are contractually obligated to report cybersecurity incidents within their environments. The Core Team performs incident analysis and triage to determine scope, severity, prioritization and required response plans to address an incident in a manner that is intended to minimize the impact to us, our assets, and our operations. In accordance with applicable legal and regulatory requirements, this analysis and triage step includes an assessment of the potential for material impact to us from a cybersecurity incident or a series of individually immaterial related incidents that are material when aggregated.
To date, we are not aware of any cybersecurity breach or other incident with respect to our systems or data that would have a material impact to our business strategy, results of operations or financial condition. Additionally, we are not aware of any cybersecurity breach or other incident experienced by anyone with whom we have a third-party relationship that has had a material impact on our systems or data. However, there can be no guarantee that we will not experience any such incidents in the future. See Item 1A. "Risk Factors" for a discussion of cybersecurity risks.
Item 2. PROPERTIES
Indemnity and the Exchange share a corporate home office campus in Erie, Pennsylvania, which comprises approximately 996,000 square feet. Additionally, we lease two office buildings and one warehouse facility from third parties and are charged rent for the related square footage we occupy.
Indemnity and the Exchange also own or lease 25 field offices in 12 states used to primarily support claims-related activities. The Exchange owns seven field offices and leases another 16 from third parties. Indemnity owns one field office and leases another from a third party. Commitments for properties leased from third parties expire periodically through 2029. We expect that most leases will be renewed or replaced upon expiration. Rental costs of shared facilities are allocated based upon square footage occupied.
Item 3. LEGAL PROCEEDINGS
Erie Indemnity Company ("Indemnity") was named as a defendant in a complaint filed on August 24, 2021, by alleged subscribers of the Erie Insurance Exchange (the "Exchange") in the Court of Common Pleas Civil Division of Allegheny County, Pennsylvania captioned TROY STEPHENSON, CHRISTINA STEPHENSON, SUSAN RUBEL, and STEVEN BARNETT, individually and on behalf of all others similarly situated (Plaintiffs) v. Erie Indemnity Company (Defendant).
The complaint seeks relief for alleged breaches of fiduciary duty by Indemnity in connection with the setting of the management fee it receives, in accordance with the terms of the Subscribers Agreement executed between Indemnity and all policyholders of the Exchange, as compensation for acting as the attorney-in-fact in the management of the Exchange. The relief sought is for the period beginning two years prior to the date of the filing of the complaint and continuing through 2021.
The complaint seeks (i) a finding that Indemnity has breached its fiduciary duties; (ii) an award of damages in an amount to be determined at trial; and (iii) such other relief, including disgorgement of profits or other injunctive relief, that the Court deems just and proper.
Service of the complaint was effectuated on September 20, 2021. A Notice of Removal to the United States District Court for the Western District of Pennsylvania was filed on October 20, 2021. On November 2, 2021, Plaintiffs filed a Notice of Voluntary Dismissal. As a result, the action was dismissed without prejudice.
On December 6, 2021, another Complaint was filed in the Court of Common Pleas of Allegheny County, Pennsylvania captioned ERIE INSURANCE EXCHANGE, an unincorporated association, by TROY STEPHENSON, CHRISTINA STEPHENSON, and STEVEN BARNETT, trustees ad litem, and alternatively, ERIE INSURANCE EXCHANGE, by TROY STEPHENSON, CHRISTINA STEPHENSON, and STEVEN BARNETT, (Plaintiff), v. ERIE INDEMNITY COMPANY, (Defendant).
This most recent complaint has the same allegation of breach of fiduciary duty by Indemnity in connection with the setting of the management fee it receives, in accordance with the terms of the Subscribers Agreement executed between Indemnity and all policyholders of the Exchange, as compensation for acting as the attorney-in-fact in the management of the Exchange.
This most recent complaint seeks the same relief, specifically, (i) a finding that Indemnity has breached its fiduciary duties; (ii) an award of damages in an amount to be determined at trial; and (iii) such other relief, including disgorgement of profits or other injunctive relief, that the Court deems just and proper.
A Notice of Removal to the United States District Court for the Western District of Pennsylvania was filed on January 27, 2022. Indemnity intends to vigorously defend against all of the allegations and requests for relief in the complaint.
By Memorandum Opinion and Order dated September 28, 2022, the Court granted the Motion for Remand and directed the case be remanded to the Court of Common Pleas of Allegheny County, Pennsylvania. On September 30, 2022, Indemnity filed a Motion to Stay the Remand Order pending an appeal to the United States Court of Appeals for the Third Circuit. On October 3, 2022, the Court granted the Stay. On October 11, 2022, Indemnity filed a Petition for Permission to Appeal the Remand Order with the Third Circuit. By Order dated November 7, 2022, a three judge panel of the Court denied the Petition to Appeal.
On November 21, 2022, Indemnity filed a Petition for Rehearing requesting that the Third Circuit permit the appeal. By Order dated January 9, 2023, the Court granted the petition for rehearing and vacated the prior Order of October 7, 2022, denying permission to appeal. On April 20, 2023, argument was held before a three-judge panel of the Third Circuit. By Opinion dated May 22, 2023, the Court affirmed the decision of the District Court finding that there was no basis for federal court jurisdiction and that the matter had been properly remanded to state court. On June 5, 2023, Indemnity filed a Petition for Panel Rehearing or Rehearing En Banc. By Order dated June 22, 2023, the Court denied the Petition. The United States District Court thereafter extended its stay of the issuance of the remand order through the conclusion of any proceedings in the United States Supreme Court challenging the decision of the United States Court of Appeals for the Third Circuit that no federal jurisdiction exists in this case.
On October 20, 2023, Indemnity filed a Petition for Writ of Certiorari with the Supreme Court of the United States. The Petition seeks a determination from the Court that the lower courts improperly denied federal jurisdiction. The Petition is currently pending before the Court.
Indemnity intends to vigorously defend against all of the allegations and requests for relief in the complaint.
Separately, Indemnity filed a Complaint in Federal Court to invoke certain provisions of the "All Writs Act" and the "Anti-Injunction Act." By filing this complaint, Indemnity seeks to protect the federal court’s prior binding, final judgments in favor of Indemnity and thereby foreclose further litigation of the claims and issues pertaining to the compensation practices that were the subject of the prior judgments.
For additional information on contingencies, see Part II, Item 8. "Financial Statements and Supplementary Data - Note 16, Commitment and Contingencies, of Notes to Financial Statements".
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
PART II
Item 5. MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Common Stock Market Prices and Dividends
Our Class A, non-voting common stock trades on The NASDAQ Stock MarketSM LLC under the symbol "ERIE". No established trading market exists for the Class B voting common stock. Broadridge Corporate Issuer Solutions, Inc. serves as our transfer agent and registrar. As of February 20, 2024, there were approximately 504 shareholders of record for the Class A non-voting common stock and 8 shareholders of record for the Class B voting common stock.
Historically, we have declared and paid cash dividends on a quarterly basis at the discretion of the Board of Directors. The payment and amount of future dividends on the common stock will be determined by the Board of Directors and will depend upon, among other things, our operating results, financial condition, cash requirements, and general business conditions at the time such payment is considered.
Stock Performance
The following graph depicts the cumulative total shareholder return, assuming reinvestment of dividends, for the periods indicated for our Class A common stock compared to the Standard & Poor's 500 Stock Index and the Standard & Poor's Supercomposite Insurance Industry Group Index. The Standard & Poor's Supercomposite Insurance Industry Group Index is made up of 56 constituent members represented by property and casualty insurers, insurance brokers, and life insurers, and is a capitalization weighted index.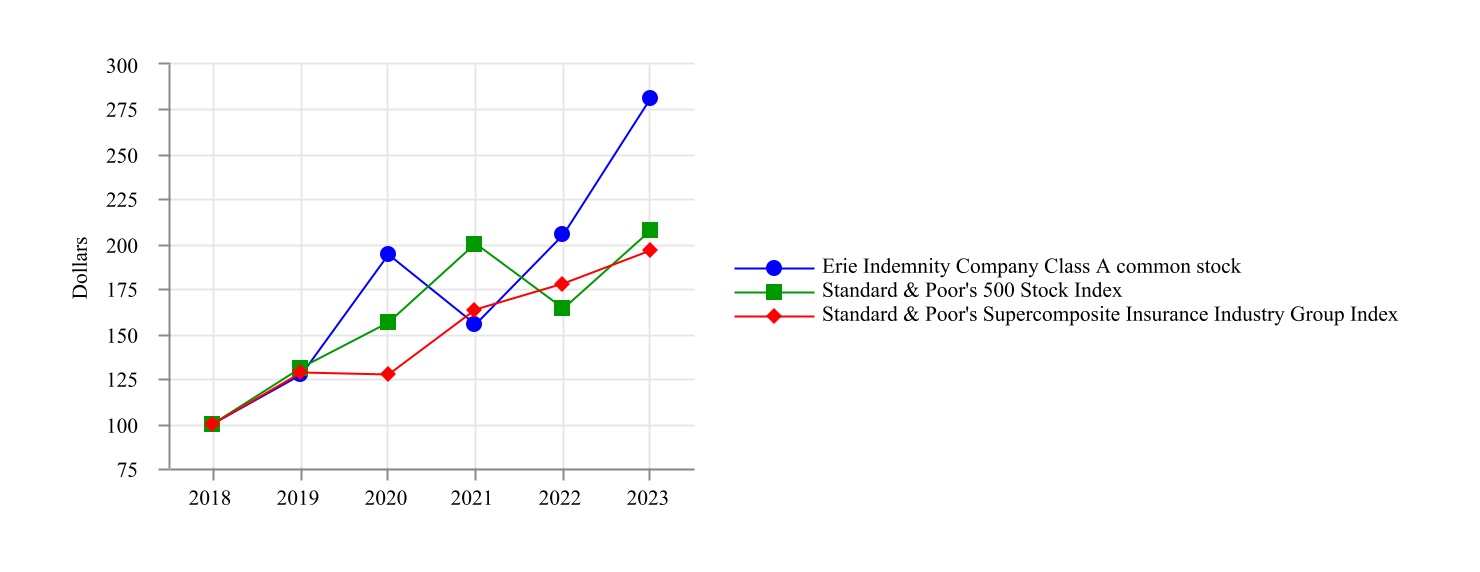
| 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | |||||||||||||||||||||||||||||||||
| Erie Indemnity Company Class A common stock | $ | 100 | (1) | $ | 127 | $ | 194 | $ | 155 | $ | 205 | $ | 281 | |||||||||||||||||||||||||
| Standard & Poor's 500 Stock Index | 100 | (1) | 131 | 156 | 200 | 164 | 207 | |||||||||||||||||||||||||||||||
| Standard & Poor's Supercomposite Insurance Industry Group Index | 100 | (1) | 128 | 127 | 163 | 178 | 196 |
(1) Assumes $100 invested at the close of trading, including reinvestment of dividends, on the last trading day preceding the first day of the fifth preceding fiscal year, in our Class A common stock, the Standard & Poor's 500 Stock Index, and the Standard & Poor's Supercomposite Insurance Industry Group Index.
Issuer Purchases of Equity Securities
We may purchase shares, from time-to-time, in the open market, through trading plans entered into with one or more brokerage firms pursuant to Rule 10b5-1 under the Securities Exchange Act of 1934, or through privately negotiated transactions. The purchase of shares is dependent upon prevailing market conditions and alternate uses of capital, and at times and in a manner that is deemed appropriate.
Our Board of Directors authorized a stock repurchase program effective January 1, 1999, allowing the repurchase of our outstanding Class A nonvoting common stock. Various approvals for continuation of this program have since been authorized, with the most recent occurring in 2011 for $150 million, which was authorized with no time limitation.
The following table presents the number and average price of our outstanding Class A nonvoting common stock shares purchased during the quarter ending December 31, 2023:
| (dollars in thousands, except per share data) | ||||||||||||||||||||||||||
| Period | Total number of shares purchased | Average price paid per share | Total number of shares purchased as part of publicly announced program | Dollar value of shares that may yet be purchased under the program | ||||||||||||||||||||||
| October 1–31, 2023 | — | $ | — | — | $ | 17,754 | ||||||||||||||||||||
| November 1–30, 2023 (1) | 1,258 | 277.03 | — | 17,754 | ||||||||||||||||||||||
| December 1–31, 2023 | — | — | — | 17,754 | ||||||||||||||||||||||
| Total | 1,258 | 277.03 | — | |||||||||||||||||||||||
*(1)*Represents shares purchased on the open market to fund the rabbi trust for the outside director deferred stock compensation plan.
See Item 8. "Financial Statements and Supplementary Data - Note 10, Incentive and Deferred Compensation Plans, of Notes to Financial Statements" contained within this report for additional information on shares purchased outside of this program.
Item 6. SELECTED FINANCIAL DATA
Not applicable.
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following discussion of financial condition and results of operations highlights significant factors influencing Erie Indemnity Company ("Indemnity", "we", "us", "our"). This discussion should be read in conjunction with the audited financial statements and related notes and all other items contained within this Annual Report on Form 10-K as these contain important information helpful in evaluating our financial condition and results of operations.
INDEX
CAUTIONARY STATEMENT REGARDING FORWARD-LOOKING INFORMATION
"Safe Harbor" Statement under the Private Securities Litigation Reform Act of 1995:
Statements contained herein that are not historical fact are forward-looking statements and, as such, are subject to risks and uncertainties that could cause actual events and results to differ, perhaps materially, from those discussed herein. Forward-looking statements relate to future trends, events or results and include, without limitation, statements and assumptions on which such statements are based that are related to our plans, strategies, objectives, expectations, intentions, and adequacy of resources. Examples of forward-looking statements are discussions relating to premium and investment income, expenses, operating results, and compliance with contractual and regulatory requirements. Forward-looking statements are not guarantees of future performance and involve risks and uncertainties that are difficult to predict. Therefore, actual outcomes and results may differ materially from what is expressed or forecasted in such forward-looking statements. Among the risks and uncertainties, in addition to those set forth in our filings with the Securities and Exchange Commission, that could cause actual results and future events to differ from those set forth or contemplated in the forward-looking statements include the following:
-
dependence upon our relationship with the Erie Insurance Exchange ("Exchange") and the management fee under the agreement with the subscribers at the Exchange;
-
dependence upon our relationship with the Exchange and the growth of the Exchange, including:
◦general business and economic conditions;
◦factors affecting insurance industry competition, including technological innovations;
◦dependence upon the independent agency system; and
◦ability to maintain our brand, including our reputation for customer service;
- dependence upon our relationship with the Exchange and the financial condition of the Exchange, including:
◦the Exchange's ability to maintain acceptable financial strength ratings;
◦factors affecting the quality and liquidity of the Exchange's investment portfolio;
◦changes in government regulation of the insurance industry;
◦litigation and regulatory actions;
◦emergence of significant unexpected events, including pandemics and economic or social inflation;
◦emerging claims and coverage issues in the industry; and
◦severe weather conditions or other catastrophic losses, including terrorism;
-
costs of providing policy issuance and renewal services to the subscribers at the Exchange under the subscriber's agreement;
-
ability to attract and retain talented management and employees;
-
ability to ensure system availability and effectively manage technology initiatives;
-
difficulties with technology or data security breaches, including cyber attacks;
-
ability to maintain uninterrupted business operations;
-
compliance with complex and evolving laws and regulations and outcome of pending and potential litigation;
-
factors affecting the quality and liquidity of our investment portfolio; and
-
ability to meet liquidity needs and access capital.
A forward-looking statement speaks only as of the date on which it is made and reflects our analysis only as of that date. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events, changes in assumptions, or otherwise.
RECENT ACCOUNTING STANDARDS
See Item 8. "Financial Statements and Supplementary Data - Note 2, Significant Accounting Policies, of Notes to Financial Statements" contained within this report for a discussion of recently issued accounting standards and the impact on our financial statements if known.
OPERATING OVERVIEW
Overview
We are a Pennsylvania business corporation that since 1925 has been the managing attorney-in-fact for the subscribers (policyholders) at the Exchange, a reciprocal insurer that writes property and casualty insurance. Our primary function as attorney-in-fact is to perform policy issuance and renewal services on behalf of the subscribers at the Exchange. We also act as attorney-in-fact on behalf of the subscribers at the Exchange, as well as the service provider for the Exchange's insurance subsidiaries, with respect to all administrative services.
The Exchange is a reciprocal insurance exchange, which is an unincorporated association of individuals, partnerships and corporations that agree to insure one another. Each applicant for insurance (a subscriber) to the Exchange signs a subscriber's agreement, which contains an appointment of Indemnity as their attorney-in-fact to transact the business of the Exchange on their behalf.
In accordance with the subscriber’s agreement for acting as attorney-in-fact in these two capacities, we retain a management fee. Management fee revenue is based upon all direct and affiliated assumed premiums written by the Exchange and the management fee rate, which is not to exceed 25%. Our Board of Directors establishes the management fee rate at least annually, generally in December for the following year. The process of setting the management fee rate includes, but is not limited to, the evaluation of current year operating results compared to both prior year and industry estimated results for both Indemnity and the Exchange, and consideration of several factors for both entities including, but not limited to: their relative financial strength and capital position; projected revenue, expense and earnings for the subsequent year; future capital needs; as well as competitive position. The management fee rate was set at 25% for 2023, 2022 and 2021. Based on analysis of the foregoing factors, our Board of Directors set the 2024 management fee rate again at 25%.
Our earnings are primarily driven by the management fee revenue generated for the services we provide on behalf o
Showing the first 8K of 94K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
Market Risk
Market risk is the risk of loss arising from adverse changes in interest rates, credit spreads, equity prices, or foreign exchange rates, as well as other relevant market rate or price changes. The volatility and liquidity in the markets in which the underlying assets are traded directly influence market risk. The following is a discussion of our primary risk exposures, including interest rate risk, investment credit risk, concentration risk, liquidity risk, and equity price risk, and how those exposures are currently managed as of December 31, 2023.
Interest Rate Risk
We invest primarily in fixed maturity investments, which comprised 85% of our invested assets at December 31, 2023. The value of the fixed maturity portfolio is subject to interest rate risk. As market interest rates decrease, the value of the portfolio increases with the opposite holding true in rising interest rate environments. We do not hedge our exposure to interest rate risk. A common measure of the interest sensitivity of fixed maturity assets is effective duration, a calculation that utilizes maturity, coupon rate, yield, and call terms to calculate an expected change in fair value given a change in interest rates. The longer the duration, the more sensitive the asset is to market interest rate fluctuations. Duration is analyzed at least quarterly to ensure that it remains in the targeted range.
A sensitivity analysis is used to measure the potential loss in future earnings, fair values, or cash flows of interest-sensitive instruments resulting from one or more selected hypothetical changes in interest rates and other market rates or prices over a selected period. The following pro forma information is presented assuming a 100-basis point parallel increase in interest rates across the yield curve at December 31 of each year and reflects the estimated effect on the fair value of our fixed maturity portfolio.
Fixed maturities interest-rate sensitivity analysis
| (dollars in thousands) | At December 31, | |||||||||||||
| 2023 | 2022 | |||||||||||||
| Fair value of fixed maturity portfolio | $ | 961,241 | $ | 894,661 | ||||||||||
| Fair value assuming 100-basis point rise in interest rates | $ | 935,444 | $ | 868,919 | ||||||||||
| Effective duration (as a percentage) | 2.7 | 2.9 | ||||||||||||
While the fixed maturity portfolio is sensitive to interest rates, the future principal cash flows that will be received by contractual maturity date are presented below at December 31, 2023 and 2022. Actual cash flows may differ from those stated as a result of calls, prepayments, or defaults.
Contractual repayments of principal by maturity date
| (in thousands) | ||||||||||||||
| Fixed maturities: | December 31, 2023 | |||||||||||||
| 2024 | $ | 81,072 | ||||||||||||
| 2025 | 96,519 | |||||||||||||
| 2026 | 79,385 | |||||||||||||
| 2027 | 116,418 | |||||||||||||
| 2028 | 137,065 | |||||||||||||
| Thereafter | 481,895 | |||||||||||||
| Total | $ | 992,354 | ||||||||||||
| Fair value | $ | 961,241 |
| (in thousands) | ||||||||||||||
| Fixed maturities: | December 31, 2022 | |||||||||||||
| 2023 | $ | 24,561 | ||||||||||||
| 2024 | 104,164 | |||||||||||||
| 2025 | 125,785 | |||||||||||||
| 2026 | 79,745 | |||||||||||||
| 2027 | 116,571 | |||||||||||||
| Thereafter | 500,905 | |||||||||||||
| Total | $ | 951,731 | ||||||||||||
| Fair value | $ | 894,661 |
Investment Credit Risk
Our objective is to earn competitive returns by investing in a diversified portfolio of securities. Our portfolios of fixed maturity securities, equity securities and, to a lesser extent, short-term investments are subject to credit risk. This risk is defined as the potential loss in fair value resulting from adverse changes in the borrower's ability to repay the debt. We manage this risk by performing upfront underwriting analysis and ongoing reviews of credit quality by position and for the portfolio in total. We do not hedge the credit risk inherent in our fixed maturity and equity securities investments.
Generally, the fixed maturities in our portfolio are rated by external rating agencies. If not externally rated, we rate them internally on a basis consistent with that used by the rating agencies. We classify all fixed maturities as available-for-sale securities, allowing us to meet our liquidity needs and provide greater flexibility to appropriately respond to changes in market conditions.
The following tables show our fixed maturity investments by rating*(1)*:
| At December 31, 2023 | ||||||||||||||||||||
| (dollars in thousands) | Amortized cost | Fair value | Percent of total | |||||||||||||||||
| AAA, AA, A | $ | 537,751 | $ | 515,175 | 54 | % | ||||||||||||||
| BBB | 324,538 | 318,362 | 33 | |||||||||||||||||
| Total investment grade | 862,289 | 833,537 | 87 | |||||||||||||||||
| BB | 51,564 | 50,170 | 5 | |||||||||||||||||
| B | 65,453 | 65,251 | 7 | |||||||||||||||||
| CCC, CC, C, and below | 13,247 | 12,283 | 1 | |||||||||||||||||
| Total non-investment grade | 130,264 | 127,704 | 13 | |||||||||||||||||
| Total | $ | 992,553 | $ | 961,241 | 100 | % | ||||||||||||||
| At December 31, 2022 | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | Amortized cost | Fair value | Percent of total | ||||||||||||||||||||||||||||||||
| AAA, AA, A | $ | 518,088 | $ | 479,413 | 54 | % | |||||||||||||||||||||||||||||
| BBB | 318,801 | 300,900 | 33 | ||||||||||||||||||||||||||||||||
| Total investment grade | 836,889 | 780,313 | 87 | ||||||||||||||||||||||||||||||||
| BB | 45,784 | 41,978 | 5 | ||||||||||||||||||||||||||||||||
| B | 66,574 | 62,530 | 7 | ||||||||||||||||||||||||||||||||
| CCC, CC, C, and below | 11,888 | 9,840 | 1 | ||||||||||||||||||||||||||||||||
| Total non-investment grade | 124,246 | 114,348 | 13 | ||||||||||||||||||||||||||||||||
| Total | $ | 961,135 | $ | 894,661 | 100 | % |
(1) Ratings are supplied by S&P, Moody's, and Fitch. The table is based upon the lowest rating for each security.
We are also exposed to a concentration of credit risk with the Exchange. See the "Transactions/Agreements with Related Parties, Intercompany Receivables" section of Item 7. "Management's Discussion and Analysis of Financial Condition and Results of Operations" contained within this report for further discussion of this risk.
Concentration Risk
While our portfolio is well diversified within each market sector, there is an inherent risk of concentration in a particular industry or sector. We continually monitor our level of exposure to individual issuers as well as our allocation to each industry and market sector against internally established policies. See the "Financial Condition" section of Item 7. "Management's Discussion and Analysis of Financial Condition and Results of Operations" contained within this report for details of investment holdings by sector.
Liquidity Risk
Periods of volatility in the financial markets can create conditions where fixed maturity investments, despite being publicly traded, can become illiquid. However, we actively manage the maturity profile of our fixed maturity portfolio such that scheduled repayments of principal occur on a regular basis.
Equity Price Risk
Our portfolio of equity securities, which primarily includes nonredeemable preferred stock, is carried on the Statements of Financial Position at estimated fair value. Equity securities are exposed to the risk of potential loss in estimated fair value resulting from an adverse change in prices ("price risk"). We do not hedge our exposure to price risk inherent in our equity investments.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
INDEX TO FINANCIAL STATEMENTS
Report of Independent Registered Public Accounting Firm
To the Shareholders and the Board of Directors of Erie Indemnity Company
Opinion on the Financial Statements
We have audited the accompanying statements of financial position of Erie Indemnity Company (the Company) as of December 31, 2023 and 2022, the related statements of operations, comprehensive income, shareholders’ equity and cash flows for each of the three years in the period ended December 31, 2023, and the related notes (collectively referred to as the “financial statements”). In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company at December 31, 2023 and 2022, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2023, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of December 31, 2023, based on criteria established in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework), and our report dated February 26, 2024 expressed an unqualified opinion thereon.
Basis for Opinion
These financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
Critical Audit Matter
The critical audit matter communicated below is a matter arising from the current period audit of the financial statements that was communicated or required to be communicated to the audit committee and that: (1) relates to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, subjective or complex judgments. The communication of the critical audit matter does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
| Proportional Cost Allocation | ||||||||
| Description of the Matter | For the year ended December 31, 2023, the Company’s administrative services reimbursement revenue totaled $737.1 million. The Company’s primary function, as attorney-in-fact, is to perform certain services on behalf of the subscribers at the Erie Insurance Exchange (Exchange) and its insurance subsidiaries, in accordance with the subscriber’s agreement and the service agreements with each of the Exchange’s insurance subsidiaries. As explained in Note 2 of the financial statements, in accordance with the approved subscriber’s agreement and service agreements, administrative services, which include costs associated with claims handling services, life insurance related operating activities, investment management, and operating overhead incurred by the Company on behalf of the Exchange and its insurance subsidiaries, are reimbursed to the Company at cost and recorded as administrative services reimbursement revenue, based on the nature of the cost or relevant utilization statistic. Auditing management’s proportional cost allocations was complex due to the multiple costs that are allocated, the extensiveness of the allocation process, and the degree of auditor judgement needed to design the nature and extent of audit procedures required to address the matter. | |||||||
| How We Addressed the Matter in Our Audit | We obtained an understanding, evaluated the design and tested the operating effectiveness of controls over the Company’s proportional cost allocations process. This included, among others, testing management’s review controls over the determination of the utilization statistics and ultimate allocation of costs to the Exchange and its insurance subsidiaries. To test the Company’s proportional cost allocations, our procedures included, among others, evaluating that the costs included in the allocations are in accordance with the subscriber’s agreement and the service agreements with each of the Exchange’s insurance subsidiaries |
Showing the first 8K of 176K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
Evaluation of Disclosure Controls and Procedures
We maintain disclosure controls and procedures designed to ensure that information required to be disclosed in our reports filed under the Securities Exchange Act of 1934, as amended, is recorded, processed, summarized and reported within the time periods specified in the Securities and Exchange Commission rules and forms, and that such information is accumulated and communicated to management, including our Chief Executive Officer and Chief Financial Officer, as appropriate, to allow for timely decisions regarding required disclosures.
As required by the Securities and Exchange Commission Rule 13a-15(e), we carried out an evaluation, under the supervision and with the participation of management, including our Chief Executive Officer and Chief Financial Officer, of the effectiveness of the design and operation of our disclosure controls and procedures as of December 31, 2023. Based upon the foregoing, our Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures were effective.
Changes in Internal Control over Financial Reporting
There has been no change in our internal controls over financial reporting during our most recent fiscal quarter that has materially affected, or is reasonably likely to materially affect our internal controls over financial reporting. Our process for evaluating controls and procedures is continuous and encompasses constant improvement of the design and effectiveness of established controls and procedures.
Management's Report on Internal Control over Financial Reporting
Management is responsible for establishing and maintaining adequate internal control over financial reporting of Erie Indemnity Company, as defined in Rules 13a-15(f) under the Exchange Act. Under the supervision and with the participation of our management, including our Chief Executive Officer and Chief Financial Officer, we conducted an evaluation of the effectiveness of the Erie Indemnity Company's internal control over financial reporting based upon the framework in the Internal Control-Integrated Framework issued in 2013 by the Committee of Sponsoring Organizations of the Treadway Commission. Based upon our evaluation under the framework in the Internal Control-Integrated Framework issued in 2013, management has concluded that Erie Indemnity Company's internal control over financial reporting was effective as of December 31, 2023.
| /s/ Timothy G. NeCastro | /s/ Julie M. Pelkowski | /s/ Jorie L. Novacek | |||||||||||||||
| Timothy G. NeCastro | Julie M. Pelkowski | Jorie L. Novacek | |||||||||||||||
| President and | Executive Vice President | Senior Vice President | |||||||||||||||
| Chief Executive Officer | and Chief Financial Officer | and Controller | |||||||||||||||
| February 26, 2024 | February 26, 2024 | February 26, 2024 |
Our independent auditor, Ernst & Young LLP, a registered public accounting firm, has issued an attestation report on our internal control over financial reporting. This report appears on the following page.
Item 9B. OTHER INFORMATION
There was no additional information in the fourth quarter of 2023 that has not already been filed in a Form 8-K.
Report of Independent Registered Public Accounting Firm
To the Shareholders and the Board of Directors of Erie Indemnity Company
Opinion on Internal Control Over Financial Reporting
We have audited Erie Indemnity Company’s internal control over financial reporting as of December 31, 2023, based on criteria established in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria). In our opinion, Erie Indemnity Company (the Company) maintained, in all material respects, effective internal control over financial reporting as of December 31, 2023, based on the COSO criteria**.**
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the statements of financial position of the Company as of December 31, 2023 and 2022, the related statements of operations, comprehensive income, shareholders’ equity and cash flows for each of the three years in the period ended December 31, 2023, and the related notes and our report dated February 26, 2024 expressed an unqualified opinion thereon.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects.
Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control Over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ Ernst & Young LLP
Indianapolis, Indiana
February 26, 2024
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
The information with respect to our outside directors, audit committee and audit committee financial experts, Section 16(a) beneficial ownership reporting compliance, and insider trading policy is incorporated herein by reference to the information statement on Schedule 14C to be filed with the Securities and Exchange Commission no later than 120 days after December 31, 2023.
We have adopted a Code of Conduct that applies to all of our outside directors, officers and employees. We have previously filed a copy of the Code of Conduct as Exhibit 14.1 to the Registrant's Form 8-K filed with the Securities and Exchange Commission on October 26, 2023. In addition to this, we have adopted a Code of Ethics for Senior Financial Officers that also applies to our Chief Executive Officer, Chief Financial Officer, Chief Accounting Officer and any other person performing similar functions. We have previously filed a copy of the Code of Ethics for Senior Financial Officers as Exhibit 14.4 to the Registrant's Form 8-K filed with the Securities and Exchange Commission on June 1, 2016. Our Code of Conduct and Code of Ethics for Senior Financial Officers are also available on our website at www.erieinsurance.com.
Executive Officers of the Registrant
| Name | Age as of 12/31/2023 | Principal Occupation and Positions for Past Five Years | ||||||||||||
| President & Chief Executive Officer: | ||||||||||||||
| Timothy G. NeCastro | 63 | President and Chief Executive Officer of the Company since August 2016; Director, Erie Family Life Insurance Company ("EFL"), Erie Insurance Company ("EIC"), Flagship City Insurance Company ("Flagship"), Erie Insurance Company of New York ("ENY") and Erie Insurance Property & Casualty Company ("EPC"). | ||||||||||||
| Executive Vice Presidents: | ||||||||||||||
| Brian W. Bolash | 58 | Executive Vice President, Secretary and General Counsel since January 2022; Senior Vice President, Secretary and General Counsel, October 2018 through December 2021; Senior Counsel and Corporate Secretary, January 2016 through September 2018; Director, EFL, EIC, Flagship, ENY and EPC. | ||||||||||||
| Sean D. Dugan | 55 | Executive Vice President, Human Resources and Corporate Services since January 2023; Senior Vice President, Human Resources, March 2020 through December 2022; Corporate Human Resources Officer, October 2018 through March 2020; Director, EFL, EIC, Flagship, ENY and EPC. | ||||||||||||
| Lorianne Feltz | 54 | Executive Vice President, Claims & Customer Service since November 2016. | ||||||||||||
| Julie M. Pelkowski | 54 | Executive Vice President and Chief Financial Officer since May 2023; Senior Vice President, Enterprise Office, March 2022 through April 2023; Senior Vice President and Controller, August 2016 through February 2022; Director, EFL, EIC, Flagship, ENY and EPC. | ||||||||||||
| Douglas E. Smith | 49 | Executive Vice President, Sales & Products since November 2016. | ||||||||||||
| Parthasarathy Srinivasa | 52 | Executive Vice President and Chief Information Officer since joining the Company in April 2022. Prior to joining the Company: Senior Vice President and Chief Data and Insurance Information Officer Verisk Analytics, 2019 through April 2022; Chief Information and Operations Officer Safe Auto Insurance (now Allstate Corporation), 2016 through 2019. |
Item 11. EXECUTIVE COMPENSATION
The information required by this item with respect to executive compensation is incorporated by reference to the information statement on Schedule 14C to be filed with the Securities and Exchange Commission no later than 120 days after December 31, 2023.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
The information with respect to security ownership of certain beneficial owners and management and securities authorized for issuance under equity compensation plans, is incorporated by reference to the information statement on Schedule 14C to be filed with the Securities and Exchange Commission no later than 120 days after December 31, 2023.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
Information with respect to certain relationships with our outside directors is incorporated by reference to the information statement on Schedule 14C to be filed with the Securities and Exchange Commission no later than 120 days after December 31, 2023.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
The information required by this item is incorporated by reference to the information statement on Schedule 14C to be filed with the Securities and Exchange Commission no later than 120 days after December 31, 2023.
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
(a) The following documents are filed as part of this report:
- Financial Statements
Included in Part II, Item 8. "Financial Statements and Supplementary Data" contained in this report.
Erie Indemnity Company*:*
-
Report of Independent Registered Public Accounting Firm on the Effectiveness of Internal Control over Financial Reporting
-
Report of Independent Registered Public Accounting Firm on the Financial Statements
-
Statements of Operations for the three years ended December 31, 2023, 2022 and 2021
-
Statements of Comprehensive Income for the three years ended December 31, 2023, 2022 and 2021
-
Statements of Financial Position as of December 31, 2023 and 2022
-
Statements of Shareholders' Equity for the three years ended December 31, 2023, 2022 and 2021
-
Statements of Cash Flows for the three years ended December 31, 2023, 2022 and 2021
-
Notes to Financial Statements
- Financial Statement Schedules
All schedules are not required, not applicable, or the information is included in the financial statements or notes thereto.
| Page | |||||
| 3. Exhibit Index | 78 |
Item 16. FORM 10-K SUMMARY
None.
EXHIBIT INDEX
(Pursuant to Item 601 of Regulation S-K)
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| February 26, 2024 | ERIE INDEMNITY COMPANY | |||||||
| (Registrant) | ||||||||
| By: | /s/ Timothy G. NeCastro | |||||||
| Timothy G. NeCastro, President and CEO | ||||||||
| (Principal Executive Officer) |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the date indicated.
| February 26, 2024 | /s/ Timothy G. NeCastro | |||||||||||||
| Timothy G. NeCastro, President and CEO | ||||||||||||||
| (Principal Executive Officer) | ||||||||||||||
| /s/ Julie M. Pelkowski | ||||||||||||||
| Julie M. Pelkowski, Executive Vice President and CFO | ||||||||||||||
| (Principal Financial Officer) | ||||||||||||||
| /s/ Jorie L. Novacek | ||||||||||||||
| Jorie L. Novacek, Senior Vice President and Controller | ||||||||||||||
| (Principal Accounting Officer) |
Board of Directors:
| /s/ J. Ralph Borneman, Jr. | /s/ C. Scott Hartz | |||||||
| J. Ralph Borneman, Jr. | C. Scott Hartz | |||||||
| /s/ Eugene C. Connell | /s/ Brian A. Hudson, Sr. | |||||||
| Eugene C. Connell | Brian A. Hudson, Sr. | |||||||
| /s/ Salvatore Correnti | /s/ George R. Lucore | |||||||
| Salvatore Correnti | George R. Lucore | |||||||
| /s/ LuAnn Datesh | /s/ Thomas W. Palmer | |||||||
| LuAnn Datesh | Thomas W. Palmer | |||||||
| /s/ Jonathan Hirt Hagen | ||||||||
| Jonathan Hirt Hagen | Elizabeth Hirt Vorsheck | |||||||
| /s/ Thomas B. Hagen | ||||||||
| Thomas B. Hagen, Chairman | ||||||||