 filings.tools
Essex Property Trust (ESS) 10-K risk factor changes: FY2013 vs FY2012
The 2013-12-31 10-K against the 2012-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A89 rewritten110 added16 removed263 unchanged
All filing items1,291 rewritten1,221 added667 removed1,385 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 1,221 added, 667 removed, 1,291 rewritten and 1,385 unchanged across 16 items that differ.
Sentences by item
21 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2013; struck-through words were in FY2012. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
89 rewritten, 110 added, 16 removed, 263 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
[removed: The Company’s] [added: Our] business, operating results, cash flows and financial condition are subject to various risks and uncertainties, including, without limitation, those set forth below, any one of which could cause the [removed: Company’s] [added: our] actual results to vary materially from recent results or from [removed: the Company’s] [added: our] anticipated future results.
The Company’s strong balance sheet, the debt capacity available on the unsecured line of credit with a bank group and access to the [added: public debt and] private placement [removed: market] [added: markets] and Fannie Mae and Freddie Mac secured debt financing provides some insulation from volatile markets.
At December 31, [removed: 2012,] [added: 2013,] the Company had approximately [removed: $2.82] [added: $3.0] billion of indebtedness (including [removed: $692.9] [added: $737.0] million of variable rate indebtedness, of which $300.0 million is subject to interest rate swaps effectively fixing the interest rate and [removed: $187.8] [added: $156.9] million is subject to interest rate protection agreements).
| | [removed: ·] [added: —] | cash flow may not be sufficient to meet required payments of principal and interest; |
| | [removed: ·] [added: —] | inability to refinance maturing indebtedness on encumbered apartment communities; |
| | [removed: ·] [added: —] | inability to comply with debt covenants could cause an acceleration of the maturity date; and |
| | [removed: ·] [added: —] | repaying debt before the scheduled maturity date could result in prepayment penalties. |
[removed: The] [added: This indebtedness includes secured mortgages, and the] communities subject to these mortgages could be foreclosed upon or otherwise transferred to the lender.
To a certain extent, our cash flow is subject to general economic, industry, regional, financial, competitive, operating, legislative, [removed: regulatory] [added: regulatory, taxation,] and other factors, many of which are beyond our control.
As of December 31, [removed: 2012,] [added: 2013,] the Company had [removed: 55] [added: 49] of its 139 consolidated communities encumbered by debt.
With respect to the [removed: 55] [added: 49] communities encumbered by debt, all of them are secured by deeds of trust relating solely to those communities.
The holders of this indebtedness will have rights with respect to these communities and lenders may seek foreclosure of communities which would reduce the Company’s income and net asset [removed: value.][added: value, and its ability to service other debt.]
In order to minimize counterparty credit risk, the [removed: Company’s policy is to enter] [added: Company enters] into hedging arrangements only with financial institutions that have a current rating of A or higher.
At December 31, [removed: 2012,] [added: 2013,] the Company had approximately [removed: $201.9] [added: $167.6] million of variable rate tax-exempt financing.
The Internal Revenue Code and rules and regulations thereunder impose various restrictions, conditions and requirements in order to allow the [removed: noteholder] [added: note holder] to exclude interest on qualified bond obligations from gross income for federal income tax purposes.
| | [removed: ·] [added: —] | the general economic climate; |
| | [removed: ·] [added: —] | local economic conditions in which the communities are located, such as oversupply of housing or a reduction in demand for rental housing; |
| | [removed: ·] [added: —] | the attractiveness of the communities to tenants; |
| | [removed: ·] [added: —] | competition from other available housing; and |
| | [removed: ·] [added: —] | the Company’s ability to provide for adequate maintenance and insurance. |
The [removed: Company's] [added: Company’s] forecast for the national economy assumes [removed: the return] [added: growth] of [removed: growth, with estimated] [added: the] gross domestic product [removed: growth] of the national economy and the economies of the western states.
| | [removed: ·] [added: —] | funds may be expended and [removed: management's] [added: management’s] time devoted to projects that may not be completed; |
| | [removed: ·] [added: —] | construction costs of a project may exceed original estimates possibly making the project economically unfeasible; |
| | [removed: ·] [added: —] | projects may be delayed due to, without limitation, adverse weather conditions, labor or material shortage; |
| | [removed: ·] [added: —] | occupancy rates and rents at a completed project may be less than anticipated; and |
| | [removed: ·] [added: —] | expenses at completed development projects may be higher than anticipated. |
The Company generated significant amounts of rental revenues for the year ended December 31, [removed: 2012,] [added: 2013,] from the Company’s communities concentrated in Southern California (Los Angeles, Orange, Santa Barbara, San Diego, and Ventura counties), Northern California (the San Francisco Bay Area), and the Seattle metropolitan area.
For the year ended December 31, [removed: 2012,] [added: 2013,] 82% of the Company’s rental revenues were generated from communities located in California.
This could have a negative impact on the Company’s financial condition and operating results, which could affect the Company’s ability to pay expected dividends to its [removed: stockholders.][added: stockholders and the Operating Partnership’s ability to pay expected distributions to unit holders.]
| | [removed: ·] [added: —] | regional, national and global economic conditions; |
| | [removed: ·] [added: —] | actual or anticipated variations in the Company’s quarterly operating results or dividends; |
| | [removed: ·] [added: —] | changes in the Company’s funds from operations or earnings estimates; |
| | [removed: ·] [added: —] | issuances of common stock, preferred stock or convertible debt securities; |
| | [removed: ·] [added: —] | publication of research reports about the Company or the real estate industry; |
| | [removed: ·] [added: —] | the general reputation of real estate investment trusts and the attractiveness of their equity securities in comparison to other equity securities (including securities issued by other real estate based companies); |
| | [removed: ·] [added: —] | general stock and bond market conditions, including changes in interest rates on fixed income securities, that may lead prospective purchasers of the Company’s stock to demand a higher annual yield from dividends; |
| | [removed: ·] [added: —] | availability to capital markets and cost of capital; |
| | [removed: ·] [added: —] | a change in analyst ratings or the Company’s credit ratings; |
| | [removed: ·] [added: —] | terrorist activity may adversely affect the markets in which the Company’s securities trade, possibly increasing market volatility and causing erosion of business and consumer confidence and spending; and |
| | [removed: ·] [added: —] | Natural disasters such as earthquakes. |
For purposes of this section, the term “stockholders” means the holders of shares of Essex Property Trust, Inc.’s common stock and preferred stock.
Set forth below are the risks that we believe are material to Essex Property Trust, Inc.’s stockholders and Essex Portfolio, L.P.’s unit holders.
You should carefully consider the following factors in evaluating our company, our properties and our business.
Risk Factors Relating to the Proposed Merger with BRE
The exchange ratio and the cash consideration will not be adjusted in the event of any change in the stock prices of either Essex or BRE.
Upon the consummation of the merger, each outstanding share of BRE common stock will be converted automatically into the right to receive 0.2971 shares of Essex common stock, with cash paid in lieu of any fractional shares, plus $12.33 in cash, without interest, each subject to certain adjustments provided for in the merger agreement.
The exchange ratio of 0.2971 and cash consideration will not be adjusted for changes in the market prices of either shares of Essex common stock or shares of BRE common stock.
Changes in the market price of shares of Essex common stock prior to the merger will affect the market value of the merger consideration that will be paid to BRE shareholders upon completion of the merger.
Stock price changes may result from a variety of factors (many of which are beyond the control of Essex and BRE), including the following factors:
| | — | market reaction to the announcement of the merger; |
| | — | changes in the respective businesses, operations, assets, liabilities and prospects of Essex and BRE; |
| | — | changes in market assessments of the business, operations, financial position and prospects of either company or the Combined Company; |
| | — | market assessments of the likelihood that the merger will be completed; |
| | — | interest rates, general market and economic conditions and other factors generally affecting the market prices of Essex common stock and BRE common stock; |
| | — | federal, state and local legislation, governmental regulation and legal developments in the businesses in which Essex and BRE operate; and |
| | — | other factors beyond the control of Essex and BRE. |
The market price of shares of Essex common stock at the closing of the merger may vary from its price on the date the merger agreement was executed and thereafter.
As a result, the market value of the merger consideration represented by the exchange ratio will also vary.
Therefore, while the number of shares of Essex common stock to be issued per share of BRE common stock is fixed, Essex stockholders cannot be sure of the market value of the merger consideration that will be paid to BRE stockholders upon completion of the merger.
Essex stockholders and unitholders of the Operating Partnership will be diluted by the merger.
The merger will dilute the ownership position of Essex stockholders and unitholders of the Operating Partnership.
Upon completion of the merger, we estimate that continuing Essex stockholders will own approximately 62% of the issued and outstanding shares of Combined Company common stock, and former BRE stockholders will own approximately 38% of the issued and outstanding common stock of the Combined Company.
Consequently, Essex stockholders and unitholders of the Operating Partnership, as a general matter, will have less influence over the management and policies of the Combined Company after the effective time of the merger than they currently exercise over the management and policies of Essex.
Failure to complete the merger could negatively impact the stock prices and the future business and financial results of Essex.
If the merger is not completed, the ongoing business of Essex could be adversely affected and Essex will be subject to a variety of risks associated with the failure to complete the merger, including the following:
| | — | Essex being required, under certain circumstances, to pay to BRE up to $10 million in expense reimbursement; |
| | — | Essex having to pay certain costs relating to the proposed merger, such as legal, accounting, financial advisor, filing, printing and mailing fees; and |
| | — | diversion of Essex management focus and resources from operational matters and other strategic opportunities while working to implement the merger. |
If the merger is not completed, these risks could materially affect the business, financial results and stock prices of Essex.
The pendency of the merger could adversely affect the business and operations of Essex.
Prior to the effective time of the merger, some tenants or vendors of Essex may delay or defer decisions, which could negatively affect the revenues, earnings, cash flows and expenses of Essex, regardless of whether the merger is completed.
Similarly, current and prospective employees of Essex may experience uncertainty about their future roles with the Combined Company following the merger, which may materially adversely affect the ability of Essex to attract and retain key personnel during the pendency of the merger.
In addition, due to operating restrictions in the merger agreement, Essex may be unable, during the pendency of the merger, to pursue strategic transactions, undertake significant capital projects, undertake certain significant financing transactions and otherwise pursue other actions, even if such actions would prove beneficial.
There can be no assurance that Essex will be able to secure the financing necessary to pay the cash portion of the merger consideration on acceptable terms, in a timely manner, or at all.
In connection with the merger, Essex has obtained commitments for up to $1.0 billion in a senior unsecured bridge loan facility to finance the cash portion of the merger consideration.
In addition, Essex is exploring additional alternatives to fund the cash portion of the merger consideration including through existing unsecured credit facilities, asset sales, joint ventures or other financing arrangements.
However, Essex has not entered into a definitive agreement for the debt financing, nor has it secured alternative financing, nor has it entered into a definitive agreement for the potential asset sales (the “Asset Sale”) in connection with the merger.
There can be no assurance that Essex will be able to secure financing to pay the cash portion of the merger consideration on acceptable terms, in a timely manner, or at all.
If Essex is unable to secure such financing, Essex will nonetheless be required to close the merger under the terms of the merger agreement.
In addition, the bridge loan facility expires on April 18, 2014 (with a right to extend up to an additional 30 days in certain circumstances) whereas the merger agreement may not be terminable until June 17, 2014.
In August 2012, the Company, through the Operating Partnership, issued $300 million of senior notes.
The Operating Partnership has also agreed to conduct an offer to exchange these senior notes for a new series of publicly registered notes (the “exchange notes”) with substantially identical terms.
He is the Chairman of the Marcus & Millichap Company (“TMMC”), which is a holding company for certain real estate brokerage and services companies.
TMMC has an interest in Pacific Urban Residential and Summerhill Homes, companies that invest in apartment communities.
| | · | the Company’s directors have terms of office of three years and the board of directors is divided into three classes with staggered terms; as a result, less than a majority of directors are up for re-election to the board in any one year; |
There are risks that Fund II may operate in ways that may adversely impact the Company’s interests.
The Company is the general partner of Essex Apartment Value Fund II, L.P. (“Fund II”), and with Fund II there are the following risks:
| | · | the Company’s partners in Fund II might remove the Company as the general partner of Fund II; |
| | · | the Company’s partners in Fund II might have economic or business interests or goals that are inconsistent with the Company’s business interests or goals; or |
Changes in real estate tax and other laws may adversely affect the Company’s results of operations.
Generally, the Company does not directly pass through costs resulting from changes in real estate tax laws to residential property tenants.
The Company also does not generally pass through increases in income, service or other taxes, to tenants under leases.
These costs may adversely affect funds from operations and the ability to make distributions to stockholders.
Similarly, compliance with changes in (i) laws increasing the potential liability for environmental conditions existing on apartment communities or the restrictions on discharges or other conditions or (ii) rent control or rent stabilization laws or other laws regulating housing may result in significant unanticipated decrease in revenue or increase in expenditures, which would adversely affect funds from operations and the ability to make distributions to stockholders.
The U.S. federal tax rate on certain corporate dividends paid to certain individuals and other non-corporate taxpayers is at a reduced rate of 15%; a rate of 20% applies to certain high-income individual taxpayers.
Dividends paid by REITs to individuals and other non-corporate stockholders are not eligible for the reduced 15% dividend rates.
An excerpt. Shown here: 40 of 89 rewritten, 40 of 110 added and all 16 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2013 filing and the FY2012 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
111 rewritten, 108 added, 161 removed, 145 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
[removed: The Company] [added: ESS] is a self-administered and self-managed REIT that acquires, develops, redevelops and manages apartment communities in selected residential areas located primarily in the West Coast of the United States.
[removed: The Company] [added: ESS] owns all of its interests in its real estate investments, directly or indirectly, through the Operating Partnership.
[removed: The Company] [added: ESS] is the sole general partner of the Operating Partnership and, as of December 31, [removed: 2012,] [added: 2013,] had an approximately [removed: 94.5%] [added: 94.6%] general partner interest in the Operating Partnership.
As of December 31, [removed: 2012,] [added: 2013,] the Company had ownership interests in [removed: 163] [added: 164] communities, comprising [removed: 33,468] [added: 34,079] apartment units, and the apartment communities are located in the following major West Coast regions:
As of December 31, [removed: 2012,] [added: 2013,] the Company also had ownership interests in [removed: five] [added: four] commercial buildings (with approximately 315,900 square feet).
As of December 31, [removed: 2012,] [added: 2013,] the Company’s development pipeline was comprised of two consolidated projects under development, [removed: seven] [added: nine] unconsolidated joint venture projects under [removed: development, two consolidated predevelopment project, one unconsolidated joint venture predevelopment project] [added: development] and one consolidated [removed: land parcel held for future development or sale] [added: predevelopment project] aggregating [removed: 2,994] [added: 2,701] units, with total incurred costs of [removed: $531.6] [added: $696.7] million, and estimated remaining project costs of approximately [removed: $463.9] [added: $407.0] million for total estimated project costs of [removed: $995.5 million.][added: $1.1 billion.]
By region, the Company's operating results for [removed: 2012] [added: 2013] and [removed: 2011] [added: 2012] and projections for [removed: 2013] [added: 2014] new housing supply, job growth, and rental income are as follows:
Southern California Region: As of December 31, [removed: 2012,] [added: 2013,] this region represented [removed: 47%] [added: 46%] of the Company’s consolidated apartment units.
During the year ended December 31, [removed: 2012,] [added: 2013,] revenues for [removed: “2012/2011] [added: “2013/2012] Same-Properties” (as defined below), or “Same-Property revenues,” increased [removed: 4.2%] [added: 4.4%] in [removed: 2012] [added: 2013] as compared to [removed: 2011.][added: 2012.]
In [removed: 2013,] [added: 2014,] the Company expects new residential supply of [removed: 11,500] [added: 15,400] multifamily and [removed: 7,135] [added: 10,500] single family homes, which represents a total new multifamily supply of [removed: 0.5%] [added: 0.7%] and [removed: 0.3%] [added: 0.5%] of total housing stock, respectively.
Northern California Region: As of December 31, [removed: 2012,] [added: 2013,] this region represented [removed: 31%] [added: 32%] of the Company’s consolidated apartment units.
[added: 2012/2011] Same-Property [removed: revenues] [added: Revenues] increased [removed: 9.6%] [added: by $29.5 million or 6.7% to $467.9 million] in 2012 [removed: as] compared to [added: $438.4 million in] 2011.
In [removed: 2013,] [added: 2014,] the Company expects new residential supply of [removed: 9,900] [added: 8,500] multifamily and [removed: 4,479] [added: 6,500] single family homes, which represents a total new multifamily supply of [removed: 1.1%] [added: 1.9%] and [removed: 0.6%,] [added: 1.3%,] respectively, of total housing stock.
Seattle Metro Region: As of December 31, [removed: 2012,] [added: 2013,] this region represented 22% of the Company’s consolidated apartment units.
[removed: Same-Property revenues] [added: 2012/2011 Non-Same Property Revenues] increased [removed: 8.4%] [added: $36.5 million or 164% to $58.8 million] in 2012 [removed: as] compared to [added: $22.3 million in] 2011.
In [removed: 2013,] [added: 2014,] the Company expects new residential supply of [removed: 6,900] [added: 10,800] multifamily and [removed: 5,888] [added: 5,225] single family homes, which represents a total new multifamily supply of [removed: 1.7%] [added: 1.3%] and [removed: 1.1%,] [added: 0.7%,] respectively, of total housing stock.
The Company expects [removed: 2013] [added: 2014] Same-Property revenues to increase [removed: between 5.0% and 6.5%] compared to [removed: 2012] [added: 2013] results, as renewal and new leases are signed at higher rents in [removed: 2013] [added: 2014] than [removed: 2012.][added: 2013.]
Same-Property operating expenses are expected to increase [removed: from 2.0%] in [removed: 2012, to a range of 3.0% to 4.0% in 2013,] [added: 2014,] and forecasted increases in property taxes account for approximately [removed: 45%] [added: 56%] of the forecasted increase in property expenses in [removed: 2013] [added: 2014] compared to [removed: 2012.][added: 2013.]
| | | As of December 31, [removed: 2012] [added: 2013] | | | | | | | | As of December 31, [removed: 2011] [added: 2012] | | | | | | |
| Southern California | | | [removed: 13,656] [added: 13,855] | | | | [removed: 47] [added: 46] | % | | | [removed: 13,205] [added: 13,656] | | | | [removed: 48] [added: 47] | % |
| Northern California | | | [removed: 8,987] [added: 9,431] | | | | [removed: 31] [added: 32] | % | | | [removed: 8,106] [added: 8,987] | | | | [removed: 30] [added: 31] | % |
| Seattle Metro | | | [removed: 6,598] [added: 6,703] | | | | 22 | % | | | [removed: 6,108] [added: 6,598] | | | | 22 | % |
| Total | | | [removed: 29,241] [added: 29,989] | | | | 100 | % | | | [removed: 27,419] [added: 29,241] | | | | 100 | % |
The Company’s average financial occupancies for the Company’s stabilized apartment communities [removed: or] [added: for] “2012/2011 Same-Properties” (stabilized properties consolidated by the Company for the years ended December 31, 2012 and 2011) remained consistent at 96.3% for 2012 and 2011.
Market rates are determined using [removed: a variety of factors such as] [added: the recently signed] effective [removed: rental] rates [added: on new leases] at the property [removed: based on recently signed leases] and [removed: asking rates for comparable properties] [added: are used as the starting point] in the [removed: market.][added: determination of the market rates of vacant units.]
The Company [removed: then increases] [added: may increase] or [removed: decreases] [added: decrease] these rates based on the supply and demand in the apartment community’s market.
Financial occupancy may not completely reflect short-term trends in physical occupancy and financial occupancy [removed: rates] [added: rates,] as disclosed by other [removed: REITs] [added: REITs,] may not be comparable to the Company’s calculation of financial occupancy.
The regional breakdown of the Company’s [added: stabilized] 2012/2011 Same-Property portfolio for financial occupancy for the years ended December 31, 2012 and 2011 is as follows:
| Northern California | | | [removed: 96.7] [added: 96.3] | % | | | 96.7 | % |
| 2012/2011 Non-Same Property Revenues (1) | | | | | | | [removed: 58,802] [added: 58,771] | | | | [removed: 22,294] [added: 22,264] | | | | [removed: 36,508] [added: 36,507] | | | | [removed: 163.8] [added: 164.0] | |
[removed: 2012/2011] [added: 2013/2012] Same-Property Revenues increased by [removed: $29.7] [added: $30.5] million or [removed: 6.7%] [added: 6.3%] to [removed: $473.1] [added: $513.0] million for [removed: 2012] [added: 2013] compared to [removed: $443.4] [added: $482.5] million in [removed: 2011.][added: 2012.]
The increase was primarily attributable to an increase in scheduled rents of [removed: $27.9] [added: $27.7] million as reflected in an increase of [removed: 6.4%] [added: 6.5%] in average rental rates from [removed: $1,388] [added: $1,393] per unit for 2011 to [removed: $1,478] [added: $1,483] per unit for 2012.
Scheduled rents increased in all regions by 3.8%, 9.5%, and [removed: 8.2%] [added: 8.3%] in Southern California, Northern California, and Seattle Metro, respectively.
Income from utility billings and other income increased by [removed: $1.3] [added: $1.2] million and $1.4 million, respectively in 2012 compared to 2011.
The increase is primarily due to the asset and property management fees earned from Wesco I and II co-investments formed during 2011, and development fees earned from the joint ventures formed in 2011 and 2012 to develop Epic, Expo, Connolly Station, [removed: Elkhorn,] [added: Park 20 (fka Elkhorn), Mosso I and Mosso II (fka] Folsom and [removed: Fifth,] [added: Fifth),] The Huxley and The Dylan development projects.
Property operating expenses, excluding real estate taxes increased [removed: $9.9] [added: $10.1] million or [removed: 8.6% for] [added: 8.9% in] 2012 compared to 2011, primarily due to the acquisition of thirteen communities and the lease-up of five development properties.
2012/2011 Same-Property operating expenses excluding real estate [removed: taxes,] [added: taxes] increased by [removed: $2.2] [added: $1.9] million or [removed: 2.0%] [added: 1.7%] for [removed: the] 2012 compared to 2011, due mainly to a $1.5 million increase in salaries, marketing, and administration costs and a $0.3 million increase in utilities due to increases in rates for water and sewer.
Real estate taxes increased [removed: $4.9] [added: $4.6] million or [removed: 11.3% for] [added: 10.5% in] 2012 compared to 2011, due primarily to the acquisition of thirteen communities and expensing property taxes instead of capitalizing the cost for communities that were previously under development.
2012/2011 Same-Property real estate taxes increased by $0.9 million or 2.3% for [removed: the] 2012 compared to 2011 due to an increase of [removed: 5.6%] [added: 5.3%] in property taxes for the Seattle Metro and [removed: a] 2.0% in property taxes for the majority of [removed: the] properties located in California regulated by [removed: Prop.][added: Proposition 13 offset by temporary reductions in assessed property valuations for selected communities located in California.]
Depreciation expense increased by $19.2 million or [removed: 12.7% for] [added: 12.8% in] 2012 compared to 2011, due to the acquisition of thirteen communities and the lease-up of five development properties.
On December 19, 2013, ESS and BRE Properties, Inc. (“BRE”) entered into a definitive agreement to combine the two companies.
Under the terms of the agreement, each BRE common share will be converted into 0.2971 newly issued shares of ESS common stock plus $12.33 in cash.
The merger is subject to customary closing conditions, including receipt of approval of ESS shareholders and BRE shareholders.
Additional information about the merger can be found in the Form S-4 filed with the SEC on January 29, 2014 and in other relevant documents that the Company files with the SEC, which are available free of charge on the Company’s website at www.essexpropertytrust.com and on the SEC’s website at www.sec.gov.
Certain statements below discuss the Company’s estimates of its 2014 regional Same-Property revenues; these estimates are for Essex on a standalone basis, excluding the impact of the proposed merger with BRE.
The Company assumes an increase of 132,400 jobs or 1.9%, and an increase in same-property revenues between 3.8% to 5.0% in 2014.
Same-Property revenues increased 8.2% in 2013 as compared to 2012.
The Company assumes an increase of 73,000 jobs or 2.5%, and an increase in same-property revenues between 6.3% to 7.8% in 2014.
Same-Property revenues increased 7.7% in 2013 as compared to 2012.
The Company assumes an increase of 39,000 jobs or 2.6%, and an increase in same-property revenues between 5.5% to 7.0% in 2014.
| | | 2013 | | | | 2012 | | |
| | | Properties | | | | 2013 | | | | 2012 | | | | Change | | | | Change | | |
| 2013/2012 Same-Properties: | | | | | | | | | | | | | | | | | | | | |
| Southern California | | | 58 | | | $ | 235,306 | | | $ | 225,435 | | | $ | 9,871 | | | | 4.4 | % |
| Northern California | | | 35 | | | | 184,508 | | | | 170,578 | | | | 13,930 | | | | 8.2 | |
| Seattle Metro | | | 29 | | | | 93,139 | | | | 86,483 | | | | 6,656 | | | | 7.7 | |
| Total 2013/2012 Same-Property revenues | | | 122 | | | | 512,953 | | | | 482,496 | | | | 30,457 | | | | 6.3 | |
| 2013/2012 Non-Same Property Revenues (1) | | | | | | | 89,050 | | | | 44,200 | | | | 44,850 | | | | 101.5 | |
| Total property revenues | | | | | | $ | 602,003 | | | $ | 526,696 | | | $ | 75,307 | | | | 14.3 | % |
Income from utility billings and other income increased by $1.0 million and $1.2 million, respectively in 2013 compared to 2012.
Occupancy decreased 10 basis points in 2013 to 96.2% compared to 96.3% in 2012.
2013/2012 Non-Same Property Revenues increased by $44.9 million or 102% to $89.1 million in 2013 compared to $44.2 million to 2012.
The increase was primarily due to revenue generated from fifteen communities acquired or consolidated since January 1, 2012 (Annaliese, Ascent, Bennett Lofts, Domain, Domaine, Essex Skyline at MacArthur Place, Fox Plaza, Montebello, Park Catalina, Park West, Reed Square, Slater 116, The Huntington, Vox and Willow Lake).
The increase in management fees was offset by a reduction of $2.3 million in asset and property management fees from the sale of eight Fund II communities since the fourth quarter of 2012.
An additional four communities owned by Fund II were sold in 2013, and the remaining two communities are expected to be sold in 2014.
Real estate taxes increased $8.9 million or 18.5% in 2013 compared to 2012, due primarily to the acquisition of fifteen communities.
2013/2012 Same-Property real estate taxes increased by $2.6 million or 6.0% for the 2013 compared to 2012 due to $1.3 million or 17.5% increase in property taxes for Seattle Metro due to higher assessed values for 2013, and an increase of 3.7% in property taxes for the majority of the properties located in California.
Depreciation expense increased by $23.2 million or 13.7% in 2013 compared to 2012, due to the acquisition of fifteen communities.
The increase is due to the capitalization of approximately $104.2 million in additions to rental properties through 2013, including $42.0 million spent on redevelopment, $21.2 million on improvements to recent acquisitions, $8.6 million on lessor required capital expenditures, and $5.3 million spent on revenue generating capital expenditures.
Approximately $92.0 million in additions to rental properties was capitalized for 2012, including $39.0 million spent on redevelopment, $13.7 million spent on improvements to recent acquisitions, and $7.7 million spent on revenue generating capital expenditures.
General and administrative expense increased $2.3 million or 9.8% in 2013 compared to 2012 primarily due to annual compensation increases for merit, investments in technology, and the addition of staff.
Merger expenses include, but are not limited to, advisor fees, legal fees, and accounting fees related to the pending merger with BRE Properties, Inc. (“BRE”).
The Company entered into a definitive agreement to combine with BRE in December 2013.
Merger expenses were $4.3 million for 2013 and zero for 2012.
Interest and other income decreased by $2.2 million in 2013 primarily due to $2.3 million of promote income earned from achieving certain performance hurdles related to the Essex Skyline co-investment in 2012.
Equity income in co-investments increased by $14.2 million to $55.9 million in 2013 compared to $41.7 million in 2012.
The increase was primarily due to the Company’s share of the gain on the sale of five Fund II communities of $38.8 million, net of internal disposition costs, and $1.4 million income earned from the early prepayment of a preferred equity investment in 2013.
Additionally, equity income increased with income earned from four communities acquired by the Wesco joint ventures in the second half of 2012 and two communities in the second quarter of 2013.
The increase in equity income in 2013 by the Wesco joint venture was offset by a decrease in income related to the sale of eight Fund II communities since the fourth quarter of 2012 including four communities sold in the third quarter of 2013.
Loss on early retirement of debt, net was $0.3 million for 2013 compared to $5.0 million in 2012.
The Company assumes an increase of 117,500 jobs or 1.7%, and an increase in rental income of 3.8% to 5.3% in 2013.
The Company assumes an increase of 68,500 jobs or 2.4%, and an increase in rental income of 6.5% to 8.0% in 2013.
The Company assumes an increase of 41,000 jobs or 2.8%, and an increase in rental income of 6.0% to 7.5% in 2013.
The Company expects 2013 Same-Property financial occupancy to be consistent with 2012 at 96.3%, and thus 2013 revenues will increase 5.0% to 6.5% due to a similar increase in scheduled rent.
Finally, Same-Property net operating income (“NOI”) which is defined as Same-Property revenues less Same-Property operating expenses is expected to moderate from a 9.2% increase for 2012 to a range of an increase of 6.0% to 8.0% in 2013.
The recently signed effective rates at the property are used as the starting point in the determination of the market rates of vacant units.
| | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Southern California | | | 58 | | | $ | 227,768 | | | $ | 218,626 | | | $ | 9,142 | | | | 4.2 | % |
| Seattle Metro | | | 28 | | | | 85,373 | | | | 78,785 | | | | 6,588 | | | | 8.4 | |
| Total 2011/2010 Same-Property revenues | | | 119 | | | | 473,134 | | | | 443,419 | | | | 29,715 | | | | 6.7 | |
| Total property revenues | | | | | | $ | 531,936 | | | $ | 465,713 | | | $ | 66,223 | | | | 14.2 | % |
2012/2011 Non-Same Property Revenues revenue increased by $36.5 million or 164% to $58.8 million in 2012 compared to $22.3 million to 2011.
13 offset by temporary reductions in assessed property valuations for select communities located in California.
This tax benefit relates to the write-off of an investment in a joint venture development project recognized during 2009.
| | | 2011 | | | | 2010 | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | Properties | | | | 2011 | | | | 2010 | | | | Change | | | | Change | | |
| 2011/2010 Same-Properties: | | | | | | | | | | | | | | | | | | | | |
| Southern California | | | 58 | | | $ | 204,748 | | | $ | 199,348 | | | $ | 5,400 | | | | 2.7 | % |
| Northern California | | | 28 | | | | 123,451 | | | | 116,796 | | | | 6,655 | | | | 5.7 | |
| Seattle Metro | | | 23 | | | | 61,827 | | | | 59,101 | | | | 2,726 | | | | 4.6 | |
| Total 2010/2009 Same-Property revenues | | | 109 | | | | 390,026 | | | | 375,245 | | | | 14,781 | | | | 3.9 | |
| 2011/2010 Non-Same Property Revenues (1) | | | | | | | 75,687 | | | | 30,483 | | | | 45,204 | | | | 148.3 | |
| Total property revenues | | | | | | $ | 465,713 | | | $ | 405,728 | | | $ | 59,985 | | | | 14.8 | % |
2011/2010 Same-Property Revenues increased by $14.8 million or 3.9% to $390.0 million for 2011 compared to $375.2 million in 2010.
Other income and free rent also increased by $0.6 million and $1.6 million, respectively in 2011 compared to 2010.
Occupancy decreased 50 basis points in 2011 to 96.4% compared to 96.9% in 2010 which resulted in a decrease in revenue of $2.5 million due to the Company’s focus on increasing renewal and new lease rents at the communities compared to 2010 and 2009 when high occupancy was the primary objective due to market conditions.
2011/2010 Non-Same Property Revenues revenue increased $45.2 million or 148% to $75.7 million in 2011 compared to $30.5 million in 2010.
The increase was primarily generated from the acquisition of twelve operating properties since January 1, 2010 (Santee Court, Courtyard off Main, Corbella at Juanita Bay, Anavia, 416 on Broadway, 101 San Fernando, The Commons, Bella Villagio, Elevation, 1000 Kiely, The Bernard, and Delano).
The increase in 2011/2010 Non-Same Property revenue is also attributable to revenue earned from eight development communities (Via, Santee Village, Bellerive, Muse, Allegro, Axis 2300, Fourth & U and Joule) and the acquisition of the Santa Clara retail center.
Real estate taxes increased $4.6 million or 11.7% for 2011 compared to 2010, due primarily to the acquisition of twelve communities and one retail center and expensing property taxes instead of capitalizing the cost for communities that were previously under development.
Same-Property real estate taxes decreased by $0.7 million or 1.9% for 2011 compared to the 2010 due to a reduction in assessed property valuations for select communities located in California and a decrease in assessed valuations for select properties in the Seattle Metro.
General and administrative expense decreased $2.6 million or 11.0% for 2011 compared to 2010 primarily due to $1.6 million in non-recurring compensation costs related to the CEO’s retirement in 2010 and certain staff in 2011 reallocated to manage newly formed co-investments including Wesco I and II.
Cost of management and other fees increased $1.9 million or 70.3% compared to 2010 primarily due to an increase in administrative costs due to hiring of additional staff to assist with the management of the Company’s co-investments including Wesco I and II and the development joint ventures formed in 2011.
Impairment and other charges of $2.3 million in 2010 relates to an expense recorded by the Company due to the hedge ineffectiveness of certain forward-starting swaps that were settled in 2010.
Amortization expense increased by $6.6 million in 2011 compared to 2010 due primarily to the settlement of forward starting swaps in the third and fourth quarters of 2010 that were applied to new 10-year secured mortgage loans, and as a result, the settlement amounts are being amortized over the ten years.
Interest and other income decreased by $10.7 million for 2011 primarily due to a decrease of $7.5 million in gains from the sales of marketable securities.
The Company sold marketable securities for a gain of $5.0 million during 2011 compared to $12.5 million in gains generated from the sale of marketable securities for 2010.
Additionally, interest on notes receivables decreased by $3.4 million in 2011 compared to 2010.
An excerpt. Shown here: 40 of 111 rewritten, 40 of 108 added and 40 of 161 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2013 filing and the FY2012 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risks
12 rewritten, 6 added, 5 removed, 20 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
As of December 31, [removed: 2012,] [added: 2013,] the Company has entered into ten interest rate swap contracts to mitigate the risk of changes in the interest-related cash outflows on $300.0 million of the five-year unsecured term debt.
As of December 31, [removed: 2012,] [added: 2013,] the Company also had [removed: $201.9] [added: $167.6] million of variable rate indebtedness, of which [removed: $187.8] [added: $156.9] million is subject to interest rate cap protection.
All of the Company’s derivative instruments are designated as cash flow hedges, and the Company does not have any fair value hedges as of December 31, [removed: 2012.][added: 2013.]
The following table summarizes the notional amount, carrying value, and estimated fair value of the Company’s derivative instruments used to hedge interest rates as of December 31, [removed: 2012.][added: 2013.]
The table also includes a sensitivity analysis to demonstrate the impact on the Company’s derivative instruments from an increase or decrease in 10-year Treasury bill interest rates by 50 basis points, as of December 31, [removed: 2012.][added: 2013.]
| Interest rate swaps | | $ | 300,000 | | | | 2016-2017 | | | $ | [removed: (6,606] [added: (2,682] | ) | | $ | [removed: (474] [added: 1,989] | [removed: )] | | $ | [removed: (11,619] [added: (6,500] | ) |
Management has estimated that the fair value of the Company’s [removed: $2.13] [added: $2.30] billion and [removed: $1.77] [added: $2.13] billion of fixed rate debt at December 31, [removed: 2012] [added: 2013] and [removed: 2011] [added: 2012] respectively, to be [removed: $2.24] [added: $2.33] billion and [removed: $1.88] [added: $2.24] billion.
Management has estimated the fair value of the Company’s [removed: $692.9] [added: $737.0] million and [removed: $593.7] [added: $692.9] million of variable rate debt at December 31, [removed: 2012] [added: 2013] and [removed: 2011,] [added: 2012,] respectively, is [removed: $671.7] [added: $719.4] million and [removed: $572.3] [added: $671.7] million based on the terms of existing mortgage notes payable and variable rate demand notes compared to those available in the marketplace ($ in thousands).
| | | [removed: 2013 | | | |] 2014 | | | | 2015 | | | | 2016 | | | | 2017 | | | | [added: 2018 | | | |] Thereafter | | | | | Total | | | | Fair value | | |
| Average interest rate | | | [removed: 5.6] [added: \-] | [removed: %] | | | 5.2 | % | | | [removed: 5.2] [added: 4.5] | % | | | [removed: 4.5] [added: 5.5] | % | | | [removed: 5.5] [added: 5.9] | % | | | [removed: 5.4] [added: 5.0] | % | | | | | | | | | |
[added: |] (1) [removed: $187.8] [added: | $156.9] million subject to interest rate caps. [added: |]
The table incorporates only those exposures that exist as of December 31, [removed: 2012;] [added: 2013;] it does not consider those exposures or positions that could arise after that date.
| Interest rate caps | | | 156,904 | | | | 2014-2018 | | | | \- | | | | 48 | | | | \- | |
| Total cash flow hedges | | $ | 456,904 | | | | 2014-2018 | | | $ | (2,682 | ) | | $ | 2,037 | | | $ | (6,500 | ) |
| Fixed rate debt | | $ | \- | | | $ | 67,461 | | | $ | 162,390 | | | $ | 222,731 | | | $ | 271,156 | | | $ | 1,572,764 | | | | $ | 2,296,502 | | | $ | 2,329,482 | |
| Variable rate debt | | $ | 20,421 | | | $ | 199,000 | | | $ | 200,000 | | | $ | 150,000 | | | $ | \- | | | $ | 167,601 | | (1 | ) | $ | 737,022 | | | $ | 719,414 | |
| Average interest rate | | | 2.2 | % | | | 2.2 | % | | | 2.5 | % | | | 2.5 | % | | | \- | | | | 1.6 | % | | | | | | | | | |
| --- | --- |
| Interest rate caps | | | 187,788 | | | | 2013-2018 | | | | \- | | | | 102 | | | | \- | |
| Total cash flow hedges | | $ | 487,788 | | | | 2013-2018 | | | $ | (6,606 | ) | | $ | (372 | ) | | $ | (11,619 | ) |
| Fixed rate debt | | $ | 38,201 | | | $ | 47,994 | | | $ | 68,926 | | | $ | 162,656 | | | $ | 225,301 | | | $ | 1,582,737 | | | | $ | 2,125,815 | | | $ | 2,237,462 | |
| Variable rate debt | | $ | 19,420 | | | $ | \- | | | $ | 141,000 | | | $ | 200,000 | | | $ | 150,000 | | | $ | 182,448 | | (1 | ) | $ | 692,868 | | | $ | 671,651 | |
| Average interest rate | | | 1.5 | % | | | \- | | | | 2.3 | % | | | 2.6 | % | | | 2.7 | % | | | 1.9 | % | | | | | | | | | |
Item 1. Business
54 rewritten, 72 added, 66 removed, 80 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
The Company is the sole general partner of the Operating Partnership and as of December 31, [removed: 2012] [added: 2013] owns a [removed: 94.5%] [added: 94.6%] general partnership interest.
In this report, the terms “Essex” or the “Company” also refer to Essex Property Trust, Inc., its Operating Partnership and [added: those entities owned or controlled by] the Operating [removed: Partnership’s subsidiaries.][added: Partnership.]
As of December 31, [removed: 2012,] [added: 2013,] the Company owned or held an interest in [removed: 163] [added: 164] communities, aggregating [removed: 33,468] [added: 34,079] units, located along the West Coast, as well as [removed: five] [added: four] commercial buildings (totaling approximately 315,900 square feet), and [removed: nine] [added: eleven] active development projects with [removed: 2,495] [added: 2,501] units in various stages of development (collectively, the “Portfolio”).
The Company’s annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and all amendments to those reports, and the Proxy Statement for its Annual Meeting of Stockholders are available, free of charge, on its website as soon as practicable after the Company files the reports with the [added: U.S.] Securities and Exchange Commission (“SEC”).
| | · | Housing demand that is based on [added: job growth,] proximity to jobs, high median [removed: incomes,] [added: incomes and] the quality of life [removed: and] [added: including] related commuting [removed: factors, as well as potential job growth.] [added: factors.] |
Recognizing that all real estate markets are cyclical, the Company regularly evaluates the results of its regional economic, and [removed: its] local market research, and adjusts the geographic focus of its portfolio accordingly.
Property Operations – The Company manages its communities by focusing on activities that [added: may] generate above-average rental growth, tenant retention/satisfaction and long-term asset appreciation.
| | · | Property Management – Oversee delivery of and quality of the housing provided to our residents and [removed: are responsible for] [added: manage] the properties financial performance. |
Acquisitions are an important component of the Company’s business plan, and during [removed: 2012,] [added: 2013,] the Company [added: and its co-investments] acquired ownership interests in [removed: fifteen] [added: eight] communities [removed: totaling $801.9] [added: comprising of 1,472 units for $462.5] million.
The following is a summary of [removed: its 2012 acquisitions:][added: 2013 acquisitions ($ in millions):]
| Property Name | [removed: |] Location | | Units | | | | Percentage | | | Ownership | | Date | | | | Price | | | [removed: | Principal | | | | Rate | | | | Rate | | |]
| Bennett Lofts [removed: (2) |] [added: (formerly Q Lofts) (1)] | San Francisco, CA | | | [removed: 113] [added: 34] | | | | 100 | % | EPLP | | | [removed: Q4 2012 | | | | 73,730 | | | | \- | | | | \-] [added: Q1 2013] | | | | [removed: \-] [added: 22.2] | |
| | [removed: (2)] [added: (1) | The 147 unit apartment community was acquired in two phases for $96.0 million.] Approximately 75% [removed: of the property] was acquired in December [removed: and] [added: 2012 with] the remainder in January [removed: 2013 for $22.2 million.] [added: 2013.] |
During [removed: 2012,] [added: 2013,] the Company sold [removed: two] [added: three] apartment communities, [added: Linden Square, Cambridge, and Brentwood] for a total of [removed: $28.3 million] [added: $57.5 million,] resulting in [removed: a gain] [added: total gains on the transactions] of [removed: $10.9] [added: $29.2] million.
The Company defines development projects as new communities that are in various stages of active development, or [removed: the community is] [added: are] in [removed: lease-up and phases of] the [removed: project are not completed.][added: process of leasing activities prior to stabilization.]
As of December 31, [removed: 2012,] [added: 2013,] the Company had two consolidated development projects and [removed: seven] [added: nine] joint venture development projects comprised of [removed: 2,495] [added: 2,501] units for an estimated cost of [removed: $928.4 million,] [added: $1.1 billion,] of which [removed: $463.9] [added: $407.0] million remains to be expended.
The Company defines the predevelopment projects as proposed communities in negotiation or in the entitlement process with [removed: a] [added: an expected] high likelihood of becoming entitled development projects.
As of December 31, [removed: 2012,] [added: 2013,] the Company had [removed: two consolidated predevelopment projects and] one [removed: unconsolidated joint venture] [added: consolidated] predevelopment project [removed: aggregating 449] [added: comprised of 200] units.
| | | | Essex | | | | | | | | As of [removed: 12/31/12] [added: 12/31/13] ($ in millions) | | | | | | | [removed: | | | | |]
| | | | Ownership | | | | | | | | Incurred | | | | Estimated | | | [removed: | Estimated | | | Projected |]
| Development Pipeline | Location | | % | | | | Units | | | | Project Cost | | | | [removed: Remaining Cost | | | |] Project Cost(1) | | | [removed: Stabilization |]
| Development Projects - Consolidated | | | | | | | | | | | | | | | | | | [removed: | | | | |]
| Total - Consolidated Development Projects | | | | | | | | 311 | | | | [removed: 19.6 | | | | 76.2 |] [added: 36.6] | | | [removed: 95.8] | [added: 99.2] | |
| Development Projects - Joint Venture | | | | | | | | | | | | | | | | | | [removed: | | | | |]
| Connolly Station [removed: (fka Linc)] | Dublin, CA | | | 55 | % | | | 309 | | | | [removed: 51.6 | | | | 42.9] [added: 88.6] | | | | 94.5 | | [removed: May-14 |]
| The Huxley [removed: (fka Fountain at La Brea)] | West Hollywood, CA | | | 50 | % | | | 187 | | | | [removed: 46.2 | | | | 28.8] [added: 71.8] | | | | 75.0 | | [removed: Jul-14 |]
| The Dylan [removed: (fka Santa Monica at La Brea)] | West Hollywood, CA | | | 50 | % | | | 184 | | | | [removed: 41.3 | | | | 34.1] [added: 64.6] | | | | 75.4 | | [removed: Oct-14 |]
| [removed: Folsom] [added: Mosso I] and [removed: Fifth] [added: Mosso II] | San Francisco, CA | | | 55 | % | | | 463 | | | | [removed: 88.5 | | | | 161.5] [added: 191.2] | | | | 250.0 | | [removed: Mar-15 |]
| [removed: Elkhorn] [added: Park 20 (formerly Elkhorn)] | San Mateo, CA | | | 55 | % | | | 197 | | | | [removed: 24.6 | | | | 51.5] [added: 47.8] | | | | 76.1 | | [removed: Dec-14 |]
| Total - Joint Venture Development Projects | | | | | | | | [removed: 2,184 | | | | 444.9 |] [added: 2,190] | | | [removed: 387.7] | [added: 646.3] | | | [removed: 832.6] | [added: 990.7] | |
| Predevelopment Projects [removed: | | | | |] [added: - Consolidated] | | | | | | | | | | | | | | | | | |
| City Centre | Moorpark, CA | | | 100 | % | | | 200 | | | | [removed: 9.7 | | | | \- |] [added: 11.6] | | | [removed: 9.7] | [added: 11.6] | |
| Epic - Phase III | San Jose, CA | | | 55 | % [removed: (3)] | | | 200 | | | | [removed: 19.8 | | | | \- |] [added: 28.0] | | | [removed: 19.8] | [added: 96.3] | |
| Total - Predevelopment Projects | | | | | | | | [removed: 449 | | | | 59.6 |] [added: 200] | | | [removed: \-] | [added: 13.8] | | | [removed: 59.6] | [added: 13.8] | |
| | (2) | The Company invested $1.0 million and has incurred [removed: $0.5] [added: $1.5] million of additional internal costs as part of an agreement to purchase the property upon receipt of [removed: temporary] certificate of occupancy for total estimated cost of $37.6 million, which is expected in the first quarter of 2014. |
As of December 31, [removed: 2012,] [added: 2013,] the Company had ownership interests in five redevelopment communities aggregating [removed: 1,056] [added: 1,312] apartment units with estimated redevelopment costs of [removed: $64.9] [added: $124.7] million, of which approximately [removed: $20.7] [added: $86.1] million remains to be expended.
During [removed: 2012,] [added: 2013,] the Company [removed: paid off $237.7] [added: repaid $103.7] million in secured debt including secured mortgage debt totaling [removed: $202.6] [added: $84.3] million at an average interest rate of [removed: 5.5%] [added: 5.4%] and [removed: $35.1] [added: $19.4] million of tax-exempt bonds.
[removed: During 2012,] [added: In January 2014,] the Company increased the capacity of the unsecured line of credit facility from [removed: $425.0] [added: $600.0] million to [removed: $500.0 million,] [added: $1.0 billion] and [added: included an accordion feature pursuant to which] the [removed: facility was increased] [added: Company could expand] to [removed: $600.0 million in January 2013.][added: $1.5 billion.]
This facility matures in December [removed: 2015] [added: 2017] with [removed: two one-year] [added: one 18-month] extension [removed: options.][added: option.]
During [removed: 2012, the Company] [added: 2013, ESS] issued [removed: 2,404,096 million] [added: 913,344] shares of common stock at an average share price of [removed: $150.26] [added: $152.92] for [removed: $357.7] [added: proceeds of $138.4] million, net of fees and commissions.
Summary of Proposed Merger with BRE Properties, Inc.
The board of directors of Essex Property Trust, Inc. and the board of directors of BRE Properties, Inc. have each unanimously approved an Agreement and Plan of Merger, dated as of December 19, 2013, as it may be amended from time to time, which we refer to as the merger agreement, by and among Essex, Bronco Acquisition Sub, Inc., a direct wholly owned subsidiary of Essex, which we refer to as Merger Sub, and BRE.
On February 5, 2014, Bronco Acquisition Sub, Inc. changed its name to BEX Portfolio, Inc. Pursuant to the merger agreement, Essex and BRE will combine through a merger of BRE with and into Merger Sub, with Merger Sub surviving the merger.
The combined company, which we refer to as the Combined Company, will retain the name “Essex Property Trust, Inc.” and will continue to trade on the New York Stock Exchange, or NYSE, under the symbol “ESS.” The executive officers of Essex immediately prior to the effective time of the merger will continue to serve as the executive officers of the Combined Company, with Michael J.
Schall continuing to serve as the President and Chief Executive Officer of the Combined Company.
The obligations of Essex and BRE to effect the merger are subject to the satisfaction or waiver of certain customary conditions set forth in the merger agreement (including the applicable approvals of each company’s stockholders).
If the merger is completed pursuant to the merger agreement, each share of BRE common stock outstanding immediately prior to the effective time of the merger will convert into the right to receive (i) 0.2971 shares of Essex common stock and (ii) $12.33 in cash, without interest, which we collectively refer to as the merger consideration, each subject to certain adjustments provided for in the merger agreement and subject to any applicable withholding tax.
As explained in more detail in the joint proxy statement/prospectus filed with a registration statement on Form S-4 filed with the SEC on January 29, 2014, by Essex (as the same may thereafter be amended), the cash amount of the merger consideration will be reduced to the extent a special distribution is authorized and declared to be paid to BRE stockholders of record as of the close of business on the business day immediately prior to the effective time of the merger as a result of any applicable asset sale (as described in the joint proxy statement/prospectus).
Essex stockholders will continue to hold their existing shares of Essex common stock.
The exchange ratio and cash amount will not be adjusted to reflect changes in the price of Essex common stock or the price of BRE common stock occurring prior to the completion of the merger.
Based on the closing price of Essex common stock on the NYSE of $147.70 on December 18, 2013, the last trading date before the announcement of the proposed merger, the merger consideration (based on the value of $43.88 in Essex common stock plus the $12.33 in cash per share) represented approximately $56.21 for each share of BRE common stock.
The value of the merger consideration will fluctuate with changes in the market price of Essex common stock.
The cash portion of the merger consideration will be reduced by the amount of any special distribution in connection with or as a result of any applicable asset sale.
Upon completion of the merger, we estimate that continuing Essex stockholders will own approximately 62% of the issued and outstanding common stock of the Combined Company, and former BRE stockholders will own approximately 38% of the issued and outstanding common stock of the Combined Company.
In connection with the proposed merger, Essex and BRE will each hold a special meeting of their respective stockholders.
At the Essex special meeting, Essex stockholders will be asked to vote on (i) a proposal to approve the issuance of Essex common stock to BRE stockholders in the merger and (ii) a proposal to approve one or more adjournments of the meeting to another date, time or place, if necessary or appropriate, to solicit additional proxies in favor of the proposal to approve the issuance of shares of Essex common stock to BRE stockholders in the merger.
At the BRE special meeting, BRE stockholders will be asked to vote on (i) a proposal to approve the merger and the other transactions contemplated by the merger agreement, (ii) an advisory (non-binding) proposal to approve certain compensation that may be paid or become payable to the named executive officers of BRE in connection with the merger, and (iii) a proposal to approve one or more adjournments of the meeting to another date, time or place, if necessary or appropriate, to solicit additional proxies in favor of the proposal to approve the merger and the other transactions contemplated by the merger agreement.
The merger agreement may also be terminated prior to the effective time of the merger by either BRE or Essex under certain conditions, including if the merger has not been consummated on or before June 17, 2014.
| | | | | | | | Essex Ownership | | | | | | | | | Purchase | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Fox Plaza Apartments | San Francisco, CA | | | 444 | | | | 100 | % | EPLP | | | Q1 2013 | | | $ | 135.0 | |
| Annaliese | Seattle, WA | | | 56 | | | | 100 | % | EPLP | | | Q1 2013 | | | | 19.0 | |
| Gas Company Lofts | Los Angeles, CA | | | 251 | | | | 50 | % | Wesco III | | | Q2 2013 | | | | 71.0 | |
| Regency at Mountain View | Mountain View, CA | | | 142 | | | | 50 | % | Wesco III | | | Q2 2013 | | | | 42.5 | |
| Slater 116 | Kirkland, WA | | | 108 | | | | 100 | % | EPLP | | | Q3 2013 | | | | 29.6 | |
| Domain | San Diego, CA | | | 379 | | | | 100 | % | EPLP | | | Q4 2013 | | | | 121.0 | |
| Vox | Seattle, WA | | | 58 | | | | 100 | % | EPLP | | | Q4 2013 | | | | 22.2 | |
| Total 2013 | | | | 1,472 | | | | | | | | | | | | $ | 462.5 | |
During the second quarter 2013, Essex Apartment Value Fund II, L.P. (“Fund II”) sold Morning Run for a total of $26.4 million.
In connection with the sale, Fund II incurred a prepayment penalty on debt of which the Company’s pro rata share was $0.2 million.
In the third quarter 2013, Fund II sold four properties for gross proceeds of $294.0 million.
In connection with the sales in the third quarter, Fund II incurred prepayment penalties on debt of which the Company’s pro rata share was $0.2 million.
The total gains on the transactions in 2013 were $146.8 million, of which the Company’s pro-rata share was $38.8 million net of internal disposition costs.
The two remaining properties in the Fund II portfolio are expected to be sold in 2014.
Also in 2013, the Company sold a land parcel held for future development located in Palo Alto, California for $9.1 million, resulting in a gain of $1.5 million.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| The Emme (formerly 64th & Christie) | Emeryville, CA | | | 100 | % | | | 190 | | | $ | 34.1 | | | $ | 61.6 | |
| The Avery (2) | Los Angeles, CA | | | 100 | % | | | 121 | | | | 2.5 | | | | 37.6 | |
| | | | | | | | | | | | | | | | | | |
| Epic - Phase II | San Jose, CA | | | 55 | % | | | 289 | | | | 87.1 | | | | 97.3 | |
| --- | --- | --- |
| | | | | | | | | Essex | | | | | | | | | | | | | Assumed | | | | Assumed | | | | Assumed | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | Ownership | | | | | | | | | Purchase | | | | Debt | | | | Debt Stated | | | | Debt Effective | | |
| Bon Terra | | Redmond, WA | | | 60 | | | | 100 | % | EPLP | | | Q1 2012 | | | $ | 16,000 | | | $ | \- | | | | \- | | | | \- | |
| Reed Square | | Sunnyvale, CA | | | 100 | | | | 100 | % | EPLP | | | Q1 2012 | | | | 23,000 | | | | \- | | | | \- | | | | \- | |
| Park Catalina | | Los Angeles, CA | | | 90 | | | | 100 | % | EPLP | | | Q2 2012 | | | | 23,650 | | | | \- | | | | \- | | | | \- | |
| Skyline (1) | | Santa Ana, CA | | | 349 | | | | 100 | % | EPLP | | | Q2 2012 | | | | 85,000 | | | | \- | | | | \- | | | | \- | |
| The Huntington | | Huntington Beach, CA | | | 276 | | | | 100 | % | EPLP | | | Q2 2012 | | | | 48,250 | | | | 30,300 | | | | 5.7 | % | | | 3.3 | % |
| Domaine | | Seattle, WA | | | 92 | | | | 100 | % | EPLP | | | Q3 2012 | | | | 34,000 | | | | 14,600 | | | | 5.7 | % | | | 3.0 | % |
| Montebello | | Kirkland, WA | | | 248 | | | | 100 | % | EPLP | | | Q3 2012 | | | | 52,000 | | | | 26,515 | | | | 5.6 | % | | | 3.1 | % |
| Park West | | San Francisco, CA | | | 126 | | | | 100 | % | EPLP | | | Q3 2012 | | | | 31,600 | | | | \- | | | | \- | | | | \- | |
| Riley Square | | Santa Clara, CA | | | 156 | | | | 50 | % | Wesco I | | | Q3 2012 | | | | 38,250 | | | | 17,500 | | | | 5.2 | % | | | 3.1 | % |
| Ascent | | Kirkland, WA | | | 90 | | | | 100 | % | EPLP | | | Q4 2012 | | | | 15,850 | | | | \- | | | | \- | | | | \- | |
| Haver Hill | | Fullerton, CA | | | 264 | | | | 50 | % | Wesco III | | | Q4 2012 | | | | 45,600 | | | | \- | | | | \- | | | | \- | |
| Madrid | | Mission Viejo, CA | | | 230 | | | | 50 | % | Wesco I | | | Q4 2012 | | | | (3 | ) | | | 33,266 | | | | 5.3 | % | | | 2.6 | % |
| Pacific Electric Lofts | | Los Angeles, CA | | | 314 | | | | 50 | % | Wesco I | | | Q4 2012 | | | | (3 | ) | | | 46,939 | | | | 4.0 | % | | | 2.5 | % |
| Willow Lake | | San Jose, CA | | | 508 | | | | 100 | % | EPLP | | | Q4 2012 | | | | 148,000 | | | | \- | | | | \- | | | | \- | |
| | | Total 2012 | | | 3,016 | | | | | | | | | | | | $ | 801,930 | | | $ | 169,120 | | | | | | | | | |
| | (1) In April 2012, the Company purchased the joint venture partner's remaining membership interest in the co-investment Essex Skyline at MacArthur Place for a purchase price of $85 million. The property is now consolidated. |
| --- | --- |
| --- | --- |
| | (3) In accordance with terms of the purchase agreements, purchase price of the properties are not being disclosed by the Company. |
| --- | --- |
Also, Essex Apartment Value Fund II sold seven communities for a total of $413.0 million.
The total gain on the transaction was $106 million, of which the Company’s pro-rata share was $29.1 million.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 64th & Christie | Emeryville, CA | | | 100 | % | | | 190 | | | $ | 18.1 | | | $ | 40.1 | | | $ | 58.2 | | Feb-15 |
| Valley Village | Valley Village, CA | | | (2 | ) | | | 121 | | | | 1.5 | | | | 36.1 | | | | 37.6 | | Jun-14 |
| | | | | | | | | | | | | | | | | | | | | | | |
| Expo | Seattle, WA | | | 50 | % | | | 275 | | | | 64.5 | | | | 5.5 | | | | 70.0 | | Apr-13 |
| Epic - Phase I and II | San Jose, CA | | | 55 | % | | | 569 | | | | 128.2 | | | | 63.4 | | | | 191.6 | | Dec-14 |
| | | | | | | | | | | | | | | | | | | | | | | |
| Main Street | Walnut Creek, CA | | | 50 | % | | | 49 | | | | 28.5 | | | | \- | | | | 28.5 | | |
| Other Projects | | | | | | | | \- | | | | 1.6 | | | | \- | | | | 1.6 | | |
| | | | | | | | | | | | | | | | | | | | | | | |
| Land Held for Future Development or Sale | | | | | | | | | | | | | | | | | | | | | | |
| Park Boulevard | Palo Alto, CA | | | (4 | ) | | | 50 | | | | 7.5 | | | | \- | | | | 7.5 | | |
| | | | | | | | | | | | | | | | | | | | | | | |
| Grand Total - Development Pipeline | | | | | | | | 2,994 | | | $ | 531.6 | | | $ | 463.9 | | | $ | 995.5 | | |
An excerpt. Shown here: 40 of 54 rewritten, 40 of 72 added and 40 of 66 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2013 filing and the FY2012 filing.
Item 3. Legal Proceedings
2 rewritten, 1 added, 0 removed, 10 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
There have been [removed: have been] an increasing number of lawsuits against owners and managers of apartment communities alleging personal injury and property damage caused by the presence of mold in residential real estate.
As of December 31, [removed: 2012,] [added: 2013,] potential liabilities for mold and other environmental liabilities are not quantifiable and an estimate of possible loss cannot be made.
The information set forth and discussed regarding litigation relating to the merger transaction with BRE in note 16, “Commitments and Contingencies”, of our notes to consolidated financial statements included in Part IV, Item 15 of this Annual Report on Form 10-K is incorporated by reference into this Item 3.
Cover and table of contents
33 rewritten, 64 added, 9 removed, 50 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
10-K 1 form10k.htm ESSEX PROPERTY TRUST, INC 10-K [removed: 12-31-2012][added: 12-31-2013]
For the fiscal year ended December 31, [removed: 2012][added: 2013]
Commission file [removed: number] [added: number:] 1-13106 [added: (Essex Property Trust, Inc.)]
| Common Stock, $.0001 par value [added: (Essex Property Trust, Inc.)] | | New York Stock Exchange |
| [removed: 4.875%] [added: 7.125%] Series [removed: G] [added: H] Cumulative [removed: Convertible] [added: Redeemable] Preferred Stock [added: (Essex Property Trust, Inc.)] | | New York Stock Exchange |
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities [removed: Act.Yesx No o][added: Act.]
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of Registrant's knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K, or any amendment to this Form 10-K. [removed: o]
As of June 30, [removed: 2012,] [added: 2013,] the aggregate market value of the voting stock held by non-affiliates of [removed: the registrant] [added: Essex Property Trust, Inc.] was [removed: $5,325,843,948.][added: $5,855,449,673.]
As of February [removed: 20, 2013, 37,907,305] [added: 24, 2014, 38,606,706] shares of common stock ($.0001 par value) [added: of Essex Property Trust, Inc.] were outstanding.
The following document is incorporated by reference in Part III of the Annual Report on Form 10-K: Proxy statement for the annual meeting of stockholders of Essex Property Trust, Inc. to be [removed: held May 14,] [added: filed within 120 days of December 31,] 2013.
[removed: 2012] [added: 2013] ANNUAL REPORT ON FORM 10-K
| Item 1. | [removed: [Business](#busines)] [added: [Business](#Item1.Business)] | 1 |
| Item 1A. | [Risk [removed: Factors](#rf)] [added: Factors](#Item1A.RiskFactors)] | 7 |
| Item 1B. | [Unresolved Staff [removed: Comments](#usc)] [added: Comments](#Item1B.UnresolvedStaffCom)] | [removed: 17] [added: 21] |
| Item 2. | [removed: [Properties](#pro)] [added: [Properties](#Item2.Properties)] | [removed: 17] [added: 21] |
| Item 3. | [Legal [removed: Proceedings](#lp)] [added: Proceedings](#Item3.LegalProceedings)] | [removed: 23] [added: 27] |
| Item 4. | [Mine Safety [removed: Disclosures](#msd)] [added: Disclosures](#Item4.MineSafetyDisclosur)] | [removed: 23] [added: 27] |
| Item 5. | [Market for Registrant's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#5)] [added: Securities](#Item5.MarketforRegistrant)] | [removed: 24] [added: 28] |
| Item 6. | [Selected Financial [removed: Data](#sfd)] [added: Data](#Item6.SelectedFinancialDa)] | [removed: 27] [added: 31] |
| Item 7. | [Management's Discussion and Analysis of Financial Condition and Results of [removed: Operations](#7)] [added: Operations](#Item7.ManagementsDiscussi)] | [removed: 28] [added: 34] |
| Item 7A. | [Quantitative and Qualitative Disclosures About Market [removed: Risks](#7a)] [added: Risks](#Item7A.QuantitativeandQua)] | [removed: 42] [added: 46] |
| Item 8. | [Financial Statements and Supplementary [removed: Data](#8)] [added: Data](#Item8.FinancialStatements)] | [removed: 43] [added: 47] |
| Item 9. | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#9)] [added: Disclosure](#Item9.ChangesinandDisagre)] | [removed: 43] [added: 47] |
| Item 9A. | [Controls and [removed: Procedures](#9a)] [added: Procedures](#Item9A.ControlsandProcedu)] | [removed: 43] [added: 47] |
| Item 9B. | [Other [removed: Information](#9b)] [added: Information](#Item9B.OtherInformation)] | [removed: 43] [added: 48] |
| Item 10. | [Directors, Executive Officers and Corporate [removed: Governance](#10)] [added: Governance](#Item10.DirectorsExecutive)] | [removed: 44] [added: 48] |
| Item 11. | [Executive [removed: Compensation](#11)] [added: Compensation](#Item11.ExecutiveCompensat)] | [removed: 44] [added: 48] |
| Item 12. | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#12)] [added: Matters](#Item12.SecurityOwnershipo)] | [removed: 44] [added: 49] |
| Item 13. | [Certain Relationships and Related Transactions, and Director [removed: Independence](#13)] [added: Independence](#Item13.CertainRelationshi)] | [removed: 44] [added: 49] |
| Item 14. | [Principal Accounting Fees and [removed: Services](#14)] [added: Services](#Item14.PrincipalAccountin)] | [removed: 44] [added: 49] |
| Item 15. | [Exhibits and Financial Statement [removed: Schedules](#exh)] [added: Schedules](#Item15.ExhibitsandFinanci)] | [removed: 45] [added: 50] |
| [removed: [Signatures](#sig)] [added: [Signatures](#SIGNATURES)] | | S-1 |
Certain factors that might cause such a difference are discussed in this report, including Item [added: in] 1A, Risk Factors of this Form 10-K.
Commission file number: 333-44467-01 (Essex Portfolio, L.P.)
ESSEX PORTFOLIO, L.P.
| Maryland (Essex Property Trust, Inc.) California (Essex Portfolio, L.P.) | | 77-0369576 (Essex Property Trust, Inc.) 77-0369575 (Essex Portfolio, L.P.) |
| Essex Property Trust, Inc. Yes x No o | Essex Portfolio, L.P. Yes o No x |
| --- | --- |
| Essex Property Trust, Inc. Yes o No x | Essex Portfolio, L.P. Yes o No x |
| --- | --- |
| Essex Property Trust, Inc. Yes x No o | Essex Portfolio, L.P. Yes x No o |
| --- | --- |
| Essex Property Trust, Inc. Yes x No o | Essex Portfolio, L.P. Yes x No o |
| --- | --- |
| Essex Property Trust, Inc. o | Essex Portfolio, L.P. o |
| --- | --- |
Essex Property Trust, Inc.:
Essex Portfolio, L.P.:
| Large accelerated filer o | Accelerated filer o | Non-accelerated filer x (Do not check if a smaller reporting company) | Smaller reporting company o |
| --- | --- | --- | --- |
| Essex Property Trust, Inc. Yes o No x | Essex Portfolio, L.P. Yes o No x |
| --- | --- |
EXPLANATORY NOTE
This report combines the annual reports on Form 10-K for the year ended December 31, 2013 of Essex Property Trust, Inc and Essex Portfolio, L.P. Unless stated otherwise or the context otherwise requires, references to “ESS” mean Essex Property Trust, a Maryland corporation that operates as a self-administered and self-managed real estate investment trust (“REIT ”), and references to “EPLP” mean Essex Portfolio, L.P. (the “Operating Partnership” ).
References to the “Company,” “we,” “us” or “our” mean collectively ESS, EPLP and those entities/subsidiaries owned or controlled by ESS and/or EPLP.
References to the “Operating Partnership” mean collectively EPLP and those entities/subsidiaries owned or controlled by EPLP.
ESS is the general partner of, and as of December 31, 2013 owned an approximate 94.6% ownership interest in EPLP.
The remaining 5.4% interest is owned by limited partners.
As the sole general partner of EPLP, ESS has exclusive control of EPLP's day-to-day management.
The Company is structured as an umbrella partnership REIT (“UPREIT”) and ESS contributes all net proceeds from its various equity offerings to the Operating Partnership.
In return for those contributions, ESS receives a number of OP Units (see definition below) in the Operating Partnership equal to the number of shares of common stock it has issued in the equity offering.
Contributions of properties to the Company can be structured as tax-deferred transactions through the issuance of OP Units in the Operating Partnership, which is one of the reasons why the Company is structured in the manner shown above.
Based on the terms of EPLP's partnership agreement, OP Units can be exchanged with ESS common stock on a one-for-one basis.
The Company maintains a one-for-one relationship between the OP Units of the Operating Partnership issued to ESS and shares of common stock.
The Company believes that combining the reports on Form 10-K of ESS and EPLP into this single report provides the following benefits:
| | · | enhances investors' understanding of the Company and the Operating Partnership by enabling investors to view the business as a whole in the same manner as management views and operates the business; |
| | · | eliminates duplicative disclosure and provides a more streamlined and readable presentation since a substantial portion of the disclosure applies to both the Company and the Operating Partnership; and |
| --- | --- | --- |
| | · | creates time and cost efficiencies through the preparation of one combined report instead of two separate reports. |
| --- | --- | --- |
Management operates the Company and the Operating Partnership as one business.
The management of ESS consists of the same members as the management of EPLP.
All of the Company's property ownership, development and related business operations are conducted through the Operating Partnership and ESS has no material assets, other than its investment in EPLP.
| Maryland | | 77-0369576 |
| 7.125% Series H Cumulative Redeemable Preferred Stock | | New York Stock Exchange |
Yes o No x
Yes x No o
Yes x No o
Yes o No x
ii

An excerpt. Shown here: all 33 rewritten, 40 of 64 added and all 9 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2013 filing and the FY2012 filing.
Item 2. Properties
213 rewritten, 23 added, 28 removed, 62 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
The Company’s Portfolio as of December 31, [removed: 2012] [added: 2013] (including communities owned by unconsolidated joint ventures, but excluding communities underlying preferred equity investments) was comprised of [removed: 163] [added: 164] apartment communities (comprising [removed: 33,468] [added: 34,079] apartment units), of which [removed: 15,444] [added: 15,725] units are located in Southern California, [removed: 10,189] [added: 10,494] units are located in the San Francisco Bay Area, and [removed: 7,835] [added: 7,860] units are located in the Seattle metropolitan area.
The Company’s apartment communities accounted for [removed: 98.4%] [added: 97.5%] of the Company’s revenues for the year ended December 31, [removed: 2012.][added: 2013.]
As of December 31, [removed: 2012,] [added: 2013,] the Company’s communities include [removed: 117] [added: 113] garden-style, [removed: 43] [added: 46] mid-rise, and [removed: 3] [added: 5] high-rise communities.
The communities have an average of approximately [removed: 206] [added: 208] units, with a mix of studio, one, two and some three-bedroom units.
| | [removed: ●] [added: ·] | attractive communities that are well maintained; and |
| | [removed: ●] [added: ·] | proactive customer [removed: service approach.] [added: service.] |
The Company owns an office building with approximately 110,000 square feet located in Irvine, California, of which the Company occupies approximately 7,150 square feet at December 31, [removed: 2012.][added: 2013.]
The Company owns Essex-Hollywood, a 35,000 square foot commercial building [removed: as] [added: and] a [added: 139,000 square foot retail site in Santa Clara, California as] future development [removed: site] [added: sites] that [removed: is] [added: are] currently 100% [removed: leased as a production studio.][added: leased.]
The following tables describe the Company’s Portfolio as of December 31, [removed: 2012.][added: 2013.]
| | | | | | | [removed: | |] Rentable | | | | | | | [removed: | | | | | | | |]
| | | | | | | [removed: | |] Square | | [removed: | |] Year | | [removed: | |] Year | | | [removed: | | | |]
| Communities (1) | | Location | | Units | | [removed: | |] Footage | | [removed: | |] Built | | [removed: | |] Acquired | | [removed: | |] Occupancy(2) | [removed: | |]
| Southern California | | | | | | | | | | | | | [removed: | | | | | | | | | |]
| Alpine Village | | Alpine, CA | | [removed: |] 301 | | [removed: | |] 254,400 | | [removed: | |] 1971 | | [removed: | |] 2002 | | [removed: | | 97 | %] [added: 97%] |
| Anavia | | Anaheim, CA | | [removed: |] 250 | | [removed: | |] 312,343 | | [removed: | |] 2009 | | [removed: | |] 2010 | | [removed: | | 95 | %] [added: 96%] |
| Barkley, The(3)(4) | | Anaheim, CA | | [removed: |] 161 | | [removed: | |] 139,800 | | [removed: | |] 1984 | | [removed: | |] 2000 | | [removed: | | 97 | %] [added: 97%] |
| Bonita Cedars | | Bonita, CA | | [removed: |] 120 | | [removed: | |] 120,800 | | [removed: | |] 1983 | | [removed: | |] 2002 | | [removed: | | 96 | %] [added: 97%] |
| Camarillo Oaks | | Camarillo, CA | | [removed: |] 564 | | [removed: | |] 459,000 | | [removed: | |] 1985 | | [removed: | |] 1996 | | [removed: | | 96 | %] [added: 96%] |
| Camino Ruiz Square | | Camarillo, CA | | [removed: |] 160 | | [removed: | |] 105,448 | | [removed: | |] 1990 | | [removed: | |] 2006 | | [removed: | | 97 | %] [added: 98%] |
| Mesa Village | | Clairemont, CA | | [removed: |] 133 | | [removed: | |] 43,600 | | [removed: | |] 1963 | | [removed: | |] 2002 | | [removed: | | 97 | %] [added: 97%] |
| Regency at Encino | | Encino, CA | | [removed: |] 75 | | [removed: | |] 78,487 | | [removed: | |] 1989 | | [removed: | |] 2009 | | [removed: | | 97 | %] [added: 97%] |
| Valley Park(4) | | Fountain Valley, CA | | [removed: |] 160 | | [removed: | |] 169,700 | | [removed: | |] 1969 | | [removed: | |] 2001 | | [removed: | | 97 | %] [added: 98%] |
| Capri at Sunny Hills(4) | | Fullerton, CA | | [removed: |] 100 | | [removed: | |] 128,100 | | [removed: | |] 1961 | | [removed: | |] 2001 | | [removed: | | 95 | %] [added: 94%] |
| Haver Hill(5) | | Fullerton, CA | | [removed: |] 264 | | [removed: | |] 224,130 | | [removed: | |] 1973 | | [removed: | |] 2012 | | [removed: | | 96 | %] [added: 94%] |
| Wilshire Promenade | | Fullerton, CA | | [removed: |] 149 | | [removed: | |] 128,000 | | [removed: | |] 1992 | | [removed: | |] 1997 | | [removed: | | 96 | %] [added: 96%] |
| Montejo(4) | | Garden Grove, CA | | [removed: |] 124 | | [removed: | |] 103,200 | | [removed: | |] 1974 | | [removed: | |] 2001 | | [removed: | | 97 | %] [added: 96%] |
| CBC Apartments | | Goleta, CA | | [removed: |] 148 | | [removed: | |] 91,538 | | [removed: | |] 1962 | | [removed: | |] 2006 | | [removed: | | 95 | %] [added: 95%] |
| [removed: Sweeps,] The [removed: (Chimney Sweep Apartments)] [added: Sweeps] | | Goleta, CA | | [removed: |] 91 | | [removed: | |] 88,370 | | [removed: | |] 1967 | | [removed: | |] 2006 | | [removed: | | 84 | %] [added: 95%] |
| 416 on Broadway | | Glendale, CA | | [removed: |] 115 | | [removed: | |] 126,782 | | [removed: | |] 2009 | | [removed: | |] 2010 | | [removed: | | 95 | %] [added: 97%] |
| Hampton Court | | Glendale, CA | | [removed: |] 83 | | [removed: | |] 71,500 | | [removed: | |] 1974 | | [removed: | |] 1999 | | [removed: | | 97 | %] [added: 97%] |
| Hampton Place | | Glendale, CA | | [removed: |] 132 | | [removed: | |] 141,500 | | [removed: | |] 1970 | | [removed: | |] 1999 | | [removed: | | 97 | %] [added: 97%] |
| Devonshire | | Hemet, CA | | [removed: |] 276 | | [removed: | |] 207,200 | | [removed: | |] 1988 | | [removed: | |] 2002 | | [removed: | | 92 | %] [added: 91%] |
| Huntington Breakers | | Huntington Beach, CA | | [removed: |] 342 | | [removed: | |] 241,700 | | [removed: | |] 1984 | | [removed: | |] 1997 | | [removed: | | 95 | %] [added: 96%] |
| The Huntington | | Huntington Beach, CA | | [removed: |] 276 | | [removed: | |] 202,256 | | [removed: | |] 1975 | | [removed: | |] 2012 | | [removed: | | 97 | %] [added: 96%] |
| Axis 2300 | | Irvine, CA | | [removed: |] 115 | | [removed: | |] 170,714 | | [removed: | |] 2010 | [removed: (6)] | [removed: | |] 2010 | | [removed: | | 95 | %] [added: 96%] |
| Hillsborough Park | | La Habra, CA | | [removed: |] 235 | | [removed: | |] 215,500 | | [removed: | |] 1999 | | [removed: | |] 1999 | | [removed: | | 96 | %] [added: 97%] |
| Trabuco Villas | | Lake Forest, CA | | [removed: |] 132 | | [removed: | |] 131,000 | | [removed: | |] 1985 | | [removed: | |] 1997 | | [removed: | | 96 | %] [added: 97%] |
| Madrid [removed: Apartments(7)] [added: Apartments(6)] | | Mission Viejo, CA | | [removed: |] 230 | | [removed: | |] 228,099 | | [removed: | |] 2000 | | [removed: | |] 2012 | | [removed: | | 97 | %] [added: 96%] |
| Marbrisa | | Long Beach, CA | | [removed: |] 202 | | [removed: | |] 122,800 | | [removed: | |] 1987 | | [removed: | |] 2002 | | [removed: | | 97 | %] [added: 96%] |
| Pathways | | Long Beach, CA | | [removed: |] 296 | | [removed: | |] 197,700 | | [removed: | | 1975 | (8) |] [added: 1975(7)] | | 1991 | | [removed: | | 96 | %] [added: 95%] |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Gas Company Lofts(5) | | Los Angeles, CA | | 251 | | 226,666 | | 2004 | | 2013 | | 94% |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Domain | | San Diego, CA | | 379 | | 345,044 | | 2013 | | 2013 | | 82% |
| | | | | 15,725 | | 13,957,790 | | | | | | 96% |
| Regency at Mountain View(5) | | Mountain View, CA | | 142 | | 127,600 | | 1970 | | 2013 | | 93% |
| Fox Plaza | | San Francisco, CA | | 444 | | 230,017 | | 1968 | | 2013 | | 94% |
| Epic, Phase I(21) | | San Jose, CA | | 280 | | 249,080 | | 2013 | | 2013 | | 49% |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | 10,494 | | 9,027,362 | | | | | | 96% |
| Slater 116 | | Kirkland, WA | | 108 | | 81,415 | | 2013 | | 2013 | | 60% |
| Annaliese | | Seattle, WA | | 56 | | 48,216 | | 2009 | | 2013 | | 94% |
| Vox | | Seattle, WA | | 58 | | 42,173 | | 2013 | | 2013 | | 96% |
| Expo(29) | | Seattle, WA | | 275 | | 190,176 | | 2012 | | 2012 | | 96% |
| | | | | 7,860 | | 6,725,614 | | | | | | 96% |
| Total/Weighted Average | | | | 34,079 | | 29,710,766 | | | | | | 96% |
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | 11 | | 315,900 | | | | | | 99% |
| | (12) | The Company has a 97% interest and an executive vice president of the Company has a 3% interest in this community. |
| | (13) | The Company has a 75% member interest. |
| | (21) | The Company has 55% ownership in this community. The community is being developed in three phases with the remaining two phases currently under development. |
| | (29) | The Company has 50% ownership in this community. |
The Company’s average financial occupancies for the Company’s stabilized communities or “2012/2011 Same-Properties” (stabilized properties consolidated by the Company for the years ended December 31, 2012 and 2011) was unchanged at 96.3% for the years ended December 31, 2012, and 2011.
| --- | --- | --- |
During 2011, the Company purchased a retail site in Santa Clara for $20.6 million.
The plans for this project are to entitle the site for 494 apartment units.
The site is currently improved with a 139,000 square foot retail space that is 100% leased.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Cambridge | | Chula Vista, CA | | | 40 | | | | 22,100 | | | | 1965 | | | | 2002 | | | | 95 | % |
| Renaissance, The(9) | | Los Angeles, CA | | | 169 | | | | 154,268 | | | | 1990 | (10) | | | 2006 | | | | 98 | % |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Brentwood(4) | | Santa Ana, CA | | | 140 | | | | 154,800 | | | | 1970 | | | | 2001 | | | | 98 | % |
| | | | | | 15,444 | | | | 13,717,248 | | | | | | | | | | | | 96 | % |
| Carlmont Woods(9) | | Belmont, CA | | | 195 | | | | 107,200 | | | | 1971 | | | | 2004 | | | | 96 | % |
| Harbor Cove(9) | | Foster City, CA | | | 400 | | | | 306,600 | | | | 1971 | | | | 2004 | | | | 96 | % |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | 10,189 | | | | 8,792,525 | | | | | | | | | | | | 97 | % |
| Morning Run(9) | | Monroe, WA | | | 222 | | | | 221,786 | | | | 1991 | | | | 2005 | | | | 97 | % |
| Eastlake 2851(9) | | Seattle, WA | | | 133 | | | | 234,086 | | | | 2008 | | | | 2008 | | | | 96 | % |
| Linden Square | | Seattle, WA | | | 183 | | | | 142,200 | | | | 1994 | | | | 2000 | | | | 96 | % |
| | | | | | 7,835 | | | | 6,913,940 | | | | | | | | | | | | 96 | % |
| Total/Weighted Average | | | | | 33,468 | | | | 29,423,713 | | | | | | | | | | | | 96 | % |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Office Buildings | | | | | | | | | | | | | | | | | | | | | | |
| Total Office Buildings | | | | | 11 | | | | 315,900 | | | | | | | | | | | | 99 | % |
| | (15) | The Company has a 97% interest. A 50% voting interest was acquired in April 2012 when the Company acquired the joint venture partner’s membership interest. |
| | (16) | The Company and EMC have a 74.0% and a 1% member interest, respectively. |
| | (26) | The Company is in the process of performing a $13.3 million redevelopment. |
| | (27) | The Company completed a $12.5 million redevelopment in 2009. |
| | (28) | The Company completed a $36.3 million redevelopment in 2012, which included the construction of 28 in-fill units in 2009. |
An excerpt. Shown here: 40 of 213 rewritten, all 23 added and all 28 removed. The counts are complete. For every sentence, read Item 2. Properties in the FY2013 filing and the FY2012 filing.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
33 rewritten, 41 added, 28 removed, 30 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
[removed: The Company’s] [added: ESS] common stock has been traded on the NYSE since June 13, 1994.
The closing price [added: of ESS stock] as of February [removed: 20, 2013] [added: 24, 2014] was [removed: $152.41.][added: $166.38.]
The approximate number of holders of record of the shares of [removed: the Company’s] [added: ESS] common stock was [removed: 259] [added: 256] as of February [removed: 20, 2013.][added: 24, 2014.]
[removed: The Company] [added: ESS] believes the actual number of stockholders is greater than the number of holders of record.
The status of the cash dividends distributed for the years ended December 31, [added: 2013,] 2012, [removed: 2011,] and [removed: 2010] [added: 2011] related to common stock, and Series F, G and [removed: Series] H preferred stock for tax purposes are as follows:
| | | [removed: 2012] [added: 2013] | | | | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011] | | |
| Ordinary income | | | [removed: 70.58] [added: 77.34] | % | | | [removed: 63.68] [added: 70.58] | % | | | [removed: 82.46] [added: 63.68] | % |
| Capital gain | | | [removed: 8.75] [added: 17.64] | % | | | [removed: 11.16] [added: 8.75] | % | | | [removed: 5.61] [added: 11.16] | % |
| Unrecaptured section 1250 capital gain | | | [removed: 7.97] [added: 5.02] | % | | | [removed: 0.74] [added: 7.97] | % | | | [removed: 0.00] [added: 0.74] | % |
| Return of capital | | | [removed: 12.70] [added: 0.00] | % | | | [removed: 24.42] [added: 12.70] | % | | | [removed: 11.93] [added: 24.42] | % |
| | | [removed: 2012] | [added: 2013] | | | [removed: 2011] | [added: 2012] | | | [removed: 2010] | [added: 2011] | |
| Ordinary income | | | [removed: 80.85] [added: 77.34] | % | | | [removed: 100.00] [added: 80.85] | % | | | [removed: 93.63] [added: 100.00] | % |
| Capital gains | | | [removed: 10.02] [added: 17.64] | % | | | [removed: 0.00] [added: 10.02] | % | | | [removed: 6.37] [added: 0.00] | % |
| Unrecaptured section 1250 capital gain | | | [removed: 9.13] [added: 5.02] | % | | | [removed: 0.00] [added: 9.13] | % | | | 0.00 | % |
Since [removed: its] [added: ESS’s] initial public offering on June 13, 1994, [added: ESS and] the [removed: Company has] [added: Operating Partnership have] paid regular quarterly [removed: dividends] [added: dividends/distributions] to its [removed: stockholders.][added: stockholders and unitholders.]
[removed: The Company has] [added: ESS] paid the following dividends per share of common [removed: stock:][added: stock and the Operating Partnership paid the following distributions per limited partner OP unit:]
| Year Ended | | Annual [removed: Dividend | |] [added: Dividend/Distribution] | | | Quarter Ended | | [removed: 2012] [added: 2013] | | | | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011] | | |
Future [removed: distributions] [added: dividends/distributions] by [added: ESS and] the [removed: Company] [added: Operating Partnership] will be at the discretion of the Board of Directors [added: of ESS] and will depend on the actual cash flows from operations of the Company, its financial condition, capital requirements, the annual distribution requirements under the REIT provisions of the Internal Revenue Code, applicable legal restrictions and such other factors as the Board of Directors deem relevant.
There are currently no contractual restrictions on [removed: the Company’s] [added: Essex Portfolio, L.P.’s] present or future ability to pay [removed: dividends.][added: distributions.]
[removed: The Company] [added: ESS] has adopted a dividend reinvestment and share purchase plan designed to provide holders of common stock with a convenient and economical means to reinvest all or a portion of their cash dividends in shares of common stock and to acquire additional shares of common stock through voluntary purchases.
Computershare, LLC, which serves as [removed: the Company’s] [added: ESS] transfer agent, administers the dividend reinvestment and share purchase plan.
See the Company’s disclosure in the [removed: 2013] [added: 2014] Proxy Statement under the heading “Equity Compensation Plan Information”, which disclosure is incorporated herein by reference.
During [removed: 2012, the Company] [added: 2013, ESS] sold [removed: 2,404,096] [added: 913,344] shares of common stock for [removed: $357.7] [added: proceeds of $138.4] million, net of commissions, at an average price of [removed: $150.26.][added: $152.92.]
During the first quarter of [removed: 2013] [added: 2014] through February [removed: 21, 2013, the Company] [added: 24, 2014, ESS] has issued [removed: 758,644] [added: 462,555] shares of common stock at an average price of [removed: $151.70] [added: $162.97] for [removed: $114.0] [added: proceeds of $74.9] million, net of fees and commissions.
These sales were pursuant to a registration statement and [removed: the Company] [added: ESS] used the net proceeds from the stock offerings to pay down debt, fund redevelopment and development pipelines, fund acquisitions, and for general corporate purposes.
In August 2007, [removed: the Company’s] [added: ESS] Board of Directors authorized a stock repurchase plan to allow [removed: the Company] [added: ESS] to acquire shares in an aggregate of up to $200 million.
[removed: The Company] [added: ESS] did not repurchase any shares during [removed: 2012, 2011] [added: 2013, 2012] and [removed: 2010.][added: 2011.]
Since [removed: the Company] [added: ESS] announced the inception of the stock repurchase plan, [removed: the Company] [added: ESS] has repurchased and retired 816,659 shares for $66.6 million at an average stock price of $81.56 per share, including commissions as of December 31, [removed: 2012.][added: 2013.]
The line graph below compares the cumulative total stockholder return on [removed: the Company’s] [added: ESS] common stock for the last five years with the cumulative total return on the S&P 500 and the NAREIT All Equity REIT index over the same period.
This comparison assumes that the value of the investment in the common stock and each index was $100 on December 31, [removed: 2007] [added: 2008] and that all dividends were reinvested (1).
[removed: 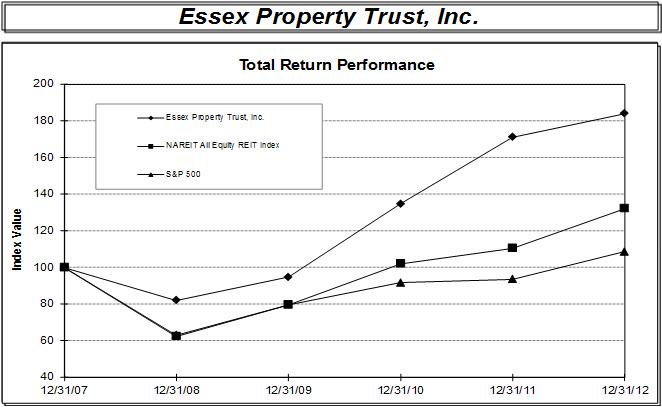][added: 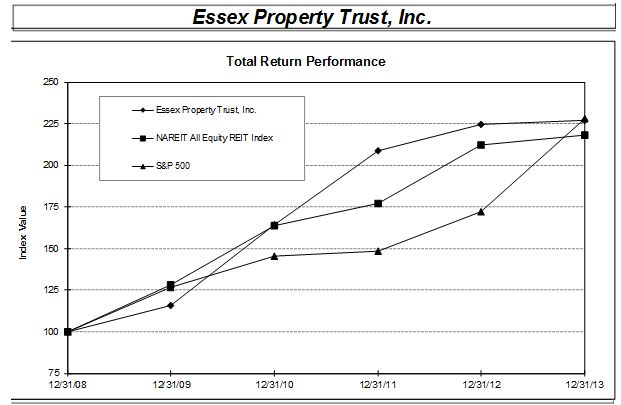]
| | | | [added: Period Ending] | | | [removed: Period Ending] | | | | | | | | | | | | | | | | | | | [added: |]
| Index | | [removed: 12/31/07] | [removed: | | |] 12/31/08 | | | | 12/31/09 | | | | 12/31/10 | | | | 12/31/11 | | | | 12/31/12 | | | [added: | 12/31/13 | | |]
| December 31, 2013 | | $ | 165.44 | | | $ | 137.53 | | | $ | 143.51 | |
| September 30, 2013 | | $ | 172.16 | | | $ | 139.64 | | | $ | 147.70 | |
| June 30, 2013 | | $ | 171.11 | | | $ | 147.56 | | | $ | 158.92 | |
| March 31, 2013 | | $ | 156.36 | | | $ | 147.06 | | | $ | 150.58 | |
There is no established public trading market for Essex Portfolio, L.P.’s OP Units.
As of February 24, 2014, there were 45 holders of record of Essex Portfolio, L.P.’s OP Units, including ESS.
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 1995 | | $ | 1.69 | | March 31, | | $ | 1.21 | | | $ | 1.10 | | | $ | 1.04 | |
| 1996 | | $ | 1.72 | | June 30, | | $ | 1.21 | | | $ | 1.10 | | | $ | 1.04 | |
| 1997 | | $ | 1.77 | | September 30, | | $ | 1.21 | | | $ | 1.10 | | | $ | 1.04 | |
| 1998 | | $ | 1.95 | | December 31, | | $ | 1.21 | | | $ | 1.10 | | | $ | 1.04 | |
| 1999 | | $ | 2.15 | | | | | | | | | | | | | | |
| 2000 | | $ | 2.38 | | Annual Dividend/Distribution | | $ | 4.84 | | | $ | 4.40 | | | $ | 4.16 | |
| 2001 | | $ | 2.80 | | | | | | | | | | | | | | |
| 2002 | | $ | 3.08 | | | | | | | | | | | | | | |
| 2003 | | $ | 3.12 | | | | | | | | | | | | | | |
| 2004 | | $ | 3.16 | | | | | | | | | | | | | | |
| 2005 | | $ | 3.24 | | | | | | | | | | | | | | |
| 2006 | | $ | 3.36 | | | | | | | | | | | | | | |
| 2007 | | $ | 3.72 | | | | | | | | | | | | | | |
| 2008 | | $ | 4.08 | | | | | | | | | | | | | | |
| 2009 | | $ | 4.12 | | | | | | | | | | | | | | |
| 2010 | | $ | 4.13 | | | | | | | | | | | | | | |
There are currently no contractual restrictions on ESS and the Operating Partnership present or future ability to pay dividends and distributions.
The Board of Directors has declared a dividend/distribution for the first quarter of 2014 of $1.21 per share.
The dividend/distribution will be payable on March 31, 2014 to shareholders/unitholders of record as of March 14, 2014.
The timing of the first quarter dividend/distribution is coordinated with BRE’s first quarter dividend, pursuant to the merger agreement.
On February 18, 2014, the ESS Board of Directors acknowledged management’s recommendation to increase the quarterly dividend by 9 cents to $1.30 per share/unit an annualized cash dividend/distribution of $5.20 per share/unit.
Future distributions by Essex Portfolio, L.P., will be at the discretion of the Board of Directors of Essex Portfolio, L.P.’s general partner, Essex Property Trust, Inc. and will depend on our actual cash flows from operations, our financial condition, capital requirements, Essex Property Trust, Inc.’s annual distribution requirements under the REIT provisions of the Internal Revenue Code, applicable legal restrictions and such other factors as the Board of Directors deem relevant.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Essex Property Trust, Inc. | | | | 100.00 | | | | 115.60 | | | | 164.28 | | | | 208.73 | | | | 224.40 | | | | 226.77 | |
| NAREIT All Equity REIT Index | | | | 100.00 | | | | 127.99 | | | | 163.76 | | | | 177.32 | | | | 212.26 | | | | 218.32 | |
| S&P 500 | | | | 100.00 | | | | 126.46 | | | | 145.51 | | | | 148.59 | | | | 172.37 | | | | 228.19 | |
Unregistered Sales of Equity Securities
During the year ended December 31, 2013, the Operating Partnership issued partnership units in private placements in reliance on the exemption from registration provided by Section 4(2) of the Securities Act, in the amounts and for the consideration set forth below:
On December 10, 2013, Essex Portfolio, L.P. issued 50,500 units under the 2014 Long-Term Incentive Plan Award agreements to twelve senior executives of the Company for no cash consideration.
During the year ended December 31, 2013, Essex Property Trust, Inc. issued an aggregate of 52,970 shares of its common stock upon the exercise of stock options.
Essex Property Trust, Inc. contributed the proceeds from the option exercises of $5.0 million to our Operating Partnership in exchange for an aggregate of 52,970 common OP Units, as required by the Operating Partnership’s partnership agreement.
During the year ended December 31, 2013, Essex Property Trust, Inc. issued an aggregate of 7,211 shares of its common stock in connection with restricted stock awards for no cash consideration.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| December 31, 2011 | | $ | 148.44 | | | $ | 111.25 | | | $ | 140.51 | |
| September 30, 2011 | | $ | 145.40 | | | $ | 119.15 | | | $ | 120.04 | |
| June 30, 2011 | | $ | 138.31 | | | $ | 122.67 | | | $ | 135.29 | |
| March 31, 2011 | | $ | 124.41 | | | $ | 109.98 | | | $ | 124.00 | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 1995 | | $ | 1.685 | | | | March 31, | | $ | 1.100 | | | $ | 1.040 | | | $ | 1.033 | |
| 1996 | | $ | 1.720 | | | | June 30, | | | 1.100 | | | | 1.040 | | | | 1.033 | |
| 1997 | | $ | 1.770 | | | | September 30, | | | 1.100 | | | | 1.040 | | | | 1.033 | |
| 1998 | | $ | 1.950 | | | | December 31, | | | 1.100 | | | | 1.040 | | | | 1.033 | |
| 1999 | | $ | 2.150 | | | | | | | | | | | | | | | | |
| 2000 | | $ | 2.380 | | | | Annual Dividend | | $ | 4.400 | | | $ | 4.160 | | | $ | 4.130 | |
| 2001 | | $ | 2.800 | | | | | | | | | | | | | | | | |
| 2002 | | $ | 3.080 | | | | | | | | | | | | | | | | |
| 2003 | | $ | 3.120 | | | | | | | | | | | | | | | | |
| 2004 | | $ | 3.160 | | | | | | | | | | | | | | | | |
| 2005 | | $ | 3.240 | | | | | | | | | | | | | | | | |
| 2006 | | $ | 3.360 | | | | | | | | | | | | | | | | |
| 2007 | | $ | 3.720 | | | | | | | | | | | | | | | | |
| 2008 | | $ | 4.080 | | | | | | | | | | | | | | | | |
| 2009 | | $ | 4.120 | | | | | | | | | | | | | | | | |
On February 20, 2013, the Company announced the Board of Directors approved a $0.44 per share increase to the annualized cash dividend.
Accordingly, the first quarter dividend distribution, payable on April 12, 2013 to stockholders as of record as of March 28, 2013, will be $1.21 per share.
On an annualized basis, the dividend represents a distribution of $4.84 per common share.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Essex Property Trust, Inc. | | | 100.00 | | | | 81.99 | | | | 94.78 | | | | 134.70 | | | | 171.15 | | | | 183.99 | |
| NAREIT All Equity REIT Index | | | 100.00 | | | | 62.27 | | | | 79.70 | | | | 101.98 | | | | 110.42 | | | | 132.18 | |
| S&P 500 | | | 100.00 | | | | 63.00 | | | | 79.68 | | | | 91.68 | | | | 93.61 | | | | 108.59 | |
An excerpt. Shown here: all 33 rewritten, 40 of 41 added and all 28 removed. The counts are complete. For every sentence, read Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities in the FY2013 filing and the FY2012 filing.
Item 6. Selected Financial Data
27 rewritten, 81 added, 29 removed, 17 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
The following tables set forth summary financial and operating information for the Company [added: and the Operating Partnership] from January 1, [removed: 2008] [added: 2009] through December 31, [removed: 2012.][added: 2013.]
| | | [removed: | | | |] Years Ended December 31, | | | | | | | | | | | | | | | [added: | | | |]
| | | [removed: 2012] [added: 2013] | | | | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011] | | | | [removed: 2009] [added: 2010] | | | | [removed: 2008] [added: 2009] | | |
| Management and other fees from affiliates | | | [removed: 11,489] [added: 11,700] | | | | [removed: 6,780] [added: 11,489] | | | | [removed: 4,551] [added: 6,780] | | | | [removed: 4,325] [added: 4,551] | | | | [removed: 5,166] [added: 4,325] | |
| [removed: (Loss) gain] [added: Loss (gain)] on early retirement of debt | | | [removed: (5,009] [added: 300] | [removed: )] | | | [removed: (1,163] [added: 5,009] | [removed: )] | | | [removed: (10] [added: 1,163] | [removed: )] | | | [removed: 4,750] [added: \-] | | | | [removed: 3,997] [added: (4,750] | [added: )] |
| Net income | | | [removed: 139,590] [added: 172,055] | | | | [removed: 57,516] [added: 139,590] | | | | [removed: 50,782] [added: 57,516] | | | | [removed: 53,739] [added: 50,782] | | | | [removed: 84,395] [added: 53,739] | |
| Net income available to common stockholders | | $ | [removed: 119,812] [added: 150,811] | | | $ | [removed: 40,368] [added: 119,812] | | | $ | [removed: 33,764] [added: 40,368] | | | $ | [removed: 82,200] [added: 33,764] | | | $ | [removed: 52,899] [added: 82,200] | |
| Income before discontinued operations available to common stockholders | | $ | [removed: 3.15] [added: 3.26] | | | $ | [removed: 0.99] [added: 3.10] | | | $ | [removed: 1.09] [added: 0.94] | | | $ | [removed: 2.66] [added: 1.03] | | | $ | [removed: 1.88] [added: 2.59] | |
| Net income available to common stockholders | | $ | [removed: 3.42] [added: 4.05] | | | $ | [removed: 1.24] [added: 3.42] | | | $ | [removed: 1.14] [added: 1.24] | | | $ | [removed: 3.01] [added: 1.14] | | | $ | [removed: 2.10] [added: 3.01] | |
| Weighted average common stock outstanding | | | [removed: 35,032] [added: 37,249] | | | | [removed: 32,542] [added: 35,032] | | | | [removed: 29,667] [added: 32,542] | | | | [removed: 27,270] [added: 29,667] | | | | [removed: 25,205] [added: 27,270] | |
| Income before discontinued operations available to common stockholders | | $ | [removed: 3.14] [added: 3.25] | | | $ | [removed: 0.99] [added: 3.09] | | | $ | [removed: 1.09] [added: 0.94] | | | $ | [removed: 2.56] [added: 1.03] | | | $ | [removed: 1.87] [added: 2.51] | |
| Net income available to common stockholders | | $ | [removed: 3.41] [added: 4.04] | | | $ | [removed: 1.24] [added: 3.41] | | | $ | [removed: 1.14] [added: 1.24] | | | $ | [removed: 2.91] [added: 1.14] | | | $ | [removed: 2.09] [added: 2.91] | |
| Weighted average common stock outstanding | | | [removed: 35,125] [added: 37,335] | | | | [removed: 32,629] [added: 35,125] | | | | [removed: 29,734] [added: 32,629] | | | | [removed: 29,747] [added: 29,734] | | | | [removed: 25,347] [added: 29,747] | |
| Cash dividend per common share | | $ | [removed: 4.40] [added: 4.84] | | | $ | [removed: 4.16] [added: 4.40] | | | $ | [removed: 4.13] [added: 4.16] | | | $ | [removed: 4.12] [added: 4.13] | | | $ | [removed: 4.08] [added: 4.12] | |
| | | [removed: 2012] [added: 2013] | | | | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011] | | | | [removed: 2009] [added: 2010] | | | | [removed: 2008] [added: 2009] | | |
| Investment in rental properties (before accumulated depreciation) | | $ | [removed: 5,033,672] [added: 5,443,757] | | | $ | [removed: 4,313,064] [added: 5,033,672] | | | $ | [removed: 3,964,561] [added: 4,313,064] | | | $ | [removed: 3,412,930] [added: 3,964,561] | | | $ | [removed: 3,279,788] [added: 3,412,930] | |
| Net investment in rental properties | | | [removed: 3,952,155] [added: 4,188,871] | | | | [removed: 3,393,038] [added: 3,952,155] | | | | [removed: 3,189,008] [added: 3,393,038] | | | | [removed: 2,663,466] [added: 3,189,008] | | | | [removed: 2,639,762] [added: 2,663,466] | |
| Real estate under development | | | [removed: 66,851] [added: 50,430] | | | | [removed: 44,280] [added: 66,851] | | | | [removed: 217,531] [added: 44,280] | | | | [removed: 274,965] [added: 217,531] | | | | [removed: 272,273] [added: 274,965] | |
| Total assets | | | [removed: 4,847,223] [added: 5,186,839] | | | | [removed: 4,036,964] [added: 4,847,223] | | | | [removed: 3,732,887] [added: 4,036,964] | | | | [removed: 3,254,637] [added: 3,732,887] | | | | [removed: 3,164,823] [added: 3,254,637] | |
| Total secured indebtedness | | | [removed: 1,565,599] [added: 1,404,080] | | | | [removed: 1,745,858] [added: 1,565,599] | | | | [removed: 2,082,745] [added: 1,745,858] | | | | [removed: 1,832,549] [added: 2,082,745] | | | | [removed: 1,588,931] [added: 1,832,549] | |
| Total unsecured indebtedness | | | [removed: 1,253,084] [added: 1,629,444] | | | | [removed: 615,000] [added: 1,253,084] | | | | [removed: 176,000] [added: 615,000] | | | | [removed: 14,893] [added: 176,000] | | | | [removed: 165,457] [added: 14,893] | |
| Cumulative convertible preferred stock | | | 4,349 | | | | 4,349 | | | | 4,349 | | | | 4,349 | | | | [removed: 145,912] [added: 4,349] | |
| Cumulative redeemable preferred stock | | | 73,750 | | | | 73,750 | | | | [removed: 25,000] [added: 73,750] | | | | 25,000 | | | | 25,000 | |
| Stockholders' equity | | | [removed: 1,764,804] [added: 1,884,619] | | | | [removed: 1,437,527] [added: 1,764,804] | | | | [removed: 1,149,946] [added: 1,437,527] | | | | [removed: 1,053,096] [added: 1,149,946] | | | | [removed: 852,227] [added: 1,053,096] | |
| | | [removed: 2012] [added: 2013] | | | | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011] | | | | [removed: 2009] [added: 2010] | | | | [removed: 2008] [added: 2009] | | |
| Net income | | [removed: $] | [removed: 139,590] [added: 172,055] | | | [removed: $] | [removed: 57,516] [added: 139,590] | | | [removed: $] | [removed: 50,782] [added: 57,516] | | | [removed: $] | [removed: 53,739] [added: 50,782] | | | [removed: $] | [removed: 84,395] [added: 53,739] | |
| Depreciation [removed: (1)] [added: and amortization] | | | [removed: 170,686] [added: 193,518] | | | | [removed: 152,543] [added: 170,686] | | | | [removed: 129,712] [added: 152,543] | | | | [removed: 118,522] [added: 129,711] | | | | [removed: 113,294] [added: 118,522] | |
Essex Property Trust, Inc. and Subsidiaries
| Rental and other property | | $ | 602,003 | | | $ | 526,696 | | | $ | 460,660 | | | $ | 400,841 | | | $ | 396,498 | |
| Income before discontinued operations | | $ | 140,882 | | | $ | 127,653 | | | $ | 46,958 | | | $ | 47,424 | | | $ | 41,244 | |
| Income from discontinued operations | | | 31,173 | | | | 11,937 | | | | 10,558 | | | | 3,358 | | | | 12,495 | |
| | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | |
| | | ($ in thousands, except per share amounts) | | | | | | | | | | | | | | | | | | |
| Funds from operations (FFO)(1): | | | | | | | | | | | | | | | | | | | | |
| Net income available to common stockholders | | $ | 150,811 | | | $ | 119,812 | | | $ | 40,368 | | | $ | 33,764 | | | $ | 82,200 | |
| Adjustments: | | | | | | | | | | | | | | | | | | | | |
| Gains not included in FFO, net of internal disposition costs | | | (67,975 | ) | | | (60,842 | ) | | | (7,543 | ) | | | \- | | | | (7,943 | ) |
| Depreciation add back from unconsolidated co-invetsments and other, net | | | 23,377 | | | | 21,194 | | | | 14,804 | | | | 7,893 | | | | 7,607 | |
| Funds from operations | | $ | 299,731 | | | $ | 250,850 | | | $ | 200,172 | | | $ | 171,368 | | | $ | 200,386 | |
| Non-core items: | | | | | | | | | | | | | | | | | | | | |
| Acquisition and merger costs | | | 5,445 | | | | 2,255 | | | | 1,231 | | | | 1,250 | | | | \- | |
| Gain on sale of marketable securities and note prepayment | | | (2,519 | ) | | | (819 | ) | | | (4,956 | ) | | | (12,491 | ) | | | (1,014 | ) |
| Co-investment promote income | | | \- | | | | (2,299 | ) | | | \- | | | | (500 | ) | | | \- | |
| CEO retirement and non-recurring payroll costs | | | \- | | | | \- | | | | \- | | | | 2,127 | | | | 4,358 | |
| Redemption of preferred stock | | | \- | | | | \- | | | | 1,949 | | | | \- | | | | (49,952 | ) |
| Impairment of development projects | | | \- | | | | \- | | | | \- | | | | \- | | | | 12,428 | |
| Other items. net (2) | | | (2,861 | ) | | | \- | | | | (2,780 | ) | | | (959 | ) | | | 32 | |
| Core funds from operations (Core FFO) | | $ | 300,096 | | | $ | 254,996 | | | $ | 196,779 | | | $ | 160,795 | | | $ | 161,488 | |
| Weighted average number of shares outstanding, diluted (FFO)(3) | | | 39,501 | | | | 37,378 | | | | 34,861 | | | | 32,028 | | | | 29,747 | |
| Funds from operations per share - diluted | | $ | 7.59 | | | $ | 6.71 | | | $ | 5.74 | | | $ | 5.35 | | | $ | 6.74 | |
| Core funds from operations per share - diluted | | $ | 7.60 | | | $ | 6.82 | | | $ | 5.64 | | | $ | 5.02 | | | $ | 5.43 | |
| | (1) | FFO is a financial measure that is commonly used in the REIT industry. The Company presents funds from operations as a supplemental operating performance measure. FFO is not used by the Company, nor should it be considered to be, as an alternative to net earnings computed under GAAP as an indicator of the Company’s operating performance or as an alternative to cash from operating activities computed under GAAP as an indicator of the Company's ability to fund its cash needs. |
FFO is not meant to represent a comprehensive system of financial reporting and does not present, nor does it intend to present, a complete picture of the Company's financial condition and operating performance.
The Company believes that net earnings computed under GAAP remain the primary measure of performance and that FFO is only meaningful when it is used in conjunction with net earnings.
The Company considers FFO and FFO excluding non-routine items (referred to as “Core FFO”) to be useful financial performance measurements of an equity REIT because, together with net income and cash flows, FFO provides investors with an additional basis to evaluate operating performance and ability of a REIT to incur and service debt and to fund acquisitions and other capital expenditures and its ability to pay dividends.
Further, the Company believes that its consolidated financial statements, prepared in accordance with GAAP, provide the most meaningful picture of its financial condition and its operating performance.
In calculating FFO, the Company follows the definition for this measure published by the National Association of Real Estate Investment Trusts (“NAREIT”), which is a REIT trade association.
The Company believes that, under the NAREIT FFO definition, the three most significant adjustments made to net income are (i) the exclusion of historical cost depreciation, (ii) the exclusion of gains and losses from the sale of previously depreciated properties and (iii) the exclusion of impairment losses on depreciated properties.
Essex agrees that these three NAREIT adjustments are useful to investors for the following reasons:
| | (a) | historical cost accounting for real estate assets in accordance with GAAP assumes, through depreciation charges, that the value of real estate assets diminishes predictably over time. NAREIT stated in its White Paper on Funds from Operations “since real estate asset values have historically risen or fallen with market conditions, many industry investors have considered presentations of operating results for real estate companies that use historical cost accounting to be insufficient by themselves.” Consequently, NAREIT’s definition of FFO reflects the fact that real estate, as an asset class, generally appreciates over time and depreciation charges required by GAAP do not reflect the underlying economic realities. |
| | (b) | REITs were created as a legal form of organization in order to encourage public ownership of real estate as an asset class through investment in firms that were in the business of long-term ownership and management of real estate. The exclusion, in NAREIT’s definition of FFO, of gains from the sales and impairment losses of previously depreciated operating real estate assets allows investors and analysts to readily identify the operating results of the long-term assets that form the core of a REIT’s activity and assists in comparing those operating results between periods. |
| --- | --- | --- |
Management has consistently applied the NAREIT definition of FFO to all periods presented.
However, other REITs in calculating FFO may vary from the NAREIT definition for this measure, and thus their disclosure of FFO may not be comparable to the Company’s calculation.
| (2) | Other items, net are non-recurring in nature and include items such as gains on non-operating assets, tax related items and early redemption of preferred equity investments. |
| --- | --- |
| REVENUES | | | | | | | | | | | | | | | | | | | | |
| Rental and other property | | $ | 531,936 | | | $ | 465,713 | | | $ | 405,728 | | | $ | 401,550 | | | $ | 397,673 | |
| | | | 543,425 | | | | 472,493 | | | | 410,279 | | | | 405,875 | | | | 402,839 | |
| EXPENSES | | | | | | | | | | | | | | | | | | | | |
| Property operating expenses | | | 174,088 | | | | 159,234 | | | | 143,164 | | | | 137,457 | | | | 130,328 | |
| Depreciation | | | 170,592 | | | | 151,428 | | | | 128,221 | | | | 116,540 | | | | 108,221 | |
| General and administrative | | | 23,307 | | | | 20,694 | | | | 23,255 | | | | 24,966 | | | | 24,725 | |
| Cost of management and other fees | | | 6,513 | | | | 4,610 | | | | 2,707 | | | | 3,096 | | | | 2,959 | |
| Impairment and other charges | | | \- | | | | \- | | | | 2,302 | | | | 13,084 | | | | 650 | |
| | | | 374,500 | | | | 335,966 | | | | 299,649 | | | | 295,143 | | | | 266,883 | |
| Earnings from operations | | | 168,925 | | | | 136,527 | | | | 110,630 | | | | 110,732 | | | | 135,956 | |
| Interest expense before amortization expense | | | (100,244 | ) | | | (91,694 | ) | | | (82,756 | ) | | | (81,196 | ) | | | (78,203 | ) |
| Amortization expense | | | (11,644 | ) | | | (11,474 | ) | | | (4,828 | ) | | | (4,820 | ) | | | (6,860 | ) |
| Interest and other income | | | 13,833 | | | | 17,139 | | | | 27,841 | | | | 13,040 | | | | 11,337 | |
| Equity income (loss) from co-investments | | | 41,745 | | | | (467 | ) | | | (1,715 | ) | | | 670 | | | | 7,820 | |
| Gain on remeasurement of co-investment | | | 21,947 | | | | \- | | | | \- | | | | \- | | | | \- | |
| Gain on the sales of real estate | | | \- | | | | \- | | | | \- | | | | 103 | | | | 4,578 | |
| Income before discontinued operations | | | 129,553 | | | | 48,868 | | | | 49,162 | | | | 43,279 | | | | 78,625 | |
| Income from discontinued operations | | | 10,037 | | | | 8,648 | | | | 1,620 | | | | 10,460 | | | | 5,770 | |
| Net income attributable to noncontrolling interest | | | (14,306 | ) | | | (10,446 | ) | | | (14,848 | ) | | | (16,631 | ) | | | (22,255 | ) |
| Net income attributable to controlling interest | | | 125,284 | | | | 47,070 | | | | 35,934 | | | | 37,108 | | | | 62,140 | |
| Dividends to preferred stockholders | | | (5,472 | ) | | | (4,753 | ) | | | (2,170 | ) | | | (4,860 | ) | | | (9,241 | ) |
| Excess (deficit) of the carrying amount of preferred stock redeemed over the cash paid to redeem preferred stock | | | \- | | | | (1,949 | ) | | | \- | | | | 49,952 | | | | \- | |
| Interest expense before amortization expense | | | 100,244 | | | | 91,694 | | | | 82,756 | | | | 81,196 | | | | 78,203 | |
| Amortization expense | | | 11,644 | | | | 11,474 | | | | 4,828 | | | | 4,820 | | | | 6,860 | |
| Tax benefit | | | \- | | | | (1,682 | ) | | | \- | | | | \- | | | | \- | |
| EBITDA(2) | | $ | 422,164 | | | $ | 311,545 | | | $ | 268,078 | | | $ | 258,277 | | | $ | 282,752 | |
| | (1) | Includes amounts classified within discontinued operations. |
| | (2) | EBITDA is an operating measure and is defined as net income before interest expense, income taxes, depreciation and amortization. EBITDA, as defined by the Company, is not a recognized measurement under U.S. generally accepted accounting principles, or GAAP. This measurement should not be considered in isolation or as a substitute for net income, cash flows from operating activities and other income or cash flow statement data prepared in accordance with GAAP, or as a measure of profitability or liquidity. The Company’s definition may not be comparable to that of other companies. |
An excerpt. Shown here: all 27 rewritten, 40 of 81 added and all 29 removed. The counts are complete. For every sentence, read Item 6. Selected Financial Data in the FY2013 filing and the FY2012 filing.
Item 9A. Controls and Procedures
8 rewritten, 10 added, 0 removed, 1 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
As of December 31, [removed: 2012, the Company] [added: 2013, ESS] carried out an evaluation, under the supervision and with the participation of management, including its Chief Executive Officer and Chief Financial Officer, of the effectiveness of the design and operation of its disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended (the “Exchange Act”)).
Based upon that evaluation, [removed: the Company’s] [added: ESS’s] Chief Executive Officer and Chief Financial Officer concluded that as of December 31, [removed: 2012, the Company’s] [added: 2013, ESS’s] disclosure controls and procedures were effective to ensure that the information required to be disclosed by [removed: the Company] [added: ESS] in the reports that [removed: the Company] [added: ESS] files or submits under the Exchange Act were recorded, processed, summarized and reported within the time periods specified in the SEC's rules and forms and that such disclosure controls and procedures were also effective to ensure that information required to be disclosed in the reports that [removed: the Company] [added: ESS] files or submits under the Exchange Act is accumulated and communicated to the [removed: Company’s] [added: ESS’s] management, including [removed: the Company’s] [added: ESS’s] Chief Executive Officer and Chief Financial Officer, to allow timely decisions regarding required disclosure.
There were no changes in [removed: the Company's] [added: ESS’s] internal control over financial reporting, that occurred during the quarter ended December 31, [removed: 2012,] [added: 2013,] that have materially affected, or are reasonably likely to materially affect, [removed: the Company's] [added: ESS’s] internal control over financial reporting.
[removed: The Company’s] [added: ESS’s] management is responsible for establishing and maintaining adequate internal control over financial reporting (as defined in Rule 13a-15(f) under the Securities Exchange Act of 1934, as amended).
[removed: The Company’s] [added: ESS’s] management assessed the effectiveness of [removed: the Company’s] [added: ESS’s] internal control over financial reporting as of December 31, [removed: 2012.][added: 2013.]
In making this assessment, [removed: the Company’s] [added: ESS’s] management used the criteria set forth [added: in the report entitled “Internal Control-Integrated Framework (1992)” published] by the Committee of Sponsoring Organizations of the Treadway Commission [removed: (“COSO”) in Internal Control-Integrated Framework.][added: (“COSO”).]
The [removed: Company’s] [added: Operating Partnership’s] management has concluded that, as of December 31, [removed: 2012,] [added: 2013,] its internal control over financial reporting was effective based on these criteria.
[removed: The Company’s] [added: ESS’s] independent registered public accounting firm, KPMG LLP, has issued an [removed: audit] [added: attestation] report [removed: on the effectiveness of its] [added: over ESS’s] internal control over financial reporting, which is included herein.
Essex Property Trust, Inc.
ESS’s management has concluded that, as of December 31, 2013, its internal control over financial reporting was effective based on these criteria.
Essex Portfolio, L.P.
As of December 31, 2013, the Operating Partnership carried out an evaluation, under the supervision and with the participation of its management, including the Chief Executive Officer and Chief Financial Officer of the general partner, of the effectiveness of the design and operation of its disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended (the “Exchange Act”)).
Based upon that evaluation, the Chief Executive Officer and Chief Financial Officer of the general partner concluded that as of December 31, 2013, the Operating Partnership’s disclosure controls and procedures were effective to ensure that the information required to be disclosed by the Operating Partnership in the reports that the files or submits under the Exchange Act were recorded, processed, summarized and reported within the time periods specified in the SEC's rules and forms and that such disclosure controls and procedures were also effective to ensure that information required to be disclosed in the reports that the Operating Partnership files or submits under the Exchange Act is accumulated and communicated to the Operating Partnership’s management, including the Chief Executive Officer and Chief Financial Officer of the general partner, to allow timely decisions regarding required disclosure.
There were no changes in the Operating Partnership’s internal control over financial reporting, that occurred during the quarter ended December 31, 2013, that have materially affected, or are reasonably likely to materially affect, the Operating Partnership’s internal control over financial reporting.
Management’s Report on Internal Control Over Financial Reporting
The Operating Partnership’s management is responsible for establishing and maintaining adequate internal control over financial reporting (as defined in Rule 13a-15(f) under the Securities Exchange Act of 1934, as amended).
The Operating Partnership’s management assessed the effectiveness of the Operating Partnership’s internal control over financial reporting as of December 31, 2013.
In making this assessment, the Operating Partnership’s management used the criteria set forth in the report entitled “Internal Control-Integrated Framework (1992)” published by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”).
Item 10. Directors, Executive Officers and Corporate Governance
0 rewritten, 1 added, 1 removed, 0 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
The information required by this Item is incorporated herein by reference from our Proxy Statement, relating to our 2014 Annual Meeting of Shareholders, under the heading “Board and Corporate Governance Matters,” to be filed with the SEC within 120 days of December 31, 2013.
The information required by Item 10 is incorporated by reference from the Company’s definitive proxy statement for its annual stockholders’ meeting to be held on May 14, 2013.
Item 11. Executive Compensation
0 rewritten, 1 added, 1 removed, 0 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
The information required by this Item is incorporated herein by reference from our Proxy Statement, relating to our 2014 Annual Meeting of Shareholders, under the headings “Executive Compensation and Other Information” and “Election of Directors – Governance, Board, and Committee Meetings: Compensation of Directors,” to be filed with the SEC within 120 days of December 31, 2013.
The information required by Item 11 is incorporated by reference from the Company’s definitive proxy statement for its annual stockholders’ meeting to be held on May 14, 2013.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
0 rewritten, 1 added, 1 removed, 0 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
The information required by this Item is incorporated herein by reference from our Proxy Statement, relating to our 2014 Annual Meeting of Shareholders, under the heading “Security Ownership of Certain Beneficial Owners and Management,” to be filed with the SEC within 120 days of December 31, 2013.
The information required by Item 12 is incorporated by reference from the Company’s definitive proxy statement for its annual stockholders’ meeting to be held on May 14, 2013.
Item 13. Certain Relationships and Related Transactions and Director Independence
0 rewritten, 1 added, 1 removed, 0 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
The information required by this Item is incorporated herein by reference from our Proxy Statement, relating to our 2014 Annual Meeting of Shareholders, under the heading “Certain Relationships and Related Transactions,” to be filed with the SEC within 120 days of December 31, 2013.
The information required by Item 13 is incorporated by reference from the Company’s definitive proxy statement for its annual stockholders’ meeting to be held on May 14, 2013.
Item 14. Principal Accounting Fees and Services
0 rewritten, 1 added, 1 removed, 1 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
The information required by this Item is incorporated herein by reference from our Proxy Statement, relating to our 2014 Annual Meeting of Shareholders, under the headings “Report of the Audit Committee” and “Fees of KPMG LLP,” to be filed with the SEC within 120 days of December 31, 2013.
The information required by Item 14 is incorporated by reference from the Company’s definitive proxy statement for its annual stockholders’ meeting to be held on May 14, 2013.
Item 15. Exhibits and Financial Statement Schedules
709 rewritten, 700 added, 320 removed, 698 unchanged
Read the full itemFY2013 item · filed February 26, 2014FY2012 item · filed February 25, 2013
| [removed: (1)] [added: Notes to] Consolidated Financial Statements | [removed: Page] [added: F-17] |
[removed: | Reports of] Independent Registered Public Accounting Firm [removed: | F-1 |]
| Consolidated Balance Sheets: As of December 31, [removed: 2012] [added: 2013] and [removed: 2011] [added: 2012] | [removed: F-4] [added: F-5] |
| Consolidated Statements of Operations: Years ended December 31, [added: 2013,] 2012, [removed: 2011,] and [removed: 2010] [added: 2011] | [removed: F-5] [added: F-6] |
| Consolidated Statements of Comprehensive [removed: Income (Loss):] [added: Income:] Years ended December 31, [added: 2013,] 2012, [removed: 2011,] and [removed: 2010] [added: 2011] | [removed: F-6] [added: F-7] |
| Consolidated Statements of Equity: Years ended December 31, [added: 2013,] 2012, [removed: 2011,] and [removed: 2010] [added: 2011] | [removed: F-7] [added: F-8] |
| Consolidated Statements of Cash Flows: Years ended December 31, [added: 2013,] 2012, [removed: 2011,] and [removed: 2010] [added: 2011] | [removed: F-8] [added: F-9] |
| Notes to [removed: the] Consolidated Financial Statements | [removed: F-10] [added: F-17] |
| [removed: (2)] [added: (3)] Financial Statement Schedule [removed: -] [added: –] Schedule III [removed: -] [added: –] Real Estate and Accumulated Depreciation as of December 31, [removed: 2011] [added: 2013.] | [removed: F-38] [added: F-47] |
| [removed: (3)] [added: (4)] See the Exhibit Index immediately following the signature page and certifications for a list of exhibits filed or incorporated by reference as part of this report. | |
We have audited the accompanying consolidated balance sheets of Essex Property Trust, Inc. and subsidiaries as of December 31, [removed: 2012] [added: 2013] and [removed: 2011,] [added: 2012,] and the related consolidated statements of operations, comprehensive [removed: income (loss),] [added: income,] equity, and cash flows for each of the years in the three-year period ended December 31, [removed: 2012.][added: 2013.]
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of Essex Property Trust, Inc. and subsidiaries as of December 31, [removed: 2012] [added: 2013] and [removed: 2011,] [added: 2012,] and the results of their operations and their cash flows for each of the years in the three-year period ended December 31, [removed: 2012,] [added: 2013,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), Essex Property Trust, Inc.’s internal control over financial reporting as of December 31, [removed: 2012,] [added: 2013,] based on criteria established in Internal Control–Integrated Framework [added: (1992)] issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO), and our report dated February [removed: 22, 2013] [added: 26, 2014] expressed an unqualified opinion on the effectiveness of Essex Property Trust, Inc.’s internal control over financial reporting.
We have audited Essex Property Trust, Inc.’s internal control over financial reporting as of December 31, [removed: 2012,] [added: 2013,] based on criteria established in Internal Control–Integrated Framework [added: (1992)] issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, Essex Property Trust, Inc. maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2012,] [added: 2013,] based on criteria established in Internal Control–Integrated Framework [added: (1992)] issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheets of Essex Property Trust, Inc. and subsidiaries as of December 31, [removed: 2012] [added: 2013] and [removed: 2011,] [added: 2012,] and the related consolidated statements of operations, comprehensive [removed: income (loss),] [added: income,] equity, and cash flows for each of the years in the three-year period ended December 31, [removed: 2012,] [added: 2013,] and our report dated February [removed: 22, 2013,] [added: 26, 2014,] expressed an unqualified opinion on those consolidated financial statements.
December 31, [removed: 2012] [added: 2013, 2012,] and 2011
| | | [added: 2013 | | | |] 2012 | | | | 2011 | | |
| Land and land improvements | | $ | [removed: 1,003,171] [added: 1,083,552] | | | $ | [removed: 860,661] [added: 1,003,171] | |
| Buildings and improvements | | | [removed: 4,030,501] [added: 4,360,205] | | | | [removed: 3,452,403] [added: 4,030,501] | |
| Less: accumulated depreciation | | | [removed: (1,081,517] [added: (1,254,886] | ) | | | [removed: (920,026] [added: (1,081,517] | ) |
| Real estate under development | | | [removed: 66,851] [added: 50,430] | | | | [removed: 44,280] [added: 66,851] | |
| Co-investments | | | [removed: 571,345] [added: 677,133] | | | | [removed: 383,412] [added: 571,345] | |
| Cash and cash equivalents-unrestricted | | | [removed: 18,606] [added: 18,491] | | | | [removed: 12,889] [added: 18,606] | |
| Cash and cash equivalents-restricted | | | [removed: 23,520] [added: 35,275] | | | | [removed: 22,574] [added: 23,520] | |
| Marketable securities | | | [removed: 92,713] [added: 90,084] | | | | [removed: 74,275] [added: 92,713] | |
| Notes and other receivables | | | [removed: 66,163] [added: 68,255] | | | | [removed: 66,369] [added: 66,163] | |
| Prepaid expenses and other assets | | | [removed: 35,003] [added: 33,781] | | | | [removed: 22,682] [added: 35,003] | |
| Deferred charges, net | | | [removed: 20,867] [added: 24,519] | | | | [removed: 17,445] [added: 20,867] | |
| Total assets | | $ | [removed: 4,847,223] [added: 5,186,839] | | | $ | [removed: 4,036,964] [added: 4,847,223] | |
| Mortgage notes payable | | $ | [removed: 1,565,599] [added: 1,404,080] | | | $ | [removed: 1,745,858] [added: 1,565,599] | |
| Unsecured debt | | | [removed: 1,112,084] [added: 1,410,023] | | | | [removed: 465,000] [added: 1,112,084] | |
| Lines of credit | | | [removed: 141,000] [added: 219,421] | | | | [removed: 150,000] [added: 141,000] | |
| Accounts payable and accrued liabilities | | | [removed: 64,858] [added: 67,183] | | | | [removed: 48,324] [added: 64,858] | |
| Construction payable | | | [removed: 5,392] [added: 8,047] | | | | [removed: 6,505] [added: 5,392] | |
| Dividends payable | | | [removed: 45,052] [added: 50,627] | | | | [removed: 39,611] [added: 45,052] | |
| Derivative liabilities | | | [removed: 6,606] [added: 2,682] | | | | [removed: 3,061] [added: 6,606] | |
| Other liabilities | | | [removed: 22,167] [added: 22,189] | | | | [removed: 20,528] [added: 22,167] | |
| Total liabilities | | | [removed: 2,962,758] [added: 3,184,252] | | | | [removed: 2,478,887] [added: 2,962,758] | |
| Cumulative convertible 4.875% Series G preferred stock; $.0001 par value: [removed: 5,890,000] [added: 5,980,000] issued, and 178,249 outstanding | | | 4,349 | | | | 4,349 | |
| (1) Consolidated Financial Statements of Essex Property Trust, Inc. | Page |
| (2) Consolidated Financial Statements of Essex Portfolio, L.P. | |
| Report of Independent Registered Public Accounting Firm | F-4 |
| Consolidated Balance Sheets: As of December 31, 2013 and 2012 | F-11 |
| Consolidated Statements of Operations: Years ended December 31, 2013, 2012, and 2011 | F-12 |
| Consolidated Statements of Comprehensive Income: Years ended December 31, 2013, 2012, and 2011 | F-13 |
| Consolidated Statements of Capital: Years ended December 31, 2013, 2012, and 2011 | F-14 |
| Consolidated Statements of Cash Flows: Years ended December 31, 2013, 2012, and 2011 | F-15 |
February 26, 2014
February 26, 2014
The General Partner
Essex Portfolio, L.P.:
We have audited the accompanying consolidated balance sheets of Essex Portfolio, L.P. (the Operating Partnership) and subsidiaries as of December 31, 2013 and 2012, and the related consolidated statements of operations, comprehensive income, capital, and cash flows for each of the years in the three-year period ended December 31, 2013.
In connection with our audits of the consolidated financial statements, we have also audited the accompanying financial statement schedule III.
These consolidated financial statements and the accompanying financial statement schedule III are the responsibility of Operating Partnership’s management.
Our responsibility is to express an opinion on these consolidated financial statements and the accompanying financial statement schedule III based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States).
Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement.
An audit includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements.
An audit also includes assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall financial statement presentation.
We believe that our audits provide a reasonable basis for our opinion.
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of Essex Portfolio, L.P. and subsidiaries as of December 31, 2013 and 2012, and the results of their operations and their cash flows for each of the years in the three-year period ended December 31, 2013, in conformity with U.S. generally accepted accounting principles.
Also in our opinion, the related financial statement schedule III, when considered in relation to the basic consolidated financial statements taken as a whole, presents fairly, in all material respects, the information set forth therein.
| | /S/ KPMG LLP |
| | KPMG LLP |
San Francisco, California
February 26, 2014
| | | 2013 | | | | 2012 | | |
| | | | 5,443,757 | | | | 5,033,672 | |
| | | | 4,188,871 | | | | 3,952,155 | |
| | | | 4,916,434 | | | | 4,590,351 | |
| Rental and other property | | $ | 602,003 | | | $ | 526,696 | | | $ | 460,660 | |
| | | | 613,703 | | | | 538,185 | | | | 467,440 | |
| Property operating, excluding real estate taxes | | | 138,736 | | | | 123,813 | | | | 113,733 | |
| Real estate taxes | | | 57,276 | | | | 48,354 | | | | 43,777 | |
| Depreciation | | | 192,420 | | | | 169,173 | | | | 150,009 | |
| Merger expenses | | | 4,284 | | | | \- | | | | \- | |
| | | | 424,998 | | | | 371,160 | | | | 332,823 | |
| Earnings from operations | | | 188,705 | | | | 167,025 | | | | 134,617 | |
| Loss on early retirement of debt, net | | | (300 | ) | | | (5,009 | ) | | | (1,163 | ) |
February 22, 2013
February 22, 2013
| | | | 5,033,672 | | | | 4,313,064 | |
| | | | 3,952,155 | | | | 3,393,038 | |
| | | | 4,590,351 | | | | 3,820,730 | |
| Rental and other property | | $ | 531,936 | | | $ | 465,713 | | | $ | 405,728 | |
| | | | 543,425 | | | | 472,493 | | | | 410,279 | |
| Property operating, excluding real estate taxes | | | 125,437 | | | | 115,528 | | | | 104,049 | |
| Real estate taxes | | | 48,651 | | | | 43,706 | | | | 39,115 | |
| Depreciation | | | 170,592 | | | | 151,428 | | | | 128,221 | |
| Impairment and other charges | | | \- | | | | \- | | | | 2,302 | |
| | | | 374,500 | | | | 335,966 | | | | 299,649 | |
| Earnings from operations | | | 168,925 | | | | 136,527 | | | | 110,630 | |
| Income before discontinued operations | | | 129,553 | | | | 48,868 | | | | 49,162 | |
| | | | | | | | | | | | | | | | | | | | | | | Distributions | | | | Accumulated | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | Additional | | | | in excess of | | | | other | | | | | | | | | | |
| Balances at December 31, 2009 | | | 1,000 | | | $ | 25,000 | | | | 28,849 | | | $ | 3 | | | $ | 1,275,251 | | | $ | (222,952 | ) | | $ | (24,206 | ) | | $ | 220,445 | | | $ | 1,273,541 | |
| Net income | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | 35,934 | | | | \- | | | | 14,848 | | | | 50,782 | |
| Sale of common stock | | | \- | | | | \- | | | | 2,354 | | | | \- | | | | 251,455 | | | | \- | | | | \- | | | | \- | | | | 251,455 | |
| Retirement of exchangeable bonds | | | \- | | | | \- | | | | \- | | | | \- | | | | (434 | ) | | | \- | | | | \- | | | | \- | | | | (434 | ) |
| Redemptions of noncontrolling interest | | | \- | | | | \- | | | | \- | | | | \- | | | | (16,347 | ) | | | \- | | | | \- | | | | (7,839 | ) | | | (24,186 | ) |
| Loss on derivative instruments - ineffectiveness | | | \- | | | | \- | | | | 2,301 | |
| Redevelopment | | | (40,200 | ) | | | (45,130 | ) | | | (14,096 | ) |
| Proceeds from tax investor | | | \- | | | | \- | | | | 1,223 | |
| Retirement of exchangeable bonds | | | \- | | | | \- | | | | (5,396 | ) |
| Note receivable settled when the company purchased the property securing the note receivable | | $ | \- | | | $ | \- | | | $ | 25,750 | |
These conversion rights may be exercised by the limited partners at any time through 2026.
| --- | --- | --- |
The Company ceases to capitalize costs such as property taxes, insurance, and interest expenses once the development activities are put on hold.
| --- | --- | --- |
| --- | --- | --- |
For preferred equity investments the Company recognizes its preferred interest as its equity in earnings.
In 2012, the Company recorded a $2.3 million promote fee in connection with acquisition of our joint venture partner's remaining membership interest in the co-investment Essex Skyline at MacArthur Place for a purchase price of $85 million.
The property is now consolidated.
There were no promote fees recognized in 2011 and 2010 in the accompanying consolidated statements of operations.
| Investment funds - US treasuries | | | 14,120 | | | | 729 | | | | 14,849 | |
| Investment funds - US treasuries | | | 11,783 | | | | 121 | | | | 11,904 | |
| Common stock | | | 10,067 | | | | 1,552 | | | | 11,619 | |
| Total | | $ | 72,203 | | | $ | 2,072 | | | $ | 74,275 | |
Interest income is generated primarily from cash balances and marketable securities as well as notes receivables.
An excerpt. Shown here: 40 of 709 rewritten, 40 of 700 added and 40 of 320 removed. The counts are complete. For every sentence, read Item 15. Exhibits and Financial Statement Schedules in the FY2013 filing and the FY2012 filing.