 filings.tools
Essex Property Trust 10-K 2015-12-31
Filed 2016-02-26. 21 sections, 525K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 ess-123115x10k.htm 10-K
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
(MARK ONE)
| x | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2015
OR
| o | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
FOR THE TRANSITION PERIOD FROM ___________ TO _____________
Commission file number: 1-13106 (Essex Property Trust, Inc.)
Commission file number: 333-44467-01 (Essex Portfolio, L.P.)
ESSEX PROPERTY TRUST, INC.
ESSEX PORTFOLIO, L.P.
(Exact name of Registrant as Specified in its Charter)
| Maryland (Essex Property Trust, Inc.) California (Essex Portfolio, L.P.) | 77-0369576 (Essex Property Trust, Inc.) 77-0369575 (Essex Portfolio, L.P.) | |
| (State or Other Jurisdiction of Incorporation or Organization) | (I.R.S. Employer Identification Number) |
1100 Park Place, Suite 200
San Mateo, California 94403
(Address of Principal Executive Offices including Zip Code)
(650) 655-7800
(Registrant's Telephone Number, Including Area Code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Name of each exchange on which registered | |
| Common Stock, $.0001 par value (Essex Property Trust, Inc.) | New York Stock Exchange | |
| 7.125% Series H Cumulative Redeemable Preferred Stock (Essex Property Trust, Inc.) | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act.
| Essex Property Trust, Inc. Yes x No o | Essex Portfolio, L.P. Yes o No x |
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act.
| Essex Property Trust, Inc. Yes o No x | Essex Portfolio, L.P. Yes o No x |
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days.
| Essex Property Trust, Inc. Yes x No o | Essex Portfolio, L.P. Yes x No o |
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files).
| Essex Property Trust, Inc. Yes x No o | Essex Portfolio, L.P. Yes x No o |
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of Registrant's knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K, or any amendment to this Form 10-K.
| Essex Property Trust, Inc. o | Essex Portfolio, L.P. o |
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act. (Check one):
Essex Property Trust, Inc.:
| Large accelerated filer x | Accelerated filer o | Non-accelerated filer o (Do not check if a smaller reporting company) | Smaller reporting company o |
Essex Portfolio, L.P.:
| Large accelerated filer o | Accelerated filer o | Non-accelerated filer x (Do not check if a smaller reporting company) | Smaller reporting company o |
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act).
| Essex Property Trust, Inc. Yes o No x | Essex Portfolio, L.P. Yes o No x |
As of June 30, 2015, the aggregate market value of the voting stock held by non-affiliates of Essex Property Trust, Inc. was $13,717,739,025. The aggregate market value was computed with reference to the closing price on the New York Stock Exchange on such date. Shares of common stock held by executive officers, directors and holders of more than ten percent of the outstanding common stock have been excluded from this calculation because such persons may be deemed to be affiliates. This exclusion does not reflect a determination that such persons are affiliates for any other purposes. There is no public trading market for the common units of Essex Portfolio, L.P. As a result, the aggregate market value of the common units held by non-affiliates of Essex Portfolio, L.P., cannot be determined.
As of February 22, 2016, 65,411,581 shares of common stock ($.0001 par value) of Essex Property Trust, Inc. were outstanding.
DOCUMENTS INCORPORATED BY REFERENCE:
The following document is incorporated by reference in Part III of the Annual Report on Form 10-K: Proxy statement for the annual meeting of stockholders of Essex Property Trust, Inc. to be filed within 120 days of December 31, 2015.
EXPLANATORY NOTE
This report combines the annual reports on Form 10-K for the year ended December 31, 2015 of Essex Property Trust, Inc. and Essex Portfolio, L.P. Unless stated otherwise or the context otherwise requires, references to “ESS” mean Essex Property Trust, Inc., a Maryland corporation that operates as a self-administered and self-managed real estate investment trust (“REIT”), and references to “EPLP” mean Essex Portfolio, L.P. (the “Operating Partnership”). Unless stated otherwise or the context otherwise requires, references to the “Company,” “Essex,” “we,” “us” or “our” mean collectively ESS, EPLP and those entities/subsidiaries owned or controlled by ESS and/or EPLP. References to the “Operating Partnership” mean collectively EPLP and those entities/subsidiaries owned or controlled by EPLP.
ESS is the general partner of, and as of December 31, 2015 owned an approximate 96.7% ownership interest in EPLP. The remaining 3.3% interest is owned by limited partners. As the sole general partner of EPLP, ESS has exclusive control of EPLP's day-to-day management.
The Company is structured as an umbrella partnership REIT (“UPREIT”) and ESS contributes all net proceeds from its various equity offerings to the Operating Partnership. In return for those contributions, ESS receives a number of OP Units (see definition below) in the Operating Partnership equal to the number of shares of common stock it has issued in the equity offering. Contributions of properties to the Company can be structured as tax-deferred transactions through the issuance of OP Units in the Operating Partnership, which is one of the reasons why the Company is structured in the manner shown above. Based on the terms of EPLP's partnership agreement, OP Units can be exchanged for ESS common stock on a one-for-one basis. The Company maintains a one-for-one relationship between the OP Units of the Operating Partnership issued to ESS and shares of common stock.
The Company believes that combining the reports on Form 10-K of ESS and EPLP into this single report provides the following benefits:
| • | enhances investors' understanding of the Company and the Operating Partnership by enabling investors to view the business as a whole in the same manner as management views and operates the business; |
| • | eliminates duplicative disclosure and provides a more streamlined and readable presentation since a substantial portion of the disclosure applies to both the Company and the Operating Partnership; and |
| • | creates time and cost efficiencies through the preparation of one combined report instead of two separate reports. |
Management operates the Company and the Operating Partnership as one business. The management of ESS consists of the same members as the management of EPLP.
All of the Company's property ownership, development and related business operations are conducted through the Operating Partnership and ESS has no material assets, other than its investment in EPLP. ESS's primary function is acting as the general partner of EPLP. As general partner with control of the Operating Partnership, the Company consolidates the Operating Partnership for financial reporting purposes. Therefore, the assets and liabilities of the Company and the Operating Partnership are the same on their respective financial statements. ESS also issues equity from time to time and guarantees certain debt of EPLP, as disclosed in this report. The Operating Partnership holds substantially all of the assets of the Company, including the Company's ownership interests in its joint ventures. The Operating Partnership conducts the operations of the business and is structured as a partnership with no publicly traded equity. Except for the net proceeds from equity offerings by the Company, which are contributed to the capital of the Operating Partnership in exchange for additional limited partnership interests in the Operating Partnership (“OP Units”) (on a one-for-one share of common stock per OP Unit basis), the Operating Partnership generates all remaining capital required by the Company's business. These sources include the Operating Partnership's working capital, net cash provided by operating activities, borrowings under its revolving credit facility, the issuance of secured and unsecured debt and equity securities and proceeds received from disposition of certain properties and joint ventures.
The Company believes it is important to understand the few differences between ESS and EPLP in the context of how ESS and EPLP operate as a consolidated company. Shareholders' equity, partners' capital and noncontrolling interests are the main areas of difference between the consolidated financial statements of the Company and those of the Operating Partnership. The limited partners of the Operating Partnership are accounted for as partners' capital in the Operating Partnership's consolidated financial statements and as noncontrolling interests in the Company's consolidated financial statements. The noncontrolling interests in the Operating Partnership's consolidated financial statements include the interests of unaffiliated partners in various consolidated partnerships and development joint venture partners. The noncontrolling interests in the Company's consolidated financial statements include (i) the same noncontrolling interests as presented in the Operating Partnership’s consolidated financial statements and (ii) limited partner OP Unit holders of the Operating Partnership. The differences between
iii
stockholders' equity and partners' capital result from differences in the equity issued at the Company and Operating Partnership levels.
To help investors understand the significant differences between the Company and the Operating Partnership, this report provides separate consolidated financial statements for the Company and the Operating Partnership; a single set of consolidated notes to such financial statements that includes separate discussions of shareholders' equity or partners' capital, earnings per share/unit; as applicable; and a combined Management's Discussion and Analysis of Financial Condition and Results of Operations.
This report also includes separate Part II, Item 9A. Controls and Procedures sections and separate Exhibits 31 and 32 certifications for each of the Company and the Operating Partnership in order to establish that the requisite certifications have been made and that the Company and the Operating Partnership are compliant with Rule 13a-15 or Rule 15d-15 of the Securities Exchange Act of 1934 and 18 U.S.C. §1350.
In order to highlight the differences between the Company and the Operating Partnership, the separate sections in this report for the Company and the Operating Partnership specifically refer to the Company and the Operating Partnership. In the sections that combine disclosure of the Company and the Operating Partnership, this report refers to actions or holdings as being actions or holdings of the Company. Although the Operating Partnership is generally the entity that directly or indirectly enters into contracts and joint ventures and holds assets and debt, reference to the Company is appropriate because the Company is one business and the Company operates that business through the Operating Partnership. The separate discussions of the Company and the Operating Partnership in this report should be read in conjunction with each other to understand the results of the Company on a consolidated basis and how management operates the Company.
iv
ESSEX PROPERTY TRUST, INC.
ESSEX PORTFOLIO, L.P.
2015 ANNUAL REPORT ON FORM 10-K
TABLE OF CONTENTS
v
PART I
Forward Looking Statements
This Form 10-K contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. Such forward-looking statements are described in Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations, in the section, “Forward Looking Statements.” Actual results could differ materially from those set forth in each forward-looking statement. Certain factors that might cause such a difference are discussed in this report, including in Item 1A, Risk Factors of this Form 10-K.
Item 1. Business
OVERVIEW
Essex Property Trust, Inc. (“Essex”, "ESS", or the “Company”) a Maryland corporation, is an S&P 500 company that operates as a self-administered and self-managed real estate investment trust (“REIT”). The Company owns all of its interest in its real estate and other investments directly or indirectly through Essex Portfolio, L.P. (the “Operating Partnership” or “EPLP”). The Company is the sole general partner of the Operating Partnership and as of December 31, 2015 owns a 96.7% general partnership interest. In this report, the terms “Essex” or the “Company” also refer to Essex Property Trust, Inc., its Operating Partnership and those entities owned or controlled by the Operating Partnership.
The Company has elected to be treated as a REIT for federal income tax purposes, commencing with the year ended December 31, 1994 as the Company completed an initial public offering on June 13, 1994. In order to maintain compliance with REIT tax rules, the Company utilizes taxable REIT subsidiaries for various revenue generating or investment activities. All taxable REIT subsidiaries are consolidated by the Company.
The Company is engaged primarily in the ownership, operation, management, acquisition, development and redevelopment of predominantly apartment communities. As of December 31, 2015, the Company owned or held an interest in 246 communities, aggregating 59,160 apartment homes, located along the West Coast, as well as four commercial buildings (totaling approximately 319,079 square feet), and eight active development projects with 2,447 apartment homes in various stages of development (collectively, the “Portfolio”).
The Company’s website address is http://www.essex.com. The Company’s annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and all amendments to those reports, and the Proxy Statement for its Annual Meeting of Stockholders are available, free of charge, on its website as soon as practicable after the Company files the reports with the U.S. Securities and Exchange Commission (“SEC”).
BUSINESS STRATEGIES
The following is a discussion of the Company’s business strategies in regards to real estate investment and management.
Business Strategies
Research Driven Approach to Investments – The Company believes that successful real estate investment decisions and portfolio growth begin with extensive regional economic research and local market knowledge. The Company continually assesses markets where the Company operates, as well as markets where the Company considers future investment opportunities by evaluating the following:
| • | Focus on markets in major metropolitan areas that have regional population in excess of one million; |
| • | Constraints on new supply driven by: (i) low availability of developable land sites where competing housing could be economically built; (ii) political growth barriers, such as protected land, urban growth boundaries, and potential lengthy and expensive development permit processes; and (iii) natural limitations to development, such as mountains or waterways; |
| • | Rental demand is enhanced by affordability of rents relative to costs of for-sale housing; and |
| • | Housing demand that is based on job growth, proximity to jobs, high median incomes and the quality of life including related commuting factors. |
Recognizing that all real estate markets are cyclical, the Company regularly evaluates the results of its regional economic, and local market research, and adjusts the geographic focus of its portfolio accordingly. The Company seeks to increase its portfolio allocation in markets projected to have the strongest local economies and to decrease such allocations in markets
projected to have declining economic conditions. Likewise, the Company also seeks to increase its portfolio allocation in markets that have attractive property valuations and to decrease such allocations in markets that have inflated valuations and low relative yields.
Property Operations – The Company manages its communities by focusing on activities that may generate above-average rental growth, tenant retention/satisfaction and long-term asset appreciation. The Company intends to achieve this by utilizing the strategies set forth below:
| • | Property Management – Oversee delivery of and quality of the housing provided to our residents and manage the properties financial performance. |
| • | Capital Preservation –Asset Management is responsible for the planning, budgeting and completion of major capital improvement projects at the Company’s communities. |
| • | Business Planning and Control – Comprehensive business plans are implemented in conjunction with significant investment decisions. These plans include benchmarks for future financial performance, based on collaborative discussions between on-site managers and senior management. |
| • | Development and Redevelopment – The Company focuses on acquiring and developing apartment communities in supply constrained markets, and redeveloping its existing communities to improve the financial and physical aspects of the Company’s communities. |
CURRENT BUSINESS ACTIVITIES
Merger with BRE Properties, Inc. in 2014
On April 1, 2014, Essex completed the merger with BRE Properties, Inc. (“BRE”). In connection with the closing of the merger, (1) BRE merged into a wholly owned subsidiary of Essex, and (2) each outstanding share of BRE common stock was converted into (i) 0.2971 shares (the “Stock Consideration”) of Essex common stock, and (ii) $7.18 in cash, (the “Cash Consideration”), plus cash in lieu of fractional shares for total consideration of approximately $4.3 billion. The Cash Consideration was adjusted as a result of the authorization and declaration of a special distribution to the stockholders of BRE of $5.15 per share of BRE common stock payable to BRE stockholders of record as of the close of business on March 31, 2014 (the “Special Dividend”). The Special Dividend was payable as a result of the closing of the sale of certain interests in assets of BRE to certain parties, which closed on March 31, 2014. Pursuant to the terms of the merger agreement, the amounts payable as a Special Dividend reduced the Cash Consideration of $12.33 payable by Essex in the merger to $7.18 per share of BRE common stock.
Essex issued approximately 23.1 million shares of Essex common stock as Stock Consideration in the merger. For purchase accounting, the value of the common stock issued by Essex upon the consummation of the merger was determined based on the closing price of BRE’s common stock on the closing date of the merger. As a result of Essex being admitted to the S&P 500 on the same date as the closing of the merger, Essex’s common stock price experienced significantly higher than usual trading volume and the closing price of $174 per share was significantly higher than its volume-weighted average trading price for the days before and after April 1, 2014. BRE’s common stock did not experience the same proportionate increase in common stock price leading up to April 1, 2014. As a result, given that a substantial component of the purchase price is an exchange of equity instruments, Essex used the closing price of BRE’s common stock on April 1, 2014 of $61 per share, less the Cash Consideration, as the fair value of the equity consideration. After deducting the Special Dividend and the Cash Consideration per share, this resulted in a value of $48.67 per share of BRE common stock which is the equivalent of approximately $164 per share of Essex common stock issued.
Acquisitions of Real Estate
Acquisitions are an important component of the Company’s business plan, and during 2015, the Company acquired ownership interests in seven communities comprised of 1,722 apartment homes for $638.1 million.
The following is a summary of 2015 acquisitions ($ in millions):
| Property Name | Location | Apartment Homes | Essex Ownership Percentage | Ownership | Quarter in 2015 | Purchase Price | ||||||||||
| 8th & Hope | Los Angeles, CA | 290 | 100 | % | EPLP | Q1 | $ | 200.0 | ||||||||
| The Huxley (1) | Los Angeles, CA | 187 | 100 | % | EPLP | Q1 | 48.8 | |||||||||
| The Dylan (1) | Los Angeles, CA | 184 | 100 | % | EPLP | Q1 | 51.3 | |||||||||
| Reveal (2) | Woodland Hills, CA | 438 | 99.75 | % | EPLP | Q2 | 73.0 | |||||||||
| Avant | Los Angeles, CA | 247 | 100 | % | EPLP | Q2 | 99.0 | |||||||||
| Avant II | Los Angeles, CA | 193 | 100 | % | EPLP | Q4 | 73.0 | |||||||||
| Enso | San Jose, CA | 183 | 100 | % | EPLP | Q4 | 93.0 | |||||||||
| Total 2015 | 1,722 | $ | 638.1 |
| (1) | In March 2015, the Company purchased the joint venture partner's remaining membership interest in The Huxley and The Dylan co-investments for a purchase price of $100.1 million. The properties are now consolidated. |
| (2) | In April 2015, the Company purchased the joint venture partner's 49.5% membership interest in the Reveal co-investment for a purchase price of $73.0 million. The property is now consolidated. |
Dispositions of Real Estate
As part of its strategic plan to own quality real estate in supply-constrained markets, the Company continually evaluates all the communities and sells those which no longer meet its strategic criteria. The Company may use the capital generated from the dispositions to invest in higher-return communities or other real estate investments, or repay debts. The Company believes that the sale of these communities will not have a material impact on its future results of operations or cash flows nor will their sale materially affect its ongoing operations. Generally, the Company seeks to have any impact of earnings dilution resulting from these dispositions offset by the positive impact of its acquisitions, development and redevelopment activities.
During 2015, the Company sold two apartment communities, Pinnacle South Mountain and Sharon Green, for a total of $308.8 million, resulting in total gains of $44.9 million. Additionally, in March 2015, the Company sold two commercial buildings, aggregating 120,000 square feet, located in Emeryville, CA, for $13.0 million, resulting in gains of $2.4 million.
Development Pipeline
The Company defines development projects as new communities that are being constructed or are newly constructed and are in a phase of lease-up and have not yet reached stabilized operations. As of December 31, 2015, the Company had two consolidated development projects and six joint venture development projects comprised of 2,447 apartment homes for an estimated cost of $1.4 billion, of which $787 million remains to be expended, of which $542 million is the Company's share.
The Company defines predevelopment projects as proposed communities in negotiation or in the entitlement process with an expected high likelihood of becoming entitled development projects. As of December 31, 2015, the Company had various consolidated predevelopment projects. The Company may also acquire land for future development purposes or sale.
The following table sets forth information regarding the Company’s development pipeline ($ in millions):
| As of | ||||||||||||||||
| 12/31/2015 | ||||||||||||||||
| Essex | Incurred | Estimated | ||||||||||||||
| Development Pipeline | Location | Ownership% | Apartment Homes | Project Cost (1) | Project Cost(1) | |||||||||||
| Development Projects - Consolidated | ||||||||||||||||
| MB 360 - Phase II | San Francisco, CA | 100 | % | 172 | $ | 119 | $ | 135 | ||||||||
| Station Park Green | San Mateo, CA | 100 | % | 599 | 83 | 354 | ||||||||||
| Total - Consolidated Development Projects | 771 | 202 | 489 | |||||||||||||
| Development Projects - Joint Venture | ||||||||||||||||
| Epic - Phase III | San Jose, CA | 55 | % | 200 | 84 | 92 | ||||||||||
| Agora(2) | Walnut Creek, CA | 51 | % | 49 | 84 | 95 | ||||||||||
| Owens | Pleasanton, CA | 55 | % | 255 | 55 | 89 | ||||||||||
| Hacienda | Pleasanton, CA | 55 | % | 251 | 37 | 86 | ||||||||||
| Century Towers | San Jose, CA | 50 | % | 376 | 93 | 172 | ||||||||||
| 500 Folsom (3) | San Francisco, CA | 50 | % | 545 | 62 | 381 | ||||||||||
| Total - Joint Venture Development Projects | 1,676 | 415 | 915 | |||||||||||||
| Predevelopment Projects - Consolidated | ||||||||||||||||
| Other Projects | various | 100 | % | — | 40 | 40 | ||||||||||
| Total - Predevelopment Projects | — | 40 | 40 | |||||||||||||
| Grand Total - Development and Predevelopment Pipeline | 2,447 | $ | 657 | $ | 1,444 |
| (1) | Includes costs related to the entire project, including both the Company's and joint venture partners' costs. Includes incurred costs and estimated costs to complete these development projects. For predevelopment projects, only incurred costs are included in estimated costs. |
| (2) | Estimated project costs for this development include costs to develop both residential and commercial space. |
| (3) | Estimated project cost for this development is net of a projected value for low-income housing tax credit proceeds and savings from tax exempt bonds. |
Redevelopment Pipeline
The Company defines the redevelopment pipeline as existing properties owned or recently acquired, which have been targeted for additional investment by the Company with the expectation of increased financial returns through property improvement. During redevelopment, apartment homes may not be available for rent and, as a result, may have less than stabilized operations. As of December 31, 2015, the Company had ownership interests in five major redevelopment communities aggregating 1,313 apartment homes with estimated redevelopment costs of $159.8 million, of which approximately $82.5 million remains to be expended.
Long Term Debt
During 2015, the Company made regularly scheduled principal payments and loan payoffs of $118.3 million of its secured mortgage notes payable at an average interest rate of 5.3%.
In March 2015, the Company issued $500 million of 3.5% senior unsecured notes that mature in April 2025. The interest is payable semi-annually in arrears on April 1st and October 1st of each year, commencing October 1, 2015, until the maturity date in April 2025. The Company used the net proceeds of this offering to repay indebtedness under the Company's $1.0 billion unsecured line of credit facility, its $25.0 million unsecured working capital line and for other general corporate purposes.
Bank Debt
As of December 31, 2015, Fitch Ratings ("Fitch"), Moody’s Investor Service, and Standard and Poor's (“S&P”) credit agencies rated Essex Property Trust, Inc. and Essex Portfolio, L.P. BBB+/Stable, Baa2/Positive, and BBB/Positive, respectively.
At December 31, 2015, the Company's $1.0 billion credit facility had an interest rate of LIBOR plus 0.95%, which is based on a tiered rate structure tied to the Company's credit ratings. In January 2016, the Company extended the maturity date on its $1.0 billion unsecured line of credit facility from December 2017 to December 2019, with one 18-month extension, exercisable by the Company and lowered the interest rate to LIBOR plus 0.90%.
Equity Transactions
During 2015, ESS issued 1,481,737 shares of common stock at an average share price of $226.46 for proceeds of $332.3 million, net of fees and commissions. ESS contributed the net proceeds to the Operating Partnership and used the proceeds to pay down debt, fund the development and redevelopment pipeline, fund acquisitions, and for general corporate purposes. During the first quarter of 2016 through February 22, 2016, ESS has not issued any shares under its equity distribution program.
Co-investments
The Company has entered into, and may continue in the future to enter into, joint ventures or partnerships (including limited liability companies) through which we own an indirect economic interest in less than 100% of the community or land owned directly by the joint venture or partnership. For each joint venture the Company holds a 50% to 55% non-controlling interest in the venture and will earn customary management fees and may earn development, asset property management fees and may also earn a promote interest.
The Company has also made, and may continue in the future to make, preferred equity investments in various multi-family development projects. The Company earns a preferred rate of return on these investments.
OFFICES AND EMPLOYEES
The Company is headquartered in San Mateo, California, and has regional offices in Woodland Hills, California; San Jose, California; Irvine, California; San Diego, California and Bellevue, Washington. As of December 31, 2015, the Company had 1,806 employees.
INSURANCE
The Company purchases general liability and all risk property, including loss of rent, insurance coverage for each of its communities. The Company also purchases limited earthquake, terrorism, environmental and flood insurance. There are certain types of losses which may not be covered or could exceed coverage limits. The insurance programs are subject to deductibles and self-insured retentions in varying amounts. The Company utilizes a wholly owned insurance subsidiary, Pacific Western Insurance LLC ("PWI") to self-insure certain earthquake and all risk losses. As of December 31, 2015, PWI has cash and marketable securities of approximately $60.3 million, and is consolidated in the Company's financial statements.
All of the Company's communities are located in areas that are subject to earthquake activity. The Company evaluates its financial loss exposure to seismic events by using actuarial loss models developed by the insurance industry and property vulnerability based on structural evaluations of seismic consultants. The Company manages this exposure, where considered appropriate, desirable, and cost-effective, by upgrading properties to increase their resistance to forces caused by seismic events, by considering available funds and coverages provided by PWI and/or by purchasing seismic insurance. The Company also purchases limited earthquake insurance for certain properties owned by the Company's co-investments.
In addition, the Company carries other types of insurance coverage related to a variety of risks and exposures.
Based on market conditions, the Company may change or potentially eliminate insurance coverages, or increase levels of self-insurance. Further, the Company may incur losses, which could be material, due to uninsured risks, deductibles and self-insured retentions, and/or losses in excess of coverage limits.
COMPETITION
There are numerous housing alternatives that compete with the Company’s communities in attracting residents. These include other apartment communities, condominiums and single-family homes. If the demand for the Company’s communities is reduced or if competitors develop and/or acquire competing housing, rental rates and occupancy may drop which may have a material adverse effect on the Company’s financial condition and results of operations.
The Company faces competition from other real estate investment trusts, businesses and other entities in the acquisition, development and operation of apartment communities. Some competitors are larger and have greater financial resources than the Company. This competition may result in increased costs of apartment communities the Company acquires and or develops.
WORKING CAPITAL
The Company believes that cash flows generated by its operations, existing cash and marketable securities balances, availability under existing lines of credit, access to capital markets and the ability to generate cash from the disposition of real estate are sufficient to meet all of its reasonably anticipated cash needs during 2016.
The timing, source and amounts of cash flows provided by financing activities and used in investing activities are sensitive to changes in interest rates, stock price, and other fluctuations in the capital markets environment, which can affect the Company’s plans for acquisitions, dispositions, development and redevelopment activities.
ENVIRONMENTAL CONSIDERATIONS
See the discussion under the caption, “Risks Related to Real Estate Investments and Our Operations - The Company’s Portfolio may have environmental liabilities” in Item 1A, Risk Factors, for information concerning the potential effect of environmental regulations on its operations, which discussion under the caption “The Company’s Portfolio may have environmental liabilities” is incorporated by reference into this Item 1.
OTHER MATTERS
Certain Policies of the Company
The Company intends to continue to operate in a manner that will not subject it to regulation under the Investment Company Act of 1940. The Company has in the past five years and may in the future (i) issue securities senior to its common stock, (ii) fund acquisition activities with borrowings under its line of credit and (iii) offer shares of common stock and/or units of limited partnership interest in the Operating Partnership or affiliated partnerships as partial consideration for property acquisitions. The Company from time to time acquires partnership interests in partnerships and joint ventures, either directly or indirectly through subsidiaries of the Company, when such entities’ underlying assets are real estate.
The Company invests primarily in apartment communities that are located in predominantly coastal markets within Southern California, the San Francisco Bay Area, and the Seattle metropolitan area. The Company currently intends to continue to invest in apartment communities in such regions. However, these practices may be reviewed and modified periodically by management.
Item 1A. RISK FACTORS
For purposes of this section, the term “stockholders” means the holders of shares of Essex Property Trust, Inc.’s common stock and preferred stock. Set forth below are the risks that we believe are material to Essex Property Trust, Inc.’s stockholders and Essex Portfolio, L.P.’s unit holders. You should carefully consider the following factors in evaluating our company, our properties and our business.
Our business, operating results, cash flows and financial condition are subject to various risks and uncertainties, including, without limitation, those set forth below, any one of which could cause our actual operating results to vary materially from recent results or from our anticipated future results.
Risks Related to Our Real Estate Investments and Operations
General real estate investment risks may adversely affect property income and values. Real estate investments are subject to a variety of risks. If the communities and other real estate investments do not generate sufficient income to meet operating expenses, including debt service and capital expenditures, cash flow and the ability to make distributions to stockholders will be adversely affected. Income from the communities may be further adversely affected by, among other things, the following factors:
| • | the general economic climate; |
| • | local economic conditions in which the communities are located, such as oversupply of housing or a reduction in demand for rental housing; |
| • | the attractiveness of the communities to tenants; |
| • | competition from other available housing alternatives; |
| • | changes in rent control or stabilization laws or other laws regulating housing; |
| • | the Company’s ability to provide for adequate maintenance and insurance; and |
| • | changes in interest rates and availability of financing. |
As leases at the communities expire, tenants may enter into new leases on terms that are less favorable to the Company. Income and real estate values also may be adversely affected by such factors as applicable laws (ex: the Americans with Disabilities Act of 1990 and tax laws). Real estate investments are relatively illiquid and, therefore, the Company’s ability to vary its portfolio promptly in response to changes in economic or other conditions may be quite limited.
Short-term leases expose us to the effects of declining market rents, and the Company may be unable to renew leases or relet units as leases expire. Substantially all of our apartment leases are for a term of one year or less. If the Company is unable to promptly renew the leases or relet the units, or if the rental rates upon renewal or reletting are significantly lower than expected rates, then the Company’s results of operations and financial condition will be adversely affected. With these short term leases, our rental revenues are impacted by declines in market rents more quickly than if our leases were for longer terms.
We may pursue acquisitions, dispositions, investments and joint ventures, which could adversely affect our results of operations. We may make acquisitions of and investments in businesses that offer complementary properties and communities to augment our market coverage, or enhance our property offerings. We may also enter into strategic alliances or joint ventures to achieve these goals. We cannot assure you that we will be able to identify suitable acquisition, investment, alliance, or joint venture opportunities, that we will be able to consummate any such transactions or relationships on terms and conditions acceptable to us, or that such transactions or relationships will be successful. In addition, our original estimates and assumptions used in assessing any acquisition may be inaccurate, and we may not realize the expected financial or strategic benefits of any such acquisition. From time to time, we may also divest portions of our business that are no longer strategically important or exit minority investments, which could materially affect our FFO, cash flows and results of operations.
These transactions or any other acquisitions or dispositions involve risks and uncertainties. For example, as a consequence of such transactions, we may assume unknown liabilities, which could ultimately lead to material costs for us. In addition, the integration of acquired businesses or other acquisitions may not be successful and could result in disruption to other parts of our business. To integrate acquired businesses or other acquisitions, we must implement our management information systems, operating systems and internal controls, and assimilate and manage the personnel of the acquired operations. There can be no assurance that all pre-acquisition property due diligence will have identified all material issues that might arise with respect to such acquired business and its properties or as to any such other acquisitions.
Any acquisition may also cause us to assume liabilities and ongoing lawsuits, acquire goodwill and other non-amortizable intangible assets that will be subject to impairment testing and potential impairment charges, incur amortization expense related
to certain intangible assets, increase our expenses and working capital requirements, and subject us to litigation, which would reduce our return on invested capital. In addition, if the businesses or properties that we acquire have a different pricing or cost structure than we do, such acquisitions may adversely affect our profitability and reduce our overall margin. Failure to manage and successfully integrate the acquisitions we make or to improve margins of the acquired businesses and products could materially harm our business, operating results and margins. Any dispositions we may make may also result in ongoing obligations to us following any such divestiture, for example as a result of any transition services or indemnities we agree to provide to the purchaser in any such transaction, which may result in additional expenses and may adversely affect our financial condition and results of operation.
Any future acquisitions we make may also require significant additional debt or equity financing, which, in the case of debt financing, would increase our leverage and potentially affect our credit ratings and, in the case of equity or equity-linked financing, could be dilutive to our existing stockholders. Any downgrades in our credit ratings associated with an acquisition could adversely affect our ability to borrow by resulting in more restrictive borrowing terms. As a result of the foregoing, we also may not be able to complete acquisitions or other strategic transactions in the future to the same extent as in the past, or at all. These and other factors could harm our ability to achieve anticipated levels of profitability at acquired operations or realize other anticipated benefits of an acquisition, and could adversely affect our business, financial condition and results of operations.
National and regional economic environments can negatively impact the Company’s operating results. The Company's forecast for the national economy assumes growth of the gross domestic product of the national economy and the economies of the west coast states. In the event of a recession, the Company could incur reductions in rental rates, occupancy levels, property valuations and increases in operating costs such as advertising and turnover expenses.
Inflation/Deflation may affect rental rates and operating expenses. Substantial inflationary or deflationary pressures could have a negative effect on rental rates and property operating expenses.
Acquisitions of communities involve various risks and uncertainties and may fail to meet expectations. The Company intends to continue to acquire apartment communities. However, there are risks that acquisitions
Showing the first 8K of 94K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
The Company’s portfolio as of December 31, 2015 (including communities owned by unconsolidated joint ventures, but excluding communities underlying preferred equity investments) was comprised of 246 apartment communities (comprising 59,160 apartment homes), of which 28,039 apartment homes are located in Southern California, 18,924 apartment homes are located in the San Francisco Bay Area, and 12,197 apartment homes are located in the Seattle metropolitan area. The Company’s apartment communities accounted for 99.3% of the Company’s revenues for the year ended December 31, 2015.
Occupancy Rates
Financial occupancy is defined as the percentage resulting from dividing actual rental revenue by total potential rental revenue (actual rental revenue for occupied apartment homes plus market rent for vacant apartment homes). When calculating actual rents for occupied apartment homes and market rents for vacant apartment homes, delinquencies and concessions are not taken into account. Total possible rental revenue represents the value of all apartment homes, with occupied apartment homes valued at contractual rental rates pursuant to leases and vacant apartment homes valued at estimated market rents. The Company believes that financial occupancy is a meaningful measure of occupancy because it considers the value of each vacant unit at its estimated market rate. Financial occupancy may not completely reflect short-term trends in physical occupancy and financial occupancy rates and the Company's calculation of financial occupancy may not be comparable to financial occupancy as disclosed by other REITs. Market rates are determined using a variety of factors such as effective rental rates at the property based on recently signed leases and asking rates for comparable properties in the market. The recently signed effective rates at the property are used as the starting point in the determination of the market rates of vacant apartment homes. The Company then increases or decreases these rates based on the supply and demand in the apartment community’s market. The Company will check the reasonableness of these rents based on its position within the market and compare the rents against the asking rents by comparable properties in the market.
For communities that are development properties in lease-up without stabilized occupancy figures, the Company believes the physical occupancy rate is the appropriate performance metric. While a community is in the lease-up phase, the Company’s primary motivation is to stabilize the property which may entail the use of rent concessions and other incentives, and thus financial occupancy which is based on contractual revenue is not considered the best metric to quantify occupancy.
Communities
The Company’s communities are primarily suburban garden-style communities and town homes comprising multiple clusters of two and three-story buildings situated on three to fifteen acres of land. As of December 31, 2015, the Company’s communities include 162 garden-style, 78 mid-rise, and 6 high-rise communities. The communities have an average of approximately 240 apartment homes, with a mix of studio, one, two and some three-bedroom apartment homes. A wide variety of amenities are available at the Company’s communities, including covered parking, fireplaces, swimming pools, clubhouses with fitness facilities, volleyball and playground areas and tennis courts.
The Company hires, trains and supervises on-site service and maintenance personnel. The Company believes that the following primary factors enhance the Company’s ability to retain tenants:
| • | located near employment centers; |
| • | attractive communities that are well maintained; and |
| • | proactive customer service. |
Commercial Buildings
The Company’s former corporate headquarters was located in two office buildings with approximately 39,600 square feet located at 925/935 East Meadow Drive, Palo Alto, California and was classified as held for sale at December 31, 2015. The Company owns an office building with approximately 106,564 square feet located in Irvine, California, of which the Company occupies approximately 8,000 square feet at December 31, 2015. The Company owns Essex-Hollywood, a 34,000 square foot commercial building and a 138,915 square foot retail site in Santa Clara, California as future development sites that are currently 100% leased.
The following tables describe the Company’s operating portfolio as of December 31, 2015. The first table describes the Company’s communities and the second table describes the Company’s other real estate assets. (See Note 8 of the Company’s consolidated financial statements for more information about the Company’s secured mortgage debt and Schedule III for a list of secured mortgage loans related to the Company’s portfolio.)
| Apartment | Rentable | Year | Year | |||||||||||
| Communities (1) | Location | Homes | Square Footage | Built | Acquired | Occupancy(2) | ||||||||
| Southern California | ||||||||||||||
| Alpine Village | Alpine, CA | 301 | 254,400 | 1971 | 2002 | 97% | ||||||||
| Anavia | Anaheim, CA | 250 | 312,343 | 2009 | 2010 | 96% |
| Apartment | Rentable | Year | Year | |||||||||||
| Communities (1) | Location | Homes | Square Footage | Built | Acquired | Occupancy(2) | ||||||||
| Barkley, The (3)(4) | Anaheim, CA | 161 | 139,800 | 1984 | 2000 | 98% | ||||||||
| Park Viridian | Anaheim, CA | 320 | 254,600 | 2008 | 2014 | 96% | ||||||||
| Bonita Cedars | Bonita, CA | 120 | 120,800 | 1983 | 2002 | 97% | ||||||||
| Camarillo Oaks | Camarillo, CA | 564 | 459,000 | 1985 | 1996 | 96% | ||||||||
| Camino Ruiz Square | Camarillo, CA | 160 | 105,448 | 1990 | 2006 | 97% | ||||||||
| Enclave at Town Square (21) | Chino Hills, CA | 124 | 89,948 | 1987 | 2014 | 97% | ||||||||
| The Heights I & II (21) | Chino Hills, CA | 332 | 324,370 | 2004 | 2014 | 96% | ||||||||
| The Summit (5) | Chino Hills, CA | 125 | 98,420 | 1989 | 2014 | 98% | ||||||||
| Pinnacle at Otay Ranch | Chula Vista, CA | 364 | 384,192 | 2001 | 2014 | 95% | ||||||||
| Mesa Village | Clairemont, CA | 133 | 43,600 | 1963 | 2002 | 98% | ||||||||
| Villa Siena | Costa Mesa, CA | 272 | 262,842 | 1974 | 2014 | 96% | ||||||||
| Emerald Pointe | Diamond Bar, CA | 160 | 134,816 | 1989 | 2014 | 96% | ||||||||
| Regency at Encino | Encino, CA | 75 | 78,487 | 1989 | 2009 | 97% | ||||||||
| The Havens (21) | Fountain Valley, CA | 440 | 414,040 | 1969 | 2014 | 96% | ||||||||
| Valley Park (4) | Fountain Valley, CA | 160 | 169,700 | 1969 | 2001 | 97% | ||||||||
| Capri at Sunny Hills (4) | Fullerton, CA | 100 | 128,100 | 1961 | 2001 | 97% | ||||||||
| Haver Hill (5) | Fullerton, CA | 264 | 224,130 | 1973 | 2012 | 96% | ||||||||
| Pinnacle at Fullerton | Fullerton, CA | 192 | 174,336 | 2004 | 2014 | 96% | ||||||||
| Wilshire Promenade | Fullerton, CA | 149 | 128,000 | 1992 | 1997 | 96% | ||||||||
| Montejo (4) | Garden Grove, CA | 124 | 103,200 | 1974 | 2001 | 97% | ||||||||
| CBC Apartments | Goleta, CA | 148 | 91,538 | 1962 | 2006 | 97% | ||||||||
| The Sweeps | Goleta, CA | 91 | 88,370 | 1967 | 2006 | 97% | ||||||||
| 416 on Broadway | Glendale, CA | 115 | 126,782 | 2009 | 2010 | 96% | ||||||||
| Hampton Court | Glendale, CA | 83 | 71,500 | 1974 | 1999 | 93% | ||||||||
| Hampton Place | Glendale, CA | 132 | 141,500 | 1970 | 1999 | 93% | ||||||||
| Devonshire | Hemet, CA | 276 | 207,200 | 1988 | 2002 | 96% | ||||||||
| Huntington Breakers | Huntington Beach, CA | 342 | 241,700 | 1984 | 1997 | 95% | ||||||||
| The Huntington | Huntington Beach, CA | 276 | 202,256 | 1975 | 2012 | 97% | ||||||||
| Axis 2300 | Irvine, CA | 115 | 170,714 | 2010 | 2010 | 97% | ||||||||
| Hillsborough Park | La Habra, CA | 235 | 215,500 | 1999 | 1999 | 97% | ||||||||
| Village Green | La Habra, CA | 272 | 175,762 | 1971 | 2014 | 97% | ||||||||
| The Palms at Laguna Niguel | Laguna Niguel, CA | 460 | 362,136 | 1988 | 2014 | 96% | ||||||||
| Trabuco Villas | Lake Forest, CA | 132 | 131,000 | 1985 | 1997 | 97% | ||||||||
| Marbrisa | Long Beach, CA | 202 | 122,800 | 1987 | 2002 | 96% | ||||||||
| Pathways | Long Beach, CA | 296 | 197,700 | 1975 | 1991 | 96% | ||||||||
| 8th & Hope | Los Angeles, CA | 290 | 298,437 | 2014 | 2015 | 79% | ||||||||
| 5600 Wilshire | Los Angeles, CA | 284 | 243,910 | 2008 | 2014 | 96% | ||||||||
| Alessio | Los Angeles, CA | 624 | 552,716 | 2001 | 2014 | 95% | ||||||||
| Avant | Los Angeles, CA | 440 | 305,989 | 2014 | 2015 | 95% | ||||||||
| The Avery (4) | Los Angeles, CA | 121 | 129,393 | 2014 | 2014 | 97% | ||||||||
| Bellerive | Los Angeles, CA | 63 | 79,296 | 2011 | 2011 | 97% | ||||||||
| Belmont Station | Los Angeles, CA | 275 | 225,000 | 2009 | 2009 | 97% | ||||||||
| Bunker Hill | Los Angeles, CA | 456 | 346,600 | 1968 | 1998 | 88% | ||||||||
| Catalina Gardens | Los Angeles, CA | 128 | 117,585 | 1987 | 2014 | 97% | ||||||||
| Cochran Apartments | Los Angeles, CA | 58 | 51,400 | 1989 | 1998 | 97% | ||||||||
| Gas Company Lofts (5) | Los Angeles, CA | 251 | 226,666 | 2004 | 2013 | 97% | ||||||||
| Jefferson at Hollywood | Los Angeles, CA | 270 | 238,119 | 2010 | 2014 | 94% | ||||||||
| Kings Road | Los Angeles, CA | 196 | 132,100 | 1979 | 1997 | 96% |
| Apartment | Rentable | Year | Year | |||||||||||
| Communities (1) | Location | Homes | Square Footage | Built | Acquired | Occupancy(2) | ||||||||
| Marbella | Los Angeles, CA | 60 | 50,108 | 1991 | 2005 | 97% | ||||||||
| Muse | Los Angeles, CA | 152 | 135,292 | 2011 | 2011 | 97% | ||||||||
| Pacific Electric Lofts (6) | Los Angeles, CA | 314 | 277,980 | 2006 | 2012 | 94% | ||||||||
| Park Catalina | Los Angeles, CA | 90 | 72,864 | 2002 | 2012 | 96% | ||||||||
| Park Place | Los Angeles, CA | 60 | 48,000 | 1988 | 1997 | 97% | ||||||||
| Regency Palm Court (5) | Los Angeles, CA | 116 | 54,844 | 1987 | 2014 | 96% | ||||||||
| Santee Court | Los Angeles, CA | 165 | 132,040 | 2004 | 2010 | 97% | ||||||||
| Santee Village | Los Angeles, CA | 73 | 69,817 | 2011 | 2011 | 97% | ||||||||
| Tiffany Court | Los Angeles, CA | 101 | 74,538 | 1987 | 2014 | 98% | ||||||||
| Wilshire La Brea | Los Angeles, CA | 478 | 354,972 | 2014 | 2014 | 95% | ||||||||
| Windsor Court (5) | Los Angeles, CA | 95 | 51,266 | 1987 | 2014 | 95% | ||||||||
| Windsor Court | Los Angeles, CA | 58 | 46,600 | 1988 | 1997 | 97% | ||||||||
| Aqua at Marina Del Rey | Marina Del Rey, CA | 500 | 479,312 | 2001 | 2014 | 95% | ||||||||
| Marina City Club (7) | Marina Del Rey, CA | 101 | 127,200 | 1971 | 2004 | 96% | ||||||||
| Mirabella | Marina Del Rey, CA | 188 | 176,800 | 2000 | 2000 | 97% | ||||||||
| Mira Monte | Mira Mesa, CA | 355 | 262,600 | 1982 | 2002 | 96% | ||||||||
| Madrid Apartments (6) | Mission Viejo, CA | 230 | 228,099 | 2000 | 2012 | 97% | ||||||||
| Hillcrest Park | Newbury Park, CA | 608 | 521,900 | 1973 | 1998 | 96% | ||||||||
| Fairways (8) | Newport Beach, CA | 74 | 107,100 | 1972 | 1999 | 96% | ||||||||
| Candlewood North | Northridge, CA | 189 | 166,910 | 1964 | 2014 | 96% | ||||||||
| Canyon Creek (21) | Northridge, CA | 200 | 148,150 | 1986 | 2014 | 96% | ||||||||
| Country Villas | Oceanside, CA | 180 | 179,700 | 1976 | 2002 | 96% | ||||||||
| Mission Hills | Oceanside, CA | 282 | 244,000 | 1984 | 2005 | 96% | ||||||||
| Renaissance at Uptown Orange | Orange, CA | 460 | 432,836 | 2007 | 2014 | 96% | ||||||||
| Mariner's Place | Oxnard, CA | 105 | 77,200 | 1987 | 2000 | 97% | ||||||||
| Monterey Villas | Oxnard, CA | 122 | 122,100 | 1974 | 1997 | 97% | ||||||||
| Tierra Vista | Oxnard, CA | 404 | 387,100 | 2001 | 2001 | 96% | ||||||||
| Arbors Parc Rose (6) | Oxnard, CA | 373 | 503,196 | 2001 | 2011 | 95% | ||||||||
| The Hallie del Mar | Pasadena, CA | 123 | 74,400 | 1972 | 1997 | 92% | ||||||||
| The Hallie del Rey | Pasadena, CA | 84 | 73,100 | 1972 | 1999 | 92% | ||||||||
| The Hallie del Sol | Pasadena, CA | 85 | 69,200 | 1972 | 1999 | 92% | ||||||||
| Stuart at Sierra Madre Villa | Pasadena, CA | 188 | 168,630 | 2007 | 2014 | 96% | ||||||||
| Villa Angelina (4) | Placentia, CA | 256 | 217,600 | 1970 | 2001 | 97% | ||||||||
| Fountain Park | Playa Vista, CA | 705 | 608,900 | 2002 | 2004 | 97% | ||||||||
| Highridge (4) | Rancho Palos Verdes, CA | 255 | 290,200 | 1972 | 1997 | 98% | ||||||||
| Cortesia at Rancho Santa Margarita | Rancho Santa Margarita, CA | 308 | 277,580 | 1999 | 2014 | 96% | ||||||||
| Pinnacle at Talega | San Clemente, CA | 362 | 355,764 | 2002 | 2014 | 96% | ||||||||
| Allure at Scripps Ranch | San Diego, CA | 194 | 207,052 | 2002 | 2014 | 96% | ||||||||
| Bernardo Crest | San Diego, CA | 216 | 205,548 | 1988 | 2014 | 96% | ||||||||
| Cambridge Park | San Diego, CA | 320 | 317,958 | 1998 | 2014 | 95% | ||||||||
| Carmel Creek | San Diego, CA | 348 | 384,216 | 2000 | 2014 | 96% | ||||||||
| Carmel Landing | San Diego, CA | 356 | 283,426 | 1989 | 2014 | 94% | ||||||||
| Carmel Summit | San Diego, CA | 246 | 225,880 | 1989 | 2014 | 97% | ||||||||
| CentrePointe | San Diego, CA | 224 | 126,700 | 1974 | 1997 | 94% | ||||||||
| Domain | San Diego, CA | 379 | 345,044 | 2013 | 2013 | 94% | ||||||||
| Esplanade (21) | San Diego, CA | 616 | 479,600 | 1986 | 2014 | 96% |
| Apartment | Rentable | Year | Year | |||||||||||
| Communities (1) | Location | Homes | Square Footage | Built | Acquired | Occupancy(2) | ||||||||
| Montanosa | San Diego, CA | 472 | 414,968 | 1990 | 2014 | 96% | ||||||||
| Summit Park | San Diego, CA | 300 | 229,400 | 1972 | 2002 | 96% | ||||||||
| Essex Skyline at MacArthur Place (9) | Santa Ana, CA | 349 | 512,791 | 2008 | 2010 | 96% | ||||||||
| Fairhaven (4) | Santa Ana, CA | 164 | 135,700 | 1970 | 2001 | 98% | ||||||||
| Parkside Court (21) | Santa Ana, CA | 210 | 152,400 | 1986 | 2014 | 97% | ||||||||
| Pinnacle at MacArthur Place | Santa Ana, CA | 253 | 262,867 | 2002 | 2014 | 96% | ||||||||
| Hope Ranch | Santa Barbara, CA | 108 | 126,700 | 1965 / 1973 | 2007 | 98% | ||||||||
| Bridgeport Coast (22) | Santa Clarita, CA | 188 | 168,198 | 2006 | 2014 | 97% | ||||||||
| Hidden Valley (10) | Simi Valley, CA | 324 | 310,900 | 2004 | 2004 | 97% | ||||||||
| Meadowood | Simi Valley, CA | 320 | 264,500 | 1986 | 1996 | 96% | ||||||||
| Shadow Point | Spring Valley, CA | 172 | 131,200 | 1983 | 2002 | 96% | ||||||||
| The Fairways at Westridge (22) | Valencia, CA | 234 | 223,330 | 2004 | 2014 | 96% | ||||||||
| Vistas of West Hills (22) | Valencia, CA | 220 | 221,119 | 2009 | 2014 | 96% | ||||||||
| Allegro | Valley Village, CA | 97 | 127,812 | 2010 | 2010 | 97% | ||||||||
| Lofts at Pinehurst, The | Ventura, CA | 118 | 71,100 | 1971 | 1997 | 97% | ||||||||
| Pinehurst (11) | Ventura, CA | 28 | 21,200 | 1973 | 2004 | 98% | ||||||||
| Woodside Village | Ventura, CA | 145 | 136,500 | 1987 | 2004 | 97% | ||||||||
| Walnut Heights | Walnut, CA | 163 | 146,700 | 1964 | 2003 | 95% | ||||||||
| The Dylan | West Hollywood, CA | 184 | 150,678 | 2014 | 2014 | 92% | ||||||||
| The Huxley | West Hollywood, CA | 187 | 154,776 | 2014 | 2014 | 93% | ||||||||
| Reveal | Woodland Hills, CA | 438 | 414,892 | 2010 | 2011 | 95% | ||||||||
| Avondale at Warner Center | Woodland Hills, CA | 446 | 331,000 | 1970 | 1999 | 96% | ||||||||
| 28,039 | 24,850,294 | 96% | ||||||||||||
| Northern California | ||||||||||||||
| Belmont Terrace | Belmont, CA | 71 | 72,951 | 1974 | 2006 | 94% | ||||||||
| Fourth & U | Berkeley, CA | 171 | 146,255 | 2010 | 2010 | 96% | ||||||||
| The Commons | Campbell, CA | 264 | 153,168 | 1973 | 2010 | 97% | ||||||||
| The Pointe at Cupertino | Cupertino, CA | 116 | 135,200 | 1963 | 1998 | 98% | ||||||||
| Connolly Station (23) | Dublin, CA | 309 | 286,348 | 2014 | 2014 | 96% | ||||||||
| Avenue 64 | Emeryville, CA | 224 | 196,896 | 2007 | 2014 | 94% | ||||||||
| Emme (23) | Emeryville, CA | 190 | 148,935 | 2015 | 2015 | 81% | ||||||||
| Foster's Landing | Foster City, CA | 490 | 415,130 | 1987 | 2014 | 96% | ||||||||
| Stevenson Place | Fremont, CA | 200 | 146,200 | 1975 | 2000 | 95% | ||||||||
| Mission Peaks | Fremont, CA | 453 | 404,034 | 1995 | 2014 | 96% | ||||||||
| Mission Peaks II | Fremont, CA | 336 | 294,720 | 1989 | 2014 | 96% | ||||||||
| Paragon Apartments | Fremont, CA | 301 | 267,047 | 2013 | 2014 | 94% | ||||||||
| Boulevard | Fremont, CA | 172 | 131,200 | 1978 | 1996 | 97% | ||||||||
| Briarwood (6) | Fremont, CA | 160 | 111,160 | 1978 | 2011 | 96% | ||||||||
| The Woods (6) | Fremont, CA | 160 | 105,280 | 1978 | 2011 | 96% | ||||||||
| City Centre (22) | Hayward, CA | 192 | 175,420 | 2000 | 2014 | 97% | ||||||||
| City View | Hayward, CA | 572 | 462,400 | 1975 | 1998 | 97% | ||||||||
| Lafayette Highlands | Lafayette, CA | 150 | 151,790 | 1973 | 2014 | 97% | ||||||||
| Apex | Milpitas, CA | 366 | 350,961 | 2014 | 2014 | 96% | ||||||||
| Regency at Mountain View (5) | Mountain View, CA | 142 | 127,600 | 1970 | 2013 | 96% | ||||||||
| Bridgeport | Newark, CA | 184 | 139,000 | 1987 | 1987 | 98% | ||||||||
| The Landing at Jack London Square | Oakland, CA | 282 | 257,796 | 2001 | 2014 | 95% |
| Apartment | Rentable | Year | Year | |||||||||||
| Communities (1) | Location | Homes | Square Footage | Built | Acquired | Occupancy(2) | ||||||||
| The Grand | Oakland, CA | 243 | 205,026 | 2009 | 2009 | 96% | ||||||||
| Radius | Redwood City, CA | 264 | 245,862 | 2015 | 2015 | 94% | ||||||||
| San Marcos | Richmond, CA | 432 | 407,600 | 2003 | 2003 | 96% | ||||||||
| Bennett Lofts | San Francisco, CA | 165 | 184,713 | 2004 | 2012 | 95% | ||||||||
| Fox Plaza | San Francisco, CA | 443 | 230,017 | 1968 | 2013 | 95% | ||||||||
| MB 360 Phase I | San Francisco, CA | 188 | 222,810 | 2014 | 2014 | 96% | ||||||||
| Mosso (23) | San Francisco, CA | 463 | 607,549 | 2014 | 2014 | 87% | ||||||||
| Park West | San Francisco, CA | 126 | 90,060 | 1958 | 2012 | 95% | ||||||||
| 101 San Fernando | San Jose, CA | 323 | 296,078 | 2001 | 2010 | 96% | ||||||||
| Bella Villagio | San Jose, CA | 231 | 227,511 | 2004 | 2010 | 97% | ||||||||
| Enso | San Jose, CA | 183 | 179,562 | 2014 | 2015 | 100% | ||||||||
| Epic - Phase I & II (13) (23) | San Jose, CA | 569 | 472,236 | 2013 | 2013 | 95% | ||||||||
| Esplanade | San Jose, CA | 278 | 279,000 | 2002 | 2004 | 96% | ||||||||
| Fountains at River Oaks | San Jose, CA | 226 | 209,954 | 1990 | 2014 | 97% | ||||||||
| Museum Park | San Jose, CA | 117 | 121,329 | 2002 | 2014 | 97% | ||||||||
| One South Market (23) | San Jose, CA | 312 | 283,268 | 2015 | 2015 | 46% | ||||||||
| Palm Valley (16) | San Jose, CA | 1,098 | 1,132,284 | 2008 | 2014 | 96% | ||||||||
| The Carlyle | San Jose, CA | 132 | 129,200 | 2000 | 2000 | 97% | ||||||||
| The Waterford | San Jose, CA | 238 | 219,600 | 2000 | 2000 | 97% | ||||||||
| Willow Lake | San Jose, CA | 508 | 471,744 | 1989 | 2012 | 96% | ||||||||
| Lakeshore Landing | San Mateo, CA | 308 | 223,972 | 1988 | 2014 | 95% | ||||||||
| Hillsdale Garden | San Mateo, CA | 697 | 611,505 | 1948 | 2006 | 97% | ||||||||
| Park 20 (23) | San Mateo, CA | 197 | 140,547 | 2015 | 2015 | 79% | ||||||||
| Deer Valley | San Rafael, CA | 171 | 167,238 | 1996 | 2014 | 97% | ||||||||
| Bel Air | San Ramon, CA | 462 | 391,000 | 1988 | 1995 | 96% | ||||||||
| Canyon Oaks | San Ramon, CA | 250 | 237,894 | 2005 | 2007 | 98% | ||||||||
| Crow Canyon | San Ramon, CA | 400 | 337,064 | 1992 | 2014 | 96% | ||||||||
| Foothill Gardens | San Ramon, CA | 132 | 155,100 | 1985 | 1997 | 97% | ||||||||
| Mill Creek at Windermere | San Ramon, CA | 400 | 381,060 | 2005 | 2007 | 97% | ||||||||
| Twin Creeks | San Ramon, CA | 44 | 51,700 | 1985 | 1997 | 97% | ||||||||
| 1000 Kiely | Santa Clara, CA | 121 | 128,486 | 1971 | 2011 | 95% | ||||||||
| Le Parc | Santa Clara, CA | 140 | 113,200 | 1975 | 1994 | 97% | ||||||||
| Marina Cove (14) | Santa Clara, CA | 292 | 250,200 | 1974 | 1994 | 96% | ||||||||
| Riley Square (6) | Santa Clara, CA | 156 | 126,900 | 1972 | 2012 | 95% | ||||||||
| Villa Granada | Santa Clara, CA | 270 | 238,841 | 2010 | 2014 | 96% | ||||||||
| Chestnut Street Apartments | Santa Cruz, CA | 96 | 87,640 | 2002 | 2008 | 97% | ||||||||
| Harvest Park | Santa Rosa, CA | 104 | 116,628 | 2004 | 2007 | 97% | ||||||||
| Bristol Commons | Sunnyvale, CA | 188 | 142,600 | 1989 | 1995 | 95% | ||||||||
| Brookside Oaks (4) | Sunnyvale, CA | 170 | 119,900 | 1973 | 2000 | 95% | ||||||||
| Lawrence Station | Sunnyvale, CA | 336 | 297,188 | 2012 | 2014 | 96% | ||||||||
| Magnolia Lane (15) | Sunnyvale, CA | 32 | 31,541 | 2001 | 2007 | 97% | ||||||||
| Magnolia Square (4) | Sunnyvale, CA | 156 | 110,824 | 1963 | 2007 | 97% | ||||||||
| Montclaire | Sunnyvale, CA | 390 | 294,100 | 1973 | 1988 | 97% | ||||||||
| Reed Square | Sunnyvale, CA | 100 | 95,440 | 1970 | 2011 | 97% | ||||||||
| Solstice | Sunnyvale, CA | 280 | 571,466 | 2014 | 2014 | 96% | ||||||||
| Summerhill Park | Sunnyvale, CA | 100 | 78,500 | 1988 | 1988 | 95% | ||||||||
| Via | Sunnyvale, CA | 284 | 309,421 | 2011 | 2011 | 96% | ||||||||
| Windsor Ridge | Sunnyvale, CA | 216 | 161,800 | 1989 | 1989 | 96% |
| Apartment | Rentable | Year | Year | |||||||||||
| Communities (1) | Location | Homes | Square Footage | Built | Acquired | Occupancy(2) | ||||||||
| Vista Belvedere | Tiburon, CA | 76 | 78,300 | 1963 | 2004 | 95% | ||||||||
| Tuscana | Tracy, CA | 30 | 29,088 | 2007 | 2007 | 99% | ||||||||
| Verandas (22) | Union City, CA | 282 | 199,092 | 1989 | 2014 | 96% | ||||||||
| 18,924 | 17,173,129 | 95% | ||||||||||||
| Seattle, Washington Metropolitan Area | ||||||||||||||
| Belcarra | Bellevue, WA | 296 | 241,567 | 2009 | 2014 | 96% | ||||||||
| BellCentre | Bellevue, WA | 248 | 181,288 | 2001 | 2014 | 96% | ||||||||
| Cedar Terrace | Bellevue, WA | 180 | 174,200 | 1984 | 2005 | 96% | ||||||||
| Courtyard off Main | Bellevue, WA | 110 | 108,388 | 2000 | 2010 | 96% | ||||||||
| Ellington at Bellevue | Bellevue, WA | 220 | 165,794 | 1994 | 2014 | 96% | ||||||||
| Emerald Ridge | Bellevue, WA | 180 | 144,000 | 1987 | 1994 | 96% | ||||||||
| Foothill Commons | Bellevue, WA | 394 | 288,300 | 1978 | 1990 | 96% | ||||||||
| Palisades, The | Bellevue, WA | 192 | 159,700 | 1977 | 1990 | 97% | ||||||||
| Park Highland | Bellevue, WA | 250 | 224,750 | 1993 | 2014 | 95% | ||||||||
| Piedmont | Bellevue, WA | 396 | 348,969 | 1969 | 2014 | 96% | ||||||||
| Sammamish View | Bellevue, WA | 153 | 133,500 | 1986 | 1994 | 97% | ||||||||
| Woodland Commons | Bellevue, WA | 302 | 217,878 | 1978 | 1990 | 95% | ||||||||
| Bothell Ridge (21) | Bothell, WA | 214 | 167,370 | 1988 | 2014 | 96% | ||||||||
| Canyon Pointe | Bothell, WA | 250 | 210,400 | 1990 | 2003 | 95% | ||||||||
| Inglenook Court | Bothell, WA | 224 | 183,600 | 1985 | 1994 | 97% | ||||||||
| Pinnacle Sonata | Bothell, WA | 268 | 343,095 | 2000 | 2014 | 95% | ||||||||
| Salmon Run at Perry Creek | Bothell, WA | 132 | 117,100 | 2000 | 2000 | 98% | ||||||||
| Stonehedge Village | Bothell, WA | 196 | 214,800 | 1986 | 1997 | 97% | ||||||||
| Highlands at Wynhaven | Issaquah, WA | 333 | 424,674 | 2000 | 2008 | 96% | ||||||||
| Park Hill at Issaquah | Issaquah, WA | 245 | 277,700 | 1999 | 1999 | 97% | ||||||||
| Wandering Creek | Kent, WA | 156 | 124,300 | 1986 | 1995 | 97% | ||||||||
| Ascent | Kirkland, WA | 90 | 75,840 | 1988 | 2012 | 97% | ||||||||
| Bridle Trails | Kirkland, WA | 108 | 99,700 | 1986 | 1997 | 97% | ||||||||
| Corbella at Juanita Bay | Kirkland, WA | 169 | 103,339 | 1978 | 2010 | 96% | ||||||||
| Evergreen Heights | Kirkland, WA | 200 | 188,300 | 1990 | 1997 | 97% | ||||||||
| Slater 116 | Kirkland, WA | 108 | 81,415 | 2013 | 2013 | 96% | ||||||||
| Montebello | Kirkland, WA | 248 | 272,734 | 1996 | 2012 | 96% | ||||||||
| Aviara (12) | Mercer Island, WA | 166 | 147,033 | 2013 | 2014 | 96% | ||||||||
| Laurels at Mill Creek | Mill Creek, WA | 164 | 134,300 | 1981 | 1996 | 97% | ||||||||
| Parkwood at Mill Creek | Mill Creek, WA | 240 | 257,160 | 1989 | 2014 | 95% | ||||||||
| The Elliot at Mukilteo (4) | Mukilteo, WA | 301 | 245,900 | 1981 | 1997 | 95% | ||||||||
| Castle Creek | Newcastle, WA | 216 | 191,900 | 1998 | 1998 | 97% | ||||||||
| Delano | Redmond, WA | 126 | 116,340 | 2005 | 2011 | 97% | ||||||||
| Elevation | Redmond, WA | 158 | 138,916 | 1986 | 2010 | 97% | ||||||||
| Redmond Hill (6) | Redmond, WA | 442 | 350,275 | 1985 | 2011 | 96% | ||||||||
| Shadowbrook | Redmond, WA | 418 | 338,880 | 1986 | 2014 | 97% | ||||||||
| The Trails of Redmond | Redmond, WA | 423 | 376,000 | 1985 | 2014 | 97% | ||||||||
| Vesta (6) | Redmond, WA | 440 | 381,675 | 1998 | 2011 | 96% | ||||||||
| Brighton Ridge | Renton, WA | 264 | 201,300 | 1986 | 1996 | 97% | ||||||||
| Fairwood Pond | Renton, WA | 194 | 189,200 | 1997 | 2004 | 97% | ||||||||
| Forest View | Renton, WA | 192 | 182,500 | 1998 | 2003 | 97% | ||||||||
| Pinnacle on Lake Washington | Renton, WA | 180 | 190,908 | 2001 | 2014 | 96% | ||||||||
| Annaliese | Seattle, WA | 56 | 48,216 | 2009 | 2013 | 96% |
| Apartment | Rentable | Year | Year | |||||||||||
| Communities (1) | Location | Homes | Square Footage | Built | Acquired | Occupancy(2) | ||||||||
| The Audrey at Belltown | Seattle, WA | 137 | 94,119 | 1992 | 2014 | 97% | ||||||||
| Ballinger Commons (21) | Seattle, WA | 485 | 407,253 | 1989 | 2014 | 96% | ||||||||
| The Bernard | Seattle, WA | 63 | 43,151 | 2008 | 2011 | 96% | ||||||||
| Cairns, The | Seattle, WA | 100 | 70,806 | 2006 | 2007 | 97% | ||||||||
| Citywalk (21) | Seattle, WA | 102 | 92,010 | 1988 | 2014 | 97% | ||||||||
| Collins on Pine | Seattle, WA | 76 | 48,733 | 2013 | 2014 | 97% | ||||||||
| Domaine | Seattle, WA | 92 | 79,421 | 2009 | 2012 | 95% | ||||||||
| Expo (16) | Seattle, WA | 275 | 190,176 | 2012 | 2012 | 97% | ||||||||
| Fountain Court | Seattle, WA | 320 | 207,000 | 2000 | 2000 | 95% | ||||||||
| Joule (17) | Seattle, WA | 295 | 191,109 | 2010 | 2010 | 96% | ||||||||
| Taylor 28 | Seattle, WA | 197 | 155,630 | 2008 | 2014 | 95% | ||||||||
| Vox | Seattle, WA | 58 | 42,173 | 2013 | 2013 | 97% | ||||||||
| Wharfside Pointe | Seattle, WA | 155 | 119,200 | 1990 | 1994 | 94% | ||||||||
| 12,197 | 10,503,985 | 96% | ||||||||||||
| Total/Weighted Average | 59,160 | 52,527,408 | 95% |
| Square | Year | Year | |||||||||||
| Other real estate assets (1) | Location | Tenants | Footage | Built | Acquired | Occupancy (2) | |||||||
| 925 / 935 East Meadow Drive (18) | Palo Alto, CA | — | 39,600 | 1988 / 1962 | 1997 / 2007 | —% | |||||||
| Essex - Hollywood (19) | Los Angeles, CA | 1 | 34,000 | 1938 | 2006 | 100% | |||||||
| Derian Office Building (20) | Irvine, CA | 8 | 106,564 | 1983 | 2000 | 100% | |||||||
| Santa Clara Retail | Santa Clara, CA | 3 | 138,915 | 1970 | 2011 | 100% | |||||||
| 12 | 319,079 | 88% |
Footnotes to the Company’s Portfolio Listing as of December 31, 2015
| (1) | Unless otherwise specified, the Company has a 100% ownership interest in each community. |
| (2) | For communities, occupancy rates are based on financial occupancy for the year ended December 31, 2015; for the commercial buildings occupancy rates are based on physical occupancy as of December 31, 2015. For an explanation of how financial occupancy and physical occupancy are calculated, see “Properties-Occupancy Rates” in this Item 2. |
| (3) | The community is subject to a ground lease, which, unless extended, will expire in 2082. |
| (4) | The Company holds a 1% special limited partner interest in the partnerships which own these apartment communities. These investments were made under arrangements whereby Essex Management Company became the 1% sole general partner and the other limited partners were granted the right to require the applicable partnership to redeem their interest for cash. Subject to certain conditions, the Company may, however, elect to deliver an equivalent number of shares of the Company’s common stock in satisfaction of the applicable partnership’s cash redemption obligation. |
| (5) | This community is owned by Wesco III. The Company has a 50% interest in Wesco III which is accounted for using the equity method of accounting. |
| (6) | This community is owned by Wesco I. The Company has a 50% interest in Wesco I which is accounted for using the equity method of accounting. |
| (7) | This community is subject to a ground lease, which, unless extended, will expire in 2067. |
| (8) | This community is subject to a ground lease, which, unless extended, will expire in 2027. |
| (9) | The Company has a 97% interest and an Executive Vice President of the Company has a 3% interest in this community. |
| (10) | The Company has a 75% member interest. |
| (11) | The community is subject to a ground lease, which, unless extended, will expire in 2028. |
| (12) | This community is subject to a ground lease, which, unless extended, will expire in 2030. |
| (13) | The community is being developed in three phases with one remaining phase currently under development. |
| (14) | A portion of this community on which 84 apartment homes are presently located is subject to a ground lease, which, unless extended, will expire in 2028. |
| (15) | The community is subject to a ground lease, which, unless extended, will expire in 2070. |
| (16) | The Company has 50% ownership in each of these communities which is accounted for using the equity method of accounting. |
| (17) | The Company has 99% ownership in this community. |
| (18) | This property was the Company's previous headquarters until December 2015 and was unoccupied at December 31, 2015. |
| (19) | The property is leased through January 2016 to a single tenant. |
| (20) | The Company occupies 8% of space in this property. |
| (21) | This community is owned by BEXAEW. The Company has a 50% interest in BEXAEW which is accounted for using the equity method of accounting. |
| (22) | This community is owned by Wesco IV. The Company has a 50% interest in Wesco IV which is accounted for using the equity method of accounting. |
| (23) | The Company has a 55% ownership in this community which is accounted for using the equity method of accounting. |
Item 3. Legal Proceedings
The information, which regards lawsuits, other proceedings and claims, set forth in Note 16, “Commitments and Contingencies”, of our notes to consolidated financial statements included in Part IV, Item 15 of this Annual Report on Form 10-K is incorporated by reference into this Item 3. In addition to such matters referred to in Note 16, the Company is subject to various other legal and/or regulatory proceedings arising in the course of its business operations. We believe that, with respect to such matters that we are currently a party to, the ultimate disposition of any such matter will not result in a material adverse effect on the Company’s financial condition, results of operations or cash flows.
Item 4. Mine Safety Disclosures
Not Applicable.
Part II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Market Information
The shares of the Company’s common stock are traded on the New York Stock Exchange (“NYSE”) under the symbol ESS. ESS common stock has been traded on the NYSE since June 13, 1994. The high, low and closing price per share of common stock reported on the NYSE for the quarters indicated are as follows:
| Quarter Ended | High | Low | Close | |||||||||
| December 31, 2015 | $ | 244.71 | $ | 214.29 | $ | 239.41 | ||||||
| September 30, 2015 | $ | 232.20 | $ | 205.72 | $ | 223.42 | ||||||
| June 30, 2015 | $ | 231.90 | $ | 208.85 | $ | 212.50 | ||||||
| March 31, 2015 | $ | 243.17 | $ | 207.26 | $ | 229.90 | ||||||
| December 31, 2014 | $ | 214.43 | $ | 176.70 | $ | 206.60 | ||||||
| September 30, 2014 | $ | 196.08 | $ | 177.68 | $ | 178.75 | ||||||
| June 30, 2014 | $ | 185.99 | $ | 164.76 | $ | 184.91 | ||||||
| March 31, 2014 | $ | 173.01 | $ | 141.79 | $ | 170.05 |
The closing price of ESS stock as of February 22, 2016 was $209.53.
There is no established public trading market for Essex Portfolio, L.P.’s OP Units.
Holders
The approximate number of holders of record of the shares of ESS common stock was 1,395 as of February 22, 2016. This number does not include stockholders whose shares are held in investment accounts by other entities. ESS believes the actual number of stockholders is greater than the number of holders of record.
As of February 22, 2016, there were 172 holders of record of Essex Portfolio, L.P.’s OP Units, including ESS.
Return of Capital
Under provisions of the Internal Revenue Code of 1986, as amended, the portion of the cash dividend, if any, that exceeds earnings and profits is considered a return of capital. The return of capital is generated due to a variety of factors, including the deduction of non-cash expenses, primarily depreciation, in the determination of earnings and profits.
The status of the cash dividends distributed for the years ended December 31, 2015, 2014, and 2013 related to common stock, and Series G and H preferred stock for tax purposes are as follows:
| 2015 | 2014 | 2013 | |||||||
| Common Stock | |||||||||
| Ordinary income | 99.28 | % | 70.03 | % | 77.34 | % | |||
| Capital gain | 0.72 | % | 21.95 | % | 17.64 | % | |||
| Unrecaptured section 1250 capital gain | — | % | 8.02 | % | 5.02 | % | |||
| 100.00 | % | 100.00 | % | 100.00 | % | ||||
| 2015 | 2014 | 2013 | |||||||
| Series G, and H Preferred stock | |||||||||
| Ordinary income | 99.28 | % | 70.03 | % | 77.34 | % | |||
| Capital gains | 0.72 | % | 21.95 | % | 17.64 | % | |||
| Unrecaptured section 1250 capital gain | — | % | 8.02 | % | 5.02 | % | |||
| 100.00 | % | 100.00 | % | 100.00 | % |
Dividends and Distributions
Since ESS’s initial public offering on June 13, 1994, ESS and the Operating Partnership have paid regular quarterly dividends/distributions to its stockholders and unitholders. ESS paid the following dividends per share of common stock and the Operating Partnership paid the following distributions per limited partner OP unit:
| Year Ended | Annual Dividend/Distribution | Quarter Ended | 2015 | 2014 | 2013 | |||||||
| 1995 | $ | 1.69 | March 31, | $1.44 | $1.21 | $1.21 | ||||||
| 1996 | $ | 1.72 | June 30, | $1.44 | $1.30 | $1.21 | ||||||
| 1997 | $ | 1.77 | September 30, | $1.44 | $1.30 | $1.21 | ||||||
| 1998 | $ | 1.95 | December 31, | $1.44 | $1.30 | $1.21 | ||||||
| 1999 | $ | 2.15 | ||||||||||
| 2000 | $ | 2.38 | Annual Dividend/Distribution | $5.76 | $5.11 | $4.84 | ||||||
| 2001 | $ | 2.80 | ||||||||||
| 2002 | $ | 3.08 | ||||||||||
| 2003 | $ | 3.12 | ||||||||||
| 2004 | $ | 3.16 | ||||||||||
| 2005 | $ | 3.24 | ||||||||||
| 2006 | $ | 3.36 | ||||||||||
| 2007 | $ | 3.72 | ||||||||||
| 2008 | $ | 4.08 | ||||||||||
| 2009 | $ | 4.12 | ||||||||||
| 2010 | $ | 4.13 | ||||||||||
| 2011 | $ | 4.16 | ||||||||||
| 2012 | $ | 4.40 |
Future dividends/distributions by ESS and the Operating Partnership will be at the discretion of the Board of Directors of ESS and will depend on the actual cash flows from operations of the Company, its financial condition, capital requirements, the annual distribution requirements under the REIT provisions of the Internal Revenue Code, applicable legal restrictions and such other factors as the Board of Directors deem relevant. There are currently no contractual restrictions on ESS and the Operating Partnership present or future ability to pay dividends and distributions.
The Board of Directors has declared a dividend/distribution for the first quarter of 2016 of $1.60 per share. The dividend/distribution will be payable on April 15, 2016 to shareholders/unitholders of record as of March 31, 2016.
Dividend Reinvestment and Share Purchase Plan
ESS has adopted a dividend reinvestment and share purchase plan designed to provide holders of common stock with a convenient and economical means to reinvest all or a portion of their cash dividends in shares of common stock and to acquire additional shares of common stock through voluntary purchases. Computershare, LLC, which serves as ESS transfer agent, administers the dividend reinvestment and share purchase plan. For a copy of the plan, contact Computershare, LLC at (312) 360-5354.
Securities Authorized for Issuance under Equity Compensation Plans
See the Company’s disclosure in the 2016 Proxy Statement under the heading “Equity Compensation Plan Information”, which disclosure is incorporated herein by reference.
Issuance of Registered Equity Securities
During 2015, ESS sold 1,481,737 shares of common stock for proceeds of $332.3 million, net of commissions, at an average price of $226.46. Common stock sales were made pursuant to a registration statement and ESS used the net proceeds from the stock offerings to pay down debt, fund redevelopment and development pipelines, fund acquisitions, and for general corporate purposes. During the first quarter of 2016 through February 22, 2016, ESS has not issued any shares of common stock.
Issuer Purchases of Equity Securities
In December 2015, ESS Board of Directors authorized a stock repurchase plan to allow ESS to acquire shares in an aggregate of up to $250 million. The program supersedes the common stock repurchase plan that Essex announced on August 30, 2007. Under the previous stock repurchase plan, ESS repurchased and retired 816,659 shares totaling $66.6 million at an average stock price of $81.56 per share, including commissions.
Performance Graph
The line graph below compares the cumulative total stockholder return on ESS common stock for the last five years with the cumulative total return on the S&P 500 and the NAREIT All Equity REIT index over the same period. This comparison assumes that the value of the investment in the common stock and each index was $100 on December 31, 2010 and that all dividends were reinvested (1).
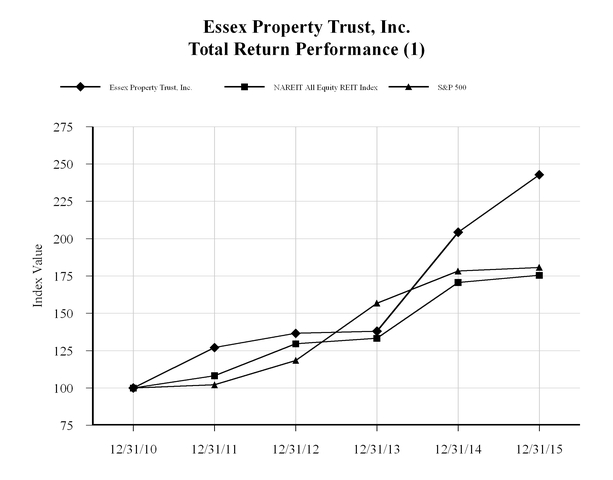
| Period Ending | ||||||||||||||||||
| Index | 12/31/2010 | 12/31/2011 | 12/31/2012 | 12/31/2013 | 12/31/2014 | 12/31/2015 | ||||||||||||
| Essex Property Trust, Inc. | 100.00 | 127.06 | 136.59 | 138.04 | 204.30 | 242.85 | ||||||||||||
| NAREIT All Equity REIT Index | 100.00 | 108.28 | 129.62 | 133.32 | 170.68 | 175.51 | ||||||||||||
| S&P 500 | 100.00 | 102.11 | 118.45 | 156.82 | 178.28 | 180.75 |
| (1) | Common stock performance data is provided by SNL Financial. |
The graph and other information furnished under the above caption “Performance Graph” in this Part II Item 5 of this Form 10-K shall not deemed to be “soliciting material” or to be “filed” with the SEC or subject to Regulation 14A or 14C, or to the liabilities of the Exchange Act, as amended.
Unregistered Sales of Equity Securities
During the years ended December 31, 2015 and 2014, the Operating Partnership issued partnership units in private placements in reliance on the exemption from registration provided by Section 4(2) of the Securities Act, in the amounts and for the consideration set forth below:
During the year ended December 31, 2015 and 2014, ESS issued an aggregate of 203,556 and 185,387 shares of its common stock upon the exercise of stock options, respectively. ESS contributed the proceeds from the option exercises of $26.5 million and $11.0 million to our Operating Partnership in exchange for an aggregate of 203,556 and 185,387 common OP Units, as required by the Operating Partnership’s partnership agreement, respectively.
During the year ended December 31, 2015 and 2014, ESS issued an aggregate of 22,939 and 126,931 shares of its common stock in connection with restricted stock awards for no cash consideration, respectively. For each share of common stock issued
by ESS in connection with such awards, our Operating Partnership issued common OP units to ESS as required by the partnership agreement, for an aggregate of 22,939 and 126,931 units during the year ended December 31, 2015 and 2014, respectively.
During the years ended December 31, 2015 and 2014, ESS issued and sold an aggregate of 1,481,737 and 2,964,315 shares of its common stock, respectively, pursuant to a registration statement and its equity distribution program. ESS contributed the net proceeds from these share issuances of $332.3 million and $534.0 million in exchange for an aggregate of 1,481,737 and 2,964,315 common OP Units, respectively, as required by the Operating Partnership's partnership agreement.
Item 6. Selected Financial Data
The following tables set forth summary financial and operating information for the ESS and the Operating Partnership from January 1, 2011 through December 31, 2015.
Essex Property Trust, Inc. and Subsidiaries
| Years Ended December 31, | ||||||||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||||||||||||
| ($ in thousands, except per share amounts) | ||||||||||||||||||||
| OPERATING DATA:(1) | ||||||||||||||||||||
| Rental and other property | $ | 1,185,498 | $ | 961,591 | $ | 603,327 | $ | 527,945 | $ | 461,866 | ||||||||||
| Management and other fees from affiliates | 8,909 | 9,347 | 7,263 | 8,457 | 5,428 | |||||||||||||||
| Income before discontinued operations | $ | 248,239 | $ | 134,438 | $ | 140,882 | $ | 127,653 | $ | 46,958 | ||||||||||
| Income from discontinued operations | — | — | 31,173 | 11,937 | 10,558 | |||||||||||||||
| Net income | 248,239 | 134,438 | 172,055 | 139,590 | 57,516 | |||||||||||||||
| Net income available to common stockholders | $ | 226,865 | $ | 116,859 | $ | 150,811 | $ | 119,812 | $ | 40,368 | ||||||||||
| Per share data: | ||||||||||||||||||||
| Basic: | ||||||||||||||||||||
| Income before discontinued operations available to common stockholders | $ | 3.50 | $ | 2.07 | $ | 3.26 | $ | 3.10 | $ | 0.94 | ||||||||||
| Net income available to common stockholders | $ | 3.50 | $ | 2.07 | $ | 4.05 | $ | 3.42 | $ | 1.24 | ||||||||||
| Weighted average common stock outstanding | 64,872 | 56,547 | 37,249 | 35,032 | 32,542 | |||||||||||||||
| Diluted: | ||||||||||||||||||||
| Income before discontinued operations available to common stockholders | $ | 3.49 | $ | 2.06 | $ | 3.25 | $ | 3.09 | $ | 0.94 | ||||||||||
| Net income available to common stockholders | $ | 3.49 | $ | 2.06 | $ | 4.04 | $ | 3.41 | $ | 1.24 | ||||||||||
| Weighted average common stock outstanding | 65,062 | 56,697 | 37,335 | 35,125 | 32,629 | |||||||||||||||
| Cash dividend per common share | $ | 5.76 | $ | 5.11 | $ | 4.84 | $ | 4.40 | $ | 4.16 |
| (1) | Reclassifications have been made in prior periods to conform to the current year’s presentation. |
| As of December 31, | ||||||||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||||||||||||
| ($ in thousands) | ||||||||||||||||||||
| BALANCE SHEET DATA:(1) | ||||||||||||||||||||
| Investment in rental properties (before accumulated depreciation) | $ | 12,331,469 | $ | 11,244,681 | $ | 5,443,757 | $ | 5,033,672 | $ | 4,313,064 | ||||||||||
| Net investment in rental properties | 10,381,577 | 9,679,875 | 4,188,871 | 3,952,155 | 3,393,038 | |||||||||||||||
| Real estate under development | 242,326 | 429,096 | 50,430 | 66,851 | 44,280 | |||||||||||||||
| Co-investments | 1,036,047 | 1,042,423 | 677,133 | 571,345 | 383,412 | |||||||||||||||
| Total assets | 12,005,091 | 11,526,732 | 5,162,320 | 4,826,356 | 4,019,519 | |||||||||||||||
| Total indebtedness | 5,315,464 | 5,080,689 | 3,009,005 | 2,797,816 | 2,343,413 | |||||||||||||||
| Redeemable noncontrolling interest | 45,452 | 23,256 | — | — | — | |||||||||||||||
| Cumulative convertible preferred stock | — | — | 4,349 | 4,349 | 4,349 | |||||||||||||||
| Cumulative redeemable preferred stock | 73,750 | 73,750 | 73,750 | 73,750 | 73,750 | |||||||||||||||
| Stockholders' equity | 6,237,733 | 6,022,672 | 1,884,619 | 1,764,804 | 1,437,527 |
| (1) | Reclassifications have been made in prior periods to conform to the current year’s presentation. Additionally, due to measurement adjustments related to the BRE merger in 2014, certain amounts do not agree to previously reported balances. |
| As of and for the years ended December 31, | ||||||||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||||||||||||
| ($ in thousands, except per share amounts) | ||||||||||||||||||||
| OTHER DATA: | ||||||||||||||||||||
| Funds from operations (FFO)(1) attributable to common stockholders and unitholders: | ||||||||||||||||||||
| Net income available to common stockholders | $ | 226,865 | $ | 116,859 | $ | 150,811 | $ | 119,812 | $ | 40,368 | ||||||||||
| Adjustments: | ||||||||||||||||||||
| Depreciation and amortization | 453,423 | 360,592 | 193,518 | 170,686 | 152,543 | |||||||||||||||
| Gains not included in FFO attributable to common stockholders and unitholders | (81,347 | ) | (50,064 | ) | (67,975 | ) | (60,842 | ) | (7,543 | ) | ||||||||||
| Depreciation add back from unconsolidated co-investments | 49,826 | 33,975 | 15,748 | 14,467 | 12,642 | |||||||||||||||
| Noncontrolling interest related to Operating Partnership units | 7,824 | 4,911 | 8,938 | 7,950 | 3,228 | |||||||||||||||
| Insurance reimbursements | (1,751 | ) | — | — | — | — | ||||||||||||||
| Depreciation attributable to third party ownership and other | (781 | ) | (1,331 | ) | (1,309 | ) | (1,223 | ) | (1,066 | ) | ||||||||||
| Funds from operations attributable to common stockholders and unitholders | $ | 654,059 | $ | 464,942 | $ | 299,731 | $ | 250,850 | $ | 200,172 | ||||||||||
| Non-core items: | ||||||||||||||||||||
| Merger and integration expenses | 3,798 | 53,530 | 4,284 | — | — | |||||||||||||||
| Acquisition and investment related costs | 2,414 | 1,878 | 1,161 | 2,255 | 1,231 | |||||||||||||||
| Gain on sale of marketable securities, note prepayment, and other investments | (598 | ) | (886 | ) | (2,519 | ) | (819 | ) | (4,956 | ) | ||||||||||
| Gain on sale of co-investments | — | — | — | — | (919 | ) | ||||||||||||||
| Gain on sale of land | — | (2,533 | ) | (1,503 | ) | — | (180 | ) | ||||||||||||
| Loss on early retirement of debt | 6,114 | 268 | 300 | 5,009 | 1,163 | |||||||||||||||
| Co-investment promote income | (192 | ) | (10,640 | ) | — | (2,299 | ) | — | ||||||||||||
| Income from early redemption of preferred equity investments | (1,954 | ) | (5,250 | ) | (1,358 | ) | — | — | ||||||||||||
| Insurance reimbursements | (2,319 | ) | — | — | — | — | ||||||||||||||
| Other non-core items, net (2) | (651 | ) | 1,852 | — | — | 268 | ||||||||||||||
| Core funds from operations (Core FFO) attributable to common stockholders and unitholders | $ | 660,671 | $ | 503,161 | $ | 300,096 | $ | 254,996 | $ | 196,779 | ||||||||||
| Weighted average number of shares outstanding, diluted (FFO)(3) | 67,310 | 58,921 | 39,501 | 37,378 | 34,861 | |||||||||||||||
| Funds from operations attributable to common stockholders and unitholders per share - diluted | $ | 9.72 | $ | 7.89 | $ | 7.59 | $ | 6.71 | $ | 5.74 | ||||||||||
| Core funds from operations attributable to common stockholders and unitholders per share - diluted | $ | 9.82 | $ | 8.54 | $ | 7.60 | $ | 6.82 | $ | 5.64 |
| (1) | FFO is a financial measure that is commonly used in the REIT industry. The Company presents funds from operations as a supplemental operating performance measure. FFO is not used by the Company, nor should it be considered to be, as an alternative to net earnings computed under GAAP as an indicator of the Company’s operating performance or as an alternative to cash from operating activities computed under GAAP as an indicator of the Company's ability to fund its cash needs. |
FFO is not meant to represent a comprehensive system of financial reporting and does not present, nor does it intend to present, a complete picture of the Company's financial condition and operating performance. The Company believes that net earnings computed under GAAP remain the primary measure of performance and that FFO is only meaningful when it is used in conjunction with net earnings. The Company considers FFO and FFO excluding non-routine items (referred to as
“Core FFO”) to be useful financial performance measurements of an equity REIT because, together with net income and cash flows, FFO provides investors with an additional basis to evaluate operating performance and ability of a REIT to incur and service debt and to fund acquisitions and other capital expenditures and its ability to pay dividends. Further, the Company believes that its consolidated financial statements, prepared in accordance with GAAP, provide the most meaningful picture of its financial condition and its operating performance.
In calculating FFO, the Company follows the definition for this measure published by the National Association of Real Estate Investment Trusts (“NAREIT”), which is a REIT trade association. The Company believes that, under the NAREIT FFO definition, the three most significant adjustments made to net income are (i) the exclusion of historical cost depreciation, (ii) the exclusion of gains and losses from the sale of previously depreciated properties and (iii) the exclusion of impairment losses on depreciated properties. Essex agrees that these three NAREIT adjustments are useful to investors for the following reasons:
| (a) | historical cost accounting for real estate assets in accordance with GAAP assumes, through depreciation charges, that the value of real estate assets diminishes predictably over time. NAREIT stated in its White Paper on Funds from Operations “since real estate asset values have historically risen or fallen with market conditions, many industry investors have considered presentations of operating results for real estate companies that use historical cost accounting to be insufficient by themselves.” Consequently, NAREIT’s definition of FFO reflects the fact that real estate, as an asset class, generally appreciates over time and depreciation charges required by GAAP do not reflect the underlying economic realities. |
| (b) | REITs were created as a legal form of organization in order to encourage public ownership of real estate as an asset class through investment in firms that were in the business of long-term ownership and management of real estate. The exclusion, in NAREIT’s definition of FFO, of gains from the sales and impairment losses of previously depreciated operating real estate assets allows investors and analysts to readily identify the operating results of the long-term assets that form the core of a REIT’s activity and assists in comparing those operating results between periods. |
Management has consistently applied the NAREIT definition of FFO to all periods presented. However, other REITs in calculating FFO may vary from the NAREIT definition for this measure, and thus their disclosure of FFO may not be comparable to the Company’s calculation.
| (2) | Other items, net are non-recurring in nature and include items such as gains on non-operating assets and tax related items. |
| (3) | Assumes conversion of all dilutive outstanding operating partnership interests in the Operating Partnership and excludes 744,346 DownREIT units for which the Operating Partnership has the ability and intention to redeem the DownREIT limited partnership units for cash and does not consider them to be common stock equivalents. |
Essex Portfolio, L.P. and Subsidiaries
| Years Ended December 31, | ||||||||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||||||||||||
| ($ in thousands, except per unit amounts) | ||||||||||||||||||||
| OPERATING DATA:(1) | ||||||||||||||||||||
| Rental and other property | $ | 1,185,498 | $ | 961,591 | $ | 603,327 | $ | 527,945 | $ | 461,866 | ||||||||||
| Management and other fees from affiliates | 8,909 | 9,347 | 7,263 | 8,457 | 5,428 | |||||||||||||||
| Income before discontinued operations | $ | 248,239 | $ | 134,438 | $ | 140,882 | $ | 127,653 | $ | 46,958 | ||||||||||
| Income from discontinued operations | — | — | 31,173 | 11,937 | 10,558 | |||||||||||||||
| Net income | 248,239 | 134,438 | 172,055 | 139,590 | 57,516 | |||||||||||||||
| Net income available to common unitholders | $ | 234,689 | $ | 121,726 | $ | 159,749 | $ | 127,771 | $ | 43,593 | ||||||||||
| Per unit data: | ||||||||||||||||||||
| Basic: | ||||||||||||||||||||
| Income before discontinued operations available to common unitholders | $ | 3.50 | $ | 2.07 | $ | 3.27 | $ | 3.11 | $ | 0.95 | ||||||||||
| Net income available to common unitholders | $ | 3.50 | $ | 2.07 | $ | 4.06 | $ | 3.43 | $ | 1.25 | ||||||||||
| Weighted average common units outstanding | 67,054 | 58,772 | 39,380 | 37,252 | 34,774 | |||||||||||||||
| Diluted: | ||||||||||||||||||||
| Income before discontinued operations available to common unitholders | $ | 3.49 | $ | 2.07 | $ | 3.26 | $ | 3.10 | $ | 0.95 | ||||||||||
| Net income available to common unitholders | $ | 3.49 | $ | 2.07 | $ | 4.05 | $ | 3.42 | $ | 1.25 | ||||||||||
| Weighted average common units outstanding | 67,244 | 58,921 | 39,467 | 37,344 | 34,861 | |||||||||||||||
| Cash distributions per common unit | $ | 5.76 | $ | 5.11 | $ | 4.84 | $ | 4.40 | $ | 4.16 |
| (1) | Reclassifications have been made in prior periods to conform to the current year’s presentation. |
| As of December 31, | ||||||||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||||||||||||
| ($ in thousands) | ||||||||||||||||||||
| BALANCE SHEET DATA:(1) | ||||||||||||||||||||
| Investment in rental properties (before accumulated depreciation) | $ | 12,331,469 | $ | 11,244,681 | $ | 5,443,757 | $ | 5,033,672 | $ | 4,313,064 | ||||||||||
| Net investment in rental properties | 10,381,577 | 9,679,875 | 4,188,871 | 3,952,155 | 3,393,038 | |||||||||||||||
| Real estate under development | 242,326 | 429,096 | 50,430 | 66,851 | 44,280 | |||||||||||||||
| Co-investments | 1,036,047 | 1,042,423 | 677,133 | 571,345 | 383,412 | |||||||||||||||
| Total assets | 12,005,091 | 11,526,732 | 5,162,320 | 4,826,356 | 4,019,519 | |||||||||||||||
| Total indebtedness | 5,315,464 | 5,080,689 | 3,009,005 | 2,797,816 | 2,343,413 | |||||||||||||||
| Redeemable noncontrolling interest | 45,452 | 23,256 | — | — | — | |||||||||||||||
| Cumulative convertible preferred interest | — | — | 4,349 | 4,349 | 4,349 | |||||||||||||||
| Cumulative redeemable preferred interest | 71,209 | 71,209 | 71,209 | 71,209 | 71,209 | |||||||||||||||
| Partners' capital | 6,287,381 | 6,073,433 | 1,932,108 | 1,811,427 | 1,486,914 |
| (1) | Reclassifications have been made in prior periods to conform to the current year’s presentation. Additionally, due to measurement adjustments related to the BRE merger in 2014, certain amounts do not agree to previously reported balances. |
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
The following discussion and analysis should be read in conjunction with the accompanying consolidated financial statements and notes thereto. These consolidated financial statements include all adjustments which are, in the opinion of management, necessary to reflect a fair statement of the results and all such adjustments are of a normal recurring nature.
OVERVIEW
ESS is a self-administered and self-managed REIT that acquires, develops, redevelops and manages apartment communities in selected residential areas located primarily in the West Coast of the United States. ESS owns all of its interests in its real estate investments, directly or indirectly, through the Operating Partnership. ESS is the sole general partner of the Operating Partnership and, as of December 31, 2015, had an approximately 96.7% general partner interest in the Operating Partnership.
The Company’s investment strategy has two components: constant monitoring of existing markets, and evaluation of new markets to identify areas with the characteristics that underlie rental growth. The Company’s strong financial condition supports its investment strategy by enhancing its ability to quickly shift acquisition, development, redevelopment, and disposition activities to markets that will optimize the performance of the portfolio.
As of December 31, 2015, the Company had ownership interests in 246 communities, comprising 59,160 apartment homes.
The Company’s apartment communities are predominately located in the following major regions:
Southern California (Los Angeles, Orange, San Diego, and Ventura counties)
Northern California (the San Francisco Bay Area)
Seattle Metro (Seattle metropolitan area)
As of December 31, 2015, the Company’s development pipeline was comprised of two consolidated projects under development, six unconsolidated joint venture projects under development and various consolidated predevelopment projects aggregating 2,447 apartment homes, with total incurred costs of $0.7 billion, and estimated remaining project costs of approximately $0.8 billion for total estimated project costs of $1.4 billion.
As of December 31, 2015, the Company also had ownership interests in four commercial buildings (with approximately 319,079 square feet).
By region, the Company's operating results for 2015 and 2014 and projections for 2016 new housing supply (defined as new multi-family apartment homes and single family homes, excluding developments with fewer than 100 apartment homes as well as senior and student housing), job growth, and rental income are as follows:
Southern California Region: As of December 31, 2015, this region represented 49% of the Company’s consolidated apartment homes. Revenues for “2015/2014 Same-Properties” (as defined below), or “Same-Property revenues,” increased 6.0% in 2015 as compared to 2014. In 2016, the Company projects new residential supply of 30,300 apartment homes and single family homes, which represents 0.5% of the total housing stock. The Company assumes an increase of 168,050 jobs or 2.2%, and an increase in Same-Property revenues of between 5.25% to 6.25% in 2016.
Northern California Region: As of December 31, 2015, this region represented 30% of the Company’s consolidated apartment homes. Same-Property revenues increased 10.5% in 2015 as compared to 2014. In 2016, the Company projects new residential supply of 18,300 apartment homes and single family homes, which represents 0.8% of the total housing stock. The Company assumes an increase of 95,300 jobs or 2.9%, and an increase in Same-Property revenues of between 8.50% to 9.50% in 2016.
Seattle Metro Region: As of December 31, 2015, this region represented 21% of the Company’s consolidated apartment homes. Same-Property revenues increased 7.7% in 2015 as compared to 2014. In 2016, the Company projects new residential supply of 16,050 apartment homes and single family homes, which represents 1.3% of the total housing stock. The Company assumes an increase of 43,100 jobs or 2.7%, and an increase in Same-Property revenues of between 6.00% to 7.00% in 2016.
The Company projects 2016 Same-Property revenues to increase compared to 2015 results, as renewal and new leases are signed at higher rents in 2016 than 2015. Same-Property operating expenses are expected to increase in 2016 by 3.25% to 4.25%.
The Company’s consolidated communities are as follows:
| As of | As of | ||||||||||
| December 31, 2015 | December 31, 2014 | ||||||||||
| Apartment Homes | % | Apartment Homes | % | ||||||||
| Southern California | 23,707 | 49 | % | 22,168 | 47 | % | |||||
| Northern California | 14,694 | 30 | % | 14,789 | 31 | % | |||||
| Seattle Metro | 10,239 | 21 | % | 10,216 | 21 | % | |||||
| Arizona | — | — | % | 552 | 1 | % | |||||
| Total | 48,640 | 100 | % | 47,725 | 100 | % |
Co-investments, including Wesco I, LLC ("Wesco I"), Wesco III, LLC ("Wesco III"), Wesco IV, LLC (“Wesco IV”), Canadian Pension Plan Investment Board ("CPPIB" or "CPP"), Palm Valley and BEXAEW, LLC (“BEXAEW”) communities, developments under construction and preferred equity interest co-investment communities are not included in the table presented above for both periods.
RESULTS OF OPERATIONS
Comparison of Year Ended December 31, 2015 to the Year Ended December 31, 2014
The Company’s average financial occupancies for the Company’s stabilized apartment communities or “2015/2014 Same-Properties” (stabilized properties consolidated by the Company for the years ended December 31, 2015 and 2014) was unchanged at 96.2% in both 2015 and 2014. Financial occupancy is defined as the percentage resulting from dividing actual rental revenue by total potential rental revenue (actual rental revenue for occupied apartment homes plus market rent for vacant apartment homes). Actual rental revenue represents contractual rental revenue pursuant to leases without considering delinquency and concessions. Total potential rental revenue represents the value of all apartment homes, with occupied apartment homes valued at contractual rental rates pursuant to leases and vacant apartment homes valued at estimated market rents. We believe that financial occupancy is a meaningful measure of occupancy because it considers the value of each vacant unit at its estimated market rate.
Market rates are determined using the recently signed effective rates on new leases at the property and are used as the starting point in the determination of the market rates of vacant apartment homes. The Company may increase or decrease these rates based on the supply and demand in the apartment community’s market. The Company will check the reasonableness of these rents based on its position within the market and compare the rents against the asking rents by comparable properties in the market. Financial occupancy may not completely reflect short-term trends in physical occupancy and financial occupancy rates and the Company's calculation of financial occupancy may not be comparable to financial occupancy as disclosed by other REITs.
The Company does not take into account delinquency and concessions to calculate actual rent for occupied apartment homes and market rents for vacant apartment homes. The calculation of financial occupancy compares contractual rates for occupied apartment homes to estimated market rents for unoccupied apartment homes, and thus the calculation compares the gross value of all apartment homes excluding delinquency and concessions. For apartment communities that are development properties in lease-up without stabilized occupancy figures, the Company believes the physical occupancy rate is the appropriate performance metric. While an apartment community is in the lease-up phase, the Company’s primary motivation is to stabilize the property which may entail the use of rent concessions and other incentives, and thus financial occupancy, which is based on contractual revenue is not considered the best metric to quantify occupancy.
The regional breakdown of the Company’s 2015/2014 Same-Property portfolio for financial occupancy for the years ended December 31, 2015 and 2014 is as follows:
| Years ended December 31, | |||||
| 2015 | 2014 | ||||
| Southern California | 96.2 | % | 96.3 | % | |
| Northern California | 96.3 | % | 96.2 | % | |
| Seattle Metro | 96.2 | % | 96.0 | % |
The following table provides a breakdown of revenue amounts, including the revenues attributable to 2015/2014 Same-Properties.
| Number of | Years Ended December 31, | Dollar | Percentage | |||||||||||||||
| Property Revenues ($ in thousands) | Properties | 2015 | 2014 | Change | Change | |||||||||||||
| 2015/2014 Same-Properties: (1) | ||||||||||||||||||
| Southern California | 58 | $ | 283,435 | $ | 267,413 | $ | 16,022 | 6.0 | % | |||||||||
| Northern California | 37 | 250,478 | 226,679 | $ | 23,799 | 10.5 | % | |||||||||||
| Seattle Metro | 34 | 124,143 | 115,219 | 8,924 | 7.7 | % | ||||||||||||
| Total 2015/2014 Same-Property revenues | 129 | 658,056 | 609,311 | 48,745 | 8.0 | % | ||||||||||||
| 2015/2014 Non-Same Property Revenues | 527,442 | 352,280 | 175,162 | 49.7 | % | |||||||||||||
| Total property revenues | $ | 1,185,498 | $ | 961,591 | $ | 223,907 | 23.3 | % |
| (1) | Same-property excludes BRE properties acquired April 1, 2014 and properties held for sale. |
2015/2014 Same-Property Revenues increased by $48.7 million or 8.0% to $658.1 million for 2015 compared to $609.3 million in 2014. The increase was primarily attributable to an increase of 8.1% in average rental rates from $1,741 per apartment home for 2014 to $1,882 per apartment home for 2015.
2015/2014 Non-Same Property Revenues increased by $175.2 million or 49.7% to $527.4 million in 2015 compared to $352.3 million in 2014. The increase was primarily due to the BRE merger and the acquisition or consolidation of ten communities, net of dispositions and properties held for sale, since January 1, 2014.
Property operating expenses, excluding real estate taxes increased $30.3 million or 14.8% in 2015 compared to 2014, primarily due to the BRE merger and the acquisition or consolidation of ten communities, net of dispositions and properties held for sale, since January 1, 2014. 2015/2014 Same-Property operating expenses excluding real estate taxes, increased by $2.3 million or 1.7% in 2015 compared to 2014, due mainly to a $1.7 million increase in repairs and maintenance.
Real estate taxes increased $20.7 million or 19.2% in 2015 compared to 2014, due primarily due to the BRE merger and the acquisition or consolidation of ten communities, net of dispositions and held for sale, since January 1, 2014. 2015/2014 Same-Property real estate taxes increased by $1.7 million or 3.2% for 2015 compared to 2014.
Depreciation and amortization expense increased by $92.8 million or 25.7% in 2015 compared to 2014, primarily due to the BRE merger and the acquisition or consolidation of ten communities, net of dispositions and properties held for sale, since January 1, 2014.
Merger and integration expenses include, but are not limited to, advisor fees, legal fees, and accounting fees related to the merger with BRE and related integration activity. The Company completed the merger with BRE on April 1, 2014. Merger and integration expenses were $3.8 million for 2015 and $53.5 million for 2014.
Interest expense increased $40.3 million or 24.5% in 2015, due to an increase in average outstanding debt primarily due to assumed debt in connection with the BRE merger in addition to a $6.8 million decrease in capitalized interest in 2015 compared to 2014, which was due to a decrease in development costs as compared to the same period in 2014.
Total return swap income of $5.7 million in 2015 consists of monthly settlements related to the Company's total return swap contracts that were entered into during the year, in connection with $257.3 million of tax-exempt mortgage notes payable. The Company had no total return swap income in 2014.
Interest and other income increased $7.3 million or 62.1% in 2015, due to an increase in the investment of mortgage backed securities, an increase of $3.1 million in insurance proceeds and $0.6 million in income from the sale of an investment.
Equity income from co-investments decreased by $18.0 million to $21.9 million in 2015 compared to $39.9 million in 2014, primarily due to events in 2014 which did not recur in 2015, including the Company’s share of the gain on the sale of two co-investment communities of $6.6 million, promote income of $10.6 million, and income from the early redemption of preferred equity investments of $5.3 million in 2014, partially offset by $2.0 million in income from the early redemption of two preferred equity investments during 2015 and an increase of $7.4 million in equity income from co-investment operations. Additionally, income from preferred equity investments decreased by approximately $5.1 million from 2014 to 2015.
Gains on sale of real estate and land increased by $1.3 million or 2.8% in 2015 compared to 2014, due primarily to $7.1 million in gains on the sales of Pinnacle South Mountain and two commercial buildings as well as a $40.2 million gain on the sale of Sharon Green during 2015 as compared to approximately $16.8 million in gains on the sales of Vista Capri North, Coldwater Canyon, Pinnacle Town Center, and a land parcel adjacent to the Company's Park Viridian property, as well as a $29.2 million gain on the sale of Mt. Sutro during 2014.
Gains on remeasurement of co-investment increased by $34.0 million in 2015 compared to 2014, due to the remeasurement of the Company's investments, as a result of the Company's acquisition of a controlling interest in The Huxley and The Dylan properties, resulting in a gain of $21.3 million, and Reveal, resulting in a gain of $12.7 million.
Comparison of Year Ended December 31, 2014 to the Year Ended December 31, 2013
The Company’s average financial occupancies for the Company’s stabilized apartment communities for “2014/2013 Same-Properties” (stabilized properties consolidated by the Company for the years ended December 31, 2014 and 2013) increased 10 basis points to 96.2% in 2014 from 96.1% in 2013. The regional breakdown of the Company’s stabilized 2014/2013 Same-Property portfolio for financial occupancy for the years ended December 31, 2014 and 2013 is as follows:
| Years ended December 31, | |||||
| 2014 | 2013 | ||||
| Southern California | 96.3 | % | 96.1 | % | |
| Northern California | 96.3 | % | 96.1 | % | |
| Seattle Metro | 96.0 | % | 96.1 | % |
The following table provides a breakdown of revenue amounts, including the revenues attributable to 2014/2013 Same-Properties.
| Number of | Years Ended December 31, | Dollar | Percentage | |||||||||||||||
| Property Revenues ($ in thousands) | Properties | 2014 | 2013 | Change | Change | |||||||||||||
| 2014/2013 Same-Properties: | ||||||||||||||||||
| Southern California | 58 | $ | 267,413 | $ | 253,503 | $ | 13,910 | 5.5 | % | |||||||||
| Northern California | 35 | 218,577 | 199,395 | 19,182 | 9.6 | % | ||||||||||||
| Seattle Metro | 29 | 115,219 | 107,225 | 7,994 | 7.5 | % | ||||||||||||
| Total 2014/2013 Same-Property revenues | 122 | 601,209 | 560,123 | 41,086 | 7.3 | % | ||||||||||||
| 2014/2013 Non-Same Property Revenues (1) | 80,059 | 43,204 | 36,855 | 85.3 | % | |||||||||||||
| 2014 BRE Legacy Property Revenues (2) | 280,323 | — | 280,323 | |||||||||||||||
| Total property revenues | $ | 961,591 | $ | 603,327 | $ | 358,264 | 59.4 | % |
| (1) | Includes eleven communities acquired after January 1, 2013, three sold communities and one redevelopment community. |
| (2) | Includes 55 stabilized properties acquired in connection with the BRE merger on April 1, 2014, and two development communities in lease-up. |
2014/2013 Same-Property Revenues increased by $41.1 million or 7.3% to $601.2 million for 2014 compared to $560.1 million in 2013. The increase was primarily attributable to an increase in scheduled rents of $39.1 million as reflected in an increase of 7.1% in average rental rates from $1,619 per unit for 2013 to $1,734 per unit for 2014. Scheduled rents increased in all regions by 5.2%, 9.5%, and 7.4% in Southern California, Northern California, and Seattle Metro, respectively. Income from utility billings and other income increased by $2.2 million and $1.1 million, respectively in 2014 compared to 2013. Financial occupancy increased 10 basis points in 2014 to 96.2% compared to 96.1% in 2013.
2014/2013 Non-Same Property Revenues increased by $36.9 million or 85.3% to $80.1 million in 2014 compared to $43.2 million to 2013. The increase was primarily due to revenue generated from eleven communities acquired or consolidated since January 1, 2013.
Management and other fees from affiliates increased $2.0 million or 28.7% to $9.3 million in 2013 compared to $7.3 million in 2012. The increase is primarily due to the asset and property management fees earned from the Wesco III, Wesco IV, and BEXAEW co-investments formed during 2014. The increase in management fees was offset by a reduction of $1.2 million in asset and property management fees from the sale of two Essex Apartment Value Fund II, L.P. ("Fund II") communities in 2014.
Property operating expenses, excluding real estate taxes increased $64.6 million or 46.1% in 2014 compared to 2013, primarily due to properties acquired in connection with the BRE merger and six other communities in 2014. 2014/2013 Same-Property operating expenses excluding real estate taxes, increased by $3.8 million or 3.0% in 2014 compared to 2013, due mainly to a $1.6 million increase in repairs and maintenance and a $1.3 million increase in utilities expense.
Real estate taxes increased $50.6 million or 88.3% in 2014 compared to 2013, due primarily to properties acquired in connection with the BRE merger and six other communities in 2014. 2014/2013 Same-Property real estate taxes increased by $2.3 million or 4.5% for 2014 compared to 2013 due to a $1.6 million or 15.6% increase in property taxes for Seattle Metro due to higher assessed values for 2014.
Depreciation and amortization expense increased by $168.2 million or 87.4% in 2014 compared to 2013, due to the acquisition of BRE and six other communities. The increase is also due to the capitalization of approximately $313.1 million in additions to rental properties through 2013, including $152.8 million spent on acquisition of and additions to real estate under development, $81.4 million spent on redevelopment, and $78.9 million spent on capital expenditures on rental properties. Approximately $122.0 million in additions to rental properties were capitalized for 2012, including $17.8 million spent on acquisitions of and additions to real estate under development, $47.3 million spent on redevelopment, and $56.9 million spent on capital expenditures on rental properties.
General and administrative expense increased $14.2 million or 53.2% in 2014 compared to 2013 primarily due to additional corporate employees from the BRE merger and $2.8 million in expenses related to the cyber-intrusion.
Merger and integration expenses include, but are not limited to, advisor fees, legal fees, and accounting fees related to the BRE merger. The Company completed the merger with BRE on April 1, 2014. Merger and integration expenses were $53.5 million for 2014 and $4.3 million for 2013.
Interest expense increased $48.0 million or 41.2% in 2014, primarily due to additional debt assumed as part of the BRE merger, offset by an increase in capitalized interest from development and redevelopment projects.
Equity income from co-investments decreased by $16.0 million to $39.9 million in 2014 compared to $55.9 million in 2013. The decrease was primarily due to the Company’s share of the gain on the sale of two Fund II communities of $6.6 million, promote income of $10.6 million, and income from early redemption of preferred equity investments of $5.3 million in 2014, compared to the Company's share of gain on the sale of five Fund II communities of $38.8 million, net of internal dispositions costs in 2013.
Liquidity and Capital Resources
The following table sets forth the Company’s cash flows for 2015, 2014 and 2013 ($ in thousands):
| For the year ended December 31, | ||||||||||||
| 2015 | 2014 | 2013 | ||||||||||
| Cash flow provided by (used in): | ||||||||||||
| Operating activities | $ | 617,410 | $ | 493,312 | $ | 304,982 | ||||||
| Investing activities | $ | (725,556 | ) | $ | (1,147,156 | ) | $ | (453,696 | ) | |||
| Financing activities | $ | 108,214 | $ | 520,610 | $ | 148,599 |
ESS’s business is operated primarily through the Operating Partnership. ESS issues public equity from time to time, but does not otherwise generate any capital itself or conduct any business itself, other than incurring certain expenses in operating as a public company which are fully reimbursed by the Operating Partnership. ESS itself does not hold any indebtedness, and its only material asset is its ownership of partnership interests of the Operating Partnership. ESS’s principal funding requirement is the payment of dividends on its common stock and preferred stock. ESS’s sole source of funding for its dividend payments is distributions it receives from the Operating Partnership.
As of December 31, 2015, ESS owned a 96.7% general partner interest and the limited partners owned the remaining 3.3% interest in the Operating Partnership.
The liquidity of ESS is dependent on the Operating Partnership’s ability to make sufficient distributions to ESS. The primary cash requirement of ESS is its payment of dividends to its stockholders. ESS also guarantees some of the Operating Partnership’s debt, as discussed further in Notes 7 and 8 of the notes to consolidated financial statements included elsewhere herein. If the Operating Partnership fails to fulfill certain of its debt requirements, which trigger the ESS’s guarantee obligations, then ESS will be required to fulfill its cash payment commitments under such guarantees. However, ESS’s only significant asset is its investment in the Operating Partnership.
For ESS to maintain its qualification as a REIT, it must pay dividends to its stockholders aggregating annually at least 90% of its REIT taxable income, excluding net capital gains. While historically ESS has satisfied this distribution requirement by making cash distributions to its stockholders, it may choose to satisfy this requirement by making distributions of cash or other property, including, in limited circumstances, ESS’s own stock. As a result of this distribution requirement, the Operating Partnership cannot rely on retained earnings to fund its ongoing operations to the same extent that other companies whose parent companies are not REITs can. ESS may need to continue to raise capital in the equity markets to fund the Operating Partnership’s working capital needs, acquisitions and developments.
At December 31, 2015, the Company had $29.7 million of unrestricted cash and cash equivalents and $137.5 million in marketable securities, of which $57.1 million were held available for sale. The Company believes that cash flows generated by its operations, existing cash and cash equivalents, marketable securities balances, availability under existing lines of credit, access to capital markets and the ability to generate cash from the disposition of real estate are sufficient to meet all of the Company’s reasonably anticipated cash needs during 2016. The timing, source and amounts of cash flows provided by financing activities and used in investing activities are sensitive to changes in interest rates and other fluctuations in the capital markets environment, which can affect the Company’s plans for acquisitions, dispositions, development and redevelopment activities.
As of December 31, 2015, the Company had $465.0 million of private placement unsecured bonds outstanding at an average interest rate of 4.5% with maturity dates ranging from March 2016 through August 2021. In January 2016, $150.0 million of these bonds bearing an interest rate of 4.36% were repaid.
As of December 31, 2015, the Company had $2.4 billion of fixed rate public bonds, net of unamortized premiums, discounts and debt issuance costs, with interest rates varying from 3.25% to 5.50% and maturity dates ranging from 2017 to 2025.
As of December 31, 2015, the Company had a $225.0 million unsecured term loan outstanding that has a variable interest rate of LIBOR plus 1.05%. The Company has entered into interest rate swap contracts for a term of five years with a notional amount totaling $225.0 million, which effectively converted the interest rate on $225.0 million of the term loan to a fixed rate of 2.4%. The $200 million tranche of this unsecured term loan has a maturity date of November 2016 and the $25 million tranche has a maturity date of August 2017.
As of December 31, 2015, the Company’s mortgage notes payable totaled $2.2 billion, net of unamortized premiums and debt issuance costs, which consisted of $1.9 billion in fixed rate debt with interest rates varying from 4.3% to 6.4% and maturity dates ranging from 2016 to 2021 and $281.7 million of tax-exempt variable rate demand notes with a weighted average interest rate of 1.2%. The tax-exempt variable rate demand notes have maturity dates ranging from 2025 to 2040, and $20.7 million is subject to interest rate caps and $257.3 million is subject to total return swaps.
The Company has two lines of credit aggregating $1.03 billion as of December 31, 2015 including a $1.0 billion unsecured line of credit. As of December 31, 2015, there was a $15.0 million balance on this unsecured line of credit with an underlying interest rate of LIBOR plus 0.95%. In January 2016, the facility maturity date was extended to December 31, 2019 with one 18-month extension, exercisable by the Company, with an underlying interest rate of LIBOR plus 0.90%. The Company also has a $25.0 million working capital unsecured line of credit agreement. As of December 31, 2015, there were no amounts outstanding on this unsecured line with an underlying interest rate of LIBOR plus 0.95%. In January 2016 the maturity date was extended to January 2018 and the interest rate was lowered to LIBOR plus 0.90%.
The Company’s unsecured line of credit and unsecured debt agreements contain debt covenants related to limitations on indebtedness and liabilities and maintenance of minimum levels of consolidated earnings before depreciation, interest and amortization. The Company was in compliance with the debt covenants as of December 31, 2015 and 2014.
The Company pays quarterly dividends from cash available for distribution. Until it is distributed, cash available for distribution is invested by the Company primarily in investment grade securities held available for sale or is used by the Company to reduce balances outstanding under its line of credit.
The Company has benefited from borrowing from Fannie Mae and Freddie Mac, and there are no assurances that these entities will lend to the Company in the future. To the extent that the Company’s access to capital and credit is at a higher cost than the Company has experienced in recent years (reflected in higher interest rates for debt financing or a lower stock price for equity financing) the Company’s ability to make acquisitions, develop communities, obtain new financing, and refinance existing borrowing at competitive rates could be adversely impacted. For the past three years the Company has primarily issued unsecured debt and repaid secured debt when it has matured to place less reliance on mortgage debt financing, and to unencumber more of the Company's communities.
Derivative Activity
The Company uses interest rate swaps, interest rate cap, and total return swap contracts to manage certain interest rate risks. The valuation of these instruments is determined using widely accepted valuation techniques including discounted cash flow analysis on the expected cash flows of each derivative. This analysis reflects the contractual terms of the derivatives, including the period to maturity, and uses observable market-based inputs, including interest rate curves. The fair values of interest rate swaps and total return swaps are determined using the market standard methodology of netting the discounted future fixed cash receipts (or payments) and the discounted expected variable cash payments (or receipts). The variable cash payments (or receipts) are based on an expectation of future interest rates (forward curves) derived from observable market interest rate curves. The Company incorporates credit valuation adjustments to appropriately reflect both its own nonperformance risk and the respective counterparties nonperformance risk in the fair value measurements.
The Company has entered into interest rate swap contracts with an aggregate notional amount of $225.0 million that effectively fixed the interest rate on the $225.0 million unsecured term loan at 2.4%. These derivatives qualify for hedge accounting.
The Company has entered into four total return swap contracts, with an aggregate notional amount of $257.3 million, that effectively converts $257.3 million of mortgage notes payable to a floating interest rate based on SIFMA plus a spread. Additionally, the total return swaps provide fair market value protection on the mortgage notes payable to our counterparties during the initial period of the total return swap until the Company's option to call the mortgage notes at par can be exercised. The Company can currently call one of the total return swaps with $114.4 million of the outstanding debt at par, while the call option on the other three total return swaps relating to $142.9 million of the outstanding debt can be exercised starting on January 1, 2017. These derivatives do not qualify for hedge accounting.
As of December 31, 2015 the Company also had nine interest rate caps totaling a notional amount of $20.7 million that effectively limit the Company’s exposure to interest rate risk by providing a ceiling on the underlying variable interest rate for $20.7 million of the Company’s tax exempt variable rate debt.
As of December 31, 2015 and 2014, the aggregate carrying value of the interest rate swap contracts was a liability of $1.0 million and $1.8 million, respectively. The aggregate carrying value of the interest rate caps was zero on the balance sheets as of both December 31, 2015 and 2014. The aggregate carrying value of the total return swaps was $4 thousand and zero as of December 31, 2015 and 2014, respectively.
Hedge ineffectiveness related to cash flow hedges, which is reported in current year income as interest expense, was not significant for the years ended December 31, 2015, 2014 and 2013.
Issuance of Common Stock
In 2014, the Company filed a new shelf registration statement with the SEC, allowing the Company to sell an undetermined number or amount of certain equity (only ESS) and debt securities as defined in the prospectus.
ESS has entered into equity distribution agreements with Cantor Fitzgerald & Co., Barclays Capital Inc., BMO Capital Markets Corp., BNP Paribas Securities Corp., Citigroup Global Markets Inc, Jefferies LLC, J.P. Morgan Securities LLC, Liquidnet, Inc., Mitsubishi UFJ Securities (USA), Inc, and UBS Securities LLC. Pursuant to its equity distribution program, in 2015, ESS issued 1,481,737 shares of common stock for $332.3 million, net of fees and commissions, and in 2014, ESS issued 2,964,315 shares of common stock for proceeds of $534.0 million, net of fees and commissions. During the first quarter of 2016 through February 22, 2016, ESS has not issued any shares of common stock pursuant to this program. Under this program, ESS may from time to time sell shares of common stock into the existing trading market at current market prices, and the Company anticipates using the net proceeds, which are contributed to the Operating Partnership, to pay down debt, fund redevelopment and development pipelines, fund acquisitions, and for general corporate purposes. As of February 22, 2016, ESS may sell an additional 1,719,109 shares under the current equity distribution program.
Capital Expenditures
Non-revenue generating capital expenditures are improvements and upgrades that extend the useful life of the property. For the year ended December 31, 2015, non-revenue generating capital expenditures totaled approximately $1,173 per apartment home. The Company projects to incur approximately $1,200 per apartment home in non-revenue generating capital expenditures for the year ending December 31, 2016. These expenditures do not include the improvements required in connection with the origination of mortgage loans, expenditures for deferred maintenance on acquisition properties, and expenditures for property renovations and improvements which are expected to generate additional revenue. The Company expects that cash from operations and/or its lines of credit will fund such expenditures. However, there can be no assurance that the actual expenditures incurred during 2016 and/or the funding thereof will not be significantly different than the Company’s current expectations.
Development and Predevelopment Pipeline
The Company defines development projects as new communities that are being constructed or are newly constructed and are in a phase of lease-up and have not yet reached stabilized operations. As of December 31, 2015, the Company had two consolidated development projects comprised of 771 apartment homes with an estimated cost of $489.0 million of which $287.0 million remains to be expended, and six unconsolidated joint venture active development projects comprised of 1,676 apartment homes with an estimated cost of $0.9 billion, of which approximately $500.0 million remains to be expended. The Company's share of these estimated remaining project costs is approximately $255.0 million.
The Company defines predevelopment projects as proposed communities in negotiation or in the entitlement process with an expected high likelihood of becoming entitled development projects. The Company may also acquire land for future development purposes or sale.
The Company expects to fund the development and predevelopment pipeline by using a combination of some or all of the following sources: its working capital, amounts available on its lines of credit, construction loans, net proceeds from public and private equity and debt issuances, and proceeds from the disposition of properties, if any.
Redevelopment Pipeline
The Company defines redevelopment communities as existing properties owned or recently acquired, which have been targeted for additional investment by the Company with the expectation of increased financial returns through property improvement. During redevelopment, apartment homes may not be available for rent and, as a result, may have less than stabilized operations. As of December 31, 2015, the Company had ownership interests in five major redevelopment communities aggregating 1,313
apartment homes with estimated redevelopment costs of $159.8 million, of which approximately $82.5 million remains to be expended.
Alternative Capital Sources
The Company utilizes co-investments as an alternative source of capital for acquisitions of both operating and development communities. As of December 31, 2015, the Company had an interest in 1,676 apartment homes of communities actively under development with joint ventures for a total estimated cost of $0.9 billion. Total estimated remaining costs total approximately $500.0 million, of which the Company estimates that its remaining investment in these development joint ventures will be approximately $255.0 million. In addition, the Company had an interest in 10,520 apartment homes of operating communities with joint ventures for a total book value of $738.9 million.
Contractual Obligations and Commercial Commitments
The following table summarizes the maturity or due dates of the Company’s contractual obligations and other commitments at December 31, 2015, and the effect such obligations could have on the Company’s liquidity and cash flow in future periods ($ in thousands):
| 2016 | 2017 and 2018 | 2019 and 2020 | Thereafter | Total | ||||||||||||||||
| Mortgage notes payable | $ | 29,714 | $ | 519,802 | $ | 1,279,300 | $ | 329,451 | $ | 2,158,267 | ||||||||||
| Unsecured debt | 350,000 | 365,000 | 75,000 | 2,300,000 | 3,090,000 | |||||||||||||||
| Lines of credit | — | — | 15,000 | — | 15,000 | |||||||||||||||
| Interest on indebtedness (1) | 221,917 | 373,819 | 266,313 | 223,734 | 1,085,783 | |||||||||||||||
| Ground leases | 2,742 | 5,484 | 5,484 | 131,851 | 145,561 | |||||||||||||||
| Operating leases | 1,695 | 3,557 | 3,792 | 12,350 | 21,394 | |||||||||||||||
| Development commitments (including co-investments) (2) | 195,218 | 329,207 | 17,235 | — | 541,660 | |||||||||||||||
| $ | 801,286 | $ | 1,596,869 | $ | 1,662,124 | $ | 2,997,386 | $ | 7,057,665 |
| (1) | Interest on indebtedness for variable debt was calculated using interest rates as of December 31, 2015. |
| (2) | Estimated project cost for development the Company's 500 Folsom project is net of a projected value for low-income housing tax credit proceeds and savings from tax exempt bonds. |
Variable Interest Entities
In accordance with accounting standards for consolidation of variable interest entities (VIEs), the Company consolidates the Operating Partnership and 19 DownREIT limited partnerships (comprising eleven communities). The Company consolidates these entities because it is deemed the primary beneficiary. The REIT has no assets or liabilities other than its investment in the Operating Partnership. The consolidated total assets and liabilities related to these DownREIT VIEs, net of intercompany eliminations, were approximately $241.0 million and $206.7 million, respectively, as of December 31, 2015, and $235.1 million and $209.1 million respectively, as of December 31, 2014. Interest holders in VIEs consolidated by the Company are allocated net income equal to the cash payments made to those interest holders for services rendered or distributions from cash flow. The remaining results of operations are generally allocated to the Company. As of December 31, 2015, the Company did not have any VIE’s of which it was not deemed to be the primary beneficiary.
Critical Accounting Policies and Estimates
The preparation of consolidated financial statements, in accordance with U.S. generally accepted accounting principles, requires the Company to make estimates and judgments that affect the reported amounts of assets, liabilities, revenues and expenses and related disclosures of contingent assets and liabilities. The Company defines critical accounting policies as those accounting policies that require the Company's management to exercise their most difficult, subjective and complex judgments. The Company’s critical accounting policies relate principally to the following key areas: (i) accounting for business combinations; (ii) consolidation under applicable accounting standards of various entities; (iii) assessing the carrying values of the Company's real estate and investments in and advances to joint ventures and affiliates; and (iv) internal cost capitalization. The Company bases its estimates on historical experience, current market conditions, and on various other assumptions that are believed to be reasonable under the circumstances. Actual results may differ from those estimates made by management.
The Company accounts for its business combinations, including the merger and other acquisitions of investments in real estate, in accordance with ASC 805-10, Business Combinations, which requires the acquired tangible and intangible assets and liabilities to be recorded at fair value, with excess purchase price, if any, recorded to goodwill. The Company must make significant assumptions in determining the fair value of the tangible and intangible assets and liabilities acquired and consideration transferred. The use of different assumptions in estimating the fair value could affect the measurement and timing of recognition of acquired assets and liabilities and related expenses.
The consideration transferred in a business combination is generally measured at fair value. For debt assumed by the Company, the fair value is determined using estimated market interest rates for debt with comparable terms in place at the time of the acquisition. For equity issued by the Company, the fair value is generally based on the fair value of the Company’s equity interests at the date of issuance.
The fair value of the tangible assets, which principally includes land and building, is determined first by valuing the property as a whole as if it were vacant, using stabilized net operating income and market specific capitalization rates. The fair value of the land and building is then recorded based on its estimated fair value.
In calculating the fair value of identified intangible assets of an acquired property, the in-place leases are valued based on in-place rent rates and estimated time and cost to lease a unit.
The initial purchase accounting is based on the Company’s preliminary assessment, which may differ when additional information becomes available. Subsequent adjustments made to the initial purchase accounting, if any, are made within the measurement period, which will be finalized within one year of the acquisition date.
The Company assesses each entity in which it has an investment or contractual relationship to determine if it may be deemed to be a VIE. If such an entity is a VIE, then the Company performs an analysis to determine who is the primary beneficiary. If the Company is the primary beneficiary, then the entity is consolidated. The analysis required to identify VIEs and primary beneficiaries is complex and judgmental, and the analysis must be applied to various types of entities and legal structures.
The Company assesses the carrying value of its real estate investments by monitoring investment market conditions and performance compared to budget for operating properties and joint ventures, and by monitoring estimated costs for properties under development. Local market knowledge and data is used to assess carrying values of properties and the market value of acquisition opportunities. Whenever events or changes in circumstances indicate that the carrying amount of a property held for investment may not be fully recoverable, the carrying amount is evaluated. If the sum of the property’s expected future cash flows (undiscounted and without interest charges) is less than the carrying amount of the property, then the Company will recognize an impairment loss equal to the excess of the carrying amount over the fair value of the property. Adverse changes in market conditions or poor operating results of real estate investments could result in impairment charges. When the Company determines that a property is held for sale, it discontinues the periodic depreciation of that property. The criteria for determining when a property is held for sale requires judgment and has potential financial statement impact as depreciation would cease and an impairment loss could occur upon determination of held for sale status. Assets held for sale are reported at the lower of the carrying amount or estimated fair value less costs to sell.
Further, the Company evaluates whether its co-investments are other than temporarily impaired and, if so, records an impairment loss equal to the excess of the co-investments' carrying value over its estimated fair value.
The Company capitalizes all direct and certain indirect costs, including interest and real estate taxes, incurred during development and redevelopment activities. Interest is capitalized on real estate assets that require a period of time to get them ready for their intended use. The amount of interest capitalized is based upon the average amount of accumulated development expenditures during the reporting period. Included in capitalized costs are management’s accounting estimates of the direct and incremental personnel costs and indirect project costs associated with the Company's development and redevelopment activities. Indirect project costs consist primarily of personnel costs associated with construction administration and development, including accounting, legal fees, and various corporate and community onsite costs that clearly relate to projects under development.
The Company bases its accounting estimates on historical experience and on various other assumptions that are believed to be reasonable under the circumstances. Actual results may vary from those estimates and those estimates could be different under different assumptions or conditions.
Net Operating Income (“NOI”)
Same-Property net operating income (“NOI”) is considered by management to be an important supplemental performance measure to earnings from operations included in the Company’s consolidated statements of income. The presentation of Same-Property NOI assists with the presentation of the Company’s operations prior to the allocation of depreciation and any corporate-level or financing-related costs. NOI reflects the operating performance of a community and allows for an easy comparison of the operating performance of individual communities or groups of communities. Prospective buyers of real estate have different financing and overhead structures, with varying marginal impacts to overhead by acquiring real estate, and NOI is considered by many in the real estate industry to be a useful measure for determining the value of a real estate asset or group of assets. The Company defines Same-Property NOI as Same-Property revenue less Same-Property operating expenses.
The reconciliation of earnings from operations to Same-Property NOI for the periods presented:
| 2015 | 2014 | 2013 | |||||||||
| Earnings from operations | $ | 331,174 | $ | 201,514 | $ | 188,705 | |||||
| Adjustments: | |||||||||||
| General and administrative | 40,090 | 40,878 | 26,684 | ||||||||
| Management and other fees from affiliates | (8,909 | ) | (9,347 | ) | (7,263 | ) | |||||
| Depreciation and amortization | 453,423 | 360,592 | 192,420 | ||||||||
| Merger and integration expenses | 3,798 | 53,530 | 4,284 | ||||||||
| Acquisition and investment related costs | 2,414 | 1,878 | 1,161 | ||||||||
| Net operating income | 821,990 | 649,045 | 405,991 | ||||||||
| Less: Non Same-Property NOI | (357,457 | ) | (229,244 | ) | (22,599 | ) | |||||
| Same-Property NOI | $ | 464,533 | $ | 419,801 | $ | 383,392 |
Forward Looking Statements
Certain statements in this "Management's Discussion and Analysis of Financial Condition and Results of Operations," and elsewhere in this Annual Report on Form 10-K which are not historical facts may be considered forward looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities and Exchange Act of 1934, as amended, including statements regarding the Company's expectations, hopes, intentions, beliefs and strategies regarding the future. Forward looking statements include statements regarding the Company's expectations as to the timing of completion of current development and redevelopment projects and the stabilization dates of such projects, expectation as to the total projected costs of development and redevelopment projects, beliefs as to the adequacy of future cash flows to meet anticipated cash needs, expectations as to the amount of non-revenue generating capital expenditures, future acquisitions, the Company's development and redevelopment pipeline and the sources of funding for it, the anticipated performance of existing properties, anticipated property and growth trends in various geographic regions, statements regarding the Company’s expected 2016 Same-Property revenue generally and in various areas, and 2016 Same-Property operating expenses, statements regarding the Company's financing activities, and the use of proceeds from such activities.
Such forward-looking statements involve known and unknown risks, uncertainties and other factors including, but not limited to, that the Company will fail to achieve its business objectives, that the actual completion of development and redevelopment projects will be subject to delays, that the stabilization dates of such projects will be delayed, that the total projected costs of current development and redevelopment projects will exceed expectations, that such development and redevelopment projects will not be completed, that development and redevelopment projects and acquisitions will fail to meet expectations, that estimates of future income from an acquired property may prove to be inaccurate, that future cash flows will be inadequate to meet operating requirements and/or will be insufficient to provide for dividend payments in accordance with REIT requirements, that the actual non-revenue generating capital expenditures will exceed the Company's current expectations, that there may be a downturn in the markets in which the Company's communities are located, that the terms of any refinancing may not be as favorable as the terms of existing indebtedness, as well as those risks, special considerations, and other factors discussed in Item 1A, Risk Factors, of this Form 10-K, and those risk factors and special considerations set forth in the Company’s other filings with the SEC which may cause the actual results, performance or achievements of the Company to be materially different from any future results, performance or achievements expressed or implied by such forward-looking statements. All forward-looking statements are made as of today, and the Company assumes no obligation to update this information.
Item 7A. Quantitative and Qualitative Disclosures About Market Risks
Interest Rate Hedging Activities
The Company’s objective in using derivatives is to add stability to interest expense and to manage its exposure to interest rate movements or other identified risks. To accomplish this objective, the Company entered into interest rate swaps as part of its cash flow hedging strategy. As of December 31, 2015, the Company has seven interest rate swap contracts to mitigate the risk of changes in the interest-related cash outflows on $225.0 million of the five-year unsecured term debt. As of December 31, 2015, the Company also had $291.7 million of variable rate indebtedness, of which $20.7 million is subject to interest rate cap protection. All of the Company’s interest rate swaps are designated as cash flow hedges as of December 31, 2015. The following table summarizes the notional amount, carrying value, and estimated fair value of the Company’s derivative instruments used to hedge interest rates as of December 31, 2015. The notional amount represents the aggregate amount of a particular security that is currently hedged at one time, but does not represent exposure to credit, interest rates or market risks. The table also includes a sensitivity analysis to demonstrate the impact on the Company’s derivative instruments from an increase or decrease in 10-year Treasury bill interest rates by 50 basis points, as of December 31, 2015.
| Carrying and | Estimated Carrying Value | |||||||||||||||||
| Maturity | Estimated | + 50 | - 50 | |||||||||||||||
| ($ in thousands) | Notional Amount | Date Range | Fair Value | Basis Points | Basis Points | |||||||||||||
| Cash flow hedges: | ||||||||||||||||||
| Interest rate swaps | $ | 225,000 | 2016-2017 | $ | (1,032 | ) | $ | (56 | ) | $ | (2,003 | ) | ||||||
| Interest rate caps | 20,674 | 2018-2019 | — | — | — | |||||||||||||
| Total cash flow hedges | $ | 245,674 | 2016-2019 | $ | (1,032 | ) | $ | (56 | ) | $ | (2,003 | ) |
Additionally, the Company has entered into total return swap contracts, with an aggregate notional amount of $257.3 million, that effectively converts $257.3 million of mortgage notes payable to a floating interest rate based on SIFMA plus a spread and had a carrying value of $4 thousand at December 31, 2015. These derivatives do not qualify for hedge accounting.
Interest Rate Sensitive Liabilities
The Company is exposed to interest rate changes primarily as a result of its line of credit and long-term debt used to maintain liquidity and fund capital expenditures and expansion of the Company’s real estate investment portfolio and operations. The Company’s interest rate risk management objective is to limit the impact of interest rate changes on earnings and cash flows and to lower its overall borrowing costs. To achieve its objectives the Company borrows primarily at fixed rates and may enter into derivative financial instruments such as interest rate swaps, caps and treasury locks in order to mitigate its interest rate risk on a related financial instrument. The Company does not enter into derivative or interest rate transactions for speculative purposes.
The Company’s interest rate risk is monitored using a variety of techniques. The table below presents the principal amounts and weighted average interest rates by year of expected maturity to evaluate the expected cash flows. Management has estimated that the fair value of the Company’s $4.8 billion of fixed rate debt at December 31, 2015, to be $4.8 billion. Management has estimated the fair value of the Company’s $525.3 million of variable rate debt at December 31, 2015, is $527.6 million based on the terms of existing mortgage notes payable and variable rate demand notes compared to those available in the marketplace ($ in thousands).
| For the Years Ended December 31, | |||||||||||||||||||||||||||||||
| 2016 | 2017 | 2018 | 2019 | 2020 | Thereafter | Total | Fair value | ||||||||||||||||||||||||
| Fixed rate debt (1) | $179,677 | $538,685 | $320,080 | $650,620 | $692,440 | $ | 2,350,056 | $ | 4,731,558 | $ | 4,835,891 | ||||||||||||||||||||
| Average interest rate | 4.5 | % | 3.3 | % | 5.5 | % | 4.3 | % | 5.0 | % | 3.8 | % | |||||||||||||||||||
| Variable rate debt (1) | $200,038 | $ | 25,495 | $ | 542 | $ | 25,592 | $ | 647 | $ | 279,395 | (2 | ) | $ | 531,709 | $ | 527,592 | ||||||||||||||
| Average interest rate | 2.3 | % | 2.3 | % | 1.1 | % | 1.8 | % | 1.1 | % | 1.2 | % |
| (1) | Represents scheduled principal payments. |
| (2) | $245.7 million is subject to interest rate protection agreements. |
The table incorporates only those exposures that exist as of December 31, 2015; it does not consider those exposures or positions that could arise after that date. As a result, the Company’s ultimate realized gain or loss, with respect to interest rate fluctuations and hedging strategies would depend on the exposures that arise during the period.
Item 8. Financial Statements and Supplementary Data
The response to this item is submitted as a separate section of this Form 10-K. See Item 15.
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
Not applicable.
Item 9A. Controls and Procedures
Essex Property Trust, Inc.
As of December 31, 2015, ESS carried out an evaluation, under the supervision and with the participation of management, including its Chief Executive Officer and Chief Financial Officer, of the effectiveness of the design and operation of its disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended (the “Exchange Act”)). Based upon that evaluation, ESS’s Chief Executive Officer and Chief Financial Officer concluded that as of December 31, 2015, ESS’s disclosure controls and procedures were effective to ensure that the information required to be disclosed by ESS in the reports that ESS files or submits under the Exchange Act were recorded, processed, summarized and reported within the time periods specified in the SEC's rules and forms and that such disclosure controls and procedures were also effective to ensure that information required to be disclosed in the reports that ESS files or submits under the Exchange Act is accumulated and communicated to the ESS’s management, including ESS’s Chief Executive Officer and Chief Financial Officer, to allow timely decisions regarding required disclosure.
There were no changes in ESS’s internal control over financial reporting, that occurred during the quarter ended December 31, 2015, that have materially affected, or are reasonably likely to materially affect, ESS’s internal control over financial reporting.
Management’s Report on Internal Control Over Financial Reporting
ESS’s management is responsible for establishing and maintaining adequate internal control over financial reporting (as defined in Rule 13a-15(f) under the Securities Exchange Act of 1934, as amended). ESS’s management assessed the effectiveness of ESS’s internal control over financial reporting as of December 31, 2015. In making this assessment, ESS’s management used the criteria set forth in the report entitled “Internal Control-Integrated Framework (2013)” published by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”). ESS’s management has concluded that, as of December 31, 2015, its internal control over financial reporting was effective based on these criteria. ESS’s independent registered public accounting firm, KPMG LLP, has issued an attestation report over ESS’s internal control over financial reporting, which is included herein.
Essex Portfolio, L.P.
As of December 31, 2015, the Operating Partnership carried out an evaluation, under the supervision and with the participation of its management, including the Chief Executive Officer and Chief Financial Officer of the general partner, of the effectiveness of the design and operation of its disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended (the “Exchange Act”)). Based upon that evaluation, the Chief Executive Officer and Chief Financial Officer of the general partner concluded that as of December 31, 2015, the Operating Partnership’s disclosure controls and procedures were effective to ensure that the information required to be disclosed by the Operating Partnership in the reports that it files or submits under the Exchange Act were recorded, processed, summarized and reported within the time periods specified in the SEC's rules and forms and that such disclosure controls and procedures were also effective to ensure that information required to be disclosed in the reports that the Operating Partnership files or submits under the Exchange Act is accumulated and communicated to the Operating Partnership’s management, including the Chief Executive Officer and Chief Financial Officer of the general partner, to allow timely decisions regarding required disclosure.
There were no changes in the Operating Partnership’s internal control over financial reporting, that occurred during the quarter ended December 31, 2015, that have materially affected, or are reasonably likely to materially affect, the Operating Partnership’s internal control over financial reporting.
Management’s Report on Internal Control Over Financial Reporting
The Operating Partnership’s management is responsible for establishing and maintaining adequate internal control over financial reporting (as defined in Rule 13a-15(f) under the Securities Exchange Act of 1934, as amended). The Operating Partnership’s management assessed the effectiveness of the Operating Partnership’s internal control over financial reporting as of December 31, 2015. In making this assessment, the Operating Partnership’s management used the criteria set forth in the report entitled “Internal Control-Integrated Framework (2013)” published by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”). The Operating Partnership’s management has concluded that, as of December 31, 2015, its internal control over financial reporting was effective based on these criteria.
Item 9B. Other Information
None.
PART III
Item 10. Directors, Executive Officers and Corporate Governance
The information required by this Item is incorporated herein by reference from our Proxy Statement, relating to our 2016 Annual Meeting of Shareholders, under the heading “Board and Corporate Governance Matters,” to be filed with the SEC within 120 days of December 31, 2015.
Item 11. Executive Compensation
The information required by this Item is incorporated herein by reference from our Proxy Statement, relating to our 2016 Annual Meeting of Shareholders, under the headings “Executive Compensation” and “Director Compensation,” to be filed with the SEC within 120 days of December 31, 2015.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information required by this Item is incorporated herein by reference from our Proxy Statement, relating to our 2016 Annual Meeting of Shareholders, under the heading “Security Ownership of Certain Beneficial Owners and Management,” to be filed with the SEC within 120 days of December 31, 2015.
Item 13. Certain Relationships and Related Transactions and Director Independence
The information required by this Item is incorporated herein by reference from our Proxy Statement, relating to our 2016 Annual Meeting of Shareholders, under the heading “Certain Relationships and Related Persons Transactions,” to be filed with the SEC within 120 days of December 31, 2015.
Item 14. Principal Accounting Fees and Services
The information required by this Item is incorporated herein by reference from our Proxy Statement, relating to our 2016 Annual Meeting of Shareholders, under the headings “Report of the Audit Committee” and “Fees Paid to KPMG LLP,” to be filed with the SEC within 120 days of December 31, 2015.
PART IV
Item 15. Exhibits and Financial Statement Schedules
(A) Financial Statements
| (1) Consolidated Financial Statements of Essex Property Trust, Inc. | Page |
| Reports of Independent Registered Public Accounting Firm | F- 1 |
| Consolidated Balance Sheets: As of December 31, 2015 and 2014 | F- 4 |
| Consolidated Statements of Income: Years ended December 31, 2015, 2014, and 2013 | F- 5 |
| Consolidated Statements of Comprehensive Income: Years ended December 31, 2015, 2014, and 2013 | F- 6 |
| Consolidated Statements of Equity: Years ended December 31, 2015, 2014, and 2013 | F- 7 |
| Consolidated Statements of Cash Flows: Years ended December 31, 2015, 2014, and 2013 | F- 10 |
| Notes to Consolidated Financial Statements | F- 20 |
| (2) Consolidated Financial Statements of Essex Portfolio, L.P. | |
| Report of Independent Registered Public Accounting Firm | F- 3 |
| Consolidated Balance Sheets: As of December 31, 2015 and 2014 | F- 12 |
| Consolidated Statements of Income: Years ended December 31, 2015, 2014, and 2013 | F- 13 |
| Consolidated Statements of Comprehensive Income: Years ended December 31, 2015, 2014, and 2013 | F- 14 |
| Consolidated Statements of Capital: Years ended December 31, 2015, 2014, and 2013 | F- 15 |
| Consolidated Statements of Cash Flows: Years ended December 31, 2015, 2014, and 2013 | F- 18 |
| Notes to Consolidated Financial Statements | F- 20 |
| (3) Financial Statement Schedule – Schedule III – Real Estate and Accumulated Depreciation as of December 31, 2015 | F- 52 |
| (4) See the Exhibit Index immediately following the signature page and certifications for a list of exhibits filed or incorporated by reference as part of this report. |
(B) Exhibits
The Company hereby files, as exhibits to this Form 10-K, those exhibits listed on the Exhibit Index referenced in Item 15(A)(4) above.
Report of Independent Registered Public Accounting Firm
The Board of Directors and Stockholders
Essex Property Trust, Inc.:
We have audited the accompanying consolidated balance sheets of Essex Property Trust, Inc. and subsidiaries as of December 31, 2015 and 2014, and the related consolidated statements of income, comprehensive income, equity, and cash
flows for each of the years in the three-year period ended December 31, 2015. In connection with our audits of the consolidated financial statements, we have also audited the accompanying financial statement schedule III. These consolidated financial statements and the accompanying financial statement schedule III are the responsibility of Essex Property Trust, Inc.’s management. Our responsibility is to express an opinion on these consolidated financial statements and the accompanying financial statement schedule III based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement. An audit includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements. An audit also includes assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall financial statement presentation. We believe that our audits provide a reasonable basis for our opinion.
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of Essex Property Trust, Inc. and subsidiaries as of December 31, 2015 and 2014, and the results of their operations and their cash flows for each of the years in the three-year period ended December 31, 2015, in conformity with U.S. generally accepted accounting principles. Also in our opinion, the related financial statement schedule III, when considered in relation to the basic consolidated financial statements taken as a whole, presents fairly, in all material respects, the information set forth therein.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), Essex Property Trust, Inc.’s internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO), and our report dated February 26, 2016 expressed an unqualified opinion on the effectiveness of Essex Property Trust, Inc.’s internal control over financial reporting.
| /S/ KPMG LLP |
| KPMG LLP |
San Francisco, California
February 26, 2016
F- 1
Report of Independent Registered Public Accounting Firm
The Board of Directors and Stockholders
Essex Property Trust, Inc.:
We have audited Essex Property Trust, Inc.’s internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). Essex Property Trust, Inc.’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Report on Internal Control over Financial Reporting, appearing under Item 9A. Our responsibility is to express an opinion on Essex Property Trust, Inc.'s internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audit also included performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of un
Showing the first 8K of 259K characters. Open the full section