 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
54K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
Overview
Expeditors International of Washington, Inc. is a global logistics company. Our services include air and ocean freight consolidation and forwarding, customs clearance, warehousing and distribution, purchase order management, vendor consolidation, time-definite transportation services, cargo insurance, specialized cargo monitoring and tracking, and other customized logistics solutions. We do not compete for overnight courier or small parcel business. As a non-asset based carrier, we do not own or operate transportation assets.
We derive our revenues from three principal sources: 1) airfreight services, 2) ocean freight and ocean services, and 3) customs brokerage and other services. These are the revenue categories presented in our financial statements.
We generate the major portion of our air and ocean freight revenues by purchasing transportation services on a wholesale basis from direct (asset-based) carriers and reselling those services to our customers on a retail basis. The difference between the rate billed to our customers (the sell rate) and the rate we pay to the carrier (the buy rate) is termed “net revenue” (a non-GAAP measure), “yield" or "margin." By consolidating shipments from multiple customers and concentrating our buying power, we are able to negotiate favorable buy rates from the direct carriers, while at the same time offering lower sell rates than customers would otherwise be able to negotiate themselves. The most significant drivers of changes in gross revenues and related transportation expenses are volume, sell rates and buy rates. Volume has a similar effect on the change in both gross revenues and related transportation expenses in each of our three primary sources of revenue.
In most cases we act as an indirect carrier. When acting as an indirect carrier, we issue a House Airway Bill (HAWB), a House Ocean Bill of Lading (HOBL) or a House Seaway Bill to customers as the contract of carriage. In turn, when the freight is physically tendered to a direct carrier, we receive a contract of carriage known as a Master Airway Bill for airfreight shipments and a Master Ocean Bill of Lading for ocean shipments. In these transactions, we evaluate whether it is appropriate to record the gross or net amount as revenue. Generally, revenue is recorded on a gross basis when we are the primary obligor, are obligated to compensate direct carriers for services performed regardless of whether customers accept the service, have latitude in establishing price, have discretion in selecting the direct carrier, have credit risk or have several but not all of these indicators. Revenue is generally recorded on a net basis where we are not primarily obligated and do not have latitude in establishing prices. Such amounts earned are determined using a fixed fee, a per unit of activity fee or a combination thereof.
For revenues earned in other capacities, for instance, when we do not issue a HAWB, a HOBL, or a House Seaway Bill or otherwise act solely as an agent for the shipper, only the commissions and fees earned for such services are included in revenues. In these transactions, we are not a principal and report only commissions and fees earned in revenue.
Customs brokerage and other services involves providing services at destination, such as helping customers clear shipments through customs by preparing and filing required documentation, calculating and providing for payment of duties and other taxes on behalf of customers as well as arranging for any required inspections by governmental agencies, and arranging for delivery. These are complicated functions requiring technical knowledge of customs rules and regulations in the multitude of countries in which we have offices.
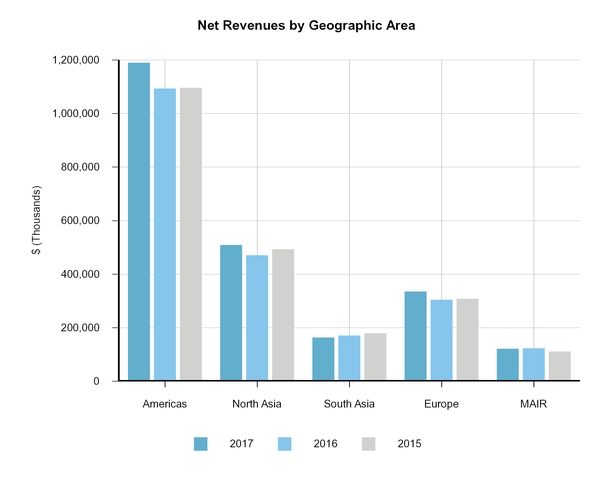
We manage our company along five geographic areas of responsibility: Americas; North Asia; South Asia; Europe; and Middle East, Africa and India (MAIR). Each area is divided into sub-regions, which are composed of operating units with individual profit and loss responsibility. Our business involves shipments between operating units and often touches more than one geographic area. The nature of the international logistics business necessitates a high degree of communication and cooperation among operating units. Because of this inter-relationship between operating units, it is very difficult to examine any one geographic area and draw meaningful conclusions as to its contribution to our overall success on a stand-alone basis. The following chart shows net revenues by geographic areas of responsibility for the years ended December 31, 2017, 2016 and 2015:
Our operating units share revenue using the same arms-length pricing methodologies that we use when our offices transact business with independent agents. Certain costs are allocated among the segments based on the relative value of the underlying services, which can include allocation based on actual costs incurred or estimated cost plus a profit margin. Our strategy closely links compensation with operating unit profitability. Individual success is closely linked to cooperation with other operating units within our network.
The mix of services varies by segment based primarily on the import or export orientation of local operations in each of our regions. In accordance with our revenue recognition policy (see Note 1. E to the consolidated financial statements of this report), almost all freight revenues and related expenses are recorded at origin and shipment profits are split between origin and destination offices by recording a commission fee or profit share revenue at destination and a corresponding commission or profit share expense as a component of origin consolidation costs.
North Asia is our largest export oriented region and accounted for 37% of revenues, 22% of net revenues and 35% of operating income for the year ended December 31, 2017. North Asia's net revenues as a percentage of revenues is lower than other segments due to the largely export nature of operations in that region.
Expeditors' Culture
From the inception of our company, management has believed that the elements required for a successful global service organization can only be assured through recruiting, training, and ultimately retaining superior personnel. We believe that our greatest challenge is now and always has been perpetuating a consistent global corporate culture, which demands:
| • | Total dedication to providing superior customer service; |
| • | Compliance with our policies and procedures and government regulations; |
| • | Aggressive marketing of all of our service offerings; |
| • | A positive, safe work environment that is inclusive and free from discrimination and harassment; |
| • | Ongoing development of key employees and management personnel; |
| • | Creation of unlimited advancement opportunities for employees dedicated to hard work, personal growth and continuous improvement; |
| • | Individual commitment to the identification and mentoring of successors for every key position so that when change occurs, a qualified and well-trained internal candidate is ready to step forward; and |
| • | Continuous identification, design and implementation of system solutions and differentiated service offerings, both technological and otherwise, to meet and exceed the needs of our customers while simultaneously delivering tools to make our employees more efficient and more effective. |
We reinforce these values with a compensation system that rewards employees for profitably managing the things they can control. This compensation system has been in place since we became a publicly traded company. There is no limit to how much a key, non-executive manager can be compensated for success. We believe in a “real world” environment where the employees of our operating units are held accountable for the profit implications of their decisions. If these decisions result in operating losses, management generally must make up these losses with future operating profits, in the aggregate, before any cash incentive compensation can be earned. Executive management, in limited circumstances, makes exceptions at the branch operating unit level. At the same time, our policies, processes and relevant training focus on such things as cargo management, risk mitigation, compliance, accounts receivable collection, cash flow and credit soundness in an attempt to help managers avoid the kinds of errors that might end a career.
We believe that our unique culture is a critical component to our continued success. We strongly believe that it is nearly impossible to predict events that, individually or in the aggregate, could have a positive or a negative impact on our future operations. As a result, management's focus is on building and maintaining a global corporate culture and an environment where well-trained employees and managers are prepared to identify and react to changes as they develop and thereby help us adapt and thrive as major trends emerge.
Our ability to provide services to customers is highly dependent on good working relationships with a variety of entities including airlines, ocean carriers, ground transportation providers and governmental agencies. The significance of maintaining acceptable working relationships with these entities has gained increased importance as a result of ongoing concern over terrorism, security, changes in governmental regulation and oversight of international trade. A good reputation helps to develop practical working understandings that will assist in meeting security requirements while minimizing potential international trade obstacles, especially as governments promulgate new regulations and increase oversight and enforcement of new and existing laws. We consider our current working relationships with these entities to be satisfactory.
Our business is also highly dependent on the financial stability and operational capabilities of the carriers we utilize. Although airline profitability has improved, many air carriers remain highly leveraged with debt. Moreover, the ocean carrier industry has incurred substantial losses in recent years. Many carriers are highly leveraged with debt and certain carriers are facing significant liquidity challenges, such as those that led to the bankruptcy filing of a major carrier that occurred in August 2016. This environment requires that we be selective in determining which carriers to utilize. Further changes in the financial stability, operating capabilities and capacity of asset-based carriers, space allotments available from carriers, governmental regulations, and/or trade accords could adversely affect our business in unpredictable ways.
International Trade and Competition
We operate in over 60 countries in the competitive global logistics industry and our activities are closely tied to the global economy. International trade is influenced by many factors, including economic and political conditions in the United States and abroad, currency exchange rates, and laws and policies relating to tariffs, trade restrictions, foreign investments and taxation. Periodically, governments consider a variety of changes to current tariffs and trade restrictions and accords. We cannot predict which, if any, of these proposals may be adopted, or the effects the adoption of any such proposal will have on our business. Doing business in foreign locations also subjects us to a variety of risks and considerations not normally encountered by domestic enterprises. In addition to being influenced by governmental policies concerning international trade, our business may also be negatively affected by political developments and changes in government personnel or policies in the United States and other countries, as well as economic turbulence, political unrest and security concerns in the nations in which we conduct business and the future impact that these events may have on international trade and oil prices.
The global logistics services industry is intensely competitive and is expected to remain so for the foreseeable future. Our pricing and terms continue to be pressured by uncertainty in global trade and economic conditions, concerns over volatile fuel costs, disruptions in port services, political unrest and fluctuating currency exchange rates. We expect these operating and competitive conditions to continue.
Ocean carriers have incurred substantial operating losses in recent years, and many are highly leveraged with debt. These financial challenges have resulted in the 2016 bankruptcy of a major carrier, as well as multiple carrier acquisitions and carrier alliance formations. Additionally, while overall global demand has recently increased, carriers continue to take delivery of new and larger ships, which creates additional capacity. When the market experiences seasonal peaks or any sort of disruption, the carriers often increase their pricing suddenly. This carrier behavior creates pricing volatility that could impact Expeditors' ability to maintain historical unitary profitability.
The global economic environment and trade growth have improved but remain uncertain. We cannot predict the impact of future changes in global trade on our operating results, freight volumes, pricing, changes in consumer demand, carrier stability and capacity, customers’ abilities
to pay or on changes in competitors' behavior. Additionally, we cannot predict the direct or indirect impact that further changes in consumer purchasing behavior, such as online shopping, could have on our business.
Critical Accounting Estimates
A summary of our significant accounting policies can be found in Note 1 to the consolidated financial statements in this report.
Management believes that the nature of our business is such that there are few complex challenges in accounting for operations. While judgments and estimates are a necessary component of any system of accounting, the use of estimates is limited primarily to the following areas:
| • | accrual of loss contingencies; |
| • | accrual of various tax liabilities and contingencies; |
| • | accounts receivable valuation; and |
| • | accrual of insurance liabilities for the portion of the related exposure that we have self-insured. |
These estimates, other than the accrual of loss contingencies and tax liabilities and contingencies, are not highly uncertain and have not historically been subject to significant change. Management believes that the methods utilized in all of these areas are non-aggressive in approach and consistent in application. Management believes that there are limited, if any, alternative accounting principles or methods which could be applied to these transactions. While the use of estimates means that actual future results may be different from those contemplated by the estimates, management believes that alternative principles and methods used for making such estimates would not produce materially different results than those reported.
The outcome of loss contingencies, including legal proceedings and claims and government investigations, brought against us are subject to significant uncertainty. An estimated loss from a contingency, such as a legal proceeding, claim or government investigation, is accrued by a charge to income if it is probable that an asset has been impaired or a liability has been incurred and the amount of the loss can be reasonably estimated. Disclosure of a loss contingency is required if there is at least a reasonable possibility that a significant loss has been incurred. In determining whether a loss should be accrued, management evaluates several factors, including advice from outside legal counsel, in order to estimate the likelihood of an unfavorable outcome and to make a reasonable estimate of the amount of loss or range of reasonably possible loss. Changes in these factors could have a material impact on our financial position, results of operations and operating cash flows for any particular quarter or year.
We are subject to taxation in multiple U.S. and foreign tax jurisdictions. As discussed in Note 1.F to the consolidated financial statements, the earnings of our foreign subsidiaries are not considered to be indefinitely reinvested outside of the U.S. and, accordingly, U.S. Federal and State income taxes have historically been provided for all undistributed earnings net of related foreign tax credits of our foreign subsidiaries.
Accounting for income taxes involves estimates and judgments. Management believes our tax positions, including intercompany transfer pricing policies, are reasonable and consistent. As a matter of course, Expeditors is audited by various taxing authorities, and sometimes these audits result in proposed assessments where the ultimate resolution could result in significant additional tax, penalties and interest payments being required. We establish liabilities when, despite our belief that the tax return positions are appropriate and consistent with tax law, we conclude that we may not be successful in realizing the tax position. In evaluating a tax position, we determine whether it is more likely than not that the position will be sustained upon examination, including resolution of any related appeals or litigation processes, based on the technical merits of the position and in consultation with qualified tax advisors. Our estimate of any ultimate tax liability contains assumptions based on past experiences, judgments about potential actions by taxing jurisdictions as well as judgments about the likely outcome of issues that have been raised by the taxing jurisdiction. We believe the estimates and assumptions used to support the evaluation of our tax positions are reasonable. However, final determinations of tax liabilities, penalties and interest could be materially different from estimates.
As discussed in further detail in Note 5 to the consolidated financial statements, on December 22, 2017 the U.S. enacted the Tax Cuts and Jobs Act (the 2017 Tax Act). The 2017 Tax Act, which is also commonly referred to as “U.S. tax reform,” significantly changes U.S. corporate income tax laws by, among other things, reducing the U.S. corporate income tax rate to 21% starting in 2018 and creating a territorial tax system with a one-time mandatory tax on previously undistributed foreign earnings of non-U.S. subsidiaries.
Prospectively, excluding the impact of any discrete items, the provisions of the 2017 Tax Act are expected to reduce our effective tax rate compared to what the rate would have otherwise been in the absence of U.S. tax reform. The ultimate impact on our effective tax rate will largely depend on the mix of pretax earnings that we generate in the U.S. as compared to the rest of the world.
Results of Operations
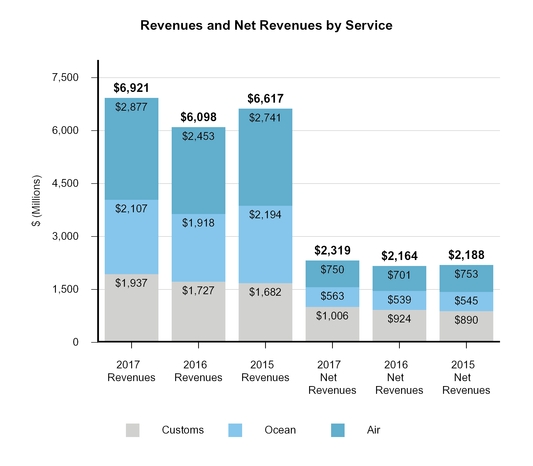
The following table shows the total net revenues (a non-GAAP measure calculated as revenues less directly related operating expenses attributable to our principal services) and our expenses for 2017, 2016, and 2015 expressed as percentages of net revenues. Management believes that net revenues are a better measure than total revenues when analyzing and discussing management's effectiveness in managing our principal services since total revenues earned by Expeditors as a freight consolidator include the carriers’ charges to us for carrying the shipment, whereas revenues earned by Expeditors in our other capacities include primarily the commissions and fees actually earned by us. Net revenue is one of our primary operational and financial measures and demonstrates our ability to manage sell rates to customers with our ability to concentrate and leverage our purchasing power through effective consolidation of shipments from multiple customers utilizing a variety of transportation carriers and optimal routings. Using net revenue also provides a commonality for comparison among various services.
The table, chart and the accompanying discussion and analysis should be read in conjunction with the consolidated financial statements and related notes thereto in this report.
| 2017 | 2016 | 2015 | ||||||||||||||||||||
| In thousands | Amount | Percent of net revenues | Amount | Percent of net revenues | Amount | Percent of net revenues | ||||||||||||||||
| Airfreight services: | ||||||||||||||||||||||
| Revenues | $ | 2,877,032 | $ | 2,453,347 | $ | 2,740,583 | ||||||||||||||||
| Expenses | 2,126,761 | 1,752,167 | 1,987,690 | |||||||||||||||||||
| Net revenues | 750,271 | 32 | % | 701,180 | 32 | % | 752,893 | 34 | % | |||||||||||||
| Ocean freight and ocean services: | ||||||||||||||||||||||
| Revenues | 2,107,045 | 1,917,494 | 2,194,004 | |||||||||||||||||||
| Expenses | 1,543,740 | 1,378,699 | 1,648,993 | |||||||||||||||||||
| Net revenues | 563,305 | 24 | 538,795 | 25 | 545,011 | 25 | ||||||||||||||||
| Customs brokerage and other services: | ||||||||||||||||||||||
| Revenues | 1,936,871 | 1,727,196 | 1,682,045 | |||||||||||||||||||
| Expenses | 931,258 | 803,135 | 792,172 | |||||||||||||||||||
| Net revenues | 1,005,613 | 44 | 924,061 | 43 | 889,873 | 41 | ||||||||||||||||
| Total net revenues | 2,319,189 | 100 | 2,164,036 | 100 | 2,187,777 | 100 | ||||||||||||||||
| Overhead expenses: | ||||||||||||||||||||||
| Salaries and related costs | 1,267,120 | 55 | 1,157,635 | 53 | 1,143,511 | 52 | ||||||||||||||||
| Other | 351,809 | 15 | 336,238 | 16 | 322,782 | 15 | ||||||||||||||||
| Total overhead expenses | 1,618,929 | 70 | 1,493,873 | 69 | 1,466,293 | 67 | ||||||||||||||||
| Operating income | 700,260 | 30 | 670,163 | 31 | 721,484 | 33 | ||||||||||||||||
| Other income, net | 18,335 | 1 | 16,693 | 1 | 15,205 | 1 | ||||||||||||||||
| Earnings before income taxes | 718,595 | 31 | 686,856 | 32 | 736,689 | 34 | ||||||||||||||||
| Income tax expense | 228,212 | 10 | 254,323 | 12 | 277,192 | 13 | ||||||||||||||||
| Net earnings | 490,383 | 21 | 432,533 | 20 | 459,497 | 21 | ||||||||||||||||
| Less net earnings attributable to the noncontrolling interest | 1,038 | — | 1,726 | — | 2,274 | — | ||||||||||||||||
| Net earnings attributable to shareholders | $ | 489,345 | 21 | % | $ | 430,807 | 20 | % | $ | 457,223 | 21 | % |
2017 compared with 2016
Airfreight services:
Airfreight services revenues increased 17% in 2017, as compared with 2016. This increase is attributed to tonnage growth across all segments and higher average sell rates, principally on exports out of North Asia and Europe. We increased sell rates in response to higher buy rates caused by an overall increase in market demand. Airfreight services expenses increased 21% in 2017 as compared with 2016, as a result of the 10% increase in tonnage and higher average buy rates due to tighter carrier capacity.
Airfreight services net revenues in 2017 increased 7%, as compared with 2016. The increase was principally due to a 10% increase in tonnage, partially offset by a 6% decrease in net revenue per kilo. Average net revenue per kilo declined in most regions primarily due to competitive market conditions and tight carrier capacity. Carriers in North Asia and South Asia increased pricing significantly as a result of higher demand relative to available capacity. North America, North Asia and Europe net revenues increased 10%, 8% and 15%, respectively, due primarily to tonnage increases of 12%, 6% and 12%, respectively. South Asia net revenues decreased 12%, despite a 12% increase in tonnage, primarily due to lower average sell rates and higher average buy rates.
Since late 2016, the global airfreight market has been experiencing imbalances between carrier capacity and demand in certain lanes, which is resulting in higher average buy rates. Customers remain focused on improving supply-chain efficiency, reducing overall logistics costs by negotiating lower rates and utilizing ocean freight whenever possible. Customers are increasingly utilizing airfreight to improve speed to market. We expect these trends to continue in conjunction with carriers' efforts to manage available capacity and the evolution of consumer purchasing behavior, such as online shopping. These conditions could be affected by new product launches during periods that have historically experienced higher demand. Historically, we have experienced lower airfreight margins in the fourth quarter as seasonal volumes increase and carriers correspondingly increase buy rates. These events, should they continue to occur, could create a higher degree of volatility in volumes and, ultimately, buy and sell rates.
Ocean freight and ocean services:
Ocean freight consolidation, direct ocean forwarding and order management are the three basic services that constitute and are collectively referred to as ocean freight and ocean services. Ocean freight and ocean services revenues increased 10% in 2017 as compared with 2016, primarily due to a 5% increase in container volume and higher average sell rates to customers. Ocean freight and ocean services expenses increased 12% in 2017 as compared with 2016, due to volume growth and higher average buy rates, resulting from overall market demand and carriers managing available capacity.
Ocean freight and ocean services net revenues increased 5% in 2017, as compared with 2016. The largest component of our ocean freight net revenue is derived from ocean freight consolidation, which represented 45% and 48% of ocean freight net revenue in 2017 and 2016, respectively.
Ocean freight consolidation net revenues decreased 1% in 2017, as compared with 2016. This decrease was due primarily to a 6% decrease in net revenue per container, largely offset by a 5% increase in volume. Direct ocean freight forwarding net revenues increased 6% due to higher volumes. Order management net revenues increased 13%, mostly resulting from higher volumes with new and existing customers, primarily in North Asia and South Asia.
North Asia ocean freight and ocean services net revenues increased 11% in 2017, as compared with 2016, due principally to 4% growth in volume and order management. North America and South Asia net revenues both increased 1%, as higher volumes were largely offset by lower margins. Europe net revenues decreased 1%, due to a decline in net revenue per container, mostly offset by volume growth.
We expect that pricing volatility will continue as customers solicit bids and carriers adapt to changing market conditions, merge or create alliances with other carriers. These conditions could result in lower margins.
Customs brokerage and other services:
Customs brokerage and other services revenues and expenses increased 12% and 16%, respectively, in 2017, as compared with 2016, primarily as a result of higher volumes.
Customs brokerage and other services net revenues increased 9% in 2017, as compared with 2016, primarily as a result of an increase in customs brokerage and road freight volumes, particularly in North America and Europe. Customers continue to seek out customs brokers with sophisticated computerized capabilities critical to an overall logistics management program, including rapid responses to changes in the regulatory and security environment.
North America net revenues increased 11% in 2017, as compared with 2016, primarily as a result of higher volumes from existing and new customers in road freight and customs brokerage services. Europe net revenues increased 12% due primarily to growth in import, road freight, and warehouse and distribution services.
Overhead expenses:
Salaries and related costs increased 9% in 2017, as compared with 2016, principally due to an increase in the number of employees, primarily in North America, South Asia and Europe, higher salaries, and an increase in bonuses resulting from higher operating income.
Historically, the relatively consistent relationship between salaries and net revenues is the result of a compensation philosophy that has been maintained since the inception of our company: offer a modest base salary and the opportunity to share in a fixed and determinable percentage of the operating profit of the business unit controlled by each key employee. Using this compensation model, changes in individual incentive compensation occur in proportion to changes in our operating income, creating a direct alignment between corporate performance and shareholder interests. Bonuses to field and executive management in 2017 were up 4.7% as compared with 2016, primarily as a result of a 4.5% increase in operating income. Our management compensation programs have always been incentive-based and performance driven. Salaries and related costs increased to 55% of net revenues in 2017, as compared with 53% in 2016.
Because our management incentive compensation programs are also cumulative, generally no management bonuses can be paid unless the relevant business unit is, from inception, cumulatively profitable. Any operating losses must be offset in their entirety by operating profits before management is eligible for a bonus. Executive management, in limited circumstances, makes exceptions at the branch operating unit level. Since the most significant portion of management compensation comes from the incentive bonus programs, we believe that this cumulative feature is a disincentive to excessive risk taking by our managers. Our services have a short operating cycle. As a result, the outcome of any higher risk transactions, such as overriding established credit limits, would be known in a relatively short time frame. Management believes that when the potential and certain impact on the bonus is fully considered in light of this short operating cycle, the potential for short-term gains that could be generated by engaging in risky business practices is sufficiently mitigated to discourage excessive and inappropriate risk taking. Management believes that both the stability and the long-term growth in revenues, net revenues and net earnings are a result of the incentives inherent in our compensation programs.
Other overhead expenses increased 5% in 2017, as compared with 2016. We continue to invest in additional technology and facilities, which resulted in higher rent and facilities expenses, technology-related fees and consulting costs. These increases were offset by a $4 million gain on the sale of a property, lower claims, the favorable resolution of an indirect tax contingency of $6 million and the recovery of certain legal and related costs totaling $8 million in 2017 compared to $5 million in 2016. We will continue to make important investments in people,
processes and technology, as well as to invest in our strategic efforts to explore new areas for profitable growth. Other overhead expenses decreased to 15% of net revenues in 2017 from 16% in 2016.
Income tax expense:
We pay income taxes in the United States and other jurisdictions. Our consolidated effective income tax rate was 31.8% in 2017, as compared with 37.0% in 2016. The change in the effective tax rate was principally due to recording the estimated impact of U.S. tax reform and to a lesser degree a result of a higher proportion of our total outstanding stock-based compensation expense being for non-qualified stock option grants and restricted stock units. The tax benefit associated with non-qualified stock option and restricted stock unit grants is recorded when the related compensation expense is recognized while the tax benefit received for incentive stock options and employee stock purchase plan shares cannot be anticipated and are recognized if and when a disqualifying disposition occurs.
Our effective tax rate is subject to variation and the effective tax rate can be more or less volatile based on the amount of pre-tax income or loss. For example, the impact of discrete items and non-deductible expenses on the effective tax rate is greater when pre-tax income is lower. Total consolidated foreign income tax expense is composed of the income tax expense of our Non-US subsidiaries as well as income based withholding taxes paid by our Non-US subsidiaries on behalf its parent for intercompany payments, including the remittance of dividends. For example our effective foreign tax rate increased from 30.9% in 2016 to 33.9% in 2017, principally due to withholding tax payments associated with dividend payments from our non-U.S. subsidiaries. Prospectively, excluding the impact of discrete items recorded in a future reporting period and any changes recorded in 2018 to provisional 2017 income tax expense amounts as discussed in Note 5 to the consolidated financial statements, the provisions of the 2017 Tax Act are expected to reduce our annual effective tax rate to an estimated rate between 31% and 34%. The ultimate impact on our effective tax rate will largely depend on the mix of pretax earnings that we generate in the U.S. as compared to the rest of the world and the other factors discussed above.
2016 compared with 2015
Airfreight services:
Airfreight services revenues decreased 10% in 2016, as compared with 2015, primarily as a result of lowering average sell rates in response to competitive market conditions. The decrease in average sell rates was partially offset by a 3% growth in airfreight tonnage. Airfreight services expenses decreased 12% in 2016 as compared with 2015, as a result of favorable buying opportunities throughout most regions due primarily to excess available carrier capacity. While not possible to quantify, sell rates and tonnage were favorably impacted in 2015 by customers converting a portion of their ocean freight shipments to airfreight due to port disruptions on the U.S. West Coast.
Airfreight services net revenues in 2016 decreased 7% as compared with 2015. The decrease was principally due to a 12% decrease in net revenue per kilo, partially offset by a 3% increase in tonnage. Average net revenue per kilo declined in most regions primarily due to competitive market conditions and rapid changes in carrier pricing caused by sporadic increases in demand. North America net revenues decreased by 6% due principally to a 3% decrease in tonnage. North Asia, South Asia and Europe net revenues decreased 10%, 9% and 2%, respectively, despite tonnage increases of 5%, 7% and 3%.
Ocean freight and ocean services:
Ocean freight and ocean services revenues decreased 13% in 2016, as compared with 2015, as we continued to lower average sell rates to customers in response to competitive market conditions and lower available buy rates from carriers. Although average sell rates to customers declined, container volumes increased 3%. Ocean freight and ocean services expenses decreased 16% in 2016 as compared with 2015, due to lower average buy rates, resulting from carrier overcapacity.
Ocean freight and ocean services net revenues decreased 1% in 2016, as compared with 2015. In 2016 and 2015, the largest component of our ocean freight net revenue was derived from ocean freight consolidation, which represented 48% and 50%, respectively, of ocean freight net revenue.
Ocean freight consolidation net revenues decreased 6% in 2016, as compared with 2015. This decrease was due primarily to an 8% decrease in net revenue per container, partially offset by a 3% increase in volume. During the latter part of the third quarter of 2016, we experienced a spike in average buy rates that began with the bankruptcy of a large ocean carrier on August 31, 2016. Direct ocean freight forwarding net revenues decreased 2% due to lower volumes principally in North America. Order management net revenues increased 11%, mostly resulting from higher volumes with new and existing customers, primarily in North Asia and South Asia.
North America ocean freight and ocean services net revenues decreased 3% in 2016, as compared with 2015, primarily due to lower direct ocean forwarding volumes and a decrease in ocean freight consolidation resulting from declining margins on imports. North Asia net revenues decreased 1% as lower margins were offset by a 1% growth in volume. Europe net revenues decreased 4%, as lower direct ocean forwarding volumes more than offset growth from order management and ocean freight consolidation. South Asia net revenues increased 6% due principally to 4% growth in volumes.
Customs brokerage and other services:
Customs brokerage and other services revenues and expenses increased 3% and 1%, respectively, in 2016, as compared with 2015, primarily as a result of increased volumes from existing and new road freight customers.
Customs brokerage and other services net revenues increased 4% in 2016, as compared with 2015, primarily as a result of an increase in road freight volumes. Customers continued to seek out customs brokers with sophisticated computerized capabilities critical to an overall logistics management program, including rapid responses to changes in the regulatory and security environment.
North America net revenues increased 5% in 2016, as compared with 2015, primarily as a result of higher volumes from existing and new customers in road freight and lower import service costs. North Asia net revenues increased 8% due primarily to growth in import and warehouse and distribution services. Europe net revenues remained constant, as compared with 2015.
Overhead expenses:
Salaries and related costs increased 1% in 2016, as compared with 2015, principally due to an increase in the number of employees, primarily in North America and Europe, partially offset by reduced bonuses from lower operating income.
Bonuses to field and executive management in 2016 were down 7% as compared with 2015, primarily as a result of a 7% decrease in operating income. Salaries and related costs increased to 53% of net revenues in 2016 as compared with 52% in 2015.
Other overhead expenses increased 4% in 2016, as compared with 2015. The increase in expenses was primarily due to higher rent and maintenance costs and technology fees, partially offset by lower claims. Other overhead expenses increased to 16% of net revenues in 2016, as compared with 15% in 2015.
Income tax expense:
Our consolidated effective income tax rate declined slightly to 37.0% in 2016, as compared to 37.6% in 2015. The decrease in the effective tax rate was principally the result of a higher proportion of our total outstanding stock-based compensation expense being for non-qualified stock option grants.
Currency and Other Risk Factors
The nature of our worldwide operations necessitates dealing with a multitude of currencies other than the U.S. dollar. This results in our being exposed to the inherent risks of volatile international currency markets and governmental interference. Some of the countries where we maintain offices and/or agency relationships have strict currency control regulations, which influence our ability to hedge foreign currency exposure. We try to compensate for these exposures by accelerating international currency settlements among our offices and agents. We may enter into foreign currency hedging transactions where there are regulatory or commercial limitations on our ability to move money freely around the world or the short-term financial outlook in any country is such that hedging is the most time-sensitive way to mitigate short-term exchange losses. Any such hedging activity during 2017, 2016 and 2015 was insignificant. We had no foreign currency derivatives outstanding at December 31, 2017 and 2016. Net foreign currency losses were approximately $13 million in 2017, and net foreign currency gains were approximately $8 million in both 2016 and 2015.
International air and ocean freight forwarding and customs brokerage are intensively competitive and are expected to remain so for the foreseeable future. There are a large number of entities competing in the international logistics industry, many of which have significantly more resources than us; however, our primary competition is confined to a relatively small number of companies within this group. The industry continues to experience consolidations into larger firms striving for stronger and more complete multinational and multi-service networks. However, regional and local brokers and forwarders remain a competitive force.
The primary competitive factors in the international logistics industry continue to be price and quality of service, including reliability, responsiveness, expertise, convenience, and scope of operations. We emphasize quality customer service and believe that our prices are competitive with those of others in the industry. Customers regularly solicit bids from competitors in order to improve service, pricing and contractual terms such as seeking longer payment terms, higher or unlimited liability limits and performance penalties. Increased competition and competitors' acceptance of expanded contractual terms could result in reduced revenues, reduced margins, higher operating costs or loss of market share, any of which would damage our results of operations and financial condition.
Larger customers utilize more sophisticated and efficient procedures for the management of their logistics supply chains by embracing strategies such as just-in-time inventory management. We believe that this trend has resulted in customers using fewer service providers with greater technological capacity and more consistent global coverage. Accordingly, sophisticated computerized customer service capabilities and a stable worldwide network have become significant factors in attracting and retaining customers. Developing and maintaining these systems and a worldwide network has added a considerable indirect cost to the services provided to customers. Smaller and middle-tier competitors, in general, do not have the resources available to develop customized systems and a worldwide network.
Liquidity and Capital Resources
Our principal source of liquidity is cash and cash equivalents, short-term investments and cash generated from operating activities. Net cash provided by operating activities for the year ended December 31, 2017 was $489 million, as compared with $529 million for 2016. This $40 million decrease is primarily due to increases in accounts receivable, partially offset by higher earnings. At December 31, 2017, working capital was $1,448 million, including cash and cash equivalents of $1,051 million. We had no long-term debt at December 31, 2017. Management believes that our current cash position and operating cash flows will be sufficient to meet our capital and liquidity requirements for at least the next 12 months and thereafter for the foreseeable future, including meeting any contingent liabilities related to standby letters of credit and other obligations.
As a customs broker, we make significant cash advances for a select group of our credit-worthy customers. These cash advances are for customer obligations such as the payment of duties and tax to customs authorities in various countries throughout the world. Cash advances are a “pass through” and are not recorded as a component of revenue and expense. The billings of such advances to customers are accounted for as a direct increase in accounts receivable from the customer and a corresponding increase in accounts payable to governmental customs authorities. As a result of these “pass through” billings, the conventional Days Sales Outstanding or DSO calculation does not directly measure collection efficiency. For customers that meet certain criteria, we have agreed to extend payment terms beyond our customary terms. Management believes that it has established effective credit control procedures, and historically has experienced relatively insignificant collection problems.
Our business historically has been subject to seasonal fluctuations in demand and this is expected to continue in the future. Cash flows fluctuate as a result of this seasonality. Historically, the first quarter shows an excess of customer collections over customer billings. This results in positive cash flow. The increased activity associated with periods of higher demand (typically commencing late second or early third quarter and continuing well into the fourth quarter) causes an excess of customer billings over customer collections. This cyclical growth in customer receivables consumes available cash.
Cash used by investing activities for the year ended December 31, 2017 was $12 million, as compared with $53 million for 2016. We had capital expenditures of $95 million in 2017 as compared with $59 million in 2016. Capital expenditures in 2017 related primarily to continuing investments in technology, the substantial completion of the construction of a building in Europe, office furniture and equipment and leasehold improvements. Occasionally, we elect to purchase buildings to house staff and to facilitate the staging of customers’ freight. In 2016, we completed a land acquisition, for which the funds had been deposited into escrow in 2014 and initiated building construction for the aforementioned building in Europe. In 2017, we completed the sale of land and buildings in Miami, Florida, which resulted in net cash proceeds of approximately $84 million. Total anticipated capital expenditures in 2018 are currently estimated to be $75 million.
Cash used in financing activities for the year ended December 31, 2017 was $425 million as compared with $299 million in 2016. We used the proceeds from stock option exercises, employee stock purchases and available cash to repurchase our common stock on the open market to limit the growth in issued and outstanding shares. During 2017 and 2016, we used cash to repurchase 8 million and 7 million shares of common stock, respectively. During 2017 and 2016, we paid dividends of $0.84 and $0.80 per share, respectively.
We have a Non-Discretionary Stock Repurchase Plan to repurchase shares from the proceeds of stock option exercises. During 2017, we repurchased 3.7 million shares at an average price of $57.47 per share. We also have a Discretionary Stock Repurchase Plan under which management is allowed to repurchase shares to reduce the issued and outstanding stock to 170 million shares of common stock. During 2017, we repurchased 4.5 million shares at an average price of $58.72 per share. See Note 3 to the consolidated financial statements for cumulative repurchases under both repurchase plans.
We follow established guidelines relating to credit quality, diversification and maturities of our investments to preserve principal and maintain liquidity. Our investment portfolio has historically not been significantly adversely impacted by disruptions in credit markets. However, there can be no assurance that our investment portfolio will not be adversely affected in the future.
We cannot predict what impact ongoing uncertainties in the global economy and political uncertainty may have on our operating results, freight volumes, pricing, changes in consumer demand, carrier stability and capacity, customers’ abilities to pay or on changes in competitors' behavior.
We maintain international unsecured bank lines of credit. At December 31, 2017, we were contingently liable for $75 million from standby letters of credit and guarantees. The standby letters of credit and guarantees relate to obligations of our foreign subsidiaries for credit extended in the ordinary course of business by direct carriers, primarily airlines, and for duty and tax deferrals available from governmental entities responsible for customs and value-added-tax (VAT) taxation. The total underlying amounts due and payable for transportation and governmental excises are properly recorded as obligations in the books of the respective foreign subsidiaries, and there would be no need to record additional expense in the unlikely event the parent company is required to perform.
| Amount of commitment expiration per period | ||||||||||||||||
| In thousands | Total amounts committed | Less than 1 year | 1 - 3 years | 3 - 5 years | After 5 years | |||||||||||
| Standby letters of credit and guarantees | $ | 75,311 | 66,929 | 6,484 | 88 | 1,810 |
At December 31, 2017, our contractual obligations are as follows:
| Payments due by period | ||||||||||||||||
| In thousands | Total | Less than 1 year | 1 - 3 years | 3 - 5 years | After 5 years | |||||||||||
| Contractual Obligations: | ||||||||||||||||
| Operating leases | $ | 259,895 | 72,148 | 103,242 | 49,949 | 34,556 | ||||||||||
| Unconditional purchase obligations | 56,116 | 51,340 | 4,776 | — | — | |||||||||||
| Construction, equipment and technology purchase obligations | 18,475 | 15,311 | 3,164 | — | — | |||||||||||
| Total contractual cash obligations | $ | 334,486 | 138,799 | 111,182 | 49,949 | 34,556 |
We typically enter into short-term unconditional purchase obligations with asset-based providers reserving space on a guaranteed basis. The pricing of these obligations varies to some degree with market conditions. We only enter into agreements that management believes we can fulfill. Historically, we have met these obligations in the normal course of business. Management believes, in line with historical experience, almost all committed purchase obligations outstanding as of December 31, 2017 will be fulfilled during 2018 in the ordinary course of business.
Our foreign subsidiaries regularly remit dividends to the U.S. parent company after evaluating their working capital requirements and needs to finance local capital expenditures. In some cases, our ability to repatriate funds from foreign operations may be subject to foreign exchange controls. At December 31, 2017, cash and cash equivalent balances of $446 million were held by our non-United States subsidiaries, of which $47 million was held in banks in the United States. Earnings of our foreign subsidiaries are not considered to be indefinitely reinvested outside of the United States and, accordingly, historically a deferred tax liability has been established for all undistributed earnings, net of foreign related tax credits, that are available to be repatriated.
As a result of U.S. tax reform, a liability of approximately $32 million for the estimate of the one-time mandatory tax on undistributed earnings of the Company's non-U.S. subsidiaries was recorded as of December 31, 2017. The cash tax effects of this deemed repatriation can be remitted in installments over an eight-year period as follows: (i) for each of the initial five years, 8% of the net tax liability is required to be remitted on an annual basis; (ii) in the sixth year, 15% of the net tax liability is required to be remitted; (iii) in the seventh year, 20% of the net tax liability is required to be remitted; and (iv) in the eighth year, the remaining 25% of the net tax liability is required to be remitted. We anticipate that we will pay this tax in installments over the eight-year period and anticipate cash payments of the deemed repatriation tax to approximate $2 million to $3 million in each of the next five years.
Impact of Inflation
To date, our business has not been adversely affected by inflation. Direct carrier rate increases could occur over the short to medium-term period. Due to the high degree of competition in the market place, these rate increases can lead to an erosion in our margins. As we are not required to purchase or maintain extensive property and equipment and have not otherwise incurred substantial interest rate-sensitive indebtedness, we currently have limited direct exposure to increased costs resulting from increases in interest rates.
Off-Balance Sheet Arrangements
As of December 31, 2017, we did not have any material off-balance-sheet arrangements, as defined in Item 303(a)(4)(ii) of SEC Regulation S-K.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK