 filings.tools
Extra Space Storage (EXR) 10-K risk factor changes: FY2021 vs FY2020
The 2021-12-31 10-K against the 2020-12-31 one, compared heading by heading and sentence by sentence.
Item 1A19 rewritten52 added28 removed171 unchanged
All filing items695 rewritten400 added302 removed1,664 unchanged
Summary
counted, not written
- Item 1A lists 28 risk factor headings: 3 new, 1 reworded and 24 unchanged since FY2020. 1 heading from FY2020 no longer appears.
- Sentence by sentence, 400 added, 302 removed, 695 rewritten and 1,664 unchanged across 18 items that differ.
- New this year: Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections.
New Item 1A headings (3)
- Failure to comply with laws and regulations relating to data privacy and protection, could adversely affect our business and our financial condition.
- Changes in the method pursuant to which the London Interbank Offered Rate (“LIBOR”) is determined and the transition to other benchmarks may adversely affect our financial results.
- Our existing indebtedness contains covenants that limit our operating flexibility and failure to comply with all covenants in our debt agreements could materially and adversely affect us.
Removed Item 1A headings (1)
- Uncertainty relating to the LIBOR calculation process and potential phasing out of LIBOR may affect our financial results.
Reworded Item 1A headings (1)
- We [added: and our vendors] rely on information
[removed: technology in our operations,][added: technology,] and any material failure, inadequacy, interruption or security failure of that technology could harm our business.
A heading is new when no FY2020 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2021; struck-through words were in FY2020. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
19 rewritten, 52 added, 28 removed, 171 unchanged
The regulatory authorities generally have broad discretion to grant, renew and revoke licenses and approvals, to promulgate, interpret and implement regulations, and to evaluate compliance with regulations through periodic examinations, audits and investigations of the affairs of insurance [added: providers.]
We may not be successful in identifying suitable stores or other assets that meet our acquisition criteria or in consummating acquisitions [removed: or investments on satisfactory terms or at all.]
We [added: and our vendors] rely on information [removed: technology in our operations,] [added: technology,] and any material failure, inadequacy, interruption or security failure of that technology could harm our business.
We rely on commercially available systems, software, tools and monitoring to provide security for [added: processing, transmission and storage of confidential tenant and other sensitive information.]
[removed: While,] [added: While] to date, we have not experienced a material security breach, this risk has generally increased as the number, intensity and sophistication of such breaches and attempted breaches from around the world have increased.
During [removed: 2020,] [added: 2021,] the United States and other countries around the world have [removed: been experiencing] [added: continued to experience] a major health pandemic related to COVID-19, which has created considerable instability and disruption in the U.S. and world economies.
[removed: Federal,] [added: In 2020, federal,] state and local jurisdictions [removed: have] issued varying forms of states of emergency orders.
Our business [removed: has been] [added: was] impacted by COVID-19 in [added: 2020 in] several ways, including reductions in new rentals and vacates due to stay-at home orders and other restrictions, lower achieved rental rates from new customers, fewer existing customer rent increases, reduced late fee collection and impaired ability to hold auctions resulting in higher accounts receivable and bad debt.
[removed: As restrictions began to lessen during the second half of 2020,] [added: During 2021] we [added: largely] saw [removed: some] [added: a] return toward normalcy, including higher achieved rates, accounts receivable and collections less than 60 days returning to historical norms, and auctions being held in most locations.
As a result of the reductions in vacates, we saw record occupancy levels [removed: in the latter half of 2020.][added: during 2021.]
This includes new information which may emerge concerning the severity of [removed: COVID-19,] [added: COVID-19 variants,] the success of actions taken to contain or treat COVID-19 and reactions by consumers, companies, governmental entities and capital markets.
As of December 31, [removed: 2020,] [added: 2021,] we held interests in [removed: 253] [added: 287] operating stores through joint ventures.
Some of these arrangements could be adversely affected by our lack of sole decision-making authority, our reliance on [removed: co-venturers] [added: co-venturers'] financial conditions and disputes between us and our co-venturers.
As of December 31, [removed: 2020,] [added: 2021,] we had approximately [removed: $5.8] [added: $6.0] billion of outstanding indebtedness.
As of December 31, [removed: 2020,] [added: 2021,] we had approximately [removed: $5.8] [added: $6.0] billion of debt outstanding, of which approximately [removed: $2.1] [added: $1.5] billion, or [removed: 36.9%] [added: 24.7%] was subject to variable interest rates (excluding debt with interest rate swaps).
This variable rate debt had a weighted average interest rate of approximately [removed: 1.6%] [added: 1.3%] per annum.
[removed: Any of these proposals or consequences could] [added: Adjustments to systems and mathematical models to properly process and account for alternative rates will be required, which may] have a material adverse effect on our financing costs, and as a result, our financial condition, operating results and cash flows.
[added: Also, we must] make distributions to stockholders aggregating annually at least 90% of our REIT taxable income, determined without regard to the dividends paid deduction and excluding net capital gains, and we will be subject to U.S. federal corporate income tax to the extent we distribute less than 100% of our REIT taxable income, without regard to the dividends paid deduction and including net capital gains.
Although we believe that we have been organized and have operated in a manner that is intended to allow us to qualify for taxation as a REIT, we can give no assurance that we have qualified or will continue to qualify as a [removed: REIT for U.S. federal income tax purposes.]
or investments on satisfactory terms or at all.
Our information technology systems and those of our third-party service providers, strategic partners and other contractors or consultants are vulnerable to attack and damage or interruption from computer viruses and malware (e.g. ransomware), malicious code, natural disasters, terrorism, war, telecommunication and electrical failures, hacking, cyberattacks, phishing attacks and other social engineering schemes, employee theft or misuse, human error (e.g., social engineering, phishing), fraud, denial or degradation of service attacks, sophisticated nation-state and nation-state-supported actors or unauthorized access or use by persons inside our organization, or persons with access to systems inside our organization.
We and certain of our service providers are from time to time, subject to cyberattacks and security incidents.
Furthermore, because the technologies used to obtain unauthorized access to, or to sabotage or disrupt, systems change frequently and often are not recognized until launched against a target, we may be unable to anticipate these techniques or implement adequate preventative measures.
We may also experience security breaches that may remain undetected for an extended period.
Even if identified, we may be unable to adequately investigate or remediate incidents or breaches due to attackers increasingly using tools and techniques that are designed to circumvent controls, to avoid detection, and to remove or obfuscate forensic evidence.
As a result of the COVID-19 pandemic, we may also face increased cybersecurity risks due to our reliance on internet technology and the number of our, as well as our service providers’, employees who are (and may continue to be) working remotely, which may create additional opportunities for cybercriminals to exploit vulnerabilities.
Failure to comply with laws and regulations relating to data privacy and protection, could adversely affect our business and our financial condition.
In the United States, both federal and various state governments have adopted, or are considering, laws, guidelines or rules for the collection, distribution, use and storage of information collected from or about consumers or their devices.
For example, the California Consumer Privacy Act of 2018 (CCPA) went into effect on January 1, 2020, and creates individual privacy rights for California consumers and increases the privacy and security obligations of entities handling certain personal information.
The CCPA provides for civil penalties for violations, as well as a private right of action for data breaches that is expected to increase data breach litigation.
Further, the California Privacy Rights Act (CPRA) recently passed in California.
The CPRA significantly
amends the CCPA and will impose additional data protection obligations on covered businesses, including additional consumer rights processes, limitations on data uses, new audit requirements for higher risk data, and opt outs for certain uses of sensitive data.
It will also create a new California data protection agency authorized to issue substantive regulations and could result in increased privacy and information security enforcement.
The majority of the provisions will go into effect on January 1, 2023, and additional compliance investment and potential business process changes may be required.
Similar laws have passed in Virginia and Colorado, and have been proposed in other states and at the federal level, reflecting a trend toward more stringent privacy legislation in the United States.
The enactment of such laws could have potentially conflicting requirements that would make compliance challenging.
Although we work to comply with applicable laws, regulations and standards, our contractual obligations and other legal obligations, these requirements are evolving and may be modified, interpreted and applied in an inconsistent manner from one jurisdiction to another, and may conflict with one another or other legal obligations with which we must comply.
Any failure or perceived failure by us or our employees, representatives, contractors, consultants, collaborators, or other third parties to comply with such requirements or adequately address privacy and security concerns, even if unfounded, could result in additional cost and liability to us, damage our reputation, and adversely affect our business and results of operations.
If our property taxes we pay increase, our cash flow would be adversely impacted, and our ability to pay any expected dividends to our stockholders and unitholders could be adversely affected.
While many of these states of emergency orders have expired or been removed, we continue to monitor existing states of emergency and prepare for any additional states of emergency orders.
We have updated many of our safety and working practices so that we are prepared to address any future states of emergency orders should they continue or be reinstated.
Changes in the method pursuant to which the London Interbank Offered Rate (“LIBOR”) is determined and the transition to other benchmarks may adversely affect our financial results.
LIBOR and certain other “benchmarks” have been the subject of continuing national, international and other regulatory guidance and proposals for reform.
In July 2017, the United Kingdom’s Financial Conduct Authority (“FCA”), which regulates LIBOR, publicly announced that it intends to phase out LIBOR, and on March 5, 2021, the FCA announced that USD LIBOR will no longer be provided by any administrator or no longer be representative immediately after December 31, 2021, in the case of one week and two month USD settings, and immediately after June 30, 2023, in the case of the remaining USD settings.
Additionally, banking regulators, including the U.S. Federal Reserve, have encouraged banks to discontinue new LIBOR debt issuances after December 31, 2021.
This announcement has several implications, including setting the spread that may be used to automatically convert contracts from LIBOR to the Secured Overnight Financing Rate ("SOFR").
SOFR is a measure of the cost of borrowing cash overnight, collateralized by U.S. Treasury securities, and is based on directly observable U.S. Treasury-backed repurchase transactions.
Although SOFR appears to be the preferred replacement rate for U.S. dollar LIBOR, it is unclear if other benchmarks may emerge or if other rates will be adopted outside of the United States.
We anticipate that the most commonly used tenors of LIBOR will continue to be available at least until June 30, 2023.
Any changes adopted by the FCA or other governing bodies in the method used for determining LIBOR may result in a sudden or prolonged increase or decrease in reported LIBOR.
If that were to occur, our interest payments could change.
In addition, uncertainty about the extent and manner of future changes may result in interest rates and/or payments that are higher or lower than if LIBOR were to remain available in its current form.
We have contracts that are indexed to LIBOR and are monitoring and evaluating the related risks, which include interest on loans and amounts received and paid on derivative instruments.
These risks arise in connection with transitioning contracts to an alternative rate, including any resulting value transfer that may occur, and are likely to vary by contract.
The value of loans, securities, or derivative instruments tied to LIBOR, as well as interest rates on our current or future indebtedness, may also be impacted if LIBOR is limited or discontinued.
For some instruments the method of transitioning to an alternative reference rate may be challenging, especially if we cannot agree with the respective counterparty about how to make the transition.
While we expect LIBOR to be available in substantially its current form until at least the end of June 30, 2023, it is possible that LIBOR will become unavailable prior to that point.
This could result, for example, if sufficient banks decline to make submissions to the LIBOR administrator.
providers.
processing, transmission and storage of confidential tenant and other sensitive information.
For example, a current California law commonly referred to as Proposition 13 generally limits annual real estate tax increases on California properties to 2% of assessed value.
However, under Proposition 13, property tax reassessment generally occurs as a result of a "change in ownership" of a property, as specially defined for purposes of those rules.
Because the property taxing authorities may not determine whether there has been a "change in ownership" or the actual reassessed value of a property for a period of time after a transaction has occurred, we may not know the impact of a potential reassessment for a considerable amount of time following a particular transaction.
In addition from time to time voters and lawmakers have announced initiatives to repeal or amend Proposition 13 to eliminate its application to commercial and industrial property and/or introduce split tax roll legislation.
Such initiatives, if successful, could increase the assessed value and/or tax rates applicable to commercial property in California, including our stores.
We are working to comply within the framework of local, county, state and federal laws as they evolve.
In that regard, we have implemented a wide range of practices to protect and support our employees and customers.
Such measures include instituting “work from home” measures at our corporate offices and call center, instituting a contactless rental process that allows our on-site employees to continue to rent storage units without physical interaction, and providing personal protective equipment to on-site employees providing essential functions so that hygiene and “social distancing” standards can be effectively managed and applied.
We have transitioned many of our interactions between customers and leasing and support staff to on-line and telephonic communications.
Due to the COVID-19 pandemic, our customers may be impacted, including through unemployment, which may impact their ability to pay rent or renew their leases.
These impacts from COVID-19 were especially prevalent during the second quarter of 2020.
Uncertainty relating to the LIBOR calculation process and potential phasing out of LIBOR may affect our financial results.
In July 2017, the Financial Conduct Authority (the authority that regulates LIBOR) announced it intended to stop compelling banks to submit rates for the calculation of LIBOR after June 30, 2021.
The Alternative Reference Rates Committee (“ARRC”) has proposed that the Secured Overnight Financing Rate (“SOFR”) is the rate that represents best practice as the alternative to LIBOR for use in derivatives and other financial contracts that are currently indexed to LIBOR.
ARRC has proposed a paced market transition plan to SOFR from LIBOR and organizations are currently working on industry wide and company specific transition plans as it relates to derivatives and cash markets exposed to LIBOR.
In November 2020, the Federal Reserve Board along with various independent groups announced the potential for certain USD LIBOR tenors to continue to be published until June 2023.
This change would allow most legacy USD LIBOR contracts to mature before disruptions occur in the USD LIBOR market, without the need to transition those contracts to SOFR.
We are not able to predict when LIBOR may be limited or discontinued or when there will be sufficient liquidity in the SOFR market.
We have outstanding debt and hedge contracts indexed to LIBOR.
Due to the extension noted above, we currently expect that all of our then-outstanding contracts indexed to LIBOR will be required to be transitioned to an alternative rate by June 30, 2023.
However, it is possible that LIBOR may be discontinued or our contracts may be transitioned to an alternative rate (which may or may not be a SOFR-based rate) prior to then.
We are monitoring industry transition plans and evaluating the risks related to our debt and hedge contracts indexed to LIBOR.
If a published U.S. dollar LIBOR rate is unavailable after 2021, the interest rates on these instruments which are indexed to LIBOR will be determined using alternative methods, which may result in interest obligations which are more than or do not otherwise correlate over time with the payments that would have been made on such debt if U.S. dollar LIBOR was available in its current form.
Further, the same costs and risks that may lead to the unavailability of U.S. dollar LIBOR may make one or more of the alternative methods impossible or impracticable to
determine.
Also, we must
An excerpt. Shown here: all 19 rewritten, 40 of 52 added and all 28 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2021 filing and the FY2020 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
90 rewritten, 47 added, 25 removed, 189 unchanged
As of December 31, 2020 [removed: and 2019,] we had no consolidated VIEs.
No material impairments were recorded in the year ended December 31, [removed: 2020.][added: 2021.]
Results for the year ended December 31, [removed: 2020] [added: 2021] included the operations of [removed: 1,197] [added: 1,268] stores [removed: (944] [added: (981] wholly-owned, [removed: six] [added: four] in consolidated joint ventures, and [removed: 247] [added: 283] in joint ventures accounted for using the equity method) compared to the results for the year ended December 31, [removed: 2019,] [added: 2020,] which included the operations of [removed: 1,171] [added: 1,197] stores [removed: (925] [added: (944] wholly-owned, [removed: five] [added: six] in a consolidated joint venture, and [removed: 241] [added: 247] in joint ventures accounted for using the equity method).
[removed: ][added: ]
| | | | [removed: 2020] [added: 2021] | | | | | | [removed: 2019] [added: 2020] | | | | | | $ Change | | | | | | % Change | | |
| Management fees and other income | | | [removed: 52,129] [added: 66,264] | | | | | | [removed: 49,890] [added: 52,129] | | | | | | [removed: 2,239] [added: 14,135] | | | | | | [removed: 4.5] [added: 27.1] | | % |
We acquired [removed: 23] [added: 74] stores during the year ended December 31, [removed: 2020] [added: 2021] and we acquired [removed: 21] [added: 23] stores [removed: and added 27 leased properties (as part of a new net lease agreement)] during the year ended December 31, [removed: 2019.][added: 2020.]
Property rental revenue also increased by [removed: $3,755] [added: $5,193] during the year ended December 31, [removed: 2020] [added: 2021] as a result of increases in occupancy at our lease-up [removed: stores, which was partially offset by a decrease of $(1,301) at our stabilized] stores.
Tenant Reinsurance—The increase in tenant reinsurance revenues was due primarily to an increase in the number of stores operated and the higher [added: average] occupancy [removed: at both our lease up and mature sites.][added: across the portfolio.]
We operated [removed: 1,921] [added: 2,096] stores at December 31, [removed: 2020,] [added: 2021,] compared to [removed: 1,817] [added: 1,921] stores at December 31, [removed: 2019.][added: 2020.]
Management Fees and Other Income—Management fees and other income represent the [removed: fee] [added: fees] collected for our management of stores owned by third parties and unconsolidated joint ventures and other transaction fee income.
The increase for the year ended December 31, [removed: 2020] [added: 2021] was primarily due to an increase in the number of stores [removed: managed, offset by non-recurring transaction fees earned in 2019.][added: managed.]
As of December 31, [removed: 2020,] [added: 2021,] we managed [removed: 977] [added: 1,115] stores for third parties and joint ventures compared to [removed: 892] [added: 977] stores as of December 31, [removed: 2019.][added: 2020.]
| General and administrative | | | [removed: 96,594] | | | | | | [removed: 89,418] | | | | | | [removed: 7,176] [added: 102,194] | | | | | | [removed: 8.0] [added: 96,594] | | [removed: %] |
| Depreciation and amortization | | | [removed: 224,444 | | | | | | 219,857] [added: $] | [added: 241,879] | | | | | [removed: 4,587] [added: $] | [added: 224,444] | | | | | [removed: 2.1] [added: $] | [added: 219,857] | [removed: %] |
Property Operations—The increase in property operations expense consists primarily of an increase of [removed: $19,954] [added: $13,440] related to acquisitions completed in [removed: 2020] [added: 2021] and [removed: 2019.][added: 2020.]
We acquired [removed: 23] [added: 74] stores during the year ended December 31, [removed: 2020] [added: 2021] and acquired [removed: 21] [added: 23] stores [removed: and added 27 leased properties (as part of a new net lease agreement)] during the year ended December 31, [removed: 2019.][added: 2020.]
We acquired [removed: 23] [added: 74] stores [removed: and completed the development of a consolidated joint venture store] during the year ended December 31, [removed: 2020,] [added: 2021,] and acquired [removed: 21 operating] [added: 23] stores during the year ended December 31, [removed: 2019.][added: 2020.]
| Gain on real estate transactions | | | [removed: $] | [removed: 18,075] | | [removed: | | | $] [added: (140,760)] | [removed: 1,205] | | | | | [removed: $] [added: (18,075)] | [removed: 16,870] | | | | | [removed: 1,400.0] [added: (1,205)] | | [removed: %] |
| Non-cash interest expense related to amortization of discount on equity component of exchangeable senior notes | | | [removed: (3,675)] [added: —] | | | | | | [removed: (4,742)] [added: (3,675)] | | | | | | [removed: 1,067] [added: 3,675] | | | | | | [removed: (22.5)] [added: (100.0)] | | % |
| Equity in earnings and dividend income from unconsolidated real estate entities | | | [removed: 22,361] | | | | | | [removed: 11,274] | | | | | | [removed: 11,087] [added: (32,358)] | | | | | | [removed: 98.3] [added: (22,361)] | | [removed: %] |
| Income tax expense | | | [removed: (13,810)] | | | | | | [removed: (11,308)] | | | | | | [removed: (2,502)] [added: 20,324] | | | | | | [removed: 22.1] [added: 13,810] | | [removed: %] |
| Total other expense, net | | | $ | [removed: (130,483)] [added: 42,565] | | | | | $ | [removed: (182,630)] [added: (130,483)] | | | | | $ | [removed: 52,147] [added: 173,048] | | | | | [removed: (28.6)] [added: (132.6)] | | % |
Interest Expense—The decrease in interest expense during the year ended December 31, [removed: 2020] [added: 2021] was primarily the result of a lower average interest rate when compared to the same period in the prior year.
Information on the total face value of debt and the average interest rate for each quarter during the years ended December 31, [removed: 2020] [added: 2021] and December 31, [removed: 2019] [added: 2020] is set forth in the following table:
| | | | [removed: 2020] | | | [removed: | | | 2019 | | | | | | 2020 | | | | | | 2019 | | | | | | 2020 | | | | | | 2019] [added: 2021] | | | | | | 2020 | | | | | | 2019 | | |
| Total face value of debt | | | [removed: $5,767,771] [added: $5,984,113] | | | | | | [removed: $5,076,501] [added: $5,767,771] | | | | | | [removed: $5,302,752] [added: $5,614,222] | | | | | | [removed: $4,844,620] [added: $5,302,752] | | | | | | [removed: $5,103,812] [added: $5,396,746] | | | | | | [removed: $5,072,936] [added: $5,103,812] | | | | | | [removed: $5,151,993] [added: $5,321,362] | | | | | | [removed: $5,039,286] [added: $5,151,993] | | |
| Average interest rate | | | [removed: 2.7%] [added: 2.6%] | | | | | | [removed: 3.3%] [added: 2.7%] | | | | | | [removed: 3.0%] [added: 2.8%] | | | | | | [removed: 3.4%] [added: 3.0%] | | | | | | [removed: 3.0%] [added: 2.8%] | | | | | | [removed: 3.5%] [added: 3.0%] | | | | | | [removed: 3.1%] [added: 2.7%] | | | | | | [removed: 3.5%] [added: 3.1%] | | |
The exchangeable senior notes [removed: both] had an effective interest rate of 4.0% relative to the carrying amount of the liability.
The total principal balance of bridge loans receivable as of December 31, [removed: 2020] [added: 2021] was [removed: $187,368,] [added: $279,042,] compared to [removed: $43,586] [added: $187,368] as of December 31, [removed: 2019.][added: 2020.]
The increase in interest income during the year ended December 31, [removed: 2020] [added: 2021] was primarily the result of interest earned on these loans as well as interest earned from our investment in preferred stock of Jernigan Capital, Inc. ("JCAP"), in connection with the acquisition of JCAP by affiliates of NexPoint Advisors, L.P., which was purchased in November 2020 for $300,000.
The increase in earnings for the year ended December 31, [removed: 2020] [added: 2021] is [removed: due primarily] [added: related in part] to the dividend income [removed: related to] [added: from] the [added: secondary investment of] SmartStop preferred stock.
Income Tax [removed: Expense— For] [added: Expense—For] the year ended December 31, [removed: 2020,] [added: 2021,] the increase in income tax expense was the result of an increase in income earned by our TRS when compared to the same period in the prior year.
Comparison of the Year Ended December 31, [removed: 2019] [added: 2021] to the Year Ended December 31, [removed: 2018][added: 2020]
The results of operations for the years ended December 31, [removed: 2019] [added: 2020] compared to December 31, [removed: 2018] [added: 2019] was included in our Annual Report on Form 10-K for the year ended December 31, [removed: 2019] [added: 2020] on page [removed: 18,] [added: 19,] under Part II, Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” which was filed with the SEC on February [removed: 25, 2020.][added: 26, 2021.]
Net earnings assume that the values of real estate assets diminish [removed: predictably over time as reflected through depreciation and amortization expenses.]
We believe that to further understand our performance, FFO should be considered along with the reported net income and cash flows in accordance with GAAP, as presented in the [added: consolidated financial statements.]
| | | | [removed: | | | 2020] [added: 2021] | | | | | | [removed: 2019] [added: 2020] | | | | | | [removed: 2018] [added: 2019] | | |
| Net income attributable to common stockholders | | | | | | $ | [removed: 481,779] [added: 827,649] | | | | | $ | [removed: 419,967] [added: 481,779] | | | | | $ | [removed: 415,289] [added: 419,967] | |
| Real estate depreciation | | | | | | [removed: 214,345] [added: 229,133] | | | | | | [removed: 206,257] [added: 214,345] | | | | | | [removed: 193,587] [added: 206,257] | | |
As of December 31, 2021 we had one consolidated VIE consisting of four stores.
| Property rental | | | $ | 1,340,990 | | | | | $ | 1,157,522 | | | | | $ | 183,468 | | | | | 15.9 | | % |
| Tenant reinsurance | | | 170,108 | | | | | | 146,561 | | | | | | 23,547 | | | | | | 16.1 | | % |
| Total revenues | | | $ | 1,577,362 | | | | | $ | 1,356,212 | | | | | $ | 221,150 | | | | | 16.3 | | % |
Property Rental—The increase in property rental revenues for the year ended December 31, 2021 was primarily the result of an increase of $151,217 at our stabilized stores related to high occupancy and increased rents to new and existing customers.
Property rental revenue also increased by $40,792 associated with acquisitions completed in 2021 and 2020.
These increases were offset by approximately $15,460 related to the sale of 16 stores into a new joint venture and 16 stores to a third party during 2021.
| Property operations | | | $ | 368,608 | | | | | $ | 360,615 | | | | | $ | 7,993 | | | | | 2.2 | | % |
| Tenant reinsurance | | | 29,488 | | | | | | 26,494 | | | | | | 2,994 | | | | | | 11.3 | | % |
| Depreciation and amortization | | | 241,879 | | | | | | 224,444 | | | | | | 17,435 | | | | | | 7.8 | | % |
| Total expenses | | | $ | 742,169 | | | | | $ | 708,147 | | | | | $ | 34,022 | | | | | 4.8 | | % |
The increase was partially offset by a decrease in expense of $(4,755) related to property sales.
The increase in tenant reinsurance expense for the year ended December 31, 2021 was due primarily to the increase in total number of stores operated compared to the prior year and major storm events that occurred causing an increase in claim payouts.
We operated 2,096 stores at December 31, 2021, compared to 1,921 stores at December 31, 2020.
During 2021, we experienced higher than average turnover and extended times to fill.
Additionally, we experienced wage pressure which led to increases in wages of approximately 10% nationwide.
These trends will directly increase general & administrative expenses in 2022.
No other material trends in specific travel or other expenses were observed.
| | | | 2021 | | | | | | 2020 | | | | | | $ Change | | | | | | % Change | | |
| Interest expense | | | (166,183) | | | | | | (168,626) | | | | | | 2,443 | | | | | | (1.4) | | % |
| Interest income | | | 49,703 | | | | | | 15,192 | | | | | | 34,511 | | | | | | 227.2 | | % |
| Equity in earnings of unconsolidated real estate ventures - gain on sale of real estate assets and purchase of joint venture partner's interest | | | 6,251 | | | | | | — | | | | | | 6,251 | | | | | | 100.0 | | % |
Gain on Real Estate Transactions — During the first quarter of 2021, we sold 16 stores to a newly established unconsolidated joint venture for a total sales price of $168,885 resulting in a gain of $63,477.
Additionally, we sold 16 stores during the fourth quarter of 2021 to a third party for a total sales price of $204,500 resulting in a gain of $73,854.
| | | | 2021 | | | | | | 2020 | | | | | | 2021 | | | | | | 2020 | | | | | | 2021 | | | | | | 2020 | | | | | | 2021 | | | | | | 2020 | | |
The notes were paid in full in November 2020.
Additionally the increases related to the higher income at our joint ventures are due to store performance and the acquisition of 45 stores with new and existing joint venture partners.
These increases were offset by the sale of our equity interest in 22 stores.
Equity in Earnings of Unconsolidated Real Estate Ventures—Gain on Sale of Real Estate Assets and Purchase of Joint Venture Partner's Interest—In June 2021, we sold our interest in two unconsolidated single store joint ventures to our joint ventures partner.
We received proceeds of $1,888 in cash and recorded a gain of $525.
Also, as of June 2021, the WICNN JV LLC and GFN JV LLC joint ventures sold all 17 of the stores owned by the joint ventures to a third party.
Subsequent to the sales, these joint ventures were dissolved.
As a result of these transactions, we recorded a gain of $5,739.
predictably over time as reflected through depreciation and amortization expenses.
| Unconsolidated joint venture gain on sale of real estate assets and purchase of partner's interest | | | | | | (6,251) | | | | | | — | | | | | | — | | |
Comparison of the Year Ended December 31, 2021 to the Year Ended December 31, 2020
| | | | | | | | | | | | | | | | | | | | | | 2021 | | | | | | 2020 | | | | | | Change | | |
| Same-store rental revenues | | | | | | | | | | | | | | | | | | | | | $ | 1,199,750 | | | | | $ | 1,054,669 | | | | | 13.8% | | |
| Same-store operating expenses | | | | | | | | | | | | | | | | | | | | | $ | 300,935 | | | | | $ | 303,831 | | | | | (1.0)% | | |
| Same-store net operating income | | | | | | | | | | | | | | | | | | | | | $ | 898,815 | | | | | $ | 750,838 | | | | | 19.7% | | |
| | | | | | | | | | | | | | | | | | | | | | | | |
| Property rental | | | $ | 1,157,522 | | | | | $ | 1,130,177 | | | | | $ | 27,345 | | | | | 2.4 | | % |
| Tenant reinsurance | | | 146,561 | | | | | | 128,387 | | | | | | 18,174 | | | | | | 14.2 | | % |
| Total revenues | | | $ | 1,356,212 | | | | | $ | 1,308,454 | | | | | $ | 47,758 | | | | | 3.6 | | % |
Property Rental—The increase in property rental revenues for the year ended December 31, 2020 was primarily the result of an increase of $25,242 associated with acquisitions completed in 2020 and 2019.
| Property operations | | | $ | 360,615 | | | | | $ | 336,050 | | | | | $ | 24,565 | | | | | 7.3 | | % |
| Tenant reinsurance | | | 26,494 | | | | | | 29,376 | | | | | | (2,882) | | | | | | (9.8) | | % |
| Total expenses | | | $ | 708,147 | | | | | $ | 674,701 | | | | | $ | 33,446 | | | | | 5.0 | | % |
There was also an increase of $3,932 related to increases in property taxes at stabilized stores.
The decrease in tenant reinsurance expense for the year ended December 31, 2020 was due primarily to a reduction in the number of claims as well as a decrease in the overall average payout on individual claims when compared to the year ended December 31, 2019.
During the year ended December 31, 2020, we recorded an additional $1,823 in compensation expense as a result of modifications to the terms of the stock-based awards related to the retirement of an executive in June 2020.
We did not observe any material trends in specific payroll, travel or other expenses that contributed significantly to the increase in general and administrative expenses apart from the increase due to the management of additional stores.
| Interest expense | | | (168,626) | | | | | | (186,526) | | | | | | 17,900 | | | | | | (9.6) | | % |
| Interest income | | | 15,192 | | | | | | 7,467 | | | | | | 7,725 | | | | | | 103.5 | | % |
Gain on Real Estate Transactions — The gain of $18,075 for the year ended December 31, 2020 was primarily the result of the sale of four properties in Florida for a total sales price of $46,592.
The gain of $1,205 for the year ended December 31, 2019, was a result of the sale of one property in New York for $11,272.
As of December 31, 2020 the exchangeable senior notes were paid off in full.
consolidated financial statements.
| | | | | | | | | | | | | | | | | | | | | |
| Same-store rental revenues | | | | | | | | | | | | | | | | | | | | | $ | 1,079,486 | | | | | $ | 1,080,781 | | | | | (0.1)% | | |
| Same-store operating expenses | | | | | | | | | | | | | | | | | | | | | $ | 309,550 | | | | | $ | 305,508 | | | | | 1.3% | | |
| Same-store net operating income | | | | | | | | | | | | | | | | | | | | | $ | 769,936 | | | | | $ | 775,273 | | | | | (0.7)% | | |
| | | | | | | | | | | | | | | | 2020 | | | | | | 2019 | | |
| | | | 2020 | | | | | | 2019 | | | | | | 2018 | | |
| Depreciation and amortization | | | $ | 224,444 | | | | | $ | 219,857 | | | | | $ | 209,050 | |
An excerpt. Shown here: 40 of 90 rewritten, 40 of 47 added and all 25 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2021 filing and the FY2020 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
2 rewritten, 0 added, 0 removed, 13 unchanged
As of December 31, [removed: 2020,] [added: 2021,] we had approximately [removed: $5,767,771] [added: $5,984,113] in total face value debt, of which approximately [removed: $2,130,551] [added: $1,477,679] was subject to variable interest rates (excluding debt with interest rate swaps).
If LIBOR were to increase or decrease by 100 basis points, the increase or decrease in interest expense on the variable rate debt would increase or decrease future earnings and cash flows by approximately [removed: $21,306] [added: $14,777] annually.
Item 1. Business
32 rewritten, 14 added, 8 removed, 107 unchanged
As of December 31, [removed: 2020] [added: 2021] we owned and/or operated [removed: 1,921] [added: 2,096] stores in [removed: 40] [added: 41] states, [removed: Washington, D.C.] and [removed: Puerto Rico,] [added: Washington, D.C.,] comprising approximately [removed: 149.2] [added: 160.9] million square feet of net rentable space in approximately [removed: 1.4] [added: 1.5] million units.
Margolis, Chief Executive Officer, [removed: 16] [added: 17] years; Scott Stubbs, Executive Vice President and Chief Financial Officer, [removed: 20] [added: 21] years; Samrat Sondhi, Executive Vice President and Chief Marketing Officer, [removed: 18] [added: 19] years; Gwyn McNeal, Executive Vice President and Chief Legal Officer, [removed: 15] [added: 16] years; Matt Herrington, Executive Vice President and Chief Operations Officer, [removed: 13] [added: 14] years; Noah Springer, Executive Vice President and Chief Strategy and Partnership Officer, [removed: 15] [added: 16] years; Zach Dickens, Executive Vice President and Chief Investment Officer, [removed: 18] [added: 19] years.
Our executive management team and board of directors have an ownership position in the Company with executive officers and directors owning approximately [removed: 2,887,647] [added: 2,054,059] shares or [removed: 2.2%] [added: 1.5%] of our outstanding common stock as of February [removed: 19, 2021.][added: 22, 2022.]
A greater portion of revenues and profits are [added: typically] realized from May through September.
According to the Self-Storage Almanac (the “Almanac”), [removed: in 2014,] the national average physical occupancy rate was [removed: 89.1%] [added: 90.2%] of net rentable square [removed: feet,] [added: feet in 2015,] compared to an average physical occupancy rate of [removed: 92.2%] [added: 94.5%] in [removed: 2020.][added: 2021.]
Our average occupancy for wholly-owned stores for [removed: 2020] [added: 2021] was [removed: 93.1%.][added: 94.8%.]
According to the Almanac, as of the end of [removed: 2020,] [added: 2021,] the top ten self-storage companies in the United States operated approximately [removed: 21.4%] [added: 21.9%] of the total U.S. stores, and the top 50 self-storage companies operated approximately [removed: 27.4%] [added: 27.9%] of the total U.S. stores.
[removed: We] [added: Our four primary competitors who] are [removed: one of five] public self-storage REITs [removed: along with] [added: are] CubeSmart, Life Storage, National Storage Affiliates and Public Storage.
Our acquisitions team continues to pursue the acquisition of multi-store portfolios and single stores [added: which can range from fully occupied to various stages of lease-up] that we believe can provide stockholder value.
In addition to the pursuit of [removed: stabilized] [added: operating] stores, from time to time we develop stores from the ground up and provide the construction capital.
[removed: long term] [added: long-term] value for our stockholders.
We expect that this trend will continue [removed: in 2021] as we continue to acquire Certificate of Occupancy stores.
To broaden the opportunities available, we have [removed: implemented] a bridge lending program, under which we provide financing to operating properties that we manage.
[removed: We anticipate that this] [added: This] program [removed: will help] [added: helps] us increase our management business, create additional future acquisition opportunities, and strengthen our relationships with partners, all while [removed: providing] [added: generating] interest and fee income.
We generally originate mortgage loans and mezzanine loans, with the intent to sell [added: many of] the mortgage loans to third parties, while retaining our interests in the mezzanine loans.
We have [removed: recently] made investments in preferred stock of other self-storage companies.
These investments benefit us by [removed: not only] providing dividend income, [removed: but also have increased] [added: increasing] our management business, [added: and] creating additional future acquisition opportunities through [removed: creating and strengthening] relationships with the companies in which we invest.
Credit Lines - We have [removed: three] [added: two] credit lines which we primarily use as [removed: short term] [added: short-term] bridge financing until we obtain longer-term financing through either debt or equity.
As of December 31, [removed: 2020,] [added: 2021,] our Credit Lines had available capacity of [removed: $1.2] [added: $1.4] billion, of which [removed: $241.0] [added: $855.0] million was undrawn.
Secured and Unsecured Debt - [removed: Historically, we had] [added: We] primarily [removed: used traditional secured mortgage] [added: use public bonds, unsecured private placement bonds and unsecured bank term] loans to finance store acquisitions and development efforts.
As of December 31, [removed: 2020,] [added: 2021,] we had [removed: $2.2] [added: $1.3] billion of secured notes payable and [removed: $2.6] [added: $4.1] billion of unsecured notes payable outstanding compared to $2.2 billion of secured notes payable and [removed: $2.7] [added: $3.2] billion of unsecured notes payable and senior exchangeable notes outstanding as of December 31, [removed: 2019.][added: 2020.]
During the year ended December 31, [removed: 2019,] [added: 2021,] we issued [removed: 1,779,200] [added: 585,685] shares of common stock through our ATM program and received net proceeds of approximately [removed: $198.8] [added: $66.6] million.
Joint Ventures - As of December 31, [removed: 2020,] [added: 2021,] we owned [removed: 253] [added: 287] of our stores through joint ventures with third parties.
We [removed: generally] manage the day-to-day operations of the stores owned in these joint ventures and have the right to participate in major decisions relating to sales of stores or financings by the applicable joint venture, but do not control the joint ventures.
For the year ended December 31, [removed: 2018,] [added: 2021,] we sold [removed: one store located in California] [added: 16 stores] for [removed: $40.2] [added: $200.3] million.
As of December 31, [removed: 2020,] [added: 2021,] we had [removed: 4,013] [added: 4,309] employees and believe our relationship with our employees is good.
In [removed: 2020,] [added: 2021,] we invited our employees to participate in an employee satisfaction survey.
Over [removed: 70%] [added: 60%] of our employees who are enrolled in our health plan participate in these programs.
In order to attract and retain [added: diverse] top talent, we offer training and development opportunities for our employees.
In [removed: 2020,] [added: 2021,] we invested in training and development for our employees, which included leadership training, communication training, [removed: individual learning plans, site manager training and mentorship programs.]
Our field employees received on average [removed: 8.2] [added: 8] hours of training in [removed: 2020.][added: 2021 and each new hire received an average of 82 hours of training in 2021.]
The Company [added: values diversity and inclusion and] undertakes a wide spectrum of initiatives to attract and retain a diverse workforce.
We also sold 1,600,000 shares of common stock in a registered offering structured as a bought deal at a price of $129.13 per share resulting in net proceeds of $206.6 million.
Our collection and processing of personal information may be subject to various data privacy and security laws, which govern the collection, use, disclosure of personal information and are constantly evolving, may conflict with each other to complicate compliance efforts and can results in investigations, proceedings, or actions that lead to significant civil and/or criminal penalties and restrictions on data processing.
At Extra Space, our culture is driven by our belief that our people are a key driver in our success.
We believe that if we focus on attracting, developing, and retaining diverse top talent at all levels of the organization, our employees will take care of our customers and drive growth for our shareholders.
We achieved an overall satisfaction score of 74% with over 78% of our employees participating in our survey.
Compensation, Health and Well Being
Training and Development
individual learning plans, site manager training and mentorship programs.
During 2021, we continued to make masks and other protective equipment available to our employees.
We also paid out more than $500,000 to employees in an effort to encourage our employees to get vaccinated against COVID-19.
In addition, we paid out more than $380,000 in relief pay to our employees who were unable to work due to testing positive for COVID-19.
Diversity and Inclusion
During 2021, the Company launched four employee resource groups that provide our employees a space to build community by celebrating their culture, providing mentoring opportunities and developing educational content for Extra Space.
Our employee population is approximately 48% female and approximately 48% have self-identified as people of color: Black or African American (16%), Hispanic or Latino (21%), Asian (3%), of two or more races (4%), Native American (0.5%), and Pacific Islander (0.5%).
More recently, we obtain unsecured bank term loans and issue unsecured private placement bonds.
Our stores are also subject to various state of emergency regulations enacted as a result of the COVID-19 pandemic and expect such regulations to remain in effect throughout 2021.
We achieved an overall satisfaction score of over 90%.
During the pandemic, we chose to close our doors to in-person customers until we could install personal protective equipment for our employees.
We understood that such a dramatic move would affect our revenues, but felt that as a company it was more important to ensure the safety of our employees.
We moved quickly to put the necessary equipment in place and reopened with a safer and more sanitized environment for our employees.
The Company has a Diversity and Inclusion Committee that has been active since 2018.
During 2020, the Company launched implicit bias and allyship training for its employees, produced videos featuring our CEO discussing the importance of diversity and inclusion to the Company.
Cover and table of contents
27 rewritten, 6 added, 5 removed, 89 unchanged
For the fiscal year ended December 31, [removed: 2020][added: 2021]
Yes ☐ No [removed: ☒.][added: ☒]
The aggregate market value of the common stock held by non-affiliates of the registrant was [removed: $11,637,515,440] [added: $21,458,986,411] based upon the closing price on the New York Stock Exchange on June 30, [removed: 2020,] [added: 2021,] the last business day of the registrant’s most recently completed second fiscal quarter.
The number of shares outstanding of the registrant’s common stock, $0.01 par value per share, as of February [removed: 19, 2021] [added: 22, 2022] was [removed: 132,033,131.][added: 134,152,540.]
Portions of the registrant’s definitive proxy statement to be issued in connection with the registrant’s annual stockholders’ meeting to be held in [removed: 2021] [added: 2022] are incorporated by reference into Part III of this Annual Report on Form 10-K.
For the Year Ended December 31, [removed: 2020][added: 2021]
| Item 1. | | | [removed: [Business](#iee212e03ad584b3dbd0ab424a97eef2b_16)] [added: [Business](#i7809e2c0fa9449f5812420732fe1e1a7_16)] | | | [removed: [4](#iee212e03ad584b3dbd0ab424a97eef2b_16)] [added: [4](#i7809e2c0fa9449f5812420732fe1e1a7_16)] | | |
| Item 1A. | | | [Risk [removed: Factors](#iee212e03ad584b3dbd0ab424a97eef2b_19)] [added: Factors](#i7809e2c0fa9449f5812420732fe1e1a7_19)] | | | [removed: [8](#iee212e03ad584b3dbd0ab424a97eef2b_19)] [added: [8](#i7809e2c0fa9449f5812420732fe1e1a7_19)] | | |
| Item 1B. | | | [Unresolved Staff [removed: Comments](#iee212e03ad584b3dbd0ab424a97eef2b_22)] [added: Comments](#i7809e2c0fa9449f5812420732fe1e1a7_22)] | | | [removed: [15](#iee212e03ad584b3dbd0ab424a97eef2b_22)] [added: [17](#i7809e2c0fa9449f5812420732fe1e1a7_22)] | | |
| Item 2. | | | [removed: [Properties](#iee212e03ad584b3dbd0ab424a97eef2b_25)] [added: [Properties](#i7809e2c0fa9449f5812420732fe1e1a7_25)] | | | [removed: [15](#iee212e03ad584b3dbd0ab424a97eef2b_25)] [added: [17](#i7809e2c0fa9449f5812420732fe1e1a7_25)] | | |
| Item 3. | | | [Legal [removed: Proceedings](#iee212e03ad584b3dbd0ab424a97eef2b_28)] [added: Proceedings](#i7809e2c0fa9449f5812420732fe1e1a7_28)] | | | [removed: [16](#iee212e03ad584b3dbd0ab424a97eef2b_28)] [added: [18](#i7809e2c0fa9449f5812420732fe1e1a7_28)] | | |
| Item 4. | | | [Mine Safety [removed: Disclosures](#iee212e03ad584b3dbd0ab424a97eef2b_31)] [added: Disclosures](#i7809e2c0fa9449f5812420732fe1e1a7_31)] | | | [removed: [16](#iee212e03ad584b3dbd0ab424a97eef2b_31)] [added: [18](#i7809e2c0fa9449f5812420732fe1e1a7_31)] | | |
| Item 5. | | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#iee212e03ad584b3dbd0ab424a97eef2b_37)] [added: Securities](#i7809e2c0fa9449f5812420732fe1e1a7_37)] | | | [removed: [16](#iee212e03ad584b3dbd0ab424a97eef2b_37)] [added: [18](#i7809e2c0fa9449f5812420732fe1e1a7_37)] | | |
| Item 6. | | | [Selected Financial [removed: Data](#iee212e03ad584b3dbd0ab424a97eef2b_40)] [added: Data](#i7809e2c0fa9449f5812420732fe1e1a7_40)] | | | [removed: [16](#iee212e03ad584b3dbd0ab424a97eef2b_40)] [added: [18](#i7809e2c0fa9449f5812420732fe1e1a7_40)] | | |
| Item 7. | | | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#iee212e03ad584b3dbd0ab424a97eef2b_43)] [added: Operations](#i7809e2c0fa9449f5812420732fe1e1a7_43)] | | | [removed: [17](#iee212e03ad584b3dbd0ab424a97eef2b_43)] [added: [19](#i7809e2c0fa9449f5812420732fe1e1a7_43)] | | |
| Item 7A. | | | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#iee212e03ad584b3dbd0ab424a97eef2b_76)] [added: Risk](#i7809e2c0fa9449f5812420732fe1e1a7_73)] | | | [removed: [26](#iee212e03ad584b3dbd0ab424a97eef2b_76)] [added: [28](#i7809e2c0fa9449f5812420732fe1e1a7_73)] | | |
| Item 8. | | | [Financial Statements and Supplementary [removed: Data](#iee212e03ad584b3dbd0ab424a97eef2b_79)] [added: Data](#i7809e2c0fa9449f5812420732fe1e1a7_76)] | | | [removed: [27](#iee212e03ad584b3dbd0ab424a97eef2b_79)] [added: [29](#i7809e2c0fa9449f5812420732fe1e1a7_76)] | | |
| Item 9. | | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#iee212e03ad584b3dbd0ab424a97eef2b_211)] [added: Disclosure](#i7809e2c0fa9449f5812420732fe1e1a7_178)] | | | [removed: [73](#iee212e03ad584b3dbd0ab424a97eef2b_211)] [added: [76](#i7809e2c0fa9449f5812420732fe1e1a7_178)] | | |
| Item 9A. | | | [Controls and [removed: Procedures](#iee212e03ad584b3dbd0ab424a97eef2b_214)] [added: Procedures](#i7809e2c0fa9449f5812420732fe1e1a7_181)] | | | [removed: [73](#iee212e03ad584b3dbd0ab424a97eef2b_214)] [added: [76](#i7809e2c0fa9449f5812420732fe1e1a7_181)] | | |
| Item 9B. | | | [Other [removed: Information](#iee212e03ad584b3dbd0ab424a97eef2b_217)] [added: Information](#i7809e2c0fa9449f5812420732fe1e1a7_184)] | | | [removed: [74](#iee212e03ad584b3dbd0ab424a97eef2b_217)] [added: [77](#i7809e2c0fa9449f5812420732fe1e1a7_184)] | | |
| Item 10. | | | [Directors, Executive Officers and Corporate [removed: Governance](#iee212e03ad584b3dbd0ab424a97eef2b_223)] [added: Governance](#i7809e2c0fa9449f5812420732fe1e1a7_190)] | | | [removed: [75](#iee212e03ad584b3dbd0ab424a97eef2b_223)] [added: [78](#i7809e2c0fa9449f5812420732fe1e1a7_190)] | | |
| Item 11. | | | [Executive [removed: Compensation](#iee212e03ad584b3dbd0ab424a97eef2b_226)] [added: Compensation](#i7809e2c0fa9449f5812420732fe1e1a7_193)] | | | [removed: [75](#iee212e03ad584b3dbd0ab424a97eef2b_226)] [added: [78](#i7809e2c0fa9449f5812420732fe1e1a7_193)] | | |
| Item 12. | | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#iee212e03ad584b3dbd0ab424a97eef2b_229)] [added: Matters](#i7809e2c0fa9449f5812420732fe1e1a7_196)] | | | [removed: [75](#iee212e03ad584b3dbd0ab424a97eef2b_229)] [added: [78](#i7809e2c0fa9449f5812420732fe1e1a7_196)] | | |
| Item 13. | | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#iee212e03ad584b3dbd0ab424a97eef2b_232)] [added: Independence](#i7809e2c0fa9449f5812420732fe1e1a7_199)] | | | [removed: [75](#iee212e03ad584b3dbd0ab424a97eef2b_232)] [added: [78](#i7809e2c0fa9449f5812420732fe1e1a7_199)] | | |
| Item 14. | | | [Principal Accounting Fees and [removed: Services](#iee212e03ad584b3dbd0ab424a97eef2b_235)] [added: Services](#i7809e2c0fa9449f5812420732fe1e1a7_202)] | | | [removed: [75](#iee212e03ad584b3dbd0ab424a97eef2b_235)] [added: [78](#i7809e2c0fa9449f5812420732fe1e1a7_202)] | | |
| Item 15. | | | [Exhibits and Financial Statement [removed: Schedules](#iee212e03ad584b3dbd0ab424a97eef2b_241)] [added: Schedules](#i7809e2c0fa9449f5812420732fe1e1a7_208)] | | | [removed: [76](#iee212e03ad584b3dbd0ab424a97eef2b_241)] [added: [79](#i7809e2c0fa9449f5812420732fe1e1a7_208)] | | |
| Item 16. | | | [Form 10-K [removed: Summary](#iee212e03ad584b3dbd0ab424a97eef2b_244)] [added: Summary](#i7809e2c0fa9449f5812420732fe1e1a7_211)] | | | [removed: [76](#iee212e03ad584b3dbd0ab424a97eef2b_241)] [added: [79](#i7809e2c0fa9449f5812420732fe1e1a7_208)] | | |
| [PART I](#i7809e2c0fa9449f5812420732fe1e1a7_13) | | | | | | [4](#i7809e2c0fa9449f5812420732fe1e1a7_13) | | |
| [PART II](#i7809e2c0fa9449f5812420732fe1e1a7_34) | | | | | | [18](#i7809e2c0fa9449f5812420732fe1e1a7_34) | | |
| Item 9C. | | | [Disclosure Regarding Foreign Jurisdictions that Prevent Inspections](#i7809e2c0fa9449f5812420732fe1e1a7_2107) | | | [77](#i7809e2c0fa9449f5812420732fe1e1a7_2107) | | |
| [PART III](#i7809e2c0fa9449f5812420732fe1e1a7_187) | | | | | | [78](#i7809e2c0fa9449f5812420732fe1e1a7_187) | | |
| [PART IV](#i7809e2c0fa9449f5812420732fe1e1a7_205) | | | | | | [79](#i7809e2c0fa9449f5812420732fe1e1a7_205) | | |
| [SIGNATURES](#i7809e2c0fa9449f5812420732fe1e1a7_214) | | | | | | [82](#i7809e2c0fa9449f5812420732fe1e1a7_214) | | |
| [PART I](#iee212e03ad584b3dbd0ab424a97eef2b_13) | | | | | | [4](#iee212e03ad584b3dbd0ab424a97eef2b_13) | | |
| [PART II](#iee212e03ad584b3dbd0ab424a97eef2b_34) | | | | | | [16](#iee212e03ad584b3dbd0ab424a97eef2b_34) | | |
| [PART III](#iee212e03ad584b3dbd0ab424a97eef2b_220) | | | | | | [75](#iee212e03ad584b3dbd0ab424a97eef2b_220) | | |
| [PART IV](#iee212e03ad584b3dbd0ab424a97eef2b_238) | | | | | | [76](#iee212e03ad584b3dbd0ab424a97eef2b_238) | | |
| [SIGNATURES](#iee212e03ad584b3dbd0ab424a97eef2b_247) | | | | | | [78](#iee212e03ad584b3dbd0ab424a97eef2b_247) | | |
Item 2. Properties
12 rewritten, 43 added, 44 removed, 22 unchanged
As of December 31, [removed: 2020,] [added: 2021,] we owned or had ownership interests in [removed: 1,197] [added: 1,268] operating stores.
Of these stores, [removed: 944] [added: 981] are wholly-owned, [removed: six] [added: four] are in [added: a] consolidated joint [removed: ventures,] [added: venture,] and [removed: 247] [added: 283] are in unconsolidated joint ventures.
In addition, we managed [removed: 724] [added: 828] stores for third parties bringing the total number of stores which we own and/or manage to [removed: 1,921.][added: 2,096.]
These stores are located in [removed: 40] [added: 41] states, [added: and] Washington, D.C. [removed: and Puerto Rico.][added: The majority of our stores are clustered around large population centers.]
[removed: 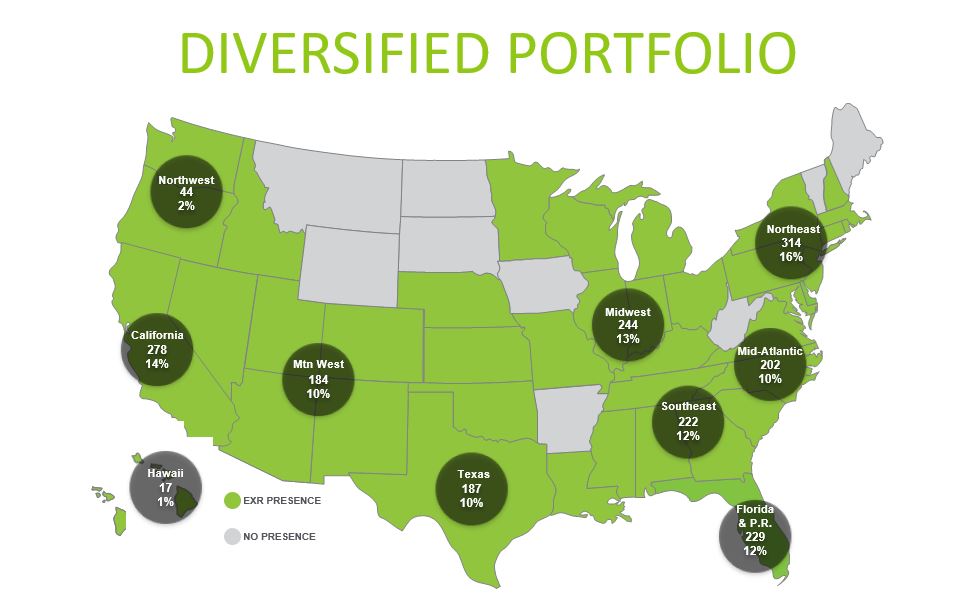][added: 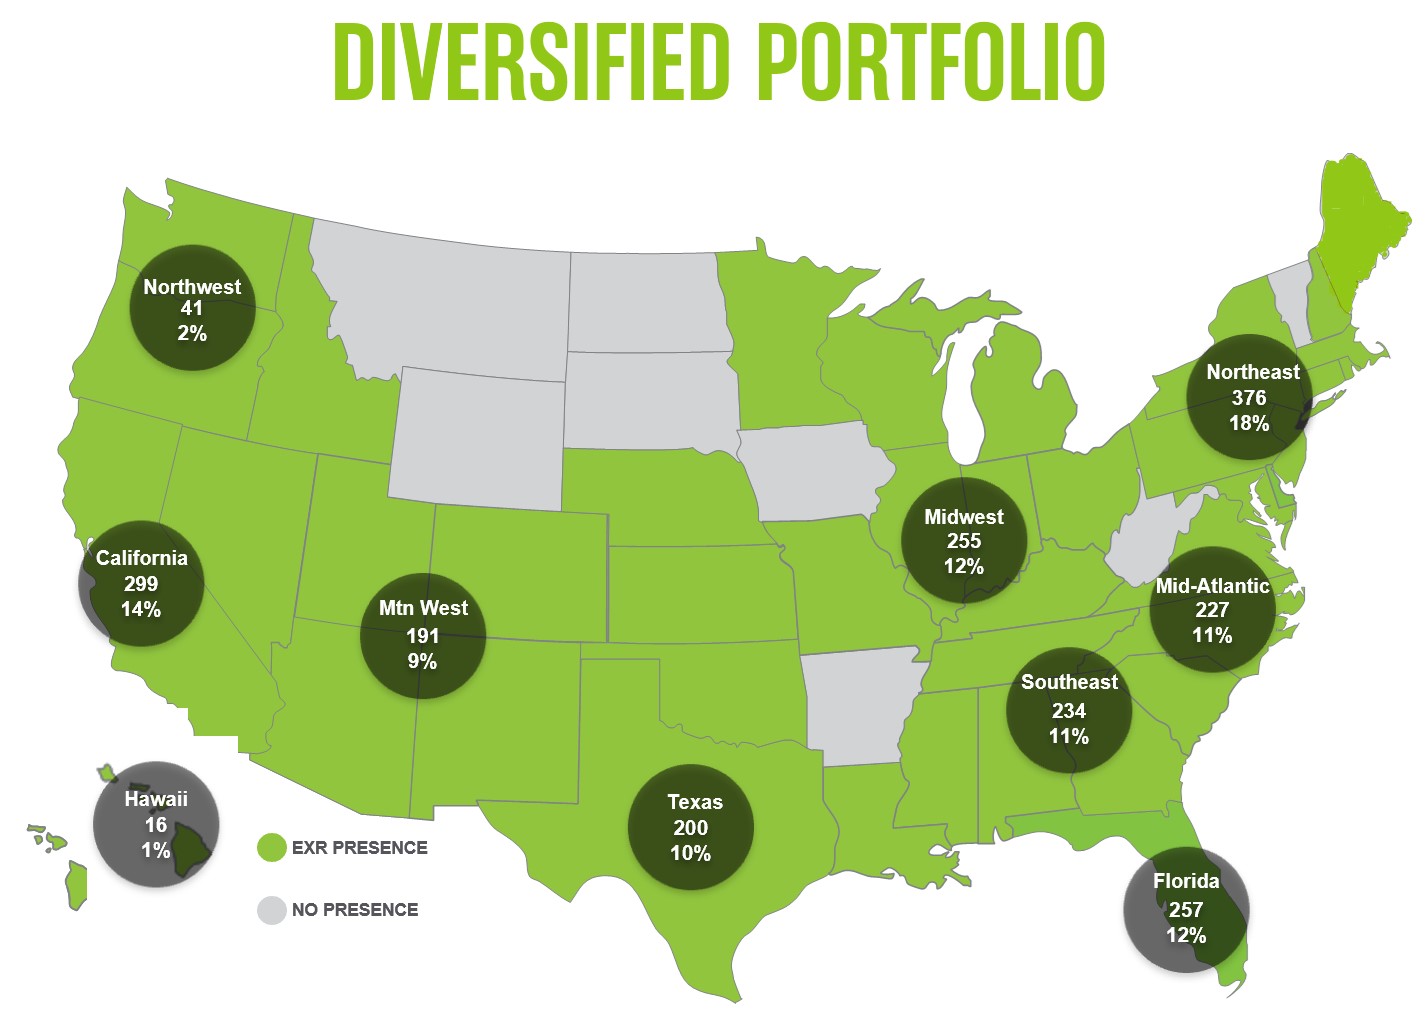]
As of December 31, [removed: 2020,] [added: 2021,] approximately [removed: 1,135,000] [added: 1,250,000] tenants were leasing storage units at the operating stores that we own and/or manage, primarily on a month-to-month basis, providing the flexibility to increase rental rates over time as market conditions permit.
For stores that were stabilized as of December 31, [removed: 2020,] [added: 2021,] the average length of stay was approximately [removed: 15.4] [added: 14.7] months.
The average annual rent per square foot for our existing customers at stabilized stores, net of discounts and bad debt, was [removed: $16.33] [added: $18.03] for the year ended December 31, [removed: 2020,] [added: 2021,] compared to [removed: $16.39] [added: $16.21] for the year ended December 31, [removed: 2019.][added: 2020.]
Average annual rent per square foot for new leases was [removed: $14.81] [added: $19.53] for the year ended December 31, [removed: 2020,] [added: 2021,] compared to [removed: $14.88] [added: $14.64] for the year ended December 31, [removed: 2019.][added: 2020.]
The average discounts, as a percentage of rental revenues, during these periods were [removed: 3.1%] [added: 3.2%] and [removed: 3.6%,] [added: 3.2%,] respectively.
| Kansas | | | 1 | | | [removed: 50,199] [added: 50,209] | | | 2 | | | 108,920 | | | 6 | | | [removed: 466,285] [added: 466,496] | | | 9 | | | [removed: 625,404] [added: 625,625] | | |
(1) REIT owned property count includes [removed: six] [added: four] stores owned in [added: a] consolidated joint [removed: ventures.][added: venture.]
| | | | As of December 31, 2021 | | | | | | | | | | | | | | | | | | | | | | | |
| Alabama | | | 8 | | | 591,634 | | | 1 | | | 75,711 | | | 7 | | | 500,522 | | | 16 | | | 1,167,867 | | |
| Arizona | | | 23 | | | 1,624,442 | | | 9 | | | 673,854 | | | 20 | | | 1,693,975 | | | 52 | | | 3,992,271 | | |
| California | | | 173 | | | 12,470,619 | | | 49 | | | 3,585,534 | | | 77 | | | 7,399,311 | | | 299 | | | 23,455,464 | | |
| Colorado | | | 17 | | | 1,151,511 | | | 3 | | | 270,604 | | | 25 | | | 1,785,787 | | | 45 | | | 3,207,902 | | |
| Connecticut | | | 6 | | | 469,426 | | | 7 | | | 575,824 | | | 8 | | | 552,007 | | | 21 | | | 1,597,257 | | |
| Delaware | | | — | | | — | | | 1 | | | 76,645 | | | 2 | | | 138,474 | | | 3 | | | 215,119 | | |
| Florida | | | 105 | | | 8,011,723 | | | 37 | | | 3,057,327 | | | 115 | | | 9,087,058 | | | 257 | | | 20,156,108 | | |
| Georgia | | | 71 | | | 5,483,850 | | | 8 | | | 648,012 | | | 22 | | | 1,753,910 | | | 101 | | | 7,885,772 | | |
| Hawaii | | | 13 | | | 863,635 | | | — | | | — | | | 3 | | | 159,388 | | | 16 | | | 1,023,023 | | |
| Idaho | | | — | | | — | | | — | | | — | | | 2 | | | 131,564 | | | 2 | | | 131,564 | | |
| Illinois | | | 37 | | | 2,821,824 | | | 10 | | | 741,698 | | | 31 | | | 2,165,181 | | | 78 | | | 5,728,703 | | |
| Indiana | | | 14 | | | 927,531 | | | 1 | | | 58,216 | | | 17 | | | 1,158,507 | | | 32 | | | 2,144,254 | | |
| Kentucky | | | 10 | | | 829,290 | | | 1 | | | 51,178 | | | 8 | | | 704,881 | | | 19 | | | 1,585,349 | | |
| Louisiana | | | 4 | | | 312,159 | | | — | | | — | | | 9 | | | 680,815 | | | 13 | | | 992,974 | | |
| Maine | | | — | | | — | | | — | | | — | | | 8 | | | 575,386 | | | 8 | | | 575,386 | | |
| Maryland | | | 34 | | | 2,848,279 | | | 7 | | | 552,868 | | | 39 | | | 2,783,152 | | | 80 | | | 6,184,299 | | |
| Massachusetts | | | 46 | | | 2,970,320 | | | 10 | | | 640,714 | | | 25 | | | 1,556,339 | | | 81 | | | 5,167,373 | | |
| Michigan | | | 8 | | | 565,449 | | | 4 | | | 302,676 | | | 5 | | | 420,218 | | | 17 | | | 1,288,343 | | |
| Minnesota | | | 7 | | | 585,125 | | | 4 | | | 305,406 | | | 15 | | | 1,130,794 | | | 26 | | | 2,021,325 | | |
| Mississippi | | | 3 | | | 231,542 | | | — | | | — | | | — | | | — | | | 3 | | | 231,542 | | |
| Missouri | | | 4 | | | 260,700 | | | 2 | | | 119,275 | | | 13 | | | 912,707 | | | 19 | | | 1,292,682 | | |
| Nebraska | | | — | | | — | | | — | | | — | | | 3 | | | 278,061 | | | 3 | | | 278,061 | | |
| Nevada | | | 14 | | | 1,038,777 | | | 4 | | | 473,751 | | | 7 | | | 744,039 | | | 25 | | | 2,256,567 | | |
| New Hampshire | | | 2 | | | 135,840 | | | 2 | | | 84,165 | | | 5 | | | 358,872 | | | 9 | | | 578,877 | | |
| New Jersey | | | 62 | | | 4,937,280 | | | 16 | | | 1,143,657 | | | 33 | | | 2,554,345 | | | 111 | | | 8,635,282 | | |
| New Mexico | | | 10 | | | 647,403 | | | 10 | | | 677,034 | | | 12 | | | 904,852 | | | 32 | | | 2,229,289 | | |
| New York | | | 28 | | | 2,042,566 | | | 18 | | | 1,503,833 | | | 30 | | | 1,898,832 | | | 76 | | | 5,445,231 | | |
| North Carolina | | | 23 | | | 1,732,374 | | | 5 | | | 401,772 | | | 17 | | | 1,298,584 | | | 45 | | | 3,432,730 | | |
| Ohio | | | 16 | | | 1,240,197 | | | 5 | | | 325,163 | | | 6 | | | 551,345 | | | 27 | | | 2,116,705 | | |
| Oklahoma | | | — | | | — | | | — | | | — | | | 18 | | | 1,458,951 | | | 18 | | | 1,458,951 | | |
| Oregon | | | 8 | | | 552,096 | | | 1 | | | 65,245 | | | 9 | | | 661,486 | | | 18 | | | 1,278,827 | | |
| Pennsylvania | | | 21 | | | 1,538,581 | | | 9 | | | 678,909 | | | 33 | | | 2,393,416 | | | 63 | | | 4,610,906 | | |
| Rhode Island | | | 2 | | | 134,902 | | | — | | | — | | | 5 | | | 422,148 | | | 7 | | | 557,050 | | |
| South Carolina | | | 23 | | | 1,713,388 | | | 11 | | | 710,450 | | | 25 | | | 2,116,885 | | | 59 | | | 4,540,723 | | |
| Tennessee | | | 21 | | | 1,776,159 | | | 12 | | | 810,966 | | | 9 | | | 642,969 | | | 42 | | | 3,230,094 | | |
| Texas | | | 101 | | | 8,267,256 | | | 23 | | | 1,844,974 | | | 76 | | | 6,608,519 | | | 200 | | | 16,720,749 | | |
| Utah | | | 10 | | | 696,966 | | | — | | | — | | | 25 | | | 1,964,335 | | | 35 | | | 2,661,301 | | |
| Virginia | | | 50 | | | 4,033,833 | | | 10 | | | 767,328 | | | 31 | | | 2,221,694 | | | 91 | | | 7,022,855 | | |
| Washington | | | 9 | | | 683,813 | | | — | | | — | | | 14 | | | 1,149,570 | | | 23 | | | 1,833,383 | | |
The majority of our stores are clustered around large population centers.
| | | | As of December 31, 2020 | | | | | | | | | | | | | | | | | | | | | | | |
| Alabama | | | 9 | | | 617,715 | | | 1 | | | 75,801 | | | 15 | | | 1,058,586 | | | 25 | | | 1,752,102 | | |
| Arizona | | | 23 | | | 1,623,320 | | | 7 | | | 468,721 | | | 20 | | | 1,639,600 | | | 50 | | | 3,731,641 | | |
| California | | | 168 | | | 12,891,223 | | | 41 | | | 3,009,131 | | | 69 | | | 6,522,683 | | | 278 | | | 22,423,037 | | |
| Colorado | | | 17 | | | 1,153,426 | | | 2 | | | 186,273 | | | 23 | | | 1,713,088 | | | 42 | | | 3,052,787 | | |
| Connecticut | | | 7 | | | 531,103 | | | 7 | | | 629,770 | | | 5 | | | 350,141 | | | 19 | | | 1,511,014 | | |
| Delaware | | | — | | | — | | | 1 | | | 76,645 | | | 2 | | | 137,913 | | | 3 | | | 214,558 | | |
| Florida | | | 92 | | | 7,090,681 | | | 32 | | | 2,656,880 | | | 97 | | | 7,636,180 | | | 221 | | | 17,383,741 | | |
| Georgia | | | 66 | | | 5,145,036 | | | 6 | | | 511,117 | | | 20 | | | 1,408,534 | | | 92 | | | 7,064,687 | | |
| Hawaii | | | 13 | | | 847,504 | | | — | | | — | | | 4 | | | 211,654 | | | 17 | | | 1,059,158 | | |
| Idaho | | | — | | | — | | | — | | | — | | | 7 | | | 712,402 | | | 7 | | | 712,402 | | |
| Illinois | | | 39 | | | 3,439,874 | | | 7 | | | 568,825 | | | 27 | | | 1,995,634 | | | 73 | | | 6,004,333 | | |
| Indiana | | | 15 | | | 949,825 | | | 1 | | | 58,166 | | | 14 | | | 865,908 | | | 30 | | | 1,873,899 | | |
| Kentucky | | | 11 | | | 931,665 | | | 1 | | | 51,118 | | | 4 | | | 364,689 | | | 16 | | | 1,347,472 | | |
| Louisiana | | | 2 | | | 163,760 | | | — | | | — | | | 8 | | | 672,089 | | | 10 | | | 835,849 | | |
| Maryland | | | 31 | | | 2,592,138 | | | 8 | | | 549,074 | | | 34 | | | 2,478,826 | | | 73 | | | 5,620,038 | | |
| Massachusetts | | | 46 | | | 2,968,416 | | | 10 | | | 640,884 | | | 13 | | | 848,599 | | | 69 | | | 4,457,899 | | |
| Michigan | | | 7 | | | 562,399 | | | 4 | | | 313,016 | | | 4 | | | 337,336 | | | 15 | | | 1,212,751 | | |
| Minnesota | | | 6 | | | 478,977 | | | 4 | | | 305,732 | | | 13 | | | 1,050,439 | | | 23 | | | 1,835,148 | | |
| Mississippi | | | 3 | | | 220,182 | | | — | | | — | | | — | | | — | | | 3 | | | 220,182 | | |
| Missouri | | | 5 | | | 332,770 | | | 2 | | | 119,275 | | | 10 | | | 690,704 | | | 17 | | | 1,142,749 | | |
| Nebraska | | | — | | | — | | | — | | | — | | | 4 | | | 389,608 | | | 4 | | | 389,608 | | |
| Nevada | | | 14 | | | 1,039,673 | | | 4 | | | 473,761 | | | 5 | | | 531,495 | | | 23 | | | 2,044,929 | | |
| New Hampshire | | | 2 | | | 135,835 | | | 2 | | | 84,165 | | | 2 | | | 117,800 | | | 6 | | | 337,800 | | |
| New Jersey | | | 60 | | | 4,744,101 | | | 17 | | | 1,246,833 | | | 19 | | | 1,438,614 | | | 96 | | | 7,429,548 | | |
| New Mexico | | | 11 | | | 719,356 | | | 6 | | | 354,190 | | | 12 | | | 890,480 | | | 29 | | | 1,964,026 | | |
| New York | | | 28 | | | 2,029,669 | | | 18 | | | 1,513,264 | | | 22 | | | 1,313,433 | | | 68 | | | 4,856,366 | | |
| North Carolina | | | 19 | | | 1,411,699 | | | 5 | | | 373,829 | | | 17 | | | 1,297,209 | | | 41 | | | 3,082,737 | | |
| Ohio | | | 17 | | | 1,310,429 | | | 5 | | | 325,863 | | | 5 | | | 428,584 | | | 27 | | | 2,064,876 | | |
| Oklahoma | | | — | | | — | | | — | | | — | | | 20 | | | 1,621,184 | | | 20 | | | 1,621,184 | | |
| Oregon | | | 6 | | | 400,193 | | | 4 | | | 281,666 | | | 12 | | | 882,762 | | | 22 | | | 1,564,621 | | |
| Pennsylvania | | | 19 | | | 1,413,791 | | | 7 | | | 513,299 | | | 26 | | | 1,961,300 | | | 52 | | | 3,888,390 | | |
| Rhode Island | | | 2 | | | 133,566 | | | — | | | — | | | 2 | | | 166,561 | | | 4 | | | 300,127 | | |
| South Carolina | | | 24 | | | 1,844,648 | | | 7 | | | 498,063 | | | 17 | | | 1,454,525 | | | 48 | | | 3,797,236 | | |
| Tennessee | | | 20 | | | 1,702,172 | | | 12 | | | 807,146 | | | 12 | | | 835,011 | | | 44 | | | 3,344,329 | | |
| Texas | | | 102 | | | 8,770,024 | | | 10 | | | 708,051 | | | 75 | | | 6,009,876 | | | 187 | | | 15,487,951 | | |
| Utah | | | 10 | | | 710,787 | | | — | | | — | | | 23 | | | 1,750,975 | | | 33 | | | 2,461,762 | | |
| Virginia | | | 46 | | | 3,682,924 | | | 7 | | | 568,278 | | | 25 | | | 1,939,830 | | | 78 | | | 6,191,032 | | |
| Washington | | | 8 | | | 589,915 | | | 1 | | | 57,290 | | | 13 | | | 1,050,655 | | | 22 | | | 1,697,860 | | |
An excerpt. Shown here: all 12 rewritten, 40 of 43 added and 40 of 44 removed. The counts are complete. For every sentence, read Item 2. Properties in the FY2021 filing and the FY2020 filing.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
5 rewritten, 4 added, 2 removed, 9 unchanged
On February [removed: 19, 2021,] [added: 22, 2022,] the closing price of our common stock as reported by the NYSE was [removed: $119.63.][added: $185.28.]
At February [removed: 19, 2021,] [added: 22, 2022,] we had [removed: 397] [added: 423] holders of record of our common stock.
In [removed: November 2017,] [added: October 2020,] our board of directors authorized a three-year share repurchase program [removed: to allow us to acquire] [added: allowing the repurchase of] shares [removed: in] [added: with an] aggregate [added: value] up to $400.0 million.
As of December 31, [removed: 2020,] [added: 2021,] we had remaining authorization to repurchase shares with an aggregate value of $400.0 million.
All unregistered sales of equity securities during the year ended December 31, [removed: 2020] [added: 2021] have previously been disclosed in filings with the SEC.
On January 6, 2022, we issued a total of 186,766 shares of common stock in connection with the acquisition of two stores.
The shares of common stock were valued at a total of $41.0 million.
The shares of common stock were issued in a private placement in reliance on Section 4(a)(2) of the Securities Act of 1933, as amended, and the rules and regulations promulgated thereunder.
We agreed to register for resale the shares issued in connection with such acquisition on or before April 6, 2022.
During the year ended December 31, 2020, we repurchased 826,797 shares at an average price of $82.09 per share, paying a total of $67.9 million.
On October 15, 2020, our board of directors authorized a new share repurchase program allowing the repurchase of shares with an aggregate value up to $400.0 million, which replaced our prior share repurchase program, which was set to expire on November 8, 2020.
Item 8. Financial Statements and Supplementary Data
479 rewritten, 222 added, 188 removed, 936 unchanged
| [Report of Independent Registered Public Accounting [removed: Firm](#iee212e03ad584b3dbd0ab424a97eef2b_85)] [added: Fir](#i7809e2c0fa9449f5812420732fe1e1a7_82)[m (PCAOB ID:](#i7809e2c0fa9449f5812420732fe1e1a7_82) 42[)](#i7809e2c0fa9449f5812420732fe1e1a7_82)] | | | [removed: [28](#iee212e03ad584b3dbd0ab424a97eef2b_85)] [added: [30](#i7809e2c0fa9449f5812420732fe1e1a7_82)] | | |
| [Consolidated Balance Sheets as of December 31, [removed: 2020 and 2019](#iee212e03ad584b3dbd0ab424a97eef2b_88)] [added: 202](#i7809e2c0fa9449f5812420732fe1e1a7_85)[1](#i7809e2c0fa9449f5812420732fe1e1a7_85) [and 20](#i7809e2c0fa9449f5812420732fe1e1a7_85)[20](#i7809e2c0fa9449f5812420732fe1e1a7_85)[](#i7809e2c0fa9449f5812420732fe1e1a7_85)] | | | [removed: [30](#iee212e03ad584b3dbd0ab424a97eef2b_88)] [added: [32](#i7809e2c0fa9449f5812420732fe1e1a7_85)] | | |
| [Consolidated Statements of Operations for the years ended December 31, [removed: 2020, 2019 and 2018](#iee212e03ad584b3dbd0ab424a97eef2b_94)] [added: 202](#i7809e2c0fa9449f5812420732fe1e1a7_88)[1](#i7809e2c0fa9449f5812420732fe1e1a7_88)[, 20](#i7809e2c0fa9449f5812420732fe1e1a7_88)[20](#i7809e2c0fa9449f5812420732fe1e1a7_88) [and 201](#i7809e2c0fa9449f5812420732fe1e1a7_88)[9](#i7809e2c0fa9449f5812420732fe1e1a7_88)[](#i7809e2c0fa9449f5812420732fe1e1a7_88)] | | | [removed: [31](#iee212e03ad584b3dbd0ab424a97eef2b_94)] [added: [33](#i7809e2c0fa9449f5812420732fe1e1a7_88)] | | |
| [Consolidated Statements of Comprehensive Income for the years ended December 31, [removed: 2020, 2019 and 2018](#iee212e03ad584b3dbd0ab424a97eef2b_97)] [added: 202](#i7809e2c0fa9449f5812420732fe1e1a7_91)[1](#i7809e2c0fa9449f5812420732fe1e1a7_91)[, 20](#i7809e2c0fa9449f5812420732fe1e1a7_91)[20](#i7809e2c0fa9449f5812420732fe1e1a7_91) [and 20](#i7809e2c0fa9449f5812420732fe1e1a7_91)[19](#i7809e2c0fa9449f5812420732fe1e1a7_91)] | | | [removed: [32](#iee212e03ad584b3dbd0ab424a97eef2b_97)] [added: [34](#i7809e2c0fa9449f5812420732fe1e1a7_91)] | | |
| [Consolidated Statements of Stockholders’ Equity for the years ended December 31, [removed: 2020, 2019 and 2018](#iee212e03ad584b3dbd0ab424a97eef2b_100)] [added: 202](#i7809e2c0fa9449f5812420732fe1e1a7_94)[1](#i7809e2c0fa9449f5812420732fe1e1a7_94)[, 20](#i7809e2c0fa9449f5812420732fe1e1a7_94)[20](#i7809e2c0fa9449f5812420732fe1e1a7_94) [and 20](#i7809e2c0fa9449f5812420732fe1e1a7_94)[19](#i7809e2c0fa9449f5812420732fe1e1a7_94)] | | | [removed: [33](#iee212e03ad584b3dbd0ab424a97eef2b_100)] [added: [35](#i7809e2c0fa9449f5812420732fe1e1a7_94)] | | |
| [Consolidated Statements of Cash Flows for the years ended December 31, [removed: 2020, 2019 and 2018](#iee212e03ad584b3dbd0ab424a97eef2b_106)] [added: 202](#i7809e2c0fa9449f5812420732fe1e1a7_97)[1](#i7809e2c0fa9449f5812420732fe1e1a7_97)[, 20](#i7809e2c0fa9449f5812420732fe1e1a7_97)[20](#i7809e2c0fa9449f5812420732fe1e1a7_97) [and 20](#i7809e2c0fa9449f5812420732fe1e1a7_97)[19](#i7809e2c0fa9449f5812420732fe1e1a7_97)] | | | [removed: [36](#iee212e03ad584b3dbd0ab424a97eef2b_106)] [added: [38](#i7809e2c0fa9449f5812420732fe1e1a7_97)] | | |
[removed: | [Notes to Consolidated Financial Statements](#iee212e03ad584b3dbd0ab424a97eef2b_109) | | | [37](#iee212e03ad584b3dbd0ab424a97eef2b_109) | | |][added: NOTES TO CONSOLIDATED FINANCIAL STATEMENTS (continued)]
| [Schedule III - Real Estate and Accumulated [removed: Depreciation](#iee212e03ad584b3dbd0ab424a97eef2b_202)] [added: Depreciation](#i7809e2c0fa9449f5812420732fe1e1a7_169)] | | | [removed: [71](#iee212e03ad584b3dbd0ab424a97eef2b_202)] [added: [74](#i7809e2c0fa9449f5812420732fe1e1a7_169)] | | |
To the Stockholders and the Board of Directors of Extra Space [removed: Storage,] [added: Storage] Inc.
We have audited the accompanying consolidated balance sheets of Extra Space [removed: Storage,] [added: Storage] Inc. (the Company) as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] the related consolidated statements of operations, comprehensive income, stockholders' equity and cash flows for each of the three years in the period ended December 31, [removed: 2020,] [added: 2021,] and the related notes and financial statement schedule listed in the Index at Item 8 (collectively referred to as the “consolidated financial statements”).
In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2020,] [added: 2021,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, [removed: 2020,] [added: 2021,] based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework), and our report dated February [removed: 26, 2021] [added: 28, 2022] expressed an unqualified opinion thereon.
The critical audit matter communicated below is a matter arising from the current period audit of the financial statements that was communicated or required to be communicated to the audit committee and that: (1) relates to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, [removed: subjective] [added: subjective,] or complex judgments.
| *Description of the Matter* | | | For the year ended December 31, [removed: 2020,] [added: 2021,] the Company completed the acquisition of [removed: 23] [added: 70] self-storage properties (“stores”) for a total purchase price of [removed: $296.7 million.] [added: $1.1 billion.] As further discussed in Note 2 of the consolidated financial statements, the transactions were accounted for as asset acquisitions, and the purchase price was allocated to the real estate assets acquired based on their relative fair values, which are estimated using unobservable inputs. | | |
| | | | Auditing the accounting for the Company’s [removed: 2020] [added: 2021] acquisitions of stores was subjective because in determining the fair value of acquired land and buildings, the Company had to rely on unobservable inputs due to the lack of available directly comparable market information. In particular, the fair value estimates were sensitive to assumptions such as price of land per square foot, and current replacement cost estimates, including adjustments for the age, class, height, square footage, condition, location, and turnkey factor associated with the acquired assets. | | |
| | | | For the [removed: 2020] [added: 2021] store acquisitions described above, our procedures [removed: included] [added: included, but were not limited to,] evaluating the Company’s valuation methodologies and [removed: testing] [added: evaluating] the significant assumptions used to determine the fair value of the assets acquired. [removed: We] [added: For certain of these asset acquisitions, we] tested the completeness and accuracy of the underlying data by, among other things, recalculating the current replacement cost of buildings and comparing the adjustments for the age, class, height, square footage, condition, location, and turnkey factor with the acquired assets to industry publications. [removed: We] [added: Additionally, we] also compared significant assumptions, including prices per square foot to third-party sources such as recent land sales. For certain of these asset acquisitions, we involved our valuation specialists to assist in the assessment of the methodology utilized by the Company, in addition to performing corroborative analyses to assess whether the conclusions in the valuation were supported by observable market data. For example, our valuation specialists used independently identified data sources to evaluate management’s selected comparable land sales and replacement cost assumptions. | | |
| | | | December 31, [removed: 2020] [added: 2021] | | | | | | December 31, [removed: 2019] [added: 2020] | | |
| [removed: Real] [added: Net non-lease real] estate [removed: assets, net] [added: assets] | | | $ | [added: 8,834,649 | | | | | $ |] 7,893,802 | | | | | $ | 7,696,864 | |
| Real estate assets - operating lease right-of-use assets | | | [removed: 252,172] [added: 227,949] | | | | | | [removed: 264,643] [added: 252,172] | | |
| Investments in unconsolidated real estate entities | | | [removed: 397,444] [added: 457,326] | | | | | | [removed: 338,054] [added: 397,444] | | |
| Investments in debt securities and notes receivable | | | [removed: 593,810] [added: 719,187] | | | | | | [removed: 43,586] [added: 593,810] | | |
| Cash and cash equivalents | | | [removed: 109,124] [added: 71,126] | | | | | | [removed: 65,746] [added: 109,124] | | |
| Restricted cash | | | [removed: 18,885] [added: 5,068] | | | | | | [removed: 4,987] [added: 18,885] | | |
| Other assets, net | | | [removed: 130,611] [added: 159,172] | | | | | | [removed: 118,497] [added: 130,611] | | |
| Total assets | | | $ | [removed: 9,395,848] [added: 10,474,477] | | | | | $ | [removed: 8,532,377] [added: 9,395,848] | |
| [removed: Exchangeable] [added: Discount on exchangeable] senior [removed: notes, net] [added: notes] | | | — | | | | | | [removed: 569,513] [added: —] | | | [added: | | | — | | |]
| Revolving lines of credit | | | [removed: 949,000] [added: 535,000] | | | | | | [removed: 158,000] [added: 949,000] | | |
| Operating lease liabilities | | | [removed: 263,485] [added: 233,356] | | | | | | [removed: 274,783] [added: 263,485] | | |
| Cash distributions in unconsolidated real estate ventures | | | [removed: 47,126] [added: 63,582] | | | | | | [removed: 45,264] [added: 47,126] | | |
| Accounts payable and accrued expenses | | | [removed: 130,012] [added: 142,285] | | | | | | [removed: 111,382] [added: 130,012] | | |
| Other liabilities | | | [removed: 272,798] [added: 291,531] | | | | | | [removed: 132,768] [added: 272,798] | | |
| Total liabilities | | | [removed: 6,459,724] [added: 6,688,501] | | | | | | [removed: 5,610,683] [added: 6,459,724] | | |
| Common stock, $0.01 par value, 500,000,000 shares authorized, [removed: 131,357,961] [added: 133,922,305] and [removed: 129,534,407] [added: 131,357,961] shares issued and outstanding at December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] respectively | | | [removed: 1,314] [added: 1,339] | | | | | | [removed: 1,295] [added: 1,314] | | |
| Additional paid-in capital | | | [removed: 3,000,458] [added: 3,285,948] | | | | | | [removed: 2,868,681] [added: 3,000,458] | | |
| Accumulated other comprehensive loss | | | [removed: (99,093)] [added: (42,546)] | | | | | | [removed: (28,966)] [added: (99,093)] | | |
| Accumulated deficit | | | [removed: (354,900)] [added: (128,245)] | | | | | | [removed: (301,049)] [added: (354,900)] | | |
| Total Extra Space Storage Inc. stockholders' equity | | | [removed: 2,547,779] [added: 3,116,496] | | | | | | [removed: 2,539,961] [added: 2,547,779] | | |
| Noncontrolling interest represented by Preferred Operating Partnership units, net | | | [removed: 172,052] [added: 259,110] | | | | | | [removed: 175,948] [added: 172,052] | | |
| Noncontrolling interests in Operating Partnership, net and other noncontrolling interests | | | [removed: 216,293] [added: 410,370] | | | | | | [removed: 205,785] [added: 216,293] | | |
| Total noncontrolling interests and equity | | | [removed: 2,936,124] [added: 3,785,976] | | | | | | [removed: 2,921,694] [added: 2,936,124] | | |
| [Notes to Consolidated Financial Statements](#i7809e2c0fa9449f5812420732fe1e1a7_100) | | | [39](#i7809e2c0fa9449f5812420732fe1e1a7_100) | | |
February 28, 2022
| Notes payable, net | | | $ | 1,320,755 | | | | | $ | 2,283,454 | |
| Unsecured term loans, net | | | 1,741,926 | | | | | | 1,194,383 | | |
| Unsecured senior notes, net | | | 2,360,066 | | | | | | 1,319,466 | | |
| Equity in earnings of unconsolidated real estate ventures - gain on sale of real estate assets and purchase of joint venture partner's interest | | | 6,251 | | | | | | — | | | | | | — | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | Noncontrolling Interests | | | | | | | | | | | | | | | | | | Extra Space Storage Inc. Stockholders' Equity | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | Preferred Operating Partnership | | | | | | Operating Partnership | | | | | | Other | | | | | | | | | | | | | | | | | | Additional Paid-in Capital | | | | | | Accumulated Other Comprehensive Loss | | | | | | Accumulated Deficit | | | | | | Total Noncontrolling Interests and Equity | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | Noncontrolling Interests | | | | | | | | | | | | | | | | | | Extra Space Storage Inc. Stockholders' Equity | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | Preferred Operating Partnership | | | | | | Operating Partnership | | | | | | Other | | | | | | | | | | | | | | | | | | Additional Paid-in Capital | | | | | | Accumulated Other Comprehensive Loss | | | | | | Accumulated Deficit | | | | | | Total Noncontrolling Interests and Equity | | | | | | | | | | | | | | | | | | | | |
| Balances at December 31, 2020 | | | | | | | | | | | | | | | | | | | | | | | | | | | $ | 172,052 | | | | | $ | 215,892 | | | | | $ | 401 | | | | | 131,357,961 | | | | | | $ | 1,314 | | | | | $ | 3,000,458 | | | | | $ | (99,093) | | | | | $ | (354,900) | | | | | $ | 2,936,124 | |
| Issuance of common stock in connection with share based compensation | | | | | | | | | | | | | | | | | | | | | | | | | | | — | | | | | | — | | | | | | — | | | | | | 148,228 | | | | | | — | | | | | | 17,303 | | | | | | — | | | | | | — | | | | | | 17,303 | | |
| Issuance of common stock, net of offering costs | | | | | | | | | | | | | | | | | | | | | | | | | | | — | | | | | | — | | | | | | — | | | | | | 2,185,685 | | | | | | 22 | | | | | | 273,167 | | | | | | — | | | | | | — | | | | | | 273,189 | | |
| Issuance of Preferred D units in the Operating Partnership in conjunction with acquisitions | | | | | | | | | | | | | | | | | | | | | | | | | | | 88,074 | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 88,074 | | |
| Purchase of remaining equity interest in existing consolidated joint venture | | | | | | | | | | | | | | | | | | | | | | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | (18,141) | | | | | | — | | | | | | — | | | | | | (18,141) | | |
| Net income (loss) | | | | | | | | | | | | | | | | | | | | | | | | | | | 14,697 | | | | | | 35,414 | | | | | | (2) | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 827,649 | | | | | | 877,758 | | |
| Other comprehensive income | | | | | | | | | | | | | | | | | | | | | | | | | | | 366 | | | | | | 2,412 | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 56,547 | | | | | | — | | | | | | 59,325 | | |
| Balances at December 31, 2021 | | | | | | | | | | | | | | | | | | | | | | | | | | | $ | 259,110 | | | | | $ | 410,053 | | | | | $ | 317 | | | | | 133,922,305 | | | | | | $ | 1,339 | | | | | $ | 3,285,948 | | | | | $ | (42,546) | | | | | $ | (128,245) | | | | | $ | 3,785,976 | |
| Depreciation and amortization | | | 241,879 | | | | | | 224,444 | | | | | | 219,857 | | |
| Equity in earnings of unconsolidated real estate ventures - gain on sale of real estate assets and purchase of joint venture partner's interest | | | (6,251) | | | | | | — | | | | | | | | |
| Proceeds from issuance of public bonds, net | | | 1,040,349 | | | | | | — | | | | | | — | | |
For comparison purposes, the Company has reclassified a portion of Notes payable, net to Unsecured term loans, net and Unsecured senior notes, net on the Consolidated Balance Sheets as of December 31, 2020, to conform to the presentation as of December 31, 2021.
The Company had one consolidated VIE consisting of four stores as of December 31, 2021 and no consolidated VIEs as of December 31, 2020.
| Fixed rate debt | | | $ | 4,643,072 | | | | | $ | 4,506,435 | | | | | $ | 3,816,530 | | | | | $ | 3,637,220 | |
Depreciation is
As of December 31, 2021 and 2020 the Operating Partnership had no exchangeable senior notes issued or outstanding.
In October and November 2020, a portion of the 3.125% Exchangeable Senior Notes due 2035 (the “2015 Notes”) were exchanged for cash and shares of the Company's common stock and the remaining 2015 Notes were redeemed for cash.
Accordingly, the number of shares included in the computation for diluted earnings per share related to the Series A Units is equal to the number of Series A Units outstanding, with no additional shares included related to the $101,700 fixed amount.
| Basic | | | $ | 6.20 | | | | | $ | 3.71 | | | | | $ | 3.27 | |
| Diluted | | | $ | 6.19 | | | | | $ | 3.71 | | | | | $ | 3.24 | |
In March 2020, the FASB issued ASU 2020-04, "*Reference Rate Reform (Topic 848): Facilitation of the Effects of Reference Rate Reform on Financial Reporting*" (“ASU 2020-04”).
ASU 2020-04 provides temporary optional guidance that provides transition relief for reference rate reform, including optional expedients and exceptions for applying GAAP to contract modifications, hedging relationships and other transactions that reference LIBOR or a reference rate that is expected to be discontinued as a result of reference rate reform if certain criteria are met.
ASU 2020-04 is effective upon issuance, and the provisions generally can be applied prospectively as of January 1, 2020 through December 31, 2024.
The Company elected to apply the hedge accounting expedients related to probability and the assessments of effectiveness for future LIBOR-indexed cash flows to assume that the index upon which future hedged transactions will be based matches the index on the corresponding derivatives.
February 26, 2021
| | | | | | | | | | | | |
| Notes payable, net | | | $ | 4,797,303 | | | | | $ | 4,318,973 | |
| Balances at December 31, 2017 | | | | | | | | | | | | | | | | | | | | | | | | | | | $ | 159,636 | | | | | $ | 213,301 | | | | | $ | 119 | | | | | 126,007,091 | | | | | | $ | 1,260 | | | | | $ | 2,569,485 | | | | | $ | 33,290 | | | | | $ | (253,284) | | | | | $ | 2,723,807 | |
| Restricted stock grants cancelled | | | | | | | | | | | | | | | | | | | | | | | | | | | — | | | | | | — | | | | | | — | | | | | | (11,771) | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | |
| Net income (loss) | | | | | | | | | | | | | | | | | | | | | | | | | | | 13,995 | | | | | | 17,797 | | | | | | (1) | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 415,289 | | | | | | 447,080 | | |
| Other comprehensive income | | | | | | | | | | | | | | | | | | | | | | | | | | | 12 | | | | | | 58 | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 1,360 | | | | | | — | | | | | | 1,430 | | |
| Balances at December 31, 2018 | | | | | | | | | | | | | | | | | | | | | | | | | | | $ | 153,096 | | | | | $ | 218,362 | | | | | $ | 240 | | | | | 127,103,750 | | | | | | $ | 1,271 | | | | | $ | 2,640,705 | | | | | $ | 34,650 | | | | | $ | (262,902) | | | | | $ | 2,785,422 | |
| Issuance of common stock, net of offering costs | | | | | | | | | | | | | | | | | | | | | | | | | | | — | | | | | | — | | | | | | — | | | | | | 1,779,200 | | | | | | 19 | | | | | | 198,808 | | | | | | — | | | | | | — | | | | | | 198,827 | | |
| Compensation expense related to stock-based awards | | | 16,281 | | | | | | 13,051 | | | | | | 11,176 | | |
These stores are located in 40 states, Washington, D.C. and Puerto Rico.
As of December 31, 2020 and 2019, the Company had no consolidated VIEs.
| Fixed rate notes payable | | | $ | 3,816,530 | | | | | $ | 3,637,220 | | | | | $ | 3,511,151 | | | | | $ | 3,417,928 | |
| Exchangeable senior notes | | | $ | — | | | | | $ | — | | | | | $ | 673,831 | | | | | $ | 575,000 | |
Equity in earnings of unconsolidated real estate ventures is recognized based on the Company's ownership interest in the earnings of each of the unconsolidated real estate entities.
Interest income is recognized as earned.
The Company purchases reinsurance for losses exceeding a set amount for any one event.
The Company does not currently have any amounts recoverable under the reinsurance arrangements.
For the year ended December 31, 2018, options to purchase approximately 36,075 shares of common stock were excluded from the computation of earnings per share as their effect would have been anti-dilutive.
| Series C Units (1) | | | — | | | | | | — | | | | | | 312,075 | | |
(1) The remainder of the Series C Units were converted to OP Units on April 25, 2019.
The Operating Partnership had $575,000 of its 3.125% Exchangeable Senior Notes due 2035 (the “2015 Notes”) issued and outstanding prior to their redemption in November 2020.
ASU 2016-02
In March 2020, the FASB issued ASU 2020-04, "Reference Rate Reform (Topic 848)." ASU 2020-04 contains practical expedients for reference rate reform related activities that impact debt, leases, derivatives and other contracts.
The guidance in ASU 2020-04 is optional and may be elected over time as reference rate reform activities occur.
In August 2020, the FASB issued ASU 2020-06, "Debt—Debt with Conversion and Other Options (Subtopic 470-20) and Derivatives and Hedging—Contracts in Entity’s Own Equity (Subtopic 815-40)." ASU 2020-06 simplifies the accounting for convertible instruments and contracts in an entity's own equity, and amended related earnings per share guidance.
The guidance in ASU 2020-06 becomes effective for fiscal years beginning after December 15, 2021.
Early adoption is permitted no earlier than the fiscal years beginning after December 15, 2020.
The guidance may be adopted on a modified or fully retrospective basis.
The Company is currently assessing the impact of the adoption of ASU 2020-06 on its consolidated financial statements.
| | | | 9,507,788 | | | | | | 9,129,559 | | |
| Total 2019 | | | 21 | | | | | | $ | 300,379 | | | | | $ | 279,313 | | | | | $ | 17,157 | | $ | — | | $ | 2,780 | | $ | 1,129 | | | | | | | | $ | 300,379 | |
No gain or loss was recognized as a result of these acquisitions.
Store Disposals
On August 16, 2018, the Company sold a store located in California that had been classified as held for sale for $40,235 in cash.
| | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
(2)In October 2019, the Company invested $150,000 in shares of newly issued convertible preferred stock of SmartStop, with an additional commitment to purchase up to $50,000 of the preferred shares over the 12 months after the original purchase.
In October 2020 the Company purchased the additional $50,000 in SmartStop convertible preferred stock that was previously committed.
(3)The Company had $31,500 and $15,450 of preferred equity in the WICNN JV LLC and GFN JV, LLC joint ventures, respectively, as of December 31, 2020.
An excerpt. Shown here: 40 of 479 rewritten, 40 of 222 added and 40 of 188 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data in the FY2021 filing and the FY2020 filing.
Item 9A. Controls and Procedures
6 rewritten, 2 added, 1 removed, 33 unchanged
[removed: (1)Management’s] [added: 1.Management’s] Report on Internal Control over Financial Reporting
Based on our evaluation, our management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2020.][added: 2021.]
We have audited Extra Space [removed: Storage,] [added: Storage] Inc.’s internal control over financial reporting as of December 31, [removed: 2020,] [added: 2021,] based on criteria established in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria).
In our opinion, Extra Space [removed: Storage,] [added: Storage] Inc. (the Company) maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2020,] [added: 2021,] based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] the related consolidated [removed: statements of operations, comprehensive income, stockholders' equity and cash flows for each of the three years in the period]
[added: statements of operations, comprehensive income, stockholders' equity and cash flows for each of the three years in the period] ended December 31, [removed: 2020,] [added: 2021,] and the related notes and financial statement schedule listed in the Index at Item 8 and our report dated February [removed: 26, 2021] [added: 28, 2022] expressed an unqualified opinion thereon.
To the Stockholders and the Board of Directors of Extra Space Storage Inc.
February 28, 2022
February 26, 2021
Item 9B. Other Information
0 rewritten, 0 added, 1 removed, 1 unchanged
PART III
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
0 rewritten, 2 added, 0 removed, 0 unchanged
New section this year
None.
PART III
Item 10. Directors, Executive Officers and Corporate Governance
1 rewritten, 0 added, 0 removed, 5 unchanged
Information required by this item is incorporated by reference to the information set forth under the captions “Information about our Executive Officers,” and “Information About the Board of Directors and its Committees” in our definitive Proxy Statement to be filed with the Securities and Exchange Commission pursuant to Regulation 14A within 120 days after December 31, [removed: 2020.][added: 2021.]
Item 11. Executive Compensation
1 rewritten, 0 added, 0 removed, 0 unchanged
Information with respect to executive compensation is incorporated by reference to the information set forth under the caption “Executive Compensation” in our definitive Proxy Statement to be filed with the Securities and Exchange Commission pursuant to Regulation 14A within 120 days after December 31, [removed: 2020.][added: 2021.]
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
1 rewritten, 0 added, 0 removed, 0 unchanged
Information with respect to security ownership of certain beneficial owners and management and related stockholder matters is incorporated by reference to the information set forth under the captions “Executive Compensation” and “Security Ownership of Directors and Officers” in our definitive Proxy Statement to be filed with the Securities and Exchange Commission pursuant to Regulation 14A within 120 days after December 31, [removed: 2020.][added: 2021.]
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 0 unchanged
Information with respect to certain relationships and related transactions is incorporated by reference to the information set forth under the captions “Information about the Board of Directors and its Committees” and “Certain Relationships and Related Transactions” in our Proxy Statement to be filed with the Securities and Exchange Commission pursuant to Regulation 14A within 120 days after December 31, [removed: 2020.][added: 2021.]
Item 14. Principal Accounting Fees and Services
1 rewritten, 0 added, 0 removed, 1 unchanged
Information with respect to principal accounting fees and services is incorporated by reference to the information set forth under the caption “Ratification of Appointment of Independent Registered Public Accounting Firm” in our Proxy Statement to be filed with the Securities and Exchange Commission pursuant to Regulation 14A within 120 days after December 31, [removed: 2020.][added: 2021.]
Item 15. Exhibits and Financial Statement Schedules
7 rewritten, 7 added, 0 removed, 45 unchanged
| [removed: [10.14](http://www.sec.gov/Archives/edgar/data/1289490/000119312516739701/d272035dex101.htm)] [added: [10.22](https://www.sec.gov/Archives/edgar/data/1289490/000162828021012952/ex101secondamendedandresta.htm)] | | | | | | [added: Second Amended and Restated] Credit Agreement, dated as of [removed: October 14, 2016,] [added: June 22, 2021,] by and among Extra Space Storage Inc., Extra Space Storage LP, U.S. Bank National Association, as administrative agent, certain other financial institutions acting as syndication agents, documentation [removed: agents, senior management] agents and lead arrangers and [removed: book] [added: books] runners, and certain lenders party thereto (incorporated by reference to Exhibit 10.1 of Form 8-K filed on [removed: October 17, 2016).] [added: June 25, 2021).] | | |
| [removed: [21.1](https://www.sec.gov/Archives/edgar/data/1289490/000162828021003458/q4202010kex211.htm)] [added: [21.1](https://www.sec.gov/Archives/edgar/data/1289490/000162828022004274/q4202110kex211.htm)] | | | | | | Subsidiaries of the Company(2) | | |
| [removed: [23.1](https://www.sec.gov/Archives/edgar/data/1289490/000162828021003458/q4202010kex231.htm)] [added: [23.1](https://www.sec.gov/Archives/edgar/data/1289490/000162828022004274/q4202110kex231.htm)] | | | | | | Consent of Ernst & Young LLP(2) | | |
| [removed: [31.1](https://www.sec.gov/Archives/edgar/data/1289490/000162828021003458/q4202010kex311.htm)] [added: [31.1](https://www.sec.gov/Archives/edgar/data/1289490/000162828022004274/q4202110kex311.htm)] | | | | | | Certification of Chief Executive Officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002.(2) | | |
| [removed: [31.2](https://www.sec.gov/Archives/edgar/data/1289490/000162828021003458/q4202010kex312.htm)] [added: [31.2](https://www.sec.gov/Archives/edgar/data/1289490/000162828022004274/q4202110kex312.htm)] | | | | | | Certification of Chief Financial Officer pursuant to Section 302 of the Sarbanes-Oxley Act of 2002.(2) | | |
| [removed: [32.1](https://www.sec.gov/Archives/edgar/data/1289490/000162828021003458/q4202010kex321.htm)] [added: [32.1](https://www.sec.gov/Archives/edgar/data/1289490/000162828022004274/q4202110kex321.htm)] | | | | | | Certifications of the Chief Executive Officer and Chief Financial Officer pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002.(2) | | |
| 101 | | | | | | The following financial information from Registrant’s Annual Report on Form 10-K for the period ended December 31, [removed: 2019,] [added: 2021,] formatted in Extensible Business Reporting Language (XBRL): (i) Consolidated Balance Sheets as of December 31, [removed: 2019] [added: 2021] and [removed: 2018;] [added: 2020;] (ii) Consolidated Statements of Operations for the years ended December 31, [removed: 2019, 2018] [added: 2021, 2020] and [removed: 2017;] [added: 2019;] (iii) Consolidated Statements of Comprehensive Income for the years ended December 31, [removed: 2019, 2018] [added: 2021, 2020] and [removed: 2017;] [added: 2019;] (iv) Consolidated Statements of Stockholders’ Equity for the years ended December 31, [removed: 2019, 2018] [added: 2021, 2020] and [removed: 2017;] [added: 2019;] (v) Consolidated Statements of Cash Flows for the years ended December 31, [removed: 2019, 2018] [added: 2021, 2020] and [removed: 2017;] [added: 2019;] and (vi) Notes to Consolidated Financial Statements(2). | | |
| [4.3](https://www.sec.gov/Archives/edgar/data/1289490/000119312521157616/d469365dex41.htm) | | | | | | Indenture, dated as of May 11, 2021, among Extra Space Storage LP, as issuer, Extra Space Storage Inc., ESS Holdings Business Trust I and ESS Holdings Business Trust II, as guarantors, and Wells Fargo Bank, National Association, as trustee (incorporated by reference to Exhibit 4.1 to the Current Report on Form 8-K filed by Extra Space Storage Inc. on May 11, 2021). | | |
| [4.4](https://www.sec.gov/Archives/edgar/data/1289490/000119312521157616/d469365dex42.htm) | | | | | | First Supplemental Indenture, dated as of May 11, 2021, among Extra Space Storage LP, as issuer, Extra Space Storage Inc., ESS Holdings Business Trust I and ESS Holdings Business Trust II, as guarantors, and Wells Fargo Bank, National Association, as trustee, including the form of the Notes and the Guarantee (incorporated by reference to Exhibit 4.2 to the Current Report on Form 8-K filed by Extra Space Storage Inc. on May 11, 2021). | | |
| [4.5](https://www.sec.gov/Archives/edgar/data/1289490/000119312521279380/d192404dex42.htm) | | | | | | Second Supplemental Indenture, dated as of September 22, 2021, among Extra Space Storage LP, as issuer, Extra Space Storage Inc., ESS Holdings Business Trust I and ESS Holdings Business Trust II, as guarantors, and Wells Fargo Bank, National Association, as trustee, including the form of the Notes and the Guarantee (incorporated by reference to Exhibit 4.2 of Form 8-K filed on September 22, 2021). | | |
| [22.1](https://www.sec.gov/Archives/edgar/data/1289490/000162828022004274/q4202110kex221.htm) | | | | | | Issuer and Guarantors of Guaranteed Securities(2) | | |
| | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Exhibit Number | | | | | | Description | | |
Item 16. Form 10K Summary
11 rewritten, 1 added, 0 removed, 31 unchanged
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ JOSEPH D. MARGOLIS | | |
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ P. SCOTT STUBBS | | |
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ GRACE KUNDE | | |
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ KENNETH M. WOOLLEY | | |
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ JOSEPH J. BONNER | | |
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ GARY CRITTENDEN | | |
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ SPENCER F. KIRK | | |
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ DENNIS LETHAM | | |
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ DIANE OLMSTEAD | | |
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ ROGER B. PORTER | | |
| Date: February [removed: 26, 2021] [added: 28, 2022] | | | | | | By: | | | | | | /s/ JULIA VANDER PLOEG | | |
| Date: February 28, 2022 | | | | | | By: | | | | | | /s/ JOSEPH D. MARGOLIS | | |