 filings.tools
Ford Motor 10-K 2023-12-31
Filed 2024-02-07. 25 sections, 794K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, DC 20549
FORM 10-K
☑ Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
For the fiscal year ended December 31, 2023
or
☐ Transition report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
For the transition period from __________ to __________
Commission file number 1-3950
Ford Motor Company
(Exact name of Registrant as specified in its charter)
| Delaware | 38-0549190 | ||||||||||
| (State of incorporation) | (I.R.S. Employer Identification No.) | ||||||||||
| One American Road | |||||||||||
| Dearborn, | Michigan | 48126 | |||||||||
| (Address of principal executive offices) | (Zip Code) |
313-322-3000
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading symbols | Name of each exchange on which registered | ||||||||||||
| Common Stock, par value $.01 per share | F | New York Stock Exchange | ||||||||||||
| 6.200% Notes due June 1, 2059 | FPRB | New York Stock Exchange | ||||||||||||
| 6.000% Notes due December 1, 2059 | FPRC | New York Stock Exchange | ||||||||||||
| 6.500% Notes due August 15, 2062 | FPRD | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None.
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☑ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☑
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☑ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☑ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
Large accelerated filer ☑ Accelerated filer ☐ Non-accelerated filer ☐ Smaller reporting company ☐
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☑
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements. ☐
Indicate by check mark whether any of those error corrections are restatements that required recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b). ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐ No ☑
As of June 30, 2023, Ford had outstanding 3,931,183,222 shares of Common Stock and 70,852,076 shares of Class B Stock. Based on the New York Stock Exchange Composite Transaction closing price of the Common Stock on that date ($15.13 per share), the aggregate market value of such Common Stock was $59,478,802,149. Although there is no quoted market for our Class B Stock, shares of Class B Stock may be converted at any time into an equal number of shares of Common Stock for the purpose of effecting the sale or other disposition of such shares of Common Stock. The shares of Common Stock and Class B Stock outstanding at June 30, 2023 included shares owned by persons who may be deemed to be “affiliates” of Ford. We do not believe, however, that any such person should be considered to be an affiliate. For information concerning ownership of outstanding Common Stock and Class B Stock, see the Proxy Statement for Ford’s Annual Meeting of Stockholders currently scheduled to be held on May 9, 2024 (our “Proxy Statement”), which is incorporated by reference under various Items of this Report as indicated below.
As of February 2, 2024, Ford had outstanding 3,902,781,032 shares of Common Stock and 70,852,076 shares of Class B Stock. Based on the New York Stock Exchange Composite Transaction closing price of the Common Stock on that date ($12.14 per share), the aggregate market value of such Common Stock was $47,379,761,728.
DOCUMENTS INCORPORATED BY REFERENCE
| Document | Where Incorporated | |||||||
| Proxy Statement* | Part III (Items 10, 11, 12, 13, and 14) |
- As stated under various Items of this Report, only certain specified portions of such document are incorporated by reference in this Report.
Exhibit Index begins on page 98
FORD MOTOR COMPANY
ANNUAL REPORT ON FORM 10-K
For the Year Ended December 31, 2023
| Table of Contents | Page | ||||||||||
| Part I | |||||||||||
| Item 1 | Business | 1 | |||||||||
| Overview | 2 | ||||||||||
| Ford Blue, Ford Model e, and Ford Pro Segment | 2 | ||||||||||
| Ford Next Segment | 6 | ||||||||||
| Ford Credit Segment | 7 | ||||||||||
| Corporate Other | 8 | ||||||||||
| Interest on Debt | 8 | ||||||||||
| Governmental Standards | 8 | ||||||||||
| Human Capital Resources | 14 | ||||||||||
| Item 1A | Risk Factors | 17 | |||||||||
| Item 1B | Unresolved Staff Comments | 30 | |||||||||
| Item 1C | Cybersecurity | 31 | |||||||||
| Item 2 | Properties | 33 | |||||||||
| Item 3 | Legal Proceedings | 34 | |||||||||
| Item 4 | Mine Safety Disclosures | 36 | |||||||||
| Item 4A | Information about our Executive Officers | 37 | |||||||||
| Part II | |||||||||||
| Item 5 | Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities | 38 | |||||||||
| Item 6 | [Reserved] | 39 | |||||||||
| Item 7 | Management’s Discussion and Analysis of Financial Condition and Results of Operations | 40 | |||||||||
| Key Trends and Economic Factors Affecting Ford and the Automotive Industry | 40 | ||||||||||
| Results of Operations - 2023 | 43 | ||||||||||
| Ford Blue Segment | 45 | ||||||||||
| Ford Model e Segment | 46 | ||||||||||
| Ford Pro Segment | 46 | ||||||||||
| Ford Next Segment | 48 | ||||||||||
| Ford Credit Segment | 49 | ||||||||||
| Corporate Other | 52 | ||||||||||
| Interest on Debt | 52 | ||||||||||
| Taxes | 52 | ||||||||||
| Results of Operations - 2022 | 53 | ||||||||||
| Ford Blue Segment | 55 | ||||||||||
| Ford Model e Segment | 56 | ||||||||||
| Ford Pro Segment | 56 | ||||||||||
| Ford Next Segment | 57 | ||||||||||
| Ford Credit Segment | 57 | ||||||||||
| Corporate Other | 58 | ||||||||||
| Interest on Debt | 58 | ||||||||||
| Taxes | 58 | ||||||||||
| Liquidity and Capital Resources | 59 | ||||||||||
| Credit Ratings | 71 | ||||||||||
| Outlook | 72 | ||||||||||
| Cautionary Note on Forward-Looking Statements | 73 | ||||||||||
| Non-GAAP Financial Measures That Supplement GAAP Measures | 75 |
Table of Contents
(continued)
| Non-GAAP Financial Measure Reconciliations | 77 | ||||||||||
| 2023 Supplemental Financial Information | 79 | ||||||||||
| Critical Accounting Estimates | 83 | ||||||||||
| Accounting Standards Issued But Not Yet Adopted | 90 | ||||||||||
| Item 7A | Quantitative and Qualitative Disclosures About Market Risk | 91 | |||||||||
| Item 8 | Financial Statements and Supplementary Data | 94 | |||||||||
| Item 9 | Changes in and Disagreements with Accountants on Accounting and Financial Disclosure | 94 | |||||||||
| Item 9A | Controls and Procedures | 95 | |||||||||
| Item 9B | Other Information | 95 | |||||||||
| Item 9C | Disclosure Regarding Foreign Jurisdictions that Prevent Inspections | 95 | |||||||||
| Part III | |||||||||||
| Item 10 | Directors, Executive Officers of Ford, and Corporate Governance | 96 | |||||||||
| Item 11 | Executive Compensation | 96 | |||||||||
| Item 12 | Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters | 96 | |||||||||
| Item 13 | Certain Relationships and Related Transactions, and Director Independence | 96 | |||||||||
| Item 14 | Principal Accounting Fees and Services | 96 | |||||||||
| Part IV | |||||||||||
| Item 15 | Exhibits and Financial Statement Schedules | 97 | |||||||||
| Item 16 | Form 10-K Summary | 102 | |||||||||
| Signatures | 103 | ||||||||||
| Ford Motor Company and Subsidiaries Financial Statements | |||||||||||
| Report of Independent Registered Public Accounting Firm | 105 | ||||||||||
| Consolidated Statements of Cash Flows | 108 | ||||||||||
| Consolidated Income Statements | 109 | ||||||||||
| Consolidated Statements of Comprehensive Income | 109 | ||||||||||
| Consolidated Balance Sheets | 110 | ||||||||||
| Consolidated Statements of Equity | 111 | ||||||||||
| Notes to the Financial Statements | 112 | ||||||||||
| Schedule II — Valuation and Qualifying Accounts | 179 |
PART I.
ITEM 1. Business.
Ford Motor Company was incorporated in Delaware in 1919. We acquired the business of a Michigan company, also known as Ford Motor Company, which had been incorporated in 1903 to produce and sell automobiles designed and engineered by Henry Ford. We are a global company based in Dearborn, Michigan. With about 177,000 employees worldwide, the Company is committed to helping build a better world, where every person is free to move and pursue their dreams. The Company’s Ford+ plan for growth and value creation combines existing strengths, new capabilities, and always-on relationships with customers to enrich experiences for customers and deepen their loyalty. Ford develops and delivers innovative, must-have Ford trucks, sport utility vehicles, commercial vans and cars, and Lincoln luxury vehicles, along with connected services. The Company does that through three customer-centered business segments: Ford Blue, engineering iconic gas-powered and hybrid vehicles; Ford Model e, inventing breakthrough electric vehicles (“EVs”) along with embedded software that defines always-on digital experiences for all customers; and Ford Pro, helping commercial customers transform and expand their businesses with vehicles and services tailored to their needs. Additionally, the Company provides financial services through Ford Motor Credit Company LLC (“Ford Credit”).
In addition to the information about Ford and our subsidiaries contained in this Annual Report on Form 10-K for the year ended December 31, 2023 (“2023 Form 10-K Report” or “Report”), extensive information about our Company can be found at http://corporate.ford.com, including information about our management team, brands, products, services, and corporate governance principles.
The corporate governance information on our website includes our Corporate Governance Principles, Code of Ethics for Senior Financial Personnel, Code of Ethics for the Board of Directors, Code of Corporate Conduct for all employees, and the Charters for each of the Committees of our Board of Directors. In addition, any amendments to our Code of Ethics or waivers granted to our directors and executive officers will be posted on our corporate website. All of these documents may be accessed by going to our corporate website, or may be obtained free of charge by writing to our Shareholder Relations Department, Ford Motor Company, One American Road, P.O. Box 1899, Dearborn, Michigan 48126-1899.
Our recent periodic reports filed with the Securities and Exchange Commission (“SEC”) pursuant to Section 13(a) or 15(d) of the Securities Exchange Act of 1934, as amended, are available free of charge at http://shareholder.ford.com. This includes recent Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q, and Current Reports on Form 8-K, as well as any amendments to those reports, and our Section 16 filings. We post each of these documents on our website as soon as reasonably practicable after it is electronically filed with the SEC. Our reports filed with the SEC also may be found on the SEC’s website at www.sec.gov.
Our Integrated Sustainability and Financial Report, which details our performance and progress toward our sustainability and corporate responsibility goals, is available at http://sustainability.ford.com.
The foregoing information regarding our website and its content is for convenience only and not deemed to be incorporated by reference into this Report nor filed with the SEC.
Item 1. Business (Continued)
OVERVIEW
On January 1, 2023, we implemented a new operating model and reporting structure. As a result of this change, we analyze the results of our business through the following segments: Ford Blue, Ford Model e, and Ford Pro (combined, replacing the previous Automotive segment); Ford Next (previously the Mobility segment); and Ford Credit. Company adjusted earnings before interest and taxes (“EBIT”) includes the financial results of these five reportable segments and Corporate Other, and net income comprises the financial results of the five reportable segments and Corporate Other, as well as Interest on Debt, Special Items, and Taxes.
Below is a description of our reportable segments and other activities as of December 31, 2023.
FORD BLUE SEGMENT
Ford Blue primarily includes the sale of Ford and Lincoln internal combustion engine (“ICE”) and hybrid vehicles, service parts, accessories, and digital services for retail customers, together with the associated costs of development, manufacture, and distribution of the vehicles, parts, accessories, and services. This segment focuses on developing Ford and Lincoln ICE and hybrid vehicles. Additionally, this segment provides hardware engineering and manufacturing capabilities to Ford Model e and manufactures vehicles on behalf of Ford Pro and, in certain cases, Ford Model e. Ford Blue also includes:
-
All sales for markets not presently in scope for Ford Model e or Ford Pro (as further described below)
-
In markets outside of the United States and Canada, sales to commercial, government, and rental customers of ICE and hybrid vehicles not considered core to Ford Pro
-
Sales of electric vehicles (“EVs”) by our unconsolidated affiliates in China
-
All sales of vehicles manufactured and sold to other OEMs
FORD MODEL E SEGMENT
Ford Model e primarily includes the sale of our electric vehicles, service parts, accessories, and digital services for retail customers, together with the associated costs of development, manufacture, and distribution of the vehicles, parts, accessories, and services. This segment focuses on developing EV and digital vehicle technologies, as well as software development. Additionally, Ford Model e provides software and connected vehicle technologies on behalf of the enterprise, and manufactures certain EVs, including for Ford Pro. Ford Model e operates in North America, Europe, and China. Ford Model e also includes EV and related sales not considered core to Ford Pro to commercial, government, and rental customers in Europe, China, and Mexico.
FORD PRO SEGMENT
Ford Pro primarily includes the sale of Ford and Lincoln vehicles, service parts, accessories, and services for commercial, government, and rental customers. Included in this segment are sales of all core Ford Pro vehicles, such as Super Duty and the Transit range of vans in North America and Europe and all sales of Ranger in Europe. In the United States and Canada, Ford Pro also includes all vehicle sales to commercial, government, and rental customers. This segment focuses on selling ICE, hybrid, and electric vehicles, and providing digital and physical services to optimize and maintain fleets, including telematics and EV charging solutions. This segment reflects external sales of vehicles produced by Ford Blue and Ford Model e and the costs (including intersegment markup) associated with acquiring vehicles for sale and providing services. Ford Pro operates in North America and Europe.
General
Our vehicle brands are Ford and Lincoln. In 2023, we sold approximately 4,413,000 vehicles at wholesale throughout the world. See “Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations” (“Item 7”) for a discussion of our calculation of wholesale unit volumes.
Item 1. Business (Continued)
Substantially all of our vehicles, parts, and accessories are sold through distributors and dealers (collectively, “dealerships”), the substantial majority of which are independently owned. At December 31, the approximate number of dealerships worldwide distributing our vehicle brands was as follows:
| Brand | 2022 | 2023 | |||||||||
| Ford | 8,596 | 8,639 | |||||||||
| Ford-Lincoln (combined) | 607 | 503 | |||||||||
| Lincoln | 408 | 385 | |||||||||
| Total | 9,611 | 9,527 |
We do not depend on any single customer or a few customers to the extent that the loss of such customers would have a material adverse effect on our business.
In addition to the products we sell to our dealerships for retail sale, we also sell vehicles to our dealerships for sale to fleet customers, including commercial fleet customers, daily rental car companies, and governments. We also sell parts and accessories, primarily to our dealerships (which, in turn, sell these products to retail customers) and to authorized parts distributors (which, in turn, primarily sell these products to retailers). We also offer extended service contracts.
The worldwide automotive industry is affected significantly by general economic and political conditions over which we have little control. Vehicles are durable goods, and consumers and businesses have latitude in determining whether and when to replace an existing vehicle. The decision whether to purchase a vehicle may be affected significantly by slowing economic growth, geopolitical events, and other factors (including the cost of purchasing and operating cars, trucks, and utility vehicles, the availability and cost of financing, cost of fuel, and electric vehicle charging availability and cost). As a result, the number of cars, trucks, and utility vehicles sold may vary substantially from year to year. Further, the automotive industry is a highly competitive business that has a wide and growing variety of product and service offerings from a growing number of manufacturers.
Our wholesale unit volumes vary with the level of total industry demand and our share of that industry demand. Our wholesale unit volumes also are influenced by the level of dealer inventory, and our ability to maintain sufficient production levels to support desired dealer inventory in the event of supplier disruptions or other types of disruptions affecting our production. Our share is influenced by how our products are perceived by customers in comparison to those offered by other manufacturers based on many factors, including price, quality, styling, reliability, safety, fuel efficiency, functionality, sustainability, and reputation. Our share also is affected by the timing and frequency of new model introductions. Our ability to satisfy changing consumer and business preferences with respect to type or size of vehicle, as well as design and performance characteristics and the services our vehicles offer, affects our sales and earnings significantly.
As with other manufacturers, the profitability of our business is affected by many factors, including:
-
Wholesale unit volumes
-
Margin of profit on each vehicle sold - which, in turn, is affected by many factors, such as:
◦Market factors - volume and mix of vehicles and options sold, and net pricing (reflecting, among other factors, incentive programs)
◦Costs of components and raw materials necessary for production of vehicles
◦Costs for customer warranty claims and additional service actions
◦Costs for safety, emissions, and fuel economy technology and equipment
- A high proportion of relatively fixed structural costs, so that small changes in wholesale unit volumes can significantly affect overall profitability
Although supply disruptions have resulted in near-term upward pressure on new vehicle prices, our industry has historically had a very competitive pricing environment, driven in part by excess capacity. For the past several decades, manufacturers typically have offered price discounts and other marketing incentives to provide value for customers and maintain market share and production levels, and we saw some of these actions resume in 2023 with more expected in 2024 as industry production and inventories improve. The decline in value of foreign currencies can also contribute significantly to competitive pressures in many of our markets.
Competitive Position. The worldwide automotive industry consists of many producers, with no single dominant producer. Certain manufacturers, however, account for the major percentage of total sales within particular countries, especially their countries of origin.
Item 1. Business (Continued)
Seasonality. We manage our vehicle production schedule based on a number of factors, including retail sales (i.e., units sold by our dealerships to their customers at retail) and dealer stock levels (i.e., the number of units held in inventory by our dealerships for sale to their customers). Historically, we have experienced some seasonal fluctuation in the business, with production in many markets tending to be higher in the first half of the year to meet demand in the spring and summer (typically the strongest sales months of the year).
Raw Materials. We purchase a wide variety of raw materials from numerous suppliers around the world for use in the production of, and development of technologies in, our vehicles. These materials include base metals (e.g., steel and aluminum), precious metals (e.g., palladium), energy (e.g., natural gas), and plastics/resins (e.g., polypropylene). As we transition to a greater mix of electric vehicles, we expect to increase our reliance on lithium, cobalt, nickel, graphite, and manganese, among other materials, for batteries. We expect to have adequate supplies or sources of availability of raw materials necessary to meet our needs; however, there always are risks and uncertainties with respect to the supply of raw materials that could impact availability in sufficient quantities and at cost effective prices to meet our needs. See “Item 1A. Risk Factors” for a discussion of the risks associated with a shortage of components or raw materials, supplier disruptions, and inflationary pressures, the “Key Trends and Economic Factors Affecting Ford and the Automotive Industry” section of Item 7 for a discussion of supplier disruptions, as well as commodity and energy price changes, and “Item 7A. Quantitative and Qualitative Disclosures about Market Risk” (“Item 7A”) for a discussion of commodity price risks.
Intellectual Property. We own or hold licenses to use numerous patents, trade secrets, copyrights, and trademarks on a global basis. We expect to continue building this portfolio as we actively pursue innovation in every part of our business. We also own numerous trademarks and service marks that contribute to the identity and recognition of our Company and its products and services globally. While our intellectual property rights in the aggregate are important to the operation of each of our businesses, we do not believe that our business would be materially affected by the expiration of any particular intellectual property right or termination of any particular intellectual property agreement.
Warranty Coverage, Field Service Actions, and Customer Satisfaction Actions. We provide warranties on vehicles we sell. Warranties are offered for specific periods of time and/or mileage and vary depending upon the type of product and the geographic location of its sale. Pursuant to these warranties, we will repair, replace, or adjust parts on a vehicle that are defective in factory-supplied materials or workmanship during the specified warranty period. In addition to the costs associated with this warranty coverage provided on our vehicles, we also incur costs as a result of field service actions (i.e., safety recalls, emission recalls, and other product campaigns) and for customer satisfaction actions.
For additional information regarding warranty and related costs, see “Critical Accounting Estimates” in Item 7 and Note 25 of the Notes to the Financial Statements.
Item 1. Business (Continued)
Wholesales
Wholesales consist primarily of vehicles sold to dealerships. For the majority of such sales, we recognize revenue when we ship the vehicles to our dealerships from our manufacturing facilities. See Item 7 for additional discussion of revenue recognition practices. Wholesales in certain key markets during the past three years were as follows:
| Wholesales (a) | |||||||||||||||||
| (in thousands of units) | |||||||||||||||||
| 2021 | 2022 | 2023 | |||||||||||||||
| United States | 1,716 | 2,012 | 2,097 | ||||||||||||||
| China (b) | 649 | 495 | 467 | ||||||||||||||
| Canada | 233 | 258 | 260 | ||||||||||||||
| United Kingdom | 227 | 263 | 243 | ||||||||||||||
| Germany | 152 | 182 | 162 | ||||||||||||||
| Türkiye | 72 | 85 | 124 | ||||||||||||||
| Italy (c) | 93 | 107 | 122 | ||||||||||||||
| France (c) | 77 | 90 | 104 | ||||||||||||||
| Other Markets | 723 | 739 | 834 | ||||||||||||||
| Total Company | 3,942 | 4,231 | 4,413 |
(a)Wholesale unit volumes include sales of medium and heavy trucks. Wholesale unit volumes also include all Ford and Lincoln badged units (whether produced by Ford or by an unconsolidated affiliate) that are sold to dealerships or others, units manufactured by Ford that are sold to other manufacturers, units distributed by Ford for other manufacturers, local brand units produced by our unconsolidated Chinese joint venture Jiangling Motors Corporation, Ltd. (“JMC”) that are sold to dealerships or others, and from the second quarter of 2021, Ford badged vehicles produced in Taiwan by Lio Ho Group. Vehicles sold to daily rental car companies that are subject to a guaranteed repurchase option (i.e., rental repurchase), as well as other sales of finished vehicles for which the recognition of revenue is deferred (e.g., consignments), also are included in wholesale unit volumes. Revenue from certain vehicles in wholesale unit volumes (specifically, Ford badged vehicles produced and distributed by our unconsolidated affiliates, as well as JMC brand vehicles) are not included in our revenue.
(b)China includes Taiwan.
(c)Not previously presented.
Sales, Industry Volume, and Market Share
Sales, industry volume, and market share in certain key markets during the past three years were as follows:
| Sales (a) | Industry Volume (b) | Market Share (c) | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (in millions of units) | (in millions of units) | (as a percentage) | |||||||||||||||||||||||||||||||||||||||||||||||||||
| 2021 | 2022 | 2023 | 2021 | 2022 | 2023 | 2021 | 2022 | 2023 | |||||||||||||||||||||||||||||||||||||||||||||
| United States | 1.9 | 1.9 | 2.0 | 15.4 | 14.2 | 16.1 | 12.4 | % | 13.1 | % | 12.4 | % | |||||||||||||||||||||||||||||||||||||||||
| China (d) | 0.6 | 0.5 | 0.5 | 26.3 | 23.9 | 25.1 | 2.4 | 2.1 | 1.8 | ||||||||||||||||||||||||||||||||||||||||||||
| Canada | 0.2 | 0.2 | 0.2 | 1.7 | 1.6 | 1.8 | 14.3 | 15.2 | 13.7 | ||||||||||||||||||||||||||||||||||||||||||||
| United Kingdom | 0.2 | 0.2 | 0.2 | 2.0 | 1.9 | 2.3 | 11.8 | 12.1 | 10.8 | ||||||||||||||||||||||||||||||||||||||||||||
| Germany | 0.2 | 0.2 | 0.2 | 3.0 | 3.0 | 3.2 | 5.7 | 5.7 | 5.1 | ||||||||||||||||||||||||||||||||||||||||||||
| Türkiye | 0.1 | 0.1 | 0.1 | 0.8 | 0.8 | 1.3 | 9.7 | 10.5 | 8.9 | ||||||||||||||||||||||||||||||||||||||||||||
| Italy (e) | 0.1 | 0.1 | 0.1 | 1.7 | 1.5 | 1.8 | 6.2 | 6.4 | 6.1 | ||||||||||||||||||||||||||||||||||||||||||||
| France (e) | 0.1 | 0.1 | 0.1 | 2.1 | 2.0 | 2.3 | 3.4 | 3.9 | 3.9 |
(a)Represents primarily sales by dealers, sales to the government, and leases to Ford management, and is based, in part, on estimated vehicle registrations; includes medium and heavy trucks.
(b)Industry volume is an internal estimate based on publicly available data collected from various government, private, and public sources around the globe; includes medium and heavy trucks.
(c)Market share represents reported retail sales of our brands as a percent of total industry volume in the relevant market or region.
(d)China includes Taiwan; China market share includes Ford brand and JMC brand vehicles produced and sold by our unconsolidated affiliates.
(e)Not previously presented.
Item 1. Business (Continued)
U.S. Sales by Type
The following table shows U.S. sales volume and U.S. wholesales (consisting primarily of vehicles sold to dealerships) segregated by electric, hybrid, and internal combustion vehicles. U.S. sales volume represents primarily sales by dealers, sales to the government, and leases to Ford management, and is based, in part, on estimated vehicle registrations and includes medium and heavy trucks.
| U.S. Sales | U.S. Wholesales | ||||||||||||||||||||||
| 2022 | 2023 | 2022 | 2023 | ||||||||||||||||||||
| Electric Vehicles | 61,575 | 72,608 | 71,418 | 99,928 | |||||||||||||||||||
| Hybrid Vehicles | 106,705 | 133,743 | 101,662 | 146,249 | |||||||||||||||||||
| Internal Combustion Vehicles | 1,696,184 | 1,789,561 | 1,839,265 | 1,850,448 | |||||||||||||||||||
| Total Vehicles | 1,864,464 | 1,995,912 | 2,012,345 | 2,096,625 |
FORD NEXT SEGMENT
The Ford Next segment (formerly the Mobility segment) primarily includes expenses and investments for emerging business initiatives aimed at creating value for Ford in vehicle-adjacent market segments.
Item 1. Business (Continued)
**FO
Showing the first 8K of 63K characters. Open the full section
Item 1A. Risk Factors (Continued)
Unlike our historical arrangements with suppliers, under multi-year offtake agreements and other long-term purchase contracts, the risks associated with lower-than-expected electric vehicle production volumes or changes in battery technology that reduce the need for certain raw materials, batteries, or their components are borne by Ford rather than our suppliers. In the event we do not purchase the materials or components pursuant to the terms of these agreements, we may be obligated to reimburse the supplier for costs it incurs. We have incurred and we may continue to incur such charges. This may be the case even if the supplier finds another purchaser, as we may be responsible for the costs of finding the new purchaser as well as any lost revenue attributable to the replacement purchaser paying a lower price than required under the pricing mechanism in our agreement.
As a result of the competition for and limited availability of the raw materials needed for our electric vehicle business, the costs of such materials are difficult to accurately forecast as they may fluctuate during the term of the offtake agreements and other long-term purchase contracts based on market conditions. Accordingly, we may be subject to increases in the prices we pay for those raw materials, and our ability to recoup such costs through increased pricing to our customers may be limited. As a result, our margins, results of operations, financial condition, and reputation may be adversely impacted by commitments we make pursuant to offtake agreements and other long-term purchase contracts.
Ford’s long-term competitiveness depends on the successful execution of Ford+. We previously announced our plan for growth and value creation – Ford+. Ford+ is focused on delivering distinctive and increasingly electric products plus “Always-On” customer relationships and user experiences. Our Ford+ plan is designed to leverage our foundational strengths to build new capabilities – enriching customer experiences and deepening loyalty. As we undertake this transformation of our business, we must integrate our strategic initiatives into a cohesive business model, and balance competing priorities, or we will not be successful. To facilitate this transformation, we are making substantial investments, recruiting new talent, and optimizing our business model, management system, and organization. Accordingly, maintaining discipline in our capital allocation continues to be important, as a strong core business and a balance sheet that provides the flexibility to invest in these new growth opportunities is critical to the success of our Ford+ plan. If we are unable to optimize our capital allocation among vehicles, services, technology, and other calls on capital, make sufficient progress to become competitive on cost and quality, or we are otherwise not successful in executing Ford+ (or are delayed for reasons outside of our control), we may not be able to realize the full benefits of our plan, which could have an adverse effect on our financial condition or results of operations. Furthermore, if we fail to make progress on our plan at the pace that shareholders expect, it may lead to an increase in shareholder activism, which may disrupt the conduct of our business and divert management’s attention and resources.
Ford’s vehicles could be affected by defects that result in recall campaigns, increased warranty costs, or delays in new model launches, and the time it takes to improve the quality of our vehicles and services could continue to have an adverse effect on our business. Government safety standards require manufacturers to remedy defects related to vehicle safety through safety recall campaigns, and a manufacturer is obligated to recall vehicles if it determines that the vehicles do not comply with a safety standard. We may also be obligated to remedy defects or potentially recall our vehicles due to defective components provided to us by our suppliers, arising from their quality issues or otherwise. NHTSA’s enforcement strategy has resulted in significant civil penalties being levied and the use of consent orders requiring direct oversight by NHTSA of certain manufacturers’ safety processes, a trend that could continue. Should we or government safety regulators determine that a safety or other defect or a noncompliance exists with respect to certain of our vehicles prior to the start of production, the launch of such vehicle could be delayed until such defect is remedied. The cost of recall and customer satisfaction actions to remedy defects in vehicles that have been sold could be substantial, particularly if the actions relate to global platforms or involve defects that are identified years after production. For example, NHTSA and the automotive industry are currently engaged in a study of the safety of approximately 56 million Takata desiccated airbag inflators in the United States. Of these, approximately three and a half million of the inflators are in our vehicles. In addition, NHTSA is considering action related to 52 million vehicles containing inflators from ARC Automotive and Delphi Automotive in the United States. Ford has 2.5 million vehicles within this population. Should NHTSA determine that these inflators contain a safety defect, Ford and other manufacturers could potentially face significant incremental recall costs. Further, to the extent recall and customer satisfaction actions relate to defective components we receive from suppliers, our ability to recover from the suppliers may be limited by the suppliers’ financial condition. We accrue the estimated cost of both base warranty coverages and field service actions at the time a vehicle is sold, and we reevaluate the adequacy of our accruals on a regular basis. In addition, from time to time, we issue extended warranties at our expense, the estimated cost of which is accrued at the time of issuance. For additional information regarding warranty and field service action costs, including our process for establishing our reserves, see “Critical Accounting Estimates” in Item 7 and Note 25 of the Notes to the Financial Statements. If warranty costs are greater than anticipated as a result of increased vehicle and component complexity, the adoption of new technologies, the time it takes to improve the quality of our products and services (or if such efforts are unsuccessful), or otherwise (including as a result of higher repair costs driven by inflation or other economic factors), such costs could continue to have an adverse effect on our financial condition or results of operations. Furthermore, launch delays, recall actions, and
Item 1A. Risk Factors (Continued)
increased warranty costs have adversely affected and could continue to adversely affect our reputation or the public perception and market acceptance of our products and services as discussed below under “Ford’s new and existing products and digital, software, and physical services are subject to market acceptance and face significant competition from existing and new entrants in the automotive and digital and software services industries, and its reputation may be harmed if it is unable to achieve the initiatives it has announced.” In an effort to improve quality, we have slowed down and may continue to slow down launches, which may result in lost sales, revenue, and profits and could have an adverse effect on our financial condition or results of operations. In addition, as a result of vehicles on hold for quality control, our inventory levels may be higher.
Ford may not realize the anticipated benefits of existing or pending strategic alliances, joint ventures, acquisitions, divestitures, or business strategies. We have invested in, formed strategic alliances with, and announced or formed joint ventures with a number of companies, and we may expand those relationships or enter into similar relationships with additional companies. These initi
Showing the first 8K of 71K characters. Open the full section
Item 1B. Unresolved Staff Comments.
None.
Item 1C. Cybersecurity.
While no organization can eliminate cybersecurity risk entirely, we devote significant resources to our security program that we believe is reasonably designed to mitigate our cybersecurity and information technology risk. Our efforts focus on protecting and enhancing the security of our information systems, software, networks, and other assets. These efforts are designed to protect against, and mitigate the effects of, among other things, cybersecurity incidents where unauthorized parties attempt to access confidential, sensitive, or personal information; potentially hold such information for ransom; destroy data; disrupt or degrade service or our operations; sabotage systems; or otherwise cause harm to the Company, our customers, suppliers, or dealers, or other key stakeholders. We employ capabilities, processes, and other security measures we believe are designed to reduce and mitigate these risks, and have requirements for our suppliers to do the same. Despite having thorough due diligence, onboarding, and cybersecurity assessment processes in place for our suppliers, the responsibility ultimately rests with our suppliers to establish and uphold their respective cybersecurity programs. Our ability to monitor the cybersecurity practices of our suppliers is limited and there can be no assurance that we can prevent or mitigate the risk of any compromise or failure in the information systems, software, networks, and other assets owned or controlled by our suppliers. When we become aware that a supplier’s cybersecurity has been compromised, we attempt to mitigate the risk to the Company, including, if appropriate and feasible, by terminating the supplier’s connection to our information systems. Notwithstanding our efforts to mitigate any such risk, there can be no assurance that the compromise or failure of supplier information systems, technology assets, or cybersecurity programs would not have an adverse effect on the security of the Company’s information systems.
In an effort to effectively prevent, detect, and respond to cybersecurity threats, we employ a multi-layered cybersecurity risk management program supervised by our Chief Information Security Officer, whose team is responsible for leading enterprise-wide cybersecurity strategy, policy, architecture, and processes. This responsibility includes identifying, considering, and assessing potentially material cybersecurity incidents on an ongoing basis, establishing processes designed to prevent and monitor potential cybersecurity risks, implementing mitigation and remedial measures, and maintaining our cybersecurity program. To do so, our program leverages both internal and external techniques and expertise. Internally, among other things, we perform penetration tests, internal tests/code reviews, and simulations using cybersecurity professionals (often referred to as “white hat hackers” or a “Red Team”), to assess vulnerabilities in our information systems and evaluate our cyber defense capabilities. We also perform phishing and social engineering simulations with, and provide cybersecurity training for, personnel with Company email and access to Company assets. On a monthly basis, we disseminate security awareness newsletters to employees to highlight emerging or urgent cybersecurity threats and best practices. Externally, we monitor notifications from the U.S. Computer Emergency Readiness Team (“CERT”) and various Information Sharing and Analysis Centers (each an “ISAC”); review customer, media, and third-party cybersecurity reports; and offer bounties to responsible third-parties who notify us of vulnerabilities they are able to detect in our cyber defenses (commonly referred to as a “Bug Bounty”). Our capabilities, processes, and other security measures also include, without limitation:
-
Security Information and Event Management (“SIEM”) software, which provides a threat detection, compliance, and security incident management system;
-
Endpoint Detection and Response (“EDR”) software, which monitors for malicious activities on external-facing endpoints (e.g., Windows workstations, servers, MAC clients, and Linux endpoints);
-
Cloud monitoring, running on primary public and private cloud environments; and
-
Disaster recovery and incident response plans, including a ransomware response plan.
We invest in enhancing our cybersecurity capabilities and strengthening our partnerships with appropriate business partners, service partners, and government and law enforcement agencies to understand the range of cybersecurity risks in the operating environment, enhance defenses, and improve resiliency against cybersecurity threats. Additionally, we are a member of the Financial Services and Information Technology ISACs and both a founding member and board member of the Automotive ISAC. Our membership with these industry cybersecurity groups assists in our efforts to protect the Company against both enterprise and in-vehicle security risks.
The Company’s global cybersecurity incident response is overseen by our Chief Information Security Officer. Our Chief Information Security Officer has served in that role for over 6 years and has over a decade of engineering and operations expertise with cybersecurity technologies and services. Our Chief Information Security Officer reports to our Chief Enterprise Technology Officer who has spent over two decades leading digital and technology organizations at both enterprise software companies and Fortune 50 enterprises. Our Chief Enterprise Technology Officer reports directly to the Chief Executive Officer.
ITEM 1C. Cybersecurity (Continued)
When a cybersecurity threat or incident is identified, our policy is to review and triage the threat or incident, and to then manage it to conclusion in accordance with our cybersecurity incident response processes. When a cybersecurity incident is determined to be significant, it is addressed by management committees using processes that leverage subject-matter expertise from across the Company. Further, we may engage third-party advisors, from time to time, as part of our incident management processes. All cybersecurity incidents that are identified as reasonably having the potential to be highly significant to the Company are brought to the attention of both the Chief Enterprise Technology Officer and General Counsel by the Chief Information Security Officer as part of our cybersecurity incident response processes.
Cybersecurity risk management is an integral part of our overall enterprise risk management program. As part of its enterprise risk management efforts, the Board meets with senior management, including the executive leadership team, to assess and respond to critical business risks. Critical enterprise risks are assessed by senior management annually and discussed with the Board. Once identified, each of the risks we view as most significant is assigned an executive risk owner who is responsible to oversee risk assessment, develop and implement mitigation plans, and provide regular updates to the Board (and/or Board committee assigned to the risk). Cybersecurity threats have been and continue to be identified as one of the Company’s top risks, with our Chief Enterprise Technology Officer and Chief Information Security Officer assigned as the executive risk owners. The Board has delegated primary responsibility for the oversight of cybersecurity and information technology risks, and the Company’s preparedness for these risks, to the Audit Committee.
As part of its oversight responsibilities, the Audit Committee receives regular updates on our cybersecurity practices as well as cybersecurity and information technology risks from our Chief Information Security Officer. These regular updates include topics related to cybersecurity practices, cyber risks, and risk management processes, such as updates to our cybersecurity programs and mitigation strategies, and other cybersecurity developments. In addition to these regular updates, as part of our incident response processes, the Chief Enterprise Technology Officer, in collaboration with the Chief Information Security Officer and General Counsel, provides updates on certain cybersecurity incidents to the Audit Committee and, in some cases, the Board. The Audit Committee reviews and provides input into and oversight of our cybersecurity processes, and in the event Ford determines it has experienced a material cybersecurity incident, the Audit Committee is notified about the incident in advance of filing a Current Report on Form 8-K.
In 2023, we did not identify any cybersecurity threats that have materially affected or are reasonably likely to materially affect our business strategy, results of operations, or financial condition. However, despite the capabilities, processes, and other security measures we employ that we believe are designed to detect, reduce, and mitigate the risk of cybersecurity incidents, we may not be aware of all vulnerabilities or might not accurately assess the risks of incidents, and such preventative measures cannot provide absolute security and may not be sufficient in all circumstances or mitigate all potential risks. Moreover, we, our suppliers, and our dealers have been the target of cybersecurity incidents and such threats are continuing and evolving, which may cause cybersecurity incidents to be more difficult to detect for periods of time. Our networks and in-vehicle systems, sharing similar architectures, could also be impacted by, or a cybersecurity incident may result from, the negligence or misconduct of insiders or third parties who have access to our networks and systems. A cybersecurity incident could harm our reputation, cause customers to lose trust in our security measures, and/or subject us to regulatory actions or litigation, which may result in fines, penalties, judgments, or injunctions, and a cybersecurity incident involving us or one of our suppliers could impact our business strategy, results of operations, financial condition, or our reputation. For additional information, see “Operational information systems, security systems, vehicles, and services could be affected by cybersecurity incidents, ransomware attacks, and other disruptions and impact Ford and Ford Credit as well as their suppliers and dealers” on page 20.
Item 2. Properties.
Our principal properties include manufacturing and assembly facilities, distribution centers, warehouses, sales or administrative offices, and testing, prototype, and operations space.
We own substantially all of our U.S. manufacturing and assembly facilities. Our facilities are situated in various sections of the country and include assembly plants, engine plants, casting plants, metal stamping plants, transmission plants, and other component plants. Most of our distribution centers are leased (we own approximately 32% of the total square footage and lease the balance). The majority of the warehouses that we operate are leased, although many of our manufacturing and assembly facilities contain some warehousing space. Substantially all of our sales offices are leased space. Approximately 85% of the total square footage of our testing, prototype, and operations space is owned by us.
In addition, we maintain and operate manufacturing plants, assembly facilities, parts distribution centers, and engineering centers outside of the United States. We own substantially all of our non-U.S. manufacturing plants, assembly facilities, and engineering centers. The majority of our parts distribution centers outside of the United States are either leased or provided by vendors under service contracts.
We and the entities that we consolidated as of December 31, 2023 use over 300 operations facilities globally, including testing and prototype, across 24 countries, and 41 manufacturing and assembly plants, which includes plants that are operated by us or our consolidated joint venture that support our Ford Blue, Ford Model e, and Ford Pro segments.
We have one significant consolidated joint venture, which is in our Ford Blue segment:
*•*Ford Vietnam Limited — a joint venture between Ford (75% partner) and Diesel Song Cong One Member Limited Liability Company (a subsidiary of the Vietnam Engine and Agricultural Machinery Corporation, which in turn is majority owned (87.43%) by the State of Vietnam represented by the Ministry of Industry and Trade) (25% partner). Ford Vietnam Limited assembles and distributes a variety of Ford passenger and commercial vehicle models. The joint venture operates one plant in Vietnam.
In addition to the plants that we operate directly or that are operated by our consolidated joint venture, additional plants that support our Ford Blue, Ford Model e, and Ford Pro segments are operated by unconsolidated joint ventures of which we are a partner. The most significant of those unconsolidated joint ventures are as follows:
*•*AutoAlliance (Thailand) Co., Ltd. (“AAT”) — a 50/50 joint venture between Ford and Mazda that owns and operates a manufacturing plant in Rayong, Thailand. AAT produces Ford and Mazda products for domestic and export sales.
-
BlueOval SK, LLC — a 50/50 joint venture among Ford, SK On Co., Ltd., and SK Battery America, Inc. (a wholly owned subsidiary of SK On) that will build and operate electric vehicle battery plants in Tennessee and Kentucky to supply batteries to Ford and Ford affiliates.
-
Changan Ford Automobile Corporation, Ltd. (“CAF”) — a 50/50 joint venture between Ford and Chongqing Changan Automobile Co., Ltd. (“Changan”). CAF operates four assembly plants, an engine plant, and a transmission plant in China where it produces and distributes a variety of Ford passenger vehicle models.
-
Ford Otomotiv Sanayi Anonim Sirketi (“Ford Otosan”) — a joint venture in Türkiye among Ford (41% partner), the Koc Group of Türkiye (41% partner), and public investors (18%) that is the sole supplier to us of the Transit, Transit Custom, and Transit Courier commercial vehicles and the Puma for Europe and the sole distributor of Ford vehicles in Türkiye. Ford Otosan also manufactures Ford heavy trucks for markets in Europe, the Middle East, and Africa. The joint venture owns three plants, a parts distribution depot, and a research and development center in Türkiye, and a combined vehicle and engine plant in Romania.
*•*JMC — a publicly-traded company in China with Ford (32% shareholder) and Nanchang Jiangling Investment Co., Ltd. (41% shareholder) as its controlling shareholders. Nanchang Jiangling Investment Co., Ltd. is a 50/50 joint venture between Changan and Jiangling Motors Company Group. The public investors in JMC own 27% of its total outstanding shares. JMC assembles Ford Transit, a series of Ford SUVs, Ford engines, and non-Ford vehicles and engines for distribution in China and in other export markets. JMC operates two assembly plants and one engine plant in Nanchang.
Item 2. Properties (Continued)
The facilities described above are, in the opinion of management, suitable and adequate for the manufacture and assembly of our and our joint ventures’ products.
The furniture, equipment, and other physical property owned by our Ford Credit operations are not material in relation to the operations’ total assets.
ITEM 3. Legal Proceedings.
The litigation process is subject to many uncertainties, and the outcome of individual matters is not predictable with assurance. See Note 25 of the Notes to the Financial Statements for a discussion of loss contingencies. Following is a discussion of our significant pending legal proceedings:
PRODUCT LIABILITY MATTERS
We are a defendant in numerous actions in state and federal courts within and outside of the United States alleging damages from injuries resulting from (or aggravated by) alleged defects in our vehicles. In many actions, no monetary amount of damages is specified or the specific amount alleged is the jurisdictional minimum. Our experience with litigation alleging a specific amount of damages suggests that such amounts, on average, bear little relation to the actual amount of damages, if any, that we will pay in resolving such matters.
In addition to pending actions, we assess the likelihood of incidents that likely have occurred but not yet been reported to us. We also take into consideration specific matters that have been raised as claims but have not yet proceeded to litigation. Individual product liability matters that have more than a remote risk of loss and such loss would likely be significant if the matter is resolved unfavorably to us would be described herein. Currently there are no such matters to report.
Below is a product liability matter currently pending against Ford:
Hill v. Ford. Plaintiffs in this product liability action pending in Georgia state court allege that the roof of a 2002 Ford F-250 involved in a rollover accident was defectively designed. During the first trial in 2018, the judge declared a mistrial, ruled that Ford’s attorneys had violated pre-trial rulings while presenting evidence, and sanctioned Ford by prohibiting Ford from introducing any evidence at the second trial to show that the roof design of the F-250 was not defective. During the second trial in August 2022, a jury found that Pep Boys (the party that sold the tires on the vehicle involved in the rollover accident) was responsible for 30% of the damages, and Ford, as a direct result of the sanctions order prohibiting Ford from presenting its defense, was responsible for 70% of the damages, resulting in $16.8 million in damages being apportioned to Ford. The jury subsequently awarded punitive damages against Ford in the amount of $1.7 billion. We filed post-trial motions seeking a new trial, and on September 14, 2023, the trial court denied our post-trial motions. On October 13, 2023, Ford filed a notice of appeal with the Georgia Court of Appeals. We believe the law supports our position that Ford is entitled to a new trial with the right to present evidence in its defense.
ASBESTOS MATTERS
Asbestos was used in some brakes, clutches, and other automotive components from the early 1900s. Along with other vehicle manufacturers, we have been the target of asbestos litigation and, as a result, are a defendant in various actions for injuries claimed to have resulted from alleged exposure to Ford parts and other products containing asbestos. Plaintiffs in these personal injury cases allege various health problems as a result of asbestos exposure, either from component parts found in older vehicles, insulation or other asbestos products in our facilities, or asbestos aboard our former maritime fleet. We believe that we are targeted more aggressively in asbestos suits because many previously targeted companies have filed for bankruptcy or emerged from bankruptcy relieved of liability for such claims.
Most of the asbestos litigation we face involves individuals who claim to have worked on the brakes of our vehicles. We are prepared to defend these cases and believe that the scientific evidence confirms our long-standing position that there is no increased risk of asbestos-related disease as a result of exposure to the type of asbestos formerly used in the brakes on our vehicles. The extent of our financial exposure to asbestos litigation remains very difficult to estimate and could include both compensatory and punitive damage awards. The majority of our asbestos cases do not specify a dollar amount for damages; in many of the other cases the dollar amount specified is the jurisdictional minimum, and the vast majority of these cases involve multiple defendants. Some of these cases may also involve multiple plaintiffs, and we may be unable to tell from the pleadings which plaintiffs are making claims against us (as opposed to other defendants). Annual payout and defense costs may become significant in the future. Our accrual for asbestos matters includes probable losses for both asserted and unasserted claims.
Item 3. Legal Proceedings (Continued)
CONSUMER MATTERS
We provide warranties on the vehicles we sell. Warranties are offered for specific periods of time and/or mileage and vary depending upon the type of product and the geographic location of its sale. Pursuant to these warranties, we will repair, replace, or adjust parts on a vehicle that are defective in factory-supplied materials or workmanship during the specified warranty period. We are a defendant in numerous actions in state and federal courts alleging breach of warranty and claiming damages based on state and federal consumer protection laws. Remedies under these statutes may include vehicle repurchase, civil penalties, and payment by Ford of the plaintiff’s attorneys’ fees. In some cases, plaintiffs also include an allegation of fraud. Remedies for a fraud claim may include contract rescission, vehicle repurchase, and punitive damages.
The cost of these litigation matters is included in our warranty costs. We accrue obligations for warranty costs at the time of sale using a patterned estimation model that includes historical information regarding the nature, frequency, and average cost of claims for each vehicle line by model year. We reevaluate the adequacy of our accruals on a regular basis.
We are currently a defendant in a significant number of litigation matters relating to the performance of vehicles, including those equipped with DPS6 transmissions.
ENVIRONMENTAL MATTERS
We have received notices under various federal and state environmental laws that we (along with others) are or may be a potentially responsible party for the costs associated with remediating numerous hazardous substance storage, recycling, or disposal sites in many states and, in some instances, for natural resource damages. We also may have been a generator of hazardous substances at a number of other sites. The amount of any such costs or damages for which we may be held responsible could be significant. Any legal proceeding arising under any federal, state, or local provisions that have been enacted or adopted regulating the discharge of materials into the environment or primarily for the purpose of protecting the environment, in which (i) a governmental authority is a party, and (ii) we believe there is the possibility of monetary sanctions (exclusive of interest and costs) in excess of $1,000,000 is described herein.
On June 16, 2022, the New Jersey Department of Environmental Protection (“NJDEP”) filed a complaint in the Superior Court of New Jersey (Bergen County) seeking natural resource damages and other claims related to the Ringwood Mines/Landfill Site located in Ringwood, New Jersey. On February 21, 2023, the court denied our motion to dismiss. We continue to defend against the NJDEP’s allegations.
CLASS ACTIONS
In light of the fact that few of the purported class actions filed against us in the past have been certified by the courts as class actions, in general we list those actions that (i) have been certified as a class action by a court of competent jurisdiction (and any additional purported class actions that raise allegations substantially similar to an existing and certified class), and (ii) have more than a remote risk of loss, and such loss would likely be significant if the action is resolved unfavorably to us. At this time, we have no such class actions filed against us.
OTHER MATTERS
Brazilian Tax Matters. One Brazilian state (São Paulo) and the Brazilian federal tax authority currently have outstanding substantial tax assessments against Ford Motor Company Brasil Ltda. (“Ford Brazil”) related to state and federal tax incentives Ford Brazil received for its operations in the Brazilian state of Bahia. The São Paulo assessment is part of a broader conflict among various states in Brazil. The federal legislature enacted laws designed to encourage the states to end that conflict, and in 2017 the states reached an agreement on a framework for resolution. Ford Brazil continues to pursue a resolution under the framework and expects the amount of any remaining assessments by the states to be resolved under that framework. The federal assessments are outside the scope of the legislation.
All of the outstanding assessments have been appealed to the relevant administrative court of each jurisdiction. To proceed with an appeal within the judicial court system, an appellant may be required to post collateral. To date, we have not been required to post any collateral. If we are required to post collateral, which could be in excess of $1 billion, we expect it to be in the form of fixed assets, surety bonds, and/or letters of credit, but we may be required to post cash collateral. Although the ultimate resolution of these matters may take many years, we consider our overall risk of loss to be remote.
Item 3. Legal Proceedings (Continued)
Transit Connect Customs Penalty Notice. U.S. Customs and Border Protection (“CBP”) ruled in 2013 that Transit Connects imported as passenger wagons and later converted into cargo vans are subject to the 25% duty applicable to cargo vehicles, rather than the 2.5% duty applicable to passenger vehicles. We filed a challenge in the U.S. Court of International Trade (“CIT”), and CIT ruled in our favor in 2017. CBP subsequently filed a notice of appeal to the U.S. Court of Appeals for the Federal Circuit, which ruled in favor of CBP. Following the U.S. Supreme Court’s denial of our petition for a writ of certiorari in 2020, we paid the increased duties for certain prior imports, plus interest, and disclosed that CBP might assert a claim for penalties. Subsequently, CBP issued a penalty notice to us dated July 22, 2021, and on November 18, 2021, CBP assessed against us a monetary penalty of $1.3 billion and additional duties of $181 million, plus interest. We are vigorously defending our actions and contesting payment of the penalty and the additional duties.
European Commission and U.K. Competition and Markets Authority Matter. On March 15, 2022, the European Commission (the “Commission”) and the U.K. Competition and Markets Authority (the “CMA”) conducted unannounced inspections at the premises of, and sent formal requests for information to, several companies and associations active in the automotive sector, including Ford. The inspections and requests for information concern possible collusion in relation to the collection, treatment, and recovery of end-of-life cars and vans (“ELVs”). We understand that the scope of the investigations includes determining whether manufacturers and importers of passenger cars and vans agreed to an approach to (i) the compensation of ELV collection, treatment, and recovery companies, and (ii) the use of data relating to the recyclability or recoverability of ELVs in marketing materials, and whether such conduct violates relevant competition laws. If a violation is found, a broad range of remedies is potentially available to the Commission and/or CMA, including imposing a fine and/or the prohibition or restriction of certain business practices. Given that this investigation is in its early stages, it is difficult to predict the outcome or what remedies, if any, may be imposed. We are cooperating with the Commission and the CMA as they complete their investigations.
Item 4. Mine Safety Disclosures.
Not applicable.
Item 4A. Information About Our Executive Officers.
Our executive officers are as follows, along with each executive officer’s position and age at February 1, 2024:
| Name | Position | Position Held Since | Age | |||||||||||||||||
| William Clay Ford, Jr. (a) | Executive Chair and Chair of the Board | September 2006 | 66 | |||||||||||||||||
| James D. Farley, Jr. (b) | President and Chief Executive Officer | October 2020 | 61 | |||||||||||||||||
| John Lawler | Chief Financial Officer | October 2020 | 57 | |||||||||||||||||
| Ashwani (“Kumar”) Galhotra | Chief Operating Officer | October 2023 | 58 | |||||||||||||||||
| Michael Amend | Chief Enterprise Technology Officer | September 2021 | 46 | |||||||||||||||||
| Theodore Cannis | CEO, Ford Pro and Ford Customer Service Division | September 2023 | 57 | |||||||||||||||||
| Steven P. Croley | Chief Policy Officer and General Counsel | July 2021 | 58 | |||||||||||||||||
| J. Doug Field | Chief EV, Digital, and Design Officer | October 2023 | 58 | |||||||||||||||||
| Andrew Frick | President, Ford Blue | October 2023 | 50 | |||||||||||||||||
| Marin Gjaja | Chief Operating Officer, Ford Model e | September 2023 | 54 | |||||||||||||||||
| Peter C. Stern | President, Integrated Services | August 2023 | 52 | |||||||||||||||||
| Jennifer Waldo | Chief People and Employee Experience Officer | May 2022 | 47 | |||||||||||||||||
| Shengpo (“Sam”) Wu | President and Chief Executive Officer, Ford of China | March 2023 | 57 | |||||||||||||||||
| Cathy O’Callaghan | Controller | June 2018 | 55 |
(a)Also a Director, Chair of the Office of the Chair and Chief Executive, Chair of the Finance Committee, and a member of the Sustainability, Innovation and Policy Committee of the Board of Directors. Mr. Ford’s daughter, Alexandra Ford English, is a member of the Board of Directors.
(b)Also a Director and member of the Office of the Chair and Chief Executive.
Except as noted below, each of the officers listed above has been employed by Ford or its subsidiaries in one or more capacities during the past five years.
Prior to joining Ford:
-
Michael Amend was President, Online, at Lowe’s from 2018 to 2021. From 2015 to 2018, Mr. Amend served as Executive Vice President, Omnichannel, at JCPenney.
-
Steven Croley was a partner in the Washington, D.C., office of Latham & Watkins from 2017 to 2021. From 2014 to 2017, Mr. Croley served as General Counsel for the U.S. Department of Energy.
-
J. Doug Field was Vice President, Special Projects Group, at Apple from 2018 to 2021. From 2013 to 2018, Mr. Field served as Tesla’s Senior Vice President of Engineering.
-
Marin Gjaja was Senior Partner and Managing Director at Boston Consulting Group (“BCG”). He had been at BCG since 1996.
-
Peter C. Stern was Vice President, Services at Apple from 2016 to 2023.
-
Jennifer Waldo was Vice President, People Business Partners at Apple from 2019 to 2022. From 2015 to 2019, Ms. Waldo was Chief Human Resources Officer at GE Digital.
-
Shengpo “Sam” Wu was Executive Vice President and President, Whirlpool Asia from 2019 until he retired from that position in 2022. He served in an advisory role and as the Vice-Chairman of Whirlpool China Co., Ltd. from 2022 to 2023. Mr. Wu joined Whirlpool Corporation in 2017 as President, Whirlpool Asia and a member of the company’s Executive Committee.
Under our by-laws, executive officers are elected by the Board of Directors at an annual meeting of the Board held for this purpose or by a resolution to fill a vacancy. Each officer is elected to hold office until a successor is chosen or as otherwise provided in the by-laws.
PART II.
ITEM 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
Market for Registrant’s Stock
Our Common Stock is listed on the New York Stock Exchange in the United States under the symbol F. As of February 2, 2024, stockholders of record of Ford included approximately 100,089 holders of Common Stock and 3 holders of Class B Stock. We believe that the number of beneficial owners is substantially greater than the number of record holders because a large portion of our Common Stock is held in “street name” by brokers.
Stock Performance Graph
The information contained in this Stock Performance Graph section shall not be deemed to be “soliciting material” or “filed” or incorporated by reference in future filings with the SEC, or subject to the liabilities of Section 18 of the Exchange Act, except to the extent that we specifically incorporate it by reference into a document filed under the Securities Act or the Exchange Act.
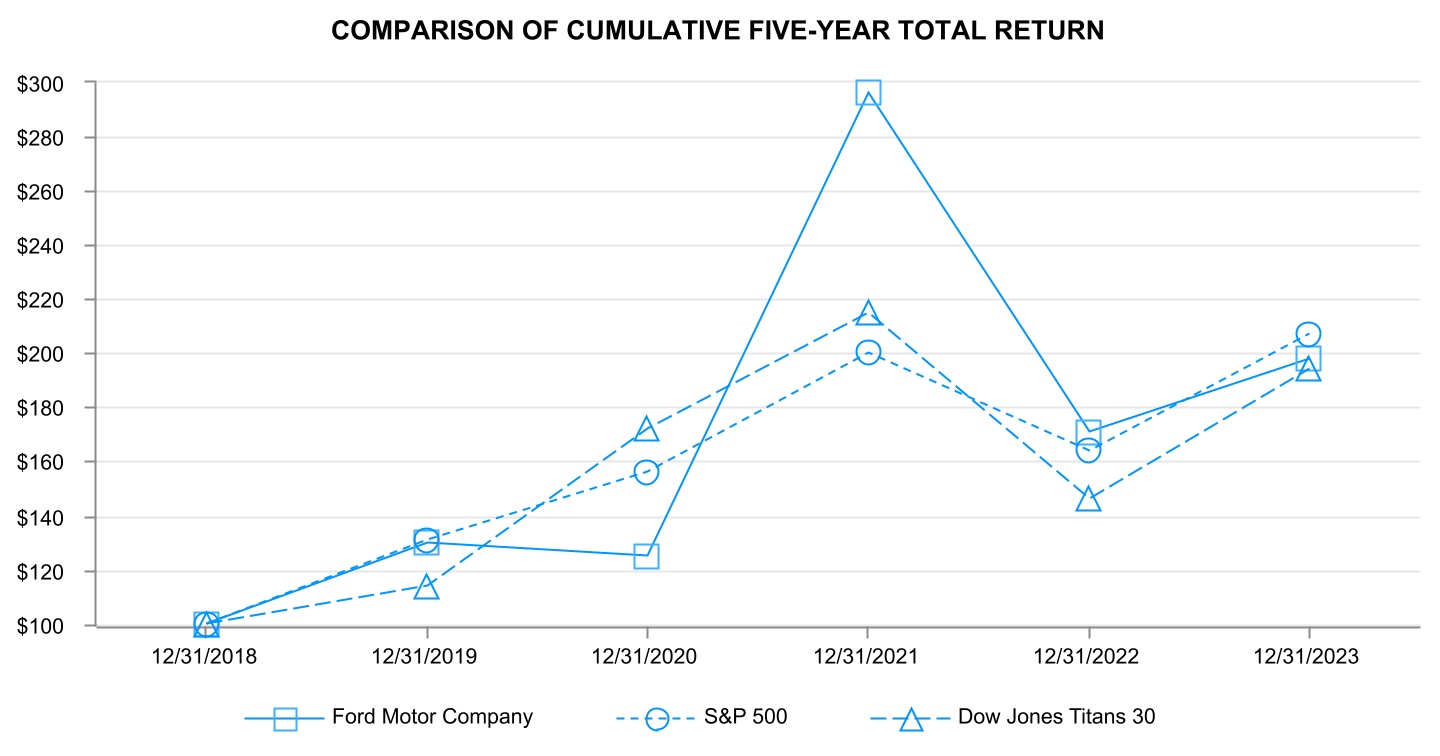
The following graph compares the cumulative total shareholder return on our Common Stock with the total return on the S&P 500 Index and the Dow Jones Automobiles & Parts Titans 30 Index for the five year period ended December 31, 2023. It shows the growth of a $100 investment on December 31, 2018, including the reinvestment of all dividends.
| Base Period | Years Ending | |||||||||||||||||||||||||||||||||||||
| Company/Index | 2018 | 2019 | 2020 | 2021 | 2022 | 2023 | ||||||||||||||||||||||||||||||||
| Ford Motor Company | 100 | 130 | 125 | 296 | 171 | 198 | ||||||||||||||||||||||||||||||||
| S&P 500 | 100 | 131 | 156 | 200 | 164 | 207 | ||||||||||||||||||||||||||||||||
| Dow Jones Automobiles & Parts Titans 30 | 100 | 114 | 172 | 215 | 146 | 194 |
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities (Continued)
Issuer Purchases of Equity Securities
In the fourth quarter of 2023, we completed a modest anti-dilutive share repurchase program to offset the dilutive effect of share-based compensation granted during 2023. The program authorized repurchases of up to 51 million shares of Ford Common Stock. As shown in the rightmost column of the table below, we do not intend to make any further purchases under this program because its anti-dilutive purpose was fulfilled after purchasing only 31 million shares.
| Period | Total Number of Shares Purchased | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly-Announced Plans or Programs | Maximum Number (or Approximate Dollar Value) of Shares that May Yet Be Purchased Under the Plans or Programs | ||||||||||||||||||||||
| October 1, 2023 through October 31, 2023 | — | $ | — | — | — | |||||||||||||||||||||
| November 1, 2023 through November 30, 2023 | 6,713,291 | 10.25 | 6,713,291 | 44,286,709 | ||||||||||||||||||||||
| December 1, 2023 through December 31, 2023 | 24,286,709 | 10.95 | 24,286,709 | 20,000,000 (a) | ||||||||||||||||||||||
| Total / Average | 31,000,000 | $ | 10.80 | 31,000,000 |
(a)The share repurchase program announced November 20, 2023 authorized repurchases of up to 51 million shares of Ford Common Stock. Although we have repurchased 31 million shares and the program was authorized for up to 51 million, we do not intend to make any further purchases under this program because its anti-dilutive purpose has been fulfilled.
In December 2023, our Board of Directors approved a modest anti-dilutive share repurchase program to offset the dilutive effect of share-based compensation expected to be granted during 2024. The program authorizes repurchases of up to 53 million shares of Ford Common Stock. The Company may repurchase shares of Common Stock from time to time through open market purchases, in privately negotiated transactions, or by other means, including through the use of trading plans intended to satisfy the conditions of Rule 10b5-1(c) under the Securities Exchange Act of 1934, as amended, in accordance with applicable securities laws and other restrictions. The timing and total amount of repurchases of Ford Common Stock under this program will depend upon business, economic, and market conditions, corporate, legal, and regulatory requirements, prevailing stock prices, trading volume, and other considerations. The share repurchase program may be suspended or discontinued at any time, and does not obligate the Company to acquire any amount of Common Stock. To the extent the Company elects to make purchases under the share repurchase program, the Company expects to utilize its existing cash and cash equivalents to fund such repurchases.
Dividends
The table below shows the dividends we paid per share of Common and Class B Stock for each quarterly period in 2022 and 2023:
| 2022 | 2023 | ||||||||||||||||||||||||||||||||||||||||||||||
| First Quarter | Second Quarter | Third Quarter | Fourth Quarter | First Quarter**(a)** | Second Quarter | Third Quarter | Fourth Quarter | ||||||||||||||||||||||||||||||||||||||||
| Dividends per share of Ford Common and Class B Stock | $ | 0.10 | $ | 0.10 | $ | 0.15 | $ | 0.15 | $ | 0.80 | $ | 0.15 | $ | 0.15 | $ | 0.15 |
(a)In the first quarter of 2023, in addition to a regular dividend of $0.15 per share, we paid a supplemental dividend of $0.65 per share.
On February 6, 2024, we declared a regular dividend of $0.15 per share and a supplemental dividend of $0.18 per share.
Subject to legally available funds, we intend to continue to pay a regular quarterly cash dividend on our outstanding Common Stock and Class B Stock. The declaration and payment of future dividends is at the sole discretion of our Board of Directors after taking into account various factors, including our financial condition, operating results, available cash, and current and anticipated cash needs.
Item 6. [Reserved.]
ITEM 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
Key Trends and Economic Factors Affecting Ford and the Automotive Industry
Production and Supply Chain. Although we saw improvements in our supply chain throughout 2023, including easing of the semiconductor shortage, we continue to face some production issues due to, among other things, labor shortages at our suppliers. Moreover, we have received and continue to receive claims from our supply base related to inflationary pressure and production disruption. Upon receipt, we evaluate those claims, and, in certain circumstances, in order to ensure continuity of supply and mitigate the impact on our production, have made payments to our suppliers, sometimes under duress. We continue to reevaluate our supply base and sourcing decisions and may in the future incur charges to improve flexibility and cost competitiveness.
Currency Exchange Rate Volatility. Globally, central banks have begun shifting from tightening policy by raising interest rates to holding rates steady or, in some markets, beginning to cut rates. As they do, they need to carefully balance the risk that inflation remains elevated against the heightened financial and economic risks associated with high interest rates. This is notable for many emerging markets, which may also face increased exposure to commodity prices and political instability, contributing to unpredictable movements in the value of their exchange rates. In addition to direct impacts on the financial flows of global automotive companies, currency movements can also impact pricing of vehicles exported to overseas markets. In most markets, exchange rates are market-determined, and all are impacted by many different macroeconomic and policy factors, and thus likely to remain volatile. However, in some markets, exchange rates are heavily influenced or controlled by governments.
Pricing Pressure. Despite vehicle pricing remaining elevated over the last year due to strong demand, supply shortages, and inflationary costs, we have already observed moderation in the rate of new and used vehicle price increases as auto production recovers from the semiconductor shortage, but it is unclear whether prices will decline fully to pre-COVID-19 pandemic levels. Over the long term, intense competition and excess capacity are likely to put downward pressure on inflation-adjusted prices for similarly-contented vehicles and contribute to a challenging pricing environment for the automotive industry in most major markets.
Electric Vehicle Market. Although we continue to invest in our electric vehicle strategy, we have observed lower-than-anticipated industrywide electric vehicle adoption rates and near-term pricing pressures, which has led us and may in the future lead us to adjust our spending, production, and/or product launches to better match the pace of electric vehicle adoption. As a result of the lower-than-anticipated adoption rates, near-term pricing pressures, and other factors, we recorded about $0.7 billion of charges in 2023 and may continue to incur charges, which could be substantial, related to payments to our electric vehicle-related suppliers (battery, raw material, or otherwise), inventory adjustments, or other matters. See Item 1A. Risk Factors for additional discussion of the risks related to lower-than-anticipated electric vehicle volumes and our planned transition to a greater mix of electric vehicles.
Commodity and Energy Prices. Prices for commodities remain volatile. In some cases, spot prices for various commodities have recently diverged somewhat, as anticipated weakening in global industrial activity mitigates price increases for base metals such as steel and aluminum, while precious metals (e.g., palladium), and raw materials that are used in batteries for electric vehicles (e.g., lithium, cobalt, nickel, graphite, and manganese, among other materials, for batteries) remain elevated. The net impact on us and our suppliers has been higher material costs overall. To help ensure supply of raw materials for critical components (e.g., batteries), we, like others in the industry, have entered into multi-year sourcing agreements and may enter into additional agreements. Similar dynamics are impacting energy markets, with Europe particularly exposed to the risk of both higher prices and constraints on supply of natural gas due to the ongoing conflict in Ukraine. Such shortages may impact facilities operated by us or our suppliers, which could have an impact on us in Europe and other regions. In the long term, the outcome of de-carbonization and electrification of the vehicle fleet may depress oil demand, but the global energy transition will also contribute to ongoing volatility of oil and other energy prices.
Vehicle Profitability. Our financial results depend on the profitability of the vehicles we sell, which may vary significantly by vehicle line. In general, larger vehicles tend to command higher prices and be more profitable than smaller vehicles. For example, in Ford Blue, our larger, more profitable vehicles had an average contribution margin that was 139% of our total average contribution margin across all vehicles, whereas our smaller vehicles had significantly lower contribution margins. In addition, government regulations aimed at reducing emissions and increasing fuel efficiency (e.g., ZEV mandates and low emission zones), and other factors that accelerate the transition to electrified vehicles, may increase the cost of vehicles by more than the perceived benefit to consumers and dampen margins.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
Trade Policy. To the extent governments in various regions implement or intensify barriers to imports, such as erecting tariff or non-tariff barriers or manipulating their currency, and provide advantages to local exporters selling into the global marketplace, there can be a significant negative impact on manufacturers based in other markets. While we believe the long-term trend will support the growth of free trade, we will continue to monitor and address the developing role that geopolitical, climate, and labor concerns are playing in trade relations.
Inflation and Interest Rates. We continue to see near-term impacts on our business due to inflation, including ongoing global price pressures in the wake of geopolitical volatility, driving up energy prices, freight premiums, and other operating costs above normal rates. Although headline inflation in the United States and Europe appears to have peaked, as gasoline and natural gas prices recede from the latest spike, core inflation (excluding food and energy prices) remains elevated and is a source of continued cost pressure on businesses and households. Interest rates have increased significantly as central banks in developed countries attempt to subdue inflation while government deficits and debt remain at high levels in many global markets. Accordingly, the eventual implications of higher government deficits and debt, tighter monetary policy, and potentially higher long-term interest rates may drive a higher cost of capital for the business. At Ford Credit, rising interest rates may impact its ability to source funding and offer financing at competitive rates, which could reduce its financing margin.
Revenue
Company excluding Ford Credit revenue is generated primarily by sales of vehicles, parts, accessories, and services from our Ford Blue, Ford Model e, and Ford Pro segments. Revenue is recorded when control is transferred to our customers (generally, our dealers and distributors). For the majority of sales, this occurs when products are shipped from our manufacturing facilities. However, we defer a portion of the consideration received when there is a separate future or stand-ready performance obligation, such as extende
Showing the first 8K of 148K characters. Open the full section
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
2023 SUPPLEMENTAL INFORMATION
The tables below provide supplemental consolidating financial information and other financial information. Company excluding Ford Credit includes our Ford Blue, Ford Model e, Ford Pro, and Ford Next reportable segments, Corporate Other, Interest on Debt, and Special Items. Eliminations, where presented, primarily represent eliminations of intersegment transactions and deferred tax netting.
Selected Cash Flow Information. The following tables provide supplemental cash flow information (in millions):
| For the Year Ended December 31, 2023 | |||||||||||||||||||||||
| Cash flows from operating activities | Company excluding Ford Credit | Ford Credit | Eliminations | Consolidated | |||||||||||||||||||
| Net income/(loss) | $ | 2,996 | $ | 1,333 | $ | — | $ | 4,329 | |||||||||||||||
| Depreciation and tooling amortization | 5,336 | 2,354 | — | 7,690 | |||||||||||||||||||
| Other amortization | 28 | (1,195) | — | (1,167) | |||||||||||||||||||
| Provision for/(Benefit from) credit and insurance losses | 107 | 331 | — | 438 | |||||||||||||||||||
| Pension and OPEB expense/(income) | 3,052 | — | — | 3,052 | |||||||||||||||||||
| Equity method investment dividends received in excess of (earnings)/losses and impairments | (29) | (4) | — | (33) | |||||||||||||||||||
| Foreign currency adjustments | (49) | (185) | — | (234) | |||||||||||||||||||
| Net realized and unrealized (gains)/losses on cash equivalents, marketable securities, and other investments | 236 | (31) | — | 205 | |||||||||||||||||||
| Net (gain)/loss on changes in investments in affiliates | (9) | — | — | (9) | |||||||||||||||||||
| Stock compensation | 446 | 14 | — | 460 | |||||||||||||||||||
| Provision for/(Benefit from) deferred income taxes | (1,032) | (617) | — | (1,649) | |||||||||||||||||||
| Decrease/(Increase) in finance receivables (wholesale and other) | — | (4,827) | — | (4,827) | |||||||||||||||||||
| Decrease/(Increase) in intersegment receivables/payables | 167 | (167) | — | — | |||||||||||||||||||
| Decrease/(Increase) in accounts receivable and other assets | (2,512) | (108) | — | (2,620) | |||||||||||||||||||
| Decrease/(Increase) in inventory | (1,219) | — | — | (1,219) | |||||||||||||||||||
| Increase/(Decrease) in accounts payable and accrued and other liabilities | 9,602 | 227 | — | 9,829 | |||||||||||||||||||
| Other | 539 | 134 | — | 673 | |||||||||||||||||||
| Interest supplements and residual value support to Ford Credit | (3,921) | 3,921 | — | — | |||||||||||||||||||
| Net cash provided by/(used in) operating activities | $ | 13,738 | $ | 1,180 | $ | — | $ | 14,918 |
| Cash flows from investing activities | |||||||||||||||||||||||
| Capital spending | $ | (8,156) | $ | (80) | $ | — | $ | (8,236) | |||||||||||||||
| Acquisitions of finance receivables and operating leases | — | (54,505) | — | (54,505) | |||||||||||||||||||
| Collections of finance receivables and operating leases | — | 44,561 | — | 44,561 | |||||||||||||||||||
| Purchases of marketable securities and other investments | (6,551) | (2,039) | — | (8,590) | |||||||||||||||||||
| Sales and maturities of marketable securities and other investments | 9,895 | 2,805 | — | 12,700 | |||||||||||||||||||
| Settlements of derivatives | 7 | (145) | — | (138) | |||||||||||||||||||
| Capital contributions to equity method investments | (2,733) | — | — | (2,733) | |||||||||||||||||||
| Other | (687) | — | — | (687) | |||||||||||||||||||
| Investing activity (to)/from other segments | — | (3) | 3 | — | |||||||||||||||||||
| Net cash provided by/(used in) investing activities | $ | (8,225) | $ | (9,406) | $ | 3 | $ | (17,628) |
| Cash flows from financing activities | |||||||||||||||||||||||
| Cash payments for dividends and dividend equivalents | $ | (4,995) | $ | — | $ | — | $ | (4,995) | |||||||||||||||
| Purchases of common stock | (335) | — | — | (335) | |||||||||||||||||||
| Net changes in short-term debt | (115) | (1,424) | — | (1,539) | |||||||||||||||||||
| Proceeds from issuance of long-term debt | — | 51,659 | — | 51,659 | |||||||||||||||||||
| Payments on long-term debt | (212) | (41,753) | — | (41,965) | |||||||||||||||||||
| Other | (102) | (139) | — | (241) | |||||||||||||||||||
| Financing activity to/(from) other segments | 3 | — | (3) | — | |||||||||||||||||||
| Net cash provided by/(used in) financing activities | $ | (5,756) | $ | 8,343 | $ | (3) | $ | 2,584 | |||||||||||||||
| Effect of exchange rate changes on cash, cash equivalents, and restricted cash | $ | (262) | $ | 158 | $ | — | $ | (104) |
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
Selected Income Statement Information. The following table provides supplemental income statement information (in millions):
| For the Year Ended December 31, 2023 | |||||||||||||||||
| Company excluding Ford Credit | Ford Credit | Consolidated | |||||||||||||||
| Revenues | $ | 165,901 | $ | 10,290 | $ | 176,191 | |||||||||||
| Total costs and expenses | 161,252 | 9,481 | 170,733 | ||||||||||||||
| Operating income/(loss) | 4,649 | 809 | 5,458 | ||||||||||||||
| Interest expense on Company debt excluding Ford Credit | 1,302 | — | 1,302 | ||||||||||||||
| Other income/(loss), net | (1,093) | 490 | (603) | ||||||||||||||
| Equity in net income/(loss) of affiliated companies | 382 | 32 | 414 | ||||||||||||||
| Income/(Loss) before income taxes | 2,636 | 1,331 | 3,967 | ||||||||||||||
| Provision for/(Benefit from) income taxes | (360) | (2) | (362) | ||||||||||||||
| Net income/(loss) | 2,996 | 1,333 | 4,329 | ||||||||||||||
| Less: Income/(loss) attributable to noncontrolling interests | (18) | — | (18) | ||||||||||||||
| Net income/(loss) attributable to Ford Motor Company | $ | 3,014 | $ | 1,333 | $ | 4,347 |
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
Selected Balance Sheet Information. The following tables provide supplemental balance sheet information (in millions):
| December 31, 2023 | ||||||||||||||||||||||||||
| Assets | Company excluding Ford Credit | Ford Credit | Eliminations | Consolidated | ||||||||||||||||||||||
| Cash and cash equivalents | $ | 14,204 | $ | 10,658 | $ | — | $ | 24,862 | ||||||||||||||||||
| Marketable securities | 14,520 | 789 | — | 15,309 | ||||||||||||||||||||||
| Ford Credit finance receivables, net | — | 46,425 | — | 46,425 | ||||||||||||||||||||||
| Trade and other receivables, net | 5,771 | 9,830 | — | 15,601 | ||||||||||||||||||||||
| Inventories | 15,651 | — | — | 15,651 | ||||||||||||||||||||||
| Other assets | 2,658 | 975 | — | 3,633 | ||||||||||||||||||||||
| Receivable from other segments | 1,716 | 1,773 | (3,489) | — | ||||||||||||||||||||||
| Total current assets | 54,520 | 70,450 | (3,489) | 121,481 | ||||||||||||||||||||||
| Ford Credit finance receivables, net | — | 55,650 | — | 55,650 | ||||||||||||||||||||||
| Net investment in operating leases | 1,052 | 20,332 | — | 21,384 | ||||||||||||||||||||||
| Net property | 40,551 | 270 | — | 40,821 | ||||||||||||||||||||||
| Equity in net assets of affiliated companies | 5,431 | 117 | — | 5,548 | ||||||||||||||||||||||
| Deferred income taxes | 16,795 | 190 | — | 16,985 | ||||||||||||||||||||||
| Other assets | 9,959 | 1,482 | — | 11,441 | ||||||||||||||||||||||
| Receivable from other segments | — | 30 | (30) | — | ||||||||||||||||||||||
| Total assets | $ | 128,308 | $ | 148,521 | $ | (3,519) | $ | 273,310 |
| Liabilities | ||||||||||||||||||||||||||
| Payables | $ | 25,092 | $ | 900 | $ | — | $ | 25,992 | ||||||||||||||||||
| Other liabilities and deferred revenue | 23,273 | 2,597 | — | 25,870 | ||||||||||||||||||||||
| Company excluding Ford Credit debt payable within one year | 477 | — | — | 477 | ||||||||||||||||||||||
| Ford Credit debt payable within one year | — | 49,192 | — | 49,192 | ||||||||||||||||||||||
| Payable to other segments | 3,373 | 116 | (3,489) | — | ||||||||||||||||||||||
| Total current liabilities | 52,215 | 52,805 | (3,489) | 101,531 | ||||||||||||||||||||||
| Other liabilities and deferred revenue | 26,519 | 1,895 | — | 28,414 | ||||||||||||||||||||||
| Company excluding Ford Credit long-term debt | 19,467 | — | — | 19,467 | ||||||||||||||||||||||
| Ford Credit long-term debt | — | 80,095 | — | 80,095 | ||||||||||||||||||||||
| Deferred income taxes | 668 | 337 | — | 1,005 | ||||||||||||||||||||||
| Payable to other segments | 30 | — | (30) | — | ||||||||||||||||||||||
| Total liabilities | $ | 98,899 | $ | 135,132 | $ | (3,519) | $ | 230,512 |
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
Selected Other Information.
Equity. At December 31, 2022, total equity attributable to Ford was $43.2 billion, a decrease of $5.3 billion compared with December 31, 2021. At December 31, 2023, total equity attributable to Ford was $42.8 billion, a decrease of $0.4 billion compared with December 31, 2022. The detail for the changes is shown below (in billions):
| 2022 vs 2021 Increase/ (Decrease) | 2023 vs 2022 Increase/ (Decrease) | ||||||||||
| Net income/(loss) | $ | (2.0) | $ | 4.3 | |||||||
| Shareholder distributions (a) | (2.5) | (5.4) | |||||||||
| Other comprehensive income/(loss) | (1.0) | 0.3 | |||||||||
| Adoption of accounting standards | — | — | |||||||||
| Common stock issued (including share-based compensation impacts) | 0.2 | 0.4 | |||||||||
| Total | $ | (5.3) | $ | (0.4) |
(a)Includes cash dividends, dividend equivalents, and anti-dilutive share repurchases.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
CRITICAL ACCOUNTING ESTIMATES
We consider an accounting estimate to be critical if: (1) the accounting estimate requires us to make assumptions about matters that were highly uncertain at the time the accounting estimate was made, and (2) changes in the estimate that are reasonably likely to occur from period to period, or use of different estimates that we reasonably could have used in the current period, would have a material impact on our financial condition or results of operations.
Management has discussed the development and selection of these critical accounting estimates with the Audit Committee of our Board of Directors. In addition, there are other items within our financial statements that require estimation, but are not deemed critical as defined above. Changes in estimates used in these and other items could have a material impact on our financial statements.
Warranties and Field Service Actions
Nature of Estimates Required. We provide base warranties on the products we sell for specific periods of time and/or mileage, which vary depending upon the type of product and the geographic location of its sale. Separately, we also periodically perform field service actions related to safety recalls, emission recalls, and other product campaigns. Pursuant to these warranties and field service actions, we will repair, replace, or adjust parts on a vehicle that are defective in factory-supplied materials or workmanship. We accrue the estimated cost of both base warranty coverages and field service actions at the time of sale. In addition, from time to time, we issue extended warranties at our expense, the estimated cost of which is accrued at the time of issuance.
Assumptions and Approach Used. We establish our estimate of base warranty obligations using a patterned estimation model. We use historical information regarding the nature, frequency, and average cost of claims for each vehicle line by model year. We reevaluate our estimate of base warranty obligations on a regular basis. Experience has shown that initial data for any given model year may be volatile; therefore, our process relies on long-term historical averages until sufficient data are available. With actual experience, we use the data to update the historical averages. We then compare the resulting accruals with present spending rates to assess whether the balances are adequate to meet expected future obligations. Based on this data, we update our estimates as necessary.
Field service actions may occur in periods beyond the base warranty coverage period. We establish our estimates of field service action obligations using a patterned estimation model. We use historical information regarding the nature, frequency, severity, and average cost of claims for each model year. We assess our obligation for field service actions on a regular basis using actual claims experience and update our estimates as necessary.
Due to the uncertainty and potential volatility of the factors used in establishing our estimates, changes in our assumptions could materially affect our financial condition and results of operations. See Note 25 of the Notes to the Financial Statements for information regarding warranty and field service action costs.
Pensions and Other Postretirement Employee Benefits
Nature of Estimates Required. The estimation of our defined benefit pension and OPEB plan obligations and expenses requires that we make use of estimates of the present value of the projected future payments to all participants, taking into consideration the likelihood of potential future events, such as demographic experience and health care cost increases. Plan obligations and expenses are based on existing retirement plan provisions. No assumption is made regarding any potential future changes to benefit provisions beyond those to which we are presently committed (e.g., in existing labor contracts).
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
Assumptions and Approach Used. The assumptions used in developing the required estimates include the following key factors:
-
Discount rates. Our discount rate assumptions are based primarily on the results of cash flow matching analyses, which match the future cash outflows for each major plan to a yield curve based on high-quality bonds specific to the country of the plan. Benefit payments are discounted at the rates on the curve to determine the year-end obligations.
-
Expected long-term rate of return on plan assets. Our expected long-term rate of return considers inputs from a range of advisors for capital market returns, adjusted for specific aspects of our investment strategy by plan. Historical returns also are considered when appropriate. The assumption is based on consideration of all inputs, with a focus on long-term trends to avoid short-term market influences.
-
Salary growth. Our salary growth assumption reflects our actual experience, long-term outlook, and assumed inflation.
-
Inflation. Our inflation assumption is based on an evaluation of external market indicators, including real gross domestic product growth and central bank inflation targets.
*•*Expected contributions. Our expected amount and timing of contributions are based on an assessment of minimum requirements, cash availability, and other considerations (e.g., funded status, avoidance of regulatory premiums and levies, and tax efficiency).
-
Retirement rates. Retirement rates are developed to reflect actual and projected plan experience.
-
Mortality rates. Mortality rates are developed to reflect actual and projected plan experience.
-
Health care cost trends. Our health care cost trend assumptions are developed based on historical cost data, the near-term outlook, and an assessment of likely long-term trends.
Assumptions are set at each year-end and are generally not changed during the year unless there is a major plan event, such as a curtailment or settlement that would trigger a plan remeasurement.
See Note 17 of the Notes to the Financial Statements for more information regarding pension and OPEB costs and assumptions.
Pension Plans
Effect of Actual Results. The year-end 2023 weighted average discount rate was 5.17% for U.S. plans and 3.98% for non-U.S. plans, reflecting decreases of 34 and 44 basis points, respectively, compared with year-end 2022. In 2023, the U.S. actual return on assets was 7.41%, which was higher than the expected long-term rate of return of 6.25%. Non-U.S. actual return on assets was 5.56%, which was higher than the expected long-term rate of return of 4.13%. The higher returns are explained primarily by gains on fixed income assets. In total, lower discount rates compared to year-end 2022, partially offset by asset gains in excess of our assumptions resulted in a net remeasurement loss of $1.8 billion, which has been recognized within net periodic benefit cost and reported as a special item.
For 2024, the expected long-term rate of return on assets is 5.93% for U.S. plans, down 32 basis points from 2023, reflecting lower capital market return expectations, and 4.53% for non-U.S. plans, up 40 basis points compared with a year ago, reflecting return expectations in those markets and a higher return seeking mix for certain plans.
De-risking Strategy. We employ a broad de-risking strategy for our global funded plans that increases the matching characteristics of our assets relative to our obligation as funded status improves. Changes in interest rates, which directly influence changes in discount rates, in addition to other factors have a significant impact on the value of our pension obligation and fixed income asset portfolio. Our de-risking strategy has increased the allocation to fixed income investments and reduced our funded status sensitivity to changes in interest rates. Changes in interest rates should result in offsetting effects in the value of our pension obligation and the value of the fixed income asset portfolio.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
Sensitivity Analysis. The December 31, 2023 pension funded status and 2024 expense are affected by year-end 2023 assumptions. Sensitivities to these assumptions may be asymmetric and are specific to the time periods noted. The effects of changes in the factors that generally have the largest impact on year-end funded status and pension expense are discussed below.
Discount rates and interest rates have the largest impact on our obligations and fixed income assets. The table below estimates the effect on our funded status of an increase/decrease in discount rates and interest rates (in millions):
| Basis Point Change | Increase/(Decrease) in December 31, 2023 Funded Status | |||||||||||||||||||
| Factor | U.S. Plans | Non-U.S. Plans | ||||||||||||||||||
| Discount rate - obligation | +/- 100 bps | $2,900/$(3,400) | $2,700/$(3,400) | |||||||||||||||||
| Interest rate - fixed income assets | +/- 100 | (2,800)/3,200 | (1,800)/2,200 | |||||||||||||||||
| Net impact on funded status | $100/$(200) | $900/$(1,200) |
The fixed income asset sensitivity shown excludes other fixed income return components (e.g., changes in credit spreads, bond coupon and active management excess returns), and growth asset returns. Other factors that affect net funded status (e.g., contributions) are not reflected.
Interest rates and the expected long-term rate of return on assets have the largest effect on pension expense. These assumptions are generally set at each year-end for expense recorded throughout the following year. The table below estimates the effect on pension expense of a higher/lower assumption for these factors (in millions):
| Basis Point Change | Increase/(Decrease) in 2024 Pension Expense | |||||||||||||||||||
| Factor | U.S. Plans | Non-U.S. Plans | ||||||||||||||||||
| Interest rate - service cost and interest cost | +/- 25 bps | $25/$(25) | $15/$(15) | |||||||||||||||||
| Expected long-term rate of return on assets | +/- 25 | (75)/75 | (55)/55 |
The effect of changing multiple factors simultaneously cannot be calculated by combining the individual sensitivities. The sensitivity of pension expense to a change in discount rate assumptions may not be linear.
Other Postretirement Employee Benefits
Effect of Actual Results. The weighted average discount rate used to determine the benefit obligation for worldwide OPEB plans at December 31, 2023 was 5.10%, compared with 5.48% at December 31, 2022, resulting in a worldwide net remeasurement loss of $286 million, which has been recognized within net periodic benefit cost and reported as a special item.
Sensitivity Analysis. Discount rates and interest rates have the largest effect on our OPEB obligation and expense. The table below estimates the effect on 2024 OPEB expense of higher/lower assumptions for these factors (in millions):
| Worldwide OPEB | ||||||||||||||||||||
| Basis Point Change | (Increase)/Decrease 2023 YE Obligation | Increase/(Decrease) 2024 Expense | ||||||||||||||||||
| Factor | ||||||||||||||||||||
| Discount rate - obligation | +/- 100 bps | $450/$(540) | N/A | |||||||||||||||||
| Interest rate - service cost and interest cost | +/- 25 | N/A | $5/$(5) |
Income Taxes
Nature of Estimates Required. We must make estimates and apply judgment in determining the provision for income taxes for financial reporting purposes. We make these estimates and judgments primarily in the following areas: (i) the calculation of tax credits, (ii) the calculation of differences in the timing of recognition of revenue and expense for tax reporting and financial statement purposes, as well as (iii) the calculation of interest and penalties related to uncertain tax positions. Changes in these estimates and judgments may result in a material increase or decrease to our tax provision, which would be recorded in the period in which the change occurs.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
Assumptions and Approach Used. We are subject to the income tax laws and regulations of the many jurisdictions in which we operate. These tax laws and regulations are complex and involve uncertainties in the application to our facts and circumstances that may be open to interpretation. We recognize benefits for these uncertain tax positions based upon a process that requires judgment regarding the technical application of the laws, regulations, and various related judicial opinions. If, in our judgment, it is more likely than not (defined as a likelihood of more than 50%) that the uncertain tax position will be settled favorably for us, we estimate an amount that ultimately will be realized. This process is inherently subjective since it requires our assessment of the probability of future outcomes. We evaluate these uncertain tax positions on a quarterly basis, including consideration of changes in facts and circumstances, such as new regulations or recent judicial opinions, as well as the status of audit activities by taxing authorities. Changes to our estimate of the amount to be realized are recorded in our provision for income taxes during the period in which the change occurred.
We must also assess the likelihood that we will be able to recover our deferred tax assets against future sources of taxable income and reduce the carrying amount of deferred tax assets by recording a valuation allowance if, based on all available evidence, it is more likely than not that all or a portion of such assets will not be realized.
This assessment, which is completed on a taxing jurisdiction basis, takes into account various types of evidence, including the following:
-
Nature, frequency, and severity of current and cumulative financial reporting losses. A pattern of objectively measured recent financial reporting losses is heavily weighted as a source of negative evidence. We generally consider cumulative pre-tax losses in the three-year period ending with the current quarter to be significant negative evidence regarding future profitability. We also consider the strength and trend of earnings, as well as other relevant factors. In certain circumstances, historical information may not be as relevant due to changes in our business operations;
-
Sources of future taxable income. Future reversals of existing temporary differences are heavily weighted sources of objectively verifiable positive evidence. Projections of future taxable income exclusive of reversing temporary differences are a source of positive evidence only when the projections are combined with a history of recent profits and can be reasonably estimated. Otherwise, these projections are considered inherently subjective and generally will not be sufficient to overcome negative evidence that includes relevant cumulative losses in recent years, particularly if the projected future taxable income is dependent on an anticipated turnaround to profitability that has not yet been achieved. In such cases, we generally give these projections of future taxable income no weight for the purposes of our valuation allowance assessment; and
-
Tax planning strategies. If necessary and available, tax planning strategies could be implemented to accelerate taxable amounts to utilize expiring carryforwards. These strategies would be a source of additional positive evidence and, depending on their nature, could be heavily weighted.
In assessing the realizability of deferred tax assets, we consider the trade-offs between cash preservation and cash outlays to preserve tax credits. We presently believe that global valuation allowances of $4.2 billion are required and that we ultimately will recover the remaining $16 billion of deferred tax assets. However, the ultimate realization of our deferred tax assets is subject to a number of variables, including our future profitability within relevant tax jurisdictions, and future tax planning and the related effects on our cash and liquidity position. Accordingly, our valuation allowances may increase or decrease in future periods.
For additional information regarding income taxes, see Note 7 of the Notes to the Financial Statements.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
Impairment of Long-Lived Assets
Asset groups are tested at the level of the smallest identifiable group of assets that generate cash inflows that are largely independent of the cash inflows from other assets or groups of assets. Asset groupings for impairment analysis are reevaluated when events occur, such as changes in organizational structure and management reporting. Following the organizational and segment structure change in the beginning of 2023, our asset groups are: Ford Blue North America, Ford Blue Europe, Ford Blue Rest of World, Ford Model e, Ford Pro, Ford Credit, and Ford Next.
Nature of Estimates Required - Held-and-Used Long-Lived Assets. We test our long-lived asset groups when changes in circumstances indicate their carrying value may not be recoverable. Events that trigger a test for recoverability include material adverse changes in projected revenues or expenses, present cash flow losses combined with a history of cash flow losses and a forecast that demonstrates significant continuing losses, significant negative industry or economic trends (including a substantial shift in consumer preference), a current expectation that a long-lived asset group will be disposed of significantly before the end of its useful life, a significant adverse change in the manner in which an asset group is used or in its physical condition, or when there is a change in the asset grouping. In addition, investing in new, emerging products (e.g., EVs) or services (e.g., connectivity) may require substantial upfront investment, which may result in initial forecasted negative cash flows in the near term. In these instances, near-term negative cash flows on their own may not be indicative of a triggering event for evaluation of impairment. In such circumstances, we also conduct a qualitative evaluation of the business growth trajectory, which includes updating our assessment of when positive cash flows are expected to be generated, confirming whether established milestones are being achieved, and assessing our ability and intent to continue to access required funding to execute the plan. If this evaluation indicates a triggering event has occurred, a test for recoverability is performed.
When a triggering event occurs, a test for recoverability is performed, comparing projected undiscounted future cash flows to the carrying value of the asset group. If the undiscounted forecasted cash flows are less than the carrying value of the assets, the asset group’s fair value is measured relying primarily on a discounted cash flow method. To the extent available, we will also consider third-party valuations of our long-lived assets that were prepared for other business purposes. An impairment charge is recognized for the amount by which the carrying value of the asset group exceeds its estimated fair value. When an impairment loss is recognized for assets to be held and used, the adjusted carrying amounts of those assets are depreciated over their remaining useful life.
Assumptions and Approach Used - Held-and-Used Long-Lived Assets. The fair value of an asset group is determined from the perspective of a market-participant considering, among other things, appropriate discount rates, valuation techniques, the most advantageous market, and assumptions about the highest and best use of the asset group.
We measure the fair value of an asset group based on market prices (i.e., the amount for which the asset could be sold to a third party) when available. When market prices are not available, we generally estimate the fair value of the asset group using the income approach and/or the market approach. The income approach uses cash flow projections. Inherent in our development of cash flow projections are assumptions and estimates derived from a review of our operating results, business plan forecasts, expected growth rates, and cost of capital, similar to those a market participant would use to assess fair value. We also make certain assumptions about future economic conditions and other data. Many of the factors used in assessing fair value are outside the control of management, and these assumptions and estimates may change in future periods.
Changes in assumptions or estimates can materially affect the fair value measurement of an asset group and, therefore, can affect the test results. The following are key assumptions we use in making cash flow projections:
*•*Business projections. We make assumptions about the demand for our products in the marketplace. These
assumptions drive our planning assumptions for volume, mix, and pricing. We also make assumptions about our cost levels (e.g., capacity utilization, cost performance). These projections are derived using our internal business plan forecasts that are updated at least annually and reviewed by our Board of Directors.
*•*Long-term growth rate. A growth rate is used to calculate the terminal value of the business and is added to the present value of the debt-free interim cash flows. The growth rate is the expected rate at which an asset group’s earnings stream is projected to grow beyond the planning period.
- Discount rate. When measuring possible impairment, future cash flows are discounted at a rate that is consistent with a weighted-average cost of capital that we anticipate a potential market participant would use. Weighted-average cost of capital is an estimate of the overall risk-adjusted pre-tax rate of return expected by equity and debt holders of a business enterprise.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
*•*Economic projections. Assumptions regarding general economic conditions are included in and affect our assumptions regarding industry sales and pricing estimates for our vehicles. These macroeconomic assumptions include, but are not limited to, industry sales volumes, inflation, interest rates, prices of raw materials (e.g., commodities), and foreign currency exchange rates.
The market approach is another method for measuring the fair value of an asset group. This approach relies on the market value (i.e., market capitalization) of companies that are engaged in the same or a similar line of business as the asset group being evaluated. In addition, to the extent available we also consider third-party valuations that were prepared for other business purposes.
During 2023, we identified triggering events related to our Ford Blue Europe asset group. In each situation in which we experienced a triggering event during the year, we tested our long-lived assets for impairment using our internal economic and business projections, and determined that the carrying values of the long-lived assets were recoverable. If, in future quarters, our economic or business projections were to change as a result of an update to our plans, a deterioration of the economic or business environment, a significant adverse change in the extent or manner in which a long-lived asset is being used, or an expectation that a long-lived asset group will be disposed of significantly before the end of its useful life, we would undertake additional testing, as appropriate, which could result in an impairment of long-lived assets.
Allowance for Credit Losses
The allowance for credit losses represents Ford Credit’s estimate of the expected lifetime credit losses inherent in finance receivables as of the balance sheet date. The adequacy of Ford Credit’s allowance for credit losses is assessed quarterly, and the assumptions and models used in establishing the allowance are evaluated regularly. Because credit losses can vary substantially over time, estimating credit losses requires a number of assumptions about matters that are uncertain. Changes in assumptions affect Ford Credit interest, operating, and other expenses on our consolidated income statements and the allowance for credit losses contained within Ford Credit finance receivables, net on our consolidated balance sheets. See Note 10 of the Notes to the Financial Statements for more information regarding allowance for credit losses.
Nature of Estimates Required. Ford Credit estimates the allowance for credit losses for receivables that share similar risk characteristics based on a collective assessment using a combination of measurement models and management judgment. The models consider factors such as historical trends in credit losses, recent portfolio performance, and forward-looking macroeconomic conditions. The models vary by portfolio and receivable type including consumer finance receivables, wholesale loans, and dealer loans. If Ford Credit does not believe the models reflect lifetime expected credit losses for the portfolio, an adjustment is made to reflect management judgment regarding qualitative factors, including economic uncertainty, observable changes in portfolio performance, and other relevant factors.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
Assumptions Used. Ford Credit’s allowance for credit losses is based on its assumptions regarding:
-
Probability of default. The expected probability of payment and time to default, which include assumptions about macroeconomic factors and recent performance; and
-
Loss given default. The percentage of the expected balance due at default that is not recoverable. The loss given default takes into account expected collateral value and future recoveries.
Macroeconomic factors used in Ford Credit’s models are country specific and include variables such as unemployment rates, personal bankruptcy filings, housing prices, and gross domestic product.
Sensitivity Analysis. Changes in the probability of default and loss given default assumptions would affect the allowance for credit losses. The effect of the indicated increase/decrease in the assumptions for Ford Credit’s U.S. Ford and Lincoln retail financing is as follows (in millions):
| Assumption | Basis Point Change | Increase/(Decrease) | ||||||||||||
| Probability of default (lifetime) | +/- 100 bps | $230/$(230) | ||||||||||||
| Loss given default | +/- 100 | 10/(10) |
Accumulated Depreciation on Vehicles Subject to Operating Leases
Accumulated depreciation on vehicles subject to operating leases reduces the value of the leased vehicles in Ford Credit’s operating lease portfolio from their original acquisition value to their expected residual value at the end of the lease term.
Ford Credit monitors residual values each month, and it reviews the adequacy of accumulated depreciation on a quarterly basis. If Ford Credit believes that the expected residual values for its vehicles have changed, it revises depreciation to ensure that net investment in operating leases (equal to the acquisition value of the vehicles less accumulated depreciation) will be adjusted to reflect Ford Credit’s revised estimate of the expected residual value at the end of the lease term. Adjustments to depreciation expense result in a change in the depreciation rates of the vehicles subject to operating leases and are recorded prospectively on a straight-line basis.
Generally, lease customers have the option to buy the leased vehicle at the end of the lease or to return the vehicle to the dealer.
Nature of Estimates Required. Each operating lease in Ford Credit’s portfolio represents a vehicle it owns that has been leased to a customer. At the time Ford Credit purchases a lease, it establishes an expected residual value for the vehicle. Ford Credit estimates the expected residual value by evaluating recent auction values, return volumes for its leased vehicles, industrywide used vehicle prices, marketing incentive plans, and vehicle quality data.
Assumptions Used. Ford Credit’s accumulated depreciation on vehicles subject to operating leases is based on assumptions regarding:
-
Auction value. Ford Credit’s projection of the market value of the vehicles when sold at the end of the lease; and
-
Return volume. Ford Credit’s projection of the number of vehicles that will be returned at lease-end.
See Note 12 of the Notes to the Financial Statements for more information regarding accumulated depreciation on vehicles subject to operating leases.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations (Continued)
Sensitivity Analysis. For returned vehicles, Ford Credit faces a risk that the amount it obtains from the vehicle sold at auction will be less than its estimate of the expected residual value for the vehicle. The impact of the change in assumptions on future auction values and return volumes would increase or decrease accumulated supplemental depreciation and depreciation expense over the remaining terms of the operating leases; however, the impact may be tempered or exacerbated based on future auction values in relation to the purchase price specified in the lease contract. A change in the assumption for an auction value will impact Ford Credit’s estimate of accumulated supplemental depreciation if the future auction value is lower than the purchase price specified in the lease contract. The effect of the indicated increase/decrease in the assumptions for Ford Credit’s U.S. Ford and Lincoln operating lease portfolio is as follows (in millions):
| Assumption | Basis Point Change | Increase/(Decrease) | ||||||||||||
| Future auction values | +/- 100 bps | $(20)/$20 | ||||||||||||
| Return volumes | +/- 100 | 5/(5) |
Adjustments to the amount of accumulated supplemental depreciation on operating leases are reflected on our balance sheets as Net investment in operating leases and on our income statements in Ford Credit interest, operating, and other expenses.
ACCOUNTING STANDARDS ISSUED BUT NOT YET ADOPTED
For a discussion of recent accounting standards, see Note 3 of the Notes to the Financial Statements.
ITEM 7A. Quantitative and Qualitative Disclosures About Market Risk
OVERVIEW
We are exposed to a variety of market and other risks, including the effects of changes in foreign currency exchange rates, commodity prices, and interest rates, as well as risks to availability of funding sources, hazard events, and specific asset risks.
We monitor and manage these exposures as an integral part of our overall risk management program, which includes regular reports to a central management committee, the Global Risk Management Committee (“GRMC”). The GRMC is chaired by our Chief Financial Officer, and the committee includes our Controller and Treasurer.
We are exposed to liquidity risk, including the possibility of having to curtail business or being unable to meet financial obligations as they come due because funding sources may be reduced or become unavailable. Our plan is to maintain funding sources to ensure liquidity through a variety of economic or business cycles. As discussed in greater detail in Item 7, our funding sources include sales of receivables in securitizations and other structured financings, unsecured debt issuances, equity and equity-linked issuances, and bank borrowings.
We are exposed to a variety of other risks, such as loss or damage to property, liability claims, and employee injury. We protect against these risks through the purchase of commercial insurance that is designed to protect us above our self-insured retentions against events that could generate significant losses.
Direct responsibility for the execution of our market risk management strategies resides with our Treasurer’s Office and is governed by written policies and procedures. Separation of duties is maintained between the development and authorization of derivative trades, the transaction of derivatives, and the settlement of cash flows. Regular audits are conducted to ensure that appropriate controls are in place and that they remain effective. In addition, our market risk exposures and our use of derivatives to manage these exposures are approved by the GRMC, and reviewed by the Audit Committee of our Board of Directors.
In accordance with our corporate risk management policies, we use derivative instruments, when available, such as forward contracts, swaps, and options that economically hedge certain exposures (foreign currency, commodity, and interest rates). We do not use derivative contracts for trading, market-making, or speculative purposes. In certain instances, we forgo hedge accounting, and in certain other instances, our derivatives do not qualify for hedge accounting. Either situation results in unrealized gains and losses that are recognized in income. For additional information on our derivatives, see Note 20 of the Notes to the Financial Statements.
The market and counterparty risks of the Company excluding Ford Credit as well as our Ford Credit segment are discussed and quantified below.
COMPANY EXCLUDING FORD CREDIT MARKET RISK
We frequently have expenditures and receipts denominated in foreign currencies, including the following: purchases and sales of finished vehicles and production parts, debt and other payables, subsidiary dividends, and investments in foreign operations. These expenditures and receipts create exposures to changes in exchange rates. We also are exposed to changes in prices of commodities used in the production of our vehicles and changes in interest rates.
Foreign currency risk, commodity risk, and interest rate risk are measured and quantified using a model to evaluate the sensitivity of market value to instantaneous, parallel shifts in rates and/or prices.
Foreign Currency Risk. Foreign currency risk is the possibility that our financial results could be worse than planned because of changes in currency exchange rates. Accordingly, our practice is to use derivative instruments to hedge our economic exposure with respect to forecasted revenues and costs, assets, liabilities, and firm commitments denominated in certain foreign currencies consistent with our overall risk management strategy. In our hedging actions, we use derivative instruments commonly used by corporations to reduce foreign exchange risk (e.g., forward contracts). The extent to which we hedge is also impacted by materiality of the risk in the context of our overall portfolio, market liquidity, and/or our ability to achieve designated hedge accounting.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk (Continued)
The net fair value of foreign exchange forward contracts (including adjustments for credit risk) as of December 31, 2023, was a liability of $319 million, compared with an asset of $236 million as of December 31, 2022. The potential change in the fair value from a 10% change in the underlying exchange rates, in U.S. dollar terms, would have been $3.1 billion at December 31, 2023, compared with $1.9 billion at December 31, 2022. The sensitivity analysis presented is hypothetical and assumes foreign exchange rate changes are instantaneous and adverse across all currencies. In reality, some of our exposures offset and foreign exchange rates move in different magnitudes and at different times, and any changes in fair value would generally be offset by changes in the underlying exposure. See Note 20 of the Notes to the Financial Statements for more information regarding our foreign currency exchange contracts.
Commodity Price Risk. Commodity price risk is the possibility that our financial results could be worse than planned because of changes in the prices of commodities used in the production of motor vehicles, such as base metals (e.g., steel, copper, and aluminum), precious metals (e.g., palladium), energy (e.g., natural gas and electricity), and plastics/resins (e.g., polypropylene). As we transition to a greater mix of electric vehicles, we expect to increase our reliance on lithium, cobalt, nickel, graphite, and manganese, among other materials, for batteries. Our practice is to use derivative instruments to hedge the price risk with respect to forecasted purchases of certain commodities consistent with our overall risk management strategy. In our hedging actions, we use derivative instruments commonly used by corporations to reduce commodity price risk (e.g., financially settled forward contracts). The extent to which we hedge is also impacted by materiality of the risk in the context of our overall portfolio, market liquidity, and/or our ability to achieve designated hedge accounting.
The net fair value of commodity forward contracts (including adjustments for credit risk) as of December 31, 2023, was a liability of $9 million, compared with a liability of $49 million as of December 31, 2022. The potential change in the fair value from a 10% change in the underlying commodity prices would have been $203 million at December 31, 2023, compared with $178 million at December 31, 2022. The sensitivity analysis presented is hypothetical and assumes commodity price changes are instantaneous and adverse across all commodities. In reality, commodity prices move in different magnitudes and at different times, and any changes in fair value would generally be offset by changes in the underlying exposure.
In addition, our purchasing organization (with guidance from the GRMC, as appropriate) negotiates contracts for the continuous supply of raw materials. In some cases, these contracts stipulate minimum purchase amounts and specific prices, and, therefore, play a role in managing commodity price risk.
Interest Rate Risk. Interest rate risk relates to the loss we could incur in our Company cash investment portfolios due to a change in interest rates. Our interest rate sensitivity analysis on our investment portfolios includes cash and cash equivalents and net marketable securities. At December 31, 2023, we had Company cash of $28.8 billion in our investment portfolios, compared to $32.3 billion at December 31, 2022. We invest the portfolios in securities of various types and maturities, the value of which are subject to fluctuations in interest rates. The investment strategy is based on clearly defined risk and liquidity guidelines to maintain liquidity, minimize risk, and earn a reasonable return on the short-term investments. In investing the cash in our investment portfolios, safety of principal is the primary objective and risk-adjusted return is the secondary objective.
At any time, a rise in interest rates could have a material adverse impact on the fair value of our portfolios. Assuming a hypothetical increase in interest rates of one percentage point, the value of our portfolios would be reduced by $222 million, as calculated as of December 31, 2023. This compares to $256 million, as calculated as of December 31, 2022. While these are our best estimates of the impact of the specified interest rate scenario, actual results could differ from those projected. The sensitivity analysis presented assumes interest rate changes are instantaneous, parallel shifts in the yield curve. In reality, interest rate changes of this magnitude are rarely instantaneous or parallel.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk (Continued)
FORD CREDIT MARKET RISK
Market risk for Ford Credit is the possibility that changes in interest and currency exchange rates will adversely affect cash flow and economic value.
Interest Rate Risk. Generally, Ford Credit’s assets and the related debt have different re-pricing periods, and consequently, respond differently to changes in interest rates.
Ford Credit’s assets consist primarily of fixed-rate retail financing and operating lease contracts and floating-rate wholesale receivables. Fixed-rate retail financing and operating lease contracts generally require customers to make equal monthly payments over the life of the contract. Wholesale receivables are originated to finance new and used vehicles held in dealers’ inventory and generally require dealers to pay a floating rate.
Debt consists primarily of short- and long-term unsecured and securitized debt. Ford Credit’s term debt instruments are principally fixed-rate and require fixed and equal interest payments over the life of the instrument and a single principal payment at maturity.
Ford Credit’s interest rate risk management objective is to reduce volatility in its cash flows and volatility in its economic value from changes in interest rates based on an established risk tolerance that may vary by market. Ford Credit uses economic value sensitivity analysis and re-pricing gap analysis to evaluate potential long-term effects of changes in interest rates. It then enters into interest rate swaps to convert portions of its floating-rate debt to fixed or its fixed-rate debt to floating to ensure that Ford Credit’s exposure falls within the established tolerances. Ford Credit also uses pre-tax cash flow sensitivity analysis to monitor the level of near-term cash flow exposure. The pre-tax cash flow sensitivity analysis measures the changes in expected cash flows associated with Ford Credit’s interest-rate-sensitive assets, liabilities, and derivative financial instruments from hypothetical changes in interest rates over a twelve-month horizon. Interest rate swaps are placed to maintain exposure within approved thresholds and the Asset-Liability Committee reviews the re-pricing mismatch monthly.
To provide a quantitative measure of the sensitivity of its pre-tax cash flow to changes in interest rates, Ford Credit uses interest rate scenarios that assume a hypothetical, instantaneous increase or decrease of one percentage point in all interest rates across all maturities (a “parallel shift”), as well as a base case that assumes that all interest rates remain constant at existing levels. In reality, interest rate changes are rarely instantaneous or parallel and rates could move more or less than the one percentage point assumed in Ford Credit’s analysis. As a result, the actual impact to pre-tax cash flow could be higher or lower than the results detailed in the table below. These interest rate scenarios are purely hypothetical and do not represent Ford Credit’s view of future interest rate movements.
Under these interest rate scenarios, Ford Credit expects more assets than debt and liabilities to re-price in the next twelve months. Other things being equal, this means that during a period of rising interest rates, the interest received on Ford Credit’s assets will increase more than the interest paid on Ford Credit’s debt, thereby initially increasing Ford Credit’s pre-tax cash flow. During a period of falling interest rates, Ford Credit would expect its pre-tax cash flow to initially decrease. Ford Credit’s pre-tax cash flow sensitivity to interest rate movement at December 31 was as follows (in millions):
| Pre-Tax Cash Flow Sensitivity | 2022 | 2023 | ||||||||||||
| One percentage point instantaneous increase in interest rates | $ | 127 | $ | 78 | ||||||||||
| One percentage point instantaneous decrease in interest rates | (127) | (78) |
While the sensitivity analysis presented is Ford Credit’s best estimate of the impacts of the specified assumed interest rate scenarios, its actual results could differ from those projected. The model Ford Credit uses to conduct this analysis is heavily dependent on assumptions. Embedded in the model are assumptions regarding the reinvestment of maturing asset principal, refinancing of maturing debt, replacement of maturing derivatives, exercise of options embedded in debt and derivatives, and predicted repayment of retail financing and operating lease contracts ahead of contractual maturity. Ford Credit’s repayment projections ahead of contractual maturity are based on historical experience. If interest rates or other factors change, Ford Credit’s actual prepayment experience could be different than projected.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk (Continued)
Foreign Currency Risk. Ford Credit’s policy is to minimize exposure to changes in currency exchange rates. To meet funding objectives, Ford Credit borrows in a variety of currencies, principally U.S. dollars, Canadian dollars, euros, sterling, and renminbi. Ford Credit faces exposure to currency exchange rates if a mismatch exists between the currency of receivables and the currency of the debt funding those receivables. When possible, receivables are funded with debt in the same currency, minimizing exposure to exchange rate movements. When a different currency is used, Ford Credit may use foreign currency swaps and foreign currency forwards to convert substantially all of its foreign currency debt obligations to the local country currency of the receivables. As a result of this policy, Ford Credit believes its market risk exposure, relating to changes in currency exchange rates at December 31, 2023, is insignificant.
Derivative Fair Values. The net fair value of Ford Credit’s derivative financial instruments at December 31, 2023 was a liability of $1.3 billion, compared to a liability of $2.0 billion at December 31, 2022.
COUNTERPARTY RISK
Counterparty risk relates to the loss we could incur if an obligor or counterparty defaulted on an investment or a derivative contract. We enter into master agreements with counterparties that allow netting of certain exposures in order to manage this risk. Exposures primarily relate to investments in fixed income instruments and derivative contracts used for managing interest rate, foreign currency exchange rate, and commodity price risk. We, together with Ford Credit, establish exposure limits for each counterparty to minimize risk and provide counterparty diversification.
Our approach to managing counterparty risk is forward-looking and proactive, allowing us to take risk mitigation actions before risks become losses. Exposure limits are established based on our overall risk tolerance, which is calculated from counterparty credit ratings and market-based credit default swap (“CDS”) spreads. The exposure limits are lower for smaller and lower-rated counterparties, counterparties that have relatively higher CDS spreads, and for longer dated exposures. Our exposures are monitored on a regular basis and included in periodic reports to our Treasurer.
Substantially all of our counterparty exposures are with counterparties that have an investment grade rating. Investment grade is our guideline for minimum counterparty long-term ratings.
Item 8. Financial Statements and Supplementary Data.
The Report of Independent Registered Public Accounting Firm, our Financial Statements, the accompanying Notes to the Financial Statements, and the Financial Statement Schedule that are filed as part of this Report are listed under “Item 15. Exhibits and Financial Statement Schedules” and are set forth beginning on page 105 immediately following the signature pages of this Report.
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure.
None.
Item 9A. Controls and Procedures.
Evaluation of Disclosure Controls and Procedures. James D. Farley, Jr., our Chief Executive Officer (“CEO”), and John T. Lawler, our Chief Financial Officer (“CFO”), have performed an evaluation of the Company’s disclosure controls and procedures, as that term is defined in Rule 13a-15(e) or 15d-15(e) of the Securities Exchange Act of 1934, as amended (“Exchange Act”), as of December 31, 2023, and each has concluded that such disclosure controls and procedures are effective to ensure that information required to be disclosed in our periodic reports filed under the Exchange Act is recorded, processed, summarized, and reported within the time periods specified by SEC rules and forms, and that such information is accumulated and communicated to the CEO and CFO to allow timely decisions regarding required disclosures.
Management’s Report on Internal Control Over Financial Reporting. Our management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rule 13a-15(f) or 15d-15(f). The Company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions or because the degree of compliance with policies or procedures may deteriorate.
Under the supervision and with the participation of our management, including our CEO and CFO, we conducted an assessment of the effectiveness of our internal control over financial reporting as of December 31, 2023. The assessment was based on criteria established in the framework Internal Control - Integrated Framework (2013), issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on this assessment, management concluded that our internal control over financial reporting was effective as of December 31, 2023.
The effectiveness of the Company’s internal control over financial reporting as of December 31, 2023 has been audited by PricewaterhouseCoopers LLP (PCAOB ID 238), an independent registered public accounting firm, as stated in its report included herein.
Changes in Internal Control Over Financial Reporting. There were no changes in internal control over financial reporting during the quarter ended December 31, 2023 that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. Other Information.
During the three months ended December 31, 2023, no director or officer of the Company adopted, modified, or terminated a “Rule 10b5-1 trading arrangement” or a “non-Rule 10b5-1 trading arrangement” as each term is defined in Item 408(a) of Regulation S-K.
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections.
Not applicable.
PART III.
Item 10. Directors, Executive Officers of Ford, and Corporate Governance.
The information required by Item 10 regarding our directors is incorporated by reference from the information under the captions “Proposal 1. Election of Directors,” “Corporate Governance – Beneficial Stock Ownership,” and “Corporate Governance – Delinquent Section 16(a) Reports” in our Proxy Statement. The information required by Item 10 regarding our executive officers appears as Item 4A under Part I of this Report. The information required by Item 10 regarding an audit committee financial expert is incorporated by reference from the information under the caption “Corporate Governance – Audit Committee Financial Expert and Auditor Rotation” in our Proxy Statement. The information required by Item 10 regarding the members of our Audit Committee of the Board of Directors is incorporated by reference from the information under the captions “Proxy Summary,” “Corporate Governance – Board Committee Functions,” “Corporate Governance – Audit Committee Financial Expert and Auditor Rotation,” and “Proposal 1. Election of Directors” in our Proxy Statement. The information required by Item 10 regarding the Audit Committee’s review and discussion of the audited financial statements is incorporated by reference from information under the caption “Audit Committee Report” in our Proxy Statement. The information required by Item 10 regarding our codes of ethics is incorporated by reference from the information under the caption “Corporate Governance – Codes of Ethics” in our Proxy Statement. In addition, we have included in Item 1 instructions for how to access our codes of ethics on our website and our Internet address. Amendments to, and waivers granted under, our Code of Ethics for Senior Financial Personnel, if any, will be posted to our website as well.
Item 11. Executive Compensation.
The information required by Item 11 is incorporated by reference from the information under the following captions in our Proxy Statement: “Director Compensation in 2023,” “Compensation Discussion and Analysis,” “Compensation Committee Report,” “Compensation Committee Interlocks and Insider Participation,” “Compensation of Named Executives,” “Summary Compensation Table,” “Grants of Plan-Based Awards in 2023,” “Outstanding Equity Awards at 2023 Fiscal Year-End,” “Option Exercises and Stock Vested in 2023,” “Pension Benefits in 2023,” “Nonqualified Deferred Compensation in 2023,” “Potential Payments Upon Termination or Change-in-Control,” and “Pay Ratio.”
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
The information required by Item 12 is incorporated by reference from the information under the captions “Equity Compensation Plan Information” and “Corporate Governance – Beneficial Stock Ownership” in our Proxy Statement.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
The information required by Item 13 is incorporated by reference from the information under the captions “Corporate Governance – Certain Relationships and Related Party Transactions” and “Corporate Governance – Independence of Directors and Relevant Facts and Circumstances” in our Proxy Statement.
Item 14. Principal Accounting Fees and Services.
The information required by Item 14 is incorporated by reference from the information under the caption “Proposal 2. Ratification of Independent Registered Public Accounting Firm” in our Proxy Statement.
PART IV.
Item 15. Exhibits and Financial Statement Schedules.
(a) 1. Financial Statements – Ford Motor Company and Subsidiaries
The following are contained in this 2023 Form 10-K Report:
-
Report of Independent Registered Public Accounting Firm.
-
Consolidated Statements of Cash Flows for the years ended December 31, 2021, 2022, and 2023.
-
Consolidated Income Statements for the years ended December 31, 2021, 2022, and 2023.
-
Consolidated Statements of Comprehensive Income for the years ended December 31, 2021, 2022, and 2023.
-
Consolidated Balance Sheets at December 31, 2022 and 2023.
-
Consolidated Statements of Equity for the years ended December 31, 2021, 2022, and 2023.
-
Notes to the Financial Statements.
The Report of Independent Registered Public Accounting Firm, the Consolidated Financial Statements, and the Notes to the Financial Statements listed above are filed as part of this Report and are set forth beginning on page 105 immediately following the signature pages of this Report.
(a) 2. Financial Statement Schedules
| Designation | Description | |||||||
| Schedule II | Valuation and Qualifying Accounts for the years ended 2021, 2022, and 2023 |
Schedule II is filed as part of this Report and is set forth on page 179 immediately following the Notes to the Financial Statements referred to above. The other schedules are omitted because they are not applicable, the information required to be contained in them is disclosed elsewhere on our Consolidated Financial Statements, or the amounts involved are not sufficient to require submission.
(a) 3. Exhibits
| Designation | Description | Method of Filing | ||||||||||||
| Exhibit 3-A | Restated Certificate of Incorporation, dated August 2, 2000. | Filed as Exhibit 3-A to our Annual Report on Form 10-K for the year ended December 31, 2000. (a) | ||||||||||||
| Exhibit 3-A-1 | Certificate of Designations of Series A Junior Participating Preferred Stock filed on September 11, 2009. | Filed as Exhibit 3.1 to our Current Report on Form 8-K filed September 11, 2009. (a) | ||||||||||||
| Exhibit 3-B | By-laws. | Filed as Exhibit 3.1 to our Form 8-K filed on December 9, 2022. (a) | ||||||||||||
| Exhibit 4-A | Tax Benefit Preservation Plan (“TBPP”) dated September 11, 2009 between Ford Motor Company and Computershare Trust Company, N.A. | Filed as Exhibit 4.1 to our Current Report on Form 8-K filed September 11, 2009. (a) | ||||||||||||
| Exhibit 4-A-1 | Amendment No. 1 to TBPP dated September 11, 2012. | Filed as Exhibit 4 to our Current Report on Form 8-K filed September 12, 2012. (a) | ||||||||||||
| Exhibit 4-A-2 | Amendment No. 2 to TBPP dated September 9, 2015. | Filed as Exhibit 4 to our Current Report on Form 8-K filed September 11, 2015. (a) | ||||||||||||
| Exhibit 4-A-3 | Amendment No. 3 to TBPP dated September 13, 2018. | Filed as Exhibit 4 to our Current Report on Form 8-K filed September 14, 2018. (a) | ||||||||||||
| Exhibit 4-A-4 | Amendment No. 4 to TBPP dated September 9, 2021. | Filed as Exhibit 4 to our Current Report on Form 8-K filed September 10, 2021. (a) | ||||||||||||
| Exhibit 4-B | Description of Securities. | Filed with this Report. | ||||||||||||
| Exhibit 10-A | Executive Separation Allowance Plan, as amended and restated effective as of January 1, 2018. (b) | Filed as Exhibit 10.1 to our Current Report on Form 8-K filed February 7, 2018. (a) | ||||||||||||
| Exhibit 10-B | Deferred Compensation Plan for Non-Employee Directors, as amended and restated as of January 1, 2012. (b) | Filed as Exhibit 10-B to our Annual Report on Form 10-K for the year ended December 31, 2011. (a) | ||||||||||||
| Exhibit 10-C | 2014 Stock Plan for Non-Employee Directors (b) | Filed as Exhibit 10-C to our Annual Report on Form 10-K for the year ended December 31, 2013. (a) | ||||||||||||
| Exhibit 10-D | Benefit Equalization Plan, as amended and restated effective as of January 1, 2022. (b) | Filed as Exhibit 10.3 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2022. (a) | ||||||||||||
| Exhibit 10-E | Description of financial counseling services provided to certain executives. (b) | Filed as Exhibit 10-E to our Annual Report on Form 10-K for the year ended December 31, 2019. (a) | ||||||||||||
| Exhibit 10-F | Defined Benefit Supplemental Executive Retirement Plan, as amended and restated effective as of January 1, 2022. (b) | Filed as Exhibit 10.4 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2022. (a) | ||||||||||||
| Exhibit 10-F-1 | Defined Contribution Supplemental Executive Retirement Plan, as amended and restated effective as of January 1, 2022. (b) | Filed as Exhibit 10.5 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2022. (a) | ||||||||||||
| Exhibit 10-G | Description of Director Compensation as of July 13, 2006. (b) | Filed as Exhibit 10-G-3 to our Quarterly Report on Form 10-Q for the quarter ended September 30, 2006. (a) | ||||||||||||
| Exhibit 10-G-1 | Amendment to Description of Director Compensation as of February 8, 2012. (b) | Filed as Exhibit 10-F-3 to our Annual Report on Form 10-K for the year ended December 31, 2011. (a) | ||||||||||||
| Exhibit 10-G-2 | Amendment to Description of Director Compensation as of July 1, 2013. (b) | Filed as Exhibit 10-G-2 to our Annual Report on Form 10-K for the year ended December 31, 2013. (a) | ||||||||||||
| Exhibit 10-G-3 | Amendment to Description of Director Compensation as of January 1, 2017. (b) | Filed as Exhibit 10-G-3 to our Annual Report on Form 10-K for the year ended December 31, 2016. (a) | ||||||||||||
| Exhibit 10-H | 2008 Long-Term Incentive Plan. (b) | Filed as Exhibit 10.1 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2008. (a) | ||||||||||||
| Exhibit 10-I | Description of Vehicle Evaluation Program for Non-Executive Directors. (b) | Filed as Exhibit 10-I to our Annual Report on Form 10-K for the year ended December 31, 2021. (a) | ||||||||||||
| Exhibit 10-J | Non-Employee Directors Life Insurance and Optional Retirement Plan as amended and restated as of December 31, 2010. (b) | Filed as Exhibit 10-I to our Annual Report on Form 10-K for the year ended December 31, 2010. (a) | ||||||||||||
| Exhibit 10-K | Description of Non-Employee Directors Accidental Death, Dismemberment and Permanent Total Disablement Indemnity. (b) | Filed as Exhibit 10-S to our Annual Report on Form 10-K for the year ended December 31, 1992. (a) | ||||||||||||
| Exhibit 10-K-1 | Description of Amendment to Basic Life Insurance and Accidental Death & Dismemberment Insurance. (b) | Filed as Exhibit 10-K-1 to our Annual Report on Form 10-K for the year ended December 31, 2013. (a) | ||||||||||||
| Exhibit 10-L | Offer Letter to Peter Stern dated July 21, 2023. (b) | Filed with this Report. | ||||||||||||
| Exhibit 10-M | Offer Letter to Doug Field dated August 26, 2021. (b) | Filed as Exhibit 10-N to our Annual Report on Form 10-K for the year ended December 31, 2021. (a) | ||||||||||||
| Exhibit 10-N | Agreement between Ford Motor Company and James D. Farley, Jr. dated August 3, 2020. (b) | Filed as Exhibit 10.1 to our Quarterly Report on Form 10-Q for the quarter ended September 30, 2020. (a) | ||||||||||||
| Exhibit 10-O | Select Retirement Plan, as amended and restated effective as of January 1, 2018. (b) | Filed as Exhibit 10.4 to our Current Report on Form 8-K filed February 7, 2018. (a) | ||||||||||||
| Exhibit 10-P | Deferred Compensation Plan, as amended and restated as of December 31, 2010. (b) | Filed as Exhibit 10-M to our Annual Report on Form 10-K for the year ended December 31, 2010. (a) | ||||||||||||
| Exhibit 10-P-1 | Suspension of Open Enrollment in Deferred Compensation Plan. (b) | Filed as Exhibit 10-M-1 to our Annual Report on Form 10-K for the year ended December 31, 2009. (a) | ||||||||||||
| Exhibit 10-Q | Annual Performance Bonus Plan, as amended May 10, 2023. (b) | Filed as Exhibit 10.1 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) |
| Designation | Description | Method of Filing | ||||||||||||
| Exhibit 10-Q-1 | Annual Incentive Compensation Plan Metrics for 2022. (b) | Filed as Exhibit 10.1 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2022. (a) | ||||||||||||
| Exhibit 10-Q-2 | Annual Performance Bonus Plan Metrics for 2023. (b) | Filed as Exhibit 10.1 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2023. (a) | ||||||||||||
| Exhibit 10-Q-3 | Performance-Based Restricted Stock Unit Metrics for 2020. (b) | Filed as Exhibit 10.2 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2020. (a) | ||||||||||||
| Exhibit 10-Q-4 | Performance-Based Restricted Stock Unit Metrics for 2021. (b) | Filed as Exhibit 10.2 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2021. (a) | ||||||||||||
| Exhibit 10-Q-5 | Performance-Based Restricted Stock Unit Metrics for 2022. (b) | Filed as Exhibit 10.2 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2022. (a) | ||||||||||||
| Exhibit 10-Q-6 | Performance-Based Restricted Stock Unit Metrics for 2023. (b) | Filed as Exhibit 10.2 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2023. (a) | ||||||||||||
| Exhibit 10-Q-7 | Corporate Officer Compensation Recoupment Policy. (b) | Filed with this Report. | ||||||||||||
| Exhibit 10-R | 2018 Long-Term Incentive Plan. (b) | Filed as Exhibit 4.1 to Registration Statement No. 333-226348. (a) | ||||||||||||
| Exhibit 10-S | 2023 Long-Term Incentive Plan. (b) | Filed as Exhibit 4.9 to Registration Statement No. 333-271592. (a) | ||||||||||||
| Exhibit 10-S-1 | Form of Stock Option Terms and Conditions for 2023 Long-Term Incentive Plan. (b) | Filed as Exhibit 10.2 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-2 | Form of Stock Option Agreement for 2023 Long-Term Incentive Plan. (b) | Filed as Exhibit 10.3 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-3 | Form of Stock Option Agreement (ISO) for 2023 Long-Term Incentive Plan. (b) | Filed as Exhibit 10.4 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-4 | Form of Stock Option Agreement (U.K. NQO) for 2023 Long-Term Incentive Plan. (b) | Filed as Exhibit 10.5 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-5 | Form of Stock Option (U.K.) Terms and Conditions for 2023 Long-Term Incentive Plan. (b) | Filed as Exhibit 10.6 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-6 | Form of Restricted Stock Grant Letter for 2023 Long-Term Incentive Plan. (b) | Filed as Exhibit 10.7 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-7 | Form of Final Award Notification Letter for Performance Stock Units. (b) | Filed as Exhibit 10.8 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-8 | Form of Annual Equity Grant Letter for 2023 Long-Term Incentive Plan V.1. (b) | Filed as Exhibit 10.9 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-9 | Form of Annual Equity Grant Letter for 2023 Long-Term Incentive Plan V.2. (b) | Filed as Exhibit 10.10 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-10 | Form of 2023 Long-Term Incentive Plan Restricted Stock Unit Agreement. (b) | Filed as Exhibit 10.11 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-11 | Form of 2023 Long-Term Incentive Plan Restricted Stock Unit Terms and Conditions. (b) | Filed as Exhibit 10.12 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-12 | Form of Final Award Agreement for Performance Stock Units under 2023 Long-Term Incentive Plan. (b) | Filed as Exhibit 10.13 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-13 | Form of Final Award Terms and Conditions for Performance Stock Units under 2023 Long-Term Incentive Plan. (b) | Filed as Exhibit 10.14 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-S-14 | Form of Notification Letter for Time-Based Restricted Stock Units under 2023 Long-Term Incentive Plan. (b) | Filed as Exhibit 10.15 to our Quarterly Report on Form 10-Q for the quarter ended June 30, 2023. (a) | ||||||||||||
| Exhibit 10-T | Description of Company Practices regarding Club Memberships for Executives. (b) | Filed as Exhibit 10-V to our Annual Report on Form 10-K for the year ended December 31, 2021. (a) | ||||||||||||
| Exhibit 10-U | Amended and Restated Credit Agreement dated as of November 24, 2009. | Filed as Exhibit 99.2 to our Current Report on Form 8-K filed November 25, 2009. (a) | ||||||||||||
| Exhibit 10-U-1 | Seventh Amendment dated as of March 15, 2012 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, and as further amended. | Filed as Exhibit 99.2 to our Current Report on Form 8-K filed March 15, 2012. (a) | ||||||||||||
| Exhibit 10-U-2 | Ninth Amendment dated as of April 30, 2013 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, and as further amended. | Filed as Exhibit 10 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2013. (a) | ||||||||||||
| Exhibit 10-U-3 | Tenth Amendment dated as of April 30, 2014 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, and as further amended. | Filed as Exhibit 10.1 to our Quarterly Report on Form 10-Q for the quarter ended March 31, 2014. (a) | ||||||||||||
| Exhibit 10-U-4 | Eleventh Amendment dated as of April 30, 2015 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, as amended and restated as of April 30, 2014, and as further amended, including the Third Amended and Restated Credit Agreement. | Filed as Exhibit 10.1 to our Current Report on Form 8-K filed May 1, 2015. (a) |
| Designation | Description | Method of Filing | ||||||||||||
| Exhibit 10-U-5 | Twelfth Amendment dated as of April 29, 2016 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, as amended and restated as of April 30, 2014, and as further amended and restated as of April 30, 2015. | Filed as Exhibit 10 to our Current Report on Form 8-K filed April 29, 2016. (a) | ||||||||||||
| Exhibit 10-U-6 | Thirteenth Amendment dated as of April 28, 2017 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, as amended and restated as of April 30, 2014, and as further amended and restated as of April 30, 2015. | Filed as Exhibit 10 to our Current Report on Form 8-K filed April 28, 2017. (a) | ||||||||||||
| Exhibit 10-U-7 | Fourteenth Amendment dated as of April 26, 2018 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, as amended and restated as of April 30, 2014, and as further amended and restated as of April 30, 2015. | Filed as Exhibit 10 to our Current Report on Form 8-K filed April 26, 2018. (a) | ||||||||||||
| Exhibit 10-U-8 | Fifteenth Amendment dated as of April 23, 2019 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, as amended and restated as of April 30, 2014, and as further amended and restated as of April 30, 2015. | Filed as Exhibit 10.1 to our Current Report on Form 8-K filed April 26, 2019. (a) | ||||||||||||
| Exhibit 10-U-9 | Sixteenth Amendment dated as of July 27, 2020 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, as amended and restated as of April 30, 2014, and as further amended and restated as of April 30, 2015. | Filed as Exhibit 10.1 to our Current Report on Form 8-K filed July 30, 2020. (a) | ||||||||||||
| Exhibit 10-U-10 | Seventeenth Amendment dated as of March 16, 2021 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, as amended and restated as of April 30, 2014, and as further amended and restated as of April 30, 2015. | Filed as Exhibit 10.1 to our Current Report on Form 8-K filed March 17, 2021. (a) | ||||||||||||
| Exhibit 10-U-11 | Eighteenth Amendment dated as of September 29, 2021 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, as amended and restated as of April 30, 2014, as amended and restated as of April 30, 2015, and as further amended, including the Fourth Amended and Restated Credit Agreement. | Filed as Exhibit 10.1 to our Current Report on Form 8-K filed September 29, 2021. (a) | ||||||||||||
| Exhibit 10-U-12 | Nineteenth Amendment dated as of June 23, 2022 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, as amended and restated as of April 30, 2014, as amended and restated as of April 30, 2015, as amended and restated as of September 29, 2021, and as further amended. | Filed as Exhibit 10.1 to our Current Report on Form 8-K filed June 23, 2022. (a) | ||||||||||||
| Exhibit 10-U-13 | Twentieth Amendment dated as of April 26, 2023 to our Credit Agreement dated as of December 15, 2006, as amended and restated as of November 24, 2009, as amended and restated as of April 30, 2014, as amended and restated as of April 30, 2015, as amended and restated as of September 29, 2021, and as further amended. | Filed as Exhibit 10.1 to our Current Report on Form 8-K filed April 26, 2023. (a) | ||||||||||||
| Exhibit 10-V | Revolving Credit Agreement dated as of April 23, 2019. | Filed as Exhibit 10.2 to our Current Report on Form 8-K filed April 26, 2019. (a) | ||||||||||||
| Exhibit 10-V-1 | First Amendment dated July 27, 2020 to the Revolving Credit Agreement dated April 23, 2019. | Filed as Exhibit 10.2 to our Current Report on Form 8-K filed July 30, 2020. (a) | ||||||||||||
| Exhibit 10-V-2 | Second Amendment dated March 16, 2021 to the Revolving Credit Agreement dated April 23, 2019. | Filed as Exhibit 10.2 to our Current Report on Form 8-K filed March 17, 2021. (a) | ||||||||||||
| Exhibit 10-V-3 | Third Amendment dated September 29, 2021 to the Revolving Credit Agreement dated April 23, 2019, and as further amended, including the First Amended and Restated Revolving Credit Agreement. | Filed as Exhibit 10.2 to our Current Report on Form 8-K filed September 29, 2021. (a) | ||||||||||||
| Exhibit 10-V-4 | Fourth Amendment dated June 23, 2022 to the Revolving Credit Agreement dated April 23, 2019, as amended and restated as of September 29, 2021, and as further amended. | Filed as Exhibit 10.2 to our Current Report on Form 8-K filed June 23, 2022. (a) | ||||||||||||
| Exhibit 10-V-5 | Fifth Amendment dated April 26, 2023 to the Revolving Credit Agreement dated April 23, 2019, as amended and restated as of September 29, 2021, and as further amended. | Filed as Exhibit 10.2 to our Current Report on Form 8-K filed April 26, 2023. (a) | ||||||||||||
| Exhibit 10-W | 364-Day Revolving Credit Agreement dated as of June 23, 2022. | Filed as Exhibit 10.3 to our Current Report on Form 8-K filed June 23, 2022. (a) | ||||||||||||
| Exhibit 10-W-1 | First Amendment dated October 26, 2022 to the 364-Day Revolving Credit Agreement dated as of June 23, 2022. | Filed as Exhibit 10 to our Current Report on Form 8-K filed October 28, 2022. (a) | ||||||||||||
| Exhibit 10-W-2 | Second Amendment dated April 26, 2023 to the 364-Day Revolving Credit Agreement dated as of June 23, 2022. | Filed as Exhibit 10.3 to our Current Report on Form 8-K filed April 26, 2023. (a) | ||||||||||||
| Exhibit 21 | List of Subsidiaries of Ford as of January 31, 2024. | Filed with this Report. |
| Designation | Description | Method of Filing | ||||||||||||
| Exhibit 23 | Consent of Independent Registered Public Accounting Firm. | Filed with this Report. | ||||||||||||
| Exhibit 24 | Powers of Attorney. | Filed with this Report. | ||||||||||||
| Exhibit 31.1 | Rule 15d-14(a) Certification of CEO. | Filed with this Report. | ||||||||||||
| Exhibit 31.2 | Rule 15d-14(a) Certification of CFO. | Filed with this Report. | ||||||||||||
| Exhibit 32.1 | Section 1350 Certification of CEO. | Furnished with this Report. | ||||||||||||
| Exhibit 32.2 | Section 1350 Certification of CFO. | Furnished with this Report. | ||||||||||||
| Exhibit 97 | Financial Statement Compensation Recoupment Policy. (b) | Filed with this Report. | ||||||||||||
| Exhibit 101.INS | Interactive Data Files pursuant to Rule 405 of Regulation S-T formatted in Inline Extensible Business Reporting Language (“Inline XBRL”). | (c) | ||||||||||||
| Exhibit 101.SCH | XBRL Taxonomy Extension Schema Document. | (c) | ||||||||||||
| Exhibit 101.CAL | XBRL Taxonomy Extension Calculation Linkbase Document. | (c) | ||||||||||||
| Exhibit 101.LAB | XBRL Taxonomy Extension Label Linkbase Document. | (c) | ||||||||||||
| Exhibit 101.PRE | XBRL Taxonomy Extension Presentation Linkbase Document. | (c) | ||||||||||||
| Exhibit 101.DEF | XBRL Taxonomy Extension Definition Linkbase Document. | (c) | ||||||||||||
| Exhibit 104 | Cover Page Interactive Data File (formatted in Inline XBRL contained in Exhibit 101). | (c) |
(a)Incorporated by reference as an exhibit to this Report (file number reference 1-3950, unless otherwise indicated).
(b)Management contract or compensatory plan or arrangement.
(c)Submitted electronically with this Report in accordance with the provisions of Regulation S-T.
Instruments defining the rights of holders of certain issues of long-term debt of Ford and of certain consolidated subsidiaries and of any unconsolidated subsidiary, for which financial statements are required to be filed with this Report, have not been filed as exhibits to this Report because the authorized principal amount of any one of such issues does not exceed 10% of the total assets of Ford and our subsidiaries on a consolidated basis. Ford agrees to furnish a copy of each of such instrument to the Securities and Exchange Commission upon request.
Item 16. Form 10-K Summary.
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, as amended, Ford has duly caused this Report to be signed on its behalf by the undersigned, thereunto duly authorized.
FORD MOTOR COMPANY
| By: | /s/ Cathy O’Callaghan | ||||
| Cathy O’Callaghan, Controller | |||||
| (principal accounting officer) | |||||
| Date: | February 6, 2024 |
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, this Report has been signed below by the following persons on behalf of Ford and in the capacities on the date indicated:
| Signature | Title | Date | ||||||||||||
| /s/ WILLIAM CLAY FORD, JR. | Director, Chair of the Board, Executive Chair, Chair of the Office of the Chair and Chief Executive, and Chair of the Finance Committee | February 6, 2024 | ||||||||||||
| William Clay Ford, Jr. | ||||||||||||||
| /s/ JAMES D. FARLEY, JR. | Director, President and Chief Executive Officer | February 6, 2024 | ||||||||||||
| James D. Farley, Jr. | (principal executive officer) | |||||||||||||
| KIMBERLY A. CASIANO* | Director | February 6, 2024 | ||||||||||||
| Kimberly A. Casiano | ||||||||||||||
| ALEXANDRA FORD ENGLISH* | Director | February 6, 2024 | ||||||||||||
| Alexandra Ford English | ||||||||||||||
| HENRY FORD III* | Director | February 6, 2024 | ||||||||||||
| Henry Ford III | ||||||||||||||
| WILLIAM W. HELMAN IV* | Director and Chair of the Sustainability, Innovation and Policy Committee | February 6, 2024 | ||||||||||||
| William W. Helman IV | ||||||||||||||
| JON M. HUNTSMAN, JR.* | Director | February 6, 2024 | ||||||||||||
| Jon M. Huntsman, Jr. | ||||||||||||||
| WILLIAM E. KENNARD* | Director and Chair of the Nominating and Governance Committee | February 6, 2024 | ||||||||||||
| William E. Kennard | ||||||||||||||
| JOHN C. MAY II* | Director | February 6, 2024 | ||||||||||||
| John C. May II | ||||||||||||||
| BETH E. MOONEY* | Director | February 6, 2024 | ||||||||||||
| Beth E. Mooney | ||||||||||||||
| LYNN VOJVODICH RADAKOVICH* | Director and Chair of the Compensation, Talent and Culture Committee | February 6, 2024 | ||||||||||||
| Lynn Vojvodich Radakovich | ||||||||||||||
| JOHN L. THORNTON* | Director | February 6, 2024 | ||||||||||||
| John L. Thornton |
| Signature | Title | Date | ||||||||||||
| JOHN B. VEIHMEYER* | Director and Chair of the Audit Committee | February 6, 2024 | ||||||||||||
| John B. Veihmeyer | ||||||||||||||
| JOHN S. WEINBERG* | Director | February 6, 2024 | ||||||||||||
| John S. Weinberg | ||||||||||||||
| /s/ JOHN T. LAWLER | Chief Financial Officer | February 6, 2024 | ||||||||||||
| John T. Lawler | (principal financial officer) | |||||||||||||
| /s/ CATHY O’CALLAGHAN | Controller | February 6, 2024 | ||||||||||||
| Cathy O’Callaghan | (principal accounting officer) | |||||||||||||
| *By: /s/ JONATHAN E. OSGOOD | February 6, 2024 | |||||||||||||
| Jonathan E. Osgood | ||||||||||||||
| Attorney-in-Fact | ||||||||||||||
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Stockholders of Ford Motor Company
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the accompanying consolidated balance sheets of Ford Motor Company and its subsidiaries (the “Company”) as of December 31, 2023 and 2022, and the related consolidated statements of income, of comprehensive income, of equity and of cash flows for each of the three years in the period ended December 31, 2023, including the related notes and financial statement schedule listed in the index appearing under Item 15(a)(2) (collectively referred to as the “consolidated financial statements”). We also have audited the Company’s internal control over financial reporting as of December 31, 2023, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, 2023 and 2022, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2023 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2023, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
Basis for Opinions
The Company’s management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in Management’s Report on Internal Control Over Financial Reporting appearing under Item 9A. Our responsibility is to express opinions on the Company’s consolidated financial statements and on the Company's internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and
Showing the first 8K of 335K characters. Open the full section