 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
85K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following is management’s discussion and analysis of certain significant factors that have affected our financial position and operating results during the periods included in the accompanying consolidated financial statements. (Dollar amounts are in thousands except for per share amounts and where otherwise noted.)
BUSINESS AND OPERATIONAL OVERVIEW
Fastenal is a North American leader in the wholesale distribution of industrial and construction supplies. We distribute these supplies through a network of approximately 2,600 company owned stores. Most of our customers are in the manufacturing and non-residential construction markets. The manufacturing market includes both original equipment manufacturers (OEM) and maintenance, repair, and operations (MRO). The non-residential construction market includes general, electrical, plumbing, sheet metal, and road contractors. Other users of our product include farmers, truckers, railroads, oil exploration, production and refinement companies, mining companies, federal, state, and local governmental entities, schools, and certain retail trades. Geographically, our stores and customers are primarily located in North America.
BUSINESS DISCUSSION
We are a growth focused organization and we constantly strive to make investments into the growth drivers of our business. These investments typically center on people. By adding more people we add to our ability to interact with and to serve our customers from our local store and to back them up in some type of support role. In recent years this investment has also centered on more industrial vending devices to serve our customers’ needs on a 24 hours a day, 7 days a week basis.
The table below summarizes our store employee count and our total employee count at the end of the periods presented. This is intended to demonstrate the energy (or capacity) added. Later in this document we discuss the average full-time equivalent employee count to help explain the expense trends in more detail. The final two items below summarize our investments in industrial vending devices and in store locations.
| Q4 2014 | Q4 2015 | Twelve-month % Change | ||||||
| End of period total store employee count | 12,293 | 13,961 | 13.6 | % | ||||
| Change in total store employee count | 1,668 | |||||||
| End of period total employee count | 18,417 | 20,746 | 12.6 | % | ||||
| Change in total employee count | 2,329 | |||||||
| Industrial vending machines (installed device count) | 46,855 | 55,510 | 18.5 | % | ||||
| Number of store locations | 2,637 | 2,622 | -0.6 | % |
For a quick recap of some positive and negative aspects of our business, we would note the following:
Positive –
| (1) | During 2015, we added 1,668 people into our stores. We stated in January 2015 we would add people in an aggressive fashion during 2015. This is the result. |
| (2) | After several years of holding back on store openings and even contracting our total store base, we plan to expand our pace of store openings in 2016 with a goal of opening 60 to 75 new stores (an increase of approximately 2% to 3% over our number of stores as of December 31, 2015). We opened 41 and 24 stores in 2015 and 2014, respectively, and we closed or consolidated 50 and 73 stores in 2015 and 2014, respectively. |
| (3) | We are seeing a very strong pace of national account signings. During 2015, we signed more new contracts (defined as new customer accounts with a multi-site contract) with national account customers than in 2014. This increase reversed the declining trend in the previous year. Similar to the third quarter of 2015, the business with our top 100 national account customers (representing approximately 25% of sales) experienced poor sales results in the fourth quarter of 2015, with net sales contraction of approximately 4.3%, while sales to our remaining national account customers (representing approximately 22% of sales) grew approximately 8.1%. |
| (4) | We have also seen an expansion of our Onsite business (defined as dedicated sales and service provided from within the customer's facility) during 2015. During the year we signed 82 new Onsite customer locations. |
| (5) | We converted approximately 800 stores to the CSP 16 (Customer Service Project 2016) format in the fourth quarter of 2015. This merchandising footprint, disclosed at our November 2015 Investor Day, involves expanded inventory placement at our store locations to enhance same-day capabilities. |
Negative –
| (1) | 2015 was hit hard by a slowdown in our business with customers connected to the oil and gas industry. Those customers include direct industry participants as well as other customers serving those participants. |
| (2) | 2015 was negatively affected by a strong U.S. dollar, relative to other currencies, which hurts our U.S. customer base (which accounts for approximately 89% of sales). |
| (3) | The net sales of our Canadian business, which grew about 4% in 'local currency' during the fourth quarter of 2015, slowed from 6% growth in the third quarter of 2015. |
| (4) | During the fourth quarter of 2015 we decided to terminate our manufacturing joint venture in Brazil and settled several unrelated disputes. These items resulted in approximately $4 million of additional expense in the quarter. We listed these as negative due to the immediate financial impact, but consider these to be positive developments allowing us to focus on growth. |
| (5) | In late November 2015, and even more so in late December 2015, we experienced a greater number and longer duration of customer plant shutdowns related to the holiday season. |
The following sections contain an overview of the following:
| 1. | Sales and sales trends – a recap of our recent sales trends and some insight into the activities with different end markets. |
| 2. | Growth drivers of our business – a recap of how we grow our business. |
| 3. | Profit drivers of our business – a recap of how we increase our profits. |
| 4. | Statement of earnings information – a recap of the components of our income statement. |
| 5. | Cash flow impact items – a recap of the operational working capital utilized in our business, and the related cash flow. |
The most important thing to note before you read this is to remember Fastenal is several businesses within itself; a fastener distributor (about 40% of our business) and a non-fastener distributor (about 60% of our business).
FASTENER SALES
First and foremost, we are a fastener distributor. We have been in this business for almost 50 years. We are good at it. We have strong capabilities at sourcing and procurement, at quality control, at logistics, and at local customer service. Each of these capabilities is focused on the customer at the end of the supply chain. This business is split about 60% production/construction needs and about 40% maintenance needs. The former is a great business, but it can be cyclical because about 75% of our manufacturing customer base is engaged in some type of heavy manufacturing. The sale of production fasteners is also a sticky business in the short-term as it is expensive and time consuming for our customers to change their supplier relationships. While our customer base values the capabilities we bring to the table, in the last twelve months this group of customers has seen a contraction in its production and therefore its need for fasteners. During this time frame, our fastener product line has seen its daily growth decrease from about 10% growth in the last six months of 2014 to about 6% contraction in the fourth quarter of 2015. Said another way, our market share gains continue to be strong, but the contraction from our existing customers, plus some price deflation, has eliminated our growth and created contraction.
NON-FASTENER SALES
Second, we have a non-fastener maintenance and supply business. We have actively pursued this business in the last 20 to 25 years. The capabilities we developed as a fastener distributor, described above, provide a backbone to growing this ‘newer’ business. This backbone has been enhanced in the last five years with our added capabilities in industrial vending. Given our local customer service, we believe we have a structural advantage in the industrial vending business. There is more to industrial vending than the device or the financial resources to deploy; we believe the ability to replenish with a local team from an integrated supply chain network (i.e., the 'Team behind the Machine') is critical to the long-term success of this channel. Because of these capabilities, the non-fastener business remains more resilient. However, similar to our fastener business, our non-fastener business has weakened in the last twelve months. During this time frame, our non-fastener product line has seen its daily sales growth decrease from about 18% growth in the last six months of 2014 to about 1% growth in the fourth quarter of 2015.
Please read through the detailed Sales and Sales Trends section later in this document for additional insight.
Our gross profit decreased from 50.5% in both the fourth quarter of 2014 and third quarter of 2015 to 49.9% in the fourth quarter of 2015. The relationship between sales and gross profit depends on our success within our large account business (an area that is still under-represented in our customer mix). The large account end market produces a below average gross profit; however, as demonstrated in recent quarters, it leverages our existing network of capabilities and allows us to enjoy strong incremental operating income growth. This customer mix change (large versus smaller), as well as our product mix change (from fasteners to non-fasteners), over time are a constant drain on our gross profit, a trend we expect to continue in the future.
However, this trend had limited relevance in the fourth quarter of 2015. Rather, we saw a noticeable squeezing of discretionary spending by our customers in November and December of 2015 (see related discussion about 2015 later in 'summarizing comments'), which produced a noticeable drop in the sale of less frequently purchased products. This resulted in all of the drop in gross profit, when compared to the third quarter of 2015 and substantially all of the change from the fourth quarter of 2014. We believe this to be a temporary issue; however, we don’t know when this drop will subside. Our gross profit is also impacted by supplier incentives. With weaker net sales growth and our tight management of inventory levels, the growth of spending with our suppliers is lower; hence, our supplier incentives are reduced.
In regards to operating expenses, we added 2,329 people to the Fastenal organization in the last twelve months (about 81% of these people were added to a store or some other type of selling location). This provided a meaningful increase in our capacity. However, we needed to fund this increased capacity. We did this by (1) managing our total operating and administrative expenses outside of payroll related costs, and (2) managing our hours worked in a very focused site by site fashion (our store headcount grew by 13.6% in the last twelve months, but our average full-time equivalent store headcount only grew by 10.2%). These two items allowed us to invest in store personnel and fund that investment in a weak economic environment. Below is a quick recap of our full-time equivalent headcount to supplement the information discussed earlier in this document:
| Q4 2014 | Q4 2015 | Twelve-month % Change | ||||||
| Average full-time equivalent store employee count | 10,376 | 11,436 | 10.2 | % | ||||
| Average full-time equivalent employee count | 15,512 | 16,901 | 9.0 | % | ||||
| Note – Full-time equivalent is based on 40 hours per week. |
We touched on our industrial vending earlier, but here is a quick recap: During the fourth quarter of 2015, we signed 4,016 devices (we signed 4,689 devices in the third quarter of 2015 and we signed 4,108 devices during the fourth quarter of 2014), our installed device count on December 31, 2015 was 55,510 (an increase of 18.5% over December 31, 2014), and the percent of total net sales to customers with industrial vending was 43.9%. Our total daily sales to customers with industrial vending during the fourth quarter of 2015 grew 0.7% over the fourth quarter of 2014. However, daily sales of non-fastener products to customers with vending grew approximately 4%, while daily sales of fasteners to customers with vending contracted approximately 8%.
Finally, some thoughts on capital allocation: During the latter half of 2014 and throughout 2015, we have been modifying our capital allocation by buying back some common stock. One factor influencing our stock buybacks is our external valuation. Our relative stock valuation has weakened over the last several years, which prompted us to reassess our cash deployment. To this end, we have spent approximately $337 million buying back stock in the last six quarters and have repurchased approximately 2.7% of our outstanding shares from the start of this time frame. We are mindful of our shareholders’ expectations relative to our dividend paying history and have primarily funded this buyback with debt. Over the last three to four years, we had dramatically increased our capital expenditures, relative to our net earnings, for the rapid deployment of distribution automation and industrial vending over where those expenditures had been in prior years. These investments will continue in the future; however, we expect capital expenditures, relative to our net earnings, will moderate and will allow us to continue to fund our cash needs for our day-to-day business primarily from continuing operations. Please read through the detailed Cash Flow Impact Items section, and the Consolidated Statements of Cash Flows later in this document, for additional insight.
SALES AND SALES TRENDS
While reading these items, it is helpful to appreciate several aspects of our marketplace: (1) it's big, the North American marketplace for industrial supplies is estimated to be in excess of $160 billion per year (and we have expanded beyond North America), (2) no company has a significant portion of this market, (3) many of the products we sell are individually inexpensive, (4) when our customer needs something quickly or unexpectedly our local store is a quick source, (5) the cost and time to manage and procure these products is meaningful, (6) the cost to move these products, many of which are bulky, can be significant, (7) many customers would prefer to reduce their number of suppliers to simplify their business, and (8) many customers would prefer to utilize various technologies to improve availability and reduce waste.
Our motto is Growth through Customer Service®. This is important given the points noted above. We believe in efficient markets – to us, this means we can grow our market share if we provide the greatest value to our customers. We believe our ability to grow is amplified if we can service our customers at the closest economic point of contact. For us, this 'closest economic point of contact' is the local store; therefore, our focus centers on understanding our customers' day, their opportunities, and their obstacles.
The concept of growth is simple, find more customers every day and increase our activity with them. However, execution is hard work. First, we recruit service-minded individuals to support our customers and their business. Second, we operate in a decentralized fashion to help identify the greatest value for our customers. Third, we have a great team behind the store to operate efficiently and to help identify new business solutions. Fourth, we do these things every day. Finally, we strive to generate strong profits; these profits produce the cash flow necessary to fund our growth and to support the needs of our customers.
SALES GROWTH
Note – Daily sales are defined as the total net sales for the period divided by the number of business days (in the United States) in the period.
Net sales and daily sales were as follows:
| 2015 | 2014 | 2013 | |||||||
| Net sales | $ | 3,869,187 | 3,733,507 | 3,326,106 | |||||
| Percentage change | 3.6 | % | 12.2 | % | 6.1 | % | |||
| Business days | 254 | 253 | 254 | ||||||
| Daily sales | $ | 15,233 | 14,757 | 13,095 | |||||
| Percentage change | 3.2 | % | 12.7 | % | 6.1 | % | |||
| Impact of currency fluctuations (primarily Canada) | -1.2 | % | -0.5 | % | -0.2 | % |
The increase in net sales in 2015, 2014, and 2013 came primarily from higher unit sales. Our growth in net sales was impacted by slight inflationary price changes in our non-fastener products and some price deflation in our fastener products, with the net impact being a slight drag on growth. The higher unit sales resulted primarily from increases in sales at older store locations (discussed below and again later in this document) and to a lesser degree the opening of new store locations in the last several years. Our growth in net sales was not meaningfully impacted by the introduction of new products or services, with one exception. Over the last several years, our industrial vending initiative has stimulated faster growth with a subset of our customers (discussed later in this document). The growth in net sales at the older store locations was due to the growth drivers of our business (discussed later in this document). The rate of growth in net sales in 2015 was hindered by weakness in the industrial production and non-residential construction industries served by us. The added growth in 2014 was largely related to two things – the expansion, which began in the latter half of 2013, in the number of our store employees and the number of district and regional leaders supporting our stores, all in effort to generate more selling energy within our stores, and a stabilization in our OEM fastener business.
The impact of the economy is best reflected in the growth performance of our stores opened greater than ten years ago (store sites opened as follows: 2015 group – opened 2005 and earlier, 2014 group – opened 2004 and earlier, and 2013 group – opened 2003 and earlier) and opened greater than five years ago (store sites opened as follows: 2015 group – opened 2010 and earlier, 2014 group – opened 2009 and earlier, and 2013 group – opened 2008 and earlier). These two groups of stores are more cyclical due to the increased market share they enjoy in their local markets. The stores opened greater than two years ago represent a consistent ‘same store’ view of our business (store sites opened as follows: 2015 group – opened 2013 and earlier, 2014 group – opened 2012 and earlier, and 2013 group – opened 2011 and earlier). The daily sales change for each of these groups was as follows:
| Store Age | 2015 | 2014 | 2013 | ||
| Opened greater than 10 years | 2.7% | 10.5% | 2.1% | ||
| Opened greater than 5 years | 2.5% | 10.9% | 3.6% | ||
| Opened greater than 2 years | 2.5% | 11.5% | 4.4% |
Note: The age groups above are measured as of the last day of each respective year.
Stores opened in 2015 contributed approximately $8,745 (or 0.2%) to 2015 net sales. Stores opened in 2014 contributed approximately $28,028 (or 0.7%) to 2015 net sales and approximately $9,762 (or 0.3%) to 2014 net sales. The rate of growth in sales of store locations generally levels off after they have been open for five years, and, as stated earlier, the sales generated at our older store locations typically vary more with the economy than do the sales of younger stores.
SALES BY PRODUCT LINE
The approximate mix of sales from the fastener product line and from the other product lines was as follows:
| 2015 | 2014 | 2013 | |||
| Fastener product line | 38% | 40% | 42% | ||
| Other product lines | 62% | 60% | 58% |
The decrease in our fastener sales as a percentage of total sales has been driven by the continued success of our non-fastener product lines, which we began to add in the 1990's, and by the growth of our industrial vending program. Since we sell primarily non-fastener products in our industrial vending machines, this program has led to greater resilience to weak industrial production of our non-fastener business compared to our fastener business.
MONTHLY SALES CHANGES, SEQUENTIAL TRENDS, AND END MARKET PERFORMANCE
This section focuses on three distinct views of our business – monthly sales changes, sequential trends, and end market performance. The first discussion regarding monthly sales changes provides a good mechanical view of our business based on the age of our stores. The second discussion provides a framework for understanding the sequential trends (that is, comparing a month to the immediately preceding month, and also looking at the cumulative change from an earlier benchmark month) in our business. Finally, we believe the third discussion regarding end market performance provides insight into activities with our various types of customers.
Monthly Sales Changes:
All company sales – During the months noted below, all of our selling locations, when combined, had daily sales growth rates of (compared to the same month in the preceding year):
| Jan. | Feb. | Mar. | Apr. | May | June | July | Aug. | Sept. | Oct. | Nov. | Dec. | ||||||||||||||||||||||||
| 2015 | 12.0 | % | 8.6 | % | 5.6 | % | 6.1 | % | 5.3 | % | 3.7 | % | 3.2 | % | 1.6 | % | -0.3 | % | -0.8 | % | -1.1 | % | -3.8 | % | |||||||||||
| 2014 | 6.7 | % | 7.7 | % | 11.6 | % | 10.0 | % | 13.5 | % | 12.7 | % | 14.7 | % | 15.0 | % | 12.9 | % | 14.6 | % | 15.3 | % | 17.4 | % | |||||||||||
| 2013 | 6.7 | % | 8.2 | % | 5.1 | % | 4.8 | % | 5.3 | % | 6.0 | % | 2.9 | % | 7.2 | % | 5.7 | % | 7.7 | % | 8.2 | % | 6.7 | % |
Stores opened greater than two years – Our stores opened greater than two years (store sites opened as follows: 2015 group – opened 2013 and earlier, 2014 group – opened 2012 and earlier, and 2013 group – opened 2011 and earlier) represent a consistent 'same-store' view of our business. During the months noted below, the stores opened greater than two years had daily sales growth rates of (compared to the same month in the preceding year):
| Jan. | Feb. | Mar. | Apr. | May | June | July | Aug. | Sept. | Oct. | Nov. | Dec. | ||||||||||||||||||||||||
| 2015 | 11.2 | % | 7.8 | % | 4.8 | % | 5.4 | % | 4.6 | % | 3.2 | % | 2.6 | % | 1.0 | % | -0.9 | % | -1.1 | % | -2.1 | % | -5.0 | % | |||||||||||
| 2014 | 5.5 | % | 6.5 | % | 10.2 | % | 8.4 | % | 12.1 | % | 11.4 | % | 13.4 | % | 14.0 | % | 11.8 | % | 13.5 | % | 14.0 | % | 16.5 | % | |||||||||||
| 2013 | 5.0 | % | 6.5 | % | 3.4 | % | 3.1 | % | 3.5 | % | 4.3 | % | 1.4 | % | 5.5 | % | 4.2 | % | 6.1 | % | 6.2 | % | 4.9 | % |
Stores opened greater than five years – The impact of the economy, over time, is best reflected in the growth performance of our stores opened greater than five years (store sites opened as follows: 2015 group – opened 2010 and earlier, 2014 group – opened 2009 and earlier, and 2013 group – opened 2008 and earlier). This group, which represented about 90% of our total sales in 2015, is more cyclical due to the increased market share they enjoy in their local markets. During the months noted below, the stores opened greater than five years had daily sales growth rates of (compared to the same month in the preceding year):
| Jan. | Feb. | Mar. | Apr. | May | June | July | Aug. | Sept. | Oct. | Nov. | Dec. | ||||||||||||||||||||||||
| 2015 | 10.8 | % | 7.2 | % | 4.8 | % | 5.6 | % | 4.6 | % | 3.1 | % | 3.1 | % | 1.3 | % | -1.1 | % | -1.0 | % | -1.8 | % | -5.3 | % | |||||||||||
| 2014 | 4.6 | % | 5.4 | % | 9.5 | % | 7.7 | % | 11.5 | % | 10.8 | % | 12.9 | % | 13.4 | % | 11.7 | % | 13.3 | % | 13.6 | % | 16.2 | % | |||||||||||
| 2013 | 3.2 | % | 5.6 | % | 2.3 | % | 2.0 | % | 2.7 | % | 3.4 | % | 0.6 | % | 4.7 | % | 3.2 | % | 5.3 | % | 6.1 | % | 4.8 | % |
Summarizing comments – There are three distinct influences to our growth: (1) execution, (2) currency fluctuations, and (3) economic fluctuations. This discussion centers on (2) and (3).
The change in currencies in foreign countries (primarily Canada) relative to the United States dollar impacted our net sales growth over the last several years. During the years 2013, 2014, and 2015, it lowered our net sales growth by 0.2%, 0.5%, and 1.2%, respectively.
During the first half of 2013, the fastener product line was heavily impacted by our industrial production business. These customers utilize our fasteners in the manufacture/assembly of their finished products. The end markets with the most pronounced weakening included heavy machinery manufacturers with exposure to: mining, military, agriculture, and construction. The daily sales growth in July 2013 and December 2013 were negatively impacted by the timing of the July 4th holiday (Thursday in 2013 versus Wednesday in 2012) and the Christmas/New Year holiday (Wednesday in 2013 versus Tuesday in 2012). This resulted in a 'lone' business day on Friday, July 5, 2013, in which many of our customers were closed, and three distinct one to two day work periods in the last two weeks of December 2013. The December 2013 impact was amplified due to poor weather conditions.
Our sales to customers engaged in light and medium duty manufacturing (largely related to consumer products) began to improve late in 2013 and into 2014. This made sense given the trends in the PMI Index at that time. In the first quarter of 2014, our sales growth was hampered in January and February due to a weak economy and foreign exchange rate fluctuations (primarily related to the Canadian dollar); however, the biggest impact was a severe winter in North America and its negative impact on our customers and our trucking network. In March 2014, the weak economy and negative foreign exchange rate fluctuations continued; however, the weather normalized and our daily sales growth expanded to 11.6%. This double digit growth in March was helped by the Easter timing (April in 2014). In the second quarter of 2014, the negative impact of the Easter timing was felt, and then a 'less noisy' picture emerged in May and June. Our sales to customers engaged in heavy machinery manufacturing (primarily serving the mining, military, agricultural, and construction end markets), which represents approximately one fifth of our business, had a very weak 2013, but stabilized late in 2013 and improved in 2014.
During 2015, our business weakened. As mentioned earlier in this document and in prior quarterly disclosures, the weakening initially involved customers tied to the oil and gas sector, but grew during the course of the year to include customers across additional industries and in geographic areas not typically associated with the oil and gas sector. In November and December one distinct trend emerged involving customer plant shutdowns. This is not uncommon during the holiday season; however, we experienced a greater number and duration of shutdowns than in prior years during both late November and late December, with the trend more pronounced in late December.
Sequential Trends:
We find it helpful to think about the monthly sequential changes in our business using the analogy of climbing a stairway – This stairway has several predictable landings where there is a pause in the sequential gain (i.e. April, July, and October to December), but generally speaking, climbs from January to October. The October landing then establishes the benchmark for the start of the next year.
History has identified these landings in our business cycle. They generally relate to months with impaired business days (certain holidays). The first landing centers on Easter, which alternates between March and April (Easter occurred in April 2015, in April 2014, and in March 2013), the second landing centers on July 4th, and the third landing centers on the approach of winter with its seasonal impact on primarily our construction business and with the Christmas/New Year holidays. The holidays we noted impact the trends because they either move from month-to-month or because they move around during the week (the July 4th and Christmas/New Year holiday impacts are examples).
The table below shows the pattern to the sequential change in our daily sales. The line labeled 'Benchmark' is an historical average of our sequential daily sales change for the period 1998 to 2013, excluding 2008 and 2009. We believe this time frame will serve to show the historical pattern and could serve as a benchmark for current performance. We excluded the 2008 to 2009 time frame because it contains an extreme economic event and we don't believe it is comparable. The '2015', '2014', and '2013' lines represent our actual sequential daily sales changes. The '15Delta', '14Delta', and '13Delta' lines indicate the difference between the 'Benchmark' and the actual results in the respective year.
| Jan.(1) | Feb. | Mar. | Apr. | May | June | July | Aug. | Sept. | Oct. | Cumulative Change from Jan. to Oct. | |||||||||||||||||||||
| Benchmark | 0.8 | % | 2.2 | % | 3.8 | % | 0.4 | % | 3.1 | % | 2.7 | % | -2.1 | % | 2.5 | % | 3.7 | % | -1.2 | % | 15.9% | ||||||||||
| 2015 | -3.6 | % | -0.1 | % | 4.2 | % | -2.1 | % | 3.4 | % | 0.9 | % | -4.3 | % | 4.1 | % | -0.9 | % | -2.0 | % | 2.9% | ||||||||||
| 15Delta | -4.4 | % | -2.3 | % | 0.4 | % | -2.5 | % | 0.3 | % | -1.8 | % | -2.2 | % | 1.6 | % | -4.6 | % | -0.8 | % | -13.0% | ||||||||||
| 2014 | -1.4 | % | 3.0 | % | 7.1 | % | -2.6 | % | 4.2 | % | 2.5 | % | -3.8 | % | 5.8 | % | 1.0 | % | -1.5 | % | 16.2% | ||||||||||
| 14Delta | -2.2 | % | 0.8 | % | 3.3 | % | -3.0 | % | 1.1 | % | -0.2 | % | -1.7 | % | 3.3 | % | -2.7 | % | -0.3 | % | 0.3% | ||||||||||
| 2013 | -0.4 | % | 2.0 | % | 3.4 | % | -1.1 | % | 1.0 | % | 3.2 | % | -5.5 | % | 5.5 | % | 2.9 | % | -2.9 | % | 8.2% | ||||||||||
| 13Delta | -1.2 | % | -0.2 | % | -0.4 | % | -1.5 | % | -2.1 | % | 0.5 | % | -3.4 | % | 3.0 | % | -0.8 | % | -1.7 | % | -7.7% | ||||||||||
(1) The January figures represent the percentage change from the previous October, whereas the remaining figures represent the percentage change from the previous month.
A graph of the sequential daily sales change pattern discussed above, starting with a base of '100' in the previous October and ending with the next October, would be as follows:

End Market Performance:
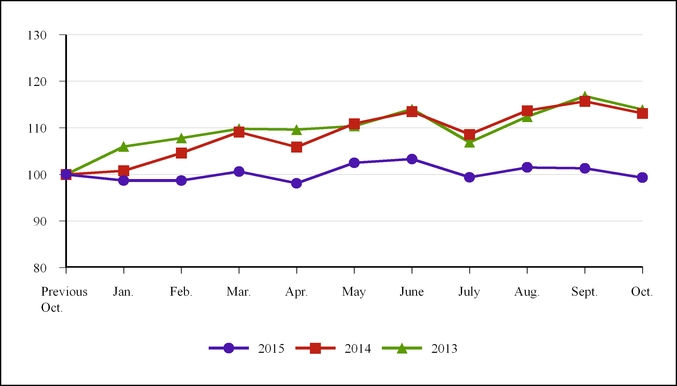
Fluctuations in end market business – The sequential trends noted above were directly linked to fluctuations in our end markets. To place this in perspective – approximately 50% of our business has historically been with customers engaged in some type of manufacturing. The daily sales growth rates to these customers, when compared to the same period in the prior year, were as follows:
| Q1 | Q2 | Q3 | Q4 | Annual | ||||||||||
| 2015 | 6.9 | % | 3.8 | % | 1.1 | % | -2.2 | % | 2.3 | % | ||||
| 2014 | 9.0 | % | 11.2 | % | 13.7 | % | 13.8 | % | 12.0 | % | ||||
| 2013 | 7.0 | % | 5.9 | % | 4.7 | % | 7.2 | % | 6.3 | % |
As indicated earlier, our manufacturing business consists of two subsets: the industrial production business (this is business where we supply products that become part of the finished goods produced by our customers and is sometimes referred to as OEM - original equipment manufacturing) and the maintenance portion (this is business where we supply products that maintain the facility or the equipment of our customers engaged in manufacturing and is sometimes referred to as MRO - maintenance, repair, and operations). The industrial business is more fastener centered, while the maintenance portion is represented by all product categories.
The best way to understand the change in our industrial production business is to examine the results in our fastener product line (just under 40% of our business) which is heavily influenced by changes in our business with heavy equipment manufacturers. From a company perspective, sales growth rates of fasteners, when compared to the same period in the prior year, were as follows (note: this information includes all end markets):
| Q1 | Q2 | Q3 | Q4 | Annual | ||||||||||
| 2015 | 5.5 | % | 0.0 | % | -4.4 | % | -6.2 | % | -1.4 | % | ||||
| 2014 | 1.6 | % | 5.5 | % | 9.9 | % | 11.4 | % | 6.9 | % | ||||
| 2013 | 1.7 | % | 1.9 | % | 1.0 | % | 1.9 | % | 1.6 | % |
By contrast, the best way to understand the change in the maintenance portion of the manufacturing business is to examine the results in our non-fastener product lines. From a company perspective, sales growth rates of non-fasteners, when compared to the same period in the prior year, were as follows (note: this information includes all end markets):
| Q1 | Q2 | Q3 | Q4 | Annual | ||||||||||
| 2015 | 11.7 | % | 9.0 | % | 5.9 | % | 1.2 | % | 6.8 | % | ||||
| 2014 | 14.2 | % | 17.1 | % | 17.6 | % | 19.0 | % | 17.2 | % | ||||
| 2013 | 10.8 | % | 8.5 | % | 8.9 | % | 12.0 | % | 10.1 | % |
The non-fastener business demonstrated greater relative resilience over the last several years, when compared to our fastener business and to the distribution industry in general, due to our strong industrial vending program. However, this business was not immune to the impact of a weak industrial environment.
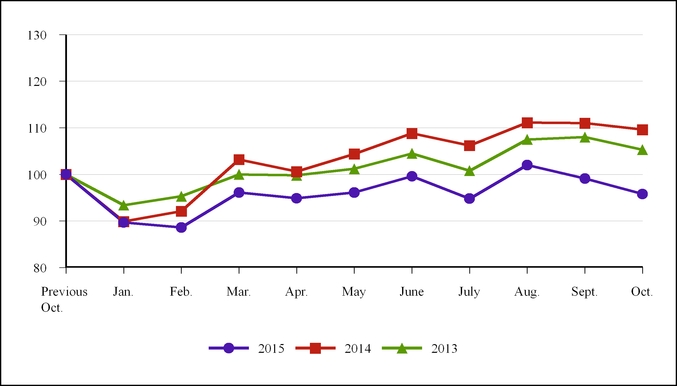
Our non-residential construction customers have historically represented 20% to 25% of our business. The daily sales growth rates to these customers, when compared to the same period in the prior year, were as follows:
| Q1 | Q2 | Q3 | Q4 | Annual | ||||||||||
| 2015 | 6.2 | % | 1.6 | % | -1.7 | % | -6.1 | % | -0.2 | % | ||||
| 2014 | 2.9 | % | 7.5 | % | 9.3 | % | 12.6 | % | 7.8 | % | ||||
| 2013 | 2.9 | % | 0.7 | % | 3.9 | % | 2.8 | % | 2.5 | % |
Our non-residential construction business is heavily influenced by the industrial economy, particularly the energy sector. The volatility and weakness of energy prices has weakened this business, particularly in the last three quarters.
A graph of the sequential daily sales trends to these two end markets in 2015, 2014, and 2013, starting with a base of '100' in the previous October and ending with the next October, would be as follows:
Manufacturing
Non-Residential Construction
GROWTH DRIVERS OF OUR BUSINESS
Note – Dollar amounts in this section are presented in whole dollars, not thousands.
We grow by continuously adding customers and by increasing the activity with each customer. We believe this growth is enhanced by great people located in close proximity to our customers. This allows us to provide a range of services and product availability that our competitors can't easily match. Historically, we expanded our reach by opening stores at a very fast pace. These openings were initially in the United States and expanded beyond the United States beginning in the mid 1990's.
For a little perspective, we began our business in 1967 with an idea to sell nuts and bolts (fasteners) through vending machines. We soon learned the technology of the 1960's wasn't ready, and also learned a lot of products didn't fit, so we went to 'Plan B': sell to business users with a direct sales force. It took us a number of years to 'work out the bugs', but ten years later we began to pick up the pace of store openings. After another ten years of expansion we had approximately 50 stores and sales of about $20 million. Our need for cash to fund our growth was growing, as was our desire to allow employee ownership. This led us to a public offering in 1987.
In our first ten years of being public (1987 to 1997), we opened stores at an annual rate approaching 30% per year. In the next ten years (1997 to 2007), we opened stores at an annual rate of approximately 10% to 15% and, since 2007, at an annual rate of approximately 1% to 8%. We opened 24 stores in 2014, at an annual rate of approximately 1%, and 41 stores in 2015, at an annual rate of approximately 2%. Our preliminary estimate for 2016 is to open 60 to 75 stores, which is an annual rate of approximately 2% to 3%.
During our almost 50 years of business existence, we have constantly evolved to better serve the market (as is described in the paragraphs below) and have always been willing to challenge our approach. In our first 20 to 25 years, we closed several store locations because we felt the market was insufficient to operate a profitable 'fastener only' business. Every one of those locations was subsequently ‘reopened’ when our business model evolved to serve these markets profitably. During the last 20 to 25 years, we have enjoyed continued success with our store-based model, but we continue to challenge our approach. This resulted in our closing approximately 85 stores in the ten years prior to 2014 - not because they weren’t successful, but rather because we felt we had a better approach to growth. During 2014, we continued to challenge our approach and closed 73 stores. Several items we think are noteworthy: the group of stores we identified for closure in the second half of 2014 was profitable in the first quarter of 2014 (our 2014 analysis measurement period); those stores operated with average sales of about $36 thousand per month. We chose to close this group because we felt this was simply a better approach to growing our business profitably. During 2015, we closed 50 stores. Similar to 2014, we chose to close this group of stores because we felt this was
simply a better approach. During the third quarter of 2014 (our 2015 analysis measurement period), 35 of these 50 stores were profitable.
There is a short-term price for closing these stores; and, since we believe we will maintain the vast majority of the sales associated with these locations and most of the impacted employees have a nearby store from which to operate, the price primarily relates to the future commitments related to the leased locations. We have recorded the impaired future costs related to these commitments. The related expense was not material as these locations have relatively short lease commitments and minimal leasehold improvements. We use the term closed; however, we consider them to be consolidated into another location since the vast majority are in close proximity to another store.
During the years, our expanding footprint has provided us with greater access to more customers, and we have continued to diversify our growth drivers. This was done to provide existing store personnel with more tools to grow their business organically, and the results of this are reflected in our earlier discussion on sales growth at stores opened greater than five years. In the early 1990's, we began to expand our product lines beyond primarily fasteners, and we added new product knowledge to our bench (the non-fastener products now represent about 60% of our sales). This was our first big effort to diversify our growth drivers. The next step began in the mid to late 1990's when we began to add sales personnel with certain specialties or focus. This began with our National Accounts group in 1995, and over time, has expanded to include individuals dedicated to: (1) sales related to our internal manufacturing division, (2) government sales, (3) internet sales, (4) construction, (5) specific products (most recently metalworking), and (6) industrial vending. Another step occurred at our sales locations (this includes Fastenal stores as well as strategic account stores and Onsite locations) and at our distribution centers, and began with a targeted merchandising and inventory placement strategy that included our 'Customer Service Project' approximately thirteen years ago and our 'Master Stocking Hub' initiative approximately eight years ago. These strategies allowed us to better target where to stock certain products (local store, regional distribution center, master stocking hub, or supplier) and allowed us to improve our fulfillment, lower our freight costs, and improve our ability to serve a broader range of customers. During 2013 and 2014, we expanded our store-based inventory offering around select industries (with an emphasis on fasteners, construction products, and safety products) and beginning in the latter half of 2013 we expanded two key employee groups: (1) the number of employees working in our stores and (2) the number of district and regional leaders supporting our stores. To improve the efficiency, accuracy, and capacity of our distribution centers, we made significant investments into distribution automation over the last several years (a majority of our facilities are now automated, and greater than 80% of our picking occurs at an automated distribution center). Finally, we also added a high frequency distribution center, internally known as T-hub, to support vending and other high frequency selling activities. During 2015, we continued to enhance the technology in our automated distribution centers, and sharpened our focus on growing our Onsite business. In the fourth quarter of 2015, we also began further expansion of our store-based inventory offering (CSP 16). This merchandising footprint involves expanded inventory placement at our store locations to enhance same-day delivery capabilities. The theme that shines through in all these changes is a simple one – invest into and support our sales machine – the local store.
Over the last several years, our industrial vending operation has been an expanding component of our store-based business. We believe industrial vending will be an important chapter in the Fastenal story; we also believe it has the potential to be transformative to industrial distribution, and that we have a 'first mover' advantage. Given this, we have been investing aggressively to maximize the advantage.
Our expanded industrial vending portfolio consists of 20 different vending devices, with the FAST 5000 device, our helix based machine (think candy machine), representing approximately 40% of the installed machines. We have learned much about these devices over the last several years and currently have target monthly revenue ranging from under $1,000 to in excess of $3,000 per device. The following two tables provide two views of our data: (1) actual device count regardless of the type of machine and (2) ‘machine equivalent' count based on the weighted target monthly revenue of each device (compared to the FAST 5000 device, which has a $2,000 monthly revenue target). For example, the 12-door locker, with target monthly revenue of $750, would be counted as ‘0.375 machine equivalent’ (0.375 = $750/$2,000).
The industrial vending information related to contracts signed during each period was as follows:
| Q1 | Q2 | Q3 | Q4 | Annual | ||||||||||||
| Device count signed during the period | 2015 | 3,962 | 5,144 | 4,689 | 4,016 | 17,811 | ||||||||||
| 2014 | 4,025 | 4,137 | 4,072 | 4,108 | 16,342 | |||||||||||
| 2013 | 6,568 | 6,084 | 4,836 | 4,226 | 21,714 | |||||||||||
| 'Machine equivalent' count signed during the period | 2015 | 2,916 | 3,931 | 3,769 | 3,319 | 13,935 | ||||||||||
| 2014 | 2,974 | 3,179 | 3,189 | 3,243 | 12,585 | |||||||||||
| 2013 | 4,825 | 4,505 | 3,656 | 3,244 | 16,230 |
The industrial vending information related to installed machines at the end of each period was as follows:
| Q1 | Q2 | Q3 | Q4 | ||||||||||||
| Device count installed at the end of the period | 2015 | 48,545 | 50,620 | 53,547 | 55,510 | ||||||||||
| 2014 | 42,153 | 43,761 | 45,596 | 46,855 | |||||||||||
| 2013 | 32,007 | 36,452 | 39,180 | 40,775 | |||||||||||
| 'Machine equivalent' count installed at the end of the | 2015 | 35,997 | 37,714 | 40,067 | 41,905 | ||||||||||
| period | 2014 | 30,326 | 31,713 | 33,296 | 34,529 | ||||||||||
| 2013 | 22,020 | 25,512 | 27,818 | 29,262 |
The following table includes some additional statistics regarding our sales and sales growth:
| Q1 | Q2 | Q3 | Q4 | ||||||||||||
| Percent of total net sales to customers with | 2015 | 40.5 | % | 40.9 | % | 42.1 | % | 43.9 | % | ||||||
| industrial vending(1) | 2014 | 37.8 | % | 37.0 | % | 37.8 | % | 39.3 | % | ||||||
| 2013 | 27.5 | % | 30.0 | % | 33.3 | % | 36.6 | % | |||||||
| Daily sales growth to customers with | 2015 | 12.3 | % | 8.6 | % | 4.8 | % | 0.7 | % | ||||||
| industrial vending(2) | 2014 | 19.7 | % | 20.9 | % | 21.9 | % | 20.0 | % | ||||||
| 2013 | 23.9 | % | 18.9 | % | 15.2 | % | 18.7 | % |
(1) The percentage of total sales (vended and traditional) to customers currently using a vending solution.
(2) The growth in total sales (vended and traditional) to customers currently using a vending solution compared to the same period in the preceding year.
Our total daily sales growth to customers with industrial vending declined during 2015, which was primarily the result of the slowdown in our business with customers connected to the oil and gas industry, including direct industry participants as well as other customers serving those participants. To put this into perspective, in the third quarter of 2015, daily sales to customers with vending grew 4.8% over the third quarter of 2014; however, daily sales of non-fastener products to customers with vending grew approximately 8%, while daily sales of fasteners to customers with vending contracted approximately 3%. Further, in the fourth quarter of 2015, daily sales to customers with vending grew 0.7% over the fourth quarter of 2014; however, daily sales of non-fastener products to customers with vending grew approximately 4%, while daily sales of fasteners to customers with vending contracted approximately 8%.
In addition to the industrial vending operation noted above, which primarily relates to our non-fastener business, we also provide bin stock programs (also known as ‘keep fill’ programs in the industry) to numerous customers. This business, which relates to both our maintenance customers (MRO fasteners and non-fasteners) and original equipment manufacturers (OEM fasteners), has many similar attributes to our industrial vending relationships. These attributes include a strong relationship with these customers, where we are often their preferred supplier, and a frequent level of business transactions. This business is performed without the aid of a vending machine, but does make use of the latest scanning technologies, scale systems, and our fully integrated distribution network to manage the supply chain for all sizes of customers. In recent years, we have begun to refer to this business as FMI (Fastenal Managed Inventory).
PROFIT DRIVERS OF OUR BUSINESS
As we state several times in this document, profit is important to us. For a distribution business profit and cash flow go hand in hand, and this cash flow funds our growth; creates value for our customers, our employees, our suppliers, and our shareholders; and provides us with short-term and long-term flexibility. Over time, we grow our profits by continuously working to grow sales and to improve our relative profitability. We achieve our improvements in relative profitability by improving our relative gross profit, by structurally lowering our operating and administrative expenses, or both.
We also grow our profits by allowing our inherent profitability to shine through - we refer to this as the 'pathway to profit'. The distinction is important. The ‘pathway to profit’ to which we refer is merely the natural ‘per store’ leverage that occurs as the average net sales per month of a store increases. There are two diverging trends that occur as a store grows; first, the gross profit percentage at a store generally declines and, second, our operating and administrative expenses as a percentage of net sales generally improve. The expense improvement starts on day one, the gross profit percentage decline typically occurs when the average sales at a store move above $100 thousand per month. Fortunately, the expense improvements typically far outweigh the gross profit percentage declines.
The best way to appreciate this dynamic is to look at the cost components of our business. The cost components of a store include the following: (1) cost of sales and (2) operating and administrative expenses. The operating and administrative expenses can be further split into (listed by relative size): (1) people costs (base pay, incentive pay, benefits, training, and payroll related taxes), (2) occupancy costs (facility expenses such as rent, property taxes, repairs, and depreciation on owned facilities, as well as utility costs, equipment expenses, and vending machine related expenses), and (3) ‘all other’ expenses. The largest component of the last category is the vehicles needed in each store to support selling activities.
The first component, costs of sales, is directly related to sales and fluctuations in sales. However, it is also heavily influenced by product and customer mix. Because of this influence, our gross profit (the residual of net sales after deducting the related cost of sales), when stated as a percentage of net sales, generally declines as the average monthly net sales of a store increases. This is due to the mix impact of larger customers.
The second component, operating and administrative expenses, does just the opposite, it generally improves as a percentage of net sales. This is due to the fixed nature of our ‘open for business’ expenses and the attractive incremental profit margin typically realized in our remaining variable expenses. The ‘open for business’ expenses are the expenses needed to ‘just keep the front door open’, and they relate to a base staffing level, a base facility cost, and base vehicle costs. These expenses do not generate a profit; however, they create the opportunity for future sales growth that will generate profits. This drives our ‘pathway to profit’.
| STATEMENT OF EARNINGS INFORMATION (percentage of net sales) for the periods ended December 31: | |||||||||
| Twelve-month Period | |||||||||
| 2015 | 2014 | 2013 | |||||||
| Net sales | 100.0 | % | 100.0 | % | 100.0 | % | |||
| Gross profit | 50.4 | % | 50.8 | % | 51.7 | % | |||
| Operating and administrative expenses | 29.0 | % | 29.8 | % | 30.3 | % | |||
| Gain on sale of property and equipment | 0.0 | % | 0.0 | % | 0.0 | % | |||
| Operating income | 21.4 | % | 21.1 | % | 21.4 | % | |||
| Net interest income (expense) | -0.1 | % | 0.0 | % | 0.0 | % | |||
| Earnings before income taxes | 21.3 | % | 21.1 | % | 21.5 | % | |||
| Note – Amounts may not foot due to rounding difference. |
Gross profit – The gross profit percentage in the first, second, third, and fourth quarters was as follows:
| Q1 | Q2 | Q3 | Q4 | |||||||||
| 2015 | 50.8 | % | 50.3 | % | 50.5 | % | 49.9 | % | ||||
| 2014 | 51.2 | % | 50.8 | % | 50.8 | % | 50.5 | % | ||||
| 2013 | 52.3 | % | 52.2 | % | 51.7 | % | 50.6 | % |
Over the last several years our gross profit has fluctuated due to our mix of store sizes, customer sizes, products, geographies, end markets, and end market uses (such as industrial production business versus maintenance business). We have previously indicated a short-term expectation for gross profit of around 51%; however, we would expect this percentage to decline over time as our average store size grows (see discussion earlier under 'Profit Drivers of our Business' and below). As stated below,
this structural gross profit change centers primarily on customer mix and, to a lesser degree, product mix. However, as discussed in the operating and administrative expenses section below, we would expect this structural change to improve operating and administrative expenses as a percentage of net sales.
Ignoring the long-term trend just noted, our short-term gross profit percentages historically fluctuate due to impacts related to (1) transactional gross profit (either related to product and customer mix or to freight), (2) organizational gross profit (sourcing strength that can occur as we leverage buying scale and efficiency), and (3) supplier incentive gross profit (impacts from supplier volume allowances). In the short-term, periods of inflation or deflation can influence the first two categories, while sudden changes in business volume can influence the third. The transactional gross profit, our most meaningful component, is heavily influenced by our store-based compensation programs, which are directly linked to sales growth and gross profit, and incentivize our employees to improve both.
An important aspect of our gross profit relates to our locations, our product mix, and our customer mix. Given the close proximity of our sales personnel to our customer’s business, we offer a very high service level with our sales, which is valued by our customers and improves our gross profit. Fasteners are our highest gross profit product line given the high transaction cost surrounding the sourcing and supply of the product for our customers. Fasteners currently account for approximately 40% of our sales. We expect any reduction in the mix of our sales attributable to fasteners to negatively impact gross profit, particularly as it relates to maintenance fasteners. Gross profit is also influenced by average store sales as noted earlier in this document. Larger stores have larger customers, whose more focused buying patterns allow us to offer them better pricing. As a result, growth in average store sales is expected to negatively impact gross profit. A final item of note, our fourth quarter has typically been the season with the most challenges surrounding gross profit. This relates to the decline in sales in November and December due to the ‘holiday season’ and due to the drop off in non-residential construction business. This drop off in sales reduces the utilization of our trucking network and can slightly reduce our gross profit.
During 2015, our gross profit, as a percentage of net sales, decreased when compared to 2014. This decrease centered on transactional impacts driven by changes in product and customer mix. Our gross profit, as a percentage of net sales, also decreased in the fourth quarter of 2015 when compared to the fourth quarter of 2014. We saw a noticeable squeezing of discretionary spending by our customers in November and December of 2015, which produced a noticeable drop in sales of less frequently purchased products. This resulted in all of the drop in gross profit when compared to the third quarter of 2015, and substantially all of the change from the fourth quarter of 2014.
During 2014, our gross profit dropped below 51%. The drop generally centered on transactional impacts driven by product and customer mix and our strong emphasis on growing average store sales.
Operating and administrative expenses - as a percentage of sales improved from 2014 to 2015.
Historically, our two largest components of operating and administrative expenses have consisted of employee related expenses (approximately 65% to 70%) and occupancy related expenses (approximately 15% to 20%). The remaining expenses cover a variety of items with selling transportation typically being the largest.
The three largest components of operating and administrative expenses grew (or contracted) as follows for the periods ended December 31 (compared to the same periods in the preceding year):
| Twelve-month Period | ||||||||
| 2015 | 2014 | 2013 | ||||||
| Employee related expenses | 0.7 | % | 11.7 | % | 4.6 | % | ||
| Occupancy related expenses | 7.4 | % | 6.9 | % | 11.2 | % | ||
| Selling transportation costs | -13.1 | % | 10.1 | % | 0.8 | % |
Employee related expenses include: (1) payroll (which includes cash compensation, stock option expense, and profit sharing), (2) health care, (3) personnel development, and (4) social taxes. The slight increase in 2015, when compared to 2014, was caused by increases in full-time equivalent headcount (see table below) and growth in our profit sharing contribution, primarily due to our expanding growth in operating income. Offsetting factors included lower performance bonuses and commissions due to the decrease in our gross profit percentage, and a focused reduction in overtime hours paid. The increase in 2014, when compared to 2013, was driven by (1) an increase in performance bonuses and commissions due to our expanding sales growth from the past year, (2) a contraction in profit sharing contribution due to lower relative profitability, and (3) an increase in health care costs. These factors, combined with an increase in full-time equivalent headcount (see table below), caused employee related costs to grow.
On average, the full-time equivalent (FTE) headcount grew as follows (compared to the same period in the preceding years):
| Twelve-month Period | ||||||||
| 2015 | 2014 | 2013 | ||||||
| Store based | 6.2 | % | 12.5 | % | 2.3 | % | ||
| Total selling (includes store) | 6.1 | % | 12.3 | % | 3.3 | % | ||
| Distribution | 6.1 | % | 11.5 | % | 4.3 | % | ||
| Manufacturing | 0.1 | % | 10.7 | % | 6.0 | % | ||
| Administrative | 6.7 | % | 8.9 | % | 7.1 | % | ||
| Total average FTE headcount | 5.9 | % | 11.9 | % | 3.8 | % |
Occupancy related expenses include: (1) building rent and depreciation, (2) building utility costs, (3) equipment related to our stores and distribution locations, and (4) industrial vending equipment (we consider the vending equipment to be a logical extension of our store operation and classify the expense as occupancy). The increase in 2015, when compared to 2014, was driven by (1) an increase in the amount of industrial vending equipment as discussed earlier in this document, and (2) an increased investment in our distribution infrastructure over the last several years, primarily related to automation. The increase in 2014, when compared to 2013, was driven by (1) an increase in the amount of industrial vending equipment as discussed earlier in this document, (2) an increase in building utility cost due to a severe winter in January and February 2014 and increases in natural gas prices during the 2014 heating season, (3) an increased investment in our distribution infrastructure over the last several years, primarily related to automation, and (4) an accrual related to store closings. In 2015 and 2014, the industrial vending component represented approximately 42% and 45%, respectively, of the increase.
Our selling transportation costs consist primarily of our store fleet as most of the distribution fleet costs are included in cost of sales. Selling transportation costs included in operating and administrative expenses contracted in 2015, when compared to 2014. This was driven by the decline in fuel costs (see discussion below). The growth in selling transportation costs included in operating and administrative expenses in 2014, when compared to 2013, was driven by the increase in store headcount and by a reduction in mileage per gallon associated with severe winter driving conditions.
The last several years have seen some variation in the cost of diesel fuel and gasoline. During the first, second, third, and fourth quarters of 2015, our total vehicle fuel costs were approximately $8.8 million, $9.1 million, $8.6 million, and $7.8 million, respectively. During the first, second, third, and fourth quarters of 2014, our total vehicle fuel costs were approximately $11.9 million, $12.5 million, $11.5 million, and $9.5 million, respectively. The changes resulted from variations in fuel costs, variations in the service levels provided to our stores from our distribution centers, changes in the number of vehicles at our store locations, changes in the number of other sales centered vehicles as a result of store openings and the expansion of our non-store sales force, and changes in driving conditions. These fuel costs include the fuel utilized in our distribution vehicles (semi-tractors, straight trucks, and sprinter trucks) which is recorded in cost of sales and the fuel utilized in our store delivery and other sales centered vehicles which is included in operating and administrative expenses (the split in the last several years has been approximately 50:50 between distribution and store and other sales centered use).
Income taxes – Income taxes, as a percentage of earnings before income taxes, were approximately 37.5%, 37.2%, and 37.1% for 2015, 2014, and 2013, respectively. The increase in our income tax rate from 2014 to 2015 was driven by an increase in valuation allowances on deferred tax assets and changes in the reserve for uncertain tax positions. Our income tax rate increased slightly from 2013 to 2014. As our international business and profits grew the past several years, the lower income tax rates in those jurisdictions, relative to the United States, have lowered our effective tax rate.
Net earnings – Net earnings, net earnings per share (EPS), percentage change in net earnings, and the percentage change in EPS, were as follows:
| Dollar Amounts | 2015 | 2014 | 2013 | ||||||
| Net earnings | $ | 516,361 | 494,150 | 448,636 | |||||
| Basic EPS | 1.77 | 1.67 | 1.51 | ||||||
| Diluted EPS | 1.77 | 1.66 | 1.51 | ||||||
| Percentage Change | 2015 | 2014 | 2013 | ||||||
| Net earnings | 4.5 | % | 10.1 | % | 6.7 | % | |||
| Basic EPS | 6.0 | % | 10.6 | % | 6.3 | % | |||
| Diluted EPS | 6.6 | % | 9.9 | % | 6.3 | % |
During 2015, the net earnings increase was greater than that of sales primarily due to the effective management of operating expenses. During 2014, the net earnings increase was less than that of sales primarily due to the reduction in the gross profit percent realized. During 2013, the net earnings increase was greater than that of sales primarily due to the expansion in the gross profit percent realized and a slightly lower income tax rate.
CASH FLOW IMPACT ITEMS
Operational working capital – Operational working capital, which we define as accounts receivable, net and inventories, are highlighted below. The annual dollar change and the annual percentage change were as follows:
| Dollar change | 2015 | 2014 | ||||
| Accounts receivable, net | $ | 6,298 | 47,746 | |||
| Inventories | 44,039 | 85,156 | ||||
| Operational working capital | $ | 50,337 | 132,902 | |||
| Annual percentage change | 2015 | 2014 | ||||
| Accounts receivable, net | 1.4 | % | 11.5 | % | ||
| Inventories | 5.1 | % | 10.9 | % | ||
| Operational working capital | 3.8 | % | 11.1 | % |
The growth in net accounts receivable noted above was comparative to our sales growth in the final two months of the year. The strong growth in recent years with our international business and of our large customer accounts has created some difficulty with managing the growth of accounts receivable relative to the growth in sales.
Our growth in inventory balances over time does not have as direct a relationship to our monthly sales patterns as does our growth in accounts receivable. This is impacted by other aspects of our business. For example, the dramatic economic slowdown in late 2008 and early 2009 caused our inventory to spike. This occurred because the lead time for inventory procurement is typically longer than the visibility we have into future monthly sales patterns. Over the last decade, we increased our relative inventory levels due to the following: (1) new store openings, (2) expanded stocking breadth at distribution centers (for example, our master stocking hub in Indianapolis expanded its product breadth over six fold from 2005 to 2011), (3) expanded direct sourcing, (4) expanded Fastenal brands (private label), (5) expanded industrial vending solutions, (6) national accounts growth, (7) international growth, and (8) expanded stocking breadth at individual stores. While all of these items impacted both 2015 and 2014, items (3) through (8) had the greatest impact.
The approximate percentage mix of inventory stocked at our stores versus our distribution center locations was as follows at year end:
| 2015 | 2014 | 2013 | ||||||
| Store | 61 | % | 56 | % | 58 | % | ||
| Distribution center | 39 | % | 44 | % | 42 | % | ||
| Total | 100 | % | 100 | % | 100 | % |
New stores open with the standard store model (CSP 16), which consists of a core stocking level of approximately $60 thousand per location. This inventory level grows as the level of business in a store grows. In the fourth quarter of 2015, we began expanding the inventory offering at our existing store locations to the CSP 16 format.
As we indicated in earlier communications, our goal is to target a ratio of annual sales to accounts receivable and inventory (Annual Sales: AR&I) of approximately a 3.0:1 ratio. On December 31, 2015 and 2014, we had a ratio of 2.8:1.
Acquisition – On October 31, 2015 we acquired certain assets of Fasteners, Inc., a regional industrial and construction supply distributor with store locations in the states of Washington, Idaho, Oregon, and Montana. The business did not have a material impact on our 2015 operating results although the all-cash acquisition had some impact on our current assets and cash flow. The acquisition is not expected to have a material impact on our overall net sales in 2016.
Liquidity and Capital Resources:
Net cash provided by operating activities — Net cash provided by operating activities in dollars and as a percentage of net earnings were as follows:
| 2015 | 2014 | 2013 | |||||||
| Net cash provided | $ | 546,940 | 499,392 | 416,120 | |||||
| % of net earnings | 105.9 | % | 101.1 | % | 92.8 | % |
In 2015, the increase in the net cash provided by operating activities was driven by growth in net earnings, and a decrease in the cash required to fund our net working capital, which includes accounts receivable and inventory changes. This was partially offset by an increase in cash paid for income taxes. In 2014, the increase in the net cash provided by operating activities was primarily due to increases in net earnings.
Net cash used in investing activities — Net cash used in investing activities in dollars and as a percentage of net earnings were as follows:
| 2015 | 2014 | 2013 | |||||||
| Net cash used | $ | 180,627 | 188,781 | 201,792 | |||||
| % of net earnings | 35.0 | % | 38.2 | % | 45.0 | % |
The changes in net cash used in investing activities were primarily related to changes in our net capital expenditures as discussed below and cash paid for acquisitions in 2015 and 2014.
Net capital expenditures (purchases of property and equipment, less proceeds from the sale of property and equipment) in dollars and as a percentage of net earnings were as follows:
| 2015 | 2014 | 2013 | |||||||
| Net capital expenditures | $ | 145,227 | 183,655 | 201,550 | |||||
| % of net earnings | 28.1 | % | 37.2 | % | 44.9 | % |
Our net capital expenditures decreased in both 2015 and 2014. This was largely related to the completion of distribution automation projects in process during 2014 and 2013.
Property and equipment expenditures in 2015, 2014, and 2013 consist of: (1) purchase of software and hardware for Fastenal’s information processing systems, (2) addition of certain pickup trucks, (3) purchase of signage, shelving, and other fixed assets related to store openings, (4) addition of manufacturing and warehouse equipment, (5) expansion or improvement of certain owned or leased store properties, (6) expansion of Fastenal’s distribution/trucking fleet, (7) purchases related to industrial vending, which primarily consists of automated vending equipment and construction of a new centralized distribution facility (2014 and 2013), and (8) costs related to enhancements to distribution centers with existing automation (2015, 2014, and 2013), and the expansion of our distribution centers in High Point, North Carolina (2015), Modesto, California (2014), Scranton, Pennsylvania (2014 and 2013), Kitchener, Ontario, Canada (2014 and 2013), Akron, Ohio (2013), Atlanta, Georgia (2013), and Indianapolis, Indiana (2013). Disposals of property and equipment consist of the planned disposition of certain pick-up trucks, semi-tractors, and trailers in the normal course of business, and the disposition of real estate relating to several store locations (2015, 2014, and 2013) and a distribution center (2015).
Set forth below is an estimate of our 2016 net capital expenditures and a recap of our 2015, 2014, and 2013 net capital expenditures.
| 2016 | 2015 | 2014 | 2013 | |||||||||
| Net Capital Expenditures | (Estimate) | (Actual) | (Actual) | (Actual) | ||||||||
| Manufacturing, warehouse and packaging equipment, industrial vending equipment, and facilities | $ | 66,000 | 112,460 | 144,649 | 164,940 | |||||||
| Shelving and related supplies for store openings and for product expansion at existing stores | 22,000 | 8,958 | 6,712 | 6,354 | ||||||||
| Data processing software and equipment | 24,000 | 19,653 | 23,978 | 12,652 | ||||||||
| Real estate and improvements to store locations | 5,000 | 4,247 | 4,091 | 9,603 | ||||||||
| Vehicles | 18,000 | 9,850 | 10,044 | 12,991 | ||||||||
| Proceeds from sale of property and equipment | (7,000 | ) | (9,941 | ) | (5,819 | ) | (4,990 | ) | ||||
| $ | 128,000 | 145,227 | 183,655 | 201,550 |
We anticipate funding our current expansion plans with cash generated from operations, from available cash and cash equivalents, and from our borrowing capacity. Because of the considerable cash needed to expand our industrial vending business, to increase the use of automation in our distribution centers, and to fund purchases of our common stock and dividends, we increased our borrowing under our $700,000 unsecured revolving credit facility. The credit facility has an expiration date of March 1, 2018.
The borrowings under the credit facility peaked during each quarter as follows:
| Peak borrowings | 2015 | 2014 | |||
| First quarter | 185,000 | 85,000 | |||
| Second quarter | 400,000 | 115,000 | |||
| Third quarter | 395,000 | 160,000 | |||
| Fourth quarter | 390,000 | 155,000 |
As of December 31, 2015, we had loans outstanding under the credit facility of $350,000 and undrawn letters of credit outstanding under the credit facility in an aggregate face amount of $36,266.
We have future commitments for facilities and equipment and for vehicles at year end. The facility and vehicle amounts primarily consist of future payments under operating leases. The expected future cash obligations related to the commitments are as follows:
| Total | 2016 | 2017 and 2018 | 2019 and 2020 | After 2020 | |||||||||||
| Facilities and equipment | $ | 247,128 | 95,789 | 113,782 | 35,978 | 1,579 | |||||||||
| Vehicles | 54,581 | 27,599 | 25,540 | 1,442 | — | ||||||||||
| Total | $ | 301,709 | 123,388 | 139,322 | 37,420 | 1,579 |
Net cash used in financing activities – Net cash used in financing activities in dollars and as a percentage of net earnings were as follows:
| 2015 | 2014 | 2013 | |||||||
| Net cash used | $ | 337,563 | 249,732 | 234,443 | |||||
| % of net earnings | 65.4 | % | 50.5 | % | 52.3 | % |
The fluctuations in net cash used in financing activities are due to changes in the level of our dividend payments and in the level of common stock purchases. These amounts were partially offset by the exercise of stock options and the related tax impact, and net borrowings under the credit facility. These items in dollars and as a percentage of earnings were as follows:
| 2015 | 2014 | 2013 | |||||||
| Dividends paid | $ | 327,101 | 296,581 | 237,456 | |||||
| % of net earnings | 63.3 | % | 60.0 | % | 52.9 | % | |||
| Common stock purchases | 292,951 | 52,942 | 9,080 | ||||||
| % of net earnings | 56.7 | % | 10.7 | % | 2.0 | % | |||
| Total returned to shareholders | $ | 620,052 | 349,523 | 246,536 | |||||
| % of net earnings | 120.1 | % | 70.7 | % | 54.9 | % | |||
| Proceeds from the exercise of stock options and the related excess tax benefits from stock-based compensation | $ | (22,489 | ) | (9,791 | ) | (12,093 | ) | ||
| % of net earnings | -4.4 | % | -2.0 | % | -2.6 | % | |||
| Cash borrowings, net | $ | (260,000 | ) | (90,000 | ) | — | |||
| % of net earnings | -50.4 | % | -18.2 | % | — | % | |||
| Net cash used | $ | 337,563 | 249,732 | 234,443 | |||||
| % of net earnings | 65.4 | % | 50.5 | % | 52.3 | % |
Cash Commitments – The portion of debt outstanding under our credit facility classified as long-term, and the maturity of that debt, is described later in Note 9 of the Notes to Consolidated Financial Statements.
Unremitted Foreign Earnings – Approximately $94,000 of cash and cash equivalents are held by non-U.S. subsidiaries. These funds may create foreign currency translation gains or losses depending on the functional currency of the entity holding the cash. There are no significant restrictions that would preclude us from bringing the majority of these funds back to the U.S. The income tax impact of repatriating cash associated with certain undistributed earnings is discussed in Note 6 of the Notes to Consolidated Financial Statements.
Stock Purchases — During 2015, we purchased 7,100,000 shares of our common stock at an average price of approximately $41.26 per share. During 2014, we purchased 1,200,000 shares of our common stock at an average price of approximately $44.12 per share. During 2013, we purchased 200,000 shares of our common stock at an average price of approximately $45.40 per share.
Dividends — We declared a quarterly dividend of $0.30 per share on January 14, 2016. We paid aggregate annual dividends per share of $1.12, $1.00, and $0.80 in 2015, 2014, and 2013, respectively.
Line of Credit — A description of our credit facility is contained in Note 9 of the Notes to Consolidated Financial Statements.
Effects of Inflation — We experienced some deflation in our fastener products and minimal price movements in our non-fastener products in 2015 and 2014, with the net impact being a slight drag on growth.
Critical Accounting Policies – Our accounting policies related to certain assets and liabilities are an integral part of our consolidated financial statements. These policies are considered critical because they require application of assumptions and judgments based on historical trends and the composition of account balances. Although we believe our reserves are adequate, the results could be materially different if our assumptions and historical trends do not reflect actual results.
Allowance for doubtful accounts – This reserve is for accounts receivable balances that are potentially uncollectible. The reserve is based on an analysis of customer accounts and our historical experience with accounts receivable write-offs. The analysis includes the aging of accounts receivable, the financial condition of a customer or industry, and general economic conditions. Historically, results have reflected the reserves previously recorded.
Inventory reserves – The reserves are for potentially obsolete or excess inventory and shrinkage. The reserves are based on an analysis of inventory trends. The analysis includes inventory levels, sales information, physical inventory counts, cycle count adjustments, and the on-hand quantities relative to the sales history for the product. Historically, results have reflected the reserves previously recorded.
Insurance reserves – These reserves are for general claims related to workers’ compensation, property and casualty losses, health claims, and other self-insured losses. The reserves are based on an analysis of external data related to our historical claim trends. Historically, results have reflected the reserves previously recorded.
New Accounting Pronouncements
A description of new accounting pronouncements is contained in Note 12 of the Notes to Consolidated Financial Statements.
Geographic Information
Information regarding our revenues and long-lived assets by geographic area is contained in Note 7 of the Notes to Consolidated Financial Statements. Risks related to our foreign operations are described earlier in this Form 10-K under the heading 'Forward-Looking Statements' and 'Item 1A. Risk Factors'.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISKS