 filings.tools
Cover and table of contents
137K characters. Original on sec.gov · Markdown
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 10-K
(Mark one)
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended December 31, 2019
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the transition period from to
Commission file number: 001-11307-01
Freeport-McMoRan Inc.
(Exact name of registrant as specified in its charter)
| Delaware | 74-2480931 | |
| (State or other jurisdiction of | (I.R.S. Employer Identification No.) | |
| incorporation or organization) |
| 333 North Central Avenue | ||||||
| Phoenix | Arizona | 85004-2189 | ||||
| (Address of principal executive offices) | (Zip Code) |
(602) 366-8100
(Registrant’s telephone number, including area code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered |
| Common Stock, par value $0.10 per share | FCX | The New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act ☑ Yes ☐ No
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. ☐ Yes ☑ No
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. ☑ Yes ☐ No
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). ☑ Yes ☐ No
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☑ | Accelerated filer | ☐ |
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ |
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). ☐ Yes ☑ No
The aggregate market value of common stock held by non-affiliates of the registrant was $13.1 billion on June 30, 2019.
Common stock issued and outstanding was 1,450,972,426 shares on January 31, 2020.
DOCUMENTS INCORPORATED BY REFERENCE
| Portions of our proxy statement for our 2020 annual meeting of stockholders are incorporated by reference into Part III (Items 10, 11, 12, 13 and 14) of this report. |
Freeport-McMoRan Inc.
i
PART I
Items 1. and 2. Business and Properties.
All of our periodic reports filed with the United States (U.S.) Securities and Exchange Commission (SEC) pursuant to Section 13(a) or 15(d) of the Securities Exchange Act of 1934, as amended, are available, free of charge, through our website, “fcx.com,” including our annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and any amendments to those reports. These reports and amendments are available through our website as soon as reasonably practicable after we electronically file or furnish such material to the SEC.
References to “we,” “us” and “our” refer to Freeport-McMoRan Inc. (FCX) and its consolidated subsidiaries. References to “Notes” refer to the Notes to Consolidated Financial Statements included herein (refer to Item 8.), and references to “MD&A” refer to Management’s Discussion and Analysis of Financial Condition and Results of Operations and Quantitative and Qualitative Disclosures About Market Risk included herein (refer to Items 7. and 7A.).
GENERAL
We are a leading international mining company with headquarters in Phoenix, Arizona. Our company was incorporated under the laws of the state of Delaware on November 10, 1987. We operate large, long-lived geographically diverse assets with significant proven and probable reserves of copper, gold and molybdenum, and we are one of the world’s largest publicly traded copper producers. Our portfolio of assets includes the Grasberg minerals district in Indonesia, one of the world’s largest copper and gold deposits; and significant mining operations in North America and South America, including the large-scale Morenci minerals district in Arizona and the Cerro Verde operation in Peru.
We believe that we have a high-quality portfolio of long-lived copper assets positioned to generate long-term value. PT Freeport Indonesia (PT-FI) continues to advance several projects in the Grasberg minerals district related to the development of its large-scale, long-lived, high-grade underground ore bodies, and we are nearing completion of a project to develop the Lone Star leachable ores near the Safford operation in eastern Arizona, which is now approximately 75 percent complete. We are also pursuing other opportunities to enhance our mines’ net present values, and we continue to advance studies for future development of our copper resources, the timing of which will be dependent on market conditions.
During 2019, we advanced initiatives in our North America and South America mining operations to enhance productivity, expand margins and reduce the capital intensity of the business through the utilization of new technology applications in combination with a more interactive operating structure. The pilot program initiated at the Bagdad mine in northwest Arizona in late 2018 was successful in utilizing data science, machine learning and integrated functional teams to address bottlenecks, provide cost benefits and drive improved overall performance. The program is now being implemented across our North America and South America operations.
During fourth-quarter 2019, PT-FI completed mining the final phase of the Grasberg open pit and continues to achieve important milestones in ramping-up production of large-scale quantities of copper and gold from its significant underground ore bodies. In aggregate, the Grasberg open pit produced over 27 billion pounds of copper and 46 million ounces of gold in the 30-year period from 1990 through 2019. As PT-FI continues to ramp-up production from its underground ore bodies, our consolidated metal production is expected to improve significantly by 2021.
Following are our ownership interests at December 31, 2019, in operating mines through our consolidated subsidiaries, Freeport Minerals Corporation (FMC) and PT-FI: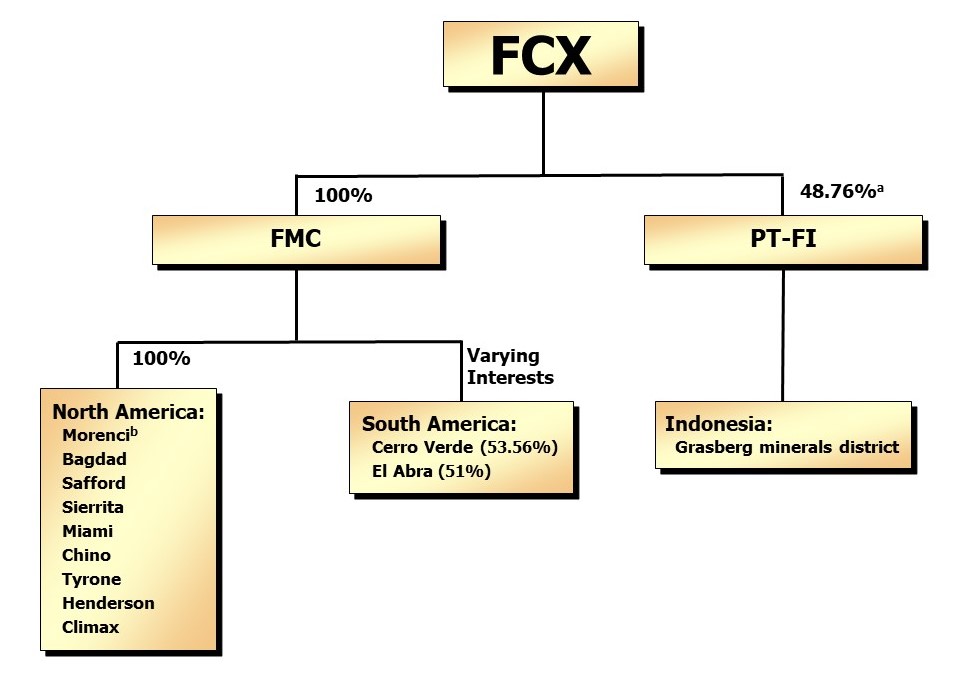
| a. | Prior to December 21, 2018, we owned 90.64 percent of PT-FI and PT-FI had an unincorporated joint venture with Rio Tinto plc (Rio Tinto). Refer to Note 2 for further discussion of the PT-FI divestment transaction and Note 3 for discussion of the former joint venture with Rio Tinto (Rio Tinto Joint Venture). |
| b. | FMC has a 72 percent undivided interest in Morenci via an unincorporated joint venture. Refer to Note 3 for further discussion. |
At December 31, 2019, our estimated consolidated recoverable proven and probable mineral reserves totaled 116.0 billion pounds of copper, 29.6 million ounces of gold and 3.58 billion pounds of molybdenum. Following is a summary of our estimated consolidated recoverable proven and probable mineral reserves at December 31, 2019, by geographic location (refer to “Mining Operations” for further discussion):
| Copper | Gold | Molybdenum | ||||||||
| North America | 40 | % | 2 | % | 80 | % | a | |||
| South America | 29 | — | 20 | |||||||
| Indonesia | 31 | 98 | — | |||||||
| 100 | % | 100 | % | 100 | % |
| a. | Our Henderson and Climax molybdenum mines contain 20 percent of our estimated consolidated recoverable proven and probable molybdenum reserves, and our North America copper mines contain 60 percent. |
In North America, we operate seven copper mines - Morenci, Bagdad, Safford, Sierrita and Miami in Arizona, and Chino and Tyrone in New Mexico, and two molybdenum mines - Henderson and Climax in Colorado. In addition to copper, certain of our North America copper mines also produce molybdenum concentrate, gold and silver. In South America, we operate two copper mines - Cerro Verde in Peru and El Abra in Chile. In addition to copper, the Cerro Verde mine also produces molybdenum concentrate and silver. In Indonesia, PT-FI operates in the Grasberg minerals district. In addition to copper, the Grasberg minerals district also produces gold and silver.
Following is a summary of the geographic locations of our consolidated copper, gold and molybdenum production for the year 2019 (refer to “Mining Operations” for further information):
| Copper | Gold | Molybdenum | |||||||
| North America | 45 | % | 2 | % | 68 | % | a | ||
| South America | 36 | — | 32 | ||||||
| Indonesia | 19 | 98 | — | ||||||
| 100 | % | 100 | % | 100 | % |
| a. | Our Henderson and Climax molybdenum mines produced 32 percent of our consolidated molybdenum production, and our North America copper mines produced 36 percent. |
The geographic locations of our operating mines are shown on the world map below. 
COPPER, GOLD AND MOLYBDENUM
Following is a brief discussion of our primary natural resources – copper, gold and molybdenum. For further discussion of historical and current market prices of these commodities, refer to MD&A and Item 1A. “Risk Factors.”
Copper
Copper is an internationally traded commodity, and its prices are determined by the major metals exchanges – the London Metal Exchange (LME), New York Mercantile Exchange (NYMEX) and Shanghai Futures Exchange. Prices on these exchanges generally reflect the worldwide balance of copper supply and demand, and can be volatile and cyclical. During 2019, the LME copper settlement price averaged $2.72 per pound, ranging from a low of $2.51 per pound to a high of $2.98 per pound, and was $2.79 per pound at December 31, 2019.
In general, demand for copper reflects the rate of underlying world economic growth, particularly in industrial production and construction. According to Wood Mackenzie, a widely followed independent metals market consultant, copper’s end-use markets (and their estimated shares of total consumption) are construction (28 percent), electrical applications (28 percent), consumer products (21 percent), transportation (12 percent) and industrial machinery (11 percent). We believe copper will continue to be essential in these basic uses as well as contribute significantly to new technologies for energy efficiencies, to advance communications and to enhance public health. Examples of areas we believe will require additional copper in the future include: (i) high efficiency motors, which consume up to 75 percent more copper than a standard motor; (ii) electric vehicles, which consume up to four times the amount of copper in terms of weight compared to vehicles of similar size with an internal combustion engine, and require copper-intensive charging station infrastructure to refuel; and (iii) renewable energy such as wind and solar, which consume four to five times the amount of copper compared to traditional fossil fuel generated power.
Gold
Gold is used for jewelry, coinage and bullion as well as various industrial and electronic applications. Gold can be readily sold on numerous markets throughout the world. Benchmark prices are generally based on London Bullion Market Association (London) quotations. During 2019, the London PM gold price averaged $1,393 per ounce, ranging from a low of $1,270 per ounce to a high of $1,546 per ounce, and was $1,515 per ounce on December 30, 2019 (there was no London PM gold price quote on December 31, 2019).
Molybdenum
Molybdenum is a key alloying element in steel and the raw material for several chemical-grade products used in catalysts, lubrication, smoke suppression, corrosion inhibition and pigmentation. Molybdenum, as a high-purity metal, is also used in electronics such as flat-panel displays and in super alloys used in aerospace. Reference prices for molybdenum are available in several publications, including Metals Week, CRU Report and Metal Bulletin. During 2019, the weekly average price of molybdenum quoted by Metals Week averaged $11.37 per pound, ranging from a low of $8.55 per pound to a high of $12.66 per pound, and was $9.23 per pound at December 31, 2019.
PRODUCTS AND SALES
Our consolidated revenues for 2019 primarily included sales of copper (79 percent), gold (11 percent) and molybdenum (8 percent). Copper concentrate sales to PT Smelting (PT-FI’s 25-percent-owned copper smelter and refinery in Gresik, Indonesia) totaled 13 percent of our consolidated revenues for the year ended December 31, 2019, and 12 percent for both the years ended December 31, 2018 and 2017, which is the only customer that accounted for 10 percent or more of our consolidated revenues during the three years ended December 31, 2019. Refer to Note 16 for a summary of our consolidated revenues and operating income (loss) by business segment and geographic area.
Copper Products
We are one of the world’s leading producers of copper concentrate, cathode and continuous cast copper rod. During 2019, 56 percent of our mined copper was sold in concentrate, 22 percent as cathode and 22 percent as rod from our North America operations. The copper ore from our mines is generally processed either by smelting and refining or by solution extraction and electrowinning (SX/EW) as described below.
Copper Concentrate. We produce copper concentrate at six of our mines in which mined ore is crushed and treated to produce a copper concentrate with copper content of approximately 20 to 30 percent. In North America, copper concentrate is produced at the Morenci, Bagdad, Sierrita and Chino mines, and a significant portion is shipped to our Miami smelter in Arizona for further processing. Copper concentrate is also produced at the Cerro Verde mine in Peru and the Grasberg minerals district in Indonesia.
Copper Cathode. We produce copper cathode at our electrolytic refinery located in El Paso, Texas, and at nine of our mines.
SX/EW cathode is produced from the Morenci, Bagdad, Safford, Sierrita, Miami, Chino and Tyrone mines in North America, and from the Cerro Verde and El Abra mines in South America*.* For ore subject to the SX/EW process, the ore is placed on stockpiles and copper is extracted from the ore by dissolving it with a weak sulphuric acid solution. The copper content of the solution is increased in two additional SX stages, and then the copper-bearing solution undergoes an EW process to produce cathode that is, on average, 99.99 percent copper. Our copper cathode is used as the raw material input for copper rod, brass mill products and for other uses.
Copper cathode is also produced at Atlantic Copper (our wholly owned copper smelting and refining unit in Spain) and PT Smelting. Copper concentrate is smelted (i.e., subjected to extreme heat) to produce copper anode, which weighs between 800 and 900 pounds and has an average copper content of 99.5 percent. The anode is further treated by electrolytic refining to produce copper cathode, which weighs between 100 and 350 pounds and has an average copper content of 99.99 percent. Refer to “Mining Operations - Smelting Facilities and Other Mining Properties” for further discussion of Atlantic Copper and PT Smelting.
Continuous Cast Copper Rod. We manufacture continuous cast copper rod at our facilities in El Paso, Texas; Norwich, Connecticut; and Miami, Arizona, primarily using copper cathode produced at our North America copper mines.
Copper Sales
North America. The majority of the copper produced at our North America copper mines and refined in our El Paso, Texas refinery is consumed at our rod plants to produce copper rod which is sold to wire and cable manufacturers. The remainder of our North America copper production is sold in the form of copper cathode or copper concentrate under U.S. dollar-denominated annual contracts. Cathode and rod contract prices are generally based on the prevailing Commodity Exchange Inc. (COMEX - a division of NYMEX) monthly average settlement price for the month of shipment and include a premium. Generally, copper cathode is sold to rod, brass or tube fabricators. During 2019, 23 percent of our North America mines’ copper concentrate sales volumes were shipped to Atlantic Copper for smelting and refining and sold as copper anode and copper cathode.
South America. Production from our South America mines is sold as copper concentrate or copper cathode under U.S. dollar-denominated, annual and multi-year contracts. During 2019, our South America mines sold approximately 77 percent of their copper production in concentrate and 23 percent as cathode.
Substantially all of our South America copper concentrate and cathode sales contracts provide final copper pricing in a specified future month (generally one to four months from the shipment date) primarily based on quoted LME monthly average settlement copper prices. Revenues from our South America concentrate sales are recorded net of royalties and treatment charges (i.e., fees paid to smelters that are generally negotiated annually). In addition, because a portion of the metals contained in copper concentrate is unrecoverable from the smelting process, revenues from our South America concentrate sales are also recorded net of allowances for unrecoverable metals, which are a negotiated term of the contracts and vary by customer.
Indonesia. PT-FI sells its production in the form of copper concentrate, which contains significant quantities of gold and silver, primarily under U.S. dollar-denominated, long-term contracts. PT-FI also sells a small amount of copper concentrate in the spot market. Following is a summary of PT-FI’s aggregate percentage of concentrate sales to unaffiliated third parties, PT Smelting and Atlantic Copper for the years ended December 31:
| 2019 | 2018 | 2017 | ||||||
| Third parties | 34 | % | 60 | % | 54 | % | ||
| PT Smelting | 64 | 38 | 46 | |||||
| Atlantic Copper | 2 | 2 | — | |||||
| 100 | % | 100 | % | 100 | % |
Substantially all of PT-FI’s concentrate sales contracts provide final copper pricing in a specified future month (generally one to four months from the shipment date) primarily based on quoted LME monthly average settlement copper prices. Revenues from PT-FI’s concentrate sales are recorded net of royalties, export duties, treatment charges and allowances for unrecoverable metals.
Gold Products and Sales
We produce gold almost exclusively from the Grasberg minerals district. The gold we produce is primarily sold as a component of our copper concentrate or in slimes, which are a product of the smelting and refining process. Gold generally is priced at the average London price for a specified month near the month of shipment. Revenues from gold sold as a component of our copper concentrate are recorded net of treatment and refining charges, royalties, export duties and allowances for unrecoverable metals. Revenues from gold sold in slimes are recorded net of refining charges.
Molybdenum Products and Sales
We are the world’s largest producer of molybdenum and molybdenum-based chemicals. In addition to production from the Henderson and Climax molybdenum mines, we produce molybdenum concentrate at certain of the North America copper mines and the Cerro Verde copper mine in Peru. The majority of our molybdenum concentrate is processed in our own conversion facilities. Our molybdenum sales are primarily priced based on the average published Metals Week price for the month prior to the month of shipment.
LABOR MATTERS
At December 31, 2019, we employed approximately 27,500 people (12,800 in North America, 6,900 in Indonesia, 6,500 in South America and 1,300 in Europe and other locations). We also had contractors that employ personnel at many of our operations, including approximately 22,300 at the Grasberg minerals district in Indonesia, 11,700 in North America, 5,900 at our South America mining operations and 700 in Europe and other locations. Employees represented by unions at December 31, 2019, are listed below, with the number of employees represented and the expiration date of the applicable union agreements:
| Location | Number of Unions | Number of Union- Represented Employees | Expiration Date | |||
| PT-FI – Indonesia | 2 | 5,020 | September 2019 | a | ||
| Cerro Verde – Peru | 1 | 3,421 | August 2021 | |||
| El Abra – Chile | 2 | 788 | April 2023 | |||
| Atlantic Copper – Spain | 3 | 484 | December 2019 | b | ||
| Kokkola - Finland | 3 | 187 | November 2020 | |||
| Rotterdam – The Netherlands | 1 | 60 | September 2022 | |||
| Kisanfu – Africa Exploration | 2 | 53 | N/A | c | ||
| Stowmarket - United Kingdom | 1 | 44 | May 2020 |
| a. | The Collective Labor Agreement (CLA) between PT-FI and its workers' unions expired in September 2019, but remains valid in accordance with Indonesia law until a new agreement is reached. A new agreement is currently under negotiation. |
| b. | The CLA between Atlantic Copper and its workers' unions expired in December 2019, but remains active by mutual agreement from both parties in accordance with Spanish law. Negotiations on a new agreement are set to begin soon. |
| c. | The CLA between Kisanfu and its unions has no expiration date, but can be amended at any time in accordance with an established process. |
Refer to Item 1A. “Risk Factors” for further information on labor matters.
ENVIRONMENTAL AND RECLAMATION MATTERS
The cost of complying with environmental laws and regulations is fundamental to and a substantial cost of our business. For information about environmental regulation, litigation and related costs, refer to Item 1A. “Risk Factors” and Notes 1 and 12.
COMPETITION
The top 10 producers of copper comprise approximately 43 percent of total worldwide mined copper production. We currently rank fourth among those producers, with approximately five percent of estimated total worldwide mined copper production. Our competitive position is based on the size, quality and grade of our ore bodies and our ability to manage costs compared with other producers. We have a diverse portfolio of mining operations with varying ore grades and cost structures. Our costs are driven by the location, grade and nature of our ore bodies, and the level of input costs, including energy, labor and equipment. The metals markets are cyclical, and our ability to maintain our competitive position over the long term is based on our ability to acquire and develop quality deposits, hire and retain a skilled workforce, and to manage our costs.
MINING OPERATIONS
Following are maps and descriptions of our mining operations in North America (including both copper and molybdenum operations), South America and Indonesia.
North America
In the U.S., most of the land occupied by our copper and molybdenum mines, concentrators, SX/EW facilities, smelter, refinery, rod mills, molybdenum roasters and processing facilities is owned by us or is located on unpatented mining claims owned by us. Certain portions of our Bagdad, Sierrita, Miami, Chino, Tyrone, Henderson and Climax operations are located on government-owned land and are operated under a Mine Plan of Operations or other use permit. We hold various federal and state permits or leases on government land for purposes incidental to mine operations.
Morenci
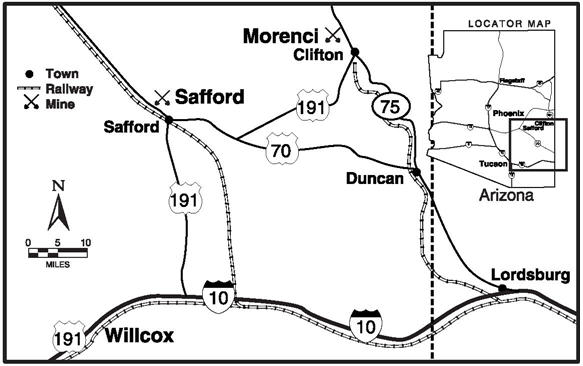
We own a 72 percent undivided interest in Morenci, with the remaining 28 percent owned by Sumitomo Metal Mining Arizona, Inc. (15 percent) and SMM Morenci, Inc. (13 percent). Each partner takes in kind its share of Morenci’s production.
Morenci is an open-pit copper mining complex that has been in continuous operation since 1939 and previously was mined through underground workings. Morenci is located in Greenlee County, Arizona, approximately 50 miles northeast of Safford on U.S. Highway 191. The site is accessible by a paved highway and a railway spur.
The Morenci mine is a porphyry copper deposit that has oxide, secondary sulfide and primary sulfide mineralization. The predominant oxide copper mineral is chrysocolla. Chalcocite is the most important secondary copper sulfide mineral, with chalcopyrite as the dominant primary copper sulfide.
The Morenci operation consists of two concentrators capable of milling 132,000 metric tons of ore per day, which produce copper and molybdenum concentrate; a 68,000 metric ton-per-day, crushed-ore leach pad and stacking system; a low-grade run-of-mine (ROM) leaching system; four SX plants; and three EW tank houses that produce copper cathode. Total EW tank house capacity is approximately 900 million pounds of copper per year. Morenci’s available mining fleet consists of one hundred and forty-one 236-metric ton haul trucks loaded by 13 shovels with bucket sizes ranging from 47 to 57 cubic meters, which are capable of moving an average of 815,000 metric tons of material per day.
Morenci’s production, including our joint venture partner’s share, totaled 1.0 billion pounds of copper and 5 million pounds of molybdenum in 2019, 1.0 billion pounds of copper and 9 million pounds of molybdenum in 2018, and 1.0 billion pounds of copper and 12 million pounds of molybdenum in 2017.
Morenci is located in a desert environment with rainfall averaging 13 inches per year. The highest bench elevation is 2,000 meters above sea level and the ultimate pit bottom is expected to have an elevation of 840 meters above sea level. The Morenci operation encompasses approximately 69,500 acres, comprising 51,300 acres of fee lands and 18,200 acres of unpatented mining claims held on public mineral estate and numerous state or federal permits, easements and rights-of-ways.
The Morenci operation’s electrical power is primarily sourced from Tucson Electric Power Company, Arizona Public Service Company and the Luna Energy facility in Deming, New Mexico. Although we believe the Morenci operation has sufficient water sources to support current operations, we are a party to litigation that may impact our water right claims or rights to continued use of currently available water supplies, which could adversely affect our water supply for the Morenci operation. Refer to Item 1A. “Risk Factors” and Item 3. “Legal Proceedings” for further discussion.
Bagdad
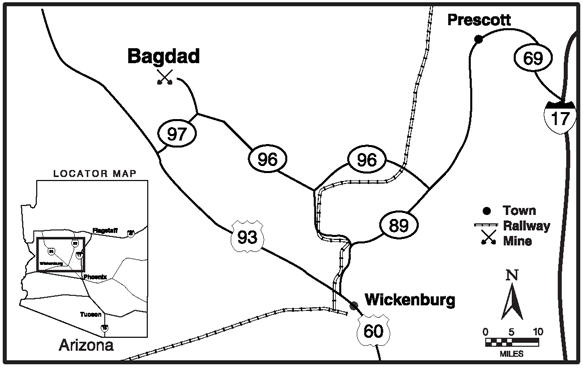
Our wholly owned Bagdad mine is an open-pit copper and molybdenum mining complex located in Yavapai County in west-central Arizona. It is approximately 60 miles west of Prescott and 100 miles northwest of Phoenix. The property can be reached by Arizona Highway 96, which ends at the town of Bagdad. The closest railroad is at Hillside, Arizona, 24 miles southeast on Arizona Highway 96. The open-pit mining operation has been ongoing since 1945, and prior mining was conducted through underground workings.
The Bagdad mine is a porphyry copper deposit containing both sulfide and oxide mineralization. Chalcopyrite and molybdenite are the dominant primary sulfides and are the primary economic minerals in the mine. Chalcocite is the most common secondary copper sulfide mineral, and the predominant oxide copper minerals are chrysocolla, malachite and azurite.
The Bagdad operation consists of an 81,600 metric ton-per-day concentrator that produces copper and molybdenum concentrate, a SX/EW plant that will produce approximately 5 million pounds per year of copper cathode from solution generated by low-grade stockpile leaching, and a pressure-leach plant to process molybdenum concentrate. The available mining fleet consists of thirty-seven 235-metric ton haul trucks loaded by six shovels with bucket sizes ranging from 30 to 48 cubic meters, which are capable of moving an average of 250,000 metric tons of material per day.
Bagdad’s production totaled 218 million pounds of copper and 13 million pounds of molybdenum in 2019, 199 million pounds of copper and 10 million pounds of molybdenum in 2018, and 173 million pounds of copper and 9 million pounds of molybdenum in 2017.
Bagdad is located in a desert environment with rainfall averaging 15 inches per year. The highest bench elevation is 1,200 meters above sea level and the ultimate pit bottom is expected to be 150 meters above sea level. The Bagdad operation encompasses approximately 33,100 acres, comprising 21,900 acres of fee lands and 11,200 acres of unpatented mining claims held on public mineral estate and numerous state or federal permits, easements and rights-of-ways.
Bagdad receives electrical power from Arizona Public Service Company. We believe the Bagdad operation has sufficient water sources to support current operations.
Safford, including Lone Star
Our wholly owned Safford mine has been in operation since 2007 and is an open-pit copper mining complex located in Graham County, Arizona, 8 miles north of the town of Safford and 170 miles east of Phoenix. The site is accessible by paved county road off U.S. Highway 70.
The Safford mine includes three copper deposits that have oxide mineralization overlaying primary copper sulfide mineralization. The predominant oxide copper minerals are chrysocolla and copper-bearing iron oxides with the predominant copper sulfide material being chalcopyrite.
The property is a mine-for-leach project and produces copper cathode. The operation consists of three open pits feeding a crushing facility with a capacity of 103,000 metric tons per day. The crushed ore is delivered to leach pads by a series of overland and portable conveyors. Leach solutions feed a SX/EW facility with a capacity of 240 million pounds of copper per year. A sulfur burner plant is also in operation at Safford, providing a cost-effective source of sulphuric acid used in SX/EW operations. The available mining fleet consists of thirty-five 235-metric ton haul trucks loaded by six shovels with bucket sizes ranging from 34 to 47 cubic meters, which are capable of moving an average of 358,000 metric tons of material per day.
Safford’s copper production totaled 110 million pounds in 2019, 123 million pounds in 2018 and 150 million pounds in 2017.
Through exploration drilling, we have identified a significant resource at our wholly owned Lone Star copper leach project located near the Safford operation in eastern Arizona. An initial project to develop the Lone Star leachable ores commenced in 2018, with first production expected during 2020. Initial production from the Lone Star leachable ores following a ramp-up period is expected to average approximately 200 million pounds of copper per year, with the potential for future expansion options. Total capital costs for the initial project, including mine equipment and pre-production stripping, are expected to approximate $850 million and will benefit from the utilization of existing infrastructure at the adjacent Safford operation. As of December 31, 2019, approximately $655 million has been incurred for this project, which is on schedule and within budget. The project also advances exposure to a significant sulfide resource. We expect to incorporate positive drilling and ongoing results in our future development plans.
Safford is located in a desert environment with rainfall averaging 10 inches per year. The highest bench elevation is 1,783 meters above sea level and the ultimate pit bottom is expected to have an elevation of 823 meters above sea level. The Safford operation encompasses approximately 94,700 acres, comprising 37,200 acres of fee lands and 57,500 acres of unpatented claims held on public mineral estate.
The Safford operation’s electrical power is primarily sourced from Tucson Electric Power Company, Arizona Public Service Company and the Luna Energy facility. Although we believe the Safford operation has sufficient water sources to support current operations as well as the Lone Star project, we are a party to litigation that may impact our water right claims or rights to continued use of currently available water supplies, which could adversely affect our water supply for the Safford operation. Refer to Item 1A. “Risk Factors” and Item 3. “Legal Proceedings” for further discussion.
Sierrita
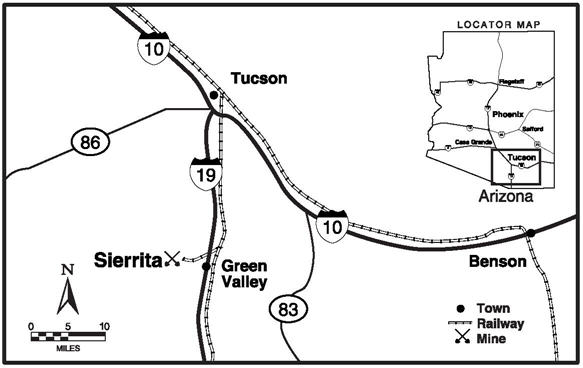
Our wholly owned Sierrita mine has been in operation since 1959 and is an open-pit copper and molybdenum mining complex located in Pima County, Arizona, approximately 20 miles southwest of Tucson and 7 miles west of the town of Green Valley and Interstate Highway 19. The site is accessible by a paved highway and by rail.
The Sierrita mine is a porphyry copper deposit that has oxide, secondary sulfide and primary sulfide mineralization. The predominant oxide copper minerals are malachite, azurite and chrysocolla. Chalcocite is the most important secondary copper sulfide mineral, and chalcopyrite and molybdenite are the dominant primary sulfides.
The Sierrita operation includes a 100,000 metric ton-per-day concentrator that produces copper and molybdenum concentrate. Sierrita also produces copper from a ROM oxide-leaching system. Cathode copper is plated at the Twin Buttes EW facility, which has a design capacity of approximately 50 million pounds of copper per year. The Sierrita operation also has molybdenum facilities consisting of a leaching circuit, two molybdenum roasters and a packaging facility. The molybdenum facilities process molybdenum concentrate produced by Sierrita, from our other mines and from third-party sources. The available mining fleet consists of twenty-two 235-metric ton haul trucks loaded by three shovels with bucket sizes ranging from 34 to 56 cubic meters, which are capable of moving an average of 175,000 metric tons of material per day.
Sierrita’s production totaled 160 million pounds of copper and 16 million pounds of molybdenum in 2019, 152 million pounds of copper and 16 million pounds of molybdenum in 2018, and 160 million pounds of copper and 15 million pounds of molybdenum in 2017.
Sierrita is located in a desert environment with rainfall averaging 14.5 inches per year. The highest bench elevation is 1,300 meters above sea level and the ultimate pit bottom is expected to be 410 meters above sea level. The Sierrita operation, including the adjacent Twin Buttes site, encompasses approximately 46,700 acres, comprising 38,300 acres of fee lands including split estate lands and 8,400 acres of unpatented mining claims held on public mineral estate.
Sierrita receives electrical power through long-term contracts with the Tucson Electric Power Company. Although we believe the Sierrita operation has sufficient water sources to support current operations, we are a party to litigation that may impact our water rights claims or rights to continued use of currently available water supplies, which could adversely affect our water supply for the Sierrita operation. Refer to Item 1A. “Risk Factors” and Item 3. “Legal Proceedings” for further discussion.
Miami
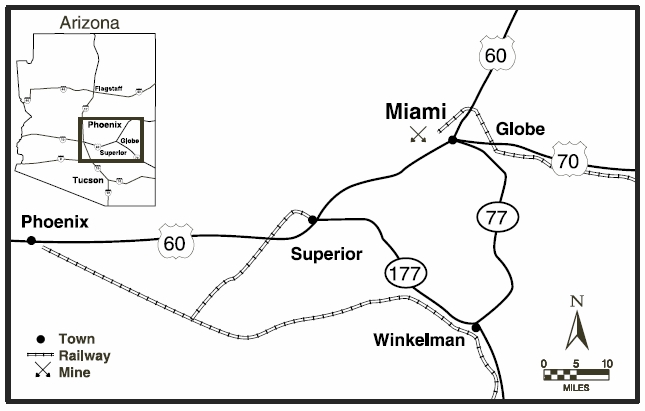
Our wholly owned Miami mine is an open-pit copper mining complex located in Gila County, Arizona, 90 miles east of Phoenix and 6 miles west of the city of Globe on U.S. Highway 60. The site is accessible by a paved highway and by rail.
The Miami mine is a porphyry copper deposit that has leachable oxide and secondary sulfide mineralization. The predominant oxide copper minerals are chrysocolla, copper-bearing clays, malachite and azurite. Chalcocite and covellite are the most important secondary copper sulfide minerals.
Since about 1915, the Miami mining operation had processed copper ore using both flotation and leaching technologies. The design capacity of the SX/EW plant is 200 million pounds of copper per year. Miami is no longer mining ore, but currently produces copper through leaching material already placed on stockpiles, which is expected to continue until 2025. Miami’s copper production totaled 15 million pounds in 2019, 16 million pounds in 2018 and 19 million pounds in 2017.
Miami is located in a desert environment with rainfall averaging 18 inches per year. The highest bench elevation is 1,390 meters above sea level and mining advanced the pit bottom to an elevation of 810 meters above sea level. Subsequent sloughing of material into the pit has filled it back to an elevation estimated to be 900 meters above sea level. The Miami operation encompasses approximately 14,700 acres, comprising 10,400 acres of fee lands and 4,300 acres of unpatented mining claims held on public mineral estate.
Miami receives electrical power through long-term contracts with the Salt River Project and natural gas through long-term contracts with El Paso Natural Gas as the transporter. We believe the Miami operation has sufficient water sources to support current operations.
Chino and Tyrone
Chino
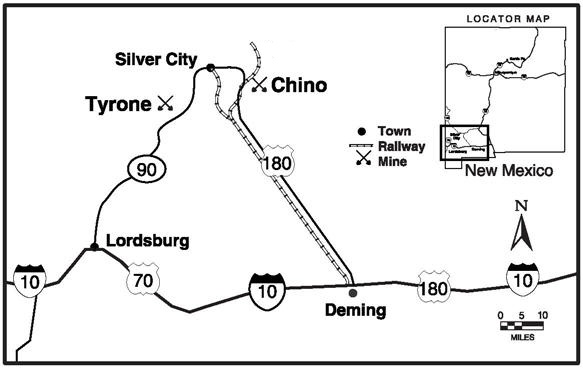
Our wholly owned Chino mine is an open-pit copper mining complex located in Grant County, New Mexico, approximately 15 miles east of the town of Silver City off of State Highway 180. The mine is accessible by paved roads and by rail. Chino has been in operation since 1910.
The Chino mine is a porphyry copper deposit with adjacent copper skarn deposits. There is leachable oxide, secondary sulfide and millable primary sulfide mineralization. The predominant oxide copper mineral is chrysocolla. Chalcocite is the most important secondary copper sulfide mineral, and chalcopyrite and molybdenite the dominant primary sulfides.
The Chino operation consists of a 36,000 metric ton-per-day concentrator that produces copper and molybdenum concentrate, and a 150 million pound-per-year SX/EW plant that produces copper cathode from solution generated by ROM leaching. The available mining fleet consists of thirty-five 240-metric ton haul trucks loaded by four shovels with bucket sizes ranging from 31 to 48 cubic meters, which are capable of moving an average of 235,000 metric tons of material per day.
Chino’s copper production totaled 175 million pounds in 2019, 173 million pounds in 2018 and 215 million pounds in 2017.
Chino is located in a desert environment with rainfall averaging 16 inches per year. The highest bench elevation is 2,250 meters above sea level and the ultimate pit bottom is expected to be 1,460 meters above sea level. The Chino operation encompasses approximately 117,300 acres, comprising 103,900 acres of fee lands and 13,400 acres of unpatented mining claims held on public mineral estate.
Chino receives power from the Luna Energy facility and from the open market. We believe Chino has sufficient water resources to support current operations.
Tyrone
Our wholly owned Tyrone mine is an open-pit copper mining complex which has been in operation since 1967. It is located in Grant County, New Mexico, 10 miles south of Silver City, New Mexico, along State Highway 90. The site is accessible by paved road and by rail.
The Tyrone mine is a porphyry copper deposit. Mineralization is predominantly secondary sulfide consisting of chalcocite, with leachable oxide mineralization consisting of chrysocolla.
Copper processing facilities consist of a SX/EW operation with a maximum capacity of approximately 100 million pounds of copper cathode per year. The available mining fleet consists of seven 240-metric ton haul trucks loaded by one shovel with a bucket size of 47 cubic meters, which is capable of moving an average of 68,000 metric tons of material per day.
Tyrone’s copper production totaled 48 million pounds in 2019, 55 million pounds in 2018 and 61 million pounds in 2017.
Tyrone is located in a desert environment with rainfall averaging 16 inches per year. The highest bench elevation is 2,000 meters above sea level and the ultimate pit bottom is expected to have an elevation of 1,475 meters above sea level. The Tyrone operation encompasses approximately 31,100 acres, comprising 19,700 acres of fee lands and 11,400 acres of unpatented mining claims held on public mineral estate.
Tyrone receives electrical power from the Luna Energy facility and from the open market. We believe the Tyrone operation has sufficient water resources to support current operations.
Henderson and Climax

Henderson
Our wholly owned Henderson molybdenum mine has been in operation since 1976 and is located 42 miles west of Denver, Colorado, off U.S. Highway 40. Nearby communities include the towns of Empire, Georgetown and Idaho Springs. The Henderson mill site is located 15 miles west of the mine and is accessible from Colorado State Highway 9. The Henderson mine and mill are connected by a 10-mile conveyor tunnel under the Continental Divide and an additional five-mile surface conveyor. The tunnel portal is located five miles east of the mill.
The Henderson mine is a porphyry molybdenum deposit, with molybdenite as the primary sulfide mineral.
The Henderson operation consists of a large block-cave underground mining complex feeding a concentrator with a current capacity of approximately 32,000 metric tons per day. Henderson has the capacity to produce approximately 18 million pounds of molybdenum per year. The majority of the molybdenum concentrate produced is shipped to our Fort Madison, Iowa, processing facility. The available underground mining equipment fleet consists of fourteen 9-metric ton load-haul-dump (LHD) units and seven 73-metric ton haul trucks, which deliver ore to a gyratory crusher feeding a series of three overland conveyors to the mill stockpiles.
Henderson’s molybdenum production totaled 12 million pounds in 2019, 14 million pounds in 2018 and 12 million pounds in 2017.
The Henderson mine is located in a mountainous region with the main access shaft at 3,180 meters above sea level. The main production levels are currently at elevations of 2,200 and 2,350 meters above sea level. This region experiences significant snowfall during the winter months.
The Henderson mine and mill operations encompass approximately 16,700 acres, comprising 13,100 acres of fee lands, 3,550 acres of unpatented mining claims held on public mineral estate and a 50-acre easement with the U.S. Forest Service for the surface portion of the conveyor corridor.
Henderson operations receive electrical power through long-term contracts with Xcel Energy and natural gas through long-term contracts with Encore Energy (with Xcel Energy as the transporter). We believe the Henderson operation has sufficient water resources to support current operations.
Climax
Our wholly owned Climax mine is located 13 miles northeast of Leadville, Colorado, off Colorado State Highway 91 at the top of Fremont Pass. The mine is accessible by paved roads.
The Climax ore body is a porphyry molybdenum deposit, with molybdenite as the primary sulfide mineral.
The Climax open-pit mine includes a 25,000 metric ton-per-day mill facility. Climax has the capacity to produce approximately 30 million pounds of molybdenum per year. The available mining fleet consists of eleven 177-metric ton haul trucks loaded by two hydraulic shovels with bucket sizes of 34 cubic meters, which are capable of moving an average of 90,000 metric tons of material per day.
Molybdenum production from Climax totaled 17 million pounds in 2019, 21 million pounds in 2018 and 20 million pounds in 2017.
The Climax mine is located in a mountainous region. The highest bench elevation is approximately 4,050 meters above sea level and the ultimate pit bottom is expected to have an elevation of approximately 3,100 meters above sea level. This region experiences significant snowfall during the winter months.
The Climax operation encompasses approximately 15,100 acres of fee lands.
Climax operations receive electrical power through long-term contracts with Xcel Energy and natural gas through long-term contracts with Encore Energy. We believe the Climax operation has sufficient water resources to support current operations.
South America
At our operations in South America, mine properties and facilities are controlled through mining claims or concessions under the general mining laws of the relevant country. The claims or concessions are owned or controlled by the operating companies in which we or our subsidiaries have a controlling ownership interest. Roads, power lines and aqueducts are controlled by easements.
Cerro Verde
We have a 53.56 percent ownership interest in Cerro Verde, with the remaining 46.44 percent held by SMM Cerro Verde Netherlands B.V. (21.0 percent), Compañia de Minas Buenaventura S.A.A. (19.58 percent) and other stockholders whose shares are publicly traded on the Lima Stock Exchange (5.86 percent).
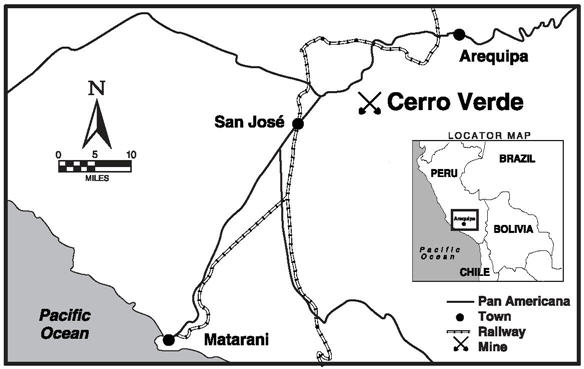
Cerro Verde is an open-pit copper and molybdenum mining complex that has been in operation since 1976 and is located 20 miles southwest of Arequipa, Peru. The site is accessible by paved highway. Cerro Verde’s copper cathode and concentrate production that is not sold locally is transported approximately 70 miles by truck and by rail to the Port of Matarani for shipment to international markets.
The Cerro Verde mine is a porphyry copper deposit that has oxide, secondary sulfide and primary sulfide mineralization. The predominant oxide copper minerals are brochantite, chrysocolla, malachite and copper “pitch.” Chalcocite and covellite are the most important secondary copper sulfide minerals. Chalcopyrite and molybdenite are the dominant primary sulfides.
Cerro Verde’s operation consists of an open-pit copper mine, a 409,500 metric ton-per-day concentrating facility, and SX/EW leaching facilities. Leach copper production is derived from a 39,000 metric ton-per-day crushed leach facility and a 100,000 metric ton-per-day ROM leach system. This SX/EW leaching operation has a capacity of approximately 200 million pounds of copper per year.
The available fleet consists of forty-five 290-metric ton haul trucks and ninety-three 230-metric ton haul trucks loaded by twelve electric shovels with bucket sizes ranging in size from 33 to 57 cubic meters and two hydraulic shovels with a bucket size of 21 cubic meters. This fleet is capable of moving an average of approximately 1,050,000 metric tons of material per day.
Cerro Verde’s production totaled 1.0 billion pounds of copper and 29 million pounds of molybdenum in 2019, 1.0 billion pounds of copper and 28 million pounds of molybdenum in 2018, and 1.1 billion pounds of copper and 27 million pounds of molybdenum in 2017.
Cerro Verde is located in a desert environment with rainfall averaging 1.5 inches per year and is in an active seismic zone. The highest bench elevation is 2,750 meters above sea level and the ultimate pit bottom is expected to be 1,553 meters above sea level. The Peru general mining law and Cerro Verde’s mining stability agreement grant the surface rights of mining concessions located on government land. Government land obtained after 1997 must be leased or purchased. Cerro Verde has a mining concession covering approximately 182,000 acres, including access to 14,600 acres granted through an easement from the Peru National Assets Office, plus 145 acres of owned property, and 1,151 acres of rights-of-way outside the mining concession area.
Cerro Verde receives electrical power, including hydro-generated power, under long-term contracts with Kallpa Generación SA, ElectroPeru and Engie Energia Peru S.A.
Water for our Cerro Verde processing operations comes from renewable sources through a series of storage reservoirs on the Rio Chili watershed that collect water primarily from seasonal precipitation. We believe the Cerro Verde operation has sufficient water resources to support current operations. For further discussion of risks associated with the availability of water, see Item 1A. “Risk Factors.”
El Abra

We own a 51 percent interest in El Abra, and the remaining 49 percent interest is held by the state-owned copper enterprise Corporación Nacional del Cobre de Chile (CODELCO).
El Abra is an open-pit copper mining complex that has been in operation since 1996 and is located 47 miles north of Calama in Chile’s El Loa province, Region II. The site is accessible by paved highway and by rail.
The El Abra mine is a porphyry copper deposit that has sulfide and oxide mineralization. The predominant primary sulfide copper minerals are bornite and chalcopyrite. There is a minor amount of secondary sulfide mineralization
as chalcocite. The oxide copper minerals are chrysocolla and pseudomalachite. There are lesser amounts of copper-bearing clays and tenorite.
The El Abra operation consists of an open-pit copper mine and a SX/EW facility with a capacity of 500 million pounds of copper cathode per year from a 125,000 metric ton-per-day crushed leach circuit and a similar-sized ROM leaching operation. The available fleet consists of twenty-three 242-metric ton haul trucks loaded by four shovels with buckets ranging in size from 29 to 41 cubic meters, which are capable of moving an average of 216,000 metric tons of material per day.
El Abra’s copper production totaled 180 million pounds in 2019, 200 million pounds in 2018 and 173 million pounds in 2017.
We continue to evaluate a large-scale expansion at El Abra to process additional sulfide material and to achieve higher recoveries. El Abra’s large sulfide resource could potentially support a major mill project similar to facilities constructed at Cerro Verde. Technical and economic studies continue to be advanced to determine the optimal scope and timing for the project.
El Abra is located in a desert environment with rainfall averaging less than one inch per year and is in an active seismic zone. The highest bench elevation is 4,195 meters above sea level and the ultimate pit bottom is expected to be 3,385 meters above sea level. El Abra controls a total of approximately 180,000 acres of mining claims covering the ore deposit, stockpiles, process plant, and water wellfield and pipeline. In addition, El Abra has land surface rights for the road between the processing plant and the mine, the water wellfield, power transmission lines and for the water pipeline from the Salar de Ascotán aquifer.
El Abra currently receives electrical power under a long-term contract with Engie Energia Chile S.A. Water for our El Abra processing operations comes from the continued pumping of groundwater from the Salar de Ascotán aquifer pursuant to regulatory approval. We believe El Abra has sufficient water rights and regulatory approvals to support current operations. For a discussion of risks associated with the availability of water, refer to Item 1A. “Risk Factors.”
Indonesia
Ownership. PT-FI is a limited liability company organized under the laws of the Republic of Indonesia. On December 21, 2018, we completed the transaction with the Indonesia government regarding PT-FI’s long-term mining rights and share ownership (refer to Note 2 for further discussion). Following the transaction, we have a 48.76 percent share ownership in PT-FI and the remaining 51.24 percent share ownership is collectively held by PT Indonesia Asahan Aluminum (Persero) (PT Inalum), an Indonesia state-owned enterprise, and PT Indonesia Papua Metal Dan Mineral (formerly known as PT Indocopper Investama), which is expected to be owned by PT Inalum and the provincial/regional government in Papua, Indonesia. The arrangements related to the transaction also provide for us and the other pre-transaction PT-FI shareholders to retain the economics of the revenue and cost sharing arrangements under the former Rio Tinto Joint Venture. As a result, our economic interest in PT-FI is expected to approximate 81 percent through 2022.
IUPK. Concurrent with closing the transaction, the Indonesia government granted PT-FI a new special mining license (IUPK) to replace its former Contract of Work (COW), enabling PT-FI to conduct operations in the Grasberg minerals district through 2041. Under the terms of the IUPK, PT-FI has been granted an extension of mining rights through 2031, with rights to extend mining rights through 2041, subject to PT-FI completing the construction of a new smelter in Indonesia within five years of closing the transaction and fulfilling its defined fiscal obligations to the Indonesia government. The IUPK, and related documentation, contains legal and fiscal terms and is legally enforceable through 2041. In addition, we, as a foreign investor, have rights to resolve investment disputes with the Indonesia government through international arbitration. Refer to Note 13 and Item 1A. “Risk Factors” for discussion of PT-FI’s IUPK and risks associated with our Indonesia mining operations.
On September 12, 2019, PT-FI received approval from the Indonesia government to increase its export quota from approximately 180,000 dry metric tons (DMT) of concentrate to approximately 680,000 DMT for the current export period, which expires March 8, 2020. Export licenses are valid for one year periods, subject to review and approval by the Indonesia government every six months, depending on smelter construction progress.
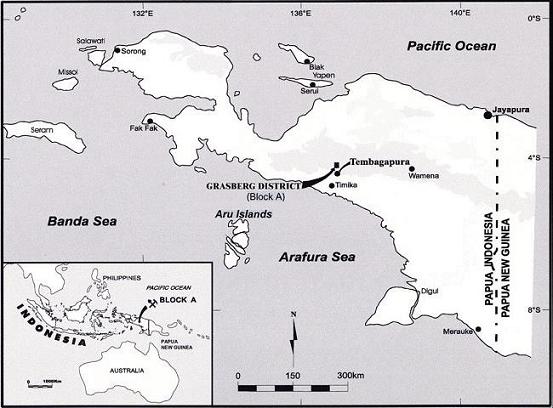
Grasberg Minerals District. PT-FI operates in the remote highlands of the Sudirman Mountain Range in the province of Papua, Indonesia, which is on the western half of the island of New Guinea. Since 1967, we and our predecessors have been the only operator of exploration and mining activities in the approximately 24,600-acre operating area. The operating area is accessible by portsite facilities (Arafura Sea) and by the Timika airport. The project area includes a 70-mile main service road from portsite to the mill complex.
After mining the final phase of the Grasberg open pit during 2019, the Grasberg minerals district includes the following underground mines that are being operated or in advanced development; the Grasberg Block Cave, the Deep Mill Level Zone (DMLZ), Big Gossan and the Deep Ore Zone (DOZ).
As further discussed in MD&A, PT-FI is ramping-up production from its significant underground ore bodies and continues to achieve important milestones to produce large-scale quantities of copper and gold. In aggregate, these underground ore bodies are expected to produce large-scale quantities of copper and gold. Refer to Item 1A. “Risk Factors” for discussion of risks associated with development projects and underground mines.
Production from the Grasberg minerals district, including the former Rio Tinto Joint Venture share, totaled 0.6 billion pounds of copper and 0.9 million ounces of gold in 2019, 1.2 billion pounds of copper and 2.7 million ounces of gold in 2018, and 1.0 billion pounds of copper and 1.6 million ounces of gold in 2017.
Our principal source of power for all of our Indonesia operations is a coal-fired power plant that we built in 1998. Diesel generators supply peaking and backup electrical power generating capacity. A combination of naturally occurring mountain streams and water derived from our underground operations provides water for our operations. Our Indonesia operations are in an active seismic zone and experience average annual rainfall of approximately 200 inches.
Grasberg Open Pit
PT-FI began open-pit mining of the Grasberg ore body in 1990. The final phase of the Grasberg open pit was mined during 2019, including the removal of the open pit ramps. In aggregate, the Grasberg open pit produced over 27 billion pounds of copper and 46 million ounces of gold in the 30-year period from 1990 through 2019.
Ore milled from the Grasberg open pit averaged 60,100 metric tons per day in 2019, 133,300 metric tons per day in 2018 and 101,800 metric tons per day in 2017.
Grasberg Block Cave
The Grasberg Block Cave ore body is the same ore body historically mined from the surface in the Grasberg open pit. Undercutting, drawbell construction and ore extraction activities in the Grasberg Block Cave underground mine continue to track expectations. Monitoring data on cave propagation in the Grasberg Block Cave underground mine is providing confidence in growing production rates over time. As existing drawpoints mature and additional drawpoints are added, cave expansion is expected to accelerate production rates to an average of 30,000 metric tons of ore per day in 2020, over 60,000 metric tons of ore per day in 2021 and 130,000 metric tons of ore per day in 2023 from five production blocks spanning 335,000 square meters.
Ore milled from the Grasberg Block Cave underground mine averaged 8,600 metric tons per day in 2019, 4,000 metric tons per day in 2018 and 3,600 metric tons per day in 2017. Production at the Grasberg Block Cave underground mine is expected to continue through 2041.
The Grasberg Block Cave fleet consists of approximately 460 pieces of mobile equipment. The primary mining equipment directly associated with production and development includes an available fleet of 52 LHD units and 35 haul trucks. Each production LHD unit typically carries approximately 11 metric tons of ore and transfer ore into 55 to 60 metric ton capacity haul trucks. In addition, the Grasberg Block Cave has a rail haulage system currently operating with 3 locomotives and 27 ore wagons that haul the ore to the first of the 3 planned gyratory crushers located underground via an automated rail system. Each ore wagon typically carries 30 metric tons.
DMLZ Underground Mine
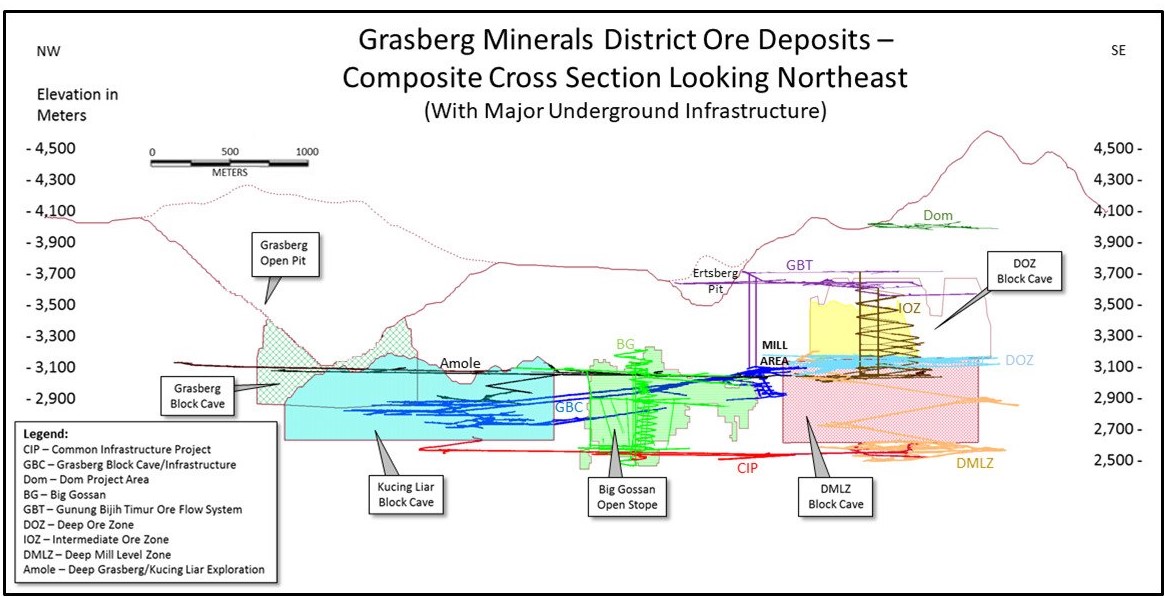
The DMLZ ore body lies below the DOZ underground mine at the 2,590-meter elevation and represents the downward continuation of mineralization in the Ertsberg East Skarn system and neighboring Ertsberg porphyry.
The DMLZ has continued its ramp-up of production. Hydraulic fracturing operations have been effective in managing rock stresses and pre-conditioning the cave following mining-induced seismic activity experienced in 2017 and 2018. Ore extraction continues to exceed expectations, averaging 14,900 metric tons of ore per day in fourth-quarter 2019 and reached approximately 16,000 metric tons of ore per day at year-end 2019. Ongoing hydraulic fracturing operations combined with continued undercutting and drawbell openings in the two currently active production blocks are expected to expand the cave, supporting higher production rates that are expected to average 29,000 metric tons of ore per day in 2020, approach 60,000 metric tons of ore per day in 2021 and 80,000 metric tons of ore per day in 2022 from three production blocks.
Ore milled from the DMLZ underground mine averaged 9,800 metric tons of ore per day in 2019, and 3,200 metric tons per day in both 2018 and 2017. Production at the DMLZ underground mine is expected to continue through 2041.
The DMLZ fleet consists of over 290 pieces of mobile equipment, which includes 22 LHD units and 9 haul trucks used in production and development activities.
Big Gossan Underground Mine
The Big Gossan ore body lies underground and adjacent to the current mill site. It is a tabular, near vertical ore body with approximate dimensions of 1,200 meters along strike and 800 meters down dip with varying thicknesses from 20 meters to 120 meters. The mine utilizes a blasthole stoping method with delayed paste backfill. Stopes of varying sizes are mined and the ore dropped down passes to a truck haulage level. Trucks are chute loaded and transport the ore to a jaw crusher. The crushed ore is then hoisted vertically via a two-skip production shaft to a level where it is loaded onto a conveyor belt. The belt carries the ore to one of the main underground conveyors where the ore is transferred and conveyed to the surface stockpiles for processing.
Ore milled from the Big Gossan underground mine averaged 6,100 metric tons per day in 2019, 3,800 metric tons per day in 2018 and 600 metric tons per day in 2017. Production at the Big Gossan underground mine is expected to continue through 2041.
The Big Gossan fleet consists of over 88 pieces of mobile equipment, which includes 12 LHD units and 9 haul trucks used in development and production activities.
DOZ Underground Mine
The DOZ ore body lies vertically below the now depleted Intermediate Ore Zone. PT-FI began production from the DOZ ore body in 1989 using open-stope mining methods, but suspended production in 1991 in favor of production from the Grasberg open pit. Production resumed in 2000 using the block-cave method and is at the 3,110-meter elevation level.
The DOZ is a mature block-cave mine that previously operated at 80,000 metric tons of ore per day. Current operating rates from the DOZ underground mine are driven by the value of the incremental DOZ ore grade compared to the ore from the DMLZ and Grasberg Block Cave underground mines. Ore milled from the DOZ underground mine averaged 25,500 metric tons per day in 2019, 33,800 metric tons per day in 2018 and 31,200 metric tons per day in 2017. Production at the DOZ underground mine is expected to continue through 2022.
The DOZ fleet consists of 186 pieces of mobile equipment. The primary mining equipment directly associated with production includes an available fleet of 40 LHD units and 19 haul trucks. The trucks dump into two gyratory crushers, and the ore is then conveyed to the surface stockpiles for processing.
Description of Indonesia Ore Bodies*.* Our Indonesia ore bodies are located within and around two main igneous intrusions, the Grasberg monzodiorite and the Ertsberg diorite. The host rocks of these ore bodies include both carbonate and clastic rocks that form the ridge crests and upper flanks of the Sudirman Range, and the igneous rocks of monzonitic to dioritic composition that intrude them. The igneous-hosted ore bodies (the Grasberg Block Cave and portions of the DOZ) occur as vein stockworks and disseminations of copper sulfides, dominated by chalcopyrite and, to a lesser extent, bornite. The sedimentary-rock hosted ore bodies (portions of the DOZ and all of the Big Gossan) occur as “magnetite-rich, calcium/magnesian skarn” replacements, whose location and orientation are strongly influenced by major faults and by the chemistry of the carbonate rocks along the margins of the intrusions.
The copper mineralization in these skarn deposits is dominated by chalcopyrite, but higher bornite concentrations are common. Moreover, gold occurs in significant concentrations in all of the district’s ore bodies, though rarely visible to the naked eye. These gold concentrations usually occur as inclusions within the copper sulfide minerals, though, in some deposits, these concentrations can also be strongly associated with pyrite.
The following diagram indicates the relative elevations (in meters) of our reported Indonesia ore bodies.
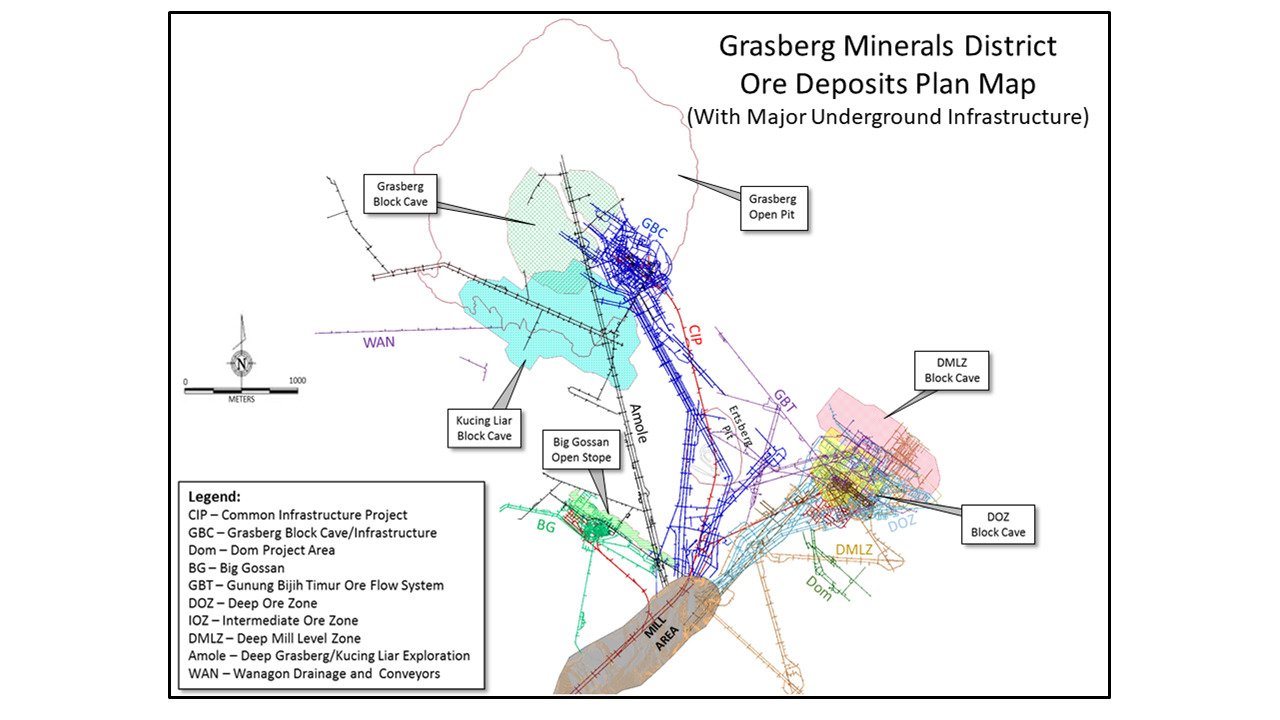
The following map, which encompasses an area of 42 square kilometers (16 square miles), indicates the relative positions and sizes of our reported Indonesia ore bodies and their locations.
Smelting Facilities and Other Mining Properties
Atlantic Copper. Our wholly owned Atlantic Copper smelter and refinery is located on land concessions from the Huelva, Spain, port authorities, which are scheduled to expire in 2039.
The design capacity of the smelter is approximately 300,000 metric tons of copper per year, and the refinery has a capacity of 286,000 metric tons of copper per year. Atlantic Copper produced 272,000 metric tons of copper anode from its smelter and 268,300 metric tons of copper cathode from its refinery in 2019; 295,300 metric tons of copper anode from its smelter and 283,100 metric tons of copper cathode from its refinery in 2018; and 283,100 metric tons of copper anode from its smelter and 271,400 metric tons of copper cathode from its refinery in 2017.
Following is a summary of Atlantic Copper’s concentrate purchases from unaffiliated third parties and our copper mining operations for the years ended December 31:
| 2019 | 2018 | 2017 | |||||||
| Third parties | 73 | % | 77 | % | 67 | % | |||
| North America copper mines | 22 | 14 | 18 | ||||||
| South America mining | 2 | 5 | 15 | ||||||
| Indonesia mining | 3 | 4 | — | ||||||
| 100 | % | 100 | % | 100 | % |
Atlantic Copper’s major maintenance turnarounds typically occur approximately every eight years, with shorter-term maintenance turnarounds in the interim. Atlantic Copper completed a 79-day major maintenance turnaround in 2013, a 16-day maintenance turnaround in 2015, a 27-day maintenance turnaround in 2017 and a 16-day maintenance turnaround in 2019. The next major maintenance turnaround is scheduled for 2021.
PT Smelting. PT-FI’s former COW required us to construct, or cause to be constructed, a smelter in Indonesia if we and the Indonesia government determined that such a project would be economically viable. In 1995, following the completion of a feasibility study, we entered into agreements relating to the formation of PT Smelting, an Indonesia company, and the construction of the copper smelter and refinery in Gresik, Indonesia. PT Smelting owns and operates the smelter and refinery. PT-FI owns 25 percent of PT Smelting, with the remainder owned by Mitsubishi
Materials Corporation (60.5 percent), Mitsubishi Corporation RtM Japan Ltd. (9.5 percent) and JX Nippon Mining & Metals Corporation (5 percent).
PT-FI’s contract with PT Smelting requires PT-FI to supply 100 percent of the copper concentrate requirements (at market rates subject to a minimum or maximum treatment charge rate) necessary for PT Smelting to produce 205,000 metric tons of copper annually on a priority basis. PT-FI may also sell copper concentrate to PT Smelting at market rates for quantities in excess of 205,000 metric tons of copper annually. PT-FI supplied 90 percent of PT Smelting’s concentrate requirements in both 2019 and 2018 and 93 percent in 2017.
In early 2017, the Indonesia government issued new regulations to address exports of unrefined metals, including copper concentrate and anode slimes, and other matters related to the mining sector. These regulations permit the export of anode slimes, which is necessary for PT Smelting to continue operating. As a result of labor disturbances and a delay in the renewal of its export license for anode slimes, PT Smelting’s operations were shut down from mid-January 2017 until early March 2017. In March 2019, PT Smelting received a one-year extension of its anode slimes export license, which currently expires March 11, 2020. Refer to Item 1A. “Risk Factors” for further discussion.
PT Smelting produced 246,100 metric tons of copper anode from its smelter and 241,200 metric tons of copper cathode from its refinery in 2019; 258,800 metric tons of copper anode from its smelter and 257,600 metric tons of copper cathode from its refinery in 2018; and 245,800 metric tons of copper anode from its smelter and 247,800 metric tons of copper cathode from its refinery in 2017.
PT Smelting’s maintenance turnarounds (which range from two weeks to a month to complete) typically are expected to occur approximately every two years, with short-term maintenance turnarounds in the interim. PT Smelting completed a 30-day maintenance turnaround during 2018, and the next major turnaround is scheduled to start in November 2020.
Miami Smelter. We own and operate a smelter at our Miami mining operation in Arizona. The smelter has been operating for over 100 years and has been upgraded numerous times during that period to implement new technologies, improve production and comply with air quality requirements. In 2018, the Miami smelter completed the installation of emission control equipment that allows it to operate in compliance with current air quality standards. Refer to Item 1A. “Risk Factors” for further discussion.
The Miami smelter processes copper concentrate primarily from our North America copper mines. Concentrate processed through the smelter totaled 641,000 metric tons in 2019, 729,900 metric tons in 2018 and 612,600 metric tons in 2017. In addition, because sulphuric acid is a by-product of smelting concentrate, the Miami smelter is also the most significant source of sulphuric acid for our North America leaching operations.
Major maintenance turnarounds (which take approximately three weeks to complete) are anticipated to occur approximately every two years for the Miami smelter. The Miami smelter completed a major maintenance turnaround in the first half of 2019, and the next major maintenance turnaround is scheduled for 2021.
Rod & Refining Operations. Our Rod & Refining operations consist of conversion facilities located in North America, including a refinery in El Paso, Texas; rod mills in El Paso, Texas, Norwich, Connecticut, and Miami, Arizona; and a specialty copper products facility in Bayway, New Jersey. We refine our copper anode production from our Miami smelter at our El Paso refinery. The El Paso refinery has the potential to operate at an annual production capacity of about 900 million pounds of copper cathode, which is sufficient to refine all of the copper anode we produce at our Miami smelter. Our El Paso refinery also produces nickel carbonate, copper telluride and autoclaved slimes material containing gold, silver, platinum and palladium.
Molybdenum Conversion Facilities. We process molybdenum concentrate at our conversion plants in the U.S. and Europe into such products as technical-grade molybdic oxide, ferromolybdenum, pure molybdic oxide, ammonium molybdates and molybdenum disulfide. We operate molybdenum roasters in Sierrita, Arizona; Fort Madison, Iowa; and Rotterdam, the Netherlands, and we operate a molybdenum pressure-leach plant in Bagdad, Arizona. We also produce ferromolybdenum for customers worldwide at our conversion plant located in Stowmarket, United Kingdom.
Freeport Cobalt. In March 2013, we acquired a cobalt chemical refinery in Kokkola, Finland, and the related sales and marketing business which provided direct end-market access for the cobalt hydroxide production at the Tenke Fungurume mine in the Democratic Republic of Congo, in which we held an interest prior to our sale of TF Holdings Limited in 2016. We, as operator, held an effective 56 percent ownership interest. The remaining effective ownership interest was held by Lundin Mining Corporation (24 percent) and La Générale des Carrières et des Mines (20 percent). The Kokkola refinery has an annual refining capacity of approximately 15,000 metric tons of cobalt.
In fourth-quarter 2019, we completed the sale of the cobalt refinery and related cobalt cathode precursor business to Umicore. Under the terms of the agreement, we separated the cobalt business, and Umicore acquired the refinery and cathode precursor business, which represents approximately 60 percent of the refinery’s historical revenues. We and the current noncontrolling interest partners in Freeport Cobalt will retain the remaining cobalt business, which is a producer of cobalt fine powders, chemicals, catalysts, ceramics and pigments.
Refer to Note 2 for additional discussion of the disposition.
Other North America Copper Mines. We also have five non-operating copper mines – Ajo, Bisbee, Tohono, Twin Buttes and Christmas, which are located in Arizona – that have been on care-and-maintenance status for several years and would require new or updated environmental studies, new permits, and additional capital investment, which could be significant, to return them to operating status.
Mining Development Projects and Exploration Activities
Capital expenditures for mining operations totaled $2.65 billion (including $1.5 billion for major projects) in 2019, $2.0 billion (including $1.2 billion for major projects) in 2018 and $1.4 billion (including $0.9 billion for major projects) in 2017. Capital expenditures for major projects during 2019 and 2018 were primarily associated with underground development activities in the Grasberg minerals district and development of the Lone Star copper leach project. Capital expenditures for major projects during 2017 were primarily associated with the Cerro Verde expansion project and underground development activities in the Grasberg minerals district. Refer to MD&A for projected capital expenditures for the year 2020.
We have several projects and potential opportunities to expand production volumes, extend mine lives and develop large-scale underground ore bodies. As further discussed in MD&A, our near-term major development projects primarily include the underground development activities in the Grasberg minerals district and development of the Lone Star copper leach project, which is nearing completion. Considering the long-term nature and large size of our development projects, actual costs and timing could vary from estimates. Additionally, in response to market conditions, the timing of our expenditures will continue to be reviewed. We continue to review our mine development and processing plans to maximize the value of our mineral reserves.
PT-FI has also committed to construct a new smelter in Indonesia by December 21, 2023. Refer to MD&A for a discussion of the smelter project.
We also have an additional long-term underground mine development project in the Grasberg minerals district for the Kucing Liar ore body, which lies on the southern flank of and underneath the southern portion of the Grasberg open pit at the 2,605-meter elevation level. We expect to mine the Kucing Liar ore body using the block-cave method. Aggregate long-term capital cost estimates for development of the Kucing Liar ore body are projected to approximate $3.6 billion, and the timing of development is under review. Additionally, full development would require $5.7 billion of capital expenditures at our processing facilities to optimize the handling of underground ore types. The timing of this project and trade-off studies are currently being reviewed.
Our mining exploration activities are generally associated with our existing mines focusing on opportunities to expand reserves and resources to support development of additional future production capacity. Exploration results continue to indicate opportunities for significant future potential reserve additions in North America and South America. Exploration spending associated with mining operations totaled $77 million in 2019, $78 million in 2018 and $72 million in 2017. Refer to MD&A for projected exploration expenditures for the year 2020.
Refer to Item 1A. “Risk Factors” for further discussion of risks associated with mine development projects and exploration activities, and PT-FI’s IUPK.
Sources and Availability of Energy, Natural Resources and Raw Materials
Our copper mining operations require significant amounts of energy, principally diesel, electricity, coal and natural gas, most of which is obtained from third parties under long-term contracts. Energy represented approximately 20 percent of our copper mine site operating costs in 2019, including purchases of approximately 230 million gallons of diesel fuel; 8,200 gigawatt hours of electricity at our North America and South America copper mining operations (we generate all of our power at our Indonesia mining operation); 675 thousand metric tons of coal for our coal power plant in Indonesia; and 1 million MMBtu (million British thermal units) of natural gas at certain of our North America mines. Based on current cost estimates, energy will approximate 20 percent of our copper mine site operating costs in 2020.
Our mining operations also require significant quantities of water for mining, ore processing and related support facilities. The loss of water rights for any of our mines, in whole or in part, or shortages of water to which we have rights, could require us to curtail or shut down mining operations. For a further discussion of risks and legal proceedings associated with the availability of water, refer to Item 1A. “Risk Factors” and Item 3. “Legal Proceedings.”
Sulphuric acid is used in the SX/EW process and is produced as a by-product of the smelting process at our smelters and from our sulfur burners at the Safford mine. Sulphuric acid needs in excess of the sulphuric acid produced by our operations are purchased from third parties.
Community and Human Rights
We have adopted policies that govern our working relationships with the communities where we operate and that are designed to guide our practices and programs in a manner that respects human rights and the culture of the local people impacted by our operations. We continue to make significant expenditures on community development, health, education, training and cultural programs, which include:
| • | comprehensive job training programs |
| • | clean water and sanitation projects |
| • | public health programs, including malaria control and human immunodeficiency virus |
| • | agricultural assistance programs |
| • | small and medium enterprise development programs |
| • | basic education programs |
| • | cultural promotion and preservation programs |
| • | community infrastructure development |
| • | charitable donations |
In December 2000, we endorsed the joint U.S. State Department-British Foreign Office Voluntary Principles on Human Rights and Security (Voluntary Principles). We participated in developing these Voluntary Principles with other major natural resource companies and international human rights organizations and they are incorporated into our human rights policy. The Voluntary Principles provide guidelines for our security programs, including interaction with host-government security personnel, private security contractors and our internal security employees.
Our human rights policy, most recently updated in August 2017, reflects our full commitment to the United Nations Guiding Principles on Business and Human Rights. We have embarked on a program to plan and conduct site-level human rights impact assessments (HRIA) at our global operations.
HRIAs help us to embed human rights considerations into our business practices, including site-level sustainable development risk registers. We completed a HRIA at our Cerro Verde operation in Peru in 2017 and at our New Mexico mining operations in 2018. We also participate in a multi-industry human rights working group to gain insight from peer companies.
We believe that our social and economic development programs are responsive to the issues raised by the local communities near our areas of operation and help us maintain good relations with the surrounding communities and avoid disruptions of mining operations. As part of our ongoing commitment to sustainable community development, we have made and expect to continue making investments in certain social programs, including in-kind support and administration, across our global operations from time to time. Over the last three years, these investments have averaged $136 million per year. Nevertheless, social and political instability in the areas of our operations may adversely impact our mining operations. Refer to Item 1A. “Risk Factors” for further discussion.
South America. Cerro Verde has provided a variety of community support projects over the years. Following engagements with regional and local governments, civic leaders and development agencies, in 2006, Cerro Verde committed to support the costs for a new potable water treatment plant to serve Arequipa. In addition, an agreement was reached with the Peru government for development of a water storage network that was financed by Cerro Verde and a distribution network that was financed by the Cerro Verde Civil Association.
Cerro Verde reached an agreement with the Regional Government of Arequipa, the National Government, the local water utility company and other local institutions to allow it to finance, engineer and construct a wastewater treatment plant for the city of Arequipa, which was completed in 2015. The wastewater treatment plant supplements existing water supplies to support Cerro Verde’s concentrator expansion and also improves the local water quality, enhances agriculture products grown in the area and reduces the risk of waterborne illnesses. In addition to these projects, Cerro Verde annually makes significant community development investments in the Arequipa region.
Security Matters. Consistent with our operating permits in Peru and our commitment to protect our employees and property, we have taken steps to provide a safe and secure working environment. As part of its security program, Cerro Verde maintains its own internal security department. Both employees and contractors perform functions such as protecting company facilities, monitoring shipments of supplies and products, assisting in traffic control and aiding in emergency response operations. The security department receives human rights and Voluntary Principles training annually. Some contractors assigned to protection of expatriate personnel are armed. These contractors also receive training in defensive driving and firearms handling. Cerro Verde’s costs for its internal civilian security department totaled $9 million in 2019 and $8 million in both 2018 and 2017.
Cerro Verde, like all businesses and residents of Peru, relies on the Peru government for the maintenance of public order, upholding the rule of law and the protection of personnel and property. The Peru government is responsible for employing police personnel and directing their operations. Cerro Verde has limited public security forces in support of its operation, with the arrangement defined through a memorandum of understanding with the Peru National Police. Cerro Verde’s share of support costs for government-provided security approximated $1 million in each of the years 2019, 2018 and 2017.
Indonesia. In 1996, PT-FI established the Freeport Partnership Fund for Community Development (the Partnership Fund) through which PT-FI has made available funding and technical assistance to support community development initiatives in the areas of health, education, economic development and local infrastructure. PT-FI had committed through December 31, 2019, to provide one percent of its annual revenue for the development of the local communities in its area of operations through the Partnership Fund. Negotiations to extend this agreement are currently underway though PT-FI will continue its contributions to ensure there are no interruptions in the implementation of approved projects. PT-FI recorded costs of $28 million in 2019, $55 million in 2018 and $44 million in 2017 for this commitment.
Historically, the Amungme and Kamoro Community Development Organization (Lembaga Pengembangan Masyarakat Amungme dan Kamoro) oversaw disbursement of the program funds PT-FI contributed to the Partnership Fund. Throughout 2019, PT-FI consulted with key stakeholders to restructure the management of the Partnership Fund in compliance with PT-FI’s IUPK. Beginning in February 2020, the Partnership Fund is now managed by a legally recognized Indonesian foundation (Yayasan Pemberdayaan Masyarakat Amungme dan Kamoro or YPMAK). YPMAK is governed by a Board of Governors consisting of seven representatives, including four from PT-FI.
In addition to the Partnership Fund, PT-FI has made and expects to continue making annual investments in public health, education, community infrastructure and local economic development.
Security Matters. Consistent with our ongoing commitment to protect our employees and property, we have taken steps to provide a safe and secure working environment. As part of its security program, PT-FI maintains its own internal civilian security department. Both employees and contractors are unarmed and perform functions such as protecting company facilities, monitoring shipments of supplies and products, assisting in traffic control and aiding in emergency response operations. The security department receives human rights training annually.
PT-FI’s costs for its internal civilian security department totaled $52 million in 2019, $59 million in 2018 and $54 million in 2017.
PT-FI, like all businesses and residents of Indonesia, relies on the Indonesia government for the maintenance of public order, upholding the rule of law and protection of personnel and property. The Grasberg minerals district has been designated by the Indonesia government as one of Indonesia’s vital national assets. This designation results in the police, and to a lesser extent, the military, playing a significant role in protecting the area of our operations. The Indonesia government is responsible for employing police and military personnel and directing their operations.
From the outset of PT-FI’s operations, the Indonesia government has looked to PT-FI to provide logistical and infrastructure support and assistance for these necessary services because of the limited resources of the Indonesia government and the remote location of and lack of development in Papua. PT-FI’s financial support of the Indonesia government security institutions assigned to PT-FI’s operations area represents a prudent response to PT-FI’s requirements and commitments to protect its workforce and property, and better ensuring that personnel are properly fed and lodged and have the logistical resources to patrol PT-FI’s roads and secure its area of operations. In addition, the provision of such support is consistent with our philosophy of responsible corporate citizenship, and reflects our commitment to pursue practices that respect human rights.
PT-FI’s support costs for the government-provided security totaled $22 million in 2019, $27 million in 2018 and $23 million in 2017. This supplemental support consists of various infrastructure and other costs, including food, housing, fuel, travel, vehicle repairs, allowances to cover incidental and administrative costs, and community assistance programs conducted by the military and police.
Refer to Item 1A. “Risk Factors” for further discussion of security risks in Indonesia.
Mining Production and Sales Data
| Years Ended December 31, | |||||||||||||||||||||
| Production | Sales | ||||||||||||||||||||
| COPPER (millions of recoverable pounds) | 2019 | 2018 | 2017 | 2019 | 2018 | 2017 | |||||||||||||||
| (FCX’s net interest in %) | |||||||||||||||||||||
| North America | |||||||||||||||||||||
| Morenci (72%)a | 730 | 684 | 737 | 717 | 700 | 713 | |||||||||||||||
| Bagdad (100%) | 218 | 199 | 173 | 218 | 197 | 164 | |||||||||||||||
| Safford (100%) | 110 | 123 | 150 | 111 | 127 | 154 | |||||||||||||||
| Sierrita (100%) | 160 | 152 | 160 | 157 | 154 | 154 | |||||||||||||||
| Miami (100%) | 15 | 16 | 19 | 15 | 16 | 18 | |||||||||||||||
| Chino (100%) | 175 | 173 | 215 | 174 | 176 | 217 | |||||||||||||||
| Tyrone (100%) | 48 | 55 | 61 | 49 | 56 | 61 | |||||||||||||||
| Other (100%) | 1 | 2 | 3 | 1 | 2 | 3 | |||||||||||||||
| Total North America | 1,457 | 1,404 | 1,518 | 1,442 | 1,428 | 1,484 | |||||||||||||||
| South America | |||||||||||||||||||||
| Cerro Verde (53.56%) | 1,003 | 1,049 | 1,062 | 1,002 | 1,051 | 1,062 | |||||||||||||||
| El Abra (51%) | 180 | 200 | 173 | 181 | 202 | 173 | |||||||||||||||
| Total South America | 1,183 | 1,249 | 1,235 | 1,183 | 1,253 | 1,235 | |||||||||||||||
| Indonesia | |||||||||||||||||||||
| Grasberg minerals districtb | 607 | 1,160 | 984 | 667 | 1,130 | 981 | |||||||||||||||
| Consolidated | 3,247 | 3,813 | 3,737 | 3,292 | c | 3,811 | c | 3,700 | c | ||||||||||||
| Less noncontrolling interests | 668 | 695 | 670 | 679 | 694 | 670 | |||||||||||||||
| Net | 2,579 | 3,118 | 3,067 | 2,613 | 3,117 | 3,030 | |||||||||||||||
| Average realized price per pound | $ | 2.73 | $ | 2.91 | $ | 2.93 | |||||||||||||||
| GOLD (thousands of recoverable ounces) | |||||||||||||||||||||
| North America (100%) | 19 | 23 | 23 | 18 | 23 | 22 | |||||||||||||||
| Indonesiab | 863 | 2,416 | 1,554 | 973 | 2,366 | 1,540 | |||||||||||||||
| Consolidated | 882 | 2,439 | 1,577 | 991 | 2,389 | 1,562 | |||||||||||||||
| Less noncontrolling interests | 162 | 228 | 145 | 182 | 223 | 144 | |||||||||||||||
| Net | 720 | 2,211 | 1,432 | 809 | 2,166 | 1,418 | |||||||||||||||
| Average realized price per ounce | $ | 1,415 | $ | 1,254 | $ | 1,268 | |||||||||||||||
| MOLYBDENUM (millions of recoverable pounds) | |||||||||||||||||||||
| Henderson (100%) | 12 | 14 | 12 | N/A | N/A | N/A | |||||||||||||||
| Climax (100%) | 17 | 21 | 20 | N/A | N/A | N/A | |||||||||||||||
| North America copper mines (100%)a | 32 | 32 | 33 | N/A | N/A | N/A | |||||||||||||||
| Cerro Verde (53.56%) | 29 | 28 | 27 | N/A | N/A | N/A | |||||||||||||||
| Consolidated | 90 | 95 | 92 | 90 | 94 | 95 | |||||||||||||||
| Less noncontrolling interest | 13 | 13 | 13 | 13 | 13 | 12 | |||||||||||||||
| Net | 77 | 82 | 79 | 77 | 81 | 83 | |||||||||||||||
| Average realized price per pound | $ | 12.61 | $ | 12.50 | $ | 9.33 |
| a. | Amounts are net of Morenci’s undivided joint venture partners’ interest. |
| b. | Effective December 21, 2018, our share ownership in PT-FI is 48.76 percent (refer to Note 2 for further discussion). Our economic interest in PT-FI is expected to approximate 81 percent through 2022 and 48.76 percent thereafter. |
| c. | Consolidated sales volumes exclude purchased copper of 379 million pounds in 2019, 356 million pounds in 2018 and 273 million pounds in 2017. |
Mineral Reserves
Proven and probable reserves were determined by the use of mapping, drilling, sampling, assaying and evaluation methods generally applied in the mining industry, as more fully discussed below. The term “reserve,” as used in the reserve data presented here, means that part of a mineral deposit that can be economically and legally extracted or produced at the time of the reserve determination. The term “proven reserves” means reserves for which (i) quantity is computed from dimensions revealed in outcrops, trenches, workings or drill holes; (ii) grade and/or quality are computed from the results of detailed sampling; and (iii) the sites for inspection, sampling and measurements are spaced so closely and the geologic character is sufficiently defined that size, shape, depth and mineral content of reserves are well established. The term “probable reserves” means reserves for which quantity and grade are computed from information similar to that used for proven reserves but the sites for sampling are farther apart or are otherwise less adequately spaced. The degree of assurance, although lower than that for proven reserves, is high enough to assume continuity between points of observation.
Our mineral reserve estimates are based on the latest available geological and geotechnical studies. We conduct ongoing studies of our ore bodies to optimize economic values and to manage risk. We revise our mine plans and estimates of recoverable proven and probable mineral reserves as required in accordance with the latest available studies. Refer to Item 1A. “Risk Factors” for discussion of risks associated with our estimates of proven and probable reserves.
Estimated recoverable proven and probable reserves at December 31, 2019, were determined using metals price assumptions of $2.50 per pound for copper, $1,200 per ounce for gold and $10 per pound for molybdenum.
For the three-year period ended December 31, 2019, LME copper settlement prices averaged $2.83 per pound, London PM gold prices averaged $1,306 per ounce and the weekly average price for molybdenum quoted by Metals Week averaged $10.50 per pound.
The estimated recoverable proven and probable reserves presented in the table below represent the estimated metal quantities from which we expect to be paid after application of estimated metallurgical recovery rates and smelter recovery rates, where applicable. Recoverable reserves are that part of a mineral deposit that we estimate can be economically and legally extracted or produced at the time of the reserve determination.
| Estimated Recoverable Proven and Probable Mineral Reserves at December 31, 2019 | |||||||||
| Copper****a (billion pounds) | Gold (million ounces) | Molybdenum (billion pounds) | |||||||
| North America | 47.2 | 0.5 | 2.87 | ||||||
| South America | 33.2 | — | 0.71 | ||||||
| Indonesiab | 35.6 | 29.1 | — | ||||||
| Consolidated basis****c | 116.0 | 29.6 | 3.58 | ||||||
| Net equity interest****d | 83.4 | 16.1 | 3.25 |
| a. | Estimated consolidated recoverable copper reserves include 1.7 billion pounds in leach stockpiles and 0.5 billion pounds in mill stockpiles (refer to “Mill and Leach Stockpiles” for further discussion). |
| b. | Reflects estimates of minerals that can be recovered through 2041. Refer to Item 1A. “Risk Factors.” |
| c. | Consolidated reserves represent estimated metal quantities after reduction for joint venture partner interests at the Morenci mine in North America (refer to Note 3 for further discussion of our Morenci joint venture). Excluded from the table above are our estimated recoverable proven and probable reserves of 375 million ounces of silver, which were determined using $15 per ounce. |
| d. | Net equity interest reserves represent estimated consolidated metal quantities further reduced for noncontrolling interest ownership (refer to Note 3 for further discussion of our ownership in subsidiaries). Excluded from the table above are our estimated recoverable proven and probable reserves of 251 million ounces of silver. Our net equity interest for estimated metal quantities in Indonesia reflects approximately 81 percent from 2020 through 2022 and 48.76 percent from 2023 through 2041. |
| Estimated Recoverable Proven and Probable Mineral Reserves | |||||||||||||||||||||||||||||||||
| at December 31, 2019 | |||||||||||||||||||||||||||||||||
| Proven Reserves | Probable Reserves | ||||||||||||||||||||||||||||||||
| Average Ore Grade | Average Ore Grade | ||||||||||||||||||||||||||||||||
| Processing | Million | Copper | Gold | Moly | Silver | Million | Copper | Gold | Moly | Silver | |||||||||||||||||||||||
| Method | metric tons | % | g/t | % | g/t | metric tons | % | g/t | % | g/t | |||||||||||||||||||||||
| North America | |||||||||||||||||||||||||||||||||
| Morenci | Mill | 767 | 0.39 | — | 0.02 | — | 172 | 0.36 | — | 0.02 | — | ||||||||||||||||||||||
| Crushed leach | 419 | 0.42 | — | — | — | 119 | 0.39 | — | — | — | |||||||||||||||||||||||
| ROM leach | 2,229 | 0.16 | — | — | — | 729 | 0.16 | — | — | — | |||||||||||||||||||||||
| Bagdad | Mill | 1,918 | 0.33 | — | a | 0.02 | 1.39 | 592 | 0.29 | — | a | 0.02 | 1.19 | ||||||||||||||||||||
| ROM leach | 14 | 0.32 | — | — | — | 11 | 0.26 | — | — | — | |||||||||||||||||||||||
| Safford, including Lone Star | Crushed leach | 641 | 0.46 | — | — | — | 171 | 0.41 | — | — | — | ||||||||||||||||||||||
| Sierrita | Mill | 2,662 | 0.23 | — | a | 0.02 | 1.17 | 299 | 0.18 | — | a | 0.02 | 0.92 | ||||||||||||||||||||
| Chino, including Cobre | Mill | 146 | 0.52 | 0.05 | 0.01 | 0.94 | 79 | 0.49 | 0.04 | — | a | 0.85 | |||||||||||||||||||||
| ROM leach | 91 | 0.32 | — | — | — | 8 | 0.32 | — | — | — | |||||||||||||||||||||||
| Tyrone | ROM leach | 44 | 0.25 | — | — | — | 5 | 0.23 | — | — | — | ||||||||||||||||||||||
| Henderson | Mill | 55 | — | — | 0.18 | — | 12 | — | — | 0.13 | — | ||||||||||||||||||||||
| Climax | Mill | 152 | — | — | 0.15 | — | 8 | — | — | 0.09 | — | ||||||||||||||||||||||
| 9,138 | 2,204 | b | |||||||||||||||||||||||||||||||
| South America | |||||||||||||||||||||||||||||||||
| Cerro Verde | Mill | 809 | 0.37 | — | 0.02 | 1.97 | 3,361 | 0.35 | — | 0.01 | 1.87 | ||||||||||||||||||||||
| Crushed leach | 39 | 0.43 | — | — | — | 10 | 0.33 | — | — | — | |||||||||||||||||||||||
| ROM leach | 26 | 0.27 | — | — | — | 21 | 0.18 | — | — | — | |||||||||||||||||||||||
| El Abra | Crushed leach | 505 | 0.43 | — | — | — | 192 | 0.38 | — | — | — | ||||||||||||||||||||||
| ROM leach | 14 | 0.30 | — | — | — | 6 | 0.28 | — | — | — | |||||||||||||||||||||||
| 1,393 | 3,590 | ||||||||||||||||||||||||||||||||
| Indonesia | |||||||||||||||||||||||||||||||||
| Grasberg Block Cave | Mill | 321 | 1.11 | 0.86 | — | 3.88 | 639 | 0.89 | 0.66 | — | 3.56 | ||||||||||||||||||||||
| DMLZ | Mill | 82 | 0.99 | 0.82 | — | 4.67 | 347 | 0.90 | 0.74 | — | 4.34 | ||||||||||||||||||||||
| Big Gossan | Mill | 17 | 2.55 | 1.03 | — | 15.71 | 38 | 2.22 | 0.95 | — | 13.26 | ||||||||||||||||||||||
| DOZ | Mill | 8 | 0.55 | 0.56 | — | 2.60 | 21 | 0.48 | 0.45 | — | 2.41 | ||||||||||||||||||||||
| Kucing Liarc | Mill | 132 | 1.33 | 1.09 | — | 7.03 | 208 | 1.20 | 1.01 | — | 6.43 | ||||||||||||||||||||||
| 561 | b | 1,252 | b | ||||||||||||||||||||||||||||||
| Total FCX - 100% Basis | 11,091 | b | 7,046 | ||||||||||||||||||||||||||||||
| a. | Amounts not shown because of rounding. |
| b. | Does not foot because of rounding. |
| c. | Would require additional capital investment, which could be significant, to bring into production. |
The reserve table above and the tables on the following pages utilize the abbreviations described below:
| • | g/t – grams per metric ton |
| • | Moly – Molybdenum |
| Estimated Recoverable Proven and Probable Mineral Reserves | |||||||||||||||||||||||||||||
| at December 31, 2019 | |||||||||||||||||||||||||||||
| (continued) | |||||||||||||||||||||||||||||
| Proven and | |||||||||||||||||||||||||||||
| Probable****a | Average Ore Grade | Recoveries****b | |||||||||||||||||||||||||||
| Processing | Million | Copper | Gold | Moly | Silver | Copper | Gold | Moly | Silver | ||||||||||||||||||||
| Method | metric tons | % | g/t | % | g/t | % | % | % | % | ||||||||||||||||||||
| North America | |||||||||||||||||||||||||||||
| Morenci | Mill | 939 | 0.38 | — | 0.02 | — | 81.5 | — | 49.2 | — | |||||||||||||||||||
| Crushed leach | 538 | 0.41 | — | — | — | 79.6 | — | — | — | ||||||||||||||||||||
| ROM leach | 2,958 | 0.16 | — | — | — | 38.8 | — | — | — | ||||||||||||||||||||
| Bagdad | Mill | 2,510 | 0.32 | — | c | 0.02 | 1.34 | 85.8 | 59.1 | 70.6 | 49.3 | ||||||||||||||||||
| ROM leach | 25 | 0.30 | — | — | — | 41.0 | — | — | — | ||||||||||||||||||||
| Safford, including Lone Star | Crushed leach | 812 | 0.45 | — | — | — | 70.5 | — | — | — | |||||||||||||||||||
| Sierrita | Mill | 2,960 | 0.23 | — | c | 0.02 | 1.14 | 83.0 | 58.4 | 77.7 | 49.3 | ||||||||||||||||||
| Chino, including Cobre | Mill | 224 | 0.51 | 0.05 | 0.01 | 0.91 | 80.0 | 77.9 | 36.8 | 78.5 | |||||||||||||||||||
| ROM leach | 100 | 0.32 | — | — | — | 45.9 | — | — | — | ||||||||||||||||||||
| Tyrone | ROM leach | 49 | 0.25 | — | — | — | 55.3 | — | — | — | |||||||||||||||||||
| Henderson | Mill | 67 | — | — | 0.17 | — | — | — | 88.5 | — | |||||||||||||||||||
| Climax | Mill | 160 | — | — | 0.15 | — | — | — | 89.5 | — | |||||||||||||||||||
| 11,342 | |||||||||||||||||||||||||||||
| South America | |||||||||||||||||||||||||||||
| Cerro Verde | Mill | 4,170 | 0.36 | — | 0.01 | 1.89 | 86.3 | — | 54.3 | 44.7 | |||||||||||||||||||
| Crushed leach | 49 | 0.41 | — | — | — | 78.9 | — | — | — | ||||||||||||||||||||
| ROM leach | 46 | 0.23 | — | — | — | 47.9 | — | — | — | ||||||||||||||||||||
| El Abra | Crushed leach | 697 | 0.42 | — | — | — | 54.7 | — | — | — | |||||||||||||||||||
| ROM leach | 20 | 0.29 | — | — | — | 38.6 | — | — | — | ||||||||||||||||||||
| 4,982 | |||||||||||||||||||||||||||||
| Indonesia | |||||||||||||||||||||||||||||
| Grasberg Block Cave | Mill | 959 | 0.97 | 0.73 | — | 3.67 | 84.0 | 63.5 | — | 55.5 | |||||||||||||||||||
| DMLZ | Mill | 429 | 0.92 | 0.75 | — | 4.40 | 86.9 | 79.1 | — | 64.3 | |||||||||||||||||||
| Big Gossan | Mill | 55 | 2.33 | 0.97 | — | 14.04 | 91.2 | 67.7 | — | 63.7 | |||||||||||||||||||
| DOZ | Mill | 29 | 0.50 | 0.48 | — | 2.46 | 88.2 | 82.1 | — | 66.4 | |||||||||||||||||||
| Kucing Liard | Mill | 340 | 1.25 | 1.04 | — | 6.66 | 85.2 | 45.3 | — | 39.8 | |||||||||||||||||||
| 1,813 | e | ||||||||||||||||||||||||||||
| Total FCX - 100% Basis | 18,137 | ||||||||||||||||||||||||||||
| a. | Amounts may not equal the sum of proven and probable reserves as presented on the previous page because of rounding. |
| b. | Recoveries are net of estimated mill and smelter losses. |
| c. | Amounts not shown because of rounding. |
| d. | Would require additional capital investment, which could be significant, to bring into production. |
| e. | Does not foot because of rounding. |
| Estimated Recoverable Proven and Probable Mineral Reserves | ||||||||||||||||
| at December 31, 2019 | ||||||||||||||||
| (continued) | ||||||||||||||||
| Recoverable Reserves | ||||||||||||||||
| Copper | Gold | Moly | Silver | |||||||||||||
| FCX’s | Processing | billion | million | billion | million | |||||||||||
| Interest | Method | lbs. | ozs. | lbs. | ozs. | |||||||||||
| North America | ||||||||||||||||
| Morenci | 72% | Mill | 6.4 | — | 0.19 | — | ||||||||||
| Crushed leach | 3.9 | — | — | — | ||||||||||||
| ROM leach | 4.0 | — | — | — | ||||||||||||
| Bagdad | 100% | Mill | 15.2 | 0.2 | 0.79 | 53.4 | ||||||||||
| ROM leach | 0.1 | — | — | — | ||||||||||||
| Safford, including Lone Star | 100% | Crushed leach | 5.6 | — | — | — | ||||||||||
| Sierrita | 100% | Mill | 12.3 | 0.1 | 1.23 | 53.6 | ||||||||||
| Chino, including Cobre | 100% | Mill | 2.0 | 0.3 | 0.01 | 5.1 | ||||||||||
| ROM leach | 0.3 | — | — | — | ||||||||||||
| Tyrone | 100% | ROM leach | 0.1 | — | — | — | ||||||||||
| Henderson | 100% | Mill | — | — | 0.22 | — | ||||||||||
| Climax | 100% | Mill | — | — | 0.47 | — | ||||||||||
| 49.9 | 0.5 | a | 2.91 | 112.1 | ||||||||||||
| Recoverable metal in stockpilesb | 1.3 | — | 0.02 | 0.1 | ||||||||||||
| 100% operations | 51.2 | 0.5 | 2.93 | 112.2 | ||||||||||||
| Consolidated | 47.2 | 0.5 | 2.87 | 112.2 | ||||||||||||
| Net equity interest | 47.2 | 0.5 | 2.87 | 112.2 | ||||||||||||
| South America | ||||||||||||||||
| Cerro Verde | 53.56% | Mill | 28.2 | — | 0.70 | 113.3 | ||||||||||
| Crushed leach | 0.3 | — | — | — | ||||||||||||
| ROM leach | 0.1 | — | — | — | ||||||||||||
| El Abra | 51% | Crushed leach | 3.5 | — | — | — | ||||||||||
| ROM leach | 0.1 | — | — | — | ||||||||||||
| 32.2 | — | 0.70 | 113.3 | |||||||||||||
| Recoverable metal in stockpilesb | 1.0 | — | 0.01 | 1.7 | ||||||||||||
| 100% operations | 33.2 | — | 0.71 | 115.0 | ||||||||||||
| Consolidated | 33.2 | — | 0.71 | 115.0 | ||||||||||||
| Net equity interest | 17.7 | — | 0.38 | 61.6 | ||||||||||||
| Indonesia | ||||||||||||||||
| Grasberg Block Cave | c | Mill | 17.2 | 14.2 | — | 62.8 | ||||||||||
| DMLZ | c | Mill | 7.6 | 8.2 | — | 39.0 | ||||||||||
| Big Gossan | c | Mill | 2.6 | 1.2 | — | 15.8 | ||||||||||
| DOZ | c | Mill | 0.3 | 0.4 | — | 1.5 | ||||||||||
| Kucing Liar | c | Mill | 8.0 | 5.1 | — | 29.0 | ||||||||||
| 100% operations | 35.6 | a | 29.1 | — | 148.2 | a | ||||||||||
| Consolidated | 35.6 | 29.1 | — | 148.2 | ||||||||||||
| Net equity interest | 18.6 | 15.6 | — | 77.6 | ||||||||||||
| Total FCX – 100% basis | 120.0 | 29.6 | 3.64 | 375.4 | ||||||||||||
| Total FCX – Consolidated basis****d | 116.0 | 29.6 | 3.58 | 375.4 | ||||||||||||
| Total FCX – Net equity interest****e | 83.4 | a | 16.1 | 3.25 | 251.4 |
| a. | Does not foot because of rounding. |
| b. | Refer to “Mill and Leach Stockpiles” for additional information. |
| c. | Effective December 21, 2018, our share ownership in PT-FI is 48.76 percent (refer to Note 2 for further discussion). Our economic interest in PT-FI is expected to approximate 81 percent through 2022 and 48.76 percent thereafter. |
| d. | Consolidated reserves represent estimated metal quantities after reduction for Morenci’s joint venture partner interests (refer to Note 3 for further discussion). |
| e. | Net equity interest represents estimated consolidated metal quantities further reduced for noncontrolling interest ownership (refer to Note 3 for further discussion of our ownership in subsidiaries). Our net equity interest for estimated metal quantities in Indonesia reflects approximately 81 percent from 2020 through 2022 and 48.76 percent from 2023 through 2041. |
In defining our open-pit reserves, we apply a “variable cutoff grade” strategy. The objective of this strategy is to maximize the net present value of our operations. We use a “break-even cutoff grade” to define the in-situ reserves for our underground ore bodies. The break-even cutoff grade is defined for a metric ton of ore as that equivalent copper grade, once produced and sold, that generates sufficient revenue to cover all operating and administrative costs associated with our production.
Our copper mines may contain other commercially recoverable metals, such as gold, molybdenum and silver. We value all commercially recoverable metals in terms of a copper equivalent percentage to determine a single cutoff grade. Copper equivalent percentage is used to express the relative value of multi-metal ores in terms of one metal. The calculation expresses the relative value of the ore using estimates of contained metal quantities, metals prices as used for reserve determination, recovery rates, treatment charges and royalties. Our molybdenum properties use a molybdenum cutoff grade.
The table below shows the minimum cutoff grade by process for each of our existing ore bodies as of December 31, 2019:
| Copper Equivalent Cutoff Grade (Percent) | Molybdenum Cutoff Grade (Percent) | ||||||
| Mill | Crushed Leach | ROM Leach | Mill | ||||
| North America | |||||||
| Morenci | 0.17 | 0.12 | 0.03 | — | |||
| Bagdad | 0.11 | — | 0.03 | — | |||
| Safford, including Lone Star | — | 0.12 | — | — | |||
| Sierrita | 0.15 | — | — | — | |||
| Chino, including Cobre | 0.22 | — | 0.08 | — | |||
| Tyrone | — | — | 0.03 | — | |||
| Henderson | — | — | — | 0.12 | |||
| Climax | — | — | — | 0.05 | |||
| South America | |||||||
| Cerro Verde | 0.15 | 0.12 | 0.08 | — | |||
| El Abra | — | 0.10 | 0.07 | — | |||
| Indonesia | |||||||
| Grasberg Block Cave | 0.67 | — | — | — | |||
| DMLZ | 0.72 | — | — | — | |||
| Big Gossan | 1.70 | — | — | — | |||
| DOZ | 0.98 | — | — | — | |||
| Kucing Liar | 0.79 | — | — | — |
Drill hole spacing data is used by mining professionals, such as geologists and geological engineers, in determining the suitability of data coverage (on a relative basis) in a given deposit type and mining method scenario so as to achieve a given level of confidence in the resource estimate. Drill hole spacing is only one of several criteria necessary to establish resource classification. Drilling programs are typically designed to achieve an optimum sample spacing to support the level of confidence in results that apply to a particular stage of development of a mineral deposit.
The following table sets forth the average drill hole spacing based on average sample distance or drill pattern spacing for proven and probable ore reserves by process type:
| Average Drill Hole Spacing (in Meters) | |||||||||
| Proven | Probable | ||||||||
| Mining Unit | Mill | Leach | Mill | Leach | |||||
| North America | |||||||||
| Morenci | Open Pit | 86 | 86 | 122 | 122 | ||||
| Bagdad | Open Pit | 86 | 86 | 122 | 122 | ||||
| Safford, including Lone Star | Open Pit | — | 86 | — | 122 | ||||
| Sierrita | Open Pit | 73 | — | 104 | — | ||||
| Chino | Open Pit | 43 | 86 | 86 | 122 | ||||
| Cobre | Open Pit | 61 | 61 | 91 | 91 | ||||
| Tyrone | Open Pit | — | 86 | — | 86 | ||||
| Henderson | Block Cave | 47 | — | 96 | — | ||||
| Climax | Open Pit | 61 | — | 91 | — | ||||
| South America | |||||||||
| Cerro Verde | Open Pit | 55 | 55 | 110 | 110 | ||||
| El Abra | Open Pit | — | 75 | — | 120 | ||||
| Indonesia | |||||||||
| Grasberg Block Cave | Block Cave | 28 | — | 67 | — | ||||
| DMLZ | Block Cave | 22 | — | 63 | — | ||||
| Big Gossan | Open Stope | 13 | — | 37 | — | ||||
| DOZ | Block Cave | 23 | — | 55 | — | ||||
| Kucing Liar | Block Cave | 39 | — | 95 | — |
Production Sequencing
The following chart illustrates our current plans for sequencing and producing our proven and probable reserves at each of our ore bodies and the years in which we currently expect production from each ore body and related stockpiles. Our proven and probable ore reserves in Indonesia reflect estimates of minerals that can be recovered through the end of 2041, and our current mine plan and planned operations are based on the assumption that PT-FI will comply with its obligations under the IUPK and receive the second 10-year extension from 2031 through 2041 (refer to Item 1A. “Risk Factors” and Note 13 for further discussion). Production volumes are typically lower in the first few years for each ore body as development activities are ongoing and as the mine ramps up to full production and production volumes may also be lower as the mine reaches the end of its life. The sequencing dates shown in the chart below include development activity that results in metal production. The ultimate timing of the start of production from our undeveloped mines is dependent upon a number of factors, including the results of our exploration and development efforts, and may vary from the dates shown below. In addition, we develop our mine plans based on maximizing the net present value from the ore bodies. Significant additional capital expenditures will be required at many of these mines in order to achieve the life-of-mine plans reflected below.
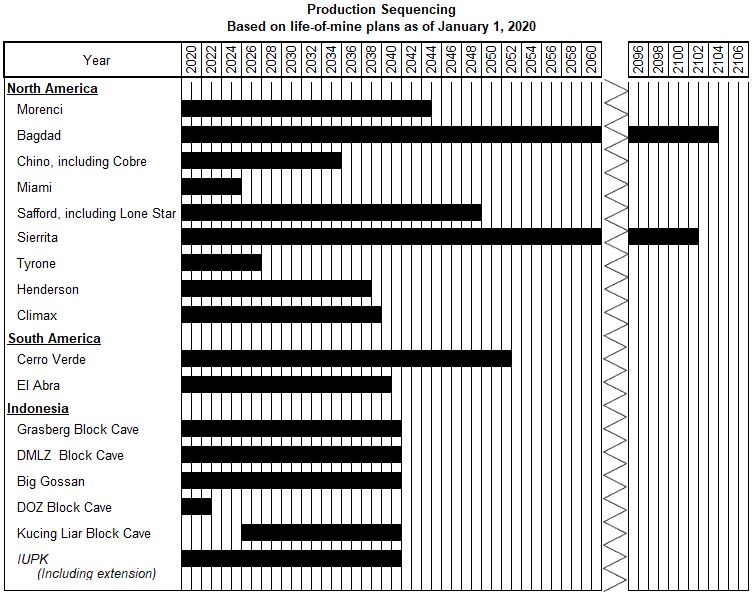
Mill and Leach Stockpiles
Mill and leach stockpiles generally contain lower grade ores that have been extracted from an ore body and are available for metal recovery. Mill stockpiles contain sulfide ores and recovery of metal is through milling, concentrating, smelting and refining or, alternatively, by concentrate leaching. Leach stockpiles contain oxide ores and certain secondary sulfide ores and recovery of metal is through exposure to acidic solutions that dissolve contained copper and deliver it in solution to extraction processing facilities.
Because it is impracticable to determine copper contained in mill and leach stockpiles by physical count, reasonable estimation methods are employed. The quantity of material delivered to mill and leach stockpiles is based on surveyed volumes of mined material and daily production records. Sampling and assaying of blasthole cuttings determine the estimated copper grades of material delivered to mill and leach stockpiles.
Expected copper recovery rates for mill stockpiles are determined by metallurgical testing. The recoverable copper in mill stockpiles, once entered into the production process, can be produced into copper concentrate almost immediately.
Expected copper recovery rates for leach stockpiles are determined using small-scale laboratory tests, small- to large-scale column testing (which simulates the production process), historical trends and other factors, including mineralogy of the ore and rock type. Total copper recovery in leach stockpiles can vary significantly from a low percentage to more than 90 percent depending on several variables, including processing methodology, processing variables, mineralogy and particle size of the rock. For newly placed material on active stockpiles, as much as 80 percent of total copper recovery may be extracted during the first year, and the remaining copper may be recovered over many years. Processes and recovery rates are monitored regularly, and recovery rate estimates are adjusted periodically as additional information becomes available and as related technology changes.
Following are our stockpiles and the estimated recoverable copper contained within those stockpiles as of December 31, 2019:
| Recoverable | ||||||||||||
| Million | Average | Recovery | Copper | |||||||||
| Metric Tons | Ore Grade (%) | Rate (%) | (billion pounds) | |||||||||
| Mill stockpiles | ||||||||||||
| Cerro Verde | 99 | 0.26 | 73.1 | 0.4 | ||||||||
| North America copper mines | 6 | 0.35 | 72.9 | 0.1 | ||||||||
| 105 | 0.5 | |||||||||||
| Leach stockpiles | ||||||||||||
| Morenci | 6,829 | 0.24 | 1.0 | 0.3 | ||||||||
| Bagdad | 499 | 0.25 | 0.5 | — | a | |||||||
| Safford, including Lone Star | 316 | 0.42 | 7.5 | 0.2 | ||||||||
| Sierrita | 650 | 0.15 | 9.5 | 0.2 | ||||||||
| Miami | 498 | 0.39 | 1.7 | 0.1 | ||||||||
| Chino, including Cobre | 1,756 | 0.25 | 3.5 | 0.3 | ||||||||
| Tyrone | 1,155 | 0.28 | 1.5 | 0.1 | ||||||||
| Cerro Verde | 512 | 0.47 | 4.7 | 0.2 | ||||||||
| El Abra | 787 | 0.44 | 4.9 | 0.4 | ||||||||
| 13,003 | b | 1.8 | ||||||||||
| Total FCX - 100% basis | 2.3 | |||||||||||
| Total FCX - Consolidated basis****c | 2.2 | |||||||||||
| Total FCX - Net equity interest****d | 1.7 |
| a. | Rounds to less than 0.1 billion pounds of recoverable copper. |
| b. | Does not foot because of rounding. |
| c. | Consolidated stockpiles represent estimated metal quantities after reduction for Morenci’s joint venture partner interests. Refer to Note 3 for further discussion. |
| d. | Net equity interest represents estimated consolidated metal quantities further reduced for noncontrolling interest ownership (refer to Note 3 for further discussion of our ownership in subsidiaries). |
Mineralized Material
We hold various properties containing mineralized material that we believe could be brought into production should market conditions warrant. However, permitting and significant capital expenditures would be required before operations could commence at these properties. Mineralized material is a mineralized body that has been delineated by appropriately spaced drilling and/or underground sampling to support the reported tonnage and average metal grades. Such a deposit cannot qualify as recoverable proven and probable reserves until legal and economic feasibility are confirmed based upon a comprehensive evaluation of development costs, unit costs, grades, recoveries and other material factors. Estimated mineralized materials as presented on the following page were assessed using prices of $3.00 per pound for copper, $1,200 per ounce for gold, $12 per pound for molybdenum and $20 per ounce for silver. Refer to Item 1A. “Risk Factors” for discussion of risks associated with our estimates of mineralized material.
| Estimated Mineralized Material | ||||||||||||||||||||||||||||
| at December 31, 2019 | ||||||||||||||||||||||||||||
| Milling Material | Leaching Material | Total Mineralized Material****a | ||||||||||||||||||||||||||
| Million | Million | Million | ||||||||||||||||||||||||||
| FCX’s | metric | Copper | Gold | Moly | Silver | metric | Copper | metric | ||||||||||||||||||||
| Interest | tons | % | g/t | % | g/t | tons | % | tons | ||||||||||||||||||||
| North America | ||||||||||||||||||||||||||||
| Morenci | 72% | 2,023 | 0.25 | — | 0.02 | — | 1,658 | 0.17 | 3,681 | |||||||||||||||||||
| Bagdad | 100% | 426 | 0.30 | — | b | 0.02 | 1.3 | 1 | 0.12 | 427 | ||||||||||||||||||
| Safford, including Lone Star | 100% | 870 | 0.46 | 0.06 | — | 1.2 | 962 | 0.29 | 1,832 | |||||||||||||||||||
| Sierrita | 100% | 1,632 | 0.18 | — | b | 0.02 | 0.9 | — | — | 1,632 | ||||||||||||||||||
| Chino, including Cobre | 100% | 282 | 0.46 | 0.04 | 0.01 | 0.8 | 29 | 0.24 | 312 | |||||||||||||||||||
| Tyrone | 100% | — | — | — | — | — | 127 | 0.25 | 127 | |||||||||||||||||||
| Henderson | 100% | 103 | — | — | 0.14 | — | — | — | 103 | |||||||||||||||||||
| Climax | 100% | 378 | — | — | 0.16 | — | — | — | 378 | |||||||||||||||||||
| Ajo | 100% | 621 | 0.36 | 0.06 | 0.01 | 0.8 | — | — | 621 | |||||||||||||||||||
| Cochise/Bisbee | 100% | — | — | — | — | — | 298 | 0.44 | 298 | |||||||||||||||||||
| Sanchez | 100% | — | — | — | — | — | 196 | 0.28 | 196 | |||||||||||||||||||
| Tohono | 100% | 275 | 0.67 | — | — | — | 284 | 0.67 | 559 | |||||||||||||||||||
| Twin Buttes | 100% | 311 | 0.47 | — | b | 0.03 | 5.1 | 103 | 0.21 | 413 | ||||||||||||||||||
| Christmas | 100% | 367 | 0.38 | 0.05 | — | b | 1.0 | — | — | 367 | ||||||||||||||||||
| South America | ||||||||||||||||||||||||||||
| Cerro Verde | 53.56% | 638 | 0.33 | — | 0.01 | 1.8 | 36 | 0.26 | 674 | |||||||||||||||||||
| El Abra | 51% | 2,015 | 0.40 | 0.02 | 0.01 | 1.3 | 163 | 0.24 | 2,178 | |||||||||||||||||||
| Indonesia | ||||||||||||||||||||||||||||
| Grasberg minerals district | 48.76% | 2,540 | 0.68 | 0.61 | — | 3.7 | — | — | — | 2,540 | ||||||||||||||||||
| Africa | ||||||||||||||||||||||||||||
| Kisanfuc | 95% | 75 | 1.84 | — | — | — | 63 | 2.43 | 138 | |||||||||||||||||||
| Total FCX - 100% basis | 12,556 | 3,920 | 16,477 | d | ||||||||||||||||||||||||
| Total FCX - Consolidated basis****e | 11,990 | 3,454 | 15,444 | |||||||||||||||||||||||||
| Total FCX - Net equity interest****f | 9,401 | 3,354 | 12,756 | |||||||||||||||||||||||||
| a. | Amounts may not equal the sum of milling and leach material because of rounding. |
| b. | Amounts not shown because of rounding. |
| c. | Stated tonnage also includes cobalt (0.95 percent for milling material and 0.99 percent for leaching material). |
| d. | Does not foot because of rounding. |
| e. | Consolidated basis represents estimated mineralized materials after reduction for Morenci’s joint venture partner interests. Refer to Note 3 for further discussion. |
| f. | Net equity interest represents estimated consolidated mineralized material further reduced for noncontrolling interest ownership. Refer to Note 3 for further discussion of our ownership in subsidiaries. |