 filings.tools
Item 6. Reserved.
199K characters. Original on sec.gov · Markdown
Item 6. Reserved.
Items 7. and 7A. Management’s Discussion and Analysis of Financial Condition and Results of Operations and Quantitative and Qualitative Disclosures About Market Risk.
In Management’s Discussion and Analysis of Financial Condition and Results of Operations and Quantitative and Qualitative Disclosures About Market Risk (MD&A), “we,” “us” and “our” refer to Freeport-McMoRan Inc. and its consolidated subsidiaries. The results of operations reported and summarized below are not necessarily indicative of future operating results (refer to “Cautionary Statement” for further discussion). References to “Notes” are Notes included in our Notes to Consolidated Financial Statements. Throughout MD&A, all references to earnings or losses per share are on a diluted basis.
This section of our Form 10-K generally discusses the results of operations for the years 2020 and 2019 and comparisons between these years. Discussion of the results of operations for the year 2018 and comparisons between the years 2019 and 2018 are not included in this Form 10-K and can be found in “Management’s Discussion and Analysis of Financial Condition and Results of Operations and Quantitative and Qualitative Disclosures About Market Risk” in Part II, Items 7. and 7A. of our Annual Report on Form 10-K for the fiscal year ended December 31, 2019.
OVERVIEW
We are a leading international mining company with headquarters in Phoenix, Arizona. We operate large, long-lived, geographically diverse assets with significant proven and probable reserves of copper, gold and molybdenum. We are one of the world’s largest publicly traded copper producers. Our portfolio of assets includes the Grasberg minerals district in Indonesia, one of the world’s largest copper and gold deposits; and significant mining operations in North America and South America, including the large-scale Morenci minerals district in Arizona and the Cerro Verde operation in Peru.
Protecting the health of our workforce and communities where we operate is a top priority and we continue to focus on safeguarding our business in an uncertain public health and economic environment. Our operating sites successfully executed our April 2020 revised operating plans implemented in response to the global COVID-19 pandemic and resulting negative impact on the global economy.
We believe that we have a high-quality portfolio of long-lived copper assets positioned to generate long-term value. The ramp-up of underground mining at PT Freeport Indonesia (PT-FI) and production from the Lone Star copper leach project are both advancing on schedule. Cerro Verde is continuing to increase milling rates while operating under strict COVID-19 restrictions and protocols that remain in place. Refer to “Operations” for further discussion. We are also pursuing other opportunities to enhance our mines’ net present values, and we continue to advance studies for future development of our resources, the timing of which will depend on market conditions. We plan to prioritize long-term development opportunities during 2021 while focusing on the continued execution of our strategic objectives of maintaining a strong balance sheet, increasing cash returns to shareholders and advancing opportunities for future growth.
Our 2020 results reflect strong cash flows and effective cost and capital expenditure management. Net income (loss) attributable to common stock totaled $599 million in 2020 and $(239) million in 2019. Our results in 2020, compared to 2019, primarily reflect higher copper and gold prices and lower production and delivery costs. Refer to “Consolidated Results” for discussion of items impacting our consolidated results for the two years ended December 31, 2020.
At December 31, 2020, we had $3.7 billion in consolidated cash and cash equivalents, $9.7 billion in total debt, and no borrowings and $3.5 billion available under our revolving credit facility.
In connection with our financing activities in 2019 and 2020, we issued a total of $4.0 billion in new senior notes and used most of the net proceeds to purchase and redeem outstanding senior notes. As a result, we have extended our debt maturities and strengthened our financial flexibility. We have no significant scheduled debt maturities in 2021. Refer to Note 8 and “Capital Resources and Liquidity” for further discussion.
We have significant mineral reserves, resources and future development opportunities within our portfolio of mining assets. At December 31, 2020, our estimated consolidated recoverable proven and probable mineral reserves totaled 113.2 billion pounds of copper, 28.9 million ounces of gold and 3.71 billion pounds of molybdenum. Refer to “Critical Accounting Estimates – Mineral Reserves” and Note 17 for further discussion.
During 2020, production from our mines totaled 3.2 billion pounds of copper, 0.9 million ounces of gold and 76 million pounds of molybdenum. Following is an allocation of our consolidated copper, gold and molybdenum production in 2020 by geographic location:
| Copper | Gold | Molybdenum | ||||||||||||||||||
| North America | 44 | % | 1 | % | 75 | % | a | |||||||||||||
| South America | 31 | — | 25 | |||||||||||||||||
| Indonesia | 25 | 99 | — | |||||||||||||||||
| 100 | % | 100 | % | 100 | % |
a.Our North America copper mines produced 43 percent of consolidated molybdenum production, and our Henderson and Climax molybdenum mines produced 32 percent.
Copper production from the Morenci mine in North America, Cerro Verde mine in Peru and the Grasberg minerals district in Indonesia together totaled 73 percent of our consolidated copper production in 2020.
OUTLOOK
Despite volatile market conditions and global economic uncertainty as a result of the ongoing COVID-19 pandemic, we continue to view the long-term outlook for our business positively, supported by limitations on supplies of copper and by the requirements for copper in the world’s economy. Our financial results vary as a result of fluctuations in market prices primarily for copper, gold and, to a lesser extent, molybdenum, as well as other factors. World market prices for these commodities have fluctuated historically and are affected by numerous factors beyond our control. Refer to “Markets” for further discussion. Because we cannot control the price of our products, the key measures that management focuses on in operating our business are sales volumes, unit net cash costs, operating cash flows and capital expenditures.
Sales Volumes
Following are our projected consolidated sales volumes for 2021 and actual consolidated sales volumes for 2020:
| 2021 | 2020 | |||||||||||||
| (Projected) | (Actual) | |||||||||||||
| Copper (millions of recoverable pounds): | ||||||||||||||
| North America copper mines | 1,465 | 1,422 | ||||||||||||
| South America mining | 1,035 | 976 | ||||||||||||
| Indonesia mining | 1,320 | 804 | ||||||||||||
| Total | 3,820 | 3,202 | ||||||||||||
| Gold (thousands of recoverable ounces) | 1,325 | 855 | ||||||||||||
| Molybdenum (millions of recoverable pounds) | 85 | a | 80 |
a.Includes 25 million pounds from our Molybdenum mines and 60 million pounds from our North America and South America copper mines.
Consolidated sales for first-quarter 2021 are expected to approximate 825 million pounds of copper, 275 thousand ounces of gold and 20 million pounds of molybdenum. Projected sales volumes are dependent on operational performance, continued progress of the ramp-up of underground mining at PT-FI, impacts and duration of the COVID-19 pandemic, timing of shipments, the Indonesia government’s extension of PT-FI’s export license beyond March 15, 2021, and other factors. For other important factors that could cause results to differ materially from projections, refer to “Cautionary Statement” and “Risk Factors” contained in Part I, Item 1A. of our annual report on Form 10-K for the year ended December 31, 2020.
Consolidated Unit Net Cash Costs
Assuming average prices of $1,850 per ounce of gold and $9.00 per pound of molybdenum and achievement of current sales volume and cost estimates, consolidated unit net cash costs (net of by-product credits) for our copper mines are expected to average $1.25 per pound of copper in 2021. The impact of price changes on 2021 consolidated unit net cash costs would approximate $0.03 per pound for each $100 per ounce change in the average price of gold and $0.01 per pound for each $2 per pound change in the average price of molybdenum. Quarterly unit net cash costs vary with fluctuations in sales volumes and realized prices, primarily for gold and molybdenum.
Consolidated Operating Cash Flows
Our consolidated operating cash flows vary with sales volumes; prices realized from copper, gold and molybdenum sales; production costs; income taxes; other working capital changes; and other factors. Based on current sales volume and cost estimates, and assuming average prices of $3.50 per pound of copper, $1,850 per ounce of gold and $9.00 per pound of molybdenum, our consolidated operating cash flows are estimated to approximate $5.5 billion (including $0.4 billion from working capital and other sources) for the year 2021. Estimated consolidated operating cash flows in 2021 also reflect a projected income tax provision of $1.8 billion (refer to “Consolidated Results - Income Taxes” for further discussion of our projected income tax rate for the year 2021). The impact of price changes during 2021 on operating cash flows would approximate $380 million for each $0.10 per pound change in the average price of copper, $120 million for each $100 per ounce change in the average price of gold and $80 million for each $2 per pound change in the average price of molybdenum.
Consolidated Capital Expenditures
Consolidated capital expenditures are expected to approximate $2.3 billion in 2021, including $1.4 billion for major projects primarily associated with underground development activities in the Grasberg minerals district and exclude estimates associated with the new smelter in Indonesia.
We expect capital expenditures for the development of the new smelter in Indonesia to approximate $0.1 billion in 2021, of which approximately 49 percent will be attributable to our equity interest. PT-FI expects these amounts to be funded by a new bank loan.
MARKETS
World prices for copper, gold and molybdenum can fluctuate significantly. During the period from January 2011 through December 2020, the London Metal Exchange (LME) copper settlement price varied from a low of $1.96 per pound in 2016 to a record high of $4.60 per pound in 2011; the London Bullion Market Association (London) PM gold price fluctuated from a low of $1,049 per ounce in 2015 to a record high of $2,067 per ounce in 2020, and the Metals Week Molybdenum Dealer Oxide weekly average price ranged from a low of $4.46 per pound in 2015 to a high of $17.88 per pound in 2011. Copper, gold and molybdenum prices are affected by numerous factors beyond our control as described further in our “Risk Factors” contained in Part I, Item 1A. of our annual report on Form 10-K for the year ended December 31, 2020.

This graph presents LME copper settlement prices and the combined reported stocks of copper at the LME, Commodity Exchange Inc., and the Shanghai Futures Exchange from January 2011 through December 2020. For the year 2020, LME copper settlement prices ranged from a low of $2.09 per pound to a high of $3.61 per pound, averaged $2.80 per pound and closed at $3.51 per pound on December 31, 2020. During 2020, copper prices were initially negatively impacted by economic uncertainty associated with the COVID-19 pandemic, but began to rise in second-quarter 2020 and continued to rise through the end of 2020 as a result of a positive economic outlook lead by China’s continued recovery, decreasing inventories and supply curtailments related to the COVID-19 pandemic. The LME copper settlement price was $3.57 per pound on January 29, 2021.
While we acknowledge the global economic turmoil associated with the ongoing COVID-19 pandemic, we continue to believe the underlying long-term fundamentals of the copper business remain positive, supported by the significant role of copper in the global economy and a challenging long-term supply environment attributable to difficulty in replacing existing large mines’ output with new production sources. Future copper prices are expected to be volatile and are likely to be influenced by the ongoing COVID-19 pandemic, demand from China and emerging markets, as well as economic activity in the United States (U.S.) and other industrialized countries, the timing of the development of new supplies of copper and production levels of mines and copper smelters.

This graph presents London PM gold prices from January 2011 through December 2020. Concerns about the global economy related to the COVID-19 pandemic, historically low U.S. interest rates and the anticipated effects of global stimulus efforts have driven increased demand for gold. For the year 2020, London PM gold prices ranged from a low of $1,474 per ounce to a record high of $2,067 per ounce, averaged $1,770 per ounce and closed at $1,888 per ounce on December 30, 2020 (there was no London PM gold price quote on December 31, 2020). The London PM gold price was $1,864 per ounce on January 29, 2021.
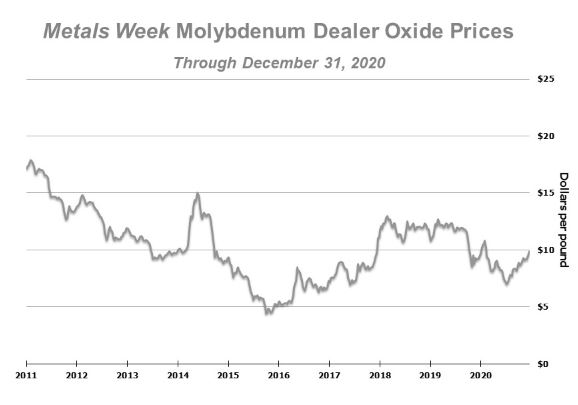
This graph presents the Metals Week Molybdenum Dealer Oxide weekly average price from January 2011 through December 2020. Molybdenum prices were negatively impacted by economic uncertainty associated with the COVID-19 pandemic in early 2020, but began to improve in the second half of 2020 as a result of increases in spot sale activity in Europe and China. For the year 2020, the weekly average price for molybdenum ranged from a low of $7.01 per pound to a high of $10.79 per pound, averaged $8.69 per pound and was $9.86 per pound on December 31, 2020. The Metals Week Molybdenum Dealer Oxide weekly average price was $10.38 per pound on January 29, 2021.
CRITICAL ACCOUNTING ESTIMATES
MD&A is based on our consolidated financial statements, which have been prepared in conformity with generally accepted accounting principles (GAAP) in the U.S. The preparation of these statements requires that we make estimates and assumptions that affect the reported amounts of assets, liabilities, revenues and expenses. We base these estimates on historical experience and on assumptions that we consider reasonable under the circumstances; however, reported results could differ from those based on the current estimates under different assumptions or conditions. The areas requiring the use of management’s estimates are also discussed in Note 1 under the subheading “Use of Estimates.” Management has reviewed the following discussion of its development and selection of critical accounting estimates with the Audit Committee of our Board of Directors (the Board).
Taxes
In preparing our consolidated financial statements, we estimate the actual amount of income taxes currently payable or receivable as well as deferred income tax assets and liabilities attributable to temporary differences between the financial statement carrying amounts of existing assets and liabilities and their respective tax bases. Deferred income tax assets and liabilities are measured using enacted tax rates expected to apply to taxable income in the years in which these temporary differences are expected to be recovered or settled. The effect on deferred income tax assets and liabilities of a change in tax rates or laws is recognized in income in the period in which such changes are enacted.
Our operations are in multiple jurisdictions where uncertainties arise in the application of complex tax regulations. Some of these tax regimes are defined by contractual agreements with the local government, while others are defined by general tax laws and regulations. We and our subsidiaries are subject to reviews of our income tax filings and other tax payments, and disputes can arise with the taxing authorities over the interpretation of our contracts or laws. Final taxes paid may be dependent upon many factors, including negotiations with taxing authorities. In certain jurisdictions, we pay a portion of the disputed amount before formally appealing an assessment. Such payment is recorded as a receivable if we believe the amount is collectible.
A valuation allowance is provided for those deferred income tax assets for which the weight of available evidence suggests that the related benefits will not be realized. In determining the amount of the valuation allowance, we consider estimated future taxable income or loss as well as feasible tax planning strategies in each jurisdiction. If we determine that we will not realize all or a portion of our deferred income tax assets, we will increase our valuation allowance. Conversely, if we determine that we will ultimately be able to realize all or a portion of the related benefits for which a valuation allowance has been provided, all or a portion of the related valuation allowance will be reduced.
Our valuation allowances totaled $4.7 billion at December 31, 2020, which covered all of our U.S. foreign tax credits, U.S. federal net operating losses, foreign net operating losses, and substantially all of our U.S. state net operating losses. Refer to Note 11 for further discussion.
Environmental Obligations
Our current and historical operating activities are subject to various national, state and local environmental laws and regulations that govern the protection of the environment, and compliance with those laws requires significant expenditures. Environmental expenditures are charged to expense or capitalized, depending upon their future economic benefits. The guidance provided by U.S. GAAP requires that liabilities for contingencies be recorded when it is probable that obligations have been incurred, and the cost can be reasonably estimated. At December 31, 2020, environmental obligations recorded in our consolidated balance sheet totaled $1.6 billion, which reflect obligations for environmental liabilities attributed to the Comprehensive Environmental Response, Compensation, and Liability Act of 1980 (CERCLA) or analogous state programs and for estimated future costs associated with environmental matters. Refer to Notes 1 and 12 for further discussion of environmental obligations, including a summary of changes in our estimated environmental obligations for the three years ended December 31, 2020.
Accounting for environmental obligations represents a critical accounting estimate because (i) changes to environmental laws and regulations and/or circumstances affecting our operations could result in significant changes to our estimates, which could have a significant impact on our results of operations, (ii) we will not incur most of these costs for a number of years, requiring us to make estimates over a long period, (iii) calculating the discounted cash flows for certain of our environmental obligations requires management to estimate projected cash flows and make long-term assumptions about inflation rates and (iv) changes in estimates used in determining our environmental obligations could have a significant impact on our results of operations.
We perform a comprehensive annual review of our environmental obligations and also review changes in facts and circumstances associated with these obligations at least quarterly. Judgments and estimates are based upon currently available facts, existing technology, presently enacted laws and regulations, remediation experience, whether or not we are a potentially responsible party (PRP), the ability of other PRPs to pay their allocated portions and take into consideration reasonably possible outcomes. Our cost estimates can change substantially as additional information becomes available regarding the nature or extent of site contamination, updated cost assumptions (including increases and decreases to cost estimates), changes in the anticipated scope and timing of remediation activities, the settlement of environmental matters, required remediation methods and actions by or against governmental agencies or private parties.
Asset Retirement Obligations
We record the fair value of our estimated asset retirement obligations (AROs) associated with tangible long-lived assets in the period incurred. Fair value is measured as the present value of cash flow estimates after considering inflation and a market risk premium. Our cost estimates are reflected on a third-party cost basis and comply with our legal obligation to retire tangible long-lived assets in the period incurred. These cost estimates may differ from financial assurance cost estimates for reclamation activities because of a variety of factors, including obtaining updated cost estimates for reclamation activities, the timing of reclamation activities, changes in scope and the exclusion of certain costs not considered reclamation and closure costs. At December 31, 2020, AROs recorded in our consolidated balance sheet totaled $2.5 billion, including $0.4 billion associated with our remaining oil and gas
operations. Refer to Notes 1 and 12 for further discussion of reclamation and closure costs, including a summary of changes in our AROs for the three years ended December 31, 2020.
Generally, ARO activities are specified by regulations or in permits issued by the relevant governing authority, and management’s judgment is required to estimate the extent and timing of expenditures. Accounting for AROs represents a critical accounting estimate because (i) we will not incur most of these costs for a number of years, requiring us to make estimates over a long period, (ii) reclamation and closure laws and regulations could change in the future and/or circumstances affecting our operations could change, either of which could result in significant changes to our current plans, (iii) the methods used or required to plug and abandon non-producing oil and gas wellbores, remove platforms, tanks, production equipment and flow lines, and restore the wellsite could change, (iv) calculating the fair value of our AROs requires management to estimate projected cash flows, make long-term assumptions about inflation rates, determine our credit-adjusted, risk-free interest rates and determine market risk premiums that are appropriate for our operations and (v) given the magnitude of our estimated reclamation, mine closure and wellsite abandonment and restoration costs, changes in any or all of these estimates could have a significant impact on our results of operations.
Mineral Reserves
Recoverable proven and probable reserves are the part of a mineral deposit that can be economically and legally extracted or produced at the time of the reserve determination. The determination of reserves involves numerous uncertainties with respect to the ultimate geology of the ore bodies, including quantities, grades and recovery rates. Estimating the quantity and grade of mineral reserves requires us to determine the size, shape and depth of our ore bodies by analyzing geological data, such as samplings of drill holes, tunnels and other underground workings. In addition to the geology of our mines, assumptions are required to determine the economic feasibility of mining these reserves, including estimates of future commodity prices and demand, the mining methods we use and the related costs incurred to develop and mine our reserves. Our estimates of recoverable proven and probable mineral reserves are prepared by and are the responsibility of our employees. These estimates are reviewed and verified regularly by independent experts in mining, geology and reserve determination.
Our consolidated estimated recoverable proven and probable reserves shown below were assessed using long-term prices of $2.50 per pound for copper, $1,200 per ounce of gold and $10 per pound of molybdenum. The following table summarizes changes in our estimated consolidated recoverable proven and probable copper, gold and molybdenum reserves during 2020 and 2019:
| Copper****a (billion pounds) | Gold (million ounces) | Molybdenum (billion pounds) | |||||||||||||||||||||
| Consolidated reserves at December 31, 2018 | 119.6 | 30.8 | 3.78 | ||||||||||||||||||||
| Net revisions | (0.4) | (0.3) | (0.11) | ||||||||||||||||||||
| Production | (3.2) | (0.9) | (0.09) | ||||||||||||||||||||
| Consolidated reserves at December 31, 2019 | 116.0 | 29.6 | 3.58 | ||||||||||||||||||||
| Net additions | 0.4 | 0.2 | 0.21 | ||||||||||||||||||||
| Production | (3.2) | (0.9) | (0.08) | ||||||||||||||||||||
| Consolidated reserves at December 31, 2020 | 113.2 | 28.9 | 3.71 | ||||||||||||||||||||
a.Includes estimated recoverable metals contained in stockpiles. See below for additional discussion of recoverable copper in stockpiles.
Refer to Note 17 and “Risk Factors” contained in Part I, Item 1A. of our annual report on Form 10-K for the year ended December 31, 2020, for further information regarding, and risks associated with, our estimated recoverable proven and probable mineral reserves.
As discussed in Note 1, we depreciate our life-of-mine mining and milling assets and values assigned to proven and probable mineral reserves using the unit-of-production (UOP) method based on our estimated recoverable proven and probable mineral reserves. Because the economic assumptions used to estimate mineral reserves may change from period to period and additional geological data is generated during the course of operations, estimates of reserves may change, which could have a significant impact on our results of operations, including changes to prospective depreciation rates and impairments of long-lived asset carrying values. Based on projected copper sales volumes, if estimated copper reserves at our mines were 10 percent higher at December 31, 2020, we estimate that our annual depreciation, depletion and amortization (DD&A) expense for 2021 would decrease by $84 million ($44 million to net income attributable to common stock), and a 10 percent decrease in copper reserves
would increase DD&A expense by $103 million ($53 million to net income attributable to common stock). We perform annual assessments of our existing assets in connection with the review of mine operating and development plans. If it is determined that assigned asset lives do not reflect the expected remaining period of benefit, any change could affect prospective DD&A rates.
As discussed below and in Note 1, we review and evaluate our long-lived assets for impairment when events or changes in circumstances indicate that the related carrying amount of such assets may not be recoverable, and changes to our estimates of recoverable proven and probable mineral reserves could have an impact on our assessment of asset recoverability.
Recoverable Copper in Stockpiles
We record, as inventory, applicable costs for copper contained in mill and leach stockpiles that are expected to be processed in the future based on proven processing technologies. Mill and leach stockpiles are evaluated periodically to ensure that they are stated at the lower of weighted-average cost or net realizable value (refer to Note 4 and “Consolidated Results” for further discussion of inventory adjustments recorded for the three years ended December 31, 2020). Accounting for recoverable copper from mill and leach stockpiles represents a critical accounting estimate because (i) it is impracticable to determine copper contained in mill and leach stockpiles by physical count, thus requiring management to employ reasonable estimation methods and (ii) recovery rates from leach stockpiles can vary significantly. Refer to Note 1 for further discussion of our accounting policy for recoverable copper in stockpiles.
At December 31, 2020, estimated consolidated recoverable copper was 1.7 billion pounds in leach stockpiles (with a carrying value of $2.0 billion) and 0.3 billion pounds in mill stockpiles (with a carrying value of $0.4 billion).
Impairment of Long-Lived Assets
As discussed in Note 1, we assess the carrying values of our long-lived mining assets when events or changes in circumstances indicate that the related carrying amounts of such assets may not be recoverable. In evaluating our long-lived mining assets for recoverability, we use estimates of pre-tax undiscounted future cash flows of our mines. Estimates of future cash flows are derived from current business plans, which are developed using near-term metal price forecasts reflective of the current price environment and management’s projections for long-term average metal prices. In addition to near- and long-term metal price assumptions, other key assumptions include estimates of commodity-based and other input costs; proven and probable mineral reserves estimates, including the timing and cost to develop and produce the reserves; value beyond proven and probable mineral reserve estimates (refer to Note 1); and the use of appropriate discount rates in the measurement of fair value. We believe our estimates and models used to determine fair value are similar to what a market participant would use. As quoted market prices are unavailable for our individual mining operations, fair value is determined through the use of after-tax discounted estimated future cash flows.
For the two years ended December 31, 2020, our evaluation of our long-lived mining assets did not result in any material impairments.
In addition to decreases in future metal price assumptions, other events that could result in future impairment of our long-lived mining assets include, but are not limited to, decreases in estimated recoverable proven and probable mineral reserves and any event that might otherwise have a material adverse effect on mine site production levels or costs. Refer to “Risk Factors” contained in Part I, Item 1A. of our annual report on Form 10-K for the year ended December 31, 2020.
CONSOLIDATED RESULTS
| Years Ended December 31, | ||||||||||||||||||||
| 2020 | 2019 | |||||||||||||||||||
| SUMMARY FINANCIAL DATA | (in millions, except per share amounts) | |||||||||||||||||||
| Revenuesa,b | $ | 14,198 | c | $ | 14,402 | d | ||||||||||||||
| Operating incomea,e,f,g | $ | 2,437 | h | $ | 1,091 | |||||||||||||||
| Net income (loss) from continuing operationsi,j,k | $ | 865 | c,l | $ | (192) | m,n,o | ||||||||||||||
| Net income (loss) attributable to common stock | $ | 599 | $ | (239) | ||||||||||||||||
| Diluted net income (loss) per share attributable to common stock | $ | 0.41 | $ | (0.17) | ||||||||||||||||
| Diluted weighted-average common shares outstanding | 1,461 | 1,451 | ||||||||||||||||||
| Operating cash flowsp | $ | 3,017 | $ | 1,482 | ||||||||||||||||
| Capital expenditures | $ | 1,961 | $ | 2,652 | ||||||||||||||||
| At December 31: | ||||||||||||||||||||
| Cash and cash equivalents | $ | 3,657 | $ | 2,020 | ||||||||||||||||
| Total debt, including current portion | $ | 9,711 | $ | 9,826 |
a.Refer to Note 16 for a summary of revenues and operating income by operating division.
b.Includes adjustments to embedded derivatives for provisionally priced concentrate and cathode sales (refer to Note 14).
c.Includes net charges totaling $62 million ($24 million to net income attributable to common stock or $0.02 per share), primarily associated with Cerro Verde tax matters and asset impairments, partly offset by net credits primarily associated with the sale of royalty assets. These net (charges) credits were recorded in revenues ($(7) million), production and delivery ($(48) million), interest expense ($(55) million) and in other expenses, net ($48 million).
d.Includes charges totaling $166 million ($91 million to net loss attributable to common stock or $0.06 per share), primarily associated with an unfavorable Indonesia Supreme Court ruling related to certain disputed PT-FI export duties (refer to Note 12).
e.Includes net gains on sales of assets totaling $473 million ($337 million to net income attributable to common stock or $0.23 per share) in 2020 and $417 million ($339 million to net loss attributable to common stock or $0.23 per share) in 2019. Refer to Note 2 and “Net Gain on Sales of Assets” below for further discussion.
f.The year 2020 includes net charges for adjustments to environmental obligations and related litigation reserves of $113 million ($113 million to net income attributable to common stock or $0.08 per share), primarily associated with a framework for the resolution of all current and future potential talc-related litigation ($132 million), partly offset by net favorable adjustments to environmental reserves ($19 million). The year 2019 includes net charges for adjustments to environmental obligations and related litigation reserves of $68 million ($68 million to net loss attributable to common stock or $0.05 per share).
g.Includes unfavorable metals inventory adjustments totaling $96 million ($94 million to net income attributable to common stock or $0.06 per share) for the year 2020 and $179 million ($144 million to net loss attributable to common stock or $0.10 per share) for the year 2019.
h.Includes charges totaling $258 million ($178 million to net income attributable to common stock or $0.12 per share) associated with (i) idle facility costs (Cerro Verde), contract cancellation and other charges directly related to the COVID-19 pandemic and (ii) our April 2020 revised operating plans (including employee separation costs) recorded in production and delivery ($202 million), depreciation, depletion and amortization ($32 million), selling, general and administrative ($16 million), and mining exploration and research ($8 million).
i.Includes after-tax net losses on early extinguishment and exchanges of debt totaling $100 million ($0.07 per share) in 2020 and $26 million ($0.02 per share) in 2019. Refer to Note 8 for further discussion.
j.Includes net tax credits (charges) of $15 million ($27 million net of noncontrolling interests or $0.02 per share) in 2020 and $(1) million ($34 million net of noncontrolling interests or $0.02 per share) in 2019. Refer to “Income Taxes” below for further discussion.
k.We defer recognizing profits on intercompany sales until final sales to third parties occur. Refer to “Operations - Smelting & Refining” for a summary of net impacts from changes in these deferrals.
l.Includes charges at PT-FI totaling $65 million ($47 million to net income attributable to common stock or $0.03 per share) associated with historical contested tax audits ($50 million) and currency exchange adjustments to value added tax receivables ($15 million). These charges were recorded in interest expense, net ($35 million) and other expenses, net ($30 million).
m.Includes net charges associated with disputed Cerro Verde royalties for prior years of $7 million to net loss attributable to common stock (less than $0.01 per share) in 2019. Net charges for the year 2019 consist of charges to production and delivery costs ($6 million) and interest expense ($10 million). Refer to Note 12 for further discussion.
n.Includes charges at PT-FI of $294 million ($288 million to net loss attributable to common stock or $0.20 per share) consisting of $234 million associated with PT-FI's historical contested tax disputes, $32 million for a currency exchange
adjustment to value-added tax receivables and $28 million for an adjustment to the settlement of the historical surface water tax matters with the local regional tax authority in Papua, Indonesia.
o.Includes net charges totaling $59 million ($26 million to net loss attributable to common stock or $0.02 per share), primarily associated with weather-related issues at El Abra, adjustments to Cerro Verde’s deferred profit sharing and mining asset impairments, partly offset by net credits mostly for asset retirement obligation adjustments.
p.Working capital and other sources totaled $665 million in 2020 and $349 million in 2019.
| Years Ended December 31, | ||||||||||||||||||||
| 2020 | 2019 | |||||||||||||||||||
| SUMMARY OPERATING DATA | ||||||||||||||||||||
| Copper (millions of recoverable pounds) | ||||||||||||||||||||
| Production | 3,206 | 3,247 | ||||||||||||||||||
| Sales, excluding purchases | 3,202 | 3,292 | ||||||||||||||||||
| Average realized price per pound | $ | 2.95 | $ | 2.73 | ||||||||||||||||
| Site production and delivery costs per pounda | $ | 1.88 | $ | 2.15 | ||||||||||||||||
| Unit net cash costs per pounda | $ | 1.48 | $ | 1.74 | ||||||||||||||||
| Gold (thousands of recoverable ounces) | ||||||||||||||||||||
| Production | 857 | 882 | ||||||||||||||||||
| Sales, excluding purchases | 855 | 991 | ||||||||||||||||||
| Average realized price per ounce | $ | 1,832 | $ | 1,415 | ||||||||||||||||
| Molybdenum (millions of recoverable pounds) | ||||||||||||||||||||
| Production | 76 | 90 | ||||||||||||||||||
| Sales, excluding purchases | 80 | 90 | ||||||||||||||||||
| Average realized price per pound | $ | 10.20 | $ | 12.61 | ||||||||||||||||
a.Reflects per pound weighted-average production and delivery costs and unit net cash costs (net of by-product credits) for all copper mines, before net noncash and other costs. For reconciliations of the per pound unit costs by operating division to production and delivery costs applicable to sales reported in our consolidated financial statements, refer to “Product Revenues and Production Costs.”
Revenues
Consolidated revenues totaled $14.2 billion in 2020 and $14.4 billion in 2019. Our revenues primarily include the sale of copper concentrate, copper cathode, copper rod, gold in concentrate and molybdenum. Following is a summary of changes in our consolidated revenues from 2019 to 2020 (in millions):
| Consolidated revenues - 2019 | $ | 14,402 | ||||||||||||
| Mining operations: | ||||||||||||||
| Lower sales volumes: | ||||||||||||||
| Copper | (246) | |||||||||||||
| Gold | (193) | |||||||||||||
| Molybdenum | (124) | |||||||||||||
| Higher (lower) averaged realized prices: | ||||||||||||||
| Copper | 704 | |||||||||||||
| Gold | 356 | |||||||||||||
| Molybdenum | (194) | |||||||||||||
| Adjustments for prior year provisionally priced copper sales | (160) | |||||||||||||
| Lower revenues from sales of purchased copper | (239) | |||||||||||||
| Lower cobalt revenues | (301) | |||||||||||||
| Lower Atlantic Copper revenues | (31) | |||||||||||||
| Lower treatment and refining charges | 42 | |||||||||||||
| Lower royalties and export duties | 77 | |||||||||||||
| Other, including intercompany eliminations | 105 | |||||||||||||
| Consolidated revenues - 2020 | $ | 14,198 |
Sales Volumes. Copper sales volumes were slightly lower in 2020, compared to 2019, primarily reflecting lower mining rates in South America associated with COVID-19 restrictions and our April 2020 revised operating plans, partly offset by higher ore grades in Indonesia. Lower gold sales volumes in 2020, compared to 2019, primarily
reflect lower mining and milling rates associated with the ramp-up of underground mining in Indonesia, partly offset by higher ore grades.
Lower molybdenum sales volumes in 2020, compared with 2019, primarily reflect lower by-product production from Cerro Verde associated with lower mining rates as a result of COVID-19 restrictions.
Refer to “Operations” for further discussion of sales volumes at our mining operations.
Realized Prices. Our consolidated revenues can vary significantly as a result of fluctuations in the market prices of copper, gold and molybdenum. In 2020, our average realized prices were 8 percent higher for copper, 29 percent higher for gold and 19 percent lower for molybdenum, compared with 2019.
Average realized copper prices include net favorable (unfavorable) adjustments to current year provisionally priced copper sales (i.e., provisionally priced sales for the years 2020 and 2019) totaling $361 million for 2020 and $(24) million for 2019. Refer to Note 14 for a summary of total adjustments to prior period and current period provisionally priced sales. As discussed below and in “Disclosures About Market Risks-Commodity Price Risk”, substantially all of our copper concentrate and cathode sales contracts provide final copper pricing in a specified future month (generally one to four months from the shipment date). We record revenues and invoice customers at the time of shipment based on then-current LME prices, which results in an embedded derivative on provisionally priced concentrate and cathode sales that is adjusted to fair value through earnings each period, using the period-end forward prices, until final pricing on the date of settlement. To the extent final prices are higher or lower than what was recorded on a provisional basis, an increase or decrease to revenues is recorded each reporting period until the date of final pricing. Accordingly, in times of rising copper prices, our revenues benefit from adjustments to the final pricing of provisionally priced sales pursuant to contracts entered into in prior periods; in times of falling copper prices, the opposite occurs. Average realized prices in 2020 also included reductions totaling $24 million related to forward sales contracts (refer to Note 14).
Prior Year Provisionally Priced Copper Sales. Net (unfavorable) favorable adjustments to prior years’ provisionally priced copper sales (i.e., provisionally priced copper sales at December 31, 2019 and 2018) recorded in consolidated revenues totaled $(102) million in 2020 and $58 million in 2019. Refer to “Disclosures About Market Risks-Commodity Price Risk” for further discussion of our provisionally priced copper sales, and to Note 14 for a summary of total adjustments to prior period and current period provisionally priced copper sales.
Cobalt Revenues. Lower cobalt revenues in 2020, compared with 2019, primarily reflect the sale of our cobalt refinery and related cobalt cathode precursor business in fourth-quarter 2019.
Purchased Copper. We purchase copper cathode primarily for processing by our Rod & Refining operations. Purchased copper volumes totaled 290 million pounds in 2020 and 379 million pounds in 2019.
Atlantic Copper Revenues. Atlantic Copper revenues totaled $2.0 billion in 2020 and $2.1 billion in 2019. Lower Atlantic Copper revenues in 2020, compared with 2019, primarily reflect lower gold sales volumes.
Treatment and Refining Charges. Revenues from our concentrate sales are recorded net of treatment charges (i.e., fees paid to smelters that are generally negotiated annually), which will vary with the sales volumes and the price of copper.
Royalties and Export Duties. Royalties are primarily for sales from PT-FI and vary with the volume of metal sold and the prices of copper and gold. PT-FI will continue to pay export duties until development progress for the new smelter in Indonesia exceeds 50 percent. The year 2019 included charges totaling $166 million, primarily associated with an unfavorable Indonesia Supreme Court ruling related to certain disputed PT-FI export duties (refer to Note 12 for further discussion). Refer to Note 13 for a summary of PT-FI’s royalties and export duties.
Production and Delivery Costs
Consolidated production and delivery costs totaled $10.0 billion in 2020, compared with $11.5 billion in 2019. Lower consolidated production and delivery costs in 2020 primarily reflect lower mining and milling rates related to (i) the ramp-up of underground mining at PT-FI, (ii) our April 2020 revised operating plans in North America and South America and (iii) COVID-19 restrictions at our Cerro Verde mine in South America. Refer to Note 16 for details of production and delivery costs by operating segment.
Charges in 2020 include $202 million associated with the COVID-19 pandemic and revised operating plans (including employee separation costs).
Mining Unit Site Production and Delivery Costs
Site production and delivery costs for our copper mining operations primarily include labor, energy and commodity-based inputs, such as sulphuric acid, reagents, liners, tires and explosives. Consolidated unit site production and delivery costs (before net noncash and other costs) for our copper mines averaged $1.88 per pound of copper in 2020 and $2.15 per pound in 2019. Consolidated site production and delivery costs per pound of copper exclude certain charges associated with the COVID-19 pandemic and implementation of our April 2020 revised operating plans totaling $0.06 per pound of copper in 2020. Lower consolidated unit site production and delivery costs in 2020, compared with 2019, primarily reflect lower costs in Indonesia, North America and South America (for the same reasons discussed in the paragraph above). Refer to “Operations – Unit Net Cash Costs” for further discussion of unit net cash costs associated with our operating divisions, and to “Product Revenues and Production Costs” for reconciliations of per pound costs by operating division to production and delivery costs applicable to sales reported in our consolidated financial statements.
Our copper mining operations require significant amounts of energy, principally diesel, electricity, coal and natural gas, most of which is obtained from third parties under long-term contracts. Our take-or-pay contractual obligations for electricity totaled approximately $301 million at December 31, 2020. We do not have take-or-pay contractual obligations for other energy commodities. Energy represented approximately 16 percent of our copper mine site operating costs in 2020, including purchases of approximately 180 million gallons of diesel fuel; 7,500 gigawatt hours of electricity at our North America and South America copper mining operations (we generate all of our power at our Indonesia mining operation); 700 thousand metric tons of coal for our coal power plant in Indonesia; and 1 million MMBtu (million British thermal units) of natural gas at certain of our North America mines. Based on current cost estimates, energy will also approximate 18 percent of our copper mine site operating costs for 2021.
Depreciation, Depletion and Amortization
Depreciation will vary under the UOP method as a result of changes in sales volumes and the related UOP rates at our mining operations. Consolidated DD&A totaled $1.5 billion in 2020 and $1.4 billion in 2019. Higher DD&A in 2020, compared with 2019, primarily relates to assets placed in service associated with the ramp-up of underground mining at PT-FI.
Metals Inventory Adjustments
Unfavorable net realizable value metals inventory adjustments totaled $96 million in 2020 and $179 million in 2019. Metals inventory adjustments in 2020 were related to volatility in copper and molybdenum prices. Metals inventory adjustments in 2019 were mostly related to volatility in copper and cobalt prices.
Selling, General and Administrative expenses
Selling, general and administrative expenses totaled $370 million in 2020 and $394 million in 2019. During second-quarter 2020, we implemented a series of actions to reduce administrative and centralized support costs in conjunction with our April 2020 revised operating plans, including a temporary reduction in certain employee benefits, furloughs and an employee separation program, and reductions in third party service costs, facilities costs, travel and other expenses. As part of the cost savings initiatives, the Board approved a 25 percent reduction in the salary of each of our Chief Executive Officer (CEO) and Chief Financial Officer (CFO) through the end of 2020. Our CEO and CFO also agreed to forgo substantially all of their reduced cash salary during 2020, which was substituted with an award of restricted stock units that vested at the end of 2020.
Mining Exploration and Research Expenses
Consolidated exploration and research expenses for our mining operations totaled $50 million in 2020 and $104 million in 2019. Lower consolidated exploration and research expenses in 2020, compared to 2019, reflect a significant reduction in exploration and research activities associated with our April 2020 revised operating plans. Exploration spending is expected to approximate $34 million in 2021, consistent with 2020.
Environmental Obligations and Shutdown Costs
Environmental obligation costs reflect net revisions to our long-term environmental obligations, which vary from period to period because of changes to environmental laws and regulations, the settlement of environmental matters and/or circumstances affecting our operations that could result in significant changes in our estimates (refer to “Critical Accounting Estimates – Environmental Obligations” for further discussion). Shutdown costs include care-
and-maintenance costs and any litigation, remediation or related expenditures associated with closed facilities or operations.
Net charges for environmental obligations and shutdown costs totaled $159 million in 2020 and $105 million in 2019. The year 2020 includes talc-related litigation charges of $132 million, primarily associated with a framework for the resolution of all current and future potential talc-related litigation, partly offset by $19 million of net favorable adjustments to environmental reserves. Refer to Note 12 for environmental obligations and litigation matters.
Net Gain on Sales of Assets
Net gain on sales of assets totaled $473 million in 2020, primarily associated with the sale of our interests in the Kisanfu undeveloped exploration project located in the Democratic Republic of Congo (DRC), and $417 million in 2019, primarily including $343 million associated with the sale of our interest in the lower zone of the Timok exploration project in Serbia and $59 million associated with the sale of our cobalt refinery in Kokkola, Finland, and related cobalt cathode precursor business.
Refer to Note 2 for further discussion of dispositions.
Interest Expense, Net
Consolidated interest costs (before capitalization and excluding interest expense associated with international tax matters) totaled $655 million in 2020 and $675 million in 2019. Refer to Note 8 for further discussion of our 2020 debt transactions. Interest expense associated with PT-FI’s historical contested tax disputes totaled $35 million in 2020 and $78 million in 2019. Interest expense associated with South America tax matters totaled $61 million in 2020 and $10 million in 2019.
Capitalized interest varies with the level of expenditures for our development projects and average interest rates on our borrowings, and totaled $147 million in 2020 and $149 million in 2019. Refer to “Operations” and “Capital Resources and Liquidity – Investing Activities” for further discussion of current development projects.
Other Income (Expense), Net
Other income (expense), net, totaled $59 million in 2020 and $(138) million in 2019. The year 2020 included the sale of royalty interests and other net credits. The year 2019 included charges at PT-FI totaling $188 million associated with historical contested tax disputes (refer to Note 11) and a currency exchange adjustment to value-added tax receivables.
Income Taxes
Following is a summary of the approximate amounts used in the calculation of our consolidated income tax provision from continuing operations for the years ended December 31 (in millions, except percentages):
| 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| Income (Loss)a | Effective Tax Rate | Income Tax (Provision) Benefit | Income (Loss)a | Effective Tax Rate | Income Tax (Provision) Benefit | |||||||||||||||||||||||||||||||||
| U.S.b | $ | (532) | 11% | $ | 60 | c | $ | (277) | N/A | $ | — | d,e | ||||||||||||||||||||||||||
| South America | 466 | 51% | (239) | f | 497 | 48% | (241) | |||||||||||||||||||||||||||||||
| Indonesia | 1,342 | 45% | (608) | g | 340 | 44% | (149) | h | ||||||||||||||||||||||||||||||
| Gain on sale of Kisanfu | 486 | N/A | (135) | — | N/A | — | ||||||||||||||||||||||||||||||||
| PT-FI historical contested tax disputesi | (44) | 5% | 2 | (201) | (39)% | (78) | ||||||||||||||||||||||||||||||||
| PT-FI export duty matter | — | N/A | — | (155) | j | 31% | 48 | |||||||||||||||||||||||||||||||
| Adjustment to deferred taxes | — | N/A | — | — | N/A | (49) | k | |||||||||||||||||||||||||||||||
| Cerro Verde royalty dispute | — | N/A | — | (16) | N/A | 2 | l | |||||||||||||||||||||||||||||||
| Eliminations and other | 79 | N/A | (24) | 118 | N/A | (43) | ||||||||||||||||||||||||||||||||
| Consolidated | $ | 1,797 | 53% | m | $ | (944) | $ | 306 | (167)% | $ | (510) |
a.Represents income (loss) from continuing operations by geographic location before income taxes and equity in affiliated companies’ net earnings.
b.In addition to our North America mining operations, the U.S. jurisdiction reflects corporate-level expenses, which include interest expense associated with senior notes, general and administrative expenses, and environmental obligations and shutdown costs.
c.Includes tax credits of $53 million associated with the reversal of the tax charge discussed in footnote e below and $6 million associated with the removal of a valuation allowance on deferred tax assets.
d.Includes tax credits of $29 million associated with adjustments to the calculation of transition tax related to U.S. tax reform and $24 million associated with state law changes and the settlement of state income tax examinations.
e.Includes a tax charge of $53 million associated with the sale of our interest in the lower zone of the Timok exploration project in Serbia.
f.Includes tax charges at Cerro Verde of $15 million ($8 million net of noncontrolling interest) primarily associated with adjustments to profit sharing for prior years.
g.Includes tax charges of $21 million ($17 million net of noncontrolling interests) associated with establishing a tax reserve related to the treatment of prior year contractor support costs and $8 million ($7 million net of noncontrolling interest) associated with an unfavorable 2012 Indonesia Supreme Court ruling.
h.Includes a tax charge of $5 million ($4 million net of noncontrolling interests) primarily for non-deductible penalties related to PT-FI’s surface water tax settlement.
i.Refer to Note 11 for further discussion of a framework for resolution of these historical contested tax disputes.
j.Refer to Note 12 for further discussion of the unfavorable Indonesia Supreme Court ruling related to certain disputed PT-FI export duties.
k.Includes net tax charges totaling $49 million ($15 million net of noncontrolling interests) primarily to adjust deferred taxes on historical balance sheet items in accordance with tax accounting principles.
l.Refer to Note 12 for a summary of charges related to Cerro Verde’s disputed royalties for prior years.
m.Our consolidated effective income tax rate is a function of the combined effective tax rates for the jurisdictions in which we operate, excluding the U.S. jurisdiction.
Assuming achievement of current sales volume and cost estimates and average prices of $3.50 per pound for copper, $1,850 per ounce for gold and $9.00 per pound for molybdenum for 2021, we estimate our consolidated effective tax rate for the year 2021 would approximate 35 percent. Changes in projected sales volumes and average prices during 2021 would incur tax impacts at estimated effective rates of 38 percent for Indonesia, 39 percent for Peru and 0 percent for the U.S.
Variations in the relative proportions of jurisdictional income result in fluctuations to our consolidated effective income tax rate. Because of our U.S. tax position, we do not record a financial statement impact for income or losses generated in the U.S.
Refer to Note 11 for further discussion of income taxes.
OPERATIONS
During 2020, we announced our commitment to the Copper Mark. The Copper Mark is a new, comprehensive assurance framework that demonstrates the industry’s responsible production practices and contribution to the United Nations Sustainable Development Goals. It is the first and only framework developed specifically for the copper industry and enables each site to demonstrate to customers, investors and other stakeholders their responsible production performance. Four of our sites were awarded the Copper Mark in 2020 (Cerro Verde, El Abra, Miami and the Atlantic Copper smelter). We have future plans to validate all of our remaining copper operating sites against the Copper Mark requirements.
During 2020, we continued to advance innovation initiatives designed to enhance productivity, expand margins and reduce the capital intensity of our business through the utilization of new technology applications in combination with a more interactive operating structure. We were successful in implementing and embedding many of these initiatives across our operations by utilizing data science, machine learning and integrated cross-functional agile teams to identify opportunities and drive improved overall performance.
North America Copper Mines
We operate seven open-pit copper mines in North America – Morenci, Bagdad, Safford (including Lone Star), Sierrita and Miami in Arizona, and Chino and Tyrone in New Mexico. All of the North America mining operations are wholly owned, except for Morenci. We record our 72 percent undivided joint venture interest in Morenci using the proportionate consolidation method.
The North America copper mines include open-pit mining, sulfide ore concentrating, leaching and solution extraction/electrowinning (SX/EW) operations. A majority of the copper produced at our North America copper mines
is cast into copper rod by our Rod & Refining segment. The remainder of our North America copper production is sold as copper cathode or copper concentrate, a portion of which is shipped to Atlantic Copper (our wholly owned smelter). Molybdenum concentrate, gold and silver are also produced by certain of our North America copper mines*.*
Operating and Development Activities. Our North America operating sites continue to focus on strong execution of operating plans. Production from the Lone Star ore body at Safford where we completed development in 2020 continues to ramp-up on schedule and is expected to exceed 200 million pounds of copper for the year 2021*.* Our plan is to advance studies for potential expansions and long-term development options for the large-scale sulfide resources at Lone Star.
After shutting down mining activities in accordance with our April 2020 revised operating plans, in January 2021, we restarted mining activities at the Chino mine at a reduced rate of approximately 100 million pounds of copper per year (approximately 50 percent of capacity).
We have substantial resources in the U.S., primarily associated with existing mining operations, and will continue to assess options for further growth.
Operating Data. Following is summary operating data for the North America copper mines for the years ended December 31:
| 2020 | 2019 | |||||||||||||
| Operating Data, Net of Joint Venture Interests | ||||||||||||||
| Copper (millions of recoverable pounds) | ||||||||||||||
| Production | 1,418 | 1,457 | ||||||||||||
| Sales, excluding purchases | 1,422 | 1,442 | ||||||||||||
| Average realized price per pound | $ | 2.82 | a | $ | 2.74 | |||||||||
| Molybdenum (millions of recoverable pounds) | ||||||||||||||
| Productionb | 33 | 32 | ||||||||||||
| 100% Operating Data | ||||||||||||||
| Leach operations | ||||||||||||||
| Leach ore placed in stockpiles (metric tons per day) | 714,300 | 750,900 | ||||||||||||
| Average copper ore grade (percent) | 0.27 | 0.23 | ||||||||||||
| Copper production (millions of recoverable pounds) | 1,047 | 993 | ||||||||||||
| Mill operations | ||||||||||||||
| Ore milled (metric tons per day) | 279,700 | 326,100 | ||||||||||||
| Average ore grade (percent): | ||||||||||||||
| Copper | 0.35 | 0.34 | ||||||||||||
| Molybdenum | 0.02 | 0.02 | ||||||||||||
| Copper recovery rate (percent) | 84.1 | 87.0 | ||||||||||||
| Copper production (millions of recoverable pounds) | 647 | 748 |
a.Includes reductions to average realized prices of $0.02 per pound of copper related to forward sales contracts covering 150 million pounds of copper sales for May and June 2020 at a fixed price of $2.34 per pound. There are no remaining forward sales contracts.
b.Refer to “Consolidated Results” for our consolidated molybdenum sales volumes, which include sales of molybdenum produced at the North America copper mines.
Copper sales volumes from our North America copper mines totaled 1.4 billion pounds in 2020 and 2019. North America copper sales are estimated to approximate 1.5 billion pounds in 2021. Refer to “Outlook” for projected molybdenum sales volumes.
Unit Net Cash Costs. Unit net cash costs per pound of copper is a measure intended to provide investors with information about the cash-generating capacity of our mining operations expressed on a basis relating to the primary metal product for our respective operations. We use this measure for the same purpose and for monitoring operating performance by our mining operations. This information differs from measures of performance determined in accordance with U.S. GAAP and should not be considered in isolation or as a substitute for measures of performance determined in accordance with U.S. GAAP. This measure is presented by other metals mining companies, although our measure may not be comparable to similarly titled measures reported by other companies.
Gross Profit per Pound of Copper and Molybdenum
The following table summarizes unit net cash costs and gross profit per pound of copper at our North America copper mines for the two years ended December 31, 2020. Refer to “Product Revenues and Production Costs” for an explanation of the “by-product” and “co-product” methods and a reconciliation of unit net cash costs per pound to production and delivery costs applicable to sales reported in our consolidated financial statements.
| 2020 | 2019 | ||||||||||||||||||||||||||||||||||
| By- | Co-Product Method | By- | Co-Product Method | ||||||||||||||||||||||||||||||||
| Product Method | Copper | Molyb- denuma | Product Method | Copper | Molyb- denuma | ||||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 2.82 | b | $ | 2.82 | $ | 8.62 | $ | 2.74 | $ | 2.74 | $ | 11.51 | ||||||||||||||||||||||
| Site production and delivery, before net noncash | |||||||||||||||||||||||||||||||||||
| and other costs shown below | 1.90 | 1.78 | 6.84 | 2.05 | 1.88 | 9.29 | |||||||||||||||||||||||||||||
| By-product credits | (0.19) | — | — | (0.24) | — | — | |||||||||||||||||||||||||||||
| Treatment charges | 0.10 | 0.10 | — | 0.11 | 0.11 | — | |||||||||||||||||||||||||||||
| Unit net cash costs | 1.81 | 1.88 | 6.84 | 1.92 | 1.99 | 9.29 | |||||||||||||||||||||||||||||
| DD&A | 0.25 | 0.23 | 0.56 | 0.24 | 0.21 | 0.72 | |||||||||||||||||||||||||||||
| Metals inventory adjustments | 0.03 | 0.03 | — | 0.02 | 0.02 | — | |||||||||||||||||||||||||||||
| Noncash and other costs, net | 0.10 | c | 0.10 | 0.09 | 0.08 | 0.07 | 0.29 | ||||||||||||||||||||||||||||
| Total unit costs | 2.19 | 2.24 | 7.49 | 2.26 | 2.29 | 10.30 | |||||||||||||||||||||||||||||
| Revenue adjustments, primarily for pricing on prior period open sales | (0.02) | (0.02) | — | — | — | — | |||||||||||||||||||||||||||||
| Gross profit per pound | $ | 0.61 | $ | 0.56 | $ | 1.13 | $ | 0.48 | $ | 0.45 | $ | 1.21 | |||||||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 1,420 | 1,420 | 1,441 | 1,441 | |||||||||||||||||||||||||||||||
| Molybdenum sales (millions of recoverable pounds)a | 33 | 32 |
a.Reflects sales of molybdenum produced by certain of the North America copper mines to our molybdenum sales company at market-based pricing.
b.Includes reductions to average realized prices of $0.02 per pound of copper related to forward sales contracts covering 150 million pounds of copper sales for May and June 2020 at a fixed price of $2.34 per pound. There are no remaining forward sales contracts.
c.Includes charges totaling $0.02 per pound of copper, primarily associated with our April 2020 revised operating plans (including employee separation costs) and the COVID-19 pandemic (including health and safety costs).
Our North America copper mines have varying cost structures because of differences in ore grades and characteristics, processing costs, by-product credits and other factors. During 2020, average unit net cash costs (net of by-product credits) for the North America copper mines ranged from $1.61 per pound to $2.28 per pound at the individual mines and averaged $1.81 per pound. Lower average unit net cash costs (net of by-product credits) of $1.81 in 2020, compared with $1.92 per pound in 2019, primarily reflect the impact of our April 2020 revised operating plans, partly offset by lower by-product credits because of lower molybdenum prices.
Average unit net cash costs (net of by-product credits) for our North America copper mines are expected to approximate $1.86 per pound of copper in 2021, based on achievement of current sales volume and cost estimates and assuming an average molybdenum price of $9.00 per pound for the year 2021. The impact of price changes during 2021 on North America’s average unit net cash costs for the year 2021 would approximate $0.05 per pound for each $2 per pound change in the average price of molybdenum.
South America Mining
We operate two copper mines in South America – Cerro Verde in Peru (in which we own a 53.56 percent interest) and El Abra in Chile (in which we own a 51 percent interest), which are consolidated in our financial statements.
South America mining includes open-pit mining, sulfide ore concentrating, leaching and SX/EW operations. Production from our South America mines is sold as copper concentrate or cathode under long-term contracts. Our South America mines also sell a portion of their copper concentrate production to Atlantic Copper. In addition to copper, the Cerro Verde mine produces molybdenum concentrate and silver.
Operating and Development Activities. During fourth-quarter 2020, Cerro Verde continued to increase milling rates to an average of 373,200 metric tons of ore per day while operating consistent with our April 2020 revised operating plans and under strict COVID-19 restrictions and protocols. We expect Cerro Verde's mill rates to average approximately 360,000 metric tons of ore per day in 2021 with the potential to ramp-up to pre-COVID-19 levels approximating 400,000 metric tons of ore per day as COVID-19 restrictions are lifted.
El Abra plans to increase operating rates during 2021 to pre-COVID-19 levels, subject to ongoing monitoring of public health conditions in Chile. Incremental copper production associated with increasing El Abra's stacking rates from 65,000 metric tons of ore per day to over 100,000 metric tons of ore per day, approximates 70 million pounds per year beginning in 2022.
We continue to evaluate a large-scale expansion at El Abra to process additional sulfide material and to achieve higher recoveries. El Abra's large sulfide resource could potentially support a major mill project similar to facilities constructed at Cerro Verde. Technical and economic studies continue to be evaluated to determine the optimal scope and timing for the project in parallel with extending the life of the current leaching operation.
Operating Data. Following is summary operating data for our South America mining operations for the years ended December 31.
| 2020 | 2019 | ||||||||||
| Copper (millions of recoverable pounds) | |||||||||||
| Production | 979 | 1,183 | |||||||||
| Sales | 976 | 1,183 | |||||||||
| Average realized price per pound | $ | 3.05 | $ | 2.71 | |||||||
| Molybdenum (millions of recoverable pounds) | |||||||||||
| Productiona | 19 | 29 | |||||||||
| Leach operations | |||||||||||
| Leach ore placed in stockpiles (metric tons per day) | 160,300 | 205,900 | |||||||||
| Average copper ore grade (percent) | 0.35 | 0.37 | |||||||||
| Copper production (millions of recoverable pounds) | 241 | 268 | |||||||||
| Mill operations | |||||||||||
| Ore milled (metric tons per day) | 331,600 | b | 393,100 | ||||||||
| Average ore grade (percent): | |||||||||||
| Copper | 0.34 | 0.36 | |||||||||
| Molybdenum | 0.01 | 0.02 | |||||||||
| Copper recovery rate (percent) | 84.3 | 83.5 | |||||||||
| Copper production (millions of recoverable pounds) | 738 | 916 |
a.Refer to “Consolidated Results” for our consolidated molybdenum sales volumes, which include sales of molybdenum produced at Cerro Verde.
b.Cerro Verde mill operations were negatively impacted by COVID-19 restrictions.
Lower consolidated copper sales volumes from South America of 1.0 billion pounds in 2020, compared with 1.2 billion pounds in 2019, primarily reflect lower ore grades and mining rates associated with COVID-19 protocols at Cerro Verde and our April 2020 revised operating plans at El Abra, partly offset by higher recovery rates.
Copper sales from South America mines are expected to approximate 1.0 billion pounds in 2021, consistent with the year 2020. Refer to “Outlook” for projected molybdenum sales volumes.
Unit Net Cash Costs. Unit net cash costs per pound of copper is a measure intended to provide investors with information about the cash-generating capacity of our mining operations expressed on a basis relating to the primary metal product for our respective operations. We use this measure for the same purpose and for monitoring operating performance by our mining operations. This information differs from measures of performance determined in accordance with U.S. GAAP and should not be considered in isolation or as a substitute for measures of performance determined in accordance with U.S. GAAP. This measure is presented by other metals mining companies, although our measure may not be comparable to similarly titled measures reported by other companies.
Gross Profit per Pound of Copper
The following table summarizes unit net cash costs and gross profit per pound of copper at our South America mining operations for the two years ended December 31, 2020. Unit net cash costs per pound of copper are reflected under the by-product and co-product methods as the South America mining operations also had sales of molybdenum and silver. Refer to “Product Revenues and Production Costs” for an explanation of the “by-product” and “co-product” methods and a reconciliation of unit net cash costs per pound to production and delivery costs applicable to sales reported in our consolidated financial statements.
| 2020 | 2019 | ||||||||||||||||||||||
| By-Product Method | Co-Product Method | By-Product Method | Co-Product Method | ||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3.05 | $ | 3.05 | $ | 2.71 | $ | 2.71 | |||||||||||||||
| Site production and delivery, before net noncash | |||||||||||||||||||||||
| and other costs shown below | 1.86 | 1.74 | 1.85 | 1.68 | |||||||||||||||||||
| By-product credits | (0.17) | — | (0.27) | — | |||||||||||||||||||
| Treatment charges | 0.15 | 0.15 | 0.18 | 0.18 | |||||||||||||||||||
| Royalty on metals | 0.01 | 0.01 | 0.01 | 0.01 | |||||||||||||||||||
| Unit net cash costs | 1.85 | 1.90 | 1.77 | 1.87 | |||||||||||||||||||
| DD&A | 0.43 | 0.41 | 0.40 | 0.36 | |||||||||||||||||||
| Noncash and other costs, net | 0.13 | a | 0.12 | 0.08 | 0.07 | ||||||||||||||||||
| Total unit costs | 2.41 | 2.43 | 2.25 | 2.30 | |||||||||||||||||||
| Revenue adjustments, primarily for pricing on | |||||||||||||||||||||||
| prior period open sales | (0.07) | (0.07) | 0.03 | 0.03 | |||||||||||||||||||
| Gross profit per pound | $ | 0.57 | $ | 0.55 | $ | 0.49 | $ | 0.44 | |||||||||||||||
| Copper sales (millions of recoverable pounds) | 976 | 976 | 1,183 | 1,183 |
a.Includes charges totaling $0.09 per pound of copper, primarily associated with idle facility (Cerro Verde) and contract cancellation costs related to the COVID-19 pandemic, and employee separation costs associated with our April 2020 revised operating plans.
Our South America mines have varying cost structures because of differences in ore grades and characteristics, processing costs, by-product credits and other factors. Higher average unit net cash costs (net of by-product credits) of $1.85 per pound of copper in 2020, compared with $1.77 per pound in 2019, primarily reflected lower sales volumes and by-product credits, partly offset by lower mining rates.
Revenues from Cerro Verde’s concentrate sales are recorded net of treatment charges, which will vary with Cerro Verde’s sales volumes and the price of copper.
Because certain assets are depreciated on a straight-line basis, South America’s unit depreciation rate may vary with asset additions and the level of copper production and sales. DD&A per pound of copper under the by-product method was $0.43 in 2020, compared with $0.40 in 2019, primarily reflecting lower sales volumes.
Revenue adjustments primarily result from changes in prices on provisionally priced copper sales recognized in prior periods. Refer to “Consolidated Results - Revenues” for further discussion of adjustments to prior period provisionally priced copper sales.
Average unit net cash costs (net of by-product credits) for our South America mines are expected to approximate $1.92 per pound of copper in 2021, based on current sales volume and cost estimates and assuming average prices of $9.00 per pound of molybdenum for the year 2021.
Indonesia Mining
PT-FI’s assets include one of the world’s largest copper and gold deposits at the Grasberg minerals district in Papua, Indonesia. PT-FI produces copper concentrate that contains significant quantities of gold and silver. We have a 48.76 percent interest in PT-FI and manage its mining operations. As further discussed in Note 2, under the terms of the shareholders agreement, our economic interest in PT-FI approximates 81 percent through 2022. PT-FI’s results are consolidated in our financial statements.
Substantially all of PT-FI’s copper concentrate is sold under long-term contracts. During 2020, 50 percent of PT-FI’s copper concentrate was sold to PT Smelting (PT-FI’s 25-percent-owned smelter and refinery in Gresik, Indonesia).
As noted below, PT-FI is discussing the potential expansion of the capacity at PT Smelting, which is expected to result in an increase in PT-FI’s ownership interest in PT Smelting.
Operating and Development Activities. The ramp-up of underground production at the Grasberg minerals district in Indonesia continues to advance on schedule. During 2020, a total of 206 new drawbells were added at the Grasberg Block Cave and DMLZ underground mines, bringing cumulative open drawbells to over 370. Combined average production from the Grasberg Block Cave and DMLZ mines approximated 85,000 metric tons of ore per day during fourth-quarter 2020 (including approximately 95,000 metric tons of ore per day during the month of December). According to the current ramp-up schedule, average production rates at the Grasberg Block Cave and DMLZ are expected to continue to accelerate, with combined average production rates expected to reach approximately 172,000 metric tons of ore per day in 2022 and 200,000 metric tons of ore per day in 2023. PT-FI expects production for the year 2021 to approximate 1.4 billion pounds of copper and 1.4 million ounces of gold, which is nearly double 2020 levels.
The successful completion of this ramp-up is expected to enable PT-FI to generate average annual production for the next several years of 1.55 billion pounds of copper and 1.6 million ounces of gold at an attractive unit net cash cost, providing significant margins and cash flows.
PT-FI's estimated annual capital spending on underground mine development projects is expected to average approximately $0.9 billion per year for the two-year period 2021 through 2022, net of scheduled contributions from PT Indonesia Asahan Aluminium (Persero) (PT Inalum, also known as MIND ID). In accordance with applicable accounting guidance, aggregate costs (before scheduled contributions from PT Inalum), which are expected to average $1.1 billion per year for the two-year period 2021 through 2022, will be reflected as an investing activity in FCX's cash flow statement, and contributions from PT Inalum will be reflected as a financing activity.
Indonesia Smelter. In connection with the extension of PT-FI’s mining rights from 2031 to 2041, PT-FI committed to construct a new smelter in Indonesia by December 21, 2023 (an extension of which has been requested as a result of the COVID-19 pandemic). A potential site for the new smelter has been selected in East Java, and ground preparation is advancing. Engineering and front-end engineering and design for the selected process technology are in progress.
As a result of COVID-19 mitigation measures, there have been disruptions to work and travel schedules of international contractors and restrictions on access to the proposed physical site of the new smelter in East Java. PT-FI continues to discuss with the Indonesia government a deferred schedule for the new smelter as well as other alternatives in light of the ongoing COVID-19 pandemic and volatile global economic conditions. On January 7, 2021, the Indonesia government levied an administrative fine of $149 million on PT-FI for failing to achieve physical development progress on the new smelter as of July 31, 2020. PT-FI does not believe an administrative fine is warranted. Refer to Note 12 and Item 1A. “Risk Factors” for further discussion.
PT-FI and PT Inalum have been discussing with the Indonesia government alternatives to PT-FI’s commitment to build a new smelter. In connection with exploring alternatives to its commitment to develop additional smelter capacity in Indonesia, PT-FI has advanced discussions with the majority owner of PT Smelting regarding an expansion of the smelter to increase smelter concentrate treatment capacity by approximately 30 percent (300,000 metric tons of concentrate per year). Commercial and financial arrangements for this potential project are being advanced and engineering is in progress. The initial estimate for the cost of the expansion of PT Smelting is $250 million, which is expected to be funded by PT-FI as a convertible loan.
An expansion of PT Smelting is expected to reduce PT-FI's smelter development commitment from 2.0 million metric tons of concentrate per year to 1.7 million metric tons per year.
While PT-FI continues to evaluate the new greenfield smelter project in East Java, it is also advancing discussions in parallel with a third party to develop the new smelter capacity at an alternate location in partnership with PT-FI.
The preliminary capital cost estimate for the new smelter in East Java approximates $3 billion, pending completion of final engineering. PT-FI had capitalized costs for the new smelter totaling $216 million as of December 31, 2020. Estimated related capital expenditures for 2021 approximate $0.1 billion. PT-FI plans to arrange financing for the project and debt service will be shared by PT-FI’s shareholders according to their respective equity ownership percentages. As a result, our future distributions from PT-FI will incorporate approximately 49 percent of the smelter debt service.
Operating Data. Following is summary operating data for our Indonesia mining operations for the years ended December 31.
| 2020 | 2019 | ||||||||||
| Operating Data | |||||||||||
| Copper (millions of recoverable pounds) | |||||||||||
| Production | 809 | 607 | |||||||||
| Sales | 804 | 667 | |||||||||
| Average realized price per pound | $ | 3.08 | $ | 2.72 | |||||||
| Gold (thousands of recoverable ounces) | |||||||||||
| Production | 848 | 863 | |||||||||
| Sales | 842 | 973 | |||||||||
| Average realized price per ounce | $ | 1,832 | $ | 1,416 | |||||||
| 100% Operating Data | |||||||||||
| Ore milled (metric tons per day): | |||||||||||
| Grasberg Block Cave underground minea | 30,800 | 8,600 | |||||||||
| DMLZ underground minea | 28,600 | 9,800 | |||||||||
| DOZ underground minea | 20,900 | 25,500 | |||||||||
| Big Gossan underground minea | 7,000 | 6,100 | |||||||||
| Grasberg open pitb | 400 | 60,100 | |||||||||
| Total | 87,700 | 110,100 | |||||||||
| Average ore grade: | |||||||||||
| Copper (percent) | 1.32 | 0.84 | |||||||||
| Gold (grams per metric ton) | 1.10 | 0.93 | |||||||||
| Recovery rates (percent): | |||||||||||
| Copper | 91.9 | 88.4 | |||||||||
| Gold | 78.1 | 75.0 | |||||||||
| Production (recoverable): | |||||||||||
| Copper (millions of pounds) | 809 | 607 | |||||||||
| Gold (thousands of ounces) | 848 | 863 |
a.Reflects ore extracted, including ore from development activities that result in metal production.
b.Includes ore from related stockpiles.
Higher consolidated copper sales of 0.8 billion pounds in 2020, compared with 0.7 billion pounds in 2019, primarily reflect higher copper ore grades, partly offset by lower mining rates as underground mining ramps up. Lower consolidated gold sales of 0.8 million ounces of gold in 2020, compared with 1.0 million ounces of gold in 2019, primarily reflect lower mining rates as underground mining ramps up, partly offset by higher gold ore grades.
Consolidated sales volumes from PT-FI are expected to approximate 1.3 billion pounds of copper and 1.3 million ounces of gold in 2021.
Unit Net Cash Costs. Unit net cash costs per pound of copper is a measure intended to provide investors with information about the cash-generating capacity of our mining operations expressed on a basis relating to the primary metal product for our respective operations. We use this measure for the same purpose and for monitoring operating performance by our mining operations. This information differs from measures of performance determined in accordance with U.S. GAAP and should not be considered in isolation or as a substitute for measures of performance determined in accordance with U.S. GAAP. This measure is presented by other metal mining companies, although our measure may not be comparable to similarly titled measures reported by other companies.
Gross Profit per Pound of Copper and per Ounce of Gold
The following table summarizes the unit net cash costs and gross profit per pound of copper and per ounce of gold at our Indonesia mining operations for the two years ended December 31, 2020. Refer to “Product Revenues and Production Costs” for an explanation of “by-product” and “co-product” methods and a reconciliation of unit net cash costs per pound to production and delivery costs applicable to sales reported in our consolidated financial statements.
| 2020 | 2019 | ||||||||||||||||||||||||||||||||||
| By- Product | Co-Product Method | By- Product | Co-Product Method | ||||||||||||||||||||||||||||||||
| Method | Copper | Gold | Method | Copper | Gold | ||||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3.08 | $ | 3.08 | $ | 1,832 | $ | 2.72 | $ | 2.72 | $ | 1,416 | |||||||||||||||||||||||
| Site production and delivery, before net noncash | |||||||||||||||||||||||||||||||||||
| and other costs shown below | 1.88 | 1.13 | 674 | 2.91 | 1.63 | 849 | |||||||||||||||||||||||||||||
| Gold and silver credits | (2.03) | — | — | (2.13) | — | — | |||||||||||||||||||||||||||||
| Treatment charges | 0.27 | 0.17 | 98 | 0.26 | 0.14 | 75 | |||||||||||||||||||||||||||||
| Export duties | 0.12 | 0.07 | 41 | 0.08 | 0.05 | 25 | |||||||||||||||||||||||||||||
| Royalty on metals | 0.19 | 0.11 | 72 | 0.16 | 0.09 | 49 | |||||||||||||||||||||||||||||
| Unit net cash costs | 0.43 | 1.48 | 885 | 1.28 | 1.91 | 998 | |||||||||||||||||||||||||||||
| DD&A | 0.72 | 0.43 | 259 | 0.61 | 0.34 | 178 | |||||||||||||||||||||||||||||
| Metals inventory adjustments | — | — | — | 0.01 | 0.01 | — | |||||||||||||||||||||||||||||
| Noncash and other costs, net | 0.11 | a | 0.07 | 41 | 0.37 | b | 0.20 | 110 | |||||||||||||||||||||||||||
| Total unit costs | 1.26 | 1.98 | 1,185 | 2.27 | 2.46 | 1,286 | |||||||||||||||||||||||||||||
| Revenue adjustments, primarily for pricing on | |||||||||||||||||||||||||||||||||||
| prior period open sales | (0.03) | (0.03) | 5 | 0.03 | 0.03 | 2 | |||||||||||||||||||||||||||||
| PT Smelting intercompany loss | (0.01) | (0.01) | (5) | (0.02) | (0.02) | (8) | |||||||||||||||||||||||||||||
| Gross profit per pound/ounce | $ | 1.78 | $ | 1.06 | $ | 647 | $ | 0.46 | $ | 0.27 | $ | 124 | |||||||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 804 | 804 | 667 | 667 | |||||||||||||||||||||||||||||||
| Gold sales (thousands of recoverable ounces) | 842 | 973 |
a.Includes COVID-19 related costs (including one-time incremental employee benefits and health and safety costs) totaling $0.02 per pound of copper.
b.Includes charges in revenues totaling $0.25 per pound of copper primarily associated with an unfavorable Indonesia Supreme Court ruling related to certain disputed PT-FI export duties, partly offset by adjustments to prior year treatment charges totaling $0.03 per pound of copper. Also includes charges of $0.04 per pound of copper associated with adjustments to the settlement of the historical surface water tax disputes with the local regional tax authority in Papua, Indonesia.
A significant portion of PT-FI’s costs are fixed and unit costs vary depending on volumes and other factors. PT-FI’s unit net cash costs (including gold and silver credits) of $0.43 per pound of copper in 2020, were lower than unit net cash credits of $1.28 per pound in 2019, primarily reflecting higher copper sales volumes and lower mining costs.
Treatment charges vary with the volume of metals sold and the price of copper, and royalties vary with the volume of metals sold and the prices of copper and gold.
PT-FI’s export duties totaled $93 million in 2020 and $56 million in 2019, and PT-FI’s royalties totaled $153 million in 2020 and $107 million in 2019. PT-FI will continue to pay export duties until development progress for the new smelter in Indonesia exceeds 50 percent. Refer to Note 13 for further discussion of PT-FI’s export duties and royalties.
Because certain assets are depreciated on a straight-line basis, PT-FI’s unit depreciation rate may vary with asset additions and the level of copper production and sales. DD&A per pound of copper under they by-product method was $0.72 in 2020, compared with $0.61 in 2019, primarily reflecting underground development assets placed in service.
Revenue adjustments primarily result from changes in prices on provisionally priced copper sales recognized in prior periods. Refer to “Consolidated Results - Revenues” for further discussion of adjustments to prior period provisionally priced copper sales.
PT Smelting intercompany loss represents the change in the deferral of 25 percent of PT-FI’s profit on sales to PT Smelting. Refer to “Operations - Smelting & Refining” below for further discussion.
Assuming an average gold price of $1,850 per ounce for 2021 and achievement of current sales volume and cost estimates, unit net cash costs (including gold and silver credits) for PT-FI are expected to approximate $0.06 per pound of copper for the year 2021. The impact of price changes during 2021 on PT-FI’s average unit net cash costs would approximate $0.09 per pound for each $100 per ounce change in the average price of gold.
PT-FI’s projected sales volumes and unit net cash costs for the year 2021 are dependent on a number of factors, including continued progress of the ramp-up of underground mining, operational performance, timing of shipments and the Indonesia government’s extension of PT-FI’s export permit. In March 2020, PT-FI received a one-year extension of its export license through March 15, 2021. Refer to Note 12 and Item 1A. “Risk Factors” for a discussion of the administrative fine levied by the Indonesia government on PT-FI for failing to achieve physical development progress on the new smelter and ongoing discussions with the Indonesia government regarding a deferred schedule for the completion of the new smelter project as well as other alternatives in light of the ongoing COVID-19 pandemic and volatile global economic conditions
Molybdenum Mines
We have two wholly owned molybdenum mines in Colorado – the Henderson underground mine and the Climax open-pit mine. The Henderson and Climax mines produce high-purity, chemical-grade molybdenum concentrate, which is typically further processed into value-added molybdenum chemical products. The majority of the molybdenum concentrate produced at the Henderson and Climax mines, as well as from our North America and South America copper mines, is processed at our own conversion facilities.
Operating and Development Activities. Production from the Molybdenum mines totaled 24 million pounds of molybdenum in 2020 and 29 million pounds in 2019. The decrease in 2020, compared with 2019, primarily reflected lower operating rates pursuant to our April 2020 revised operating plans in response to market conditions. Refer to “Consolidated Results” for our consolidated molybdenum operating data, which includes sales of molybdenum produced at our Molybdenum mines, and from our North America and South America copper mines, and refer to “Outlook” for projected consolidated molybdenum sales volumes.
Unit Net Cash Costs Per Pound of Molybdenum. Unit net cash costs per pound of molybdenum is a measure intended to provide investors with information about the cash-generating capacity of our mining operations expressed on a basis relating to the primary metal product for our respective operations. We use this measure for the same purpose and for monitoring operating performance by our mining operations. This information differs from measures of performance determined in accordance with U.S. GAAP and should not be considered in isolation or as a substitute for measures of performance determined in accordance with U.S. GAAP. This measure is presented by other metals mining companies, although our measure may not be comparable to similarly titled measures reported by other companies.
Unit net cash costs for our Molybdenum mines of $9.50 per pound of molybdenum in 2020 were lower than $10.80 per pound in 2019, primarily reflecting lower mining and input costs associated with our April 2020 revised operating plans. Average unit net cash costs for our Molybdenum mines do not include noncash and other costs, which include charges totaling $0.29 per pound of molybdenum primarily associated with our April 2020 revised operating plans (including employee separation costs) and contract cancellation costs related to the COVID-19 pandemic. Based on current sales volume and cost estimates, average unit net cash costs for the Molybdenum mines are expected to approximate $9.80 per pound of molybdenum for the year 2021. Refer to “Product Revenues and Production Costs” for a reconciliation of unit net cash costs per pound to production and delivery costs applicable to sales reported in our consolidated financial statements.
Smelting & Refining
We wholly own and operate a smelter in Arizona (Miami smelter), a refinery in Texas (El Paso refinery) and a smelter and refinery in Spain (Atlantic Copper). Additionally, PT-FI owns 25 percent of a smelter and refinery in Gresik, Indonesia (PT Smelting), which is expected to increase in connection with the potential expansion of PT Smelting. See “Indonesia Smelter” for additional information regarding the potential PT Smelting expansion. Treatment charges for smelting and refining copper concentrate consist of a base rate per pound of copper and per ounce of gold and are generally fixed. Treatment charges represent a cost to our mining operations and income to Atlantic Copper and PT Smelting. Thus, higher treatment charges benefit our smelter operations and adversely affect our mining operations. Our North America copper mines are less significantly affected by changes in
treatment charges because these operations are largely integrated with our Miami smelter and El Paso refinery. Through this form of downstream integration, we are assured placement of a significant portion of our concentrate production.
During 2019, we incurred charges totaling $38 million for a maintenance turnaround at the Miami smelter. The next major maintenance turnaround at the Miami smelter is scheduled for first-quarter 2021, for which we expect to incur charges of approximately $60 million.
Atlantic Copper smelts and refines copper concentrate and markets refined copper and precious metals in slimes. Following is an allocation of Atlantic Copper’s concentrate purchases from unaffiliated third parties and our copper mining operations for the two years ended December 31, 2020:
| 2020 | 2019 | ||||||||||
| Third parties | 79 | % | 73 | % | |||||||
| North America copper mines | 10 | 22 | |||||||||
| South America mining | 7 | 2 | |||||||||
| Indonesia mining | 4 | 3 | |||||||||
| 100 | % | 100 | % |
During 2019, we incurred charges totaling $16 million for a short-term maintenance turnaround at the Atlantic Copper smelter. The next major maintenance turnaround at the Atlantic Copper smelter is scheduled for second-quarter 2022.
Atlantic Copper has take-or-pay contractual obligations for the procurement of copper concentrate totaling $2.9 billion at December 31, 2020, that provide for deliveries of specified volumes at market-based prices.
PT-FI’s contract with PT Smelting provides for PT-FI to supply 100 percent of the copper concentrate requirements (subject to a minimum or maximum treatment charge rate) necessary for PT Smelting to produce 205,000 metric tons of copper annually on a priority basis. PT-FI may also sell copper concentrate to PT Smelting at market rates for quantities in excess of 205,000 metric tons of copper annually. PT-FI supplied 74 percent of PT Smelting’s concentrate requirements in 2020 and 90 percent in 2019. PT Smelting processed 50 percent of PT-FI’s concentrate production in 2020 and 64 percent of such production in 2019 .
PT Smelting produced 276,900 metric tons of copper anode from its smelter and 273,000 metric tons of copper cathode from its refinery in 2020; and 246,100 metric tons of copper anode from its smelter and 241,200 metric tons of copper cathode from its refinery in 2019.
In January 2021, PT Smelting received a six-month extension of its anodes slimes export license, which currently expires July 18, 2021.
PT Smelting’s maintenance turnarounds (which range from two weeks to a month to complete) typically are expected to occur approximately every two years, with short-term maintenance turnarounds in the interim. PT Smelting completed a 30-day maintenance turnaround during December 2020, and the next major turnaround is scheduled for the second half of 2022.
We defer recognizing profits on sales from our mining operations to Atlantic Copper and on 25 percent of PT-FI’s sales to PT Smelting until final sales to third parties occur. Changes in these deferrals attributable to variability in intercompany volumes resulted in net (reductions) additions to operating income totaling $(7) million ($1 million to net income attributable to common stock) in 2020 and $(22) million ($(18) million to net loss attributable to common stock) in 2019. Our net deferred profits on our inventories at Atlantic Copper and PT Smelting to be recognized in future periods’ net income attributable to common stock totaled $54 million at December 31, 2020. Quarterly variations in ore grades, the timing of intercompany shipments and changes in product prices will result in variability in our net deferred profits and quarterly earnings. We currently expect first-quarter 2021 results to reflect an increase in net deferred profits, totaling an approximate $50 million reduction to net income, associated with an anticipated increase in sales to Atlantic Copper as a result of the major maintenance turnaround at the Miami smelter noted above, which will be recognized in future periods as Atlantic Copper sells final refined products to third parties.
CAPITAL RESOURCES AND LIQUIDITY
During second-quarter 2020, we announced revised operating plans in response to the global COVID-19 pandemic and resulting negative impact on the global economy. The revised operating plans allowed us to maximize cash flow and protect liquidity and to preserve asset values in an uncertain economic environment.
Our consolidated operating cash flows vary with sales volumes; prices realized from copper, gold and molybdenum sales; production costs; income taxes; other working capital changes; and other factors. A large component of our production costs are related to energy. See “Consolidated Results” for further discussion of our energy requirements and related costs. We believe that we have a high-quality portfolio of long-lived copper assets positioned to generate long-term value. We recently completed the Lone Star copper leach project at our Safford operation in southeastern Arizona, and PT-FI has several projects in the Grasberg minerals district related to the development of its large-scale, long-lived, high-grade underground ore bodies. We are also evaluating other opportunities to enhance net present values, and we continue to consider future development of our copper resources, the timing of which will be dependent on market conditions. We believe that our cash generating capability and financial condition, together with our credit facility, will be adequate to meet our operating, investing and financing needs.
Subject to future commodity prices for copper, gold, and molybdenum, we expect estimated consolidated operating cash flows of $5.5 billion in 2021, plus available cash, to be sufficient to fund our capital expenditures of $2.3 billion in 2021, as well as projected spending on the new smelter in Indonesia and other cash requirements for the year, including common stock dividends and approximately $0.6 billion of noncontrolling interest distributions. Refer to “Outlook” for further discussion of projected operating cash flows and capital expenditures for 2021.
At December 31, 2020, we had $7.2 billion in liquidity, comprised of $3.7 billion in consolidated cash and $3.5 billion of availability under our revolving credit facility.
In connection with our financing activities in 2019 and 2020, we issued a total of $4.0 billion in new senior notes and used most of the net proceeds to purchase and redeem outstanding senior notes. As a result, we have extended our debt maturities and strengthened our financial flexibility. We have no significant scheduled debt maturities in 2021.
In February 2021, the Board reinstated a cash dividend on our common stock at an annual rate of $0.30 per share. The Board intends to declare a quarterly dividend of $0.075 per share, with the initial quarterly dividend expected to be paid on May 3, 2021. The Board also adopted a new financial policy for the allocation of cash flows aligned with our strategic objectives of maintaining a strong balance sheet, increasing cash returns to shareholders and advancing opportunities for future growth. Under the new policy, up to 50 percent of available cash flows generated after planned capital spending and distributions to noncontrolling interests would be allocated to shareholder returns and the balance to debt reduction and investments in value enhancing growth projects. The new payout policy will be implemented following achievement of a net debt (total consolidated debt less total consolidated cash and cash equivalents) target in the range of $3 billion to $4 billion, excluding project debt for additional smelter capacity in Indonesia. Under current market conditions and with continued strong execution of our plans, we currently expect to reach this target in early 2022 (refer to “Cautionary Statement”).
Cash
Following is a summary of the U.S. and international components of consolidated cash and cash equivalents available to the parent company, net of noncontrolling interests’ share, taxes and other costs at December 31, 2020 (in billions):
| Cash at domestic companies | $ | 2.9 | |||||||||
| Cash at international operations | 0.8 | ||||||||||
| Total consolidated cash and cash equivalents | 3.7 | ||||||||||
| Noncontrolling interests’ share | (0.4) | ||||||||||
| Cash, net of noncontrolling interests’ share | $ | 3.3 | |||||||||
| Withholding taxes | — | a | |||||||||
| Net cash available | $ | 3.3 |
a.Rounds to less than $0.1 billion.
Cash held at our international operations is generally used to support our foreign operations’ capital expenditures, operating expenses, debt repayments, working capital or other cash needs. Management believes that sufficient
liquidity is available in the U.S. from cash balances and availability from our revolving credit facility. We have not elected to permanently reinvest earnings from our foreign subsidiaries, and we have recorded deferred tax liabilities for foreign earnings that are available to be repatriated to the U.S. From time to time, our foreign subsidiaries distribute earnings to the U.S. through dividends that are subject to applicable withholding taxes and noncontrolling interests’ share.
Debt
At December 31, 2020, consolidated debt totaled $9.7 billion, with a related weighted-average interest rate of 4.6 percent. We had no borrowings, $10 million in letters of credit issued and approximately $3.5 billion available under our revolving credit facility at December 31, 2020. Refer to “Financing Activities” below and Note 8 for further discussion of debt.
In December 2020, Cerro Verde prepaid $0.3 billion on its Term Loan that was scheduled to mature in December 2021. The remaining balance of $0.5 billion matures in June 2022 (refer to Note 8).
In June 2020, we amended our revolving credit facility to provide additional flexibility on certain financial covenants. The key changes under the amendment include a suspension of the total leverage ratio through June 30, 2021, and a reduction in the interest expense coverage ratio to a minimum of 2.0x through December 31, 2021. We also agreed to a minimum liquidity covenant of $1 billion (consisting of consolidated unrestricted cash and availability under the revolving credit facility) applicable to each quarter through June 30, 2021, and additional restrictions on priority debt and liens, and on the payment of dividends through December 31, 2021. At December 31, 2020, we were in compliance with our revolving credit facility covenants.
As further discussed in Note 10, in February 2021, the Board reinstated a cash dividend on our common stock. Prior to the Board’s declaration of the initial quarterly dividend, we will deliver a covenant reversion notice, at which time the financial covenants and other restrictions, including the dividend restriction, will revert to the limits applicable prior to the June 2020 amendment.
During 2020, we completed the sale of $2.8 billion of senior notes and used most of the net proceeds to purchase and redeem senior notes maturing in 2021, 2022, 2023 and 2024. The remaining net proceeds were used for general corporate purposes.
In August 2019, we completed the sale of $1.2 billion of senior notes and used the net proceeds to fund the make-whole redemption of all of our outstanding senior notes maturing in 2023, and the concurrent tender offers to purchase a portion of our senior notes maturing in 2021 and 2022.
For additional information regarding our debt arrangements, refer to Note 8.
Operating Activities
We generated consolidated operating cash flows of $3.0 billion in 2020 (including $0.7 billion from working capital and other sources) and $1.5 billion in 2019 (including $0.3 billion from working capital and other sources).
Higher operating cash flows for 2020, compared with 2019, primarily reflect higher copper prices, lower production and delivery costs associated with lower mining rates, and cost reductions associated with our April 2020 revised operating plans.
Investing Activities
Capital Expenditures. Capital expenditures, including capitalized interest, totaled $2.0 billion for the year 2020, including $1.2 billion for major projects primarily associated with underground development activities in the Grasberg minerals district and the now complete Lone Star copper leach project. Capital expenditures, including capitalized interest, totaled $2.7 billion for the year 2019, including $1.5 billion for major projects.
A large portion of the capital expenditures relate to projects that are expected to add significant production and cash flow in future periods, enabling us to continue to generate operating cash flows exceeding capital expenditures in future years. Refer to “Outlook” for further discussion of projected capital expenditures for 2021.
Proceeds from Sales of Assets. Proceeds from sales of assets totaled $0.7 billion for the year 2020, primarily related to the sale of Kisanfu, our undeveloped exploration project in the DRC ($550 million), contingent consideration associated with the 2016 sale of the Tenke Fungurume Mining assets in the DRC ($60 million), the
collection of proceeds related to the 2019 sale of the Timok exploration assets in Serbia ($45 million) and the sale of royalty assets ($31 million).
Proceeds from sales of assets totaled $0.6 billion for the year 2019, primarily associated with sales of (i) our interest in the lower zone of the Timok exploration project in Serbia, (ii) our cobalt refinery in Kokkola, Finland, and related cobalt cathode precursor business and (iii) interests in oil and gas properties, including $50 million in contingent consideration associated with the 2016 sale of onshore California oil and gas properties.
Refer to Note 2 for further discussion of acquisitions and dispositions.
Financing Activities
Debt Transactions. Net repayments of debt in 2020 totaled $0.2 billion, primarily reflecting the repayment of $0.3 billion under Cerro Verde’s Term Loan.
Net repayments of debt in 2019 totaled $1.3 billion, primarily consisting of the redemption of $1.0 billion aggregate principal amount of our senior notes maturing in 2020 and the repayment of $200 million under the Cerro Verde Term Loan. Additionally, during 2019, we issued $1.2 billion in new senior notes and used the net proceeds to redeem and purchase senior notes maturing in 2021, 2022 and 2023.
Refer to Note 8 for further discussion of debt transactions.
Cash Dividends and Distributions Paid. We paid dividends on our common stock totaling $73 million in 2020 (associated with the $0.05 per share common stock cash dividend declared in December 2019) and $291 million in 2019.
As further discussed in Note 10, in February 2021, the Board reinstated a cash dividend on our common stock and also adopted a new financial policy for the allocation of cash flows aligned with our strategic objectives of maintaining a strong balance sheet, increasing cash returns to shareholders and advancing opportunities for future growth. The declaration and payment of future dividends is at the discretion of the Board and will be assessed on an ongoing basis, taking into account our financial results, cash requirements, future prospects, global economic conditions, and other factors deemed relevant by the Board.
There were no cash dividends or distributions paid to noncontrolling interests in 2020 and $82 million in 2019. These payments will vary based on the operating results and cash requirements of our consolidated subsidiaries.
Contributions from Noncontrolling Interests. We received equity contributions from PT Inalum for their share of capital spending on PT-FI underground mine development projects and costs for the new smelter in Indonesia totaling $156 million in 2020 and $165 million in 2019.
CONTINGENCIES
Environmental
The cost of complying with environmental laws is a fundamental and substantial cost of our business. At December 31, 2020, we had $1.6 billion recorded in our consolidated balance sheet for environmental obligations attributed to CERCLA or analogous state programs and for estimated future costs associated with environmental obligations that are considered probable based on specific facts and circumstances.
We incurred environmental capital expenditures and other environmental costs (including our joint venture partners’ shares) to comply with applicable environmental laws and regulations that affect our operations totaling $0.3 billion in 2020 and $0.4 billion in 2019. For 2021, we expect to incur approximately $0.4 billion of aggregate environmental capital expenditures and other environmental costs. The timing and amount of estimated payments could change as a result of changes in regulatory requirements, changes in scope and timing of reclamation and plug and abandonment activities, the settlement of environmental matters and the rate at which actual spending occurs on continuing matters.
In August 2020, the co-conveners of the Global Tailings Review, which included the International Council on Mining and Metals (ICMM), an industry group of which we are a founding member, published the first Global Industry Standard on Tailings Management (the Tailings Standard). The Tailings Standard includes 77 requirements across 6 key areas including the design, construction, operation and monitoring of tailings facilities, management and governance, emergency response and long-term recovery, and public disclosure. ICMM has committed that
members will implement the Tailings Standard within three years for certain facilities and within five years for all others. ICMM members have prepared a guidance document focused on practices that drive safe tailings management and prepared a conformance protocol document to be used by companies on demonstrating implementation of the Tailings Standard; both documents are expected to be published in early 2021. As a member of ICMM, which has endorsed the Tailings Standard, we are moving toward implementation and have begun undertaking an extensive, multi-year analysis of our tailings facilities to ensure conformance with the Tailings Standard. We are assessing the costs of complying with the new Tailings Standard.
Refer to Note 12 and “Risk Factors” contained in Part I, Item 1A. of our annual report on Form 10-K for the year ended December 31, 2020, for further information about environmental regulation, including significant environmental matters.
Asset Retirement Obligations
We recognize AROs as liabilities when incurred, with the initial measurement at fair value. These obligations, which are initially estimated based on discounted cash flow estimates, are accreted to full value over time through charges to cost of sales. Mine reclamation costs for disturbances are recorded as an ARO and as a related asset retirement cost (ARC) (included in property, plant, equipment and mine development costs) in the period of disturbance. Oil and gas plugging and abandonment costs are recognized as an ARO and as a related ARC (included in oil and gas properties) in the period in which the well is drilled or acquired. For non-operating properties without reserves, changes to the ARO are recorded in earnings. Our cost estimates are reflected on a third-party cost basis and comply with our legal obligation to retire tangible, long-lived assets. At December 31, 2020, we had $2.5 billion recorded in our consolidated balance sheet for AROs, including $0.4 billion related to our oil and gas properties. Spending on AROs totaled $156 million in 2020 and $170 million in 2019 (including $38 million in 2020 and $77 million in 2019 for our oil and gas operations). For 2021, we expect to incur approximately $0.3 billion in aggregate ARO payments (including $0.1 billion for our oil and gas operations). Refer to Note 12 for further discussion.
Litigation and Other Contingencies
Refer to Notes 2 and 12, and “Legal Proceedings” contained in Part I, Item 3. of our annual report on Form 10-K for the year ended December 31, 2020, for further discussion of contingencies associated with legal proceedings and other matters.
DISCLOSURES ABOUT MARKET RISKS
Commodity Price Risk
Our consolidated revenues from our mining operations include the sale of copper concentrate, copper cathode, copper rod, gold, molybdenum and other metals by our North America and South America mines, the sale of copper concentrate (which also contains significant quantities of gold and silver) by our Indonesia mining operations, the sale of molybdenum in various forms by our molybdenum operations, and the sale of copper cathode, copper anode and gold in anode and slimes by Atlantic Copper. Our financial results will vary with fluctuations in the market prices of the commodities we produce, primarily copper and gold, and to a lesser extent molybdenum and silver. For projected sensitivities of our operating cash flow to changes in commodity prices, refer to “Outlook.” World market prices for these commodities have fluctuated historically and are affected by numerous factors beyond our control. Refer to “Risk Factors” contained in Part I, Item 1A. of our annual report on Form 10-K for the year ended December 31, 2020, for further discussion of financial risks associated with fluctuations in the market prices of the commodities we sell.
During 2020, our mined copper was sold 51 percent in concentrate, 28 percent as cathode and 21 percent as rod from North America operations. Substantially all of our copper concentrate and cathode sales contracts provide final copper pricing in a specified future month (generally one to four months from the shipment date) based primarily on quoted LME monthly average copper settlement prices. We receive market prices based on prices in the specified future period, which results in price fluctuations recorded through revenues until the date of settlement. We record revenues and invoice customers at the time of shipment based on then-current LME prices, which results in an embedded derivative on our provisionally priced concentrate and cathode sales that is adjusted to fair value through earnings each period, using the period-end forward prices, until final pricing on the date of settlement. To the extent final prices are higher or lower than what was recorded on a provisional basis, an increase or decrease to revenues is recorded each reporting period until the date of final pricing. Accordingly, in times of rising copper prices, our revenues benefit from adjustments to the final pricing of provisionally priced sales pursuant to contracts entered into in prior periods; in times of falling copper prices, the opposite occurs.
Following are the (unfavorable) favorable impacts of net adjustments to the prior years’ provisionally priced copper sales for the years ended December 31 (in millions, except per share amounts):
| 2020 | 2019 | ||||||||||||||||
| Revenues | $ | (102) | $ | 58 | |||||||||||||
| Net income attributable to common stock | $ | (42) | $ | 24 | |||||||||||||
| Net income per share attributable to common stock | $ | (0.03) | $ | 0.02 |
At December 31, 2020, we had provisionally priced copper sales at our copper mining operations totaling 320 million pounds of copper (net of intercompany sales and noncontrolling interests) recorded at an average price of $3.52 per pound, subject to final pricing over the next several months. We estimate that each $0.05 change in the price realized from the December 31, 2020, provisional price recorded would have an approximate $10 million effect on 2021 net income attributable to common stock. The LME copper settlement price closed at $3.57 per pound on January 29, 2021.
Foreign Currency Exchange Risk
The functional currency for most of our operations is the U.S. dollar. Substantially all of our revenues and a significant portion of our costs are denominated in U.S. dollars; however, some costs and certain asset and liability accounts are denominated in local currencies, including the Indonesia rupiah, Australian dollar, Peruvian sol, Chilean peso and euro. We recognized foreign currency translation gains on balances denominated in foreign currencies totaling $34 million in 2020 and $24 million in 2019. Generally, our operating results are positively affected when the U.S. dollar strengthens in relation to those foreign currencies and are adversely affected when the U.S. dollar weakens in relation to those foreign currencies.
Following is a summary of estimated annual payments and the impact of changes in foreign currency rates on our annual operating costs:
| Exchange Rate per $1 at December 31, | Estimated Annual Payments | 10% Change in Exchange Rate (in millions of U.S. dollars)a | |||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | (in local currency) | (in millions of U.S. dollars)b | Increase | Decrease | ||||||||||||||||||||||||||||||||||||
| Indonesia | |||||||||||||||||||||||||||||||||||||||||
| Rupiah | 14,034 | 13,832 | 11.9 trillion | $ | 848 | $ | (77) | $ | 94 | ||||||||||||||||||||||||||||||||
| Australian dollar | 1.30 | 1.43 | 195 million | $ | 150 | $ | (14) | $ | 17 | ||||||||||||||||||||||||||||||||
| South America | |||||||||||||||||||||||||||||||||||||||||
| Peruvian sol | 3.62 | 3.32 | 2.1 billion | $ | 573 | $ | (52) | $ | 64 | ||||||||||||||||||||||||||||||||
| Chilean peso | 711 | 749 | 175 billion | $ | 246 | $ | (22) | $ | 27 | ||||||||||||||||||||||||||||||||
| Atlantic Copper | |||||||||||||||||||||||||||||||||||||||||
| Euro | 0.82 | 0.89 | 138 million | $ | 169 | $ | (15) | $ | 19 |
a.Reflects the estimated impact on annual operating costs assuming a 10 percent increase or decrease in the exchange rate reported at December 31, 2020.
b.Based on exchange rates at December 31, 2020.
Interest Rate Risk
At December 31, 2020, we had total debt maturities based on principal amounts of $9.8 billion, of which approximately 6 percent was variable-rate debt with interest rates primarily based on the London Interbank Offered Rate. The table below presents average interest rates for our scheduled maturities of principal for our outstanding debt and the related fair values at December 31, 2020 (in millions, except percentages):
| 2021 | 2022 | 2023 | 2024 | 2025 | Thereafter | Fair Value | |||||||||||||||||||||||||||||||||||
| Fixed-rate debt | $ | 4 | $ | 524 | $ | 996 | $ | 730 | $ | — | $ | 6,963 | $ | 10,428 | |||||||||||||||||||||||||||
| Average interest rate | — | % | 3.6 | % | 3.9 | % | 4.6 | % | — | % | 5.1 | % | 4.9 | % | |||||||||||||||||||||||||||
| Variable-rate debt | $ | 32 | $ | 529 | $ | — | $ | — | $ | — | $ | 8 | $ | 566 | |||||||||||||||||||||||||||
| Average interest rate | 1.2 | % | 2.0 | % | — | % | — | % | — | % | 3.8 | % | 2.0 | % |
NEW ACCOUNTING STANDARDS
Refer to Note 1 for discussion of a recently adopted accounting standard.
PRODUCT REVENUES AND PRODUCTION COSTS
Mining Product Revenues and Unit Net Cash Costs
Unit net cash costs per pound of copper and molybdenum are measures intended to provide investors with information about the cash-generating capacity of our mining operations expressed on a basis relating to the primary metal product for the respective operations. We use this measure for the same purpose and for monitoring operating performance by our mining operations. This information differs from measures of performance determined in accordance with U.S. GAAP and should not be considered in isolation or as a substitute for measures of performance determined in accordance with U.S. GAAP. These measures are presented by other metals mining companies, although our measures may not be comparable to similarly titled measures reported by other companies.
We present gross profit per pound of copper in the following tables using both a “by-product” method and a “co-product” method. We use the by-product method in our presentation of gross profit per pound of copper because (i) the majority of our revenues are copper revenues, (ii) we mine ore, which contains copper, gold, molybdenum and other metals, (iii) it is not possible to specifically assign all of our costs to revenues from the copper, gold, molybdenum and other metals we produce, (iv) it is the method used to compare mining operations in certain industry publications and (v) it is the method used by our management and the Board to monitor operations and to compare mining operations in certain industry publications. In the co-product method presentations, shared costs are allocated to the different products based on their relative revenue values, which will vary to the extent our metals sales volumes and realized prices change.
We show revenue adjustments for prior period open sales as separate line items. Because these adjustments do not result from current period sales, these amounts have been reflected separately from revenues on current period sales. Noncash and other costs, which are removed from site production and delivery costs in the calculation of unit net cash costs, consist of items such as stock-based compensation costs, start-up costs, inventory adjustments, long-lived asset impairments, restructuring and/or unusual charges. As discussed above, gold, molybdenum and other metal revenues at copper mines are reflected as credits against site production and delivery costs in the by-product method. The following schedules are presentations under both the by-product and co-product methods together with reconciliations to amounts reported in our consolidated financial statements.
North America Copper Mines Product Revenues, Production Costs and Unit Net Cash Costs
| Year Ended December 31, 2020 | ||||||||||||||||||||||||||||||||
| (In millions) | By-Product | Co-Product Method | ||||||||||||||||||||||||||||||
| Method | Copper | Molybdenuma | Otherb | Total | ||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 4,005 | c | $ | 4,005 | $ | 281 | $ | 83 | $ | 4,369 | |||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 2,700 | 2,529 | 223 | 44 | 2,796 | |||||||||||||||||||||||||||
| By-product credits | (268) | — | — | — | — | |||||||||||||||||||||||||||
| Treatment charges | 139 | 136 | — | 3 | 139 | |||||||||||||||||||||||||||
| Net cash costs | 2,571 | 2,665 | 223 | 47 | 2,935 | |||||||||||||||||||||||||||
| DD&A | 355 | 330 | 18 | 7 | 355 | |||||||||||||||||||||||||||
| Metals inventory adjustments | 52 | 49 | — | 3 | 52 | |||||||||||||||||||||||||||
| Noncash and other costs, net | 138 | d | 133 | 3 | 2 | 138 | ||||||||||||||||||||||||||
| Total costs | 3,116 | 3,177 | 244 | 59 | 3,480 | |||||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | (22) | (22) | — | — | (22) | |||||||||||||||||||||||||||
| Gross profit | $ | 867 | $ | 806 | $ | 37 | $ | 24 | $ | 867 | ||||||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 1,420 | 1,420 | ||||||||||||||||||||||||||||||
| Molybdenum sales (millions of recoverable pounds)a | 33 | |||||||||||||||||||||||||||||||
| Gross profit per pound of copper/molybdenum: | ||||||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 2.82 | c | $ | 2.82 | $ | 8.62 | |||||||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 1.90 | 1.78 | 6.84 | |||||||||||||||||||||||||||||
| By-product credits | (0.19) | — | — | |||||||||||||||||||||||||||||
| Treatment charges | 0.10 | 0.10 | — | |||||||||||||||||||||||||||||
| Unit net cash costs | 1.81 | 1.88 | 6.84 | |||||||||||||||||||||||||||||
| DD&A | 0.25 | 0.23 | 0.56 | |||||||||||||||||||||||||||||
| Metals inventory adjustments | 0.03 | 0.03 | — | |||||||||||||||||||||||||||||
| Noncash and other costs, net | 0.10 | d | 0.10 | 0.09 | ||||||||||||||||||||||||||||
| Total unit costs | 2.19 | 2.24 | 7.49 | |||||||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | (0.02) | (0.02) | — | |||||||||||||||||||||||||||||
| Gross profit per pound | $ | 0.61 | $ | 0.56 | $ | 1.13 | ||||||||||||||||||||||||||
| Reconciliation to Amounts Reported | ||||||||||||||||||||||||||||||||
| Metals | ||||||||||||||||||||||||||||||||
| Production | Inventory | |||||||||||||||||||||||||||||||
| Revenues | and Delivery | DD&A | Adjustments | |||||||||||||||||||||||||||||
| Totals presented above | $ | 4,369 | $ | 2,796 | $ | 355 | $ | 52 | ||||||||||||||||||||||||
| Treatment charges | (15) | 124 | — | — | ||||||||||||||||||||||||||||
| Noncash and other costs, net | — | 138 | — | — | ||||||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | (22) | — | — | — | ||||||||||||||||||||||||||||
| Eliminations and other | 32 | 42 | — | — | ||||||||||||||||||||||||||||
| North America copper mines | 4,364 | 3,100 | 355 | 52 | ||||||||||||||||||||||||||||
| Other mininge | 13,642 | 10,595 | 1,103 | 16 | ||||||||||||||||||||||||||||
| Corporate, other & eliminations | (3,808) | (3,664) | 70 | 28 | ||||||||||||||||||||||||||||
| As reported in our consolidated financial statements | $ | 14,198 | $ | 10,031 | $ | 1,528 | $ | 96 |
a.Reflects sales of molybdenum produced by certain of the North America copper mines to our molybdenum sales company at market-based pricing.
b.Includes gold and silver product revenues and production costs.
c.Includes reductions to revenues and average realized prices totaling $24 million ($0.02 per pound of copper) related to forward sales contracts covering 150 million pounds of copper sales for May and June 2020 at a fixed price of $2.34 per pound.
d.Includes charges totaling $32 million ($0.02 per pound of copper) primarily associated with our April 2020 revised operating plans (including employee separation costs) and the COVID-19 pandemic (including health and safety costs).
e.Represents the combined total for our other mining operations as presented in Note 16.
North America Copper Mines Product Revenues, Production Costs and Unit Net Cash Costs
| Year Ended December 31, 2019 | ||||||||||||||||||||||||||||||||
| (In millions) | By-Product | Co-Product Method | ||||||||||||||||||||||||||||||
| Method | Copper | Molybdenuma | Otherb | Total | ||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3,950 | $ | 3,950 | $ | 370 | $ | 84 | $ | 4,404 | ||||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 2,957 | 2,711 | 299 | 53 | 3,063 | |||||||||||||||||||||||||||
| By-product credits | (348) | — | — | — | — | |||||||||||||||||||||||||||
| Treatment charges | 161 | 155 | — | 6 | 161 | |||||||||||||||||||||||||||
| Net cash costs | 2,770 | 2,866 | 299 | 59 | 3,224 | |||||||||||||||||||||||||||
| DD&A | 348 | 318 | 23 | 7 | 348 | |||||||||||||||||||||||||||
| Metals inventory adjustments | 30 | 30 | — | — | 30 | |||||||||||||||||||||||||||
| Noncash and other costs, net | 110 | 98 | 9 | 3 | 110 | |||||||||||||||||||||||||||
| Total costs | 3,258 | 3,312 | 331 | 69 | 3,712 | |||||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | 4 | 4 | — | — | 4 | |||||||||||||||||||||||||||
| Gross profit | $ | 696 | $ | 642 | $ | 39 | $ | 15 | $ | 696 | ||||||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 1,441 | 1,441 | ||||||||||||||||||||||||||||||
| Molybdenum sales (millions of recoverable pounds)a | 32 | |||||||||||||||||||||||||||||||
| Gross profit per pound of copper/molybdenum: | ||||||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 2.74 | $ | 2.74 | $ | 11.51 | ||||||||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 2.05 | 1.88 | 9.29 | |||||||||||||||||||||||||||||
| By-product credits | (0.24) | — | — | |||||||||||||||||||||||||||||
| Treatment charges | 0.11 | 0.11 | — | |||||||||||||||||||||||||||||
| Unit net cash costs | 1.92 | 1.99 | 9.29 | |||||||||||||||||||||||||||||
| DD&A | 0.24 | 0.21 | 0.72 | |||||||||||||||||||||||||||||
| Metals inventory adjustments | 0.02 | 0.02 | — | |||||||||||||||||||||||||||||
| Noncash and other costs, net | 0.08 | 0.07 | 0.29 | |||||||||||||||||||||||||||||
| Total unit costs | 2.26 | 2.29 | 10.30 | |||||||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | — | — | — | |||||||||||||||||||||||||||||
| Gross profit per pound | $ | 0.48 | $ | 0.45 | $ | 1.21 | ||||||||||||||||||||||||||
| Reconciliation to Amounts Reported | ||||||||||||||||||||||||||||||||
| Metals | ||||||||||||||||||||||||||||||||
| Production | Inventory | |||||||||||||||||||||||||||||||
| Revenues | and Delivery | DD&A | Adjustments | |||||||||||||||||||||||||||||
| Totals presented above | $ | 4,404 | $ | 3,063 | $ | 348 | $ | 30 | ||||||||||||||||||||||||
| Treatment charges | (60) | 101 | — | — | ||||||||||||||||||||||||||||
| Noncash and other costs, net | — | 110 | — | — | ||||||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | 4 | — | — | — | ||||||||||||||||||||||||||||
| Eliminations and other | 38 | 45 | 1 | — | ||||||||||||||||||||||||||||
| North America copper mines | 4,386 | 3,319 | 349 | 30 | ||||||||||||||||||||||||||||
| Other miningc | 13,054 | 11,126 | 979 | 57 | ||||||||||||||||||||||||||||
| Corporate, other & eliminations | (3,038) | (2,911) | 84 | 92 | ||||||||||||||||||||||||||||
| As reported in our consolidated financial statements | $ | 14,402 | $ | 11,534 | $ | 1,412 | $ | 179 |
a.Reflects sales of molybdenum produced by certain of the North America copper mines to our molybdenum sales company at market-based pricing.
b.Includes gold and silver product revenues and production costs.
c.Represents the combined total for our other mining operations as presented in Note 16.
South America Mining Product Revenues, Production Costs and Unit Net Cash Costs
| Year Ended December 31, 2020 | |||||||||||||||||||||||
| (In millions) | By-Product | Co-Product Method | |||||||||||||||||||||
| Method | Copper | Othera | Total | ||||||||||||||||||||
| Revenues, excluding adjustments | $ | 2,976 | $ | 2,976 | $ | 209 | $ | 3,185 | |||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 1,816 | 1,701 | 158 | 1,859 | |||||||||||||||||||
| By-product credits | (166) | — | — | — | |||||||||||||||||||
| Treatment charges | 152 | 152 | — | 152 | |||||||||||||||||||
| Royalty on metals | 6 | 6 | — | 6 | |||||||||||||||||||
| Net cash costs | 1,808 | 1,859 | 158 | 2,017 | |||||||||||||||||||
| DD&A | 421 | 391 | 30 | 421 | |||||||||||||||||||
| Metals inventory adjustments | 3 | 3 | — | 3 | |||||||||||||||||||
| Noncash and other costs, net | 122 | b | 115 | 7 | 122 | ||||||||||||||||||
| Total costs | 2,354 | 2,368 | 195 | 2,563 | |||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | (70) | (70) | — | (70) | |||||||||||||||||||
| Gross profit | $ | 552 | $ | 538 | $ | 14 | $ | 552 | |||||||||||||||
| Copper sales (millions of recoverable pounds) | 976 | 976 | |||||||||||||||||||||
| Gross profit per pound of copper: | |||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3.05 | $ | 3.05 | |||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 1.86 | 1.74 | |||||||||||||||||||||
| By-product credits | (0.17) | — | |||||||||||||||||||||
| Treatment charges | 0.15 | 0.15 | |||||||||||||||||||||
| Royalty on metals | 0.01 | 0.01 | |||||||||||||||||||||
| Unit net cash costs | 1.85 | 1.90 | |||||||||||||||||||||
| DD&A | 0.43 | 0.41 | |||||||||||||||||||||
| Metals inventory adjustments | — | — | |||||||||||||||||||||
| Noncash and other costs, net | 0.13 | b | 0.12 | ||||||||||||||||||||
| Total unit costs | 2.41 | 2.43 | |||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | (0.07) | (0.07) | |||||||||||||||||||||
| Gross profit per pound | $ | 0.57 | $ | 0.55 | |||||||||||||||||||
| Reconciliation to Amounts Reported | |||||||||||||||||||||||
| Metals | |||||||||||||||||||||||
| Production | Inventory | ||||||||||||||||||||||
| Revenues | and Delivery | DD&A | Adjustments | ||||||||||||||||||||
| Totals presented above | $ | 3,185 | $ | 1,859 | $ | 421 | $ | 3 | |||||||||||||||
| Treatment charges | (152) | — | — | — | |||||||||||||||||||
| Royalty on metals | (6) | — | — | — | |||||||||||||||||||
| Noncash and other costs, net | — | 122 | — | — | |||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | (70) | — | — | — | |||||||||||||||||||
| Eliminations and other | (2) | (3) | — | — | |||||||||||||||||||
| South America mining | 2,955 | 1,978 | 421 | 3 | |||||||||||||||||||
| Other miningc | 15,051 | 11,717 | 1,037 | 65 | |||||||||||||||||||
| Corporate, other & eliminations | (3,808) | (3,664) | 70 | 28 | |||||||||||||||||||
| As reported in our consolidated financial statements | $ | 14,198 | $ | 10,031 | $ | 1,528 | $ | 96 |
a.Includes silver sales of 3.4 million ounces ($21.86 per ounce average realized price). Also reflects sales of molybdenum produced by Cerro Verde to our molybdenum sales company at market-based pricing.
b.Includes charges totaling $91 million ($0.09 per pound of copper) primarily associated with idle facility (Cerro Verde) and contract cancellation costs related to the COVID-19 pandemic, and employee separation costs associated with our April 2020 revised operating plans.
c.Represents the combined total for our other mining operations as presented in Note 16.
South America Mining Product Revenues, Production Costs and Unit Net Cash Costs
| Year Ended December 31, 2019 | |||||||||||||||||||||||
| (In millions) | By-Product | Co-Product Method | |||||||||||||||||||||
| Method | Copper | Othera | Total | ||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3,213 | $ | 3,213 | $ | 358 | $ | 3,571 | |||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 2,185 | 1,991 | 245 | 2,236 | |||||||||||||||||||
| By-product credits | (307) | — | — | — | |||||||||||||||||||
| Treatment charges | 212 | 212 | — | 212 | |||||||||||||||||||
| Royalty on metals | 7 | 6 | 1 | 7 | |||||||||||||||||||
| Net cash costs | 2,097 | 2,209 | 246 | 2,455 | |||||||||||||||||||
| DD&A | 474 | 427 | 47 | 474 | |||||||||||||||||||
| Metals inventory adjustments | 2 | 2 | — | 2 | |||||||||||||||||||
| Noncash and other costs, net | 94 | 90 | 4 | 94 | |||||||||||||||||||
| Total costs | 2,667 | 2,728 | 297 | 3,025 | |||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | 37 | 37 | — | 37 | |||||||||||||||||||
| Gross profit | $ | 583 | $ | 522 | $ | 61 | $ | 583 | |||||||||||||||
| Copper sales (millions of recoverable pounds) | 1,183 | 1,183 | |||||||||||||||||||||
| Gross profit per pound of copper: | |||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 2.71 | $ | 2.71 | |||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 1.85 | 1.68 | |||||||||||||||||||||
| By-product credits | (0.27) | — | |||||||||||||||||||||
| Treatment charges | 0.18 | 0.18 | |||||||||||||||||||||
| Royalty on metals | 0.01 | 0.01 | |||||||||||||||||||||
| Unit net cash costs | 1.77 | 1.87 | |||||||||||||||||||||
| DD&A | 0.40 | 0.36 | |||||||||||||||||||||
| Metals inventory adjustments | — | — | |||||||||||||||||||||
| Noncash and other costs, net | 0.08 | 0.07 | |||||||||||||||||||||
| Total unit costs | 2.25 | 2.30 | |||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | 0.03 | 0.03 | |||||||||||||||||||||
| Gross profit per pound | $ | 0.49 | $ | 0.44 | |||||||||||||||||||
| Reconciliation to Amounts Reported | |||||||||||||||||||||||
| Metals | |||||||||||||||||||||||
| Production | Inventory | ||||||||||||||||||||||
| Revenues | and Delivery | DD&A | Adjustments | ||||||||||||||||||||
| Totals presented above | $ | 3,571 | $ | 2,236 | $ | 474 | $ | 2 | |||||||||||||||
| Treatment charges | (212) | — | — | — | |||||||||||||||||||
| Royalty on metals | (7) | — | — | — | |||||||||||||||||||
| Noncash and other costs, net | — | 94 | — | — | |||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | 37 | — | — | — | |||||||||||||||||||
| Eliminations and other | (1) | (4) | — | — | |||||||||||||||||||
| South America mining | 3,388 | 2,326 | 474 | 2 | |||||||||||||||||||
| Other miningb | 14,052 | 12,119 | 854 | 85 | |||||||||||||||||||
| Corporate, other & eliminations | (3,038) | (2,911) | 84 | 92 | |||||||||||||||||||
| As reported in our consolidated financial statements | $ | 14,402 | $ | 11,534 | $ | 1,412 | $ | 179 |
a.Includes silver sales of 4.7 million ounces ($16.57 per ounce average realized price). Also reflects sales of molybdenum produced by Cerro Verde to our molybdenum sales company at market-based pricing.
b.Represents the combined total for our other mining operations as presented in Note 16.
Indonesia Mining Product Revenues, Production Costs and Unit Net Cash Costs
| Year Ended December 31, 2020 | |||||||||||||||||||||||||||||
| (In millions) | By-Product | Co-Product Method | |||||||||||||||||||||||||||
| Method | Copper | Gold | Silvera | Total | |||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 2,475 | $ | 2,475 | $ | 1,545 | $ | 81 | $ | 4,101 | |||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 1,508 | 910 | 568 | 30 | 1,508 | ||||||||||||||||||||||||
| Gold and silver credits | (1,630) | — | — | — | — | ||||||||||||||||||||||||
| Treatment charges | 219 | 132 | 83 | 4 | 219 | ||||||||||||||||||||||||
| Export duties | 93 | 56 | 35 | 2 | 93 | ||||||||||||||||||||||||
| Royalty on metals | 153 | 90 | 60 | 3 | 153 | ||||||||||||||||||||||||
| Net cash costs | 343 | 1,188 | 746 | 39 | 1,973 | ||||||||||||||||||||||||
| DD&A | 580 | 350 | 219 | 11 | 580 | ||||||||||||||||||||||||
| Noncash and other costs, net | 93 | b | 56 | 35 | 2 | 93 | |||||||||||||||||||||||
| Total costs | 1,016 | 1,594 | 1,000 | 52 | 2,646 | ||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | (20) | (20) | 4 | — | (16) | ||||||||||||||||||||||||
| PT Smelting intercompany loss | (11) | (7) | (4) | — | (11) | ||||||||||||||||||||||||
| Gross profit | $ | 1,428 | $ | 854 | $ | 545 | $ | 29 | $ | 1,428 | |||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 804 | 804 | |||||||||||||||||||||||||||
| Gold sales (thousands of recoverable ounces) | 842 | ||||||||||||||||||||||||||||
| Gross profit per pound of copper/per ounce of gold: | |||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3.08 | $ | 3.08 | $ | 1,832 | |||||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 1.88 | 1.13 | 674 | ||||||||||||||||||||||||||
| Gold and silver credits | (2.03) | — | — | ||||||||||||||||||||||||||
| Treatment charges | 0.27 | 0.17 | 98 | ||||||||||||||||||||||||||
| Export duties | 0.12 | 0.07 | 41 | ||||||||||||||||||||||||||
| Royalty on metals | 0.19 | 0.11 | 72 | ||||||||||||||||||||||||||
| Unit net cash costs | 0.43 | 1.48 | 885 | ||||||||||||||||||||||||||
| DD&A | 0.72 | 0.43 | 259 | ||||||||||||||||||||||||||
| Noncash and other costs, net | 0.11 | b | 0.07 | 41 | |||||||||||||||||||||||||
| Total unit costs | 1.26 | 1.98 | 1,185 | ||||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | (0.03) | (0.03) | 5 | ||||||||||||||||||||||||||
| PT Smelting intercompany loss | (0.01) | (0.01) | (5) | ||||||||||||||||||||||||||
| Gross profit per pound/ounce | $ | 1.78 | $ | 1.06 | $ | 647 | |||||||||||||||||||||||
| Reconciliation to Amounts Reported | |||||||||||||||||||||||||||||
| Production | |||||||||||||||||||||||||||||
| Revenues | and Delivery | DD&A | |||||||||||||||||||||||||||
| Totals presented above | $ | 4,101 | $ | 1,508 | $ | 580 | |||||||||||||||||||||||
| Treatment charges | (219) | — | — | ||||||||||||||||||||||||||
| Export duties | (93) | — | — | ||||||||||||||||||||||||||
| Royalty on metals | (153) | — | — | ||||||||||||||||||||||||||
| Noncash and other costs, net | (6) | 87 | — | ||||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | (16) | — | — | ||||||||||||||||||||||||||
| PT Smelting intercompany loss | — | 11 | — | ||||||||||||||||||||||||||
| Indonesia mining | 3,614 | 1,606 | 580 | ||||||||||||||||||||||||||
| Other miningc | 14,392 | 12,089 | 878 | ||||||||||||||||||||||||||
| Corporate, other & eliminations | (3,808) | (3,664) | 70 | ||||||||||||||||||||||||||
| As reported in our consolidated financial statements | $ | 14,198 | $ | 10,031 | $ | 1,528 |
a.Includes silver sales of 3.6 million ounces ($22.40 per ounce average realized price).
b.Includes COVID-19 related costs (including one-time incremental employee benefits and health and safety costs) of $14 million ($0.02 per pound of copper).
c.Represents the combined total for our other mining operations as presented in Note 16.
Indonesia Mining Product Revenues, Production Costs and Unit Net Cash Costs
| Year Ended December 31, 2019 | |||||||||||||||||||||||||||||
| (In millions) | By-Product | Co-Product Method | |||||||||||||||||||||||||||
| Method | Copper | Gold | Silvera | Total | |||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 1,814 | $ | 1,814 | $ | 1,378 | $ | 40 | $ | 3,232 | |||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 1,938 | 1,088 | 826 | 24 | 1,938 | ||||||||||||||||||||||||
| Gold and silver credits | (1,419) | — | — | — | — | ||||||||||||||||||||||||
| Treatment charges | 171 | 96 | 73 | 2 | 171 | ||||||||||||||||||||||||
| Export duties | 56 | 31 | 24 | 1 | 56 | ||||||||||||||||||||||||
| Royalty on metals | 107 | 58 | 48 | 1 | 107 | ||||||||||||||||||||||||
| Net cash costs | 853 | 1,273 | 971 | 28 | 2,272 | ||||||||||||||||||||||||
| DD&A | 406 | 228 | 173 | 5 | 406 | ||||||||||||||||||||||||
| Metals inventory adjustments | 5 | 5 | — | — | 5 | ||||||||||||||||||||||||
| Noncash and other costs, net | 246 | b | 136 | 107 | 3 | 246 | |||||||||||||||||||||||
| Total costs | 1,510 | 1,642 | 1,251 | 36 | 2,929 | ||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | 18 | 18 | 1 | — | 19 | ||||||||||||||||||||||||
| PT Smelting intercompany loss | (17) | (10) | (7) | — | (17) | ||||||||||||||||||||||||
| Gross profit | $ | 305 | $ | 180 | $ | 121 | $ | 4 | $ | 305 | |||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 667 | 667 | |||||||||||||||||||||||||||
| Gold sales (thousands of recoverable ounces) | 973 | ||||||||||||||||||||||||||||
| Gross profit per pound of copper/per ounce of gold: | |||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 2.72 | $ | 2.72 | $ | 1,416 | |||||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 2.91 | 1.63 | 849 | ||||||||||||||||||||||||||
| Gold and silver credits | (2.13) | — | — | ||||||||||||||||||||||||||
| Treatment charges | 0.26 | 0.14 | 75 | ||||||||||||||||||||||||||
| Export duties | 0.08 | 0.05 | 25 | ||||||||||||||||||||||||||
| Royalty on metals | 0.16 | 0.09 | 49 | ||||||||||||||||||||||||||
| Unit net cash costs | 1.28 | 1.91 | 998 | ||||||||||||||||||||||||||
| DD&A | 0.61 | 0.34 | 178 | ||||||||||||||||||||||||||
| Metals inventory adjustments | 0.01 | 0.01 | — | ||||||||||||||||||||||||||
| Noncash and other costs, net | 0.37 | b | 0.20 | 110 | |||||||||||||||||||||||||
| Total unit costs | 2.27 | 2.46 | 1,286 | ||||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | 0.03 | 0.03 | 2 | ||||||||||||||||||||||||||
| PT Smelting intercompany loss | (0.02) | (0.02) | (8) | ||||||||||||||||||||||||||
| Gross profit per pound/ounce | $ | 0.46 | $ | 0.27 | $ | 124 | |||||||||||||||||||||||
| Reconciliation to Amounts Reported | |||||||||||||||||||||||||||||
| Metals | |||||||||||||||||||||||||||||
| Production | Inventory | ||||||||||||||||||||||||||||
| Revenues | and Delivery | DD&A | Adjustments | ||||||||||||||||||||||||||
| Totals presented above | $ | 3,232 | $ | 1,938 | $ | 406 | $ | 5 | |||||||||||||||||||||
| Treatment charges | (171) | — | — | — | |||||||||||||||||||||||||
| Export duties | (56) | — | — | — | |||||||||||||||||||||||||
| Royalty on metals | (107) | — | — | — | |||||||||||||||||||||||||
| Noncash and other costs, net | (146) | 100 | — | — | |||||||||||||||||||||||||
| Other revenue adjustments, primarily for pricing on prior period open sales | 19 | — | — | — | |||||||||||||||||||||||||
| PT Smelting intercompany loss | — | 17 | — | — | |||||||||||||||||||||||||
| Indonesia mining | 2,771 | 2,055 | 406 | 5 | |||||||||||||||||||||||||
| Other miningc | 14,669 | 12,390 | 922 | 82 | |||||||||||||||||||||||||
| Corporate, other & eliminations | (3,038) | (2,911) | 84 | 92 | |||||||||||||||||||||||||
| As reported in our consolidated financial statements | $ | 14,402 | $ | 11,534 | $ | 1,412 | $ | 179 |
a.Includes silver sales of 2.5 million ounces ($16.15 per ounce average realized price).
b.Includes charges in revenues totaling $166 million ($0.25 per pound of copper), primarily associated with an unfavorable Indonesia Supreme Court ruling related to certain disputed PT-FI export duties, partly offset by adjustments to prior year treatment charges totaling $20 million ($0.03 per pound of copper). Also includes charges of $28 million ($0.04 per pound of copper) associated with adjustments to the settlement of the historical surface water tax disputes with the local regional tax authority in Papua, Indonesia.
c.Represents the combined total for our other mining operations as presented in Note 16.
Molybdenum Mines Product Revenues, Production Costs and Unit Net Cash Costs
| Years Ended December 31, | ||||||||||||||||||||||||||
| (In millions) | 2020 | 2019 | ||||||||||||||||||||||||
| Revenues, excluding adjustmentsa | $ | 243 | $ | 369 | ||||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 211 | 293 | ||||||||||||||||||||||||
| Treatment charges and other | 21 | 25 | ||||||||||||||||||||||||
| Net cash costs | 232 | 318 | ||||||||||||||||||||||||
| DD&A | 57 | 62 | ||||||||||||||||||||||||
| Metals inventory adjustments | 10 | 50 | ||||||||||||||||||||||||
| Noncash and other costs, net | 19 | b | 6 | |||||||||||||||||||||||
| Total costs | 318 | 436 | ||||||||||||||||||||||||
| Gross loss | $ | (75) | $ | (67) | ||||||||||||||||||||||
| Molybdenum sales (millions of recoverable pounds)a | 24 | 29 | ||||||||||||||||||||||||
| Gross loss per pound of molybdenum: | ||||||||||||||||||||||||||
| Revenues, excluding adjustmentsa | $ | 9.94 | $ | 12.51 | ||||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 8.65 | 9.95 | ||||||||||||||||||||||||
| Treatment charges and other | 0.85 | 0.85 | ||||||||||||||||||||||||
| Unit net cash costs | 9.50 | 10.80 | ||||||||||||||||||||||||
| DD&A | 2.34 | 2.11 | ||||||||||||||||||||||||
| Metals inventory adjustments | 0.42 | 1.69 | ||||||||||||||||||||||||
| Noncash and other costs, net | 0.75 | b | 0.20 | |||||||||||||||||||||||
| Total unit costs | 13.01 | 14.80 | ||||||||||||||||||||||||
| Gross loss | $ | (3.07) | $ | (2.29) | ||||||||||||||||||||||
| Reconciliation to Amounts Reported | ||||||||||||||||||||||||||
| Metals | ||||||||||||||||||||||||||
| Production | Inventory | |||||||||||||||||||||||||
| Year Ended December 31, 2020 | Revenues | and Delivery | DD&A | Adjustments | ||||||||||||||||||||||
| Totals presented above | $ | 243 | $ | 211 | $ | 57 | $ | 10 | ||||||||||||||||||
| Treatment charges and other | (21) | — | — | — | ||||||||||||||||||||||
| Noncash and other costs, net | — | 19 | — | — | ||||||||||||||||||||||
| Molybdenum mines | 222 | 230 | 57 | 10 | ||||||||||||||||||||||
| Other miningc | 17,784 | 13,465 | 1,401 | 58 | ||||||||||||||||||||||
| Corporate, other & eliminations | (3,808) | (3,664) | 70 | 28 | ||||||||||||||||||||||
| As reported in our consolidated financial statements | $ | 14,198 | $ | 10,031 | $ | 1,528 | $ | 96 | ||||||||||||||||||
| Year Ended December 31, 2019 | ||||||||||||||||||||||||||
| Totals presented above | $ | 369 | $ | 293 | $ | 62 | $ | 50 | ||||||||||||||||||
| Treatment charges and other | (25) | — | — | — | ||||||||||||||||||||||
| Noncash and other costs, net | — | 6 | — | — | ||||||||||||||||||||||
| Molybdenum mines | 344 | 299 | 62 | 50 | ||||||||||||||||||||||
| Other miningc | 17,096 | 14,146 | 1,266 | 37 | ||||||||||||||||||||||
| Corporate, other & eliminations | (3,038) | (2,911) | 84 | 92 | ||||||||||||||||||||||
| As reported in our consolidated financial statements | $ | 14,402 | $ | 11,534 | $ | 1,412 | $ | 179 | ||||||||||||||||||
a.Reflects sales of the Molybdenum mines’ production to the molybdenum sales company at market-based pricing. On a consolidated basis, realizations are based on the actual contract terms for sales to third parties; as a result, our consolidated average realized price per pound of molybdenum will differ from the amounts reported in this table.
b.Includes charges totaling $7 million ($0.29 per pound of molybdenum) primarily associated with contract cancellation costs related to the COVID-19 pandemic and employee separation costs associated with April 2020 revised operating plans.
c.Represents the combined total for our other mining operations as presented in Note 16. Also includes amounts associated with the molybdenum sales company, which includes sales of molybdenum produced by the Molybdenum mines and by certain of the North America and South America copper mines.
GUARANTOR SUMMARIZED FINANCIAL INFORMATION
All of the senior notes issued by Freeport-McMoRan Inc. (FCX) are fully and unconditionally guaranteed on a senior basis jointly and severally by Freeport-McMoRan Oil & Gas LLC (FM O&G LLC), as guarantor, which is a 100-percent-owned subsidiary of FCX Oil & Gas LLC (FM O&G) and FCX. The guarantee is an unsecured obligation of the guarantor and ranks equal in right of payment with all existing and future indebtedness of FM O&G LLC, including indebtedness under our revolving credit facility. The guarantee ranks senior in right of payment with all of FM O&G LLC’s future subordinated obligations and is effectively subordinated in right of payment to any debt of FM O&G LLC’s subsidiaries. The indentures provide that FM O&G LLC’s guarantee obligations may be released or terminated upon: (i) the sale of all or substantially all of the equity interests or assets of FM O&G LLC to a third party that is not our subsidiary or our affiliate; (ii) FM O&G LLC no longer having any obligations under any FM O&G senior notes or any refinancing thereof and no longer being a co-borrower or guarantor of any of our obligations under the revolving credit facility or any other senior debt or, in each case, any refinancing thereof; or (iii) the discharge of our obligations under the indentures in accordance with their terms.
The following summarized financial data includes information regarding FCX, as issuer, FM O&G LLC, as guarantor, and all our other non-guarantor subsidiaries at December 31, 2020, and 2019, and for the year ended December 31, 2020.
| FCX | FM O&G LLC | Non-guarantor | Consolidated | |||||||||||||||||||||||||||||
| Issuer | Guarantor | Subsidiaries | Eliminations | FCX | ||||||||||||||||||||||||||||
| December 31, 2020 | ||||||||||||||||||||||||||||||||
| Current assets | $ | 65 | $ | 697 | $ | 9,287 | $ | (746) | $ | 9,303 | ||||||||||||||||||||||
| Noncurrent assets | 785 | 6 | 32,806 | (756) | 32,841 | |||||||||||||||||||||||||||
| Current liabilities | 187 | 31 | 3,964 | (765) | 3,417 | |||||||||||||||||||||||||||
| Noncurrent liabilities | 9,433 | 11,208 | 15,075 | (15,657) | 20,059 | |||||||||||||||||||||||||||
| December 31, 2019 | ||||||||||||||||||||||||||||||||
| Current assets | $ | 154 | $ | 657 | $ | 7,778 | $ | (674) | $ | 7,915 | ||||||||||||||||||||||
| Noncurrent assets | 1,620 | 22 | 32,692 | (1,440) | 32,894 | |||||||||||||||||||||||||||
| Current liabilities | 323 | 42 | 3,550 | (706) | 3,209 | |||||||||||||||||||||||||||
| Noncurrent liabilities | 9,180 | 10,892 | 15,975 | (15,895) | 20,152 | |||||||||||||||||||||||||||
| Year Ended December 31, 2020 | ||||||||||||||||||||||||||||||||
| Revenues | $ | — | $ | 26 | $ | 14,172 | $ | — | $ | 14,198 | ||||||||||||||||||||||
| Operating (loss) income | (30) | (10) | 2,489 | (12) | 2,437 | |||||||||||||||||||||||||||
| Net income (loss) | 599 | a | (302) | a | 865 | (297) | 865 |
a.Net income (loss) equals net income (loss) attributable to common stockholders because net income attributable to noncontrolling interests is zero for issuer and guarantor.
CAUTIONARY STATEMENT
Our discussion and analysis contains forward-looking statements in which we discuss our potential future performance. Forward-looking statements are all statements other than statements of historical facts, such as plans, projections, or expectations relating to ore grades and milling rates; business outlook; production and sales volumes; unit net cash costs; cash flows; capital expenditures; liquidity; operating costs; operating plans; our financial policy; our expectations regarding PT-FI’s ramp-up of underground mining activities and future cash flows through 2022; PT-FI's development, financing, construction and completion of a new smelter in Indonesia and possible expansion of the smelter at PT Smelting; our commitments to deliver responsibly produced copper, including plans to implement and validate all of our operating sites under specific frameworks; improvements in operating procedures and technology; exploration efforts and results; development and production activities, rates and costs; tax rates; export quotas and duties; the impact of copper, gold and molybdenum price changes; the impact of deferred intercompany profits on earnings; mineralization and reserve estimates; execution of the settlement agreements associated with the Louisiana coastal erosion cases and talc-related litigation; descriptions of our objectives, strategies, plans, goals or targets, including our net debt target, anticipated improvements in energy efficiency at certain operating sites, and environmental, social and governance (ESG) targets; and future dividend payments, share purchases and sales, including under the Board’s financial policy. The words “anticipates,” “may,” “can,” “plans,” “believes,” “estimates,” “expects,” “projects,” "targets," “intends,” “likely,” “will,” “should,” “could,” “to be,” ”potential," “assumptions,” “guidance,” “future” and any similar expressions are intended to identify those assertions as forward-looking statements. The declaration and payment of future dividends is at the discretion of the Board and will depend on our financial results, cash requirements, future prospects, global economic conditions, and other factors deemed relevant by the Board. In accordance with the June 2020 amendment to the revolving credit facility, we are currently restricted from declaring or paying common stock dividends through December 31, 2021. Prior to the Board’s declaration of the initial quarterly dividend, we will deliver a covenant reversion notice, which would eliminate the restriction on the declaration or payment of common stock dividends.
We caution readers that forward-looking statements are not guarantees of future performance and actual results may differ materially from those anticipated, expected, projected or assumed in the forward-looking statements. Important factors that can cause our actual results to differ materially from those anticipated in the forward-looking statements include, but are not limited to, changes in our credit rating; changes in our cash requirements, financial position, financing plans or investment plans; changes in general market, economic, tax, regulatory or industry conditions; the duration and scope of and uncertainties associated with the COVID-19 pandemic, and the impact thereof on commodity prices, our business and the global economy and any related actions taken by governments and businesses; our ability to contain and mitigate the risk of spread or major outbreak of COVID-19 at our operating sites, including at PT-FI’s remote operating site in Papua; supply of and demand for, and prices of, copper, gold and molybdenum; mine sequencing; changes in mine plans or operational modifications, delays, deferrals or cancellations; production rates; timing of shipments; results of feasibility studies; potential inventory adjustments; potential impairment of long-lived mining assets; the potential effects of violence in Indonesia generally and in the province of Papua; the Indonesia government's extension of PT-FI's export license after March 15, 2021; risks associated with underground mining; satisfaction of requirements in accordance with PT-FI's special mining license to extend mining rights from 2031 through 2041; the Indonesia government's approval of a deferred schedule for completion of the new smelter in Indonesia; expected results from improvements in operating procedures and technology, including innovation initiatives; industry risks; regulatory changes; political and social risks; labor relations, including labor-related work stoppages; weather- and climate-related risks; environmental risks; our plans and ability to implement ESG practices; litigation; cybersecurity incidents; changes in general market, economic and industry conditions; financial condition of our customers, suppliers, vendors, partners and affiliates, particularly during weak economic conditions and extended periods of volatile commodity prices; reductions in liquidity and access to capital; our ability to comply with our responsible production commitments under specific frameworks and any changes to such frameworks; and other factors described in more detail in Part I, Item 1A. “Risk Factors” of our annual report on Form 10-K for the year ended December 31, 2020.
Investors are cautioned that many of the assumptions upon which our forward-looking statements are based are likely to change after the forward-looking statements are made, including for example commodity prices, which we cannot control, and production volumes and costs, some aspects of which we may not be able to control. Further, we may make changes to our business plans that could affect our results. We caution investors that we do not intend to update forward-looking statements more frequently than quarterly notwithstanding any changes in our assumptions, changes in business plans, actual experience or other changes, and we undertake no obligation to update any forward-looking statements.
This annual report on Form 10-K for the year ended December 31, 2020, also contains the financial measure unit net cash costs per pound of copper and molybdenum, which is not recognized under U.S. GAAP. Refer to “Operations – Unit Net Cash Costs” for further discussion of unit net cash costs associated with our operating divisions, and to “Product Revenues and Production Costs” for reconciliations of per pound costs by operating division to production and delivery costs applicable to sales reported in our consolidated financial statements.
Previous: Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities. · Next: Item 8. Financial Statements and Supplementary Data.