 filings.tools
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
117K characters. Original on sec.gov · Markdown
Item 2. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
In Management’s Discussion and Analysis of Financial Condition and Results of Operations (MD&A), “we,” “us” and “our” refer to Freeport-McMoRan Inc. (FCX) and its consolidated subsidiaries. You should read this discussion in conjunction with our consolidated financial statements, the related MD&A and the discussion of our Business and Properties in our annual report on Form 10-K for the year ended December 31, 2021 (2021 Form 10-K), filed with the United States (U.S.) Securities and Exchange Commission (SEC). The results of operations reported and summarized below are not necessarily indicative of future operating results (refer to “Cautionary Statement” for further discussion). References to “Notes” are Notes included in our Notes to Consolidated Financial Statements (Unaudited). Throughout MD&A, all references to income or losses per share are on a diluted basis.
OVERVIEW
We are a leading international mining company with headquarters in Phoenix, Arizona. We operate large, long-lived, geographically diverse assets with significant proven and probable mineral reserves of copper, gold and molybdenum. We are one of the world’s largest publicly traded copper producers. Our portfolio of assets includes the Grasberg minerals district in Indonesia, one of the world’s largest copper and gold deposits; and significant mining operations in North America and South America, including the large-scale Morenci minerals district in Arizona and the Cerro Verde operation in Peru.
Our results for the third-quarter and first nine months of 2022 reflect strong production performance, with increased consolidated copper and gold production and sales volumes when compared to the prior year periods. Despite the decline in copper prices and current economic uncertainty, we continue to generate positive operating income and operating cash flows, although the decline in copper prices over the first nine months of 2022 and ongoing cost pressures have had a negative impact on our operating results. We believe the actions we have taken in recent years to build a solid balance sheet, successfully expand low-cost operations, and maintain flexible growth options while maintaining liquidity will allow us to continue to execute our business plans in a prudent manner, while preserving substantial future asset values.
The London Metal Exchange (LME) copper settlement price reached a high of $4.87 per pound in March 2022, supported by copper's increasingly important role in decarbonization technologies and limited mine supply. Beginning in June 2022, a series of macro-economic factors (including concerns about the global economy, Chinese economic data, European energy crisis, rising U.S. interest rates and currency exchange rates related to the strength of the U.S. dollar) led to a decline in copper prices. The LME copper settlement price declined to $3.74 per pound at June 30, 2022, and further declined during third-quarter 2022 to $3.47 per pound at September 30, 2022, and was $3.41 per pound on October 31, 2022. However, physical market fundamentals remain tight as evidenced by low levels of global exchange stocks. Our global customer base reports healthy demand for copper. Despite uncertain market conditions in the near-term, we believe the outlook for copper fundamentals in the medium- and long-term remains favorable, with studies indicating that demand for copper may double in 15 years based on the global movement towards decarbonization. We also believe substantial new mine supply development will be required to meet the goals of the global energy transition, and current prices for copper are insufficient to support new mine supply development, which is expected to add to future supply deficits.
Historically, copper prices have been correlated to various input costs, including energy and other commodity-related consumables. However, during 2022, prices for a number of commodity-related consumables have increased at a time when copper prices have declined. We believe a return to historical long-term correlation and improved supply chain conditions and labor markets, which have experienced limitations on available labor, would reduce costs and improve operational efficiencies. We plan to continue focusing on executing our operating plans to drive efficiencies that may help mitigate cost increases should they continue.
Our management team and global organization have substantial experience and success in executing under volatile market conditions and a challenging operating environment. We benefit from a diversified portfolio of operations with an attractive cost structure, long-lived reserves, optionality in our project pipeline and a solid balance sheet and strong liquidity position.
Net income attributable to common stockholders totaled $404 million in third-quarter 2022 and $2.8 billion for the first nine months of 2022, which were lower compared with $1.4 billion in third-quarter 2021 and $3.2 billion for the first nine months of 2021, primarily reflecting lower average realized copper prices and increased energy, supplies
and other input costs, partly offset by higher copper and gold sales volumes. Refer to “Consolidated Results” for further discussion.
At September 30, 2022, we had consolidated debt of $10.7 billion and consolidated cash and cash equivalents of $8.6 billion, resulting in net debt of $2.1 billion ($1.3 billion excluding net debt for the greenfield smelter and precious metals refinery (PMR) in Indonesia - collectively, the Indonesia smelter projects). Refer to “Net Debt” for reconciliations of consolidated debt and consolidated cash and cash equivalents to net debt.
At September 30, 2022, we had $3.5 billion of availability under our revolving credit facility, and PT Freeport Indonesia (PT-FI) and Cerro Verde had $1.3 billion and $350 million, respectively, of availability under their revolving credit facilities. In October 2022, we entered into a new $3.0 billion, five-year, unsecured revolving credit facility that replaced our prior $3.5 billion revolving credit facility.
Refer to Note 5 and “Capital Resources and Liquidity” for further discussion.
OUTLOOK
As further discussed in "Risk Factors" in Part I, Item 1A. of our 2021 Form 10-K, our financial results vary as a result of fluctuations in market prices primarily for copper, gold and, to a lesser extent, molybdenum, as well as other factors. World market prices for these commodities have fluctuated historically and are affected by numerous factors beyond our control. Copper prices, in particular, experienced a significant drop beginning in second-quarter 2022, which continued into third-quarter 2022. Refer to “Markets” below for further discussion. Despite uncertain market conditions in the near-term, we continue to believe the outlook for copper fundamentals in the medium- and long-term remains favorable. Because we cannot control the prices of our products, the key measures that management focuses on in operating our business are sales volumes, unit net cash costs, operating cash flows and capital expenditures.
Consolidated Sales Volumes
Following are our projected consolidated sales volumes for the year 2022:
| Copper (millions of recoverable pounds): | |||||||||||||||||
| North America copper mines | 1,471 | ||||||||||||||||
| South America mining | 1,150 | ||||||||||||||||
| Indonesia mining | 1,570 | ||||||||||||||||
| Total | 4,191 | ||||||||||||||||
| Gold (millions of recoverable ounces) | 1.8 | ||||||||||||||||
| Molybdenum (millions of recoverable pounds) | 76 | a | |||||||||||||||
a.Projected molybdenum sales include 46 million pounds produced by our North America and South America copper mines and 30 million pounds produced by our Molybdenum mines.
Consolidated sales volumes in fourth-quarter 2022 are expected to approximate 1.0 billion pounds of copper, 420 thousand ounces of gold and 20 million pounds of molybdenum. Projected sales volumes are dependent on operational performance, weather-related conditions, timing of shipments, and other factors detailed in the “Cautionary Statement” below.
For other important factors that could cause results to differ materially from projections, refer to “Risk Factors” contained in Part I, Item 1A. of our 2021 Form 10-K.
Consolidated Unit Net Cash Costs
Our operations continue to face significant cost pressures, including from high energy prices (which represent about 20 percent of our site operating costs), labor and costs for consumables such as sulfuric acid and explosives. Assuming average prices of $1,700 per ounce of gold and $18.00 per pound of molybdenum in fourth-quarter 2022 and achievement of current sales volume and cost estimates, consolidated unit net cash costs (net of by-product credits) for our copper mines are expected to average $1.55 per pound of copper for the year 2022 (including $1.68 per pound of copper in fourth-quarter 2022). The impact of price changes during fourth-quarter 2022 on consolidated unit net cash costs for the year 2022 would approximate $0.02 per pound of copper for each $100 per ounce change in the average price of gold and less than $0.01 per pound of copper for each $2.00 per pound
change in the average price of molybdenum. Quarterly unit net cash costs vary with fluctuations in sales volumes and realized prices, primarily for gold and molybdenum.
Consolidated Operating Cash Flows
Our consolidated operating cash flows vary with sales volumes; prices realized from copper, gold and molybdenum sales; production costs; income taxes; other working capital changes; and other factors. Based on current sales volume and cost estimates, and assuming average prices of $3.50 per pound for copper, $1,700 per ounce for gold, and $18.00 per pound for molybdenum in fourth-quarter 2022, our consolidated operating cash flows are estimated to approximate $4.7 billion (net of $1.4 billion of working capital and other uses) for the year 2022. Estimated consolidated operating cash flows for the year 2022 also reflect an estimated income tax provision of $2.1 billion (refer to “Consolidated Results – Income Taxes” for further discussion of our projected income tax rate for the year 2022). The impact of price changes during fourth-quarter 2022 on operating cash flows would approximate $100 million for each $0.10 per pound change in the average price of copper, $35 million for each $100 per ounce change in the average price of gold and $15 million for each $2.00 per pound change in the average price of molybdenum.
Consolidated Capital Expenditures
Capital expenditures are expected to approximate $3.6 billion for the year 2022 (including $1.8 billion for major mining projects and $0.9 billion for the Indonesia smelter projects). Projected capital expenditures for major mining projects include $1.4 billion for planned projects primarily associated with underground mine development in the Grasberg minerals district and supporting mill and power capital costs and $0.4 billion for discretionary growth projects (development of Kucing Liar and expansion projects at El Abra and Lone Star). We closely monitor market conditions and will continue to adjust our operating plans, including capital expenditures, to protect our liquidity and preserve our asset values, as necessary.
Capital expenditures for the Indonesia smelter projects are being funded with proceeds from PT-FI's senior notes and its available revolving credit facility. Construction of the additional domestic smelter capacity will result in the elimination of export duties, providing an offset to the economic cost associated with the Indonesia smelter projects. Based on current development progress of additional smelting capacity, PT-FI expects export duties to be reduced from the current rate of 5 percent to 2.5 percent by the end of 2022.
MARKETS
World prices for copper, gold and molybdenum can fluctuate significantly. During the period from January 2012 through September 2022, the LME copper settlement price varied from a low of $1.96 per pound in 2016 to a record high of $4.87 per pound in 2022; the London Bullion Market Association (London) PM gold price fluctuated from a low of $1,049 per ounce in 2015 to a record high of $2,067 per ounce in 2020; and the Metals Week Molybdenum Dealer Oxide weekly average price ranged from a low of $4.46 per pound in 2015 to a high of $20.01 per pound in 2021. Copper, gold and molybdenum prices are affected by numerous factors beyond our control as described further in “Risk Factors” contained in Part I, Item 1A. of our 2021 Form 10-K.
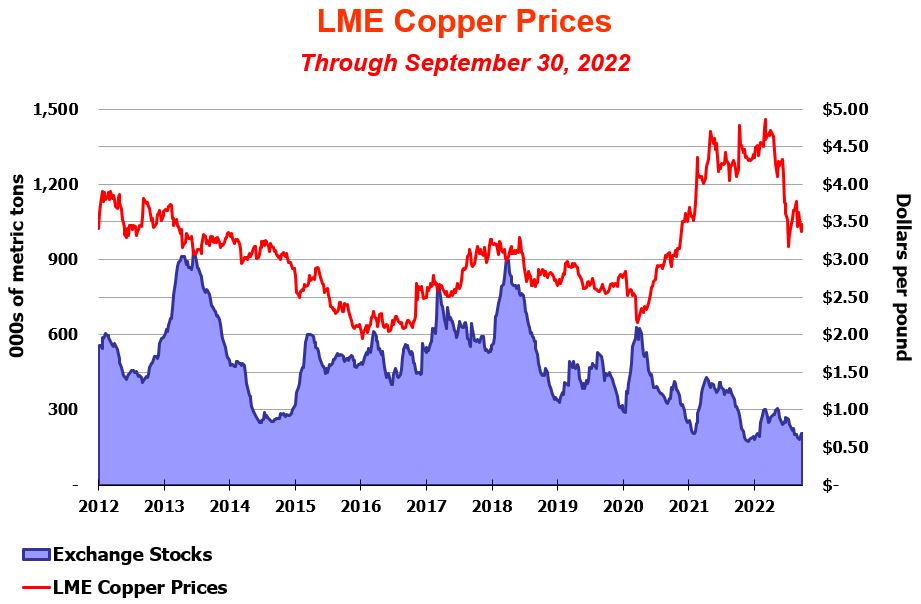
This graph presents LME copper settlement prices and the combined reported stocks of copper at the LME, Commodity Exchange Inc., and the Shanghai Futures Exchange from January 2012 through September 2022. During third-quarter 2022, LME copper settlement prices ranged from a low of $3.18 per pound to a high of $3.77 per pound, averaged $3.51 per pound and settled at $3.47 per pound on September 30, 2022. Beginning in June 2022, copper prices declined sharply and many analysts project that near-term copper prices will continue to be challenged by a series of macro-economic factors (including concerns about the global economy, Chinese economic data, European energy crisis as a result of Russia’s invasion of Ukraine, rising U.S. interest rates and currency exchange rates related to the strength of the U.S. dollar). However, physical market tightness continues to contrast with negative price sentiment in the copper market. The LME copper settlement price was $3.41 per pound on October 31, 2022.
We believe long-term fundamentals for copper remain positive. We continue to believe future demand will be supported by copper’s role in the global transition to renewable power, electric vehicles and other carbon-reduction initiatives, and continued urbanization in developing countries. The small number of approved, large-scale projects scheduled beyond those that have been announced, the long lead times required to permit and build new mines and declining ore grades at existing operations continue to highlight the fundamental supply challenges for copper.

This graph presents London PM gold prices from January 2012 through September 2022. During third-quarter 2022, London PM gold prices ranged from a low of $1,634 per ounce to a high of $1,808 per ounce, averaged $1,729 per ounce, and closed at $1,672 per ounce on September 30, 2022. The strength of the U.S. dollar and treasury yields resulting from expectations of additional interest rate increases by the U.S. Federal Reserve have negatively impacted gold prices. The London PM gold price was $1,639 per ounce on October 31, 2022.

This graph presents the Metals Week Molybdenum Dealer Oxide weekly average price from January 2012 through September 2022. During third-quarter 2022, the weekly average price of molybdenum ranged from a low of $14.10 per pound to a high of $18.37 per pound, averaged $16.20 per pound, and was $18.37 per pound on September 30, 2022. Higher molybdenum prices at the end of the quarter reflect tight supply and steady demand. The Metals Week Molybdenum Dealer Oxide weekly average price was $18.85 per pound on October 31, 2022.
CONSOLIDATED RESULTS
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||
| SUMMARY FINANCIAL DATA | (in millions, except per share amounts) | |||||||||||||||||||||||||
| Revenuesa,b | $ | 5,003 | $ | 6,083 | $ | 17,022 | $ | 16,681 | ||||||||||||||||||
| Operating incomea | $ | 962 | $ | 2,462 | $ | 5,507 | $ | 6,061 | ||||||||||||||||||
| Net income attributable to common stockc | $ | 404 | d | $ | 1,399 | e | $ | 2,771 | d | $ | 3,200 | e | ||||||||||||||
| Diluted net income per share of common stock | $ | 0.28 | $ | 0.94 | $ | 1.90 | $ | 2.16 | ||||||||||||||||||
| Diluted weighted-average shares of common stock outstanding | 1,439 | 1,484 | 1,455 | 1,481 | ||||||||||||||||||||||
| Operating cash flowsf | $ | 758 | $ | 1,965 | $ | 4,070 | $ | 5,435 | ||||||||||||||||||
| Capital expenditures | $ | 836 | $ | 541 | $ | 2,422 | $ | 1,344 | ||||||||||||||||||
| At September 30: | ||||||||||||||||||||||||||
| Cash and cash equivalents | $ | 8,578 | $ | 7,672 | $ | 8,578 | $ | 7,672 | ||||||||||||||||||
| Total debt, including current portion | $ | 10,690 | $ | 9,665 | $ | 10,690 | $ | 9,665 | ||||||||||||||||||
a.Refer to Note 9 for a summary of revenues and operating income by operating division.
b.Includes (unfavorable) favorable adjustments to prior period provisionally priced concentrate and cathode copper sales totaling $(228) million ($(95) million to net income attributable to common stock or $(0.07) per share) in third-quarter 2022, $(9) million ($(3) million to net income attributable to common stock or less than $(0.01) per share) in third-quarter 2021, $58 million ($24 million to net income attributable to common stock or $0.02 per share) for the first nine months of 2022 and $169 million ($65 million to net income attributable to common stock or $0.05 per share) for the first nine months of 2021. Refer to Note 6 for further discussion.
c.We defer recognizing profits on intercompany sales until final sales to third parties occur. Refer to “Operations – Smelting and Refining” for a summary of net impacts from changes in these deferrals.
d.Includes net credits (charges) totaling $29 million ($0.02 per share) in third-quarter 2022 and $(23) million ($(0.02) per share) for the first nine months of 2022. Net credits in third-quarter 2022 were primarily associated with gains on early extinguishment of debt and favorable adjustments associated with international tax audits, partly offset by metals inventory adjustments. The first nine months of 2022 also included net charges at PT-FI primarily associated with an administrative fine levied by the Indonesia government and a reserve for exposure associated with export duties.
e.Includes net credits (charges) totaling $79 million ($0.05 per share) in third-quarter 2021 and $(16) million ($(0.01) per share) for the first nine months of 2021. Net credits in third-quarter 2021 were primarily associated with tax credits related to the release of valuation allowances at PT-FI and a gain on the sale of our remaining cobalt business. The first nine months of 2021 also included net charges for nonrecurring labor-related charges at Cerro Verde and contested matters at PT-FI (including historical tax audits and an administrative fine levied by the Indonesia government).
f.Working capital and other (uses) sources totaled $(269) million in third-quarter 2022, $180 million in third-quarter 2021, $(980) million for the first nine months of 2022 and $367 million for the first nine months of 2021.
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||
| SUMMARY OPERATING DATA | ||||||||||||||||||||||||||
| Copper (millions of recoverable pounds) | ||||||||||||||||||||||||||
| Production | 1,056 | 987 | 3,140 | 2,810 | ||||||||||||||||||||||
| Sales, excluding purchases | 1,060 | 1,033 | 3,171 | 2,787 | ||||||||||||||||||||||
| Average realized price per pound | $ | 3.50 | $ | 4.20 | $ | 3.88 | $ | 4.22 | ||||||||||||||||||
| Site production and delivery costs per pounda | $ | 2.35 | $ | 1.88 | $ | 2.16 | $ | 1.92 | b | |||||||||||||||||
| Unit net cash costs per pounda | $ | 1.75 | $ | 1.24 | $ | 1.50 | $ | 1.36 | ||||||||||||||||||
| Gold (thousands of recoverable ounces) | ||||||||||||||||||||||||||
| Production | 448 | 374 | 1,339 | 976 | ||||||||||||||||||||||
| Sales, excluding purchases | 480 | 402 | 1,365 | 965 | ||||||||||||||||||||||
| Average realized price per ounce | $ | 1,683 | $ | 1,757 | $ | 1,786 | $ | 1,780 | ||||||||||||||||||
| Molybdenum (millions of recoverable pounds) | ||||||||||||||||||||||||||
| Production | 19 | 23 | 63 | 63 | ||||||||||||||||||||||
| Sales, excluding purchases | 17 | 20 | 56 | 63 | ||||||||||||||||||||||
| Average realized price per pound | $ | 17.05 | $ | 18.61 | $ | 18.64 | $ | 14.36 | ||||||||||||||||||
a.Reflects per pound weighted-average production and delivery costs and unit net cash costs (net of by-product credits) for all copper mines, before net noncash and other costs. For reconciliations of per pound unit costs by operating division to production and delivery costs applicable to sales reported in our consolidated financial statements, refer to “Product Revenues and Production Costs.”
b.Includes $0.03 per pound of copper associated with nonrecurring labor-related costs at Cerro Verde.
Revenues
Consolidated revenues totaled $5.0 billion in third-quarter 2022, $6.1 billion in third-quarter 2021, $17.0 billion for the first nine months of 2022 and $16.7 billion for the first nine months of 2021. Revenues from our mining operations primarily include the sale of copper concentrate, copper cathode, copper rod, gold in concentrate and molybdenum. Refer to Note 9 for a summary of product revenues.
Following is a summary of changes in our consolidated revenues between periods (in millions):
| Three Months Ended September 30 | Nine Months Ended September 30 | |||||||||||||
| Consolidated revenues - 2021 period | $ | 6,083 | $ | 16,681 | ||||||||||
| Higher (lower) sales volumes: | ||||||||||||||
| Copper | 117 | 1,622 | ||||||||||||
| Gold | 137 | 712 | ||||||||||||
| Molybdenum | (42) | (89) | ||||||||||||
| (Lower) higher average realized prices: | ||||||||||||||
| Copper | (742) | (1,078) | ||||||||||||
| Gold | (35) | 7 | ||||||||||||
| Molybdenum | (28) | 241 | ||||||||||||
| Adjustments for prior period provisionally priced copper sales | (219) | (111) | ||||||||||||
| Lower Atlantic Copper revenues | (174) | (504) | ||||||||||||
| Higher (lower) revenues from purchased copper | 44 | (310) | ||||||||||||
| Higher treatment charges | (6) | (80) | ||||||||||||
| Lower (higher) royalties and export duties | 5 | (165) | ||||||||||||
| Other, including intercompany eliminations | (137) | 96 | ||||||||||||
| Consolidated revenues - 2022 period | $ | 5,003 | $ | 17,022 | ||||||||||
Sales Volumes. Consolidated copper and gold sales volumes increased in the 2022 periods, compared with the 2021 periods, primarily reflecting increased operating rates at the Grasberg minerals district and Cerro Verde. Refer to “Operations” for further discussion of sales volumes at our mining operations.
Realized Prices. Our consolidated revenues can vary significantly as a result of fluctuations in the market prices of copper, gold and molybdenum. Average realized prices in third-quarter 2022, compared with third-quarter 2021,
were 17 percent lower for copper, 4 percent lower for gold and 8 percent lower for molybdenum, and average realized prices for the first nine months of 2022, compared with the first nine months of 2021, were 8 percent lower for copper, less than 1 percent higher for gold and 30 percent higher for molybdenum.
Average realized copper prices include net (unfavorable) favorable adjustments to current period provisionally priced copper sales totaling $(44) million in third-quarter 2022, $(93) million in third-quarter 2021, $(832) million for the first nine months of 2022 and $54 million for the first nine months of 2021. As discussed in Note 6, substantially all of our copper concentrate and cathode sales contracts provide final copper pricing in a specified future month (generally one to four months from the shipment date) based primarily on quoted LME monthly average copper prices. We record revenues and invoice customers at the time of shipment based on then-current LME prices, which results in an embedded derivative on provisionally priced concentrate and cathode sales that is adjusted to fair value through earnings each period, using the period-end forward prices, until final pricing on the date of settlement. To the extent final prices are higher or lower than what was recorded on a provisional basis, an increase or decrease to revenues is recorded each reporting period until the date of final pricing. Accordingly, in times of rising copper prices, our revenues benefit from adjustments to the final pricing of provisionally priced sales pursuant to contracts entered into in prior periods; in times of falling copper prices, the opposite occurs.
Prior Period Provisionally Priced Copper Sales. Net (unfavorable) favorable adjustments to prior periods’ provisionally priced copper sales (i.e., provisionally priced sales at June 30, 2022 and 2021, and December 31, 2021 and 2020) recorded in consolidated revenues totaled $(228) million in third-quarter 2022, $(9) million in third-quarter 2021, $58 million for the first nine months of 2022 and $169 million for the first nine months of 2021. Refer to Notes 6 and 9 for a summary of total adjustments to prior period and current period provisionally priced sales.
At September 30, 2022, we had provisionally priced copper sales totaling 523 million pounds of copper (net of intercompany sales and noncontrolling interests) recorded at an average of $3.45 per pound, subject to final pricing over the next several months. We estimate that each $0.05 change in the price realized from the September 30, 2022, provisional price recorded would have an approximate $16 million effect on our 2022 net income attributable to common stock. The LME copper price settled at $3.41 per pound on October 31, 2022.
Atlantic Copper Revenues. Atlantic Copper revenues totaled $609 million in third-quarter 2022 and $1.8 billion for the first nine months of 2022, compared with $783 million in third-quarter 2021 and $2.3 billion for the first nine months of 2021. Lower revenues in the 2022 periods, compared with 2021 periods, primarily reflect reduced operations as a result of a scheduled major maintenance turnaround that was substantially completed by the end of second-quarter 2022 and lower copper prices.
Purchased Copper. We purchase copper cathode primarily for processing by our Rod & Refining operations. The volumes of copper purchases vary depending on cathode production from our operations and totaled 48 million pounds in third-quarter 2022, 28 million pounds in third-quarter 2021, 86 million pounds for the first nine months of 2022 and 149 million pounds for the first nine months of 2021. The increase in revenues associated with purchased copper in third-quarter, compared to third-quarter 2021, reflects the impact of higher purchases, partly offset by lower copper prices. The decrease in revenues associated with purchased copper for the first nine months of 2022, compared to the first nine months of 2021, reflects the impact of lower purchases and copper prices.
Treatment Charges. Revenues from our concentrate sales are recorded net of treatment charges (i.e., fees paid to smelters that are generally negotiated annually), which will vary with the sales volumes and the price of copper. The increase in the treatment charges in the 2022 periods primarily reflects higher copper sales volumes.
Royalties and Export Duties. Royalties are primarily on PT-FI sales and vary with the volume of metal sold and the prices of copper and gold. PT-FI currently pays duties on concentrate exports of 5 percent, declining to 2.5 percent when development progress for additional smelting capacity in Indonesia exceeds 30 percent, and eliminated when development progress for additional smelting capacity in Indonesia exceeds 50 percent. Based on current development progress of additional smelting capacity, PT-FI expects export duties to be reduced from the current rate of 5 percent to 2.5 percent by the end of 2022. Lower royalties and export duties in third-quarter 2022, compared to third-quarter 2021, primarily reflect a significant metals price decline beginning in second-quarter 2022. Higher royalties and export duties in the first nine months of 2022, compared to the first nine months of 2021, are primarily associated with increased copper and gold sales volumes, partly offset by the decline in metals prices. Refer to “Operations – Indonesia Mining” for further discussion of the current progress on additional smelting capacity in Indonesia and to Note 9 for a summary of royalty expense and export duties.
Production and Delivery Costs
We continue to experience significant cost pressures, principally associated with energy prices (which represent approximately 20 percent of our site operating costs), labor and for consumables such as sulfuric acid and explosives. These cost pressures resulted in higher consolidated production and delivery costs, which totaled $3.4 billion in third-quarter 2022, $3.0 billion in third-quarter 2021, $9.5 billion for the first nine months of 2022 and $8.9 billion for the first nine months of 2021. Higher costs for the first nine months of 2022 were partly offset by lower costs at Atlantic Copper related to reduced operations as a result of a scheduled major maintenance turnaround that was substantially completed by the end of second-quarter 2022.
Site Production and Delivery Costs Per Pound. Site production and delivery costs for our copper mining operations primarily include labor, energy and other commodity-based inputs, such as sulfuric acid, explosives, steel, reagents, liners and tires. Consolidated site production and delivery costs (before net noncash and other costs) for our copper mines averaged $2.35 per pound of copper in third-quarter 2022, $1.88 per pound of copper in third-quarter 2021, $2.16 per pound of copper for the first nine months of 2022 and $1.92 per pound of copper for the first nine months of 2021.
Higher consolidated site production and delivery costs per pound of copper for the third quarter and first nine months of 2022, compared with the third quarter and first nine months of 2021, primarily reflect higher energy prices and increased costs for consumables such as sulfuric acid, explosives, key equipment parts and other supplies and services. Refer to “Operations – Unit Net Cash Costs” for further discussion of unit net cash costs associated with our operating divisions and to “Product Revenues and Production Costs” for reconciliations of per pound costs by operating division to production and delivery costs applicable to sales reported in our consolidated financial statements.
Depreciation, Depletion and Amortization
Depreciation will vary under the unit-of-production (UOP) method as a result of changes in sales volumes and the related UOP rates at our mining operations. Consolidated depreciation, depletion and amortization (DD&A) totaled $508 million in third-quarter 2022, $528 million in third-quarter 2021, $1.5 billion for the first nine months of 2022 and $1.4 billion for the first nine months of 2021.
Metals Inventory Adjustments
Metals inventory adjustments totaled $25 million in third-quarter 2022, $14 million in third-quarter 2021, $43 million for the first nine months of 2022, and $15 million for the first nine months of 2021, primarily reflecting net realizable value (NRV) inventory adjustments related to lower market prices for copper and higher costs associated with revised estimated recoverable copper at El Abra. Metals inventory adjustments for the 2022 periods also include stockpile write-offs at Cerro Verde ($1 million in third-quarter 2022 and $10 million for the first nine months of 2022).
Interest Expense, Net
Consolidated interest costs (before capitalization) totaled $182 million in third-quarter 2022, $157 million in third-quarter 2021, $524 million for the first nine months of 2022 and $482 million for the first nine months of 2021. Higher interest costs (before capitalization) in the 2022 periods are primarily related to PT-FI's senior notes that were issued in April 2022. Substantially all of our outstanding debt is fixed rate.
Capitalized interest varies with the level of qualifying assets associated with our development projects and average interest rates on our borrowings. Capitalized interest totaled $42 million in third-quarter 2022, $19 million in third-quarter 2021, $101 million for the first nine months of 2022 and $51 million for the first nine months of 2021. The increase in capitalized interest in the 2022 periods, compared with the 2021 periods, is related to major mining projects primarily associated with underground development activities in the Grasberg minerals district and development of the greenfield smelter in Indonesia. Refer to “Capital Resources and Liquidity – Investing Activities” for discussion of capital expenditures associated with our major development projects.
Net Gain on Sale of Assets
Net gain on sales of assets totaled $60 million in third-quarter 2021 and $63 million for the first nine months of 2021, primarily reflecting the sale of Freeport Cobalt.
Net Gain on Early Extinguishment of Debt
Net gain on early extinguishment of debt totaled $20 million in third-quarter 2022 associated with senior note purchases and $28 million for the first nine months of 2022, consisting of $38 million associated with senior note purchases, partly offset by a charge of $10 million associated with the repayment of the PT-FI term loan. Refer to Note 5 for further discussion.
Income Taxes
Following is a summary of the approximate amounts used in the calculation of our consolidated income tax provision (in millions, except percentages):
| Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | |||||||||||||||||||||||||||||||||||||
| Income (Loss)a | Effective Tax Rate | Income Tax (Provision) Benefit | Income (Loss)a | Effective Tax Rate | Income Tax (Provision) Benefit | |||||||||||||||||||||||||||||||||
| U.S.b | $ | 854 | 1 | % | c | $ | (5) | $ | 1,324 | 1 | % | c | $ | (7) | ||||||||||||||||||||||||
| South America | 802 | 36 | % | (287) | d | 1,425 | 40 | % | (576) | |||||||||||||||||||||||||||||
| Indonesia | 3,480 | 39 | % | (1,363) | 2,940 | 37 | % | (1,101) | e | |||||||||||||||||||||||||||||
| Eliminations and other | 43 | N/A | (25) | (3) | N/A | 19 | ||||||||||||||||||||||||||||||||
| Rate adjustmentf | — | N/A | (30) | — | N/A | (9) | ||||||||||||||||||||||||||||||||
| Consolidated FCX | $ | 5,179 | 33 | % | $ | (1,710) | $ | 5,686 | 29 | % | $ | (1,674) | ||||||||||||||||||||||||||
a.Represents income before income taxes and equity in affiliated companies’ net earnings (losses).
b.In addition to our North America mining operations, the U.S. jurisdiction reflects corporate-level expenses, which include interest expense associated with senior notes, general and administrative expenses, and environmental obligations and shutdown costs.
c.Includes valuation allowance release on prior year unbenefited net operating losses (NOLs).
d.Includes a tax credit of $31 million ($16 million net of noncontrolling interest) primarily associated with completion of Cerro Verde's 2016 tax audit.
e.Includes net tax benefits of $69 million ($55 million net of noncontrolling interest) associated with the release of a portion of the valuation allowances recorded against PT Rio Tinto Indonesia NOLs and $24 million ($19 million net of noncontrolling interest) primarily associated with the reversal of a tax reserve related to the treatment of prior year contractor support costs; partly offset by a tax charge of $10 million ($8 million net of noncontrolling interest) associated with the audit of PT-FI's 2019 tax returns.
f.In accordance with applicable accounting rules, we adjust our interim provision for income taxes equal to our consolidated tax rate.
Assuming achievement of current sales volume and cost estimates and average prices of $3.50 per pound for copper, $1,700 per ounce for gold and $18.00 per pound for molybdenum in fourth-quarter 2022, we estimate our consolidated effective tax rate for the year 2022 would approximate 34 percent (which would result in a 38 percent effective tax rate in fourth-quarter 2022). Changes in projected sales volumes and average prices during fourth-quarter 2022 would incur tax impacts at estimated effective rates of 40 percent for Peru, 38 percent for Indonesia and 0 percent for the U.S.
On August 16, 2022, the U.S. Inflation Reduction Act of 2022 (the Inflation Reduction Act) was signed into law, which includes, among other provisions, (i) a new corporate alternative minimum tax of 15 percent on the adjusted financial statement income (AFSI) of corporations with average AFSI exceeding $1.0 billion over a three-year period and (ii) a new excise tax of 1 percent on the fair market value of net corporate stock repurchases. The provisions of the Inflation Reduction Act are effective for tax years beginning after December 31, 2022. We continue to analyze the impacts of the Inflation Reduction Act on our future results of operations.
OPERATIONS
Responsible Production
2021 Climate Report. In September 2022, we published our updated Climate Report which details our ongoing initiatives to reduce our greenhouse gas (GHG) emissions, improve energy efficiency, evaluate and integrate the use of lower carbon and renewable energy sources and enhance our resilience to future climate-related risks. We continue to advance GHG emissions reduction initiatives across our global operations and established our 2030 GHG reduction targets that collectively cover nearly 100 percent of our Scope 1 and 2 GHG emissions.
The Copper Mark. We are committed to validating all of our copper producing sites with the Copper Mark, a comprehensive assurance framework designed to demonstrate the copper industry's responsible production practices. To achieve the Copper Mark, each site is required to complete an external assurance process to assess conformance with 32 environmental, social and governance (ESG) requirements. To date, we have achieved the Copper Mark at all 11 of our eligible copper producing sites in North America, South America and Europe, and PT-FI has signed a letter of commitment and initiated the validation process.
ICMM. We are a founding member of the International Council on Mining & Metals (ICMM), an organization dedicated to a safe, fair and sustainable mining and metals industry, aiming continuously to strengthen ESG performance across the global mining and metals industry. As a member company, we are required to implement the 10 Mining Principles which define good ESG practices, and associated position statements, while also meeting 39 performance expectations and producing an externally verified sustainability report in accordance with the Global Reporting Initiative Standards subject to the ICMM Assurance & Validation Procedure.
Leaching Innovation Initiatives
We are advancing efforts to improve copper recovery from all ore types using leaching processes. Several initiatives ongoing across our North America and South America operations incorporate new applications, technologies and data analytics. We believe these leaching innovation initiatives provide potential opportunities to produce incremental copper from our large existing leach stockpiles and lower-grade material currently classified as waste. Initial results support the potential for incremental low-cost additions to our production and reserve profile.
Feasibility and Optimization Studies
We are engaged in various studies associated with potential future expansion projects primarily at our mining operations. The costs for these studies are charged to production and delivery costs as incurred and totaled $34 million in third-quarter 2022, $20 million in third-quarter 2021, $84 million for the first nine months of 2022 and $36 million for the first nine months of 2021. We estimate the costs of these studies will approximate $160 million for the year 2022 (including approximately $75 million in fourth-quarter 2022), compared with approximately $60 million for the year 2021, subject to market conditions and other factors.
North America Copper Mines
We operate seven open-pit copper mines in North America – Morenci, Bagdad, Safford (including Lone Star), Sierrita and Miami in Arizona, and Chino and Tyrone in New Mexico. All of the North America mining operations are wholly owned, except for Morenci. We record our 72 percent undivided joint venture interest in Morenci using the proportionate consolidation method.
The North America copper mines include open-pit mining, sulfide-ore concentrating, leaching and solution extraction/electrowinning (SX/EW) operations. A majority of the copper produced at our North America copper mines is cast into copper rod by our Rod & Refining segment. The remainder of our North America copper production is sold as copper cathode or copper concentrate, a portion of which is shipped to Atlantic Copper (our wholly owned smelter). Molybdenum concentrate, gold and silver are also produced by certain of our North America copper mines*.*
Operating and Development Activities. We have substantial reserves and future opportunities in the U.S., primarily associated with existing mining operations.
Lone Star is increasing its operating rates to achieve targeted production of approximately 300 million pounds of copper per year from oxide ores by 2023 (compared with the initial design capacity of 200 million pounds per year). The oxide project at Lone Star advances the opportunity for development of the underlying, large-scale sulfide resources. We are also increasing exploration in the area to support metallurgical testing and mine development planning for a potential significant long-term investment to build additional scale on an economically attractive basis.
We are planning an expansion to double the concentrator capacity of the Bagdad operation in northwest Arizona. We are engaging stakeholders and conducting a feasibility study, which is expected to be completed in 2023. The timing of future development will be dependent on market conditions and other economic factors.
Operating Data. Following is summary consolidated operating data for the North America copper mines:
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||||||||
| Operating Data, Net of Joint Venture Interests | ||||||||||||||||||||||||||||||||
| Copper (millions of recoverable pounds) | ||||||||||||||||||||||||||||||||
| Production | 373 | 377 | 1,109 | 1,090 | ||||||||||||||||||||||||||||
| Sales, excluding purchases | 361 | 375 | 1,131 | 1,072 | ||||||||||||||||||||||||||||
| Average realized price per pound | $ | 3.57 | $ | 4.34 | $ | 4.17 | $ | 4.24 | ||||||||||||||||||||||||
| Molybdenum (millions of recoverable pounds) | ||||||||||||||||||||||||||||||||
| Productiona | 7 | 9 | 22 | 26 | ||||||||||||||||||||||||||||
| 100% Operating Data | ||||||||||||||||||||||||||||||||
| Leach operations | ||||||||||||||||||||||||||||||||
| Leach ore placed in stockpiles (metric tons per day) | 622,200 | 579,100 | 684,200 | 656,900 | ||||||||||||||||||||||||||||
| Average copper ore grade (percent) | 0.30 | 0.30 | 0.29 | 0.29 | ||||||||||||||||||||||||||||
| Copper production (millions of recoverable pounds) | 260 | 270 | 759 | 797 | ||||||||||||||||||||||||||||
| Mill operations | ||||||||||||||||||||||||||||||||
| Ore milled (metric tons per day) | 294,600 | 274,300 | 297,600 | 269,000 | ||||||||||||||||||||||||||||
| Average ore grade (percent): | ||||||||||||||||||||||||||||||||
| Copper | 0.36 | 0.39 | 0.37 | 0.38 | ||||||||||||||||||||||||||||
| Molybdenum | 0.02 | 0.03 | 0.02 | 0.03 | ||||||||||||||||||||||||||||
| Copper recovery rate (percent) | 82.3 | 81.6 | 82.2 | 80.9 | ||||||||||||||||||||||||||||
| Copper production (millions of recoverable pounds) | 174 | 170 | 538 | 476 | ||||||||||||||||||||||||||||
a.Refer to “Consolidated Results” for our consolidated molybdenum sales volumes, which include sales of molybdenum produced at the North America copper mines.
Our consolidated copper sales volumes from North America totaled 361 million pounds in third-quarter 2022, 375 million pounds in third-quarter 2021, and 1.1 billion pounds for both the first nine months of 2022 and 2021. The changes in sales volumes for the 2022 periods, compared with the 2021 periods, primarily reflect timing of shipments as production volumes in the 2022 periods approximated the 2021 periods.
North America copper sales are estimated to approximate 1.5 billion pounds for the year 2022.
Unit Net Cash Costs. Unit net cash costs per pound of copper is a measure intended to provide investors with information about the cash-generating capacity of our mining operations expressed on a basis relating to the primary metal product for our respective operations. We use this measure for the same purpose and for monitoring operating performance by our mining operations. This information differs from measures of performance determined in accordance with U.S. generally accepted accounting principles (GAAP) and should not be considered in isolation or as a substitute for measures of performance determined in accordance with U.S. GAAP. This measure is presented by other metals mining companies, although our measure may not be comparable to similarly titled measures reported by other companies.
Gross Profit (Loss) per Pound of Copper and Molybdenum
The following table summarizes unit net cash costs and gross profit (loss) per pound at our North America copper mines. Refer to “Product Revenues and Production Costs” for an explanation of the “by-product” and “co-product” methods and a reconciliation of unit net cash costs per pound to production and delivery costs applicable to sales reported in our consolidated financial statements.
| Three Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | |||||||||||||||||||||||||||||||||||||
| By- Product Method | Co-Product Method | By- Product Method | Co-Product Method | |||||||||||||||||||||||||||||||||||
| Copper | Molyb- denuma | Copper | Molyb- denuma | |||||||||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3.57 | $ | 3.57 | $ | 16.75 | $ | 4.34 | $ | 4.34 | $ | 16.69 | ||||||||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 2.76 | 2.51 | 15.60 | 2.12 | 1.93 | 8.97 | ||||||||||||||||||||||||||||||||
| By-product credits | (0.30) | — | — | (0.39) | — | — | ||||||||||||||||||||||||||||||||
| Treatment charges | 0.10 | 0.09 | — | 0.09 | 0.09 | — | ||||||||||||||||||||||||||||||||
| Unit net cash costs | 2.56 | 2.60 | 15.60 | 1.82 | 2.02 | 8.97 | ||||||||||||||||||||||||||||||||
| DD&A | 0.28 | 0.25 | 0.95 | 0.25 | 0.23 | 0.73 | ||||||||||||||||||||||||||||||||
| Metals inventory adjustments | 0.01 | 0.01 | — | 0.03 | 0.03 | — | ||||||||||||||||||||||||||||||||
| Noncash and other costs, net | 0.10 | b | 0.09 | 0.60 | 0.08 | b | 0.08 | 0.23 | ||||||||||||||||||||||||||||||
| Total unit costs | 2.95 | 2.95 | 17.15 | 2.18 | 2.36 | 9.93 | ||||||||||||||||||||||||||||||||
| Revenue adjustments, primarily for pricing on prior period open sales | (0.06) | (0.06) | — | (0.02) | (0.02) | — | ||||||||||||||||||||||||||||||||
| Gross profit (loss) per pound | $ | 0.56 | $ | 0.56 | $ | (0.40) | $ | 2.14 | $ | 1.96 | $ | 6.76 | ||||||||||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 361 | 361 | 375 | 375 | ||||||||||||||||||||||||||||||||||
| Molybdenum sales (millions of recoverable pounds)a | 7 | 9 |
| Nine Months Ended September 30, | ||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | |||||||||||||||||||||||||||||||||||||
| By- Product Method | Co-Product Method | By- Product Method | Co-Product Method | |||||||||||||||||||||||||||||||||||
| Copper | Molyb- denuma | Copper | Molyb- denuma | |||||||||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 4.17 | $ | 4.17 | $ | 17.87 | $ | 4.24 | $ | 4.24 | $ | 13.09 | ||||||||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 2.54 | 2.33 | 12.87 | 2.11 | 1.95 | 7.54 | ||||||||||||||||||||||||||||||||
| By-product credits | (0.33) | — | — | (0.32) | — | — | ||||||||||||||||||||||||||||||||
| Treatment charges | 0.10 | 0.10 | — | 0.09 | 0.09 | — | ||||||||||||||||||||||||||||||||
| Unit net cash costs | 2.31 | 2.43 | 12.87 | 1.88 | 2.04 | 7.54 | ||||||||||||||||||||||||||||||||
| DD&A | 0.27 | 0.25 | 0.88 | 0.26 | 0.24 | 0.59 | ||||||||||||||||||||||||||||||||
| Metals inventory adjustments | 0.01 | 0.01 | — | 0.01 | 0.01 | — | ||||||||||||||||||||||||||||||||
| Noncash and other costs, net | 0.09 | b | 0.08 | 0.40 | 0.10 | b | 0.09 | 0.12 | ||||||||||||||||||||||||||||||
| Total unit costs | 2.68 | 2.77 | 14.15 | 2.25 | 2.38 | 8.25 | ||||||||||||||||||||||||||||||||
| Revenue adjustments, primarily for pricing on prior period open sales | (0.01) | (0.01) | — | 0.01 | 0.01 | — | ||||||||||||||||||||||||||||||||
| Gross profit per pound | $ | 1.48 | $ | 1.39 | $ | 3.72 | $ | 2.00 | $ | 1.87 | $ | 4.84 | ||||||||||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 1,131 | 1,131 | 1,072 | 1,072 | ||||||||||||||||||||||||||||||||||
| Molybdenum sales (millions of recoverable pounds)a | 22 | 26 | ||||||||||||||||||||||||||||||||||||
a.Reflects sales of molybdenum produced by certain of the North America copper mines to our molybdenum sales company at market-based pricing.
b.Includes $0.06 per pound of copper in third-quarter 2022, $0.03 per pound of copper in third-quarter 2021, $0.04 per pound of copper for the first nine months of 2022 and $0.02 per pound of copper for the first nine months of 2021 for feasibility and optimization studies.
Our North America copper mines have varying cost structures because of differences in ore grades and characteristics, processing costs, by-product credits and other factors. Our mining operations continue to experience significant cost inflation, principally associated with higher energy and other input costs, resulting in higher average unit net cash costs (net of by-product credits) for the North America copper mines of $2.56 per pound of copper in third-quarter 2022 and $2.31 per pound for the first nine months of 2022, compared with $1.82 per pound in third-quarter 2021 and $1.88 per pound for the first nine months of 2021. Third-quarter 2022 also reflects lower molybdenum by-product credits primarily associated with lower molybdenum volumes.
Because certain assets are depreciated on a straight-line basis, North America’s average unit depreciation rate may vary with asset additions and the level of copper production and sales.
Revenue adjustments primarily result from changes in prices on provisionally priced copper sales recognized in prior periods. Refer to “Consolidated Results – Revenues” for further discussion of adjustments to prior period provisionally priced copper sales.
Average unit net cash costs (net of by-product credits) for our North America copper mines are expected to approximate $2.35 per pound of copper for the year 2022, based on achievement of current sales volume and cost estimates and assuming an average molybdenum price of $18.00 per pound in fourth-quarter 2022. North America’s average unit net cash costs for the year 2022 would change by approximately $0.01 per pound for each $2 per pound change in the average price of molybdenum in fourth-quarter 2022.
South America Mining
We operate two copper mines in South America – Cerro Verde in Peru (in which we own a 53.56 percent interest) and El Abra in Chile (in which we own a 51 percent interest), which are consolidated in our financial statements.
South America mining includes open-pit mining, sulfide-ore concentrating, leaching and SX/EW operations. Production from our South America mines is sold as copper concentrate or cathode under long-term contracts. Our South America mines also sell a portion of their copper concentrate production to Atlantic Copper. In addition to copper, the Cerro Verde mine produces molybdenum concentrate and silver.
Operating and Development Activities. During third-quarter 2022, milling rates at Cerro Verde's concentrator averaged 403,900 metric tons of ore per day and are currently expected to average over 400,000 metric tons of ore per day in fourth-quarter 2022.
Operating rates at El Abra have returned to pre-COVID-19 levels and increased mining and stacking activities are expected to result in an approximate 30 percent increase in El Abra copper production for the year 2022, compared with the year 2021.
El Abra's large sulfide resource supports a potential major mill project similar to the large-scale concentrator constructed at Cerro Verde in 2015. Technical and economic studies continue to be evaluated to determine the optimal scope and timing for the sulfide project. We are considering options to invest in water infrastructure to provide options to extend existing operations, while continuing to monitor potential changes in Chile’s regulatory and fiscal matters. We will defer major investment decisions pending clarity on Chile’s regulatory and fiscal matters.
Operating Data. Following is summary consolidated operating data for South America mining:
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||
| Copper (millions of recoverable pounds) | ||||||||||||||||||||||||||
| Production | 302 | 260 | 862 | 764 | ||||||||||||||||||||||
| Sales | 293 | 280 | 845 | 769 | ||||||||||||||||||||||
| Average realized price per pound | $ | 3.47 | $ | 4.12 | $ | 3.73 | $ | 4.21 | ||||||||||||||||||
| Molybdenum (millions of recoverable pounds) | ||||||||||||||||||||||||||
| Productiona | 4 | 5 | 18 | 14 | ||||||||||||||||||||||
| Leach operations | ||||||||||||||||||||||||||
| Leach ore placed in stockpiles (metric tons per day) | 175,200 | 171,600 | 157,700 | 171,900 | ||||||||||||||||||||||
| Average copper ore grade (percent) | 0.34 | 0.30 | 0.35 | 0.33 | ||||||||||||||||||||||
| Copper production (millions of recoverable pounds) | 85 | 62 | 217 | 188 | ||||||||||||||||||||||
| Mill operations | ||||||||||||||||||||||||||
| Ore milled (metric tons per day) | 403,900 | 380,300 | 408,500 | 381,500 | ||||||||||||||||||||||
| Average ore grade (percent): | ||||||||||||||||||||||||||
| Copper | 0.32 | 0.31 | 0.32 | 0.30 | ||||||||||||||||||||||
| Molybdenum | 0.01 | 0.01 | 0.01 | 0.01 | ||||||||||||||||||||||
| Copper recovery rate (percent) | 85.4 | 86.1 | 85.5 | 86.3 | ||||||||||||||||||||||
| Copper production (millions of recoverable pounds) | 217 | 199 | 645 | 576 |
a.Refer to “Consolidated Results” for our consolidated molybdenum sales volumes, which include sales of molybdenum produced at Cerro Verde.
Our consolidated copper sales volumes from South America totaled 293 million pounds in third-quarter 2022, 280 million pounds in third-quarter 2021, 845 million pounds for the first nine months of 2022 and 769 million pounds for the first nine months of 2021. Higher copper sales volumes in the 2022 periods, compared with the 2021 periods, primarily reflect higher mining and milling rates and higher ore grades.
Copper sales from South America mining are expected to approximate 1.15 billion pounds for the year 2022.
Unit Net Cash Costs. Unit net cash costs per pound of copper is a measure intended to provide investors with information about the cash-generating capacity of our mining operations expressed on a basis relating to the primary metal product for our respective operations. We use this measure for the same purpose and for monitoring operating performance by our mining operations. This information differs from measures of performance determined in accordance with U.S. GAAP and should not be considered in isolation or as a substitute for measures of performance determined in accordance with U.S. GAAP. This measure is presented by other metals mining companies, although our measure may not be comparable to similarly titled measures reported by other companies.
Gross Profit per Pound of Copper
The following table summarizes unit net cash costs and gross profit per pound of copper at our South America mining operations. Refer to “Product Revenues and Production Costs” for an explanation of the “by-product” and “co-product” methods and a reconciliation of unit net cash costs per pound to production and delivery costs applicable to sales reported in our consolidated financial statements.
| Three Months Ended September 30, | ||||||||||||||||||||||||||
| 2022 | 2021 | |||||||||||||||||||||||||
| By-Product Method | Co-Product Method | By-Product Method | Co-Product Method | |||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3.47 | $ | 3.47 | $ | 4.12 | $ | 4.12 | ||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 2.60 | 2.47 | 2.14 | 1.96 | ||||||||||||||||||||||
| By-product credits | (0.16) | — | (0.38) | — | ||||||||||||||||||||||
| Treatment charges | 0.13 | 0.14 | 0.13 | 0.13 | ||||||||||||||||||||||
| Royalty on metals | 0.01 | — | 0.01 | 0.01 | ||||||||||||||||||||||
| Unit net cash costs | 2.58 | 2.61 | 1.90 | 2.10 | ||||||||||||||||||||||
| DD&A | 0.34 | 0.32 | 0.40 | 0.36 | ||||||||||||||||||||||
| Metals inventory adjustments | 0.07 | 0.07 | — | — | ||||||||||||||||||||||
| Noncash and other costs, net | 0.09 | 0.08 | 0.07 | 0.06 | ||||||||||||||||||||||
| Total unit costs | 3.08 | 3.08 | 2.37 | 2.52 | ||||||||||||||||||||||
| Revenue adjustments, primarily for pricing on prior period open sales | (0.25) | (0.25) | (0.03) | (0.03) | ||||||||||||||||||||||
| Gross profit per pound | $ | 0.14 | $ | 0.14 | $ | 1.72 | $ | 1.57 | ||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 293 | 293 | 280 | 280 |
| Nine Months Ended September 30, | ||||||||||||||||||||||||||
| 2022 | 2021 | |||||||||||||||||||||||||
| By-Product Method | Co-Product Method | By-Product Method | Co-Product Method | |||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3.73 | $ | 3.73 | $ | 4.21 | $ | 4.21 | ||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 2.50 | 2.33 | 2.20 | a | 2.04 | |||||||||||||||||||||
| By-product credits | (0.31) | — | (0.31) | — | ||||||||||||||||||||||
| Treatment charges | 0.15 | 0.15 | 0.13 | 0.13 | ||||||||||||||||||||||
| Royalty on metals | 0.01 | 0.01 | 0.01 | 0.01 | ||||||||||||||||||||||
| Unit net cash costs | 2.35 | 2.49 | 2.03 | 2.18 | ||||||||||||||||||||||
| DD&A | 0.35 | 0.32 | 0.40 | 0.36 | ||||||||||||||||||||||
| Metals inventory adjustments | 0.04 | 0.04 | — | — | ||||||||||||||||||||||
| Noncash and other costs, net | 0.07 | 0.06 | 0.07 | 0.06 | ||||||||||||||||||||||
| Total unit costs | 2.81 | 2.91 | 2.50 | 2.60 | ||||||||||||||||||||||
| Revenue adjustments, primarily for pricing on prior period open sales | 0.04 | 0.04 | 0.13 | 0.13 | ||||||||||||||||||||||
| Gross profit per pound | $ | 0.96 | $ | 0.86 | $ | 1.84 | $ | 1.74 | ||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 845 | 845 | 769 | 769 | ||||||||||||||||||||||
a.Includes $0.10 per pound of copper for the first nine months of 2021 associated with nonrecurring labor-related costs at Cerro Verde.
Our South America mines have varying cost structures because of differences in ore grades and characteristics, processing costs, by-product credits and other factors. Our mining operations continue to experience significant cost inflation, principally associated with higher energy and other input costs, resulting in higher average unit net cash costs (net of by-product credits) for South America mining of $2.58 per pound of copper in third-quarter 2022 and $2.35 per pound of copper for the first nine months of 2022, compared with $1.90 per pound of copper in third-quarter 2021 and $2.03 per pound of copper for the first nine months of 2021. Third-quarter 2022, compared with third-quarter 2021, also reflects lower molybdenum by-product credits primarily associated with lower molybdenum prices and volumes.
As discussed in Note 3, a change in estimate of recoverable copper in the existing leach stockpile at El Abra resulted in a 135-million-pound reduction to its work in-process inventory volumes, which resulted in a higher average cost per pound of copper. Lower copper prices combined with a higher average cost per pound of copper resulted in the recognition of NRV adjustments at El Abra in third-quarter 2022 (refer to Note 3).
Revenues from Cerro Verde’s concentrate sales are recorded net of treatment charges, which will vary with Cerro Verde’s sales volumes and the price of copper.
Because certain assets are depreciated on a straight-line basis, South America’s unit depreciation rate may vary with asset additions and the level of copper production and sales.
Revenue adjustments primarily result from changes in prices on provisionally priced copper sales recognized in prior periods. Refer to “Consolidated Results – Revenues” for further discussion of adjustments to prior period provisionally priced copper sales.
Average unit net cash costs (net of by-product credits) for South America mining are expected to approximate $2.38 per pound of copper for the year 2022, based on current sales volume and cost estimates and assuming an average price of $18.00 per pound of molybdenum in fourth-quarter 2022.
In September 2022, El Abra and its two workers' unions signed new collective labor agreements (CLAs), which expire on April 30, 2026. No significant charges are expected to be recorded associated with the new CLAs.
Indonesia Mining
PT-FI operates one of the world’s largest copper and gold mines at the Grasberg minerals district in Papua, Indonesia. PT-FI produces copper concentrate that contains significant quantities of gold and silver. We have a 48.76 percent interest in PT-FI and manage its mining operations. As further discussed in Note 3 of our 2021 Form 10-K, under the terms of the 2018 shareholders agreement, our economic interest in PT-FI approximates 81 percent through 2022, and 48.76 percent thereafter. PT-FI’s results are consolidated in our financial statements.
Substantially all of PT-FI’s copper concentrate is sold under long-term contracts. During the first nine months of 2022, 35 percent of PT-FI’s concentrate production was sold to PT Smelting (PT-FI’s 39.5-percent owned copper smelter and refinery in Gresik, Indonesia). See “Smelting and Refining” below for a discussion of PT-FI’s tolling arrangement with PT Smelting commencing in 2023.
Operating and Development Activities. PT-FI currently has three underground operating mines in the Grasberg minerals district: Grasberg Block Cave, Deep Mill Level Zone (DMLZ) and Big Gossan. In late 2021, PT-FI achieved quarterly copper and gold production volumes approximating 100 percent of projected annualized levels of approximately 1.6 billion pounds of copper and 1.6 million ounces of gold.
PT-FI's milling rates for ore produced from its underground mines averaged 190,800 metric tons of ore per day for the first nine months of 2022, and PT-FI expects to achieve a similar milling rate in fourth-quarter 2022. The installation of additional milling facilities at PT-FI is currently expected to be completed in the second half of 2023, which would increase milling capacity to approximately 240,000 metric tons of ore per day and provide for continued annualized copper and gold production volumes of approximately 1.6 billion pounds of copper and 1.6 million ounces of gold. PT-FI is also advancing a mill recovery project with the installation of a new copper cleaner circuit that is expected to be completed in the first half of 2024, and is expected to provide incremental metal production of approximately 60 million pounds of copper and 40 thousand ounces of gold per year.
For the year 2022, PT-FI's estimated capital spending on the Grasberg Block Cave and DMLZ underground projects, including construction of a dual-fuel power plant, is expected to approximate $1.0 billion, net of scheduled contributions from PT Indonesia Asahan Aluminium (Persero) (PT Inalum, also known as MIND ID). In accordance with applicable accounting guidance, the aggregate costs (before scheduled contributions from PT Inalum), which are expected to approximate $1.2 billion for the year 2022, will be reflected as an investing activity in our cash flow statement, and contributions from PT Inalum will be reflected as a financing activity.
Kucing Liar. PT-FI commenced long-term mine development activities for its Kucing Liar deposit during 2021, which is expected to produce over 6 billion pounds of copper and 5 million ounces of gold between 2028 and the end of 2041. Pre-production development activities will occur over an approximate 10-year timeframe, and capital investments are expected to average approximately $400 million per year over the next 10 years (including approximately $130 million for the year 2022). At full operating rates, annual production from Kucing Liar is expected to approximate 600 million pounds of copper and 500 thousand ounces of gold, providing PT-FI with sustained long-term, large-scale and low-cost production. Kucing Liar will benefit from substantial shared infrastructure and PT-FI's experience and long-term success in block-cave mining.
Indonesia Smelter. In connection with PT-FI’s 2018 agreement with the Indonesia government to secure the extension of its long-term mining rights, PT-FI committed to construct additional domestic smelting capacity totaling 2 million metric tons of concentrate per year by the end of 2023 (subject to force majeure provisions). In accordance with Indonesia regulations, PT-FI submits a smelter progress report to the Indonesia government for review every six months (refer to Note 8).
PT-FI is actively engaged in the following projects for additional domestic smelting capacity:
-
Construction of a greenfield smelter in Gresik, Indonesia with a capacity to process approximately 1.7 million metric tons of copper concentrate per year. The smelter construction is advancing and is expected to be completed as soon as feasible in 2024 at an estimated cost of $3.0 billion, including $2.8 billion for a construction contract (excluding capitalized interest, owner’s costs and commissioning) and $0.2 billion for investment in a desalinization plant.
-
Expansion of PT Smelting's capacity by 30 percent to 1.3 million metric tons of concentrate per year, which is expected to be completed by the end of 2023. PT-FI completed agreements in November 2021 with the majority owner of PT Smelting to implement the expansion plans. PT-FI is funding the cost of the expansion, estimated to approximate $250 million, with a loan that will convert to equity, increasing ownership in PT Smelting from a 39.5 percent ownership interest to a majority ownership interest once the expansion is complete. PT-FI will consolidate PT Smelting's results following the increase to a majority ownership.
*•*Construction of a PMR to process gold and silver from the greenfield smelter and PT Smelting at an estimated cost of $400 million.
Capital expenditures for the Indonesia smelter projects are being funded with proceeds from PT-FI's senior notes and its available revolving credit facility.
Construction of the additional domestic smelter capacity will result in the elimination of export duties, providing an offset to the economic cost associated with the Indonesia smelter projects. Based on current development progress of additional smelting capacity, PT-FI expects export duties to be reduced from the current rate of 5 percent to 2.5 percent by the end of 2022.
Mining Rights. PT-FI and the Indonesia government have begun preliminary discussions regarding the extension of PT-FI's mining rights under its special mining license (IUPK) beyond 2041. PT-FI believes an extension beyond 2041 would enable continuity of operations and the identification of additional resource development opportunities in the Grasberg minerals district.
Operating Data. Following is summary consolidated operating data for Indonesia mining:
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||
| Copper (millions of recoverable pounds) | ||||||||||||||||||||||||||
| Production | 381 | 350 | 1,169 | 956 | ||||||||||||||||||||||
| Sales | 406 | 378 | 1,195 | 946 | ||||||||||||||||||||||
| Average realized price per pound | $ | 3.45 | $ | 4.11 | $ | 3.71 | $ | 4.21 | ||||||||||||||||||
| Gold (thousands of recoverable ounces) | ||||||||||||||||||||||||||
| Production | 445 | 371 | 1,330 | 968 | ||||||||||||||||||||||
| Sales | 476 | 399 | 1,356 | 957 | ||||||||||||||||||||||
| Average realized price per ounce | $ | 1,683 | $ | 1,757 | $ | 1,786 | $ | 1,780 | ||||||||||||||||||
| Ore extracted and milled (metric tons per day): | ||||||||||||||||||||||||||
| Grasberg Block Cave underground mine | 100,600 | 76,500 | 100,900 | 64,300 | ||||||||||||||||||||||
| DMLZ underground mine | 81,400 | 59,700 | 79,000 | 53,500 | ||||||||||||||||||||||
| Big Gossan underground mine | 7,600 | 7,400 | 7,500 | 7,500 | ||||||||||||||||||||||
| Other adjustmentsa | (900) | 13,800 | 3,400 | 16,300 | ||||||||||||||||||||||
| Total | 188,700 | 157,400 | 190,800 | 141,600 | ||||||||||||||||||||||
| Average ore grades: | ||||||||||||||||||||||||||
| Copper (percent) | 1.17 | 1.30 | 1.20 | 1.32 | ||||||||||||||||||||||
| Gold (grams per metric ton) | 1.07 | 1.05 | 1.06 | 1.04 | ||||||||||||||||||||||
| Recovery rates (percent): | ||||||||||||||||||||||||||
| Copper | 90.1 | 90.1 | 89.8 | 90.0 | ||||||||||||||||||||||
| Gold | 77.2 | 78.6 | 77.9 | 77.8 |
a.Also includes ore extracted and milled from the Deep Ore Zone underground mine ore body, which was depleted at the end of 2021.
Our consolidated copper and gold sales from PT-FI totaled 406 million pounds and 476 thousand ounces in third-quarter 2022 and 1.2 billion pounds and 1.4 million ounces for the first nine months of 2022, compared with copper and gold sales of 378 million pounds and 399 thousand ounces in third-quarter 2021 and 946 million pounds and 957 thousand ounces for the first nine months of 2021. The increase in sales volumes for the 2022 periods, primarily reflects increased operating rates at the Grasberg minerals district, partially offset by lower copper ore grades.
Consolidated sales volumes from PT-FI are expected to approximate 1.6 billion pounds of copper and 1.8 million ounces of gold for the year 2022.
Unit Net Cash Costs. Unit net cash costs per pound of copper is a measure intended to provide investors with information about the cash-generating capacity of our mining operations expressed on a basis relating to the primary metal product for our respective operations. We use this measure for the same purpose and for monitoring operating performance by our mining operations. This information differs from measures of performance determined in accordance with U.S. GAAP and should not be considered in isolation or as a substitute for measures of performance determined in accordance with U.S. GAAP. This measure is presented by other metals mining companies, although our measure may not be comparable to similarly titled measures reported by other companies.
Gross Profit per Pound of Copper and per Ounce of Gold
The following table summarizes the unit net cash costs and gross profit per pound of copper and per ounce of gold at our Indonesia mining operations. Refer to “Product Revenues and Production Costs” for an explanation of “by-product” and “co-product” methods and a reconciliation of unit net cash costs per pound to production and delivery costs applicable to sales reported in our consolidated financial statements.
| Three Months Ended September 30, | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | ||||||||||||||||||||||||||||||||||
| By-Product Method | Co-Product Method | By-Product Method | Co-Product Method | ||||||||||||||||||||||||||||||||
| Copper | Gold | Copper | Gold | ||||||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3.45 | $ | 3.45 | $ | 1,683 | $ | 4.11 | $ | 4.11 | $ | 1,757 | |||||||||||||||||||||||
| Site production and delivery, before net noncash and other credits shown below | 1.81 | a | 1.13 | 553 | 1.46 | 0.99 | 424 | ||||||||||||||||||||||||||||
| Gold and silver credits | (2.00) | — | — | (1.97) | — | — | |||||||||||||||||||||||||||||
| Treatment charges | 0.23 | 0.15 | 72 | 0.24 | 0.16 | 69 | |||||||||||||||||||||||||||||
| Export duties | 0.20 | 0.12 | 61 | 0.19 | 0.13 | 54 | |||||||||||||||||||||||||||||
| Royalty on metals | 0.20 | 0.12 | 67 | 0.25 | 0.18 | 63 | |||||||||||||||||||||||||||||
| Unit net cash costs | 0.44 | 1.52 | 753 | 0.17 | 1.46 | 610 | |||||||||||||||||||||||||||||
| DD&A | 0.65 | 0.41 | 200 | 0.74 | 0.50 | 215 | |||||||||||||||||||||||||||||
| Noncash and other credits, net | (0.02) | b | (0.01) | (7) | — | — | — | ||||||||||||||||||||||||||||
| Total unit costs | 1.07 | 1.92 | 946 | 0.91 | 1.96 | 825 | |||||||||||||||||||||||||||||
| Revenue adjustments, primarily for pricing on prior period open sales | (0.39) | (0.39) | (36) | — | — | 16 | |||||||||||||||||||||||||||||
| PT Smelting intercompany profit (loss) | 0.15 | 0.09 | 45 | (0.04) | (0.03) | (12) | |||||||||||||||||||||||||||||
| Gross profit per pound/ounce | $ | 2.14 | $ | 1.23 | $ | 746 | $ | 3.16 | $ | 2.12 | $ | 936 | |||||||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 406 | 406 | 378 | 378 | |||||||||||||||||||||||||||||||
| Gold sales (thousands of recoverable ounces) | 476 | 399 |
| Nine Months Ended September 30, | |||||||||||||||||||||||||||||||||||
| 2022 | 2021 | ||||||||||||||||||||||||||||||||||
| By-Product Method | Co-Product Method | By-Product Method | Co-Product Method | ||||||||||||||||||||||||||||||||
| Copper | Gold | Copper | Gold | ||||||||||||||||||||||||||||||||
| Revenues, excluding adjustments | $ | 3.71 | $ | 3.71 | $ | 1,786 | $ | 4.21 | $ | 4.21 | $ | 1,780 | |||||||||||||||||||||||
| Site production and delivery, before net noncash and other costs shown below | 1.55 | a | 0.99 | 476 | 1.49 | 1.03 | 434 | ||||||||||||||||||||||||||||
| Gold and silver credits | (2.11) | — | — | (1.91) | — | — | |||||||||||||||||||||||||||||
| Treatment charges | 0.24 | 0.15 | 74 | 0.24 | 0.17 | 70 | |||||||||||||||||||||||||||||
| Export duties | 0.20 | 0.13 | 63 | 0.15 | 0.10 | 45 | |||||||||||||||||||||||||||||
| Royalty on metals | 0.24 | 0.16 | 70 | 0.26 | 0.18 | 66 | |||||||||||||||||||||||||||||
| Unit net cash costs | 0.12 | 1.43 | 683 | 0.23 | 1.48 | 615 | |||||||||||||||||||||||||||||
| DD&A | 0.65 | 0.41 | 199 | 0.76 | 0.52 | 222 | |||||||||||||||||||||||||||||
| Noncash and other costs, net | 0.02 | b | 0.01 | 5 | 0.01 | 0.01 | 1 | ||||||||||||||||||||||||||||
| Total unit costs | 0.79 | 1.85 | 887 | 1.00 | 2.01 | 838 | |||||||||||||||||||||||||||||
| Revenue adjustments, primarily for pricing on prior period open sales | 0.02 | 0.02 | 2 | 0.08 | 0.08 | (5) | |||||||||||||||||||||||||||||
| PT Smelting intercompany profit (loss) | 0.03 | 0.02 | 9 | (0.11) | (0.08) | (33) | |||||||||||||||||||||||||||||
| Gross profit per pound/ounce | $ | 2.97 | $ | 1.90 | $ | 910 | $ | 3.18 | $ | 2.20 | $ | 904 | |||||||||||||||||||||||
| Copper sales (millions of recoverable pounds) | 1,195 | 1,195 | 946 | 946 | |||||||||||||||||||||||||||||||
| Gold sales (thousands of recoverable ounces) | 1,356 | 957 | |||||||||||||||||||||||||||||||||
a.Includes $0.05 per pound of copper in third-quarter 2022 and $0.02 per pound of copper for the first nine months of 2022 for nonrecurring costs associated with PT-FI’s environmental commitments.
b.Includes net credits totaling $0.05 per pound of copper in third-quarter 2022 and $0.02 per pound of copper for the first nine months of 2022 associated with historical tax audits.
PT-FI’s unit net cash costs (net of gold and silver credits) of $0.44 per pound of copper in third-quarter 2022 were higher than $0.17 per pound of copper in third-quarter 2021, primarily reflecting higher energy costs and increased operating rates, partly offset by higher sales volumes. PT-FI’s unit net cash costs (net of gold and silver credits) of
$0.12 per pound of copper for the first nine months of 2022, were lower than $0.23 per pound of copper for the first nine months of 2021, primarily reflecting higher gold and silver credits and copper sales volumes, partially offset by higher energy costs and export duties.
Treatment charges vary with the volume of metals sold and the price of copper, and royalties vary with the volume of metals sold and the prices of copper and gold.
PT-FI’s export duties totaled $80 million in third-quarter 2022, $71 million in third-quarter 2021, $245 million for the first nine months of 2022 and $145 million for the first nine months of 2021. The increase in export duties for the 2022 periods, compared with the 2021 periods, primarily reflects higher export sales volumes.
PT-FI’s royalties of $81 million in third-quarter 2022 were lower than the $94 million in third-quarter 2021, primarily reflecting lower average copper prices, partially offset by higher sales volumes. PT-FI’s royalties of $281 million for the first nine months of 2022 were higher than the $234 million for the first nine months of 2021, primarily reflecting higher sales volumes, partially offset by lower copper prices.
Because certain assets are depreciated on a straight-line basis, PT-FI’s unit depreciation rate may vary with asset additions and the level of copper production and sales. The decrease in the DD&A rate per pound of copper for the 2022 periods, compared with the 2021 periods, primarily reflects higher volumes associated with increased operating rates and the depletion of the Deep Ore Zone underground mine during 2021, partly offset by significant underground development assets being placed into service.
Revenue adjustments primarily result from changes in prices on provisionally priced copper sales recognized in prior periods. Refer to “Consolidated Results – Revenues” for further discussion of adjustments to prior period provisionally priced copper sales.
PT Smelting intercompany profit (loss) represents the change in the deferral of 39.5 percent of PT-FI’s profit on sales to PT Smelting. Refer to “Smelting and Refining” below for further discussion.
Assuming an average gold price of $1,700 per ounce in fourth-quarter 2022 and achievement of current sales volume and cost estimates, unit net cash costs (net of gold and silver credits) for PT-FI are expected to approximate $0.19 per pound of copper for the year 2022. PT-FI's average unit net cash costs for the year 2022 would change by approximately $0.04 per pound of copper for each $100 per ounce change in the average price of gold in fourth-quarter 2022.
PT-FI’s projected sales volumes and unit net cash costs for the year 2022 are dependent on a number of factors, including operational performance and timing of shipments.
Molybdenum Mines
We operate two wholly owned molybdenum mines in Colorado – the Climax open-pit mine and the Henderson underground mine. The Climax and Henderson mines produce high-purity, chemical-grade molybdenum concentrate, which is typically further processed into value-added molybdenum chemical products. The majority of the molybdenum concentrate produced at the Climax and Henderson mines, as well as from our North America and South America copper mines, is processed at our conversion facilities.
Operating and Development Activities. Production from the Molybdenum mines totaled 8 million pounds of molybdenum in third-quarter 2022, 9 million pounds in third-quarter 2021 and 23 million pounds for both the first nine months of 2022 and 2021. Refer to “Consolidated Results” for our consolidated molybdenum operating data, which includes sales of molybdenum produced at our Molybdenum mines and from our North America and South America copper mines. Refer to “Outlook” for projected consolidated molybdenum sales volumes.
Unit Net Cash Costs Per Pound of Molybdenum. Unit net cash costs per pound of molybdenum is a measure intended to provide investors with information about the cash-generating capacity of our mining operations expressed on a basis relating to the primary metal product for our respective operations. We use this measure for the same purpose and for monitoring operating performance by our mining operations. This information differs from measures of performance determined in accordance with U.S. GAAP and should not be considered in isolation or as a substitute for measures of performance determined in accordance with U.S. GAAP. This measure is presented by other metals mining companies, although our measure may not be comparable to similarly titled measures reported by other companies.
Average unit net cash costs for our Molybdenum mines of $12.10 per pound of molybdenum in third-quarter 2022 and $11.22 per pound of molybdenum for the first nine months of 2022 were higher than average unit net cash costs of $8.54 per pound of molybdenum for both the third-quarter 2021 and the first nine months of 2021, primarily reflecting increased contract labor and higher energy and other input costs. Based on current sales volume and cost estimates, average unit net cash costs for the Molybdenum mines are expected to approximate $11.45 per pound of molybdenum for the year 2022.
Refer to “Product Revenues and Production Costs” for a reconciliation of unit net cash costs per pound to production and delivery costs applicable to sales reported in our consolidated financial statements.
Smelting and Refining
We wholly own and operate the Miami smelter in Arizona, the El Paso refinery in Texas and Atlantic Copper, a smelter and refinery in Spain. Additionally, PT-FI has a 39.5 percent ownership interest in PT Smelting and expects its ownership to increase to a majority interest upon completion of the expansion of PT Smelting’s smelting capacity. Treatment charges for smelting and refining copper concentrate consist of a base rate per pound of copper and per ounce of gold and are generally fixed. Treatment charges represent a cost to our mining operations and income to Atlantic Copper and PT Smelting. Thus, higher treatment charges benefit our smelter operations and adversely affect our mining operations. Our North America copper mines are less significantly affected by changes in treatment charges because these operations are largely integrated with our Miami smelter and El Paso refinery.
Through this form of downstream integration, we are assured placement of a significant portion of our concentrate production.
Atlantic Copper smelts and refines copper concentrate and markets refined copper and precious metals in slimes. During the first nine months of 2022, Atlantic Copper’s concentrate purchases included 37 percent from our copper mining operations and 63 percent from third parties.
Atlantic Copper’s major maintenance turnarounds typically occur approximately every eight years, with shorter-term maintenance turnarounds in the interim. Atlantic Copper substantially completed a 78-day major maintenance turnaround in second-quarter 2022 and incurred maintenance charges and idle facility costs totaling $41 million for the first nine months of 2022.
Our Miami smelter completed a major maintenance turnaround in second-quarter 2021 and incurred maintenance charges and idle facility costs totaling $87 million for the first nine months of 2021. Major maintenance turnarounds at the Miami smelter are anticipated to occur approximately every two or three years, with the next major maintenance turnaround scheduled for the first half of 2024.
PT-FI’s current contract with PT Smelting provides for PT-FI to supply 100 percent of the copper concentrate requirements (subject to a minimum or maximum treatment charge rate) necessary for PT Smelting to produce 205,000 metric tons of copper annually on a priority basis. PT-FI may also sell copper concentrate to PT Smelting at market rates for quantities in excess of 205,000 metric tons of copper annually.
Commencing in 2023, PT-FI's commercial arrangement with PT Smelting will convert to a tolling arrangement. PT-FI will pay PT Smelting a tolling fee to smelt and refine its concentrate and will retain title of all products for sale to third parties. This is not expected to result in a significant change in PT-FI's economics but will impact the timing of PT-FI's sales during 2023. We estimate that approximately 80 million pounds of copper and 130 thousand ounces of gold from PT-FI’s production in first-quarter 2023 will be deferred in inventory until final sale later in 2023.
We defer recognizing profits on sales from our mining operations to Atlantic Copper and on 39.5 percent of PT-FI’s sales to PT Smelting until final sales to third parties occur. Changes in these deferrals attributable to variability in intercompany volumes resulted in net additions (reductions) to operating income totaling $33 million ($14 million to net income attributable to common stock) in third-quarter 2022, $41 million ($48 million to net income attributable to common stock) in third-quarter 2021, $73 million ($37 million to net income attributable to common stock) for the first nine months of 2022 and $(144) million ($(97) million to net income attributable to common stock) for the first nine months of 2021. Our net deferred profits on our inventories at Atlantic Copper and PT Smelting to be recognized in future periods’ net income attributable to common stock totaled $105 million at September 30, 2022. Quarterly variations in ore grades, the timing of intercompany shipments and changes in product prices will result in variability in our net deferred profits and quarterly earnings.
CAPITAL RESOURCES AND LIQUIDITY
Our consolidated operating cash flows vary with sales volumes; prices realized from copper, gold and molybdenum sales; production costs; income taxes; other working capital changes; and other factors. We believe the actions we have taken in recent years to build a solid balance sheet, successfully expand low-cost operations and maintain flexible growth options while maintaining sufficient liquidity, will allow us to continue to execute our business plans in a prudent manner despite current economic uncertainty while preserving substantial future asset values. We are closely monitoring market conditions and will continue to adjust our operating plans to protect liquidity and preserve our asset values, if necessary. We will maintain a solid balance sheet and strong liquidity position as we focus on building long-term value in our business, executing our operating plans safely, responsibly and efficiently, and prudently managing costs and capital expenditures.
Based on current sales volume, cost and metal price estimates discussed in “Outlook,” our projected consolidated operating cash flows for the year 2022 of $4.7 billion are expected to exceed projected capital expenditures of $2.7 billion, which excludes $0.9 billion of projected capital expenditures for the Indonesia smelter projects that are being funded with proceeds from PT-FI’s senior notes and its available revolving credit facility. Projected capital expenditures for the year 2022 include $1.8 billion for major mining projects associated with underground mine development in the Grasberg minerals district (including activities at Kucing Liar and supporting mill and power capital costs) and advancement of expansion projects at El Abra and Lone Star.
We have cash on hand and the financial flexibility to fund capital expenditures and our other cash requirements for the year, including noncontrolling interest distributions, income tax payments, debt repayments, common stock dividends (base and variable) and any share repurchases. At September 30, 2022, we had $8.6 billion in consolidated cash and cash equivalents. In October 2022, we entered into a new $3.0 billion, five-year, fully available unsecured revolving credit facility that replaced our prior revolving credit facility. In addition, PT-FI and Cerro Verde have $1.3 billion and $350 million, respectively, of availability under their revolving credit facilities.
Financial Policy. Our financial policy is aligned with our strategic objectives of maintaining a solid balance sheet and increasing cash returns to shareholders while advancing opportunities for future growth. The policy includes a base dividend and a performance-based payout framework, whereby up to 50 percent of available cash flows generated after planned capital spending and distributions to noncontrolling interest would be allocated to shareholder returns and the balance to debt reduction and investments in value enhancing growth projects, subject to us maintaining our net debt at a level not to exceed the net debt target of $3.0 billion to $4.0 billion (excluding project debt for additional smelting capacity in Indonesia). The Board will review the structure of the performance-based payout framework at least annually.
At September 30, 2022, our net debt, excluding net debt for the Indonesia smelter projects, totaled $1.3 billion. Refer to "Net Debt."
Cash
Following is a summary of the U.S. and international components of consolidated cash and cash equivalents available to the parent company, excluding cash committed for the Indonesia smelter projects and net of noncontrolling interests’ share, taxes and other costs at September 30, 2022 (in billions):
| Cash at domestic companies | $ | 4.6 | |||||||||
| Cash at international operations | 4.0 | ||||||||||
| Total consolidated cash and cash equivalents | 8.6 | ||||||||||
| Cash for Indonesia smelter projects | (2.2) | a | |||||||||
| Noncontrolling interests’ share | (0.6) | ||||||||||
| Cash, net of noncontrolling interests’ share | 5.8 | ||||||||||
| Withholding taxes | (0.1) | ||||||||||
| Net cash available | $ | 5.7 |
a.Remaining net proceeds from PT-FI's April 2022 senior notes offering.
Cash held at our international operations is generally used to support our foreign operations’ capital expenditures, operating expenses, debt repayments, working capital and other tax payments, or other cash needs. Management believes that sufficient liquidity is available in the U.S. from cash balances and availability from our revolving credit facility. We have not elected to permanently reinvest earnings from our foreign subsidiaries, and we have recorded deferred tax liabilities for foreign earnings that are available to be repatriated to the U.S. From time to
time, our foreign subsidiaries distribute earnings to the U.S. through dividends that are subject to applicable withholding taxes and noncontrolling interests’ share.
Debt
At September 30, 2022, we had consolidated debt of $10.7 billion, with a weighted-average interest rate of 5.0 percent. Substantially all of our outstanding debt is fixed rate. We had no borrowings outstanding and $8 million in letters of credit issued under our $3.5 billion revolving credit facility. Additionally, at September 30, 2022, no amounts were drawn under PT-FI’s $1.3 billion revolving credit facility or Cerro Verde’s $350 million revolving credit facility.
In October 2022, we entered into a new $3.0 billion, five-year, unsecured revolving credit facility that replaced our prior revolving credit facility. Refer to Note 5 for further discussion.
Operating Activities
We generated operating cash flows of $4.1 billion (net of $1.0 billion of working capital and other uses) for the first nine months of 2022 and $5.4 billion (including $0.4 billion of working capital and other sources) for the first nine months of 2021. Lower operating cash flows for the first nine months of 2022, compared with the first nine months of 2021, primarily reflect an increase in income tax payments at our international operations and lower copper prices, partly offset by higher copper and gold sales volumes, and other working capital changes.
Additionally, for the first nine months of 2021, Cerro Verde made payments totaling $421 million associated with the balance of its royalty dispute liabilities.
Investing Activities
Capital Expenditures. Capital expenditures, including capitalized interest, totaled $2.4 billion for the first nine months of 2022, including approximately $1.2 billion for major mining projects primarily associated with underground development activities in the Grasberg minerals district and $0.5 billion for the Indonesia smelter projects. Capital expenditures for the Indonesia smelter projects are being funded with proceeds from PT-FI's senior notes and its available revolving credit facility. Refer to “Outlook” for further discussion of projected capital expenditures for the year 2022.
Capital expenditures, including capitalized interest, totaled $1.3 billion for the first nine months of 2021, including approximately $0.9 billion for major mining projects primarily associated with underground development activities in the Grasberg minerals district and $0.1 billion for the Indonesia smelter projects.
Proceeds from Sale of Freeport Cobalt. In September 2021, we completed the sale of Freeport Cobalt to Jervois Global Limited (Jervois) for $208 million, including net cash proceeds of $150 million and shares of Jervois.
Proceeds from Sales of Assets. Proceeds from sales of assets totaled $102 million for the first nine months of 2022 and $21 million for the first nine months of 2021. In May 2022, we sold all of the shares we owned in Jervois for proceeds of $60 million.
Loans to PT Smelting for Expansion. PT-FI made loans to PT Smelting totaling $51 million during the first nine months of 2022 to fund PT Smelting’s expansion project.
Acquisition of Minority Interest in PT Smelting. On April 30, 2021, PT-FI acquired 14.5 percent of the outstanding common stock of PT Smelting for $33 million, increasing its ownership interest from 25 percent to 39.5 percent.
Financing Activities
Debt Transactions. Net borrowings of debt totaled $1.3 billion for the first nine months of 2022 and net payments of debt totaled $39 million for the first nine months of 2021. Net borrowings for the first nine months of 2022 reflected borrowings under PT-FI’s $3.0 billion senior notes offering that was completed in April 2022, partly offset by the repayment of borrowings under PT-FI’s term loan ($0.6 billion) and Cerro Verde’s term loan ($0.3 billion), and repayments of FCX's senior notes in open market transactions ($0.9 billion). Refer to Note 5 for further discussion.
Cash Dividends on Common Stock. We paid cash dividends on our common stock totaling $652 million for the first nine months of 2022 and $220 million for the first nine months of 2021. The declaration and payment of dividends (base or variable) is at the discretion of the Board and will depend on our financial results, cash requirements, business prospects, global economic conditions and other factors deemed relevant by the Board. Refer to Note 5,
Previous: Item 1. Financial Statements. · Next: Item 1A. “Risk Factors” contained in Part I of our 2021 Form 10-K, “Cautionary Statement” below and discussion of our financial policy above.