 filings.tools
Item 16. Form 10-K Summary
411K characters. Original on sec.gov · Markdown
Item 16. Form 10-K Summary
None.
- 51 -
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, as amended, the Registrant has duly caused this Report to be signed on its behalf by the undersigned, thereunto duly authorized.
| FEDEX CORPORATION | |||
|---|---|---|---|
| Dated: July 20, 2020 | By: | /s/ Frederick W. Smith | |
| Frederick W. Smith | |||
| Chairman and Chief Executive Officer |
Power of Attorney. KNOW ALL PERSONS BY THESE PRESENTS, that each person whose signature appears below hereby constitutes and appoints Frederick W. Smith, Michael C. Lenz and John L. Merino, and each of them, his or her true and lawful attorneys-in-fact and agents, with full power of substitution and resubstitution, for him or her and in his or her name, place and stead, in any and all capacities, to sign any and all amendments to this Annual Report on Form 10-K, and to file the same, with any and all exhibits thereto, and other documents in connection therewith, with the Securities and Exchange Commission, and hereby grants to such attorneys-in-fact and agents, and each of them, full power and authority to do and perform each and every act and thing requisite and necessary to be done in connection therewith, as fully to all intents and purposes as he or she might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact and agents, or any of them, or their or his substitute or substitutes, may lawfully do or cause to be done by virtue hereof.
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, this Report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the dates indicated.
| Signature | Capacity | Date | ||
|---|---|---|---|---|
| /s/ Frederick W. Smith | Chairman and Chief Executive | July 20, 2020 | ||
| Frederick W. Smith | Officer and Director (Principal Executive Officer) | |||
| /s/ Alan B. Graf, Jr. | Executive Vice President and | July 20, 2020 | ||
| Alan B. Graf, Jr. | Chief Financial Officer (Principal Financial Officer) | |||
| /s/ John L. Merino | Corporate Vice President and Principal | July 20, 2020 | ||
| John L. Merino | Accounting Officer (Principal Accounting Officer) | |||
| /s/ John A. Edwardson | Director | July 20, 2020 | ||
| John A. Edwardson | ||||
| /s/ Marvin R. Ellison | Director | July 20, 2020 | ||
| Marvin R. Ellison | ||||
| /s/ Susan Patricia Griffith | Director | July 20, 2020 | ||
| Susan Patricia Griffith | ||||
| /s/ John C. (“Chris”) Inglis | Director | July 20, 2020 | ||
| John C. (“Chris”) Inglis | ||||
| /s/ Kimberly A. Jabal | Director | July 20, 2020 | ||
| Kimberly A. Jabal | ||||
| /s/ Shirley Ann Jackson | Director | July 20, 2020 | ||
| Shirley Ann Jackson |
- 52 -
| Signature | Capacity | Date | ||
|---|---|---|---|---|
| /s/ R. Brad Martin | Director | July 20, 2020 | ||
| R. Brad Martin | ||||
| /s/ Joshua Cooper Ramo | Director | July 20, 2020 | ||
| Joshua Cooper Ramo | ||||
| /s/ Susan C. Schwab | Director | July 20, 2020 | ||
| Susan C. Schwab | ||||
| /s/ David P. Steiner | Director | July 20, 2020 | ||
| David P. Steiner | ||||
| /s/ Rajesh Subramaniam | Director | July 20, 2020 | ||
| Rajesh Subramaniam | ||||
| /s/ Paul S. Walsh | Director | July 20, 2020 |
Paul S. Walsh
- 53 -
FINANCIAL SECTION TABLE OF CONTENTS
- 54 -
MANAGEMENT’S DISCUSSION AND ANALYSIS OF RESULTS OF OPERATIONS AND
FINANCIAL CONDITION
OVERVIEW OF FINANCIAL SECTION
The financial section of the FedEx Corporation (“FedEx” or the “Company”) Annual Report on Form 10-K (“Annual Report”) consists of the following: Management’s Discussion and Analysis of Results of Operations and Financial Condition (“MD&A”), the Consolidated Financial Statements and the notes to the Consolidated Financial Statements, and Other Financial Information, all of which include information about our significant accounting policies and practices and the transactions that underlie our financial results. The following MD&A describes the principal factors affecting the results of operations, liquidity, capital resources, contractual cash obligations and critical accounting estimates of FedEx. The discussion in the financial section should be read in conjunction with the other sections of this Annual Report, particularly “Item 1. Business” and our detailed discussion of risk factors included in this MD&A.
ORGANIZATION OF INFORMATION
Our MD&A is composed of three major sections: Results of Operations and Outlook, Financial Condition and Critical Accounting Estimates. These sections include the following information:
| • | Results of operations includes an overview of our consolidated 2020 results compared to 2019 results. This section also includes a discussion of key actions and events that impacted our results, as well as our outlook for 2021. Discussion and analysis of 2018 results and year-over-year comparisons between 2019 results and 2018 results can be found in “Item 7. Management’s Discussion and Analysis of Results of Operations and Financial Condition” of our Annual Report for the year ended May 31, 2019. |
|---|
| • | The overview is followed by a financial summary and analysis (including a discussion of both historical operating results and our outlook for 2021) for each of our transportation segments. |
|---|
| • | Our financial condition is reviewed through an analysis of key elements of our liquidity, capital resources and contractual cash obligations, including a discussion of our cash flows, our financial commitments and our liquidity outlook for 2021. |
|---|
| • | Critical accounting estimates discusses those financial statement elements that we believe are most important to understanding the material judgments and assumptions incorporated in our financial results. |
|---|
| • | We conclude with a discussion of risks and uncertainties that may impact our financial condition and operating results. |
|---|
DESCRIPTION OF BUSINESS SEGMENTS
We provide a broad portfolio of transportation, e-commerce and business services through companies competing collectively, operating independently and managed collaboratively, under the respected FedEx brand. Our primary operating companies are Federal Express Corporation (“FedEx Express”), including TNT Express B.V. (“TNT Express”), the world’s largest express transportation company; FedEx Ground Package System, Inc. (“FedEx Ground”), a leading North American provider of small-package ground delivery services; and FedEx Freight Corporation (“FedEx Freight”), a leading North American provider of less-than-truckload (“LTL”) freight transportation services. These companies represent our major service lines and, along with FedEx Corporate Services, Inc. (“FedEx Services”), constitute our reportable segments.
Our FedEx Services segment provides sales, marketing, information technology, communications, customer service, technical support, billing and collection services, and certain back-office functions that support our operating segments. The operating costs of the FedEx Services segment are allocated to the business units it serves. See “Reportable Segments” for further discussion and refer to “Item 1. Business” for a more detailed description of each of our operating companies.
- 55 -
The key indicators necessary to understand our operating results include:
| • | the overall customer demand for our various services based on macroeconomic factors and the global economy; |
|---|
| • | the volumes of transportation services provided through our networks, primarily measured by our average daily volume and shipment weight and size; |
|---|
| • | the mix of services purchased by our customers; |
|---|
| • | the prices we obtain for our services, primarily measured by yield (revenue per package or pound or revenue per shipment or hundredweight for LTL freight shipments); |
|---|
| • | our ability to manage our cost structure (capital expenditures and operating expenses) to match shifting volume levels; and |
|---|
| • | the timing and amount of fluctuations in fuel prices and our ability to recover incremental fuel costs through our fuel surcharges. |
|---|
Many of our operating expenses are directly impacted by revenue and volume levels, and we expect these operating expenses to fluctuate on a year-over-year basis consistent with changes in revenue and volumes. Therefore, the discussion of operating expense captions focuses on the key drivers and trends impacting expenses other than those factors strictly related to changes in revenue and volumes. The line item “Other operating expense” includes costs associated with outside service contracts (such as facility services and cargo handling, temporary labor and security), insurance, professional fees and uniforms.
Except as otherwise specified, references to years indicate our fiscal year ended May 31, 2020 or ended May 31 of the year referenced and comparisons are to the corresponding period of the prior year. References to our transportation segments include, collectively, the FedEx Express segment, the FedEx Ground segment and the FedEx Freight segment.
- 56 -
RESULTS OF O****PERATIONS AND OUTLOOK
CONSOLIDATED RESULTS
The following table compares summary operating results (dollars in millions, except per share amounts) for the years ended May 31:
| 2020(1) | 2019(1) | Percent Change | |||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Consolidated revenue | $ | 69,217 | $ | 69,693 | (1 | ) | |||||||
| Operating income (loss): | |||||||||||||
| FedEx Express segment | 996 | 2,176 | (54 | ) | |||||||||
| FedEx Ground segment | 2,014 | 2,663 | (24 | ) | |||||||||
| FedEx Freight segment | 580 | 615 | (6 | ) | |||||||||
| Corporate, other and eliminations | (1,173 | ) | (988 | ) | (19 | ) | |||||||
| Consolidated operating income | 2,417 | 4,466 | (46 | ) | |||||||||
| Operating margin: | |||||||||||||
| FedEx Express segment | 2.8 | % | 5.8 | % | (300 | ) | bp | ||||||
| FedEx Ground segment | 8.9 | % | 13.0 | % | (410 | ) | bp | ||||||
| FedEx Freight segment | 8.2 | % | 8.1 | % | 10 | bp | |||||||
| Consolidated operating margin | 3.5 | % | 6.4 | % | (290 | ) | bp | ||||||
| Consolidated net income | $ | 1,286 | $ | 540 | 138 | ||||||||
| Diluted earnings per share | $ | 4.90 | $ | 2.03 | 141 |
The following table shows changes in revenue and operating results by reportable segment for 2020 compared to 2019 (in millions):
| Year-over-Year Changes | ||||||||
|---|---|---|---|---|---|---|---|---|
| Revenue | Operating Results(1) | |||||||
| FedEx Express segment | $ | (1,818 | ) | $ | (1,180 | ) | ||
| FedEx Ground segment | 2,211 | (649 | ) | |||||
| FedEx Freight segment | (480 | ) | (35 | ) | ||||
| FedEx Services segment | — | — | ||||||
| Corporate, other and eliminations | (389 | ) | (185 | ) | ||||
| $ | (476 | ) | $ | (2,049 | ) |
| (1) | The following is a summary of the effects of the (costs) benefits of certain key items affecting our financial results (in millions) for the years ended May 31: |
|---|
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Items affecting Operating Results: | ||||||||
| Goodwill and other asset impairment charges | $ | (435 | ) | $ | — | |||
| TNT Express integration expenses | (270 | ) | (388 | ) | ||||
| Business realignment costs | — | (320 | ) | |||||
| Litigation and legal matters | — | (46 | ) | |||||
| $ | (705 | ) | $ | (754 | ) | |||
| Item affecting Net Income: | ||||||||
| Mark-to-market (“MTM”) retirement plans accounting adjustment, net of tax | $ | (583 | ) | $ | (2,981 | ) |
Overview
During 2020, an outbreak of a new strain of coronavirus (“COVID-19”) was declared a pandemic by the World Health Organization. The COVID-19 pandemic had a negative impact on the demand for our commercial services during 2020 due to its disruption of global manufacturing, supply chains and consumer spending. In addition, the COVID-19 pandemic and ongoing trade disputes have significantly increased economic and demand uncertainty. The various stay-at-home orders and shut down of commercial activities in major markets around the world also led to unprecedented demand for residential delivery services, rivaling our peak holiday season traffic. We incurred increased costs associated with this demand and lower composite yields than our typical volume. The length and severity of the impact to our results is currently uncertain, although we are beginning to see some signs of improvement in commercial activity. See “Impact of the COVID-19 Pandemic” below for more information.
- 57 -
Weaker global economic conditions, including the impact of the COVID-19 pandemic, negatively impacted our results in 2020. In addition, our results in 2020 were negatively impacted by the elimination of business from a large customer, higher self-insurance accruals, increased costs to expand services, the continued mix shift to lower-yielding services and a more competitive pricing environment. These factors were partially offset by residential delivery volume growth at FedEx Ground and increased yields at FedEx Freight. Lower variable incentive compensation expenses benefited our results by approximately $320 million in 2020. We recognized $369 million ($366 million, net of tax, or $1.40 per diluted share) of goodwill and other asset impairment charges associated with the FedEx Office and Print Services, Inc. (“FedEx Office”) and FedEx Logistics, Inc. (“FedEx Logistics”) operating segments in the fourth quarter of 2020. Our 2020 results also include $66 million ($50 million, net of tax, or $0.19 per diluted share) of asset impairment charges associated with the decision to permanently retire certain aircraft and related engines at FedEx Express. See the “Goodwill and Other Asset Impairment Charges” section of this MD&A for more information.
Consolidated net income in 2020 includes a pre-tax noncash loss of $794 million ($583 million, net of tax, or $2.22 per diluted share) associated with our fourth quarter MTM retirement plans accounting adjustment. See the “Retirement Plans MTM Adjustment” section of this MD&A and Note 13 of the accompanying consolidated financial statements. Consolidated net income for 2020 also includes a tax benefit of $133 million ($0.51 per diluted share) from the reduction of a valuation allowance on certain foreign tax loss carryforwards, a tax benefit of $71 million ($0.27 per diluted share) related to the Coronavirus Aid, Relief, and Economic Security Act (“CARES Act”), which allows tax losses to be offset against income from prior years that was taxed at higher rates. Additionally, consolidated net income for 2020 includes a tax expense of $51 million ($0.19 per diluted share) due to a change in deferred tax balances related to future foreign tax credits from our international structure. See the “Income Taxes” section of this MD&A and Note 12 of the accompanying consolidated financial statements.
We incurred TNT Express integration expenses totaling $270 million ($209 million, net of tax, or $0.80 per diluted share) in 2020, a decrease of $118 million from 2019. The integration expenses are predominantly incremental costs directly associated with the integration of TNT Express (acquired in fiscal year 2016), including professional and legal fees, salaries and wages, travel and advertising expenses. Internal salaries and wages are included only to the extent the individuals are assigned full-time to integration activities. These costs were recognized at FedEx Express and FedEx Corporate. The identification of these costs as integration-related expenditures is subject to our disclosure controls and procedures.
Impact of the COVID-19 Pandemic
Business-to-business demand across all of our businesses was negatively impacted by the COVID-19 pandemic in 2020. We began to experience business impacts from the COVID-19 pandemic as early as January 2020 when transpacific traffic was affected by the shutdowns in China and the curtailment of commercial air flights. While commercial volumes were down due to business closures across the world, FedEx Ground residential delivery volumes increased to seasonal peak levels during the fourth quarter of 2020 due to stay-at-home orders and other pandemic responsive measures. The shift in mix negatively impacted operating margins and operating results. In addition, the COVID-19 pandemic negatively impacted FedEx Office’s operating performance during 2020, and store closures resulting from the pandemic contributed to the FedEx Office goodwill impairment charge recorded in 2020. See the “Goodwill and Other Asset Impairment Charges” section of this MD&A for more information.
During 2020, we incurred approximately $125 million of increased operating expenses related to personal protective equipment and medical/safety supplies, as well as additional security and cleaning services, in order to protect our team members and customers as we continue to provide essential services during the COVID-19 pandemic. Additionally, in response to the COVID-19 pandemic, we (i) increased hiring at FedEx Ground to keep pace with increased demand for residential services and (ii) increased transpacific and charter flight hours to align capacity with demand at FedEx Express. See Part 1, Item 1 of this Annual Report under the caption “COVID-19 Pandemic” for more information.
We remain committed to assisting our customers as they work to manage their supply chains and inventories. Additionally, we are capitalizing on the opportunity to deliver higher-yielding shipments due to the capacity reductions in Asia. We are at the same time seeking to mitigate the impact of the COVID-19 pandemic on our financial position and operations by continuing to implement our transformation initiatives.
We have also taken the following actions to improve liquidity and strengthen our financial position.
| • | Reduced expected 2021 capital expenditures by approximately $1.0 billion from the prior year, including decreasing spending on vehicles and trailers, delaying facility expansions and postponing certain information technology initiatives. |
|---|
| • | Implemented temporary surcharges on all oversized and residential U.S. domestic FedEx Express and FedEx Ground packages, effective June 8, 2020, and on international package and airfreight shipments, effective April 6, 2020, at FedEx Express. We also temporarily suspended money-back guarantees for all FedEx Express, FedEx Ground, FedEx Freight and same-day FedEx Office services. |
|---|
| • | Suspended voluntary pension funding in 2021. |
|---|
- 58 -
| • | Revised the terms of our $2.0 billion five-year credit agreement (the “Five-Year Credit Agreement”) and our $1.5 billion 364-day credit agreement (the “364-Day Credit Agreement” and together with the Five-Year Credit Agreement, the “Credit Agreements”) to further enhance our financial flexibility. Additionally, we issued $3.0 billion of senior unsecured debt under our shelf registration statement in April 2020. See Note 6 of the accompanying consolidated financial statements for additional information. |
|---|
| • | Deferred payment of the employer portion of social security taxes through December 31, 2020, as provided by the CARES Act, which was enacted on March 27, 2020. This is expected to provide us with approximately $625 million of additional liquidity during 2020 and 2021. |
|---|
| • | Reduced our aviation excise taxes as provided by the CARES Act, which is expected to benefit 2021 by approximately $110 million to $160 million, depending upon the timing and pace of an economic recovery and return to pre-COVID-19 pandemic shipping volumes. We recognized a $37 million benefit for the two-month period this excise tax holiday was in effect during the fourth quarter of 2020. |
|---|
| • | Lowered our 2021 cash outflows for income taxes under the CARES Act. See Note 12 of the accompanying consolidated financial statements for more information related to such provisions. |
|---|
- 59 -
The following graphs for FedEx Express, FedEx Ground and FedEx Freight show selected volume trends (in thousands) for the years ended May 31:

| (1) | International domestic average daily package volume relates to our international intra-country operations. International export average daily package volume relates to our international priority and economy services. |
|---|
| (2) | International average daily freight pounds relate to our international priority, economy and airfreight services. |
|---|
- 60 -
The following graphs for FedEx Express, FedEx Ground and FedEx Freight show selected yield trends for the years ended May 31:

| (1) | International export revenue per package relates to our international priority and economy services. International domestic revenue per package relates to our international intra-country operations. |
|---|
| (2) | International freight revenue per pound relates to our international priority, economy and airfreight services. |
|---|
- 61 -
Revenue
Revenue decreased 1% in 2020 primarily due to the elimination of business from a large customer and the impact from macroeconomic weakness, including the impact of the COVID-19 pandemic. Even though our revenue and operating income comparisons were negatively affected by the elimination of business from a large customer, our customer base is diverse and no one customer comprises more than 3% of our consolidated revenue. In addition, lower fuel surcharges at all transportation segments negatively impacted revenue in 2020. These items were partially offset by residential delivery volume growth at FedEx Ground, including the sharp increase in demand resulting from the stay-at-home orders and other responsive measures caused by the COVID-19 pandemic.
We implemented average list price increases at the beginning of the calendar year at each of our transportation segments. Some customers have contracts that are not subject to these general rate increases. We also implemented temporary surcharges on oversize, residential and international shipments in response to the COVID-19 pandemic.
At FedEx Ground, revenue increased 11% in 2020 due to residential delivery volume growth, partially offset by the decline in commercial delivery volume and the elimination of business from a large customer. Revenue at FedEx Express decreased 5% in 2020 primarily due to lower package revenue as a result of the elimination of business from a large customer and the impact of the COVID-19 pandemic. In addition, unfavorable exchange rates and lower freight revenue negatively impacted revenue in 2020. FedEx Freight revenue decreased 6% in 2020 due to decreased average daily shipments, partially offset by higher revenue per shipment.
Goodwill and Other Asset Impairment Charges
In 2020, we recorded $358 million of goodwill impairment charges, of which $348 million was associated with FedEx Office and the remainder at FedEx Supply Chain Distribution System, Inc. (“FedEx Supply Chain”). As a result, the goodwill attributed to each of these reporting units has been fully impaired. The COVID-19 pandemic resulted in store closures and declining print revenue at FedEx Office during the fourth quarter of 2020 and is expected to continue to negatively impact its near-term operating performance. We also recorded $11 million of other asset impairment charges at the FedEx Logistics operating segment.
In 2020, we made the decision to permanently retire from service 10 Airbus A310-300 aircraft and 12 related engines at FedEx Express to align with the needs of the U.S. domestic network and modernize its aircraft fleet. As a consequence of this decision, noncash impairment charges of $66 million ($50 million, net of tax, or $0.19 per diluted share) were recorded in the FedEx Express segment in 2020. Seven of these aircraft were temporarily idled. For additional information regarding these impairment charges, see the “Critical Accounting Estimates” section of this MD&A and Note 4 of the accompanying consolidated financial statements.
Business Realignment Costs
During 2019, we conducted a program to offer voluntary cash buyouts to eligible U.S.-based employees in certain staff functions. As a result of this program, approximately 1,500 employees left the Company. Costs of the benefits provided under the U.S.-based voluntary employee buyout program were recognized in 2019 when eligible employees accepted their offers. Payments under this program were made at the time of departure and totaled approximately $50 million in 2020 and $220 million in 2019.
- 62 -
Lease Accounting Change
Effective June 1, 2019, we adopted new accounting guidance that had a material impact on our balance sheet but did not materially impact consolidated operating results and had no impact on operating cash flows. In order to properly align the lease and rental expenses to the appropriate line items in accordance with the new standard, a reclassification from other operating expense to rentals and landing fees of approximately $181 million and maintenance and repairs expense to rentals and landing fees of approximately $49 million was made. Such reclassifications are excluded from the year-over-year expense change discussion below and in each transportation segment’s results. See Note 2 of the accompanying consolidated financial statements for a discussion of the adoption of the accounting guidance.
Operating Expenses
The following table compares operating expenses expressed as dollar amounts (in millions) and as a percent of revenue for the years ended May 31:
| Percent | Percent of Revenue | |||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020(1) | 2019(1) | Change | 2020(1) | 2019(1) | ||||||||||||||||
| Operating expenses: | ||||||||||||||||||||
| Salaries and employee benefits | $ | 25,031 | $ | 24,776 | 1 | 36.2 | % | 35.6 | % | |||||||||||
| Purchased transportation | 17,466 | 16,654 | 5 | 25.2 | 23.9 | |||||||||||||||
| Rentals and landing fees | 3,712 | 3,360 | 10 | 5.4 | 4.8 | |||||||||||||||
| Depreciation and amortization | 3,615 | 3,353 | 8 | 5.2 | 4.8 | |||||||||||||||
| Fuel | 3,156 | 3,889 | (19 | ) | 4.6 | 5.6 | ||||||||||||||
| Maintenance and repairs | 2,893 | 2,834 | 2 | 4.2 | 4.0 | |||||||||||||||
| Goodwill and other asset impairment charges(2) | 435 | — | NM | 0.6 | — | |||||||||||||||
| Business realignment costs(3) | — | 320 | NM | — | 0.5 | |||||||||||||||
| Other(4) | 10,492 | 10,041 | 4 | 15.1 | 14.4 | |||||||||||||||
| Total operating expenses | 66,800 | 65,227 | 2 | 96.5 | 93.6 | |||||||||||||||
| Total operating income | $ | 2,417 | $ | 4,466 | (46 | ) | 3.5 | % | 6.4 | % |
| (1) | Includes TNT Express integration expenses of $270 million in 2020 and $388 million in 2019. |
|---|
| (2) | Includes goodwill and other asset impairment charges in 2020 associated with the FedEx Office, FedEx Express and FedEx Logistics operating segments. |
|---|
| (3) | Includes costs associated with our U.S.-based voluntary employee buyout program in 2019. |
|---|
| (4) | Other expenses in 2019 include $46 million of costs incurred in connection with the settlement of a legal matter involving FedEx Ground. |
|---|
Our results declined in 2020 primarily due to weaker global economic conditions, including the impact of the COVID-19 pandemic, the elimination of business from a large customer, higher self-insurance accruals and increased costs to expand services. Self-insurance costs were higher primarily due to increased costs associated with vehicle accidents at FedEx Ground. The rising cost of vehicle accidents is occurring throughout the transportation industry as reflected in the rise of third-party insurance rates. We have prioritized incremental investments in safety technology to address these trends. In addition, continued mix shift to lower-yielding services and a more competitive pricing environment negatively impacted our results during 2020. These factors were partially offset by residential delivery volume growth at FedEx Ground and increased yields at FedEx Freight in 2020. The year-over-year variable incentive compensation expense benefited operating income by approximately $320 million in 2020. We recognized $369 million ($366 million, net of tax, or $1.40 per diluted share) of goodwill and other asset impairment charges associated with the FedEx Office and FedEx Logistics operating segments in the fourth quarter of 2020. Additionally, we recorded asset impairment charges of $66 million ($50 million, net of tax, or $0.19 per diluted share) associated with the decision to permanently retire certain aircraft and related engines at FedEx Express.
Purchased transportation costs increased 5% in 2020 primarily due to higher volumes and increased contractor settlement rates at FedEx Ground, including expanding residential delivery to seven days per week year-round. These items were partially offset by lower volumes, including the impact of the COVID-19 pandemic at FedEx Express and FedEx Freight, favorable exchange rates at FedEx Express and lower utilization of third-party transportation providers at FedEx Freight. Other operating expense increased 4% in 2020 primarily due to higher self-insurance accruals, increased costs associated with the COVID-19 pandemic, higher bad debt expense and higher outside service contract expense. Depreciation and amortization expense increased 8% in 2020 primarily due to continued strategic investment programs at all of our transportation segments.
- 63 -
Fuel
The following graph for our transportation segments shows our average cost of jet and vehicle fuel per gallon for the years ended May 31:
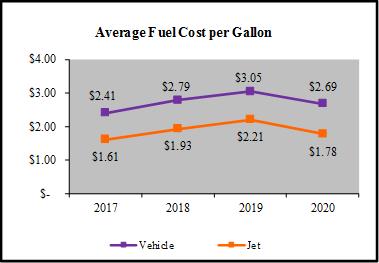
Fuel expense decreased 19% during 2020 due to decreased fuel prices. Fuel prices represent only one component of the factors we consider meaningful in understanding the impact of fuel on our business. Consideration must also be given to the fuel surcharge revenue we collect. Accordingly, we believe discussion of the net impact of fuel on our results, which is a comparison of the year-over-year change in these two factors, is important to understand the impact of fuel on our business. In order to provide information about the impact of fuel surcharges on the trend in revenue and yield growth, we have included the comparative weighted-average fuel surcharge percentages in effect for 2020 and 2019 in the accompanying discussions of each of our transportation segments.
Most of our fuel surcharges are adjusted on a weekly basis. The fuel surcharge is based on a weekly fuel price from two weeks prior to the week in which it is assessed. Some FedEx Express international fuel surcharges incorporate a timing lag of approximately six to eight weeks.
The manner in which we purchase fuel also influences the net impact of fuel on our results. For example, our contracts for jet fuel purchases at FedEx Express are tied to various indices, including the U.S. Gulf Coast index. While many of these indices are aligned, each index may fluctuate at a different pace, driving variability in the prices paid for jet fuel. Furthermore, under these contractual arrangements, approximately 70% of our jet fuel is purchased based on the index price for the preceding week, with the remainder of our purchases tied primarily to the index price for the preceding month and preceding day, rather than based on daily spot rates. These contractual provisions mitigate the impact of rapidly changing daily spot rates on our jet fuel purchases.
Because of the factors described above, our operating results may be affected should the market price of fuel suddenly change by a significant amount or change by amounts that do not result in an adjustment in our fuel surcharges, which can significantly affect our earnings either positively or negatively in the short-term. For more information, see “Risk Factors” below.
We routinely review our fuel surcharges and periodically update the tables used to determine our fuel surcharges at all of our transportation segments. The net impact of fuel on operating income described below and for each segment below does not include the impact from these ordinary-course table changes.
The net impact of fuel had a slight benefit to operating income in 2020 as decreased fuel prices outpaced lower fuel surcharges.
The net impact of fuel on our operating results does not consider the effects that fuel surcharge levels may have on our business, including changes in demand and shifts in the mix of services purchased by our customers. In addition, our purchased transportation expense may be impacted by fuel costs. While fluctuations in fuel surcharge percentages can be significant from period to period, fuel surcharges represent one of the many individual components of our pricing structure that impact our overall revenue and yield. Additional components include the mix of services sold, the base price and extra service charges we obtain for these services and the level of pricing discounts offered.
- 64 -
Other Income and Expense
Interest expense increased $84 million in 2020 primarily due to debt issuances during the year.
Retirement Plans MTM Adjustment
We incurred a pre-tax noncash MTM net loss of $794 million in 2020 ($583 million, net of tax, or $2.22 per diluted share) and a net loss of $3.9 billion in 2019 ($3.0 billion, net of tax, or $11.22 per diluted share) from actuarial adjustments to pension and postretirement healthcare plans related to the measurement of plan assets and liabilities. The net loss in 2020 is attributable to a significantly lower discount rate, partially offset by higher than expected asset returns. The net loss in 2019 is attributable to a significantly lower discount rate, changes in actuarial estimates regarding rates of retirement, disability and salary increases and lower than expected asset returns. For more information, see the “Critical Accounting Estimates” section of this MD&A and Note 1 and Note 13 of the accompanying consolidated financial statements.
Income Taxes
The following table sets forth our income tax expense (benefit) (dollars in millions) and effective tax rates for the years ended May 31:
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Taxes computed at federal statutory rate | $ | 350 | $ | 138 | ||||
| (Decreases) increases in income tax from: | ||||||||
| Valuation allowance | (129 | ) | (79 | ) | ||||
| Goodwill impairment charges | 75 | — | ||||||
| Benefit from U.S. tax loss carryback to prior years | (71 | ) | — | |||||
| Non-deductible expenses | 70 | 79 | ||||||
| State and local income taxes, net of federal benefit | 53 | 44 | ||||||
| U.S. deferred tax adjustment related to foreign operations | 51 | — | ||||||
| Foreign operations | 38 | (1 | ) | |||||
| Uncertain tax positions | (14 | ) | 8 | |||||
| Foreign tax rate enactments | (10 | ) | 50 | |||||
| Benefits from share-based payments | (5 | ) | (18 | ) | ||||
| Tax Cuts and Jobs Act (“TCJA”) | — | (71 | ) | |||||
| Foreign tax credits from distributions | — | (8 | ) | |||||
| Other, net | (25 | ) | (27 | ) | ||||
| Provision for income taxes | $ | 383 | $ | 115 | ||||
| Effective Tax Rate | 23.0 | % | 17.6% |
The 2020 tax rate includes a benefit of $133 million from the reduction of a valuation allowance on certain foreign tax loss carryforwards due to operational changes which impacted the determination of the realizability of the deferred tax asset in that jurisdiction. The 2020 tax rate also includes a deferred income tax expense of $51 million for a change in deferred tax balances related to future foreign tax credits from our international structure as a result of changes in legal entity forecasts during the fourth quarter. The 2020 tax rate was negatively impacted by decreased earnings in certain non-U.S. jurisdictions.
On March 27, 2020, the CARES Act was enacted to address the economic impact of the COVID-19 pandemic in the United States. Among other things, the CARES Act allows a five-year carryback period for tax losses generated in 2019 through 2021. As a result, an income tax benefit of $71 million was recorded in 2020 in connection with a tax loss generated during 2020 that the CARES Act will now allow to be carried back to 2015, a tax year when the U.S. federal income tax rate was 35%.
During the fourth quarter of 2020, we filed a non-automatic Application for Change in Accounting Method with the Internal Revenue Service (“IRS”) to change the method of accounting for depreciation to retroactively apply final tax regulations issued during the year to certain assets placed in service during 2018 and 2019. If the IRS approves our request, we will recognize an income tax benefit in 2021 of approximately $130 million and increase our estimated income tax refund from the carryback to 2015 by approximately $330 million.
We maintain an ongoing process to review our corporate legal entity structure to ensure it is aligned with business operations and regulatory environments in which we operate. A potential outcome of recent reviews could include changing the tax status of certain foreign entities within our structure and favorably impact our effective tax rate in the first half of 2021 primarily through the adjustment of U.S. deferred tax balances related to our foreign operations.
- 65 -
The 2019 tax rate includes a benefit of $90 million from the reduction of a valuation allowance on tax loss carryforwards due to certain business operational changes from the integration of FedEx Express and TNT Express in a local jurisdiction, which impacted our determination of the realizability of the deferred tax asset in that jurisdiction and an expense of $50 million from the impact on our deferred taxes attributable to a lower tax rate in the Netherlands. The 2019 tax rate was favorably impacted by the TCJA, which resulted in benefits of $75 million from accelerated deductions claimed on our 2018 U.S. income tax return filed in 2019.
During 2019, the U.S. Treasury Department issued final regulations covering the one-time transition tax on unrepatriated foreign earnings, which was enacted as part of the TCJA. Certain guidance included in these final regulations is inconsistent with our interpretation that led to the recognition of a $233 million cumulative benefit through 2019. Notwithstanding this inconsistency, we remain confident in our interpretation of the TCJA and intend to defend this position through litigation, if necessary. However, if we are ultimately unsuccessful in defending our position, we may be required to reverse the benefit previously recorded.
During 2019, we completed our accounting for the tax effects of the TCJA within the one-year measurement period allowed under Staff Accounting Bulletin 118. As a result, we recorded an adjustment to tax expense of $4 million recognized in 2019 as a revision of the provisional benefit associated with the remeasurement of our net U.S. deferred tax liability.
For more information on income taxes, see the “Critical Accounting Estimates” section of this MD&A and Note 12 of the accompanying consolidated financial statements.
Business Acquisitions
See Note 3 of the accompanying consolidated financial statements for a discussion of business acquisitions.
Outlook
The uncertainty over the continuing and ultimate impact the COVID-19 pandemic will have on the global economy generally, and our business in particular, makes any expectations for 2021 inherently less certain. The timing and pace of an economic recovery from the COVID-19 pandemic are currently the most profound uncertainties affecting our business. While we anticipate increased demand for residential services to continue at FedEx Ground in 2021, we expect weak global economic conditions, significant uncertainty concerning the health impacts of COVID-19 and increased supplies and other costs caused by the pandemic to continue to impact our results of operations, cash flows and liquidity in 2021.
While restrictions on commercial air traffic are in place, we expect continued strong demand for international priority shipments and charter flights in 2021. However, our international operations are much more sensitive to changes in global trade than our U.S. domestic operations because of the higher concentration of business-to-business shipments internationally. We will continue to manage network capacity, flexing our network and making adjustments as needed to align with volumes and operating conditions.
During 2021, we will expand FedEx Ground seven-day residential delivery coverage to more than 95 percent of the U.S. population. In addition, we will continue to focus on last-mile residential delivery optimization by directing certain U.S. day-definite residential FedEx Express shipments into the FedEx Ground network to increase efficiency and lower our cost-to-serve. We also are focused on improving revenue quality and lowering costs through investments in technology aimed at improving productivity and safety.
During 2021, we will continue to execute our TNT Express integration plans, and we are scheduled to complete the integration of the FedEx Express and TNT Express linehaul and pickup-and-delivery operations and begin offering an enhanced portfolio of international services. We will leverage the capabilities that TNT Express adds to our portfolio, which are expected to improve our European revenue and profitability. While we expect to make significant progress on integration activities in 2021, particularly in Europe, integration work will continue after 2021. Due to delays caused by the COVID-19 pandemic, we now expect to complete the final phase of international air network interoperability in early calendar 2022 rather than the fall of calendar 2021.
We expect to incur approximately $175 million of integration expenses in 2021 in the form of professional fees, outside service contracts, salaries and wages and other operating expenses. We expect the aggregate integration program expenses to be approximately $1.7 billion through the completion of the physical network integration of TNT Express into FedEx Express in 2022. We may incur additional costs, including investments that will further transform and optimize the combined businesses and FedEx Express’s international business. The timing and amount of integration and other expenses and capital investments may change as we revise and implement our plans.
Our capital expenditures for 2021 are expected to be approximately $4.9 billion, a decrease of $1.0 billion from 2020 due to decreasing spending on vehicles and trailers, delaying facility expansions and postponing certain information technology initiatives. Our 2021 expected capital expenditures include FedEx Express investments in aircraft fleet modernization, strategic investments to improve productivity and safety, and the Indianapolis and Memphis hub modernization and expansion programs at FedEx Express.
- 66 -
Our aircraft fleet modernization and hub modernization and expansion programs at FedEx Express are multi-year programs that will entail significant investments over the next several years. See the “Contractual Cash Obligations and Off-Balance Sheet Arrangements” section of this MD&A for details of our capital commitments for 2021 and beyond. We will continue to evaluate our investments in critical long-term strategic projects to ensure our capital expenditures are expected to generate high returns on investment and are balanced with our outlook for global economic conditions. For additional details on key 2021 capital projects, refer to the “Financial Condition – Capital Resources” and “Financial Condition – Liquidity Outlook” sections of this MD&A.
See “Risk Factors” and “Forward-Looking Statements” for a discussion of these and other potential risks and uncertainties that could materially affect our future performance.
Seasonality of Business
Our businesses are cyclical in nature, as seasonal fluctuations affect volumes, revenue and earnings. Historically, the U.S. express package business experiences an increase in volumes in late November and December. International business, particularly in the Asia-to-U.S. market, peaks in October and November in advance of the U.S. holiday sales season. Our first and third fiscal quarters, because they are summer vacation and post winter-holiday seasons, have historically experienced lower volumes relative to other periods. Normally, the fall is the busiest shipping period for FedEx Ground, while late December, June and July are the slowest periods. However, FedEx Ground experienced unplanned peak-level volumes during the fourth quarter of 2020 due to the COVID-19 pandemic. For FedEx Freight, the spring and fall are the busiest periods and the latter part of December through February is the slowest period. Shipment levels, operating costs and earnings for each of our companies can also be adversely affected by inclement weather, particularly the impact of severe winter weather in our third fiscal quarter. See “Risk Factors” below for more information.
RECENT ACCOUNTING GUIDANCE
See Note 2 of the accompanying consolidated financial statements for a discussion of recent accounting guidance.
REPORTABLE SEGMENTS
FedEx Express, FedEx Ground and FedEx Freight represent our major service lines and, along with FedEx Services, constitute our reportable segments. Our reportable segments include the following businesses:
| FedEx Express Segment | FedEx Express (express transportation) |
|---|---|
| TNT Express (international express transportation, small-package ground delivery and freight transportation) FedEx Custom Critical, Inc. (“FedEx Custom Critical”) (time-critical transportation) | |
| FedEx Ground Segment | FedEx Ground (small-package ground delivery) |
| FedEx Freight Segment | FedEx Freight (LTL freight transportation) |
| FedEx Services Segment | FedEx Services (sales, marketing, information technology, communications, customer service, technical support, billing and collection services and back-office functions) |
Effective March 1, 2020, the results of FedEx Custom Critical are included in the FedEx Express segment prospectively as the impact to prior periods was not material. This change was made to reflect our internal management reporting structure.
FEDEX SERVICES SEGMENT
The operating expense line item “Intercompany charges” on the accompanying consolidated financial statements of our transportation segments reflects the allocations from the FedEx Services segment to the respective operating segments. The allocations of net operating costs are based on metrics such as relative revenue or estimated services provided.
The FedEx Services segment provides direct and indirect support to our operating segments, and we allocate all of the net operating costs of the FedEx Services segment to reflect the full cost of operating our businesses in the results of those segments. We review and evaluate the performance of our transportation segments based on operating income (inclusive of FedEx Services segment allocations). For the FedEx Services segment, performance is evaluated based on the impact of its total allocated net operating costs on our operating segments. We believe these allocations approximate the net cost of providing these functions. Our allocation methodologies are refined periodically, as necessary, to reflect changes in our businesses.
- 67 -
COR****PORATE, OTHER AND ELIMINATIONS
Corporate and other includes corporate headquarters costs for executive officers and certain legal and finance functions, as well as certain other costs and credits not attributed to our core business. These costs are not allocated to the other business segments. Also, the results of the FedEx Office and FedEx Logistics operating segments are included in corporate and other.
FedEx Office provides an array of document and business services and retail access to our customers for our package transportation businesses. FedEx Logistics provides integrated supply chain management solutions, specialty transportation, customs brokerage and global ocean and air freight forwarding.
In 2020, the decrease in revenue in “Corporate, other and eliminations” was due primarily to weaker economic conditions resulting from the COVID-19 pandemic. The comparison of operating loss between 2020 and 2019 at “Corporate, other and eliminations” is affected by goodwill and other asset impairment charges at the FedEx Office and FedEx Logistics operating segments of $369 million in 2020 and the costs associated with our business realignment activities of $320 million during 2019.
Certain FedEx operating companies provide transportation and related services for other FedEx companies outside their reportable segment. Billings for such services are based on negotiated rates, which we believe approximate fair value, and are reflected as revenue of the billing segment. These rates are adjusted from time to time based on market conditions. Such intersegment revenue and expenses are eliminated in our consolidated results and are not separately identified in the following segment information because the amounts are not material.
- 68 -
FEDEX EXPRESS SEGMENT
FedEx Express offers a wide range of U.S. domestic and international shipping services for delivery of packages and freight including priority, deferred and economy services, which provide delivery on a time-definite or day-definite basis. The following table compares revenue, operating expenses, operating income (dollars in millions), operating margin and operating expenses as a percent of revenue for the years ended May 31:
| 2020 | 2019 | Percent Change | ||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue: | ||||||||||||||||||||
| Package: | ||||||||||||||||||||
| U.S. overnight box | $ | 7,234 | $ | 7,663 | (6 | ) | ||||||||||||||
| U.S. overnight envelope | 1,776 | 1,829 | (3 | ) | ||||||||||||||||
| U.S. deferred | 4,038 | 4,225 | (4 | ) | ||||||||||||||||
| Total U.S. domestic package revenue | 13,048 | 13,717 | (5 | ) | ||||||||||||||||
| International priority | 7,354 | 7,405 | (1 | ) | ||||||||||||||||
| International economy | 3,082 | 3,446 | (11 | ) | ||||||||||||||||
| Total international export package revenue | 10,436 | 10,851 | (4 | ) | ||||||||||||||||
| International domestic(1) | 4,179 | 4,540 | (8 | ) | ||||||||||||||||
| Total package revenue | 27,663 | 29,108 | (5 | ) | ||||||||||||||||
| Freight: | ||||||||||||||||||||
| U.S. | 2,998 | 3,025 | (1 | ) | ||||||||||||||||
| International priority | 1,915 | 2,070 | (7 | ) | ||||||||||||||||
| International economy | 1,930 | 2,123 | (9 | ) | ||||||||||||||||
| International airfreight | 270 | 314 | (14 | ) | ||||||||||||||||
| Total freight revenue | 7,113 | 7,532 | (6 | ) | Percent of Revenue | |||||||||||||||
| Other(2) | 737 | 691 | 7 | 2020 | 2019 | |||||||||||||||
| Total revenue | 35,513 | 37,331 | (5 | ) | 100.0 | % | 100.0 | % | ||||||||||||
| Operating expenses: | ||||||||||||||||||||
| Salaries and employee benefits | 13,764 | 13,748 | — | 38.7 | 36.8 | |||||||||||||||
| Purchased transportation | 4,832 | 5,186 | (7 | ) | 13.6 | 13.9 | ||||||||||||||
| Rentals and landing fees | 2,045 | 1,908 | 7 | 5.8 | 5.1 | |||||||||||||||
| Depreciation and amortization | 1,894 | 1,801 | 5 | 5.3 | 4.8 | |||||||||||||||
| Fuel | 2,664 | 3,310 | (20 | ) | 7.5 | 8.9 | ||||||||||||||
| Maintenance and repairs | 1,874 | 1,888 | (1 | ) | 5.3 | 5.1 | ||||||||||||||
| Goodwill and other asset impairment charges | 66 | — | NM | 0.2 | — | |||||||||||||||
| Intercompany charges | 1,956 | 2,039 | (4 | ) | 5.5 | 5.5 | ||||||||||||||
| Other | 5,422 | 5,275 | 3 | 15.3 | 14.1 | |||||||||||||||
| Total operating expenses | 34,517 | 35,155 | (2 | ) | 97.2 | % | 94.2 | % | ||||||||||||
| Operating income | $ | 996 | $ | 2,176 | (54 | ) | ||||||||||||||
| Operating margin | 2.8 | % | 5.8 | % | (300 | ) | bp |
| (1) | International domestic revenue relates to our international intra-country operations. |
|---|
| (2) | Includes the operations of FedEx Custom Critical. |
|---|
- 69 -
The following table compares selected statistics (in thousands, except yield amounts) for the years ended May 31:
| 2020 | 2019 | Percent Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Package Statistics | ||||||||||||
| Average daily package volume (ADV): | ||||||||||||
| U.S. overnight box | 1,211 | 1,285 | (6 | ) | ||||||||
| U.S. overnight envelope | 521 | 539 | (3 | ) | ||||||||
| U.S. deferred | 1,076 | 1,077 | — | |||||||||
| Total U.S. domestic ADV | 2,808 | 2,901 | (3 | ) | ||||||||
| International priority | 559 | 538 | 4 | |||||||||
| International economy | 282 | 293 | (4 | ) | ||||||||
| Total international export ADV | 841 | 831 | 1 | |||||||||
| International domestic(1) | 2,337 | 2,471 | (5 | ) | ||||||||
| Total ADV | 5,986 | 6,203 | (3 | ) | ||||||||
| Revenue per package (yield): | ||||||||||||
| U.S. overnight box | $ | 23.51 | $ | 23.38 | 1 | |||||||
| U.S. overnight envelope | 13.43 | 13.31 | 1 | |||||||||
| U.S. deferred | 14.78 | 15.39 | (4 | ) | ||||||||
| U.S. domestic composite | 18.30 | 18.54 | (1 | ) | ||||||||
| International priority | 51.75 | 53.96 | (4 | ) | ||||||||
| International economy | 43.03 | 46.16 | (7 | ) | ||||||||
| International export composite | 48.83 | 51.21 | (5 | ) | ||||||||
| International domestic(1) | 7.04 | 7.20 | (2 | ) | ||||||||
| Composite package yield | 18.19 | 18.40 | (1 | ) | ||||||||
| Freight Statistics | ||||||||||||
| Average daily freight pounds: | ||||||||||||
| U.S. | 8,528 | 8,577 | (1 | ) | ||||||||
| International priority | 4,895 | 5,250 | (7 | ) | ||||||||
| International economy | 13,450 | 14,347 | (6 | ) | ||||||||
| International airfreight | 1,535 | 1,644 | (7 | ) | ||||||||
| Total average daily freight pounds | 28,408 | 29,818 | (5 | ) | ||||||||
| Revenue per pound (yield): | ||||||||||||
| U.S. | $ | 1.38 | $ | 1.38 | — | |||||||
| International priority | 1.54 | 1.55 | (1 | ) | ||||||||
| International economy | 0.56 | 0.58 | (3 | ) | ||||||||
| International airfreight | 0.69 | 0.75 | (8 | ) | ||||||||
| Composite freight yield | 0.99 | 0.99 | — |
| (1) | International domestic statistics relate to our international intra-country operations. |
|---|
FedEx Express Segment Revenue
FedEx Express segment revenue decreased 5% in 2020 primarily due to lower package revenue as a result of the elimination of business from a large customer and the impact of the COVID-19 pandemic. In addition, lower fuel surcharges, unfavorable exchange rates and lower freight revenue negatively impacted revenue in 2020.
U.S. domestic package average daily volumes decreased 3% in 2020 driven by the elimination of business from a large customer and the impact of the COVID-19 pandemic. U.S. domestic package yields decreased 1% in 2020 primarily due to lower fuel surcharges and lower base yields. Average daily freight pounds decreased 5% in 2020 primarily due to lower volume in freight services as a result of macroeconomic weakness, including the impact of the COVID-19 pandemic, and trade uncertainty. International export average daily volumes increased 1% in 2020 due to volume growth in the first three quarters of 2020, partially offset by the impact of the COVID-19 pandemic in the fourth quarter of 2020. International export package yields decreased 5% in 2020 primarily driven by base yield declines, lower fuel surcharges and unfavorable exchange rates. International domestic package average daily volumes decreased 5% in 2020 primarily due to the COVID-19 pandemic. International domestic package yields decreased 2% in 2020 as base yield improvement was more than offset by unfavorable exchange rates.
- 70 -
FedEx Express’s U.S. domestic and outbound fuel surcharge and international fuel surcharges ranged as follows for the years ended May 31:
| 2020 | 2019 | ||||||||
|---|---|---|---|---|---|---|---|---|---|
| U.S. Domestic and Outbound Fuel Surcharge: | |||||||||
| Low | 0.5 | % | 5.5 | % | |||||
| High | 8.6 | 10.8 | |||||||
| Weighted-average | 6.3 | 7.5 | |||||||
| International Export and Freight Fuel Surcharge: | |||||||||
| Low | — | 5.8 | |||||||
| High | 19.3 | 18.1 | |||||||
| Weighted-average | 14.0 | 14.1 | |||||||
| International Domestic Fuel Surcharge: | |||||||||
| Low | 3.2 | 2.3 | |||||||
| High | 24.5 | 20.6 | |||||||
| Weighted-average | 7.3 | 5.9 |
FedEx Express Segment Operating Income
FedEx Express segment operating income decreased 54% in 2020 primarily due to weaker global economic conditions, including the impact of the COVID-19 pandemic, a more competitive pricing environment and the elimination of business from a large customer. During 2020, we recorded asset impairment charges of $66 million associated with the decision to permanently retire certain aircraft and related engines (see “Goodwill and Other Asset Impairment Charges” above for more information).
FedEx Express segment results include approximately $222 million of TNT Express integration expenses in 2020, a decrease of $103 million from 2019.
Purchased transportation expense decreased 7% in 2020 primarily due to lower volumes, including the impact of the COVID-19 pandemic, and favorable exchange rates. Other operating expense increased 3% in 2020 primarily due to increased costs associated with the COVID-19 pandemic, increased bad debt expense and higher outside service contract expense. Depreciation and amortization expense increased 5% in 2020 primarily due to continued investment in aircraft and related equipment.
Fuel expense decreased 20% in 2020 due to decreased fuel prices. The net impact of fuel had a slight benefit to operating income in 2020 as decreased fuel prices outpaced lower fuel surcharges. See the “Results of Operations and Outlook – Consolidated Results – Fuel” section of this MD&A for a description and additional discussion of the net impact of fuel on our operating results.
FedEx Express Segment Outlook
We expect the significance of the COVID-19 pandemic, including the extent of its effect on our results, to be dictated by, among other things, its duration, the success of efforts to contain it and the impact of actions taken in response. The timing and pace of an economic recovery from the COVID-19 pandemic are uncertain. While airfreight capacity continues to be limited due to restrictions on commercial activities, we will continue to provide needed services and add flights as necessary to support demand and we are well positioned to adjust to market conditions to assist our customers as they work to manage their supply chain and inventories. We are flexing our network and making adjustments as needed to align capacity with volumes and operating conditions.
We expect the uncertainty in global economic conditions to negatively impact revenue and operating income in 2021. During 2021, FedEx Express will continue to implement actions to reduce costs to serve, improve efficiencies and adjust its air and ground network cost structure. We continue to focus on optimizing the cost of last-mile residential deliveries by directing certain U.S. day-definite, residential FedEx Express shipments into the FedEx Ground network. We expect last-mile optimization will allow us to increase efficiency and lower our cost-to-serve as e-commerce growth continues to impact our service mix. We expect the FedEx Express segment to incur approximately $100 million of TNT Express integration expenses in 2021. See the “Outlook” section of this MD&A for additional information regarding the integration of TNT Express.
Capital expenditures at FedEx Express are expected to significantly decrease in 2021 as we delay facility investments and decrease spending on vehicles and trailers, as well as ground support equipment.
- 71 -
FEDEX GROUND SEGMENT
FedEx Ground service offerings include day-certain delivery to businesses in the U.S. and Canada and to 100% of U.S. residences. The following table compares revenue, operating expenses, operating income (dollars in millions), operating margin, selected package statistics (in thousands, except yield amounts) and operating expenses as a percent of revenue for the years ended May 31:
| 2020 | 2019 | Percent Change | Percent of Revenue | ||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | ||||||||||||||||||||
| Revenue | $ | 22,733 | $ | 20,522 | 11 | 100.0 | % | 100.0 | % | ||||||||||||
| Operating expenses: | |||||||||||||||||||||
| Salaries and employee benefits | 4,060 | 3,413 | 19 | 17.9 | 16.6 | ||||||||||||||||
| Purchased transportation | 10,799 | 9,174 | 18 | 47.5 | 44.7 | ||||||||||||||||
| Rentals | 989 | 791 | 25 | 4.3 | 3.9 | ||||||||||||||||
| Depreciation and amortization | 789 | 728 | 8 | 3.5 | 3.5 | ||||||||||||||||
| Fuel | 15 | 14 | 7 | 0.1 | 0.1 | ||||||||||||||||
| Maintenance and repairs | 392 | 336 | 17 | 1.7 | 1.6 | ||||||||||||||||
| Intercompany charges | 1,581 | 1,521 | 4 | 6.9 | 7.4 | ||||||||||||||||
| Other | 2,094 | 1,882 | 11 | 9.2 | 9.2 | ||||||||||||||||
| Total operating expenses | 20,719 | 17,859 | 16 | 91.1 | % | 87.0 | % | ||||||||||||||
| Operating income | $ | 2,014 | $ | 2,663 | (24 | ) | |||||||||||||||
| Operating margin | 8.9 | % | 13.0 | % | (410 | ) | bp | ||||||||||||||
| Average daily package volume | 9,997 | 8,952 | 12 | ||||||||||||||||||
| Revenue per package (yield) | $ | 8.93 | $ | 8.97 | — |
FedEx Ground Segment Revenue
FedEx Ground segment revenue increased 11% in 2020 due to residential delivery volume growth, including the sharp increase in demand resulting from the stay-at-home orders and other responsive measures caused by the COVID-19 pandemic, partially offset by the decline in commercial delivery volume and the elimination of business from a large customer. Average daily volume increased 12% in 2020 primarily due to continued growth in residential services driven by e-commerce. FedEx Ground yields remained flat in 2020 primarily due to lower base yields offset by an increase in extra services.
The FedEx Ground fuel surcharge is based on a rounded average of the national U.S. on-highway average price for a gallon of diesel fuel, as published by the Department of Energy. The fuel surcharge ranged as follows for the years ended May 31:
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Low | 5.8 | % | 6.3 | % | ||||
| High | 7.3 | 7.8 | ||||||
| Weighted-average | 6.7 | 6.9 |
FedEx Ground Segment Operating Income
FedEx Ground segment operating income decreased 24% in 2020 due to increased costs to expand services, higher self-insurance accruals and the elimination of business from a large customer. In addition, continued mix shift to lower-yielding services, as well as a more competitive pricing environment, negatively impacted our results in 2020. These items were partially offset by residential delivery volume growth in 2020. The COVID-19 pandemic had a positive impact on revenue and a negative impact on expenses but did not have a material impact on operating income in 2020.
Purchased transportation expense increased 18% in 2020 due to higher volumes and increased contractor settlement rates, including expanding operations to seven days per week year-round. Salaries and employee benefits expense increased 19% in 2020 due to additional staffing to support volume growth, including expansion to seven-day-per-week year-round operations, and merit increases, partially offset by lower variable incentive compensation expenses. Other operating expense increased 11% in 2020 primarily due to higher self-insurance accruals of approximately $230 million.
The net impact of fuel had a slight benefit to operating income in 2020 as decreased fuel prices outpaced lower fuel surcharges. See the “Results of Operations and Outlook – Consolidated Results – Fuel” section of this MD&A for a description and additional discussion of the net impact of fuel on our operating results.
- 72 -
FedEx Ground Segment Outlook
We anticipate increased demand for residential services to continue at FedEx Ground in 2021. Building on investments made in 2020 to expand the FedEx Ground residential service offering, we will expand seven-day residential delivery coverage to more than 95 percent of the U.S. population by September 2020. We also are adding new regional sort facilities designed to handle shorter-zone residential volumes into certain key markets. Although the timing and pace of an economic recovery from the COVID-19 pandemic are uncertain and the uncertainty is expected to have an impact on commercial volumes in 2021, we remain well positioned to adjust to market conditions to assist our customers as they manage their supply chains and inventories.
To support these operational changes, FedEx Ground is making strategic investments to modernize and optimize its linehaul network and improve scheduling at its hubs and stations, leading to productivity improvement. Significant progress was made in the integration of FedEx SmartPost packages into the standard FedEx Ground operations in 2020 and this transition will be completed in the first half of 2021, generating last-mile efficiency through increased delivery density. Strategic investments made in 2020 for safety technology will remain a critical focus in 2021 to improve the safety throughout the FedEx Ground network.
We believe these initiatives will allow for the more efficient use of our existing assets, which will drive improved performance and enhance our competitive position over the long term. To support these strategic investments, capital expenditures in 2021 at FedEx Ground are expected to increase.
See “Risk Factors” and “Forward-Looking Statements” for a discussion of these and other potential risks and uncertainties that could materially affect our future performance.
- 73 -
FEDEX FREIGHT SEGMENT
FedEx Freight LTL service offerings include priority services when speed is critical and economy services when time can be traded for savings. The following table compares revenue, operating expenses, operating income (dollars in millions), operating margin, selected statistics and operating expenses as a percent of revenue for the years ended May 31:
| Percent | Percent of Revenue | ||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | Change | 2020 | 2019 | |||||||||||||||||
| Revenue | $ | 7,102 | $ | 7,582 | (6 | ) | 100.0 | % | 100.0 | % | |||||||||||
| Operating expenses: | |||||||||||||||||||||
| Salaries and employee benefits | 3,449 | 3,639 | (5 | ) | 48.5 | 48.0 | |||||||||||||||
| Purchased transportation | 695 | 932 | (25 | ) | 9.8 | 12.3 | |||||||||||||||
| Rentals | 208 | 172 | 21 | 2.9 | 2.3 | ||||||||||||||||
| Depreciation and amortization | 381 | 332 | 15 | 5.4 | 4.4 | ||||||||||||||||
| Fuel | 476 | 563 | (15 | ) | 6.7 | 7.4 | |||||||||||||||
| Maintenance and repairs | 247 | 245 | 1 | 3.5 | 3.2 | ||||||||||||||||
| Intercompany charges | 516 | 535 | (4 | ) | 7.3 | 7.1 | |||||||||||||||
| Other | 550 | 549 | — | 7.7 | 7.2 | ||||||||||||||||
| Total operating expenses | 6,522 | 6,967 | (6 | ) | 91.8 | % | 91.9 | % | |||||||||||||
| Operating income | $ | 580 | $ | 615 | (6 | ) | |||||||||||||||
| Operating margin | 8.2 | % | 8.1 | % | 10 | bp | |||||||||||||||
| Average daily shipments (in thousands): | |||||||||||||||||||||
| Priority | 72.5 | 78.4 | (8 | ) | |||||||||||||||||
| Economy | 30.5 | 34.3 | (11 | ) | |||||||||||||||||
| Total average daily shipments | 103.0 | 112.7 | (9 | ) | |||||||||||||||||
| Weight per shipment: | |||||||||||||||||||||
| Priority | 1,146 | 1,207 | (5 | ) | |||||||||||||||||
| Economy | 986 | 1,064 | (7 | ) | |||||||||||||||||
| Composite weight per shipment | 1,098 | 1,164 | (6 | ) | |||||||||||||||||
| Revenue per shipment: | |||||||||||||||||||||
| Priority | $ | 260.39 | $ | 250.95 | 4 | ||||||||||||||||
| Economy | 301.55 | 300.02 | 1 | ||||||||||||||||||
| Composite revenue per shipment | $ | 273.72 | $ | 265.98 | 3 | ||||||||||||||||
| Revenue per hundredweight: | |||||||||||||||||||||
| Priority | $ | 22.73 | $ | 20.78 | 9 | ||||||||||||||||
| Economy | 30.59 | 28.19 | 9 | ||||||||||||||||||
| Composite revenue per hundredweight | $ | 24.92 | $ | 22.85 | 9 |
FedEx Freight Segment Revenue
FedEx Freight segment revenue decreased 6% in 2020 primarily due to decreased average daily shipments, partially offset by higher revenue per shipment. Average daily shipments decreased 9% in 2020 due to lower demand for our service offerings as a result of the COVID-19 pandemic and related supply chain disruptions. Revenue per shipment increased 3% in 2020 primarily due to higher base rates reflecting our ongoing revenue quality initiatives, partially offset by lower weight per shipment.
The weekly indexed fuel surcharge is based on the average of the U.S. on-highway prices for a gallon of diesel fuel, as published by the Department of Energy. The indexed FedEx Freight fuel surcharge ranged as follows for the years ended May 31:
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Low | 21.0 | % | 23.4 | % | ||||
| High | 24.4 | 25.6 | ||||||
| Weighted-average | 23.4 | 24.5 |
FedEx Freight Segment Operating Income
FedEx Freight segment operating income decreased 6% in 2020 due to the impact of lower volumes as a result of the COVID-19 pandemic and weaker economic conditions. Continued focus on yield management and aligning our cost structure with current and anticipated business levels benefited operating results in 2020.
- 74 -
Purchased transportation decreased 25% in 2020 primarily due to lower utilization of third-party transportation providers and lower volumes. Salaries and employee benefits decreased 5% in 2020 primarily due to lower volumes, partially offset by merit increases.
Fuel expense decreased 15% in 2020 primarily due to decreased fuel prices. The net impact of fuel had a significantly negative impact to operating income in 2020 as lower fuel surcharges outpaced decreased fuel prices. See the “Results of Operations and Outlook – Consolidated Results – Fuel” section of this MD&A for a description and additional discussion of the net impact of fuel on our operating results.
FedEx Freight Segment Outlook
Our FedEx Freight business is significantly impacted by changes in industrial production, which has been negatively impacted by the COVID-19 pandemic. In addition, the timing and pace of an economic recovery from the COVID-19 pandemic are uncertain.
In 2021, we will continue to manage our network and cost structure to align with volume levels, maintain our focus on yield management and profitable growth and improve our operational productivity and efficiencies through increased use of technology. We will continue to evaluate new service offerings that will deliver improved customer experiences and set us apart from the competition. Our employee-based, company-branded FedEx Freight Direct standard and premium residential service offerings will be available to 90% of the U.S. population in the second half of 2021. This service offering addresses the large, bulky and hard-to-handle surging e-commerce market and supports on-going collaboration with FedEx Ground.
Given the uncertainty around the COVID-19 pandemic, capital expenditures at FedEx Freight are expected to decrease significantly in 2021 and will consist primarily of vehicle replacement and strategic investments to modernize our operations.
- 75 -
FINANCIAL CONDITION
LIQUIDITY
Cash and cash equivalents totaled $4.9 billion at May 31, 2020, compared to $2.3 billion at May 31, 2019. The following table provides a summary of our cash flows for the years ended May 31 (in millions):
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Operating activities: | ||||||||
| Net income | $ | 1,286 | $ | 540 | ||||
| Retirement plans mark-to-market adjustment | 794 | 3,882 | ||||||
| Gain from sale of business | — | (8 | ) | |||||
| Business realignment costs | — | 101 | ||||||
| Goodwill and other asset impairment charges | 435 | — | ||||||
| Other noncash charges and credits | 6,674 | 3,589 | ||||||
| Changes in assets and liabilities | (4,092 | ) | (2,491 | ) | ||||
| Cash provided by operating activities | 5,097 | 5,613 | ||||||
| Investing activities: | ||||||||
| Capital expenditures | (5,868 | ) | (5,490 | ) | ||||
| Business acquisitions, net of cash acquired | — | (66 | ) | |||||
| Proceeds from asset dispositions and other | 22 | 83 | ||||||
| Cash used in investing activities | (5,846 | ) | (5,473 | ) | ||||
| Financing activities: | ||||||||
| Principal payments on debt | (2,548 | ) | (1,436 | ) | ||||
| Proceeds from debt issuances | 6,556 | 2,463 | ||||||
| Dividends paid | (679 | ) | (683 | ) | ||||
| Purchase of treasury stock | (3 | ) | (1,480 | ) | ||||
| Other | 55 | 97 | ||||||
| Cash provided by (used in) financing activities | 3,381 | (1,039 | ) | |||||
| Effect of exchange rate changes on cash | (70 | ) | (47 | ) | ||||
| Net increase (decrease) in cash and cash equivalents | $ | 2,562 | $ | (946 | ) | |||
| Cash and cash equivalents at end of period | $ | 4,881 | $ | 2,319 |
Cash Provided by Operating Activities. Cash flows from operating activities decreased $516 million in 2020 primarily due to lower operating earnings and higher accounts receivable resulting from, among other things, the impacts of the COVID-19 pandemic, partially offset by lower variable incentive compensation payments and lower tax payments.
Cash Used in Investing Activities. Capital expenditures were 7% higher in 2020 primarily due to higher spending related to facilities at FedEx Express, increased spending on information technology at FedEx Services, FedEx Express and FedEx Freight and increased spending on package handling equipment at FedEx Ground, partially offset by lower spending related to aircraft at FedEx Express. See “Capital Resources” below for a more detailed discussion of capital expenditures during 2020.
Financing Activities. We used the net proceeds of our 2020 debt issuances (i) to make voluntary contributions to our tax-qualified U.S. domestic pension plans (“U.S. Pension Plans”), (ii) to redeem the $400 million aggregate principal amount of 2.30% notes due February 1, 2020 and the €500 million aggregate principal amount of 0.50% notes due April 9, 2020, (iii) to repay $1.5 billion of borrowings under our 364-Day Credit Agreement that we drew on March 18, 2020 and $136 million of commercial paper outstanding under our commercial paper program and (iv) for general corporate purposes. We used the net proceeds of our 2019 debt issuances to redeem the $750 million aggregate principal amount of 8.00% notes due January 15, 2019, pay the €500 million aggregate principal amount of floating-rate notes that matured on April 11, 2019 and for general corporate purposes. As of May 31, 2020, no commercial paper was outstanding.
- 76 -
The following table provides a summary of repurchases of our common stock for the periods ended May 31 (dollars in millions, except per share amounts):
| 2020 | 2019 | |||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Total Number of Shares Purchased | Average Price Paid per Share | Total Purchase Price | Total Number of Shares Purchased | Average Price Paid per Share | Total Purchase Price | |||||||||||||||||||
| Common stock repurchases | 20,000 | $ | 156.90 | $ | 3 | 6,640,000 | $ | 222.94 | $ | 1,480 |
In January 2016, our Board of Directors approved a stock repurchase program of up to 25 million shares. Shares under the current repurchase program may be repurchased from time to time in the open market or in privately negotiated transactions. The timing and volume of repurchases are at the discretion of management, based on the capital needs of the business, the market price of FedEx common stock and general market conditions. No time limit was set for the completion of the program, and the program may be suspended or discontinued at any time. As of May 31, 2020, 5.1 million shares remained under the current stock repurchase authorization.
During the fourth quarter of 2020, our Credit Agreements were amended to increase the ratio of debt to consolidated earnings (excluding noncash retirement plans MTM adjustments, noncash pension service costs and noncash asset impairment charges) before interest, taxes, depreciation and amortization (“adjusted EBITDA”) as follows: 3.75:1.0 at May 31, 2020; 4.75:1.0 at August 31, 2020; 4.9:1.0 at November 30, 2020; 4.75:1.0 at February 28, 2021; and 3.75:1.0 at May 31, 2021, with the ratio reverting to 3.5:1.0 at August 31, 2021 and thereafter. The amendments to the Credit Agreements revised the adjusted EBITDA definition to exclude noncash pension service costs (as noted above) and also temporarily restrict us from repurchasing any shares of our common stock or increasing the amount of our quarterly dividend payable per share of common stock from $0.65 per share between May 27, 2020 and May 31, 2021. See Note 6 of the accompanying consolidated financial statements for additional information regarding the Credit Agreements.
CAPITAL RESOURCES
Our operations are capital intensive, characterized by significant investments in aircraft, package handling and sort equipment, vehicles and trailers, technology and facilities. The amount and timing of capital additions depend on various factors, including pre-existing contractual commitments, anticipated volume growth, domestic and international economic conditions, new or enhanced services, geographical expansion of services, availability of satisfactory financing and actions of regulatory authorities.
The following table compares capital expenditures by asset category and reportable segment for the years ended May 31 (in millions):
| 2020 | 2019 | Percent Change | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Aircraft and related equipment | $ | 1,628 | $ | 2,202 | (26 | ) | ||||||
| Package handling and ground support equipment | 910 | 777 | 17 | |||||||||
| Vehicles and trailers | 1,056 | 982 | 8 | |||||||||
| Information technology | 915 | 751 | 22 | |||||||||
| Facilities and other | 1,359 | 778 | 75 | |||||||||
| Total capital expenditures | $ | 5,868 | $ | 5,490 | 7 | |||||||
| FedEx Express segment | $ | 3,560 | $ | 3,550 | — | |||||||
| FedEx Ground segment | 1,083 | 808 | 34 | |||||||||
| FedEx Freight segment | 539 | 544 | (1 | ) | ||||||||
| FedEx Services segment | 527 | 440 | 20 | |||||||||
| Other | 159 | 148 | 7 | |||||||||
| Total capital expenditures | $ | 5,868 | $ | 5,490 | 7 |
Capital expenditures increased during 2020 primarily due to higher spending related to facilities at FedEx Express, increased spending on information technology at FedEx Services, FedEx Express and FedEx Freight and increased spending on package handling equipment at FedEx Ground, partially offset by lower spending related to aircraft at FedEx Express.
- 77 -
GUARANTOR FINANCIAL INFORMATION
We are providing the following information in compliance with Rule 13-01 of Regulation S-X, “Financial Disclosures about Guarantors and Issuers of Guaranteed Securities” with respect to our senior unsecured debt securities. As of May 31, 2020, we had outstanding $21.5 billion of senior unsecured debt securities. Substantially all of the senior unsecured notes were issued by FedEx under a shelf registration statement and are guaranteed by certain direct and indirect subsidiaries of FedEx (“Guarantor Subsidiaries”). See Note 6 of the accompanying consolidated financial statements for additional information regarding the terms of the senior unsecured debt securities. FedEx owns, directly or indirectly, 100% of each Guarantor Subsidiary. The guarantees are (1) unsecured obligations of the respective Guarantor Subsidiary, (2) rank equally with all of their other unsecured and unsubordinated indebtedness, and (3) are full and unconditional and joint and several. If we sell, transfer or otherwise dispose of all of the capital stock or all or substantially all of the assets of a Guarantor Subsidiary to any person that is not an affiliate of FedEx, the guarantee of that Guarantor Subsidiary will terminate and holders of debt securities will no longer have a direct claim against such subsidiary under the guarantee.
The following tables present summarized financial information for FedEx (as Parent) and the Guarantor Subsidiaries on a combined basis after transactions and balances within the combined entities have been eliminated.
Parent and Guarantor Subsidiaries
The following table presents the summarized balance sheet information as of May 31, 2020 (in millions):
| Current Assets | $ | 11,014 | ||
|---|---|---|---|---|
| Intercompany Receivable | 3,431 | |||
| Total Assets | 61,678 | |||
| Current Liabilities | 7,030 | |||
| Intercompany Payable | — | |||
| Total Liabilities | 49,325 |
The following table presents the summarized statement of income information as of May 31, 2020 (in millions):
| Revenue | $ | 50,178 | ||
|---|---|---|---|---|
| Intercompany Charges, net | (2,674 | ) | ||
| Operating Income | 2,191 | |||
| Intercompany Charges, net | 165 | |||
| Income Before Income Taxes | 1,454 | |||
| Net Income | $ | 1,009 |
LIQUIDITY OUTLOOK
The COVID-19 pandemic has negatively impacted the global economy, disrupted global supply chains and created significant volatility and disruption in financial markets. An extended period of global supply chain and economic disruption could materially adversely affect our business, results of operations, access to sources of liquidity and financial condition. In response to current business and economic conditions, we are taking actions to manage our cash flow and improve our liquidity, including review and consideration of opportunities and strategies for capital expenditure reductions and deferrals, as previously discussed, operating expense reductions and consideration of alternative financing sources in addition to our credit facilities and unsecured debt markets. While we have experienced some slowing in the collection of accounts receivable due to the effect of the COVID-19 pandemic on our customers and an increase in credit risk, particularly in the retail industry, our cash flows and overall liquidity have not been materially impacted at this point based on our credit management process and working capital management. We expect to benefit from certain of the relief provisions of recently enacted and any future government programs intended to provide economic relief to U.S. and global businesses in response to the COVID-19 pandemic, including relief from certain income, excise and payroll taxes in the United States pursuant to the CARES Act. See “Impact of the COVID-19 Pandemic” above for more information.
We believe that our cash and cash equivalents, which totaled $4.9 billion at May 31, 2020, cash flow from operations and available financing sources will be adequate to meet our liquidity needs, including working capital, capital expenditure requirements, debt payment obligations, pension contributions, if any, and TNT Express integration expenses. Our cash and cash equivalents balance at May 31, 2020 includes $1.1 billion of cash in foreign jurisdictions associated with our permanent reinvestment strategy. We are able to access the majority of this cash without a material tax cost, as the enactment of the TCJA significantly reduced the cost of repatriating foreign earnings from a U.S. tax perspective. We do not believe that the indefinite reinvestment of these funds impairs our ability to meet our U.S. domestic debt or working capital obligations.
- 78 -
Our capital expenditures are expected to be approximately $4.9 billion in 2021, which will include aircraft modernization at FedEx Express and strategic investments to improve productivity and safety. In addition, we are making investments over multiple years of approximately $1.5 billion to significantly expand the FedEx Express Indianapolis hub and approximately $1.5 billion to modernize the FedEx Express Memphis World Hub. We expect approximately 45% of capital expenditures in 2021 to be designated for growth initiatives. Our expected capital expenditures for 2021 include $1.7 billion for delivery of aircraft and related equipment and progress payments toward future aircraft deliveries at FedEx Express.
We have several aircraft modernization programs underway that are supported by the purchase of Boeing 777 Freighter (“B777F”) and Boeing 767-300 Freighter (“B767F”) aircraft. These aircraft are significantly more fuel-efficient per unit than the aircraft types previously utilized, and these expenditures are necessary to achieve significant long-term operating savings and to replace older aircraft. Our ability to delay the timing of these aircraft-related expenditures is limited without incurring significant costs to modify existing purchase agreements.
During 2020, FedEx Express exercised options to purchase an additional six B767F aircraft for delivery in 2022. Additionally, during 2020, FedEx Express executed two contract amendments rescheduling two B777F aircraft deliveries from 2023 to 2022 and two B767F aircraft deliveries from 2022 to 2023.
In fourth quarter of 2020, we received notice from certain aircraft manufacturers (i) rescheduling four B767F aircraft deliveries from 2020 to 2021, as well as two B767F aircraft deliveries from 2021 to 2022, and (ii) rescheduling certain Cessna SkyCourier 408 and ATR 72-600F aircraft between 2021 and 2026.
On June 25, 2020, FedEx Express executed a contract amendment rescheduling B767F aircraft deliveries as follows: 2021 – 18 aircraft; 2022 – 11 aircraft; 2023 – 13 aircraft; and 2024 – 4 aircraft.
We have a shelf registration statement filed with the Securities and Exchange Commission (“SEC”) that allows us to sell, in one or more future offerings, any combination of our unsecured debt securities and common stock.
During the fourth quarter of 2020, we entered into the Credit Agreements. The Credit Agreements are available to finance our operations and other cash flow needs. The Five-Year Credit Agreement expires in March 2025 and includes a $250 million letter of credit sublimit. The 364-Day Credit Agreement expires in March 2021. See Note 6 of the accompanying consolidated financial statements for a description of the terms and significant covenants of the Credit Agreements, including additional temporary covenants restricting common stock repurchases and dividend increases during 2021.
For 2021, we do not anticipate making voluntary contributions to our U.S. Pension Plans. As noted in our discussion of critical accounting estimates, we do not anticipate contributions to our U.S. Pension Plans will be required for the foreseeable future based on our funded status and the fact we have a credit balance related to our cumulative excess voluntary pension contributions over those required that exceeds $3 billion. The credit balance is subtracted from plan assets to determine the minimum funding requirements. Therefore, we could eliminate all required contributions to our principal U.S. Pension Plans for several years if we were to choose to waive part of that credit balance in any given year. Our U.S. Pension Plans have ample funds to meet expected benefit payments.
On June 15, 2020, our Board of Directors declared a quarterly dividend of $0.65 per share of common stock. The dividend was paid on July 13, 2020 to stockholders of record as of the close of business on June 29, 2020. Each quarterly dividend payment is subject to review and approval by our Board of Directors, and we evaluate our dividend payment amount on an annual basis.
Standard & Poor’s has assigned us a senior unsecured debt credit rating of BBB, a commercial paper rating of A-2 and a ratings outlook of “negative.” Moody’s Investors Service has assigned us an unsecured debt credit rating of Baa2, a commercial paper rating of P-2 and a ratings outlook of “negative.” If our credit ratings drop, our interest expense may increase. If our commercial paper ratings drop below current levels, we may have difficulty utilizing the commercial paper market. If our senior unsecured debt credit ratings drop below investment grade, our access to financing may become limited.
- 79 -
CONTRACTUAL CASH OBLIGATIONS AND OFF-BALANCE SHEET ARRANGEMENTS
The following table sets forth a summary of our contractual cash obligations as of May 31, 2020. Certain of these obligations are reflected in our balance sheet, while others are disclosed as future obligations. We have certain contingent liabilities that are not accrued in our balance sheet in accordance with accounting principles generally accepted in the United States. These contingent liabilities are not included in the table below. We have other long-term liabilities reflected in our balance sheet, including deferred income taxes, qualified and nonqualified pension and postretirement healthcare plan liabilities and other self-insurance accruals. Unless statutorily required, the payment obligations associated with these liabilities are not reflected in the table below due to the absence of scheduled maturities. Accordingly, this table is not meant to represent a forecast of our total cash expenditures for any of the periods presented.
| Payments Due by Fiscal Year (Undiscounted) (in millions) | ||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2021 | 2022 | 2023 | 2024 | 2025 | Thereafter | Total | ||||||||||||||||||||||
| Operating activities: | ||||||||||||||||||||||||||||
| Operating leases | $ | 2,349 | $ | 2,240 | $ | 1,987 | $ | 1,665 | $ | 1,434 | $ | 6,906 | $ | 16,581 | ||||||||||||||
| Non-capital purchase obligations and other | 1,254 | 823 | 619 | 503 | 635 | 3,074 | 6,908 | |||||||||||||||||||||
| Interest on long-term debt | 798 | 783 | 755 | 734 | 704 | 11,413 | 15,187 | |||||||||||||||||||||
| Investing activities: | ||||||||||||||||||||||||||||
| Aircraft and aircraft-related capital commitments | 1,891 | 2,514 | 1,801 | 456 | 250 | 42 | 6,954 | |||||||||||||||||||||
| Other capital purchase obligations | 61 | 25 | 23 | 1 | 1 | 4 | 115 | |||||||||||||||||||||
| Financing activities: | ||||||||||||||||||||||||||||
| Debt | — | 1,197 | 1,567 | 750 | 1,700 | 16,542 | 21,756 | |||||||||||||||||||||
| Finance leases | 67 | 26 | 25 | 24 | 81 | 646 | 869 | |||||||||||||||||||||
| Total | $ | 6,420 | $ | 7,608 | $ | 6,777 | $ | 4,133 | $ | 4,805 | $ | 38,627 | $ | 68,370 |
Open purchase orders that are cancelable are not considered unconditional purchase obligations for financial reporting purposes and are not included in the table above. Such purchase orders often represent authorizations to purchase rather than binding agreements. See Note 17 of the accompanying consolidated financial statements for more information on such purchase orders.
Operating Activities
The amounts reflected in the table above for operating leases represent undiscounted future minimum lease payments under noncancelable operating leases (principally facilities and aircraft) with an initial or remaining term in excess of one year at May 31, 2020. Under the new lease accounting rules, the majority of these leases are recognized at the net present value on the balance sheet as a liability with an offsetting right-to-use asset effective in 2020. See Note 7 of the accompanying consolidated financial statements for further information. Credit rating agencies routinely use information concerning minimum lease payments required for our operating leases to calculate our debt capacity.
The amounts reflected for purchase obligations represent noncancelable agreements to purchase goods or services that are not capital-related. Such contracts include those for printing and advertising and promotions contracts.
Included in the table above within the caption entitled “Non-capital purchase obligations and other” is our estimate of the current portion of the liability ($80 million) for uncertain tax positions. We cannot reasonably estimate the timing of the long-term payments or the amount by which the liability will increase or decrease over time; therefore, the long-term portion of the liability ($49 million) is excluded from the table. See Note 12 of the accompanying consolidated financial statements for further information.
The amounts reflected in the table above for interest on long-term debt represent future interest payments due on our long-term debt.
Investing Activities
The amounts reflected in the table above for capital purchase obligations represent noncancelable agreements to purchase capital-related equipment. Such contracts include those for certain purchases of aircraft, aircraft modifications, vehicles and trailers, facilities, computers and other equipment.
As of May 31, 2020, we had $633 million in deposits and progress payments on aircraft purchases and other planned aircraft-related transactions.
- 80 -
Financing Activities
We have certain financial instruments representing potential commitments, not reflected in the table above, that were incurred in the normal course of business to support our operations, including standby letters of credit and surety bonds. These instruments are required under certain U.S. self-insurance programs and are also used in the normal course of operations. The underlying liabilities insured by these instruments are reflected in our balance sheets, where applicable. Therefore, no additional liability is reflected for the letters of credit and surety bonds themselves.
The amounts reflected in the table above for long-term debt represent future scheduled principal payments on our long-term debt.
The amounts reflected in the table above for finance leases represent undiscounted future minimum lease payments under noncancelable finance leases with an initial or remaining term in excess of one year at May 31, 2020.
We do not have any guarantees or other off-balance sheet financing arrangements, including variable interest entities, which we believe could have a material impact on our financial condition or liquidity.
OTHER BUSINESS MATTERS
On June 24, 2019, FedEx filed suit in U.S. District Court in the District of Columbia seeking to enjoin the U.S. Department of Commerce from enforcing prohibitions contained in the Export Administration Regulations (the “EARs”) against FedEx. FedEx believes that the EARs violate common carriers’ rights to due process under the Fifth Amendment of the U.S. Constitution as they unreasonably hold common carriers strictly liable for shipments that may violate the EARs without requiring evidence that the carriers had knowledge of any violations.
The China State Post Bureau is currently conducting an investigation into the operations of FedEx Express regarding the handling of certain packages while attempting to comply with the EARs. FedEx Express has and will continue to fully cooperate with the Chinese authorities on the investigation.
CRITICAL ACCOUNTING ESTIMATES
The preparation of financial statements in accordance with accounting principles generally accepted in the United States requires management to make significant judgments and estimates to develop amounts reflected and disclosed in the financial statements. In many cases, there are alternative policies or estimation techniques that could be used. We maintain a thorough process to review the application of our accounting policies and to evaluate the appropriateness of the many estimates that are required to prepare the financial statements of a complex, global corporation. However, even under optimal circumstances, estimates routinely require adjustment based on changing circumstances and new or better information.
The estimates discussed below include the financial statement elements that are either the most judgmental or involve the selection or application of alternative accounting policies and are material to our financial statements. Management has discussed the development and selection of these critical accounting estimates with the Audit Committee of our Board of Directors and with our independent registered public accounting firm.
RETIREMENT PLANS
OVERVIEW. We sponsor programs that provide retirement benefits to most of our employees. These programs include defined benefit pension plans, defined contribution plans and postretirement healthcare plans and are described in Note 13 of the accompanying consolidated financial statements. The rules for pension accounting are complex and can produce volatility in our earnings, financial condition and liquidity.
We are required to record annual year-end adjustments to our financial statements for the net funded status of our defined benefit pension and postretirement healthcare plans. The funded status of our plans also impacts our liquidity; however, the cash funding rules operate under a completely different set of assumptions and standards than those used for financial reporting purposes. As a result, our actual cash funding requirements can differ materially from our reported funded status.
- 81 -
Over the past several years, we have taken numerous actions to reduce pension-related risk and expense, including the introduction of our portable pension account benefit, freezing our traditional pension benefit, employing a liability-driven investment strategy and permitting certain former employees with a traditional pension benefit to make a one-time, irrevocable election to receive their benefits in a lump-sum distribution. In May 2018, we entered into an agreement with Metropolitan Life Insurance Company to purchase a group annuity contract representing the transfer of approximately $6 billion of our U.S. Pension Plan obligations. The transaction transferred responsibility for pension benefits to Metropolitan Life Insurance Company for approximately 41,000 of our retirees and beneficiaries who satisfied certain conditions and were receiving a monthly benefit from participating U.S. Pension Plans. There was no change to the pension benefits for any plan participants as a result of this transaction. The purchase of the group annuity contract was funded directly by assets of the U.S. Pension Plans. The group annuity contract reduced the size of our U.S. Pension Plans, reduced our exposure to market risk and associated balance sheet volatility and eliminated the investment, administrative and Pension Benefit Guaranty Corporation premium expenses for approximately 41,000 retirees. We recognized a $210 million one-time settlement loss in connection with this transaction, which was included in our 2018 year-end MTM retirement plans accounting adjustment.
In November 2019, we announced the closing of our U.S.-based defined benefit pension plans to new non-union employees hired on or after January 1, 2020. We will introduce an all-401(k)-plan retirement benefit structure for eligible employees with a higher company match of up to 8% across all U.S.-based operating companies. During 2021, current eligible employees under the Portable Pension Account (PPA) pension formula will be given a one-time option to continue to be eligible for pension compensation credits under the existing PPA formula and remain in the existing 401(k) plan with its company match of up to 3.5%, or to cease receiving compensation credits under the PPA and move to the new 401(k) plan with the higher match of up to 8%. Changes to the new 401(k) plan structure become effective beginning January 1, 2022. While this new program will provide employees greater flexibility and reduce our long-term pension costs, it will not have a material impact on current or near-term financial results.
The “Salaries and employee benefits” caption of our accompanying consolidated income statements includes retirement plan expense associated with service costs. The “Other retirement plans (expense) income” caption of our accompanying consolidated income statements includes our fourth quarter MTM adjustment, expense associated with prior service and interest costs, the expected return on assets (“EROA”) and settlements. A summary of our retirement plan costs over the past two years is as follows (in millions):
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Defined benefit pension plans | $ | 148 | $ | 111 | ||||
| Defined contribution plans | 574 | 561 | ||||||
| Postretirement healthcare plans | 85 | 75 | ||||||
| Retirement plans MTM loss | 794 | 3,882 | ||||||
| $ | 1,601 | $ | 4,629 |
The components of the MTM adjustments are as follows (in millions):
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Discount rate change | $ | 2,997 | $ | 1,780 | ||||
| Demographic experience: | ||||||||
| Current year actuarial loss | 50 | 739 | ||||||
| Change in future assumptions | (229 | ) | 887 | |||||
| Actual versus expected return on assets | (2,024 | ) | 476 | |||||
| Total MTM loss | $ | 794 | $ | 3,882 |
Service cost for our defined benefit pension and postretirement healthcare plans was $906 million in 2020 and $818 million in 2019 and is expected to be approximately $985 million in 2021.
- 82 -
2020
The weighted-average discount rate for all our pension and postretirement healthcare plans decreased 64 basis points from 3.69% at May 31, 2019 to 3.05% at May 31, 2020. The demographic experience in 2020 reflects an update to our mortality assumption and a current-year actuarial loss due to unfavorable experience compared to various demographic assumptions. The actual rate of return, which is net of all fees and expenses, on our U.S. Pension Plan assets of 15.00% was higher than our expected return of 6.75%, as return seeking assets, primarily equities, were positive despite equity market volatility. Additionally, fixed income assets performed as expected as interest rates declined.
2019
The demographic experience in 2019 reflected updates to several forward-looking assumptions, including retirement rates, disability incidence rates and salary increase assumptions, and a current-year actuarial loss due to unfavorable experience compared to various demographic assumptions. The actual rate of return, which is net of all fees and expenses, on our U.S. Pension Plan assets of 4.05% was lower than our expected return of 6.75%, as lower than expected equity returns negatively impacted return-seeking assets while fixed-income assets performed as expected due to declining interest rates.
DISCOUNT RATE. The discount rate is the interest rate used to discount the estimated future benefit payments that have been accrued to date (the projected benefit obligation or “PBO”) to their net present value and to determine the succeeding year’s ongoing pension expense (prior to any year-end MTM adjustment). The discount rate is determined each year at the plan measurement date. The discount rate for our U.S. Pension Plans at each measurement date was as follows:
| Measurement Date | Discount Rate | |||||
|---|---|---|---|---|---|---|
| 5/31/2020 | 3.14 | % | ||||
| 5/31/2019 | 3.85 | |||||
| 5/31/2018 | 4.27 |
We determine the discount rate with the assistance of actuaries, who calculate the yield on a theoretical portfolio of high-grade corporate bonds (rated Aa or better). In developing this theoretical portfolio, we select bonds that match cash flows to benefit payments, limit our concentration by industry and issuer, and apply screening criteria to ensure bonds with a call feature have a low probability of being called. To the extent scheduled bond proceeds exceed the estimated benefit payments in a given period, the calculation assumes those excess proceeds are reinvested at one-year forward rates.
The measurement of our PBO and the related impact on our annual MTM adjustment is highly sensitive to the discount rate assumption. For our largest pension plan, a 50-basis-point increase in the discount rate would have decreased our 2020 PBO by approximately $1.8 billion and a 50-basis-point decrease in the discount rate would have increased our 2020 PBO by approximately $2.0 billion. However, our annual net pension expense is less sensitive to changes in the discount rate. For example, a one-basis-point increase in the discount rate for our largest pension plan would have a $42 million effect on the fourth quarter MTM adjustment but only a net $100,000 impact on net pension expense.
PLAN ASSETS. The expected average rate of return on plan assets is a long-term, forward-looking assumption. It is required to be the expected future long-term rate of earnings on plan assets. Our pension plan assets are invested primarily in publicly tradable securities, and our pension plans hold only a minimal investment in FedEx common stock that is entirely at the discretion of third-party pension fund investment managers. As part of our strategy to manage pension costs and funded status volatility, we follow a liability-driven investment strategy to better align plan assets with liabilities.
Establishing the expected future rate of investment return on our pension assets is a judgmental matter, which we review on an annual basis and revise as appropriate. Management considers the following factors in determining this assumption:
| • | the duration of our pension plan liabilities, which drives the investment strategy we can employ with our pension plan assets; |
|---|
| • | the types of investment classes in which we invest our pension plan assets and the expected compound geometric return we can reasonably expect those investment classes to earn over time, net of all fees and expenses; and |
|---|
| • | the investment returns we can reasonably expect our investment management program to achieve in excess of the returns we could expect if investments were made strictly in indexed funds. |
|---|
For consolidated pension expense, we assumed a 6.75% expected long-term rate of return on our U.S. Pension Plan assets in 2020 and 2019. The historical annual return on our U.S. Pension Plan assets, calculated on a compound geometric basis, was 7.7%, net of all fees and expenses, for the 15-year period ended May 31, 2020. For our U.S. Pension Plans, a one basis-point change in our EROA would impact our 2021 pension expense by $2.5 million.
- 83 -
FUNDED STATUS. The following is information concerning the funded status of our pension plans as of May 31 on a financial reporting basis (in millions):
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Funded Status of Plans: | ||||||||
| Projected benefit obligation (PBO) | $ | 32,441 | $ | 28,855 | ||||
| Fair value of plan assets | 28,691 | 24,898 | ||||||
| Funded status of the plans | $ | (3,750 | ) | $ | (3,957 | ) | ||
| Cash Amounts: | ||||||||
| Cash contributions during the year | $ | 1,154 | $ | 1,125 | ||||
| Benefit payments during the year | $ | 987 | $ | 806 |
FUNDING. The funding requirements for our U.S. Pension Plans are governed by the Pension Protection Act of 2006, which has aggressive funding requirements in order to avoid benefit payment restrictions that become effective if the funded status determined under IRS rules falls below 80% at the beginning of a plan year. All of our U.S. Pension Plans have funded status levels in excess of 80% and our plans are fully funded under the Employee Retirement Income Security Act. Additionally, current benefit payments do not materially impact our total plan assets (benefit payments for our U.S. Pension Plans for 2020 were approximately $873 million, or 3.2% of plan assets).
Over the past several years, we have made voluntary contributions to our U.S. Pension Plans in excess of the minimum required contributions. For 2021, no pension contributions are required for our U.S. Pension Plans, as they are fully funded under the Employee Retirement Income Security Act, and no voluntary contributions are anticipated.
See Note 13 of the accompanying consolidated financial statements for further information about our retirement plans.
INCOME TAXES
We are subject to income taxes in the U.S. and numerous foreign jurisdictions. Our income taxes are a function of our income, statutory tax rates and tax planning opportunities available to us in the various jurisdictions in which we operate. The acquisition of TNT Express in 2016 expanded our foreign operations significantly and increased the complexity of our global operations from an income tax perspective. The tax laws in the various jurisdictions are complex and subject to different interpretations by us and the respective governmental taxing authorities. As a result, significant judgment is required in determining our tax expense and in evaluating our tax positions, including evaluating uncertainties. Also, our effective tax rate is significantly affected by the earnings generated in each jurisdiction, so unexpected fluctuations in the geographic mix of earnings could significantly impact our tax rate. Our intercompany transactions are based on globally accepted transfer pricing principles, which align profits with the business operations and functions of the various legal entities in our international business.
We evaluate our tax positions quarterly and adjust the balances as new information becomes available. These evaluations are based on factors including, but not limited to, changes in facts or circumstances, changes in tax laws or their interpretations, audit activity and changes in our business. In addition, management considers the advice of third parties in making conclusions regarding tax consequences.
Tax contingencies arise from uncertainty in the application of tax rules throughout the many jurisdictions in which we operate. Despite our belief that our tax return positions are consistent with applicable tax laws, taxing authorities could challenge certain positions. We record tax benefits for uncertain tax positions based upon management’s evaluation of the information available at the reporting date. To be recognized in the financial statements, a tax benefit must be at least more likely than not of being sustained based on the technical merits. The benefit for positions meeting the recognition threshold is measured as the largest benefit more likely than not of being realized upon ultimate settlement with a taxing authority that has full knowledge of all relevant information. Significant judgment is required in making these determinations and adjustments to unrecognized tax benefits may be necessary to reflect actual taxes payable upon settlement.
Deferred income tax assets represent amounts available to reduce income taxes payable on taxable income in future years. Such assets arise because of temporary differences between the financial reporting and tax bases of assets and liabilities, as well as from net operating loss and tax credit carryforwards. We evaluate the recoverability of these future tax deductions and credits by assessing the adequacy of future expected taxable income from all sources, including reversal of taxable temporary differences, forecasted operating earnings and available tax planning strategies. These sources of income rely heavily on estimates to make this determination so there is a risk that these estimates will have to be revised as new information is received. To the extent we do not consider it more likely than not that a deferred tax asset will be recovered, a valuation allowance is established. We believe we will generate sufficient future taxable income to realize the tax benefits related to the remaining net deferred tax assets in our consolidated balance sheets that are not subject to valuation allowances. We record the taxes for global intangible low-taxed income as a period cost.
- 84 -
Our income tax positions are based on currently enacted tax laws, including the TCJA and the CARES Act. As further guidance is issued by the U.S. Treasury Department, the IRS and other standard-setting bodies, any resulting changes to our estimates will be treated in accordance with the relevant accounting guidance.
For more information, including impacts from the TCJA and the CARES Act, see the “Income Taxes” section of this MD&A and Note 12 of the accompanying consolidated financial statements.
SELF-INSURANCE ACCRUALS
We are self-insured up to certain limits for costs associated with workers’ compensation claims, vehicle accidents and general business liabilities, and benefits paid under employee healthcare and disability programs. Our reserves are established for estimates of loss on reported claims, including incurred-but-not-reported claims. Self-insurance accruals reflected in our balance sheet were $3.3 billion at May 31, 2020 and $3.0 billion at May 31, 2019. Approximately 36% of these accruals were classified as current liabilities.
Our self-insurance accruals are primarily based on the actuarially estimated cost of claims incurred as of the balance sheet date. These estimates include consideration of factors such as severity of claims, frequency and volume of claims, healthcare inflation, seasonality and plan designs. Cost trends on material accruals are updated each quarter. We self-insure up to certain limits that vary by type of risk. Periodically, we evaluate the level of insurance coverage and adjust insurance levels based on risk tolerance and premium expense. Where estimable, losses covered by insurance are recognized on a gross basis with a corresponding insurance receivable.
We believe the use of actuarial methods to account for these liabilities provides a consistent and effective way to measure these highly judgmental accruals. However, the use of any estimation technique in this area is inherently sensitive given the magnitude of claims involved and the length of time until the ultimate cost is known. We believe our recorded obligations for these expenses are consistently measured on a conservative basis. Nevertheless, changes in healthcare costs, accident frequency and severity, insurance retention levels and other factors can materially affect the estimates for these liabilities.
LONG-LIVED ASSETS
USEFUL LIVES AND SALVAGE VALUES. Our business is capital intensive, with approximately 56% of our owned assets invested in our transportation and information systems infrastructures.
The depreciation or amortization of our capital assets over their estimated useful lives, and the determination of any salvage values, requires management to make judgments about future events. Because we utilize many of our capital assets over relatively long periods (the majority of aircraft costs are depreciated over 15 to 30 years), we periodically evaluate whether adjustments to our estimated service lives or salvage values are necessary to ensure these estimates properly match the economic use of the asset. This evaluation may result in changes in the estimated lives and residual values used to depreciate our aircraft and other equipment. For our aircraft, we typically assign no residual value due to the utilization of these assets in cargo configuration, which results in little to no value at the end of their useful life. These estimates affect the amount of depreciation expense recognized in a period and, ultimately, the gain or loss on the disposal of the asset. Changes in the estimated lives of assets will result in an increase or decrease in the amount of depreciation recognized in future periods and could have a material impact on our results of operations (as described below). Historically, gains and losses on disposals of operating equipment have not been material. However, such amounts may differ materially in the future due to changes in business levels, technological obsolescence, accident frequency, regulatory changes and other factors beyond our control.
IMPAIRMENT. As of May 31, 2020, the FedEx Express global air network included a fleet of 679 aircraft (including approximately 300 supplemental aircraft) that provide delivery of packages and freight to more than 220 countries and territories through a wide range of U.S. and international shipping services. While certain aircraft are utilized in primary geographic areas (U.S. versus international), we operate an integrated global network, and utilize our aircraft and other modes of transportation to achieve the lowest cost of delivery while maintaining our service commitments to our customers. Because of the integrated nature of our global network, our aircraft are interchangeable across routes and geographies, giving us flexibility with our fleet planning to meet changing global economic conditions and maintain and modify aircraft as needed.
Because of the lengthy lead times for aircraft manufacture and modifications, we must anticipate volume levels and plan our fleet requirements years in advance, and make commitments for aircraft based on those projections. Furthermore, the timing and availability of certain used aircraft types (particularly those with better fuel efficiency) may create limited opportunities to acquire these aircraft at favorable prices in advance of our capacity needs. These activities create risks that asset capacity may exceed demand. At May 31, 2020, all of our purchased aircraft were placed into service.
- 85 -
The accounting test for whether an asset held for use is impaired involves first comparing the carrying value of the asset with its estimated future undiscounted cash flows. If the cash flows do not exceed the carrying value, the asset must be adjusted to its current fair value. We operate integrated transportation networks, and accordingly, cash flows for most of our operating assets are assessed at a network level, not at an individual asset level for our analysis of impairment. Further, decisions about capital investments are evaluated based on the impact to the overall network rather than the return on an individual asset. We make decisions to remove certain long-lived assets from service based on projections of reduced capacity needs or lower operating costs of newer aircraft types, and those decisions may result in an impairment charge. Assets held for disposal must be adjusted to their estimated fair values less costs to sell when the decision is made to dispose of the asset and certain other criteria are met. The fair value determinations for such aircraft may require management estimates, as there may not be active markets for some of these aircraft. Such estimates are subject to revision from period to period.
In the normal management of our aircraft fleet, we routinely idle aircraft and engines temporarily due to maintenance cycles and adjustments of our network capacity to match seasonality and overall customer demand levels. Temporarily idled assets are classified as available-for-use, and we continue to record depreciation expense associated with these assets. These temporarily idled assets are assessed for impairment on a quarterly basis. The criteria for determining whether an asset has been permanently removed from service (and, as a result, is potentially impaired) include, but are not limited to, our global economic outlook and the impact of our outlook on our current and projected volume levels, including capacity needs during our peak shipping seasons; the introduction of new fleet types or decisions to permanently retire an aircraft fleet from operations; and changes to planned service expansion activities. At May 31, 2020, we had 14 aircraft temporarily idled. These aircraft have been idled for an average of five months and are expected to return to revenue service in order to meet expected demand.
During 2020, we made the decision to permanently retire from service 10 Airbus A310-300 aircraft and 12 related engines at FedEx Express to align with the needs of the U.S. domestic network and modernize its aircraft fleet. As a consequence of this decision, noncash impairment charges of $66 million ($50 million, net of tax, or $0.19 per diluted share) were recorded in the FedEx Express segment in the second quarter. Seven of these aircraft were temporarily idled.
During the fourth quarter of 2020, in consideration of the impact of the COVID-19 pandemic on certain of our businesses, we reviewed long-lived assets in our retail and logistics business units for impairment. Based on our reviews, we recognized immaterial asset impairment charges related to the FedEx Logistics operating segment.
LEASES. We utilize operating leases to finance certain of our aircraft, facilities and equipment. Such arrangements typically shift the risk of loss on the residual value of the assets at the end of the lease period to the lessor. In accordance with the new lease accounting standard adopted June 1, 2019, we had approximately $14 billion in operating lease liabilities and related right-of-use assets on the balance sheet as of May 31, 2020. The weighted-average remaining lease term of all operating leases outstanding at May 31, 2020 was approximately ten years.
Our leases generally contain options to extend or terminate the lease. We reevaluate our leases on a regular basis to consider the economic and strategic incentives of exercising the renewal options, and how they align with our operating strategy. Therefore, substantially all the renewal option periods are not included within the lease term and the associated payments are not included in the measurement of the right-of-use asset and lease liability as the options to extend are not reasonably certain at lease commencement.
The lease liabilities are measured at the lease commencement date and determined using the present value of the minimum lease payments not paid and our incremental borrowing rate, which approximates the rate at which we would borrow, on a collateralized basis, over the term of a lease in the applicable currency environment. The interest rate implicit in the lease is generally not determinable in transactions where we are the lessee.
The determination of whether a lease is accounted for as a finance lease or an operating lease requires management to make estimates primarily about the fair value of the asset and its estimated economic useful life. In addition, our evaluation includes ensuring we properly account for build-to-suit lease arrangements and making judgments about whether various forms of lessee involvement during the construction period allow the lessee to control the underlying leased asset during the construction period. We believe we have well-defined and controlled processes for making these evaluations, including obtaining third-party appraisals for material transactions to assist us in making these evaluations.
GOODWILL. As of May 31, 2020, we had $6.4 billion of recorded goodwill from our business acquisitions, representing the excess of the purchase price over the fair value of the net assets acquired. As of May 31, 2019, we had $6.9 billion of recorded goodwill from our business acquisitions, representing the excess of the aggregate purchase price over the fair value of the net assets acquired. Several factors give rise to goodwill in our acquisitions, such as the expected benefit from synergies of the combination and the existing workforce of the acquired business.
- 86 -
Goodwill is reviewed at least annually for impairment. In our evaluation of goodwill impairment, we perform a qualitative assessment that requires management judgment and the use of estimates to determine if it is more likely than not that the fair value of a reporting unit is less than its carrying amount. An entity has an unconditional option to bypass the qualitative assessment for any reporting unit and proceed directly to performing the quantitative goodwill impairment test. An entity may resume performing the qualitative assessment in any subsequent period. We performed both qualitative and quantitative assessments of goodwill in the fourth quarter of 2020 and 2019. This included comparing the fair value of the reporting unit to its carrying value (including attributable goodwill). Fair value is estimated using standard valuation methodologies (principally the income or market approach classified as Level 3 within the fair value hierarchy) incorporating market participant considerations and management’s assumptions on revenue growth rates, operating margins, discount rates and expected capital expenditures. Estimates used by management can significantly affect the outcome of the impairment test. Changes in forecasted operating results and other assumptions could materially affect these estimates. Due to the level of uncertainty from the COVID-19 pandemic, we adjusted our procedures for testing goodwill in 2020 by incorporating sensitivities in our valuations performed using the income approach.
We recorded an impairment charge of $358 million attributable to our FedEx Office and FedEx Supply Chain reporting units in the fourth quarter of 2020. The COVID-19 pandemic resulted in store closures and declining print revenue at FedEx Office during the fourth quarter of 2020 and is expected to continue to negatively impact its near-term operating performance. Based on these factors, our outlook for the FedEx Office business and retail industry changed in the fourth quarter of 2020, which contributed $348 million to the goodwill impairment charge.
While there are several factors negatively impacting near-term results at FedEx Express, including weak global economic conditions and the timing and amount of TNT Express integration program expenses, FedEx Express continues to be an established profitable business with a fair value that exceeds its carrying value based on our valuation performed during the fourth quarter of 2020. In addition, our other reporting units with significant recorded goodwill include FedEx Ground and FedEx Freight. We evaluated these reporting units during the fourth quarters of 2020 and 2019. The estimated fair value of each of these reporting units significantly exceeded their carrying values as of the end of 2020 and 2019; therefore, we do not believe that any of these reporting units were impaired as of the balance sheet dates.
LEGAL AND OTHER CONTINGENCIES
We are subject to various loss contingencies in connection with our operations. Contingent liabilities are difficult to measure, as their measurement is subject to multiple factors that are not easily predicted or projected. Further, additional complexity in measuring these liabilities arises due to the various jurisdictions in which these matters occur, which makes our ability to predict their outcome highly uncertain. Moreover, different accounting rules must be employed to account for these items based on the nature of the contingency. Accordingly, significant management judgment is required to assess these matters and to make determinations about the measurement of a liability, if any. Certain pending loss contingencies are described in Note 18 of the accompanying consolidated financial statements. In the opinion of management, the aggregate liability, if any, of individual matters or groups of related matters not specifically described in Note 18 is not expected to be material to our financial position, results of operations or cash flows. The following describes our methods and associated processes for evaluating these matters.
Because of the complex environment in which we operate, we are subject to numerous legal proceedings and claims, including those relating to general commercial matters, governmental enforcement actions, employment-related claims and FedEx Ground’s service providers. Accounting guidance for contingencies requires an accrual of estimated loss from a contingency, such as a non-income tax or other legal proceeding or claim, when it is probable (i.e., the future event or events are likely to occur) that a loss has been incurred and the amount of the loss can be reasonably estimated. This guidance also requires disclosure of a loss contingency matter when, in management’s judgment, a material loss is reasonably possible or probable.
During the preparation of our financial statements, we evaluate our contingencies to determine whether it is probable, reasonably possible or remote that a liability has been incurred. A loss is recognized for all contingencies deemed probable and estimable, regardless of amount. For unresolved contingencies with potentially material exposure that are deemed reasonably possible, we evaluate whether a potential loss or range of loss can be reasonably estimated.
Our evaluation of these matters is the result of a comprehensive process designed to ensure that accounting recognition of a loss or disclosure of these contingencies is made in a timely manner and involves our legal and accounting personnel, as well as external counsel where applicable. The process includes regular communications during each quarter and scheduled meetings shortly before the completion of our financial statements to evaluate any new legal proceedings and the status of existing matters.
In determining whether a loss should be accrued or a loss contingency disclosed, we evaluate, among other factors:
| • | the current status of each matter within the scope and context of the entire lawsuit or proceeding (e.g., the lengthy and complex nature of class-action matters); |
|---|
- 87 -
| • | the procedural status of each matter; |
|---|
| • | any opportunities to dispose of a lawsuit on its merits before trial (i.e., motion to dismiss or for summary judgment); |
|---|
| • | the amount of time remaining before a trial date; |
|---|
| • | the status of discovery; |
|---|
| • | the status of settlement, arbitration or mediation proceedings; and |
|---|
| • | our judgment regarding the likelihood of success prior to or at trial. |
|---|
In reaching our conclusions with respect to accrual of a loss or loss contingency disclosure, we take a holistic view of each matter based on these factors and the information available prior to the issuance of our financial statements. Uncertainty with respect to an individual factor or combination of these factors may impact our decisions related to accrual or disclosure of a loss contingency, including a conclusion that we are unable to establish an estimate of possible loss or a meaningful range of possible loss. We update our disclosures to reflect our most current understanding of the contingencies at the time we issue our financial statements. However, events may arise that were not anticipated and the outcome of a contingency may result in a loss to us that differs materially from our previously estimated liability or range of possible loss.
Despite the inherent complexity in the accounting and disclosure of contingencies, we believe that our processes are robust and thorough and provide a consistent framework for management in evaluating the potential outcome of contingencies for proper accounting recognition and disclosure.
RISK FACTORS
A wide range of factors could materially adversely affect our business, results of operations, financial condition, access to sources of liquidity and the price of our common stock. The most significant of these factors include the following:
The COVID-19 pandemic has adversely affected, and we expect will continue to adversely affect, our business, results of operations and financial condition. The COVID-19 pandemic has negatively impacted the global economy, disrupted global supply chains and created significant volatility and disruption of financial markets. Due to the crucial role we play in moving supply chains and delivering critical relief, we are considered an essential business and we continue to operate under and respond to evolving state-of-emergency and stay-at-home orders issued in the U.S. and globally. The disruption of global supply chains and the global economy has materially affected our business, results of operations and financial condition. We expect the full impact of the COVID-19 pandemic, including the extent of its effect on our financial condition and results of operations, to be dictated by future developments which remain uncertain and cannot be predicted, such as its duration and spread, the success of efforts to contain it, the possibility of subsequent widespread outbreaks, and the impact of actions taken in response. The COVID-19 pandemic has had, and we expect will continue to have, certain negative impacts on our business, including, but not limited to, the following:
| • | The COVID-19 pandemic has had a rapid and significant negative impact on the global economy. The disruption of global supply chains, interruption in economic activity, preventative measures taken to alleviate the pandemic (such as stay-at-home orders and other responsive measures), and increased economic uncertainty caused by the pandemic have resulted in increased global economic weakness of an unknown duration. Deteriorating global economic conditions have reduced business-to-business demand across all of our transportation businesses. The various stay-at-home orders and shut down of commercial activities in major markets around the world has also led to unprecedented demand for residential delivery services, rivaling our peak holiday season traffic. We incurred increased costs associated with this demand and lower composite yields than our typical service mix, which negatively impacted our results of operations during 2020. Prolonged economic weakness, including an extended period of elevated levels of unemployment in the U.S., could further reduce discretionary consumer spending and consumer confidence, which could have a further adverse effect on our results of operations. |
|---|
| • | We have made significant operational adjustments to align our services with shipping volumes and operating conditions and to comply with evolving governmental orders, rules and regulations. As a result, we are incurring additional operating expenses as we adjust to dramatically changed and continuously evolving market dynamics and operating conditions, and we may continue to incur similar expenses in the future. Additionally, we have reduced planned 2021 capital expenditures by decreasing planned spending on vehicles and trailers, delaying facility expansions and postponing certain information technology initiatives. The COVID-19 pandemic has also delayed completion of capital improvements and certain other initiatives in Europe related to the integration of TNT Express. If we are unable to remain agile and continue to flex our networks to align with shipping volumes, customer needs, market demands and operating conditions, or are unable to continuously respond to evolving governmental policies for the duration of a prolonged period of economic recovery, our business operations could be negatively impacted, which could have a further adverse effect on our results of operations. |
|---|
- 88 -
| • | We rely on a global workforce and our business demands we take measures to protect the health and safety of our team members, customers and others with whom we do business, while continuing to effectively manage our employees and maintain business operations. We have taken additional measures and incurred additional expenses to protect the health and safety of our team members and the public, and continue to work with customers to accommodate special requests around modified store hours, closings, and delivery alternatives to comply with applicable government restrictions and safety guidance. Due to the size, scope and geographically dispersed nature of our operations, the expenses we incur to protect the health and safety of certain of our employees may be higher than similar expenses incurred by companies in other industries. Additionally, our business operations may be disrupted if a significant portion of our workforce is unable to work safely and effectively due to illness, quarantines, government actions, or other restrictions or measures responsive to the pandemic, or if members of senior management or our Board of Directors are unable to perform their duties for an extended period of time. Measures taken across our business operations to address health and safety may not be sufficient to prevent the spread of COVID-19 among our team members, customers and others. Therefore, we could face operational disruptions and incur additional expenses, including devoting additional resources to assisting employees diagnosed with COVID-19 and further changing health and safety protocols and processes, that could adversely affect our business and results of operations. |
|---|
| • | A significant number of our employees as well as customers and others with whom we do business continue to work remotely in response to the COVID-19 pandemic. Our business operations may be disrupted, and we may experience increased risk of adverse effects to our business, if a significant portion of our workforce or certain business operations are negatively impacted as a result of remote work arrangements, including due to cyber risks or other disruption to our technology infrastructure. Further, if our FedEx Express Memphis World Hub or another key operating facility experiences closures or worker shortages as a result of COVID-19, whether temporary or sustained, our business operations would be significantly disrupted. |
|---|
| • | Cost management and various cost-containment actions implemented across our business in response to the COVID-19 pandemic could hinder execution of our business strategy, including deferral of planned capital projects. These actions could result in increased costs to successfully implement our business strategy and effectively respond to changes in market dynamics, and could adversely affect our business and results of operations. For additional discussion, see Part 1, Item 1 of this Annual Report under the caption “Strategy.” |
|---|
| • | We cannot be certain that loss or delay in the collection of accounts receivable will not have a material adverse effect on our results of operations and financial condition. For additional discussion, see “Management’s Discussion and Analysis of Results of Operations and Financial Condition—Financial Condition—Liquidity Outlook.” |
|---|
To the extent the COVID-19 pandemic adversely affects our business and financial results, it may also have the effect of heightening many other risks described in this section, any of which could materially and adversely affect our business, results of operations and financial condition. Such risks include, but are not limited to, additional changes in international trade policies and relations; our ability to successfully integrate the businesses and operations of FedEx Express and TNT Express in the expected time frame and at the expected cost; our strong reputation and the value of the FedEx brand; our ability to manage our capital intensive businesses; changes to the business and financial soundness of the U.S. Postal Service (“USPS”); workforce availability; employee healthcare benefit costs; constraints, volatility or disruption in the capital markets and our ability to access sources of financing and liquidity; and the impact of litigation or claims from customers, team members, suppliers, regulators or other third parties relating to the COVID-19 pandemic or our actions in response to the pandemic.
We are directly affected by the state of the economy and anti-trade measures. While macroeconomic risks apply to most companies, we are particularly vulnerable. The transportation industry is highly cyclical and especially susceptible to trends in economic activity. Our primary business is to transport goods, so our business levels are directly tied to the purchase and production of goods — key macroeconomic measurements. When individuals and companies purchase and produce fewer goods, we transport fewer goods, and as companies expand the number of distribution centers and move manufacturing closer to consumer markets, we transport goods shorter distances. In addition, we have a relatively high fixed-cost structure, which is difficult to quickly adjust to match shifting volume levels. Moreover, as we continue to grow our international business, we are increasingly affected by the health of the global economy, the rate of growth of global trade, world trade policies, international taxes, government-to-government relations and the typically more volatile economies of emerging markets. For instance, anti-trade and protectionist measures adopted by the U.S. or other countries in which we do business, such as trade controls, tariffs, quotas, embargoes, sanctions, or retaliation by another country against such measures, could result in economic uncertainty and instability, resulting in fewer goods being transported globally. In 2020, we saw a customer preference for slower, less costly shipping services. Additionally, during 2020 weakness in the global economy adversely affected our results of operations, and we expect such weakness to continue to be present during 2021.
- 89 -
A significant data breach or other disruption to our technology infrastructure could disrupt our operations and result in the loss of critical confidential information, adversely impacting our reputation, business or results of operations. Our ability to attract and retain customers, to efficiently operate our businesses, and to compete effectively depends in part upon the sophistication, security and reliability of our technology network, including our ability to provide features of service that are important to our customers, to protect our confidential business information and the information provided by our customers, and to maintain customer confidence in our ability to protect our systems and to provide services consistent with their expectations. For example, we rely on information technology to receive package level information in advance of physical receipt of packages, to track items that move through our delivery systems, to efficiently plan deliveries, to execute billing processes, and to track and report financial and operational data. We are subject to risks imposed by data breaches and operational disruptions, including through cyberattack or cyber-intrusion, including by computer hackers, foreign governments, cyber terrorists, cyber criminals and malicious employees or other insiders. Data breaches of companies and governments have increased in recent years as the number, intensity and sophistication of attempted attacks and intrusions from around the world have increased and we, our customers and third parties increasingly store and transmit data by means of connected information technology systems. Additionally, risks such as code anomalies, “Acts of God,” transitional challenges in migrating operating company functionality to our FedEx enterprise automation platforms, data leakage, cyber-fraud and human error pose a direct threat to our products, services, systems and data and could result in unauthorized or block legitimate access to sensitive or confidential data regarding our operations, customers, employees, and suppliers, including personal information. The technology infrastructure of acquired businesses, as well as their practices related to the use and maintenance of data, could also present issues that we were not able to identify prior to the acquisition.
We also depend on and interact with the technology and systems of third parties, including our customers and third-party service providers such as cloud service providers and delivery services. Such third parties may host, process or have access to information we maintain about our company, customers, employees and vendors or operate systems that are critical to our business operations and services. Like us, these third parties are subject to risks imposed by data breaches, cyberattacks and other events or actions that could damage, disrupt or close down their networks or systems. We have security processes, protocols and standards in place, including contractual provisions requiring such security measures, that are applicable to such third parties and are designed to protect information that is held by them, or to which they have access, as a result of their engagements with us. Nevertheless, a cyberattack could defeat one or more of such third parties’ security measures, allowing an attacker to obtain information about our company, customers, employees and vendors or disrupt our operations. These third parties may also experience operational disruptions or human error that could result in unauthorized access to sensitive or confidential data regarding our operations, customers, employees and suppliers, including personal information.
A disruption to our complex, global technology infrastructure, including those impacting our computer systems and websites, could result in the loss of confidential business or customer information, require substantial repairs or replacements, resulting in significant costs, and lead to the temporary or permanent transfer by customers of some or all of their business to our competitors. The foregoing could harm our reputation and adversely impact our operations, customer service and results of operations. Additionally, a security breach could require us to devote significant management resources to address the problems created. These types of adverse impacts could also occur in the event the confidentiality, integrity or availability of company and customer information was compromised due to a data loss by FedEx or a trusted third party. We or the third parties with which we share information may not discover any security breach and loss of information for a significant period of time after the security breach occurs.
Recently, there has also been heightened regulatory and enforcement focus on data protection in the U.S. (at both the state and federal level) and abroad, and an actual or alleged failure to comply with applicable U.S. or foreign data protection regulations or other data protection standards may expose us to litigation (including, in some instances, class action litigation), fines, sanctions or other penalties, which could harm our reputation and adversely impact our business, results of operations and financial condition. This regulatory environment is increasingly challenging and may present material obligations and risks to our business, including significantly expanded compliance burdens, costs and enforcement risks. For example, the European Union’s (“EU”) General Data Protection Regulation (“GDPR”), which became effective in May 2018, greatly increases the jurisdictional reach of EU law and adds a broad array of requirements related to personal data, including individual notice and opt-out preferences and the public disclosure of significant data breaches. Additionally, violations of the GDPR can result in fines of as much as 4% of a company’s annual revenue. Other governments have enacted or are enacting similar data protection laws, including data localization laws that require data to stay within their borders. All of these evolving compliance and operational requirements, as well as the uncertain interpretation and enforcement of laws, impose significant costs and regulatory risks that are likely to increase over time.
- 90 -
We have invested and continue to invest in technology security initiatives, information-technology risk management, business continuity and disaster recovery plans, including investments to retire and replace end-of-life systems. The development and maintenance of these measures is costly and requires ongoing monitoring and updating as technologies change and efforts to overcome security measures become increasingly more frequent, intense and sophisticated. Despite our efforts, we are not fully insulated from data breaches, technology disruptions, data loss and cyber-fraud, which could adversely impact our competitiveness and results of operations. For instance, in June 2017 TNT Express worldwide operations were significantly affected due to the infiltration of an information-technology virus known as NotPetya. In May 2017 FedEx was one of many companies attacked by the rapidly spreading ransomware described as WannaCry that exploited vulnerability in a third-party software program and infected computers using that program, encrypting files and holding them for ransom. During the third quarter of 2018, we discovered an unsecured server hosted by one of our third-party cloud service providers, which exposed some archived account information related to a service discontinued after our 2015 acquisition of Bongo International, LLC. The server has been secured, and we have found no indication that any information has been misappropriated in connection with the incident. Additionally, during 2020, we experienced continual attempts by cyber criminals, some of which were successful, to gain access to customer accounts for the purposes of fraudulently diverting and misappropriating items being transported in our network. None of the WannaCry ransomware attack, unsecured server or 2020 fraudulent cyber activities caused a material disruption to our systems or resulted in any material costs to FedEx.
While we have significant security processes and initiatives in place, we may be unable to detect or prevent a breach or disruption in the future. Additionally, while we have insurance coverage designed to address certain aspects of cyber risks in place, such insurance coverage may be insufficient to cover all losses or all types of claims that may arise.
Additional changes in international trade policies and relations could significantly reduce the volume of goods transported globally and adversely affect our business and results of operations. The U.S. government has made significant changes in U.S. trade policy and has taken certain actions that have negatively impacted U.S. trade, including imposing tariffs on certain goods imported into the United States. To date, several governments, including the EU, China and India, have imposed tariffs on certain goods imported from the United States. These actions contributed to weakness in the global economy that adversely affected our results of operations during fiscal 2019 and fiscal 2020, and we expect such weakness to continue to be present during fiscal 2021. Any further changes in U.S. or international trade policy could trigger additional retaliatory actions by affected countries, resulting in “trade wars” and further increased costs for goods transported globally, which may reduce customer demand for these products if the parties having to pay those tariffs increase their prices, or in trading partners limiting their trade with countries that impose anti-trade measures. Political uncertainty surrounding international trade and other disputes could also have a negative effect on business and consumer confidence and spending. Such conditions could have an adverse effect on our business, results of operations and financial condition, as well as on the price of our common stock.
Additionally, the U.S. government has taken action to limit the ability of domestic companies to engage in commerce with certain foreign entities under certain circumstances, and foreign governments may investigate our compliance with these restrictions. For example, the China State Post Bureau is currently conducting an investigation into the operations of FedEx Express regarding its handling of certain packages while attempting to comply with the EARs. Furthermore, given the nature of our business and our global recognizability, foreign governments may target FedEx by limiting the ability of foreign entities to do business with us in certain instances, imposing monetary or other penalties or taking other retaliatory action, which could have an adverse effect on our business, results of operations and financial condition, as well as on the price of our common stock. For additional discussion, see “Management’s Discussion and Analysis of Results of Operations and Financial Condition—Other Business Matters.”
The failure to successfully integrate the businesses and operations of FedEx Express and TNT Express in the expected time frame and at the expected cost may adversely affect our future results. Prior to FedEx’s acquisition of TNT Express in 2016, FedEx Express and TNT Express operated as independent companies. There can be no assurances that these businesses can be integrated successfully. Expected integration costs have increased significantly since the acquisition was completed, and parts of the integration have taken longer than initially expected. It is possible that the integration process could result in higher than currently expected integration costs, the loss of customers, the disruption of ongoing businesses, unexpected integration issues, or the loss of key historical FedEx Express or TNT Express employees. It is also possible that the overall integration process will take longer than currently anticipated.
- 91 -
Specifically, the following issues, among others, must be addressed as we integrate the operations of FedEx Express and TNT Express in order to realize the anticipated benefits of the transaction:
| • | combining the companies’ physical networks and operations, including integration of the companies’ linehaul and pickup-and-delivery operations and air networks, and corporate functions; |
|---|
| • | combining the businesses of FedEx Express and TNT Express and meeting the capital requirements of the combination in a manner that permits us to achieve the operating and financial results we anticipated from the acquisition, the failure of which could result in the anticipated benefits of the transaction not being realized in the time frame currently anticipated, or at all; |
|---|
| • | integrating and consolidating the companies’ administrative and information-technology infrastructure and computer systems, and modernizing certain TNT Express systems which suffered from underinvestment prior to the acquisition; |
|---|
| • | integrating and restructuring the corporate entities; |
|---|
| • | integrating workforces and consulting with works councils and employee representatives while continuing to provide consistent, high-quality service to customers; |
|---|
| • | integrating and unifying the offerings and services available to historical FedEx Express and TNT Express customers; |
|---|
| • | harmonizing the companies’ operating practices, employee development and compensation programs, integrity and compliance programs, terms and conditions of contracts of carriage, internal controls and other policies, procedures and processes; |
|---|
| • | integrating the companies’ financial reporting and internal control systems; |
|---|
| • | maintaining existing agreements with customers and service providers and avoiding delays in entering into new agreements with prospective customers and service providers; |
|---|
| • | addressing possible differences in business backgrounds, corporate cultures and management philosophies; |
|---|
| • | addressing employee social issues so as to maintain efficient and effective labor and employee relations; |
|---|
| • | coordinating rebranding and marketing efforts; |
|---|
| • | managing the movement of certain positions to different locations; |
|---|
| • | managing potential unknown and unidentified liabilities, including liabilities that are significantly larger than currently anticipated, and unforeseen increased expenses or delays associated with the integration process; and |
|---|
| • | managing the expanded operations of a significantly larger, more complex company. |
|---|
All of these factors could adversely affect FedEx’s results of operations, delay or decrease the expected accretive effect of the acquisition and negatively impact the price of our common stock. The expected financial benefits of the acquisition may also be delayed or decreased by reductions in our base business levels due to the continued impact of the COVID-19 pandemic and economic weakness in Europe or other factors. In addition, at times the attention of certain members of our management may be focused on the integration of the businesses of FedEx Express and TNT Express and diverted from day-to-day business operations, which may disrupt our business. Further, we may not achieve the expected financial benefits from any costs incurred in addition to our integration program expenses related to investments to further transform and optimize the combined businesses and FedEx Express’s international business.
- 92 -
Failure to successfully implement our business strategy and effectively respond to changes in market dynamics will cause our future financial results to suffer. We are making significant investments and other decisions in connection with our long-term business strategy which includes our ability to meet the demands of e-commerce, such as aircraft fleet modernization and hub modernization and expansion at FedEx Express, expansion of FedEx Ground residential delivery operations to seven days per week year-round, the integration of FedEx SmartPost packages into the standard FedEx Ground operations, last-mile residential delivery optimization and autonomous delivery. We are also implementing various cost-containment actions, including limited hiring and discretionary spending. Such initiatives and enhancements may require us to make significant capital expenditures. We have also incurred, and may continue to incur, increased operating expenses in connection with certain changes to our business strategy. Additionally, in developing our business strategy, we make certain assumptions including, but not limited to, those related to customer demand and the mix of services to be purchased by our customers, competition and the global economy; and actual market, economic and other conditions may be different from our assumptions. As technology, customer behavior and market conditions continue to evolve, it is important that we maintain the relevance of our brand and service offerings to our customers. If we are not able to successfully implement our business strategy and effectively respond to changes in market dynamics, our future financial results will suffer. For additional discussion, see Part I, Item 1 of this Annual Report under the caption “Strategy.”
Our businesses depend on our strong reputation and the value of the FedEx brand. The FedEx brand name symbolizes high-quality service, reliability and speed. FedEx is one of the most widely recognized, trusted and respected brands in the world, and the FedEx brand is one of our most important and valuable assets. In addition, we have a strong reputation among customers and the general public for high standards of social and environmental responsibility and corporate governance and ethics. The FedEx brand name and our corporate reputation are powerful sales and marketing tools, and we devote significant resources to promoting and protecting them. Adverse publicity (whether or not justified) relating to activities by our team members or others with whom we do business, such as customer service mishaps, accidents, catastrophes or incidents involving aircraft or vehicles operated by us, data breaches or technology infrastructure disruptions, noncompliance with laws or the shipment of certain items pursuant to our obligation as a common carrier operating under federal law, could tarnish our reputation and reduce the value of our brand. With the increase in the use of social media outlets such as Facebook, YouTube, Instagram and Twitter, adverse publicity can be disseminated quickly and broadly, making it increasingly difficult for us to effectively respond. Damage to our reputation and loss of brand equity could reduce demand for our services and thus have an adverse effect on our financial condition, liquidity and results of operations, as well as require additional resources to rebuild our reputation and restore the value of our brand.
Our failure to retain or attract employee talent or maintain our company culture could adversely impact our business. Our success depends upon the efforts and abilities of our high-quality employees, many of whom are longstanding FedEx team members. Difficulties in motivating, rewarding, retaining and recruiting employee talent, including successors to members of senior management, or the unexpected loss of such individuals resulting in the depletion of our institutional knowledge base, could have an adverse impact on our business, results of operations, reputation and the price of our common stock. Additionally, our company culture is important to providing high-quality customer service and having a productive workforce and could be adversely affected by our growing operations and other factors. If we fail to maintain the strength of our company culture, our competitive ability and our business may be harmed.
The United Kingdom’s withdrawal from the EU could adversely impact our business, results of operations and financial condition. On January 31, 2020, the United Kingdom left the EU (“Brexit”). The United Kingdom and EU are now in a transitional period during which the United Kingdom will maintain access to the EU single market and to the global trade deals negotiated by the EU on behalf of its members, and remain subject to EU law, until December 31, 2020.
The uncertainty regarding the status of Brexit has negatively impacted the United Kingdom’s and the EU’s economies. This negative impact will likely continue until the United Kingdom and EU reach and implement a definitive resolution on their future trading relationship. Any additional impact of Brexit will depend on the terms of such resolution. Even if the United Kingdom maintains access to the EU single market and trade deals following the transition period, Brexit could result in further economic downturn globally. If the United Kingdom ultimately loses access to the EU single market and trade deals, significant market and economic disruption would likely occur, our customer experience, service quality and international operations would likely be negatively impacted, and the demand for our services could be depressed.
Additionally, we may face new regulations regarding trade, aviation, tax, security and employees, among others, in the United Kingdom. Compliance with such regulations could be costly, negatively impacting our business, results of operations and financial condition. Brexit could also adversely affect European and worldwide economic and market conditions and could contribute to instability in global financial and foreign exchange markets, including volatility in the value of the euro and the British pound.
- 93 -
Our transportation businesses are impacted by the price and availability of jet and vehicle fuel. We must purchase large quantities of fuel to operate our aircraft and vehicles, and the price and availability of fuel is beyond our control and can be highly volatile. In addition, our purchased transportation expense may be impacted by fuel costs. To date, we have been mostly successful in mitigating over time the expense impact of higher fuel costs through our indexed fuel surcharges, as the amount of the surcharges is closely linked to the market prices for fuel. If we are unable to maintain or increase our fuel surcharges because of competitive pricing pressures or some other reason, fuel costs could adversely impact our operating results. As of May 31, 2020, we had no derivative financial instruments to reduce our exposure to fuel price fluctuations. Even if we are able to offset the cost of fuel with our surcharges, high fuel surcharges could move our customers away from our higher-yielding express services to our lower-yielding deferred or ground services or even reduce customer demand for our services altogether. In addition, disruptions in the supply of fuel could have a negative impact on our ability to operate our transportation networks. Weather-related events, natural disasters, political disruptions or wars involving oil-producing countries, economic sanctions imposed against oil-producing countries or specific industry participants, changes in governmental policy concerning fuel production, transportation, taxes or marketing, changes in refining capacity, environmental concerns and other unpredictable events may impact fuel supply and could result in shortages in the future.
Our businesses are capital intensive, and we must make capital decisions based upon projected volume levels. We make significant investments in aircraft, package handling facilities, vehicles, technology, sort equipment and other assets to support our transportation and business networks. We also make significant investments to rebrand, integrate and grow the companies that we acquire. The amount and timing of capital investments depend on various factors, including our anticipated volume growth. We must make commitments to purchase or modify aircraft years before the aircraft are actually needed. We must predict volume levels and fleet requirements and make commitments for aircraft based on those projections. Missing our projections could result in too much or too little capacity relative to our shipping volumes. Overcapacity could lead to below-market asset dispositions or write-downs, as well as negatively impact operating margins, and undercapacity could negatively impact service levels.
We face intense competition. The transportation and business services markets are both highly competitive and sensitive to price and service, especially in periods of little or no macroeconomic growth. Some of our competitors have more financial resources and competitive advantages than we do, appear willing to operate at little or no margin to gain market share, or they are owned, controlled or subsidized by foreign governments, which enables them to raise capital more easily. We also compete with regional transportation providers that operate smaller and less capital-intensive transportation networks and startup companies that combine technology with crowdsourcing to focus on local market needs. In addition, some high-volume package shippers are developing and implementing in-house delivery capabilities and utilizing independent contractors for deliveries, which could in turn reduce our revenues and market share. For example, Amazon.com is investing significant capital to establish a network of hubs, aircraft and vehicles.
We believe we compete effectively with these companies — for example, by providing more reliable service at compensatory prices. However, the existence of an irrational pricing environment could limit our ability not only to maintain or increase our prices (including our fuel surcharges in response to rising fuel costs), but also to maintain or grow our revenues and market share. While we believe we compete effectively through our current and planned service offerings, if our current competitors or potential future competitors offer a broader range of services, more effectively bundle their services, or offer services at lower prices, it could impede our ability to maintain or grow our market share. Moreover, if high-volume package shippers further develop or expand internal capabilities for the services we provide, it may reduce our revenue and could negatively impact our financial condition and results of operations. News regarding such developments or expansions could also negatively impact the price of our common stock. Additionally, advancements in technology, such as advanced safety systems; automated package sorting, handling and delivery; autonomous delivery; vehicle platooning; alternative fuel vehicles; and digitization of freight services, may necessitate that we increase investments in order to remain competitive, and our customers may not be willing to accept higher rates to cover the cost of these investments.
Government regulation and enforcement are evolving and unfavorable changes could harm our business. We are subject to regulation under a wide variety of U.S. federal and state and non-U.S. regulations, laws, and policies. There can be no assurance that such regulations, laws and policies will not be changed in ways that will decrease the demand for our services, subject us to escalating costs or require us to modify our business models and objectives, harming our financial results. In particular, legislative, regulatory or other actions that U.S. and non-U.S. governments have undertaken or are considering in areas such as data privacy and sovereignty, taxes, foreign exchange intervention in response to currency volatility, currency controls that could restrict the movement of liquidity from particular jurisdictions, trade controls, tariffs, quotas, embargoes or sanctions in the U.S. or other countries, complex economic sanctions, export controls, additional security requirements, additional requirements on employees (including our pilots) and benefits, environmental standards, tax reform and accounting may have an adverse effect on our operations, liquidity, capital requirements, effective tax rate and performance. For additional discussion, see Part I, Item 1 of this Annual Report under the caption “Regulation.”
- 94 -
We could be subject to adverse changes in regulations and interpretations or challenges to our tax positions. We are subject to taxation in the U.S. and numerous foreign jurisdictions. From time to time, changes in tax laws or regulations may be enacted that could significantly affect our overall tax liability. Such changes may require new and complex computations to be performed, significant judgments, estimates and calculations to be made, and the preparation and analysis of information not previously relevant or regularly produced.
Standard-setting bodies could interpret or issue guidance on how provisions of certain tax laws and regulations will be applied or otherwise administered that is different from our interpretation and we may be required to make adjustments to amounts that we have recorded that may adversely impact our results of operations and financial condition. For example, in January 2019, the U.S. Treasury Department issued final regulations covering the one-time transition tax on unrepatriated foreign earnings, which was enacted as part of the TCJA. Certain guidance included in these final regulations is inconsistent with our interpretation that led to the recognition of benefits of $233 million. If we are ultimately unsuccessful in defending our position with respect to our interpretation of the TCJA, we may be required to reverse these benefits.
If we do not successfully execute or effectively operate, integrate, leverage and grow acquired businesses, our financial results and reputation may suffer. Our strategy for long-term growth, productivity and profitability depends in part on our ability to make prudent strategic acquisitions and to realize the benefits we expect when we make those acquisitions. In furtherance of this strategy, in addition to TNT Express, we have acquired businesses in Europe, Latin America, Africa, the U.S., Asia and Australia over the past several years. Acquisitions involve special accounting, regulatory, compliance, information technology, human resources, cultural and other risks. While we expect our past and future acquisitions to enhance our value proposition to customers and improve our long-term profitability, there can be no assurance that we will realize our expectations within the time frame we have established, if at all, or that we can continue to support the value we allocate to these acquired businesses, including their goodwill or other intangible assets. For example, in 2020 we incurred a goodwill impairment charge of $358 million related to FedEx Office and FedEx Supply Chain, eliminating all of the goodwill attributable to these reporting units. For additional information, see “Management’s Discussion and Analysis of Results of Operations and Financial Condition—Results of Operations and Outlook—Consolidated Results—Goodwill and Other Asset Impairment Charges.”
Labor organizations attempt to organize groups of our employees from time to time, and potential changes in labor laws could make it easier for them to do so. If we are unable to continue to maintain good relationships with our employees and avoid having labor organizations organize groups of our employees, our operating costs could significantly increase and our operational flexibility could be significantly reduced. Despite continual organizing attempts by labor unions, other than the pilots at FedEx Express and drivers at one FedEx Freight, Inc. facility, our U.S. employees have thus far chosen not to unionize (we acquired FedEx Supply Chain in 2015, which already had a small number of employees who are members of unions). Additionally, certain of FedEx Express’s non-U.S. employees are unionized.
The U.S. Congress has, in the past, considered adopting changes in labor laws, however, that would make it easier for unions to organize units of our employees. For example, there is always a possibility that Congress could remove most FedEx Express employees from the jurisdiction of the Railway Labor Act of 1926, as amended (the “RLA”). For additional discussion of the RLA, see Part I, Item 1 of this Annual Report under the caption “Regulation.” Such legislation could expose our customers to the type of service disruptions that the RLA was designed to prevent — local work stoppages in key areas that interrupt the timely flow of shipments of time-sensitive, high-value goods throughout our global network. Such disruptions could threaten our ability to provide competitively priced shipping options and ready access to global markets.
There is also the possibility that Congress could pass other labor legislation that could adversely affect our companies, such as FedEx Ground and FedEx Freight, whose employees are governed by the National Labor Relations Act of 1935, as amended (“NLRA”). In addition, federal and state governmental agencies, such as the National Mediation Board and the National Labor Relations Board, have and may continue to take actions that could make it easier for our employees to organize under the RLA or NLRA. Finally, changes to federal or state laws governing employee classification could impact the status of FedEx Ground’s service providers as independent employers of drivers. If FedEx Ground is deemed to be an employer or joint employer of the drivers of these service providers, labor organizations could more easily organize these individuals, our operating costs could increase materially and we could incur significant capital outlays.
FedEx Ground relies on service providers to conduct its linehaul and pickup-and-delivery operations, and the status of these service providers as direct employers of drivers providing these services is being challenged. We are defending joint-employer cases where it is alleged that FedEx Ground should be treated as an employer of the drivers employed by service providers engaged by FedEx Ground. We incur certain costs, including legal fees, in defending the status of service providers engaged by FedEx Ground as direct employers of their drivers. We continue to believe that FedEx Ground is not an employer or joint employer of the drivers of these independent businesses. However, adverse determinations in these matters could, among other things, entitle service providers’ drivers to certain wage payments from the service providers and FedEx Ground, and result in employment and withholding tax and benefit liability for FedEx Ground.
- 95 -
We are self-insured for certain costs associated with our operations, and insurance and claims expenses could have a material adverse effect on us. We are self-insured up to certain limits that vary by type of risk for costs associated with workers’ compensation claims, vehicle accidents and general business liabilities, and benefits paid under employee healthcare and disability programs. Our reserves are established for estimates of loss on reported claims, including incurred-but-not-reported claims. Our self-insurance accruals are primarily based on estimated costs determined by actuarial methods. Estimated costs include consideration of a variety of factors and related assumptions such as the severity of claims, frequency and volume of claims, healthcare inflation, seasonality and plan designs, which may be subject to a high degree of variability. Periodically, we evaluate the level of insurance coverage and adjust insurance levels based on risk tolerance and premium expense. However, the use of any estimation technique in this area is inherently sensitive. Material increases in the magnitude of claims, changes to healthcare costs, accident frequency and severity, insurance retention levels, judgment and settlement amounts, associated legal expenses and other factors could result in unfavorable differences between actual self-insurance costs and our reserve estimates. As a result, our insurance costs could increase materially which could adversely affect our results of operations and financial condition.
Disruptions or modifications in service by the USPS or changes in its business or financial soundness could have an adverse effect on our operations and financial results. The USPS is a vendor and significant customer of FedEx. In particular, the USPS is the largest customer of FedEx Express, which provides domestic air transportation services for the USPS’s First Class Mail, Priority Mail Express and Priority Mail and transportation and delivery for the USPS’s international delivery service. FedEx Express’s contract with the USPS for domestic services expires in September 2024. The COVID-19 pandemic has negatively impacted mail volumes and mix resulting in a further decrease in revenues and negative financial impact for the USPS. Additionally, the USPS continues to experience budgetary uncertainty as well as increased political debate regarding potential privatization or restructuring of its operations. Disruptions or modifications in service by the USPS as a result of financial difficulties or changes in its business, including the ability to access capital, any structural changes to its operations, network, service offerings or pricing, could adversely affect our operations, negatively impacting our revenue, results of operations and financial condition.
Proposed pilot flight and duty time regulations could impair our operations and impose substantial costs on us. In September 2010, the Federal Aviation Administration (“FAA”) proposed regulations that would change the flight and duty time rules applicable to all-cargo air carriers. When the FAA issued final regulations in December 2011 (the “2011 regulations”), all-cargo carriers, including FedEx Express, were exempt from these new requirements. Instead, all-cargo carriers were required to continue complying with previously enacted flight and duty time rules and allowed to pursue the development of fatigue risk management systems to develop fatigue mitigations unique to each operation. In December 2012, the FAA reaffirmed the exclusion of all-cargo carriers from the 2011 regulations, and litigation in the U.S. Court of Appeals for the District of Columbia affirmed the FAA’s decision. However, legislation has recently been introduced in the U.S. Senate and U.S. House of Representatives that, if adopted, would require all-cargo carriers to comply with the 2011 regulations. Required compliance with the 2011 regulations would make it more difficult to avoid pilot fatigue and could impose substantial costs on us in order to maintain operational reliability.
The transportation infrastructure continues to be a target of terrorist activities. Because transportation assets continue to be a target of terrorist activities, governments around the world are adopting or are considering adopting stricter security requirements that will increase operating costs and potentially slow service for businesses, including those in the transportation industry. For example, the U.S. Transportation Security Administration (“TSA”) requires FedEx Express to comply with a Full All-Cargo Aircraft Operator Standard Security Plan, which contains evolving and strict security requirements. Additionally, the International Civil Aviation Organization currently allows a member state to permit carriers and other entities to determine, without government oversight, which shippers and shipments are secure for purposes of putting those shipments on all-cargo aircraft. This allowance will be removed by July 2021 and may require us to undergo additional screening and oversight by the TSA and similar government agencies internationally. Security requirements such as these are not static, but change periodically as the result of regulatory and legislative requirements, imposing additional security costs and creating a level of uncertainty for our operations. Thus, it is reasonably possible that these rules or other future security requirements could impose material costs on us or slow our service to our customers. The impact on our operations of avoiding areas of the world, including airspace, in which there are geopolitical conflicts and the targeting of aircraft by parties to those conflicts can also be significant. Moreover, a terrorist attack directed at FedEx or other aspects of the transportation infrastructure could disrupt our operations and adversely impact demand for our services.
- 96 -
The regulatory environment for global aviation or other transportation rights may impact our operations and increase our operating costs. Our extensive air network is critical to our success. Our right to serve foreign points is subject to the approval of the Department of Transportation and generally requires a bilateral agreement between the U.S. and foreign governments. In addition, we must obtain the permission of foreign governments to provide specific flights and services. Our operations outside of the U.S., such as FedEx Express’s growing international domestic operations, are also subject to current and potential regulations, including certain postal regulations and licensing requirements, that restrict, make difficult and sometimes prohibit, the ability of foreign-owned companies such as FedEx Express to compete effectively in parts of the international domestic transportation and logistics market. Regulatory or executive actions affecting global aviation or transportation rights or a failure to obtain or maintain aviation or other transportation rights in important international markets could impair our ability to operate our networks. Further, our ability to obtain or maintain aviation or other transportation rights internationally may be adversely affected by changes in international trade policies and relations.
We are subject to other extensive regulatory and legal compliance requirements that may result in significant costs. For instance, the FAA from time to time issues directives and other regulations relating to the maintenance and operation of aircraft that require significant expenditures in order to comply. High-profile accidents, catastrophes or incidents involving aircraft may trigger increased regulatory and legal compliance requirements. These requirements can be issued with little or no notice, or can otherwise impact our ability to efficiently or fully utilize our aircraft, and in some instances have resulted in the temporary grounding of aircraft types altogether. Further, our business may be adversely impacted when government agencies cease to operate as expected, including due to partial shutdowns, sequestrations or similar events, which may result in, among other things, disruption in the ability of government agencies to grant required regulatory approvals. For additional discussion, see Part I, Item 1 of this Annual Report under the caption “Regulation.”
We may be affected by global climate change or by legal, regulatory or market responses to such change. Concern over climate change, including the impact of global warming, has led to significant U.S. and international legislative and regulatory efforts to limit greenhouse gas (“GHG”) emissions, including our aircraft and vehicle engine emissions. Increasingly, state and local governments are also considering GHG regulatory requirements. Compliance with such regulation and the associated potential cost is complicated by the fact that various countries and regions are following different approaches to the regulation of climate change. Increased regulation regarding GHG emissions, especially aircraft or vehicle engine emissions, could impose substantial costs on us, especially at FedEx Express. These costs include an increase in the cost of the fuel and other energy we purchase and capital costs associated with updating or replacing our aircraft or vehicles prematurely. Until the timing, scope and extent of such possible regulation becomes known, we cannot predict its effect on our cost structure or our operating results. It is reasonably possible, however, that it could materially increase our operating expenses and have an adverse direct or indirect effect on our business, if instituted. For additional discussion of regulatory responses to climate change, including the Carbon Offsetting and Reduction Scheme for International Aviation and the Paris climate accord, see Part I, Item 1 of this Annual Report under the caption “Regulation.”
Moreover, even without such regulation, increased awareness and any adverse publicity in the global marketplace about the GHGs emitted by companies in the airline and transportation industries could harm our reputation and reduce customer demand for our services, especially our air express services. Finally, given the broad and global scope of our operations and our susceptibility to global macroeconomic trends, we are particularly vulnerable to the physical risks of climate change that could affect all of humankind, such as shifts in weather patterns and world ecosystems.
Increasing costs, the volatility of costs and funding requirements and other legal mandates for employee benefits, especially pension and healthcare benefits, could adversely impact our results of operations, financial condition and liquidity. We sponsor programs that provide retirement benefits to most of our employees. These programs include defined benefit pension plans, defined contribution plans and postretirement healthcare plans. The costs of providing pension and other retirement benefit plans are dependent on numerous assumptions, such as discount rates, expected long-term investment returns on plan assets, future salary increases, employee turnover, mortality, retirement ages, government regulations, and the frequency and amount of our required or voluntary contributions made to the plans. Changes in actuarial assumptions and differences between the assumptions and actual values, as well as significant declines in the value of investments that fund our pension and other postretirement plans, if not offset or mitigated by a decline in plan liabilities, could increase pension and other postretirement expense, and we could be required from time to time to fund the pension plans with significant amounts of cash. Such cash funding obligations could adversely affect our results of operations and liquidity. Additionally, the rules for pension and retirement benefit plan accounting are complex, involve numerous assumptions and can produce volatility in our results of operations, financial condition and liquidity. For example, our fourth quarter 2020 MTM retirement plans accounting adjustment resulted in a pre-tax noncash $794 million loss ($583 million, net of tax, or $2.22 per diluted share). For additional information on our MTM retirement plans accounting adjustment, see “Management’s Discussion and Analysis of Results of Operations and Financial Condition—Results of Operations and Outlook—Consolidated Results—Retirement Plans MTM Adjustments” and Note 13 of the accompanying consolidated financial statements.
- 97 -
Our inability to quickly and effectively restore operations following adverse weather or a localized disaster or disturbance in a key geography could adversely impact our business and results of operations. While we operate several integrated networks with assets distributed throughout the world, there are concentrations of key assets within our networks that are exposed to adverse weather conditions or localized risks from natural or manmade disasters such as earthquakes, volcanoes, wildfires, hurricanes, conflicts or unrest, terrorist attacks or other disturbances, actual or threatened. Additionally, shifts in weather patterns caused by climate change could increase the frequency, severity or duration of certain adverse weather conditions. Prolonged interruptions or disruptions at a key location such as our FedEx Express Memphis World Hub or one of our information-technology centers could adversely impact our business and results of operations. We also may incur significant costs to reestablish or relocate these functions. Moreover, resulting economic dislocations, including supply chain and fuel disruptions, could adversely impact demand for our services resulting in an adverse effect on our business and results of operations.
Our autonomous delivery strategy is dependent upon our ability to successfully mitigate unique technological, operational and regulatory risks. In 2019, we announced the development through a partnership of an autonomous delivery device designed to help retailers make same-day and last-mile deliveries to their customers, and in 2020, we announced our collaboration with two business partners to launch a pilot drone delivery service to explore methods of enhancing last-mile residential delivery service. Autonomous delivery is a new and evolving market, which makes it difficult to predict its acceptance, growth, the magnitude and timing of necessary investments and other trends. This aspect of our business strategy is subject to a variety of risks inherent with the development of new technologies, including: the ability to continue to develop autonomous delivery software and hardware; access to sufficient capital; our ability to develop and maintain necessary partnerships; risks related to the manufacture of autonomous devices; and significant competition from other companies, some of which may have more resources and capital to devote to autonomous technologies than we do.
In addition, we face risks related to the commercial deployment of autonomous delivery devices on our targeted timeline or at all, including consumer acceptance, achievement of adequate safety and other performance standards and compliance with uncertain, evolving and potentially conflicting federal and state regulations. To the extent accidents, cybersecurity breaches or other adverse events associated with our autonomous delivery devices occur, we could be subject to liability, government scrutiny, further regulation and reputational damage. Any of the foregoing could adversely impact our results of operations, financial condition and growth prospects.
Constraints, volatility or disruption in the capital markets, our failure to maintain our current credit ratings, commercial paper ratings and senior unsecured debt credit ratings, or our inability to meet credit agreement financial covenants could adversely affect our liquidity, increase our interest expense and limit our financing options. Our ability to obtain financing depends on a variety of factors, such as economic and market conditions, the regulatory environment for banks and other financial institutions, the availability of credit, our credit ratings and our reputation with potential lenders. Historically, we have relied on the public debt capital markets to fund portions of our capital investments and other expenditures and access to the commercial paper market as part of our working capital management strategy. Our continued access to these markets, and the terms of such access, depend on multiple factors including the condition of the debt capital markets, our operating performance and our credit ratings. Standard & Poor’s has assigned us a senior unsecured debt credit rating of BBB, a commercial paper rating of A-2 and a ratings outlook of “negative.” Moody’s Investors Service has assigned us an unsecured debt credit rating of Baa2, a commercial paper rating of P-2 and a ratings outlook of “negative.” These ratings are based on a number of factors, including assessments of our financial strength and financial policies. If our credit ratings drop, our interest expense may increase and our access to financing may become limited. If our commercial paper ratings drop below current levels, we may have difficulty utilizing the commercial paper market. If our senior unsecured debt credit ratings drop below investment grade, our access to financing may become limited.
Further, if we are unable to maintain the ratio of debt to adjusted EBITDA required by our Credit Agreements, our access to financing could become limited. In addition, increased volatility or disruption in the debt capital markets could adversely affect our ability to refinance existing debt. See Note 6 of the accompanying consolidated financial statements for additional information regarding recent amendments to the Credit Agreements, including with respect to the debt to adjusted EBITDA covenant. A change in our access to one or more of these sources of capital may reduce our ability to access other sources of capital and financing, adversely affecting our business operations and liquidity. Without sufficient sources of liquidity, we could be required to take actions that limit our business operations or experience limitations in our ability to pursue business opportunities.
- 98 -
We are also subject to other risks and uncertainties, including:
| • | widespread outbreak of an illness or any other communicable disease, or any other public health crisis; |
|---|
| • | human capital management risks, including changes in our ability to attract and retain drivers, package and freight handlers, commercial pilots and other employees, as well as health and safety issues; |
|---|
| • | the increasing costs of compliance with federal, state and foreign governmental agency mandates (including the Foreign Corrupt Practices Act and the U.K. Bribery Act) and defending against inappropriate or unjustified enforcement or other actions by such agencies; |
|---|
| • | changes in foreign currency exchange rates, especially in the euro, Chinese yuan, British pound, Canadian dollar, Australian dollar and Mexican peso, which can affect our sales levels and foreign currency sales prices; |
|---|
| • | any liability resulting from and the costs of defending against class-action, derivative and other litigation, such as wage-and-hour, joint employment, securities and discrimination and retaliation claims, and any other legal or governmental proceedings, including the matters discussed in Note 18 of the accompanying consolidated financial statements; |
|---|
| • | the outcome of future negotiations to reach new collective bargaining agreements — including with the union that represents the pilots of FedEx Express (the current pilot agreement is scheduled to become amendable in November 2021) and with the union elected in 2015 to represent drivers at a FedEx Freight, Inc. facility in the U.S.; |
|---|
| • | the impact of technology developments on our operations and on demand for our services, and our ability to continue to identify and eliminate unnecessary information-technology redundancy and complexity throughout the organization; |
|---|
| • | governmental underinvestment in transportation infrastructure, which could increase our costs and adversely impact our service levels due to traffic congestion or sub-optimal routing of our vehicles and aircraft; |
|---|
| • | stockholder activism, which could divert the attention of management and our board of directors from our business, hinder execution of our business strategy, give rise to perceived uncertainties as to our future and cause the price of our common stock to fluctuate significantly; and |
|---|
| • | the alternative interest rates we are able to negotiate with counterparties pursuant to the relevant provisions of our Credit Agreements in the event the London Interbank Offered Rate or the euro interbank offered rate cease to exist and we make borrowings under the agreements. |
|---|
- 99 -
FORWARD-LOOKING STATEMENTS
Certain statements in this Annual Report, including (but not limited to) those contained in the “Business” section of Part I, the “Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities” section of Part II, the “Impact of the COVID-19 Pandemic,” “Income Taxes,” “Outlook” (including segment outlooks), “Recent Accounting Guidance,” “Liquidity Outlook,” “Contractual Cash Obligations and Off-Balance Sheet Arrangements,” “Critical Accounting Estimates” and “Risk Factors” sections of “Management’s Discussion and Analysis of Results of Operations and Financial Condition,” and the “Recent Accounting Guidance,” “Long-Term Debt and Other Financing Arrangements,” “Income Taxes,” “Retirement Plans,” “Commitments” and “Contingencies” notes to the consolidated financial statements, are “forward-looking” statements within the meaning of the Private Securities Litigation Reform Act of 1995 with respect to our financial condition, results of operations, cash flows, plans, objectives, future performance and business. Forward-looking statements include those preceded by, followed by or that include the words “will,” “may,” “could,” “would,” “should,” “believes,” “expects,” “anticipates,” “plans,” “estimates,” “targets,” “projects,” “intends” or similar expressions. These forward-looking statements involve risks and uncertainties. Actual results may differ materially from those contemplated (expressed or implied) by such forward-looking statements, because of, among other things, the risk factors identified above and the other risks and uncertainties you can find in our press releases and other SEC filings.
As a result of these and other factors, no assurance can be given as to our future results and achievements. Accordingly, a forward-looking statement is neither a prediction nor a guarantee of future events or circumstances and those future events or circumstances may not occur. You should not place undue reliance on the forward-looking statements, which speak only as of the date of this report. We are under no obligation, and we expressly disclaim any obligation, to update or alter any forward-looking statements, whether as a result of new information, future events or otherwise.
- 100 -
MANAGEMENT’S REPORT ON INTERNAL
CONTROL OVER FINANCIAL REPORTING
Our management is responsible for establishing and maintaining adequate internal control over financial reporting (as defined in Rules 13a-15(f) and 15d-15(f) under the Securities Exchange Act of 1934, as amended). Our internal control over financial reporting includes, among other things, defined policies and procedures for conducting and governing our business, sophisticated information systems for processing transactions and a properly staffed, professional internal audit department. Mechanisms are in place to monitor the effectiveness of our internal control over financial reporting and actions are taken to correct all identified deficiencies. Our procedures for financial reporting include the active involvement of senior management, our Audit Committee and our staff of highly qualified financial and legal professionals.
Management, with the participation of our principal executive and financial officers, assessed our internal control over financial reporting as of May 31, 2020, the end of our fiscal year. Management based its assessment on criteria established in Internal Control–Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria).
Based on this assessment, management has concluded that our internal control over financial reporting was effective as of May 31, 2020.
The effectiveness of our internal control over financial reporting as of May 31, 2020, has been audited by Ernst & Young LLP, the independent registered public accounting firm who also audited the Company’s consolidated financial statements included in this Annual Report on Form 10-K. Ernst & Young LLP’s report on the Company’s internal control over financial reporting is included in this Annual Report on Form 10-K.
- 101 -
Report of Independent Registered Public Accounting Firm
To the Stockholders and Board of Directors of
FedEx Corporation
Opinion on Internal Control Over Financial Reporting
We have audited FedEx Corporation’s internal control over financial reporting as of May 31, 2020, based on criteria established in Internal Control — Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria). In our opinion, FedEx Corporation (the Company) maintained, in all material respects, effective internal control over financial reporting as of May 31, 2020, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of May 31, 2020 and 2019, the related consolidated statements of income, comprehensive income, cash flows and changes in common stockholders’ investment for each of the three years in the period ended May 31, 2020, and the related notes and our report dated July 20, 2020 expressed an unqualified opinion thereon.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects.
Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control Over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ Ernst & Young LLP
Memphis, Tennessee
July 20, 2020
- 102 -
Report of Independent Registered Public Accounting Firm
To the Stockholders and Board of Directors of
FedEx Corporation
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of FedEx Corporation (the Company) as of May 31, 2020 and 2019, the related consolidated statements of income, comprehensive income, cash flows and changes in common stockholders’ investment for each of the three years in the period ended May 31, 2020, and the related notes (collectively referred to as the “consolidated financial statements”). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at May 31, 2020 and 2019, and the results of its operations and its cash flows for each of the three years in the period ended May 31, 2020, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of May 31, 2020, based on criteria established in Internal Control — Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated July 20, 2020 expressed an unqualified opinion thereon.
Adoption of ASU No. 2016-02
As discussed in Note 2 to the consolidated financial statements, the Company changed its method of accounting for leases in 2020 due to the adoption of Accounting Standards Update (ASU) No. 2016-02, Leases (Topic 842), and related amendments.
Basis for Opinion
These financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
- 103 -
Critical Audit Matters
The critical audit matters communicated below are matters arising from the current period audit of the consolidated financial statements that were communicated or required to be communicated to the audit committee and that: (1) relate to accounts or disclosures that are material to the consolidated financial statements and (2) involved our especially challenging, subjective or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matters below, providing separate opinions on the critical audit matters or on the accounts or disclosures to which they relate.
| Pension Projected Benefit Obligation | ||
| Description of the Matter | At May 31, 2020, the Company’s aggregated U.S. pension plans’ projected benefit obligation was $30.2 billion and exceeded the fair value of the U.S. pension plans’ assets of $27.0 billion, resulting in an unfunded pension obligation of $3.2 billion. The U.S. pension plans’ net periodic benefit cost for the year ended May 31, 2020 was $950 million. As explained in Note 13 to the consolidated financial statements, the Company sponsors defined benefit pension plans that provide retirement benefits to certain U.S. employees. The Company’s U.S. pension plans’ projected benefit obligations are measured using actuarial techniques that reflect management’s assumptions for discount rate, salary increases, expected retirement, mortality, and employee turnover. Auditing the U.S. pension plans’ projected benefit obligation was complex due to the highly judgmental nature of the discount rate used in the measurement process. The discount rate is developed by utilizing the yield on a theoretical portfolio of high-grade corporate bonds that match cash flows to benefit payments, limit the concentration by industry and issuer, and apply screening criteria to exclude bonds with a call feature unless they have a low probability of being called. The discount rate had a significant effect on the pension projected benefit obligation. | |
| How We Addressed the Matter in Our Audit | We obtained an understanding, evaluated the design and tested the operating effectiveness of controls over management’s process for estimating the pension plans’ projected benefit obligation, including management’s review of the significant assumptions and assessment of the data inputs provided to the actuary. To test the U.S. pension plans’ projected benefit obligation, our audit procedures included, among others, evaluating the methodologies used, the significant actuarial assumptions described above, and the underlying data used by the Company. We compared the actuarial assumptions used by management to historical trends and evaluated the change in the pension plans’ projected benefit obligation from the prior year due to the change in service cost, interest cost, actuarial gains and losses, benefit payments, contributions and other activities. In addition, we involved our actuarial specialists to assist in evaluating management’s methodology for determining the discount rate. As part of this assessment, we compared management’s selected discount rate to an independently developed range of reasonable discount rates. Additionally, we compared the pension plans’ projected future cash flows to the prior year projections and compared the current year benefits paid to the prior year projected cash flows. We also tested the completeness and accuracy of the underlying data, including the participant data provided to management’s actuarial specialists. |
- 104 -
| Valuation of Self-Insurance Accruals | ||
| Description of the Matter | At May 31, 2020, the Company’s self-insurance accruals reflected in the balance sheet were $3.3 billion. As explained in Note 1 to the consolidated financial statements, self-insurance accruals include costs associated with workers’ compensation claims, vehicle accidents and general business liabilities, and benefits paid under employee healthcare and disability programs. These accrued liabilities are primarily based on the actuarial estimation of the cost of claims, including incurred-but-not-reported (IBNR) claims. Auditing the Company's self-insurance accruals is complex and required us to use our actuarial specialists due to the significant measurement uncertainty associated with the estimate, the application of management judgment, and the use of various actuarial methods. In addition, the accruals are sensitive due to the volume of claims and the amount of time that can pass before the final cost is known. | |
| How We Addressed the Matter in Our Audit | We obtained an understanding, evaluated the design and tested the operating effectiveness of controls over the Company’s process of estimating self-insurance accruals, including management's review of the assumptions used, results of calculations and assessment of data underlying the accruals. To evaluate the self-insurance accruals, our audit procedures included, among others, testing the completeness and accuracy of the underlying claims data used by the Company. We involved our actuarial specialists to assist in our evaluation of the methodologies applied by management in determining the actuarially determined accrual and in reviewing the Company's reinsurance contracts by policy year to assess the Company's self-insured retentions, deductibles, and coverage limits. We compared the Company's accrued amounts to a range developed by our actuarial specialists. |
/s/ Ernst & Young LLP
We have served as the Company’s auditor since 2002.
Memphis, Tennessee
July 20, 2020
- 105 -
FEDEX CORPORATION
CONSOLIDATED BALANCE SHEETS
(IN MILLIONS)
| May 31, | ||||||||
|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | |||||||
| ASSETS | ||||||||
| CURRENT ASSETS | ||||||||
| Cash and cash equivalents | $ | 4,881 | $ | 2,319 | ||||
| Receivables, less allowances of $390 and $300 | 10,102 | 9,116 | ||||||
| Spare parts, supplies and fuel, less allowances of $335 and $335 | 572 | 553 | ||||||
| Prepaid expenses and other | 828 | 1,098 | ||||||
| Total current assets | 16,383 | 13,086 | ||||||
| PROPERTY AND EQUIPMENT, AT COST | ||||||||
| Aircraft and related equipment | 24,518 | 22,793 | ||||||
| Package handling and ground support equipment | 11,382 | 10,409 | ||||||
| Information technology | 6,884 | 6,268 | ||||||
| Vehicles and trailers | 9,101 | 8,339 | ||||||
| Facilities and other | 13,139 | 11,702 | ||||||
| 65,024 | 59,511 | |||||||
| Less accumulated depreciation and amortization | 31,416 | 29,082 | ||||||
| Net property and equipment | 33,608 | 30,429 | ||||||
| OTHER LONG-TERM ASSETS | ||||||||
| Operating lease right-of-use assets, net | 13,917 | — | ||||||
| Goodwill | 6,372 | 6,884 | ||||||
| Other assets | 3,257 | 4,004 | ||||||
| Total other long-term assets | 23,546 | 10,888 | ||||||
| $ | 73,537 | $ | 54,403 |
The accompanying notes are an integral part of these consolidated financial statements.
- 106 -
FEDEX CORPORATION
CONSOLIDATED BALANCE SHEETS
(IN MILLIONS, EXCEPT SHARE DATA)
| May 31, | ||||||||
|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | |||||||
| LIABILITIES AND COMMON STOCKHOLDERS’ INVESTMENT | ||||||||
| CURRENT LIABILITIES | ||||||||
| Current portion of long-term debt | $ | 51 | $ | 964 | ||||
| Accrued salaries and employee benefits | 1,569 | 1,741 | ||||||
| Accounts payable | 3,269 | 3,030 | ||||||
| Operating lease liabilities | 1,923 | — | ||||||
| Accrued expenses | 3,532 | 3,278 | ||||||
| Total current liabilities | 10,344 | 9,013 | ||||||
| LONG-TERM DEBT, LESS CURRENT PORTION | 21,952 | 16,617 | ||||||
| OTHER LONG-TERM LIABILITIES | ||||||||
| Deferred income taxes | 3,162 | 2,821 | ||||||
| Pension, postretirement healthcare and other benefit obligations | 5,019 | 5,095 | ||||||
| Self-insurance accruals | 2,104 | 1,899 | ||||||
| Operating lease liabilities | 12,195 | — | ||||||
| Deferred lease obligations | — | 531 | ||||||
| Other liabilities | 466 | 670 | ||||||
| Total other long-term liabilities | 22,946 | 11,016 | ||||||
| COMMITMENTS AND CONTINGENCIES | ||||||||
| COMMON STOCKHOLDERS’ INVESTMENT | ||||||||
| Common stock, $0.10 par value; 800 million shares authorized; 318 million shares issued as of May 31, 2020 and 2019 | 32 | 32 | ||||||
| Additional paid-in capital | 3,356 | 3,231 | ||||||
| Retained earnings | 25,216 | 24,648 | ||||||
| Accumulated other comprehensive loss | (1,147 | ) | (865 | ) | ||||
| Treasury stock, at cost | (9,162 | ) | (9,289 | ) | ||||
| Total common stockholders’ investment | 18,295 | 17,757 | ||||||
| $ | 73,537 | $ | 54,403 |
The accompanying notes are an integral part of these consolidated financial statements.
- 107 -
FEDEX CORPORATION
CONSOLIDATED STATEMENTS OF INCOME
(IN MILLIONS, EXCEPT PER SHARE AMOUNTS)
| Years ended May 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | 2018 | ||||||||||
| REVENUE | $ | 69,217 | $ | 69,693 | $ | 65,450 | ||||||
| OPERATING EXPENSES: | ||||||||||||
| Salaries and employee benefits | 25,031 | 24,776 | 23,795 | |||||||||
| Purchased transportation | 17,466 | 16,654 | 15,101 | |||||||||
| Rentals and landing fees | 3,712 | 3,360 | 3,361 | |||||||||
| Depreciation and amortization | 3,615 | 3,353 | 3,095 | |||||||||
| Fuel | 3,156 | 3,889 | 3,374 | |||||||||
| Maintenance and repairs | 2,893 | 2,834 | 2,622 | |||||||||
| Goodwill and other asset impairment charges | 435 | — | 380 | |||||||||
| Business realignment costs | — | 320 | — | |||||||||
| Other | 10,492 | 10,041 | 9,450 | |||||||||
| 66,800 | 65,227 | 61,178 | ||||||||||
| OPERATING INCOME | 2,417 | 4,466 | 4,272 | |||||||||
| OTHER (EXPENSE) INCOME: | ||||||||||||
| Interest expense | (672 | ) | (588 | ) | (558 | ) | ||||||
| Interest income | 55 | 59 | 48 | |||||||||
| Other retirement plans (expense) income | (122 | ) | (3,251 | ) | 598 | |||||||
| Other, net | (9 | ) | (31 | ) | (7 | ) | ||||||
| (748 | ) | (3,811 | ) | 81 | ||||||||
| INCOME BEFORE INCOME TAXES | 1,669 | 655 | 4,353 | |||||||||
| PROVISION FOR INCOME TAXES (BENEFIT) | 383 | 115 | (219 | ) | ||||||||
| NET INCOME | $ | 1,286 | $ | 540 | $ | 4,572 | ||||||
| BASIC EARNINGS PER COMMON SHARE | $ | 4.92 | $ | 2.06 | $ | 17.08 | ||||||
| DILUTED EARNINGS PER COMMON SHARE | $ | 4.90 | $ | 2.03 | $ | 16.79 |
The accompanying notes are an integral part of these consolidated financial statements.
- 108 -
FEDEX CORPORATION
CONSOLIDATED STATEMENTS OF COMPREHENSIVE INCOME
(IN MILLIONS)
| Years Ended May 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | 2018 | ||||||||||
| NET INCOME | $ | 1,286 | $ | 540 | $ | 4,572 | ||||||
| OTHER COMPREHENSIVE LOSS: | ||||||||||||
| Foreign currency translation adjustments, net of tax benefit of $18 in 2020, $29 in 2019, and tax expense of $16 in 2018 | (254 | ) | (195 | ) | (74 | ) | ||||||
| Amortization of prior service credit and other, net of tax benefits of $25 in 2020, $28 in 2019, and $37 in 2018. | (79 | ) | (92 | ) | (89 | ) | ||||||
| (333 | ) | (287 | ) | (163 | ) | |||||||
| COMPREHENSIVE INCOME | $ | 953 | $ | 253 | $ | 4,409 |
The accompanying notes are an integral part of these consolidated financial statements.
- 109 -
FEDEX CORPORATION
CONSOLIDATED STATEMENTS OF CASH FLOWS
(IN MILLIONS)
| Years ended May 31, | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | 2018 | ||||||||||
| OPERATING ACTIVITIES | ||||||||||||
| Net income | $ | 1,286 | $ | 540 | $ | 4,572 | ||||||
| Adjustments to reconcile net income to cash provided by operating activities: | ||||||||||||
| Depreciation and amortization | 3,615 | 3,353 | 3,095 | |||||||||
| Provision for uncollectible accounts | 442 | 295 | 246 | |||||||||
| Other noncash items and deferred income taxes | 2,449 | (233 | ) | (231 | ) | |||||||
| Stock-based compensation | 168 | 174 | 167 | |||||||||
| Retirement plans mark-to-market adjustment | 794 | 3,882 | (10 | ) | ||||||||
| Gain from sale of business | — | (8 | ) | (85 | ) | |||||||
| Business realignment costs | — | 101 | — | |||||||||
| Goodwill and other asset impairment charges | 435 | — | 380 | |||||||||
| Changes in assets and liabilities: | ||||||||||||
| Receivables | (1,331 | ) | (873 | ) | (1,049 | ) | ||||||
| Other current assets | (59 | ) | (25 | ) | (135 | ) | ||||||
| Pension and postretirement healthcare assets and liabilities, net | (908 | ) | (909 | ) | (2,345 | ) | ||||||
| Accounts payable and other liabilities | (1,787 | ) | (571 | ) | 141 | |||||||
| Other, net | (7 | ) | (113 | ) | (72 | ) | ||||||
| Cash provided by operating activities | 5,097 | 5,613 | 4,674 | |||||||||
| INVESTING ACTIVITIES | ||||||||||||
| Capital expenditures | (5,868 | ) | (5,490 | ) | (5,663 | ) | ||||||
| Business acquisitions, net of cash acquired | — | (66 | ) | (179 | ) | |||||||
| Proceeds from sale of business | — | — | 123 | |||||||||
| Proceeds from asset dispositions and other | 22 | 83 | 42 | |||||||||
| Cash used in investing activities | (5,846 | ) | (5,473 | ) | (5,677 | ) | ||||||
| FINANCING ACTIVITIES | ||||||||||||
| Principal payments on debt | (2,548 | ) | (1,436 | ) | (38 | ) | ||||||
| Proceeds from debt issuances | 6,556 | 2,463 | 1,480 | |||||||||
| Proceeds from stock issuances | 64 | 101 | 327 | |||||||||
| Dividends paid | (679 | ) | (683 | ) | (535 | ) | ||||||
| Purchase of treasury stock | (3 | ) | (1,480 | ) | (1,017 | ) | ||||||
| Other, net | (9 | ) | (4 | ) | 10 | |||||||
| Cash provided by (used in) financing activities | 3,381 | (1,039 | ) | 227 | ||||||||
| Effect of exchange rate changes on cash | (70 | ) | (47 | ) | 72 | |||||||
| Net increase (decrease) in cash and cash equivalents | 2,562 | (946 | ) | (704 | ) | |||||||
| Cash and cash equivalents at beginning of period | 2,319 | 3,265 | 3,969 | |||||||||
| Cash and cash equivalents at end of period | $ | 4,881 | $ | 2,319 | $ | 3,265 |
The accompanying notes are an integral part of these consolidated financial statements.
- 110 -
FEDEX CORPORATION
CONSOLIDATED STATEMENTS OF CHANGES IN COMMON STOCKHOLDERS’ INVESTMENT
(IN MILLIONS, EXCEPT SHARE DATA)
| Common Stock | Additional Paid-in Capital | Retained Earnings | Accumulated Other Comprehensive Loss | Treasury Stock | Total | |||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Balance at May 31, 2017 | $ | 32 | $ | 3,005 | $ | 20,833 | $ | (415 | ) | $ | (7,382 | ) | $ | 16,073 | ||||||||||
| Net income | — | — | 4,572 | — | — | 4,572 | ||||||||||||||||||
| Other comprehensive loss, net of tax of $21 | — | — | — | (163 | ) | — | (163 | ) | ||||||||||||||||
| Purchase of treasury stock (4.3 million shares) | — | — | — | — | (1,017 | ) | (1,017 | ) | ||||||||||||||||
| Cash dividends declared ($2.00 per share) | — | — | (535 | ) | — | — | (535 | ) | ||||||||||||||||
| Employee incentive plans and other (3.1 million shares issued) | — | 112 | (47 | ) | — | 421 | 486 | |||||||||||||||||
| Balance at May 31, 2018 | 32 | 3,117 | 24,823 | (578 | ) | (7,978 | ) | 19,416 | ||||||||||||||||
| Net income | — | — | 540 | — | — | 540 | ||||||||||||||||||
| Other comprehensive loss, net of tax of $57 | — | — | — | (287 | ) | — | (287 | ) | ||||||||||||||||
| Purchase of treasury stock (6.6 million shares) | — | — | — | — | (1,480 | ) | (1,480 | ) | ||||||||||||||||
| Cash dividends declared ($2.60 per share) | — | — | (683 | ) | — | — | (683 | ) | ||||||||||||||||
| Employee incentive plans and other (1.3 million shares issued) | — | 114 | (32 | ) | — | 169 | 251 | |||||||||||||||||
| Balance at May 31, 2019 | 32 | 3,231 | 24,648 | (865 | ) | (9,289 | ) | 17,757 | ||||||||||||||||
| Net income | — | — | 1,286 | — | — | 1,286 | ||||||||||||||||||
| Other comprehensive loss, net of tax of $43 | — | — | — | (333 | ) | — | (333 | ) | ||||||||||||||||
| Purchase of treasury stock (0.02 million shares) | — | — | — | — | (3 | ) | (3 | ) | ||||||||||||||||
| Cash dividends declared ($2.60 per share) | — | — | (679 | ) | — | — | (679 | ) | ||||||||||||||||
| Employee incentive plans and other (1.0 million shares issued) | — | 125 | (35 | ) | — | 130 | 220 | |||||||||||||||||
| Adoption of new accounting standards on June 1, 2019(1) | — | — | (4 | ) | — | — | (4 | ) | ||||||||||||||||
| Reclassification to retained earnings due to the adoption of a new accounting standard on June 1, 2019(2) | — | — | — | 51 | — | 51 | ||||||||||||||||||
| Balance at May 31, 2020 | $ | 32 | $ | 3,356 | $ | 25,216 | $ | (1,147 | ) | $ | (9,162 | ) | $ | 18,295 |
| (1) | Relates to the adoption of Accounting Standards Update (“ASU”) 2016-02 and ASU 2018-02. |
|---|
| (2) | Relates to the adoption of ASU 2018-02. |
|---|
The accompanying notes are an integral part of these consolidated financial statements.
- 111 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
NOTE 1: DESCRIPTION OF BUSINESS SEGMENTS AND SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES
DESCRIPTION OF BUSINESS SEGMENTS. FedEx Corporation (“FedEx”) provides a broad portfolio of transportation, e-commerce and business services through companies competing collectively, operating independently and managed collaboratively, under the respected FedEx brand. Our primary operating companies are Federal Express Corporation (“FedEx Express”), the world’s largest express transportation company; FedEx Ground Package System, Inc. (“FedEx Ground”), a leading North American provider of small-package ground delivery services; and FedEx Freight Corporation (“FedEx Freight”), a leading North American provider of less-than-truckload (“LTL”) freight transportation. These companies represent our major service lines and, along with FedEx Corporate Services, Inc. (“FedEx Services”), constitute our reportable segments. Our FedEx Services segment provides sales, marketing, information technology, communications, customer service, technical support, billing and collection services, and certain back-office functions that support our transportation segments (FedEx Express, FedEx Ground and FedEx Freight) and other business units.
FISCAL YEARS. Except as otherwise specified, references to years indicate our fiscal year ended May 31, 2020 or ended May 31 of the year referenced.
RECLASSIFICATIONS. Certain reclassifications have been made to the prior years’ consolidated financial statements to conform to the current year’s presentation.
PRINCIPLES OF CONSOLIDATION. The consolidated financial statements include the accounts of FedEx and its subsidiaries, substantially all of which are wholly owned. All significant intercompany accounts and transactions have been eliminated in consolidation.
REVENUE RECOGNITION.
Satisfaction of Performance Obligation
A performance obligation is a promise in a contract to transfer a distinct good or service to the customer, and is the basis of revenue recognition in accordance with U.S. generally accepted accounting principles (“GAAP”). To determine the proper revenue recognition method for contracts, we evaluate whether two or more contracts should be combined and accounted for as one single contract and whether the combined or single contract should be accounted for as more than one performance obligation. For most of our contracts, the customer contracts with us to provide distinct services within a single contract, primarily transportation services. Substantially all of our contracts with customers for transportation services include only one performance obligation, the transportation services themselves. However, if a contract is separated into more than one performance obligation, we allocate the total transaction price to each performance obligation in an amount based on the estimated relative standalone selling prices of the promised goods or services underlying each performance obligation. We frequently sell standard transportation services with observable standalone sales prices. In these instances, the observable standalone sales are used to determine the standalone selling price.
For transportation services, revenue is recognized over time as we perform the services in the contract because of the continuous transfer of control to the customer. Our customers receive the benefit of our services as the goods are transported from one location to another. If we were unable to complete delivery to the final location, another entity would not need to reperform the transportation service already performed. As control transfers over time, revenue is recognized based on the extent of progress towards completion of the performance obligation. The selection of the method to measure progress towards completion requires judgment and is based on the nature of the products or services to be provided. We use the cost-to-cost measure of progress for our package delivery contracts because it best depicts the transfer of control to the customer which occurs as we incur costs on our contracts. Under the cost-to-cost measure of progress, the extent of progress towards completion is measured based on the ratio of costs incurred to date to the total estimated costs at completion of the performance obligation. Revenue, including ancillary or accessorial fees and reductions for estimated customer incentives, is recorded proportionally as costs are incurred. Costs to fulfill include labor and other direct costs and an allocation of indirect costs. For our freight and freight forwarding contracts, an output method of progress based on time-in-transit is utilized as the timing of costs incurred does not best depict the transfer of control to the customer.
We also provide customized customer-specific solutions, such as supply chain management solutions and inventory and service parts logistics, through which we provide the service of integrating a complex set of tasks and components into a single capability. For these arrangements, the majority of which are conducted by our FedEx Logistics, Inc. (“FedEx Logistics”) operating segment, the entire contract is accounted for as one performance obligation. For these performance obligations, we typically have a right to consideration from customers in an amount that corresponds directly with the value to the customers of our performance completed to date, and as such we recognize revenue in the amount to which we have a right to invoice the customer.
- 112 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
Contract Modification
Contracts are often modified to account for changes in the rates we charge our customers or to add additional distinct services. We consider contract modifications to exist when the modification either creates new enforceable rights and obligations or alters the existing arrangement. Contract modifications that add distinct goods or services are treated as separate contracts. Contract modifications that do not add distinct goods or services typically change the price of existing services. These contract modifications are accounted for prospectively as the remaining performance obligations are distinct.
Variable Consideration
Certain contracts contain customer incentives, guaranteed service refunds and other provisions that can either increase or decrease the transaction price. These incentives are generally awarded based upon achieving certain performance metrics. We estimate variable consideration as the most likely amount to which we expect to be entitled. We include estimated amounts of revenue, which may be reduced by incentives or other contract provisions, in the transaction price to the extent it is probable that a significant reversal of cumulative revenue recognized will not occur when the uncertainty associated with the variable consideration is resolved. Our estimates of variable consideration and determination of whether to include estimated amounts in the transaction price are based on an assessment of anticipated customer spending and all information (historical, current and forecasted) that is reasonably available to us.
Principal vs. Agent Considerations
Transportation services are provided with the use of employees and independent businesses that contract with FedEx. GAAP requires us to evaluate whether our businesses themselves promise to transfer services to the customer (as the principal) or to arrange for services to be provided by another party (as the agent) using a control model. Based on our evaluation of the control model, we determined that FedEx is the principal to the transaction for most of these services and revenue is recognized on a gross basis based on the transfer of control to the customer. Costs associated with independent businesses providing transportation services are recognized as incurred and included in the caption “Purchased transportation” in the accompanying consolidated statements of income.
Our contract logistics, global trade services and certain transportation businesses engage in certain transactions wherein they act as agents. Revenue from these transactions is recorded on a net basis. Net revenue includes billings to customers less third-party charges, including transportation or handling costs, fees, commissions and taxes and duties.
Contract Assets and Liabilities
Contract assets include billed and unbilled amounts resulting from in-transit shipments, as we have an unconditional right to payment only once all performance obligations have been completed (e.g., packages have been delivered). Contract assets are generally classified as current and the full balance is converted each quarter based on the short-term nature of the transactions. Our contract liabilities consist of advance payments and billings in excess of revenue. The full balance of deferred revenue is converted each quarter based on the short-term nature of the transactions.
Gross contract assets related to in-transit shipments totaled $563 million and $533 million at May 31, 2020 and May 31, 2019, respectively. Contract assets, net of deferred unearned revenue were $456 million and $364 million at May 31, 2020 and May 31, 2019, respectively. Contract assets are included within current assets in the accompanying consolidated balance sheets. Contract liabilities related to advance payments from customers were $10 million and $11 million at May 31, 2020 and May 31, 2019, respectively. Contract liabilities are included within current liabilities in the accompanying consolidated balance sheets.
Payment terms
Certain of our revenue-producing transactions are subject to taxes, such as sales tax, assessed by governmental authorities. We present these revenues net of tax. Under the typical payment terms of our customer contracts, the customer pays at periodic intervals (e.g., every 15 days, 30 days, 45 days, etc.) for shipments included on invoices received. It is not customary business practice to extend payment terms past 90 days, and as such, we do not have a practice of including a significant financing component within our revenue contracts with customers.
Disaggregation of Revenue
See Note 14 for disclosure of disaggregated revenue for the periods ended May 31. This presentation is consistent with how we organize our segments internally for making operating decisions and measuring performance.
- 113 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
CREDIT RISK. We routinely grant credit to many of our customers for transportation and business services without collateral. The risk of credit loss in our trade receivables is substantially mitigated by our credit evaluation process, short collection terms and sales to a large number of customers, as well as the low revenue per transaction for most of our services. Allowances for potential credit losses are determined based on historical experience and the impact of current economic conditions. Historically, credit losses have been within management’s expectations.
ADVERTISING. Advertising and promotion costs are expensed as incurred and are classified in other operating expenses. Advertising and promotion expenses were $427 million in 2020, $468 million in 2019 and $442 million in 2018.
CASH EQUIVALENTS. Cash in excess of current operating requirements is invested in short-term, interest-bearing instruments with maturities of three months or less at the date of purchase and is stated at cost, which approximates market value.
SPARE PARTS, SUPPLIES AND FUEL. Spare parts (principally aircraft-related) are reported at weighted-average cost. Allowances for obsolescence are provided for spare parts currently identified as excess or obsolete as well as expected to be on hand at the date the aircraft are retired from service. These allowances are provided over the estimated useful life of the related aircraft and engines. The majority of our supplies and fuel are reported at weighted-average cost.
PROPERTY AND EQUIPMENT. Expenditures for major additions, improvements and flight equipment modifications are capitalized when such costs are determined to extend the useful life of the asset or are part of the cost of acquiring the asset. Expenditures for equipment overhaul costs of engines or airframes prior to their operational use are capitalized as part of the cost of such assets as they are costs required to ready the asset for its intended use. Maintenance and repairs costs are charged to expense as incurred, except for certain aircraft engine maintenance costs incurred under third-party service agreements. These agreements result in costs being expensed based on cycles or hours flown and are subject to annual escalation. These service contracts transfer risk to third-party service providers and generally fix the amount we pay for maintenance to the service provider as a rate per cycle or flight hour, in exchange for maintenance and repairs under a predefined maintenance program. We capitalize certain direct internal and external costs associated with the development of internal-use software. Gains and losses on sales of property used in operations are classified within operating expenses and historically have been nominal.
For financial reporting purposes, we record depreciation and amortization of property and equipment on a straight-line basis over the asset’s service life or related lease term, if shorter. For income tax purposes, depreciation is computed using accelerated methods when applicable.
The depreciable lives and net book value of our property and equipment are as follows (dollars in millions):
| Net Book Value at May 31, | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|
| Range | 2020 | 2019 | ||||||||
| Wide-body aircraft and related equipment | 15 to 30 years | $ | 13,448 | $ | 11,975 | |||||
| Narrow-body and feeder aircraft and related equipment | 5 to 18 years | 2,478 | 2,696 | |||||||
| Package handling and ground support equipment | 3 to 30 years | 4,499 | 4,157 | |||||||
| Information technology | 2 to 10 years | 1,795 | 1,553 | |||||||
| Vehicles and trailers | 3 to 15 years | 4,345 | 4,042 | |||||||
| Facilities and other | 2 to 40 years | 7,043 | 6,006 |
Substantially all property and equipment have no material residual values. The majority of aircraft costs are depreciated on a straight-line basis over 15 to 30 years. We periodically evaluate the estimated service lives and residual values used to depreciate our property and equipment.
Depreciation and amortization expense, excluding gains and losses on sales of property and equipment used in operations, was $3.6 billion in 2020, $3.4 billion in 2019 and $3.1 billion in 2018. Depreciation and amortization expense includes amortization of assets under finance lease.
CAPITALIZED INTEREST. Interest on funds used to finance the acquisition and modification of aircraft, including purchase deposits, construction of certain facilities, and development of certain software up to the date the asset is ready for its intended use, is capitalized and included in the cost of the asset if the asset is actively under construction. Capitalized interest was $54 million in 2020, $64 million in 2019 and $61 million in 2018.
- 114 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
IMPAIRMENT OF LONG-LIVED ASSETS. Long-lived assets are reviewed for impairment when circumstances indicate the carrying value of an asset may not be recoverable. For assets that are to be held and used, an impairment is recognized when the estimated undiscounted cash flows associated with the asset or group of assets is less than their carrying value. If impairment exists, an adjustment is made to write the asset down to its fair value, and a loss is recorded as the difference between the carrying value and fair value. Fair values are determined based on quoted market values, discounted cash flows or internal and external appraisals, as applicable. Assets to be disposed of are carried at the lower of carrying value or estimated net realizable value.
We operate integrated transportation networks so cash flows for most of our operating assets to be held and used are assessed at a network level, not at an individual asset level, for our analysis of impairment.
In the second quarter of 2020, we made the decision to permanently retire from service 10 Airbus A310-300 aircraft and 12 related engines at FedEx Express to align with the needs of the U.S. domestic network and modernize its aircraft fleet. As a consequence of this decision, we recognized noncash impairment charges of $66 million ($50 million, net of tax, or $0.19 per diluted share) in the FedEx Express segment in the second quarter of 2020. Seven of these aircraft had been temporarily idled.
In the normal management of our aircraft fleet, we routinely idle aircraft and engines temporarily due to maintenance cycles and adjustments of our network capacity to match seasonality and overall customer demand levels. Temporarily idled assets are classified as available-for-use, and we continue to record depreciation expense associated with these assets. These temporarily idled assets are assessed for impairment and remaining life on a quarterly basis. The criteria for determining whether an asset has been permanently removed from service (and, as a result, is potentially impaired) include, but are not limited to, our global economic outlook and the impact of our outlook on our current and projected volume levels, including capacity needs during our peak shipping seasons; the introduction of new fleet types or decisions to permanently retire an aircraft fleet from operations; and changes to planned service expansion activities. At May 31, 2020, we had 14 aircraft temporarily idled. These aircraft have been idled for an average of five months and are expected to return to revenue service.
SALE OF BUSINESS. During 2018, we sold a non-core business of TNT Express B.V. (“TNT Express”) and recorded a gain of $85 million in the FedEx Express segment.
GOODWILL. Goodwill is recognized for the excess of the purchase price over the fair value of tangible and identifiable intangible net assets of businesses acquired. Several factors give rise to goodwill in our acquisitions, such as the expected benefits from synergies of the combination and the existing workforce of the acquired business. Goodwill is reviewed at least annually for impairment. In our evaluation of goodwill impairment, we perform a qualitative assessment to determine if it is more likely than not that the fair value of a reporting unit is less than its carrying amount. If the qualitative assessment is not conclusive, we proceed to test goodwill for impairment, including comparing the fair value of the reporting unit to its carrying value (including attributable goodwill). Fair value for our reporting units is determined using an income or market approach incorporating market participant considerations and management’s assumptions on revenue growth rates, operating margins, discount rates and expected capital expenditures. Fair value determinations may include both internal and third-party valuations. Unless circumstances otherwise dictate, we perform our annual impairment testing in the fourth quarter.
See Note 4 for additional information.
INTANGIBLE ASSETS. Intangible assets primarily include customer relationships, technology assets and trademarks acquired in business combinations. Intangible assets are amortized over periods ranging from 3 to 15 years, either on a straight-line basis or on a basis consistent with the pattern in which the economic benefits are realized.
PENSION AND POSTRETIREMENT HEALTHCARE PLANS. Our defined benefit pension and other postretirement benefit plans are measured using actuarial techniques that reflect management’s assumptions for discount rate, investment returns on plan assets, salary increases, expected retirement, mortality, employee turnover and future increases in healthcare costs. We determine the discount rate (which is required to be the rate at which the projected benefit obligation (“PBO”) could be effectively settled as of the measurement date) with the assistance of actuaries, who calculate the yield on a theoretical portfolio of high-grade corporate bonds (rated Aa or better) with cash flows that are designed to match our expected benefit payments in future years. We use the fair value of plan assets to calculate the expected return on assets (“EROA”) for interim and segment reporting purposes. Our EROA is a judgmental estimate which is reviewed on an annual basis and revised as appropriate.
- 115 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
The accounting guidance related to employers’ accounting for defined benefit pension and other postretirement plans requires recognition in the balance sheet of the funded status of these plans. We use “mark-to-market” or MTM accounting and immediately recognize changes in the fair value of plan assets and actuarial gains or losses in our results annually in the fourth quarter each year. The annual MTM adjustment is recognized at the corporate level and does not impact segment results. The remaining components of pension and postretirement healthcare expense, primarily service and interest costs and the EROA, are recorded on a quarterly basis. Only service cost is recognized in segment level operating results.
INCOME TAXES. Deferred income taxes are provided for the tax effect of temporary differences between the tax basis of assets and liabilities and their reported amounts in the financial statements. The liability method is used to account for income taxes, which requires deferred taxes to be recorded at the statutory rate expected to be in effect when the taxes are paid.
Deferred income tax assets represent amounts available to reduce income taxes payable on taxable income in future years. Such assets arise because of temporary differences between the financial reporting and tax bases of assets and liabilities, as well as from net operating loss and tax credit carryforwards. We evaluate the recoverability of these future tax deductions and credits by assessing the adequacy of future expected taxable income from all sources, including reversal of taxable temporary differences, forecasted operating earnings and available tax planning strategies. These sources of income rely heavily on estimates to make this determination and, thus, there is a risk that these estimates will have to be revised as new information is received. To the extent we do not consider it more likely than not that a deferred tax asset will be recovered, a valuation allowance is established. We believe we will generate sufficient future taxable income to realize the tax benefits related to the remaining net deferred tax assets in our consolidated balance sheets that are not subject to valuation allowances. We record the taxes for global intangible low-taxed income as a period cost.
We recognize liabilities for uncertain income tax positions based on a two-step process. The first step is to evaluate the tax position for recognition by determining if the weight of available evidence indicates that it is more likely than not that the position will be sustained on audit, including resolution of related appeals or litigation processes, if any. The second step requires us to estimate and measure the tax benefit as the largest amount that is more than 50% likely to be realized upon ultimate settlement. It is inherently difficult and subjective to estimate such amounts, as we must determine the probability of various possible outcomes. We reevaluate these uncertain tax positions on a quarterly basis or when new information becomes available to management. These reevaluations are based on factors including, but not limited to, changes in facts or circumstances, changes in tax law, successfully settled issues under audit and new audit activity. Such a change in recognition or measurement could result in the recognition of a tax benefit or an increase to the related provision.
We classify interest related to income tax liabilities as interest expense, and if applicable, penalties are recognized as a component of income tax expense. The income tax liabilities and accrued interest and penalties that are due within one year of the balance sheet date are presented as current liabilities. The noncurrent portion of our income tax liabilities and accrued interest and penalties are recorded in the caption “Other liabilities” in the accompanying consolidated balance sheets.
SELF-INSURANCE ACCRUALS. We are self-insured for costs associated with workers’ compensation claims, vehicle accidents and general business liabilities, and benefits paid under employee healthcare and disability programs. Accruals are primarily based on the actuarially estimated cost of claims, which includes incurred-but-not-reported claims. Current workers’ compensation claims, vehicle and general liability, employee healthcare claims and long-term disability are included in accrued expenses. We self-insure up to certain limits that vary by operating company and type of risk. Periodically, we evaluate the level of insurance coverage and adjust insurance levels based on risk tolerance and premium expense.
LEASES. We lease certain facilities, aircraft, equipment and vehicles under operating and finance leases. A determination of whether a contract contains a lease is made at the inception of the arrangement. Our leased facilities include national, regional and metropolitan sorting facilities, retail facilities and administrative buildings.
Our leases generally contain options to extend or terminate the lease. We reevaluate our leases on a regular basis to consider the economic and strategic incentives of exercising the renewal options, and how they align with our operating strategy. Therefore, substantially all the renewal option periods are not included within the lease term and the associated payments are not included in the measurement of the right-of-use asset and lease liability as the options to extend are not reasonably certain at lease commencement.
The lease liabilities are measured at the lease commencement date and determined using the present value of the minimum lease payments not yet paid and our incremental borrowing rate, which approximates the rate at which we would borrow, on a collateralized basis, over the term of a lease in the applicable currency environment. The interest rate implicit in the lease is generally not determinable in transactions where we are the lessee.
- 116 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
For real estate leases, we account for lease components and non-lease components (such as common area maintenance) as a single lease component. Certain real estate leases require additional payments based on sales volume and index-based rate increases, as well as reimbursement for real estate taxes, common area maintenance and insurance, which are expensed as incurred as variable lease costs. Certain leases contain fixed lease payments for items such as real estate taxes, common area maintenance and insurance. These fixed payments are considered part of the lease payment and included in the right-of-use assets and lease liabilities.
See Note 7 for additional information.
DEFERRED GAINS. Prior to the adoption of ASU 2016-02 on June 1, 2019, gains on the sale and leaseback of aircraft and other property and equipment were deferred and amortized ratably over the life of the lease as a reduction of rent expense. Substantially all of these deferred gains, which are included in other non-current liabilities, related to aircraft transactions.
DERIVATIVE FINANCIAL INSTRUMENTS. Our risk management strategy includes the select use of derivative instruments to reduce the effects of volatility in foreign currency exchange exposure on operating results and cash flows. In accordance with our risk management policies, we do not hold or issue derivative instruments for trading or speculative purposes. All derivative instruments are recognized in the financial statements at fair value, regardless of the purpose or intent for holding them.
When we become a party to a derivative instrument and intend to apply hedge accounting, we formally document the hedge relationship and the risk management objective for undertaking the hedge, which includes designating the instrument for financial reporting purposes as a fair value hedge, a cash flow hedge, or a net investment hedge.
If a derivative is designated as a cash flow hedge, the entire change in the fair value of the hedging instrument included in the assessment of hedge effectiveness is recorded in other comprehensive income. For net investment hedges, the entire change in the fair value is recorded in other comprehensive income. Any portion of a change in the fair value of a derivative that is considered to be ineffective, along with the change in fair value of any derivatives not designated in a hedging relationship, is immediately recognized in the income statement. We do not have any derivatives designated as a cash flow hedge for any period presented. During 2020, we designated €392 million of debt as a net investment hedge to reduce the volatility of the U.S. dollar value of a portion of our net investment in a euro-denominated consolidated subsidiary. As of May 31, 2020, the hedge remains effective.
FOREIGN CURRENCY TRANSLATION. Translation gains and losses of foreign operations that use local currencies as the functional currency are accumulated and reported, net of applicable deferred income taxes, as a component of Accumulated Other Comprehensive Income (“AOCI”) within common stockholders’ investment. Transaction gains and losses that arise from exchange rate fluctuations on transactions denominated in a currency other than the local currency are included in the caption “Other, net” in the accompanying consolidated statements of income and were immaterial for each period presented.
EMPLOYEES UNDER COLLECTIVE BARGAINING ARRANGEMENTS. The pilots of FedEx Express, who are a small number of its total employees, are employed under a collective bargaining agreement that took effect on November 2, 2015. The collective bargaining agreement is scheduled to become amendable in November 2021. Other than the pilots at FedEx Express, a small number of our employees are members of unions.
STOCK-BASED COMPENSATION. The accounting guidance related to share-based payments requires recognition of compensation expense for stock-based awards using a fair value method. We use the Black-Scholes option pricing model to calculate the fair value of stock options. The value of restricted stock awards is based on the stock price of the award on the grant date. We record stock-based compensation expense in the “Salaries and employee benefits” caption in the accompanying consolidated statements of income. We issue new shares or treasury shares from stock repurchases to cover employee stock option exercises and restricted stock grants.
TREASURY SHARES. In January 2016, our Board of Directors authorized a stock repurchase program of up to 25 million shares. During 2020, we repurchased 0.02 million shares of FedEx common stock at an average price of $156.90 per share for a total of $3 million. As of May 31, 2020, 5.1 million shares remained under the stock repurchase authorization. Shares under the current repurchase program may be repurchased from time to time in the open market or in privately negotiated transactions. The timing and volume of repurchases are at the discretion of management, based on the capital needs of the business, the market price of FedEx common stock and general market conditions. No time limit was set for the completion of the program, and the program may be suspended or discontinued at any time.
In 2019, we repurchased 6.6 million shares of FedEx common stock at an average price of $222.94 per share for a total of $1.5 billion. In 2018, we repurchased 4.3 million shares of FedEx common stock at an average price of $237.45 per share for a total of $1.0 billion.
- 117 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
During the fourth quarter of 2020, we amended our amended and restated $2.0 billion five-year credit agreement (the “Five-Year Credit Agreement”) and our $1.5 billion 364-day credit agreement (the “364-Day Credit Agreement” and together with the Five-Year Credit Agreement, the “Credit Agreements”). The amendments to the Credit Agreements, among other things, temporarily restrict us from repurchasing any shares of our common stock between May 27, 2020 and May 31, 2021. See Note 6 for more information on the amendments to the Credit Agreements.
DIVIDENDS DECLARED PER COMMON SHARE. On June 15, 2020, our Board of Directors declared a quarterly dividend of $0.65 per share of common stock. The dividend was paid on July 13, 2020 to stockholders of record as of the close of business on June 29, 2020. Each quarterly dividend payment is subject to review and approval by our Board of Directors, and we evaluate our dividend payment amount on an annual basis. The amendments to the Credit Agreements discussed above under “Treasury Shares” temporarily restrict us from increasing the amount of our quarterly dividend payable per share of common stock from $0.65 per share between May 27, 2020 and May 31, 2021. There are no other material restrictions on our ability to declare dividends, nor are there any material restrictions on the ability of our subsidiaries to transfer funds to us in the form of cash dividends, loans or advances.
BUSINESS REALIGNMENT COSTS. During 2019, we conducted a program to offer voluntary cash buyouts to eligible U.S.-based employees in certain staff functions. As a result of this program, approximately 1,500 employees left the Company. Costs of the benefits provided under the U.S.-based voluntary employee buyout program were recognized in 2019 when eligible employees accepted their offers. Payments under this program were made at the time of departure and totaled approximately $50 million in 2020 and $220 million in 2019.
USE OF ESTIMATES. The preparation of our consolidated financial statements requires the use of estimates and assumptions that affect the reported amounts of assets and liabilities, the reported amounts of revenue and expenses and the disclosure of contingent liabilities. Management makes its best estimate of the ultimate outcome for these items based on historical trends and other information available when the financial statements are prepared. Changes in estimates are recognized in accordance with the accounting rules for the estimate, which is typically in the period when new information becomes available to management. Areas where the nature of the estimate makes it reasonably possible that actual results could materially differ from amounts estimated include: self-insurance accruals; retirement plan obligations; long-term incentive accruals; tax liabilities; loss contingencies; litigation claims; impairment assessments on long-lived assets (including goodwill); and that rely on projections of future cash flows and purchase price allocations.
The new strain of coronavirus (“COVID-19”) in 2020 and the efforts to contain it have negatively impacted the global economy, disrupted manufacturing operations and global supply chains and created significant volatility and disruption of financial markets. In addition, the COVID-19 pandemic has significantly increased economic and demand uncertainty. See Item 7 (“Management’s Discussion and Analysis of Results of Operations and Financial Condition”) of this Annual Report on Form 10-K for more information about the COVID-19 pandemic and its effects on our business, results of operations and financial condition. The Company believes the estimates and assumptions underlying our financial statements are reasonable and supportable based on the information available at the time the financial statements were prepared. However, uncertainty over the impact COVID-19 will have on the global economy and our business in particular makes many of the estimates and assumptions reflected in our 2020 consolidated financial statements inherently less certain. Therefore, actual results may ultimately differ from those estimates to a greater degree than historically.
NOTE 2: RECENT ACCOUNTING GUIDANCE
New accounting rules and disclosure requirements can significantly impact our reported results and the comparability of our financial statements. We believe the following new accounting guidance is relevant to the readers of our financial statements.
Recently Adopted Accounting Standards
In 2016, the Financial Accounting Standards Board (“FASB”) issued a new lease accounting standard, which requires lessees to put most leases on their balance sheets but recognize the expenses in their income statements in a manner similar to current practice. Lessees are required to recognize a lease liability for the obligation to make lease payments and a right-of-use asset for the right to use the underlying asset for the lease term. Expenses related to leases determined to be operating leases are recognized on a straight-line basis, while those determined to be finance leases are recognized following a front-loaded expense profile in which interest and amortization are presented separately in the income statement.
- 118 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
We adopted this new standard on June 1, 2019 using a modified retrospective transition method. Under this approach, we did not adjust the balance sheet for comparative periods but recorded a cumulative effect adjustment to retained earnings on June 1, 2019. We have elected the package of practical expedients permitted under the transition guidance within the new standard, which, among other things, allows us to carry forward the historical accounting relating to lease identification and classification for existing leases upon adoption. We also elected the practical expedient to not separate lease and non-lease components for the majority of our classes of assets. For leases in which the lease and non-lease components have been combined, the lease expense includes expenses such as common area maintenance. We have made an accounting policy election not to recognize leases with an initial term of 12 months or less on the consolidated balance sheet.
The adoption of the new lease accounting standard resulted in the recognition of an operating lease liability of $14.2 billion and an operating right-of-use asset of $14.1 billion, with an immaterial impact on our income statement compared to the previous lease accounting model. Existing prepaid asset and net deferred rent liability balances of $154 million and $309 million, respectively, were recorded to the right-of-use asset. The cumulative effect of the adoption to retained earnings was an increase of $57 million ($47 million, net of tax), primarily related to the reclassification of deferred gains related to sale-leasebacks of aircraft. Substantially all of our lease arrangements are operating leases under the new standard. The new standard had a material impact on our balance sheet but did not materially impact consolidated operating results and had no impact on operating cash flows.
See Note 1 “Leases” and Note 7 for additional information.
In February 2018, the FASB issued ASU 2018-02 that permits companies to reclassify the income tax effect of the Tax Cuts and Jobs Act (“TCJA”) on items within AOCI to retained earnings. We adopted this new standard on June 1, 2019.
In March 2020, the Securities and Exchange Commission (“SEC”) amended Rule 3-10 of Regulation S-X regarding financial disclosure requirements for registered debt offerings involving subsidiaries as either issuers or guarantors and affiliates whose securities are pledged as collateral. This new guidance narrows the circumstances that require separate financial statements of subsidiary issuers and guarantors and streamlines the alternative disclosures required in lieu of those statements. This rule is effective January 4, 2021 (fiscal 2021) with earlier adoption permitted. We adopted this new standard in the fourth quarter of 2020. Accordingly, summarized financial information has been presented only for the issuer and guarantors of the Company’s registered debt securities for the most recent fiscal year, and the location of the required disclosures has been moved outside the Notes to Consolidated Financial Statements and is provided in the “Financial Condition—Guarantor Financial Information” section of “Management’s Discussion and Analysis of Results of Operations and Financial Condition.”
New Accounting Standards and Accounting Standards Not Yet Adopted
In June 2016, the FASB issued ASU 2016-13 that changes how entities will measure credit losses for most financial assets and certain other instruments that are not measured at fair value through net income. We adopted this standard effective June 1, 2020 (fiscal 2021). This standard will not have a material impact on our consolidated financial statements and related disclosures.
In August 2018, the FASB issued ASU 2018-15 that reduces the complexity of accounting for costs of implementing a cloud computing service arrangement and aligns the accounting for capitalizing implementation costs of hosting arrangements, regardless of whether they convey a license to the hosted software. We adopted this standard effective June 1, 2020 (fiscal 2021) and applied these changes prospectively. This standard will not have a material impact on our consolidated financial statements and related disclosures.
In December 2019, the FASB issued ASU 2019-12, which is intended to simplify various aspects related to accounting for income taxes. ASU 2019-12 removes certain exceptions to the general principles in Topic 740 and also clarifies and amends existing guidance to improve consistent application. This standard is effective June 1, 2021 (fiscal 2022). We adopted this standard effective June 1, 2020 (fiscal 2021). This new standard will not have a material impact on our consolidated financial statements and related disclosures.
NOTE 3: BUSINESS COMBINATIONS
On May 1, 2019, we acquired the international express division of FC (Flying Cargo) Express Ltd. (“Flying Cargo”) for $67 million in cash from operations. The majority of the purchase price was allocated to goodwill. The financial results of this acquired business are included in the FedEx Express segment from the date of acquisition and were not material to our results of operations. Therefore, pro forma financial information has not been provided.
- 119 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
On October 1, 2018, we acquired the controlling interest in an existing joint venture with Swiss Post, which operates a Swiss-wide transport system with connections to TNT Express’s global network. The controlling interest was acquired through the noncash contribution of a complementary Swiss business into the venture, resulting in the recognition of an immaterial gain. The majority of the purchase price was allocated to goodwill and other intangibles. The financial results of this acquired business are included in the FedEx Express segment from the date of acquisition and were not material to our results of operations. Therefore, pro forma financial information has not been provided.
On March 23, 2018, we acquired P2P Mailing Limited, a leading provider of worldwide, low-cost e-commerce transportation solutions, for £92 million ($135 million) in cash from operations. The majority of the purchase price was allocated to goodwill. The financial results of this acquired business are included in the FedEx Logistics operating segment from the date of acquisition and were not material to our results of operations. Therefore, pro forma financial information has not been provided.
On October 13, 2017, we acquired Northwest Research, Inc., a leader in inventory research and management, for $50 million in cash from operations. The majority of the purchase price was allocated to property and equipment. The financial results of this acquired business are included in the FedEx Services segment from the date of acquisition and were not material to our results of operations. Therefore, pro forma financial information has not been provided.
NOTE 4: GOODWILL AND OTHER INTANGIBLE ASSETS
GOODWILL. The carrying amount of goodwill attributable to each reportable operating segment and changes therein are as follows (in millions):
| FedEx Express Segment | FedEx Ground Segment | FedEx Freight Segment | Corporate, Other and Eliminations | Total | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Goodwill at May 31, 2018 | $ | 5,100 | $ | 840 | $ | 767 | $ | 1,950 | $ | 8,657 | ||||||||||
| Accumulated impairment charges | — | — | (133 | ) | (1,551 | ) | (1,684 | ) | ||||||||||||
| Balance as of May 31, 2018 | 5,100 | 840 | 634 | 399 | 6,973 | |||||||||||||||
| Goodwill acquired(1) | 126 | — | — | — | 126 | |||||||||||||||
| Other(2) | (210 | ) | — | — | (5 | ) | (215 | ) | ||||||||||||
| Balance as of May 31, 2019 | 5,016 | 840 | 634 | 394 | 6,884 | |||||||||||||||
| Impairment charges | — | — | — | (358 | ) | (358 | ) | |||||||||||||
| Other(2) | (147 | ) | — | — | (7 | ) | (154 | ) | ||||||||||||
| Balance as of May 31, 2020 | $ | 4,869 | $ | 840 | $ | 634 | $ | 29 | $ | 6,372 | ||||||||||
| Accumulated goodwill impairment charges as of May 31, 2020 | $ | — | $ | — | $ | (133 | ) | $ | (1,909 | ) | $ | (2,042 | ) |
| (1) | Goodwill acquired relates to the acquisitions of Flying Cargo and the controlling interest in an existing joint venture with Swiss Post. See Note 3 for more information. |
|---|
| (2) | Primarily currency translation adjustments, purchase price allocation-related adjustments, and acquired goodwill related to immaterial acquisitions. |
|---|
We recorded an impairment charge of $358 million attributable to our FedEx Office and Print Services, Inc. (“FedEx Office”) and FedEx Supply Chain Distribution System, Inc. (“FedEx Supply Chain”) reporting units in the fourth quarter of 2020. The COVID-19 pandemic resulted in store closures and declining print revenue at FedEx Office during the fourth quarter of 2020 and is expected to continue to negatively impact its near-term operating performance. Based on these factors, our outlook for the FedEx Office business and retail industry changed in the fourth quarter of 2020, which contributed $348 million to the goodwill impairment charge.
While there are several factors negatively impacting near-term results at FedEx Express, including weak global economic conditions and the timing and amount of TNT Express integration program expenses, FedEx Express continues to be an established profitable business with a fair value that exceeds its carrying value based on our valuation performed during the fourth quarter of 2020. In addition, our other reporting units with significant recorded goodwill include FedEx Ground and FedEx Freight. We evaluated these reporting units during the fourth quarters of 2020 and 2019. The estimated fair value of each of these reporting units significantly exceeded their carrying values as of the end of 2020 and 2019; therefore, we do not believe that any of these reporting units were impaired as of the balance sheet dates. No impairments of goodwill were recognized in 2019.
- 120 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
In 2018, we incurred a goodwill impairment charge of $374 million related to FedEx Supply Chain, eliminating substantially all of the goodwill attributable to this reporting unit. In our evaluation of the goodwill of this reporting unit, we compared the fair value of the reporting unit to its carrying value (including attributable goodwill). Fair value was estimated using standard valuation methodologies (principally the income and market approach classified as Level 3 within the fair value hierarchy) incorporating market participant considerations and management’s assumptions on revenue growth rates, operating margins, discount rates and expected capital expenditures. The key factors contributing to the goodwill impairment were underperformance of the FedEx Supply Chain business during 2018, including base business erosion, and the failure to attain the level of operating synergies and revenue and profit growth anticipated at the time of the acquisition. Based on these factors, our outlook for the business and industry changed in the fourth quarter of 2018.
OTHER INTANGIBLE ASSETS. The summary of our intangible assets and related accumulated amortization at May 31, 2020 and 2019 is as follows (in millions):
| 2020 | 2019 | |||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Gross Carrying Amount | Accumulated Amortization | Net Book Value | Gross Carrying Amount | Accumulated Amortization | Net Book Value | |||||||||||||||||||
| Customer relationships | $ | 641 | $ | (327 | ) | $ | 314 | $ | 685 | $ | (293 | ) | $ | 392 | ||||||||||
| Technology | 65 | (57 | ) | 8 | 66 | (51 | ) | 15 | ||||||||||||||||
| Trademarks and other | 132 | (132 | ) | — | 137 | (128 | ) | 9 | ||||||||||||||||
| Total | $ | 838 | $ | (516 | ) | $ | 322 | $ | 888 | $ | (472 | ) | $ | 416 |
Amortization expense for intangible assets was $66 million in 2020, $82 million in 2019 and $87 million in 2018.
Expected amortization expense for the next five years is as follows (in millions):
| 2021 | $ | 49 | |
|---|---|---|---|
| 2022 | 43 | ||
| 2023 | 40 | ||
| 2024 | 39 | ||
| 2025 | 38 |
NOTE 5: SELECTED CURRENT LIABILITIES
The components of selected current liability captions at May 31 were as follows (in millions):
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Accrued Salaries and Employee Benefits | ||||||||
| Salaries | $ | 436 | $ | 425 | ||||
| Employee benefits, including variable compensation | 319 | 552 | ||||||
| Compensated absences | 814 | 764 | ||||||
| $ | 1,569 | $ | 1,741 | |||||
| Accrued Expenses | ||||||||
| Self-insurance accruals | $ | 1,223 | $ | 1,104 | ||||
| Taxes other than income taxes | 417 | 304 | ||||||
| Other | 1,892 | 1,870 | ||||||
| $ | 3,532 | $ | 3,278 |
- 121 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
NOTE 6: LONG-TERM DEBT AND OTHER FINANCING ARRANGEMENTS
The components of long-term debt (net of discounts and debt issuance costs), along with maturity dates for the years subsequent to May 31, 2020, are as follows (in millions):
| May 31, | ||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | |||||||||||||
| Interest Rate% | Maturity | |||||||||||||
| Senior unsecured debt: | 2.30 | 2020 | $ | — | $ | 400 | ||||||||
| 3.40 | 2022 | 498 | 497 | |||||||||||
| 2.625-2.70 | 2023 | 748 | 747 | |||||||||||
| 4.00 | 2024 | 747 | 746 | |||||||||||
| 3.2-3.80 | 2025 | 1,687 | 696 | |||||||||||
| 3.25 | 2026 | 745 | 745 | |||||||||||
| 3.30 | 2027 | 446 | 446 | |||||||||||
| 3.40 | 2028 | 496 | 495 | |||||||||||
| 4.20 | 2029 | 397 | 396 | |||||||||||
| 3.1-4.25 | 2030 | 1,732 | — | |||||||||||
| 4.90 | 2034 | 495 | 495 | |||||||||||
| 3.90 | 2035 | 494 | 494 | |||||||||||
| 3.875-4.10 | 2043 | 984 | 984 | |||||||||||
| 5.10 | 2044 | 742 | 742 | |||||||||||
| 4.10 | 2045 | 641 | 641 | |||||||||||
| 4.55-4.75 | 2046 | 2,461 | 2,460 | |||||||||||
| 4.40 | 2047 | 735 | 735 | |||||||||||
| 4.05 | 2048 | 986 | 986 | |||||||||||
| 4.95 | 2049 | 835 | 835 | |||||||||||
| 5.25 | 2050 | 1,225 | — | |||||||||||
| 4.50 | 2065 | 246 | 246 | |||||||||||
| 7.60 | 2098 | 237 | 237 | |||||||||||
| Euro senior unsecured debt: | 0.50 | 2020 | — | 559 | ||||||||||
| 0.70 | 2022 | 695 | 713 | |||||||||||
| 1.00 | 2023 | 815 | 836 | |||||||||||
| 0.45 | 2026 | 541 | — | |||||||||||
| 1.625 | 2027 | 1,351 | 1,387 | |||||||||||
| 1.30 | 2032 | 539 | — | |||||||||||
| Total senior unsecured debt | 21,518 | 17,518 | ||||||||||||
| Other debt | — | 1 | ||||||||||||
| Finance lease obligations | 485 | 62 | ||||||||||||
| 22,003 | 17,581 | |||||||||||||
| Less current portion | 51 | 964 | ||||||||||||
| $ | 21,952 | $ | 16,617 |
Interest on our U.S. dollar fixed-rate notes is paid semi-annually. Interest on our euro fixed-rate notes is paid annually. The weighted average interest rate on long-term debt was 3.6% as of May 31, 2020. Long-term debt, including current maturities and exclusive of finance leases, had estimated fair values of $22.8 billion at May 31, 2020 and $17.8 billion at May 31, 2019. The estimated fair values were determined based on quoted market prices and the current rates offered for debt with similar terms and maturities. The fair value of our long-term debt is classified as Level 2 within the fair value hierarchy. This classification is defined as a fair value determined using market-based inputs other than quoted prices that are observable for the liability, either directly or indirectly.
We have a shelf registration statement filed with the SEC that allows us to sell, in one or more future offerings, any combination of our unsecured debt securities and common stock.
- 122 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
During July 2019, we issued $2.1 billion of senior unsecured debt under our current shelf registration statement, comprised of $1.0 billion of 3.10% fixed-rate notes due in August 2029, €500 million of 0.45% fixed-rate notes due in August 2025 and €500 million of 1.30% fixed-rate notes due in August 2031. We used the net proceeds to make voluntary contributions to our tax-qualified U.S. domestic pension plans (“U.S. Pension Plans”) during the first quarter of 2020 and to redeem the $400 million aggregate principal amount of 2.30% notes due February 1, 2020 and the €500 million aggregate principal amount of 0.50% notes due April 9, 2020. The remaining net proceeds are being used for general corporate purposes.
On March 17, 2020, we entered into an amended and restated $2.0 billion Five-Year Credit Agreement and a $1.5 billion 364-Day Credit Agreement. The Five-Year Credit Agreement expires in March 2025 and includes a $250 million letter of credit sublimit. The 364-Day Credit Agreement expires in March 2021. The Credit Agreements are available to finance our operations and other cash flow needs.
On March 18, 2020, we elected to draw $1.5 billion under the 364-Day Credit Agreement to increase our cash position to preserve financial flexibility in light of disrupted access to commercial paper markets and uncertainty in the global financial markets resulting from the COVID-19 pandemic.
During April 2020, we issued $3.0 billion of senior unsecured debt under our current shelf registration statement, comprised of $1.0 billion of 3.80% fixed-rate notes due in May 2025, $750 million of 4.25% fixed-rate notes due in May 2030 and $1.25 billion of 5.25% fixed-rate notes due in May 2050. We used the net proceeds to repay the $1.5 billion of outstanding borrowings under the 364-Day Credit Agreement, repay $136 million of commercial paper outstanding under our commercial paper program and for general corporate purposes.
The Credit Agreements contain a financial covenant requiring us to maintain a ratio of debt to consolidated earnings (excluding noncash retirement plans MTM adjustments, noncash pension service costs and noncash asset impairment charges) before interest, taxes, depreciation and amortization (“adjusted EBITDA”) of not more than 3.5 to 1.0, calculated as of the end of the applicable quarter on a rolling four-quarters basis. On May 27, 2020, we amended the Credit Agreements to revise the adjusted EBITDA definition to exclude noncash pension service costs (as noted above) and to increase the ratio of debt to adjusted EBITDA as follows: 3.75:1.0 at May 31, 2020; 4.75:1.0 at August 31, 2020; 4.9:1.0 at November 30, 2020; 4.75:1.0 at February 28, 2021; and 3.75:1.0 at May 31, 2021, with the ratio reverting to 3.5:1.0 at August 31, 2021 and thereafter. The amendments to the Credit Agreements also contain temporary covenants restricting us from repurchasing any shares of our common stock or increasing the amount of our quarterly dividend payable per share of common stock from $0.65 per share between May 27, 2020 and May 31, 2021. The ratio of our debt to adjusted EBITDA was 3.0 to 1.0 at May 31, 2020.
We believe the covenants discussed above are the only significant restrictive covenant in the Credit Agreements. The Credit Agreements contain other customary covenants that do not, individually or in the aggregate, materially restrict the conduct of our business. We are in compliance with the financial covenant and all other covenants in the Credit Agreements and do not expect the covenants to affect our operations, including our liquidity or expected funding needs. If we failed to comply with the financial covenant or any other covenants in the Credit Agreements, our access to financing could become limited. We had $250 million of the letter of credit sublimit unused under our revolving credit facility as of May 31, 2020.
As of May 31, 2020, no commercial paper was outstanding.
- 123 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
NOTE 7: LEASES
Disclosure Subsequent to the Adoption of the New Lease Accounting Standard (ASU 2016-02)
The following table is a summary of the components of net lease cost for the period ended May 31, 2020 (in millions):
| 2020 | |||||
|---|---|---|---|---|---|
| Operating lease cost(1) | $ | 2,668 | |||
| Finance lease cost: | |||||
| Amortization of right-of-use assets | 18 | ||||
| Interest on lease liabilities | 12 | ||||
| Total finance lease cost | 30 | ||||
| Short-term lease cost | 197 | ||||
| Variable lease cost(1) | 1,160 | ||||
| Net lease cost | $ | 4,055 |
(1) Expenses are primarily accounted for in the “Rentals and landing fees” line item. Additional amounts related to embedded leases are accounted for in the “Purchased transportation,” “Fuel” and “Other” line items in the accompanying consolidated statements of income.
Supplemental cash flow information related to leases for the period ended May 31 is as follows (in millions):
| 2020 | ||||
|---|---|---|---|---|
| Cash paid for amounts included in the measurement of lease liabilities: | ||||
| Operating cash flows paid for operating leases | $ | 2,608 | ||
| Operating cash flows paid for interest portion of finance leases | 14 | |||
| Financing cash flows paid for principal portion of finance leases | 84 | |||
| Right-of-use assets obtained in exchange for new operating lease liabilities | $ | 1,915 | ||
| Right-of-use assets obtained in exchange for new finance lease liabilities | $ | 484 |
Supplemental balance sheet information related to leases as of May 31 is as follows (dollars in millions):
| 2020 | ||||
|---|---|---|---|---|
| Operating leases: | ||||
| Operating lease right-of-use assets, net | $ | 13,917 | ||
| Current portion of operating lease liabilities | 1,923 | |||
| Operating lease liabilities | 12,195 | |||
| Total operating lease liabilities | $ | 14,118 | ||
| Finance leases: | ||||
| Net property and equipment | $ | 480 | ||
| Current portion of long-term debt | 51 | |||
| Long-term debt, less current portion | 434 | |||
| Total finance lease liabilities | $ | 485 | ||
| Weighted-average remaining lease term | ||||
| Operating leases | 9.9 | |||
| Finance leases | 32.0 | |||
| Weighted-average discount rate | ||||
| Operating leases | 3.19 | % | ||
| Finance leases | 3.58 | % |
- 124 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
We utilize certain aircraft, land, facilities, retail locations and equipment under finance and operating leases that expire at various dates through 2060. We leased 5% of our total aircraft fleet under operating leases as of May 31, 2020 and 6% as of May 31, 2019. A portion of our supplemental aircraft are leased by us under agreements that provide for cancellation upon 30 days’ notice. Our leased facilities include national, regional and metropolitan sorting facilities, retail facilities and administrative buildings.
A summary of future minimum lease payments under noncancelable operating and finance leases with an initial or remaining term in excess of one year at May 31, 2020 is as follows (in millions):
| Aircraft and Related Equipment | Facilities and Other | Total Operating Leases | Finance Leases | Total Leases | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2021 | $ | 250 | $ | 2,099 | $ | 2,349 | $ | 67 | $ | 2,416 | ||||||||||
| 2022 | 233 | 2,007 | 2,240 | 26 | 2,266 | |||||||||||||||
| 2023 | 198 | 1,789 | 1,987 | 25 | 2,012 | |||||||||||||||
| 2024 | 102 | 1,563 | 1,665 | 24 | 1,689 | |||||||||||||||
| 2025 | 69 | 1,365 | 1,434 | 81 | 1,515 | |||||||||||||||
| Thereafter | 245 | 6,661 | 6,906 | 646 | 7,552 | |||||||||||||||
| Total lease payments | 1,097 | 15,484 | 16,581 | 869 | 17,450 | |||||||||||||||
| Less imputed interest | (92 | ) | (2,371 | ) | (2,463 | ) | (384 | ) | (2,847 | ) | ||||||||||
| Present value of lease liability | $ | 1,005 | $ | 13,113 | $ | 14,118 | $ | 485 | $ | 14,603 |
While certain of our lease agreements contain covenants governing the use of the leased assets or require us to maintain certain levels of insurance, none of our lease agreements include material financial covenants or limitations.
As of May 31, 2020, FedEx has entered into additional leases which have not yet commenced and are therefore not part of the right-of-use asset and liability. These leases are generally for build-to-suit facilities and have undiscounted future payments of approximately $1.6 billion, and will commence when FedEx gains beneficial access to the leased asset. Commencement dates are expected to be from fiscal 2021 to fiscal 2022.
FedEx Express makes payments under certain leveraged operating leases that are sufficient to pay principal and interest on certain pass-through certificates. The pass-through certificates are not direct obligations of, or guaranteed by, FedEx or FedEx Express.
We are the lessee under certain operating leases covering a portion of our leased aircraft in which the lessors are trusts established specifically to purchase, finance and lease these aircraft to us. These leasing entities are variable interest entities. We are not the primary beneficiary of the leasing entities, as the lease terms are at market at the inception of the lease and do not include a residual value guarantee, fixed-price purchase option or similar feature that obligates us to absorb decreases in value or entitles us to participate in increases in the value of the aircraft. Therefore, we are not required to consolidate any of these entities as the primary beneficiary. Our maximum exposure under these leases is included in the summary of future minimum lease payments.
Comparative Disclosures Prior to the Adoption of the New Lease Accounting Standard (ASU 2016-02)
The following table is a summary of the Company’s net rental expense for operating leases for the years ended May 31, 2019 and 2018 (in millions):
| 2019 | 2018 | |||||||
|---|---|---|---|---|---|---|---|---|
| Minimum rentals | $ | 2,875 | $ | 2,913 | ||||
| Contingent rentals(1) | 222 | 194 | ||||||
| $ | 3,097 | $ | 3,107 |
| (1) | Contingent rentals are based on equipment usage. |
|---|
- 125 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
Future minimum lease payments under noncancelable operating leases with an initial or remaining term in excess of one year at May 31, 2019 were as follows (in millions):
| Aircraft and Related Equipment | Facilities and Other | Total Operating Leases | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | $ | 288 | $ | 2,209 | $ | 2,497 | ||||||
| 2021 | 230 | 2,033 | 2,263 | |||||||||
| 2022 | 212 | 1,816 | 2,028 | |||||||||
| 2023 | 154 | 1,625 | 1,779 | |||||||||
| 2024 | 58 | 1,428 | 1,486 | |||||||||
| Thereafter | 85 | 7,977 | 8,062 | |||||||||
| Total | $ | 1,027 | $ | 17,088 | $ | 18,115 |
NOTE 8: PREFERRED STOCK
Our Certificate of Incorporation authorizes the Board of Directors, at its discretion, to issue up to 4,000,000 shares of preferred stock. The stock is issuable in series, which may vary as to certain rights and preferences, and has no par value. As of May 31, 2020, none of these shares had been issued.
NOTE 9: ACCUMULATED OTHER COMPREHENSIVE INCOME
The following table provides changes in AOCI, net of tax, reported in the consolidated financial statements for the years ended May 31 (in millions; amounts in parentheses indicate debits to AOCI):
| 2020 | 2019 | 2018 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Foreign currency translation loss: | ||||||||||||
| Balance at beginning of period | $ | (954 | ) | $ | (759 | ) | $ | (685 | ) | |||
| Translation adjustments | (254 | ) | (195 | ) | (74 | ) | ||||||
| Reclassification to retained earnings due to the adoption of ASU 2018-02 | 1 | — | — | |||||||||
| Balance at end of period | (1,207 | ) | (954 | ) | (759 | ) | ||||||
| Retirement plans adjustments: | ||||||||||||
| Balance at beginning of period | 89 | 181 | 270 | |||||||||
| Prior service cost (credit) arising during period | 3 | — | (4 | ) | ||||||||
| Reclassifications from AOCI | (82 | ) | (92 | ) | (85 | ) | ||||||
| Reclassification to retained earnings due to the adoption of ASU 2018-02 | 50 | — | — | |||||||||
| Balance at end of period | 60 | 89 | 181 | |||||||||
| Accumulated other comprehensive loss at end of period | $ | (1,147 | ) | $ | (865 | ) | $ | (578 | ) |
The following table presents details of the reclassifications from AOCI for the years ended May 31 (in millions; amounts in parentheses indicate debits to earnings):
| Amount Reclassified from AOCI | Affected Line Item in the Income Statement | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | 2018 | ||||||||||||
| Amortization of retirement plans prior service credits, before tax | $ | 107 | $ | 120 | $ | 121 | Other retirement plans (expense) income | |||||||
| Income tax benefit | (25 | ) | (28 | ) | (36 | ) | Provision for income taxes | |||||||
| AOCI reclassifications, net of tax | $ | 82 | $ | 92 | $ | 85 | Net income |
NOTE 10: STOCK-BASED COMPENSATION
Our total stock-based compensation expense for the years ended May 31 was as follows (in millions):
| 2020 | 2019 | 2018 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Stock-based compensation expense | $ | 168 | $ | 174 | $ | 167 |
We have two types of equity-based compensation: stock options and restricted stock.
- 126 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
STOCK OPTIONS. Under the provisions of our incentive stock plan, key employees and non-employee directors may be granted options to purchase shares of our common stock at a price not less than its fair market value on the date of grant. Vesting requirements are determined at the discretion of the Compensation Committee of our Board of Directors. Option-vesting periods range from one to four years, with 82% of our options vesting ratably over four years. Compensation expense associated with these awards is recognized on a straight-line basis over the requisite service period of the award.
RESTRICTED STOCK. Under the terms of our incentive stock plan, restricted shares of our common stock are awarded to key employees. All restrictions on the shares expire ratably over a four-year period. Shares are valued at the market price on the date of award. The terms of our restricted stock provide for continued vesting subsequent to the employee’s retirement. Compensation expense associated with these awards is recognized on a straight-line basis over the shorter of the requisite service period or the stated vesting period.
ASSUMPTIONS. The key assumptions for the Black-Scholes valuation method include the expected life of the option, stock price volatility, a risk-free interest rate and dividend yield. The following table includes the weighted-average Black-Scholes value of our stock option grants, the intrinsic value of options exercised (in millions) and the key weighted-average assumptions used in the valuation calculations for options granted during the years ended May 31, followed by a discussion of our methodology for developing each of the assumptions used in the valuation model:
| 2020 | 2019 | 2018 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Weighted-average Black-Scholes value | $ | 33.97 | $ | 61.42 | $ | 55.72 | ||||||
| Intrinsic value of options exercised | $ | 44 | $ | 122 | $ | 359 | ||||||
| Black-Scholes Assumptions: | ||||||||||||
| Expected lives | 6.4 years | 6.4 years | 6.5 years | |||||||||
| Expected volatility | 23 | % | 21 | % | 23 | % | ||||||
| Risk-free interest rate | 1.91 | % | 2.94 | % | 2.07 | % | ||||||
| Dividend yield | 1.630 | % | 0.935 | % | 0.796 | % |
The expected life represents an estimate of the period of time options are expected to remain outstanding, and we examine actual stock option exercises to determine the expected life of the options. Options granted have a maximum term of 10 years. Expected volatilities are based on the actual changes in the market value of our stock and are calculated using daily market value changes from the date of grant over a past period equal to the expected life of the options. The risk-free interest rate is the U.S. Treasury Strip rate posted at the date of grant having a term equal to the expected life of the option. The expected dividend yield is the annual rate of dividends per share over the exercise price of the option.
The following table summarizes information regarding stock option activity for the year ended May 31, 2020:
| Stock Options | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Shares | Weighted- Average Exercise Price | Weighted- Average Remaining Contractual Term | Aggregate Intrinsic Value (in millions)(1) | |||||||||||||
| Outstanding at June 1, 2019 | 13,622,515 | $ | 166.89 | |||||||||||||
| Granted | 3,839,144 | 159.77 | ||||||||||||||
| Exercised | (763,104 | ) | 83.70 | |||||||||||||
| Forfeited | (573,810 | ) | 192.34 | |||||||||||||
| Outstanding at May 31, 2020 | 16,124,745 | $ | 167.79 | 6.2 | $ | 118 | ||||||||||
| Exercisable | 9,654,040 | $ | 154.19 | 4.7 | $ | 118 | ||||||||||
| Expected to vest | 5,975,696 | $ | 188.09 | 8.4 | $ | — | ||||||||||
| Available for future grants | 27,415,296 |
| (1) | Only presented for options with market value at May 31, 2020 in excess of the exercise price of the option. |
|---|
The options granted during 2020 are primarily related to our principal annual stock option grant in June 2019.
- 127 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
The following table summarizes information regarding vested and unvested restricted stock for the year ended May 31, 2020:
| Restricted Stock | ||||||||
|---|---|---|---|---|---|---|---|---|
| Shares | Weighted- Average Grant Date Fair Value | |||||||
| Unvested at June 1, 2019 | 324,478 | $ | 217.76 | |||||
| Granted | 207,012 | 158.58 | ||||||
| Vested | (154,449 | ) | 200.84 | |||||
| Forfeited | (5,351 | ) | 197.07 | |||||
| Unvested at May 31, 2020 | 371,690 | $ | 192.19 |
During the year ended May 31, 2019, there were 149,579 shares of restricted stock granted with a weighted-average fair value of $253.28 per share. During the year ended May 31, 2018, there were 155,624 shares of restricted stock granted with a weighted-average fair value of $212.60 per share.
Stock option vesting during the years ended May 31 was as follows:
| Stock Options | ||||||||
|---|---|---|---|---|---|---|---|---|
| Vested during the year | Fair value (in millions) | |||||||
| 2020 | 2,073,310 | $ | 99 | |||||
| 2019 | 2,249,301 | $ | 115 | |||||
| 2018 | 2,465,493 | $ | 112 |
As of May 31, 2020, there was $209 million of total unrecognized compensation cost, net of estimated forfeitures, related to unvested share-based compensation arrangements. This compensation expense is expected to be recognized on a straight-line basis over the remaining weighted-average vesting period of approximately two years.
Total shares outstanding or available for grant related to equity compensation at May 31, 2020 represented 14% of the total outstanding common and equity compensation shares and equity compensation shares available for grant.
NOTE 11: COMPUTATION OF EARNINGS PER SHARE
The calculation of basic and diluted earnings per common share for the years ended May 31 was as follows (in millions, except per share amounts):
| 2020 | 2019 | 2018 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Basic earnings per common share: | ||||||||||||
| Net earnings allocable to common shares(1) | $ | 1,284 | $ | 539 | $ | 4,566 | ||||||
| Weighted-average common shares | 261 | 262 | 267 | |||||||||
| Basic earnings per common share | $ | 4.92 | $ | 2.06 | $ | 17.08 | ||||||
| Diluted earnings per common share: | ||||||||||||
| Net earnings allocable to common shares(1) | $ | 1,284 | $ | 539 | $ | 4,566 | ||||||
| Weighted-average common shares | 261 | 262 | 267 | |||||||||
| Dilutive effect of share-based awards | 1 | 3 | 5 | |||||||||
| Weighted-average diluted shares | 262 | 265 | 272 | |||||||||
| Diluted earnings per common share | $ | 4.90 | $ | 2.03 | $ | 16.79 | ||||||
| Anti-dilutive options excluded from diluted earnings per common share | 11.7 | 5.4 | 2.5 |
| (1) | Net earnings available to participating securities were immaterial in all periods presented. |
|---|
- 128 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
NOTE 12: INCOME TAXES
The components of the provision for income taxes for the years ended May 31 were as follows (in millions):
| 2020 | 2019 | 2018 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Current provision (benefit) | ||||||||||||
| Domestic: | ||||||||||||
| Federal | $ | (230 | ) | $ | (107 | ) | $ | (540 | ) | |||
| State and local | 67 | 64 | 43 | |||||||||
| Foreign | 198 | 243 | 461 | |||||||||
| 35 | 200 | (36 | ) | |||||||||
| Deferred provision (benefit) | ||||||||||||
| Domestic: | ||||||||||||
| Federal | 475 | (61 | ) | 271 | ||||||||
| State and local | 1 | (7 | ) | 125 | ||||||||
| Foreign | (128 | ) | (17 | ) | (579 | ) | ||||||
| 348 | (85 | ) | (183 | ) | ||||||||
| $ | 383 | $ | 115 | $ | (219 | ) |
Pre-tax earnings of foreign operations for 2020, 2019 and 2018 were $634 million, $929 million and $958 million, respectively. These amounts represent only a portion of total results associated with international shipments and do not represent our international results of operations.
A reconciliation of total income tax expense and the amount computed by applying the statutory federal income tax rate (21% in 2020, 21% in 2019 and 29.2% in 2018) to income before taxes for the years ended May 31 is as follows (in millions):
| 2020 | 2019 | 2018 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Taxes computed at federal statutory rate | $ | 350 | $ | 138 | $ | 1,271 | ||||||
| (Decreases) increases in income tax from: | ||||||||||||
| Valuation allowance | (129 | ) | (79 | ) | 31 | |||||||
| Goodwill impairment charge | 75 | — | 109 | |||||||||
| Benefit from U.S. tax loss carryback to prior years | (71 | ) | — | — | ||||||||
| Non-deductible expenses | 70 | 79 | 81 | |||||||||
| State and local income taxes, net of federal benefit | 53 | 44 | 119 | |||||||||
| U.S. deferred tax adjustments related to foreign operations | 51 | — | — | |||||||||
| Foreign operations | 38 | (1 | ) | 25 | ||||||||
| Uncertain tax positions | (14 | ) | 8 | 86 | ||||||||
| Foreign tax rate enactments | (10 | ) | 50 | 6 | ||||||||
| Benefits from share-based payments | (5 | ) | (18 | ) | (60 | ) | ||||||
| TCJA(1) | — | (71 | ) | (1,354 | ) | |||||||
| Foreign tax credits from distributions | — | (8 | ) | (225 | ) | |||||||
| Corporate structuring transactions(2) | — | — | (255 | ) | ||||||||
| Other, net | (25 | ) | (27 | ) | (53 | ) | ||||||
| Provision for income taxes (benefit) | $ | 383 | $ | 115 | $ | (219 | ) | |||||
| Effective Tax Rate | 23.0 | % | 17.6 | % | (5.0 | )% |
| (1) | Primary components in 2018 were a $1.15 billion benefit from the remeasurement of our net U.S. deferred tax liability and a $204 million one-time benefit from a contribution to our U.S. Pension Plans in 2018. |
|---|
| (2) | The 2018 net benefit consists of foreign deferred tax benefits of $434 million, which were partially offset by U.S. deferred tax expenses of $179 million. |
|---|
- 129 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
The 2020 tax rate includes a benefit of $133 million from the reduction of a valuation allowance on certain foreign tax loss carryforwards due to operational changes which impacted the determination of the realizability of the deferred tax asset in that jurisdiction. The 2020 tax rate also includes a deferred income tax expense of $51 million for a change in deferred tax balances related to future foreign tax credits from our international structure as a result of changes in legal entity forecasts during the fourth quarter. The 2020 tax rate was negatively impacted by decreased earnings in certain non-U.S. jurisdictions.
On March 27, 2020, the Coronavirus Aid, Relief, and Economic Security Act (“CARES Act”) was enacted to address the economic impact of the COVID-19 pandemic in the United States. Among other things, the CARES Act allows a five-year carryback period for tax losses generated in 2019 through 2021. As a result, an income tax benefit of $71 million was recorded in 2020 in connection with a tax loss generated during 2020 that the CARES Act will now allow to be carried back to 2015, a tax year when the U.S. federal income tax rate was 35%.
The 2019 tax rate includes a benefit of $90 million from the reduction of a valuation allowance on tax loss carryforwards due to certain business operational changes from the integration of FedEx Express and TNT Express in a local jurisdiction, which impacted our determination of the realizability of the deferred tax asset in that jurisdiction and an expense of $50 million from the impact on our deferred taxes attributable to a lower tax rate in the Netherlands. The 2019 tax rate was also favorably impacted by the TCJA, which resulted in benefits of approximately $75 million from accelerated deductions claimed on our 2018 U.S. income tax return filed in 2019 and approximately $40 million from the lower statutory tax rate on fiscal 2019 earnings.
The 2018 tax rate was favorably impacted by the TCJA, which resulted in a provisional benefit of $1.15 billion from the remeasurement of our net U.S. deferred tax liability. In addition, we recognized a one-time benefit of $204 million from a $1.5 billion contribution to our U.S. Pension Plans in 2018. Our 2018 tax rate also included a net benefit of $255 million from corporate structuring transactions as part of the ongoing integration of FedEx Express and TNT Express and a benefit of $225 million from foreign tax credits generated by distributions to the U.S. from our foreign operations. The 2018 tax rate was negatively impacted by an increase in uncertain tax positions for income tax audits.
The TCJA, enacted on December 22, 2017, significantly changed the U.S. corporate income tax system by reducing our U.S. statutory federal income tax rate from 35% to 21% (due to our May 31 fiscal year-end, the lower rate was phased in, resulting in a U.S. statutory federal rate of 29.2% for 2018 and a statutory federal rate of 21% for 2019 and subsequent years).
During 2019, the U.S. Treasury Department issued final regulations covering the one-time transition tax on unrepatriated foreign earnings, which was enacted as part of the TCJA. Certain guidance included in these final regulations is inconsistent with our interpretation that led to the recognition of a $233 million cumulative benefit through 2019. Notwithstanding this inconsistency, we remain confident in our interpretation of the TCJA and intend to defend this position through litigation, if necessary. However, if we are ultimately unsuccessful in defending our position, we may be required to reverse the benefit previously recorded.
In December 2017, the SEC staff issued Staff Accounting Bulletin (“SAB”) 118 to provide guidance to registrants in accounting for income taxes under the TCJA. In accordance with SAB 118, we made reasonable estimates and recorded provisional amounts for the TCJA during 2018. Under the transitional provisions of SAB 118, we had a one-year measurement period to complete the accounting for the initial tax effects of the TCJA. During 2019, we completed our accounting for the tax effects of the TCJA and recorded a $4 million tax expense to adjust the $1.15 billion provisional benefit recorded in 2018.
As provided for in the TCJA, our historical earnings were subject to the one-time transition tax and can now be repatriated to the U.S. with a de minimis tax cost. We continue to assert that both our historical and current earnings in our foreign subsidiaries are permanently reinvested and therefore no deferred taxes or withholding taxes have been provided, including deferred taxes on any additional outside basis difference (e.g., stock basis differences attributable to acquisition or other permanent differences).
- 130 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
The significant components of deferred tax assets and liabilities as of May 31 were as follows (in millions):
| 2020 | 2019 | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Deferred Tax Assets | Deferred Tax Liabilities | Deferred Tax Assets | Deferred Tax Liabilities | |||||||||||||
| Property, equipment, leases and intangibles(1) | $ | 3,819 | $ | 8,745 | $ | 592 | $ | 4,633 | ||||||||
| Employee benefits | 1,448 | — | 1,256 | — | ||||||||||||
| Self-insurance accruals | 647 | — | 585 | — | ||||||||||||
| Other | 579 | 375 | 510 | 340 | ||||||||||||
| Net operating loss/credit carryforwards | 1,262 | — | 1,139 | — | ||||||||||||
| Valuation allowances | (450 | ) | — | (590 | ) | — | ||||||||||
| $ | 7,305 | $ | 9,120 | $ | 3,492 | $ | 4,973 |
| (1) | Includes impact from adoption of the new lease accounting standard in 2020. See Note 7 for additional information. |
|---|
The net deferred tax liabilities as of May 31 have been classified in the balance sheets as follows (in millions):
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Noncurrent deferred tax assets(1) | $ | 1,347 | $ | 1,340 | ||||
| Noncurrent deferred tax liabilities | (3,162 | ) | (2,821 | ) | ||||
| $ | (1,815 | ) | $ | (1,481 | ) |
| (1) | Noncurrent deferred tax assets are included in the line item “Other Assets” in our accompanying consolidated balance sheets. |
|---|
We have approximately $3.6 billion of net operating loss carryovers in various foreign jurisdictions and $1.1 billion of state operating loss carryovers. The valuation allowances primarily represent amounts reserved for operating loss carryforwards, which expire over varying periods starting in 2021. Therefore, we establish valuation allowances if it is more likely than not that deferred income tax assets will not be realized. We believe that we will generate sufficient future taxable income to realize the tax benefits related to the remaining net deferred tax assets in our consolidated balance sheets. See Note 1 above for more information on our policy for assessing the recoverability of deferred tax assets and valuation allowances.
We are subject to taxation in the U.S. and various U.S. state, local and foreign jurisdictions. The Internal Revenue Service (“IRS”) is currently auditing our 2016 and 2017 tax returns. It is reasonably possible that certain income tax return proceedings will be completed during the next 12 months and could result in a change in our balance of unrecognized tax benefits. The expected impact of any changes would not be material to our consolidated financial statements. During 2020, the IRS closed the audit of our 2014 and 2015 income tax returns. The settlement of this audit did not have a material impact to our consolidated financial statements.
A reconciliation of the beginning and ending amount of unrecognized tax benefits is as follows (in millions):
| 2020 | 2019 | 2018 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Balance at beginning of year | $ | 164 | $ | 161 | $ | 67 | ||||||
| Increases for tax positions taken in the current year | 3 | — | 3 | |||||||||
| Increases for tax positions taken in prior years | 4 | 31 | 103 | |||||||||
| Increase for business acquisition | — | — | — | |||||||||
| Decreases for tax positions taken in prior years | (10 | ) | (4 | ) | (10 | ) | ||||||
| Settlements | (31 | ) | (21 | ) | (2 | ) | ||||||
| Decreases from lapse of statute of limitations | — | — | — | |||||||||
| Changes due to currency translation | (1 | ) | (3 | ) | — | |||||||
| Balance at end of year | $ | 129 | $ | 164 | $ | 161 |
Our liabilities recorded for uncertain tax positions include $127 million at May 31, 2020 and $141 million at May 31, 2019 associated with positions that, if favorably resolved, would provide a benefit to our income tax expense. We classify interest related to income tax liabilities as interest expense and, if applicable, penalties are recognized as a component of income tax expense. The balance of accrued interest and penalties was $41 million on May 31, 2020 and $38 million on May 31, 2019. Total interest and penalties included in our consolidated statements of income are immaterial.
- 131 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
It is difficult to predict the ultimate outcome or the timing of resolution for tax positions. Changes may result from the conclusion of ongoing audits, appeals or litigation in state, local, federal and foreign tax jurisdictions, or from the resolution of various proceedings between U.S. and foreign tax authorities. Our liability for uncertain tax positions includes no matters that are individually or collectively material to us. It is reasonably possible that the amount of the benefit with respect to certain of our unrecognized tax positions will increase or decrease within the next 12 months, but an estimate of the range of the reasonably possible changes cannot be made. However, we do not expect that the resolution of any of our uncertain tax positions will have a material effect on us.
NOTE 13: RETIREMENT PLANS
We sponsor programs that provide retirement benefits to most of our employees. These programs include defined benefit pension plans, defined contribution plans and postretirement healthcare plans.
The accounting guidance related to postretirement benefits requires recognition in the balance sheet of the funded status of defined benefit pension and other postretirement benefit plans, and the recognition in either expense or AOCI of unrecognized gains or losses and prior service costs or credits. We use MTM accounting for the recognition of our actuarial gains and losses related to our defined benefit pension and postretirement healthcare plans as described in Note 1. The funded status is measured as the difference between the fair value of the plan’s assets and the PBO of the plan.
A summary of our retirement plan costs over the past three years is as follows (in millions):
| 2020 | 2019 | 2018 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Defined benefit pension plans | $ | 148 | $ | 111 | $ | 150 | ||||||
| Defined contribution plans | 574 | 561 | 527 | |||||||||
| Postretirement healthcare plans | 85 | 75 | 74 | |||||||||
| Retirement plans MTM loss (gain) | 794 | 3,882 | (10 | ) | ||||||||
| $ | 1,601 | $ | 4,629 | $ | 741 |
The components of the MTM adjustments are as follows (in millions):
| 2020 | 2019 | 2018 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Discount rate change | $ | 2,997 | $ | 1,780 | $ | (613 | ) | |||||
| Demographic experience: | ||||||||||||
| Current year actuarial loss | 50 | 739 | 419 | |||||||||
| Change in future assumptions | (229 | ) | 887 | (37 | ) | |||||||
| Actual versus expected return on assets | (2,024 | ) | 476 | 11 | ||||||||
| Annuity contract purchase | — | — | 210 | |||||||||
| Total MTM loss (gain) | $ | 794 | $ | 3,882 | $ | (10 | ) |
2020
The weighted-average discount rate for all our pension and postretirement healthcare plans decreased from 3.69% at May 31, 2019 to 3.05% at May 31, 2020. The demographic experience in 2020 reflects an update to our mortality assumption and a current-year actuarial loss due to unfavorable experience compared to various demographic assumptions. The actual rate of return, which is net of all fees and expenses, on our U.S. Pension Plan assets of 15.00% was higher than our expected return of 6.75%, as return seeking assets, primarily equities, were positive despite equity market volatility. Additionally, fixed income assets performed as expected as interest rates declined.
2019
The weighted-average discount rate for all our pension and postretirement healthcare plans decreased from 4.11% at May 31, 2018 to 3.69% at May 31, 2019. The demographic experience in 2019 reflects updates to several forward-looking assumptions, including retirement rates, disability incidence rates and salary increase assumptions, and a current-year actuarial loss due to unfavorable experience compared to various demographic assumptions. The actual rate of return, which is net of all fees and expenses, on our U.S. Pension Plan assets of 4.05% was lower than our expected return of 6.75%, as lower than expected equity returns negatively impacted return-seeking assets while fixed-income assets performed as expected due to declining interest rates.
- 132 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
2018
The weighted-average discount rate for all of our pension and postretirement healthcare plans increased from 3.98% at May 31, 2017 to 4.11% at May 31, 2018. The demographic experience in 2018 reflects a liability loss due to unfavorable results related to various demographic assumptions. The annuity contract purchase loss relates to the contract with Metropolitan Life Insurance Company as discussed below. The actual rate of return, which is net of all fees and expenses, on our U.S. Pension Plan assets of 6.30% was slightly lower than our expected return of 6.50% primarily due to generally flat returns in the long-duration fixed-income portfolio partially offset by strong returns from global equities.
PENSION PLANS. Our largest pension plan covers certain U.S. employees age 21 and over, with at least one year of service. Pension benefits for most employees are accrued under a cash balance formula we call the Portable Pension Account (“PPA”). Under the PPA, the retirement benefit is expressed as a dollar amount in a notional account that grows with annual credits based on pay, age and years of credited service, and interest on the notional account balance. The PPA benefit is payable as a lump sum or an annuity at retirement at the election of the employee. The plan interest credit rate varies from year to year based on a U.S. Treasury index. Prior to 2009, certain employees earned benefits using a traditional pension formula (based on average earnings and years of service). Benefits under this formula were capped on May 31, 2008 for most employees.
We also sponsor or participate in nonqualified benefit plans covering certain of our U.S. employee groups and other pension plans covering certain of our international employees. The international defined benefit pension plans provide benefits primarily based on earnings and years of service and are funded in compliance with local laws and practices. The majority of our international obligations are for defined benefit pension plans in the Netherlands and the United Kingdom.
In May 2018, we entered into an agreement with Metropolitan Life Insurance Company to purchase a group annuity contract and transfer approximately $6 billion of our U.S. Pension Plan obligations. The transaction transferred responsibility for pension benefits to Metropolitan Life Insurance Company for approximately 41,000 of our retirees and beneficiaries who satisfied certain conditions and were receiving a monthly benefit from participating U.S. Pension Plans. There was no change to the pension benefits for any plan participants as a result of this transaction. The purchase of the group annuity contract was funded directly by assets of the U.S. Pension Plans. We recognized a $210 million one-time settlement loss in connection with this transaction, which was included in our 2018 year-end MTM retirement plans accounting adjustment.
In November 2019, we announced the closing of our U.S.-based defined benefit pension plans to new non-union employees hired on or after January 1, 2020. We will introduce an all-401(k)-plan retirement benefit structure for eligible employees with a higher company match of up to 8% across all U.S.-based operating companies. During 2021, current eligible employees under the PPA pension formula will be given a one-time option to continue to be eligible for pension compensation credits under the existing PPA formula and remain in the existing 401(k) plan with its company match of up to 3.5%, or to cease receiving compensation credits under the PPA and move to the new 401(k) plan with the higher match of up to 8%. Changes to the new 401(k) plan structure become effective beginning January 1, 2022. While this new program will provide employees greater flexibility and reduce our long-term pension costs, it will not have a material impact on current or near-term financial results.
POSTRETIREMENT HEALTHCARE PLANS. Certain of our subsidiaries offer medical, dental and vision coverage to eligible U.S. retirees and their eligible dependents and a small number of international employees. U.S. employees covered by the principal plan become eligible for these benefits at age 55 and older, if they have permanent, continuous service of at least 10 years after attainment of age 45 if hired prior to January 1, 1988, or at least 20 years after attainment of age 35 if hired on or after January 1, 1988. Postretirement healthcare benefits are capped at 150% of the 1993 per capita projected employer cost, which has been reached under most plans, so these benefits are not subject to future inflation.
Effective January 1, 2018, certain of our U.S. postretirement healthcare benefits were converted to a lump-sum benefit in a notional retiree health reimbursement account (HRA) for eligible participants. The HRA is available to reimburse a participant for qualifying healthcare premium costs and limits the company liability to the HRA account balance. The amount of the credit is based on age at January 1, 2018 or upon age at retirement thereafter. In connection with this change, retiree health coverage was closed to most new employees hired on or after January 1, 2018.
PENSION PLAN ASSUMPTIONS. The accounting for pension and postretirement healthcare plans includes numerous assumptions, such as: discount rates; expected long-term investment returns on plan assets; future salary increases; employee turnover; mortality; and retirement ages.
- 133 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
Weighted-average actuarial assumptions used to determine the benefit obligations and net periodic benefit cost of our plans are as follows:
| U.S. Pension Plans | International Pension Plans | Postretirement Healthcare Plans | ||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | 2018 | 2020 | 2019 | 2018 | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||||
| Discount rate used to determine benefit obligation | 3.14 | % | 3.85 | % | 4.27 | % | 1.79 | % | 1.92 | % | 2.37 | % | 2.95 | % | 3.70 | % | 4.33 | % | ||||||||||||||||||
| Discount rate used to determine net periodic benefit cost | 3.85 | 4.27 | 4.08 | 1.92 | 2.34 | 2.43 | 3.70 | 4.33 | 4.32 | |||||||||||||||||||||||||||
| Rate of increase in future compensation levels used to determine benefit obligation | 5.17 | 5.10 | 4.43 | 2.19 | 2.27 | 2.26 | — | — | — | |||||||||||||||||||||||||||
| Rate of increase in future compensation levels used to determine net periodic benefit cost | 5.10 | 4.43 | 4.47 | 2.43 | 2.22 | 2.42 | — | — | — | |||||||||||||||||||||||||||
| Expected long-term rate of return on assets | 6.75 | 6.75 | 6.50 | 3.26 | 3.12 | 3.09 | — | — | — | |||||||||||||||||||||||||||
| Interest crediting rate used to determine net periodic benefit cost | 4.00 | 4.00 | 4.00 | 2.20 | 2.20 | 2.20 | — | — | — | |||||||||||||||||||||||||||
| Interest crediting rate used to determine benefit obligation | 4.00 | 4.00 | 4.00 | 2.00 | 2.20 | 2.20 | — | — | — |
Our U.S. Pension Plan assets are invested primarily in publicly tradable securities, and our pension plans hold only a minimal investment in FedEx common stock that is entirely at the discretion of third-party pension fund investment managers. As part of our strategy to manage pension costs and funded status volatility, we follow a liability-driven investment strategy to better align plan assets with liabilities.
Establishing the expected future rate of investment return on our pension assets is a judgmental matter, which we review on an annual basis and revise as appropriate. Management considers the following factors in determining this assumption:
| • | the duration of our pension plan liabilities, which drives the investment strategy we can employ with our pension plan assets; |
|---|
| • | the types of investment classes in which we invest our pension plan assets and the expected compound geometric return we can reasonably expect those investment classes to earn over time, net of all fees and expenses; and |
|---|
| • | the investment returns we can reasonably expect our investment management program to achieve in excess of the returns we could expect if investments were made strictly in indexed funds. |
|---|
For consolidated pension expense, we assumed a 6.75% expected long-term rate of return on our U.S. Pension Plan assets in 2020 and 2019, and 6.50% in 2018. For the 15-year period ended May 31, 2020, our actual return was 7.70%, net of all fees and expenses.
The investment strategy for our U.S. Pension Plan assets is to utilize a diversified mix of public equities and fixed-income and alternative investments to earn a long-term investment return that meets our pension plan obligations. Our largest asset classes are Corporate Fixed Income Securities and Government Fixed Income Securities (which are largely benchmarked against the Barclays Long Government, Barclays Long Corporate or the Citigroup 20+ STRIPS indices), and U.S. and non-U.S. Equities (which are mainly benchmarked to the S&P 500 Index and MSCI indices). Accordingly, we do not have any significant concentrations of risk. Active management strategies are utilized within the plan in an effort to realize investment returns in excess of market indices. Our investment strategy also includes the limited use of derivative financial instruments on a discretionary basis to improve investment returns and manage portfolio risk.
The following is a description of the valuation methodologies used for investments measured at fair value:
| • | Cash and cash equivalents. Level 1 investments include cash, cash equivalents and foreign currency valued using exchange rates. Level 2 investments include short-term investment funds which are collective funds priced at a constant value by the administrator of the funds. |
|---|
| • | Domestic, international and global equities. Level 1 investments are valued at the closing price or last trade reported on the major market on which the individual securities are traded. |
|---|
| • | Fixed income. We determine the fair value of Level 2 corporate bonds, U.S. and non-U.S. government securities and other fixed income securities by using bid evaluation pricing models or quoted prices of securities with similar characteristics. |
|---|
- 134 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
| • | Alternative Investments. The valuation of Level 3 investments requires significant judgment due to the absence of quoted market prices, the inherent lack of liquidity and the long-term nature of such assets. Investments in private equity, debt, real estate, hedge funds and other private investments are valued at estimated fair value based on quarterly financial information received from the investment advisor and/or general partner. These estimates incorporate factors such as contributions and distributions, market transactions, market comparables and performance multiples. |
|---|
The fair values of investments by level and asset category and the weighted-average asset allocations for our U.S. Pension Plans and our most significant international pension plans at the measurement date are presented in the following table (in millions):
| Plan Assets at Measurement Date | ||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | ||||||||||||||||||||||
| Asset Class (U.S. Plans) | Fair Value | Actual % | Target Range %(1) | Quoted Prices in Active Markets Level 1 | Other Observable Inputs Level 2 | Unobservable Inputs Level 3 | ||||||||||||||||
| Cash and cash equivalents | $ | 709 | 3 | % | 0 - 5% | $ | 278 | $ | 431 | |||||||||||||
| Equities | 30 - 50 | |||||||||||||||||||||
| U.S. large cap equity(2) | 3,070 | 11 | 1,172 | |||||||||||||||||||
| International equities(2) | 3,314 | 12 | 2,738 | |||||||||||||||||||
| Global equities(2) | 1,350 | 5 | ||||||||||||||||||||
| U.S. SMID cap equity | 673 | 3 | 673 | |||||||||||||||||||
| Fixed income securities | 50 - 70 | |||||||||||||||||||||
| Corporate | 7,983 | 30 | 7,983 | |||||||||||||||||||
| Government(2) | 6,928 | 26 | 4,652 | |||||||||||||||||||
| Mortgage-backed and other(2) | 634 | 2 | 170 | |||||||||||||||||||
| Alternative investments(2) | 2,264 | 8 | 0 - 15 | $ | 416 | |||||||||||||||||
| Other | 53 | — | 57 | (3 | ) | |||||||||||||||||
| Total U.S. plan assets | $ | 26,978 | 100 | % | $ | 4,918 | $ | 13,233 | $ | 416 | ||||||||||||
| Asset Class (International Plans) | ||||||||||||||||||||||
| Cash and cash equivalents | $ | 9 | 1 | % | $ | 9 | ||||||||||||||||
| Equities | ||||||||||||||||||||||
| International equities(2) | 72 | 5 | ||||||||||||||||||||
| Global equities(2) | 218 | 15 | ||||||||||||||||||||
| Fixed income securities | ||||||||||||||||||||||
| Corporate(2) | 342 | 23 | ||||||||||||||||||||
| Government(2) | 510 | 34 | ||||||||||||||||||||
| Mortgage-backed and other(2) | 188 | 12 | 318 | |||||||||||||||||||
| Other(2) | 158 | 10 | 13 | $ | 63 | |||||||||||||||||
| Total international plan assets | $ | 1,497 | 100 | % | $ | 340 | $ | 63 |
| (1) | Target ranges have not been provided for international plan assets as they are managed at an individual country level. |
|---|
| (2) | Certain investments that are measured at fair value using the net asset value per share (or its equivalent) practical expedient have not been classified in the fair value hierarchy but are included in the total. |
|---|
- 135 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
| Plan Assets at Measurement Date | ||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2019 | ||||||||||||||||||||||
| Asset Class (U.S. Plans) | Fair Value | Actual % | Target Range %(1) | Quoted Prices in Active Markets Level 1 | Other Observable Inputs Level 2 | Unobservable Inputs Level 3 | ||||||||||||||||
| Cash and cash equivalents | $ | 570 | 2 | % | 0 - 5% | $ | 50 | $ | 520 | |||||||||||||
| Equities | 30 - 50 | |||||||||||||||||||||
| U.S. large cap equity(2) | 2,546 | 11 | 875 | |||||||||||||||||||
| International equities(2) | 3,306 | 14 | 2,700 | |||||||||||||||||||
| Global equities(2) | 1,451 | 6 | ||||||||||||||||||||
| U.S. SMID cap equity | 731 | 3 | 730 | 1 | ||||||||||||||||||
| Fixed income securities | 50 - 70 | |||||||||||||||||||||
| Corporate | 6,794 | 29 | 6,794 | |||||||||||||||||||
| Government(2) | 5,384 | 23 | 3,742 | |||||||||||||||||||
| Mortgage-backed and other(2) | 622 | 3 | 175 | |||||||||||||||||||
| Alternative investments(2) | 1,963 | 9 | 0 - 15 | $ | 302 | |||||||||||||||||
| Other | (47 | ) | — | (45 | ) | (2 | ) | |||||||||||||||
| Total U.S. plan assets | $ | 23,320 | 100 | % | $ | 4,310 | $ | 11,230 | $ | 302 | ||||||||||||
| Asset Class (International Plans) | ||||||||||||||||||||||
| Cash and cash equivalents | $ | 57 | 4 | % | $ | 57 | ||||||||||||||||
| Equities | ||||||||||||||||||||||
| International equities(2) | 72 | 5 | ||||||||||||||||||||
| Global equities(2) | 206 | 15 | ||||||||||||||||||||
| Fixed income securities | ||||||||||||||||||||||
| Corporate(2) | 322 | 24 | ||||||||||||||||||||
| Government(2) | 438 | 32 | 290 | |||||||||||||||||||
| Mortgage-backed and other(2) | 167 | 12 | ||||||||||||||||||||
| Other(2) | 112 | 8 | 10 | $ | 17 | |||||||||||||||||
| Total international plan assets | $ | 1,374 | 100 | % | $ | 357 | $ | 17 | ||||||||||||||
| (1) | Target ranges have not been provided for international plan assets as they are managed at an individual country level. |
|---|
| (2) | Certain investments that are measured at fair value using the net asset value per share (or its equivalent) practical expedient have not been classified in the fair value hierarchy but are included in the total. |
|---|
The change in fair value of Level 3 assets that use significant unobservable inputs is shown in the table below (in millions):
| U.S. Pension Plans | ||||||||
|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | |||||||
| Balance at beginning of year | $ | 302 | $ | 209 | ||||
| Actual return on plan assets: | ||||||||
| Assets held during current year | 19 | 11 | ||||||
| Assets sold during the year | 16 | 13 | ||||||
| Purchases, sales and settlements | 79 | 69 | ||||||
| Balance at end of year | $ | 416 | $ | 302 |
- 136 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
The following tables provide a reconciliation of the changes in the pension and postretirement healthcare plans’ benefit obligations and fair value of assets over the two-year period ended May 31, 2020 and a statement of the funded status as of May 31, 2020 and 2019 (in millions):
| U.S. Pension Plans | International Pension Plans | Postretirement Healthcare Plans | ||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | 2020 | 2019 | 2020 | 2019 | |||||||||||||||||||
| Accumulated Benefit Obligation (“ABO”) | $ | 29,272 | $ | 25,915 | $ | 2,012 | $ | 2,084 | ||||||||||||||||
| Changes in PBO and Accumulated Postretirement Benefit Obligation (“APBO”) | ||||||||||||||||||||||||
| PBO/APBO at the beginning of year | $ | 26,554 | $ | 22,653 | $ | 2,301 | $ | 2,167 | $ | 1,221 | $ | 955 | ||||||||||||
| Service cost | 768 | 689 | 96 | 94 | 42 | 35 | ||||||||||||||||||
| Interest cost | 1,000 | 951 | 43 | 49 | 44 | 40 | ||||||||||||||||||
| Actuarial loss (gain) | 2,817 | 3,016 | (87 | ) | 127 | 85 | 266 | |||||||||||||||||
| Benefits paid | (940 | ) | (755 | ) | (41 | ) | (38 | ) | (127 | ) | (123 | ) | ||||||||||||
| Settlements | — | — | (6 | ) | (13 | ) | — | — | ||||||||||||||||
| Other | — | — | (64 | ) | (85 | ) | 49 | 48 | ||||||||||||||||
| PBO/APBO at the end of year | $ | 30,199 | $ | 26,554 | $ | 2,242 | $ | 2,301 | $ | 1,314 | $ | 1,221 | ||||||||||||
| Change in Plan Assets | ||||||||||||||||||||||||
| Fair value of plan assets at the beginning of year | $ | 23,320 | $ | 22,057 | $ | 1,578 | $ | 1,509 | $ | — | $ | — | ||||||||||||
| Actual return on plan assets | 3,530 | 984 | 146 | 94 | — | — | ||||||||||||||||||
| Company contributions | 1,068 | 1,034 | 86 | 91 | 77 | 73 | ||||||||||||||||||
| Benefits paid | (940 | ) | (755 | ) | (41 | ) | (38 | ) | (127 | ) | (123 | ) | ||||||||||||
| Settlements | — | — | (6 | ) | (13 | ) | — | — | ||||||||||||||||
| Other | — | — | (50 | ) | (65 | ) | 50 | 50 | ||||||||||||||||
| Fair value of plan assets at the end of year | $ | 26,978 | $ | 23,320 | $ | 1,713 | $ | 1,578 | $ | — | $ | — | ||||||||||||
| Funded Status of the Plans | $ | (3,221 | ) | $ | (3,234 | ) | $ | (529 | ) | $ | (723 | ) | $ | (1,314 | ) | $ | (1,221 | ) | ||||||
| Amount Recognized in the Balance Sheet at May 31: | ||||||||||||||||||||||||
| Noncurrent asset | $ | — | $ | — | $ | 142 | $ | 82 | $ | — | $ | — | ||||||||||||
| Current pension, postretirement healthcare and other benefit obligations | (38 | ) | (70 | ) | (17 | ) | (16 | ) | (104 | ) | (87 | ) | ||||||||||||
| Noncurrent pension, postretirement healthcare and other benefit obligations | (3,183 | ) | (3,164 | ) | (654 | ) | (789 | ) | (1,210 | ) | (1,134 | ) | ||||||||||||
| Net amount recognized | $ | (3,221 | ) | $ | (3,234 | ) | $ | (529 | ) | $ | (723 | ) | $ | (1,314 | ) | $ | (1,221 | ) | ||||||
| Amounts Recognized in AOCI and not yet reflected in Net Periodic Benefit Cost: | ||||||||||||||||||||||||
| Prior service (credit) cost and other | $ | (68 | ) | $ | (173 | ) | $ | (7 | ) | $ | (6 | ) | $ | 1 | $ | 1 |
Our pension plans included the following components at May 31 (in millions):
| PBO | Fair Value of Plan Assets | Funded Status | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | ||||||||||||
| Qualified | $ | 30,004 | $ | 26,978 | $ | (3,026 | ) | |||||
| Nonqualified | 195 | — | (195 | ) | ||||||||
| International Plans | 2,242 | 1,713 | (529 | ) | ||||||||
| Total | $ | 32,441 | $ | 28,691 | $ | (3,750 | ) | |||||
| 2019 | ||||||||||||
| Qualified | $ | 26,300 | $ | 23,320 | $ | (2,980 | ) | |||||
| Nonqualified | 254 | — | (254 | ) | ||||||||
| International Plans | 2,301 | 1,578 | (723 | ) | ||||||||
| Total | $ | 28,855 | $ | 24,898 | $ | (3,957 | ) |
- 137 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
The table above provides the PBO, fair value of plan assets and funded status of our pension plans on an aggregated basis. The following tables present our plans on a disaggregated basis to show those plans (as a group) whose assets did not exceed their liabilities. The fair value of plan assets for pension plans with a PBO or ABO in excess of plan assets at May 31 were as follows (in millions):
| PBO Exceeds the Fair Value of Plan Assets | ||||||||
|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | |||||||
| U.S. Pension Benefits | ||||||||
| Fair value of plan assets | $ | 26,978 | $ | 23,320 | ||||
| PBO | (30,199 | ) | (26,554 | ) | ||||
| Net funded status | $ | (3,221 | ) | $ | (3,234 | ) | ||
| International Pension Benefits | ||||||||
| Fair value of plan assets | $ | 205 | $ | 1,125 | ||||
| PBO | (876 | ) | (1,929 | ) | ||||
| Net funded status | $ | (671 | ) | $ | (804 | ) |
| ABO Exceeds the Fair Value of Plan Assets | ||||||||
|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | |||||||
| U.S. Pension Benefits | ||||||||
| ABO(1) | $ | (29,272 | ) | $ | (25,915 | ) | ||
| Fair value of plan assets | 26,978 | 23,320 | ||||||
| PBO | (30,199 | ) | (26,554 | ) | ||||
| Net funded status | $ | (3,221 | ) | $ | (3,234 | ) | ||
| International Pension Benefits | ||||||||
| ABO(1) | $ | (637 | ) | $ | (1,709 | ) | ||
| Fair value of plan assets | 175 | 1,120 | ||||||
| PBO | (840 | ) | (1,925 | ) | ||||
| Net funded status | $ | (665 | ) | $ | (805 | ) |
| (1) | ABO not used in determination of funded status. |
|---|
Contributions to our U.S. Pension Plans for the years ended May 31 were as follows (in millions):
| 2020 | 2019 | |||||||
|---|---|---|---|---|---|---|---|---|
| Required | $ | — | $ | — | ||||
| Voluntary | 1,000 | 1,000 | ||||||
| $ | 1,000 | $ | 1,000 |
For 2021, no pension contributions are required for our U.S. Pension Plans as they are fully funded under the Employee Retirement Income Security Act.
Net periodic benefit cost for the three years ended May 31 were as follows (in millions):
| U.S. Pension Plans | International Pension Plans | Postretirement Healthcare Plans | ||||||||||||||||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | 2019 | 2018 | 2020 | 2019 | 2018 | 2020 | 2019 | 2018 | ||||||||||||||||||||||||||||
| Service cost | $ | 768 | $ | 689 | $ | 679 | $ | 96 | $ | 94 | $ | 97 | $ | 42 | $ | 35 | $ | 36 | ||||||||||||||||||
| Interest cost | 1,000 | 951 | 1,115 | 43 | 49 | 49 | 44 | 40 | 39 | |||||||||||||||||||||||||||
| Expected return on plan assets | (1,601 | ) | (1,505 | ) | (1,624 | ) | (52 | ) | (47 | ) | (46 | ) | — | — | — | |||||||||||||||||||||
| Amortization of prior service credit | (105 | ) | (118 | ) | (118 | ) | (2 | ) | (2 | ) | (2 | ) | — | — | (1 | ) | ||||||||||||||||||||
| Actuarial losses (gains) and other | 888 | 3,537 | 37 | (179 | ) | 80 | (38 | ) | 85 | 265 | (9 | ) | ||||||||||||||||||||||||
| Net periodic benefit cost | $ | 950 | $ | 3,554 | $ | 89 | $ | (94 | ) | $ | 174 | $ | 60 | $ | 171 | $ | 340 | $ | 65 |
- 138 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
Amounts recognized in other comprehensive income were primarily related to amortization of prior service cost in our U.S. Pension Plans of $105 million in 2020 and $118 million in 2019 ($80 million, net of tax, in 2020 and $91 million, net of tax, in 2019).
Benefit payments, which reflect expected future service, are expected to be paid as follows for the years ending May 31 (in millions):
| U.S. Pension Plans | International Pension Plans | Postretirement Healthcare Plans | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2021 | $ | 1,008 | $ | 50 | $ | 104 | ||||||
| 2022 | 1,093 | 46 | 113 | |||||||||
| 2023 | 1,154 | 51 | 121 | |||||||||
| 2024 | 1,242 | 57 | 126 | |||||||||
| 2025 | 1,331 | 62 | 120 | |||||||||
| 2026-2030 | 7,967 | 414 | 433 |
These estimates are based on assumptions about future events. Actual benefit payments may vary significantly from these estimates.
Future medical benefit claims costs are estimated to increase at an annual rate of 5.70% during 2021, decreasing to an annual growth rate of 4.50% in 2037 and thereafter.
- 139 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
NOTE 14: BUSINESS SEGMENTS AND DISAGGREGATED REVENUE
FedEx Express, FedEx Ground and FedEx Freight represent our major service lines and, along with FedEx Services, constitute our reportable segments. Our reportable segments include the following businesses:
| FedEx Express Segment | FedEx Express (express transportation) |
|---|---|
| TNT Express (international express transportation, small-package ground delivery and freight transportation) FedEx Custom Critical Inc. (“FedEx Custom Critical”) (time-critical transportation) | |
| FedEx Ground Segment | FedEx Ground (small-package ground delivery) |
| FedEx Freight Segment | FedEx Freight (LTL freight transportation) |
| FedEx Services Segment | FedEx Services (sales, marketing, information technology, communications, customer service, technical support, billing and collection services and back-office functions) |
Effective June 1, 2019, the results of the FedEx Office operating segment are included in “Corporate, other and eliminations.” This change was made to reflect our internal management reporting structure. Prior year amounts have been revised to reflect current year presentation.
Effective March 1, 2020, the results of FedEx Custom Critical are included in the FedEx Express segment prospectively as the impact to prior periods was not material. This change was made to reflect our internal management reporting structure.
FedEx Services Segment
The FedEx Services segment operates combined sales, marketing, administrative and information-technology functions in shared services operations that support our transportation businesses and allow us to obtain synergies from the combination of these functions. For the international regions of FedEx Express, some of these functions are performed on a regional basis and reported by FedEx Express in their natural expense line items. The FedEx Services segment includes FedEx Services, which provides sales, marketing, information technology, communications, customer service, technical support, billing and collection services for U.S. customers of our major business units and certain back-office support to our other companies.
The FedEx Services segment provides direct and indirect support to our operating segments, and we allocate all of the net operating costs of the FedEx Services segment to reflect the full cost of operating our transportation businesses in the results of those segments. We review and evaluate the performance of our transportation segments based on operating income (inclusive of FedEx Services segment allocations). For the FedEx Services segment, performance is evaluated based on the impact of its total allocated net operating costs on our operating segments.
Operating expenses for each of our transportation segments include the allocations from the FedEx Services segment to the respective transportation segments. These allocations also include charges and credits for administrative services provided between operating companies. The allocations of net operating costs are based on metrics such as relative revenue or estimated services provided. We believe these allocations approximate the net cost of providing these functions. Our allocation methodologies are refined periodically, as necessary, to reflect changes in our businesses.
- 140 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
Other Intersegment Transactions
Corporate and other includes corporate headquarters costs for executive officers and certain legal and finance functions, as well as certain other costs and credits not attributed to our core business. These costs are not allocated to the other business segments.
Also included in corporate and other is the FedEx Office operating segment, which provides an array of document and business services and retail access to our customers for our package transportation businesses, and the FedEx Logistics operating segment, which provides integrated supply chain management solutions, specialty transportation, customs brokerage and global ocean and air freight forwarding.
Certain FedEx operating companies provide transportation and related services for other FedEx companies outside their reportable segment. Billings for such services are based on negotiated rates, which we believe approximate fair value, and are reflected as revenue of the billing segment. These rates are adjusted from time to time based on market conditions. Such intersegment revenue and expenses are eliminated in our consolidated results and are not separately identified in the following segment information, because the amounts are not material.
- 141 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
The following table provides a reconciliation of reportable segment revenue, depreciation and amortization, operating income (loss) and segment assets to consolidated financial statement totals (in millions) for the years ended or as of May 31:
| FedEx Express Segment | FedEx Ground Segment | FedEx Freight Segment | FedEx Services Segment | Corporate, other and eliminations | Consolidated Total | |||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Revenue | ||||||||||||||||||||||||
| 2020 | $ | 35,513 | $ | 22,733 | $ | 7,102 | $ | 22 | $ | 3,847 | $ | 69,217 | ||||||||||||
| 2019 | 37,331 | 20,522 | 7,582 | 22 | 4,236 | 69,693 | ||||||||||||||||||
| 2018 | 36,172 | 18,395 | 6,812 | 28 | 4,043 | 65,450 | ||||||||||||||||||
| Depreciation and amortization | ||||||||||||||||||||||||
| 2020 | $ | 1,894 | $ | 789 | $ | 381 | $ | 413 | $ | 138 | $ | 3,615 | ||||||||||||
| 2019 | 1,801 | 728 | 332 | 355 | 137 | 3,353 | ||||||||||||||||||
| 2018 | 1,679 | 681 | 296 | 308 | 131 | 3,095 | ||||||||||||||||||
| Operating income (loss) | ||||||||||||||||||||||||
| 2020(1) | $ | 996 | $ | 2,014 | $ | 580 | $ | — | $ | (1,173 | ) | $ | 2,417 | |||||||||||
| 2019(2) | 2,176 | 2,663 | 615 | — | (988 | ) | 4,466 | |||||||||||||||||
| 2018(3) | 2,172 | 2,556 | 490 | — | (946 | ) | 4,272 | |||||||||||||||||
| Segment assets(4) | ||||||||||||||||||||||||
| 2020 | $ | 41,252 | $ | 24,700 | $ | 6,434 | $ | 7,285 | $ | (6,134 | ) | $ | 73,537 | |||||||||||
| 2019 | 33,247 | 17,561 | 4,736 | 6,061 | (7,202 | ) | 54,403 | |||||||||||||||||
| 2018 | 31,753 | 15,458 | 4,251 | 5,501 | (4,633 | ) | 52,330 |
| (1) | Includes TNT Express integration expenses of $270 million. These expenses are included in “Corporate, other and eliminations” and the FedEx Express segment. Also includes noncash goodwill and other asset impairment charges of $435 million primarily related to goodwill impairment at FedEx Office and from the decision to permanently retire certain aircraft and related engines at FedEx Express. |
|---|
| (2) | Includes TNT Express integration expenses (including restructuring charges) of $388 million. These expenses are included in “Corporate, other and eliminations” and the FedEx Express segment. Also includes business realignment costs of $320 million included in “Corporate, other and eliminations” and costs incurred in connection with the settlement of a legal matter involving FedEx Ground of $46 million. |
|---|
| (3) | Includes TNT Express integration expenses (including restructuring charges) of $477 million. These expenses are included in “Corporate, other and eliminations” and the FedEx Express segment. Also includes goodwill and other asset impairment charges of $380 million included in “Corporate, other and eliminations.” |
|---|
| (4) | Segment assets include intercompany receivables. |
|---|
The following table provides a reconciliation of reportable segment capital expenditures to consolidated totals for the years ended May 31 (in millions):
| FedEx Express Segment | FedEx Ground Segment | FedEx Freight Segment | FedEx Services Segment | Other | Consolidated Total | ||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020 | $ | 3,560 | $ | 1,083 | $ | 539 | $ | 527 | $ | 159 | $ | 5,868 | |||||||||||||
| 2019 | 3,550 | 808 | 544 | 440 | 148 | 5,490 | |||||||||||||||||||
| 2018 | 3,461 | 1,178 | 490 | 411 | 123 | 5,663 |
- 142 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
The following table presents revenue by service type and geographic information for the years ended or as of May 31 (in millions):
| 2020 | 2019(1) | 2018(1) | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| REVENUE BY SERVICE TYPE | ||||||||||||
| FedEx Express segment: | ||||||||||||
| Package: | ||||||||||||
| U.S. overnight box | $ | 7,234 | $ | 7,663 | $ | 7,273 | ||||||
| U.S. overnight envelope | 1,776 | 1,829 | 1,788 | |||||||||
| U.S. deferred | 4,038 | 4,225 | 3,738 | |||||||||
| Total U.S. domestic package revenue | 13,048 | 13,717 | 12,799 | |||||||||
| International priority | 7,354 | 7,405 | 7,461 | |||||||||
| International economy | 3,082 | 3,446 | 3,255 | |||||||||
| Total international export package revenue | 10,436 | 10,851 | 10,716 | |||||||||
| International domestic(2) | 4,179 | 4,540 | 4,637 | |||||||||
| Total package revenue | 27,663 | 29,108 | 28,152 | |||||||||
| Freight: | ||||||||||||
| U.S. | 2,998 | 3,025 | 2,797 | |||||||||
| International priority | 1,915 | 2,070 | 2,105 | |||||||||
| International economy | 1,930 | 2,123 | 1,916 | |||||||||
| International airfreight | 270 | 314 | 368 | |||||||||
| Total freight revenue | 7,113 | 7,532 | 7,186 | |||||||||
| Other(3) | 737 | 691 | 834 | |||||||||
| Total FedEx Express segment | 35,513 | 37,331 | 36,172 | |||||||||
| FedEx Ground segment | 22,733 | 20,522 | 18,395 | |||||||||
| FedEx Freight segment | 7,102 | 7,582 | 6,812 | |||||||||
| FedEx Services segment | 22 | 22 | 28 | |||||||||
| Other and eliminations(4) | 3,847 | 4,236 | 4,043 | |||||||||
| $ | 69,217 | $ | 69,693 | $ | 65,450 | |||||||
| GEOGRAPHICAL INFORMATION(5) | ||||||||||||
| Revenue: | ||||||||||||
| U.S. | $ | 48,404 | $ | 47,584 | $ | 43,581 | ||||||
| International: | ||||||||||||
| FedEx Express segment | 19,177 | 20,424 | 20,417 | |||||||||
| FedEx Ground segment | 479 | 467 | 407 | |||||||||
| FedEx Freight segment | 192 | 207 | 181 | |||||||||
| FedEx Services segment | 1 | 1 | 1 | |||||||||
| Other | 964 | 1,010 | 863 | |||||||||
| Total international revenue | 20,813 | 22,109 | 21,869 | |||||||||
| $ | 69,217 | $ | 69,693 | $ | 65,450 | |||||||
| Noncurrent assets: | ||||||||||||
| U.S. | $ | 45,691 | $ | 33,189 | $ | 30,362 | ||||||
| International | 11,463 | 8,128 | 8,627 | |||||||||
| $ | 57,154 | $ | 41,317 | $ | 38,989 |
| (1) | Prior year amounts have been revised to conform to the current year presentation. |
|---|
| (2) | International domestic revenue relates to our intra-country operations. |
|---|
| (3) | Includes the operations of FedEx Custom Critical. |
|---|
| (4) | Includes the FedEx Office and FedEx Logistics operating segments. |
|---|
| (5) | International revenue includes shipments that either originate in or are destined to locations outside the United States, which could include U.S. payors. Noncurrent assets include property and equipment, goodwill and other long-term assets. Our flight equipment is registered in the U.S. and is included as U.S. assets; however, many of our aircraft operate internationally. |
|---|
- 143 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
NOTE 15: SUPPLEMENTAL CASH FLOW INFORMATION
Cash paid for interest expense and income taxes for the years ended May 31 was as follows (in millions):
| 2020 | 2019 | 2018 | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Cash payments for: | ||||||||||||
| Interest (net of capitalized interest) | $ | 639 | $ | 617 | $ | 524 | ||||||
| Income taxes | $ | 389 | $ | 407 | $ | 760 | ||||||
| Income tax refunds received | (353 | ) | (36 | ) | (571 | ) | ||||||
| Cash tax payments, net | $ | 36 | $ | 371 | $ | 189 |
NOTE 16: GUARANTEES AND INDEMNIFICATIONS
In conjunction with certain transactions, primarily the lease, sale or purchase of real estate, operating assets or services in the ordinary course of business and in connection with business sales and acquisitions, we may provide routine guarantees or indemnifications (e.g., environmental, fuel, tax and intellectual property infringement), the terms of which range in duration, and often they are not limited and have no specified maximum obligation. As a result of the TNT Express acquisition, we have assumed a guarantee related to the demerger of TNT Express and PostNL Holding B.V., which occurred in 2011, for pension benefits earned prior to the date of the demerger. The risk of making payments associated with this guarantee is remote. The overall maximum potential amount of the obligation under such guarantees and indemnifications cannot be reasonably estimated. Historically, we have not been required to make significant payments under our guarantee or indemnification obligations and no material amounts have been recognized in our financial statements for the underlying fair value of these obligations.
NOTE 17: COMMITMENTS
Annual purchase commitments under various contracts as of May 31, 2020 were as follows (in millions):
| Aircraft and Aircraft Related | Other(1) | Total | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2021 | $ | 2,177 | $ | 949 | $ | 3,126 | ||||||
| 2022 | 2,772 | 590 | 3,362 | |||||||||
| 2023 | 2,036 | 407 | 2,443 | |||||||||
| 2024 | 697 | 263 | 960 | |||||||||
| 2025 | 660 | 226 | 886 | |||||||||
| Thereafter | 2,723 | 397 | 3,120 | |||||||||
| Total | $ | 11,065 | $ | 2,832 | $ | 13,897 |
| (1) | Primarily equipment and advertising contracts. |
|---|
The amounts reflected in the table above for purchase commitments represent noncancelable agreements to purchase goods or services. As of May 31, 2020, our obligation to purchase one Boeing 767-300 Freighter (“B767F”) aircraft and six Boeing 777 Freighter (“B777F”) aircraft is conditioned upon there being no event that causes FedEx Express or its employees not to be covered by the Railway Labor Act of 1926, as amended. Open purchase orders that are cancelable are not considered unconditional purchase obligations for financial reporting purposes and are not included in the table above.
We have several aircraft modernization programs underway that are supported by the purchase of B777F and B767F aircraft. These aircraft are significantly more fuel-efficient per unit than the aircraft types previously utilized, and these expenditures are necessary to achieve significant long-term operating savings and to replace older aircraft. Our ability to delay the timing of these aircraft-related expenditures is limited without incurring significant costs to modify existing purchase agreements.
- 144 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
As of May 31, 2020, we had $633 million in deposits and progress payments on aircraft purchases and other planned aircraft-related transactions. These deposits are classified in the “Other assets” caption of our accompanying consolidated balance sheets. Aircraft and aircraft-related contracts are subject to price escalations. The following table is a summary of the key aircraft we are committed to purchase as of May 31, 2020, with the year of expected delivery:
| Cessna SkyCourier 408 | ATR 72-600F | B767F | B777F | Total | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2021 | — | 4 | 20 | 2 | 26 | |||||||||||||||
| 2022 | 9 | 7 | 18 | 5 | 39 | |||||||||||||||
| 2023 | 12 | 6 | 8 | 2 | 28 | |||||||||||||||
| 2024 | 12 | 6 | — | 4 | 22 | |||||||||||||||
| 2025 | 12 | 6 | — | 2 | 20 | |||||||||||||||
| Thereafter | 5 | 1 | — | — | 6 | |||||||||||||||
| Total | 50 | 30 | 46 | 15 | 141 |
During 2020, FedEx Express exercised options to purchase an additional six B767F aircraft for delivery in 2022. Additionally, FedEx Express executed two contract amendments rescheduling two B777F aircraft deliveries from 2023 to 2022 and two B767F aircraft deliveries from 2022 to 2023.
In the fourth quarter of 2020, we received notice from certain aircraft manufacturers (i) rescheduling four B767F aircraft deliveries from 2020 to 2021, as well as two B767F aircraft deliveries from 2021 to 2022, and (ii) rescheduling certain Cessna SkyCourier 408 and ATR 72-600F aircraft between 2021 and 2026.
On June 25, 2020, FedEx Express executed a contract amendment rescheduling B767F aircraft deliveries as follows: 2021 – 18 aircraft; 2022 – 11 aircraft; 2023 – 13 aircraft; and 2024 – 4 aircraft.
NOTE 18: CONTINGENCIES
Service Provider Lawsuits. FedEx Ground is defending lawsuits in which it is alleged that FedEx Ground should be treated as a joint employer of drivers employed by service providers engaged by FedEx Ground. These cases are in varying stages of litigation, and we are not currently able to estimate an amount or range of potential loss in all of these matters. However, we do not expect to incur, individually or in the aggregate, a material loss in these matters. Nevertheless, adverse determinations in these matters could, among other things, entitle service providers’ drivers to certain wage payments from the service providers and FedEx Ground, and result in employment and withholding tax and benefit liability for FedEx Ground. We continue to believe that FedEx Ground is not an employer or joint employer of the drivers of these independent businesses.
Federal Securities Litigation and Derivative Lawsuits. On June 26, 2019 and July 2, 2019, FedEx and certain present and former officers were named as defendants in two putative class action securities lawsuits filed in the U.S. District Court for the Southern District of New York. The complaints, which have been consolidated, allege violations of Sections 10(b) and 20(a) of the Securities Exchange Act of 1934, as amended, and Rule 10b-5 promulgated thereunder relating to alleged misstatements or omissions in FedEx’s public filings with the SEC and other public statements during the period from September 19, 2017 to December 18, 2018. We are not currently able to estimate the probability of loss or the amount or range of potential loss, if any, at this stage of the litigation.
On September 17, 2019 and November 6, 2019, FedEx, its Board of Directors and certain present and former directors and officers were named as defendants in two stockholder derivative lawsuits filed in the U.S. District Court for the District of Delaware. The complaints, which were subsequently consolidated, repeated the allegations in the federal securities litigation complaints, and asserted new claims against the FedEx Board of Directors and certain present and former directors and officers for breach of fiduciary duty, waste of corporate assets, unjust enrichment, insider selling and violations of the federal securities laws. On June 24, 2020, the consolidated lawsuit was dismissed with prejudice. Any appeal of the dismissal must be made by July 24, 2020.
- 145 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
Derivative Lawsuit Related to New York Cigarette Litigation. On October 3, 2019, FedEx and certain present and former FedEx directors and officers were named as defendants in a stockholder derivative lawsuit filed in the Delaware Court of Chancery. The complaint alleges the defendants breached their fiduciary duties in connection with the activities alleged in lawsuits filed by the City of New York and the State of New York against FedEx Ground in December 2013 and November 2014 and against FedEx Ground and FedEx Freight in July 2017. The underlying lawsuits related to the alleged shipment of cigarettes to New York residents in contravention of several statutes, as well as common law nuisance claims, and were dismissed by the court in December 2018 following entry into a final settlement agreement for approximately $35 million. The settlement did not include any admission of liability by FedEx Ground or FedEx Freight. In addition to the settlement amount, we recognized approximately $10 million for certain attorney’s fees in connection with the underlying lawsuits. We are not currently able to estimate the probability of loss or the amount or range of potential loss, if any, at this stage of the lawsuit. On August 14, 2019, a separate stockholder derivative lawsuit alleging similar breaches of fiduciary duty was filed in the Delaware Court of Chancery. The plaintiff voluntarily dismissed this lawsuit on June 25, 2020.
Environmental Matters. SEC regulations require disclosure of certain environmental matters when a governmental authority is a party to the proceedings and the proceedings involve potential monetary sanctions that management reasonably believes could exceed $100,000.
Prior to our acquisition of TNT Express, a lawsuit was filed in Simões Filho, Bahia, Brazil against a subsidiary of TNT Express alleging violations of Brazilian environmental laws. Specifically, the lawsuit alleges that in 2012, certain employees unlawfully discarded non-toxic trash on a highway. We could be subject to monetary sanctions and fines related to such activity that exceed $100,000. We believe that the aggregate amount of any such sanctions and fines will be immaterial.
Other Matters. FedEx and its subsidiaries are subject to other legal proceedings that arise in the ordinary course of business, including certain lawsuits containing various class-action allegations of wage-and-hour violations in which plaintiffs claim, among other things, that they were forced to work “off the clock,” were not paid overtime or were not provided work breaks or other benefits. In the opinion of management, the aggregate liability, if any, with respect to these other actions will not have a material adverse effect on our financial position, results of operations or cash flows.
NOTE 19: RELATED PARTY TRANSACTIONS
Our Chairman and Chief Executive Officer, Frederick W. Smith, currently holds an approximate 10% ownership interest in the Washington, D.C. National Football League professional football team and is a member of its board of directors. FedEx has a multi-year naming rights agreement with Washington Football, Inc. granting us certain marketing rights, including the right to name the stadium where the team plays and other events are held “FedExField.”
- 146 -
FEDEX CORPORATION
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS
NOTE 20: SUMMARY OF QUARTERLY OPERATING RESULTS (UNAUDITED)
| (in millions, except per share amounts) | First Quarter | Second Quarter | Third Quarter | Fourth Quarter | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2020(1) | ||||||||||||||||
| Revenue | $ | 17,048 | $ | 17,324 | $ | 17,487 | $ | 17,358 | ||||||||
| Operating income | 977 | 554 | 411 | 475 | ||||||||||||
| Net income (loss)(2) | 745 | 560 | 315 | (334 | ) | |||||||||||
| Basic earnings (loss) per common share(3) | 2.86 | 2.15 | 1.21 | (1.28 | ) | |||||||||||
| Diluted earnings (loss) per common share(3) | 2.84 | 2.13 | 1.20 | (1.28 | ) | |||||||||||
| 2019(4) | ||||||||||||||||
| Revenue | $ | 17,052 | $ | 17,824 | $ | 17,010 | $ | 17,807 | ||||||||
| Operating income | 1,071 | 1,168 | 911 | 1,316 | ||||||||||||
| Net income (loss)(5) | 835 | 935 | 739 | (1,969 | ) | |||||||||||
| Basic earnings (loss) per common share(3) | 3.15 | 3.56 | 2.83 | (7.56 | ) | |||||||||||
| Diluted earnings (loss) per common share(3) | 3.10 | 3.51 | 2.80 | (7.56 | ) |
| (1) | The fourth quarter, third quarter, second quarter and first quarter of 2020 include $63 million, $72 million, $64 million and $71 million, respectively, of TNT Express integration expenses. The fourth quarter includes $369 million of goodwill and other asset impairment charges associated with the FedEx Office and FedEx Logistics operating segments and a net loss of $794 million related to the annual MTM retirement plans accounting adjustment. The second quarter of 2020 includes asset impairment charges of $66 million related to the permanent retirement of 10 Airbus A310-300 aircraft and 12 related engines at FedEx Express. |
|---|
| (2) | The fourth quarter of 2020 includes a tax benefit of $71 million in connection with the 2020 U.S. tax loss that can be offset against income in prior years under the CARES Act and a tax expense of $51 million due to a change in deferred tax balances related to foreign tax operations. The second quarter of 2020 includes a tax benefit of $133 million from the reduction of a valuation allowance on certain foreign tax loss carryforwards. |
|---|
| (3) | The sum of the quarterly earnings per share may not equal annual amounts due to differences in the weighted-average number of shares outstanding during the respective periods. |
|---|
| (4) | The fourth quarter, third quarter, second quarter and first quarter of 2019 include $84 million, $69 million, $114 million and $121 million, respectively, of TNT Express integration expenses (including any restructuring charges). The fourth quarter and third quarter of 2019 include business realignment costs of $316 million and $4 million, respectively. The fourth quarter includes a net loss of $3.9 billion related to the annual MTM retirement plans accounting adjustment. The second quarter of 2019 includes costs incurred in connection with the settlement of a legal matter involving FedEx Ground of $46 million. |
|---|
| (5) | The third quarter of 2019 includes a tax benefit of $90 million from the reduction of a valuation allowance on certain tax loss carryforwards and a tax expense of $50 million related to a lower tax rate in the Netherlands applied to our deferred tax balances. The second quarter of 2019 includes a tax benefit of approximately $60 million from accelerated deductions claimed on our 2018 U.S. income tax return. In addition, we recognized a tax expense of $4 million in the second quarter of 2019 as a revision of the provisional benefit associated with the remeasurement of our net U.S. deferred tax liability upon completion of the accounting for the tax effects of the TCJA. |
|---|
- 147 -
QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
INTEREST RATES. While we currently have market risk sensitive instruments related to interest rates, we have no significant exposure to changing interest rates on our long-term debt. As disclosed in Note 6 to the accompanying consolidated financial statements, we had outstanding fixed-rate long-term debt (exclusive of finance leases) with an estimated fair value of $22.8 billion at May 31, 2020 and outstanding fixed- and floating-rate long-term debt (exclusive of finance leases) with an estimated fair value of $17.8 billion at May 31, 2019. Market risk for long-term debt is estimated as the potential decrease in fair value resulting from a hypothetical 10% increase in interest rates and amounts to approximately $303 million as of May 31, 2020 and approximately $390 million as of May 31, 2019. The underlying fair values of our long-term debt were estimated based on quoted market prices or on the current rates offered for debt with similar terms and maturities.
We have interest rate risk with respect to our pension and postretirement benefit obligations. Changes in interest rates impact our liabilities associated with these retirement plans, as well as the amount of pension and postretirement benefit expense recognized. Declines in the value of plan assets could diminish the funded status of our pension plans and potentially increase our requirement to make contributions to the plans. Substantial investment losses on plan assets would also increase net pension expense.
FOREIGN CURRENCY. While we are a global provider of transportation, e-commerce and business services, the majority of our transactions during the periods presented in this Annual Report on Form 10-K are denominated in U.S. dollars. The principal foreign currency exchange rate risks to which we are exposed are in the euro, Chinese yuan, British pound, Canadian dollar, Australian dollar and Mexican peso. Historically, our exposure to foreign currency fluctuations is more significant with respect to our revenue than our expenses, as a significant portion of our expenses are denominated in U.S. dollars, such as aircraft and fuel expenses. Foreign currency fluctuations had a slightly positive impact on operating income in 2020 and 2019. However, favorable foreign currency fluctuations also may have had an offsetting impact on the price we obtained or the demand for our services, which is not quantifiable. At May 31, 2020, the result of a uniform 10% strengthening in the value of the dollar relative to the currencies in which our transactions are denominated would result in a decrease in operating income of $201 million for 2021, assuming operations were consistent with the prior year. This theoretical calculation assumes that each exchange rate would change in the same direction relative to the U.S. dollar, which is not consistent with our actual experience in foreign currency transactions. In addition to the direct effects of changes in exchange rates, fluctuations in exchange rates also affect the volume of sales or the foreign currency sales price as competitors’ services become more or less attractive. The sensitivity analysis of the effects of changes in foreign currency exchange rates does not factor in a potential change in sales levels or local currency prices.
We maintain derivative financial instruments to manage foreign currency fluctuations related to probable future transactions and cash flows denominated in currencies other than the currency of the transacting entity which impacts our exposure to foreign currency exchange risk. These derivatives are not designated as hedges and are accounted for at fair value with any profit or loss recorded in income, which was immaterial for 2020 and 2019.
COMMODITY. While we have market risk for changes in the price of jet and vehicle fuel, this risk is largely mitigated by our indexed fuel surcharges. For additional discussion of our indexed fuel surcharges, see the “Results of Operations and Outlook — Consolidated Results — Fuel” section of “Management’s Discussion and Analysis of Results of Operations and Financial Condition.”
- 148 -
SELECTED FINANCIAL DATA
The following table sets forth (in millions, except per share amounts and other operating data) certain selected consolidated financial and operating data for FedEx Corporation (“FedEx”) as of and for the five years ended May 31, 2020. This information should be read in conjunction with the Consolidated Financial Statements, Management’s Discussion and Analysis of Results of Operations and Financial Condition and other financial data appearing elsewhere in this Annual Report on Form 10-K. Defined terms used below have the meaning set forth in Management’s Discussion and Analysis of Results of Operations and Financial Condition.
| 2020(1)(2)(3) | 2019(2)(3)(4) | 2018(2)(3)(5)(8) | 2017(2)(3)(6)(8) | 2016(3)(7)(8) | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Operating Results | ||||||||||||||||||||
| Revenue | $ | 69,217 | $ | 69,693 | $ | 65,450 | $ | 60,319 | $ | 50,365 | ||||||||||
| Operating income | 2,417 | 4,466 | 4,272 | 4,566 | 4,168 | |||||||||||||||
| Income before income taxes | 1,669 | 655 | 4,353 | 4,579 | 2,740 | |||||||||||||||
| Net income | 1,286 | 540 | 4,572 | 2,997 | 1,820 | |||||||||||||||
| Per Share Data | ||||||||||||||||||||
| Earnings per share: | ||||||||||||||||||||
| Basic | $ | 4.92 | $ | 2.06 | $ | 17.08 | $ | 11.24 | $ | 6.59 | ||||||||||
| Diluted | $ | 4.90 | $ | 2.03 | $ | 16.79 | $ | 11.07 | $ | 6.51 | ||||||||||
| Average shares of common stock outstanding | 261 | 262 | 267 | 266 | 276 | |||||||||||||||
| Average common and common equivalent shares outstanding | 262 | 265 | 272 | 270 | 279 | |||||||||||||||
| Cash dividends declared | $ | 2.60 | $ | 2.60 | $ | 2.00 | $ | 1.60 | $ | 1.00 | ||||||||||
| Financial Position | ||||||||||||||||||||
| Property and equipment, net | $ | 33,608 | $ | 30,429 | $ | 28,154 | $ | 25,981 | $ | 24,284 | ||||||||||
| Total assets(9) | 73,537 | 54,403 | 52,330 | 48,552 | 45,959 | |||||||||||||||
| Long-term debt, less current portion(9) | 21,952 | 16,617 | 15,243 | 14,909 | 13,733 | |||||||||||||||
| Common stockholders’ investment | 18,295 | 17,757 | 19,416 | 16,073 | 13,784 | |||||||||||||||
| Other Operating Data | ||||||||||||||||||||
| FedEx Express aircraft fleet | 679 | 681 | 670 | 657 | 643 |
| (1) | Results for 2020 include noncash goodwill and other asset impairment charges of $435 million ($416 million, net of tax, or $1.58 per diluted share) primarily related to goodwill impairment at FedEx Office and from the decision to permanently retire certain aircraft and related engines at FedEx Express. |
|---|
| (2) | Results include TNT Express integration expenses (including any restructuring charges) of $270 million ($209 million, net of tax, or $0.80 per diluted share) in 2020, $388 million ($314 million, net of tax, or $1.18 per diluted share) in 2019, $477 million ($372 million, net of tax, or $1.36 per diluted share) in 2018 and $327 million ($245 million, net of tax, or $0.91 per diluted share) in 2017. These expenses are included in “Corporate, other and eliminations” and the FedEx Express segment. |
|---|
| (3) | Results include the following: MTM retirement plans accounting adjustments: net loss of $794 million ($583 million, net of tax, or $2.22 per diluted share) in 2020 and net loss of $3.9 billion ($3.0 billion, net of tax, or $11.22 per diluted share) in 2019; net gains of $10 million ($9 million, net of tax, or $0.03 per diluted share) in 2018 and $24 million ($6 million, net of tax, or $0.02 per diluted share) in 2017; and a net loss of $1.5 billion ($946 million, net of tax, or $3.39 per diluted share) in 2016. See Note 1 and Note 13 to the accompanying consolidated financial statements for additional information. |
|---|
- 149 -
| (4) | Results for 2019 include business realignment charges of $320 million ($243 million, net of tax, or $0.91 per diluted share), costs incurred in connection with the settlement of a legal matter involving FedEx Ground of $46 million ($43 million, net of tax, or $0.16 per diluted share) and a net U.S. deferred tax liability remeasurement of $4 million ($0.02 per diluted share) for lower tax rates. |
|---|
| (5) | Results for 2018 include tax benefits of $2.1 billion ($7.71 per diluted share), which includes benefits of $1.6 billion related to the TCJA as follows: a provisional benefit of $1.15 billion ($4.22 per diluted share) for the remeasurement of our net U.S. deferred tax liability for lower tax rates; a benefit of $204 million ($0.75 per diluted share) from an incremental pension contribution made in the third quarter and deductible against prior year taxes at 35%; and a benefit of approximately $265 million ($0.97 per diluted share) for the phase-in of the reduced tax rate applied to 2018 earnings. The remaining 2018 tax benefits include a net benefit of $255 million ($0.94 per diluted share) from corporate structuring transactions as part of the ongoing integration of FedEx Express and TNT Express and a benefit of $225 million ($0.83 per diluted share) from foreign tax credits associated with distributions to the U.S. from foreign operations. In addition, 2018 results include $380 million ($379 million, net of tax, or $1.39 per diluted share) of goodwill and other asset impairment charges related to FedEx Supply Chain and charges of $8 million ($6 million, net of tax, or $0.02 per diluted share) for legal reserves related to certain U.S. Customs and Border Protection (“CBP”) matters involving FedEx Logistics. |
|---|
| (6) | Results for 2017 include charges for legal reserves related to certain CBP matters involving FedEx Logistics for $39 million ($24 million, net of tax, or $0.09 per diluted share) and charges in connection with the settlement of and certain expected losses relating to independent contractor litigation matters at FedEx Ground in the amount of $22 million ($13 million, net of tax, or $0.05 per diluted share). |
|---|
| (7) | Results for 2016 include provisions related to independent contractor litigation matters at FedEx Ground for $256 million, net of recognized immaterial insurance recovery ($158 million, net of tax, or $0.57 per diluted share), and expenses related to the settlement of a CBP notice of action involving FedEx Logistics in the amount of $69 million, net of recognized immaterial insurance recovery ($43 million, net of tax, or $0.15 per diluted share). Total transaction, financing and integration-planning expenses related to our TNT Express acquisition, as well as TNT Express’s immaterial financial results from the time of acquisition, were $132 million ($125 million, net of tax, or $0.45 per diluted share) during 2016. In addition, 2016 results include a $76 million ($0.27 per diluted share) favorable tax impact from an internal corporate legal entity restructuring to facilitate the integration of FedEx Express and TNT Express. |
|---|
| (8) | Includes reclassifications to conform to the current year presentation of newly adopted pension guidance which requires us to report only the service cost component in the “Salaries and employee benefits” line item. The other components of net benefit cost are required to be presented in the income statement in other income, outside of income from operations. |
|---|
| (9) | Includes adjustments in 2016 related to our adoption of an accounting standard that requires us to classify debt issuance costs related to a recognized debt liability as a direct deduction from the carrying amount of that debt liability, rather than as an asset. |
|---|
- 150 -
Report of Independent Registered Public Accounting Firm
To the Stockholders and Board of Directors of
FedEx Corporation
We have audited the consolidated financial statements of FedEx Corporation (the Company) as of May 31, 2020 and 2019, and for each of the three years in the period ended May 31, 2020, and have issued our report thereon dated July 20, 2020 included elsewhere in this Form 10-K. Our audits of the consolidated financial statements included the financial statement schedule listed in Item 15(a) of this Form 10-K (the “schedule”). This schedule is the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s schedule, based on our audits.
In our opinion, the schedule presents fairly, in all material respects, the information set forth therein when considered in conjunction with the consolidated financial statements.
/s/ Ernst & Young LLP
Memphis, Tennessee
July 20, 2020
- 151 -
SCHEDULE II
FEDEX CORPORATION
VALUATION AND QUALIFYING ACCOUNTS
FOR THE YEARS ENDED MAY 31, 2020, 2019 AND 2018
(IN MILLIONS)
| ADDITIONS | ||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| DESCRIPTION | BALANCE AT BEGINNING OF YEAR | CHARGED TO EXPENSES | CHARGED TO OTHER ACCOUNTS | DEDUCTIONS | BALANCE AT END OF YEAR | |||||||||||||||
| Accounts Receivable Reserves: | ||||||||||||||||||||
| Allowance for Doubtful Accounts | ||||||||||||||||||||
| 2020 | $ | 121 | $ | 442 | $ | — | $ | 388 | (a) | 175 | ||||||||||
| 2019 | 199 | 295 | — | 373 | (a) | 121 | ||||||||||||||
| 2018 | 115 | 246 | — | 162 | (a) | 199 | ||||||||||||||
| Allowance for Revenue Adjustments | ||||||||||||||||||||
| 2020 | $ | 179 | $ | — | $ | 1,286 | (b) | $ | 1,250 | (c) | $ | 215 | ||||||||
| 2019 | 202 | — | 1,192 | (b) | 1,215 | (c) | 179 | |||||||||||||
| 2018 | 137 | — | 1,173 | (b) | 1,108 | (c) | 202 | |||||||||||||
| Inventory Valuation Allowance: | ||||||||||||||||||||
| 2020 | $ | 335 | $ | 33 | $ | — | $ | 33 | $ | 335 | ||||||||||
| 2019 | 268 | 28 | 75 | 36 | 335 | |||||||||||||||
| 2018 | 237 | 27 | 6 | 2 | 268 |
| (a) | Uncollectible accounts written off, net of recoveries, and other adjustments. |
|---|
| (b) | Principally charged against revenue. |
|---|
| (c) | Service failures, rebills and other. |
|---|
- 152 -
Previous: Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES