 filings.tools
F5 10-K 2021-09-30
Filed 2021-11-16. 22 sections, 399K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
Form 10-K
(Mark One)
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the fiscal year ended September 30, 2021
or
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 | ||||
| For the transition period from to . |
Commission File Number 000-26041
F5, Inc.
(Exact name of Registrant as specified in its charter)
| Washington | 91-1714307 | |||||||
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) |
801 5th Avenue
Seattle, Washington 98104
(Address of principal executive offices, including zip code)
(206) 272-5555
(Registrant’s telephone number, including area code)
F5 Networks, Inc.
(Former name or former address, if changed since last report)
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbol(s) | Name of Each Exchange on Which Registered | ||||||
| Common stock, no par value | FFIV | NASDAQ Global Select Market |
Securities registered pursuant to Section 12(g) of the Act:
None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the Registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company” and "emerging growth company" in Rule 12b-2 of the Exchange Act. (Check one):
| Large Accelerated Filer | ☑ | Accelerated Filer | ☐ | |||||||||||||||||
| Non-accelerated Filer | ☐ (Do not check if a smaller reporting company) | Smaller Reporting Company | ☐ | |||||||||||||||||
| Emerging Growth Company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☒
As of March 31, 2021, the aggregate market value of the Registrant’s Common Stock held by non-affiliates of the Registrant was $12,481,712,486 based on the closing sales price of the Registrant’s Common Stock on the NASDAQ Global Select Market on that date.
As of November 8, 2021, the number of shares of the Registrant’s common stock outstanding was 61,229,388.
DOCUMENTS INCORPORATED BY REFERENCE
Information required in response to Part III of this Form 10-K (Items 10, 11, 12, 13 and 14) is hereby incorporated by reference to the specified portions of the Registrant’s Definitive Proxy Statement for the Annual Shareholders Meeting for fiscal year 2021, which Definitive Proxy Statement shall be filed with the Securities and Exchange Commission pursuant to Regulation 14A within 120 days of the end of the fiscal year to which this Report relates.
F5, INC.
ANNUAL REPORT ON FORM 10-K
For the Fiscal Year Ended September 30, 2021
Table of Contents
Forward-Looking Statements
This Annual Report on Form 10-K contains forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934 and Section 27A of the Securities Act of 1933. These statements include, but are not limited to, statements about our plans, objectives, expectations, strategies, intentions or other characterizations of future events or circumstances and are generally identified by the words “expects,” “anticipates,” “intends,” “plans,” “believes,” “seeks,” “estimates,” and similar expressions. These forward-looking statements are based on current information and expectations and are subject to a number of risks and uncertainties. Our actual results could differ materially and adversely from those expressed or implied by these forward-looking statements. Factors that could cause or contribute to such differences include, but are not limited to, those discussed under “Item 1A. Risk Factors” below and in other documents we file from time to time with the Securities and Exchange Commission. We assume no obligation to revise or update any such forward-looking statements.
Unless the context otherwise requires, in this Annual Report on Form 10-K, the terms “F5,” “the Company,” “we,” “us,” and “our” refer to F5, Inc. and its subsidiaries. Our fiscal year ends on September 30, and fiscal years are referred to by the calendar year in which they end. For example, “fiscal year 2021” and “fiscal 2021” refer to the fiscal year ended September 30, 2021.
Item 1. Business
General
F5 is a multi-cloud application security and delivery company. We see a world where we enable our customers’ applications to adapt to changing environments, automating redundant processes for greater efficiencies, expanding and contracting based on performance needs, protecting themselves, and securing points of vulnerability. Adaptive applications bring intelligence and real-time changes to the world of application deployments, which today are mostly static and manual.
Our enterprise-grade solutions are available in a range of consumption models, from on-premises to managed services, optimized for multi-cloud environments. In connection with our solutions, we offer a broad range of professional services, including consulting, training, installation, maintenance, and other technical support services.
On January 25, 2021, we completed the acquisition of Volterra, a provider of edge-as-a-service platform solutions. The F5+Volterra platform will be designed to address challenges found with current edge solutions that are built on CDNs and have limited security features. F5’s new enterprise-focused edge will be security-first and app-driven, with unlimited scale.
Our customers include large enterprise businesses, public sector institutions, governments, and service providers. We conduct our business globally and manage our business by geography. Our business is organized into three geographic regions: Americas; Europe, the Middle East, and Africa (EMEA); and the Asia Pacific region (APAC).
Our revenue is comprised of services revenue and product revenue. While the majority of our product revenue today is derived from appliance sales, we are actively managing a transformation to a software- and SaaS-driven business with product revenue from software sales growing 40% in fiscal year 2021 and representing 40% of product revenue.
At the end of fiscal 2021, we had product backlog of approximately $124.9 million. Backlog is primarily systems-based and represents orders confirmed with a purchase order for products to be fulfilled and invoiced, generally within 90 days to customers with approved credit status. Orders are subject to cancellation, rescheduling by customers, or product specification changes by customers. Although we believe that the backlog orders are firm, purchase orders may be canceled by the customer prior to fulfillment without significant penalty. For this reason, we believe that our product backlog at any given date is not a reliable indicator of future revenues.
F5 was incorporated on February 26, 1996 in the state of Washington. Our headquarters is in Seattle, Washington, and our mailing address is 801 5th Avenue, Seattle, Washington 98104-1663. The telephone number at that location is (206) 272-5555. Our website is www.f5.com. We have 80 subsidiaries, branch offices, or representative offices worldwide. Through a link on the Investor Relations section of our website, we make available the following filings as soon as reasonably possible after they are electronically filed with or furnished to the Securities and Exchange Commission (SEC): our Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K, and any amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act. All such filings are available free of charge. The information posted on our website is not incorporated into this report.
Strategy and Priorities
F5 is focused on solving our customers’ most important application challenges and we have continued to evolve our business as our customer’s needs have changed. Today, our customers need to securely and cost effectively deliver extraordinary digital experiences to their end users, which include employees, consumers and partners. F5’s portfolio of multi-cloud application security and delivery technologies enables our customers to scale, secure and optimize both traditional and modern applications, making those amazing digital experiences possible. Adaptive applications utilize an architectural approach that can rapidly respond to changes in performance, global availability, or security problems across one or more infrastructure environments and with little to no human interaction. These apps are enabled by a near-real-time collection of live application telemetry, analyzed by machine learning and artificial intelligence techniques, and harnessed to automation toolchains to rapidly adjust infrastructure to new conditions.
Key components of our strategy include:
Bringing our adaptive application vision to life
F5 is uniquely positioned to deliver adaptive applications. Through our organic investments and the acquisitions of NGINX in May 2019, Shape Security in January 2020, and Volterra in January 2021, we have assembled the broadest portfolio of application security and delivery technologies in the market today. As a result of the continued evolution of our BIG-IP family, we enable customers to transition traditional applications from data centers to multi-cloud environments while maintaining private data center levels of security. At the same time, we are enabling modern application architectures with our NGINX technologies, F5 SaaS offerings, and Aspen Mesh. Our State of Application Strategy Report 2021 shows 87% of organizations are managing a complex application portfolio spanning traditional and modern architectures. F5 is unique in our ability to span both traditional and modern architectures, as a result, our customers are able to provision consistent, and industry-leading application security across their combined traditional and modern application portfolio. In addition, we are leveraging our access to application data and our analytics capabilities to enable automation and unlock business insights for our customers.
Transforming how customers experience F5
As we expand the role we play for our customers, we are also transforming how our customers experience F5. We have made it easier for our customers to procure, deploy, manage, and upgrade our technologies by introducing new consumption models and continuing to evolve our solutions’ capabilities.
As we have expanded our offerings, we are better able to solve a broader range of customer challenges and increasingly, customers are choosing a suite of F5 solutions. Going forward we will leverage and grow our foundational capabilities in data and insights, digital sales, and SaaS-delivered capabilities to deliver consistent world-class customer experiences, including simple, integrated and friction-free consumption of our technologies. We will continue to improve customer awareness and understanding of F5’s expanded portfolio with a focus on buying personas and business needs and intend to enhance our digital customer experiences to deliver both growth and efficiency.
Capturing growth in security and software
Our ability to serve both traditional and modern architectures means we are uniquely suited to provide consistent, industry-leading security across our customers entire application estate. Over the last ten years, enterprises were focused on protecting their networks from attack. Attacks are now focused on the applications with threats like malware, bots, and API penetration.
Our acquisition of Shape Security brings the leader in online fraud and abuse prevention, adding protection against automated attacks, bots, and targeted fraud, to F5’s world-class portfolio of application security and delivery technologies. Volterra’s SaaS platform will help detect threats more rapidly and reduce neutralization times. Together, F5’s portfolio provides maximum protection and reduced risk for all applications across data centers, cloud, and the edge. This reduces our customers’ total cost of application security by reducing standalone products and leveraging a unified portfolio of on-premises and SaaS-based controls.
In the last several years, we have significantly enhanced and expanded our software offerings. Our meaningful software growth over the last two years has largely been driven by steps we have taken to improve automation and orchestration in our BIG-IP software, making it easier to procure, deploy and upgrade, as well as the introduction of new flexible commercial models, including annual and longer-term subscriptions. We expect to drive continued software and SaaS growth from additional enhancements to our BIG-IP family, as well as advancements and continued customer adoption of NGINX, application security, Shape, and Volterra solutions.
F5 Products and Solutions
F5’s portfolio of multi-cloud application security and delivery technologies are enabling customers to address the challenges of delivering differentiated digital experiences to their customers.
Simplifying traditional app delivery for multi-cloud environments
Our BIG-IP family of offerings provides feature-rich, highly programmable and configurable application delivery solutions for traditional applications in enterprises and service providers. Traditional applications are based on monolithic, three-tier, or client-server architectures. Such traditional applications are the most ubiquitous application architecture today, and many organizations continue to rely exclusively on traditional applications to power the most mission-critical business applications, customer facing digital interfaces and internally used applications.
For most organizations, the priority around traditional applications is maximizing operational efficiency and minimizing the total cost of ownership. BIG-IP has established itself as the leading application security and delivery technology for traditional applications, providing load balancing, and DNS (domain name system) services. Many customers also use the advanced security capabilities of BIG-IP, including WAF (web application firewall), carrier-grade firewall and NAT (network address translation), identity-aware proxy, SSL-VPN, and SSL (securer sockets layer) offloading, that are available as tightly-integrated modules or extensions. Via the F5 Automation Toolchain, BIG-IP capabilities easily integrate into orchestration frameworks such as Ansible, HashiCorp Terraform, OpenShift, and Cloud Foundry as part of a CI/CD pipeline. BIG-IPs “best-of-suite” approach helps standardize and consolidate application delivery and security functions into a single solution, and enables automating the functions to reduce operational cost.
BIG-IP capabilities are available in software-only Virtual Editions (VEs) that deploy on any standard hypervisor in private and public clouds and are available in many performance throughput options. VEs can be deployed on public clouds, including Amazon Web Services, Microsoft Azure, and Google Cloud Platform, through Bring Your Own License (BYOL) and the public cloud marketplaces. VEs are available via utility pricing (via public cloud marketplaces), short- and long-term subscriptions, and perpetual licensing models. In addition, F5 offers customers additional licensing, consumption flexibility, and value via our flexible consumption program or multi-year subscriptions.
F5 BIG-IQ Centralized Management provides central management, analytics, and automation for BIG-IP instances. Available in virtual or physical form factors, BIG-IQ simplifies, enhances management of, and reduces customer operational costs associated with BIG-IP deployments.
F5’s physical systems are designed to enhance the performance of our software by leveraging a combination of custom FPGA logic and off-the-shelf silicon, providing a balance of cost and flexibility. Currently, we offer two types of physical configurations: BIG-IP iSeries appliances and chassis-based VIPRION and VELOS systems. Both BIG-IP iSeries and our chassis-based systems run the same BIG-IP software modules as are available in the Virtual Edition and are licensed on a perpetual basis or subscription basis. To help customers comply with regulatory requirements and protect sensitive data, our physical systems are certified up to NIST FIPS 140-2 Level 2 and Common Criteria Evaluation Assurance Level (EAL 4+). BIG-IP iSeries appliances and chassis-based systems differ primarily in their performance and size characteristics resulting from the hardware components and configurations that make up these systems. As we align to modern architectures, we also added the VELOS chassis-based system to our lineup. VELOS relies on a Kubernetes-based platform layer that is integrated tightly with F5’s TMOS software. In addition, going to a microservice-based platform layer allows VELOS to provide new and exciting features that were not possible in previous generations of F5 BIG-IP platforms.
Enabling modern app delivery at scale
To better address the needs of digitally transforming enterprises that have a mix of traditional, three-tier architectures and cloud-first microservices architectures, our NGINX technologies offer lightweight, agile ADC and API management software for container-built applications, CI/CD workflows, and microservices. Our NGINX technology enables developer and DevOps agility to get applications to market quickly, with security and automation closer to the code.
Our NGINX product offerings are:
-
NGINX Plus, an all-in-one load balancer, web server, content cache, and API gateway for modern applications.
-
NGINX Controller, which provides orchestration and analytics for NGINX Plus.
-
NGINX Ingress Controller and NGINX Service Mesh, which provide traffic management for Kubernetes clusters.
-
NGINX App Protect, which integrates F5’s market-leading WAF with the flexibility and performance of NGINX Plus.
We believe NGINX solutions help our customers enable adaptive applications in container, cloud-native, and microservices environments, providing the ease-of-use and flexibility developers require while also delivering the scale, security, reliability, and enterprise readiness network operations teams demand.
F5 SaaS offerings support modern cloud application delivery and security use cases for cloud-native applications, making it easier for developers and DevOps engineers to build in the application services required for production.
Securing applications and APIs everywhere
F5’s advanced application security services, including DDoS (distributed denial of service) mitigation, WAF (web application firewall), bot protection, SSL/TLS traffic decryption, and API discovery/control provide best-in-class protection for applications and infrastructure across any deployment model, from on-premises to multi-cloud to the network edge.
For protecting web applications from advanced threats and malware, F5 has several solutions. F5 Advanced WAF has been an industry-leading web application firewall for many years. It employs countermeasures to detect and stop evolving application-layer threats, integrating behavioral analysis and dynamic code injections as its two main mechanisms to more completely assess the threat associated with any given client session.
NGINX App Protect provides web application protection with self-service access and API-driven integration into automation and orchestration frameworks. Often referred to as “shifting security left,” this ensures security is applied earlier in the software development lifecycle and covers the full portfolio of modern and long-tail applications in the enterprise.
Shape's technology addresses the increasing sophistication of automated bot attacks as well as fraud and abuse. Shape’s artificial intelligence platform protects the largest banks, airlines, retailers, and federal agencies against bots and fraud which bypass best-practice industry security controls. Shape protects more than one billion accounts worldwide against credential stuffing attacks, the industry’s leading cybersecurity threat.
Shape’s advanced technology consists of next-generation client-side JavaScript and SDKs (software development kits), horizontally scalable reverse proxy and API services, and large-scale machine learning, analytics, and data platform systems, which work together to deliver the highest anti-fraud efficacy in the industry. This technology is sold as integrated, fully-managed services in an “outcome-as-a-service” cybersecurity model.
Volterra provides advanced machine learning (ML)-based API protection through API auto-discovery and control. Volterra VoltMesh automatically discovers all APIs in an application environment without the need for manual DevOps/DevSecOps actions. It then automatically allows only those APIs that are safe and required for a given workflow. It also baselines API activity and continually monitors for anomalous behavior to ensure ongoing protection in the often-dynamic environment of modern applications.
Silverline provides customers fully-managed application security. Current offerings include Silverline Web Application Firewall, Silverline DDoS Protection, and Silverline Threat Intelligence Services. These services provide enterprise and service provider customers with F5’s proven security technologies coupled with world-class security professionals. Silverline’s Security Operations Center experts set up, manage, and support each customer's application solutions as an extension to the customer’s staff. In F5’s third fiscal quarter, Shape technology was combined with F5's Silverline managed services platform to launch Silverline Shape Defense, creating a version of Shape’s technology platform capabilities for customers who prefer a managed service.
Depending on the level of protection required, customers can route traffic through the Silverline cloud-based platform 24/7 or only when an attack is detected. Silverline Managed Services also provides an affordable and straightforward deployment alternative for customers who want to minimize the upfront costs and expense of maintaining on-premises solutions. For large enterprises, subscribing to Silverline Managed Services in conjunction with our on-premises DDoS Hybrid Defender and Advanced WAF can provide the first line of defense against attacks, and prevent them from having a significant downtime impact on their application or network services.
Unlocking the value of application insights
Shape’s technology platform enables generalized AI-powered user analytics. While Shape has focused on using these capabilities to detect advanced fraud and abuse, going forward, the same technology is being integrated throughout F5 to create general AI-powered user analytics capabilities within and beyond cybersecurity use cases.
Service Provider Solutions
BIG-IP offerings also comprise our service provider solutions that address the complex requirements for enabling fast, secure, reliable communications among the elements of existing infrastructures such as 4G/LTE and evolving to newly designed cloud-native 5G networks, network functions virtualization (NFV) environments, and edge computing.
In addition to the solutions described above, F5 also offers solutions for fixed and mobile service provider customers to enable fast, secure, reliable communications in their networks. These solutions include intelligent traffic management services to classify and manipulate network traffic to successfully manage and migrate to newer technologies such as IPv4 to IPv6 and 4G to 5G. Our carrier-class network firewall services are used to secure the Gi/N6 interface, secure signaling threats and IoT applications, and detect and mitigate DDoS attacks. Our solutions are also used by our customers to secure complex signaling for mobility protocols like Diameter, SIP, and GTP, as well as IoT protocols. All F5 software solutions can be delivered on dedicated F5 hardware, as Virtual Network Functions (VNFs) that can use F5 VNF Manager or other industry solutions to deploy and manage VNF instances, and are evolving as Container Network Functions (CNF).
Competition
As F5 expands its reach and role into a broader set of multi-cloud solutions, the companies that we consider competitors evolves as well. In addition to server load balancing, traffic management, and other functions normally associated with application delivery, our suite of solutions has expanded our addressable market into security, and policy management, where we compete with a number of companies focused on niche areas of application security.
Within application delivery, we compete against Citrix Systems and a number of other competitors that have a smaller market presence or limited feature set, such as Amazon Web Services, HAProxy, Kemp Technologies, Microsoft Azure, and VMware.
We see emerging demand to support modern, container-based applications with new capabilities including managing APIs, optimizing Kubernetes traffic management, load balancing cloud-native and hybrid cloud applications and providing service mesh. For these use cases, we compete against emerging players like Apogee and Kong.
In application security, we compete with companies that provide web application firewalls, bot detection and mitigation, carrier-grade firewall, carrier-grade NAT, SSL orchestration, access policy management, DDoS protection, and fraud defense. Competitors include Akamai, Citrix Systems, Imperva, Juniper Networks, and Symantec/Blue Coat. With the addition of Shape, additional fraud, abuse, and analytics solutions become indirect competitors, including Akamai, Cloudflare, Imperva (Distil Networks), Fastly (Signal Sciences) and PerimeterX.
Volterra’s use cases include multi-cloud networking, as well as security offered as SaaS, competing with the likes of Imperva, Fastly, Akamai, and Cloudflare.
The principal competitive factors in the markets in which we compete include form factor, consumption model, ecosystem integrations, features and performance, customer support, brand recognition, scope of distribution and sales channels, and pricing. Some of our competitors have already tried or plan to adopt aggressive pricing policies to gain market share. However, because F5 offers superior performance, broad functionality, including lighter-weight options with NGINX and Volterra, we believe that we can and will compete effectively against such pricing policies.
Corporate Functions
Customer Services and Technical Support
In connection with our products, we offer a broad range of professional services including consulting, training, installation, maintenance, and other technical support services.
We believe that our ability to provide consistent, high-quality customer service and technical support is a key factor in attracting and retaining large enterprise and service provider customers. Accordingly, we offer a broad range of support services that includes installation, phone and online technical support, hardware repair and replacement, software updates, online tools, consulting, and training services.
We provide these services directly to end users and also utilize a multi-tiered support model, leveraging the capabilities of our channel partners. Our technical support staff is strategically located in regional service centers to support our global customer base.
Product Development
We believe our future success depends on our ability to maintain technology leadership by continuing to improve our products and by developing new products to meet the changing needs of our customers and partners. Our engineering
organization uses standard processes for the development, documentation, and quality control of services, software, and systems that are designed to meet these goals. These processes include working with our business development and marketing teams, customers, and partners to identify technology innovation opportunities to better meet the evolving needs of our addressable markets.
Over 90 percent of our engineers are engaged in software, SaaS, and managed services development in several major locations including Seattle, Washington; Hyderabad, India; Tel Aviv, Israel; San Jose and San Francisco, California; Cork, Ireland; and Moscow, Russia.
Our hardware engineering team is located in Spokane, Washington; San Jose, California; and Tel Aviv, Israel.
Smaller development sites including Boulder, Colorado; Warsaw, Poland; and Billerica, Massachusetts also support the core development teams in the larger centers.
Members of all our engineering teams collaborate closely with one another to ensure the interoperability and performance of our solutions.
We believe that robust and constant innovation is a necessity for F5, so we are also innovating in new ways. For more than a year now, we have had dedicated teams focused on testing new disruptive innovations in technology, business models, or customer segments. We expect innovations resulting from the work of these teams will be complementary to our goal of delivering the broadest and most consistent portfolio of solutions across cloud and on-premises environments.
We rely on a combination of patent, copyright, trademark, and trade secret laws and restrictions on disclosure to protect our intellectual property rights. F5 holds 433 patents in the United States and has 59 international patents (with applications pending for various aspects of our technology). Our future success depends in part on our ability to protect our proprietary rights to the technologies used in our principal products. Despite our efforts to protect our proprietary rights, unauthorized parties may attempt to copy aspects of our products or to obtain and use trade secrets or other information that we regard as proprietary. In addition, the laws of some foreign countries do not protect our proprietary rights as fully as the laws of the United States. Any issued patent may not preserve our proprietary position, and competitors or others may develop technologies similar to or superior to our technology. Our failure to enforce and protect our intellectual property rights could harm our business, operating results, and financial condition.
In addition to our own proprietary software, we incorporate software licensed from several third-party sources into our products. These are generally term licenses which may renew annually and that generally provide for certain rights and licenses to support our customers post termination. While we may not be able to renew all of these licenses in the future, we believe that alternative technologies for these licenses are available both domestically and internationally.
During the fiscal years ended September 30, 2021, 2020 and 2019, we had research and product development expenses of $512.6 million, $441.3 million, and $408.1 million, respectively.
Sales and Marketing
Our customers include a wide variety of enterprises and service providers among Fortune 1000 and Business Week Global 1000 companies, including those in technology, telecommunications, financial services, transportation, education, manufacturing, healthcare, and government. In fiscal year 2021, sales outside of the Americas represented 44.0% of our net revenues. Refer to Note 16 of our consolidated financial statements included in this Annual Report on Form 10-K for additional information regarding our revenues by geographic area.
Sales
We sell our products and services to large and medium enterprise customers, including federal government entities, financial services customers and service providers through a variety of routes to market and channels. Our sales teams sell our products and services directly to customers by working closely with our channel partners including distributors, value-added resellers (VARs), managed service providers (MSPs), and systems integrators.
F5 sales teams. Our inside sales team generates and qualifies leads from marketing and helps manage accounts by serving as a liaison between the field and internal corporate resources. Our outside sales team works directly with partners and customers across the globe. Our field sales personnel are located in major cities in three sales regions: the Americas (primarily the United States); Europe, the Middle East, and Africa (EMEA); and the Asia Pacific region (APAC). Field sales personnel work closely with our channel partners to sell our products and services to their customers. We reward partners that identify new business and provide sales expertise for our portfolio of products and solutions through various incentive programs. Systems engineers, with deep technical domain expertise, support our regional sales account managers and channel partners providing pre-sale technical solution engineering and support, as needed.
Distributors, VARs, and MSPs. As a key component of our sales strategy, we have established relationships with a number of large national and international distributors, local and specialized distributors, VARs, and MSPs. We derive a majority of our product sales from VARs and MSPs, relying on our large distributors for fulfillment, training, and partner enablement.
Our agreements with our channel partners are not exclusive and do not prevent them from selling competitive products. These agreements typically have one-year terms with no obligation to renew, and typically do not provide for exclusive sales territories or minimum purchase requirements.
For fiscal year 2021, sales to two of our worldwide distributors, Ingram Micro, Inc. and Synnex Corporation represented 19.2% and 11.1% of our total revenues, respectively. Our agreements with distributors are standard, non-exclusive distribution agreements that renew automatically on an annual basis and generally can be terminated by either party with 90 days written notice prior to the start of any renewal term. The agreements grant certain distributors the right to distribute our products to resellers, with no minimum purchase requirements.
Systems integrators. We also market our products through strategic relationships with systems integrators, including Dell Services, DXC, HP Enterprise Services, and IBM Global Services, who include our products as core components of application deployments or network-based solutions they deploy for their customers. In most cases, systems integrators do not directly purchase our products for resale to their customers. Instead they typically recommend and/or manage our products as a part of broader solutions supporting enterprise applications and Internet facing systems that incorporate our technology for security, high availability, and enhanced performance.
Resellers and technology partners. Historically, our ability to compete with much larger companies has been strengthened through partnerships with large systems and software vendors. Currently, we partner with many technology partners and public cloud providers who resell our products. We have ongoing partnerships with the major cloud providers such as Amazon Web Services (AWS), Microsoft Azure, and Google Cloud Platform and have expanded our reseller routes to market to include their public cloud marketplaces. F5 has recently signed a Strategic Collaboration Agreement (SCA) with AWS, and are actively engaged with Microsoft Azure on private offers levering our software on Azure. Our business development team manages these relationships and closely monitors adjacent and complementary markets for opportunities to partner with those whose solutions are complementary to ours and could enable us to expand our addressable market.
Marketing
As we continue to expand our offerings and advance our range of consumption models (e.g., from on-premises to managed services), we continue to focus on driving a compelling and unique value proposition of F5 among our existing customers as well as new buying centers. In addition to revitalizing our brand in the market, our expansion into new buying centers among existing customers (DevOps for example), exploration of new routes to market (such as public cloud marketplaces), and acquisition of a host of net new customers, compels us to increase our focus and investments in more digitally-enabled, personalized and effortless experiences at scale.
We are increasing our focus on efforts to drive momentum behind our brand and reputation to deliver clarity, guidance and inspiration among our existing customers, future customers, partners, and employees around our evolving strategy behind F5’s unique offering. Additionally, to best support our growth as we transform our role in driving value for our customers, we are transforming marketing from a cost center to a revenue center to serve as a meaningful and predictable source of opportunities, customer growth and revenues. The critical success factors in this shift are increased investments in digital technologies, requisite competencies, and shifting our culture to adopt an agile mindset as we use data to constantly improve our contributions to our customers and ultimately our shareholders.
Manufacturing
We outsource the manufacturing of our pre-configured hardware platforms to a third-party contract manufacturer, Flex Ltd. ("Flex"), for building, assembling, and testing according to our specifications at Flex's facilities in Guadalajara, Mexico and Zhuhai, China. Flex also performs the following activities on our behalf: material procurement, PCB assembly and test, final assembly, system test, quality control, and direct shipment.
We provide a rolling forecast that allows Flex to stock component parts and other materials, plan capacity, and build finished goods inventory in anticipation of end-user demand. Flex procures components in volumes consistent with our forecast, assembles the products, and tests them according to our specifications. Generally, we do not own the system components. Hardware components for our products consist primarily of commodity parts and certain custom components. Many of our components are purchased from sources which we believe are readily available from other suppliers. However, we currently purchase several hardware components used in the assembly of our products from a number of single or limited
sources. Lead times for these components vary significantly and are increasing in light of global shortages of critical components. Global supply chain constraints in the wake of the COVID-19 pandemic continue to decrease our visibility into component availability and lead times even for commodity components. Also, if the components are unused or the products are not sold within specified periods of time, we may incur carrying charges or obsolete material charges for components that our contract manufacturers purchased to build products to meet our forecast or customer orders.
Systems built in Guadalajara are shipped to the Flex fulfillment center in Milpitas, California for distribution primarily to distributors, value-added resellers, or end users in EMEA and the Americas. Systems built and fulfilled in Zhuhai are for distribution to partners and customers in APAC. Title to the products transfers from Flex to us and then to our customers upon shipment from a designated fulfillment location.
Employees
As of September 30, 2021, we had 6,461 employees – over 99% of whom were full time employees. Our employees are in 47 countries with 52% of employees in the United States. None of our employees are represented by a labor union. We have experienced no work stoppages and believe that our employee relations are in good standing, as evidenced by our bi-annual employee engagement survey results.
Culture and engagement
In 2018, we defined and launched BeF5. BeF5 conveys our Guiding Principle of “Do the right thing” and the five behaviors which unite F5ers and which we expect all employees to emulate. In early 2021, these behaviors were updated (updating “We choose speed” to “We make F5 more agile”) and language to describe each was refined based on employee feedback.
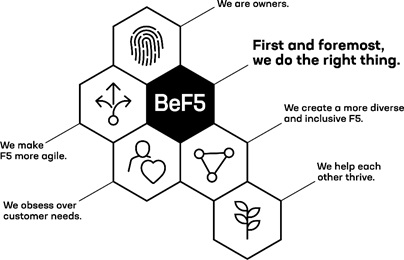
In 2019, we defined and created our principles for leadership, referred to as LeadF5.
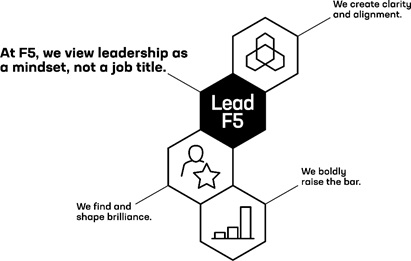
Communications, performance management, development, and a number of other employee engagement activities connect and reinforce BeF5 and LeadF5.
F5 supports employees and our culture through competitive benefits, regular communications through formal (quarterly all hands with extensive question and answer sessions with execs) and informal (“Monday Minute” newsletter and company intranet) means, and a quarterly Zoom Out Day, dedicated to learning and exploring new ideas. During the current global crisis surrounding COVID-19, racial injustice, political uncertainty and natural disasters, we have provided employees and leaders with a variety of support and resources to help them thrive, including new wellness programs, educational series, and four additional days of time off dedicated to wellness.
F5 also provides flexible working opportunities through our Freedom to Flex program which allows employees to choose whether to work in an office, remotely or a blend of the two. Established in 2018, Freedom to Flex has provided the foundation for our flexibility throughout the pandemic and will continue to remain in place after it is safe to re-open all offices fully. Most of our workforce will have the option to remain working remotely some or all of the time. To support the increased use of the Freedom to Flex program going forward, resources and learning opportunities are available for managers and leaders to assist in effectively leading hybrid teams (defined as teams which have some employees in office and others remote from office), and technology to support ongoing connection and productivity among these hybrid teams.
Employee experience and sentiment is measured through global employee surveys at least twice each year, with Belonging (“I feel a sense of belonging at F5”) as our keystone measure. As of May 2021, employees reported high satisfaction on several key questions:
-
81% of employees favorably rate “I feel a sense of belonging at F5."
-
88% of employees favorably rate “I am proud to work for F5."
-
87% of employees favorably rate “F5 really demonstrates a commitment to ‘We create a more diverse and inclusive F5’”
-
87% of employees favorably rate “F5 has a great culture."
-
94% of employees favorably rate “F5 has demonstrated that employee well-being and health is a priority during the coronavirus outbreak."
Growth and development
Ongoing development of our workforce is supported across multiple learning organizations within F5, providing opportunities to improve technical and professional knowledge, better understand our business and products, and strengthen management and leadership. Example opportunities include a mentoring program, LeadF5 Coaching, which provides an opportunity for several hundred employees to receive professional and personal coaching annually, and through learning paths created to support specific areas of knowledge, including deepening their knowledge of BeF5 and LeadF5. Employees have access to multiple third-party resources to enhance the learning opportunities developed internally.
Diversity and Inclusion
F5 believes our differences—when embraced with humility and respect—drive smarter decisions, increased innovation, stronger performance, and a culture where everyone can be themselves and reach their full potential.
Employee Inclusion Groups (EIGs) – F5 Ability, F5 Appreciates Blackness, F5 Connects Women, F5 Latinx e Hispanos Unidos, F5 Military Veterans, F5 Multicultural and F5 Pride – bring people together across F5 around the world. All seven EIGs are led by employees, with a dedicated annual budget and executive sponsor. F5’s EIG leaders participate in an F5 sponsored leadership development program with dedicated time toward cultivating their EIG and growing as a leader themselves. In fiscal 2021, our EIG leaders received an end of the year bonus for their contributions. Participation in these leadership roles will be bonus eligible going forward. In this way, F5 continues to invest in a thriving community of diverse individuals.
We have also steadily increased our transparency in both our actions and the accompanying results culminating in our inaugural F5 Diversity and Inclusion Report available at f5.com. Therein, you will see progress made on both our culture of belonging and representation at F5. We continue to actively build a culture where everyone feels they can be themselves and reach their full potential.
Compensation and Benefits
F5 offers a competitive Total Rewards package intended to attract, retain and motivate our employees. Our package includes market-competitive pay, incentive plans, restricted stock unit grants (RSUs), an Employee Stock Purchase Plan, retirement plans, healthcare, paid time off and family leave.
Environmental, Social & Governance
At F5, we care deeply not just about what we do, but how we do it. We consider this our “human-first” approach to the way we conduct our business, and it is reflected in our expanded commitment to Environmental, Social and Governance (ESG) – extending from the environmental sustainability of our products and operations to the well-being of our employees and our communities.
Environmental. F5 is committed to business practices that preserve the environment upon which our society and economy depend. As we develop a comprehensive program that recognizes F5’s full environmental impact, our focus is on: expanding the volume of our environmental data collection; increasing the breadth of our environmental disclosures; standardizing our carbon reporting processes and metrics; and exploring all options for carbon reduction, mitigation and removal. This will result in F5 disclosing science-aligned targets for Scope 1 and 2 in fiscal year 2022 and declaring 2030 Science-based targets with the Science Based Target Initiative (SBTi) in fiscal year 2023.
Social. In addition to the employee programs and benefits outlined in the Human Capital Management section above, we continue to prioritize F5 Global Good, the community development initiative that amplifies our employee engagement and diversity and inclusion programs. In fiscal year 2021, more than half of all worldwide employees participated in Global Good programs, volunteering over 6,000 hours and directing the entirety of F5’s donations, through both the company matching program and grant selection committees. F5 and its employees donated over $4.8 million to over 2,900 non-profits worldwide in fiscal year 2021.
Governance. Our guiding principle to do the right thing for each other, our customers, our shareholders, and our communities is set forth in F5’s Code of Business Conduct and Ethics, compliance training programs and most importantly, in the behaviors and principles we measure all employees on: BeF5 and LeadF5. In addition, F5 added oversight of our ESG programs by expanding the charter of the Nominating and Governance Committee of the board of directors, as well as expanded our ESG disclosures aligned to the Sustainability Accounting Standards Board (SASB) in our inaugural F5 ESG Report available at investors.f5.com.
Executive Officers of the Registrant
The following table sets forth certain information with respect to our executive officers as of November 16, 2021:
| Name | Age | Position | ||||||||||||
| François Locoh-Donou | 50 | President, Chief Executive Officer and Director | ||||||||||||
| Tom Fountain | 45 | Executive Vice President of Global Services and Chief Strategy Officer | ||||||||||||
| Geng Lin | 57 | Executive Vice President and Chief Technology Officer | ||||||||||||
| Frank Pelzer | 51 | Executive Vice President and Chief Financial Officer | ||||||||||||
| Scot Rogers | 54 | Executive Vice President and General Counsel | ||||||||||||
| Haiyan Song | 56 | Executive Vice President and General Manager, Security and Distributed Cloud | ||||||||||||
| Kara Sprague | 41 | Executive Vice President and General Manager, App Delivery and Enterprise Product Ops | ||||||||||||
| Chad Whalen | 50 | Executive Vice President of Worldwide Sales | ||||||||||||
| Ana White | 48 | Executive Vice President and Chief People Officer | ||||||||||||
| Mika Yamamoto | 49 | Executive Vice President and Chief Marketing and Customer Experience Officer |
François Locoh-Donou has served as our President, Chief Executive Officer and member of our Board of Directors since April 2017. Prior to joining F5, Mr. Locoh-Donou served as Senior Vice President and Chief Operating Officer of Ciena Corporation. During his more than 15 years at Ciena, Mr. Locoh-Donou served in several leadership positions. From August 2011 to October 2015, he served as Ciena’s Senior Vice President, Global Products Group. Previously, he served as Ciena’s Vice President and General Manager, Europe, Middle East and Africa from June 2005 to August 2011. He holds an M.B.A. from Stanford University, a 'Mastere' in Optical Telecommunications from the National Institute of Telecommunications of Paris (ENST), and a 'Diplome d'Ingenieur' in Physics Engineering from the National Institute of Physics in Marseille (ENSPM), France. Mr. Locoh-Donou serves on the board of Capital One Financial Corporation (NYSE: COF). He is also the co-founder of Cajou Espoir, a cashew-processing facility that employs several hundred people in rural Togo, 80 percent of whom are women. Cajou Espoir exports more than 400 tons of cashew kernels annually to the U.S. and Europe.
Tom Fountain has served as our Executive Vice President of Global Services and Chief Strategy Officer since June 2020. Mr. Fountain joined F5 in January 2018 as Executive Vice President and Chief Strategy Officer. Mr. Fountain is responsible for F5’s global services organization, including global support, consulting, and services teams. He is also responsible for F5’s corporate strategy, corporate development, technology partnerships, our service provider business, and new business incubations. From November 2012 to January 2018, Mr. Fountain served as Senior Vice President for Strategy and Corporate Development at McAfee LLC, Vice President of Strategy and Operations at Intel Corporation, and Senior Vice President for Strategy and Corporate Development at McAfee Incorporated. Previously, Mr. Fountain served as Vice President and General Manager of the Content and Media Business Unit at Juniper Networks from December 2011 to November 2012 and Vice President of Corporate Strategy at Juniper Networks from February 2009 to December 2011. Earlier in his career, Mr. Fountain was a venture capitalist at Mayfield Fund from June 2003 to February 2009 and co-founder and engineering leader at Ingrian Networks from December 1999 to June 2004. He holds an M.B.A., an M.S. in Computer Science, an M.S. in Electrical Engineering, and a B.S. in Computer Systems Engineering, each from Stanford University.
Geng Lin joined F5 as our Executive Vice President and Chief Technology Officer in July 2019. Mr. Lin is responsible for the technical vision for the company with a focus on next-generation technological capabilities through organic and inorganic innovation, including advanced research initiatives and strategic partnerships. Prior to joining F5, Mr. Lin was the Managing Director, Chief Development Officer and Head of Engineering for consumer and community banking for J.P. Morgan Chase from September 2017 to June 2019. Previously, he served as Head of Service Engineering for Next Billion Users, CTO of Corporate Networks at Google, CTO of Network Business at Dell and CTO of Cisco’s IBM Alliance. Mr. Lin is an industry-leading expert in distributed systems, software-defined infrastructure, and cloud services. He is a contributing author of two books on cloud and data-intensive computing and holds nine U.S. patents. Mr. Lin received B.Sc. and M.Sc. degrees in Computer Science from Peking University and a Ph.D. degree in Computer Science from the University of British Columbia.
Frank Pelzer has served as our Executive Vice President and Chief Financial Officer since May 2018. He oversees F5's worldwide financial planning, analysis, accounting, reporting, and internal auditing procedures, as well as investor relations. Prior to joining F5, Mr. Pelzer served as President and Chief Operating Officer of the Cloud Business Group at SAP, responsible for the execution of strategy and operations of the company's Software as a Service (SaaS) portfolio including Concur, Ariba, Fieldglass, SuccessFactors, and Hybris. Prior to that, he served as Chief Financial Officer of Concur Technologies, before it was acquired by SAP in 2014. Mr. Pelzer has also held senior leadership positions at Deutsche Bank and Credit Suisse Group. Mr. Pelzer serves on the board of directors for Benefitfocus, Limeade, and Modumetal. He holds a B.A. from Dartmouth College and an M.B.A. from the Tuck School of Business at Dartmouth College.
Scot Rogers has served as our Executive Vice President and General Counsel since January 2014. Mr. Rogers has held a variety of positions in F5's legal department since 2005, including most recently as Senior Vice President and Associate General Counsel immediately prior to his promotion to Executive Vice President. From 2002 through 2005, Mr. Rogers was the General Counsel for Xpediate Consulting, a healthcare technology and consulting company located in the San Francisco Bay Area. Prior to becoming a corporate counsel, he spent eight years in private practice as a commercial litigator. He is a graduate of the University of Texas and holds a J.D. from the Dedman School of Law of Southern Methodist University.
Haiyan Song joined F5 in 2021 as Executive Vice President and General Manager, Security and Distributed Cloud, responsible for the company’s security product and managed services portfolio. Previously, Ms. Song led Splunk’s Security business as Senior Vice President and General Manager of Security Markets. In her more than 20-year career, she has held several leadership positions, including Vice President and General Manager at HP ArcSight, Vice President of Engineering at ArcSight, and Vice President of Engineering at SenSage. Ms. Song started her career at IBM/Informix, building trusted relational database management systems for Federal customers. Ms. Song currently serves on the board of CSG, a provider of revenue management and digital payments. She holds an M.S. from Florida Atlantic University and studied Computer Science in Tsinghua University in China.
Kara Sprague is Executive Vice President and General Manager, App Delivery and Enterprise Product Ops. She is responsible for F5’s BIG-IP Application Delivery and Security product portfolio management, products and solutions. Prior to joining F5 in 2017, Ms. Sprague held various leadership positions across the technology practice of McKinsey & Company. Most recently she led the Technology, Media, and Telecom Practice for the Western Region. Prior to McKinsey, Ms. Sprague was on the engineering staff of Oracle, Agilent Technologies, and Hewlett-Packard. She holds a bachelor's degree and two master's degrees from Massachusetts Institute of Technology and serves on the board of Girls Who Code.
Chad Whalen has served as our Executive Vice President of Worldwide Sales since July 2018. He is responsible for F5’s global sales strategy and brings over 20 years of experience leading global teams across Europe, Asia, and North and South America in network infrastructure, security, and SaaS. Mr. Whalen joined F5 in 2017 to lead the Cloud Sales team. Prior to joining F5, he ran strategic alliances at Fortinet, worldwide sales and services at Jasper, Americas sales and field operations at Ciena and global sales and marketing at World Wide Packets (WWP). He holds a B.A. in Business Administration and Management from Eastern Washington University.
Ana White has served as our Executive Vice President and Chief People Officer since January 2018. She is responsible for the F5’s people, practices, and professional growth programs; recruiting; diversity and inclusion; organizational development; and employee advocacy initiatives. Ms. White comes to F5 from Microsoft, where she led global Human Resources teams for over 18 years across multiple business units. Most recently, she acted as General Manager, Human Resources for Microsoft’s Business Development, Finance, HR and Legal organizations with responsibility for their teams’ HR strategy, talent management, diversity and inclusion, and organizational capability as well as HR Business Insights across Microsoft. Prior to that, Ms. White led HR for the Marketing and Consumer Business organization. Prior to Microsoft, she was a Compensation and Benefits Consultant at Willis Towers Watson. She holds a B.S. in Mathematics from Seattle University, and serves on the taskforce for both the Seattle University Center for Science and Innovation and the board of Childhaven.
Mika Yamamoto joined F5 in May 2019 in the newly created role of Executive Vice President and Chief Marketing and Customer Experience Officer. In this role, she is responsible for leading the company’s marketing strategies across segments, channels, and geographies, and ensuring customers remain at the forefront of the company’s Digital Transformation initiative. Prior to joining F5, Ms. Yamamoto served as Global President of Marketo, where she led the company’s go-to-market strategy after it was acquired by Adobe. Ms. Yamamoto previously served as Chief Digital Marketing Officer and CMO for SAP. In addition, she has held senior leadership roles at Amazon Books, Microsoft Windows and Microsoft Stores, Gartner Research and Accenture. She holds a B.A. in Commerce, Economics and Marketing from Queen’s University in Canada and serves on the board of the Rainier Valley Food Bank.
Item 1A. Risk Factors
In addition to the other information in this report, the following risk factors should be carefully considered in evaluating our company and operations.
Our business could be adversely impacted by conditions affecting the information technology market
A substantial portion of our business depends on the demand for information technology by large enterprise customers and service providers. In addition to the challenges presented by new cloud computing models, we are dependent upon the overall economic health of our current and prospective customers and the continued growth and evolution of the Internet. International, national, regional and local economic conditions, such as recessionary economic cycles, protracted economic slowdown or further deterioration of the economy could adversely impact demand for our products. Demand for our products and services depends substantially upon the general demand for application delivery products and associated services, which fluctuates based on numerous factors, including capital spending levels and growth of our current and prospective customers, as well as general economic conditions. Moreover, the purchase of our products is often discretionary and may involve a significant commitment of capital and other resources. Future economic projections for the information technology sector are uncertain as companies continue to reassess their spending for technology projects and embrace new models for delivery of IT services, such as cloud computing and highly orchestrated software defined networking environments. As a result, spending priorities for our current and future customers may vary and demand for our products and services may be impacted. In addition, customer buying patterns are changing over time and more customers seek to rent software on a subscription basis and to reduce their total cost of ownership. These evolving business models could lead to changes in demand and licensing strategies, which could have a material adverse effect on our business, results of operations and financial condition.
Cloud-based computing trends present competitive and execution risks
Customers are transitioning to a hybrid computing environment utilizing various cloud-based software and services accessed via various smart client devices. Pricing and delivery models are evolving and our competitors are developing and deploying cloud-based services for customers. In addition, new cloud infrastructures are enabling the emergence of new competitors including large cloud providers who offer their own application security and delivery functionality as well as smaller companies targeting the growing numbers of "born in the cloud" applications. We are devoting significant resources to develop and deploy our own competing cloud-based software and services strategies. While we believe our expertise and investments in software and infrastructure for cloud-based services provides us with a strong foundation to compete, it is uncertain whether our strategies will attract the customers or generate the revenue required to be successful. In addition to software development costs, we are incurring costs to build and maintain infrastructure to support cloud-computing services. These costs may reduce the operating margins we have previously achieved. Whether we are successful in this new business model depends on our execution in a number of areas, including:
-
continuing to innovate and bring to market compelling cloud-based services that generate increasing traffic and market share;
-
maintaining the utility, compatibility and performance of our software on the growing array of cloud computing platforms and the enhanced interoperability requirements associated with orchestration of cloud computing environments; and
-
implementing the infrastructure to deliver our own cloud-based services.
These new business models may reduce our revenues or operating margins and could have a material adverse effect on our business, results of operations and financial condition.
Industry consolidation may result in increased competition
Some of our competitors have made acquisitions or entered into partnerships or other strategic relationships to offer a more comprehensive solution than they had previously offered. We have also entered into large, strategic partnerships to enhance our competitive position in the marketplace. As IT companies attempt to strengthen or maintain their market positions in the evolving application delivery, mobility, cloud networking and cloud platform markets, these companies continue to seek to deliver comprehensive IT solutions to end users and combine enterprise-level hardware and software solutions that may compete with our solutions and which could negatively impact our partnerships. These consolidators or potential consolidators may have significantly greater financial, technical and other resources than we do and may be better positioned to acquire and offer complementary products and services. The companies resulting from these possible combinations may create more compelling product and service offerings and be able to offer greater pricing flexibility or sales and marketing support for such offerings than we can. These heightened competitive pressures could result in a loss of customers or a reduction in our revenues or revenue growth rates, all of which could adversely affect our business, results of operations and financial condition.
We may not be able to compete effectively in the emerging application delivery and security market
The markets we serve are new, rapidly evolving and highly competitive, and we expect competition to persist and intensify in the future. As we expand our reach and role into a broader set of multi-cloud solutions, the companies that we consider competitors evolves as well. In addition to server load balancing, traffic management, and other functions normally associated with application delivery, our suite of solutions has expanded our addressable market into security, and policy management, where we compete with a number of companies focused on niche areas of application security.
Within application delivery we compete against Citrix Systems and a number of other competitors that have a smaller market presence or limited feature set, such as Amazon Web Services, HAProxy, Kemp Technologies, Microsoft Azure, and VMware.
We see emerging demand to support modern, container-based applications with new capabilities including managing APIs, optimizing Kubernetes traffic management, and load balancing cloud-native and hybrid cloud applications. For these use cases we compete against emerging players like Apogee and Kong.
In application security, we compete with companies that provide web application firewalls, bot detection and mitigation, carrier-grade firewall, carrier-grade NAT, SSL orchestration, access policy management, DDoS protection, and fraud defense. Competitors include Akamai, Citrix Systems, Imperva, Juniper Networks, and Symantec/Blue Coat. With the addition of Shape, additional fraud, abuse, and analytics solutions become indirect competitors, including Akamai, Cloudflare, Imperva (Distil Networks), Fastly (Signal Sciences) and PerimeterX.
Volterra’s use cases include multi-cloud networking, as well as security offered as SaaS, competing with the likes of Imperva, Fastly, Akamai, and Cloudflare.
We expect to continue to face additional competition as new participants enter our markets. As we continue to expand globally, we may see new competitors in different geographic regions. In addition, larger companies with significant resources, brand recognition, and sales channels may form alliances with or acquire competing application services solutions from other companies and emerge as significant competitors. Potential competitors
Showing the first 8K of 70K characters. Open the full section
Item 1B. Unresolved Staff Comments
Not applicable.
Item 2. Properties
We lease our principal administrative, sales, marketing, research and development facilities, which are located in Seattle, Washington and consist of approximately 515,000 square feet. In May 2017, we entered into a lease agreement for the building in Seattle, Washington that now serves as our corporate headquarters. This lease will expire in 2033 with an option for renewal.
We believe that our existing properties are in good condition and suitable for the conduct of our business. We also lease additional office space for product development and sales and support personnel in the United States and internationally. We believe that our future growth can be accommodated by our current facilities or by leasing additional space if necessary.
Item 3. Legal Proceedings
See Note 13 - Commitments and Contingencies of the Notes to Financial Statements (Part II, Item 8 of this Form 10-K) for information regarding legal proceedings in which we are involved.
Item 4. Mine Safety Disclosures
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Market Prices of Common Stock
Our common stock is traded on the Nasdaq Global Select Market under the symbol “FFIV.” The following table sets forth the high and low sales prices of our common stock as reported on the Nasdaq Global Select Market.
| Fiscal Year 2021 | Fiscal Year 2020 | |||||||||||||||||||||||||
| High | Low | High | Low | |||||||||||||||||||||||
| First Quarter | $ | 178.09 | $ | 121.77 | $ | 153.00 | $ | 128.51 | ||||||||||||||||||
| Second Quarter | $ | 215.91 | $ | 173.41 | $ | 141.31 | $ | 79.78 | ||||||||||||||||||
| Third Quarter | $ | 216.15 | $ | 174.34 | $ | 153.56 | $ | 101.42 | ||||||||||||||||||
| Fourth Quarter | $ | 215.56 | $ | 181.98 | $ | 156.36 | $ | 116.79 |
The last reported sales price of our common stock on the Nasdaq Global Select Market on November 8, 2021 was $223.16.
As of November 8, 2021, there were 43 holders of record of our common stock. As many of our shares of common stock are held by brokers and other institutions on behalf of shareholders, we are unable to estimate the total number of beneficial holders of our common stock represented by these record holders.
Dividend Policy
Our policy has been to retain cash for use in our business, for investment in acquisitions and to repurchase shares of our common stock. Accordingly, we have not paid dividends and do not anticipate declaring dividends on our common stock in the foreseeable future.
Unregistered Securities Sold in 2021
We did not sell any unregistered shares of our common stock during the fiscal year 2021.
Issuer Purchases of Equity Securities
On October 31, 2018, we announced that our Board of Directors authorized an additional $1.0 billion for our common stock share repurchase program. This authorization is incremental to the existing $4.4 billion program, initially approved in October 2010 and expanded in each fiscal year thereafter. Acquisitions for the share repurchase programs will be made from time to time in private transactions, accelerated share repurchase programs, or open market purchases as permitted by securities laws and other legal requirements. The programs can be terminated at any time.
On February 3, 2021, the Company entered into Accelerated Share Repurchase (ASR) agreements with two financial institutions under which the Company paid an aggregate of $500 million. The ASR agreements were accounted for as two separate transactions (1) a repurchase of common stock and (2) an equity-linked contract on the Company's own stock. Upon execution of the ASR agreements, the Company received an initial delivery of 2.1 million shares for an aggregate price of $400 million, based on the market price of $194.91 per share of the Company's common stock on the date of the transaction. The initial shares received by the Company were retired immediately upon receipt. The equity-linked contract for the remaining $100 million, representing remaining shares to be delivered by the financial institutions under the ASR agreements, was recorded to common stock as of March 31, 2021 and was settled in the third quarter of fiscal 2021 with the Company receiving 449,049 additional shares, which were retired immediately upon receipt. The total ASR resulted in a repurchase of 2.5 million shares of the Company's common stock at a volume weighted average repurchase price, less an agreed upon discount, of $199.90 per share. The shares received by the Company were retired, accounted for as a reduction to stockholder’s equity in the Condensed Consolidated Balance Sheets, and treated as a repurchase of common stock for purposes of calculating earnings per share. The Company was not required to make any additional cash payments or delivery of common stock to the financial institutions upon settlement of the agreements.
During fiscal year 2021, we repurchased and retired 2,501,279 shares at an average price of $199.90 per share and as of September 30, 2021, we had $773 million remaining authorized to purchase shares.
Performance Measurement Comparison of Shareholder Return
The following graph compares the annual percentage change in the cumulative total return on shares of our common stock, the Nasdaq Composite Index and the S&P 500 Index for the period commencing September 30, 2016, and ending September 30, 2021.
Comparison of Cumulative Total Return
On Investment Since September 30, 2016*

The Company’s closing stock price on September 30, 2021, the last trading day of the Company’s 2021 fiscal year, was $198.78 per share.
- Assumes that $100 was invested September 30, 2016 in shares of Common Stock and in each index, and that all dividends were reinvested. Shareholder returns over the indicated period should not be considered indicative of future shareholder returns.
**Item 6.**Selected Financial Data
Item 6. is no longer required as the Company has adopted certain provisions within the amendments to Regulation S-K that eliminate Item 301.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
The following discussion of our financial condition and results of operations contains forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934 and Section 27A of the Securities Act of 1933. These statements include, but are not limited to, statements about our plans, objectives, expectations, strategies, intentions or other characterizations of future events or circumstances and are generally identified by the words “expects,” “anticipates,” “intends,” “plans,” “believes,” “seeks,” “estimates,” and similar expressions. These forward-looking statements are based on current information and expectations and are subject to a number of risks and uncertainties. Our actual results could differ materially from those expressed or implied by these forward-looking statements. Factors that could cause or contribute to such differences include, but are not limited to, those discussed under “Item 1A. Risk Factors” herein and in other documents we file from time to time with the Securities and Exchange Commission. We assume no obligation to revise or update any such forward-looking statements.
Overview
F5 is a leading provider of multi-cloud application security and delivery solutions which enable our customers to develop, deploy, operate, secure, and govern applications in any architecture, from on-premises to the public cloud. Our enterprise-grade application services are available as cloud-based, software-as-a-service, and software-only solutions optimized for multi-cloud environments, with modules that can run independently, or as part of an integrated solution on our high-performance appliances. We market and sell our products primarily through multiple indirect sales channels in the Americas (primarily the United States); Europe, the Middle East, and Africa (EMEA); and the Asia Pacific region (APAC). Enterprise customers (Fortune 1000 or Business Week Global 1000 companies) in the technology, telecommunications, financial services, transportation, education, manufacturing, and health care industries, along with government customers, continue to make up the largest percentage of our customer base.
Our management team monitors and analyzes a number of key performance indicators in order to manage our business and evaluate our financial and operating performance on a consolidated basis. Those indicators include:
-
Revenues. Approximately 48% of our fiscal year 2021 revenues were derived from sales of our application security and delivery products including our BIG-IP appliances and VIPRION chassis and related software modules and our software-only Virtual Editions; Local Traffic Manager (LTM), DNS Services (formerly Global Traffic Manager); Advanced Firewall Manager (AFM) and Policy Enforcement Manager (PEM), that leverage the unique performance characteristics of our hardware and software architecture; and products that incorporate acquired technology, including Application Security Manager (ASM) and Access Policy Manager (APM); NGINX Plus and NGINX Controller; Shape Defense and Enterprise Defense; and the Secure Web Gateway and Silverline DDoS and Application security offerings which are sold to customers on a subscription basis. Approximately 52% of our fiscal year 2021 revenues were derived from the sales of global services including annual maintenance contracts, training and consulting services. We carefully monitor the sales mix of our revenues within each reporting period. We believe customer acceptance rates of our new products and feature enhancements are indicators of future trends. We also consider overall revenue concentration by customer and by geographic region as additional indicators of current and future trends. We are also monitoring the uncertainty related to the impacts that the COVID-19 pandemic has on the global economy and our customer base.
-
Cost of revenues and gross margins. We strive to control our cost of revenues and thereby maintain our gross margins. Significant items impacting cost of revenues are hardware costs paid to our contract manufacturers, third-party software license fees, software-as-a-service infrastructure costs, amortization of developed technology and personnel and overhead expenses. Our margins have remained relatively stable; however, factors such as sales price, product and services mix, inventory obsolescence, returns, component price increases, warranty costs, and the uncertainty surrounding the COVID-19 pandemic and its potential impacts to our supply chain could significantly impact our gross margins from quarter to quarter and represent significant indicators we monitor on a regular basis.
-
Operating expenses. Operating expenses are substantially driven by personnel and related overhead expenses. Existing headcount and future hiring plans are the predominant factors in analyzing and forecasting future operating expense trends. Other significant operating expenses that we monitor include marketing and promotions, travel, professional fees, computer costs related to the development of new products and provision of services, facilities and depreciation expenses.
-
Liquidity and cash flows. Our financial condition remains strong with significant cash and investments. The decrease in cash and investments for fiscal year 2021 was primarily due to $500.0 million of cash required for the repurchase of shares under our Accelerated Share Repurchase agreements and $411.3 million in cash paid for the acquisition of businesses, primarily Volterra in the second quarter of fiscal 2021. The decrease in cash and investments for fiscal year 2021 was partially offset by cash provided by operating activities of $645.2 million. Going forward, we believe the primary driver of cash flows will be net income from operations. We will continue to evaluate possible acquisitions of, or investments in businesses, products, or technologies that we believe are strategic, which may require the use of cash. Additionally, on January 31, 2020, we
entered into a Revolving Credit Agreement (the "Revolving Credit Agreement") that provides for a senior unsecured revolving credit facility in an aggregate principal amount of $350.0 million (the "Revolving Credit Facility"). We have the option to increase commitments under the Revolving Credit Facility from time to time, subject to certain conditions, by up to $150.0 million. As of September 30, 2021, there were no outstanding borrowings under the Revolving Credit Facility, and we had available borrowing capacity of $350.0 million.
- Balance sheet. We view cash, short-term and long-term investments, deferred revenue, accounts receivable balances and days sales outstanding as important indicators of our financial health. Deferred revenues continued to increase in fiscal 2021 due to the growth of our subscriptions business, including the acquired deferred revenue associated with the Volterra acquisition. Our days sales outstanding for the fourth quarter of fiscal year 2021 was 45. Days sales outstanding is calculated by dividing ending accounts receivable by revenue per day for a given quarter.
Critical Accounting Policies and Estimates
Our consolidated financial statements have been prepared in accordance with accounting principles generally accepted in the United States of America. The preparation of these financial statements requires us to make estimates and judgments that affect the reported amounts of assets, liabilities, revenues and expenses, and related disclosure of contingent assets and liabilities. We base our estimates on historical experience and on various other assumptions that are believed to be reasonable under the circumstances. Actual results may differ from these estimates under different assumptions or conditions.
We believe that, of our significant accounting policies, which are described in Note 1 of the notes to the consolidated financial statements, the following accounting policies involve a greater degree of judgment and complexity. Accordingly, these are the policies we believe are the most critical to aid in fully understanding and evaluating our consolidated financial condition and results of operations.
Revenue Recognition. On October 1, 2018, we adopted the new revenue recognition standard by applying the modified retrospective approach to those contracts which were not completed as of October 1, 2018. Results for reporting periods beginning after October 1, 2018 are presented under the new revenue recognition standard, while prior period amounts are not adjusted and continue to be reported under the accounting standards in effect for the prior periods.
We sell products through distributors, resellers, and directly to end users. Revenue related to our contracts with customers is recognized by following a five-step process:
-
Identify the contract(s) with a customer. Evidence of a contract generally consists of a purchase order issued pursuant to the terms and conditions of a distributor, reseller or end user agreement.
-
Identify the performance obligations in the contract. Performance obligations are identified in our contracts and include hardware, hardware-based software, software-only solutions, cloud-based subscription services as well as a broad range of service performance obligations including consulting, training, installation and maintenance.
-
Determine the transaction price. The purchase price stated in an agreed upon purchase order is generally representative of the transaction price. We offer several programs in which customers are eligible for certain levels of rebates if certain conditions are met. When determining the transaction price, we consider the effects of any variable consideration.
-
Allocate the transaction price to the performance obligations in the contract. The transaction price in a contract is allocated based upon the relative standalone selling price of each distinct performance obligation identified in the contract.
-
Recognize revenue when (or as) the entity satisfies a performance obligation. We satisfy performance obligations either over time or at a point in time as discussed in further detail below. Revenue is recognized at the time the related performance obligation is satisfied by transferring control of promised products and services to a customer.
Revenue is recognized net of any taxes collected, which are subsequently remitted to governmental authorities. Shipping and handling fees charged to our customers are recognized as product revenue in the period shipped and the related costs for providing these services are recorded as a cost of sale.
The following is a description of the principal activities from which we generate revenue:
Product
Revenue from the sale of our hardware and perpetual software products is generally recognized at a point in time when the product has been fulfilled and the customer is obligated to pay for the product. We also offer several products by subscription, either through term-based license agreements or as a service through our cloud-based platform. Revenue for term-based license agreements is recognized at a point in time, when we deliver the software license to the customer and the
subscription term has commenced. For our software-as-a-service offerings, revenue is recognized ratably as the services are provided. Hardware, including the software run on those devices is considered Systems revenue. Perpetual or subscription software offerings that are deployed on a standalone basis, along with software sold as a service are considered Software revenue. When rights of return are present and we cannot estimate returns, revenue is recognized when such rights of return lapse. Payment terms to customers are generally net 30 days to net 60 days.
Global Services
Revenues for post-contract customer support (PCS) are recognized on a straight-line basis over the service contract term. PCS includes a limited period of telephone support, updates, repair or replacement of any failed product or component that fails during the term of the agreement, bug fixes and rights to upgrades, when and if available. Consulting services are customarily billed at fixed hourly rates, plus out-of-pocket expenses, and revenues are recognized as the consulting is completed. Similarly, training revenue is recognized as the training is completed.
Contract Acquisition Costs
Sales commissions earned by our sales force are considered incremental and recoverable costs of obtaining a contract with a customer. Sales commissions for initial service contracts and subscription offerings are deferred and then amortized as an expense on a straight-line basis over the period of benefit which management has determined to be 4.5 years and 3 years, respectively.
Significant Judgments
We enter into certain contracts with customers, including flexible consumption programs and multi-year subscriptions, with non-standard terms and conditions. Management exercises significant judgment in assessing contractual terms in these arrangements to identify and evaluate performance obligations. Management allocates consideration to each performance obligation based on relative fair value using standalone selling price and recognizes associated revenue as control is transferred to the customer.
Business Combinations. Our business combinations are accounted for under the acquisition method. We allocate the fair value of purchase consideration to the tangible and intangible assets acquired and liabilities assumed based on their estimated fair values. The excess of the fair value of purchase consideration over the fair values of these identifiable assets and liabilities is recorded as goodwill. Such valuations require management to make significant estimates and assumptions, especially with respect to intangible assets.
On January 22, 2021, we completed our acquisition of Volterra, Inc. for a total purchase price of $427.2 million, of which approximately $59.5 million of finite-lived developed technology was recorded. Management valued the developed technology using the relief-from-royalty method under the income approach. Management applied significant judgment in estimating the fair value of the acquired developed technology, which involved the use of a significant assumption with respect to the royalty rate.
COVID-19 Update
Management has prioritized a human-first approach to the COVID-19 pandemic. For F5, this means ensuring the health and safety of employees, their families and our communities. Further, this approach extends to our customers as we look for ways that we can support their operations during this crisis.
While our analysis shows COVID-19 did not have a significant impact on our results of operations for the fiscal year ended September 30, 2021, the impacts of the global pandemic on our business and financial outlook are currently unknown. Global supply chain constraints in the wake of the COVID-19 pandemic continue to decrease our visibility into component availability and lead times are increasing for critical components necessary for the assembly of our hardware products. We are undertaking efforts to mitigate these supply chain constraints, but unavailability of components may impact our ability to complete assembly of our hardware products thereby limiting our ability to fulfill our sales to our customers. In addition, we are conducting business with substantial modifications to employee travel, employee work locations, and virtualization or cancellation of certain sales and marketing events, among other modifications. We will continue to actively monitor the situation and may take further actions that alter our business operations as may be required by federal, state or local authorities, or that we determine are in the best interests of our employees, customers, partners, suppliers and stockholders. It is not clear what the potential effects any such alterations or modifications may have on our business, including the effects on our customers and prospects, or on our financial results.
Results of Operations
The following discussion and analysis should be read in conjunction with our consolidated financial statements and related notes included elsewhere in this Annual Report on Form 10-K.
| Years Ended September 30, | ||||||||||||||||||||
| 2021 | 2020 | 2019 | ||||||||||||||||||
| (in thousands, except percentages) | ||||||||||||||||||||
| Net revenues | ||||||||||||||||||||
| Products | $ | 1,247,084 | $ | 1,025,856 | $ | 985,591 | ||||||||||||||
| Services | 1,356,332 | 1,324,966 | 1,256,856 | |||||||||||||||||
| Total | $ | 2,603,416 | $ | 2,350,822 | $ | 2,242,447 | ||||||||||||||
| Percentage of net revenues | ||||||||||||||||||||
| Products | 47.9 | % | 43.6 | % | 44.0 | % | ||||||||||||||
| Services | 52.1 | 56.4 | 56.0 | |||||||||||||||||
| Total | 100.0 | % | 100.0 | % | 100.0 | % |
Net Revenues. Total net revenues increased 10.7% in fiscal year 2021 from fiscal year 2020, compared to an increase of 4.8% in fiscal year 2020 from the prior year. Overall revenue growth for the year ended September 30, 2021 was due to increases in both product and service revenue. The product revenue increase was driven by software revenue increases, specifically from the addition of the software-as-a-service product offerings through the Shape acquisition and our subscription-based offerings, which include software sold via our flexible consumption program or multi-year subscriptions. Service revenues increased as a result of our increased installed base of products. In addition, our stand-alone security product revenue and our global services revenue associated with security continued to grow in fiscal 2021. Revenues outside of the United States represented 47.5%, 48.1% and 49.3% of net revenues in fiscal years 2021, 2020 and 2019, respectively.
Net Product Revenues. Net product revenues increased 21.6% in fiscal year 2021 from fiscal year 2020, compared to an increase of 4.1% in fiscal year 2020 from the prior year. The increase of $221.2 million in net product sales for fiscal year 2021 was due to an increase in both software and systems revenue compared to the same period in the prior year. The increase of $40.3 million in net product sales for fiscal year 2020 was primarily due to an increase in software sales compared to the prior year, partially offset by a decrease in systems revenue.
The following presents net product revenues by systems and software (in thousands):
| Years Ended September 30, | ||||||||||||||||||||
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Net product revenues | ||||||||||||||||||||
| Systems revenue | $ | 748,192 | $ | 668,313 | $ | 745,798 | ||||||||||||||
| Software revenue | 498,892 | 357,543 | 239,793 | |||||||||||||||||
| Total net product revenue | $ | 1,247,084 | $ | 1,025,856 | $ | 985,591 | ||||||||||||||
| Percentage of net product revenues | ||||||||||||||||||||
| Systems revenue | 60.0 | % | 65.1 | % | 75.7 | % | ||||||||||||||
| Software revenue | 40.0 | 34.9 | 24.3 | |||||||||||||||||
| Total net product revenue | 100.0 | % | 100.0 | % | 100.0 | % |
Net Service Revenues. Net service revenues increased 2.4% in fiscal year 2021 from fiscal year 2020, compared to an increase of 5.4% in fiscal year 2020 from the prior year. The increases in service revenue were the result of increased purchases or renewals of maintenance contracts driven by additions to our installed base of products.
The following distributors of our products accounted for more than 10% of total net revenue:
| Years Ended September 30, | ||||||||||||||||||||
| 2021 | 2020 | 2019 | ||||||||||||||||||
| Ingram Micro, Inc. | 19.2 | % | 16.7 | % | 18.2 | % | ||||||||||||||
| Tech Data | — | — | 10.2 | % | ||||||||||||||||
| Westcon Group, Inc. | — | — | 10.0 | % | ||||||||||||||||
| Synnex Corporation | 11.1 | % | — | — | ||||||||||||||||
The following distributors of our products accounted for more than 10% of total receivables:
| September 30, | ||||||||||||||
| 2021 | 2020 | |||||||||||||
| Ingram Micro, Inc. | 12.6 | % | 14.1 | % | ||||||||||
| Synnex Corporation | 11.9 | % | 11.4 | % | ||||||||||
| Carahsoft Technology | 11.5 | % | — | |||||||||||
No other distributors accounted for more than 10% of total net revenue or receivables.
| Years Ended September 30, | ||||||||||||||||||||
| 2021 | 2020 | 2019 | ||||||||||||||||||
| (in thousands, except percentages) | ||||||||||||||||||||
| Cost of net revenues and gross profit | ||||||||||||||||||||
| Products | $ | 286,293 | $ | 215,275 | $ | 174,986 | ||||||||||||||
| Services | 206,853 | 192,612 | 181,591 | |||||||||||||||||
| Total | 493,146 | 407,887 | 356,577 | |||||||||||||||||
| Gross profit | $ | 2,110,270 | $ | 1,942,935 | $ | 1,885,870 | ||||||||||||||
| Percentage of net revenues and gross margin (as a percentage of related net revenue) | ||||||||||||||||||||
| Products | 23.0 | % | 21.0 | % | 17.8 | % | ||||||||||||||
| Services | 15.3 | 14.5 | 14.4 | |||||||||||||||||
| Total | 18.9 | 17.4 | 15.9 | |||||||||||||||||
| Gross margin | 81.1 | % | 82.6 | % | 84.1 | % |
Cost of Net Product Revenues. Cost of net product revenues consist of finished products purchased from our contract manufacturers, manufacturing overhead, freight, warranty, provisions for excess and obsolete inventory, software-as-a-service infrastructure costs and amortization expenses in connection with developed technology from acquisitions. Cost of net product revenues increased to $286.3 million in fiscal year 2021, up 33.0% from the prior year, primarily due to software product revenue growth. Cost of net product revenues increased to $215.3 million in fiscal year 2020 from $175.0 million in fiscal year 2019, primarily due to an increase in revenue and related managed service costs from the Shape acquisition.
Cost of Net Service Revenues. Cost of net service revenues consist of the salaries and related benefits of our professional services staff, travel, facilities and depreciation expenses. Cost of net service revenues as a percentage of net service revenues increased to 15.3% in fiscal year 2021 compared to 14.5% in fiscal year 2020 and 14.4% in fiscal year 2019. Professional services headcount at the end of fiscal 2021 increased to 1,014 from 965 at the end of fiscal 2020. Professional services headcount at the end of fiscal year 2020 increased to 965 from 925 at the end of fiscal 2019. In addition, cost of net service revenues included stock-based compensation expense of $22.1 million, $20.8 million and $18.3 million for fiscal years 2021, 2020 and 2019, respectively.
| Years Ended September 30, | ||||||||||||||||||||
| 2021 | 2020 | 2019 | ||||||||||||||||||
| (in thousands, except percentages) | ||||||||||||||||||||
| Operating expenses | ||||||||||||||||||||
| Sales and marketing | $ | 929,983 | $ | 843,178 | $ | 748,619 | ||||||||||||||
| Research and development | 512,627 | 441,324 | 408,058 | |||||||||||||||||
| General and administrative | 273,635 | 258,366 | 210,730 | |||||||||||||||||
| Restructuring charges | — | 7,800 | — | |||||||||||||||||
| Total | $ | 1,716,245 | $ | 1,550,668 | $ | 1,367,407 | ||||||||||||||
| Operating expenses (as a percentage of net revenue) | ||||||||||||||||||||
| Sales and marketing | 35.7 | % | 35.9 | % | 33.4 | % | ||||||||||||||
| Research and development | 19.7 | 18.8 | 18.2 | |||||||||||||||||
| General and administrative | 10.5 | 11.0 | 9.4 | |||||||||||||||||
| Restructuring charges | — | 0.3 | — | |||||||||||||||||
| Total | 65.9 | % | 66.0 | % | 61.0 | % |
Sales and Marketing. Sales and marketing expenses consist of the salaries, commissions and related benefits of our sales and marketing staff, the costs of our marketing programs, including public relations, advertising and trade shows, travel, facilities, and depreciation expenses. Sales and marketing expense increased 10.3% in fiscal year 2021 from the prior year, as compared to a year-over-year increase of 12.6% in fiscal year 2020. The increase in sales and marketing expense for fiscal year 2021 was primarily due to increases in commissions and personnel costs of $57.3 million, compared to the prior year. The increases in commissions and personnel costs were driven by growth in sales and marketing employee headcount during fiscal year 2021, including employees from the acquisition of Volterra, as well as higher commissions related to software sales. Sales and marketing headcount at the end of fiscal year 2021 increased to 2,479 from 2,395 at the end of fiscal year 2020. Sales and marketing expenses for fiscal year 2021 also included impairment charges of $11.5 million related to the exit of certain facilities. In fiscal year 2020, the increase in sales and marketing expense was primarily due to increases in commissions and personnel costs of $75.4 million, compared to the prior year. The increases in commissions and personnel costs were driven by growth in sales and marketing employee headcount during fiscal year 2020, including employees from the acquisition of Shape, as well as higher commissions related to software sales. Sales and marketing headcount at the end of fiscal year 2020 increased to 2,395 from 2,146 at the end of fiscal year 2019. Sales and marketing expense included stock-based compensation expense of $104.6 million, $88.4 million and $69.5 million for fiscal years 2021, 2020 and 2019, respectively.
Research and Development. Research and development expenses consist of the salaries and related benefits of our product development personnel, prototype materials and other expenses related to the development of new and improved products, facilities and depreciation expenses. Research and development expense increased 16.2% in fiscal year 2021, compared to the prior year. The increase in research and development expense for fiscal year 2021 was primarily due to increased personnel costs of $48.8 million, compared to the prior year. The increase in personnel costs were driven by growth in research and development employee headcount during fiscal year 2021, including employees from the acquisition of Volterra. Research and development headcount at the end of fiscal year 2021 increased to 1,884 from 1,797 at the end of fiscal year 2020. Research and development expenses for fiscal year 2021 also included impairment charges of $13.0 million related to the exit of certain facilities. In fiscal year 2020, research and development expense increased 8.2%, compared to the prior year. The increase in research and development expense for fiscal year 2020 was primarily due to increased personnel costs of $18.2 million, compared to the prior year. The increase in personnel costs were driven by growth in research and development employee headcount during fiscal year 2020, including employees from the acquisition of Shape. Research and development headcount at the end of fiscal year 2020 increased to 1,797 from 1,556 at the end of fiscal year 2019. Research and development expense included stock-based compensation expense of $67.2 million, $50.3 million and $40.9 million for fiscal years 2021, 2020 and 2019, respectively.
General and Administrative. General and administrative expenses consist of the salaries, benefits and related costs of our executive, finance, information technology, human resource and legal personnel, third-party professional service fees, bad debt charges, facilities and depreciation expenses. General and administrative expense increased 5.9% in fiscal year 2021, compared to the prior year. The increase in general and administrative expense for fiscal year 2021 was primarily due to increased personnel costs of $11.7 million, compared to the prior year. The increase in personnel costs were driven by growth in general and administrative employee headcount during fiscal year 2021, including employees from the acquisition of Volterra. General and administrative headcount at the end of fiscal year 2021 increased to 829 from 704 at the end of fiscal year 2020. General and administrative expenses for fiscal year 2021 also included impairment charges of $9.9 million related to the exit of certain facilities. In fiscal year 2020, general and administrative expense increased 22.6% compared to the prior year. The increase in general and administrative expense for fiscal year 2020 was primarily due to an increase of $19.2 million in fees paid to outside consultants for legal, accounting and tax services, primarily related to the acquisition of Shape. In addition, personnel costs increased $18.5 million, compared to the prior year due to growth in general and administrative headcount, including employees from the acquisition of Shape. General and administrative headcount at the end of fiscal year 2020 increased to 704 from 593 at the end of fiscal year 2019. General and administrative expense included stock-based compensation expense of $42.4 million, $37.8 million and $32.2 million for fiscal years 2021, 2020 and 2019, respectively.
Restructuring charges. In the first fiscal quarter of 2020, we completed a restructuring plan to align strategic and financial objectives and optimize resources for long-term growth. As a result of these initiatives, we recorded a restructuring charge of $7.8 million related to a reduction in workforce that is reflected in our results for the year ended September 30, 2020. There were no restructuring expenses recorded for the year ended September 30, 2021.
| Years Ended September 30, | ||||||||||||||||||||
| 2021 | 2020 | 2019 | ||||||||||||||||||
| (in thousands, except percentages) | ||||||||||||||||||||
| Other income and income taxes | ||||||||||||||||||||
| Income from operations | $ | 394,025 | $ | 392,267 | $ | 518,463 | ||||||||||||||
| Other (expense) income, net | (7,088) | 4,130 | 22,648 | |||||||||||||||||
| Income before income taxes | 386,937 | 396,397 | 541,111 | |||||||||||||||||
| Provision for income taxes | 55,696 | 88,956 | 113,377 | |||||||||||||||||
| Net income | $ | 331,241 | $ | 307,441 | $ | 427,734 | ||||||||||||||
| Other income and income taxes (as percentage of net revenue) | ||||||||||||||||||||
| Income from operations | 15.1 | % | 16.7 | % | 23.1 | % | ||||||||||||||
| Other (expense) income, net | (0.3) | 0.2 | 1.0 | |||||||||||||||||
| Income before income taxes | 14.8 | 16.9 | 24.1 | |||||||||||||||||
| Provision for income taxes | 2.1 | 3.8 | 5.0 | |||||||||||||||||
| Net income | 12.7 | % | 13.1 | % | 19.1 | % |
Other (Expense) Income, Net. Other (expense) income, net, consists primarily of interest income and expense and foreign currency transaction gains and losses. Other (expense) income, net decreased $11.2 million in fiscal year 2021, as compared to fiscal year 2020 and decreased $18.5 million in fiscal year 2020, as compared to fiscal year 2019. The decrease in other (expense) income, net for fiscal year 2021 was primarily due to a decrease of $9.8 million in interest income from our investments compared to the same period in the prior year, and an increase in foreign currency losses of $2.3 million, compared to the prior year. The decrease in other (expense) income, net for fiscal year 2020 as compared to fiscal year 2019 was primarily due to a decrease of $13.1 million in interest income from our investments. In addition, interest expense increased $7.5 million for fiscal year 2020 compared to the prior year as a result of $400.0 million of debt issued as part of our acquisition of Shape in January 2020.
Provision for Income Taxes. We recorded a 14.4% provision for income taxes for fiscal year 2021, compared to 22.4% in fiscal year 2020 and 21.0% in fiscal year 2019. The decrease in the effective tax rate from fiscal year 2020 to 2021 is primarily due to the discrete impact from filing the Company's fiscal year 2020 U.S. federal income tax return and the tax impact from stock based compensation. The increase in the effective tax rate from fiscal year 2019 to 2020 is primarily due to an increase in the tax impact from stock based compensation and other non-deductible expenses.
We record a valuation allowance to reduce our deferred tax assets to the amount we believe is more likely than not to be realized. In making these determinations we consider historical and projected taxable income, and ongoing prudent and feasible tax planning strategies in assessing the appropriateness of a valuation allowance. The net increase in the valuation allowance of $7.8 million for fiscal year 2021 and $9.1 million for fiscal year 2020 was primarily related to tax net operating losses and credits incurred in certain foreign jurisdictions and state tax carryforwards. Our net deferred tax assets as of September 30, 2021, 2020 and 2019 were $125.8 million, $44.6 million, and $27.4 million respectively.
Our worldwide effective tax rate may fluctuate based on a number of factors, including variations in projected taxable income in the various geographic locations in which we operate, changes in the valuation of our net deferred tax assets, resolution of potential exposures, tax positions taken on tax returns filed in the various geographic locations in which we operate, and the introduction of new accounting standards or changes in tax laws or interpretations thereof in the various geographic locations in which we operate. We have recorded liabilities to address potential tax exposures related to business and income tax positions we have taken that could be challenged by taxing authorities. The ultimate resolution of these potential exposures may be greater or less than the liabilities recorded which could result in an adjustment to our future tax expense.
Liquidity and Capital Resources
We have funded our operations with our cash balances, cash generated from operations and proceeds from public offerings of our securities.
| Years Ended September 30, | ||||||||||||||||||||
| 2021 | 2020 | 2019 | ||||||||||||||||||
| (in thousands) | ||||||||||||||||||||
| Liquidity and Capital Resources | ||||||||||||||||||||
| Cash and cash equivalents and investments | $ | 1,043,385 | $ | 1,312,828 | $ | 1,330,684 | ||||||||||||||
| Cash provided by operating activities | 645,196 | 660,898 | 747,841 | |||||||||||||||||
| Cash used in investing activities | (445,335) | (747,002) | (414,634) | |||||||||||||||||
| Cash (used in) provided by financing activities | (468,280) | 337,243 | (155,447) |
Cash and cash equivalents, short-term investments and long-term investments totaled $1,043.4 million as of September 30, 2021, compared to $1,312.8 million as of September 30, 2020, representing a decrease of $269.4 million. The decrease was primarily due to $500.0 million of cash required for the repurchase of outstanding common stock under our Accelerated Share Repurchase agreements in fiscal year 2021 and $411.3 million in cash paid for the acquisition of businesses, primarily Volterra in the second quarter of fiscal 2021. The decrease was also driven by $30.7 million of capital expenditures related to the expansion of our facilities to support our operations worldwide as well as investments in information technology infrastructure and equipment purchases to support our core business activities. The decrease was partially offset by cash provided by operating activities of $645.2 million. As of September 30, 2021, 54.9% of our cash and cash equivalents and investment balances were outside of the U.S. The cash and cash equivalents and investment balances outside of the U.S. are subject to fluctuation based on the settlement of intercompany balances. In fiscal year 2020, the decrease to cash and cash equivalents, short-term investments and long-term investments from the prior year was primarily due to $955.6 million in cash paid for the acquisition of Shape in the second quarter of fiscal 2020 as well as $100.0 million of cash required for the repurchase of outstanding common stock under our share repurchase program in fiscal year 2020 and $59.9 million of capital expenditures related to the expansion of our facilities to support our operations worldwide. The decrease was partially offset by cash provided by operating activities of $660.9 million and $400.0 million in cash proceeds from the issuance of debt in connection with our acquisition of Shape. As of September 30, 2020, 59.1% of our cash and cash equivalents and investment balances were outside of the U.S.
Cash provided by operating activities during fiscal year 2021 was $645.2 million compared to $660.9 million in fiscal year 2020 and $747.8 million in fiscal year 2019. Cash provided by operating activities resulted primarily from cash generated from net income, after adjusting for non-cash charges such as stock-based compensation, depreciation and amortization charges and changes in operating assets and liabilities.
Cash from operations could be affected by various risks and uncertainties, including, but not limited to, the effects of the COVID-19 pandemic and other risks detailed in Part I, Item 1A titled “Risk Factors”. However, we anticipate our current cash, cash equivalents and investment balances, anticipated cash flows generated from operations, and available borrowing capacity on the Revolver Credit Facility will be sufficient to meet our liquidity needs.
Cash used in investing activities during fiscal year 2021 was $445.3 million compared to cash used in investing activities of $747.0 million in fiscal year 2020 and $414.6 million in fiscal year 2019. Cash used in investing activities for fiscal year 2021 was primarily the result of $411.3 million in cash paid for the acquisition businesses, primarily Volterra in the second quarter of fiscal 2021, along with capital expenditures related to maintaining our operations worldwide and the purchase of investments, partially offset by the maturity and sale of investments. Cash used in investing activities for fiscal year 2020 was primarily the result of $955.6 million in cash paid for the acquisition of Shape, along with capital expenditures related to maintaining our operations worldwide and the purchase of investments, partially offset by the maturity and sale of investments. Cash used in investing activities for fiscal year 2019 was primarily the result of $611.6 million in cash paid for the acquisition of NGINX, along with capital expenditures related to the build-out of our new corporate headquarters and the purchase of investments, partially offset by the maturity and sale of investments.
Cash used in financing activities was $468.3 million for fiscal year 2021, compared to cash provided by financing activities of $337.2 million for fiscal year 2020 and cash used in financing activities of $155.4 million for fiscal year 2019. Cash used in financing activities for fiscal year 2021 included $500.0 million to repurchase shares under our Accelerated Share Repurchase agreements, as well as $20.0 million in cash used to make principal payments on our term loan and $14.0 million in cash used for taxes related to net share settlement of equity awards. Cash used in financing activities was partially offset by cash received from the exercise of employee stock options and stock purchases under our employee stock purchase plan of $65.8 million. Cash provided by financing activities for fiscal year 2020 included $400.0 million in cash proceeds from a term
loan, as well as cash received from the exercise of employee stock options and stock purchases under our employee stock purchase plan of $52.8 million, partially offset by $100.0 million in cash used to repurchase common stock under our share repurchase program and $10.0 million in cash used to make a principal payment on our term loan. Cash used in financing activities for fiscal year 2019 included $201.0 million to repurchase common stock under our share repurchase program, which was partially offset by cash received from the exercise of employee stock options and stock purchases under our employee stock purchase plan of $45.6 million.
On January 31, 2020, we entered into a Revolving Credit Agreement (the "Revolving Credit Agreement") that provides for a senior unsecured revolving credit facility in an aggregate principal amount of $350.0 million (the "Revolving Credit Facility"). We have the option to increase commitments under the Revolving Credit Facility from time to time, subject to certain conditions, by up to $150.0 million. As of September 30, 2021, there were no outstanding borrowings under the Revolving Credit Facility, and we had available borrowing capacity of $350.0 million.
Based on our current operating and capital expenditure forecasts, we believe that our existing cash and investment balances, together with cash generated from operations should be sufficient to meet our operating requirements for the next twelve months. Our future capital requirements will depend on many factors, including our rate of revenue growth, the expansion of our sales and marketing activities, the timing and extent of expansion into new territories, the timing of introductions of new products and enhancements of existing products, the continuing market acceptance of our products and cash paid for future acquisitions.
Obligations and Commitments
As of September 30, 2021, we had approximately $75.2 million of tax liabilities, including interest and penalties, related to uncertain tax positions (See Note 9 to our Consolidated Financial Statements). Because of the high degree of uncertainty regarding the settlement of these liabilities, we are unable to estimate the years in which future cash outflows may occur.
As of September 30, 2021, our principal commitments consisted of borrowings under the Term Loan Facility and obligations outstanding under operating leases.
In connection with the acquisition of Shape, on January 24, 2020, we entered into a Term Credit Agreement ("Term Credit Agreement") with certain institutional lenders that provides for a senior unsecured term loan facility in an aggregate principal amount of $400.0 million (the "Term Loan Facility"). The proceeds from the Term Loan Facility were primarily used to finance the acquisition of Shape and related expenses. As of September 30, 2021, $370.0 million of principal amount under the Term Loan Facility was outstanding. There is a financial covenant that requires us to maintain a leverage ratio, calculated as of the last day of each fiscal quarter, of consolidated total indebtedness to consolidated EBITDA. This covenant may result in a higher interest rate on our outstanding principal borrowings on the Term Loan Facility in future periods, depending on the Company's performance. We will monitor the effect that the COVID-19 pandemic may have on our leverage ratio calculation but do not believe there will be a material impact to the interest payable on our borrowings under the Term Loan Facility. Refer to Note 7 of our Consolidated Financial Statements for the scheduled principal maturities of the Term Loan Facility as of September 30, 2021.
We outsource the manufacturing of our pre-configured hardware platforms to contract manufacturers who assemble each product to our specifications. Our agreement with our largest contract manufacturer allows them to procure component inventory on our behalf based upon a rolling production forecast. We are contractually obligated to purchase the component inventory in accordance with the forecast, unless we give notice of order cancellation in advance of applicable lead times.
Recently Adopted Accounting Standards
In August 2018, the FASB issued ASU 2018-15, Intangibles - Goodwill and Other - Internal-Use Software (Subtopic 350-40) (ASU 2018-15), which aligns the requirements for capitalizing implementation costs incurred in a hosting arrangement that is a service contract with the requirements for capitalizing implementation costs incurred to develop or obtain internal-use software, and hosting arrangements that include an internal-use software license. The accounting for the service element of a hosting arrangement that is a service contract is not affected by the amendments in this update. The Company adopted this new standard prospectively on October 1, 2020. The adoption of this standard did not have a material impact to the Company’s consolidated financial statements or disclosures.
In June 2016, the FASB issued ASU 2016-13, Financial Instruments - Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments (ASU 2016-13), which modifies the accounting for credit losses for most financial assets and requires the use of an expected loss model, replacing the currently used incurred loss method. Under this model, entities will be required to estimate the lifetime expected credit loss on such instruments and record an allowance to offset the amortized cost basis of the financial asset, resulting in a net presentation of the amount expected to be collected on the financial asset. The Company adopted this new standard on October 1, 2020 using the modified retrospective approach. The adoption of this standard did not have a material impact on the Company’s condensed consolidated financial statements.
Recently Issued Accounting Pronouncements
In October 2021, the FASB issued ASU 2021-08, Business Combinations (Topic 805): Accounting for Contract Assets and Contract Liabilities from Contracts with Customers. The new guidance requires contract assets and contract liabilities acquired in a business combination to be recognized and measured by the acquirer on the acquisition date in accordance with ASC 606, Revenue from Contracts with Customers, as if it had originated the contracts. Under the current business combinations guidance, such assets and liabilities are recognized by the acquirer at fair value on the acquisition date. The new standard is effective for fiscal years, and interim periods within those fiscal years, beginning after December 15, 2022. Early adoption is permitted. The adoption of the standard will impact future business combinations and require us to measure acquired contract assets and liabilities in accordance with ASC 606. We expect the impact of the standard to result in measuring acquired contract assets and liabilities as if we had originated the contracts. The standard will not impact acquired contract assets or liabilities from business combinations occurring prior to the effective date of adoption.
Item 7A. Quantitative and Qualitative Disclosure About Market Risk
Interest Rate Risk. Our cash equivalents consist of high-quality securities, as specified in our investment policy guidelines. The policy limits the amount of credit exposure to any one issue or issuer to a maximum of 5% of the total portfolio with the exception of U.S. treasury and agency securities and money market funds, which are exempt from size limitation. The policy requires investments in securities that mature in three years or less, with the average maturity being no greater than one and a half years. These securities are subject to interest rate risk and will decrease in value if interest rates increase. A hypothetical increase in interest rates of 100 basis points at September 30, 2021 could result in a market value reduction for our portfolio of approximately $3.4 million.
Foreign Currency Risk. The majority of our sales and expenses are denominated in U.S. dollars and as a result, we have not experienced significant foreign currency transaction gains and losses to date. While we have conducted some transactions in foreign currencies during the fiscal year ended 2021 and expect to continue to do so, we do not anticipate that foreign currency transaction gains or losses will be significant at our current level of operations. However, as we continue to expand our operations internationally, transaction gains or losses may become significant in the future. We have not engaged in foreign currency hedging to date. However, we may do so in the future.
Item 8. Financial Statements and Supplementary Data
F5, INC.
INDEX TO CONSOLIDATED FINANCIAL STATEMENTS
Report of Independent Registered Public Accounting Firm
To the Board of Directors and Shareholders of F5, Inc.
Opinions on the Financial Statements and Internal Control over Financial Reporting
We have audited the accompanying consolidated balance sheets of F5, Inc. and its subsidiaries (the “Company”) as of September 30, 2021 and 2020, and the related consolidated statements of income, of comprehensive income, of shareholders’ equity and of cash flows for each of the three years in the period ended September 30, 2021, including the related notes (collectively referred to as the “consolidated financial statements”). We also have audited the Company's internal control over financial reporting as of September 30, 2021, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of September 30, 2021 and 2020**,** and the results of its operations and its cash flows for each of the three years in the period ended September 30, 2021 in conformity with accounting principles generally accepted in the United States of America. Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of September 30, 2021, based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
Changes in Accounting Principles
As discussed in Notes 8 and 1 to the consolidated financial statements, the Company changed the manner in which it accounts for leases as of October 1, 2019 and the manner in which it accounts for revenues from contracts with customers as of October 1, 2018.
Basis for Opinions
The Company's management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in Management's Report on Internal Control over Financial Reporting appearing under Item 9A. Our responsibility is to express opinions on the Company’s consolidated financial statements and on the Company's internal control over financial reporting based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud, and whether effective internal control over financial reporting was maintained in all material respects.
Our audits of the consolidated financial statements included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
Critical Audit Matters
The critical audit matter communicated below is a matter arising from the current period audit of the consolidated financial statements that was communicated or required to be communicated to the audit committee and that (i) relates to accounts or disclosures that are material to the consolidated financial statements and (ii) involved our especially challenging, subjective, or complex judgments. The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
Acquisition of Volterra, Inc. – Valuation of the Developed Technology Intangible Asset
As described in Notes 1 and 3 to the consolidated financial s
Showing the first 8K of 179K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
Evaluation of Disclosure Controls and Procedures
The Company maintains disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934, as amended (the “Exchange Act”)) that are designed to ensure that required information is recorded, processed, summarized and reported within the required timeframe, as specified in the rules set forth by the Securities Exchange Commission. Our disclosure controls and procedures are also designed to ensure that information required to be disclosed is accumulated and communicated to management, including the Chief Executive Officer and Chief Financial Officer, to allow timely decisions regarding required disclosures.
Our management, with the participation of our Chief Executive Officer and Chief Financial Officer, evaluated the effectiveness of our disclosure controls and procedures as of September 30, 2021 and, based on this evaluation, our Chief Executive Officer and Chief Financial Officer have concluded that our disclosure controls and procedures were effective as of September 30, 2021.
Management’s Report on Internal Control over Financial Reporting
Management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rules 13a-15(f) and 15d-15(f). Internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate. Management conducted an assessment of the effectiveness of our internal control over financial reporting as of September 30, 2021. In making this assessment, management used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission in Internal Control — Integrated Framework (2013). Based on the results of this assessment and on those criteria, management concluded that our internal control over financial reporting was effective as of September 30, 2021.
The effectiveness of the Company’s internal control over financial reporting as of September 30, 2021, has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which appears herein.
Changes in Internal Control over Financial Reporting
During the fourth fiscal quarter, there were no changes to our internal control over financial reporting that materially affected, or are reasonably likely to materially affect, our internal controls over financial reporting.
Although the majority of F5's global workforce is working remotely as a result of the COVID-19 pandemic, there were no material changes to our existing internal controls over financial reporting as a result of this.
Item 9B. Other Information
Item 10. Directors, Executive Officers and Corporate Governance
Certain information required by this item regarding the Company’s directors and executive officers is incorporated herein by reference to the sections entitled “Board of Directors — Nominees and Continuing Directors,” “Corporate Governance — Committees of the Board — Audit Committee” and “— Code of Ethics for Senior Financial Officers” and “— Director Nomination,” and “Security Ownership of Certain Beneficial Owners and Management — Section 16(a) Beneficial Ownership Reporting Compliance” in the Company’s definitive Proxy Statement that will be furnished to the SEC no later than January 28, 2022 (the “Proxy Statement”). Additional information regarding the Company’s directors and executive officers is set forth in Item 1 of Part I of this Annual Report on Form 10-K under the caption “Directors and Executive Officers of the Registrant.”
Item 11. Executive Compensation
The information required by this item is incorporated by reference to the sections entitled “Executive Compensation” and “Corporate Governance — Committees of the Board — Compensation Committee” and “— Compensation Committee Interlocks and Insider Participation” and “— Compensation Committee Report” in the Proxy Statement.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Shareholder Matters
The information required by this item is incorporated by reference to the section entitled “Security Ownership of Certain Beneficial Owners and Management” in the Proxy Statement.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information required by this item is incorporated by reference to the sections entitled “Board of Directors — Director Independence” and “Corporate Governance — Related Person Transactions Policy and Procedures” and “— Certain Relationships and Related Person Transactions” in the Proxy Statement.
Item 14. Principal Accountant Fees and Services
The information required by this item is incorporated by reference to the section entitled “Executive Compensation — Fees Paid to PricewaterhouseCoopers LLP” and “— Audit Committee Pre-Approval Procedures” and “— Annual Independence Determination” in the Proxy Statement.
PART IV
Item 15. Exhibits and Financial Statement Schedules
(a)Documents filed as part of this report are as follows:
1.Consolidated Financial Statements:
Our Consolidated Financial Statements are listed in the Index to Consolidated Financial Statements.
2.Financial Statement Schedule:
Financial statement schedules have been omitted because the information required to be set forth therein is not applicable, material, or is shown in the Consolidated Financial Statements or the notes hereto.
3.Exhibits:
The required exhibits are included at the end of this Annual Report on Form 10-K and are described in the Exhibit Index immediately preceding the first exhibit.
Item 16. Form 10-K Summary
Not applicable.
EXHIBIT INDEX
| Exhibit Number | Exhibit Description | ||||||||||
| 101.CAL | * | — | Inline XBRL Taxonomy Extension Calculation Linkbase Document | ||||||||
| 101.DEF | * | — | Inline XBRL Taxonomy Extension Definition Linkbase Document | ||||||||
| 101.LAB | * | — | Inline XBRL Taxonomy Extension Label Linkbase Document | ||||||||
| 101.PRE | * | — | Inline XBRL Taxonomy Extension Presentation Linkbase Document | ||||||||
| 104 | * | — | Cover Page Interactive Data File (embedded within the Inline XBRL document) |
- Filed herewith.
§ Indicates a management contract or compensatory plan or arrangement.
- Schedules and annexes have been omitted pursuant to Item 601(a)(5) of Regulation S-K. A copy of any omitted schedule and/or annex will be furnished supplementally to the Securities and Exchange Commission upon request.
(1)Incorporated by reference from Current Report on Form 8-K dated March 11, 2019 and filed with the SEC on March 11, 2019.
(2)Incorporated by reference from Current Report on Form 8-K dated December 19, 2019 and filed with the SEC on December 24, 2019.
(3)Incorporated by reference from Current Report on Form 8-K dated January 5, 2021 and filed with the SEC on January 7, 2021.
(4)Incorporated by reference from Current Report on Form 8-K dated November 15, 2021 and filed with the SEC on November 15, 2021.
(5)Incorporated by reference from Current Report on Form 8-K dated November 15, 2021 and filed with the SEC on November 15, 2021.
(6)Incorporated by reference from Exhibit 4.1 of Registration Statement on Form S-1, File No. 333-75817.
(7)Incorporated by reference from Current Report on Form 8-K dated January 24, 2020 and filed with the SEC on January 24, 2020.
(8)Incorporated by reference from Quarterly Report on Form 10-Q for the quarter ended December 31, 2019.
(9)Incorporated by reference from Current Report on Form 8-K dated May 3, 2017 and filed with the SEC on May 3, 2017.
(10)Incorporated by reference from Exhibit 10.1 of Registration Statement on Form S-1, File No. 333-75817.
(11)Incorporated by reference from Current Report on Form 8-K dated March 14, 2019 and filed with the SEC on March 14, 2019.
(12)Incorporated by reference from Current Report on Form 8-K dated April 29, 2009 and filed with the SEC on May 4, 2009.
(13)Incorporated by reference from Registration Statement on Form S-8 File No. 333-179794.
(14)Incorporated by reference from Current Report on Form 8-K dated March 11, 2021 and filed with the SEC on March 15, 2021.
(15)Incorporated by reference from Registration Statement on Form S-8 File No. 333-231802.
(16)Incorporated by reference from Quarterly Report on Form 10-Q for the quarter ended June 30, 2019.
(17)Incorporated by reference from Form S-8 filed with the SEC on February 3, 2020.
(18)Incorporated by reference from Annual Report on Form 10-K for the year ended September 30, 2017.
(19)Incorporated by reference from Annual Report on Form 10-K for the year ended September 30, 2020.
(20)Incorporated by reference from Registration Statement on Form S-8 File No. 333-252616.
(21)Incorporated by reference from Registration Statement on Form S-8 File No. 333-260656.
(22)Incorporated by reference from Current Report on Form 8-K dated January 27, 2017 and filed with the SEC on January 30, 2017.
(23)Incorporated by reference from Current Report on Form 8-K dated April 20, 2018 and filed with the SEC on April 25, 2018.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| F5, INC. | |||||||||||
| By: | /s/ FRANÇOIS LOCOH-DONOU | ||||||||||
| François Locoh-Donou | |||||||||||
| Chief Executive Officer and President |
Dated: November 16, 2021
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the Registrant and in the capacities and on the dates indicated.
| Signature | Title | Date | ||||||||||||||||||
| By: | /s/ FRANÇOIS LOCOH-DONOU | Chief Executive Officer, President, and Director (principal executive officer) | November 16, 2021 | |||||||||||||||||
| François Locoh-Donou | ||||||||||||||||||||
| By: | /S/ FRANCIS J. PELZER | Executive Vice President, Chief Financial Officer (principal financial officer and principal accounting officer) | November 16, 2021 | |||||||||||||||||
| Francis J. Pelzer | ||||||||||||||||||||
| By: | /S/ ALAN J. HIGGINSON | Director | November 16, 2021 | |||||||||||||||||
| Alan J. Higginson | ||||||||||||||||||||
| By: | /S/ SANDRA BERGERON | Director | November 16, 2021 | |||||||||||||||||
| Sandra Bergeron | ||||||||||||||||||||
| By: | /S/ ELIZABETH BUSE | Director | November 16, 2021 | |||||||||||||||||
| Elizabeth Buse | ||||||||||||||||||||
| By: | /S/ MICHAEL L. DREYER | Director | November 16, 2021 | |||||||||||||||||
| Michael L. Dreyer | ||||||||||||||||||||
| By: | /S/ PETER KLEIN | Director | November 16, 2021 | |||||||||||||||||
| Peter Klein | ||||||||||||||||||||
| By: | /S/ NIKHIL MEHTA | Director | November 16, 2021 | |||||||||||||||||
| Nikhil Mehta | ||||||||||||||||||||
| By: | /S/ MARIE MYERS | Director | November 16, 2021 | |||||||||||||||||
| Marie Myers | ||||||||||||||||||||
| By: | /S/ SRIPADA SHIVANANDA | Director | November 16, 2021 | |||||||||||||||||
| Sripada Shivananda | ||||||||||||||||||||
| By: | /S/ MICHAEL MONTOYA | Director | November 16, 2021 | |||||||||||||||||
| Michael Montoya |