 filings.tools
Fidelity National Information Services 10-K 2021-12-31
Filed 2022-02-23. 19 sections, 487K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
________________________________________________________
Form 10-K
________________________________________________________
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 | |||||||
For the fiscal year ended December 31, 2021
Or
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
| For the transition period from | to |
Commission File No. 001-16427
________________________________________________________
Fidelity National Information Services, Inc.
(Exact name of registrant as specified in its charter)
Georgia 37-1490331
(State or other jurisdiction of incorporation or organization) (I.R.S. Employer Identification No.)
601 Riverside Avenue
Jacksonville, Florida 32204
(Address of principal executive offices) (Zip Code)
(904) 438-6000
(Registrant’s telephone number, including area code)
| Securities registered pursuant to Section 12(b) of the Act: | ||||||||||||||
| Trading | Name of each exchange | |||||||||||||
| Title of each class | Symbol(s) | on which registered | ||||||||||||
| Common Stock, par value $0.01 per share | FIS | New York Stock Exchange | ||||||||||||
| 1.700% Senior Notes due 2022 | FIS22B | New York Stock Exchange | ||||||||||||
| 0.125% Senior Notes due 2022 | FIS22C | New York Stock Exchange | ||||||||||||
| 0.750% Senior Notes due 2023 | FIS23A | New York Stock Exchange | ||||||||||||
| 1.100% Senior Notes due 2024 | FIS24A | New York Stock Exchange | ||||||||||||
| 0.625% Senior Notes due 2025 | FIS25B | New York Stock Exchange | ||||||||||||
| 1.500% Senior Notes due 2027 | FIS27 | New York Stock Exchange | ||||||||||||
| 1.000% Senior Notes due 2028 | FIS28 | New York Stock Exchange | ||||||||||||
| 2.250% Senior Notes due 2029 | FIS29 | New York Stock Exchange | ||||||||||||
| 2.000% Senior Notes due 2030 | FIS30 | New York Stock Exchange | ||||||||||||
| 3.360% Senior Notes due 2031 | FIS31 | New York Stock Exchange | ||||||||||||
| 2.950% Senior Notes due 2039 | FIS39 | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act: None
(Title of Class)
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of "large accelerated filer," "accelerated filer," "smaller reporting company" and "emerging growth company" in Rule 12b-2 of the Exchange Act. (Check one):
| Large accelerated filer | ☒ | Accelerated filer | ☐ | Non-accelerated filer ☐ (Do not check if a smaller reporting company) | Smaller reporting company | ☐ | Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management's assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act) Yes ☐ No ☒
As of June 30, 2021, the last business day of the registrant's most recently completed second fiscal quarter, the aggregate market value of the registrant's common stock held by nonaffiliates was $87,314,922,669 based on the closing sale price of $141.67 on that date as reported by the New York Stock Exchange. For the purposes of the foregoing sentence only, all directors and executive officers of the registrant were assumed to be affiliates. The number of shares outstanding of the registrant's common stock, $0.01 par value per share, was 609,590,707 as of February 21, 2022.
The information in Part III hereof is incorporated herein by reference to the registrant’s Proxy Statement on Schedule 14A for the fiscal year ended December 31, 2021, to be filed within 120 days after the close of the fiscal year that is the subject of this Report.
FIDELITY NATIONAL INFORMATION SERVICES, INC.
2021 FORM 10-K ANNUAL REPORT
TABLE OF CONTENTS
Unless stated otherwise or the context otherwise requires, all references to "FIS," "we," "our," "us," the "Company" or the "registrant" are to Fidelity National Information Services, Inc., a Georgia corporation, and its subsidiaries. Also, amounts in tables may not sum or calculate due to rounding.
PART I
Item 1. Business
Overview
FIS is a leading provider of technology solutions for merchants, banks, and capital markets firms globally. Our employees are dedicated to advancing the way the world pays, banks and invests by applying our scale, deep expertise and data-driven insights. We help our clients use technology in innovative ways to solve business-critical challenges and deliver superior experiences for their customers. Headquartered in Jacksonville, Florida, FIS is a Fortune 500® company and is a member of Standard & Poor's 500® Index.
FIS is incorporated under the laws of the State of Georgia as Fidelity National Information Services, Inc. and our stock is traded under the trading symbol "FIS" on the New York Stock Exchange.
We have grown both organically and through acquisitions. Organic growth has been driven by a number of factors, including growth of our customers’ businesses, our internal development of new solutions that enhance our client offerings, and our sales and marketing efforts to expand our customer base and addressable markets. Acquisitions have contributed additional solutions and services that complement or enhance our offerings, diversify our client base, expand our geographic coverage, and provide entry into new and attractive adjacent markets that align with our strategic objectives. We continue to strategically allocate resources to both organic and inorganic growth initiatives to enhance the long-term value of our business.
FIS reports its financial performance based on the following segments: Merchant Solutions ("Merchant"), Banking Solutions ("Banking"), Capital Market Solutions ("Capital Markets") and Corporate and Other. See "Segment Information" below for additional discussion of our solutions and customers. See also Notes 2, 4 and 21 to the consolidated financial statements for additional information about our revenue.
Competitive Strengths
We believe our competitive strengths include the following:
-
Brand. FIS has built a highly respected brand known globally for innovation and thought leadership in the financial services and merchant sectors.
-
Extensive Domain Expertise and Portfolio Breadth. FIS' significant expertise in the markets and domains we serve has enabled us to bring to market a broad range of innovative software applications and service offerings. This broad portfolio of solutions includes a wide range of flexible service arrangements, from managed processing arrangements, either at the client site or hosted at an FIS location, including data centers or our private cloud, to traditional license and maintenance approaches. This broad solution set allows us to bundle tailored or integrated services to compete effectively.
-
Excellent and Long-term Relationships with Clients. A significant percentage of FIS' business with our clients relates to applications and services provided under multi-year, recurring contracts. The nature of these relationships allows us to develop close partnerships with our clients, resulting in high client retention rates. As the breadth of FIS' service offerings has expanded, we have found that our deep and broad access within our clients' organizations presents greater opportunities for cross-selling and up-selling solutions to our clients.
*•*Modern and Cloud-based Technologies. FIS leverages the modern architectures of our software applications and our ability to integrate many of our services with the services of others to provide customized solutions that respond to individualized client needs. We have made significant investment in modernizing our platforms and solutions and in moving our server compute into our private cloud located in our strategic data centers, supplemented by public clouds in certain regions, to increase speed of delivery to clients and increase solution availability to industry-best levels.
*•*Global Distribution and Scale. We are a global leader in many of the markets we serve, supported by a large, knowledgeable talent pool of employees around the world. Our worldwide presence and global scale enable us to
leverage our array of solution offerings, client relationships, and modern infrastructure to drive revenue growth and operating efficiency.
Strategy
Our mission is to deliver superior solutions and services to our clients and to expand our client base to generate sustained revenue and earnings growth for our shareholders. Our strategy to achieve this goal is built on the following pillars:
-
Build, Buy, or Partner to Add Solutions to Win New Clients and Cross-sell to Existing Clients. We continue to invest in organic growth through internal software development as well as through acquisitions and equity investments that complement and extend our existing solutions and capabilities, providing us with additional solutions to cross sell to existing clients and to capture the interest of new clients. We also partner from time to time with other entities to provide comprehensive offerings to our clients and prospects. By investing in solution innovation, we continue to expand our value proposition to our clients and prospects.
-
Support Our Clients Through Innovation. Changing market dynamics, particularly in the areas of digital delivery, information security and regulation, are transforming the way our clients operate, which is driving incremental demand for our integrated solutions and services built around our intellectual property. As clients and prospects evaluate technology, business process changes and vendor risks, our depth of service capabilities enable us to become involved earlier in their planning and design process and assist them as they manage these changes.
-
Drive Efficiency and Scalability. We strive to improve the efficiency of our operations through investments in new technologies, processes and infrastructure modernization. We also leverage a one-to-many operating model to drive high incremental margins on revenue growth, while also providing cost-effective solutions for our clients.
-
Expansive Distribution. Through our global sales force and strategic commercial partnerships, we drive growth through client additions and through the expansion of existing client relationships in support of our clients' growth ambitions. Our clients across our strategic global markets reach across the size spectrum from large enterprises and financial institutions, including global or multi-national clients, to small businesses and community or regional financial institutions.
-
Allocate Our Capital and Resources Strategically. As we make decisions with respect to building, buying or partnering to drive innovation in support of our clients, we prioritize the allocation of capital and other resources to the opportunities providing the highest client benefit and growth potential. We also continually review our portfolio of assets and businesses to assess their fit with our strategy and will from time to time decide to wind down or divest businesses or assets to redeploy capital to our areas of strategic focus. We believe that keeping our team and our capital strategically focused benefits our existing clients and our ability to win new clients.
Segment Information
As a result of the Company's acquisition of Worldpay on July 31, 2019, the Company reorganized its reportable segments in the quarter ended September 30, 2019, into Merchant, Banking, Capital Markets, and Corporate and Other. Reportable segments are organized based on solution offerings and target markets. The Company regularly assesses its portfolio of assets and reclassified certain non-strategic businesses from Merchant, Banking, and Capital Markets into Corporate and Other during the year ended December 31, 2020. These operations represented approximately 3% of 2020 revenue and were recast in all prior-period segment information presented.
Our consolidated results generally do not reflect pronounced seasonality. However, revenue and margins for each segment may reflect stronger or weaker quarters given the nature of our solutions offered. The Merchant business, in particular, is historically subject to seasonal fluctuations in revenue as a result of consumer spending patterns, with Merchant revenue and profitability being strongest in the fourth quarter and weakest in the first quarter. The novel coronavirus and its variants ("COVID-19" or "the pandemic") adversely impacted revenue particularly in Merchant beginning in February 2020 and has had some impact on seasonality seen in past years.
For information about current trends in market demand, see "Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations - Business Trends and Conditions*.*"
Revenue by Segment
The table below summarizes our revenue by reporting segment (in millions):
| 2021 | 2020 | 2019 | |||||||||||||||
| Merchant Solutions | $ | 4,496 | $ | 3,767 | $ | 1,942 | |||||||||||
| Banking Solutions | 6,396 | 5,944 | 5,592 | ||||||||||||||
| Capital Market Solutions | 2,624 | 2,440 | 2,318 | ||||||||||||||
| Corporate and Other | 361 | 401 | 481 | ||||||||||||||
| Total Consolidated Revenue | $ | 13,877 | $ | 12,552 | $ | 10,333 |
Merchant Solutions ("Merchant")
The Merchant segment is focused on serving merchants of all sizes globally, enabling them to accept, authorize and settle electronic payment transactions. Merchant includes all aspects of payment processing, including value-added services, such as security, fraud prevention, advanced data analytics, foreign currency management and numerous funding options. Merchant serves clients in over 100 countries. Our Merchant clients are highly diversified, including global enterprises, national retailers, and small- to medium-sized businesses ("SMB"). The Merchant segment utilizes broad and varied distribution channels, including direct sales forces and multiple referral partner relationships that provide us with access to new and existing markets.
Our solutions in this segment include the following:
- Enterprise. Our enterprise acquiring solutions primarily focus on enabling both card-present and omni-channel payment acceptance for North American clients with more than $5 million in annual sales volume as well as all international clients.
*•*Software-led SMB. Our software-led SMB acquiring solutions primarily focus on North American clients with less than $5 million in annual sales volume. These clients typically leverage software to accept payments, and we employ independent software vendor ("ISV") and other partnership models to distribute our solutions and services to these clients. Integrating our merchant acquiring capabilities into software created by partners enables us to serve a diversity of industry verticals and sub-verticals.
*•*Global eCommerce. Our global eCommerce solutions primarily provide card-not-present merchant acquiring capabilities to digitally focused merchants that primarily sell their goods and services online. Our platforms enable both domestic and international capabilities, providing a customizable and scalable solution to our clients with best-in-class authorization rates.
Banking Solutions ("Banking")
The Banking segment is focused on serving financial institutions of all sizes with core processing software, transaction processing software and complementary applications and services, many of which interact directly with core processing software. We sell these solutions and services on either a bundled or stand-alone basis. Clients in this segment include global financial institutions, U.S. regional and community banks, credit unions and commercial lenders, as well as government institutions and other commercial organizations. Banking serves clients in more than 100 countries. We provide our clients integrated solutions characterized by multi-year processing contracts that generate highly recurring revenue. The predictable nature of cash flows generated from the Banking segment provides opportunities for further investments in innovation, integration, information and security, and compliance in a cost-effective manner.
Our solutions in this segment include the following:
- Core Processing and Ancillary Applications. Our core processing software applications are designed to run banking processes for our financial institution clients, including deposit and lending systems, customer management, and other central management systems. Clients use these applications to maintain the primary records of their customer accounts. Our diverse selection of market-focused core processing software applications enables FIS to compete effectively in a wide range of markets. We continue to invest in our core modernization efforts to further differentiate our offerings for the long term. We also offer a number of services that are ancillary to the primary applications listed above, including branch automation, back-office support systems and compliance support.
-
Digital, including Internet, Mobile and eBanking. Our comprehensive suite of retail delivery applications enables financial institutions to integrate and streamline customer-facing operations and back-office processes, thereby improving customer interaction across all channels (e.g., branch offices, internet, mobile, ATM, and call centers). FIS' focus on consumer access has driven significant market innovation in this area, with multi-channel and multi-host solutions and a strategy that provides tight integration of services and a seamless customer experience. We have been providing our large regional banking customers in the U.S. with Digital One, an integrated digital banking platform, and are now adding functionality and offering Digital One to our community bank clients. Digital One is integrated into several of the core banking platforms offered by FIS and is also offered to customers of non-FIS core banking systems.
-
Fraud, Risk Management and Compliance. Our decision solutions offer a spectrum of options that cover the account lifecycle from helping to identify qualified account applicants to managing existing customer accounts and fraud. Our applications enable Know Your Customer, new account decisioning and opening, account and transaction management, fraud management and collections. Our risk management services use our proprietary risk management models and data sources to assist in detecting fraud and assessing the risk of opening a new account. Our systems use a combination of advanced authentication procedures, predictive analytics, artificial intelligence modeling and proprietary and shared databases to assess and detect fraud risk for deposit transactions for financial institutions.
-
Card and Retail Payment. Our card and retail payment technology and services allow clients to issue VISA®, MasterCard® or other payment network-branded credit and debit cards or other electronic payment cards for use by both consumer and business accounts. Card transactions continue to increase as a percentage of total point-of-sale payments, which fuels continuing demand for card-related services. We offer EMV (Europay, MasterCard and Visa) integrated circuit cards, often referred to as chip cards, as well as a variety of stored-value card types and loyalty programs, including our Premium Payback service that allows our financial institutions' customers to use loyalty points at a variety of merchant point-of-sale systems. Our integrated services range from card production and activation to processing to an extensive range of fraud management services and value-added loyalty programs designed to increase card usage and fee-based revenue for financial institutions and merchants. The majority of our programs are full service, including most of the operations and support necessary for an issuer to operate a credit card program. We do not make credit decisions for our card issuing clients. We are also a leading provider of prepaid card services, which include digital cards, gift cards and reloadable cards, with end-to-end solutions for development, processing and administration of stored-value programs, including government benefit programs. Our closed-loop gift card solutions and loyalty programs provide merchants compelling solutions to drive consumer loyalty.
-
Electronic Funds Transfer and Network. Our electronic funds transfer and debit card processing businesses offer settlement and card management solutions for financial institution card issuers. We provide traditional ATM-based debit network access through NYCE, other branded networks, and emerging real-time payment alternatives. Our networks connect millions of cards and point-of-sale locations nationwide, providing consumers with secure, real-time access to their money. Also through our networks, clients such as financial institutions, retailers and independent ATM operators can capitalize on the efficiency, consumer convenience and security of electronic real-time payments, real-time account-to-account transfers, and strategic alliances such as surcharge-free ATM network arrangements.
-
Wealth and Retirement. We provide wealth and retirement solutions that help banks, trust companies, brokerage firms, insurance firms, retirement plan professionals, benefit administrators and independent advisors acquire, service and grow their client relationships. We provide solutions for client acquisition, transaction management, trust accounting and recordkeeping that can be deployed stand-alone or as part of an integrated wealth or retirement platform, or on an outsourced basis.
*•*Item Processing and Output Services. Our item processing services furnish financial institutions with the technology needed to capture data from checks, transaction tickets and other items; image and sort items; process exceptions through keying; and perform balancing, archiving and the production of statements. Our item processing services are performed at one of our multiple item processing centers located throughout the U.S. or on-site at client locations. Our extensive solutions include distributed (i.e., non-centralized) data capture, mobile deposit capture, check and remittance processing, fraud detection, and document and report management. Clients encompass banks and corporations of all sizes, from de novo banks to the largest financial institutions and corporations. We offer a number of output services that are ancillary to the primary solutions we provide, including print and mail capabilities, document composition software and solutions, and card personalization fulfillment services. Our print and mail services offer complete computer output solutions for the creation, management and delivery of print and fulfillment
needs. We provide our card personalization fulfillment services for branded credit cards and branded and non-branded debit and prepaid cards.
Capital Market Solutions ("Capital Markets")
The Capital Markets segment is focused on serving global financial services clients with a broad array of buy- and sell-side solutions. Clients in this segment operate in more than 100 countries and include asset managers, buy- and sell-side securities brokerage and trading firms, insurers, private equity firms, and other commercial organizations. Our buy- and sell-side solutions include a variety of mission-critical applications for recordkeeping, data and analytics, trading, financing and risk management. Capital Markets clients purchase our solutions and services in various ways including licensing and managing technology "in-house," using consulting and third-party service providers, as well as procuring fully outsourced end-to-end solutions. Our long-established relationships with many of these financial and commercial institutions generate significant recurring revenue. We have made, and continue to make, investments in modern platforms, advanced technologies, open APIs, machine learning and artificial intelligence, and regulatory technology to support our Capital Markets clients.
Our solutions in this segment include the following:
-
Securities Processing and Finance. Our offerings help financial institutions to increase the efficiency, transparency and control of their back-office trading operations, post-trade processing and settlement including derivative solutions, risk management, securities lending, syndicated lending, tax processing, and regulatory compliance. The breadth of our offerings also facilitates advanced business intelligence and market data distribution based on our extensive market data access.
-
Global Trading. Our trading solutions provide trade execution, data and network solutions to financial institutions, corporations and municipalities in North America, Europe and other global markets across a variety of asset classes. Our trade execution and network solutions help both buy- and sell-side firms improve execution quality, decrease overall execution costs and address trade connectivity challenges.
-
Asset Management and Insurance. We offer solutions that help institutional investors, insurance companies, hedge funds, private equity firms, fund administrators and securities transfer agents improve both investment decision-making and operational efficiency, while managing risk and increasing transparency. Our asset management solutions support every stage of the investment process, from research and portfolio management, to valuation, risk management, compliance, investment accounting, transfer agency and client reporting. Our insurance solutions help support front-office and back-office functions including actuarial risk calculations, policy administration and financial and investment accounting and reporting for a variety of insurance lines, including life and health, annuities and pensions, property and casualty, and reinsurance.
-
Corporate Liquidity. Our corporate liquidity solutions help chief financial officers and treasurers manage working capital by reducing risk and improving communication and response time between a company's buyers, suppliers, banks and other stakeholders. Our end-to-end collaborative financial management framework helps bring together receivables, treasury and payments for a single view of cash and risk, which helps our clients optimize business processes for enhanced liquidity management.
Corporate and Other
The Corporate and Other segment consists of corporate overhead expense, certain leveraged functions and miscellaneous expenses that are not included in the operating segments, as well as certain non-strategic businesses that we plan to wind down or sell. The overhead and leveraged costs relate to corporate marketing, corporate finance and accounting, human resources, legal, and amortization of acquisition-related intangibles and other costs, such as acquisition and integration expenses, that are not considered when management evaluates revenue-generating segment performance.
Sales and Marketing
Our sales personnel have expertise in particular solutions and markets as well as across our various client segments. We believe that focusing our expertise on clients in specific markets and tailoring integrated solution sets to participants in those markets enables us to better serve our clients and makes our offerings more attractive to prospects. We target the majority of our prospects via direct and/or indirect field sales, as well as inbound and outbound lead generation, telesales and virtual sales efforts.
Our global marketing team develops and leads the execution of global, industry-specific and geographic-based strategic marketing plans in support of the segments' reputation and relationship building goals in addition to their revenue and profitability goals. Key components of our strategic plans include brand amplification and digital enablement; market and competitive research; voice of the customer and client engagement; thought leadership; integrated go-to-market programs; internal communications and readiness; journalists and social media engagement, industry analyst relations; client events; trade shows; high-touch client programs; demand generation campaigns; account- and deal-based marketing programs; collateral development and management across digital and online channels; and the launch of new products to market.
Patents, Copyrights, Trademarks and Other Intellectual Property
In general, we own the intellectual property and proprietary rights that are necessary to conduct our business and are important to our future success, including trademarks, trade names, trade secrets, copyrights and patents. We license certain items from third parties under arms-length agreements for varying terms, including some "open source" licenses.
We rely on a combination of contractual restrictions, internal security practices, patents, trade secrets, copyrights and applicable law to establish and protect our software, technology and expertise worldwide. We rely on trademark law to protect our rights in our brands. We intend to continue taking appropriate measures to protect our intellectual property rights, including by legal action when necessary and appropriate.
Competition
The markets for our solutions and services are intensely competitive. Depending on the business line, our primary competitors include, but are not limited to, internal technology or software development departments within financial institutions or other large companies, merchant acquirers, global eCommerce providers, global and regional companies providing payment services, third-party payment processors, securities exchanges, asset managers, card associations, clearing networks or associations, trust companies, independent computer services firms, companies that develop and deploy software applications, companies owned by global banks selling new competitive solutions, companies that provide customized development, implementation and support services, emerging technology innovators, and business process outsourcing companies. Many of these companies compete with us across multiple solutions, markets and geographies. Some of these competitors possess greater financial, sales and marketing resources than we do. Competitive factors impacting the success of our solutions and services include the quality of the technology-based application or service, application features and functions, ease of delivery and integration, the ability to maintain, enhance and support the applications or services, price and overall relationship management. We believe that we compete vigorously in each of these categories. In addition, we believe our domain expertise, combined with our ability to offer multiple applications, services and integrated solutions, enhances our competitiveness against companies with more limited offerings. Our ability to innovate and scale digital payments and services during the COVID-19 pandemic has been a competitive advantage as well.
Research and Development
Our research and development activities primarily relate to the modernization of our proprietary core processing software applications and the design and development of next generation digital solutions, processing systems, software applications and risk management platforms. We expect to continue our practice of investing an appropriate level of resources to maintain, enhance and extend the functionality of our proprietary systems and software applications, to develop new and innovative software applications and systems to address emerging technology trends in response to the needs of our clients and to enhance the capabilities of our outsourcing infrastructure. In addition, we intend to offer services compatible with new and emerging delivery channels.
As part of our research and development process, we evaluate current and emerging technology for compatibility with our existing and future software platforms. To this end, we engage with various hardware and software vendors in the evaluation of various new and existing technologies. Where appropriate, we use third-party technology components in the development of our software applications and service offerings. We typically utilize enterprise license agreements or strive to ensure that either alternative suppliers or transfer rights exist in order to ensure the continuity of supply of third-party technology components used in the development of our software applications and service offerings. As a result, we are not materially dependent upon any third-party technology components. Third-party software may be used for highly specialized business functions depending on our ability to develop the functionality internally within time and budget constraints. Additionally, third-party software may be used for routine, commonplace functions within a technology platform environment. We work with our clients to determine the appropriate timing and approach to introduce technology or infrastructure changes to our applications and services. During
the years ended December 31, 2021, 2020 and 2019, we incurred research and development costs that were non-capitalizable of approximately 2% to 4% of revenue.
Government Regulation
Our services are subject to a broad range of complex federal, state, and international regulations and requirements, as well as requirements under the rules of self-regulatory organizations including, without limitation, federal truth-in-lending and truth-in-savings rules, state money transmission laws, state cybersecurity protection laws, data protection and privacy laws, usury laws, laws governing state trust charters, the Equal Credit Opportunity Act, the Electronic Funds Transfer Act, the Fair Credit Reporting Act, the Fair Debt Collection Practices Act, the Bank Service Company Act, the Bank Secrecy Act, the USA Patriot Act, the Internal Revenue Code, the Employee Retirement Income Security Act, the Health Insurance Portability and Accountability Act, the Community Reinvestment Act and the Dodd-Frank Wall Street Reform and Consumer Protection Act (the "Dodd-Frank Act"), the Securities Exchange Act of 1934, the Investment Advisors Act of 1940 (the "1940 Act"), anti-corruption laws including the U.S. Foreign Corrupt Practices Act and U.K. Bribery Act, the rules and regulations of the Financial Industry Regulatory Authority ("FINRA"), the Securities and Exchange Commission ("SEC"), the Federal Financial Institutions Examination Council ("FFIEC"), the Consumer Financial Protection Bureau ("CFPB"), the Financial Conduct Authority in the U.K. ("FCA") and the Payment Systems Regulator in the U.K. ("PSR"), De Nederlandsche Bank ("DNB") in the Netherlands, the Ministry of Economy, Trade and Industry in Japan ("METI"), Bank Negara in Malaysia and state financial services regulators (including enforcement of state cybersecurity laws). The compliance of our services and applications with these and other applicable laws and regulations depends on a variety of factors, including the manner in which our clients use them. In some cases, we are directly subject to regulatory oversight and examination. In other cases, our clients are contractually responsible for determining what is required of them under applicable laws and regulations and utilize our solutions and services to achieve compliance with those laws and regulations. In either case, the failure of our services to comply with applicable laws and regulations may result in suspension or revocation of the permission-based regulatory licenses, restrictions on our ability to provide those services, the imposition of civil fines and/or criminal penalties, and/or reputational damage. Further, regulatory authorities have the power to, among other things, enjoin "unsafe or unsound" practices, require affirmative actions to correct any violation or practice, issue administrative orders that can be judicially enforced and direct the sale of subsidiaries or other assets. We may be adversely affected by increased regulatory scrutiny or related negative publicity.
The principal areas of regulation impacting our business are the following:
- Oversight by Banking Regulators. As a provider of electronic data processing and back-office services to financial institutions, FIS is subject to regulatory oversight and examination by the FFIEC, an interagency body of federal banking regulators including the Federal Deposit Insurance Corporation ("FDIC"), the Office of the Comptroller of the Currency ("OCC"), the Board of Governors of the Federal Reserve System ("FRB"), the National Credit Union Administration ("NCUA") (collectively, the Federal Banking Agencies or "FBA") and the CFPB, as part of the Multi-Regional Data Processing Servicer ("MDPS") program. The MDPS program includes technology suppliers that provide mission-critical applications for a large number of financial institutions that are regulated by multiple regulatory agencies. Periodic information technology examination assessments are performed using FFIEC Interagency guidelines to identify potential risks that could adversely affect serviced financial institutions, determine compliance with applicable laws and regulations that affect the services provided to financial institutions and ensure the services we provide to financial institutions do not create systemic risk to the banking system or impact the safe and sound operation of the financial institutions we process. In addition, independent auditors annually review several of our operations to provide reports on internal controls for our clients. We are also subject to review and examination by state and international regulatory authorities under state and foreign laws and rules that regulate many of the same activities that are described above, including electronic data processing, payments and back-office services for financial institutions and the use of consumer information.
Our U.S.-based wealth and retirement business holds a charter in the state of Georgia which makes us subject to the regulatory compliance requirements of the Georgia Department of Banking and Finance. As a result, we are also authorized to provide trust services in various additional states subject to additional applicable state regulations.
- Oversight by Securities Regulators. Our subsidiary that conducts our broker-dealer business in the U.S. is registered as a broker-dealer with the SEC, is a member of FINRA, and is registered as a broker-dealer in numerous states. Our broker-dealer is subject to regulation and oversight by the SEC. In addition, FINRA, a self-regulatory organization that is subject to oversight by the SEC, adopts and enforces rules governing the conduct, and examines the activities, of its member firms, including our broker-dealer. State securities regulators and various exchanges, including the New York
Stock Exchange, also have regulatory or oversight authority over our broker-dealer. Broker-dealers are subject to regulations that cover all aspects of the securities business, including sales methods, trade practices among broker-dealers, public and private securities offerings, use and safekeeping of customers' funds and securities, capital structure, record keeping, the financing of customers' purchases and the conduct and qualifications of directors, officers and employees. In particular, as a registered broker-dealer and member of a self-regulatory organization, we are subject to the SEC's uniform net capital rule, Rule 15c3-1. Rule 15c3-1 specifies the minimum level of net capital a broker-dealer must maintain and also requires that a significant part of a broker-dealer's assets be kept in relatively liquid form. The SEC and various self-regulatory organizations impose rules that require notification when net capital falls below certain predefined criteria, limit the ratio of subordinated debt to equity in the regulatory capital composition of a broker-dealer and constrain the ability of a broker-dealer to expand its business under certain circumstances. Additionally, the SEC's uniform net capital rule imposes certain requirements that may have the effect of prohibiting a broker-dealer from distributing or withdrawing capital and requiring prior notice to the SEC for certain withdrawals of capital.
Our subsidiaries also include an SEC-registered transfer agent. Our registered transfer agent is subject to the Securities Exchange Act of 1934 and the rules and regulations promulgated thereunder. These laws and regulations generally grant the SEC and other supervisory bodies broad administrative powers to address non-compliance with regulatory requirements. Sanctions that may be imposed for non-compliance with these requirements include the suspension of individual employees, limitations on engaging in certain activities for specified periods of time or for specified types of clients, the revocation of registrations, other censures and significant fines.
Subsidiaries engaged in activities outside the U.S. are regulated by various government agencies in the particular jurisdiction where they are chartered, incorporated and/or conduct their business activity. For example, pursuant to the U.K. Financial Services and Markets Act 2000 ("FSMA"), certain of our subsidiaries are subject to regulations promulgated and administered by the FCA. The FSMA and rules promulgated thereunder govern all aspects of the U.K. investment business, including sales, research and trading practices, provision of investment advice, use and safekeeping of client funds and securities, regulatory capital, recordkeeping, margin practices and procedures, approval standards for individuals, anti-money laundering, periodic reporting and settlement procedures.
-
Payment Services Oversight. Our payment services business is a technology service provider to U.S. financial institutions and is, therefore, subject to oversight and examination by the FFIEC. Our payment services businesses are also subject to regulation, supervision, and enforcement authority of numerous governmental and regulatory bodies in the jurisdictions in which they operate, which include the CFPB, the DNB in the Netherlands, the METI in Japan, Bank Negara in Malaysia and the FCA and the PSR in the U.K. These various regulatory regimes require compliance in respect of many aspects of our payment services business including without limitation corporate governance and oversight functions, capital requirements, liquidity, safeguarding, fee regulation adherence, technology and cyber resilience, anti-money laundering and sanctions. Because the PSR is an economic regulator in the U.K., it has the power to apply remedies in relation to the functioning of the card acquiring market in the U.K. The European Commission also has overall authority to enforce and establish new standards or guidance. which may require banks and authorized payments providers in our Merchant business to modify current pricing and fee structures in the European Union ("E.U.").
-
Sanctions/Anti-Money Laundering. We are subject to certain economic and trade sanctions programs that are administered by the U.S. Treasury's Office of Foreign Assets Control (referred to as "OFAC"), which prohibit or restrict transactions to or from, or dealings with, specified countries, their governments, and in certain circumstances, their nationals, and with individuals and entities that are specially-designated nationals of those countries, narcotics traffickers, and terrorists or terrorist organizations. Similar anti-money laundering laws, including the U.K. Criminal Finances Act, apply to movements of currency and payments through electronic transactions and to dealings with persons specified in lists maintained by the country equivalents to OFAC in several other countries. We have implemented policies, procedures, and internal controls that are designed to comply with the regulations and economic sanctions programs administered by OFAC, as well as all other applicable anti-money laundering laws and regulations. Those policies and procedures require the screening of third parties with which the Company does business, including clients and vendors.
-
Privacy and Data Protection. The Company is subject to an increasing number of privacy and data protection laws, regulations and directives globally (referred to collectively as "Privacy Laws"), many of which place restrictions on the Company's ability to efficiently transfer, access and use personal data across its business. The legislative and regulatory landscape for privacy and data protection continues to evolve.
Our financial institution clients operating in the U.S. are required to comply with privacy regulations imposed under the Gramm-Leach-Bliley Act (referred to as "GLBA") and numerous similar state laws. GLBA and those state laws place restrictions on the use of non-public personal information. All financial institutions must disclose detailed privacy policies to their customers and offer them the opportunity to direct the financial institution not to share information with third parties. The regulations under GLBA, however, permit financial institutions to share information with non-affiliated parties who perform services for the financial institutions. As a provider of services to financial institutions, we are required to comply with the privacy laws and are bound by the same limitations on disclosure of the information received from our clients as apply to the financial institutions themselves. A determination that there have been violations of privacy laws could expose us to significant damage awards, fines and other penalties that could, individually or in the aggregate, materially harm our business and reputation.
The Company is subject to the E.U.'s General Data Protection Regulation ("GDPR"), which applies to all organizations processing the personal data of individuals in the E.U., regardless of where such organization is based. The GDPR has heightened our data protection compliance obligations, impacted our businesses' collection, processing and retention of personal data and imposed stricter standards for reporting data breaches. In June 2021, the European Commission issued new Standard Contractual Clauses ("SCCs"), and the European Data Protection Board ("EDPB") issued the final version of its recommendations in response to the Court of Justice of the European Union's decision in Data Protection Commissioner v. Facebook Ireland Ltd, Maximilian Schrems (known as the "Schrems II" case). These new clauses and guidance require us to update contracts with third parties, to implement new processes, and to undertake supplemental measures for transfers of personal information to certain countries, including the U.S. The U.K. Information Commissioner's Office ("ICO") has announced that the U.K. will issue separate revised SCCs as a result of the breach. Compliance with these new and evolving regulations may require us to change our policies, procedures and operational infrastructure, which could be time-consuming and costly. The GDPR also imposes significant penalties for non-compliance.
Certain operations of the Company are also subject to the California Consumer Privacy Act ("CCPA"), the California Privacy Rights Act ("CPRA"), the Virginia Consumer Data Protection Act ("VCDPA"), and other similar state laws that provide consumers with additional data protection rights, including the right to be informed about the personal information collected by third parties and the use of that personal information, and impose obligations on companies in connection with the use of personal information. Further, certain operations of the Company became subject to the Brazilian General Personal Data Protection Act in August 2020 and the Chinese Personal Information Protection Law in November 2021. The Company has adopted a comprehensive global privacy program to assess and manage these evolving risks and continues to monitor new data privacy laws throughout the jurisdictions in which we do business, including data localization requirements in applicable jurisdictions.
In addition, our businesses are increasingly subject to laws and regulations relating to surveillance, encryption and data onshoring in the jurisdictions in which we operate. Compliance with these laws and regulations may require us to change our technology for information security, operational infrastructure, policies and procedures, which could be time-consuming and costly.
-
Money Transfer. Elements of our cash access and money transmission businesses are registered as a Money Services Business and are subject to the USA Patriot Act and reporting requirements of the Bank Secrecy Act and U.S. Treasury Regulations. These businesses may also be subject to certain state and local licensing requirements. The Financial Crimes Enforcement Network, state attorneys general, and other agencies have enforcement responsibility over laws relating to money laundering, currency transmission, and licensing. In applicable states, we have obtained money transmitter licenses. However, changes to state money transmission laws and regulations, including changing interpretations and the implementation of new or varying regulatory requirements, may result in the need for additional or expanded money transmitter licenses, additional capital allocations or changes in the way in which we deliver certain services.
-
Consumer Reporting and Protection. Our decision solutions subsidiary, ChexSystems, maintains a database of consumer information used to provide various account opening services including credit scoring analysis and is subject to the Federal Fair Credit Reporting Act ("FCRA") and similar state laws. The FCRA regulates consumer reporting agencies ("CRAs"), including ChexSystems, and governs the accuracy, fairness, and privacy of information in the files of CRAs that engage in the practice of assembling or evaluating certain information relating to consumers for certain specified purposes. CRAs are required to follow reasonable procedures to assure maximum possible accuracy of information concerning the individual about whom the report relates and, if a consumer disputes the accuracy of any
information in the consumer's file, to conduct a reasonable investigation within statutory timelines. The FCRA imposes many other requirements on CRAs and users of consumer report information. Regulatory enforcement of the FCRA is under the purview of the United States Federal Trade Commission, the CFPB, and state attorneys general, acting alone or in concert with one another. CRAs are also regulated by a number of states, including New York, with consumer reporting laws that are not pre-empted by the FCRA. In furtherance of our objectives of data accuracy, fair treatment of consumers, protection of consumers' personal information, and compliance with these laws, we have made considerable investment to maintain a high level of security for our computer systems in which consumer data resides, and we maintain consumer relations call centers to facilitate accurate and timely handling of consumer requests for information and handling disputes. We also are focused on ensuring our operating environments safeguard and protect consumer's personal information in compliance with these laws.
Our consumer reporting and consumer-facing businesses are subject to CFPB Bulletin 2013-7 (a successor to the former Regulation AA - Unfair Deceptive Acts or Practices), which defines Unfair, Deceptive or Abusive Acts or Practices ("UDAAP"). This specific bulletin states that UDAAPs can cause significant financial injury to consumers, erode consumer confidence, and undermine fair competition in the financial marketplace. Original creditors and other covered persons and service providers under the Dodd-Frank Act involved in collecting debt related to any consumer financial product or service are subject to the prohibition against UDAAPs in the Dodd-Frank Act.
-
Debt Collection. Our collection services are subject to the Federal Fair Debt Collection Practices Act and various state collection laws and licensing requirements. The Federal Trade Commission, as well as state attorneys general and other agencies, have enforcement responsibility over the collection laws, as well as the various credit reporting laws.
-
Anti-Corruption. FIS is subject to applicable anti-corruption laws, such as the U.S. Foreign Corrupt Practices Act and the U.K. Bribery Act, in the jurisdictions in which it operates. Anti-corruption laws generally prohibit offering, promising, giving, or authorizing others to give anything of value, either directly or indirectly, to a government official or private party in order to influence official action or otherwise gain an unfair business advantage, such as to obtain or retain business. FIS has implemented policies, procedures, training and internal controls that are designed to comply with such laws, rules and regulations.
The foregoing list of laws and regulations to which our Company is subject is not exhaustive, and the regulatory framework governing our operations changes continuously. Enactment of new laws and regulations may increasingly affect the operations of our business, directly and indirectly, which could result in substantial regulatory compliance costs, litigation expense, adverse publicity, and/or loss of revenue.
Information Security
Globally, attacks on information technology systems continue to grow in frequency, complexity and sophistication. This is a trend we expect to continue. Such attacks have become a point of focus for individuals, businesses and governmental entities. The objectives of these attacks include, among other things, gaining unauthorized access to systems to facilitate financial fraud, disrupt operations, cause denial of service events, corrupt data, and steal non-public information. These circumstances present both a threat and an opportunity for FIS. As part of our business, we electronically receive, process, store and transmit a wide range of confidential information, including sensitive customer information and personal consumer data. We also operate payment, cash access and prepaid card systems.
FIS remains focused on making strategic investments in information security to protect our clients and our information systems. These investments include both capital expenditures and operating expenses related to hardware, software, personnel and consulting services. We also participate in industry and governmental initiatives to improve information security for our clients. Through the expertise we have gained with this ongoing focus and involvement, we have developed fraud, security, risk management and compliance solutions to target this growth opportunity in the financial services industry.
For more information on Information Security, see "Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations."
Human Capital Management
Employee Population
As of December 31, 2021, we had more than 65,000 employees, including over 40,000 employees principally employed outside of the U.S. None of our U.S. workforce currently is unionized. Approximately 12,000 of our employees, primarily in Brazil and Europe, are represented by labor unions or works councils.
Health and Safety
The health and safety of our employees is a key priority. In 2021, we hired our first ever Global Head of Well-Being to lead our efforts related to all aspects of employee wellness. Throughout the COVID-19 pandemic, we have leveraged our company-wide Pandemic Plan and Crisis Management team to ensure we are caring for the needs of our employees. We continue to follow safety protocols and procedures throughout our facilities for employees who continued to work on site. In addition, for employees impacted by COVID-19, we have provided enhanced paid time off to deal with personal illness or to care for family members, and we have expanded FIS Cares globally to assist our colleagues in need. FIS Cares is a colleague-funded giving program designed to help our employees in times of need.
Corporate Culture/Inclusion and Diversity
Our culture stems from embracing our corporate values as we work together to win as one team, lead with integrity and strive to be the change for our colleagues, clients and communities. The Company believes that inclusion and diversity are at the core of our corporate values. The diversity of our workforce helps us use our collective strengths to innovate and deliver the best products and solutions for our clients. Our Board of Directors and senior leaders are united in championing inclusion and diversity within our workforce through their leadership in prioritizing equality and diversity in our human resource decision making throughout the Company. The Company sponsors Inclusion Networks, which are led by employees who share common backgrounds and experiences. These groups support their members while promoting the Company's overall goal of fostering an inclusive work environment. Current FIS Inclusion Networks include Women, Asian, Black, Latinx, Disability, LGBTQ+, Rising Professionals, Veterans, and Working Families, all governed by an Enterprise Inclusion & Diversity Council which includes participation and leadership of senior executives of the Company. The Chief Executive Officer and the Chief People Officer regularly update the Company's Board of Directors on human capital management and inclusion and diversity initiatives.
Talent Management
Our colleagues are primary stakeholders in our organization, and we are strategic in attracting talent that adds to our collective strengths to innovate and deliver an exemplary client experience. We have increased our hiring program for recent college graduates who are critical to building our pipeline of future leaders, and for those who remain with us, we have implemented a program to help pay down their college tuition debt. We have an inclusive culture where employees receive the development needed to grow their careers and deliver high-quality outcomes. Our practices include a comprehensive performance feedback culture that includes quarterly performance reviews, access to a variety of online and self-paced learning resources, as well as virtual and face-to-face development offerings, targeted development programs for high-potential and senior management employees, opportunities to apply for open roles to move within the Company and executive-level succession planning.
Available Information
Our website address is www.fisglobal.com. We make our Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q, and Current Reports on Form 8-K, and any amendments to those reports, available, free of charge, on that website as soon as reasonably practicable after we file or furnish them to the SEC. Our Corporate Governance Policy and Code of Business Conduct and Ethics are also available on our website and are available in print, free of charge, to any shareholder who mails a request to the Corporate Secretary, Fidelity National Information Services, Inc., 601 Riverside Avenue, Jacksonville, FL 32204 USA. Other corporate governance-related documents can be found at our website as well. However, the information found on our website is not a part of this or any other report.
Item 1A. Risk Factors
In addition to the normal risks of business, we are subject to significant risks and uncertainties, including those listed below and others described elsewhere in this Annual Report on Form 10-K. Any of the risks described herein could result in a significant adverse effect on our results of operations and financial condition.
Risks Related to Our Business and Operations
The extent to which the COVID-19 pandemic and measures taken in response thereto impact our business, results of operations, liquidity and financial condition will depend on the effectiveness of vaccines and other medical developments to further decrease the spread of COVID-19 and its impact on global and local economies.
Global health concerns relating to COVID-19 and related government actions taken to reduce the spread of the virus have continued to weigh on the macroeconomic environment, but the impact of COVID-19 on global and local economies has been reduced in areas where such governmental actions, including the distribution of vaccines, have been more widespread. Economic activity increased in many areas throughout 2021, including, most notably, an increase in consumer and business spending by digital methods compared to 2020 when the impact of COVID-19 first arose. In the fourth quarter of 2021, some governmental restrictions were re-imposed based upon a resurgence of COVID-19 in many areas of the U.S. and Europe, which resulted in an adverse impact on payment volumes and transactions compared to those anticipated following the easing of restrictions in the prior two quarters. In addition, we have continued to see adverse impacts on spending in discretionary spending verticals, including travel, airlines and restaurants. These changes in spending affected our business, results of operations and financial condition throughout 2021 and will likely continue to have such an impact in 2022, although the magnitude and duration of their ultimate effect is not possible to predict. The distribution of vaccines against COVID-19 curtailed the impact of the pandemic in 2021 in many of the larger countries in which we do business, but the timing of a complete recovery remains uncertain as new variants of COVID-19 continue to evolve and spread.
We may experience additional pandemic-related financial impacts due to a number of operational factors, including:
-
increased risk of merchant and card issuer failures and credit settlement and chargeback risk;
-
increased risk of meeting client service contractual obligations due to government lock-down or other orders where it is not possible to provide certain client-facing services from home or to promptly transfer them to other locations, causing potential loss of revenue or contractual penalties due to failure to meet service level requirements as well as potential legal disputes and associated costs regarding force majeure or other related contract defenses;
-
increased cyber and payment fraud risk related to COVID-19, as cybercriminals attempt to profit from the disruption, given increased online banking, eCommerce and other online activity;
-
challenges to the availability and reliability of our solutions and services due to changes to normal operations, including the possibility of one or more clusters of COVID-19 cases occurring at our data centers, contact centers or operations centers, affecting our employees or affecting the systems or employees of our clients or other third parties on which we depend;
-
an increased volume of unanticipated client and regulatory requests for information and support, or additional regulatory requirements, which could require additional resources and costs to address, including, for example, government initiatives to reduce or eliminate payments costs or fees to merchants;
-
continued incremental costs directly related to COVID-19, although their magnitude is uncertain; and
-
the general impact of recession and instability of markets across the globe.
Additional uncertainty is added in the U.S. by conflicting federal and state laws, regulations and executive orders regarding whether vaccinations for COVID-19 may be required in the workplace. Until challenges to these laws are finally decided by the courts, there is uncertainty as to what businesses may require for employees to return to the workplace. We have modified our business practices to allow for more hybrid schedules as to when employees need to be in the office in an attempt to meet the changes in the workplace in today's world, as well as allowing continued work from home, at least temporarily, where appropriate to accommodate others not taking the vaccine in order to provide a safe workplace. There is no certainty that such measures will be sufficient to mitigate all of the risks posed by the virus or will otherwise be satisfactory to government authorities. Further, the ability of our senior management and employees to get to work has been disrupted across multiple locations, whether in their own offices or at client sites, due, among other things, to government work and travel restrictions, including mandatory shutdowns.
In addition, we have extended at times during the pandemic higher-than-usual levels of credit to our merchant clients as part of funds settlement in connection with payments to their customers, for, among other things, refunds for cancelled trips and events. If the speed of repayments to us by our merchant clients is substantially slower than expected over an extended period
of time, or if our merchant clients cease operations such that we are unable to collect on the credit advanced by us for these payments or for any chargeback liability, it could have a material adverse effect on our liquidity, results of operations and financial condition.
The extent to which COVID-19 impacts our business, results of operations and financial condition will depend on future developments, which remain uncertain and are difficult to predict, including, but not limited to, the duration and spread of the pandemic and its variants, its severity, the actions to contain the virus or treat its impact, and how quickly and to what extent normal economic and operating conditions can resume. We may experience materially adverse impacts to our business as a result of the pandemic's global economic impact, including the availability of credit and our ability to comply with the covenants of our credit agreement, adverse impacts on our liquidity, our ability to meet our deleveraging targets, and any recession that has occurred or may occur in the future. Such impacts may also have a material effect on one or more of the estimates and assumptions used to evaluate goodwill impairment and could result in future goodwill impairment.
There are no comparable recent events that provide guidance as to the effect the spread and duration of COVID-19 as a global pandemic may have, and, as a result, the ultimate impact of the pandemic is highly uncertain and subject to change. We do not yet know the full extent of the impacts on our business, our operations or the global economy as a whole. However, the impacts of the pandemic could have a material adverse effect on our results of operations, liquidity or financial condition and heighten many of our known risks described in the remainder of this "Risk Factors" section*.*
Security breaches or attacks, or our failure to comply with information security laws or regulations or industry security requirements, could harm our business by disrupting delivery of services and damaging the reputation of FIS and could result in a breach of one or more client contracts.
FIS electronically receives, processes, stores and transmits sensitive business information of its clients. In addition, FIS collects personal consumer data, such as names and addresses, social security numbers, driver's license numbers, cardholder data and payment histo
Showing the first 8K of 92K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
FIS' corporate headquarters is located at 601 Riverside Avenue, Jacksonville, Florida. In addition, FIS owns or leases support centers, data processing facilities and other facilities at approximately 120 locations. We believe our facilities and equipment are generally well maintained and are in good operating condition. We believe that the equipment we own and our various facilities are adequate for our present and foreseeable business needs.
Item 3. Legal Proceedings
In the ordinary course of business, the Company is involved in various pending and threatened litigation matters related to its business and operations, some of which include claims for punitive or exemplary damages. The Company believes no such currently pending or threatened actions are likely to have a material adverse effect on its consolidated financial position. With respect to litigation in which the Company is involved generally, please note the following:
-
These matters raise difficult and complicated factual and legal issues and are subject to many uncertainties and complexities.
-
The Company reviews all of its litigation on an ongoing basis and follows the authoritative provision for accounting for contingencies when making accrual and disclosure decisions. A liability must be accrued if (a) it is probable that a liability has been incurred and (b) the amount of loss can be reasonably estimated. If one of these criteria has not been met, disclosure is required when there is at least a reasonable possibility that a material loss may be incurred. When assessing reasonably possible and probable outcomes, the Company bases decisions on the assessment of the ultimate outcome following all appeals. Legal fees associated with defending litigation matters are expensed as incurred.
See Note 16 to the consolidated financial statements for information about certain legal matters and indemnifications and warranties.
Item 4. Mine Safety Disclosures
Not applicable.
PART II
Item 5. Market for Registrant's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Our common stock trades on the New York Stock Exchange under the ticker symbol "FIS."
As of January 31, 2022, there were approximately 10,295 shareholders of record of our common stock.
We currently expect to continue to pay quarterly dividends. In January 2022, the Board of Directors approved a quarterly dividend increase of 21% to $0.47 per share beginning with the first quarter of 2022. A regular quarterly dividend of $0.47 per common share is payable on March 25, 2022, to shareholders of record as of the close of business on March 11, 2022. Consistent with our capital allocation strategy, we plan to increase our annual dividend approximately 20% per year over the
next several years, as compared to approximately 10% per year increases in recent years, to gradually increase our dividend payout ratio, beginning with the quarterly dividend payable in March 2022. However, the amount, declaration and payment of future dividends is at the discretion of the Board of Directors and depends on, among other things, our investment opportunities (including potential mergers and acquisitions), results of operations, financial condition, cash requirements, future prospects, the duration and impact of the COVID-19 pandemic, and other factors that may be considered relevant by our Board of Directors, including legal and contractual restrictions. Additionally, the payment of cash dividends may be limited by covenants in certain debt agreements.
Item 12. of Part III contains information concerning securities authorized for issuance under our equity compensation plans.
The share repurchase plan approved by the Board of Directors in 2017 expired as of December 31, 2020. Management temporarily suspended share repurchases during 2020 as a result of the Worldpay transaction to accelerate debt repayment. In January 2021, our Board of Directors approved a new share repurchase program under which it authorized the Company to repurchase up to 100 million shares of our common stock at management's discretion from time to time on the open market or in privately negotiated transactions and through Rule 10b5-1 plans. The new repurchase program has no expiration date and may be suspended for periods, amended or discontinued at any time.
The graph below compares the cumulative 5-year total return of holders of Fidelity National Information Services, Inc.'s common stock with the cumulative total returns of the S&P 500 index and S&P Supercap Data Processing & Outsourced Services index. The graph assumes that the value of the investment in our common stock and in each index (including reinvestment of dividends) was $100 on December 31, 2016 and tracks it through December 31, 2021.
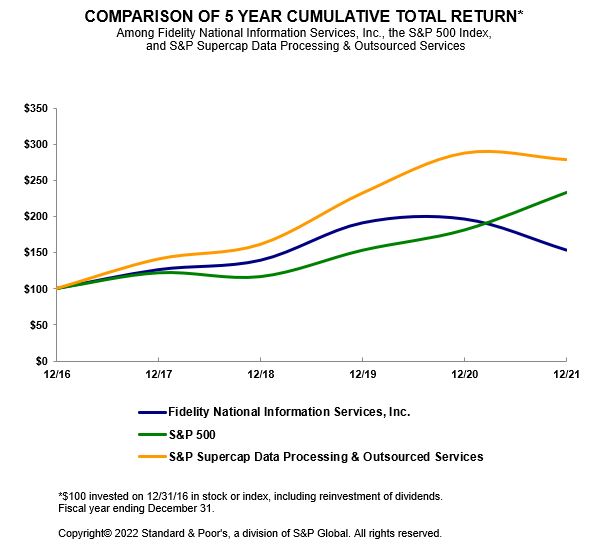
| 12/16 | 12/17 | 12/18 | 12/19 | 12/20 | 12/21 | |||||||||||||||
| Fidelity National Information Services, Inc. | 100 | 126.03 | 139.04 | 190.72 | 195.98 | 153.07 | ||||||||||||||
| S&P 500 | 100 | 121.83 | 116.49 | 153.17 | 181.35 | 233.41 | ||||||||||||||
| S&P Supercap Data Processing & Outsourced Services | 100 | 140.86 | 161.14 | 232.03 | 287.36 | 278.22 |
The stock price performance included in this graph is not necessarily indicative of future stock price performance.
Item 6. Reserved
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
The following section discusses management's view of the financial condition and results of operations of FIS and its consolidated subsidiaries as of December 31, 2021 and 2020, and for the years ended December 31, 2021, 2020 and 2019, unless otherwise noted.
This section should be read in conjunction with our audited consolidated financial statements and related notes included elsewhere in this Annual Report. Management's Discussion and Analysis of Financial Condition and Results of Operations contains forward-looking statements. See "Forward-Looking Information" and "Risk Factors" in Item 1A of this Annual Report for a discussion of the uncertainties, risks and assumptions associated with these forward-looking statements that could cause future results to differ materially from those reflected in this section.
Business Trends and Conditions
Our revenue is primarily derived from a combination of technology and processing services, transaction fees, professional services and software license fees. While we are a global company and do business around the world, the majority of our revenue is generated by clients in the U.S. The majority of our international revenue is generated by clients in the U.K., Germany, Australia, Brazil, Canada, and India. In addition, the majority of our revenue has historically been recurring and has been provided under multi-year Banking and Capital Markets contracts that contribute relative stability to our revenue stream. These services, in general, are considered critical to our clients' operations. Although Merchant has a lesser percentage of multi-year contracts, substantially all of our Merchant revenue is recurring, derived from transaction processing fees that fluctuate with the number or value of transactions processed, among other variable measures associated with consumer activity. Professional services revenue is typically non-recurring, though recognition often occurs over time rather than at a point in time. Sales of software licenses are typically non-recurring with point-in-time recognition and are less predictable.
The distribution of vaccines against COVID-19 curtailed the impact of the pandemic in 2021 in many of the larger countries in which we do business, but the timing of a complete recovery remains uncertain as new variants of COVID-19 continue to impact consumer spending. Economic activity increased in many areas throughout 2021, including, most notably, an increase in consumer and business spending by digital methods compared to 2020 when the impact of COVID-19 first arose. In the fourth quarter of 2021, some governmental restrictions were re-imposed based upon a resurgence of variants of COVID-19 in many areas of the U.S. and Europe, which resulted in an adverse impact on payment volumes and transactions over those anticipated following the easing of restrictions in the prior two quarters. In addition, we have continued to see adverse impacts on spending in discretionary spending verticals, including travel, airlines and restaurants, although the impact has lessened compared to 2020. These changes in spending affected our business, results of operations and financial condition throughout 2021 and will likely continue to have an impact in 2022, although the magnitude and duration of their ultimate effect is not possible to predict.
We extended higher-than-usual levels of credit to our merchant clients during the first part of the pandemic as part of funds settlement in connection with payments to their customers, for, among other things, refunds for cancelled trips as cases of COVID-19 spread across the globe. The level of credit extended to our merchant clients has since normalized. We are potentially exposed to losses if our merchant customers are unable to repay the credit we have extended or to fund their liability for chargebacks due to closure, insolvency, bankruptcy or other reasons. Our potential liability for chargebacks did not have a material impact on our liquidity for the three- and twelve-month periods ended December 31, 2021, and we continue to monitor for impact on our liquidity, results of operations and financial condition.
We continue to assist financial institutions in migrating to outsourced integrated technology solutions to improve their profitability and address increasing and ongoing regulatory requirements. As a provider of outsourced solutions, we benefit from multi-year recurring revenue streams, which help moderate the effects of broader year-to-year economic and market
changes that otherwise might have a larger impact on our results of operations. We believe our integrated solutions and outsourced services are well-positioned to address this outsourcing trend across the markets we serve.
Over the last five years, we have moved over 80% of our server compute, primarily in North America, to our FIS cloud located in our strategic data centers. This allows us to further enhance security for our clients' data and increases the flexibility and speed with which we can provide solutions and services to our clients, at lesser cost. We have also completed our data center consolidation program in 2021, generating savings for the Company of over $250 million in run-rate annual expense since the program's inception in mid-2016.
Following the successful modernization of our IT infrastructure and consolidation of our data centers, we are now accelerating the modernization of our strategic applications and sunsetting of our redundant platforms. Our multi-year platform modernization initiative is designed to create a componentized, cloud-native set of capabilities that can be consumed by clients as end-to-end business applications or as individual components. Although our platform modernization will result in additional near-term costs, we expect it will result in improvements in our operational efficiencies over time.
We continue to invest in modernization, innovation and integrated solutions and services to meet the demands of the markets we serve and compete with global banks, financial and other technology providers, and emerging technology innovators. We invest both organically and through investment opportunities in companies building complementary technologies in the financial services space. Our internal efforts in research and development activities have related primarily to the modernization of our proprietary core systems in each of our segments, design and development of next-generation digital and innovative solutions and development of processing systems and related software applications and risk management platforms. We have increased our investments in these areas in each of the last three years. We expect to continue our practice of investing an appropriate level of resources to maintain, enhance and extend the functionality of our proprietary systems and existing software applications, to develop new and innovative software applications and systems to address emerging technology trends in response to the needs of our clients and to enhance the capabilities of our outsourcing infrastructure. We will also be developing software that will accelerate bringing new capabilities and innovation to market.
In addition, we are investing in the development of new solutions and venture opportunities by establishing FIS Impact Ventures. This group prioritizes development of, and investment in, next-generation technology and innovation.
Since the beginning of the pandemic, the Company has taken several actions to protect its employees while maintaining business continuity, including implementing its comprehensive Pandemic Plan. For example, when the COVID-19 variants impacted India in the second quarter, we rolled out several benefits to help our employees there, including providing vaccines to over 15,000 employees and dependents. The Pandemic Plan includes site-specific plans as well as travel restrictions, medical response protocols, work-from-home strategies and enhanced cleaning within our locations. As a critical infrastructure provider for the global economy, FIS continues to operate around the world to serve our clients.
The spread of COVID-19 has caused us to modify our business practices, and we may take further actions as may be required by government authorities or as we determine are in the best interests of our employees, clients and business partners. While FIS has outfitted employees to provide services from home or transferred work to other locations, we recently began a limited reopening of offices in certain locations where the COVD-19 infection rates have been significantly reduced. In many locations, a hybrid work status will allow employees to work from home and the office.
Consumer preference continues to shift from traditional branch banking services to digital banking solutions, and our clients seek to provide a single integrated banking experience through their branch, mobile, internet and voice banking channels. The COVID-19 pandemic has resulted in accelerating digitization of banking and payment services by requiring, in many cases, banks and bank customers to transact through digital channels. We have been providing our large regional banking customers in the U.S. with Digital One, an integrated digital banking platform, and are now adding functionality and offering Digital One to our community bank clients to provide a consistent, omnichannel experience for consumers of banking services across self-service channels like mobile banking and online banking, as well as supporting channels for bank staff operating in bank branches and contact centers. The uniform customer experience extends to support a broad range of financial services including opening new accounts, servicing of existing accounts, money movement, and personal financial management, as well as other consumer, small business and commercial banking capabilities. Digital One is integrated into several of the core banking platforms offered by FIS and is also offered to customers of non-FIS core banking systems.
We anticipate consolidation within the banking industry will continue, primarily in the form of merger and acquisition activity among financial institutions, which we believe would broadly be detrimental to the profitability of the financial technology industry. However, consolidation resulting from specific merger and acquisition transactions may be beneficial to
our business. When consolidations of financial institutions occur, merger partners often operate systems obtained from competing service providers. The newly formed entity generally makes a determination to migrate its core and payments systems to a single platform. When a financial institution processing client is involved in a consolidation, we may benefit by their expanding the use of our services if such services are chosen to survive the consolidation and to support the newly combined entity. Conversely, we may lose revenue if we are providing services to both entities, or if a client of ours is involved in a consolidation and our services are not chosen to survive the consolidation and to support the newly combined entity. It is also possible that larger financial institutions resulting from consolidation may have greater leverage in negotiating terms or could decide to perform in-house some or all of the services that we currently provide or could provide. We seek to mitigate the risks of consolidations by offering other competitive services to take advantage of specific opportunities at the surviving company.
As of the end of 2021, our achievement of revenue synergies from the Worldpay acquisition have exceeded our targets, driven by successful cross-sell of our heritage FIS solutions into heritage Worldpay clients and leveraging our heritage Worldpay sales and distribution teams, expanding on our existing relationships with financial institutions to establish merchant referral agreements and optimizing our network routing capabilities. We have also exceeded our original target for expense synergies, as we have successfully integrated organizational structures, reduced corporate overhead and achieved cost savings within our operating environment.
We continue to see demand in the payments market for innovative solutions that will deliver faster, more convenient payment options in mobile channels, internet applications, in-store cards, and the growing area of cryptocurrencies. The payment processing industry is adopting new technologies, developing new solutions and services, evolving new business models, and being affected by new market entrants and by an evolving regulatory environment. As merchants and financial institutions respond to these changes by seeking services to help them enhance their own offerings to consumers, including the ability to accept card-not-present ("CNP") payments in eCommerce and mobile environments as well as contactless cards and mobile wallets at the point-of-sale, FIS believes that payment processors will seek to develop additional capabilities in order to serve clients' evolving needs. To facilitate this expansion, we believe that payment processors will need to enhance their technology platforms so they can deliver these capabilities and differentiate their offerings from other providers. The COVID-19 pandemic has accelerated digitization of payment services by requiring, in many cases, businesses and consumers to transact through digital channels.
We believe that these market changes present both an opportunity and a risk for us, and we cannot predict which emerging technologies or solutions will be successful. However, FIS believes that payment processors, like FIS, that have scalable, integrated business models, provide solutions across the payment processing value chain and utilize broad distribution capabilities will be best positioned to enable emerging alternative electronic payment technologies. Further, FIS believes that its depth of capabilities and breadth of distribution will enhance its position as emerging payment technologies are adopted by merchants and other businesses. FIS' ability to partner with non-financial institution enterprises, such as mobile payment providers and internet, retail and social media companies, continues to create attractive growth opportunities as these new entrants seek to become more active participants in the development of alternative electronic payment technologies and to facilitate the convergence of retail, online, mobile and social commerce applications.
Globally, attacks on information technology systems continue to grow in frequency, complexity and sophistication. This is a trend we expect to continue. Such attacks have become a point of focus for individuals, businesses and governmental entities. The objectives of these attacks include, among other things, gaining unauthorized access to systems to facilitate financial fraud, disrupt operations, cause denial of service events, corrupt data, and steal non-public information. These circumstances present both a threat and an opportunity for FIS. As part of our business, we electronically receive, process, store and transmit a wide range of confidential information, including sensitive customer information and personal consumer data. We also operate payment, cash access and prepaid card systems.
FIS remains focused on making strategic investments in information security to protect our clients and our information systems. These investments include both capital expenditures and operating expense related to hardware, software, personnel and consulting services. We also participate in industry and governmental initiatives to improve information security for our clients. Through the expertise we have gained with this ongoing focus and involvement, we have developed fraud, security, risk management and compliance solutions to target this growth opportunity in the financial services industry.
Critical Accounting Policies and Estimates
The accounting policies and estimates described below are those we consider critical in preparing our consolidated financial statements. These policies require management to make estimates, judgments and assumptions that affect the reported
amounts of assets and liabilities and disclosures with respect to contingent assets and liabilities at the date of the consolidated financial statements and the reported amounts of revenue and expenses during the reporting periods. Actual amounts could differ from those estimates. See Note 2 to the consolidated financial statements for a more detailed description of the significant accounting policies that have been followed in preparing our consolidated financial statements.
Revenue Recognition
The most critical judgments required in applying ASC 606, Revenue Recognition from Customers, and our revenue recognition policy relate to the determination of whether we are the principal or the agent with respect to transactions involving third parties, the determination of distinct performance obligations and the evaluation of the standalone selling price for each performance obligation.
The Company generates revenue in a number of ways, including from the delivery of account- or transaction-based processing, SaaS, BPaaS, cloud offerings, software licensing, software-related services and professional services. Certain contracts contain non-standard terms that require judgment to determine the appropriate impact on revenue recognition.
Technology or services from third parties are frequently embedded in or combined with our applications or service offerings. Whether we recognize revenue based on the gross amount billed to a customer as a principal or the net amount retained as an agent involves judgment that depends on the relevant facts and circumstances, including whether the Company has control of the technology or service prior to it being transferred to the customer and the level of contractual responsibilities and obligations for delivering the application or service.
Contracts containing multiple promised solutions or services require judgment to determine whether individual promised solutions or services can be considered distinct or should instead be combined with other promised solutions or services in the contract. We assess the solutions and services promised in our contracts with customers and identify a performance obligation for each promise to transfer to the customer a solution or service (or bundle of solutions or services) that is distinct - i.e., if a solution or service is separately identifiable from other items in the bundled package and if a customer can benefit from it on its own or with other resources that are readily available to the customer.
The transaction price (including any discounts or rebates) is allocated among distinct goods and services in a contract that includes multiple performance obligations based on their relative standalone selling prices. Judgment may be required to determine standalone selling prices for each performance obligation and whether it depicts the amount we expect to receive in exchange for the related good or service. For performance obligations that are not sold separately, we estimate the standalone selling prices considering all reasonably available information and maximizing observable inputs using various approaches including historical pricing, cost plus margin, adjusted market and residual approaches. The cost-plus-margin approach, in particular, requires judgment, including the estimation of the costs required to complete the performance obligation. These estimates are based primarily on the scope and complexity of the obligation, platform migration timelines, expected account or transaction volumes, and internal and external labor rates. We have not made significant changes in our cost estimates under this approach in the reporting period. For significant contracts for which the cost-plus-margin approach was used to estimate the standalone selling price, a 10% change in our cost assumptions would not have a significant impact on the amount reported during the period.
Due to the large number, broad nature and average size of our individual customer contracts, the impact of judgments and assumptions that we apply in recognizing revenue for any single contract is not likely to have a material effect on our consolidated operations or financial position. However, the accounting policies that we apply across similar contracts, products or classes of clients could significantly influence the timing and amount of revenue recognized in our historical and future results of operations or financial position.
Purchase Accounting
We allocate the purchase price of acquired businesses to the assets acquired and liabilities assumed in the transaction at their estimated fair values. The estimates used to determine the fair value of long-lived assets, such as intangible assets and software, are complex and require a significant amount of management judgment. We typically engage third-party valuation specialists to assist us in making fair value determinations. The third-party valuation specialists generally use discounted cash flow models, which require internally-developed assumptions, to determine the acquisition fair value of customer relationship intangible assets and developed technology software assets. Assumptions for customer relationship asset valuations typically include forecasted revenue attributable to existing customer contracts and relationships, estimated annual attrition, forecasted EBITDA margin, and estimated weighted average cost of capital and discount rates. Assumptions for software asset valuations
typically include forecasted revenue attributable to the software assets, obsolescence rates, estimated royalty rates and estimated weighted average cost of capital and discount rates. The forecasted revenue and EBITDA margins used in the discounted cash flow models are critical estimates in determining the fair value of customer relationships and developed technology software assets as these estimates are influenced by many factors including historical financial information and management’s expectation for future operating results as a combined company.
While we use our best estimates and assumptions to determine the fair values of the assets acquired and the liabilities assumed, our estimates are inherently uncertain and subject to refinement. As a result, during the measurement period, which may be up to one year from the acquisition date, we record adjustments to the assets acquired and liabilities assumed. Upon the conclusion of the measurement period, any subsequent adjustments are recorded to our consolidated statements of earnings.
See Note 3 to the consolidated financial statements for discussion of the Payrix acquisition in 2021, the Virtus acquisition in 2020 and Worldpay acquisition in 2019. The Payrix acquisition in the current year is not considered material to warrant additional disclosure regarding estimation uncertainty.
Goodwill Impairment
The Company assesses goodwill for impairment by reporting unit on an annual basis during the fourth quarter or more frequently if circumstances indicate potential impairment. Our reporting units are the same as our primary operating segments, with additional reporting units for certain non-strategic businesses within the Corporate and Other segment. Goodwill impairment assessments require a significant amount of management judgment, and a meaningful change in one or more of the underlying forecasts, estimates, or assumptions used in testing goodwill for impairment could result in a material impact on the Company's results of operations and financial position. Based on the results of our assessments, $94 million of goodwill related to certain non-strategic businesses within the Corporate and Other segment was impaired in 2020. For all other reporting units for all periods presented, goodwill was not impaired.
Our impairment test may first consider qualitative factors to determine whether it is more likely than not that a reporting unit's carrying amount exceeds its fair value. Qualitative factors include macroeconomic conditions, industry and market conditions, cost factors, overall financial performance and events affecting the reporting unit or Company as a whole, including a sustained decrease in stock price. If we conclude that it is more likely than not that the reporting unit's fair value is less than its carrying amount as a result of the qualitative assessment, or we elect to bypass the qualitative assessment for a reporting unit, then we must perform the quantitative assessment for that reporting unit.
When a quantitative assessment is triggered, we typically engage third-party valuation specialists to assist us in determining the fair value of the reporting unit based on a weighted average of multiple valuation techniques, typically a combination of an income approach and a market approach. The income approach calculates a value based upon the present value of estimated future cash flows, while the market approach uses earnings multiples of similarly situated guideline public companies. The income approach involves the use of significant estimates and assumptions regarding forecasted revenue, growth rates, operating margins, capital expenditures, and other factors used to calculate estimated future cash flows. In addition, risk-adjusted discount rates and future economic and market conditions and other assumptions are applied. The market approach involves the selection of guideline public companies and earnings multiples considering factors such as markets of operation, solutions offered, and risk profiles. The income approach used to assess goodwill for impairment is a critical estimate because the forecasted growth rate assumption (including long-term growth assumption) underlying the estimated future cash flows is subject to management’s judgment based upon the best available market information, internal forecasts and operating plans. A deterioration in this assumption could adversely impact our results.
For each of 2021 and 2019, we began our annual assessment with the qualitative assessment and concluded that it remained more likely than not that the fair value of each of our reporting units continued to exceed their respective carrying amounts. For 2020, we began our annual assessment for the Banking Solutions and Capital Market Solutions reporting units with qualitative assessments and concluded that it remained more likely than not that the fair value of each of the reporting units continued to exceed their respective carrying amounts. Based on the qualitative assessments performed for the Banking Solutions and Capital Market Solutions reporting units and the substantial excess of fair value over carrying amount in our previous third-party valuations performed in 2015 for the related businesses, we believe the likelihood of obtaining materially different results based on a change of assumptions is low.
For Merchant Solutions, we began our 2020 annual assessment with a quantitative assessment due to the economic impact of the COVID-19 pandemic on our Merchant Solutions business and its primary operations being recently acquired as part of the Worldpay acquisition. As a result of the assessment, the fair value of the reporting unit was estimated to be in excess of its
carrying amount by approximately 4%. The fair value was determined with the assistance of third-party valuation specialists, using an equal weighting of the income and market approaches based on an evaluation of the availability and relevance of guideline public companies having similar risks, participating in similar markets, and providing similar solutions for their customers. Under the income approach for the Merchant Solutions reporting unit, management estimated the fair value by forecasting future cash flows using internal forecasts, which were developed considering historical operating performance, expected economic conditions and industry and market trends, including the impact of the COVID-19 global pandemic and expected impact of planned business initiatives. At the end of the forecast period, we used a long-term growth rate to determine the terminal value based on an evaluation of the minimum expected terminal growth rate of the Merchant Solutions reporting unit, as well as broader economic considerations such as inflation and foreign exchange rates. In computing the present value of estimated future cash flows, we used a risk-adjusted discount rate based on an assessment of the weighted average cost of capital for the Merchant Solutions reporting unit and relevant guideline public companies. We believe the discount rate used was commensurate with the risks and uncertainties inherent in the Merchant Solutions business and in our internally developed forecasts, though the rate is subject to change in future periods based on changes in the U.S. Treasury rate, inflation, and other factors.
For Merchant Solutions in 2021, we performed a qualitative assessment for our annual assessment. In addition to the factors noted above that are considered when performing such an assessment, we considered actual results for 2021 and updated internal forecasts as compared to prior internal forecasts and other assumptions used in the 2020 quantitative annual assessment. As a result of the assessment, we determined that the indicated fair value of the reporting unit was estimated to be in excess of carrying amount by a similar percentage as determined by the prior year’s quantitative assessment. We concluded for 2021 that it remained more likely than not that the fair value of the Merchant Solutions reporting unit continued to exceed its carrying amount; however, given the results of the 2020 quantitative and 2021 qualitative annual assessments, the reporting unit is at risk for future goodwill impairment as it is reasonably possible that future developments related to the economic impact of the COVID-19 pandemic on our Merchant Solutions business, such as an extended duration of the pandemic and/or government-imposed shutdowns, prolonged economic downturn or recession, or lack of governmental support for recovery, could have a material impact on one or more of the estimates and assumptions used to evaluate goodwill impairment and could result in future goodwill impairment.
Related-Party Transactions
We are a party to certain historical related-party agreements as discussed in Note 18 to the consolidated financial statements.
Consolidated Results of Operations
This section generally discusses fiscal year 2021 compared to 2020. Discussions of fiscal year 2020 compared to 2019 not included herein can be found in Part II, "Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations" of our Annual Report on Form 10-K for fiscal year 2020, filed with the Securities and Exchange Commission on February 18, 2021.
| Year ended December 31, | |||||||||||||||||||||||
| 2021 | 2020 | $ Change | % Change | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Revenue | $ | 13,877 | $ | 12,552 | $ | 1,325 | 11 | % | |||||||||||||||
| Cost of revenue | (8,682) | (8,348) | (334) | 4 | |||||||||||||||||||
| Gross profit | 5,195 | 4,204 | 991 | 24 | |||||||||||||||||||
| Gross profit margin | 37 | % | 33 | % | |||||||||||||||||||
| Selling, general and administrative expenses | (3,938) | (3,516) | (422) | 12 | |||||||||||||||||||
| Asset impairments | (202) | (136) | (66) | 49 | |||||||||||||||||||
| Operating income | 1,055 | 552 | 503 | 91 | |||||||||||||||||||
| Operating margin | 8 | % | 4 | % |
Revenue
Revenue increased primarily due to the continued global economic recovery from the COVID-19 pandemic leading to increased Merchant volumes, increased demand for our newly developed offerings in Banking, and strong new sales driving Capital Markets managed services and other recurring revenue growth. Revenue also benefited from a favorable foreign
currency impact, which was primarily related to a weaker U.S. Dollar versus the Euro and the British Pound Sterling. See Segment Results of Operations below for more detailed explanation.
Cost of Revenue, Gross Profit and Gross Profit Margin
Cost of revenue increased primarily due to the revenue variances noted above and benefited from a positive shift in revenue mix. Gross profit and gross profit margin increased primarily due to revenue growth, a positive shift in revenue mix and continued expense management. This increase was partially offset by $183 million of incremental amortization expense associated with shortened estimated useful lives and accelerated amortization methods for certain software and deferred contract cost assets driven by the Company's platform modernization.
Selling, General and Administrative Expenses
Selling, general and administrative expenses increased primarily due to higher compensation expense, including incentive compensation, and accelerated stock compensation expense recorded during the first quarter of 2021 associated with the establishment of the Qualified Retirement Equity Program that modified our existing stock compensation plans as described in Note 17 to the consolidated financial statements. These increases were partially offset by lower discretionary spending during the COVID-19 pandemic.
Asset Impairments
During 2021, the Company recorded $202 million of asset impairments for certain software and deferred contract cost assets driven by the Company's platform modernization. During 2020, the Company recorded asset impairments totaling $136 million related to goodwill for certain non-strategic businesses and to certain long-lived assets related to reducing office space.
Operating Income and Operating Margin
The annual change in operating income resulted from the revenue and cost variances noted above. The operating margin during 2021 increased primarily due to a positive shift in revenue mix and continued expense management, partially offset by asset impairments of $202 million, accelerated amortization expense, and higher compensation expense discussed above as compared to prior year. The operating margin during 2020 was negatively impacted by higher acquired intangible asset amortization expense, higher acquisition, integration and other costs and asset impairments of $136 million.
Total Other Income (Expense), Net
| Year ended December 31, | |||||||||||||||||||||||
| 2021 | 2020 | $ Change | % Change | ||||||||||||||||||||
| Other income (expense): | (In millions) | ||||||||||||||||||||||
| Interest expense, net | $ | (214) | $ | (334) | $ | 120 | (36) | % | |||||||||||||||
| Other income (expense), net | (52) | 48 | (100) | NM | |||||||||||||||||||
| Total other income (expense), net | $ | (266) | $ | (286) | 20 | (7) |
The decrease in interest expense, net is primarily due to lower outstanding debt and lower weighted average interest rate on the outstanding debt throughout the year.
Other income (expense), net for 2021 includes net gains on equity security investments without readily determinable fair values of $218 million (see Note 11 to the consolidated financial statements), a gain on the sale of our equity ownership interest in Cardinal Holdings of approximately $225 million (see Note 18 to the consolidated financial statements) and a loss on extinguishment of debt of approximately $528 million relating to tender premiums, make-whole amounts, and fees; the write-off of unamortized bond discounts and debt issuance costs; and losses on related derivative instruments. The foregoing loss resulted from the debt refinancing activity we undertook in the first quarter of 2021 (see Note 12 to the consolidated financial statements), which will substantially reduce our ongoing interest expense. Other income (expense), net also includes fair value adjustments on certain other non-operating assets and liabilities and foreign currency transaction remeasurement gains.
Other income (expense), net for 2020 primarily includes the fair value adjustment on certain non-operating assets and liabilities, foreign currency transaction remeasurement gains and losses and the settlement recorded for the Reliance Trust claims, which is further described in Note 16 to the consolidated financial statements.
Provision (Benefit) for Income Taxes
| Year ended December 31, | |||||||||||||||||||||||
| 2021 | 2020 | $ Change | % Change | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Provision (benefit) for income taxes | $ | 371 | $ | 96 | $ | 275 | NM | ||||||||||||||||
| Effective tax rate | 47 | % | 36 | % |
The effective tax rate for the 2021 period includes the one-time net remeasurement of certain deferred tax liabilities due to the increase in the U.K. corporate statutory tax rate from 19% to 25% effective April 1, 2023, enacted on June 10, 2021. The effective tax rate for the 2020 period includes the one-time net remeasurement of certain deferred tax liabilities due to the increase in the U.K. corporate statutory tax rate from 17% to 19% enacted on July 22, 2020.
Segment Results of Operations
This section generally discusses fiscal year 2021 compared to 2020. Discussions of fiscal year 2020 compared to 2019 not included herein can be found in Part II, "Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations" of our Annual Report on Form 10-K for fiscal year 2020, filed with the Securities and Exchange Commission on February 18, 2021.
FIS reports its financial performance based on the following segments: Merchant Solutions, Banking Solutions, Capital
Market Solutions, and Corporate and Other. The Company reclassified certain non-strategic businesses from Merchant Solutions, Banking Solutions, and Capital Market Solutions into Corporate and Other during the year ended December 31, 2020, and recast all prior-period segment information presented.
Adjusted EBITDA is defined as net earnings (loss) before net interest expense, net other income (expense), income tax provision (benefit), equity method investment earnings (loss), depreciation and amortization, and excludes certain costs and other transactions that management deems non-operational in nature. This measure is reported to the chief operating decision maker for purposes of making decisions about allocating resources to the segments and assessing their performance. For this reason, Adjusted EBITDA, as it relates to our segments, is presented in conformity with FASB ASC Topic 280, Segment Reporting. The non-operational items affecting the segment profit measure generally include purchase price amortization of acquired intangible assets as well as acquisition, integration and certain other costs and asset impairments. Adjusted EBITDA also excludes incremental and direct costs resulting from the COVID-19 pandemic. These costs and adjustments are recorded in the Corporate and Other segment for the periods discussed below. Adjusted EBITDA for the respective segments excludes the foregoing costs and adjustments. Financial information, including details of Adjusted EBITDA, for each of our segments is set forth in Note 21 to the consolidated financial statements.
Merchant Solutions
| Years ended December 31, | $ Change | % Change | |||||||||||||||||||||
| 2021 vs | 2021 vs | ||||||||||||||||||||||
| 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Revenue | $ | 4,496 | $ | 3,767 | $ | 729 | 19 | % | |||||||||||||||
| Adjusted EBITDA | $ | 2,262 | $ | 1,752 | 510 | 29 | |||||||||||||||||
| Adjusted EBITDA margin | 50.3 | % | 46.5 | % | |||||||||||||||||||
| Adjusted EBITDA margin basis points change | 380 |
Revenue increased primarily due to easing lockdown restrictions and the continued global economic recovery from the COVID-19 pandemic. For 2021, revenue increased due to higher card-present volumes contributing 12% to growth and card-not-present volumes contributing 5% to growth. Revenue also benefited from a favorable foreign currency impact contributing 2% to growth and was primarily related to a weaker U.S. Dollar versus the British Pound Sterling.
Adjusted EBITDA increased primarily due to the revenue impacts noted above. Adjusted EBITDA margin increased primarily due to revenue growth, higher-margin revenue mix and continued expense management.
Banking Solutions
| Years ended December 31, | $ Change | % Change | |||||||||||||||||||||
| 2021 vs | 2021 vs | ||||||||||||||||||||||
| 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Revenue | $ | 6,396 | $ | 5,944 | $ | 452 | 8 | % | |||||||||||||||
| Adjusted EBITDA | $ | 2,874 | $ | 2,556 | 318 | 12 | |||||||||||||||||
| Adjusted EBITDA margin | 44.9 | % | 43.0 | % | |||||||||||||||||||
| Adjusted EBITDA margin basis points change | 190 |
Revenue increased primarily due to recurring revenue contributing 6% to growth, driven by strong new sales, including newly developed offerings, and increased volumes due to the continued global economic recovery from the COVID-19 pandemic. Non-recurring revenue also contributed 2% to growth, primarily due to the timing of termination fees.
Adjusted EBITDA increased primarily due to the revenue impacts noted above. Adjusted EBITDA margin increased primarily due to higher-margin revenue mix and continued expense management.
Capital Market Solutions
| Years ended December 31, | $ Change | % Change | |||||||||||||||||||||
| 2021 vs | 2021 vs | ||||||||||||||||||||||
| 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Revenue | $ | 2,624 | $ | 2,440 | $ | 184 | 8 | % | |||||||||||||||
| Adjusted EBITDA | $ | 1,271 | $ | 1,147 | 124 | 11 | |||||||||||||||||
| Adjusted EBITDA margin | 48.4 | % | 47.0 | % | |||||||||||||||||||
| Adjusted EBITDA margin basis points change | 140 |
Revenue increased primarily due to recurring revenue contributing 4% and non-recurring revenue contributing 3% to growth driven by strong new sales driving outsourced solutions and services, as well as favorable timing of license renewals. The growth of recurring revenue led to an increase in professional services revenue, with much of the services being delivered in a virtual capacity given the ongoing COVID-19 pandemic. Revenue also benefited from a favorable foreign currency impact contributing 1% to growth and was primarily related to a weaker U.S. Dollar versus the British Pound Sterling.
Adjusted EBITDA increased primarily due to the revenue impacts noted above. Adjusted EBITDA margin increased primarily due to higher-margin revenue mix and continued expense management.
Corporate and Other
| Years ended December 31, | $ Change | % Change | |||||||||||||||||||||
| 2021 vs | 2021 vs | ||||||||||||||||||||||
| 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||
| (In millions) | |||||||||||||||||||||||
| Revenue | $ | 361 | $ | 401 | $ | (40) | (10) | % | |||||||||||||||
| Adjusted EBITDA | $ | (290) | $ | (195) | (95) | 49 |
The Corporate and Other segment results consist of selling, general and administrative expenses and depreciation and intangible asset amortization not otherwise allocated to the reportable segments. Corporate and Other also includes operations from certain non-strategic businesses.
Revenue decreased primarily due to client attrition in our non-strategic businesses.
Adjusted EBITDA decreased primarily due to the revenue impact noted above as well as higher compensation expense compared to prior year.
Liquidity and Capital Resources
Cash Requirements
Our ongoing cash requirements include operating expenses, income taxes, tax receivable obligations, mandatory debt service payments, capital expenditures, stockholder dividends, regulatory requirements, working capital and timing differences in settlement-related assets and liabilities and may include discretionary debt repayments, share repurchases and business acquisitions. Our principal sources of funds are cash generated by operations and borrowings, including the capacity under our Revolving Credit Facility, the U.S. commercial paper program and the Euro-commercial paper program discussed in Note 12 to the consolidated financial statements.
As of December 31, 2021, the Company had $3,375 million of available liquidity, including $2,010 million of cash and cash equivalents and $1,365 million of capacity available under its Revolving Credit Facility. Approximately $900 million of cash and cash equivalents is held by our foreign entities, including amounts related to regulatory requirements. The majority of our domestic cash and cash equivalents relates to settlement payables and net deposits-in-transit, which are typically settled within a few business days. Debt outstanding totaled $20.4 billion, with an effective weighted average interest rate of 0.9%.
The Company's liquidity has improved during 2021 as compared to at the onset of the COVID-19 pandemic. However, our liquidity could be impacted if economic conditions deteriorate or as a result of governmental measures that might be imposed in response to the COVID-19 pandemic or any recurrence or related variants thereof.
The Company remains committed to reducing its leverage incurred in the Worldpay acquisition while ensuring ample liquidity and expects to reach its target leverage by the end of the second quarter of 2022.
We believe that our current level of cash and cash equivalents plus cash flows from operations will be sufficient to fund our operating cash requirements, capital expenditures and mandatory debt service payments for the next 12 months and the foreseeable future.
We currently expect to continue to pay quarterly dividends. In January 2022, the Board of Directors approved a quarterly dividend increase of 21% to $0.47 per share beginning with the first quarter of 2022. A regular quarterly dividend of $0.47 per common share is payable on March 25, 2022, to shareholders of record as of the close of business on March 11, 2022. Consistent with our capital allocation strategy, we plan to increase our annual dividend approximately 20% per year over the next several years, as compared to approximately 10% per year increases in recent years, to gradually increase our dividend payout ratio, beginning with the quarterly dividend payable in March 2022. However, the amount, declaration and payment of future dividends is at the discretion of the Board of Directors and depends on, among other things, our investment opportunities (including potential mergers and acquisitions), results of operations, financial condition, cash requirements, future prospects, the duration and impact of the COVID-19 pandemic, and other factors that may be considered relevant by our Board of Directors, including legal and contractual restrictions. Additionally, the payment of cash dividends may be limited by covenants in certain debt agreements.
The share repurchase plan approved by the Board of Directors in 2017 expired as of December 31, 2020. Management temporarily suspended share repurchases during 2020 as a result of the Worldpay transaction to accelerate debt repayment. In January 2021, our Board of Directors approved a new share repurchase program under which it authorized the Company to repurchase up to 100 million shares of our common stock at management's discretion from time to time on the open market or in privately negotiated transactions and through Rule 10b5-1 plans. The new share repurchase program has no expiration date and may be suspended for periods, amended or discontinued at any time. Under the new share repurchase program, the Company repurchased approximately 15 million shares for $2.0 billion during 2021. Approximately 85 million shares remain available for repurchase as of December 31, 2021. In 2020, there were no share repurchases, and in 2019, we repurchased approximately 4 million shares for $400 million.
Cash Flows from Operations
Cash flows from operations were $4,810 million, $4,442 million and $2,410 million in 2021, 2020 and 2019, respectively. Our net cash provided by operating activities consists primarily of net earnings, adjusted to add back depreciation and amortization and other non-cash items. Cash flows from operations increased $368 million in 2021 and $2,032 million in 2020. The 2021 increase in cash flows from operations is primarily due to an increase in operating income, partially offset by working capital and settlement timing. The 2020 increase in cash flows from operations is primarily due to increased cash flow from the Worldpay operations, including the timing of settlement activity, partially offset by Worldpay integration-related expenses and lower net earnings from the COVID-19 pandemic.
Capital Expenditures and Other Investing Activities
Our principal capital expenditures are for software (purchased and internally developed) and additions to property and equipment. We invested approximately $1,251 million, $1,129 million and $828 million in capital expenditures (excluding other financing obligations for certain hardware and software) during 2021, 2020 and 2019, respectively. We expect to continue investing in property and equipment, purchased software and internally developed software to support our business.
In 2021, we received approximately $367 million of cash for the net proceeds from the sale of our equity ownership interest in Cardinal Holdings. We used approximately $767 million, $469 million and $6,629 million of cash (net of cash acquired, including restricted cash) during 2021, 2020, and 2019 for the Payrix, Virtus, and Worldpay acquisitions, respectively. See Note 3 to the consolidated financial statements.
Financing
For more information regarding the Company's debt and financing activity, see Note 12 to the consolidated financial statements.
Contractual Obligations
FIS' long-term contractual obligations generally include its long-term debt, interest on long-term debt, lease payments on certain of its property and equipment and payments for certain purchase commitments and other obligations. See Notes 12, 14 and 16 to the consolidated financial statements for information on our long-term debt, operating leases and Tax Receivable Agreement obligations, respectively. The following table summarizes FIS' other significant contractual obligations and commitments as of December 31, 2021 (in millions):
| Payments Due in | ||||||||||||||||||||||||||||||||
| Less than | 1-3 | 3-5 | More than | |||||||||||||||||||||||||||||
| Total | 1 Year | Years | Years | 5 Years | ||||||||||||||||||||||||||||
| Interest (1) | $ | 2,478 | $ | 220 | $ | 392 | $ | 411 | $ | 1,455 | ||||||||||||||||||||||
| Purchase commitments (2) | 795 | 388 | 361 | 46 | — | |||||||||||||||||||||||||||
| Total | $ | 3,273 | $ | 608 | $ | 753 | $ | 457 | $ | 1,455 |
(1)The calculations above assume that (a) applicable margins and commitment fees remain constant; (b) all floating-rate debt is priced at the rates in effect as of December 31, 2021; (c) no refinancing occurs at debt maturity; (d) only mandatory debt repayments are made; (e) no new hedging transactions are effected; and (f) there are no currency effects.
(2)Includes obligations principally related to software, maintenance support, and telecommunication and network services as well as to third-party processors to provide gateway authorization and other processing services. Also includes the capital obligation related to the construction of our new headquarters.
Recent Accounting Pronouncements
No new accounting pronouncement adopted, issued or effective during the fiscal year had or is expected to have a material impact on our consolidated financial statements or disclosures.
Item 7A. Quantitative and Qualitative Disclosure About Market Risks
Market Risk
We are exposed to market risks primarily from changes in interest rates and foreign currency exchange rates. Such risks may be exacerbated by the effects of the COVID-19 pandemic. We periodically use certain derivative financial instruments, including interest rate swaps and foreign currency forward contracts, to manage interest rate and foreign currency risk. We do not use derivatives for trading purposes, to generate income or to engage in speculative activity.
Interest Rate Risk
In addition to existing cash balances and cash provided by operating activities, we use fixed-rate and variable-rate debt to finance our operations. We are exposed to interest rate risk on these debt obligations and related interest rate swaps.
Our fixed-rate senior notes (as included in Note 12 to the consolidated financial statements) represent the majority of our fixed-rate long-term debt obligations as of December 31, 2021. The carrying value, excluding the fair value of the interest rate swaps described below and unamortized discounts, of our senior notes was $16.2 billion as of December 31, 2021. The fair value of our senior notes was approximately $16.8 billion as of December 31, 2021. The potential reduction in fair value of the senior notes from a hypothetical 10 percent increase in market interest rates would not be material to the overall fair value of the debt.
Our variable-rate risk principally relates to borrowings under our U.S. commercial paper program, Euro-commercial paper program, and Revolving Credit Facility (as included in Note 12 to the consolidated financial statements) and interest rate swaps on our fixed-rate long-term debt (collectively, "variable-rate debt"). At December 31, 2021, our weighted-average cost of debt was 0.9% with a weighted-average maturity of 5.4 years; 62% of our debt was fixed rate, and the remaining 38% was variable-rate debt. A 100 basis-point increase in the weighted-average interest rate on our variable-rate debt would have increased our 2021 annual interest expense by $78 million. We performed the foregoing sensitivity analysis based solely on the principal amount of our variable-rate debt as of December 31, 2021. This sensitivity analysis does not take into account any changes that occurred in the prior 12 months or that may take place in the next 12 months in the amount of our outstanding debt. Further, this sensitivity analysis assumes the change in interest rates is applicable for an entire year. For comparison purposes, based on principal amounts of variable-rate debt outstanding as of December 31, 2020, and calculated in the same manner as set forth above, an increase of 100 basis points in the weighted-average interest rate would have increased our annual interest expense by approximately $51 million.
As of December 31, 2021, the following interest rate swaps converting the interest rate exposure on certain of our senior notes from fixed to variable are outstanding (in millions):
| Weighted | Weighted | |||||||||||||||||||
| Notional Amount by | Average | Average | ||||||||||||||||||
| Currency | Maturities | Receive Rate | Pay Rate | |||||||||||||||||
| $ | 1,854 | 2029 - 2031 | 2.74 | % | 1.70 | % | ||||||||||||||
| £ | 925 | 2029 - 2031 | 3.00 | % | 2.47 | % | ||||||||||||||
| € | 500 | 2024 | 1.10 | % | 0.33 | % |
By entering into the aforementioned swap agreements, we have assumed risks associated with variable interest rates based upon LIBOR. Changes in the overall level of interest rates affect the interest expense that we recognize. We designated the interest rate swaps as fair value hedges for accounting purposes as described in Note 13 to the consolidated financial statements. A 100 basis-point increase in the 3-month USD LIBOR rate, 6-month GBP LIBOR rate, and 3-month Euribor rate, as applicable, for the interest rate swaps outstanding as of December 31, 2021 and 2020, would increase our annual interest expense by approximately $37 million and $6 million, respectively.
Foreign Currency Risk
We are exposed to foreign currency risks that arise from normal business operations. These risks include the translation of local currency balances of foreign subsidiaries, transaction gains and losses associated with intercompany loans with foreign subsidiaries and transactions denominated in currencies other than a location's functional currency. We manage the exposure to these risks through a combination of normal operating activities and the use of foreign currency forward contracts and non-derivative and derivative investment hedges.
Our exposure to foreign currency exchange risks generally arises from our non-U.S. operations, to the extent they are conducted in local currency. Changes in foreign currency exchange rates affect translations of revenue denominated in currencies other than the U.S. Dollar. During the years ended December 31, 2021, 2020 and 2019, we generated approximately $2,833 million, $2,432 million and $1,852 million, respectively, in revenue denominated in currencies other than the U.S. Dollar. The major currencies to which our revenue is exposed are the British Pound Sterling, Euro, Brazilian Real, Indian Rupee and Australian Dollar. A 10% movement in average exchange rates for these currencies (assuming a simultaneous and immediate 10% change in all of such rates for the relevant period) would have resulted in the following increase or decrease in our reported revenue for the years ended December 31, 2021, 2020 and 2019 (in millions):
| Currency | 2021 | 2020 | 2019 | |||||||||||||||||
| Pound Sterling | $ | 177 | $ | 141 | $ | 87 | ||||||||||||||
| Euro | 34 | 35 | 31 | |||||||||||||||||
| Real | 14 | 12 | 16 | |||||||||||||||||
| Rupee | 11 | 10 | 11 | |||||||||||||||||
| Australian Dollar | 8 | 7 | 7 | |||||||||||||||||
| Total increase or decrease | $ | 244 | $ | 205 | $ | 152 |
While our results of operations have been impacted by the effects of currency fluctuations, our international operations' revenue and expenses are generally denominated in local currency, which reduces our economic exposure to foreign exchange risk in those jurisdictions.
Our foreign exchange risk management policy permits the use of derivative instruments, such as forward contracts and options, to reduce volatility in our results of operations and/or cash flows resulting from foreign exchange rate fluctuations. We do not enter into foreign currency derivative instruments for trading purposes or to engage in speculative activity. We do periodically enter into foreign currency forward contracts to hedge foreign currency exposure to intercompany loans and other balance sheet items. The Company also utilizes foreign currency-denominated debt and cross-currency interest rate swaps designated as net investment hedges in order to reduce the volatility of the net investment value of certain of its Euro and Pound Sterling functional subsidiaries (see Note 13 to the consolidated financial statements).
Item 8. Financial Statements and Supplementary Data
FIDELITY NATIONAL INFORMATION SERVICES, INC.
AND SUBSIDIARIES
INDEX TO FINANCIAL INFORMATION
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Stockholders and Board of Directors
Fidelity National Information Services, Inc.:
Opinion on Internal Control Over Financial Reporting
We have audited Fidelity National Information Services, Inc. and subsidiaries' (the Company) internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of December 31, 2021 and 2020, the related consolidated statements of earnings, comprehensive earnings, equity, and cash flows for each of the years in the three-year period ended December 31, 2021, and the related notes (collectively, the consolidated financial statements), and our report dated February 23, 2022 expressed an unqualified opinion on those consolidated financial statements.
Basis for Opinion
The Company's management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management's Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company's internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audit also included performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control Over Financial Reporting
A company's internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company's internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company's assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ KPMG LLP
Jacksonville, Florida
February 23, 2022
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Stockholders and Board of Directors
Fidelity National Information Services, Inc.:
Opinion on the Consolidated Financial Statements
We have audited the accompanying consolidated balance sheets of Fidelity National Information Services, Inc. and subsidiaries (the Company) as of December 31, 2021 and 2020, the related consolidated statements of earnings, comprehensive earnings, equity, and cash flows for each of the years in the three-year period ended December 31, 2021, and the related notes (collectively, the consolidated financial statements). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2021 and 2020, and the results of its operations and its cash flows for each of the years in the three-year period ended December 31, 2021, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, 2021, based on criteria established in Internal Control – Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission, and our report dated February 23, 2022 expressed an unqualified opinion on the effectiveness of the Company's internal control over financial reporting.
Basis for Opinion
These consolidated financial statements are the responsibility of the Compan
Showing the first 8K of 202K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
As of the end of the year covered by this report, we carried out an evaluation, under the supervision and with the participation of our principal executive officer and principal financial officer, of the effectiveness of the design and operation of our disclosure controls and procedures, as such term is defined in Rule 13a-15 (e) under the Securities Exchange Act of 1934, as amended (the "Exchange Act"). Based on this evaluation, our principal executive officer and principal financial officer concluded that our disclosure controls and procedures were effective to ensure that information required to be disclosed by us in the reports that we file or submit under the Exchange Act is (a) recorded, processed, summarized and reported within the time periods specified in the Commission's rules and forms and (b) accumulated and communicated to management, including our principal executive and principal financial officers, as appropriate to allow timely decisions regarding required disclosure.
There have been no changes in our internal control over financial reporting that occurred during the most recent fiscal quarter that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
MANAGEMENT'S REPORT ON INTERNAL CONTROL OVER FINANCIAL REPORTING
Management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Exchange Act Rules 13a-15(f). Under the supervision and with the participation of our management, including our principal executive officer and principal financial officer, we conducted an evaluation of the effectiveness of our internal control over financial reporting. Management has adopted the framework in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission ("COSO"). Based on our evaluation under this framework, our management concluded that our internal control over financial reporting was effective as of December 31, 2021. KPMG LLP, an independent registered public accounting firm, has issued an attestation report on our internal control over financial reporting as set forth in Item 8.
Item 9B. Other Information
None.
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
Not applicable.
PART III
Items 10-14.
Within 120 days after the close of its fiscal year, the Company intends to file with the Securities and Exchange Commission a definitive proxy statement pursuant to Regulation 14A of the Securities Exchange Act of 1934, as amended, which will include the matters required by these items and is incorporated herein by reference.
PART IV
Item 15. Exhibits and Financial Statement Schedules
(1)Financial Statement Schedules: All schedules have been omitted because they are not applicable, not material or the required information is included in the consolidated financial statements or notes thereto.
(2)Exhibits: The following is a complete list of exhibits included as part of this report, including those incorporated by reference. A list of those documents filed with this report is set forth on the Exhibit Index appearing elsewhere in this report and is incorporated by reference.
| Incorporated by Reference | ||||||||||||||||||||
| Exhibit | SEC File | Filed/ Furnished | ||||||||||||||||||
| No. | Exhibit Description | Form | Number | Exhibit | Filing Date | Herewith | ||||||||||||||
| 101.INS | XBRL Instance Document - the instance document does not appear in the Interactive Data File because its XBRL tages are embedded within the Inline XBRL document. | * | ||||||||||||||||||
| 101.SCH | Inline XBRL Taxonomy Extension Schema Document. | * | ||||||||||||||||||
| 101.CAL | Inline XBRL Taxonomy Extension Calculation Linkbase Document. | * | ||||||||||||||||||
| 101.DEF | Inline XBRL Taxonomy Extension Definition Linkbase Document. | * | ||||||||||||||||||
| 101.LAB | Inline XBRL Taxonomy Extension Label Linkbase Document. | * | ||||||||||||||||||
| 101.PRE | Inline XBRL Taxonomy Extension Presentation Linkbase Document. | * | ||||||||||||||||||
| 104 | Cover Page Interactive Data File (formatted as Inline XBRL and contained in Exhibit (101). | * |
(1) Management contract or compensatory plan or arrangement.
*Filed or furnished herewith
+ Pursuant to Rule 406T of Regulation S-T, the Interactive Data Files on Exhibit 101 hereto are deemed not filed or part of a registration statement or prospectus for purposes of Sections 11 or 12 of the Securities Act of 1933, as amended, are deemed not filed for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, and otherwise are not subject to liability under those sections.
Item 16. Form 10-K Summary
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| FIDELITY NATIONAL INFORMATION SERVICES, INC. | |||||||||||
| Date: | February 23, 2022 | By: | /s/ GARY A. NORCROSS | ||||||||
| Gary A. Norcross | |||||||||||
| Chairman and Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Date: | February 23, 2022 | By: | /s/ JAMES W. WOODALL | ||||||||
| James W. Woodall | |||||||||||
| Chief Financial Officer | |||||||||||
| (Principal Financial Officer) | |||||||||||
| Date: | February 23, 2022 | By: | /s/ THOMAS K. WARREN | ||||||||
| Thomas K. Warren | |||||||||||
| Chief Accounting Officer | |||||||||||
| (Principal Accounting Officer) | |||||||||||
| Date: | February 23, 2022 | By: | /s/ GARY A. NORCROSS | ||||||||
| Gary A. Norcross | |||||||||||
| Chairman and Chief Executive Officer | |||||||||||
| Date: | February 23, 2022 | By: | /s/ ELLEN R. ALEMANY | ||||||||
| Ellen R. Alemany | |||||||||||
| Director | |||||||||||
| Date: | February 23, 2022 | By: | /s/ JEFFREY A. GOLDSTEIN | ||||||||
| Jeffrey A. Goldstein | |||||||||||
| Director | |||||||||||
| Date: | February 23, 2022 | By: | /s/ LISA A. HOOK | ||||||||
| Lisa A. Hook | |||||||||||
| Director | |||||||||||
| Date: | February 23, 2022 | By: | /s/ KEITH W. HUGHES | ||||||||
| Keith W. Hughes | |||||||||||
| Director | |||||||||||
| Date: | February 23, 2022 | By: | /s/ GARY L. LAUER | ||||||||
| Gary L. Lauer | |||||||||||
| Director | |||||||||||
| Date: | February 23, 2022 | By: | /s/ LOUISE M. PARENT | ||||||||
| Louise M. Parent | |||||||||||
| Director |
| Date: | February 23, 2022 | By: | /s/ BRIAN T. SHEA | ||||||||
| Brian T. Shea | |||||||||||
| Director | |||||||||||
| Date: | February 23, 2022 | By: | /s/ JAMES B. STALLINGS, JR. | ||||||||
| James B. Stallings, Jr. | |||||||||||
| Director | |||||||||||
| Date: | February 23, 2022 | By: | /s/ JEFFREY E. STIEFLER | ||||||||
| Jeffrey E. Stiefler | |||||||||||
| Director |