 filings.tools
Fiserv 10-K 2020-12-31
Filed 2021-02-26. 22 sections, 601K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, DC 20549
FORM 10-K
| ☑ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 | |||||||
| For the fiscal year ended: | December 31, 2020 |
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 For the transition period from to |
Commission file number: 1-38962
Fiserv, Inc.
(Exact Name of Registrant as Specified in Its Charter)
| Wisconsin | 39-1506125 | |||||||
| (State or Other Jurisdiction of Incorporation or Organization) | (I. R. S. Employer Identification No.) |
| 255 Fiserv Drive | Brookfield, | WI | 53045 | ||||||||
| (Address of Principal Executive Offices and zip code) |
(262) 879-5000
(Registrant’s Telephone Number, Including Area Code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
| Common Stock, par value $0.01 per share | FISV | The NASDAQ Stock Market LLC | ||||||||||||
| 0.375% Senior Notes due 2023 | FISV23 | The NASDAQ Stock Market LLC | ||||||||||||
| 1.125% Senior Notes due 2027 | FISV27 | The NASDAQ Stock Market LLC | ||||||||||||
| 1.625% Senior Notes due 2030 | FISV30 | The NASDAQ Stock Market LLC | ||||||||||||
| 2.250% Senior Notes due 2025 | FISV25 | The NASDAQ Stock Market LLC | ||||||||||||
| 3.000% Senior Notes due 2031 | FISV31 | The NASDAQ Stock Market LLC |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☑ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or 15(d) of the Act. Yes ☐ No ☑
Indicate by check mark whether the registrant: (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☑ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☑ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☑ | Accelerated filer | ☐ | |||||||||||
| Non-accelerated filer | ☐ | Smaller reporting company | ☐ | |||||||||||
| Emerging growth company | ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☑
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes ☐ No ☑
The aggregate market value of the common stock of the registrant held by non-affiliates as of June 30, 2020 (the last trading day of the second fiscal quarter) was $65,119,434,315 based on the closing price of the registrant’s common stock on the NASDAQ Global Select Market on that date. The number of shares of the registrant’s common stock, $0.01 par value per share, outstanding at February 19, 2021 was 669,459,877.
DOCUMENTS INCORPORATED BY REFERENCE
Part III of this report incorporates information by reference to the registrant’s proxy statement for its 2021 annual meeting of shareholders, which proxy statement will be filed with the Securities and Exchange Commission no later than 120 days after the close of the fiscal year ended December 31, 2020.
TABLE OF CONTENTS
i
FORWARD-LOOKING STATEMENTS
This Annual Report on Form 10-K contains “forward-looking statements” intended to qualify for the safe harbor from liability established by the Private Securities Litigation Reform Act of 1995. Forward-looking statements include those that express a plan, belief, expectation, estimation, anticipation, intent, contingency, future development or similar expression, and can generally be identified as forward-looking because they include words such as “believes,” “anticipates,” “expects,” “could,” “should” or words of similar meaning. Statements that describe our future plans, objectives or goals are also forward-looking statements. The forward-looking statements in this report involve significant risks and uncertainties, and a number of factors, both foreseen and unforeseen, could cause actual results to differ materially from our current expectations. The factors that may affect our results include, among others, the following, many of which are, and will be, amplified by the COVID-19 pandemic: the duration and intensity of the COVID-19 pandemic including how quickly the global economy recovers from the impact of the pandemic; governmental and private sector responses to the COVID-19 pandemic and the impact of such responses on us; the impact of the COVID-19 pandemic on our employees, clients, vendors, operations and sales; the possibility that we may be unable to achieve expected synergies and operating efficiencies from the acquisition of First Data Corporation (“First Data”) within the expected time frames; the integration of First Data may be more difficult, time-consuming or costly than expected; profitability following the transaction may be lower than expected, including due to unexpected costs, charges or expenses resulting from the transaction; operating costs, customer loss and business disruption (including, without limitation, difficulties in maintaining relationships with employees, customers, clients or suppliers) may be greater than expected following the transaction; unforeseen risks relating to our liabilities or those of First Data may exist; our ability to meet expectations regarding the accounting and tax treatments of the transaction; our ability to compete effectively against new and existing competitors and to continue to introduce competitive new products and services on a timely, cost-effective basis; changes in customer demand for our products and services; the ability of our technology to keep pace with a rapidly evolving marketplace; the successful management of our merchant alliance program which involves several alliances not under our sole control; the impact of a security breach or operational failure on our business including disruptions caused by other participants in the global financial system; the failure of our vendors and merchants to satisfy their obligations; the successful management of credit and fraud risks in our business and merchant alliances; changes in local, regional, national and international economic or political conditions and the impact they may have on us and our customers; the effect of proposed and enacted legislative and regulatory actions affecting us or the financial services industry as a whole; our ability to comply with government regulations and applicable card association and network rules; the protection and validity of intellectual property rights; the outcome of pending and future litigation and governmental proceedings; our ability to successfully identify, complete and integrate acquisitions, and to realize the anticipated benefits associated with the same; the impact of our strategic initiatives; our ability to attract and retain key personnel; volatility and disruptions in financial markets that may impact our ability to access preferred sources of financing and the terms on which we are able to obtain financing or increase our cost of borrowing; adverse impacts from currency exchange rates or currency controls; changes in corporate tax and interest rates; and other factors identified in this Annual Report on Form 10-K for the year ended December 31, 2020 and in other documents that we file with the Securities and Exchange Commission. You should consider these factors carefully in evaluating forward-looking statements and are cautioned not to place undue reliance on such statements, which speak only as of the date of this report. We undertake no obligation to update forward-looking statements to reflect events or circumstances occurring after the date of this report. We are not including the information provided on the websites referenced herein as part of, or incorporating such information by reference into, this Annual Report on Form 10-K.
PART I
In this report, all references to “we,” “us,” “our” and “Fiserv” refer to Fiserv, Inc. (“Fiserv”), and, unless the context otherwise requires, its consolidated subsidiaries.
Item 1. Business
Overview
Fiserv, Inc. is a leading global provider of payments and financial services technology solutions. We are publicly traded on the NASDAQ Global Select Market and part of the S&P 500 Index. We serve clients around the globe, including banks, credit unions, other financial institutions, corporate clients and merchants. We help clients achieve best-in-class results through a commitment to innovation and excellence in areas including account processing and digital banking solutions; card issuer processing and network services; payments; e-commerce; merchant acquiring and processing; and the Clover® cloud-based point-of-sale (“POS”) solution. Most of the services we provide are necessary for our clients to operate their businesses and are, therefore, non-discretionary in nature. We service our global client base by working among our geographic teams across various regions: the United States and Canada; Europe, Middle East and Africa; Latin America; and Asia Pacific.
In 2020, we had $14.9 billion in total revenue, $1.9 billion in operating income and $4.1 billion of net cash provided by operating activities from continuing operations. Processing and services revenue, which in 2020 represented 82% of our total revenue, is primarily generated from account- and transaction-based fees under multi-year contracts that generally have high renewal rates. We have operations and offices located both within the United States (the “U.S.” or “domestic”) and outside of the U.S. (“international”) with revenues from domestic and international products and services as a percentage of total revenue as follows for the years ended December 31:
| (In millions) | 2020 | 2019 | 2018 | |||||||||||||||||
| Total revenue | $ | 14,852 | $ | 10,187 | $ | 5,823 | ||||||||||||||
| Domestic | 87 | % | 88 | % | 94 | % | ||||||||||||||
| International | 13 | % | 12 | % | 6 | % | ||||||||||||||
We have grown our business by signing new clients, expanding the products and services we provide to existing clients, offering new and enhanced products and services developed through innovation and acquisition, and extending our capabilities geographically, all of which have enabled us to deliver a wide range of integrated products and services and created new opportunities for growth.
Our headquarters are located at 255 Fiserv Drive, Brookfield, Wisconsin 53045, and our telephone number is (262) 879-5000.
Effective in the first quarter of 2020, we realigned our reportable segments to reflect our new management structure and organizational responsibilities (“Segment Realignment”) following the July 2019 acquisition of First Data. Our operations are comprised of the Merchant Acceptance (“Acceptance”) segment, the Financial Technology (“Fintech”) segment and the Payments and Network (“Payments”) segment.
Acceptance
The businesses in our Acceptance segment provide a wide range of commerce-enabling solutions and serve merchants of all sizes around the world. These services include POS merchant acquiring and digital commerce services; mobile payment services; security and fraud protection products; CaratSM, our omnichannel commerce solution; and our cloud-based Clover POS platform. We distribute the products and services in the global Acceptance businesses through a variety of channels, including direct sales teams, strategic partnerships with agent sales forces, independent software vendors (“ISVs”), financial institutions, and other strategic partners in the form of joint venture alliances, revenue sharing alliances (“RSAs”), and referral agreements. Merchants, financial institutions and distribution partners in the Acceptance segment are frequently clients of our other segments.
Acceptance solutions enable businesses to securely accept consumers’ electronic payment transactions online or in-person. Payment transactions represent credit, debit, stored-value and loyalty payments, whether at a physical POS device, a mobile device such as a smart-phone or tablet, or an e-commerce transaction over the internet. Services include payment authorization; settlement; charge-back management; and solutions that secure payment data from end-to-end, including TransArmor®, our encryption, tokenization, and PCI compliance solution for data in-transit.
Omnichannel Commerce Solutions
Our Carat solution is designed to enable large merchants to offer a simple and secure payment experience to their customers across multiple channels, including accepting e-commerce payments online or in-store and enabling consumer purchasing experiences such as curbside and in-store pickup (sometimes referred to as “omnichannel”). Through a single interface with the merchant, a variety of our solutions can be integrated, including omnichannel gateway, global payments acceptance, open foreign exchange multi-currency, advanced artificial intelligence-powered authorization optimization, fraud detection, and digital payouts. By offering a variety of payment and related services via a single interface, Carat enhances the payment experience for a customer, optimizes the value and quality of transactions for the merchant, and enables pioneering payment transactions such as voice-enabled commerce and payments via the connected car.
Clover from Fiserv
Built for small and mid-sized businesses (“SMBs”), our cloud-based Clover POS platform is a comprehensive business-management solution that enables businesses to maximize their operating efficiencies, while allowing their customers to pay using a debit or credit card or via mobile payment options. The Clover platform includes hardware and software technology necessary to enable SMB merchants to accept payments, process transactions, provide online ordering, have an e-commerce presence, and generate consumer loyalty through Clover’s customer engagement tools. Clover is one of the largest open architecture platforms of commerce-enabling solutions and applications in the world. By integrating next-generation hardware and software applications, Clover has also become a leader in enabling omnichannel commerce solutions for SMBs, with touchless commerce through QR code-based payments, online ordering solutions, or a virtual terminal. Clover solutions also help small business owners gain faster access to capital through advanced access to receivables.
Distribution Channels and Partnerships
Acceptance businesses distribute solutions and services through direct sales teams, as well as partnerships with hundreds of indirect non-bank sales forces, including independent sales agents, independent sales organizations (“ISOs”), ISVs, value-added retailers (“VARs”), and payment services providers (“PSPs”). Partnerships with ISOs, ISVs, VARs and PSPs provide specialized sales capabilities and integrated merchant technology solutions to support our partners, help them grow their business and manage their portfolios. Partner technology tools enable real-time access to portfolio activity and pricing management. We also provide marketing services, data analytics and other tools that enable partners to further expand their businesses through local communities, e-commerce channels, and specific industry verticals.
In addition, the businesses in our Acceptance segment leverage powerful sales capabilities for hundreds of financial institution and non-financial institution partners to distribute their products and solutions through strategic arrangements including joint venture alliances (merchant alliances), RSAs, and referral agreements. These strategic alliances combine our commerce-enabling technology, processing capabilities and management expertise with the distribution channels, footprint and customer relationships of our partners.
Fintech
The businesses in our Fintech segment provide financial institutions around the world with the technology solutions they need to run their operations, including products and services that enable financial institutions to process customer deposit and loan accounts and manage an institution’s general ledger and central information files. As a complement to the core account processing functionality, the businesses in the global Fintech segment also provide digital banking, financial and risk management, cash management, professional services and consulting, item processing and source capture, and other products and services that support numerous types of financial transactions. Some of the businesses in the Fintech segment provide products or services to corporate clients to facilitate the management of financial processes and transactions. Many of the products and services offered in the Fintech segment are integrated with products and services provided by our other segments.
Account Processing
We provide account servicing and management technology products and services to our depository institution clients, as well as a range of integrated, value-added banking products and services. Account processing solutions enable a financial institution to operate systems that process customer deposit and loan accounts, an institution’s general ledger, central information files and other financial information. These solutions also include security, report generation and other features that financial institutions need to process transactions for their customers, as well as to facilitate compliance with applicable regulations. Although many of our clients obtain a majority of their processing requirements from us, our software design allows clients to start with one application and, as needed, add applications and features developed by us or by third parties. We support a broad range of client-owned peripheral devices manufactured by a variety of vendors, which reduce a new client’s initial conversion expenses, enhance existing clients’ ability to change technology and broaden our market opportunity.
The principal account processing solutions used by our bank clients are Cleartouch®, DNA®, Precision®, Premier® and Signature®. The principal account processing solutions primarily used by our credit union clients are CharlotteSM, CubicsPlus®, CUnify™, CUSA®, DataSafe®, DNA, Galaxy®, OnCU®, Portico®, Reliance®, Spectrum® and XP2®. The Signature and DNA solutions are available both domestically and internationally. Account processing solutions are offered primarily as an outsourced service or can be installed on client-owned computer systems or those hosted by third parties.
Our account processing business also provides consulting services, business operations services and related software products that enable the transition of check capture from branch and teller channels to digital self-service deposit channels, including mobile, merchant and ATM. Through the Fiserv® Clearing Network, we provide check clearing and image exchange services. Other products and services include image archive with online retrieval, in-clearings, exceptions and returns, statements and fraud detection.
Financial and Risk Management Solutions
Our Financial and Risk Management Solutions business provides products and services that deliver operating efficiencies and management insight that enable our clients to protect, manage and grow their businesses. Our Digital Efficiency Solutions include Frontier™ (a reconciliation product), Nautilus® (a content management product) and Prologue™ Financials, which combines enterprise performance management and financial control offerings to deliver budgeting and planning, financial accounting, and automated reconciliation and account certification tools to facilitate a robust assessment environment and efficient processes for our clients. These solutions are further complemented by fraud detection and mitigation through our Fraud and Financial Crimes Risk Management Solutions. Our Deposit Liquidity Solutions enable our clients to retain, monetize and grow their deposit account base while analyzing customer demand and providing for customer short-term liquidity. Our Commercial Payments Solutions provide financial institutions with the infrastructure they need to process, route and settle non-card-based electronic payments, including Automated Clearing House (“ACH”), wire and instant payments, and to efficiently manage associated information flows. Clients may use payment platform applications on a licensed or hosted basis, and as an add-on to existing legacy technology or as a stand-alone comprehensive modern payments platform.
Digital Channels
Our principal digital consumer and business banking products are Architect™, Corillian Online®, Corillian® Business Online, Mobiliti™, Mobiliti Business™, and SecureNow™. Our Corillian product suite supports multiple lines of banking businesses and has been designed to be highly scalable to meet the evolving needs of our clients. This structure enables our clients to deploy new services by adding and integrating applications, such as electronic bill payment, person-to-person payments and personal financial management tools, to any internet-connected point-of-presence. Our Mobiliti product suite provides a variety of mobile banking and payments services to our clients and their customers via mobile browser, downloadable application for smartphones and tablets, text message, and Amazon® Alexa® voice banking. Our Architect product suite supports online, mobile and tablet banking for retail and small business customers on a single platform. Each of these suites enables customers to complete balance inquiries, view their transaction history, make bill payments, and transfer funds between accounts and to other people. Our SecureNow product delivers real-time cybersecurity defense capability, integrates industry-leading controls into a single platform, and is pre-integrated with key Fiserv digital assets, including Corillian Online, Architect and other Fiserv platforms, for rapid deployment.
Payments
The businesses in our Payments segment provide financial institutions and corporate clients around the world with the products and services required to process digital payment transactions. This includes card transactions such as debit, credit and prepaid card processing and services; a range of network services, security and fraud protection products; card production and print services. In addition, the Payments segment businesses offer non-card digital payment software and services, including bill payment, account-to-account transfers, person-to-person payments, electronic billing, and security and fraud protection products. Clients of the global Payments segment businesses reflect a wide range of industries, including merchants, distribution partners and financial institution customers in our other segments.
Network and Debit Processing
Our network and debit processing business is a leader in electronic funds transfer services and provides a total payments solution through a variety of products and services. We provide financial institution clients with a full range of debit processing services, including ATM managed services; tokenization, loyalty and reward programs; customized authorization processing; gateway processing to payment networks; and risk management products. We own and operate the Accel®, STAR® and MoneyPass® networks, which serve financial institutions, providing access to funds at the point-of-sale and via ATMs, inclusive of CardFree CashSM access as well as via EMV® chip and traditional magnetic stripe cards. Our debit processing also provides a range of security, risk and fraud management solutions, which incorporate machine-learning-based predictive
technology, that help financial institutions securely operate and grow their business by preventing fraud. Our networks’ POS support delivers comprehensive coverage of PIN and PIN-less authentication support at physical and e-commerce merchants domestically. Our digital enablement capability provides our clients’ customers with mobile-based, customizable card management and alert tools that drive engagement and revenue for card issuers, and our risk management tools and portfolio management services are integrated with real-time fraud decisioning.
Output Solutions
Our output solutions business provides business communication products and services to clients across a wide variety of industries, including financial services, healthcare, retail, utilities, and travel and entertainment. We provide various channels for clients to communicate, build relationships and maximize customer engagement and loyalty, while limiting costs of a personalized and integrated consumer experience. Our products and services include electronic document management through our electronic document delivery products and services; card manufacturing, personalization and mailing; statement production and mailing; design and fulfillment of direct mail services; forms distribution; laser printing and mailing; and branded merchandise.
Electronic Payments
Our electronic payments business is comprised of electronic bill payment and presentment services and other electronic payment services for businesses and consumers, such as person-to-person payments, account-to-account transfers, and account opening and funding. Our principal electronic bill payment and presentment product, CheckFree® RXP®, allows our clients’ customers to: manage household bills via an easy-to-use, online tool; view billing and payment information; pay and manage all of their bills in one place; and complete same-day or next-day bill payments to a wide range of billers and others.
Our person-to-person payments and account-to-account transfer services allow consumers a convenient way to send and receive money while offering financial institutions the opportunity to generate new transaction-based revenue, attract new accounts and increase loyalty among existing customers. In addition to Popmoney®, a solution owned by Fiserv, we partner with Early Warning Services, LLC to offer a turnkey implementation of its Zelle® real-time person-to-person payments service. Our turnkey solution simplifies the implementation of Zelle by providing interface, risk management, alerting, settlement and other services to clients.
Credit Processing
Our credit processing business provides solutions to financial institutions and other issuers of credit, such as banks, group service providers, retailers and consumer finance companies, to enable them to process transactions on behalf of their customers. Depending on the market and our clients’ needs, we deliver these solutions through our proprietary outsourced services platforms, software application licenses, or software-as-a-service hosted in the cloud. Our solutions in North America use our proprietary OptisSM platform to provide transaction authorization and posting, account maintenance and settlement. Our VisionPLUSTM software is used globally as both a processing solution and a licensed software solution that enables clients to process their own transactions, depending on the market. We also provide financial institutions with professional services and customer servicing, including call center solutions and back-office processing.
Biller Solutions
Our biller business provides electronic billing and payment services to companies that deliver bills to their customers, such as utilities, telephone and cable companies, lending institutions, and insurance providers, enabling our biller clients to reduce costs, collect payments faster through multiple channels, increase customer satisfaction, and provide customers flexible, easy-to-use ways to view and pay their bills. Our clients’ customers access our electronic billing and payment systems by viewing or paying a bill through a financial institution’s bill payment application, using a biller’s website, mobile application, automated phone system or customer service representative, through www.mycheckfree.com, or by paying in-person at one of more than 30,000 nationwide walk-in payment locations operated by our agents. These diverse options allow our clients’ customers to view and pay bills wherever, whenever and however they feel most comfortable. Furthermore, because our biller clients are able to receive all of these services from us, we can eliminate the operational complexity and expense of supporting multiple vendor systems or in-house developed systems.
Prepaid Solutions
Our prepaid solutions include stored value cards offered by our Gift Solutions and Money Network® businesses. Gift Solutions provides end-to-end, omnichannel solutions to securely implement and manage gift card programs that help clients drive revenue, engagement and loyalty. These solutions include physical and digital gift card fulfillment, program management, e-commerce gift card storefronts, security and fraud protection, transaction processing services, incentive and rebate cards as well
as reloadable and non-reloadable prepaid cards that may be used with a variety of mobile applications. The Money Network service simplifies payment distribution for organizations while reducing or eliminating expenses associated with issuing traditional paper checks. This service also provides consumers without bank accounts with fast, digital access to manage their money, including wages. Money Network solutions include Electronic Payroll Delivery, digital disbursements and corporate incentives as well as single-load and reloadable prepaid account options. Accountholders of the Money Network Electronic Payroll Delivery Service have access to a Money Network Card, Money Network Checks and a robust mobile app to manage their account anytime, anywhere.
Other
Investment Services
In 2020, we sold a majority interest of our Investment Services business, subsequently renamed as Tegra118 Wealth Solutions, Inc. (“Tegra118”), which is reported within Corporate and Other following the Segment Realignment. Our remaining minority ownership interest in Tegra118 is accounted for as an equity method investment. Tegra118 provides technology products and services to financial service organizations, including broker dealers, registered investment advisors, banks, asset managers and insurance companies that deliver financial advice and managed account products to U.S. retail investors. The business’ primary product, the Unified Wealth Platform, is a real-time portfolio management, trading and reporting system used by some of the largest brokerage firms and asset managers in the U.S. offering managed accounts.
Impact of COVID-19 Pandemic
In 2019, a novel strain of coronavirus (“COVID-19”) was identified and has since continued to spread. In March 2020, the World Health Organization recognized the COVID-19 outbreak as a pandemic. In response to the COVID-19 pandemic, the governments of many countries, states, cities and other geographic regions have taken actions to prevent the spread of COVID-19, such as imposing travel restrictions and bans, quarantines, social distancing guidelines, shelter-in-place or lock-down orders and other similar limitations which adversely impacted the global economy in 2020. Additional information regarding the impact of the COVID-19 pandemic on our business can be found under the section titled “Recent Market Conditions” included within Part II, Item 7, “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” of this Annual Report on Form 10-K and risks related to the COVID-19 pandemic can be found under Part I, Item 1A, “Risk Factors,” of this Annual Report on Form 10-K.
Our Strategy
Our aspiration is to move money and information in a way that moves the world. Our purpose is to deliver superior value for our clients through leading technology, targeted innovation and excellence in everything we do. We are focused on operating businesses where we have: deep industry expertise that enables us to serve the market with high effectiveness; a strong competitive position, currently or via a clear path in the foreseeable future; long-term, trusted client relationships that are based on recurring services and transactions; differentiated solutions that deliver value to our clients through integration and innovation; and strong management to execute strategies in a disciplined manner. Consistent with this focus, we continue to operate our business in accordance with the following strategic framework:
*•*Client Relationship Value. We plan to increase the number and breadth of our client relationships by, among other actions: continuing to integrate our products and services; introducing new products and services that are aligned with market needs; combining products and services to deliver enhanced, integrated value propositions; and improving the quality of our client service and support.
-
Innovation. We seek to be an innovation leader, utilizing our assets and capabilities to be at the forefront of our industry and enable our clients to deliver best-in-class results.
-
Operational Effectiveness and Integration of First Data. We believe we can further improve the quality of our client delivery while reducing our costs by using the opportunities created by our size and scale and by effectively integrating the operations of First Data. By streamlining our overall cost structure, including the rationalization of duplicate costs, we expect to meet or exceed planned cost synergies and improve the quality of products and services that we provide to our clients.
*•*Portfolio Management. We expect to acquire businesses when we identify: a compelling strategic need, such as a product, service or technology that helps meet client demand; an opportunity to change industry dynamics; a way to achieve business scale; or similar considerations. We expect to divest businesses that are not in line with our market, product or financial strategies.
- Capital Discipline. We intend to make capital allocation decisions that offer the best prospects for our long-term growth and profitability, which may include, among other matters, internal investment, repayment of debt, repurchases of our own shares or acquisitions.
Servicing the Market
The financial technology industry is highly dynamic, with new innovations entering the market and driving the expectations of our clients globally. The markets for our solutions have specific needs and requirements, with strong emphasis placed by clients on quality, security, service reliability, timely introduction of new capabilities and features, flexibility and value. This requires us to continue our strong emphasis on solution development to meet and exceed the specific needs of our clients. We believe that our financial strength and decades of specialized market knowledge enable us to support our clients to meet their changing preferences. In addition, we believe that our focus on quality, innovation, client service and our commitment of substantial resources to training and technical support helps us to identify and fulfill the needs of our clients.
Product Development
To meet the changing technology needs of our clients, we continually develop, maintain and enhance our products and systems. Our development and technology operations apply the expertise of multiple teams to design, develop and maintain specialized processing systems. Our products and solutions are designed to meet the preferences and diverse requirements of the international, national, regional or local market-specific merchant and financial services environments of our clients. In developing our products, we use current software development principles, such as service-oriented architecture, to create efficiencies, and we stress interaction with and responsiveness to the needs of our clients.
Resources
Our business depends on a variety of resources to operate including products and services provided to us by third parties. For example, we rely on our human capital resources for product development (including product design and coding), sales, operations (including customer service, technology support, security and compliance) and management; access to financial and telecommunication networks; computers, servers, mainframes and other data processing equipment; and Clover POS devices. We periodically review our resource requirements and sources, as well as our relationships with key vendors, to best meet the needs of our business including global sourcing efforts and alternate supplier resourcing. More information regarding our human capital resources can be found below under “Human Capital.” We believe we have access to the resources necessary for our current business needs.
Intellectual Property
We regard our software, transaction processing services and related products as proprietary, and we use a combination of patent, copyright, trademark and trade secret laws, internal security practices, employee confidentiality and assignment agreements, and third-party non-disclosure agreements to protect our intellectual property assets. Our patents cover innovations relating to numerous financial software and hardware products and services, and we continue, where appropriate, to seek and secure patents with respect to our ongoing innovations. We believe that we possess all proprietary rights necessary to conduct our business.
Competition
The market for technology products and services in the industries we serve is fragmented, highly competitive, and served by a multitude of large and small firms. Our principal competitors include other vendors and providers of financial services technology and payment systems, data processing affiliates of large companies, processing centers owned or operated as user cooperatives, financial institutions, merchant acquirers, ISOs, ISVs, payments companies and payment network operators. Our competitors also include global and local IT product and services companies and payment service providers and processors. We expect competition to continue to increase as new companies enter our markets and existing competitors expand or consolidate their product lines and services. Some of these competitors possess substantial financial, sales and marketing resources and can compete with us in various ways, including through the use of integrated product offerings and through pricing and long-standing relationships. Depending on the product or service, competitive factors may include quality, security, innovation, breadth or novelty of features and functionality, client satisfaction, market opportunity, integration, agility, global reach, multiple distribution channels, service reliability and performance standards, timely introduction of new products and features, platform scalability and flexibility, and value. We believe that we compete favorably in each of these categories. Additional information about competition in our segments is provided below.
Acceptance
Our Acceptance segment competes with merchant acquirers, including Fidelity National Information Services, Inc. (“FIS”), Global Payments Inc. (“Global Payments”), Nexi Payments S.p.A. and Wordline SA (“Worldline”), as well as with financial institutions that provide acquiring and processing services to businesses on their own, such as Paymentech, LLC, a subsidiary of JPMorgan Chase & Co.; Elavon Inc., a subsidiary of U.S. Bancorp; Barclaycard, a division of Barclays bank; and Bank of America Corporation. In many cases, our alliance and commercial partners, such as ISOs and ISVs, compete against each other. We also compete with merchant services providers like Square, Inc., Adyen N.V. and Stripe, Inc., and in Europe, our Acceptance segment also competes with a growing number of local providers who offer their services in multiple markets in the region. In addition, payment networks, such as Visa Inc. (“Visa”), Mastercard Incorporated (“Mastercard”) and American Express Company, and large technology, media and other providers are increasingly offering products and services that compete with our suite of merchant acquiring solutions.
Fintech
Our products and services in the Fintech segment compete with large, diversified software and service companies and independent suppliers of software products. Existing and potential financial institution clients could also develop and use their own in-house systems. In addition, we compete with vendors that offer similar transaction processing products and services to financial institutions, including Computer Services, Inc., Finastra Limited, FIS, Infosys Ltd., International Business Machines Corporation, Jack Henry and Associates Inc. (“Jack Henry”), NCR Corporation, Oracle Corporation, SAP SE, Global Payments, Temenos AG, Q2 Holdings, Inc. (“Q2”) and nCino, Inc.
Payments
The businesses in our Payments segment primarily compete with businesses that offer consumer payment solutions and a number of payment and card issuer processors, including ACI Worldwide, Inc., FIS, Jack Henry, Mastercard, Paymentus Corporation, PayPal Holdings, Inc., Q2, R.R. Donnelley & Sons Company, Global Payments, Visa, The Western Union Company and Wordline. In addition to traditional payments competitors, large technology, media and other emerging financial technology providers are increasingly seeking to provide alternative payment and financing solutions. Existing and potential financial institution and other corporate clients could also develop and use their own in-house systems or custom-designed solutions instead of our products and services.
Government Regulation
Our operations, and the products and services that we offer, are subject to various U.S. federal, state and local regulation, as well as regulation outside the U.S., and to other rules, such as those promulgated by various payment networks and banking authorities. Failure to comply with these rules and regulations may result in the suspension or revocation of licenses or registrations, the limitation, suspension or termination of service and/or the imposition of civil and criminal penalties, including fines. In addition, we may be required, among other things, to make significant additional investments to comply with such rules and regulations, to modify our products or services or the manner in which they are provided, or to limit or change the amount or types of revenue we are able to generate.
The Dodd-Frank Act. The Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010 (“Dodd-Frank Act”) in the U.S. resulted in significant changes to the regulation of the financial services industry. Among other things, the Dodd-Frank Act established the Consumer Financial Protection Bureau (“CFPB”) which is empowered to conduct rule-making and supervision related to, and enforcement of, “federal consumer financial laws,” some of which apply to products and services offered by our clients. The CFPB conducts direct examinations of, and has issued guidance that applies to, “supervised banks and nonbanks” as well as “supervised service providers” like us. The Dodd-Frank Act also: caps debit interchange rates for certain card issuers; prohibits debit payment card networks from restricting card issuers from contracting with other payment card networks; prohibits card issuers and payment networks from restricting the ability of merchants to direct the routing of debit card transactions; requires all debit card issuers in the U.S. to participate in at least two unaffiliated debit payment card networks; and generally prohibits network exclusivity arrangements for prepaid card and healthcare debit card issuers. These regulations impact our card processing businesses and our clients’ ability to generate revenue.
Financial Institution Regulations. Because a number of our businesses provide data processing services for financial institutions, we are subject to examination by the U.S. Federal Financial Institutions Examination Council (“FFIEC”), which is a formal interagency body empowered to examine significant service providers to financial institutions. The member agencies of the FFIEC include the Federal Reserve Board, the Federal Deposit Insurance Corporation, the Office of the Comptroller of the Currency, the National Credit Union Administration, and the CFPB. We are also subject to examination by the first three of these agencies which refer to themselves as the Federal Banking Agencies when acting together. A subsidiary that engages in
certain trust activities is subject to regulation, examination, and oversight by the Division of Banking of the Colorado Department.
Under the Second Payment Services Directive (2015/2366/EC) in the European Union (“E.U.”) (PSD2), a number of our subsidiaries hold either payment institution licenses or electronic money licenses in the E.U. member states in which such subsidiaries do business. As payment institutions or electronic money institutions, those subsidiaries are subject to regulation and oversight in the applicable E.U. member states, which includes, among other obligations, a requirement to maintain specified regulatory capital. In addition, several subsidiaries outside of the U.S. provide services such as merchant terminal leasing, debit processing, acquiring, issuing, factoring and/or settlement that make them subject to regulation by financial services supervisory agencies, including the Financial Conduct Authority (“FCA”) in the United Kingdom (“U.K.”), the Federal Financial Supervision Agency in Germany, the National Bank of Poland, the Reserve Bank of Australia, and the Monetary Authority of Singapore.
Association and Network Rules. We are subject to rules of Mastercard, Visa, INTERAC, PULSE and other payment networks. In order to provide processing services, a number of our subsidiaries are registered with Visa and/or Mastercard as service providers for member institutions. A number of our subsidiaries outside the U.S. are direct members or associate members of Visa and Mastercard for purposes of conducting merchant acquiring. Various subsidiaries are also processor level members of numerous debit and electronic benefits transaction networks or are otherwise subject to various network rules in connection with processing services and other services we provide. As such, we are subject to applicable card association, network and national scheme rules that could subject us to fines or penalties. We are subject to network operating rules promulgated by Nacha relating to payment transactions processed by us using the ACH network and to various federal and state laws regarding such operations, including laws pertaining to electronic benefits transactions.
Privacy and Information Security Regulations. We provide services that are subject to various federal, state and foreign privacy laws and regulations, as well as association and network privacy rules, which govern, among other things, the collection, processing, storage, deletion, use and disclosure of personal information. These laws and rules contain a variety of obligations including the safeguarding of personal information, the provision of notices and use and disclosure rights. The regulations and rules are complex and evolving and can provide for significant penalties or the suspension or termination of our member registrations or certifications for non-compliance.
In the U.S., we are subject to various federal and state privacy and security laws. The U.S. Gramm-Leach-Bliley Act (“GLBA”) requires financial institutions to explain their information sharing practices to their customers and to safeguard sensitive data. We are subject to the GLBA and have privacy and security obligations to our clients who are regulated by the GLBA. The U.S. Health Insurance Portability and Accountability Act of 1996 (“HIPAA”), together with the HIPAA Privacy Rule, governs the use and disclosure of protected health information in healthcare treatment, payment and operations by covered entities. We have obligations under the California Consumer Privacy Act (the “CCPA”), which gives California consumers more control over the personal information businesses hold about them, as both a “business” and as a “service provider.” We are also subject to the U.S. Federal Trade Commission (“FTC”) Act, which empowers the FTC to prohibit unfair and deceptive privacy practices. In addition to the FTC Act, the FTC is also responsible for overseeing and enforcing the privacy provisions over certain aspects of the GLBA and the Fair Credit Reporting Act (“FCRA”), each of which is applicable to our businesses in certain circumstances. We are also subject to the separate security breach notification laws of each of the 50 states, the District of Columbia, Guam, Puerto Rico and the U.S. Virgin Islands.
In the E.U., we are subject to the General Data Protection Regulation (“GDPR”), a comprehensive approach to personal data protection with enforcement that can lead to penalties of up to the greater of twenty million Euro or four percent of a company’s global revenue. With the U.K.’s exit from the E.U. Single Market and Customs Union on December 31, 2020, there is uncertainty surrounding transfers of personal data from the E.U. to the U.K. There are currently transitional provisions in place stating that transfers of personal data from the E.U. to the U.K. will not be considered transfers of personal data to a third country for a transitional period of up to six months from January 1, 2021. If the transitional period ends without an appropriate resolution, transfers of personal data to the U.K. may be impacted. There are numerous additional privacy laws and regulations that apply to our businesses around the world which can provide for significant penalties. Some of these data protection laws, including the GDPR, restrict the international transfer of personal data absent lawfully recognized transfer mechanisms which can differ depending on the countries to which the data is being transferred.
Money Transmission and Payment Instrument Licensing and Regulations. We are subject to various U.S. federal, state and foreign laws and regulations governing money transmission and the issuance and sale of payment instruments, including some of our prepaid products. In the U.S., most states license money transmitters and issuers of payment instruments. Many states exercise authority over the operations of our services related to money transmission and payment instruments and, as part of this authority, subject us to periodic examinations. Many states require money transmitters, issuers of payment instruments and
their agents to comply with federal and state anti-money laundering laws and regulations and often require the licensee to maintain certain levels of net worth.
Credit Reporting and Debt Collections Regulations. TeleCheck, our check acceptance business, is subject to FCRA and various similar state laws. The collection business within our subsidiary TRS Recovery Services, Inc. (“TRS”) is subject to the U.S. federal Fair Debt Collection Practices Act and various similar state laws. TRS maintains licenses in a number of states in order to engage in collection in those states. TeleCheck and TRS are also subject to regulation, supervision and examination from the CFPB. Additional regulations may be imposed in the future, including laws regulating activities with respect to current or emerging technology such as automated dialers or pre-recorded messaging or calls to cellular phones, which could impair the collection by TRS of returned checks and those purchased under TeleCheck’s guarantee services. Moreover, reducing or eliminating access to or the use of certain information or proscribing the maintenance or use of consumer databases could reduce the effectiveness of TeleCheck’s risk management tools or otherwise increase its costs of doing business. In addition, several of our subsidiaries are subject to comparable local laws regarding collection activities and obtaining credit reports and our U.K. subsidiary described above also holds FCA licenses for debt collection activities.
Unfair Trade Practice Regulations. We and our clients are subject to various federal, state and foreign laws prohibiting unfair or deceptive trade practices. Various regulatory enforcement agencies, including the FTC and state attorneys general, have authority to take action against parties that engage in unfair or deceptive trade practices or violate other laws, rules and regulations. If we process payments for a merchant or other client in violation of laws, rules and regulations, we could be subject to enforcement actions and incur losses and liabilities that may impact our business.
Anti-Money Laundering, Anti-Bribery, and Sanctions Regulations. We are subject to anti-money laundering laws and regulations, including the Bank Secrecy Act (the “BSA”). Among other things, the BSA requires money services businesses (such as money transmitters, issuers of money orders and official checks, and providers of prepaid access) to develop and implement anti-money laundering programs. Our acquiring businesses outside the U.S. are subject to anti-money laundering laws and regulations in the countries where they operate. Our Money Network Financial, LLC subsidiary provides prepaid access for various open loop prepaid programs for which it is the program manager and therefore must meet the requirements of the Financial Crimes Enforcement Network.
We are subject to anti-corruption laws and regulations, including the U.S. Foreign Corrupt Practices Act (“FCPA”) and similar laws outside of the U.S. such as the U.K. Bribery Act, that prohibit the making or offering of improper payments to foreign government officials and political figures. The FCPA has a broad reach and requires maintenance of appropriate records and adequate internal controls to prevent and detect possible FCPA violations.
We are also subject to certain economic and trade sanctions programs that are administered by the U.S. Treasury Department’s Office of Foreign Assets Control (“OFAC”), which prohibit or restrict transactions to or from, or dealings with, specified countries, governments, individuals and entities that are specially-designated nationals of those countries, including narcotics traffickers and terrorists or terrorist organizations. Other group entities may be subject to additional local sanctions requirements in other relevant jurisdictions.
Similar anti-money laundering, counter terrorist financing and proceeds of crime laws apply to movements of currency and payments through electronic transactions and to dealings with persons specified in lists maintained by the country equivalents to OFAC lists in several other countries and require specific data retention obligations to be observed by intermediaries in the payment process. Our businesses in those jurisdictions are subject to those data retention obligations.
Communications Laws. We are subject to various federal and state laws that govern telephone calls and the issuance of text messages to clients and consumers in the U.S. as well as to regulations that impose requirements on marketing emails sent to U.S residents. Our international subsidiaries are subject to equivalent laws in applicable jurisdictions.
Indirect Regulatory Requirements. A number of our clients are subject to various regulations and compliance obligations that do not apply directly to us but impact the services that we provide to our clients. To remain competitive, we have expended, and expect to expend in the future, significant resources to develop and update our products and services to assist our clients to meet various compliance obligations. In addition, independent auditors annually review many of our operations to provide internal control evaluations for our clients and their auditors.
Human Capital
As of December 31, 2020, we had over 44,000 employees worldwide, approximately 17,000 of whom were employed outside the U.S. Successful execution of our strategy depends on attracting, developing and retaining highly qualified talent at all levels of our organization. We do this by focusing on our commitment to diversity and inclusion and employee development, retention, engagement and well-being.
Diversity and Inclusion
We are committed to cultivating a diverse, respectful and inclusive workplace. In 2020, we undertook a series of initiatives comprising our “Forward Together” plan to enhance our existing diversity and inclusion programs. Through this plan, we committed to:
-
Improve diversity at all levels across the organization, including increasing the representation of women and minorities in leadership positions, requiring consideration of diverse candidates for senior leadership positions, dedicating talent acquisition resources focused on hiring diverse individuals and deepening relationships with historically Black colleges and universities, industry networks, and military and veterans’ organizations;
-
Increase employee awareness through: education and participation in diversity and inclusion programs, such as inclusive leader assessment and coaching program to develop the competencies necessary to create an inclusive workplace; our Forward Together Accountability Pledge pursuant to which our senior leaders commit to advance our Forward Together plan; eight Employee Resource Groups (“ERGs”) across 10 countries for associates to connect, support each other and elevate their professional development; and a host of diversity and inclusion training courses available to all employees;
-
Invest $50 million to support Black- and minority-owned small businesses through financial assistance, technology solutions, strategic partnership and subject matter expertise; and
-
Strengthen partnerships with organizations focused on human rights, racial equity and social justice including work by our ERGs with community organizations and groups to provide mentorship opportunities and serve as force multipliers for talent acquisition, employee engagement and diversity efforts.
Development and Retention
We are committed to creating a high-performance culture that consistently delivers excellence for our clients and long-term value for our shareholders while providing a workplace experience for our employees that values leadership, innovation, diversity and collaboration. Our performance management process promotes differentiation based on contributions toward our strategic business objectives and overall success. Career development is an important part of our overall value proposition for employees. We provide employees with opportunities to grow, regardless of job level, within the organization including through targeted online learning, our Leading Women program designed to accelerate the professional growth of female top talent, our Leading Fiserv program designed to develop critical leadership skills for frontline managers, and our Vision to Results leadership program focused on driving our One Fiserv approach to enterprise goals. We also focus on internal mobility and redeployment to ensure we provide talented employees the best opportunity for internal success while retaining their skill sets.
Engagement
To assess employee engagement, we seek and collect employee feedback through our annual Your Voice employee engagement survey, distributed to all associates worldwide. The survey focuses on the following categories: Engagement; Manager Effectiveness; Client Experience; Trust; Diversity and Inclusion; Communication and Teamwork; and Well-Being. More than 90% of our associates responded to the survey in 2020. Our engagement scores improved over the prior year and were higher than the comparable average benchmarks, most landing in the top decile of companies surveyed. These results are particularly notable given that the survey was completed in the midst of driving a transformational corporate integration and the global COVID-19 pandemic, which manifested in most of our associates working remotely. In addition to assessing engagement, the survey results enable us to gain insight into employee perspectives and issues which we use to enhance processes, set priorities and respond quickly to associate concerns.
Well-Being and Safety
We are focused on delivering a comprehensive and competitive benefits offering as part of our total rewards strategy. We provide associates with access to a holistic suite of well-being programs and benefits focused on physical, financial, social and emotional resources. These programs are supported by complementary policies such as paid parental and military service leave policies.
In response to the COVID-19 pandemic, we have taken a number of actions to protect the health, safety and well-being of our employees while continuing to serve our clients. These actions include, among others, requiring most of our employees to work
remotely, suspending non-essential travel, suspending all non-essential visitors to our facilities, disinfecting facilities and workspaces extensively and frequently, providing personal protective equipment to employees and requiring employees who must be present at our facilities to adhere to a variety of safety protocols. We expanded paid time-off for employees impacted by COVID-19, provided increased pay for certain employees involved in critical infrastructure who could not work remotely, and expanded our Fiserv Cares program to benefit employees in need around the world. We expect to continue such safety and wellness measures for the foreseeable future and may take further actions, or adapt these existing policies, as government authorities may require or recommend or as we may determine to be in the best interest of our employees, clients, vendors and shareholders.
Available Information
Our website address is www.fiserv.com. We are not including the information provided on our website as a part of, or incorporating it by reference into, this Annual Report on Form 10-K. We make available free of charge (other than an investor’s own internet access charges) through our website our annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to these reports, as soon as reasonably practicable after we electronically file such material with, or furnish such material to, the Securities and Exchange Commission.
Item 1A. Risk Factors
You should carefully consider each of the risks described below, together with all of the other information contained in this Annual Report on Form 10-K, before making an investment decision with respect to our securities. If any of the following risks develop into actual events, our business, results of operations or financial condition could be materially and adversely affected, and you may lose all or part of your investment.
Competitive and Business Risks
We operate in a competitive business environment and may not be able to compete effectively.
The markets for our products and services are highly competitive from new and existing competitors. Our principal competitors include other vendors and providers of financial services technology and payment systems, data processing affiliates of large companies, processing centers owned or operated as user cooperatives, financial institutions, independent sales organizations (“ISOs”), independent software vendors, payments companies and payment network operators. Our competitors vary in size and in the scope and breadth of the services they offer. Many of our larger existing and potential clients have historically developed their key applications in-house. As a result, we may compete against our existing or potential clients’ in-house capabilities. In addition, we expect that the markets in which we compete will continue to attract new technologies and well-funded competitors, including large technology, telecommunication, media and other companies not historically in the financial services and payments industries, start-ups and international providers of products and services similar to ours. In addition, participants in the financial services, payments and technology industries may merge, create joint ventures or engage in other business combinations, alliances and consolidations that may strengthen their existing business services or create new payment services that compete with our services. We cannot provide any assurance that we will be able to compete successfully against current or future competitors or that competitive pressures faced by us in the markets in which we operate will not materially and adversely affect our business, results of operations and financial condition.
If we fail to keep pace with technological change, we could lose clients or have trouble attracting new clients, and our ability to grow may be limited.
The markets for our products and services are characterized by constant and rapid technological change, frequent introduction of new products and services, and increasing client expectations. Our ability to enhance our current products and services and to develop and introduce innovative products and services will significantly affect our future success. We may not be successful in developing, marketing or selling new products and services that meet these demands or achieve market acceptance. We must anticipate and respond to these changes in order to remain competitive within our relevant markets. For example, our ability to provide innovative point-of-sale technology to our merchant clients could have an impact on our merchant acquiring business, and new services and technologies that we develop may be impacted by industry-wide solutions and standards related to tokenization or other safety, fraud prevention and security technologies. If we are unable to anticipate or respond to technological changes or evolving industry standards on a timely basis, our ability to remain competitive could be materially adversely affected. In addition, the success of certain of our products and services rely, in part, on financial institutions, corporate and other third parties to promote the use of our products and services by their customers. If we are unsuccessful in offering products or services that gain market acceptance and compete effectively, or if third parties insufficiently promote our products and services, it would likely have a material adverse effect on our ability to retain existing clients, to attract new ones and to grow profitably.
If we are unable to renew client contracts at favorable terms, we could lose clients and our results of operations and financial condition may be adversely affected.
Failure to achieve favorable renewals of client contracts could negatively impact our business. At the end of the contract term, clients have the opportunity to renegotiate their contracts with us or to consider whether to engage one or more of our competitors to provide products and services or to perform the services in-house. Some of our competitors may offer more attractive prices, features or other services that we do not offer, and some clients may desire to perform the services themselves. Larger clients may be able to seek lower prices from us when they renew or extend a contract or the client’s business has significant volume changes. In addition, larger clients may reduce the services we provide if they decide to move services in-house. Further, our small merchant business clients may seek reduced fees due to pricing competition, their own financial condition, or pressures from their customers. On some occasions, these factors result in lower revenue from a client than we had anticipated based on our previous agreement with that client. If we are not successful in achieving high renewal rates and favorable contract terms, our results of operations and financial condition may be materially and adversely affected.
Our business depends, in part, on our merchant relationships and alliances, and if we are unable to maintain these relationships and alliances, our business may be adversely affected.
Under our alliance program, a bank or other institution forms an alliance with us, generally on an exclusive basis, either contractually or through a separate legal entity. Merchant contracts may be contributed to the alliance by us and/or the bank or institution. The banks and other institutions generally provide card association sponsorship, clearing and settlement services and typically act as a merchant referral source when the institution has an existing banking or other relationship with such merchant. We provide transaction processing and related functions to the alliance. Both we and our alliance partners may also provide management, sales, marketing and other administrative services. The alliance structure allows us to be the processor for multiple financial institutions, any one of which may be selected by the merchant as its bank partner. Our merchant acquiring business depends, in part, on our merchant relationships, alliances and other distribution channels. There can be no guarantee that we will achieve growth in our merchant relationships, alliances or other distribution channels. In addition, our contractual arrangements with merchants and merchant alliance partners are for fixed terms and may allow for early termination upon the occurrence of certain events. There can be no assurance that we will be able to renew our contractual arrangements with these merchants or merchant alliance partners on similar terms or at all. The loss of merchant relationships or alliance partners could negatively impact our business and have a material adverse effect on our results of operations and financial condition.
Changes in card association and debit network fees or products could increase costs or otherwise limit our operations.
From time to time, card associations and debit networks, including the card networks which we own and operate, increase the processing and other fees (including what is commonly called “interchange fees”) that they charge. It is possible that competitive and other pressures will result in us absorbing a portion of such increases in the future, or not being able to increase our own fees, which would increase our operating costs, reduce our profit margin, limit our growth, and adversely affect our business, results of ope
Showing the first 8K of 72K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
At December 31, 2020, we owned 20 properties and leased 161 properties globally. These locations are used for operational, sales, management and administrative purposes. As a normal part of our business operations, including in connection with the integration of companies that we acquire, we regularly review our real estate portfolio. We may choose to acquire or dispose of properties in order to maintain a real estate footprint designed to maximize collaboration, innovation and communication in ways that enable us to best serve our clients and to create more opportunities for professional growth and development for our associates.
Item 3. Legal Proceedings
In the normal course of business, we or our subsidiaries are named as defendants in lawsuits in which claims are asserted against us. In the opinion of management, the liabilities, if any, which may ultimately result from such lawsuits are not expected to have a material adverse effect on our consolidated financial statements.
Item 4. Mine Safety Disclosures
Not applicable.
INFORMATION ABOUT OUR EXECUTIVE OFFICERS
The names of our executive officers as of February 26, 2021, together with their ages, positions and business experience are described below:
| Name | Age | Title | ||||||
| Frank J. Bisignano | 61 | President and Chief Executive Officer | ||||||
| Guy Chiarello | 61 | Chief Administrative Officer | ||||||
| Christopher M. Foskett | 63 | Executive Vice President, Global Sales | ||||||
| Robert W. Hau | 55 | Chief Financial Officer | ||||||
| Lynn S. McCreary | 61 | Chief Legal Officer and Secretary | ||||||
| Devin B. McGranahan | 51 | Executive Vice President, Senior Group President | ||||||
| Byron C. Vielehr | 57 | Chief Digital and Data Officer |
Mr. Bisignano has served as Chief Executive Officer since July 2020 and a director and President since July 2019. He served as Chief Operating Officer from July 2019 until July 2020. Mr. Bisignano joined Fiserv as part of the acquisition of First Data Corporation, where he served as chief executive officer since 2013 and chairman since 2014. From 2005 to 2013, he held various executive positions with JPMorgan Chase & Co., a global financial services firm, including co-chief operating officer, chief executive officer of mortgage banking and chief administrative officer. From 2002 to 2005, Mr. Bisignano served as chief executive officer for Citigroup’s Global Transactions Services business and a member of Citigroup’s Management Committee.
Mr. Chiarello has served as Chief Administrative Officer since July 2019. Mr. Chiarello joined Fiserv as part of the acquisition of First Data Corporation, where he served as president since 2013. From 2008 to 2013, he served as chief information officer of JPMorgan Chase & Co., a global financial services firm. From 1985 to 2008, Mr. Chiarello served in various technology and leadership roles including chief information officer at Morgan Stanley, a global financial services firm.
Mr. Foskett has served as Executive Vice President, Global Sales since July 2019. Mr. Foskett joined Fiserv as part of the acquisition of First Data Corporation, where he served as executive vice president, head of corporate and business development since 2015 and co-head of global financial services since 2018. He joined First Data Corporation in 2014 as head of global, strategic and national accounts. From 2011 to 2014, Mr. Foskett served as managing director, head of North American treasury services and global head of sales for treasury services at JPMorgan Chase & Co., a global financial services firm. From 2009 to 2011, he was managing director, global head of financial institutions at National Australia Bank, an Australian financial institution. From 1991 to 2008, Mr. Foskett was managing director in Citigroup’s Corporate & Investment Bank leading several global businesses. Prior to that, he was employed by Goldman Sachs & Co. and Merrill Lynch & Co. focusing on mergers and acquisitions.
Mr. Hau has served as Chief Financial Officer since 2016. Before joining Fiserv, Mr. Hau served as executive vice president and chief financial officer at TE Connectivity Ltd., a global technology and manufacturing company, from 2012 to 2016. From 2009 to 2012, he served as executive vice president and chief financial officer at Lennox International Inc., a provider of products and services in the heating, air conditioning, and refrigeration markets; and from 2006 to 2009, he served as vice president and chief financial officer for the aerospace business group of Honeywell International, Inc., a technology and manufacturing company. Mr. Hau joined Honeywell (initially AlliedSignal) in 1987 and served in a variety of senior financial leadership positions, including vice president and chief financial officer for the company’s aerospace electronic systems unit and for its specialty materials business group.
Ms. McCreary has served as Chief Legal Officer and Secretary since 2013. Ms. McCreary joined Fiserv in 2010 as senior vice president and deputy general counsel. Prior to joining Fiserv, Ms. McCreary was a partner with the law firm of Bryan Cave LLP from 1996 to 2010, including serving as managing partner of its San Francisco, California office from its opening in 2008 to 2010. Ms. McCreary began her career in financial services with positions at Citicorp Person-to-Person and Metropolitan Life Insurance Company’s mortgage subsidiary, Metmor Financial, Inc.
Mr. McGranahan has served as Executive Vice President, Senior Group President since 2018 and joined Fiserv in 2016 as group president, Billing and Payments Group. Before joining Fiserv, Mr. McGranahan served as a senior partner at McKinsey & Company, a global management consulting firm. While there, he held a variety of senior management roles, including leader of the global insurance practice from 2013 to 2016 and co-chair of the global senior partner election committee from 2013 to 2015. In addition, Mr. McGranahan served as co-leader of the North America financial services practice from 2009 to 2016. He joined McKinsey & Company in 1992 and served in a variety of other leadership positions prior to 2009, including leader of the North American property and casualty practice and managing partner of the Pittsburgh office.
Mr. Vielehr has served as Chief Digital and Data Officer since January 2021. He previously served as Executive Vice President, Senior Group President from 2019 to January 2021, Chief Administrative Officer from 2018 to 2019, and as Group President, Depository Institution Services Group from 2013 to 2018. Prior to joining Fiserv, from 2005 to 2013, Mr. Vielehr served in a succession of senior executive positions with The Dun & Bradstreet Corporation, a provider of commercial information and business insight solutions, most recently as president of international and global operations. He also previously served as president and chief operating officer of Northstar Systems International, Inc., a developer of wealth management software (now part of SEI Investments Company), from 2004 to 2005. Mr. Vielehr has more than 25 years of experience in the financial services and technology industries, including a variety of executive leadership roles at Merrill Lynch & Co. and Strong Capital Management.
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Market Price Information
Our common stock is traded on the NASDAQ Global Select Market under the symbol “FISV.” At December 31, 2020, our common stock was held by 1,690 shareholders of record and by a significantly greater number of shareholders who hold shares in nominee or street name accounts with brokers. We have never paid dividends on our common stock and we do not anticipate paying dividends in the foreseeable future. For additional information regarding our expected use of capital, refer to the discussion in this report under the heading “Management’s Discussion and Analysis of Financial Condition and Results of Operations – Liquidity and Capital Resources.”
Issuer Purchases of Equity Securities
The table below sets forth information with respect to purchases made by or on behalf of us or any “affiliated purchaser” (as defined in Rule 10b-18(a)(3) under the Securities Exchange Act of 1934) of shares of our common stock during the three months ended December 31, 2020:
| Period | Total Number of Shares Purchased | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs (1) | Maximum Number of Shares that May Yet Be Purchased Under the Plans or Programs (1) | ||||||||||||||||||||||
| October 1-31, 2020 | — | $ | — | — | 7,486,000 | |||||||||||||||||||||
| November 1-30, 2020 | — | — | — | 67,486,000 | ||||||||||||||||||||||
| December 1-31, 2020 | 1,818,000 | 110.04 | 1,818,000 | 65,668,000 | ||||||||||||||||||||||
| Total | 1,818,000 | 1,818,000 | ||||||||||||||||||||||||
(1)On August 8, 2018 and November 19, 2020, our board of directors authorized the purchase of up to 30.0 million and 60.0 million shares of our common stock, respectively. These authorizations do not expire.
In connection with the vesting of restricted stock awards, shares of common stock are delivered to the Company by employees to satisfy tax withholding obligations. The following table summarizes such purchases of common stock during the three months ended December 31, 2020:
| Period | Total Number of Shares Purchased | Average Price Paid per Share | Total Number of Shares Purchased as Part of Publicly Announced Plans or Programs | Maximum Number of Shares that May Yet Be Purchased Under the Plans or Programs | ||||||||||||||||||||||
| October 1-31, 2020 | — | $ | — | — | — | |||||||||||||||||||||
| November 1-30, 2020 | — | — | — | — | ||||||||||||||||||||||
| December 1-31, 2020 | 30,900 | (1) | 113.86 | — | — | |||||||||||||||||||||
| Total | 30,900 | — | ||||||||||||||||||||||||
(1)Shares surrendered to us to satisfy tax withholding obligations in connection with the vesting of restricted stock awards issued to employees.
Stock Performance Graph
The stock performance graph and related information presented below is not deemed to be “soliciting material” or to be “filed” with the Securities and Exchange Commission or subject to Regulation 14A or 14C under the Securities Exchange Act of 1934 or to the liabilities of Section 18 of the Securities Exchange Act of 1934 and will not be deemed to be incorporated by reference into any filing under the Securities Act of 1933 or the Securities Exchange Act of 1934, except to the extent we specifically incorporate it by reference into such a filing.
The following graph compares the cumulative total shareholder return on our common stock for the five years ended December 31, 2020 with the S&P 500 Index and the NASDAQ US Benchmark Transaction Processing Services Index (the “Index”). Prior to September 21, 2020, the Index was known as the NASDAQ US Benchmark Financial Administration Index. The Index, as renamed, is identical to the NASDAQ US Benchmark Financial Administration Index prior to its name change on September 21, 2020. The graph assumes that $100 was invested on December 31, 2015 in our common stock and each index and that all dividends were reinvested. No cash dividends have been declared on our common stock. The comparisons in the graph are required by the Securities and Exchange Commission and are not intended to forecast or be indicative of possible future performance of our common stock.
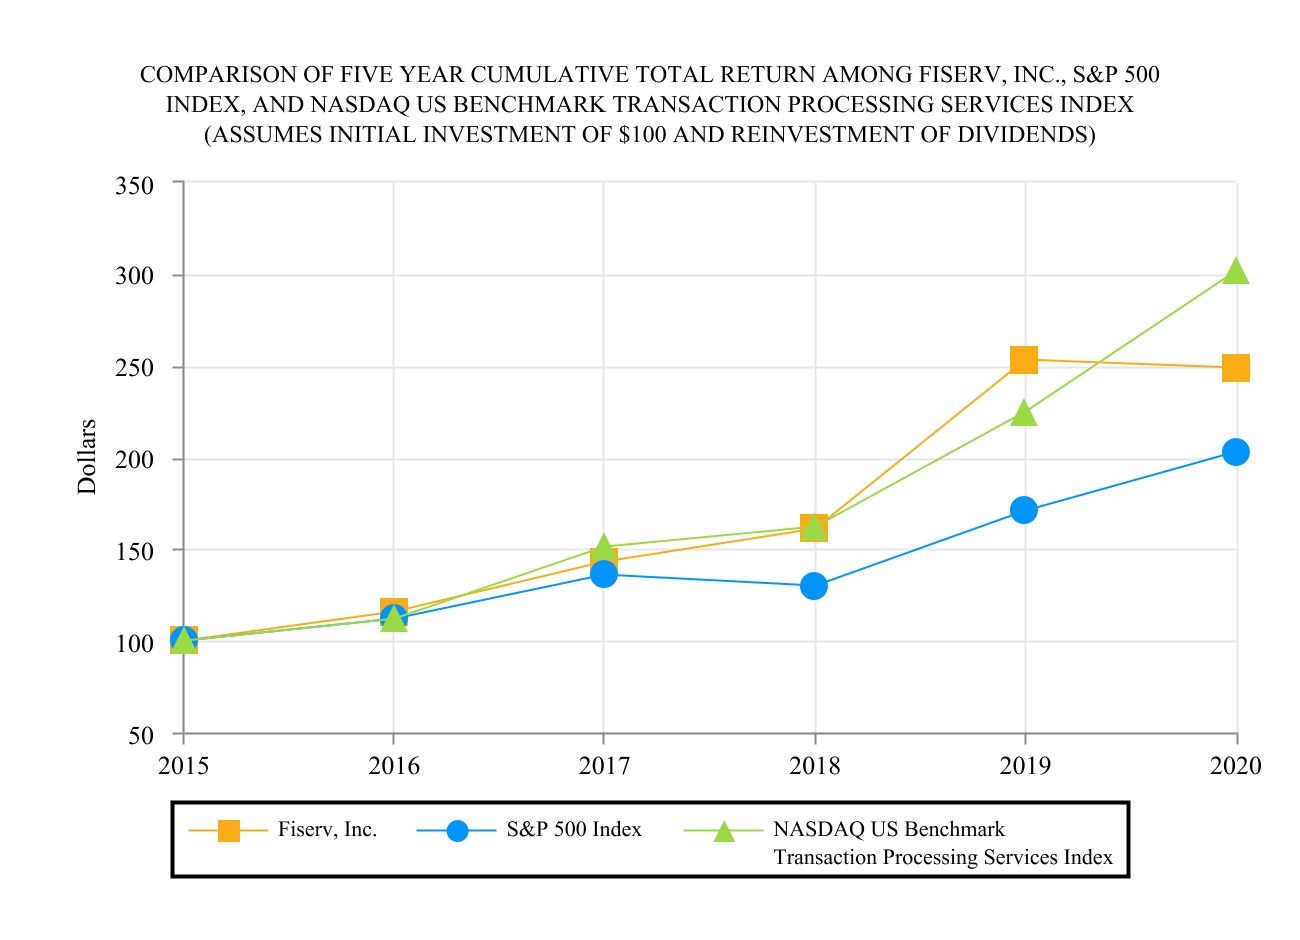
| December 31, | |||||||||||||||||||||||||||||||||||
| 2015 | 2016 | 2017 | 2018 | 2019 | 2020 | ||||||||||||||||||||||||||||||
| Fiserv, Inc. | $ | 100 | $ | 116 | $ | 143 | $ | 161 | $ | 253 | $ | 249 | |||||||||||||||||||||||
| S&P 500 Index | 100 | 112 | 136 | 130 | 171 | 203 | |||||||||||||||||||||||||||||
| NASDAQ US Benchmark Transaction Processing Services Index | 100 | 112 | 151 | 162 | 225 | 302 |
Item 6. Selected Financial Data
The following data should be read in conjunction with the consolidated financial statements and accompanying notes and the sections entitled “Management’s Discussion and Analysis of Financial Condition and Results of Operations” contained in this Annual Report on Form 10-K. The selected historical data presented below has been affected by the First Data and other acquisitions, dispositions and transactional gains recorded by our unconsolidated affiliates, debt financing activities, foreign currency fluctuations, the tax effects related to share-based payment awards and by the Tax Cuts and Jobs Act enacted in December 2017. In addition, effective January 1, 2020, we adopted Accounting Standards Update (“ASU”) No. 2016-13, Financial Instruments - Credit Losses (Topic 326), using the required modified retrospective approach, which resulted in a cumulative-effect decrease to beginning retained earnings of $45 million. Effective January 1, 2019, we adopted ASU No. 2016-02, Leases (Topic 842), and its related amendments using the optional transition method applied to all leases. The adoption of the new lease standard resulted in the recognition of lease liabilities and right-of-use assets on the consolidated balance sheet beginning January 1, 2019. Under the optional transition approach, prior period amounts have not been restated. Effective January 1, 2018, we adopted ASU No. 2014-09, Revenue from Contracts with Customers, and its related amendments using the modified retrospective transition approach applied to all contracts. Under this transition approach, prior period amounts have not been restated. All per share amounts are presented on a split-adjusted basis to retroactively reflect the two-for-one stock split that was completed in the first quarter of 2018.
| (In millions, except per share data) | 2020 | 2019 | 2018 | 2017 | 2016 | ||||||||||||||||||||||||
| Total revenue | $ | 14,852 | $ | 10,187 | $ | 5,823 | $ | 5,696 | $ | 5,505 | |||||||||||||||||||
| Income from continuing operations | $ | 975 | $ | 914 | $ | 1,187 | $ | 1,232 | $ | 930 | |||||||||||||||||||
| Income from discontinued operations, net of income taxes | — | — | — | 14 | — | ||||||||||||||||||||||||
| Net income | 975 | 914 | 1,187 | 1,246 | 930 | ||||||||||||||||||||||||
| Less: net income attributable to noncontrolling interests and redeemable noncontrolling interests | 17 | 21 | — | — | — | ||||||||||||||||||||||||
| Net income attributable to Fiserv, Inc. | $ | 958 | $ | 893 | $ | 1,187 | $ | 1,246 | $ | 930 | |||||||||||||||||||
| Net income attributable to Fiserv, Inc. per share – basic: | |||||||||||||||||||||||||||||
| Continuing operations | $ | 1.42 | $ | 1.74 | $ | 2.93 | $ | 2.92 | $ | 2.11 | |||||||||||||||||||
| Discontinued operations | — | — | — | 0.03 | — | ||||||||||||||||||||||||
| Total | $ | 1.42 | $ | 1.74 | $ | 2.93 | $ | 2.95 | $ | 2.11 | |||||||||||||||||||
| Net income attributable to Fiserv, Inc. per share – diluted: | |||||||||||||||||||||||||||||
| Continuing operations | $ | 1.40 | $ | 1.71 | $ | 2.87 | $ | 2.86 | $ | 2.08 | |||||||||||||||||||
| Discontinued operations | — | — | — | 0.03 | — | ||||||||||||||||||||||||
| Total | $ | 1.40 | $ | 1.71 | $ | 2.87 | $ | 2.89 | $ | 2.08 | |||||||||||||||||||
| Total assets | $ | 74,619 | $ | 77,539 | $ | 11,262 | $ | 10,289 | $ | 9,743 | |||||||||||||||||||
| Long-term debt (including short-term and current maturities) | 20,684 | 21,899 | 5,959 | 4,900 | 4,562 | ||||||||||||||||||||||||
| Fiserv, Inc. shareholders’ equity | 32,330 | 32,979 | 2,293 | 2,731 | 2,541 | ||||||||||||||||||||||||
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
Management’s discussion and analysis of financial condition and results of operations is provided as a supplement to our consolidated financial statements and accompanying notes to help provide an understanding of our financial condition, the changes in our financial condition and our results of operations. Our discussion is organized as follows:
-
Overview. This section contains background information on our company and the services and products that we provide, acquisitions and dispositions, our enterprise priorities, and the trends affecting our industry in order to provide context for management’s discussion and analysis of our financial condition and results of operations.
-
Critical accounting policies and estimates. This section contains a discussion of the accounting policies that we believe are important to our financial condition and results of operations and that require judgment and estimates on the part of management in their application. In addition, all of our significant accounting policies, including critical accounting policies, are summarized in Note 1 to the accompanying consolidated financial statements.
-
Results of operations. This section contains an analysis of our results of operations presented in the accompanying consolidated statements of income by comparing the results for the year ended December 31, 2020 to the results for the year ended December 31, 2019 and by comparing the results for the year ended December 31, 2019 to the results for the year ended December 31, 2018.
-
Liquidity and capital resources. This section provides an analysis of our cash flows and a discussion of our outstanding debt and commitments at December 31, 2020.
Overview
Company Background
We are a leading global provider of payments and financial services technology solutions. We provide account processing and digital banking solutions; card issuer processing and network services; payments; e-commerce; merchant acquiring and processing; and the Clover® cloud-based point-of-sale (“POS”) solution. We serve clients around the globe, including banks, credit unions, other financial institutions, corporate clients and merchants.
On July 29, 2019, we acquired First Data Corporation (“First Data”), a global leader in commerce-enabling technology and solutions for merchants, financial institutions and card issuers. Effective in the first quarter of 2020, we realigned our reportable segments to reflect our new management structure and organizational responsibilities (“Segment Realignment”) following the acquisition of First Data.
Our operations are comprised of the Merchant Acceptance (“Acceptance”) segment, the Financial Technology (“Fintech”) segment and the Payments and Network (“Payments”) segment. The consolidated financial statements include the financial results of First Data from the date of acquisition. Segment results for the years ended December 31, 2019 and 2018 have been restated to reflect the Segment Realignment.
The Acceptance segment provides a wide range of commerce-enabling solutions to merchants of all sizes and types around the world. These solutions include POS merchant acquiring and digital commerce services; mobile payment services; security and fraud protection products and services; CaratSM, our omnichannel commerce solution; and our cloud-based Clover POS platform, which includes a marketplace for proprietary and third-party business applications. The businesses in the Acceptance segment are subject to a modest level of seasonality, with the first quarter generally experiencing the lowest level of revenue and the fourth quarter experiencing the highest level of revenue.
The Fintech segment provides financial institutions around the world with technology solutions that enable them to process customer deposit and loan accounts and manage general ledger and central information files, as well as other products and services that support numerous types of financial transactions such as digital banking, financial and risk management, cash management, professional services and consulting, and item processing and source capture services. Our businesses in this segment also provide products and services to corporate clients to facilitate the management of financial processes and transactions.
The Payments segment primarily provides financial institutions and corporate clients with the products and services required to process digital payment transactions, including card transactions such as debit, credit and prepaid card processing and services, a range of network services, security and fraud protection products, card production and print services. In addition, our businesses in this segment offer non-card digital payment software and services, including bill payment, account-to-account transfers, person-to-person payments, electronic billing, and security and fraud protection products.
The majority of our revenue is generated from recurring account- and transaction-based fees under multi-year contracts with high renewal rates. Most of the services we provide within our segments are necessary for our clients to operate their businesses and are, therefore, non-discretionary in nature.
Corporate and Other supports the reportable segments described above, and consists of amortization of acquisition-related intangible assets, unallocated corporate expenses and other activities that are not considered when we evaluate segment performance, such as gains or losses on sales of businesses, costs associated with acquisition and divestiture activity, and our Output Solutions postage reimbursements. Corporate and Other also includes the historical results of our Investment Services business, of which we sold a 60% controlling interest in February 2020, as well as certain transition services revenue associated with various dispositions.
Acquisitions and Dispositions
We frequently review our portfolio to ensure we have the right set of businesses to execute on our strategy. We expect to acquire businesses when we identify: a compelling strategic need, such as a product, service or technology that helps meet client demand; an opportunity to change industry dynamics; a way to achieve business scale; or similar considerations. We expect to divest businesses that are not in line with our market, product or financial strategies.
Acquisitions
On March 2, 2020, we acquired MerchantPro Express LLC (“MerchantPro”), an independent sales organization (“ISO”) that provides processing services, POS equipment and merchant cash advances to businesses across the United States. MerchantPro is included within the Acceptance segment and further expands our merchant services business. On March 18, 2020, we acquired Bypass Mobile, LLC (“Bypass”), an independent software vendor and innovator in enterprise POS systems for sports and entertainment venues, food service management providers and national restaurant chains. Bypass is included within the Acceptance segment and further enhances our omni-commerce capabilities, enabling enterprise businesses to deliver a seamless customer experience that spans physical and digital channels. On May 11, 2020, we acquired Inlet, LLC (“Inlet”), a provider of secure digital delivery solutions for enterprise and middle-market billers’ invoices and statements. Inlet is included within the Payments segment and further enhances our digital bill payment strategy. We acquired these businesses for an aggregate purchase price of $167 million, net of $2 million of acquired cash, and including earn-out provisions estimated at a fair value of $45 million.
On July 29, 2019, we acquired First Data for a total purchase price of $46.5 billion by acquiring 100% of the First Data stock that was issued and outstanding as of the date of acquisition. As a result of the acquisition, First Data stockholders received 286 million shares of common stock of Fiserv, Inc., at an exchange ratio of 0.303 shares of Fiserv, Inc.
Showing the first 8K of 111K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
Market risk refers to the risk that a change in the level of one or more market prices, interest rates, currency exchange rates, indices, correlations or other market factors, such as liquidity, will result in losses for a certain financial instrument or group of financial instruments. We are exposed to certain market risks, primarily from fluctuations in interest rates and foreign currency exchange rates. Our senior management actively monitors these risks.
Interest Rate Risk
In addition to existing cash balances and cash provided by operating activities, we use a combination of fixed- and variable-rate debt instruments to finance our operations. We are exposed to interest rate risk on certain of these debt obligations. We had fixed- and variable-rate debt, excluding finance leases and other financing obligations, with varying maturities for an aggregate carrying amount of $18.3 billion and $1.8 billion, respectively, at December 31, 2020. Our fixed-rate debt at December 31, 2020 primarily consisted of fixed-rate senior notes with a fair value of $20.7 million, based on matrix pricing which considers readily observable inputs of comparable securities. The potential change in fair value of our fixed-rate senior notes from a hypothetical 1% change in market interest rates would not alone impact any decisions to repurchase our outstanding fixed-rate debt instruments before their maturity. Our variable-rate debt at December 31, 2020 primarily consisted of outstanding borrowings on our revolving credit facility, variable rate term loan, foreign lines of credit and debt associated with the receivables securitization agreement. Based on our outstanding debt balances and interest rates at December 31, 2020, a hypothetical 1% increase in market interest rates related to our variable-rate debt would increase annual interest expense by approximately $18 million. This sensitivity analysis assumes the outstanding debt balances at December 31, 2020 and the change in market interest rates is applicable for an entire year.
In connection with processing electronic payments transactions, the funds we receive from subscribers are invested into short-term, highly liquid investments from the time we collect the funds until payments are made to the applicable recipients. Fluctuations in market interest rates affect the interest-related income that we earn on these investments. A hypothetical 1% decrease in market interest rates would decrease annual interest-related income related to settlement assets by approximately
$30 million over the next twelve months. This sensitivity analysis assumes the subscriber fund balances at December 31, 2020 and the change in market interest rates is applicable for an entire year.
Foreign Currency Risk
We conduct business globally and are exposed to foreign currency risk from changes in the value of underlying assets and liabilities of our non-U.S. dollar-denominated foreign investments and foreign currency transactions. We manage the exposure to these risks through the use of foreign currency forward exchange contracts and non-derivative net investment hedges.
Our exposure to foreign currency exchange risks generally arise from our non-U.S. operations to the extent they are conducted in local currency. Approximately 13% and 12% of our total revenue was generated outside the U.S in 2020 and 2019, respectively. The major currencies to which our revenues are exposed are the Euro, the British Pound, the Indian Rupee and the Argentine Peso. A strengthening or weakening of the U.S. dollar relative to the currencies in which our revenue and profits are denominated by 10% would have resulted in a decrease or increase , respectively, in our reported pre-tax income as follows at December 31:
| (In millions) | 2020 | 2019 | |||||||||||||||||||||||||||
| Euro | $ | 7 | $ | 7 | |||||||||||||||||||||||||
| British Pound | 3 | 4 | |||||||||||||||||||||||||||
| Indian Rupee | 2 | 3 | |||||||||||||||||||||||||||
| Argentine Peso | 3 | 2 | |||||||||||||||||||||||||||
| Other | 5 | 9 | |||||||||||||||||||||||||||
| Total increase or decrease | $ | 20 | $ | 25 | |||||||||||||||||||||||||
We have entered into foreign currency forward exchange contracts, which have been designated as cash flow hedges, to hedge foreign currency exposure to our operating costs in India. At December 31, 2020, the notional amount of these derivatives was approximately $259 million, with a positive fair value of $9 million. In addition, we designated our foreign currency-denominated senior notes as net investment hedges to reduce exposure to changes in the value of our net investments in certain foreign subsidiaries due to changes in foreign currency exchange rates.
Refer to Item 1A in Part I of this Annual Report on Form 10-K for an additional discussion of risks and potential risks of the COVID-19 pandemic on our business.
Item 8. Financial Statements and Supplementary Data
Index to Consolidated Financial Statements
Fiserv, Inc.
Consolidated Statements of Income
| In millions, except per share data | ||||||||||||||||||||
| Year Ended December 31, | 2020 | 2019 | 2018 | |||||||||||||||||
| Revenue: | ||||||||||||||||||||
| Processing and services (1) | $ | 12,215 | $ | 8,573 | $ | 4,975 | ||||||||||||||
| Product | 2,637 | 1,614 | 848 | |||||||||||||||||
| Total revenue | 14,852 | 10,187 | 5,823 | |||||||||||||||||
| Expenses: | ||||||||||||||||||||
| Cost of processing and services | 5,841 | 4,016 | 2,324 | |||||||||||||||||
| Cost of product | 1,971 | 1,293 | 745 | |||||||||||||||||
| Selling, general and administrative | 5,652 | 3,284 | 1,228 | |||||||||||||||||
| Gain on sale of businesses | (464) | (15) | (227) | |||||||||||||||||
| Total expenses | 13,000 | 8,578 | 4,070 | |||||||||||||||||
| Operating income | 1,852 | 1,609 | 1,753 | |||||||||||||||||
| Interest expense, net | (709) | (473) | (189) | |||||||||||||||||
| Debt financing activities | — | (47) | (14) | |||||||||||||||||
| Other income (expense) | 28 | (6) | 5 | |||||||||||||||||
| Income before income taxes and income from investments in unconsolidated affiliates | 1,171 | 1,083 | 1,555 | |||||||||||||||||
| Income tax provision | (196) | (198) | (378) | |||||||||||||||||
| Income from investments in unconsolidated affiliates | — | 29 | 10 | |||||||||||||||||
| Net income | 975 | 914 | 1,187 | |||||||||||||||||
| Less: net income attributable to noncontrolling interests and redeemable noncontrolling interests | 17 | 21 | — | |||||||||||||||||
| Net income attributable to Fiserv, Inc. | $ | 958 | $ | 893 | $ | 1,187 | ||||||||||||||
| Net income attributable to Fiserv, Inc. per share – basic | $ | 1.42 | $ | 1.74 | $ | 2.93 | ||||||||||||||
| Net income attributable to Fiserv, Inc. per share – diluted | $ | 1.40 | $ | 1.71 | $ | 2.87 | ||||||||||||||
| Shares used in computing net income attributable to Fiserv, Inc. per share: | ||||||||||||||||||||
| Basic | 672.1 | 512.3 | 405.5 | |||||||||||||||||
| Diluted | 683.4 | 522.6 | 413.7 | |||||||||||||||||
(1)Includes processing and other fees charged to related party investments accounted for under the equity method of $236 million, $112 million and $28 million for the years ended December 31, 2020, 2019 and 2018, respectively (see Notes 9 and 20).
Fiserv, Inc.
Consolidated Statements of Comprehensive Income
| In millions | ||||||||||||||||||||
| Year Ended December 31, | 2020 | 2019 | 2018 | |||||||||||||||||
| Net income | $ | 975 | $ | 914 | $ | 1,187 | ||||||||||||||
| Other comprehensive (loss) income: | ||||||||||||||||||||
| Fair market value adjustment on cash flow hedges, net of income tax (provision) benefit of ($2 million), $46 million and $2 million | 5 | (134) | (5) | |||||||||||||||||
| Reclassification adjustment for net realized gains on cash flow hedges included in cost of processing and services, net of income tax benefit of $0 million, $0 million and $0 million | (1) | (1) | (1) | |||||||||||||||||
| Reclassification adjustment for net realized losses on cash flow hedges included in net interest expense, net of income tax provision of $5 million, $3 million and $2 million | 16 | 10 | 4 | |||||||||||||||||
| Unrealized losses on defined benefit pension plans, net of income tax benefit of $2 million and $1 million | (6) | (4) | — | |||||||||||||||||
| Foreign currency translation | (186) | 8 | (11) | |||||||||||||||||
| Total other comprehensive loss | (172) | (121) | (13) | |||||||||||||||||
| Comprehensive income | $ | 803 | $ | 793 | $ | 1,174 | ||||||||||||||
| Less: net income attributable to noncontrolling interests and redeemable noncontrolling interests | 17 | 21 | — | |||||||||||||||||
| Less: other comprehensive income (loss) attributable to noncontrolling interests | 35 | (8) | — | |||||||||||||||||
| Comprehensive income attributable to Fiserv, Inc. | $ | 751 | $ | 780 | $ | 1,174 |
See accompanying notes to consolidated financial statements.
Fiserv, Inc.
Consolidated Balance Sheets
| | | | | | | | | | | | | | | | | --- |
Showing the first 8K of 272K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
Not applicable.
Item 9A. Controls and Procedures
*(a)*Disclosure Controls and Procedures
Our management, with the participation of our chief executive officer and chief financial officer, evaluated the design and operation of our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934). Based on this evaluation, our chief executive officer and chief financial officer concluded that our disclosure controls and procedures were effective as of December 31, 2020.
*(b)*Management Report on Internal Control Over Financial Reporting
Management’s Annual Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting, as such term is defined in Rule 13a-15(f) under the Securities Exchange Act of 1934. Our internal control over financial reporting is designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to risk that controls may become inadequate because of changes in conditions.
Our management assessed the effectiveness of our internal control over financial reporting as of December 31, 2020. In making this assessment, management used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission in Internal Control – Integrated Framework (2013). Based on management’s assessment, our management believes that, as of December 31, 2020, our internal control over financial reporting was effective based on those criteria.
Our independent registered public accounting firm has issued their attestation report on our internal control over financial reporting. The report is included below under the heading “Report of Independent Registered Public Accounting Firm on Internal Control Over Financial Reporting.”
*(c)*Changes in Internal Control Over Financial Reporting
There was no change in our internal control over financial reporting that occurred during the quarter ended December 31, 2020 that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
*(d)*Report of Independent Registered Public Accounting Firm on Internal Control Over Financial Reporting
Our independent registered public accounting firm, Deloitte & Touche LLP, assessed the effectiveness of our internal control over financial reporting and has issued their report as set forth below.
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the Shareholders and the Board of Directors of Fiserv, Inc.:
Opinion on Internal Control over Financial Reporting
We have audited the internal control over financial reporting of Fiserv, Inc. and subsidiaries (the “Company”) as of December 31, 2020, based on criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2020, based on criteria established in Internal Control — Integrated Framework (2013) issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements as of and for the year ended December 31, 2020, of the Company and our report dated February 26, 2021, expressed an unqualified opinion on those financial statements and included an explanatory paragraph regarding the Company’s adoption of a new accounting standard.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Annual Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control over Financial Reporting
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
/s/ Deloitte & Touche LLP
Milwaukee, Wisconsin
February 26, 2021
Item 9B. Other Information
None.
PART III
Item 10. Directors, Executive Officers and Corporate Governance
Except for information concerning our executive officers included in Part I of this Form 10-K under the caption “Information About Our Executive Officers,” which is incorporated by reference herein, and the information regarding our Code of Conduct below, the information required by Item 10 is incorporated by reference to the information set forth under the captions “Our Board of Directors – Who We Are,” “Our Board of Directors – How We Are Selected, Elected and Evaluated,” and “Our Board of Directors – How We Are Organized – Our Committees – Audit Committee” in our definitive proxy statement for our 2021 annual meeting of shareholders, which will be filed with the Securities and Exchange Commission no later than 120 days after the close of the fiscal year ended December 31, 2020.
Our board of directors has adopted a Code of Conduct and Business Ethics (“Code of Conduct”) that applies to all of our directors and employees, including our chief executive officer, chief financial officer, chief accounting officer and other persons performing similar functions as well as our other executive officers. We have posted a copy of our Code of Conduct on the “About – Investor Relations – Corporate Governance – Governance Documents” section of our website at www.fiserv.com. We intend to satisfy the disclosure requirements under Item 5.05 of Form 8-K regarding amendments to, or waivers from, the Code of Conduct by posting such information on the “About – Investor Relations” section of our website at www.fiserv.com. We are not including the information contained on our website as part of, or incorporating it by reference into, this report.
Item 11. Executive Compensation
The information required by Item 11 is incorporated by reference to the information set forth under the captions “Our Board of Directors – How We Are Paid,” “Compensation Discussion and Analysis,” “Compensation Committee Report,” “Compensation Committee Interlocks and Insider Participation,” “Executive Compensation,” and “Pay Ratio” in our definitive proxy statement for our 2021 annual meeting of shareholders, which will be filed with the Securities and Exchange Commission no later than 120 days after the close of the fiscal year ended December 31, 2020.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information set forth under the caption “Our Shareholders – Common Stock Ownership” in our definitive proxy statement for our 2021 annual meeting of shareholders, which will be filed with the Securities and Exchange Commission no later than 120 days after the close of the fiscal year ended December 31, 2020, is incorporated by reference herein.
Equity Compensation Plan Information
The table below sets forth information with respect to compensation plans under which equity securities are authorized for issuance as of December 31, 2020.
| (a) | (b) | (c) | |||||||||
| Plan Category | Number of shares to be issued upon exercise of outstanding options, warrants and rights | Weighted-average exercise price of outstanding options, warrants and rights | Number of shares remaining available for future issuance under equity compensation plans (excluding securities reflected in column (a)) | ||||||||
| Equity compensation plans approved by our shareholders (1) | 10,151,547 (2) | 56.59 (3) | 30,452,373 (4) | ||||||||
| Equity compensation plans not approved by our shareholders | N/A | N/A | N/A | ||||||||
| Total (5) | 10,151,547 (2) | 56.59 (3) | 30,452,373 (4) |
(1)Columns (a) and (c) of the table above do not include 2,436,442 unvested restricted stock units outstanding under the Amended and Restated Fiserv, Inc. 2007 Omnibus Incentive Plan (the “Incentive Plan”) or 24,230,938 shares authorized for issuance under the Fiserv, Inc. Amended and Restated Employee Stock Purchase Plan.
(2)Consists of options outstanding under the Incentive Plan; 149,132 shares subject to performance share units under the Incentive Plan at the actual award level where the conditions to vesting have been satisfied; 1,027,049 shares subject to performance share units under the Incentive Plan at the target award level where the conditions to vesting have not yet been satisfied; and 98,924 shares subject to non-employee director deferred compensation notional units under the Incentive Plan.
(3)Represents the weighted-average exercise price of outstanding options under the Incentive Plan and does not take into account outstanding performance share units or non-employee director deferred compensation notional units under the Incentive Plan.
(4)Reflects the number of shares available for future issuance under the Incentive Plan.
(5)This table does not include 5,812,408 options outstanding under the 2007 Stock Incentive Plan for Key Employees of First Data Corporation and its Affiliates (the “2007 First Data Plan”) and the First Data Corporation 2015 Omnibus Incentive Plan (the “2015 First Data Plan” and together with the 2007 First Data Plan, the “First Data Plans”) as of December 31, 2020 at a weighted-average exercise price of $42.00. We assumed the First Data Plans in connection with our acquisition of First Data Corporation on July 29, 2019 and converted certain outstanding First Data equity awards into corresponding equity awards relating to common stock of Fiserv, Inc. in accordance with an exchange ratio in the merger agreement as further described in Note 4 to the accompanying consolidated financial statements. This table also does not include 2,906,696 shares of restricted stock and restricted stock units outstanding under the 2015 First Data Plan, as of December 31, 2020. No additional equity awards will be made under the First Data Plans.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information required by Item 13 is incorporated by reference to the information set forth under the captions “Our Board of Directors – How We Are Organized – Our Independence,” and “Our Board of Directors – How We Govern – Review, Approval or Ratification of Transactions with Related Persons,” in our definitive proxy statement for our 2021 annual meeting of shareholders, which will be filed with the Securities and Exchange Commission no later than 120 days after the close of the fiscal year ended December 31, 2020.
Item 14. Principal Accounting Fees and Services
The information required by Item 14 is incorporated by reference to the information set forth under the captions “Independent Registered Public Accounting Firm and Fees” and “Audit Committee Pre-Approval Policy” in our definitive proxy statement for our 2021 annual meeting of shareholders, which will be filed with the Securities and Exchange Commission no later than 120 days after the close of the fiscal year ended December 31, 2020.
PART IV
Item 15. Exhibits, Financial Statement Schedules
Financial Statement Schedules
Financial statement schedules have been omitted because they are not applicable or the required information is shown in the consolidated financial statements or accompanying notes.
Exhibits
The exhibits listed in the accompanying exhibit index are filed as part of this Annual Report on Form 10-K.
EXHIBIT INDEX
_____
- This exhibit is a management contract or compensatory plan or arrangement.
** Filed with this Annual Report on Form 10-K are the following documents formatted in iXBRL (Inline Extensible Business Reporting Language): (i) the Consolidated Statements of Income for the years ended December 31, 2020, 2019,
and 2018, (ii) the Consolidated Statements of Comprehensive Income for the years ended December 31, 2020, 2019, and 2018, (iii) the Consolidated Balance Sheets at December 31, 2020 and 2019, (iv) the Consolidated Statements of Equity for the years ended December 31, 2020, 2019, and 2018, (v) the Consolidated Statements of Cash Flows for the years ended December 31, 2020, 2019, and 2018, and (vi) Notes to Consolidated Financial Statements.
(1)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on January 18, 2019, and incorporated herein by reference.
(2)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on February 27, 2018, and incorporated herein by reference.
(3)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on November 2, 2020, and incorporated herein by reference.
(4)Previously filed as an exhibit to the Company’s Annual Report on Form 10-K filed on February 27, 2020, and incorporated herein by reference.
(5)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on September 20, 2018, and incorporated herein by reference.
(6)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on February 7, 2019, and incorporated herein by reference.
(7)Previously filed as an exhibit to the Company’s Annual Report on Form 10-K filed on February 21, 2019, and incorporated herein by reference.
(8)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on July 29, 2019, and incorporated herein by reference.
(9)Previously filed as an exhibit to the Company’s Registration Statement on Form S-3 (File No. 333‑147309) filed on November 13, 2007, and incorporated herein by reference.
(10)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on June 14, 2011, and incorporated herein by reference.
(11)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on September 25, 2012, and incorporated herein by reference.
(12)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on May 22, 2015, and incorporated herein by reference.
(13)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on September 25, 2018, and incorporated herein by reference.
(14)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on June 24, 2019, and incorporated herein by reference.
(15)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on July 1, 2019, and incorporated herein by reference.
(16)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on May 13, 2020, and incorporated herein by reference.
(17)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on September 9, 2019, and incorporated herein by reference.
(18)Previously filed as an exhibit to the Company’s Quarterly Report on Form 10-Q filed on May 2, 2018, and incorporated herein by reference.
(19)Previously filed as an exhibit to the Company’s Annual Report on Form 10-K filed on February 24, 2012, and incorporated herein by reference.
(20)Previously filed as an exhibit to the Company’s Annual Report on Form 10-K filed on February 23, 2017, and incorporated herein by reference.
(21)Previously filed as an exhibit to the Company’s Quarterly Report on Form 10-Q filed on August 2, 2017, and incorporated herein by reference.
(22)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on December 1, 2017, and incorporated herein by reference.
(23)Previously filed as an exhibit to the Company’s Annual Report on Form 10-K filed on February 20, 2015, and incorporated herein by reference.
(24)Previously filed as an exhibit to the Company’s Post-Effective Amendment No. 1 on Form S-8 to the Form S-4 Registration Statement of Fiserv, Inc. filed July 29, 2019, and incorporated herein by reference.
(25)Previously filed as an exhibit to the Company’s Quarterly Report on Form 10-Q filed on November 7, 2019, and incorporated herein by reference.
(26)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on December 23, 2008, and incorporated herein by reference.
(27)Previously filed as an exhibit to the Company’s Annual Report on Form 10-K filed on February 27, 2009, and incorporated herein by reference.
(28)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on December 30, 2009, and incorporated herein by reference.
(29)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on April 1, 2016, and incorporated herein by reference.
(30)Previously filed as an exhibit to the Company’s Quarterly Report on Form 10-Q filed on May 8, 2020, and incorporated herein by reference.
(31)Previously filed as an exhibit to the Company’s Quarterly Report on Form 10-Q filed on October 30, 2013, and incorporated herein by reference.
(32)Previously filed as an exhibit to the Company’s Annual Report on Form 10-K filed on February 20, 2014, and incorporated herein by reference.
(33)Previously filed as an exhibit to the Company’s Current Report on Form 8-K filed on February 16, 2016, and incorporated herein by reference.
(34)Previously filed as an exhibit to the Company’s Quarterly Report on Form 10-Q filed on May 6, 2016, and incorporated herein by reference.
(35)Previously filed as an exhibit to First Data Corporation’s Annual Report on Form 10-K filed on February 27, 2015 and incorporated herein by reference.
(36)Previously filed as an exhibit to the Company’s Annual Report on Form 10-K filed on February 28, 2008, and incorporated herein by reference.
Item 16. Form 10-K Summary
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized on February 26, 2021.
| FISERV, INC. | ||||||||
| By: | /s/ Frank J. Bisignano | |||||||
| Frank J. Bisignano | ||||||||
| President and Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities indicated on February 26, 2021.
| Name | Capacity | |||||||
| /s/ Denis J. O’Leary | Chairman of the Board | |||||||
| Denis J. O’Leary | ||||||||
| /s/ Frank J. Bisignano | Director, President and Chief Executive Officer (Principal Executive Officer) | |||||||
| Frank J. Bisignano | ||||||||
| /s/ Robert W. Hau | Chief Financial Officer (Principal Financial Officer) | |||||||
| Robert W. Hau | ||||||||
| /s/ Kenneth F. Best | Chief Accounting Officer (Principal Accounting Officer) | |||||||
| Kenneth F. Best | ||||||||
| /s/ Alison Davis | Director | |||||||
| Alison Davis | ||||||||
| /s/ Henrique De Castro | Director | |||||||
| Henrique De Castro | ||||||||
| /s/ Harry F. DiSimone | Director | |||||||
| Harry F. DiSimone | ||||||||
| /s/ Dennis F. Lynch | Director | |||||||
| Dennis F. Lynch | ||||||||
| /s/ Heidi G. Miller | Director | |||||||
| Heidi G. Miller | ||||||||
| /s/ Scott C. Nuttall | Director | |||||||
| Scott C. Nuttall | ||||||||
| /s/ Doyle R. Simons | Director | |||||||
| Doyle R. Simons | ||||||||
| /s/ Kevin M. Warren | Director | |||||||
| Kevin M. Warren | ||||||||