 filings.tools
Gen Digital 10-K 2017-03-31
Filed 2017-05-19. 21 sections, 360K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 symc33117-10k.htm 10-K
UNITED STATES SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
Form 10-K
(Mark One)
| þ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the Fiscal Year Ended March 31, 2017
or
| o | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
For the Transition Period from to
Commission File Number 000-17781
Symantec Corporation
(Exact name of the registrant as specified in its charter)
| Delaware | 77-0181864 | |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. employer Identification no.) | |
| 350 Ellis Street | ||
| Mountain View, California | 94043 | |
| (Address of principal executive offices) | (zip code) |
Registrant’s telephone number, including area code:
(650) 527-8000
Securities registered pursuant to Section 12(b) of the Act:
| Common Stock, par value $0.01 per share (Title of each class) | The NASDAQ Stock Market LLC (Name of each exchange on which registered) |
Securities registered pursuant to Section 12(g) of the Act:
None
(Title of class)
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes þ No o
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or 15(d) of the Exchange Act. Yes o No þ
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes þ No o
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes þ No o
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. þ
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer”, “smaller reporting company,” and “emerging growth company” in Rule 12b-2 of the Exchange Act. (Check one):
| Large accelerated filer þ | Accelerated filer o | Non-accelerated filer o | Smaller reporting company o | |||
| (Do not check if a smaller reporting company) | Emerging growth company o | |||||
| If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. o |
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Exchange Act). Yes o No þ
Aggregate market value of the voting stock held by non-affiliates of the registrant, based upon the closing sale price of Symantec common stock on September 30, 2016 as reported on the NASDAQ Global Select Market: $15,559,432,822.
Number of shares outstanding of the registrant’s common stock as of April 28, 2017: 608,240,301
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the registrant’s definitive Proxy Statement for the 2017 Annual Meeting of Stockholders are incorporated herein by reference into Part III of this Annual Report on Form 10-K where indicated. Such proxy statement will be filed with the Securities and Exchange Commission within 120 days of the registrant’s fiscal year ended March 31, 2017.
SYMANTEC CORPORATION
FORM 10-K
For the Fiscal Year Ended March 31, 2017
TABLE OF CONTENTS
“Symantec,” “we,” “us,” “our,” and “the Company” refer to Symantec Corporation and all of its subsidiaries. Symantec, the Symantec Logo and Norton are trademarks or registered trademarks of Symantec in the United States (“U.S.”) and other countries. Other names may be trademarks of their respective owners.
FORWARD-LOOKING STATEMENTS AND FACTORS THAT MAY AFFECT FUTURE RESULTS
The discussion below contains forward-looking statements, which are subject to safe harbors under the Securities Act of 1933, as amended (the “Securities Act”) and the Exchange Act of 1934, as amended (the “Exchange Act”). Forward-looking statements include references to our ability to utilize our deferred tax assets, as well as statements including words such as “expects,” “plans,” “anticipates,” “believes,” “estimates,” “predicts,” “projects,” and similar expressions. In addition, projections of our future financial performance, anticipated growth and trends in our businesses and in our industries, the anticipated impacts of acquisitions, and of our restructurings, our intent to pay quarterly cash dividends in the future, the actions we intend to take as part of our new strategy, the expected impact of our new strategy and other characterizations of future events or circumstances are forward-looking statements. These statements are only predictions, based on our current expectations about future events and may not prove to be accurate. We do not undertake any obligation to update these forward-looking statements to reflect events occurring or circumstances arising after the date of this report. These forward-looking statements involve risks and uncertainties, and our actual results, performance, or achievements could differ materially from those expressed or implied by the forward-looking statements on the basis of several factors.
These and other risks are described under Item 1A, Risk Factors. We encourage you to read that section carefully.
PART I
Item 1. Business
Overview
Symantec Corporation is a global leader in cybersecurity. We operate our business on a global civilian cyber intelligence threat network that tracks a vast number of threats across the Internet from hundreds of millions of mobile devices, endpoints, and servers across the globe. We believe one of our competitive advantages is our database of threat indicators. This database allows us to reduce the number of false positives and provide faster and better protection for customers through our products. We are leveraging our capabilities to deliver integrated platforms for customers. We are also pioneering solutions in markets such as cloud security, digital safety, advanced threat protection, identity protection, information protection and cyber security services.
Founded in 1982, Symantec has operations in more than 40 countries. Our principal executive offices are located at 350 Ellis Street, Mountain View, California, 94043. Our Internet home page is located at www.symantec.com.
Strategy
Our strategy is to deliver comprehensive cyber security platforms for both enterprises and consumers.
Our enterprise security strategy is to deliver an Integrated Cyber Defense Platform that allows Symantec products to share threat intelligence and improve security outcomes for customers across all control points. Symantec is the leading vendor in protecting users, information, web and messaging across an integrated platform.
Our consumer digital safety strategy is to deliver the most comprehensive consumer digital safety solutions to help people protect their information, identities, devices and families.
Following the completion of the sale of our former information management business (“Veritas”) in the fourth quarter of fiscal 2016, we completed the acquisitions of Blue Coat, Inc. (“Blue Coat”) and LifeLock, Inc. (“LifeLock”) in fiscal 2017 in order to expand our offerings in both our operating segments, as described below.
Business highlights
During fiscal 2017, we took the following actions in support of our business:
| • | With the divestiture of Veritas completed, we refocused Symantec as a pure cybersecurity company. In the second fiscal quarter, we completed the acquisition of Blue Coat, a provider of advanced web and cloud security solutions for global enterprises and governments, to complement our Enterprise Security offerings. The aggregate purchase price of the Blue Coat acquisition was $4.7 billion in net consideration, of which $4.5 billion consisted of cash consideration including the repayment of approximately $1.9 billion in Blue Coat’s debt. Following the closing of the Blue Coat acquisition, we appointed Blue Coat’s Chief Executive Officer as our Chief Executive Officer and Blue Coat’s President and Chief Operating Officer as our President and Chief Operating Officer, respectively, in the second quarter of fiscal 2017. In addition, we appointed Blue Coat’s Chief Financial Officer to the position of our Executive Vice President and Chief Financial Officer in the third quarter of fiscal 2017. |
| • | In the fourth fiscal quarter, we completed the acquisition of LifeLock, a provider of proactive identity theft protection services for consumers and consumer risk management services for enterprises, for approximately $2.3 billion in net consideration. |
| • | We increased the size of our Board of Directors and appointed representatives of Silver Lake Partners and Bain Capital to our Board of Directors. |
| ▪ | We released new products and services: |
| ◦ | We launched Symantec Endpoint Protection 14, a solution that fuses endpoint technologies with advanced machine learning and memory exploit mitigation in a single agent, delivering a multi-layered solution designed to stop a wide variety of advanced threats and respond at the endpoint. |
| ◦ | We introduced Symantec Endpoint Protection Cloud, a new solution for small and mid-sized businesses (SMBs) designed to protect them from targeted attacks and ransomware. Symantec Endpoint Protection Cloud is for organizations with fewer than 1,000 employees that are looking for an effective way to protect corporate and personal devices on the corporate network. |
| ◦ | We announced Cloud Workload Protection, a solution designed to deliver automated security policy enforcement and protect applications from unknown exploits inside of both Amazon Web Service and Microsoft Azure. Cloud Workload Protection automates security for public cloud workloads delivering metered usage billing, rapid workload discovery, increased visibility and elastic protection to help ensure safe cloud workload adoption. |
| ▪ | We integrated Blue Coat and Symantec products: |
| ◦ | We announced the integration of Symantec Data Loss Prevention (“DLP”) with Symantec CloudSOC (formerly Blue Coat’s Elastica CloudSOC Cloud Access Security Broker) and Cloud Data Protection products to address the needs of the cloud generation. This integrated solution provides visibility and control over all sensitive |
content that users upload, store and share via the cloud, protecting confidential information through the stages of its lifecycle.
| ◦ | We integrated our Symantec DLP with our cloud-delivered Web Security Service, providing a seamless platform to help ensure a safe web experience and protect organizational data. |
| ◦ | We combined Symantec and Blue Coat’s security telemetry which has led to a series of significant protection improvements as well as discoveries of new attack campaigns. |
| • | Symantec’s Board of Directors increased the company’s share repurchase authorization by $510 million. In the fourth fiscal quarter, Symantec entered into accelerated stock repurchase agreements to repurchase an aggregate of $500 million of the company’s common stock. |
Operating segments, products and services
Our operating segments are significant strategic business units that offer different products and services distinguished by customer needs. Our operating segments are: Consumer Digital Safety and Enterprise Security.
Consumer Digital Safety
Our Consumer Digital Safety segment focuses on providing a comprehensive Digital Safety solution to protect information, devices, networks and the identities of consumers. This solution includes our Norton-branded services, which provide multi-layer security across major desktop and mobile operating systems, public Wi-Fi connections, and home networks, to defend against increasingly complex online threats to individuals, families and small businesses, and our LifeLock-branded identity protection services. Our LifeLock-branded identity protection services primarily consist of identifying and notifying users of identity-related and other events and assisting users in remediating their impact. With the addition of LifeLock-branded identity protection services, we are providing a comprehensive digital safety platform designed to protect information across devices, customer identities and the connected home and family and accelerating our leadership in Consumer Digital Safety to protect all aspects of consumers’ digital lives.
Enterprise Security
Our Enterprise Security segment protects organizations so they can securely conduct business while leveraging new platforms and data. Our Enterprise Security segment includes our endpoint protection products, endpoint management, messaging protection products, information protection products, cyber security services, website security and advanced web and cloud security offerings. Our enterprise endpoint and network security and management offerings support evolving endpoints and networks, providing advanced threat protection while helping reduce cost and complexity. These solutions are delivered through various methods, such as software, appliance, Software-as-a-Service (“SaaS”) and managed services.
The addition of Blue Coat’s suite of network and cloud security products to our innovative Enterprise Security product portfolio has enhanced our threat protection and information protection products while providing us with complementary products, such as advanced web and cloud security solutions, that address the network and cloud security needs of enterprises. This augmentation of our product portfolio, together with the integration of Blue Coat’s large threat database with our global civilian cyber intelligence threat network, allows us to provide an integrated cyber defense platform, addressing both endpoint and network security, and offer differentiated security solutions. It also positions us well to introduce new cybersecurity solutions that address the ever-evolving threat landscape, the changes introduced by the shift to mobile and cloud along with the adoption of Internet of Things (IoT) devices. Our enhanced portfolio also positions us well to address the challenges created by regulatory and privacy concerns.
Financial information by segment and geographic region
For information regarding our revenue by segment, revenue by geographical area, and property and equipment by geographical area, see Note 2 to the Consolidated Financial Statements in this annual report. For information regarding the amount and percentage of our revenue contributed by each of our segments and our financial information, including information about geographic areas in which we operate, see Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations. For information regarding risks associated with our international operations, see Item 1A, Risk Factors.
Sales and go-to-market strategy
Our go-to-market network includes direct sales forces and broad e-commerce capabilities, as well as indirect sales resources that support our global partner ecosystem. We also maintain strategic relationships with a number of original equipment manufacturers (“OEMs”), Internet service providers (“ISPs”), wireless carriers, and retail and online stores through which we market and sell our products.
Consumer
We sell and market our consumer products and services to individuals, households and small businesses globally. We bring these products to market through direct marketing and co-marketing programs supported by our e-commerce and telesales platforms. In addition, we utilize Internet-based resellers, system builders, ISPs, employee benefits providers, wireless carriers, retailers, and OEMs to distribute our offerings worldwide.
Commercial
We sell and market our products and related services to small, medium and large customers through field sales and inside sales forces that leverage indirect sales partners around the world that are specifically trained and certified to sell our solutions. These partners include national solution providers, regional solution providers, national account resellers, global/federal system integrators and managed service providers. Our products and services are also available on our e-commerce platform, as well as through authorized distributors and OEMs, which incorporate our technologies into their products, bundle our products with their offerings, or serve as authorized resellers of our products.
Enterprise
We sell and market our products and related services to large enterprises, including government and public sector customers, through our field sales force. This field sales team is responsible for leveraging our global partner ecosystem primarily targeting senior executives and IT department personnel responsible for managing a company’s highest-order IT initiatives.
Research and development
Symantec embraces a global research and development strategy to drive organic innovation. Our engineers and researchers are focused on delivering new versions of existing product lines as well as developing entirely new offerings to drive the company’s leadership in cybersecurity. We also have a technology research organization focused on short, medium, and longer-term applied research projects, with the goal of transferring completed innovations into our product groups for commercialization.
Symantec’s Security Technology and Response organization consists of a global team of security engineers, threat analysts, and researchers that provide the underlying functionality, content, and support for many of our consumer, commercial and enterprise security products. Our security experts analyze threat telemetry collected through our vast cyber intelligence networks to protect our customers against current and emerging threats. Our research and development teams also leverage this vast amount of data and related insights to develop new technologies and approaches, including our Unified Security analytics platform, in order to improve security outcomes for our customers.
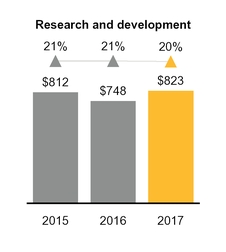
Research and development expenses were $823 million, $748 million, and $812 million in fiscal 2017, 2016, and 2015, respectively, representing approximately 20%, 21% and 21% of revenue in fiscal 2017, 2016 and 2015, respectively. The percentage fluctuates between periods as a result of a variety of factors, including changes in sales level and foreign currency exchange rates. We believe that technical leadership is essential to our success, and we expect to continue to commit substantial resources to research and development.
Support
Symantec has support facilities throughout the world, staffed by technical product experts knowledgeable in the operating environments in which our products are deployed. Our technical support experts assist customers with issue resolution and threat detection.
Our consumer support program provides self-help online services and phone, chat, and email support to consumers worldwide. Most of our Norton Security products come with automatic downloads of the latest virus definitions, application bug fixes, and patches, as well as a “Virus Protection Promise,” which in some markets provides free virus removal services to customers whose protected computers become infected. Our LifeLock offerings come with support 24x7x365 and remediation services during normal business hours.
We provide customers various levels of enterprise support offerings. Our enterprise security support program offers annual maintenance support contracts, including content, upgrades, and technical support. Our standard technical support includes: self-service options delivered by telephone or electronically during the contracted-for hours, immediate patches for severe problems, periodic software updates, and access to our technical knowledge base and frequently asked questions.
Significant customers
In each of fiscal 2017, 2016 and 2015, no customer accounted for more than 10% of our total net revenues. Two distributors and one distributor accounted for more than 10% of our gross accounts receivable as of March 31, 2017 and April 1, 2016, respectively.
Acquisitions
Our strategy will be complemented by business combinations that fit strategically and meet specific profitability hurdles. Our acquisitions are designed to enhance the features and functionality of our existing products and extend our product leadership in core markets. We consider time-to-market, synergies with existing products, and potential market share gains when evaluating the economics of acquisitions of technologies, product lines, or companies. We may acquire or dispose of other technologies, products, and companies in the future. See Note 6 to the Consolidated Financial Statements for information regarding our acquisitions in fiscal 2017.
Competition
Our markets are consolidating, highly competitive, and subject to rapid changes in technology. The competitive landscape has changed significantly over the past few years, with new competition arising. Much of the market growth has come from startups whose focus is on solving a specific customer issue or delivering a niche-oriented product and from larger integration providers that increasingly are looking to put various types of protection into their platforms. We are focused on delivering
comprehensive customer solutions, integrating across our broad product portfolio and partnering with other technology providers to differentiate ourselves from the competition. We believe that the principal competitive factors necessary to be successful in our industry include product quality and effectiveness, time-to-market, price, reputation, financial stability, breadth of product offerings, customer support, brand recognition, and effective sales and marketing efforts.
In addition to the competition we face from direct competitors, we face indirect or potential competition from retailers, application providers, operating system providers, network equipment manufacturers, and other OEMs who may provide various solutions and functions in their current and future products. We also compete for access to retail distribution channels and for spending at the retail level and in corporate accounts. In addition, we compete with other software companies, operating system providers, network equipment manufacturers, and other OEMs to acquire technologies, products, or companies and to publish software developed by third parties. We also compete with other software companies in our effort to place our products on the computer equipment sold to consumers and enterprises by OEMs.
Most of the channels in which our products are offered are highly competitive. Some of our consumer competitors are intensely focused on customer acquisition, which has led competitors to offer their technology for free, engage in aggressive marketing, or enter into competitive partnerships. We view our competitive landscape as follows:
| • | Our primary security competitors are McAfee (formerly Intel Security), Microsoft Corporation (“Microsoft”), and Trend Micro Inc. There are also several freeware providers and regional security companies that we compete against. |
| • | For our consumer backup offerings, our primary competitors are Carbonite, Inc. and Dell EMC. |
| • | In Identity Protection, our competitors are the credit bureaus that include Experian, Equifax, and TransUnion, as well as others, such as Affinion, EWS, Intersections, CSID, and LexisNexis. |
| • | In the Secure Socket Layer Certificate market, our primary competitors are Comodo Group, Inc., DigiCert, Inc. and Let’s Encrypt. |
| • | In the email security market, our primary competitors are Proofpoint, Inc. and Microsoft. |
| • | Our primary competitors in the managed security services business are SecureWorks Corporation and International Business Machines Corporation (“IBM”). |
| • | Our principal competitors in the web security gateway market are McAfee, Zscaler, Inc. (“Zscaler”), Forcepoint LLC and Cisco Systems, Inc. (“Cisco”). In addition, we expect additional competition from other established and emerging companies as the web security gateway market continues to develop and expand through further consolidation. |
| • | Our principal competitors in the cloud security services market are Zscaler and Cisco. In addition, we expect additional competition from other established and emerging companies as the market for security-as-a-service continues to develop and expand and as consolidation occurs. |
| • | Our principal competitors in the advanced threat protection market and incident response, analytics and forensics market include McAfee, IBM and Dell EMC as well as independent security vendors such as Palo Alto Networks Inc., FireEye, Inc., Niksun and Trend Micro Inc. Further, as new IT budgets are created to support next-generation threat protection, we expect to compete with more highly specialized vendors as well as larger vendors that may continue to acquire or bundle their products. |
| • | Our principal competitors in the WAN optimization market are Riverbed Technology, Inc. and Cisco. In addition, we expect additional competition from other established and emerging companies as the WAN optimization market continues to develop and expand and as consolidation occurs. |
Intellectual property
Protective measures
We regard some of the features of our internal operations, software, and documentation as proprietary and rely on copyright, patent, trademark and trade secret laws, confidentiality procedures, contractual arrangements, and other measures to protect our proprietary information. Our intellectual property is an important and valuable asset that enables us to gain recognition for our products, services, and technology and enhance our competitive position.
As part of our confidentiality procedures, we generally enter into non-disclosure agreements with our employees, distributors, and corporate partners and we enter into license agreements with respect to our software, documentation, and other proprietary information. These license agreements are generally non-transferable and have either a perpetual or subscription based time limited term. We also educate our employees on trade secret protection and employ measures to protect our facilities, equipment, and networks.
Trademarks, patents, copyrights, and licenses
Symantec and the Symantec logo are trademarks or registered trademarks in the U.S. and other countries. In addition to Symantec and the Symantec logo, we have used, registered, or applied to register other specific trademarks and service marks to help distinguish our products, technologies, and services from those of our competitors in the U.S. and foreign countries and jurisdictions. We enforce our trademark, service mark, and trade name rights in the U.S. and abroad. The duration of our trademark registrations varies from country to country, and in the U.S. we generally are able to maintain our trademark rights and renew any trademark registrations for as long as the trademarks are in use.
We have approximately 2,100 patents, in addition to foreign patents and pending U.S. and foreign patent applications, which relate to various aspects of our products and technology. The duration of our patents is determined by the laws of the country of issuance and for the U.S. is typically 17 years from the date of issuance of the patent or 20 years from the date of filing of the patent application resulting in the patent, which we believe is adequate relative to the expected lives of our products.
Our products are protected under U.S. and international copyright laws and laws related to the protection of intellectual property and proprietary information. We take measures to label such products with the appropriate proprietary rights notices, and we actively enforce such rights in the U.S. and abroad. However, these measures may not provide sufficient protection, and our intellectual property rights may be challenged. In addition, we license some intellectual property from third parties for use in our products, and generally must rely on the third party to protect the licensed intellectual property rights. While we believe that our ability to maintain and protect our intellectual property rights is important to our success, we also believe that our business as a whole is not materially dependent on any particular patent, trademark, license, or other intellectual property right.
Seasonality
As is typical for many large technology companies, our business is seasonal. Orders are generally higher in our third and fourth fiscal quarters and lower in our first and second fiscal quarters. Revenue generally reflects similar seasonal patterns but to a lesser extent than orders because revenue is not recognized until an order is shipped or services are performed and other revenue recognition criteria are met, and because a significant portion of our in-period revenue comes from our deferred revenue balance.
Employees
As of March 31, 2017, we employed more than 13,000 people worldwide.
Available information
Our Internet home page is located at www.symantec.com. We make available free of charge our annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports as soon as reasonably practicable after we electronically file such material with the Securities and Exchange Commission (“SEC”) on our investor relations website located at www.symantec.com/invest. The information contained, or referred to, on our website is not part of this annual report unless expressly noted. The SEC maintains a website that contains reports, proxy and information statements, and other information regarding our filings at http://www.sec.gov. In addition, you may read and copy any filing that we make with the SEC at the public reference room maintained by the SEC, located at 100 F Street, N.E., Washington, D.C. 20549. Please call the SEC at 1-800-SEC-0330 for further information about the public reference room.
Item 1A. Risk Factors
A description of the risk factors associated with our business is set forth below. The list is not exhaustive and you should carefully consider these risks and uncertainties before investing in our common stock.
If we are unsuccessful at addressing our business challenges, our business and results of operations may be adversely affected and our ability to invest in and grow our business could be limited.
For the last few years, we have experienced a number of transitions as we have attempted to revitalize our business model, improve execution and innovate new products and services. These transitions have involved changes to management and other key personnel, shifts in our strategic direction and, more recently, changes to our corporate structure as a result of the divestiture of Veritas and the acquisition of Blue Coat. In particular, in connection with our acquisition of Blue Coat, we experienced changes to our executive team during the second and third quarters of fiscal 2017, appointing three former Blue Coat executive officers to the positions of Chief Executive Officer, President and Chief Operating Officer, and Executive Vice President and Chief Financial Officer. Transitions of these kind can be disruptive, can result in the loss of institutional focus and employee morale and make the execution of business strategies more difficult. We are also focused on addressing dynamic and accelerating market trends, such as the continued decline in the PC market, the market shifts towards mobility, the continued transition towards cloud-based solutions and architectural shifts in the provision of security, all of which has made it more difficult for us to compete effectively and requires us to improve our product and service offerings. We may experience delays in the anticipated timing of activities related to our efforts to address these challenges and higher than expected or unanticipated execution costs. In addition, we are vulnerable to increased risks associated with these efforts and the broad range of geographic regions in which we and our customers and partners operate. If we do not succeed in these efforts, or if these efforts are more costly or time-consuming than expected, our business and results of operations may be adversely affected, which could limit our ability to invest in and grow our business.
Fluctuations in demand for our products and services are driven by many factors, and a decrease in demand for our products could adversely affect our financial results.
We are subject to fluctuations in demand for our products and services due to a variety of factors, including market transitions, general economic conditions, competition, product obsolescence, technological change, shifts in buying patterns, financial difficulties and budget constraints of our current and potential customers, awareness of security threats to IT systems and other factors. While such factors may, in some periods, increase product sales, fluctuations in demand can also negatively impact our product sales. If demand for our products and solutions declines, whether due to general economic conditions or a shift in buying patterns, our revenues and margins would likely be adversely affected.
Additionally, since Blue Coat’s business historically experienced a major product refresh cycle approximately once every five
years, as hardware appliances reach the end of their useful life, we anticipate that we will experience fluctuations in demand as we enter and exit cycles in which many of our customers refresh their install base of hardware appliance products with our latest equipment, replacing older versions of the hardware that have reached the end of their useful life and are no longer supported under maintenance contracts. Our appliances generally have a five year end-of-life date from the date of purchase, which we expect will extend refresh cycles for our hardware appliances over a multi-year period and reduce the impact of a product refresh cycle in any one period. However, we cannot assure you that we will not experience uneven demand for these products in any one period, causing our business and results of operations to be adversely affected.
A refresh cycle also creates an opportunity for our competitors to try to displace our existing product deployments for our customers, who may be more inclined to consider other product solutions at a time when they otherwise need to replace our existing products that have reached the end of their useful life. The extent to which customers decide to refresh by purchasing products from our current or future competitors as opposed to purchasing our new products may significantly impact our current period product revenues as well as future service revenue.
Our business depends on customers renewing their arrangements for maintenance, subscriptions, managed security services and SaaS offerings.
A large portion of our revenue is derived from arrangements for maintenance, subscriptions, managed security services and SaaS offerings, yet existing customers have no contractual obligation to purchase additional solutions after the initial subscription or contract period. Our customers’ renewal rates may decline or fluctuate as a result of a number of factors, including their level of satisfaction with our solutions or our customer support, customer budgets and the pricing of our solutions compared with the solutions offered by our competitors, any of which may cause our revenue to grow more slowly than expected, if at all. Accordingly, we must invest significant time and resources in providing ongoing value to our customers. If these efforts fail, or if our customers do not renew for other reasons, or if they renew on terms less favorable to us, our revenue may decline and our business will suffer.
If we are unable to develop new and enhanced products and services that achieve widespread market acceptance, or if we are unable to continually improve the performance, features, and reliability of our existing products and services or adapt our business model to keep pace with industry trends, our business and operating results could be adversely affected.
Our future success depends on our ability to respond to the rapidly changing needs of our customers by developing or introducing new products, product upgrades and services on a timely basis. We have in the past incurred, and will continue to incur, significant research and development expenses as we strive to remain competitive. Additionally, we must continually address the challenges of dynamic and accelerating market trends, such as the emergence of advanced persistent threats in the security space, the continued decline in the PC market and the market shift towards mobility and the increasing transition towards cloud-based solutions, all of which have made it more difficult for us to compete effectively. For example, we have been increasingly investing in solutions that address the cloud security market, particularly our acquisition of Blue Coat, but we cannot be certain that the cloud security market will develop at a rate or in the manner we expect or that we will be able to compete successfully with more established competitors in the cloud security market. Customers may require features and capabilities that our current solutions do not have. Our failure to develop solutions that satisfy customer preferences in a timely and cost-effective manner may harm our ability to renew our subscriptions with existing customers and to create or increase demand for our solutions and may adversely impact our operating results. New product development and introduction involves a significant commitment of time and resources and is subject to a number of risks and challenges including:
| • | Managing the length of the development cycle for new products and product enhancements, which has frequently been longer than we originally expected; |
Showing the first 8K of 87K characters. Open the full section
Item 1B. Unresolved Staff Comments
None.
Item 2. Properties
Our properties consist primarily of owned and leased office facilities for sales, research and development, administrative, customer service, and technical support personnel. Our corporate headquarters is located in Mountain View, California where we occupy facilities totaling approximately 794,000 square feet, of which 723,000 square feet is owned and 71,000 square feet is leased. We also lease an additional 116,000 square feet in the San Francisco Bay Area. Our leased facilities are occupied under agreements that expire on various dates through fiscal 2026. The following table presents the approximate square footage of our facilities as of March 31, 2017:
| Approximate Square Footage (1) | |||||
| Owned | Leased | ||||
| (In thousands) | |||||
| Americas (U.S., Canada and Latin America) | 1,512 | 952 | |||
| EMEA (Europe, Middle East and Africa) | 177 | 295 | |||
| APJ (Asia Pacific and Japan) | — | 1,088 | |||
| Total approximate square footage | 1,689 | 2,335 |
| (1) | Included in the total square footage above are vacant and available-for-lease properties totaling approximately 196,000 square feet. Total square footage excludes approximately 588,000 square feet relating to facilities subleased to third parties. |
We believe that our existing facilities are adequate for our current needs and that the productive capacity of our facilities is substantially utilized.
Item 3. Legal Proceedings
Information with respect to this Item may be found under the heading “Litigation contingencies” in Note 12 to the Consolidated Financial Statements in this Annual Report on Form 10-K which information is incorporated into this Item 3 by reference.
Item 4. Mine Safety Disclosures
Not applicable.
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Price range of common stock and number of stockholders
Our common stock is traded on the NASDAQ Global Select Market under the symbol “SYMC.” As of March 31, 2017, there were 1,763 stockholders of record. The high and low closing sales prices set forth below are as reported on the NASDAQ Global Select Market during each quarter of the two most recent fiscal years.
| 2017 | 2016 | ||||||||||||||||||||||||||||||
| Fourth Quarter | Third Quarter | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | First Quarter | ||||||||||||||||||||||||
| High | $ | 30.83 | $ | 25.45 | $ | 25.27 | $ | 21.24 | $ | 20.88 | $ | 21.37 | $ | 23.47 | $ | 25.90 | |||||||||||||||
| Low | $ | 24.01 | $ | 23.49 | $ | 20.28 | $ | 16.60 | $ | 16.62 | $ | 19.50 | $ | 19.33 | $ | 23.03 |
Stock performance graph
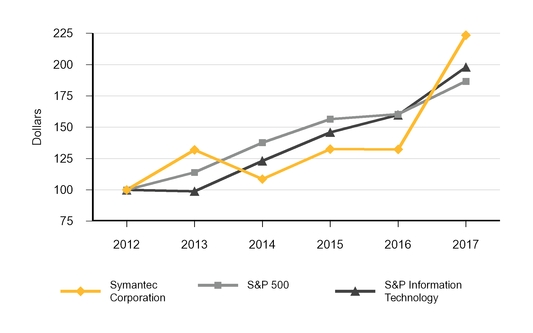
The graph below compares the cumulative total stockholder return on our common stock with the cumulative total return on the S&P 500 Composite Index and the S&P Information Technology Index for the five fiscal years ended March 31, 2017 (assuming the initial investment of $100 in our common stock and in each of the other indices on the last day of trading for fiscal 2011, and the reinvestment of all dividends). The comparisons in the graph below are based on historical data and are not indicative of, nor intended to forecast the possible future performance of our common stock.
COMPARISON OF FIVE-YEAR CUMULATIVE TOTAL RETURN
Among Symantec Corporation, the S&P 500 Index
and the S&P Information Technology Index
This performance graph shall not be deemed “filed” for purposes of Section 18 of the Exchange Act or otherwise subject to the liabilities under that Section, and shall not be deemed to be incorporated by reference into any filing of Symantec under the Securities Act or the Exchange Act.
Dividends
During fiscal 2017, 2016 and 2015, we declared and paid aggregate cash dividends and dividend equivalents of $222 million or $0.30 per common share, $3.0 billion or $4.60 per common share, and $413 million or $0.60 per common share, respectively. Dividends declared and paid each quarter during fiscal 2017, 2016 and 2015 were $0.075, $0.15 and $0.15 per share, respectively. Additionally, a special dividend of $4.00 per share was declared and paid in the fourth quarter of fiscal 2016. See Note 10 to the Consolidated Financial Statements for additional information regarding our dividends. All future dividends are subject to the approval of our Board of Directors.
Repurchases of our equity securities
Through our stock repurchase programs we have repurchased shares of our common stock since the fourth quarter of fiscal 2004. Under these programs, shares may be repurchased on the open market and through accelerated stock repurchase (“ASR”) transactions. Stock repurchases during the three months ended March 31, 2017, were as follows:
| (In millions, except per share data) | Total Number of Shares Purchased (1) | Average Price Paid per Share (1) | Total Number of Shares Purchased as Part of Publicly Announced Program | Maximum Dollar Value of Shares That May Yet Be Purchased Under the Plans or Programs (2) | ||||||||||
| December 31, 2016 to January 27, 2017 | — | $ | — | — | $ | 1,300 | ||||||||
| January 28, 2017 to February 24, 2017 | — | $ | — | — | $ | 1,300 | ||||||||
| February 25, 2017 to March 31, 2017 | 14.2 | $ | — | 14.2 | $ | 800 | ||||||||
| Total number of shares repurchased | 14.2 | 14.2 |
| (1) | Pursuant to the March 2017 ASR, we made an upfront payment of $500 million and received and retired an initial delivery of 14.2 million shares of our common stock in March 2017. On May 19, 2017, which was in our first quarter of fiscal 2018, the ASR was completed, which, per the terms of the agreements, resulted in us receiving an additional 2.2 million shares of our common stock (these shares were excluded from the table above, as they were received after March 31, 2017). The total shares received under the terms of the ASR were 16.4 million, with an average price paid per share of $30.51. See Note 10 to the Consolidated Financial Statements for additional information regarding our stock repurchase programs. |
| (2) | The approximate dollar value of the shares that may yet be purchased under the plans or programs for the period from February 25, 2017 to March 31, 2017 is reduced by the $500 million that reflects the aggregate value of the stock held back by the financial institutions pending final settlement of our ASR agreement. The remaining $800 million authorization, to be completed in future periods, does not have an expiration date. |
Item 6. Selected Financial Data
The following selected consolidated financial data is derived from our Consolidated Financial Statements. This data should be read in conjunction with our Consolidated Financial Statements and related notes included in this annual report and with Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. Historical results may not be indicative of future results.
Five-Year Summary
| Summary of operations: | Year Ended (1) | ||||||||||||||||||
| (In millions, except per share data) | March 31, 2017 (2) | April 1, 2016 (3) | April 3, 2015 | March 28, 2014 | March 29, 2013 | ||||||||||||||
| Net revenues | $ | 4,019 | $ | 3,600 | $ | 3,956 | $ | 4,183 | $ | 4,268 | |||||||||
| Operating income (loss) | $ | (100 | ) | $ | 457 | $ | 154 | $ | 144 | $ | (60 | ) | |||||||
| Income (loss) from continuing operations | $ | (236 | ) | $ | (821 | ) | $ | 109 | $ | 91 | $ | (138 | ) | ||||||
| Income from discontinued operations, net of income taxes (4) | $ | 130 | $ | 3,309 | $ | 769 | $ | 807 | $ | 893 | |||||||||
| Net income (loss) | $ | (106 | ) | $ | 2,488 | $ | 878 | $ | 898 | $ | 755 | ||||||||
| Income (loss) per share - basic: (5) | |||||||||||||||||||
| Continuing operations | $ | (0.38 | ) | $ | (1.23 | ) | $ | 0.16 | $ | 0.13 | $ | (0.20 | ) | ||||||
| Discontinued operations | $ | 0.21 | $ | 4.94 | $ | 1.12 | $ | 1.16 | $ | 1.27 | |||||||||
| Net income (loss) per share - basic | $ | (0.17 | ) | $ | 3.71 | $ | 1.27 | $ | 1.29 | $ | 1.08 | ||||||||
| Income (loss) per share - diluted: (5) | |||||||||||||||||||
| Continuing operations | $ | (0.38 | ) | $ | (1.23 | ) | $ | 0.16 | $ | 0.13 | $ | (0.20 | ) | ||||||
| Discontinued operations | $ | 0.21 | $ | 4.94 | $ | 1.10 | $ | 1.15 | $ | 1.27 | |||||||||
| Net income (loss) per share - diluted | $ | (0.17 | ) | $ | 3.71 | $ | 1.26 | $ | 1.28 | $ | 1.08 | ||||||||
| Weighted-average shares outstanding: | |||||||||||||||||||
| Basic | 618 | 670 | 689 | 696 | 701 | ||||||||||||||
| Diluted | 618 | 670 | 696 | 704 | 701 | ||||||||||||||
| Cash dividends declared per common share | $ | 0.30 | $ | 4.60 | $ | 0.60 | $ | 0.60 | $ | — |
| Consolidated Balance Sheets Data: | |||||||||||||||||||
| (In millions) | March 31, 2017 (6) (9) | April 1, 2016 (8) | April 3, 2015 | March 28, 2014 (7) | March 29, 2013 | ||||||||||||||
| Total assets | $ | 18,174 | $ | 11,767 | $ | 13,233 | $ | 13,539 | $ | 14,508 | |||||||||
| Long-term debt | $ | 6,876 | $ | 2,207 | $ | 1,746 | $ | 2,095 | $ | 2,094 | |||||||||
| Total stockholders’ equity | $ | 3,487 | $ | 3,676 | $ | 5,935 | $ | 5,797 | $ | 5,476 |
| (1) | We have a 52/53-week fiscal year. Our fiscal 2015 was a 53-week year whereas fiscal 2017, 2016, 2014, and 2013, each consisted of 52 weeks. |
| (2) | We acquired Blue Coat on August 1, 2016 and LifeLock on February 9, 2017 and the results of operations of those entities are included from their respective dates of acquisition. See Note 6 to the Consolidated Financial Statements for more information. |
| (3) | In fiscal 2016, we recorded $1.1 billion in income tax expense related to unremitted earnings of foreign subsidiaries from the proceeds of the sale of Veritas. This charge is presented in loss from continuing operations in the Consolidated Statements of Operations for fiscal 2016. See Note 5 to the Consolidated Financial Statements for more information. |
| (4) | In fiscal 2016, we sold the assets of Veritas to Carlyle for a net gain of $3.0 billion, which is presented as part of income from discontinued operations, net of income taxes in the Consolidated Statements of Operations for fiscal 2016. See Note 13 to the Consolidated Financial Statements for more information. |
| (5) | Net income per share amounts may not add due to rounding. |
| (6) | In fiscal 2017, we acquired total assets of $5.9 billion and $2.9 billion from Blue Coat and LifeLock, respectively. See Note 6 to the Consolidated Financial Statements for more information on our acquisitions. |
| (7) | In fiscal 2014, the principal balance on our 1.00% Convertible Senior Notes matured and was settled by a cash payment of $1.0 billion. At the time of issuance of the 1.00% notes, we granted warrants to affiliates of certain initial purchasers of the notes whereby they had the option to purchase up to 52.7 million shares of our common stock. All the warrants expired unexercised during the second quarter of fiscal 2014. In the fourth quarter of fiscal 2016, we issued $500 million in principal amount of 2.50% Convertible Senior Notes, due in April of 2021. |
| (8) | In fiscal 2016, the principal balance on our 2.75% Senior Notes due September 15, 2015, matured and was settled by a cash payment of $350 million. |
| (9) | In fiscal 2017, we issued $3.8 billion in Senior Term Facilities due at various dates from May 2019 to August 2021, $1.25 billion in 2.0% Convertible Senior Notes due in August of 2021 and $1.1 billion in 5% Senior Notes due in April of 2025. The proceeds from these issuances were used primarily to fund our Blue Coat and LifeLock acquisitions. In addition, we reclassified $710 million to short-term obligations due to our Board’s approval to prepay some of our Senior Term Facility and $600 million of our 2.75% Senior Notes due June 15, 2017. See Note 8 to the Consolidated Financial Statements for more information on the Company’s long-term debt. |
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
Please read the following discussion and analysis of our financial condition and results of operations together with our Consolidated Financial Statements and related Notes thereto included under Item 15 of this Annual Report on Form 10-K.
OVERVIEW
Fiscal calendar and basis of presentation
We have a 52/53-week fiscal year ending on the Friday closest to March 31. Unless otherwise stated, references to years in this report relate to fiscal year and periods ended March 31, 2017, April 1, 2016 and April 3, 2015. Our fiscal 2017 and 2016 were 52-week years whereas our fiscal 2015 was a 53-week year.
The results of Veritas are presented as discontinued operations in our Consolidated Statements of Operations and thus have been excluded from continuing operations and segment results for all reported periods. Accordingly, the following discussion reflects our current segment reporting structure, which was reduced from three to two segments, and segment results for all reported periods have been adjusted to conform to the current segment structure. In addition, the following discussion relates to our continuing operations unless stated otherwise.
Financial highlights and business trends
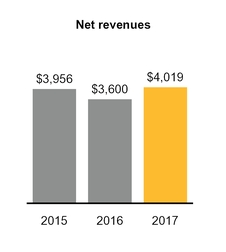
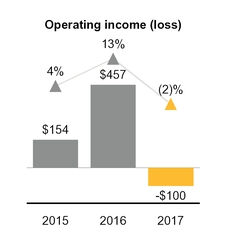
The following charts provide an overview of key financial metrics for each of the last three fiscal years in millions, except for percentage of revenues.


In fiscal 2017, we made two key acquisitions to expand our offerings in both our operating segments:
| • | In August 2016, we acquired Blue Coat, a provider of advanced web security solutions for global enterprises and governments. The addition of Blue Coat’s suite of network and cloud security products to our Enterprise Security segment has enhanced our existing portfolio of threat protection and information protection products while positioning us to provide new cybersecurity solutions that address the ever-evolving threat landscape. |
| • | In February 2017, we acquired LifeLock, a provider of proactive identity theft protection services for consumers and consumer risk management services for enterprises. The addition of LifeLock’s identity and fraud protection offerings to our Consumer Digital Safety segment allows us to provide a comprehensive digital safety solution designed to protect information across devices and users in the connected home and family. |
| • | See Note 6 of the Consolidated Financial Statements for additional information about our acquisitions. |
Here are our key financial results for continuing operations in fiscal 2017 as compared to fiscal 2016:
| • | Consolidated revenue increased by 12%, primarily driven by a 22% increase in revenue from our Enterprise Security segment due to the acquisition of Blue Coat. |
| • | Consumer Digital Safety segment revenue remained relatively flat as the Norton-branded product revenue decline of 4% was largely offset by increased revenue of $67 million due to the acquisition of LifeLock. During fiscal 2017, the Norton-branded product revenue decline improved year-over-year as we benefited from the shift to subscription-based contracts. |
| • | Our gross margin decreased four percentage points primarily due to lower relative gross margins on Blue Coat and LifeLock revenue as a result of the impact of acquisition-related write-downs of pre-acquisition deferred revenues. Additionally, our gross margin was negatively impacted by amortization of $122 million of acquired Blue Coat and LifeLock intangible assets and the write-up of acquired inventory of $24 million related to the Blue Coat acquisition. |
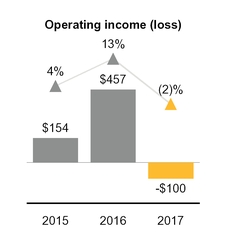
| • | Our operating margin decreased fifteen percentage points primarily due to increased operating expenses as a result of Blue Coat and LifeLock post-acquisition operating expenses including stock-based compensation from assumed equity awards and amortization of acquired intangible assets. We also incurred acquisition-related and integration expenses of $120 million related to the Blue Coat and LifeLock acquisitions. In addition, restructuring, transition, and other related costs increased year-over-year as a result of the implementation of new cost saving initiatives. |
| • | Cash paid for income taxes increased $779 million, primarily due to the one-time payment related to the gain on sale from the divestiture of Veritas during fiscal 2016. |
| • | Deferred revenue increased 6% to $2.8 billion from $2.6 billion as of March 31, 2017 and April 1, 2016, respectively, mainly as a result of our Blue Coat and LifeLock acquisitions. The increase was partly offset by the amortization of deferred revenue from Veritas retained contracts. |
We expect our operating margin to fluctuate in future periods as a result of a number of factors, including our operating results and the timing and amount of expenses incurred.
RESULTS OF OPERATIONS
Segment operating results
Enterprise Security Segment by fiscal year
Our Enterprise Security segment protects organizations so they can securely conduct business while leveraging new platforms and data. The following tables are in millions except for percentage of revenues.
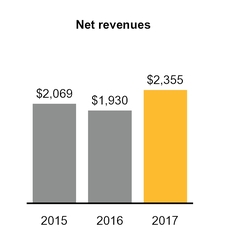

2017 compared to 2016
Revenue increased $425 million, or 22%, primarily due to $427 million in revenue from sales of Blue Coat network protection products. Due to the fair value adjustment of deferred revenue as a result of the accounting for the Blue Coat acquisition, we excluded revenue of $116 million in the post-acquisition period. In addition, services revenue increased $16 million while revenue from sales of endpoint management solutions decreased $23 million. Operating income increased $85 million, or 83%, primarily due to increased revenue, a reduction of expenses from new and ongoing cost savings initiatives, and favorable currency fluctuations of $16 million, and a decrease in unallocated corporate charges of $22 million. These increases were partially offset by increased expenses associated with the Blue Coat acquisition in the post-acquisition period, and acquired inventory write-up related to the Blue Coat acquisition of $24 million.
2016 compared to 2015
Revenue decreased $139 million, or 7%, primarily due to unfavorable foreign currency fluctuations of $90 million, as well as decrease in sales of endpoint management solutions and our mail cloud security products. Operating income decreased $191 million, or 65%, primarily due to decreased revenue and increased allocation of stranded costs. These stranded costs consist of overhead expenses resulting from the sale of Veritas and primarily include information technology infrastructure and services, and real estate costs. In addition, revenue decreased partially due to the impact of the additional week from the 53-week fiscal 2015 year.
Consumer Digital Safety Segment by fiscal year
Our Consumer Digital Safety segment focuses making it simple for customers to be productive and protected at home and at work. The following tables are in millions except for percentage of revenues.

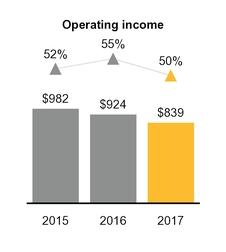
2017 compared to 2016
Revenue decreased $6 million primarily due to a decline in revenue from sales of Norton-branded products of $73 million as the revenue generated from customer additions was not sufficient to replace revenue lost through customer attrition. The decline was largely offset by a $67 million increase in revenue due to the acquisition of LifeLock. Due to the fair value adjustment of deferred revenue as a result of the accounting for the LifeLock acquisition, we excluded revenue of $28 million in the post-acquisition period. While the trend of declining revenues from sales of Norton-branded products continued in fiscal 2017, we began to benefit from the shift to subscription-based contracts, resulting in a lower decline in fiscal 2017 as compared to the prior two fiscal years. Operating income decreased $85 million, or 9%, primarily due to the Norton revenue decline coupled with a loss from LifeLock’s operations. LifeLock’s operating loss was a result of the deferred revenue fair value write-down.
2016 compared to 2015
Revenue decreased $217 million, or 11%, primarily due to new Norton customer acquisition not being sufficient to replace Norton customers lost through natural attrition and a reduction in revenue from OEM arrangements. Unfavorable currency fluctuations of $81 million also contributed to the decline in revenue. Operating income decreased $58 million, or 6%, primarily due to the decreases in revenue in this segment, which were partially offset by reductions in cost of revenue, sales and marketing and research and development expenses.
Net revenues by geographical region by fiscal year
Revenue by country as presented below is based on the billing location of the customer.
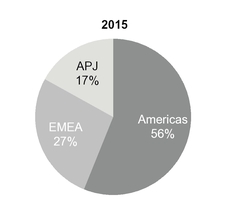
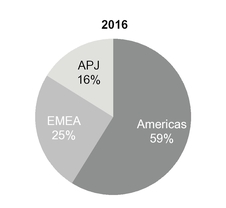
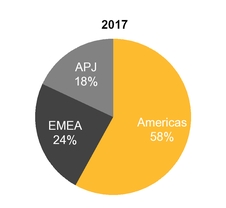
| Total: | $ | 3,956 | million | Total: | $ | 3,600 | million | Total: | $ | 4,019 | million |
Note: Americas include U.S., Canada and Latin America; EMEA includes Europe, Middle East and Africa; APJ includes Asia Pacific and Japan.
2017 compared to 2016
Fluctuations in the U.S. dollar compared to foreign currencies favorably impacted our international revenue by approximately $20 million for fiscal 2017 as compared to fiscal 2016. Fiscal 2017 revenue for the APJ region was favorably impacted by foreign currency fluctuations of $33 million. Fiscal 2017 revenue for the EMEA region was unfavorably impacted by foreign currency fluctuations of $13 million.
2016 compared to 2015
Fluctuations in the U.S. dollar compared to foreign currencies unfavorably impacted our international revenue by approximately $171 million for fiscal 2016 as compared to fiscal 2015. Fiscal 2016 revenue for the EMEA and APJ regions decreased primarily due to unfavorable foreign currency fluctuations of $119 million and $49 million, respectively, compared to fiscal 2015.
Our international sales are expected to continue to be a significant portion of our revenue. As a result, we expect revenue to continue to be affected by foreign currency exchange rates as compared to the U.S. dollar. We are unable to predict the extent to which revenue in future periods will be impacted by changes in foreign currency exchange rates. If international sales become a greater portion of our total sales in the future, changes in foreign currency exchange rates may have a potentially greater impact on our revenue and operating results.
Cost of revenues by fiscal year
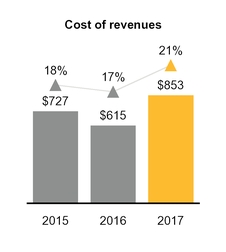
Cost of revenues consists primarily of technical support costs, costs of billable services, fees to OEMs under revenue-sharing agreements, hardware costs, and fulfillment costs, as well as intangible asset amortization, and is presented below in millions except for percentage of revenues.
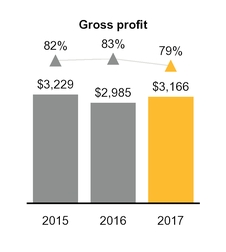
2017 compared to 2016
Our cost of revenues increased $238 million primarily due to $122 million of increased amortization related to the acquired Blue Coat and LifeLock intangible assets and other costs related to sales of the acquired Blue Coat and LifeLock products including an acquired product inventory fair value write-up of $24 million. These increases in cost of revenues were partially offset by a decrease in unallocated corporate charges of $22 million.
2016 compared to 2015
Our cost of revenues decreased $112 million primarily due to favorable currency effects, a decrease in OEM royalty fees, and a decrease in service related and content delivery expenses.
Operating expenses by fiscal year
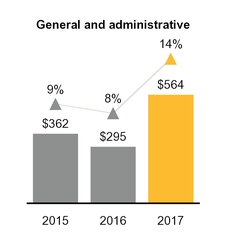
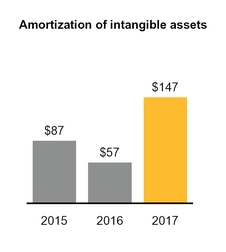
The following charts are in millions except for percentage of revenues.
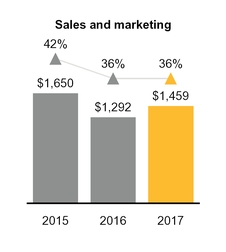
2017 compared to 2016
Sales and marketing expense increased $167 million primarily as a result of the acquisitions of Blue Coat and LifeLock, increased stock-based compensation expense of $54 million and increased integration expense of $24 million. These increases were partially offset by a reduction of expenses from new and ongoing cost savings initiatives and decreased unallocated corporate charges of $88 million.
Research and development expense increased $75 million primarily as a result of the acquisition of Blue Coat and an increase of $54 million of stock-based compensation expense. These increases were partially offset by a reduction of expenses from new and ongoing cost savings initiatives and decreased unallocated corporate charges of $44 million.
General and administrative expense increased $269 million primarily as a result of the acquisition of Blue Coat and an increase of $160 million of stock-based compensation expense. In addition, we incurred increased acquisition-related and integration expenses of $79 million. These increases were partly offset by a reduction of expenses from new and ongoing cost savings initiatives and decreased unallocated corporate charges of $32 million.
Our stock-based compensation in operating expenses increased $268 million primarily due to the equity awards assumed in the Blue Coat and LifeLock acquisitions, and the expected level of achievement for performance-based restricted stock units
(“PRUs”) granted in fiscal 2017. Our stock-based compensation expense will continue to fluctuate in future periods as a result of a number of factors including the achievement levels of PRU performance conditions.
Amortization of intangible assets increased $90 million primarily due to the intangible assets of $2.9 billion acquired in the Blue Coat and LifeLock acquisitions.
2016 compared to 2015
Sales and marketing expense decreased $358 million primarily due to a reduction of unallocated corporate charges of $328 million.
Research and development expense decreased $64 million primarily due to a reduction of unallocated corporate charges of $76 million.
General and administrative expenses decreased $67 million primarily due to a reduction of unallocated corporate charges of $91 million, partially offset by an increase in stock-based compensation expense.
Amortization of intangible assets decreased $30 million primarily due to certain intangible assets becoming fully amortized during fiscal 2015.
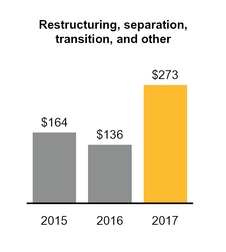
Restructuring, separation, transition, and other
We initiated a restructuring plan in the first quarter of fiscal 2017 to reduce complexity by means of long-term structural improvements. We expect to reduce headcount and close certain facilities in connection with the restructuring plan. These actions are expected to be completed in fiscal 2018. On an annual basis we expect this restructuring plan to generate net cost efficiencies and cost synergies which, when completed, will favorably impact our continuing operating expenses in excess of $550 million. As of March 31, 2017, in connection with this restructuring plan, we expect to incur approximately $240 million to $290 million in expenses in fiscal 2018.
Additionally, we expect continuing significant transition costs associated with the implementation of a new enterprise resource planning system and costs to automate business processes, as well as significant charges related to the integration of Blue Coat and LifeLock.
See Note 4 to the Consolidated Financial Statements for further information on our restructuring, separation, transition, and other related costs.
Non-operating expense, net by fiscal year
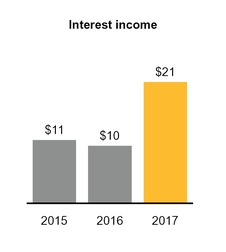
The following charts are in millions.


2017 compared to 2016
Non-operating expense, net, increased $97 million to $162 million from $65 million as of March 31, 2017 and April 1, 2016, respectively, primarily driven by an increase in interest expense of $133 million, mainly related to our increased borrowings in fiscal 2017. The non-operating expense, net increase was partially offset by increased income from transition service agreements (“TSA”) of $14 million, pursuant to which we provided Veritas certain limited services. See Note 8 and Note 13 to the Consolidated Financial Statements for more information about our debt and TSAs.
2016 compared to 2015
Non-operating expense, net, increased $12 million primarily due to net foreign currency remeasurement losses.
Provision for income taxes by fiscal year
We are a U.S.-based multinational company subject to tax in multiple U.S. and international tax jurisdictions. A substantial portion of our international earnings were generated from subsidiaries organized in Ireland and Singapore. Our results of operations would be adversely affected to the extent that our geographical mix of income becomes more weighted toward
jurisdictions with higher tax rates and would be favorably affected to the extent the relative geographic mix shifts to lower tax jurisdictions. Any change in our mix of earnings is dependent upon many factors and is therefore difficult to predict. See Note 5 to the Consolidated Financial Statements for more information.
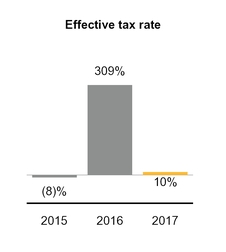
The following charts are in millions except for percentages.
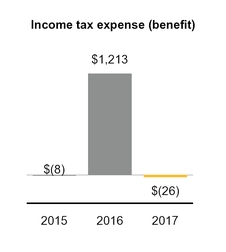
2017 compared to 2016
The decrease in our effective tax rate in 2017 as compared to 2016 was primarily driven by tax expense of $1.1 billion in 2016 for providing U.S. taxes on certain undistributed foreign earnings, primarily those attributable to the sale of Veritas, partially offset by tax expense of $52 million in 2017 related to the loss of tax attributes as a result of restructuring activities.
2016 compared to 2015
The increase in our effective tax rate in 2016 compared to 2015 was primarily driven by $1.1 billion of tax expense in 2016 for providing U.S. taxes on certain undistributed foreign earnings, primarily those attributable to the sale of Veritas.
LIQUIDITY AND CAPITAL RESOURCES
Sources and uses of cash
We have historically relied on cash flow from operations, borrowings under credit facilities, issuances of debt and equity securities, and sale of business, more recently, for our liquidity needs. As of March 31, 2017, we had cash, cash equivalents and short-term investments of $4.3 billion, of which $9 million is included in our other current assets. We also have an unused credit facility of $1.0 billion resulting in a liquidity position of approximately $5.3 billion. As of March 31, 2017, $3.3 billion in cash, cash equivalents, and short-term investments were held by our foreign subsidiaries. We have provided U.S. deferred taxes on a portion of our undistributed foreign earnings sufficient to address the incremental U.S. tax that would be due if we needed such portion of these funds to support our operations in the U.S.
Our principal cash requirements primarily consists of acquisitions, payment of taxes, operating expenses and working capital, capital expenditures, payment of principal and interest on debt, and restructuring and integration costs. Also, we may engage, from time to time, in the open market purchase of our notes prior to their maturity. Furthermore, our capital allocation strategy contemplates a quarterly cash dividend. In addition, we regularly evaluate our ability to repurchase shares of our common stock.
Cash flows
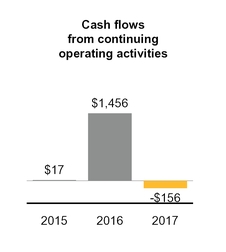
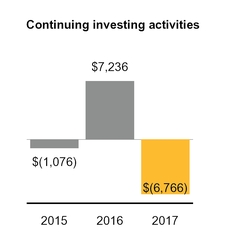
The following charts summarize cash provided by (used in) our Consolidated Statements of Cash Flows for fiscal 2015, 2016 and 2017 in millions.
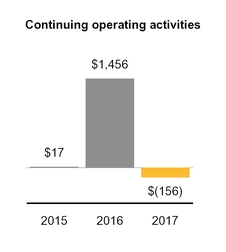

Continuing operating activities
Our primary source of cash from continuing operating activities has been from cash collections from our customers. Due to seasonality, our orders are generally higher in our third and fourth fiscal quarters and lower in our first and second fiscal quarters. We therefore expect cash inflows from continuing operating activities to be affected by fluctuations in billings and timing of collections.
Our primary uses of cash from our continuing operating activities include payments for income taxes, payments for compensation and related costs, payments to our resellers and distribution partners, and other general corporate expenditures.
The change in continuing operating activities in fiscal 2017 compared to fiscal 2016 was primarily due to the cash payment for taxes of $887 million as a result of the gain on sale from the divestiture of Veritas, changes in working capital, and lower income from continuing operations, adjusted for non-cash items.
The change in continuing operating activities in fiscal 2016 compared to fiscal 2015 was primarily due to changes in working capital and higher income from continuing operations, adjusted for non-cash items.
Restructuring Plan. We initiated a restructuring plan in the first quarter of fiscal 2017 to reduce complexity by means of long-term structural improvements. We expect to reduce headcount and close certain facilities in connection with this restructuring plan. The total remaining cash payments in connection with the restructuring plan are expected to be approximately $270 million to $305 million. These actions are expected to be completed in fiscal 2018. See Note 4 to the Consolidated Financial Statements for more information on our restructuring plans.
Continuing investing activities
Our investing cash flows consist primarily of acquisitions, capital expenditures and investment purchases, sales, and maturities. The change in continuing investing activities in fiscal 2017 compared to fiscal 2016 was primarily due to the net cash consideration paid for our acquisitions of Blue Coat and LifeLock during fiscal 2017 of $4.5 billion and $2.2 billion, respectively. In addition, our investing activities decreased due to the absence of proceeds from the divestiture of Veritas of $6.5 billion in fiscal 2016, and reduced proceeds from maturities and sales of short-term investments of $1.3 billion. The decrease was partially offset by reduced purchases of short-term investments of $378 million during fiscal 2016.
The change in continuing investing activities in fiscal 2016 compared to fiscal 2015 was primarily due to proceeds received from the divestiture of Veritas of $6.5 billion, increased proceeds from maturities and sales of short-term investments of $331 million, and decreases in our purchases of short-term investments of $1.4 billion.
Dissenter shares. As of March 31, 2017, we have accrued $68 million for dissenting shareholders as a result of our LifeLock acquisition.
Short-term investments. In order to achieve greater investment diversification and higher yields while maintaining our objectives of preservation of capital, liquidity, and safety, we plan to increase our holdings of short-term investments.
Continuing financing activities
Our financing cash flows consist primarily of issuance and repayment of debt, repurchases of common stock, and payment of dividends and dividend equivalents to stockholders. In fiscal 2017, our financing activities provided $5.3 billion of cash compared to $4.7 billion use of cash in fiscal 2016. The change in fiscal 2017 was primarily driven by our borrowing activities with net proceeds of $6.1 billion partially offset by reduction in stock repurchases of $1.4 billion and decrease in quarterly dividend payments from $0.15 per share in fiscal 2016 to $0.075 per share in fiscal 2017. The dividend payments in fiscal 2016 also included a special dividend of $4.00 per share subsequent to the divestiture of Veritas.
The change in continuing financing activities in fiscal 2016 compared to fiscal 2015 was primarily due to increased cash dividends and dividend equivalent payments of $2.6 billion, increased repurchases of common stock of $1.3 billion and an increase in the repayment of maturing senior notes and other obligations of $347 million, partially offset by proceeds from the issuance of convertible senior notes of $500 million.
We have made, and may from time to time in the future make, optional repayments of our debt obligations, which may include repurchases of our outstanding debt, depending on various factors, such as market conditions.
Interest payments on $3.7 billion of our variable-rate borrowings are subject to change based on market interest rates.
Borrowings. Proceeds from and repayments of borrowings fluctuate from year to year based on the amounts paid to fund acquisitions, and debt repayments. The charts below set forth total debt issued, repaid and the amount of unused credit facility for fiscal 2015, 2016 and 2017 in millions.
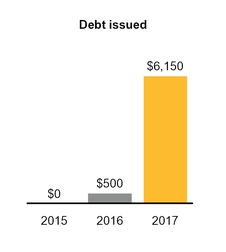
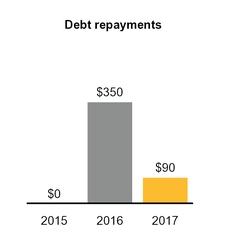

Credit ratings. Our credit ratings were lowered as a result of the debt we incurred due to the LifeLock acquisition. Our borrowing costs depend, in part, on our credit ratings and any further actions taken by these credit rating agencies to lower our credit ratings will likely increase our borrowing costs.
See Note 8 to the Consolidated Financial Statements for further information on our debt repayments and borrowings.
Prepayments of debt. Subsequent to March 31, 2017, we prepaid $710 million of our Senior Term Loan A-5 and $100 million of our Senior Term Loan A-1 on April 5, 2017 and May 5, 2017, respectively.
Share repurchases and dividends. Under our stock repurchase programs, we may purchase shares of our outstanding common stock through open market and through ASR transactions. On November 20, 2016, our Board of Directors increased the authorization under our stock repurchase program by $510 million. In March 2017, we entered into ASR agreements with financial institutions (the “March 2017 ASR”) to repurchase an aggregate $500 million of our common stock. The remaining $800 million authorization, to be completed in future periods, does not have an expiration date.
On May 10, 2017, we declared a cash dividend of $0.075 per share of common stock to be paid on June 21, 2017 to all stockholders of record as of the close of business on June 7, 2017. All shares of common stock issued and outstanding and unvested RSUs and PRUs as of the record date will be entitled to the dividend and dividend equivalents, respectively. Any future dividends and dividend equivalents will be subject to the approval of our Board of Directors.
The chart below sets forth information on our share repurchases and dividends and dividend equivalents paid in fiscal 2015, 2016 and 2017 in millions.

See Note 10 to the Consolidated Financial Statements for more information on our share repurchases and dividends and dividend equivalents.
Contractual obligations
The following is a schedule by years of our significant contractual obligations as of March 31, 2017:
| Payments Due by Fiscal Period | |||||||||||||||||||
| (In millions) | Total | 2018 | 2019 - 2020 | 2021 - 2022 | Thereafter | ||||||||||||||
| Debt (1) | $ | 8,310 | $ | 1,310 | $ | 2,000 | $ | 3,500 | $ | 1,500 | |||||||||
| Interest payments on debt (2) | 1,059 | 208 | 405 | 246 | 200 | ||||||||||||||
| Purchase obligations (3) | 154 | 125 | 28 | 1 | — | ||||||||||||||
| Operating leases (4) | 327 | 88 | 125 | 73 | 41 | ||||||||||||||
| Total | $ | 9,850 | $ | 1,731 | $ | 2,558 | $ | 3,820 | $ | 1,741 |
| (1) | See Note 8 to the Consolidated Financial Statements for further information on our debt. |
| (2) | Interest payments were calculated based on the contractual terms of the related Senior Notes, Convertible Senior Notes and Senior Term Facilities. Interest on variable rate debt was calculated using the interest rate in effect as of March 31, 2017. See Note 8 to the Consolidated Financial Statements for further information on the Senior Notes, Convertible Senior Notes and Senior Term Facilities. |
| (3) | These amounts are associated with agreements for purchases of goods or services generally including agreements that are enforceable and legally binding and that specify all significant terms, including fixed or minimum quantities to be purchased; fixed, minimum, or variable price provisions; and the approximate timing of the transaction. The table above also includes agreements to purchase goods or services that have cancellation provisions requiring little or no payment. The amounts under such contracts are included in the table above because management believes that cancellation of these contracts is unlikely and we expect to make future cash payments according to the contract terms or in similar amounts for similar materials. |
| (4) | We have entered into various non-cancelable operating lease agreements that expire on various dates through fiscal 2026. The amounts in the table above exclude expected sublease income. |
Due to the uncertainty with respect to the timing of future cash flows associated with our unrecognized tax benefits as of March 31, 2017 we are unable to make reasonably reliable estimates of the period of cash settlement with the respective taxing authorities. Therefore, $251 million in long-term income taxes payable has been excluded from the contractual obligations table. See Note 5 to the Consolidated Financial Statements for further information.
Indemnifications
In the ordinary course of business, we may provide indemnifications of varying scope and terms to customers, vendors, lessors, business partners, subsidiaries and other parties with respect to certain matters, including, but not limited to, losses arising out of our breach of agreements or representations and warranties made by us. Refer to Note 12 to the Consolidated Financial Statements for further information on our indemnifications.
CRITICAL ACCOUNTING POLICIES AND ESTIMATES
The methods, estimates and judgments that we use in applying our accounting policies have a significant impact on our financial position and the results that we report in our Consolidated Financial Statements. Some of these policies required us to make subjective estimates and apply judgment regarding matters that are inherently uncertain.
Our most critical estimates included:
| • | The allocation of revenue to various components of our multiple element arrangements which may contain hardware, software, licenses, maintenance and service contracts. |
| • | The valuation and allocation of the purchase price paid for acquired assets and liabilities assumed in connection with our acquisitions, which impacts our gross margin and operating expenses in periods subsequent to the acquisition. |
| • | The evaluation of the recoverability of long-lived assets (property, and equipment, identified intangibles, and goodwill), which impacts gross margin or operating expenses when we record impairments or accelerate their depreciation or amortization. |
| • | The determination of the fair value of stock options using a Black-Scholes options pricing model, which impact our gross margin and operating expenses over the option’s vesting period. |
| • | The recognition and measurement of current and deferred income taxes (including the measurement of current and deferred income taxes, including the measurement of uncertain tax positions), which impact our provision for taxes as well as tax-related assets and liabilities. |
| • | The recognition and measurement of loss contingencies, which impact gross margin or operating expenses when we recognize a loss contingency, revise the estimate for a loss contingency, or record an asset impairment. |
See Note 1 to the Consolidated Financial Statements in this annual report for further information on our critical accounting estimates and policies.
Recently issued authoritative guidance
Revenue Recognition - Contracts with Customers. In May 2014, the Financial Accounting Standards Board (“FASB”) issued new authoritative guidance for revenue from contracts with customers. The standard’s core principle is that a company will recognize revenue when it transfers promised goods or services to customers in an amount that reflects the consideration that the company expects to receive in exchange for those goods or services. In doing so, companies will need to use more judgment and make more estimates than under current guidance. These may include identifying performance obligations in the contract, estimating the amount of variable consideration to include in the transaction price, and allocating the transaction price to each separate performance obligation. In March 2016, the FASB clarified implementation guidance on principal versus agent considerations. In April 2016, the FASB issued guidance related to identifying performance obligations and licensing which reduces the cost and complexity of applying certain aspects of the guidance both at implementation and on an ongoing basis.
The new guidance may be applied retrospectively to each prior period presented (“retrospective”) or retrospectively with cumulative effect recognized in retained earnings as of the date of adoption (“modified retrospective”). We expect to adopt the new standard on a modified retrospective basis in the first quarter of fiscal 2019. We are currently evaluating the impact of the adoption of this guidance on our Consolidated Financial Statements.
Financial Instruments - Recognition and Measurement. In January 2016, the FASB issued new authoritative guidance on financial instruments. The new guidance enhances the reporting model for financial instruments, which includes amendments to address aspects of recognition, measurement, presentation and disclosure. The new guidance will be effective for us in our first quarter of fiscal 2019. Early adoption is permitted under limited circumstances but we do not intend to adopt the provisions of the new guidance early. We are currently evaluating the impact of the adoption of this guidance on our Consolidated Financial Statements.
Leases. In February 2016, the FASB issued new guidance on lease accounting which will require lessees to recognize assets and liabilities on their balance sheet for the rights and obligations created by operating leases and will also require disclosures designed to give users of financial statements information on the amount, timing, and uncertainty of cash flows arising from leases. The new guidance will be effective for us in our first quarter of fiscal 2020. Early adoption is permitted but we do not plan to adopt the provisions of the new guidance early. We are currently evaluating the impact of the adoption of this guidance on our Consolidated Financial Statements.
Employee Stock-Based Compensation. In March 2016, the FASB issued new guidance on accounting for employee stock-based compensation, which requires all income tax effects of awards to be recognized in the income statement when the awards vest or are settled, as well as revising guidance related to classification of awards as either equity or liabilities, accounting for forfeitures and classification of excess tax benefits or deficiencies on the statement of cash flows. We are electing to continue to estimate forfeitures to determine the amount of compensation cost to be recognized in each period. We do not anticipate a material impact on the Consolidated Financial Statements from the cumulative effect of these changes. The new guidance will be effective for us in our first quarter of fiscal 2018.
Credit Losses. In June 2016, the FASB issued new authoritative guidance on credit losses which changes the impairment model for most financial assets and certain other instruments. For trade receivables and other instruments, we will be required to use a new forward-looking “expected loss” model. Additionally, for available-for-sale debt securities with unrealized losses, we will measure credit losses in a manner similar to today, except that the losses will be recognized as allowances rather than
reductions in the amortized cost of the securities. The standard will be effective for us in our first quarter of fiscal 2021. We are currently evaluating the impact of the adoption of this guidance on our Consolidated Financial Statements.
Income Taxes - Intra-Entity Asset Transfers Other Than Inventory. In October 2016, the FASB issued new authoritative guidance that requires entities to immediately recognize the tax consequences of intercompany asset transfers, excluding inventory, at the transaction date, rather than deferring the tax consequences under current U.S. GAAP. The standard will be effective for us in our first quarter of fiscal 2019, and requires a modified retrospective transition method. We are currently evaluating the impact of the adoption of this guidance and anticipate it will have a material impact on our Consolidated Financial Statements.
Item 7A. Quantitative and Qualitative Disclosures about Market Risk
We are exposed to various market risks related to fluctuations in interest rates and foreign currency exchange rates. We may use derivative financial instruments to mitigate certain risks in accordance with our investment and foreign exchange policies. We do not use derivatives or other financial instruments for trading or speculative purposes.
Interest rate risk
As of March 31, 2017, we had $4.6 billion in principal amount of fixed-rate Senior Notes and Convertible Senior Notes outstanding, with a carrying amount of $4.6 billion and a fair value of $4.6 billion, based on level 2 inputs. As of April 1, 2016, we had $2.3 billion in principal amount of fixed-rate Senior Notes outstanding, with a carrying amount of $2.2 billion and a fair value of $2.3 billion, based on level 2 inputs.
We have considered the historical volatility of interest rates and determined that it is possible that adverse changes in interest rates related to our fixed and variable rate debt could occur. A reasonably possible hypothetical adverse change of 50-basis points could result in a $92 million fair value reduction of our fixed-rate borrowings as of March 31, 2017, compared to a $41 million fair value reduction as of April 1, 2016. A reasonably possible hypothetical adverse change of 50-basis points in the effective interest rate of our $3.7 billion of variable-rate borrowings could result in an incremental $19 million of pre-tax interest expense on an annualized basis.
Foreign currency exchange rate risk
We conduct business in numerous currencies through our worldwide operations and, as such, we are exposed to foreign currency risk. Our entities conduct their businesses in the primary local currency in which they operate, however, they may also conduct business in other currencies. To the extent our entities hold monetary assets or liabilities, earn revenues or incur costs in currencies other than the entity’s functional currency, they are exposed to foreign exchange gains or losses and impacts to margins as a result. As part of our foreign currency risk mitigation strategy, we have entered into foreign exchange forward contracts with up to six months in duration to help mitigate foreign exchange risk, however we are not able to mitigate all of our foreign exchange risk. We have considered historical trends in exchange rates and determined that it is possible that adverse changes in exchange rates for any currency could occur. The estimated impacts of a ten percent appreciation or depreciation of foreign currency are as follows in millions:
| March 31, 2017 | April 1, 2016 | |||||||||||||||||||||||
| Change in Fair Value Due to 10% | Change in Fair Value Due to 10% | |||||||||||||||||||||||
| Foreign Exchange Forward Contract | Notional Amount | Appreciation | Depreciation | Notional Amount | Appreciation | Depreciation | ||||||||||||||||||
| Purchased | $ | 492 | $ | 49 | $ | (49 | ) | $ | 693 | $ | 69 | $ | (69 | ) | ||||||||||
| Sold | (204 | ) | (20 | ) | 20 | (198 | ) | (19 | ) | 19 | ||||||||||||||
| Total net outstanding contracts | $ | 288 | $ | 29 | $ | (29 | ) | $ | 495 | $ | 50 | $ | (50 | ) |
We do not use derivative financial instruments for speculative trading purposes, nor do we hedge our foreign currency exposure in a manner that entirely offsets the effects of the changes in foreign exchange rates.
Item 8. Financial Statements and Supplementary Data
The Consolidated Financial Statements and related disclosures included in Part IV, Item 15 of this annual report are incorporated by reference into this Item 8.
Selected Quarterly Financial Data (Unaudited)
| Fiscal 2017 | Fiscal 2016 | ||||||||||||||||||||||||||||||
| (In millions, except per share data) | Fourth Quarter | Third Quarter | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | First Quarter | |||||||||||||||||||||||
| Net revenues | $ | 1,115 | $ | 1,041 | $ | 979 | $ | 884 | $ | 873 | $ | 909 | $ | 906 | $ | 912 | |||||||||||||||
| Gross profit | 856 | 806 | 769 | 735 | 726 | 759 | 746 | 754 | |||||||||||||||||||||||
| Operating income (loss) | (178 | ) | (16 | ) | (12 | ) | 106 | 128 | 146 | 100 | 83 | ||||||||||||||||||||
| Income (loss) from continuing operations | (177 | ) | (56 | ) | (69 | ) | 66 | (1,013 | ) | 114 | 53 | 25 | |||||||||||||||||||
| Income (loss) from discontinued operations, net of income taxes | 34 | 102 | (75 | ) | 69 | 3,058 | 56 | 103 | 92 | ||||||||||||||||||||||
| Net income (loss) | (143 | ) | 46 | (144 | ) | 135 | 2,045 | 170 | 156 | 117 | |||||||||||||||||||||
| Income (loss) per share - basic: | |||||||||||||||||||||||||||||||
| Continuing operations | $ | (0.29 | ) | $ | (0.09 | ) | $ | (0.11 | ) | $ | 0.11 | $ | (1.56 | ) | $ | 0.17 | $ | 0.08 | $ | 0.04 | |||||||||||
| Discontinued operations | $ | 0.06 | $ | 0.16 | $ | (0.12 | ) | $ | 0.11 | $ | 4.70 | $ | 0.08 | $ | 0.15 | $ | 0.13 | ||||||||||||||
| Net income (loss) per share - basic | $ | (0.23 | ) | $ | 0.07 | $ | (0.23 | ) | $ | 0.22 | $ | 3.15 | $ | 0.26 | $ | 0.23 | $ | 0.17 | |||||||||||||
| Income (loss) per share - diluted: | |||||||||||||||||||||||||||||||
| Continuing operations | $ | (0.29 | ) | $ | (0.09 | ) | $ | (0.11 | ) | $ | 0.11 | $ | (1.56 | ) | $ | 0.17 | $ | 0.08 | $ | 0.04 | |||||||||||
| Discontinued operations | $ | 0.06 | $ | 0.16 | $ | (0.12 | ) | $ | 0.11 | $ | 4.70 | $ | 0.08 | $ | 0.15 | $ | 0.13 | ||||||||||||||
| Net income (loss) per share - diluted | $ | (0.23 | ) | $ | 0.07 | $ | (0.23 | ) | $ | 0.22 | $ | 3.15 | $ | 0.25 | $ | 0.23 | $ | 0.17 |
Note: Net income (loss) per share amounts may not add due to rounding.
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
a) Evaluation of Disclosure Controls and Procedures
The SEC defines the term “disclosure controls and procedures” to mean a company’s controls and other procedures that are designed to ensure that information required to be disclosed in the reports that it files or submits under the Exchange Act is recorded, processed, summarized, and reported, within the time periods specified in the SEC’s rules and forms. “Disclosure controls and procedures” include, without limitation, controls and procedures designed to ensure that information required to be disclosed by an issuer in the reports that it files or submits under the Exchange Act is accumulated and communicated to the issuer’s management, including its principal executive and principal financial officers, or persons performing similar functions, as appropriate to allow timely decisions regarding required disclosure. Our disclosure controls and procedures are designed to provide reasonable assurance that such information is accumulated and communicated to our management. Our management (with the participation of our Chief Executive Officer and Chief Financial Officer) has conducted an evaluation of the effectiveness of our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) of the Securities Exchange Act). Based on such evaluation, our Chief Executive Officer and our Chief Financial Officer have concluded that our disclosure controls and procedures were effective at the reasonable assurance level as of the end of the period covered by this report.
b) Management’s Report on Internal Control over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over financial reporting (as defined in Rules 13a-15(f) and 15d-15(f) of the Exchange Act) for Symantec. Our management, with the participation of our Chief Executive Officer and our Chief Financial Officer, has conducted an evaluation of the effectiveness of our internal control over financial reporting as of March 31, 2017, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (“COSO”).
In accordance with guidance issued by the Securities and Exchange Commission, companies are permitted to exclude acquisitions from their final assessment of internal control over financial reporting for the first fiscal year in which the acquisition occurred. Our management’s evaluation of internal control over financial reporting excluded the internal control activities of Blue
Coat and LifeLock, which we acquired in August 2016 and February 2017, respectively, as discussed in Note 6 to the Consolidated Financial Statements. We have included the financial results of Blue Coat and LifeLock in the Consolidated Financial Statements from the dates of acquisition. Total revenues subject to Blue Coat’s internal control over financial reporting represented approximately 11% of our consolidated revenues for the fiscal year ended March 31, 2017. Total assets subject to Blue Coat’s internal control over financial reporting represented approximately 4% of our consolidated total assets as of March 31, 2017. Total revenues subject to LifeLock’s internal control over financial reporting represented approximately 2% of our consolidated revenues for the fiscal year ended March 31, 2017. Total assets subject to LifeLock’s internal control over financial reporting represented approximately 2% of our consolidated total assets as of March 31, 2017. Blue Coat’s and LifeLock’s goodwill and intangible assets were subject to our management’s evaluation of internal control over financial reporting.
Our management has concluded that, as of March 31, 2017, our internal control over financial reporting was effective at the reasonable assurance level based on these criteria.
The Company’s independent registered public accounting firm has issued an attestation report regarding its assessment of the Company’s internal control over financial reporting as of March 31, 2017, which is included in Part IV, Item 15 of this annual report.
c) Changes in Internal Control over Financial Reporting
There were no changes in our internal control over financial reporting during the quarter ended March 31, 2017, that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
d) Limitations on Effectiveness of Controls
Our management, including our Chief Executive Officer and Chief Financial Officer, does not expect that our disclosure controls and procedures or our internal controls will prevent all errors and all fraud. A control system, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. Further, the design of a control system must reflect the fact that there are resource constraints, and the benefits of controls must be considered relative to their costs. Because of the inherent limitations in all control systems, no evaluation of controls can provide absolute assurance that all control issues and instances of fraud, if any, within our company have been detected. Accordingly, our disclosure controls and procedures provide reasonable assurance of achieving their objectives.
Item 9B. Other Information
The information below is reported in lieu of information that would be reported under Items 5.03 under Form 8-K.
On May 17, 2017, our Board of Directors (the “Board”) adopted amendments to our Bylaws, as amended (the “Bylaws”), to implement proxy access. As amended, the Bylaws include a new Section 1.13 permitting a stockholder, or a group of up to 50 stockholders, owning continuously for at least three years a number of shares of our common stock that constitutes at least 3% of the outstanding shares of our common stock, to nominate and include in our proxy materials director nominees constituting up to the greater of two individuals or 20% of the Board, provided that the stockholder(s) and the nominee(s) satisfy the requirements specified in the Bylaws. The amended Bylaws also reflect certain conforming and clarifying changes in Section 1.12 of the Bylaws.
The description of the Bylaws contained herein is qualified in its entirety by reference to the Bylaws, a copy of which is filed herewith as Exhibit 3.05 and is incorporated herein by reference.
PART III
Item 10. Directors, Executive Officers and Corporate Governance
The information required by this item will be included under the caption “Directors, Executive Officers, and Corporate Governance” in our Proxy Statement for the 2017 Annual Meeting of Stockholders to be filed with the SEC within 120 days of the fiscal year ended March 31, 2017 (“2017 Proxy Statement”) and is incorporated herein by reference.
Item 11. Executive Compensation
The information required by this item will be included under the caption “Executive Compensation” in our 2017 Proxy Statement and is incorporated herein by reference.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information required by this item will be included under the caption “Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters” in our 2017 Proxy Statement and is incorporated herein by reference.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information required by this item will be included under the caption “Certain Relationships and Related Transactions, and Director Independence” in our 2017 Proxy Statement and is incorporated herein by reference.
Item 14. Principal Accounting Fees and Services
The information required by this item will be included under the caption “Principal Accountant Fees and Services” in our 2017 Proxy Statement and is incorporated herein by reference.
PART IV
Item 15. Exhibits, Financial Statement Schedules
Upon written request, we will provide, without charge, a copy of this annual report, including the Consolidated Financial Statements and financial statement schedule. All requests should be sent to:
Symantec Corporation
Attn: Investor Relations
350 Ellis Street
Mountain View, California 94043
(650) 527-8000
The following documents are filed as part of this report:
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
The Board of Directors and Stockholders
Symantec Corporation:
We have audited the accompanying consolidated balance sheets of Symantec Corporation and subsidiaries as of March 31, 2017 and April 1, 2016, and the related consolidated statements of operations, comprehensive income (loss), stockholders’ equity, and cash flows for each of the years in the three-year period ended March 31, 2017. We also have audited Symantec Corporation’s internal control over financial reporting as of March 31, 2017, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). Symantec Corporation’s management is responsible for these consolidated financial statements, for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting, included in Management’s Report on Internal Control over Financial Reporting appearing under Item 9A.b). Our responsibility is to express an opinion on these consolidated financial statements and an opinion on Symantec Corporation’s internal control over financial reporting based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audits to obtain reasonable assurance about whether the financial statements are free of material misstatement and whether effective internal control over financial reporting was maintained in all material respects. Our audits of the consolidated financial statements included examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements, assessing the accounting principles used and significant estimates made by management, and evaluating the overall financial statement presentation. Our audit of internal control over financial reporting included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audits also included performing such other procedures as we considered necessary in the circumstances. We believe that our audits provide a reasonable basis for our opinions.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of Symantec Corporation and subsidiaries as of March 31, 2017 and April 1, 2016, and the results of their operations and their cash flows for each of the years in the thre
Showing the first 8K of 168K characters. Open the full section